Dynegy — Non-Deal Roadshow (September 2008)
42 slides from Dynegy's roadshow presentation, Sep 2, 2008
Slide 1: Positioned to Deliver Growth & Enhanced Stockholder Value
Positioned to Deliver Growth & Enhanced Stockholder Value Marketing Meetings September 2008 Investor & Public Relations | Norelle Lundy, Vice President | Nir Grossman, Senior Director | 713-507-6466 | [email protected]
Slide 2: Forward-looking Statements
Forward-looking Statements This presentation contains statements reflecting assumptions, expectations, projections, intentions or beliefs about future events that are intended as “forward- looking statements.” You can identify these statements, including those relating to Dynegy’s 2008 financial est
Slide 3: Dynegy at a Glance
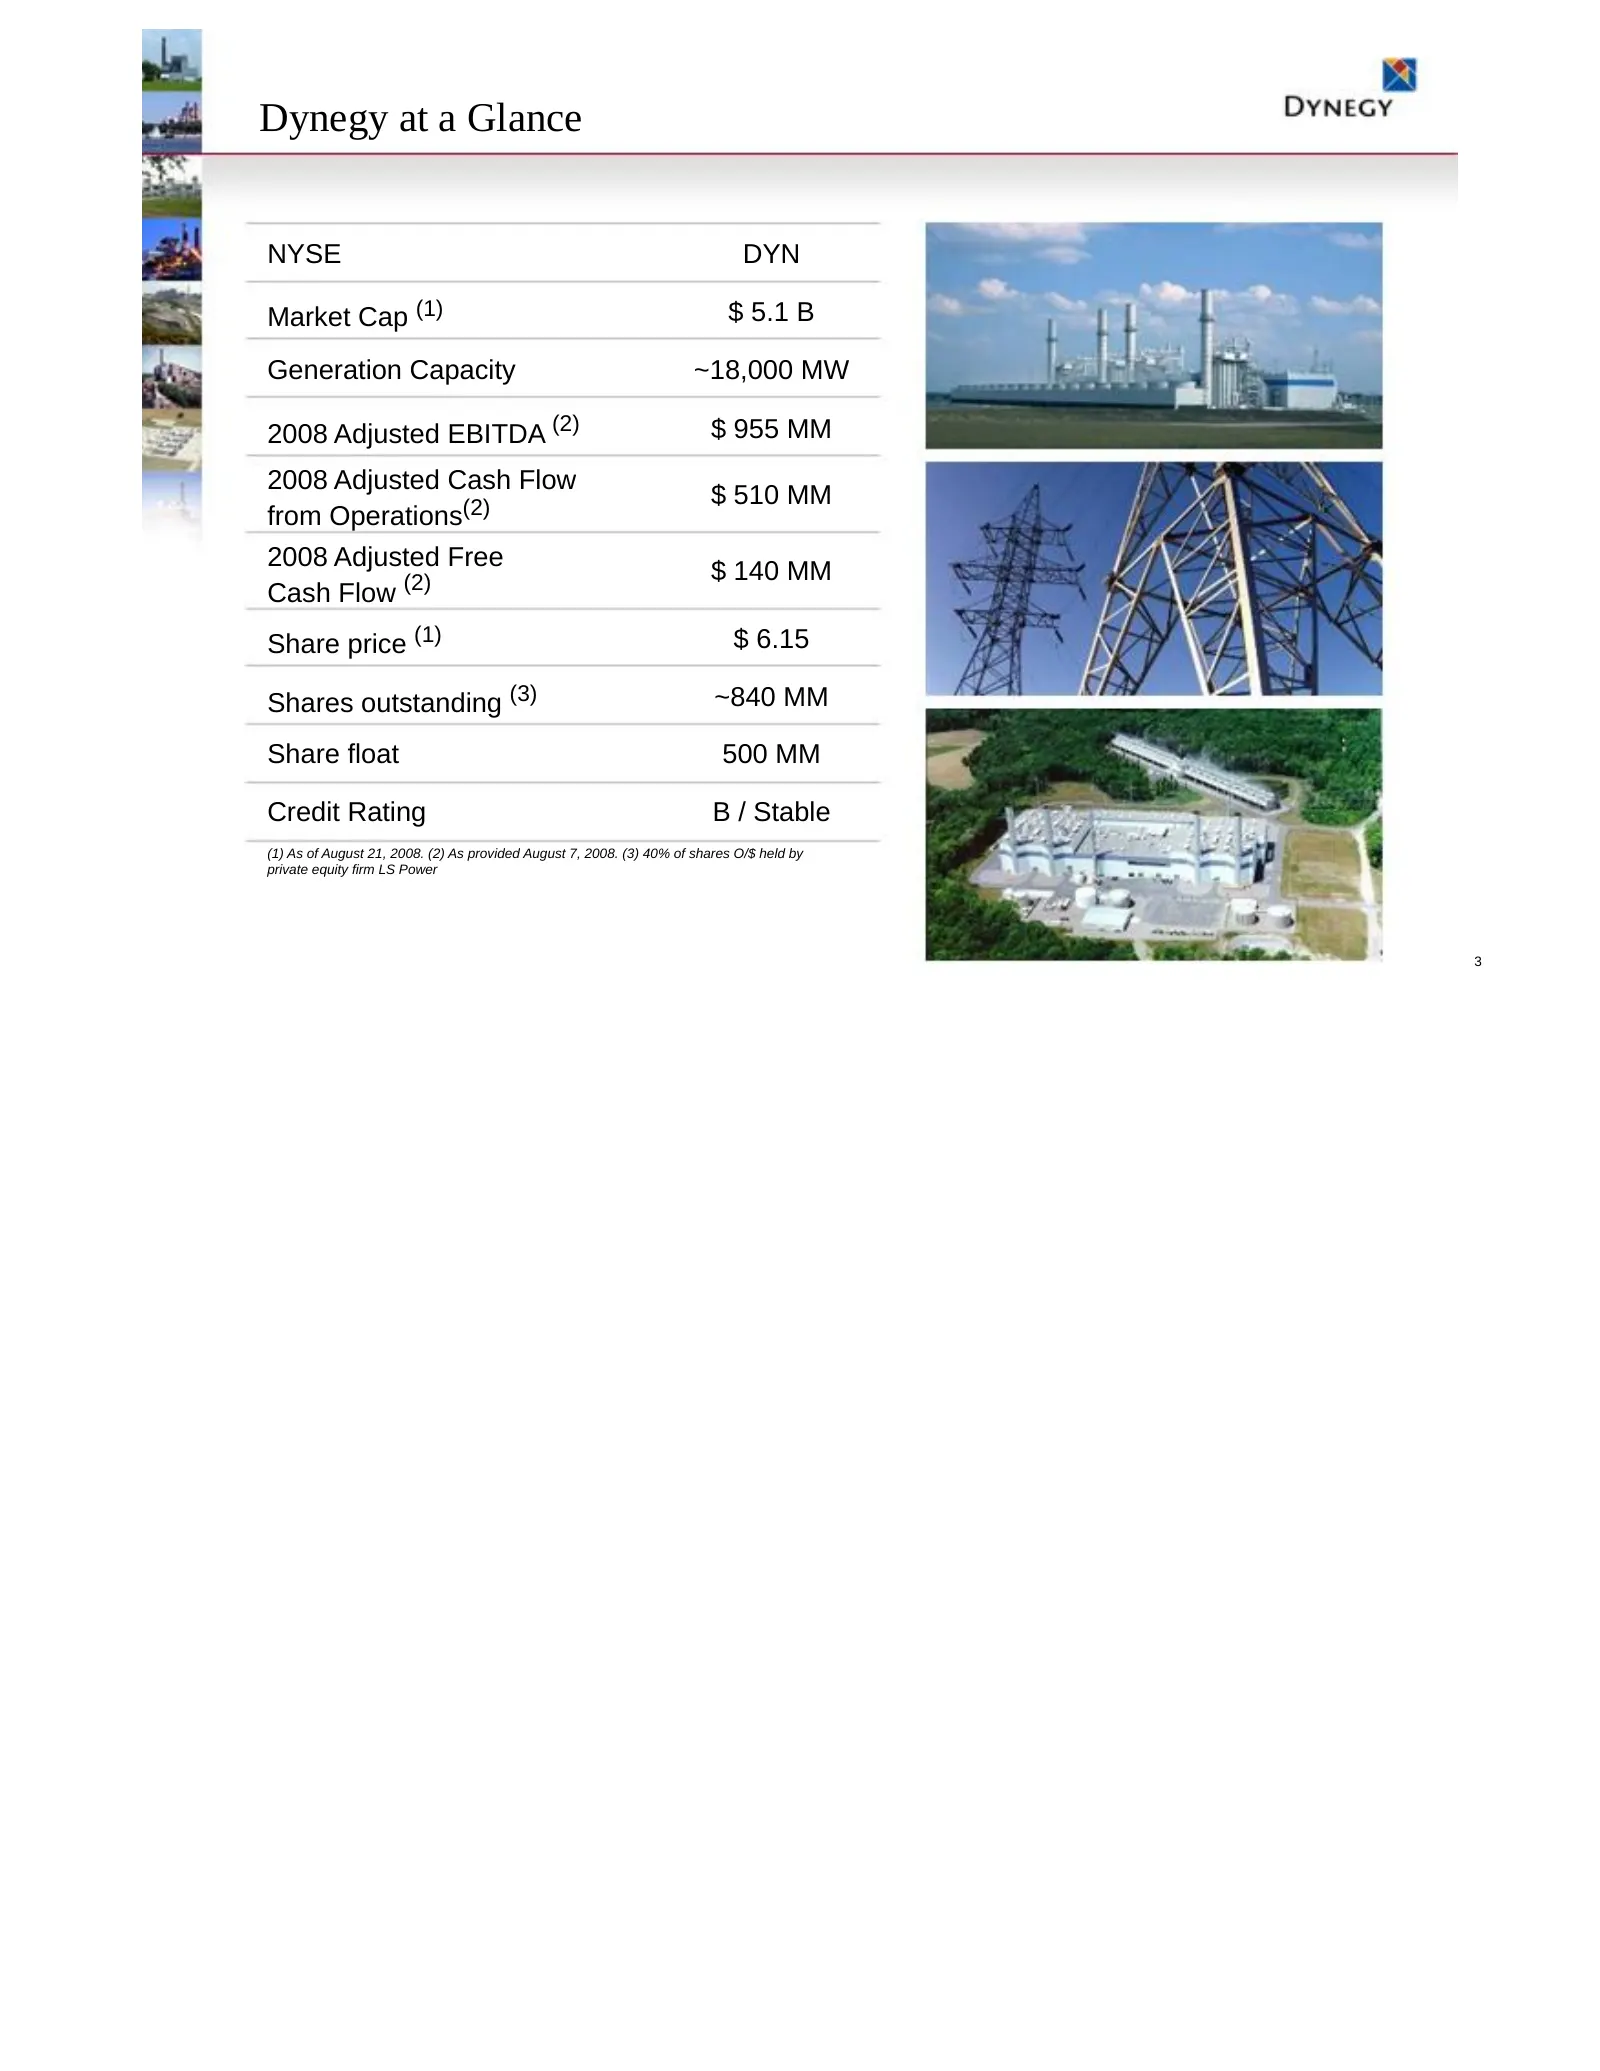
Dynegy at a Glance NYSE DYN Market Cap (1) $ 5.1 B Generation Capacity ~18,000 MW 2008 Adjusted EBITDA (2) $ 955 MM 2008 Adjusted Cash Flow $ 510 MM from Operations(2) 2008 Adjusted Free $ 140 MM Cash Flow (2) Share price (1) $ 6.15 Shares outstanding (3) ~840 MM Share float 500 MM Credit Rating B /
Slide 4: Power Industry Overview
Power Industry Overview
Slide 5: The Power Industry Value Chain
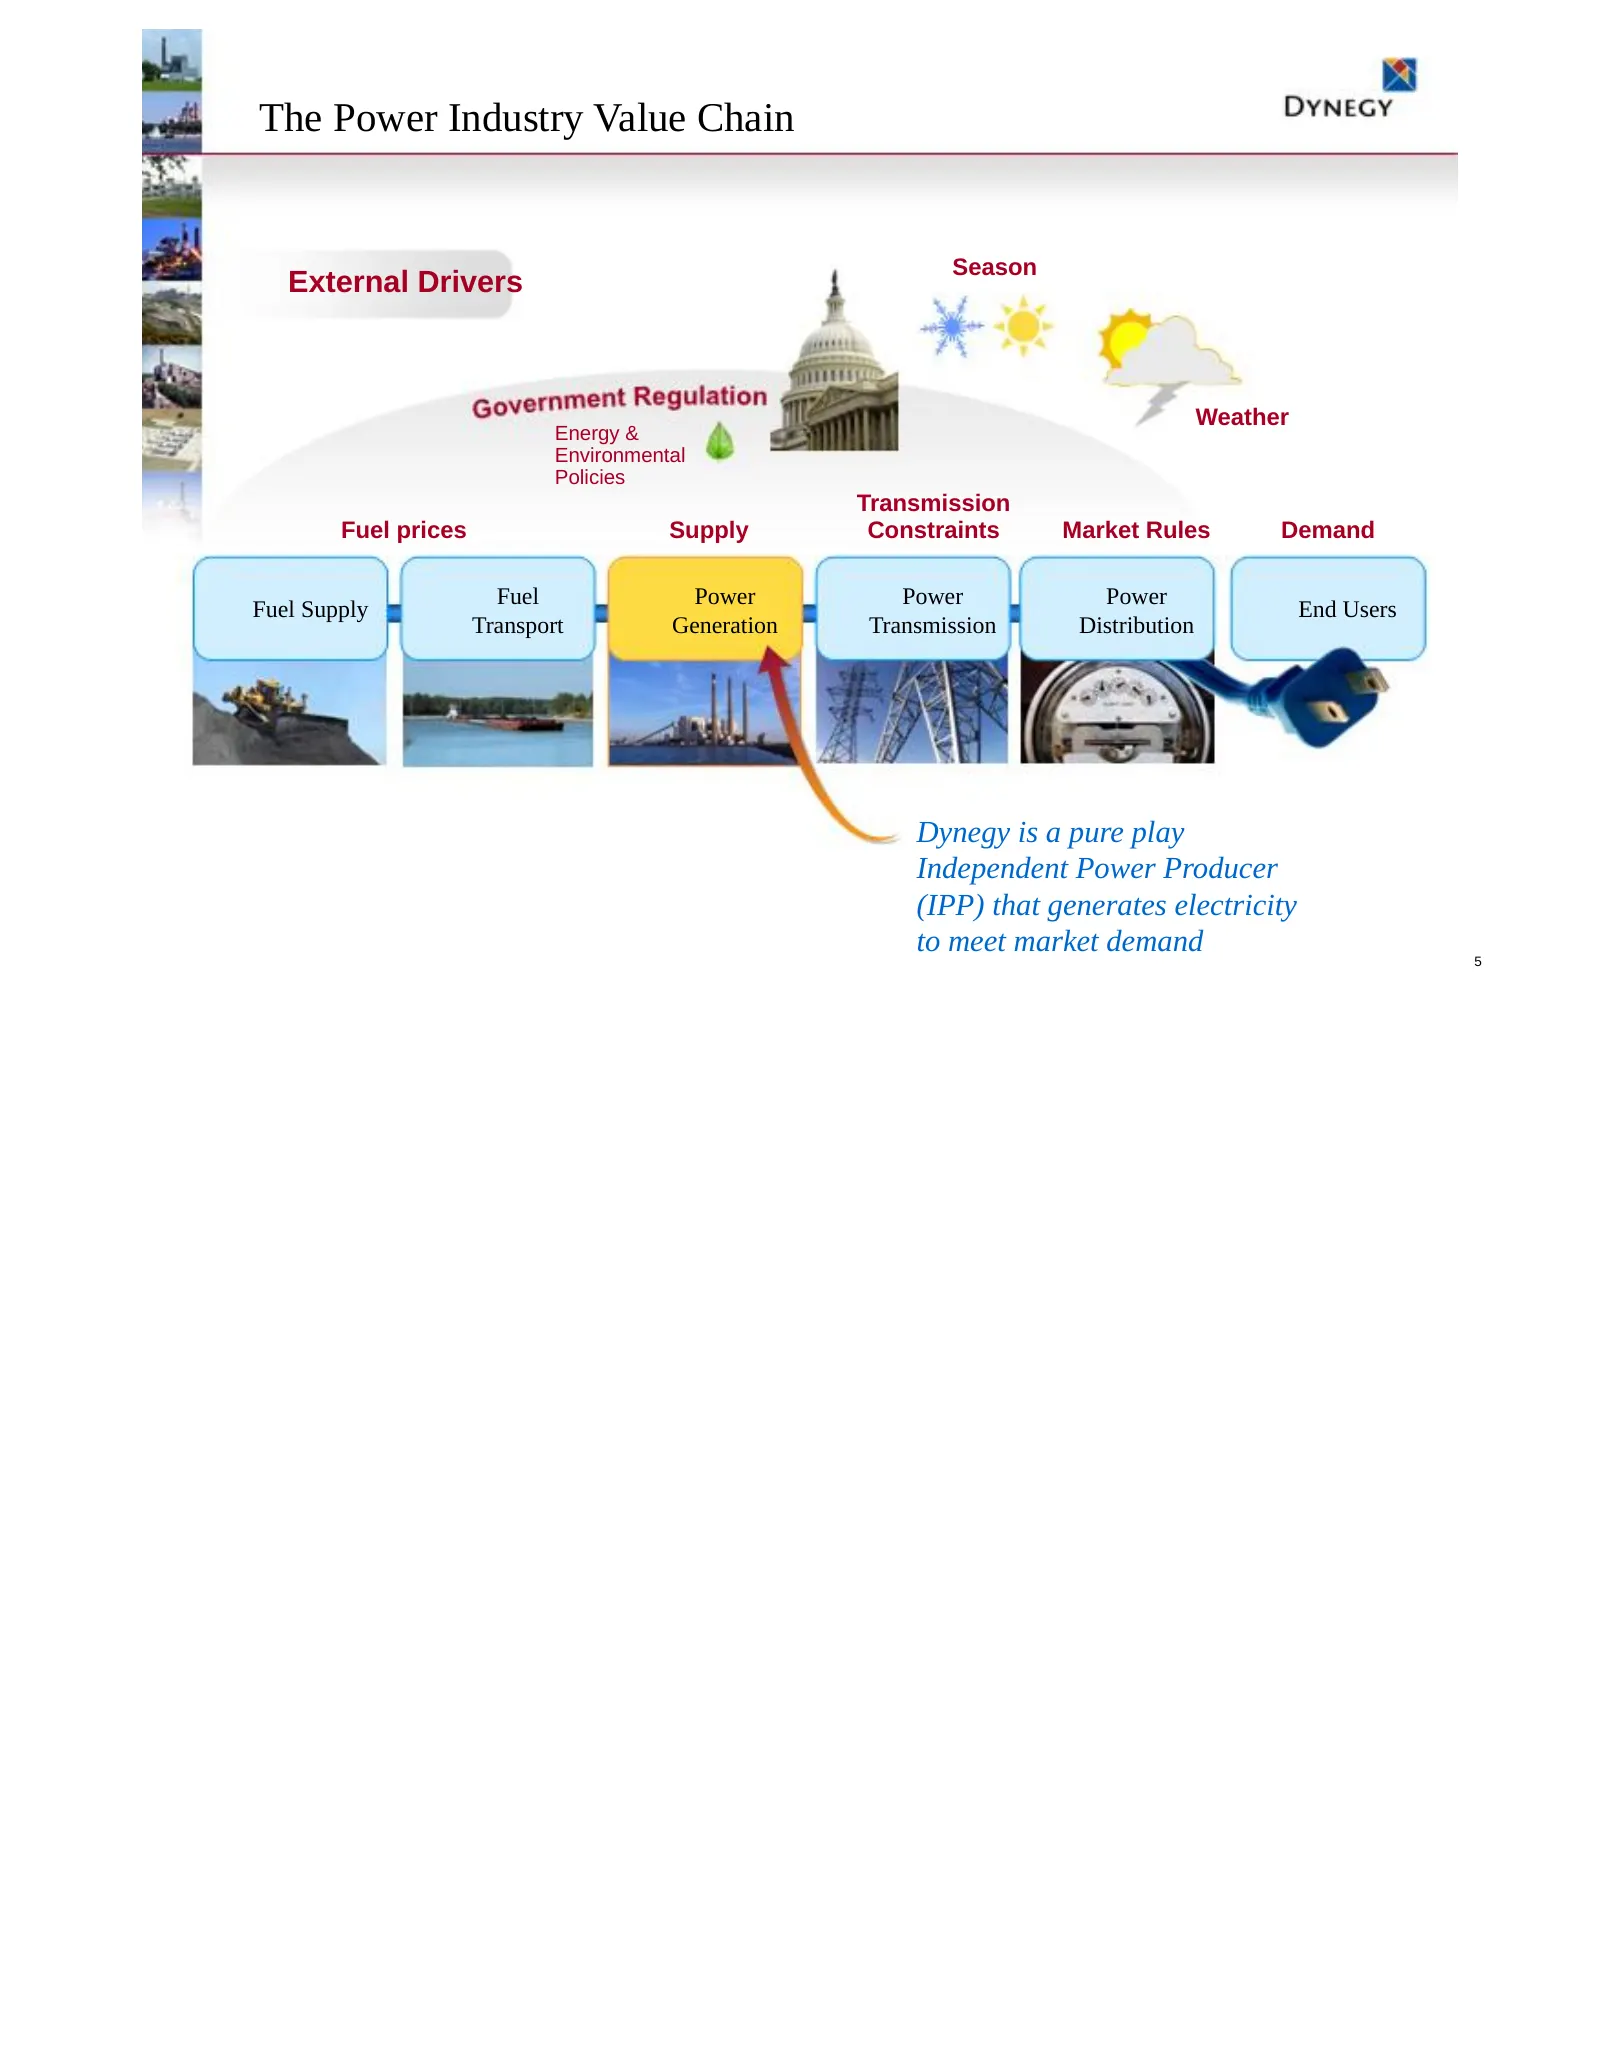
The Power Industry Value Chain Season External Drivers Weather Energy & Environmental Policies Transmission Fuel prices Supply Constraints Market Rules Demand Fuel Power Power Power Fuel Supply End Users Transport Generation Transmission Distribution Dynegy is a pure play Independent Power Producer
Slide 6: Trailing 12-Month Trends
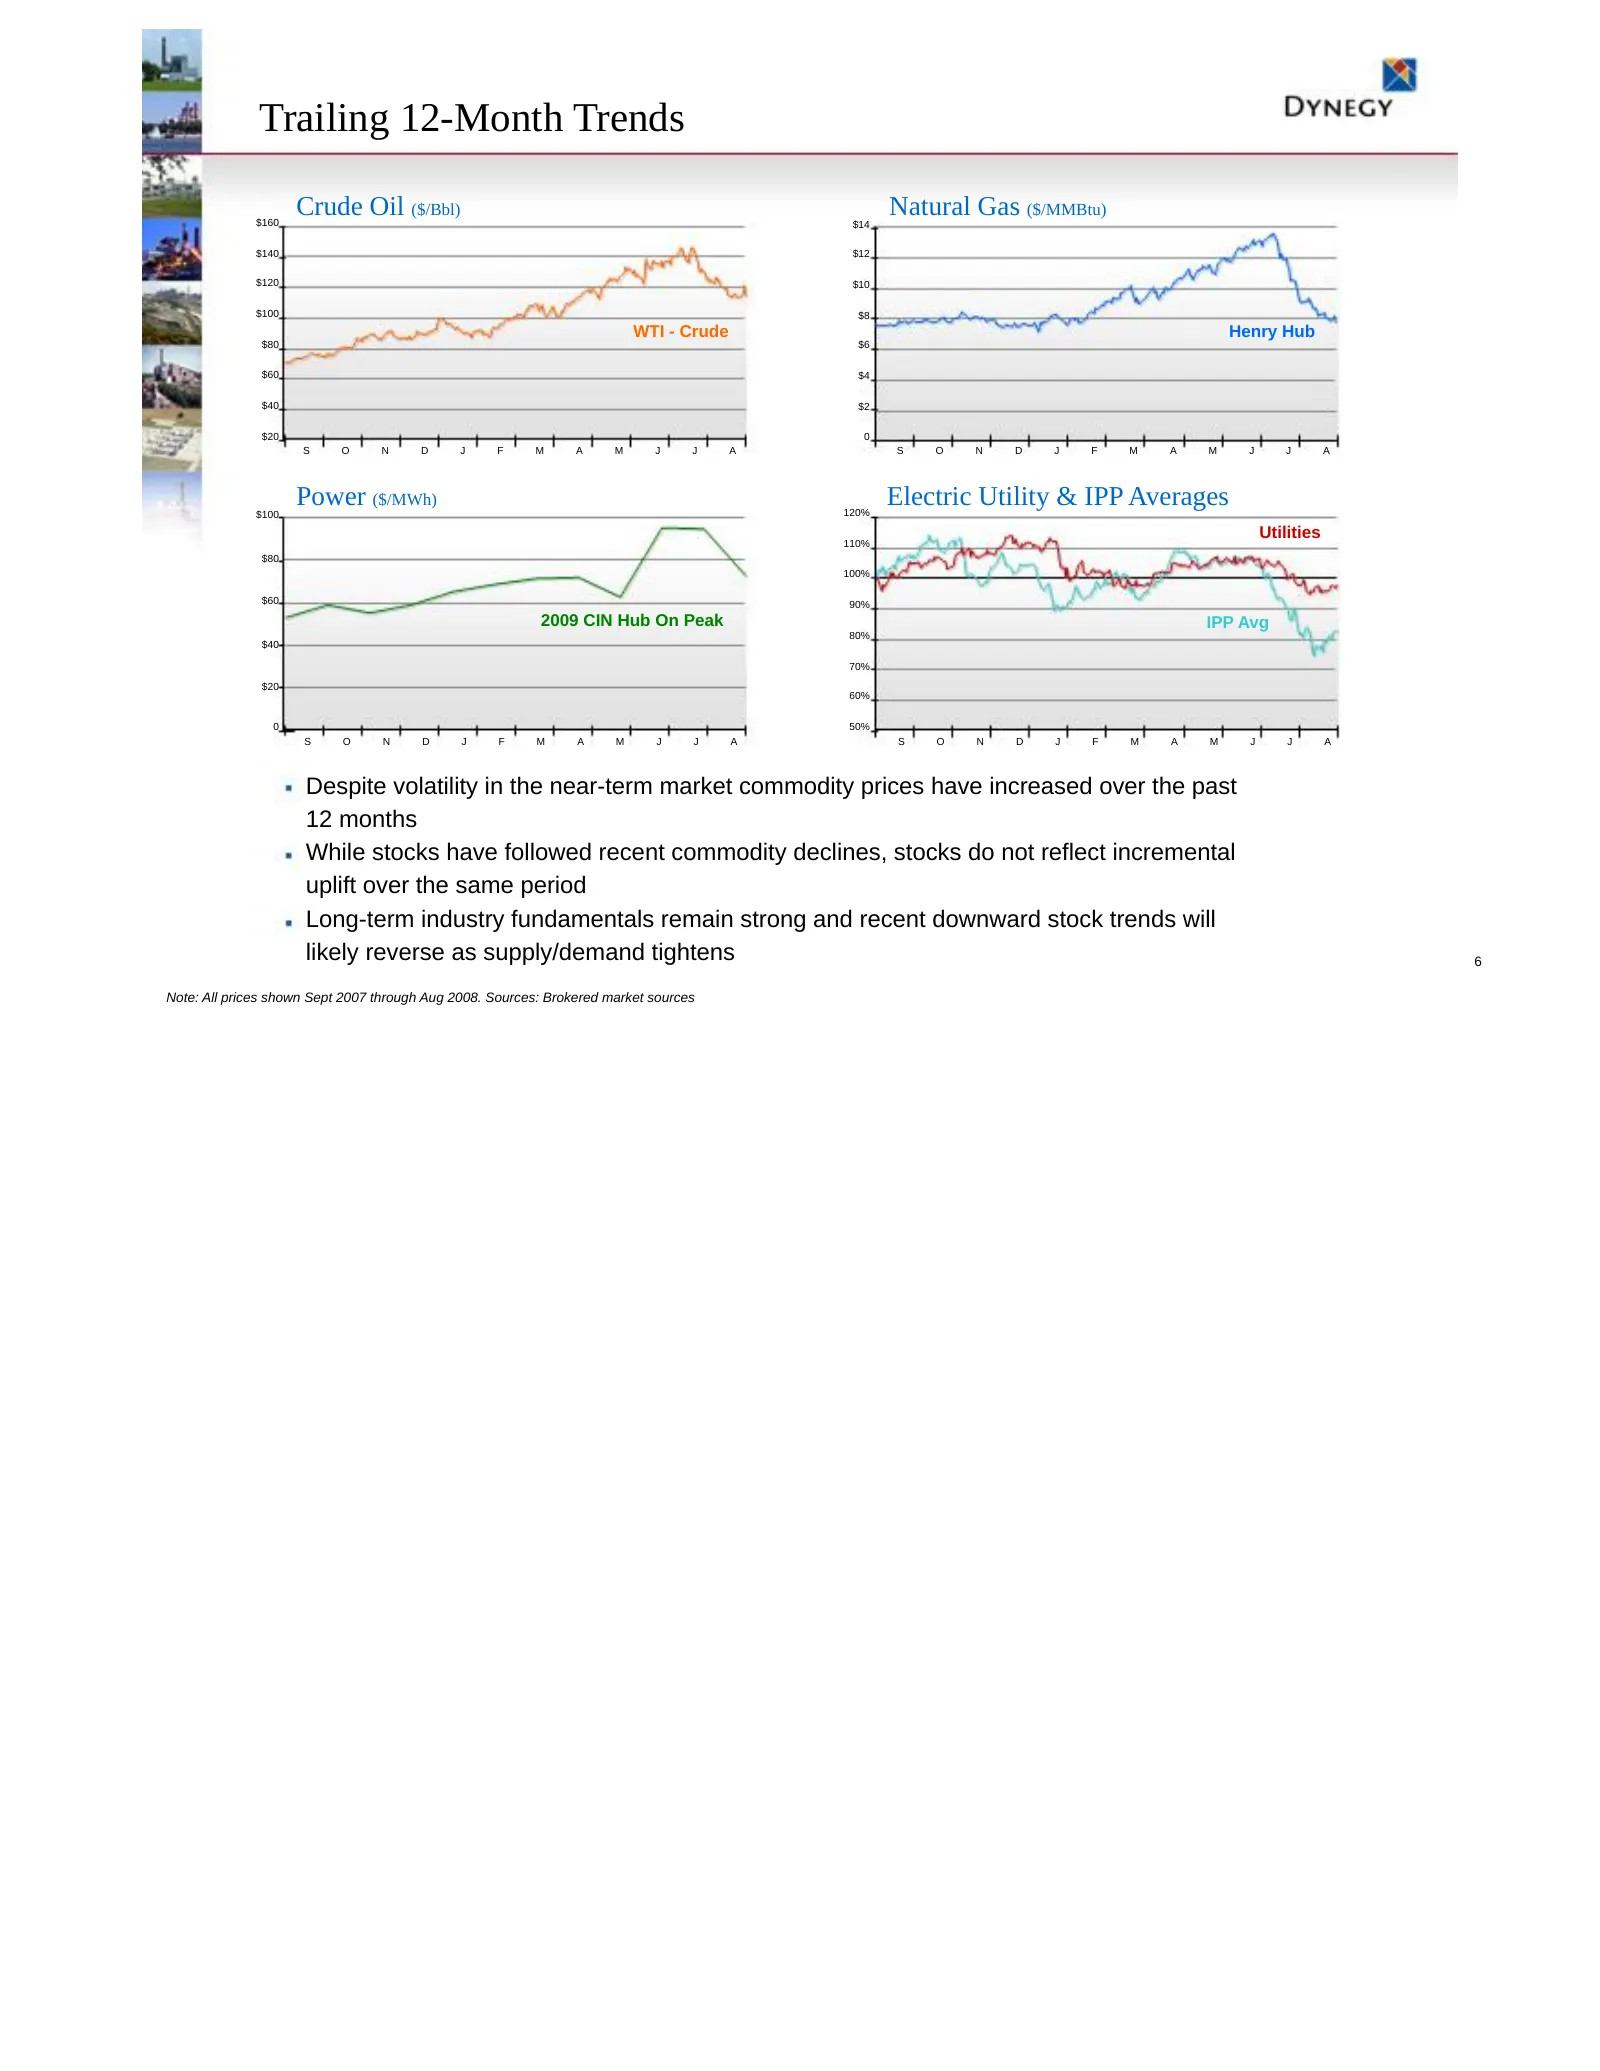
Trailing 12-Month Trends $160 Crude Oil ($/Bbl) $14 Natural Gas ($/MMBtu) $140 $12 $120 $10 $100 $8 WTI - Crude Henry Hub $80 $6 $60 $4 $40 $2 $20 0 S O N D J F M A M J J A S O N D J F M A M J J A $100 Power ($/MWh) 120% Electric Utility & IPP Averages Utilities 110% $80 100% $60 90% 2009 CIN Hub On
Slide 7: Electricity Market Growing in an Uncertain Environment
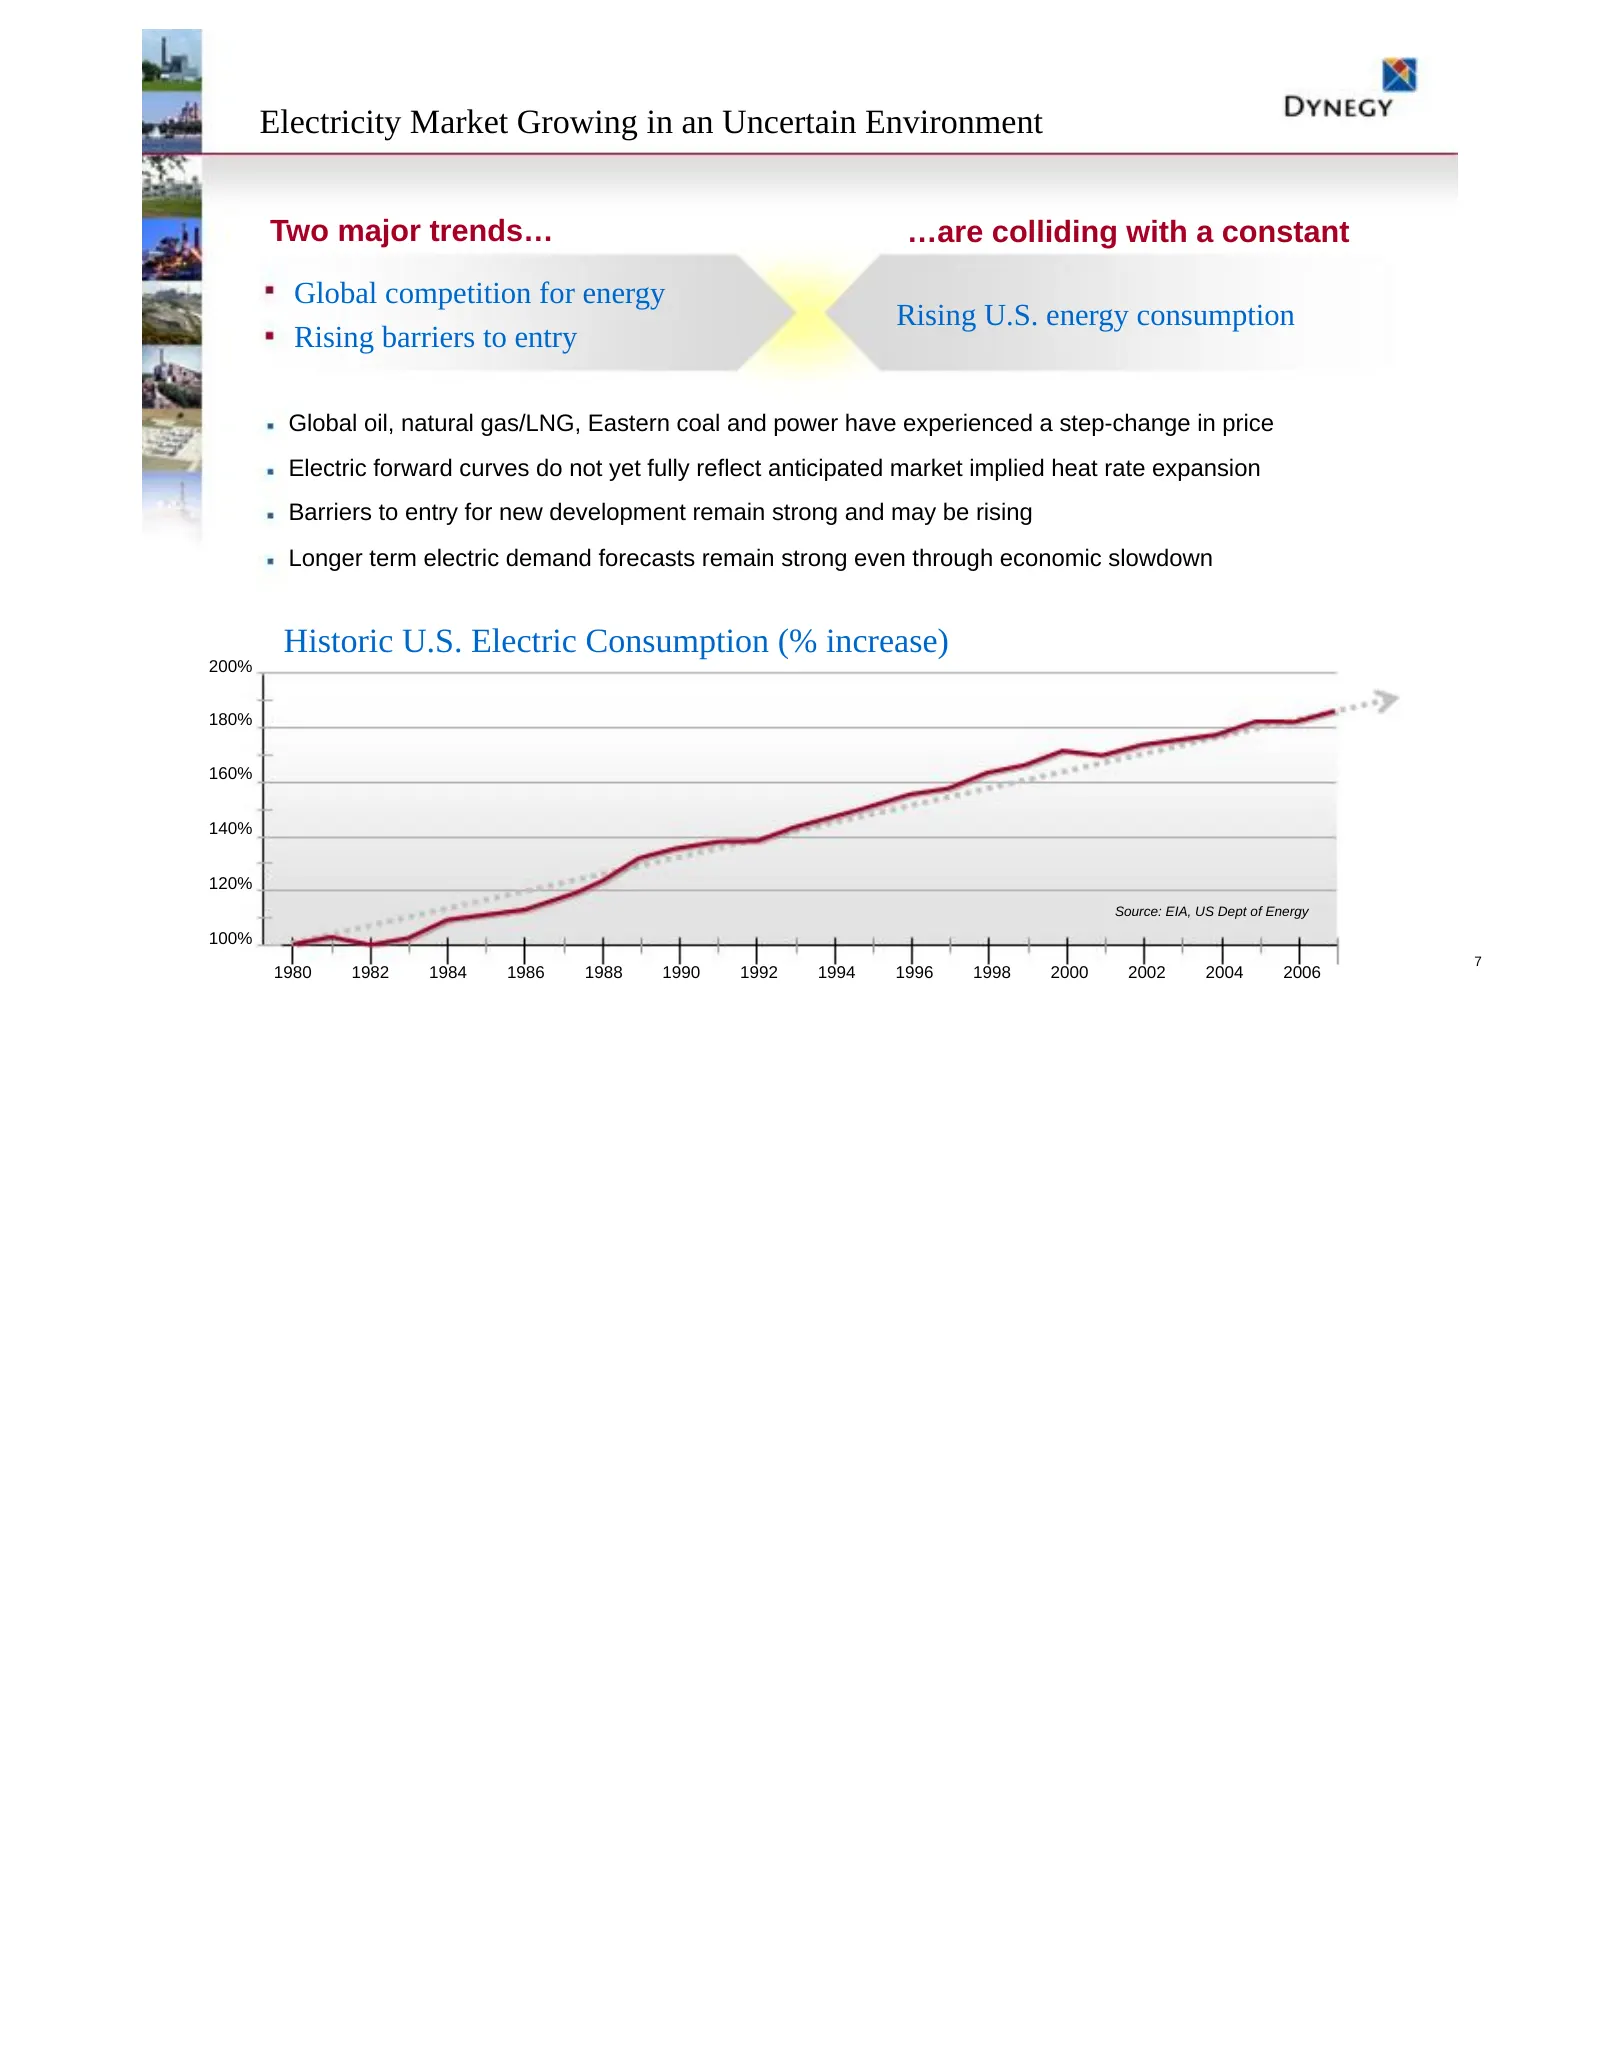
Electricity Market Growing in an Uncertain Environment Two major trends… …are colliding with a constant Global competition for energy Rising U.S. energy consumption Rising barriers to entry Global oil, natural gas/LNG, Eastern coal and power have experienced a step-change in price Electric forward c
Slide 8: Why Invest in the Power Generation Sector?
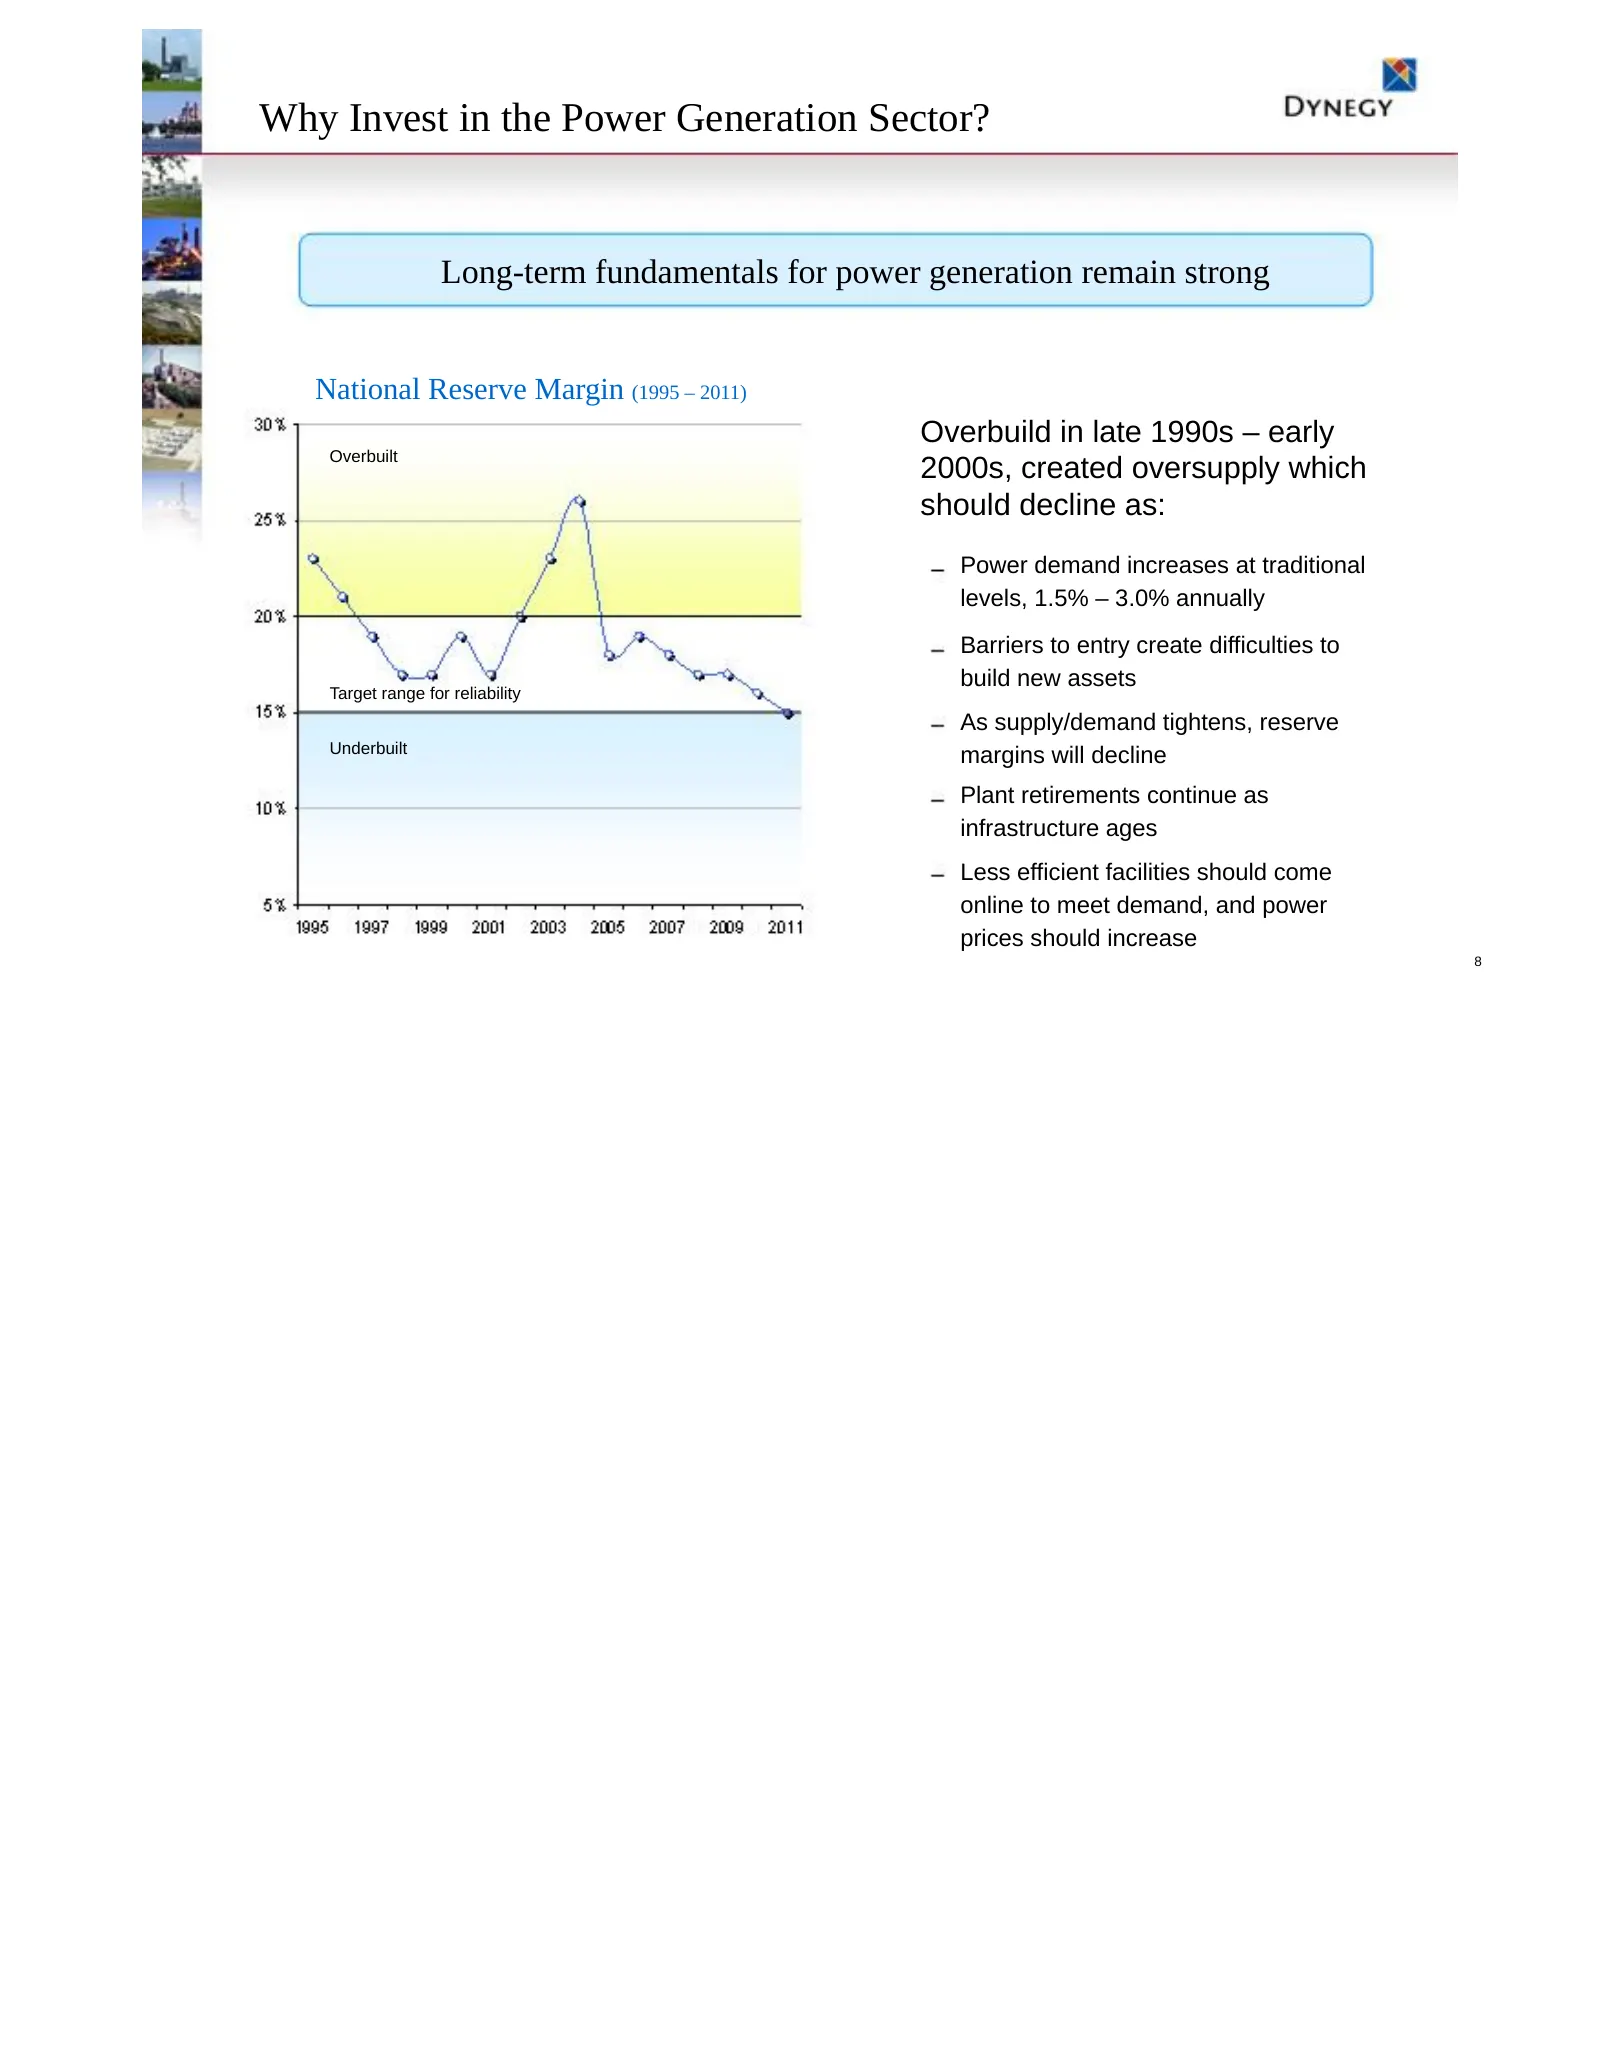
Why Invest in the Power Generation Sector? Long-term fundamentals for power generation remain strong National Reserve Margin (1995 – 2011) Overbuild in late 1990s – early Overbuilt 2000s, created oversupply which should decline as: Power demand increases at traditional levels, 1.5% – 3.0% annually B
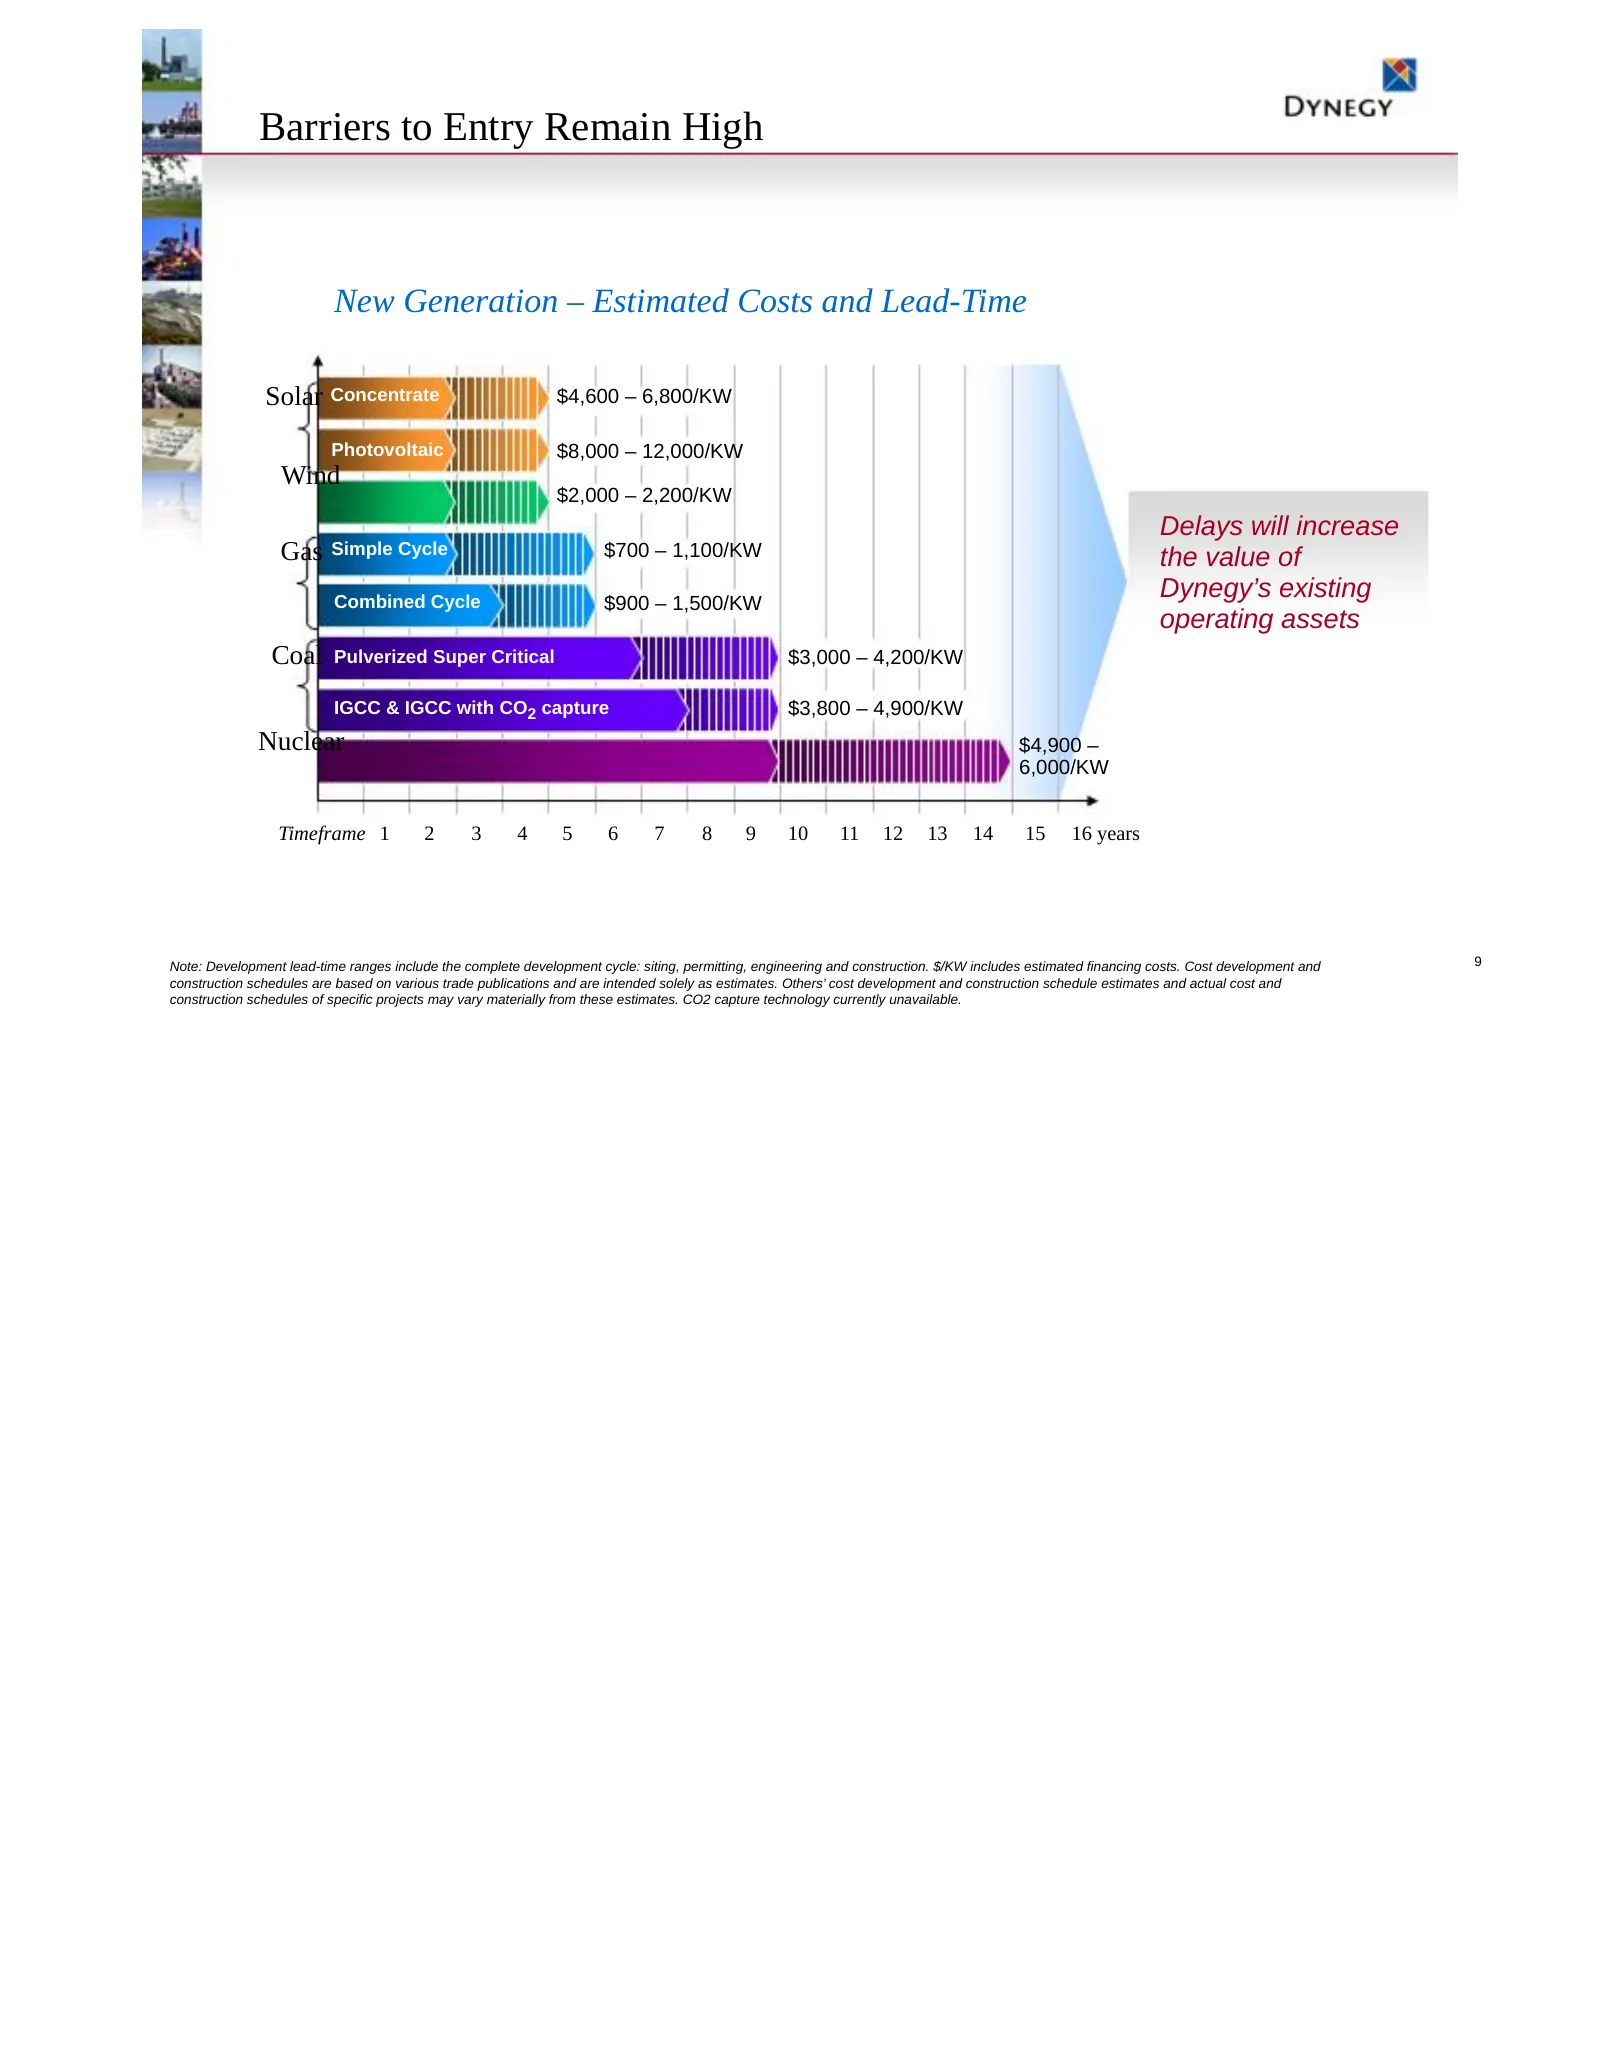
Slide 9: Barriers to Entry Remain High
Barriers to Entry Remain High New Generation – Estimated Costs and Lead-Time Solar Concentrate $4,600 – 6,800/KW Photovoltaic $8,000 – 12,000/KW Wind $2,000 – 2,200/KW Delays will increase Gas Simple Cycle $700 – 1,100/KW the value of Combined Cycle $900 – 1,500/KW Dynegy’s existing operating assets
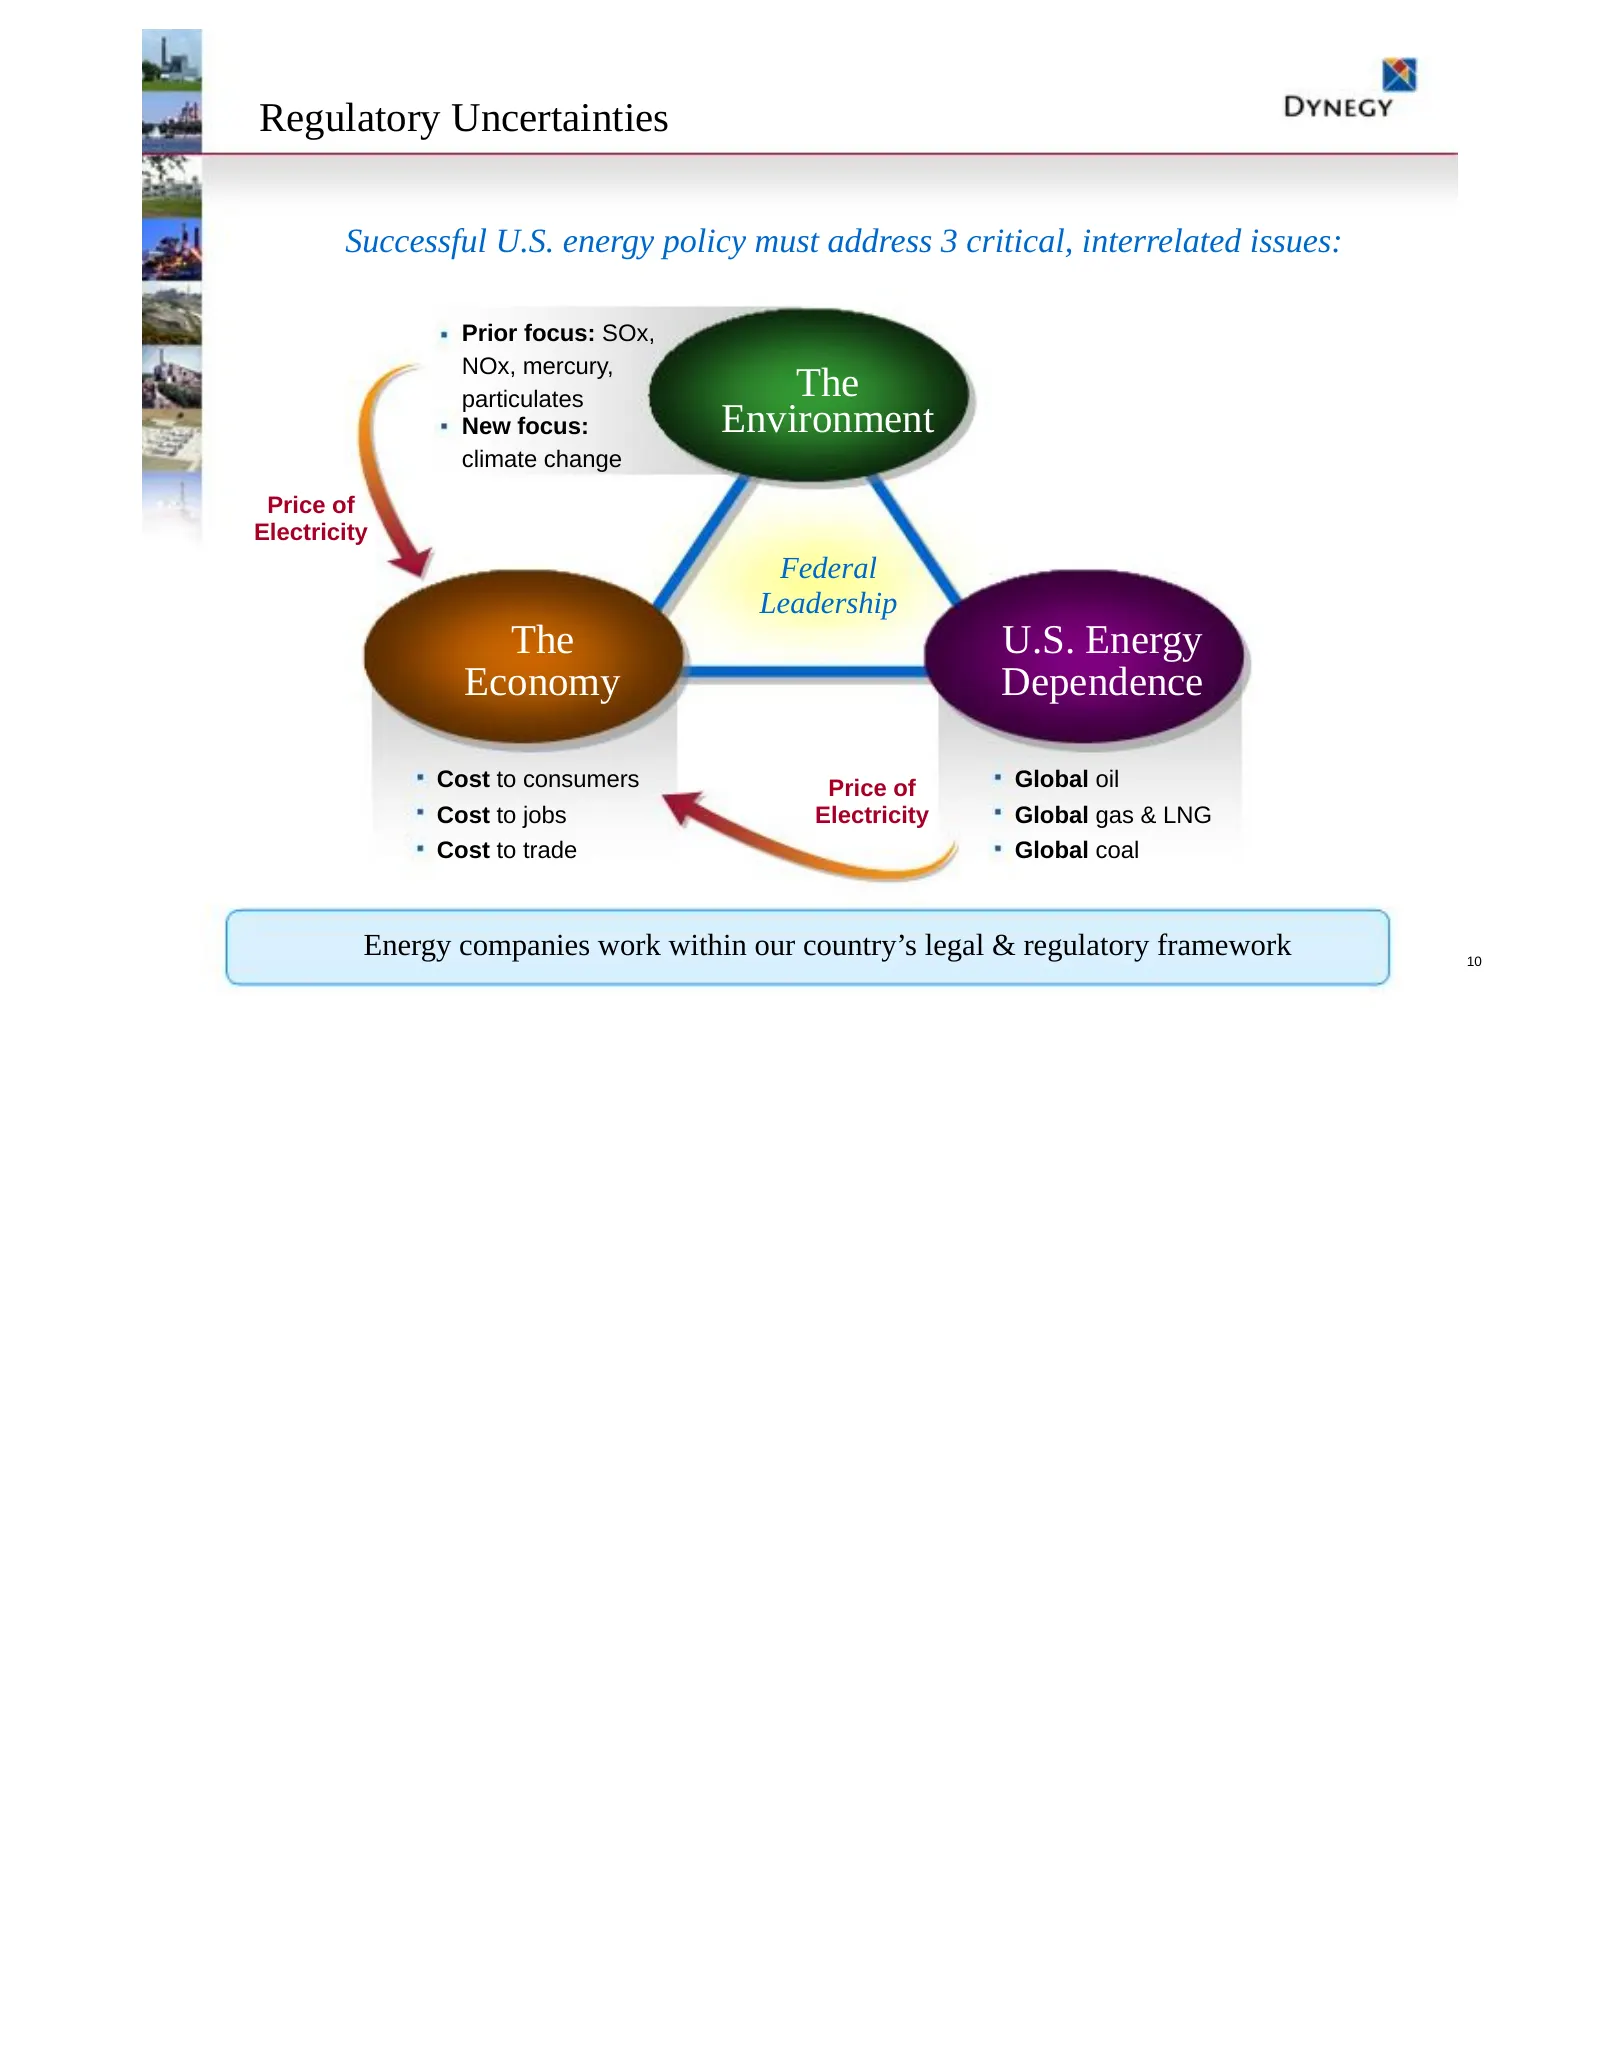
Slide 10: Regulatory Uncertainties
Regulatory Uncertainties Successful U.S. energy policy must address 3 critical, interrelated issues: Prior focus: SOx, NOx, mercury, particulates The New focus: Environment climate change Price of Electricity Federal Leadership The U.S. Energy Economy Dependence Cost to consumers Price of Global oil
Slide 11: Dynegy Overview
Dynegy Overview
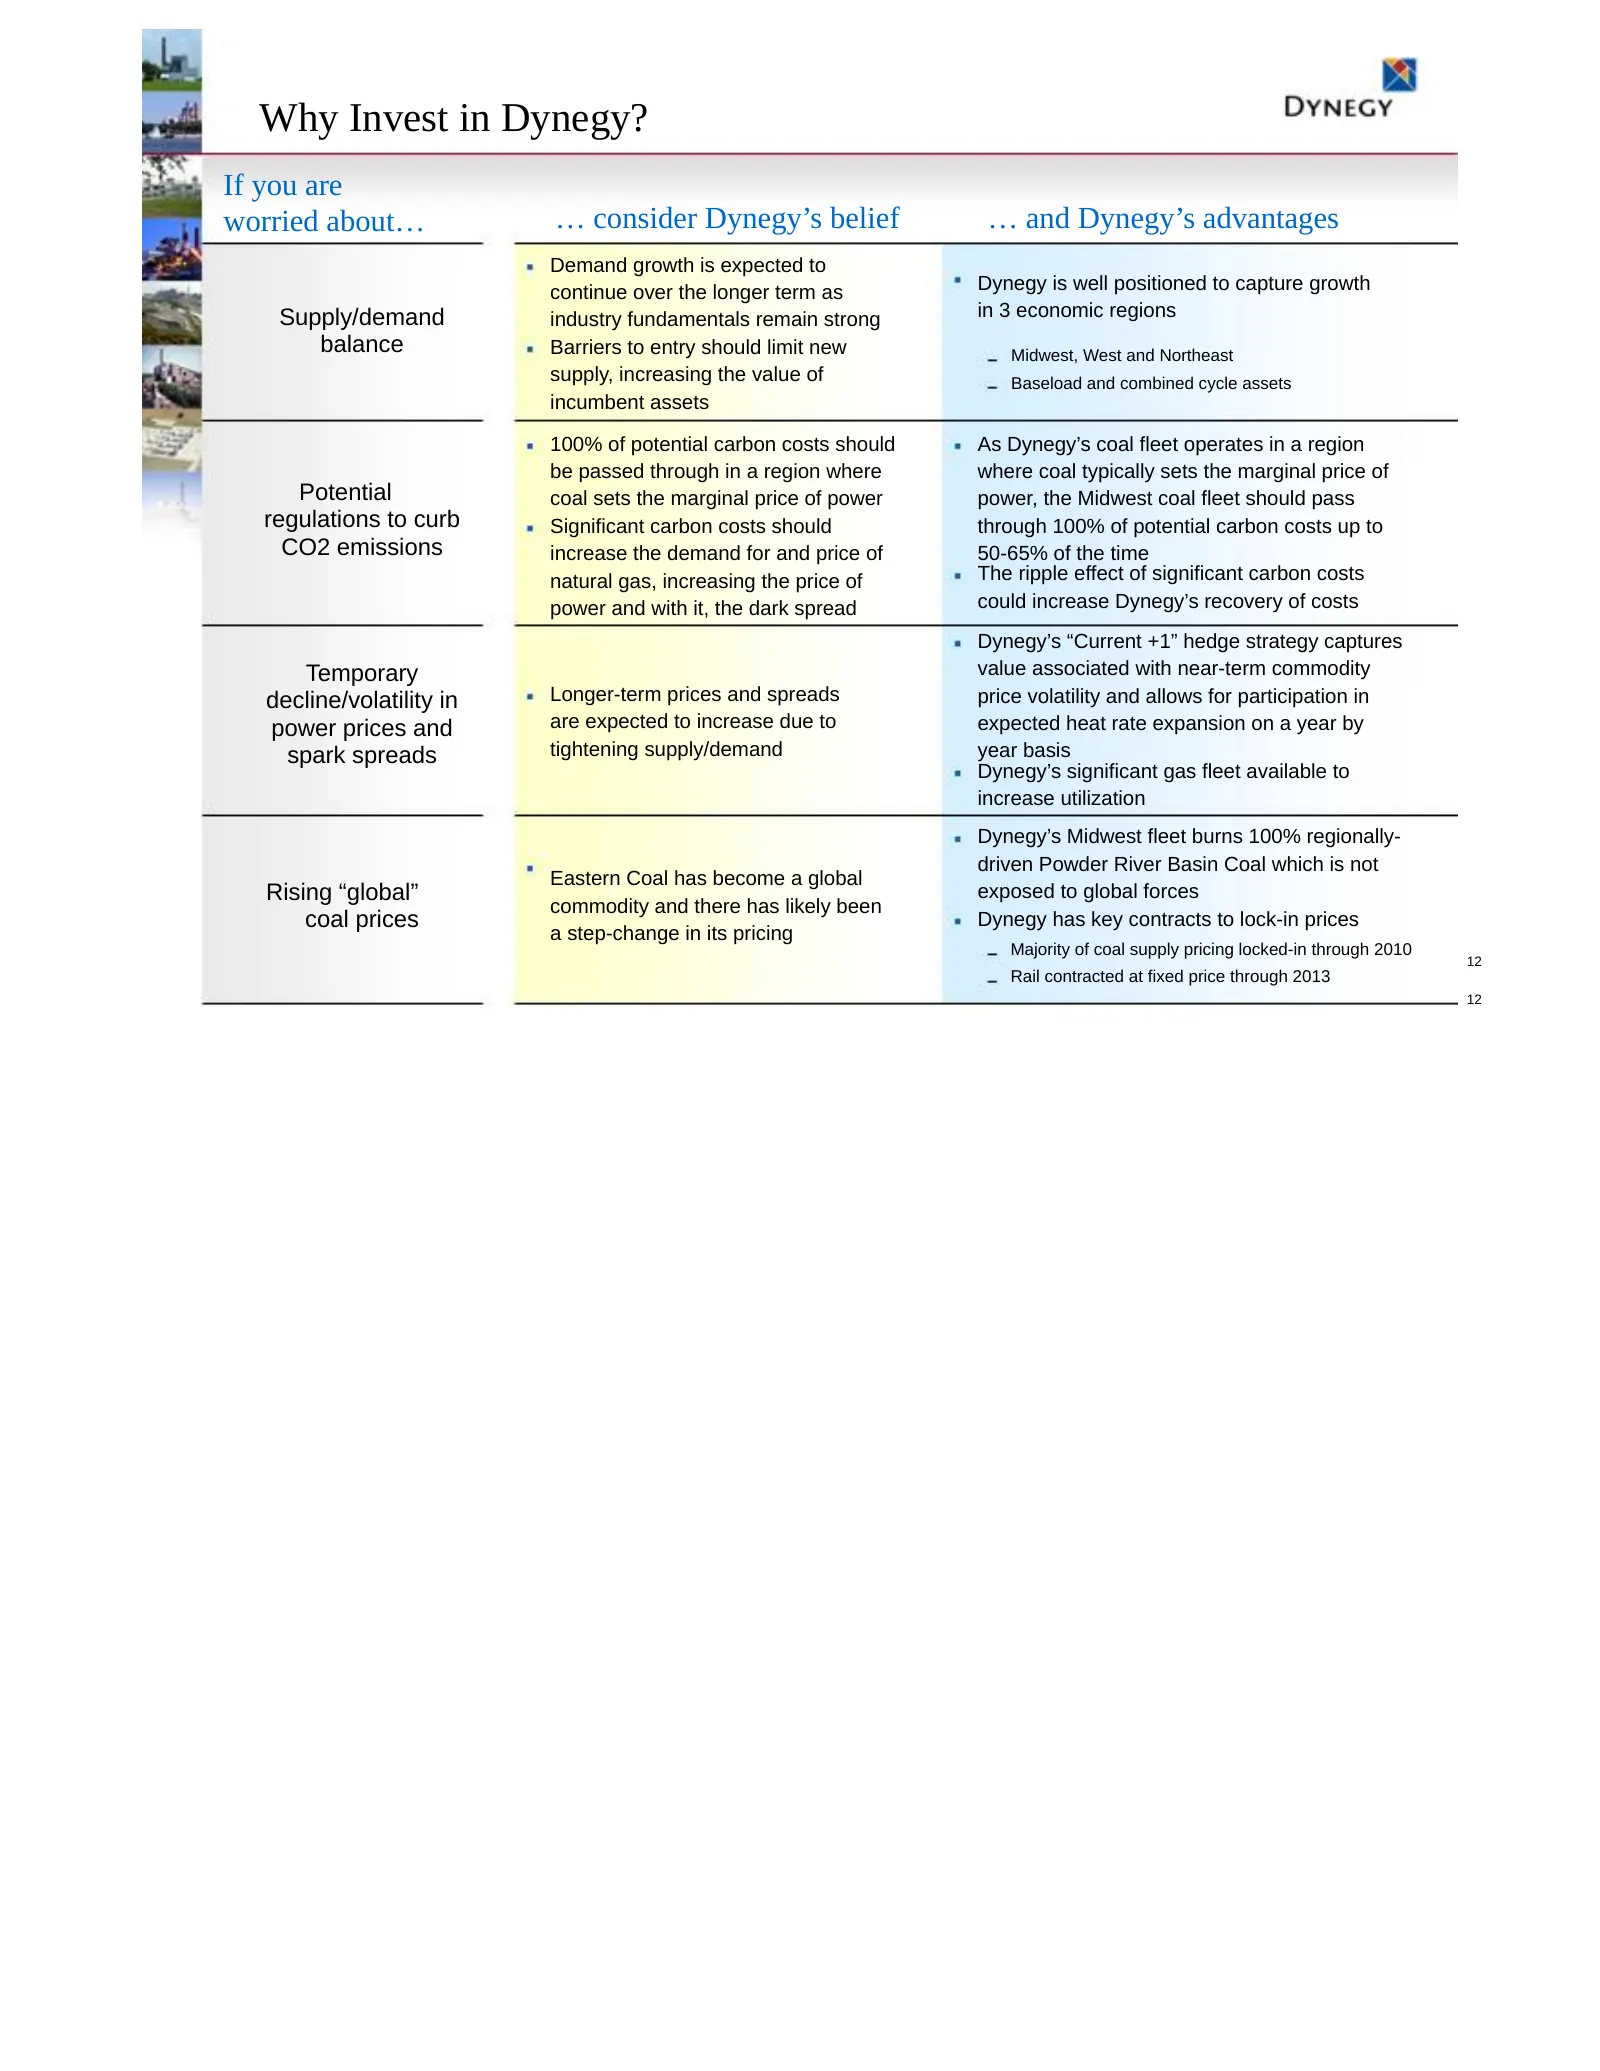
Slide 12: Why Invest in Dynegy?
Why Invest in Dynegy? If you are worried about… … consider Dynegy’s belief … and Dynegy’s advantages Demand growth is expected to continue over the longer term as Dynegy is well positioned to capture growth Supply/demand industry fundamentals remain strong in 3 economic regions balance Barriers to e
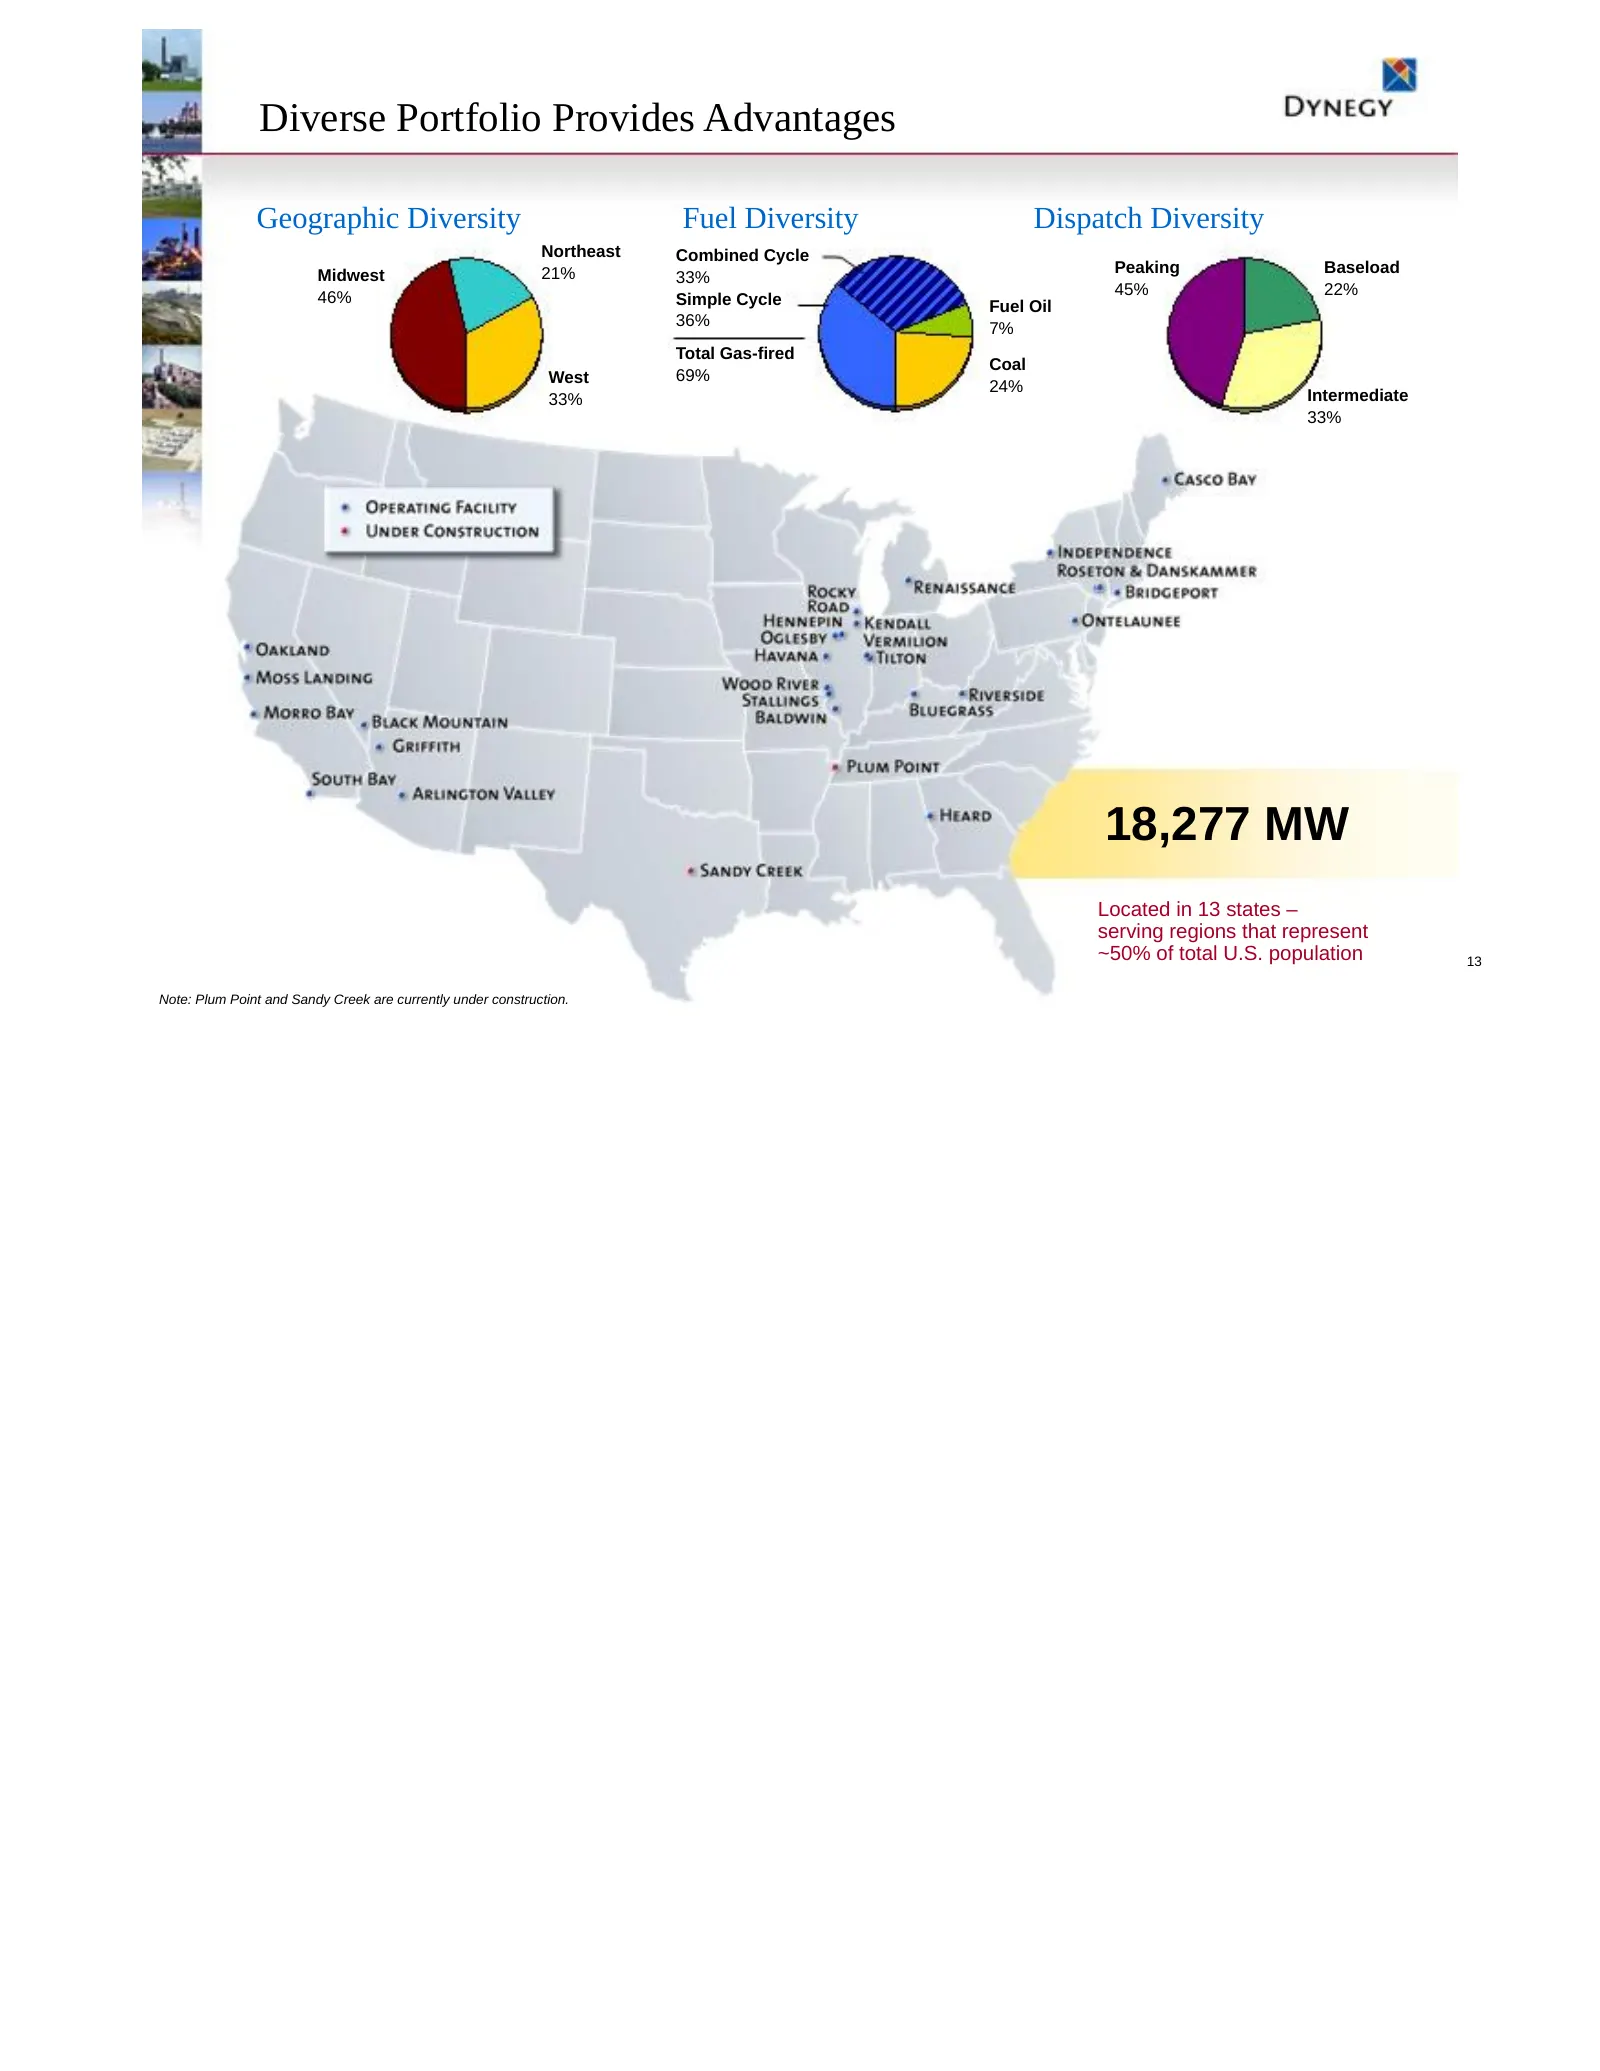
Slide 13: Diverse Portfolio Provides Advantages
Diverse Portfolio Provides Advantages Geographic Diversity Fuel Diversity Dispatch Diversity Northeast Combined Cycle Midwest 21% Peaking Baseload 33% 46% 45% 22% Simple Cycle Fuel Oil 36% 7% Total Gas-fired Coal West 69% 24% 33% Intermediate 33% 18,277 MW Located in 13 states – serving regions that
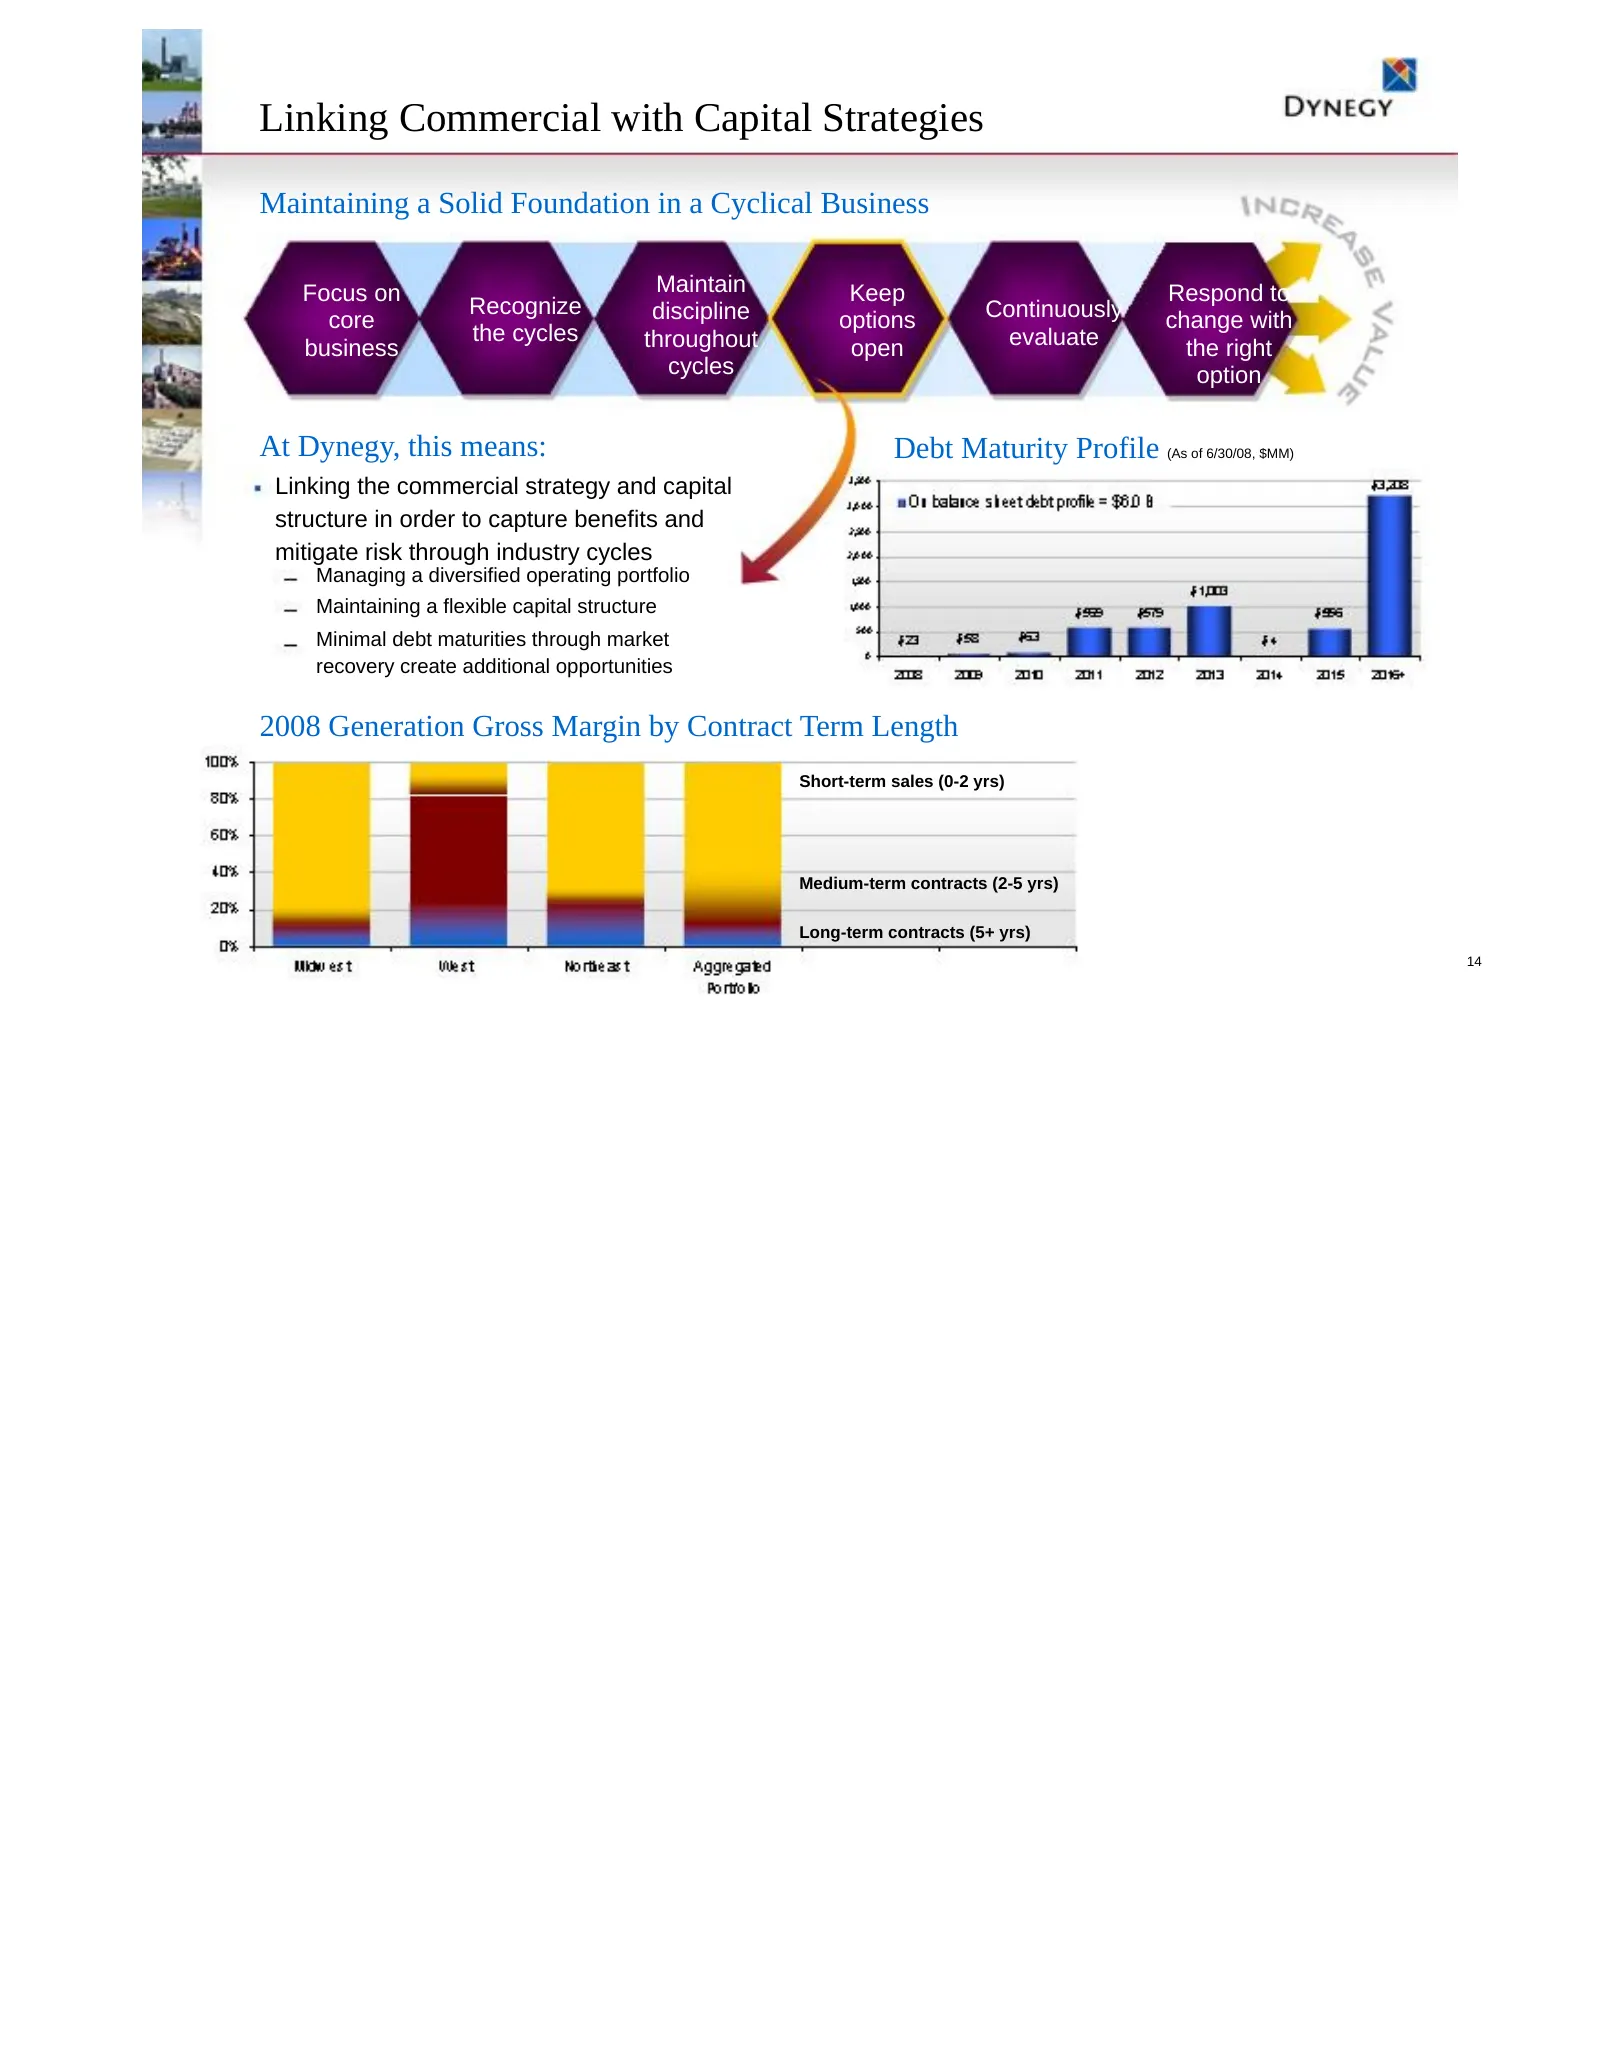
Slide 14: Linking Commercial with Capital Strategies
Linking Commercial with Capital Strategies Maintaining a Solid Foundation in a Cyclical Business Focus on Maintain Keep Respond to Recognize discipline Continuously core options change with the cycles throughout evaluate business open the right cycles option At Dynegy, this means: Debt Maturity Prof
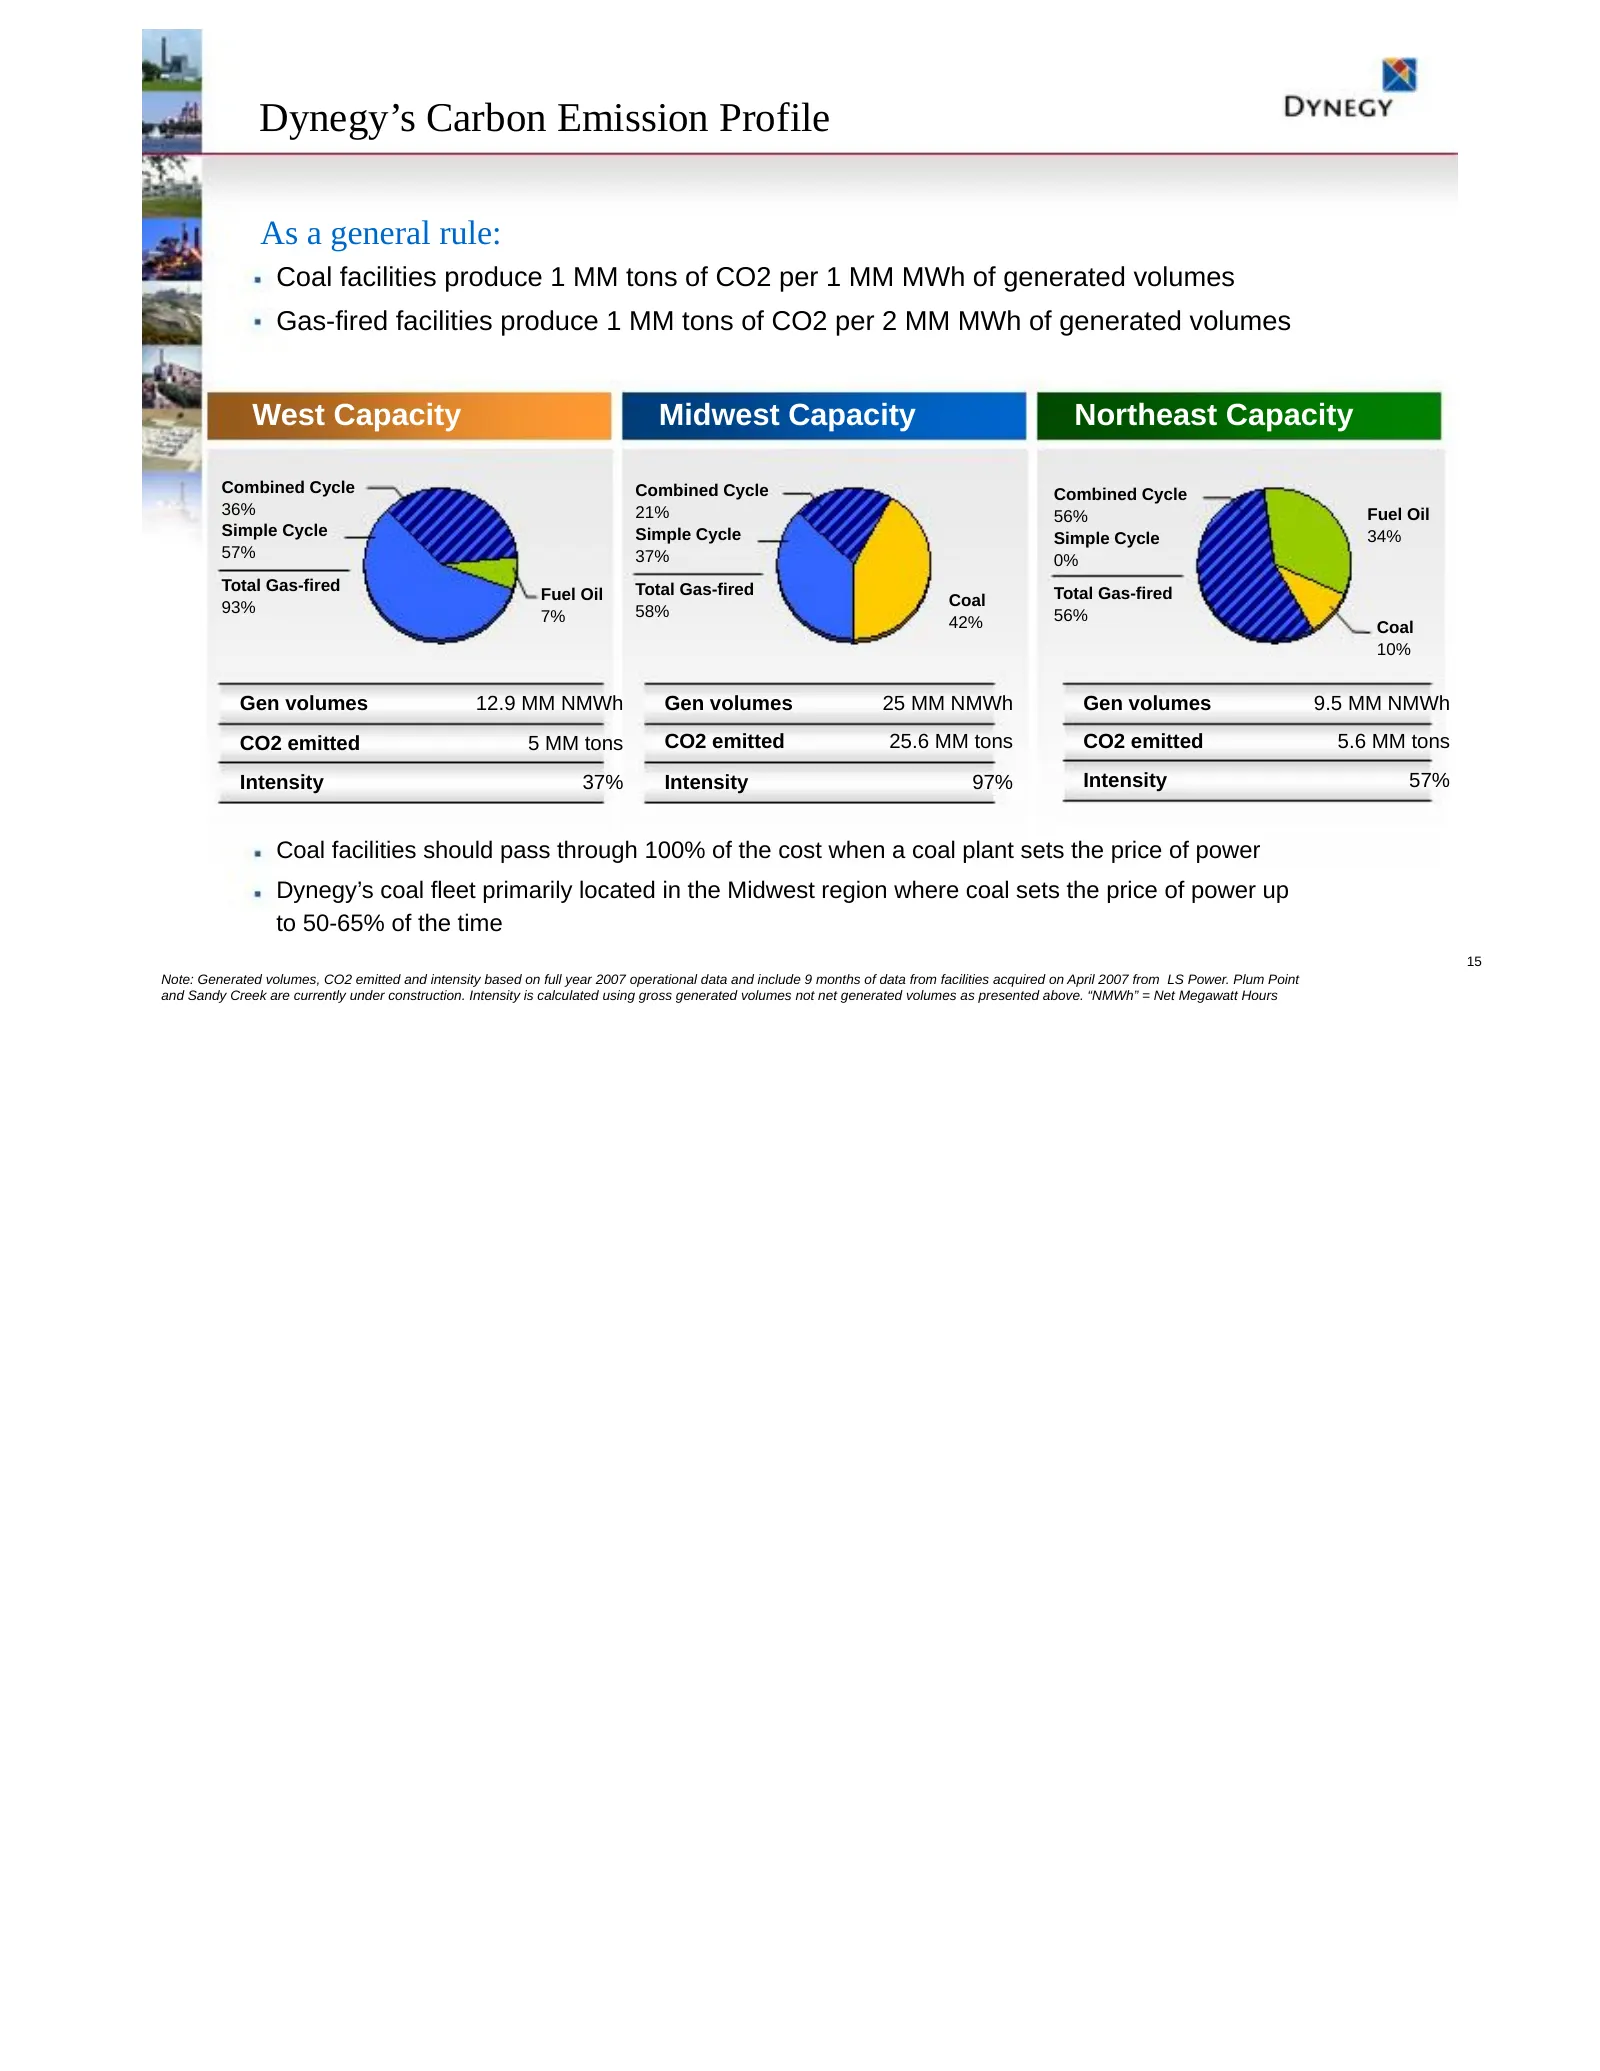
Slide 15: Dynegy's Carbon Emission Profile
Dynegy’s Carbon Emission Profile As a general rule: Coal facilities produce 1 MM tons of CO2 per 1 MM MWh of generated volumes Gas-fired facilities produce 1 MM tons of CO2 per 2 MM MWh of generated volumes West Capacity Midwest Capacity Northeast Capacity Combined Cycle Combined Cycle Combined Cycl
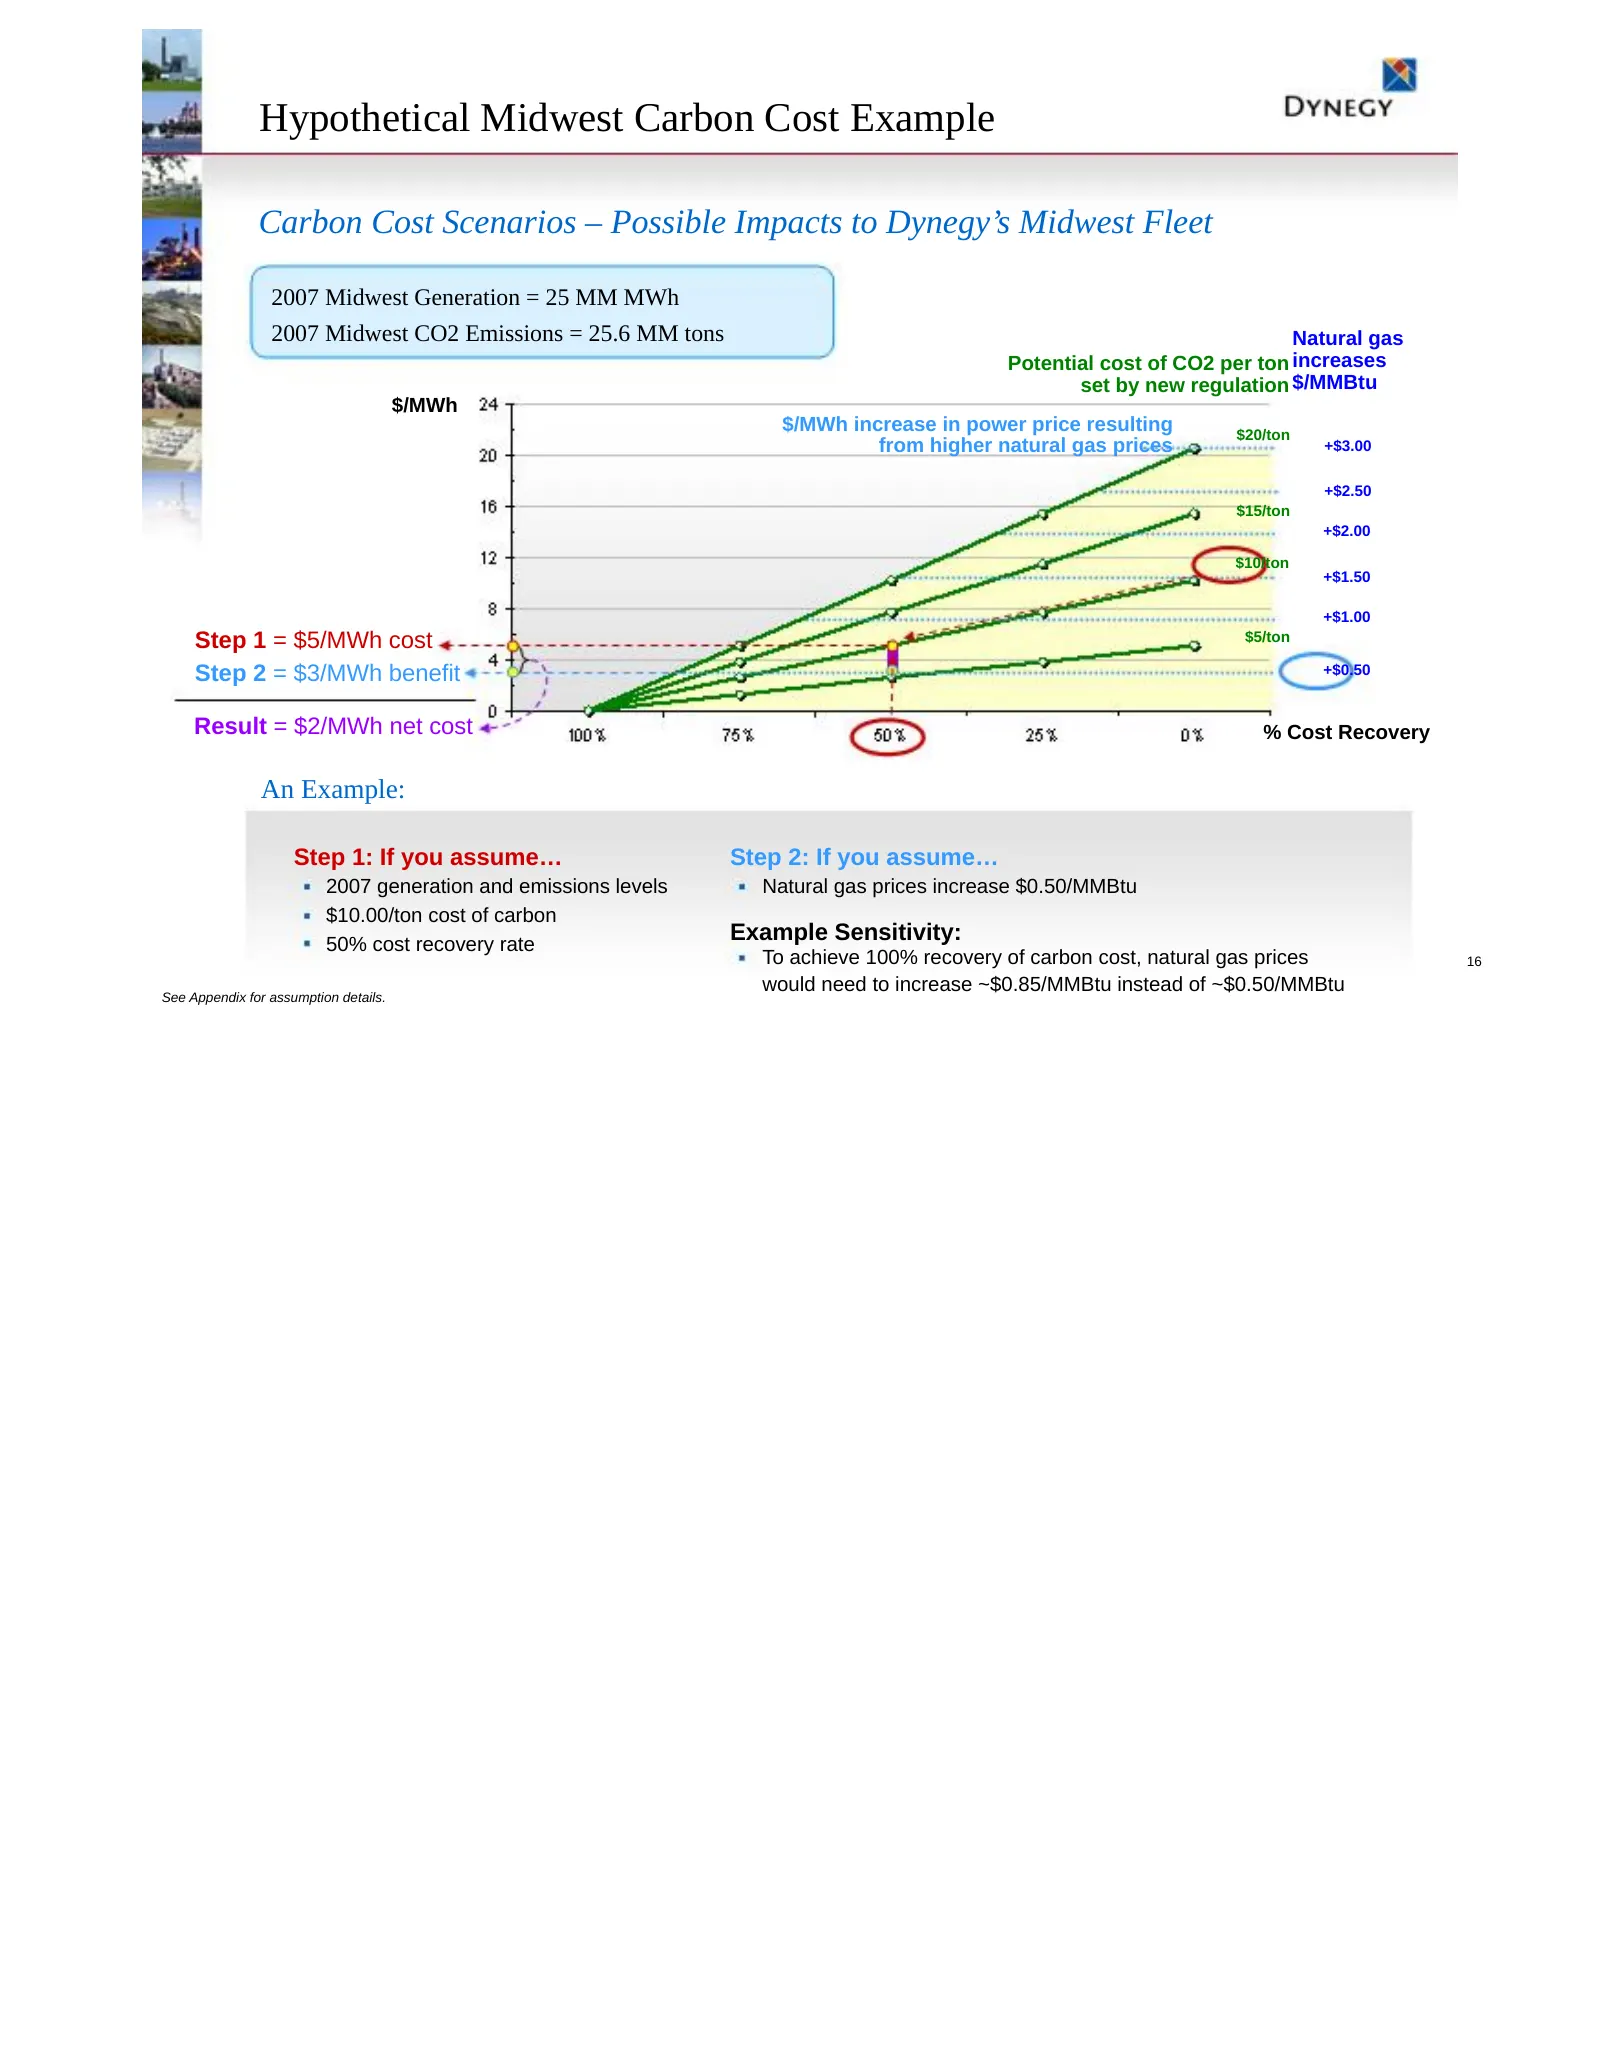
Slide 16: Hypothetical Midwest Carbon Cost Example
Hypothetical Midwest Carbon Cost Example Carbon Cost Scenarios – Possible Impacts to Dynegy’s Midwest Fleet 2007 Midwest Generation = 25 MM MWh 2007 Midwest CO2 Emissions = 25.6 MM tons Natural gas Potential cost of CO2 per ton increases set by new regulation $/MMBtu $/MWh $/MWh increase in power pr
Slide 17: Managing Supply Contracts Offers Advantages
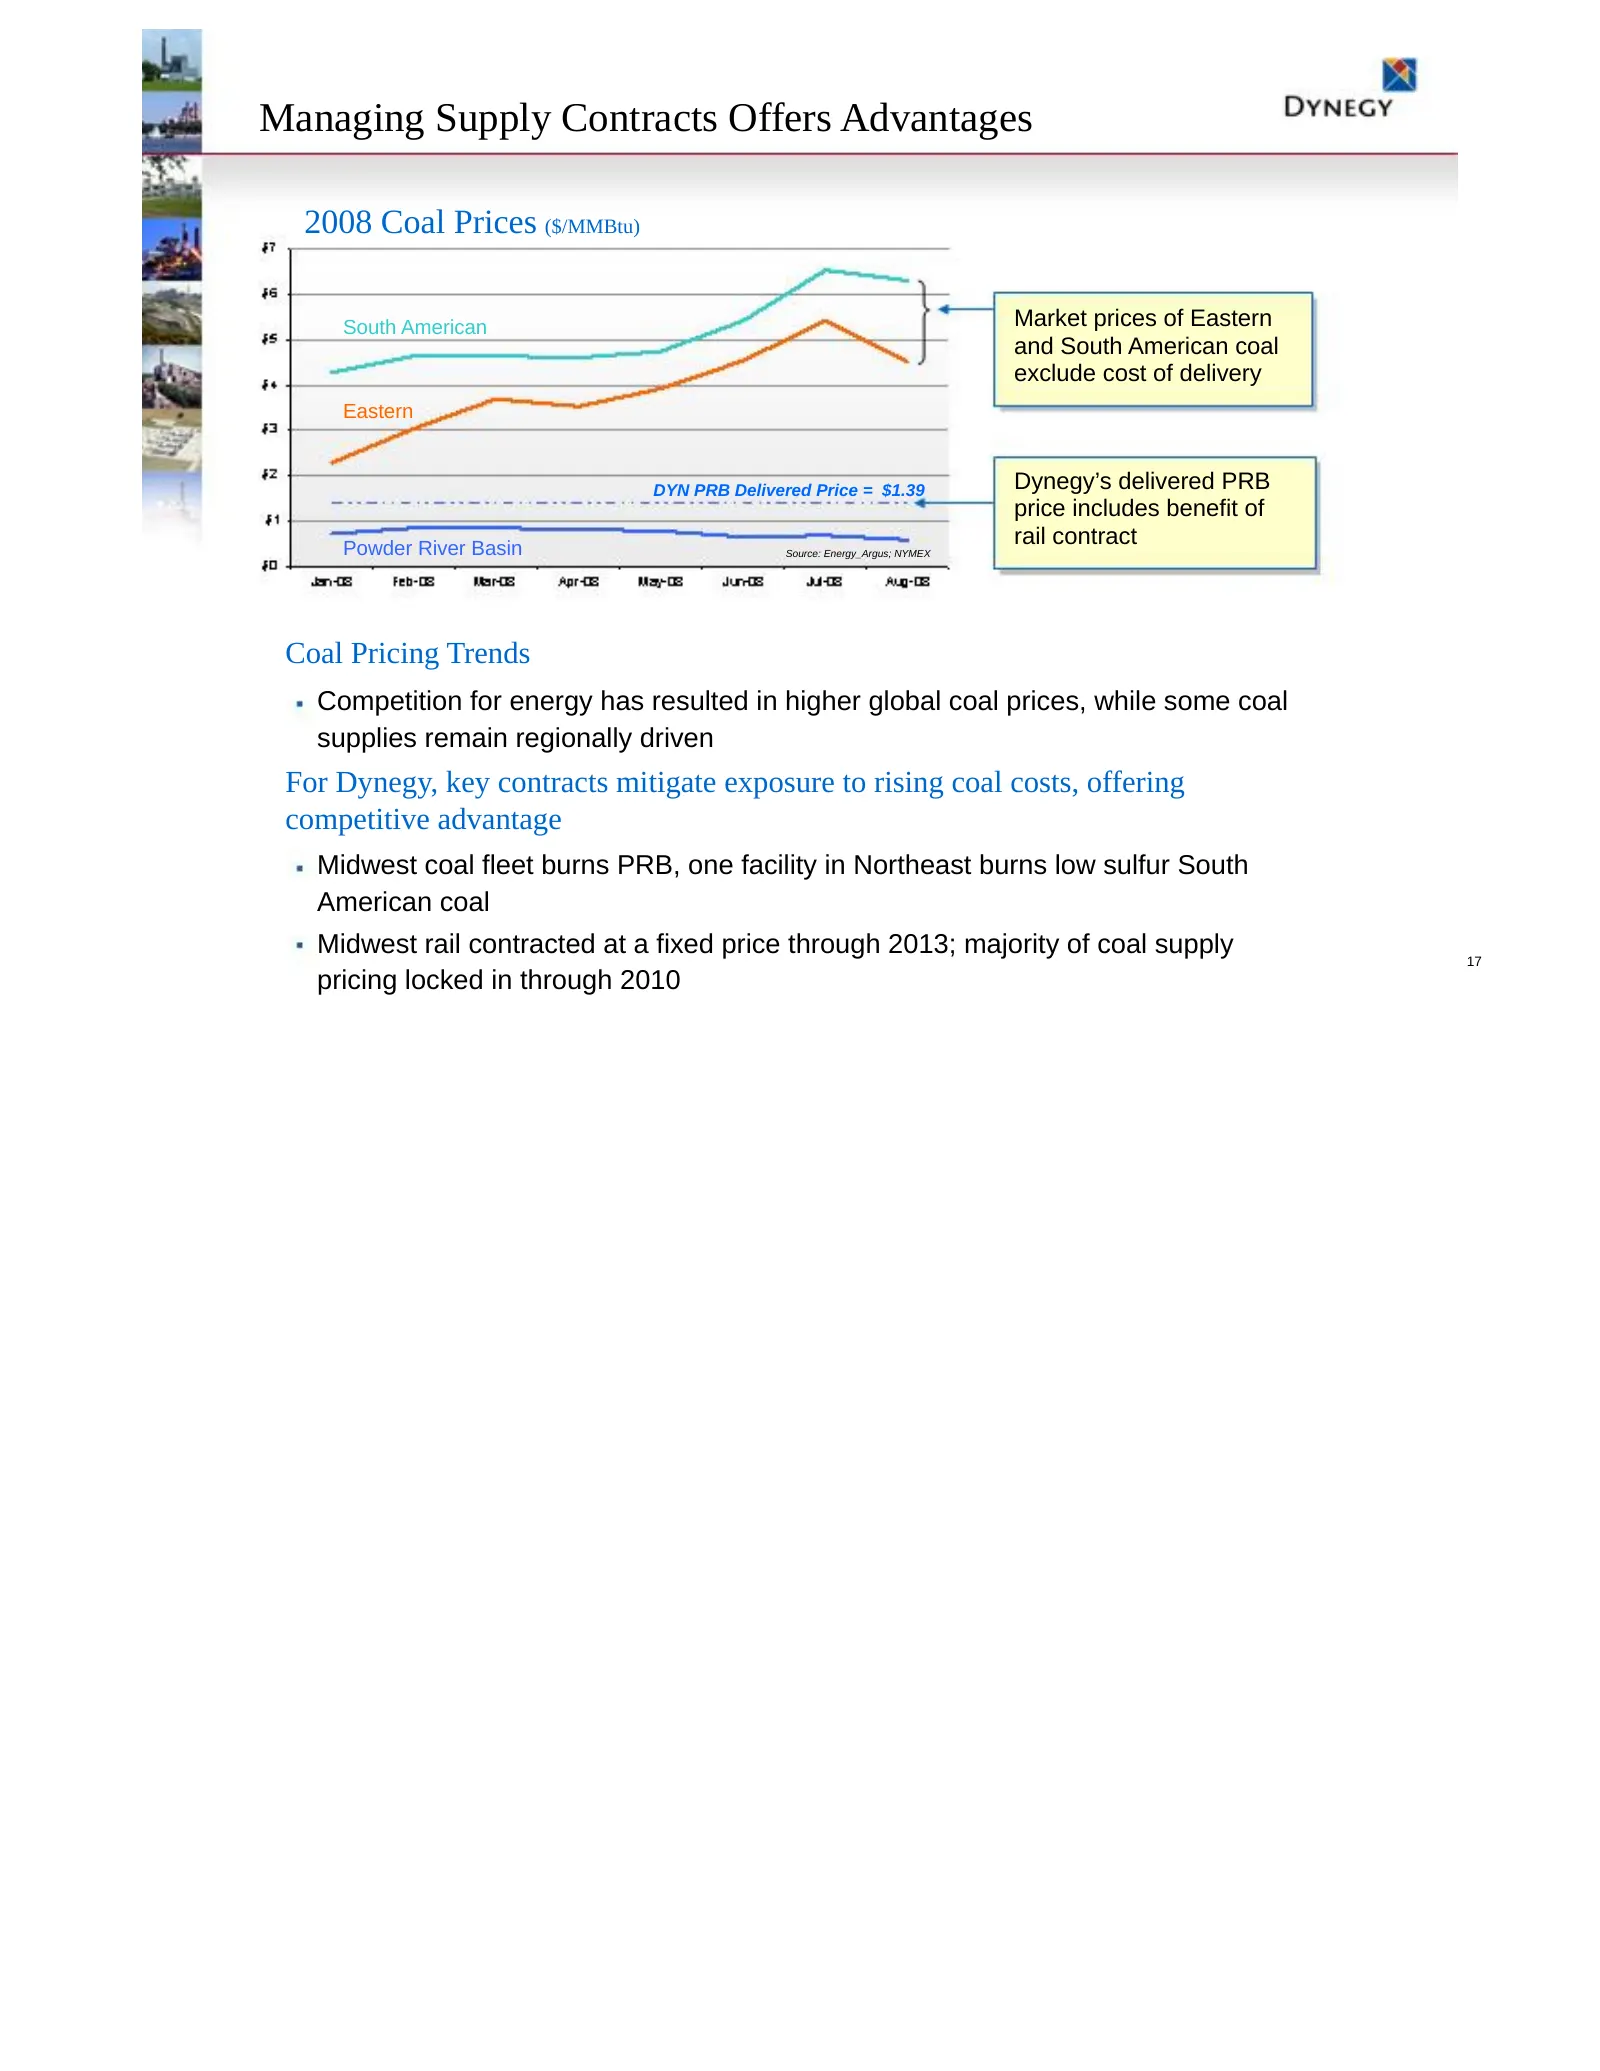
Managing Supply Contracts Offers Advantages 2008 Coal Prices ($/MMBtu) South American Market prices of Eastern and South American coal exclude cost of delivery Eastern DYN PRB Delivered Price = $1.39 Dynegy’s delivered PRB price includes benefit of Powder River Basin rail contract Source: Energy_Arg
Slide 18: Current Market Creates Opportunities for Dynegy
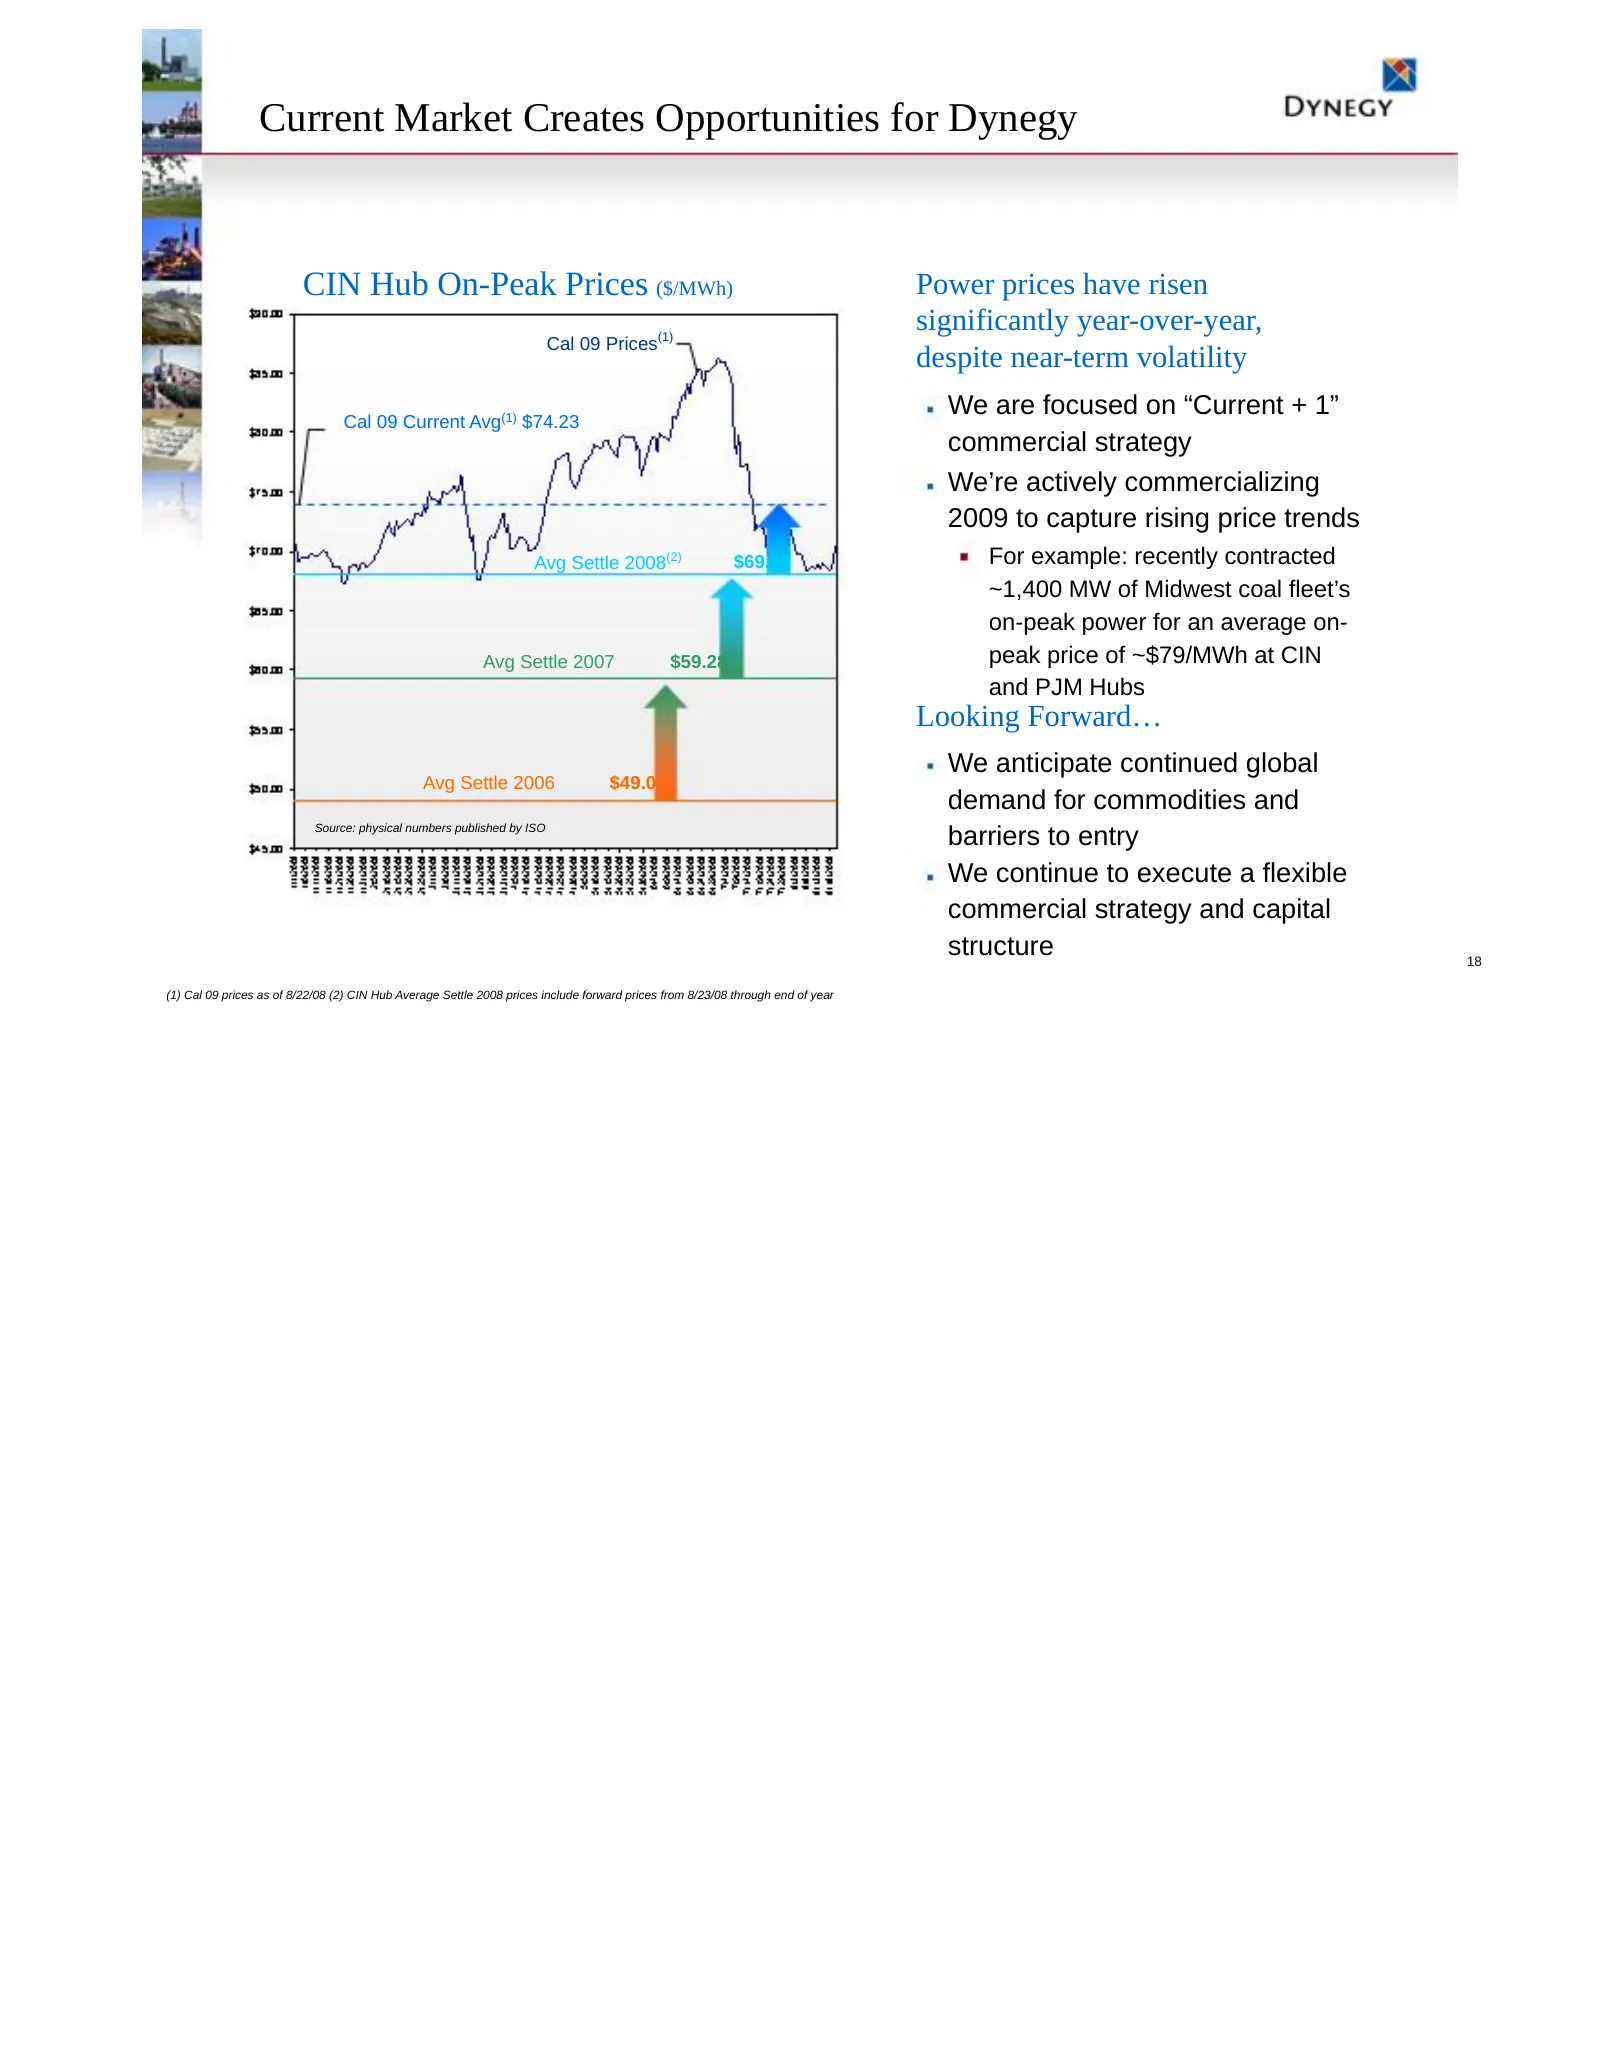
Current Market Creates Opportunities for Dynegy CIN Hub On-Peak Prices ($/MWh) Power prices have risen significantly year-over-year, Cal 09 Prices(1) despite near-term volatility We are focused on “Current + 1” Cal 09 Current Avg(1) $74.23 commercial strategy We’re actively commercializing 2009 to c
Slide 19: Why Invest in Dynegy?
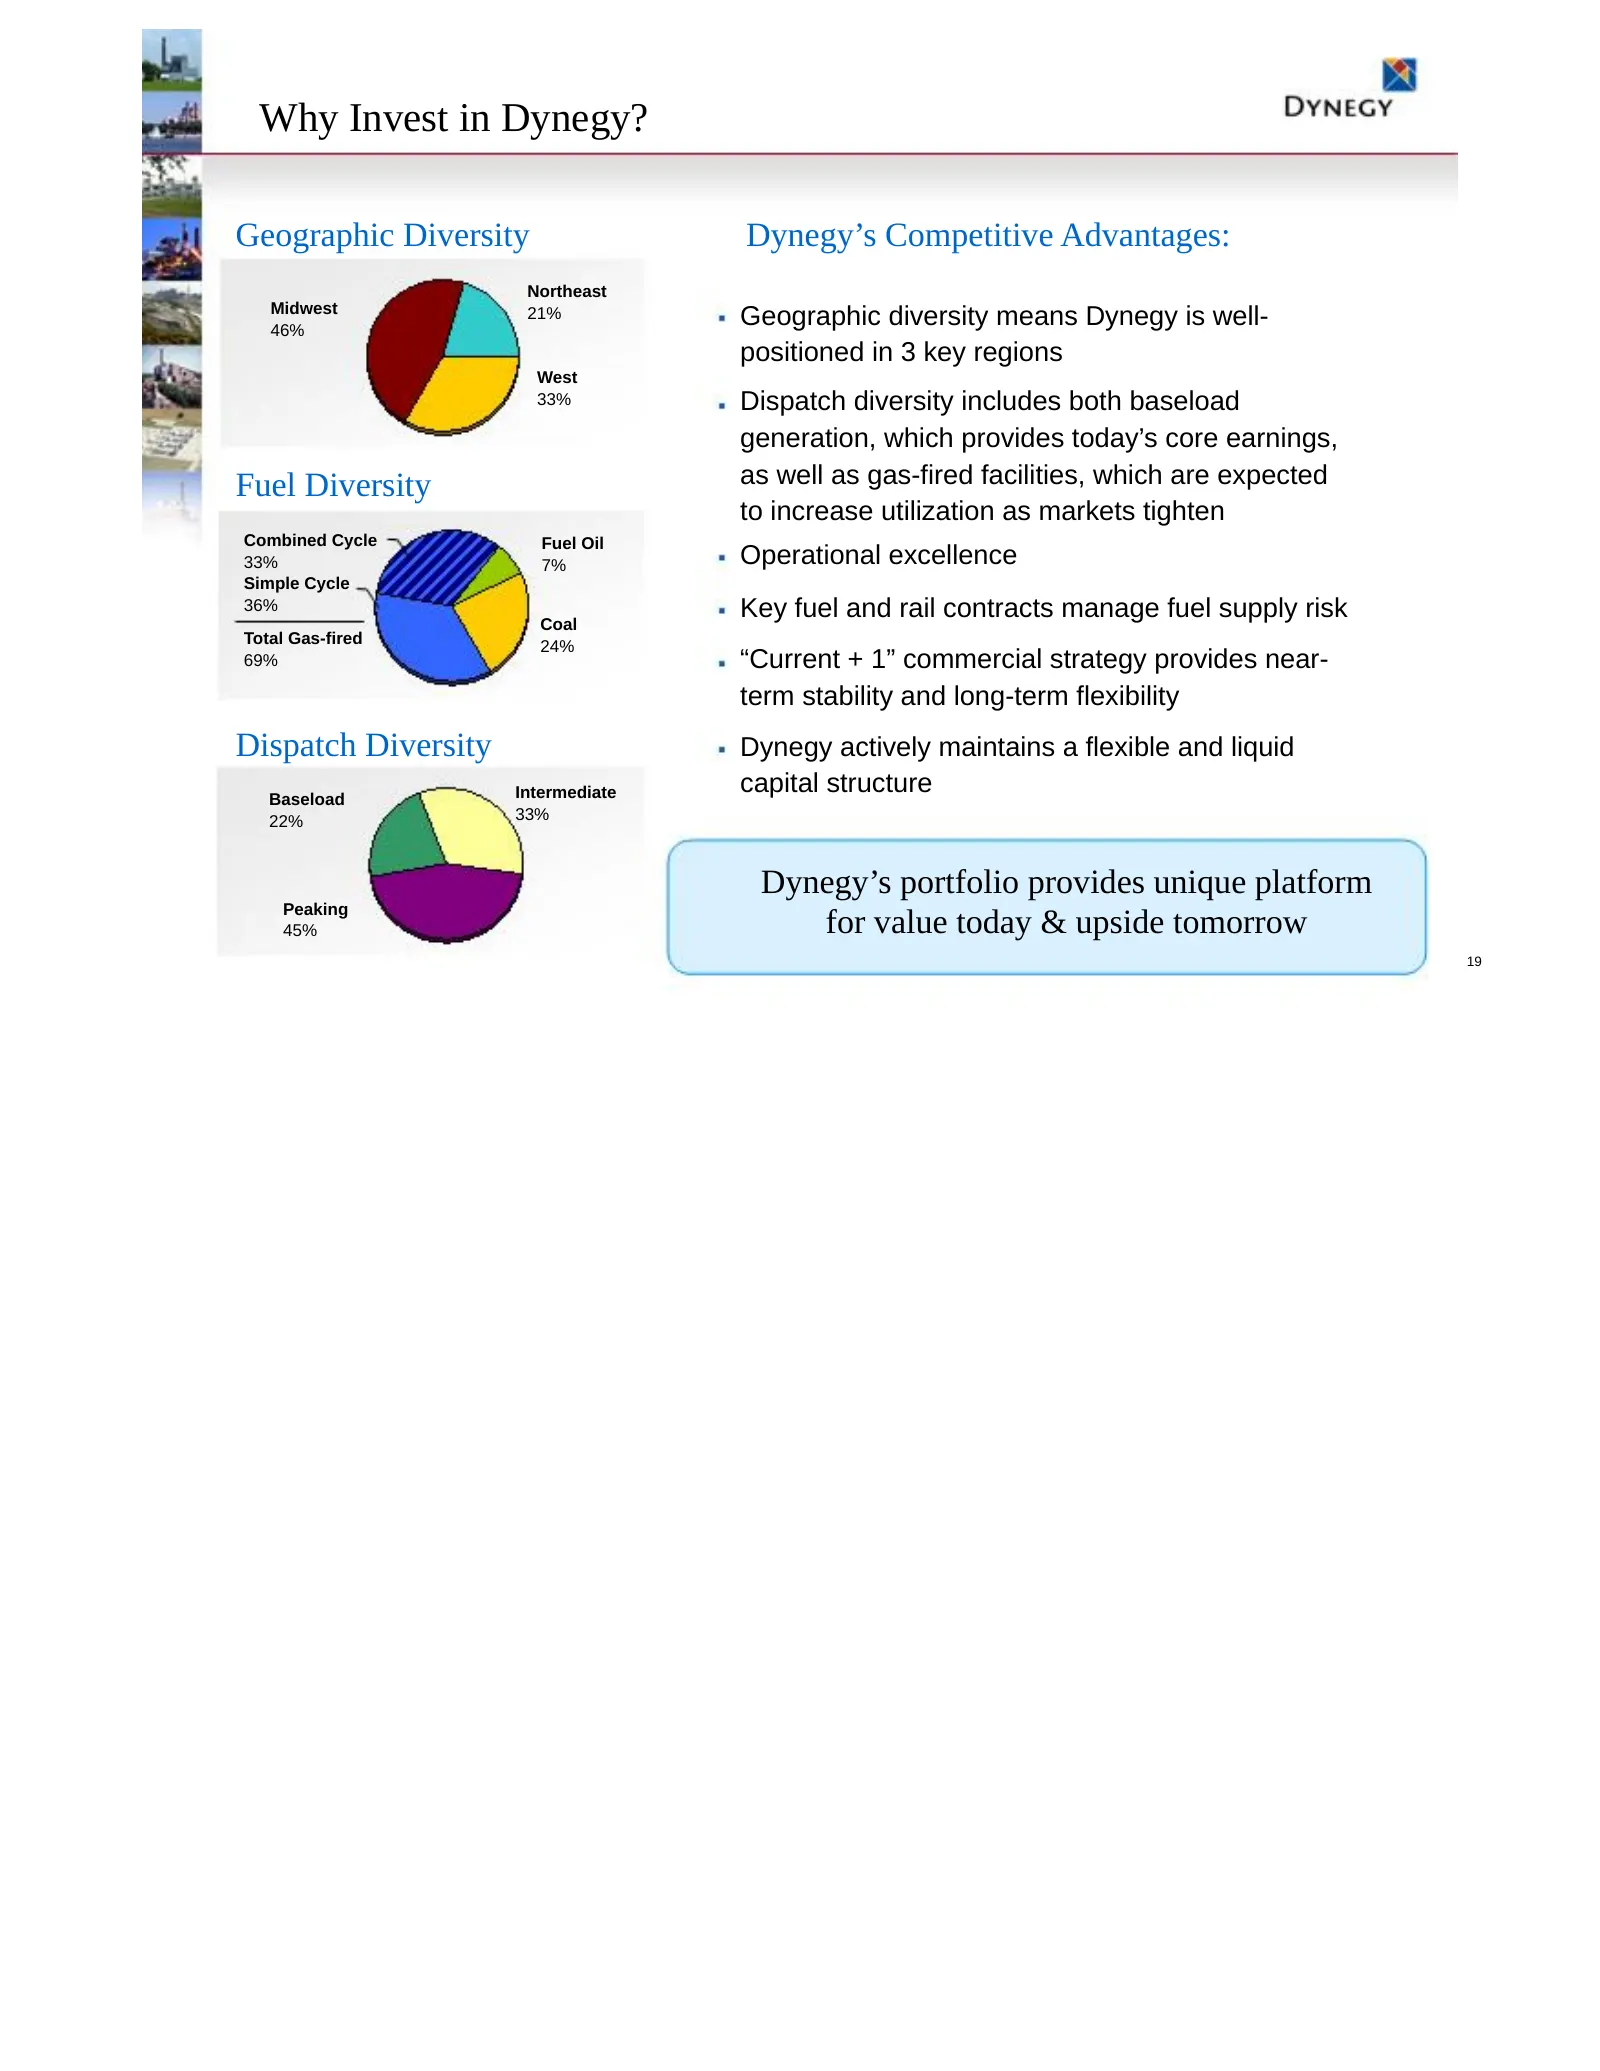
Why Invest in Dynegy? Geographic Diversity Dynegy’s Competitive Advantages: Northeast Midwest 46% 21% Geographic diversity means Dynegy is well- positioned in 3 key regions West 33% Dispatch diversity includes both baseload generation, which provides today’s core earnings, Fuel Diversity as well as
Slide 20: Investment Proposition
Investment Proposition
Slide 21: We Believe Dynegy is Significantly Undervalued
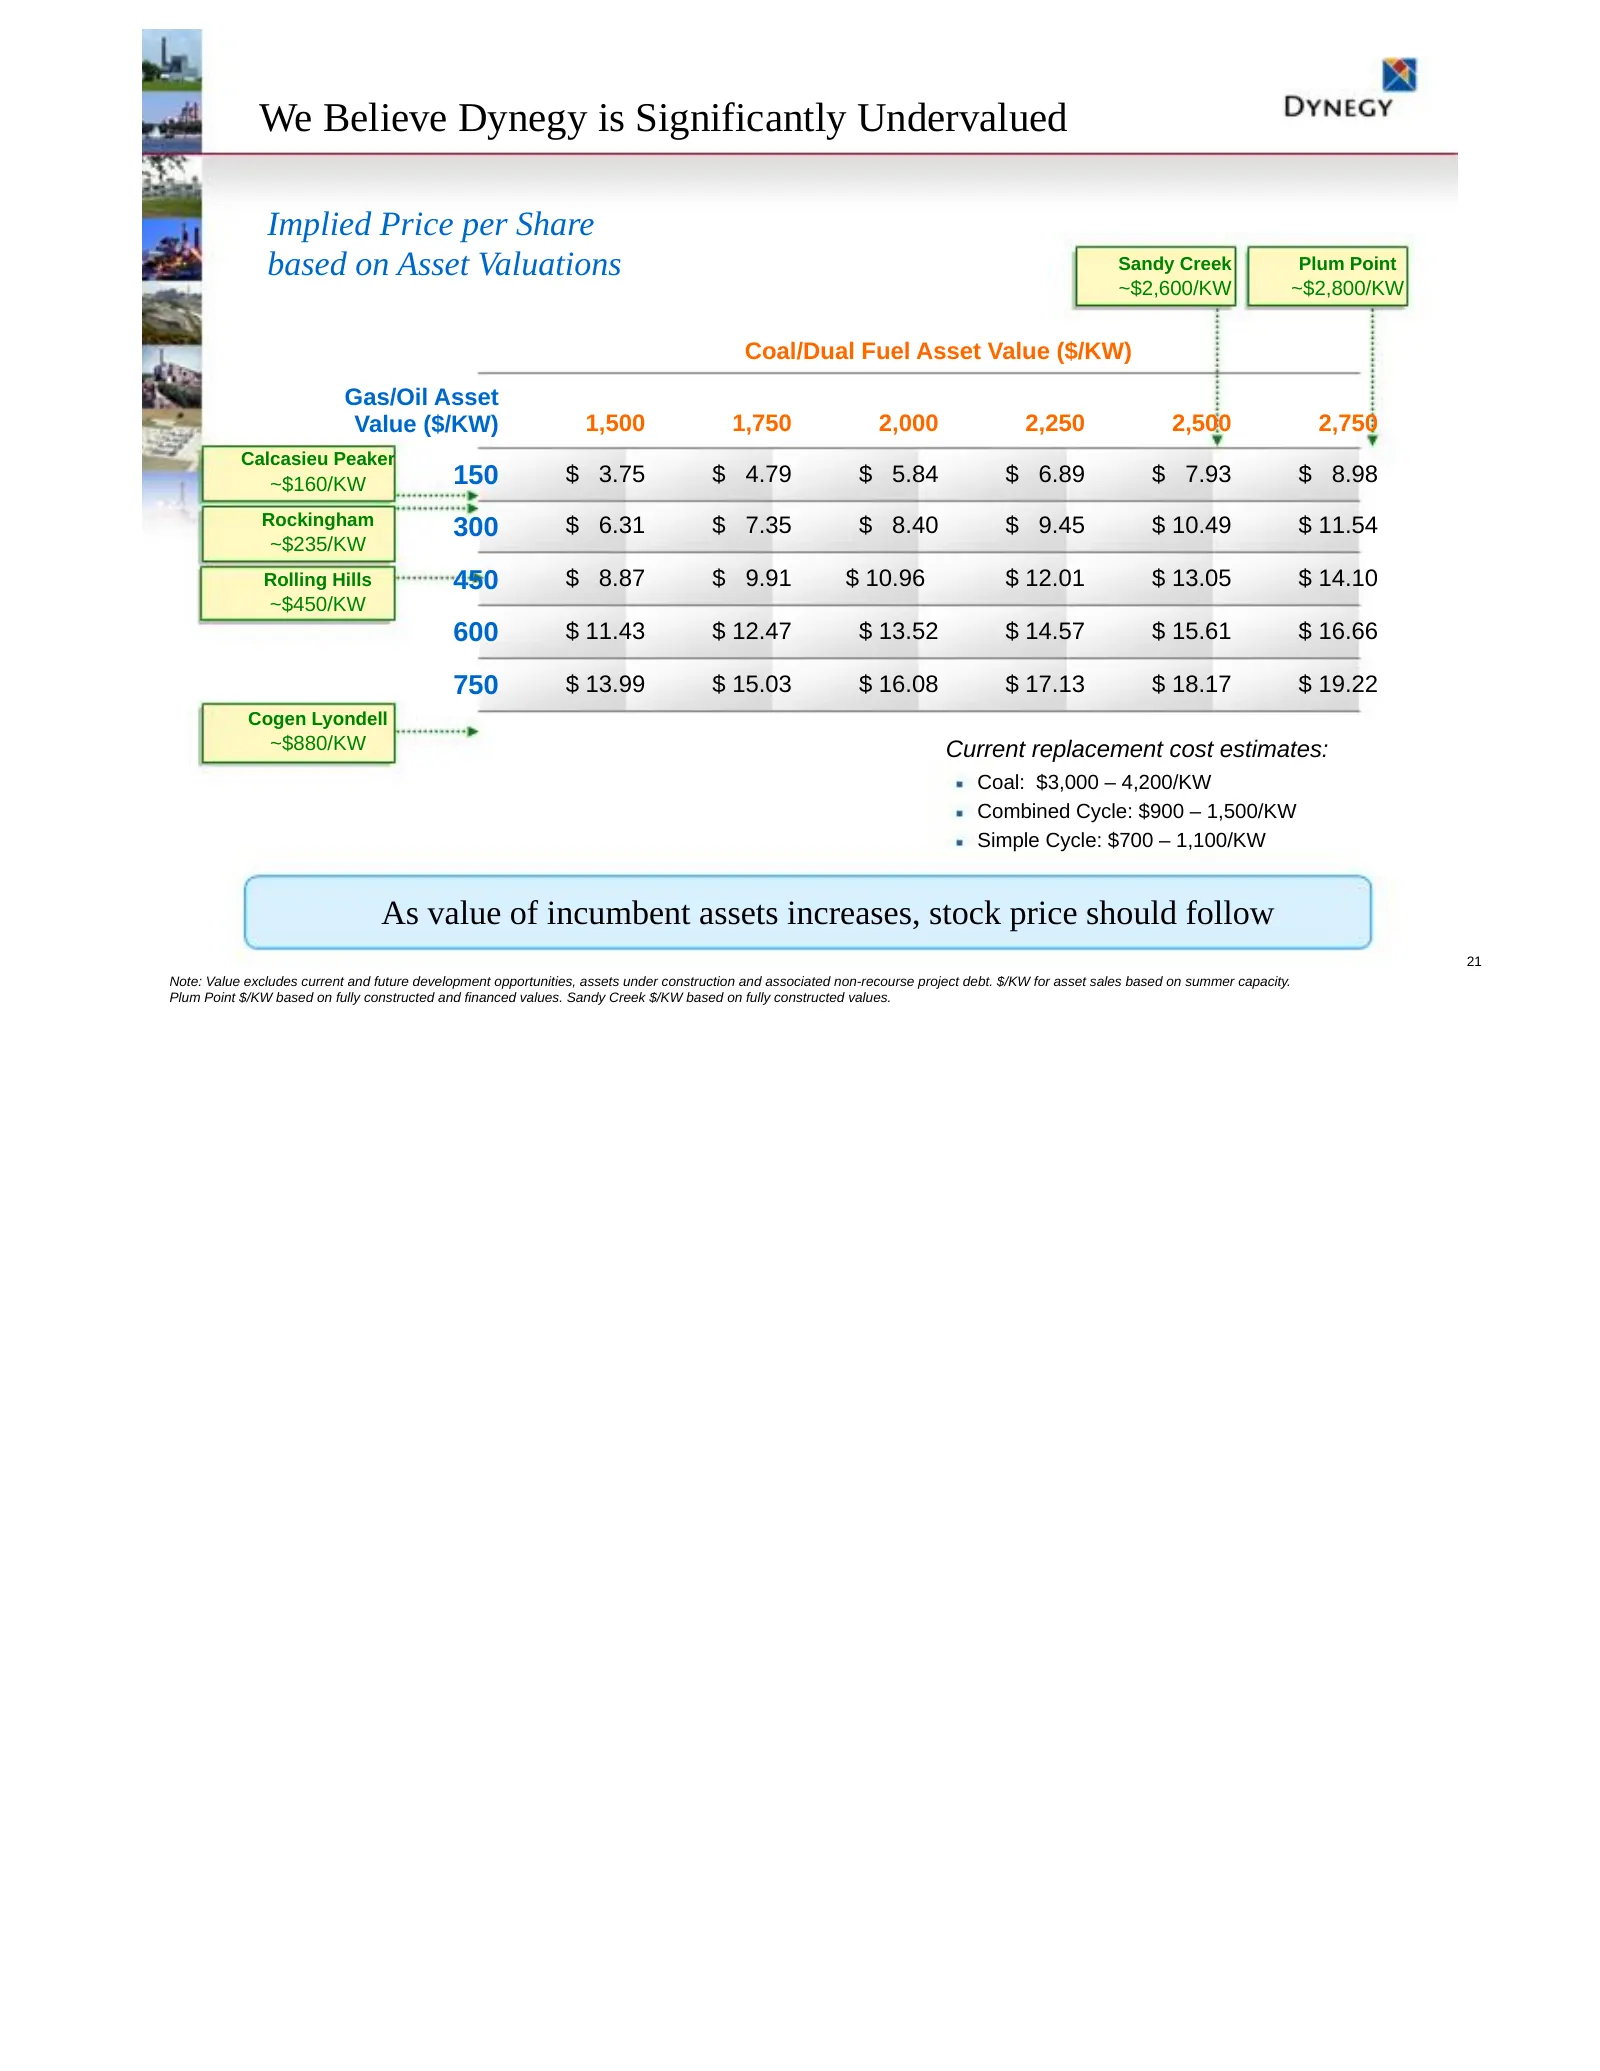
We Believe Dynegy is Significantly Undervalued Implied Price per Share based on Asset Valuations Sandy Creek Plum Point ~$2,600/KW ~$2,800/KW Coal/Dual Fuel Asset Value ($/KW) Gas/Oil Asset Value ($/KW) 1,500 1,750 2,000 2,250 2,500 2,750 Calcasieu Peaker ~$160/KW 150 $ 3.75 $ 4.79 $ 5.84 $ 6.89 $ 7
Slide 22: Appendix
Appendix
Slide 23: From Clearing House to IPP
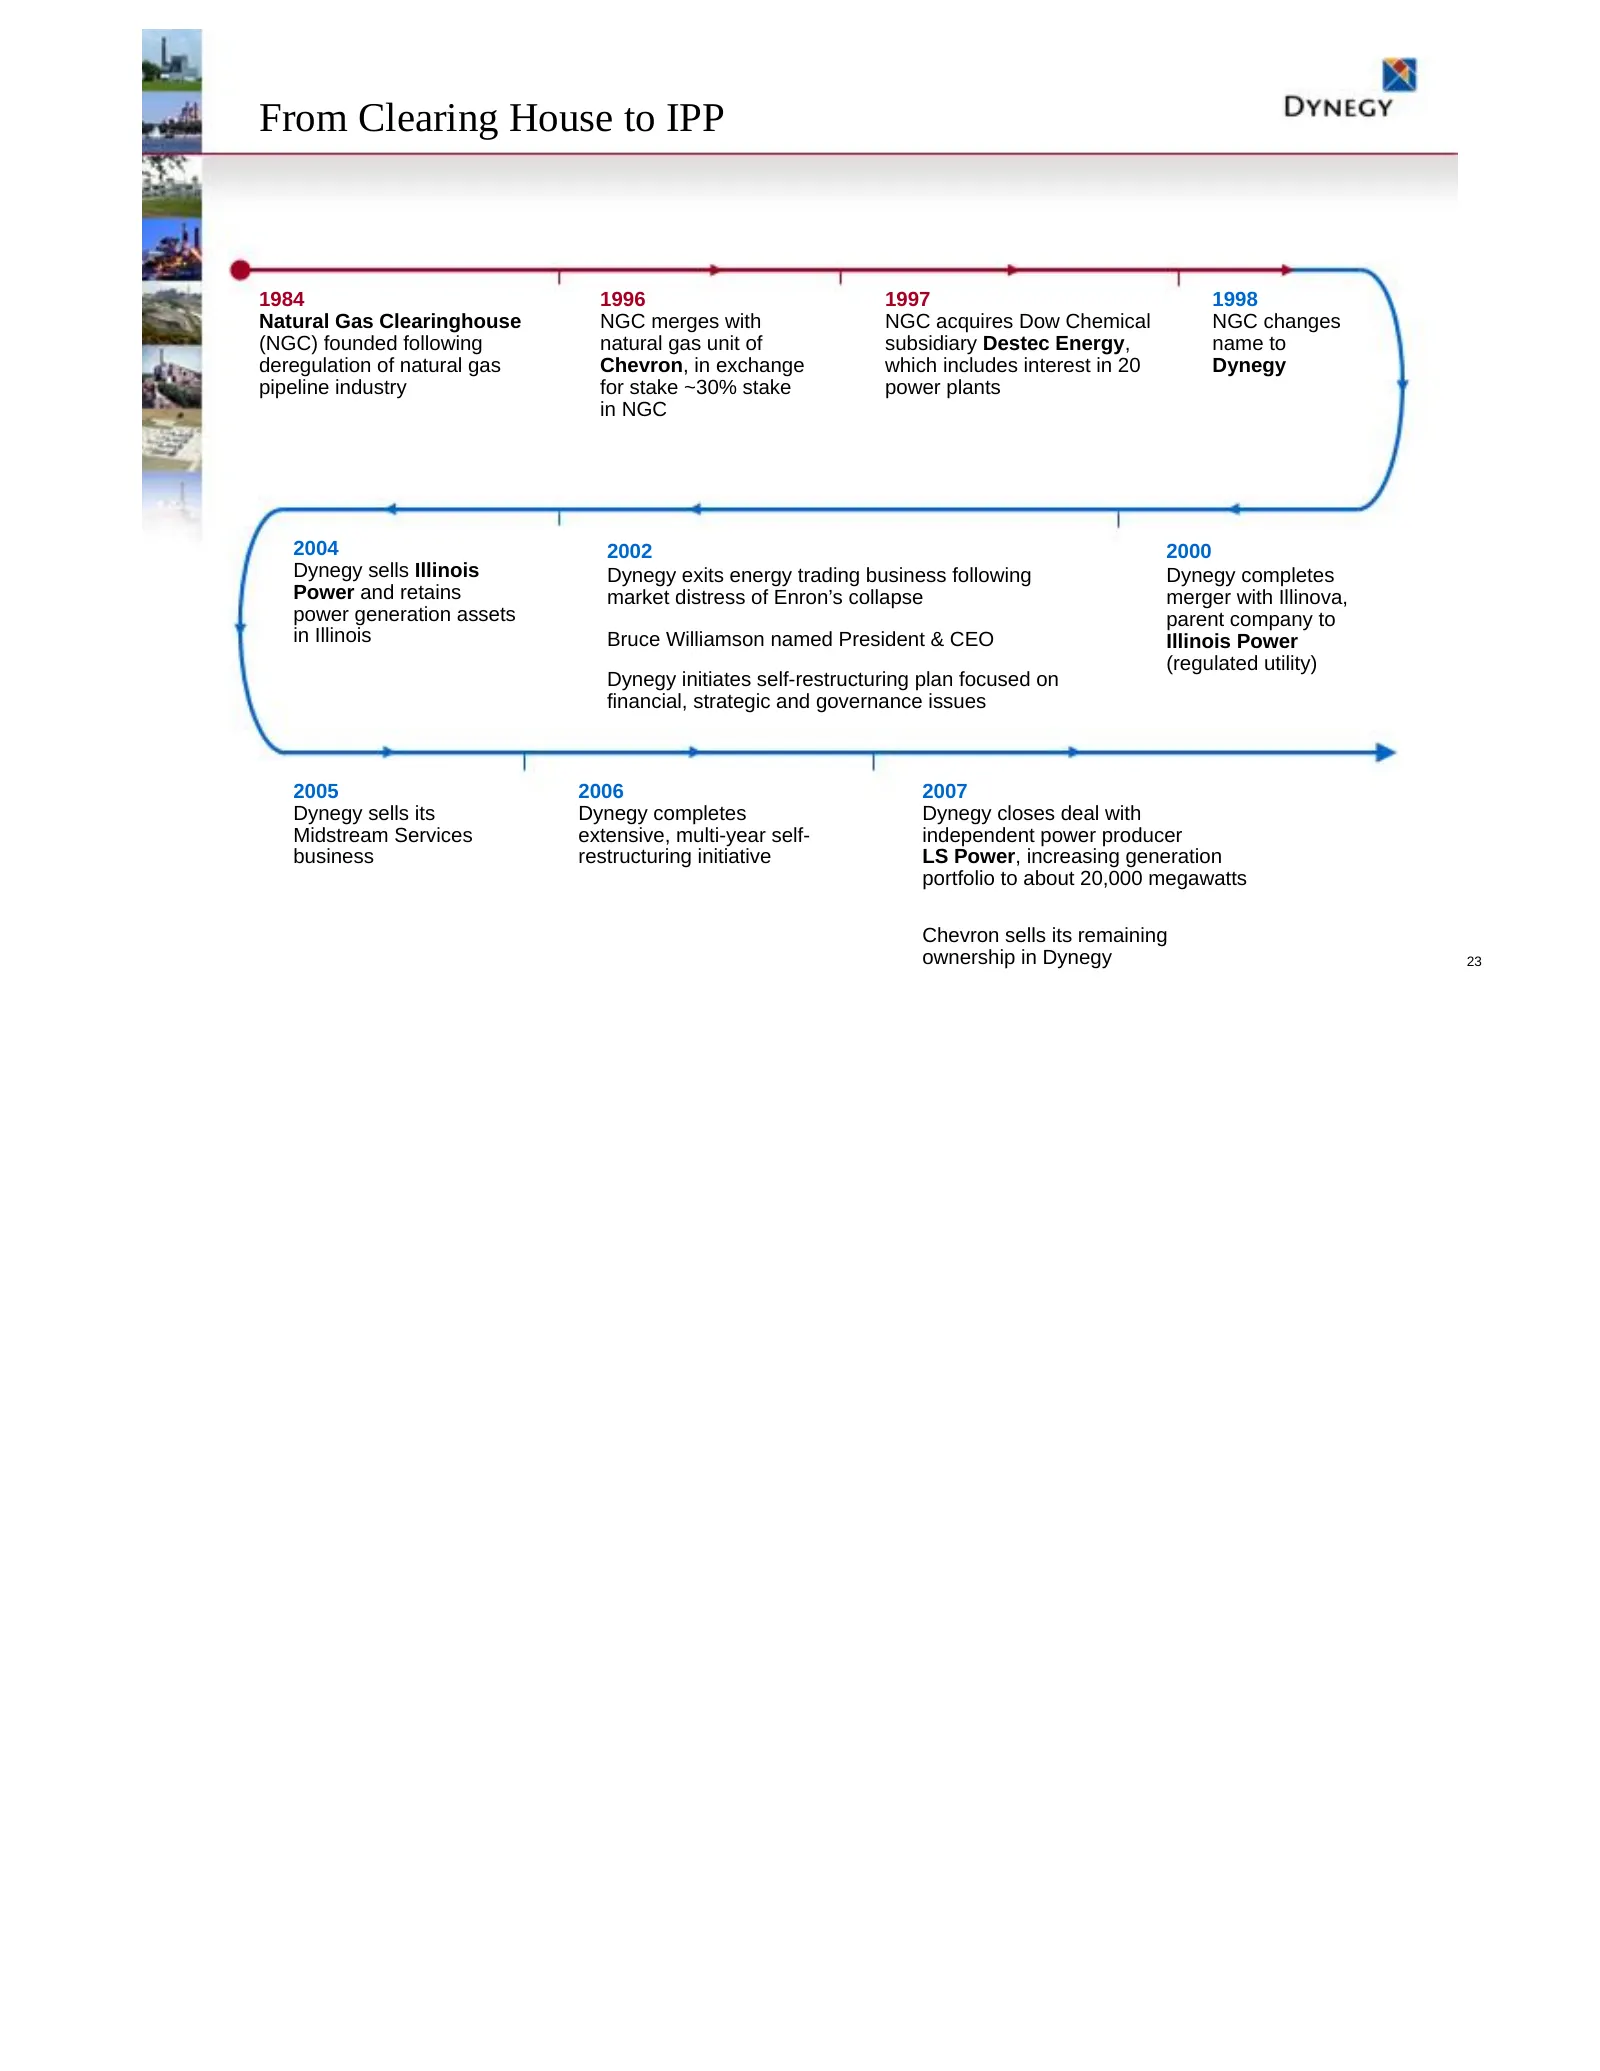
From Clearing House to IPP 1984 1996 1997 1998 Natural Gas Clearinghouse NGC merges with NGC acquires Dow Chemical NGC changes (NGC) founded following natural gas unit of subsidiary Destec Energy, name to deregulation of natural gas Chevron, in exchange which includes interest in 20 Dynegy pipeline
Slide 24: Replacement Costs
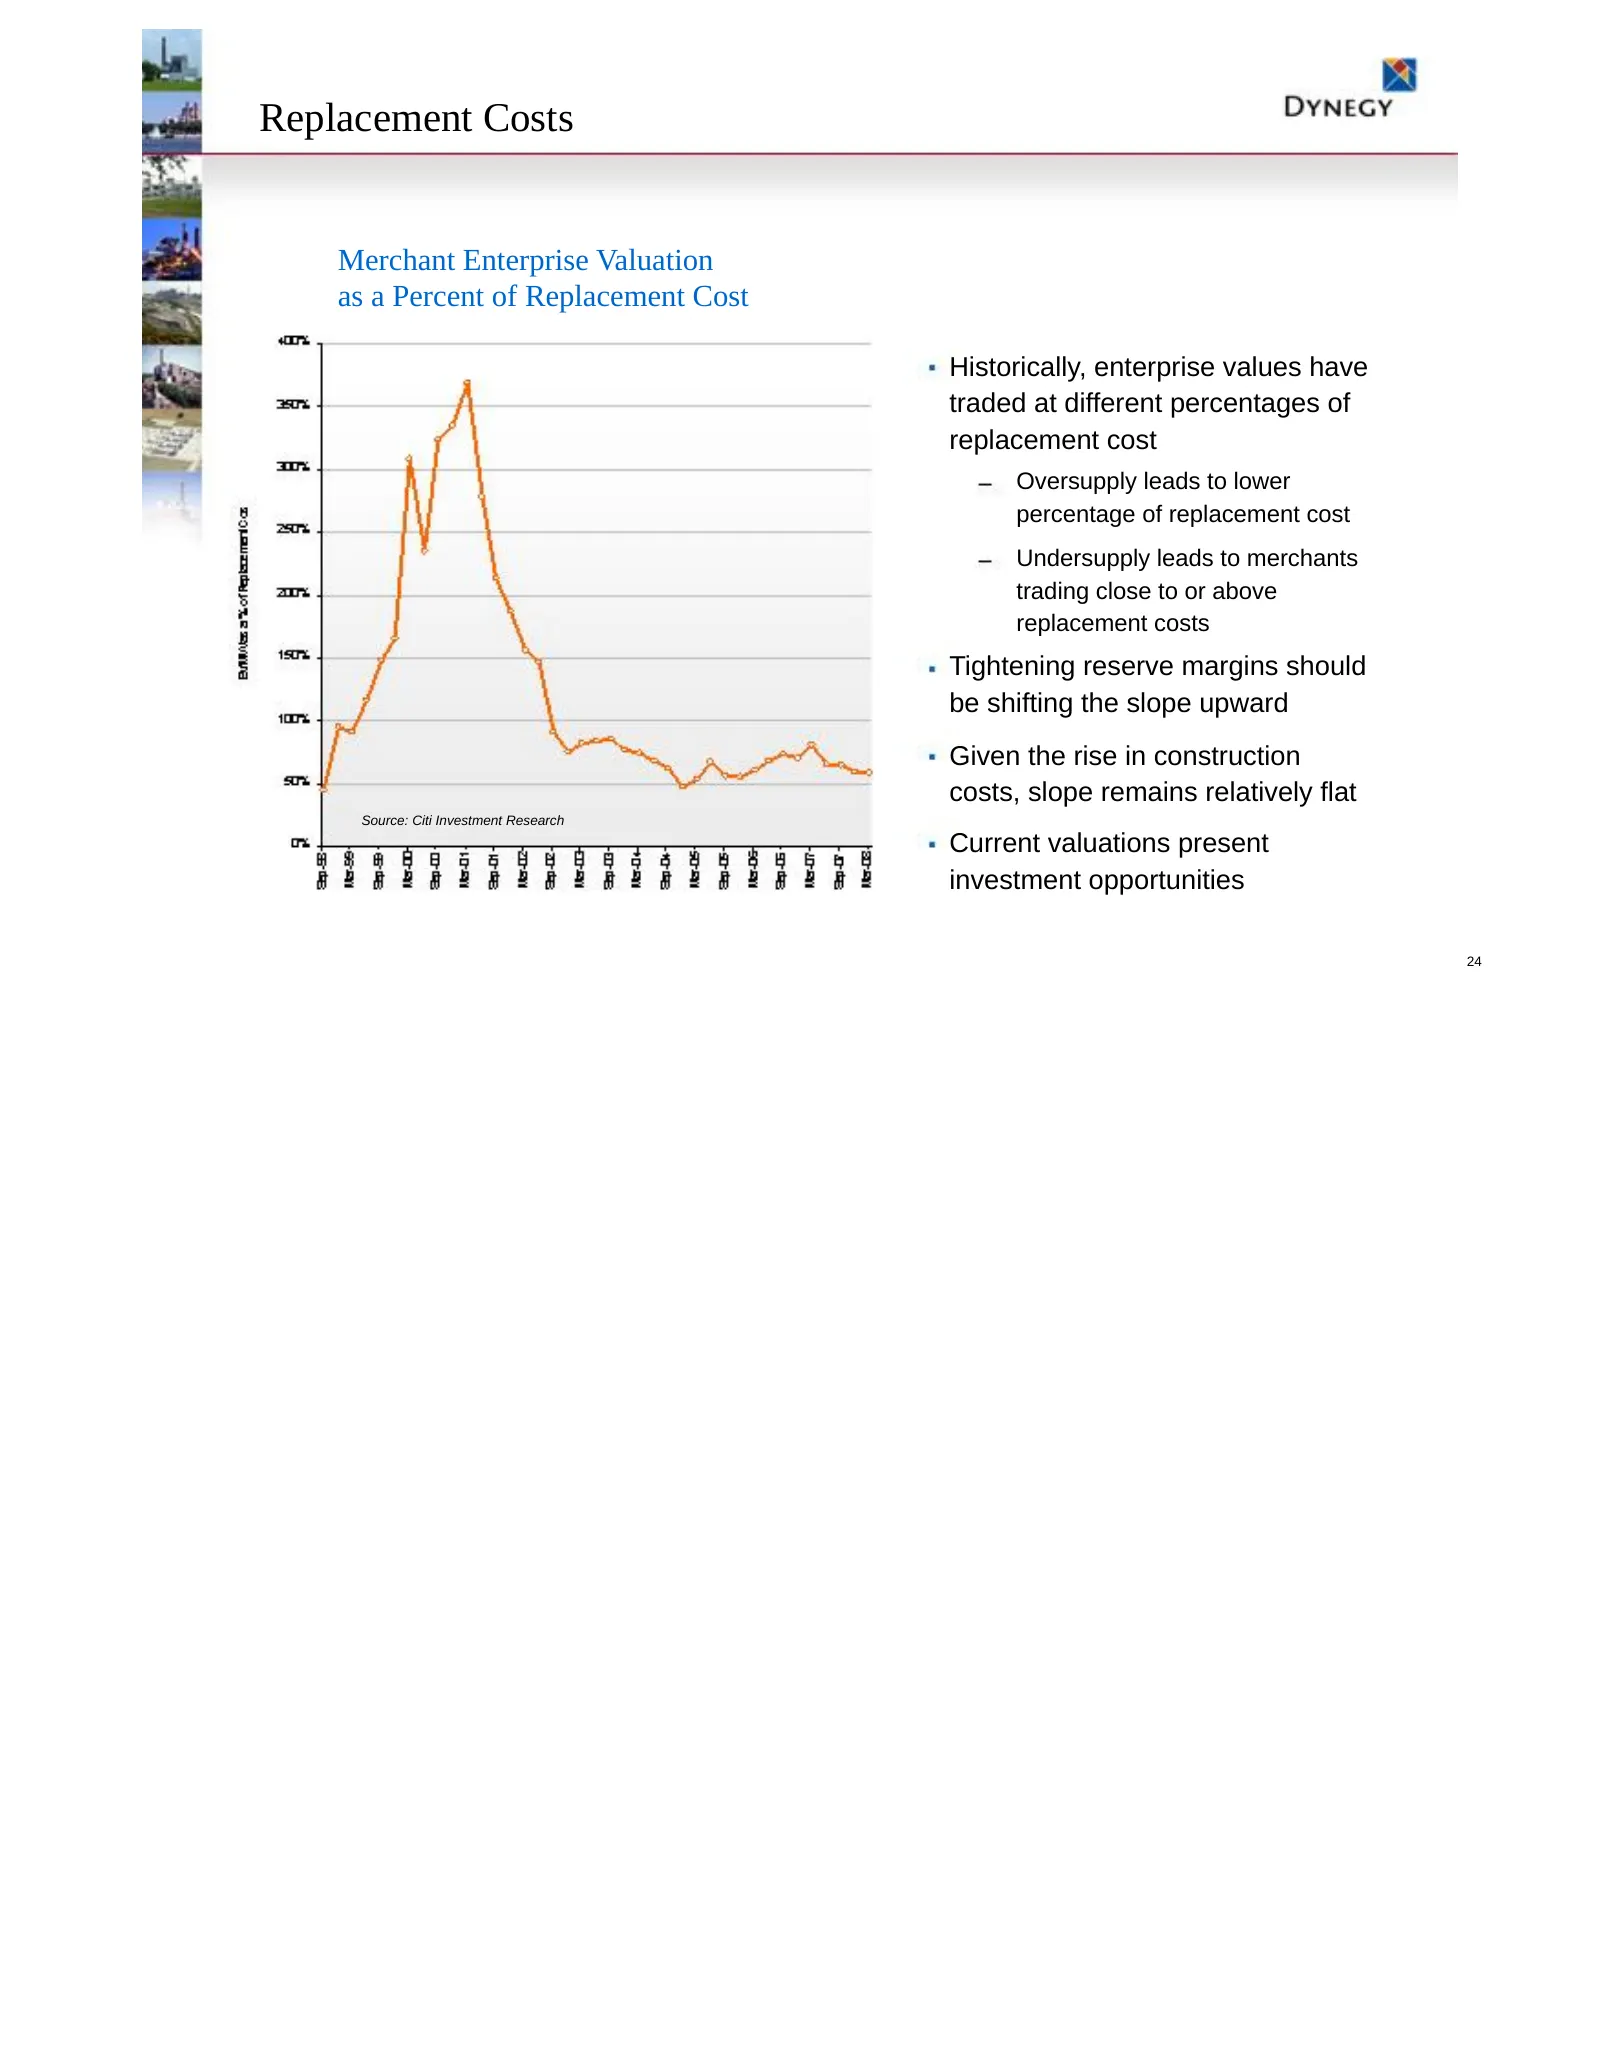
Replacement Costs Merchant Enterprise Valuation as a Percent of Replacement Cost Historically, enterprise values have traded at different percentages of replacement cost Oversupply leads to lower percentage of replacement cost Undersupply leads to merchants trading close to or above replacement cost
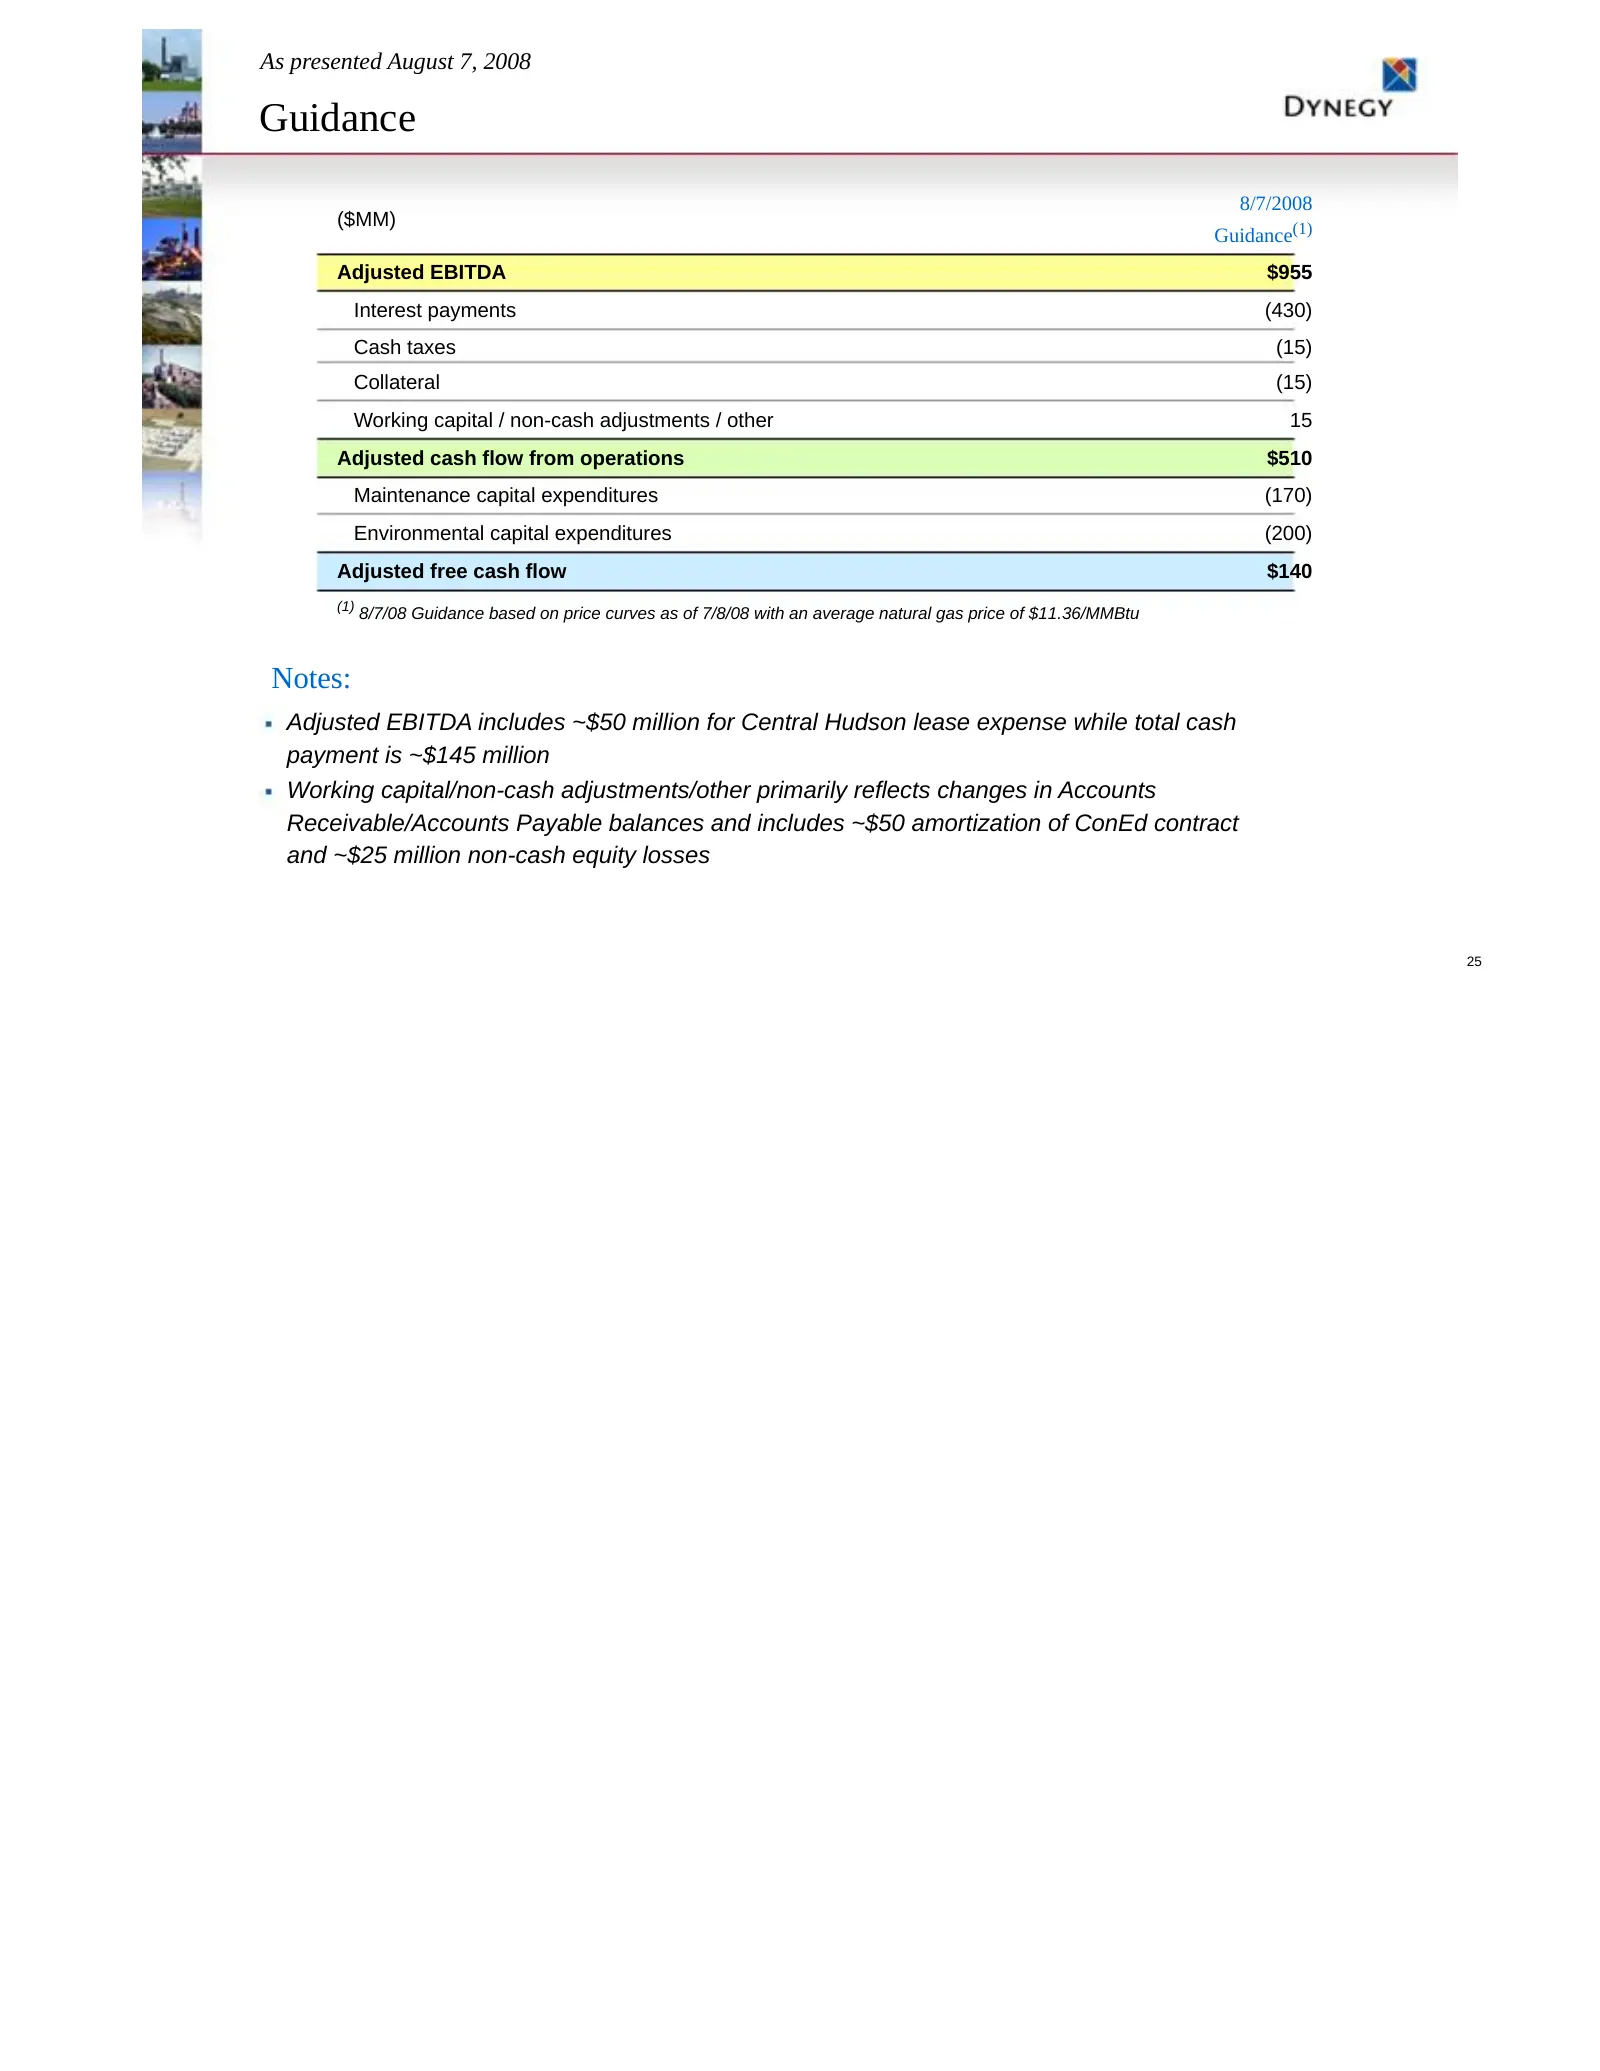
Slide 25: Guidance
As presented August 7, 2008 Guidance 8/7/2008 ($MM) Guidance(1) Adjusted EBITDA $955 Interest payments (430) Cash taxes (15) Collateral (15) Working capital / non-cash adjustments / other 15 Adjusted cash flow from operations $510 Maintenance capital expenditures (170) Environmental capital expendit
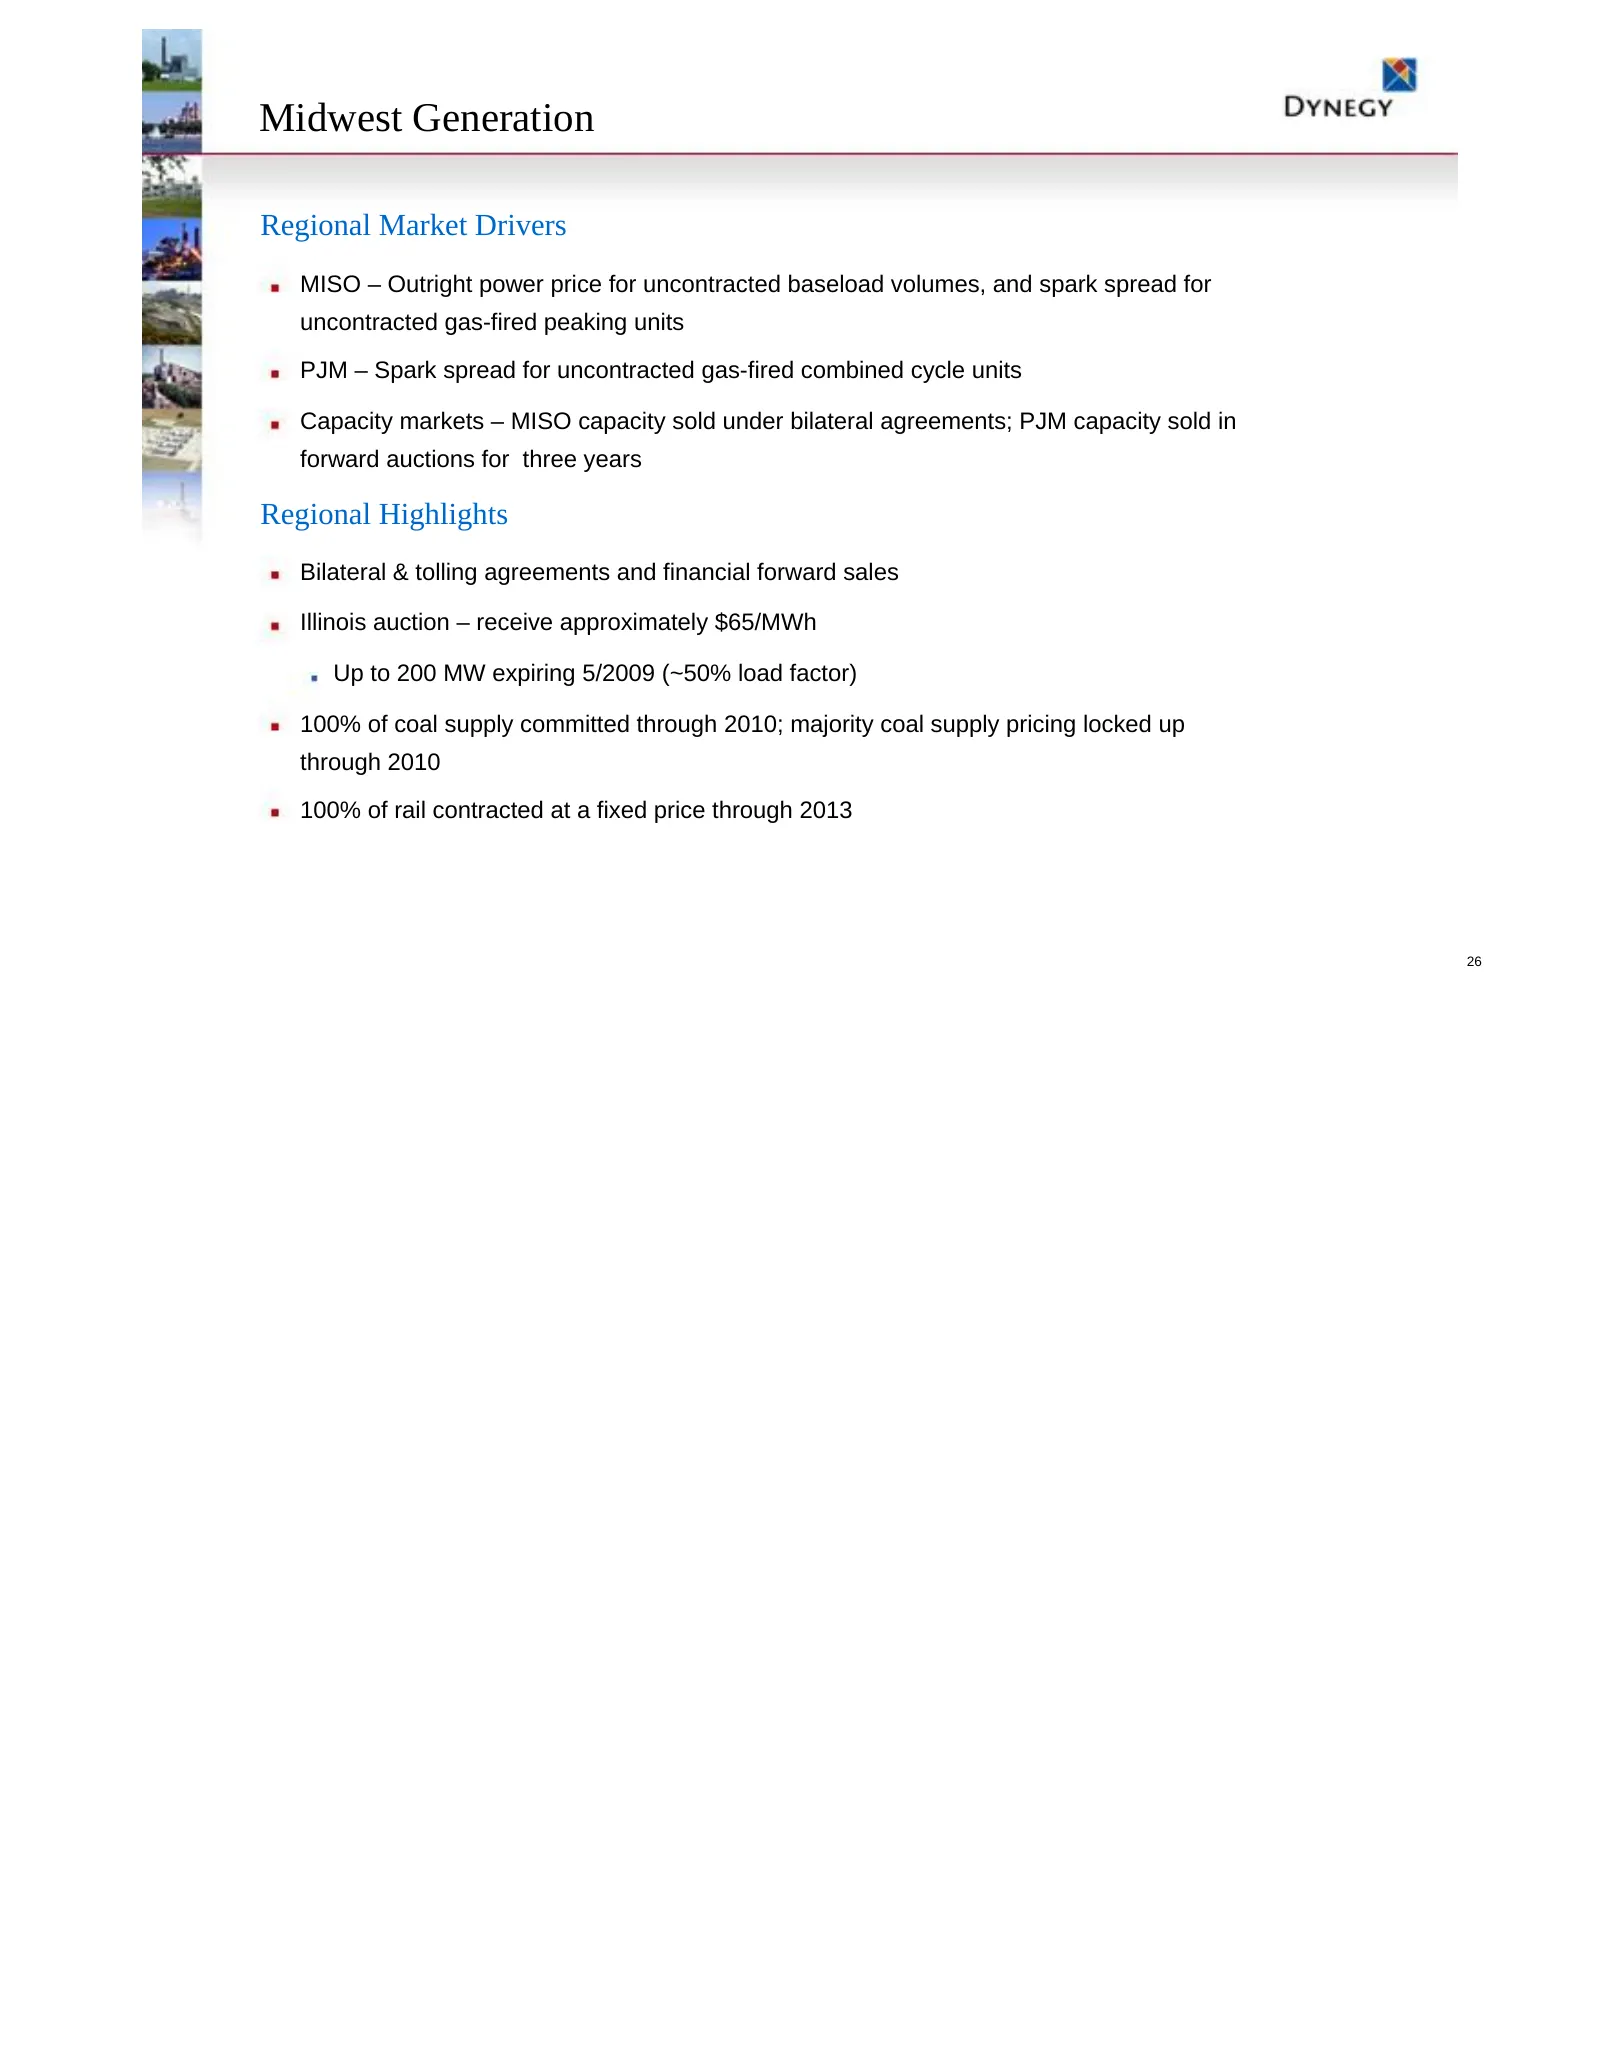
Slide 26: Midwest Generation
Midwest Generation Regional Market Drivers MISO – Outright power price for uncontracted baseload volumes, and spark spread for uncontracted gas-fired peaking units PJM – Spark spread for uncontracted gas-fired combined cycle units Capacity markets – MISO capacity sold under bilateral agreements; PJM
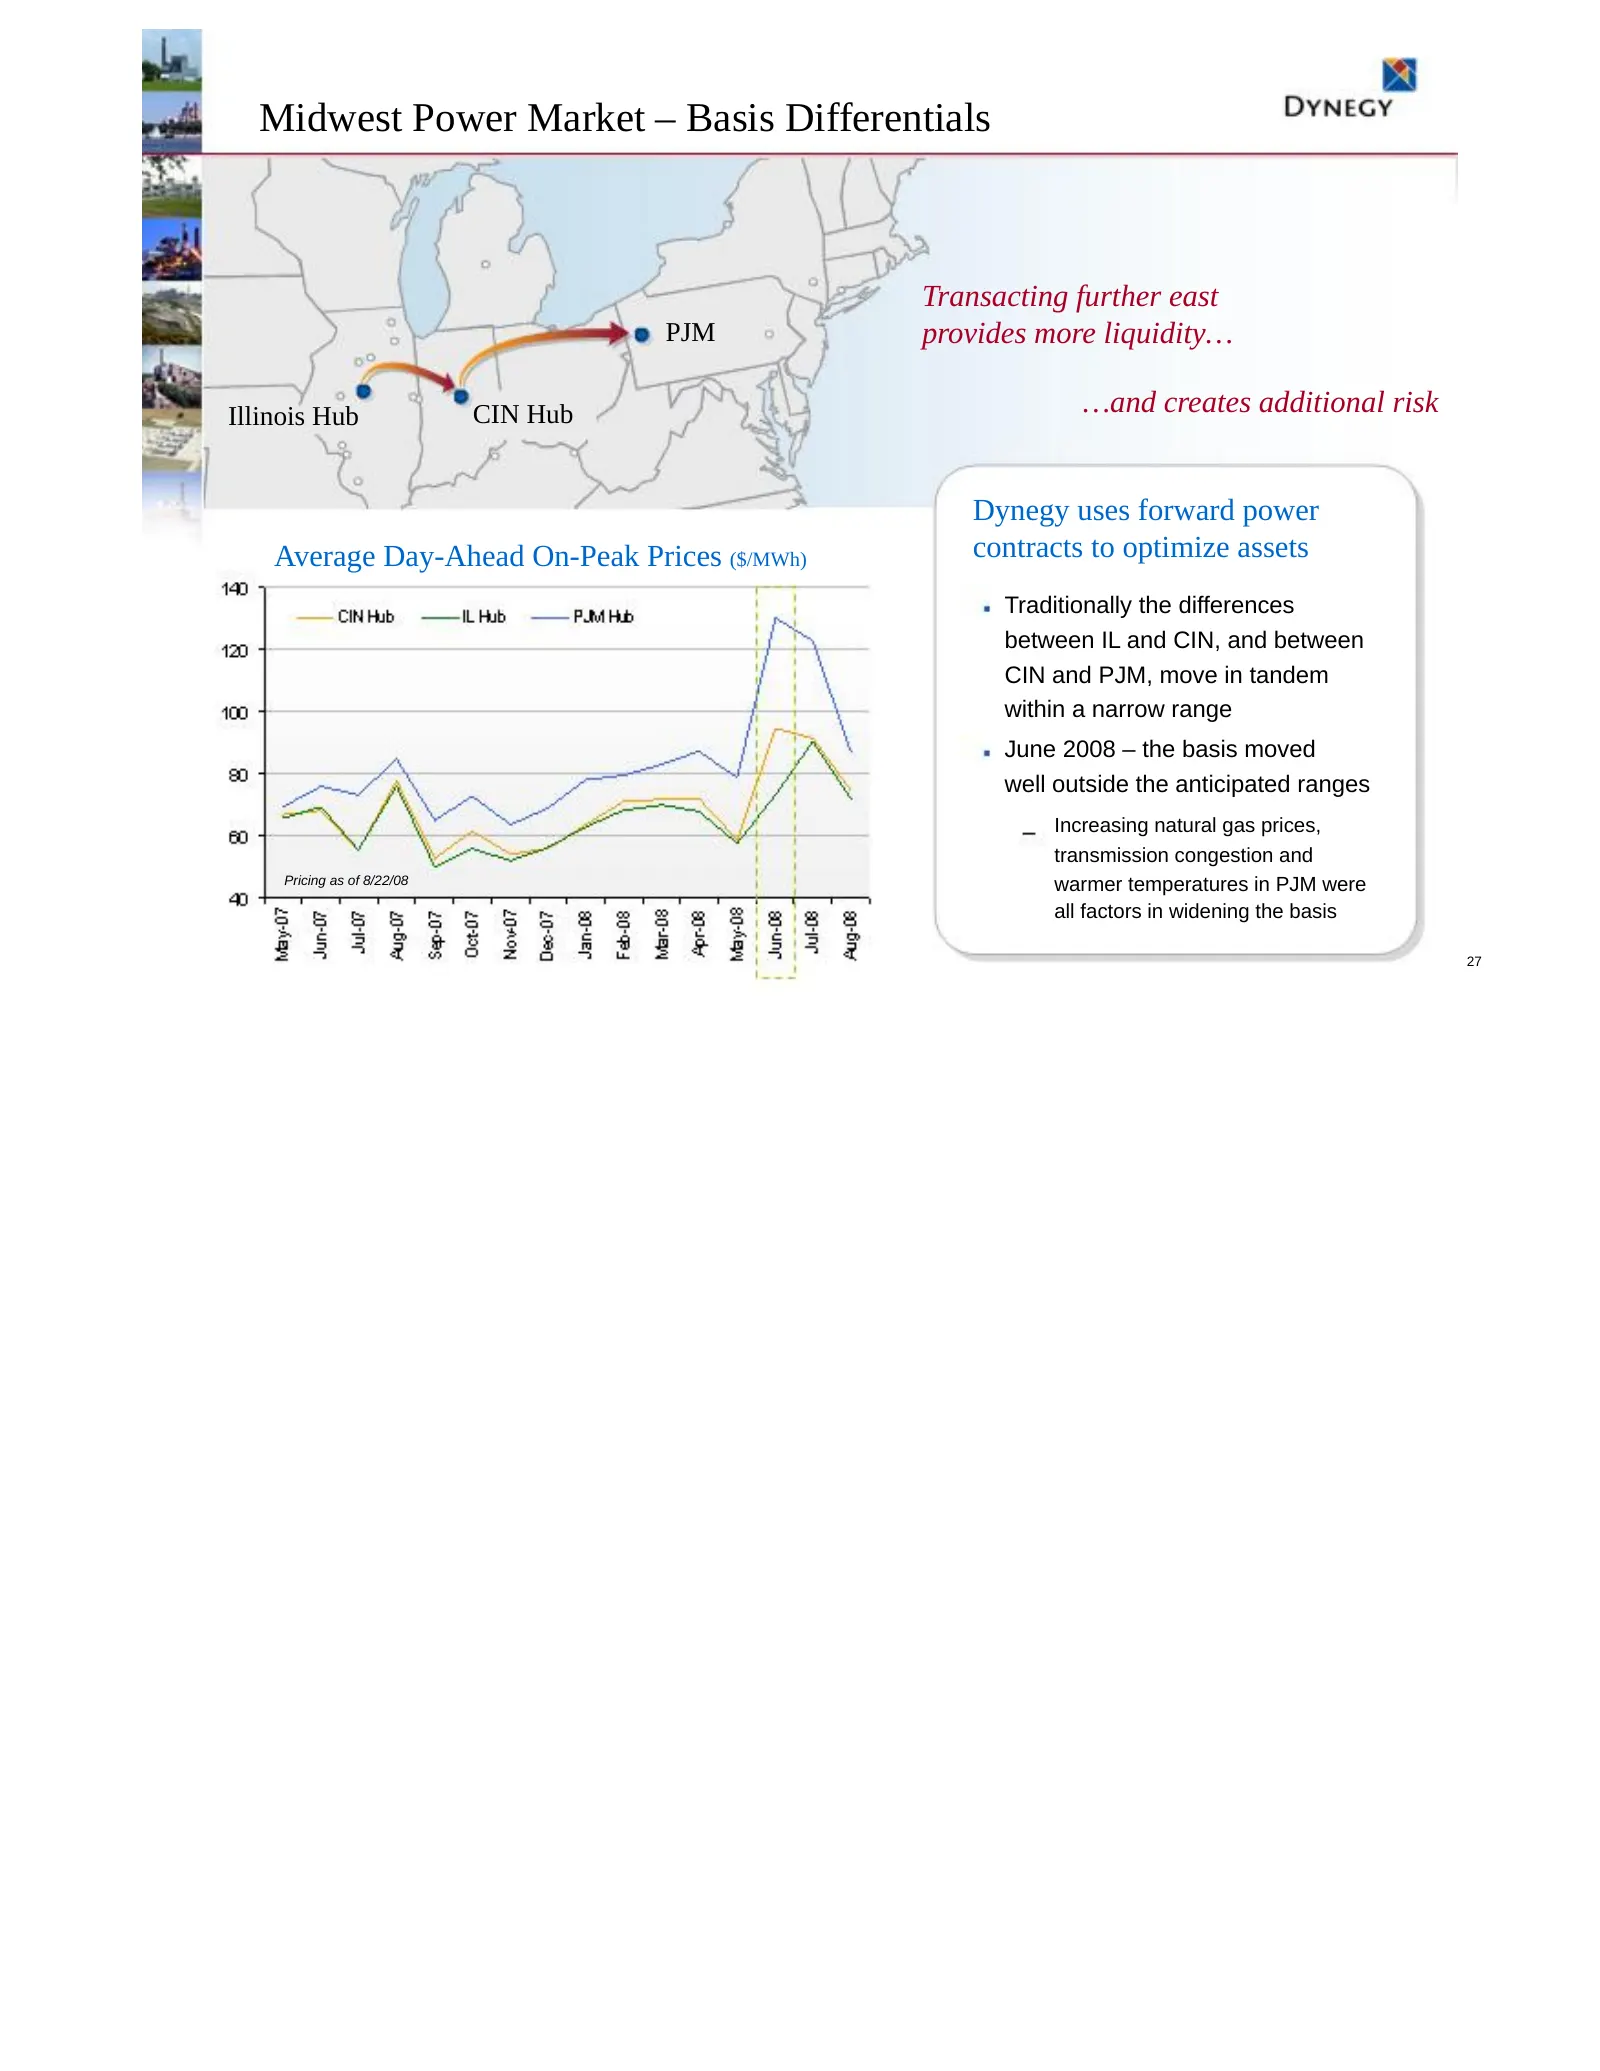
Slide 27: Midwest Power Market – Basis Differentials
Midwest Power Market – Basis Differentials Transacting further east PJM provides more liquidity… Illinois Hub CIN Hub …and creates additional risk Dynegy uses forward power Average Day-Ahead On-Peak Prices ($/MWh) contracts to optimize assets Traditionally the differences between IL and CIN, and bet
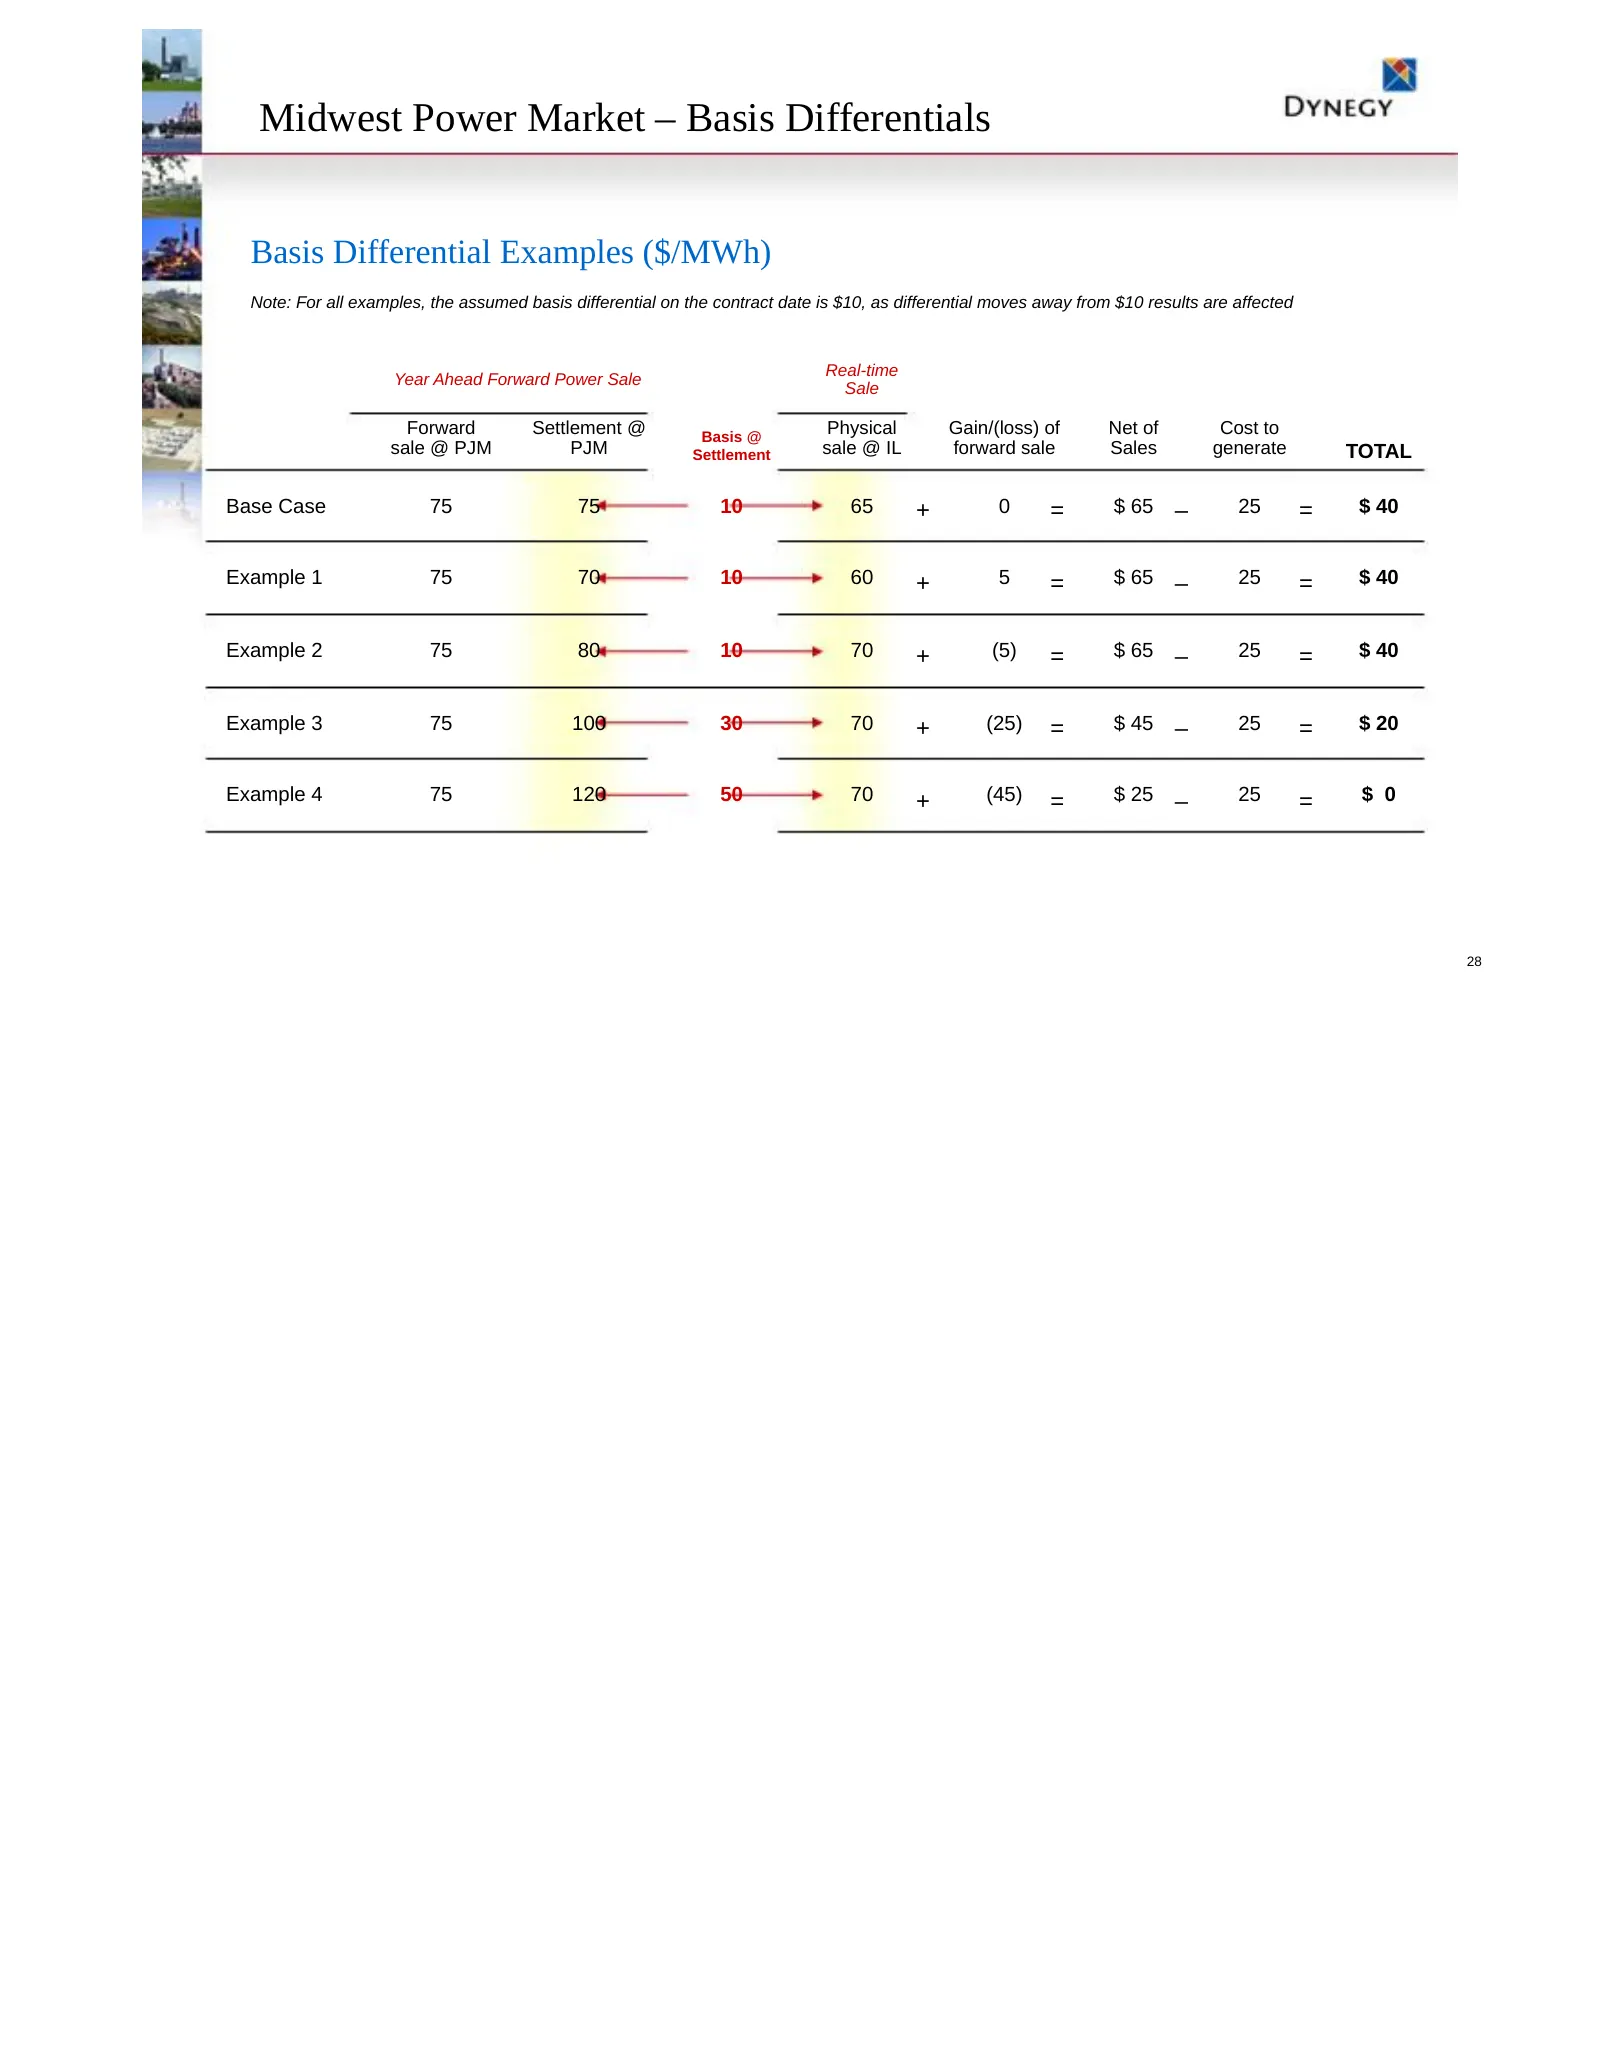
Slide 28: Midwest Power Market – Basis Differentials
Midwest Power Market – Basis Differentials Basis Differential Examples ($/MWh) Note: For all examples, the assumed basis differential on the contract date is $10, as differential moves away from $10 results are affected Real-time Year Ahead Forward Power Sale Sale Forward Settlement @ Basis @ Physic
Slide 29: West Generation
West Generation Regional Market Drivers Spark spread for uncontracted gas-fired combined cycle and peaking units, and ancillary services California has no formal capacity auction market; greater demand is expected for capacity in 2009 as utilities will have reduced Resource Adequacy requirements Reg
Slide 30: Northeast Generation
Northeast Generation Regional Market Drivers NYISO – Spark spread for uncontracted combined cycle gas and fuel oil units, and outright power price for uncontracted baseload coal volumes ISO-NE – Spark spread for uncontracted combined cycle gas units New England – formal capacity market auction for 2
Slide 31: EBITDA Sensitivity to Natural Gas
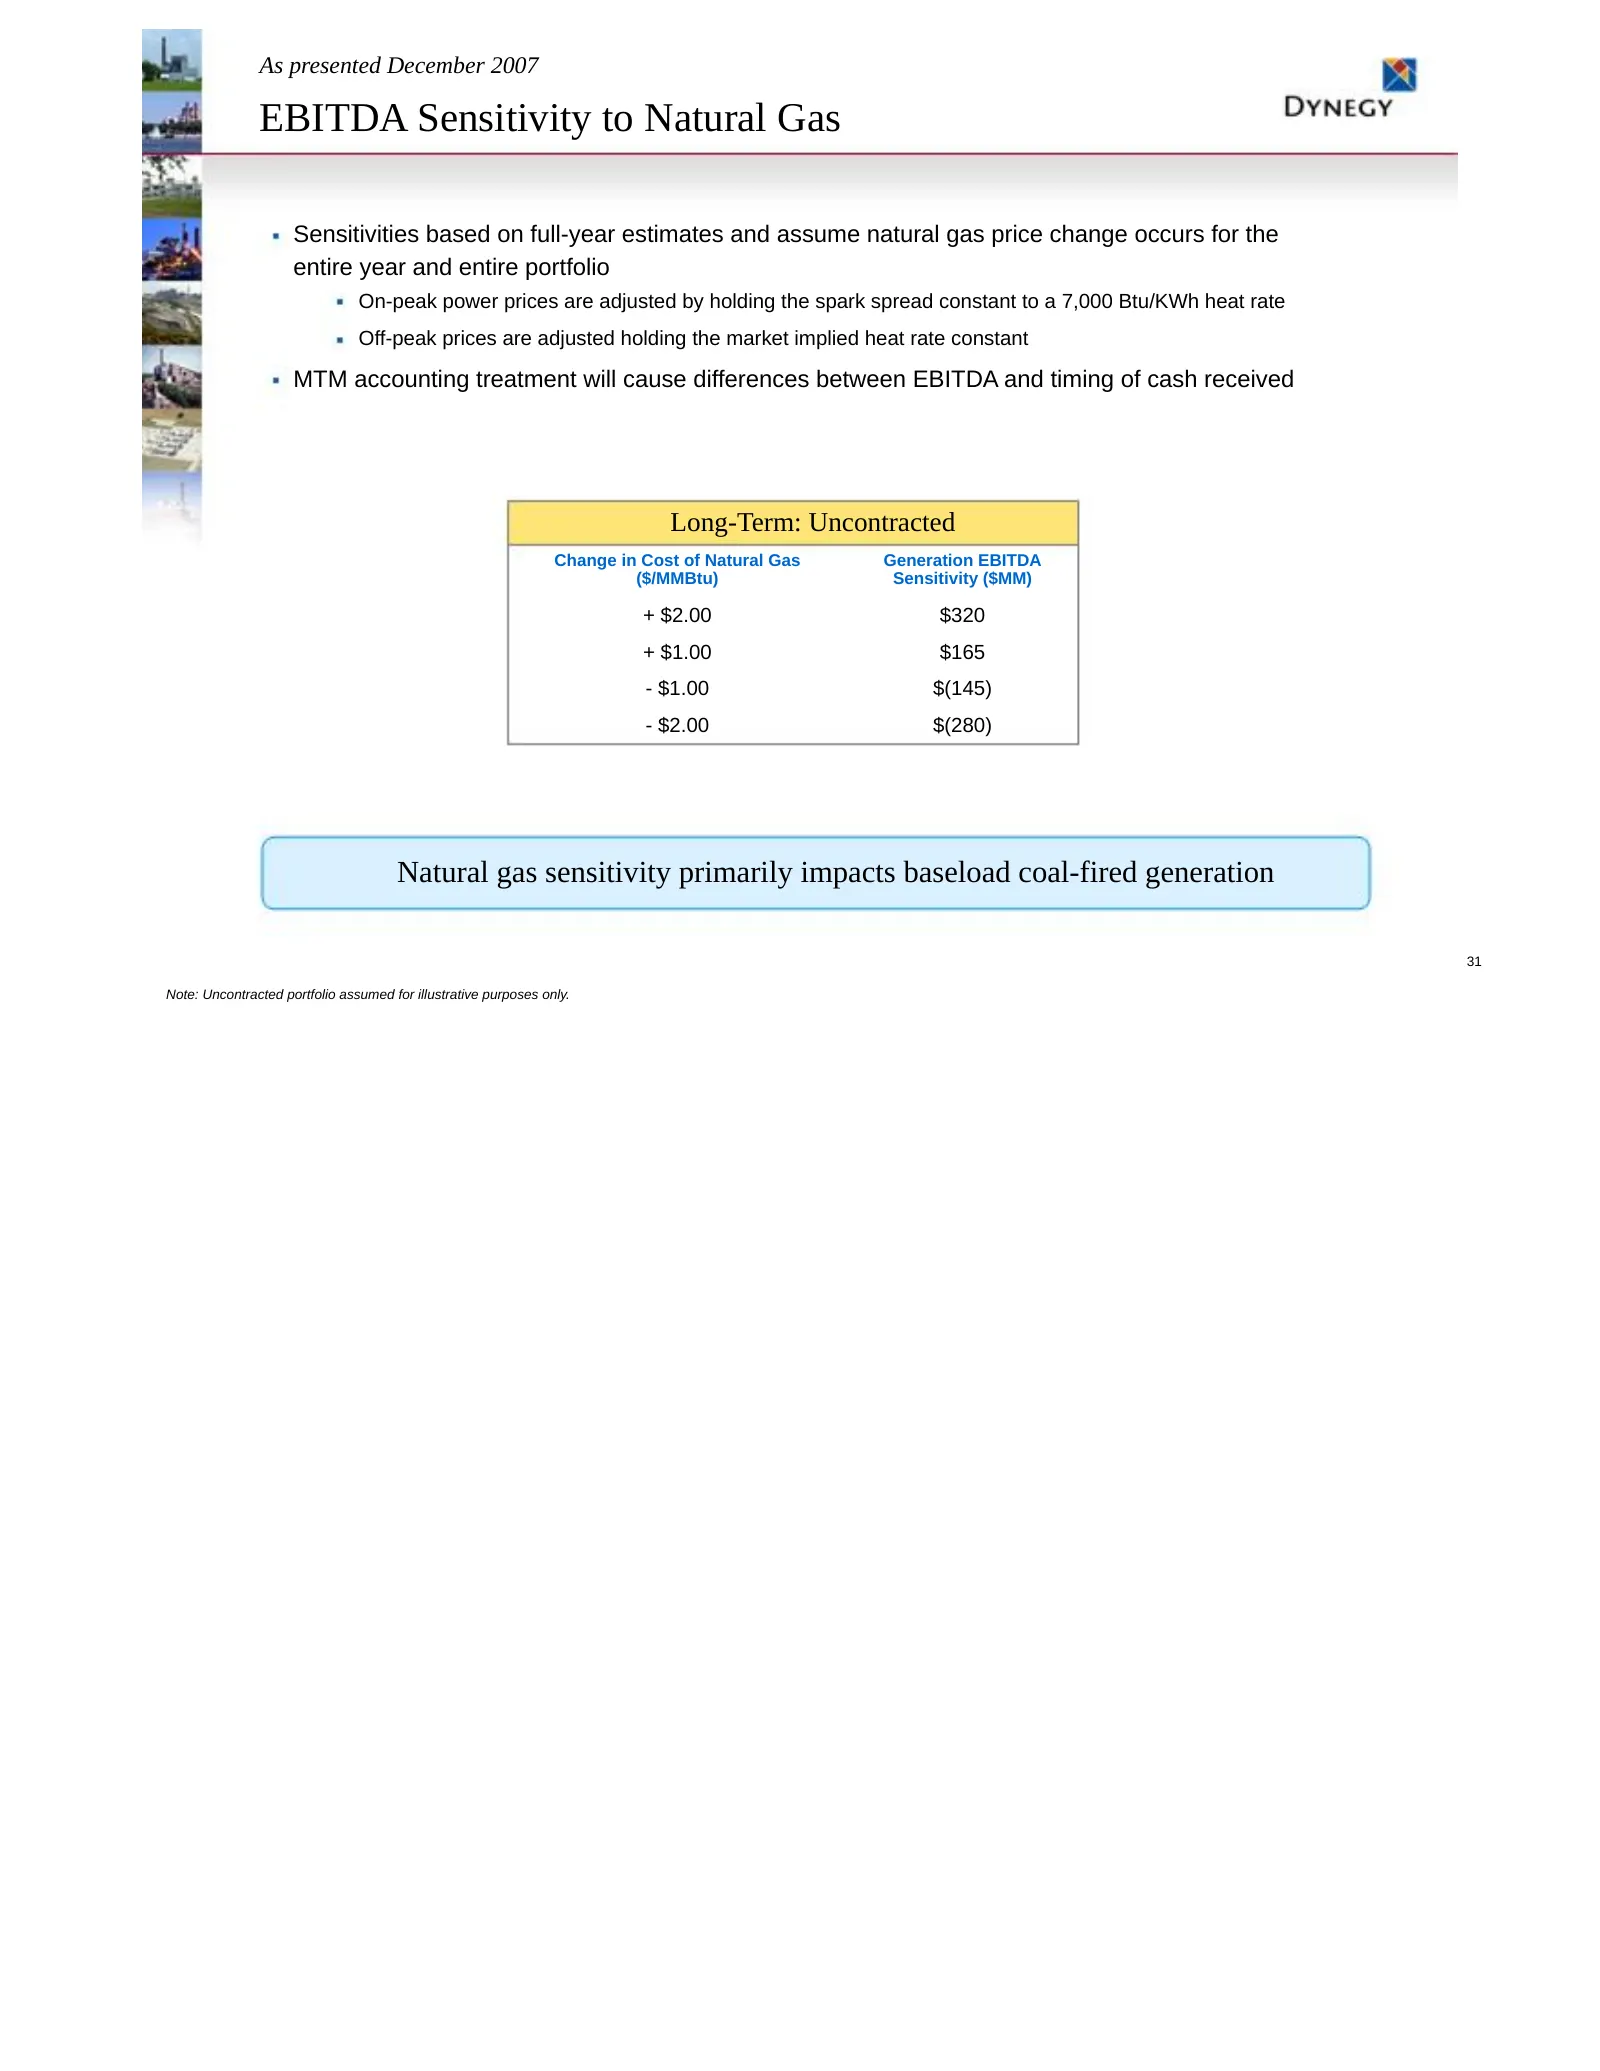
As presented December 2007 EBITDA Sensitivity to Natural Gas Sensitivities based on full-year estimates and assume natural gas price change occurs for the entire year and entire portfolio On-peak power prices are adjusted by holding the spark spread constant to a 7,000 Btu/KWh heat rate Off-peak pri
Slide 32: EBITDA Sensitivity to Market Implied Heat Rates
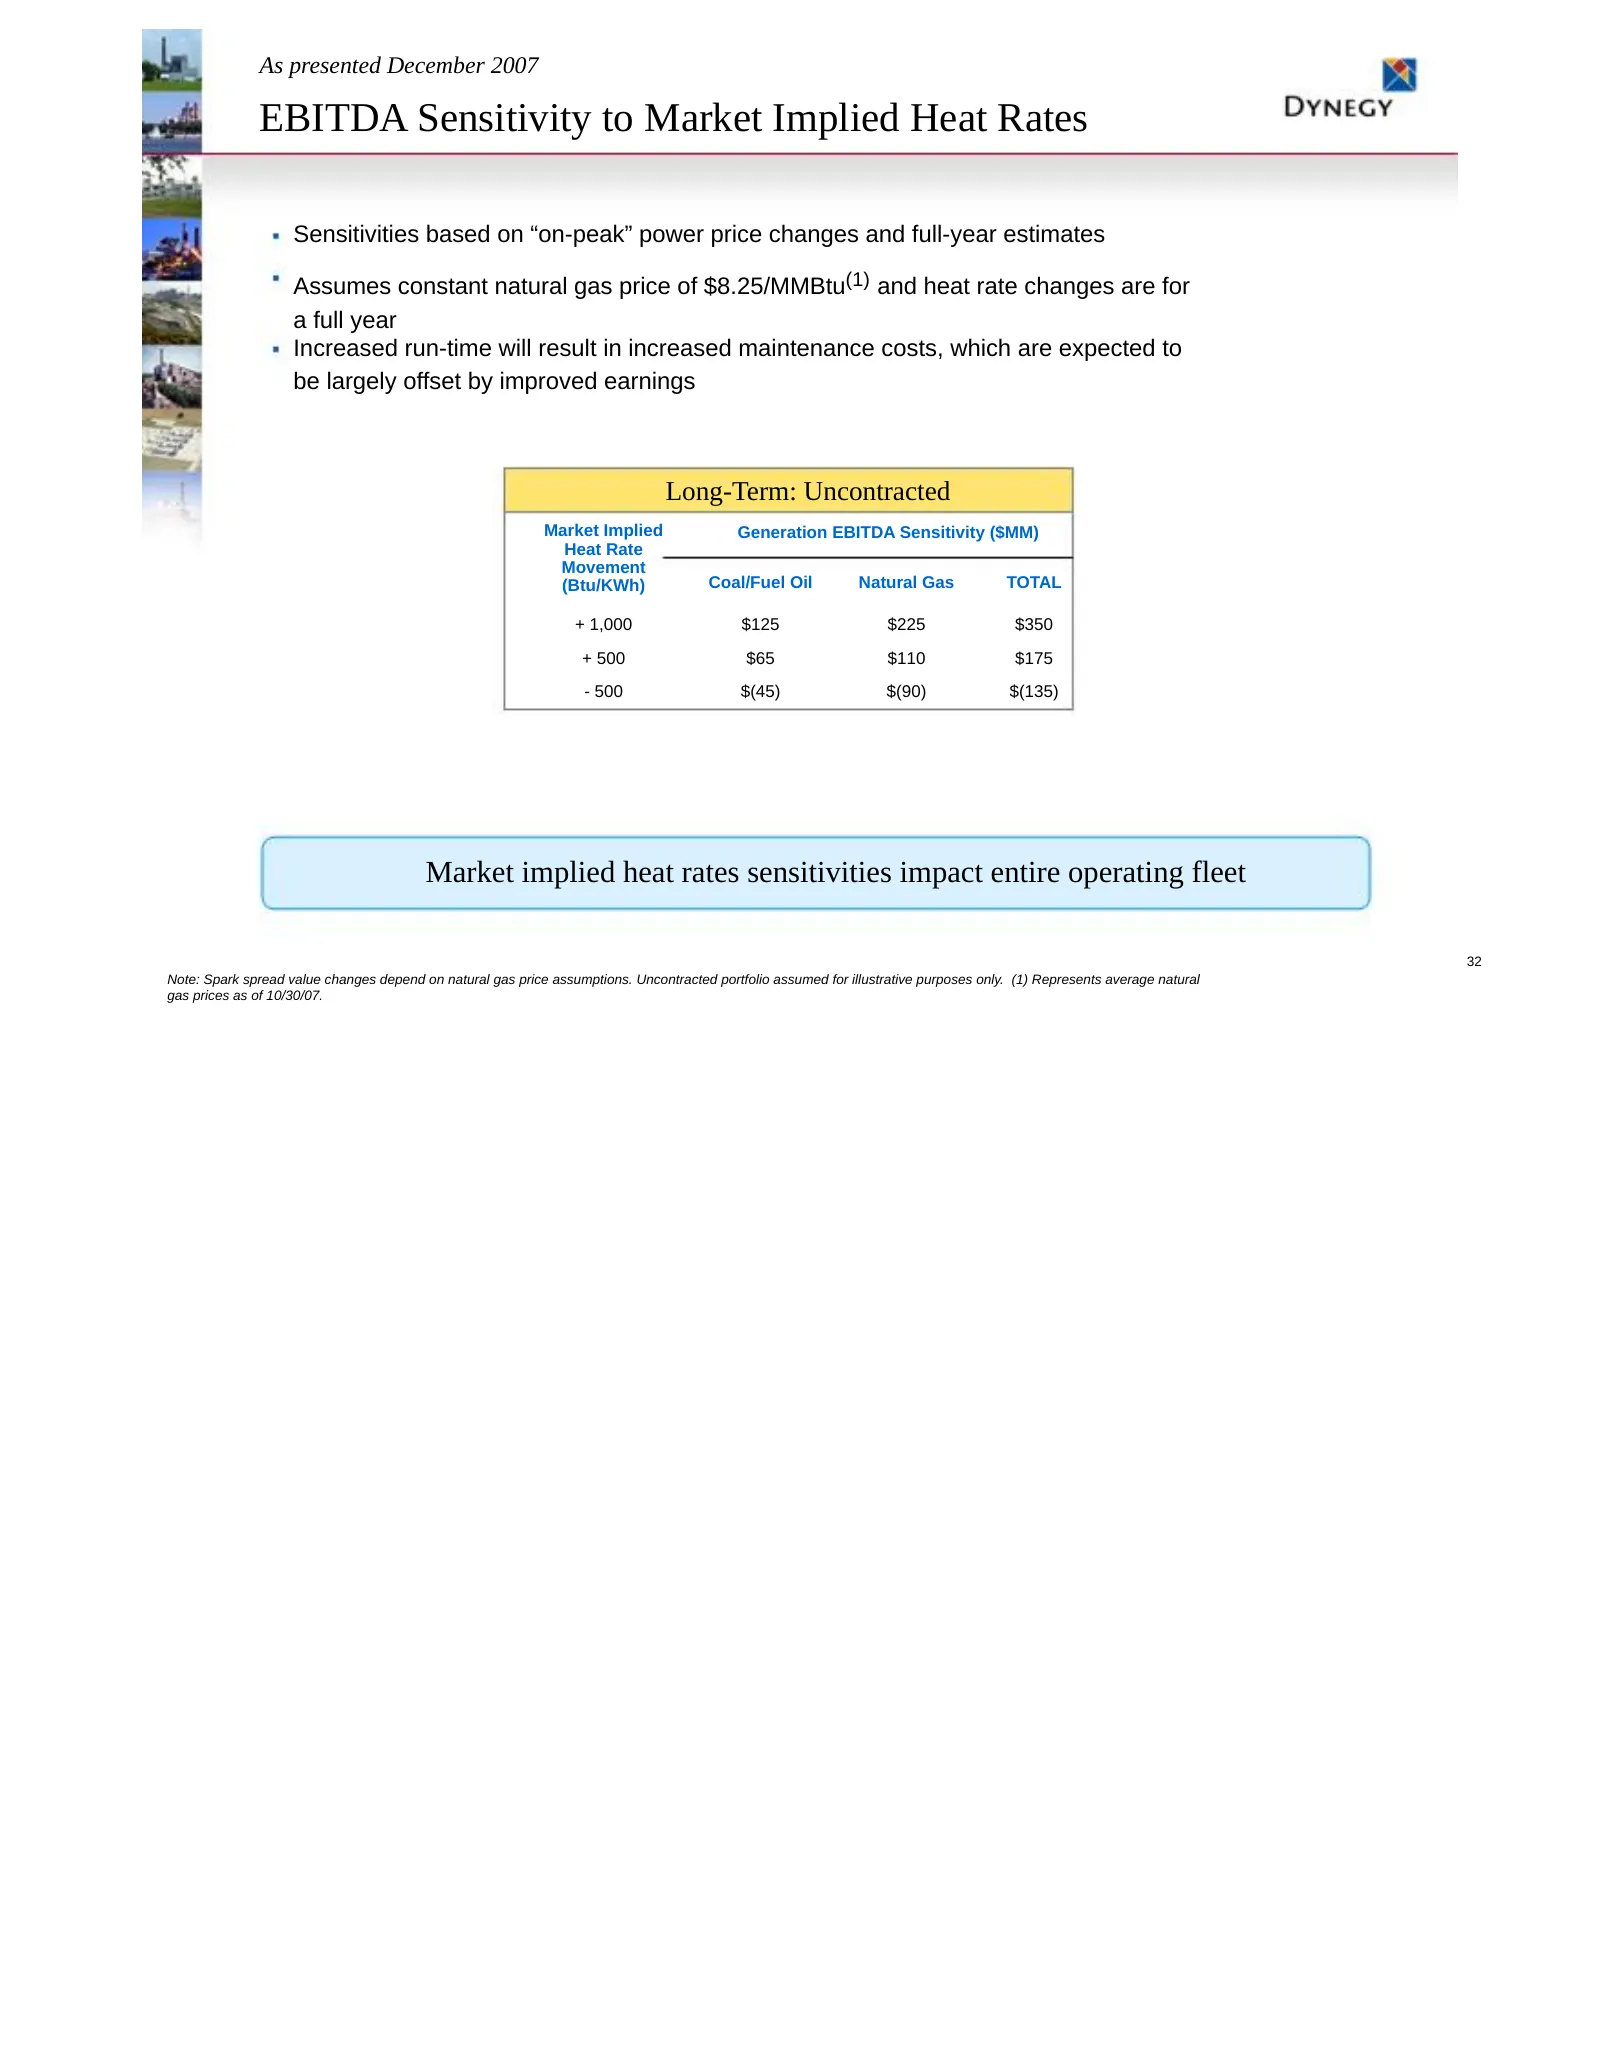
As presented December 2007 EBITDA Sensitivity to Market Implied Heat Rates Sensitivities based on “on-peak” power price changes and full-year estimates Assumes constant natural gas price of $8.25/MMBtu(1) and heat rate changes are for a full year Increased run-time will result in increased maintenan
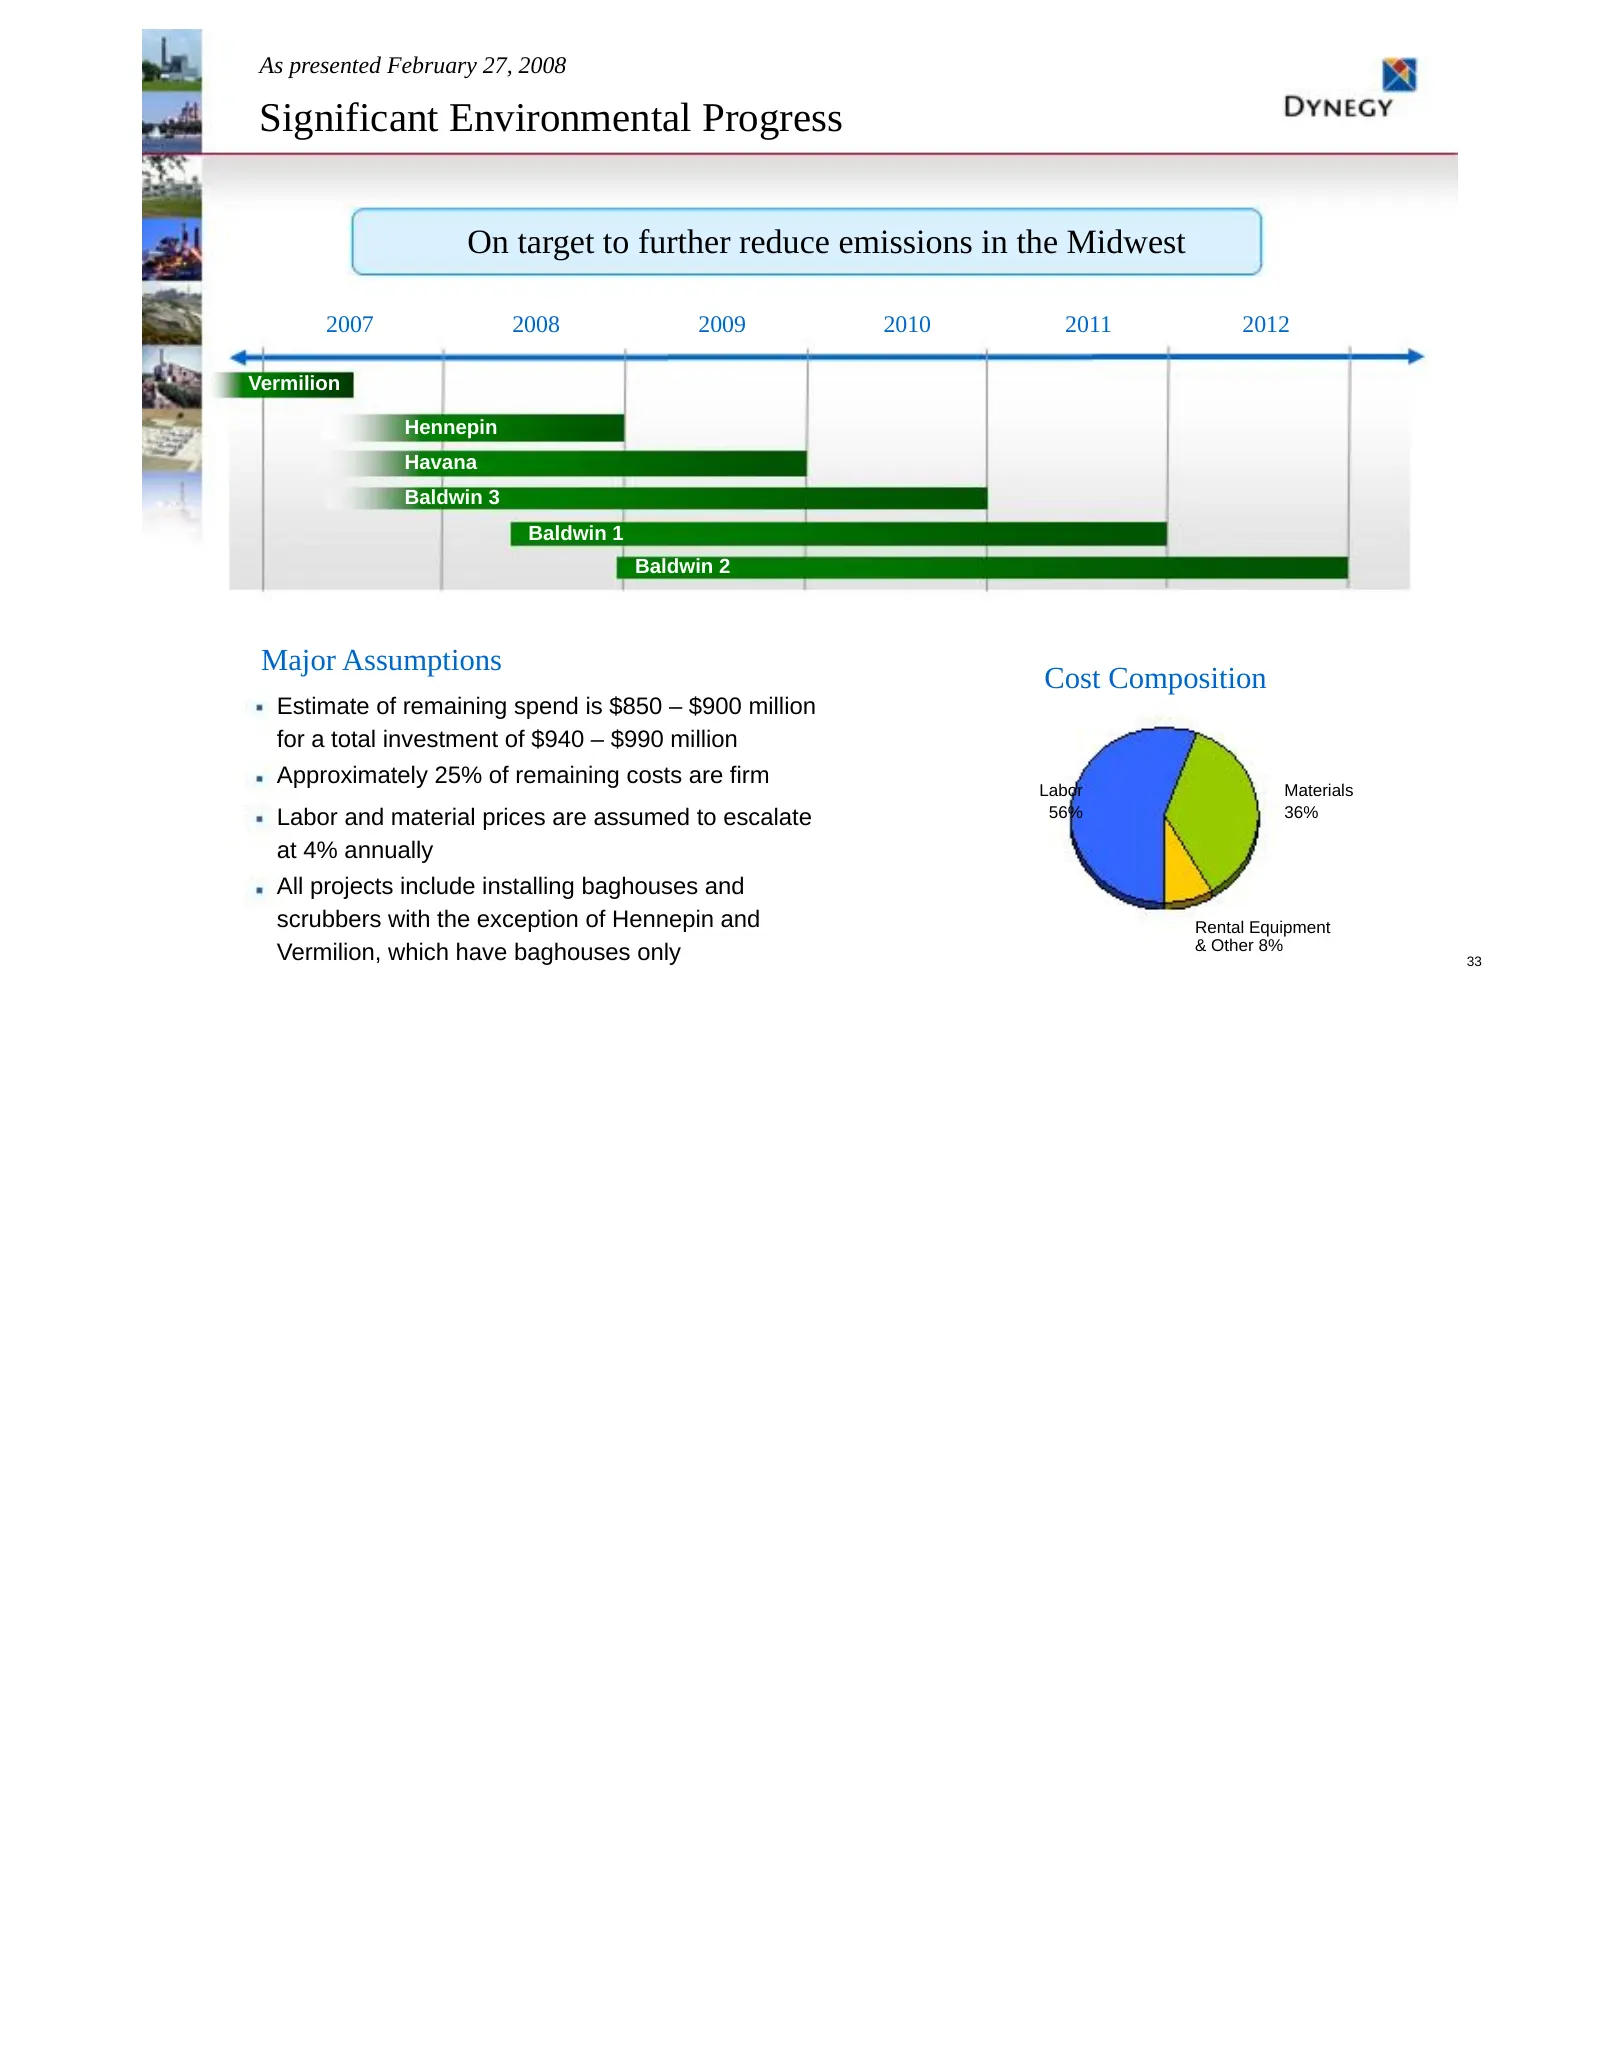
Slide 33: Significant Environmental Progress
As presented February 27, 2008 Significant Environmental Progress On target to further reduce emissions in the Midwest 2007 2008 2009 2010 2011 2012 Vermilion Hennepin Havana Baldwin 3 Baldwin 1 Baldwin 2 Major Assumptions Cost Composition Estimate of remaining spend is $850 – $900 million for a tot
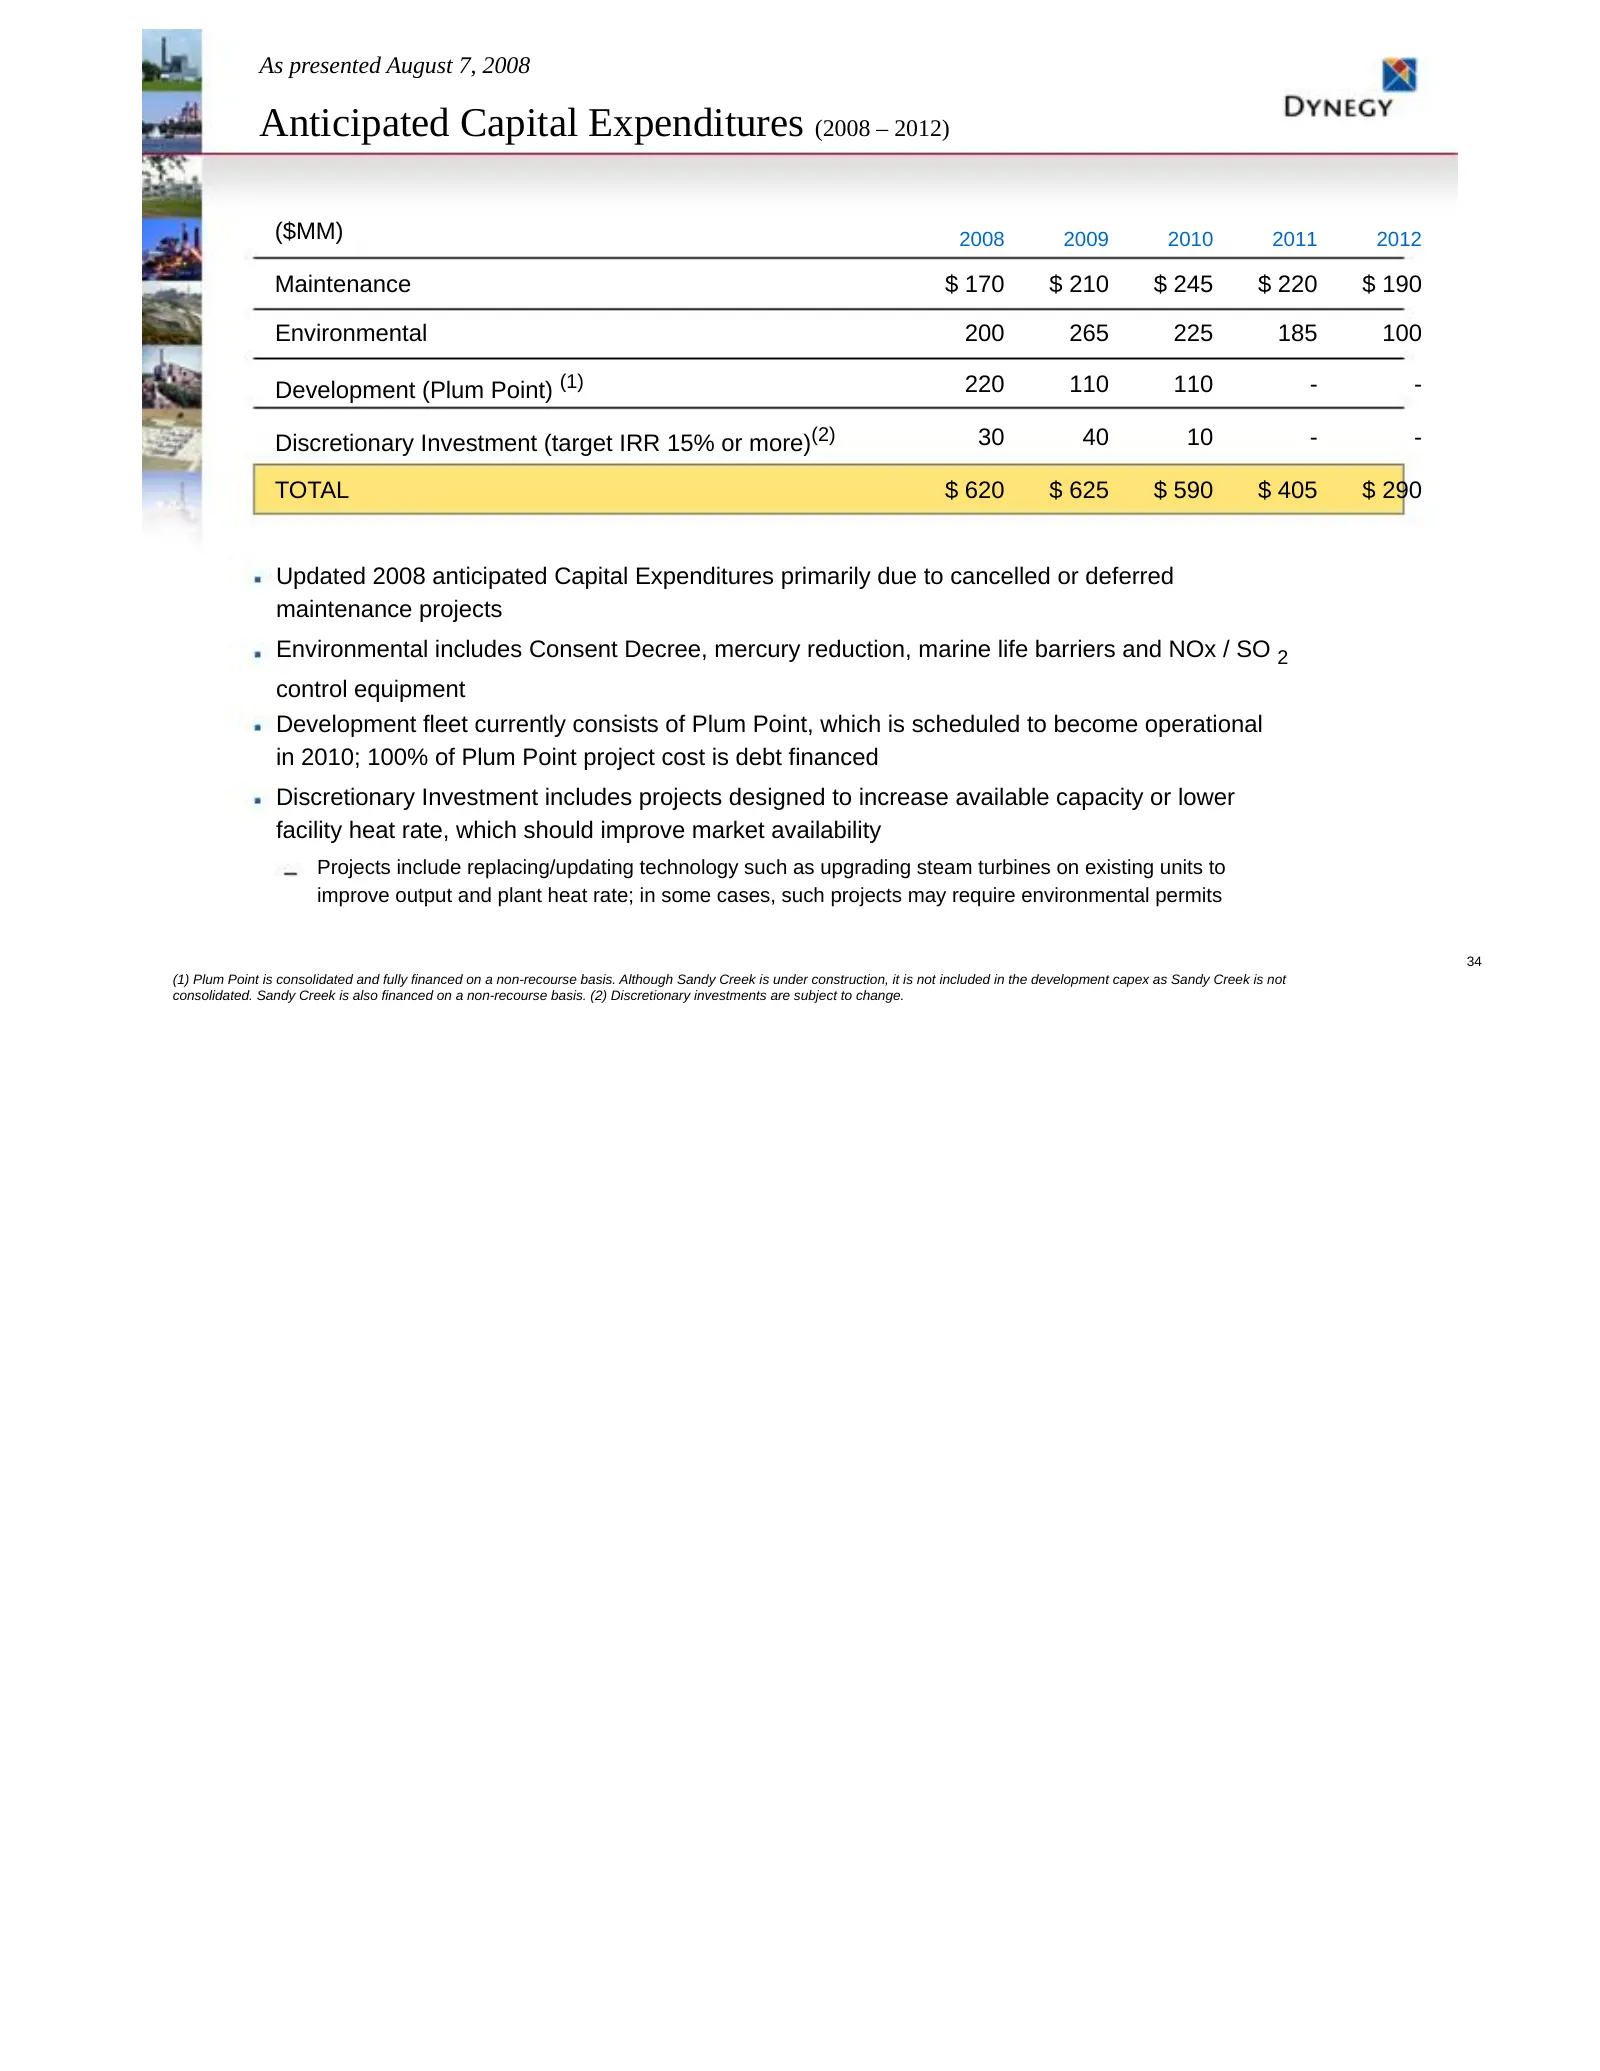
Slide 34: Anticipated Capital Expenditures (2008 – 2012)
As presented August 7, 2008 Anticipated Capital Expenditures (2008 – 2012) ($MM) 2008 2009 2010 2011 2012 Maintenance $ 170 $ 210 $ 245 $ 220 $ 190 Environmental 200 265 225 185 100 Development (Plum Point) (1) 220 110 110 - - Discretionary Investment (target IRR 15% or more)(2) 30 40 10 - - TOTAL $
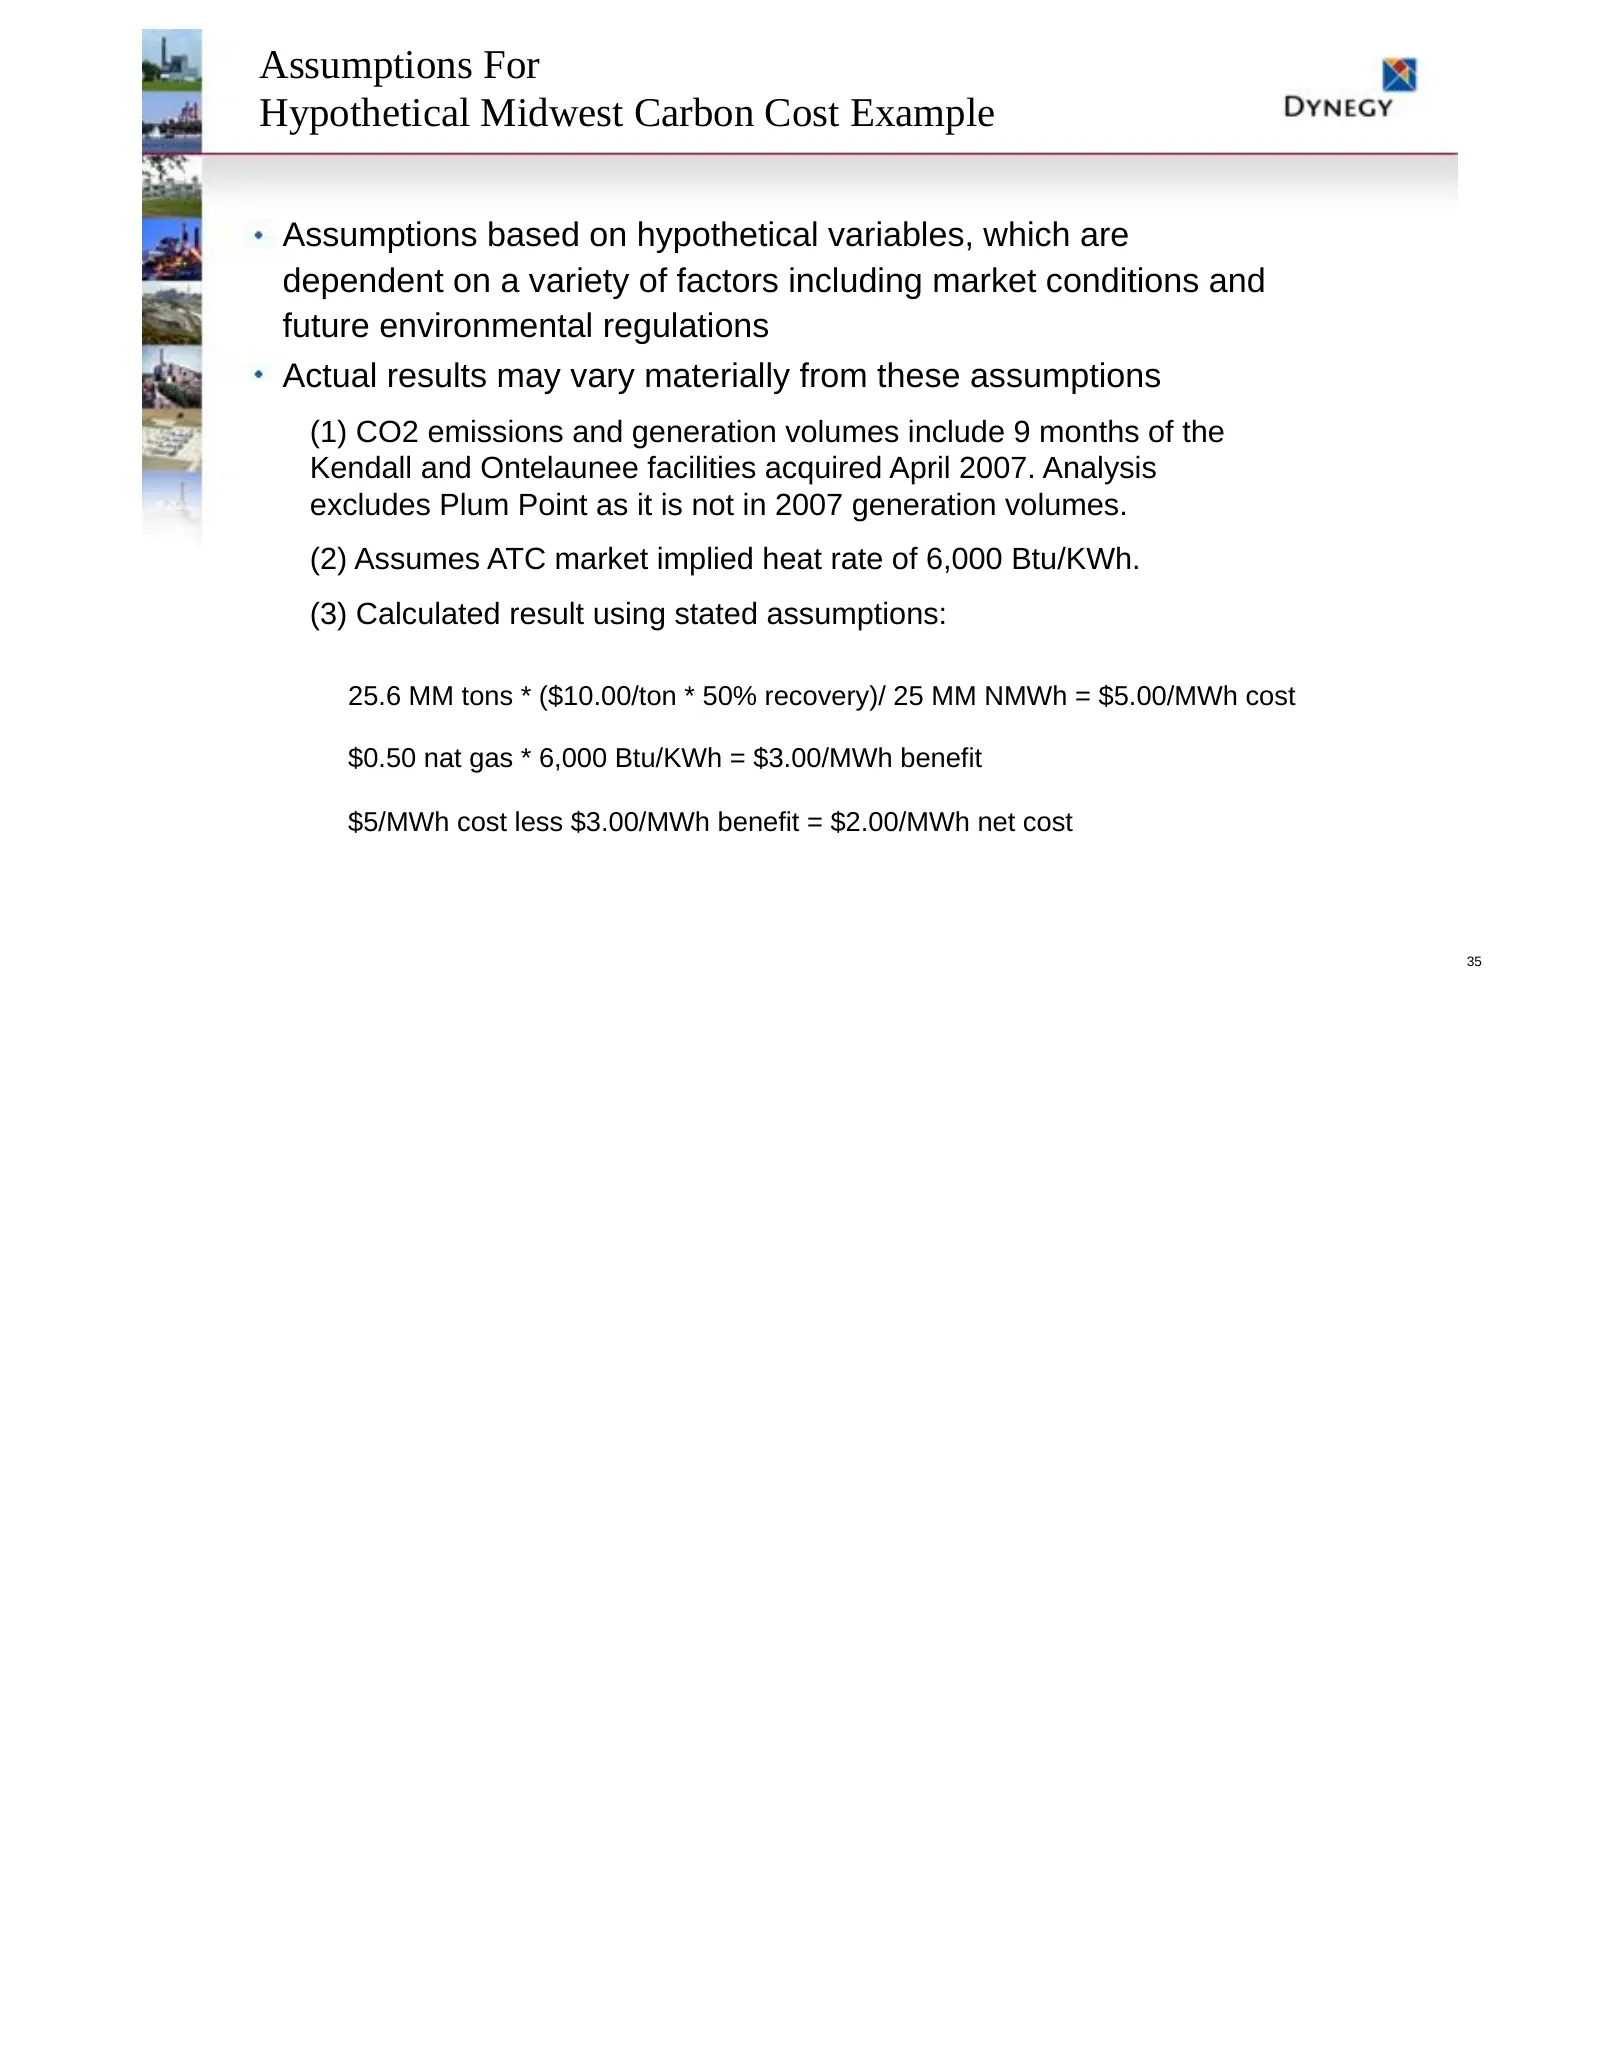
Slide 35: Assumptions For Hypothetical Midwest Carbon Cost Example
Assumptions For Hypothetical Midwest Carbon Cost Example Assumptions based on hypothetical variables, which are dependent on a variety of factors including market conditions and future environmental regulations Actual results may vary materially from these assumptions (1) CO2 emissions and generatio
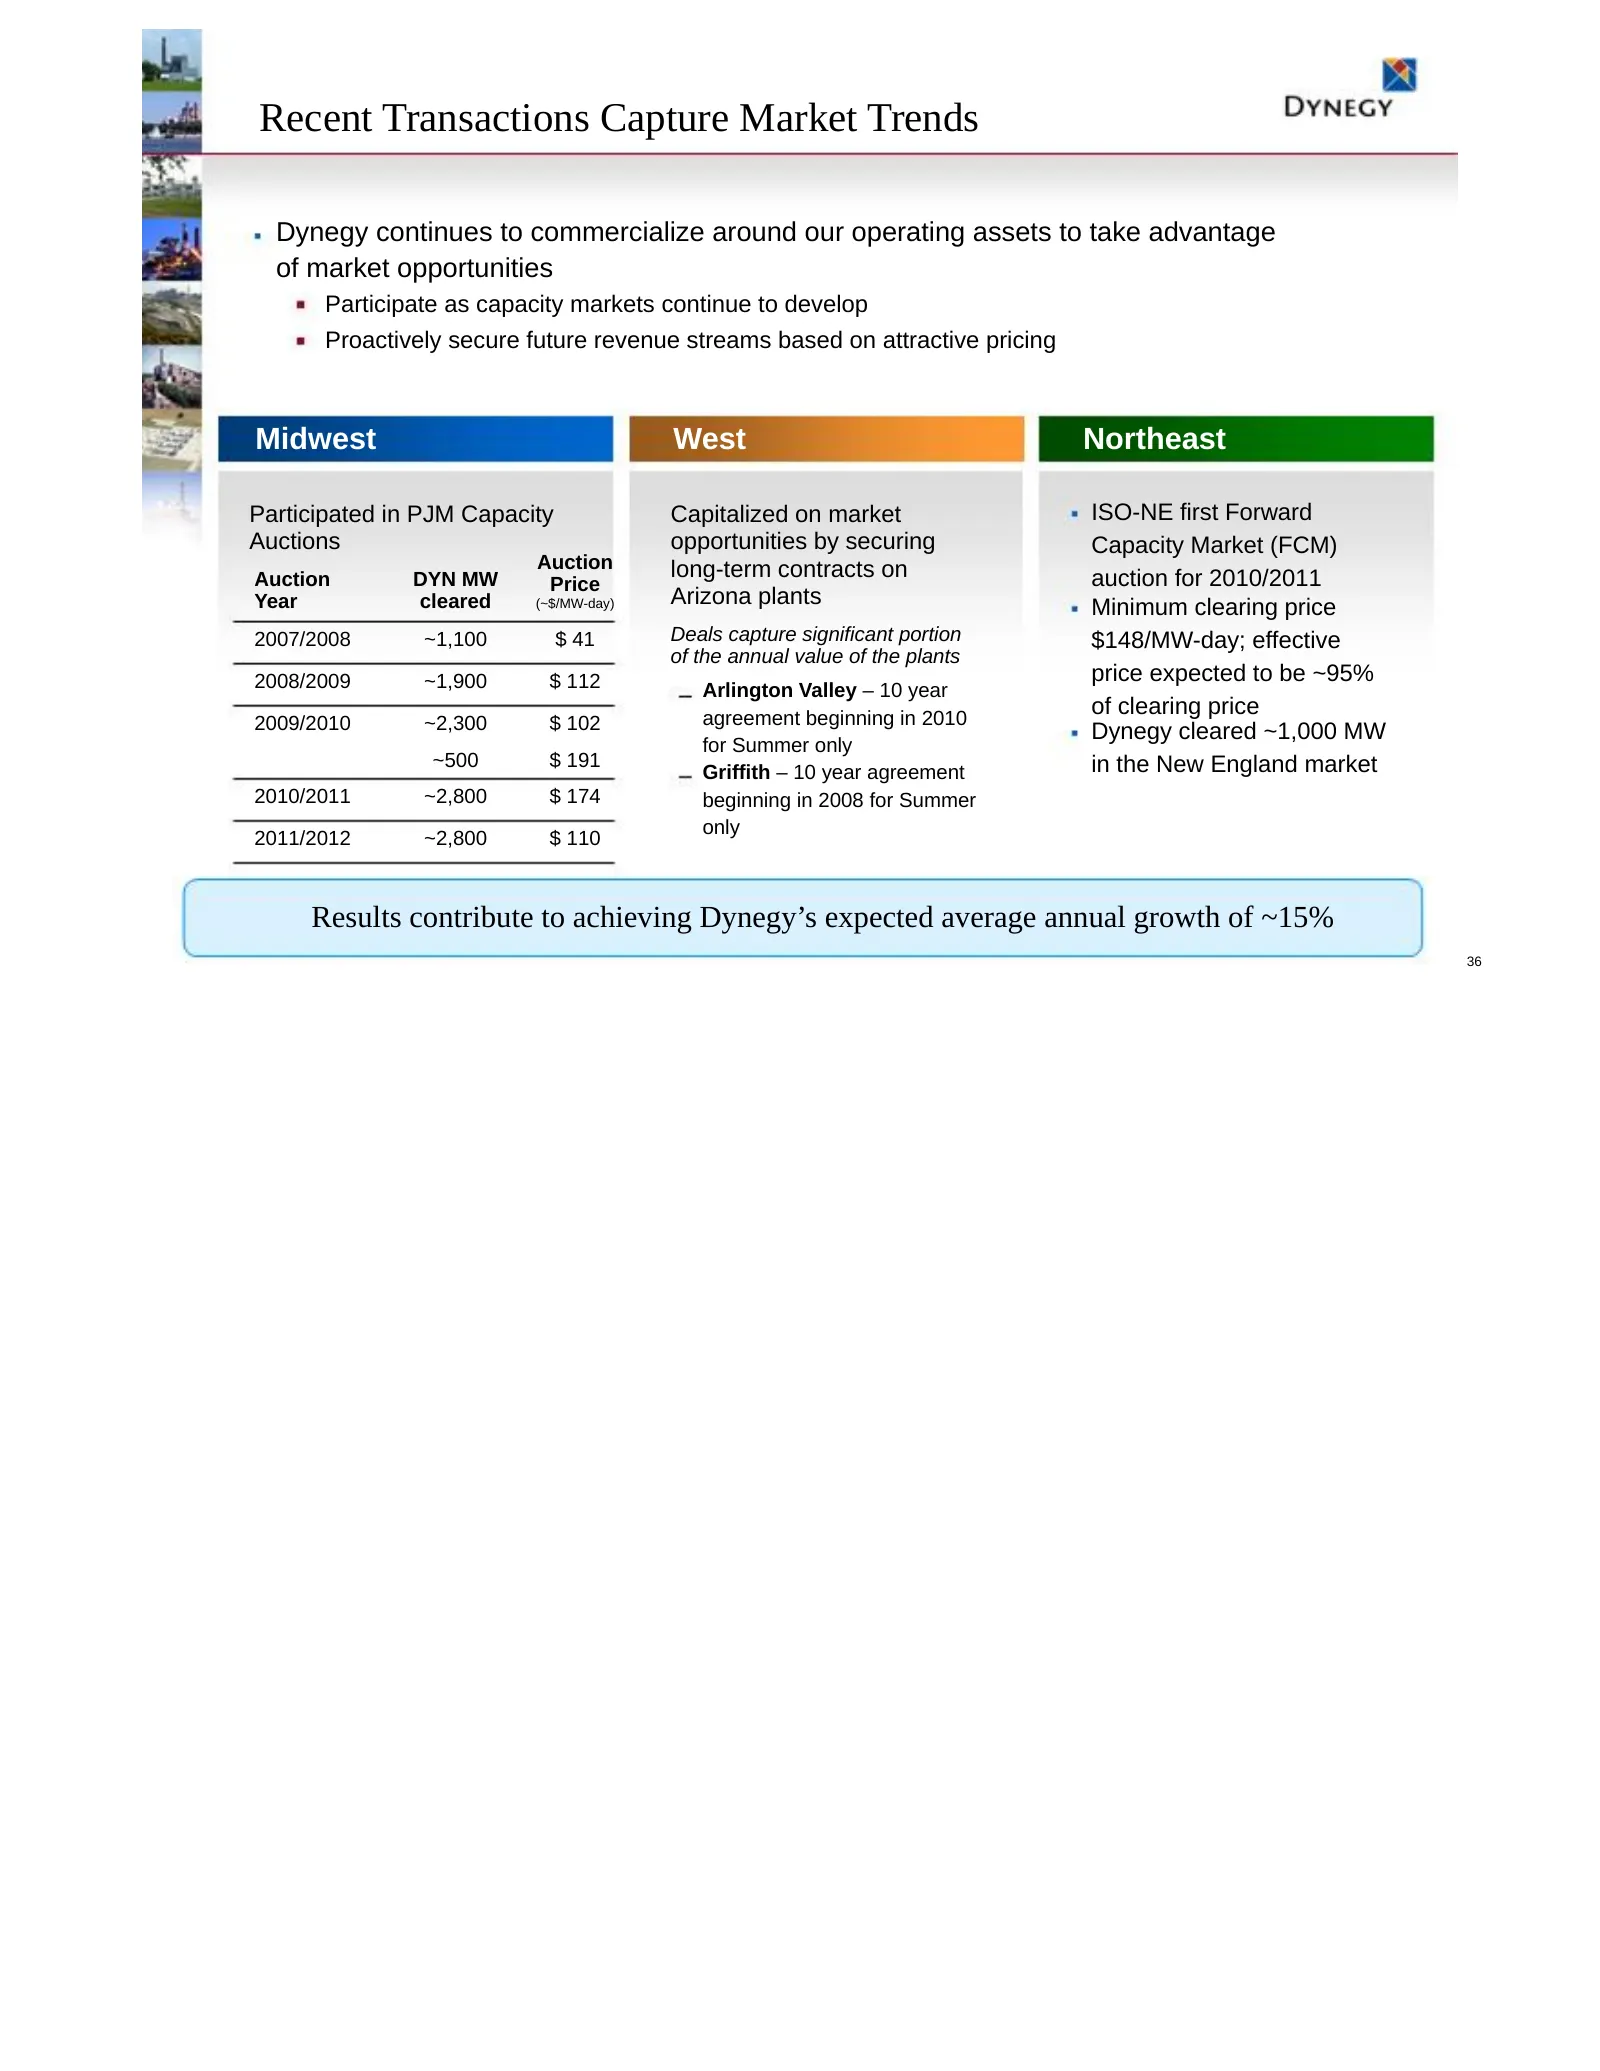
Slide 36: Recent Transactions Capture Market Trends
Recent Transactions Capture Market Trends Dynegy continues to commercialize around our operating assets to take advantage of market opportunities Participate as capacity markets continue to develop Proactively secure future revenue streams based on attractive pricing Midwest West Northeast Participa
Slide 37: Development Detail
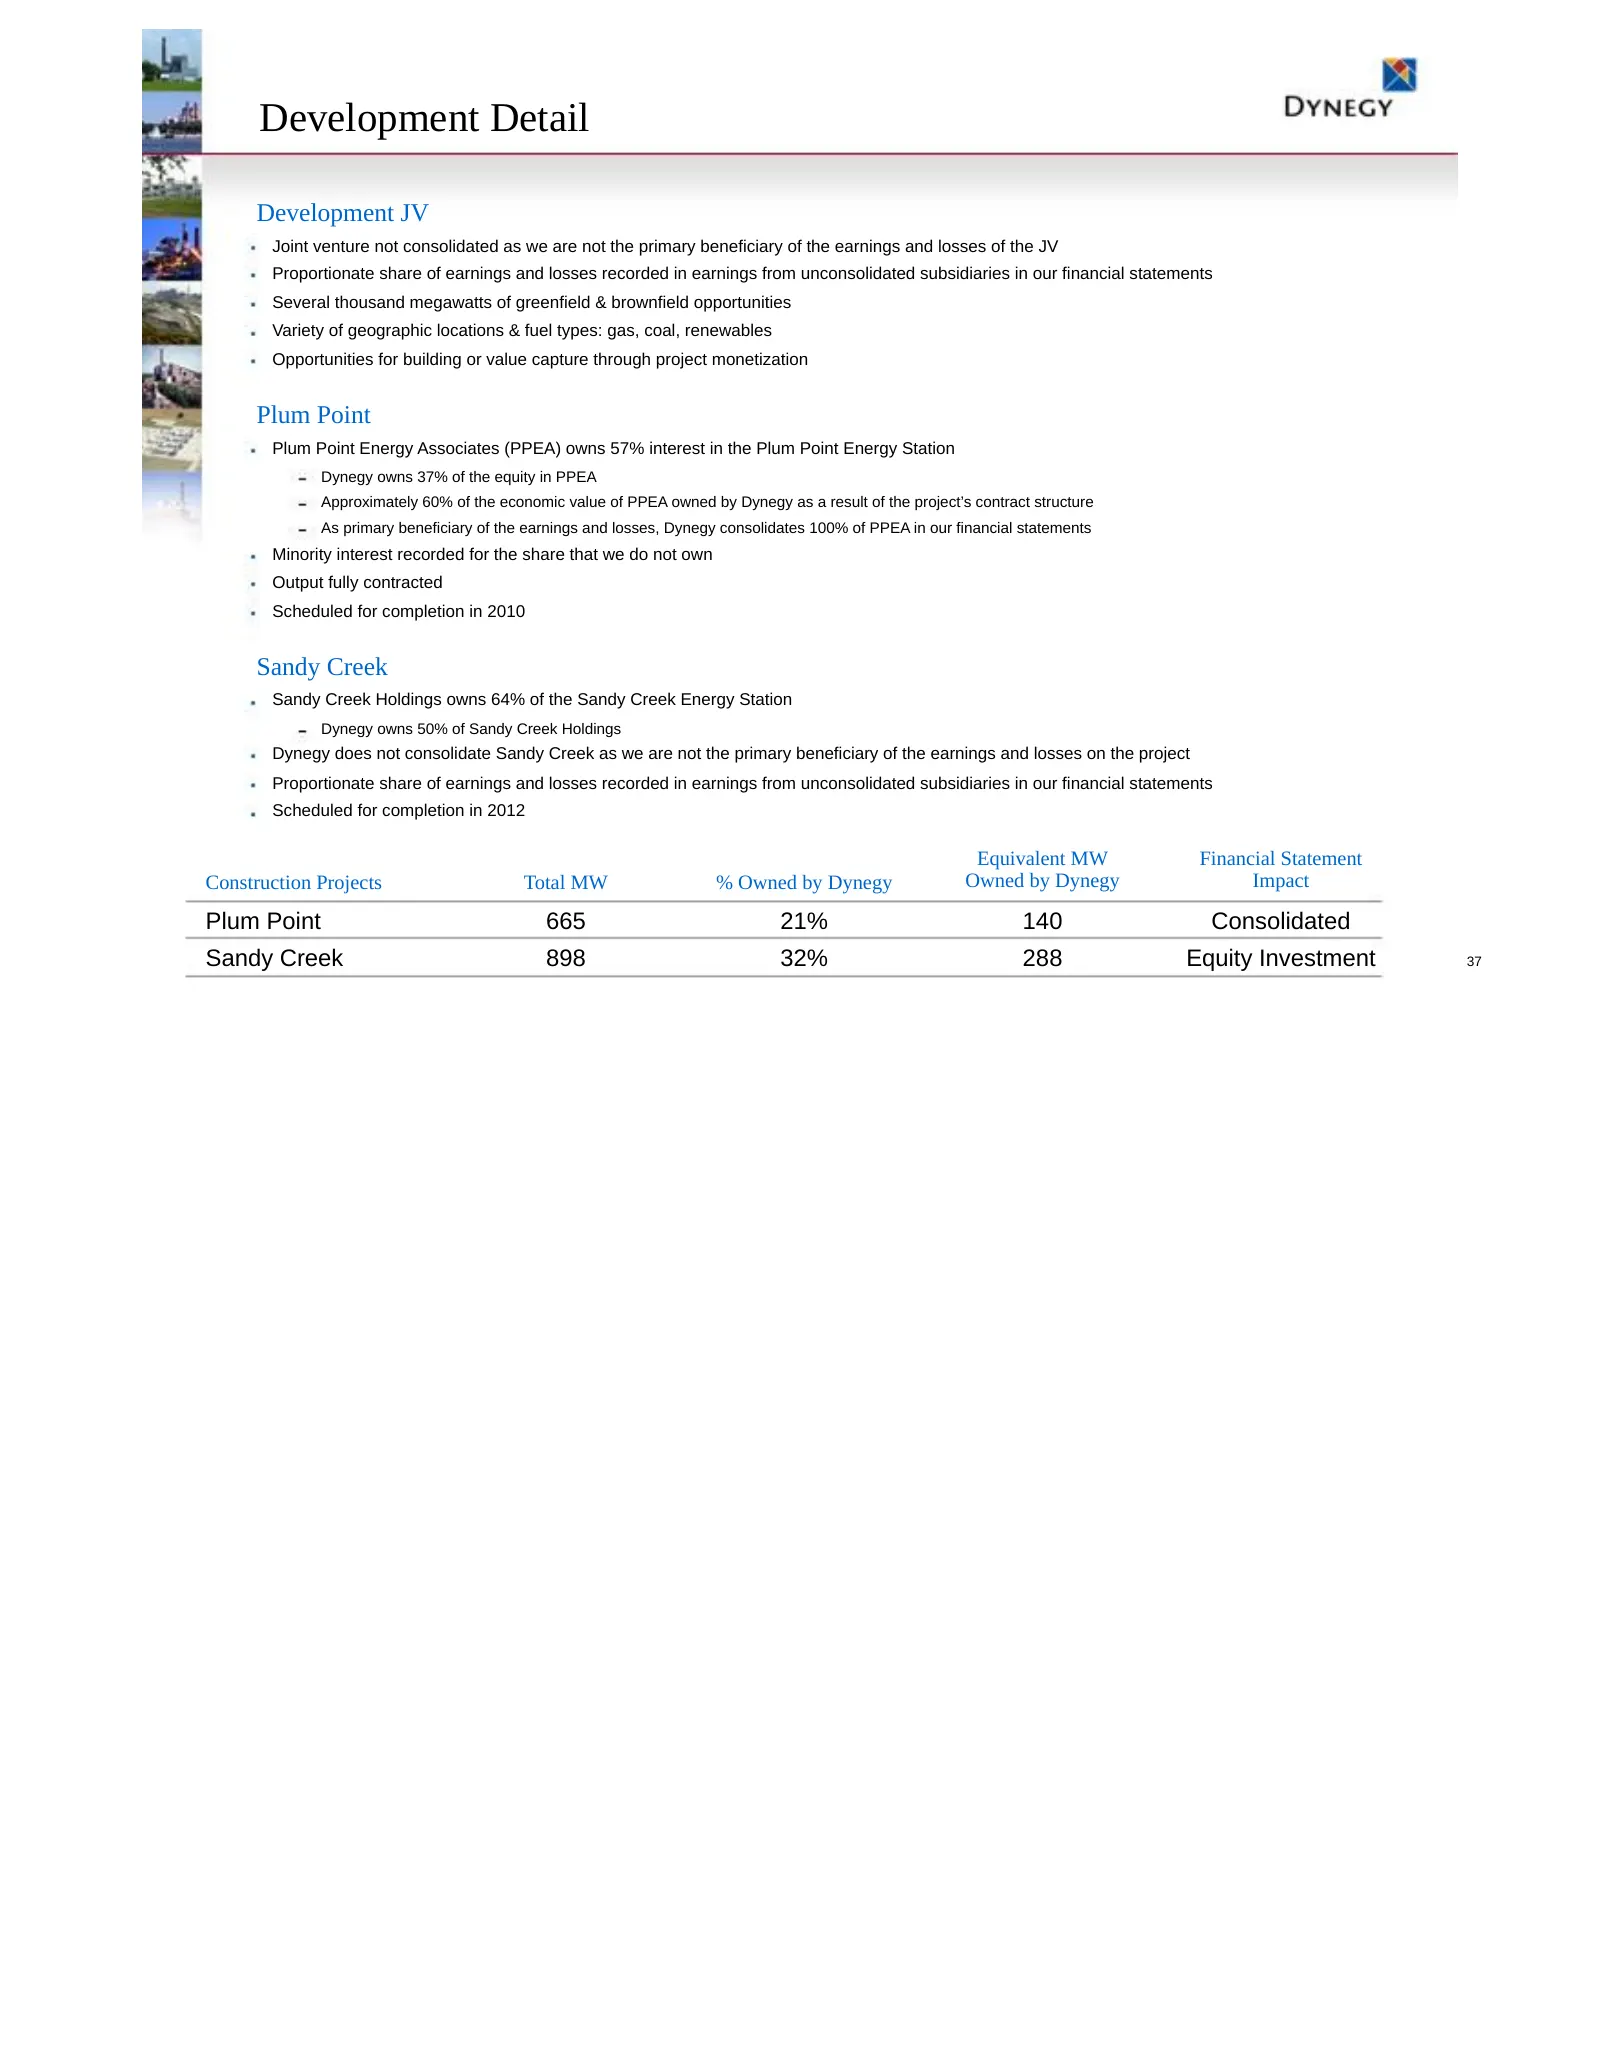
Development Detail Development JV Joint venture not consolidated as we are not the primary beneficiary of the earnings and losses of the JV Proportionate share of earnings and losses recorded in earnings from unconsolidated subsidiaries in our financial statements Several thousand megawatts of green
Slide 38: Debt & Other Obligations Capital Structure – 6/30/08
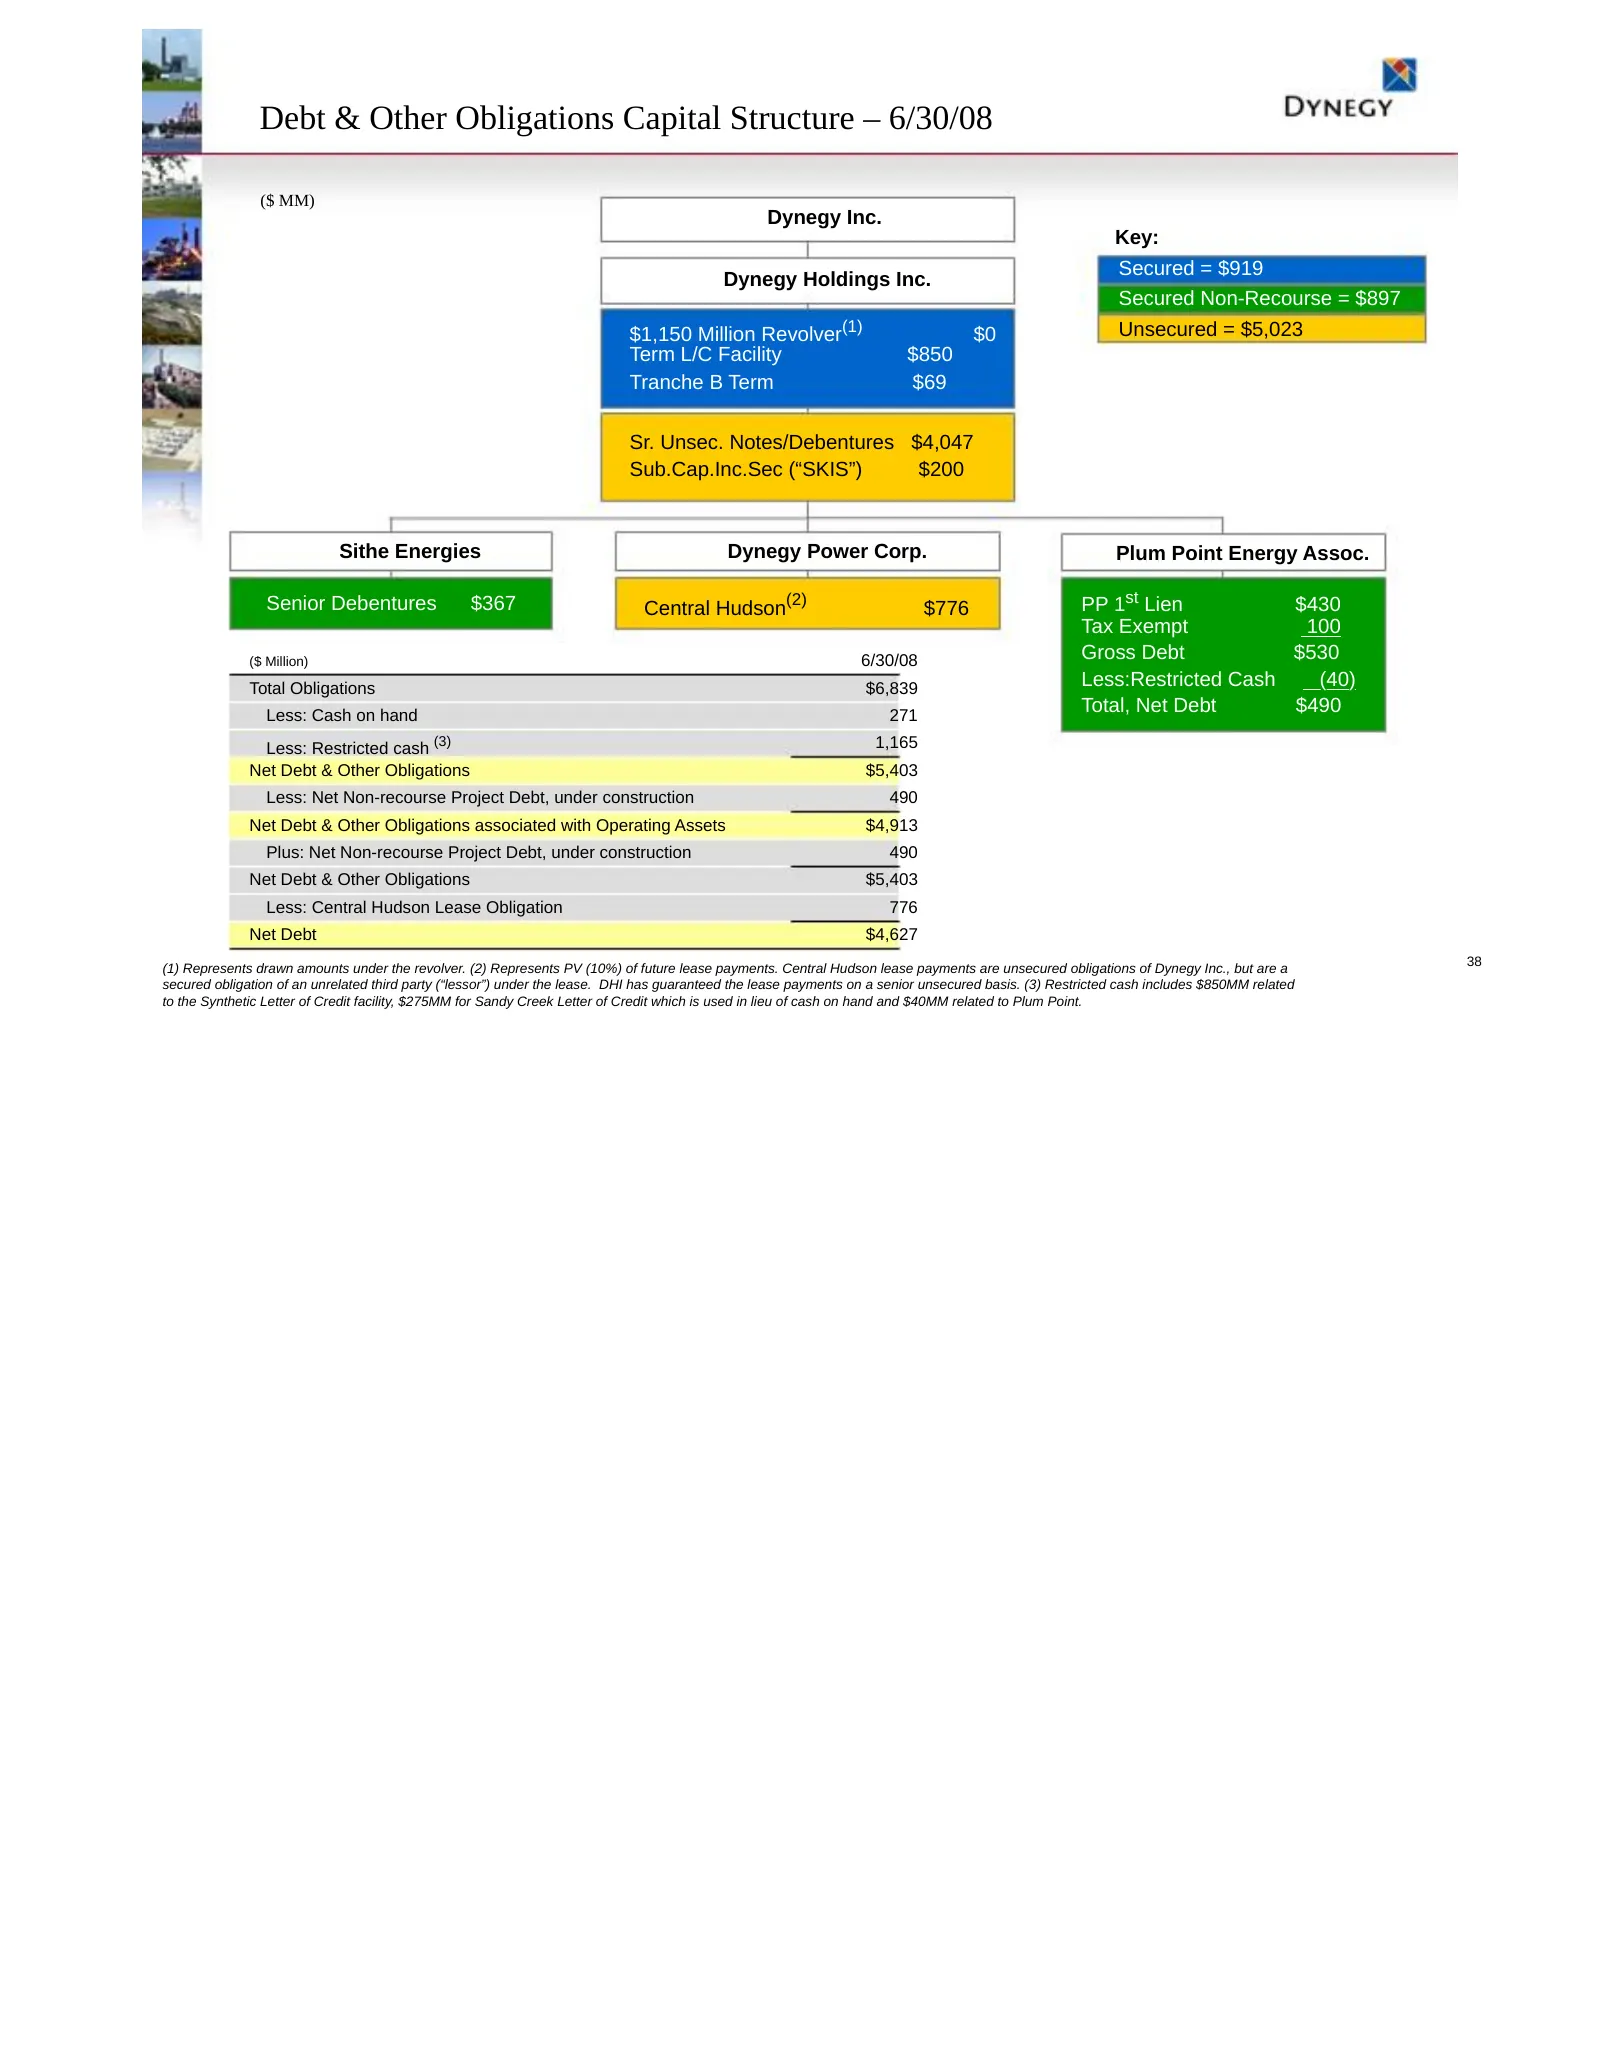
Debt & Other Obligations Capital Structure – 6/30/08 ($ MM) Dynegy Inc.. Key: Secured = $919 Dynegy Holdings Inc. Secured Non-Recourse = $897 $1,150 Million Revolver(1) $0 Unsecured = $5,023 Term L/C Facility $850 Tranche B Term $69 Sr. Unsec. Notes/Debentures $4,047 Sub.Cap.Inc.Sec (“SKIS”) $200 Si
Slide 39: Liquidity ($ MM)
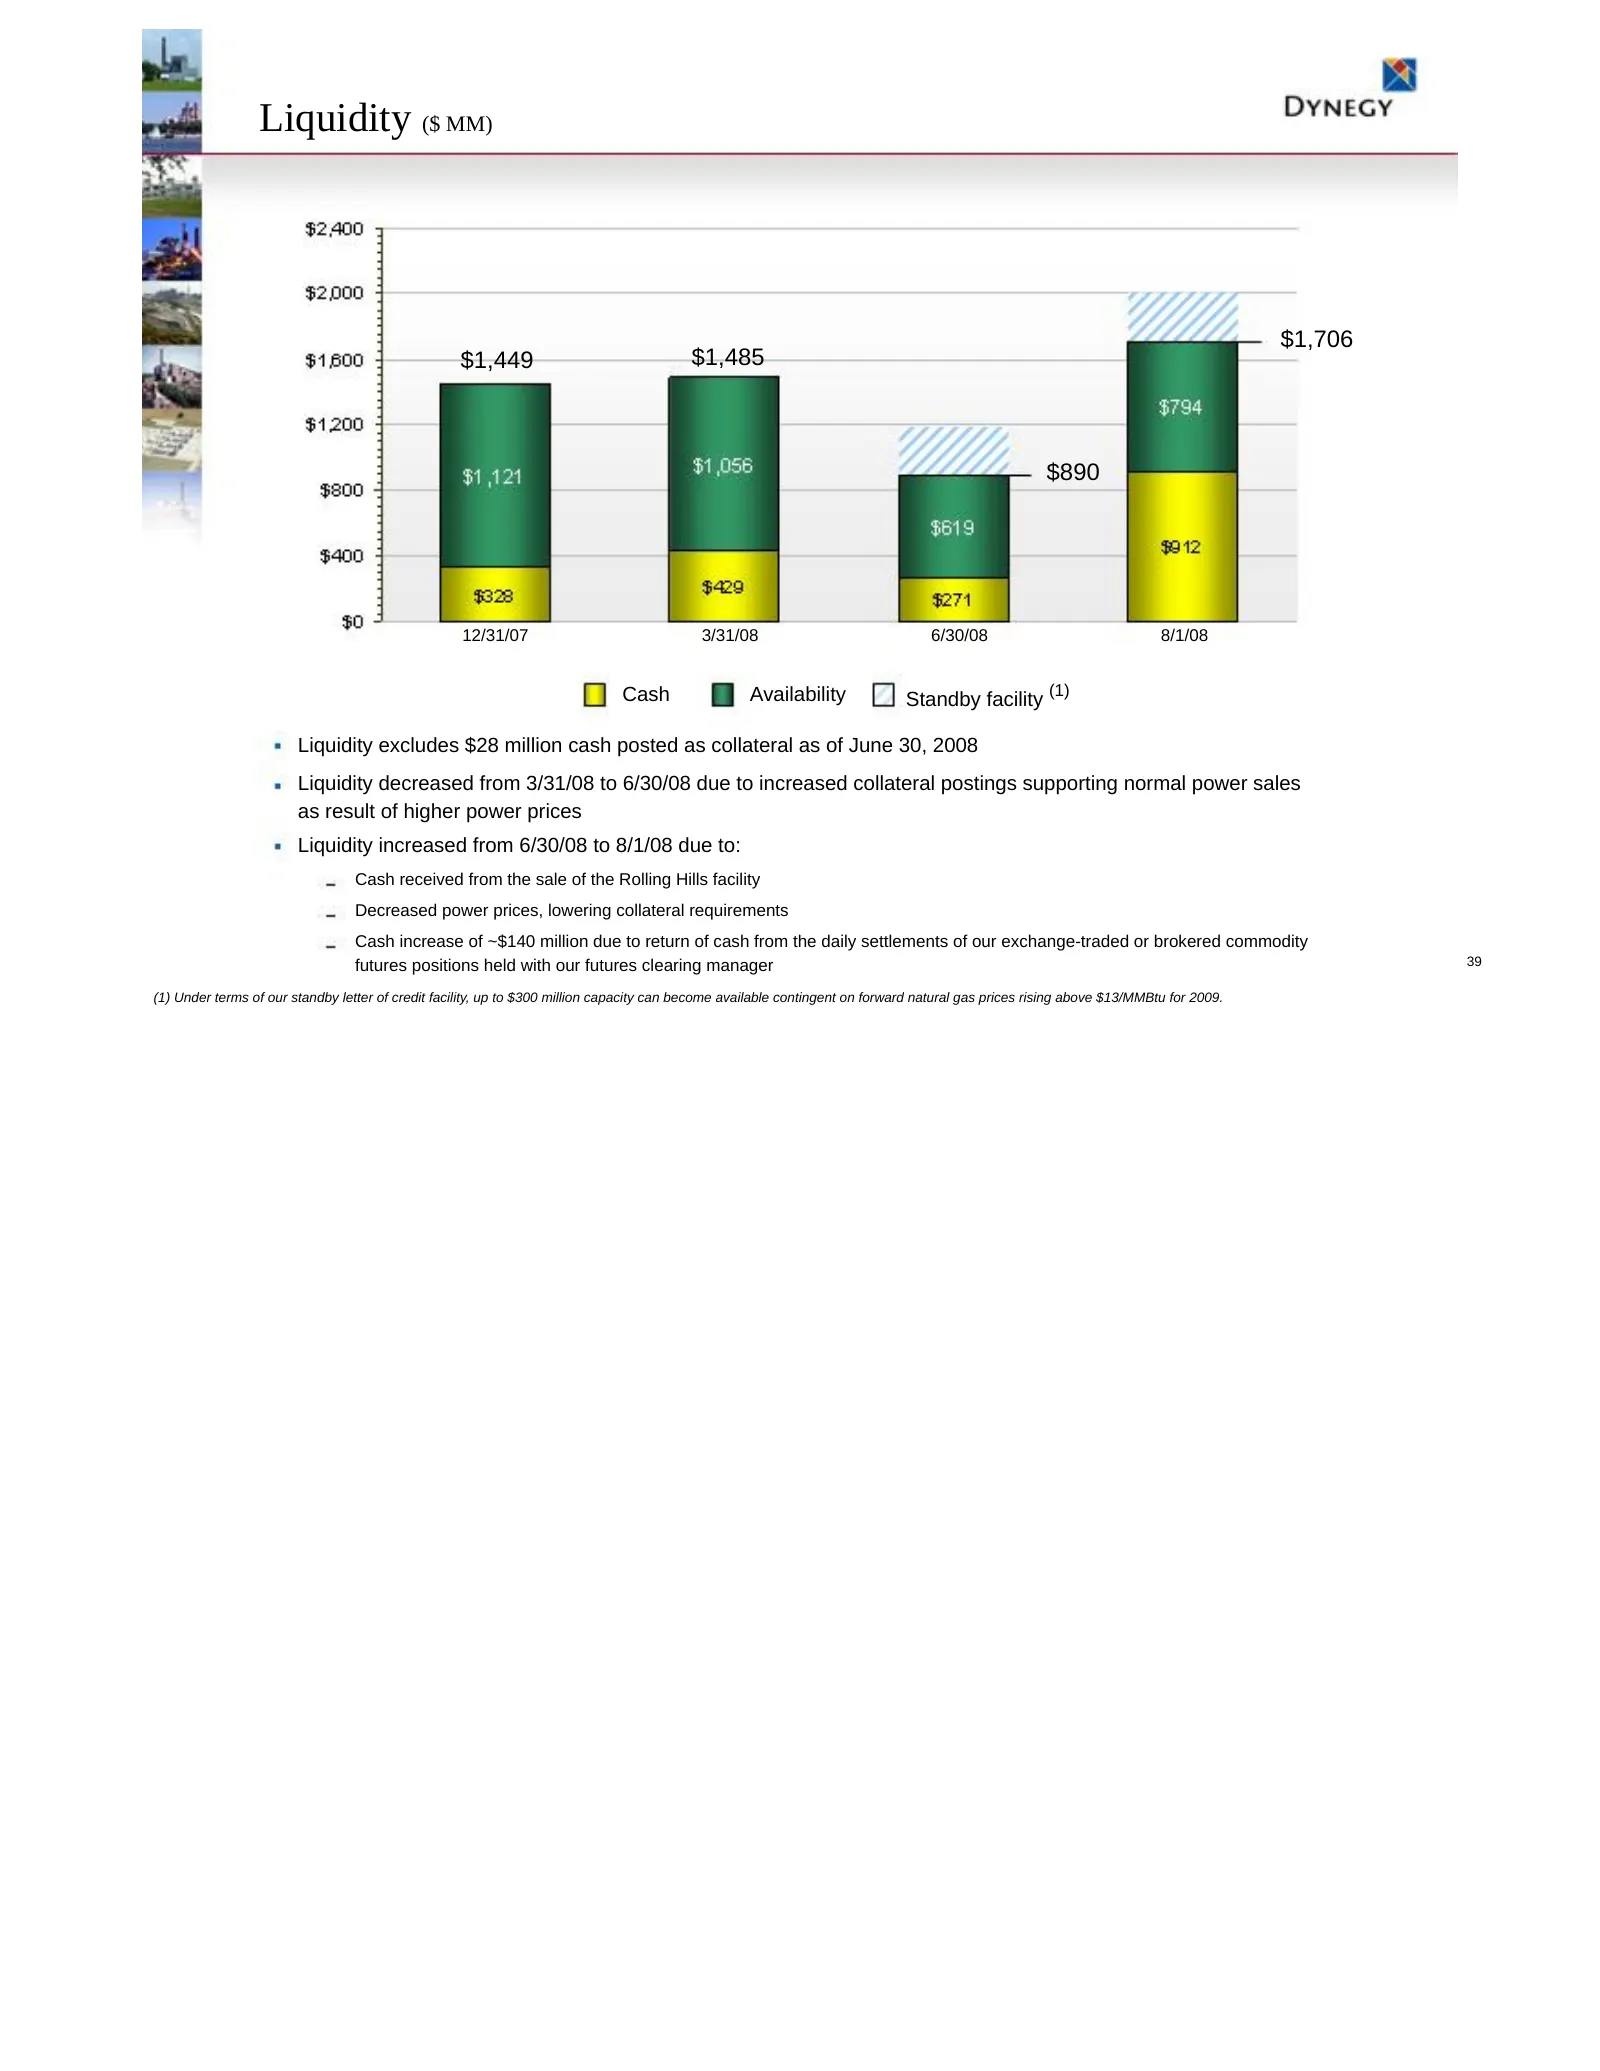
Liquidity ($ MM) $1,706 $1,449 $1,485 $890 12/31/07 3/31/08 6/30/08 8/1/08 Cash Availability Standby facility (1) Liquidity excludes $28 million cash posted as collateral as of June 30, 2008 Liquidity decreased from 3/31/08 to 6/30/08 due to increased collateral postings supporting normal power sale
Slide 40: Reg G Reconciliation – 2008 Guidance
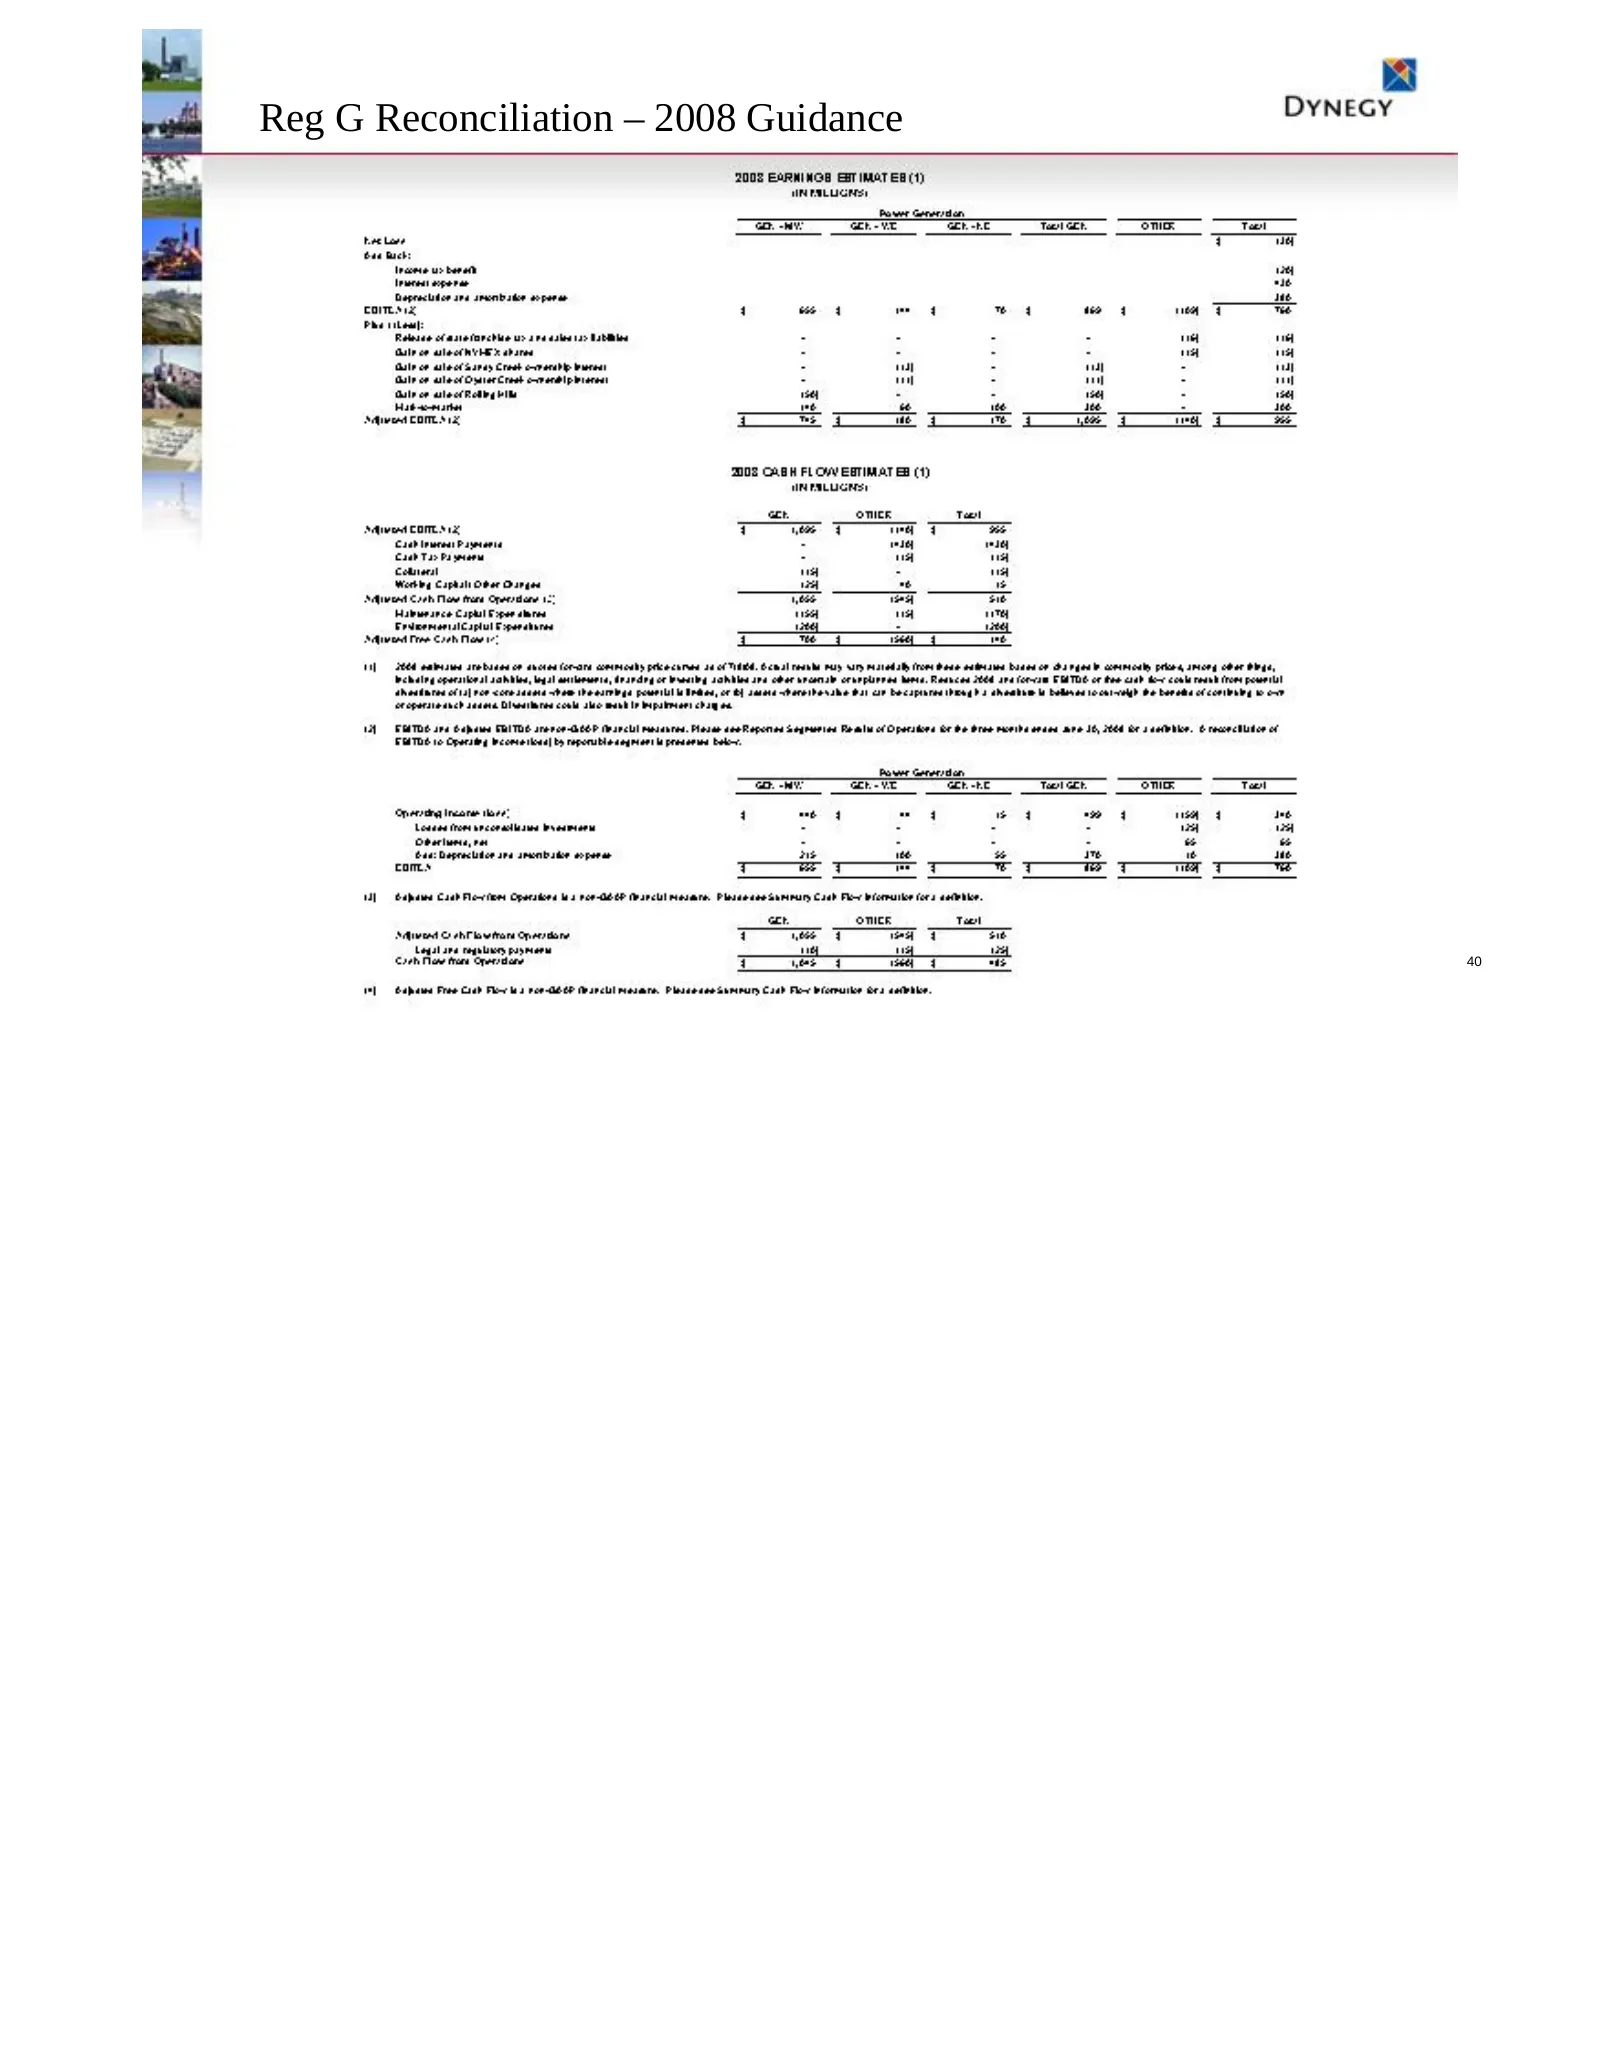
Reg G Reconciliation – 2008 Guidance 40
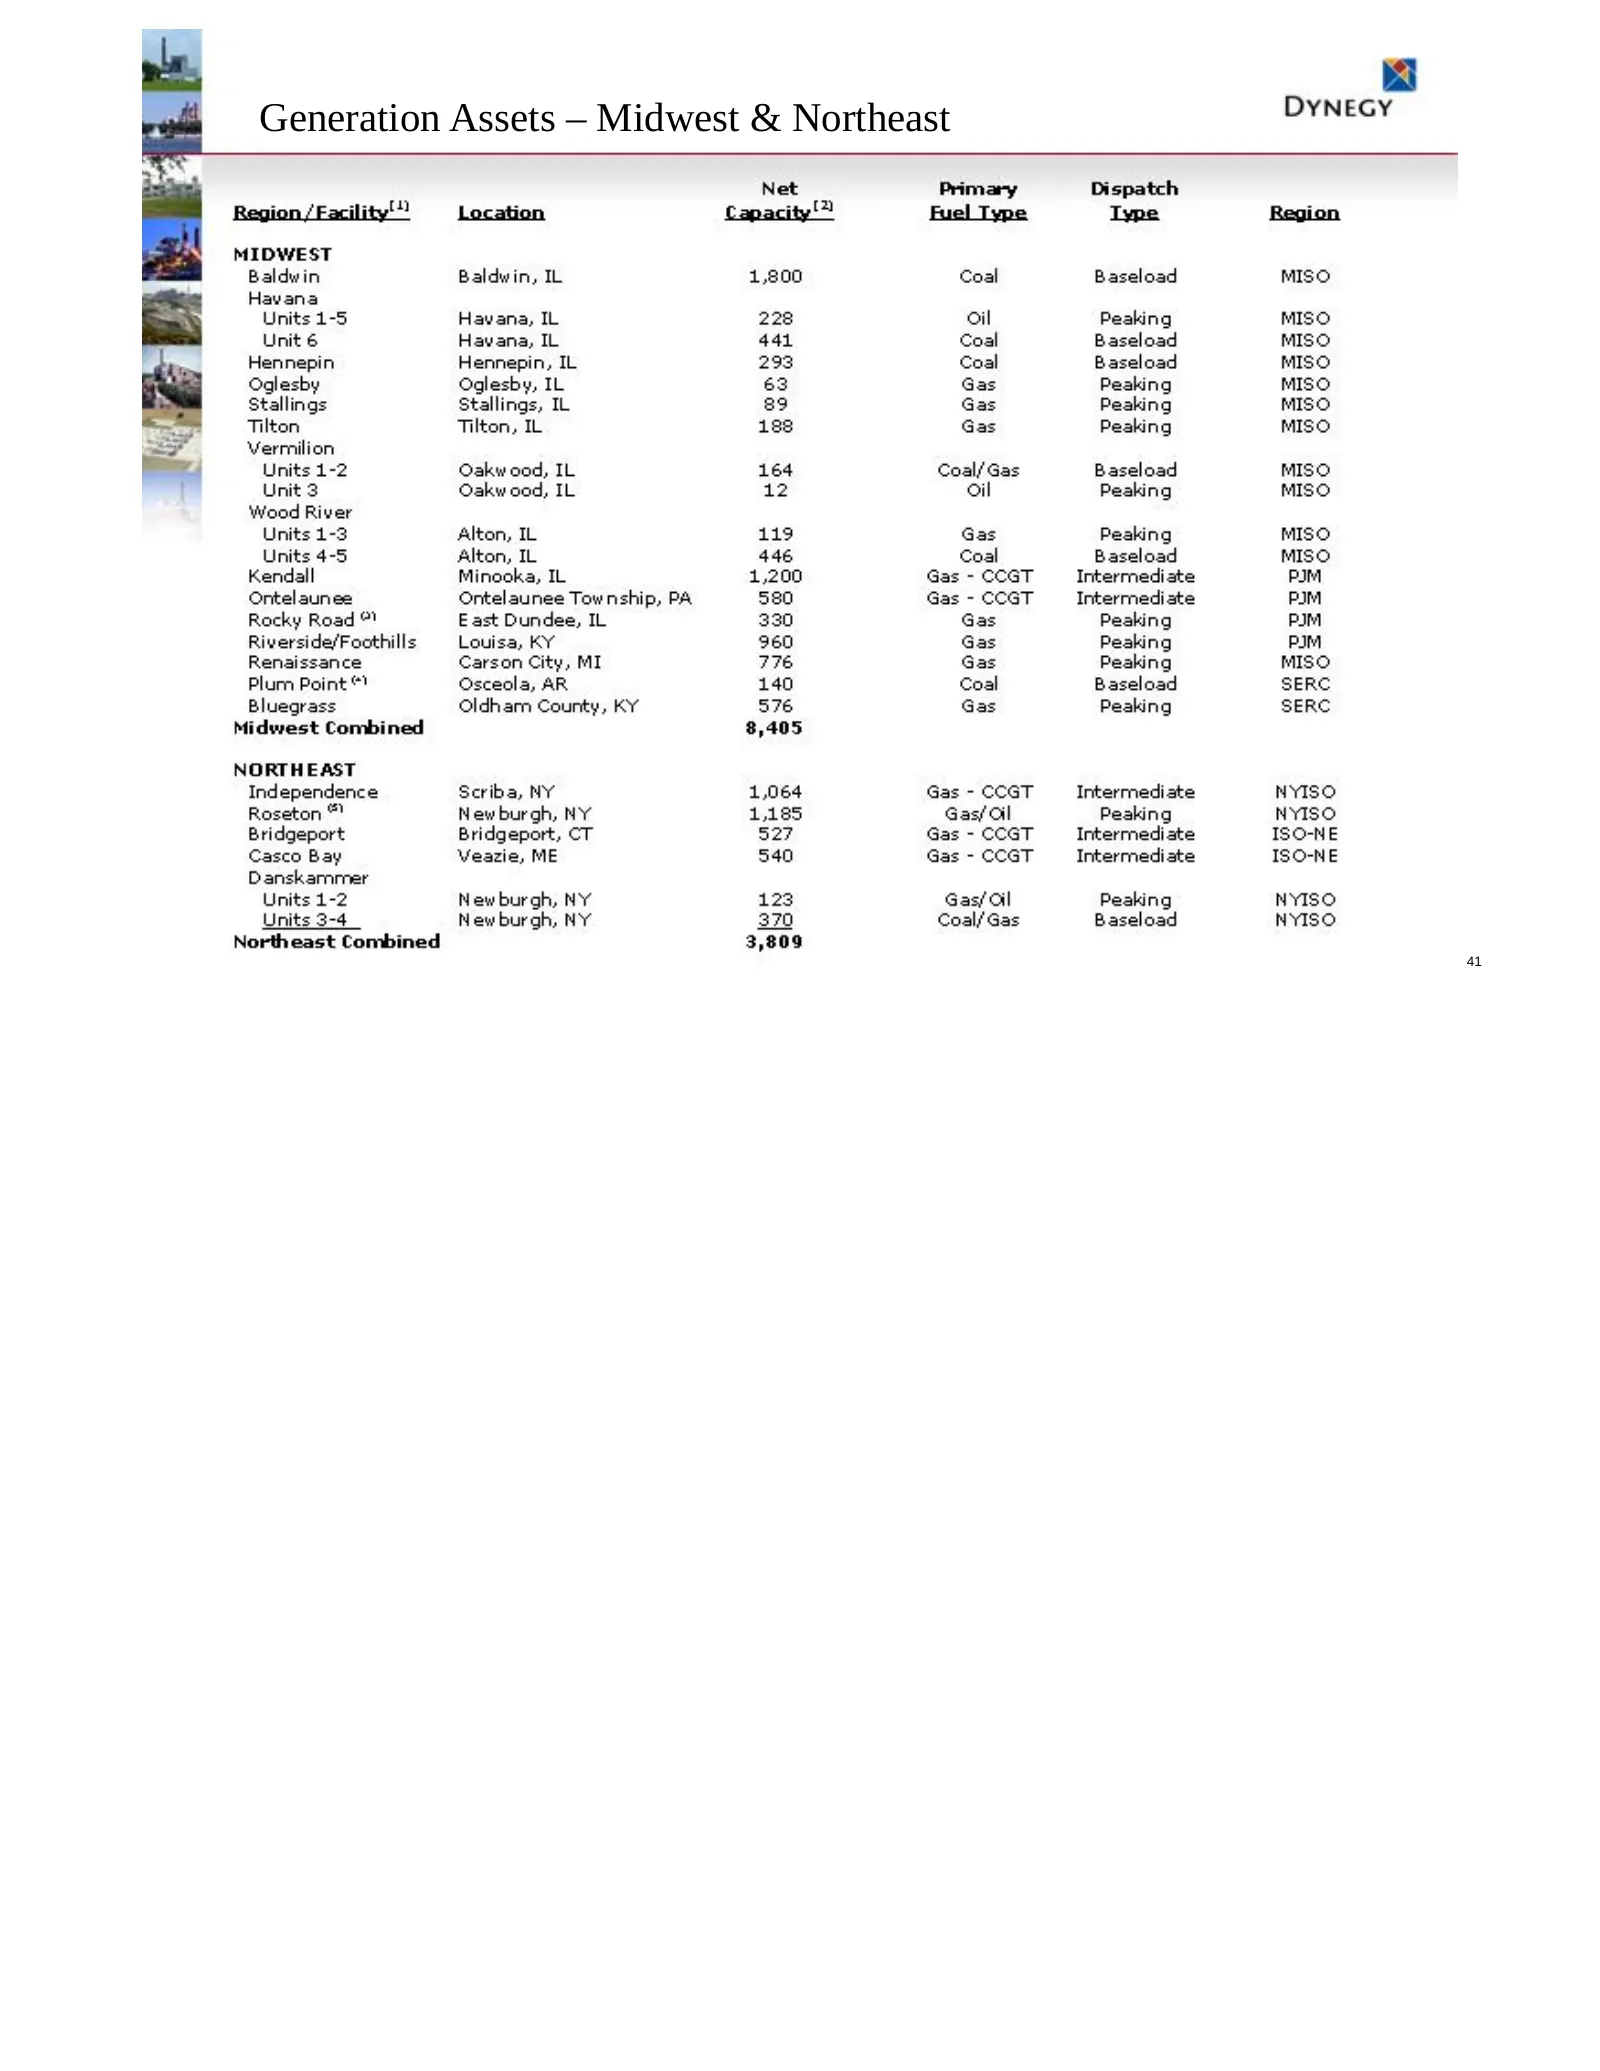
Slide 41: Generation Assets – Midwest & Northeast
Generation Assets – Midwest & Northeast 41
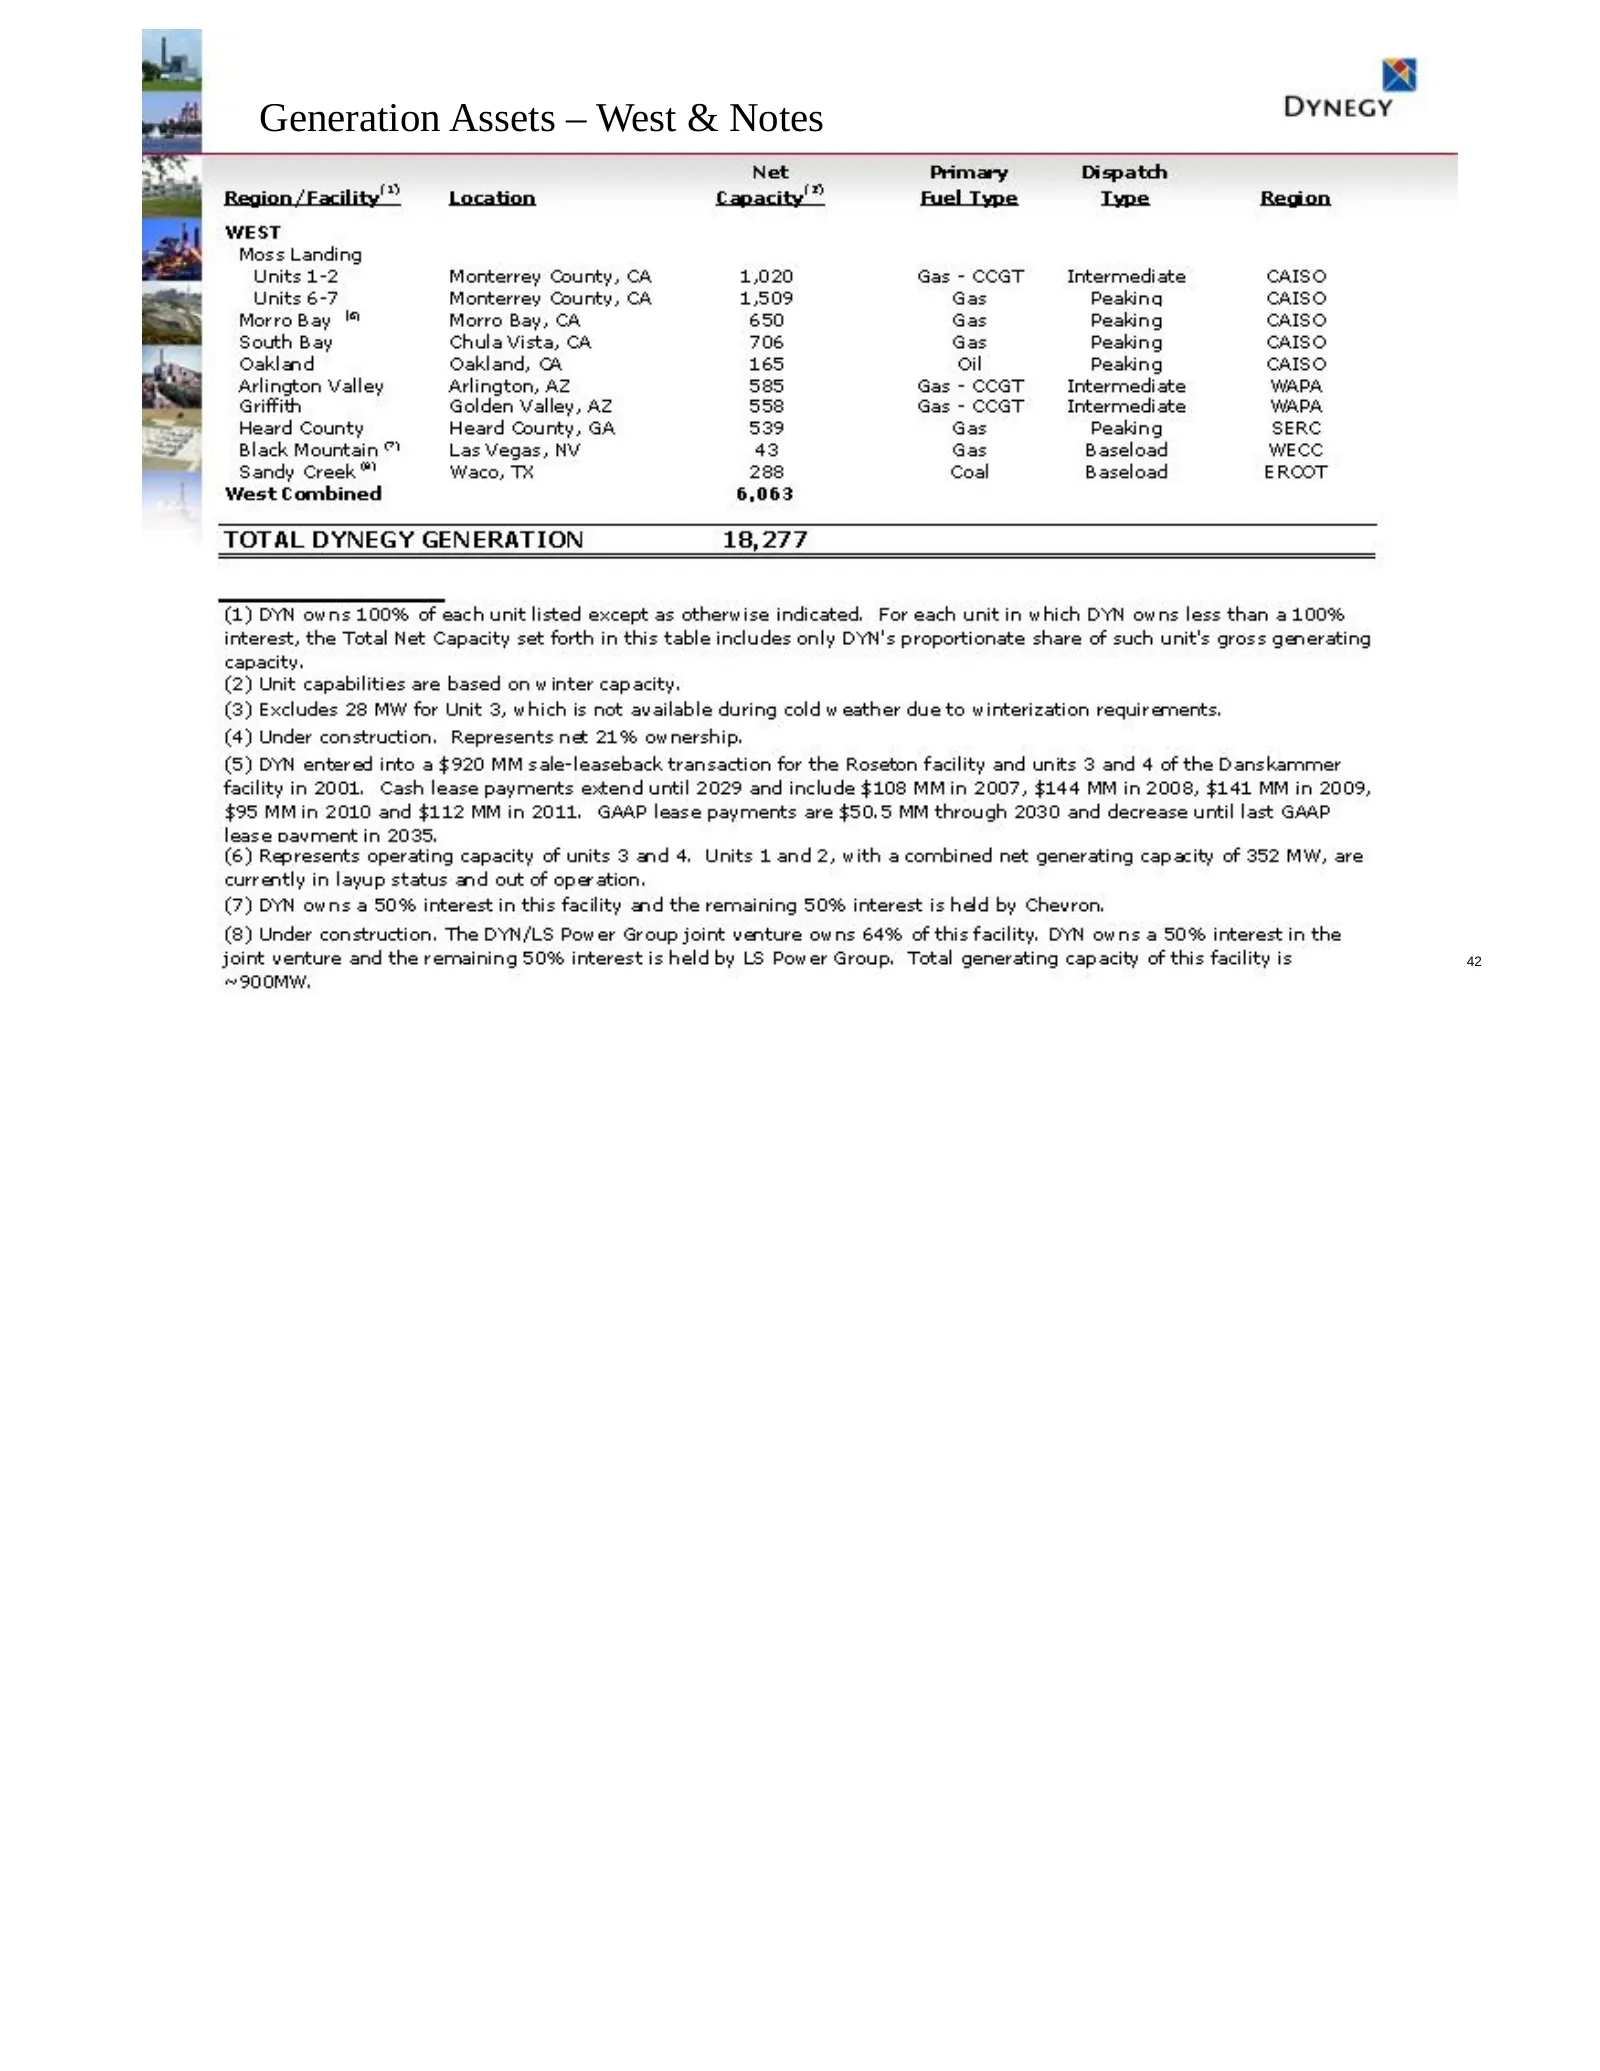
Slide 42: Generation Assets – West & Notes
Generation Assets – West & Notes 42
Source: SEC EDGAR · 8-K filed Sep 2, 2008
More decks from Dynegy Inc
 FY2017 Earnings Presentation30 slides · Feb 26, 2018
 Debt Investor Presentation (December 2017)10 slides · Dec 11, 2017
 Merger or Acquisition (October 2017)28 slides · Oct 31, 2017
 Debt Investor Presentation (October 2016)44 slides · Oct 3, 2016
 IPO Roadshow (June 2016)17 slides · Jun 15, 2016
 Investor Day (April 2014)94 slides · Apr 11, 2014