Teppco Partners LP — MLP Investor Conference 2007
35 slides from Teppco Partners LP's conference presentation, Mar 8, 2007
Slide 1: TEPPCO Partners, L.P. MLP Investor Conference
TEPPCO Partners, L.P. MLP Investor Conference March 8, 2007 Bill Manias Vice President and Chief Financial Officer
Slide 2: Forward-looking Statements
Forward-looking Statements The material and information furnished in this presentation includes "forward-looking statements" within the meaning of the federal securities laws. All statements that express belief, expectation, estimates or intentions, as well as those that are not statements of histor
Slide 3: Forward-looking Statements
Forward-looking Statements trucking and railroad freight, agricultural usage and military usage; the demand for propane is sensitive to the weather and prevailing economic conditions; the demand for petrochemicals is dependent upon prices for products produced from petrochemicals; the demand for cru
Slide 4: TEPPCO System Map
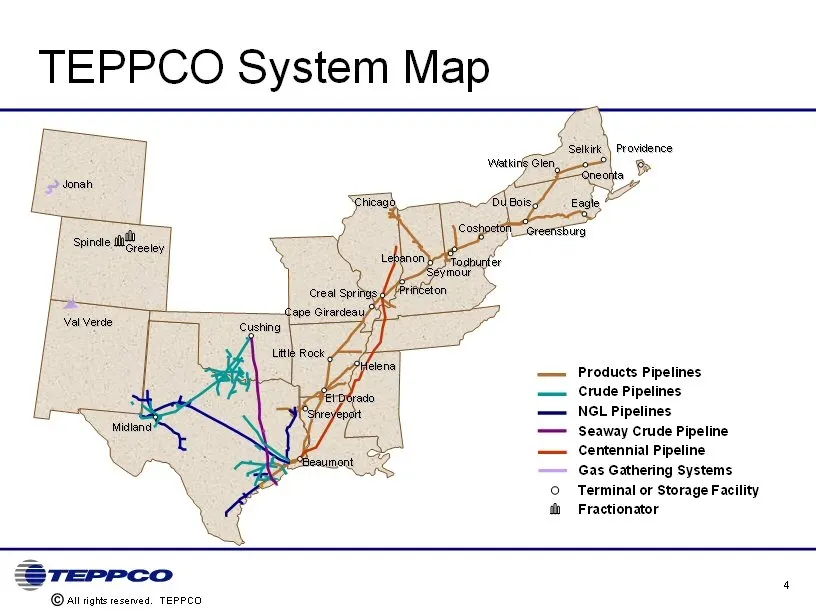
TEPPCO System Map Spina tl Val Verde Products Pipelines Crude Pipelines NGL Pipelines Seaway Crude Pipeline Centennial Pipeline Gas Gathering Systems © Terminal or Storage Facility th Fractionator ©All rights reserved. TEPPCO
Slide 5: Partnership Overview
Partnership Overview One of the oldest publicly traded partnerships with an enterprise value of $5.3 billion Ranks 267 on the Fortune 500 list 17% compound annual growth over a 16-year period since IPO Greater than 90% fee-based business from diversified asset base Transportation, storage and termin
Slide 6: Record EBITDA from Diversified Base of Assets
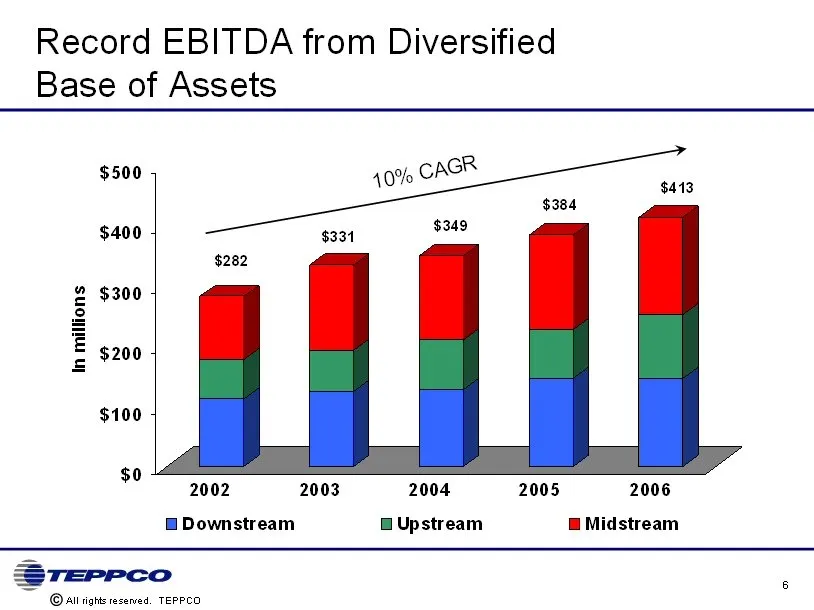
Record EBITDA from Diversified Base of Assets
Slide 7: Business Overview and 2006 Results
Business Overview and 2006 Results
Slide 8: TEPPCO's Downstream Business
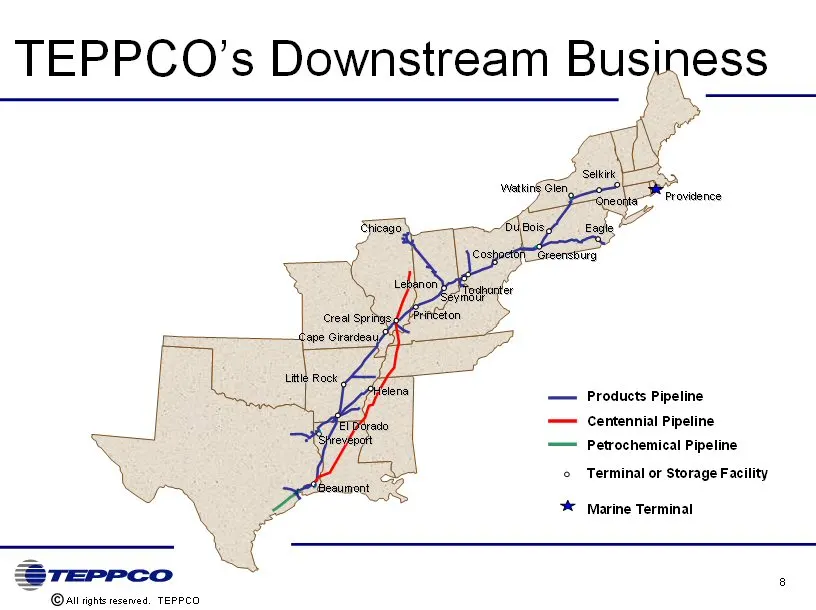
TEPPCO's Downstream Business
Slide 9: Downstream Segment Review
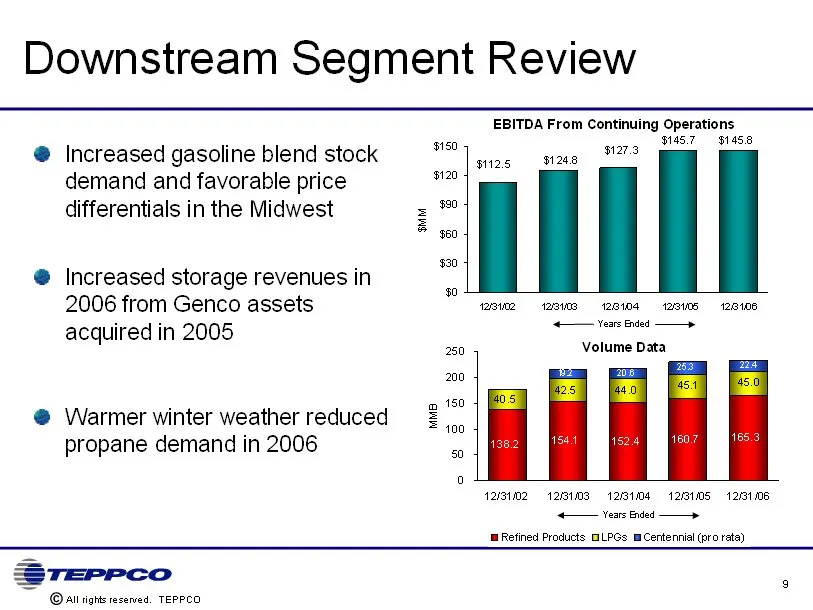
Downstream Segment Review Increased gasoline blend stock demand and favorable price differentials in the Midwest Increased storage revenues in 2006 from Genco assets acquired in 2005 Warmer winter weather reduced propane demand in 2006
Slide 10: TEPPCO's Upstream Business
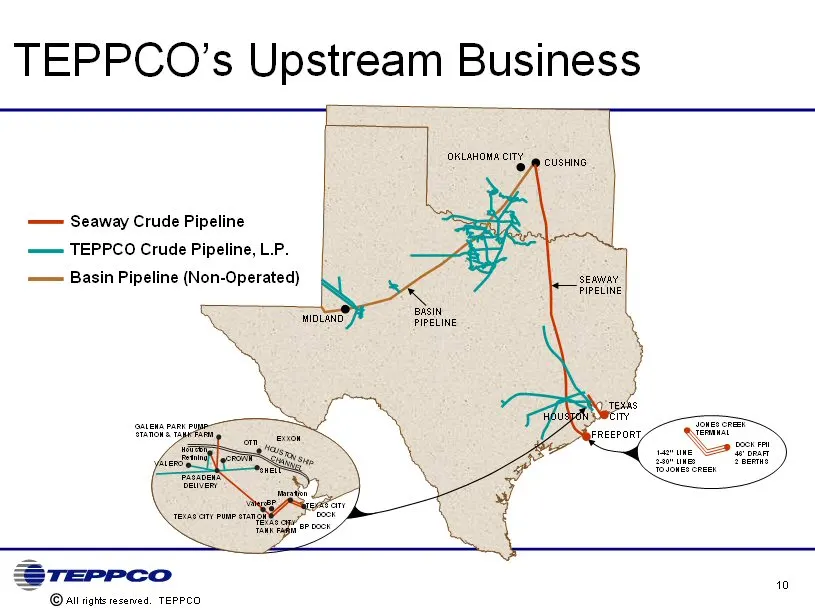
TEPPCO’s Upstream Business OKLAHOMA CITY custano —— Seaway Crude Pipeline —— TEPPCO Crude Pipeline, LP. — Basin Pipeline (Non-Operated) seaay 10 ©All rights reserved. TEPPCO
Slide 11: Upstream Segment Review
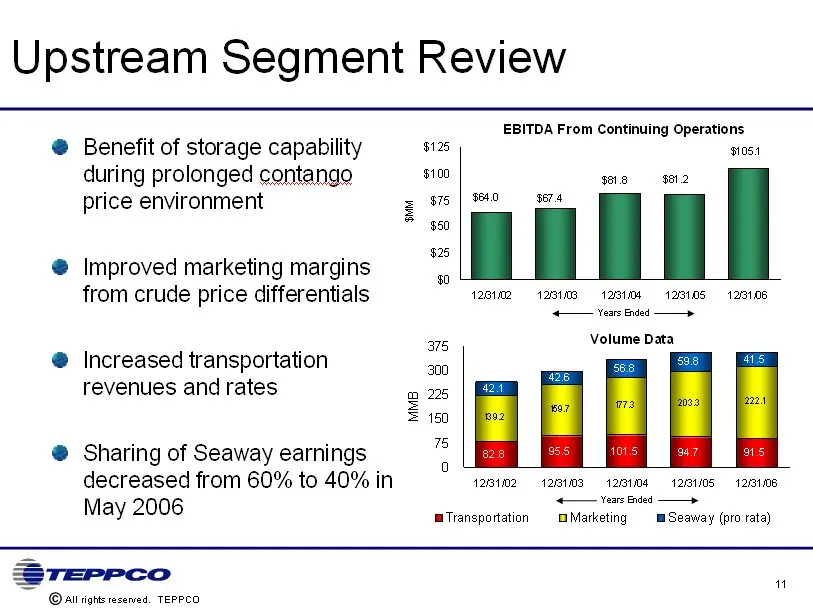
Upstream Segment Review Benefit of storage capability during prolonged contango price environment Improved marketing margins from crude price differentials Increased transportation revenues and rates Sharing of Seaway earnings decreased from 60% to 40% in May 2006
Slide 12: TEPPCO's Midstream Business
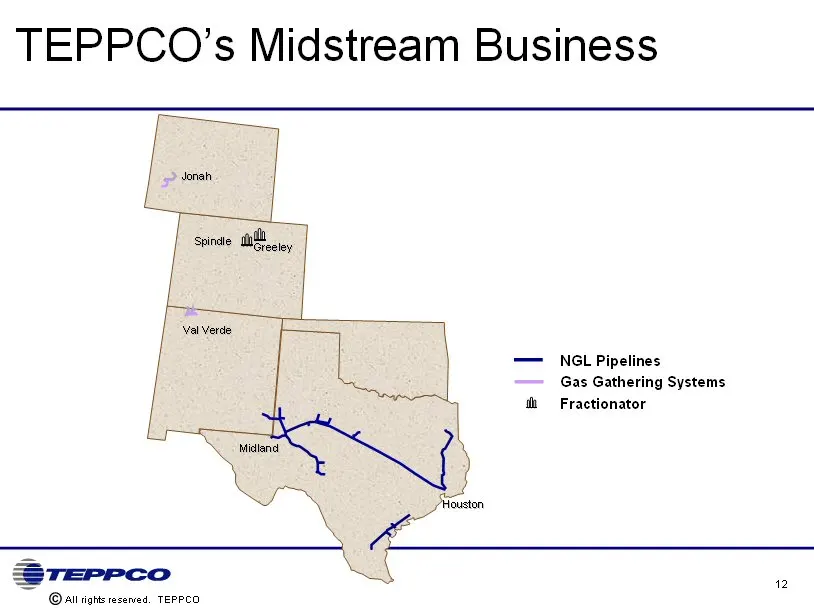
TEPPCO's Midstream Business
Slide 13: Midstream Segment Review
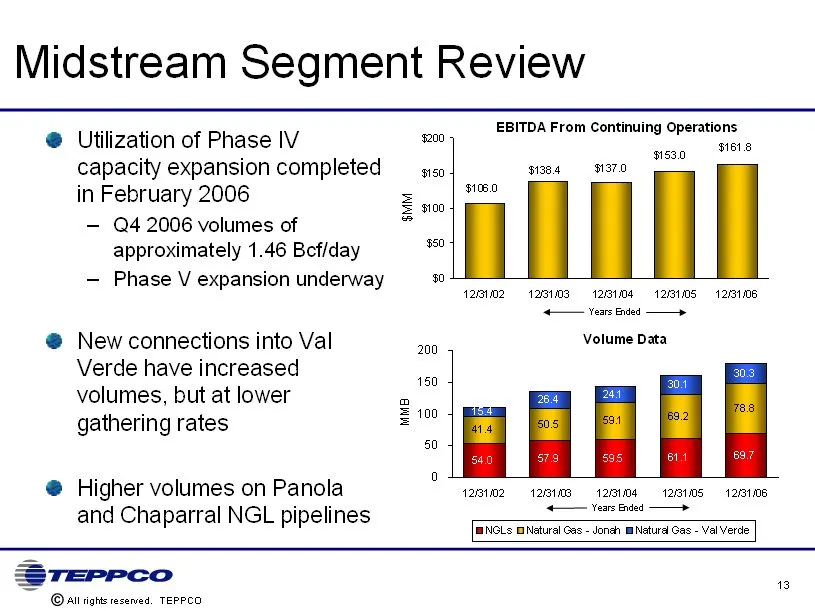
Midstream Segment Review Utilization of Phase IV capacity expansion completed in February 2006 Q4 2006 volumes of approximately 1.46 Bcf/day Phase V expansion underway New connections into Val Verde have increased volumes, but at lower gathering rates Higher volumes on Panola and Chaparral NGL pipel
Slide 14: Growth Outlook and Capital Projects Update
Growth Outlook and Capital Projects Update
Slide 15: 2006 Initiatives Position TEPPCO for Continued Growth
2006 Initiatives Position TEPPCO for Continued Growth Issued LP units in return for reduction of the GP's maximum share of incentive distributions from 50% to 25% Lowers future cost of equity capital Better alignment of GP with LP unit holders Senior leadership team assembled and committed to long-t
Slide 16: Trends Expected to Drive TEPPCO's Long-Term Business Growth
Trends Expected to Drive TEPPCO's Long-Term Business Growth Canadian crude imports to the U.S. will increase Crude imports to the U.S. Gulf Coast (USGC) will increase Refined products imports to the U.S. will increase Changes in commercial terminal ownership and operations Standards for use of ethan
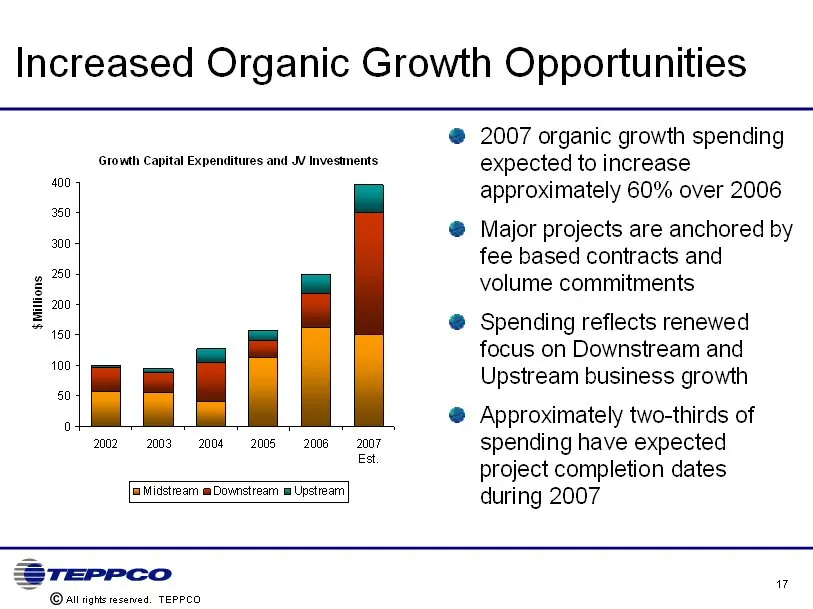
Slide 17: Increased Organic Growth Opportunities
Increased Organic Growth Opportunities 2007 organic growth spending expected to increase approximately 60% over 2006 Major projects are anchored by fee based contracts and volume commitments Spending reflects renewed focus on Downstream and Upstream business growth Approximately two-thirds of spendi
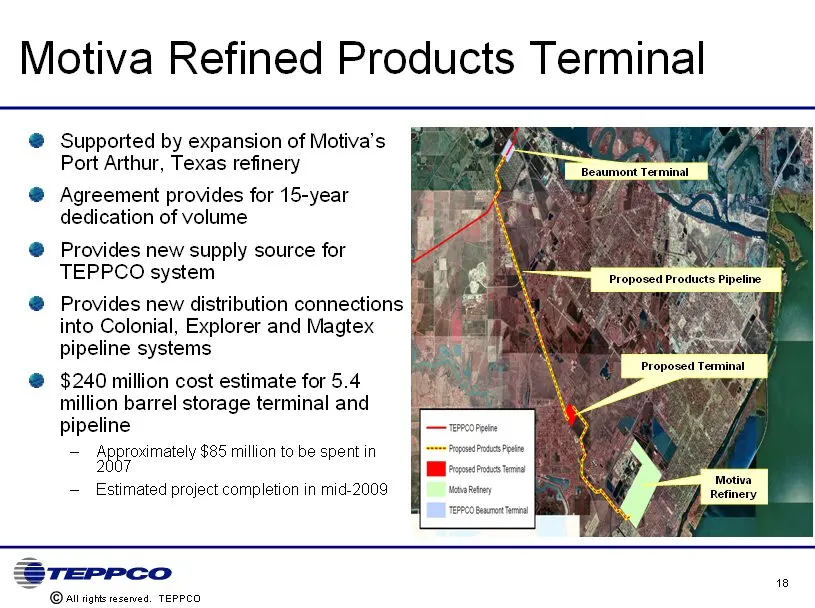
Slide 18: Motiva Refined Products Terminal
Motiva Refined Products Terminal Supported by expansion of Motiva's Port Arthur, Texas refinery Agreement provides for 15-year dedication of volume Provides new supply source for TEPPCO system Provides new distribution connections into Colonial, Explorer and Magtex pipeline systems $240 million cost
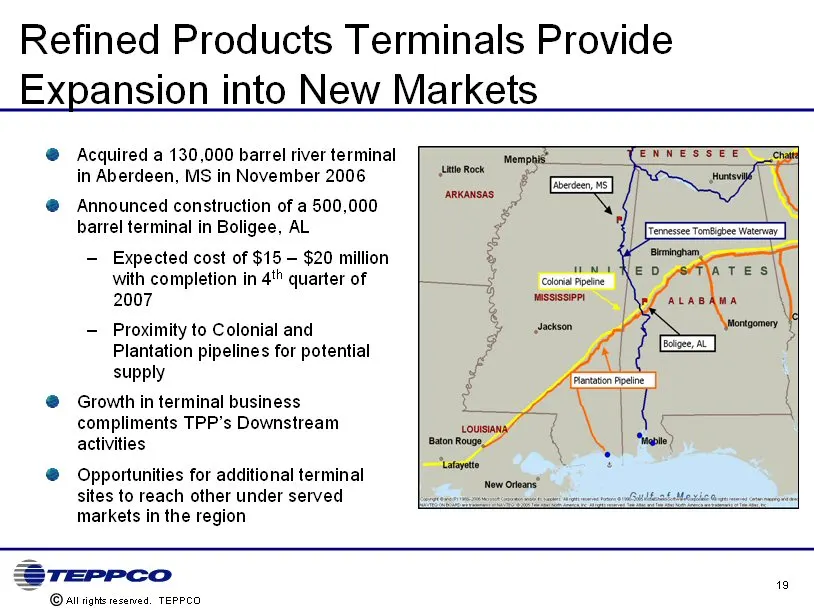
Slide 19: Refined Products Terminals Provide Expansion into New Markets
Refined Products Terminals Provide Expansion into New Markets Acquired a 130,000 barrel river terminal in Aberdeen, MS in November 2006 Announced construction of a 500,000 barrel terminal in Boligee, AL Expected cost of $15 - $20 million with completion in 4th quarter of 2007 Proximity to Colonial a
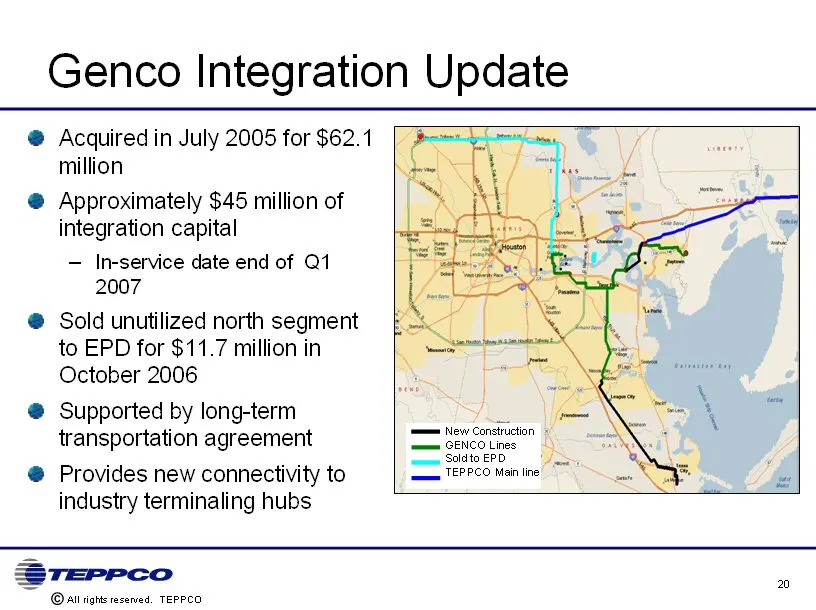
Slide 20: Genco Integration Update
Genco Integration Update Acquired in July 2005 for $62.1 million Approximately $45 million of integration capital In-service date end of Q1 2007 Sold unutilized north segment to EPD for $11.7 million in October 2006 Supported by long-term transportation agreement Provides new connectivity to industr
Slide 21: Jonah Gas Gathering Phase V Expansion
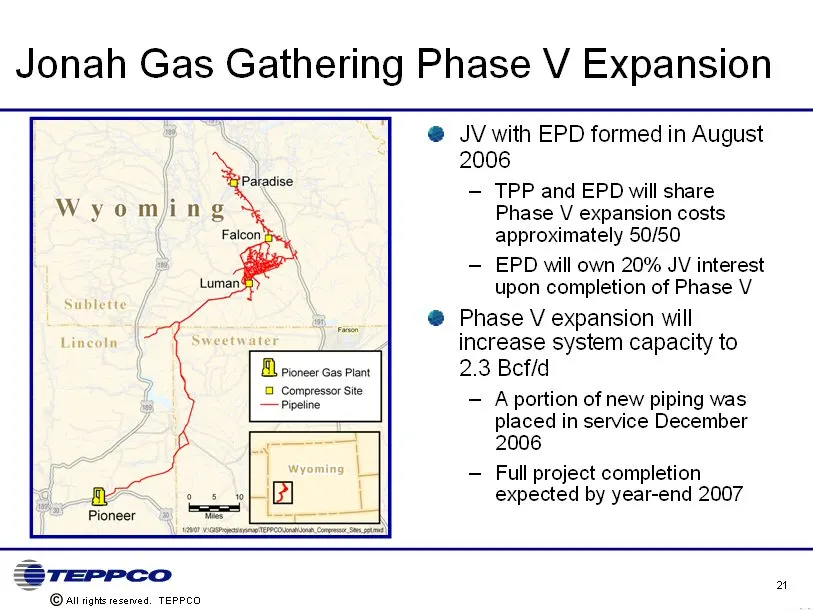
Jonah Gas Gathering Phase V Expansion JV with EPD formed in August 2006 TPP and EPD will share Phase V expansion costs approximately 50/50 EPD will own 20% JV interest upon completion of Phase V Phase V expansion will increase system capacity to 2.3 Bcf/d A portion of new piping was placed in servic
Slide 22: Smaller Projects Provide Attractive Returns
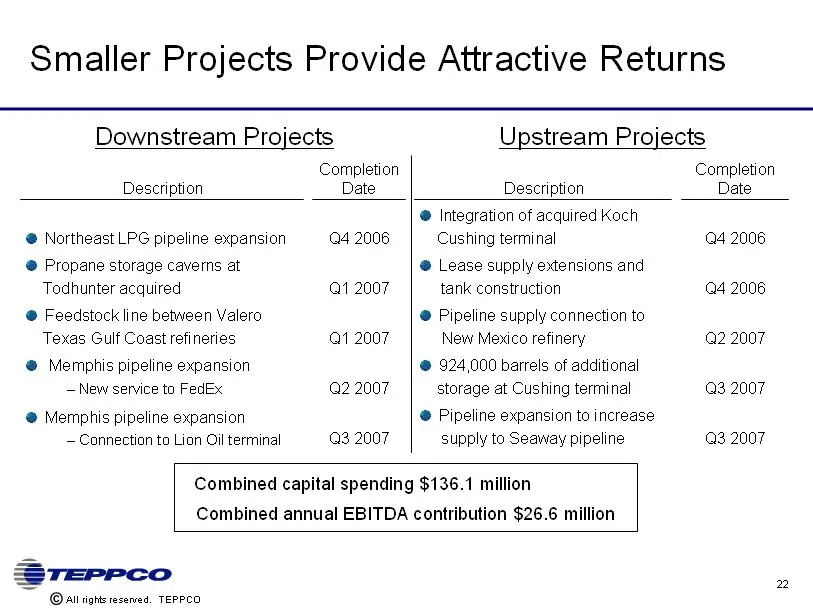
Smaller Projects Provide Attractive Returns Downstream Projects Upstream Projects Description Completion Date Description Completion Date Northeast LPG pipeline expansion Q4 2006 Integration of acquired Koch Cushing terminal Q4 2006 Propane storage caverns at Todhunter acquired Q1 2007 Lease supply
Slide 23: Financial Overview and 2007 Outlook
Financial Overview and 2007 Outlook
Slide 24: Financial Strengths
Financial Strengths Fee-based cash flows with limited commodity exposure Diversified assets provide greater stability of earnings Investment grade ratings with stable outlooks from S and P and Moody's Financial metrics to support future growth opportunities Visible growth opportunities in core opera
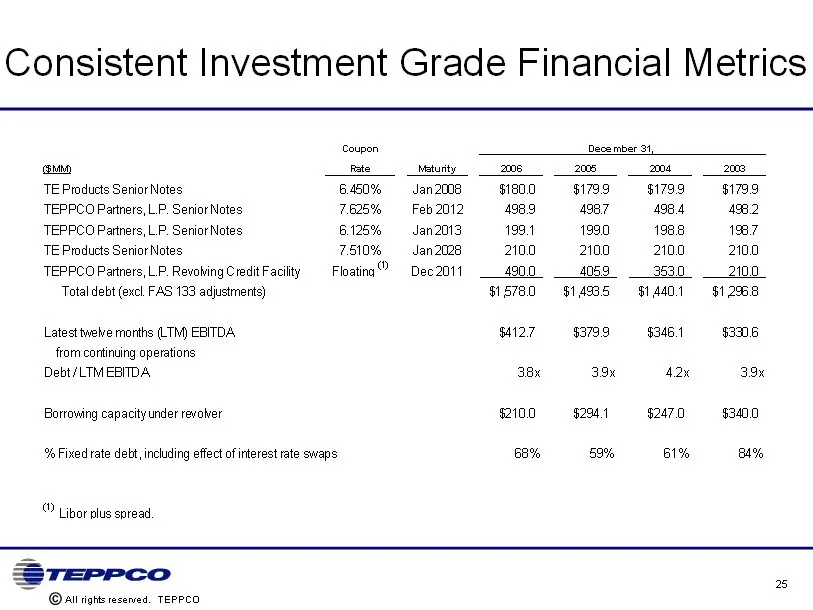
Slide 25: Consistent Investment Grade Financial Metrics
Consistent Investment Grade Financial Metrics
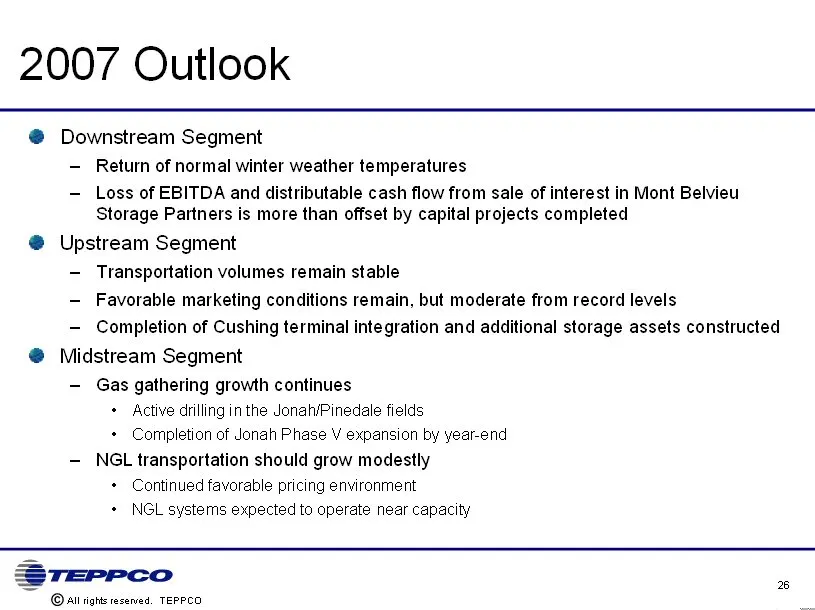
Slide 26: 2007 Outlook
2007 Outlook Downstream Segment Return of normal winter weather temperatures Loss of EBITDA and distributable cash flow from sale of interest in Mont Belvieu Storage Partners is more than offset by capital projects completed Upstream Segment Transportation volumes remain stable Favorable marketing c
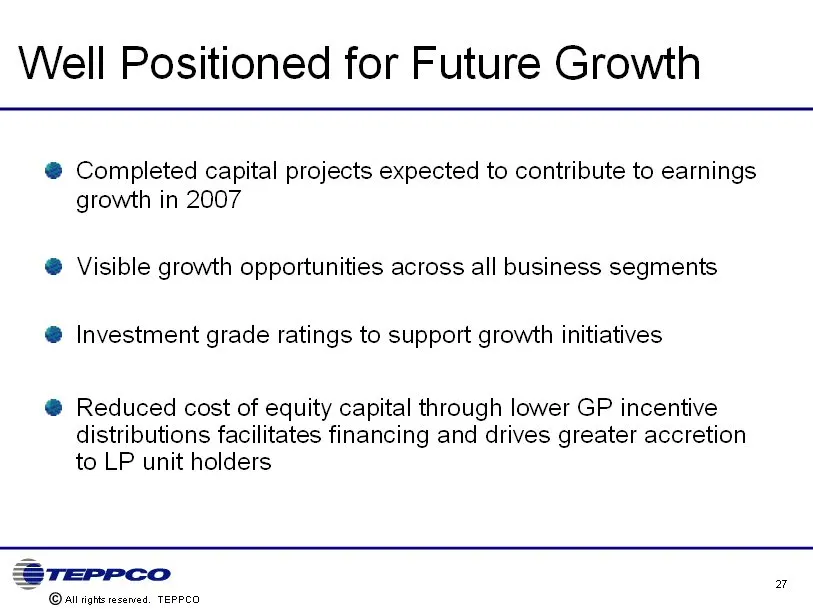
Slide 27: Well Positioned for Future Growth
Well Positioned for Future Growth Completed capital projects expected to contribute to earnings growth in 2007 Visible growth opportunities across all business segments Investment grade ratings to support growth initiatives Reduced cost of equity capital through lower GP incentive distributions faci
Slide 28: Questions and Answers
Questions and Answers NYSE: TPP www.teppco.com (800) 659-0059
Slide 29: Appendix
Appendix |All rights reserved. TEPPCO
Slide 30: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures
Slide 31: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures
Slide 32: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures
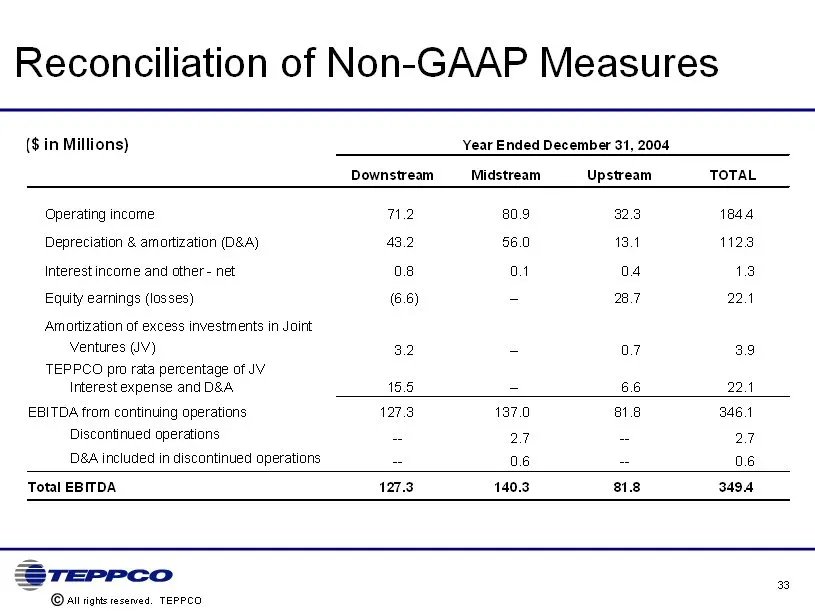
Slide 33: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures
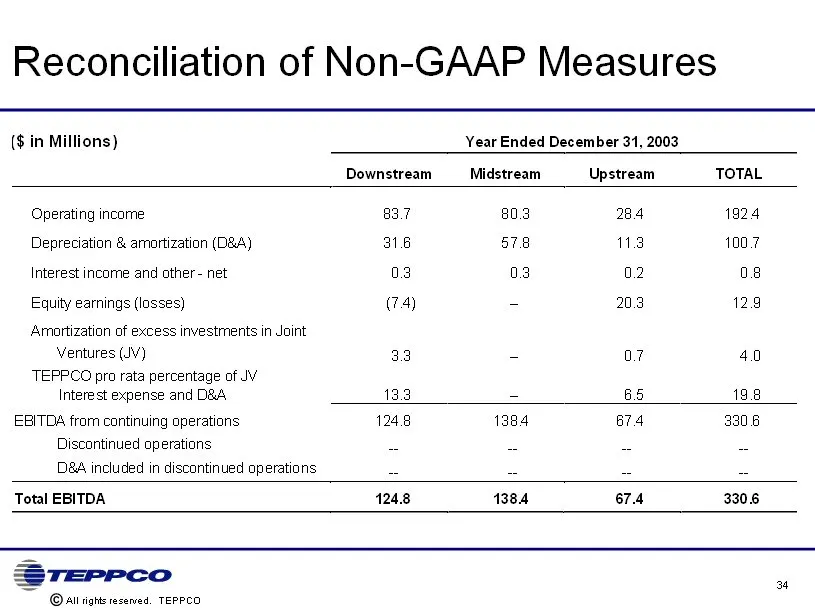
Slide 34: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures
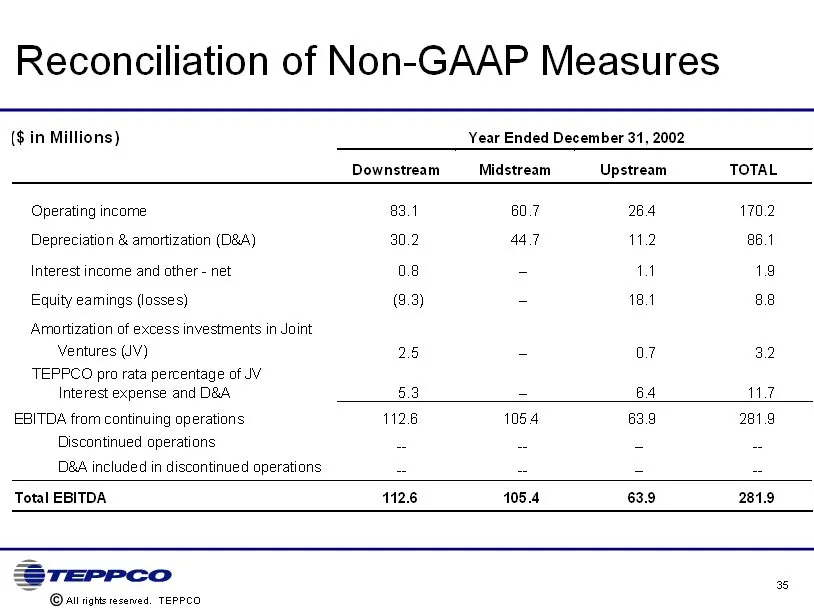
Slide 35: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures
Source: SEC EDGAR · 8-K filed Mar 8, 2007
More decks from Teppco Partners LP
 Morgan Stanley MLP Reception (October 2009)26 slides · Oct 7, 2009
 Master Limited Partnerships Investor Conference (September 2009)27 slides · Sep 16, 2009
 Wells Fargo Retail Meeting (September 2009)27 slides · Sep 15, 2009
 Barclays Capital CEO Energy/Power Conference 200929 slides · Sep 9, 2009
 Merger or Acquisition (August 2009)29 slides · Aug 26, 2009
 Wachovia Securities Investor Presentation (June 2007)51 slides · Jun 1, 2007