Southern Union — Lehman Brothers 2008 CEO Energy/Power Conference
49 slides from Southern Union's conference presentation, Sep 4, 2008
Slide 1: Lehman Brothers 2008 CEO Energy/Power Conference
Lehman Brothers 2008 CEO Energy/Power Conference New York September 4, 2008 www.sug.com
Slide 2: Forward-Looking Statements
Forward-Looking Statements Statements contained in this presentation that include company expectations or predictions of the future are forward-looking statements intended to be covered by the safe harbor provisions of the Securities Act of 1933 and the Securities Exchange Act of 1934. It is importa
Slide 3: Agenda
Agenda • Southern Union Company Overview • Creating Shareholder Value • Segment Information & Growth Drivers • 2008 Financial Outlook • Conclusion • Appendix 3
Slide 4: Southern Union Company Overview
Southern Union Company Overview
Slide 5: Southern Union Transformation
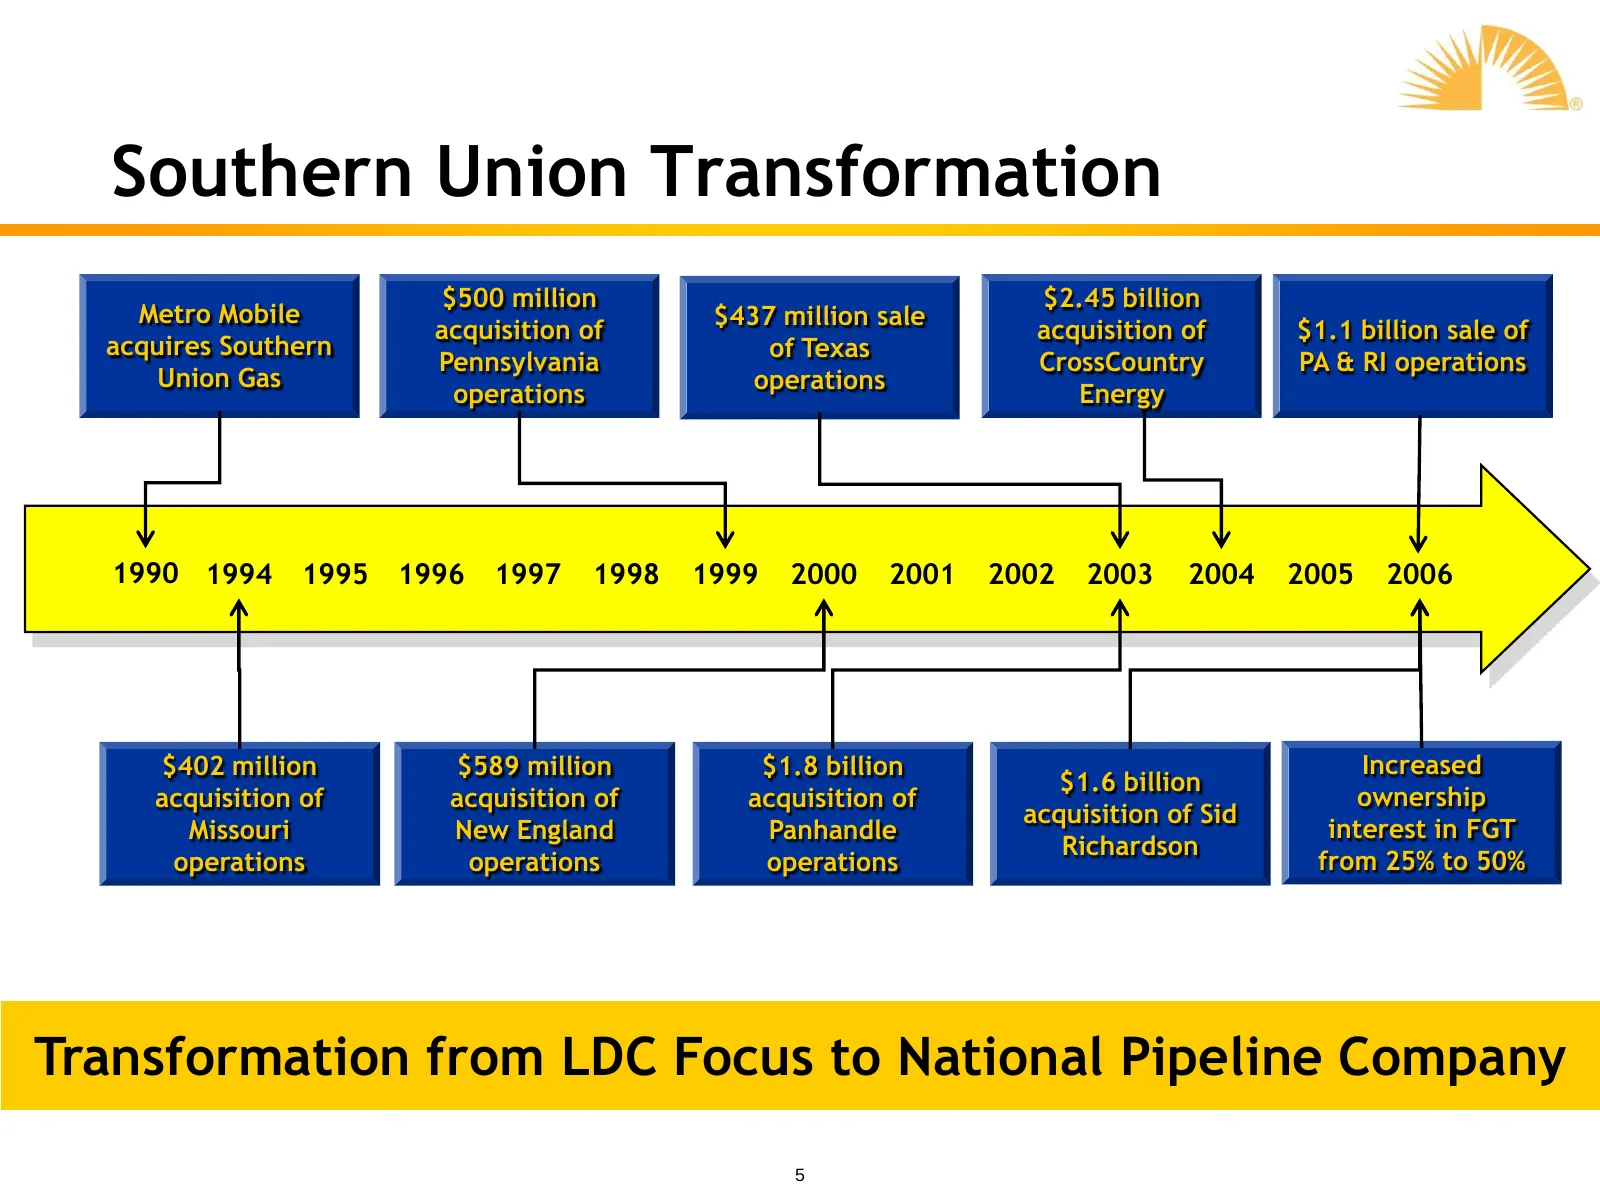
Southern Union Transformation $500 million $2.45 billion Metro Mobile $437 million sale acquisition of acquisition of $1.1 billion sale of acquires Southern of Texas Pennsylvania CrossCountry PA & RI operations Union Gas operations operations Energy 1990 1994 1995 1996 1997 1998 1999 2000 2001 2002
Slide 6: High Quality Assets
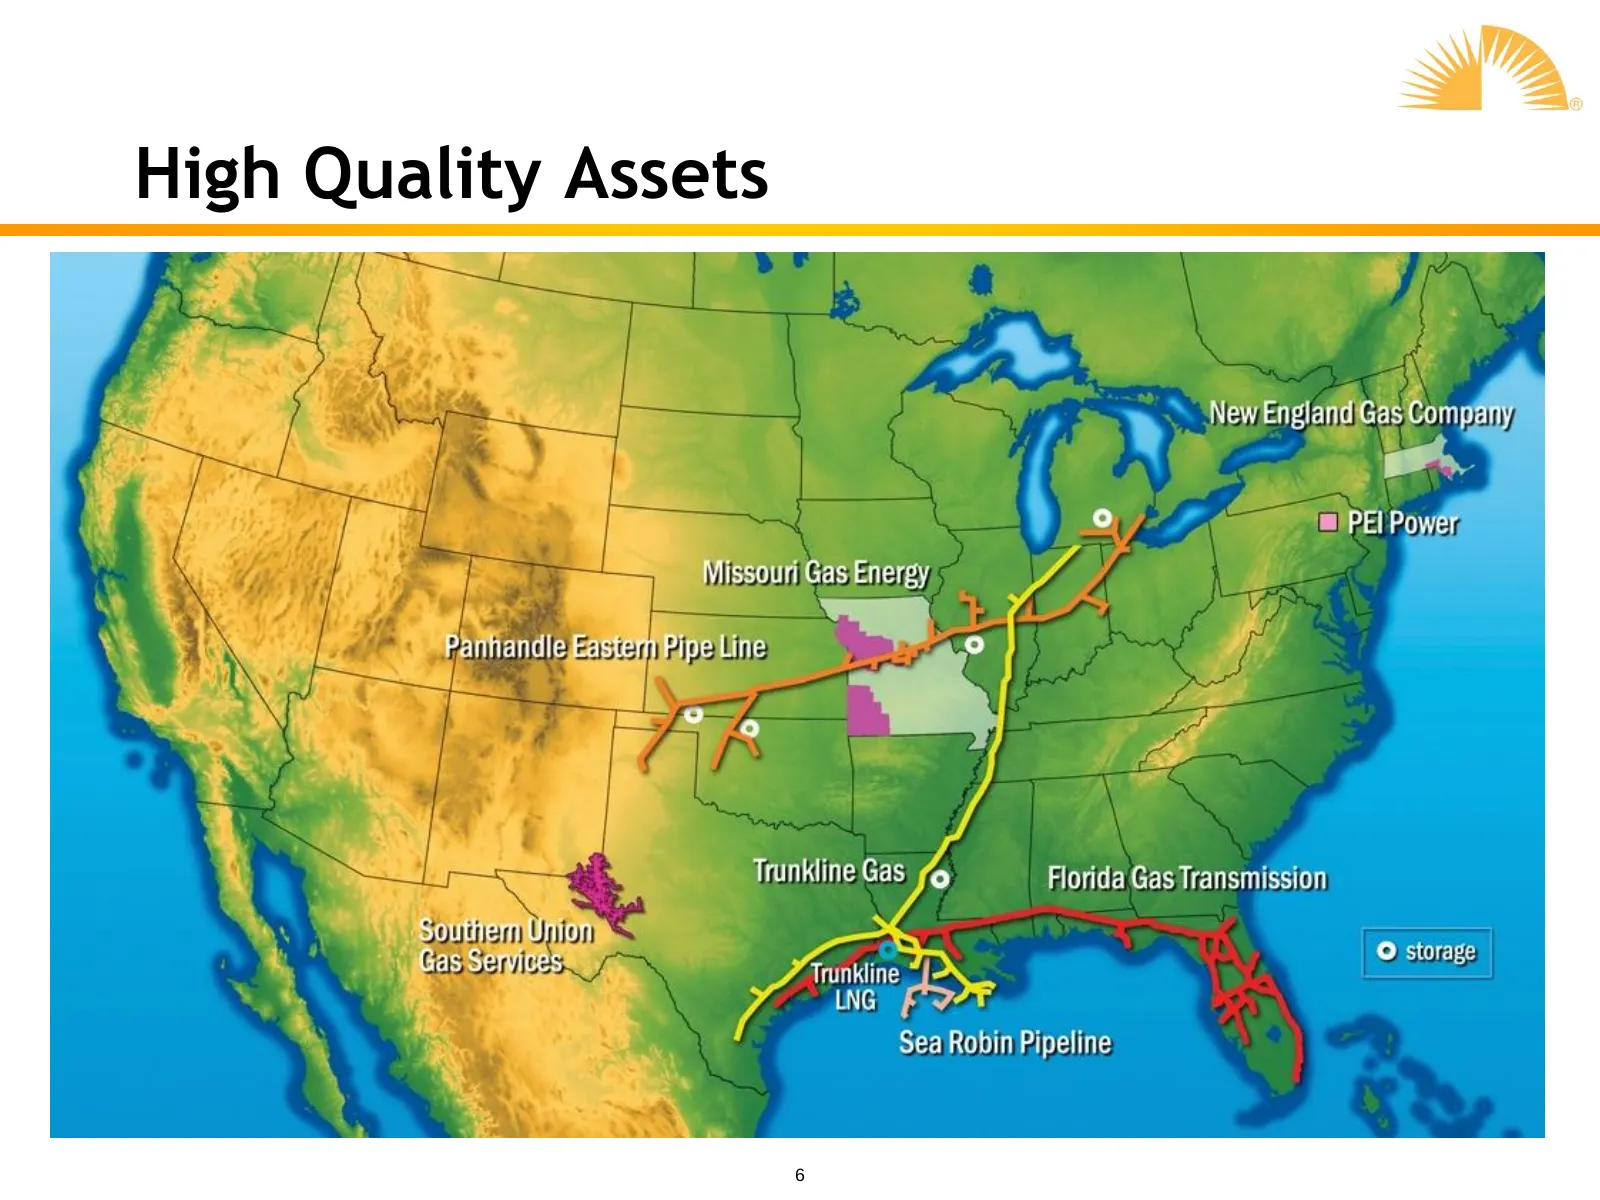
High Quality Assets ee Si Newengland Gas Companys 7 PEI Power = ] Missoun Gas Energy ae ah ... Line “=a Li | ra ae.) Trunkline Gas fo Florida Gas Transmission © storage Trunkline - LNG Sea Robin Pipeline
Slide 7: Business Segments
Business Segments Ni
Slide 8: Transportation & Storage
Transportation & Storage • Vast pipeline network with access to diverse supply sources and growing markets • Approximately 15,000 miles of interstate pipelines with transportation capacity of 7.8 Bcf/d • North America’s largest liquefied natural gas (LNG) import terminal with peak send out of 2.1 Bc
Slide 9: Gathering & Processing
Gathering & Processing • Extensive system in the prolific Permian Basin • Approximately 4,800 miles of pipelines • Five processing plants (four active) with a capacity of 470 MMcf/d • Eight treating plants (five active) with a capacity of 765 MMcf/d 9
Slide 10: Distribution & Other
Distribution & Other • Distribution serves approximately 550,000 customers in Missouri and Massachusetts • PEI Power owns interests in and operates 70 MW of “green energy” focused generating assets which supply electricity into the PJM Grid 10
Slide 11: Creating Shareholder Value
Creating Shareholder Value Ni
Slide 12: Value Creation
Value Creation • Value creation will come from: –Organic growth projects –Strategic initiatives –Prudent financial management Enhancing Shareholder Value 12
Slide 13: Organic Growth Projects
Organic Growth Projects • Vast pipeline network with access to multiple supply sources and diverse markets will help fuel organic growth • Analyze trends in the natural gas industry to identify opportunities • Recent open seasons: – FGT Phase VIII expansion – FGT Pascagoula lateral to serve GulfLNG
Slide 14: Strategic Initiatives
Strategic Initiatives • Evaluate and pursue market opportunities – Strategic acquisitions – Partnership or joint venture opportunities • Continue to evaluate market conditions for creating an MLP for gathering and processing assets Focus on Value Creation Opportunities 14
Slide 15: Prudent Financial Management
Prudent Financial Management • Preservation of investment grade ratings is important for: – Lower financing costs/eliminates collateral requirements – Improves rate making and regulatory relationships • Free cash flow may be used for: – Organic growth projects – Share repurchases – Increased dividen
Slide 16: Transportation & Storage
Transportation & Storage Ni
Slide 17: Transportation & Storage Assets
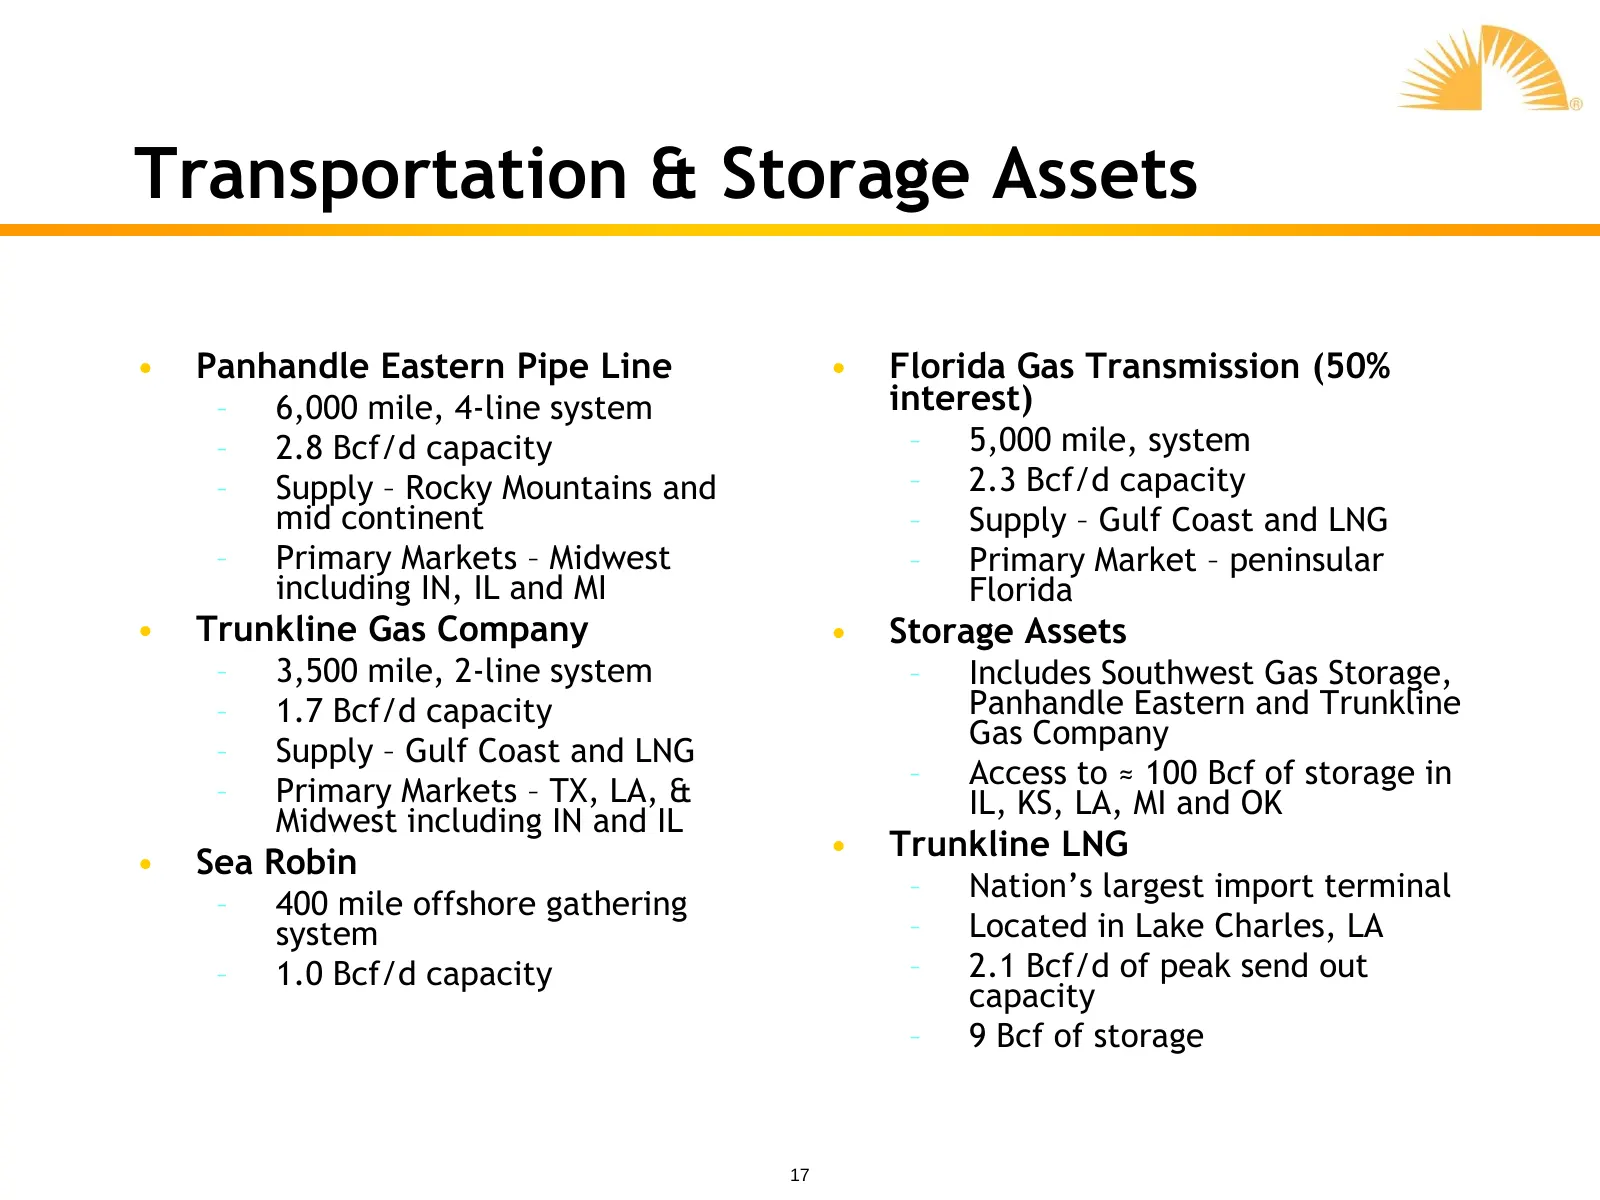
Transportation & Storage Assets • Panhandle Eastern Pipe Line • Florida Gas Transmission (50% – 6,000 mile, 4-line system interest) – 2.8 Bcf/d capacity – 5,000 mile, system – Supply – Rocky Mountains and – 2.3 Bcf/d capacity mid continent – Supply – Gulf Coast and LNG – Primary Markets – Midwest –
Slide 18: T&S Growth Drivers
T&S Growth Drivers Ni
Slide 19: Trunkline Field Zone Expansion
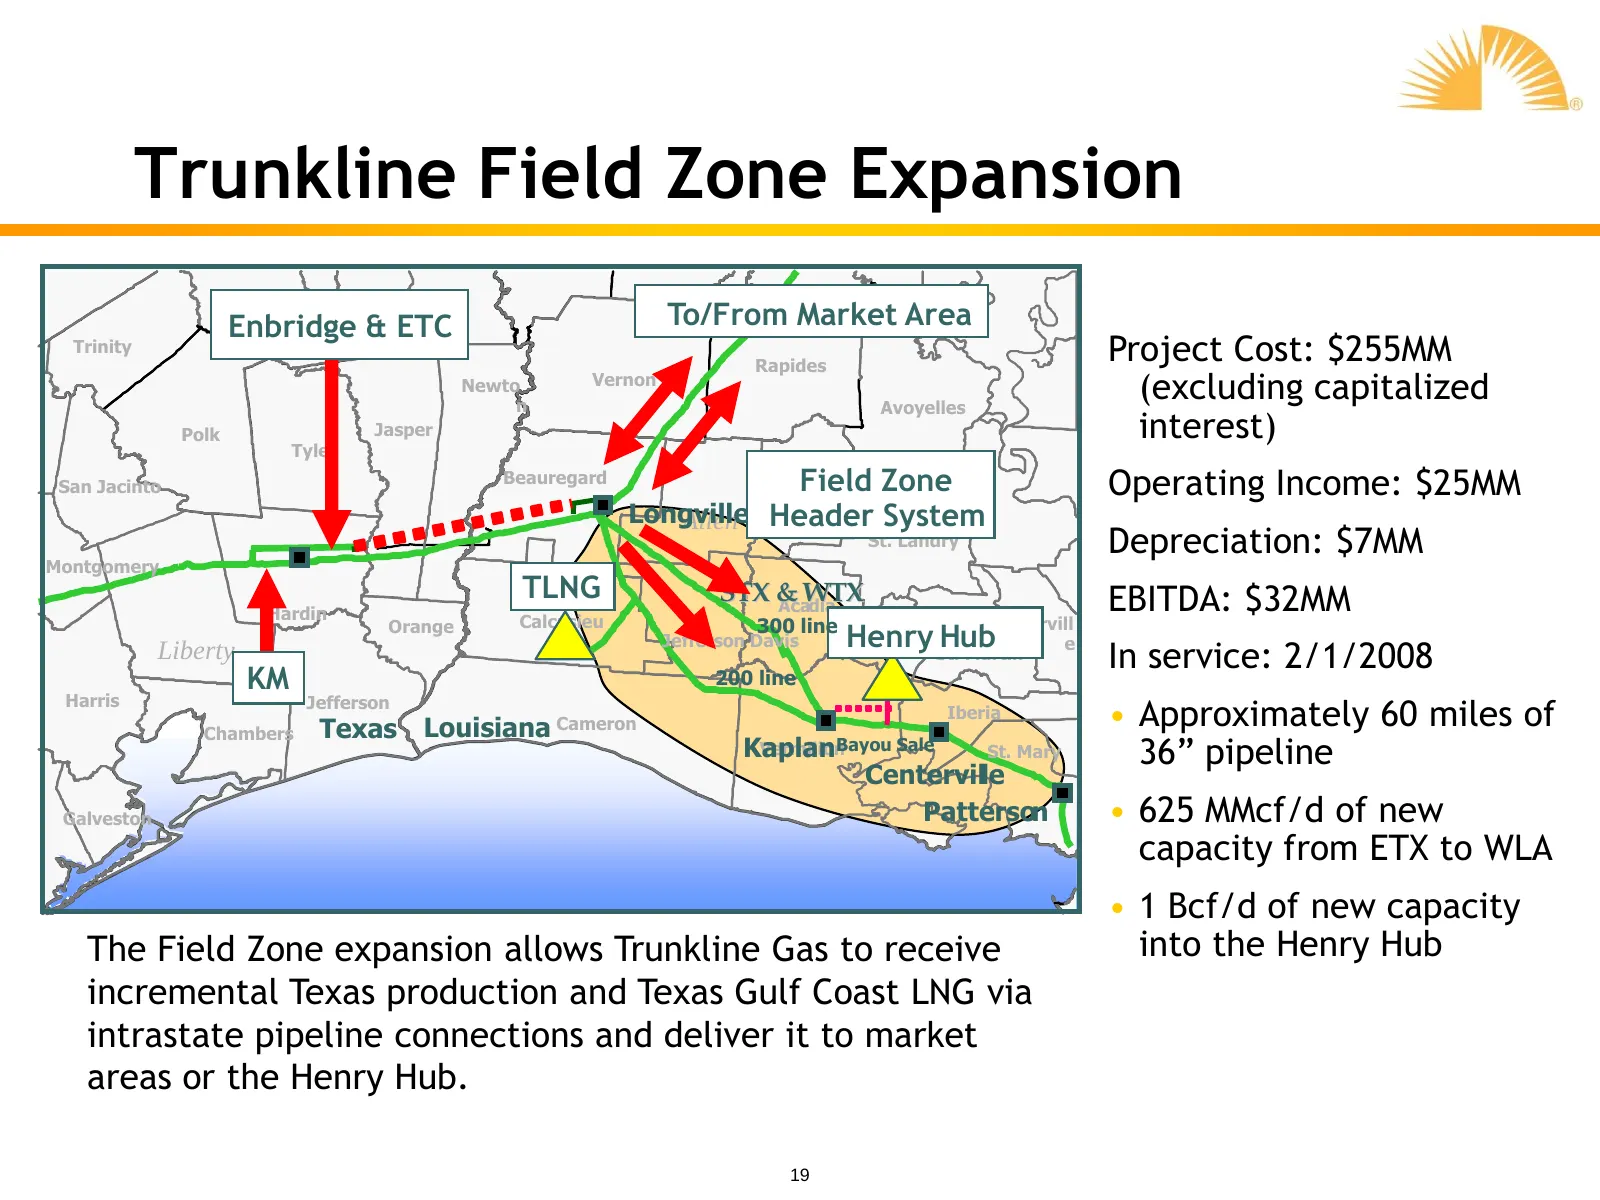
Trunkline Field Zone Expansion Enbridge Angelina & ETC To/From Market Area Trinity Rapides Project Cost: $255MM Newto n Vernon Avoyelles (excluding capitalized Polk Jasper interest) Tyler San Jacinto Beauregard Field Zone Evangeline Operating Income: $25MM Allen Header System Longville St. Landry De
Slide 20: Trunkline LNG: Infrastructure Enhancement Project
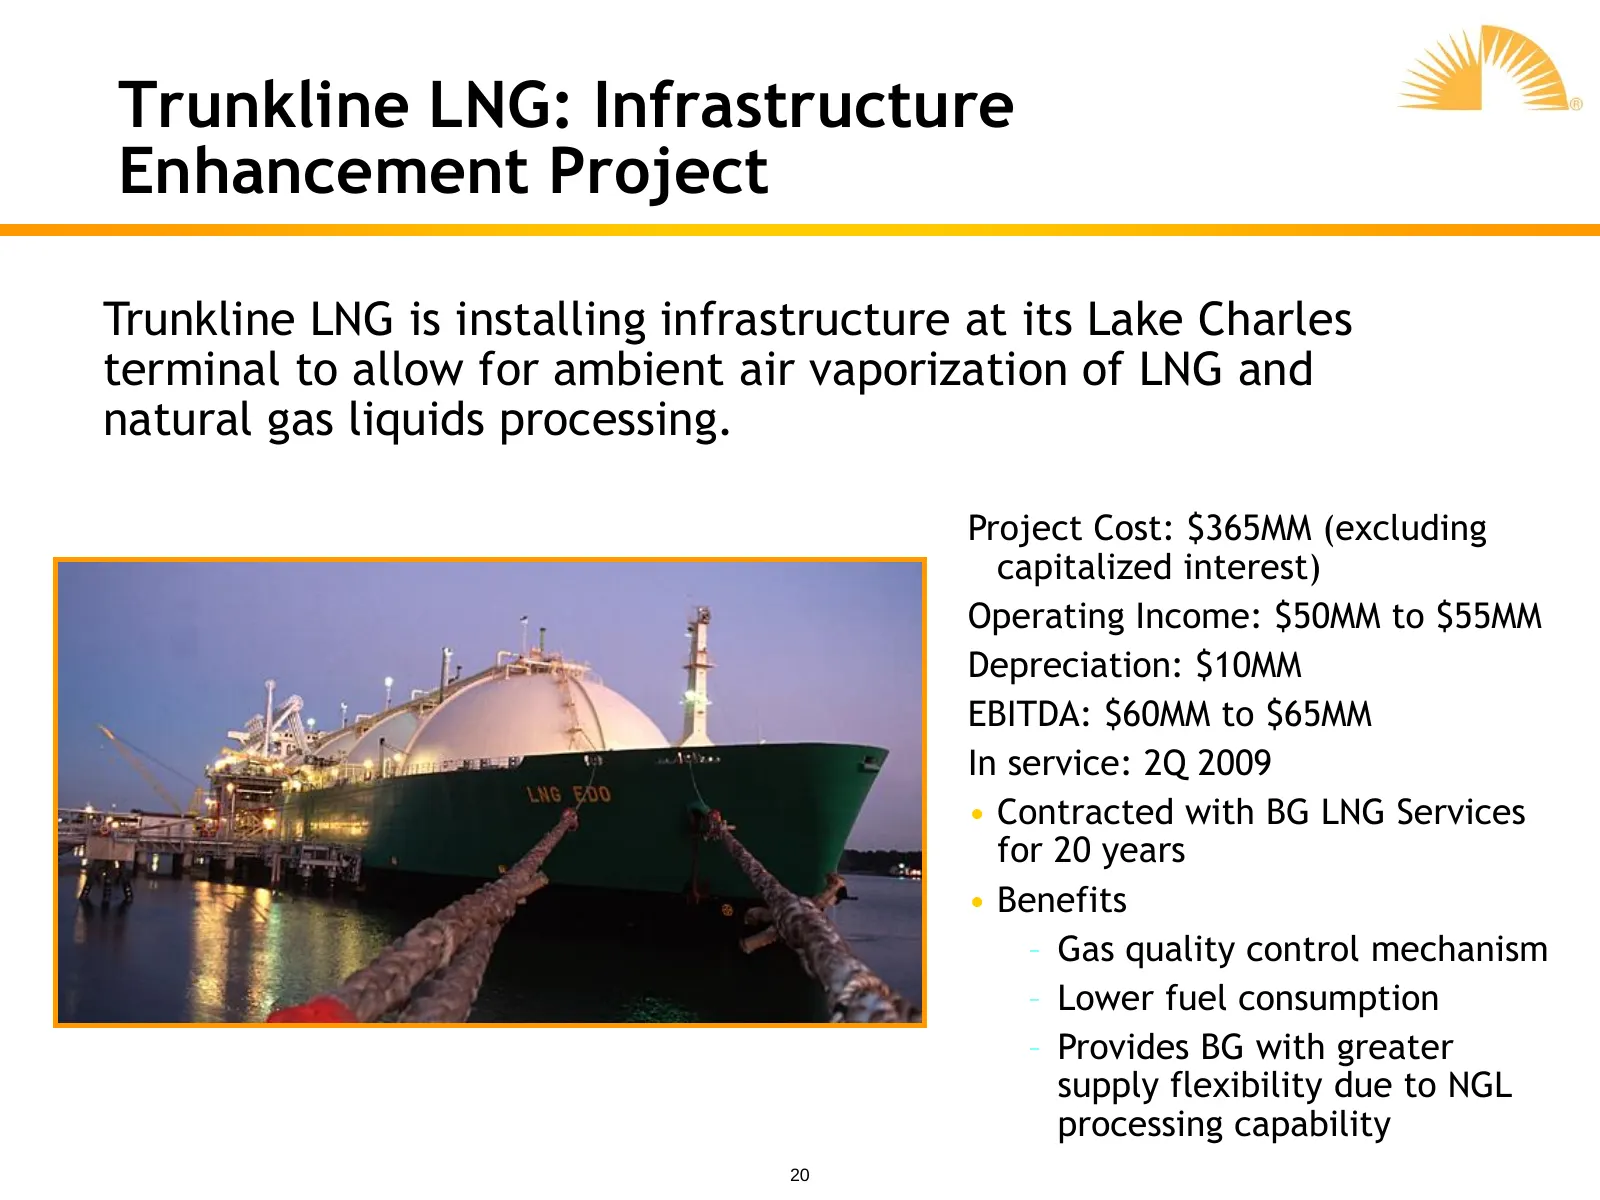
Trunkline LNG: Infrastructure Enhancement Project Trunkline LNG is installing infrastructure at its Lake Charles terminal to allow for ambient air vaporization of LNG and natural gas liquids processing. Project Cost: $365MM (excluding capitalized interest) Operating Income: $50MM to $55MM Depreciati
Slide 21: FGT Phase VIII Expansion
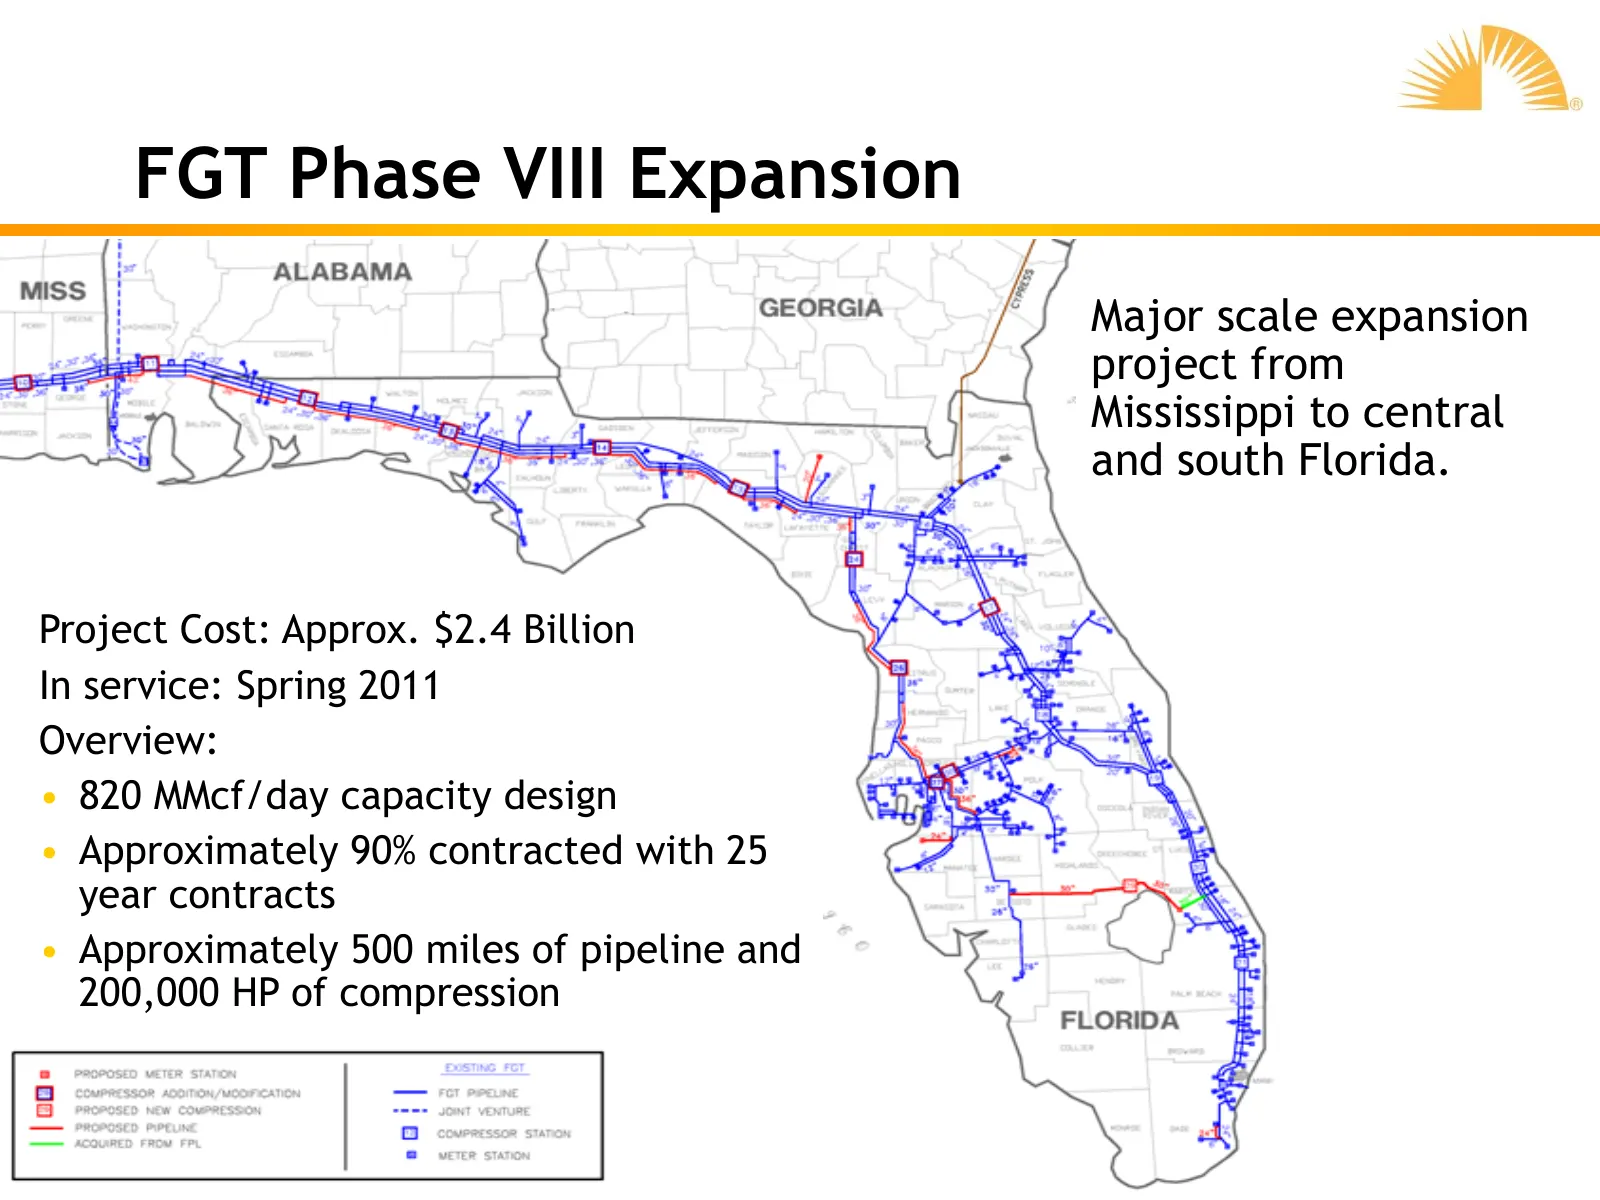
FGT Phase VIII Expansion Major scale expansion project from Mississippi to central and south Florida. Project Cost: Approx. $2.4 Billion In service: Spring 2011 Overview: • 820 MMcf/day capacity design • Approximately 90% contracted with 25 year contracts • Approximately 500 miles of pipeline and 20
Slide 22: FGT Phase VIII Expansion Timeline
FGT Phase VIII Expansion Timeline • Open season ran January 14 through February 15 • Expect to file FERC Certificate – Fall 2008 • Expect FERC Approval – Fall 2009 • Target In-Service Date – Spring 2011 • Expect operating income of $240 to $260 million, depreciation of $50 million and EBITDA of appr
Slide 23: FGT Pascagoula Lateral
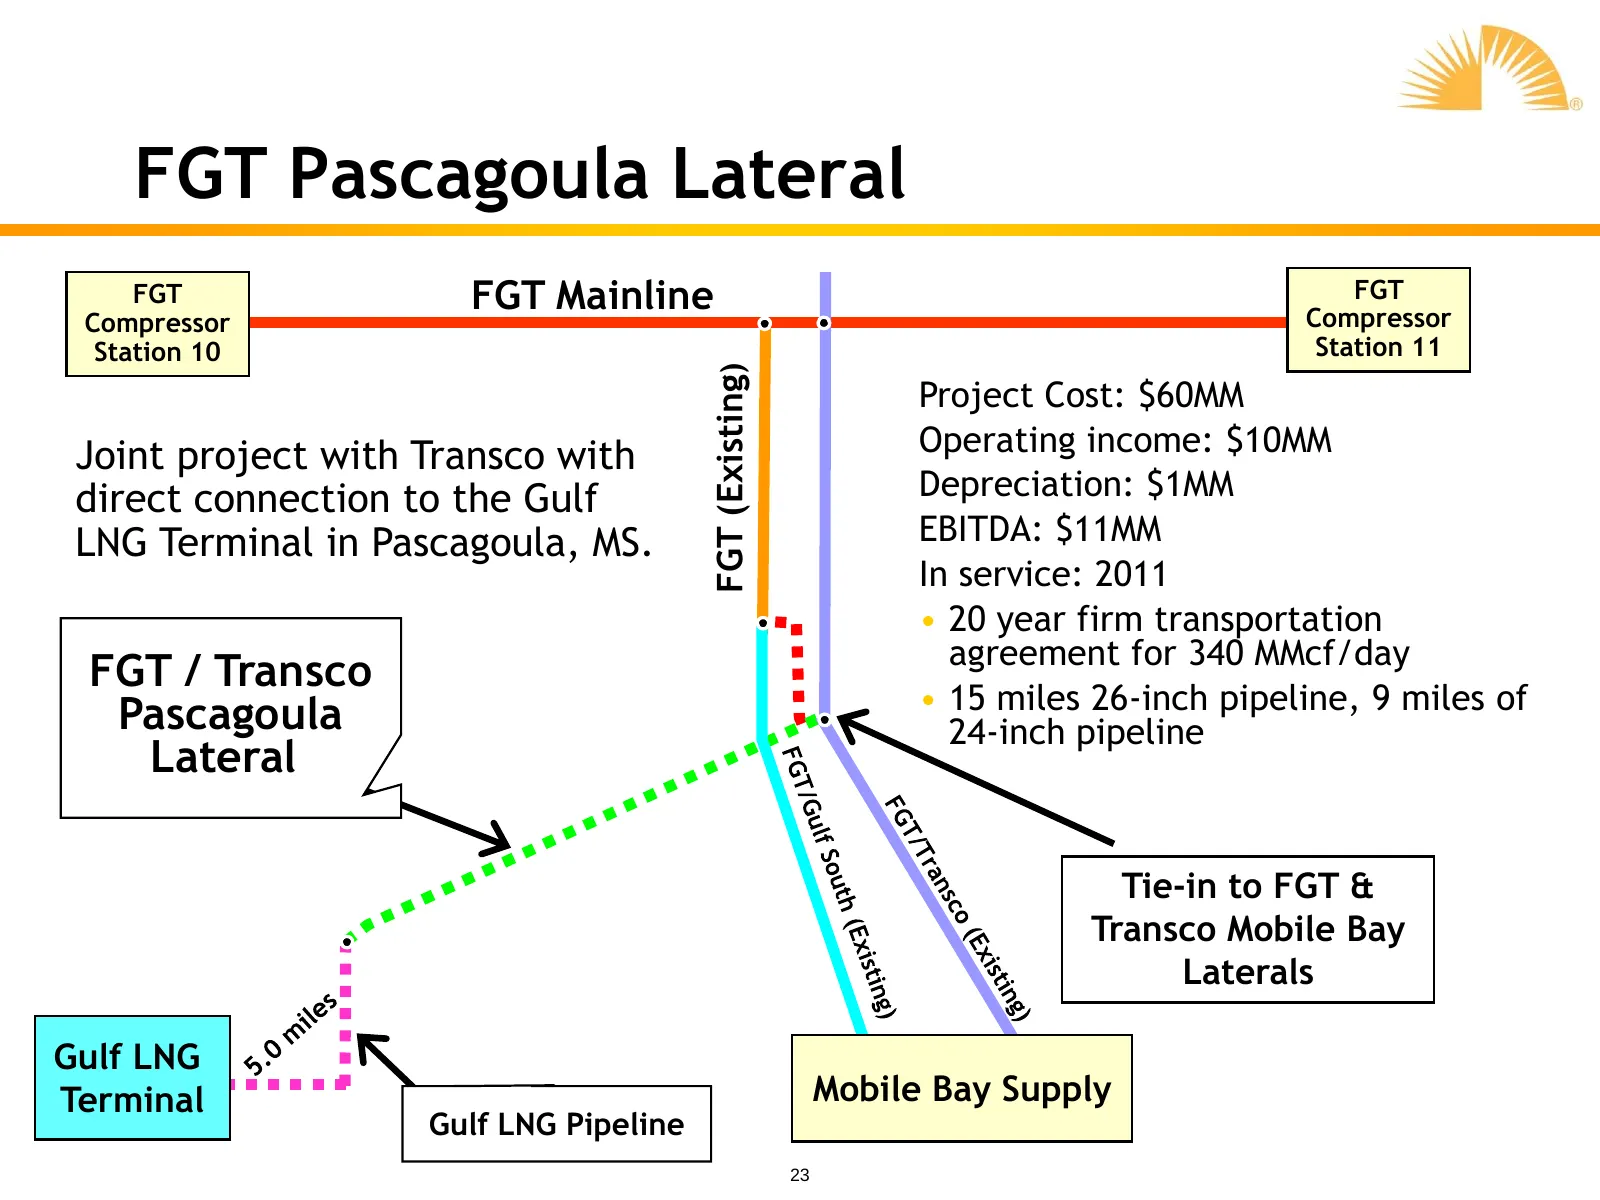
FGT Pascagoula Lateral FGT FGT Mainline FGT Compressor Compressor Station 10 Station 11 FGT (Existing) Project Cost: $60MM Joint project with Transco with Operating income: $10MM direct connection to the Gulf Depreciation: $1MM LNG Terminal in Pascagoula, MS. EBITDA: $11MM In service: 2011 • 20 year
Slide 24: Gathering & Processing
Gathering & Processing Ni
Slide 25: Map of Operations
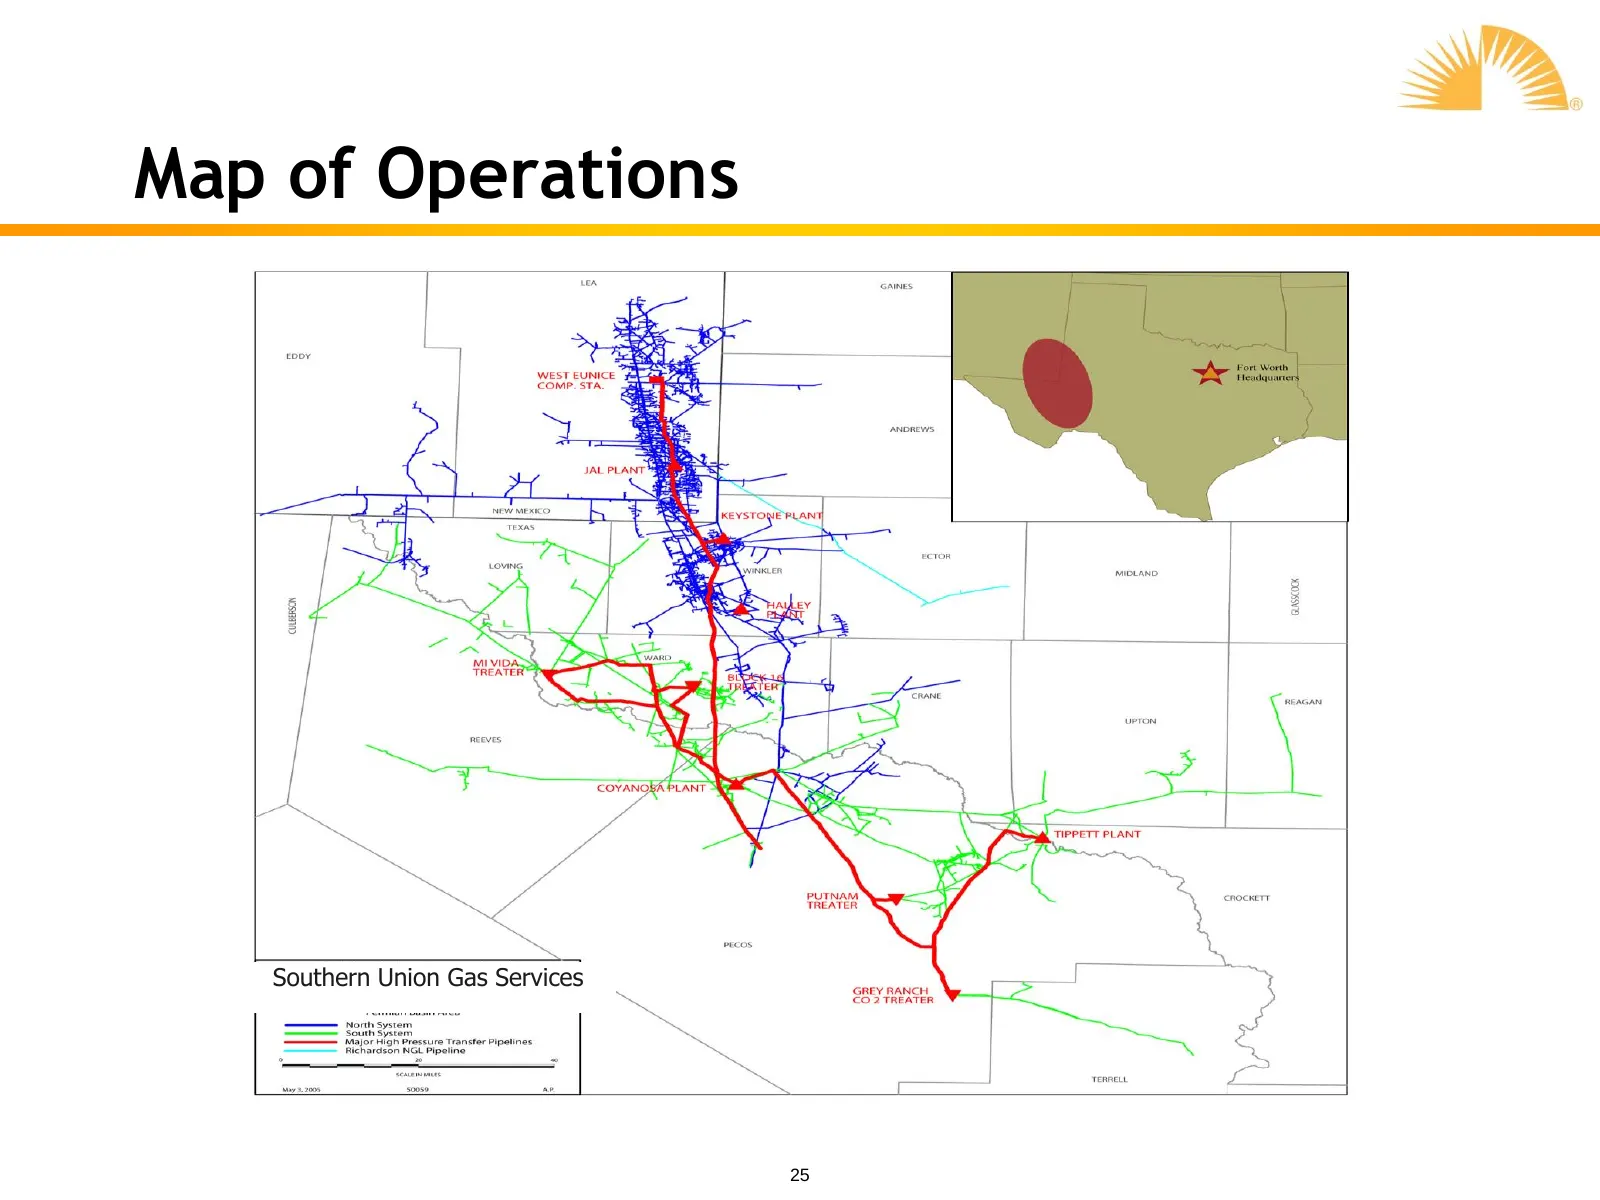
Map of Operations •Southern Union Gas Services 25
Slide 26: SUGS Overview
SUGS Overview • Located in prolific, long-lived Permian Basin • Approximately 4,800 miles of gas and liquids pipelines covering 16 counties in West Texas/Southeast New Mexico • Two fully-integrated midstream systems connected via high-pressure pipeline network – North System: Jal and Keystone – Sout
Slide 27: North System
North System • Consists of the Jal and Keystone Systems – Large diameter predominately low pressure pipelines – Wellhead volume of 250,000 MMBtu/d of 5.0 GPM sour gas – 220 MMcf/d cryogenic plant capacity – 23,000 bbls/d NGL production – 40 tons/d sulfur plant capacity – Recent compression and high
Slide 28: South System
South System • Consists of the Mi Vida, Coyanosa and Tippett Systems – High pressure integrated sweet and sour gas gathering system – Wellhead volume 330,000 MMBtu/d – 190 MMcf/d cryogenic processing capacity – Plant inlet of 175 MMcf/d of 3.5 GPM gas producing 11,200 bbls/d of NGLs – 370 MMcf/d tre
Slide 29: High Pressure Transfer System
High Pressure Transfer System • Acquired 84 miles of 16-inch/24-inch pipelines from NNG in 2004 • Installed 16 miles of 16-inch high pressure sour gas pipeline between Keystone and Jal in June 2007 • Provides operational flexibility – Transfer processable gas between plants – Move sour, lean gas bet
Slide 30: Diversified, Active Producer Portfolio
Diversified, Active Producer Portfolio • Stable and active producer base • Diversified portfolio of oil and gas companies • Strong producer relationships – Focus on customer service • Significant customers include Chesapeake, Anadarko, Apache, ExxonMobil, ConocoPhillips, ChevronTexaco, BEPCo, Devon
Slide 31: Gas Supply – Contract Risk Mitigation
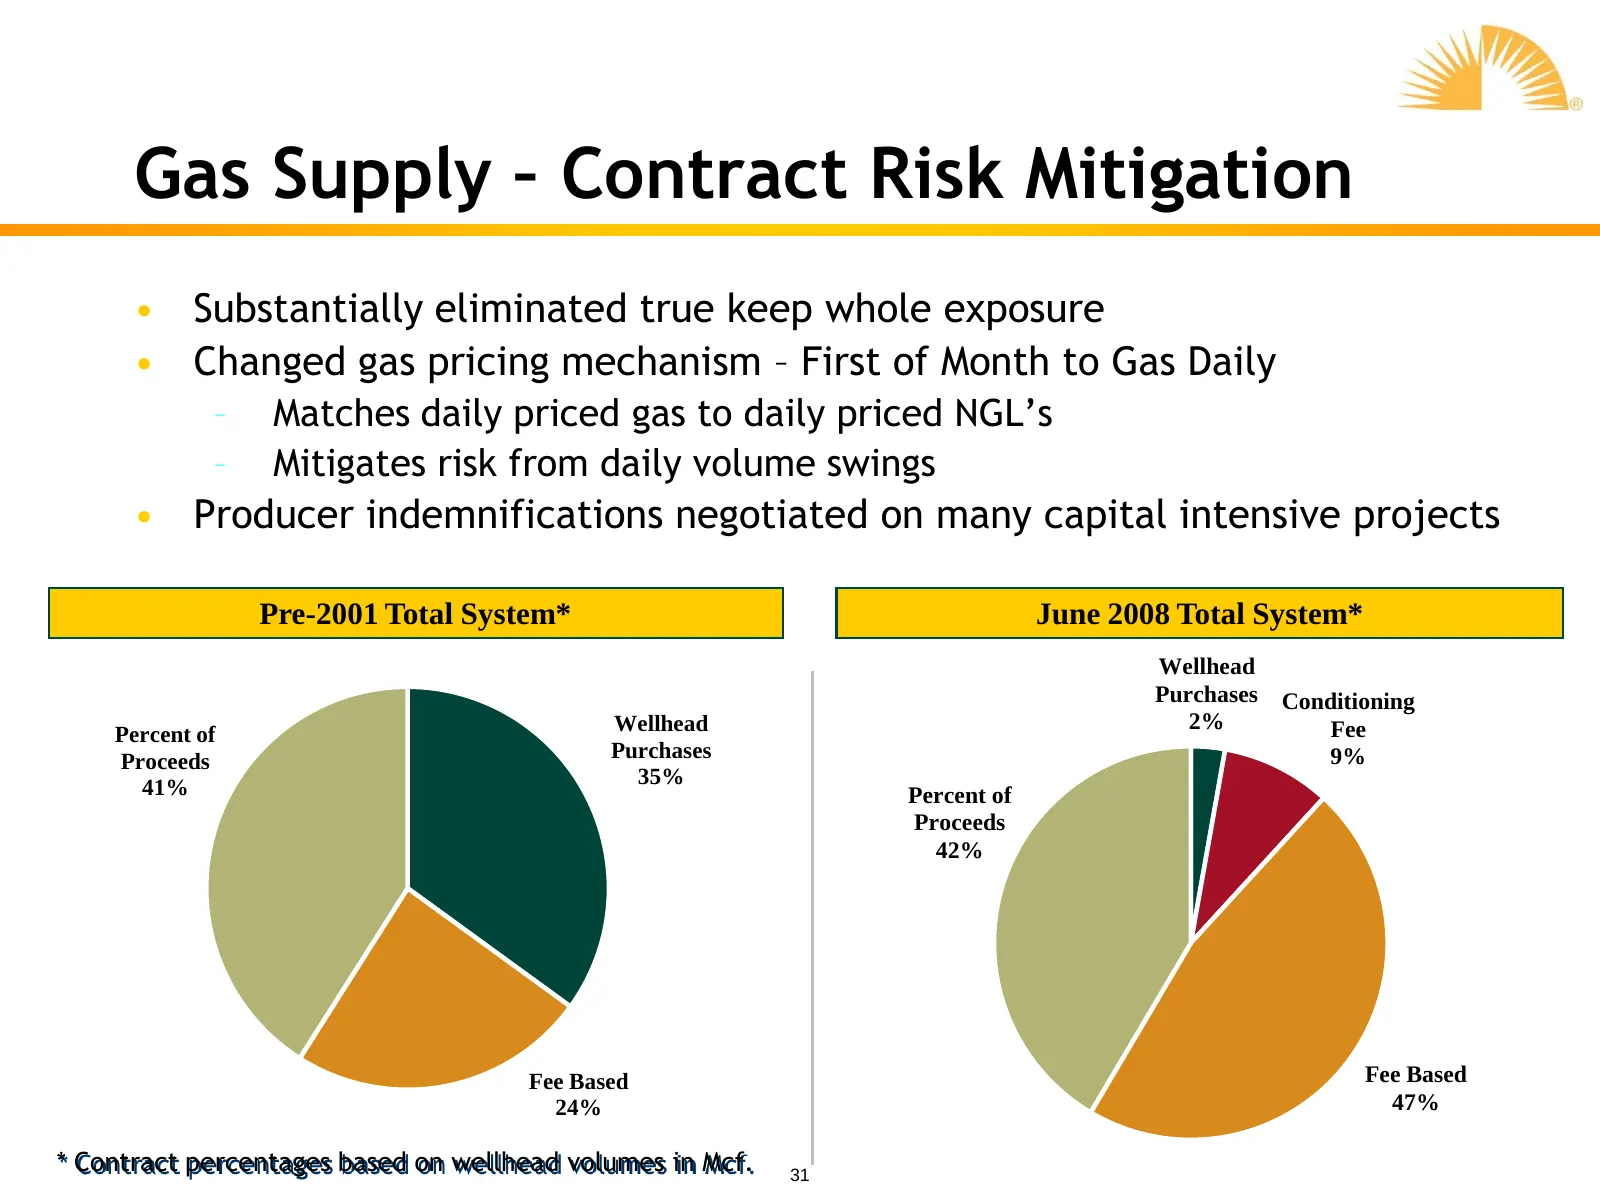
Gas Supply – Contract Risk Mitigation • Substantially eliminated true keep whole exposure • Changed gas pricing mechanism – First of Month to Gas Daily – Matches daily priced gas to daily priced NGL’s – Mitigates risk from daily volume swings • Producer indemnifications negotiated on many capital in
Slide 32: Key Assumptions for 2008
Key Assumptions for 2008 • Positive processing spread environment allows conversion of equity into mostly natural gas liquids • Equity volumes average 40,000 to 45,000 MMBtu/d (converted from NGL gallons to BTUs) • Normalized FF&U levels • Incorporates current hedging program 32
Slide 33: Hedged Positions
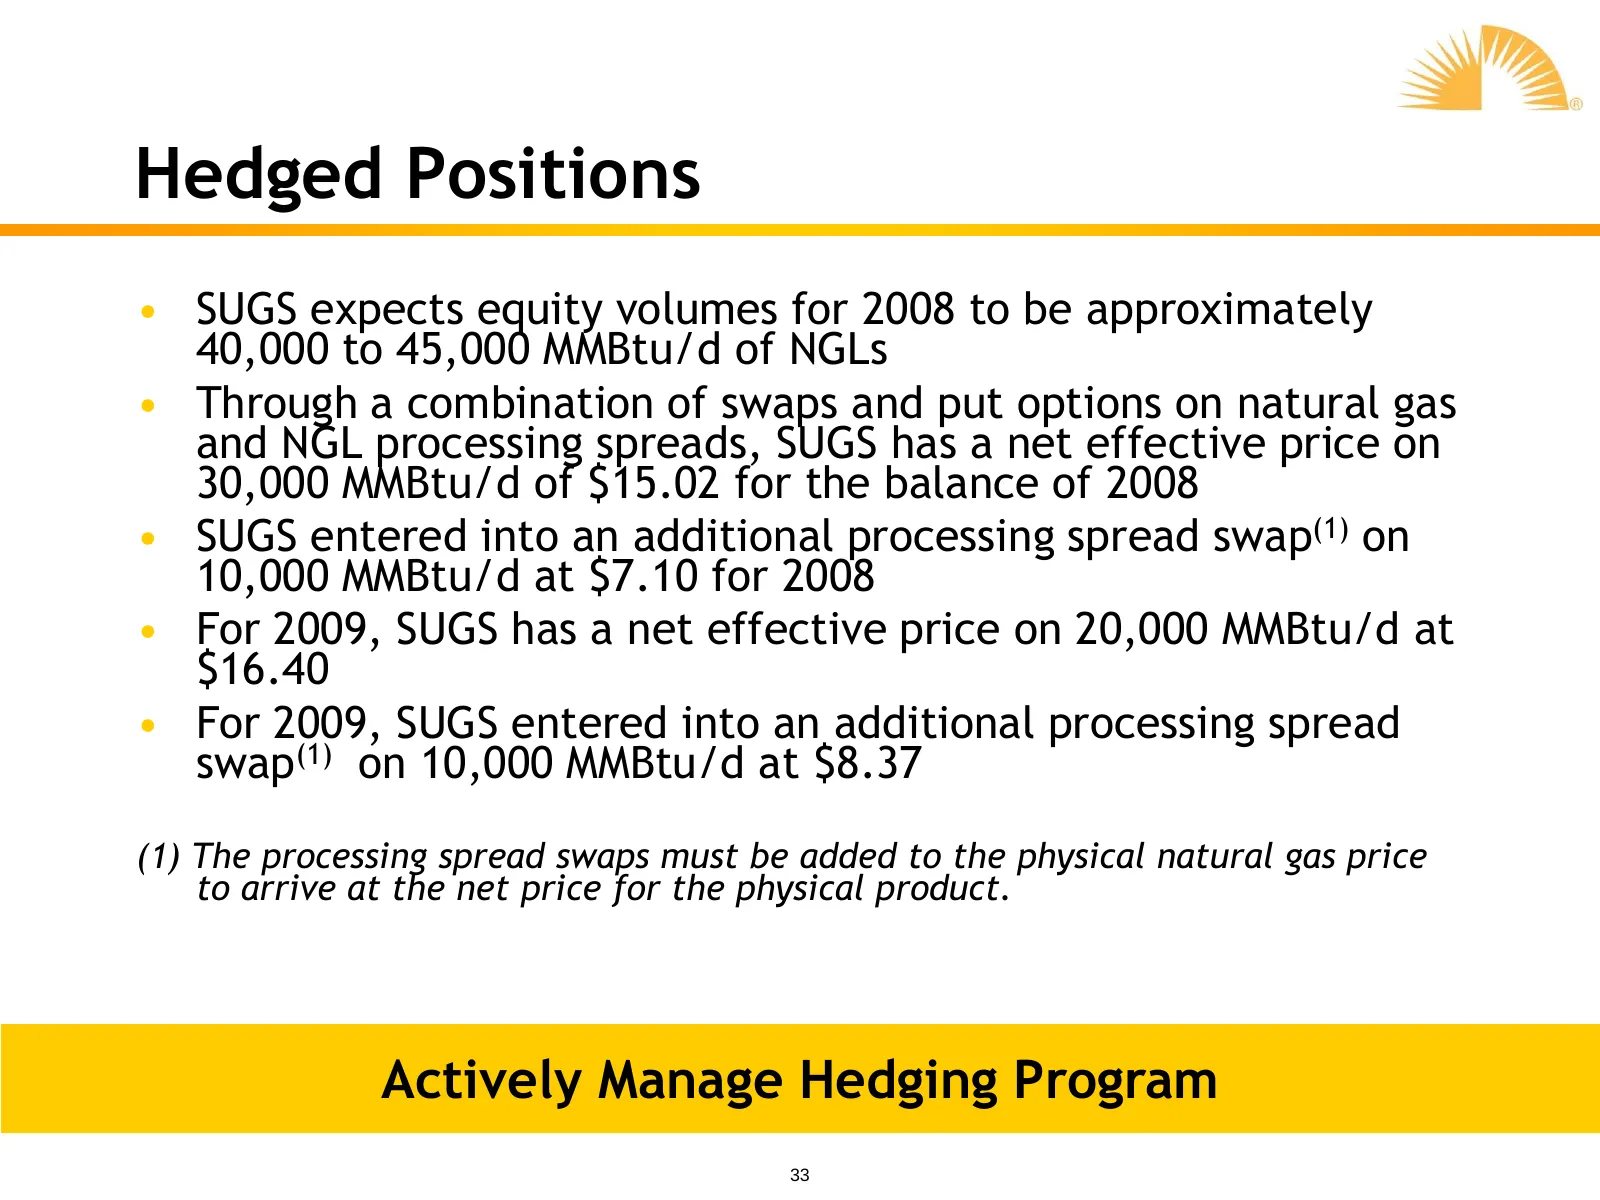
Hedged Positions • SUGS expects equity volumes for 2008 to be approximately 40,000 to 45,000 MMBtu/d of NGLs • Through a combination of swaps and put options on natural gas and NGL processing spreads, SUGS has a net effective price on 30,000 MMBtu/d of $15.02 for the balance of 2008 • SUGS entered i
Slide 34: G&P Growth Drivers
G&P Growth Drivers Ni
Slide 35: Growth Drivers
Growth Drivers • Aggressively pursue new business • Operating & maintenance expense management • Invest capital throughout the system to ensure efficiency • Exploit competitive advantages 35
Slide 36: SUGS Growth Projects
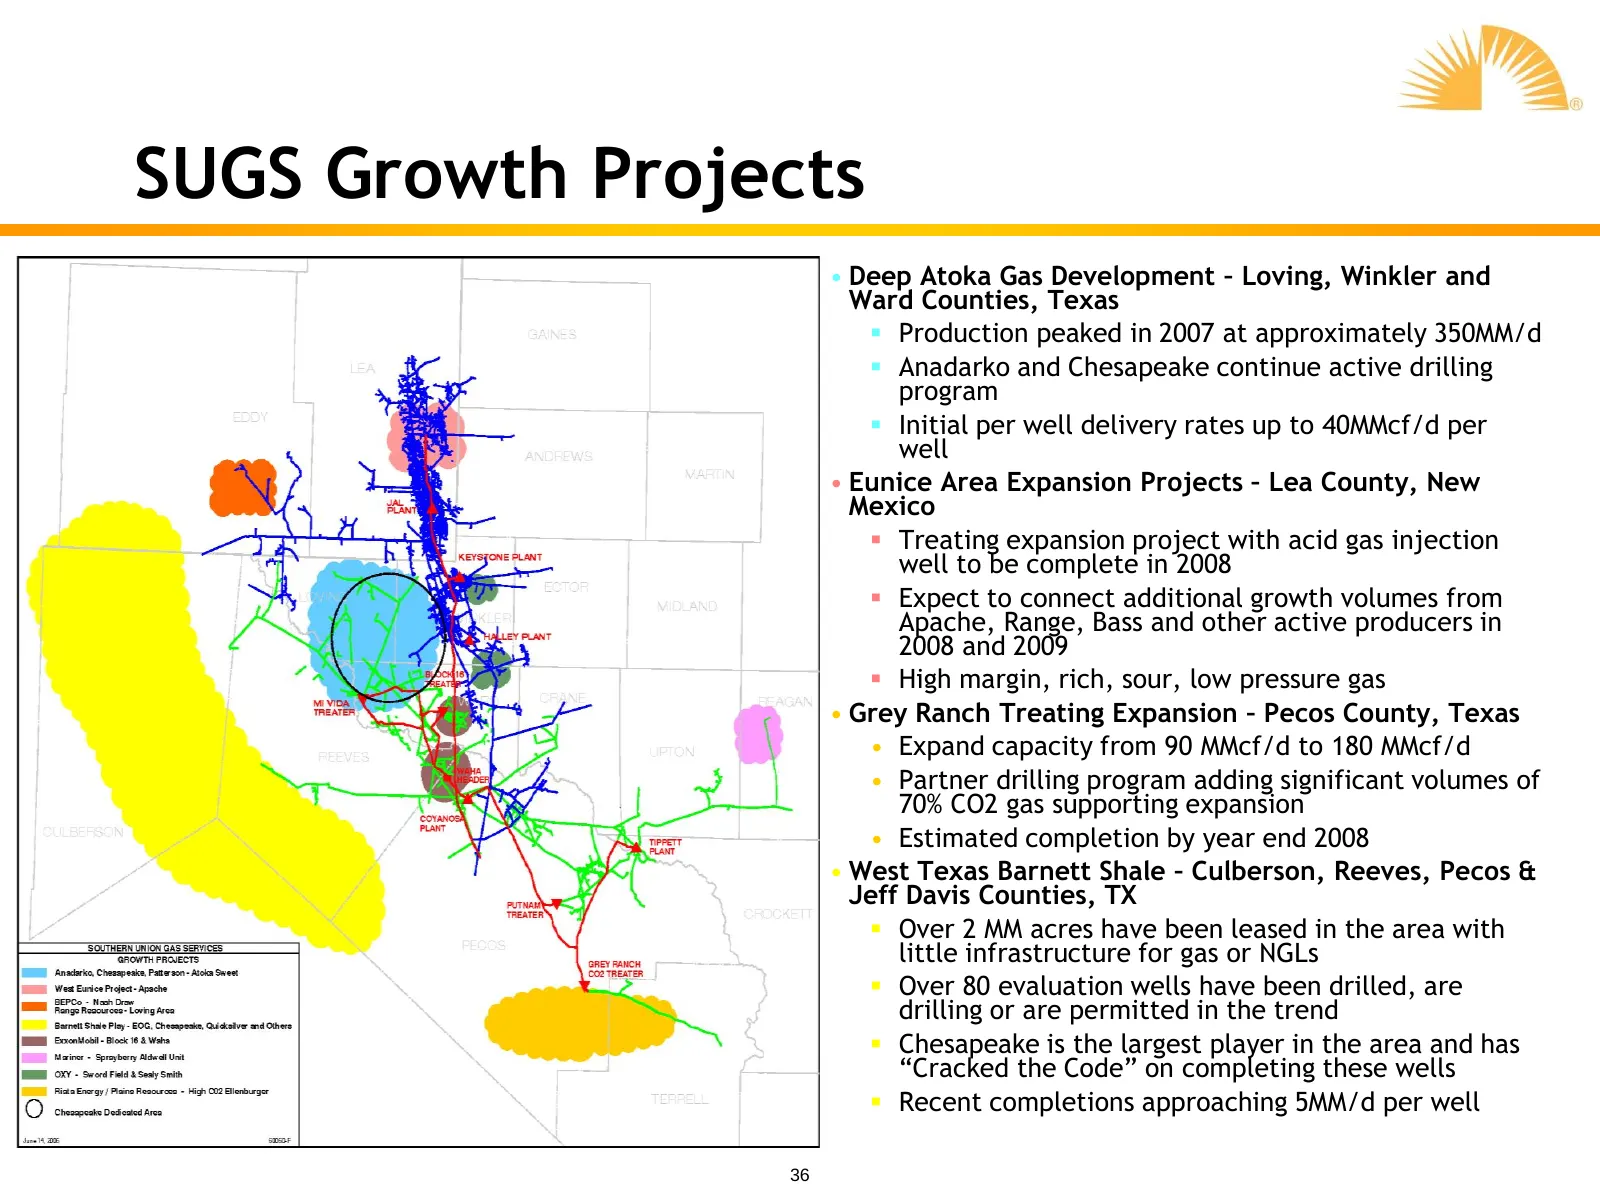
SUGS Growth Projects • Deep Atoka Gas Development – Loving, Winkler and Ward Counties, Texas Production peaked in 2007 at approximately 350MM/d Anadarko and Chesapeake continue active drilling program Initial per well delivery rates up to 40MMcf/d per well • Eunice Area Expansion Projects – Le
Slide 37: Distribution & Other
Distribution & Other Ni
Slide 38: Missouri Gas Energy
Missouri Gas Energy Missouri Gas Energy is a local distribution company serving central and western Missouri • Provides natural gas to over 500,000 customers • Nearly 13,000 miles of main and service lines • MGE received a $27.2MM annual revenue increase in 2007 – MGE received a straight fixed-varia
Slide 39: New England Gas Company
New England Gas Company New England Gas Company is a local distribution company serving North Attleboro and Fall River, MA • Provides natural gas to 50,000 customers • Nearly 2,000 miles of main and service lines • NEGCO received a $4.6MM annual revenue increase in 2007 – Settlement includes mechani
Slide 40: 2008 Outlook
2008 Outlook Ni
Slide 41: Guidance and EBITDA Outlook
Guidance and EBITDA Outlook • 2008 earnings guidance – SUG’s earnings guidance range is $1.80 to $1.90 per share – Guidance range is driven by: Commodity price impact on unhedged gathering & processing volumes and operating efficiency Operating and maintenance expense containment Timing and am
Slide 42: Pro forma EBITDA Guidance
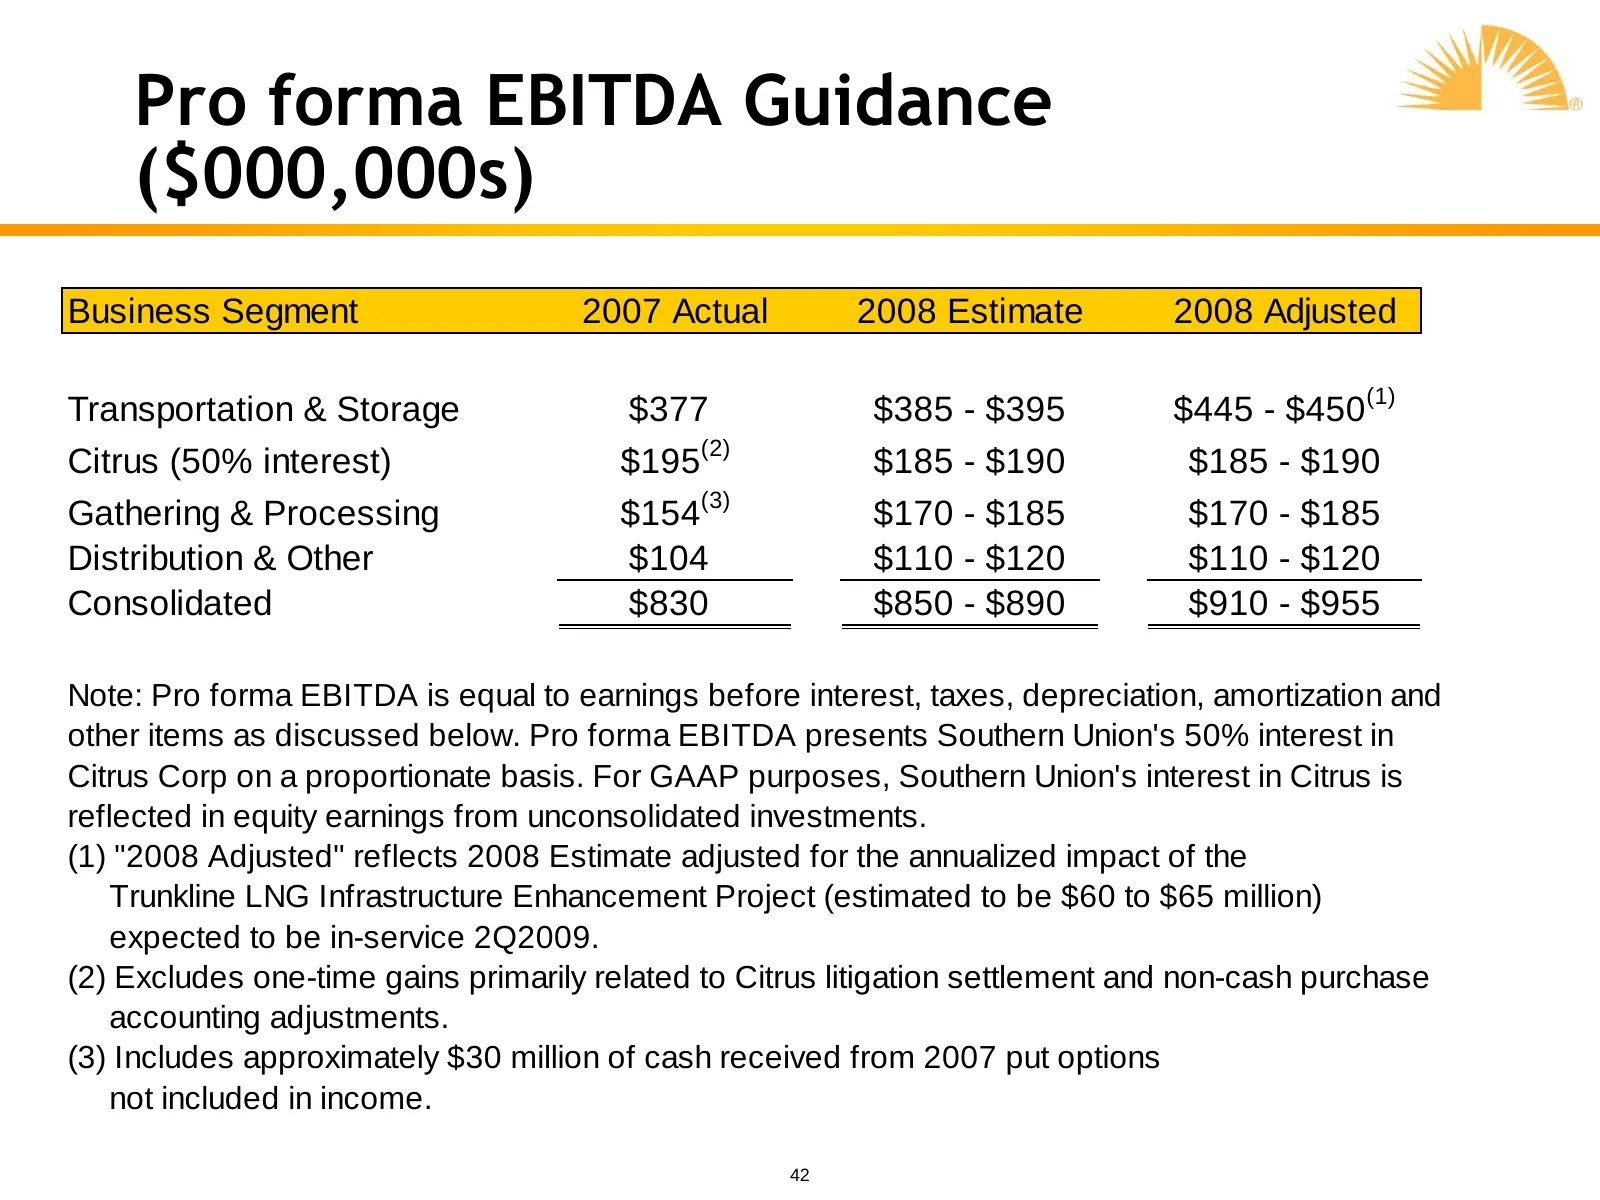
Pro forma EBITDA Guidance ($000,000s) Business Segment 2007 Actual 2008 Estimate 2008 Adjusted Transportation & Storage $377 $385 - $395 $445 - $450(1) Citrus (50% interest) $195(2) $185 - $190 $185 - $190 Gathering & Processing $154(3) $170 - $185 $170 - $185 Distribution & Other $104 $110 - $120 $
Slide 43: 2008 Capital Expenditure Guidance
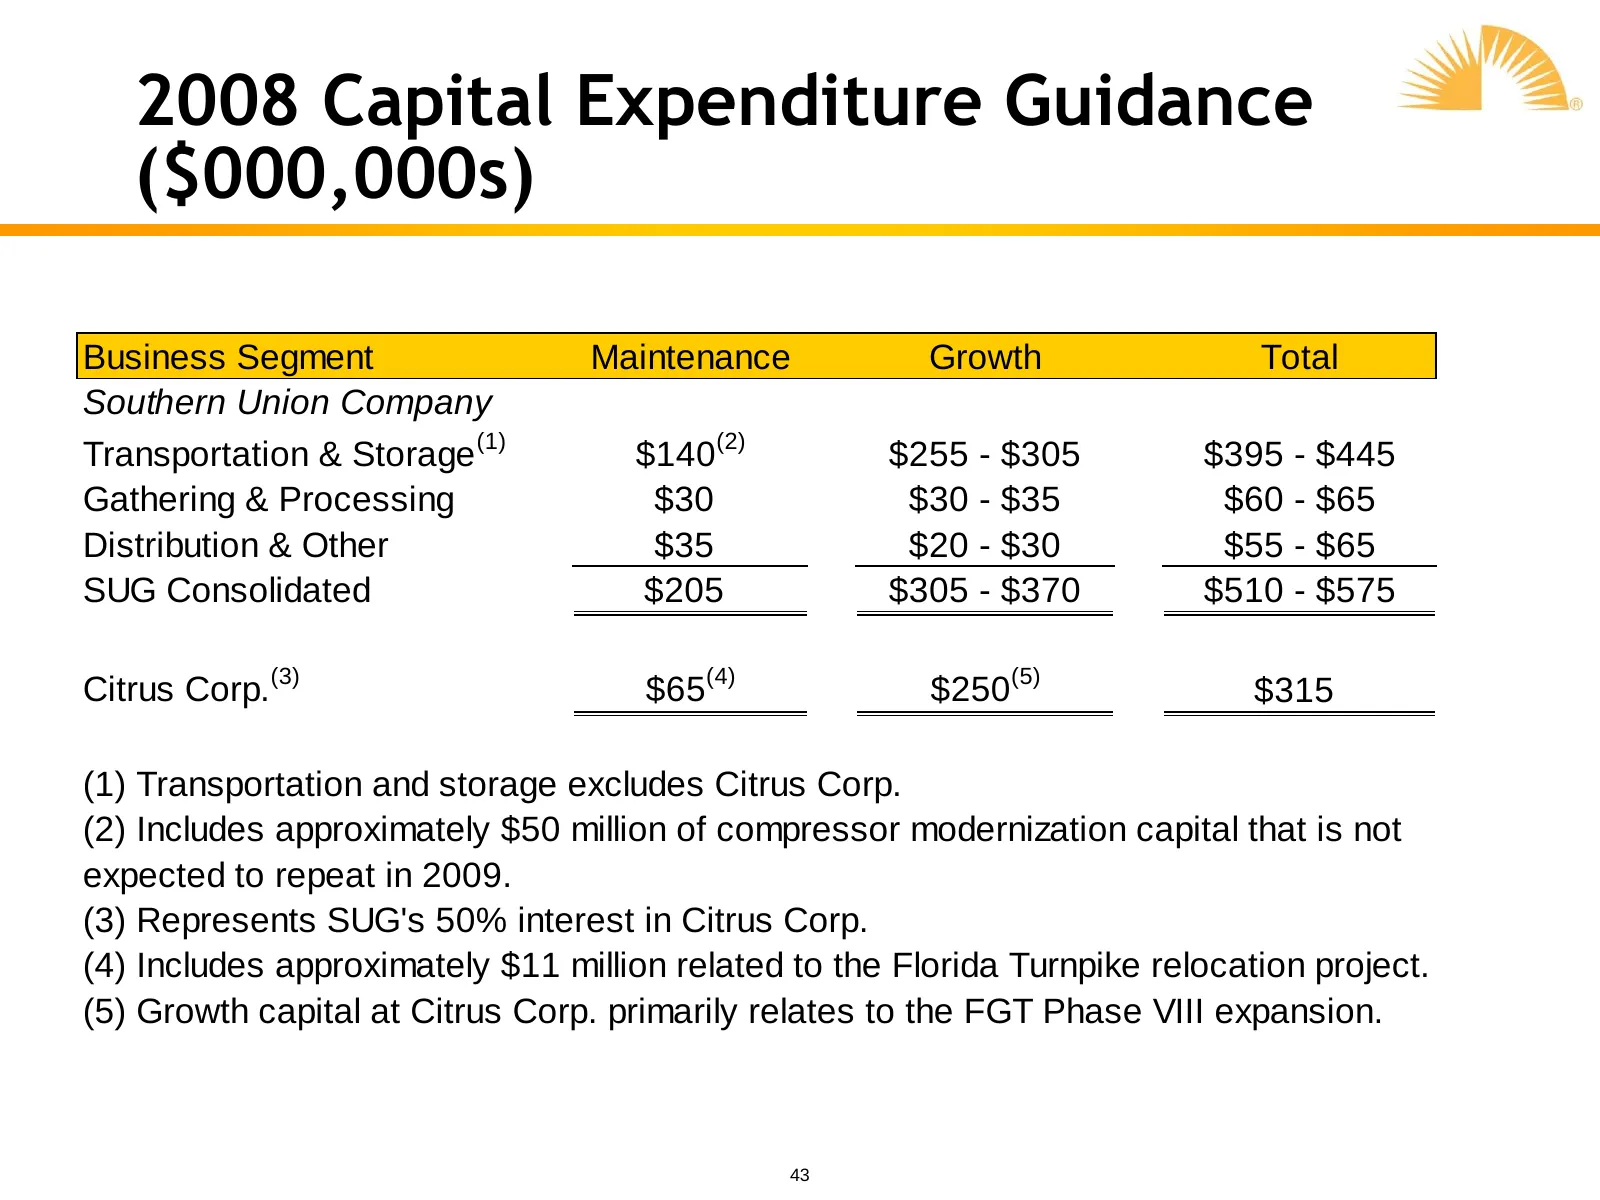
2008 Capital Expenditure Guidance ($000,000s) Business Segment Maintenance Growth Total Southern Union Company Transportation & Storage (1) $140(2) $255 - $305 $395 - $445 Gathering & Processing $30 $30 - $35 $60 - $65 Distribution & Other $35 $20 - $30 $55 - $65 SUG Consolidated $205 $305 - $370 $5
Slide 44: 2008 EBITDA by Segment
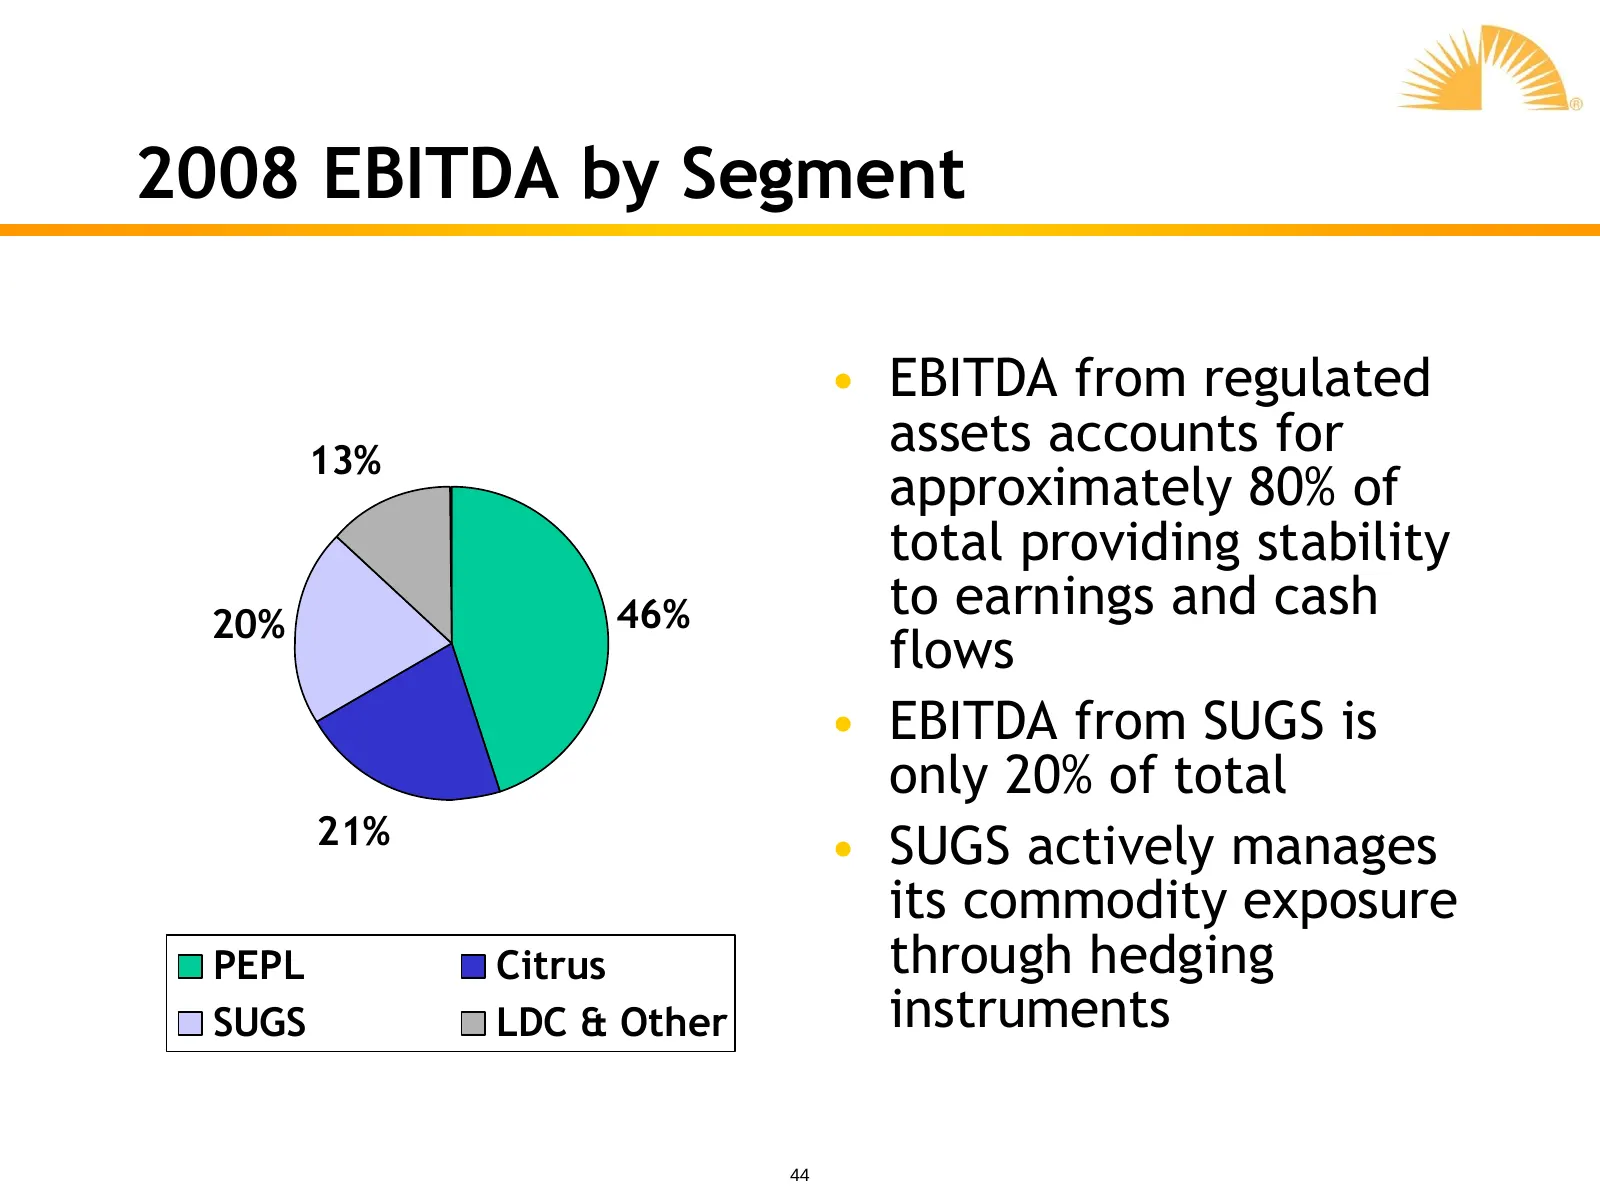
2008 EBITDA by Segment • EBITDA from regulated 13% assets accounts for approximately 80% of total providing stability 20% 46% to earnings and cash flows • EBITDA from SUGS is only 20% of total 21% • SUGS actively manages its commodity exposure PEPL Citrus through hedging SUGS LDC & Other instruments
Slide 45: Conclusion
Conclusion yr
Slide 46: Summary
Summary • Compelling vision and clear strategic plan going forward – Strategic transformation and value creation achieved – Organic growth projects with clear visibility towards earnings growth and value creation – Balance preservation of investment grade credit ratings and return of capital to shar
Slide 47: Appendix
Appendix yr
Slide 48: Company Facts
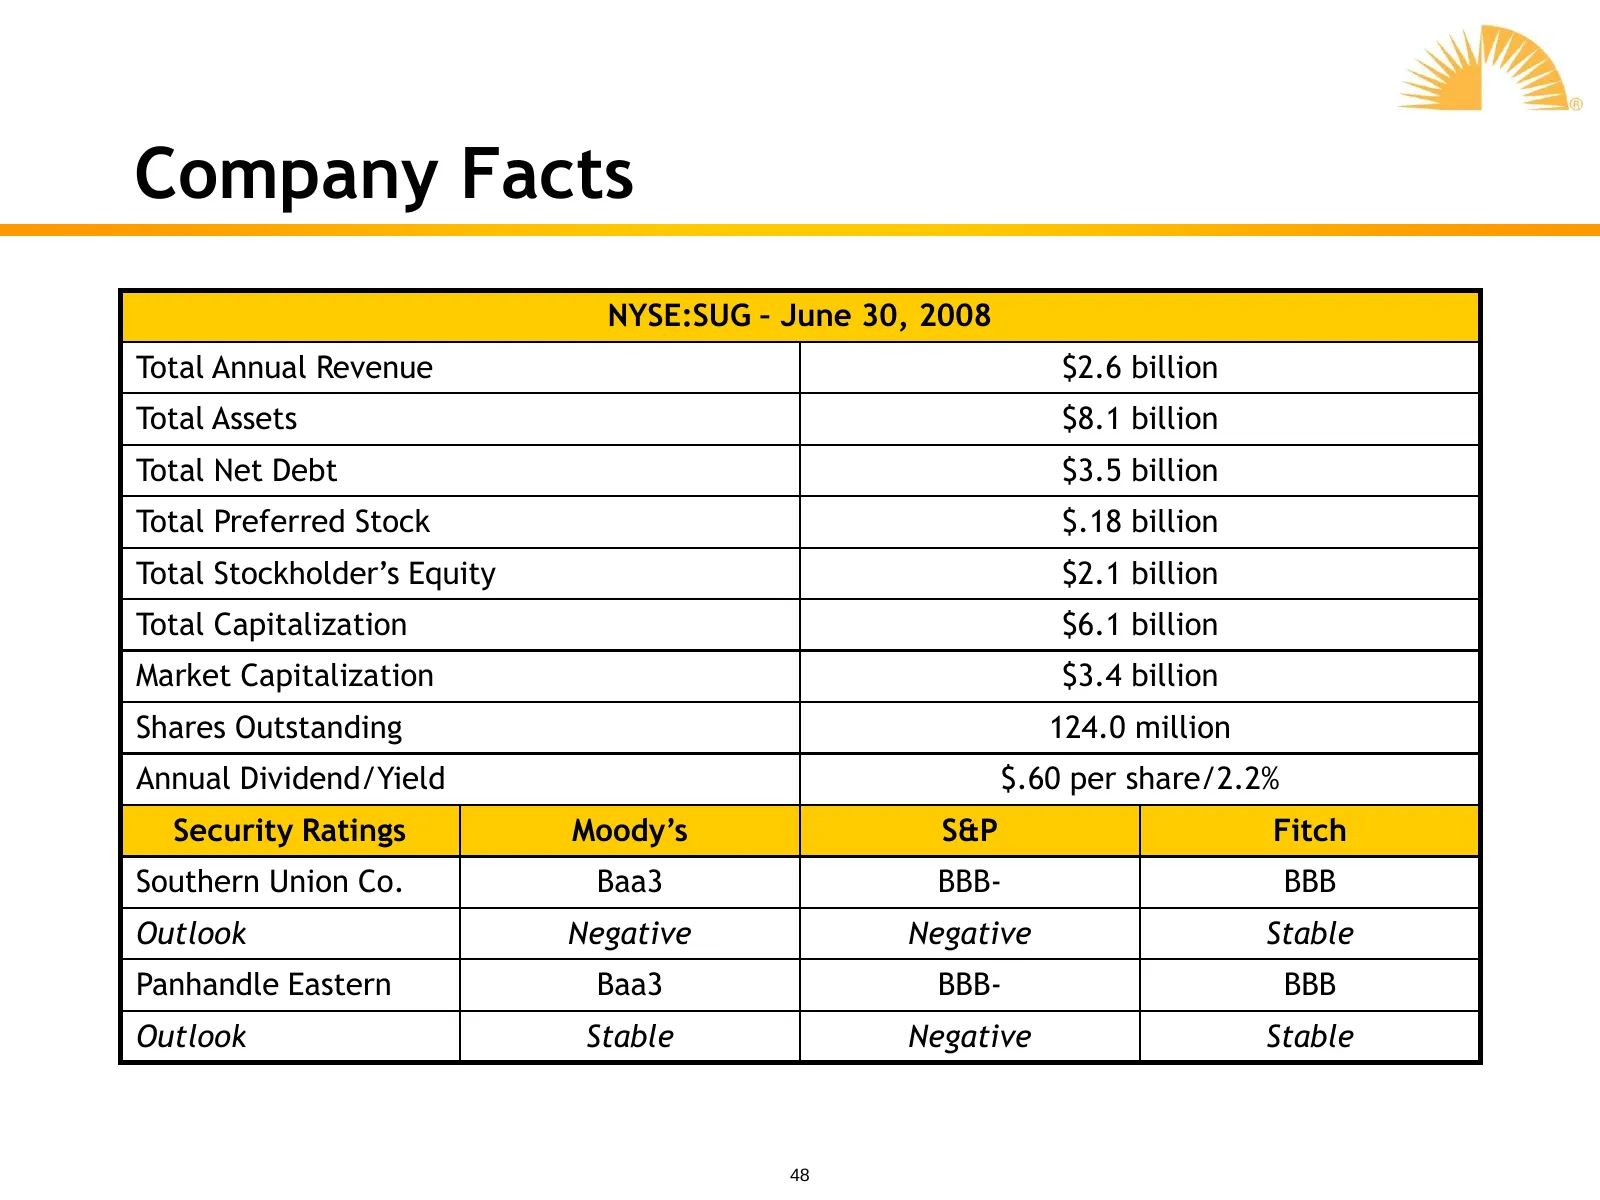
Company Facts NYSE:SUG – June 30, 2008 Total Annual Revenue $2.6 billion Total Assets $8.1 billion Total Net Debt $3.5 billion Total Preferred Stock $.18 billion Total Stockholder’s Equity $2.1 billion Total Capitalization $6.1 billion Market Capitalization $3.4 billion Shares Outstanding 124.0 mill
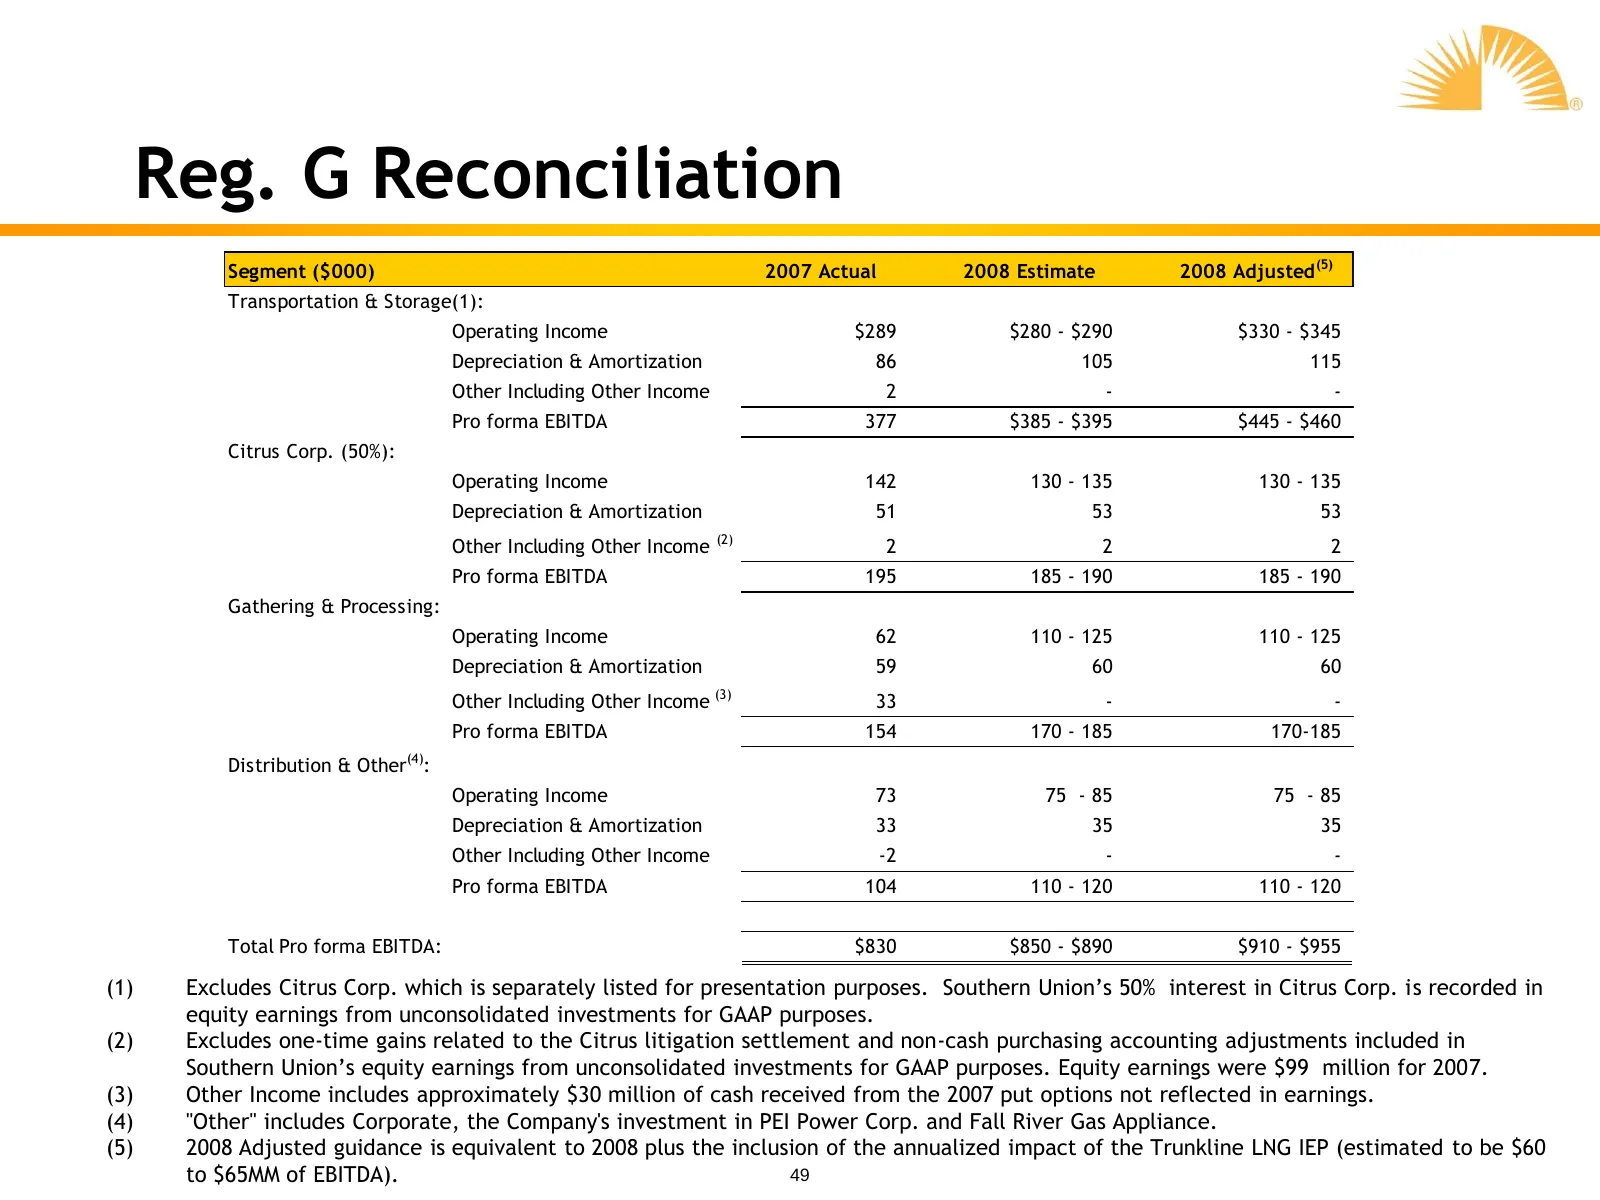
Slide 49: Reg. G Reconciliation
Reg. G Reconciliation Segment ($000) 2007 Actual 2008 Estimate 2008 Adjusted (5) Transportation & Storage(1): Operating Income $289 $280 - $290 $330 - $345 Depreciation & Amortization 86 105 115 Other Including Other Income 2 - - Pro forma EBITDA 377 $385 - $395 $445 - $460 Citrus Corp. (50%): Opera
Source: SEC EDGAR · 8-K filed Sep 4, 2008
More decks from Southern Union Co
 Barclays Capital Investment Grade Energy and Pipeline Conference 201232 slides · Mar 8, 2012
 Debt Investor Presentation (February 2012)33 slides · Feb 22, 2012
 Merger or Acquisition (July 2011)11 slides · Jul 5, 2011
 Merger or Acquisition (June 2011)22 slides · Jun 16, 2011
 Investor Presentation (February 2011)37 slides · Feb 25, 2011
 BMO Capital Markets 2010 Utilities and Pipelines Day23 slides · Nov 30, 2010