Cole Real Estate Investments Inc
Cole Real Estate Investments — Cole Credit Property Trust III — Merger or Acquisition (March 2013)
16 slides from Cole Real Estate Investments's merger presentation, Mar 27, 2013
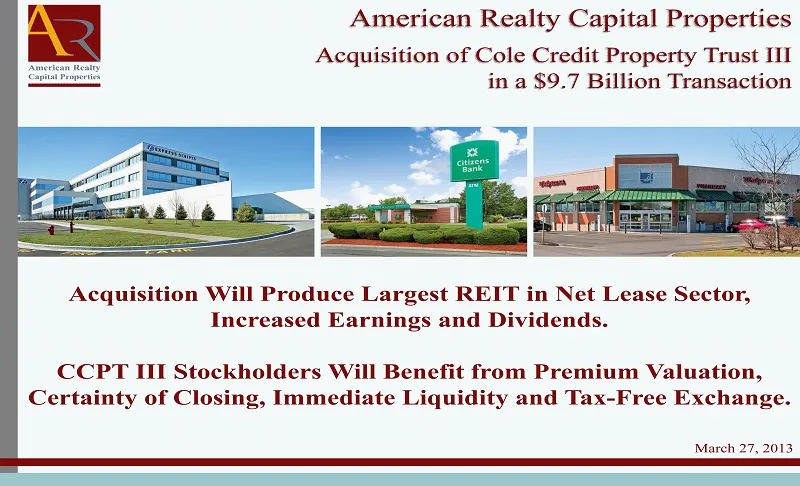
Slide 1: Acquisition of Cole Credit Property Trust III in a $9.7 Billion Transaction
February 2013 American Realty Capital Properties Acquisition of Cole Credit Property Trust III in a $ 9.7 Billion Transaction March 27, 2013 Acquisition Will Produce Largest REIT in Net Lease Sector, Increased Earnings and Dividends. CCPT III Stockholders W ill Benefit from Premium Valuation, Certai
Slide 2: Additional Information about the Proposed Transaction and Where to Find It
2 Additional Information about the Proposed Transaction and Where to Find It This communication does not constitute an offer to sell or the solicitation of an offer to buy any securities or a solicitation of any vote or approval. This communication relates to a business combination transaction with
Slide 3: Forward-Looking Statements
3 Forward - Looking Statements Information set forth in this communication (including information included or incorporated by reference herein) contains “forward - looking statements” (as defined in Section 21E of the Securities Exchange Act of 1934), which reflect ARCP’s expectations regarding futu
Slide 4: ARCP is Offering to Purchase CCPT III: Consideration Terms
4 ; CCPT III Stockholder Consideration: (i) $13.59 per CCPT III share minimum floor value with a fixed 0.80 exchange ratio or (ii) $12.50 per share in cash (1) . ; Floor, No Cap: Proposal guarantees an exchange value of not less than $13.59 per CCPT III share with no limit on the potential upside. ;
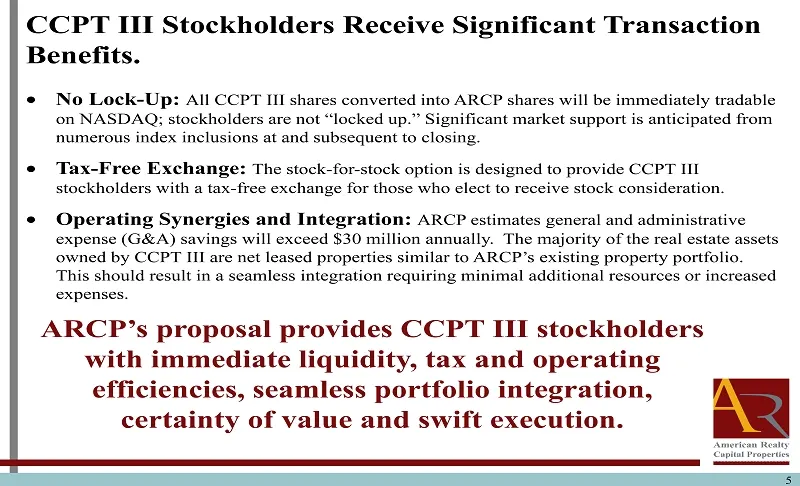
Slide 5: Benefits to CCPT III Stockholders: No Lock-Up, Tax-Free Exchange, Synergies
5 ; No Lock - Up: All CCPT III shares converted into ARCP shares will be immediately tradable on NASDAQ; stockholders are not “ locked up.” Significant market support is anticipated from numerous index inclusions at and subsequent to closing. ; Tax - Free Exchange: The stock - for - stock option is
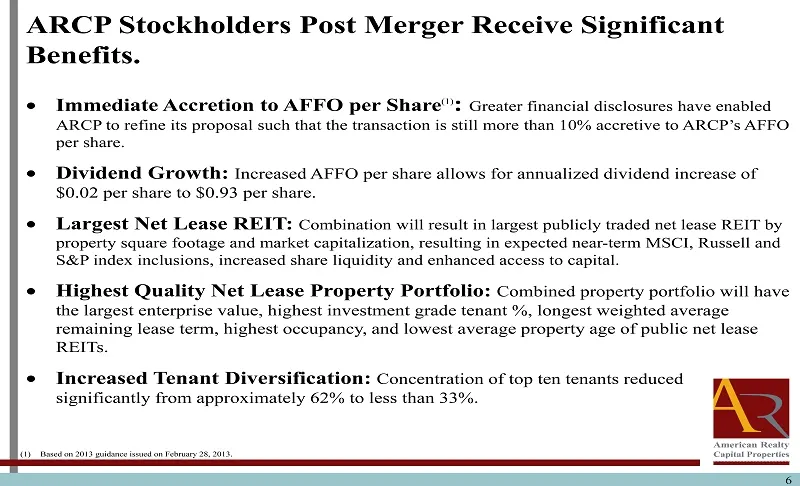
Slide 6: Benefits to ARCP: Accretion, Dividend Growth, Largest Net Lease REIT
6 ; Immediate Accretion to AFFO per Share (1) : Greater financial disclosures have enabled ARCP to refine its proposal such that the transaction is still more than 10% accretive to ARCP’s AFFO per share. ; Dividend Growth: Increased AFFO per share allows for annualized dividend increase of $0.02 per
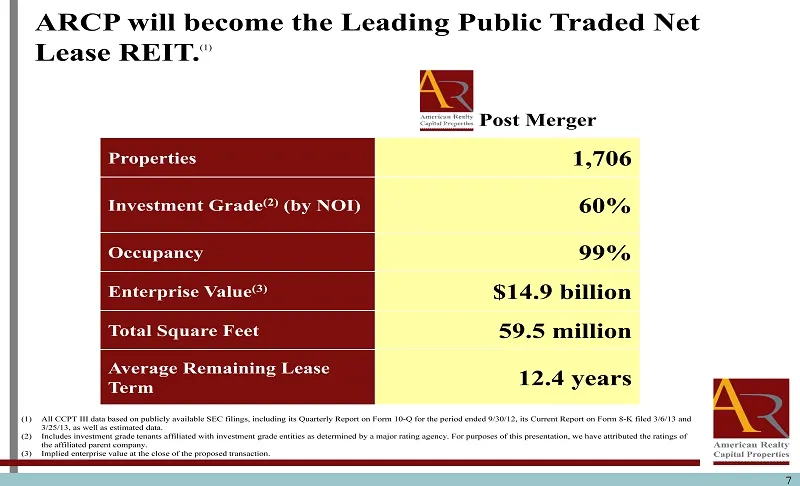
Slide 7: ARCP will become the Leading Public Traded Net Lease REIT
Properties 1,706 Investment Grade (2) (by NOI) 60% Occupancy 99% Enterprise Value (3) $14.9 billion Total Square Feet 59.5 million Average Remaining Lease Term 12.4 years ARCP will become the Leading Public Traded Net Lease REIT. (1) Post Merger (1) All CCPT III data based on publicly available SEC
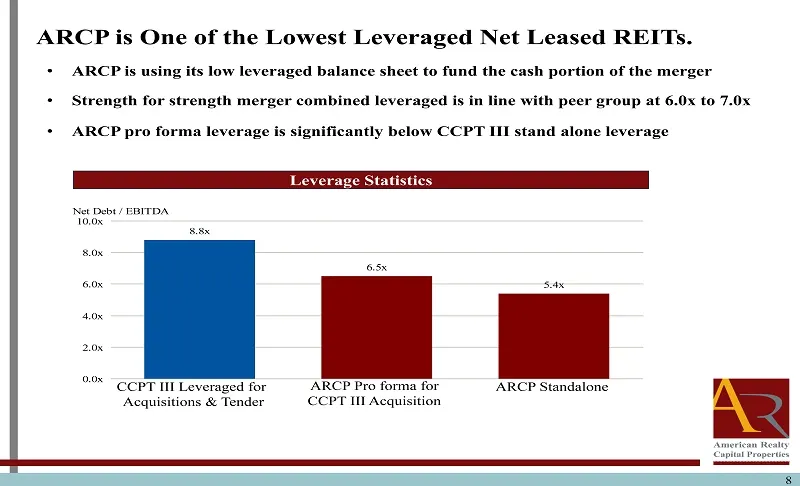
Slide 8: ARCP is One of the Lowest Leveraged Net Leased REITs
ARCP is One of the Lowest Leveraged Net Leased REITs. 8 • ARCP is using its low leveraged balance sheet to fund the cash portion of the merger Leverage Statistics 8.8x 6.5x 5.4x 0.0x 2.0x 4.0x 6.0x 8.0x 10.0x Net Debt / EBITDA ARCP Standalone ARCP Pro forma for CCPT III Acquisition CCPT III Leverage
Slide 9: Cost Impact to CCPT III Stockholders Internalizing Cole
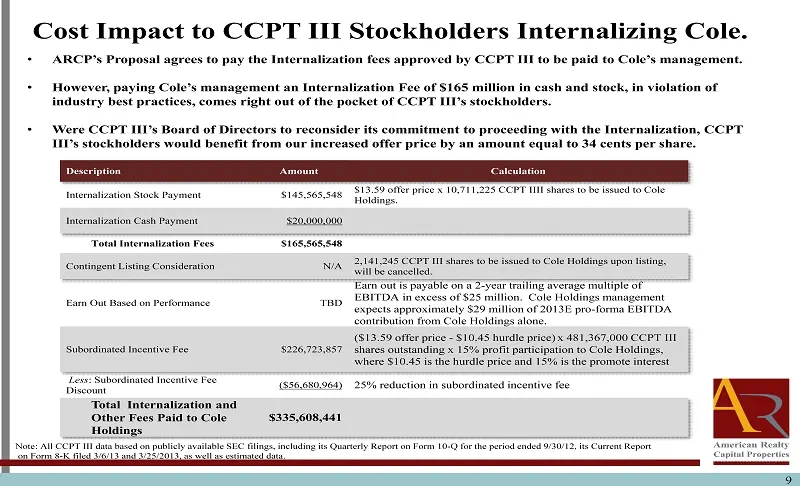
Cost Impact to CCPT III Stockholders Internalizing Cole. 9 Note: All CCPT III data based on publicly available SEC filings, including its Quarterly Report on Form 10 - Q for the period ended 9/30 /12, its Current Report on Form 8 - K filed 3/6/13 and 3/25/2013, as well as estimated data. • ARCP’s Pr
Slide 10: Our Proposal Provides Certainty of Value
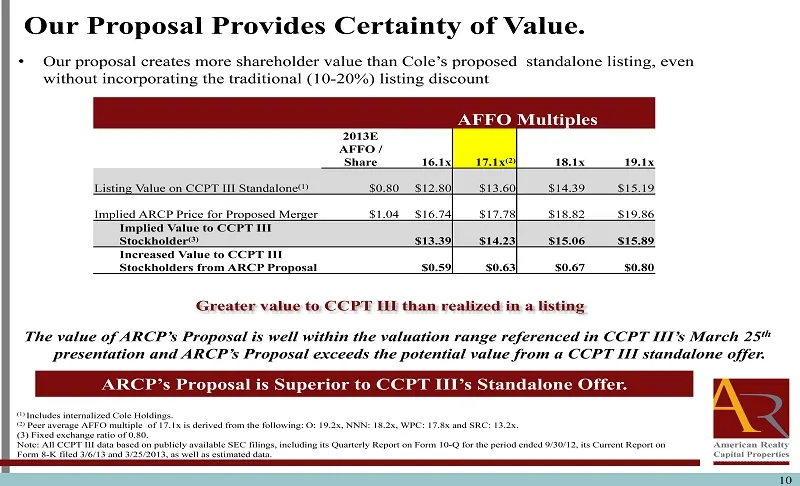
AFFO Multiples 2013E AFFO / Share 16.1x 17.1x (2) 18.1x 19.1x Listing Value on CCPT III Standalone (1) $0.80 $12.80 $13.60 $14.39 $15.19 Implied ARCP Price for Proposed Merger $1.04 $16.74 $17.78 $18.82 $19.86 Implied Value to CCPT III Stockholder (3) $13.39 $14.23 $15.06 $15.89 Increased Value to C
Slide 11: ARCP Post Merger Versus Net Lease Peer Group
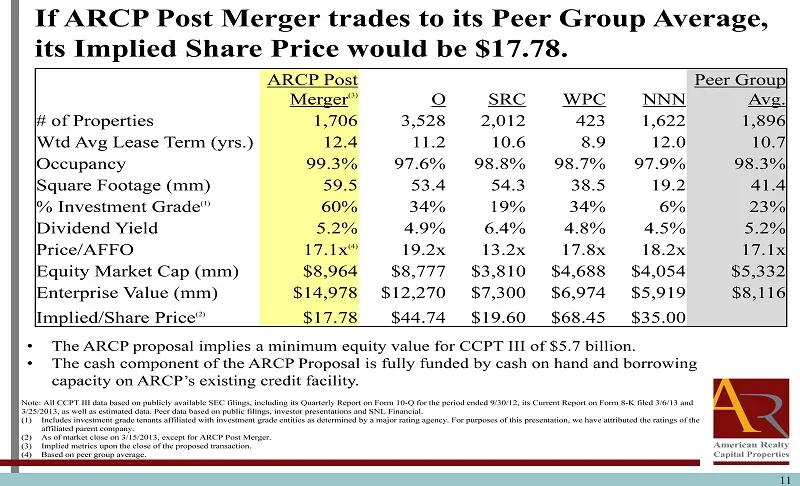
ARCP Post Merger (3) O SRC WPC NNN Peer Group Avg. # of Properties 1,706 3,528 2,012 423 1,622 1,896 Wtd Avg Lease Term (yrs.) 12.4 11.2 10.6 8.9 12.0 10.7 Occupancy 99.3% 97.6% 98.8% 98.7% 97.9% 98.3% Square Footage (mm) 59.5 53.4 54.3 38.5 19.2 41.4 % Investment Grade (1) 60% 34% 19% 34% 6% 23% Di
Slide 12: Appendix
12 Appendix
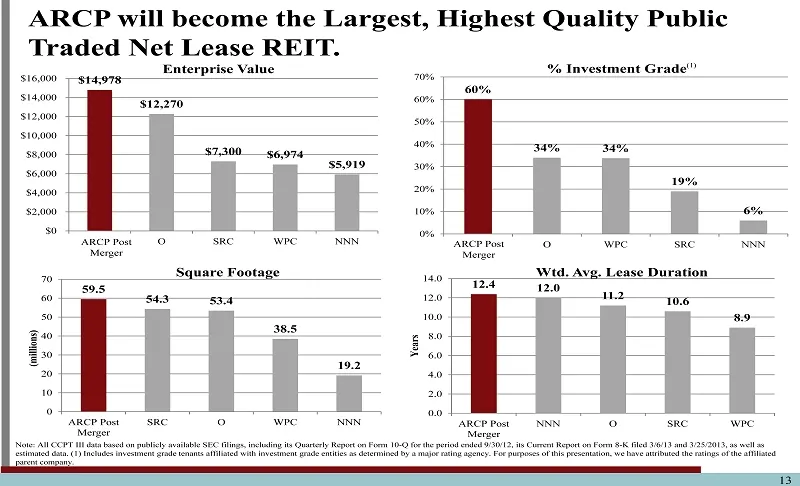
Slide 13: ARCP will become the Largest, Highest Quality Public Traded Net Lease REIT
$ 14,978 $12,270 $7,300 $6,974 $5,919 $0 $2,000 $4,000 $6,000 $8,000 $10,000 $12,000 $14,000 $16,000 New Co O SRC WPC NNN Enterprise Value ARCP will become the Largest, Highest Quality Public Traded Net Lease REIT. 13 60% 34% 34% 19% 6% 0% 10% 20% 30% 40% 50% 60% 70% New Co O WPC SRC NNN % Investmen
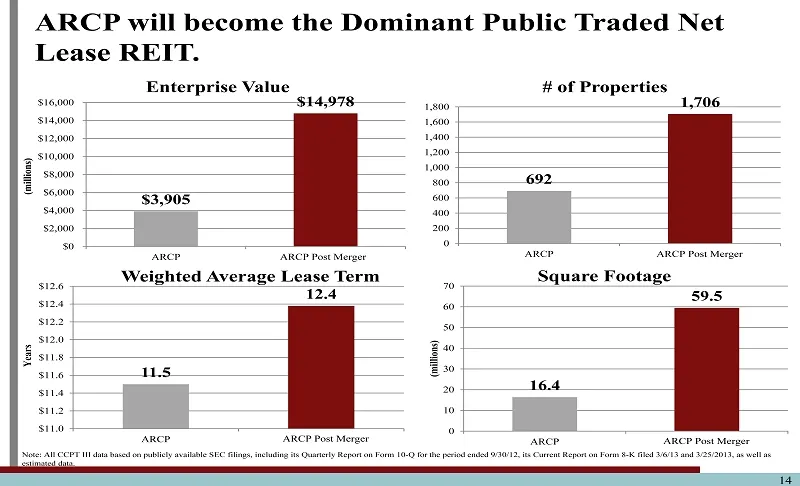
Slide 14: ARCP will become the Dominant Public Traded Net Lease REIT
ARCP will become the Dominant Public Traded Net Lease REIT. 692 1,706 0 200 400 600 800 1,000 1,200 1,400 1,600 1,800 ARCP New Co # of Properties $ 3,905 $ 14,978 $0 $2,000 $4,000 $6,000 $8,000 $10,000 $12,000 $14,000 $16,000 ARCP New Co (millions) Enterprise Value 14 11.5 12.4 $11.0 $11.2 $11.4 $11
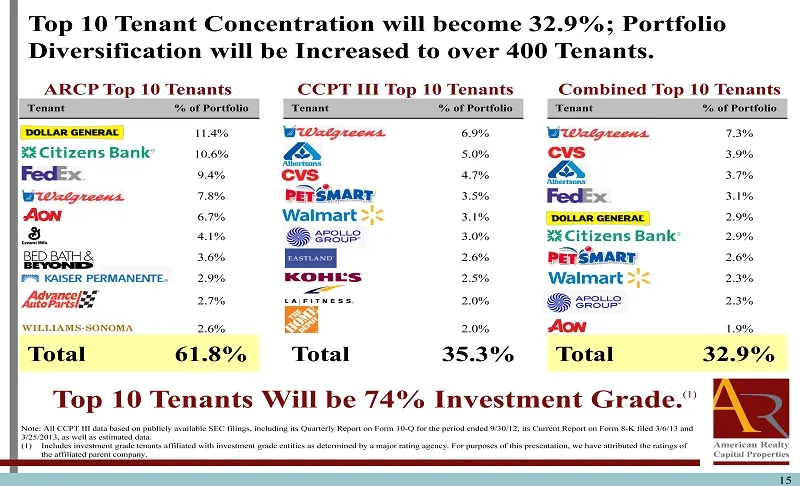
Slide 15: Top Tenant Concentration and Portfolio Diversification
Top 10 Tenant Concentration will become 32.9%; Portfolio Diversification will be Increased to over 400 Tenants. Top 10 Tenants Will be 74 % Investment Grade. (1) Tenant % of Portfolio Tenant % of Portfolio Tenant % of Portfolio 11.4% 6.9% 7.3% 10.6% 5.0% 3.9% 9.4% 4.7% 3.7% 7.8% 3.5% 3.1% 6.7% 3.1%
Slide 16: Funds from Operations and Adjusted Funds from Operations
16 Funds from Operations and Adjusted Funds from Operations ARCP considers FFO and AFFO, which is FFO as adjusted to exclude acquisition - related fees and expenses, amortization of above - market lease assets and liabilities, amortization of deferred financing costs, straight - line rent, non - cas
Source: SEC EDGAR · 425 filed Mar 27, 2013
More decks from Cole Real Estate Investments Inc
 Merger or Acquisition (January 2014)7 slides · Jan 3, 2014
 Merger or Acquisition (November 2013)34 slides · Nov 13, 2013
 Q3 2013 Earnings Presentation22 slides · Nov 5, 2013
 Merger or Acquisition (October 2013)31 slides · Oct 23, 2013
 Merger or Acquisition (October 2013)31 slides · Oct 23, 2013
 Cole Credit Property Trust III — Proxy Contest (April 2013)14 slides · Apr 23, 2013