Cole Real Estate Investments Inc
Cole Real Estate Investments — Merger or Acquisition (October 2013)
31 slides from Cole Real Estate Investments's merger presentation, Oct 23, 2013
Slide 1: ARCP and Cole Merge to Create World’s Largest Net Lease REIT
ARCP and Cole Merge to Create World’s Largest Net Lease REIT
Slide 2: Forward-looking statements
2 Information set forth herein (including information included or incorporated by reference herein) contains “forward - looking statements” (as defined in Section 21 E of the Securities Exchange Act of 1934 , as amended), which reflect American Realty Capital Properties, Inc . ’s (“ARCP”), CapLease,
Slide 3: Executive Summary
3 Executive Summary Merger Creates the World’s Largest Net Lease REIT: 64% larger than the closest comparable net lease REIT. Size and scale create operating and revenue efficiencies including lower cost of capital, superior growth opportunities and higher investor returns. Significant Operating Eff
Slide 4: Summary of Material Merger Terms
4 Summary of Material Merger Terms Consideration per Cole Common Share: • 1.0929 ARCP shares fixed exchange ratio or $13.82 cash • Aggregate cash election limited to 20% (subject to proration) • Implied stock consideration of $14.59 represents a 13.8% premium to Cole stockholders based on closing pr
Slide 5: Stockholder Benefits: Net Lease Leadership
Stockholder Benefits Net Lease Leadership 5
Slide 6: Net Lease Leadership: World’s Largest Net Lease REIT
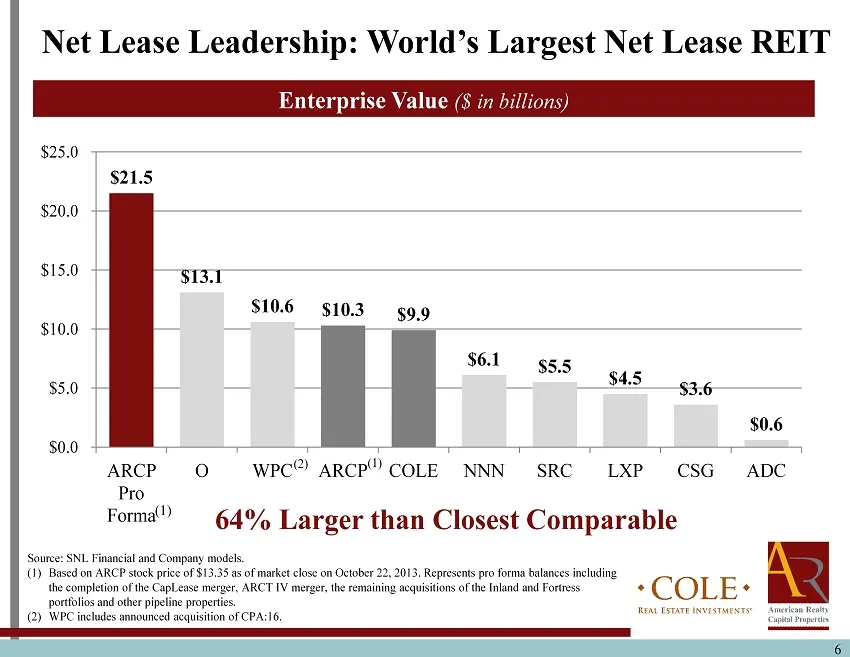
6 Net Lease Leadership: World’s Largest Net Lease REIT Enterprise Value ($ in billions) $21.5 $13.1 $10.6 $10.3 $9.9 $6.1 $5.5 $4.5 $3.6 $0.6 $0.0 $5.0 $10.0 $15.0 $20.0 $25.0 ARCP Pro Forma O WPC ARCP COLE NNN SRC LXP CSG ADC 64% Larger than Closest Comparable (1) Source: SNL Financial and C ompany
Slide 7: Valuation Benefits of Scale; AFFO Multiple and Dividend Yield
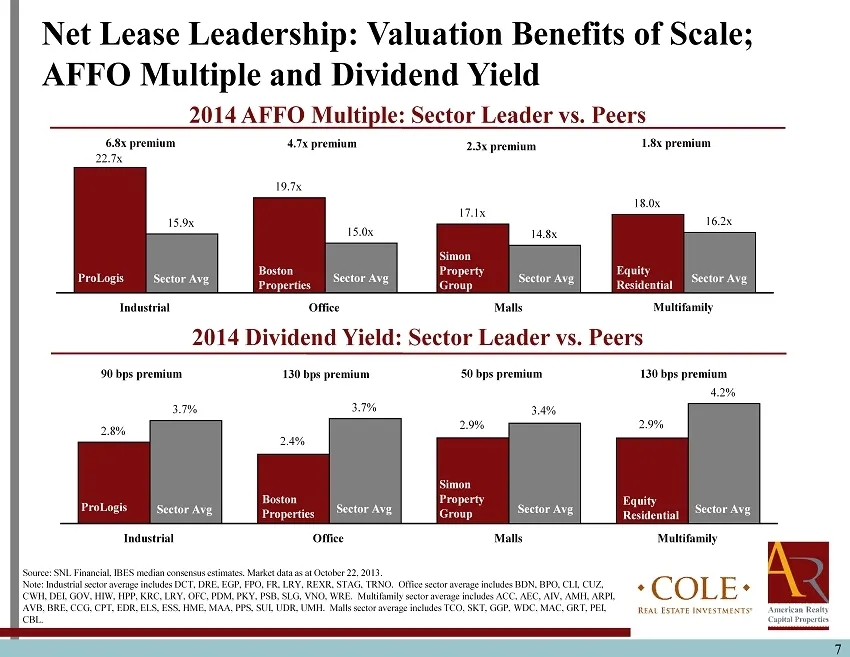
7 2014 AFFO Multiple: Sector Leader vs. Peers 2014 Dividend Yield: Sector Leader vs. Peers Source: SNL Financial, IBES median consensus estimates. Market data as at October 22, 2013. Note: Industrial sector average includes DCT, DRE, EGP, FPO, FR, LRY, REXR, STAG, TRNO. Office sector average include
Slide 8: REIT Equity Cap, Industry, S&P Inclusion, Dividend Yield, Analysts
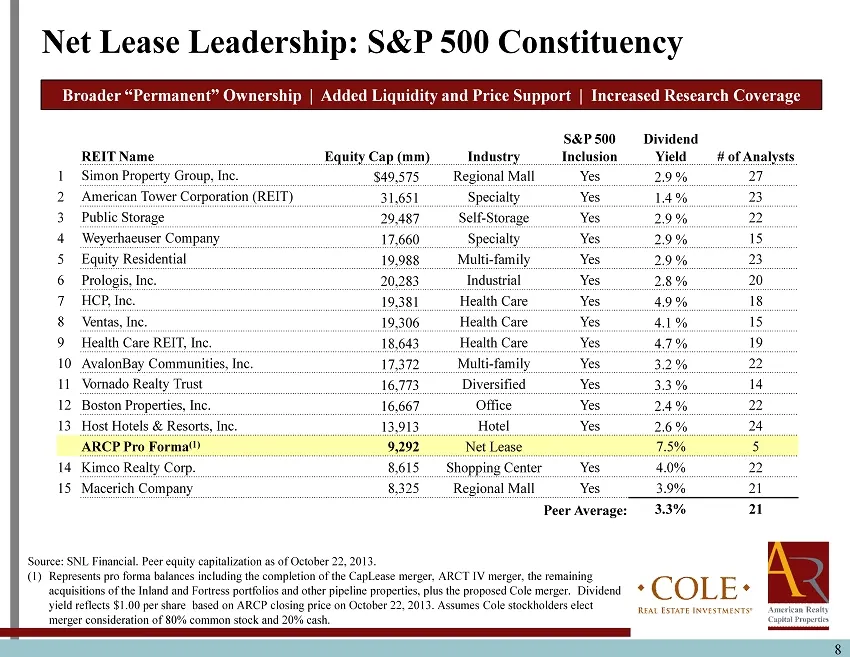
8 REIT Name Equity Cap (mm) Industry S&P 500 Inclusion Dividend Yield # of Analysts 1 Simon Property Group, Inc. $49,575 Regional Mall Yes 2.9 % 27 2 American Tower Corporation (REIT) 31,651 Specialty Yes 1.4 % 23 3 Public Storage 29,487 Self - Storage Yes 2.9 % 22 4 Weyerhaeuser Company 17,660 Spec
Slide 9: Greater MSCI US REIT Index (RMZ) Weighting
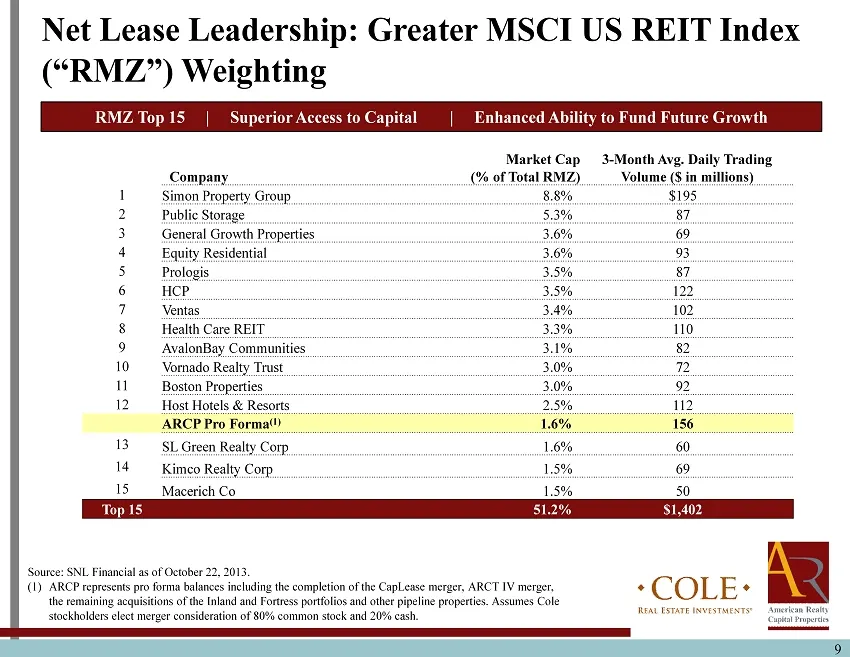
9 Net Lease Leadership: Greater MSCI US REIT Index (“RMZ ”) Weighting Source: SNL Financial as of October 22, 2013 . (1) ARCP represents pro forma balances including the completion of the CapLease merger, ARCT IV merger, the remaining acquisitions of the Inland and Fortress portfolios and other pipe
Slide 10: Net Lease Leadership: Sector Growth and Consolidation
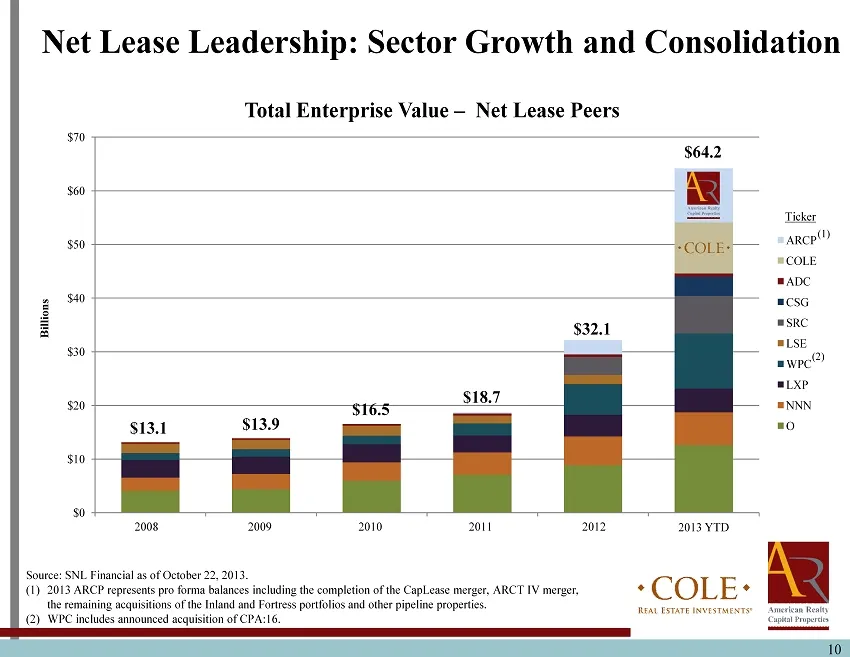
$0 $10 $20 $30 $40 $50 $60 $70 2008 FY 2009 FY 2010 FY 2011 FY 2012 FY 2013 YTD Billions Total Enterprise Value – Net Lease Peers ARCP COLE ADC CSG SRC LSE WPC LXP NNN O 10 Net Lease Leadership: Sector Growth and Consolidation Source: SNL Financial as of October 22, 2013. (1) 2013 ARCP r epresents p
Slide 11: Net Lease Leadership: Capitalizing on Consolidation
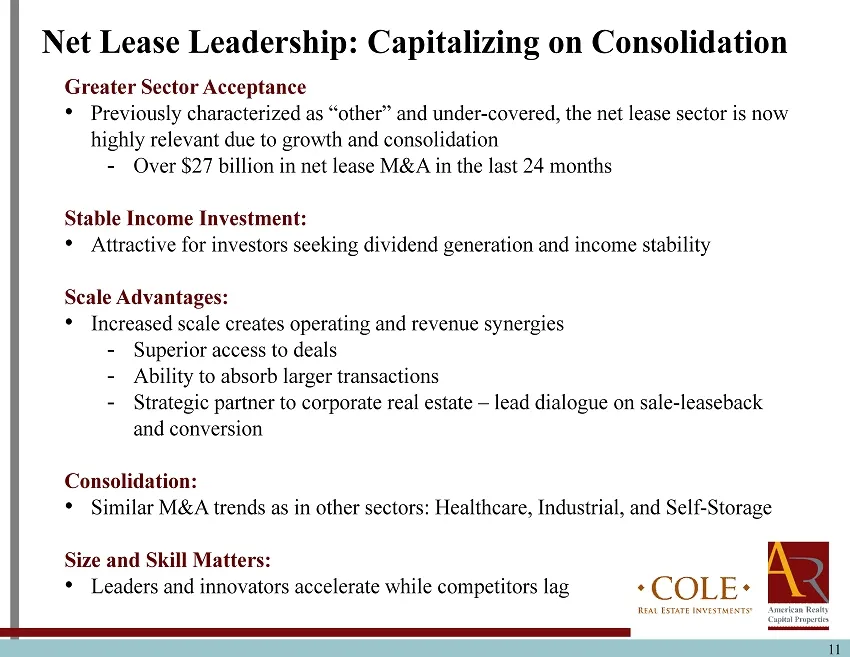
11 Net Lease Leadership: Capitalizing on Consolidation Greater Sector Acceptance • Previously characterized as “other” and under - covered, the net lease sector is now highly relevant due to growth and consolidation - Over $27 billion in net lease M&A in the last 24 months Stable Income Investment:
Slide 12: Stockholder Benefits: Best-in-Class Portfolio
Stockholder Benefits Best - in - Class Portfolio 12
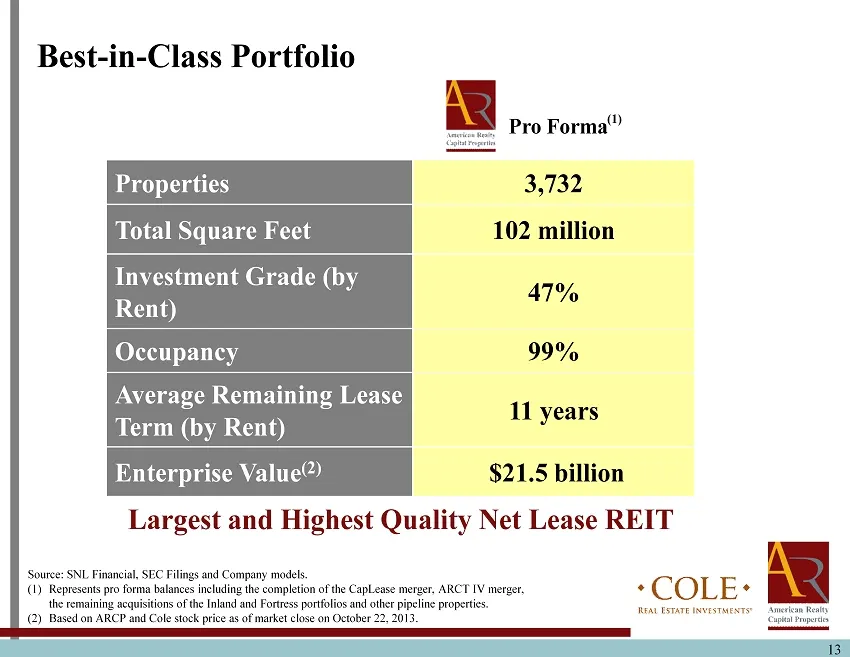
Slide 13: Largest and Highest Quality Net Lease REIT
Properties 3,732 Total Square Feet 102 million Investment Grade (by Rent) 47% Occupancy 99% Average Remaining Lease Term (by Rent) 11 years Enterprise Value (2) $21.5 billion Pro Forma 13 Source: SNL Financial, SEC Filings and Company models . (1) Represents pro forma balances including the completi
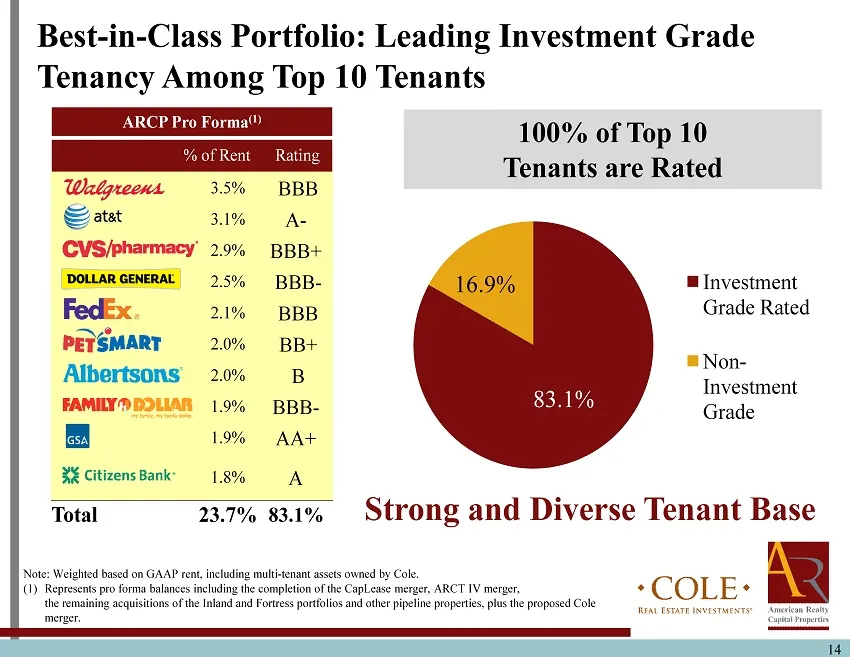
Slide 14: Leading Investment Grade Tenancy
100% of Top 10 Tenants are Rated 14 ARCP Pro Forma (1) % of Rent Rating 3.5% BBB 3.1% A - 2.9% BBB+ 2.5% BBB - 2.1% BBB 2.0% BB+ 2.0% B 1.9% BBB - 1.9% AA+ 1.8% A Total 23.7% 83.1% Best - in - Class Portfolio: Leading Investment Grade Tenancy Among Top 10 Tenants Strong and Diverse Tenant Base Note:
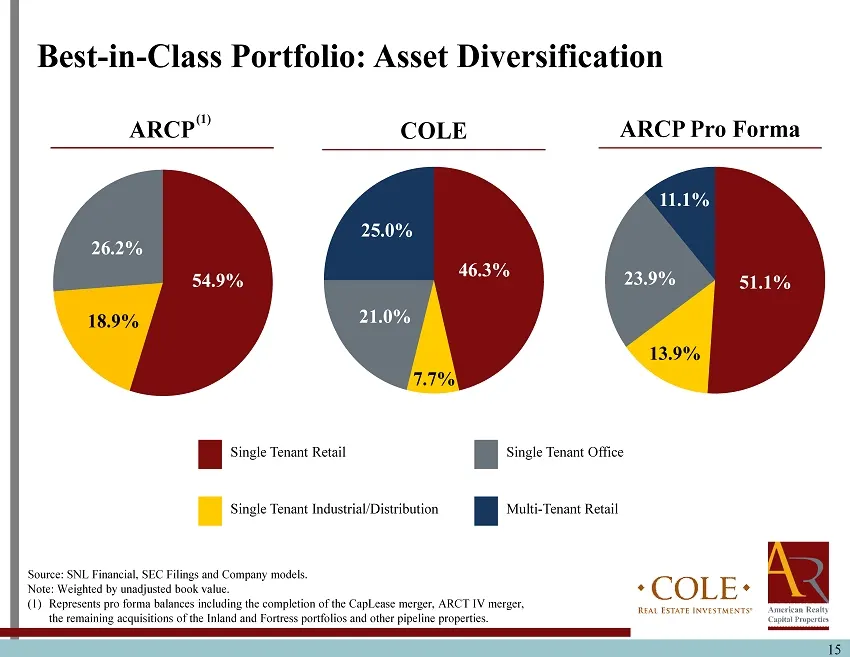
Slide 15: Asset Diversification
15 Single Tenant Retail Single Tenant Industrial/Distribution Single Tenant Office Multi - Tenant Retail 54.9% 26.2% 18.9% 23.9% 11.1% 51.1% 13.9% ARCP ARCP Pro Forma Source : SNL Financial, SEC Filings and Company models . Note: Weighted by unadjusted book value. (1) Represents pro forma balances i
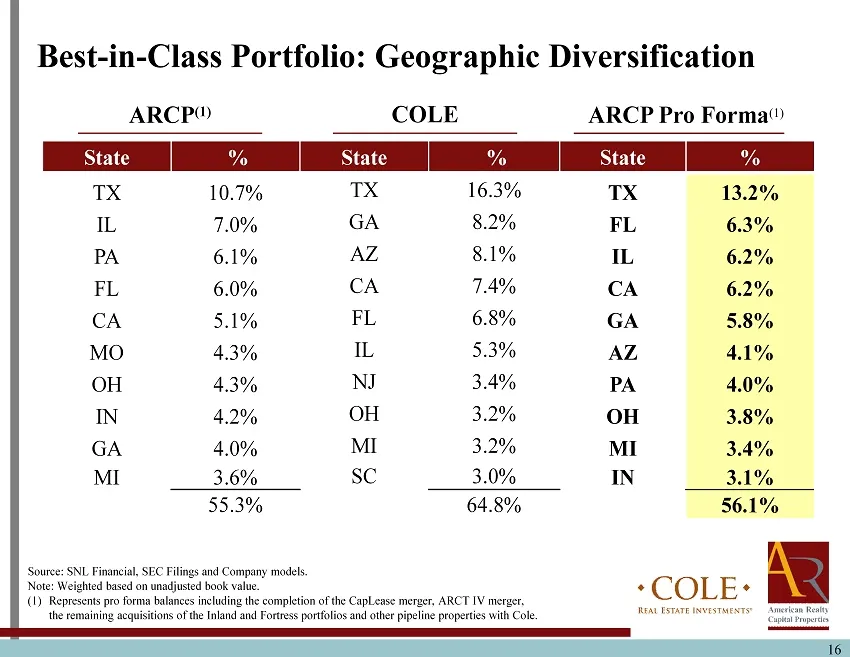
Slide 16: Geographic Diversification
16 ARCP (1) ARCP Pro Forma (1) COLE Best - in - Class Portfolio: Geographic D iversification State % State % State % TX 10.7% TX 16.3% TX 13.2% IL 7.0% GA 8.2% FL 6.3% PA 6.1% AZ 8.1% IL 6.2% FL 6.0% CA 7.4% CA 6.2% CA 5.1% FL 6.8% GA 5.8% MO 4.3% IL 5.3% AZ 4.1% OH 4.3% NJ 3.4% PA 4.0% IN 4.2% OH 3
Slide 17: Attractive Lease Maturity Profile
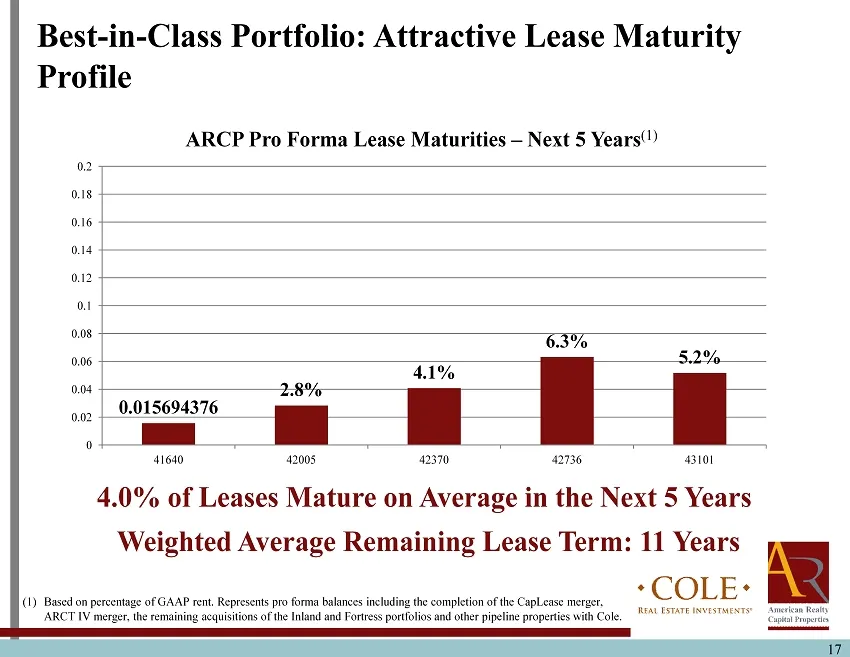
17 17 (1) Based on percentage of GAAP rent. Represents pro forma balances including the completion of the CapLease merger, ARCT IV merger, the remaining acquisitions of the Inland and Fortress portfolios and other pipeline properties with Cole . 4.0% of Leases Mature on Average in the Next 5 Years B
Slide 18: Stockholder Benefits: Financial Benefits
Stockholder Benefits Financial Benefits 18
Slide 19: AFFO Growth, Dividends, Efficiencies and Cost of Capital
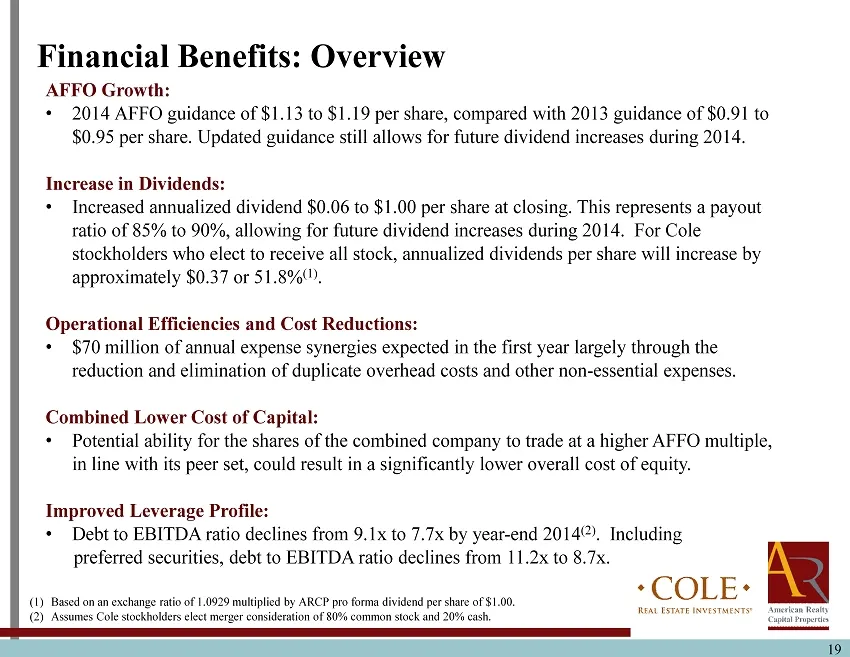
19 AFFO Growth: • 2014 AFFO guidance of $1.13 to $1.19 per share, compared with 2013 guidance of $0.91 to $0.95 per share. Updated guidance still allows for future dividend increases during 2014. Increase in Dividends: • Increased annualized dividend $0.06 to $1.00 per share at closing. This represe
Slide 20: Pro Forma Earnings Guidance
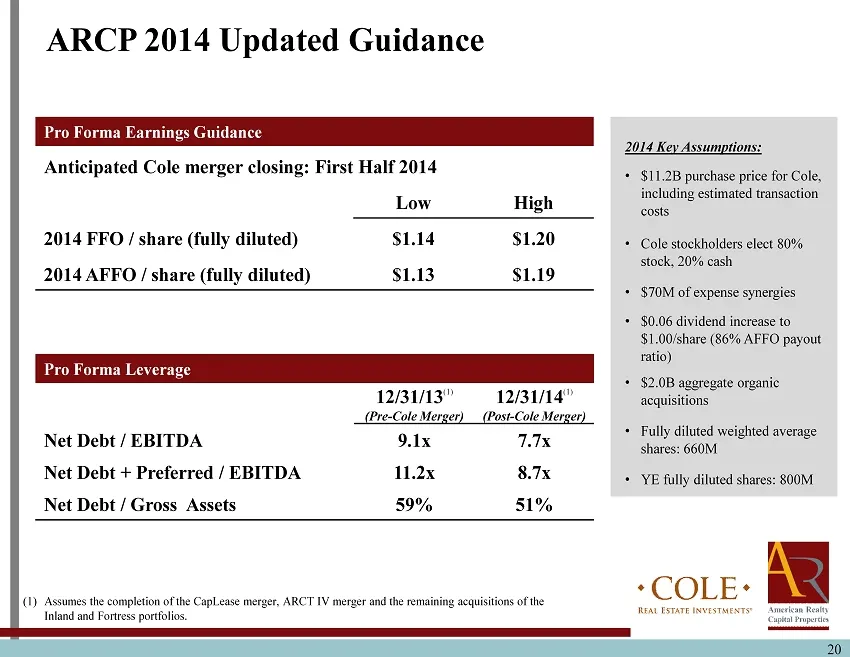
20 Pro Forma Earnings Guidance Anticipated Cole merger closing: First Half 2014 Low High 2014 FFO / share (fully diluted) $1.14 $1.20 2014 AFFO / share (fully diluted) $1.13 $1.19 ARCP 2014 Updated Guidance Pro Forma Leverage 12/31/13 (1) (Pre - Cole Merger) 12/31/14 (1) (Post - Cole Merger) Net Deb
Slide 21: Financial Benefits: Increased Dividend
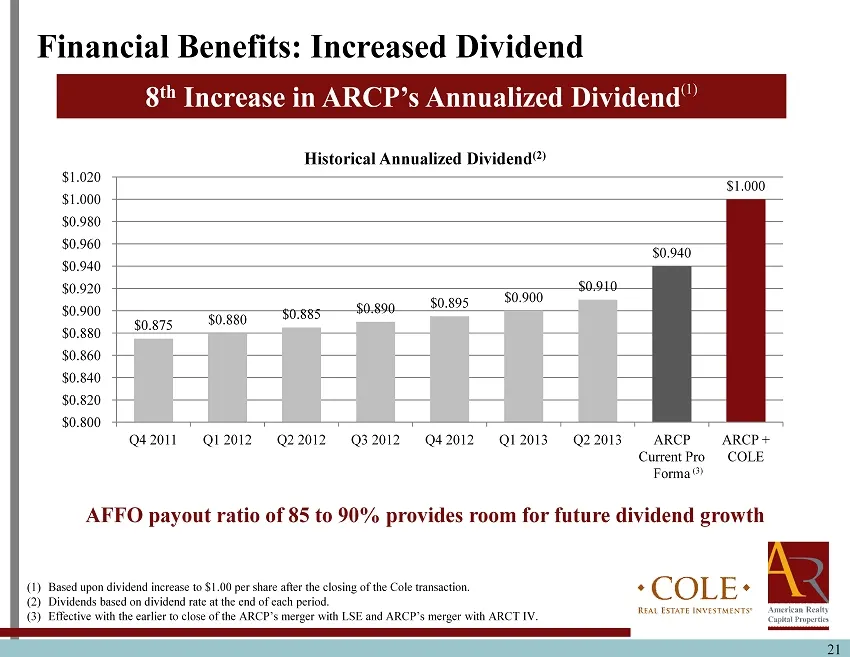
21 AFFO payout ratio of 85 to 90% provides room for future dividend growth $0.875 $0.880 $0.885 $0.890 $0.895 $0.900 $0.910 $0.940 $1.000 $0.800 $0.820 $0.840 $0.860 $0.880 $0.900 $0.920 $0.940 $0.960 $0.980 $1.000 $1.020 Q4 2011 Q1 2012 Q2 2012 Q3 2012 Q4 2012 Q1 2013 Q2 2013 ARCP Current Pro Forma
Slide 22: Expected Synergies: $70 Million in Year One
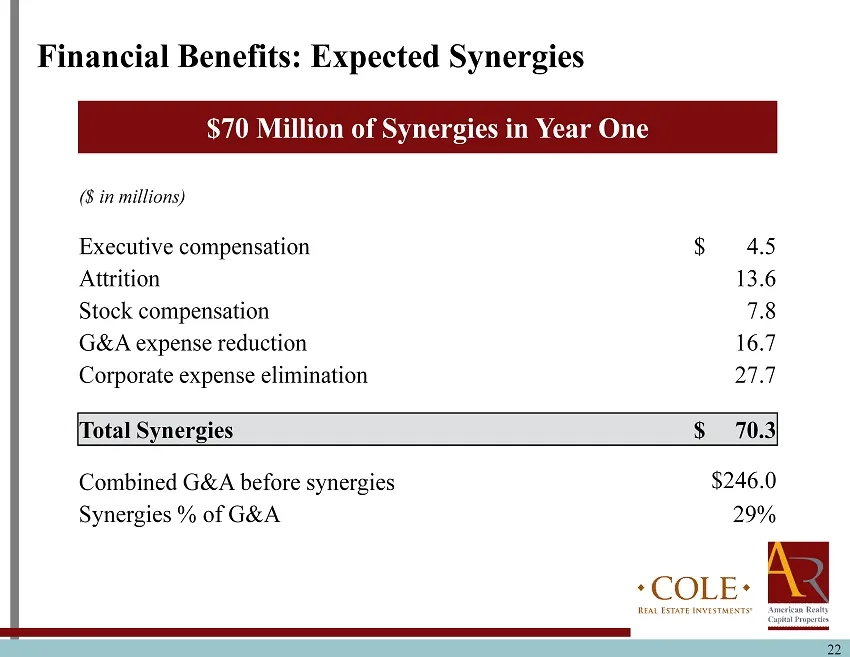
22 ($ in millions) Executive compensation $ 4.5 Attrition 13.6 Stock compensation 7.8 G&A expense reduction 16.7 Corporate expense elimination 27.7 Total Synergies $ 70.3 Combined G&A before synergies $246.0 Synergies % of G&A 29% $70 Million of Synergies in Year One Financial Benefits: Expected Syn
Slide 23: Integration: Significant Experience
Integration Significant Experience 23
Slide 24: Integration Experience
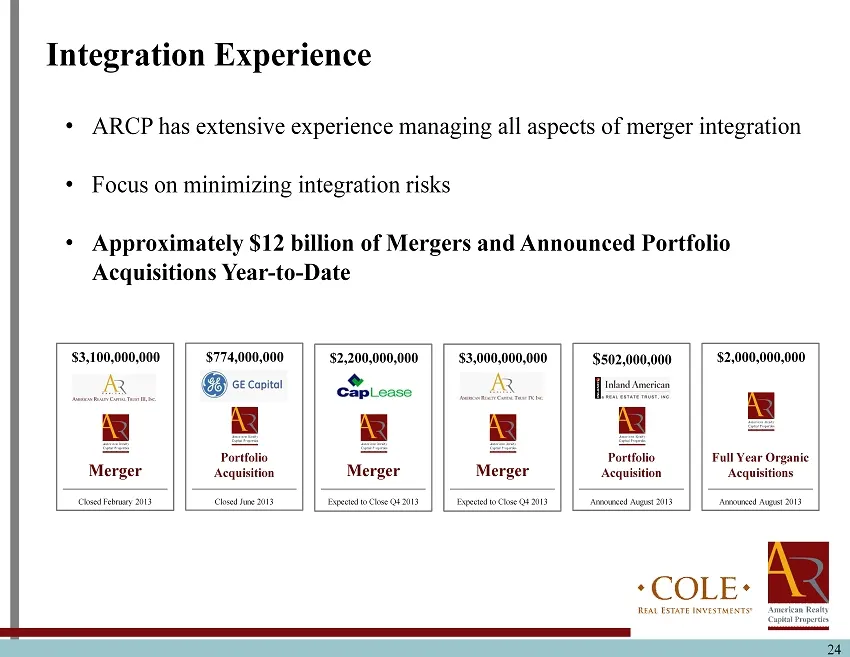
24 Integration Experience • ARCP has extensive experience managing all aspects of merger integration • Focus on minimizing integration risks • Approximately $12 billion of Mergers and Announced Portfolio Acquisitions Year - to - Date Announced August 2013 $ 502,000,000 Portfolio Acquisition $774,000
Slide 25: Cole Private Capital Management: Here to Stay
25 Cole Private Capital Management: Here to Stay Cole Today: Premier Sponsor: • A premier net lease non - traded REIT sponsor with more than $8.1 billion equity capital raised since 2007 Powerful Distribution Capacity: • Deep broker - dealer and financial advisor relationships across the entire non
Slide 26: Pro Forma Organizational Chart
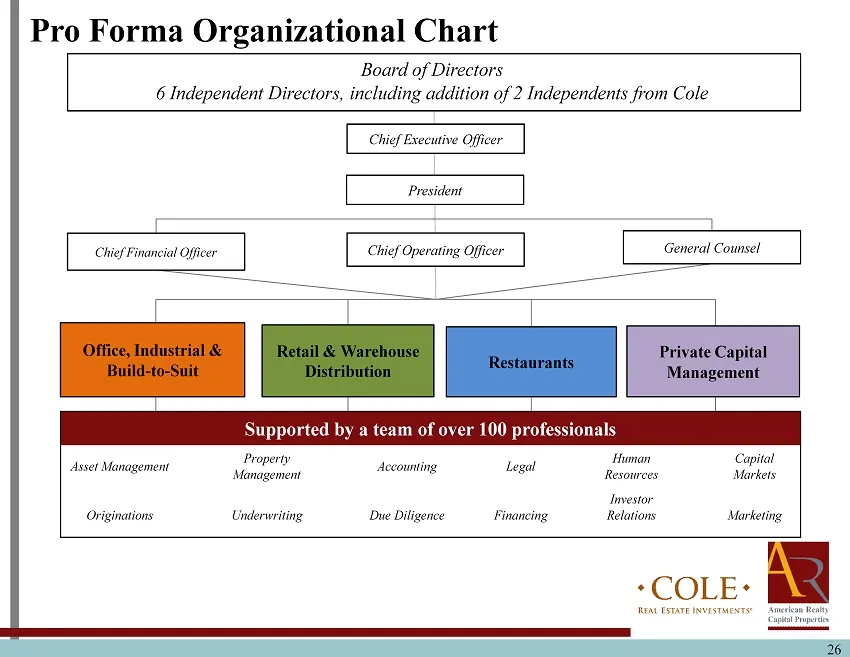
26 Office, Industrial & Build - to - Suit Retail & Warehouse Distribution Restaurants Private Capital Management General Counsel Chief Operating Officer Chief Financial Officer President Pro Forma Organizational Chart Supported by a team of over 100 professionals Asset Management Property Management
Slide 27: ARCP Offers a Compelling Value Proposition
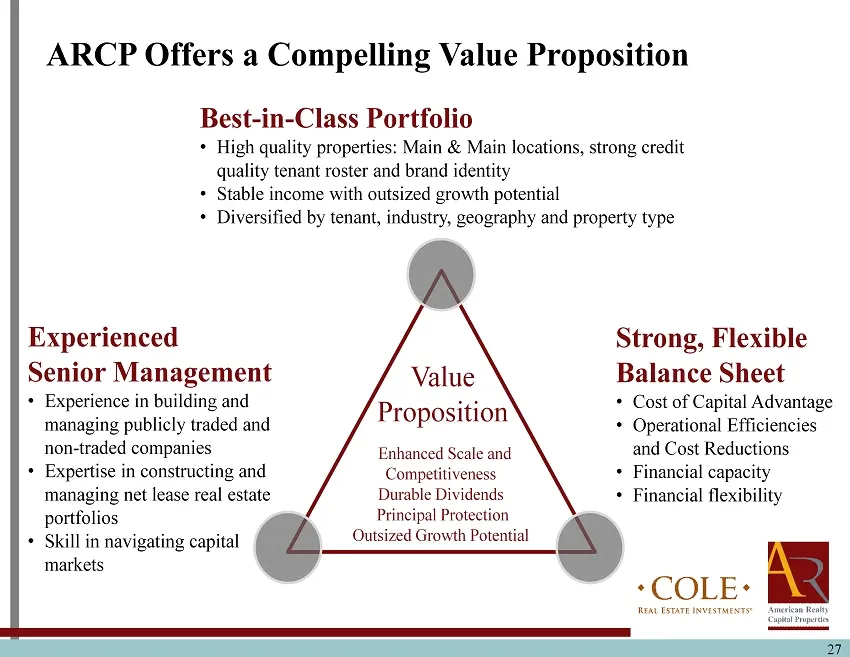
27 Experienced Senior Management • Experience in building and managing publicly traded and non - traded companies • Expertise in constructing and managing net lease real estate portfolios • Skill in navigating capital markets Best - in - Class Portfolio • High quality properties: Main & Main locatio
Slide 28: Non-GAAP – FFO/AFFO Reconciliation
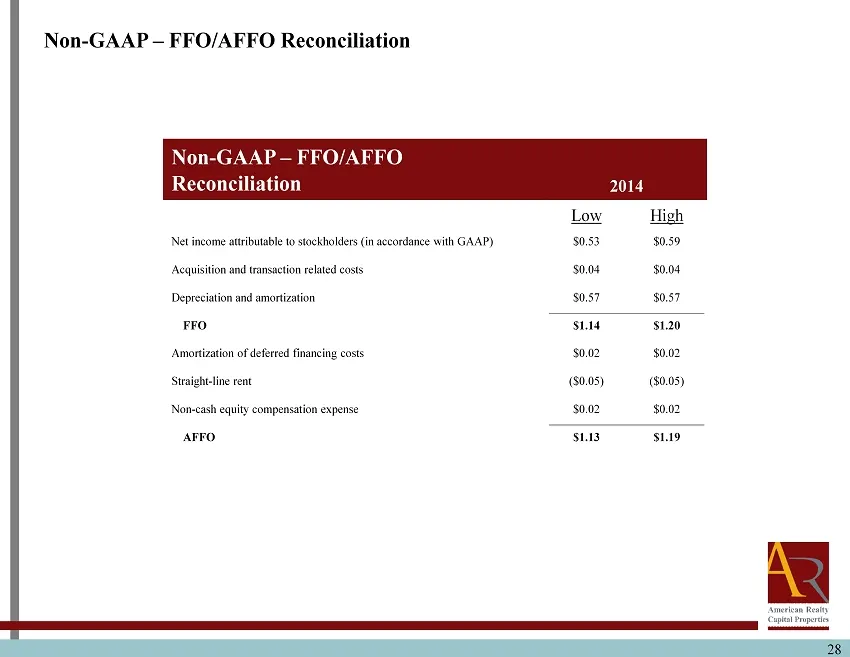
28 Non - GAAP – FFO/AFFO Reconciliation 2014 Low High Net income attributable to stockholders (in accordance with GAAP) $0.53 $0.59 Acquisition and transaction related costs $0.04 $0.04 Depreciation and amortization $0.57 $0.57 FFO $1.14 $1.20 Amortization of deferred financing costs $0.02 $0.02 Str
Slide 29: Funds from Operations and Adjusted Funds from Operations
29 Funds from Operations and Adjusted Funds from Operations ARCP considers funds from operations (“FFO”) and AFFO, which is FFO as adjusted to exclude acquisition - related fees and expenses, amortization of above - market lease assets and liabilities, amortization of deferred financing costs, strai
Slide 30: Additional Information: Cole Merger
30 This communication does not constitute an offer to sell or the solicitation of an offer to buy any securities or a solicitation of any vote or approval . In connection with the proposed Cole merger, ARCP and Cole expect to prepare and file with the SEC a registration statement on Form S - 4 conta
Slide 31: Additional Information: ARCT IV Merger
31 This communication does not constitute an offer to sell or the solicitation of an offer to buy any securities or a solicitation of any vote or approval . In connection with the proposed ARCT IV merger, ARCP and ARCT IV expect to prepare and file with the SEC an amendment to their proxy statement/
Source: SEC EDGAR · 425 filed Oct 23, 2013
More decks from Cole Real Estate Investments Inc
 Merger or Acquisition (January 2014)7 slides · Jan 3, 2014
 Merger or Acquisition (November 2013)34 slides · Nov 13, 2013
 Q3 2013 Earnings Presentation22 slides · Nov 5, 2013
 Merger or Acquisition (October 2013)31 slides · Oct 23, 2013
 Cole Credit Property Trust III — Proxy Contest (April 2013)14 slides · Apr 23, 2013
 Cole Credit Property Trust III — Merger or Acquisition (April 2013)18 slides · Apr 2, 2013