CenterState Bank — CenterState Banks — The Burton Partnership Annual Meeting 2013
32 slides from CenterState Bank's conference presentation, Mar 27, 2013
Slide 1: The Burton Partnership Annual Meeting
The Burton Partnership Annual Meeting March 27, 2013 Ernie Pinner Chairman & CEO CenterState Banks, Inc. Holding Company John Corbett President & CEO CenterState Bank of Florida, N.A. Exhibit 99.1
Slide 2: Forward Looking Statement
2 This presentation contains forward-looking statements, as defined by Federal Securities Laws, relating to present or future trends or factors affecting the operations, markets and products of CenterState Banks, Inc. (CSFL). These statements are provided to assist in the understanding of future fin
Slide 3: Company Overview
Company Overview
Slide 4: Corporate Overview
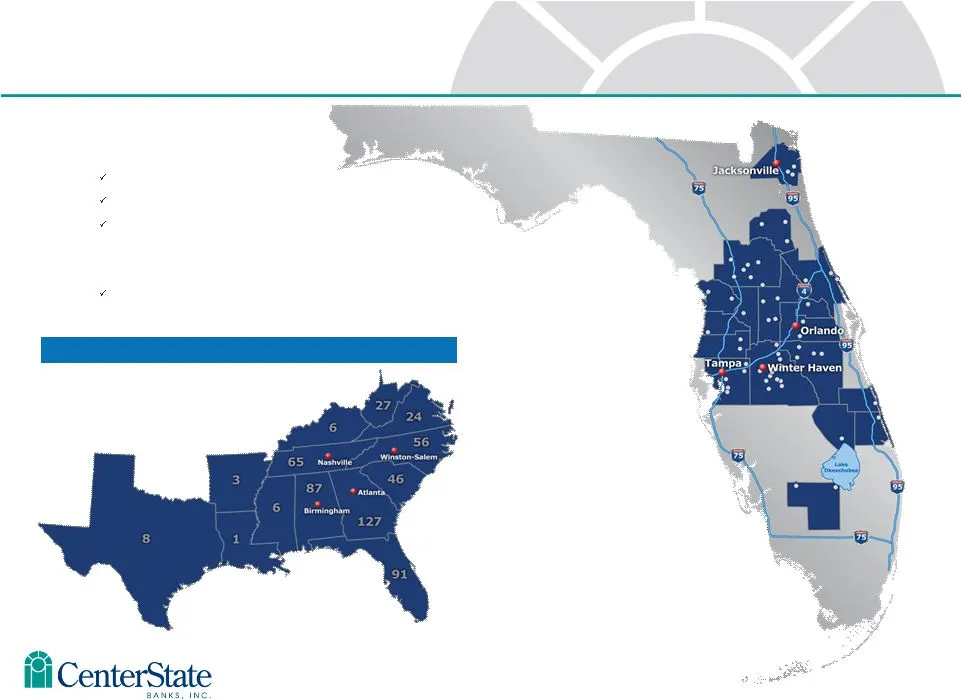
Correspondent Banking Market Data as of 12/31/12 • Headquartered in Davenport, FL $2.4 billion in assets $1.4 billion in loans $2.0 billion in deposits • Company formed: June 2000 1 Subsidiary Bank Corporate Overview
Slide 5: Conservative Balance Sheet as of December 31
• CAPITAL - Total Risk-Based Capital Ratio – 17.9% • LIQUIDITY - Loans / Assets - 61% • LOANS WITH THIRD PARTY PROTECTION – 25% 21% of loans are covered by loss sharing agreements with the FDIC 4% subject to “Put Back” agreement with TD Bank ending January 20, 2013 • ASSETS WITH THIRD PARTY PROTECTI
Slide 6: Opportunistic through the Crisis
Non – FDIC Acquisitions FDIC Acquisitions New Fee-Based Business Lines Strategic Expansion & Management Lift-Outs Ocala National Bank Olde Cypress Community Bank Independent National Bank of Ocala Community National Bank of Bartow Central Florida State Bank First Guaranty Bank & Trust Co. TD Bank di
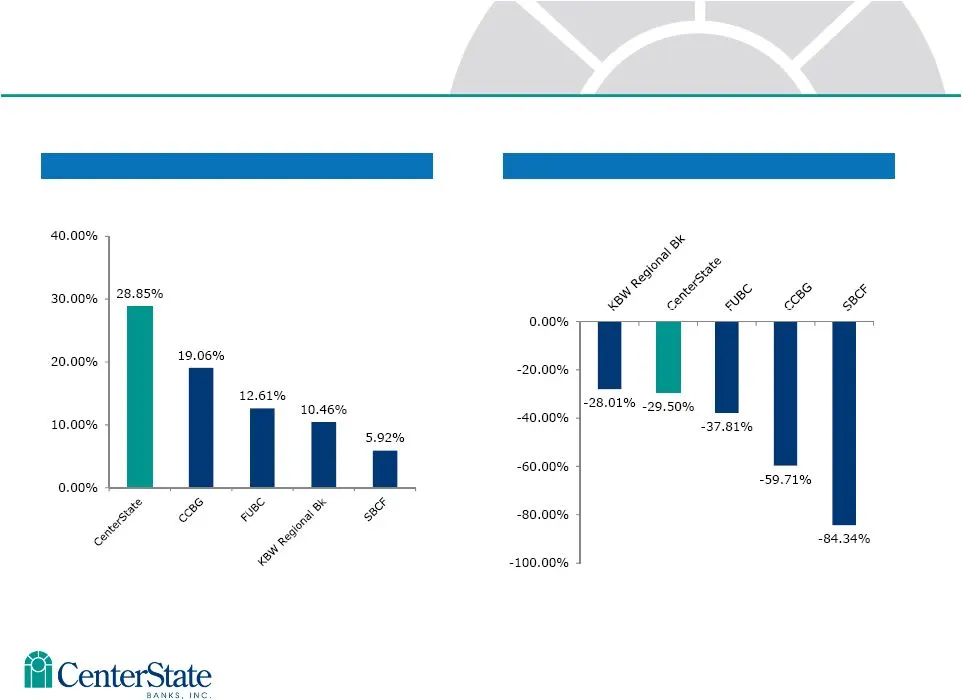
Slide 7: One Year - 2012 Five Year - 2007 to 2012
One Year - 2012 Five Year - 2007 to 1012 Price Change %
Slide 8: Florida is on the Mend
Florida is on the Mend
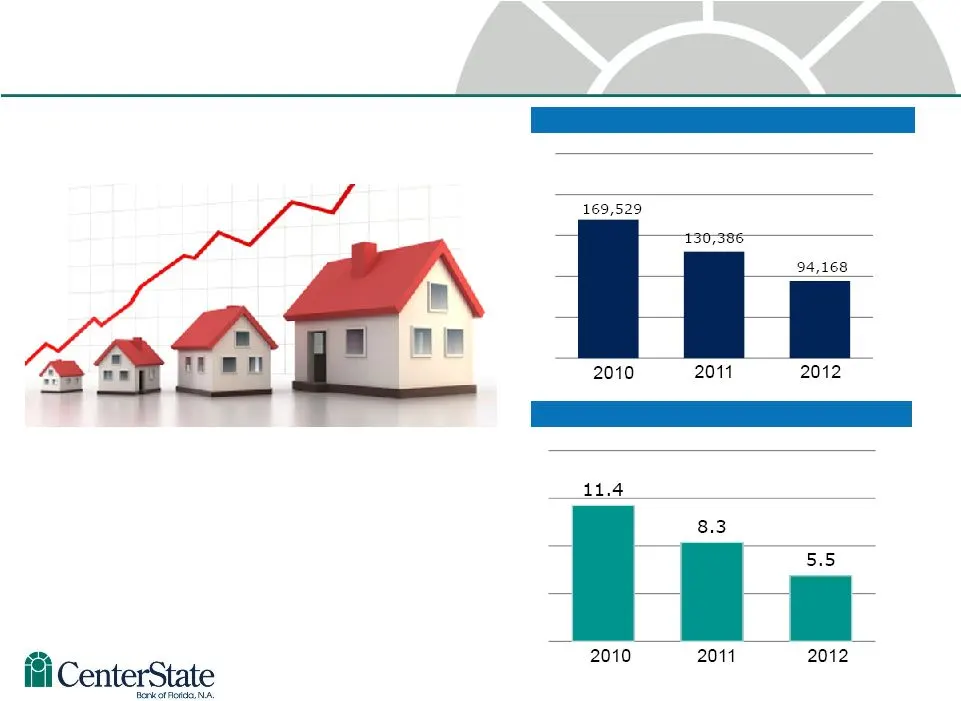
Slide 9: Housing is now a Tailwind
Single Family Inventory Months Supply of Inventory Housing is now a Tailwind • Median single family home prices are up 14% from last year • Pending home sales are up 31% from last year • Median days on the market are down 17% from last year Source: Florida Realtors Yearly and Monthly Market Detail –
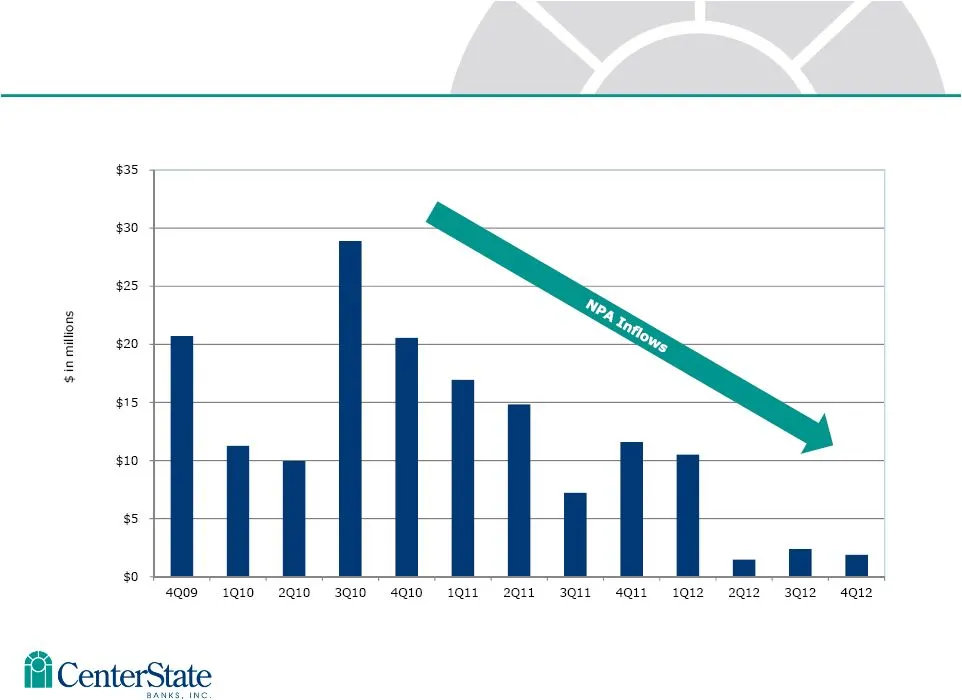
Slide 10: NPA Inflows – Slowing Down
NPA Inflows – Slowing Down Excluding FDIC covered assets
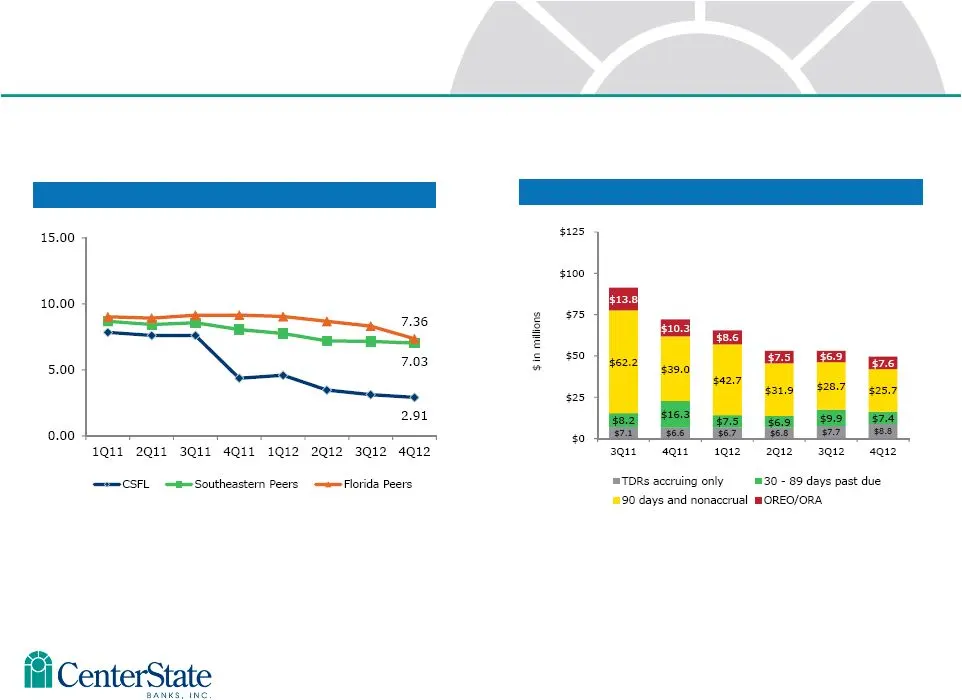
Slide 11: Credit Quality Trends - Improving
NPAs / Loans & OREO (%) Problem Loan Trends 14 Source: SNL Financial and Company filings. Peer information updated quarterly Nonperforming assets include 90 days or more past due. Southeastern peers include ABCB, BTFG, PNFP, RNST, SCBT, UBSH and UCBI. Florida peers include all banks headquartered in
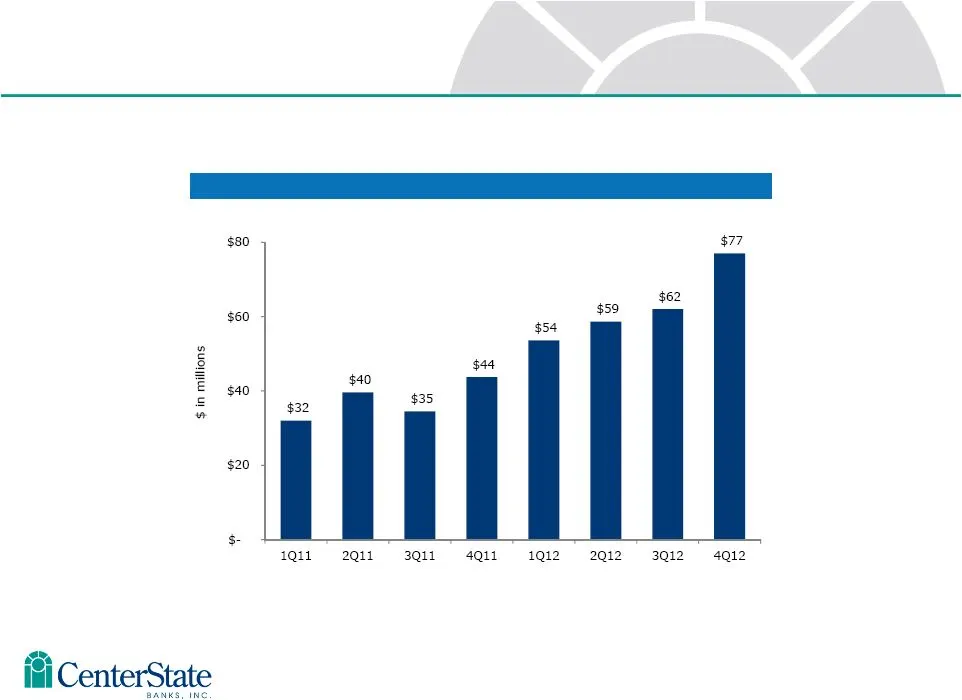
Slide 12: New Loan Production
New Loan Production Loan Trends as of December 31, Excluding FDIC covered assets
Slide 13: Core Earnings on the Rise
Core Earnings on the Rise
Slide 14: Profitability Metrics
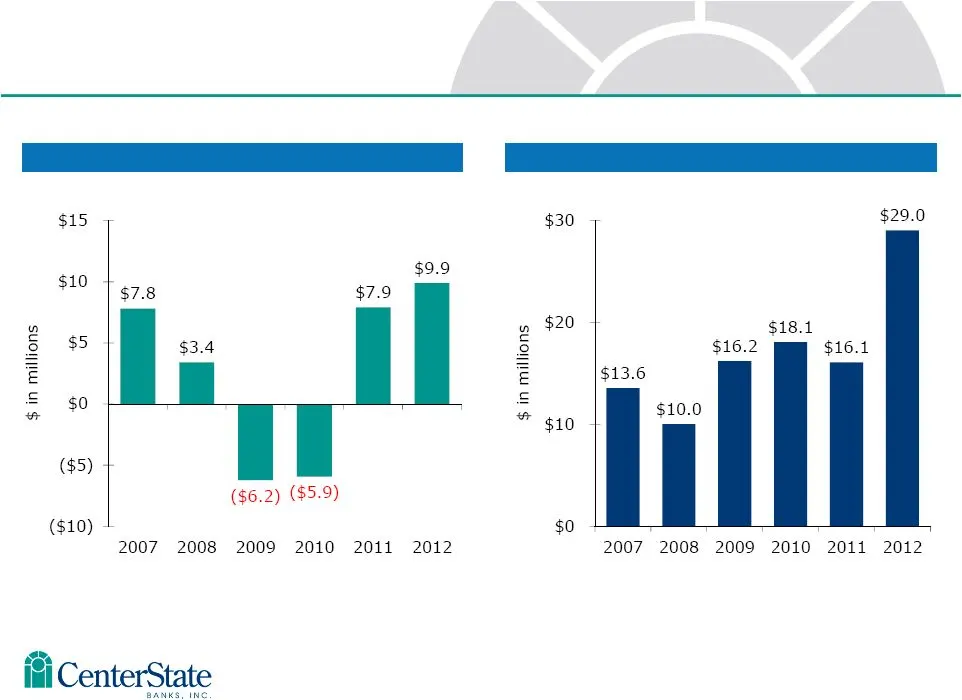
Net Income Pre-Tax Pre-Provision Income ¹ 1. Pre-tax pre-provision income (“PTPP”) is a non-GAAP measure that if defined as income (loss) before income tax excluding provision for loan losses, gain on sale of available for sale securities, income from FDIC loan pool impairment, OREO indemnification
Slide 15: Building Franchise Value with Core Deposits
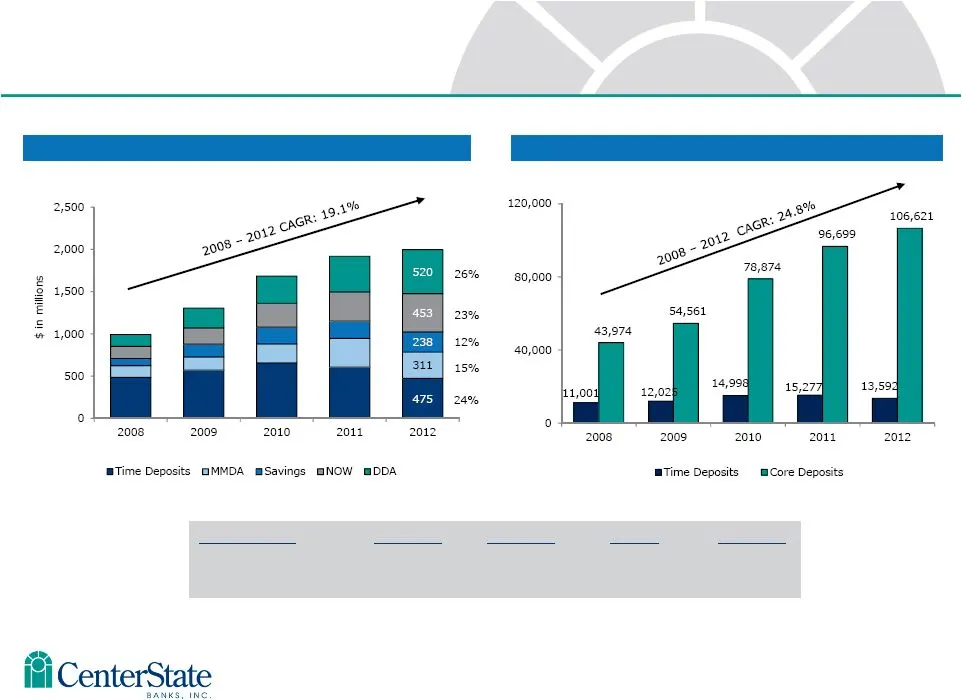
Total Deposits Number of Deposit Accounts 9 • Value of core deposits not fully realized in this low rate environment. • Approximately 120,213 total accounts - $16,614 average balance per account Core deposits defined as non-time deposits. DDA and NOW 12/31/11 12/31/12 Change % Change Balance $767MM
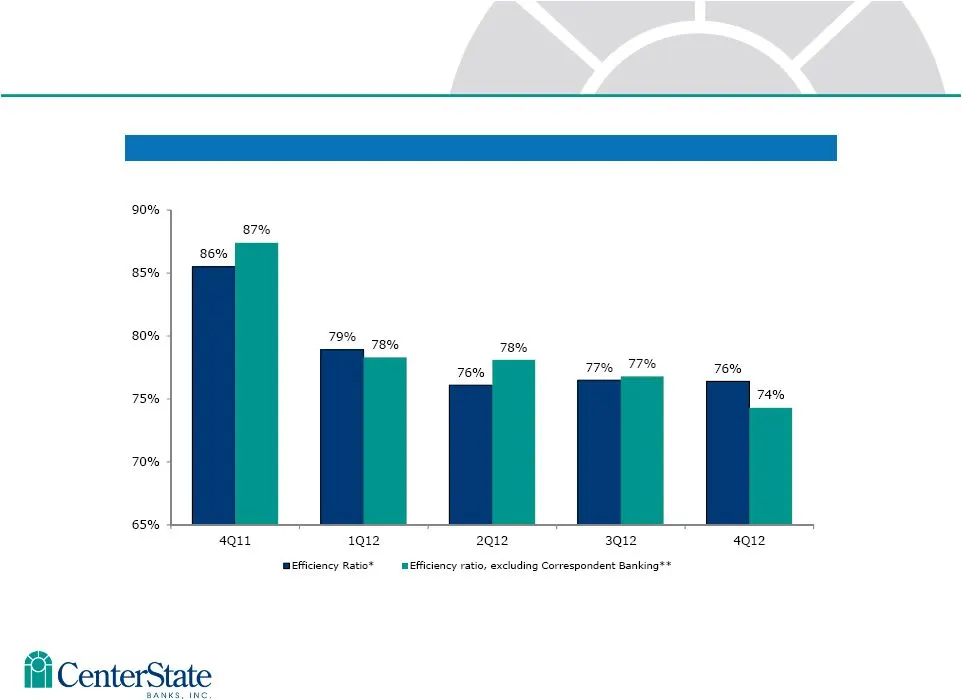
Slide 16: Focus on Efficiency and Core Earnings
11 Branch Consolidation – 15 ( 11 FDIC / 4 Legacy) Reduction in Force - Data Processing Conversions – Complete July 2012 Merger of Subsidiaries – Complete June 2012 Focus on Efficiency and Core Earnings -
Slide 17: Operating Efficiencies
10 Efficiency Ratio Operating Efficiencies * Efficiency Ratio is defined as follows: [non-interest expense – intangible amortization – credit related expenses – merger related expenses – other nonrecurring expense] / [net interest income (fully tax equivalent) + non-interest income – gain on sale of
Slide 18: Banking Consolidation
Banking Consolidation
Slide 19: Recent M&A Transactions
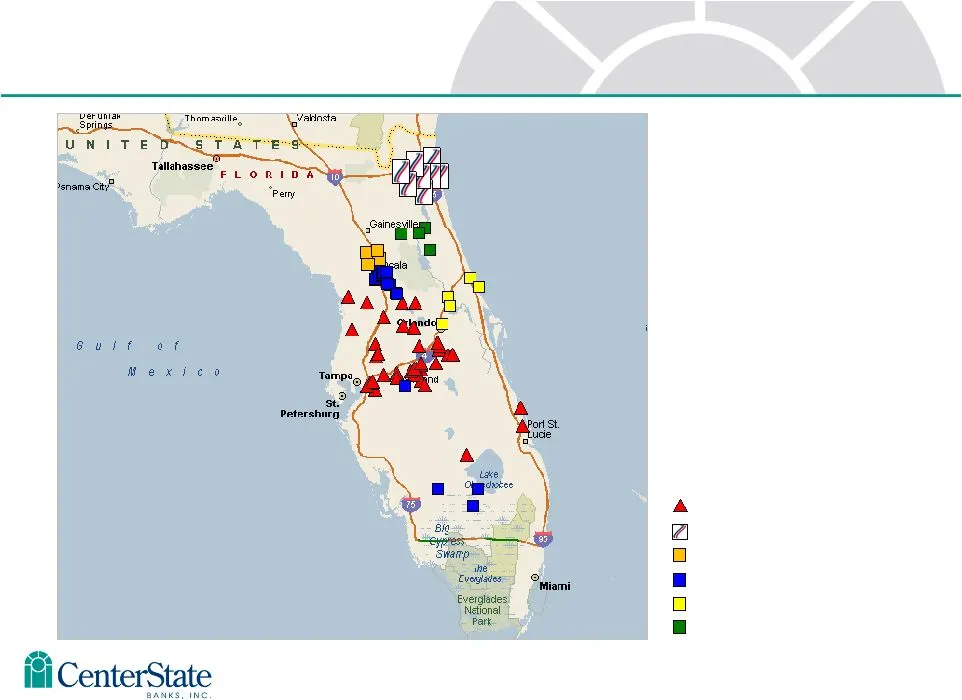
Source: SNL Financial Legacy CSFL Branch First Guaranty Bank (FDIC) Central FL State Bank (FDIC) Three FDIC Acquisitions (3Q 2010) Federal Trust Acquisition (Nov 2011) TD Branch Acquisition (Jan 2011) Jacksonville Recent M&A Transactions
Slide 20: Banks with Texas Ratio over 200%
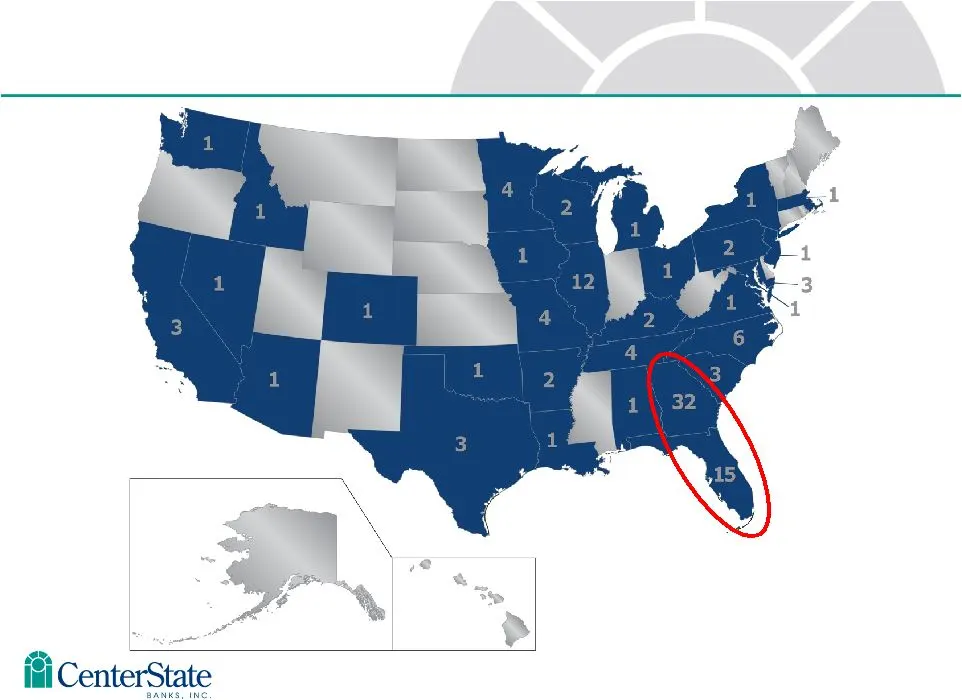
17 42% Source: SNL Financial Data as of 12/31/12 or MRQ Banks with Texas Ratio over 200%
Slide 21: CSFL – Best Positioned Florida Consolidator
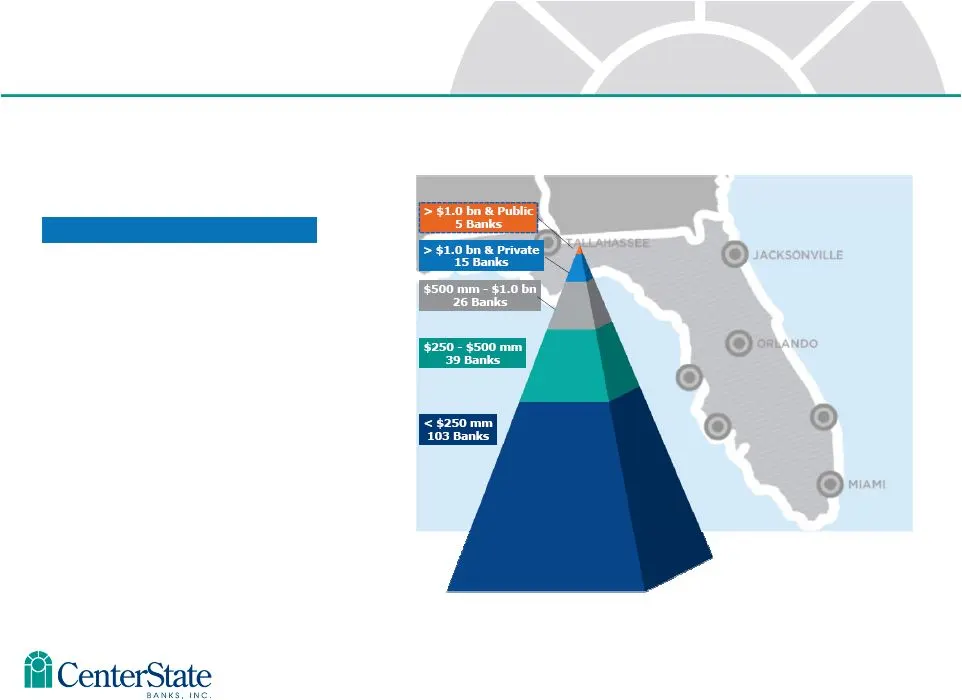
18 CSFL Advantages • CSFL is one of only five major exchange traded banks headquartered in FL with assets between $1 billion and $10 billion • Proven experience through 8 successful acquisitions in the past 3 years • Disproportionate number of sellers versus very few buyers • The number of small, di
Slide 22: Summary
• Lifetime local bankers with common lineage • Florida economy improving • CSFL metrics improving with better performance anticipated • Best positioned consolidator in the state Summary
Slide 23: Appendix
Appendix
Slide 24: Capital
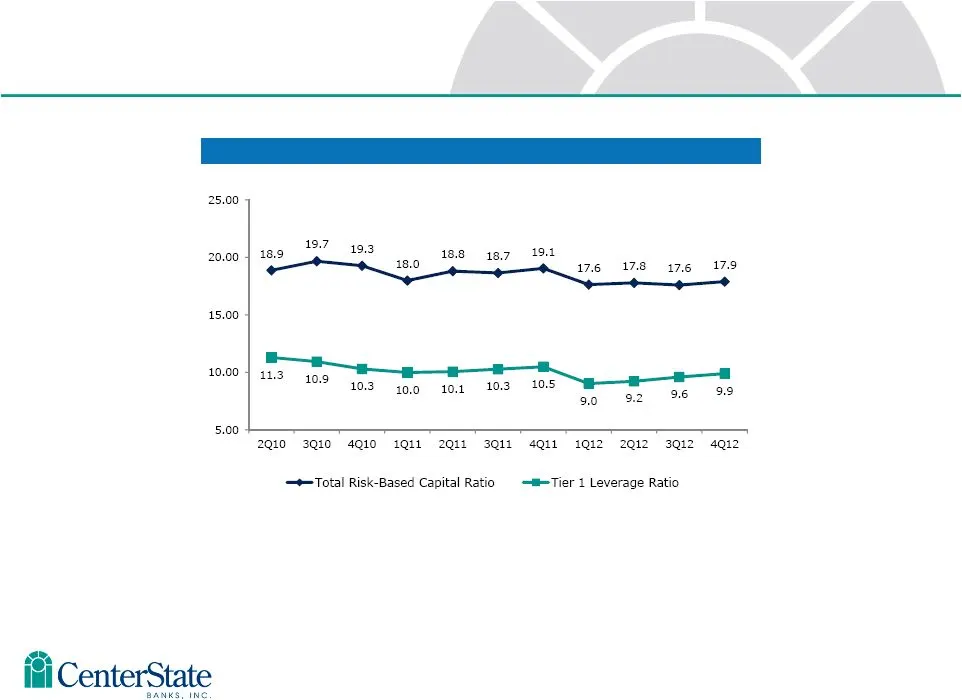
Total Risk-Based & Tier 1 Leverage 22 • Two successful capital raises in 2009 and 2010 totaling $114 million • First publicly traded bank in Florida to successfully complete a capital raise during financial crisis in 2009 • Over “Blue Chip” active institutional investors – Average daily volume (3m)
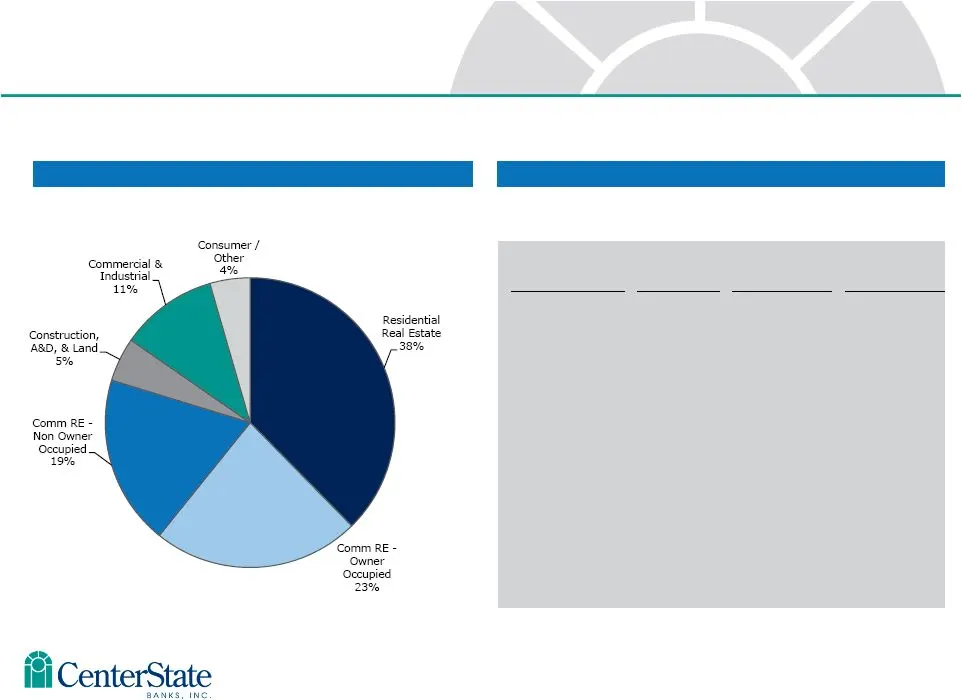
Slide 25: Total Loans by Type
Total Loans by Type Total Loans Detail Loan Type No. of Loans Balance Avg Loan Balance Residential Real Estate 4,021 $ 429 MM $106,700 CRE-Owner Occupied $ 264 MM $366,200 CRE-Non Owner Occupied $ 216 MM $452,800 Construction, A&D, & Land $ 56 MM $129,000 Commercial & Industrial 1,205 $ 124 MM $102,
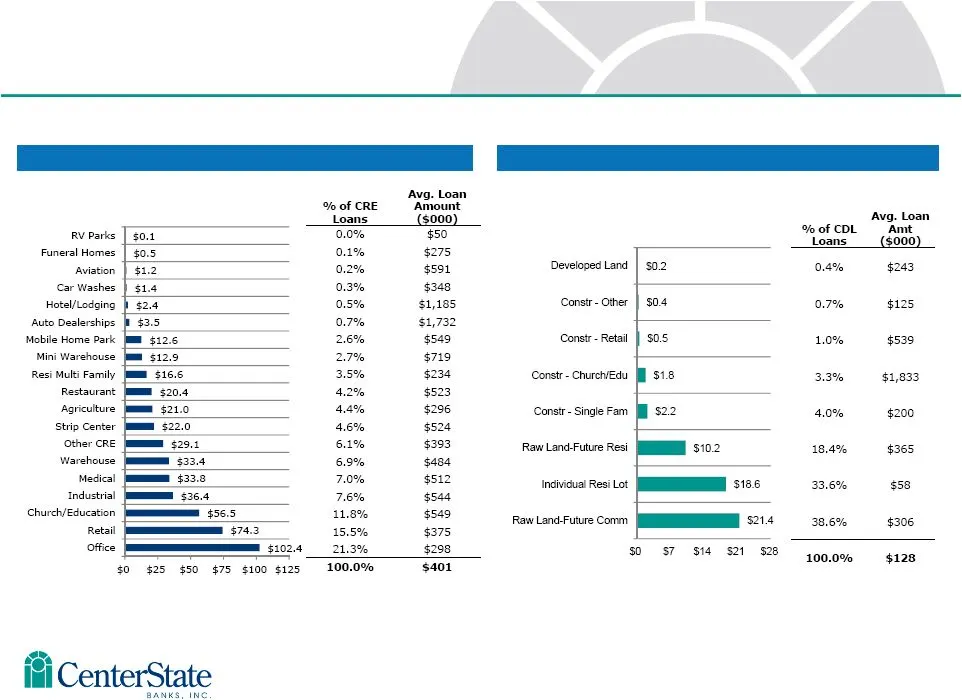
Slide 26: CRE Concentrations as of December 31
Commercial Real Estate by Type ($MM) Construction Loans by Type ($MM) 25 C&D concentration – 14% vs. 100% • 55% Owner Occupied CRE concentration – 107% vs. 300% CRE Concentrations as of December 31, Excluding FDIC covered assets
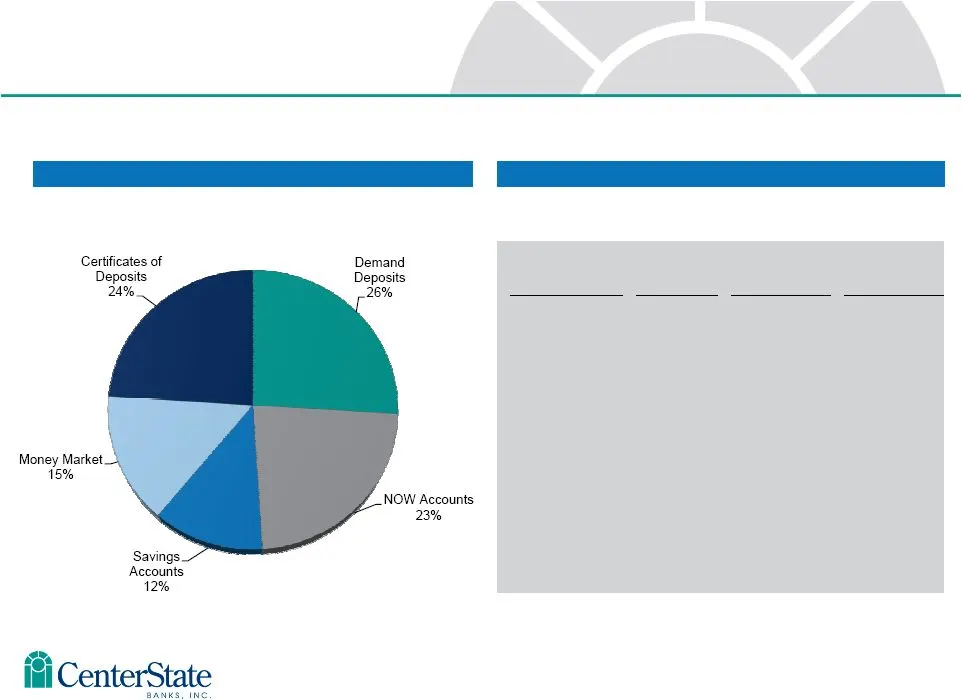
Slide 27: Total Deposits by Type
Total Deposits by Type Total Deposits Detail 23 Total Deposit Portfolio as of December 31, Deposit Type No. of Deposits Balance Avg Deposit Balance Demand Deposits 37,741 $ 520 MM $13,800 Now Accounts 47,329 $ 453 MM $9,600 Savings Deposits 18,217 $ 238 MM $13,000 Money Market 3,334 $ 311 MM $93,400
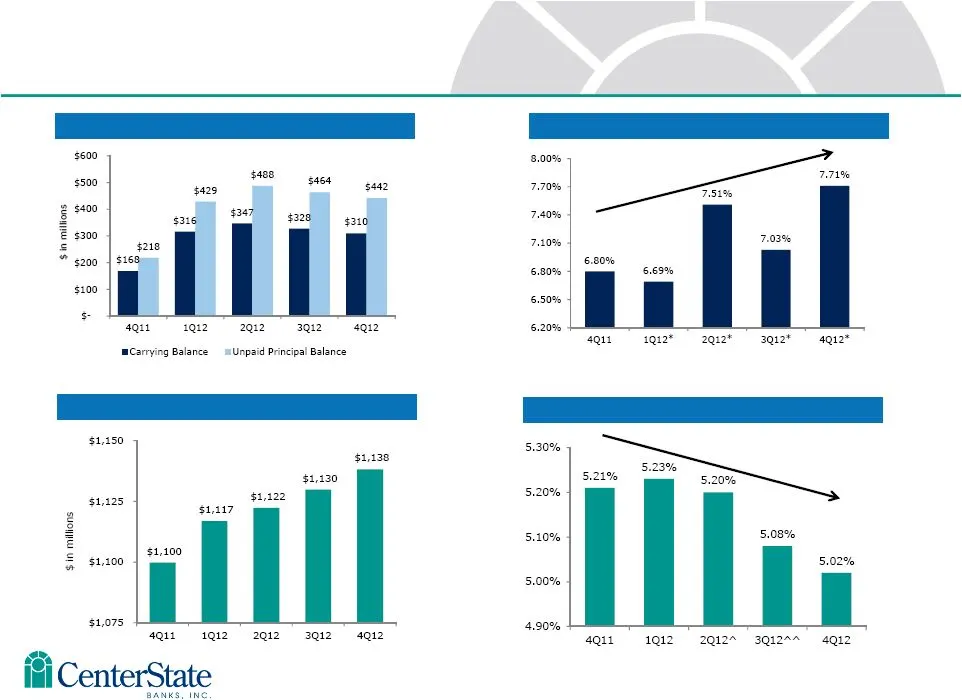
Slide 28: Loans – Yields and Averages
Covered Loans - Average Yields Covered Loans – Average Balances Non-Covered Loans – Average Balance Non-Covered Loans – Average Yields Loans – Yields and Averages * Adjusted for measurement period adjustment. ^ Adjusted for non-accrual loan upgrades ^^ Adjusted for excess cash flows relating to one
Slide 29: Net Interest Margin
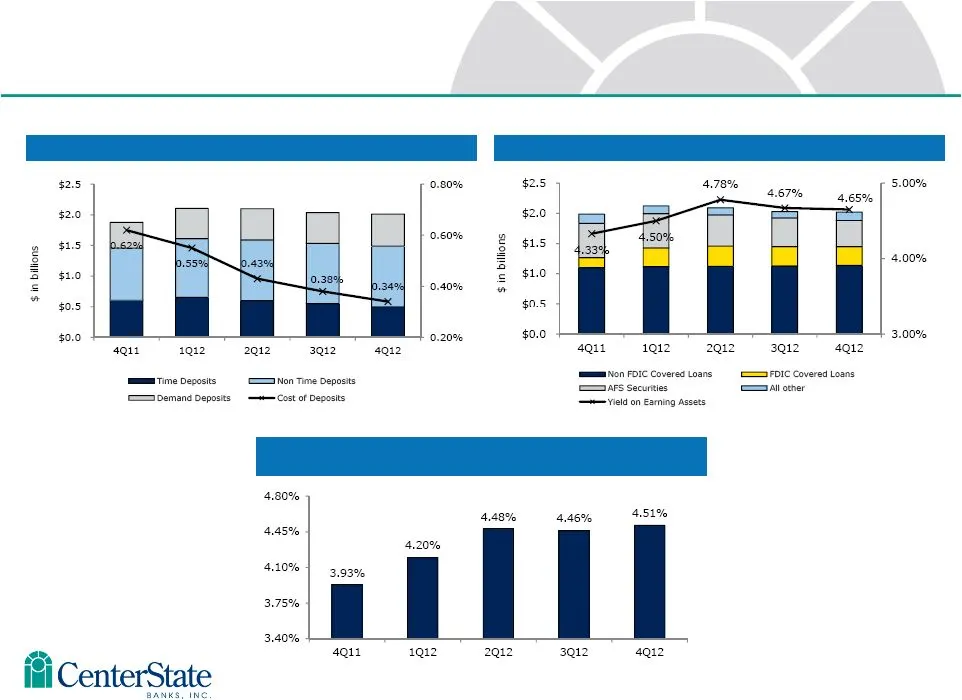
8 Costs of Deposits Yield on Interest Earning Assets Net Interest Margin (excluding Correspondent Division) Net Interest Margin
Slide 30: Indemnification Asset amortization and FDIC covered loan accretion
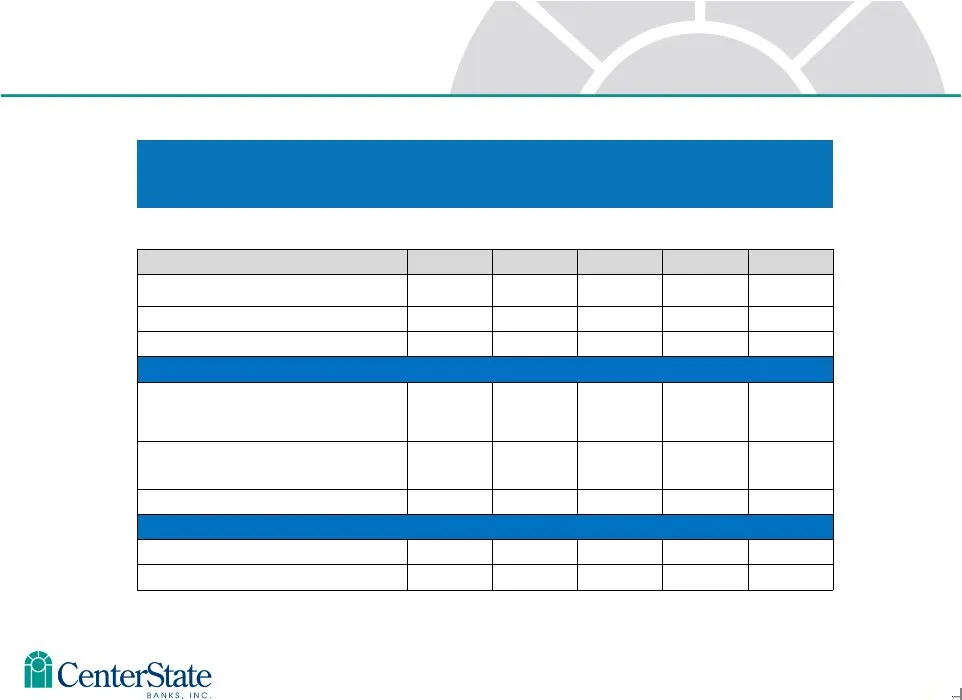
30 Indemnification Asset (“IA”) amortization and its effect on FDIC covered loan interest accretion ($ in thousands) 4Q11 1Q12 2Q12 3Q12 4Q12 Average FDIC covered loans $167,512 $316,421 $347,191 $327,847 $309,502 Interest accretion $2,873 $5,265 $6,480 $5,796 $6,001 Yield 6.80% 6.69% 7.51% 7.03% 7.
Slide 31: NPA Breakout as of December 31
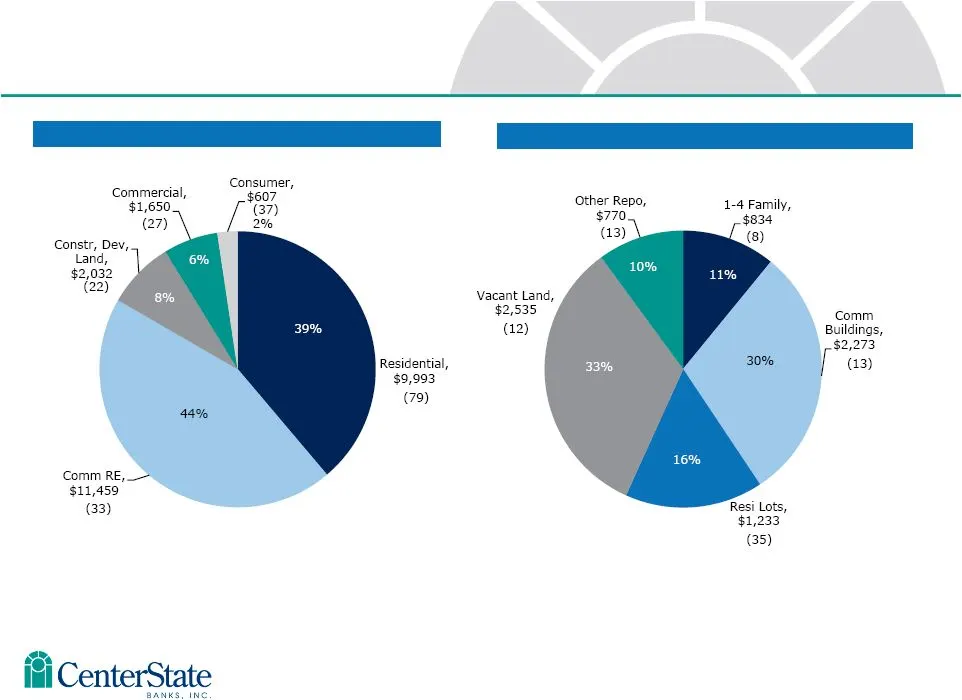
Non-Performing Loans ($M) Data as of 6/30/12 OREO & Repo ($M) • $7,645M • OREO & Repos are carried at 42% of Unpaid Principal Balance • $25,741M (2.26% of Gross Loans) • NPLs are carried at 77% of Unpaid Principal Balance • Current NPLs at 36% NPA Breakout as of December 31, Excluding FDIC covered a
Slide 32: Credit Cost
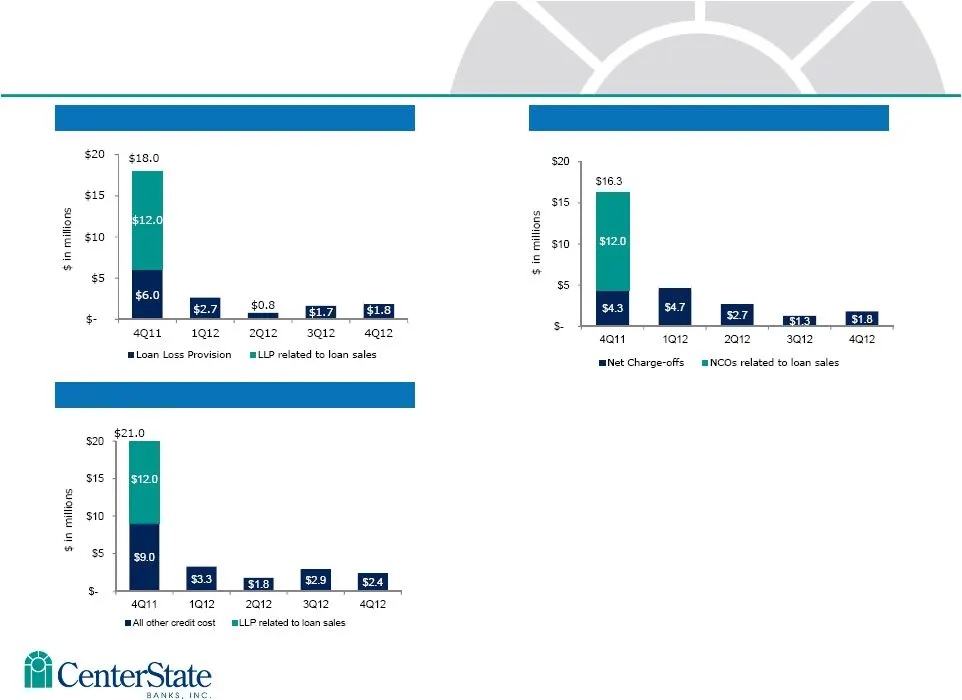
Net Charge-Offs (NCOs) Loan Loss Provision (LLP) Total Credit Costs Excludes FDIC covered loans • Provision expense trending downward • Net charge-offs trending downward • Total credit cost trending downward Credit Cost
Source: SEC EDGAR · 8-K filed Mar 27, 2013
More decks from CenterState Bank Corporation
 IPO Roadshow (May 2020)42 slides · May 21, 2020
 D.A. Davidson 22nd Annual Financial Institution Virtual Conference (May 2020)25 slides · May 6, 2020
 Q1 2020 Earnings Presentation25 slides · Apr 23, 2020
 Merger or Acquisition (January 2020)24 slides · Jan 27, 2020
 Q3 2019 Earnings Presentation28 slides · Nov 4, 2019
 Investor Presentation (July 2019)28 slides · Jul 30, 2019