Whitney — KBW Regional Bank Conference 2008
31 slides from Whitney's conference presentation, Feb 28, 2008
Slide 1: Whitney Holding Corporation KBW Regional Bank Conference
Whitney Holding Corporation KBW Regional Bank Conference February 28, 2008 John C. Hope III, President & COO Thomas L. Callicutt, Jr., EVP and CFO Lewis P. Rogers, EVP Credit Administration
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation may include forward-looking statements containing expectations about future conditions and descriptions of future plans and strategies. Whitney's ability to accurately predict the effects of future plans or strategies is inherently limited such that actua
Slide 3: Thomas L. Callicutt, Jr., Chief Financial Officer
Thomas L. Callicutt, Jr. Chief Financial Officer
Slide 4: A Growing, Diversified Company
A Growing, Diversified Company 125-year old name started in New Orleans Weathered many types of storms Corporate philosophy: Soundness Profitability Growth In that order of priority Over locations across 5 states Focus on Relationship Banking “It Takes a Whitney Banker”
Slide 5: 2007 Earnings Summary
2007 2006 (Period-end) Total Assets $11.0B $10.2B Total Loans $7.6B $7.0B Total Deposits $8.6B $8.4B Net Income $151MM $145MM E.P.S. (diluted) $2.23 $2.20 2007 Earnings Summary • Net income $151 million • Earnings per share (diluted) $2.23 • Merger with Signature Financial Holdings in St. Petersburg
Slide 6: Net Interest Margin - Asset Sensitive
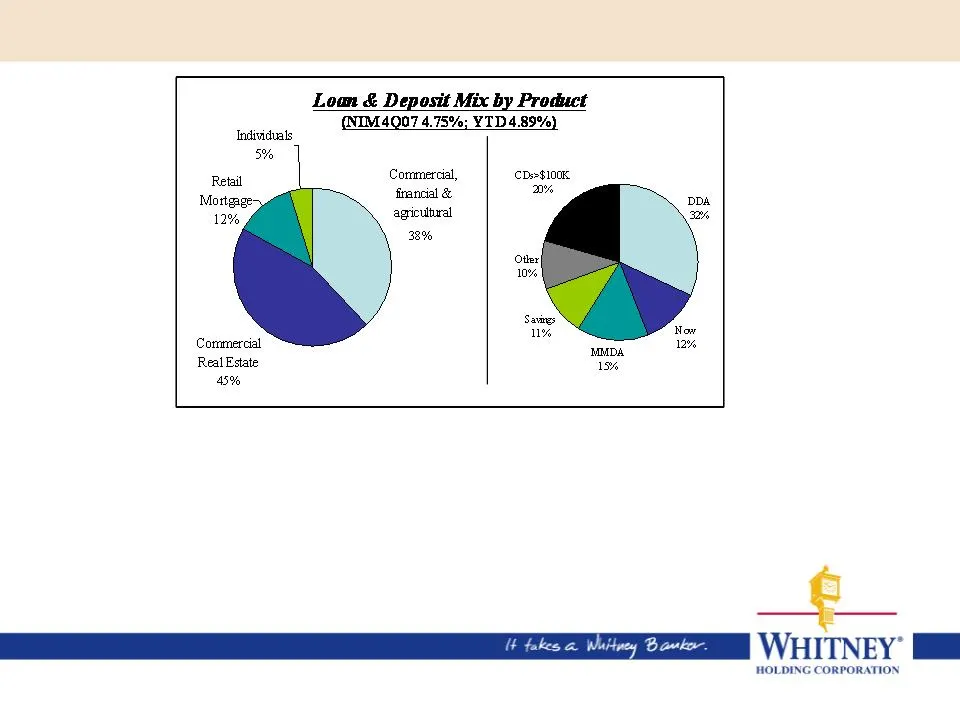
* NIM remains at the top of the peer group * Loan portfolio - 53% variable rate (28% tied to Libor; 25% tied to Prime) * Shift in funding mix from DDA to higher cost deposits * Active management of loan and deposit pricing * Liquidity in the deposit base * Moderately asset-sensitive +100bp instantan
Slide 7: Emphasis On Fee-Based Business Growth
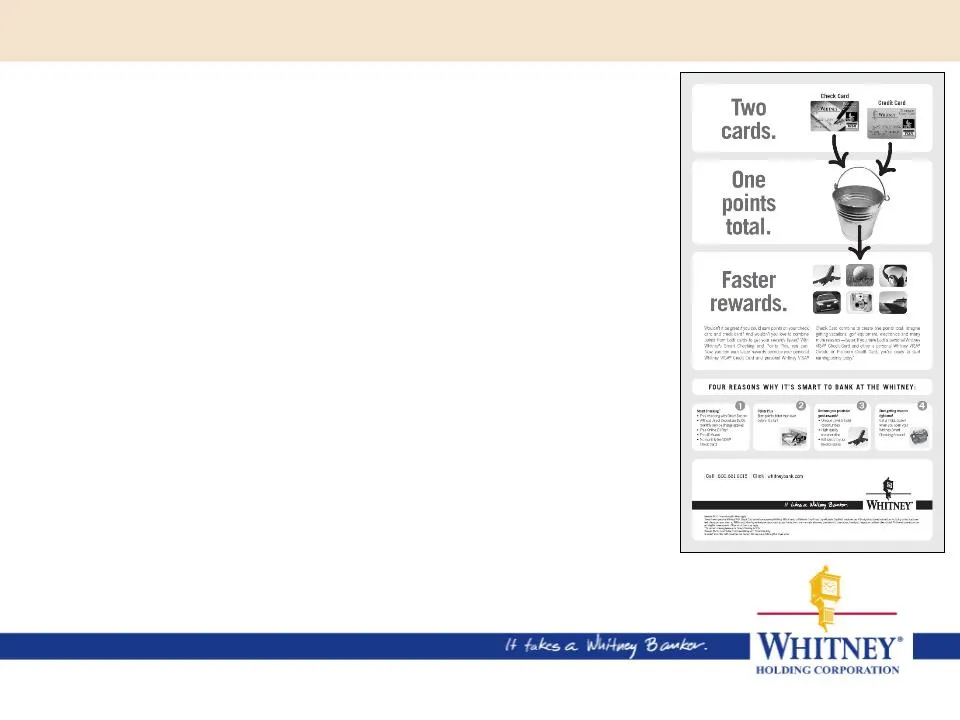
Emphasis On Fee-Based Business Growth • Fees up 12.5% from 2006 (excludes insurance gain) – Improvement noted in all recurring revenue sources • Service Charges on Deposits is the largest component of fee income – Deposit service charges up 9% from a year earlier • Bank card fees increased 10% from
Slide 8: Strategic Review Includes Cost Control Programs
• Total noninterest expense up 3% from 2006 – Includes impact from Signature merger • Expenses currently reflect a more normal level of activity • Efficiency ratio at 62% (normalized for insurance gain) • Current level of expenses is being addressed – Total noninterest expense in 4Q07 decreased 2% f
Slide 9: Sound Capital Levels
12/31/07 Equity to Assets 11.51% Tangible Equity to Assets 8.24% Tier I Leverage 8.79% Sound Capital Levels
Slide 10: New Orleans Update
New Orleans Update • Tourism, conventions, festivals and sporting events back on track in 2008 – Sugar Bowl – BCS Championship – Mardi Gras – NBA All-Star Game – PGA Tour – French Quarter Festival – Jazz Festival • Road Home program continuing to pay benefits
Slide 11: Lewis P. Rogers, Credit Administration
Lewis P. Rogers Credit Administration
Slide 12: Commercial and Business Banking Focus
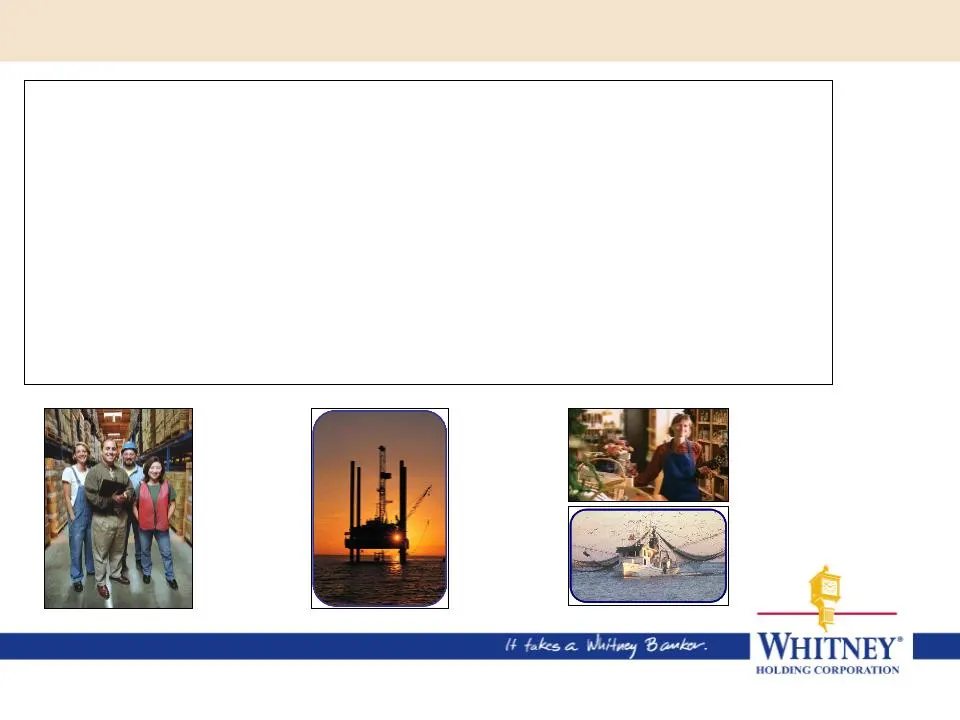
Commercial and Business Banking Focus • Commercial portfolio 83% • Consumer portfolio 17% • No Indirect portfolio • No meaningful exposure to subprime home mortgage loans • Minimal Credit Card portfolio • Commercial customers diversified by industry – Oil & gas approximately 10% • Real Estate portfo
Slide 13: Diversified By Geography
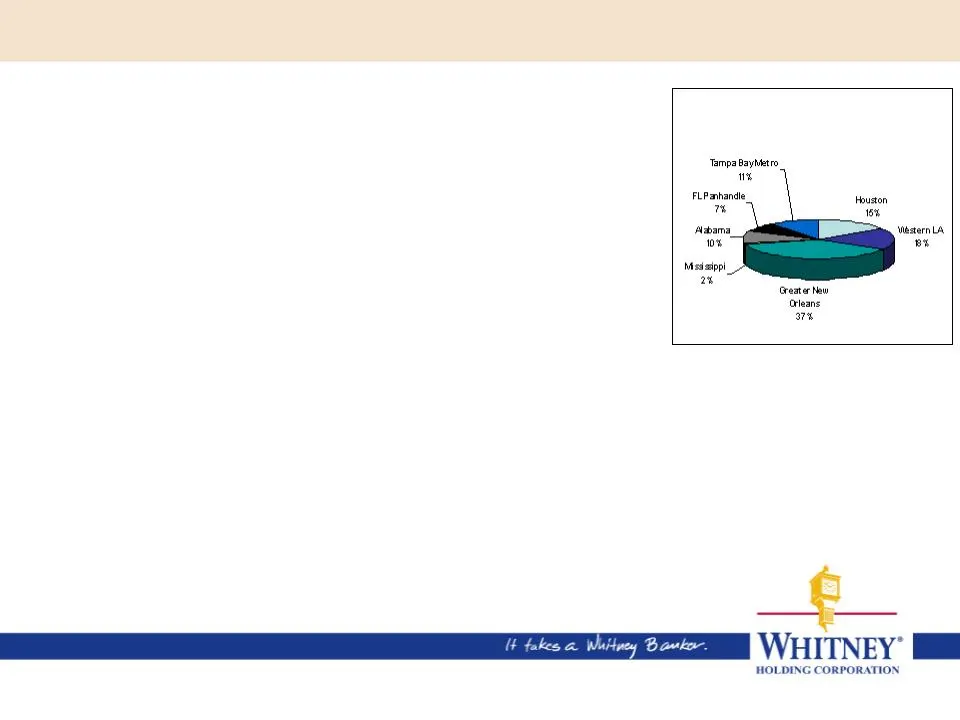
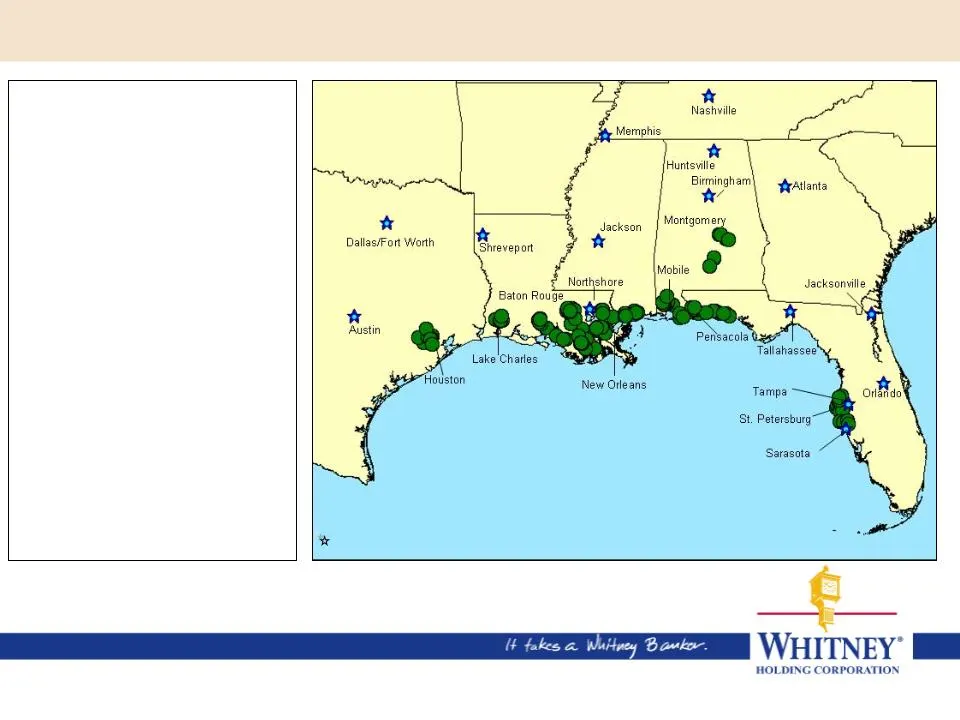
Diversified By Geography Total Loans $7.6 billion – 37% serviced in metro New Orleans – 15% serviced in Houston – 18% serviced in Florida • 7% serviced from the panhandle • 11% serviced from the Tampa Bay metro area – Loan growth supported by economic and market conditions in Texas, Alabama and Loui
Slide 14: A Strong Monitoring Process Is Key
A Strong Monitoring Process Is Key One of our core strengths is understanding and managing credit risk – Seasoned, well understood credit culture – Consistent application and monitoring of standards throughout the Company – Lending officers are responsible for ongoing monitoring and assignment of ri
Slide 15: Loans Internally Classified as Having Above Normal Credit Risks
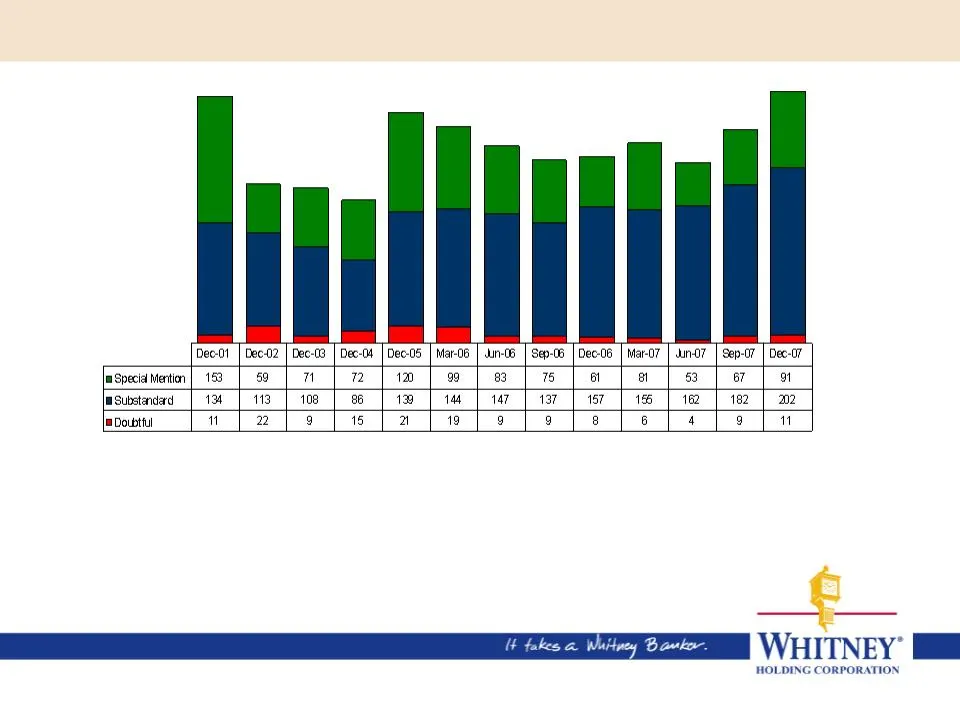
In millions Loans Internally Classified as Having Above Normal Credit Risks - 40% residential development, investment and other residential purpose loans (Produced most of the overall net increase during the year) - 30% nonresidential RE loans (Underlying collateral fairly evenly divided between inc
Slide 16: Prompt Identification Of Risk
Prompt Identification Of Risk • 4Q07 increase: – Predominantly from residential-related loans mainly in Florida and Alabama – Over half of these loans had been included in criticized loans in earlier periods
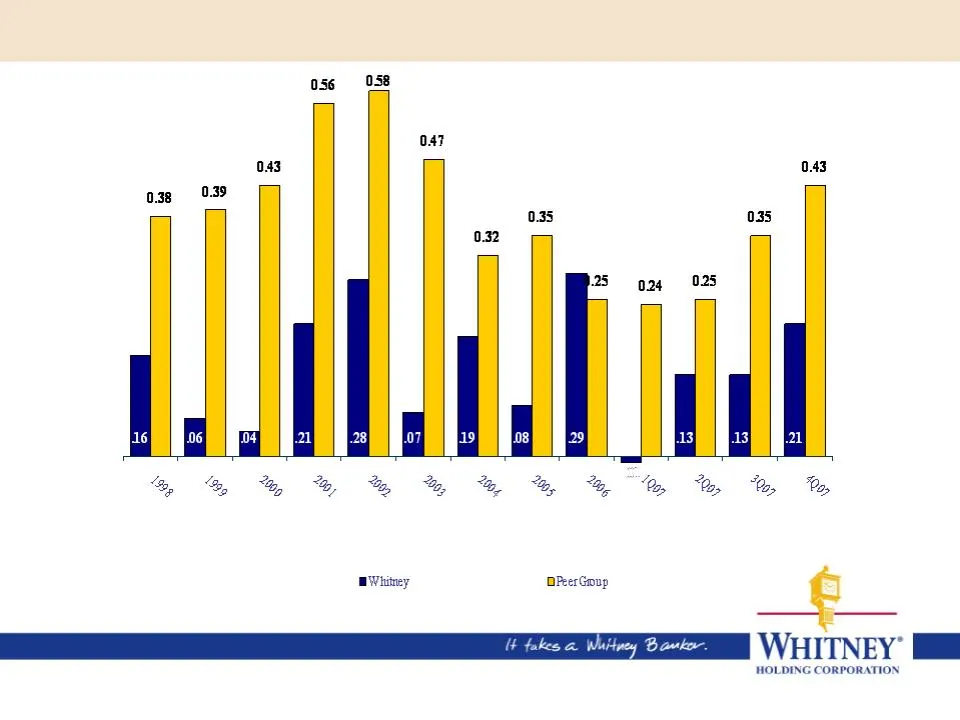
Slide 17: Historical Trend: Net Charge-Offs At or Below Peers
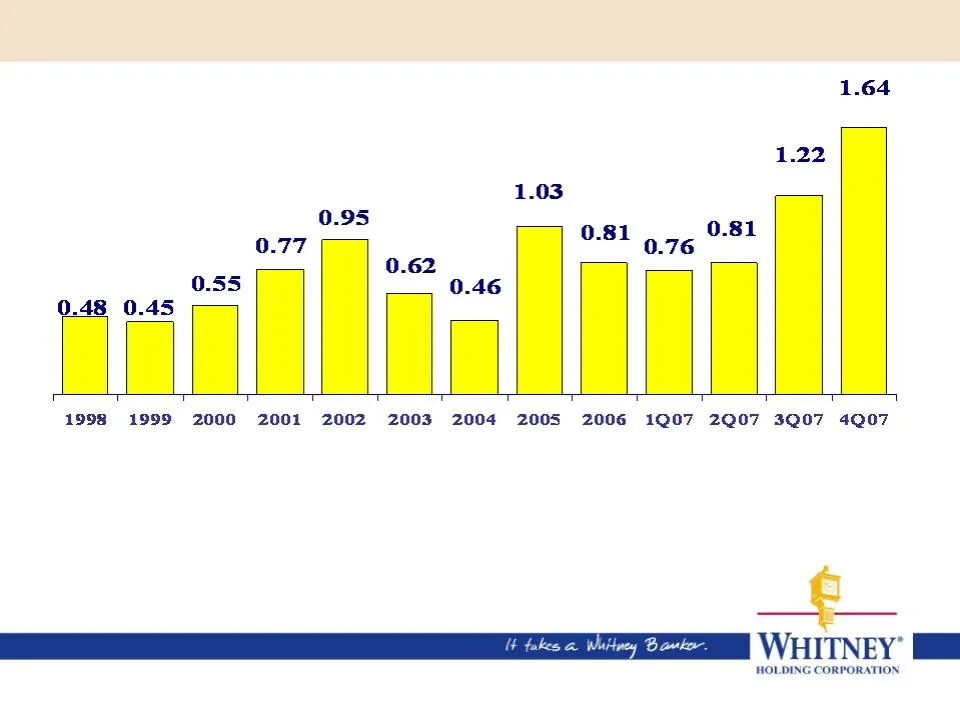
Historical Trend: Net Charge-Offs At or Below Peers Percent Net Charge-offs to Average Loans
Slide 18: Allowance For Loan Losses
Allowance For Loan Losses • Methodology for determining the allowance is a consistent process – Important factors are re-evaluated quarterly to respond to changing conditions • Allowance encompasses three elements – Allowances established for losses on criticized loans – Allowances based on historic
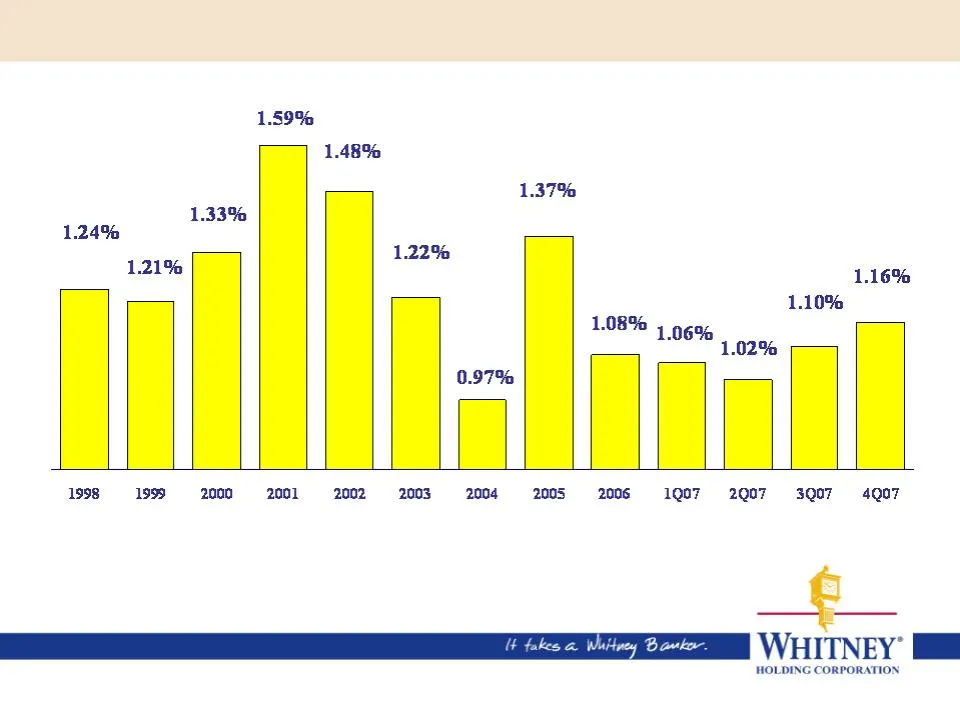
Slide 19: Allowance for loan losses trend
1.59% 1.16% 1.10% 1.08% 1 gga 1.02% 1998 = 1999 2000 2001 2002 2003 2004 «= 2005 200 )39= 1907 )§=2Q07 «= 3Q07 «= 4QN7 WHITNEY’
Slide 20: Strong Credit Culture
Strong Credit Culture • Multiple controls within our credit culture • Weekly loan committee process • No individual lending authority over $2MM (relationship) • Prompt identification of problem loans • Thorough work-out process • Healthy level of recoveries
Slide 21: John C. Hope III, President & Chief Operating Officer
John C. Hope III President & Chief Operating Officer
Slide 22: Whitney Is A Very Good, Very Strong Bank
Whitney Is A Very Good, Very Strong Bank • Strong credit culture • Strong NIM • Strong balance sheet and solid capital position • Operational resiliency • Geographic diversification
Slide 23: Currently Faced With Challenging Environment
Currently Faced With Challenging Environment § The net interest margin is already the top in its peer group in the midst of an unfavorable rate environment § Balance sheet growth is slow due to the current business cycle § Lower credit costs are no longer a contributor to earnings § Fee-based busine
Slide 24: Focus & Discipline: A Key To Continued Success
Focus & Discipline: A Key To Continued Success • Balance sheet management – Less vulnerable to changes in interest rates • Capital management • Credit remains a core strength • Reduction of expenses • Focus on segmentation – Commercial & Business Banking • Branch rationalization and realignment – Br
Slide 25: Revenue Generation
Revenue Generation • Trust & Wealth Management • Mortgage Banking • Treasury Management • Card Services • Acquisitions have added to existing business or provided new lines of business
Slide 26: Acquisitions Are Important To Our Growth
Acquisitions Are Important To Our Growth • Since 1994 successfully merged banks – Assets: $3.7B – Loans: $2.3B – Deposits: $3.4B – States: – Branches: – FTE: 1,450 • Following the flow of commerce • Expand our footprint even wider • Take advantage of any opportunity Represent possible future Whitney
Slide 27: Whitney's Mission Will Not Change
Whitney’s Mission Will Not Change Our mission is to deliver extraordinary value and service, along with superior results, to our customers and shareholders while providing leadership to our local communities and outstanding career opportunities to our valued employees. We do this within the framewor
Slide 28: Whitney's Guiding Principles Will Not Change
Whitney’s Guiding Principles Will Not Change • Soundness - This ensures our continuity and promotes the trust of our customers, shareholders and communities. • Profitability - We focus on profitability, since it is not only a gauge of our success, but ensures that we will have the capital we need to
Slide 29: Focused On A Long-Term Strategy
Focused On A Long-Term Strategy • Only a FEW banks have the ability to transform themselves – F ocus – E xecution – W ill • Working towards maintaining a level of consistent, quality earnings over time • Difficulties and challenges will need to be overcome • We have a good start and a great group of
Slide 30: Service, Knowledge, Relationship-focus
• Service • Knowledge • Relationship-focus • Friendly • Community-conscious
Slide 31: Whitney Holding Corporation KBW Regional Bank Conference
Whitney Holding Corporation KBW Regional Bank Conference February 28, 2008 John C. Hope III, President & COO Thomas L. Callicutt, Jr., EVP and CFO Lewis P. Rogers, EVP Credit Administration
Source: SEC EDGAR · 8-K filed Feb 28, 2008
More decks from Whitney Holding Corp
 Q4 2010 Earnings Presentation15 slides · Jan 27, 2011
 Merger or Acquisition (December 2010)18 slides · Dec 23, 2010
 Merger or Acquisition (December 2010)18 slides · Dec 22, 2010
 Stifel Nicolaus Bank & Thrift Conference 201030 slides · Nov 2, 2010
 Q3 2010 Earnings Presentation16 slides · Oct 26, 2010
 Q2 2010 Earnings Presentation18 slides · Jul 27, 2010