Tellurian — Magellan Petroleum — IPAA OGIS Florida Investor Conference (February 2013)
16 slides from Tellurian's conference presentation, Feb 14, 2013
Slide 1: Delivering Shareholder Value
NASDAQ: MPET February 2013 Delivering Shareholder Value Exhibit 99.1
Slide 2: Forward Looking Statements
1 Forward Looking Statements Statements in this presentation which are not historical in nature are intended to be, and are hereby identified as, forward-looking statements for purposes of the Private Securities Litigation Reform Act of 1995. These statements about Magellan and Magellan Petroleum Au
Slide 3: The Company
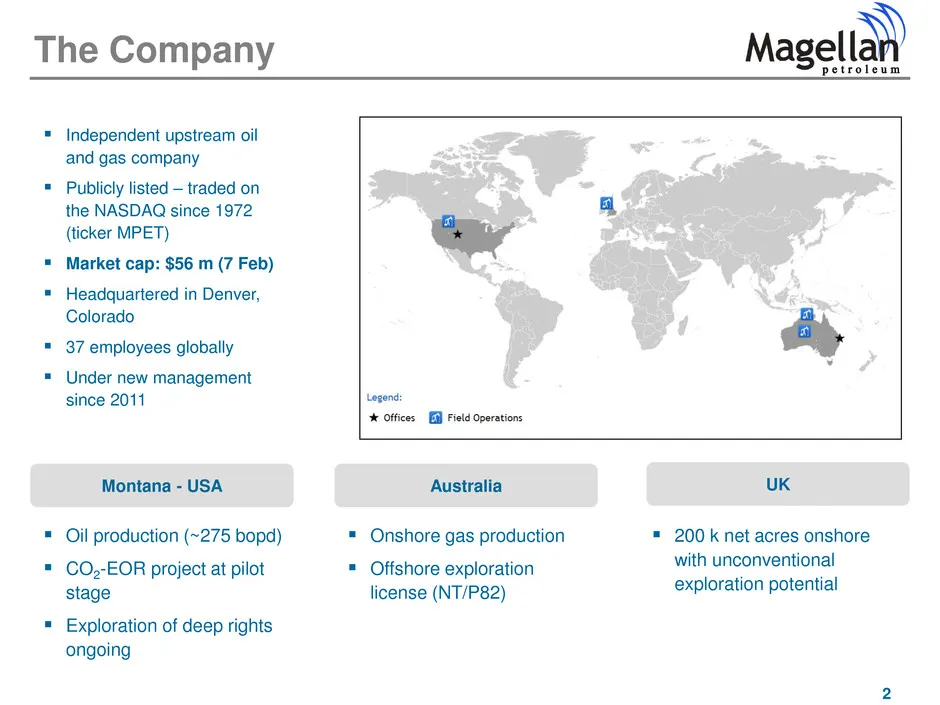
2 The Company Independent upstream oil and gas company Publicly listed – traded on the NASDAQ since 1972 (ticker MPET) Market cap: $56 m (7 Feb) Headquartered in Denver, Colorado 37 employees globally Under new management since 2011 Oil production (~275 bopd) CO2-EOR project at pilot
Slide 4: Investment Considerations
3 Exploration and development company with existing production and three high- growth assets Favorable market dynamics – Strong oil pricing in the US – Australian gas market – robust pricing – OECD countries only Attractive Company economics – Stable base level of production and reserves in US
Slide 5: Reserves Overview
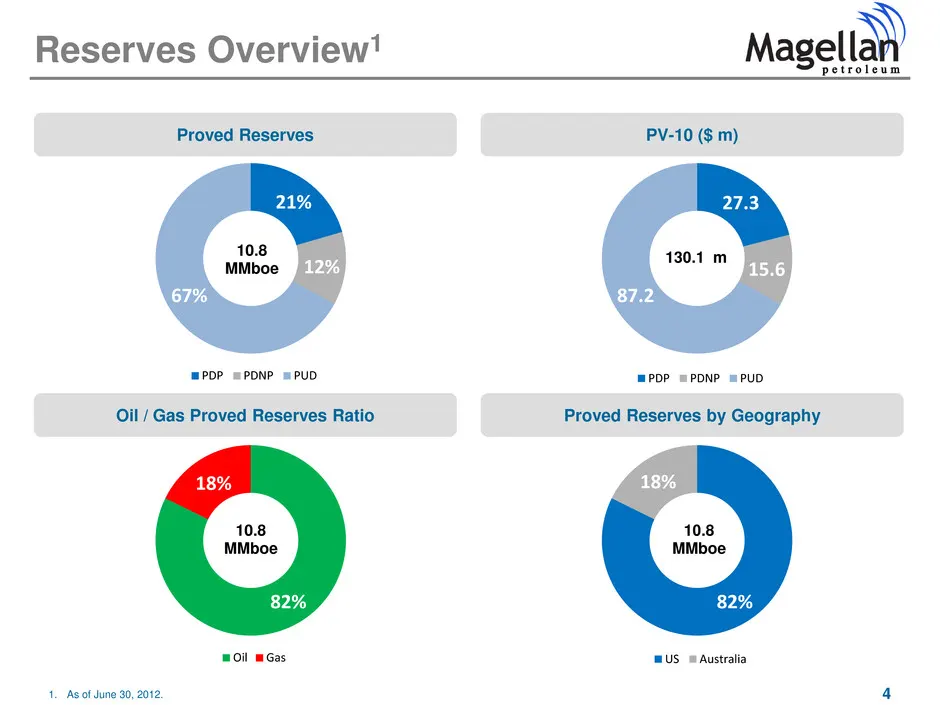
4 27.3 15.6 87.2 PDP PDNP PUD 130.1 m 82% 18% US Australia 10.8 MMboe 82% 18% Oil Gas 10.8 MMboe 21% 12% 67% PDP PDNP PUD 10.8 MMboe PV-10 ($ m) Oil / Gas Proved Reserves Ratio Proved Reserves by Geography Proved Reserves Reserves Overview1 1. As of June 30, 2012.
Slide 6: Management team and chairman
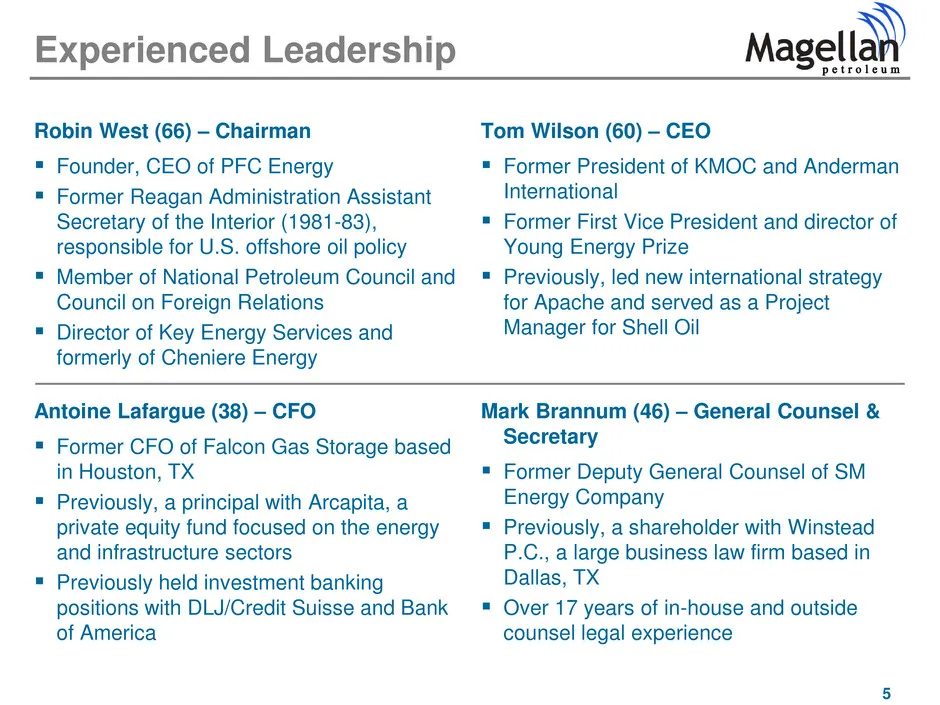
5 Antoine Lafargue (38) – CFO Former CFO of Falcon Gas Storage based in Houston, TX Previously, a principal with Arcapita, a private equity fund focused on the energy and infrastructure sectors Previously held investment banking positions with DLJ/Credit Suisse and Bank of America Mark Brannum
Slide 7: Poplar acreage in the Williston Basin
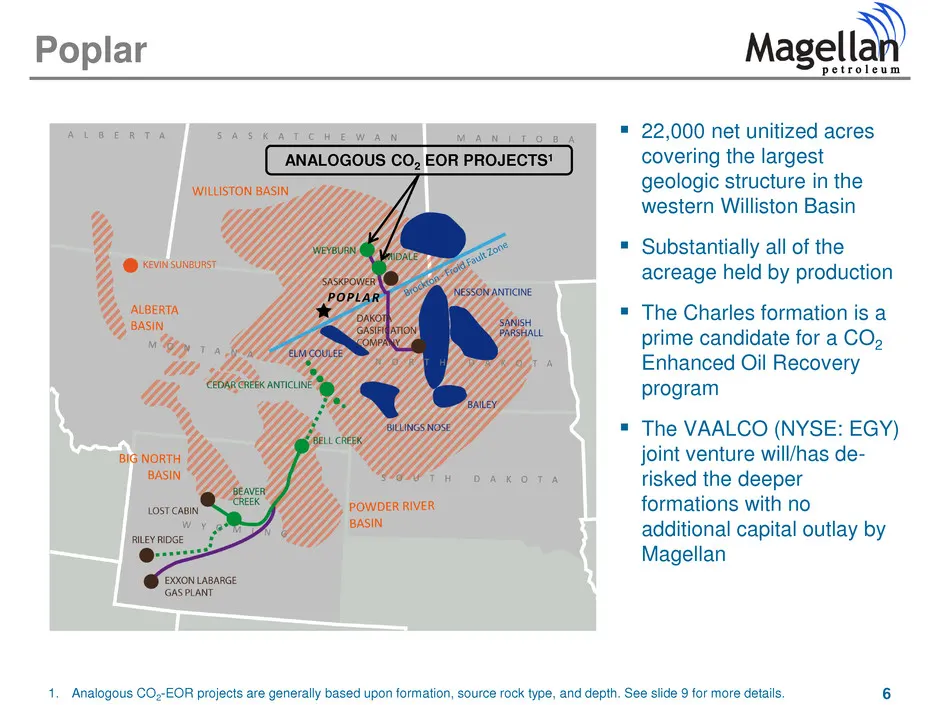
6 22,000 net unitized acres covering the largest geologic structure in the western Williston Basin Substantially all of the acreage held by production The Charles formation is a prime candidate for a CO2 Enhanced Oil Recovery program The VAALCO (NYSE: EGY) joint venture will/has de- risked t
Slide 8: Poplar: Several reserve development opportunities
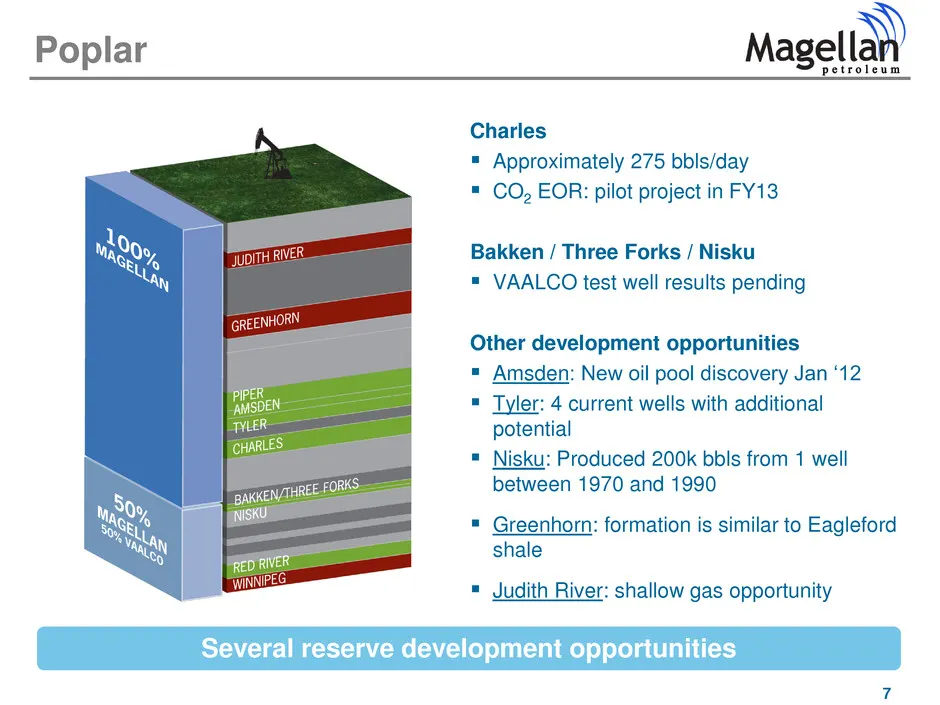
7 Charles Approximately 275 bbls/day CO2 EOR: pilot project in FY13 Bakken / Three Forks / Nisku VAALCO test well results pending Other development opportunities Amsden: New oil pool discovery Jan ‘12 Tyler: 4 current wells with additional potential Nisku: Produced 200k bbls from 1 well
Slide 9: Development milestones for de-risking project
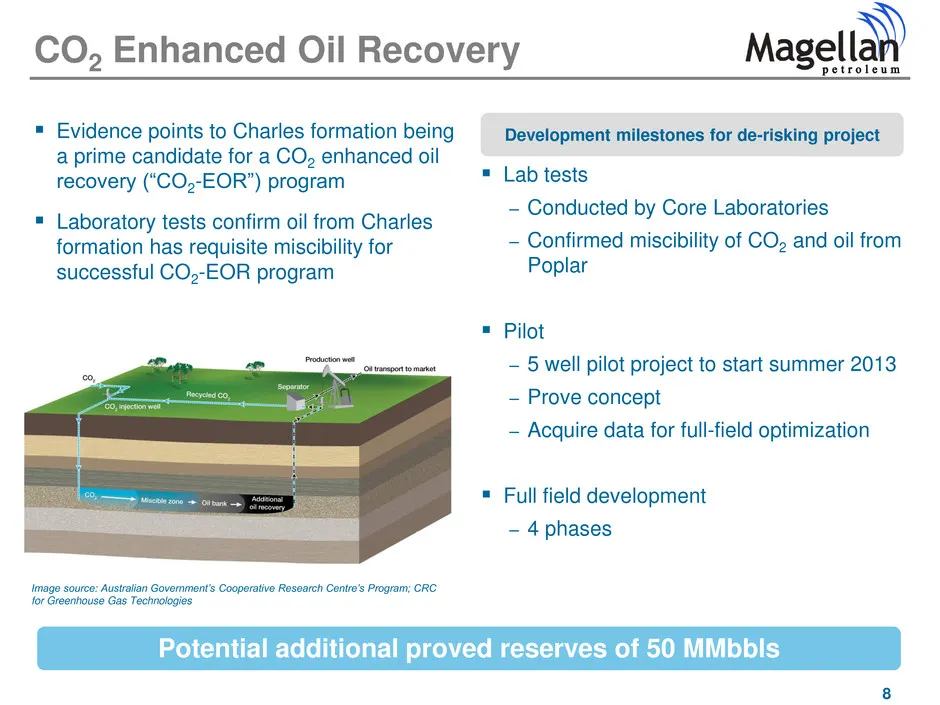
8 Development milestones for de-risking project Evidence points to Charles formation being a prime candidate for a CO2 enhanced oil recovery (“CO2-EOR”) program Laboratory tests confirm oil from Charles formation has requisite miscibility for successful CO2-EOR program Lab tests – Conducted by
Slide 10: CO2-EOR Analogs: Recovery Potential
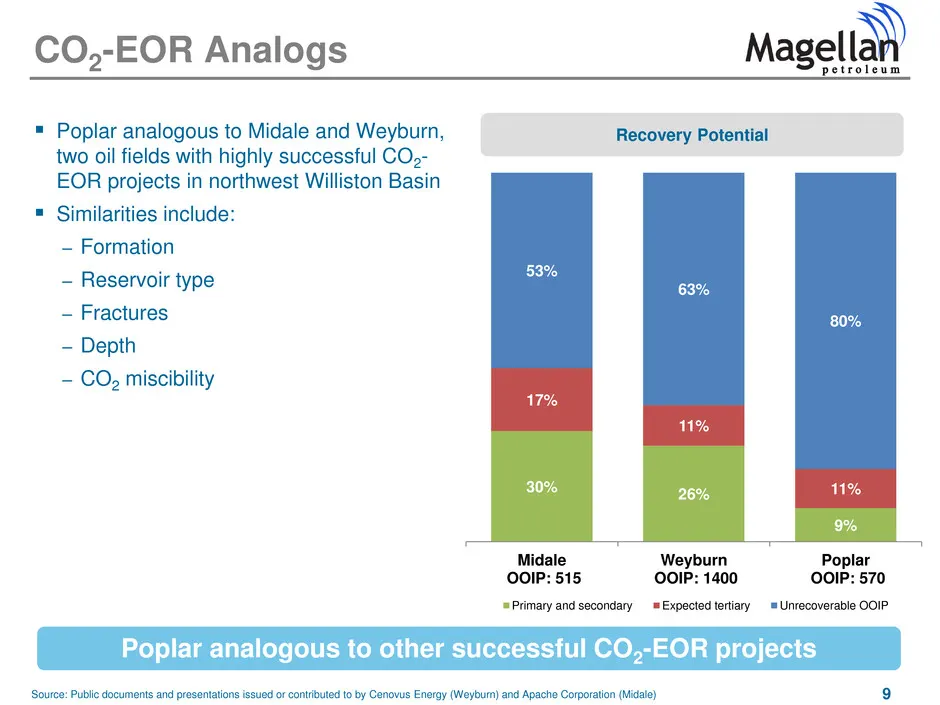
9 Recovery Potential Poplar analogous to Midale and Weyburn, two oil fields with highly successful CO2- EOR projects in northwest Williston Basin Similarities include: – Formation – Reservoir type – Fractures – Depth – CO2 miscibility CO2-EOR Analogs Poplar analogous to other successful CO2-EOR
Slide 11: Poplar – VAALCO Farm-Out
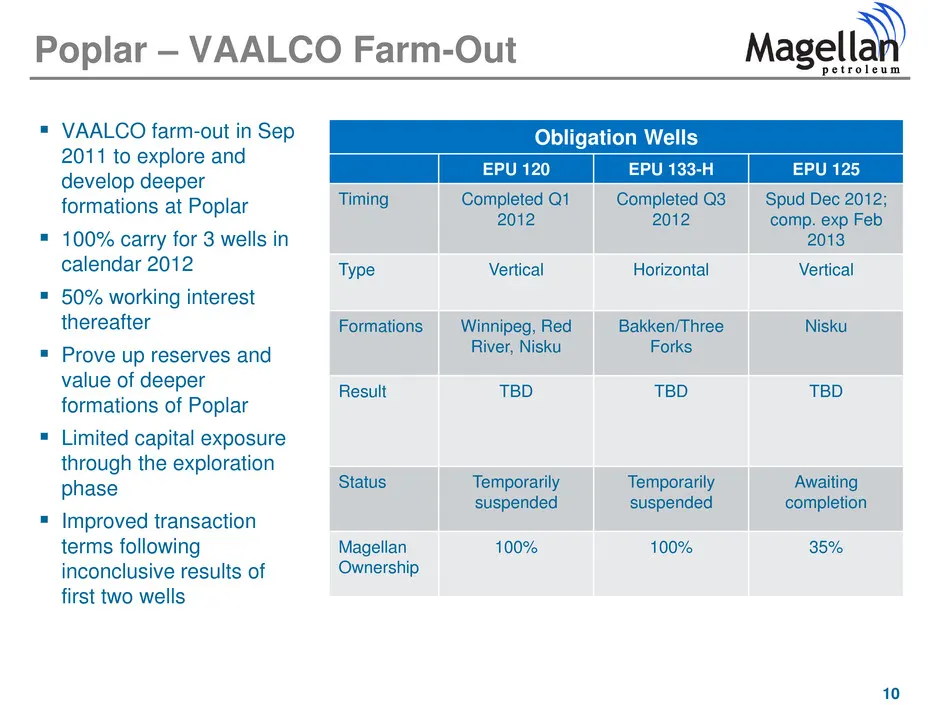
10 VAALCO farm-out in Sep 2011 to explore and develop deeper formations at Poplar 100% carry for 3 wells in calendar 2012 50% working interest thereafter Prove up reserves and value of deeper formations of Poplar Limited capital exposure through the exploration phase Improved transaction
Slide 12: Australian Onshore Assets
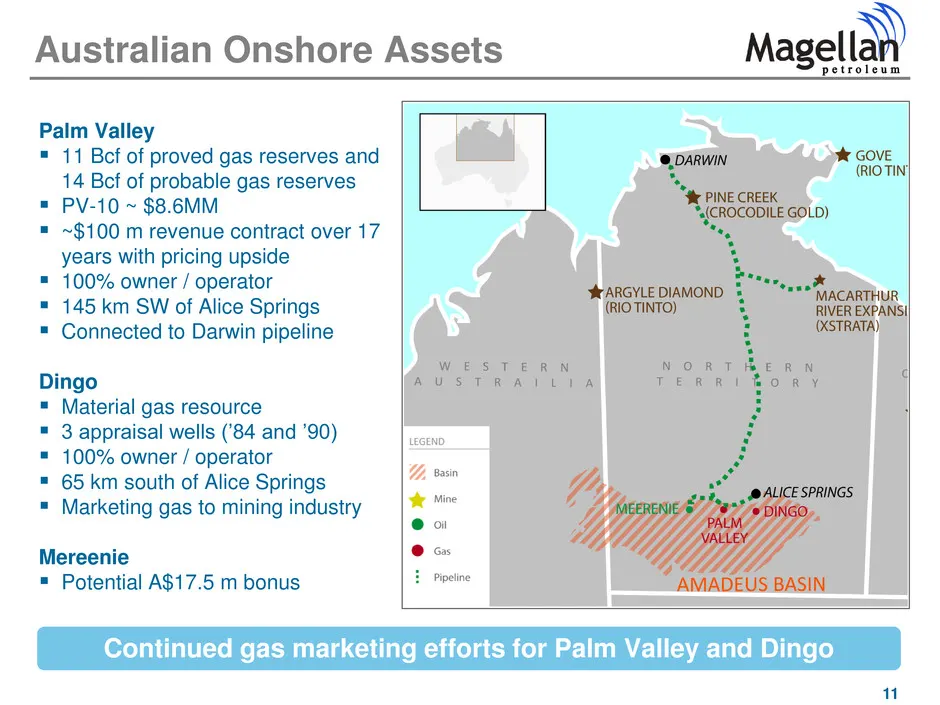
11 Palm Valley 11 Bcf of proved gas reserves and 14 Bcf of probable gas reserves PV-10 ~ $8.6MM ~$100 m revenue contract over 17 years with pricing upside 100% owner / operator 145 km SW of Alice Springs Connected to Darwin pipeline Dingo Material gas resource 3 appraisal wells (’84
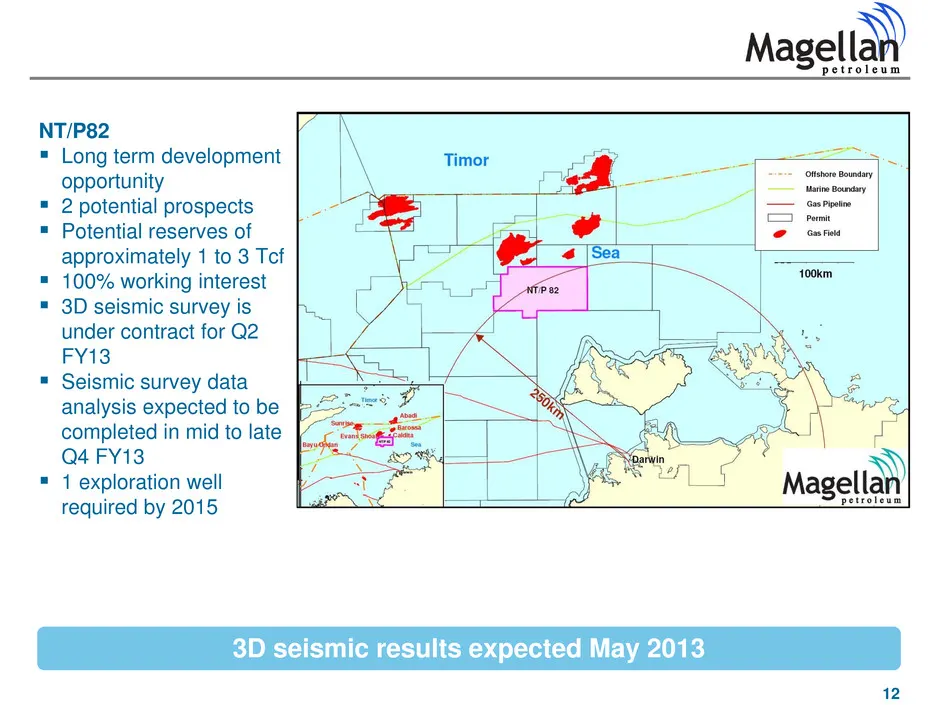
Slide 13: NT/P82
12 NT/P82 Long term development opportunity 2 potential prospects Potential reserves of approximately 1 to 3 Tcf 100% working interest 3D seismic survey is under contract for Q2 FY13 Seismic survey data analysis expected to be completed in mid to late Q4 FY13 1 exploration well require
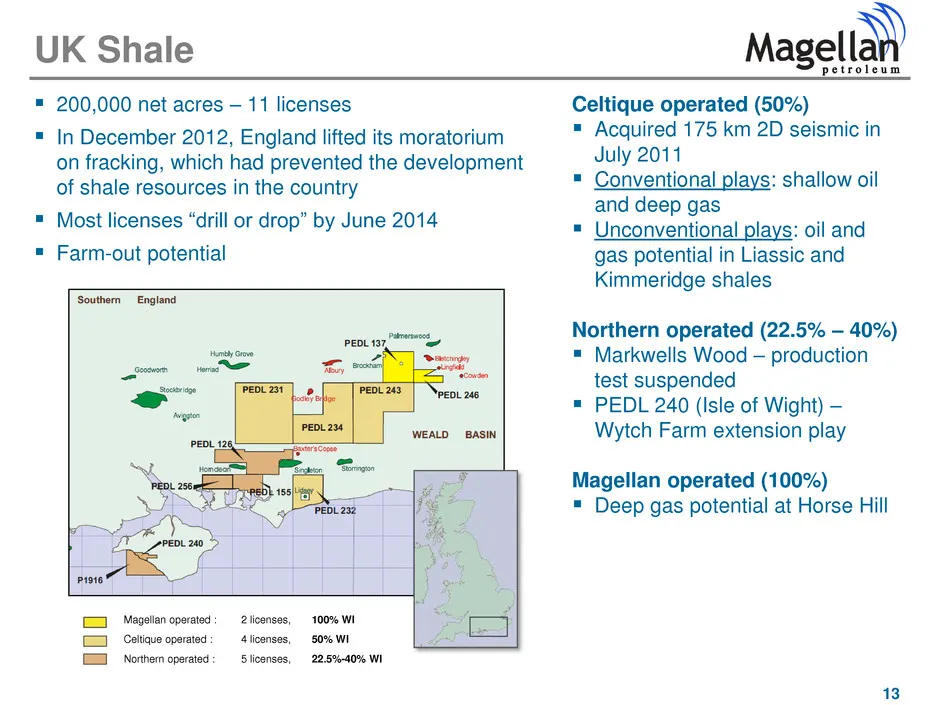
Slide 14: UK Shale
13 200,000 net acres – 11 licenses In December 2012, England lifted its moratorium on fracking, which had prevented the development of shale resources in the country Most licenses “drill or drop” by June 2014 Farm-out potential Celtique operated (50%) Acquired 175 km 2D seismic in July 201
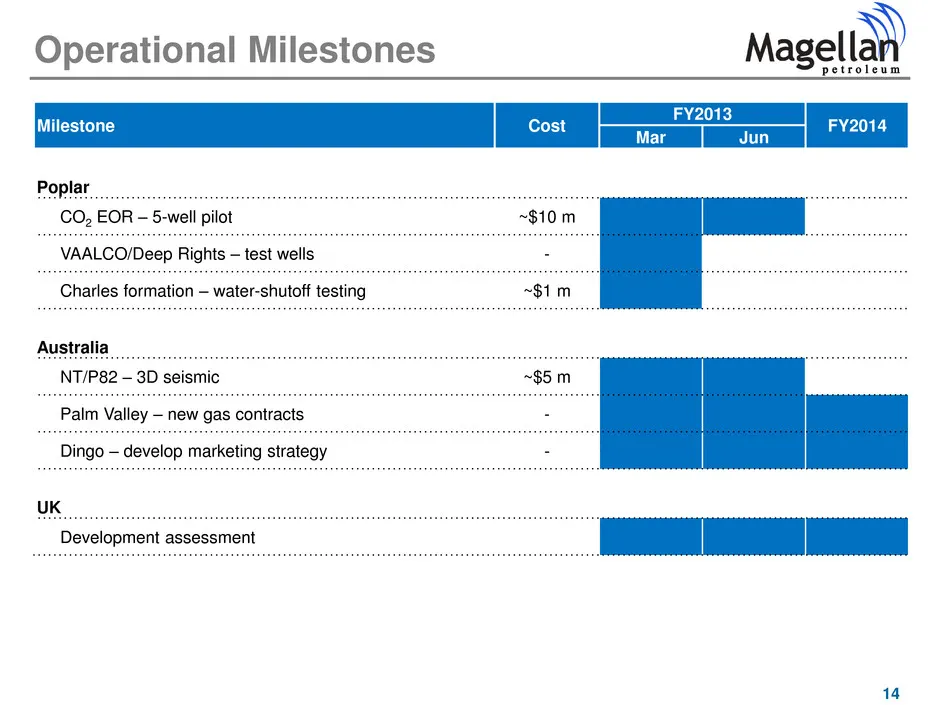
Slide 15: Operational Milestones
14 Operational Milestones Milestone Cost FY2013 FY2014 Mar Jun Poplar CO2 EOR – 5-well pilot ~$10 m VAALCO/Deep Rights – test wells - Charles formation – water-shutoff testing ~$1 m Australia NT/P82 – 3D seismic ~$5 m Palm Valley – new gas contracts - Dingo – develop marketing strategy - UK Developm
Slide 16: Questions?
a Magellay Questions? petr Magellan
Source: SEC EDGAR · 8-K filed Feb 14, 2013
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (November 2022)19 slides · Nov 2, 2022