Bryn Mawr Bank — Shareholder Meeting (May 2012)
19 slides from Bryn Mawr Bank's shareholder meeting presentation, May 2, 2012
Slide 1: Annual Shareholders Meeting
Exhibit 99.3 Annual Shareholders Meeting May 2, 2012 Bryn Mawr Bank Corporation NASDAQ: BMTC
Slide 2: Safe Harbor
Safe Harbor This presentation contains statements which, to the extent that they are not recitations of historical fact may constitute forward-looking statements for purposes of the Securities Act of 1933, as amended, and the Securities Exchange Act of 1934, as amended. Please see the section titled
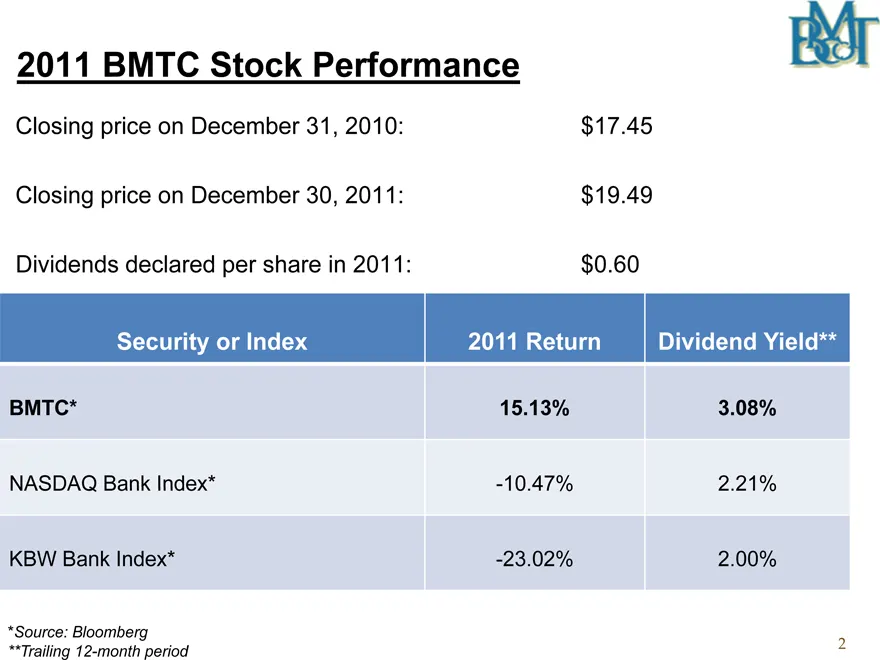
Slide 3: 2011 BMTC Stock Performance
2011 BMTC Stock Performance Closing price on December 31, 2010: $17.45 Closing price on December 30, 2011: $19.49 Dividends declared per share in 2011: $0.60 Security or Index 2011 Return Dividend Yield** BMTC* 15.13% 3.08% NASDAQ Bank Index* -10.47% 2.21% KBW Bank Index* -23.02% 2.00% *Source: Bloo
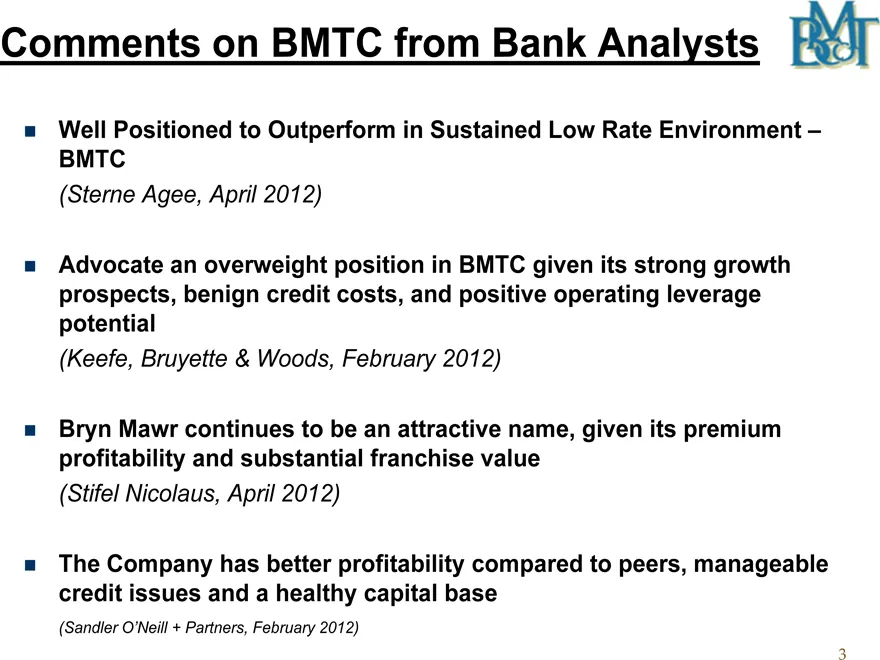
Slide 4: Comments on BMTC from Bank Analysts
Comments on BMTC from Bank Analysts Well Positioned to Outperform in Sustained Low Rate Environment –BMTC (Sterne Agee, April 2012) Advocate an overweight position in BMTC given its strong growth prospects, benign credit costs, and positive operating leverage potential (Keefe, Bruyette & Woods, Febr
Slide 5: 2012 Strategic Initiatives
2012 Strategic Initiatives Focus on the net interest margin Continued emphasis on strong credit quality Integrate, streamline and assimilate recent acquisitions into more effective and efficient wealth operations Lower the efficiency ratio Explore growth opportunity in the Delaware market
Slide 6: First Bank of Delaware Transaction
First Bank of Delaware Transaction Purchasing approximately $100 million in deposits and loans Opportunity to enter an attractive market with critical mass Establishing a branch location in Wilmington, Delaware Increase our brand awareness—support our other Delaware businesses Expected to close in t
Slide 7: Acquisition of Davidson Trust Company
Acquisition of Davidson Trust Company Expected to close in the 2nd Quarter 2012 Purchase price $10.5 Million in cash. Expected to be accretive to earnings per share in the first 12 months* Profile: Approximately $1 Billion in assets under management and supervision 30 year history in market 80% Inve
Slide 8: Quarterly Net Interest Margin
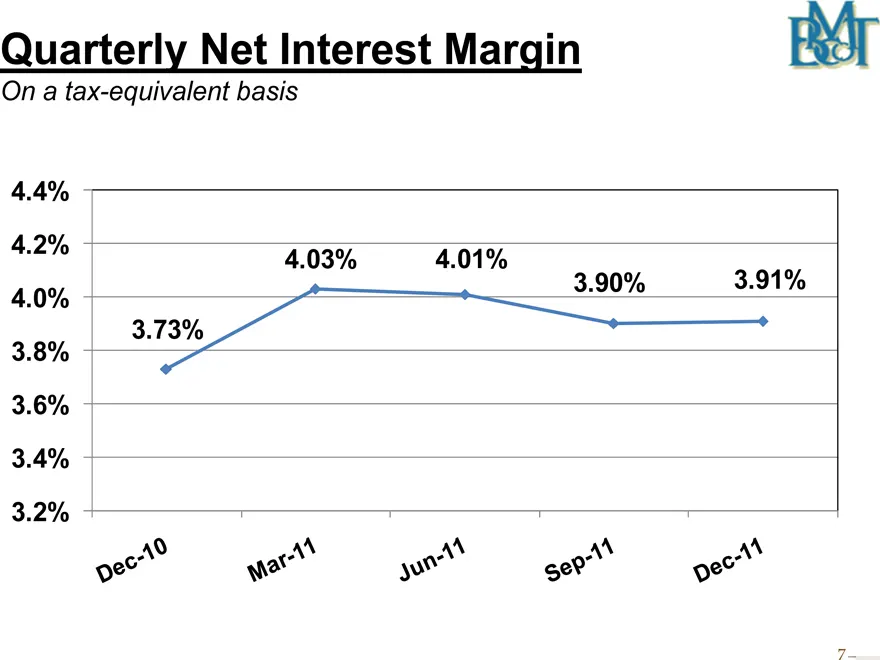
Quarterly Net Interest Margin On a tax-equivalent basis 4.4% 4.2% 4.0% 3.8% 3.6% 3.4% 3.2% 3.73% 4.03% 4.01% 3.90% 3.91% Dec-10 Mar-11 Jun-11 Sep-11 Dec-11
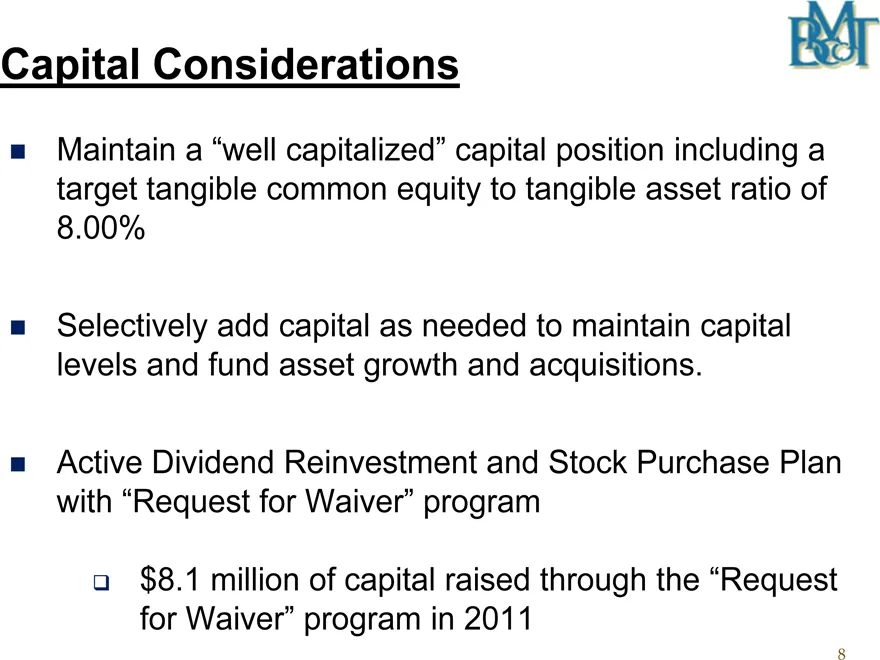
Slide 9: Capital Considerations
Capital Considerations Maintain a “well capitalized” capital position including a target tangible common equity to tangible asset ratio of 8.00% Selectively add capital as needed to maintain capital levels and fund asset growth and acquisitions. Active Dividend Reinvestment and Stock Purchase Plan w
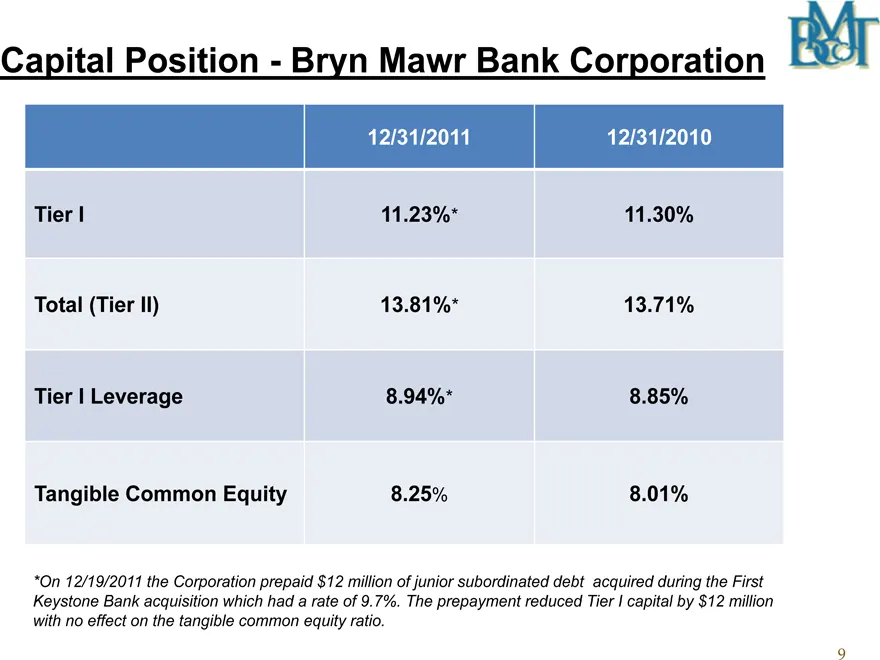
Slide 10: Capital Position—Bryn Mawr Bank Corporation
Capital Position—Bryn Mawr Bank Corporation 12/31/2011 12/31/2010 Tier I 11.23%* 11.30% Total (Tier II) 13.81%* 13.71% Tier I Leverage 8.94%* 8.85% Tangible Common Equity 8.25% 8.01% *On 12/19/2011 the Corporation prepaid $12 million of junior subordinated debt acquired during the First Keystone Ban
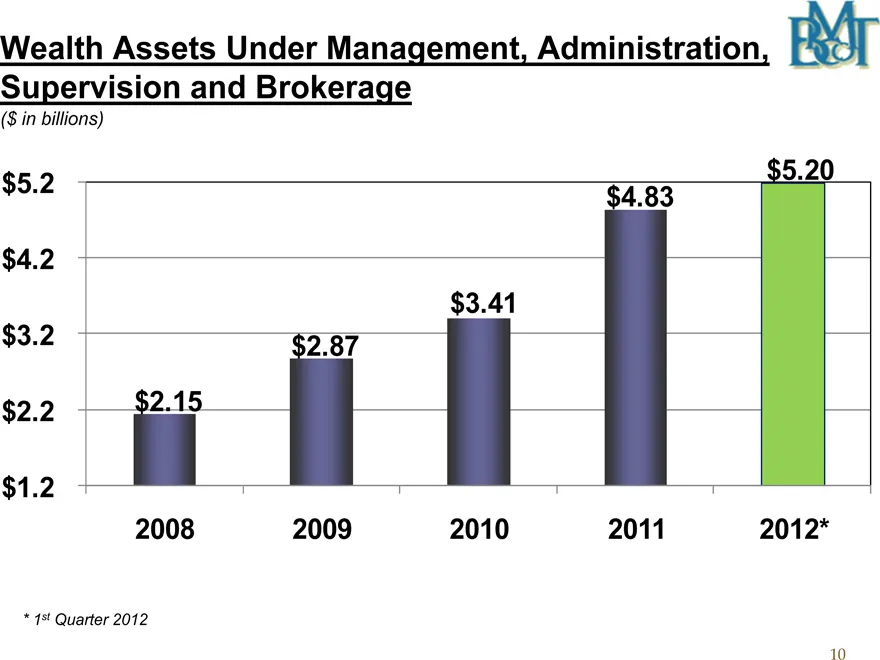
Slide 11: Wealth Assets Under Management, Administration, Supervision and Brokerage
Wealth Assets Under Management, Administration, Supervision and Brokerage ($ in billions) $5.2 $5.20 $4.83 $4.2 $3.41 $3.2 $2.87 $2.2 $2.15 $1.2 2008 2009 2010 2011 2012* * 1st Quarter 2012
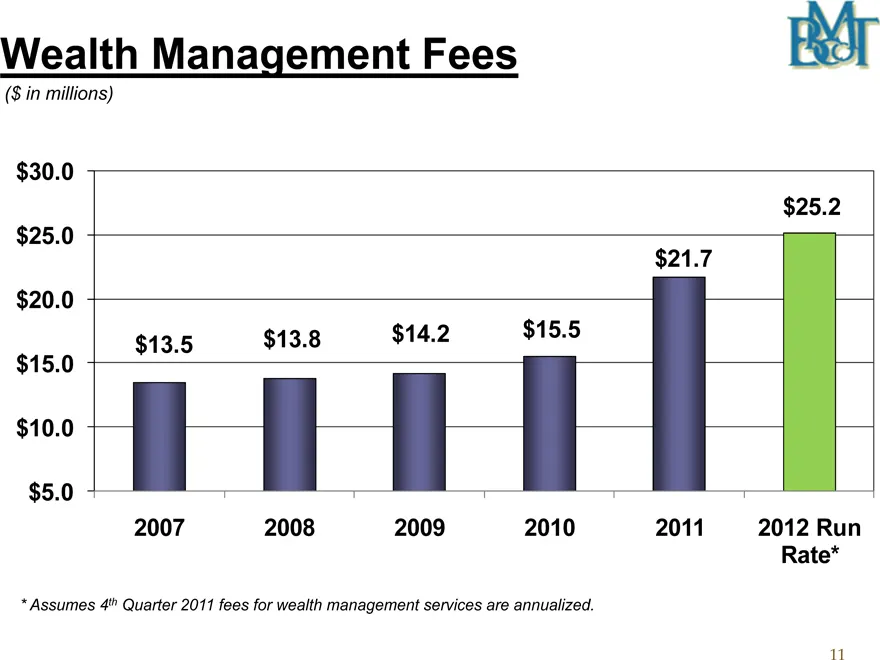
Slide 12: Wealth Management Fees
Wealth Management Fees ($ in millions) $30.0 $25.2 $25.0 $21.7 $20.0 $13.5 $13.8 $14.2 $15.5 $15.0 $10.0 $5.0 2007 2008 2009 2010 2011 2012 Run Rate* * Assumes 4th Quarter 2011 fees for wealth management services are annualized.
Slide 13: Loan & Lease Growth
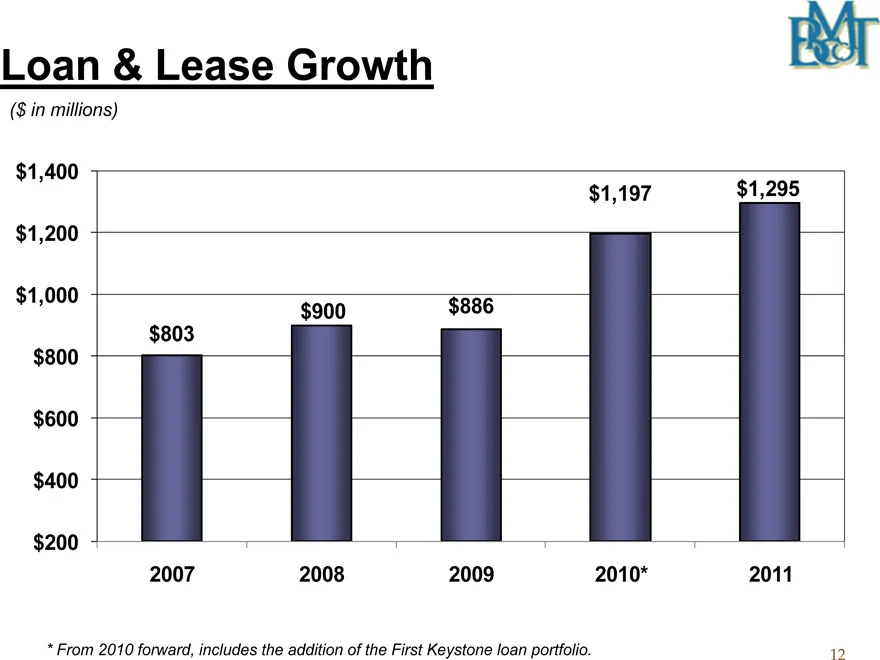
Loan & Lease Growth ($ in millions) $1 ,400 $1,197 $1,295 $1,200 $1,000 $900 $886 $803 $800 $600 $400 $200 2007 2008 2009 2010* 2011 * From 2010 forward, includes the addition of the First Keystone loan portfolio.
Slide 14: Total Deposits
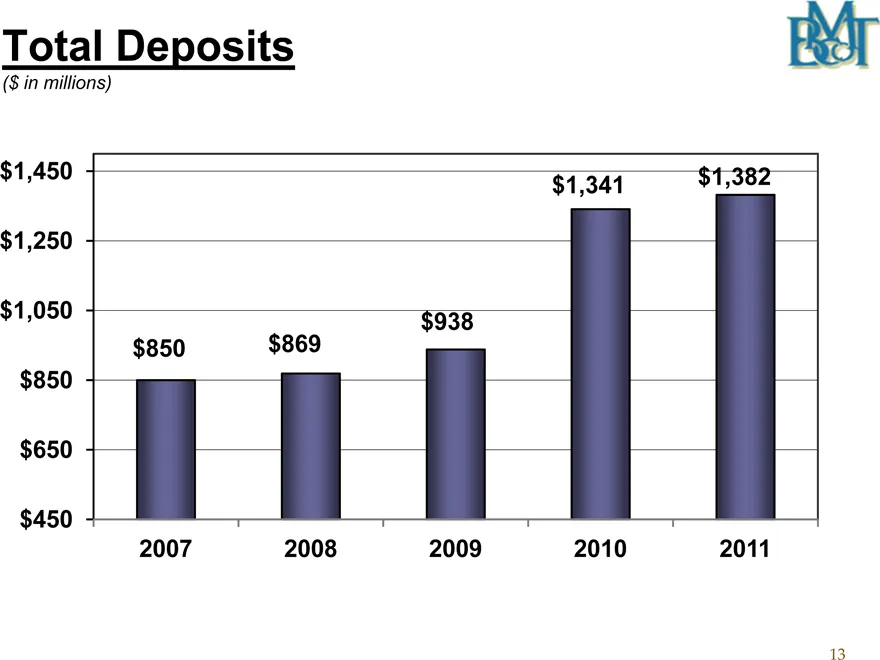
Total Deposits ($ in millions) $1,450 $1,341 $1,382 $1,250 $1,050 $938 $850 $869 $850 $650 $450 2007 2008 2009 2010 2011
Slide 15: Summary
Summary Outstanding franchise in a stable market Focus on Wealth Services, Business Banking and “high touch” Retail Banking Investing in growth opportunities today for anticipated earnings growth tomorrow Sound business strategy, strong asset quality, well capitalized and solid risk management proce
Slide 16: Safe Harbor
Safe Harbor This presentation contains statements which, to the extent that they are not recitations of historical fact may constitute forward-looking statements for purposes of the Securities Act of 1933, as amended, and the Securities Exchange Act of 1934, as amended. Such forward-looking statemen
Slide 17: Safe Harbor (continued)
Safe Harbor (continued) Such factors include, among others, our need for capital, our ability to control operating costs and expenses, and to manage loan and lease delinquency rates; the credit risks of lending activities and overall quality of the composition of our loan, lease and securities portf
Slide 18: Safe Harbor (continued)
Safe Harbor (continued) For a complete discussion of the assumptions, risks and uncertainties related to our business, you are encouraged to review our filings with the Securities and Exchange Commission, including our most recent annual report on Form 10-K, as well as any changes in risk factors th
Slide 19: Safe Harbor (continued)
Safe Harbor (continued) No offer to purchase securities of the Corporation will be made or accepted prior to receipt by an investor of an Offering Memorandum and relevant subscription documentation, all of which must be reviewed together with the Corporation’s then-current financial statements and,
Source: SEC EDGAR · 8-K filed May 2, 2012
More decks from Bryn Mawr Bank Corporation
 Merger or Acquisition (March 2021)20 slides · Mar 10, 2021
 Q4 2020 Earnings Presentation16 slides · Jan 22, 2021
 Q3 2020 Earnings Presentation14 slides · Oct 23, 2020
 Investor Presentation (September 2020)17 slides · Sep 21, 2020
 Q2 2020 Earnings Presentation14 slides · Jul 21, 2020
 Q1 2020 Earnings Presentation13 slides · Apr 21, 2020