Markwest Energy Partners LP — Barclays CEO Energy-Power Conference 2013
24 slides from Markwest Energy Partners LP's conference presentation, Sep 12, 2013
Slide 1: Barclays CEO Energy-Power Conference September 2013
BARCLAYS CEO ENERGY-POWER CONFERENCE SEPTEMBER 2013
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements and information. These forward-looking statements, which in many instances can be identified by words like “could,” “may,” “will,” “should,” “expects,” “plans,” “project,” “anticipates,” “believes,” “planned,” “proposed
Slide 3: Non-GAAP Measures
Non-GAAP Measures Distributable Cash Flow, Adjusted EBITDA, and Net Operating Margin are not measures of performance calculated in accordance with GAAP, and should not be considered separately from or as a substitute for net income, income from operations, or cash flow as reflected in our financial
Slide 4: Key Investment Considerations
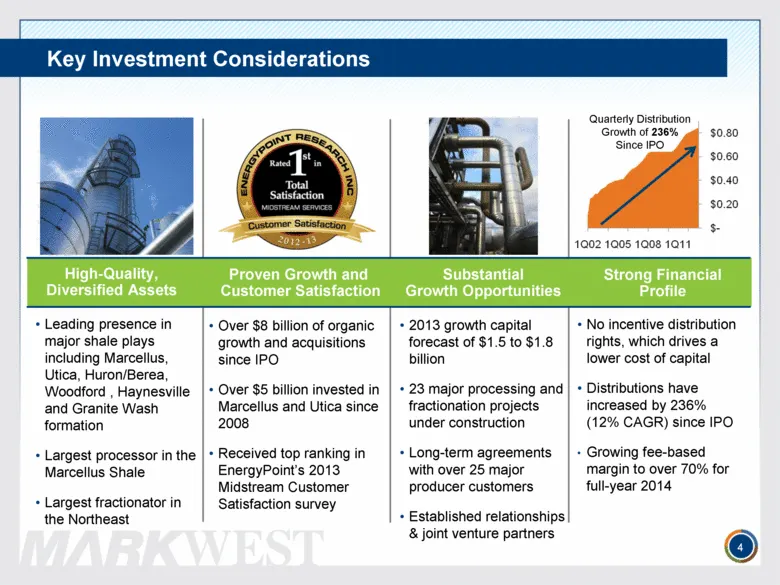
Key Investment Considerations 4 High-Quality, Diversified Assets Proven Growth and Customer Satisfaction Substantial Growth Opportunities Strong Financial Profile Leading presence in major shale plays including Marcellus, Utica, Huron/Berea, Woodford , Haynesville and Granite Wash formation Largest
Slide 5: MarkWest Assets: Expansion and Diversification
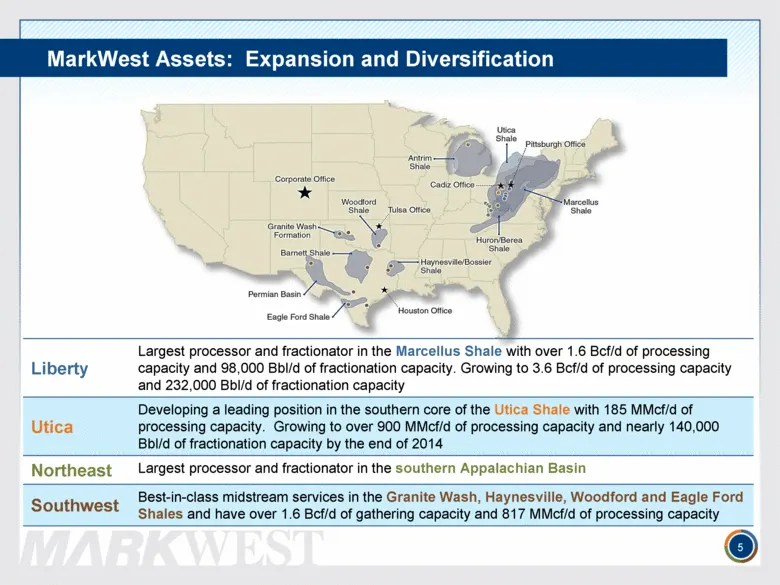
MarkWest Assets: Expansion and Diversification 5 Liberty Largest processor and fractionator in the Marcellus Shale with over 1.6 Bcf/d of processing capacity and 98,000 Bbl/d of fractionation capacity. Growing to 3.6 Bcf/d of processing capacity and 232,000 Bbl/d of fractionation capacity Utica Deve
Slide 6: Growth Driven By Customer Satisfaction
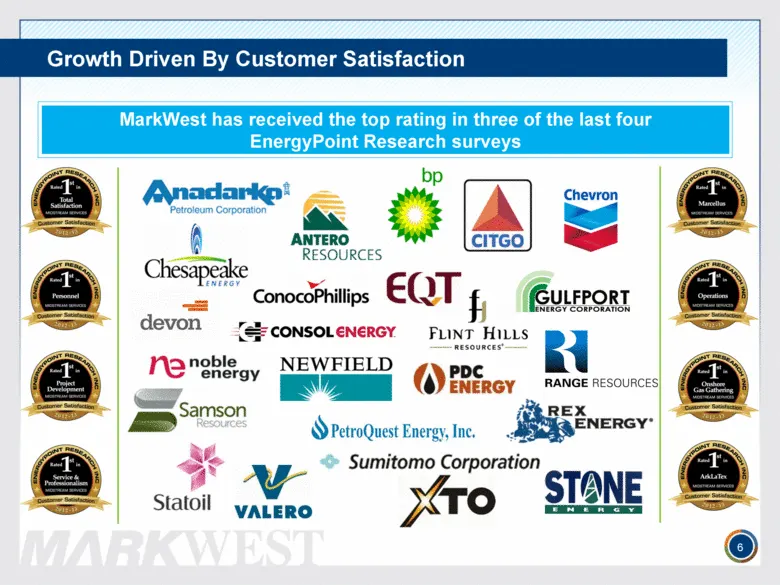
Growth Driven By Customer Satisfaction 6 MarkWest has received the top rating in three of the last four EnergyPoint Research surveys
Slide 7: Marcellus and Utica: Major Projects Map
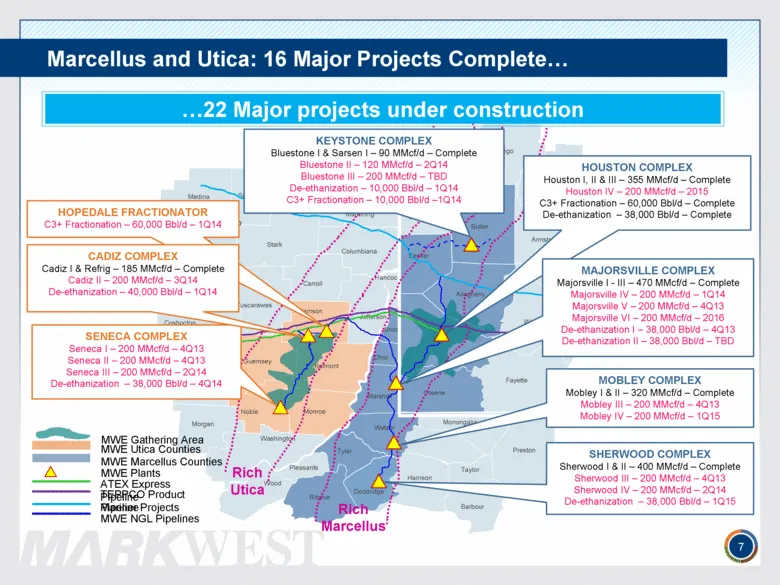
Barbour Brooke Doddridge Hancock Harrison Marion Marshall Monongalia Ohio Pleasants Preston Ritchie Taylor Tyler Wetzel Wood Belmont Carroll Columbiana Coshocton Guernsey Harrison Holmes Mahoning Medina Monroe Morgan Muskingum Noble Portage Stark Summit Trumbull Tuscarawas Washington Wayne Allegheny
Slide 8: Liberty Segment
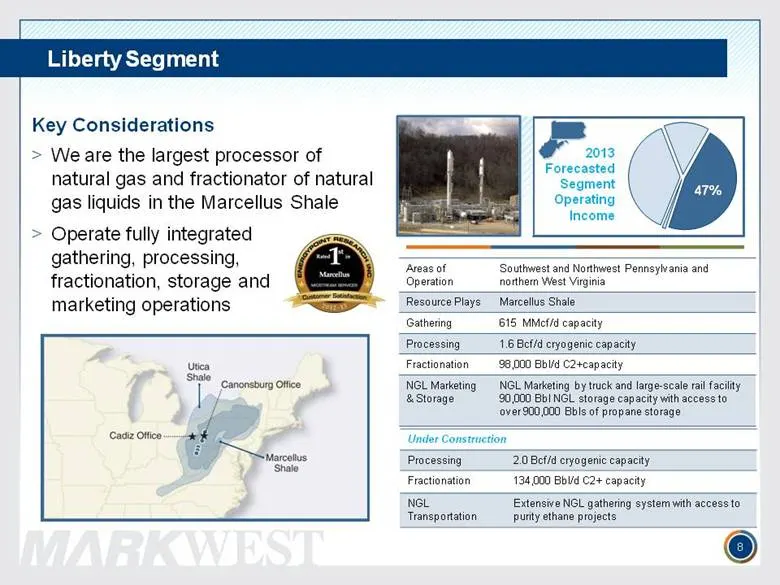
Liberty Segment 2013 Forecasted Segment Operating Income Key Considerations We are the largest processor of natural gas and fractionator of natural gas liquids in the Marcellus Shale Areas of Operation Southwest and Northwest Pennsylvania and northern West Virginia Resource Plays Marcellus Shale Gat
Slide 9: MarkWest Liberty: Current Processing Capacity of 1.6 Bcf/d
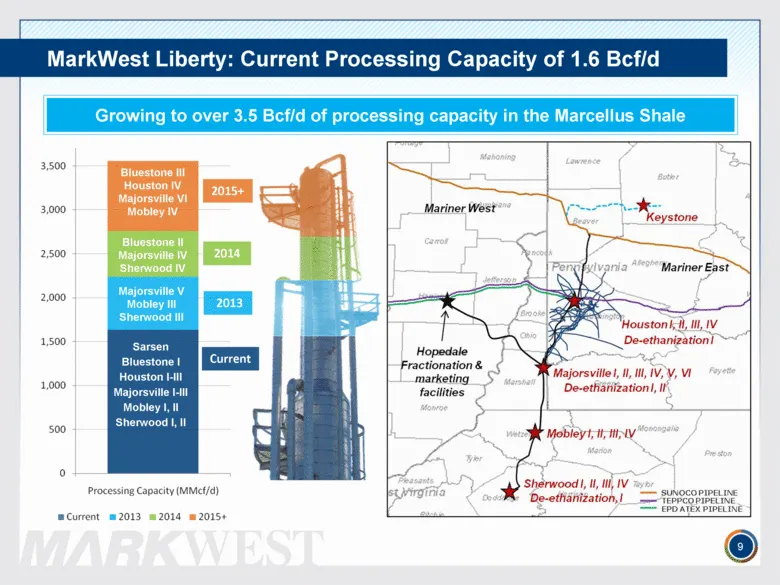
MarkWest Liberty: Current Processing Capacity of 1.6 Bcf/d 9 Sarsen Bluestone I Houston I-III Majorsville I-III Mobley I, II Sherwood I, II Majorsville V Mobley III Sherwood III Bluestone II Majorsville IV Sherwood IV 2014 2013 Current Growing to over 3.5 Bcf/d of processing capacity in the Marcellu
Slide 10: Utica Segment: Areas of Operation
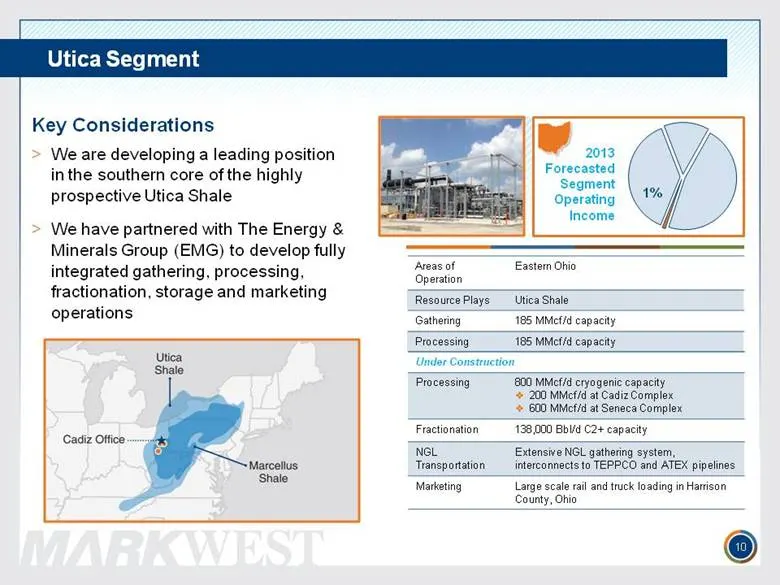
Areas of Operation Eastern Ohio Resource Plays Utica Shale Gathering 185 MMcf/d capacity Processing 185 MMcf/d capacity Utica Segment 10 Key Considerations We are developing a leading position in the southern core of the highly prospective Utica Shale We have partnered with The Energy & Minerals Gro
Slide 11: Utica Processing Capacity
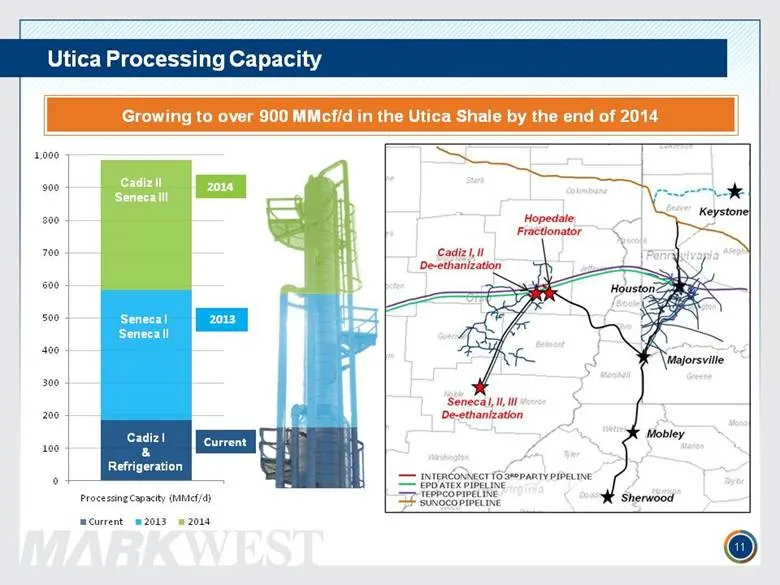
Utica Processing Capacity 11 Cadiz I & Refrigeration Seneca I Seneca II Cadiz II Seneca III 2014 2013 Current Growing to over 900 MMcf/d in the Utica Shale by the end of 2014
Slide 12: Northeast: Supply & Demand – NGLs
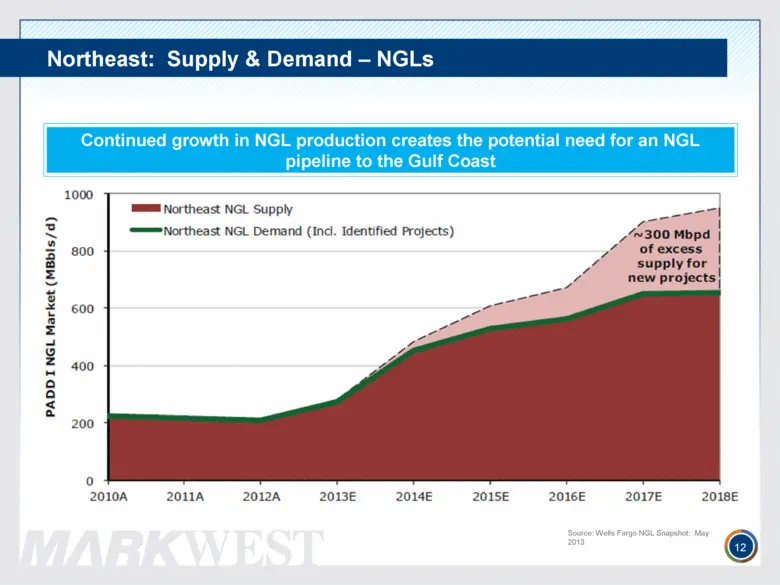
Northeast: Supply & Demand – NGLs 12 Continued growth in NGL production creates the potential need for an NGL pipeline to the Gulf Coast Source: Wells Fargo NGL Snapshot: May 2013
Slide 13: Kinder Morgan/MarkWest Utica EMG – Joint Venture
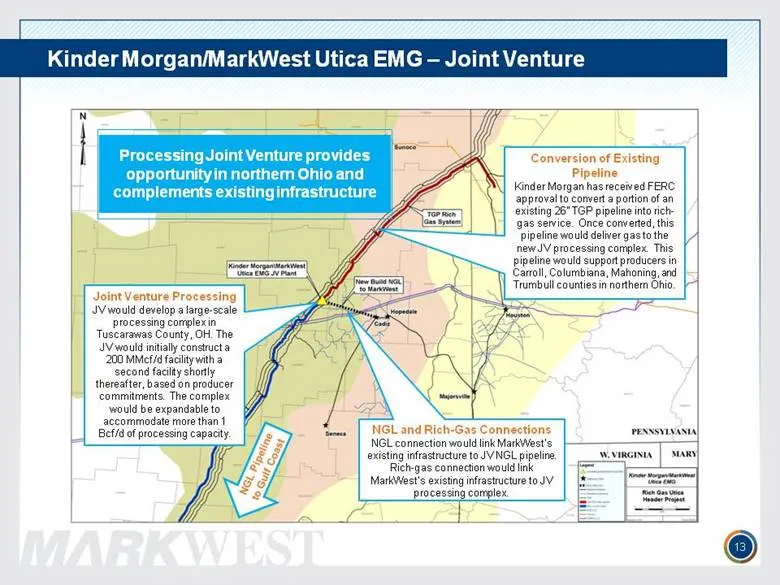
Kinder Morgan/MarkWest Utica EMG – Joint Venture 13 Conversion of Existing Pipeline Kinder Morgan has received FERC approval to convert a portion of an existing 26” TGP pipeline into rich-gas service. Once converted, this pipeline would deliver gas to the new JV processing complex. This pipeline wou
Slide 14: Kinder Morgan/MarkWest Utica EMG – Joint Venture
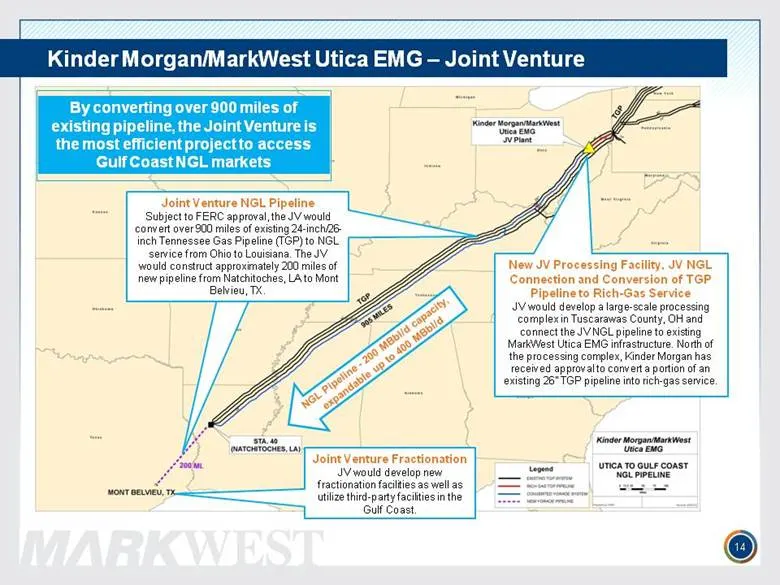
Kinder Morgan/MarkWest Utica EMG – Joint Venture Joint Venture Fractionation JV would develop new fractionation facilities as well as utilize third-party facilities in the Gulf Coast. New JV Processing Facility, JV NGL Connection and Conversion of TGP Pipeline to Rich-Gas Service JV would develop a
Slide 15: Granite Wash: Expanding our Presence
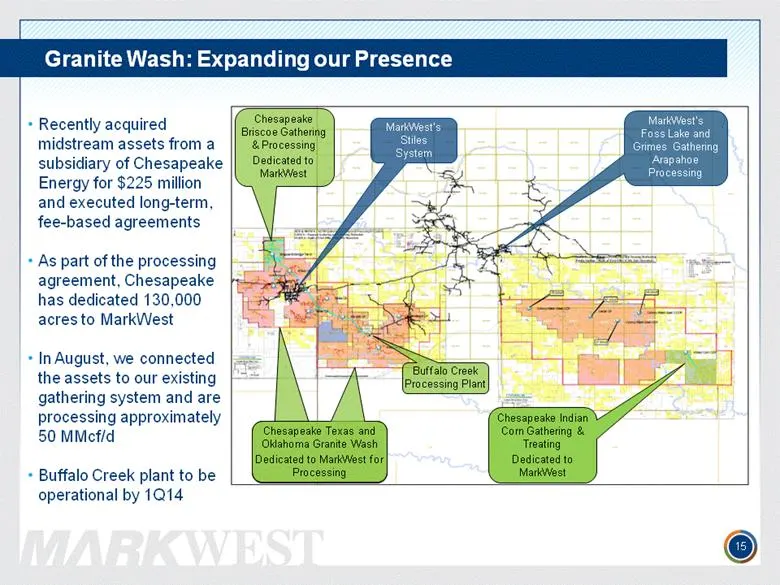
Granite Wash: Expanding our Presence Chesapeake Indian Corn Gathering & Treating Dedicated to MarkWest Chesapeake Briscoe Gathering & Processing Dedicated to MarkWest MarkWest’s Foss Lake and Grimes Gathering Arapahoe Processing MarkWest’s Stiles System Chesapeake Texas and Oklahoma Granite Wash Ded
Slide 16: DCF and Capital Investments
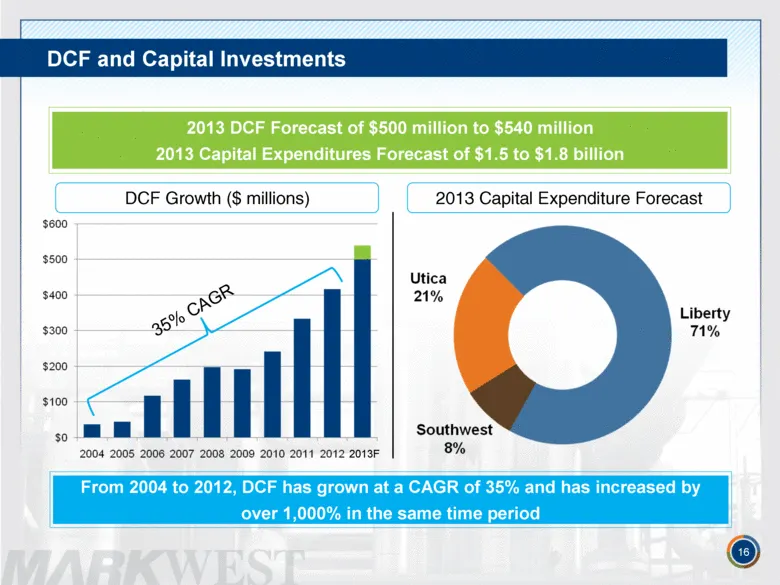
DCF and Capital Investments 16 2013 Capital Expenditure Forecast DCF Growth ($ millions) 35% CAGR 16 2013 DCF Forecast of $500 million to $540 million 2013 Capital Expenditures Forecast of $1.5 to $1.8 billion From 2004 to 2012, DCF has grown at a CAGR of 35% and has increased by over 1,000% in the
Slide 17: Increasing Fee-Based Margin
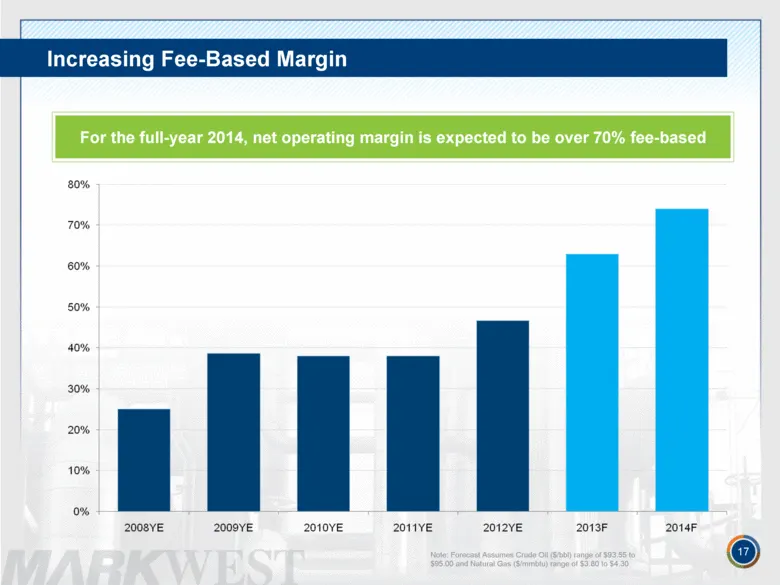
Note: Forecast Assumes Crude Oil ($/bbl) range of $93.55 to $95.00 and Natural Gas ($/mmbtu) range of $3.80 to $4.30 17 For the full-year 2014, net operating margin is expected to be over 70% fee-based Increasing Fee-Based Margin
Slide 18: Total Return Since 2009
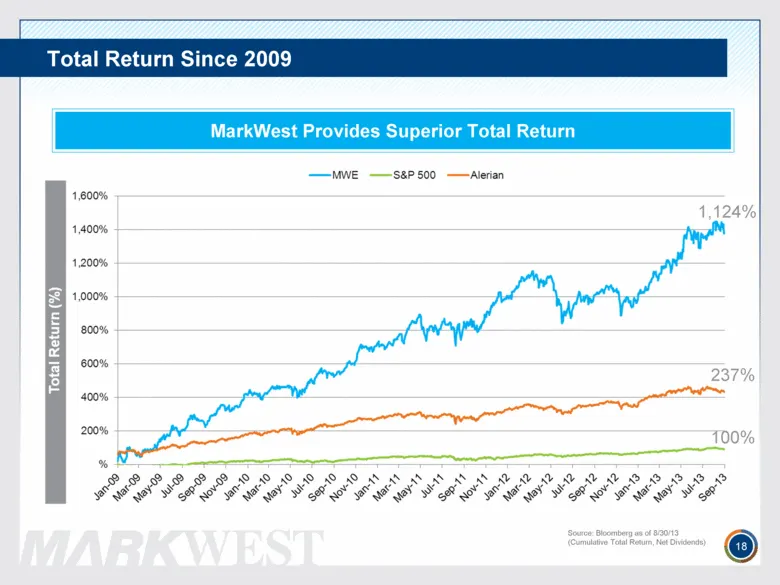
Total Return Since 2009 18 Source: Bloomberg as of 8/30/13 (Cumulative Total Return, Net Dividends) MarkWest Provides Superior Total Return 237% 100% 1,124%
Slide 19: Keys to Success: Execute, Execute, Execute
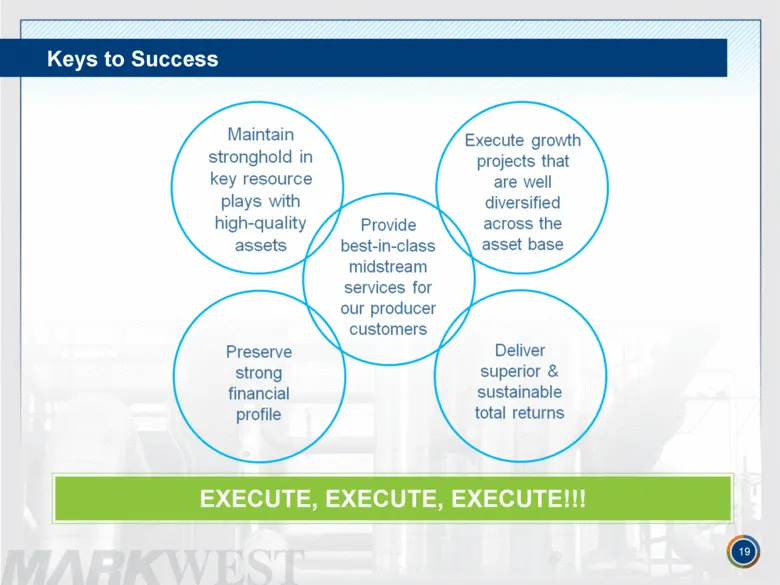
Keys to Success EXECUTE, EXECUTE, EXECUTE!!! 19
Slide 20: Appendix
APPENDIX
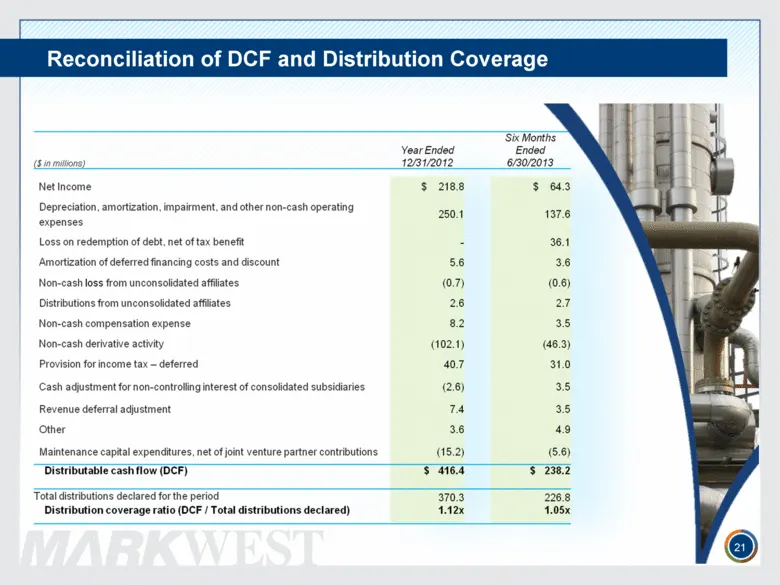
Slide 21: Reconciliation of DCF and Distribution Coverage
Reconciliation of DCF and Distribution Coverage 21
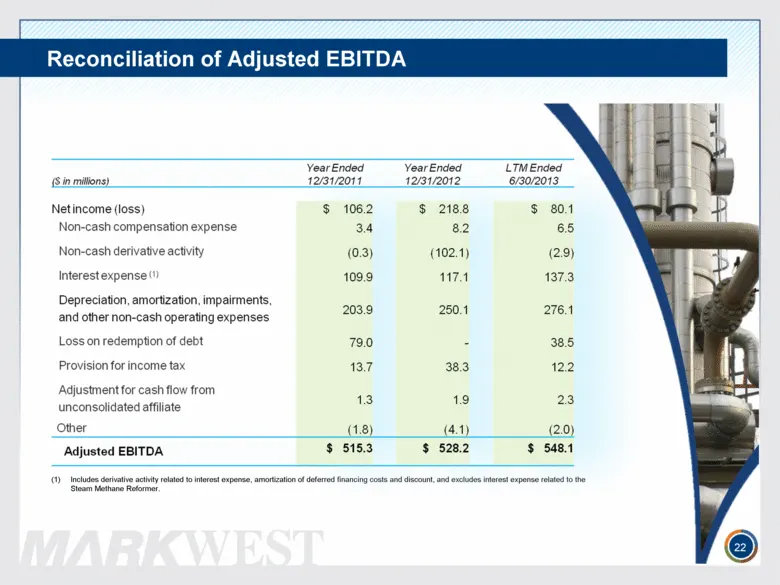
Slide 22: Reconciliation of Adjusted EBITDA
Reconciliation of Adjusted EBITDA 22 Includes derivative activity related to interest expense, amortization of deferred financing costs and discount, and excludes interest expense related to the Steam Methane Reformer.
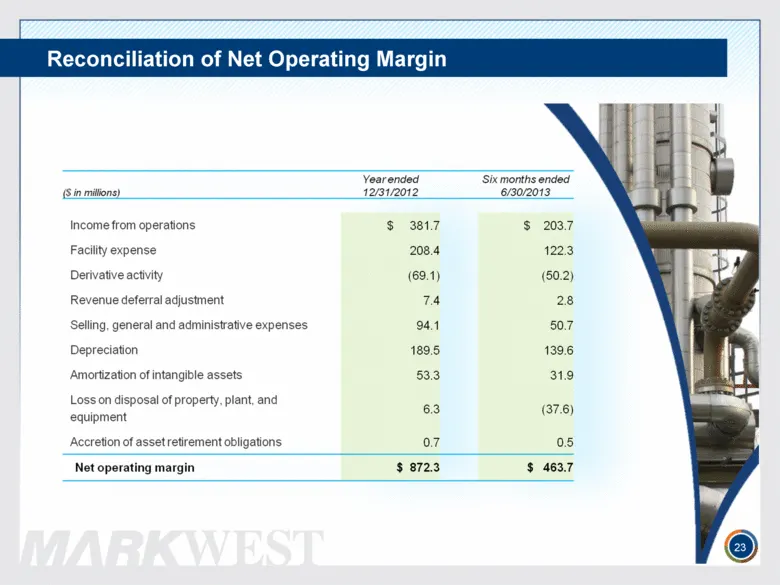
Slide 23: Reconciliation of Net Operating Margin
Reconciliation of Net Operating Margin 23
Slide 24: Contact and Investor Relations
1515 Arapahoe Street Tower 1, Suite 1600 Denver, Colorado 80202 Phone: 303-925-9200 Investor Relations: 866-858-0482 Email: [email protected] Website: www.markwest.com
Source: SEC EDGAR · 8-K filed Sep 12, 2013
More decks from Markwest Energy Partners LP
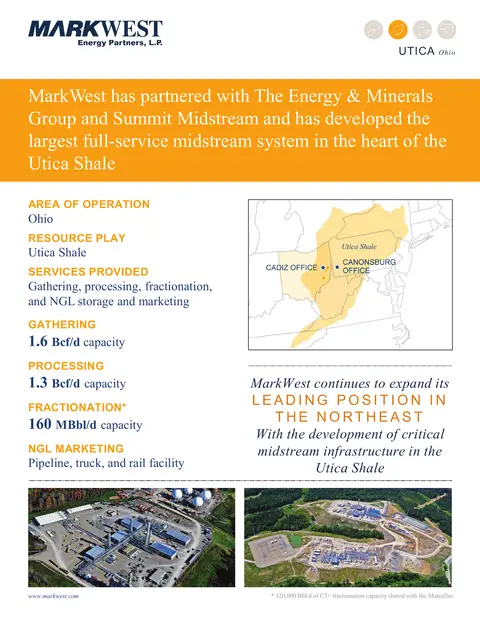 Fact Sheet (July 2017)1 slide · July 2017
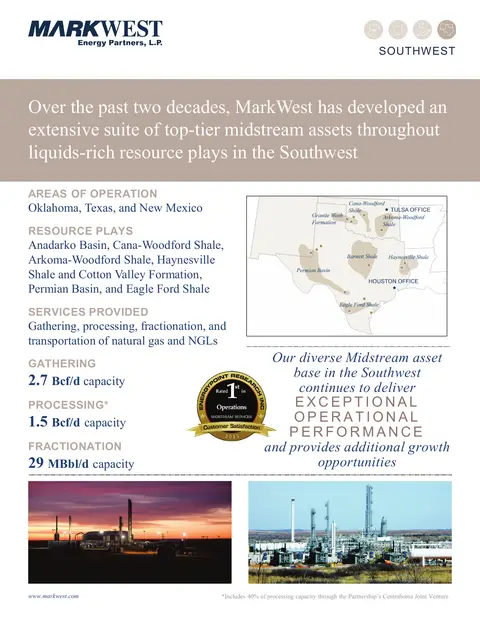 Fact Sheet (July 2017)1 slide · July 2017
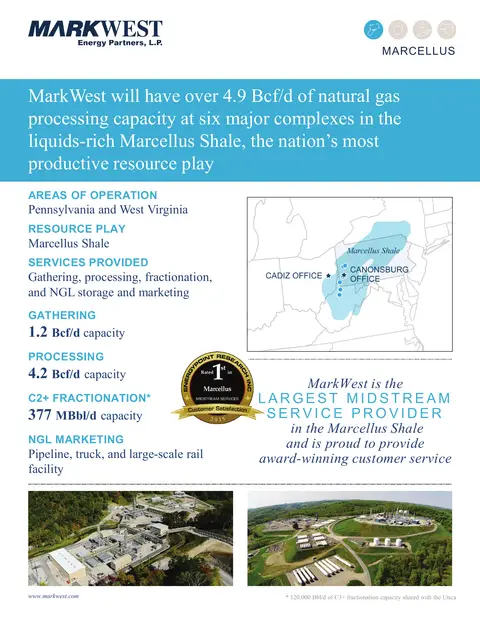 Fact Sheet (July 2017)1 slide · July 2017
 Markwest Energy Partners L P — Investor Day (December 2015)116 slides · Dec 3, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 13, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 12, 2015