Copano Energy L.L.C — Morgan Keegan 2008 Equity Conference
31 slides from Copano Energy L.L.C's conference presentation, Sep 4, 2008
Slide 1: Morgan Keegan 2008 Equity Conference
Morgan Keegan 2008 Equity Conference Memphis, TN NASDAQ: CPNO September 5, 2008
Slide 2: Disclaimer
Disclaimer Statements made by representatives of Copano Energy, L.L.C. (the "Company") during this presentation may constitute "forward-looking statements" as defined by the Securities and Exchange Commission. All statements, other than statements of historical facts, made by representatives of the
Slide 3: Introduction to Copano
Introduction to Copano Midstream energy company providing services to natural gas producers since our founding in 1992 Operations are focused in Oklahoma, Texas and Wyoming Service throughput volumes approximate 1,700,000 MMBtu per day of natural gas Equity Market cap: $1.8 billion(1) Enterprise val
Slide 4: Copano's Business Strategy
Copano's Business Strategy Pursue growth from our existing assets Pursue complementary acquisitions and organic expansion opportunities Reduce sensitivity of our cash flows to commodity price fluctuations Exploit the operating flexibility of our assets Expand our geographic scope into new regions wh
Slide 5: Operations
Operations Operations Disciplined Growth LLC Structure Financial Strength
Slide 6: Three leading producing regions
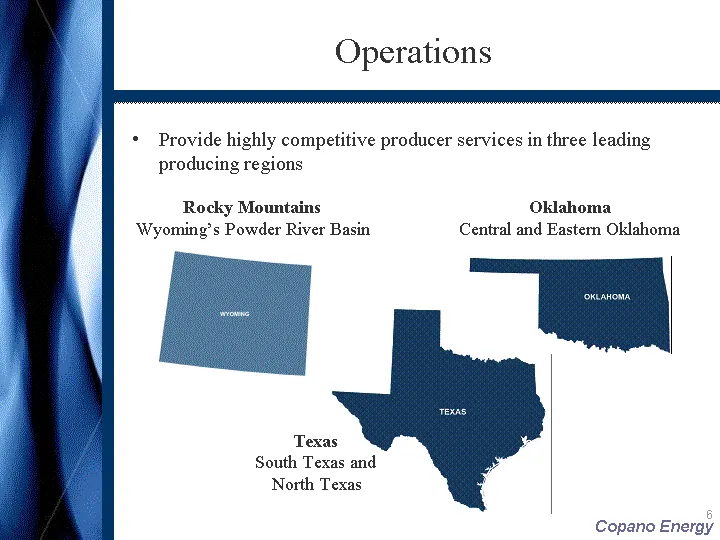
Provide highly competitive producer services in three leading producing regions Operations Texas South Texas and North Texas Oklahoma Central and Eastern Oklahoma Rocky Mountains Wyoming's Powder River Basin
Slide 7: Oklahoma Operations
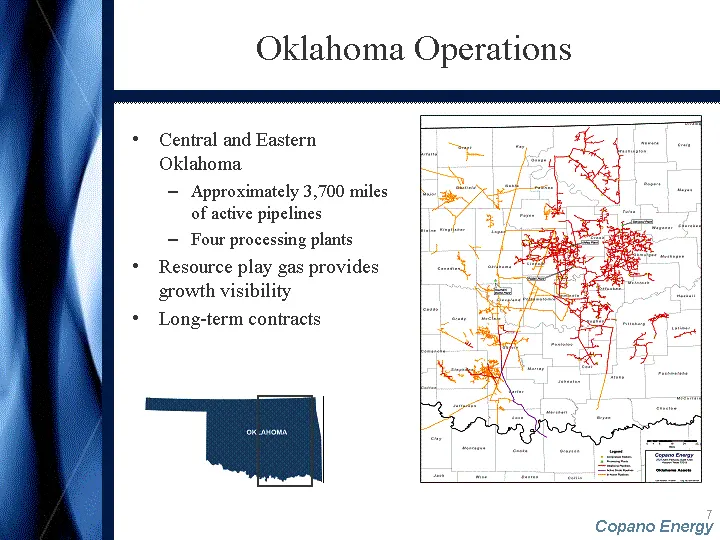
Central and Eastern Oklahoma Approximately 3,700 miles of active pipelines Four processing plants Resource play gas provides growth visibility Long-term contracts Oklahoma Operations
Slide 8: Texas Operations
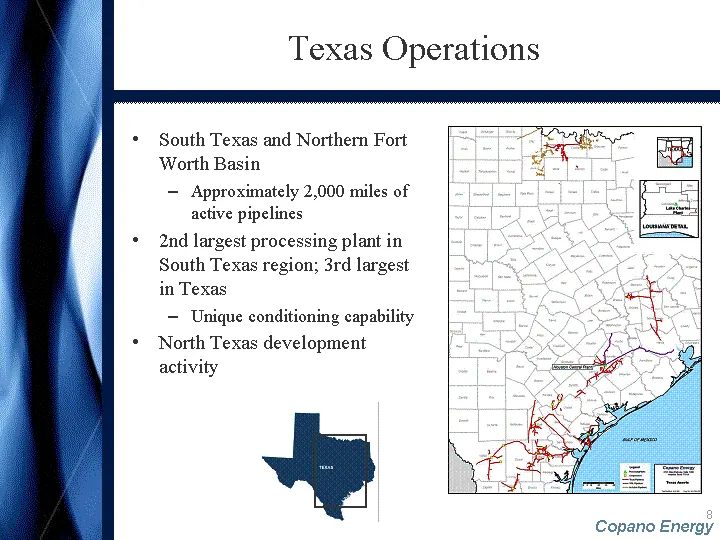
Texas Operations South Texas and Northern Fort Worth Basin Approximately 2,000 miles of active pipelines 2nd largest processing plant in South Texas region; 3rd largest in Texas Unique conditioning capability North Texas development activity
Slide 9: Rocky Mountain Operations
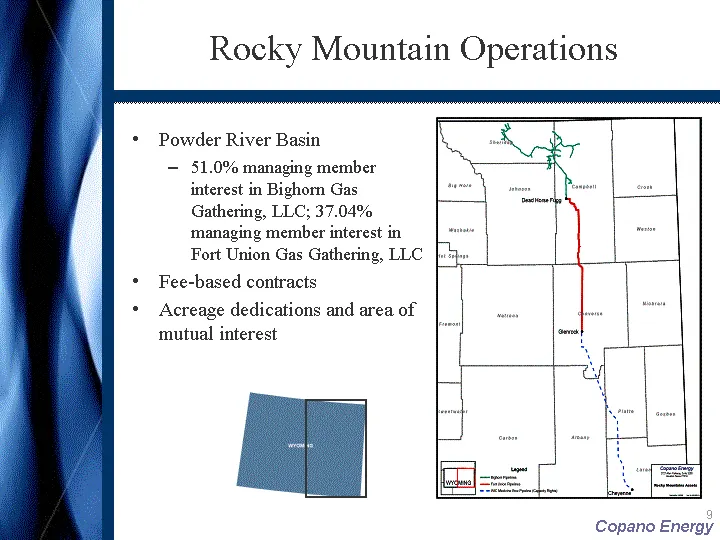
Rocky Mountain Operations Powder River Basin 51.0% managing member interest in Bighorn Gas Gathering, LLC; 37.04% managing member interest in Fort Union Gas Gathering, LLC Fee-based contracts Acreage dedications and area of mutual interest
Slide 10: Disciplined Growth
Disciplined Growth Disciplined Growth Financial Strength LLC Structure Operations
Slide 11: Total Return Performance
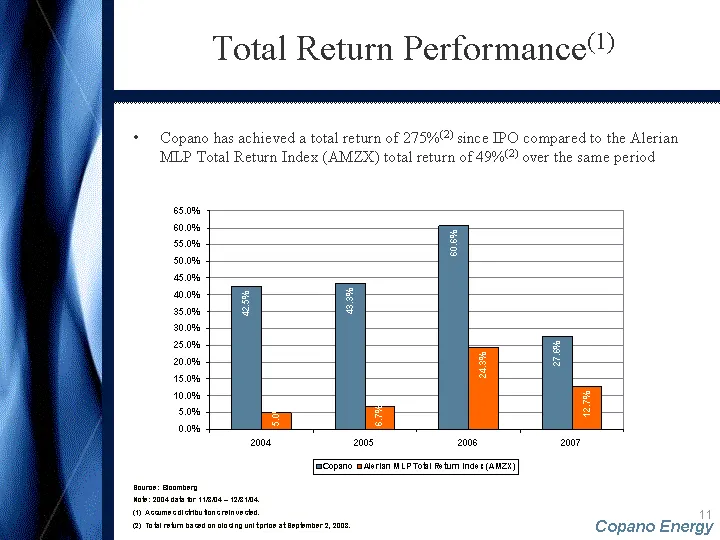
Total Return Performance(1) Copano has achieved a total return of 275%(2) since IPO compared to the Alerian MLP Total Return Index (AMZX) total return of 49%(2) over the same period Source: Bloomberg Note: 2004 data for 11/8/04 - 12/31/04. (1) Assumes distributions reinvested. (2) Total return based
Slide 12: Proven Growth Track Record
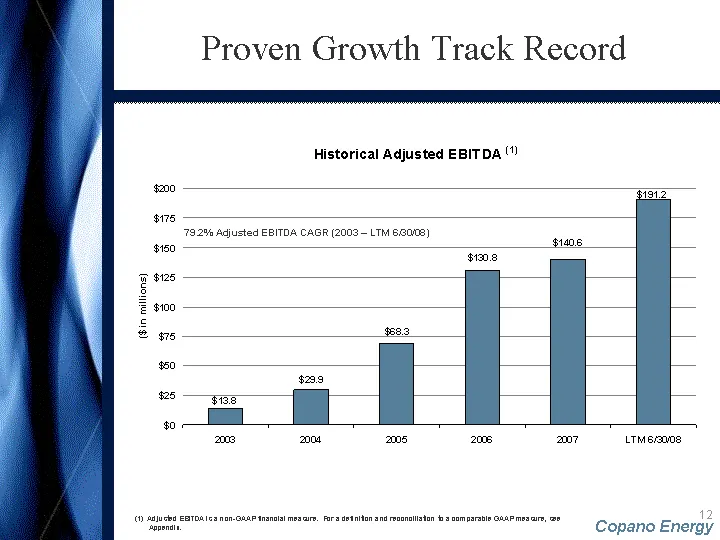
Proven Growth Track Record (1) Adjusted EBITDA is a non-GAAP financial measure. For a definition and reconciliation to a comparable GAAP measure, see Appendix. 79.2% Adjusted EBITDA CAGR (2003 - LTM 6/30/08)
Slide 13: Growth-Oriented History
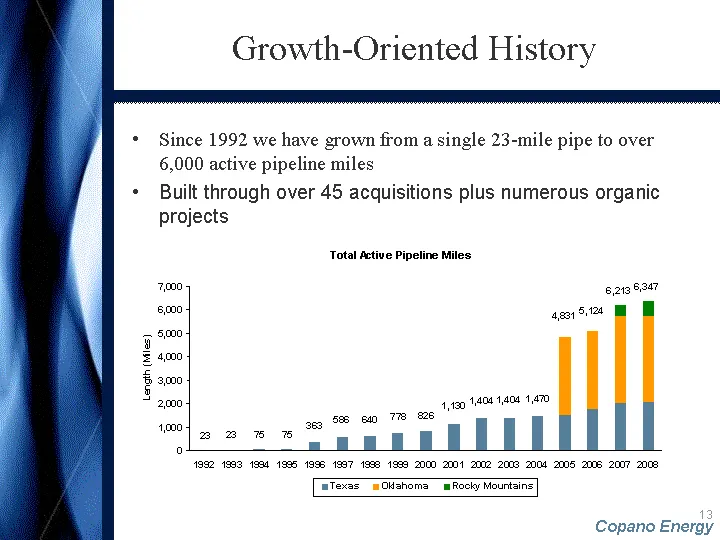
Growth-Oriented History Since 1992 we have grown from a single 23-mile pipe to over 6,000 active pipeline miles Built through over 45 acquisitions plus numerous organic projects
Slide 14: Approach to Acquisitions
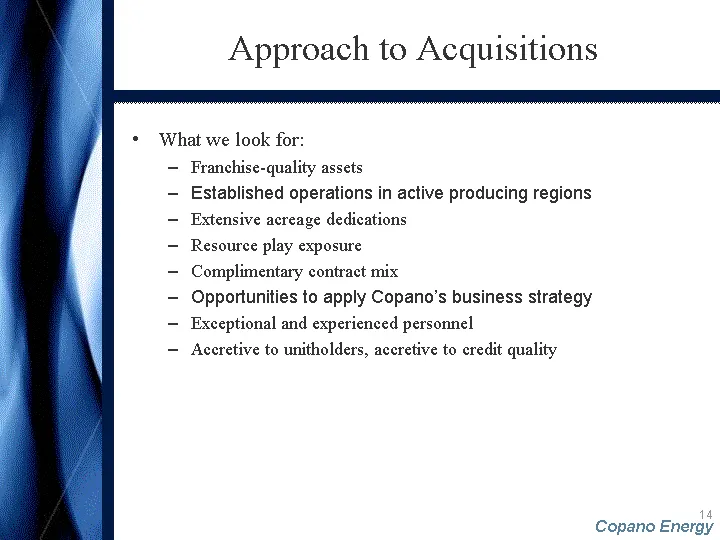
Approach to Acquisitions What we look for: Franchise-quality assets Established operations in active producing regions Extensive acreage dedications Resource play exposure Complimentary contract mix Opportunities to apply Copano's business strategy Exceptional and experienced personnel Accretive to
Slide 15: Impact of Resource Play Gas
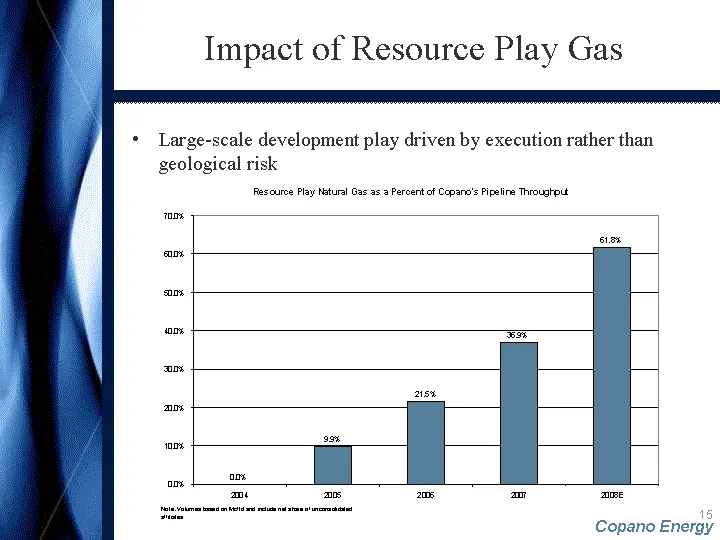
Impact of Resource Play Gas Large-scale development play driven by execution rather than geological risk
Slide 16: Bolt-On & Organic Growth
Bolt-On & Organic Growth Rate of return exceeds minimum threshold Regional managers encouraged to develop bolt-on and organic growth opportunities Planned 2008 new project capital spending of approximately $160 million Note: 2008E capital spending includes unconsolidated affiliates' spending based o
Slide 17: Selected Recent Capital Projects
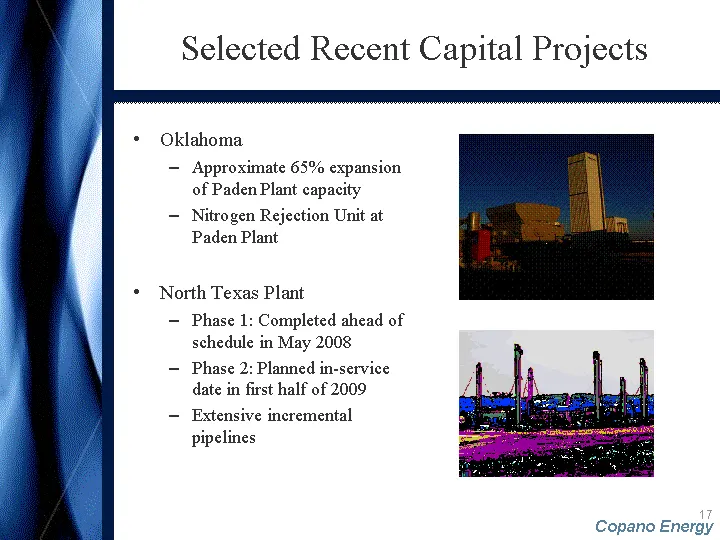
Selected Recent Capital Projects Oklahoma Approximate 65% expansion of Paden Plant capacity Nitrogen Rejection Unit at Paden Plant North Texas Plant Phase 1: Completed ahead of schedule in May 2008 Phase 2: Planned in-service date in first half of 2009 Extensive incremental pipelines
Slide 18: LLC Structure
LLC Structure LLC Structure Financial Strength Disciplined Growth Operations
Slide 19: Structure & Benefits
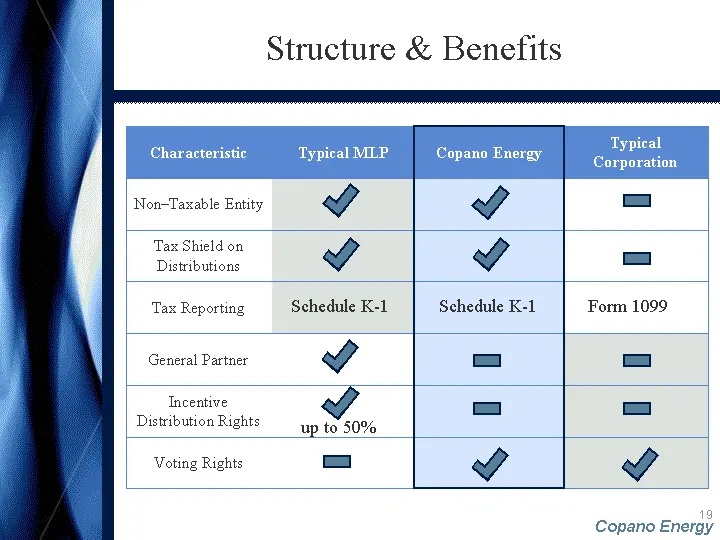
Structure & Benefits Characteristic Typical MLP Copano Energy Typical Corporation Non-Taxable Entity Tax Shield on Distributions Tax Reporting General Partner Incentive Distribution Rights Voting Rights up to 50% Schedule K-1 Schedule K-1 Form 1099
Slide 20: CPNO vs. Typical MLP Distributions
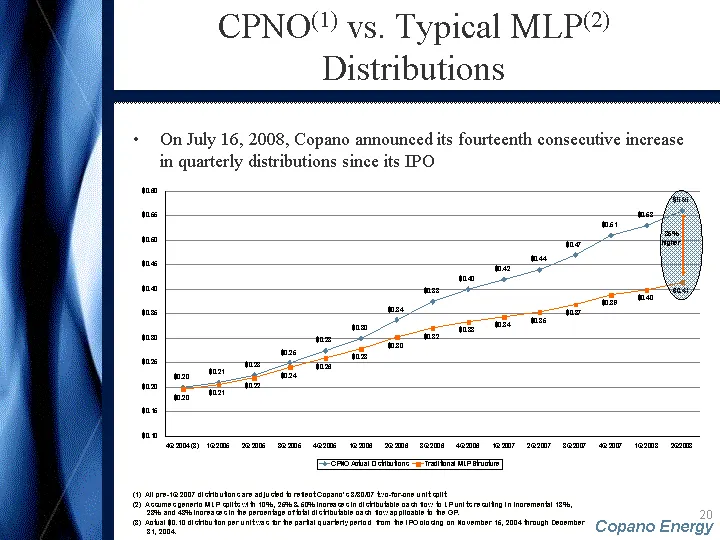
CPNO(1) vs. Typical MLP(2) Distributions On July 16, 2008, Copano announced its fourteenth consecutive increase in quarterly distributions since its IPO (1) All pre-1Q 2007 distributions are adjusted to reflect Copano's 3/30/07 two-for-one unit split. (2) Assumes generic MLP splits with 10%, 25% & 5
Slide 21: General Partner Incentive Distribution Loads
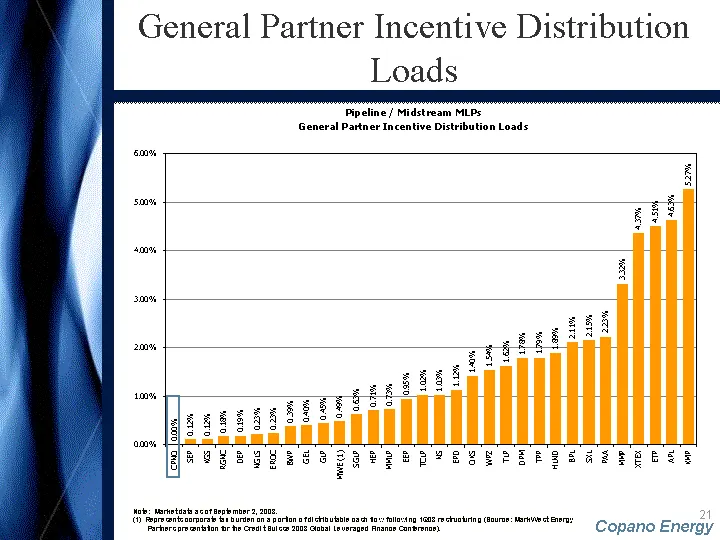
General Partner Incentive Distribution Loads Note: Market data as of September 2, 2008. (1) Represents corporate tax burden on a portion of distributable cash flow following 1Q08 restructuring (Source: MarkWest Energy Partners presentation for the Credit Suisse 2008 Global Leveraged Finance Conferen
Slide 22: Financial Strength
Financial Strength Financial Strength LLC Structure Disciplined Growth Operations
Slide 23: Financial Policy
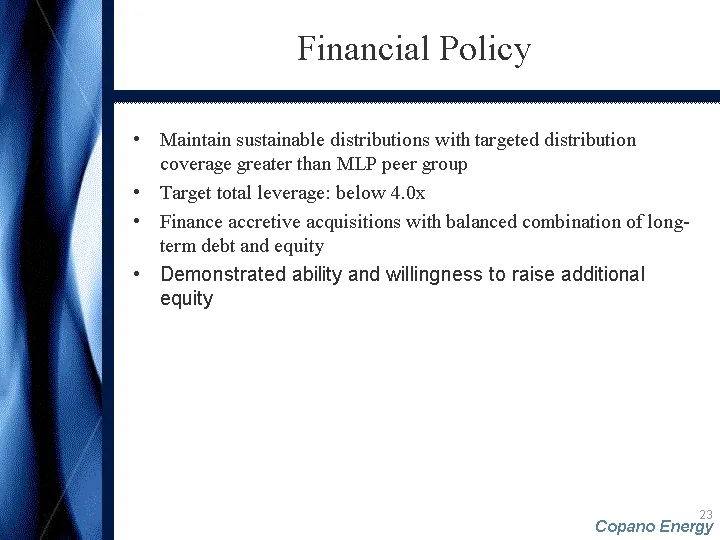
Financial Policy Maintain sustainable distributions with targeted distribution coverage greater than MLP peer group Target total leverage: below 4.0x Finance accretive acquisitions with balanced combination of long- term debt and equity Demonstrated ability and willingness to raise additional equity
Slide 24: Financial Structure
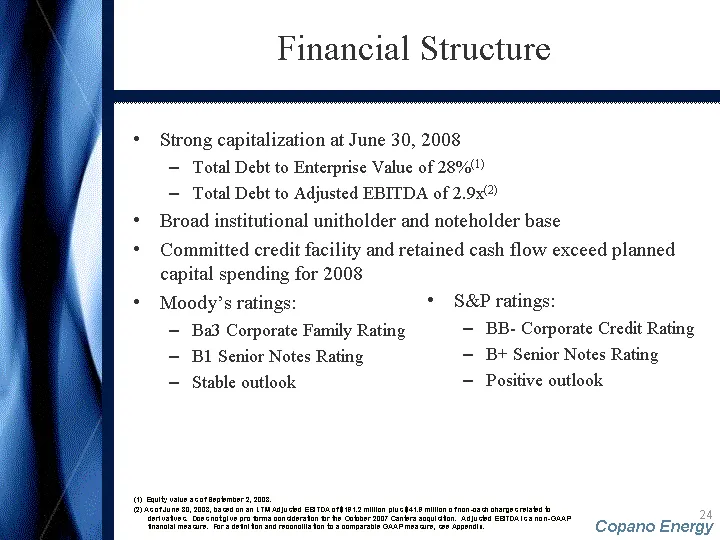
Financial Structure Strong capitalization at June 30, 2008 Total Debt to Enterprise Value of 28%(1) Total Debt to Adjusted EBITDA of 2.9x(2) Broad institutional unitholder and noteholder base Committed credit facility and retained cash flow exceed planned capital spending for 2008 Moody's ratings: B
Slide 25: Financial Position
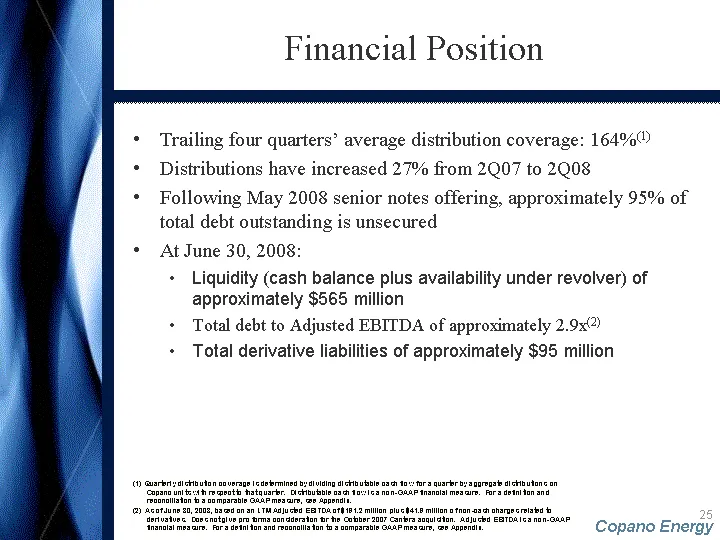
Financial Position Trailing four quarters' average distribution coverage: 164%(1) Distributions have increased 27% from 2Q07 to 2Q08 Following May 2008 senior notes offering, approximately 95% of total debt outstanding is unsecured At June 30, 2008: Liquidity (cash balance plus availability under re
Slide 26: Hedging Program and Risk Management
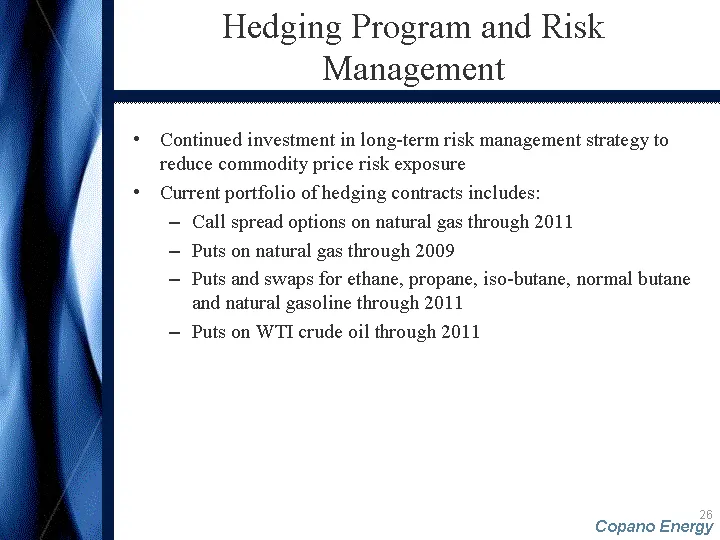
Hedging Program and Risk Management Continued investment in long-term risk management strategy to reduce commodity price risk exposure Current portfolio of hedging contracts includes: Call spread options on natural gas through 2011 Puts on natural gas through 2009 Puts and swaps for ethane, propane,
Slide 27: Experienced Management Team
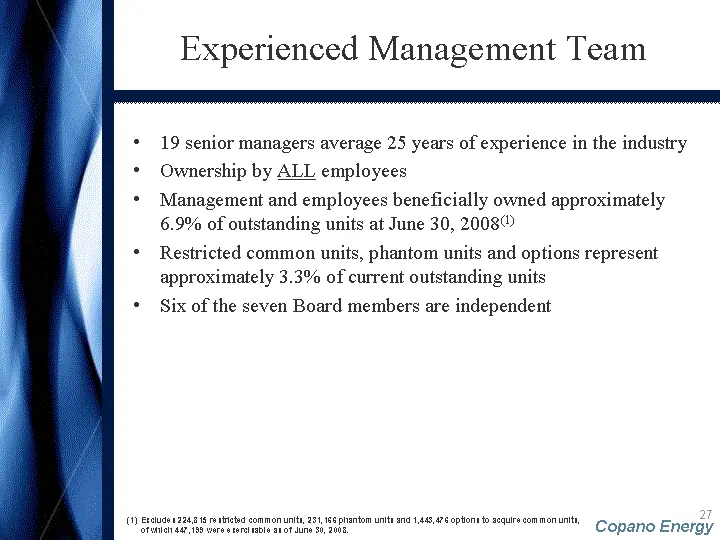
Experienced Management Team 19 senior managers average 25 years of experience in the industry Ownership by ALL employees Management and employees beneficially owned approximately 6.9% of outstanding units at June 30, 2008(1) Restricted common units, phantom units and options represent approximately
Slide 28: Appendix
Appendix 28 Copano Energy
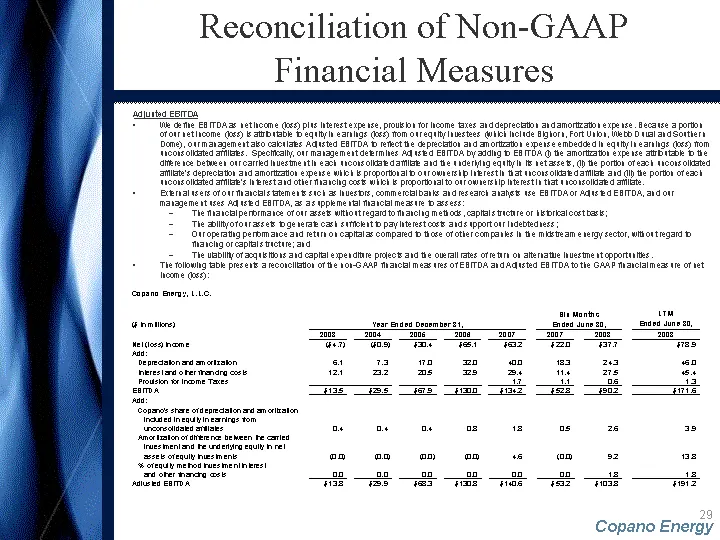
Slide 29: Reconciliation of Non-GAAP Financial Measures: Adjusted EBITDA
Reconciliation of Non-GAAP Financial Measures Adjusted EBITDA We define EBITDA as net income (loss) plus interest expense, provision for income taxes and depreciation and amortization expense. Because a portion of our net income (loss) is attributable to equity in earnings (loss) from our equity inv
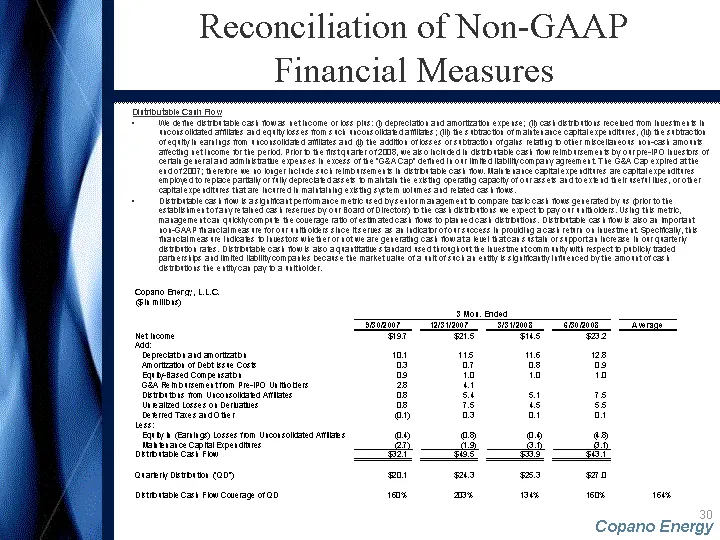
Slide 30: Reconciliation of Non-GAAP Financial Measures: Distributable Cash Flow
Reconciliation of Non-GAAP Financial Measures Distributable Cash Flow We define distributable cash flow as net income or loss plus: (i) depreciation and amortization expense; (ii) cash distributions received from investments in unconsolidated affiliates and equity losses from such unconsolidated aff
Slide 31: September 5, 2008
NASDAQ: CPNO September 5, 2008
Source: SEC EDGAR · 8-K filed Sep 4, 2008
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011