Copano Energy L.L.C — Investor Presentation (May 2011)
50 slides from Copano Energy L.L.C's investor presentation, May 17, 2011
Slide 1: May 2011 Investor Presentation
May 2011 Investor Presentation NASDAQ: CPNO
Slide 2: Disclaimer
Disclaimer This presentation includes “forward-looking statements,” as defined in the federal securities laws. Statements that address activities or events that Copano believes will or may occur in the future are forward-looking statements. These statements include, but are not limited to, statement
Slide 3: Introduction to Copano
Introduction to Copano Independent midstream company founded in 1992 ■ Producer focused ■ Entrepreneurial approach ■ Focus on long-term accretive growth ■ Publicly traded LLC ● No general partner or incentive distribution rights ● Tax benefits similar to MLPs, but with corporate governance of a C-co
Slide 4: Key Metrics
Key Metrics Service throughput volumes approximate 1,500,000 MMBtu/d of natural gas (1) Approximately 6,700 miles of active pipelines 10 natural gas processing plants with over 1.2 Bcf/d of combined processing capacity One NGL fractionation facility with total capacity of 22,000 Bbls/d ■ Expansion u
Slide 5: Business Strategy
Business Strategy To build a diversified midstream company with scale and stability of cash flows, above-average returns on invested capital and “investment-grade quality” distributions Key tenets of business strategy: ■ Executing on organic growth opportunities and bolt-on acquisitions ■ Reducing s
Slide 6: Agenda
Agenda Eagle Ford Shale Growth Projects Business Segment Outlook Financing and Commodity Price Sensitivity Conclusions
Slide 7: Eagle Ford Shale Landscape
Eagle Ford Shale Landscape Eagle Ford Shale is currently the best-situated U.S. shale play ■ Regulatory environment familiar with industry ■ Land owners are more industry-friendly ■ Some existing infrastructure ■ Proximity to large consuming market, industrial load and petrochemical markets Signific
Slide 8: Copano's Eagle Ford Shale Strategy
Copano’s Eagle Ford Shale Strategy Utilize existing assets as a platform to provide additional midstream solutions for rich Eagle Ford Shale production in excess of 1 Bcf/d of gas and just under 100,000 Bbls/d of NGLs Leverage existing assets ■ Gathering ■ Processing ■ Fractionation ■ NGL transporta
Slide 9: Northern Eagle Ford Shale
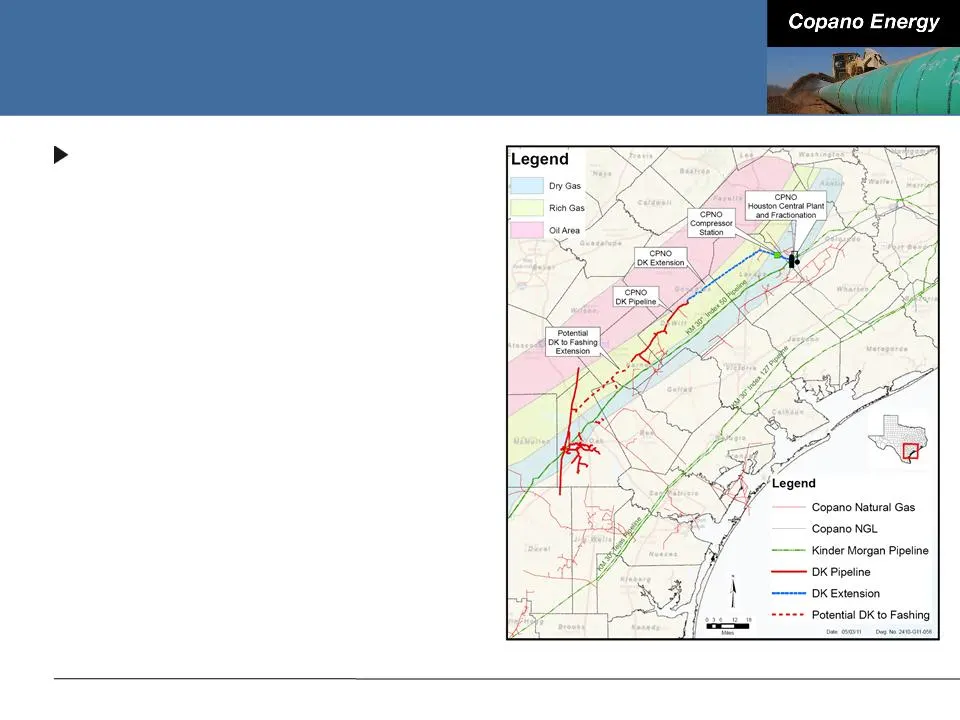
Northern Eagle Ford Shale DK pipeline ■ Existing pipeline - 38 miles of 24” pipe placed into full service October ■ February 2011 - announced extension of existing pipeline back to Houston Central complex ● Additional 58 miles of 24” pipe ● Expected completion in 4Q 2011 ■ Current capacity of 225,00
Slide 10: Northern Eagle Ford Shale
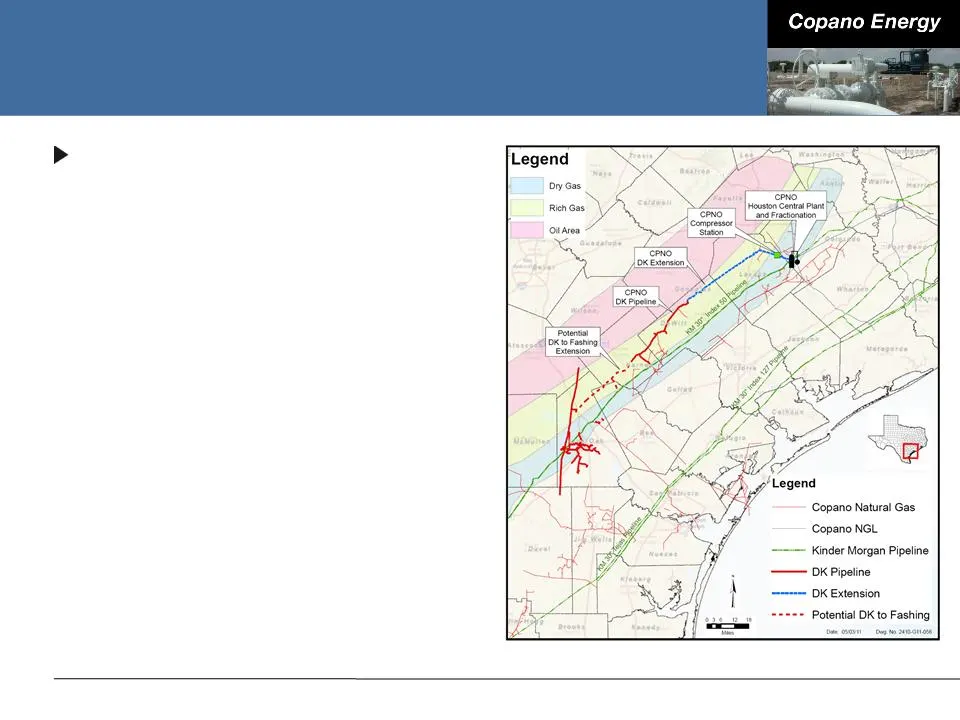
Northern Eagle Ford Shale DK pipeline ■ Services the most prolific rich gas window in the Eagle Ford Shale ■ Loops Kinder Morgan Index 50 pipeline, effectively boosting pipeline capacity to Houston Central ■ Key producer contracts with Abraxas, GeoSouthern, Petrohawk, Pioneer, Riley and others ■ Exi
Slide 11: Southern Eagle Ford Shale
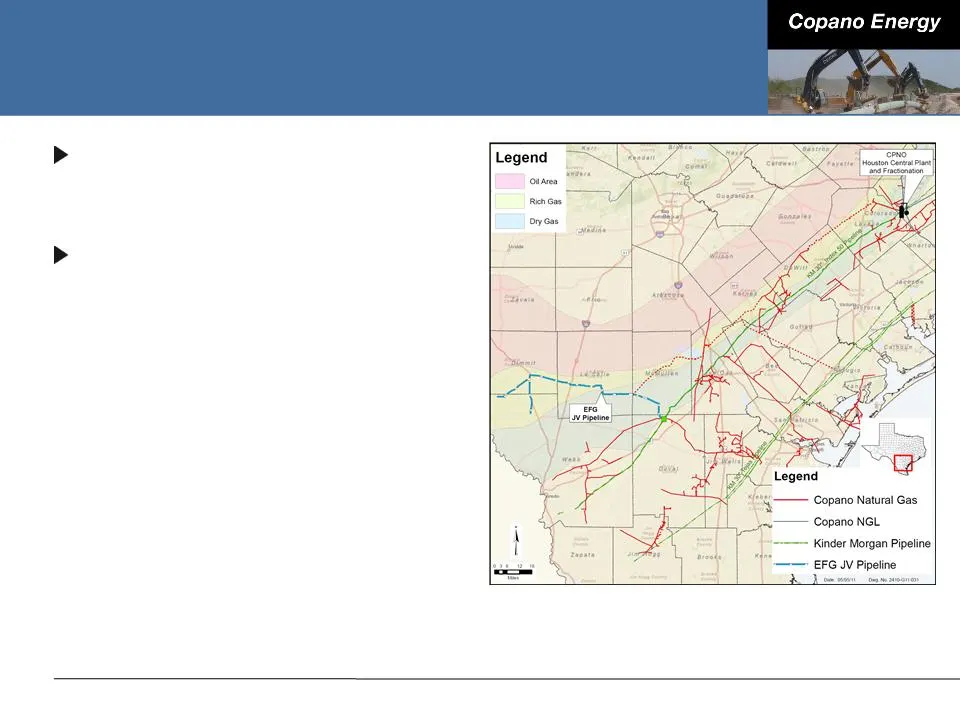
Southern Eagle Ford Shale Eagle Ford Gathering (EFG) ■ 50/50 JV with Kinder Morgan EFG pipeline ■ 114 miles of 30” and 24” pipe - currently under construction ■ Expected completion 3Q 2011 ■ Nominal capacity of 600,000 MMBtu/d ■ Long-term, fee-based contracts with aggregate volume commitments approa
Slide 12: Eagle Ford Gathering Crossover Project
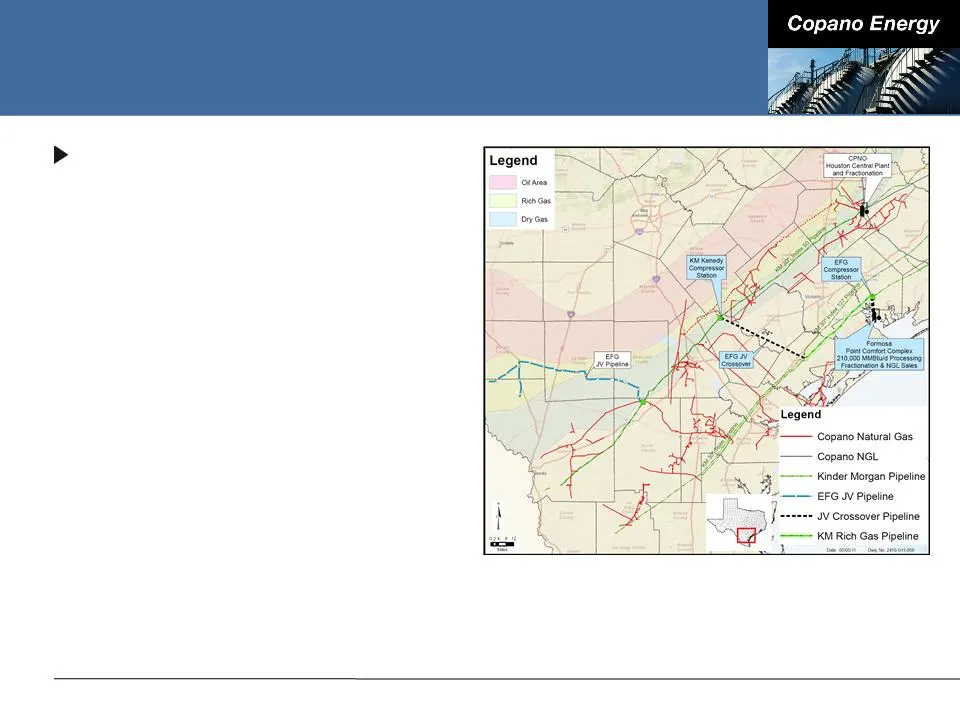
Eagle Ford Gathering Crossover Project Crossover project ■ 66 miles of 24” and 20” pipe connecting Kinder Morgan’s Index 50 and Tejas 30” pipelines to Formosa ● Nominal pipeline capacity of 400,000 MMBtu/d ● Expected completion 4Q 2011 ■ Allows an incremental 210,000 MMBtu/d of gas to flow on Eagle
Slide 13: Houston Central Complex
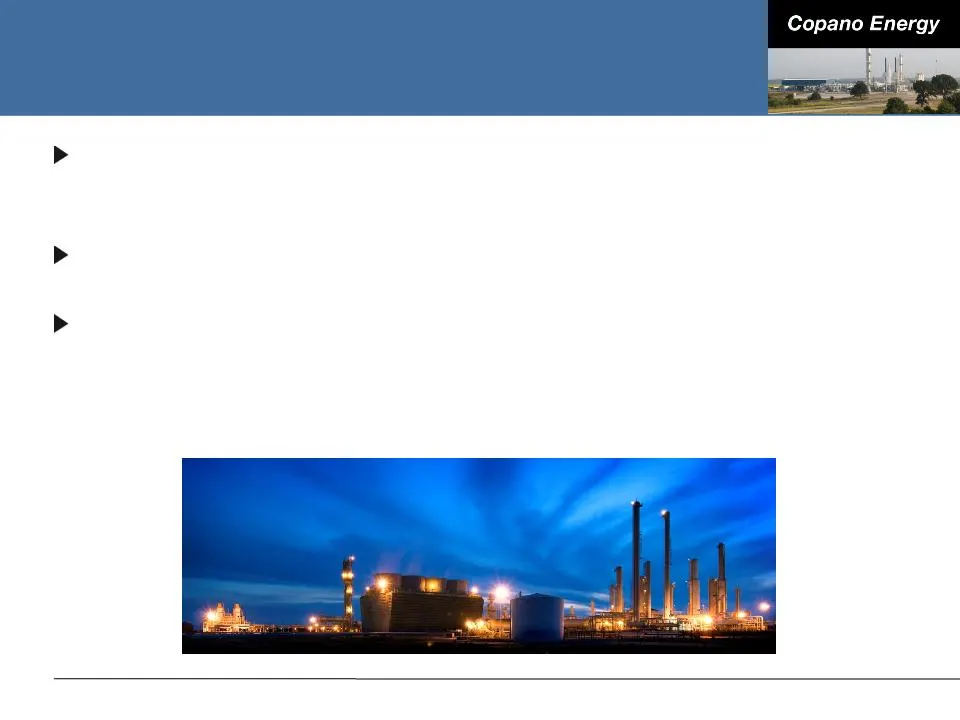
Houston Central Complex Current capacity of 700 MMcf/d ■ 500 MMcf/d of lean oil processing ■ 200 MMcf/d of cryogenic processing Multiple residue interconnects ■ Anticipated additional connection - Tres Palacios storage and header system Cryogenic processing expansion of 400 MMcf/d in process ■ Impro
Slide 14: Houston Central Complex
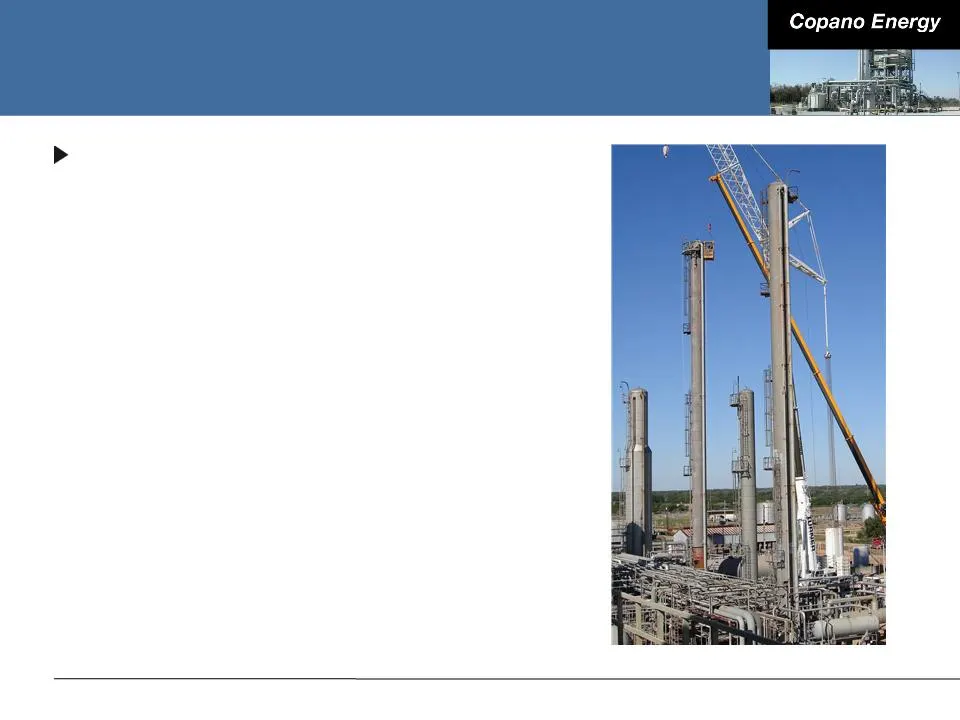
Houston Central Complex Fractionation expansion ■ Responding to increased producer demand, liquids handling capacity will double at Houston Central complex ■ Fractionation expansion from 22,000 Bbls/d to 44,000 Bbls/d ● All ethane and propane will move to Dow through Copano purity pipelines ■ Total
Slide 15: Liberty NGL Pipeline
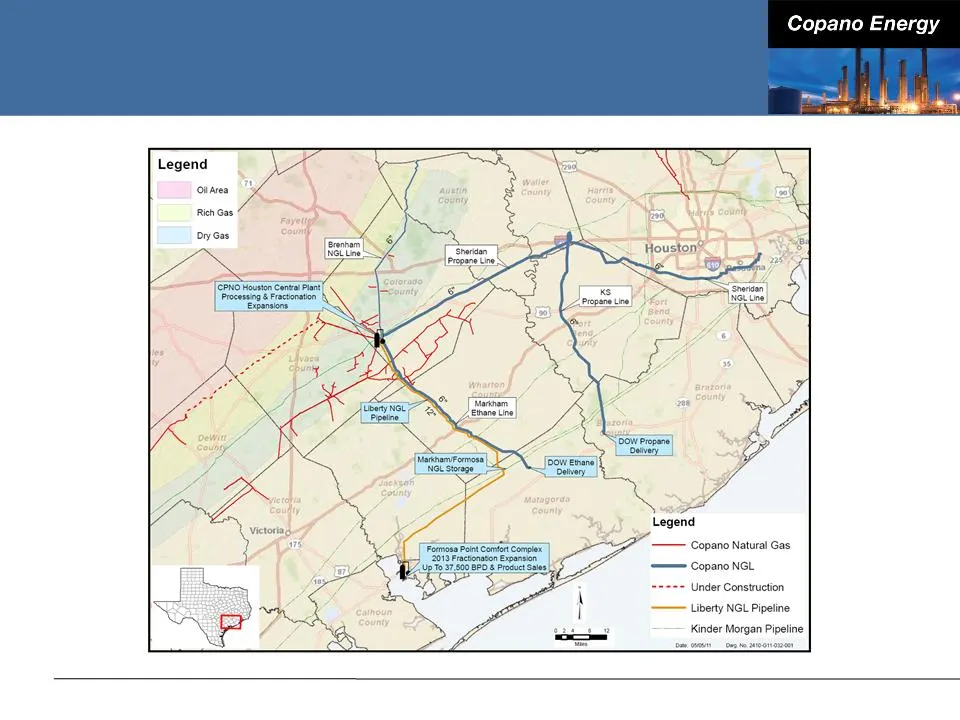
Liberty NGL Pipeline 83-mile, 12” NGL pipeline extending from the Houston Central complex to Markham NGL storage and Formosa’s Point Comfort complex ■ Total capacity of 75,000 Bbls/d ■ Constructed through 50/50 JV with Energy Transfer ■ Expected completion early 3Q 2011 Long-term fractionation and p
Slide 16: Houston Central NGL Infrastructure
Houston Central NGL Infrastructure
Slide 17: Gulf Coast Petrochemical Market Access
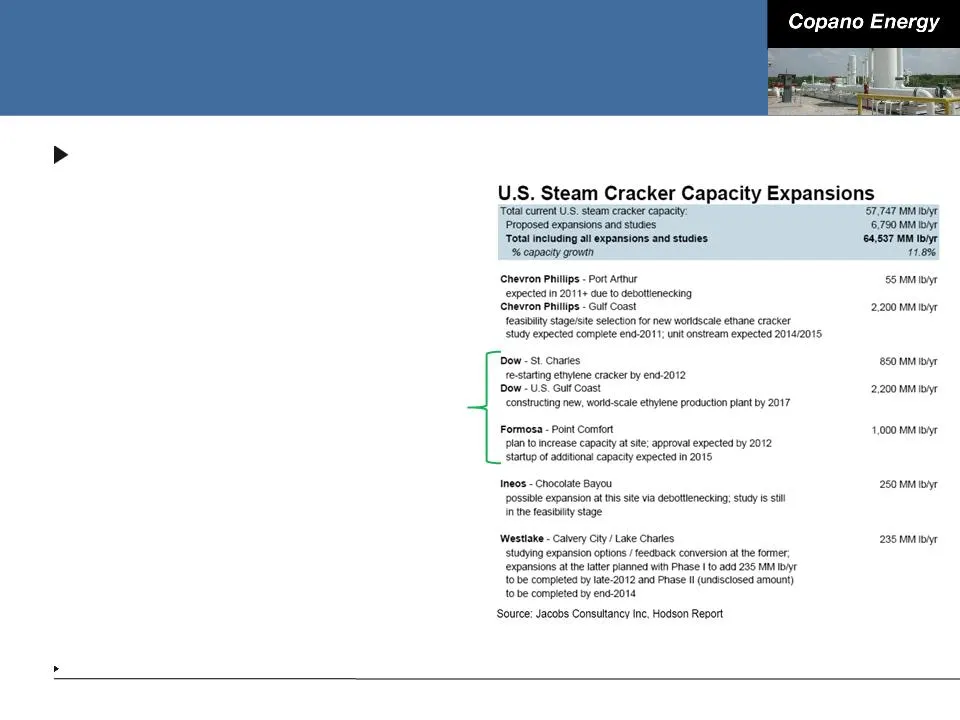
Gulf Coast Petrochemical Market Access Copano has access to Dow and, upon completion of the Liberty NGL pipeline, Formosa ■ Among the largest end users of NGLs in the U.S. ■ Taking into account announced expansions, Dow and Formosa’s combined steam cracker capacity is approximately 19% of total U.S.
Slide 18: Summary of Eagle Ford Shale Infrastructure
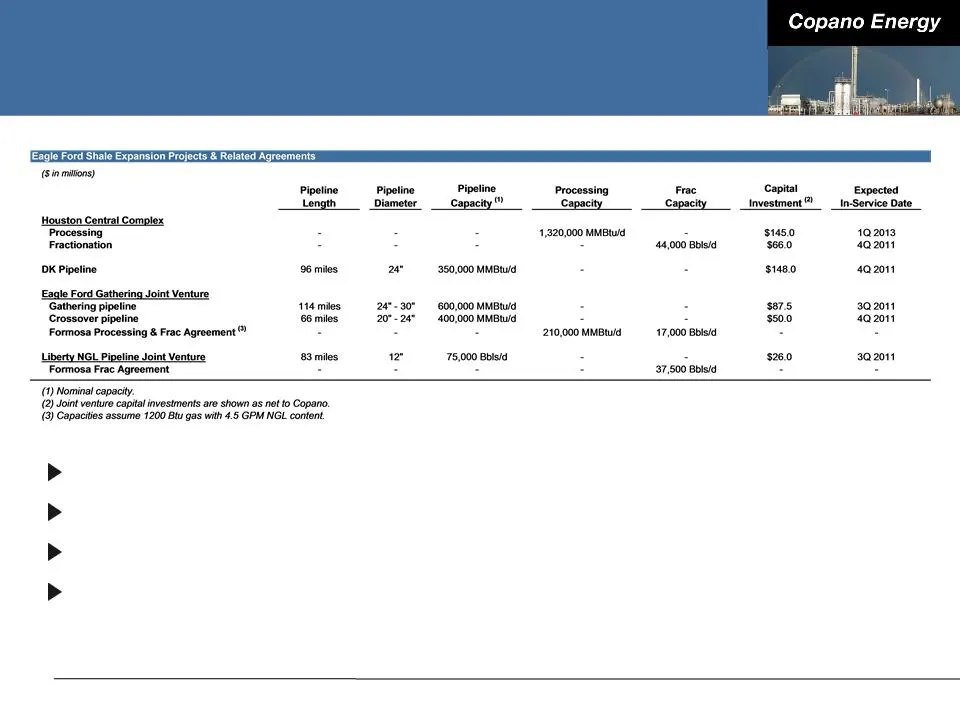
Summary of Eagle Ford Shale Infrastructure Total capital investment of over $500 million In excess of 1 Bcf/d of pipeline and processing capacity Approaching 100,000 Bbls/d of fractionation capacity Access to multiple markets for residue gas and NGLs
Slide 19: Combined Eagle Ford Shale Map
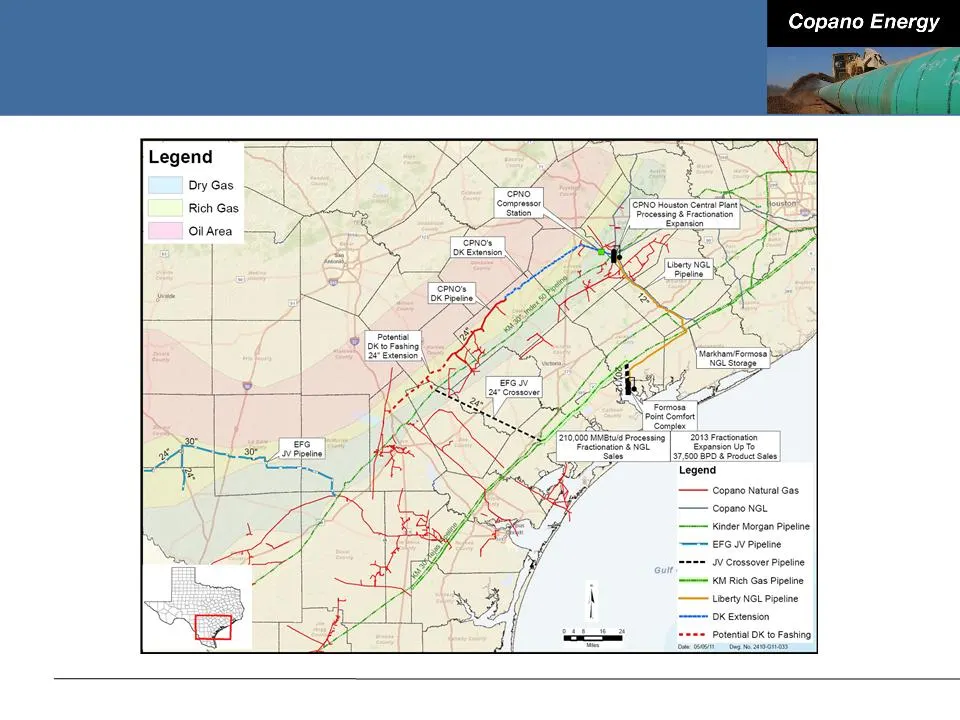
Combined Eagle Ford Shale Map
Slide 20: Business Segment Outlook
Business Segment Outlook Eagle Ford Shale Growth Projects Business Segment Outlook Financing and Commodity Price Sensitivity Conclusions
Slide 21: Texas Recent Developments
Texas Recent Developments Saint Jo system ■ Primarily long-term gathering, treating and processing fee-for-service business ■ Plant fully committed under contracts ■ System volumes have been averaging approximately 62,000 MMBtu/d Eagle Ford Shale ■ Houston Central complex processing expansion ● Perm
Slide 22: Texas Outlook
Texas Outlook Saint Jo system ■ 16 rigs running in the area ● Still on track to connect approximately 150 wells in 2011 ● Leasing activity continues ■ Based on producer discussions, expect activity to remain high Eagle Ford Shale ■ Potential addition of interruptible volumes on Eagle Ford Gathering
Slide 23: Oklahoma Recent Developments
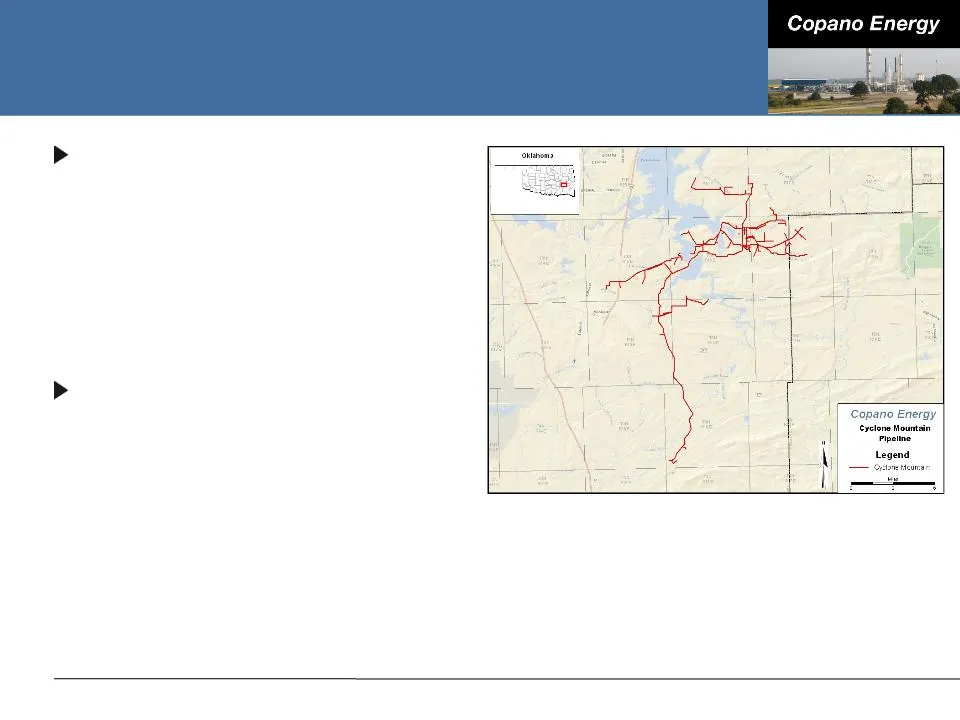
Oklahoma Recent Developments Significant drilling activity in the Woodford Shale around the Cyclone Mountain system ■ Average 1Q 2011 volumes of approximately 75,000 MMBtu/d vs. average 4Q 2010 of approximately 59,000 MMBtu/d Current system capacity approximately 120 MMcf/d ■ System expansion likely
Slide 24: Oklahoma Outlook
Oklahoma Outlook Rich gas (primarily Hunton dewatering play) ■ Drilling activity has increased slightly in 2Q 2011 compared to 1Q 2011 ■ 3 rigs currently running in the Hunton and 13 rigs in other rich gas areas ■ Attractive processing upgrade and low geologic risk ■ 2Q 2011 volumes expected to be s
Slide 25: Rocky Mountains Outlook
Rocky Mountains Outlook Drilling and dewatering will be driven by commodity prices and producer economics 2Q 2011 volumes for Bighorn expected to be slightly lower vs. 1Q 2Q 2011 volumes for Fort Union expected to be lower vs. 1Q 2011 due to the start-up of Bison pipeline ■ Do not expect material im
Slide 26: Financing and Commodity Price Sensitivity
Financing and Commodity Price Sensitivity Eagle Ford Shale Growth Projects Business Segment Outlook Financing and Commodity Price Sensitivity Conclusions
Slide 27: Liquidity and Capitalization
Liquidity and Capitalization At March 31, 2011: ■ $69 million cash ■ $550 million revolving credit facility ● Approximately $310 million available ● Matures October 2012 ■ $583 million senior notes ● $332.7 million 8.125% senior notes due 2016 (fully redeemed in 2Q 2011) ● $249.5 million 7.75% senio
Slide 28: Commodity Price Exposure
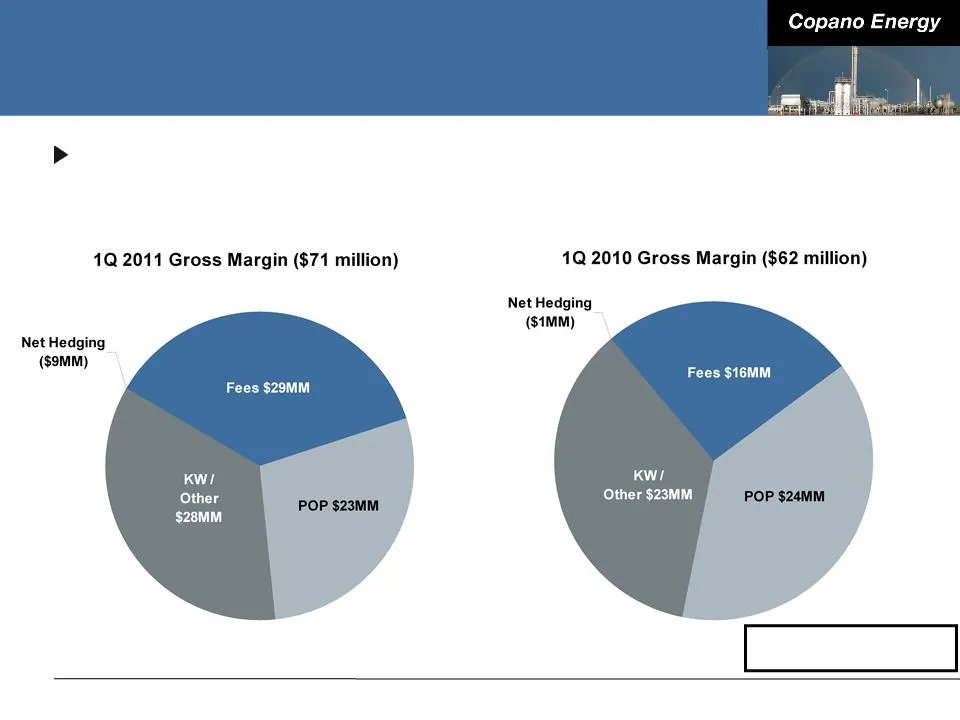
Commodity Price Exposure As Eagle Ford Shale and North Barnett Shale Combo volumes grow, transition to more fee-based volumes will continue to reduce direct commodity price exposure Note: Includes Copano’s share of gross margin from unconsolidated affiliates. Approximate percentages based on Copano
Slide 29: Hedging Strategy
Hedging Strategy Option-based, product-specific 2011 hedged at or near policy limits ■ Approximately 70% of ethane, propane, butane, natural gasoline and condensate price exposure is hedged Will continue adding to 2013 hedging positions during 2011
Slide 30: Conclusions
Conclusions Eagle Ford Shale Growth Projects Business Segment Outlook Financing and Commodity Price Sensitivity Conclusions
Slide 31: Conclusions
Conclusions Focused on execution in the Eagle Ford Shale Strong producer activity in north Texas continues Focused on growth opportunities in the Woodford Shale in Oklahoma Continue to evaluate strategic M&A opportunities Shift to predominately fee-based contract mix underway Ample liquidity and acc
Slide 32: Copano Energy
Copano Energy OF mle
Slide 33: Oklahoma Assets
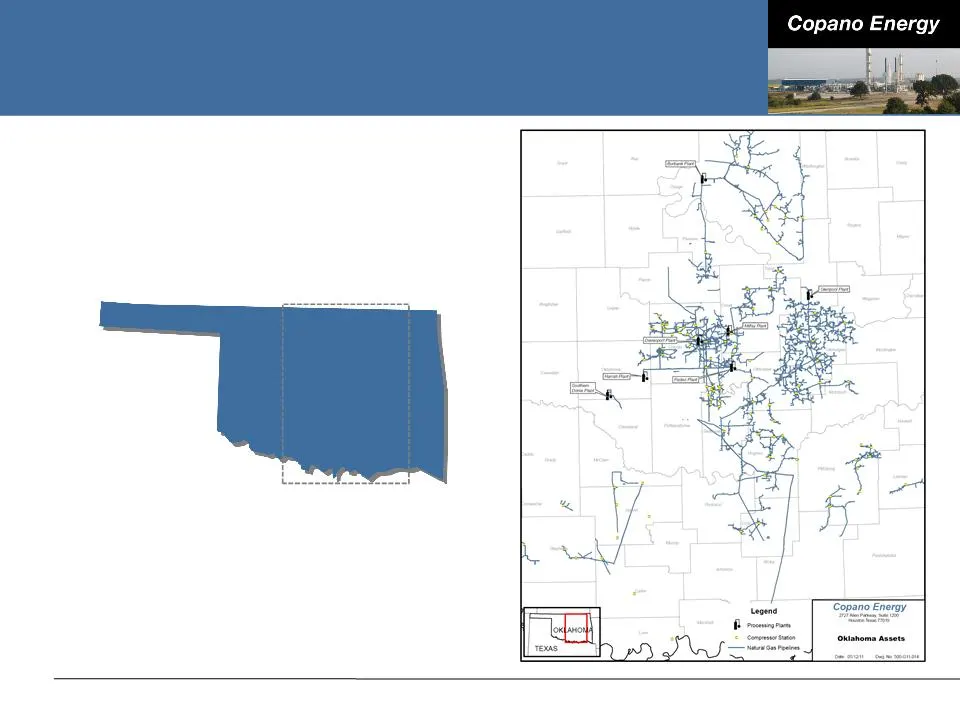
Oklahoma Assets OKLAHOMA
Slide 34: South Texas Assets
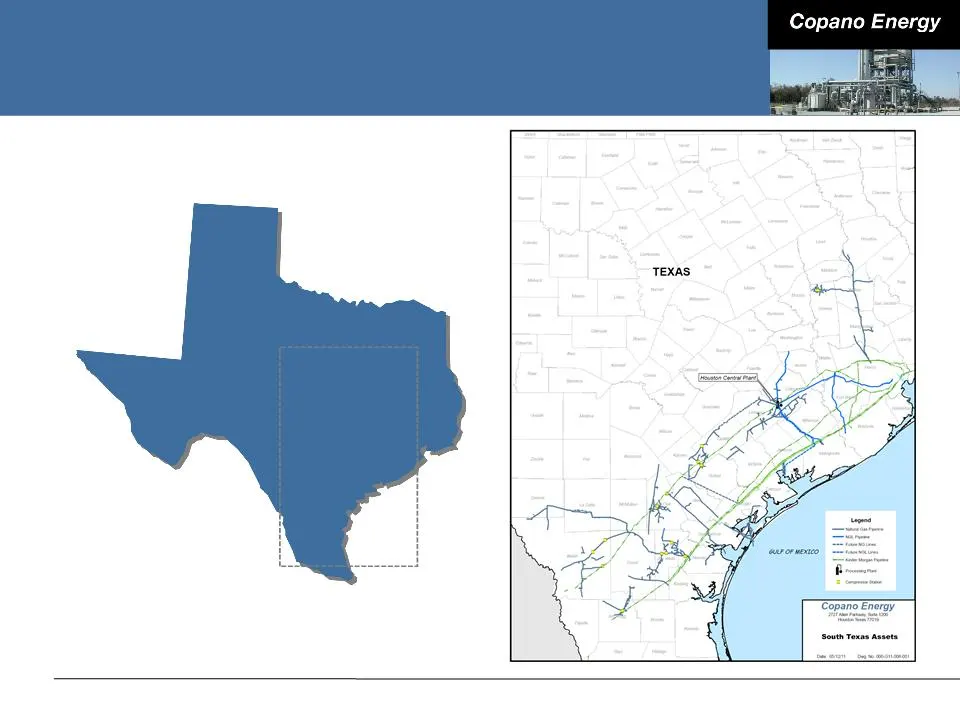
South Texas Assets TEXAS
Slide 35: North Texas Assets
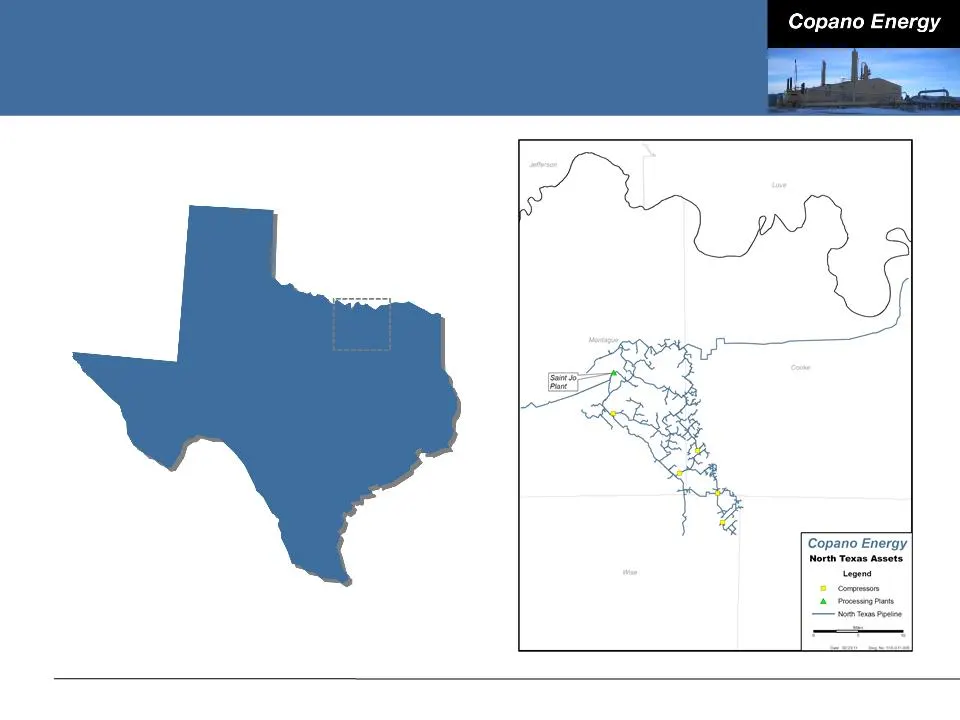
Copano Energy Copano Energy North Texas Assets Legend © cee
Slide 36: Rocky Mountains Assets
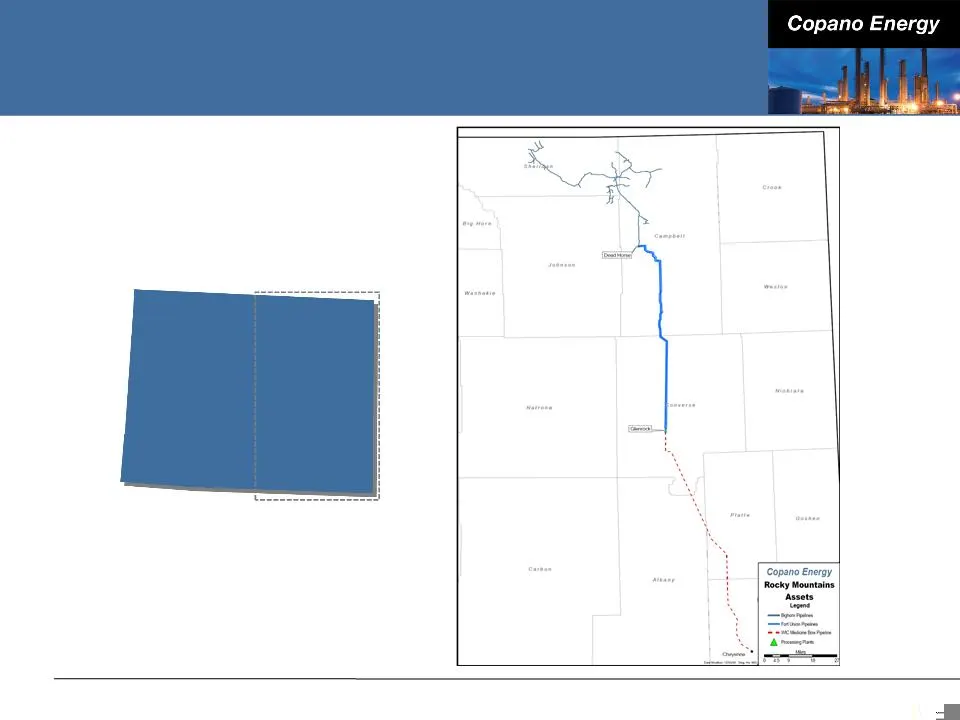
Rocky Mountains Assets WYOMING
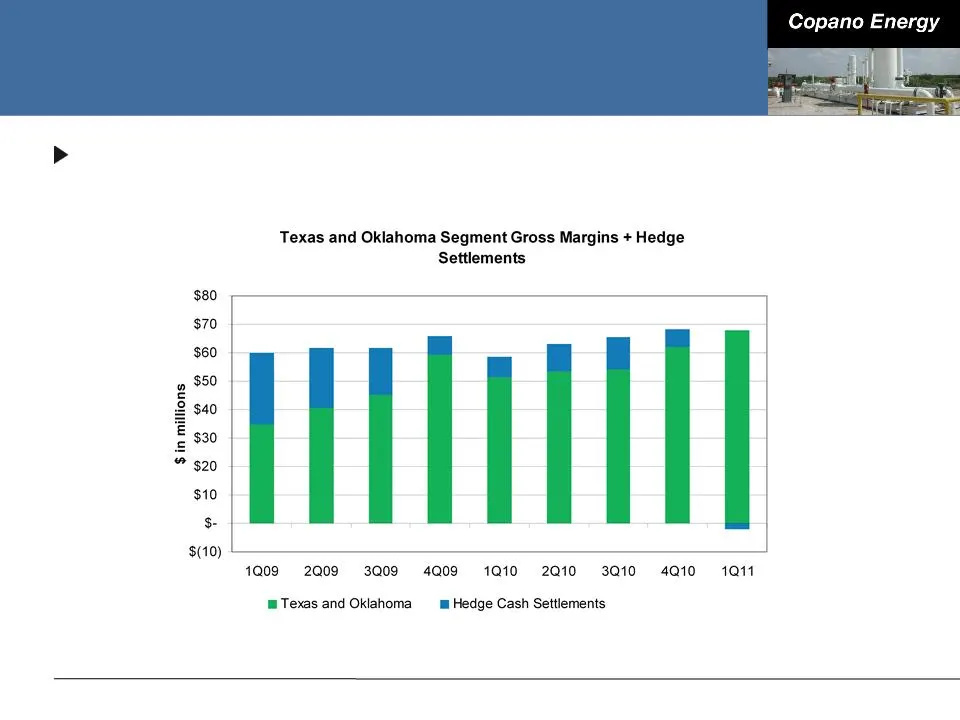
Slide 37: Combined Commodity-Sensitive Segment Margins and Hedging Settlements
Combined Commodity-Sensitive Segment Margins and Hedging Settlements Copano’s hedge portfolio supports cash flow stability
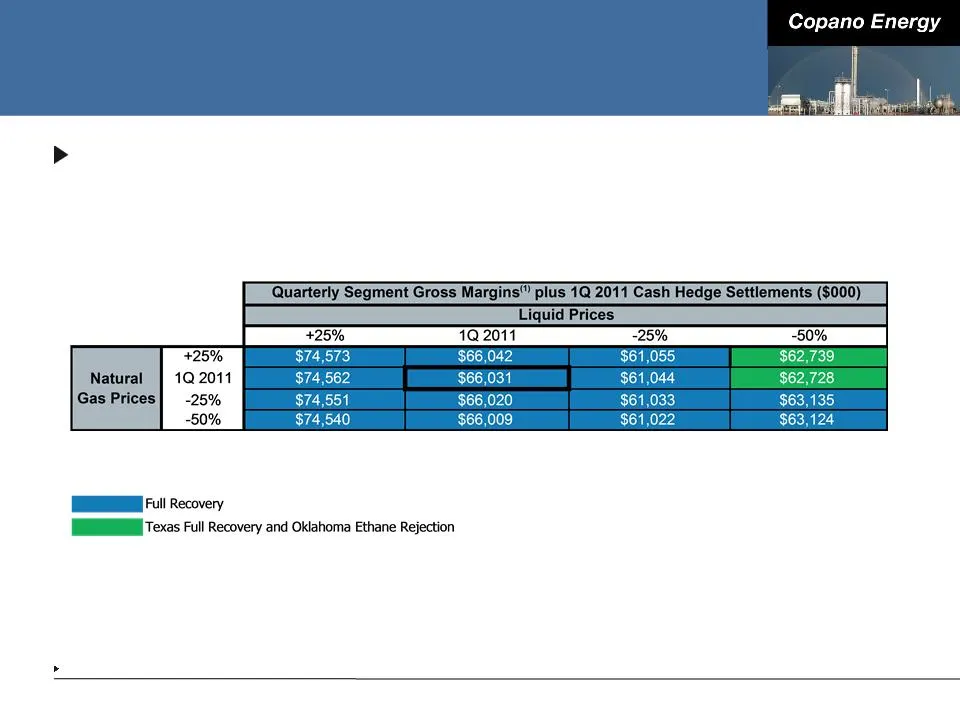
Slide 38: Commodity-Related Margin Sensitivities
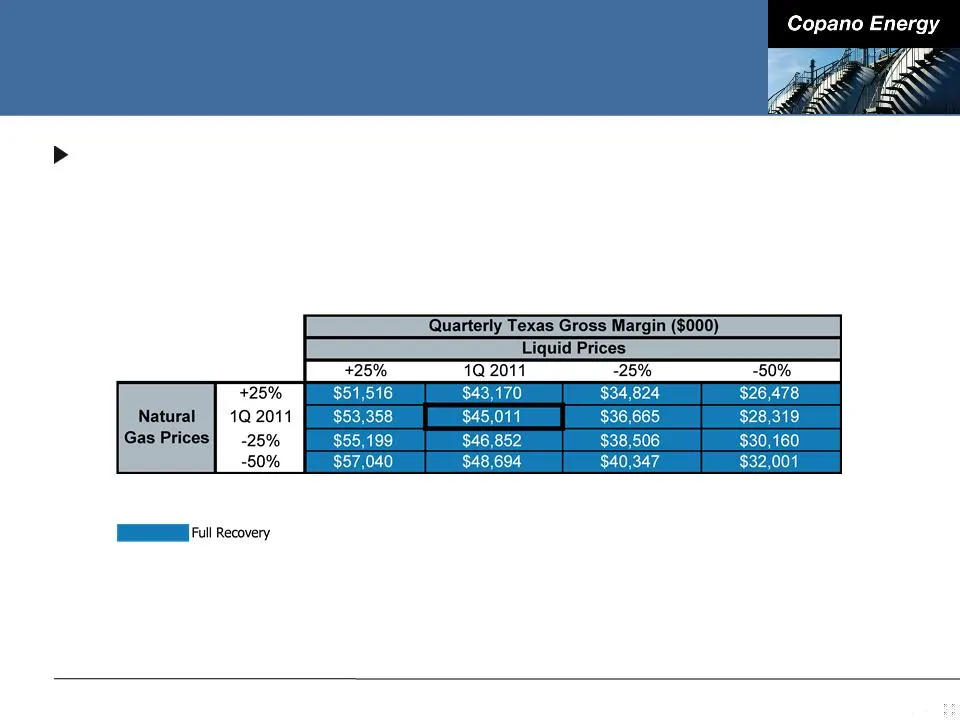
Commodity-Related Margin Sensitivities Matrix reflects 1Q 2011 wellhead and plant inlet volumes, adjusted using Copano’s 2011 planning model Consists of Texas and Oklahoma Segment gross margins.
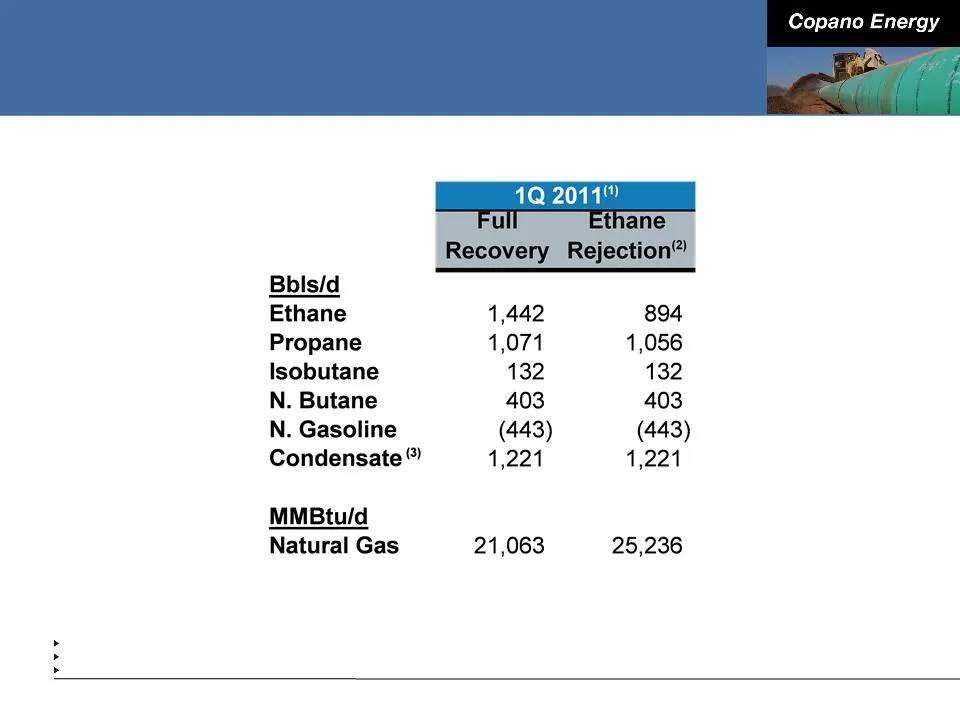
Slide 39: Oklahoma Net Commodity Exposure
Oklahoma Net Commodity Exposure Note: See explanation of processing modes in this Appendix. Values reflect rounding. Source: Copano Energy internal financial planning models. Ethane rejection at Paden plant is limited by nitrogen rejection facilities. Reflects impact of producer delivery point alloc
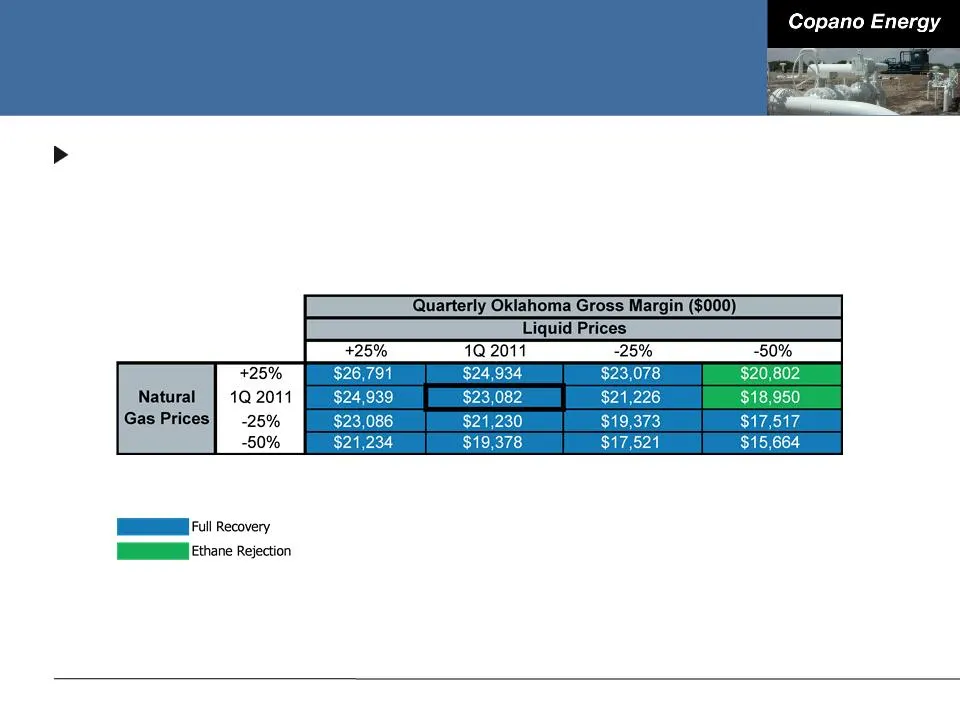
Slide 40: Oklahoma Commodity Price Sensitivities
Oklahoma Commodity Price Sensitivities Oklahoma segment gross margins excluding hedge settlements ■ Matrix reflects 1Q 2011 volumes, adjusted using Copano’s 2011 planning model Note: Please see this Appendix for definitions of processing modes and additional details.
Slide 41: Texas Net Commodity Exposure
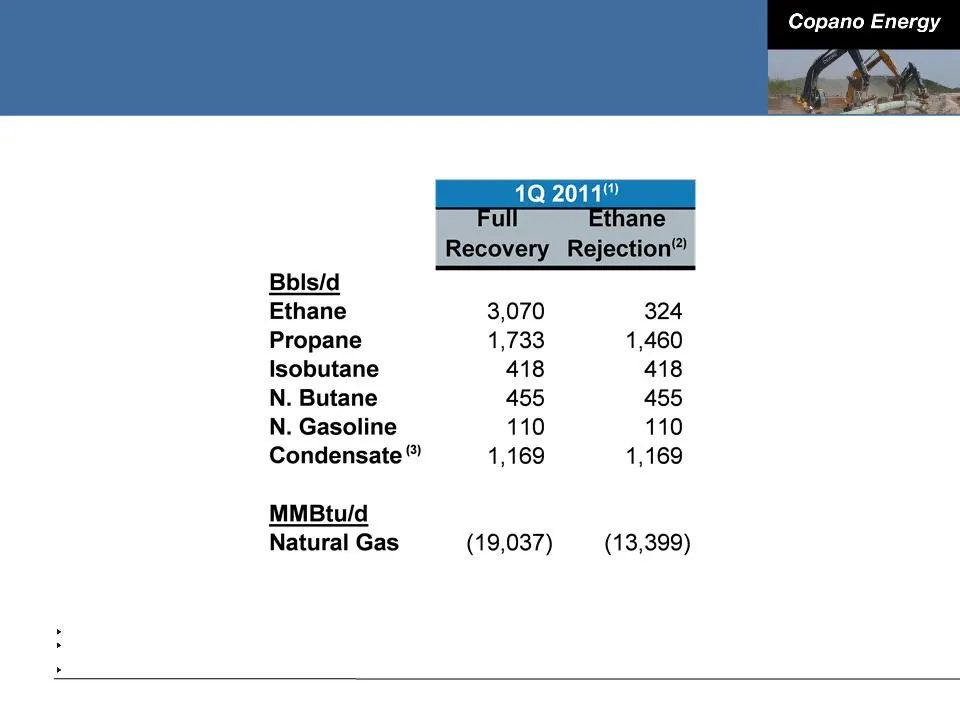
Texas Net Commodity Exposure Note: See explanation of processing modes in this Appendix. Source: Copano Energy internal financial planning models. Based on 1Q 2011 daily wellhead/plant inlet volumes. Fractionation at Houston Central complex permits significant reductions in ethane recoveries in etha
Slide 42: Texas Commodity Price Sensitivities
Texas Commodity Price Sensitivities Texas segment gross margins excluding hedge settlements ■ Matrix reflects 1Q 2011 volumes and operating conditions, adjusted using Copano’s 2011 planning model Note: Please see this Appendix for definitions of processing modes and additional details.
Slide 43: Rocky Mountains Sensitivities
Rocky Mountains Sensitivities 1Q 2011 Adjusted EBITDA volume sensitivity (positive or negative impact) ■ Bighorn: 10,000 MMBtu/d = $255,000 (1) ■ Fort Union: 10,000 MMBtu/d = immaterial impact until physical volumes exceed long-term contractual volume commitments ● 1Q 2011 pipeline throughput: 434,7
Slide 44: Hedging Impact of Commodity Price Sensitivities
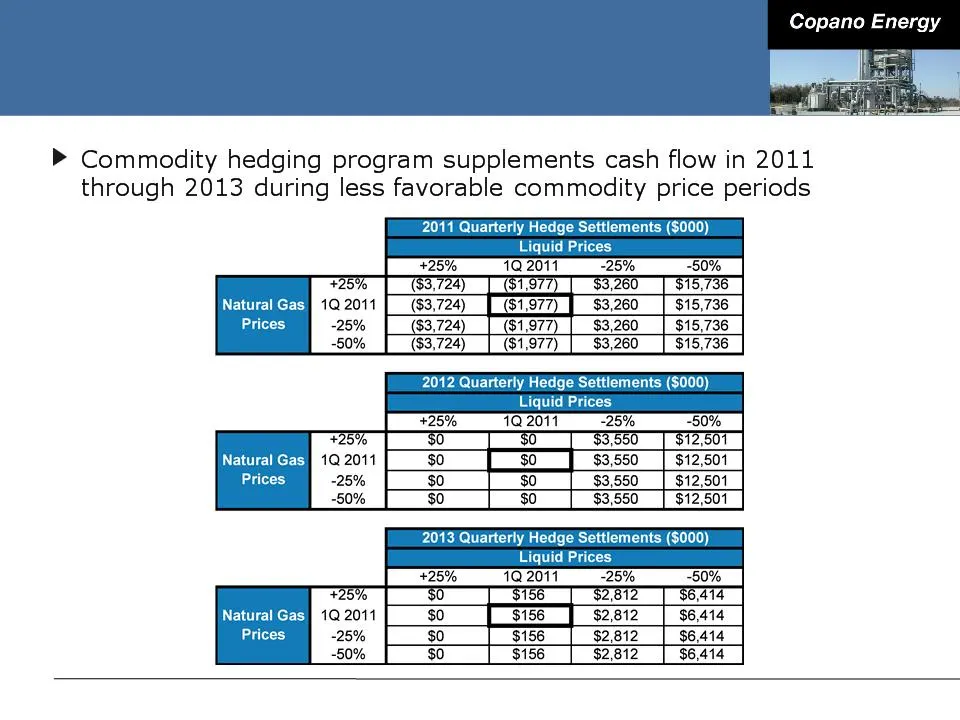
Hedging Impact of Commodity Price Sensitivities
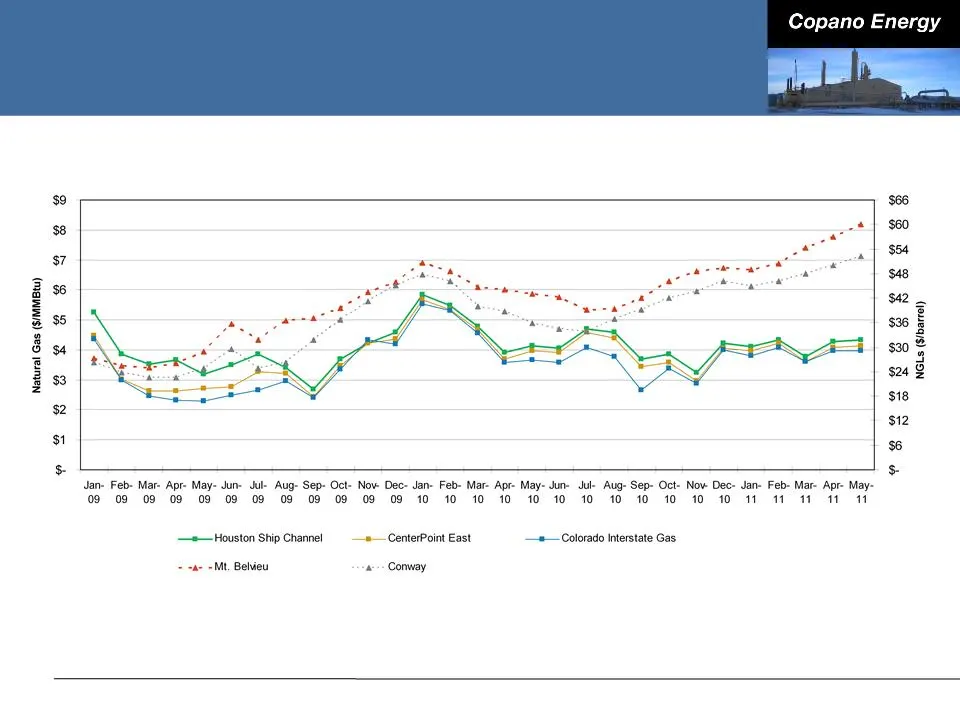
Slide 45: Historical Commodity Prices
Historical Commodity Prices Note: NGL prices for Jan-09 through Mar-11 are calculated based on the weighted-average product mix for the period indicated. NGL prices for Apr-11 through May-11 are calculated based on the first quarter 2011 product mix.
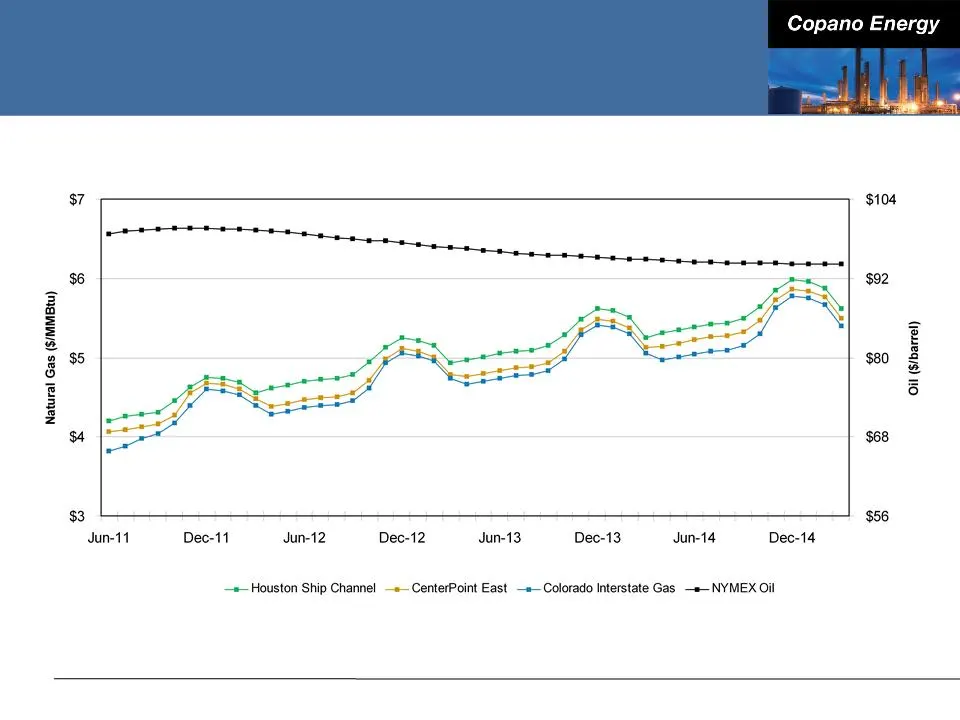
Slide 46: Forward Commodity Prices
Forward Commodity Prices Note: Forward prices as of May 10, 2011
Slide 47: Processing Modes
Processing Modes Full Recovery Texas and Oklahoma - If the value of recovered NGLs exceeds the fuel and gas shrinkage costs of recovering NGLs Ethane Rejection Texas and Oklahoma - If the value of ethane is less than the fuel and shrinkage costs to recover ethane (in Oklahoma, ethane rejection at Pa
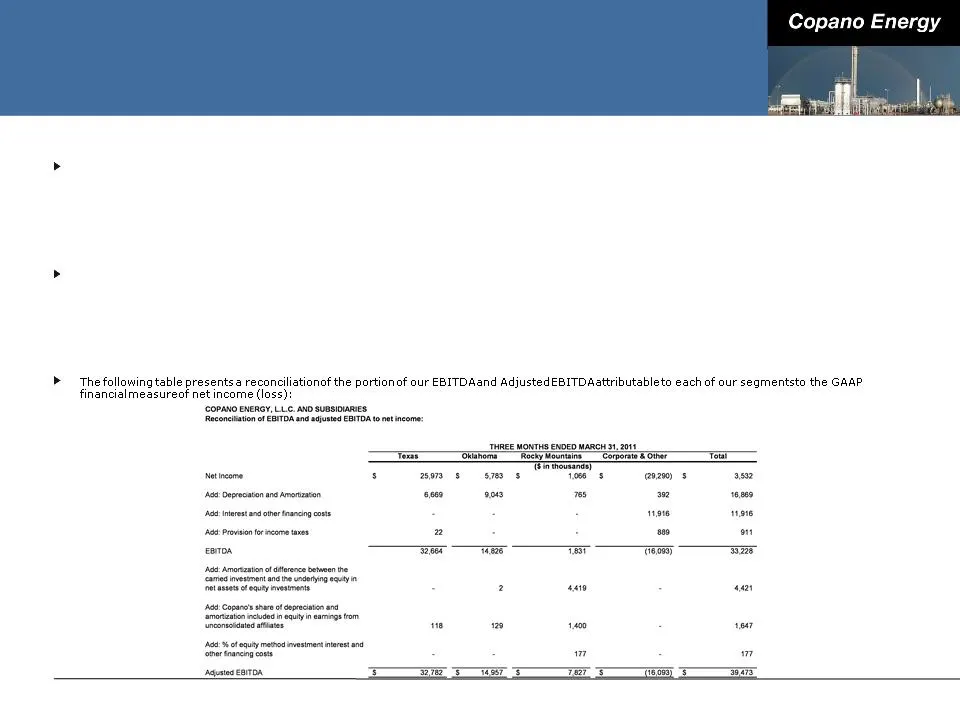
Slide 48: Reconciliation of Non-GAAP Financial Measures
Reconciliation of Non-GAAP Financial Measures Adjusted EBITDA We define EBITDA as net income (loss) plus interest expense, provision for income taxes and depreciation and amortization expense. Because a portion of our net income (loss) is attributable to equity in earnings (loss) from our equity inv
Slide 49: Reconciliation of Non-GAAP Financial Measures
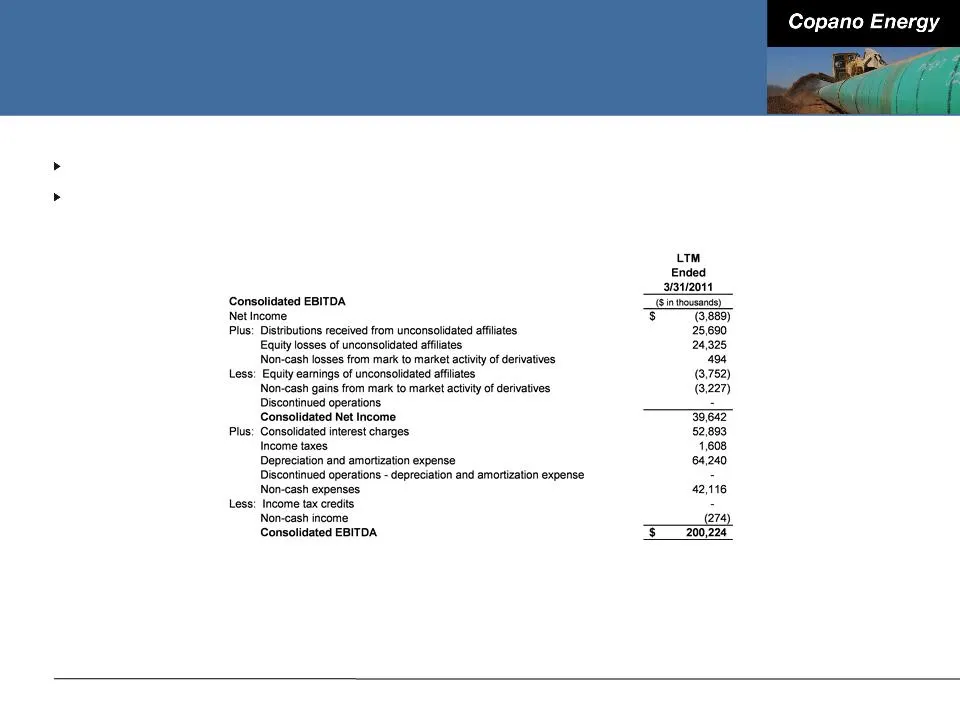
Reconciliation of Non-GAAP Financial Measures Consolidated EBITDA EBITDA is also a financial measure that, with negotiated pro forma adjustments relating to acquisitions completed during the period, is reported to our lenders as Consolidated EBITDA and is used to compute our financial covenants unde
Slide 50: Definitions of Non-GAAP Financial Measures
Definitions of Non-GAAP Financial Measures Total Distributable Cash Flow We define total distributable cash flow as net income plus: (i) depreciation, amortization and impairment expense (including amortization expense relating to the option component of our risk management portfolio); (ii) cash dis
Source: SEC EDGAR · 8-K filed May 17, 2011
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011