Wheeling Pittsburgh — Proxy Contest (September 2006)
21 slides from Wheeling Pittsburgh's proxy contest presentation, Sep 29, 2006
Slide 1: Schedule 14A
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 (Amendment No. ) Filed by the Registrant ¨ Filed by a Party other than the Registrant x Check the appropriate box: ¨ Preliminary Proxy
Slide 2: Fee offset and previous filing information
¨ Check box if any part of the fee is offset as provided by Exchange Act Rule 0-11(a)(2) and identify the filing for which the offsetting fee was paid previously. Identify the previous filing by registration statement number, or the Form or Schedule and the date of its filing. (1) Amount Previously
Slide 3: September 2006
* S E P T E MB E R 2 0 0 6 * * * * * * * * * * ** * * * * * * * *
Slide 4: Esmark proxy statement legend and important information
Esmark Incorporated, together with the other participants indicated below, filed a revised preliminary proxy statement with the SEC on September 22, 2006 relating to the solicitation of proxies for the election of a slate of director nominees at the 2006 annual meeting of shareholders of Wheeling-Pi
Slide 5: Agenda
Agenda Page Overview 2 Formation of Esmark Strategy comes first not later 10 acquisitions in 3 years…our process Why buy a steel mill? The Wheeling Pitt transaction The financial and strategic logic 2
Slide 6: Founding the Company
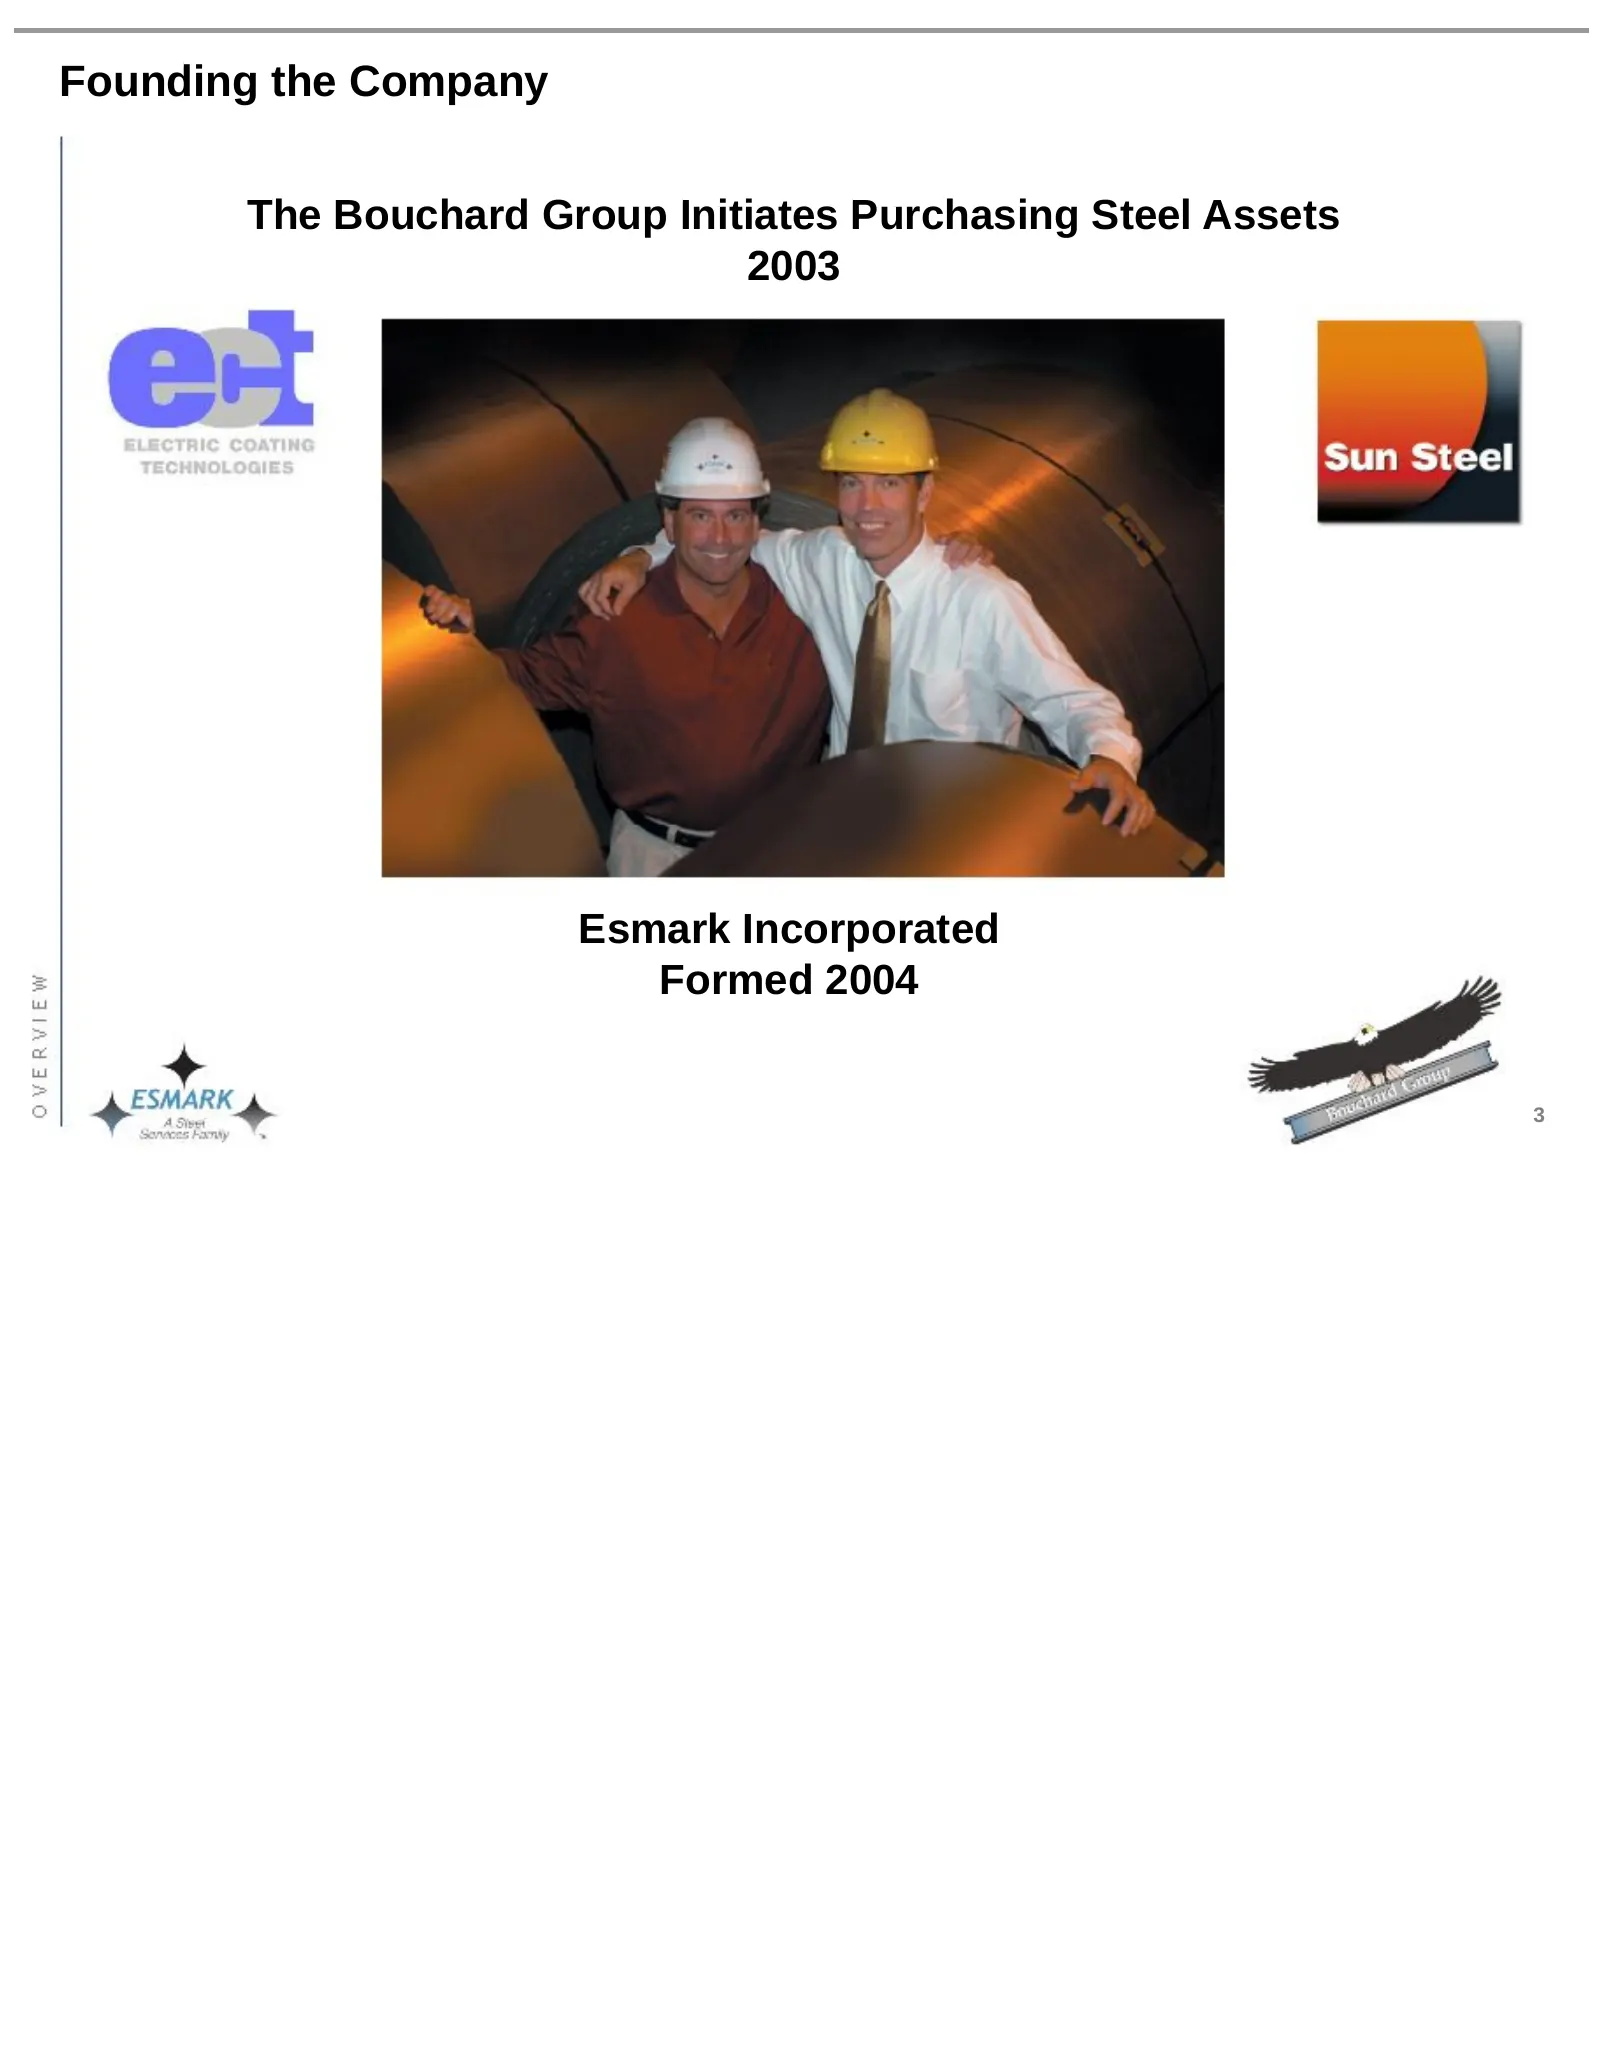
Founding the Company The Bouchard Group Initiates Purchasing Steel Assets 2003 Esmark Incorporated Formed 2004 3
Slide 7: Jack Welch quote on business leadership
“Good business leaders create a vision, articulate the vision passionately, own the vision, and relentlessly drive to completion” Jack Welch 4
Slide 8: Esmark Today… 3 Years Later
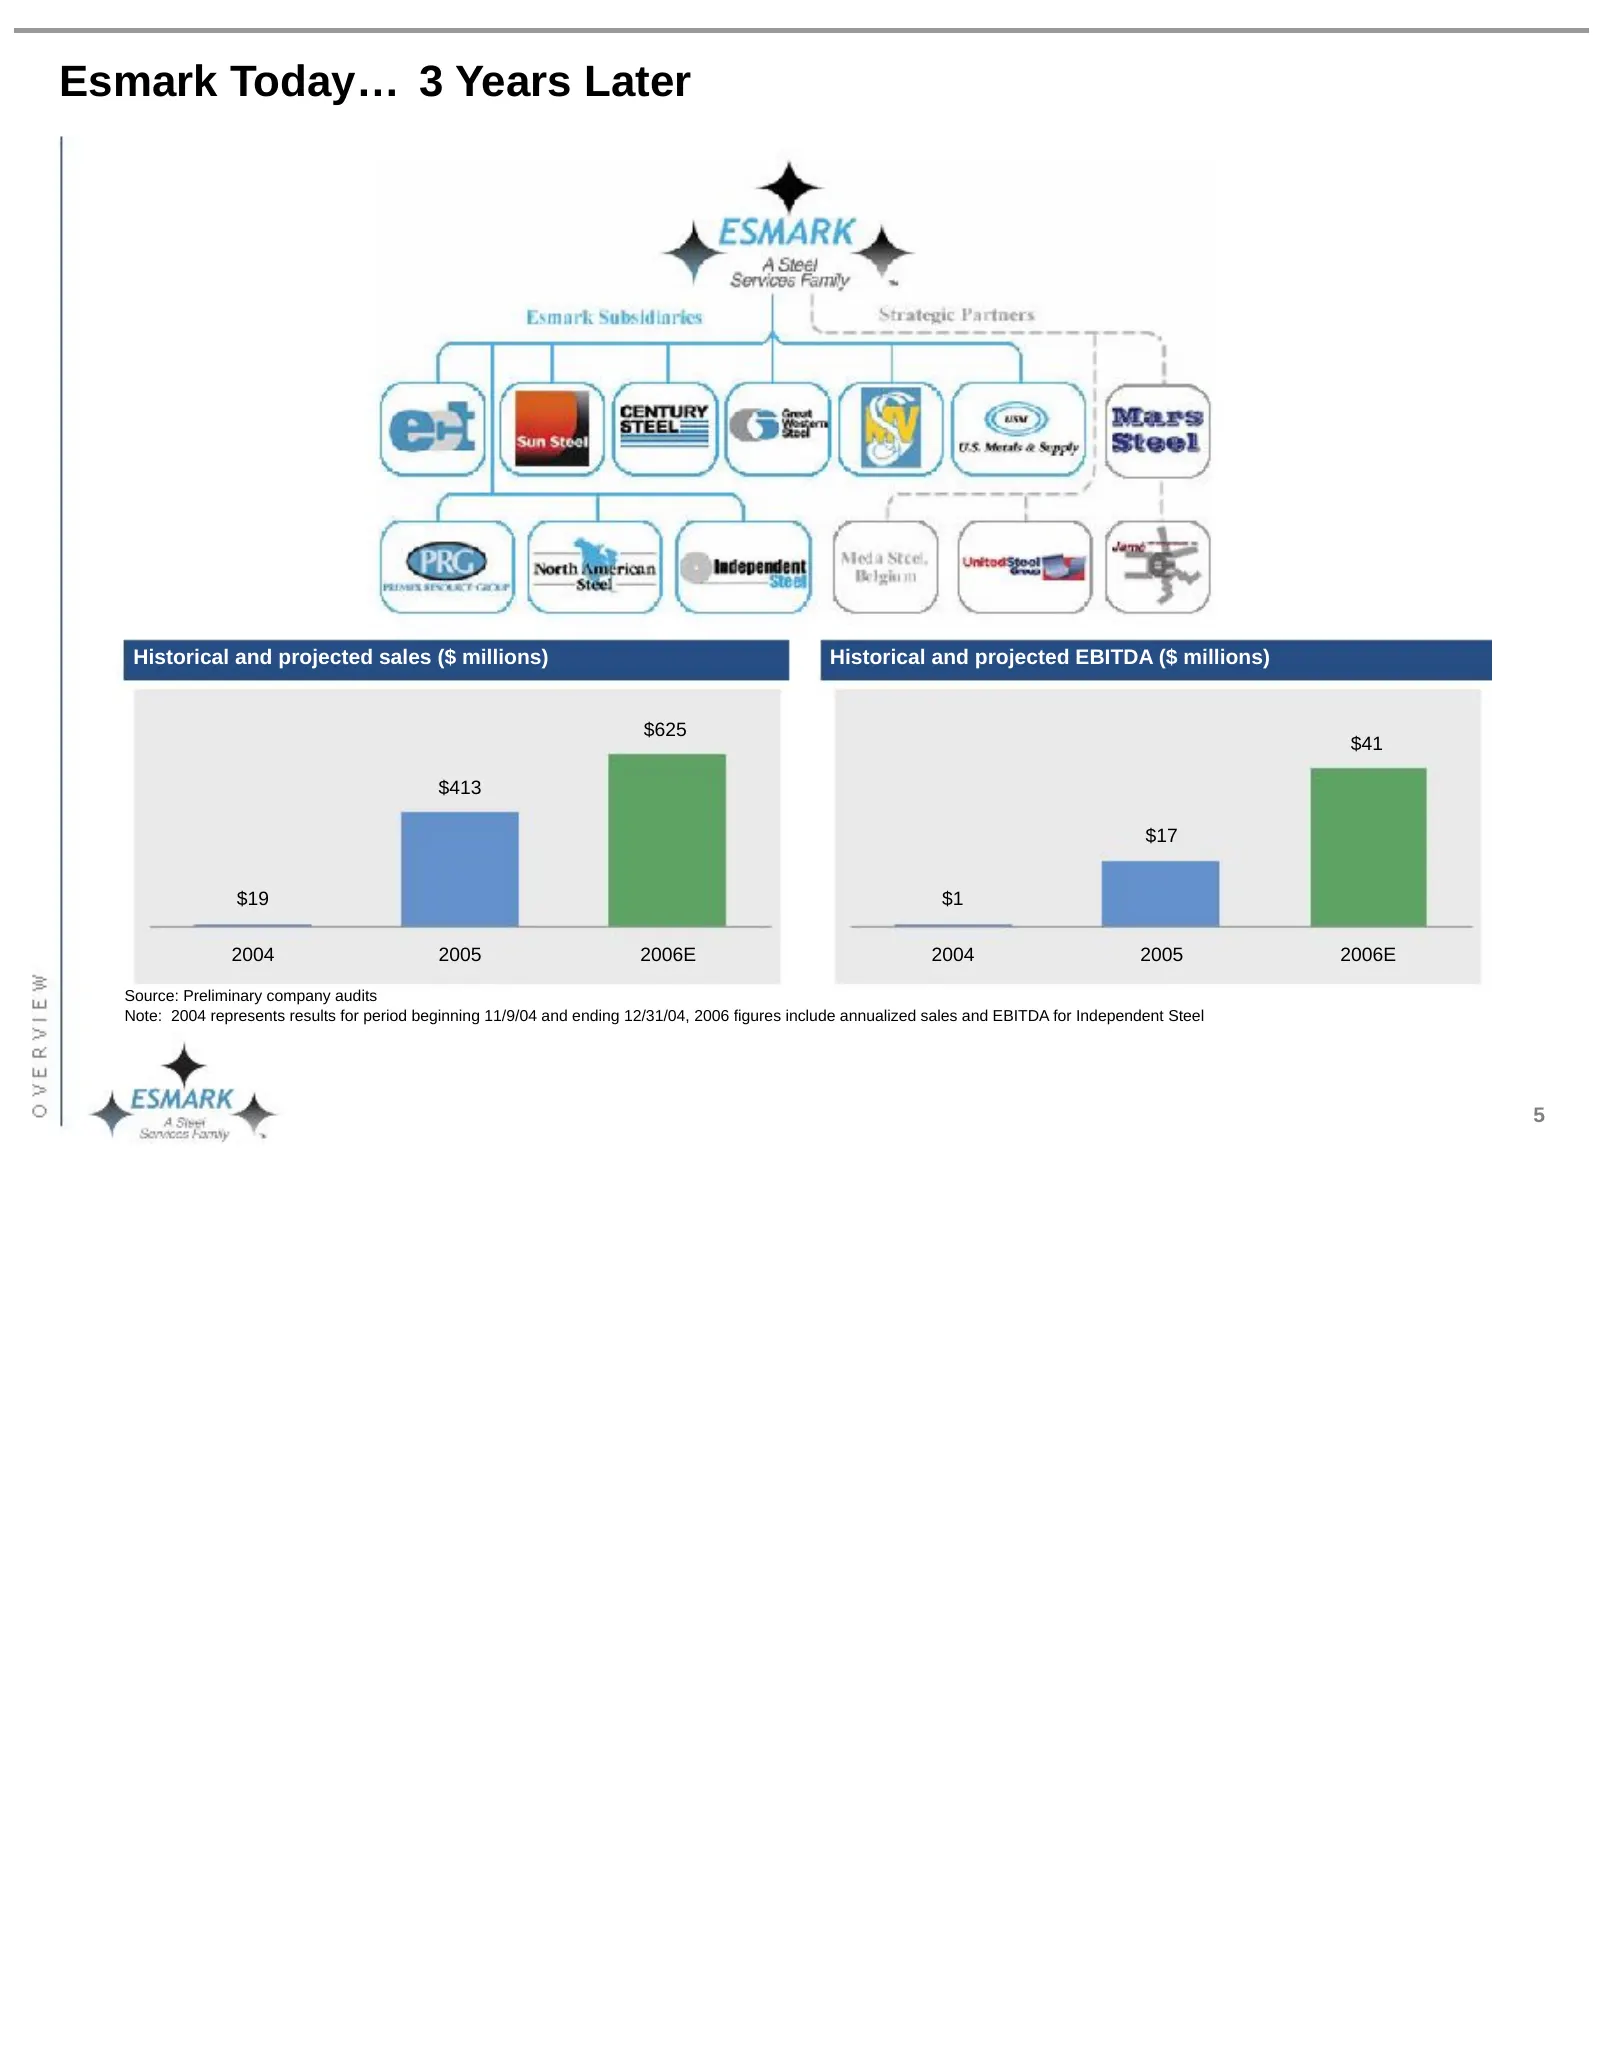
Esmark Today… 3 Years Later Historical and projected sales ($ millions) Historical and projected EBITDA ($ millions) $625 $41 $413 $17 $19 $1 2004 2005 2006E 2004 2005 2006E Source: Preliminary company audits Note: 2004 represents results for period beginning 11/9/04 and ending 12/31/04, 2006 figure
Slide 9: Esmark Acquisition Timeline
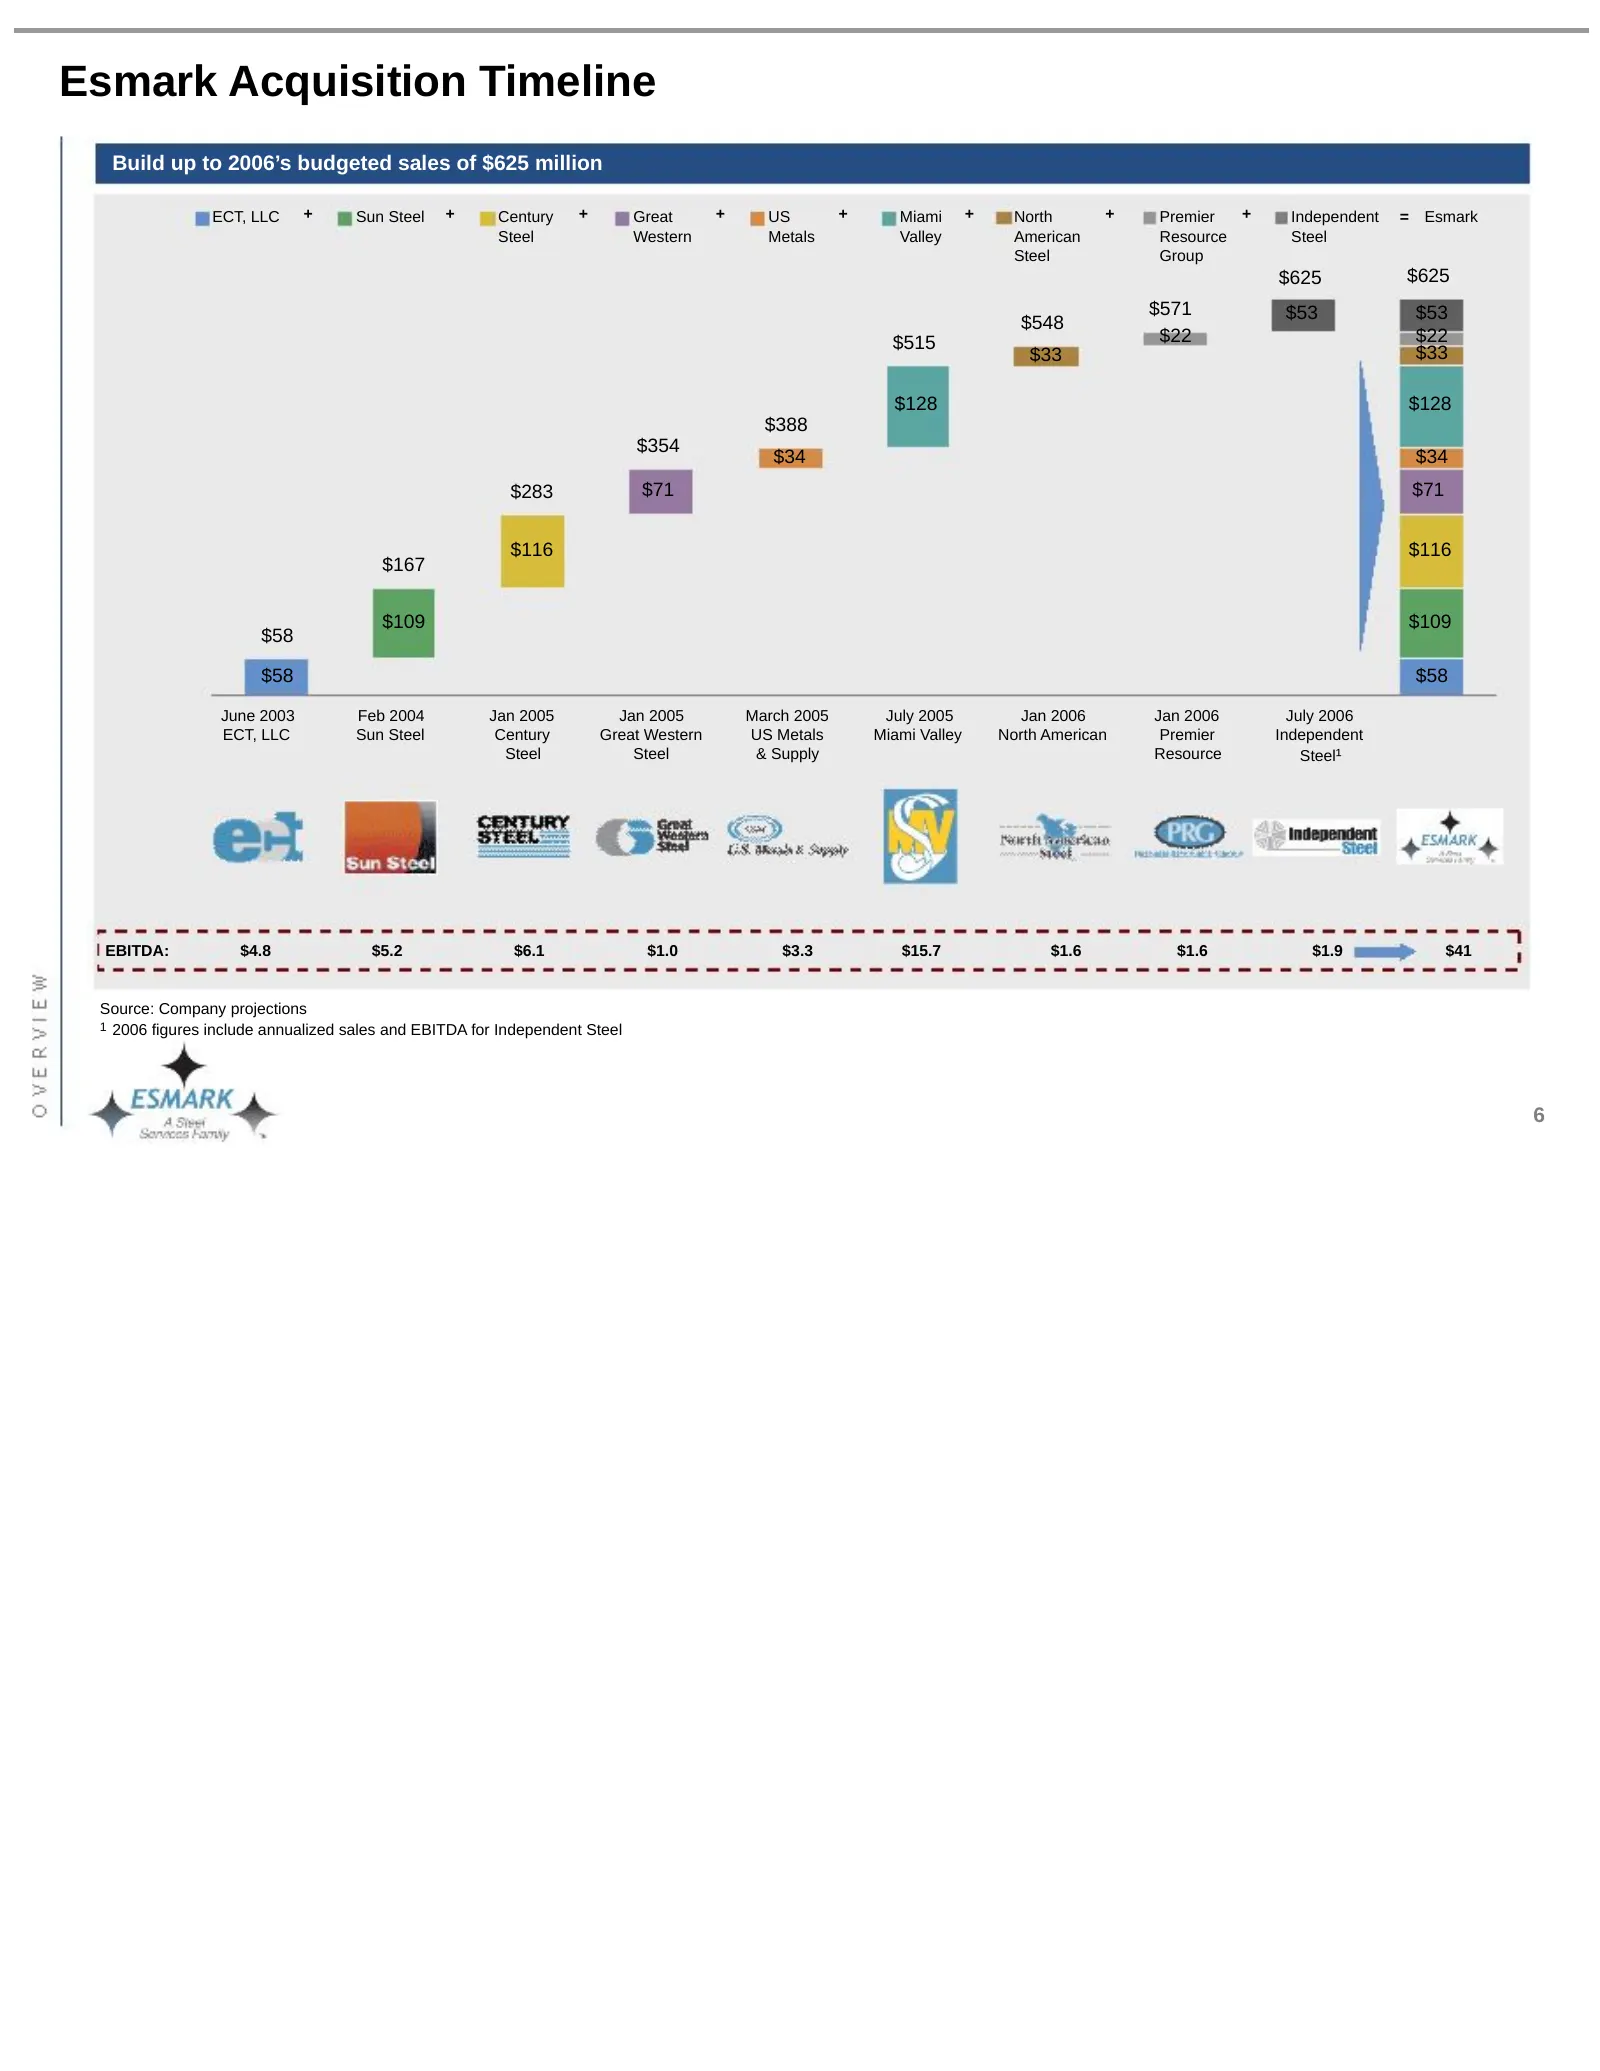
Esmark Acquisition Timeline Build up to 2006’s budgeted sales of $625 million ECT, LLC + Sun Steel + Century + Great + US + Miami + North + Premier + Independent = Esmark Steel Western Metals Valley American Resource Steel Steel Group $625 $625 $571 $53 $53 $548 $515 $22 $22 $33 $33 $128 $128 $388 $
Slide 10: Esmark's Position in Domestic Steel Distribution
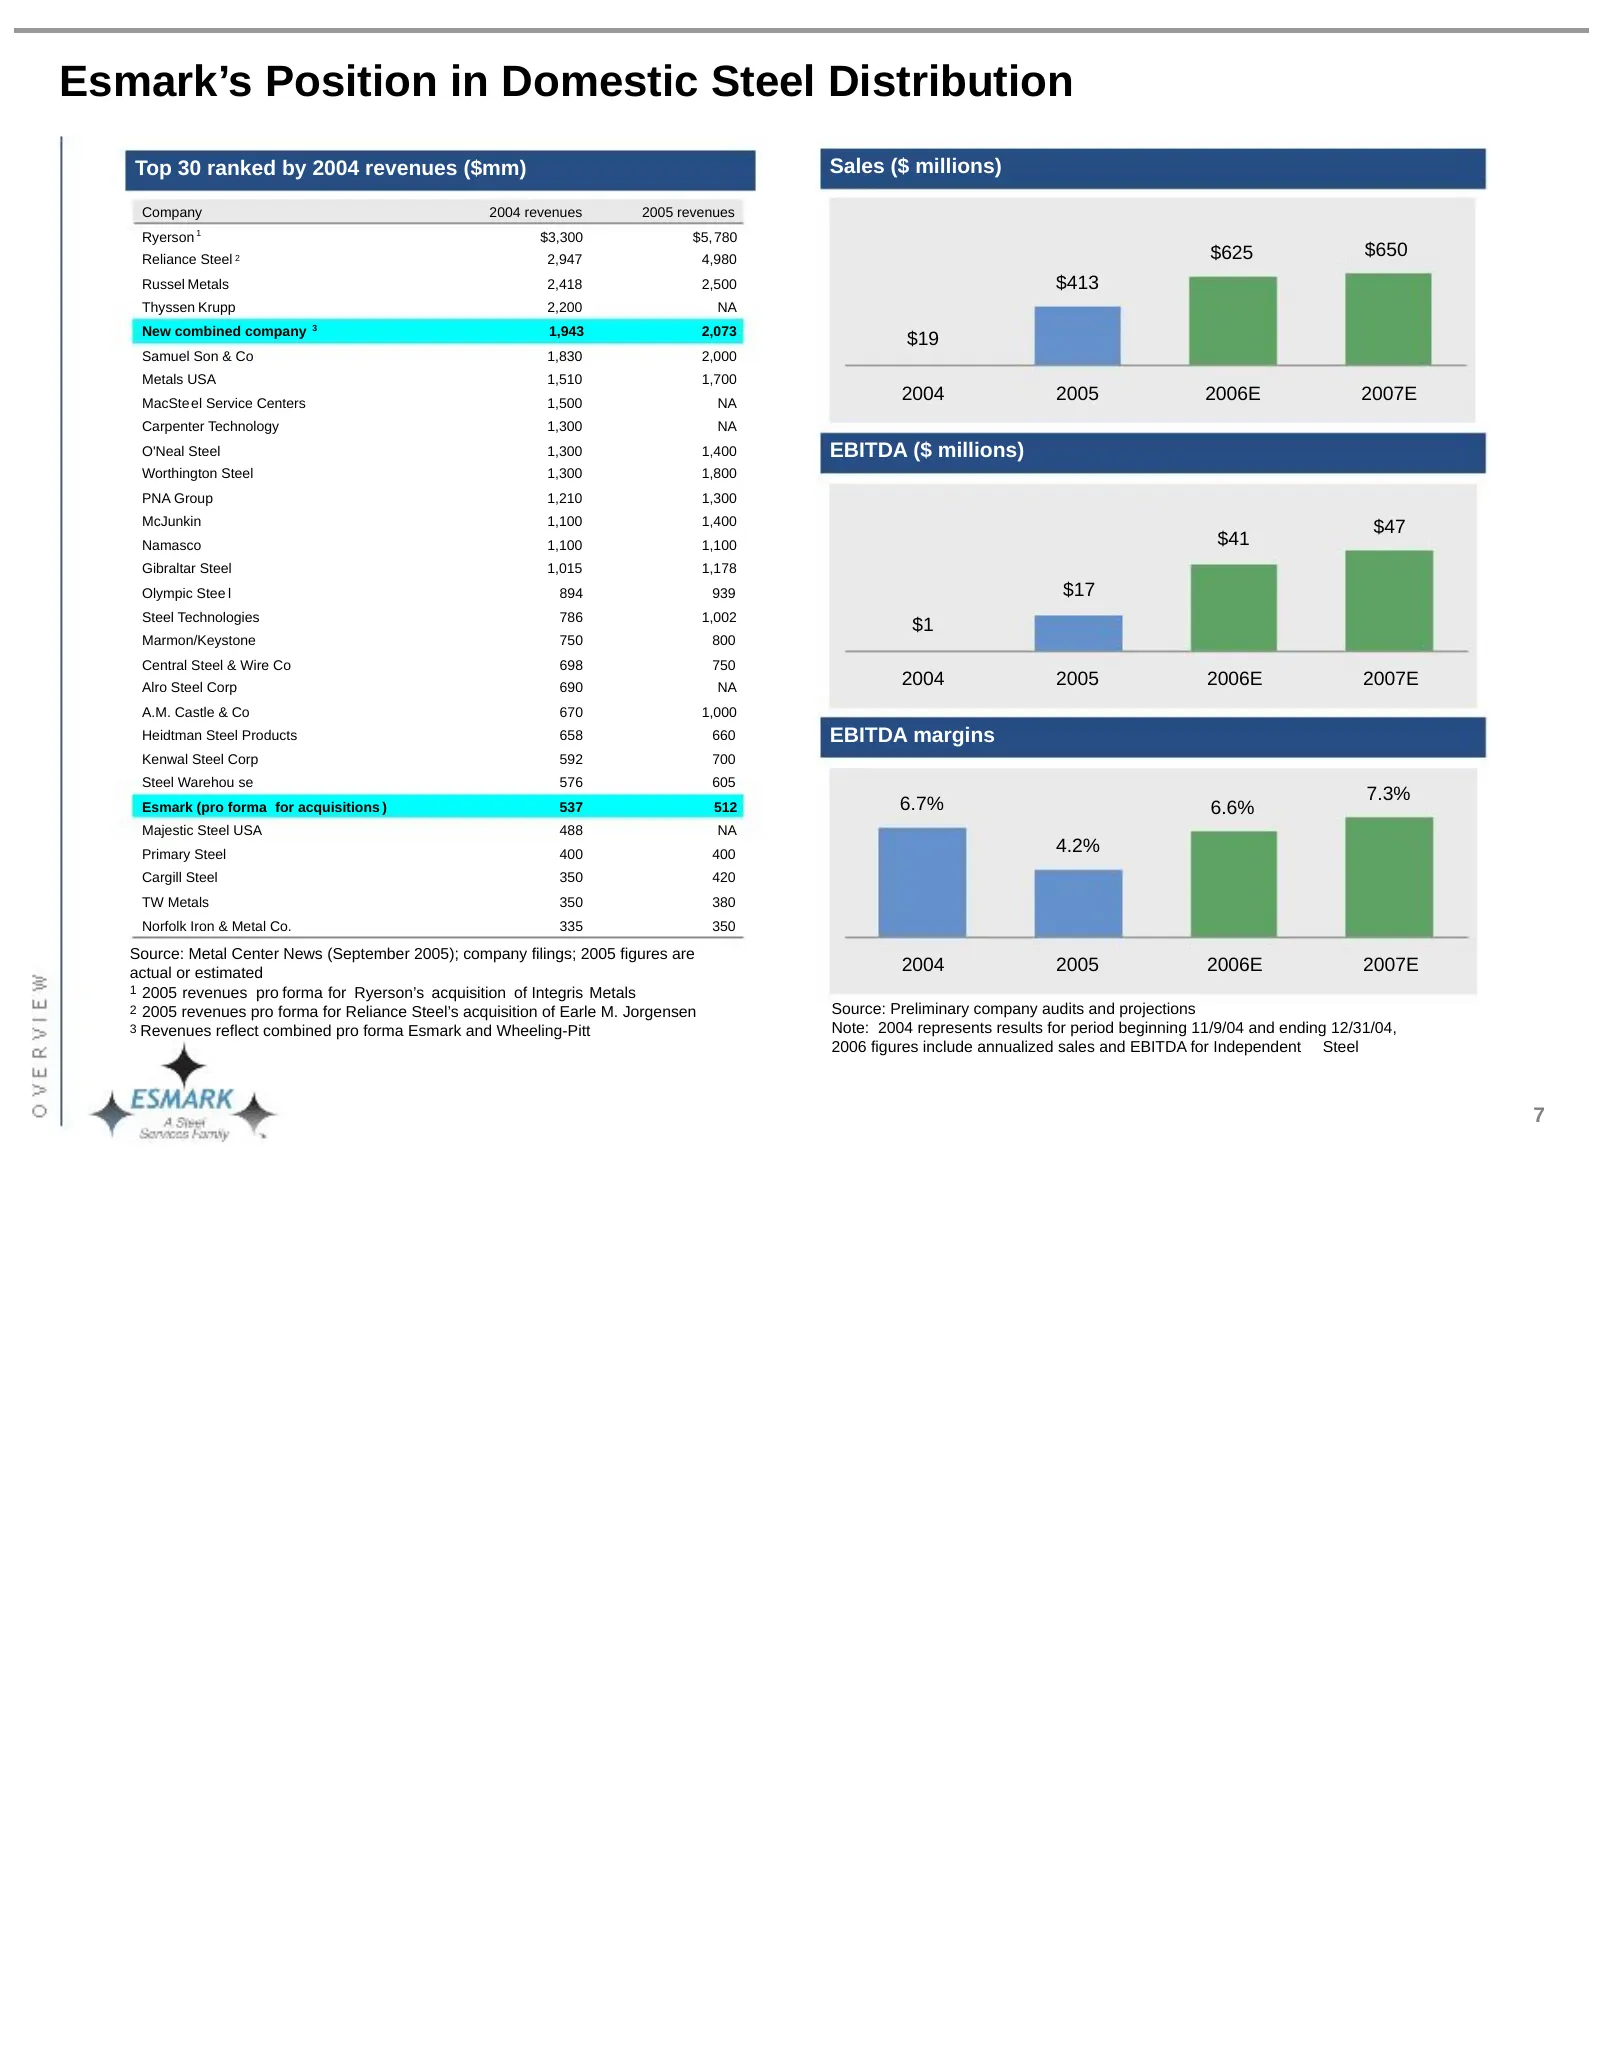
Esmark’s Position in Domestic Steel Distribution Top 30 ranked by 2004 revenues ($mm) Sales ($ millions) Company 2004 revenues 2005 revenues Ryerson 1 $3,300 $5, 780 Reliance Steel 2 2,947 4,980 $625 $650 Russel Metals 2,418 2,500 $413 Thyssen Krupp 2,200 NA New combined company 3 1,943 2,073 $19 Sa
Slide 11: Organic growth must be supplemented by successful acquisitions
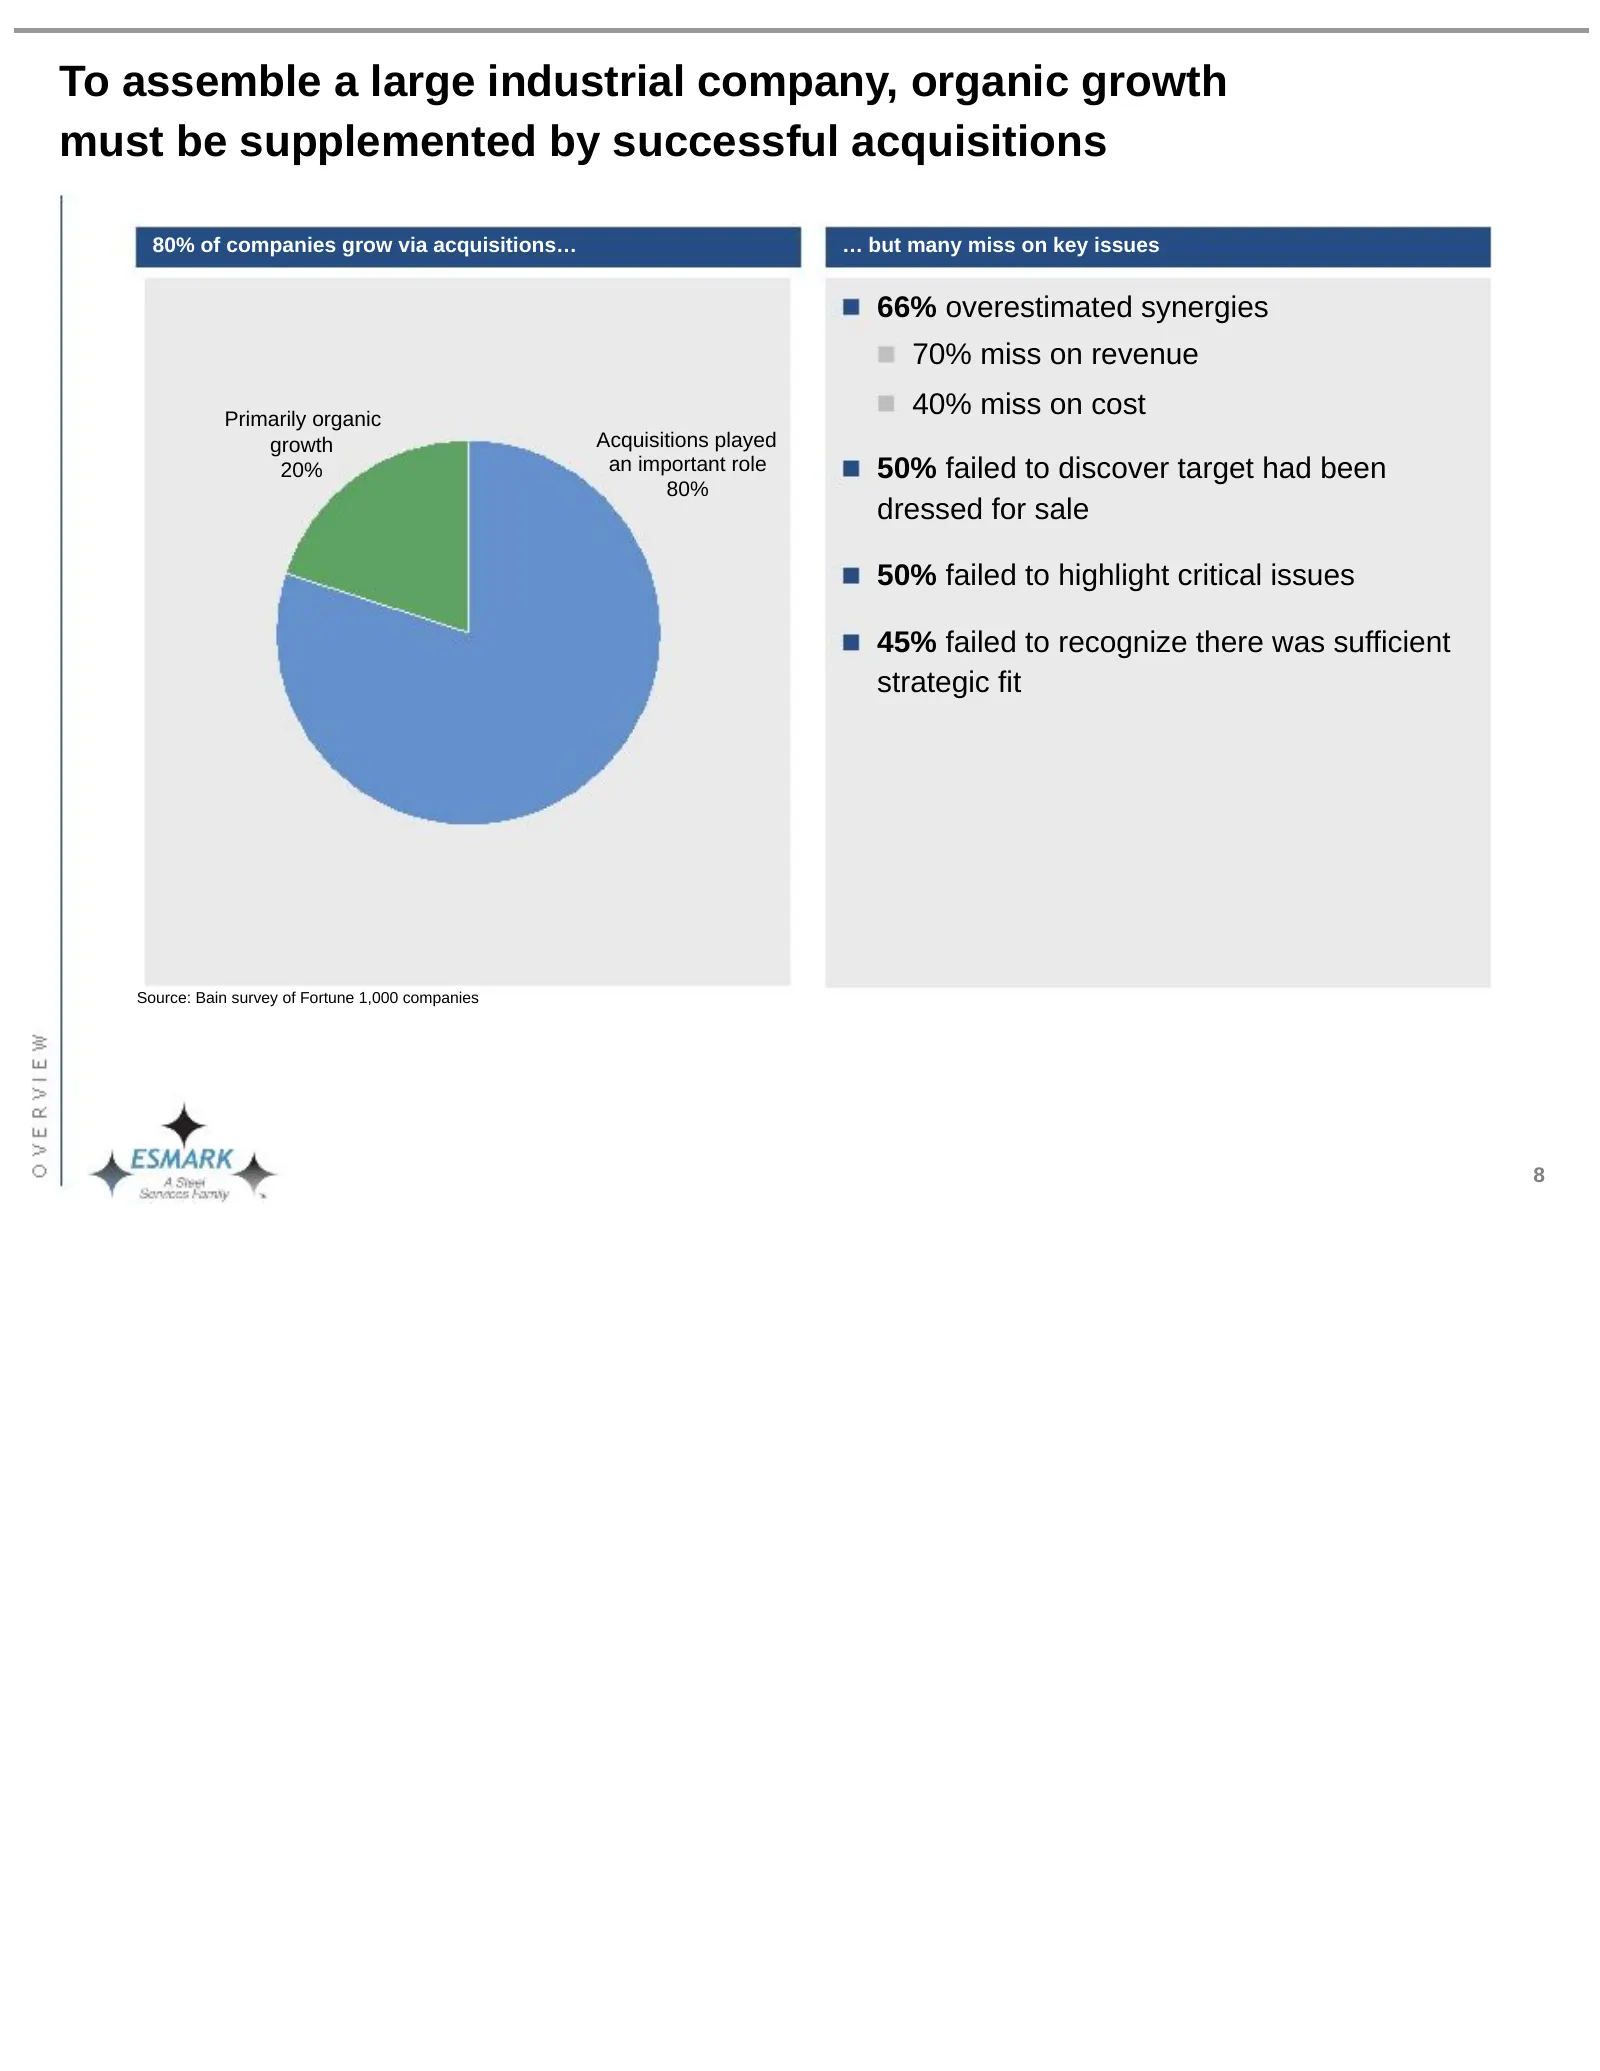
To assemble a large industrial company, organic growth must be supplemented by successful acquisitions 80% of companies grow via acquisitions… … but many miss on key issues 66% overestimated synergies 70% miss on revenue Primarily organic 40% miss on cost growth Acquisitions played 20% an important
Slide 12: Acquisition Formula: Attention to Detail + The Human Dimension
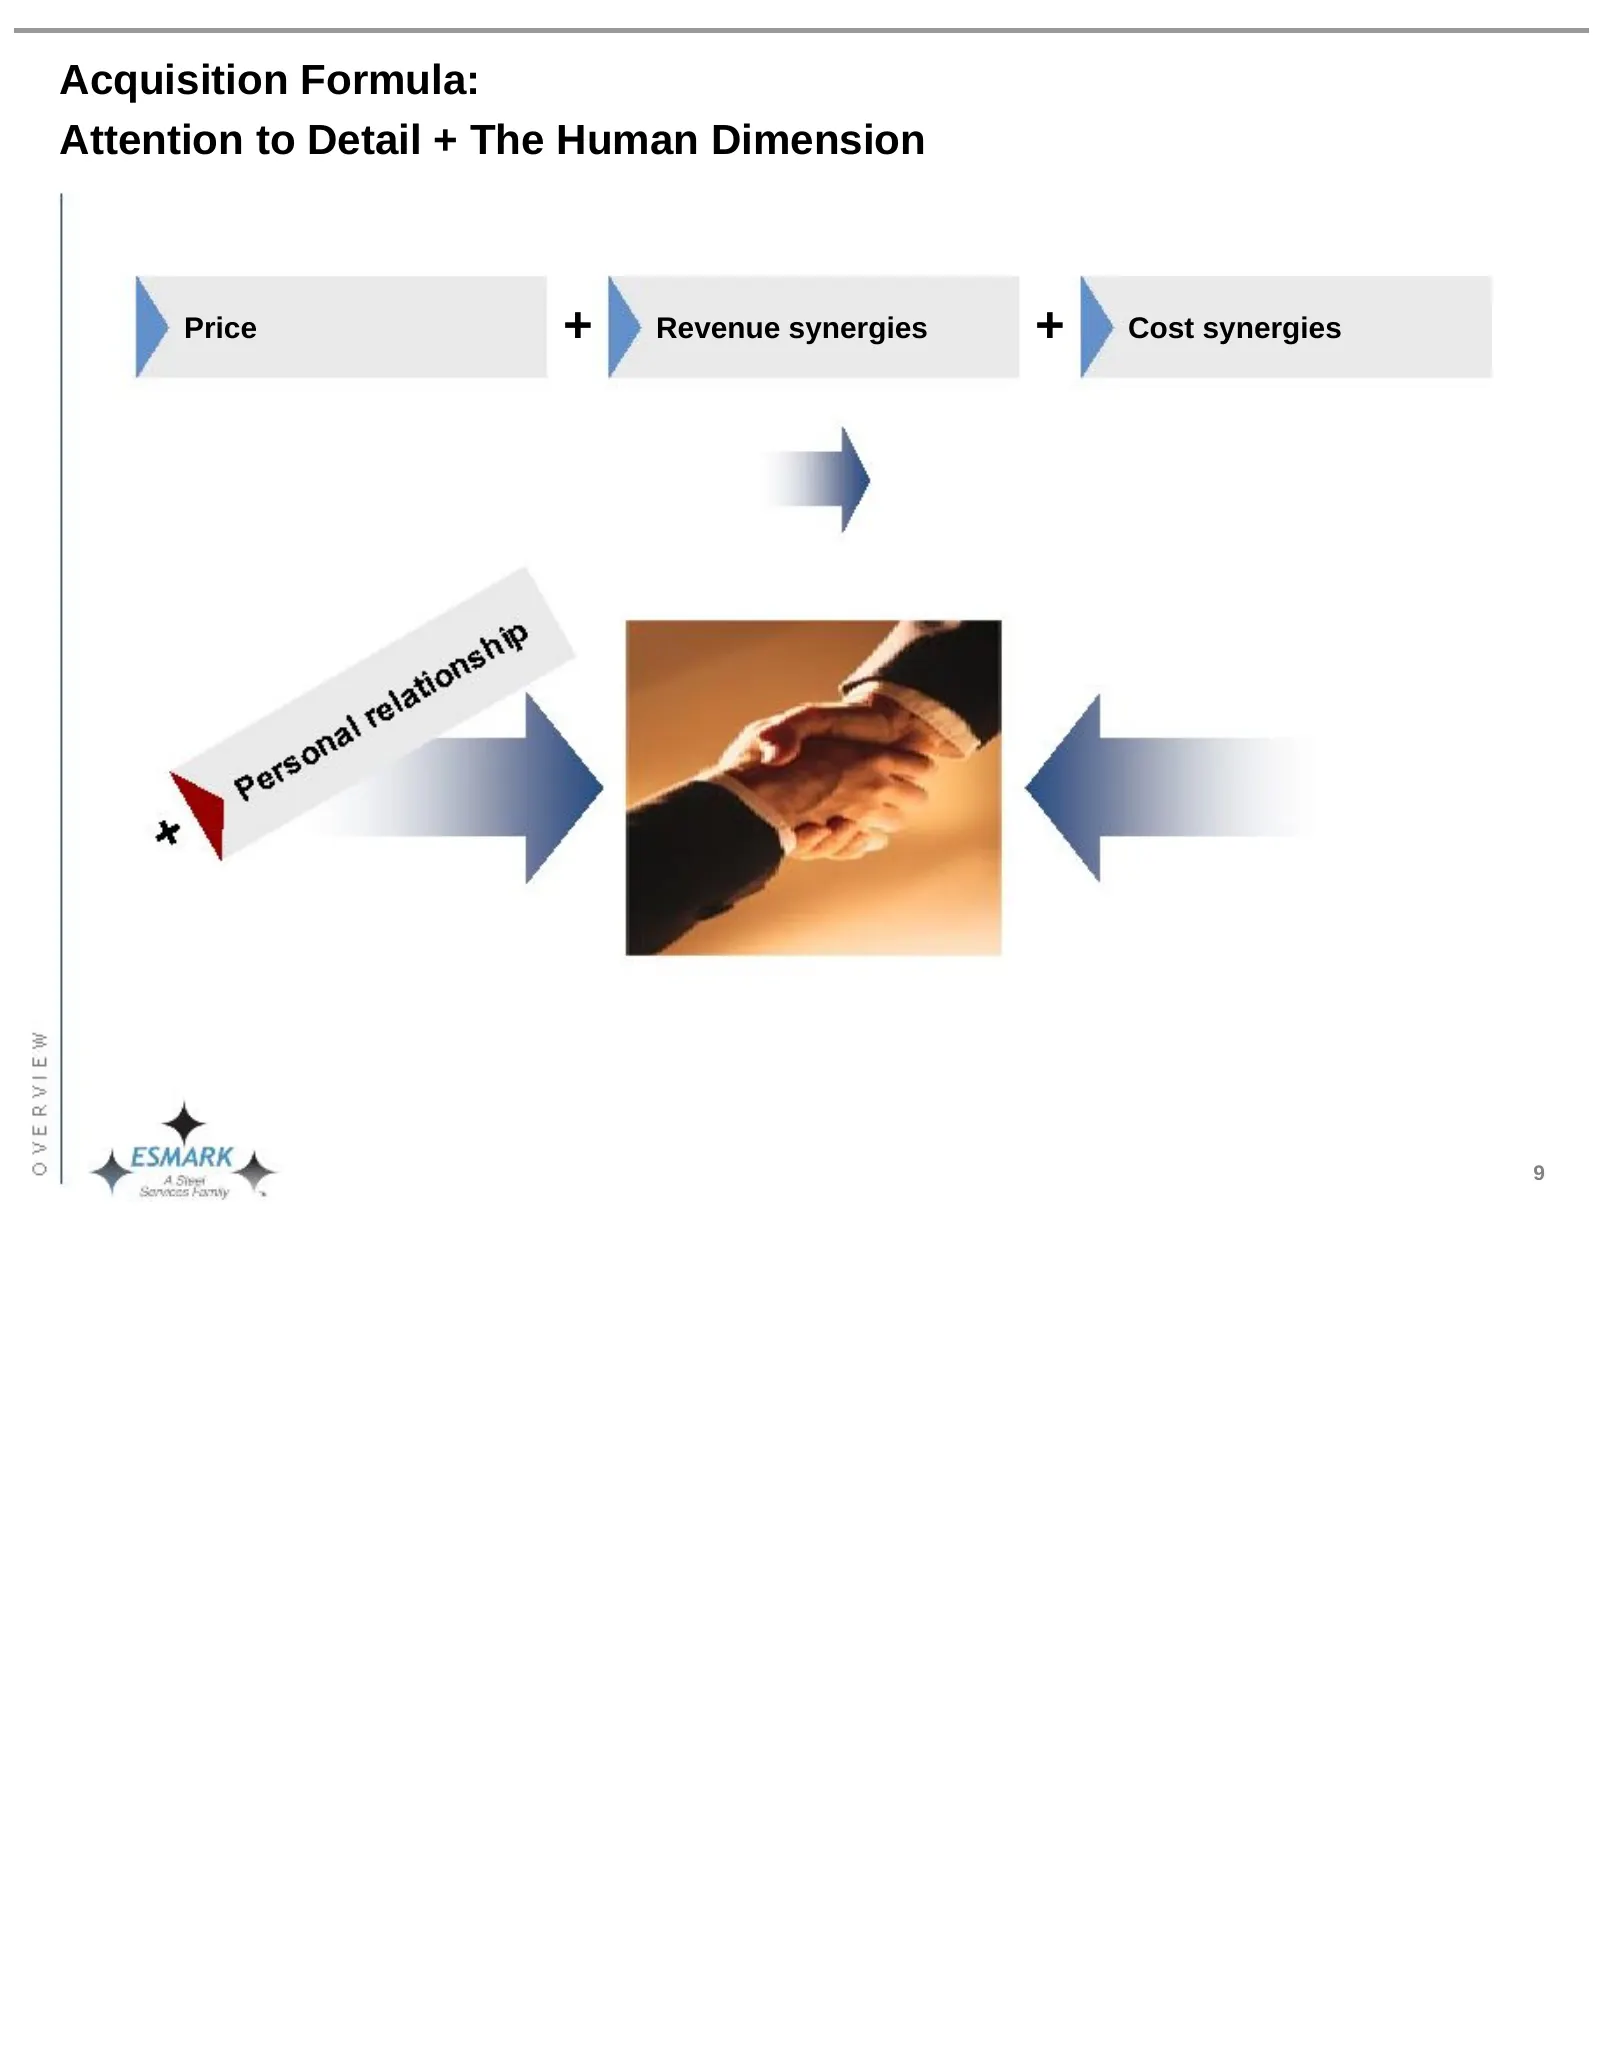
Acquisition Formula: Attention to Detail + The Human Dimension Price + Revenue synergies + Cost synergies 9
Slide 13: Esmark's Process; No Special Orders
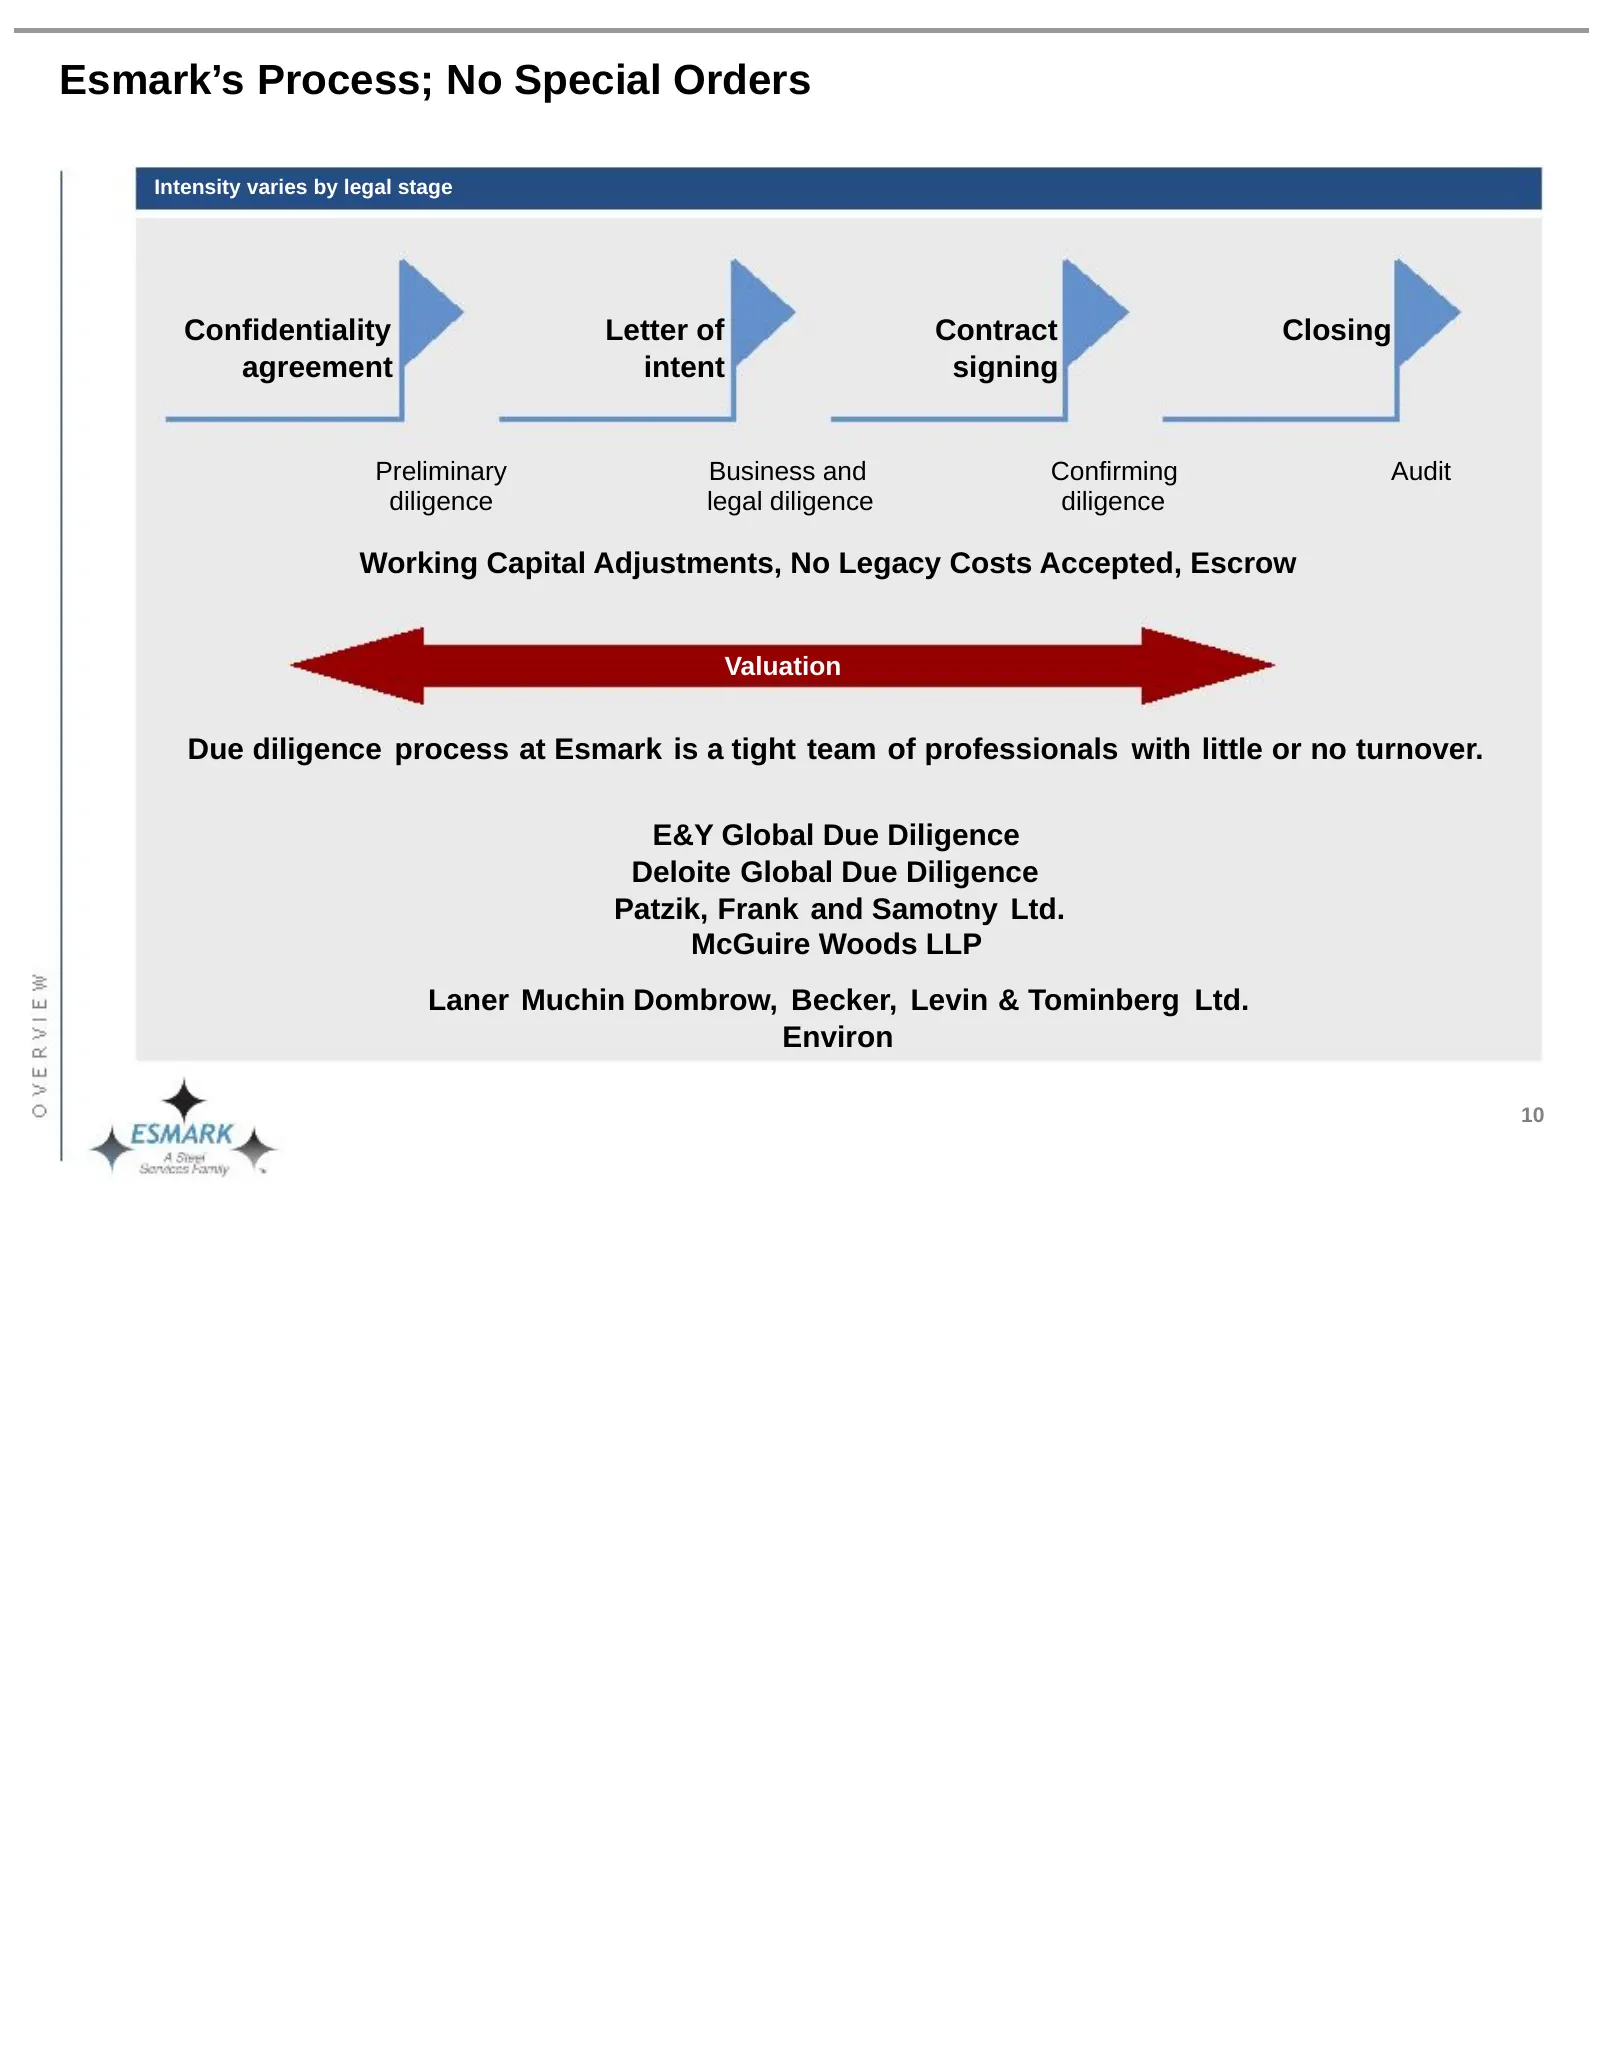
Esmark’s Process; No Special Orders Intensity varies by legal stage Confidentiality Letter of Contract Closing agreement intent signing Preliminary Business and Confirming Audit diligence legal diligence diligence Working Capital Adjustments, No Legacy Costs Accepted, Escrow Valuation Due diligence
Slide 14: Finished Files text exercise
FINISHED FILES ARE THE RE SULT OF YEARS OF SCIENTI FIC STUDY COMBINED WITH THE EXPERIENCE OF YEARS... 11
Slide 15: Where does a Mill fit in the Esmark strategy?
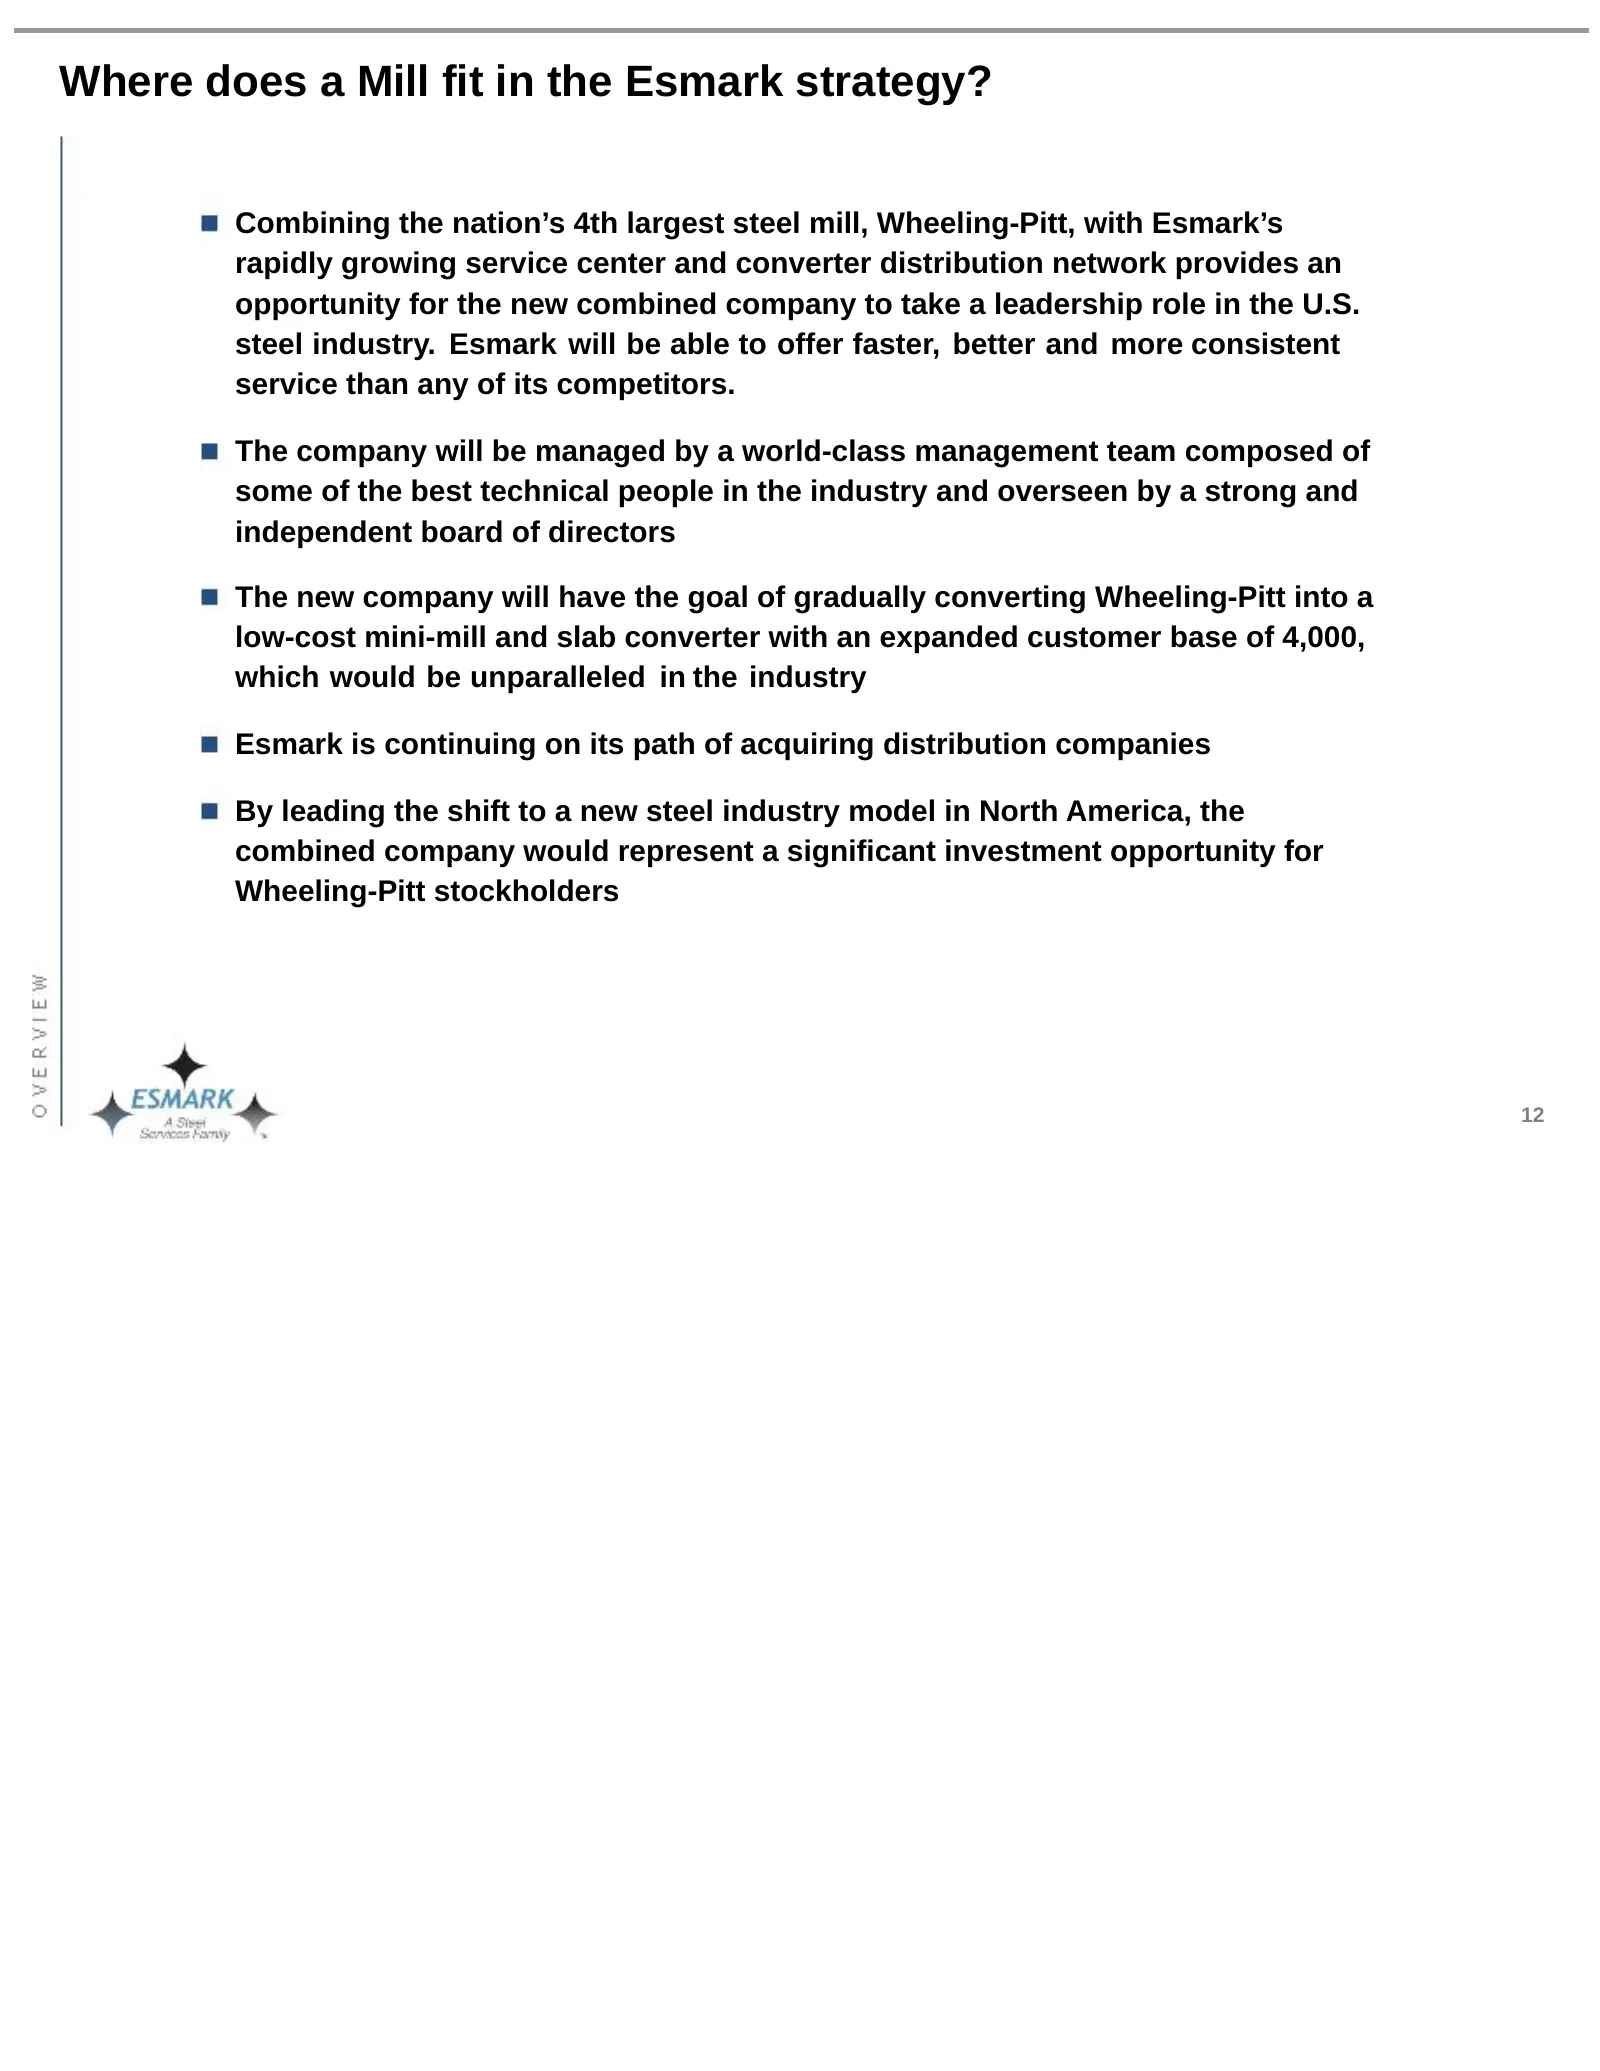
Where does a Mill fit in the Esmark strategy? Combining the nation’s 4th largest steel mill, Wheeling-Pitt, with Esmark’s rapidly growing service center and converter distribution network provides an opportunity for the new combined company to take a leadership role in the U.S. steel industry. Esmar
Slide 16: Esmark's offer to reverse merge with WPSC
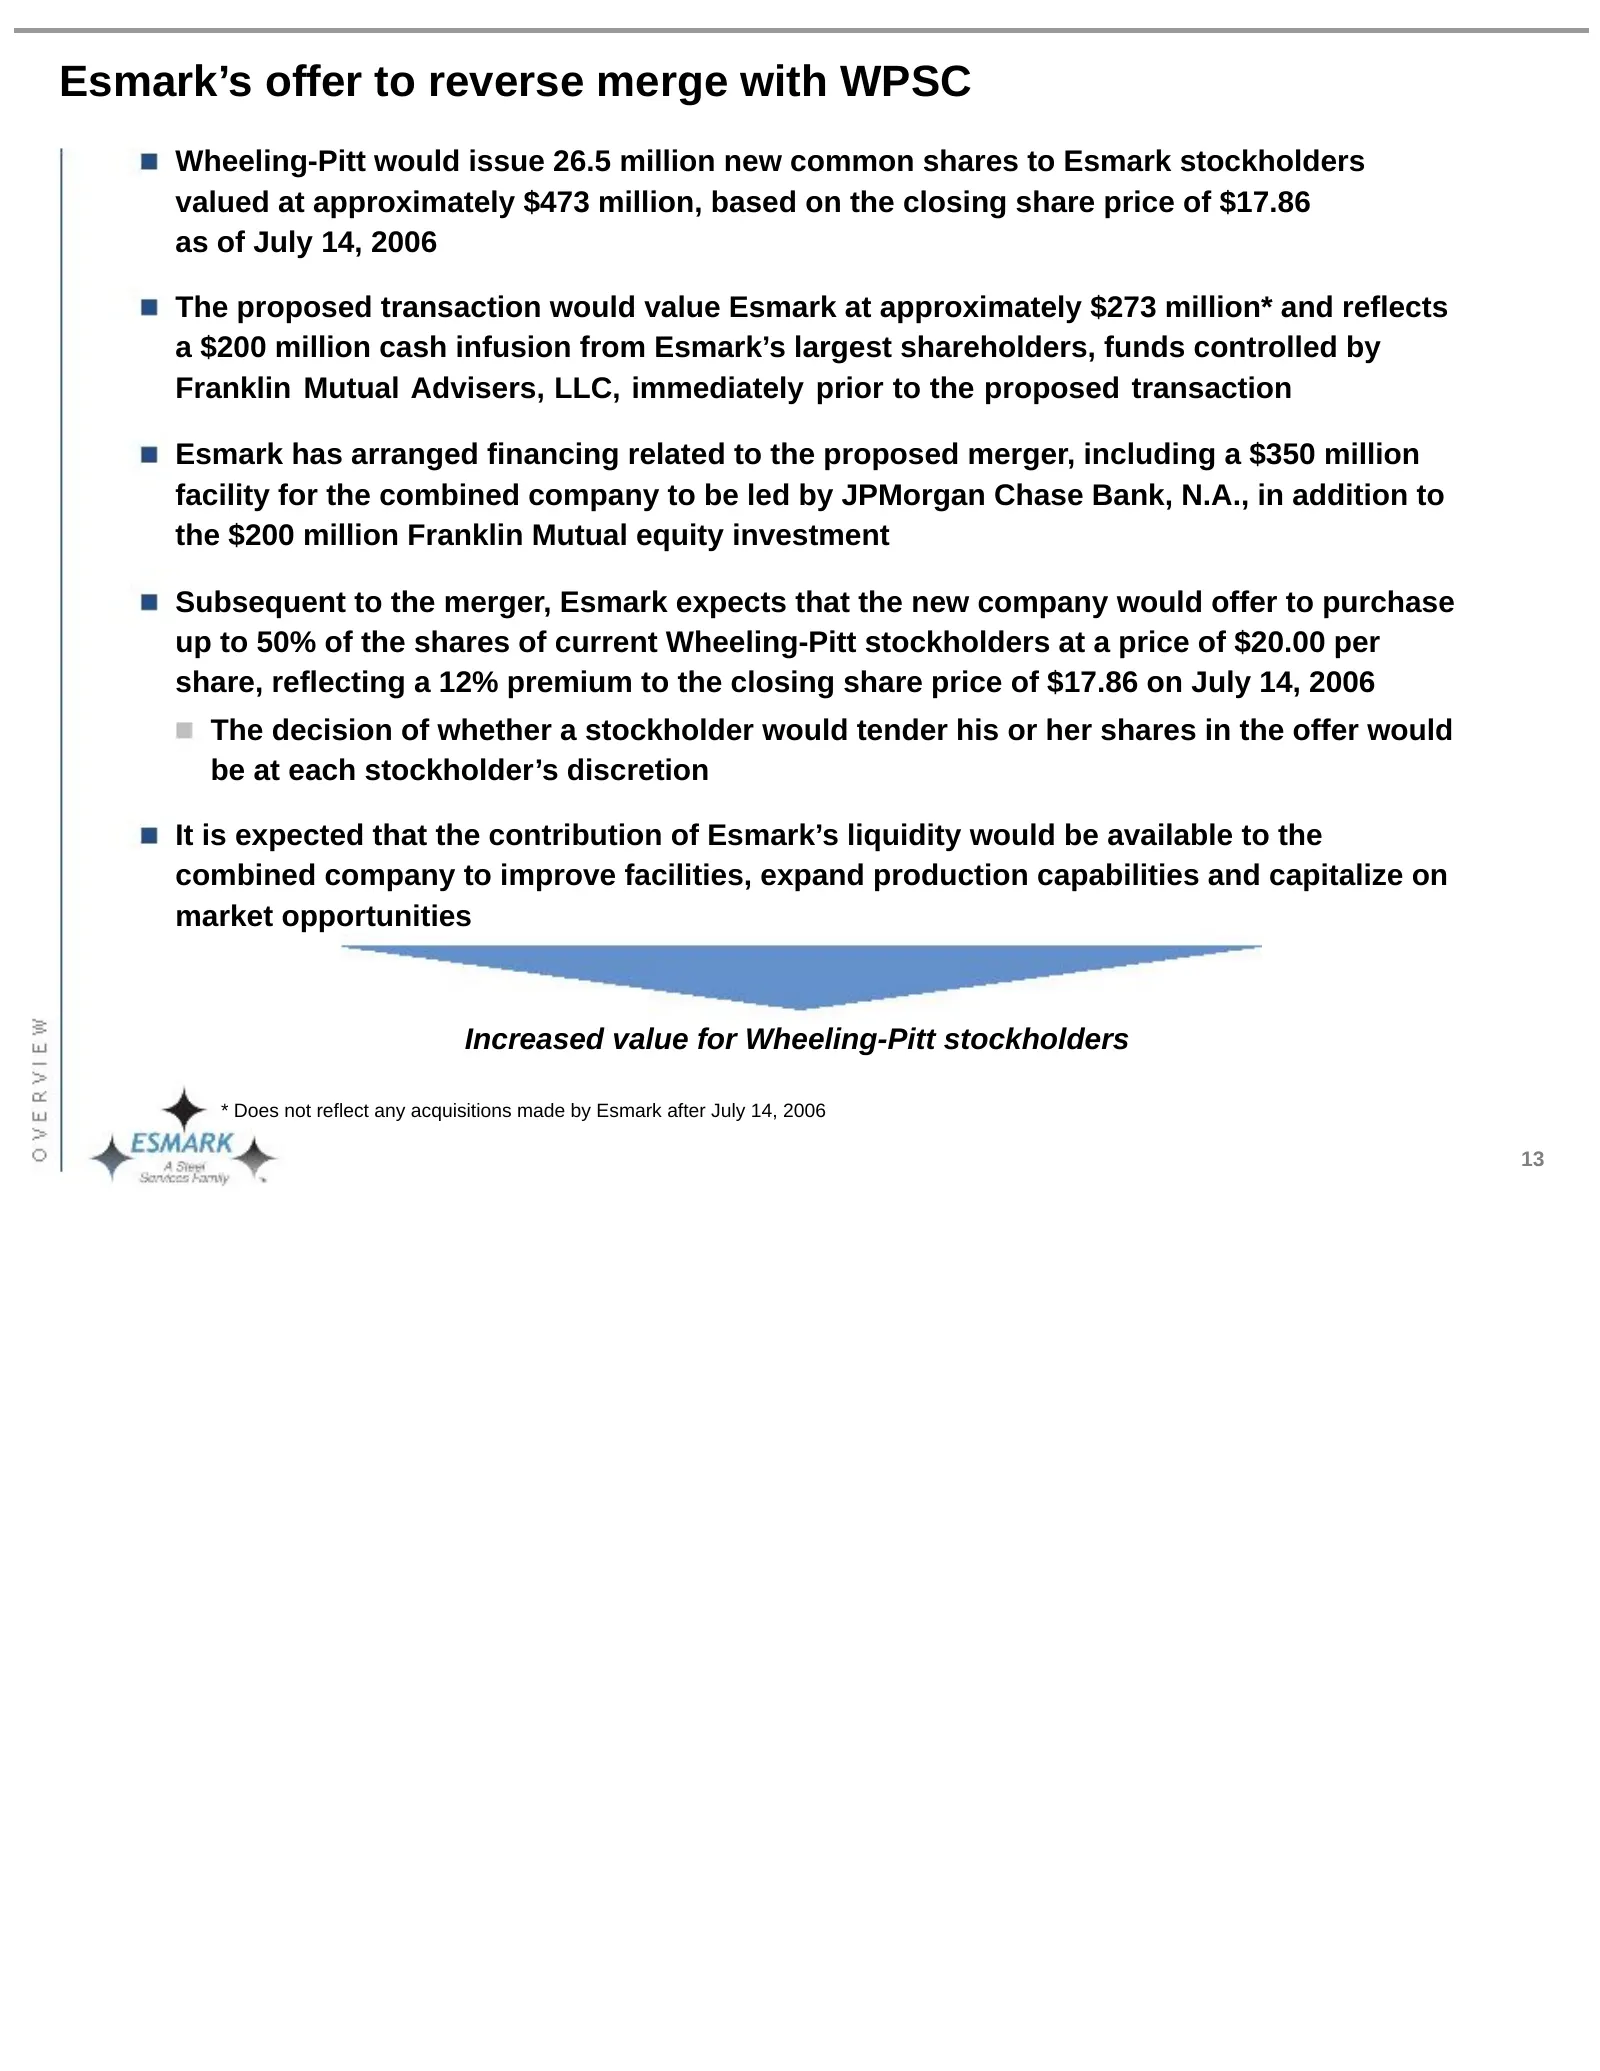
Esmark’s offer to reverse merge with WPSC Wheeling-Pitt would issue 26.5 million new common shares to Esmark stockholders valued at approximately $473 million, based on the closing share price of $17.86 as of July 14, 2006 The proposed transaction would value Esmark at approximately $273 million* an
Slide 17: Financial Logic: Post WPSC, high distribution multiple
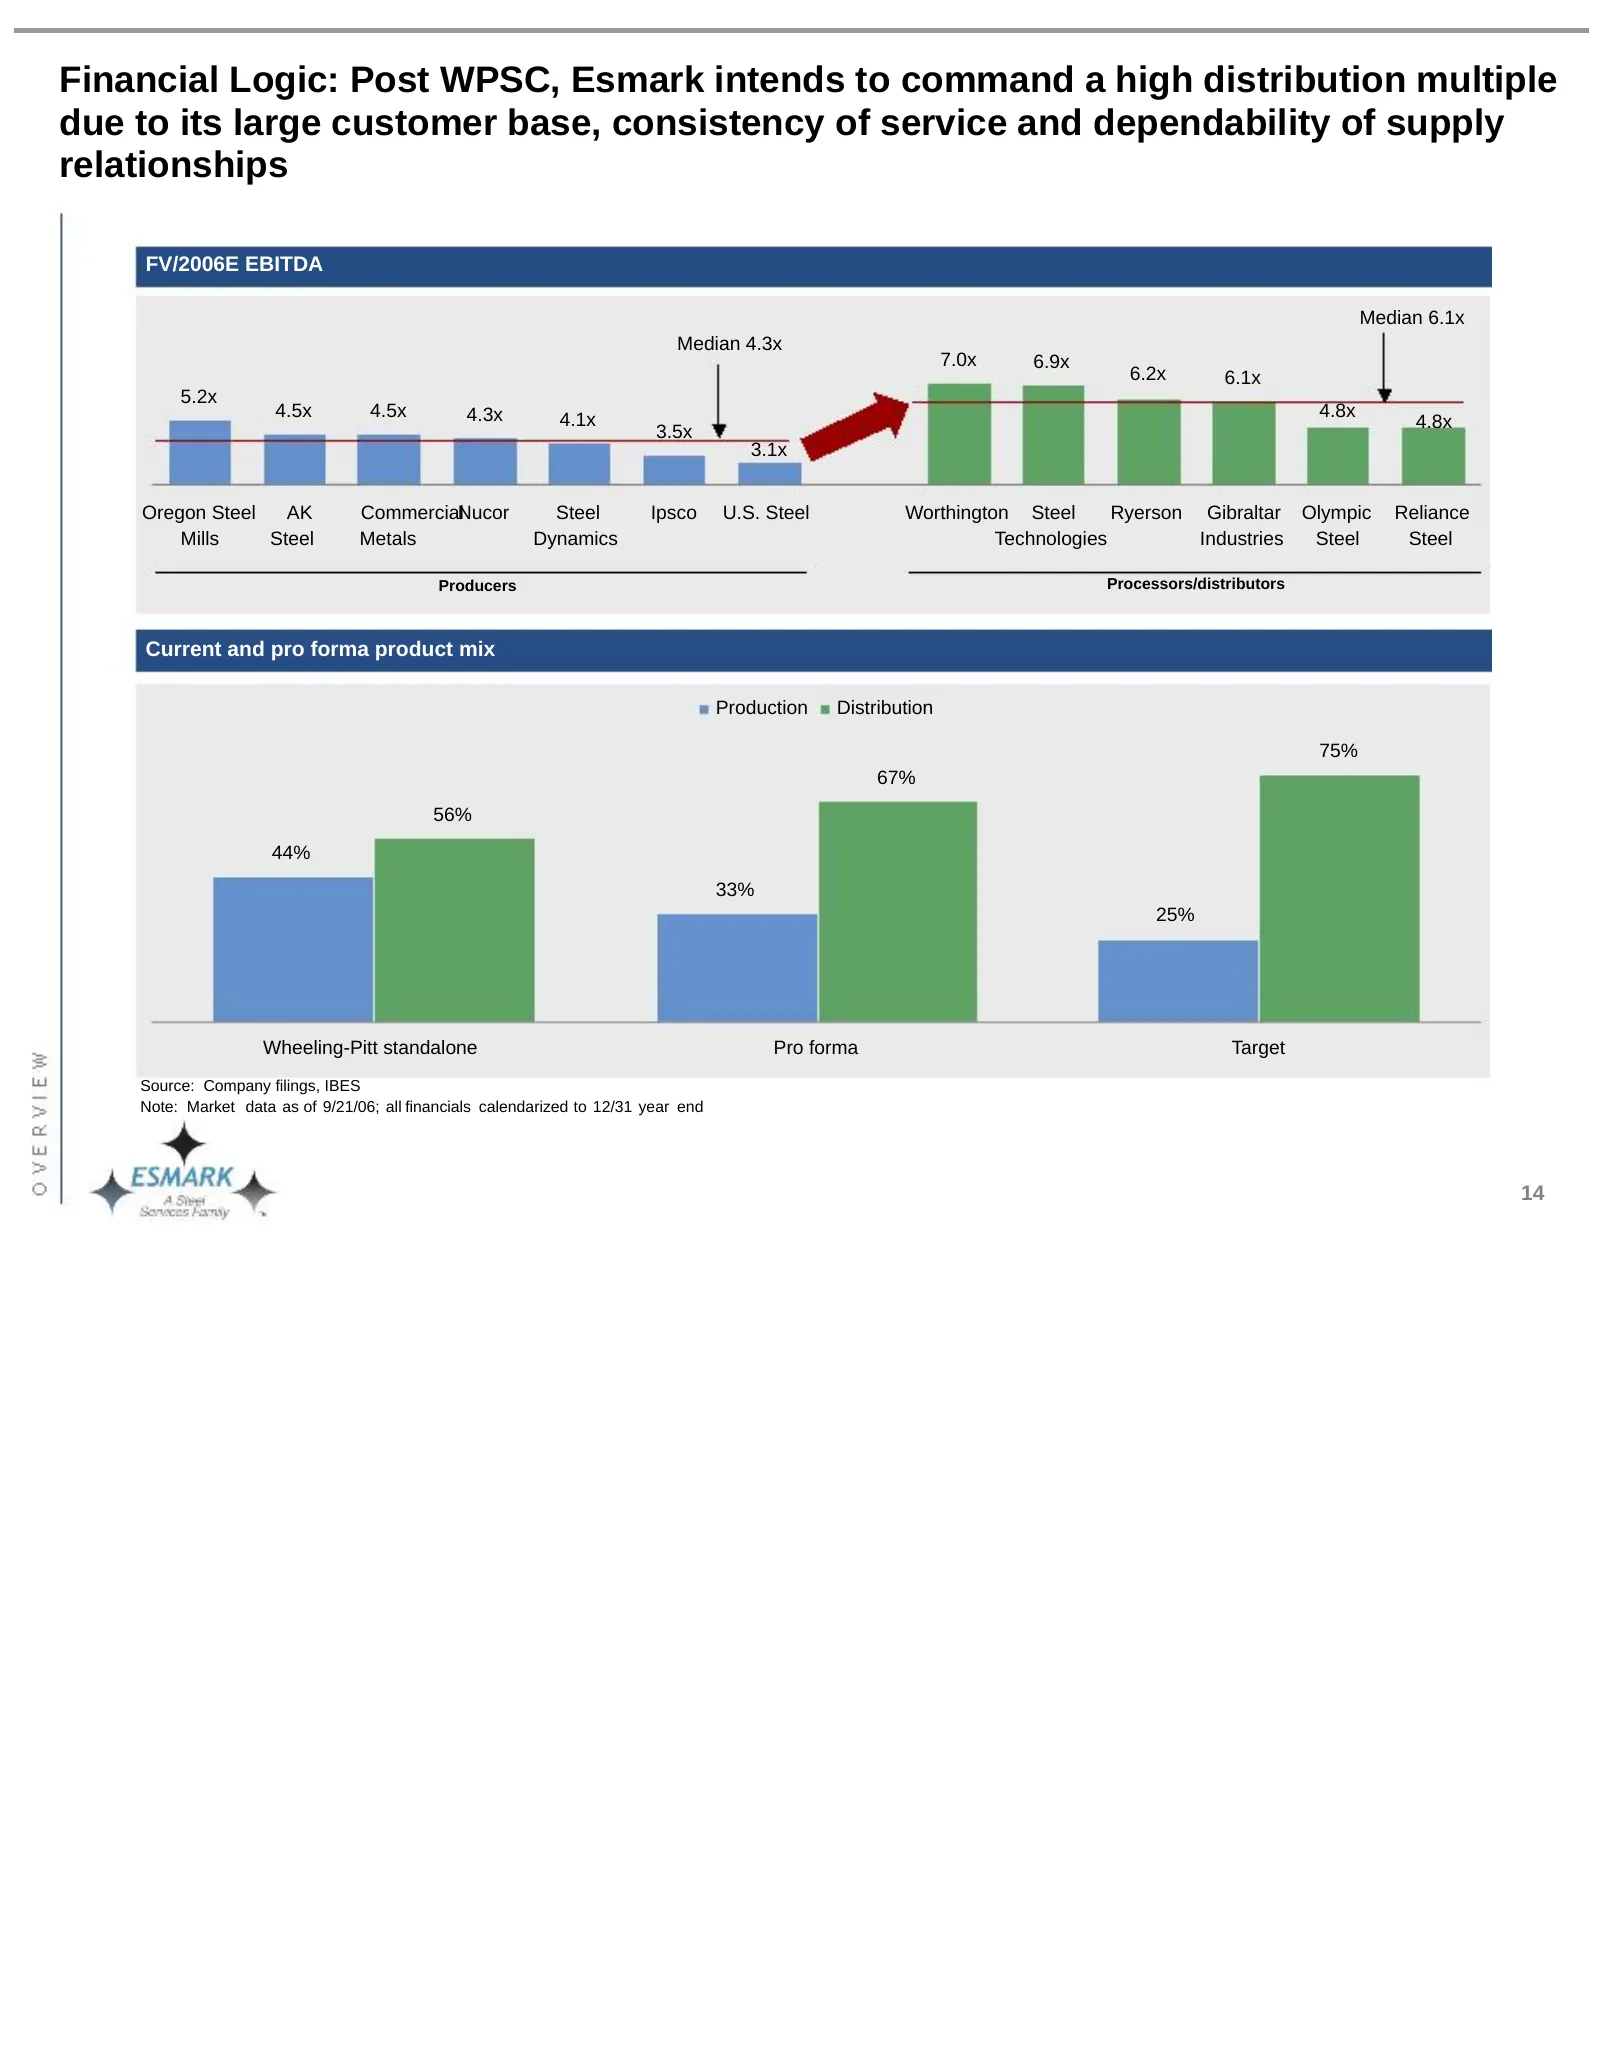
Financial Logic: Post WPSC, Esmark intends to command a high distribution multiple due to its large customer base, consistency of service and dependability of supply relationships FV/2006E EBITDA Median 6.1x Median 4.3x 7.0x 6.9x 6.2x 6.1x 5.2x 4.5x 4.5x 4.3x 4.1x 4.8x 4.8x 3.5x 3.1x Oregon Steel AK
Slide 18: Esmark's valuation versus the comparable peers
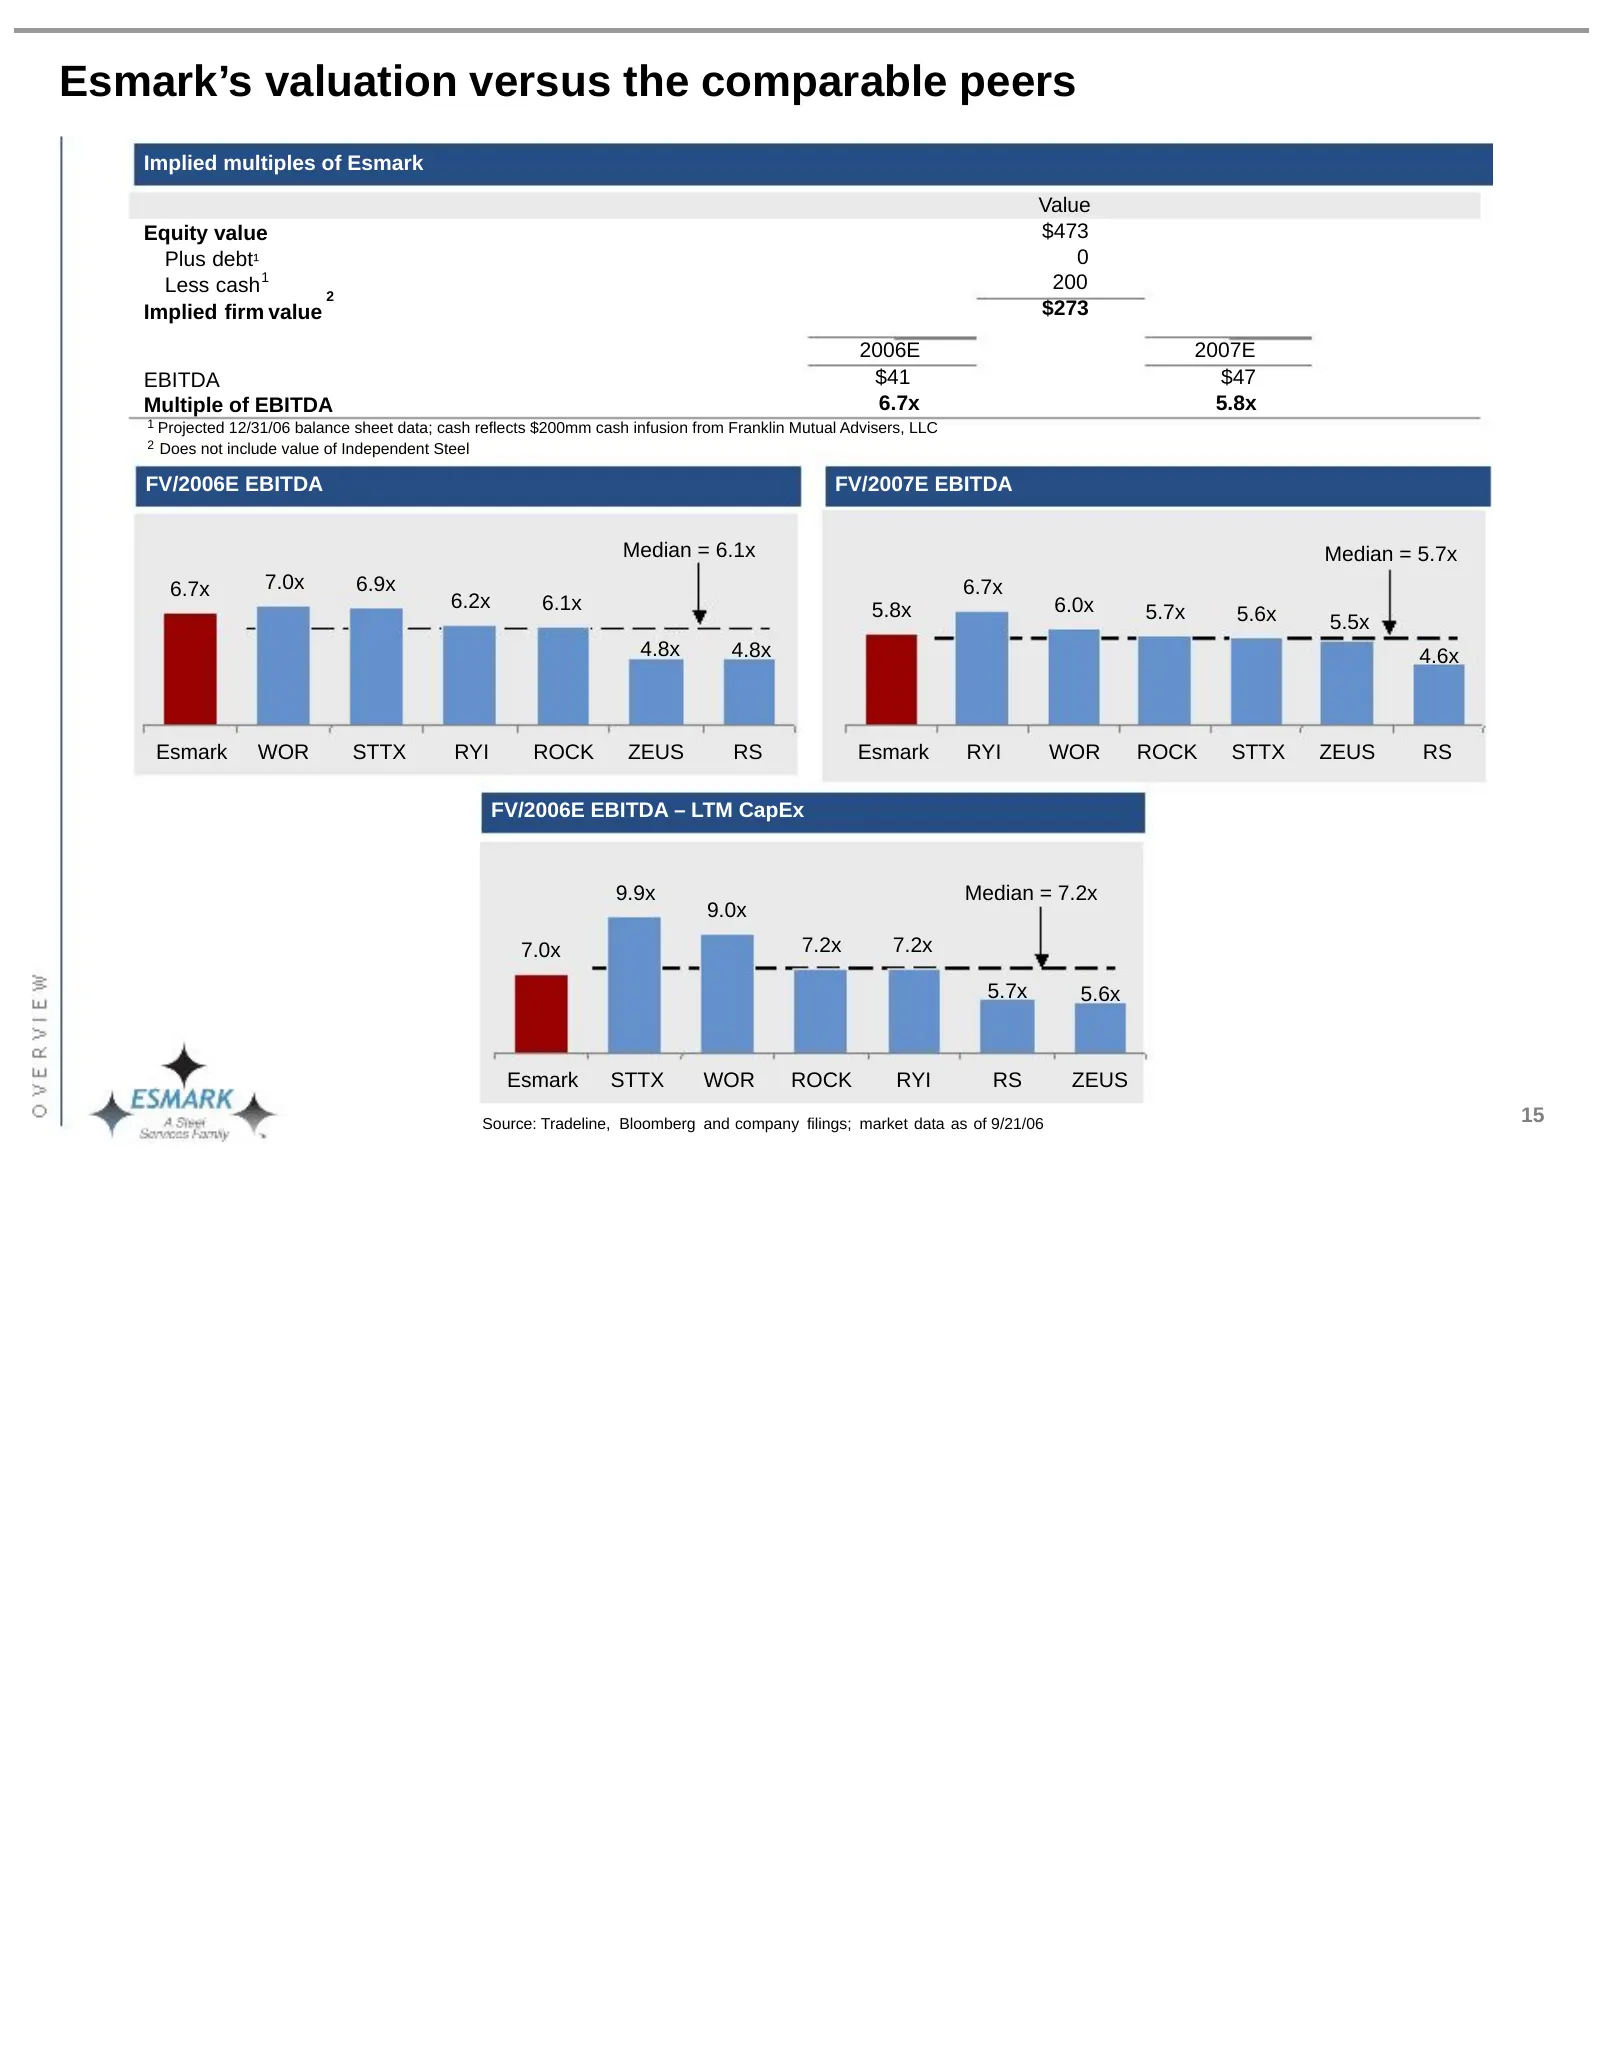
Esmark’s valuation versus the comparable peers Implied multiples of Esmark Value Equity value $473 Plus debt¹ 0 1 Less cash 200 2 Implied firm value $273 2006E 2007E EBITDA $41 $47 Multiple of EBITDA 6.7x 5.8x 1 Projected 12/31/06 balance sheet data; cash reflects $200mm cash infusion from Franklin
Slide 19: Industrial Logic
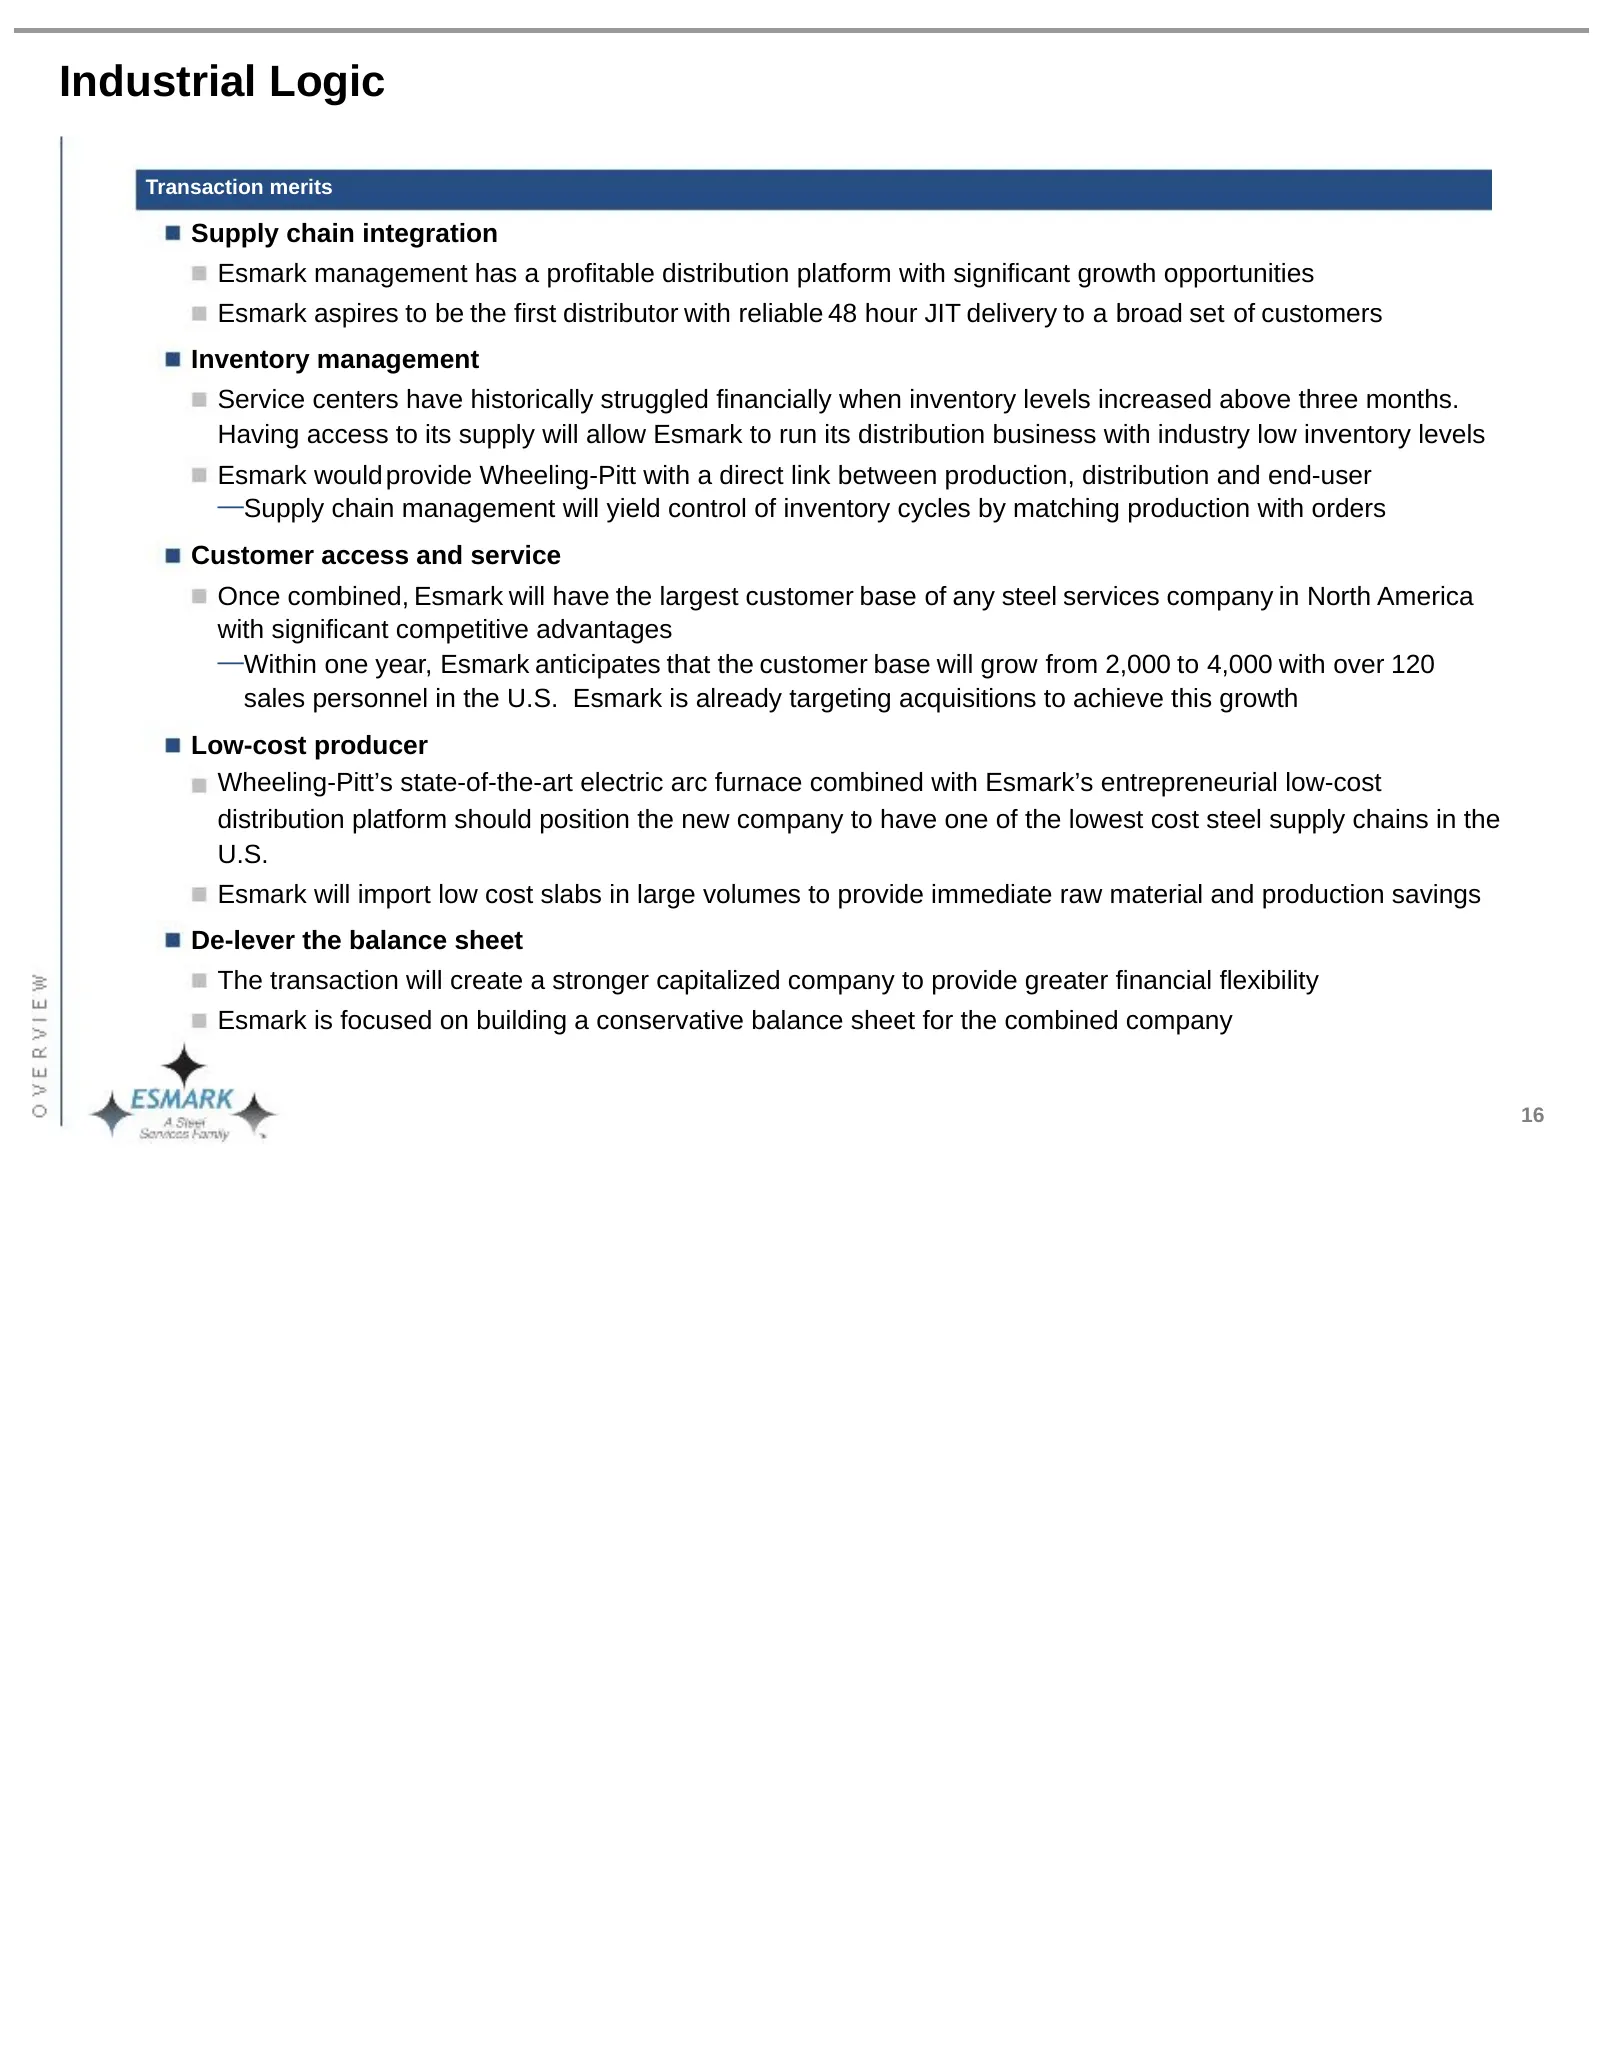
Industrial Logic Transaction merits Supply chain integration Esmark management has a profitable distribution platform with significant growth opportunities Esmark aspires to be the first distributor with reliable 48 hour JIT delivery to a broad set of customers Inventory management Service centers h
Slide 20: Esmark's Strong Director Slate
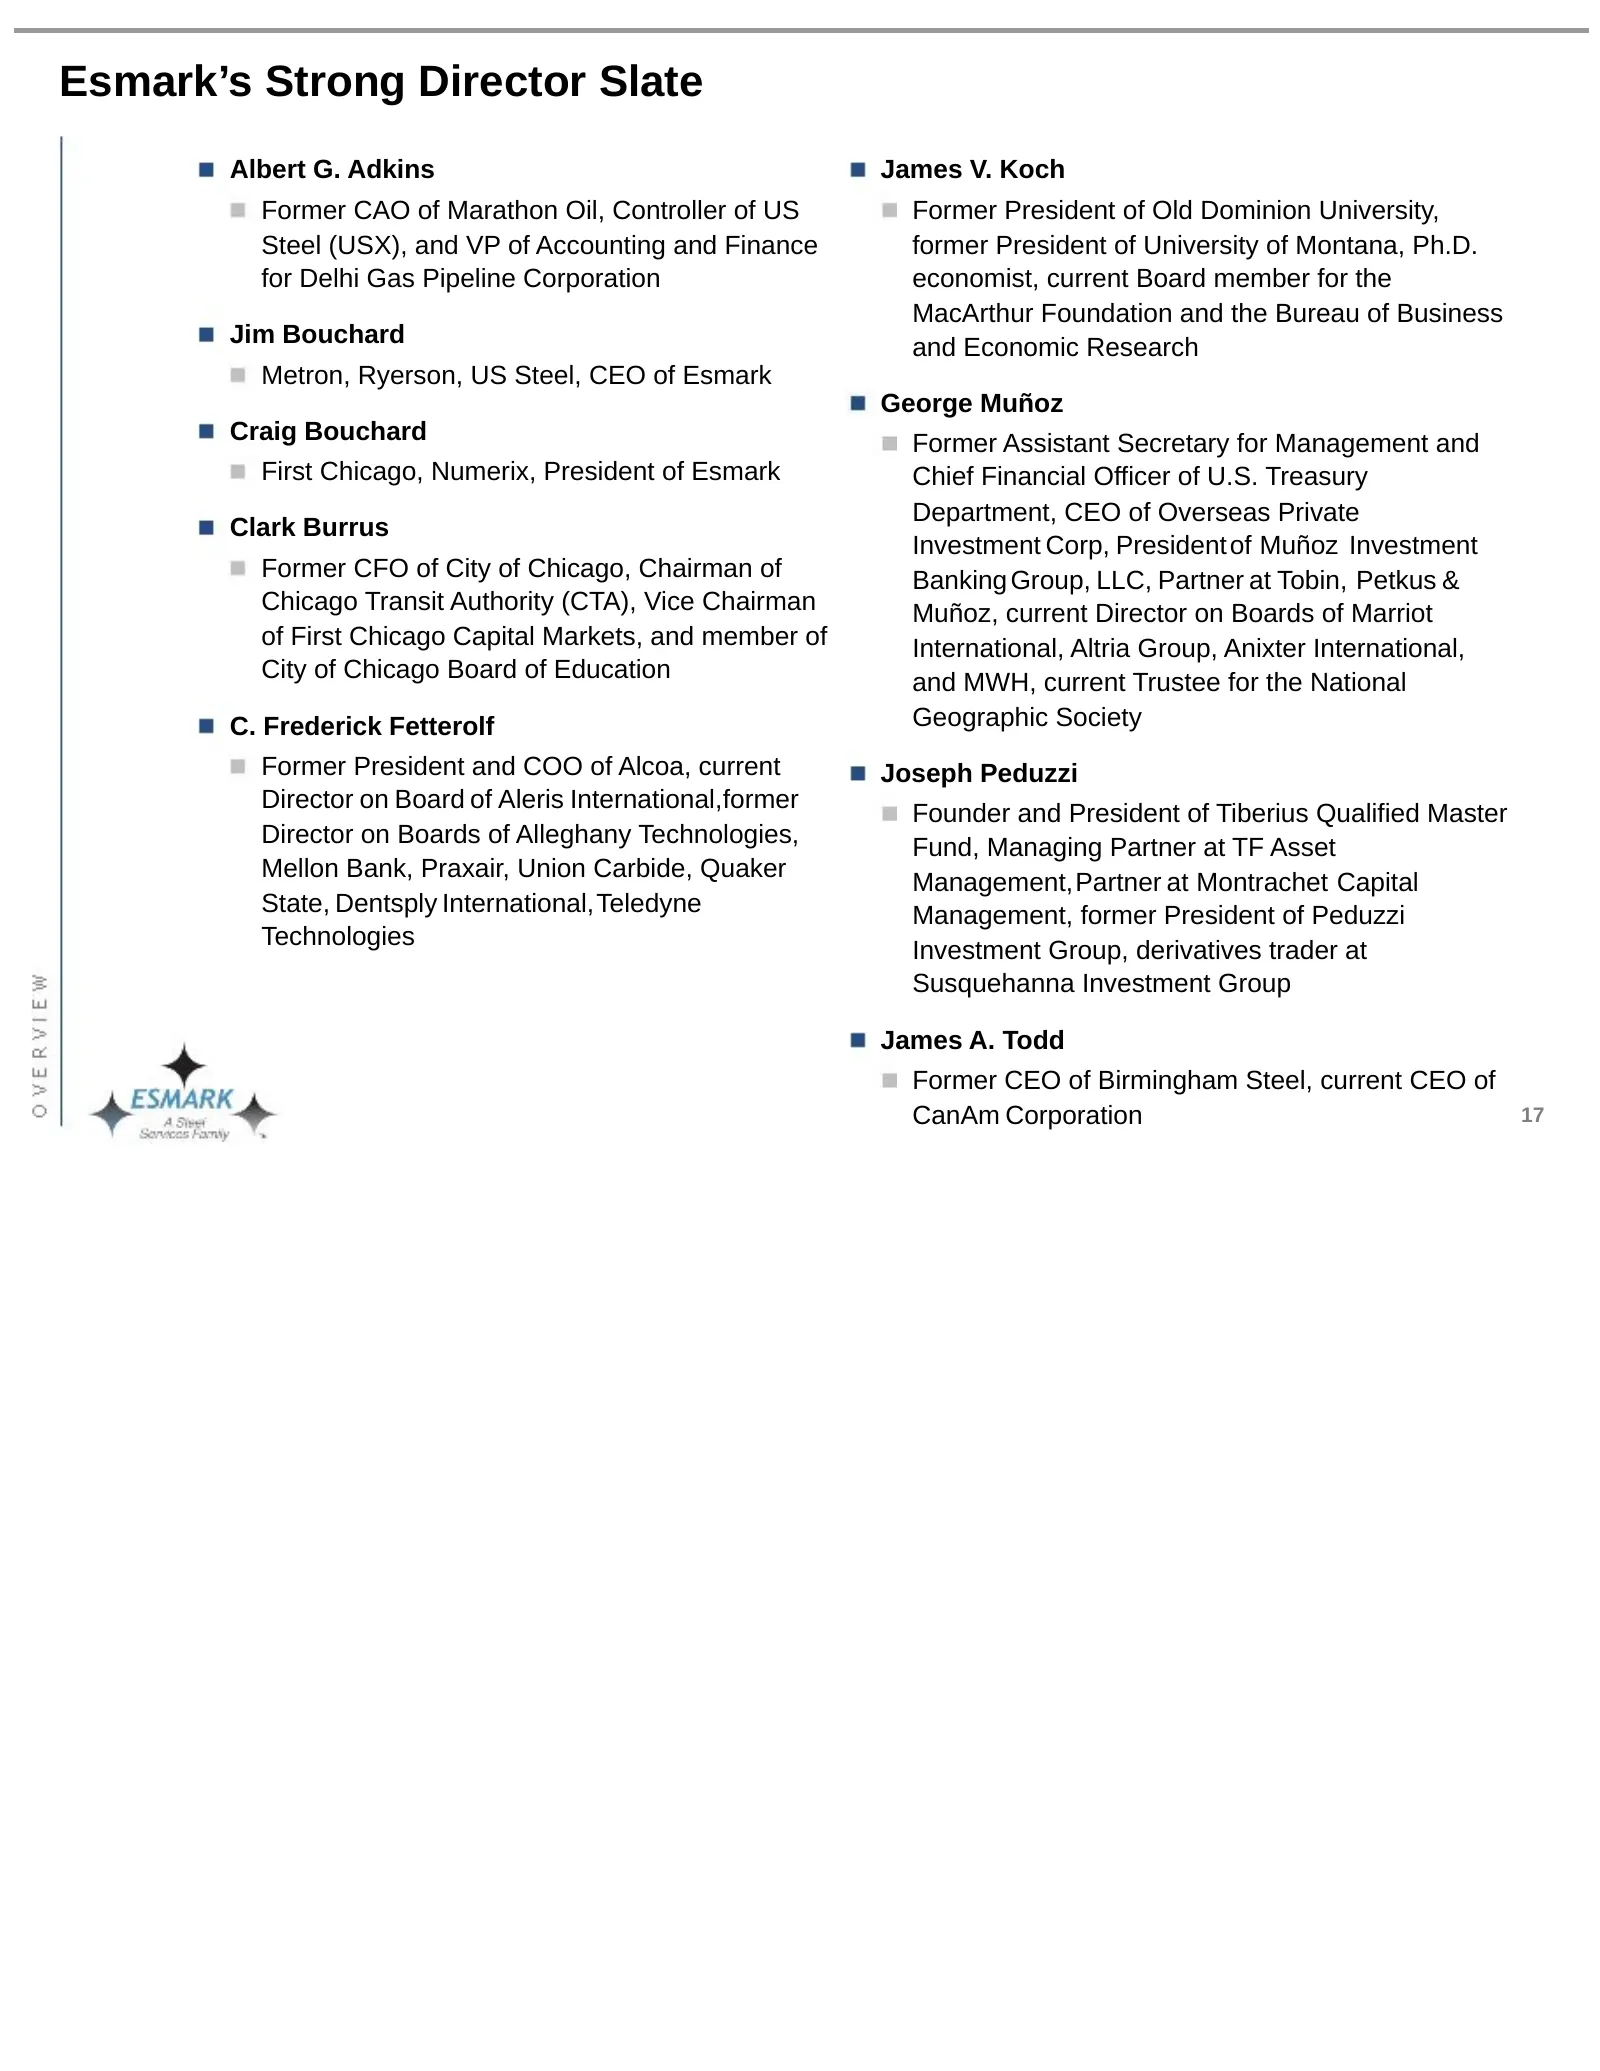
Esmark’s Strong Director Slate Albert G. Adkins James V. Koch Former CAO of Marathon Oil, Controller of US Former President of Old Dominion University, Steel (USX), and VP of Accounting and Finance former President of University of Montana, Ph.D. for Delhi Gas Pipeline Corporation economist, current
Slide 21: Warren Buffett quote on shareholders
“Companies are owned by Shareholders and the management work for the Shareholders!! It’s their capital.” Warren Buffet 18
Source: SEC EDGAR · DFAN14A filed Sep 29, 2006
More decks from Wheeling Pittsburgh Corp
 Merger or Acquisition (December 2006)22 slides · Dec 7, 2006
 Merger or Acquisition (November 2006)46 slides · Nov 13, 2006
 Proxy Contest (November 2006)40 slides · Nov 7, 2006
 Proxy Contest (November 2006)44 slides · Nov 6, 2006
 Proxy Contest (September 2006)34 slides · Sep 28, 2006
 KeyBanc Conference 200647 slides · Sep 13, 2006