Wheeling Pittsburgh — KeyBanc Conference 2006
47 slides from Wheeling Pittsburgh's conference presentation, Sep 13, 2006
Slide 1: Wheeling Pittsburgh Corporation KeyBanc Conference September 13, 2006
Wheeling Pittsburgh Corporation KeyBanc Conference September 13, 2006
Slide 2: Presentation Agenda
Presentation Agenda Page(s) FORWARD LOOKING STATEMENTS 2 STRATEGIC GOALS: POST BANKRUPTCY 3 RECENT COMPANY PERFORMANCE 4 Operations 5-14 Financial 15-20 WPSC: M&A 21 Strategic Goals: Post Bankruptcy (cont'd) 22-23 Internal M&A Process 24-25 CSN Proposal 26-39 Q&A / Notes 40 APPENDIX: COMPANY BACKGRO
Slide 3: Forward Looking Statements
The information contained in this presentation, other than historical information, consists of forward-looking statements within the meaning of Section 27A of the Securities Act and Section 21E of the Securities Exchange Act. In particular, statements containing estimates or projections of future op
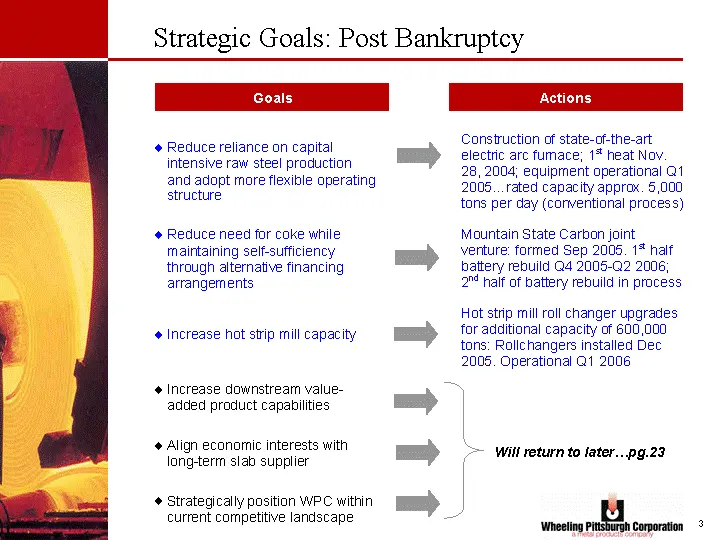
Slide 4: Strategic Goals: Post Bankruptcy
Strategic Goals: Post Bankruptcy Actions Goals
Slide 5: II. Recent Company Performance
II. RECENT COMPANY PERFORMANCE
Slide 6: Operations: Production, Quality and Reliability
II. RECENT COMPANY PERFORMANCE Operations: Production, Quality and Reliability
Slide 7: Production — Blast Furnace
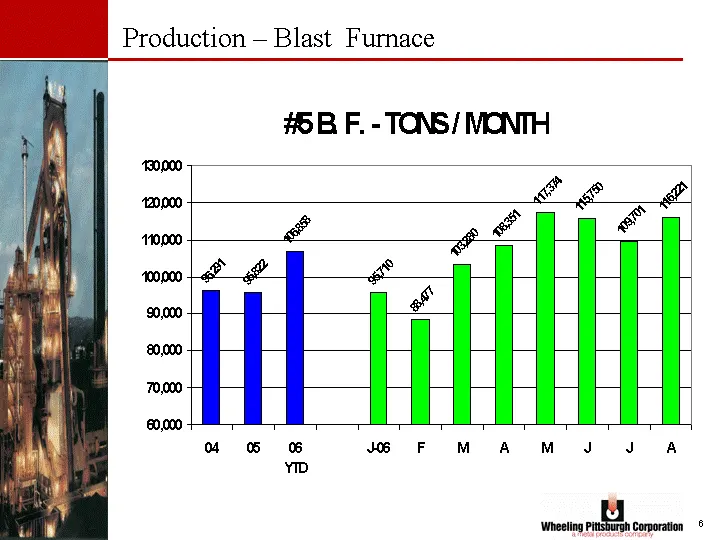
Production — Blast Furnace 60,000
Slide 8: Trended Production - EAF
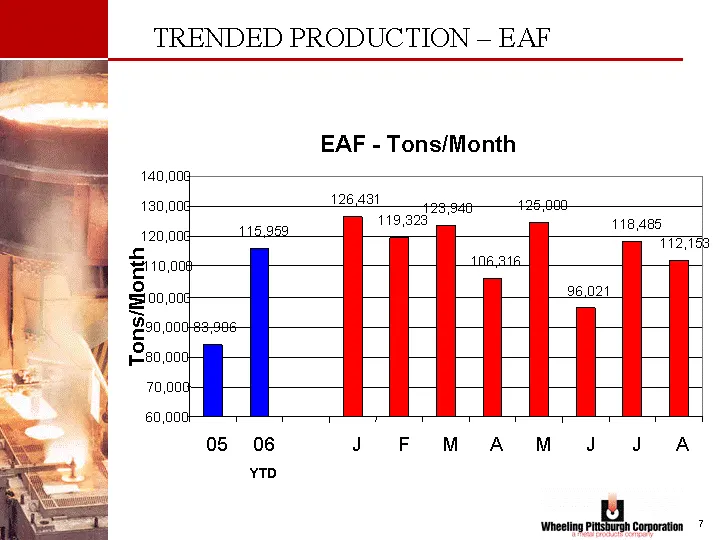
EAF - Tons/Month 83,906 115,959 126,431 119,323 123,940 106,316 125,000 96,021 118,485 112,153 60,000 70,000 80,000 90,000 100,000 110,000 120,000 130,000 140,000 05 06 YTD J F M A M J J A Tons/Month TRENDED PRODUCTION - EAF
Slide 9: Trended Production - Caster
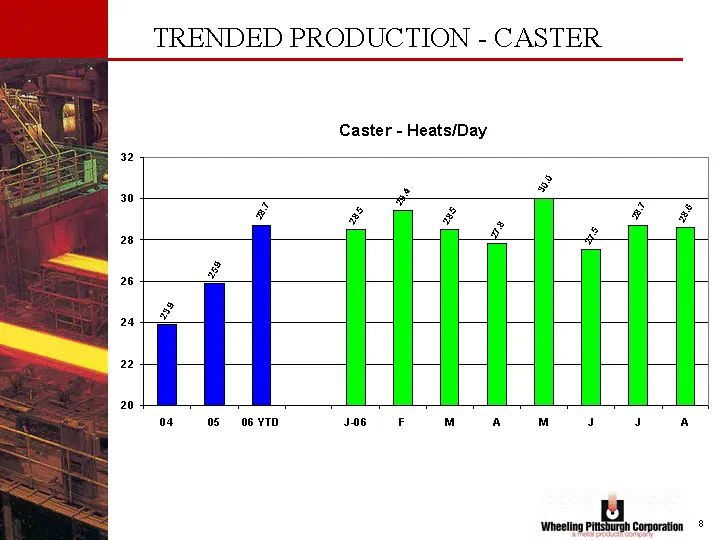
TRENDED PRODUCTION - CASTER. Caster - Heats/Day 5 > > > s $ gf, gf § 2 E: ? | 8 04 05 OB YTD 6 oF mM A M 4s soa
Slide 10: Production and Quality - Hot Strip Mill
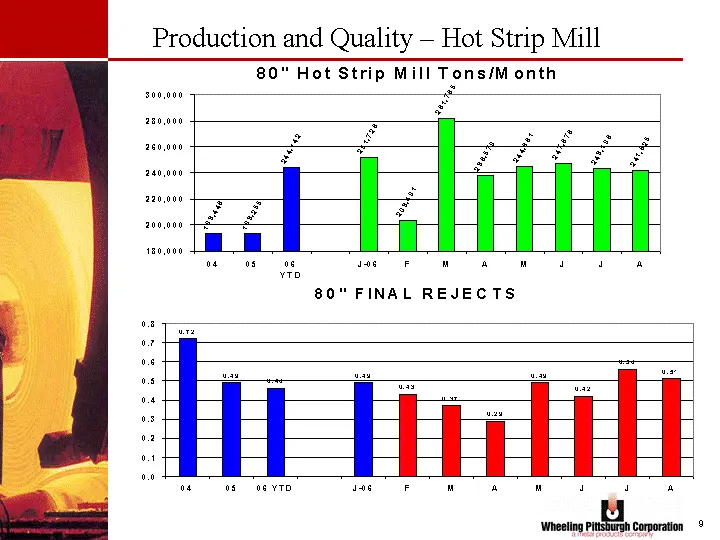
Production and Quality - Hot Strip Mill
Slide 11: Production and Quality - Allenport
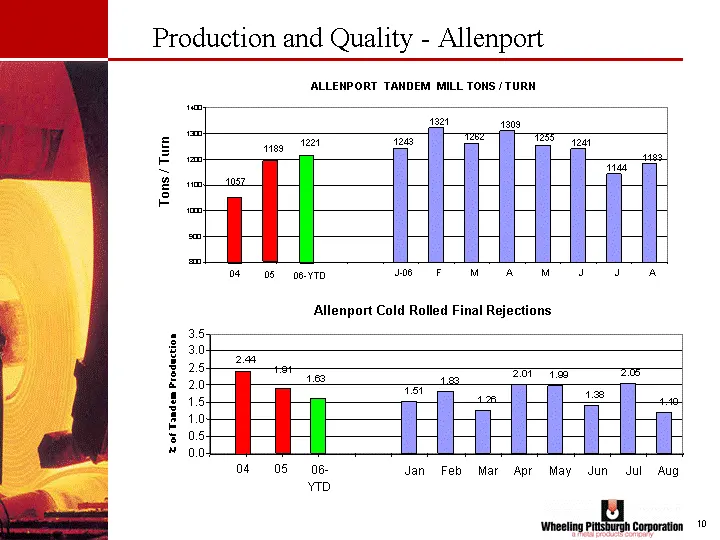
ALLENPORT TANDEM MILL TONS / TURN 1057 1189 1221 1243 1321 1262 1309 1255 1241 1144 1183 800 900 1000 1100 1200 1300 1400 04 05 06-YTD J-06 F M A M J J A Tons / Turn Allenport Cold Rolled Final Rejections 2.44 1.91 1.63 1.51 1.83 1.26 2.01 1.99 1.38 2.05 1.19 0.0 0.5 1.0 1.5 2.0 2.5 3.0 3.5 04 05 06
Slide 12: Production and Quality - Yorkville
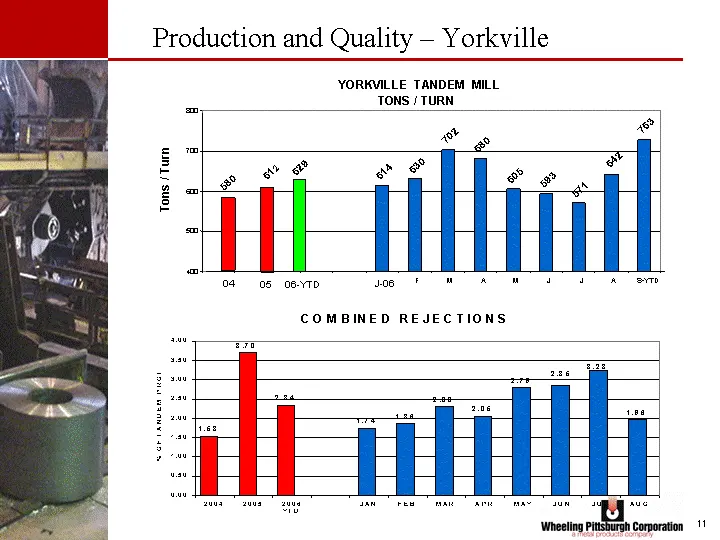
YORKVILLE TANDEM MILL TONS / TURN 580 612 629 614 630 702 680 605 593 571 642 763 400 500 600 700 800 04 05 06-YTD J-06 F M A M J J A S-YTD Tons / Turn Production and Quality - Yorkville
Slide 13: Production and Quality - Martins Ferry
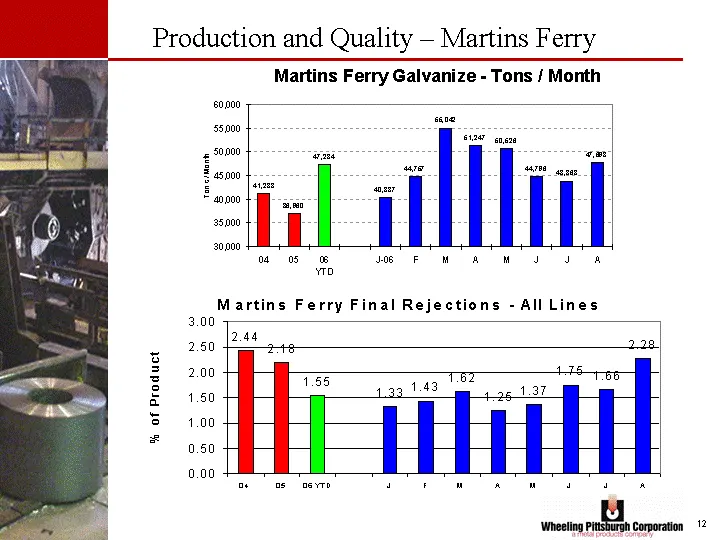
Production and Quality - Martins Ferry
Slide 14: Reliability Improvement - Selected Examples
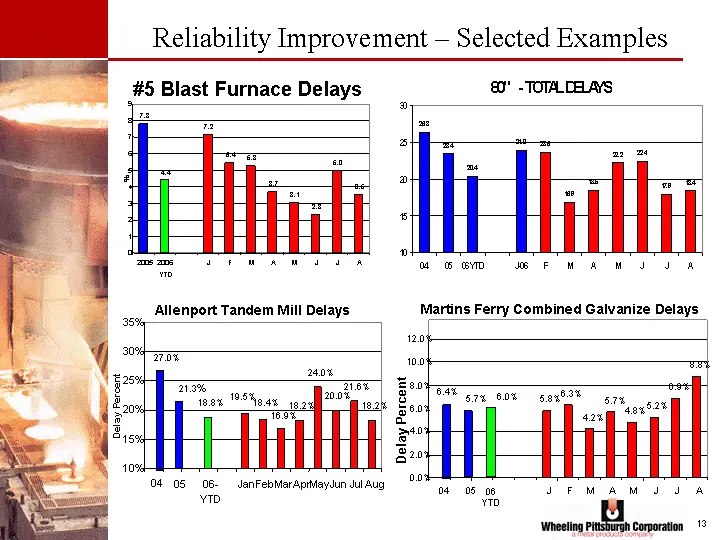
#5 Blast Furnace Delays 7.8 4.4 7.2 5.4 5.3 3.7 3.1 2.3 5.0 3.5 0 1 2 3 4 5 6 7 8 9 2005 2006 YTD J F M A M J J A % Martins Ferry Combined Galvanize Delays 6.4% 5.7% 6.0% 5.8% 6.3% 4.2% 5.7% 4.8% 5.2% 6.9% 8.8% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 04 05 06 YTD J F M A M J J A Delay Percent Allenport
Slide 15: Reliability Index
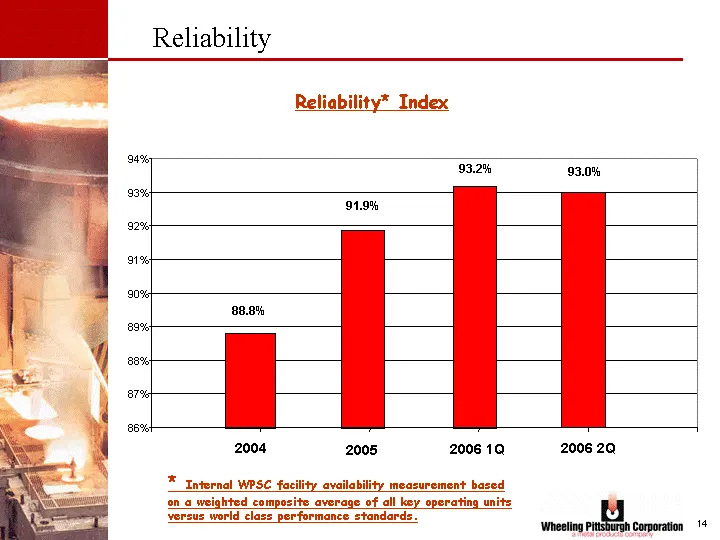
88.8% 91.9% 93.2% 93.0% 86% 87% 88% 89% 90% 91% 92% 93% 94% 2004 2005 2006 1Q 2006 2Q Reliability* Index Reliability * Internal WPSC facility availability measurement based on a weighted composite average of all key operating units versus world class performance standards.
Slide 16: II. Recent Company Performance B. Financial
II. RECENT COMPANY PERFORMANCE B. Financial
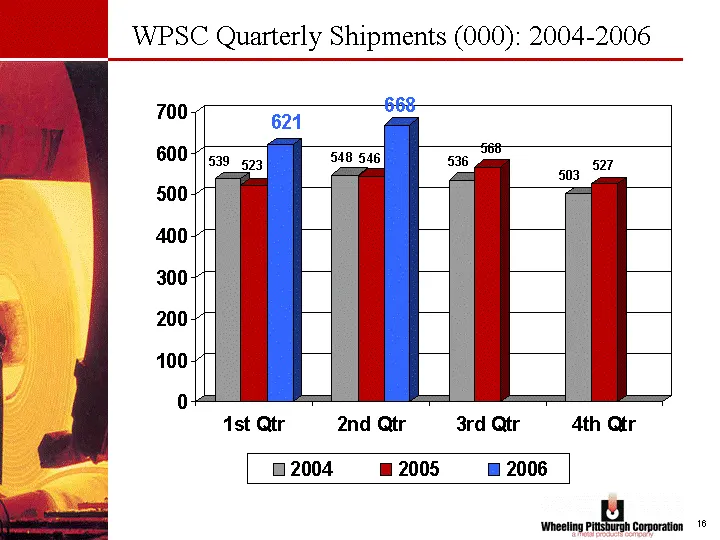
Slide 17: WPSC Quarterly Shipments (000): 2004-2006
WPSC Quarterly Shipments (000): 2004-2006
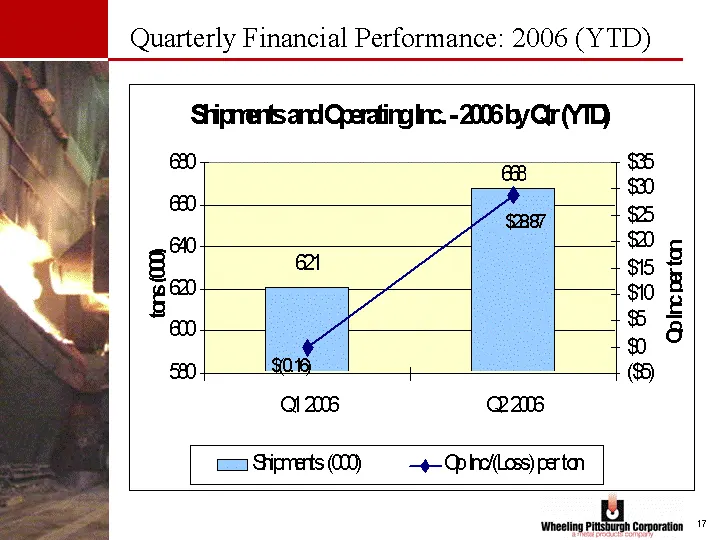
Slide 18: Quarterly Financial Performance: 2006 (YTD)
Quarterly Financial Performance: 2006 (YTD)
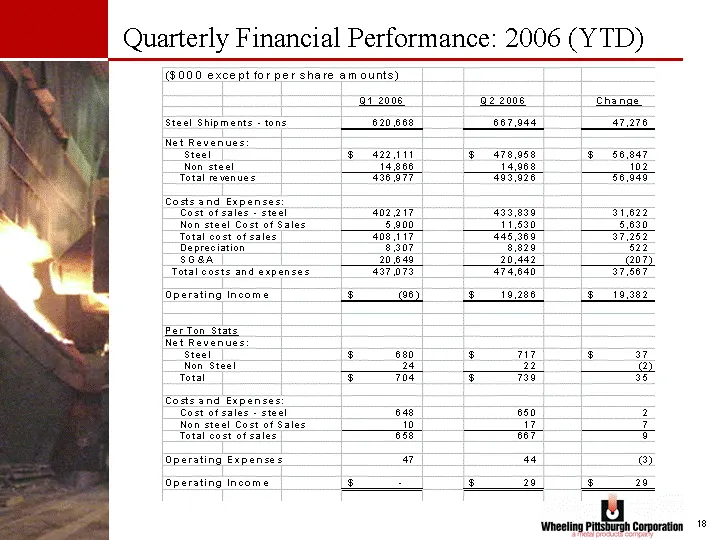
Slide 19: Quarterly Financial Performance: 2006 (YTD)
Quarterly Financial Performance: 2006 (YTD)
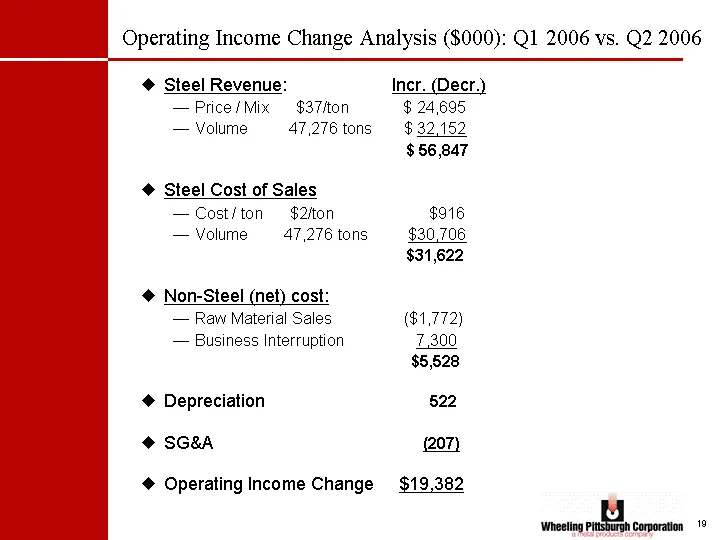
Slide 20: Operating Income Change Analysis: Q1 2006 vs. Q2 2006
Operating Income Change Analysis ($000): Q1 2006 vs. Q2 2006 Steel Revenue: Incr. (Decr.) Price / Mix $37/ton $ 24,695 Volume 47,276 tons $ 32,152 $ 56,847 Steel Cost of Sales Cost / ton $2/ton $916 Volume 47,276 tons $30,706 $31,622 Non-Steel (net) cost: Raw Material Sales ($1,772) Business Interru
Slide 21: Credit Facility Analysis
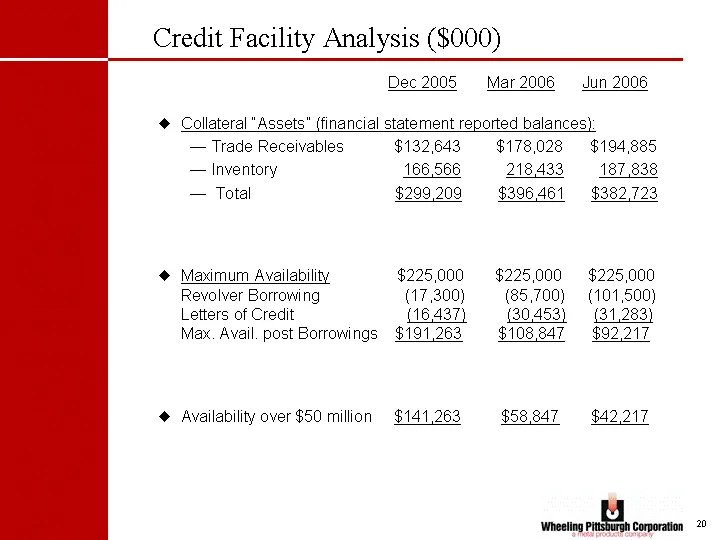
Credit Facility Analysis ($000) Dec 2005 Mar 2006 Jun 2006 Collateral "Assets" (financial statement reported balances): Trade Receivables $132,643 $178,028 $194,885 Inventory 166,566 218,433 187,838 Total $299,209 $396,461 $382,723 Maximum Availability $225,000 $225,000 $225,000 Revolver Borrowing (
Slide 22: III. M&A
III. M&A
Slide 23: III. M&A A. Strategic Goals - Cont'd
III. M&A A. Strategic Goals - Cont'd
Slide 24: Wheeling-Pittsburgh's Strategic Goals - Cont'd
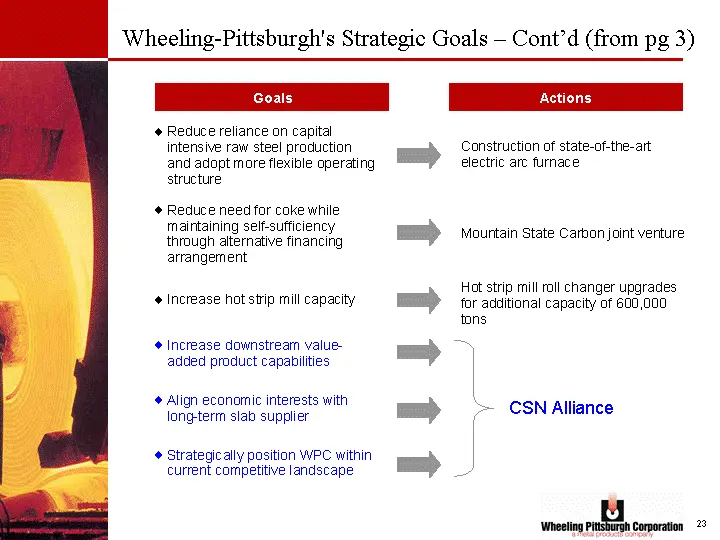
Wheeling-Pittsburgh's Strategic Goals - Cont'd (from pg 3) Actions Goals
Slide 25: III. M&A B. Internal Process
III. M&A B. Internal Process
Slide 26: M&A: Extensive and Rigorous Internal Process
M&A: Extensive and Rigorous Internal Process In exploratory talks with broad range of parties regarding strategic alternatives in most recent 18 months and signed confidentiality agreements with several parties Proposals received from Esmark and CSN CSN proposal and business plan jointly developed w
Slide 27: III. M&A C. CSN Proposal
III. M&A C. CSN Proposal
Slide 28: Transaction Summary - CSN Proposal
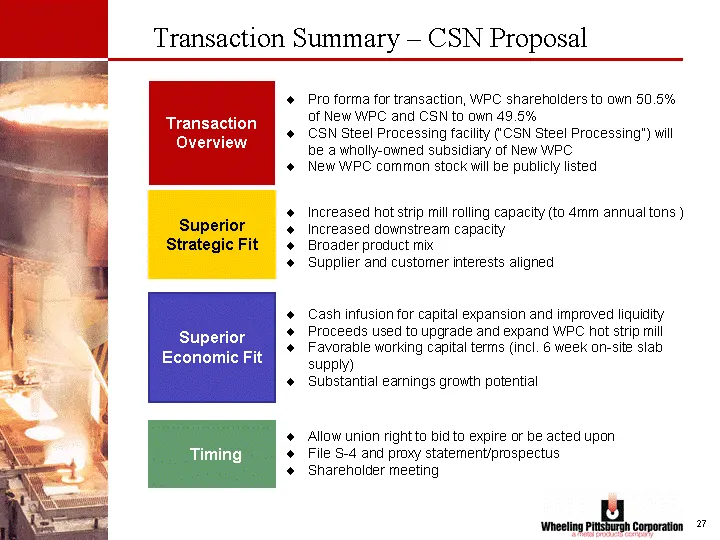
Transaction Summary - CSN Proposal Transaction Overview Superior Economic Fit Timing Superior Strategic Fit Pro forma for transaction, WPC shareholders to own 50.5% of New WPC and CSN to own 49.5% CSN Steel Processing facility ("CSN Steel Processing") will be a wholly-owned subsidiary of New WPC New
Slide 29: CSN Overview
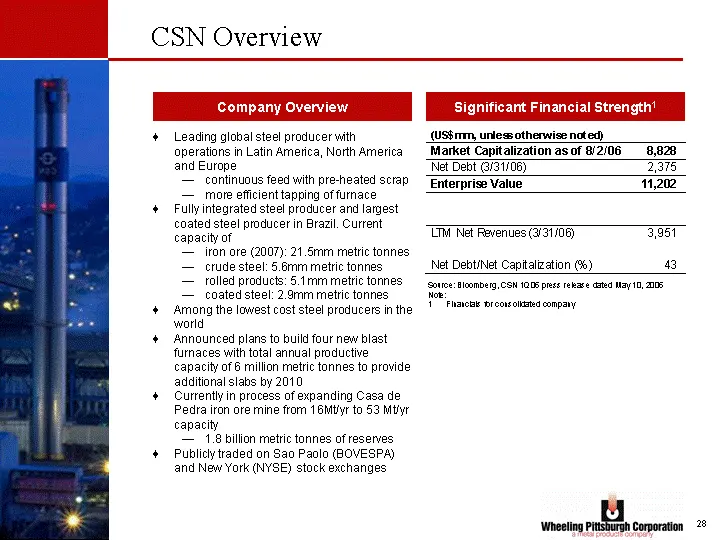
CSN Overview Leading global steel producer with operations in Latin America, North America and Europe continuous feed with pre-heated scrap more efficient tapping of furnace Fully integrated steel producer and largest coated steel producer in Brazil. Current capacity of iron ore (2007): 21.5mm metri
Slide 30: CSN Steel Processing Overview
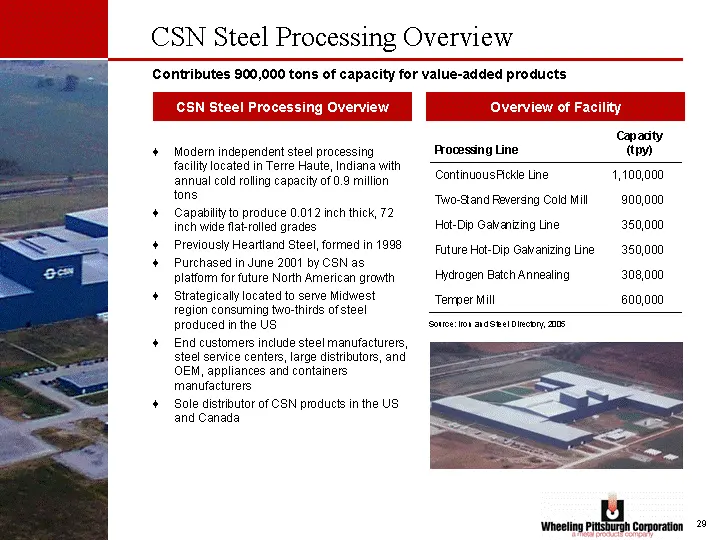
Contributes 900,000 tons of capacity for value-added products CSN Steel Processing Overview CSN Steel Processing Overview Overview of Facility Modern independent steel processing facility located in Terre Haute, Indiana with annual cold rolling capacity of 0.9 million tons Capability to produce 0.01
Slide 31: Pro Forma Corporate Structure at Closing
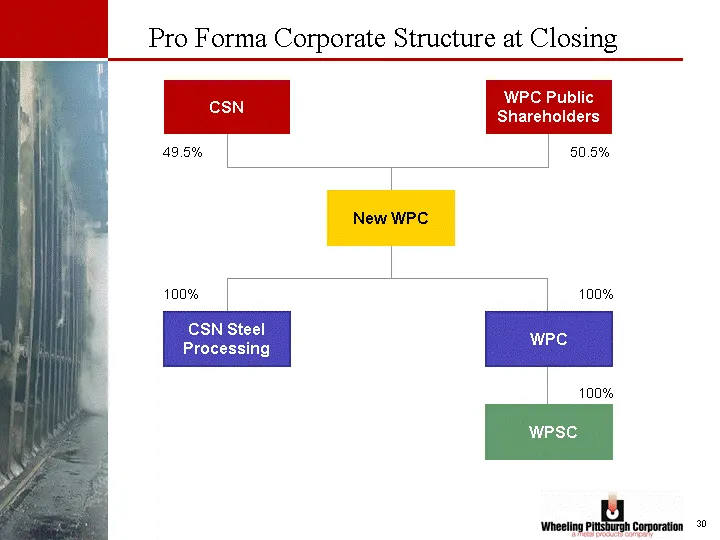
Pro Forma Corporate Structure at Closing CSN WPC Public Shareholders New WPC CSN Steel Processing WPC WPSC 100% 100% 100% 49.5% 50.5%
Slide 32: Governance Provisions and Shareholder Rights
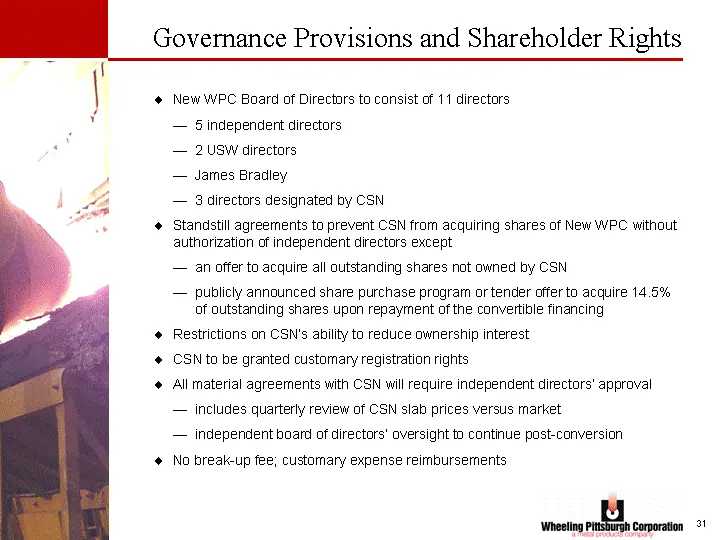
Governance Provisions and Shareholder Rights New WPC Board of Directors to consist of 11 directors 5 independent directors 2 USW directors James Bradley 3 directors designated by CSN Standstill agreements to prevent CSN from acquiring shares of New WPC without authorization of independent directors
Slide 33: CSN Proposal: Superior Strategic Fit
CSN Proposal: Superior Strategic Fit Upgrade of hot strip mill and increased capacity to 4.0mm tons energy efficient new furnace will drive a competitive cost structure through gas savings additional throughput of 600,000 tons reduces costs per ton significant operating efficiencies and improved pro
Slide 34: Significantly Enhanced Shipments
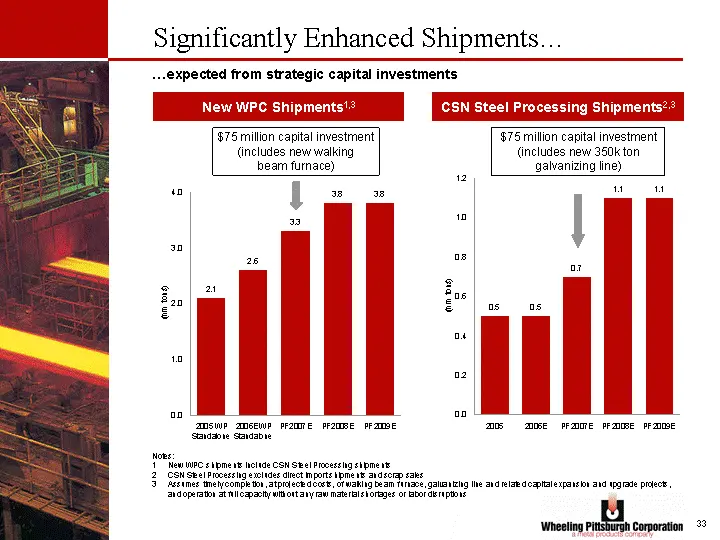
Significantly Enhanced Shipments... ....expected from strategic capital investments New WPC Shipments1,3 CSN Steel Processing Shipments2,3 $75 million capital investment (includes new walking beam furnace) $75 million capital investment (includes new 350k ton galvanizing line) Notes: 1 New WPC shipm
Slide 35: Broader Value-Added Product Offering
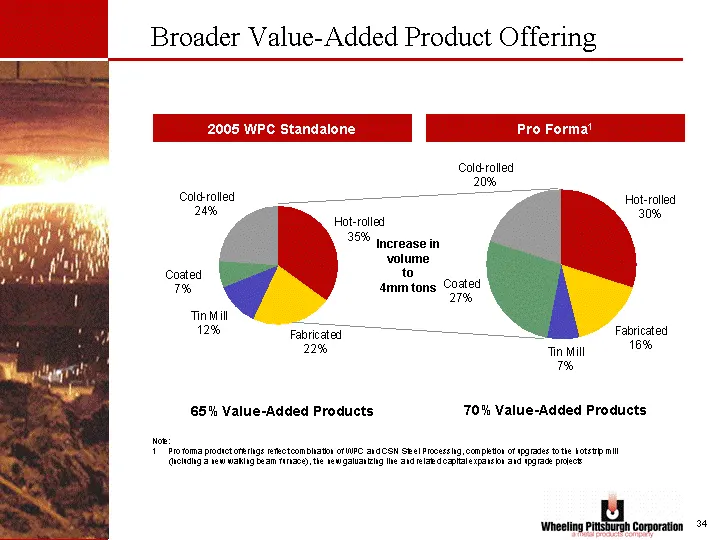
Broader Value-Added Product Offering 65% Value-Added Products 70% Value-Added Products 2005 WPC Standalone Pro Forma1 Increase in volume to 4mm tons Note: 1 Pro forma product offerings reflect combination of WPC and CSN Steel Processing, completion of upgrades to the hot strip mill (including a new
Slide 36: CSN Proposal: Superior Economic Fit
CSN Proposal: Superior Economic Fit Slab agreement provides long-term guaranteed source of supply alignment of economic interests promotes reliable supply promotes flexible cost structure favorable working capital terms Substantial earnings growth Higher shipment level / downstream products Operatin
Slide 37: Flexible Cost Structure
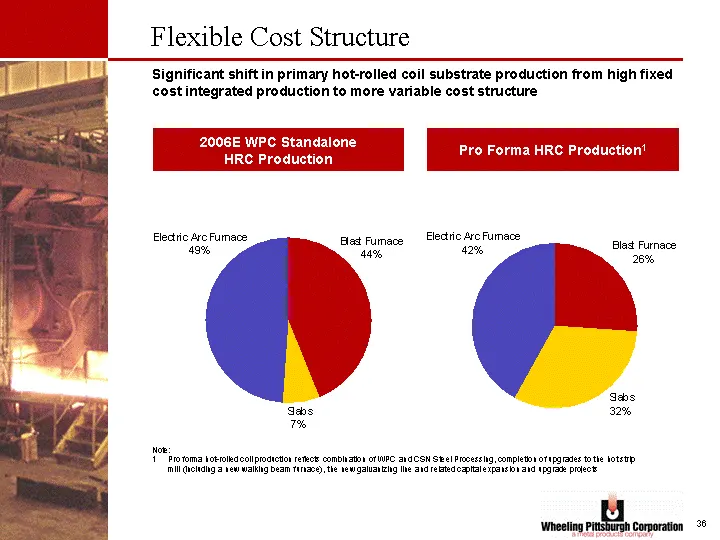
Flexible Cost Structure Significant shift in primary hot-rolled coil substrate production from high fixed cost integrated production to more variable cost structure 2006E WPC Standalone HRC Production Pro Forma HRC Production1 Note: 1 Pro forma hot-rolled coil production reflects combination of WPC
Slide 38: Significant Pro Forma Earnings Potential
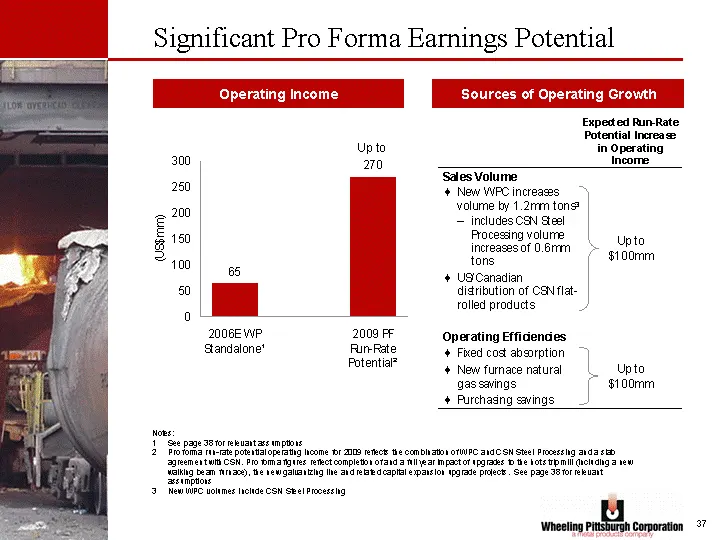
Significant Pro Forma Earnings Potential Operating Income Sources of Operating Growth Up to Notes: 1 See page 38 for relevant assumptions 2 Pro forma run-rate potential operating income for 2009 reflects the combination of WPC and CSN Steel Processing and a slab agreement with CSN. Pro forma figures
Slide 39: Assumptions For Run-Rate Operating Earnings Potential
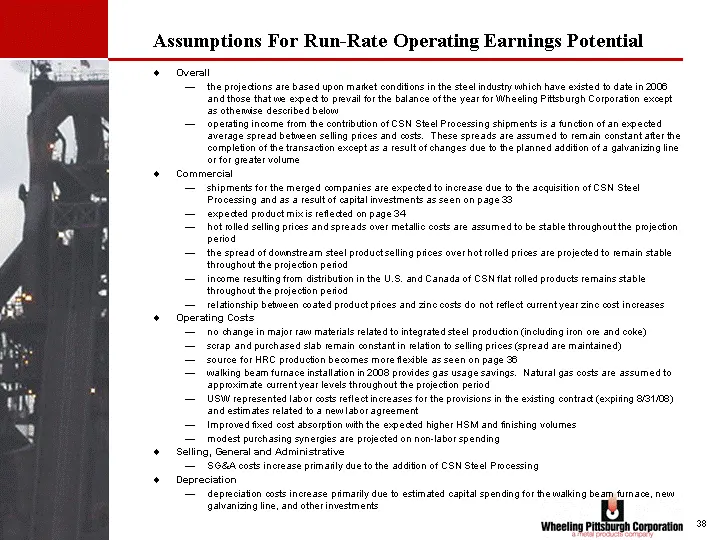
Assumptions For Run-Rate Operating Earnings Potential Overall the projections are based upon market conditions in the steel industry which have existed to date in 2006 and those that we expect to prevail for the balance of the year for Wheeling Pittsburgh Corporation except as otherwise described be
Slide 40: Superior Pro Forma Financial and Liquidity Position
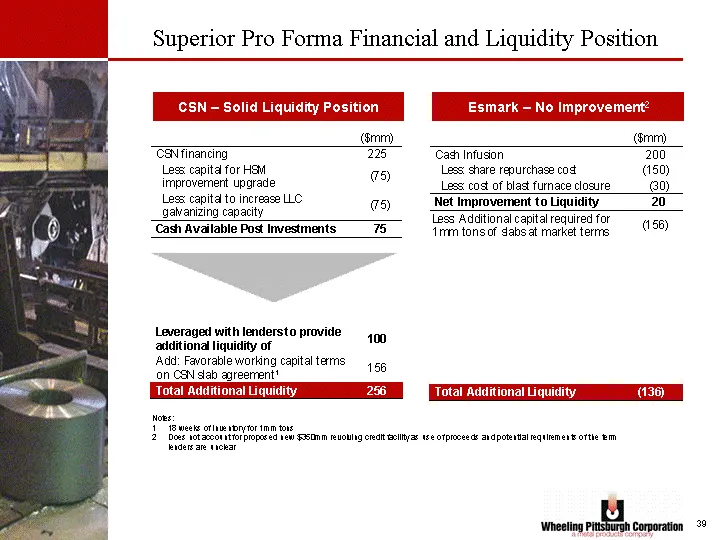
CSN - Solid Liquidity Position Esmark - No Improvement2 Notes: 1 18 weeks of inventory for 1mm tons 2 Does not account for proposed new $350mm revolving credit facility as use of proceeds and potential requirements of the term lenders are unclear Superior Pro Forma Financial and Liquidity Position
Slide 41: Presentation Summary
Presentation Summary + Q&A med tecme “
Slide 42: Appendix: Company Background
Appendix: Company Background
Slide 43: Wheeling Pittsburgh: Company Overview
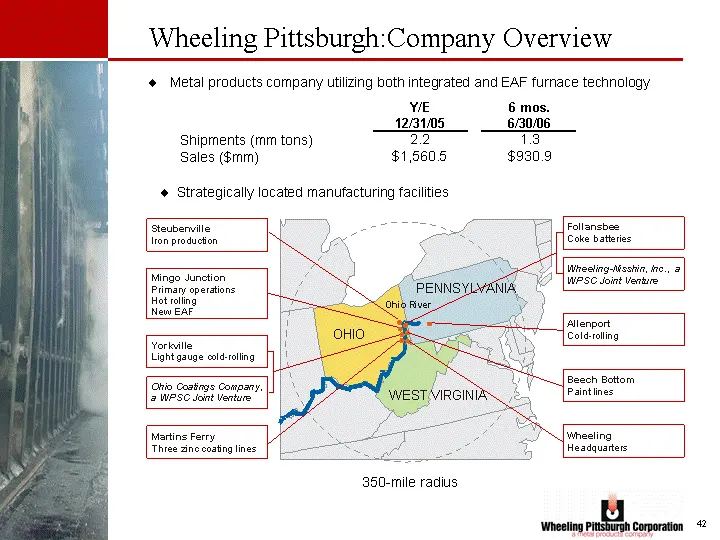
Steubenville Iron production Wheeling Headquarters Allenport Cold-rolling Beech Bottom Paint lines OHIO PENNSYLVANIA Ohio River WEST VIRGINIA Mingo Junction Primary operations Hot rolling New EAF Martins Ferry Three zinc coating lines Yorkville Light gauge cold-rolling Ohio Coatings Company, a WPSC
Slide 44: Diverse Value-Added Product Offerings
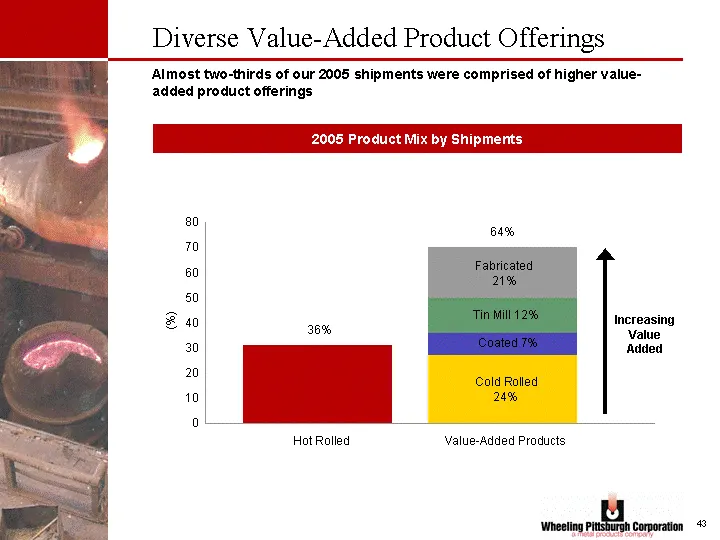
36% Cold Rolled 24% Fabricated 21% Tin Mill 12% Coated 7% 0 10 20 30 40 50 60 70 80 Hot Rolled Value-Added Products (%) Diverse Value-Added Product Offerings Almost two-thirds of our 2005 shipments were comprised of higher value- added product offerings 2005 Product Mix by Shipments Increasing Value
Slide 45: Differentiated Marketing Strategy
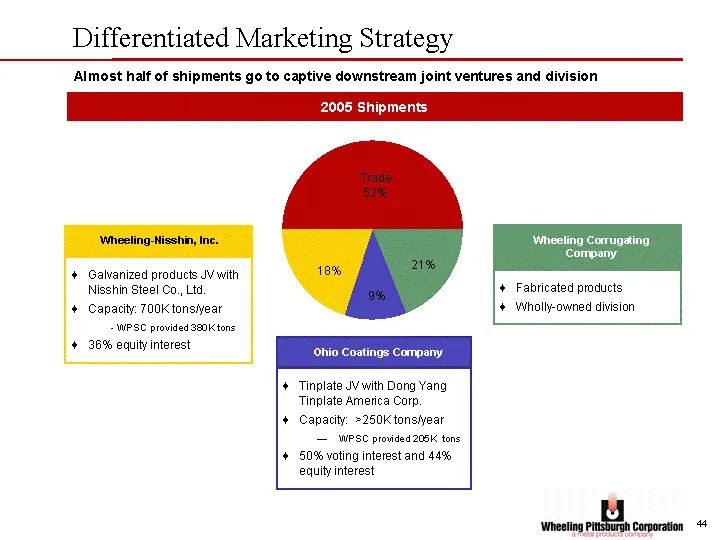
Differentiated Marketing Strategy Almost half of shipments go to captive downstream joint ventures and division 2005 Shipments Tinplate JV with Dong Yang Tinplate America Corp. Capacity: >250K tons/year WPSC provided 205K tons 50% voting interest and 44% equity interest Ohio Coatings Company Fabrica
Slide 46: Leadership in Fabricated Products
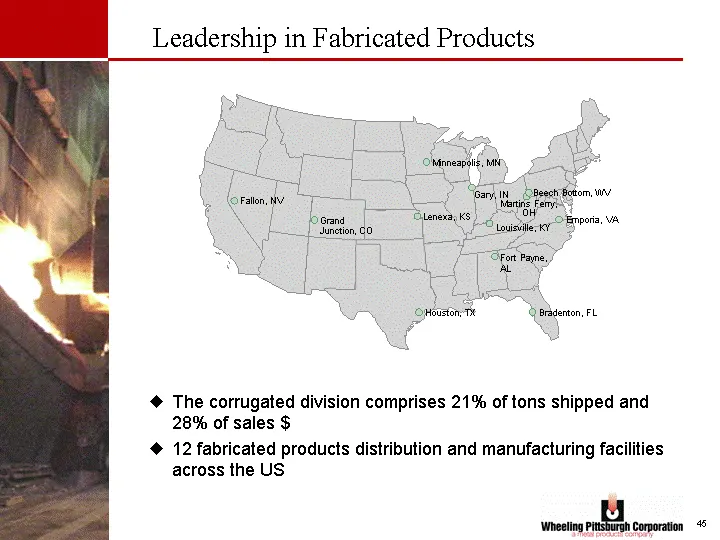
Leadership in Fabricated Products The corrugated division comprises 21% of tons shipped and 28% of sales $ 12 fabricated products distribution and manufacturing facilities across the US Fort Payne, AL Houston, TX Lenexa, KS Louisville, KY Minneapolis, MN Gary, IN Emporia, VA Grand Junction, CO Brade
Slide 47: Leading Market Shares in Fabricated Products
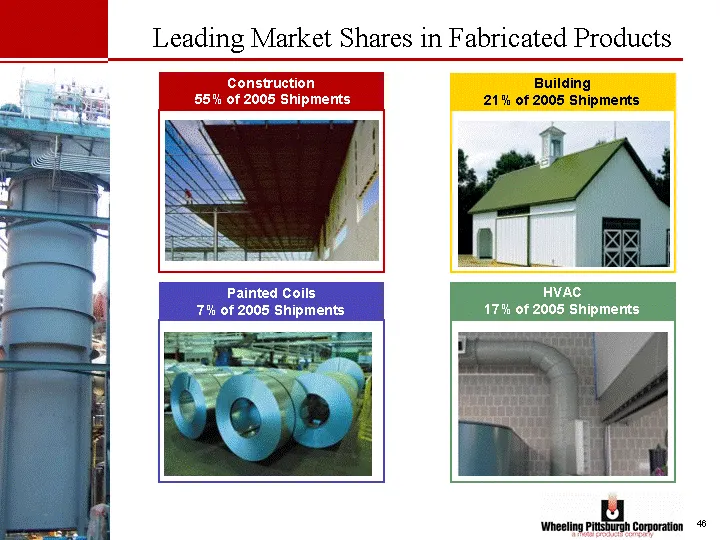
Leading Market Shares in Fabricated Products Construction 55% of 2005 Shipments Building 21% of 2005 Shipments Painted Coils 7% of 2005 Shipments HVAC 17% of 2005 Shipments
Source: SEC EDGAR · DEFA14A filed Sep 13, 2006
More decks from Wheeling Pittsburgh Corp
 Merger or Acquisition (December 2006)22 slides · Dec 7, 2006
 Merger or Acquisition (November 2006)46 slides · Nov 13, 2006
 Proxy Contest (November 2006)40 slides · Nov 7, 2006
 Proxy Contest (November 2006)44 slides · Nov 6, 2006
 Proxy Contest (September 2006)21 slides · Sep 29, 2006
 Proxy Contest (September 2006)34 slides · Sep 28, 2006