Diamond Foods — Barclays Capital Back-to-School Consumer Conference 2011
41 slides from Diamond Foods's conference presentation, Sep 7, 2011
Slide 1: Diamond Foods Platform for Future Growth
Diamond Foods Platform for Future Growth Michael J. Mendes Chairman, President and CEO Barclays Capital Back-to-School Consumer Conference September 7, 2011 Diamond
Slide 2: Important Information
Important Information This document contains forward-looking statements as defined by the Private Securities Litigation Reform Act of 1995, including projections of Diamond’s results. The words “anticipate,” “expect,” “believe,” “goal,” “plan,” “intend,” “estimate,” “may,” “will,” “would” and simila
Slide 3: Additional Information
Additional Information In connection with the proposed transaction between Diamond and P&G, Diamond filed a preliminary proxy which has not yet become effective. Investors are urged to read the proxy statement/prospectus and any other relevant documents when they become ‘available, because they will
Slide 4: Diamond Foods Branded Snack Food Leader
Diamond Foods Branded Snack Food Leader Close in 2011 Building, Acquiring and Portfolio of Premium Brands Energizing Brands Driving Category Growth 4
Slide 5: Strong and Growing Retail Sales
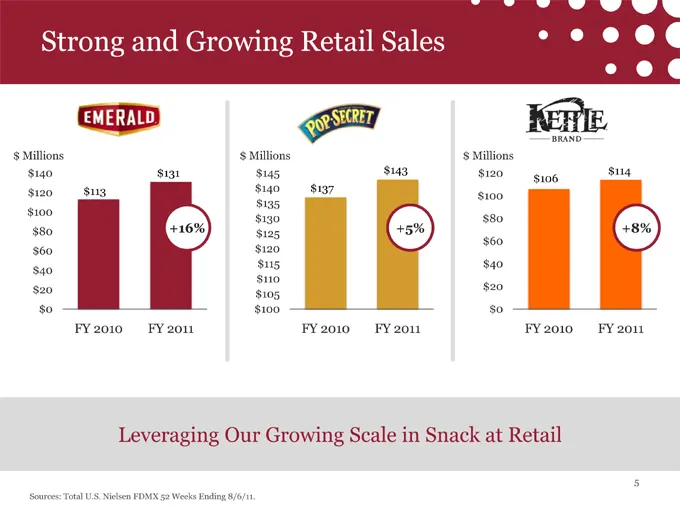
Strong and Growing Retail Sales $ Millions $ Millions $ Millions $140 $131 $145 $143 $120 $114 $106 $120 $113 $140 $137 $100 $135 $100 $130 $80 $80 +16% $125 +5% +8% $60 $60 $120 $115 $40 $40 $110 $20 $20 $105 $0 $100 $0 FY 2010 FY 2011 FY 2010 FY 2011 FY 2010 FY 2011 Leveraging Our Growing Scale in
Slide 6: Exceeding Category Performance
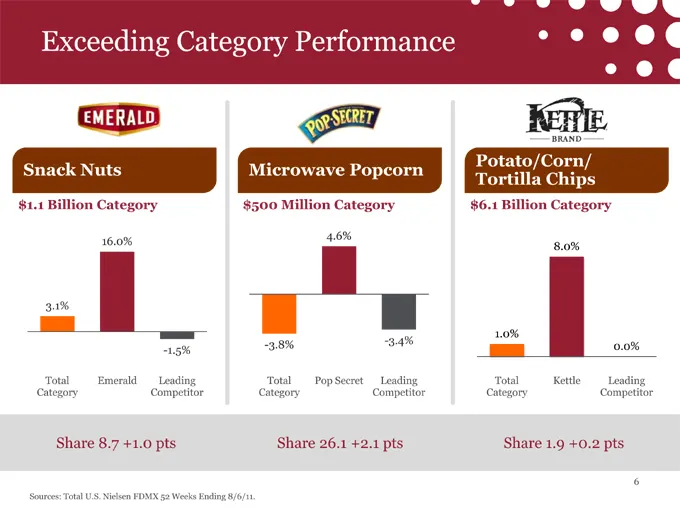
Exceeding Category Performance Potato/Corn/ Snack Nuts Microwave Popcorn Tortilla Chips $1.1 Billion Category $500 Million Category $6.1 Billion Category 4.6% 16.0% 8.0% 3.1% 1.0% -3.8% -3.4% -1.5% 0.0% Total Emerald Leading Total Pop Secret Leading Total Kettle Leading Category Competitor Category
Slide 7: Outstanding Financial Performance
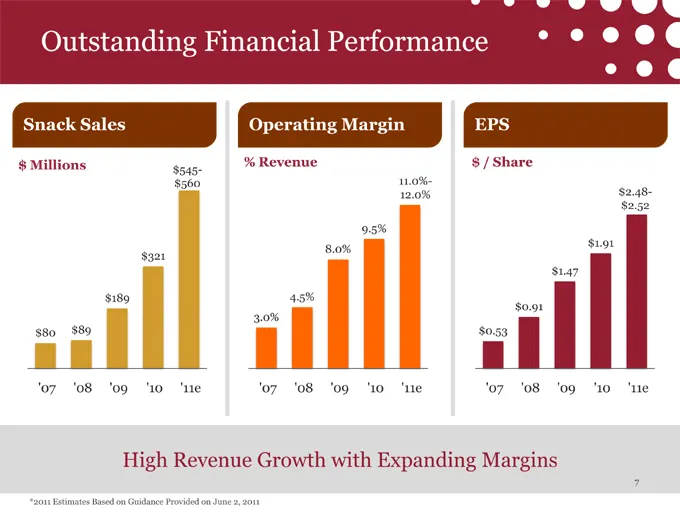
Outstanding Financial Performance Snack Sales Operating Margin EPS $ Millions % Revenue $ / Share $545-$560 11.0%- $2.48-12.0% $2.52 9.5% $1.91 8.0% $321 $1.47 $189 4.5% 3.0% $0.91 $80 $89 $0.53 ‘07 ‘08 ‘09 ‘10 ‘11e ‘07 ‘08 ‘09 ‘10 ‘11e ‘07 ‘08 ‘09 ‘10 ‘11e High Revenue Growth with Expanding Margins
Slide 8: Becoming a Global Snack Leader
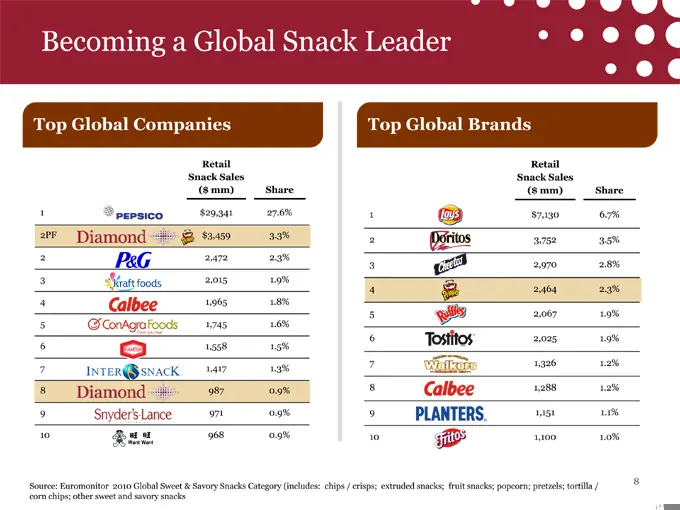
Becoming a Global Snack Leader Top Global Companies Top Global Brands Retail Retail Snack Sales Snack Sales ($ mm) Share ($ mm) Share 1 $29,341 27.6% 1 $7,130 6.7% 2PF $3,459 3.3% 2 3,752 3.5% 2 2,472 2.3% 3 2,970 2.8% 3 2,015 1.9% 4 2,464 2.3% 4 1,965 1.8% 5 2,067 1.9% 5 1,745 1.6% 6 2,025 1.9% 6 1
Slide 9: Platform for Future Growth
Platform for Future Growth Innovation Execution Integration Unique Products and Retail Merchandising Expanding Capacity Dynamic Consumer and Operational and Distribution Support Excellence Worldwide Diamond Foods High Growth Global Snack Food Company 9
Slide 10: Culture of Product Innovation
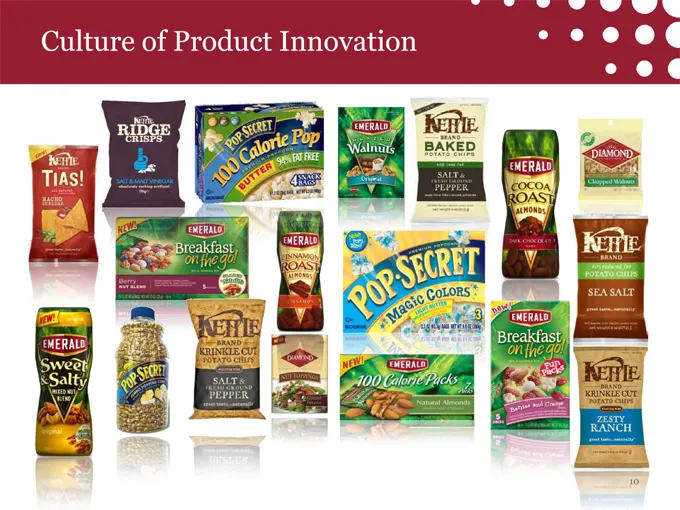
Culture of Product Innovation 10
Slide 11: Emerald: Sweet Platform Innovation
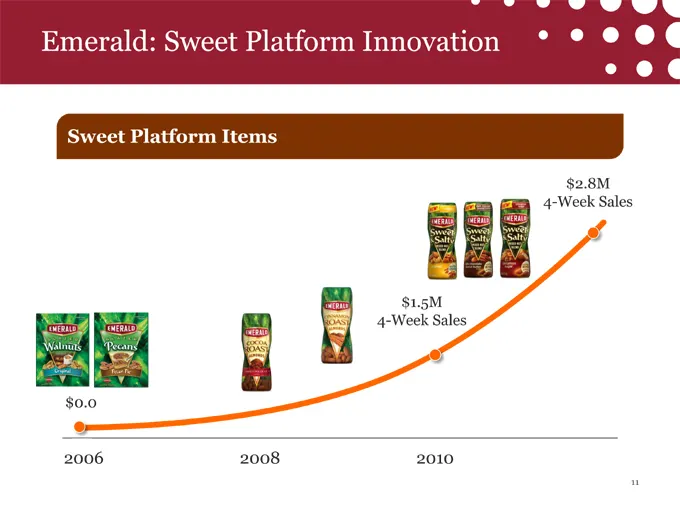
Emerald: Sweet Platform Innovation Sweet Platform Items $2.8M 4-Week Sales $1.5M 4-Week Sales $0.0 2006 2008 2010 11
Slide 12: Expanding Better-for-You Innovation
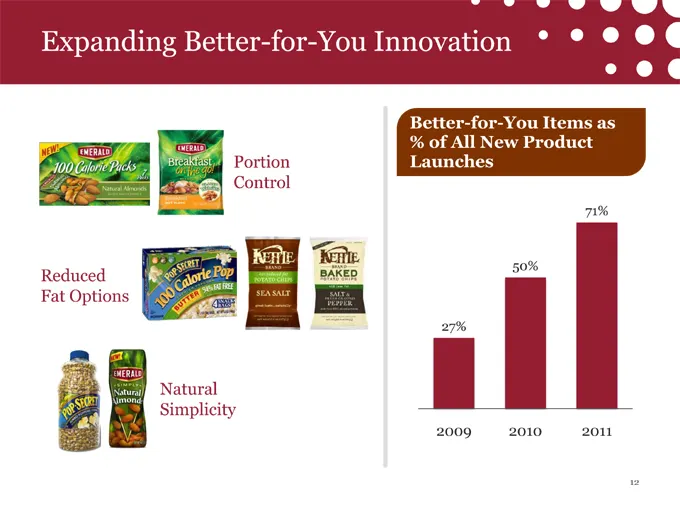
Expanding Better-for-You Innovation Better-for-You Items as % of All New Product Portion Launches Control 71% 50% Reduced Fat Options 27% Natural Simplicity 2009 2010 2011 12
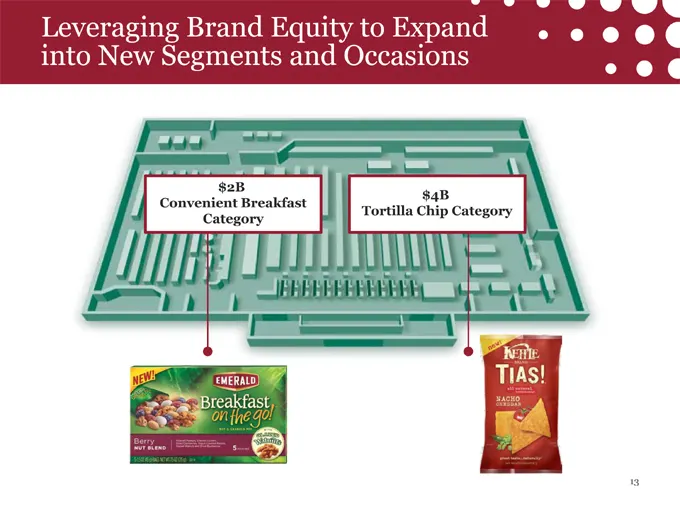
Slide 13: Leveraging Brand Equity to Expand into New Segments and Occasions
Leveraging Brand Equity to Expand into New Segments and Occasions $2B $4B Convenient Breakfast Tortilla Chip Category Category 13
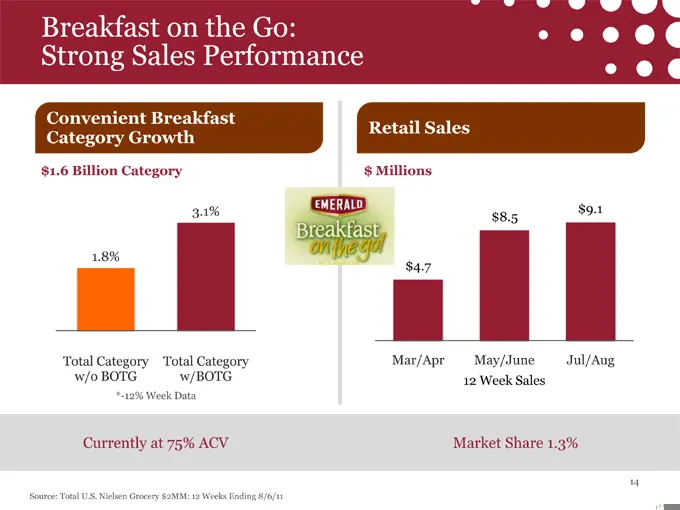
Slide 14: Breakfast on the Go: Strong Sales Performance
Breakfast on the Go: Strong Sales Performance Convenient Breakfast Retail Sales Category Growth $1.6 Billion Category $ Millions 3.1% $9.1 $8.5 1.8% $4.7 Total Category Total Category Mar/Apr May/June Jul/Aug w/o BOTG w/BOTG 12 Week Sales *-12% Week Data Currently at 75% ACV Market Share 1.3% 14 Sou
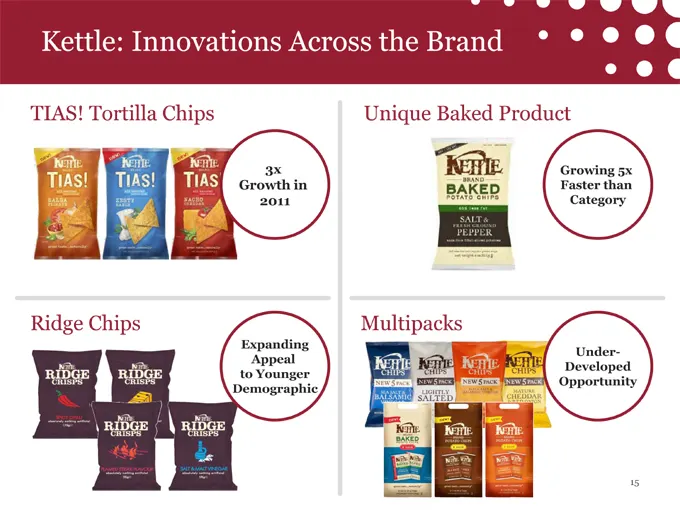
Slide 15: Kettle: Innovations Across the Brand
Kettle: Innovations Across the Brand TIAS! Tortilla Chips Unique Baked Product 3x Growing 5x Growth in Faster than 2011 Category Ridge Chips Multipacks Expanding Under-Appeal Developed to Younger Opportunity Demographic 15
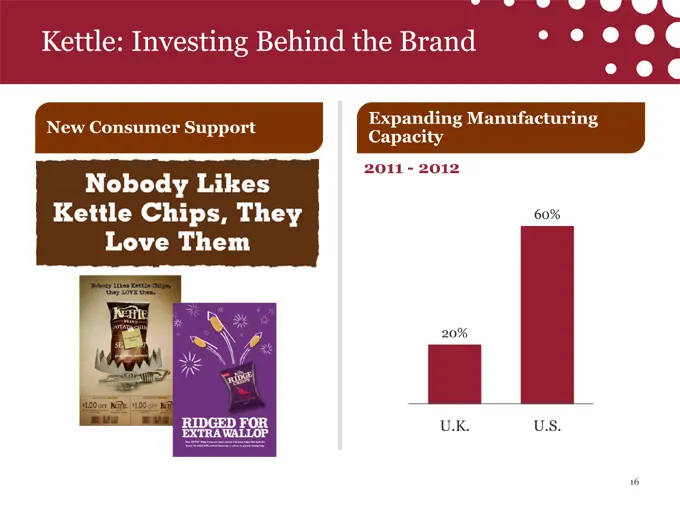
Slide 16: Kettle: Investing Behind the Brand
Kettle: Investing Behind the Brand Expanding Manufacturing New Consumer Support Capacity 2011—2012 60% 20% U.K. U.S. 16
Slide 17: Pop Secret: Exceeding Expectations
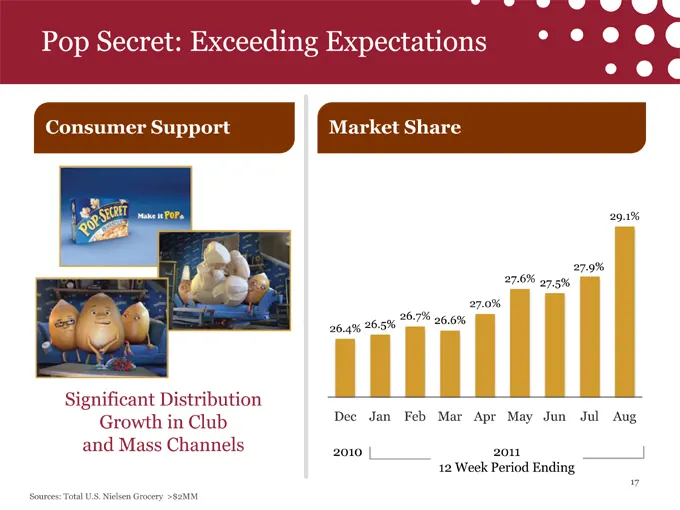
Pop Secret: Exceeding Expectations Consumer Support Market Share 29.1% 27.9% 27.6% 27.5% 27.0% 26.7% 26.6% 26.4% 26.5% Significant Distribution Growth in Club Dec Jan Feb Mar Apr May Jun Jul Aug and Mass Channels 2010 2011 12 Week Period Ending 17 Sources: Total U.S. Nielsen Grocery >$2MM
Slide 18: Pringles: Innovation and Customization by Market
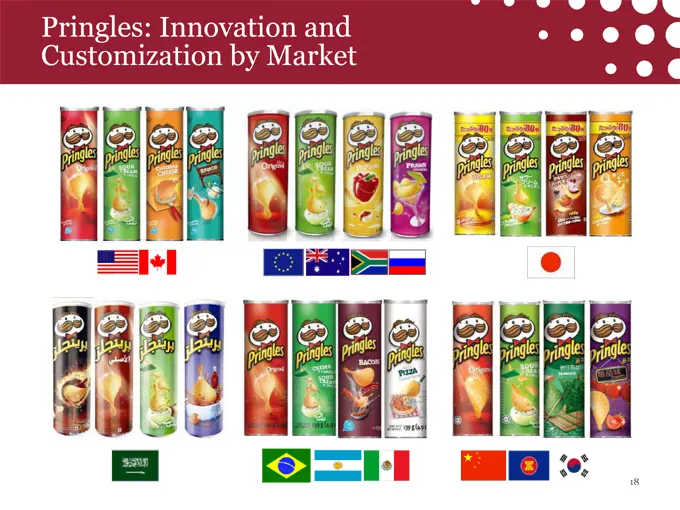
Pringles: Innovation and Customization by Market 18
Slide 19: Pringles: New Products
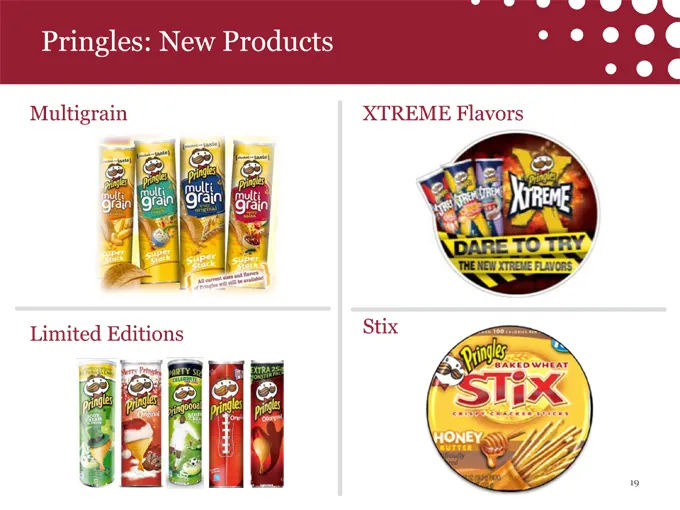
Pringles: New Products Multigrain XTREME Flavors Limited Editions Stix 19
Slide 20: History of Brand Building and Retail Execution
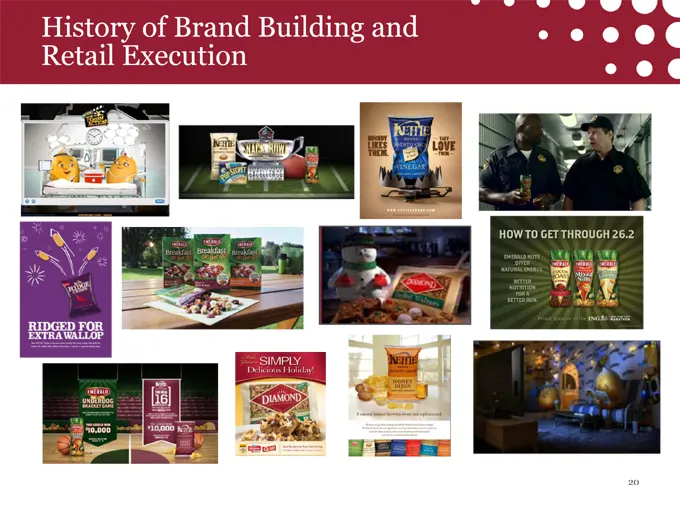
History of Brand Building and Retail Execution 20
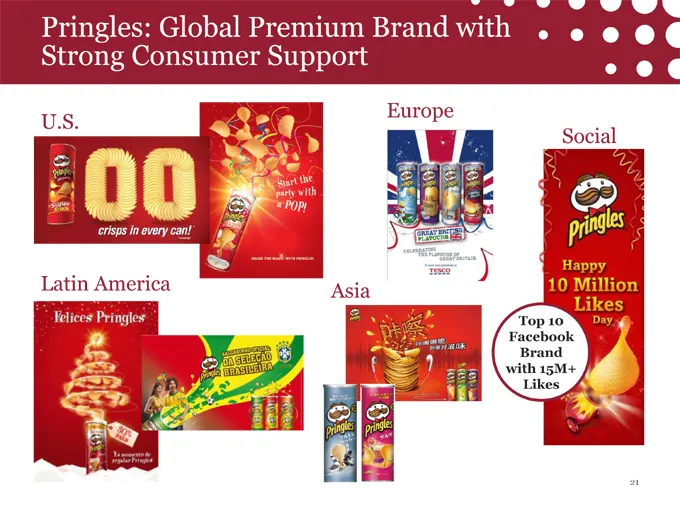
Slide 21: Pringles: Global Premium Brand with Strong Consumer Support
Pringles: Global Premium Brand with Strong Consumer Support Europe U.S. Social Latin America Asia Top 10 Facebook Brand with 15M+ Likes 21
Slide 22: Lloyd J. Johnson, EVP and Chief Sales Officer
Lloyd J. Johnson EVP and Chief Sales Officer
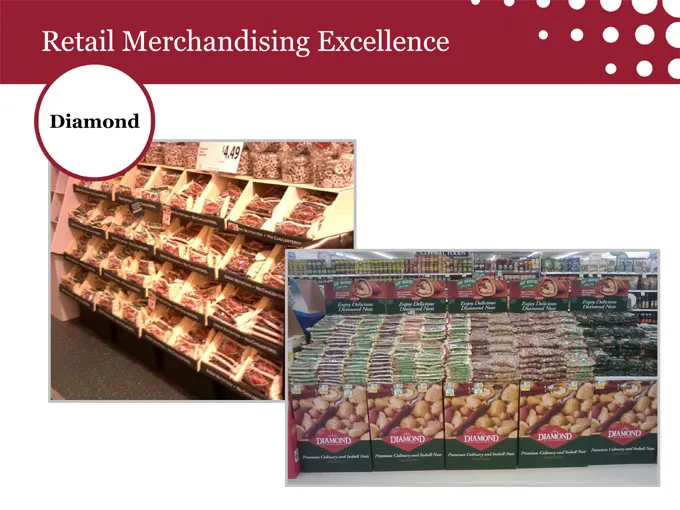
Slide 23: Retail Merchandising Excellence: Diamond
Retail Merchandising Excellence Diamond
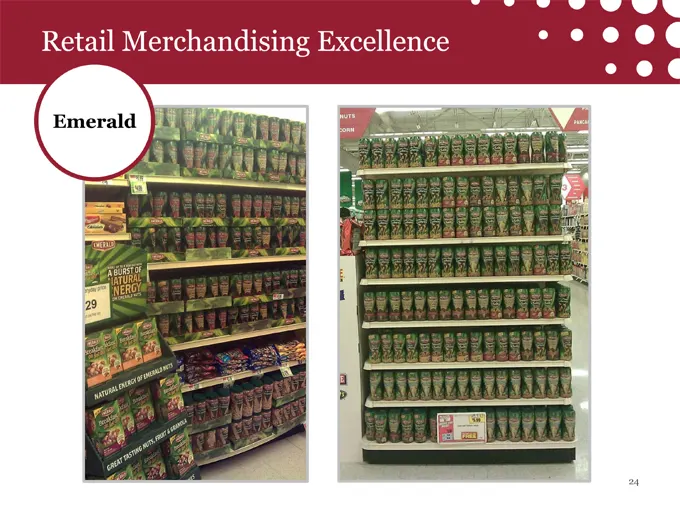
Slide 24: Retail Merchandising Excellence: Emerald
Retail Merchandising Excellence Emerald
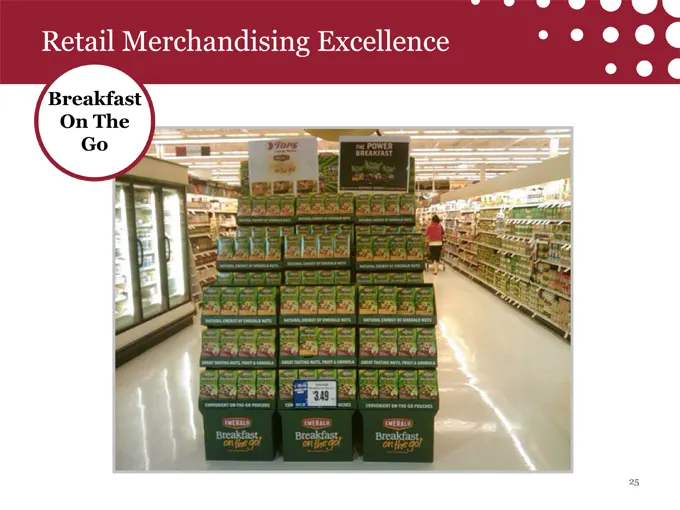
Slide 25: Retail Merchandising Excellence: Breakfast On The Go
Retail Merchandising Excellence Breakfast On The Go
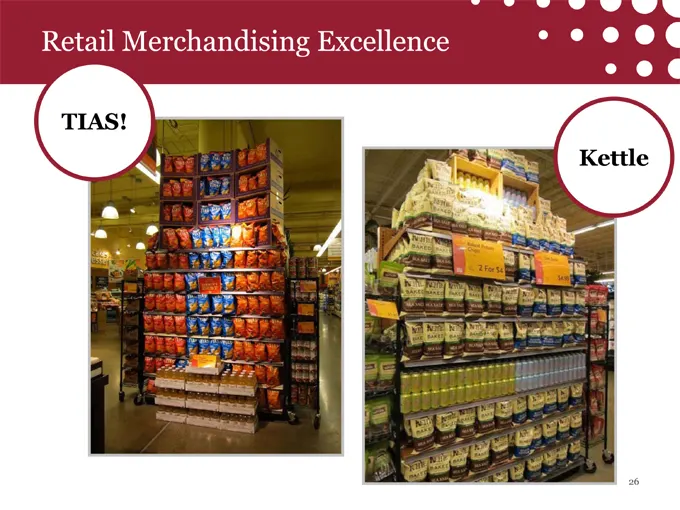
Slide 26: Retail Merchandising Excellence: TIAS! Kettle
Retail Merchandising Excellence TIAS! Kettle
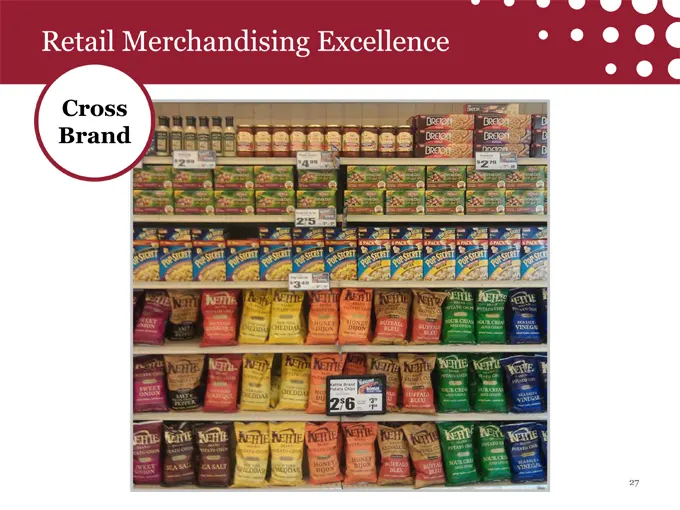
Slide 27: Retail Merchandising Excellence: Cross Brand
Retail Merchandising Excellence Cross Brand
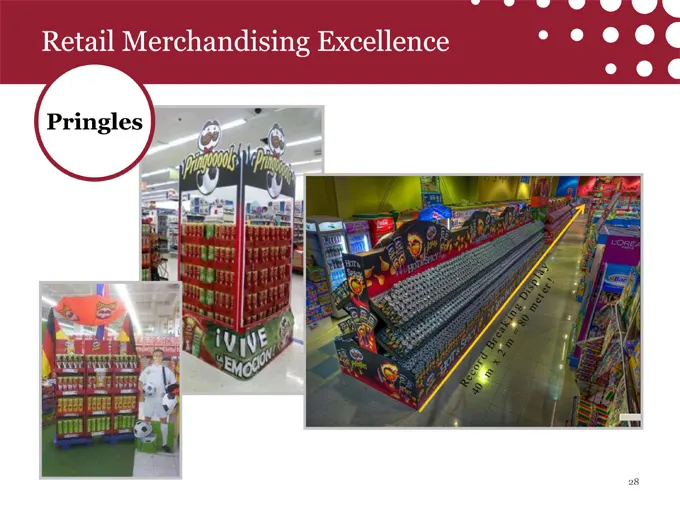
Slide 28: Retail Merchandising Excellence: Pringles
Retail Merchandising Excellence Pringles 28
Slide 29: Significant U.S. Distribution Runway
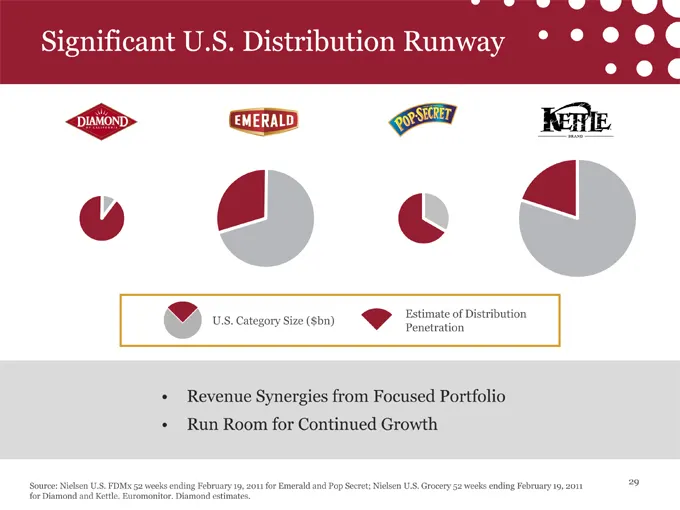
Significant U.S. Distribution Runway Estimate of Distribution U.S. Category Size ($bn) Penetration • Revenue Synergies from Focused Portfolio • Run Room for Continued Growth 29 Source: Nielsen U.S. FDMx 52 weeks ending February 19, 2011 for Emerald and Pop Secret; Nielsen U.S. Grocery 52 weeks endin
Slide 30: Diversified U.S. Retail Channel Presence
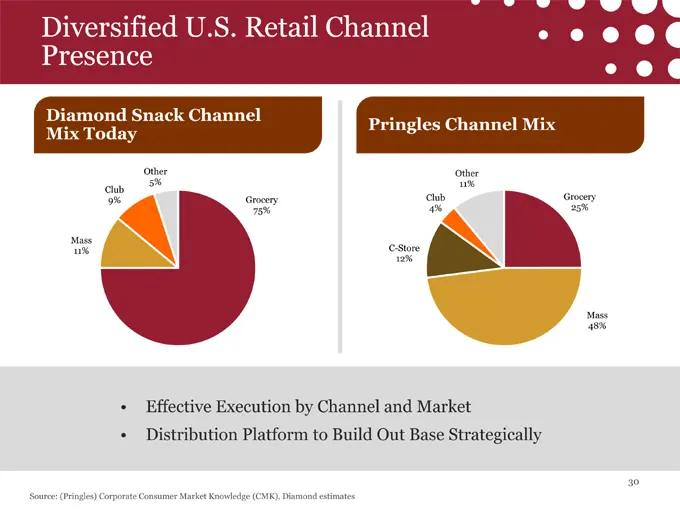
Diversified U.S. Retail Channel Presence Diamond Snack Channel Pringles Channel Mix Mix Today Other Other 5% 11% Club 9% Grocery Club Grocery 75% 4% 25% Mass 11% C-Store 12% Mass 48% • Effective Execution by Channel and Market • Distribution Platform to Build Out Base Strategically 30 Source: (Pring
Slide 31: Steven M. Neil, EVP, Chief Financial and Administrative Officer
Steven M. Neil EVP, Chief Financial and Administrative Officer
Slide 32: Pringles: Attractive Integration Opportunity
Pringles: Attractive Integration Opportunity • Iconic, Profitable $1B+ Brand • Geographic Diversity • Worldwide Manufacturing Footprint • Global Distribution Reach • Financially Compelling Fit 32
Slide 33: Product and Manufacturing Advantages
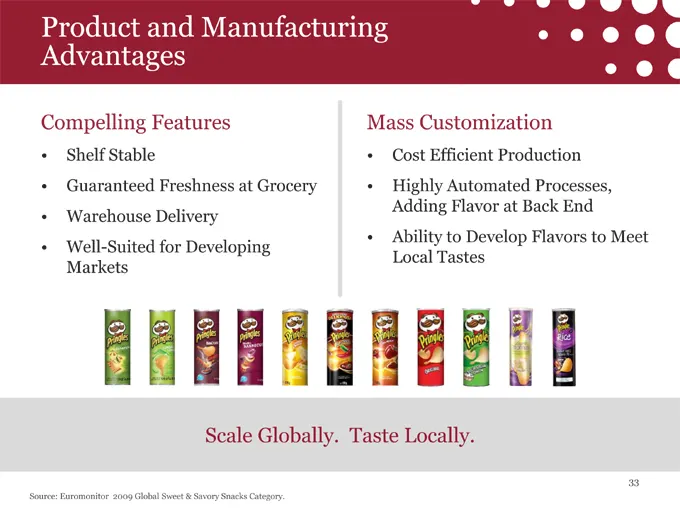
Product and Manufacturing Advantages Compelling Features Mass Customization • Shelf Stable • Cost Efficient Production • Guaranteed Freshness at Grocery • Highly Automated Processes, Adding Flavor at Back End • Warehouse Delivery • Ability to Develop Flavors to Meet • Well-Suited for Developing Loca
Slide 34: Strengthened Snack Platform and Geographic Diversity
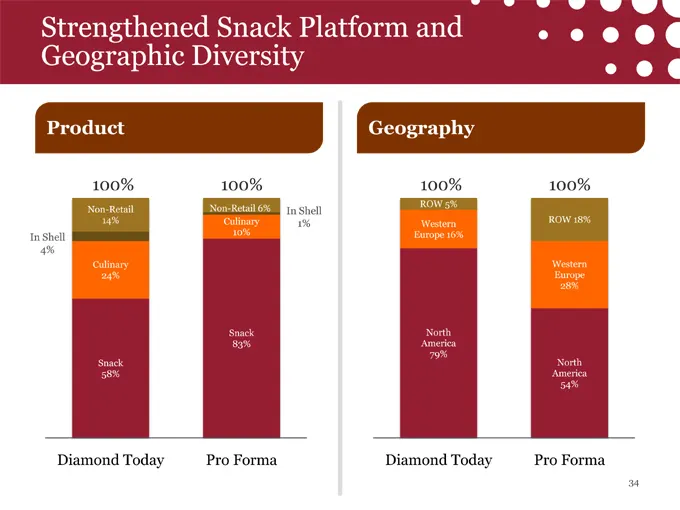
Strengthened Snack Platform and Geographic Diversity Product Geography 100% 100% 100% 100% Non-Retail 6% ROW 5% Non-Retail In Shell 14% Culinary 1% Western ROW 18% 10% Europe 16% In Shell 4% Culinary Western 24% Europe 28% Snack North 83% America Snack 79% North 58% America 54% Diamond Today Pro For
Slide 35: Global Manufacturing and Distribution Footprint
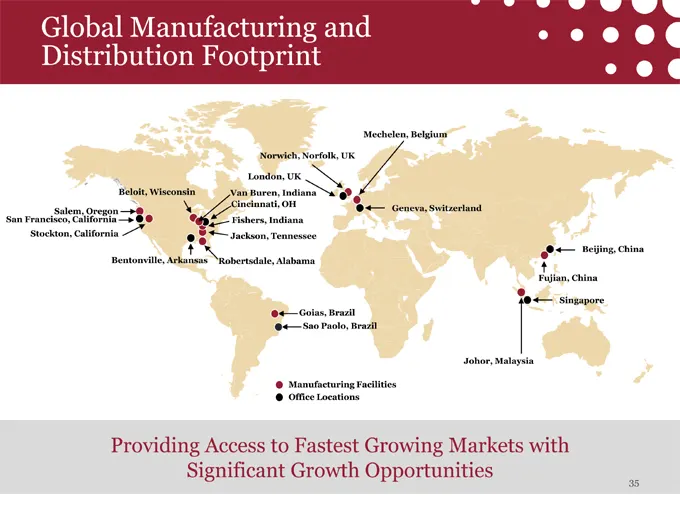
Global Manufacturing and Distribution Footprint Mechelen, Belgium Norwich, Norfolk, UK London, UK Beloit, Wisconsin Van Buren, Indiana Cincinnati, OH Salem, Oregon Geneva, Switzerland San Francisco, California Fishers, Indiana Stockton, California Jackson, Tennessee Beijing, China Bentonville, Arkan
Slide 36: Significant Increase in Cash Generation
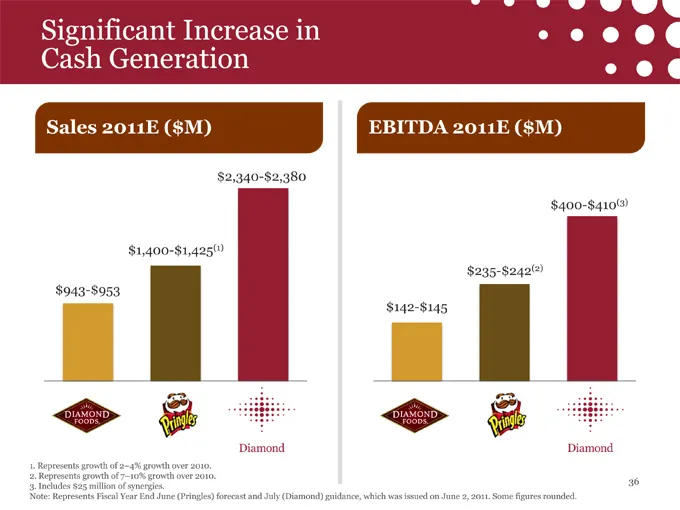
Significant Increase in Cash Generation Sales 2011E ($M) EBITDA 2011E ($M) $2,340-$2,380 $400-$410(3) $1,400-$1,425(1) $235-$242(2) $943-$953 $142-$145 1. Represents growth of 2–4% growth over 2010. 2. Represents growth of 7–10% growth over 2010. 36 3. Includes $25 million of synergies. Note: Repres
Slide 37: Margin Expansion and De-Levering
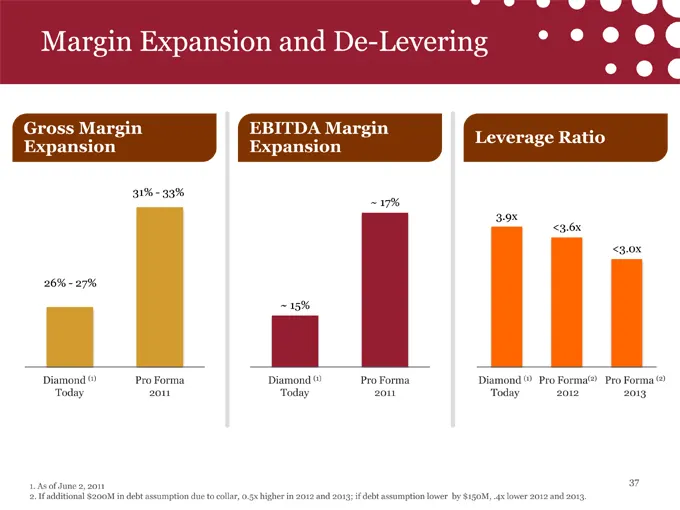
Margin Expansion and De-Levering Gross Margin EBITDA Margin Leverage Ratio Expansion Expansion 31%—33% ~ 17% 3.9x <3.6x <3.0x 26%—27% ~ 15% Diamond (1) Pro Forma Diamond (1) Pro Forma Diamond (1) Pro Forma(2) Pro Forma (2) Today 2011 Today 2011 Today 2012 2013 37 1. As of June 2, 2011 2. If addition
Slide 38: Mitigating Commodity Headwinds
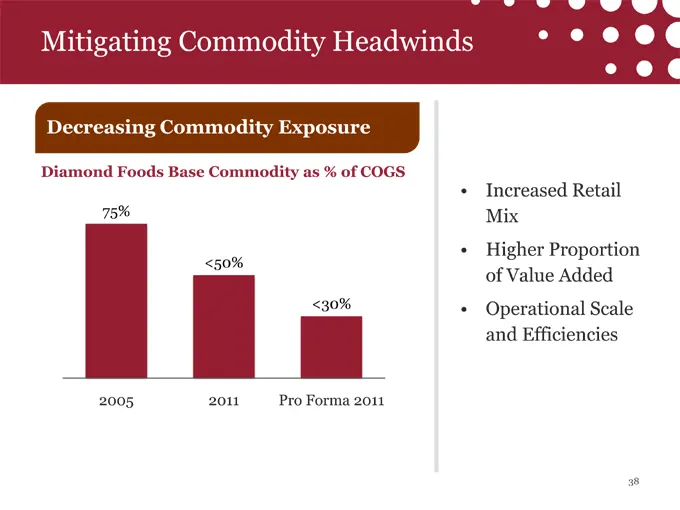
Mitigating Commodity Headwinds Decreasing Commodity Exposure Diamond Foods Base Commodity as % of COGS • Increased Retail 75% Mix • Higher Proportion <50% of Value Added <30% • Operational Scale and Efficiencies 2005 2011 Pro Forma 2011 38
Slide 39: Financial Targets
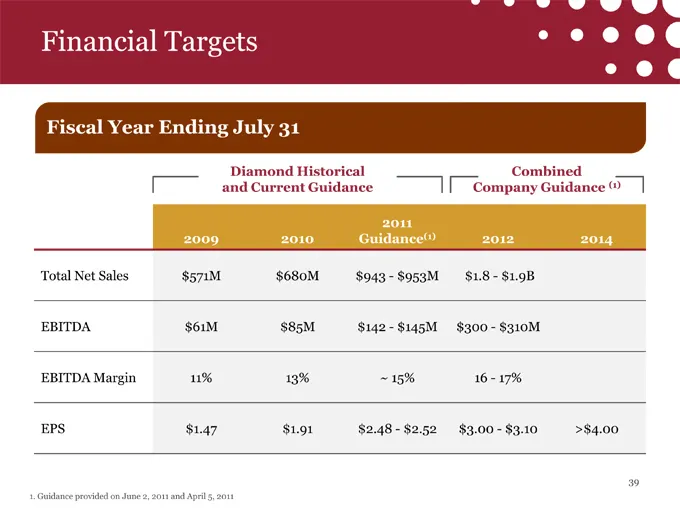
Financial Targets Fiscal Year Ending July 31 Diamond Historical Combined and Current Guidance Company Guidance (1) 2011 2009 2010 Guidance(1) 2012 2014 Total Net Sales $571M $680M $943—$953M $1.8—$1.9B EBITDA $61M $85M $142—$145M $300—$310M EBITDA Margin 11% 13% ~ 15% 16—17% EPS $1.47 $1.91 $2.48—$2
Slide 40: Platform for Future Growth
Platform for Future Growth Innovation Execution Integration Dynamic Strong Proven 40
Slide 41: Diamond Foods Platform for Future Growth
Diamond Foods Platform for Future Growth Diamond
Source: SEC EDGAR · 425 filed Sep 7, 2011
More decks from Diamond Foods Inc
 Investor Presentation (June 2013)21 slides · Jun 17, 2013
 Investor Presentation (April 2013)21 slides · Apr 29, 2013
 Investor Presentation (February 2013)20 slides · Feb 26, 2013
 Q3 2012 Earnings Presentation18 slides · Nov 14, 2012
 Debt Investor Presentation (May 2012)18 slides · May 23, 2012
 Merger or Acquisition (June 2011)23 slides · Jun 21, 2011