Capstar Financial Holdings Inc
Capstar Financial — Investor Presentation (May 2017)
40 slides from Capstar Financial's investor presentation, May 10, 2017
Slide 1: Investor Presentation May 2017
Nasdaq: CSTR Investor Presentation May 2017 Claire W. Tucker, President and Chief Executive Officer Rob Anderson, Chief Financial Officer and Chief Administrative Officer Exhibit 99.1
Slide 2: Terminology, Market Data and Non-GAAP Disclaimer
Terminology The terms “we,” “our,” “us,” “the Company,” “CSTR” and “CapStar” that appear in this presentation refer to CapStar Financial Holdings, Inc. and its wholly-owned subsidiary, CapStar Bank. The terms “CapStar Bank,” “the bank” and “our bank” that appear in this presentation refer CapStar Ba
Slide 3: Forward-Looking Statements
Certain statements in this presentation are forward-looking statements that reflect our current views with respect to, among other things, future events and our financial and operational performance. These statements are often, but not always, made through the use of words or phrases such as “may,”
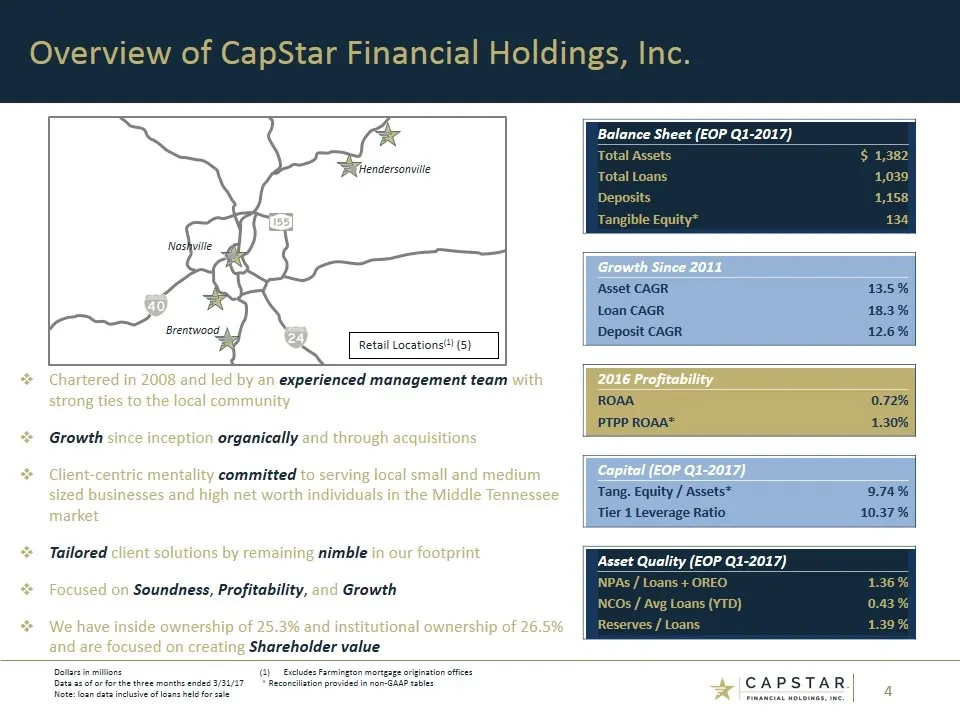
Slide 4: Overview of CapStar Financial Holdings, Inc.
Overview of CapStar Financial Holdings, Inc. Chartered in 2008 and led by an experienced management team with strong ties to the local community Growth since inception organically and through acquisitions Client-centric mentality committed to serving local small and medium sized businesses and high
Slide 5: Our Growth has Predominantly Been Organic
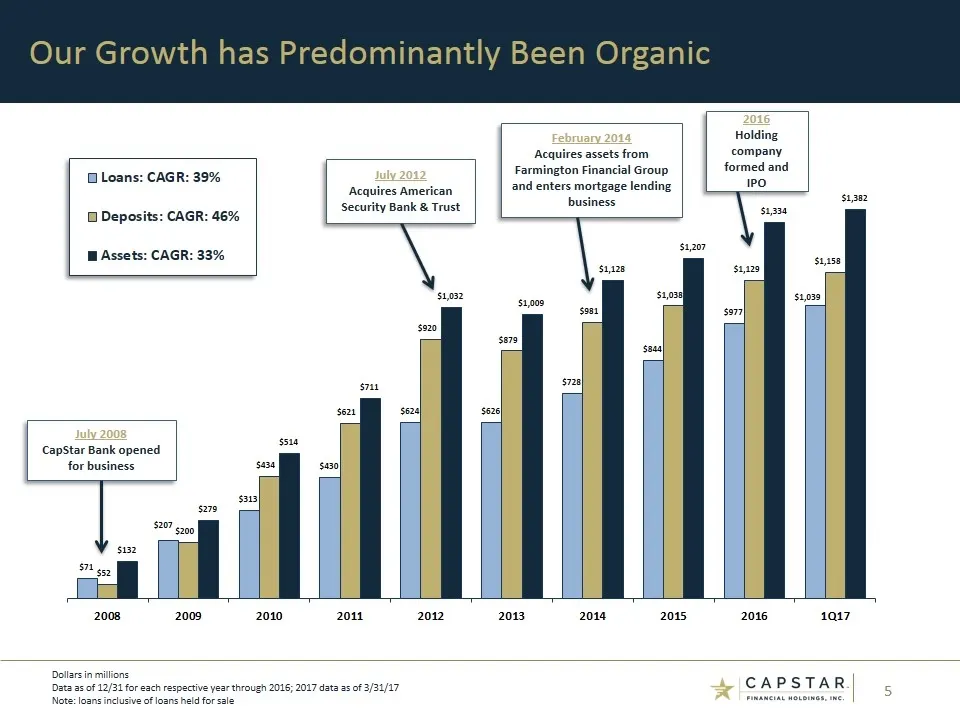
Our Growth has Predominantly Been Organic Dollars in millions Data as of 12/31 for each respective year through 2016; 2017 data as of 3/31/17 Note: loans inclusive of loans held for sale July 2008 CapStar Bank opened for business July 2012 Acquires American Security Bank & Trust February 2014 Acquir
Slide 6: Nashville Deposit Market Share
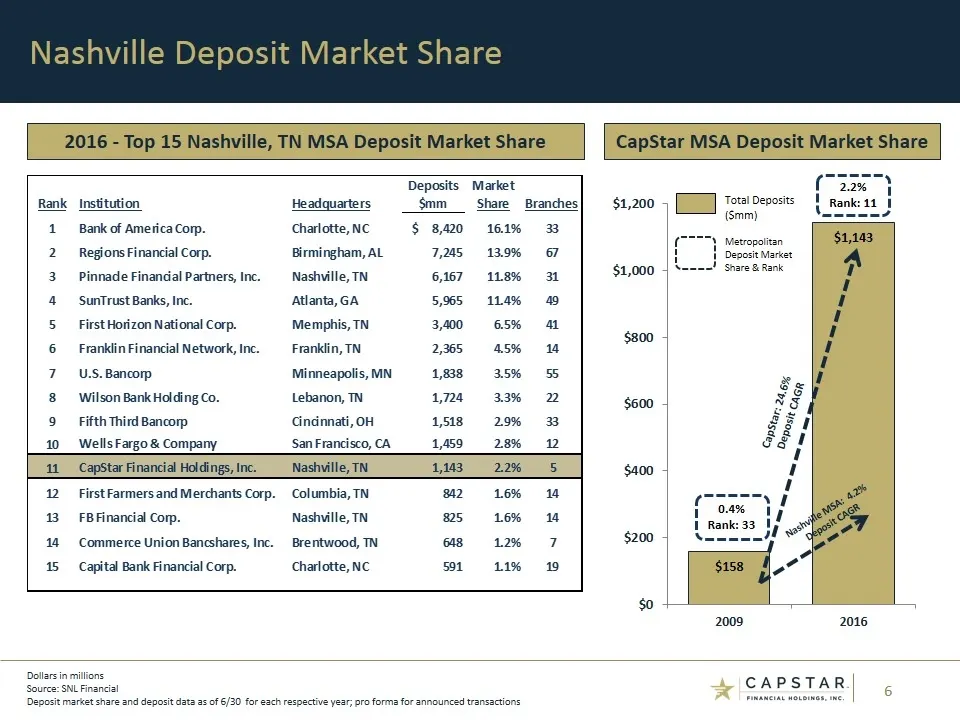
Nashville Deposit Market Share Dollars in millions Source: SNL Financial Deposit market share and deposit data as of 6/30 for each respective year; pro forma for announced transactions 2016 - Top 15 Nashville, TN MSA Deposit Market Share CapStar MSA Deposit Market Share 2.2% Rank: 11 CapStar: 24.6%
Slide 7: Franchise Highlights
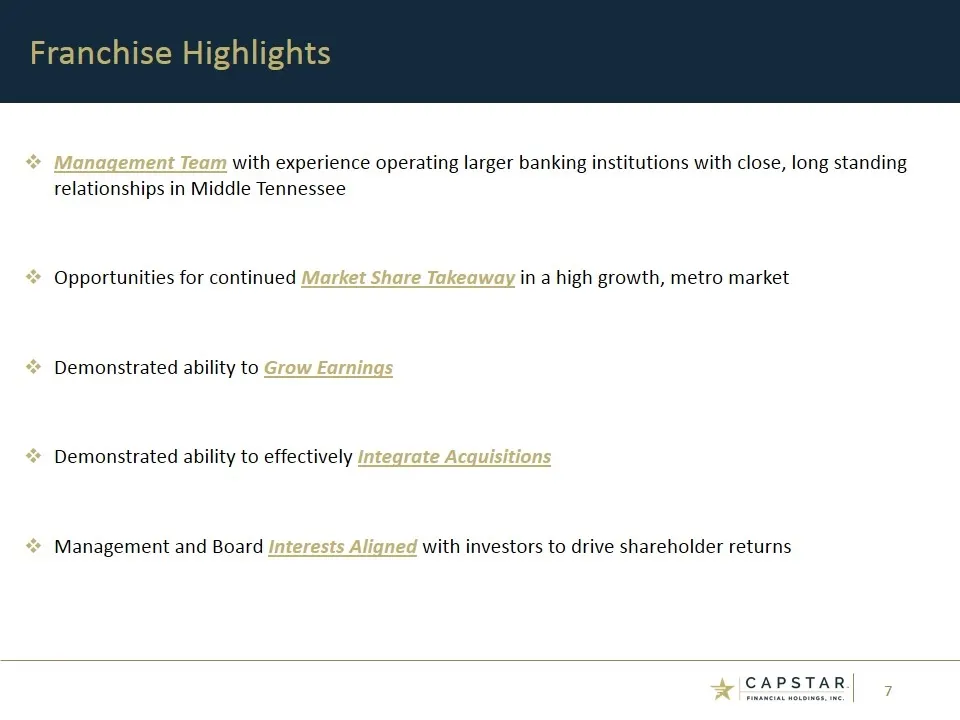
Franchise Highlights Management Team with experience operating larger banking institutions with close, long standing relationships in Middle Tennessee Opportunities for continued Market Share Takeaway in a high growth, metro market Demonstrated ability to Grow Earnings Demonstrated ability to effect
Slide 8: Our Culture
Experienced bankers with extensive industry knowledge Product expertise in a range of business sectors Strong credit quality Tailored client solutions Funding focus on core deposits Organic and acquisitive growth Our Culture
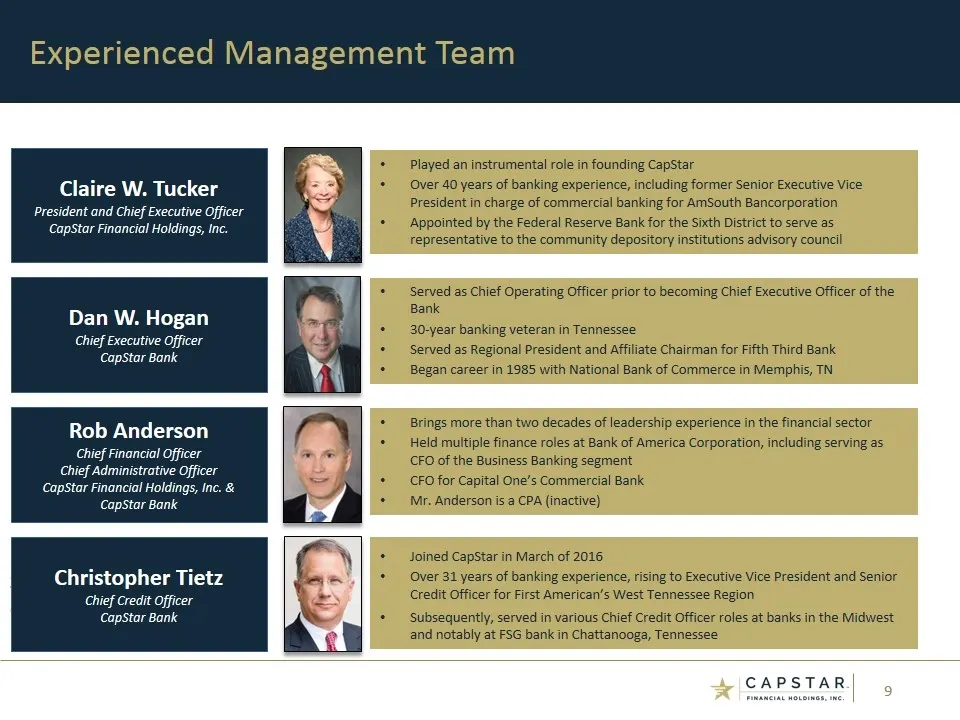
Slide 9: Experienced Management Team
Joined CapStar in March of 2016 Over 31 years of banking experience, rising to Executive Vice President and Senior Credit Officer for First American’s West Tennessee Region Subsequently, served in various Chief Credit Officer roles at banks in the Midwest and notably at FSG bank in Chattanooga, Tenn
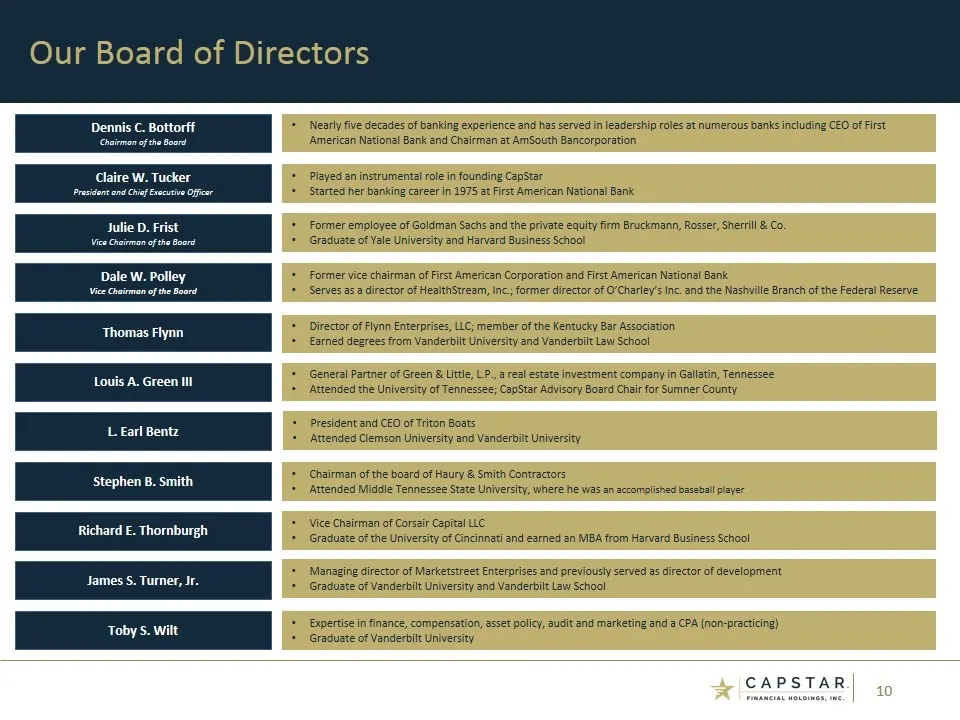
Slide 10: Our Board of Directors
Our Board of Directors Claire W. Tucker President and Chief Executive Officer Played an instrumental role in founding CapStar Started her banking career in 1975 at First American National Bank Dennis C. Bottorff Chairman of the Board Nearly five decades of banking experience and has served in leader
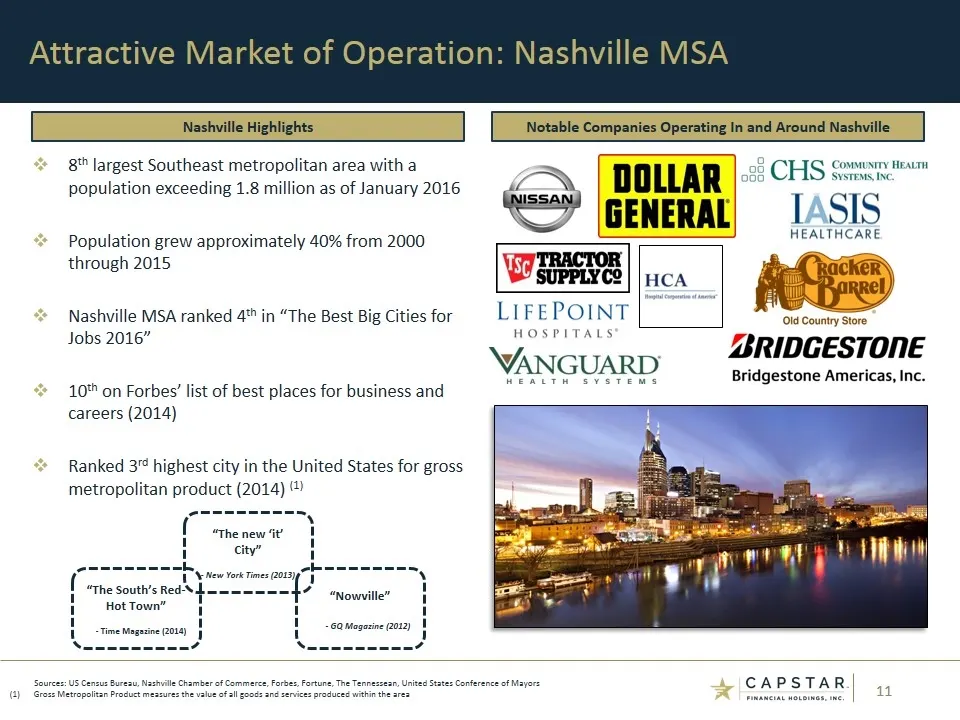
Slide 11: Attractive Market of Operation: Nashville MSA
8th largest Southeast metropolitan area with a population exceeding 1.8 million as of January 2016 Population grew approximately 40% from 2000 through 2015 Nashville MSA ranked 4th in “The Best Big Cities for Jobs 2016” 10th on Forbes’ list of best places for business and careers (2014) Ranked 3rd h
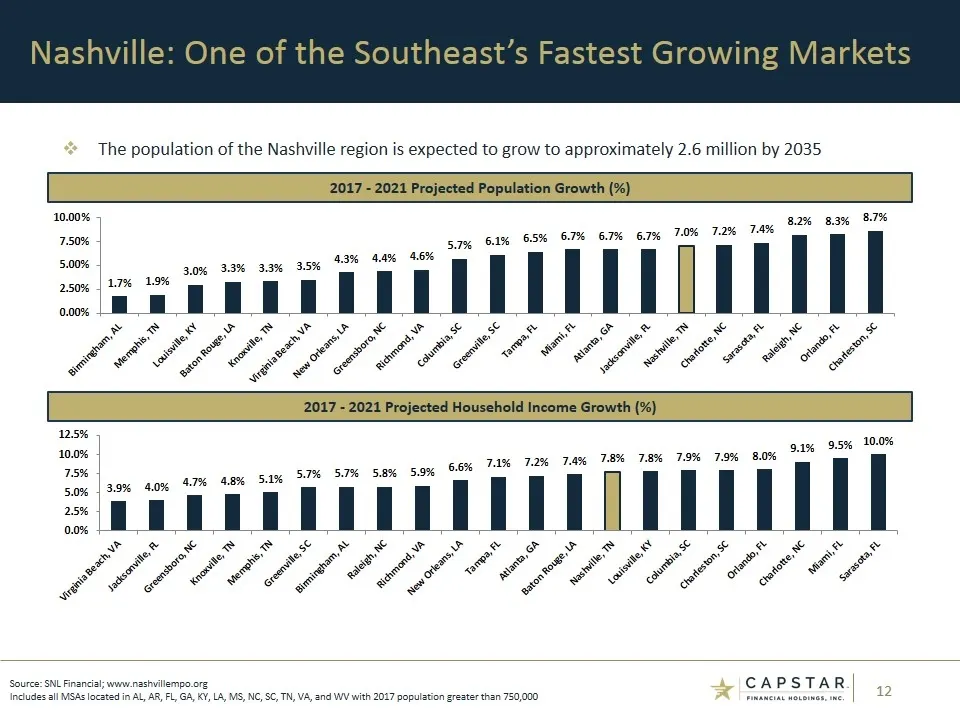
Slide 12: Nashville: One of the Southeast's Fastest Growing Markets
The population of the Nashville region is expected to grow to approximately 2.6 million by 2035 Nashville: One of the Southeast’s Fastest Growing Markets Source: SNL Financial; www.nashvillempo.org Includes all MSAs located in AL, AR, FL, GA, KY, LA, MS, NC, SC, TN, VA, and WV with 2017 population g
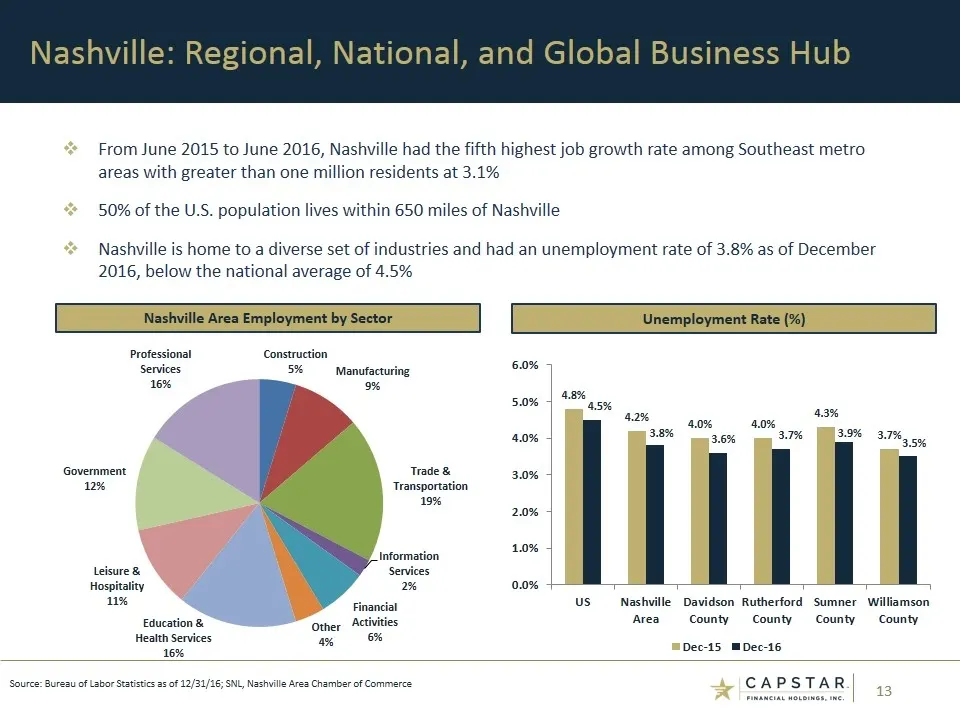
Slide 13: Nashville: Regional, National, and Global Business Hub
From June 2015 to June 2016, Nashville had the fifth highest job growth rate among Southeast metro areas with greater than one million residents at 3.1% 50% of the U.S. population lives within 650 miles of Nashville Nashville is home to a diverse set of industries and had an unemployment rate of 3.8
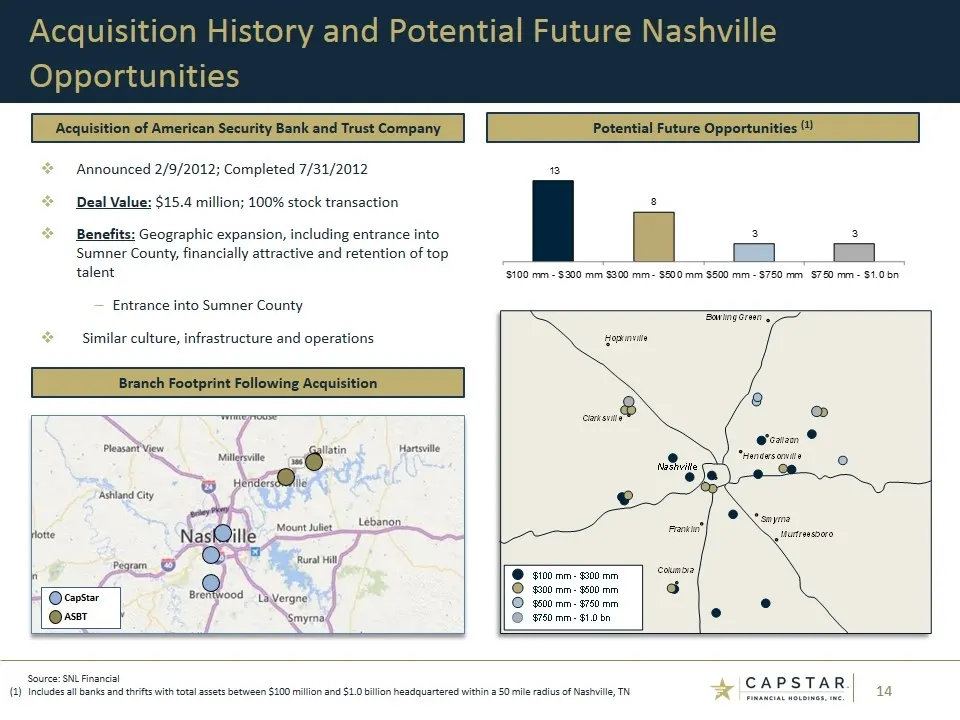
Slide 14: Acquisition History and Potential Future Nashville Opportunities
Announced 2/9/2012; Completed 7/31/2012 Deal Value: $15.4 million; 100% stock transaction Benefits: Geographic expansion, including entrance into Sumner County, financially attractive and retention of top talent Entrance into Sumner County Similar culture, infrastructure and operations Acquisition H
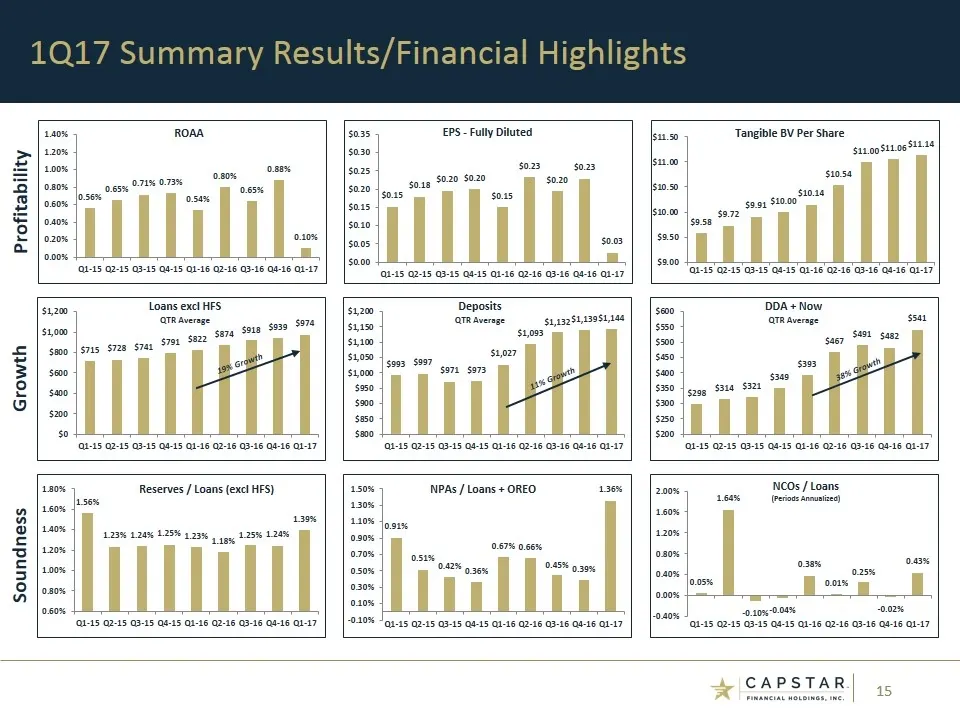
Slide 15: 1Q17 Summary Results/Financial Highlights
1Q17 Summary Results/Financial Highlights Soundness Profitability Growth 19% Growth 11% Growth 38% Growth
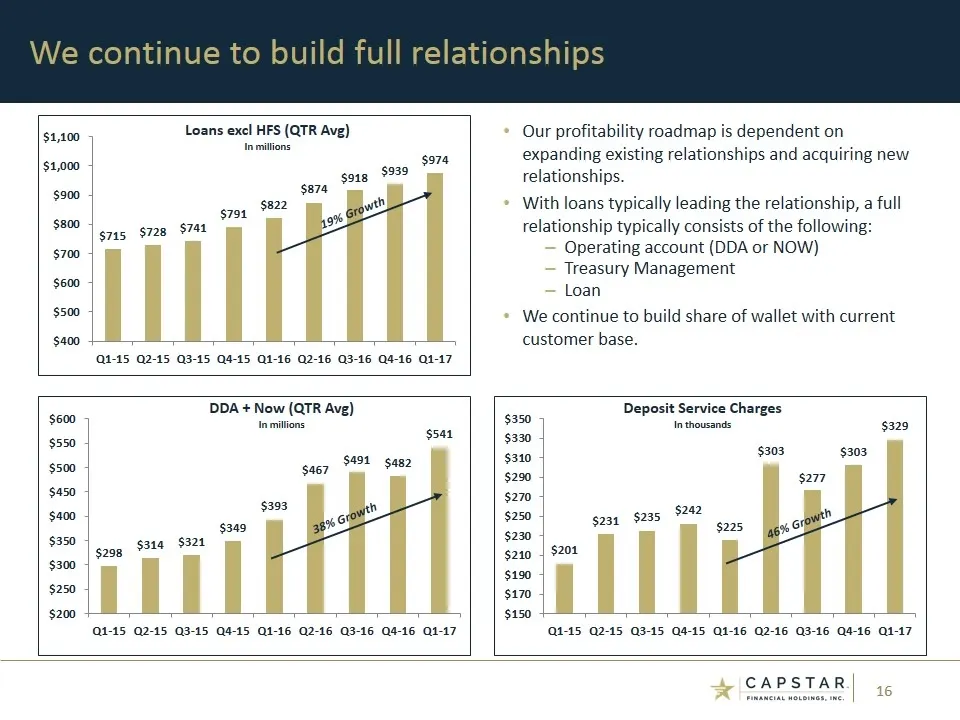
Slide 16: Profitability Roadmap: Building Full Relationships
Our profitability roadmap is dependent on expanding existing relationships and acquiring new relationships. With loans typically leading the relationship, a full relationship typically consists of the following: Operating account (DDA or NOW) Treasury Management Loan We continue to build share of wa
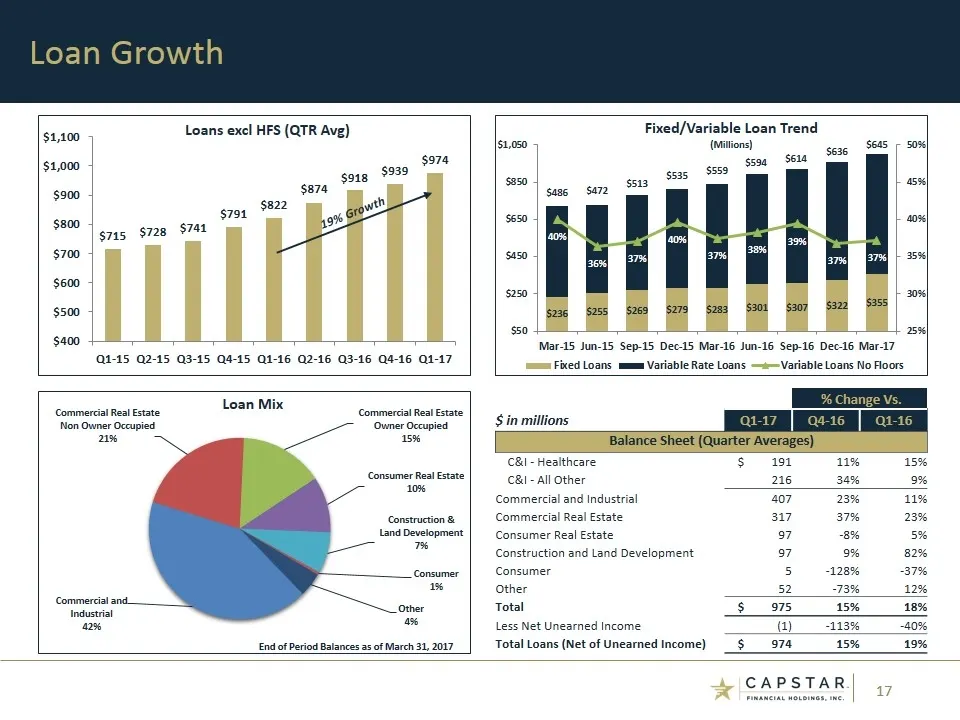
Slide 17: Loan Growth
Loan Growth 19% Growth % Change Vs. $ in millions Q1-17 Q4-16 Q1-16 Balance Sheet (Quarter Averages) C&I - Healthcare $ 191 11% 15% C&I - All Other 216 34% 9% Commercial and Industrial 407 23% 11% Commercial Real Estate 317 37% 23% Consumer Real Estate 97 -8% 5% Construction and Land Development 97
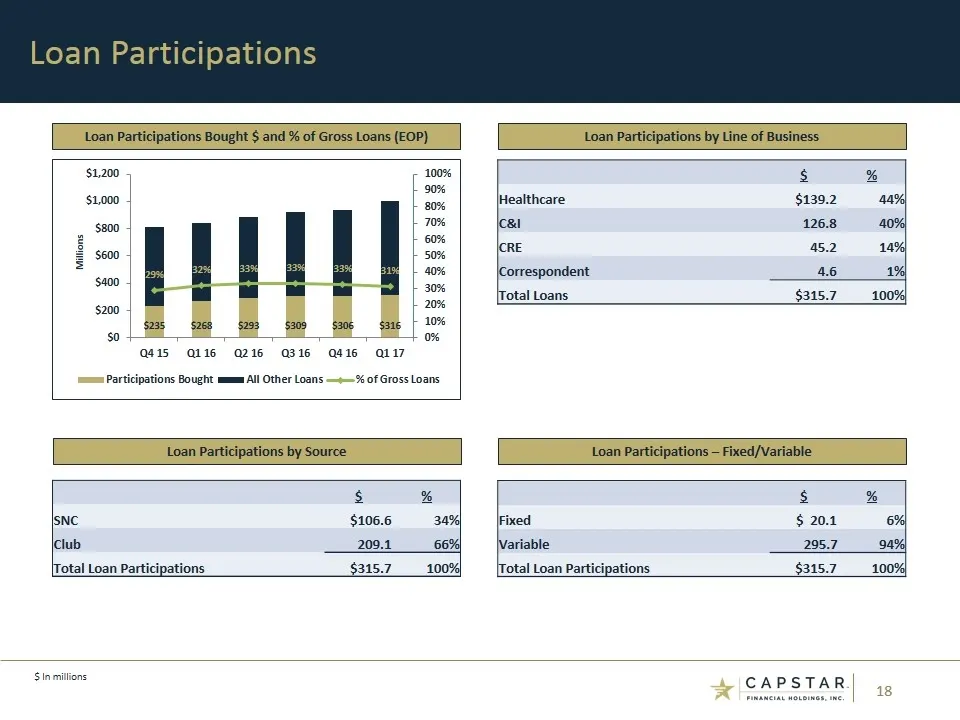
Slide 18: Loan Participations
Loan Participations $ % Fixed $ 20.1 6% Variable 295.7 94% Total Loan Participations $315.7 100% Loan Participations by Source Loan Participations – Fixed/Variable Loan Participations Bought $ and % of Gross Loans (EOP) Loan Participations by Line of Business $ % Healthcare $139.2 44% C&I 126.8 40%
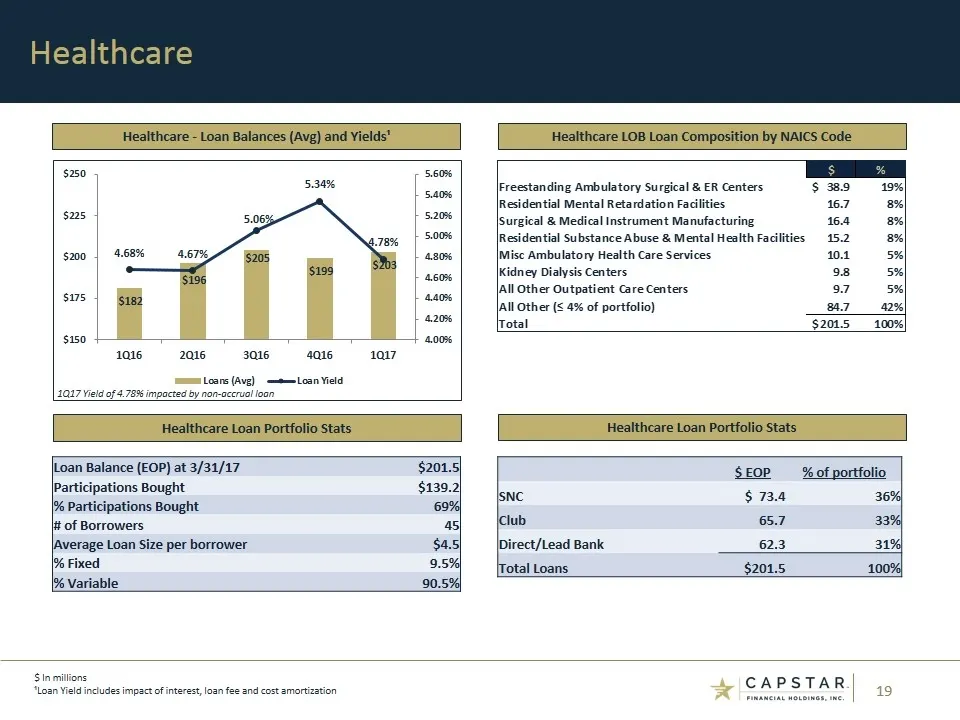
Slide 19: Healthcare Loan Portfolio
Healthcare Loan Balance (EOP) at 3/31/17 $201.5 Participations Bought $139.2 % Participations Bought 69% # of Borrowers 45 Average Loan Size per borrower $4.5 % Fixed 9.5% % Variable 90.5% $ EOP % of portfolio SNC $ 73.4 36% Club 65.7 33% Direct/Lead Bank 62.3 31% Total Loans $201.5 100% Healthcare
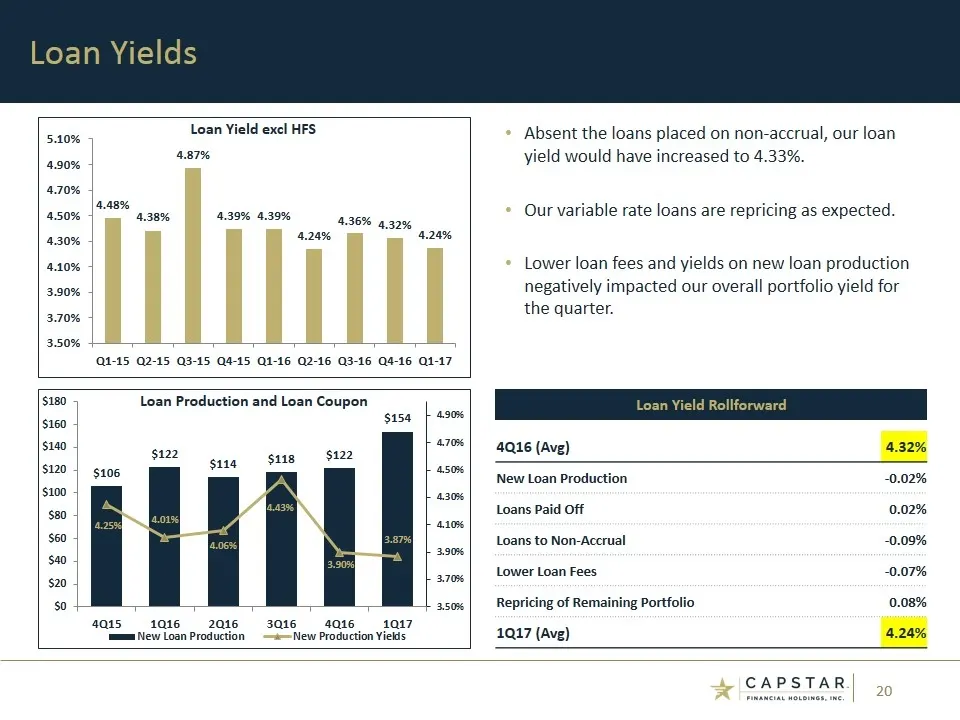
Slide 20: Loan Yields
Loan Yields Absent the loans placed on non-accrual, our loan yield would have increased to 4.33%. Our variable rate loans are repricing as expected. Lower loan fees and yields on new loan production negatively impacted our overall portfolio yield for the quarter. Loan Yield Rollforward 4Q16 (Avg) 4.
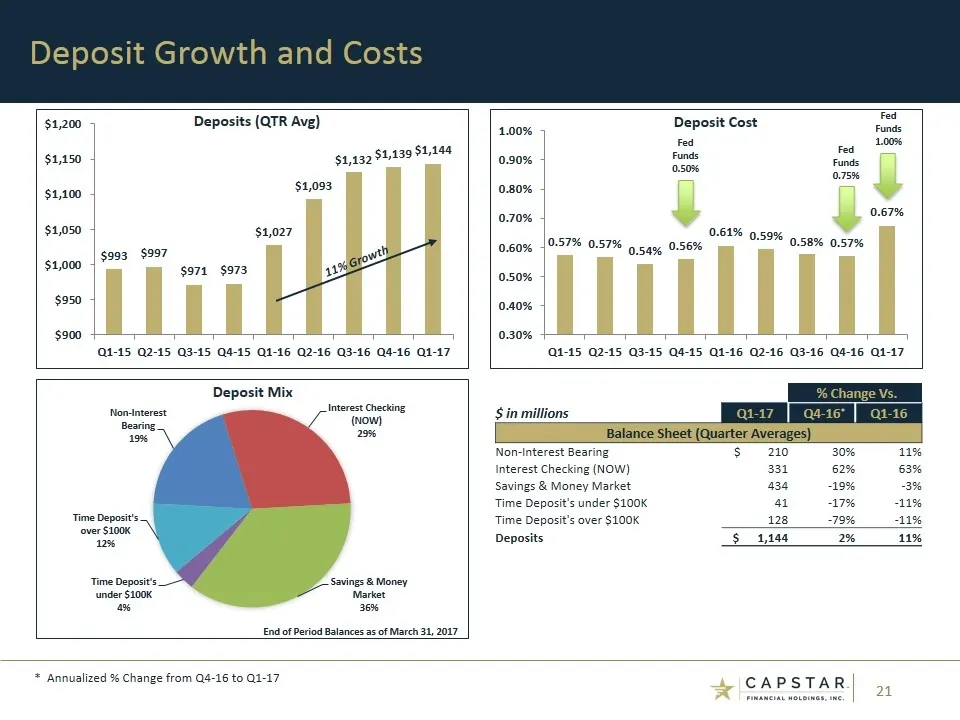
Slide 21: Deposit Growth and Costs
Deposit Growth and Costs 11% Growth % Change Vs. $ in millions Q1-17 Q4-16 Q1-16 Balance Sheet (Quarter Averages) Non-Interest Bearing $ 210 30% 11% Interest Checking (NOW) 331 62% 63% Savings & Money Market 434 -19% -3% Time Deposit's under $100K 41 -17% -11% Time Deposit's over $100K 128 -79% -11%
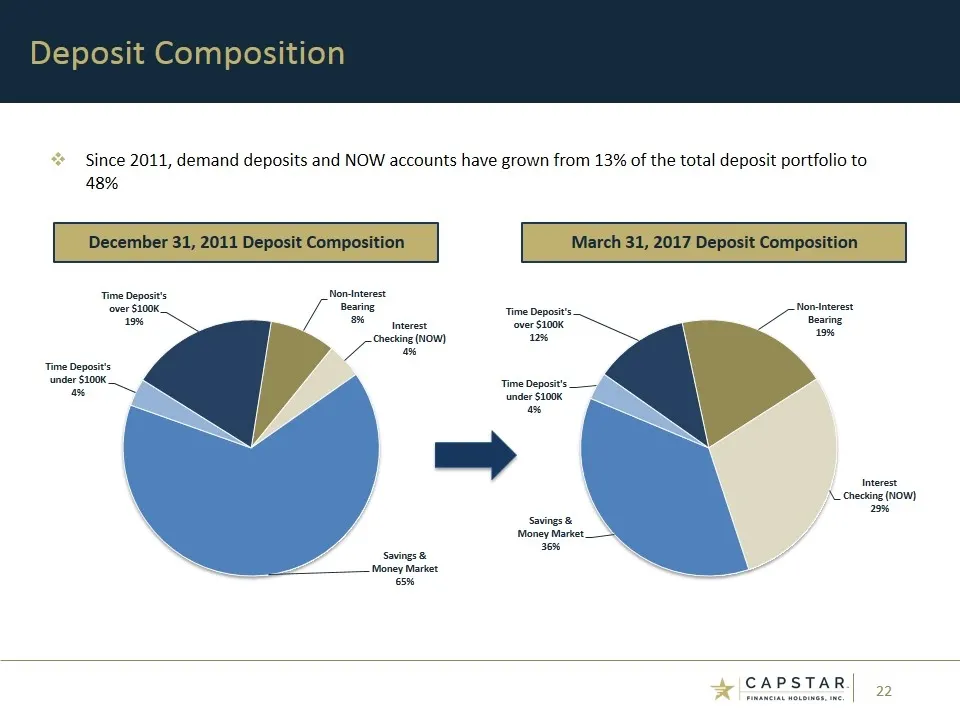
Slide 22: Deposit Composition
December 31, 2011 Deposit Composition Deposit Composition March 31, 2017 Deposit Composition Since 2011, demand deposits and NOW accounts have grown from 13% of the total deposit portfolio to 48%
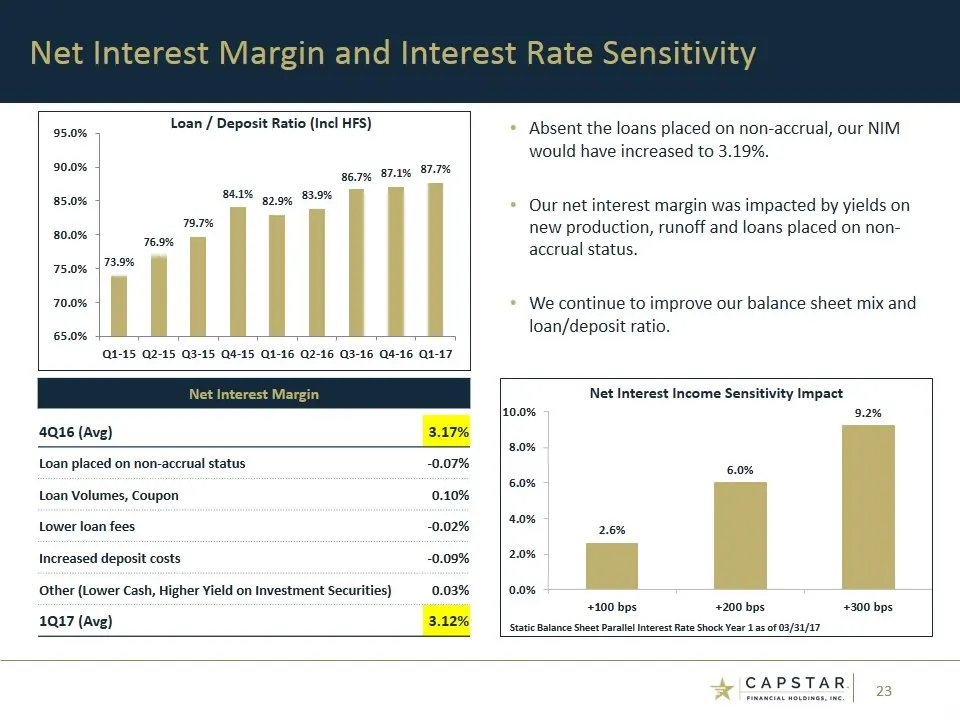
Slide 23: Net Interest Margin and Interest Rate Sensitivity
Net Interest Margin and Interest Rate Sensitivity Absent the loans placed on non-accrual, our NIM would have increased to 3.19%. Our net interest margin was impacted by yields on new production, runoff and loans placed on non-accrual status. We continue to improve our balance sheet mix and loan/depo
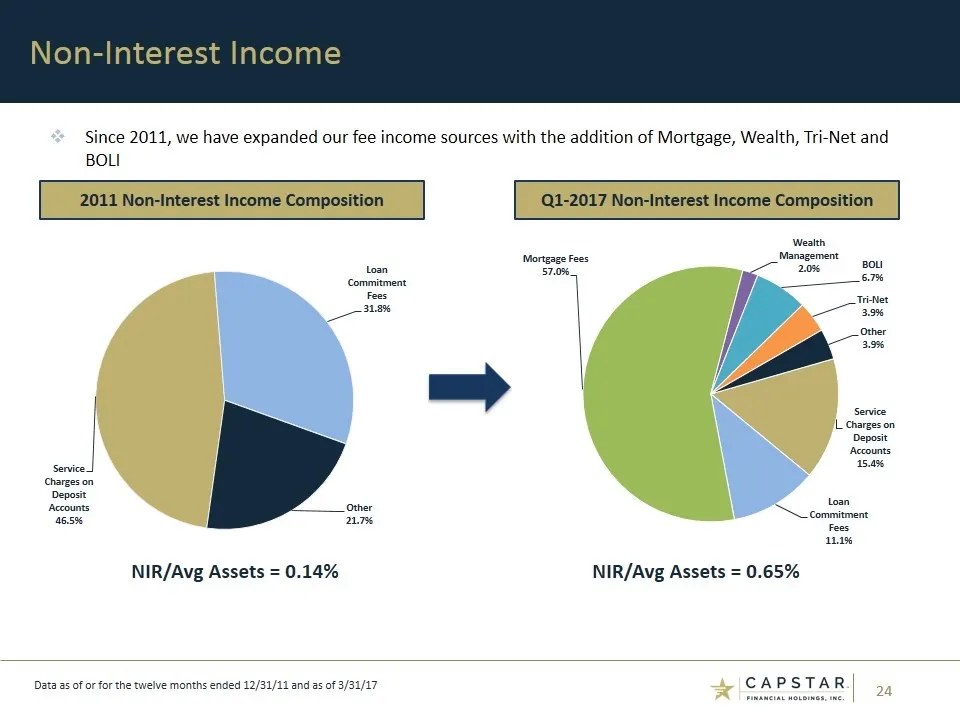
Slide 24: Non-Interest Income
Non-Interest Income 2011 Non-Interest Income Composition Q1-2017 Non-Interest Income Composition Since 2011, we have expanded our fee income sources with the addition of Mortgage, Wealth, Tri-Net and BOLI Data as of or for the twelve months ended 12/31/11 and as of 3/31/17 NIR/Avg Assets = 0.14% NIR
Slide 25: Non-Interest Income by Quarter
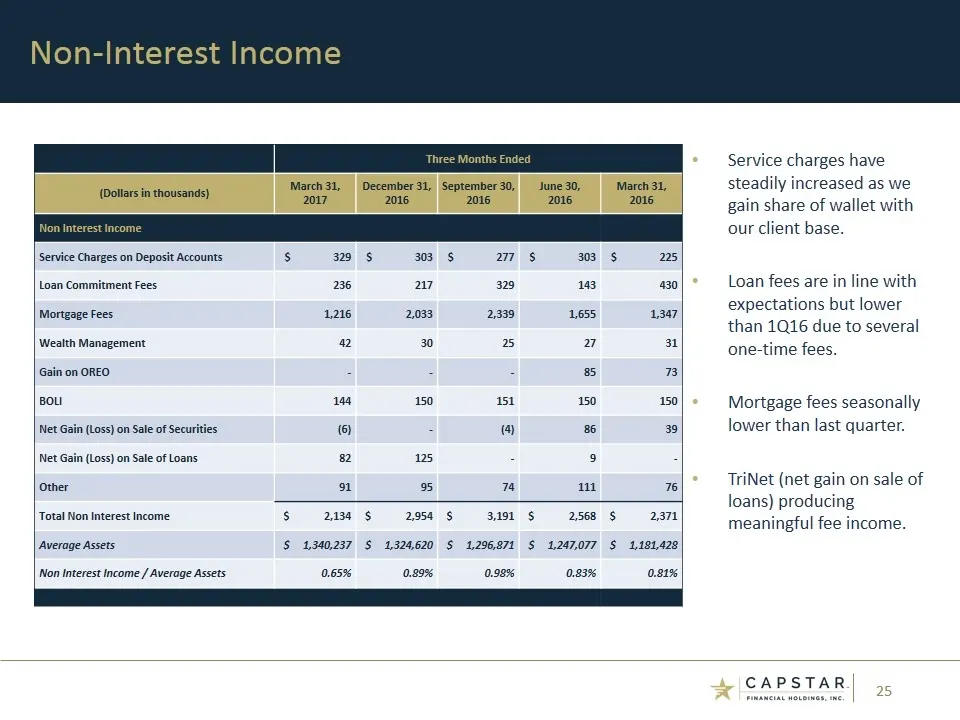
Service charges have steadily increased as we gain share of wallet with our client base. Loan fees are in line with expectations but lower than 1Q16 due to several one-time fees. Mortgage fees seasonally lower than last quarter. TriNet (net gain on sale of loans) producing meaningful fee income. Non
Slide 26: Mortgage Operations
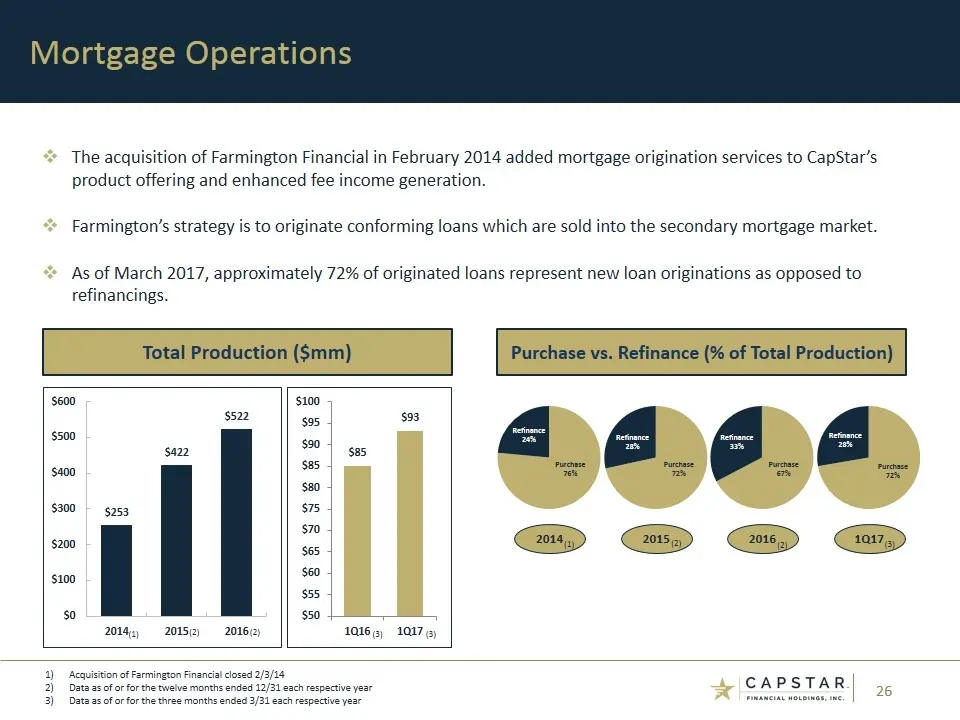
Total Production ($mm) Mortgage Operations Purchase vs. Refinance (% of Total Production) Acquisition of Farmington Financial closed 2/3/14 Data as of or for the twelve months ended 12/31 each respective year Data as of or for the three months ended 3/31 each respective year The acquisition of Farmi
Slide 27: Non-Interest Expense
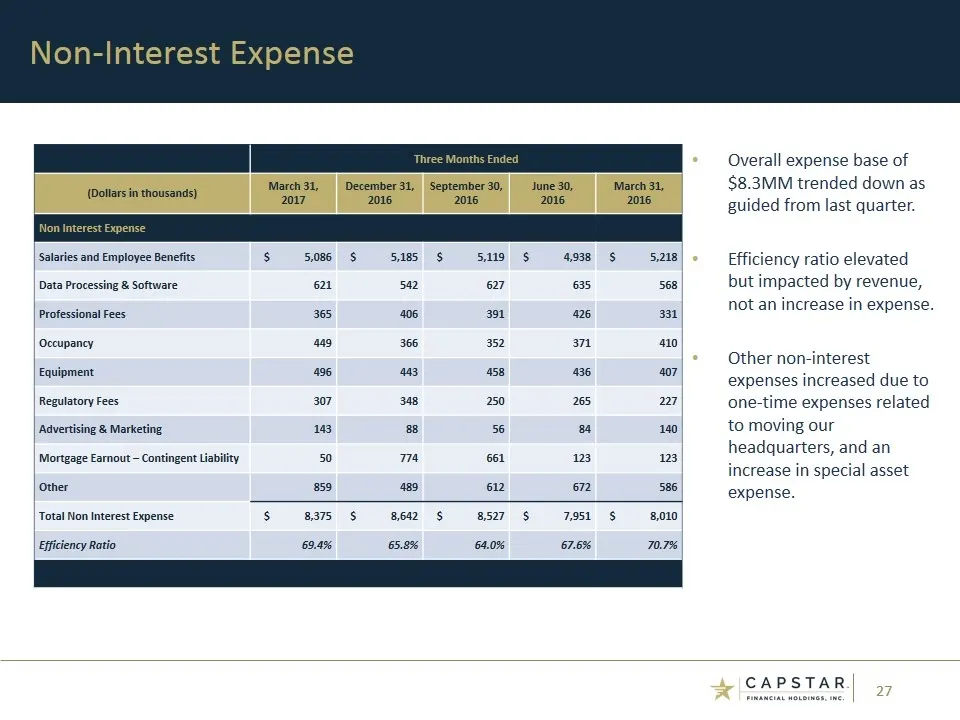
Non-Interest Expense Three Months Ended (Dollars in thousands) March 31, December 31, September 30, June 30, March 31, 2017 2016 2016 2016 2016 Non Interest Expense Salaries and Employee Benefits $ 5,086 $ 5,185 $ 5,119 $ 4,938 $ 5,218 Data Processing & Software 621 542 627 635 568 Professional Fees
Slide 28: Credit Quality Metrics
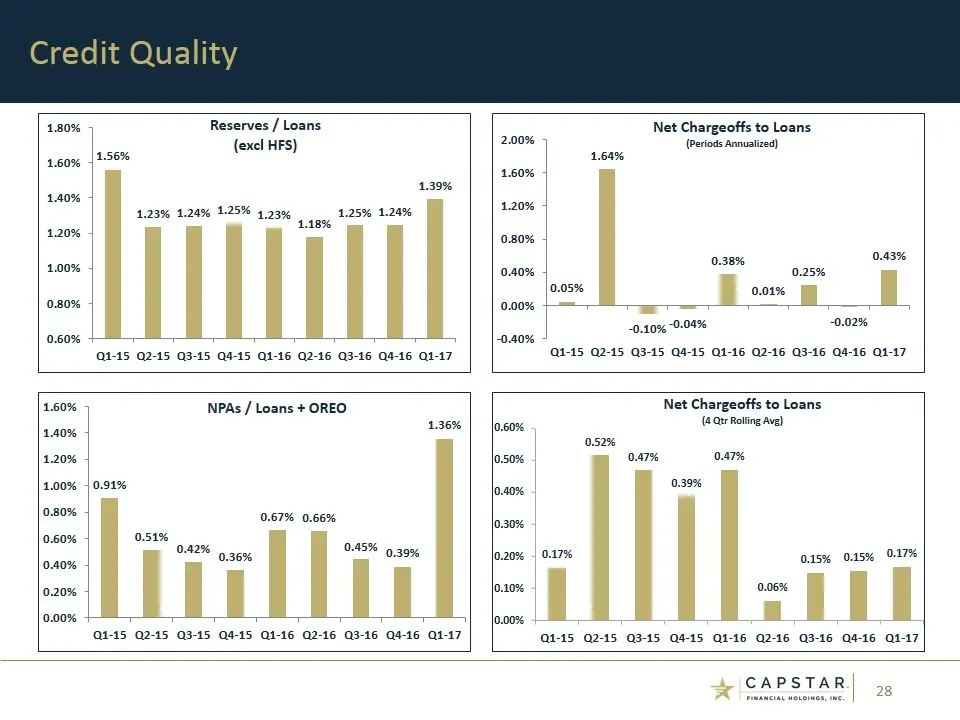
1.80% 1.60% serves / Loans te: (excl HFS) 1.56% 1.23% 1.24% 1.25% 4.2396 1.18% Q1-15 02-15 03-15 Q4-15 Q1-16 02-16 1.25% 1.24% 03-16 04-16 Q1-17 Net Chargeofts to a 2.00% (Periods Annuatizes) 0.1096 -0-04% -0.02% Q1-15 02-15 03-15 Q4-15 Q1-16 O2-16 03-16 Q4-16 O1-17 NPAs / Loans + ORE 0.67% 0.66% 0
Slide 29: Credit Quality
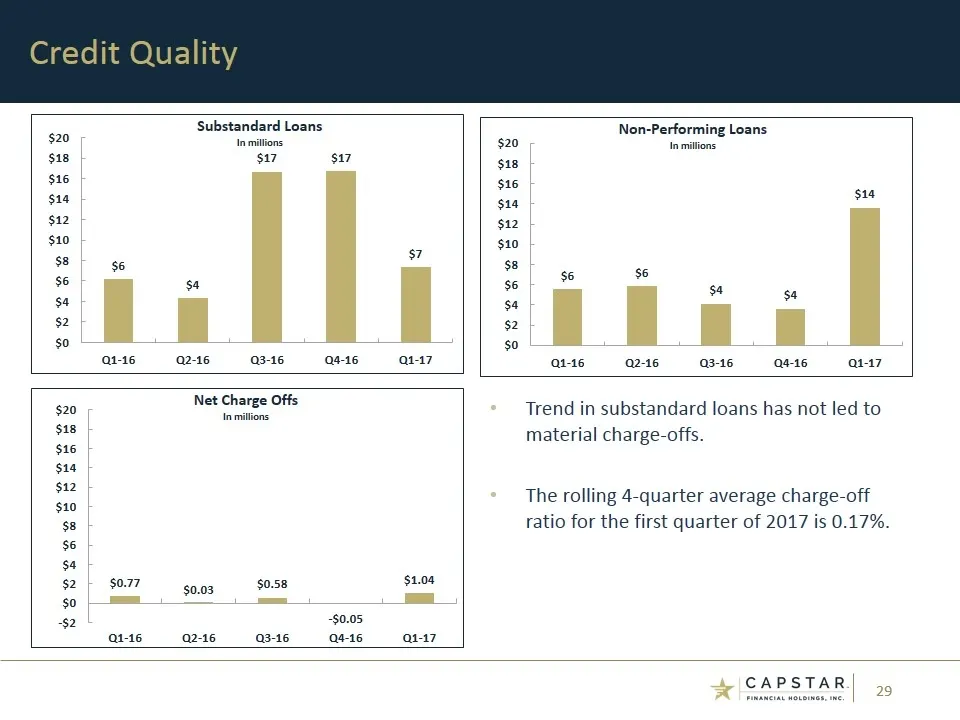
Credit Quality Trend in substandard loans has not led to material charge-offs. The rolling 4-quarter average charge-off ratio for the first quarter of 2017 is 0.17%.
Slide 30: Capital
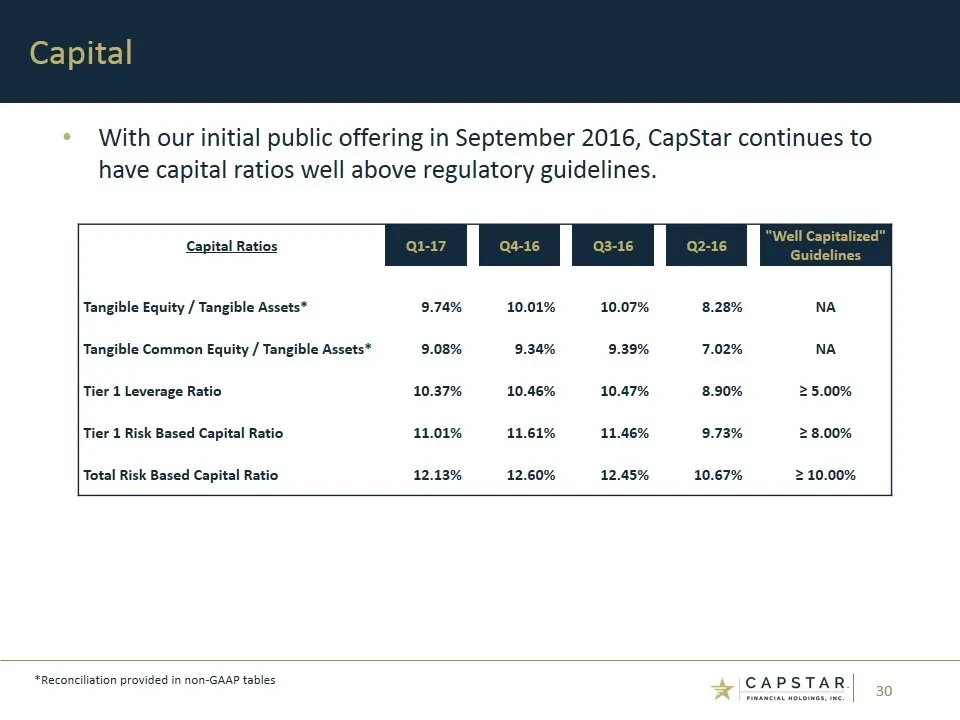
With our initial public offering in September 2016, CapStar continues to have capital ratios well above regulatory guidelines. Capital *Reconciliation provided in non-GAAP tables Capital Ratios Q1-17 Q4-16 Q3-16 Q2-16 "Well Capitalized" Guidelines Tangible Equity / Tangible Assets* 9.74% 10.01% 10.0
Slide 31: Roadmap to 1.00% ROAA
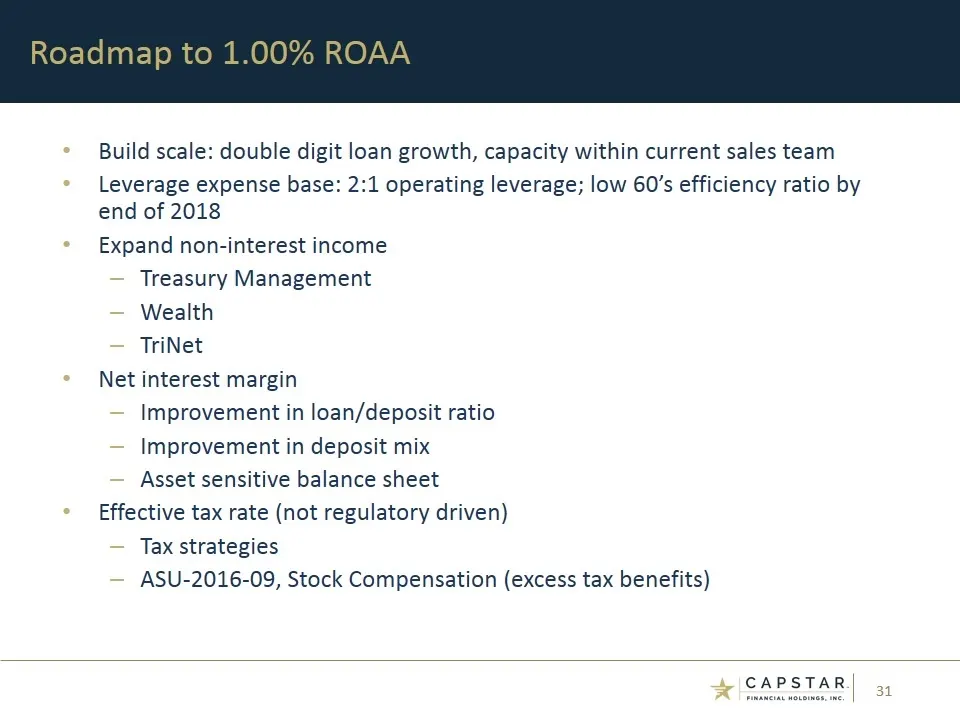
Build scale: double digit loan growth, capacity within current sales team Leverage expense base: 2:1 operating leverage; low 60’s efficiency ratio by end of 2018 Expand non-interest income Treasury Management Wealth TriNet Net interest margin Improvement in loan/deposit ratio Improvement in deposit
Slide 32: Franchise Value
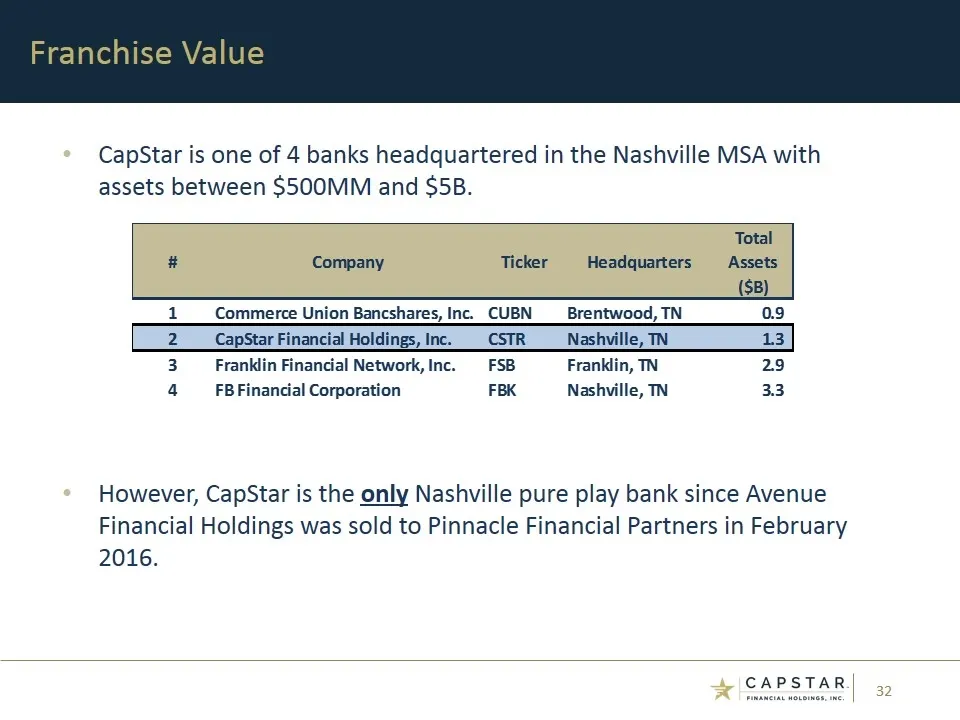
CapStar is one of 4 banks headquartered in the Nashville MSA with assets between $500MM and $5B. However, CapStar is the only Nashville pure play bank since Avenue Financial Holdings was sold to Pinnacle Financial Partners in February 2016. Franchise Value
Slide 33: Key Takeaways
CapStar’s strategy remains one of sound, profitable growth We are disappointed in first quarter performance Proactively re-evaluating and refining our Healthcare strategy Focused on consistently driving performance throughout the company We remain committed to achieving a 1.0% ROAA by the end of 201
Slide 34: Contact Information
CapStar Financial Holdings, Inc. 1201 Demonbreun Street, Suite 700 Nashville, TN 37203 Mail: P.O. Box 305065 Nashville, TN 37230-5065 (615) 732-6400 Telephone www.capstarbank.com (615) 732-6455 Email: [email protected] Contact Information Investor Relations Executive Leadership Claire W. Tucker Pre
Slide 35: Appendix: Non-GAAP Tables
Appendix: Non-GAAP Tables A |CAPSTAR| 35
Slide 36: Non-GAAP Financial Measures: Pre-Tax Pre-Provision Net Income
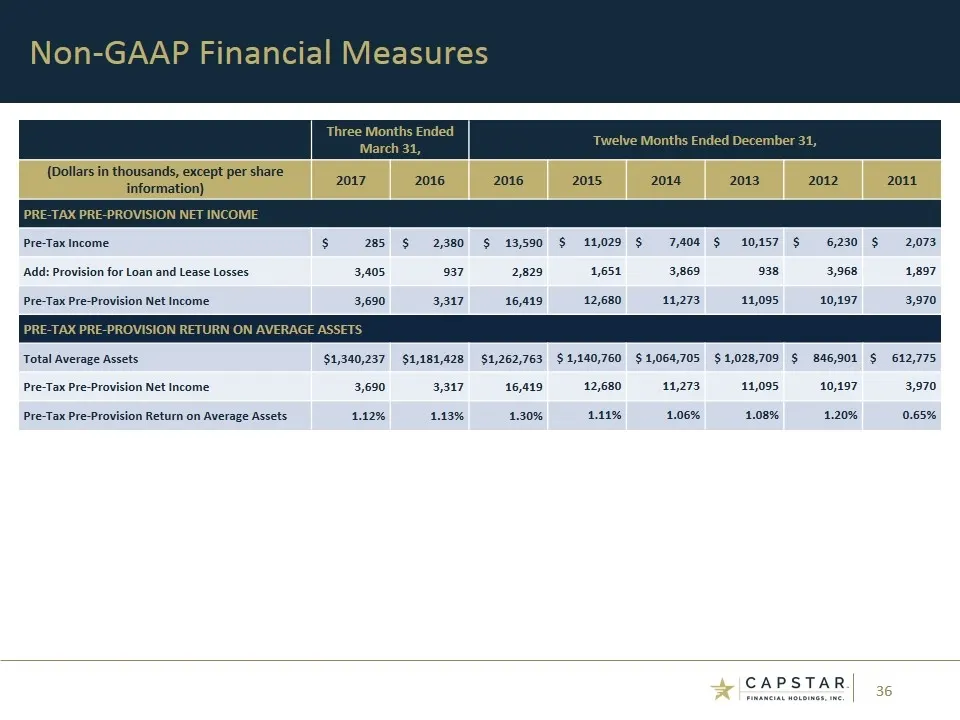
Three Months Ended March 31, Twelve Months Ended December 31, (Dollars in thousands, except per share information) 2017 2016 2016 2015 2014 2013 2012 2011 PRE-TAX PRE-PROVISION NET INCOME Pre-Tax Income $ 285 $ 2,380 $ 13,590 $ 11,029 $ 7,404 $ 10,157 $ 6,230 $ 2,073 Add: Provision for Loan and Leas
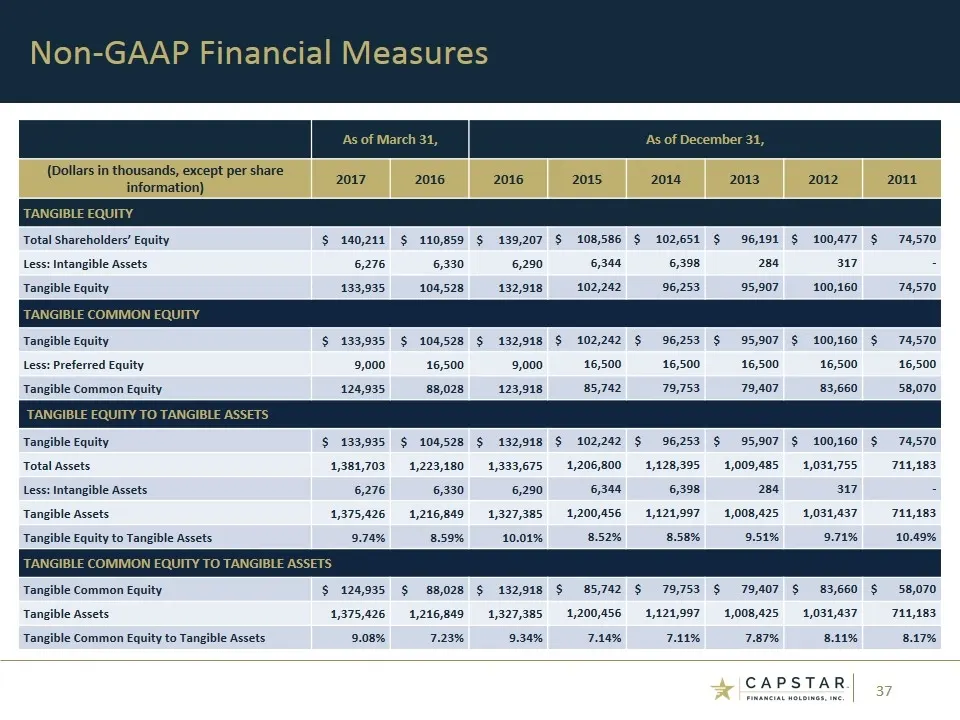
Slide 37: Tangible Equity and Tangible Common Equity
As of March 31, As of December 31, (Dollars in thousands, except per share information) 2017 2016 2016 2015 2014 2013 2012 2011 TANGIBLE EQUITY Total Shareholders’ Equity $ 140,211 $ 110,859 $ 139,207 $ 108,586 $ 102,651 $ 96,191 $ 100,477 $ 74,570 Less: Intangible Assets 6,276 6,330 6,290 6,344 6,3
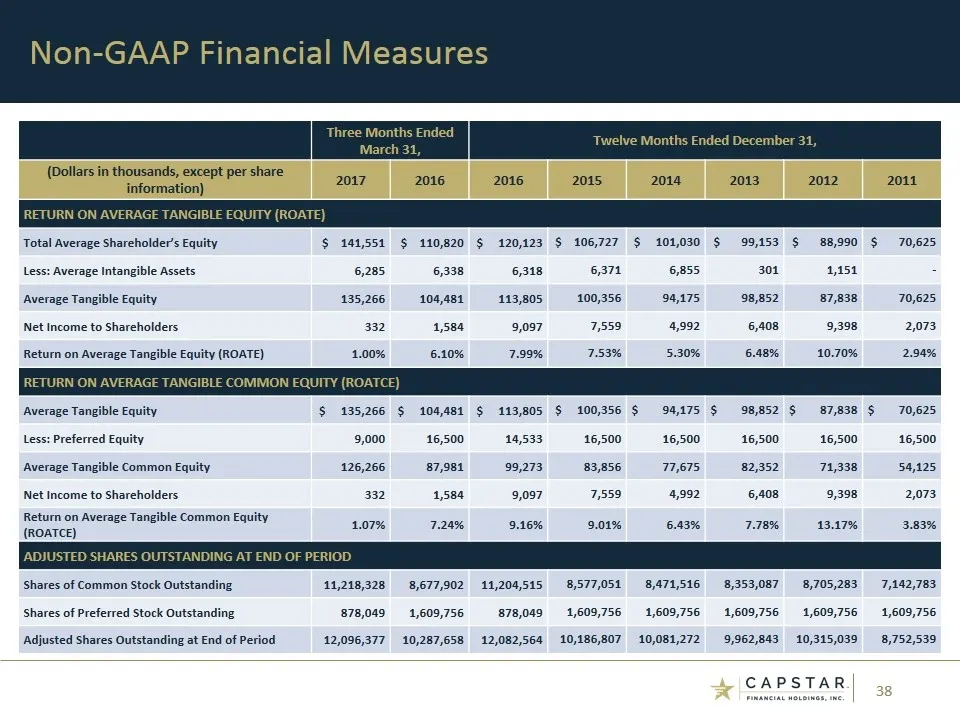
Slide 38: Return on Average Tangible Equity
Three Months Ended March 31, Twelve Months Ended December 31, (Dollars in thousands, except per share information) 2017 2016 2016 2015 2014 2013 2012 2011 RETURN ON AVERAGE TANGIBLE EQUITY (ROATE) Total Average Shareholder’s Equity $ 141,551 $ 110,820 $ 120,123 $ 106,727 $ 101,030 $ 99,153 $ 88,990
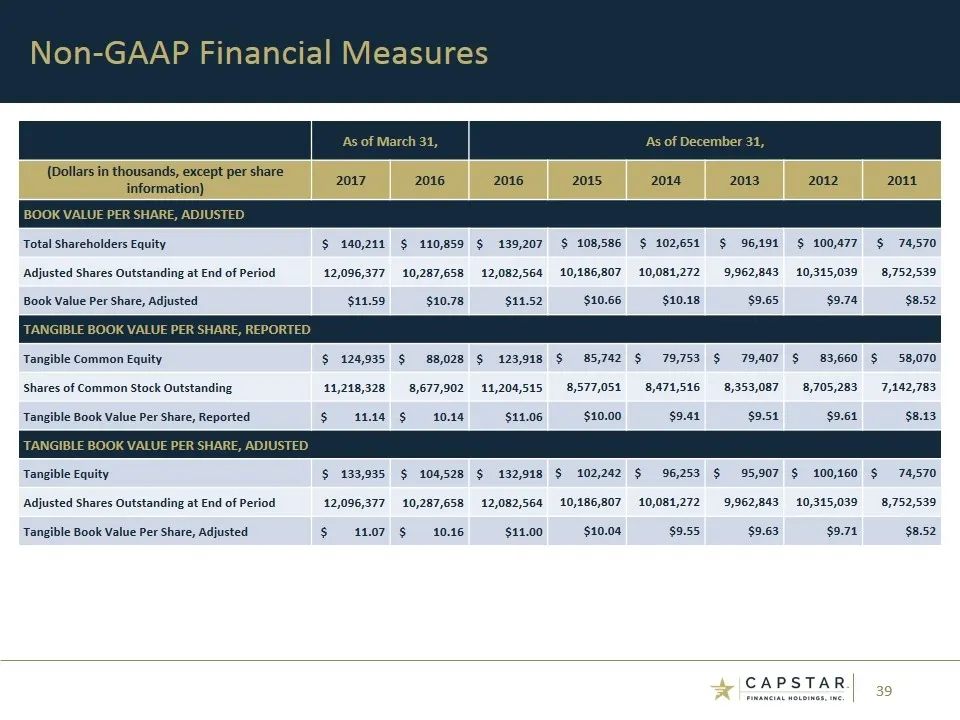
Slide 39: Book Value and Tangible Book Value Per Share
As of March 31, As of December 31, (Dollars in thousands, except per share information) 2017 2016 2016 2015 2014 2013 2012 2011 BOOK VALUE PER SHARE, ADJUSTED Total Shareholders Equity $ 140,211 $ 110,859 $ 139,207 $ 108,586 $ 102,651 $ 96,191 $ 100,477 $ 74,570 Adjusted Shares Outstanding at End of
Slide 40: CapStar Financial Holdings, Inc.
+ CAPSTAR. | FINANCIAL HOLDINGS, INC.
Source: SEC EDGAR · 8-K filed May 10, 2017
More decks from Capstar Financial Holdings Inc
 Q4 2023 Earnings Presentation6 slides · Jan 23, 2024
 Merger or Acquisition (October 2023)16 slides · Oct 26, 2023
 Q2 2023 Earnings Presentation22 slides · Jul 21, 2023
 Q1 2023 Earnings Presentation32 slides · Apr 21, 2023
 Q4 2022 Earnings Presentation27 slides · Jan 20, 2023
 Investor Presentation (December 2022)31 slides · Dec 13, 2022