Markwest Energy Partners LP — Argus Americas LPG Summit (February 2013)
23 slides from Markwest Energy Partners LP's conference presentation, Feb 7, 2013
Slide 1: Argus Americas LPG Summit
Argus Americas LPG Summit Randy Nickerson, SVP & CCO February 7, 2013
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements and information. These forward-looking statements, which in many instances can be identified by words like “could,” “may,” “will,” “should,” “expects,” “plans,” “project,” “anticipates,” “believes,” “planned,” “proposed
Slide 3: Key Investment Considerations
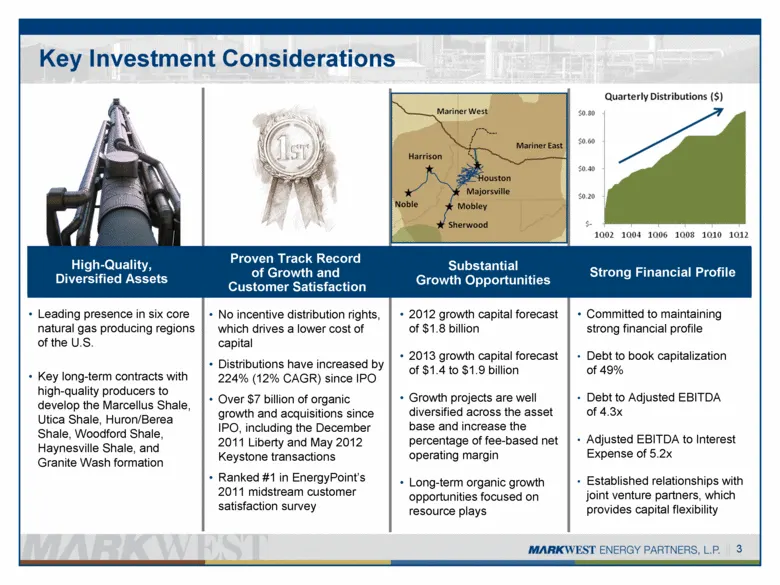
Key Investment Considerations High-Quality, Diversified Assets Proven Track Record of Growth and Customer Satisfaction Substantial Growth Opportunities Strong Financial Profile Leading presence in six core natural gas producing regions of the U.S. Key long-term contracts with high-quality producers
Slide 4: MarkWest Operational Assets
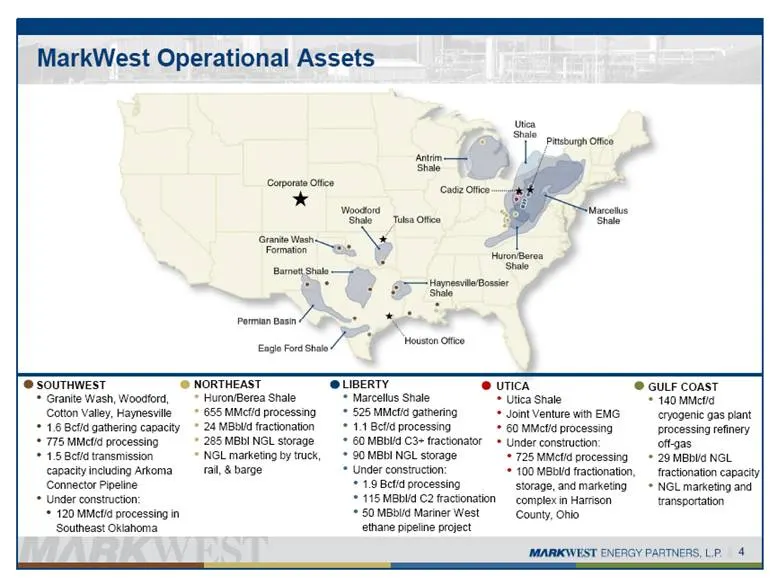
MarkWest Operational Assets UTICA Utica Shale Joint Venture with EMG 60 MMcf/d processing Under construction: 725 MMcf/d processing 100 MBbl/d fractionation, storage, and marketing complex in Harrison County, Ohio SOUTHWEST Granite Wash, Woodford, Cotton Valley, Haynesville 1.6 Bcf/d gathering capac
Slide 5: U.S. Shale Plays are Driving Natural Gas Supply
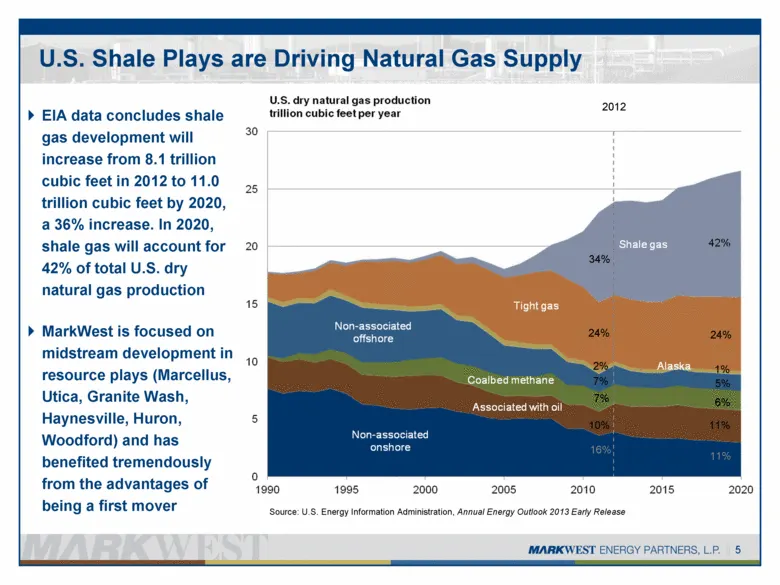
U.S. Shale Plays are Driving Natural Gas Supply 5 EIA data concludes shale gas development will increase from 8.1 trillion cubic feet in 2012 to 11.0 trillion cubic feet by 2020, a 36% increase. In 2020, shale gas will account for 42% of total U.S. dry natural gas production MarkWest is focused on m
Slide 6: U.S. Shale Play Volume Growth
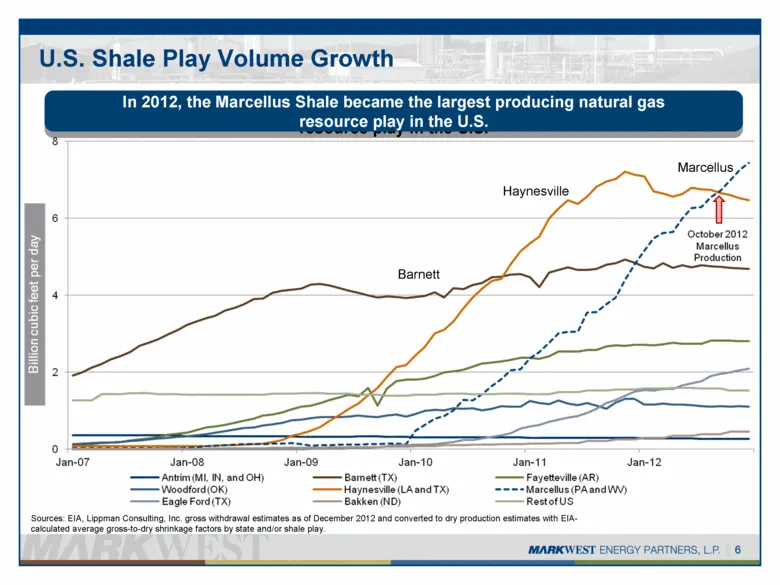
U.S. Shale Play Volume Growth 6 In 2012, the Marcellus Shale became the largest producing natural gas resource play in the U.S. Sources: EIA, Lippman Consulting, Inc. gross withdrawal estimates as of December 2012 and converted to dry production estimates with EIA-calculated average gross-to-dry shr
Slide 7: Growth Driven by Customer Satisfaction
Growth Driven by Customer Satisfaction 7 Ranked #1 in Midstream Customer Satisfaction Survey for 2011 Since 2006, we have been ranked #1 or #2 by EnergyPoint Research
Slide 8: MarkWest Liberty: Current Processing Capacity of 1.1 Bcf/d
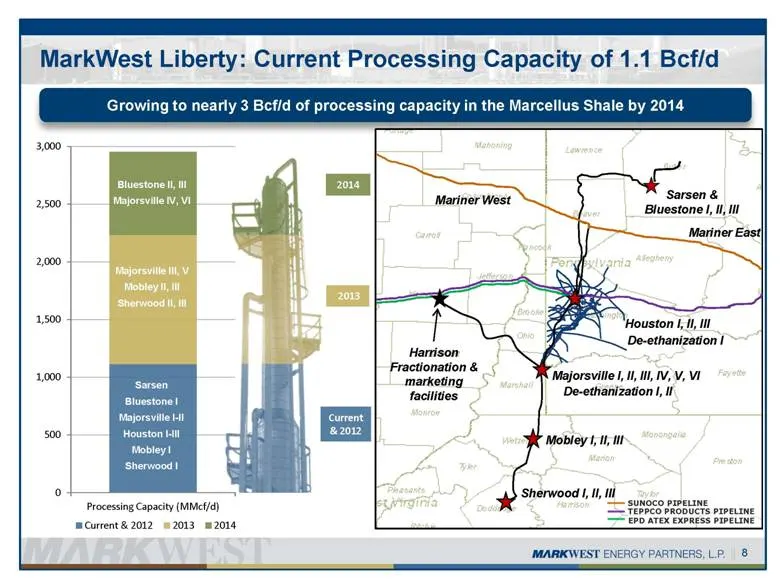
MarkWest Liberty: Current Processing Capacity of 1.1 Bcf/d 8 Growing to nearly 3 Bcf/d of processing capacity in the Marcellus Shale by 2014 TEPPCO PRODUCTS PIPELINE SUNOCO PIPELINE EPD ATEX EXPRESS PIPELINE Mariner West De-ethanization I Houston I, II, III De-ethanization I, II Majorsville I, II, I
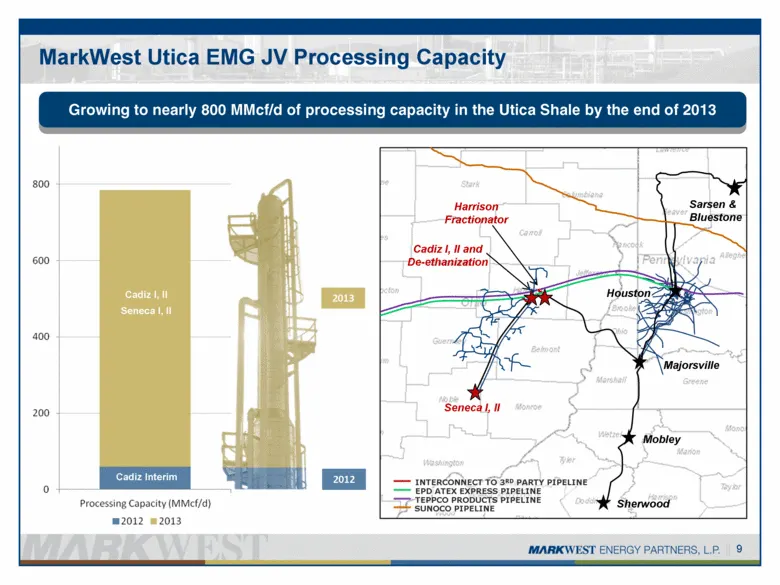
Slide 9: MarkWest Utica EMG JV Processing Capacity
MarkWest Utica EMG JV Processing Capacity 9 Growing to nearly 800 MMcf/d of processing capacity in the Utica Shale by the end of 2013 Cadiz Interim Cadiz I, II Seneca I, II 2013 2012 Mobley Sherwood Houston Majorsville Seneca I, II Harrison Fractionator TEPPCO PRODUCTS PIPELINE EPD ATEX EXPRESS PIPE
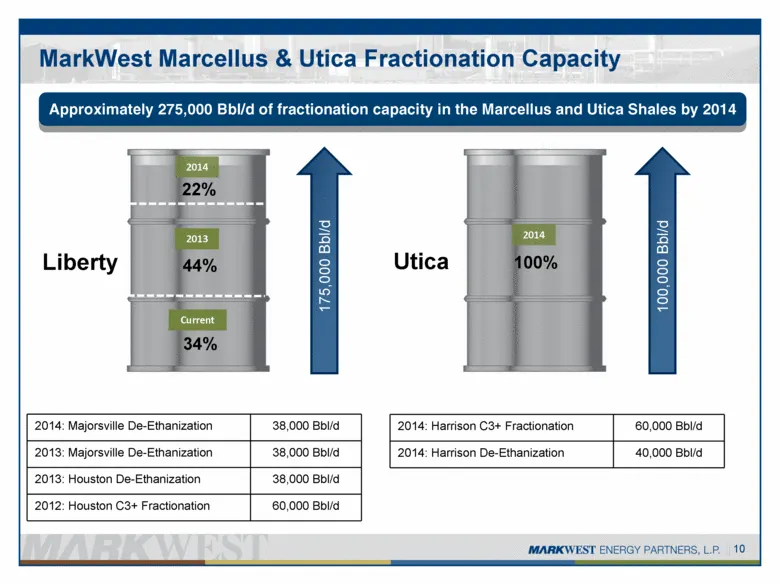
Slide 10: MarkWest Marcellus & Utica Fractionation Capacity
100% 34% 44% 22% MarkWest Marcellus & Utica Fractionation Capacity 10 Approximately 275,000 Bbl/d of fractionation capacity in the Marcellus and Utica Shales by 2014 2014 2013 Current 2014: Majorsville De-Ethanization 38,000 Bbl/d 2013: Majorsville De-Ethanization 38,000 Bbl/d 2013: Houston De-Ethan
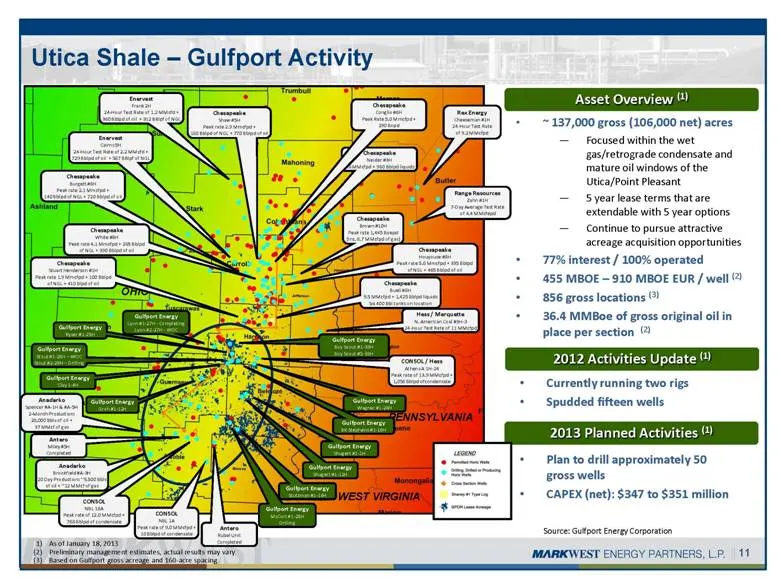
Slide 11: Utica Shale – Gulfport Activity
11 Utica Shale – Gulfport Activity 11 Source: Gulfport Energy Corporation ~ 137,000 gross (106,000 net) acres Focused within the wet gas/retrograde condensate and mature oil windows of the Utica/Point Pleasant 5 year lease terms that are extendable with 5 year options Continue to pursue attractive a
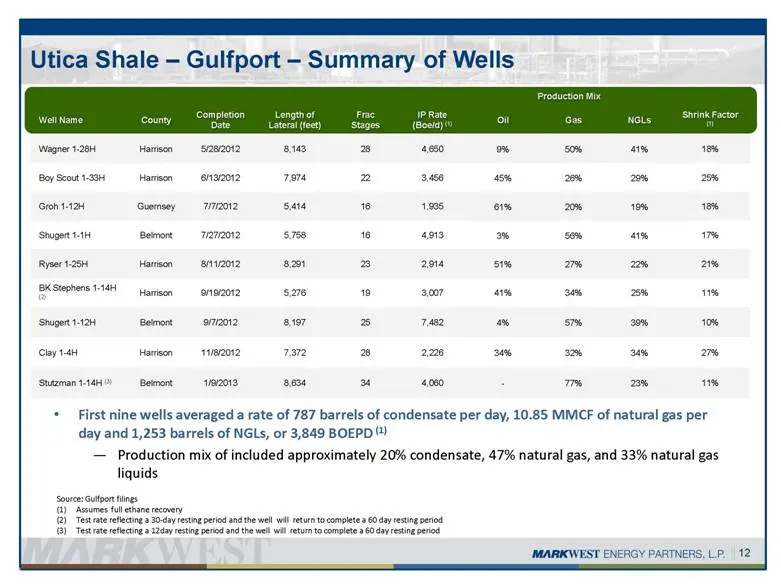
Slide 12: Utica Shale – Gulfport – Summary of Wells
12 Utica Shale – Gulfport – Summary of Wells 12 First nine wells averaged a rate of 787 barrels of condensate per day, 10.85 MMCF of natural gas per day and 1,253 barrels of NGLs, or 3,849 BOEPD (1) Production mix of included approximately 20% condensate, 47% natural gas, and 33% natural gas liquids
Slide 13: Utica Shale – Antero Activity Summary
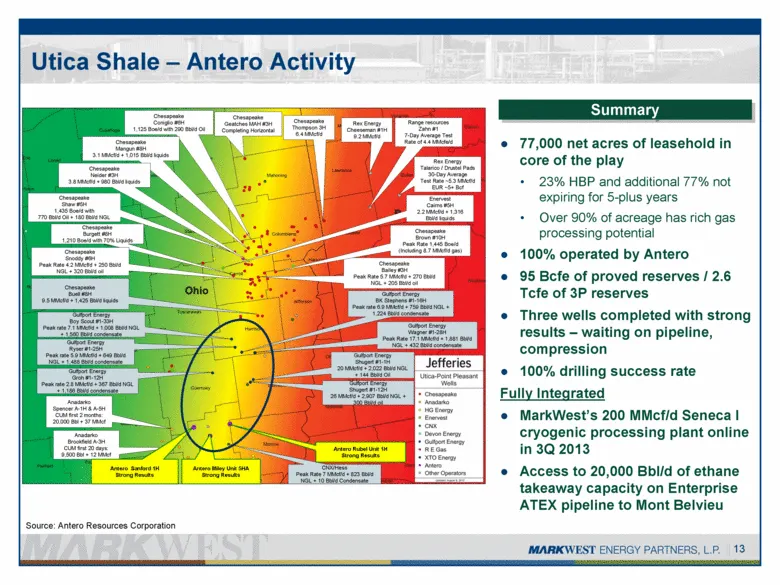
77,000 net acres of leasehold in core of the play 23% HBP and additional 77% not expiring for 5-plus years Over 90% of acreage has rich gas processing potential 100% operated by Antero 95 Bcfe of proved reserves / 2.6 Tcfe of 3P reserves Three wells completed with strong results – waiting on pipelin
Slide 14: Rex Energy Utica Overview
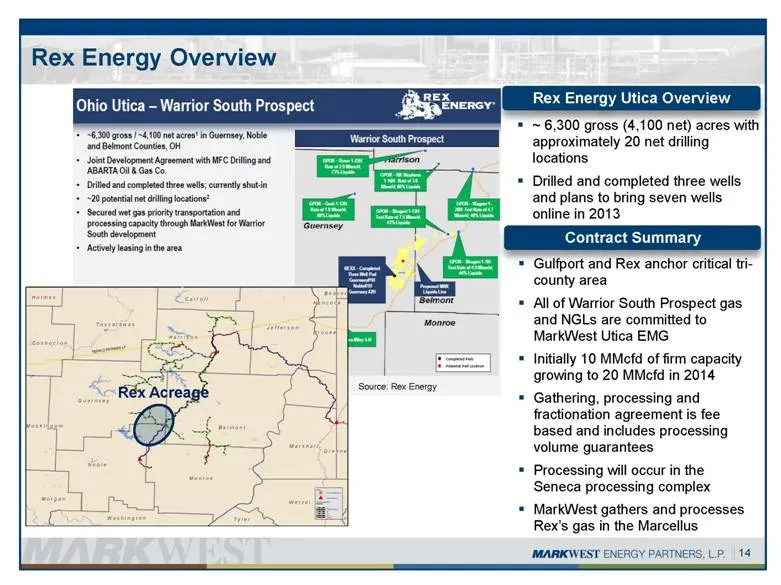
~ 6,300 gross (4,100 net) acres with approximately 20 net drilling locations Drilled and completed three wells and plans to bring seven wells online in 2013 Rex Energy Utica Overview Contract Summary Gulfport and Rex anchor critical tri-county area All of Warrior South Prospect gas and NGLs are comm
Slide 15: Additional Producers in Core Area
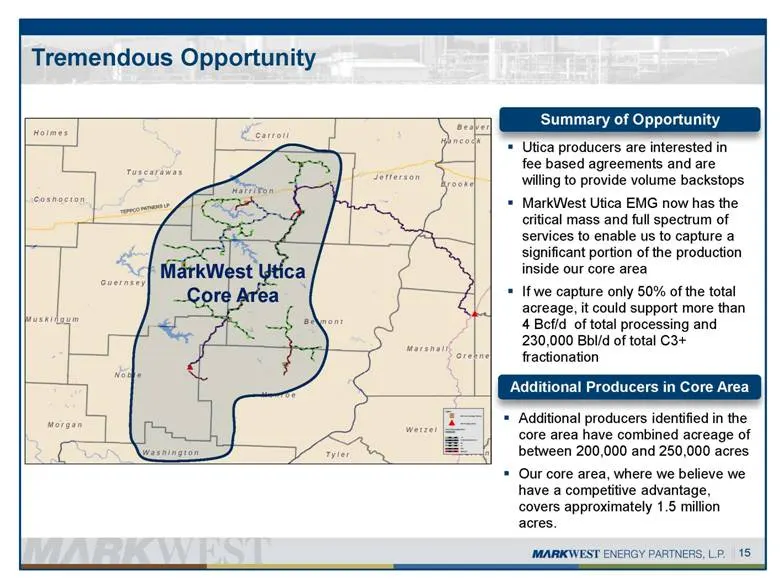
Additional producers identified in the core area have combined acreage of between 200,000 and 250,000 acres Our core area, where we believe we have a competitive advantage, covers approximately 1.5 million acres. Additional Producers in Core Area Summary of Opportunity Utica producers are interested
Slide 16: MarkWest Marcellus and Utica Processed Gas Volumes
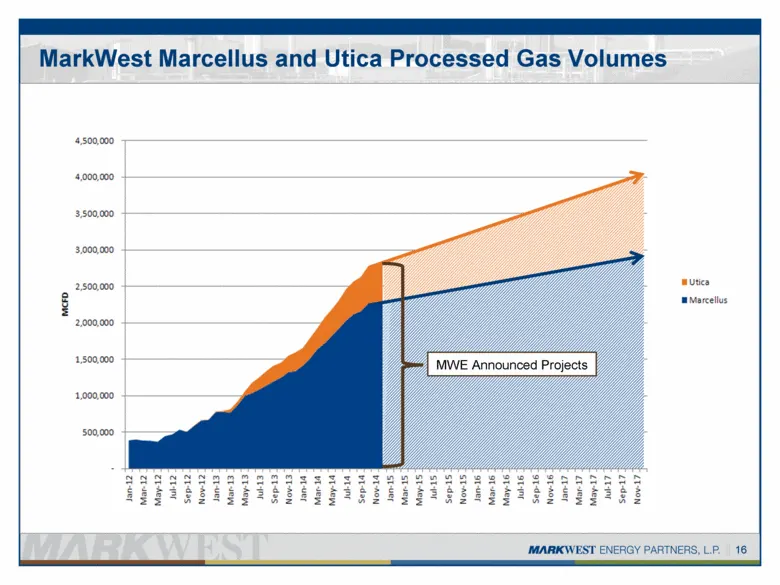
MarkWest Marcellus and Utica Processed Gas Volumes 16 MWE Announced Projects
Slide 17: MarkWest Marcellus and Utica Potential C3+ Volumes
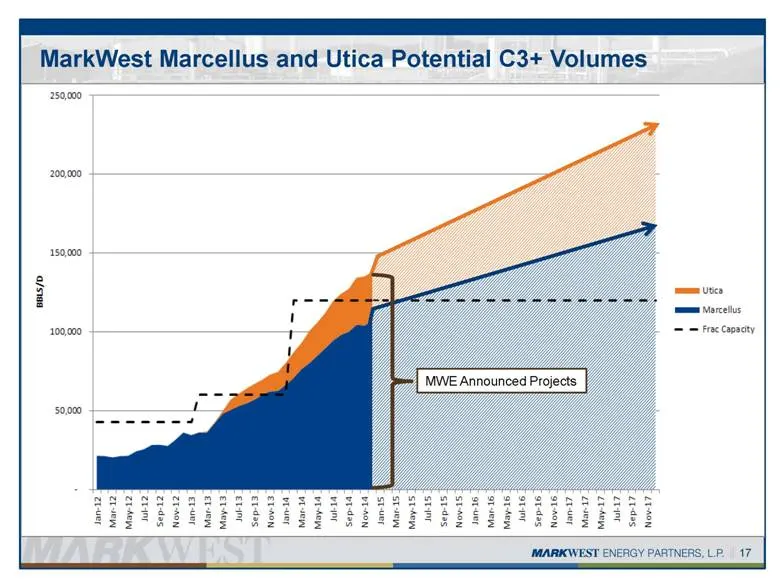
MarkWest Marcellus and Utica Potential C3+ Volumes 17 MWE Announced Projects
Slide 18: MarkWest Marcellus and Utica Potential Ethane Volumes
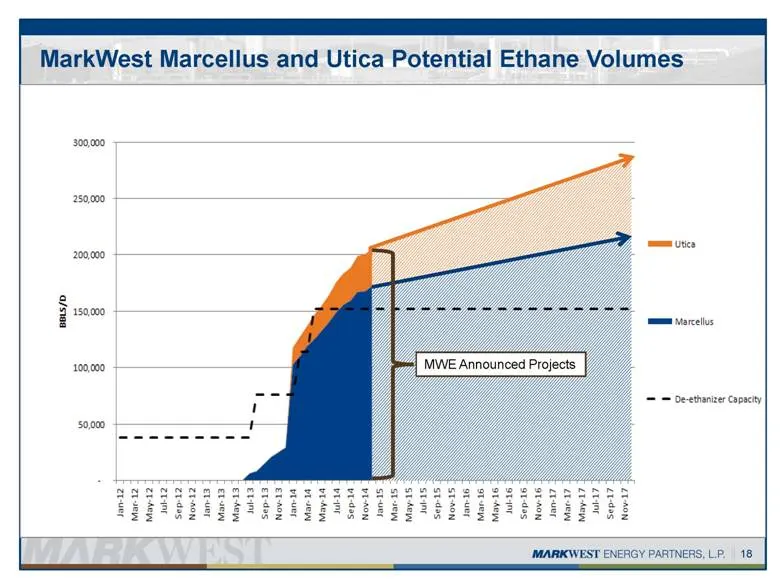
MarkWest Marcellus and Utica Potential Ethane Volumes 18 MWE Announced Projects
Slide 19: MarkWest's Perspective on Northeast Ethane Production
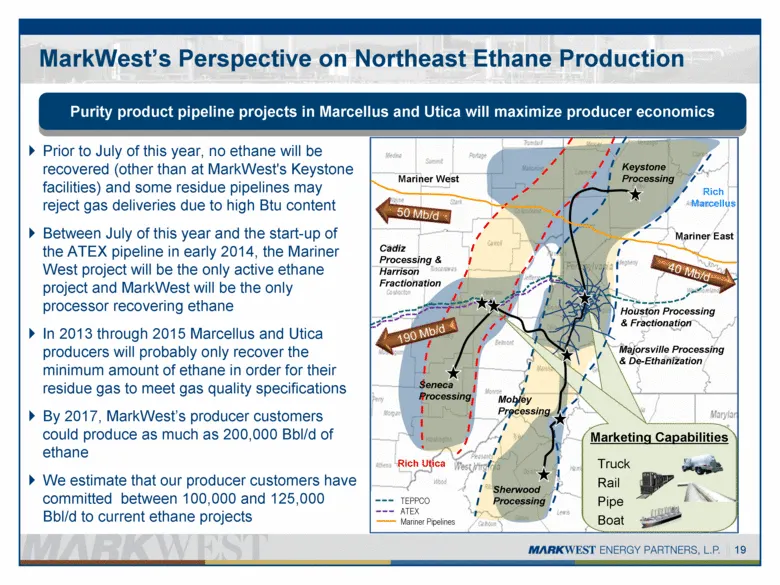
MarkWest’s Perspective on Northeast Ethane Production Prior to July of this year, no ethane will be recovered (other than at MarkWest's Keystone facilities) and some residue pipelines may reject gas deliveries due to high Btu content Between July of this year and the start-up of the ATEX pipeline in
Slide 20: Northeast Propane Supply and Demand
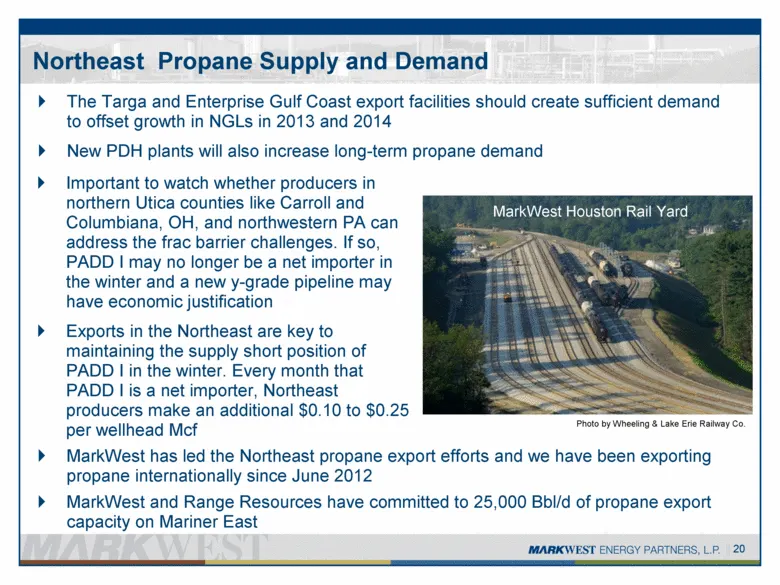
Northeast Propane Supply and Demand 20 The Targa and Enterprise Gulf Coast export facilities should create sufficient demand to offset growth in NGLs in 2013 and 2014 New PDH plants will also increase long-term propane demand MarkWest has led the Northeast propane export efforts and we have been exp
Slide 21: Northeast Butanes and Gasoline Supply and Demand
Northeast Butanes and Gasoline Supply and Demand 21 Marcellus natural gasoline already serves western Canadian heavy oil markets and Utica condensate production will increase access to these markets. Marcellus natural gasoline will maintain its transportation advantage over the US Gulf Coast supplie
Slide 22: Keys to Success
Keys to Success Maintain stronghold in key resource plays with high-quality assets Execute growth projects that are well diversified across the asset base 22 EXECUTE, EXECUTE, EXECUTE!!! Provide best-in-class midstream services for our producer customers Preserve strong financial profile Deliver sup
Slide 23: Contact Information
1515 ARAPAHOE STREET TOWER 1, SUITE 1600 DENVER, COLORADO 80202 PHONE: 303-925-9200 INVESTOR RELATIONS: 866-858-0482 EMAIL: [email protected] WEBSITE: WWW.MARKWEST.COM
Source: SEC EDGAR · 8-K filed Feb 7, 2013
More decks from Markwest Energy Partners LP
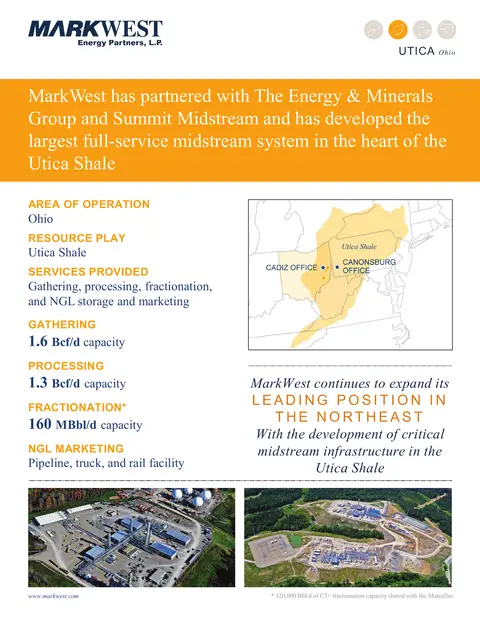 Fact Sheet (July 2017)1 slide · July 2017
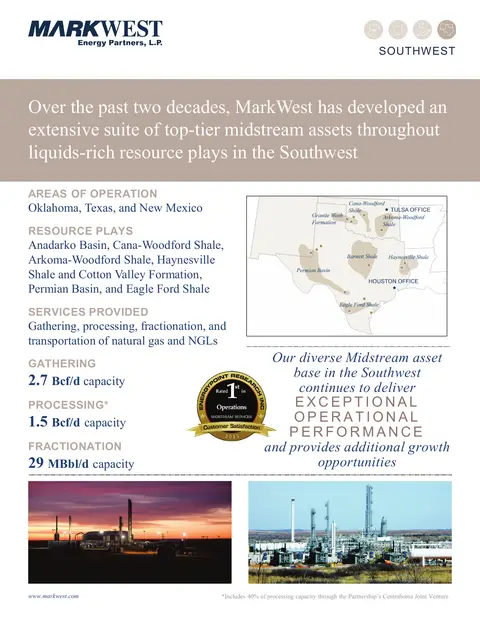 Fact Sheet (July 2017)1 slide · July 2017
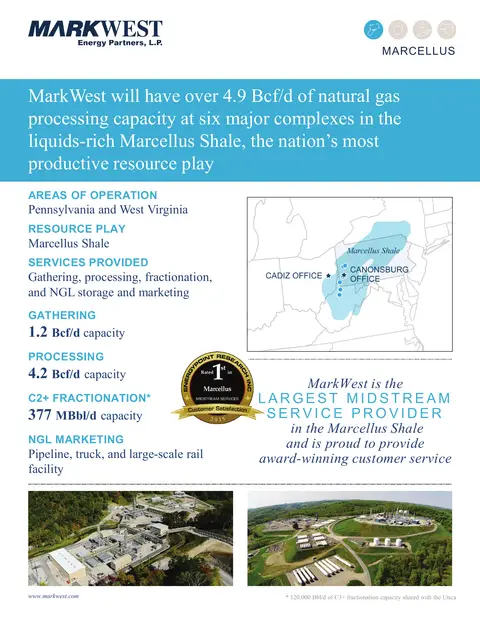 Fact Sheet (July 2017)1 slide · July 2017
 Markwest Energy Partners L P — Investor Day (December 2015)116 slides · Dec 3, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 13, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 12, 2015