New Germany Fund Inc · NYSE:GF
New Germany Fund — Proxy Contest (May 2007)
21 slides from New Germany Fund's proxy contest presentation, May 1, 2007
Slide 1: The New Germany Fund, Inc.
The New Germany Fund, Inc. This solicitation is made on behalf of The New Germany Fund, Inc. and may be used by the Fund's directors and officers in communicating with stockholders. Stockholders are advised to read the Preliminary Proxy Statement and the Definitive Proxy Statement, when it becomes a
Slide 2: Contents
Contents Overview Qualified Slate of Directors Corporate Governance Short-Term vs. Long-Term Interests The Fund
Slide 3: Overview
Overview New Gemmany Fund, ine. 2
Slide 4: Overview - The Fund
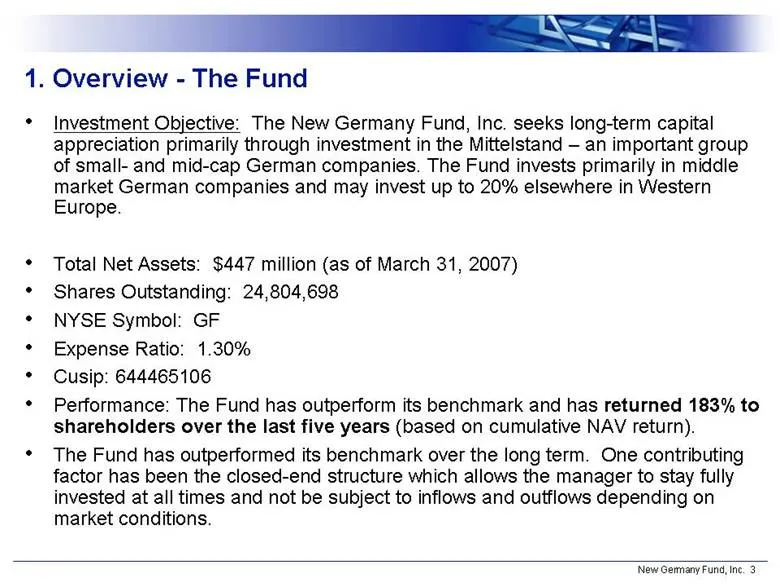
1. Overview - The Fund Investment Objective: The New Germany Fund, Inc. seeks long-term capital appreciation primarily through investment in the Mittelstand – an important group of small- and mid-cap German companies. The Fund invests primarily in middle market German companies and may invest up to
Slide 5: Overview – The Issues: Proposal 1
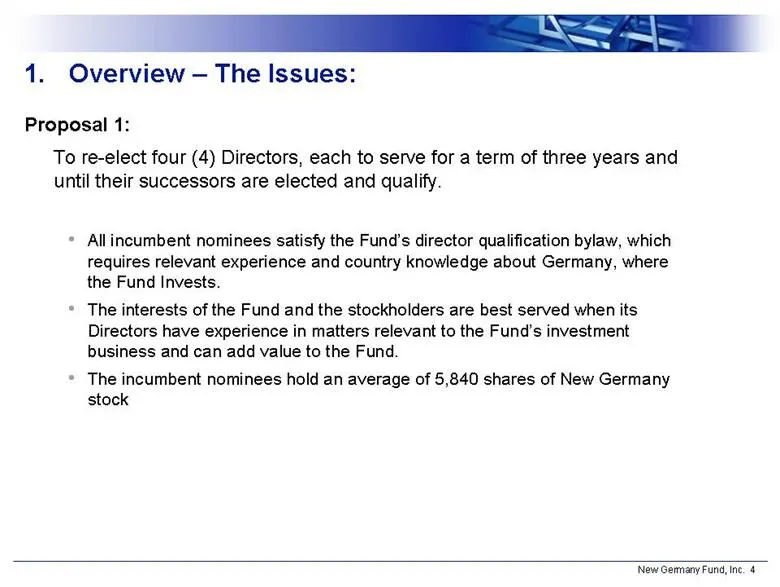
Overview – The Issues: Proposal 1: To re-elect four (4) Directors, each to serve for a term of three years and until their successors are elected and qualify. All incumbent nominees satisfy the Fund’s director qualification bylaw, which requires relevant experience and country knowledge about German
Slide 6: Overview – The Issues: Proposal 3
Overview – The Issues: Proposal 3: Shareholder proposal that the Fund should promptly conduct a self-tender offer for 30% of its shares at 96% of net asset value. Conducting a tender offer for 30% of outstanding shares would decrease assets by at least 30%. A large reduction in assets would lead to
Slide 7: New Germany Fund Proposes Qualified Slate of Directors
New Germany Fund Proposes Qualified Slate of Directors
Slide 8: GF Proposes Qualified Slate: Current Director Candidates
2. GF Proposes Qualified Slate: Current Director Candidates The four nominated directors are better qualified than the dissident nominees. They have extensive experience in German investment and business matters. Board Nominees Mr. Goeltz was for over 8 years the chief financial officer of the large
Slide 9: GF Proposes Qualified Slate: Current Director Candidates
2. GF Proposes Qualified Slate: Current Director Candidates The four nominated directors are better qualified than the dissident nominees. They have extensive experience in German investment and business matters. Board Nominees For over 20 years, Mr. Wadsworth has been the President of his consultin
Slide 10: GF Proposes Qualified Slate: Opportunity Partners’ Self-Serving Interests
2. GF Proposes Qualified Slate: Opportunity Partners’ Self-Serving Interests A private investment partnership controlled by Phillip Goldstein, Mr. Goldstein and his affiliates have a history of engaging in proxy contests with closed-end funds This year, Goldstein has filed proxy materials for the Fr
Slide 11: Corporate Governance
Corporate Governance ‘New Germany Fund, ne. 10,
Slide 12: Corporate Governance: Independence of Board
3. Corporate Governance: Independence of Board The Fund has always had a majority of independent directors (currently over 80%) For over six years none of the directors have been Deutsche Bank employees. Independent directors meet in executive sessions with special counsel to the independent directo
Slide 13: Corporate Governance: Ability to Represent All Stockholders
3. Corporate Governance: Ability to Represent All Stockholders Board nominees will reflect the interests of all stockholders. Directors are obliged by Maryland law to act in the best interests of the Fund as a continuing entity. The dissident directors do not have an open mind. They are publicly com
Slide 14: Corporate Governance: Director Qualification Bylaws
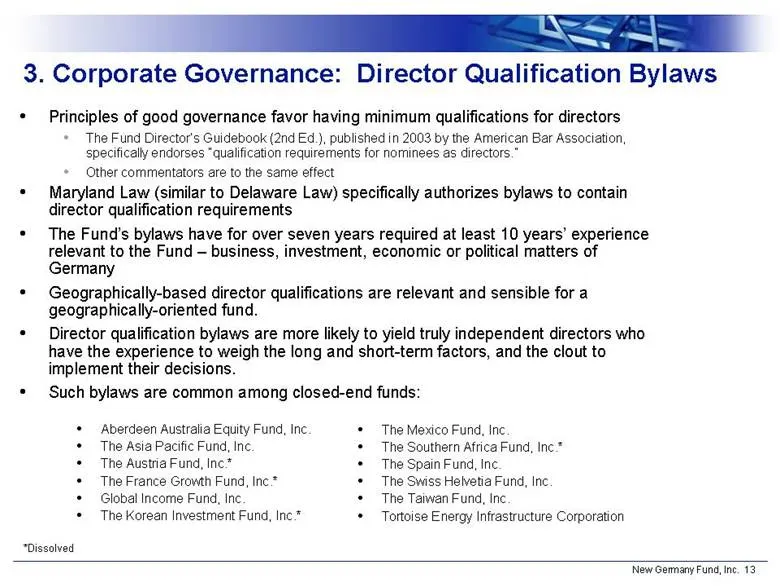
3. Corporate Governance: Director Qualification Bylaws Principles of good governance favor having minimum qualifications for directors The Fund Director’s Guidebook (2nd Ed.), published in 2003 by the American Bar Association, specifically endorses “qualification requirements for nominees as directo
Slide 15: Short-Term vs. Long-Term Interests
Short-Term vs. Long-Term Interests
Slide 16: Short-Term vs. Long-Term Interests: Excellent Performance
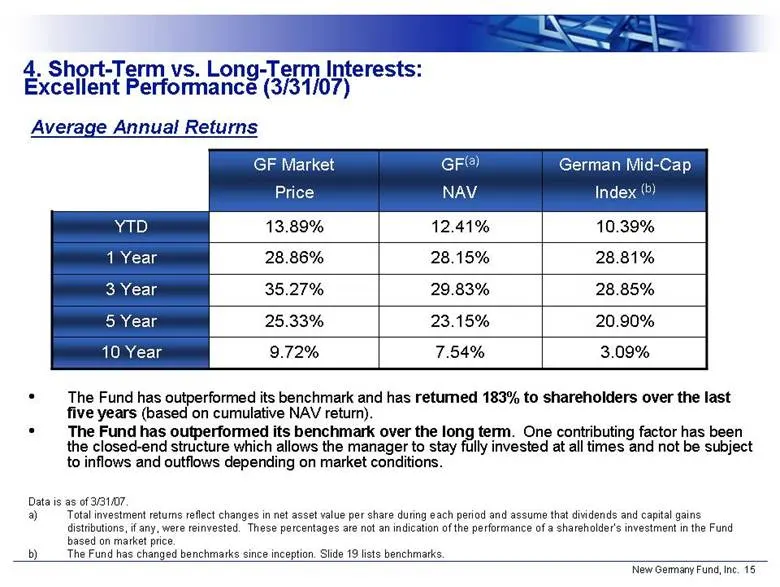
4. Short-Term vs. Long-Term Interests: Excellent Performance (3/31/07) Average Annual Returns The Fund has outperformed its benchmark and has returned 183% to shareholders over the last five years (based on cumulative NAV return). The Fund has outperformed its benchmark over the long term. One contr
Slide 17: Short-Term vs. Long-Term Interests: Proposal 3 Tender Offer
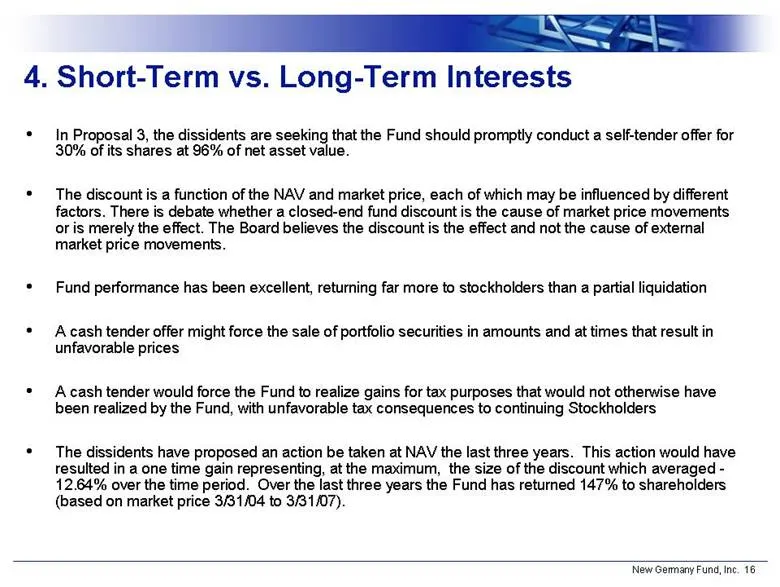
4. Short-Term vs. Long-Term Interests In Proposal 3, the dissidents are seeking that the Fund should promptly conduct a self-tender offer for 30% of its shares at 96% of net asset value. The discount is a function of the NAV and market price, each of which may be influenced by different factors. The
Slide 18: Efforts to Address the Discount
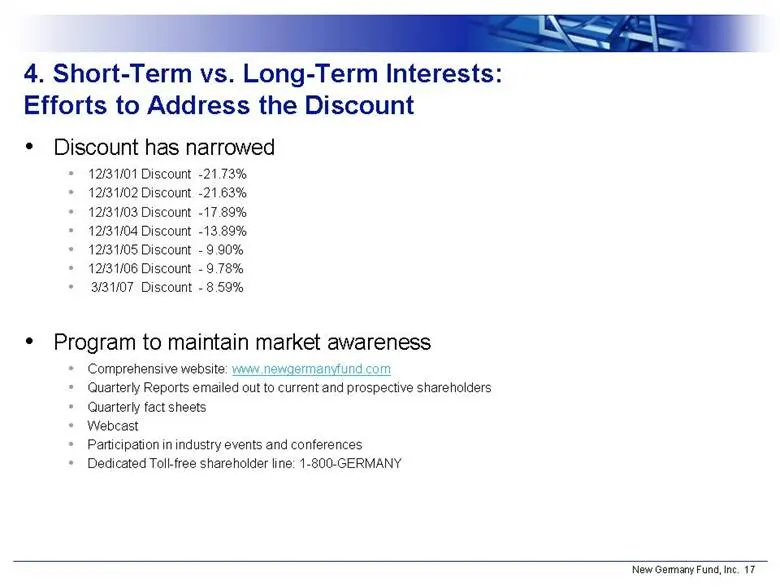
4. Short-Term vs. Long-Term Interests: Efforts to Address the Discount Discount has narrowed 12/31/01 Discount -21.73% 12/31/02 Discount -21.63% 12/31/03 Discount -17.89% 12/31/04 Discount -13.89% 12/31/05 Discount - 9.90% 12/31/06 Discount - 9.78% 3/31/07 Discount - 8.59% Program to maintain market
Slide 19: The New Germany Fund, Inc.
The New Germany Fund, Inc. ‘New GemanyFund, Ine. 18
Slide 20: Important Notes
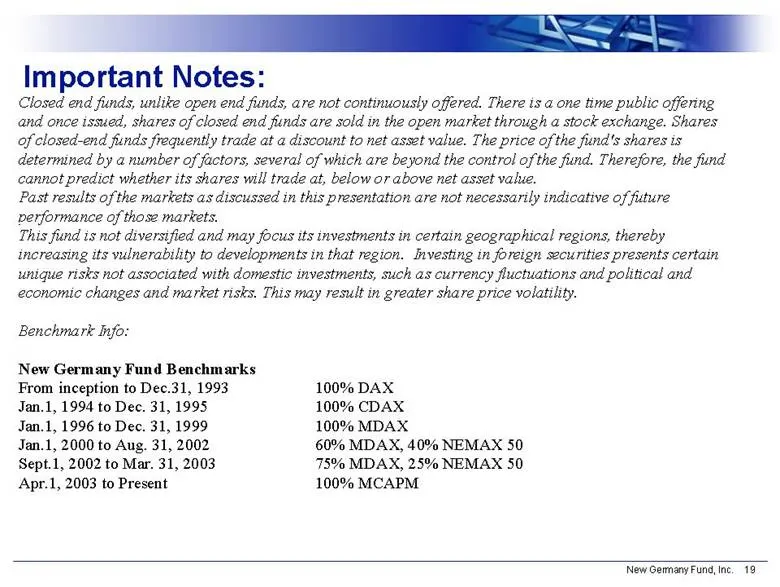
Important Notes: Closed end funds, unlike open end funds, are not continuously offered. There is a one time public offering and once issued, shares of closed end funds are sold in the open market through a stock exchange. Shares of closed - end funds frequently trade at a di scount to net asset valu
Slide 21: Important Notes
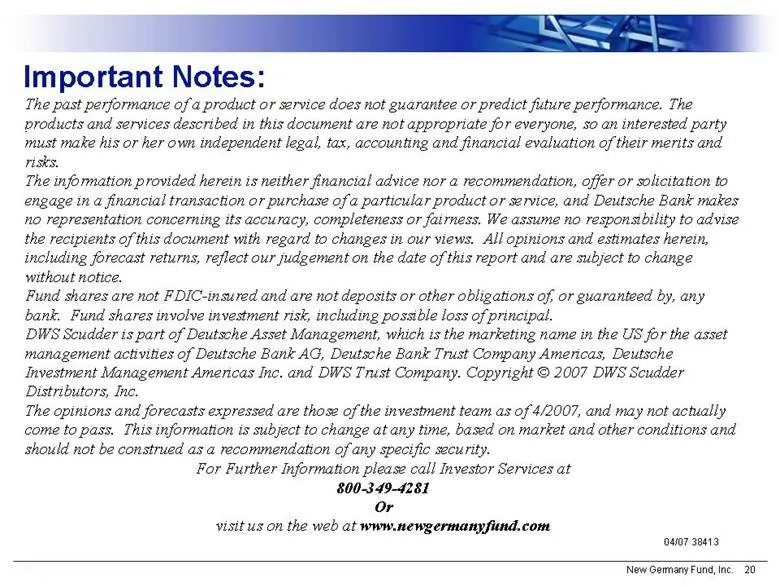
Important Notes: 04/07 38413 The past performance of a product or service does not guarantee or predict future performance. The products and services described in this document are not appropriate for everyone, so an interested party must make his or her own independent legal, tax, ac counting and f
Source: SEC EDGAR · DEFA14A filed May 1, 2007