PHH — Friedman, Billings, Ramsey & Co. Fall Investor Conference 2009
37 slides from PHH's conference presentation, Dec 1, 2009
Slide 1: Friedman, Billings, Ramsey & Co. Fall Investor Conference
Friedman, Billings, Ramsey & Co. Fall Investor Conference December 1, 2009 Exhibit 99.1
Slide 2: Important Disclosures
Important Disclosures Forward Looking Statements Statements in this presentation that are not historical facts are forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Such forward-
Slide 3: Presenters
Presenters Jerry Selitto, President and Chief Executive Officer Sandra Bell, Executive Vice President and Chief Financial Officer
Slide 4: Introduction to PHH
Introduction to PHH PHH is a leading outsource provider of mortgage & vehicle fleet management services. Our revenue drivers include mortgage origination and servicing, fleet leasing and fleet management. My priorities are: To manage the company as one company with a disciplined financial focus to d
Slide 5: Financial Highlights
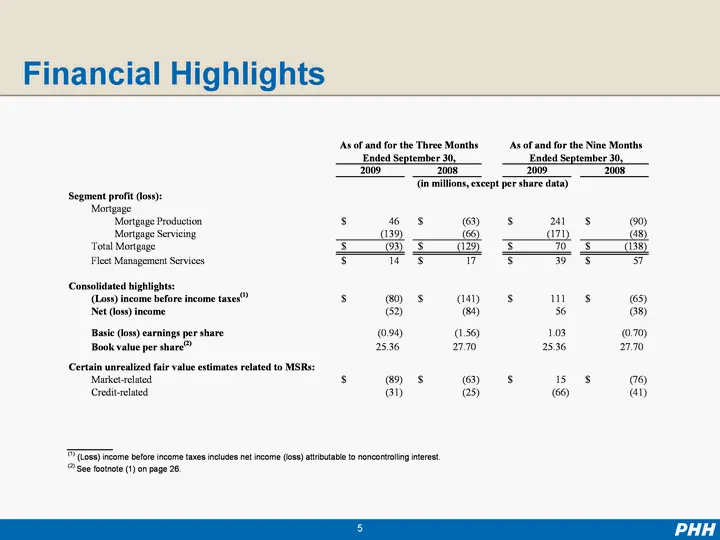
Financial Highlights ‘Asof and forthe Three Months Ax of and for the Nine Months Ended September 30, Ended September 30, 2005, 2008 72009, 2008 ‘Gamilions;exeept per share data) Segment profit os): Mortgage ‘Mortgage Production s ~ 8 @) 21 co) Mortgage Servicing 39) (66) 171 8) “Total Mortgage Toy S
Slide 6: Key Metrics
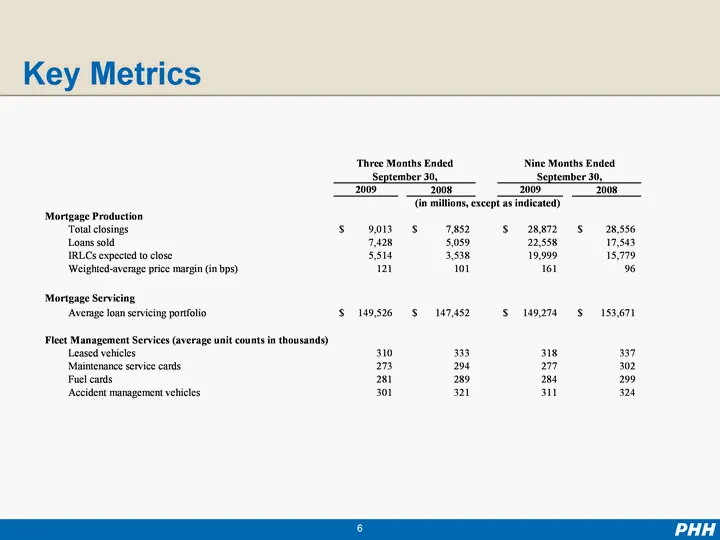
Key Metrics ‘Three Months Ended [Nine Months Ended September 30, September 30, 7009 2008 7009 2008 “Gi millions, except as indicated) “Mortgage Production Total closings S901 $7882 $-28B2_-$— 28.56 Loans sold 7428 5089 22.558 17583 IRLCs expected to close Sst 3538 19999 1579 Weighted average price m
Slide 7: Mortgage Segments
Mortgage Segments
Slide 8: Our Mortgage Business
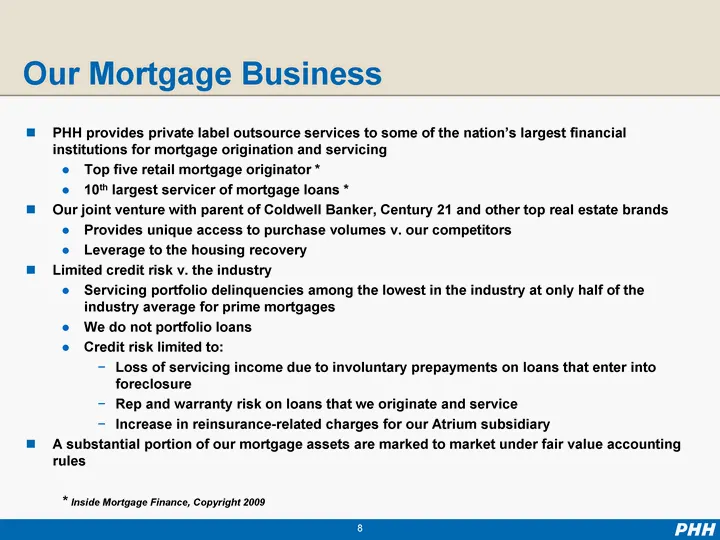
Our Mortgage Business PHH provides private label outsource services to some of the nation's largest financial institutions for mortgage origination and servicing Top five retail mortgage originator * 10th largest servicer of mortgage loans * Our joint venture with parent of Coldwell Banker, Century
Slide 9: Experience Across Distinct Markets With Mortgage Needs
Financial Institutions Real Estate Brands Experience Across Distinct Markets With Mortgage Needs
Slide 10: Consumer Points of Entry and PHH Competencies
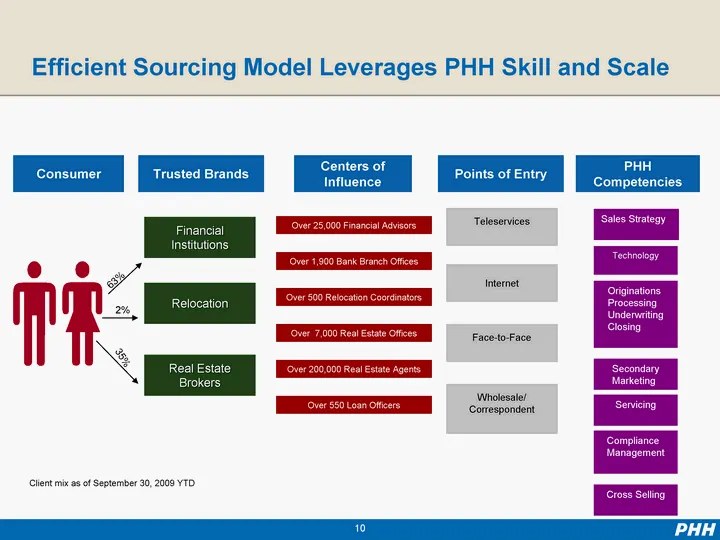
Consumer Points of Entry PHH Competencies Relocation Real Estate Brokers Financial Institutions Face-to-Face Wholesale/ Correspondent Teleservices Trusted Brands Centers of Influence Internet Sales Strategy Originations Processing Underwriting Closing Secondary Marketing Servicing Cross Selling Tech
Slide 11: Mortgage Segments Outlook
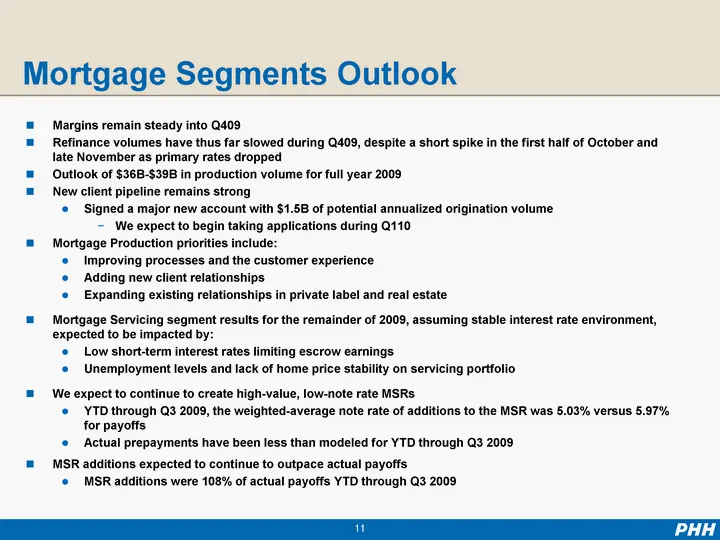
Mortgage Segments Outlook Margins remain steady into Q409 Refinance volumes have thus far slowed during Q409, despite a short spike in the first half of October and late November as primary rates dropped Outlook of $36B-$39B in production volume for full year 2009 New client pipeline remains strong
Slide 12: Fleet Management Services Segment
Fleet Management Services Segment
Slide 13: Fleet Management
Fleet Management Clients include governments and major corporations in the U.S. and Canada Fleets are: Typically 75 vehicles or more used in business application and geographically dispersed Majority of 600,000 vehicles managed as of 12/31/08 are cars and light trucks Total fleet costs for our clien
Slide 14: Fleet Management Fee-Based Revenues
Fleet Management Focused on driving earnings from fee-based revenues: Monthly management fees Fees in connection with the acquisition and disposition of vehicles Fees generated per incident for maintenance and accident management services and for fuel Both from our clients and from our supplier netw
Slide 15: Our clients
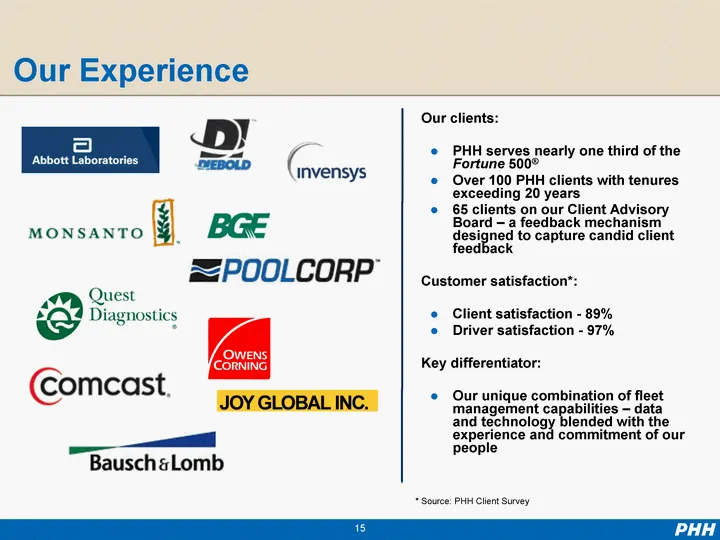
Our clients: PHH serves nearly one third of the Fortune 500(r) Over 100 PHH clients with tenures exceeding 20 years 65 clients on our Client Advisory Board - a feedback mechanism designed to capture candid client feedback Customer satisfaction*: Client satisfaction - 89% Driver satisfaction - 97% Ke
Slide 16: Fleet Management Services Outlook: Market Update
Fleet Management Services Outlook Market Update Clients continue to right-size fleets, reflecting the economy Pent-up vehicle demand expected to positively impact 2010 Industry continues to see lease pricing more reflective of lessor's debt costs Positioned to fund our clients' expected fleet needs
Slide 17: Fleet Management Services Outlook
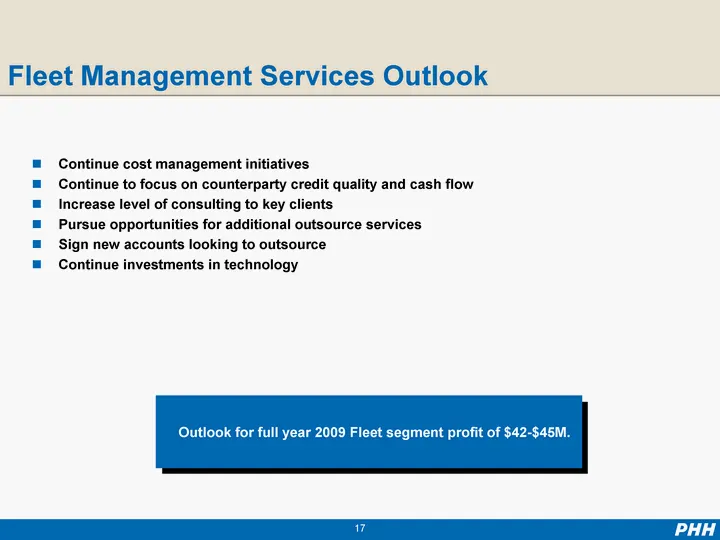
Fleet Management Services Outlook Continue cost management initiatives Continue to focus on counterparty credit quality and cash flow Increase level of consulting to key clients Pursue opportunities for additional outsource services Sign new accounts looking to outsource Continue investments in tech
Slide 18: Summary
Summary
Slide 19: Investment Highlights: Mortgage Outsourcing Business
Mortgage Outsourcing Business Exclusive real estate relationship provides unique access to the purchase markets v. our competitors Leverage to turn around in the housing market Relationships with several top wealth management firms drives higher quality lending Limited credit exposure v. industry We
Slide 20: Investment Highlights: Fleet Management Business
Investment Highlights Fleet Management business Low credit risk Positioned to fund our clients' expected fleet needs Award-winning technology and service delivery De minimus residual risk on fleet vehicles Only 5% of our lease portfolio carries any substantial residual risk
Slide 21: Appendix
Appendix
Slide 22: Third Quarter 2009 and 2008 Segment Results
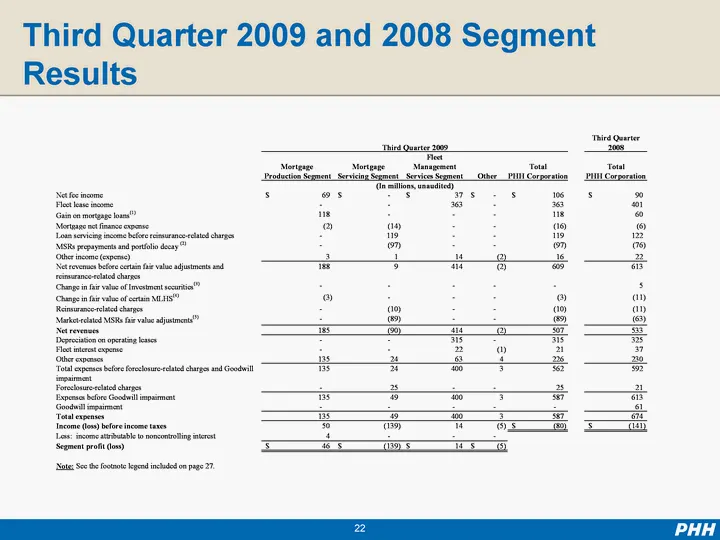
Third Quarter 2009 and 2008 Segment Results
Slide 23: Impact of Credit-Related Charges and Fair Value Adjustments, Q3
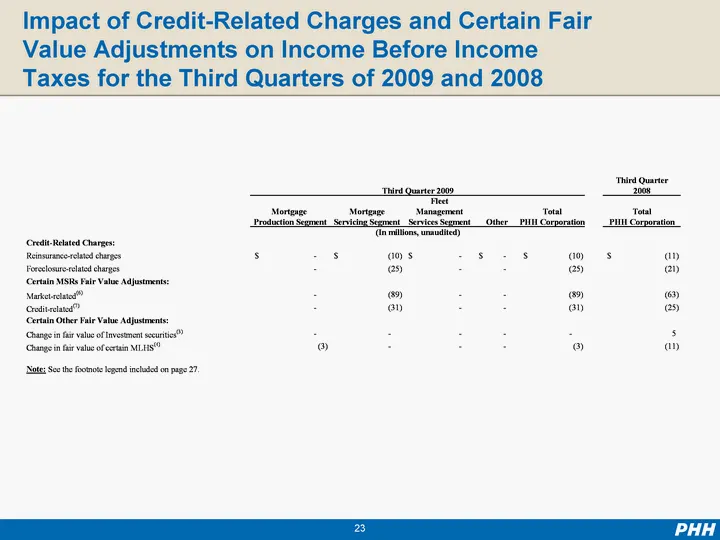
Impact of Credit-Related Charges and Certain Fair Value Adjustments on Income Before Income Taxes for the Third Quarters of 2009 and 2008
Slide 24: Nine Months 2009 and 2008 Segment Results
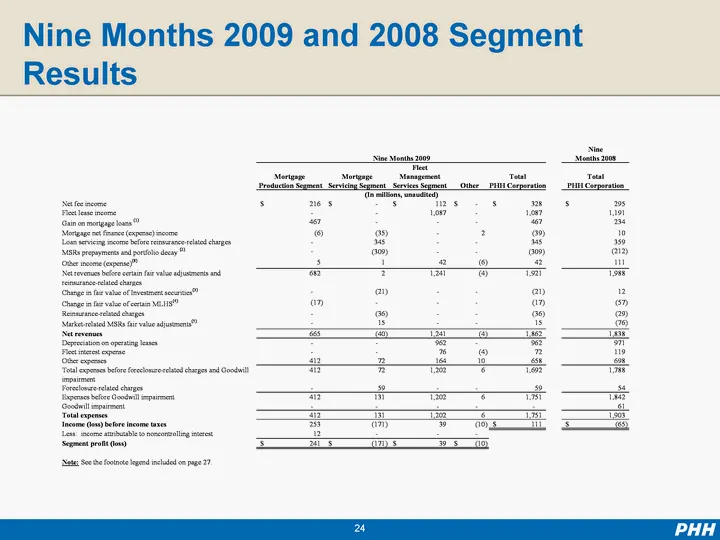
Nine Months 2009 and 2008 Segment Results
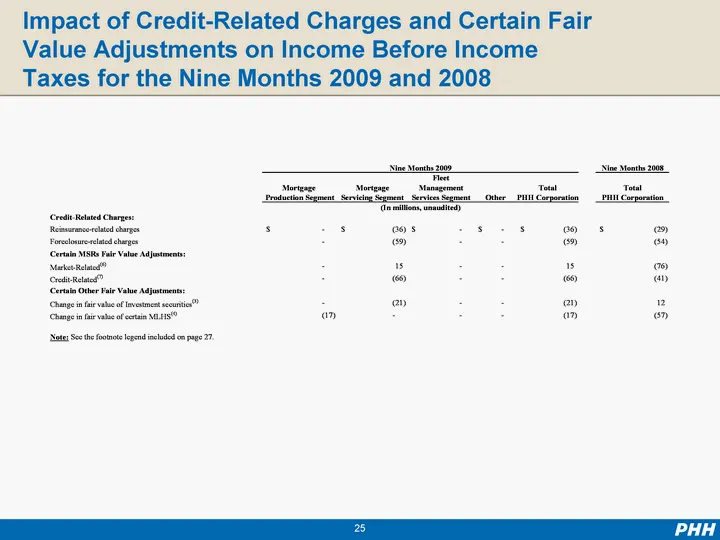
Slide 25: Impact of Credit-Related Charges and Fair Value Adjustments, Nine Months
Impact of Credit-Related Charges and Certain Fair Value Adjustments on Income Before Income Taxes for the Nine Months 2009 and 2008
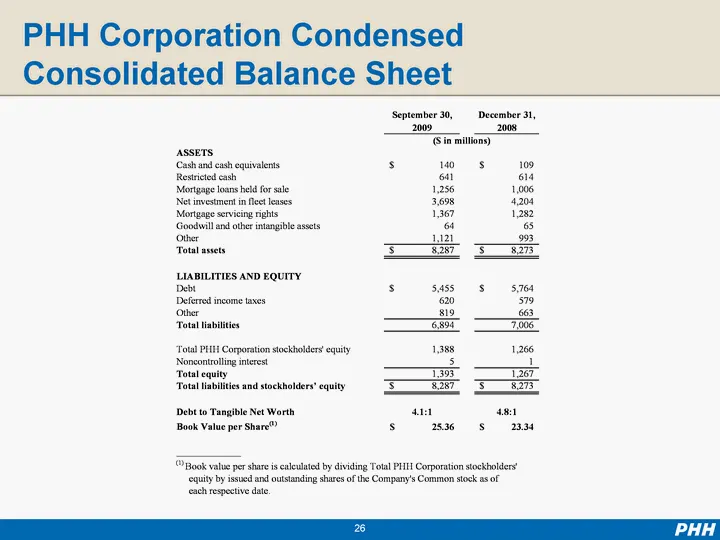
Slide 26: PHH Corporation Condensed Consolidated Balance Sheet
PHH Corporation Condensed Consolidated Balance Sheet
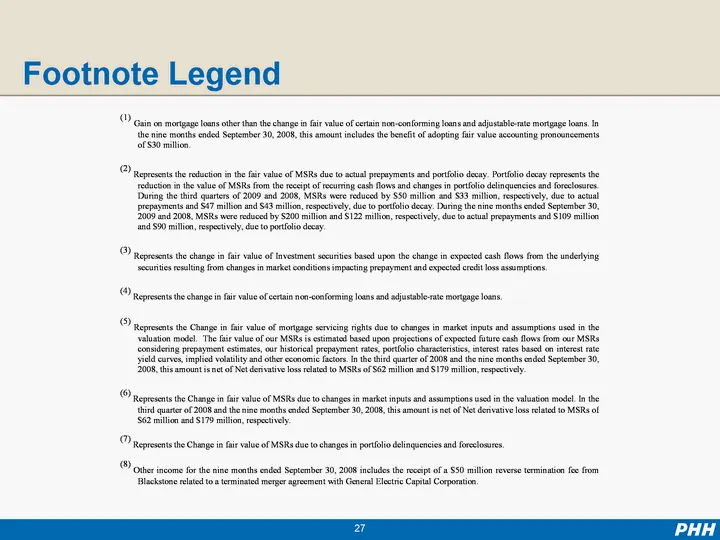
Slide 27: Footnote Legend
Footnote Legend © ain ca morgage loans ter han the chang i ir wae of cari non-conforming lan and adjustable moigage ans. It ‘heme mothe endo Setonber 30,2008, this anount inloder he neo doping hr ale acoutingponcneaments stsb0 mee © represents the acon the fr vale of MSRe dc to aul popyment nd pao d
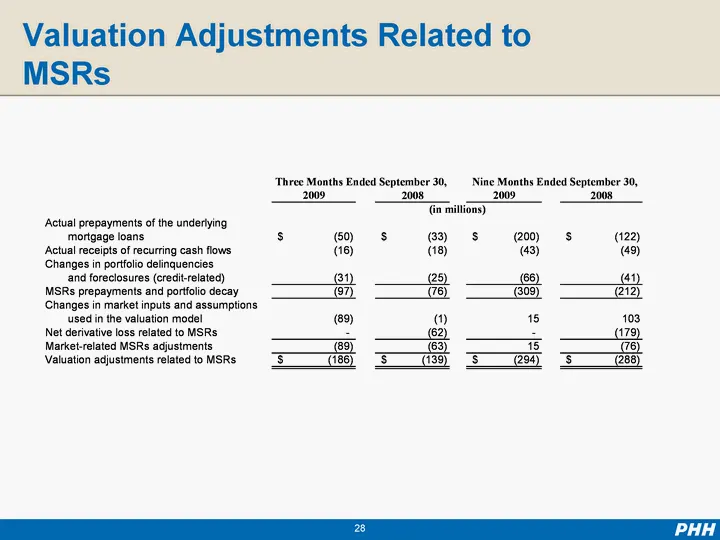
Slide 28: Valuation Adjustments Related to MSRs
Valuation Adjustments Related to MSRs
Slide 29: Mortgage Production Segment Pricing Margin and Volume
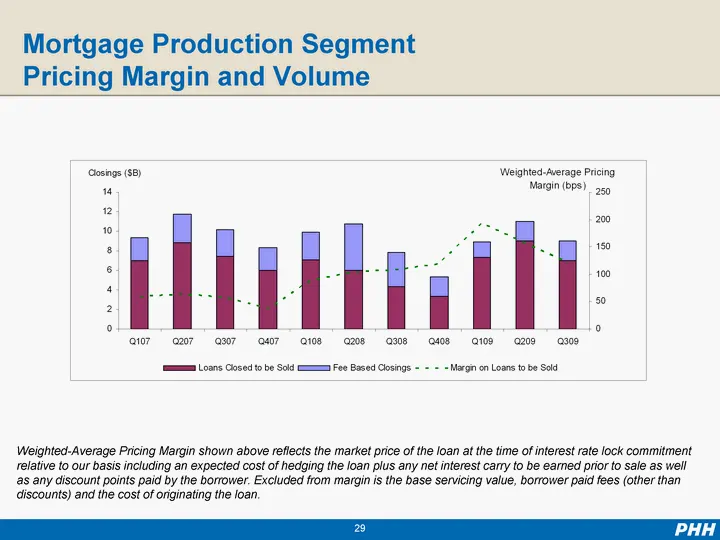
Mortgage Production Segment Pricing Margin and Volume Weighted-Average Pricing Margin shown above reflects the market price of the loan at the time of interest rate lock commitment relative to our basis including an expected cost of hedging the loan plus any net interest carry to be earned prior to
Slide 30: Mortgage Production Segment 2009 Annualized Potential Profitability Sensitivity
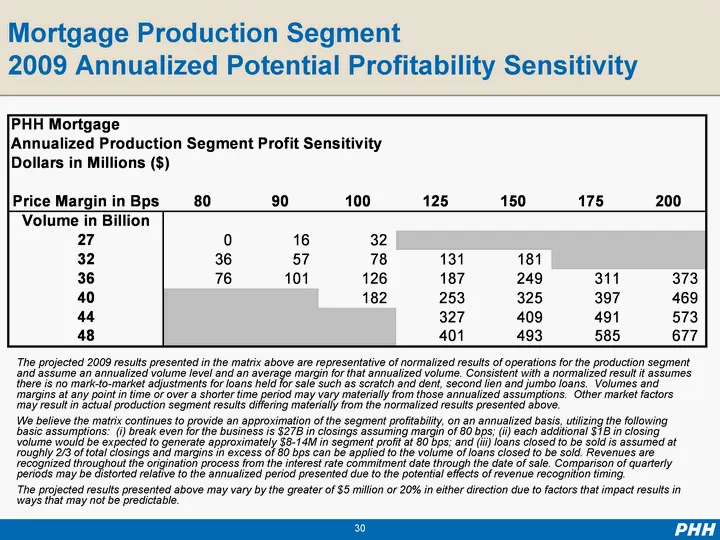
Mortgage Production Segment 2009 Annualized Potential Profitability Sensitivity The projected 2009 results presented in the matrix above are representative of normalized results of operations for the production segment and assume an annualized volume level and an average margin for that annualized v
Slide 31: Superior Mortgage Servicing Portfolio Performance
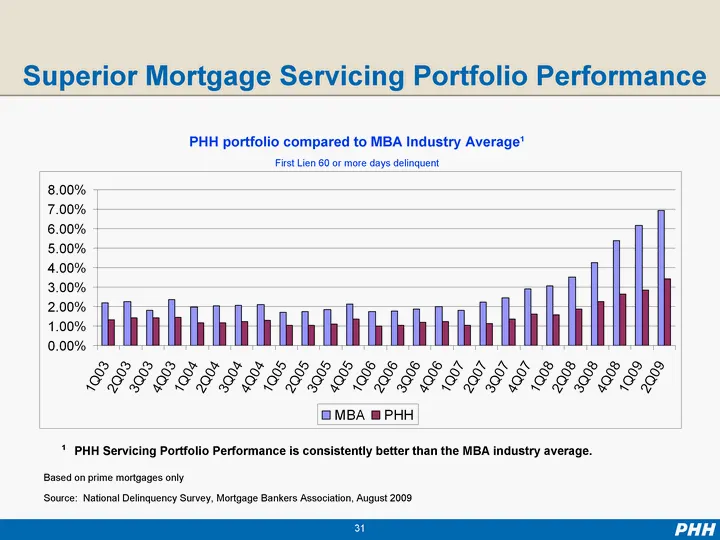
Superior Mortgage Servicing Portfolio Performance PHH portfolio compared to MBA Industry Average1 First Lien 60 or more days delinquent Based on prime mortgages only Source: National Delinquency Survey, Mortgage Bankers Association, August 2009 1 PHH Servicing Portfolio Performance is consistently b
Slide 32: Limited Credit Risk
Limited Credit Risk As a reminder, we carry limited credit risk v. industry Do not portfolio loans Did not participate in subprime lending, Option ARMs or other higher risk products Strong high quality underwriting culture mitigates the potential for loss Credit risk arises in three primary ways: Im
Slide 33: Impact of Delinquencies on Credit Risk
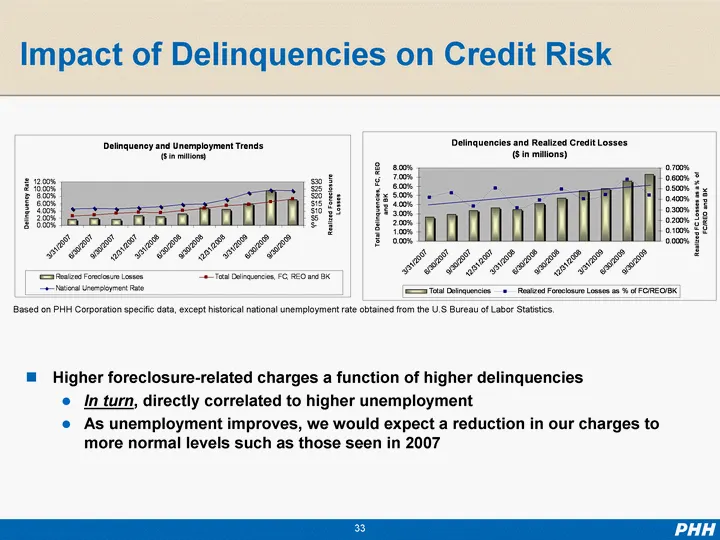
Impact of Delinquencies on Credit Risk Higher foreclosure-related charges a function of higher delinquencies In turn, directly correlated to higher unemployment As unemployment improves, we would expect a reduction in our charges to more normal levels such as those seen in 2007 Based on PHH Corporat
Slide 34: Mortgage Recourse & Reserves
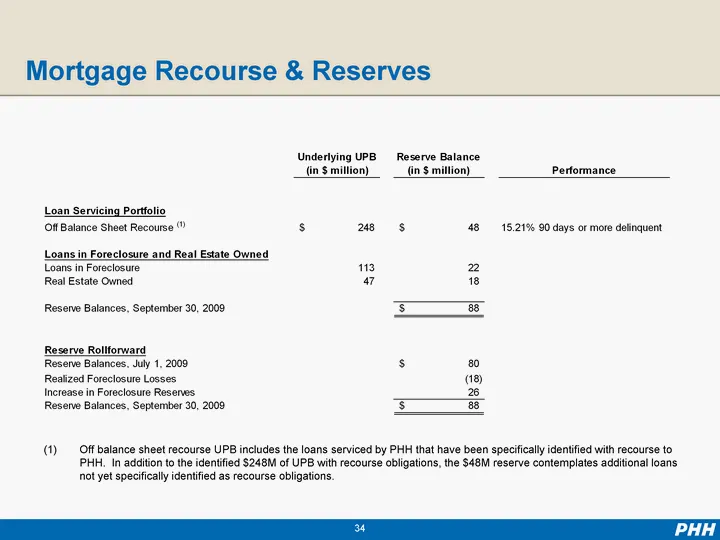
Mortgage Recourse & Reserves Off balance sheet recourse UPB includes the loans serviced by PHH that have been specifically identified with recourse to PHH. In addition to the identified $248M of UPB with recourse obligations, the $48M reserve contemplates additional loans not yet specifically identi
Slide 35: Atrium Reinsurance
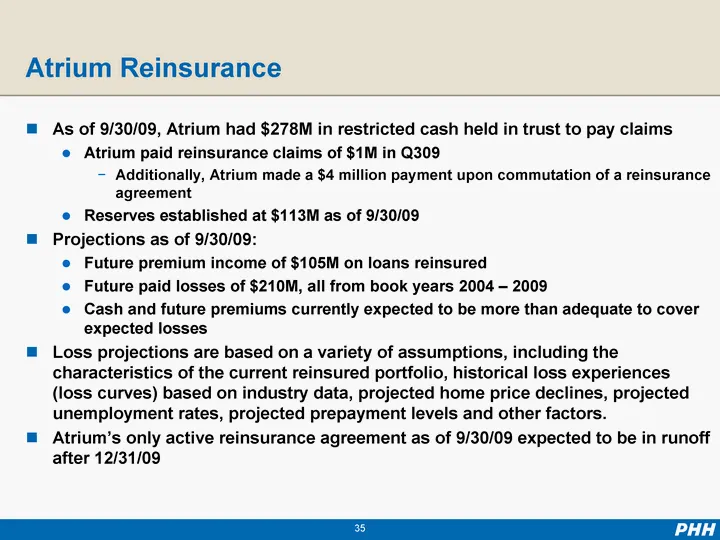
As of 9/30/09, Atrium had $278M in restricted cash held in trust to pay claims Atrium paid reinsurance claims of $1M in Q309 Additionally, Atrium made a $4 million payment upon commutation of a reinsurance agreement Reserves established at $113M as of 9/30/09 Projections as of 9/30/09: Future premiu
Slide 36: Mortgage Segments Sensitivities
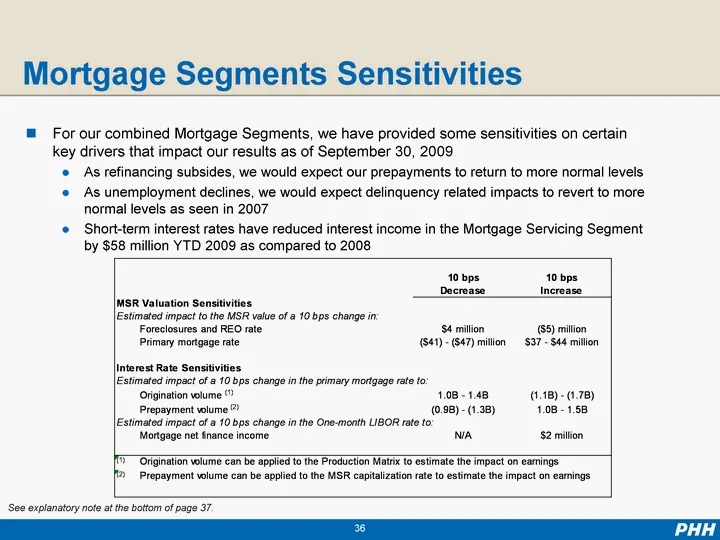
Mortgage Segments Sensitivities For our combined Mortgage Segments, we have provided some sensitivities on certain key drivers that impact our results as of September 30, 2009 As refinancing subsides, we would expect our prepayments to return to more normal levels As unemployment declines, we would
Slide 37: Sensitivity Example
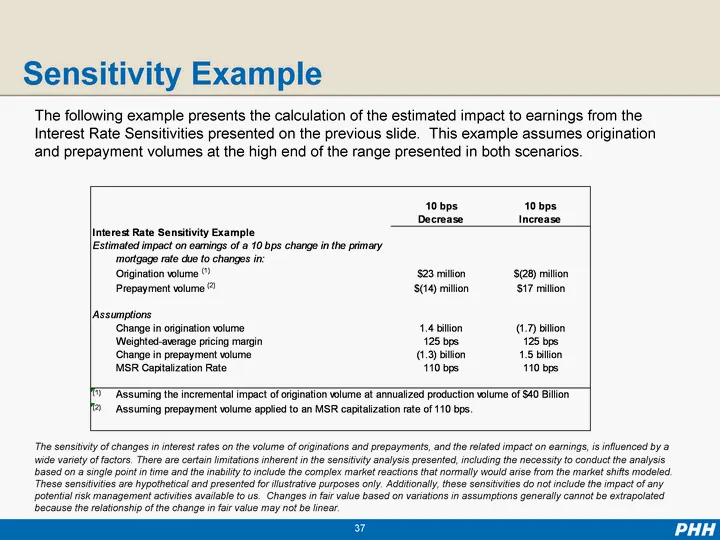
Sensitivity Example The following example presents the calculation of the estimated impact to earnings from the Interest Rate Sensitivities presented on the previous slide. This example assumes origination and prepayment volumes at the high end of the range presented in both scenarios. The sensitivi
Source: SEC EDGAR · 8-K filed Dec 1, 2009
More decks from PHH Corporation
 Merger or Acquisition (February 2018)12 slides · Feb 28, 2018
 Q1 2017 Earnings Presentation34 slides · May 10, 2017
 Investor Presentation (February 2013)26 slides · Feb 12, 2013
 KBW Investment Management & Specialty Finance Conference 201116 slides · Jun 7, 2011
 FBR Capital Markets Fall Investor Conference 201016 slides · Nov 29, 2010
 Q2 2010 Earnings Presentation13 slides · Aug 3, 2010