Transatlantic — Merger or Acquisition (August 2011)
24 slides from Transatlantic's merger presentation, Aug 18, 2011
Slide 1: The TransAllied Merger is the Superior Combination
The TransAllied Merger is the Superior Combination August 2011
Slide 2: Forward-looking statements and additional information
1 This presentation contains forward-looking statements that involve a number of risks and uncertainties. Statements that are not historical facts, including statements about our beliefs and expectations, are forward-looking statements. Any forward-looking statements made in this presentation reflec
Slide 3: The TransAllied merger is the best possible combination
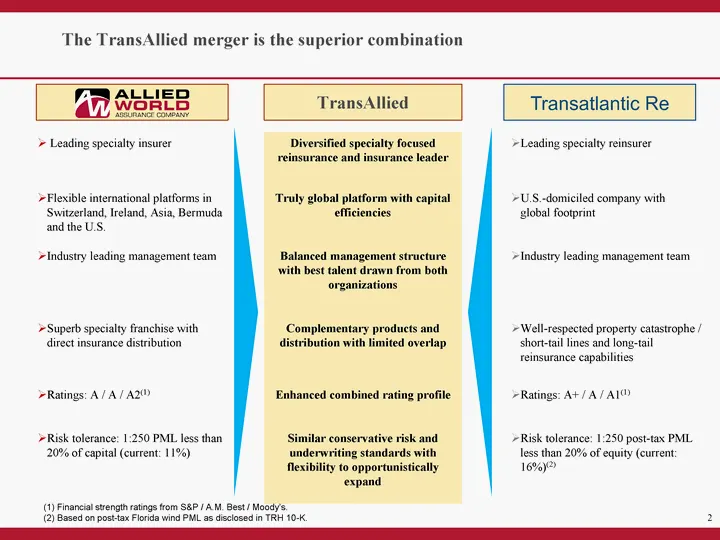
Industry leading management team Industry leading management team Superb specialty franchise with direct insurance distribution Well-respected property catastrophe / short-tail lines and long-tail reinsurance capabilities Ratings: A / A / A2(1) Ratings: A+ / A / A1(1) Risk tolerance: 1:250 PML less
Slide 4: TransAllied definitive merger agreement vs. Validus unsolicited takeover proposal
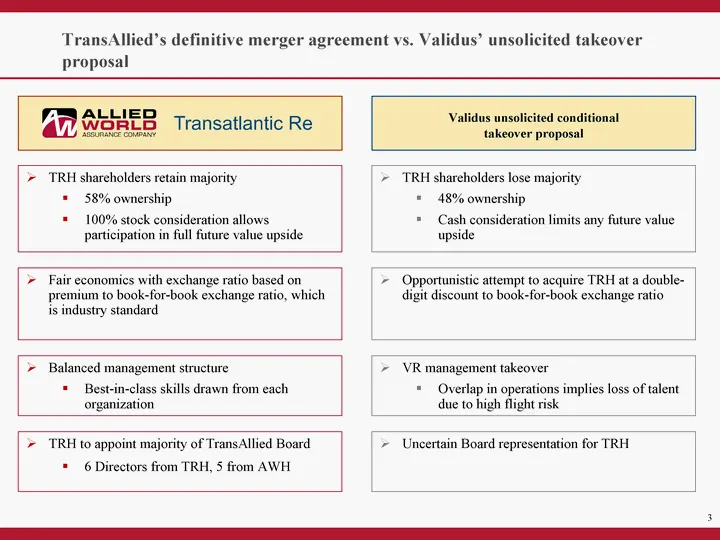
TransAllied's definitive merger agreement vs. Validus' unsolicited takeover proposal Validus unsolicited conditional takeover proposal Fair economics with exchange ratio based on premium to book-for-book exchange ratio, which is industry standard Opportunistic attempt to acquire TRH at a double- dig
Slide 5: The TransAllied merger is the SUPERIOR combination
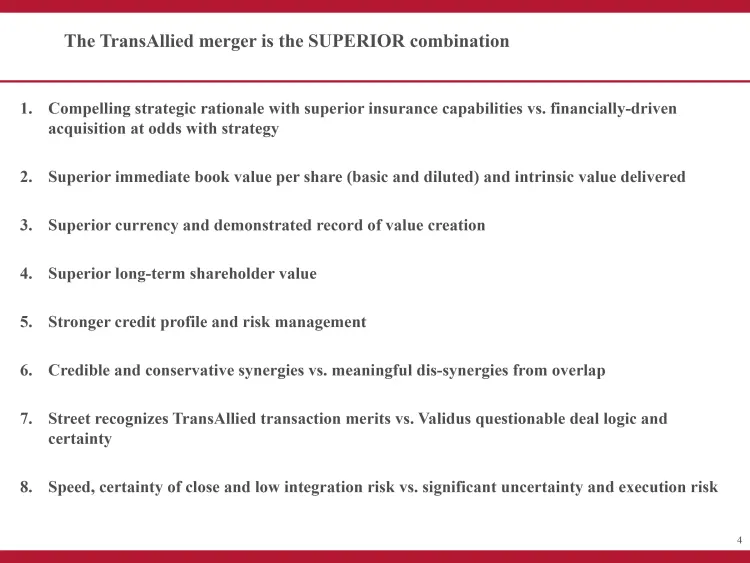
Compelling strategic rationale with superior insurance capabilities vs. financially-driven acquisition at odds with strategy Superior immediate book value per share (basic and diluted) and intrinsic value delivered Superior currency and demonstrated record of value creation Superior long-term shareh
Slide 6: Compelling strategic rationale with superior insurance capabilities
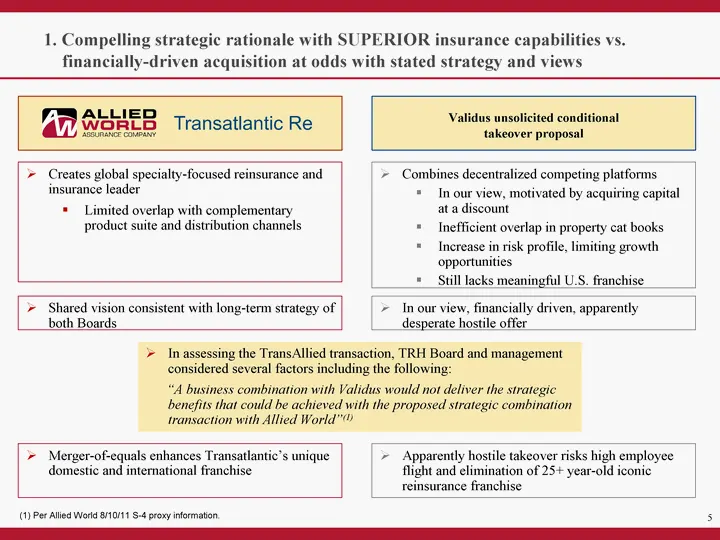
1. Compelling strategic rationale with SUPERIOR insurance capabilities vs. financially-driven acquisition at odds with stated strategy and views Creates global specialty-focused reinsurance and insurance leader Limited overlap with complementary product suite and distribution channels Combines decen
Slide 7: Validus' views on casualty
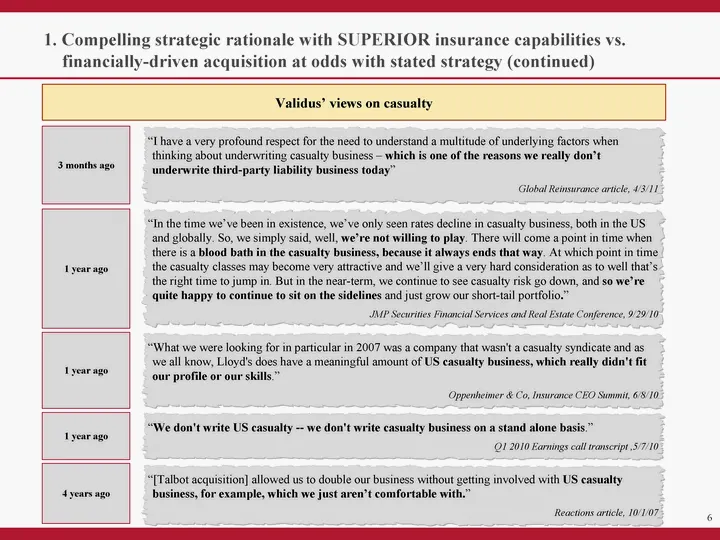
6 Validus' views on casualty "I have a very profound respect for the need to understand a multitude of underlying factors when thinking about underwriting casualty business - which is one of the reasons we really don't underwrite third-party liability business today" Global Reinsurance article, 4/3/
Slide 8: Superior immediate book value per share and intrinsic value
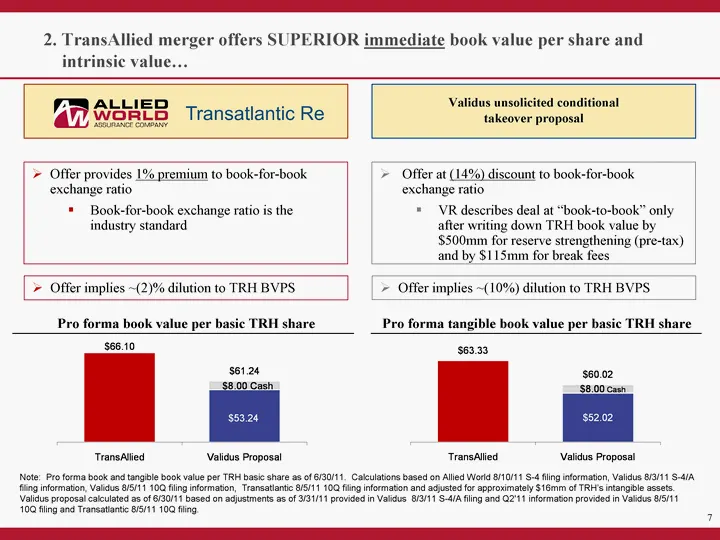
2. TransAllied merger offers SUPERIOR immediate book value per share and intrinsic value... Offer provides 1% premium to book-for-book exchange ratio Book-for-book exchange ratio is the industry standard Offer at (14%) discount to book-for-book exchange ratio VR describes deal at "book-to-book" only
Slide 9: Superior long-term value (intrinsic value)
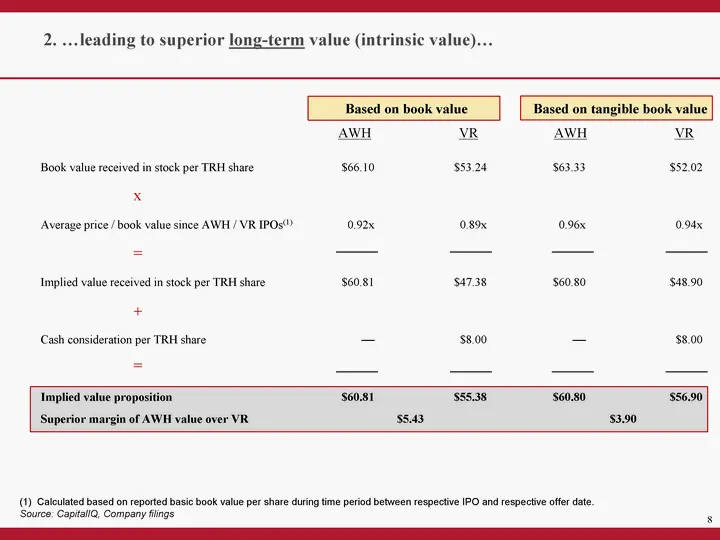
8 Book value received in stock per TRH share Average price / book value since AWH / VR IPOs(1) Implied value received in stock per TRH share Cash consideration per TRH share Implied value proposition Based on tangible book value AWH VR Based on book value AWH VR $66.10 0.92x $60.81 -- $60.81 $53.24
Slide 10: Vs. immediate shareholder value destruction
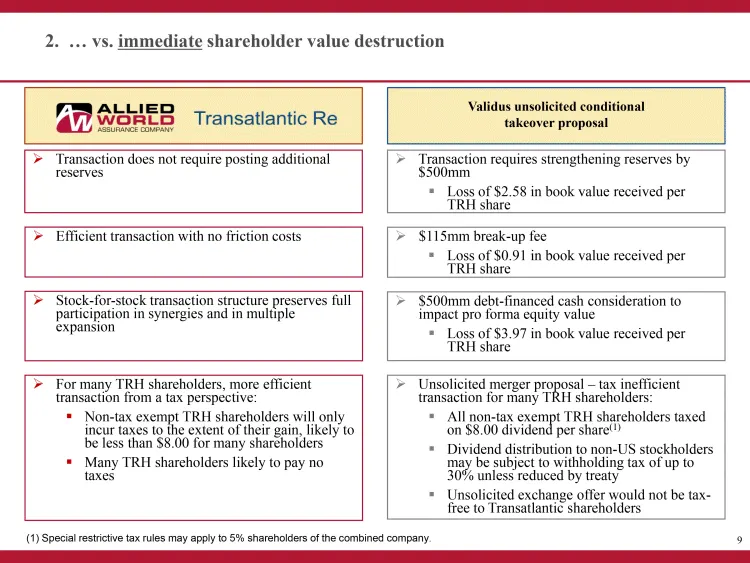
2. ... vs. immediate shareholder value destruction Transaction does not require posting additional reserves Transaction requires strengthening reserves by $500mm Loss of $2.58 in book value received per TRH share $115mm break-up fee Loss of $0.91 in book value received per TRH share Efficient transa
Slide 11: Vs. immediate shareholder value destruction (continued)
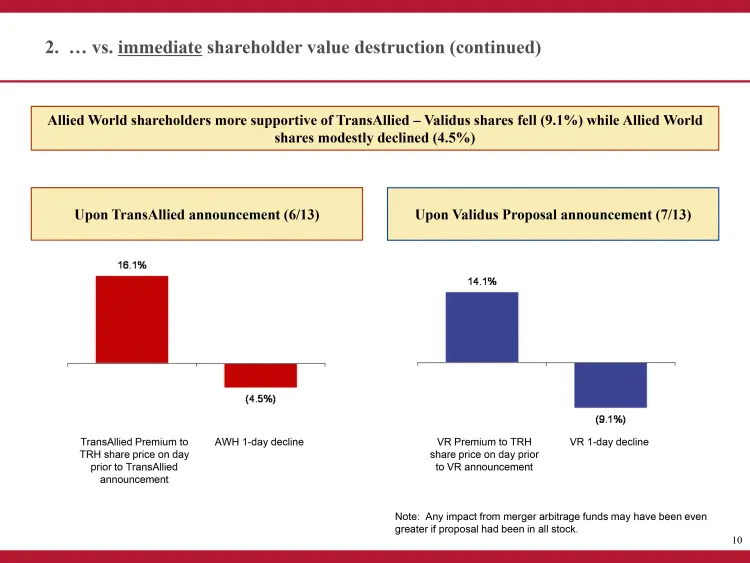
2. ... vs. immediate shareholder value destruction (continued) Allied World shareholders more supportive of TransAllied - Validus shares fell (9.1%) while Allied World shares modestly declined (4.5%) Upon Validus Proposal announcement (7/13) Upon TransAllied announcement (6/13) 10 Note: Any impact f
Slide 12: Allied World delivers superior currency and record of value creation
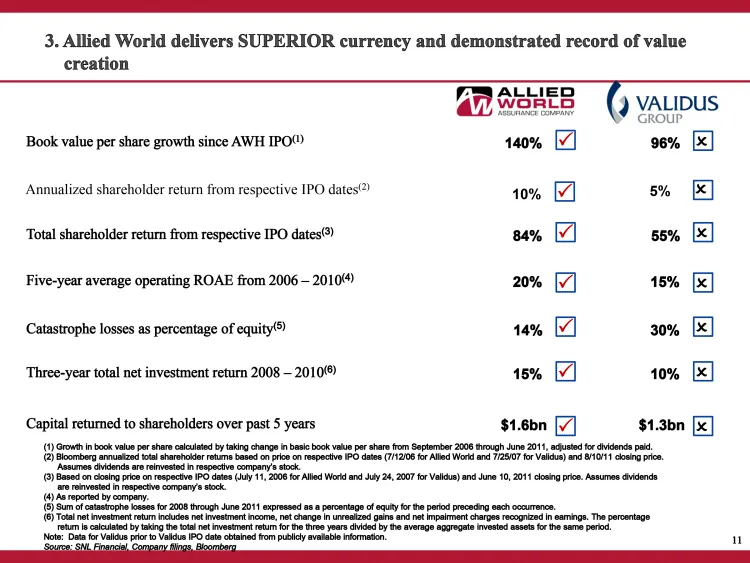
3. Allied World delivers SUPERIOR currency and demonstrated record of value creation (1) Growth in book value per share calculated by taking change in basic book value per share from September 2006 through June 2011, adjusted for dividends paid. (2) Bloomberg annualized total shareholder returns bas
Slide 13: Superior currency and value creation (continued)
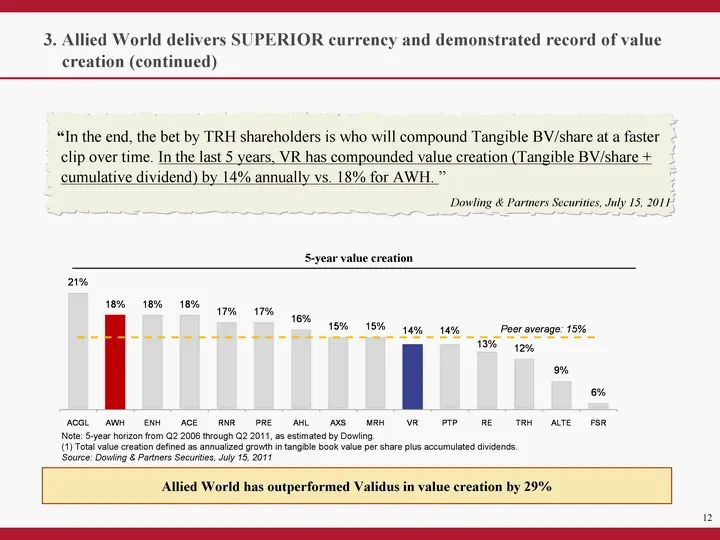
3. Allied World delivers SUPERIOR currency and demonstrated record of value creation (continued) "In the end, the bet by TRH shareholders is who will compound Tangible BV/share at a faster clip over time. In the last 5 years, VR has compounded value creation (Tangible BV/share + cumulative dividend)
Slide 14: Operating ROE and investment returns
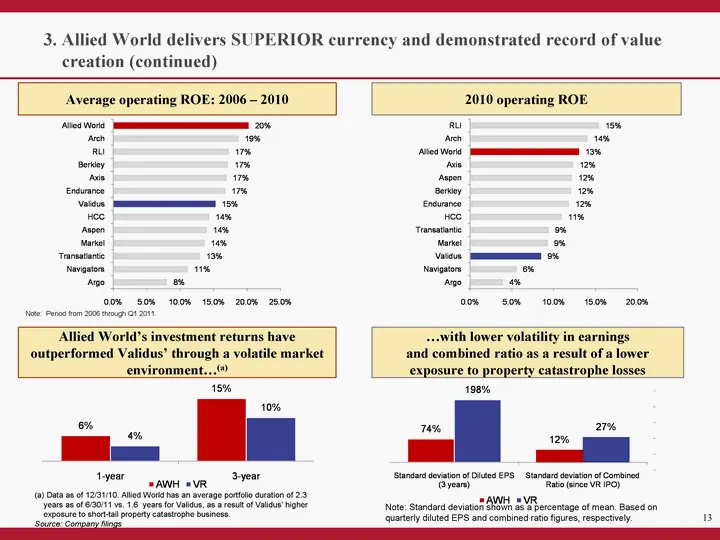
13 Average operating ROE: 2006 - 2010 2010 operating ROE Note: Period from 2006 through Q1 2011. Allied World's investment returns have outperformed Validus' through a volatile market environment...(a) ....with lower volatility in earnings and combined ratio as a result of a lower exposure to proper
Slide 15: TransAllied merger creates superior long-term shareholder value
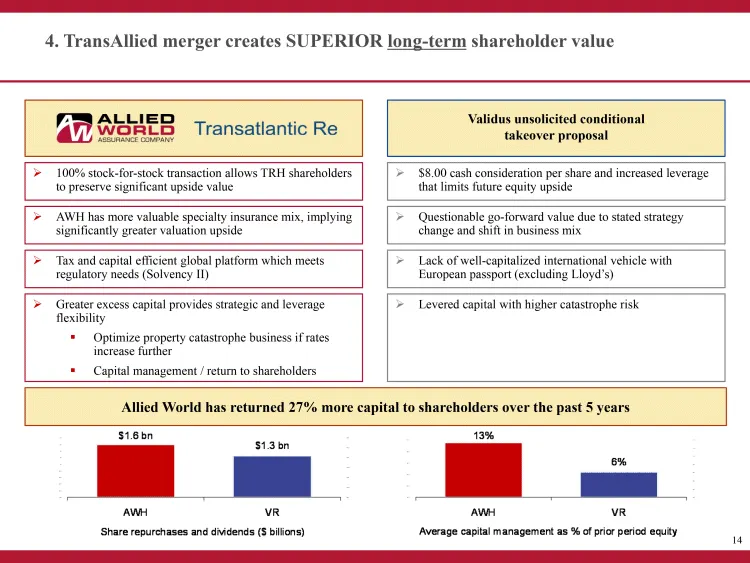
4. TransAllied merger creates SUPERIOR long-term shareholder value 100% stock-for-stock transaction allows TRH shareholders to preserve significant upside value $8.00 cash consideration per share and increased leverage that limits future equity upside AWH has more valuable specialty insurance mix, i
Slide 16: More diversified and less exposed to catastrophe losses
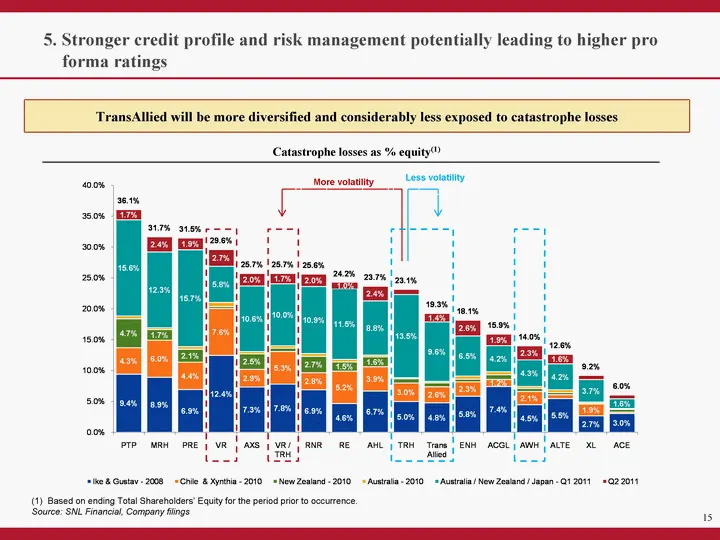
15 TransAllied will be more diversified and considerably less exposed to catastrophe losses 5. Stronger credit profile and risk management potentially leading to higher pro forma ratings (1) Based on ending Total Shareholders' Equity for the period prior to occurrence. Source: SNL Financial, Company
Slide 17: Stronger credit profile and risk management (continued)
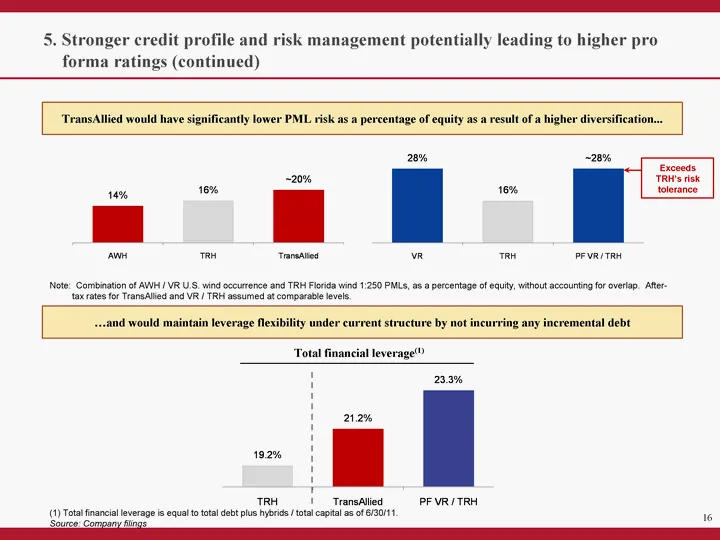
16 Note: Combination of AWH / VR U.S. wind occurrence and TRH Florida wind 1:250 PMLs, as a percentage of equity, without accounting for overlap. After- tax rates for TransAllied and VR / TRH assumed at comparable levels. TransAllied would have significantly lower PML risk as a percentage of equity
Slide 18: Financial strength ratings and agency reactions
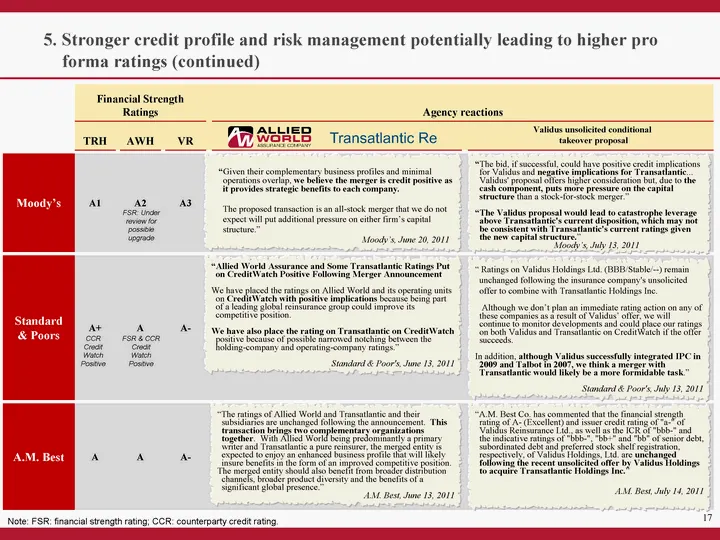
17 5. Stronger credit profile and risk management potentially leading to higher pro forma ratings (continued) Financial Strength Ratings Financial Strength Ratings Financial Strength Ratings Financial Strength Ratings Financial Strength Ratings Agency reactions Agency reactions Agency reactions TRH
Slide 19: Credible and conservative synergies vs. dis-synergies from overlap
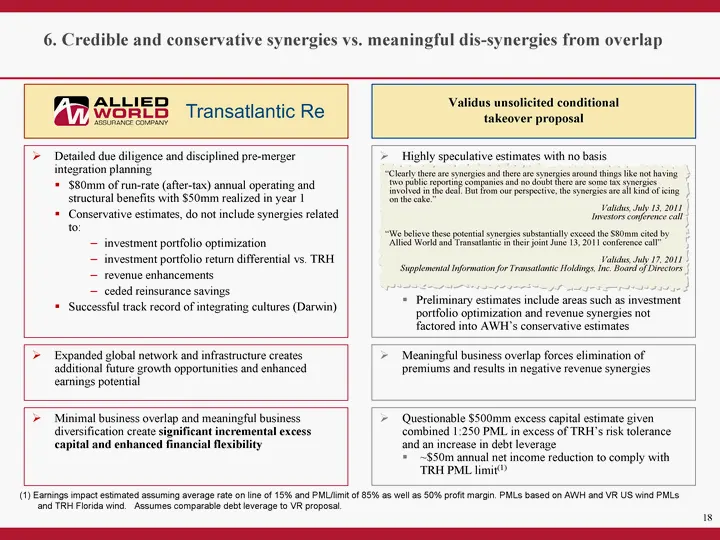
6. Credible and conservative synergies vs. meaningful dis-synergies from overlap Detailed due diligence and disciplined pre-merger integration planning $80mm of run-rate (after-tax) annual operating and structural benefits with $50mm realized in year 1 Conservative estimates, do not include synergie
Slide 20: Synergies and earnings power (continued)
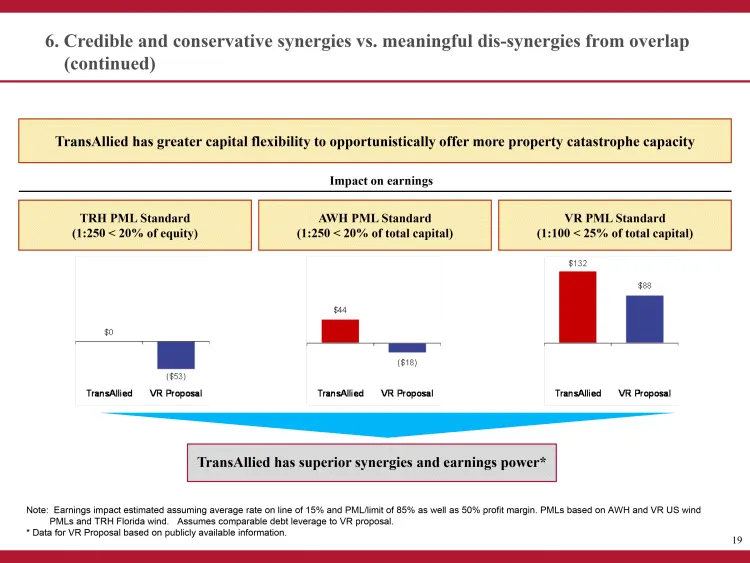
19 AWH PML Standard (1:250 < 20% of total capital) TRH PML Standard (1:250 < 20% of equity) TransAllied has superior synergies and earnings power* TransAllied has greater capital flexibility to opportunistically offer more property catastrophe capacity VR PML Standard (1:100 < 25% of total capital)
Slide 21: IPC Management - year later
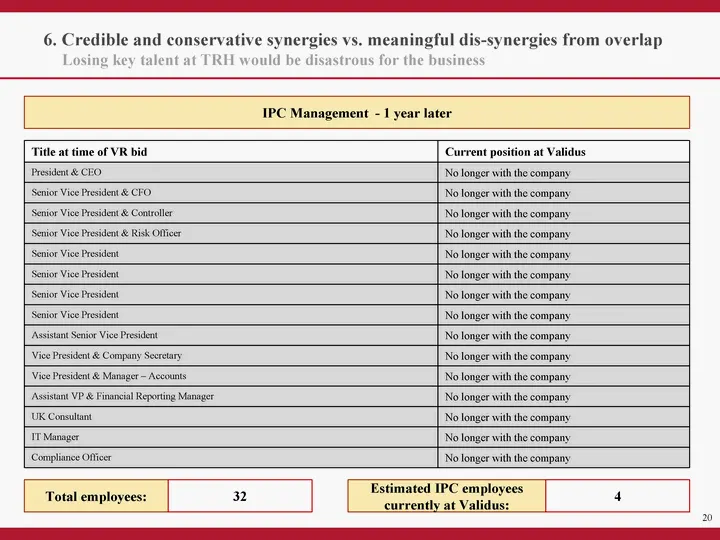
20 IPC Management - 1 year later 6. Credible and conservative synergies vs. meaningful dis-synergies from overlap Losing key talent at TRH would be disastrous for the business Title at time of VR bid Current position at Validus President & CEO No longer with the company Senior Vice President & CFO N
Slide 22: Analyst commentary on the transactions
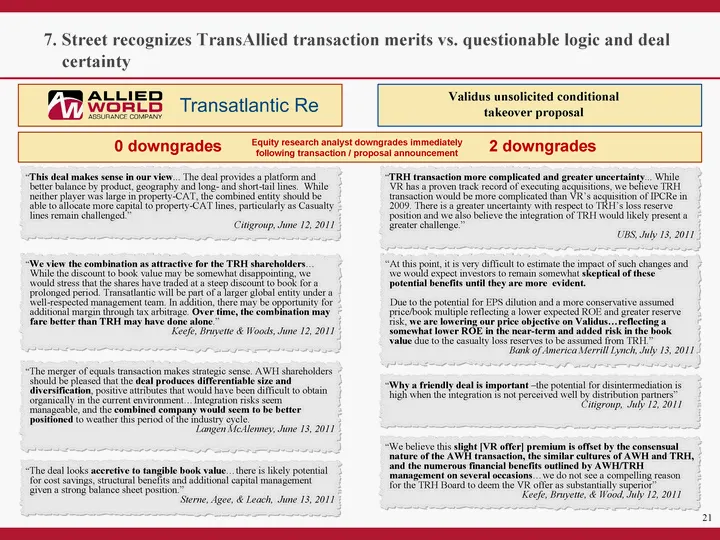
21 "This deal makes sense in our view... The deal provides a platform and better balance by product, geography and long- and short-tail lines. While neither player was large in property-CAT, the combined entity should be able to allocate more capital to property-CAT lines, particularly as Casualty l
Slide 23: Speed, certainty of close and low integration risk
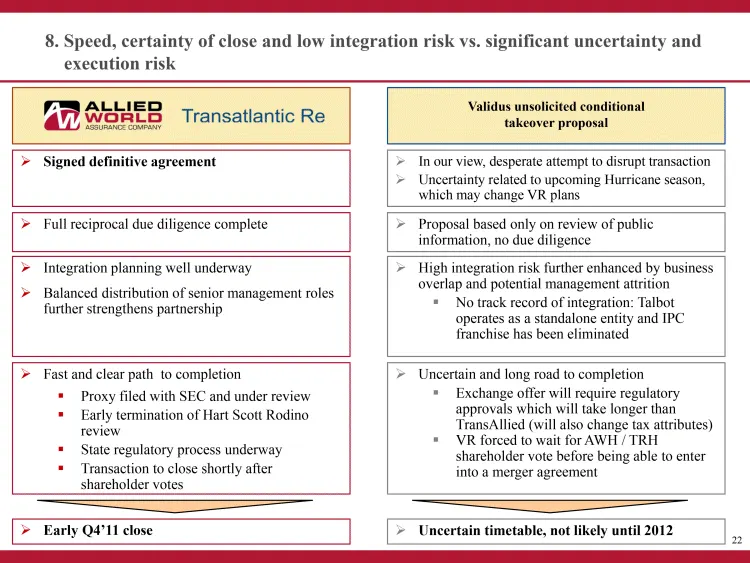
8. Speed, certainty of close and low integration risk vs. significant uncertainty and execution risk Signed definitive agreement In our view, desperate attempt to disrupt transaction Uncertainty related to upcoming Hurricane season, which may change VR plans Full reciprocal due diligence complete Pr
Slide 24: The TransAllied Merger is the Best Possible Combination
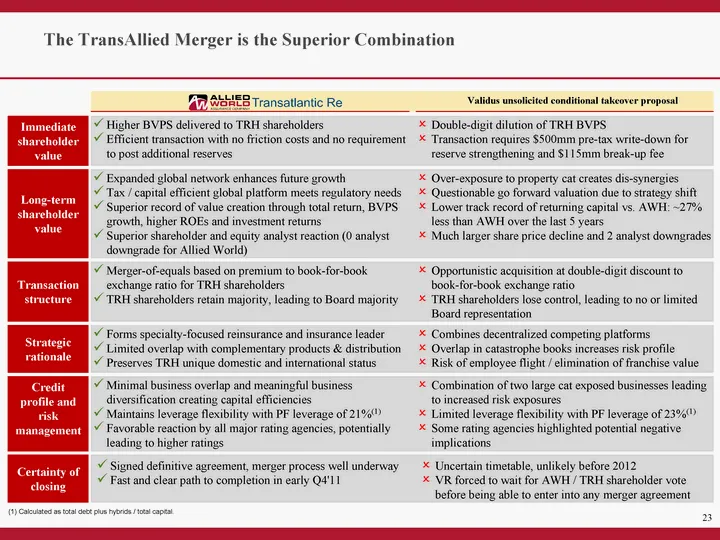
The TransAllied Merger is the Best Possible Combination - SUPERIOR in All Respects Immediate shareholder value Higher BVPS delivered to TRH shareholdersEfficient transaction with no friction costs and no requirement to post additional reserves Double-digit dilution of TRH BVPSTransaction requires $5
Source: SEC EDGAR · 425 filed Aug 18, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011