Airtran — Raymond James Growth Airline Conference 2007
27 slides from Airtran's conference presentation, Feb 2, 2007
Slide 1: Raymond James Growth Airline Conference February 1, 2007
Raymond James Growth Airline Conference February 1, 2007 Raymond James Growth Airline Conference February 1, 2007 Exhibit 99.1
Slide 2: Forward Looking Information
2 Forward Looking Information Certain of the statements, including, except in connection with AirTran’s offer to exchange with respect to Midwest Air Group, Inc. (“Midwest”), contained herein should be considered “forward-looking statements” within the meaning of the Private Securities Litigation Re
Slide 3: AirTran Airways Today
3 Youngest all-Boeing fleet in America — 127 Airplanes – 87 717s / 40 737s 54 cities served — Announced Daytona Beach FL, Newburgh NY, Phoenix AZ, St. Louis MO, and San Diego CA in 2007 8 consecutive years of profitability — One of two consistently profitable airlines AirTran Airways Today AirTran A
Slide 4: AirTran Airways Business Model
4 To provide a superior product with very low costs — Assigned seating — Business Class Only major U.S. airline with business class on every flight — Convenient distribution Internet, telephone reservations, and travel agencies — XM Radio and oversized luggage bins — Friendly crewmembers Provide val
Slide 5: AirTran Has Very Low Costs
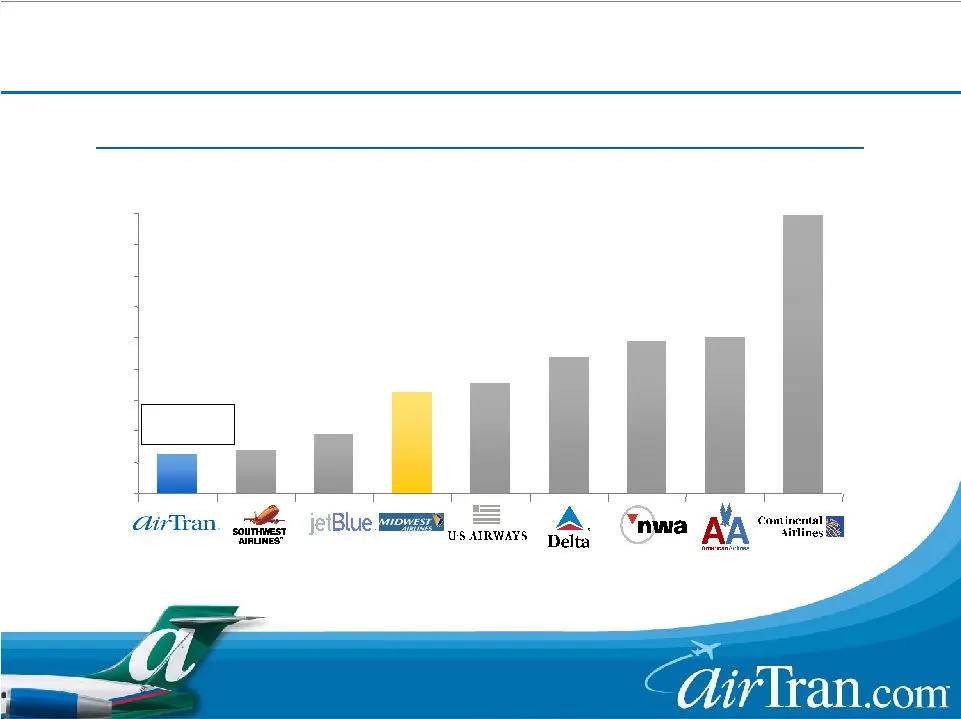
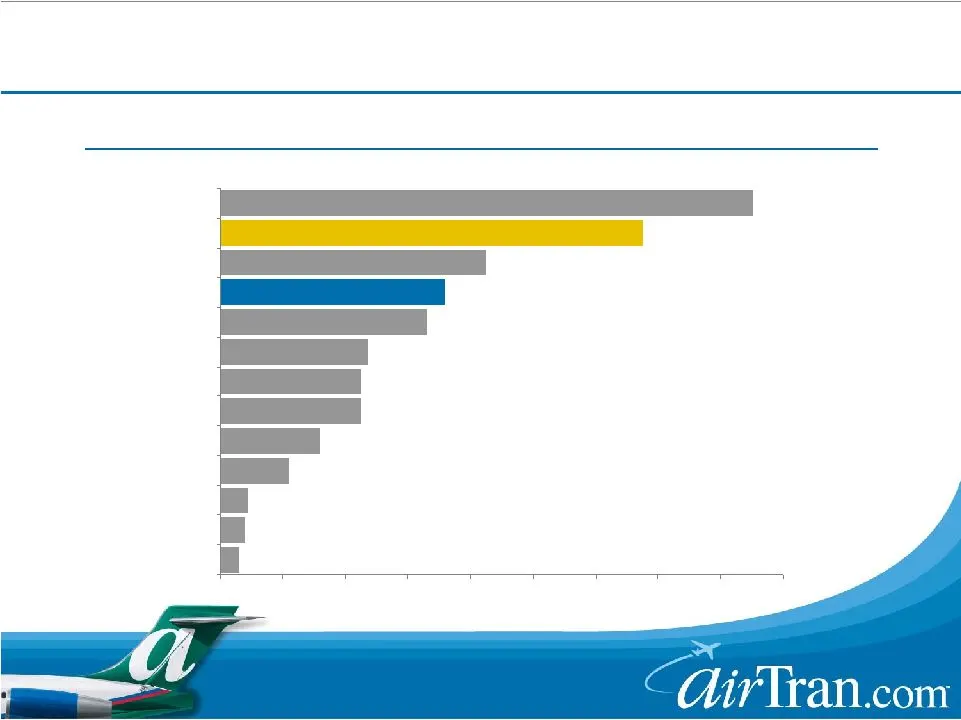
5 Industry Cost Comparison Non-Fuel Unit Costs at 651 Miles for First Nine Months 2006 (cents) While legacy costs are down, gap remains large AirTran Has Very Low Costs AirTran Has Very Low Costs Excludes fuel and special items Q406 =5.94 cents
Slide 6: AirTran's Non-Fuel Unit Cost Trend
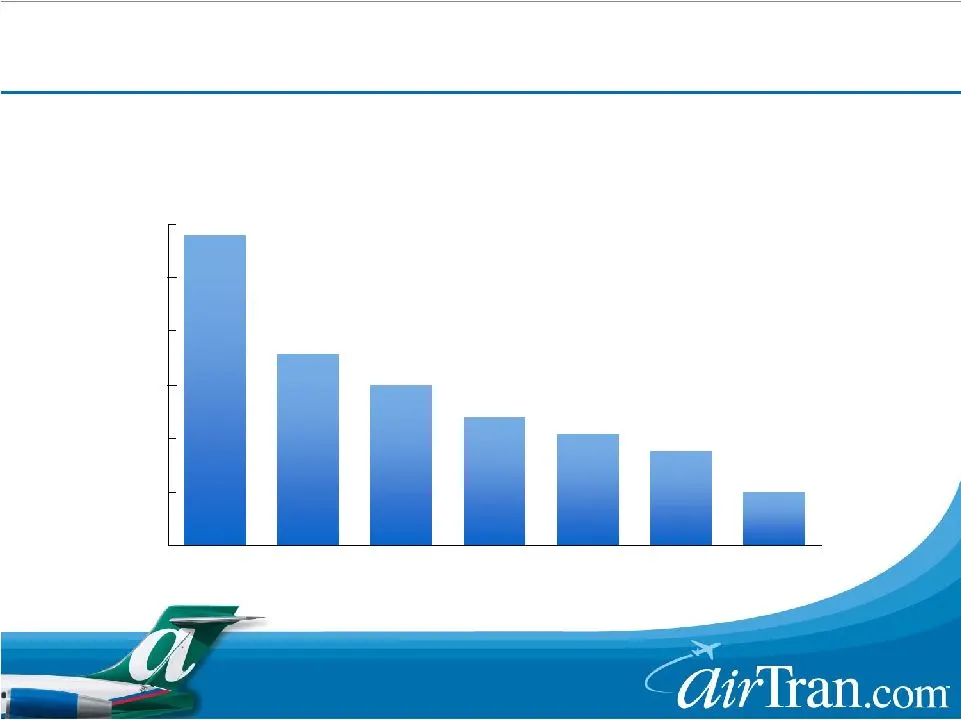
6 5.75 6.00 6.25 6.50 6.75 7.00 7.25 2001 2002 2003 2004 2005 2006 2007E * Excludes non-recurring special items (cents per mile) AirTran’s Non-Fuel Unit Cost Trend -3% Projecting A Sixth Consecutive Year of Cost Reductions Projecting A Sixth Consecutive Year of Cost Reductions
Slide 7: Low Cost Fleet Plan
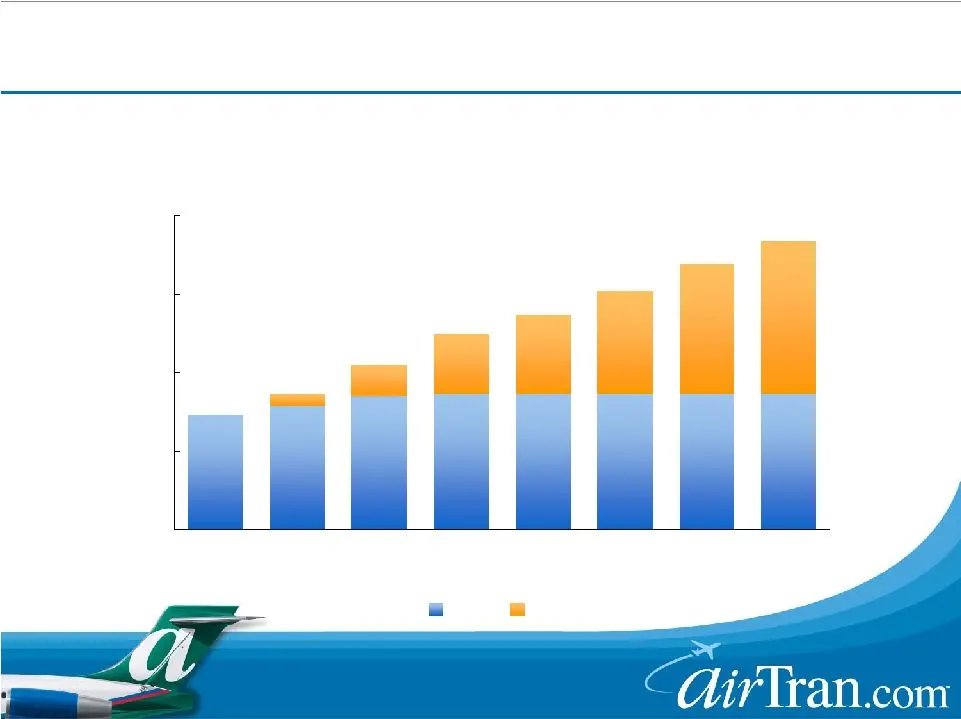
7 2003 2004 2005 2006 2007 2008 2009 2010 717s 737s Aircraft Currently 127 Aircraft: 87 717s / 40 737s Low Cost Fleet Plan Low Cost Fleet Plan
Slide 8: AirTran Maintains High Airline Quality Rating
8 2004 2003 2002 2001 2005 JetBlue AirTran Southwest United Alaska America West Northwest American Continental ATA JetBlue Alaska Southwest America West US Airways Northwest Continental AirTran United ATA US Airways Alaska Southwest America West Continental American Delta United Northwest American E
Slide 9: JD Power Survey Validates Strong Products
9 2006 JD Power North American Airlines Survey; Overall Customer Satisfaction Northwest Airlines United Airlines US Airways Alaska Airlines American Airlines Delta Airlines Spirit Airlines Continental Airlines Frontier Airlines AirTran Airways Southwest Airlines Midwest Airlines JetBlue Airways Mean
Slide 10: Revenue Outlook Is Improving
10 Q406 unit revenue growth slowed, primarily in Atlanta markets — Capacity growth was robust AirTran increased frequency in short haul Atlanta routes to secure access to additional gates Delta increased capacity over 10% from summer levels Q107 capacity outlook is improved — AirTran’s capacity rede
Slide 11: Delta Capacity In AirTran's Atlanta Markets Is Declining
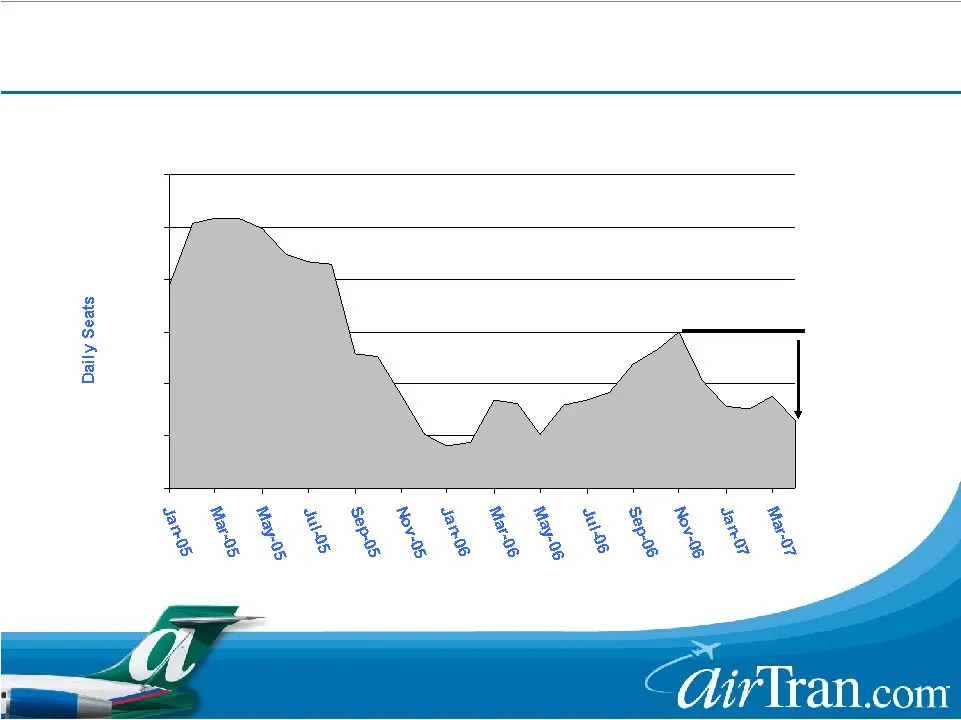
11 55,000 60,000 65,000 70,000 75,000 80,000 85,000 Delta Bankruptcy Delta Capacity In AirTran’s Atlanta Markets Is Declining Delta Capacity In AirTran’s Atlanta Markets Is Declining -12%
Slide 12: Fuel Is Also Creating Significant Earnings Momentum
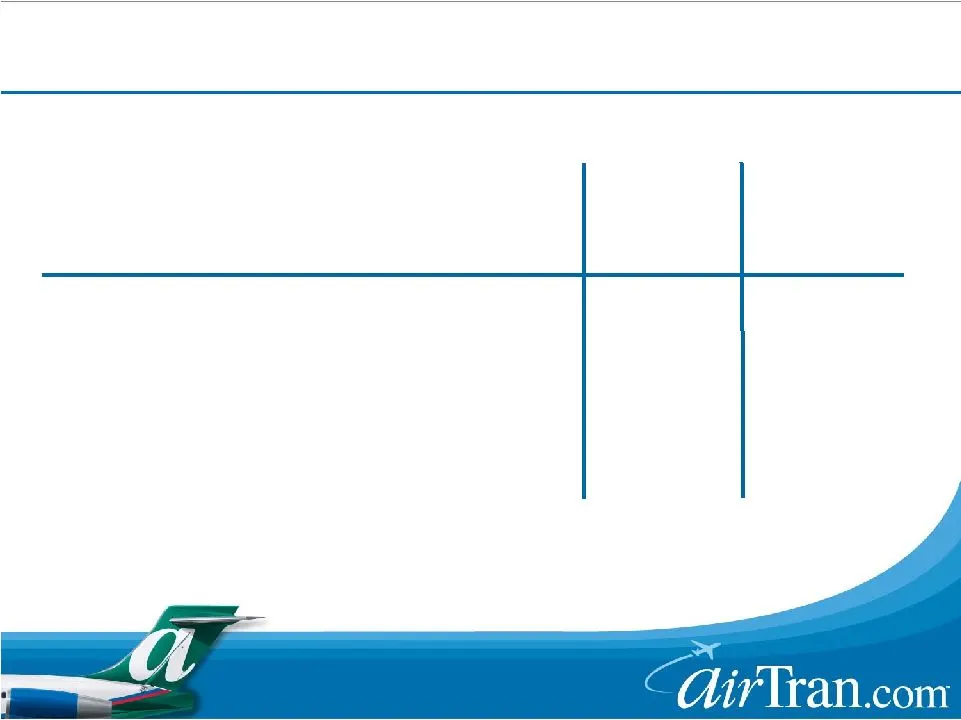
12 -$0.49 NA +$0.49 EPS Change from $60 +$80 NA -$80 Change from $60 ($MM) $800 $720 $640 2007E Fuel Expense ($MM) $70 Crude $60 Crude $50 Crude Forward Curve Company Estimates Fuel Is Also Creating Significant Earnings Momentum Fuel Is Also Creating Significant Earnings Momentum
Slide 13: Midwest Air Group Update
13 Midwest Air Group Update Midwest Air Group Update
Slide 14: Powerful Strategic Rationale
14 Network Fleet Financial AirTran & Midwest Are Stronger Together Than As Independent Entities Complementary route networks with limited overlap Combine AirTran’s strong East Coast network with Midwest’s hubs in Milwaukee and Kansas City Improved scale in consolidating industry with improved increm
Slide 15: Combined carrier well positioned in key markets
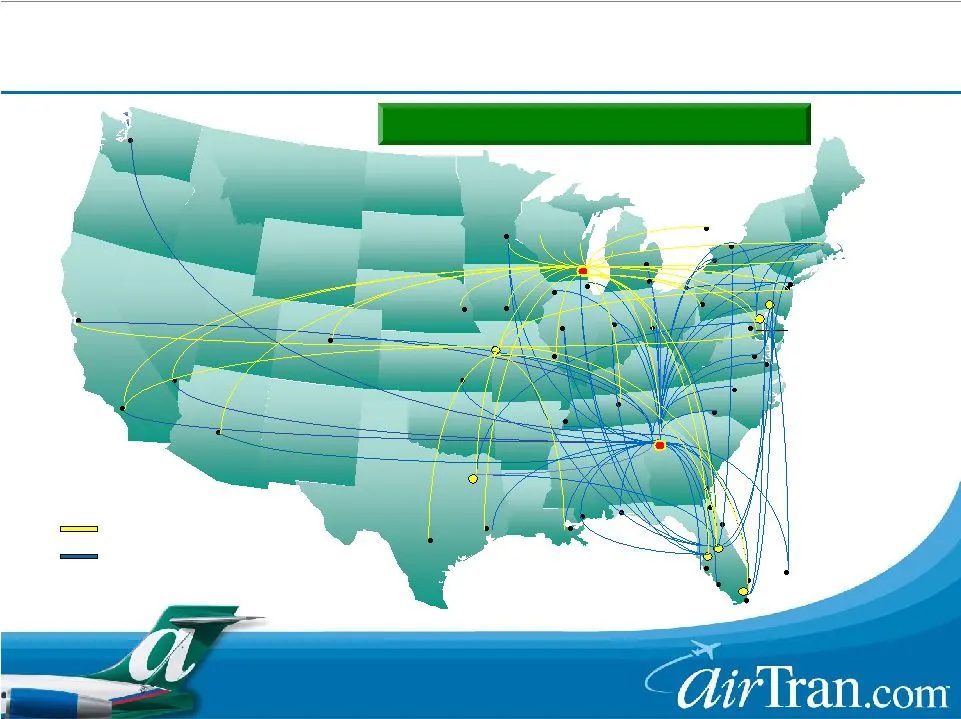
15 Combined carrier will be well positioned in key markets throughout the Eastern, Midwestern and Southeastern U.S. West Palm Beach West Palm Beach Newport News Newport News Newark Newark Washington, D.C. Washington, D.C. Grand Bahama Grand Bahama Minneapolis Minneapolis Buffalo Buffalo Boston Bosto
Slide 16: Girt an.com
> Girt an.com
Slide 17: Merger Creates Instant Diversification
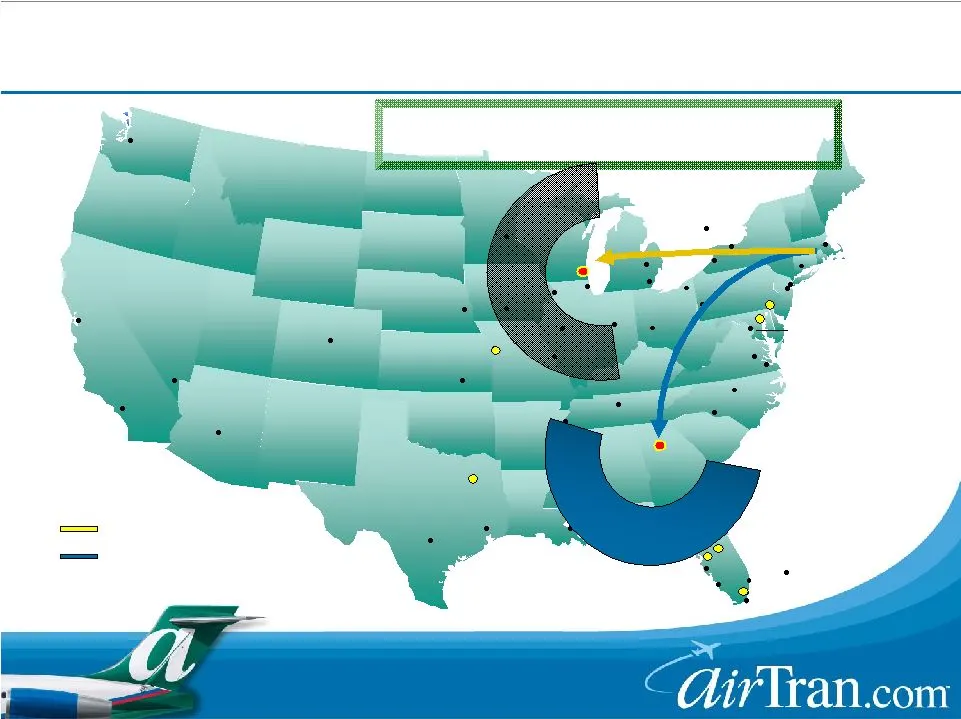
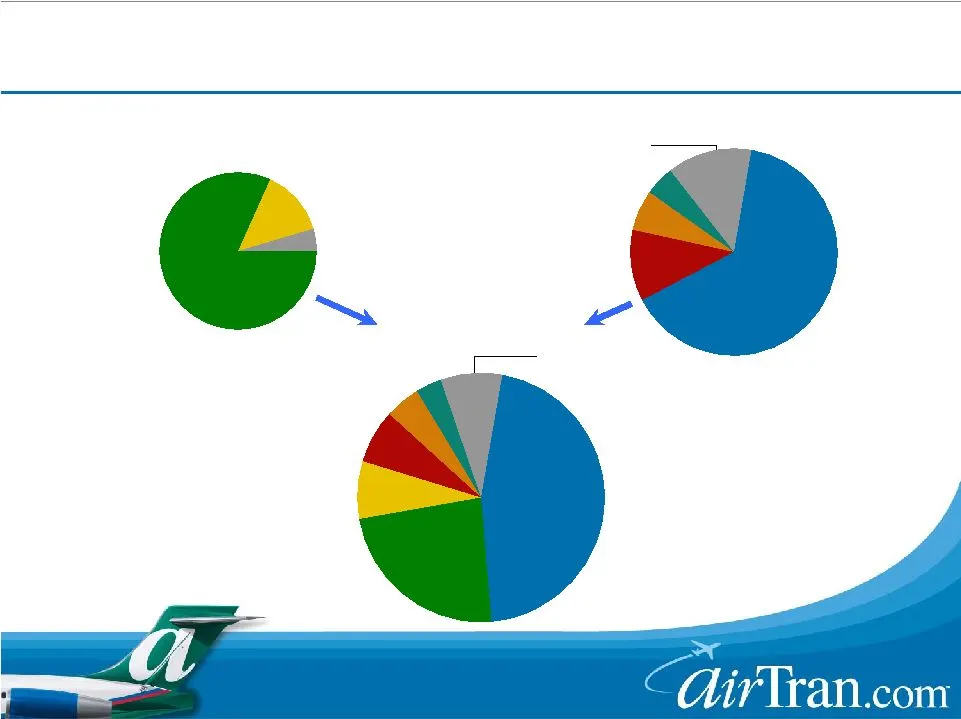
17 46% 24% 7% 5% 3% 8% 64% 11% 7% 5% 13% 83% 4% 7% 13% Midwest Network AirTran Network Combined Network Milwaukee Kansas City Other Atlanta Orlando Baltimore Chicago Other Atlanta Milwaukee Kansas City Orlando Baltimore Chicago Other Share of departures Merger Creates Instant Diversification Merger
Slide 18: Potential Combination Synergies
18 Many of these opportunities could be lost if Midwest Air Group delays and continues MD-80/Regional Jet fleet renewal Network Synergies Improve fleet and capacity utilization Increase aircraft utilization Cost Synergies Replace MD-80s with cost efficient 737s Maintenance & facilities efficiencies
Slide 19: Midwest Business Model Is Struggling To Adapt
19 History rooted in premium product to serve Milwaukee — Premium strategy has not delivered consistent profits since 2000 — Strategies were changed to add an all-coach product (Saver Service), buy-on board, and now a 50-seat regional jet expansion — Revised strategies have provided one year of mode
Slide 20: Midwest Revenue Is Concentrated
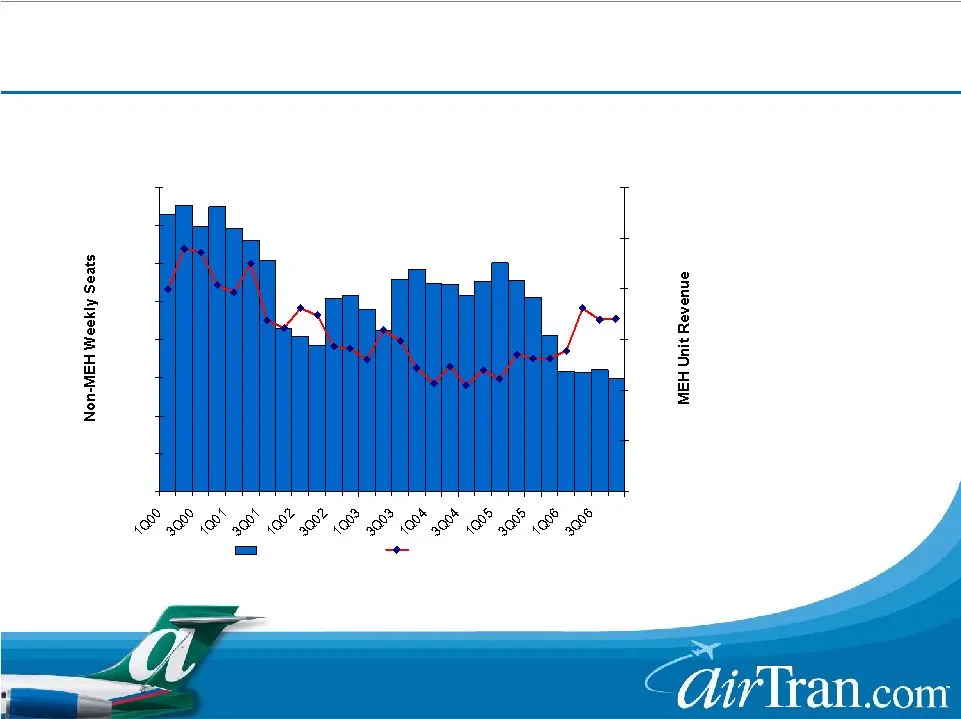
20 At 58%, Midwest has an exceptionally high percentage of its revenue concentrated in its top 20 markets — AirTran 30%, Alaska 30%, Southwest 16% High revenue concentration increases the vulnerability to competitive incursions 25% of their total daily revenue is in just five markets 23% of their re
Slide 21: Midwest Revenue is Highly Susceptible to Competition
21 Midwest Revenue is Highly Susceptible to Competition Midwest Revenue is Highly Susceptible to Competition Source: APGDAT 30,000 35,000 40,000 45,000 50,000 55,000 60,000 65,000 70,000 4.00 6.00 8.00 10.00 12.00 14.00 16.00 Other Airline Seats Midwest Unit Revenue cents Midwest revenue performance
Slide 22: Midwest Strategic Growth Plan Is Flawed
22 Relies on inefficient aircraft — 50 seat regional jets and old MD-80s Assumes no change in the competitive landscape Implied RASM growth in excess of 10% — Immediate contribution on new 50 seat regional jets — Despite 6 new cities and 12 new routes Does not recognize tax expense Future strategy i
Slide 23: Midwest Has Not Delivered Since 2001
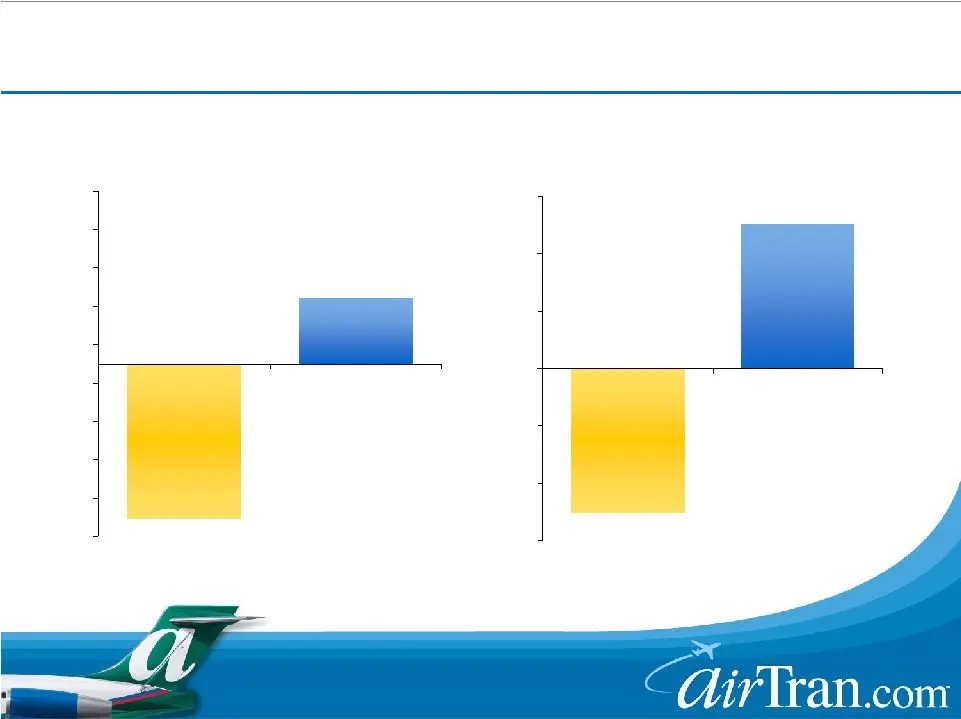
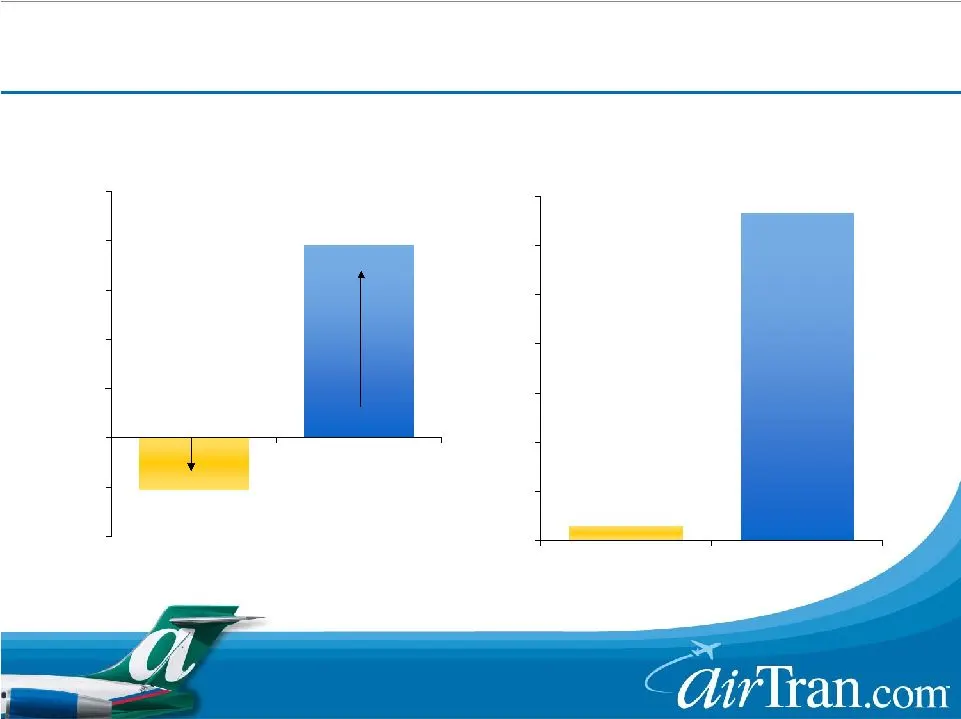
23 Operating Margin 2002-2006 -9.0% -7.0% -5.0% -3.0% -1.0% 1.0% 3.0% 5.0% 7.0% 9.0% MEH AAI Cum. Net Profit -$150 -$100 -$50 $0 $50 $100 $150 MEH AAI Midwest Has Not Delivered Since 2001 Midwest Has Not Delivered Since 2001 ($MM)
Slide 24: Midwest Has Not Delivered Since 2001
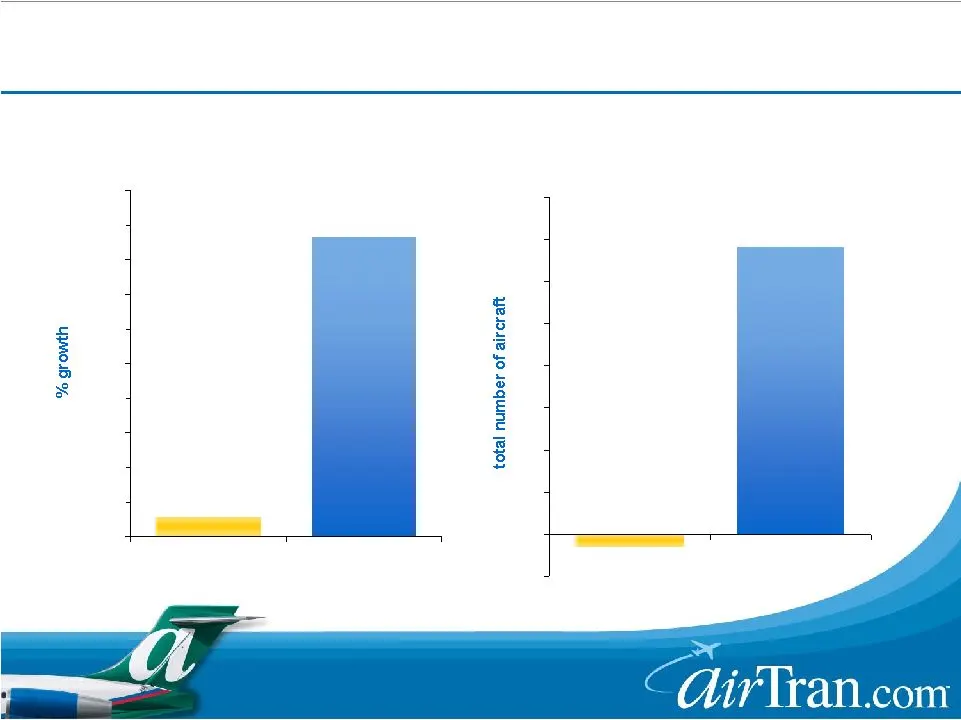
24 Growth in Employees 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% MEH AAI 160 jobs in 5 years 3,441 jobs in 5 years Change in Fleet Size -10 MEH AAI -3 planes in 5 years 68 planes in 5 years Midwest Has Not Delivered Since 2001 Midwest Has Not Delivered Since 2001
Slide 25: Midwest Has Not Delivered Since 2001
25 2006: 11.74 2002: 6.60 Cum. Change in Stock Price 2002-2006 -40.0% -20.0% 0.0% 20.0% 40.0% 60.0% 80.0% 100.0% MEH AAI Cum. Change in Market Cap. (millions) 0% 20% 40% 60% 80% 100% 120% 140% MEH AAI 2002: 14.60 2006: 11.50 2006: $214MM 2006: $1,069MM Midwest Has Not Delivered Since 2001 Midwest Ha
Slide 26: AirTran Is Committed To Midwest Transaction
26 Offering a significant premium to stand alone opportunity — Mix of cash and stock provides upside for investors Investors supporting AirTran’s efforts should tender their shares — Conditional tender does not limit ultimate value received Nominated a slate of experienced, independent directors Air
Slide 27: Summary
27 AirTran has great fundamentals — Young fleet — Positioned to become the low cost leader — Strong East Coast presence Competitive environment in Atlanta is moderating AirTran and Midwest are stronger together than alone Midwest transaction presents significant benefits for all — Shareholders — Emp
Source: SEC EDGAR · 8-K filed Feb 2, 2007
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010