Airtran — Citigroup Small and Mid-Cap Conference 2007
32 slides from Airtran's conference presentation, Mar 16, 2007
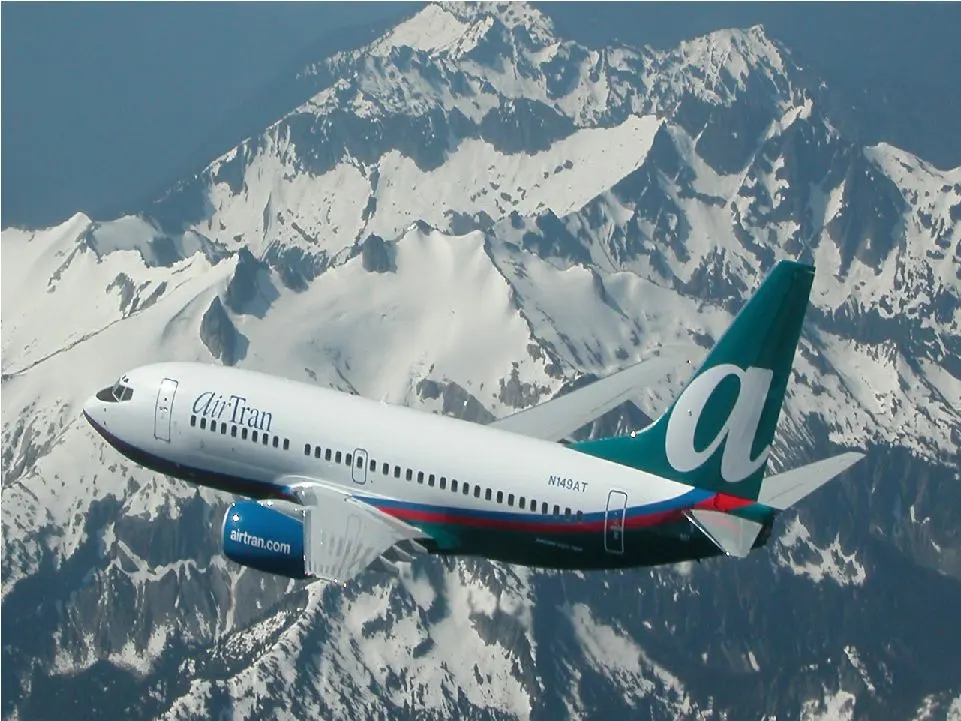
Slide 1: Citigroup Small and Mid-Cap Conference
Citigroup Small and Mid-Cap Conference March 14, 2007 Exhibit 99.1 Citigroup Small and Mid-Cap Conference March 14, 2007
Slide 2: Forward Looking Information
2 Forward Looking Information Certain of the statements contained herein should be considered “forward-looking statements,” including, except in connection with the Offer (as defined below) within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements m
Slide 3: Safe Harbor Disclosure
3 Safe Harbor Disclosure Safe Harbor Disclosure Additional Information This document relates, in part, to the offer (the “ Offer ”) by AirTran, through its wholly-owned subsidiary, Galena Acquisition Corp. (“ Galena ”), to exchange each issued and outstanding share of common stock and Series A Junio
Slide 4: AirTran Airways Today
4 Youngest all-Boeing fleet in America — 132 Airplanes – 87 717s / 45 737s 56 cities served — Announced Charleston SC, Daytona Beach FL, Newburgh NY, Phoenix AZ, Portland ME, St. Louis MO, and San Diego CA in 2007 Consistent record of profitability — One of two consistently profitable airlines AirTr
Slide 5: AirTran Airways Business Model
5 To provide a superior product with very low costs — Assigned seating — Business Class Only major U.S. airline with business class on every flight — Convenient distribution Internet, telephone reservations, and travel agencies — XM Radio and oversized luggage bins — Friendly crewmembers Provide val
Slide 6: AirTran Has Very Low Costs
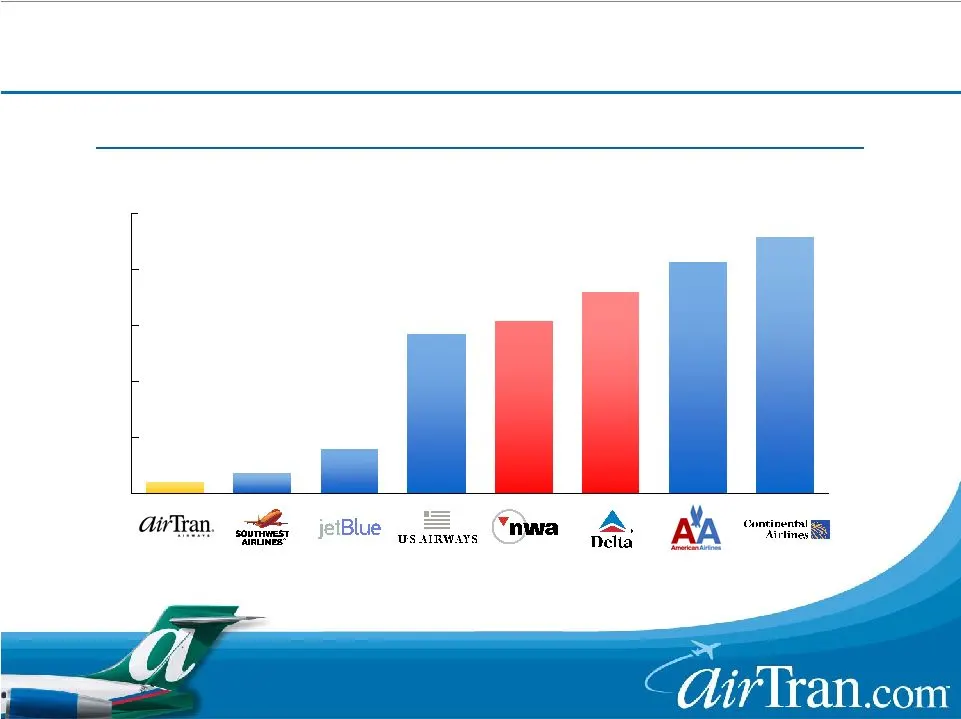
6 (cents) AirTran Has Very Low Costs AirTran Has Very Low Costs While legacy costs are down, gap remains large * Excludes fuel and special items Industry Cost Comparison Non-Fuel Unit Costs at 652 Miles for 2006 Q406 =5.94 cents
Slide 7: Projecting A Sixth Consecutive Year Of Cost Reductions
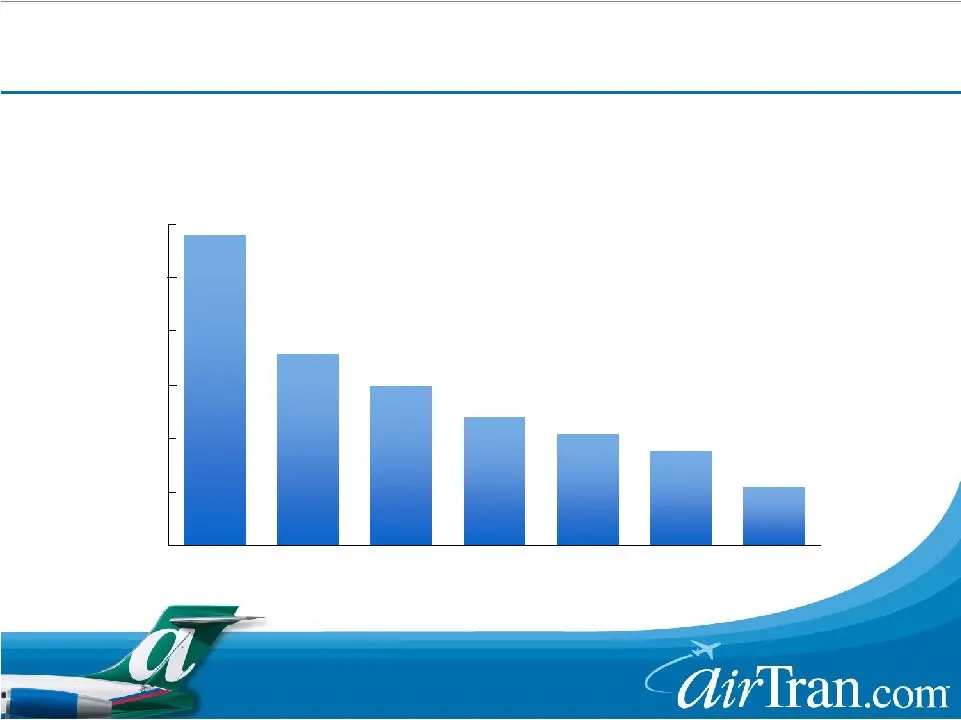
7 5.75 6.00 6.25 6.50 6.75 7.00 7.25 2001 2002 2003 2004 2005 2006 2007E * Excludes non-recurring special items (cents per mile) AirTran’s Non-Fuel Unit Cost Trend -3% Projecting A Sixth Consecutive Year Of Cost Reductions Projecting A Sixth Consecutive Year Of Cost Reductions
Slide 8: What Creates AirTran's Low Cost Advantage?
8 Productive workforce at all levels Young, simplified fleet — Fuel efficient — Attractive ownership costs Efficient use of facilities Competition for heavy maintenance contracts Low cost distribution — Over 70% of sales are directly with AirTran (Reservations or AirTran.com) What Creates AirTran’s
Slide 9: New 737 Aircraft Will Continue To Drive Down Costs
9 Increases crew productivity — No additional staffing required — 17% increase in seats Transcontinental range increases productivity — Utilization now 12-13 hrs/day versus 11 hrs/day on 717s Even better fuel economy than the 717 per seat Order timing was at the bottom of the market (June 2003) — Ne
Slide 10: AirTran Is Poised To Become Industry Low Cost Provider
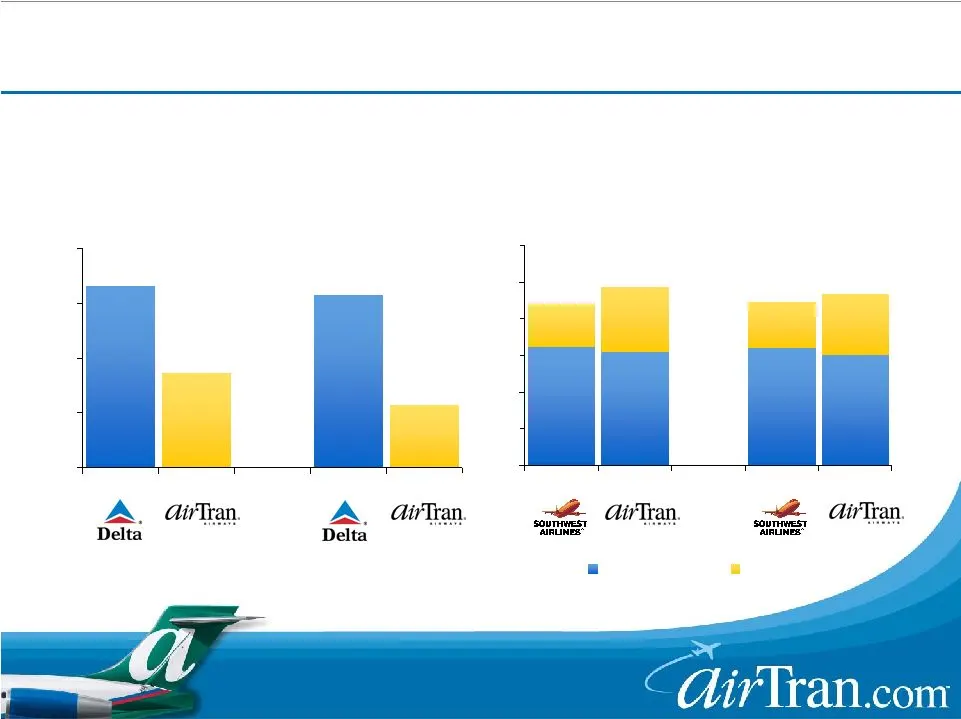
10 Non-Fuel CASM Q201 Q201 Q206 Q206 2006 2006 2007E 2007E Non-Fuel CASM Fuel CASM AAI 11% Higher AAI 3-4% Higher AAI -39% Lower AAI -30% Lower (cents) (cents) Despite bankruptcy, cost advantage vs. Delta has widened Cost gap vs. Southwest has narrowed AirTran Is Poised To Become Industry Low Cost P
Slide 11: AirTran Delivers Both Low Cost And High Quality
11 2004 2003 2002 2001 2005 JetBlue AirTran Southwest United Alaska America West Northwest American Continental ATA JetBlue Alaska Southwest America West US Airways Northwest Continental AirTran United ATA US Airways Alaska Southwest America West Continental American Delta United Northwest American
Slide 12: Leading Consumer Survey Validates Strong Products
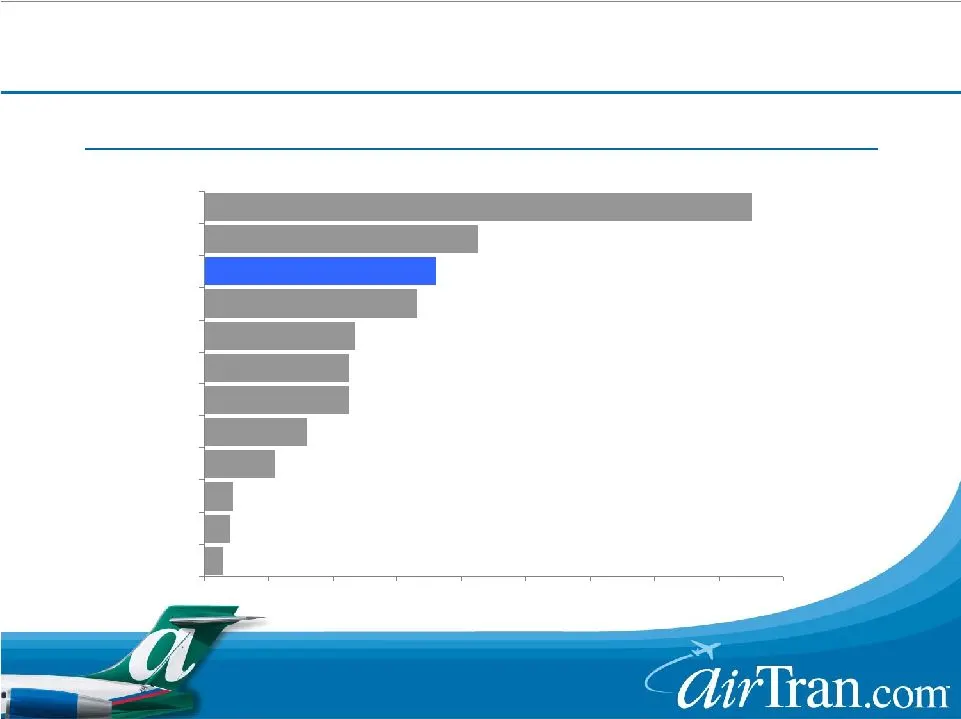
12 Overall Customer Satisfaction Northwest Airlines United Airlines US Airways Alaska Airlines American Airlines Delta Airlines Spirit Airlines Continental Airlines Frontier Airlines AirTran Airways Southwest Airlines JetBlue Airways Mean / Weighted Average Leading Consumer Survey Validates Strong P
Slide 13: Low Cost And Modern Jets Create Great Growth Opportunities
13 Low Cost And Modern Jets Create Great Low Cost And Modern Jets Create Great Growth Opportunities Growth Opportunities
Slide 14: Route Map June 2000
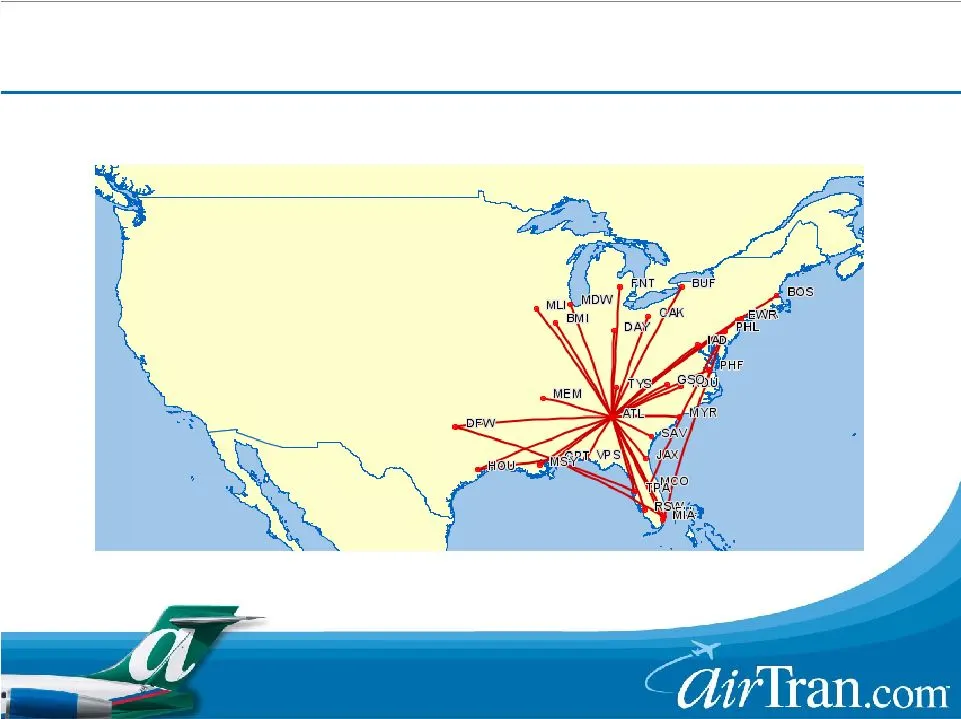
14 Route Map Route Map June 2000 Cities: 30 Cities: 30 Routes: 36 Routes: 36
Slide 15: Route Map June 2003
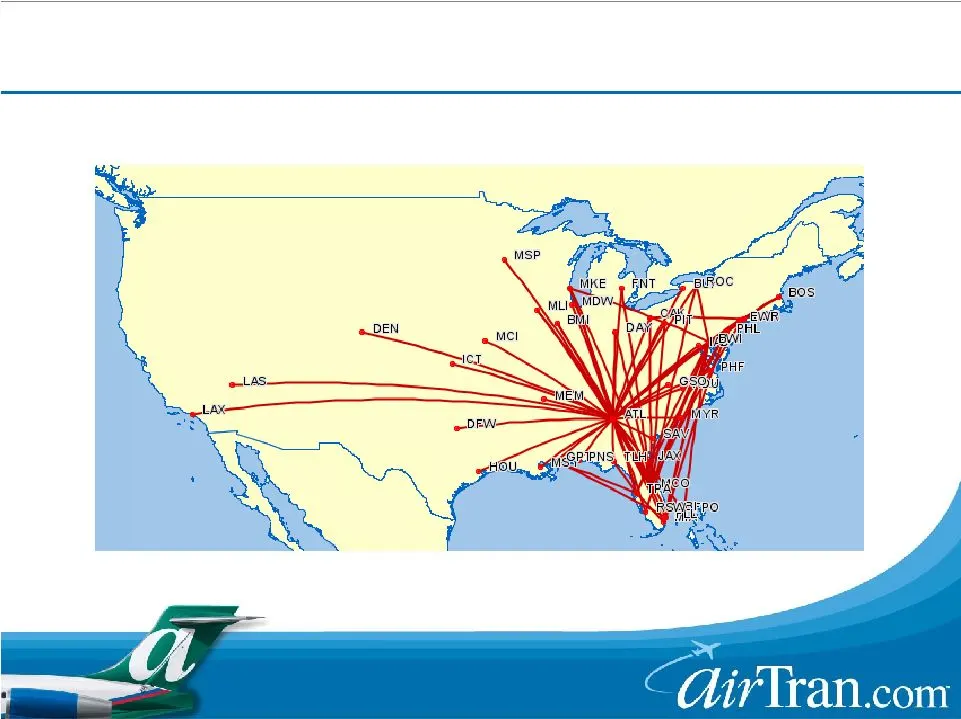
15 Route Map Route Map June 2003 Cities: 42 Cities: 42 Routes: 71 Routes: 71
Slide 16: Route Map June 2007
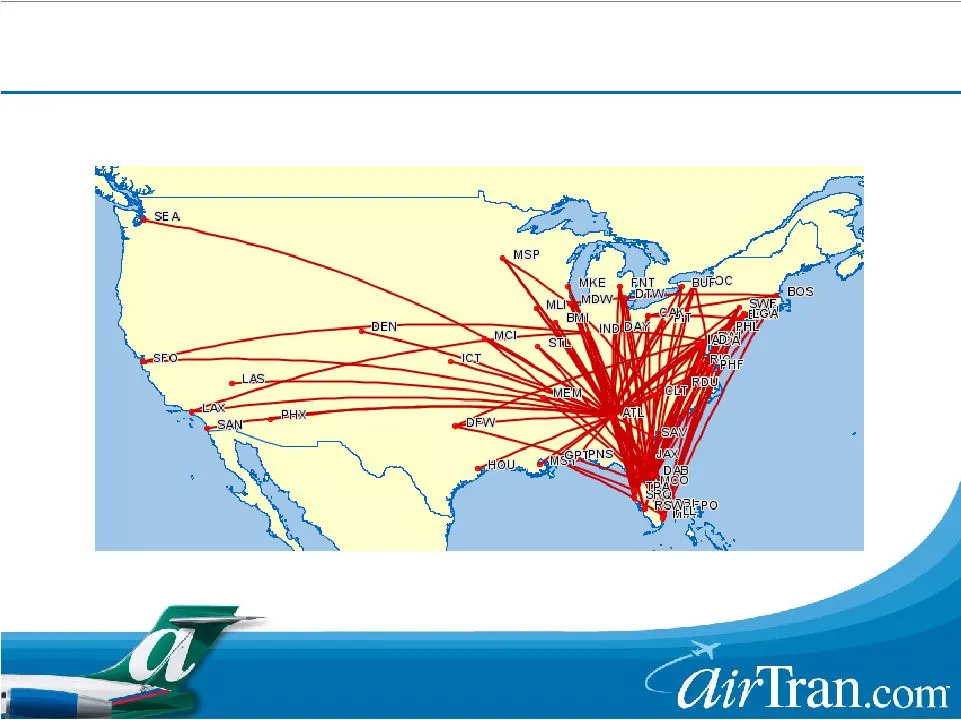
16 Route Map Route Map June 2007 Cities: 56 Cities: 56 Routes: 125 Routes: 125
Slide 17: Network Breadth Drives Cost And Revenue Efficiencies (2000)
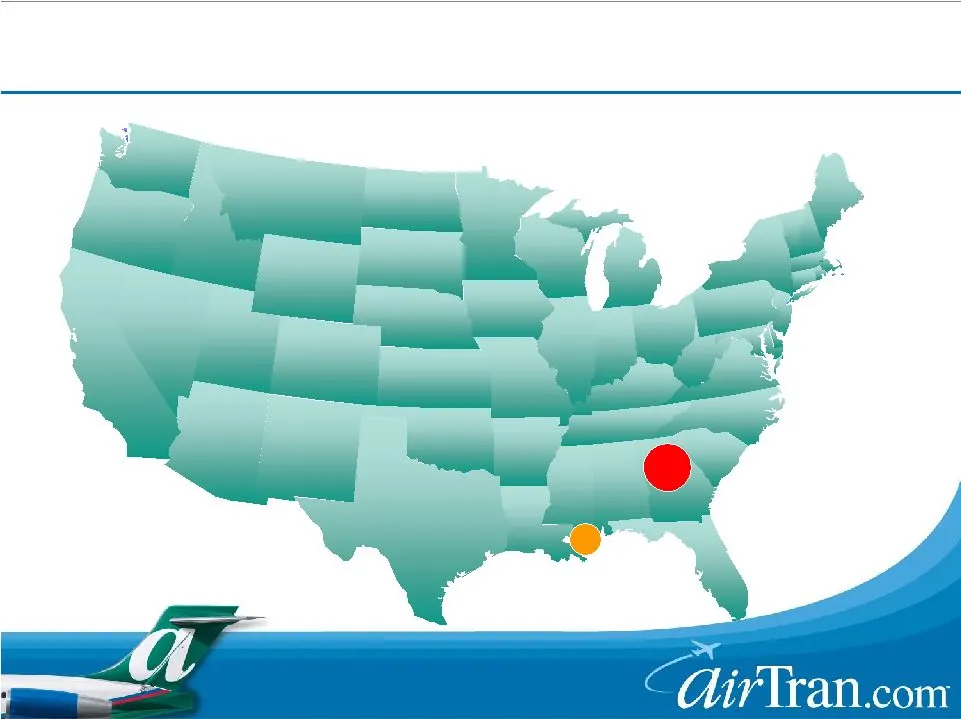
17 30 Gulfport/Biloxi Gulfport/Biloxi Atlanta Atlanta Network Breadth Drives Cost And Revenue Efficiencies Network Breadth Drives Cost And Revenue Efficiencies June 2000
Slide 18: Network Breadth Drives Cost And Revenue Efficiencies (2003)
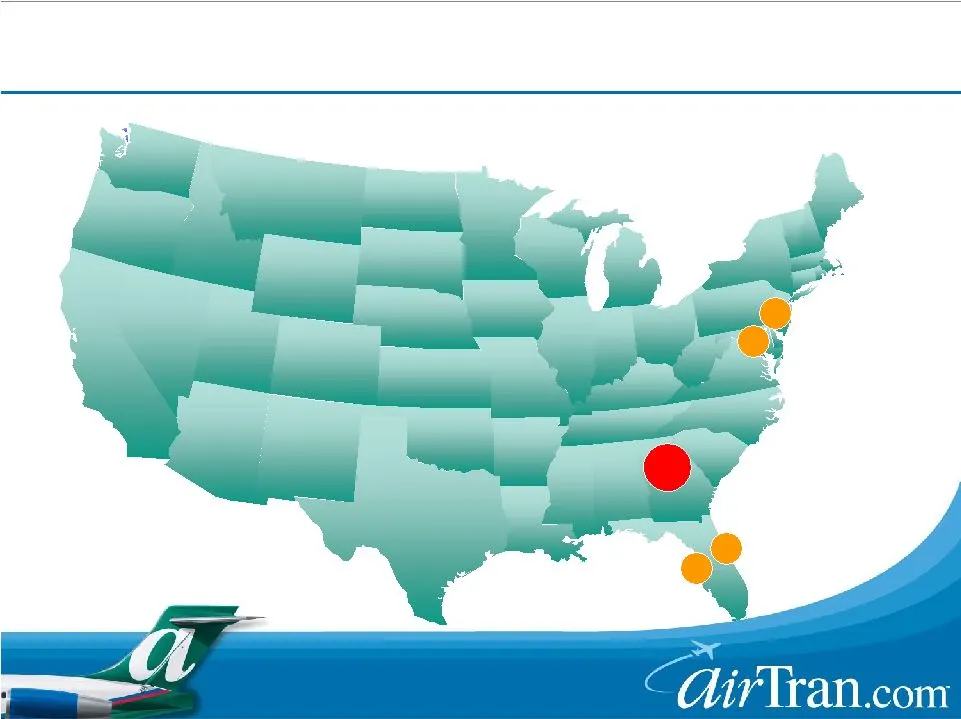
18 42 Orlando Orlando Atlanta Atlanta June 2003 Baltimore Baltimore Tampa Tampa Philadelphia Philadelphia Network Breadth Drives Cost And Revenue Efficiencies Network Breadth Drives Cost And Revenue Efficiencies
Slide 19: Network Breadth Drives Cost And Revenue Efficiencies (2007)
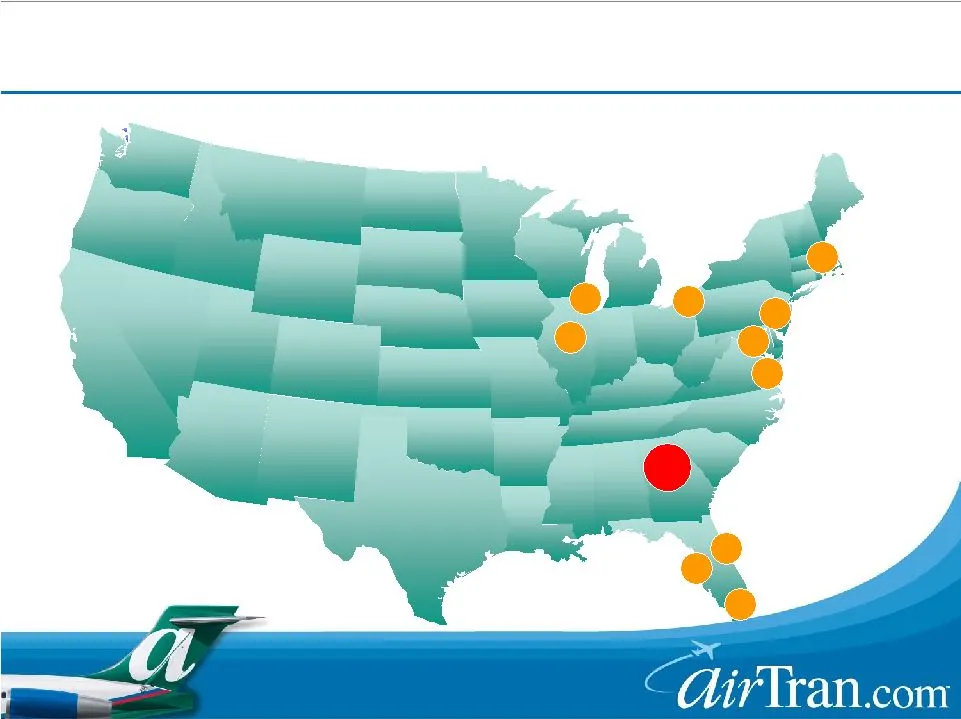
19 54 Orlando Orlando Atlanta Atlanta June 2007 Baltimore Baltimore Tampa Tampa Philadelphia Philadelphia Newport News Newport News Akron / Canton Akron / Canton Boston Boston Ft. Lauderdale Ft. Lauderdale Indianapolis Indianapolis Chicago Chicago Network Breadth Drives Cost And Revenue Efficiencies
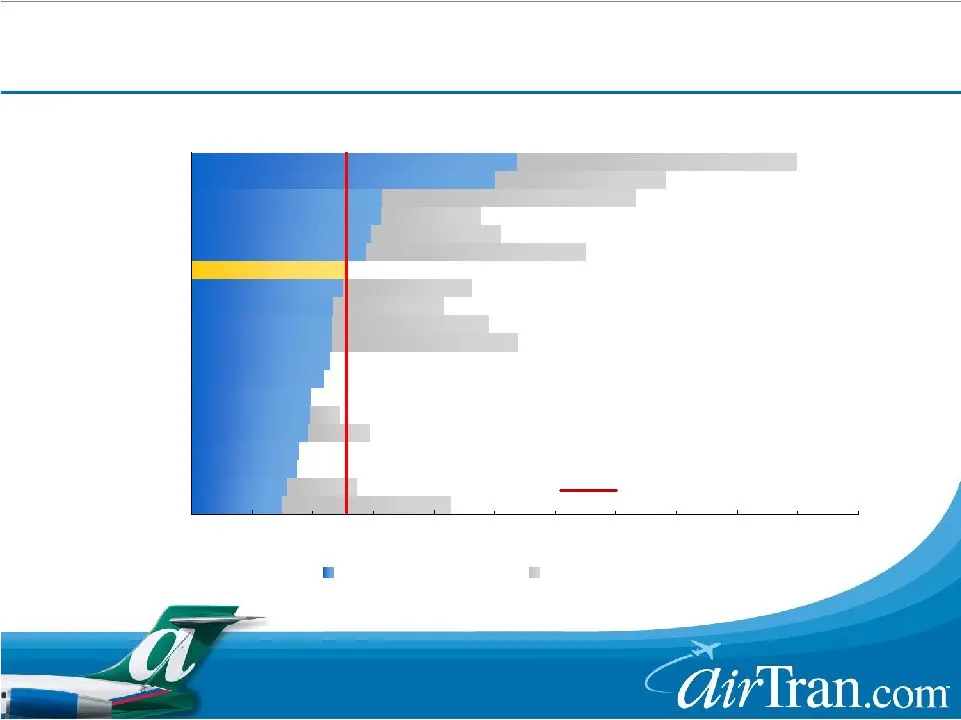
Slide 20: AirTran's Atlanta Hub Is Now One Of The Nation's Largest Mainline Hubs
20 1,000 1,100 LCC-Philadelphia UAUA-San Francisco LUV-Baltimore JBLU-New York LCC-Phoenix AA-Miami LUV-Phoenix LUV-Chicago LUV-Las Vegas LCC-Charlotte AA-Chicago CAL-Newark UAUA-Denver AAI-Atlanta UAUA-Chicago NWAC-Detroit NWAC-Minneapolis CAL-Houston AA-Dallas DAL-Atlanta Mainline Departures Regio
Slide 21: Low Cost Fleet Plan
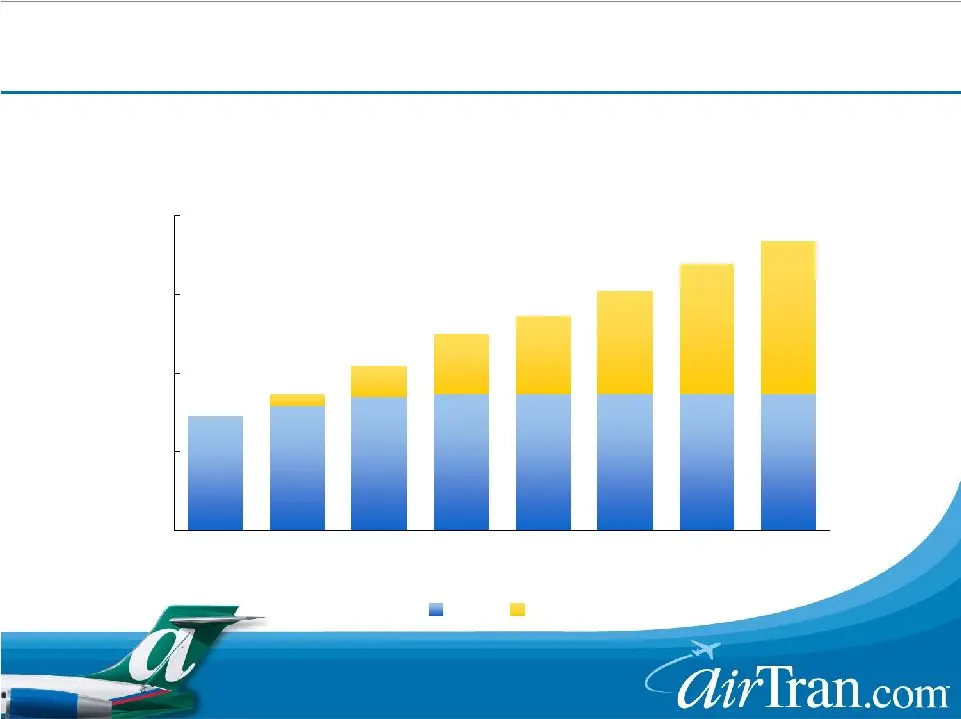
21 2003 2004 2005 2006 2007 2008 2009 2010 717s 737s Aircraft Currently 132 Aircraft: 87 717s / 45 737s Low Cost Fleet Plan Low Cost Fleet Plan
Slide 22: AirTran Has A Demonstrated Record Of Growth And Profitability
22 AirTran Has A Demonstrated Record Of AirTran Has A Demonstrated Record Of Growth And Profitability Growth And Profitability 15.5 8.1 10.1 100.5 10.7 Profit ($MM) Mainline Aircraft 8,100 7,400 6,700 5,900 5,300 4,700 FTE's Daily Flights Cities Served 2007E 2006 2005 2004 2003 2002
Slide 23: Revenue Outlook Is Improving
23 Q406 unit revenue growth slowed, primarily in Atlanta markets — Capacity growth was robust AirTran increased frequency in short haul Atlanta routes to secure access to additional gates Delta increased capacity over 10% from summer levels Q107 capacity outlook is improved — AirTran’s capacity rede
Slide 24: Competitive Capacity In AirTran's Atlanta Markets Are Declining
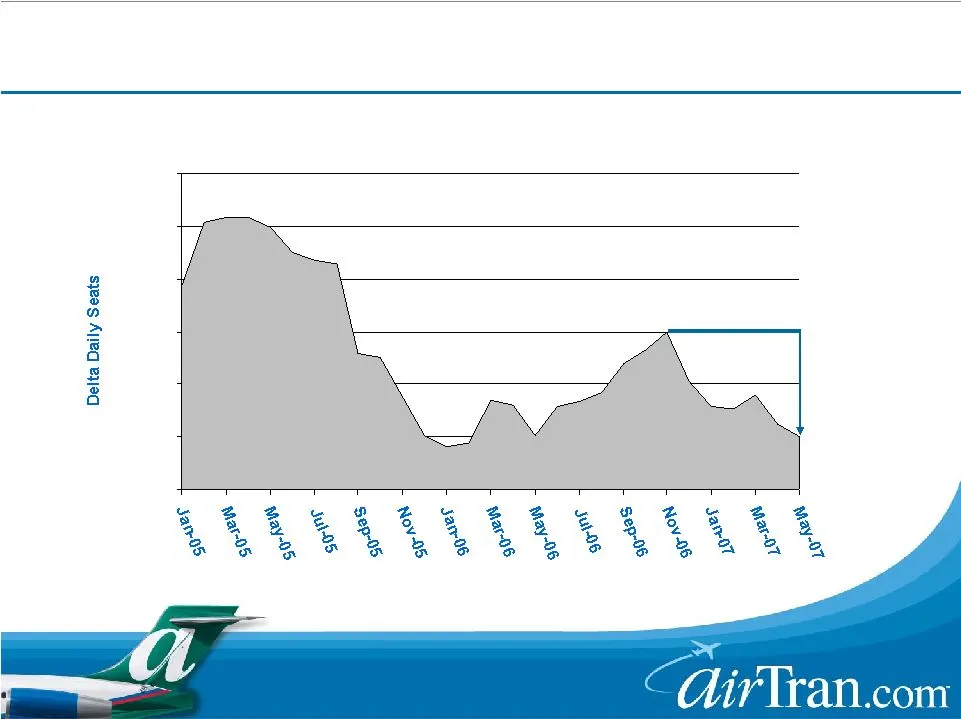
24 55,000 60,000 65,000 70,000 75,000 80,000 85,000 Competitive Capacity In AirTran’s Atlanta Competitive Capacity In AirTran’s Atlanta Markets Are Declining Markets Are Declining -16%
Slide 25: AirTran Continues To Manage Fuel Exposure
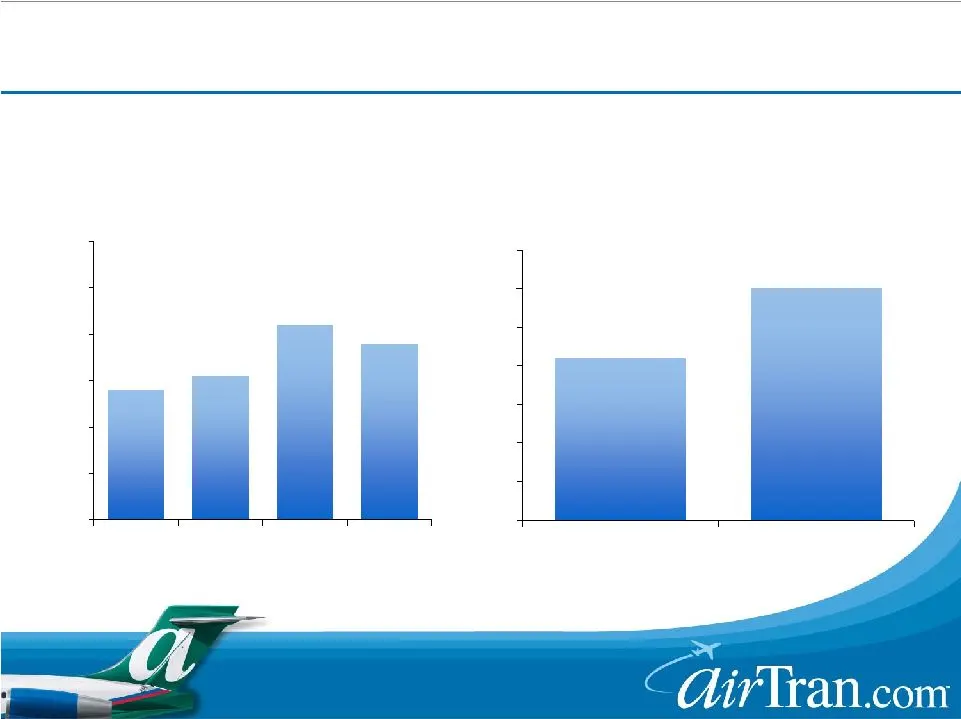
25 28% 31% 42% 38% ASMs per Gallon 2000 2006 >40% improvement AirTran's Current Hedge Position 0% 10% 20% 30% 40% 50% 60% Q107 Q207 Q307 Q407 $2.00/gal to $2.05/gal Forecast $2.05/gal to $2.10/gal Forecast $2.05/gal to $2.10/gal Forecast $2.00/gal to $2.05/gal Forecast AirTran Continues To Manage Fu
Slide 26: Midwest Air Group Update
26 Midwest Air Group Update Midwest Air Group Update
Slide 27: Powerful Strategic Rationale
27 Network Fleet Financial AirTran & Midwest Are Stronger Together Than As Independent Entities Complementary route networks with limited overlap Combine AirTran’s strong East Coast network with Midwest’s hubs in Milwaukee and Kansas City Improved scale in consolidating industry with improved increm
Slide 28: Complementary Route Networks
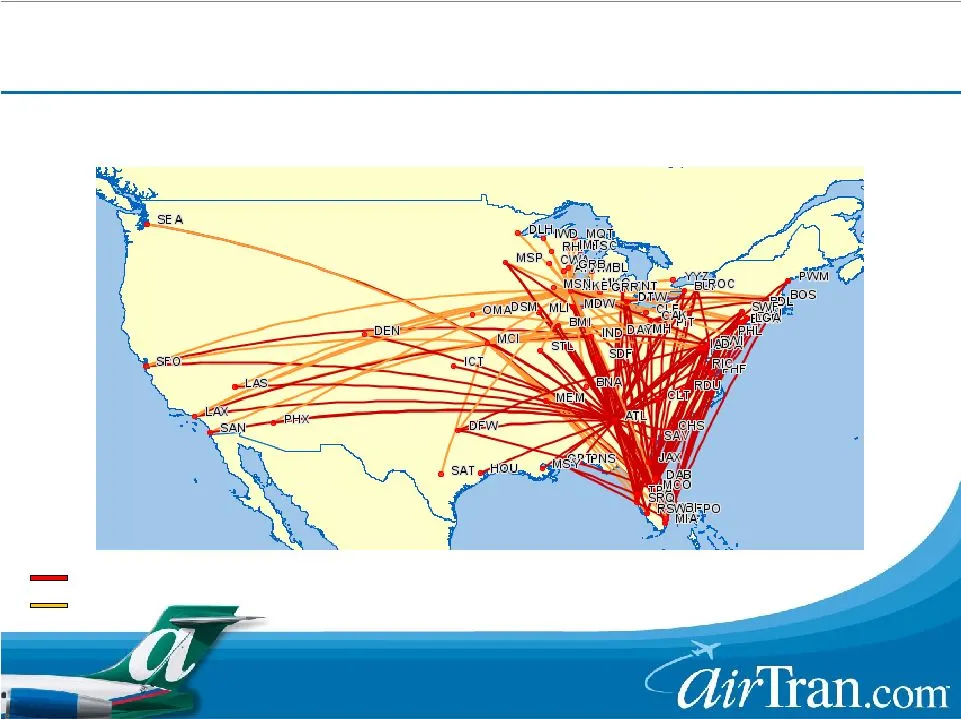
28 AirTran Midwest Combined carrier will be well positioned in key markets throughout the Eastern, Midwestern and Southeastern U.S. Complementary Route Networks Complementary Route Networks
Slide 29: Merger Creates Instant Diversification
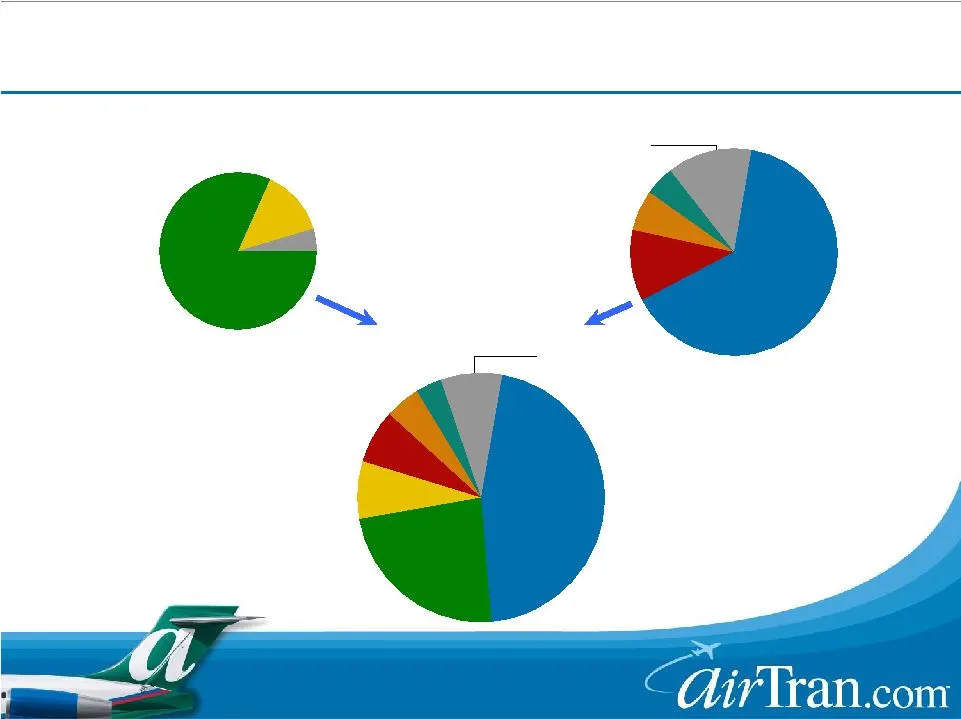
29 46% 24% 7% 5% 3% 8% 64% 11% 7% 5% 13% 83% 4% 7% 13% Midwest Network AirTran Network Combined Network Milwaukee Kansas City Other Atlanta Orlando Baltimore Chicago Other Atlanta Milwaukee Kansas City Orlando Baltimore Chicago Other Share of departures Merger Creates Instant Diversification Merger
Slide 30: Potential Combination Synergies
30 Network Synergies Improve fleet and capacity utilization Increase aircraft utilization Cost Synergies Replace MD-80s with cost efficient 737s Maintenance & facilities efficiencies Adapt best practices from both companies Total Annual Run-Rate Synergies $40MM+ $20MM+ $60MM+ Potential Combination S
Slide 31: Summary
31 AirTran has great fundamentals — Young fleet — Positioned to become the low cost leader — Strong East Coast presence Competitive environment in Atlanta is moderating AirTran and Midwest are stronger together than alone Midwest transaction presents significant benefits for all constituents Summary
Slide 32
Source: SEC EDGAR · 8-K filed Mar 16, 2007
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010