Tellurian — Credit Suisse Vail Conference (February 2017)
26 slides from Tellurian's conference presentation, Feb 14, 2017
Slide 1: Investor presentation, Credit Suisse Vail Conference
Investor presentation Credit Suisse Vail Conference Meg Gentle, President & CEO NASDAQ: TELL Exhibit 99.1
Slide 2: Notice
Notice This presentation has been prepared exclusively for informational purposes and does not constitute an offer to buy, sell or exchange any financial instruments. This presentation is not intended to provide legal, tax or investment advice. This presentation contains many forward-looking stateme
Slide 3: Introducing Tellurian Inc. (NASDAQ: TELL)
Introducing Tellurian Inc. (NASDAQ: TELL) Inception: In February 2016, Charif Souki & Martin Houston co-founded Tellurian Investments Inc. Strategy: Low-cost LNG provider capable of optimizing an integrated value chain Project: Driftwood LNG (DWLNG), a 26 mtpa LNG export facility near Lake Charles,
Slide 4: Global gas demand – expecting steady growth
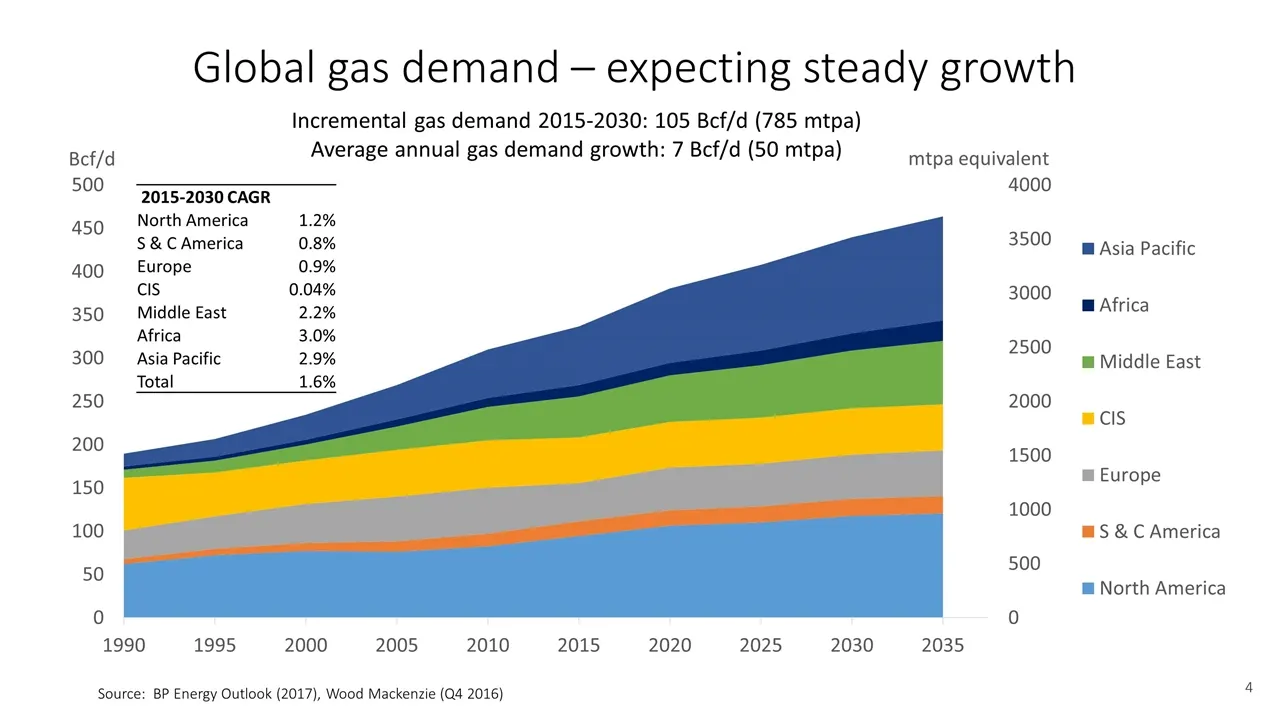
Global gas demand – expecting steady growth Source: BP Energy Outlook (2017), Wood Mackenzie (Q4 2016) 2015-2030 CAGR North America 1.2% S & C America 0.8% Europe 0.9% CIS 0.04% Middle East 2.2% Africa 3.0% Asia Pacific 2.9% Total 1.6% Incremental gas demand 2015-2030: 105 Bcf/d (785 mtpa) Average a
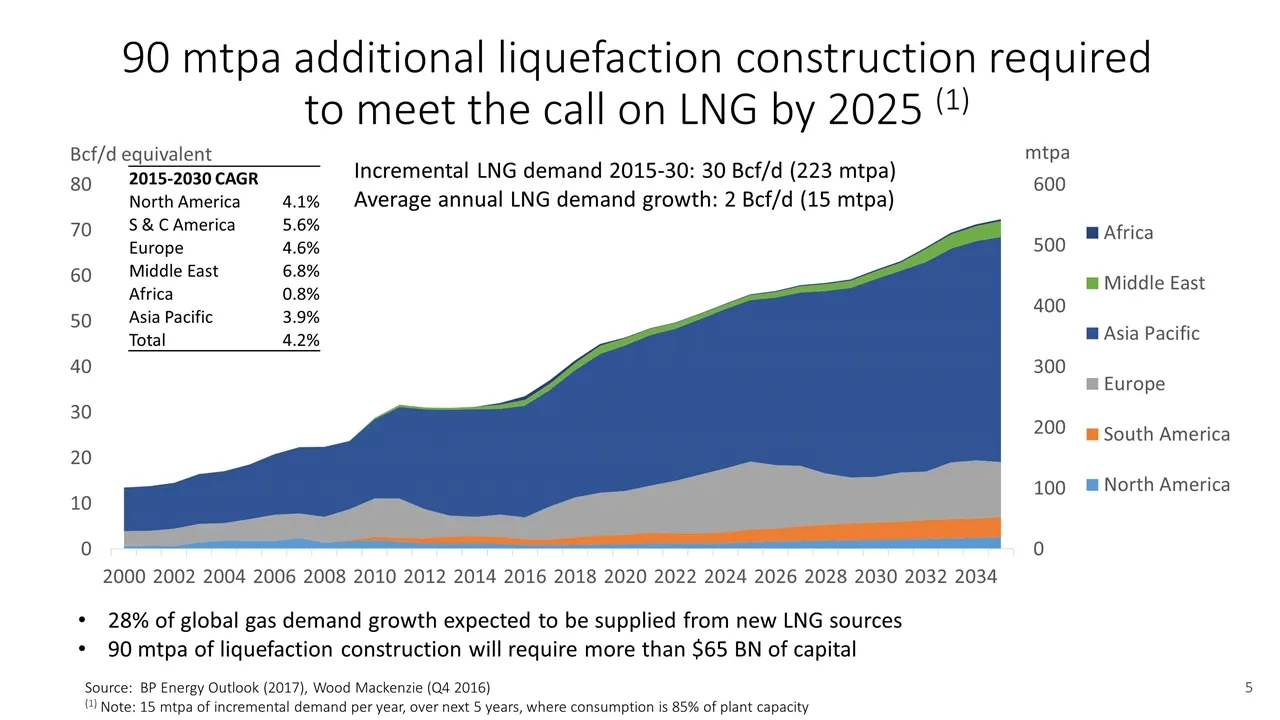
Slide 5: Additional liquefaction construction required to meet the call on LNG by 2025
90 mtpa additional liquefaction construction required to meet the call on LNG by 2025 (1) Source: BP Energy Outlook (2017), Wood Mackenzie (Q4 2016) (1) Note: 15 mtpa of incremental demand per year, over next 5 years, where consumption is 85% of plant capacity 2015-2030 CAGR North America 4.1% S & C
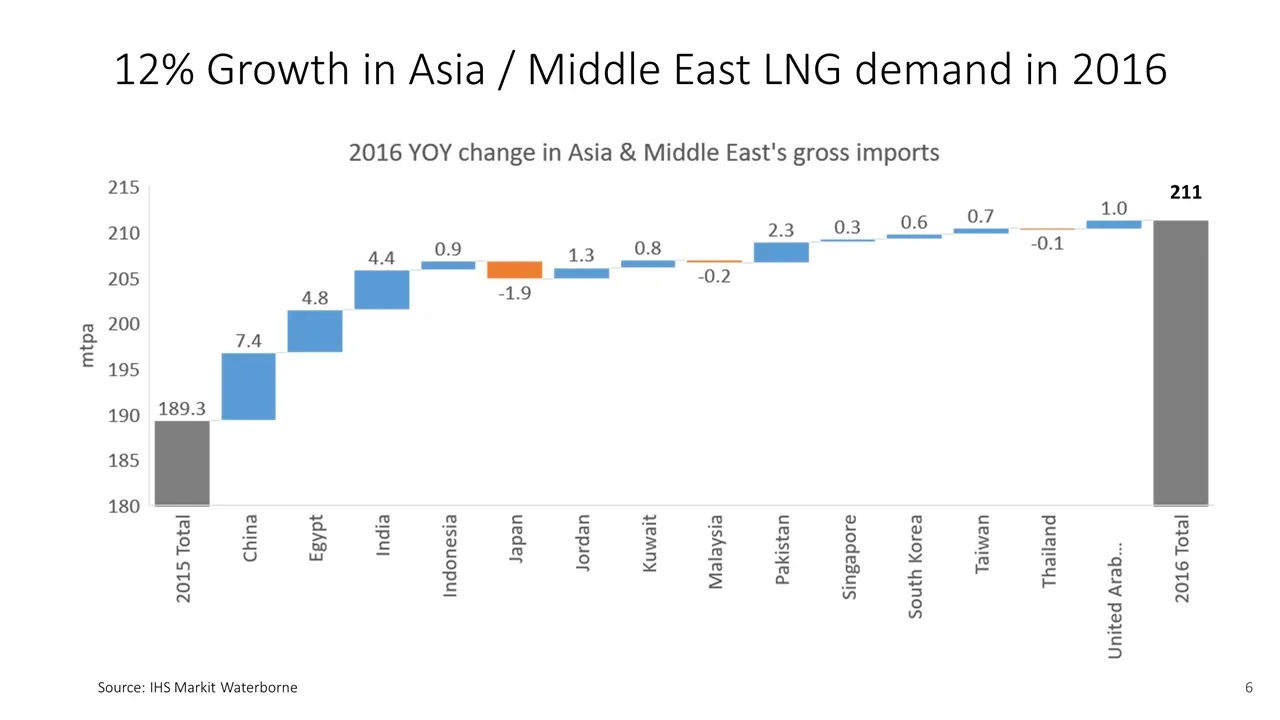
Slide 6: Growth in Asia / Middle East LNG demand in 2016
12% Growth in Asia / Middle East LNG demand in 2016 Source: IHS Markit Waterborne 211
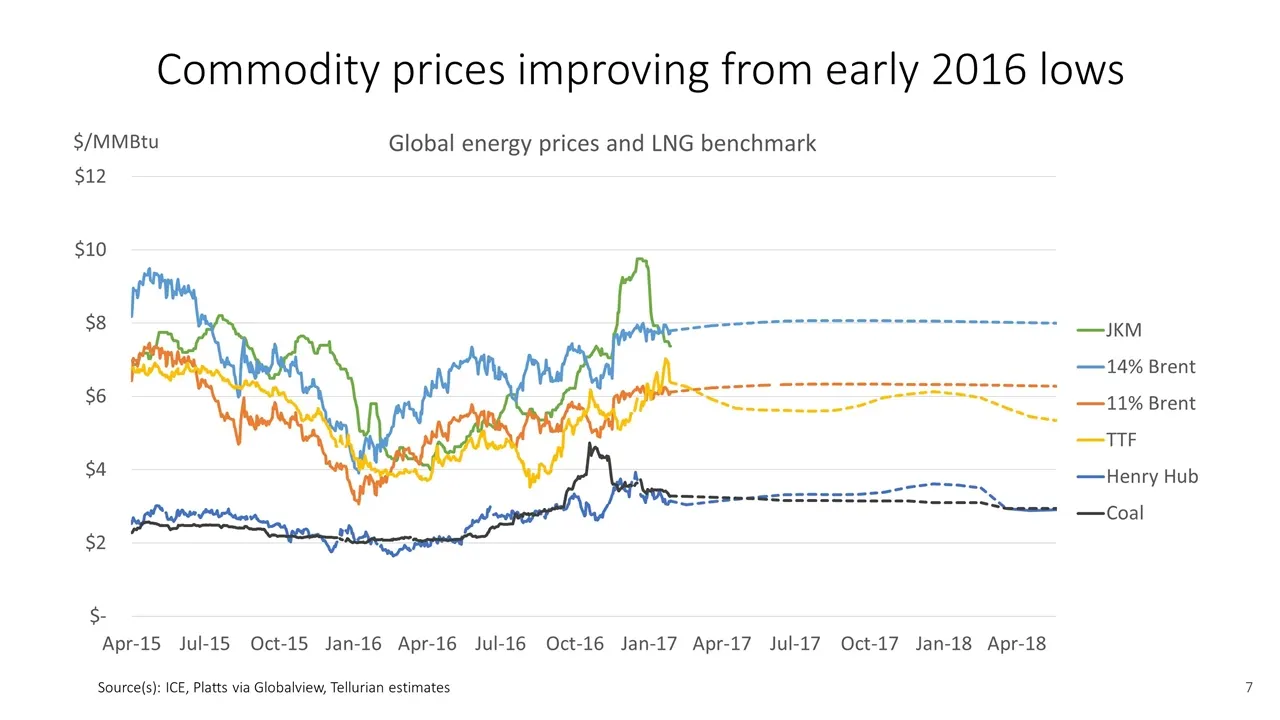
Slide 7: Commodity prices improving from early 2016 lows
Commodity prices improving from early 2016 lows Source(s): ICE, Platts via Globalview, Tellurian estimates
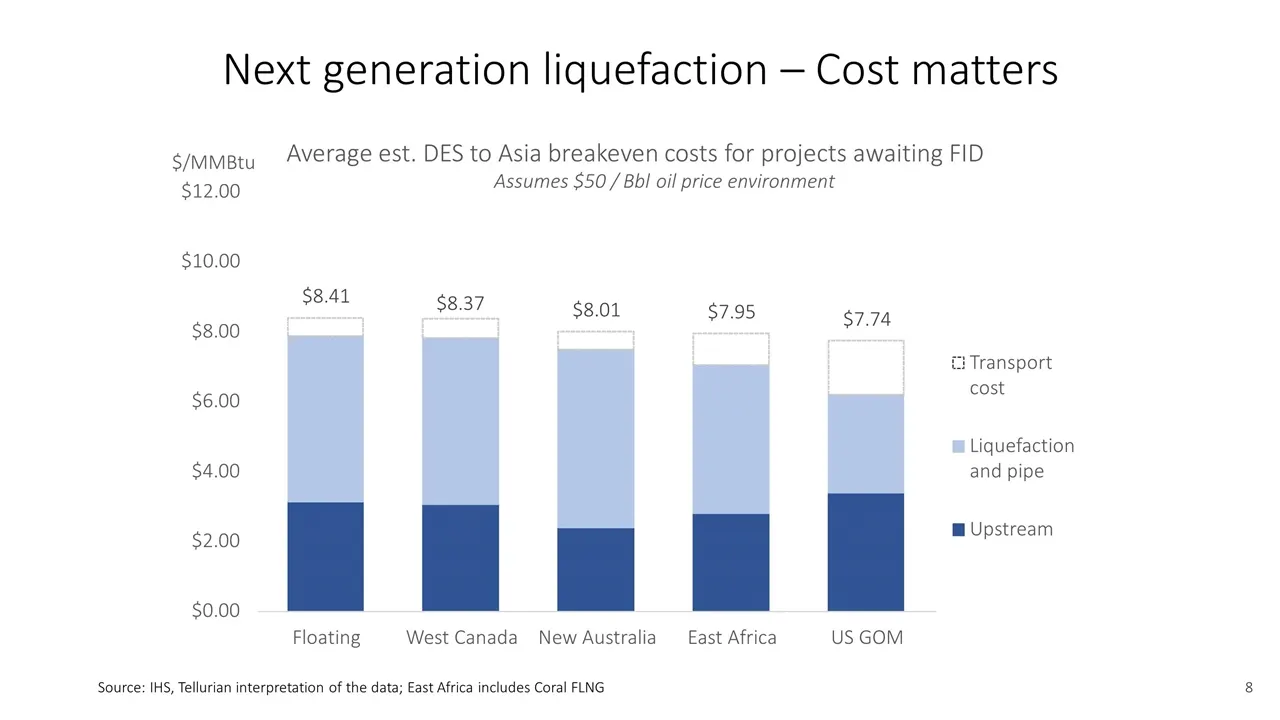
Slide 8: Next generation liquefaction – Cost matters
Next generation liquefaction – Cost matters Source: IHS, Tellurian interpretation of the data; East Africa includes Coral FLNG $8.41 $8.37 $8.01 $7.95 $7.74 $0.00 $2.00 $4.00 $6.00 $8.00 $10.00 $12.00 Floating West Canada New Australia East Africa US GOM $/MMBtu Average est. DES to Asia breakeven co
Slide 9: Seeking lowest cost gas supply
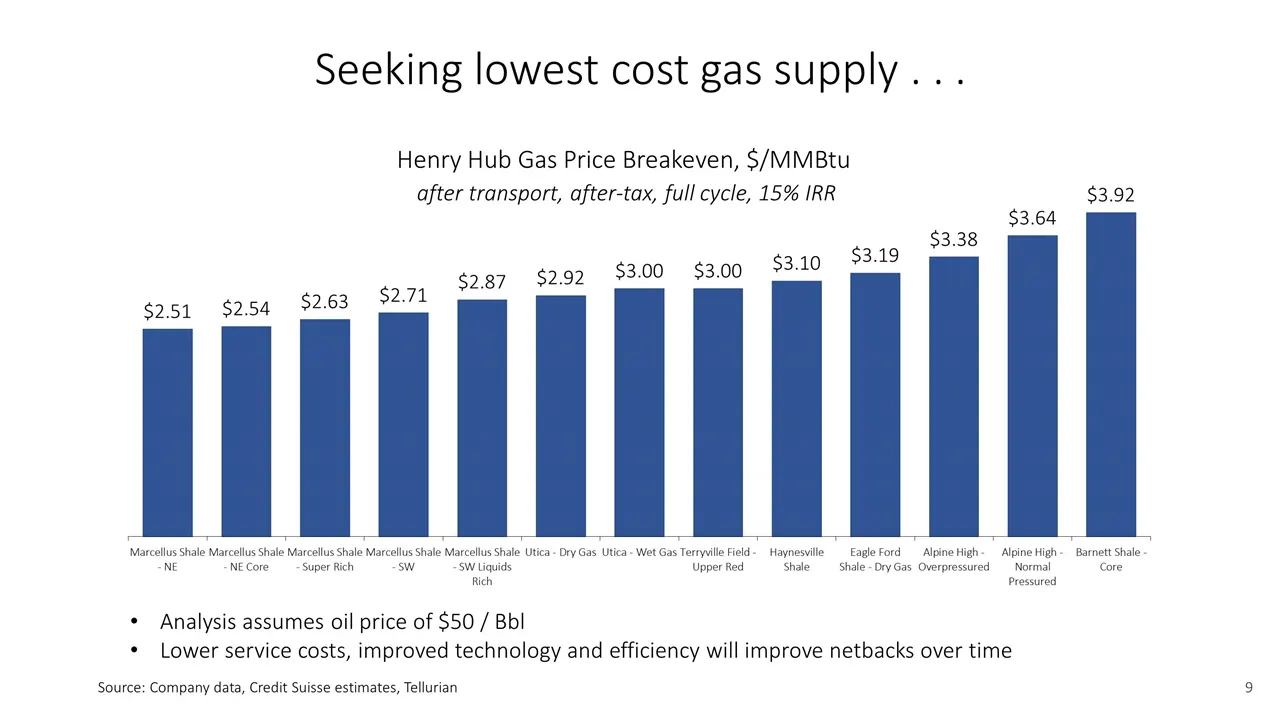
Seeking lowest cost gas supply . . . Source: Company data, Credit Suisse estimates, Tellurian Analysis assumes oil price of $50 / Bbl Lower service costs, improved technology and efficiency will improve netbacks over time
Slide 10: Driftwood LNG: 26 mtpa LNG export facility in Louisiana
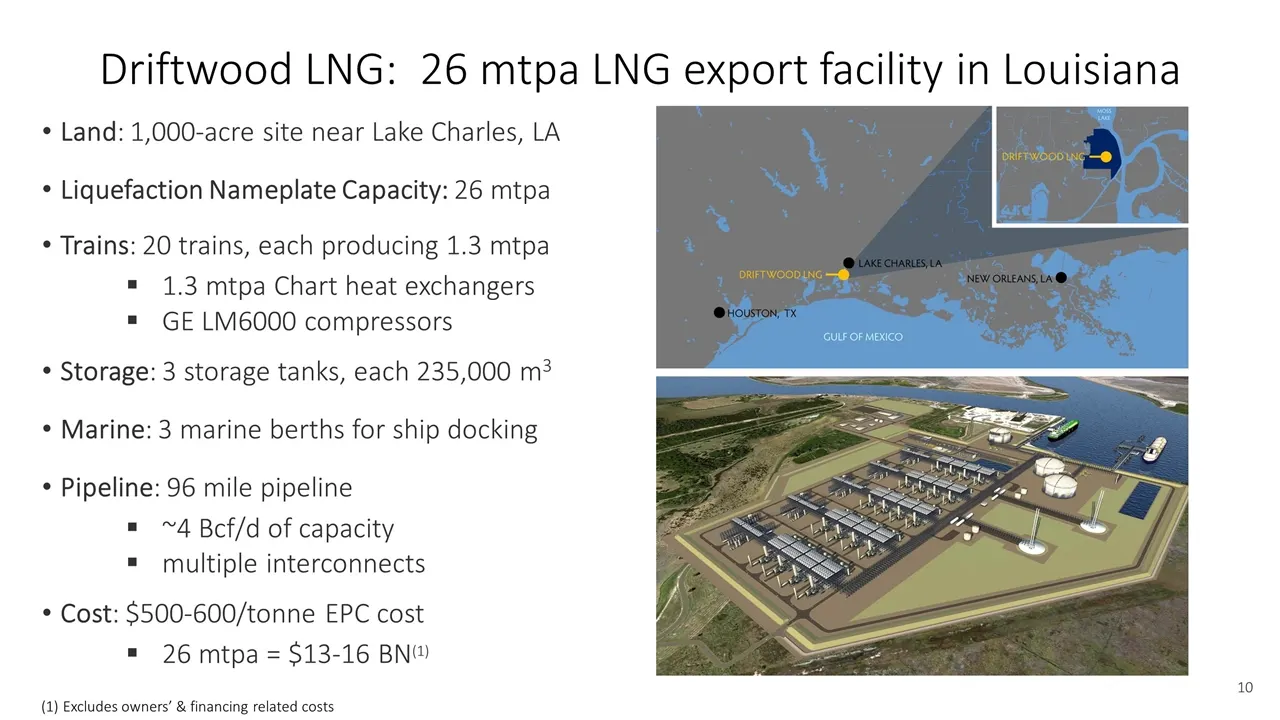
Driftwood LNG: 26 mtpa LNG export facility in Louisiana Land: 1,000-acre site near Lake Charles, LA Liquefaction Nameplate Capacity: 26 mtpa Trains: 20 trains, each producing 1.3 mtpa 1.3 mtpa Chart heat exchangers GE LM6000 compressors Storage: 3 storage tanks, each 235,000 m3 Marine: 3 marine bert
Slide 11: Key project partners
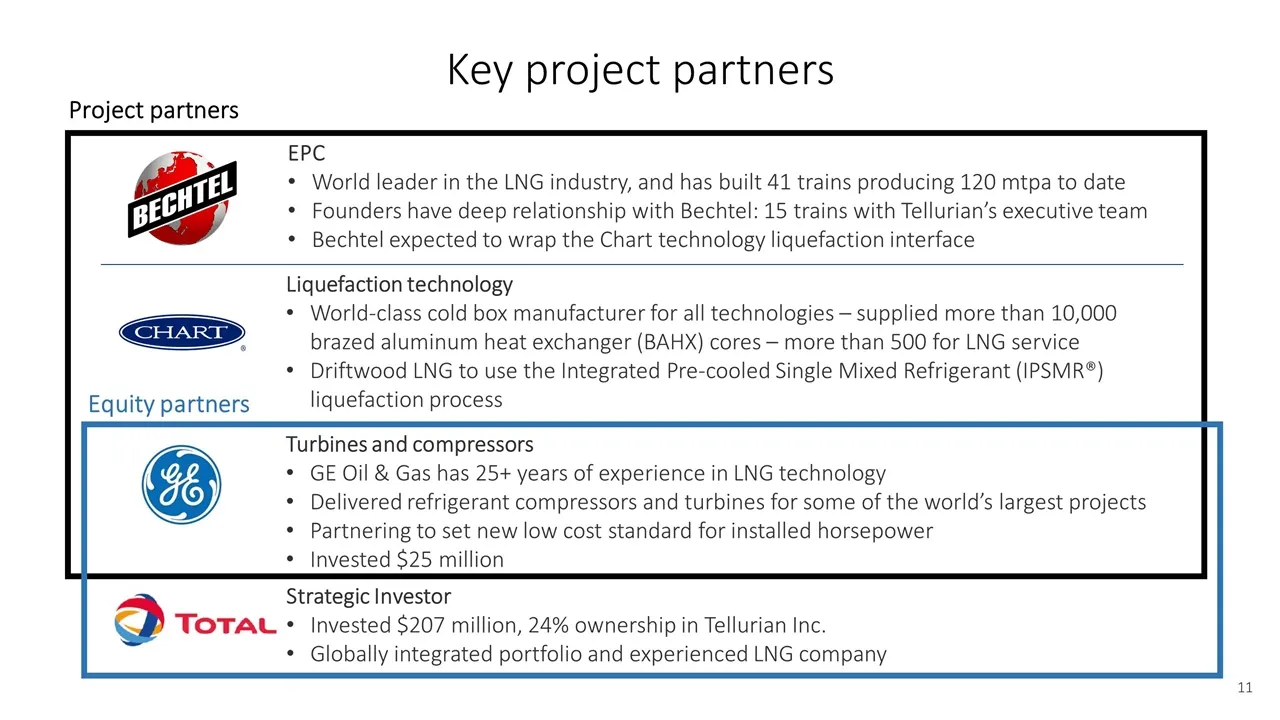
Key project partners EPC World leader in the LNG industry, and has built 41 trains producing 120 mtpa to date Founders have deep relationship with Bechtel: 15 trains with Tellurian’s executive team Bechtel expected to wrap the Chart technology liquefaction interface Liquefaction technology World-cla
Slide 12: Driftwood LNG – estimated project timeline
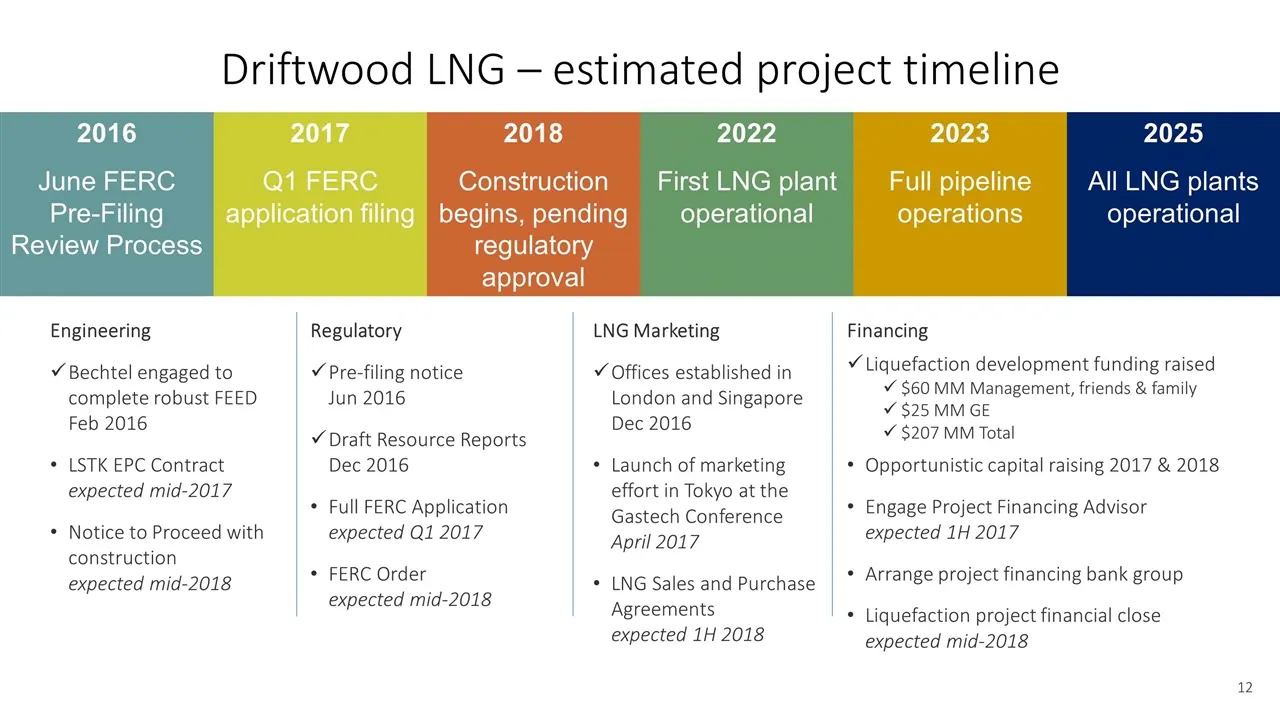
Driftwood LNG – estimated project timeline 2016 June FERC Pre-Filing Review Process 2017 Q1 FERC application filing 2018 Construction begins, pending regulatory approval 2022 First LNG plant operational 2023 Full pipeline operations 2025 All LNG plants operational Engineering Bechtel engaged to comp
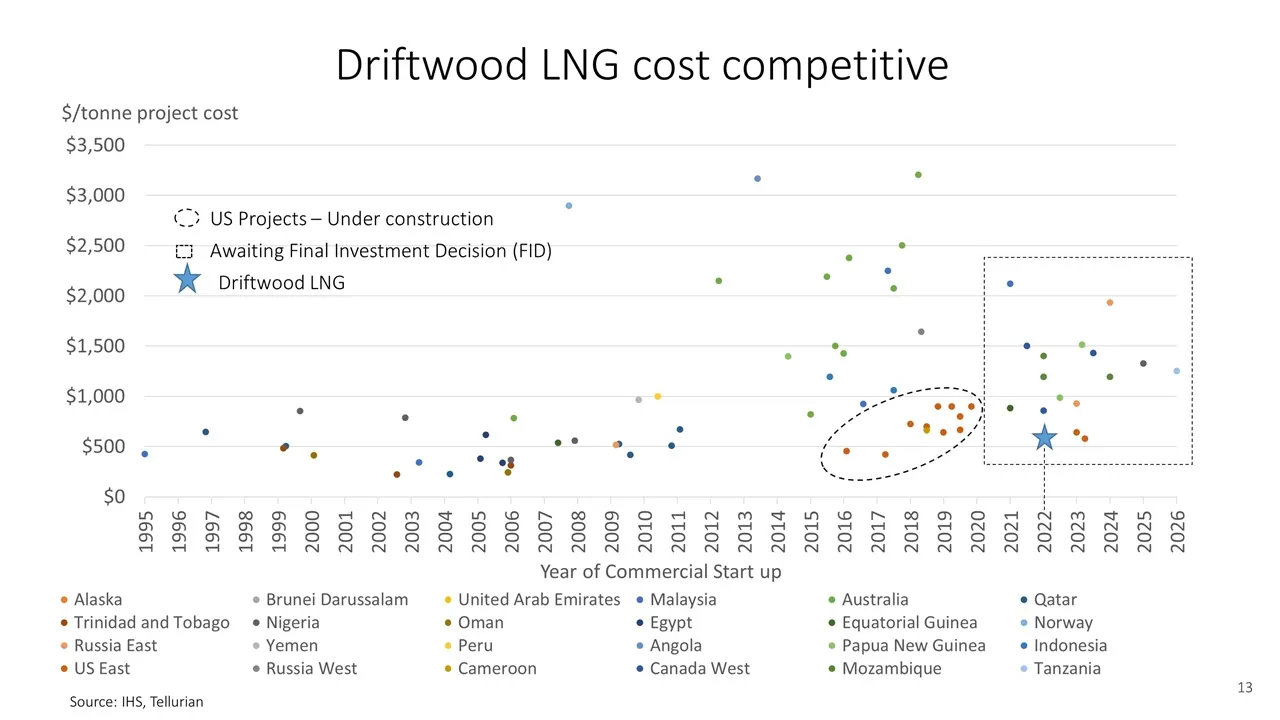
Slide 13: Driftwood LNG cost competitive
Driftwood LNG cost competitive Source: IHS, Tellurian Driftwood LNG Awaiting Final Investment Decision (FID) US Projects – Under construction
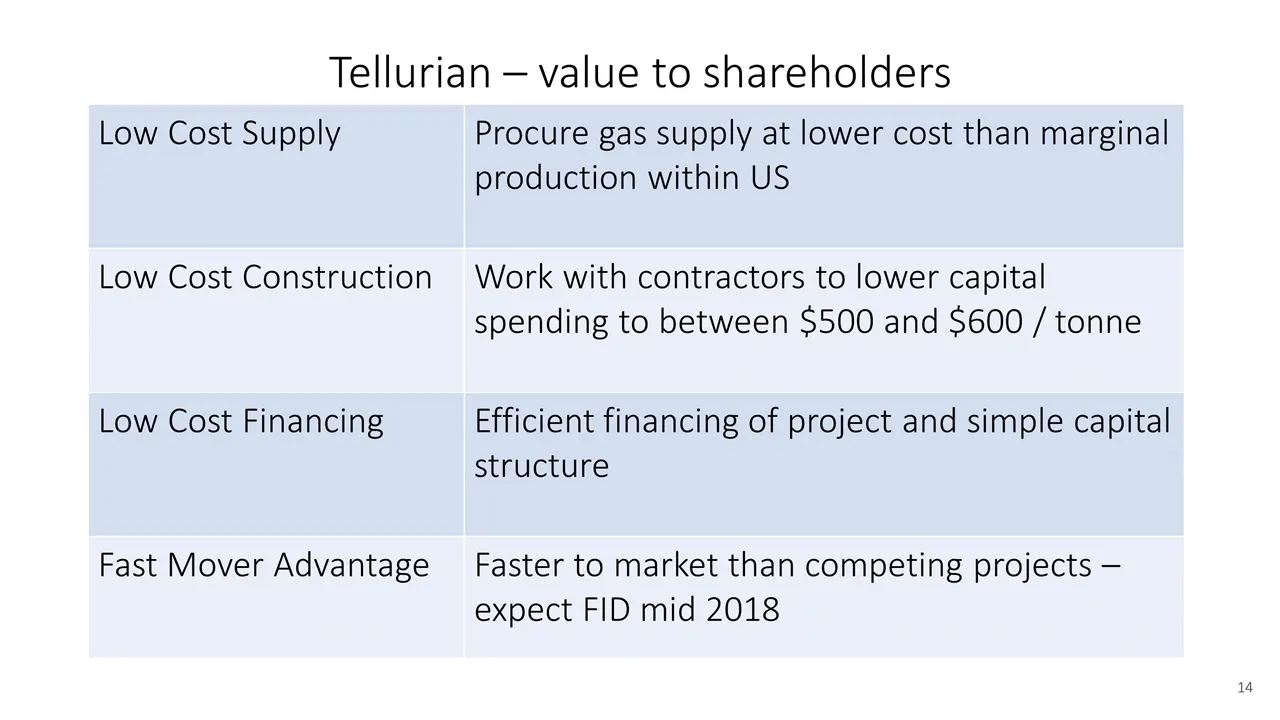
Slide 14: Tellurian – value to shareholders
Tellurian – value to shareholders Low Cost Supply Procure gas supply at lower cost than marginal production within US Low Cost Construction Work with contractors to lower capital spending to between $500 and $600 / tonne Low Cost Financing Efficient financing of project and simple capital structure
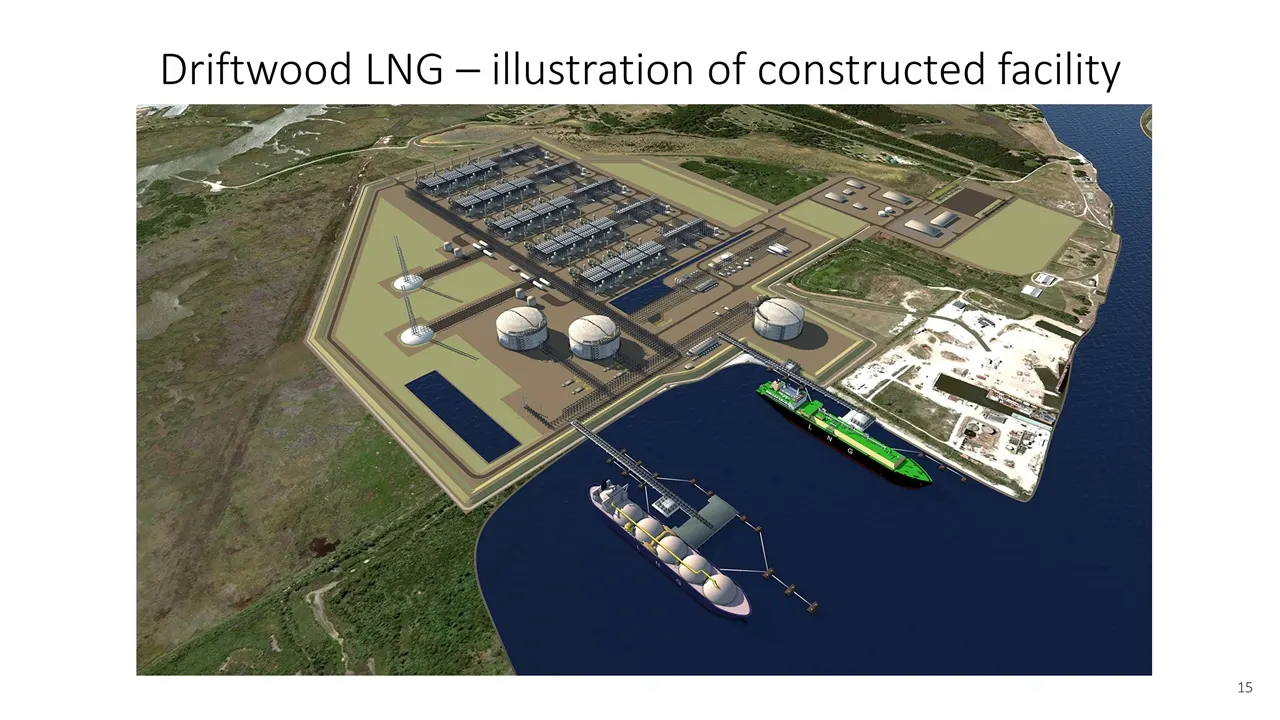
Slide 15: Driftwood LNG – illustration of constructed facility
Driftwood LNG – illustration of constructed facility
Slide 16: Thank you
TELLURIAN Thank you
Slide 17: Investor Contacts
Investor Contacts Investor Relations Amit Marwaha, 832-485-2004 [email protected] David Castaneda, 414-351-9758 [email protected] Public Relations Joi Lecznar, 832-962-4044 [email protected]
Slide 18: Appendix
Appendix
Slide 19: Corporate org chart
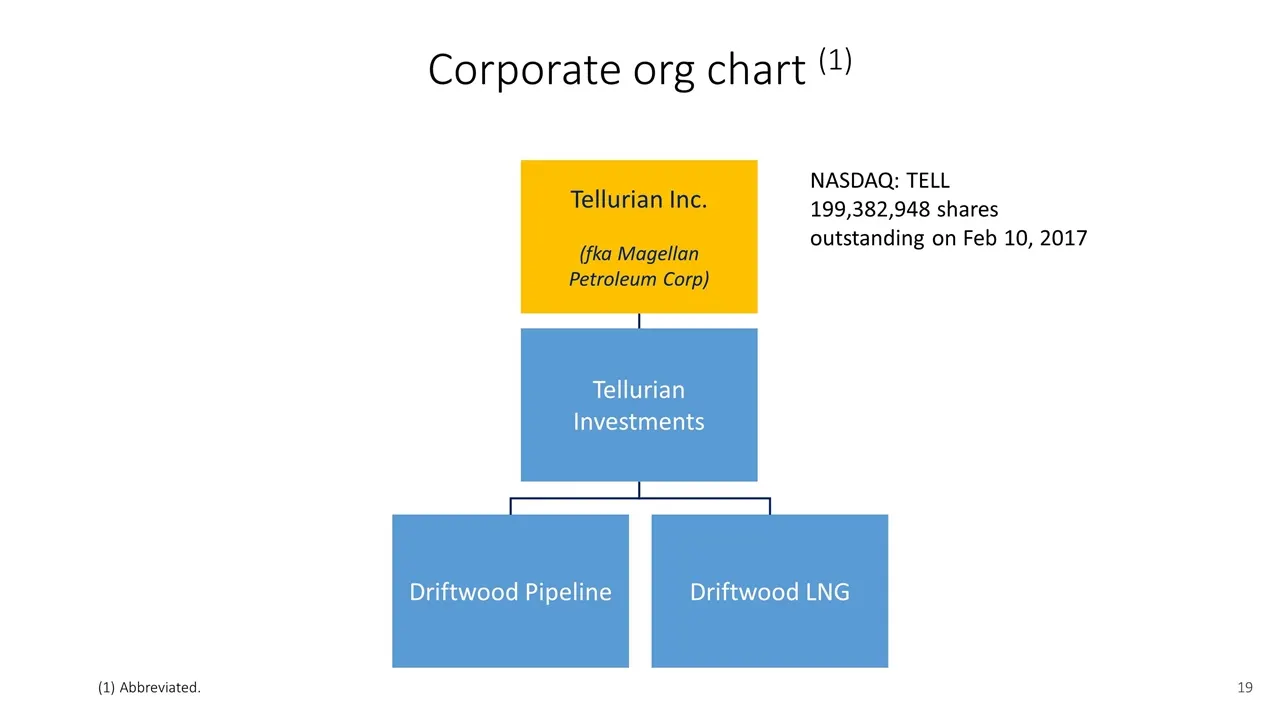
Corporate org chart (1) (1) Abbreviated. Tellurian Inc. (fka Magellan Petroleum Corp) Tellurian Investments Driftwood LNG Driftwood Pipeline NASDAQ: TELL 199,382,948 shares outstanding on Feb 10, 2017
Slide 20: Charif Souki, Chairman and management biographies
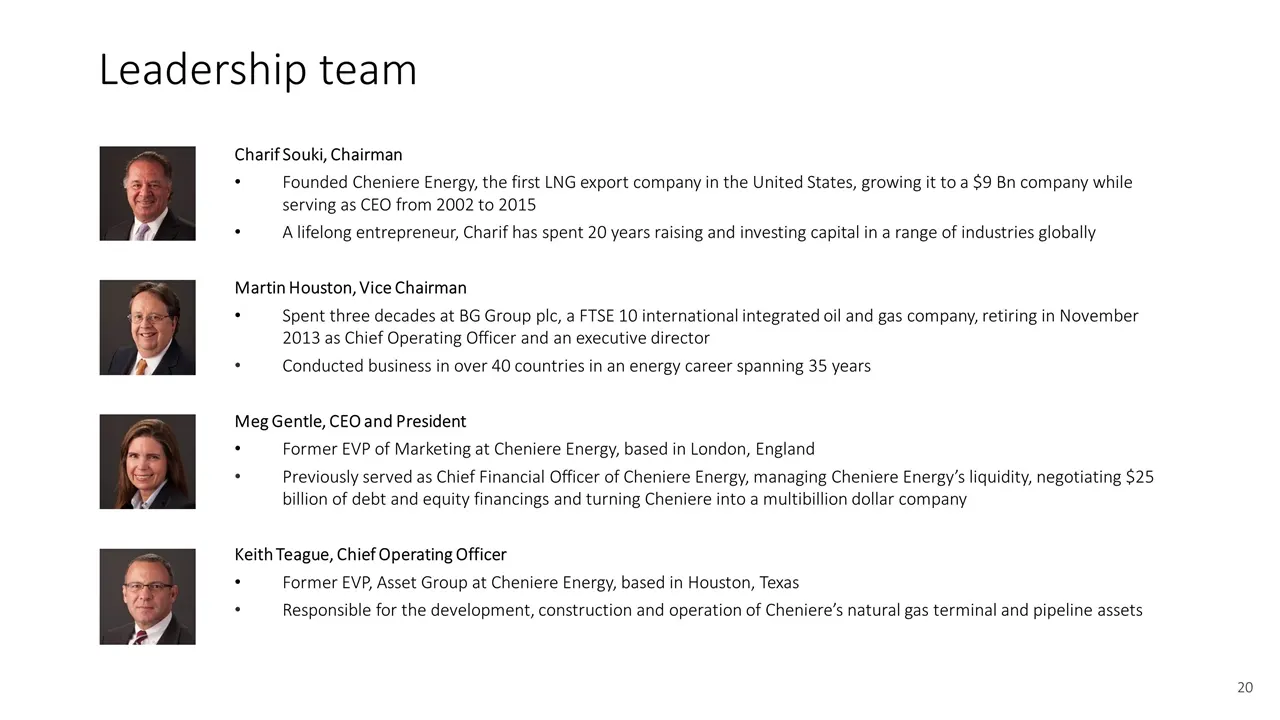
Charif Souki, Chairman Founded Cheniere Energy, the first LNG export company in the United States, growing it to a $9 Bn company while serving as CEO from 2002 to 2015 A lifelong entrepreneur, Charif has spent 20 years raising and investing capital in a range of industries globally Martin Houston, V
Slide 21: Leadership team
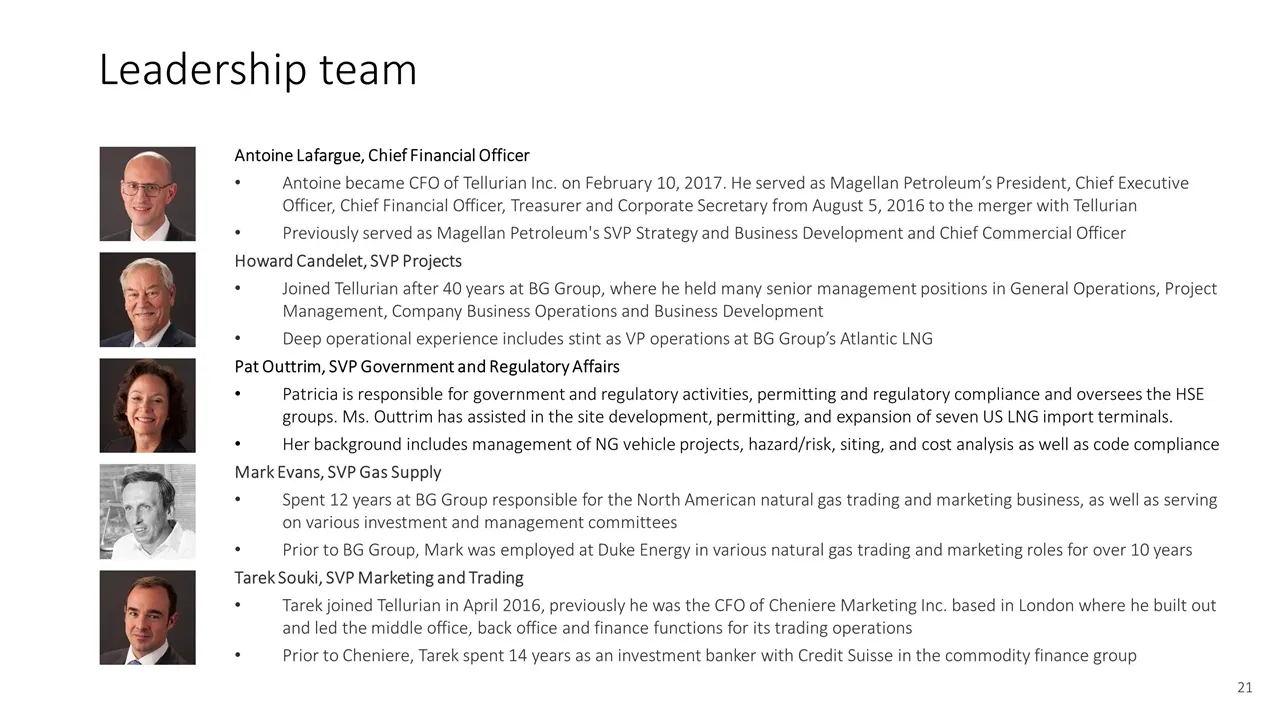
Leadership team Antoine Lafargue, Chief Financial Officer Antoine became CFO of Tellurian Inc. on February 10, 2017. He served as Magellan Petroleum’s President, Chief Executive Officer, Chief Financial Officer, Treasurer and Corporate Secretary from August 5, 2016 to the merger with Tellurian Previ
Slide 22: Experience matters
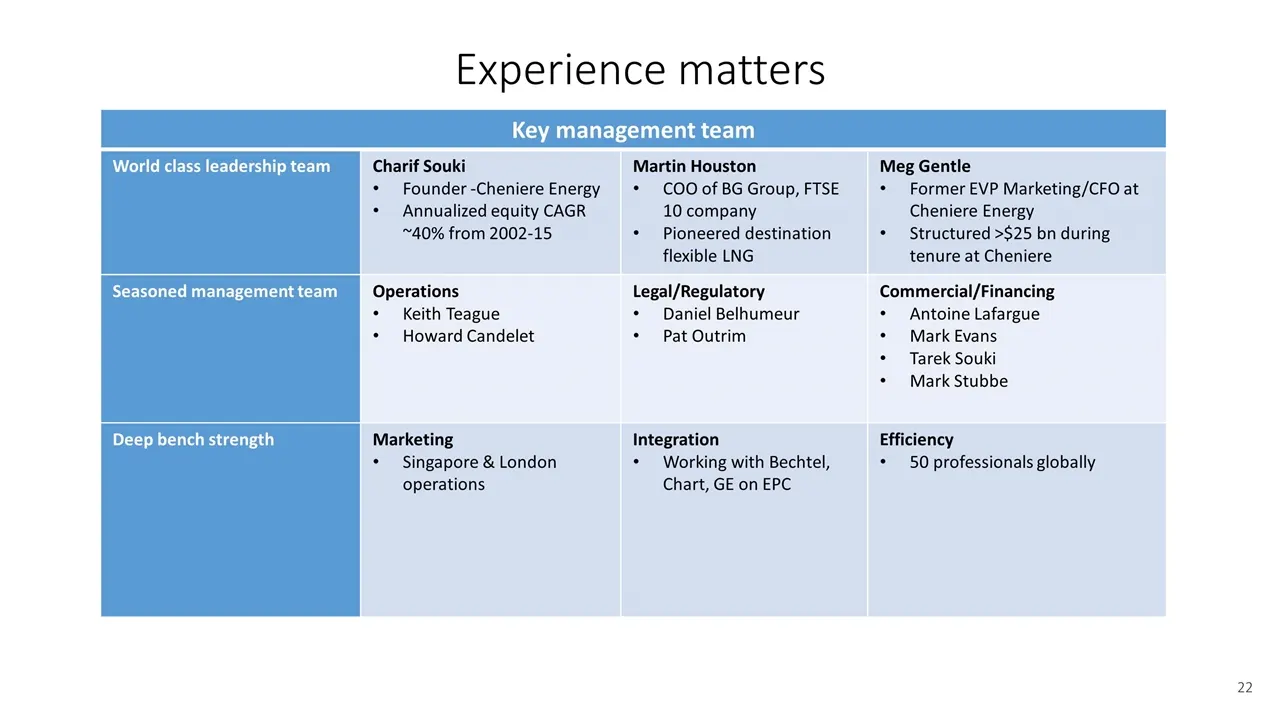
Experience matters Key management team World class leadership team Charif Souki Founder -Cheniere Energy Annualized equity CAGR ~40% from 2002-15 Martin Houston COO of BG Group, FTSE 10 company Pioneered destination flexible LNG Meg Gentle Former EVP Marketing/CFO at Cheniere Energy Structured >$25
Slide 23: DWLNG vs. traditional LNG plant – design
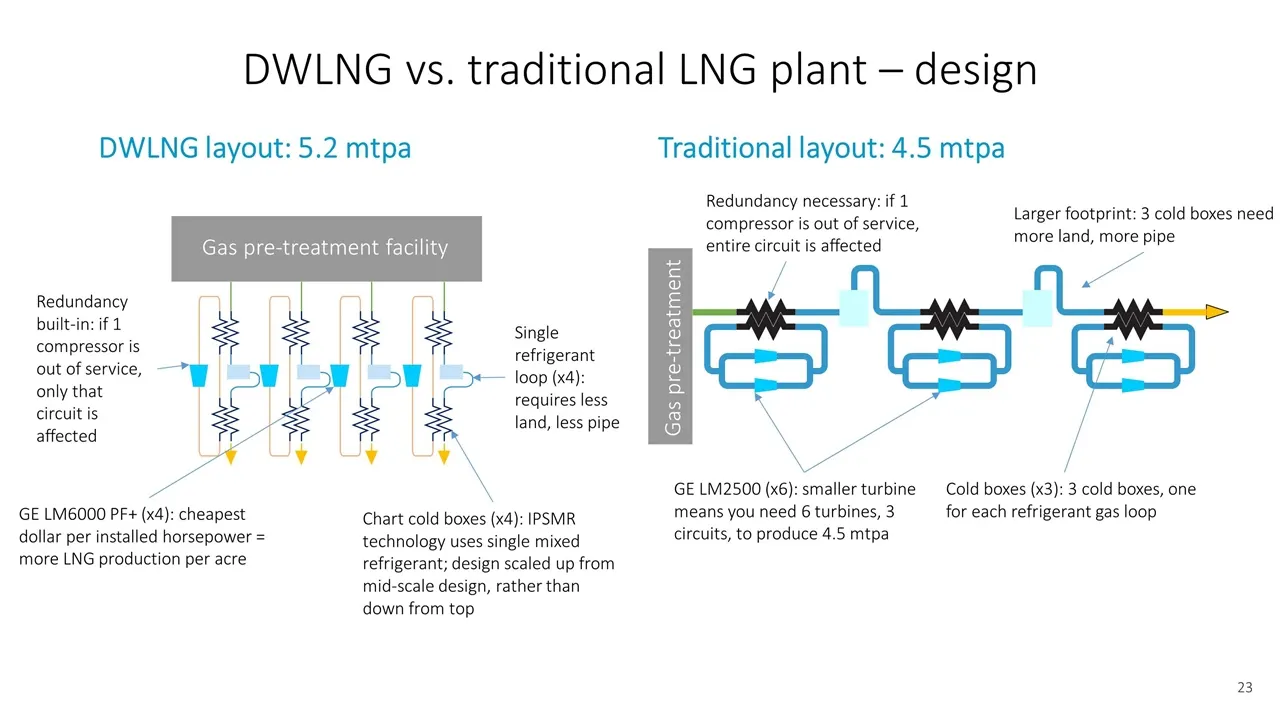
DWLNG vs. traditional LNG plant – design DWLNG layout: 5.2 mtpa Traditional layout: 4.5 mtpa GE LM6000 PF+ (x4): cheapest dollar per installed horsepower = more LNG production per acre Gas pre-treatment facility Chart cold boxes (x4): IPSMR technology uses single mixed refrigerant; design scaled up
Slide 24: Timeline to FID and status
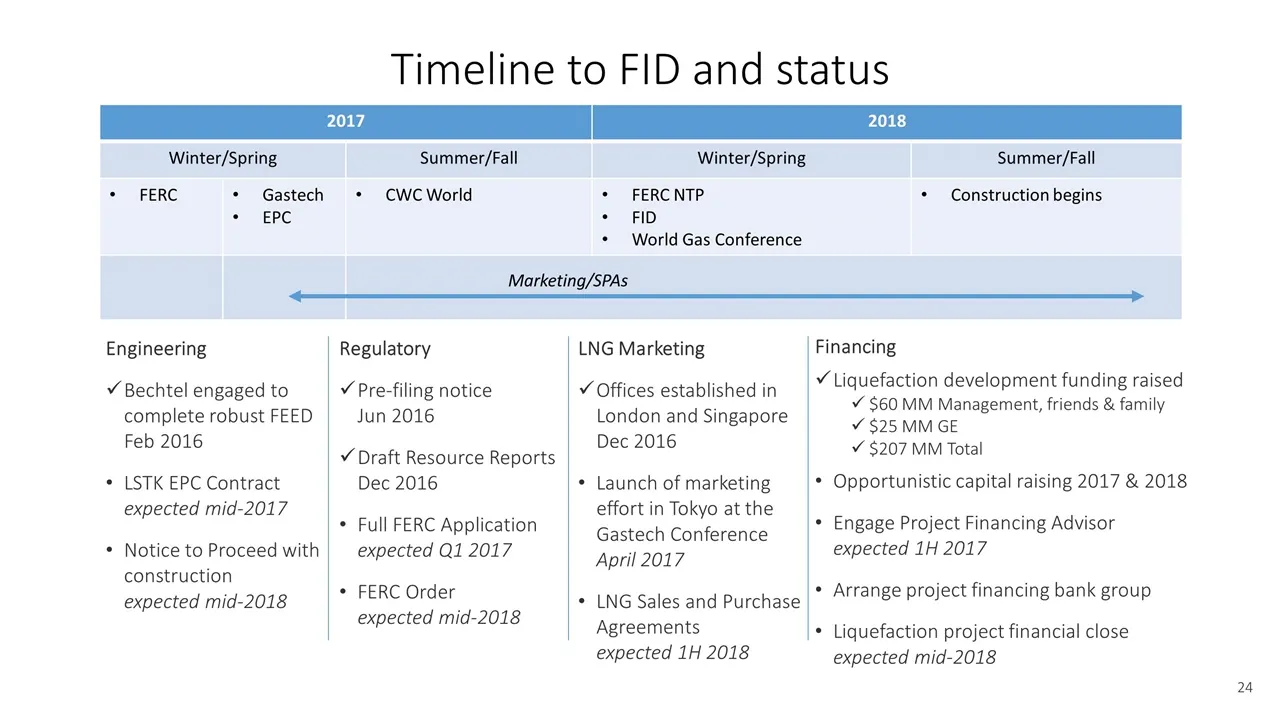
Timeline to FID and status 2017 2018 Winter/Spring Summer/Fall Winter/Spring Summer/Fall FERC Gastech EPC CWC World FERC NTP FID World Gas Conference Construction begins Marketing/SPAs Engineering Bechtel engaged to complete robust FEED Feb 2016 LSTK EPC Contract expected mid-2017 Notice to Proceed
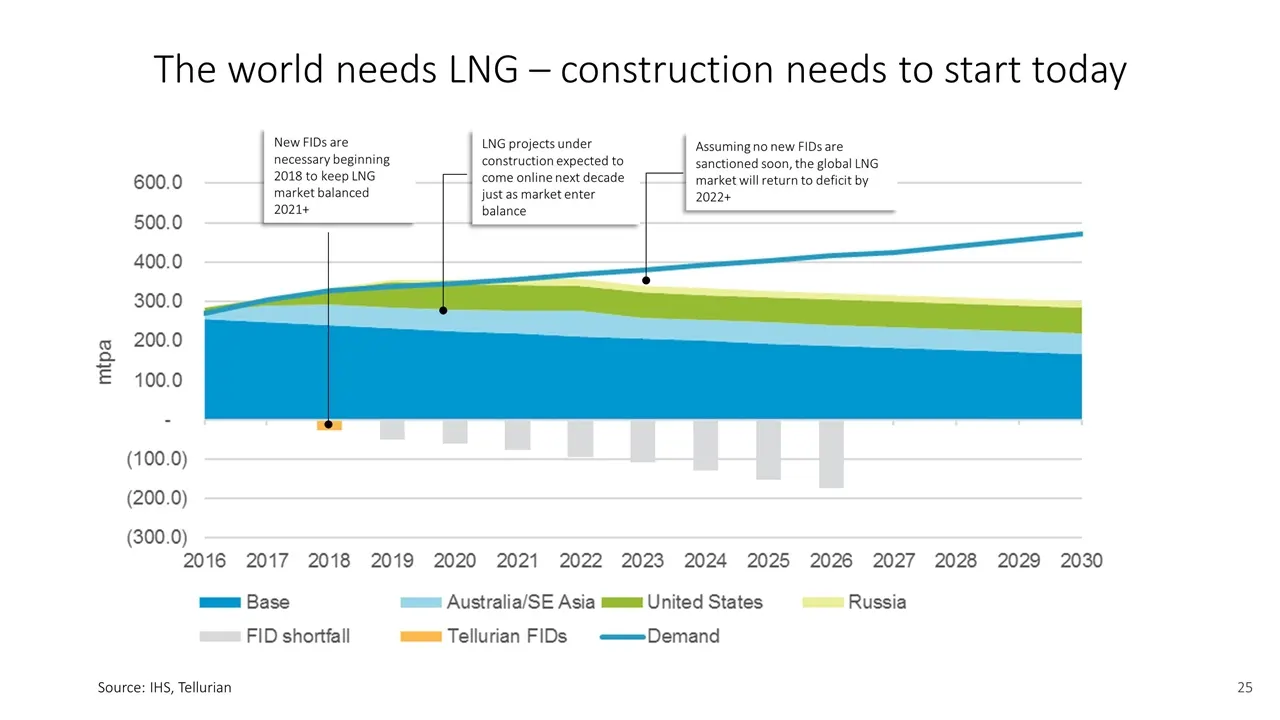
Slide 25: The world needs LNG – construction needs to start today
The world needs LNG – construction needs to start today Source: IHS, Tellurian New FIDs will be needed from 2018 if we are to keep the market in balance from 2021 onwards Assuming no new FIDs are sanctioned soon, the global LNG market will return to deficit by 2022+ New FIDs are necessary beginning
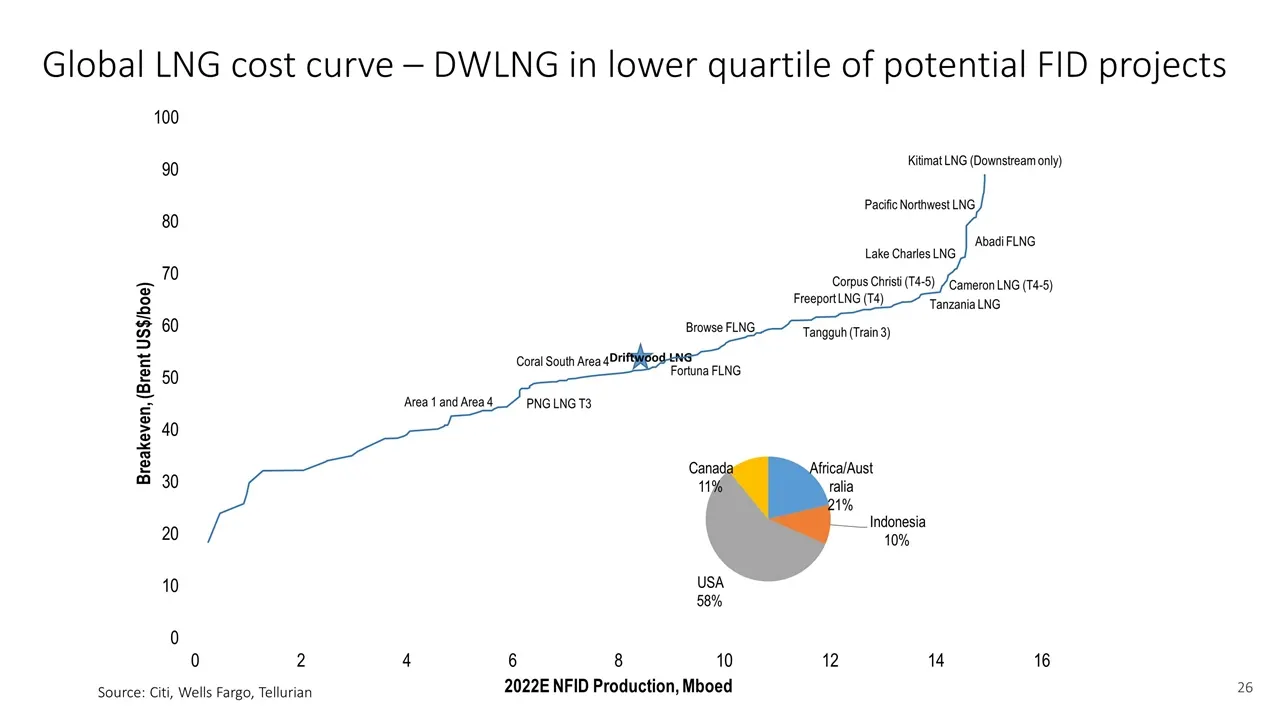
Slide 26: Global LNG cost curve – DWLNG in lower quartile
Global LNG cost curve – DWLNG in lower quartile of potential FID projects Source: Citi, Wells Fargo, Tellurian Driftwood LNG
Source: SEC EDGAR · 8-K filed Feb 14, 2017
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (November 2022)19 slides · Nov 2, 2022