Western Asset Mortgage Capital
Western Asset Mortgage Capital — Q1 2022 Earnings Presentation
31 slides from Western Asset Mortgage Capital's earnings presentation, May 5, 2022
Slide 1: First Quarter 2022 Investor Presentation
First Quarter 2022 Investor Presentation May 5, 2022
Slide 2: Forward-looking statements
We make forward-looking statements in this presentation that are subject to risks and uncertainties, many of which are difficult to predict and are generally beyond the Company's control. In particular, it is difficult to fully assess the impact of COVID-19 at this time due to, among other factors,
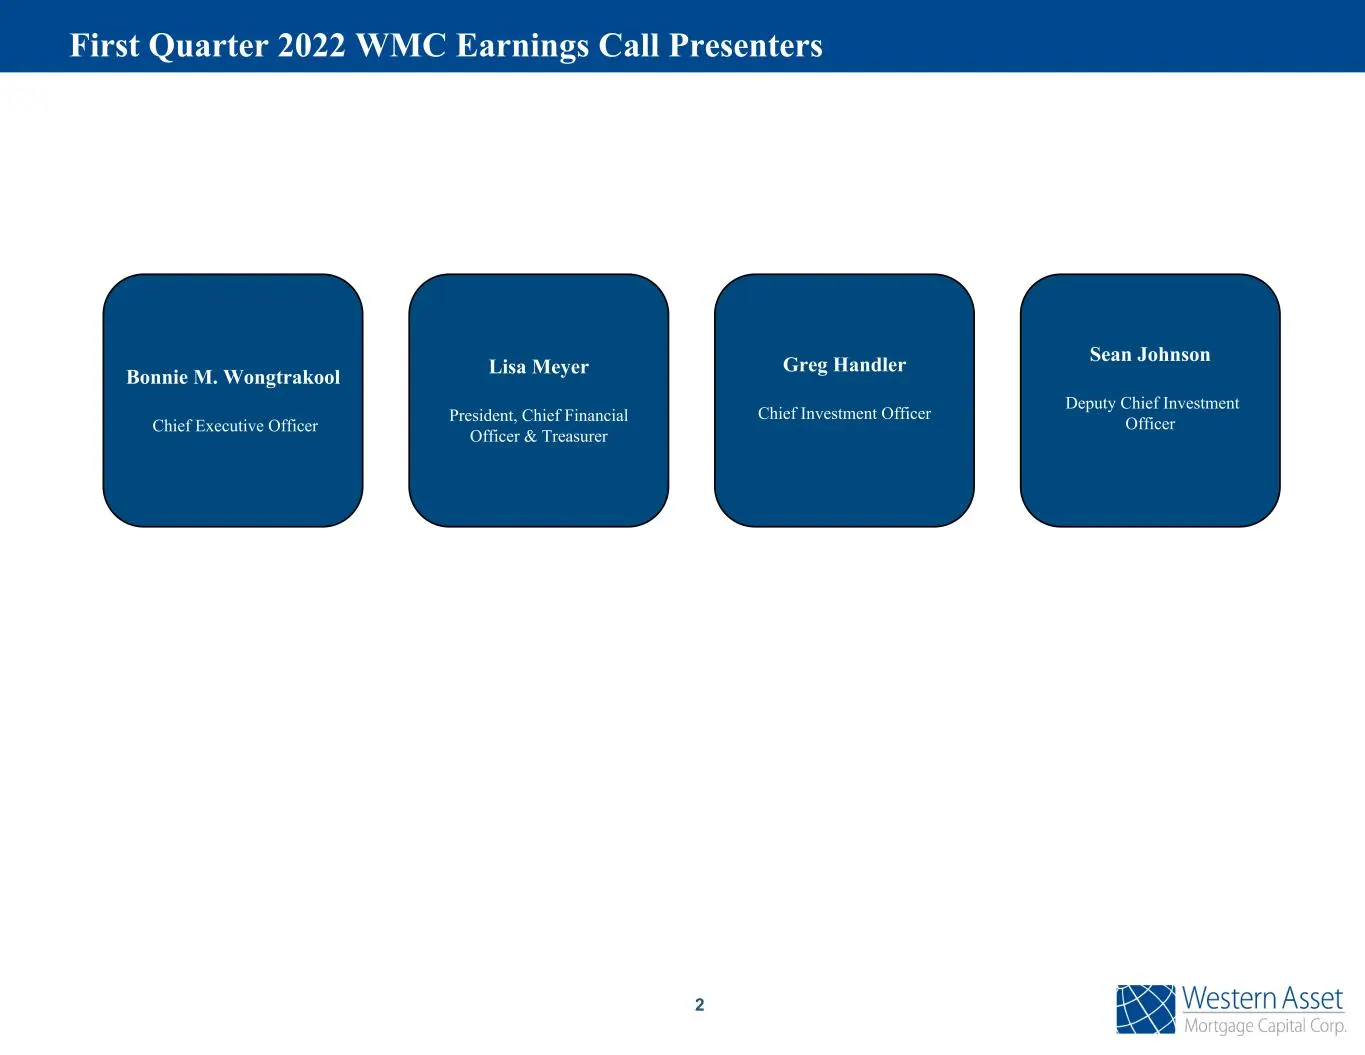
Slide 3: First Quarter 2022 WMC Earnings Call Presenters
Lisa Meyer President, Chief Financial Officer & Treasurer Bonnie M. Wongtrakool Chief Executive Officer Greg Handler Chief Investment Officer 2 Sean Johnson Deputy Chief Investment Officer First Quarter 2022 WMC Earnings Call Presenters
Slide 4: Overview of Western Asset Mortgage Capital Corporation
3 Western Asset Mortgage Capital Corporation (“WMC”) is a public REIT that benefits from the leading fixed income management capabilities of Western Asset Management Company, LLC ("Western Asset") • One of the world’s leading global fixed income managers, known for team management, proprietary resea
Slide 5: Our Manager's 2022 Outlook
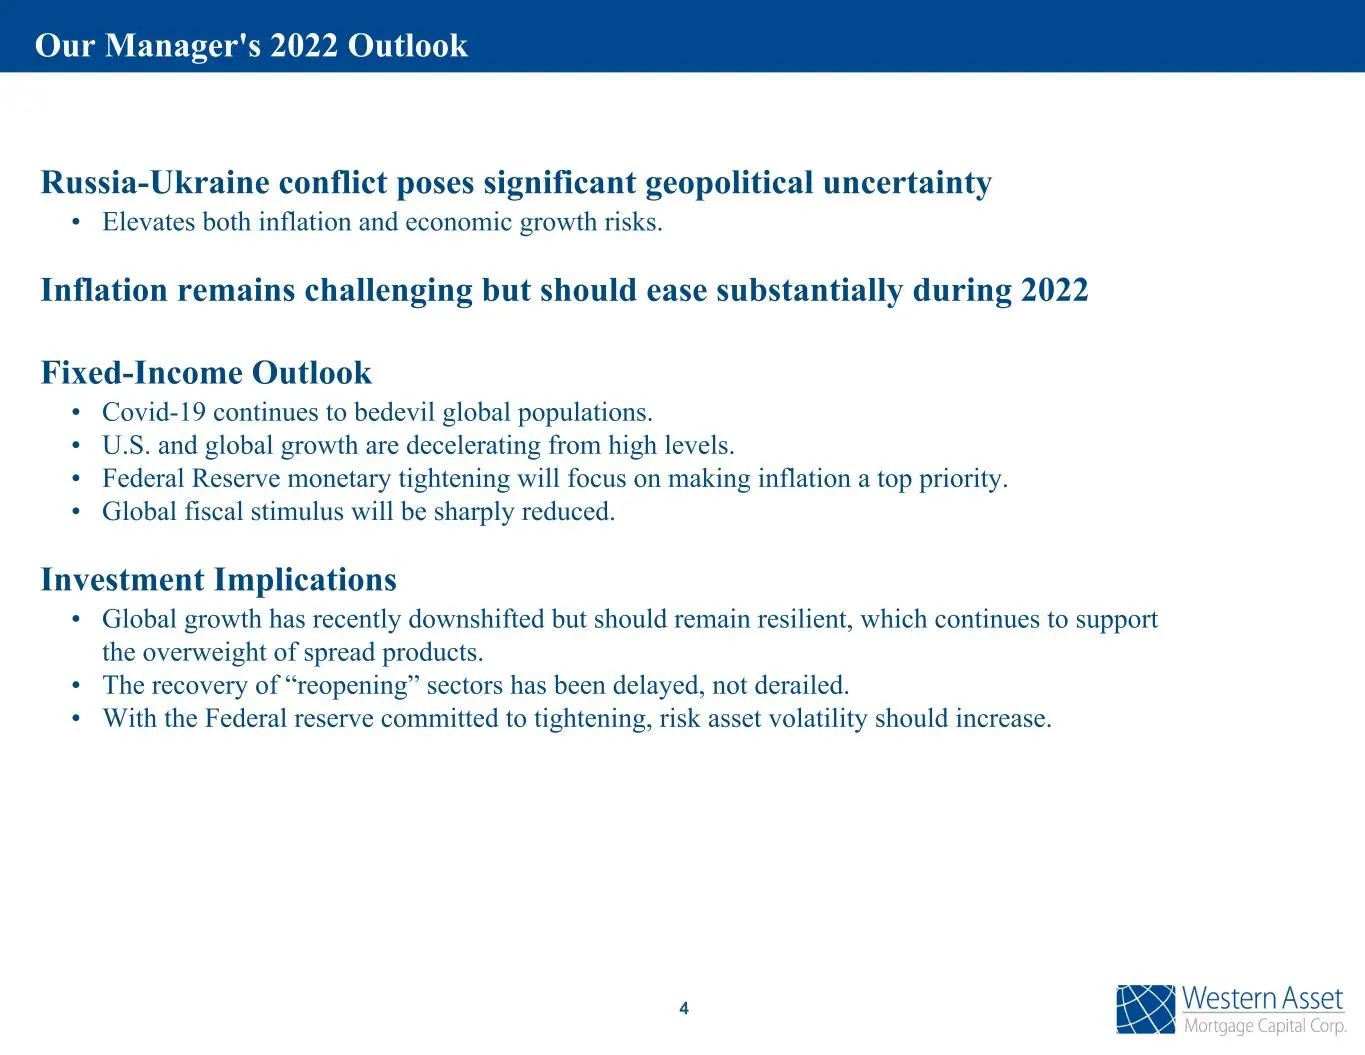
Our Manager's 2022 Outlook Russia-Ukraine conflict poses significant geopolitical uncertainty • Elevates both inflation and economic growth risks. Inflation remains challenging but should ease substantially during 2022 Fixed-Income Outlook • Covid-19 continues to bedevil global populations. • U.S. a
Slide 6: Mortgage & Consumer Credit Outlook
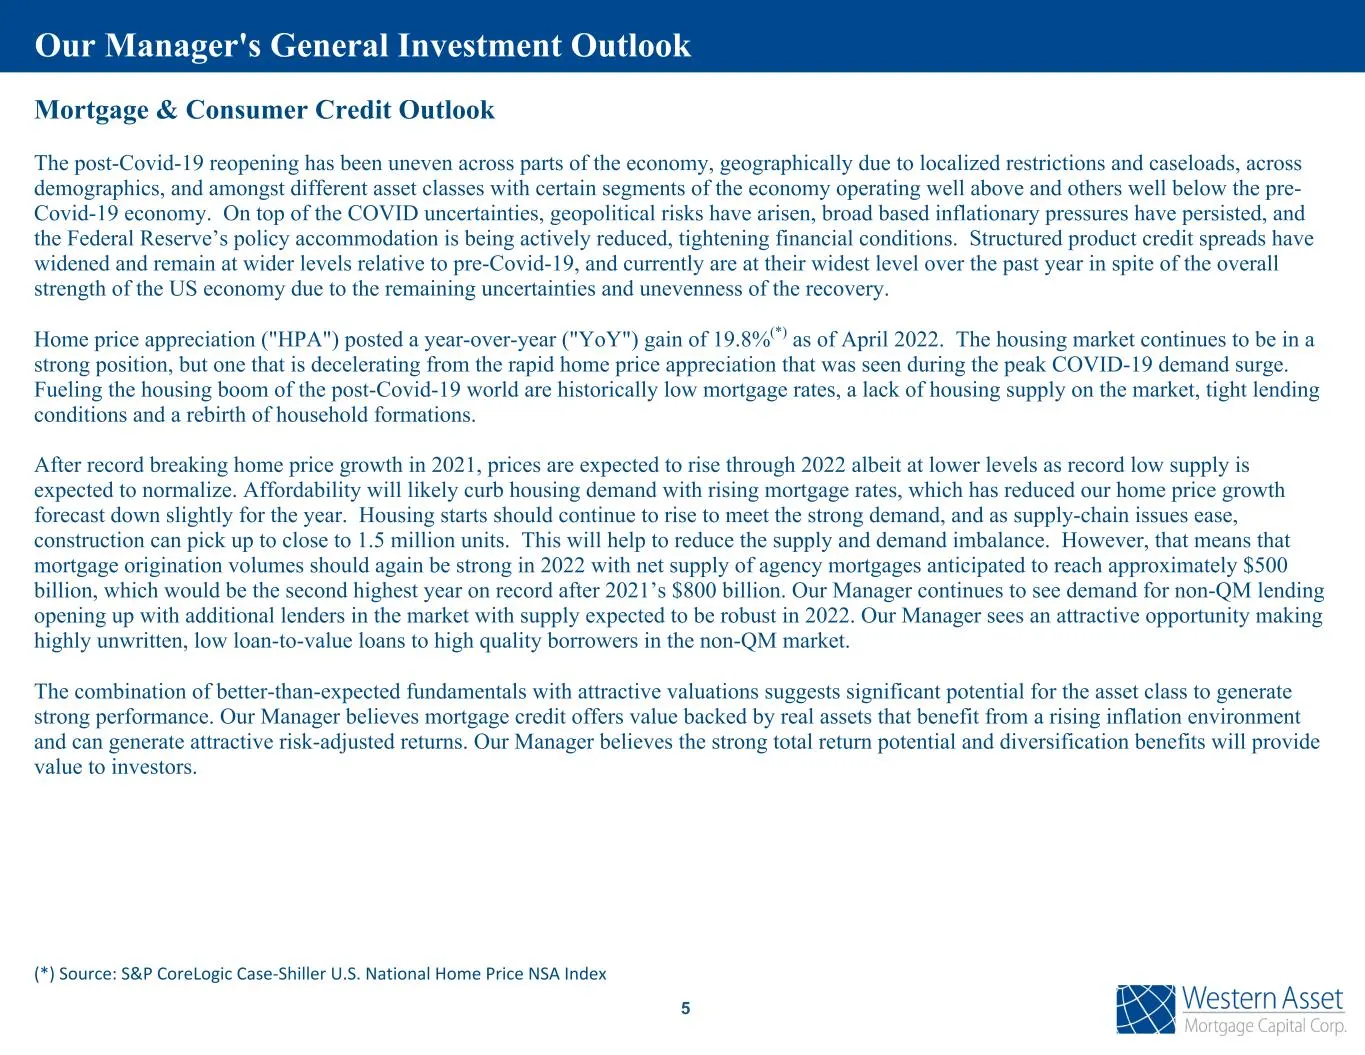
Mortgage & Consumer Credit Outlook The post-Covid-19 reopening has been uneven across parts of the economy, geographically due to localized restrictions and caseloads, across demographics, and amongst different asset classes with certain segments of the economy operating well above and others well b
Slide 7: US Housing Market Lending Activity
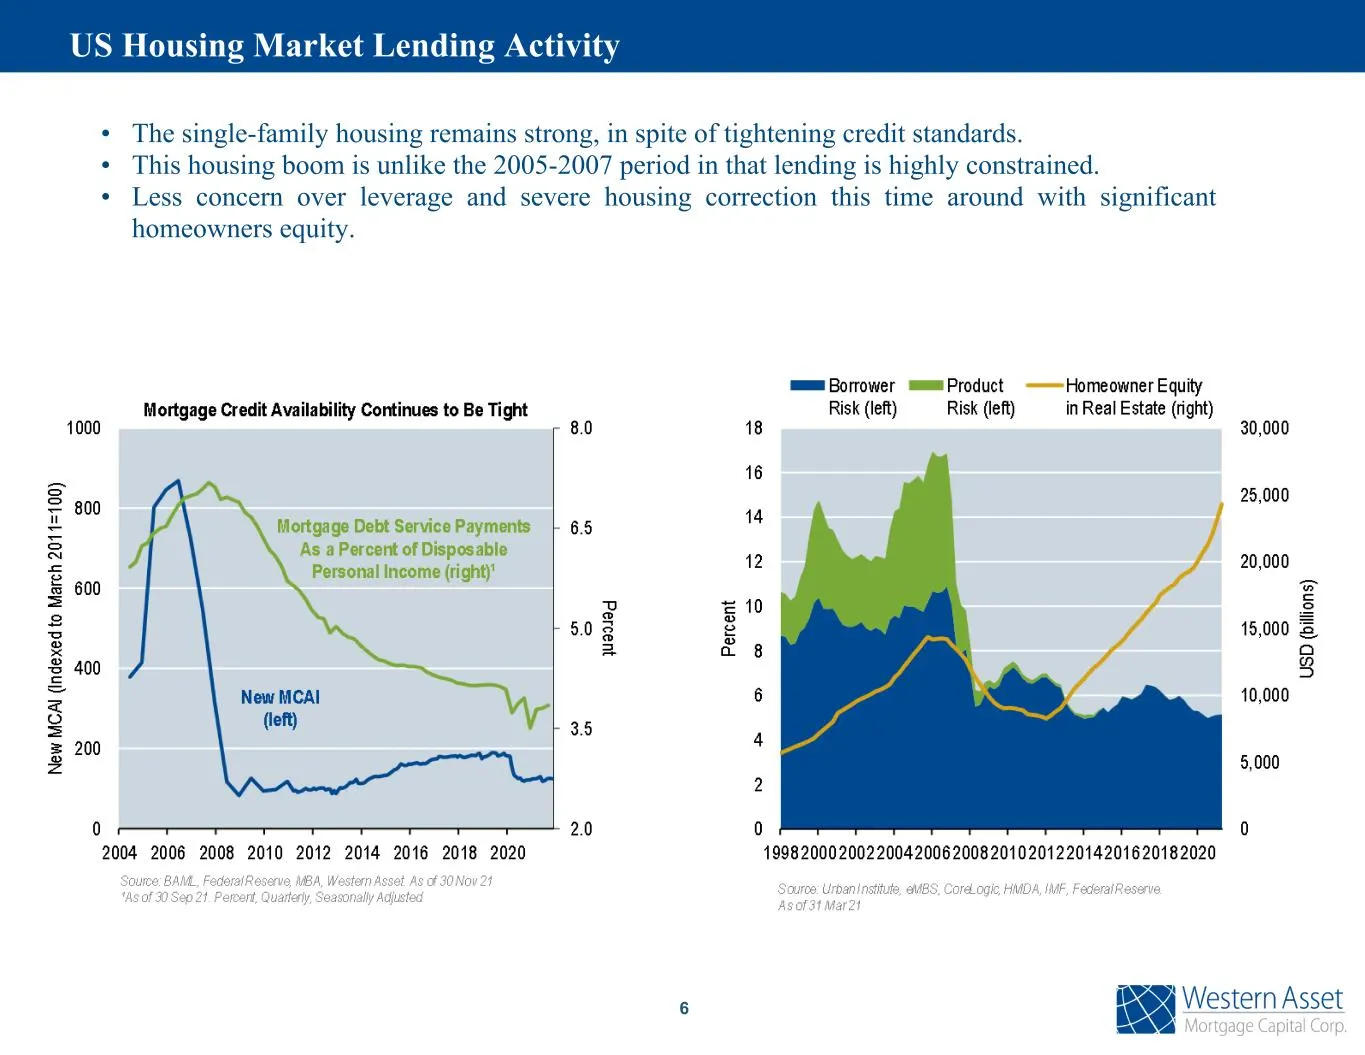
6 • The single-family housing remains strong, in spite of tightening credit standards. • This housing boom is unlike the 2005-2007 period in that lending is highly constrained. • Less concern over leverage and severe housing correction this time around with significant homeowners equity. US Housing
Slide 8: Housing Market Expected to Moderate
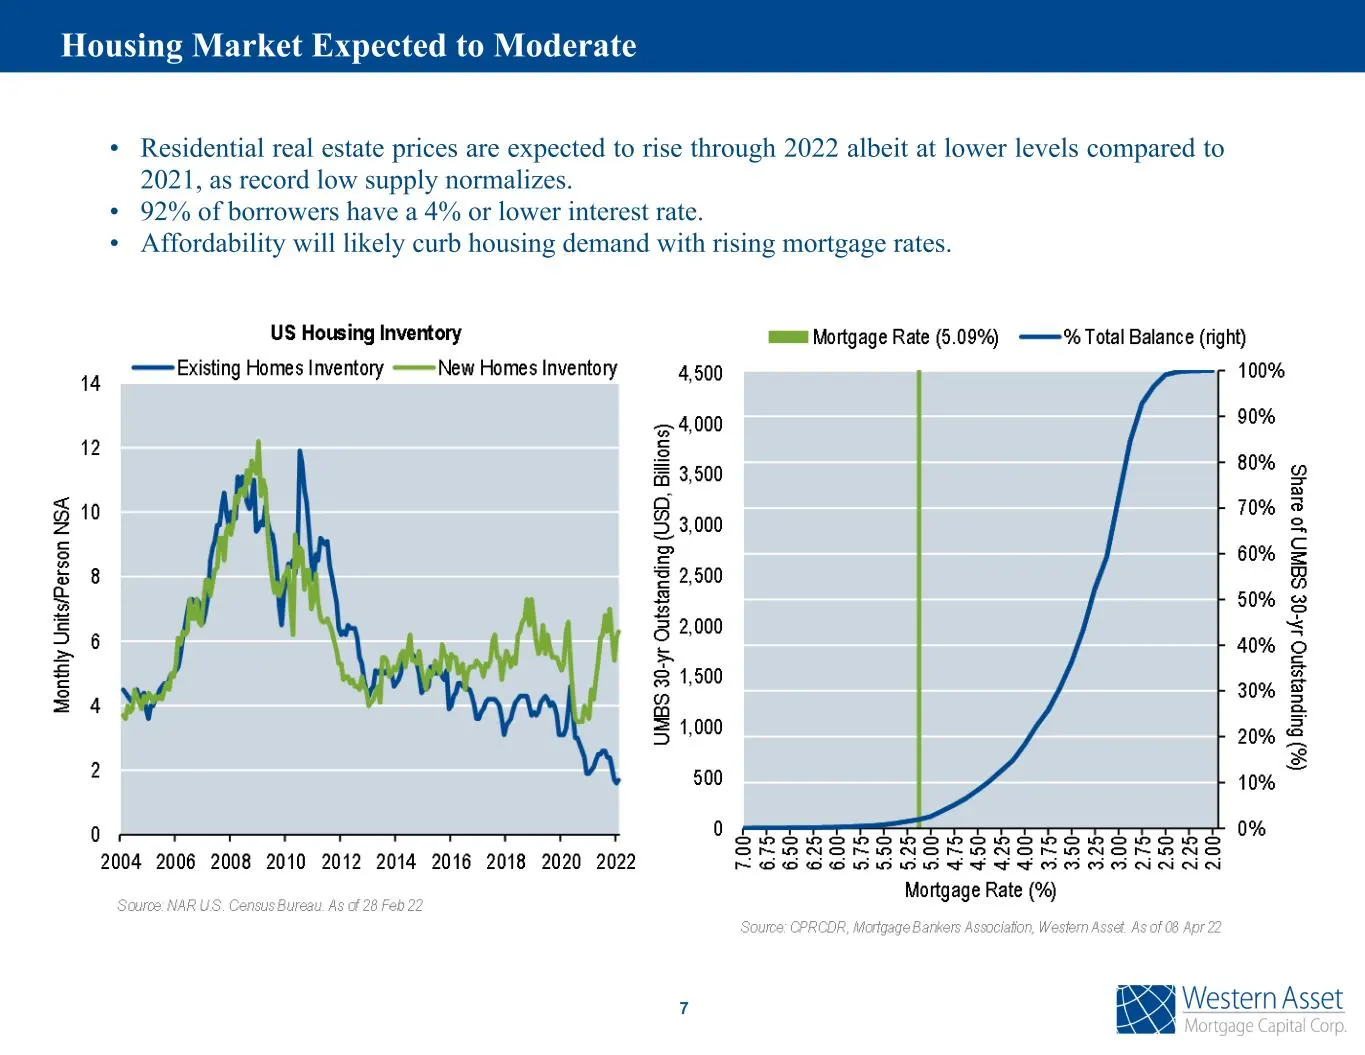
7 • Residential real estate prices are expected to rise through 2022 albeit at lower levels compared to 2021, as record low supply normalizes. • 92% of borrowers have a 4% or lower interest rate. • Affordability will likely curb housing demand with rising mortgage rates. Housing Market Expected to M
Slide 9: CMBS Delinquency
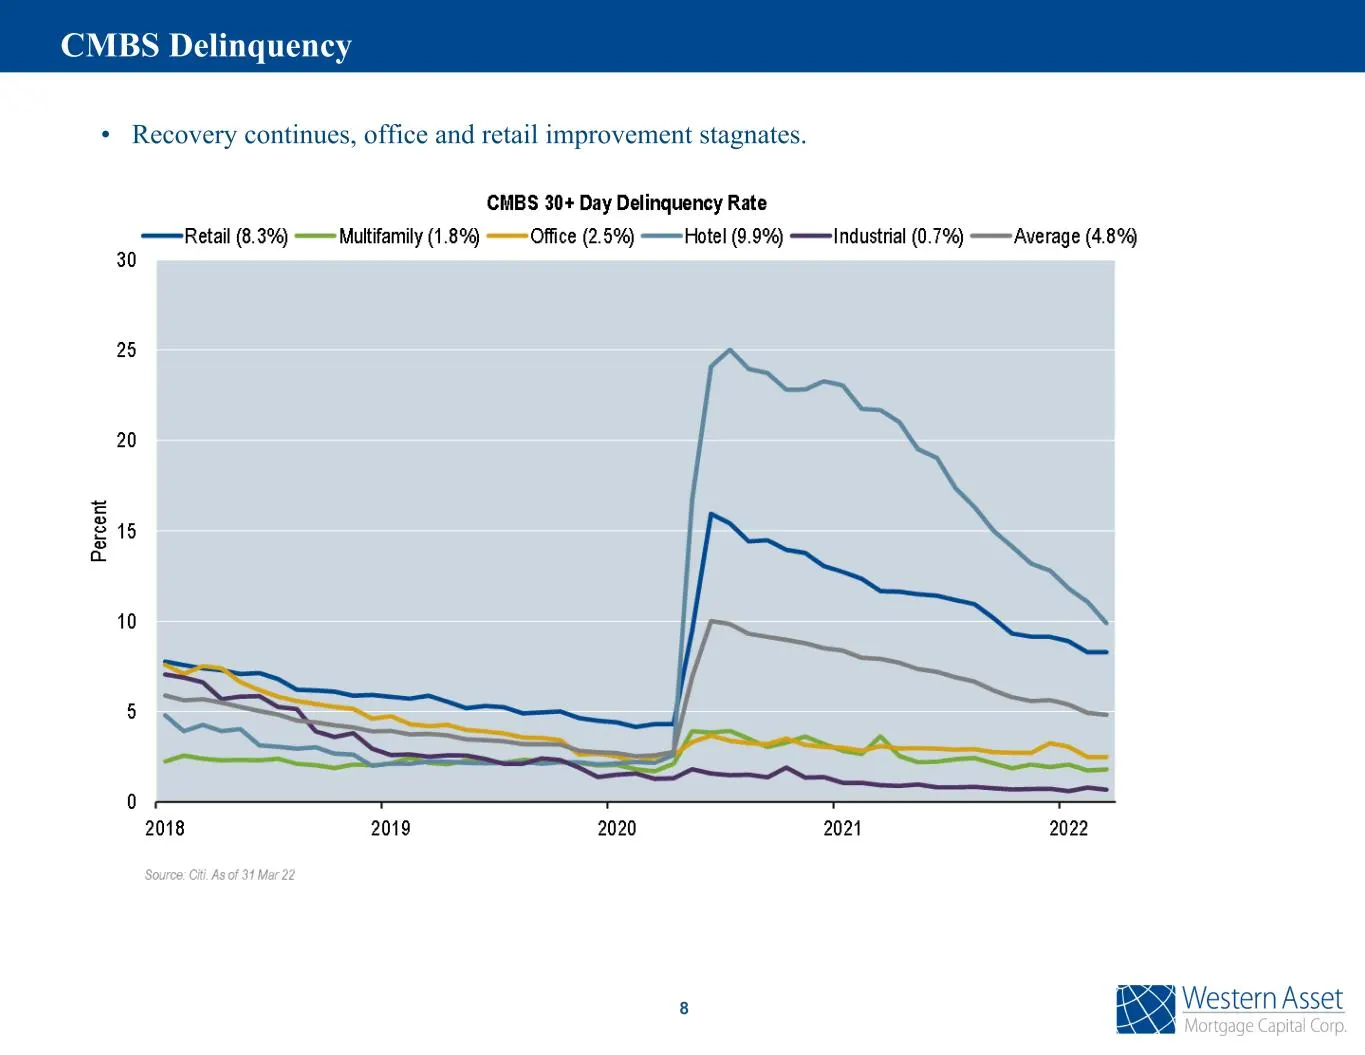
8 CMBS Delinquency • Recovery continues, office and retail improvement stagnates.
Slide 10: Investment Strategy
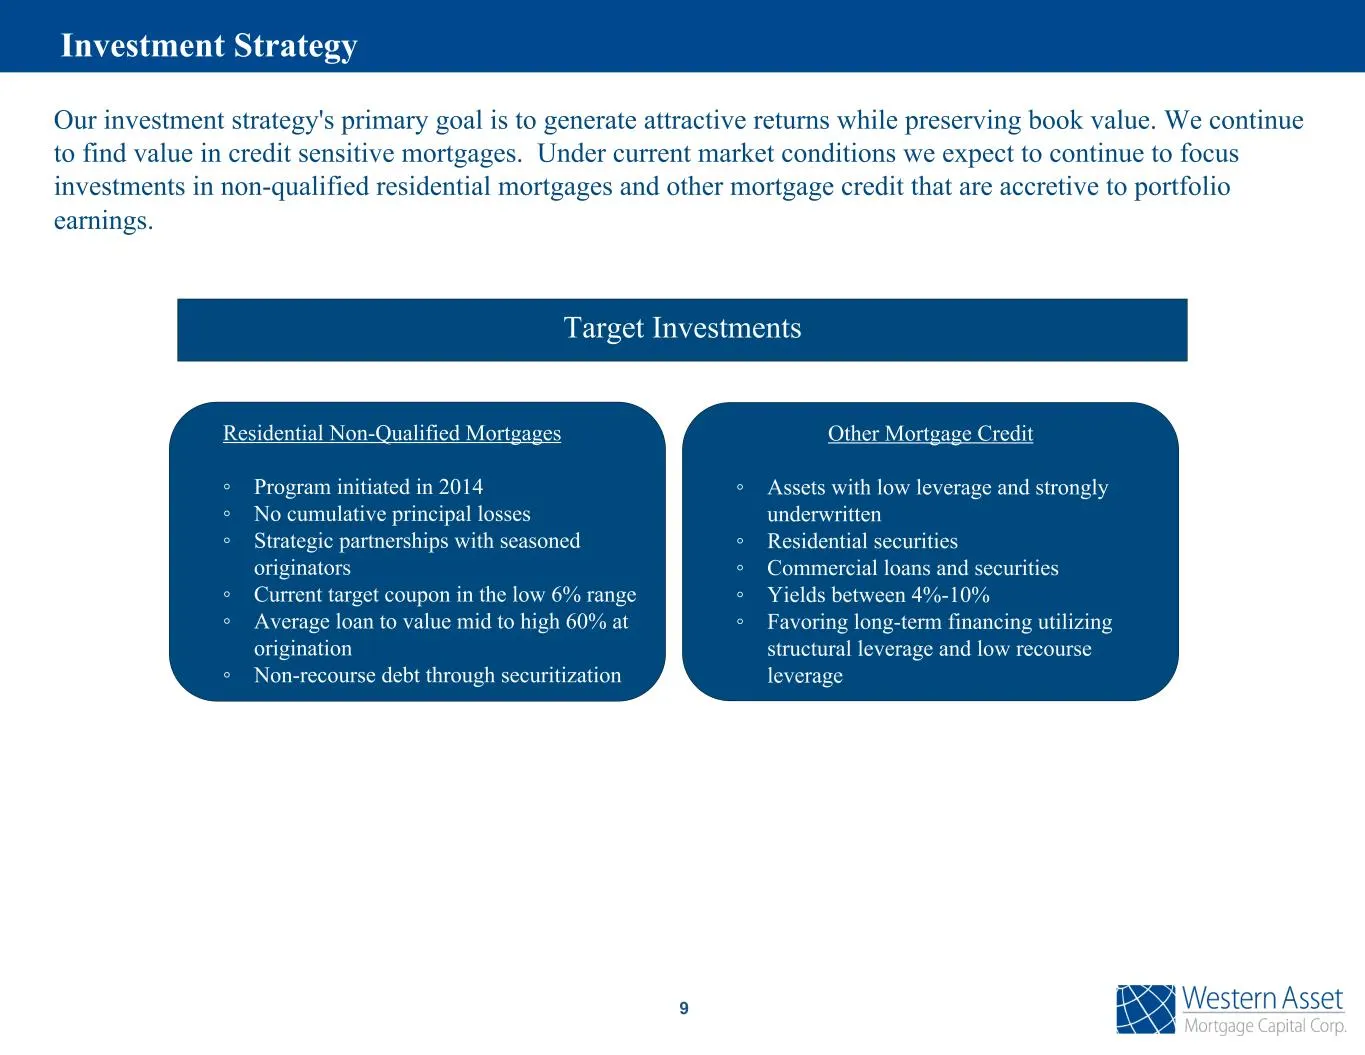
9 Investment Strategy Our investment strategy's primary goal is to generate attractive returns while preserving book value. We continue to find value in credit sensitive mortgages. Under current market conditions we expect to continue to focus investments in non-qualified residential mortgages and o
Slide 11: Company Business Update
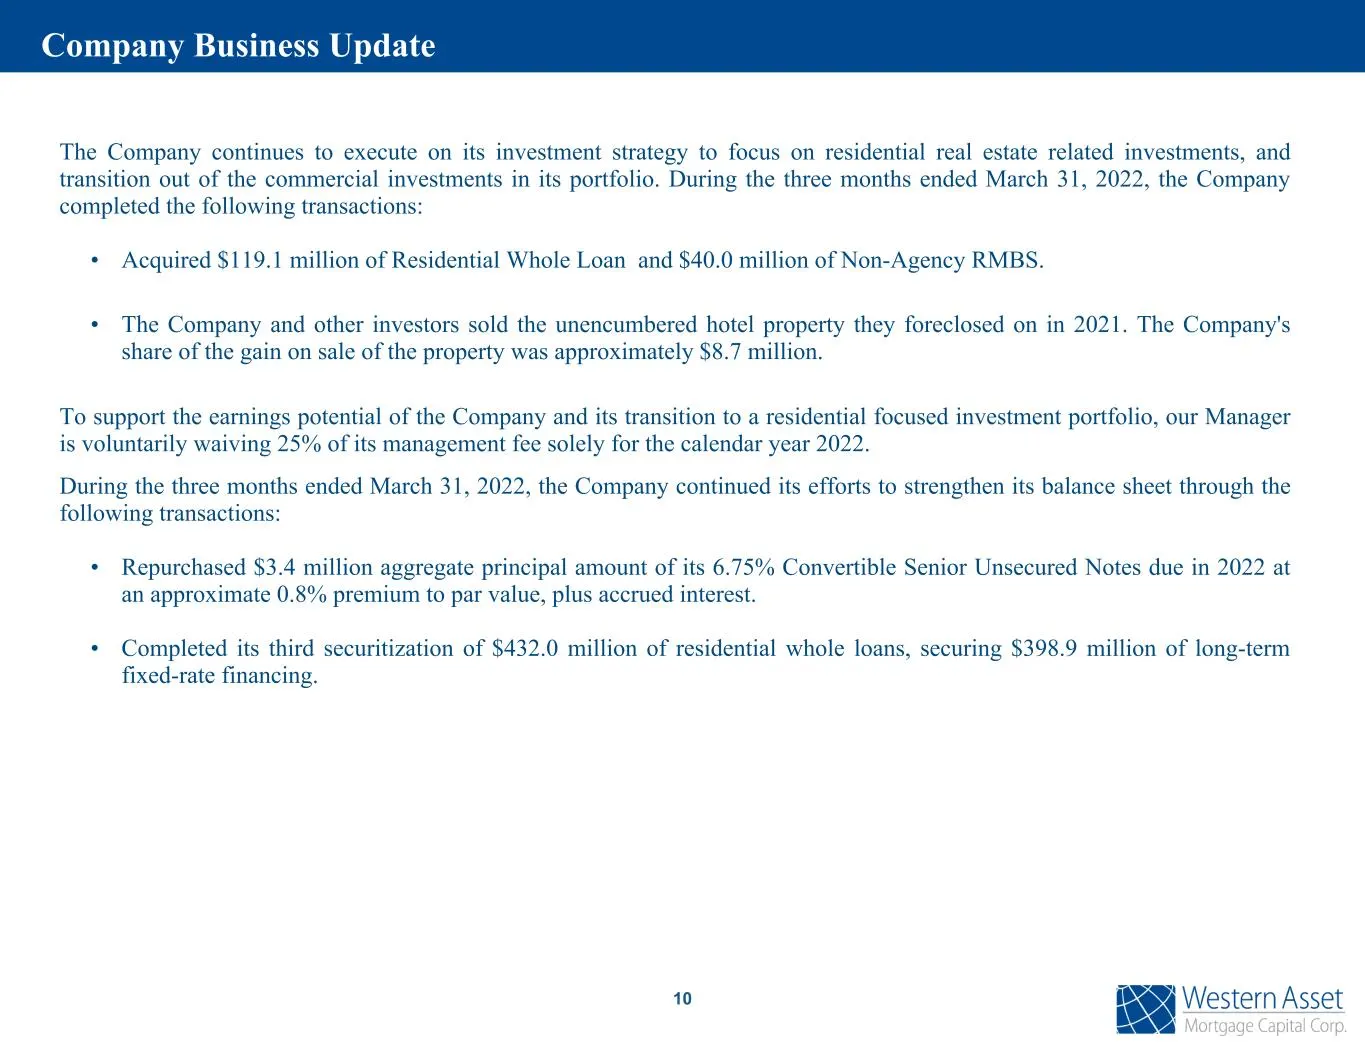
Company Business Update The Company continues to execute on its investment strategy to focus on residential real estate related investments, and transition out of the commercial investments in its portfolio. During the three months ended March 31, 2022, the Company completed the following transactio
Slide 12: First Quarter Financial Results
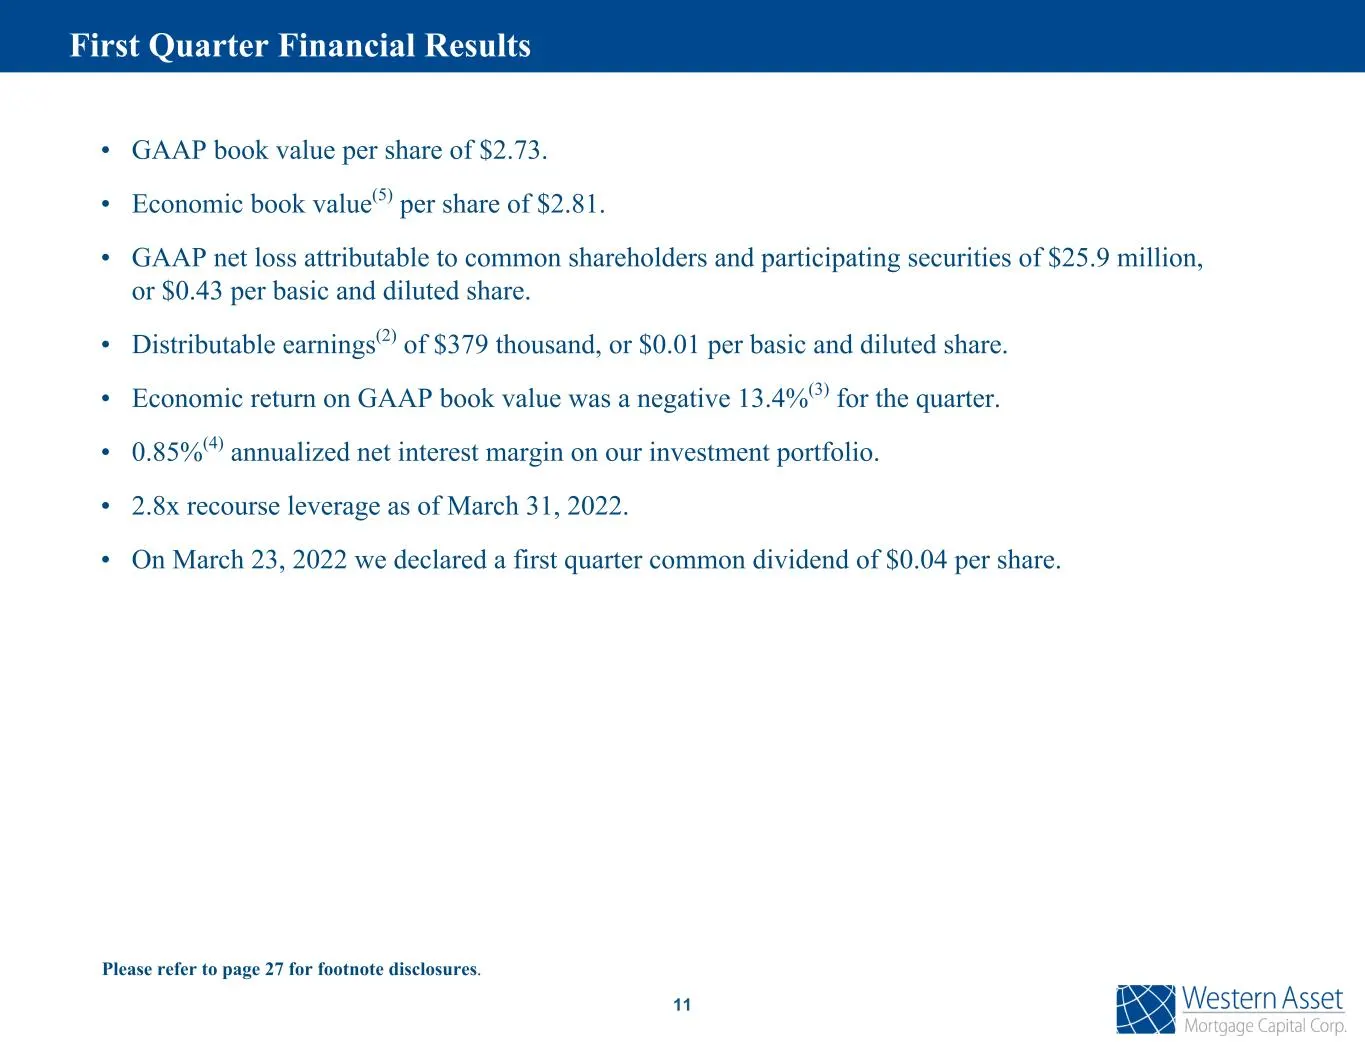
11 Please refer to page 27 for footnote disclosures. • GAAP book value per share of $2.73. • Economic book value(5) per share of $2.81. • GAAP net loss attributable to common shareholders and participating securities of $25.9 million, or $0.43 per basic and diluted share. • Distributable earnings(2)
Slide 13: WMC Key Metrics as of March 31, 2022
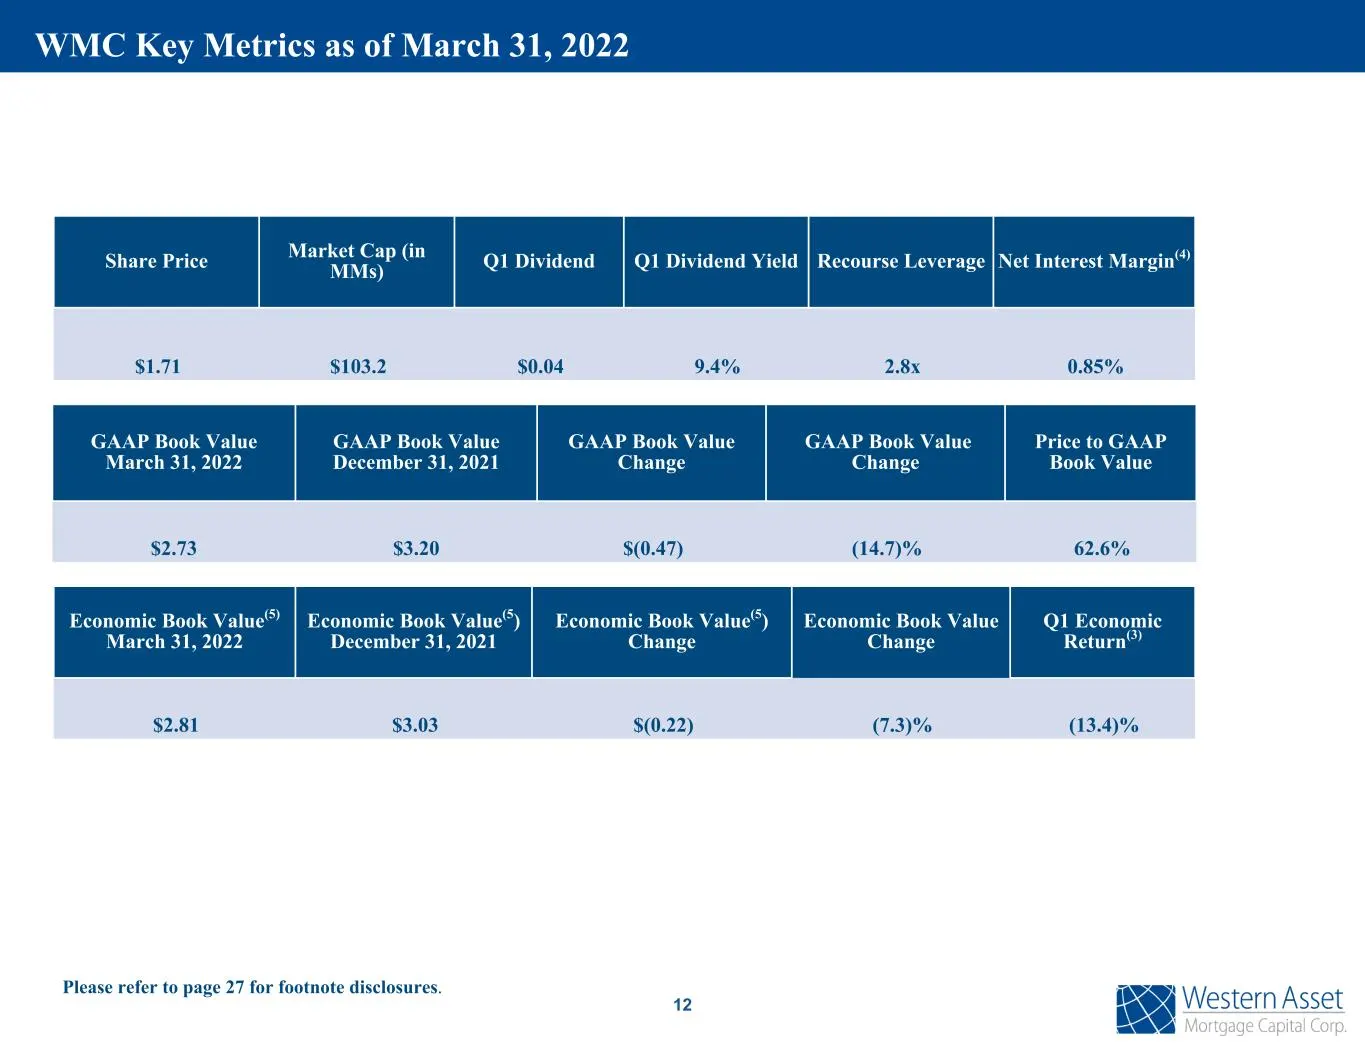
12 The following are the Company's key metrics as of December 31, 2021; Share Price Market Cap (in MMs) Q1 Dividend Q1 Dividend Yield Recourse Leverage Net Interest Margin(4) $1.71 $103.2 $0.04 9.4% 2.8x 0.85% Economic Book Value(5) March 31, 2022 Economic Book Value(5) December 31, 2021 Economic Bo
Slide 14: Portfolio Summary
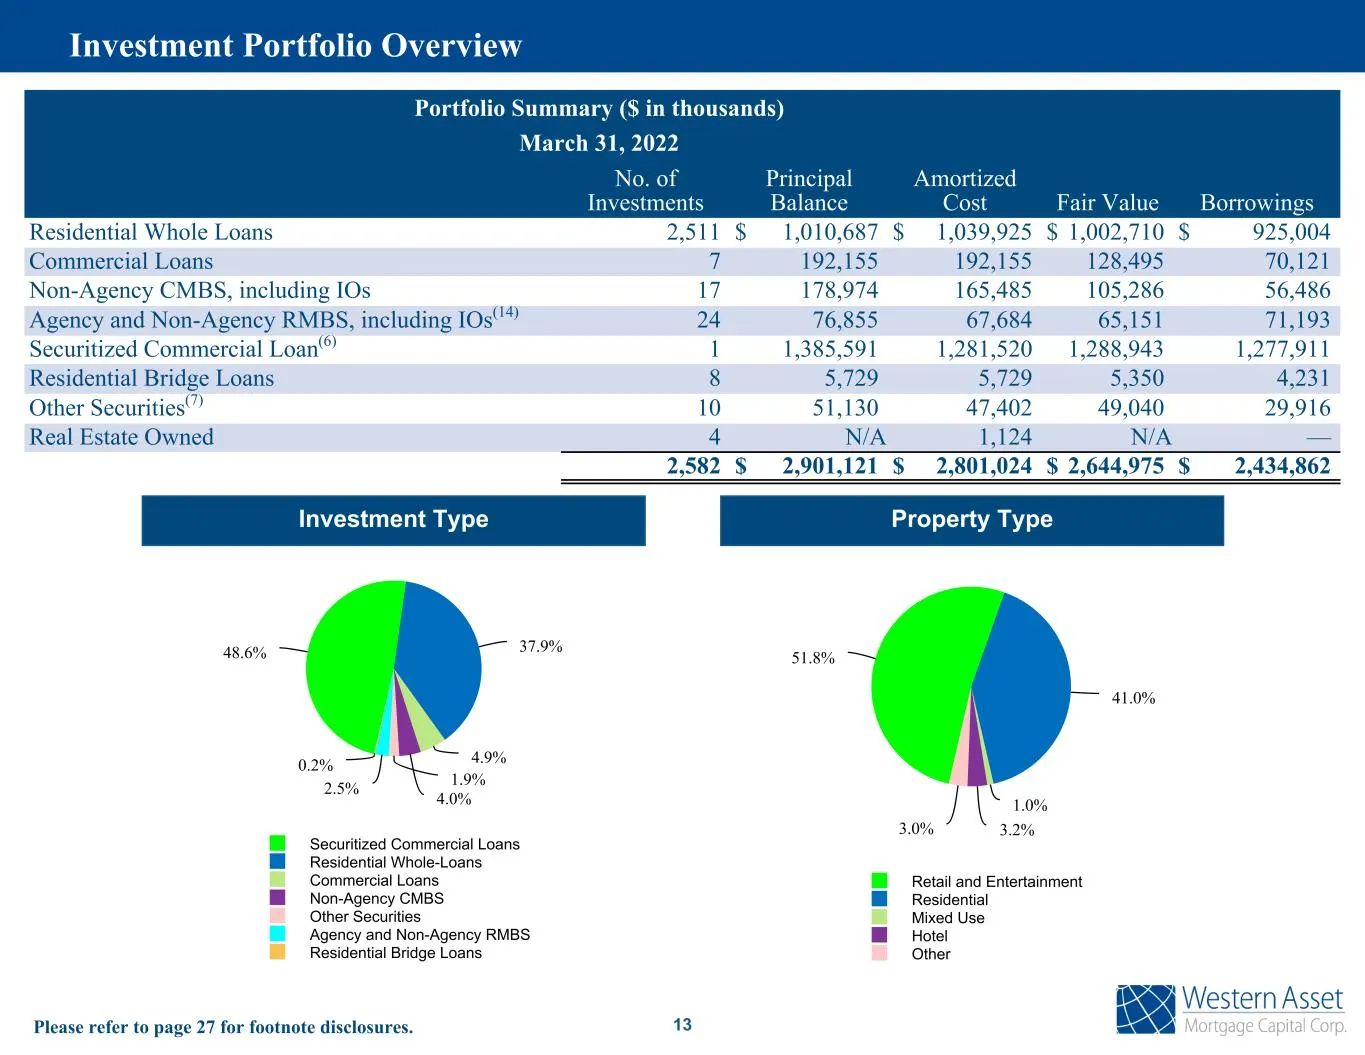
Portfolio Summary ($ in thousands) March 31, 2022 No. of Investments Principal Balance Amortized Cost Fair Value Borrowings Residential Whole Loans 2,511 $ 1,010,687 $ 1,039,925 $ 1,002,710 $ 925,004 Commercial Loans 7 192,155 192,155 128,495 70,121 Non-Agency CMBS, including IOs 17 178,974 165,485
Slide 15: Residential Whole Loans
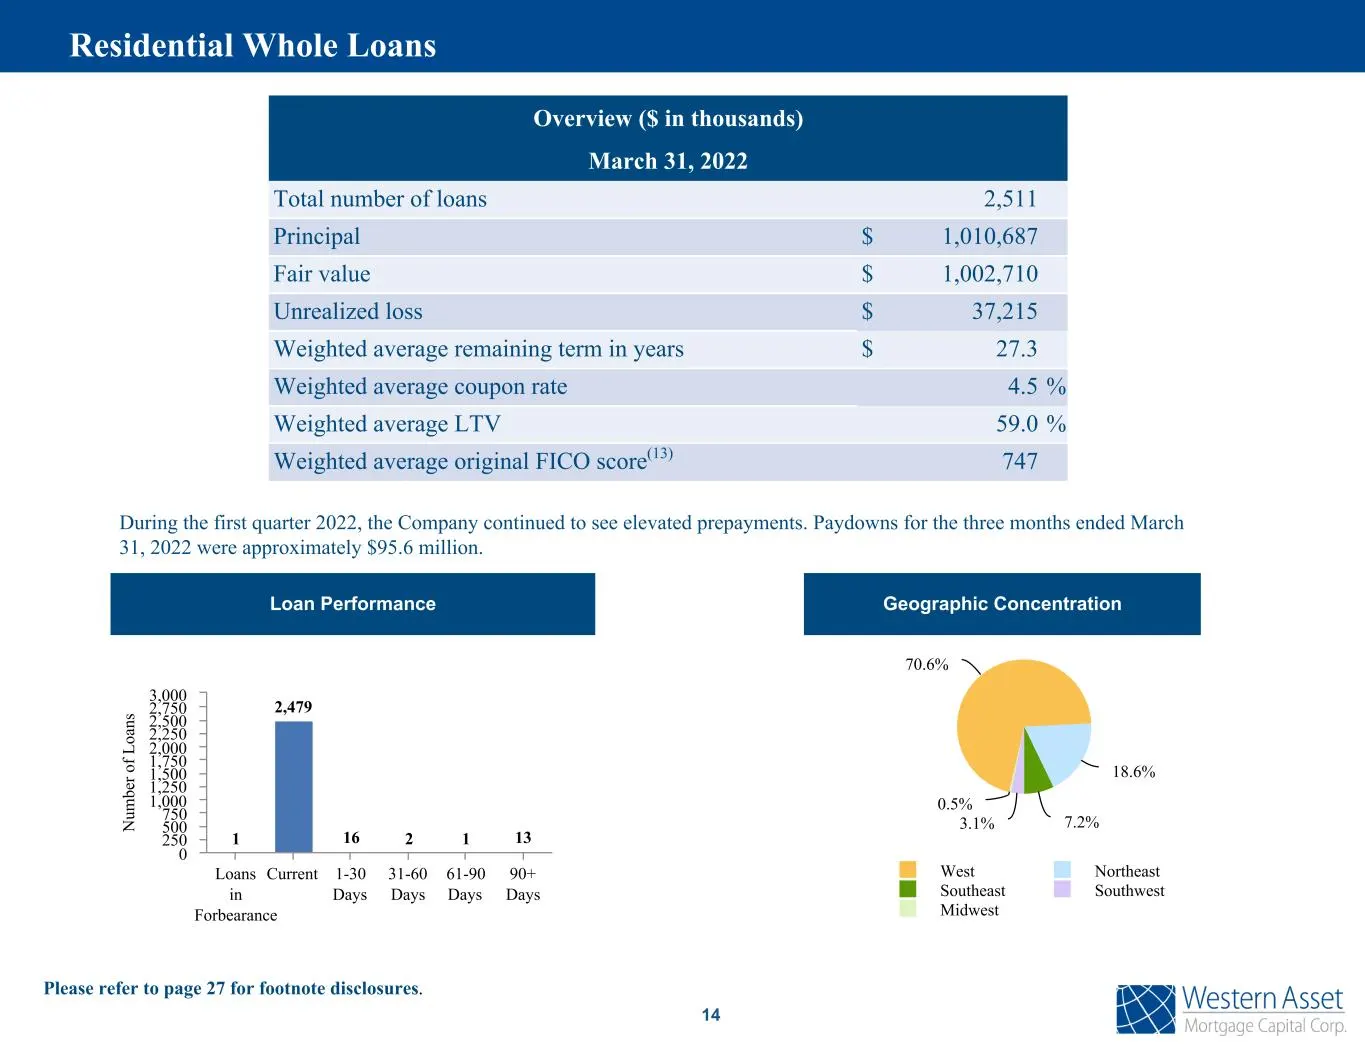
14 Overview ($ in thousands) March 31, 2022 Total number of loans 2,511 Principal $ 1,010,687 Fair value $ 1,002,710 Unrealized loss $ 37,215 Weighted average remaining term in years $ 27.3 Weighted average coupon rate 4.5 % Weighted average LTV 59.0 % Weighted average original FICO score(13) 747 Lo
Slide 16: Commercial Loans
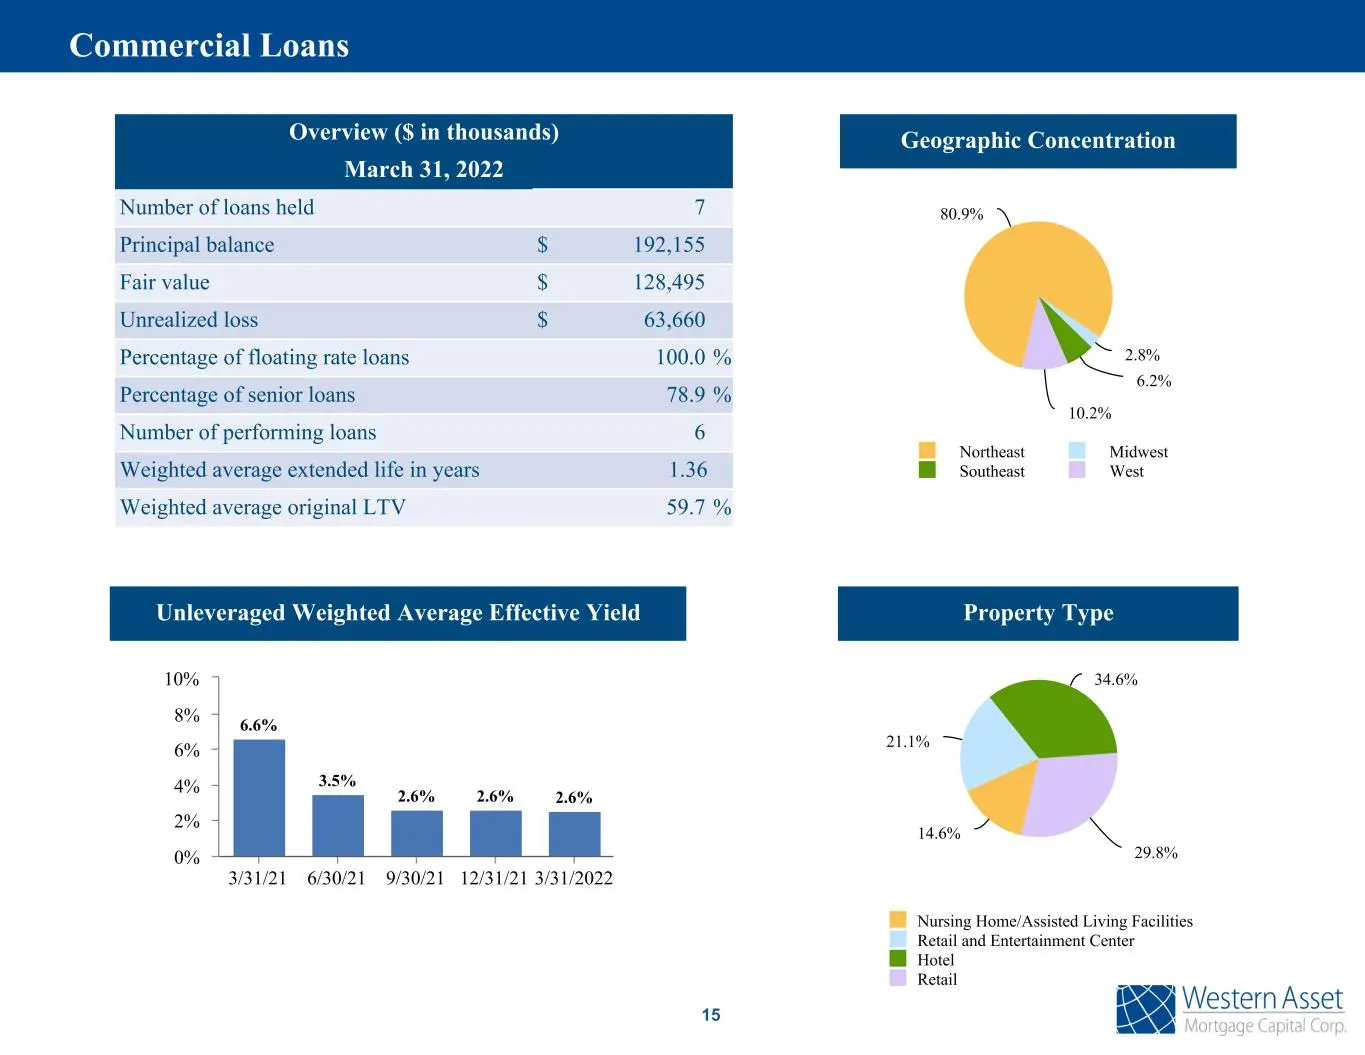
15 Overview ($ in thousands) March 31, 2022 Number of loans held 7 Principal balance $ 192,155 Fair value $ 128,495 Unrealized loss $ 63,660 Percentage of floating rate loans 100.0 % Percentage of senior loans 78.9 % Number of performing loans 6 Weighted average extended life in years 1.36 Weighted
Slide 17: Commercial loan detail
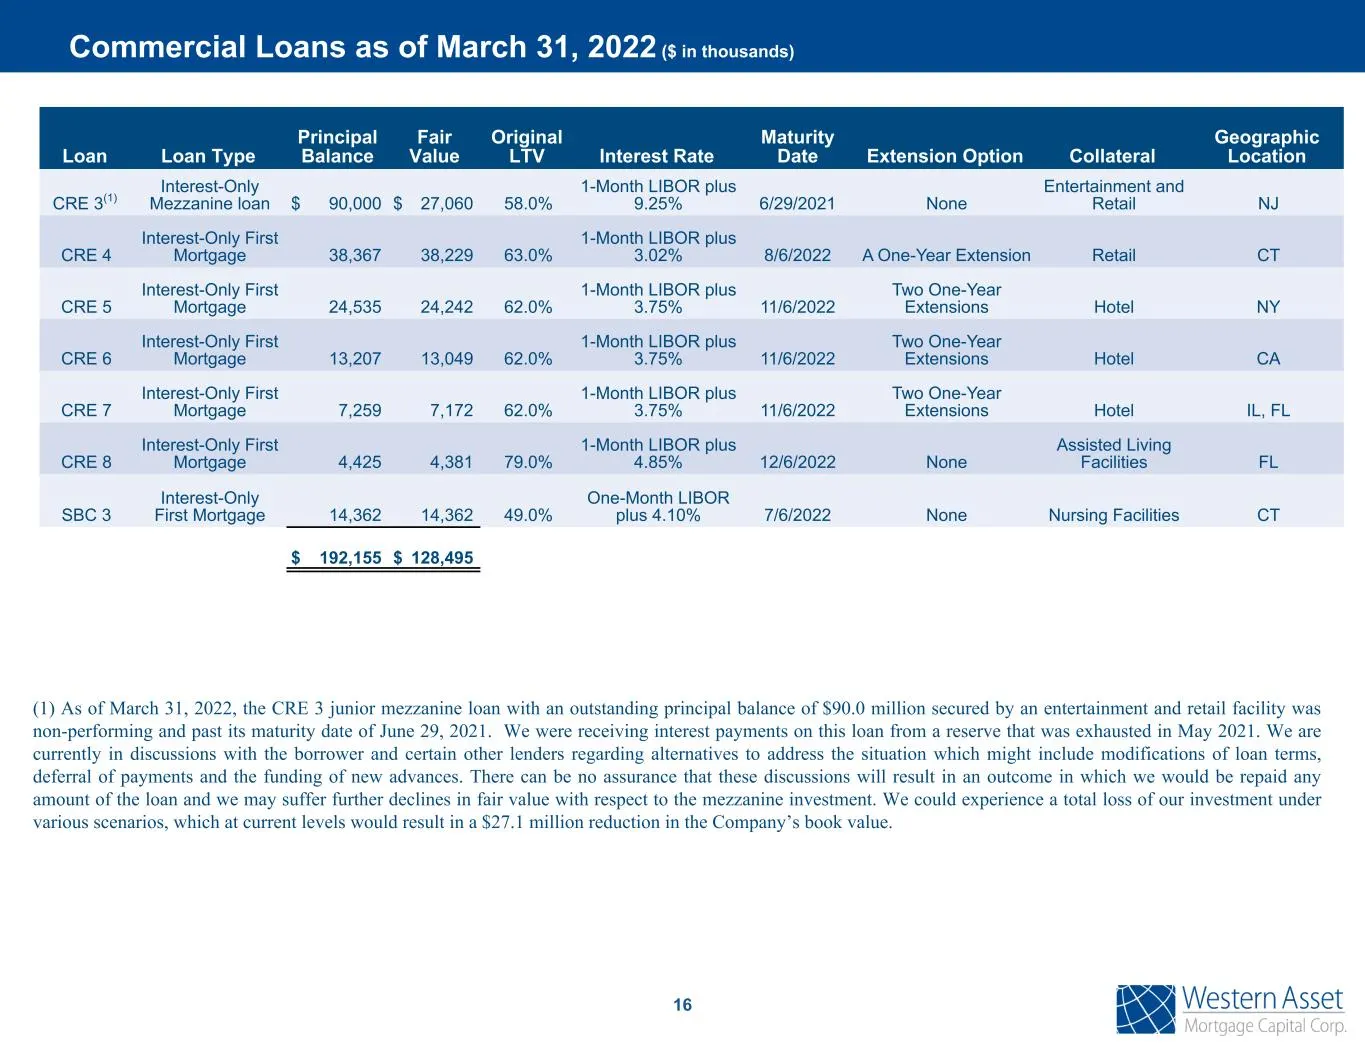
16 Loan Loan Type Principal Balance Fair Value Original LTV Interest Rate Maturity Date Extension Option Collateral Geographic Location CRE 3(1) Interest-Only Mezzanine loan $ 90,000 $ 27,060 58.0% 1-Month LIBOR plus 9.25% 6/29/2021 None Entertainment and Retail NJ CRE 4 Interest-Only First Mortgage
Slide 18: CRE Pro-Forma Analysis
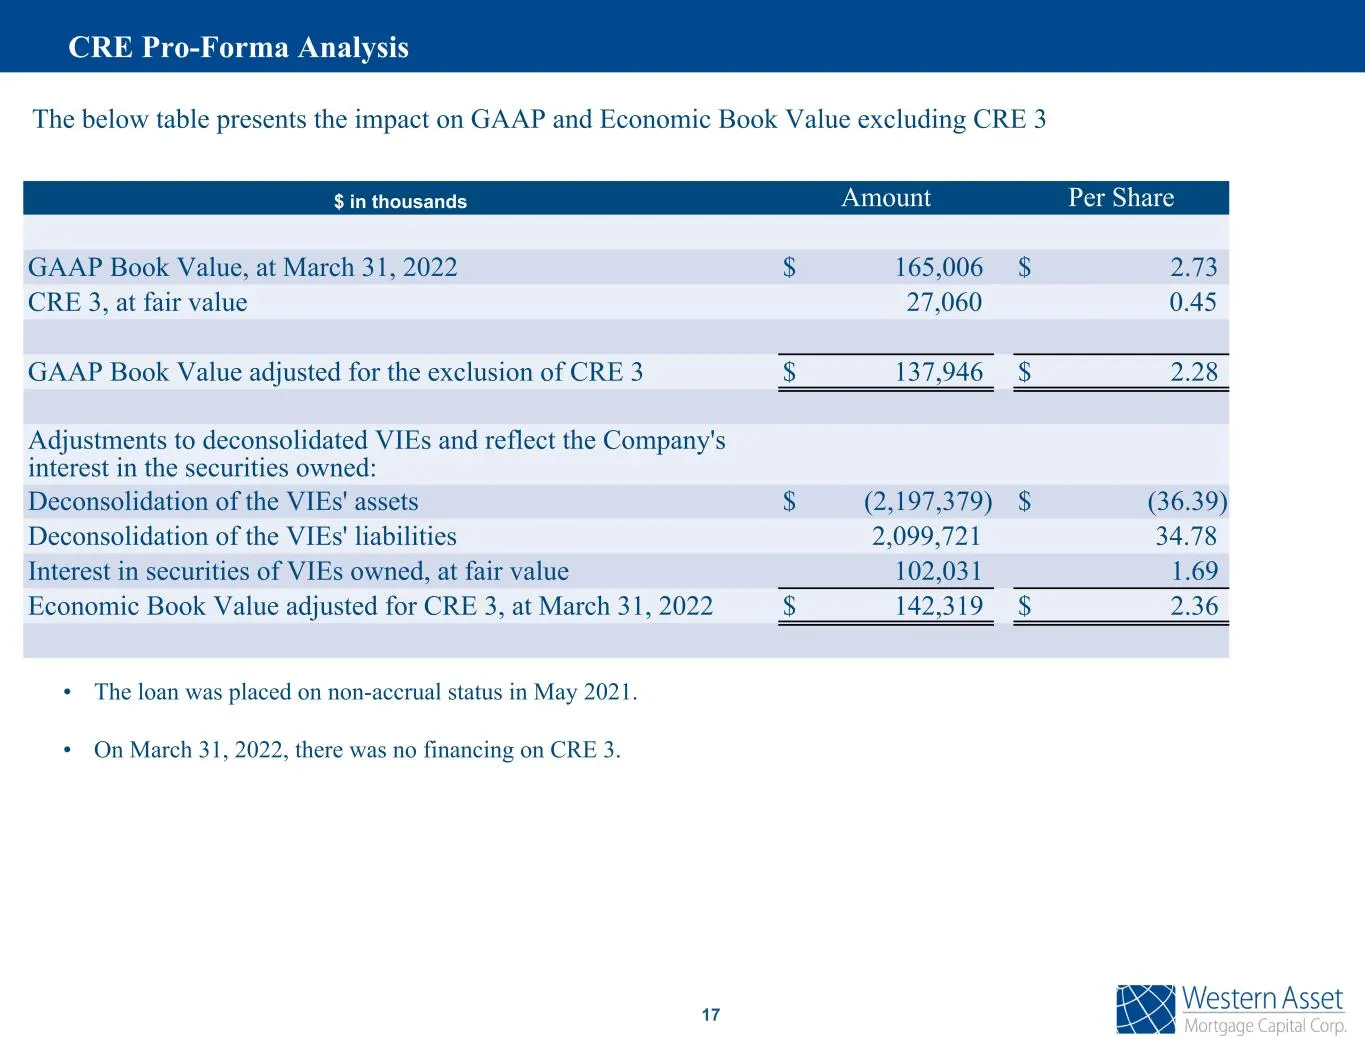
17 CRE Pro-Forma Analysis The below table presents the impact on GAAP and Economic Book Value excluding CRE 3 • The loan was placed on non-accrual status in May 2021. • On March 31, 2022, there was no financing on CRE 3. $ in thousands Amount Per Share GAAP Book Value, at March 31, 2022 $ 165,006 $
Slide 19: Non-Agency CMBS Investments
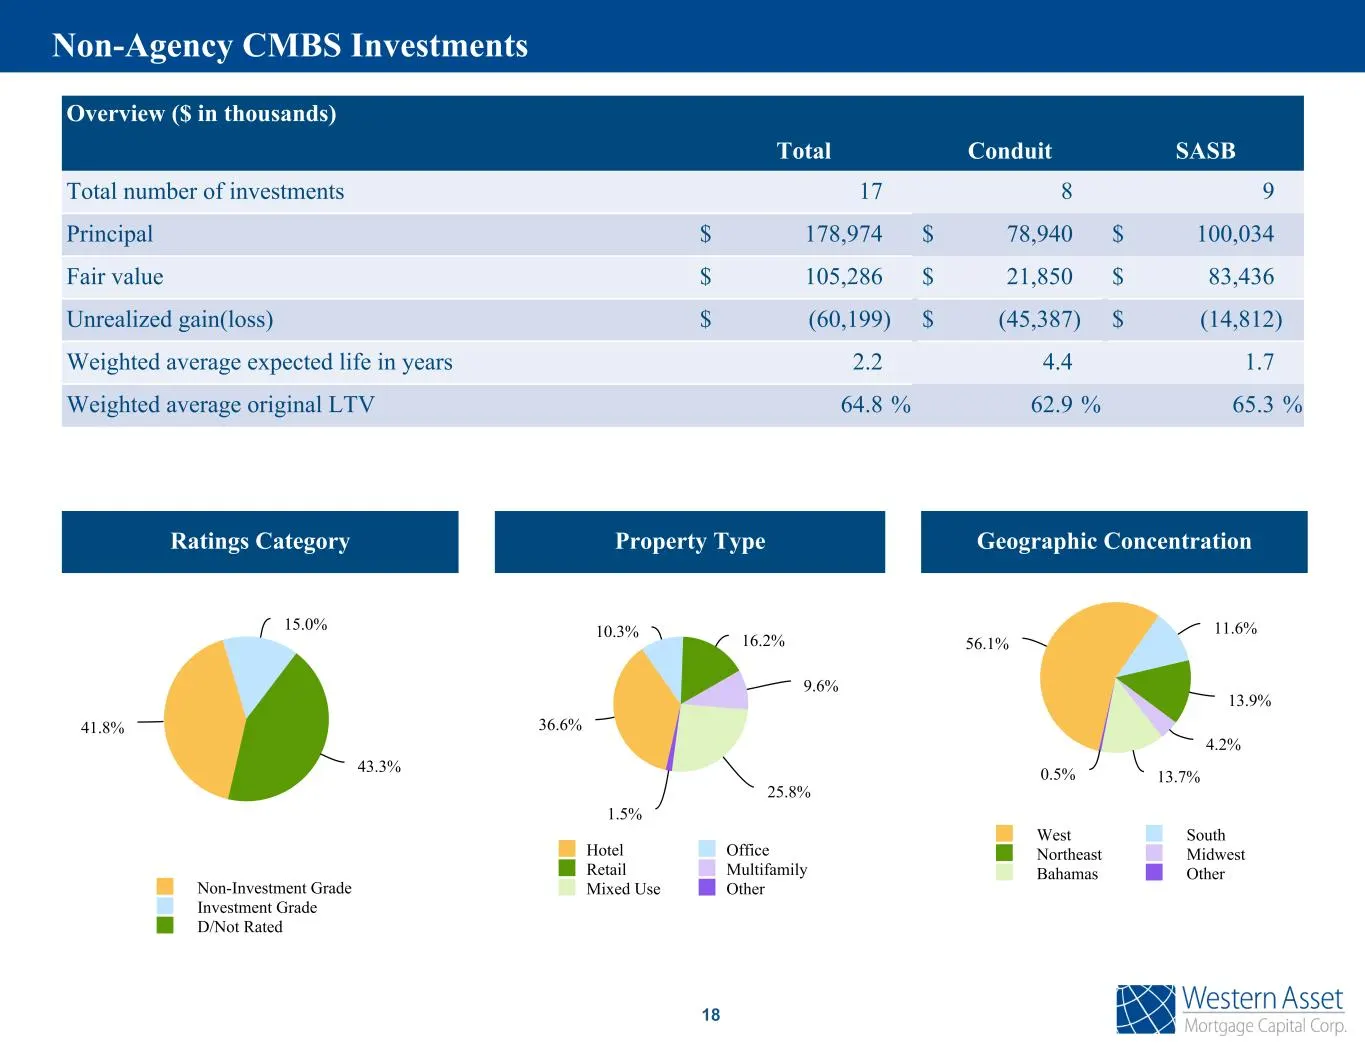
18 Overview ($ in thousands) Total Conduit SASB Total number of investments 17 8 9 Principal $ 178,974 $ 78,940 $ 100,034 Fair value $ 105,286 $ 21,850 $ 83,436 Unrealized gain(loss) $ (60,199) $ (45,387) $ (14,812) Weighted average expected life in years 2.2 4.4 1.7 Weighted average original LTV 64
Slide 20: Securitized Commercial Loan Portfolio
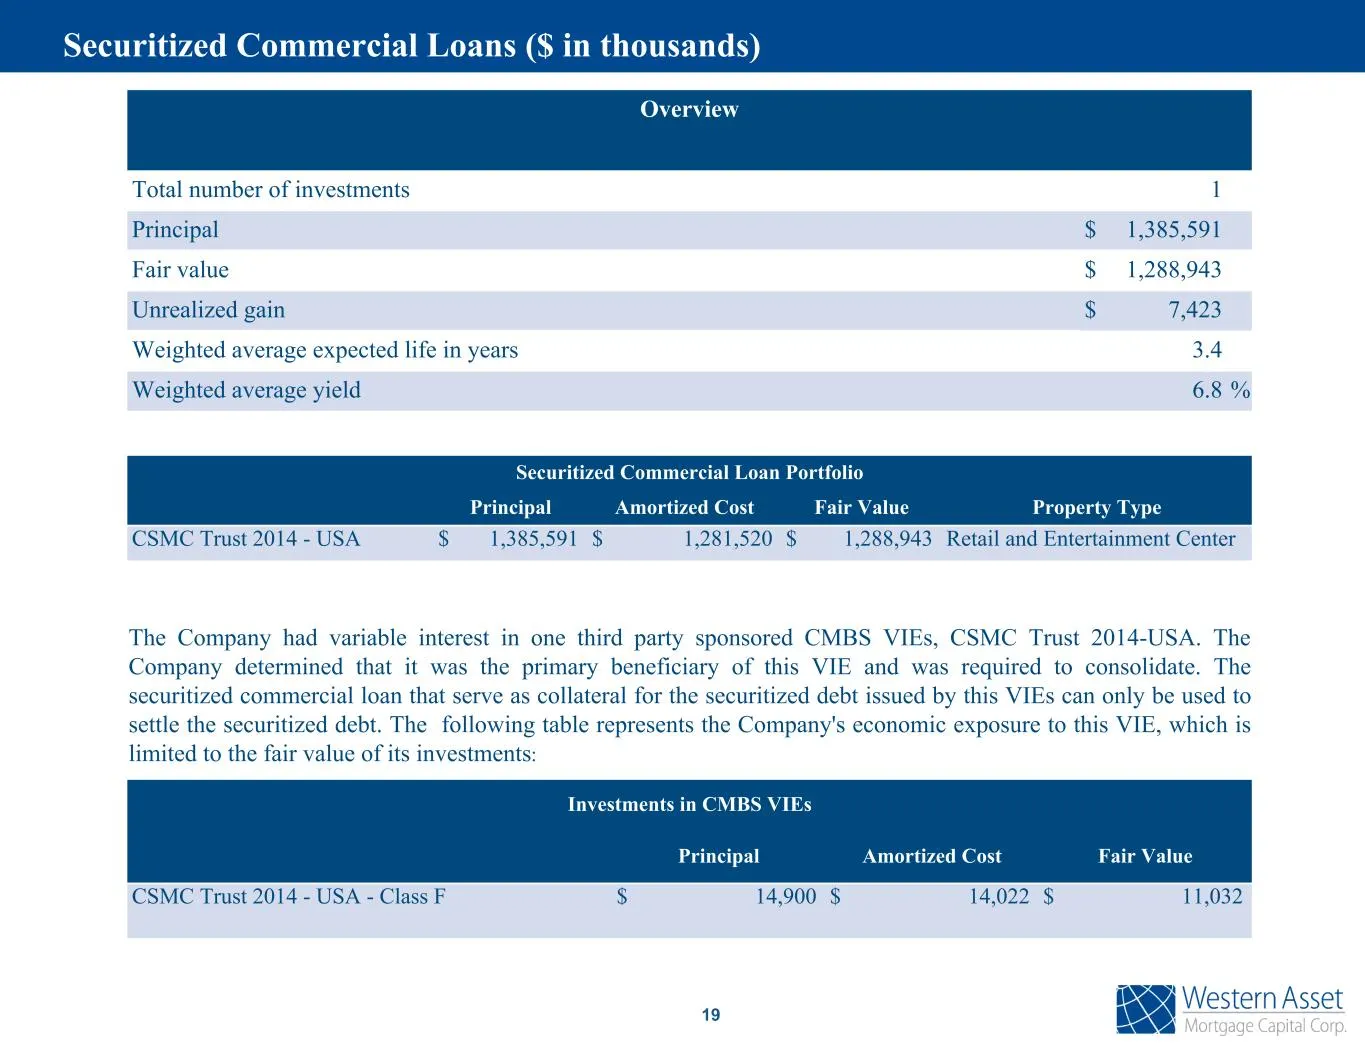
19 Overview Total number of investments 1 Principal $ 1,385,591 Fair value $ 1,288,943 Unrealized gain $ 7,423 Weighted average expected life in years 3.4 Weighted average yield 6.8 % Securitized Commercial Loan Portfolio Principal Amortized Cost Fair Value Property Type CSMC Trust 2014 - USA $ 1,38
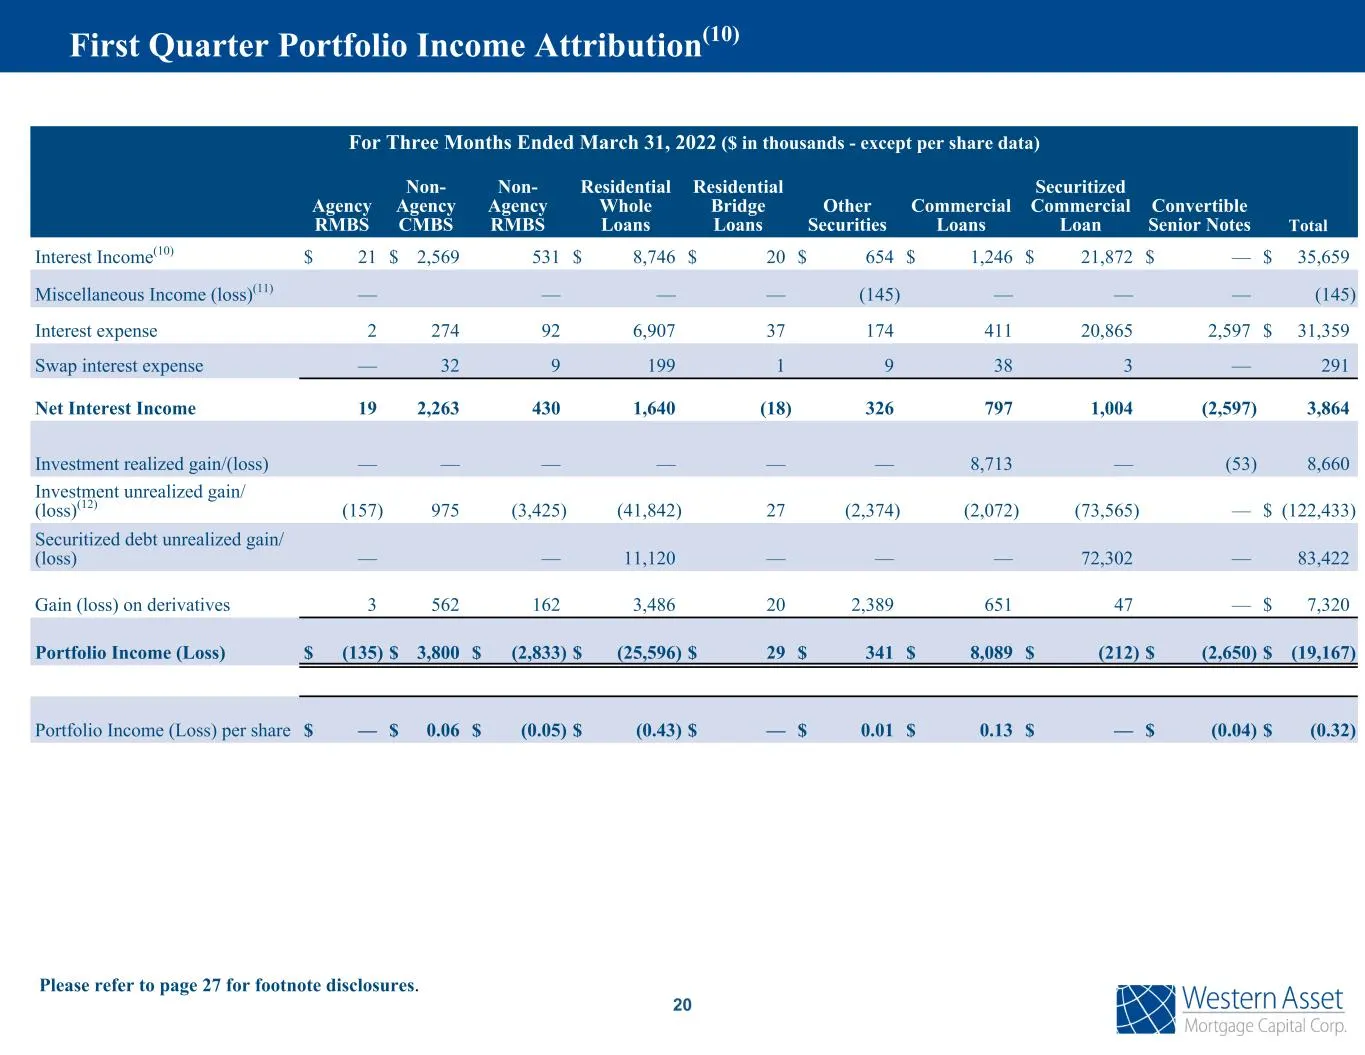
Slide 21: Results by investment type, three months ended March 31, 2022
20 Please refer to page 27 for footnote disclosures. For Three Months Ended March 31, 2022 ($ in thousands - except per share data) Agency RMBS Non- Agency CMBS Non- Agency RMBS Residential Whole Loans Residential Bridge Loans Other Securities Commercial Loans Securitized Commercial Loan Convertible
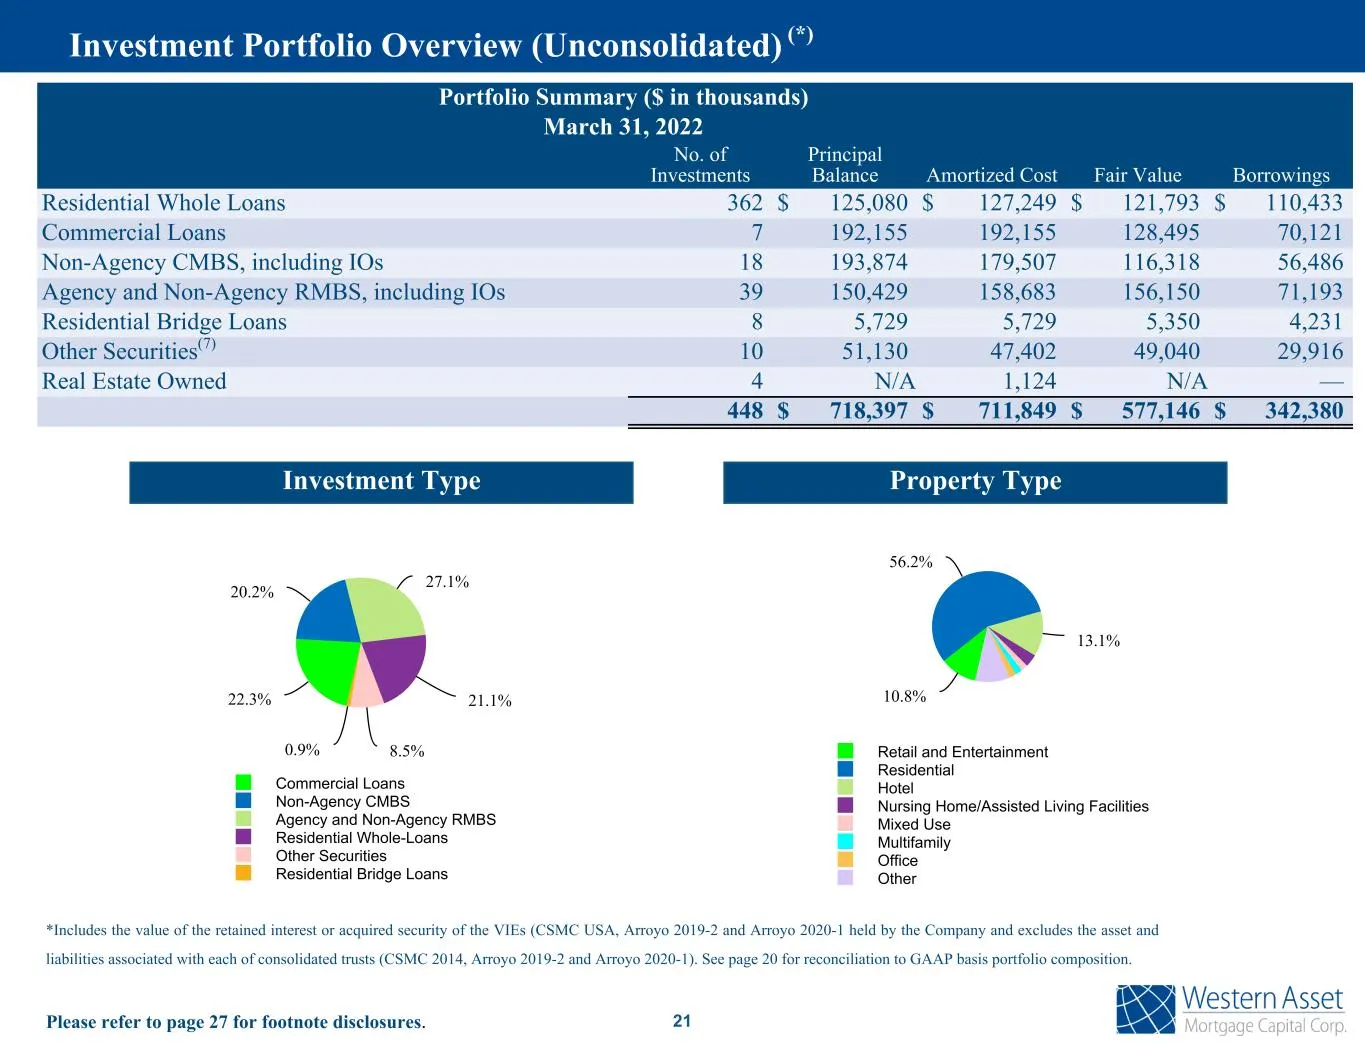
Slide 22: Investment Type
Investment Type 22.3% 20.2% 27.1% 21.1% 8.5%0.9% Commercial Loans Non-Agency CMBS Agency and Non-Agency RMBS Residential Whole-Loans Other Securities Residential Bridge Loans Portfolio Summary ($ in thousands) March 31, 2022 No. of Investments Principal Balance Amortized Cost Fair Value Borrowings R
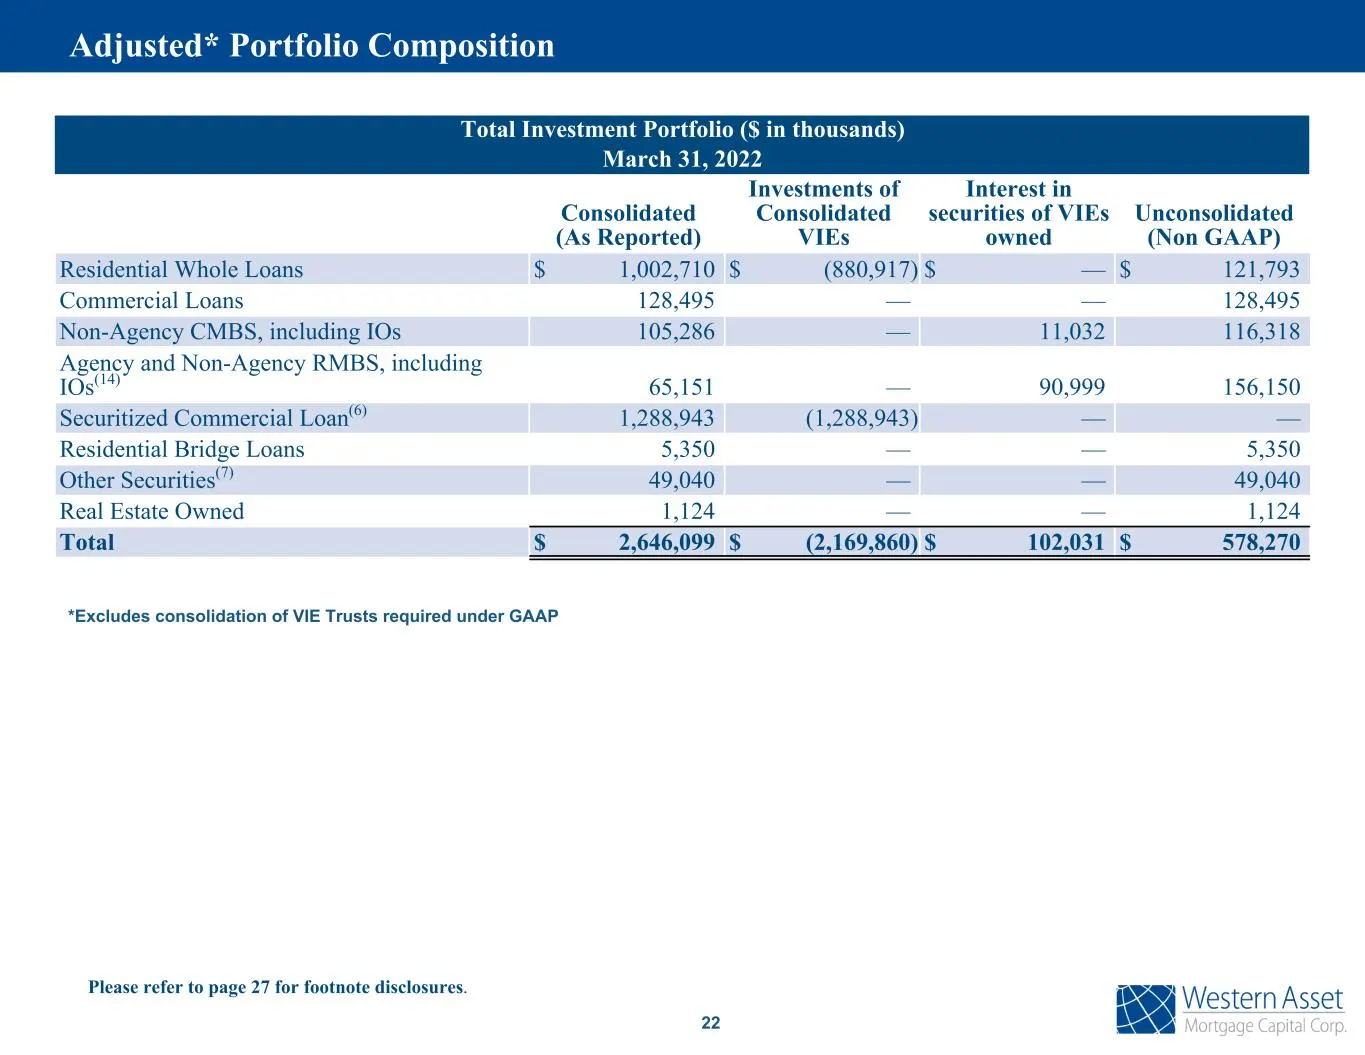
Slide 23: Adjusted Portfolio Composition
22 *Excludes consolidation of VIE Trusts required under GAAP Please refer to page 27 for footnote disclosures. Total Investment Portfolio ($ in thousands) March 31, 2022 Consolidated (As Reported) Investments of Consolidated VIEs Interest in securities of VIEs owned Unconsolidated (Non GAAP) Residen
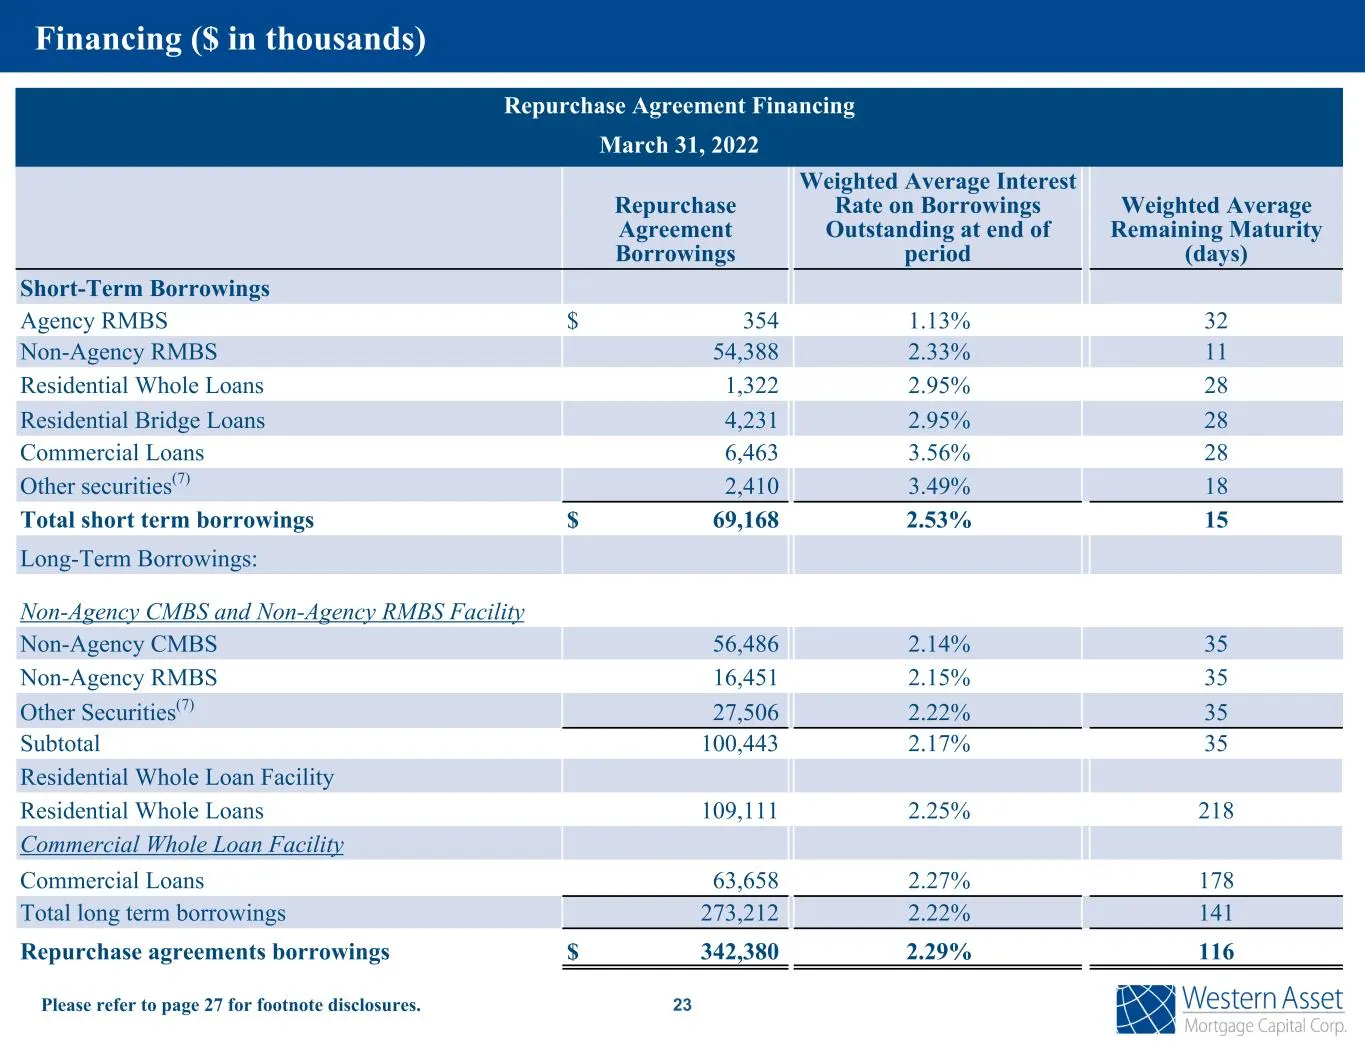
Slide 24: Repurchase Agreement Financing
Repurchase Agreement Financing March 31, 2022 Repurchase Agreement Borrowings Weighted Average Interest Rate on Borrowings Outstanding at end of period Weighted Average Remaining Maturity (days) Short-Term Borrowings Agency RMBS $ 354 1.13% 32 Non-Agency RMBS 54,388 2.33% 11 Residential Whole Loans
Slide 25: Long-Term Financing Facilities
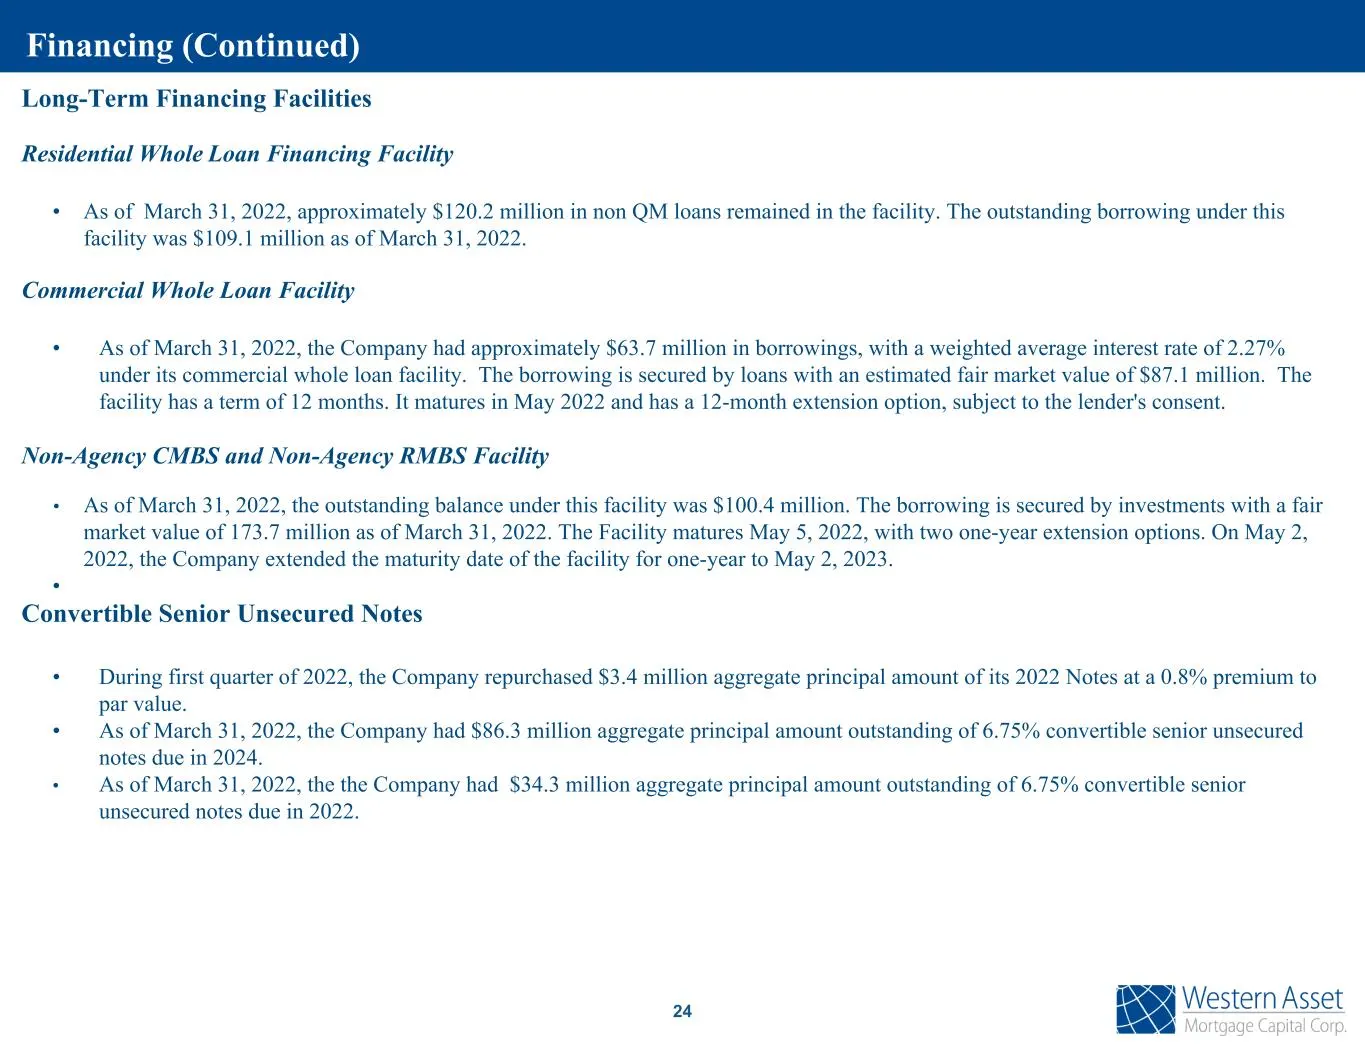
Long-Term Financing Facilities Residential Whole Loan Financing Facility • As of March 31, 2022, approximately $120.2 million in non QM loans remained in the facility. The outstanding borrowing under this facility was $109.1 million as of March 31, 2022. Commercial Whole Loan Facility • As of March
Slide 26: Non-Recourse Financings
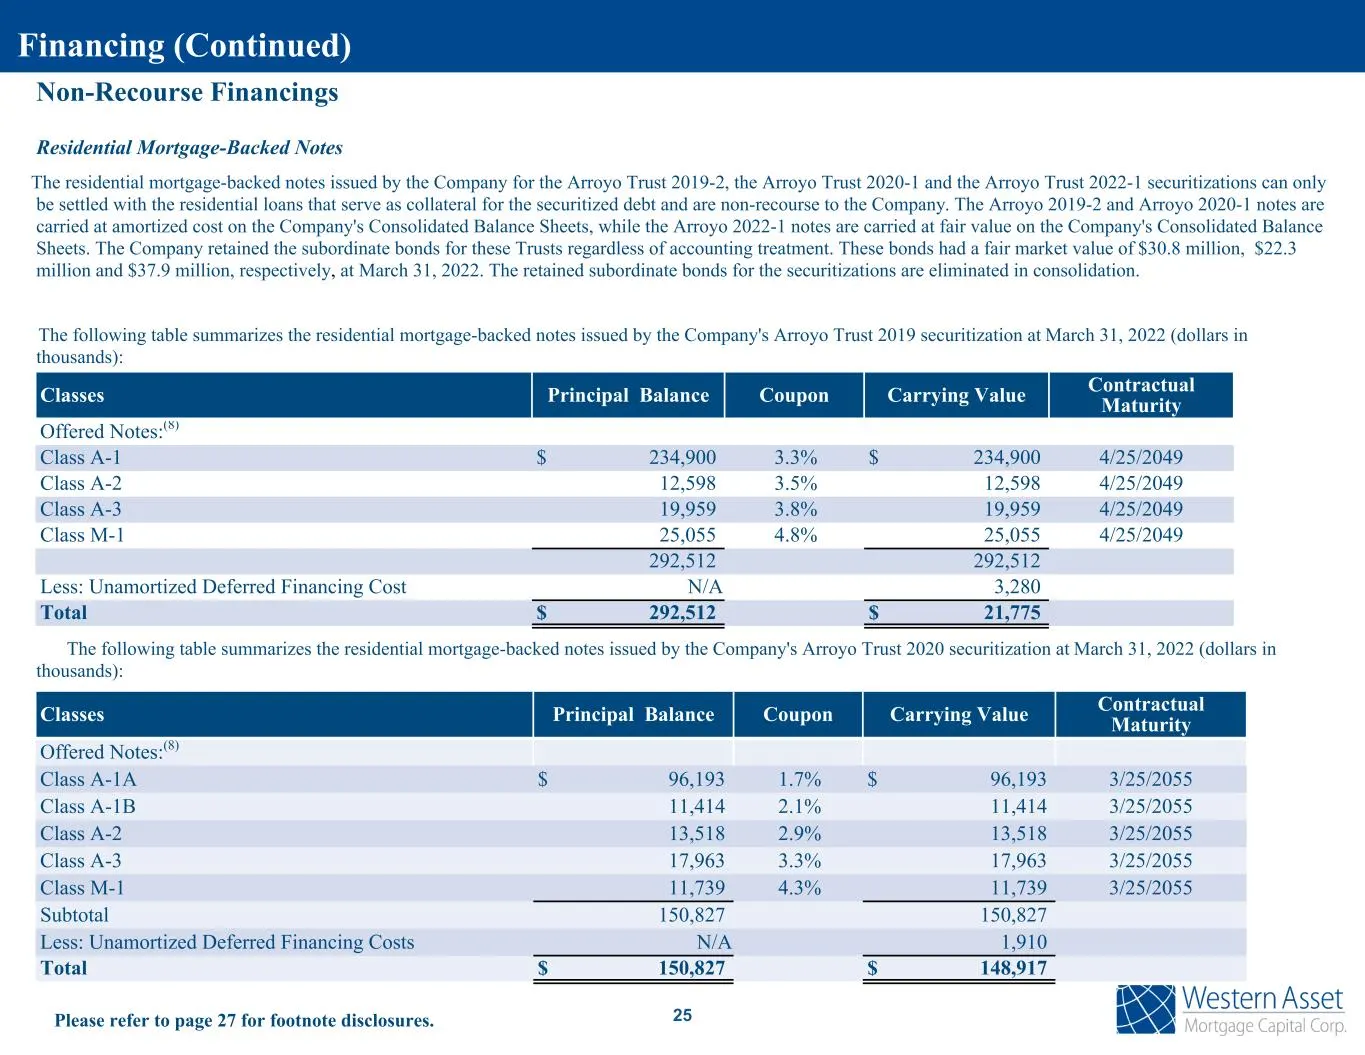
Non-Recourse Financings Residential Mortgage-Backed Notes The residential mortgage-backed notes issued by the Company for the Arroyo Trust 2019-2, the Arroyo Trust 2020-1 and the Arroyo Trust 2022-1 securitizations can only be settled with the residential loans that serve as collateral for the secur
Slide 27: Commercial Mortgage backed Notes
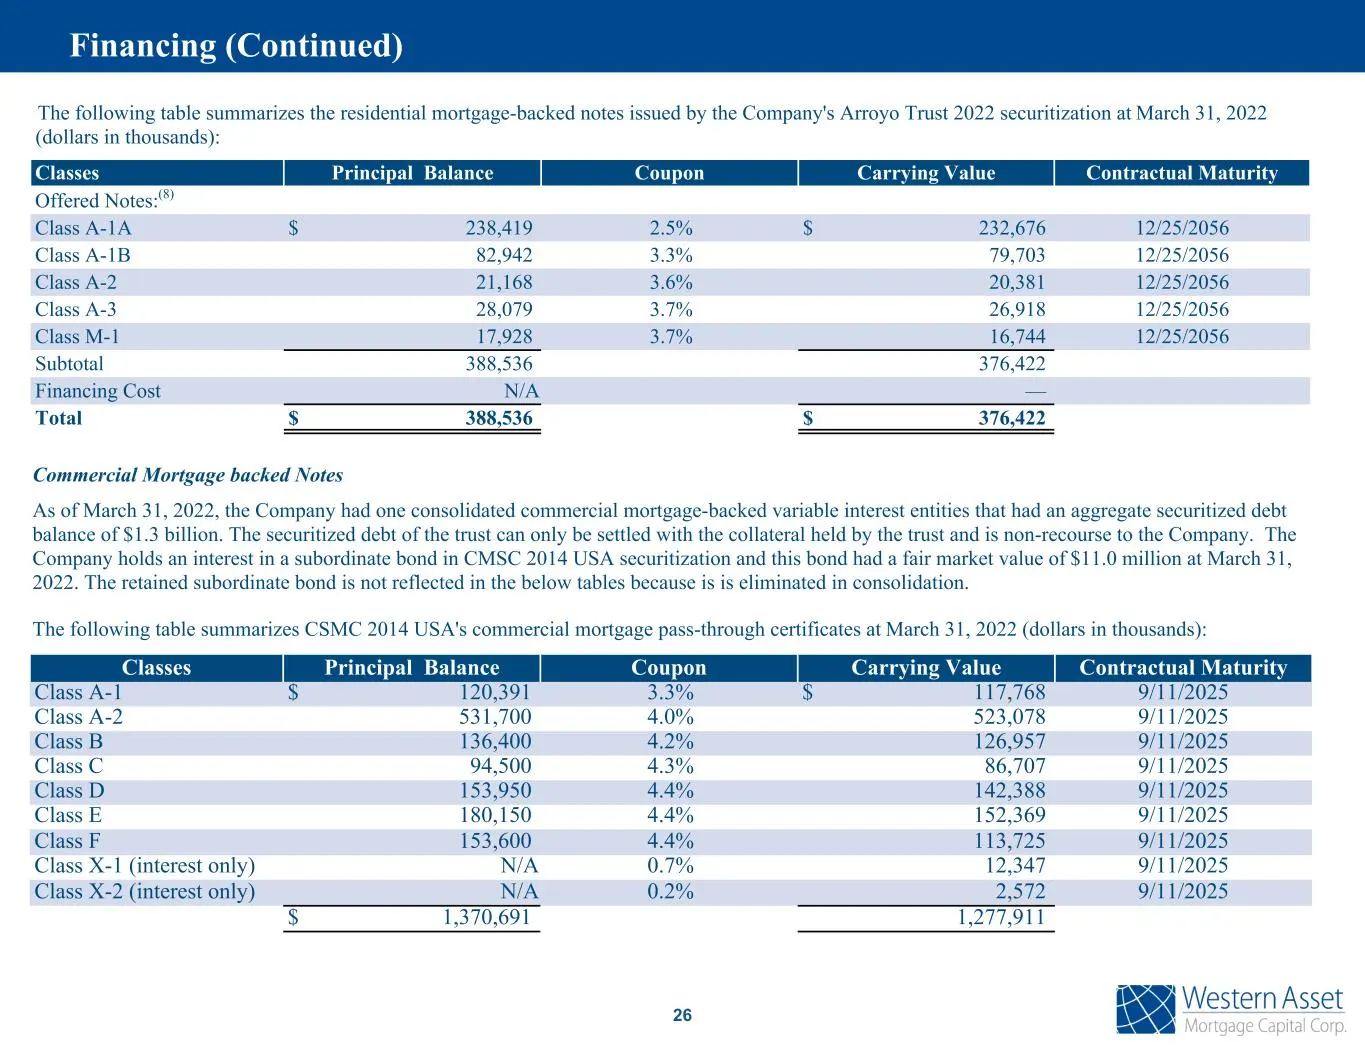
26 Commercial Mortgage backed Notes As of March 31, 2022, the Company had one consolidated commercial mortgage-backed variable interest entities that had an aggregate securitized debt balance of $1.3 billion. The securitized debt of the trust can only be settled with the collateral held by the trust
Slide 28: Footnotes and definitions
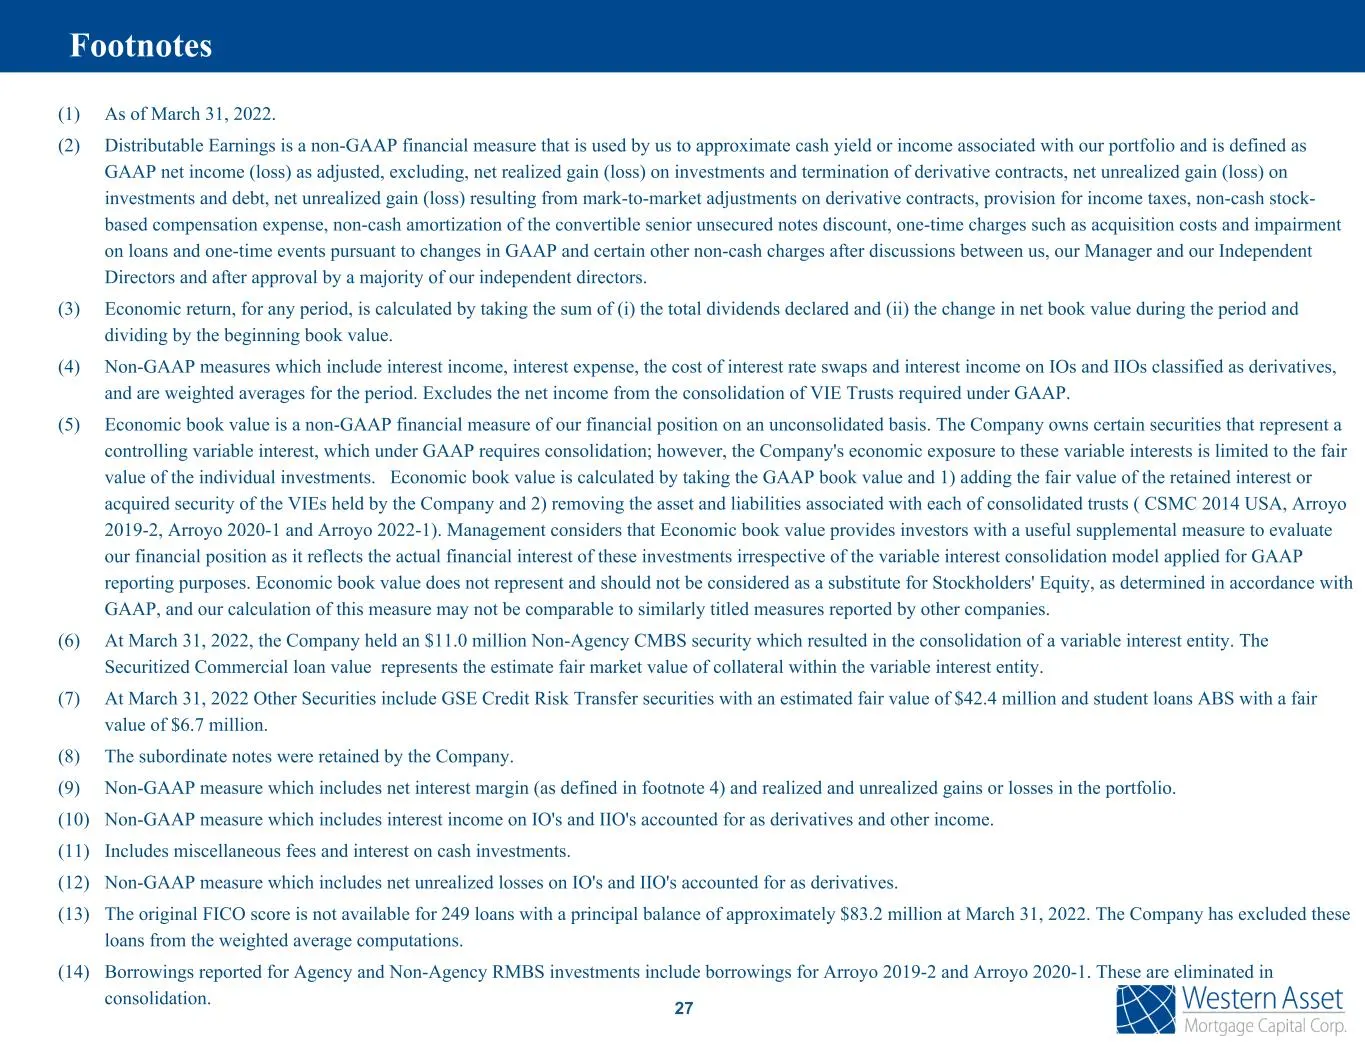
27 (1) As of March 31, 2022. (2) Distributable Earnings is a non-GAAP financial measure that is used by us to approximate cash yield or income associated with our portfolio and is defined as GAAP net income (loss) as adjusted, excluding, net realized gain (loss) on investments and termination of der
Slide 29: Supplemental Information
28 Supplemental Information
Slide 30: Book Value Roll Forward
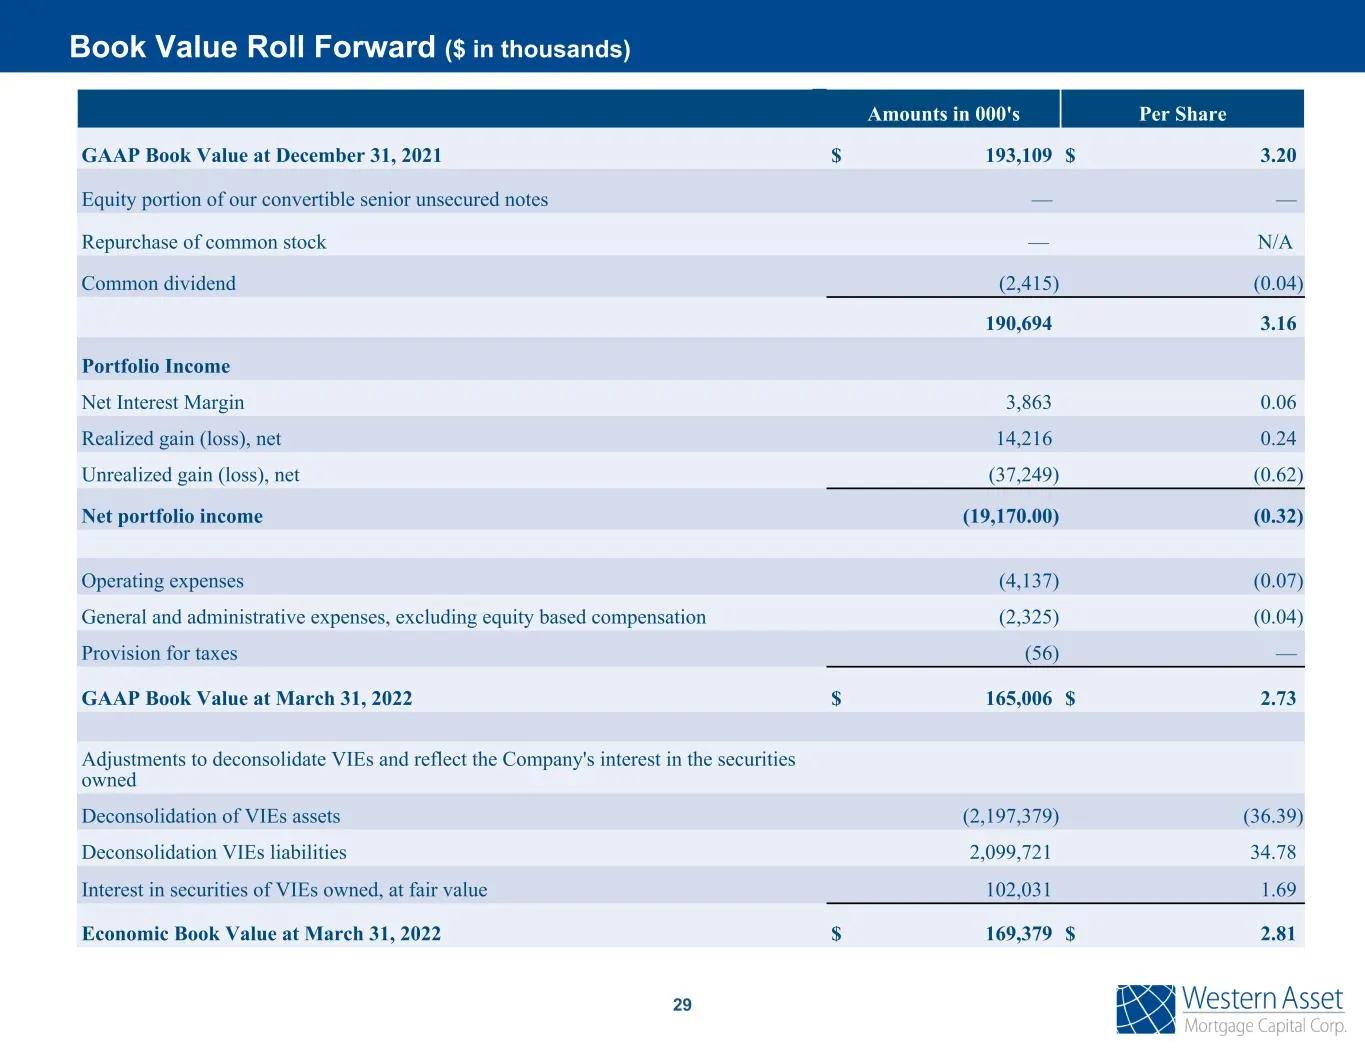
29 Book Value Roll Forward ($ in thousands) Amounts in 000's Per Share GAAP Book Value at December 31, 2021 $ 193,109 $ 3.20 Equity portion of our convertible senior unsecured notes — — Repurchase of common stock — N/A Common dividend (2,415) (0.04) 190,694 3.16 Portfolio Income Net Interest Margin
Slide 31: Contact Information
Western Asset Mortgage Capital Corporation c/o Financial Profiles, Inc. 11601 Wilshire Blvd., Suite 1920 Los Angeles, CA 90025 www.westernassetmcc.com Investor Relations Contact: Larry Clark Tel: (310) 622-8223 [email protected] Contact Information
Source: SEC EDGAR · 8-K filed May 5, 2022
More decks from Western Asset Mortgage Capital
 Merger or Acquisition (August 2023)9 slides · Aug 9, 2023
 Q2 2023 Earnings Presentation32 slides · Aug 8, 2023
 Merger or Acquisition (July 2023)9 slides · Jul 13, 2023
 Merger or Acquisition (June 2023)16 slides · Jun 28, 2023
 Q1 2023 Earnings Presentation33 slides · May 4, 2023
 Q4 2022 Earnings Presentation34 slides · Mar 2, 2023