Supervalu — Lehman Brothers 9th Annual Retail Seminar (May 2006)
24 slides from Supervalu's conference presentation, May 2, 2006
Slide 1: Forging the Future of Grocery Retailing
Forging the Future of Grocery Retailing Jeff Noddle, Chairman and CEO Pamela Knous, EVP and Chief Financial Officer Lehman Brothers 9 th Annual Retail Seminar May 2, 2006 Filed by SUPERVALU INC. Pursuant to Rule 425 under the Securities Act of 1933 Subject Company: SUPERVALU INC., File #1-5418
Slide 2: Forward-Looking Statement
Forward-Looking Statement CAUTIONARY STATEMENTS RELEVANT TO FORWARD-LOOKING INFORMATION FOR THE PURPOSE OF “SAFE HARBOR” PROVISIONS OF THE PRIVATE SECURITIES LITIGATION REFORM ACT OF 1995 Except for the historical and factual information contained herein, the matters set forth in this presentation,
Slide 3: In the Home Stretch of Transaction
In the Home Stretch of Transaction Final stages of acquisition moving as planned Proxy finalized Friday, April 28th Will provide combined company earnings guidance in mid-May Annual meeting date set: May 30 Executive management team to be named soon Closing expected by mid-June
Slide 4: Creating the New SUPERVALU
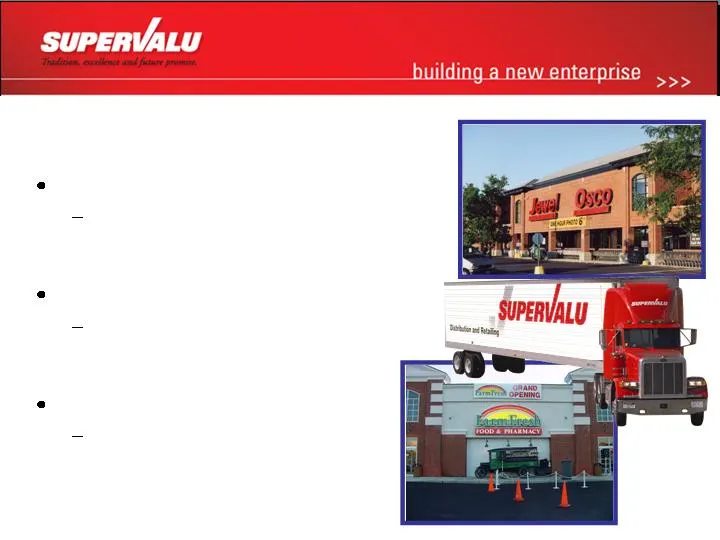
Creating the New SUPERVALU Unprecedented opportunity Selected established, premier retail properties in major urban markets Unparalleled service network Coast-to-coast retail presence supported by industry-leading supply chain backbone Focused on success SUPERVALU has a proven track record of succes
Slide 5: We intend to transform SUPERVALU into a national retail powerhouse
“ We intend to transform SUPERVALU into a national retail powerhouse that embraces changing demographics and keeps the needs of the customer central to our mission.” -- Jeff Noddle
Slide 6: Shaping SUPERVALU's Future
SUPERVALU is actively shaping its future and positioning itself to succeed in the grocery retailing industry Shaping SUPERVALU’s Future Responding to New Realities, Opportunities in the Grocery Retail Sector Channel Blur - Everybody is selling food Non-traditional retailers capitalizing on shifting
Slide 7: Creating Sustainable Success
Scale and Diversity of Retail Formats Strong Supply Chain Backbone Empowered People Successfully competing requires a multi-faceted approach to achieve sustainable grocery retail success Creating Sustainable Success Serve diverse customer needs and wants Extreme Value Price Impact Traditional/Full S
Slide 8: Once-in-a-lifetime Opportunity
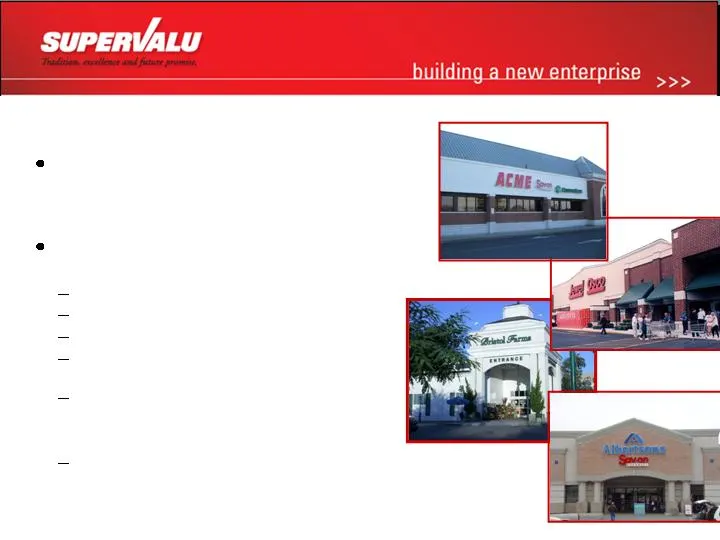
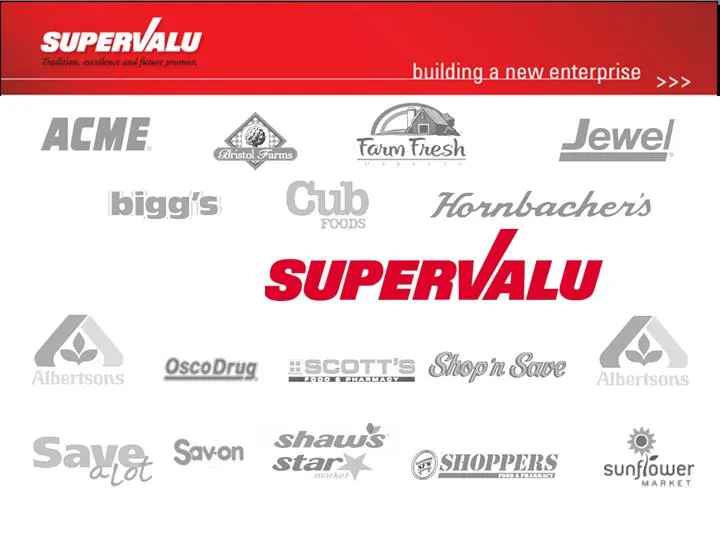
Once-in-a-lifetime Opportunity Immediate leading positions in major urban markets and premier locations Acquired brands are household names Acme Markets - Philadelphia Bristol Farms- California Jewel - Chicago Shaw’s and Star Markets – Boston/New England 569 Albertsons stores in Idaho, Southern Cali
Slide 9: A National Retail Powerhouse Fueled by Industry-Leading Supply Chain Support
A National Retail Powerhouse Fueled by Industry-Leading Supply Chain Support Taking the No. 3 spot in the Grocery Industry By Revenue 2,505 stores in premier locations across U.S. Store Network 878 locations create 8 th largest pharmacy provider in U.S. In-store Pharmacies Fuel Centers 80% Retail Mi
Slide 10: Leading Positions in Large and Growing Markets
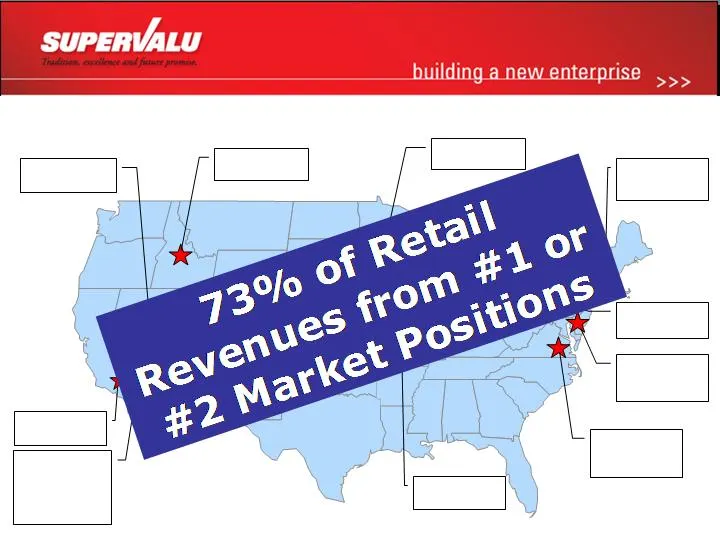
Las Vegas # 1 Market Share Southern Cal. # 1 in Orange County and # 2 in San Diego Market Share Mpls. / St. Paul # 1 Market Share Boston / New England # 2 Market Share Philadelphia # 1 Market Share St. Louis # 2 Market Share Washington D.C. / Baltimore # 3 Market Share Leading Positions in Large and
Slide 11: 73% of Retail Revenues from #1 or #2 Market Positions
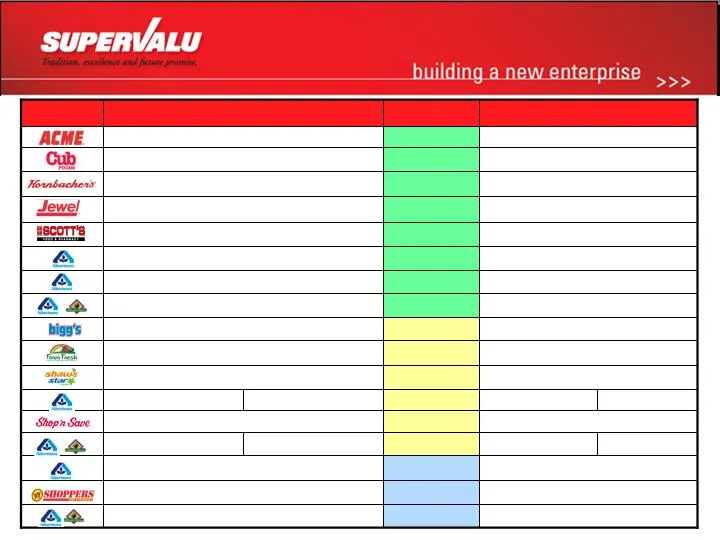
73% of Retail Revenues from #1 or #2 Market Positions Share Rank Banner Largest Competitor(s) MSA Markets Safeway, Kroger San Diego, Ventura, CA Kroger, Wal-Mart Salt Lake City/Ogden, UT Kroger #1 Las Vegas, NV #3 #3 #3 #2 #2 #2 #2 #2 #2 #1 #1 #1 #1 #1 #1 #1 Sun Mart Fargo, ND Giant, Safeway Washing
Slide 12: Everyone's Favorite Question: What About Wal-Mart
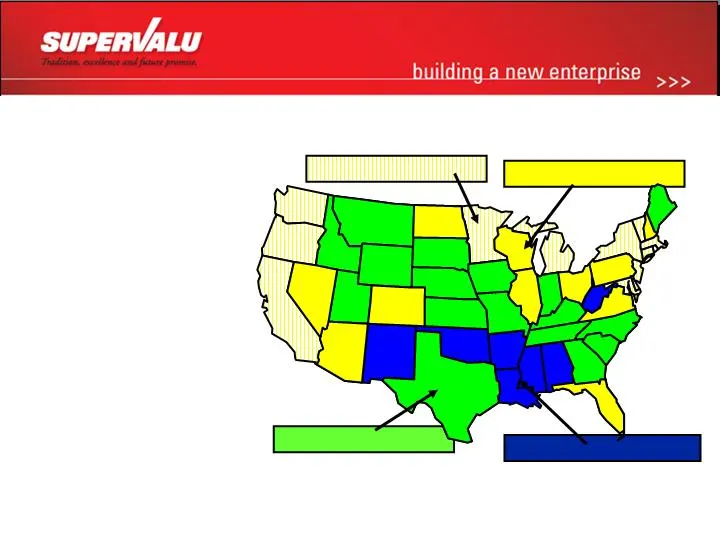
High Share States Everyone’s Favorite Question: What About Wal-Mart States with the most Wal-Mart stores Texas 415 Florida 224 California 194 Illinois 158 Ohio 151 Pennsylvania 139 Georgia 137 Missouri 132 North Carolina 130 Tennessee 119 Source: http://www.walmartfacts.com , 2/1/06 Low Share States
Slide 13: Stacking up against Wal-Mart
Chain Trend 2005 2003 Market Market Share Stacking up against Wal-Mart Not Significant Not Significant WMT 2.2% 1.8% WMT 23.3% 20.9% Acme Philadelphia 1.1% 0.7% WMT 12.2% 12.3% Albertsons Los Angeles WMT Albertsons Jewel WMT Shop’n Save WMT Farm Fresh 18.1% 25.8% 36.6% 10.8% 20.9% 22.6% 19.1% 27.6%
Slide 14: Pamela Knous: Creating a New SUPERVALU
Pamela Knous Executive Vice President and Chief Financial Officer Creating a New SUPERVALU
Slide 15: The New SUPERVALU: A Solid Platform for Growth
The New SUPERVALU: A Solid Platform for Growth The Financial Power of the New SUPERVALU is Compelling Immediately double-digit accretive after financing costs and additional share issuance – excluding one-time transaction costs Mix of retail increases dramatically and powers business model Strong ca
Slide 16: A Transformed Business Model
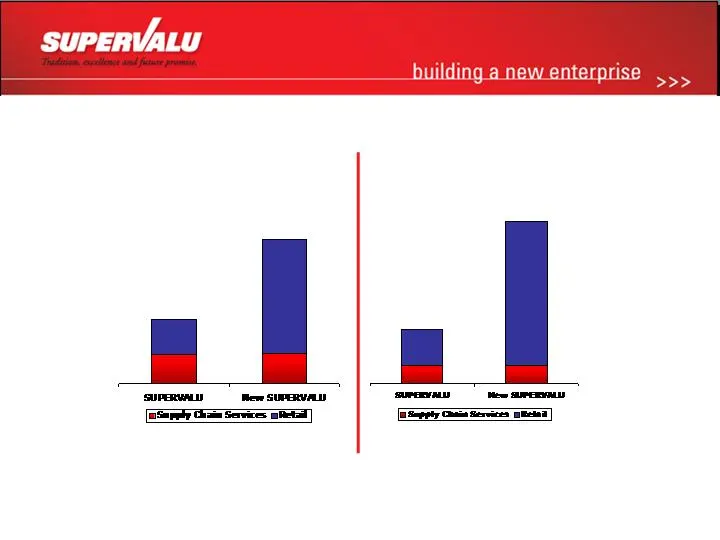
47% 53% 20% 80% 33% 67% 11% 89% A Transformed Business Model ($ Billions) $20 $44 $0.9 $2.7 Sales EBITDA SVU figures represent F06 actuals, ABS figures represent management estimates
Slide 17: Investing in our Future
Sufficient Capital Dollars to Grow and Support Store Network $34 B Retail Sales 3.98% 2.78% Investing in our Future Kroger Safeway A New SUPERVALU (Retail only) 2.9% *Based on First Call data and company data A Safeway’s figures represent cash cap ex as % of sales Fiscal 2007 Projected Retail CapEx
Slide 18: Investing in the Store Fleet in FY 2007
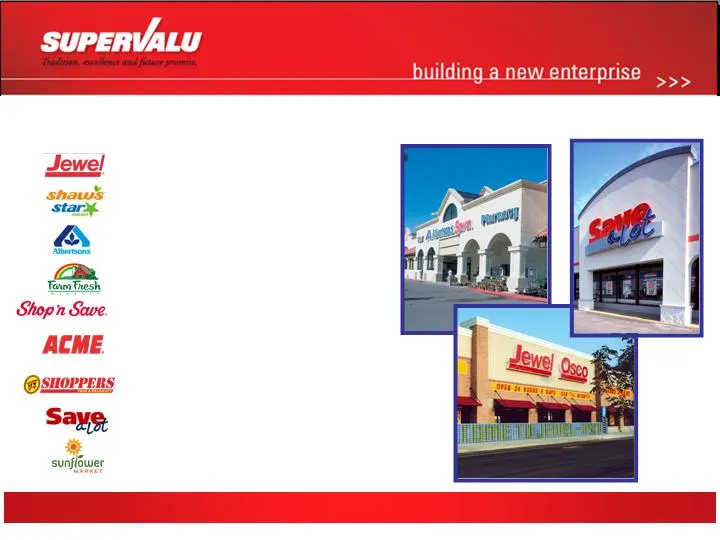
Goal: 80% of Stores New or Newly Remodeled in Last 7 Years Investing in the Store Fleet in FY 2007 6 new stores, 18 remodels 5 new stores, 14 remodels 6 new stores, 13 remodels 5 new stores, 3 remodels 4 new stores, 2 remodels 2 new stores, 11 remodels 2 new stores, 7 remodels 50-75 new stores, 250
Slide 19: Financial Summary
Financial Summary Financial Discipline Embedded In Our Culture Maintain Dividend Policy Commitment To Return to Investment Grade
Slide 20: Creating a Grocery Retail Powerhouse
Creating a Grocery Retail Powerhouse
Slide 21: Expect Synergies to be Realized by the End of the Third Full Year
Expect Synergies to be Realized by the End of the Third Full Year Anticipated Synergies Breakdown $150 - $175 million Total Pretax Synergies $25 - $30 million Supply Chain Optimization $50 - $60 million Corporate Synergies $75 - $85 million Retail Leverage and Efficiencies
Slide 22: Unlock the Value in the Combined Enterprise
Unlock the Value in the Combined Enterprise Strong banner-level leadership at Alberstons Planned and thoughtful transition effort underway Bringing two powerful organizations together Preserving local focus and customer experience is a strategic key Rich set of competencies to leverage the new enter
Slide 23: Unlocking the Value in the New SUPERVALU
Unlocking the Value in the New SUPERVALU No. 3 grocery retailer in the nation The industry’s best regional nameplates A broad-based future growth potential The right formula for sustainable grocery retail success The best place to work in the industry The best place to invest in the sector Forging t
Slide 24: The New
THE NEW Northwestern / Intermountain Southern California
Source: SEC EDGAR · 425 filed May 2, 2006
More decks from Supervalu Inc
 Shareholder Meeting (August 2018)14 slides · Aug 16, 2018
 Proxy Contest (July 2018)175 slides · Jul 24, 2018
 Proxy Contest (July 2018)60 slides · Jul 17, 2018
 Proxy Contest (May 2018)9 slides · May 29, 2018
 Proxy Contest (March 2018)79 slides · Mar 28, 2018
 Debt Investor Presentation (January 2013)40 slides · Jan 28, 2013