Markwest Energy Partners LP — Markwest Energy Partners L P — Merger or Acquisition (September 2015)
81 slides from Markwest Energy Partners LP's merger presentation, Sep 9, 2015
Slide 1: Investor Presentation September 2015
Investor Presentation September 2015
Slide 2: Forward-Looking Statements
Forward‐Looking Statements This presentation contains forward-looking statements within the meaning of federal securities laws regarding MPLX LP (“MPLX”), Marathon Petroleum Corporation (“MPC”), and MarkWest Energy Partners, L.P. (“MWE”). These forward-looking statements relate to, among other thing
Slide 3: Additional Information
Additional Information Additional Information This communication may be deemed to be solicitation material in respect of the proposed transaction. In connection with the proposed transaction, a registration statement on Form S-4 has been filed with the SEC and includes a preliminary proxy statement
Slide 4: Key Investment Highlights
Key Investment Highlights Announced transformative combination with MarkWest Energy Partners, L.P. Affirmed anticipated distribution growth of 29 percent in 2015, expects 25 percent compound annual LP distribution growth for combined entity through 2017, and approximately 20 percent growth in 20
Slide 5: Substantial Acceleration of MPLX
Substantial Acceleration of MPLX Acquired additional 30.5 percent interest in MPLX Pipe Line Holdings on December 1, 2014 for $800 MM (represents ~10.0x multiple of NTM EBITDA) Announced MPLX/MarkWest combination creates a very attractive distribution growth profile for an extended period of time
Slide 6: Strategic Relationship with Sponsor Marathon Petroleum
Strategic Relationship with Sponsor Marathon Petroleum Fortune 25 company Investment grade credit profile Fourth largest U.S. refiner – Largest in Midwest 2014 Revenues and other income: $98.1 B 2014 Net income attributable to MPC: $2.52 B Approximately 2,760 Speedway convenience stores
Slide 7: MPC's Focused and Integrated Network
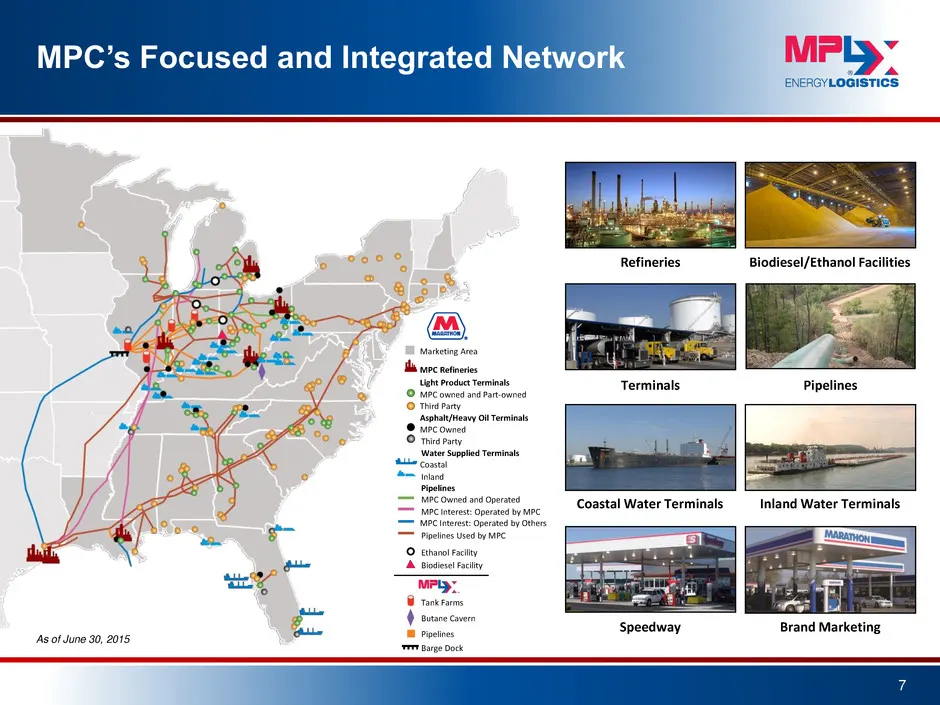
MPC’s Focused and Integrated Network 7 As of June 30, 2015 Pipelines Coastal Water Terminals Inland Water Terminals Refineries Brand Marketing Biodiesel/Ethanol Facilities Terminals Speedway Marketing Area MPC Refineries Light Product Terminals MPC owned and Part-owned Third Party Asphalt/Heavy Oil
Slide 8: MPC's Currently Identified Eligible MLP EBITDA
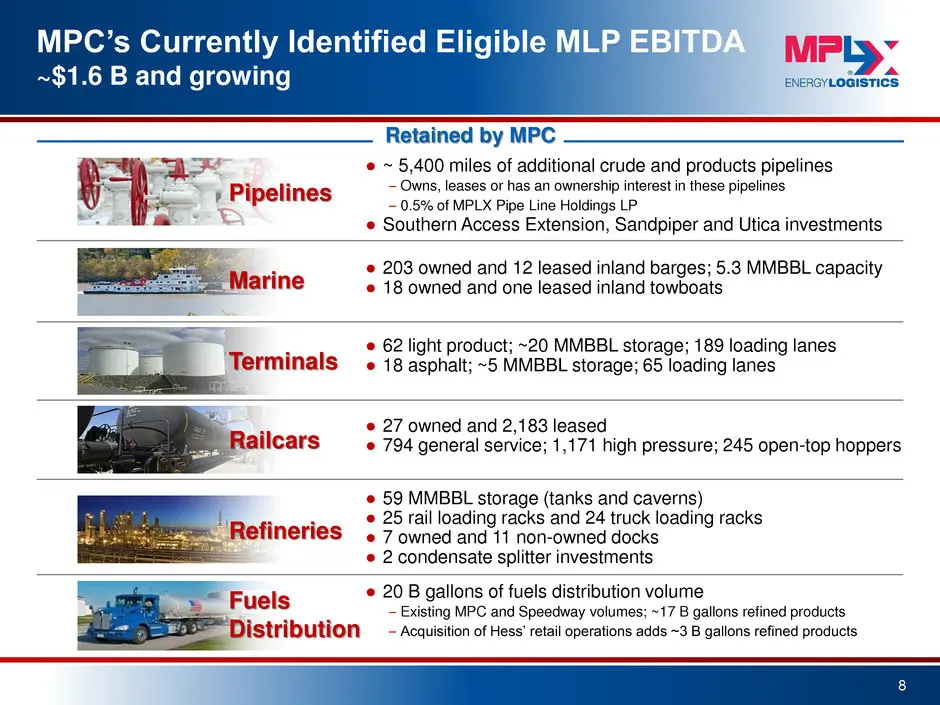
MPC’s Currently Identified Eligible MLP EBITDA ~$1.6 B and growing 8 Retained by MPC ● 59 MMBBL storage (tanks and caverns) ● 25 rail loading racks and 24 truck loading racks ● 7 owned and 11 non-owned docks ● 2 condensate splitter investments ● 27 owned and 2,183 leased ● 794 general service; 1,171
Slide 9: MPC Drop-down Strategy Considerations
MPC Drop-down Strategy Considerations Committed to significant acceleration of MPLX’s annual LP distribution growth rate – Affirmed anticipated distribution growth of 29 percent in 2015, expects 25 percent compound annual LP distribution growth for combined entity through 2017, and approximately 2
Slide 10: MPC and MPLX Strategically Located Assets
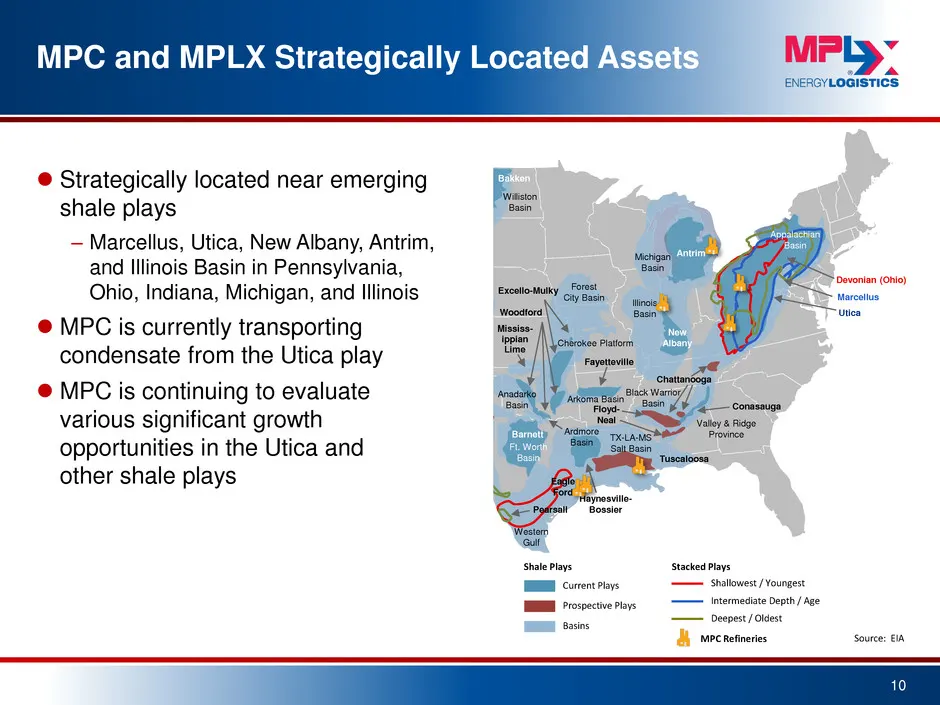
MPC and MPLX Strategically Located Assets Strategically located near emerging shale plays – Marcellus, Utica, New Albany, Antrim, and Illinois Basin in Pennsylvania, Ohio, Indiana, Michigan, and Illinois MPC is currently transporting condensate from the Utica play MPC is continuing to evaluate
Slide 11: MPLX Assets are Integral to MPC
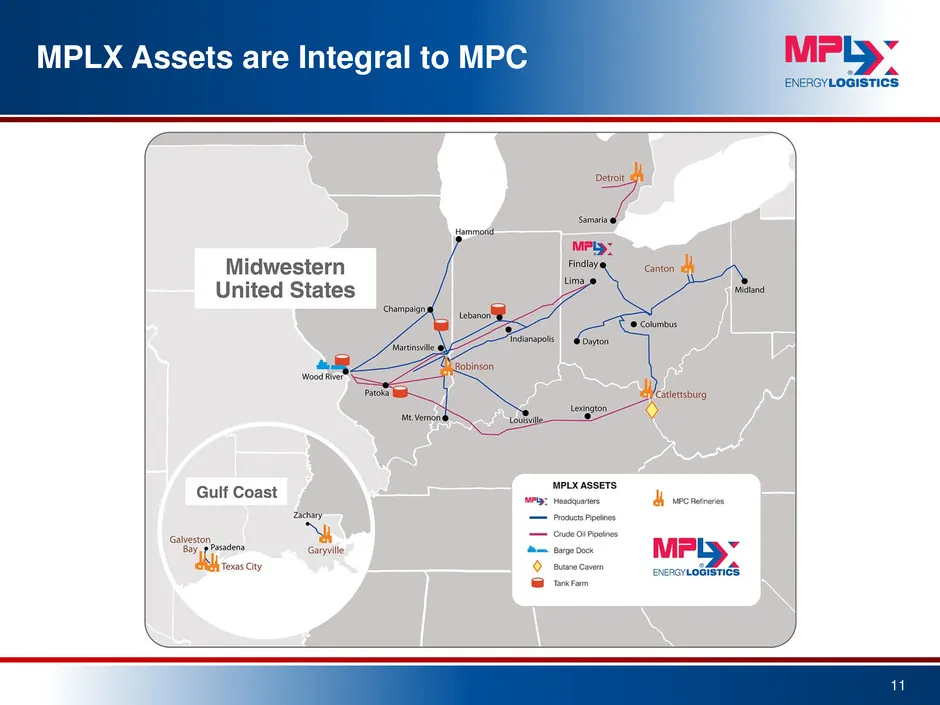
MPLX Assets are Integral to MPC 11
Slide 12: Other Major MPLX Assets
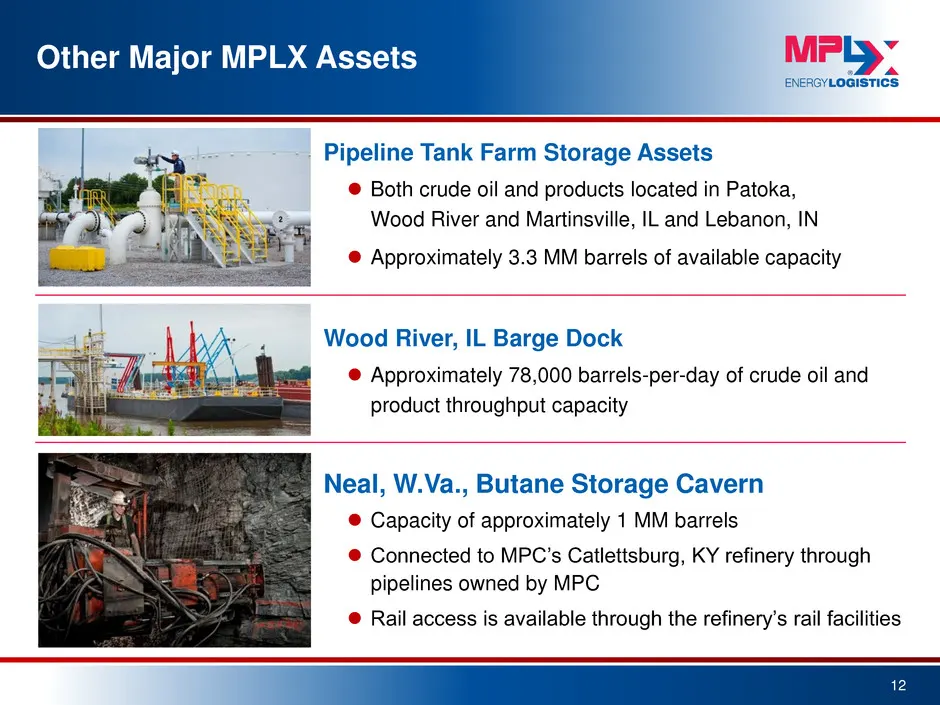
Other Major MPLX Assets Pipeline Tank Farm Storage Assets Both crude oil and products located in Patoka, Wood River and Martinsville, IL and Lebanon, IN Approximately 3.3 MM barrels of available capacity 12 Neal, W.Va., Butane Storage Cavern Capacity of approximately 1 MM barrels Connected t
Slide 13: High-quality, Well-maintained Asset Base
High-quality, Well-maintained Asset Base MPLX continually invests in the maintenance and integrity of its assets Uses a patented integrity management program to enhance pipeline safety and reliability Top-tier reputation and active industry involvement 13 Certifications, Initiatives and Indust
Slide 14: Significant Capital Plan
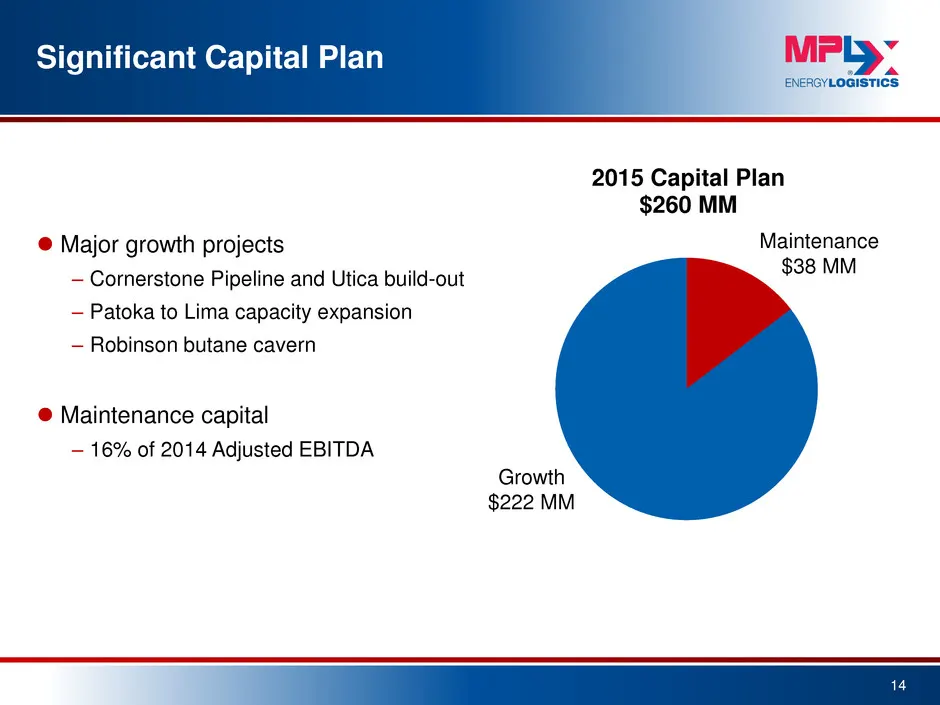
Significant Capital Plan Major growth projects – Cornerstone Pipeline and Utica build-out – Patoka to Lima capacity expansion – Robinson butane cavern Maintenance capital – 16% of 2014 Adjusted EBITDA 14 2015 Capital Plan $260 MM Maintenance $38 MM Growth $222 MM
Slide 15: Stable and Predictable Cash Flows
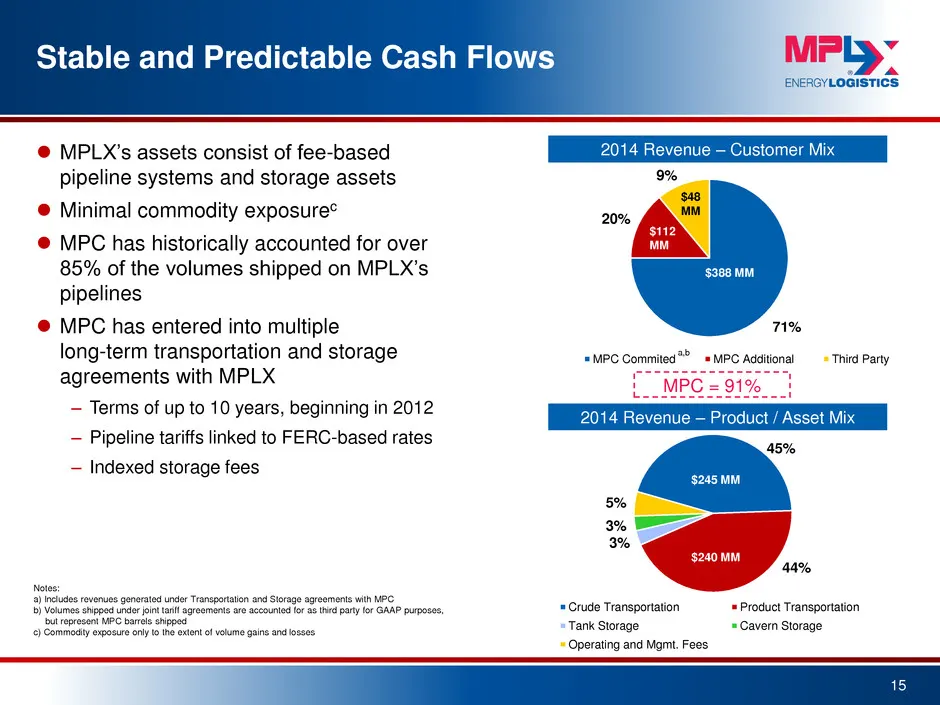
71% 20% 9% MPC Commited MPC Additional Third Party Stable and Predictable Cash Flows MPLX’s assets consist of fee-based pipeline systems and storage assets Minimal commodity exposurec MPC has historically accounted for over 85% of the volumes shipped on MPLX’s pipelines MPC has entered into
Slide 16: MPC Investing in Significant Growth Projects: Sandpiper
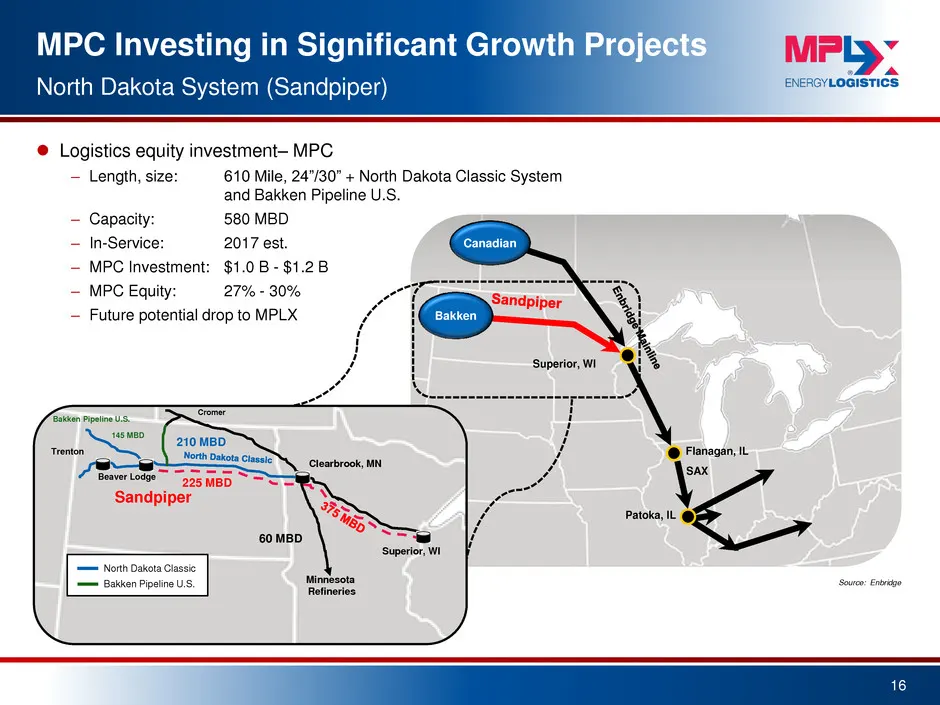
MPC Investing in Significant Growth Projects 16 North Dakota System (Sandpiper) Logistics equity investment– MPC – Length, size: 610 Mile, 24”/30” + North Dakota Classic System and Bakken Pipeline U.S. – Capacity: 580 MBD – In-Service: 2017 est. – MPC Investment: $1.0 B - $1.2 B – MPC Equity: 27%
Slide 17: MPC Investing in Significant Growth Projects: SAX
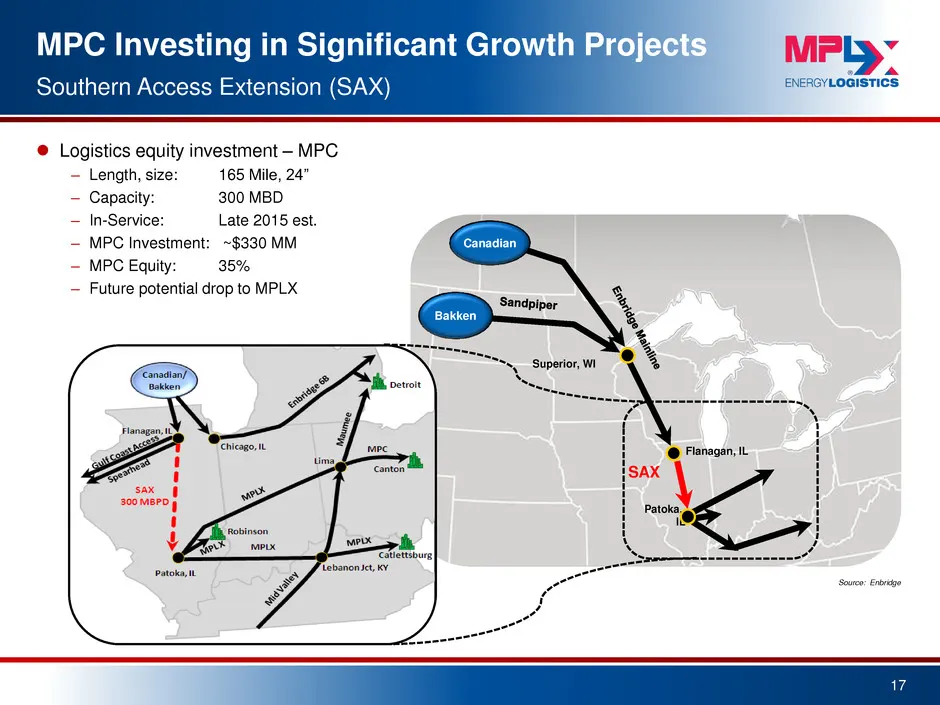
MPC Investing in Significant Growth Projects 17 Southern Access Extension (SAX) Logistics equity investment – MPC – Length, size: 165 Mile, 24” – Capacity: 300 MBD – In-Service: Late 2015 est. – MPC Investment: ~$330 MM – MPC Equity: 35% – Future potential drop to MPLX Superior, WI Canadian Bakken
Slide 18: MPLX/MPC Utica Build-Out Connectivity
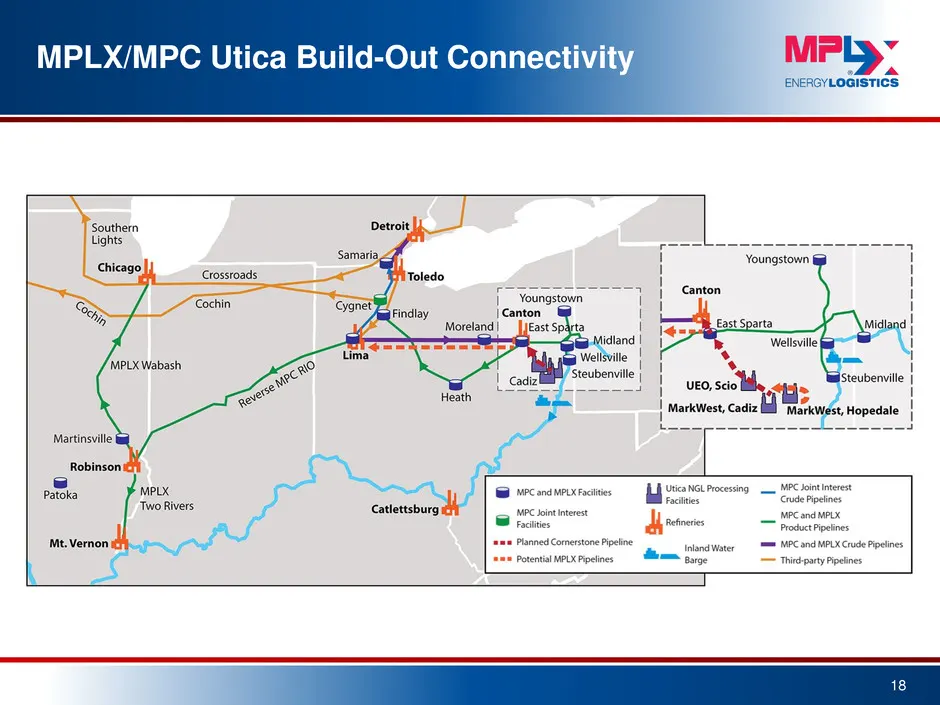
MPLX/MPC Utica Build-Out Connectivity 18
Slide 19: MPLX Developing a Comprehensive Utica System
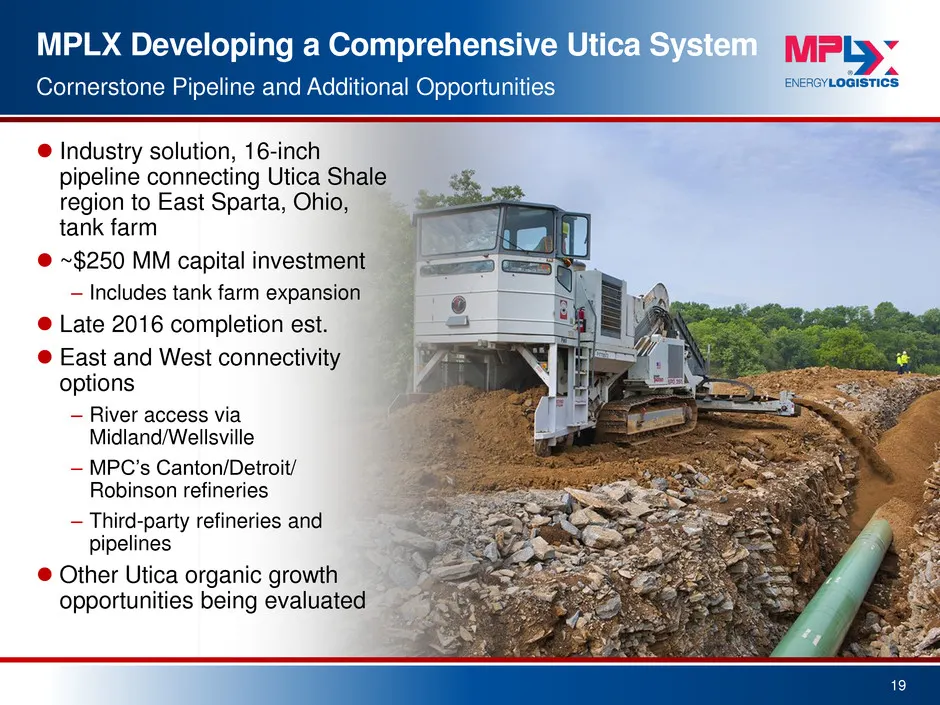
MPLX Developing a Comprehensive Utica System 19 Cornerstone Pipeline and Additional Opportunities Industry solution, 16-inch pipeline connecting Utica Shale region to East Sparta, Ohio, tank farm ~$250 MM capital investment – Includes tank farm expansion Late 2016 completion est. East and We
Slide 20: MPLX Strong Financial Flexibility to Manage and Grow Asset Base
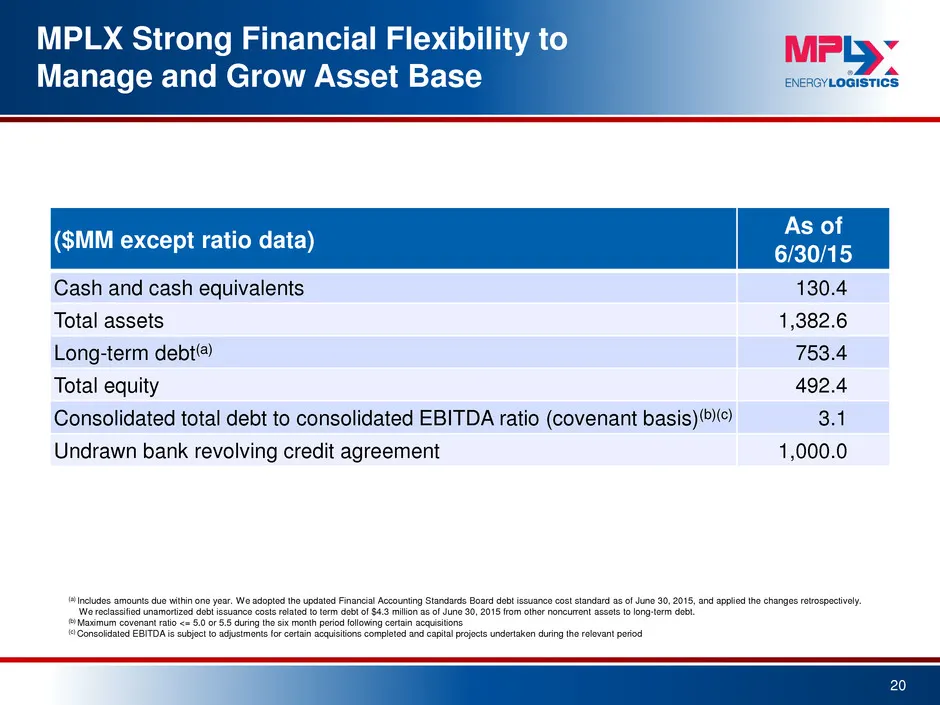
MPLX Strong Financial Flexibility to Manage and Grow Asset Base 20 ($MM except ratio data) As of 6/30/15 Cash and cash equivalents 130.4 Total assets 1,382.6 Long-term debt(a) 753.4 Total equity 492.4 Consolidated total debt to consolidated EBITDA ratio (covenant basis)(b)(c) 3.1 Undrawn bank revolv
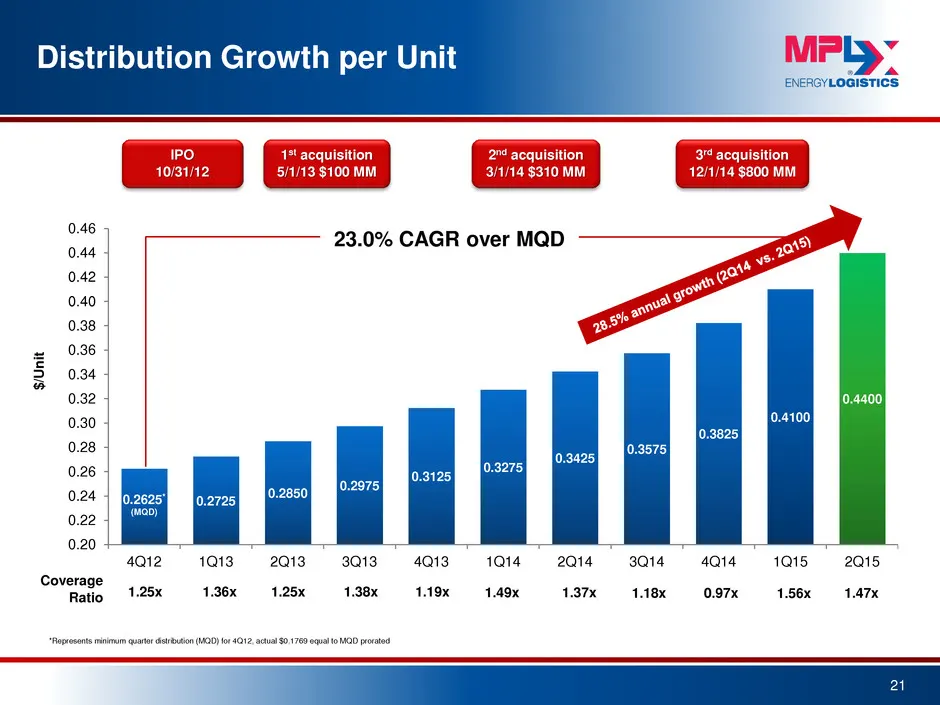
Slide 21: Distribution Growth per Unit
0.2625* (MQD) 0.2725 0.2850 0.2975 0.3125 0.3275 0.3425 0.3575 0.3825 0.4100 0.4400 0.20 0.22 0.24 0.26 0.28 0.30 0.32 0.34 0.36 0.38 0.40 0.42 0.44 0.46 4Q12 1Q13 2Q13 3Q13 4Q13 1Q14 2Q14 3Q14 4Q14 1Q15 2Q15 $ /U ni t 1.49x 1.37x 1.56x 1.47x Distribution Growth per Unit *Represents minimum quarter
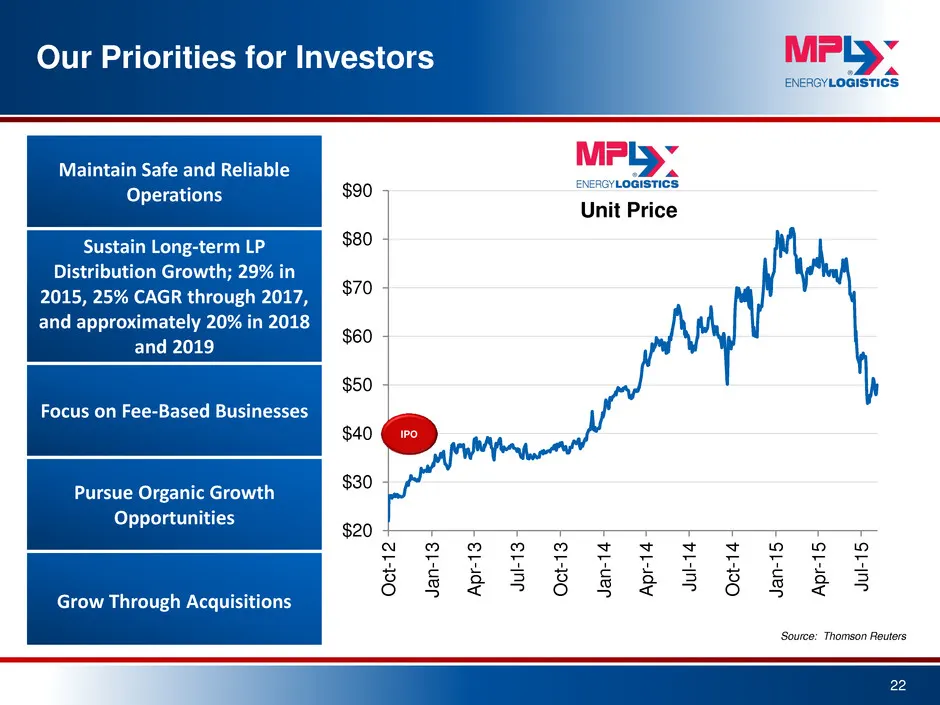
Slide 22: Our Priorities for Investors
Our Priorities for Investors 22 Maintain Safe and Reliable Operations Sustain Long-term LP Distribution Growth; 29% in 2015, 25% CAGR through 2017, and approximately 20% in 2018 and 2019 Focus on Fee-Based Businesses Pursue Organic Growth Opportunities Grow Through Acquisitions $20 $30 $40 $50 $60 $
Slide 23: Appendix
23 Appendix
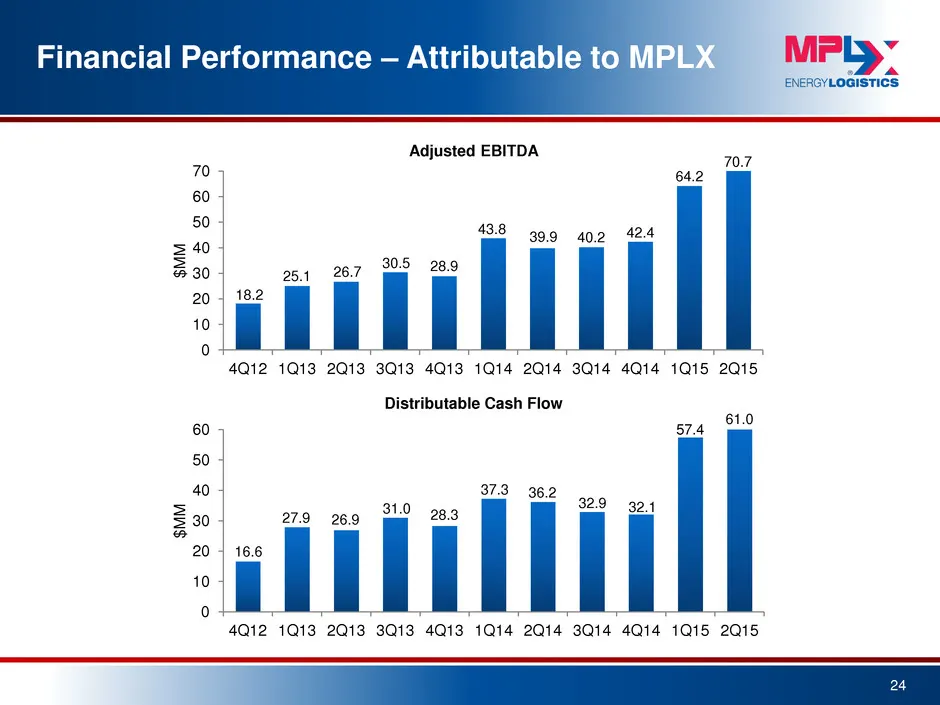
Slide 24: Financial Performance – Attributable to MPLX
Financial Performance – Attributable to MPLX 24 18.2 25.1 26.7 30.5 28.9 43.8 39.9 40.2 42.4 64.2 0 10 20 30 40 50 60 70 4Q12 1Q13 2Q13 3Q13 4Q13 1Q14 2Q14 3Q14 4Q14 1Q15 2Q15 $ M M Adjusted EBITDA 70.7 16.6 27.9 26.9 31.0 28.3 37.3 36.2 32.9 32.1 57.4 61.0 0 10 20 30 40 50 60 4Q12 1Q13 2Q13 3Q13 4Q
Slide 25: Net Income 2Q 2015 vs. 2Q 2014 Variance Analysis
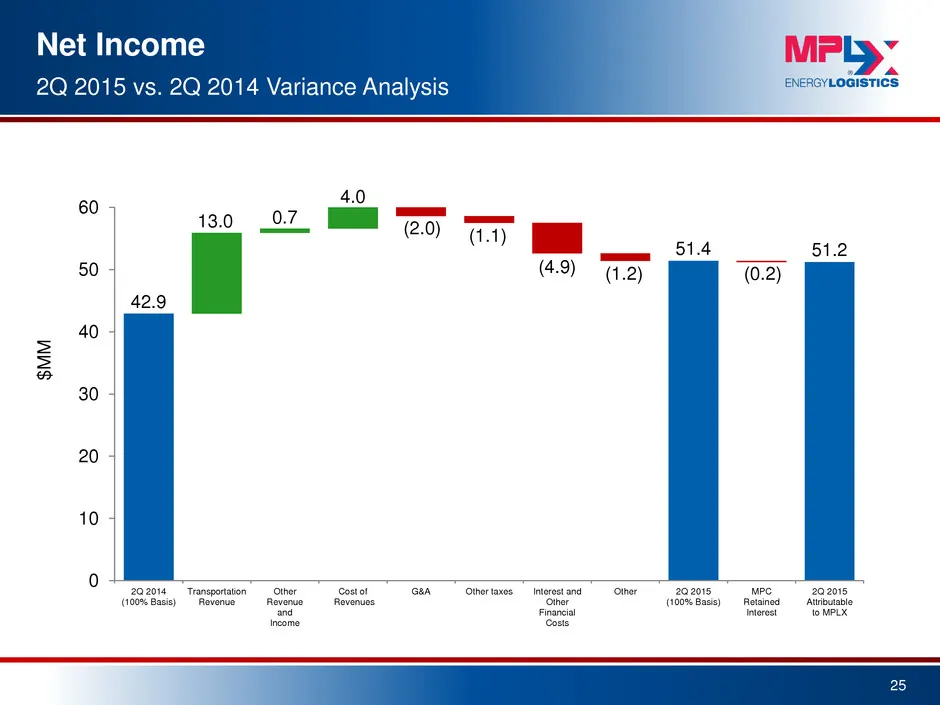
Net Income 25 2Q 2015 vs. 2Q 2014 Variance Analysis 42.9 13.0 0.7 4.0 (2.0) (1.1) (4.9) (1.2) 51.4 (0.2) 51.2 0 10 20 30 40 50 60 2Q 2014 (100% Basis) Transportation Revenue Other Revenue and Income Cost of Revenues G&A Other taxes Interest and Other Financial Costs Other 2Q 2015 (100% Basis) MPC Re
Slide 26: Deficiency Payment Effect Example
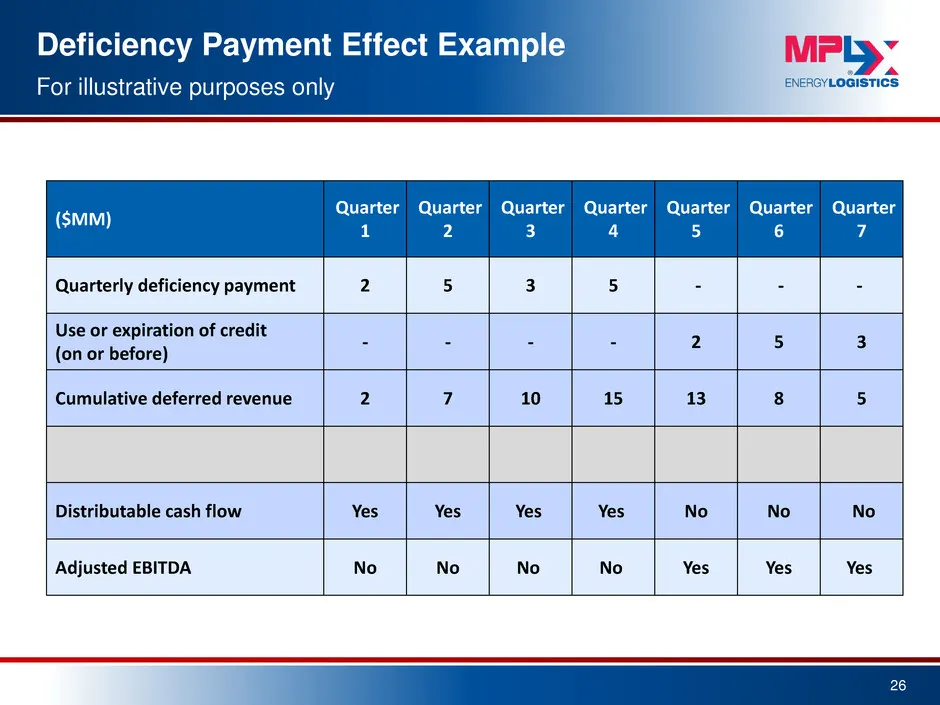
Deficiency Payment Effect Example 26 For illustrative purposes only ($MM) Quarter 1 Quarter 2 Quarter 3 Quarter 4 Quarter 5 Quarter 6 Quarter 7 Quarterly deficiency payment 2 5 3 5 - - - Use or expiration of credit (on or before) - - - - 2 5 3 Cumulative deferred revenue 2 7 10 15 13 8 5 Distributab
Slide 27: MPLX and MPC are Aligned
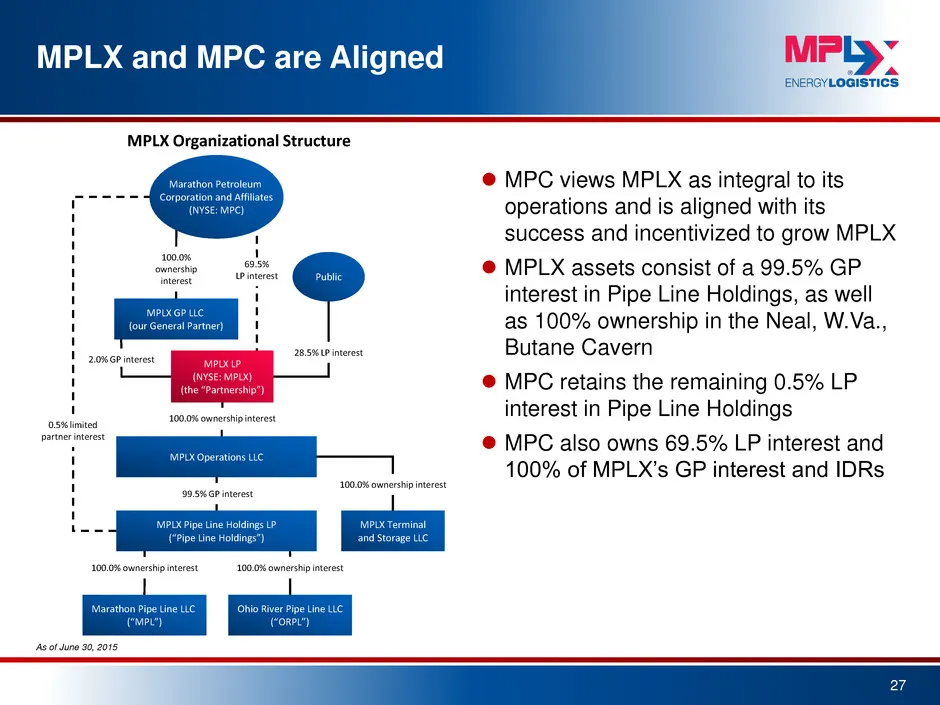
MPLX and MPC are Aligned MPC views MPLX as integral to its operations and is aligned with its success and incentivized to grow MPLX MPLX assets consist of a 99.5% GP interest in Pipe Line Holdings, as well as 100% ownership in the Neal, W.Va., Butane Cavern MPC retains the remaining 0.5% LP in
Slide 28: Incentive Distribution Rights
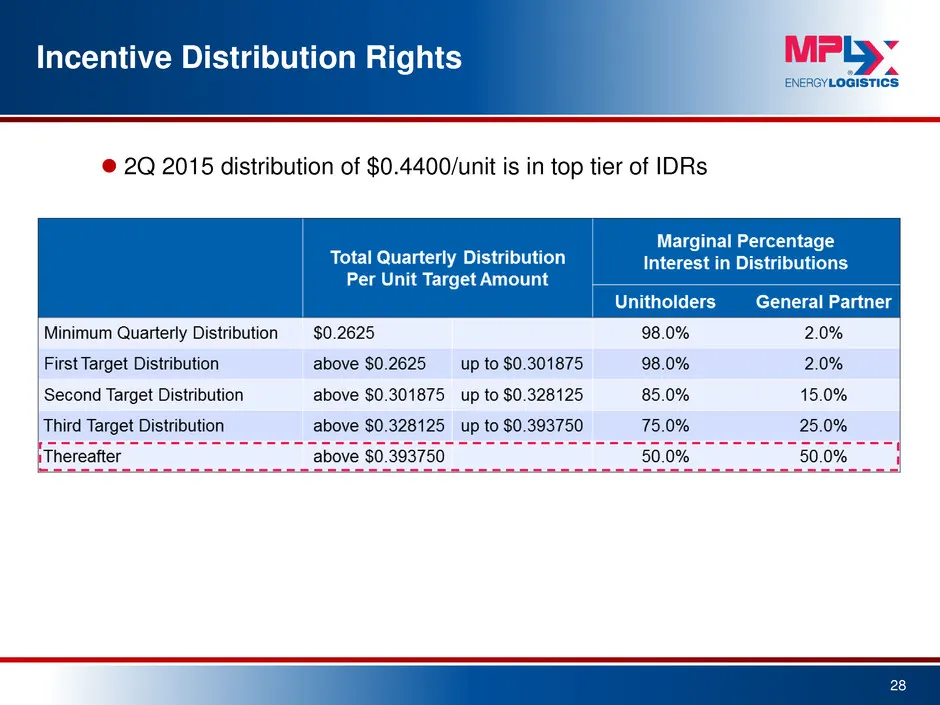
Incentive Distribution Rights 2Q 2015 distribution of $0.4400/unit is in top tier of IDRs 28
Slide 29: Crude Oil Pipeline System
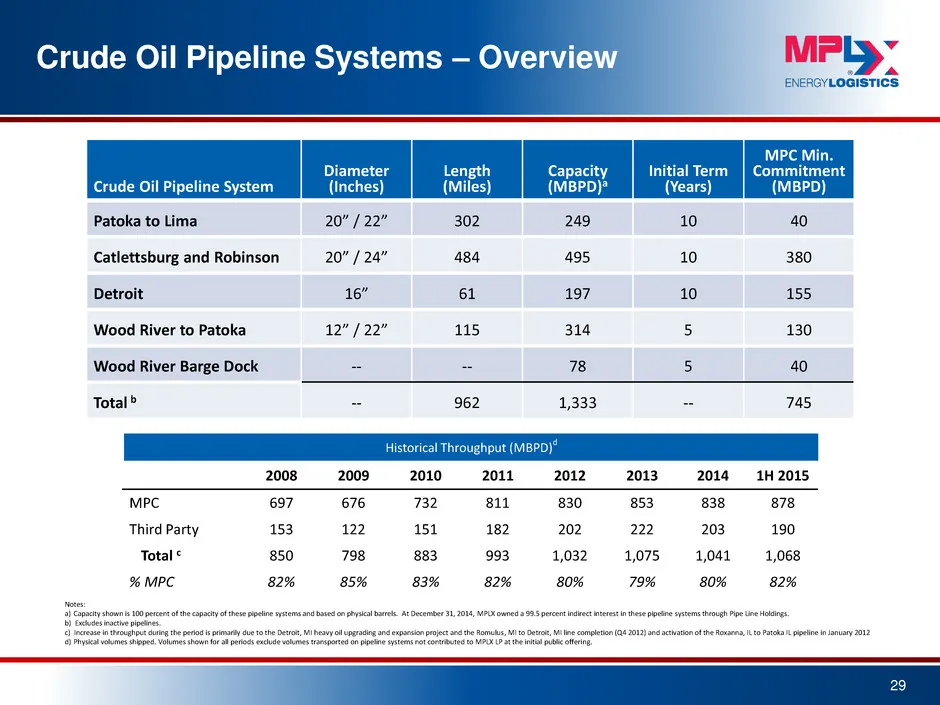
Crude Oil Pipeline System Diameter (Inches) Length (Miles) Capacity (MBPD)a Initial Term (Years) MPC Min. Commitment (MBPD) Patoka to Lima 20” / 22” 302 249 10 40 Catlettsburg and Robinson 20” / 24” 484 495 10 380 Detroit 16” 61 197 10 155 Wood River to Patoka 12” / 22” 115 314 5 130 Wood River Barg
Slide 30: Crude Oil Pipeline Systems – Overview
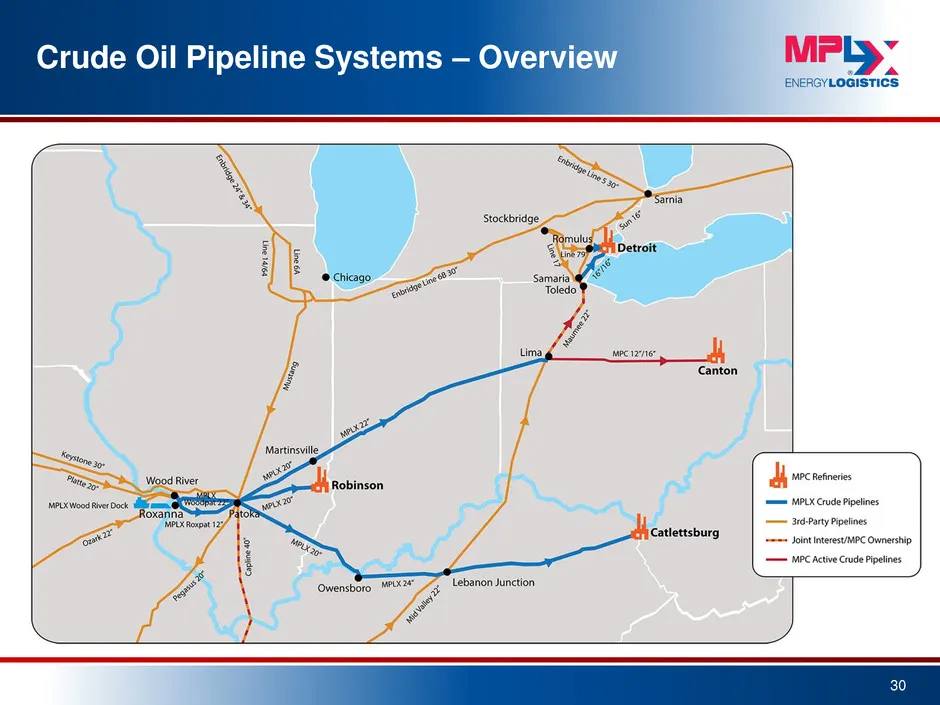
Crude Oil Pipeline Systems – Overview 30
Slide 31: Patoka to Lima Crude System
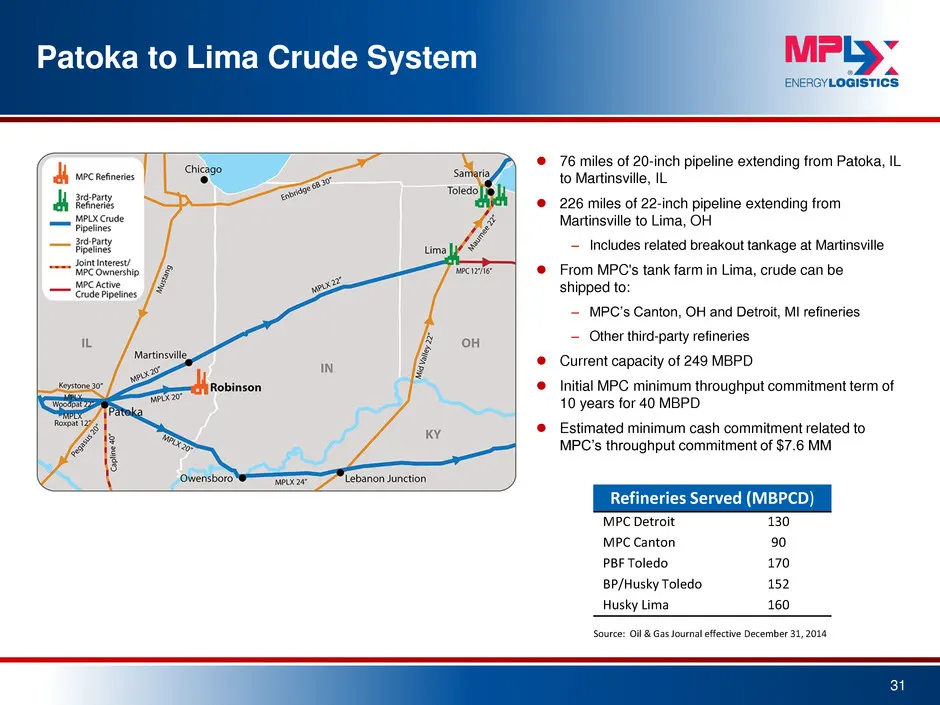
Patoka to Lima Crude System 76 miles of 20-inch pipeline extending from Patoka, IL to Martinsville, IL 226 miles of 22-inch pipeline extending from Martinsville to Lima, OH – Includes related breakout tankage at Martinsville From MPC's tank farm in Lima, crude can be shipped to: – MPC’s Canton
Slide 32: Catlettsburg and Robinson Crude System
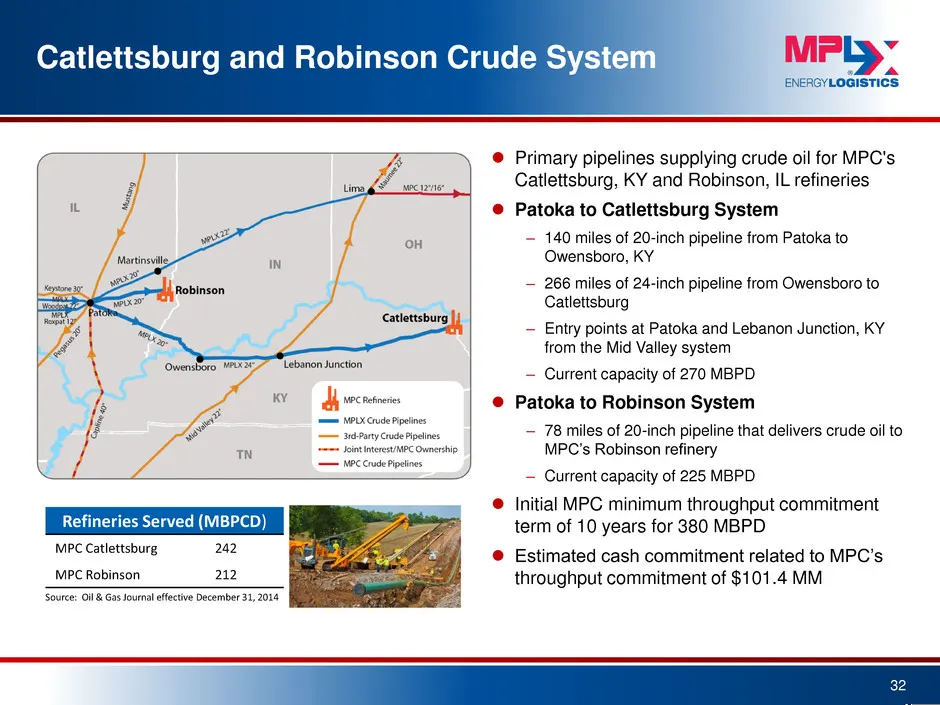
Catlettsburg and Robinson Crude System Primary pipelines supplying crude oil for MPC's Catlettsburg, KY and Robinson, IL refineries Patoka to Catlettsburg System – 140 miles of 20-inch pipeline from Patoka to Owensboro, KY – 266 miles of 24-inch pipeline from Owensboro to Catlettsburg – Entry po
Slide 33: Detroit Crude System
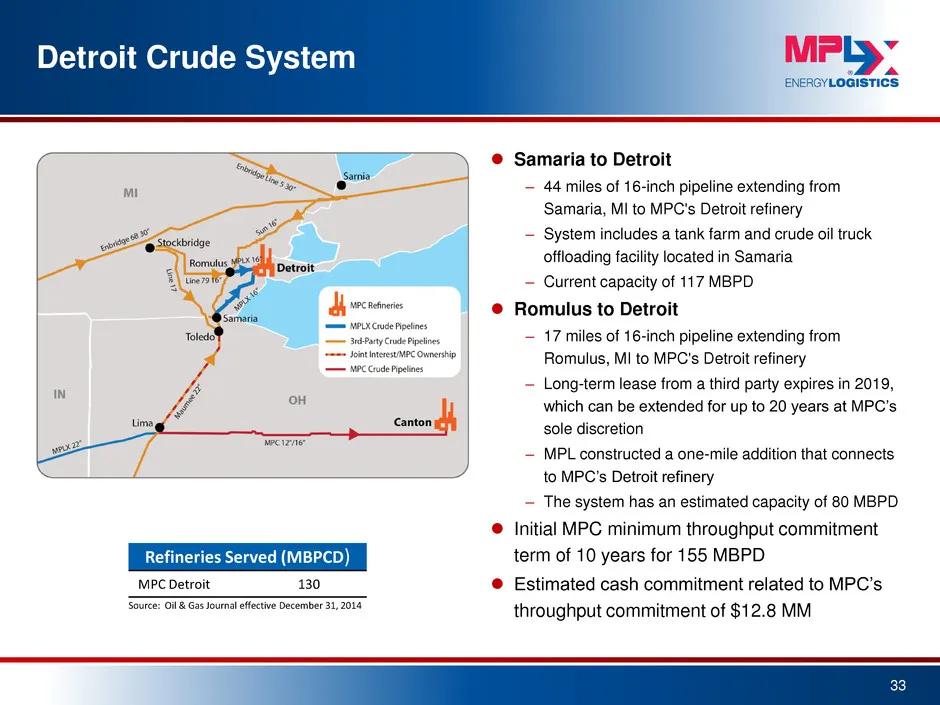
Detroit Crude System Samaria to Detroit – 44 miles of 16-inch pipeline extending from Samaria, MI to MPC's Detroit refinery – System includes a tank farm and crude oil truck offloading facility located in Samaria – Current capacity of 117 MBPD Romulus to Detroit – 17 miles of 16-inch pipeline ex
Slide 34: Wood River to Patoka Crude System
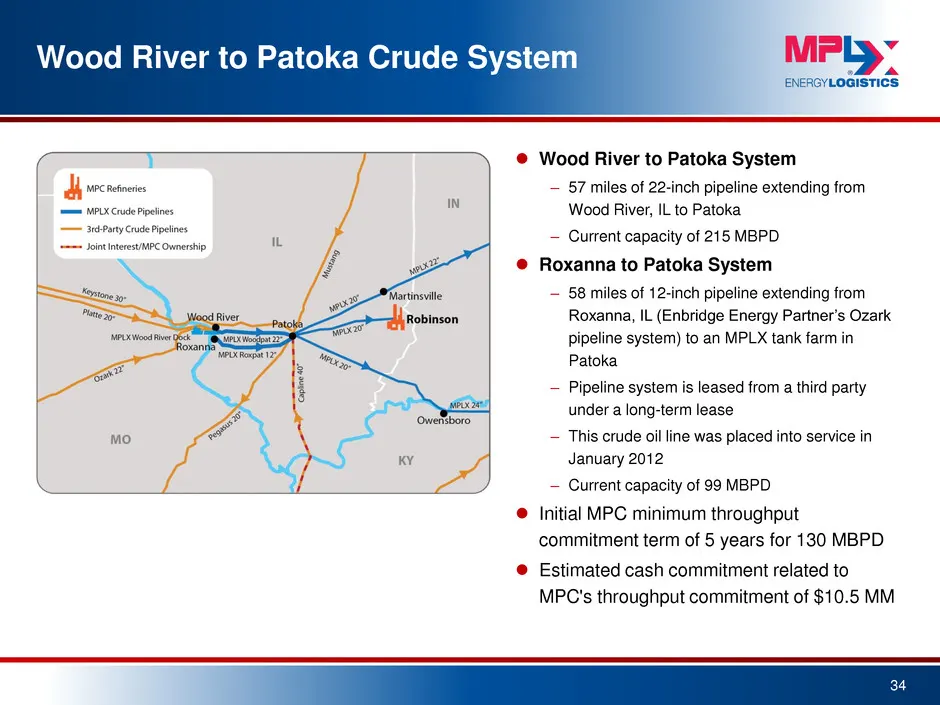
Wood River to Patoka Crude System Wood River to Patoka System – 57 miles of 22-inch pipeline extending from Wood River, IL to Patoka – Current capacity of 215 MBPD Roxanna to Patoka System – 58 miles of 12-inch pipeline extending from Roxanna, IL (Enbridge Energy Partner’s Ozark pipeline system)
Slide 35: Midwest Product Pipelines – Overview
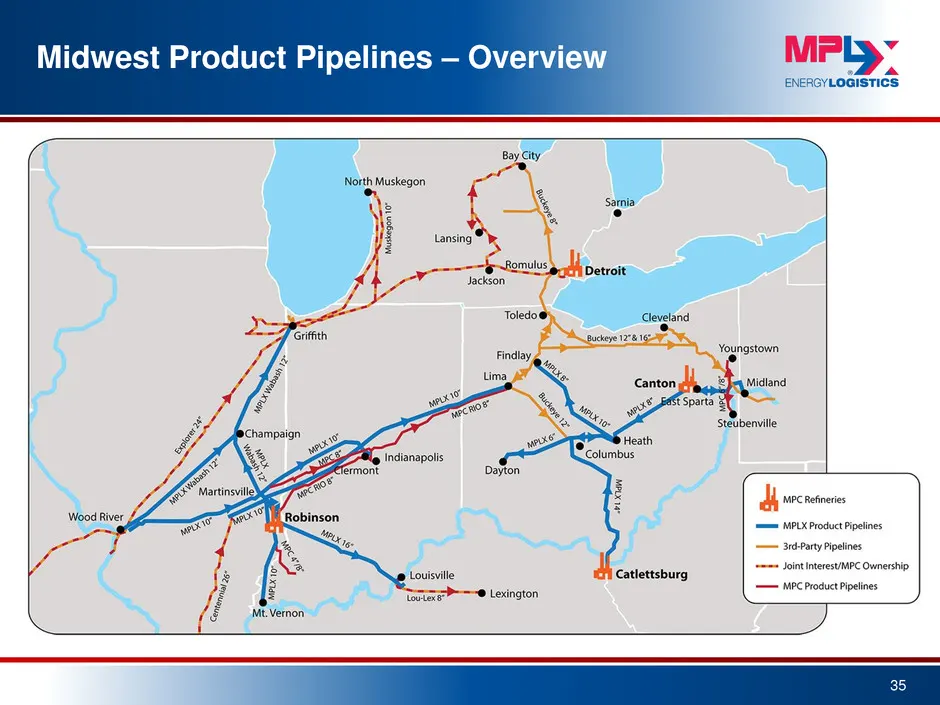
Midwest Product Pipelines – Overview 35
Slide 36: Gulf Coast Product Pipelines – Overview
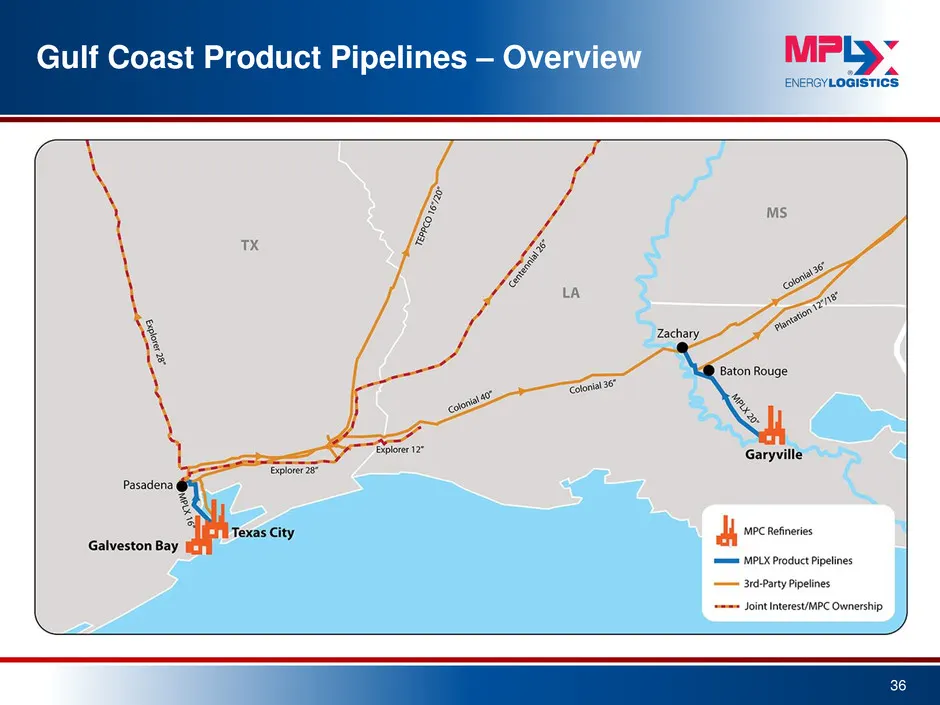
Gulf Coast Product Pipelines – Overview 36
Slide 37: Product Pipeline Systems – Overview
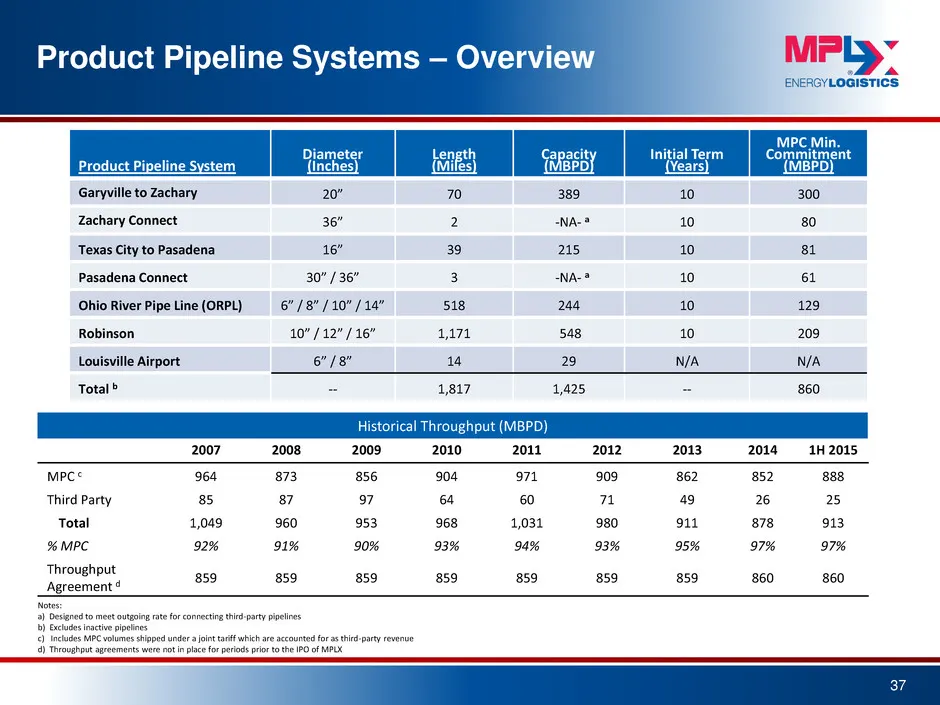
Product Pipeline Systems – Overview 37 Notes: a) Designed to meet outgoing rate for connecting third-party pipelines b) Excludes inactive pipelines c) Includes MPC volumes shipped under a joint tariff which are accounted for as third-party revenue d) Throughput agreements were not in place for perio
Slide 38: Garyville Products System
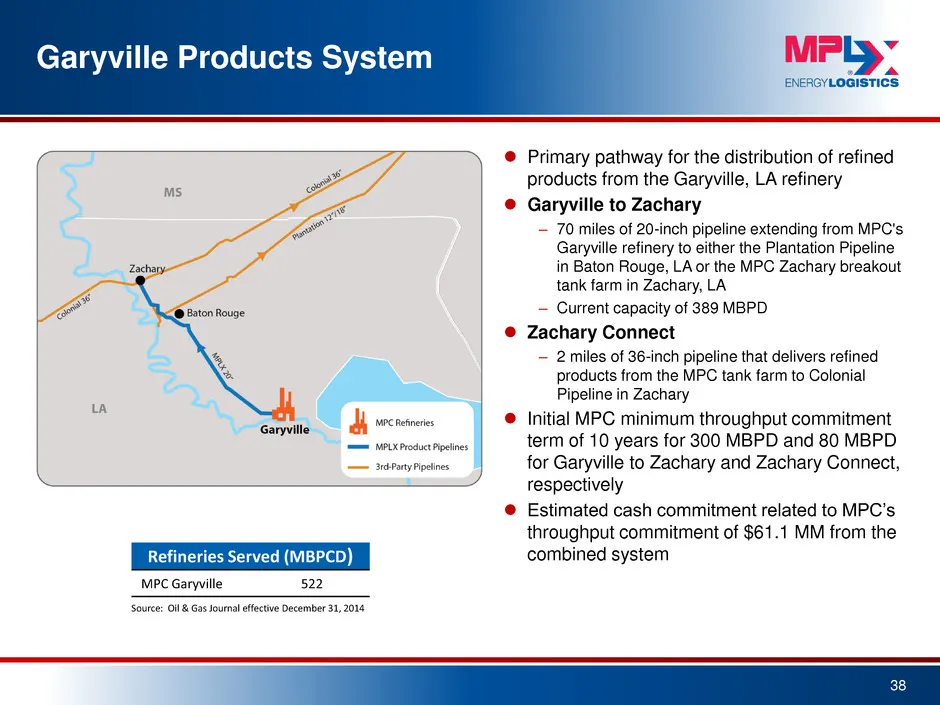
Garyville Products System Primary pathway for the distribution of refined products from the Garyville, LA refinery Garyville to Zachary – 70 miles of 20-inch pipeline extending from MPC's Garyville refinery to either the Plantation Pipeline in Baton Rouge, LA or the MPC Zachary breakout tank far
Slide 39: Texas City Products System
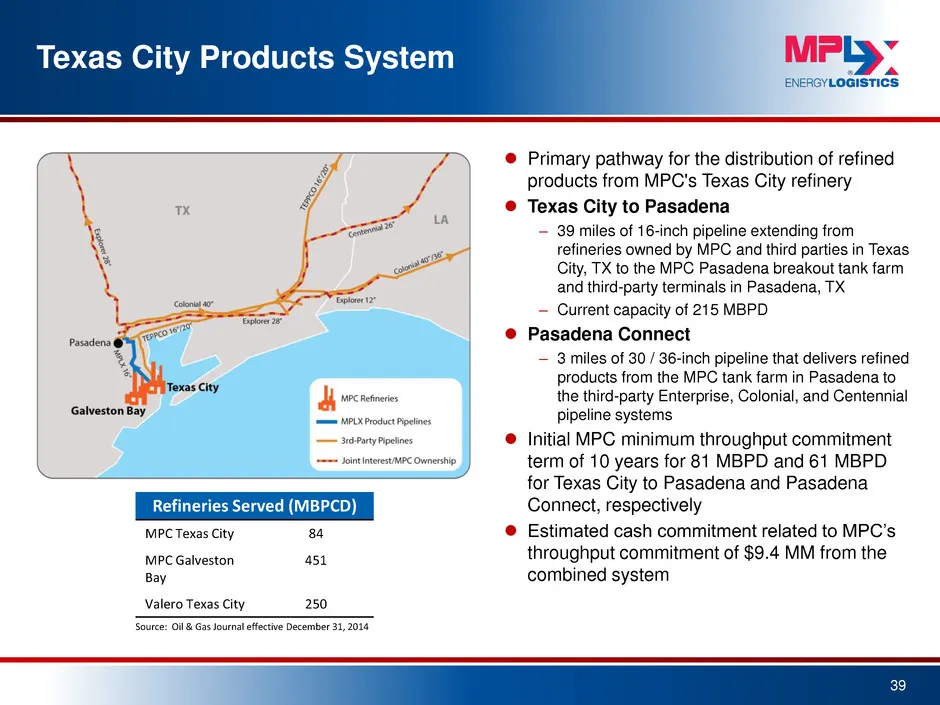
Texas City Products System Primary pathway for the distribution of refined products from MPC's Texas City refinery Texas City to Pasadena – 39 miles of 16-inch pipeline extending from refineries owned by MPC and third parties in Texas City, TX to the MPC Pasadena breakout tank farm and third-par
Slide 40: Ohio River Pipe Line (ORPL) Products Systems
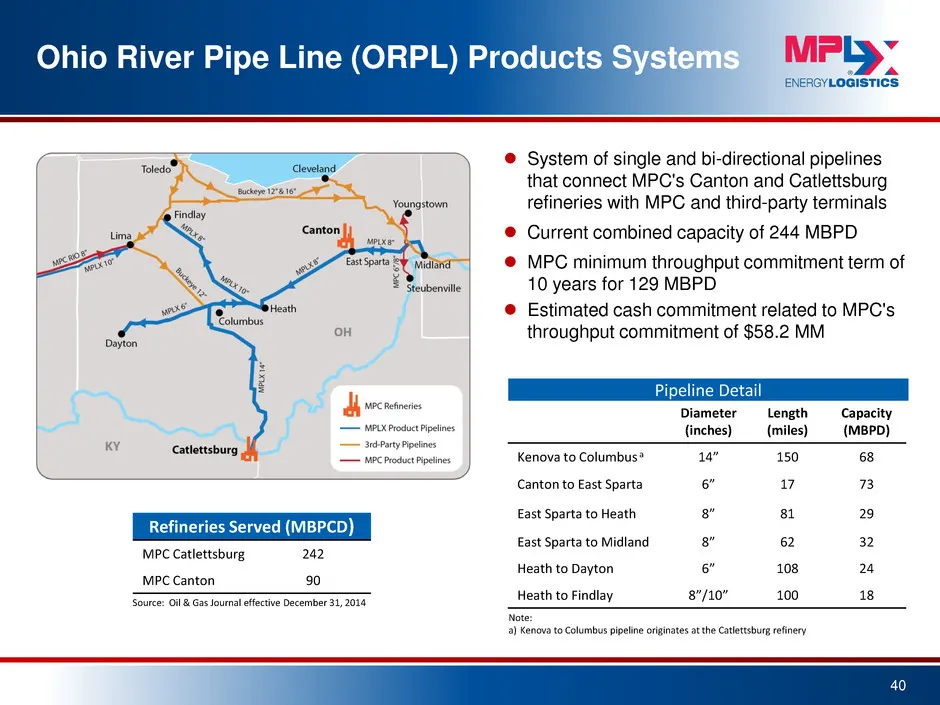
Ohio River Pipe Line (ORPL) Products Systems System of single and bi-directional pipelines that connect MPC's Canton and Catlettsburg refineries with MPC and third-party terminals Current combined capacity of 244 MBPD MPC minimum throughput commitment term of 10 years for 129 MBPD Estimated
Slide 41: Robinson Products System
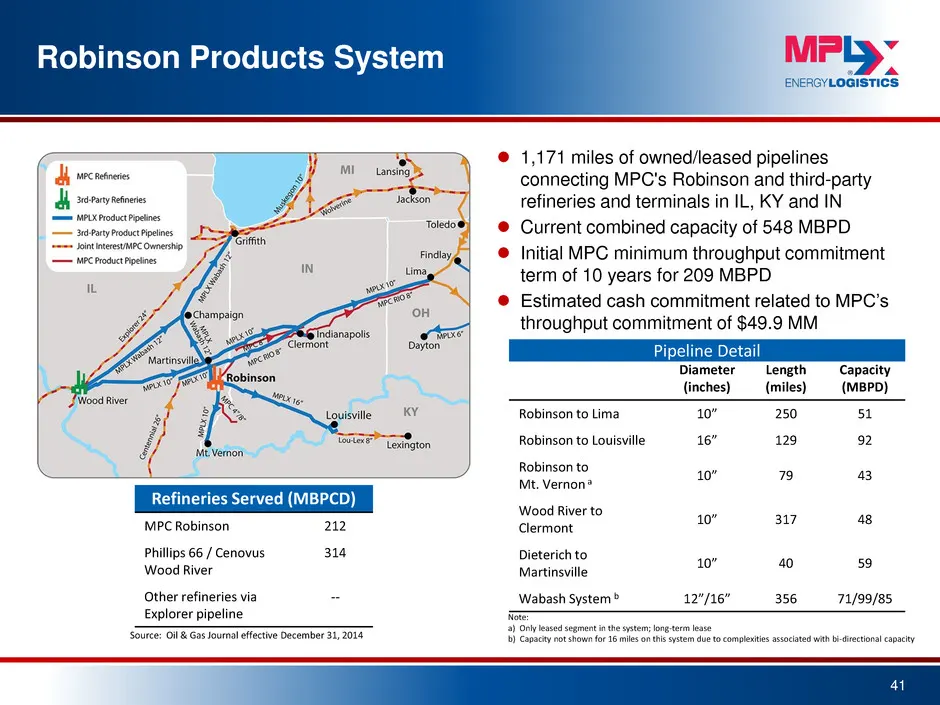
Robinson Products System 1,171 miles of owned/leased pipelines connecting MPC's Robinson and third-party refineries and terminals in IL, KY and IN Current combined capacity of 548 MBPD Initial MPC minimum throughput commitment term of 10 years for 209 MBPD Estimated cash commitment related t
Slide 42: Other Major MPLX Assets
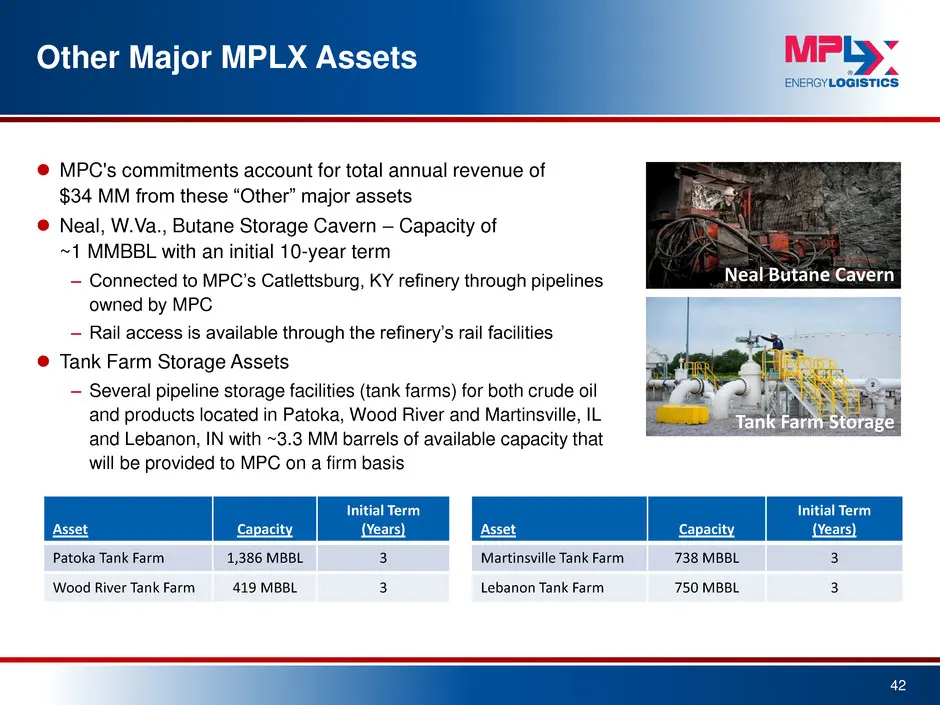
Other Major MPLX Assets MPC's commitments account for total annual revenue of $34 MM from these “Other” major assets Neal, W.Va., Butane Storage Cavern – Capacity of ~1 MMBBL with an initial 10-year term – Connected to MPC’s Catlettsburg, KY refinery through pipelines owned by MPC – Rail access
Slide 43: Capital Expenditures & Investments
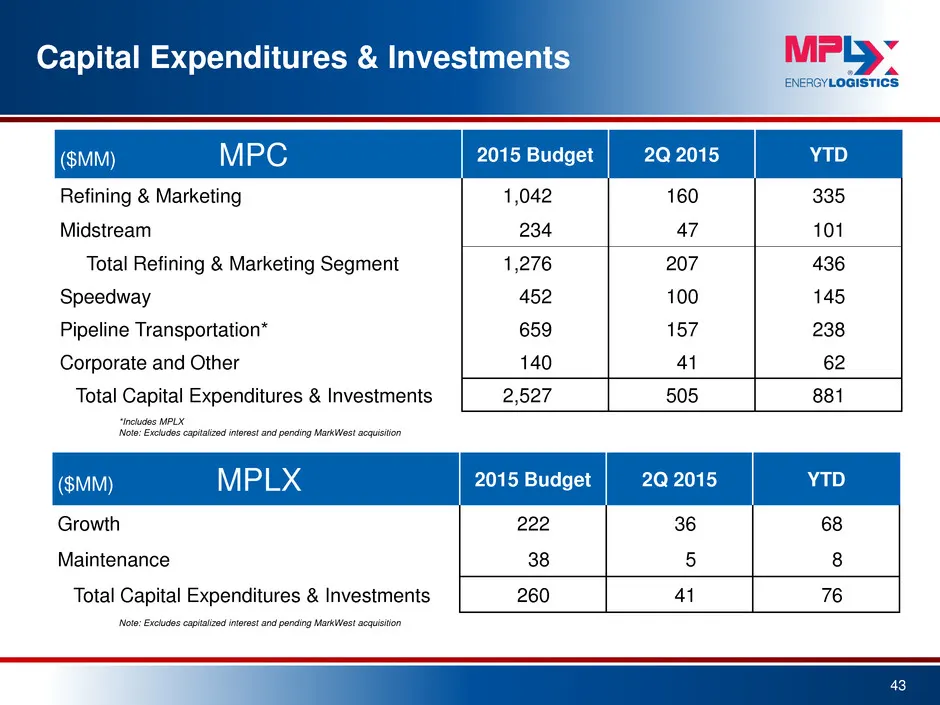
Capital Expenditures & Investments 43 Note: Excludes capitalized interest and pending MarkWest acquisition ($MM) MPLX 2015 Budget 2Q 2015 YTD Growth 222 36 68 Maintenance 38 5 8 Total Capital Expenditures & Investments 260 41 76 *Includes MPLX Note: Excludes capitalized interest and pending MarkWest
Slide 44: MPC's Fully Integrated Downstream System
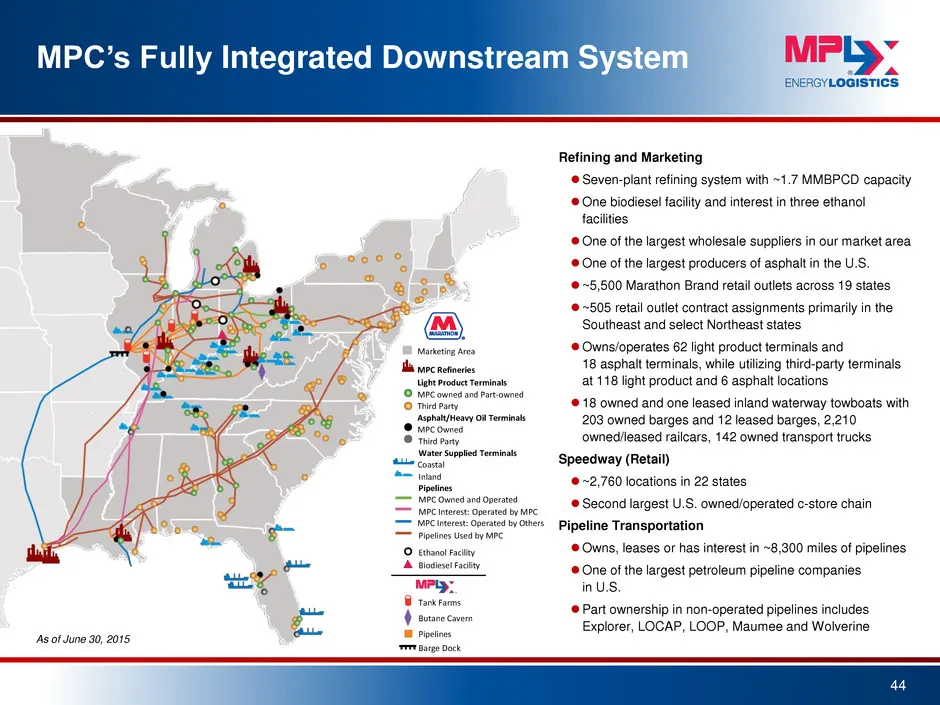
MPC’s Fully Integrated Downstream System 44 Refining and Marketing Seven-plant refining system with ~1.7 MMBPCD capacity One biodiesel facility and interest in three ethanol facilities One of the largest wholesale suppliers in our market area One of the largest producers of asphalt in the U.S.
Slide 45: MPC 2015 Value Drivers
MPC 2015 Value Drivers Top-tier safety and environmental performance Integrated downstream system Growing Midstream/MPLX –MPLX/MWE merger Enhancing margins in our refining operations Speedway – Hess integration Capital return to shareholders –Strong and growing dividend –Share repurchase progr
Slide 46: MPC Focused Return of Capital to Shareholders
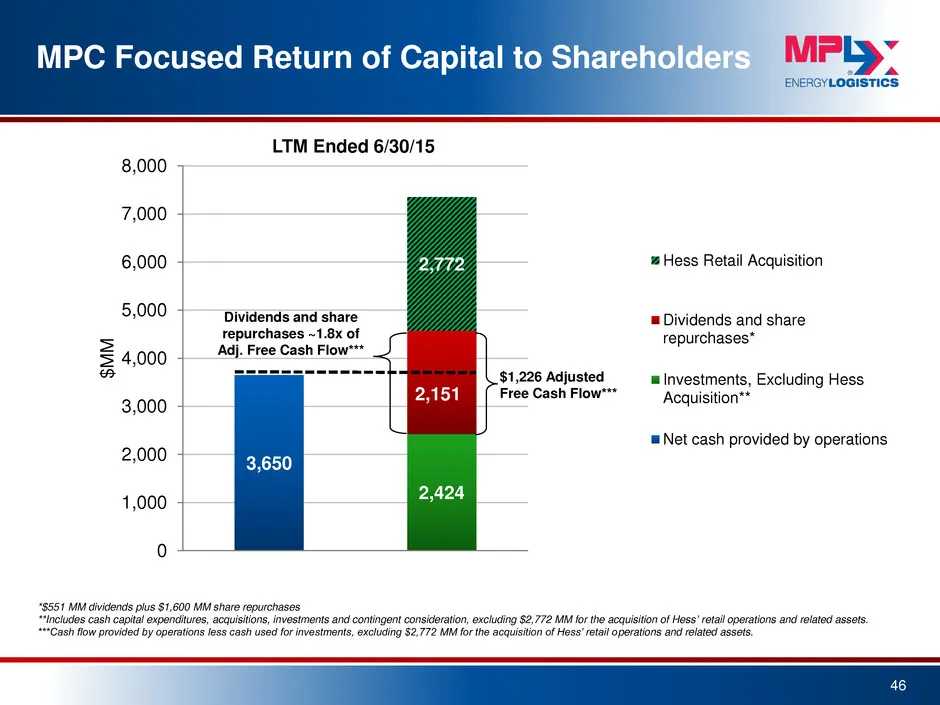
MPC Focused Return of Capital to Shareholders 46 *$551 MM dividends plus $1,600 MM share repurchases **Includes cash capital expenditures, acquisitions, investments and contingent consideration, excluding $2,772 MM for the acquisition of Hess ’ retail operations and related assets. ***Cash flow prov
Slide 47: MPC Delivering Consistent Return of Capital
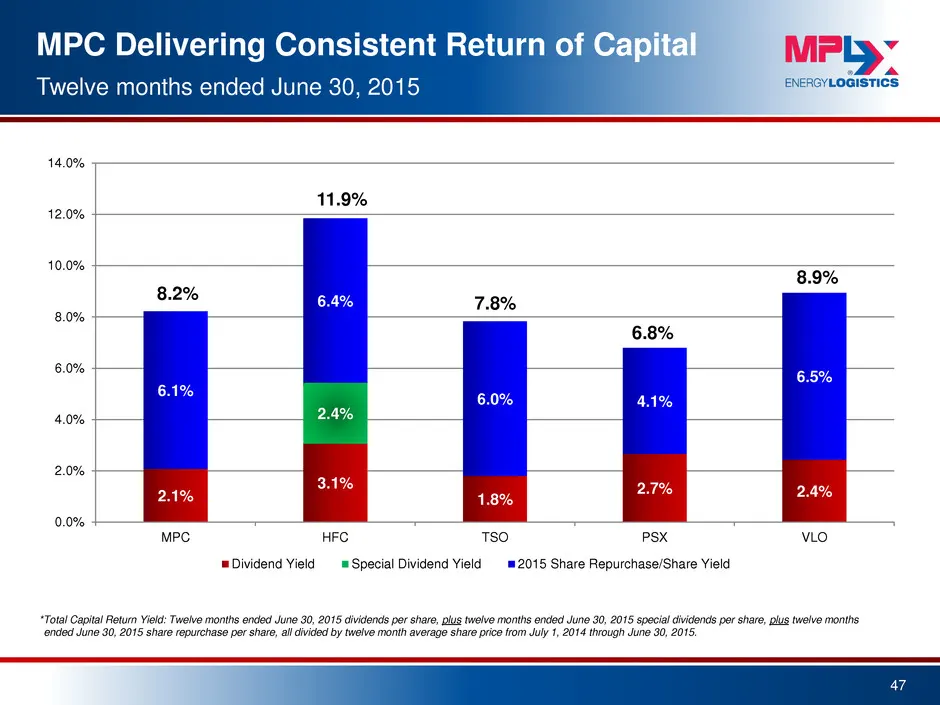
2.1% 3.1% 1.8% 2.7% 2.4% 2.4% 6.1% 6.4% 6.0% 4.1% 6.5% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% MPC HFC TSO PSX VLO Dividend Yield Special Dividend Yield 2015 Share Repurchase/Share Yield MPC Delivering Consistent Return of Capital 47 Twelve months ended June 30, 2015 8.2% 11.9% 6.8% 7.8% 8.9% *To
Slide 48: MPC Performing Consistently in the Top Tier
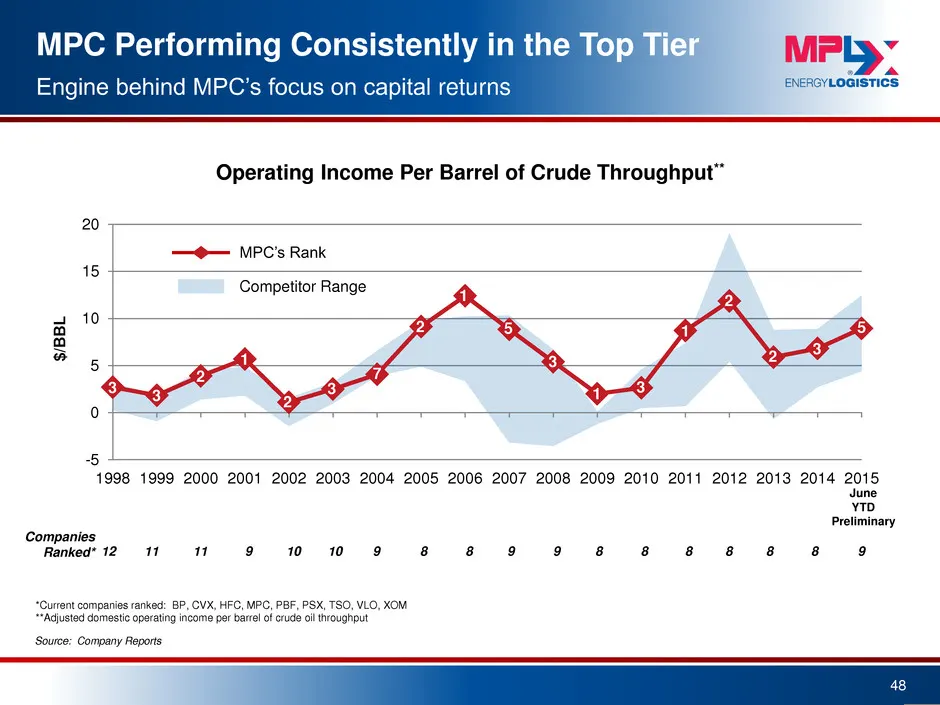
MPC Performing Consistently in the Top Tier 48 Engine behind MPC’s focus on capital returns Source: Company Reports Operating Income Per Barrel of Crude Throughput** *Current companies ranked: BP, CVX, HFC, MPC, PBF, PSX, TSO, VLO, XOM **Adjusted domestic operating income per barrel of crude oil thr
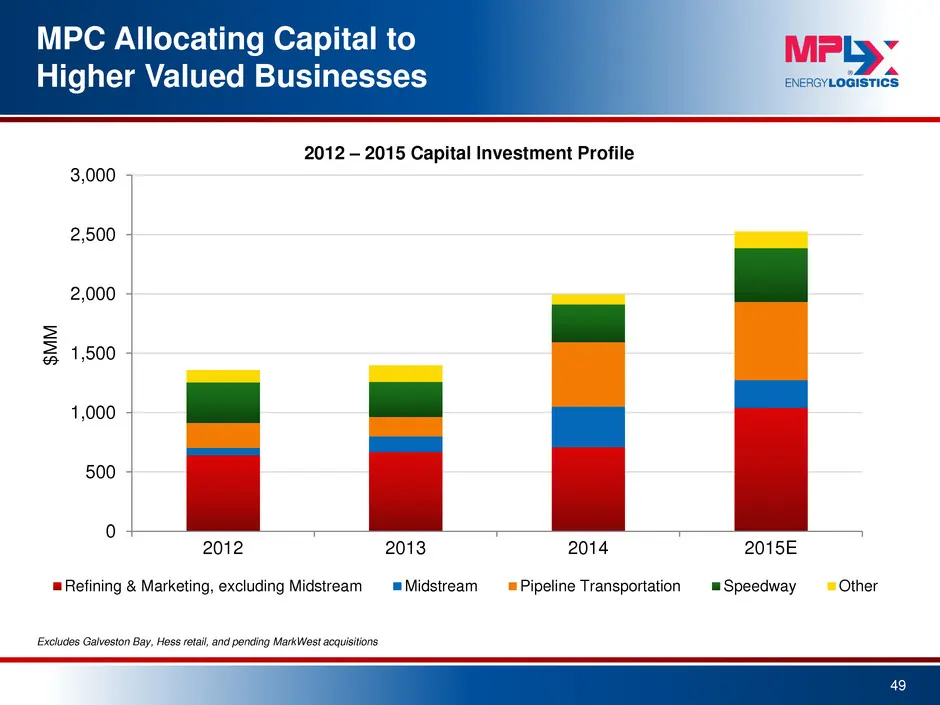
Slide 49: MPC Allocating Capital to Higher Valued Businesses
MPC Allocating Capital to Higher Valued Businesses 49 Excludes Galveston Bay, Hess retail, and pending MarkWest acquisitions 2012 – 2015 Capital Investment Profile 0 500 1,000 1,500 2,000 2,500 3,000 2012 2013 2014 2015E $ M M Refining & Marketing, excluding Midstream Midstream Pipeline Transportati
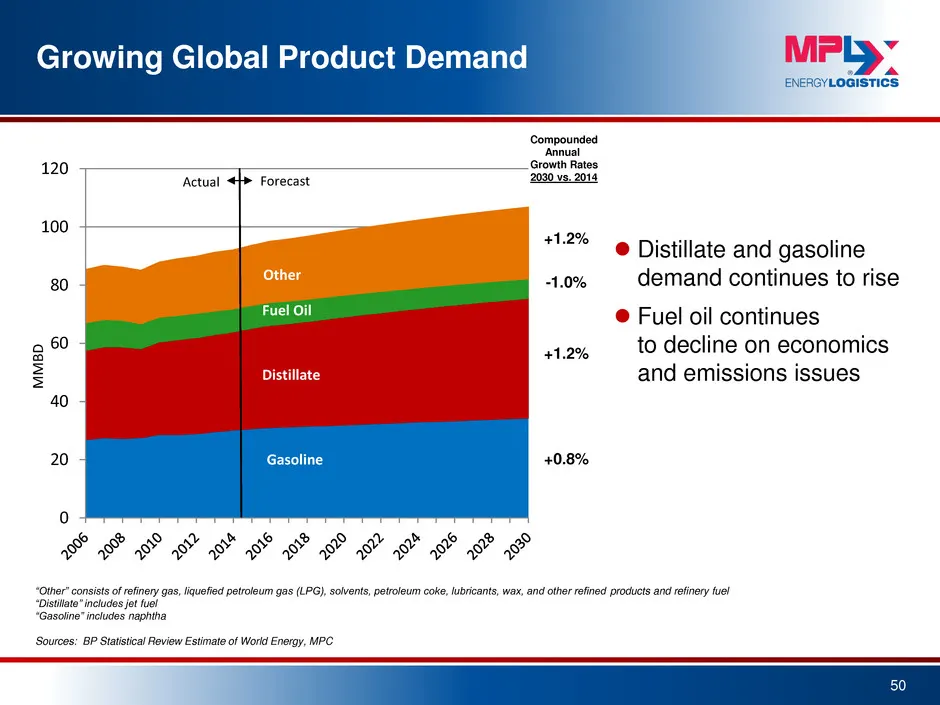
Slide 50: Growing Global Product Demand
Growing Global Product Demand Distillate and gasoline demand continues to rise Fuel oil continues to decline on economics and emissions issues 50 Sources: BP Statistical Review Estimate of World Energy, MPC Gasoline Distillate Fuel Oil Other +1.2% -1.0% +1.2% +0.8% Compounded Annual Growth Rates
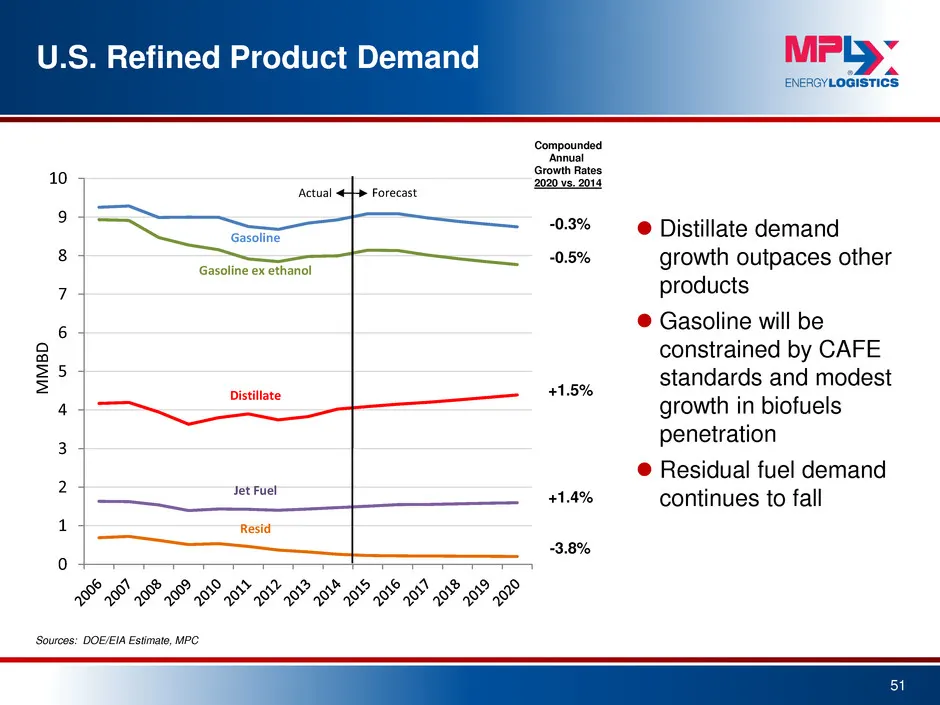
Slide 51: U.S. Refined Product Demand
U.S. Refined Product Demand Distillate demand growth outpaces other products Gasoline will be constrained by CAFE standards and modest growth in biofuels penetration Residual fuel demand continues to fall 51 -0.3% -0.5% +1.5% +1.4% -3.8% Compounded Annual Growth Rates 2020 vs. 2014 Sources: DO
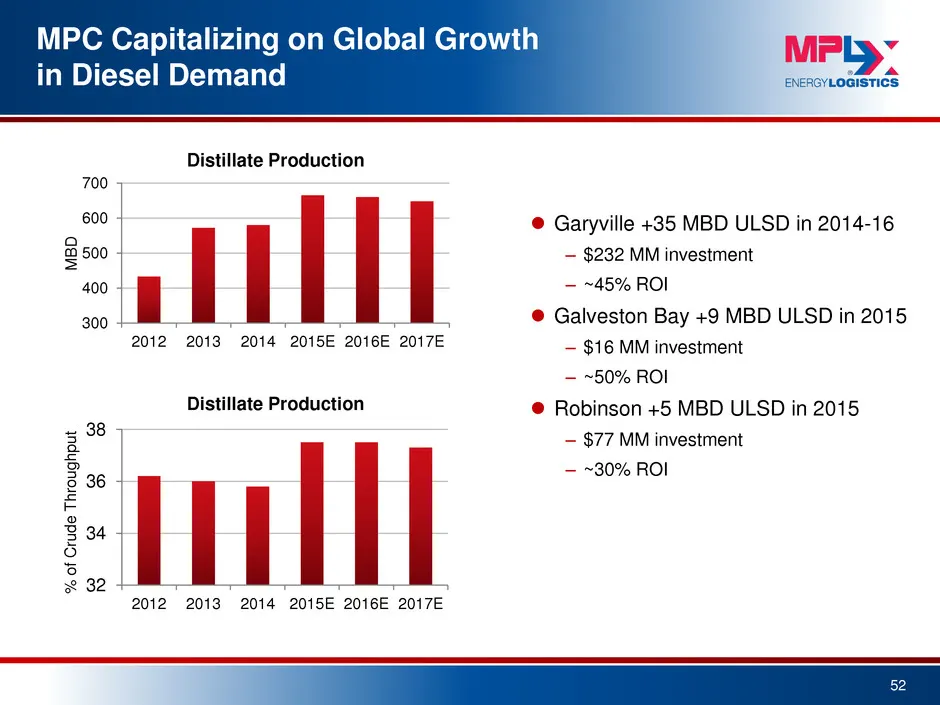
Slide 52: MPC Capitalizing on Global Growth in Diesel Demand
MPC Capitalizing on Global Growth in Diesel Demand Garyville +35 MBD ULSD in 2014-16 – $232 MM investment – ~45% ROI Galveston Bay +9 MBD ULSD in 2015 – $16 MM investment – ~50% ROI Robinson +5 MBD ULSD in 2015 – $77 MM investment – ~30% ROI 52 32 34 36 38 2012 2013 2014 2015E 2016E 2017E % o
Slide 53: Forward Curves
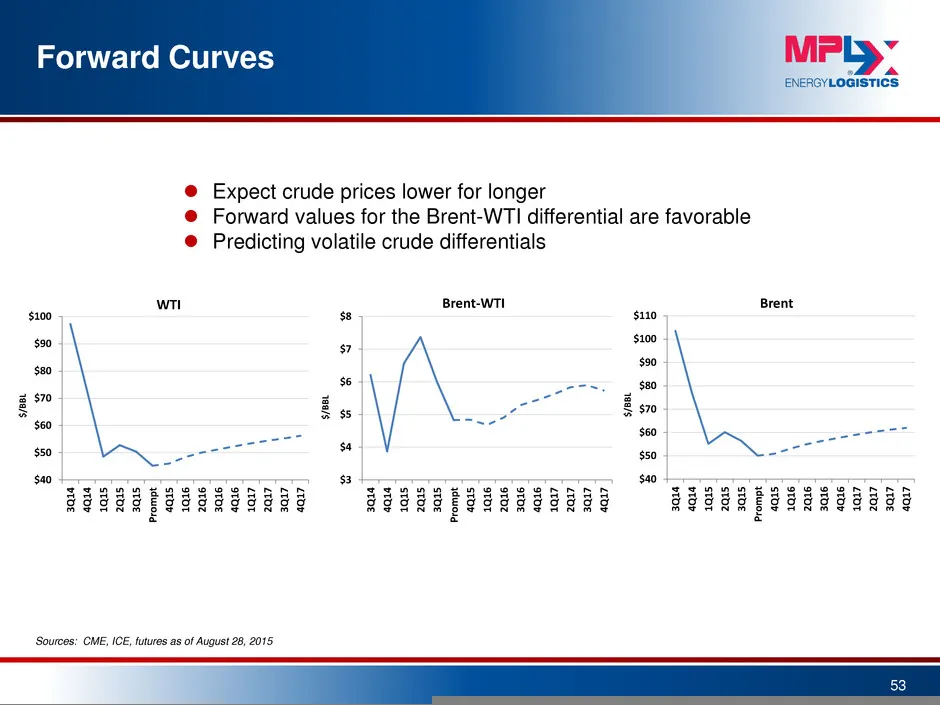
Forward Curves 53 Sources: CME, ICE, futures as of August 28, 2015 Expect crude prices lower for longer Forward values for the Brent-WTI differential are favorable Predicting volatile crude differentials $40 $50 $60 $70 $80 $90 $100 $110 3Q 14 4Q 14 1Q 15 2Q 15 3Q 15 Pr omp t 4Q 15 1Q 16 2Q 16
Slide 54: Sustaining U.S. Refining Advantage
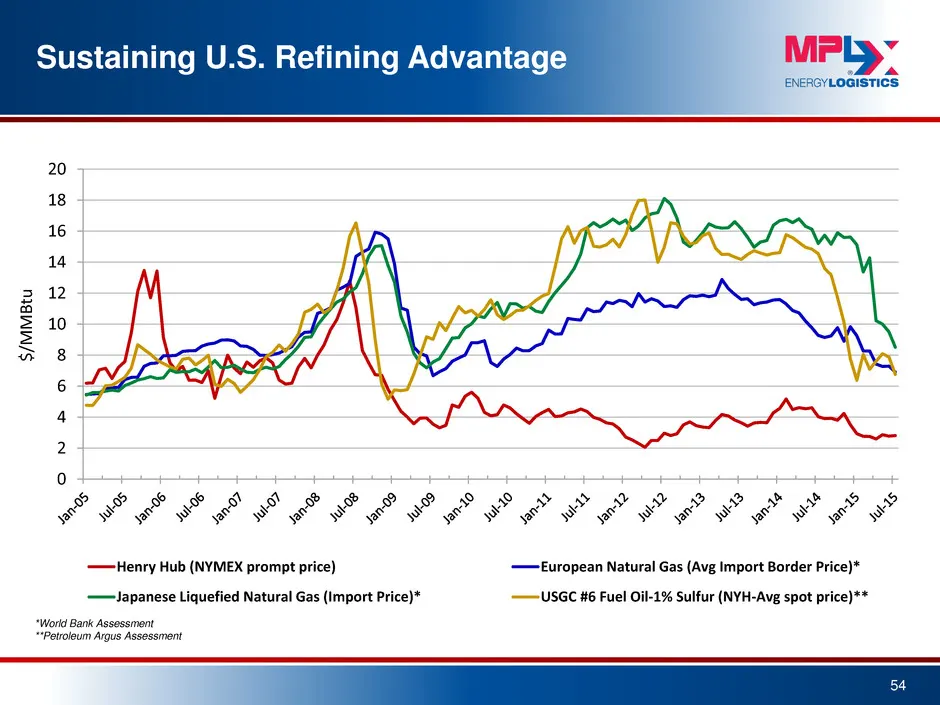
Sustaining U.S. Refining Advantage 54 *World Bank Assessment **Petroleum Argus Assessment 0 2 4 6 8 10 12 14 16 18 20 $ /MM B tu Henry Hub (NYMEX prompt price) European Natural Gas (Avg Import Border Price)* Japanese Liquefied Natural Gas (Import Price)* USGC #6 Fuel Oil-1% Sulfur (NYH-Avg spot pric
Slide 55: U.S. Refined Product Exports Increasing
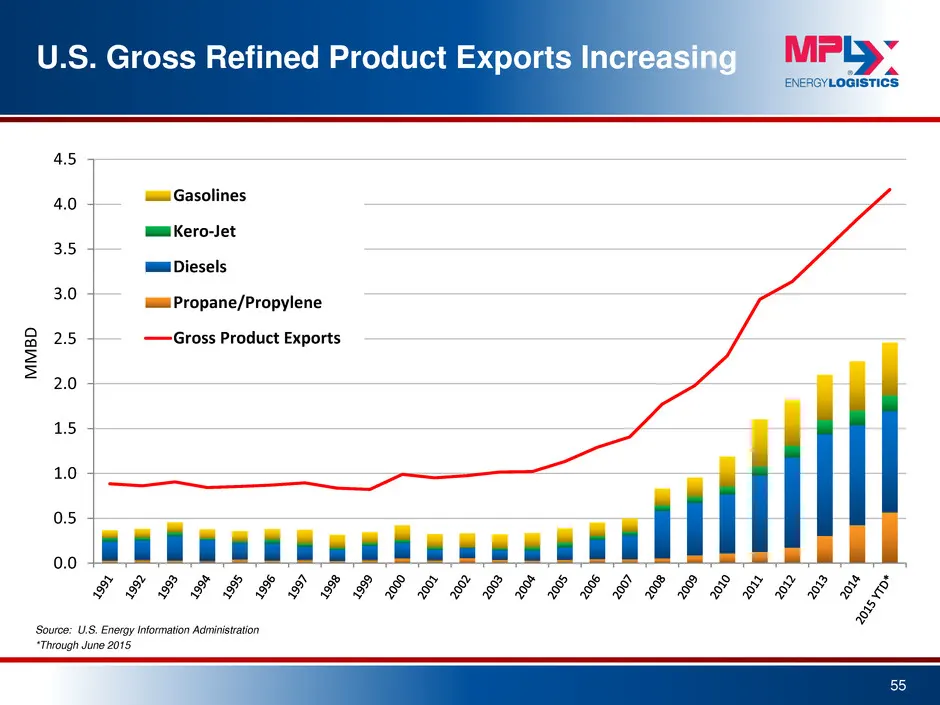
0.0 0.5 1.0 1.5 2.0 2.5 3.0 3.5 4.0 4.5 MMB D Gasolines Kero-Jet Diesels Propane/Propylene Gross Product Exports U.S. Gross Refined Product Exports Increasing 55 Source: U.S. Energy Information Administration *Through June 2015
Slide 56: MPC Growing Gulf Coast Export Capabilities
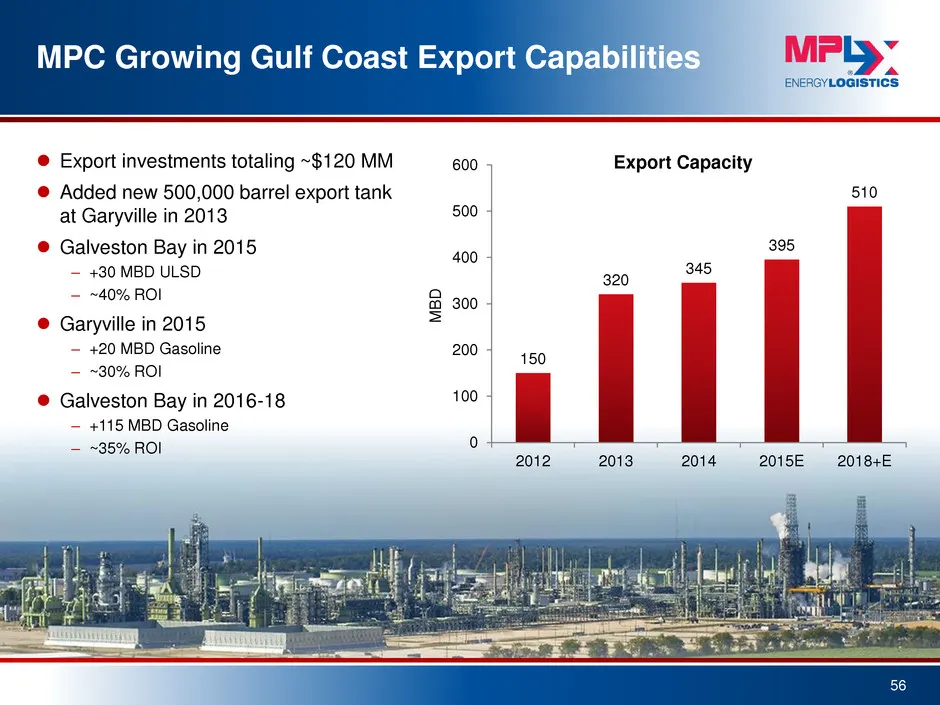
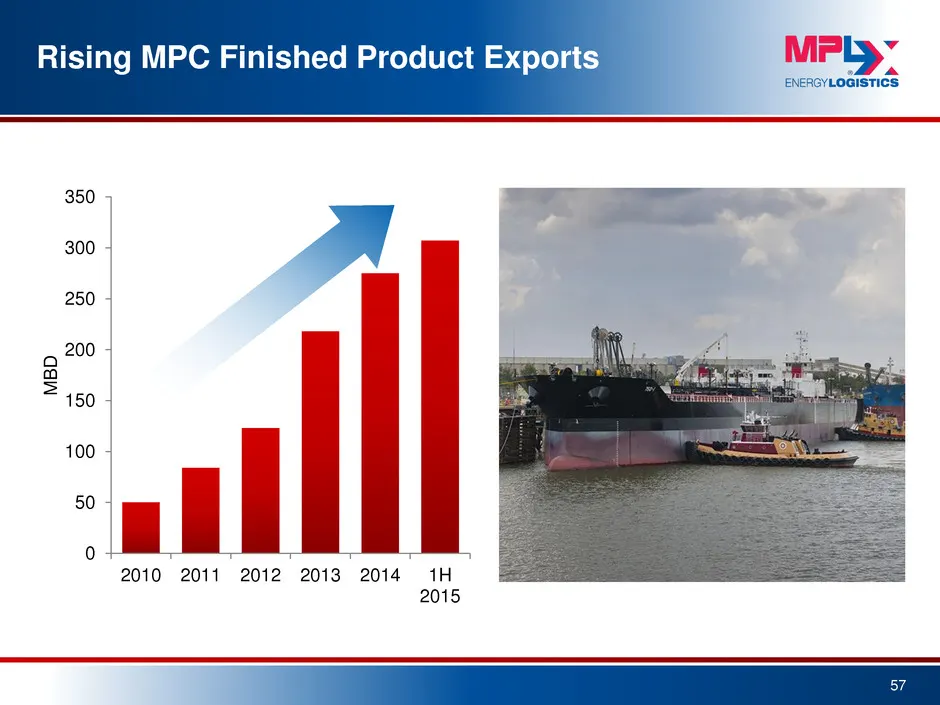
MPC Growing Gulf Coast Export Capabilities Export investments totaling ~$120 MM Added new 500,000 barrel export tank at Garyville in 2013 Galveston Bay in 2015 – +30 MBD ULSD – ~40% ROI Garyville in 2015 – +20 MBD Gasoline – ~30% ROI Galveston Bay in 2016-18 – +115 MBD Gasoline – ~35% ROI
Slide 57: Rising MPC Finished Product Exports
0 50 100 150 200 250 300 350 2010 2011 2012 2013 2014 1H 2015 M B D Rising MPC Finished Product Exports 57
Slide 58: Rising North American Crude & NGLs Production
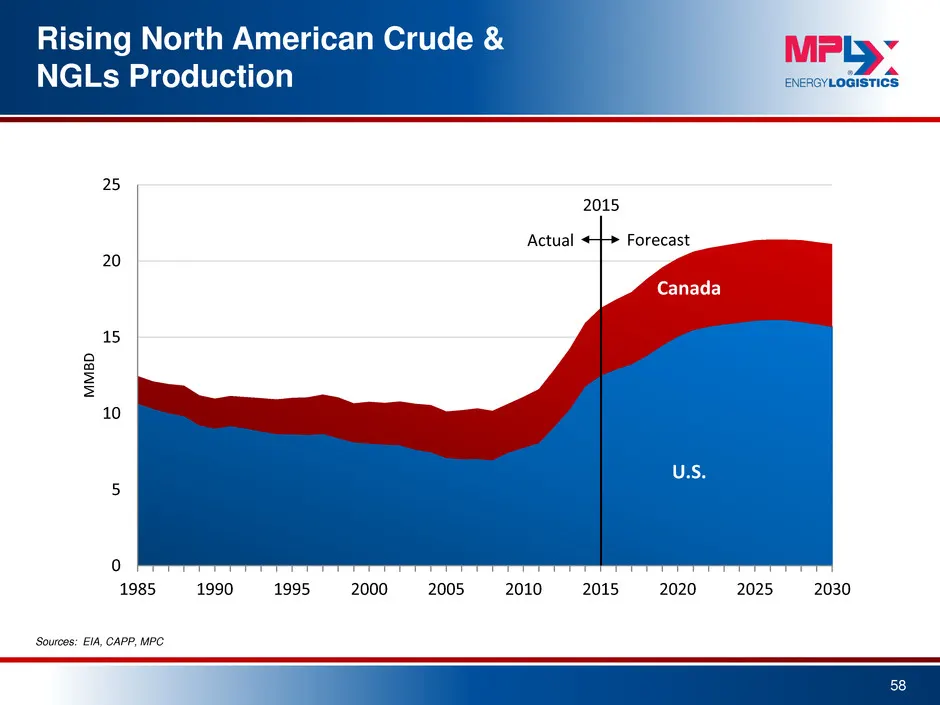
Rising North American Crude & NGLs Production 58 Sources: EIA, CAPP, MPC 0 5 10 15 20 25 1985 1990 1995 2000 2005 2010 2015 2020 2025 2030 M M B D U.S. Canada Forecast Actual 2015
Slide 59: Growing Crude Oil Supply
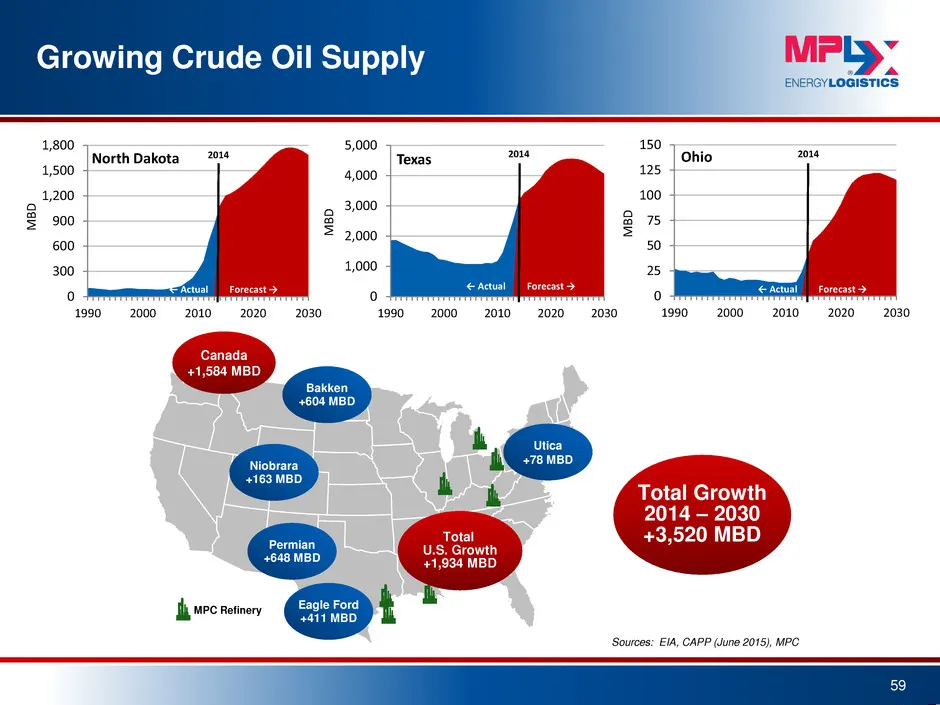
0 300 600 900 1,200 1,500 1,800 1990 2000 2010 2020 2030 MB D North Dakota ← Actual Forecast → 2014 0 1,000 2,000 3,000 4,000 5,000 1990 2000 2010 2020 2030 MB D Texas ← Actual Forecast → 2014 0 25 50 75 100 125 150 1990 2000 2010 2020 2030 MB D Ohio ← Actual Forecast → 2014 Total Growth 2014 – 2030
Slide 60: Refining Capacity in Advantaged Regions
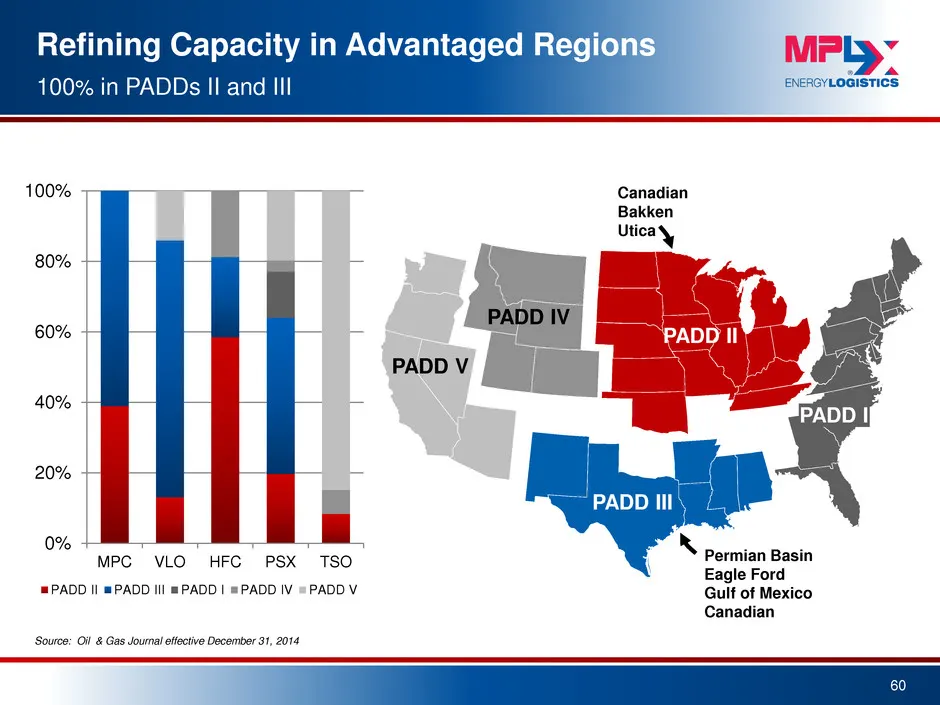
Refining Capacity in Advantaged Regions 60 100% in PADDs II and III 0% 20% 40% 60% 80% 100% MPC VLO HFC PSX TSO PADD II PADD III PADD I PADD IV PADD V Source: Oil & Gas Journal effective December 31, 2014 PADD III PADD V PADD IV PADD II Canadian Bakken Utica Permian Basin Eagle Ford Gulf of Mexico C
Slide 61: Compelling Advantage for Pipeline and Marine
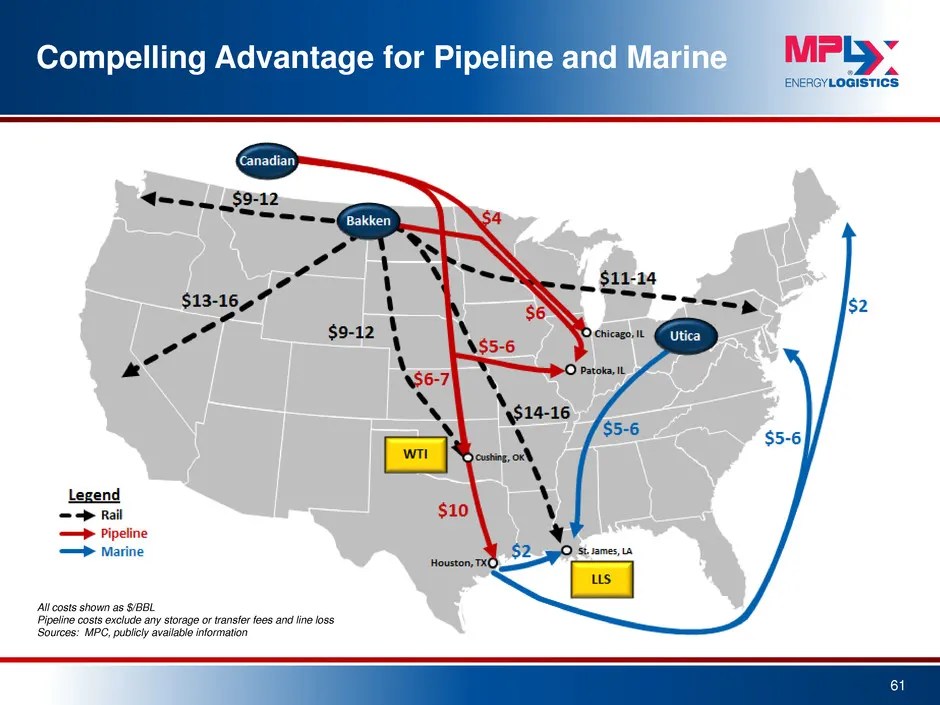
Compelling Advantage for Pipeline and Marine 61 All costs shown as $/BBL Pipeline costs exclude any storage or transfer fees and line loss Sources: MPC, publicly available information
Slide 62: MPC Creating Crude/Condensate Advantage
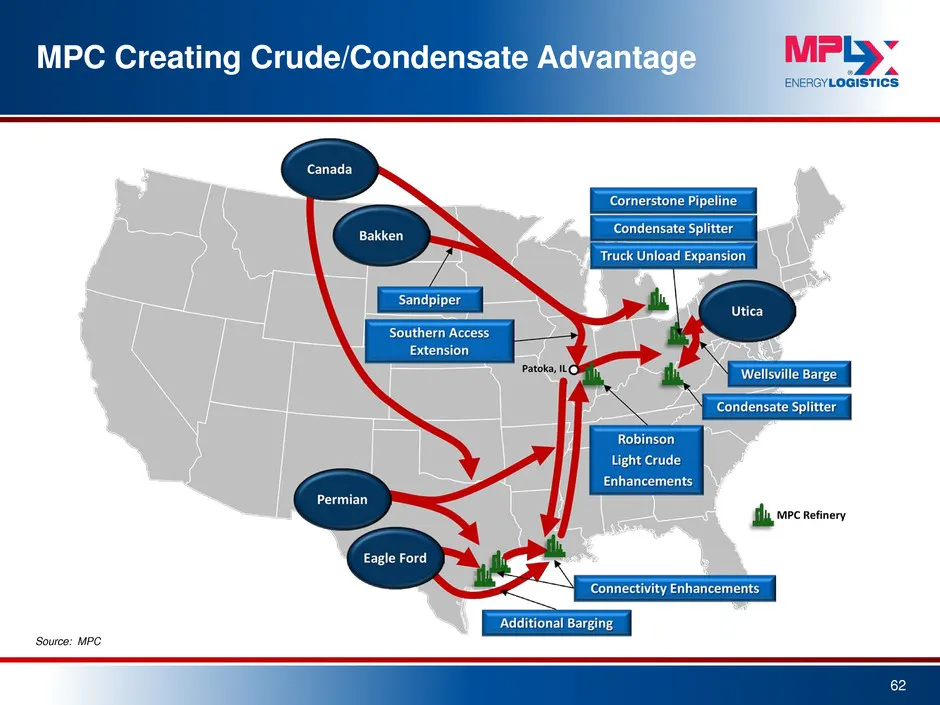
MPC Creating Crude/Condensate Advantage 62 Source: MPC
Slide 63: U.S./Canada Key Existing and Planned Pipelines
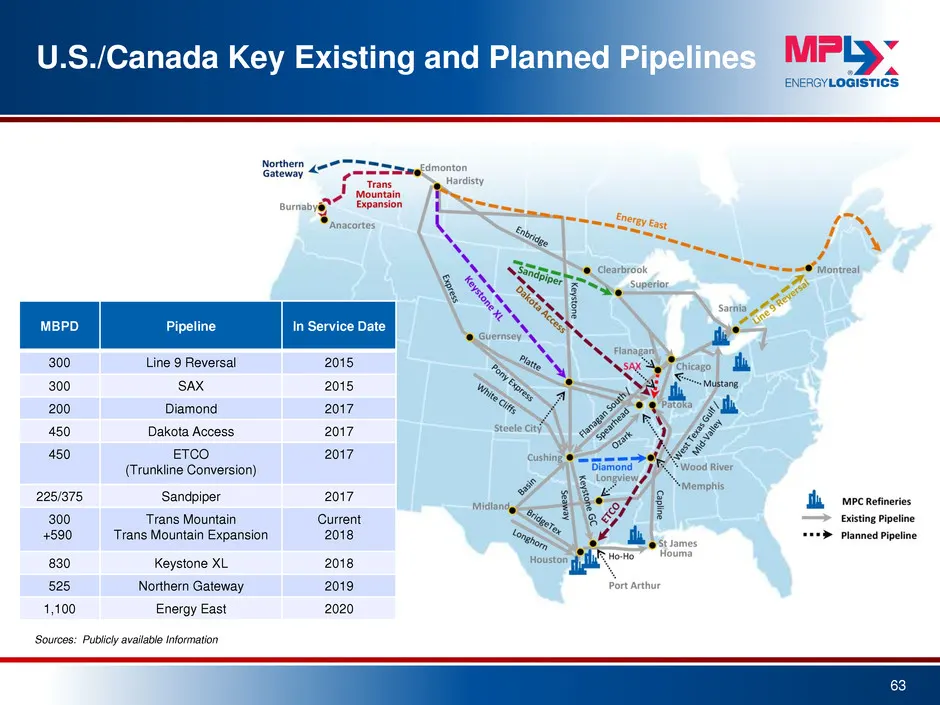
U.S./Canada Key Existing and Planned Pipelines 63 Sources: Publicly available Information MBPD Pipeline In Service Date 300 Line 9 Reversal 2015 300 SAX 2015 200 Diamond 2017 450 Dakota Access 2017 450 ETCO (Trunkline Conversion) 2017 225/375 Sandpiper 2017 300 +590 Trans Mountain Trans Mountain Exp
Slide 64: MPC Balance in Refining Network
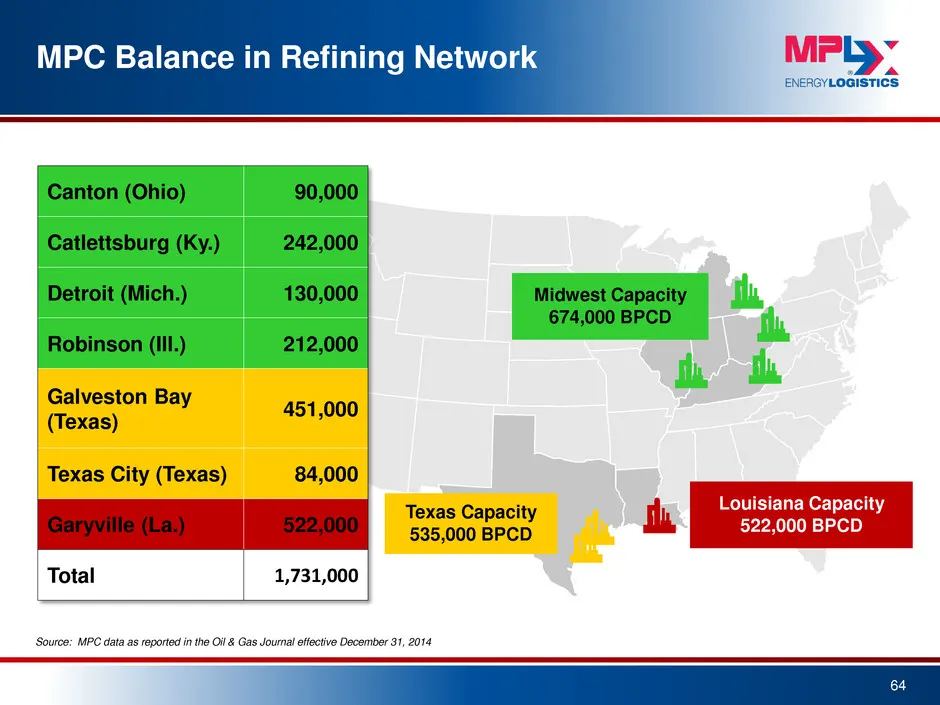
MPC Balance in Refining Network 64 Source: MPC data as reported in the Oil & Gas Journal effective December 31, 2014 Midwest Capacity 674,000 BPCD Louisiana Capacity 522,000 BPCD Texas Capacity 535,000 BPCD Canton (Ohio) 90,000 Catlettsburg (Ky.) 242,000 Detroit (Mich.) 130,000 Robinson (Ill.) 212,0
Slide 65: MPC Key Strengths
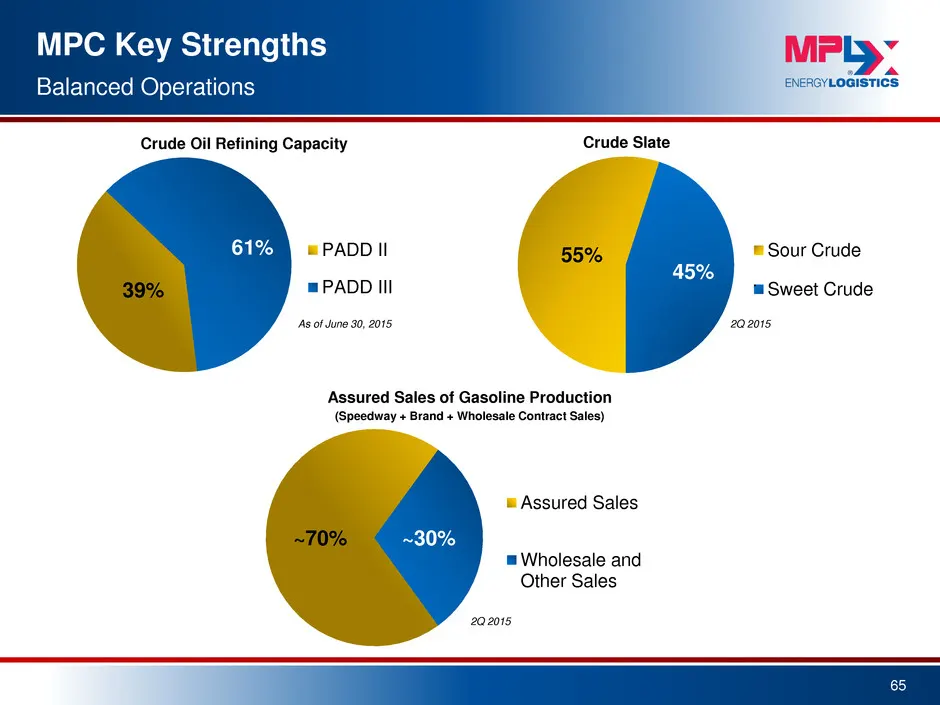
MPC Key Strengths 65 Balanced Operations 39% 61% Crude Oil Refining Capacity PADD II PADD III 55% 45% Crude Slate Sour Crude Sweet Crude ~70% ~30% Assured Sales Wholesale and Other Sales Assured Sales of Gasoline Production (Speedway + Brand + Wholesale Contract Sales) As of June 30, 2015 2Q 2015 2Q
Slide 66: MPC Increasing Light Sweet Crude and Condensate Capacity
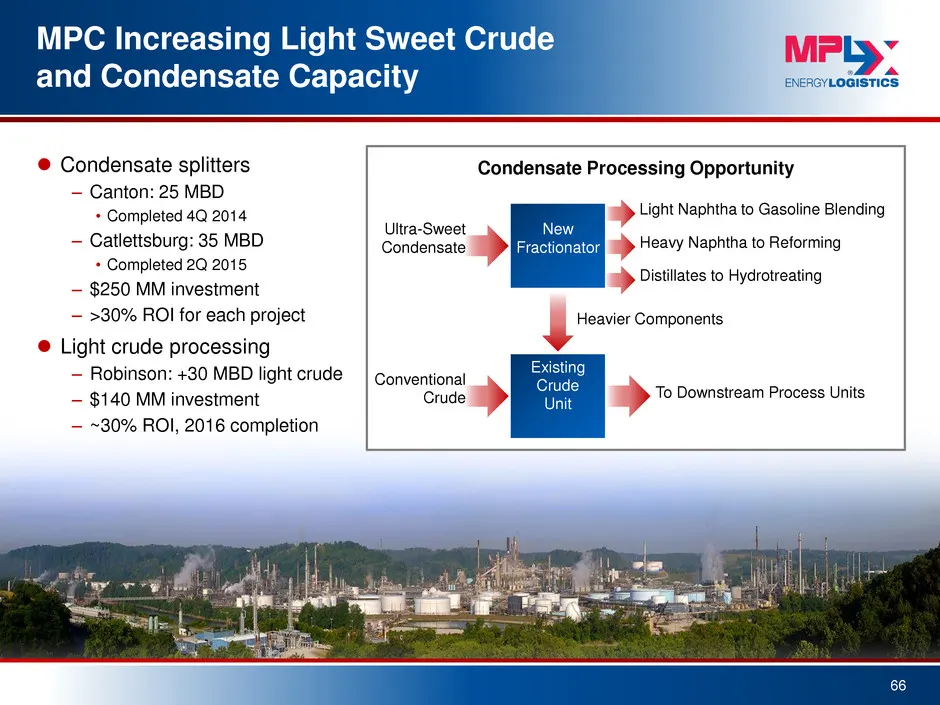
MPC Increasing Light Sweet Crude and Condensate Capacity 66 Condensate splitters – Canton: 25 MBD • Completed 4Q 2014 – Catlettsburg: 35 MBD • Completed 2Q 2015 – $250 MM investment – >30% ROI for each project Light crude processing – Robinson: +30 MBD light crude – $140 MM investment – ~30% ROI
Slide 67: MPC Leveraging Existing Capacity to Run Light Sweet Crude
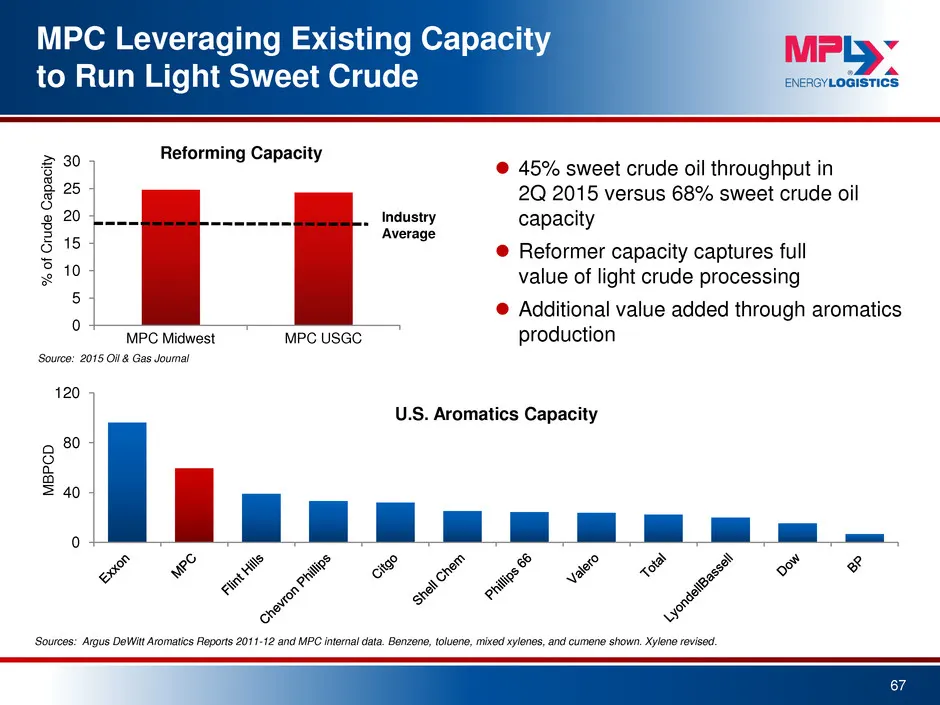
MPC Leveraging Existing Capacity to Run Light Sweet Crude 45% sweet crude oil throughput in 2Q 2015 versus 68% sweet crude oil capacity Reformer capacity captures full value of light crude processing Additional value added through aromatics production 67 0 5 10 15 20 25 30 MPC Midwest MPC USGC
Slide 68: Galveston Bay Driving Value
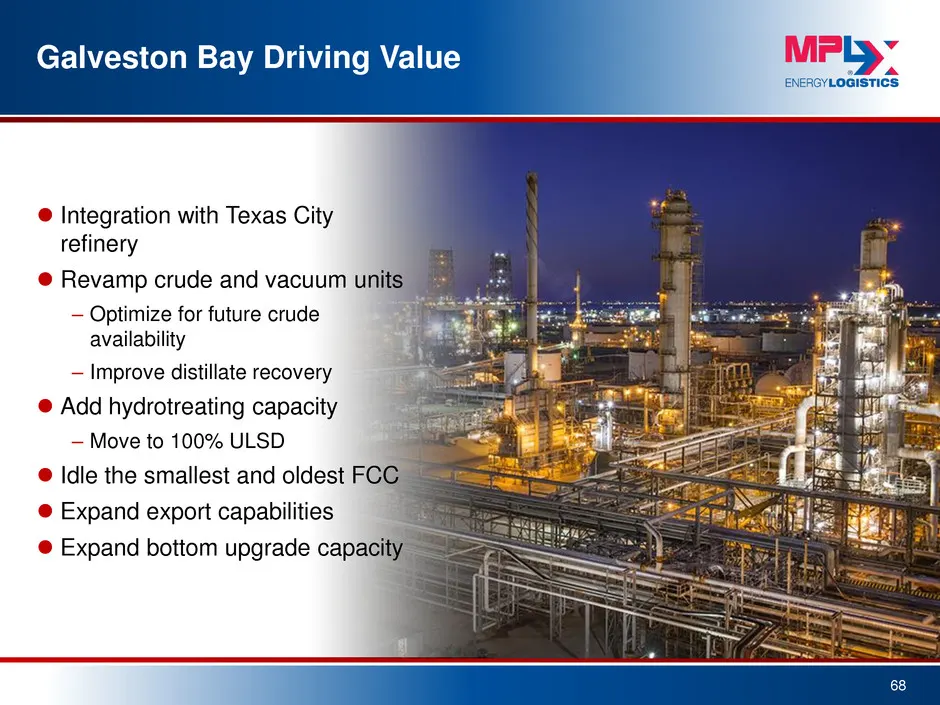
Galveston Bay Driving Value 68 Integration with Texas City refinery Revamp crude and vacuum units – Optimize for future crude availability – Improve distillate recovery Add hydrotreating capacity – Move to 100% ULSD Idle the smallest and oldest FCC Expand export capabilities Expand botto
Slide 69: Speedway Value
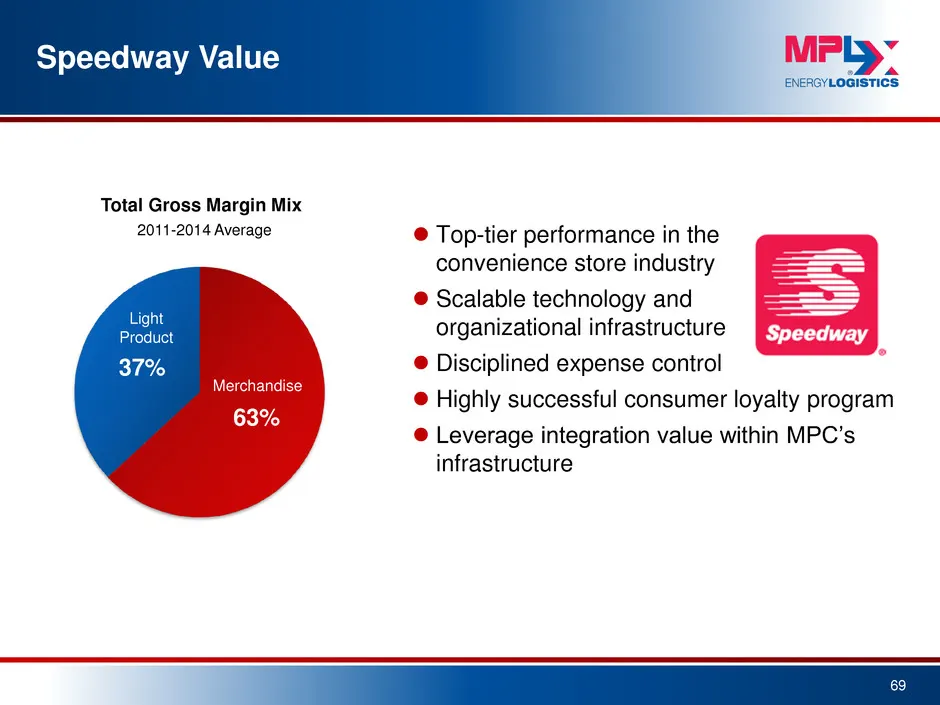
Speedway Value Top-tier performance in the convenience store industry Scalable technology and organizational infrastructure Disciplined expense control Highly successful consumer loyalty program Leverage integration value within MPC’s infrastructure 69 63% 37% Total Gross Margin Mix Light
Slide 70: MPC Acquisition of Hess Retail Transaction Overview
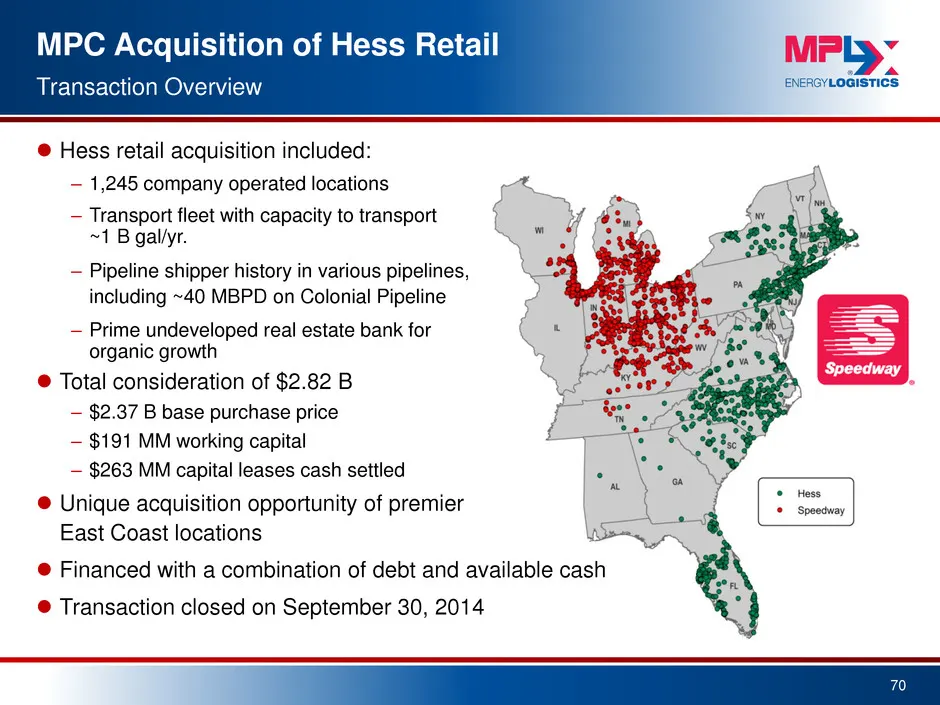
MPC Acquisition of Hess Retail 70 Transaction Overview Hess retail acquisition included: – 1,245 company operated locations – Transport fleet with capacity to transport ~1 B gal/yr. – Pipeline shipper history in various pipelines, including ~40 MBPD on Colonial Pipeline – Prime undeveloped real es
Slide 71: Integration to Best in Class Platform
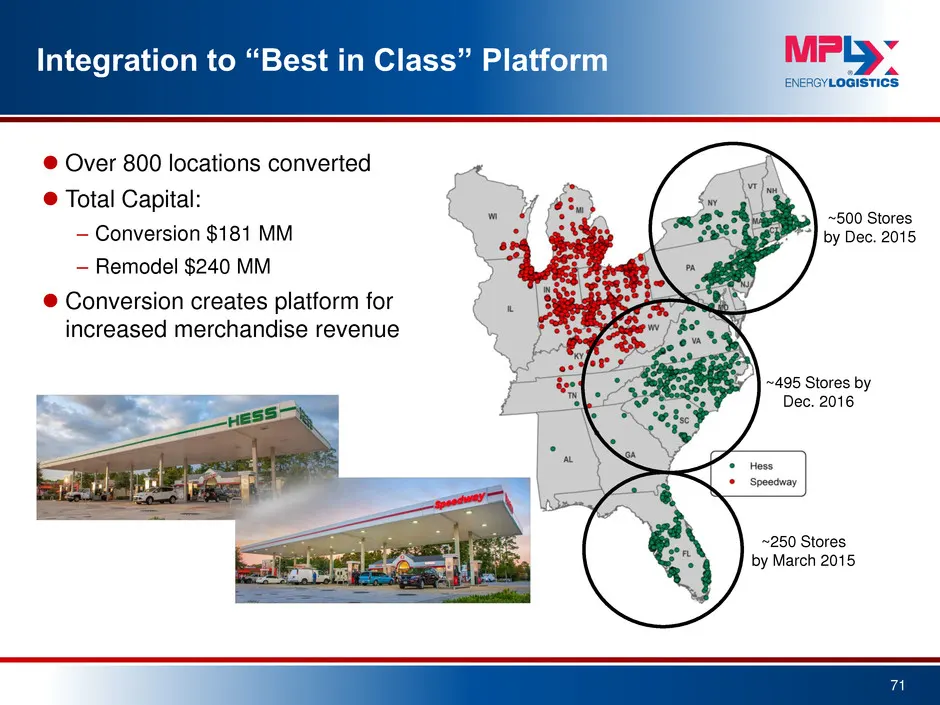
Integration to “Best in Class” Platform 71 ~250 Stores by March 2015 ~500 Stores by Dec. 2015 ~495 Stores by Dec. 2016 Over 800 locations converted Total Capital: – Conversion $181 MM – Remodel $240 MM Conversion creates platform for increased merchandise revenue
Slide 72: Transformative Transaction for MPC and Speedway
Accelerates strategy to grow higher valued and stable cash-flow businesses Provides larger integrated platform for growth in new markets Meaningfully expands scale and provides multiple levels of strategic optionality Continued commitment to balance value enhancing investments in the busines
Slide 73: Enhances Strategic Value for MPC's Integrated System
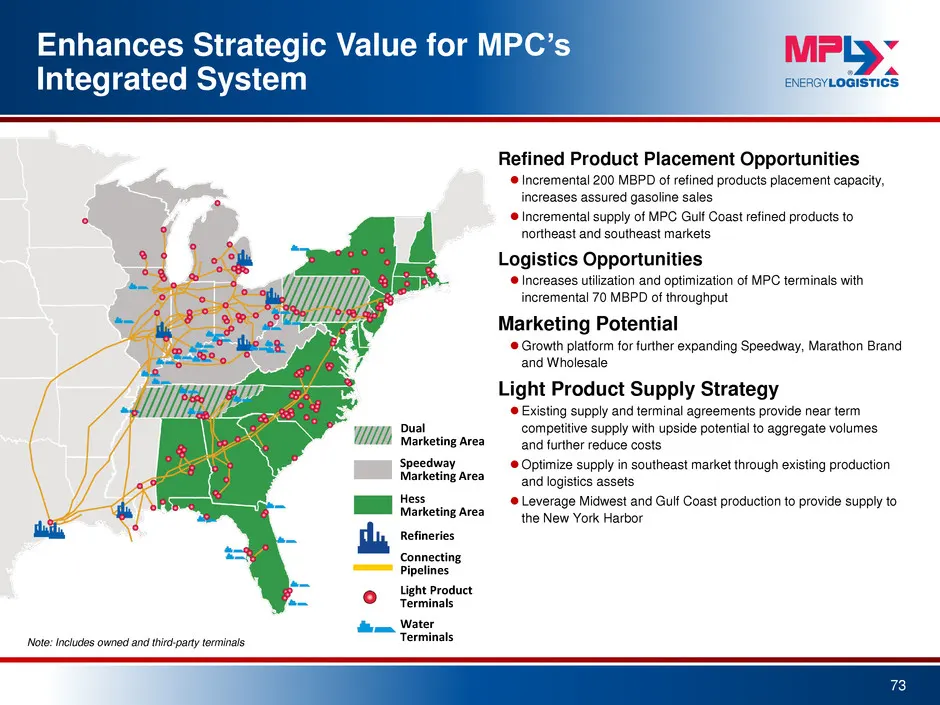
Enhances Strategic Value for MPC’s Integrated System 73 Refined Product Placement Opportunities Incremental 200 MBPD of refined products placement capacity, increases assured gasoline sales Incremental supply of MPC Gulf Coast refined products to northeast and southeast markets Logistics Opportu
Slide 74: Synergies and Marketing Enhancements Will Drive Value for MPC
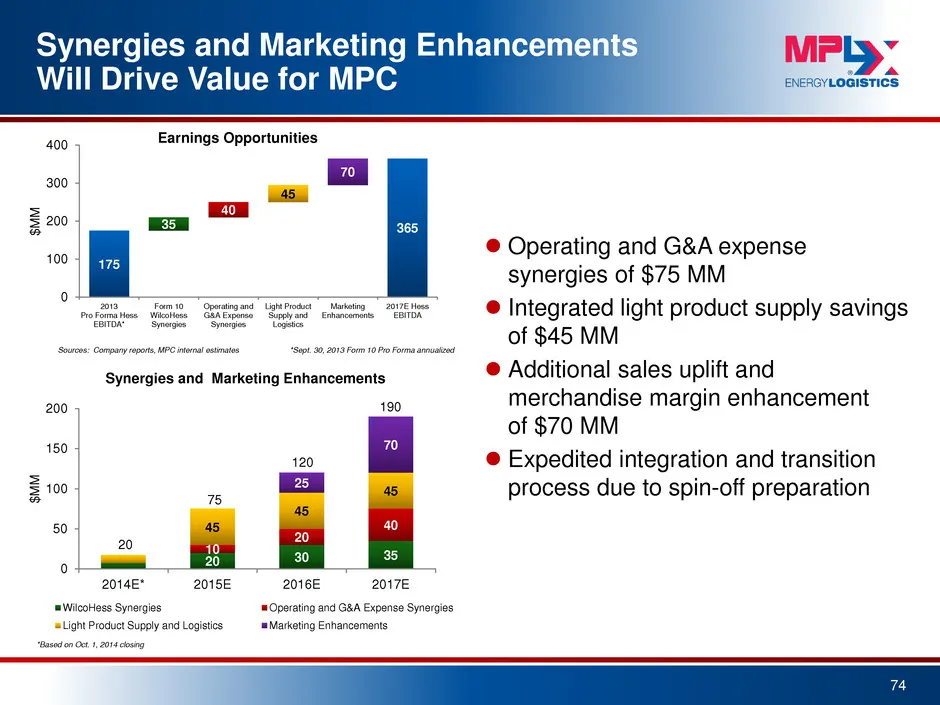
Synergies and Marketing Enhancements Will Drive Value for MPC 74 Operating and G&A expense synergies of $75 MM Integrated light product supply savings of $45 MM Additional sales uplift and merchandise margin enhancement of $70 MM Expedited integration and transition process due to spin-off p
Slide 75: Focus on Improving Light Product Breakeven
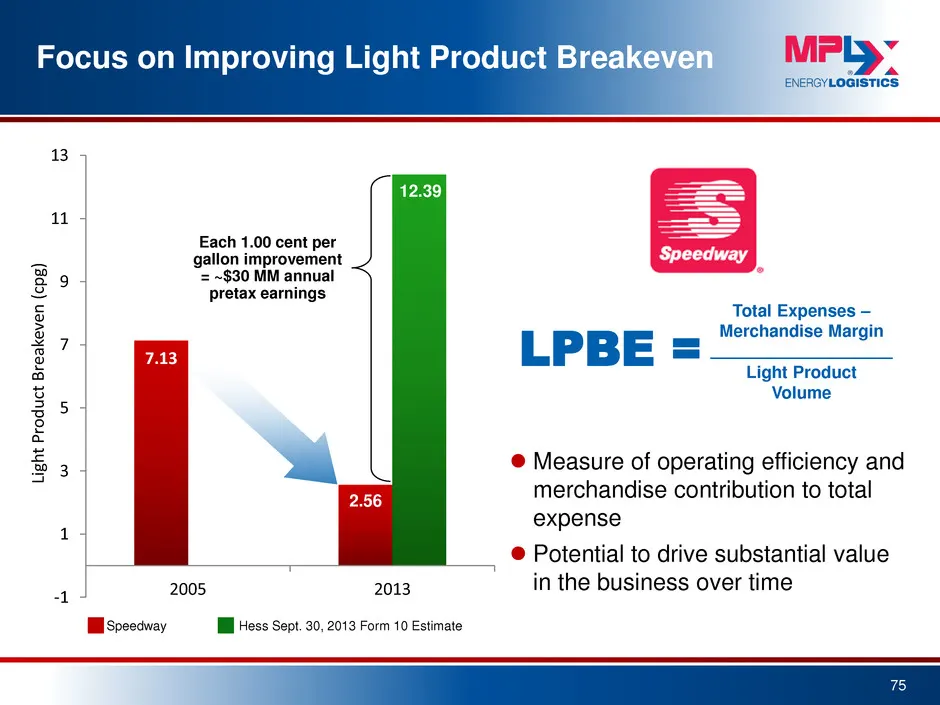
7.13 -1 1 3 5 7 9 11 13 2005 2013 Lig h t P rod u ct B rea ke ve n ( cp g) Focus on Improving Light Product Breakeven Measure of operating efficiency and merchandise contribution to total expense Potential to drive substantial value in the business over time 75 2.56 12.39 Each 1.00 cent per gall
Slide 76: Speedway and Hess Side-by-Side Comparison
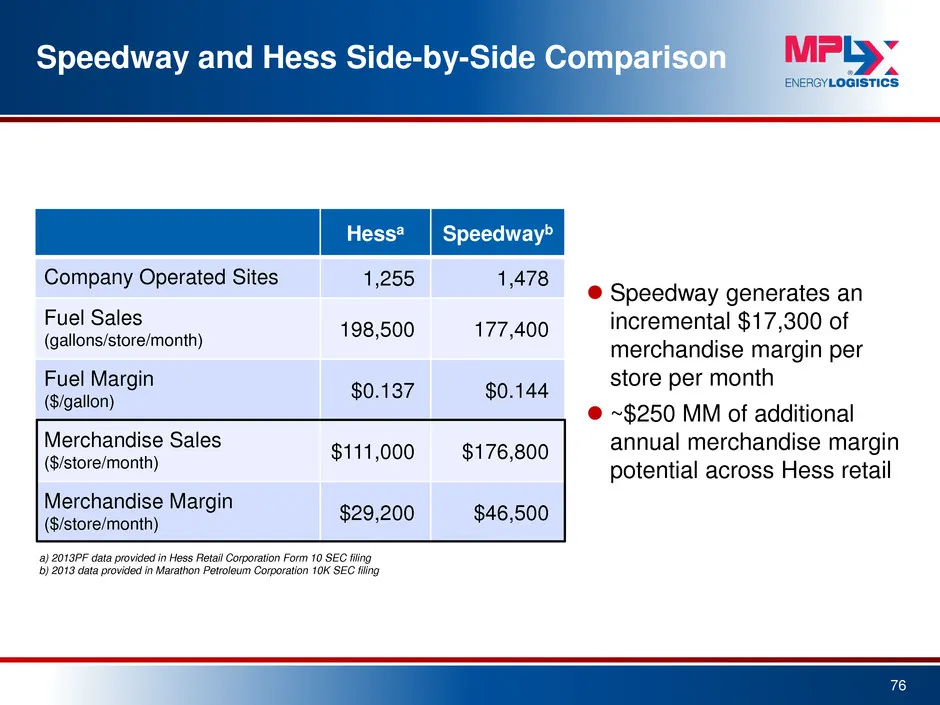
Speedway and Hess Side-by-Side Comparison Speedway generates an incremental $17,300 of merchandise margin per store per month ~$250 MM of additional annual merchandise margin potential across Hess retail 76 Hessa Speedwayb Company Operated Sites 1,255 1,478 Fuel Sales (gallons/store/month) 198,5
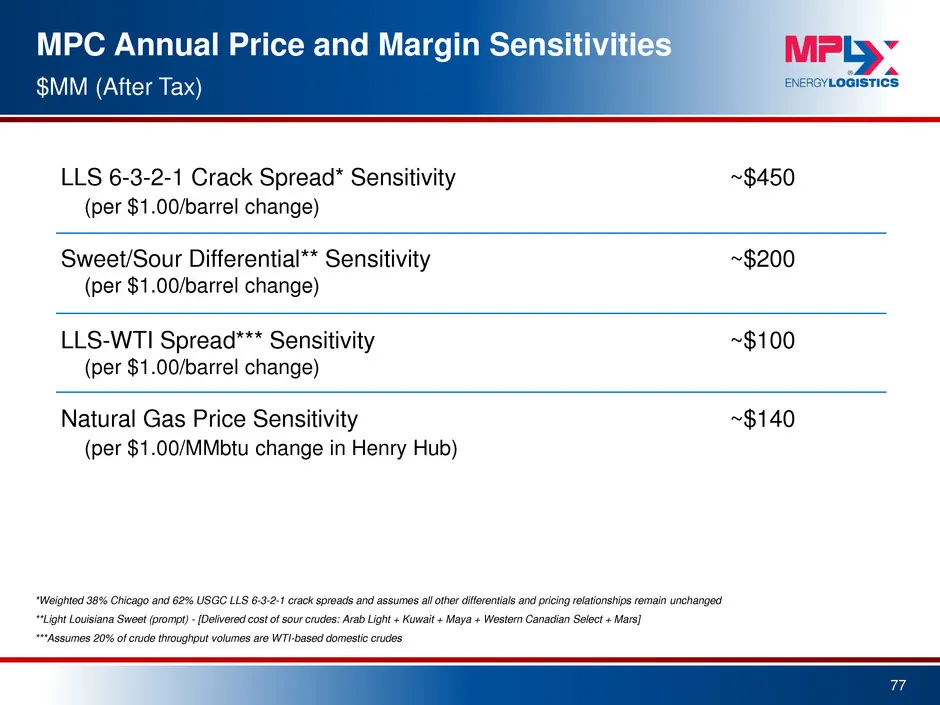
Slide 77: MPC Annual Price and Margin Sensitivities
MPC Annual Price and Margin Sensitivities 77 $MM (After Tax) LLS 6-3-2-1 Crack Spread* Sensitivity ~$450 (per $1.00/barrel change) Sweet/Sour Differential** Sensitivity ~$200 (per $1.00/barrel change) LLS-WTI Spread*** Sensitivity ~$100 (per $1.00/barrel change) Natural Gas Price Sensitivity ~$140 (
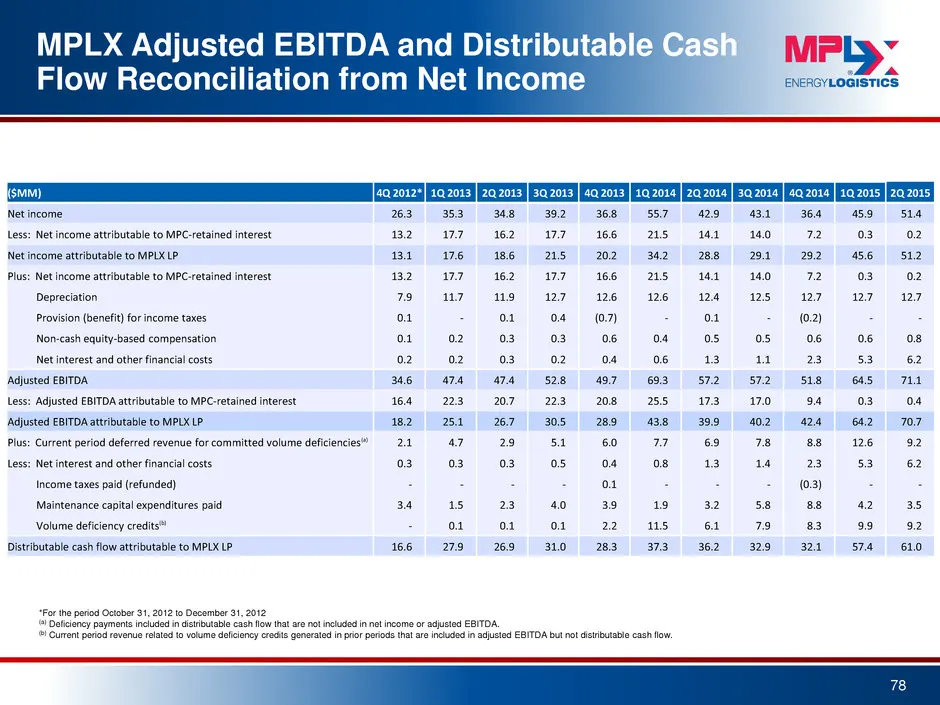
Slide 78: MPLX Adjusted EBITDA and Distributable Cash Flow Reconciliation
MPLX Adjusted EBITDA and Distributable Cash Flow Reconciliation from Net Income 78 *For the period October 31, 2012 to December 31, 2012 (a) Deficiency payments included in distributable cash flow that are not included in net income or adjusted EBITDA. (b) Current period revenue related to volume de
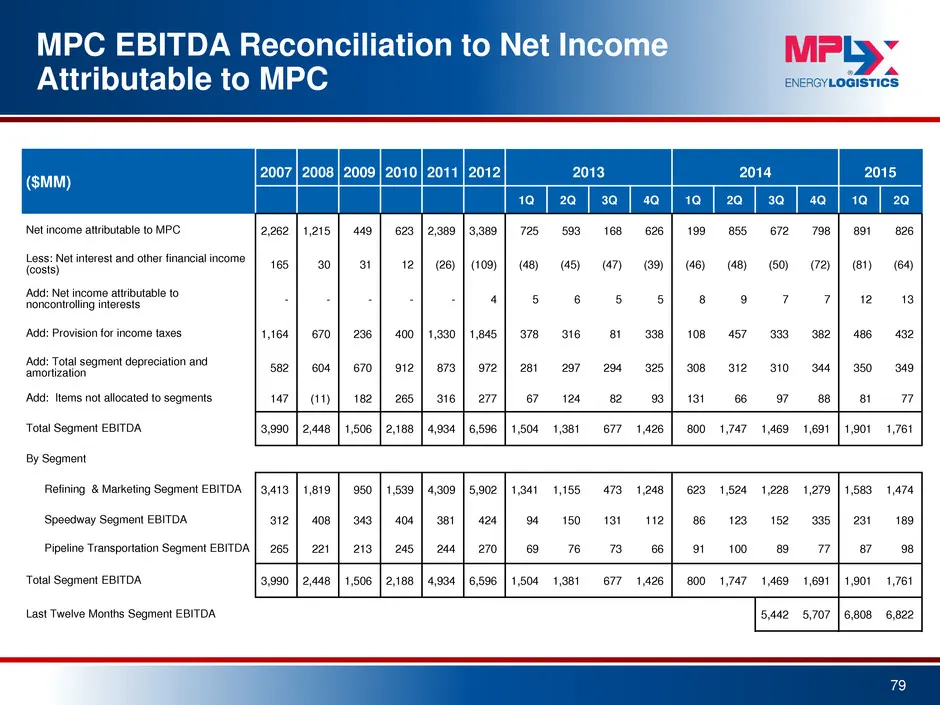
Slide 79: MPC EBITDA Reconciliation to Net Income Attributable to MPC
MPC EBITDA Reconciliation to Net Income Attributable to MPC 79 ($MM) 2007 2008 2009 2010 2011 2012 2013 2014 2015 1Q 2Q 3Q 4Q 1Q 2Q 3Q 4Q 1Q 2Q Net income attributable to MPC 2,262 1,215 449 623 2,389 3,389 725 593 168 626 199 855 672 798 891 826 Less: Net interest and other financial income (costs)
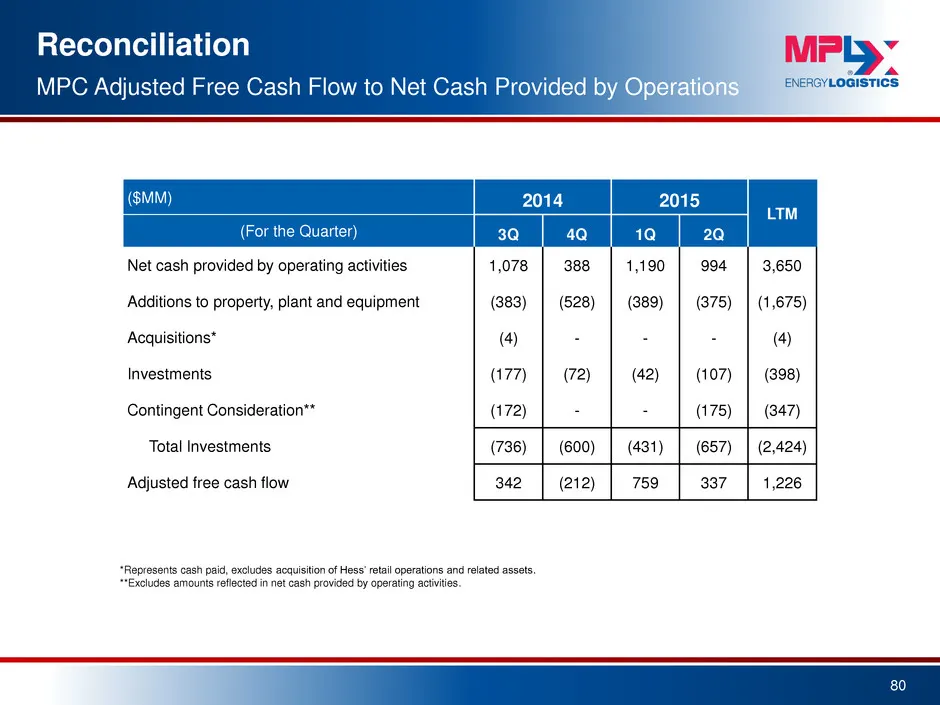
Slide 80: Reconciliation MPC Adjusted Free Cash Flow
Reconciliation 80 MPC Adjusted Free Cash Flow to Net Cash Provided by Operations *Represents cash paid, excludes acquisition of Hess’ retail operations and related assets. **Excludes amounts reflected in net cash provided by operating activities. ($MM) 2014 2015 LTM (For the Quarter) 3Q 4Q 1Q 2Q Net
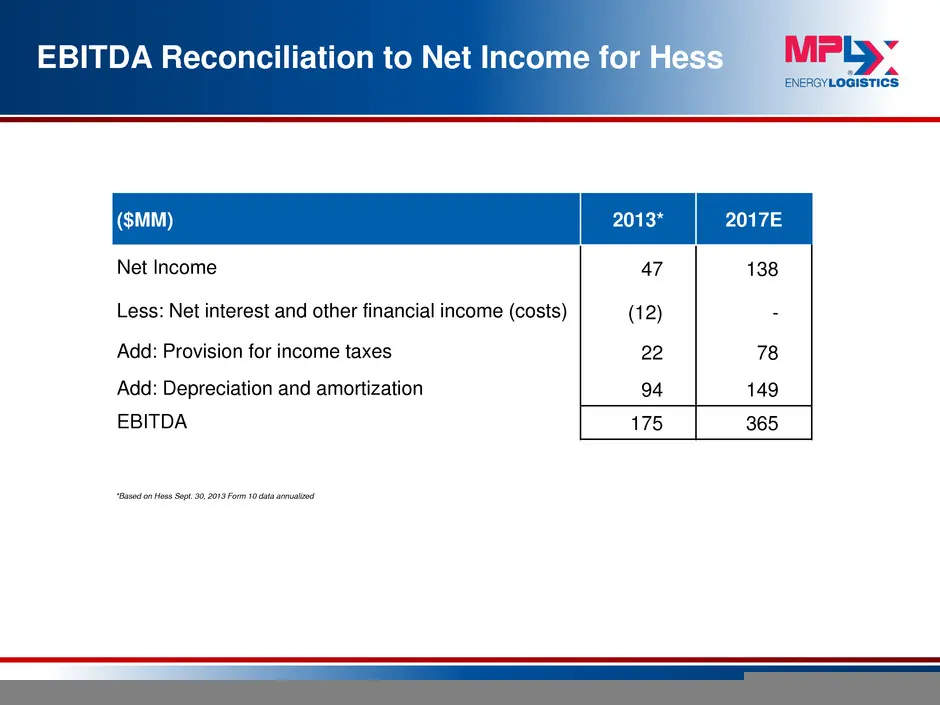
Slide 81: EBITDA Reconciliation to Net Income for Hess
EBITDA Reconciliation to Net Income for Hess 81 *Based on Hess Sept. 30, 2013 Form 10 data annualized ($MM) 2013* 2017E Net Income 47 138 Less: Net interest and other financial income (costs) (12) - Add: Provision for income taxes 22 78 Add: Depreciation and amortization 94 149 EBITDA 175 365
Source: SEC EDGAR · 425 filed Sep 9, 2015
More decks from Markwest Energy Partners LP
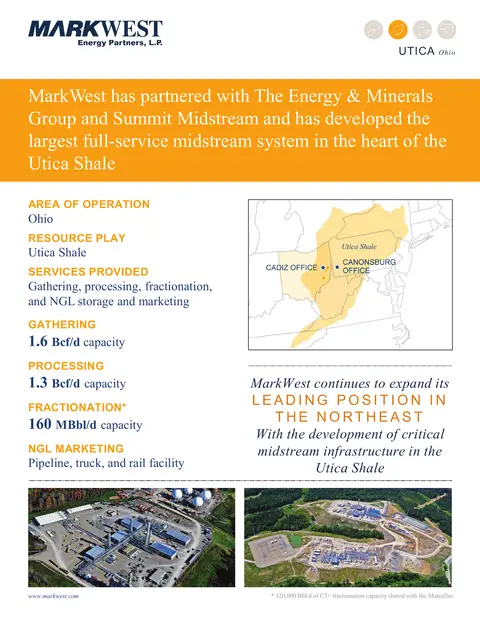 Fact Sheet (July 2017)1 slide · July 2017
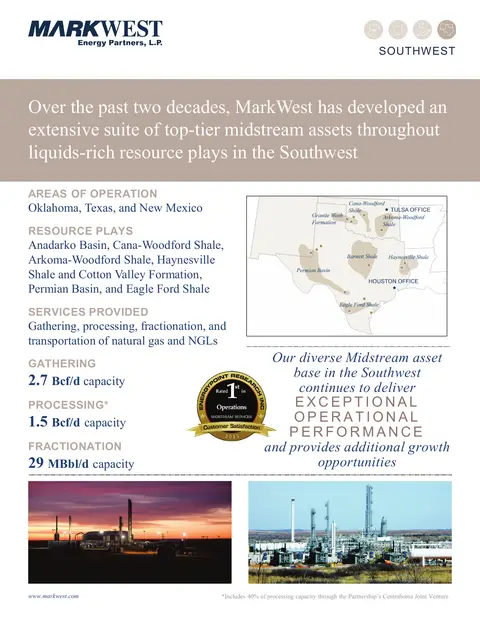 Fact Sheet (July 2017)1 slide · July 2017
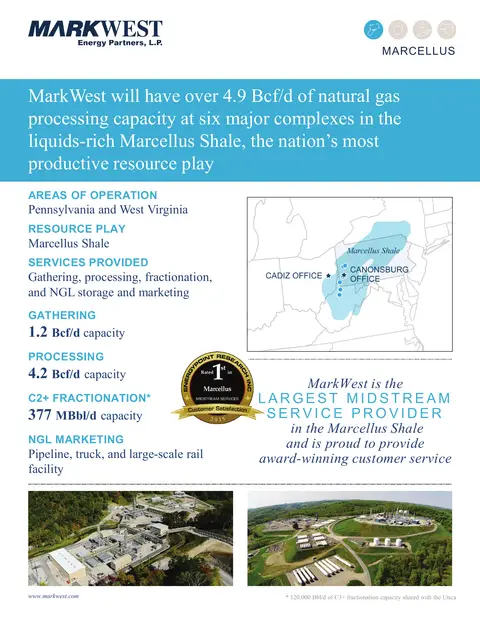 Fact Sheet (July 2017)1 slide · July 2017
 Markwest Energy Partners L P — Investor Day (December 2015)116 slides · Dec 3, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 13, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 12, 2015