Hudson City Bancorp — Barclays Capital Global Financial Services Conference 2010
41 slides from Hudson City Bancorp's conference presentation, Sep 13, 2010
Slide 1: Barclays Capital Global Financial Services Conference September 13, 2010
BARCLAYS CAPITAL GLOBAL FINANCIAL SERVICES CONFERENCE SEPTEMBER 13, 2010
Slide 2: Forward-Looking Statement
Forward-Looking Statement This presentation may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include, but are not limited to, statements about (i) Hudson City Bancorp, Inc.'s "Hudson City" or "HCBK") p
Slide 3: Background
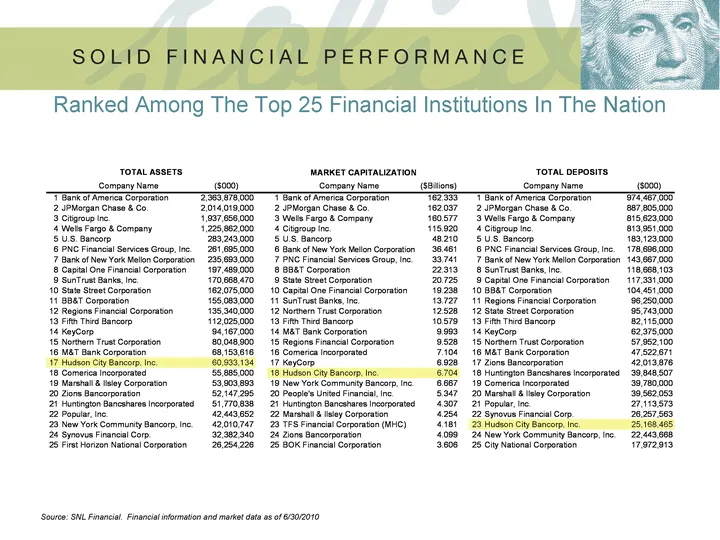
Background Market Cap of $6.28 billion as of June 30, 2010 Ranked #17 of the U.S. financial institutions by asset size Largest thrift institution 135 branch offices in New York, New Jersey and Connecticut
Slide 4: Simple, Consistent Operating Model
Simple, Consistent Operating Model Originate and purchase single family mortgage loans A jumbo originator and purchaser Retain all loans originated and purchased High credit quality Multiple mortgage loan distribution channels Retail (our own agents and extensive branch network) Retail (mortgage bro
Slide 5: Overview of the six months ended June 30, 2010
Overview of the six months ended June 30, 2010 Earnings of $291.5 million or $0.59 diluted earnings per share Asset growth of $665.4 million. Assets decreased $288.5 million during the second quarter of 2010 as we slowed our growth Mortgage loan production of $3.37 billion Deposits increased $590.4
Slide 6: Earnings and Dividends
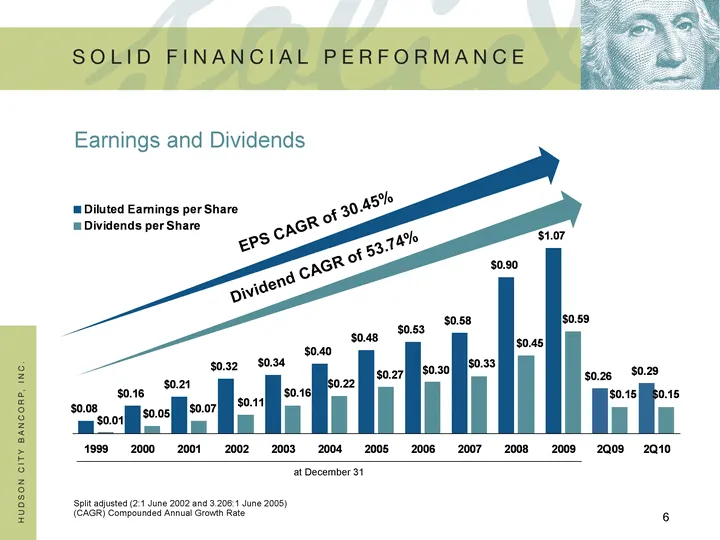
Diluted Earnings per Share Dividends per Share 1999 0.075 0.008 2000 0.162 0.045 2001 0.212 0.073 2002 0.315 0.108 2003 0.34 0.162 2004 0.402 0.218 2005 0.48 0.268 2006 0.53 0.3 2007 0.58 0.33 2008 0.9 0.45 2009 1.07 0.59 2Q09 0.26 0.15 2Q10 0.29 0.15 Split adjusted (2:1 June 2002 and 3.206:1 June 2
Slide 7: Asset Growth
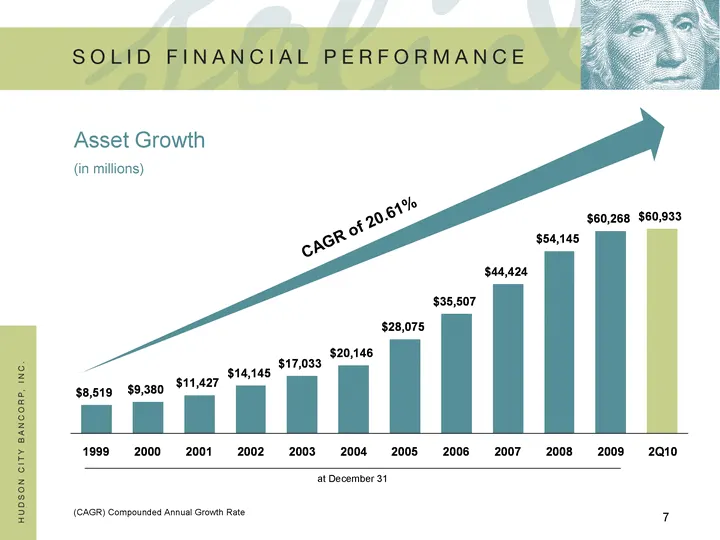
Asset Growth (in millions) (CAGR) Compounded Annual Growth Rate Total Assets 1999 8519 2000 9380.373 2001 11426.768 2002 14144.604 2003 17033.36 2004 20145.981 2005 28075 2006 35507 2007 44424 2008 54145 2009 60268 2Q10 60933 CAGR of 20.61% at December 31
Slide 8: Securities
Securities Securities totaled $27.0 billion, approximately 44% of Balance Sheet as of June 30, 2010 All securities are issued by one of the following government sponsored enterprises carrying an implied credit guarantee FNMA, FHLMC, GNMA, FHLB The high quality of our securities portfolio contributes
Slide 9: Investment Portfolio Composition/Strategy
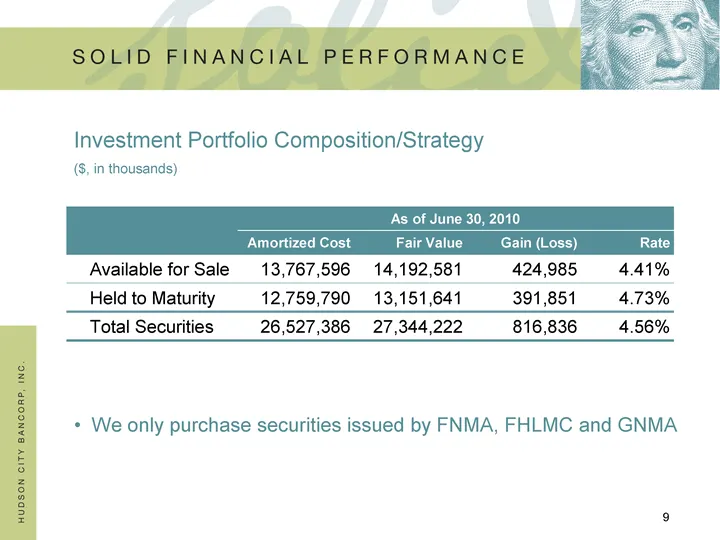
Investment Portfolio Composition/Strategy As of June 30, 2010 As of June 30, 2010 As of June 30, 2010 As of June 30, 2010 Amortized Cost Fair Value Gain (Loss) Rate Available for Sale 13,767,596 14,192,581 424,985 4.41% Held to Maturity 12,759,790 13,151,641 391,851 4.73% Total Securities 26,527,386
Slide 10: Liquidity
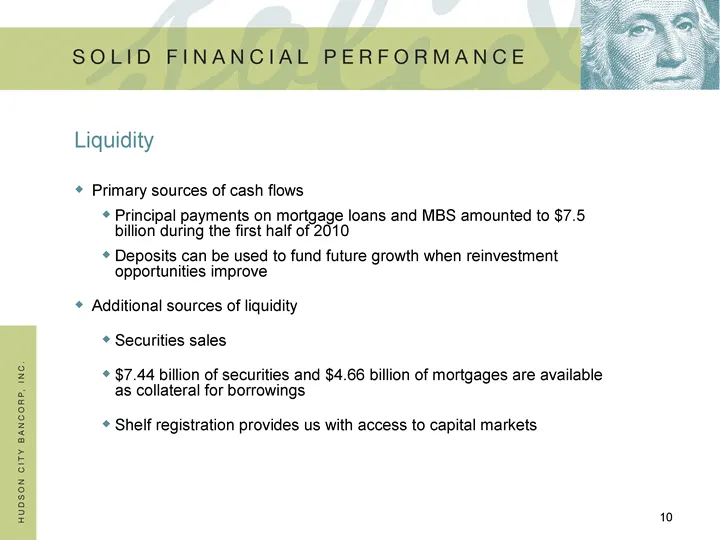
Liquidity Primary sources of cash flows Principal payments on mortgage loans and MBS amounted to $7.5 billion during the first half of 2010 Deposits can be used to fund future growth when reinvestment opportunities improve Additional sources of liquidity Securities sales $7.44 billion of securities
Slide 11: Mortgage Loans
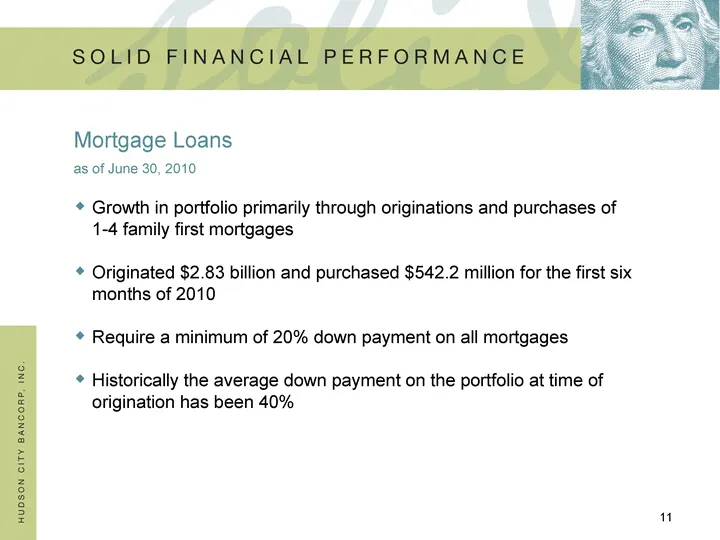
Mortgage Loans Growth in portfolio primarily through originations and purchases of 1-4 family first mortgages Originated $2.83 billion and purchased $542.2 million for the first six months of 2010 Require a minimum of 20% down payment on all mortgages Historically the average down payment on the por
Slide 12: What We Haven't Done...
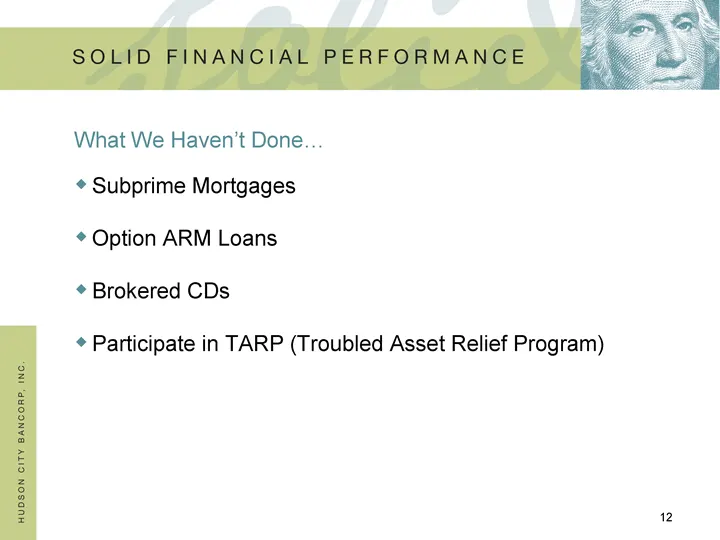
What We Haven't Done... Subprime Mortgages Option ARM Loans Brokered CDs Participate in TARP (Troubled Asset Relief Program)
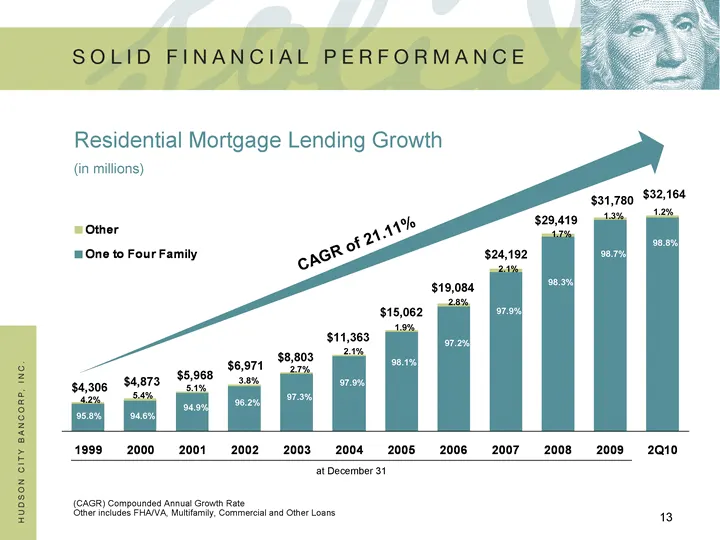
Slide 13: Residential Mortgage Lending Growth
One to Four Family Other 1999 4125.03 180.85 2000 4609.61 263.13 2001 5663.79 304.38 2002 6706.01 264.89 2003 8565.38 237.68 2004 11124.42 238.62 2005 14775.82 286.18 2006 18561.467 522.15 2007 23683.97 508.032 2008 28948 471 2009 31430 350 2Q10 31778.032 385.968 Residential Mortgage Lending Growth
Slide 14: Allowance and Provision Process
Allowance and Provision Process We follow a systematic and disciplined methodology in determining the Allowance for Loan Losses We obtain updated valuations on loans by the time they are 180 days past due, and record charge-offs as required Consider the housing market and economic factors before mak
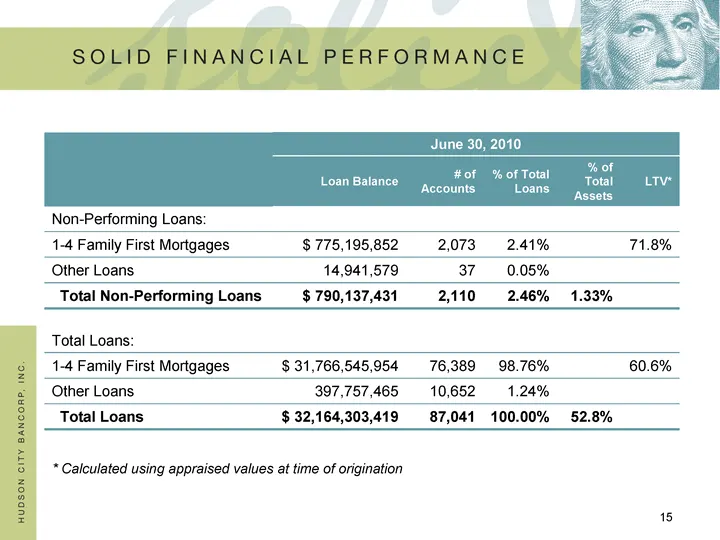
Slide 15: Non-Performing and Total Loans as of June 30, 2010
June 30, 2010 June 30, 2010 June 30, 2010 June 30, 2010 June 30, 2010 Loan Balance # of Accounts % of Total Loans % of Total Assets LTV* Non-Performing Loans: 1-4 Family First Mortgages $ 775,195,852 2,073 2.41% 71.8% Other Loans 14,941,579 37 0.05% Total Non-Performing Loans $ 790,137,431 2,110 2.4
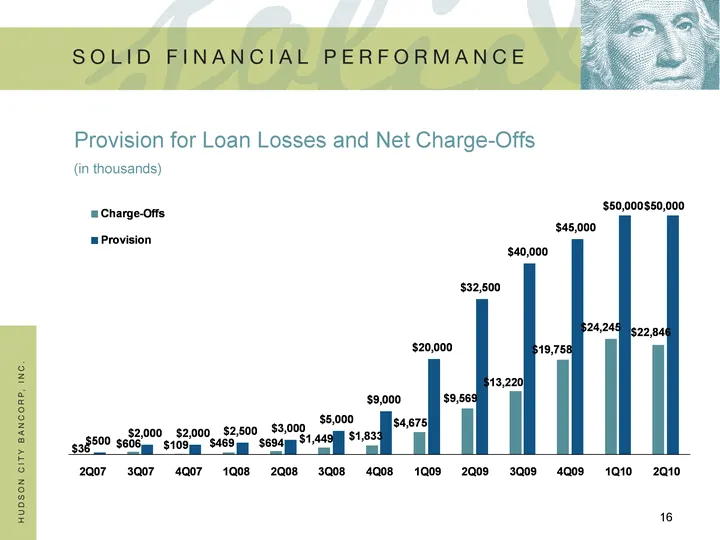
Slide 16: Provision for Loan Losses and Net Charge-Offs
Provision for Loan Losses and Net Charge-Offs Charge-Offs Provision 2Q07 36 500 3Q07 606 2000 4Q07 109 2000 1Q08 469 2500 2Q08 694 3000 3Q08 1449 5000 4Q08 1833 9000 1Q09 4675 20000 2Q09 9569 32500 3Q09 13220 40000 4Q09 19758 45000 1Q10 24245 50000 2Q10 22846 50000 (in thousands)
Slide 17: Asset Quality
Asset Quality The annualized ratio of net charge-offs to average loans was 0.30% for Hudson City as compared to 2.36%* for banks with assets greater than $50 billion Foreclosed real estate was $21.7 million at June 30, 2010, representing 52 properties. We sold 38 foreclosed properties during the fir
Slide 18: Home Price Index for Major U.S. Markets vs. Market Peak
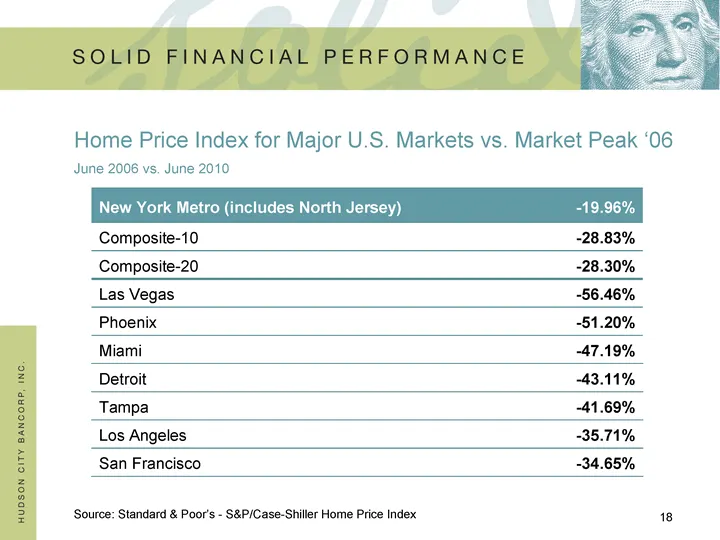
Home Price Index for Major U.S. Markets vs. Market Peak '06 June 2006 vs. June 2010 Source: Standard & Poor's - S&P/Case-Shiller Home Price Index New York Metro (includes North Jersey) -19.96% Composite-10 -28.83% Composite-20 -28.30% Las Vegas -56.46% Phoenix -51.20% Miami -47.19% Detroit -43.11% T
Slide 19: Home Price Index for New York Metro
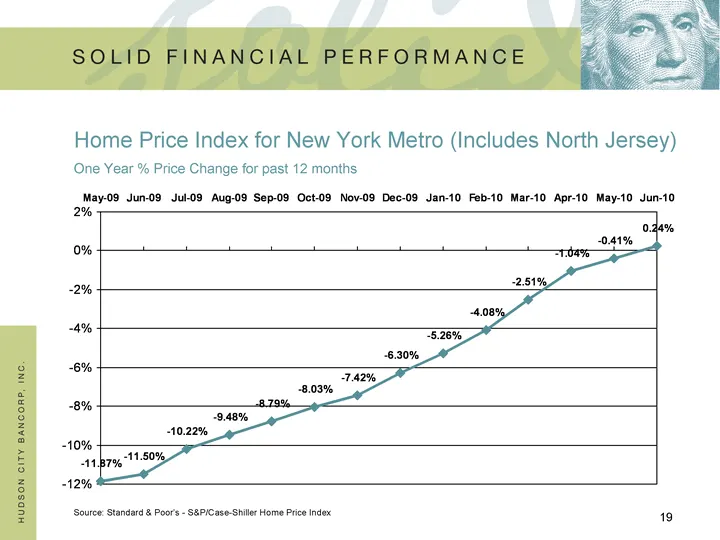
Home Price Index for New York Metro (Includes North Jersey) One Year % Price Change for past 12 months Source: Standard & Poor's - S&P/Case-Shiller Home Price Index 5/1/2009 6/1/2009 7/1/2009 8/1/2009 9/1/2009 10/1/2009 11/1/2009 12/1/2009 1/1/2010 2/1/2010 3/1/2010 4/1/2010 5/1/2010 6/1/2010 NY Met
Slide 20: Loan Geographic Exposure as of June 30, 2010
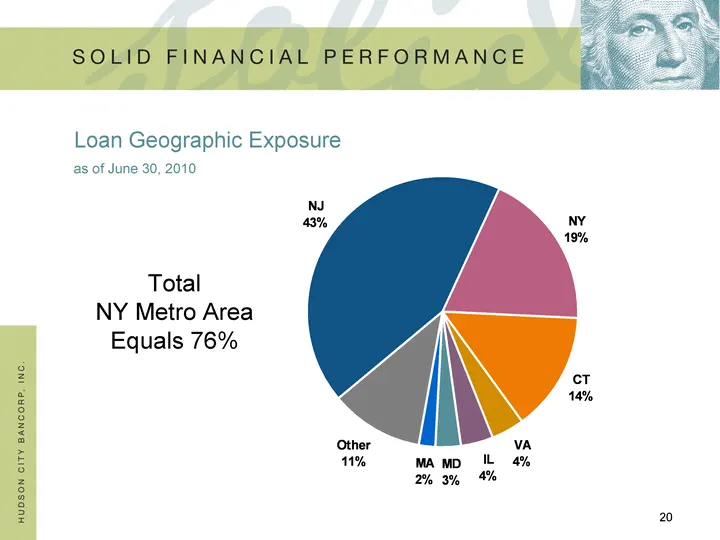
Loan Geographic Exposure as of June 30, 2010 Total NY Metro Area Equals 76% NJ NY CT VA IL MD MA Other 0.43 0.19 0.14 0.04 0.04 0.03 0.02 0.11
Slide 21: Deposits
Deposits Seventeen new branches since January 2008 $10.02 billion added since January 2008 Internet deposits of $248 million since December 2008 $188 million average deposits per branch as of June 30, 2010 hudsoncitysavingsbank.com
Slide 22: Deposit Growth
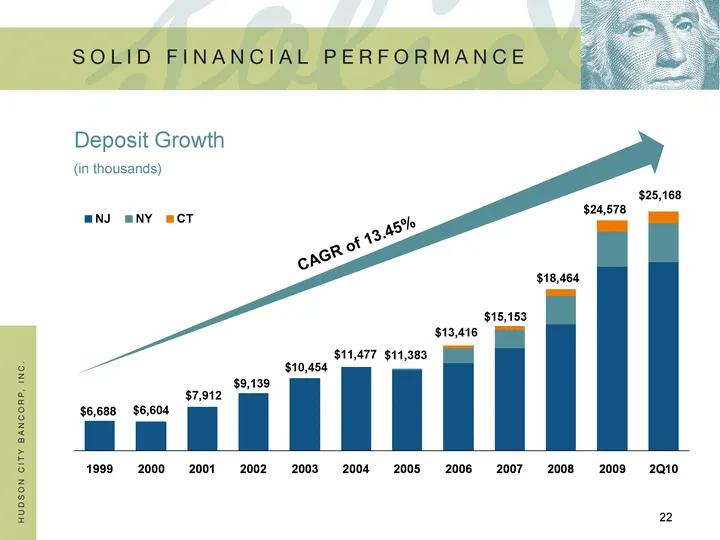
Deposit Growth NJ NY CT 1999 6688.044 0 0 2000 6604.121 0 0 2001 7912.762 0 0 2002 9138.629 0 0 2003 10453.78 0 0 2004 11463.674 13.626 0 2005 11230.96 152.34 0 2006 11833.411 1311.481 270.695 2007 13152.263 1665.786 335.333 2008 15297.492 2521.037 645.513 2009 20419 3172 987 2Q10 20857 3506 1026 (i
Slide 23: Attractive Branch Network
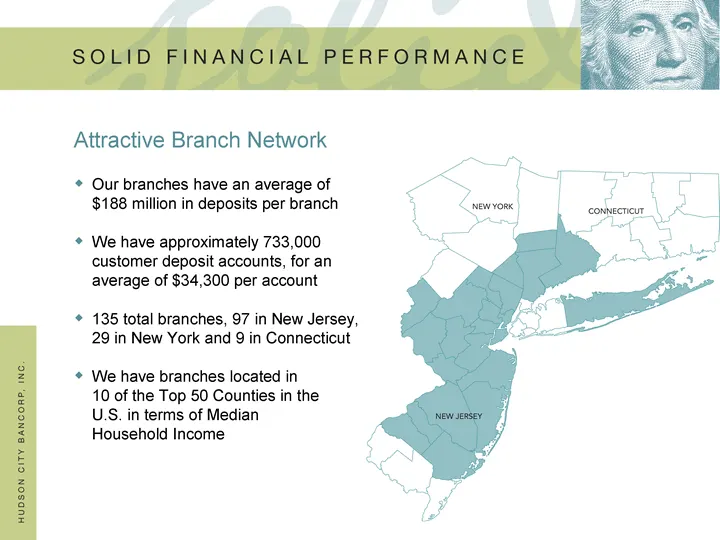
Attractive Branch Network Our branches have an average of $188 million in deposits per branch We have approximately 733,000 customer deposit accounts, for an average of $34,300 per account 135 total branches, 97 in New Jersey, 29 in New York and 9 in Connecticut We have branches located in 10 of the
Slide 24: Growth in Desirable Markets
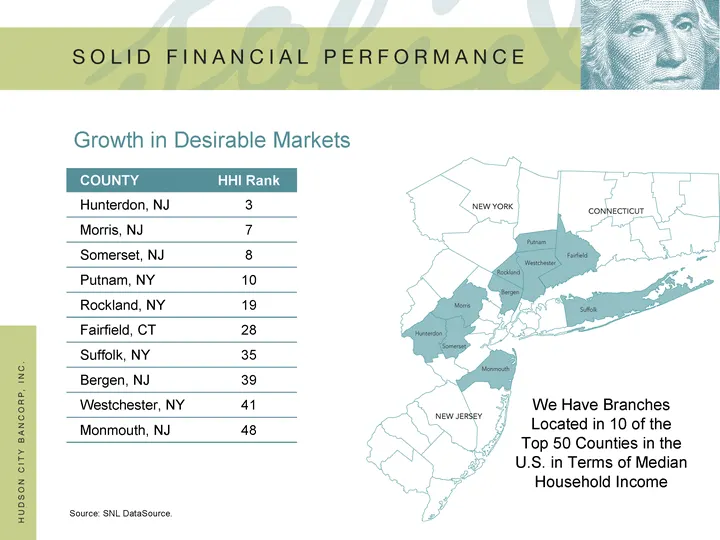
Growth in Desirable Markets COUNTY HHI Rank Hunterdon, NJ 3 Morris, NJ 7 Somerset, NJ 8 Putnam, NY 10 Rockland, NY 19 Fairfield, CT 28 Suffolk, NY 35 Bergen, NJ 39 Westchester, NY 41 Monmouth, NJ 48 Source: SNL DataSource. We Have Branches Located in 10 of the Top 50 Counties in the U.S. in Terms of
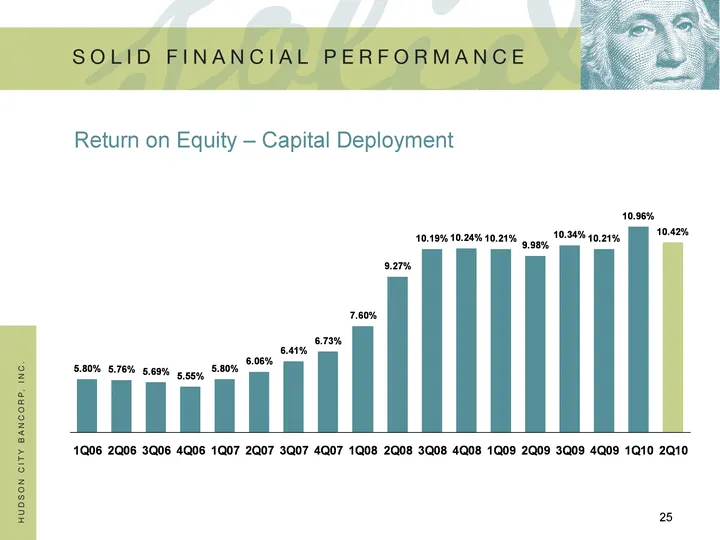
Slide 25: Return on Equity - Capital Deployment
Return on Equity - Capital Deployment 1Q06 2Q06 3Q06 4Q06 1Q07 2Q07 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 2Q09 3Q09 4Q09 1Q10 2Q10 ROE 0.058 0.0576 0.0569 0.0555 0.058 0.0606 0.0641 0.0673 0.076 0.0927 0.1019 0.1024 0.1021 0.0998 0.1034 0.1021 0.1096 0.1042
Slide 26: Dividends
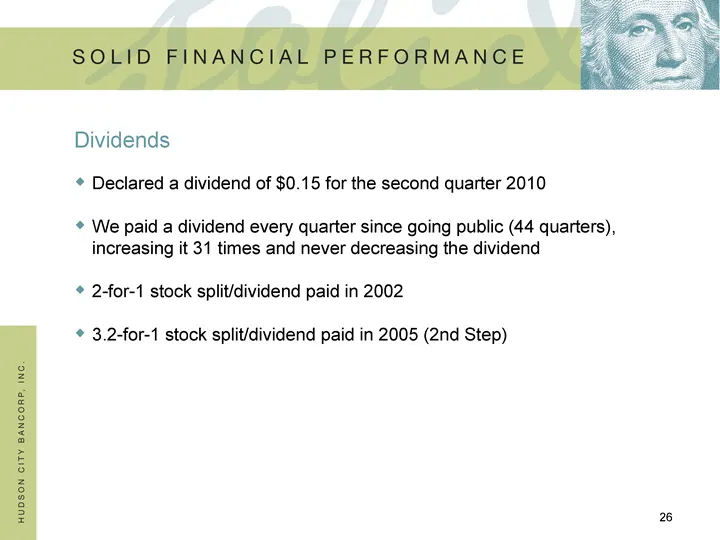
Dividends Declared a dividend of $0.15 for the second quarter 2010 We paid a dividend every quarter since going public (44 quarters), increasing it 31 times and never decreasing the dividend 2-for-1 stock split/dividend paid in 2002 3.2-for-1 stock split/dividend paid in 2005 (2nd Step)
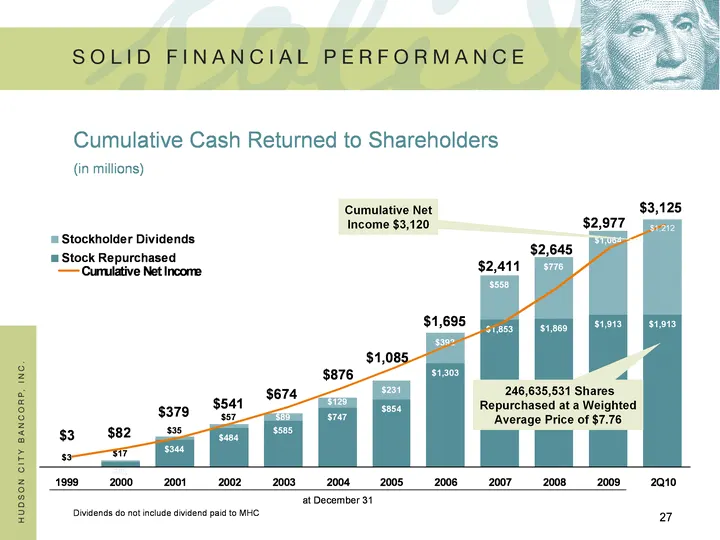
Slide 27: Cumulative Cash Returned to Shareholders
HUDSON ciTY BANCORP, INC. SOLID FINANCIAL PERFORMANCE Cumulative Cash Returned to Shareholders {in millions) Cumulative Net Income $3,120 '= Stockholder Dividends = Stock Repurchased — Cumulative Net income 246,635,531 Shares Repurchased at a Weighted Average Price of $7.76 Dividends donot include a
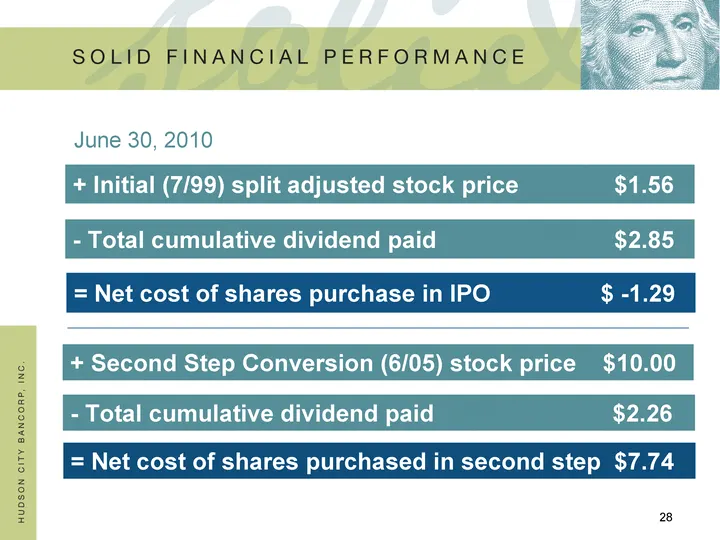
Slide 28: Net cost of shares purchased: IPO and second step
+ Initial (7/99) split adjusted stock price $1.56 - - Total cumulative dividend paid $2.85 = Net cost of shares purchase in IPO $ -1.29 June 30, 2010 + Second Step Conversion (6/05) stock price $10.00 - - Total cumulative dividend paid $2.26 = Net cost of shares purchased in second step $7.74
Slide 29: Quarterly Comparison
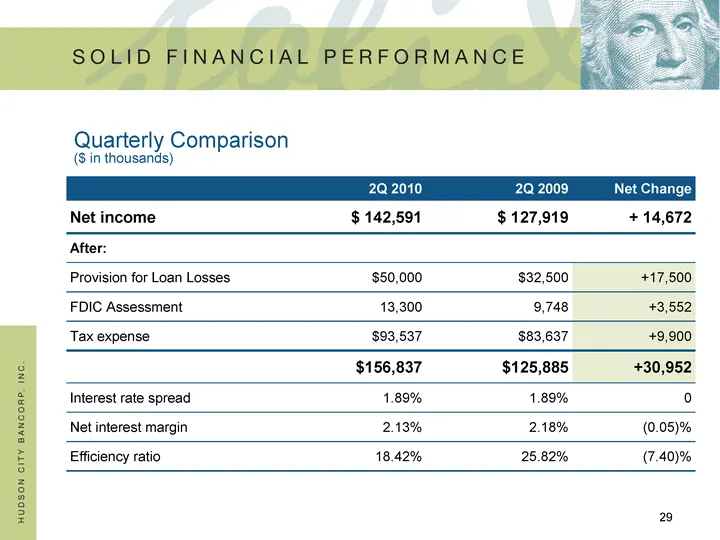
Quarterly Comparison 2Q 2010 2Q 2009 Net Change Net income $ 142,591 $ 127,919 + 14,672 After: Provision for Loan Losses $50,000 $32,500 +17,500 FDIC Assessment 13,300 9,748 +3,552 Tax expense $93,537 $83,637 +9,900 $156,837 $125,885 +30,952 Interest rate spread 1.89% 1.89% 0 Net interest margin 2.1
Slide 30: Industry-Leading Operational Efficiency
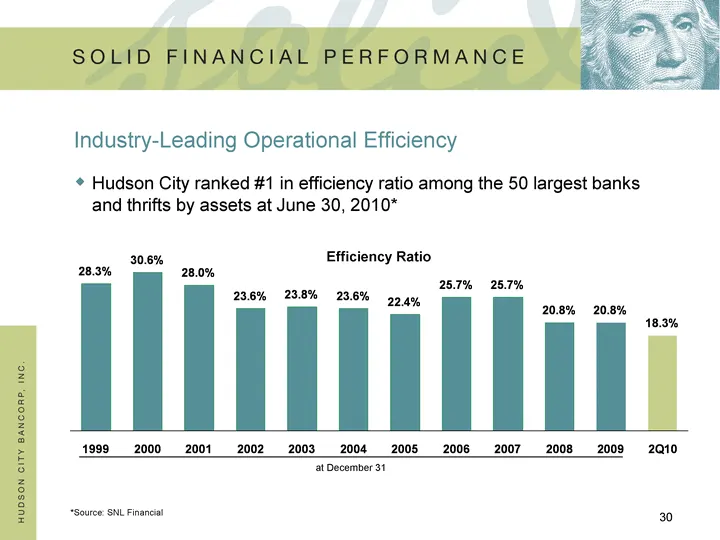
*Source: SNL Financial Industry-Leading Operational Efficiency Hudson City ranked #1 in efficiency ratio among the 50 largest banks and thrifts by assets at June 30, 2010* Efficiency Ratio 1999 0.283 2000 0.3055 2001 0.2804 2002 0.236 2003 0.2381 2004 0.236 2005 0.224 2006 0.257 2007 0.257 2008 0.20
Slide 31: Expense Discipline
Expense Discipline Hudson City's efficiency ratio was 18.34% for the first six months of 2010 The annualized ratio of non-interest expense to average assets was 0.43% for the first six months 2010 Hudson City is an industry leader for both of these ratios Efficient operations means we need to pay on
Slide 32: Winning Formula
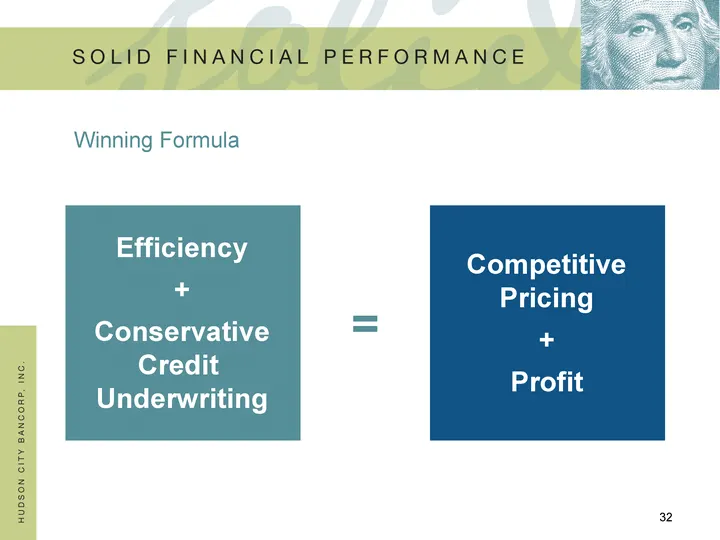
Efficiency + Conservative Credit Underwriting Competitive Pricing + Profit Winning Formula =
Slide 33: HCBK Ownership Breakdown
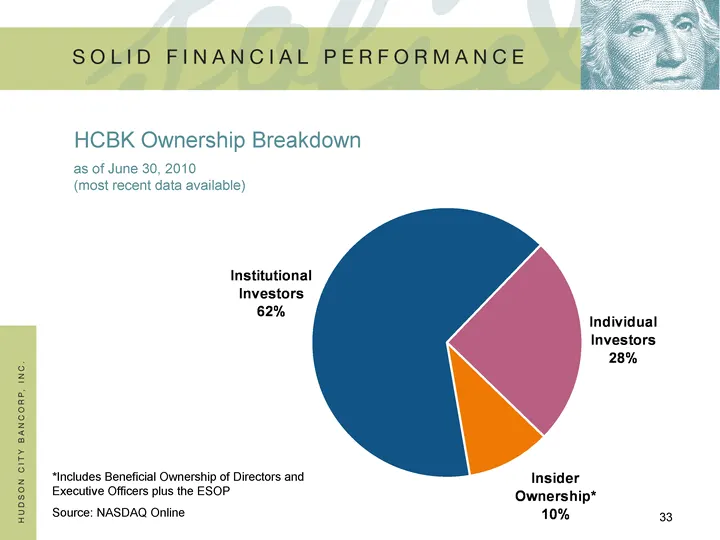
HCBK Ownership Breakdown as of June 30, 2010 (most recent data available) *Includes Beneficial Ownership of Directors and Executive Officers plus the ESOP Source: NASDAQ Online Institutional Investors Individual Investors Insider Ownership* 0.65 0.25 0.1
Slide 34: Positioned for a Rising Interest Rate Environment
Positioned for a Rising Interest Rate Environment Approximately 54% of funding is comprised of longer term borrowings with an average cost of 4.07%. Extended the maturity and put dates of borrowed funds Deposits priced higher than competition Extended the maturity of time deposits (from less than on
Slide 35: Ranked Among The Top Financial Institutions In The Nation
Ranked Among The Top 25 Financial Institutions In The Nation Source: SNL Financial. Financial information and market data as of 6/30/2010
Slide 36: Shelf Registration
Shelf Registration Hudson City filed an automatic shelf registration statement with the SEC in December 2009 Will provide Hudson City with access to the capital markets in an expedited manner No specific time table for offering Creates flexibility to quickly respond to strategic opportunities and re
Slide 37: Regulatory Reform
Regulatory Reform How will the Reform Act impact Hudson City? New Regulatory Regime Bureau of Consumer Financial Protection Financial Stability Oversight Council OTS to be abolished and its functions allocated to OCC, FRB and FDIC Capital Requirements Consolidated holding company capital requirement
Slide 38: Regulatory Reform: provisions that do not impact Hudson City
Regulatory Reform Significant provisions that do NOT impact Hudson City Trust preferred shares no longer included in regulatory capital for a bank our size - all of our capital is common We are not affected by prohibitions on certain forms of proprietary trading and hedge fund investments We are not
Slide 39: GSE Reform
GSE Reform GSEs originally created to provide a secondary market to serve a public purpose such as meeting the needs of low and moderate income borrowers GSEs now control over 97% of all loan production Increase in conforming loan limits adversely affected portfolio lenders such as Hudson City Credi
Slide 40: Among the Best-Managed Banks in America
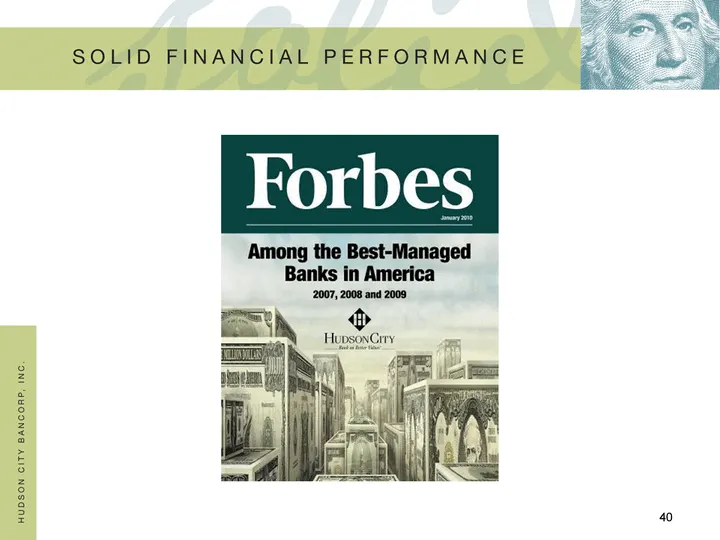
HUDSON ciTY BANCORP, INC SOLID FINANCIAL PERFORMANCE Forbes Among the Best-Managed Banks in America 2007, 2008 and 2009
Slide 41: Barclays Capital Global Financial Services Conference September 13, 2010
BARCLAYS CAPITAL GLOBAL FINANCIAL SERVICES CONFERENCE SEPTEMBER 13, 2010
Source: SEC EDGAR · 8-K filed Sep 13, 2010
More decks from Hudson City Bancorp Inc
 Citigroup 2013 US Financial Services Conference30 slides · Mar 6, 2013
 BancAnalysts Association of Boston Conference 201229 slides · Nov 2, 2012
 Barclays Global Financial Services Conference 201234 slides · Sep 10, 2012
 Merger or Acquisition (August 2012)32 slides · Aug 27, 2012
 Shareholder Meeting (April 2012)20 slides · Apr 25, 2012
 Shareholder Meeting (April 2011)38 slides · Apr 19, 2011