Hudson City Bancorp — Investor Presentation (November 2009)
36 slides from Hudson City Bancorp's investor presentation, Nov 10, 2009
Slide 1: Hudson City Bank on Better Values
HupsonCity Bank on Better Values
Slide 2: Forward-Looking Statement
Forward-Looking Statement This presentation may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include, but are not limited to, statements about (i) Hudson City Bancorp, Inc.'s "Hudson City" or "HCBK") p
Slide 3: Background
Background Market Cap over $6.8 billion Ranked in the top twenty-five U.S. financial institutions by asset size Largest thrift institution 131 branch offices in the New York, New Jersey & Connecticut financial strength O U R Y E A R T O S H I N E
Slide 4: Simple, Consistent Operating Model
Simple, Consistent Operating Model Originate and purchase single family mortgage loans A jumbo originator and purchaser Retain all loans originated and purchased Outstanding credit quality Multiple mortgage loan distribution channels Retail (our own agents and extensive branch network) Retail (mortg
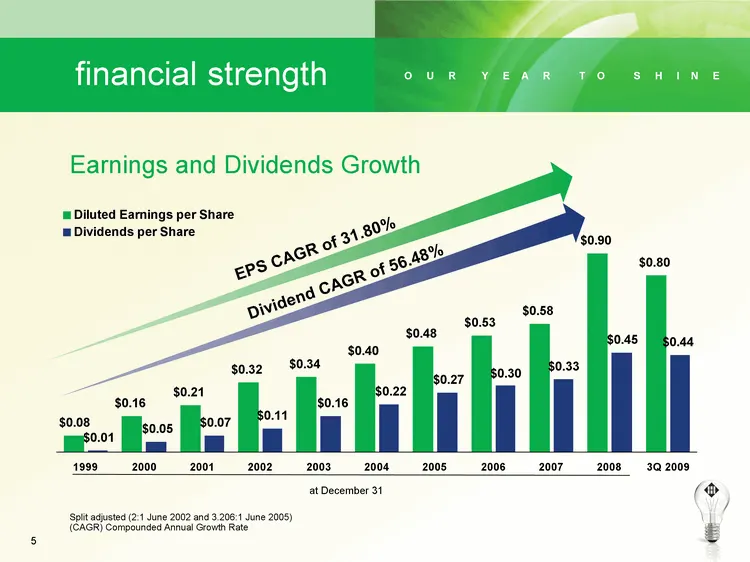
Slide 5: Earnings and Dividends Growth
financial strength O U R Y E A R T O S H I N E $0.08 $0.16 $0.21 $0.32 $0.34 $0.40 $0.48 $0.53 $0.58 $0.90 $0.80 $0.44 $0.45 $0.33 $0.30 $0.27 $0.22 $0.16 $0.11 $0.07 $0.05 $0.01 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 3Q 2009 Diluted Earnings per Share Dividends per Share Split adjusted (
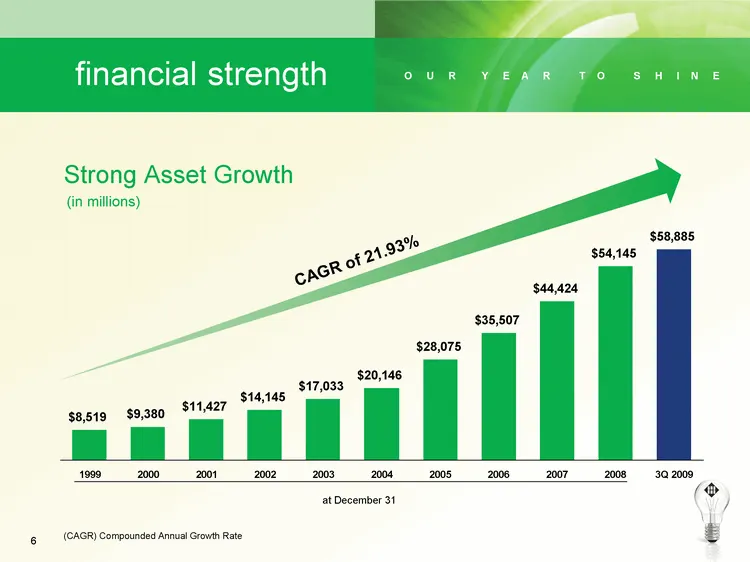
Slide 6: Strong Asset Growth
financial strength O U R Y E A R T O S H I N E $8,519 $9,380 $11,427 $14,145 $17,033 $20,146 $28,075 $35,507 $44,424 $54,145 $58,885 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 3Q 2009 Strong Asset Growth (in millions) (CAGR) Compounded Annual Growth Rate at December 31 CAGR of 21.93% CAGR of
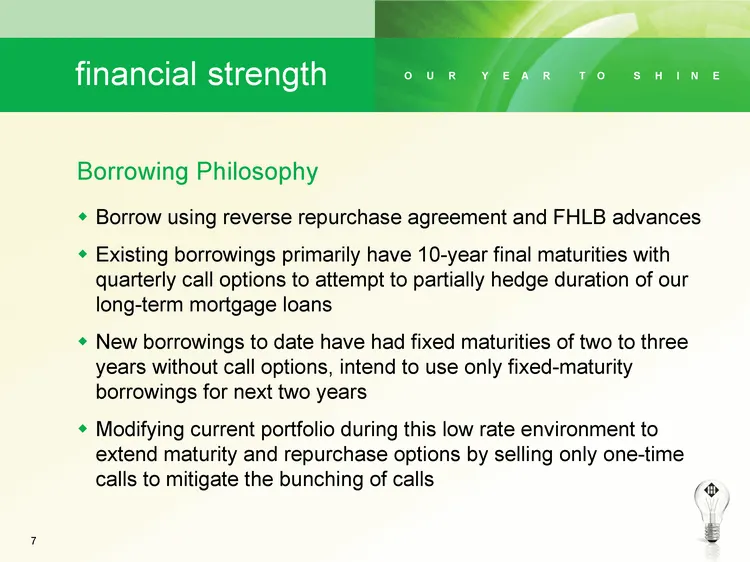
Slide 7: Borrowing Philosophy
Borrowing Philosophy Borrow using reverse repurchase agreement and FHLB advances Existing borrowings primarily have 10-year final maturities with quarterly call options to attempt to partially hedge duration of our long-term mortgage loans New borrowings to date have had fixed maturities of two to t
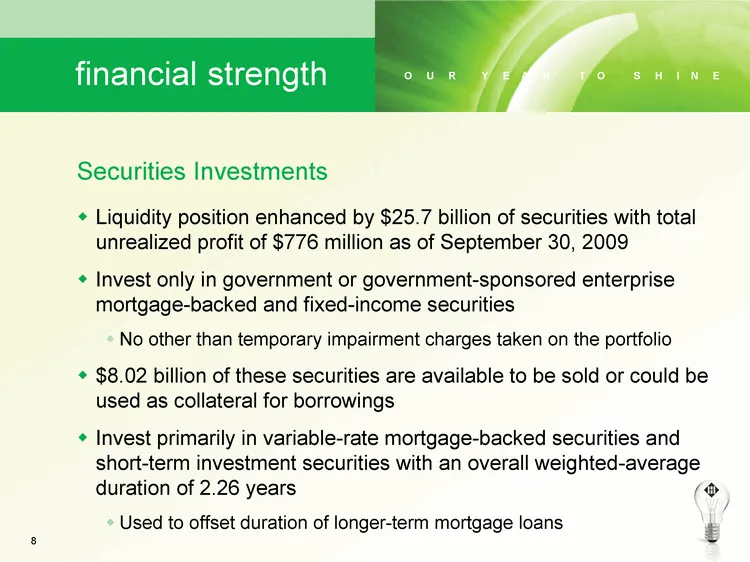
Slide 8: Securities Investments
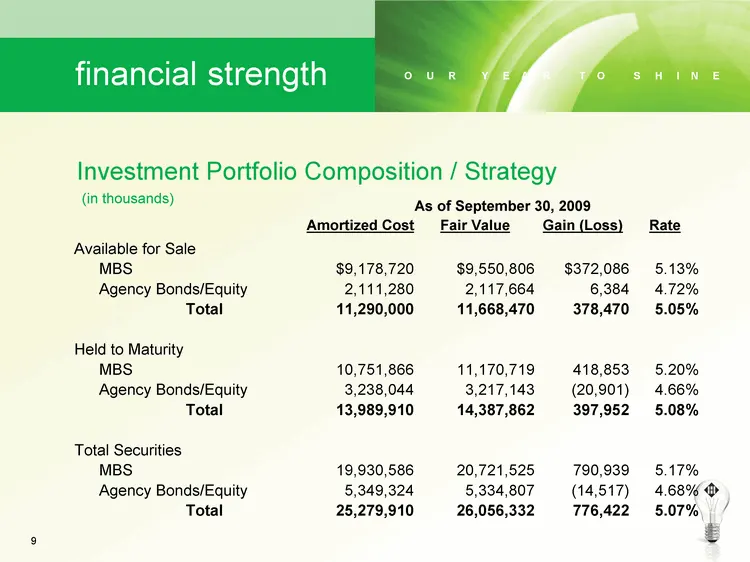
Securities Investments Liquidity position enhanced by $25.7 billion of securities with total unrealized profit of $776 million as of September 30, 2009 Invest only in government or government-sponsored enterprise mortgage-backed and fixed-income securities No other than temporary impairment charges
Slide 9: Investment Portfolio Composition / Strategy
Investment Portfolio Composition / Strategy financial strength O U R Y E A R T O S H I N E As of September 30, 2009 As of September 30, 2009 As of September 30, 2009 As of September 30, 2009 Amortized Cost Fair Value Gain (Loss) Rate Available for Sale Available for Sale Available for Sale Available
Slide 10: Mortgage Loans
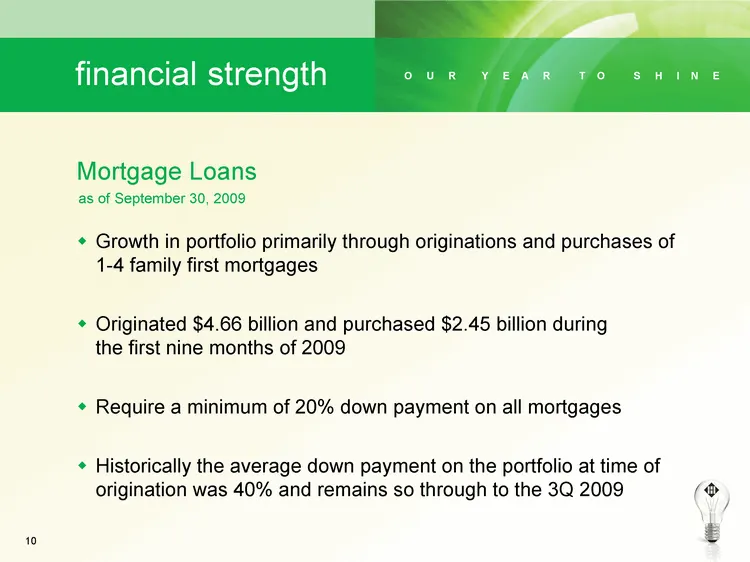
Mortgage Loans Growth in portfolio primarily through originations and purchases of 1-4 family first mortgages Originated $4.66 billion and purchased $2.45 billion during the first nine months of 2009 Require a minimum of 20% down payment on all mortgages Historically the average down payment on the
Slide 11: What We Haven't Done...
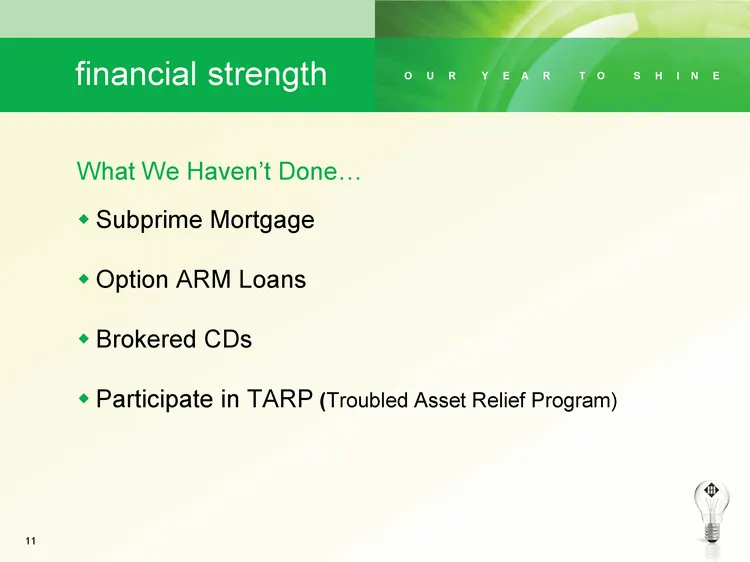
What We Haven't Done... Subprime Mortgage Option ARM Loans Brokered CDs Participate in TARP (Troubled Asset Relief Program) financial strength O U R Y E A R T O S H I N E
Slide 12: One to Four Family Residential Mortgage Lending Growth
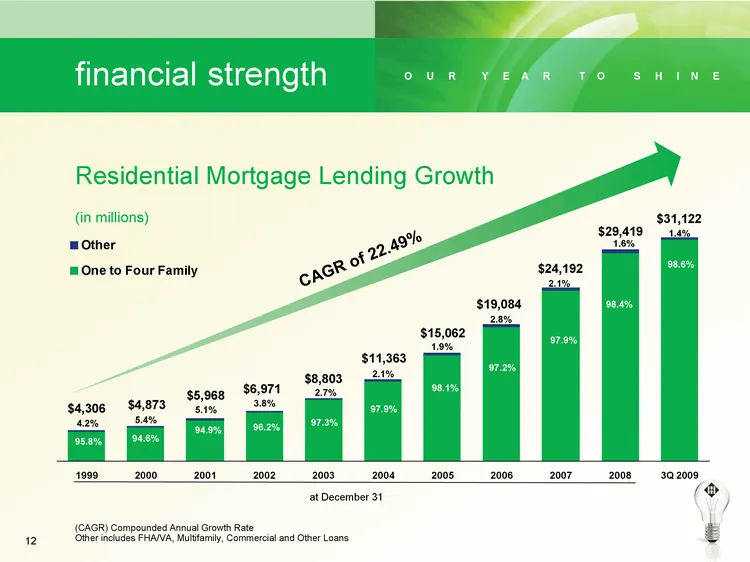
financial strength O U R Y E A R T O S H I N E 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 3Q 2009 Other One to Four Family Residential Mortgage Lending Growth (CAGR) Compounded Annual Growth Rate Other includes FHA/VA, Multifamily, Commercial and Other Loans 95.8% 94.6% 94.9% 96.2% 97.3% 97.9
Slide 13: Loan Geographic Exposure
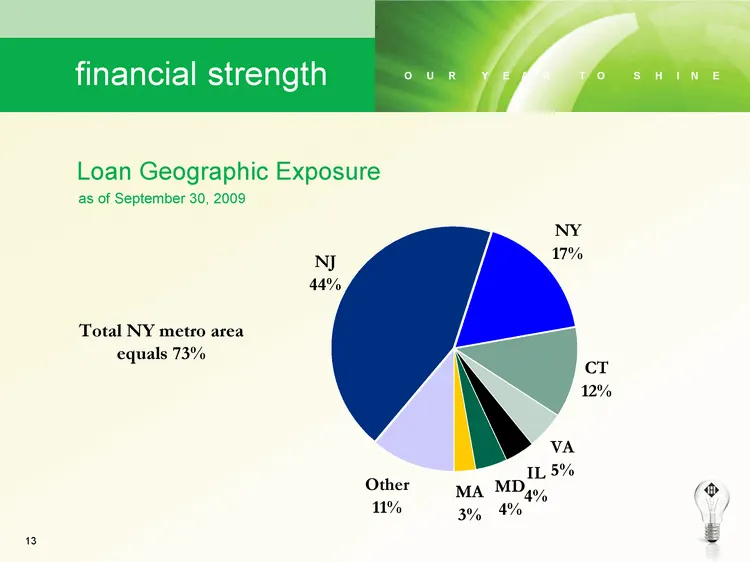
Loan Geographic Exposure financial strength O U R Y E A R T O S H I N E as of September 30, 2009 Total NY metro area equals 73% NJ 44% NY 17% CT 12% VA 5% IL 4% MD 4% MA 3% Other 11%
Slide 14: Loan Balances and Non-Performing Loans
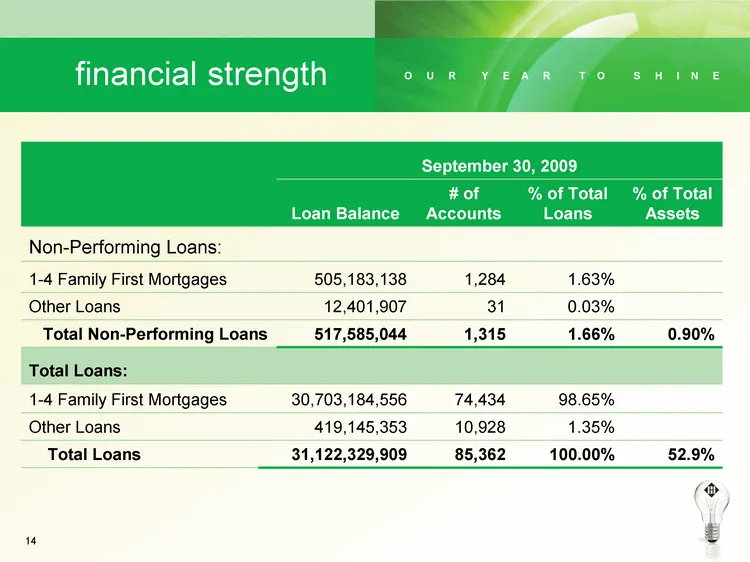
September 30, 2009 September 30, 2009 September 30, 2009 September 30, 2009 Loan Balance # of Accounts % of Total Loans % of Total Assets Non-Performing Loans: Non-Performing Loans: 1-4 Family First Mortgages 1-4 Family First Mortgages 505,183,138 1,284 1.63% Other Loans Other Loans 12,401,907 31 0.
Slide 15: Home Price Index for Major U.S. Markets
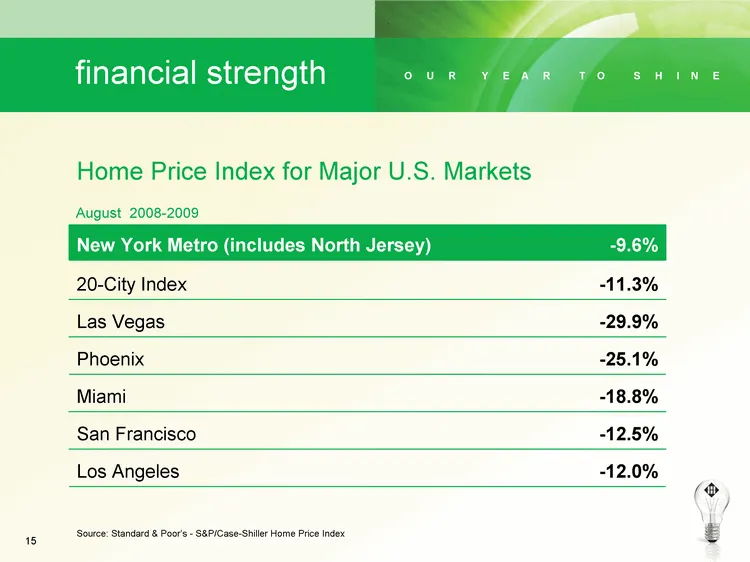
financial strength O U R Y E A R T O S H I N E Home Price Index for Major U.S. Markets 20-City Index -11.3% Las Vegas -29.9% Phoenix -25.1% Miami -18.8% San Francisco -12.5% Los Angeles -12.0% August 2008-2009 Source: Standard & Poor's - S&P/Case-Shiller Home Price Index New York Metro (includes Nor
Slide 16: Deposits
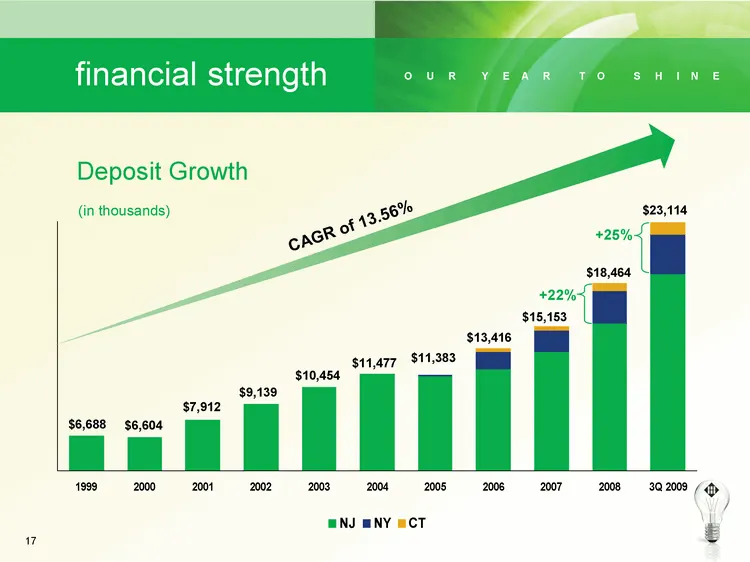
hudsoncitysavingsbank.com F I N A N C I A L S T R E N G T H Deposits 12 new branches since January 2008 $7.96 billion added since January 2008 Internet deposits of $183 million since December 2008 $175 million average deposits per branch
Slide 17: Deposit Growth
Deposit Growth financial strength O U R Y E A R T O S H I N E 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 3Q 2009 NJ NY CT (in thousands) $6,604 $7,912 $9,139 $10,454 $11,477 $11,383 $13,416 $15,153 $18,464 $23,114 $6,688 CAGR of 13.56% CAGR of 13.56% +22% +25%
Slide 18: Attractive Branch Network
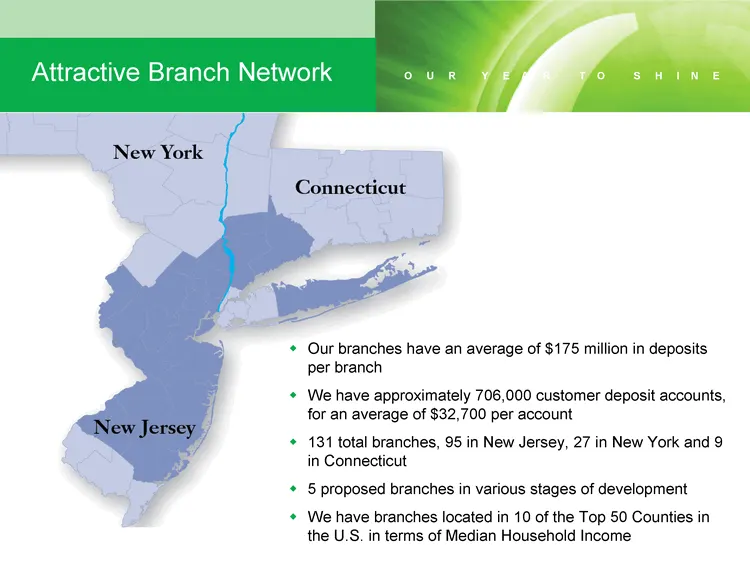
O U R Y E A R T O S H I N E Our branches have an average of $175 million in deposits per branch We have approximately 706,000 customer deposit accounts, for an average of $32,700 per account 131 total branches, 95 in New Jersey, 27 in New York and 9 in Connecticut 5 proposed branches in various stag
Slide 19: Return on Equity - Capital Deployment
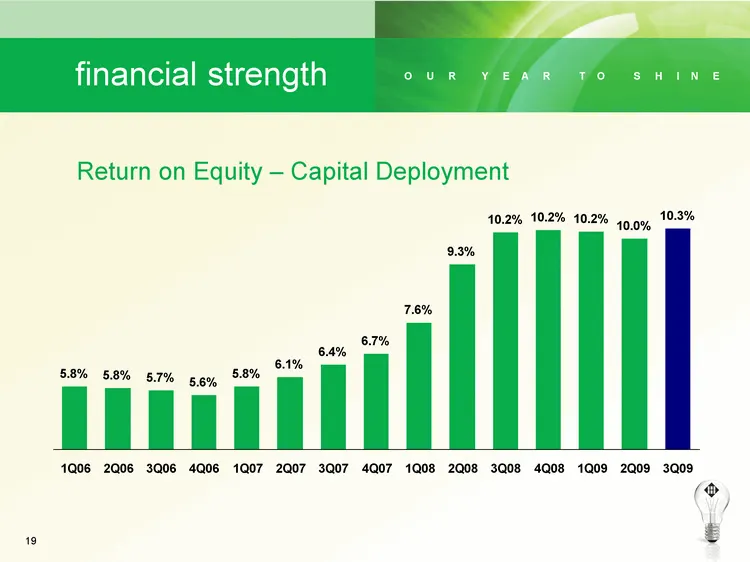
Return on Equity - Capital Deployment financial strength O U R Y E A R T O S H I N E 5.8% 5.8% 5.7% 5.6% 5.8% 6.1% 6.4% 6.7% 7.6% 9.3% 10.2% 10.2% 10.2% 10.0% 10.3% 1Q06 2Q06 3Q06 4Q06 1Q07 2Q07 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 2Q09 3Q09
Slide 20: Industry-Leading Operational Efficiency
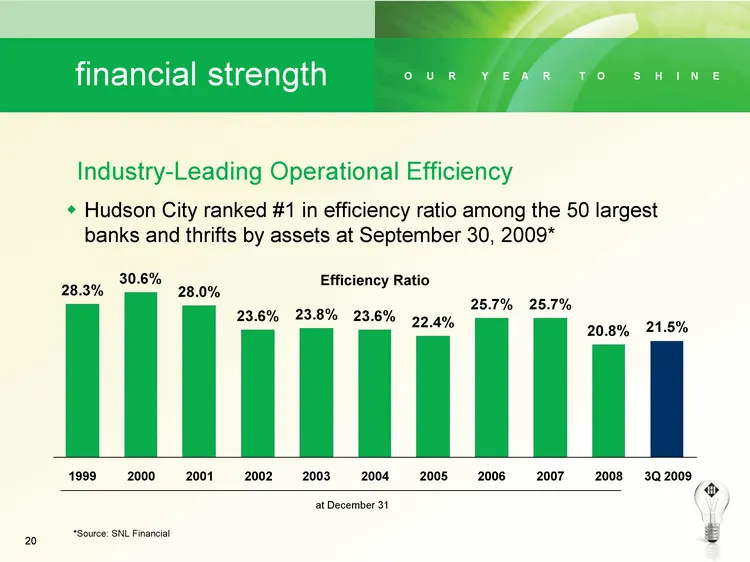
*Source: SNL Financial Industry-Leading Operational Efficiency Hudson City ranked #1 in efficiency ratio among the 50 largest banks and thrifts by assets at September 30, 2009* Efficiency Ratio at December 31 financial strength O U R Y E A R T O S H I N E 21.5% 20.8% 25.7% 25.7% 22.4% 23.6% 23.8% 23
Slide 21: Expense Discipline
Expense Discipline For the third quarter of 2009 Hudson City's efficiency ratio was 19.18%, the annualized ratio of non-interest expense to average assets was 0.43% Hudson City is an industry leader for both of these ratios Efficient operations means we need to pay only $0.19 to generate $1.00 of ea
Slide 22: Winning Formula
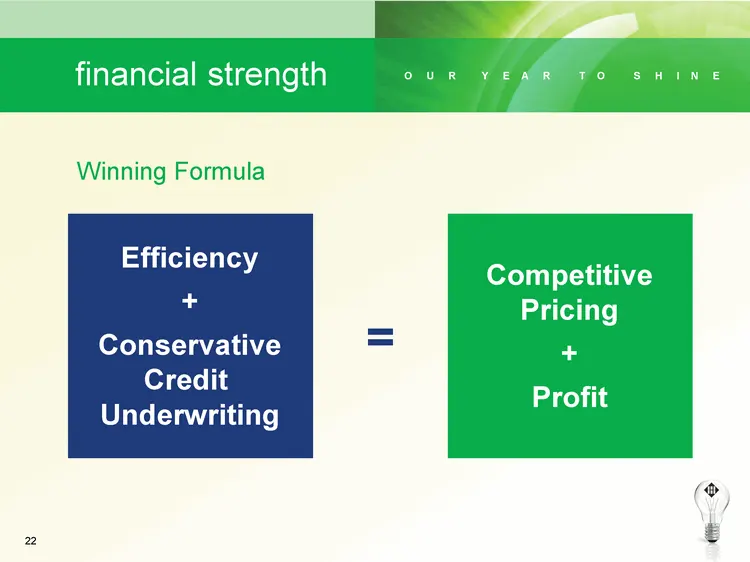
Efficiency + Conservative Credit Underwriting Competitive Pricing + Profit Winning Formula = financial strength O U R Y E A R T O S H I N E
Slide 23: HCBK Ownership Breakdown
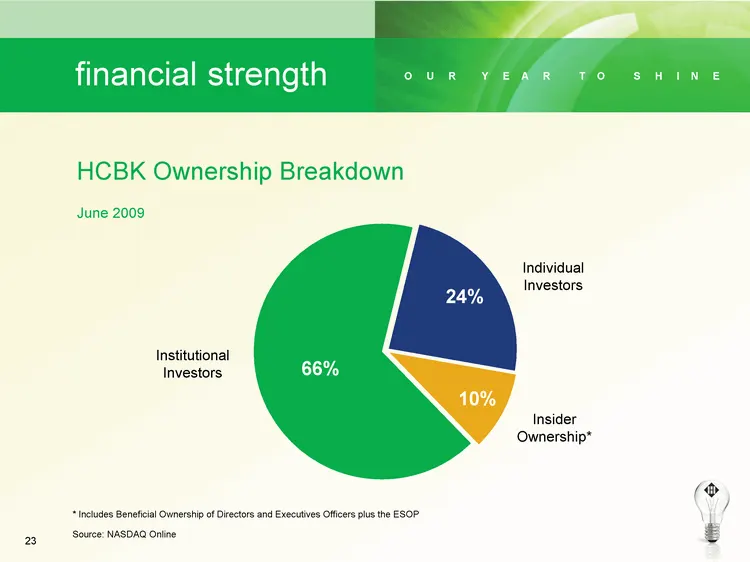
HCBK Ownership Breakdown Institutional Investors Individual Investors Insider Ownership* * Includes Beneficial Ownership of Directors and Executives Officers plus the ESOP Source: NASDAQ Online June 2009 financial strength O U R Y E A R T O S H I N E 66% 24% 10%
Slide 24: Financial Strength
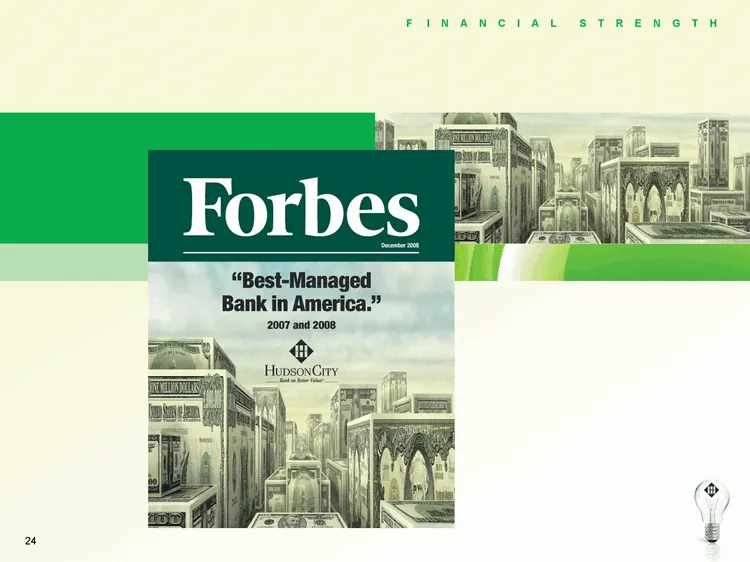
FINANCIAL STRENGTH “Best-Mana Bank in imotiea ” or
Slide 25: Results
Ret results
Slide 26: Overview of Third Quarter 2009
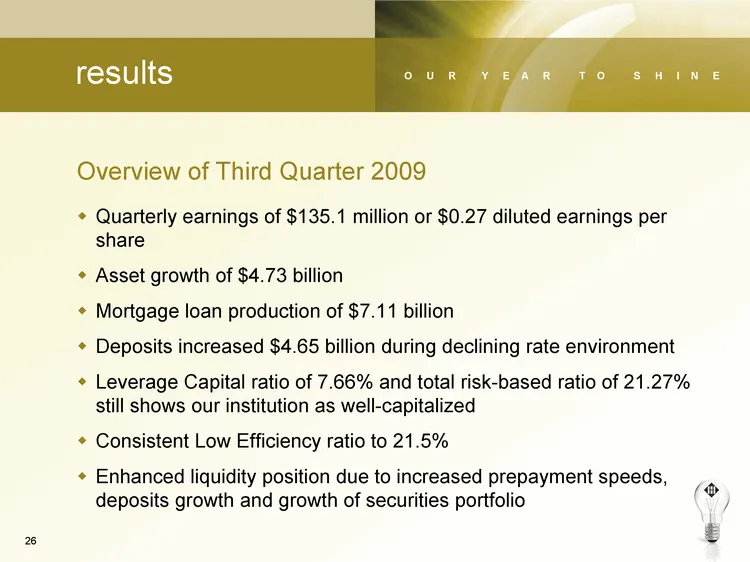
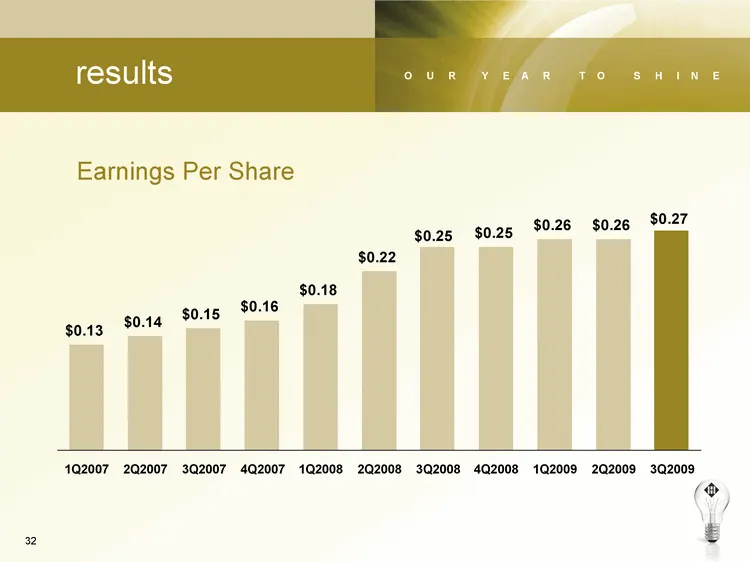
Overview of Third Quarter 2009 Quarterly earnings of $135.1 million or $0.27 diluted earnings per share Asset growth of $4.73 billion Mortgage loan production of $7.11 billion Deposits increased $4.65 billion during declining rate environment Leverage Capital ratio of 7.66% and total risk-based rati
Slide 27: Third Quarter Comparison
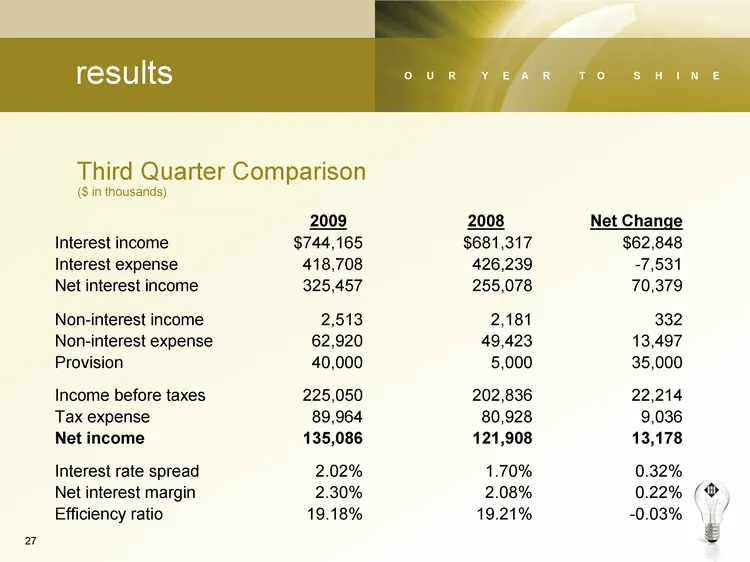
Third Quarter Comparison results O U R Y E A R T O S H I N E 2009 2008 Net Change Interest income $744,165 $681,317 $62,848 Interest expense 418,708 426,239 -7,531 Net interest income 325,457 255,078 70,379 Non-interest income 2,513 2,181 332 Non-interest expense 62,920 49,423 13,497 Provision 40,00
Slide 28: Nine Months Comparison
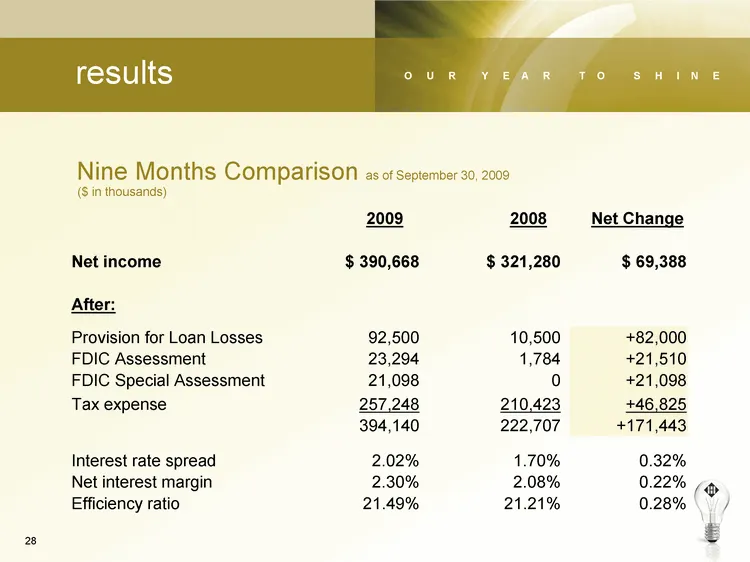
Nine Months Comparison as of September 30, 2009 results O U R Y E A R T O S H I N E 2009 2008 Net Change Net income $ 390,668 $ 321,280 $ 69,388 After: Provision for Loan Losses 92,500 10,500 +82,000 FDIC Assessment 23,294 1,784 +21,510 FDIC Special Assessment 21,098 0 +21,098 Tax expense 257,248 21
Slide 29: Historical Credit Quality
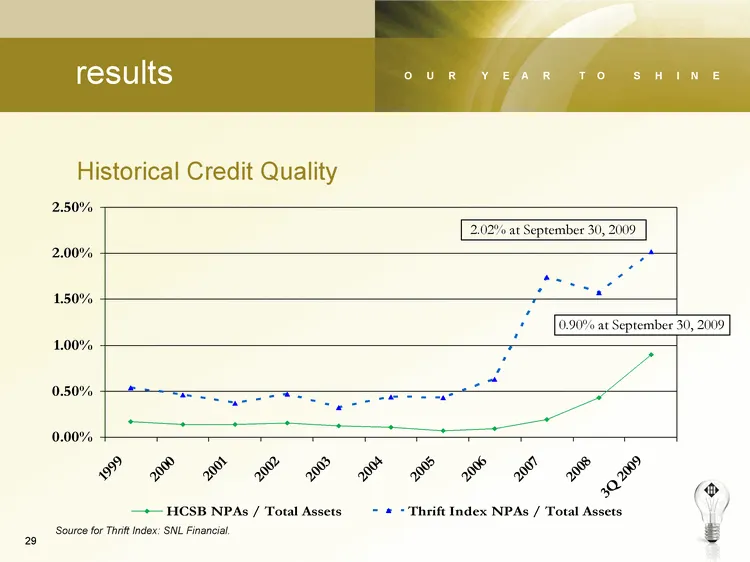
Historical Credit Quality results O U R Y E A R T O S H I N E 2.02% at September 30, 2009 Source for Thrift Index: SNL Financial. 0.90% at September 30, 2009 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 3Q 2009 HCSB NPAs / Total Assets Thrift Index NPAs / Tot
Slide 30: Allowance and Provision Process
Allowance and Provision Process Have followed a systematic disciplined methodology in determining the Allowance for Loan Losses Perform re-appraisals on loans by the time they are 180 days past due, charging-off loans when required Consider the housing market and economic factors before making provi
Slide 31: Provision for Loan Losses and Net Charge-offs
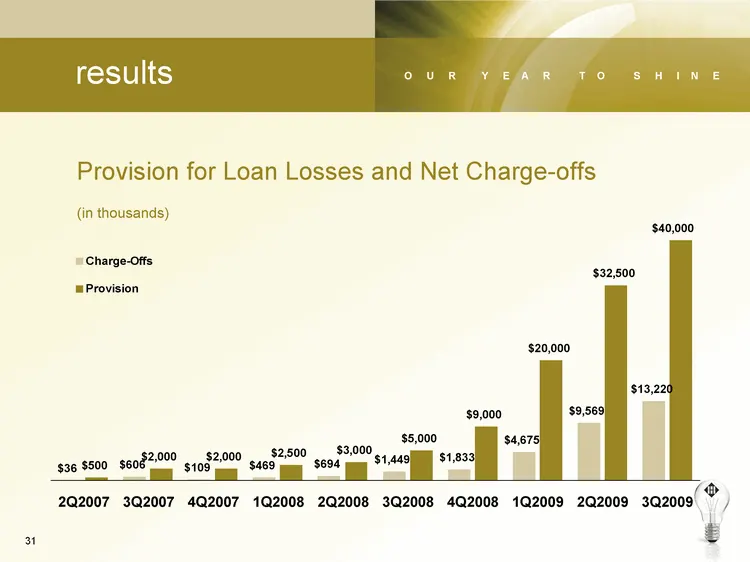
Provision for Loan Losses and Net Charge-offs results O U R Y E A R T O S H I N E (in thousands) $36 $606 $109 $469 $694 $1,449 $1,833 $4,675 $9,569 $13,220 $500 $2,000 $2,000 $2,500 $3,000 $5,000 $9,000 $20,000 $32,500 $40,000 2Q2007 3Q2007 4Q2007 1Q2008 2Q2008 3Q2008 4Q2008 1Q2009 2Q2009 3Q2009 Ch
Slide 32: Earnings Per Share
Earnings Per Share results O U R Y E A R T O S H I N E $0.13 $0.14 $0.15 $0.16 $0.18 $0.22 $0.25 $0.26 $0.26 $0.27 $0.25 1Q2007 2Q2007 3Q2007 4Q2007 1Q2008 2Q2008 3Q2008 4Q2008 1Q2009 2Q2009 3Q2009
Slide 33: Dividends
Dividends Dividend increased to $0.15 versus $0.13 in 3Q2008 We paid a dividend every quarter since going public (41 quarters), increasing it 31 times and never decreasing the dividend 2-for-1 stock split / dividend paid in 2002 3.2-for-1stock split / dividend paid in 2005 (2nd Step) results O U R Y
Slide 34: Dividends Declared
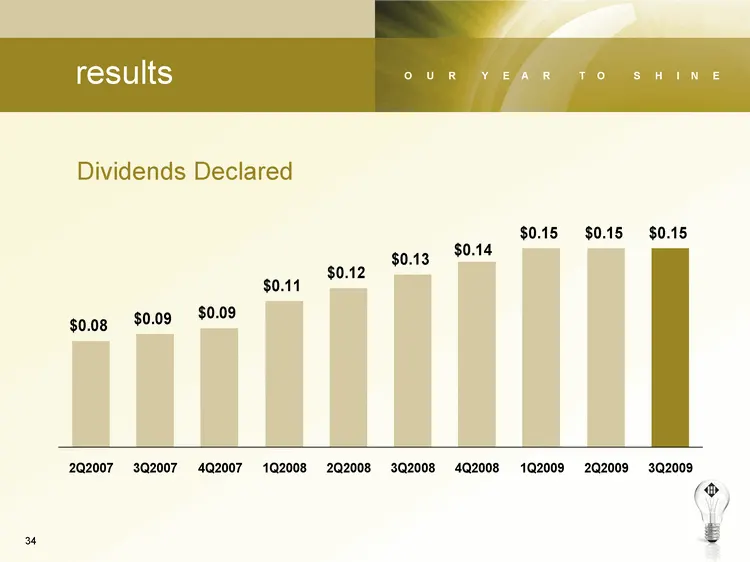
Dividends Declared results O U R Y E A R T O S H I N E $0.08 $0.09 $0.09 $0.11 $0.12 $0.13 $0.15 $0.15 $0.15 $0.14 2Q2007 3Q2007 4Q2007 1Q2008 2Q2008 3Q2008 4Q2008 1Q2009 2Q2009 3Q2009
Slide 35: "Comp Group" Characteristics
"Comp Group" Characteristics Asset Size and Market Capitalization Superior Asset Quality Mortgages underwritten and held on the books Efficiency Ratio less than 25% Average over 58% for largest 50 Banks and Thrifts Did not participate in TARP Paid dividend every quarter since going public Dividend Y
Slide 36: Hudson City Bank on Better Values
HupsonCity Bank on Better Values
Source: SEC EDGAR · 8-K filed Nov 10, 2009
More decks from Hudson City Bancorp Inc
 Citigroup 2013 US Financial Services Conference30 slides · Mar 6, 2013
 BancAnalysts Association of Boston Conference 201229 slides · Nov 2, 2012
 Barclays Global Financial Services Conference 201234 slides · Sep 10, 2012
 Merger or Acquisition (August 2012)32 slides · Aug 27, 2012
 Shareholder Meeting (April 2012)20 slides · Apr 25, 2012
 Shareholder Meeting (April 2011)38 slides · Apr 19, 2011