Airtran — Bear Stearns Transportation Conference 2006
26 slides from Airtran's conference presentation, Jan 30, 2006
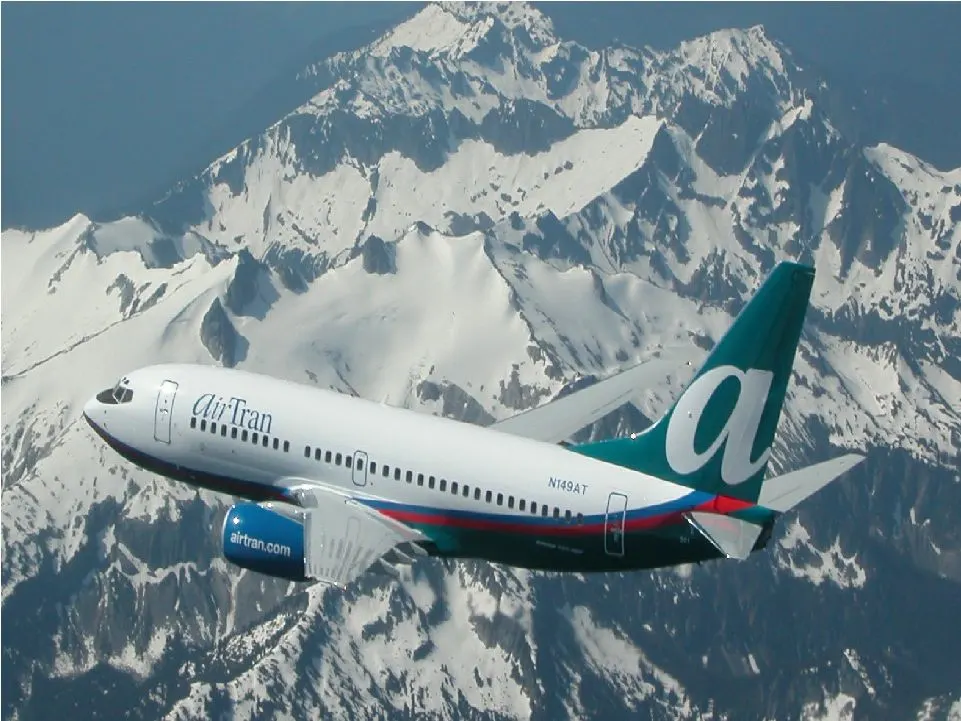
Slide 1: Investor Update January 2006
Investor Update January 2006 Exhibit 99.1
Slide 2: Safe Harbor Disclosure
Safe Harbor Disclosure Please note that the discussion today may contain forward looking statements that involve risks and uncertainties including those relating to the company’s ability to develop new markets, its fleet and growth plans, its low cost advantage vs. competitors, its ability to obtain
Slide 3: AirTran Is Well Positioned For The Future
AirTran Is Well Positioned For The Future • Low-costs with the right sized jet aircraft • Excellent growth opportunities • Industry restructuring will provide significant benefits
Slide 4: AirTran Airways Fact Sheet
AirTran Airways Fact Sheet • Youngest all-Boeing fleet in America – 106 Airplanes - 85 717s/21 737s • 49 cities served • 7 consecutive years of profitability – One of three consistently profitable airlines • Stable and experienced management
Slide 5: AirTran Has Low Costs
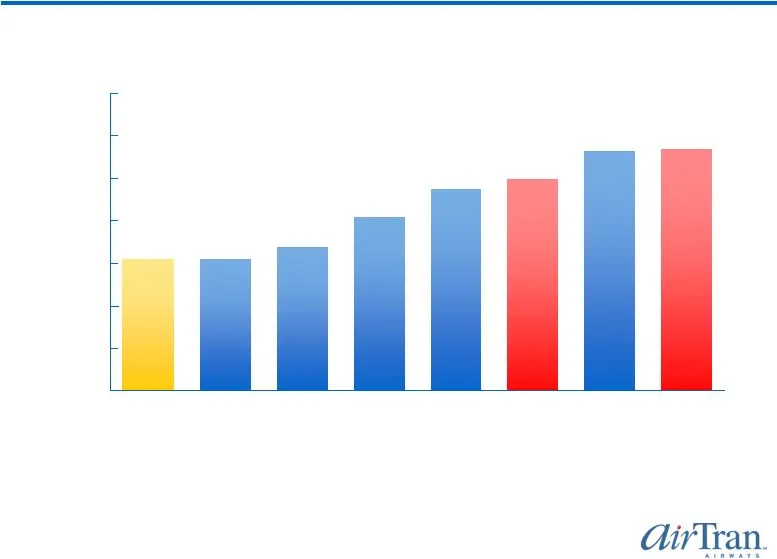
AirTran Has Low Costs Source: Company Reports/DOT filings/Company estimates While legacy airline costs are down – the gap remains large Non Fuel Unit Costs at 653 miles 0.00 2.00 4.00 6.00 8.00 10.00 12.00 14.00 AAI LUV JBLU AWA UAIRQ DAL AMR NWAC Cents per Mile
Slide 6: What Creates AirTran's Low Cost Advantage?
What Creates AirTran’s Low Cost Advantage? • Productive workforce at all levels • Young, simplified fleet – Fuel efficient – Attractive ownership costs • Efficient use of facilities • Competition for heavy maintenance contracts • Low cost distribution – Over 70% of sales are directly with AirTran
Slide 7: Lowering Costs Is Not A One Time Event
Lowering Costs Is Not A One Time Event AirTran's Non Fuel Unit Cost Trend 6.00 6.25 6.50 6.75 7.00 7.25 7.50 Cents per Mile *Excludes non-recurring special items.
Slide 8: AirTran Has Low Costs and a Great Product
AirTran Has Low Costs and a Great Product • Assigned seating • Business class – Unlike legacy airlines, business class on every flight • Convenient distribution – Internet – No fee telephone reservations and airport sales – Travel agencies • XM Radio and oversized luggage bins • Friendly crewmembers
Slide 9: Low Costs Help Keep Our Balance Sheet Strong
($MM) 12/31/03 12/31/04 12/31/05 * Average coupon 11% in 2001, 7% in 2005 Low Costs Help Keep Our Balance Sheet Strong Total Cash & Investments Aircraft Deposits Long Term Debt* Stockholders’ Equity Working Capital 348.5 50.0 246.8 302.2 229.0 390.1 133.5 457.9 353.2 109.1 342.3 69.8 298.5 334.0 197
Slide 10: Low Costs and Small Jets Creates Great Growth Opportunities
Low Costs and Small Jets Creates Great Growth Opportunities
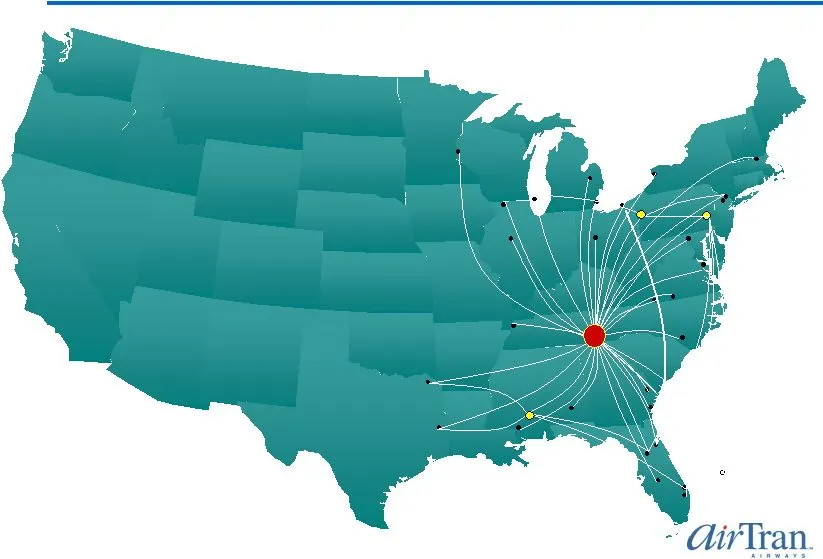
Slide 11: AirTran Airways Route Network Summer 2001
AirTran Airways Route Network Summer 2001 Grand Bahama Atlanta Minneapolis Buffalo/Niagara Boston Dallas/Ft. Worth Gulfport/Biloxi Houston New Orleans Tampa Miami Ft. Lauderdale Ft. Walton Beach Memphis Jacksonville Orlando Ft. Myers Savannah Myrtle Beach Raleigh / / Durham Newport News/Williamsburg
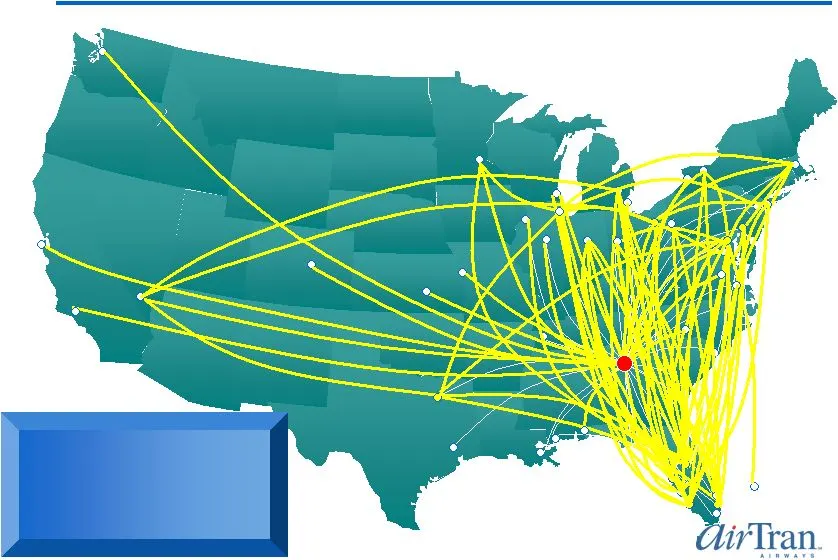
Slide 12: AirTran Airways Route Network Has Evolved
Since September 2001: 18 new cities 71 new routes Ft. Lauderdale Ft. Lauderdale Miami Miami West Palm Beach West Palm Beach Denver Denver Pensacola Pensacola Wichita Wichita Houston Houston Gulfport Gulfport Dallas Dallas Los Angeles Los Angeles Kansas City Kansas City Memphis Memphis Minneapolis Mi
Slide 13: AirTran's Diversification Strategies
Baltimore Akron- Canton Growth by Replacement - MetroJet Growth by Development AirTran’s Diversification Strategies Dayton Boston Atlanta Orlando, Tampa, Ft. Lauderdale, Fort Myers, Freeport Sarasota Rochester Charlotte Atlanta New York Boston Dallas Las Vegas Ft. Lauderdale Fort Myers Orlando Tampa
Slide 14: AirTran Continues To Build City Strength
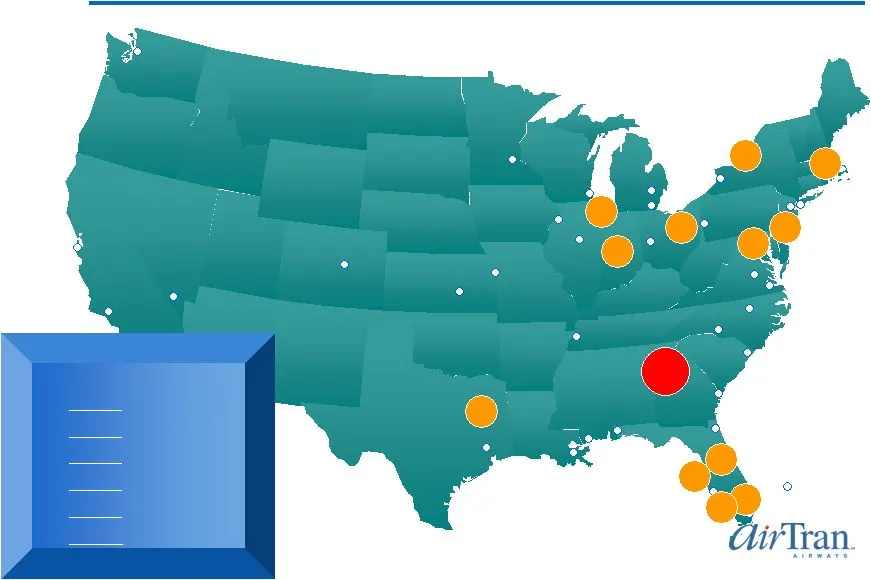
New York Cities >=5 destinations Jan01 2 Jan02 3 Jan03 4 Jan04 8 Jan05 9 Jun06 13 48 Bloomington Buffalo Newark Pittsburgh Miami West Palm Beach Denver Pensacola Freeport Wichita Houston Gulfport Los Angeles Kansas City Memphis Moline Minneapolis New Orleans San Francisco AirTran Continues To Build
Slide 15: Atlanta Has Also Grown Significantly
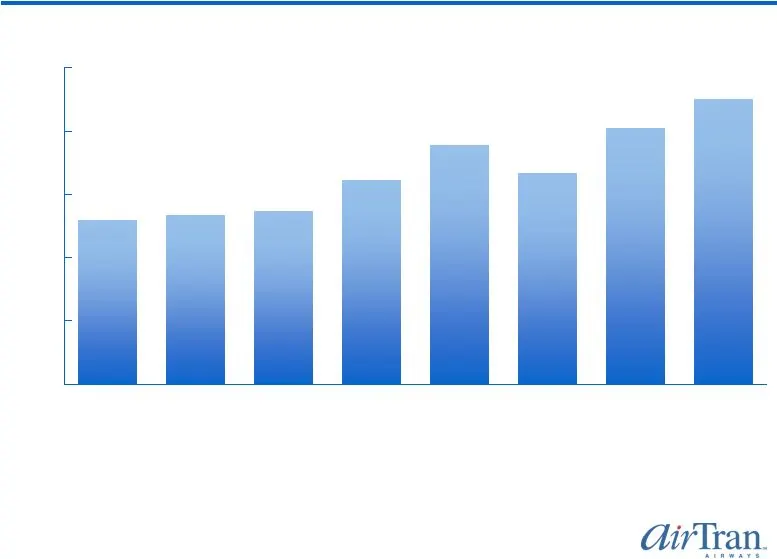
Atlanta Has Also Grown Significantly Jan Jan Jan Jan Jan Jan Jan Jun Daily Departures
Slide 16: AirTran's Atlanta Hub is Now One of the Nations Largest Mainline Hubs
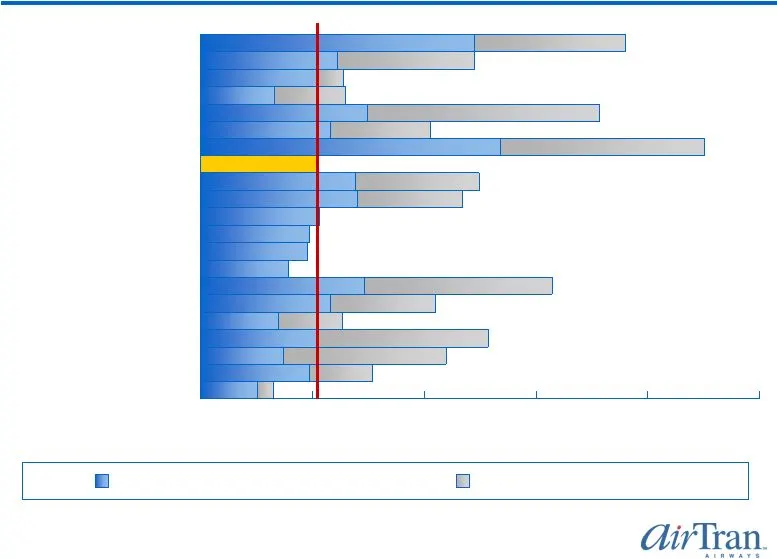
AirTran’s Atlanta Hub is Now One of the Nations Largest Mainline Hubs LCC-Las Vegas LCC-Phoenix LCC-Philadelphia LCC-Charlotte UAL-San Francisco UAL-Denver UAL-Chicago LUV-Baltimore LUV-Chicago LUV-Phoenix LUV-Las Vegas NWAC-Minneapolis NWAC-Detroit AAI-Atlanta DAL-Atlanta CAL-Newark CAL-Houston ALK
Slide 17: The 737 Has Also Expanded Our Opportunities
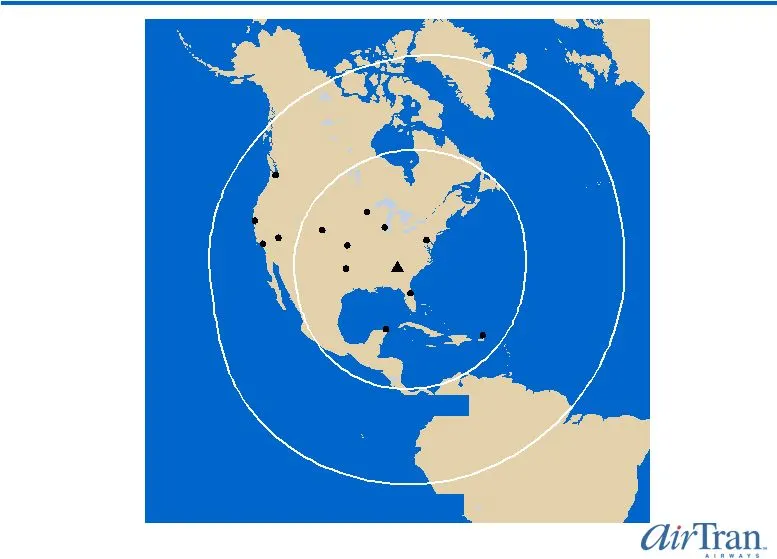
717-200 / BR715 737-700 / CFM56 The 737 Has Also Expanded Our Opportunities Baltimore Wichita Seattle San Francisco Los Angeles Las Vegas Denver Dallas Minneapolis Chicago Orlando Cancun San Juan ATLANTA
Slide 18: The 737 Will Become Our Primary Growth Vehicle
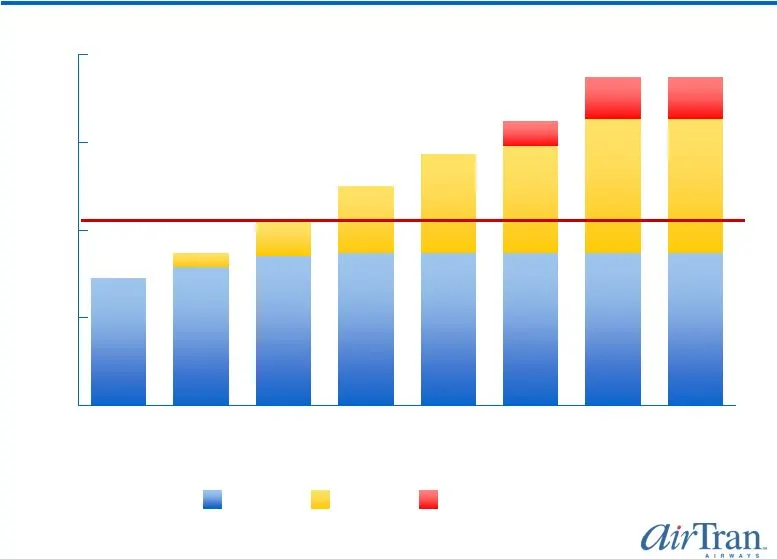
The 737 Will Become Our Primary Growth Vehicle 717s 737s 737 Options
Slide 19: Market Opportunities Favor Low Cost Narrowbody Aircraft
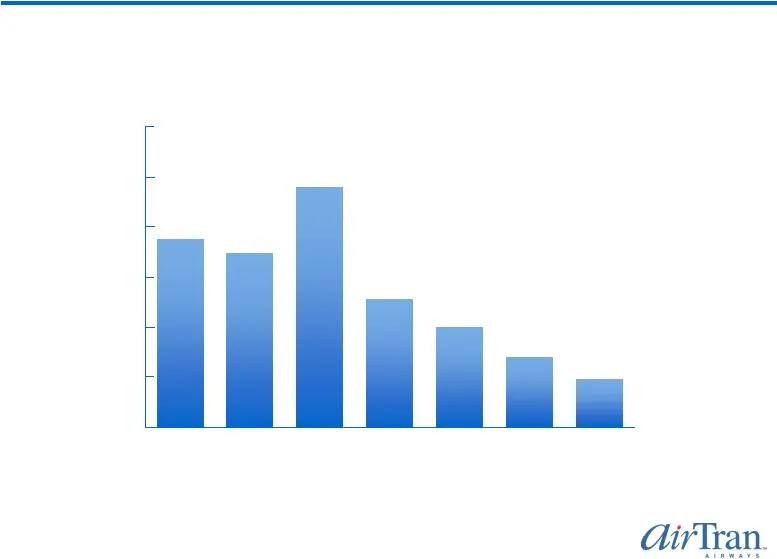
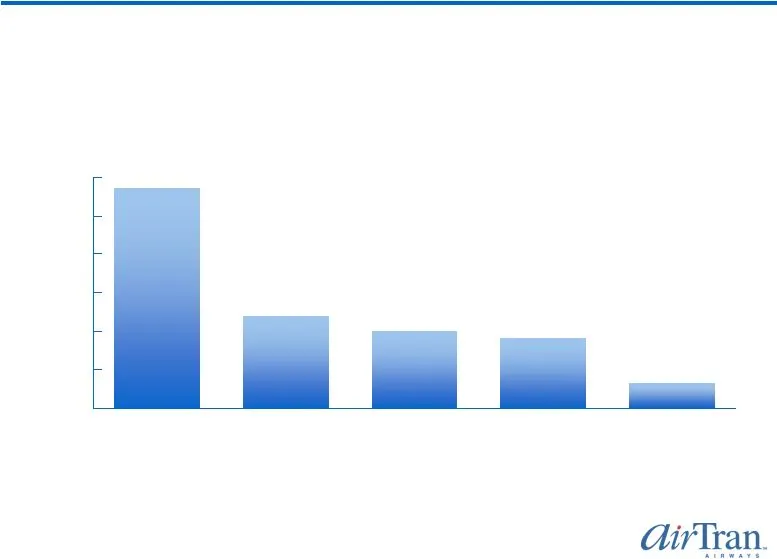
Market Opportunities Favor Low Cost Narrowbody Aircraft Number of Markets with over 100 passengers per day 100-199 200-299 300-499 500-999 1000+ # of markets passengers per day
Slide 20: Industry Restructuring Will Provide Significant Benefits For AirTran
Industry Restructuring Will Provide Significant Benefits For AirTran
Slide 21: Capacity Continues To Exit AirTran Markets
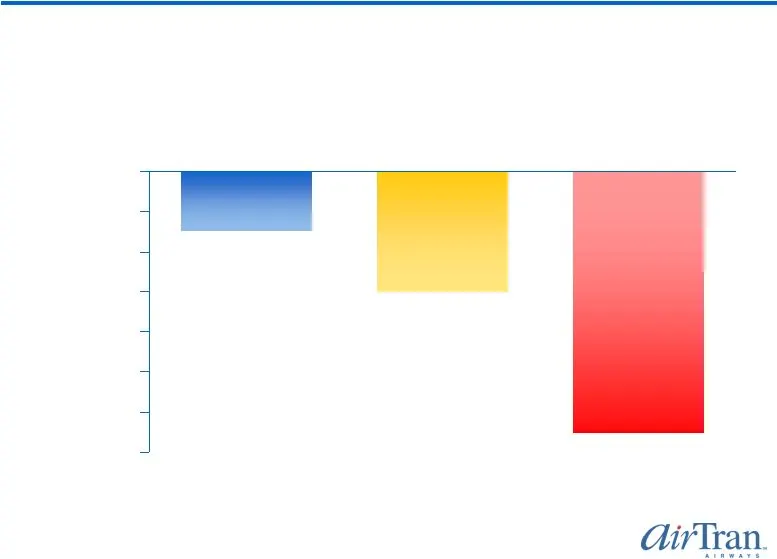
Capacity Continues To Exit AirTran Markets -14% -12% -10% -8% -6% -4% -2% 0% Domestic AirTran Markets AirTran Atlanta Markets Q106 Change in ASMs
Slide 22: Capacity in AirTran's Atlanta Markets
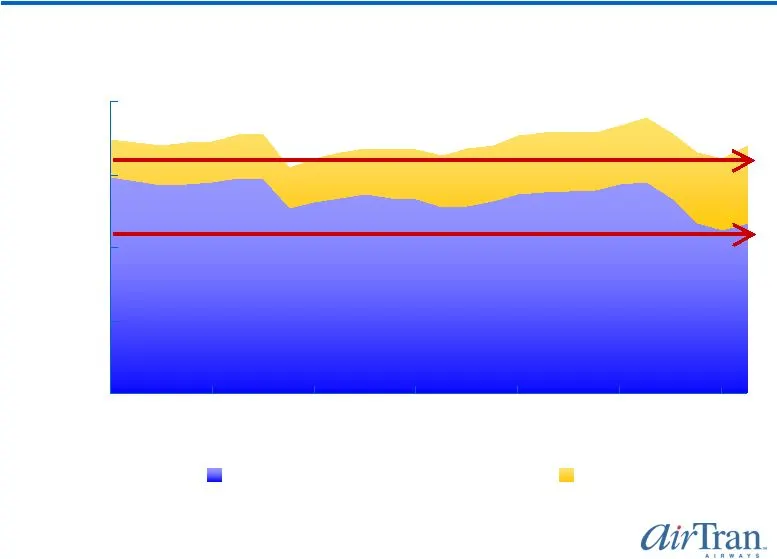
Capacity in AirTran’s Atlanta Markets 50,000 100,000 150,000 200,000 Mar00 Mar02 Mar04 Mar06 Other Airlines AirTran Daily Seats
Slide 23: Capacity Cuts Are Helping Revenue Environment
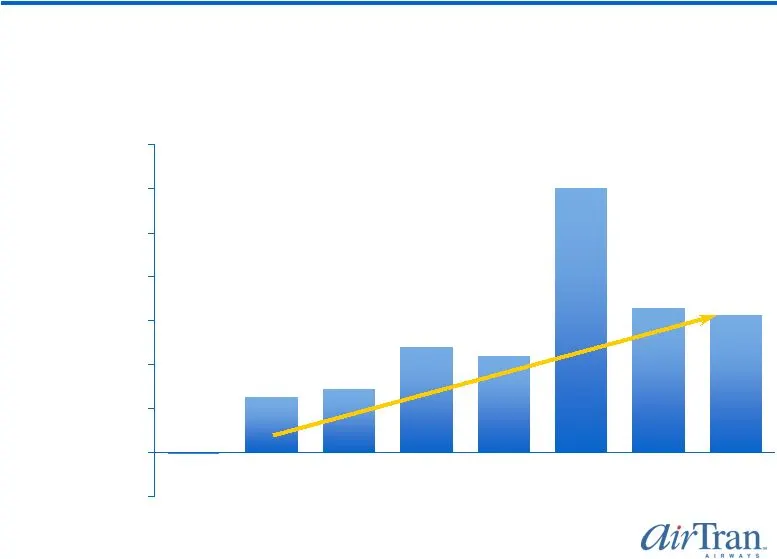
Capacity Cuts Are Helping Revenue Environment Yr/Yr Change in AirTran's Unit Revenue -5.0% 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% 35.0% Q105 May05 Jun05 Jul05 Aug05 Sep05 Q305 Q405 *Excludes non-recurring special items.
Slide 24: Fuel and Revenue Are Significant Earnings Variables
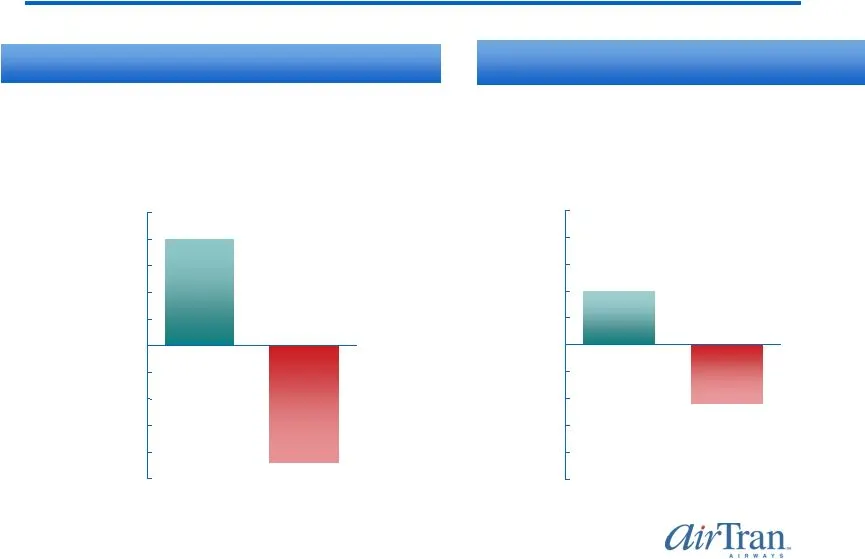
EPS Impact of a 1% change in RASM EPS Impact of a $5/bbl change in crude oil EPS Impact of a 1% change in RASM Fuel and Revenue Are Significant Earnings Variables EPS Impact of a $5/bbl change in crude oil -$0.25 -$0.20 -$0.15 -$0.10 -$0.05 $0.00 $0.05 $0.10 $0.15 $0.20 $0.25 1% RASM Increase 1% RAS
Slide 25: Additional Benefits of Industry Restructuring
Additional Benefits of Industry Restructuring • Fuel prices are accelerating the rate of change • Domestic capacity likely to stay constrained – Bankruptcies will result in more returned aircraft – Larger aircraft are moving to international routes – Narrow-body aircraft are essentially sold out • D
Slide 26: AirTran Is Well Positioned For The Future
AirTran Is Well Positioned For The Future • Low costs, right size equipment – AirTran can make money where others can’t • AirTran has excellent growth opportunities – Replacing inefficient legacy capacity – Connecting existing cities that have strong demand – New market opportunities • Big beneficia
Source: SEC EDGAR · 8-K filed Jan 30, 2006
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010