Transatlantic — SPAC Merger (August 2011)
73 slides from Transatlantic's SPAC merger presentation, Aug 23, 2011
Slide 1: Greater Current and Long-Term Value for Transatlantic Stockholders
Greater Current and Long-Term Value for Transatlantic Stockholders August 2011 Building a Global Reinsurance Leader FILED BY VALIDUS HOLDINGS, LTD. PURSUANT TO RULE 425 UNDER THE SECURITIES ACT OF 1933 AND DEEMED FILED PURSUANT TO RULE 14a-12 UNDER THE SECURITIES EXCHANGE ACT OF 1934 SUBJECT COMPANY
Slide 2: Cautionary Note Regarding Forward-looking Statements
Cautionary Note Regarding Forward-looking Statements This presentation may include forward-looking statements, both with respect to Validus and its industry, that reflect Validus' current views with respect to future events and financial performance. Statements that include the words "expect," "inte
Slide 3: Additional Information and Participants in the Solicitation
Additional Information and Participants in the Solicitation Additional Information about the Proposed Transaction and Where to Find It: Validus has commenced an exchange offer to acquire all of the outstanding shares of common stock of Transatlantic for 1.5564 Validus voting common shares and $8.00
Slide 4: Note on Non-GAAP Financial Measures
Note on Non-GAAP Financial Measures In presenting the Company’s results herein, management has included and discussed certain schedules containing underwriting income, net operating income (loss), annualized return on average equity and diluted book value per common share that are not calculated und
Slide 5: The Transatlantic Board is Failing its Stockholders
The Transatlantic Board is Failing its Stockholders Transatlantic Stockholders Should Reject the Inferior AWAC Takeover Offer
Slide 6: Validus is Fully Committed to a Transaction with Transatlantic
Validus is Fully Committed to a Transaction with Transatlantic On July 12, 2011, Validus announced its Superior Proposal for a combination with Transatlantic and sought to engage with Transatlantic’s board Creation of a global reinsurance leader Higher market value than Allied World’s (“AWAC”) infer
Slide 7: Superior Market Value for Transatlantic Stockholders
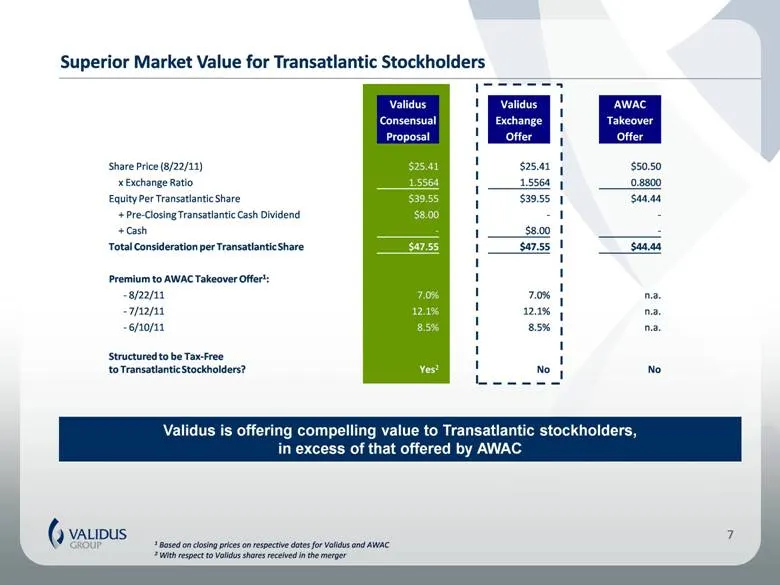
Validus Validus AWAC Consensual Exchange Takeover Proposal Offer Offer Share Price (8/22/11) $25.41 $25.41 $50.50 x Exchange Ratio 1.5564 1.5564 0.8800 Equity Per Transatlantic Share $39.55 $39.55 $44.44 + Pre-Closing Transatlantic Cash Dividend $8.00 - - + Cash - $8.00 - Total Consideration per Tra
Slide 8: The Transatlantic Board is not Aligned with its Stockholders
The Transatlantic Board is not Aligned with its Stockholders We believe the Transatlantic board: 8 Validus believes that the Transatlantic board's actions have not served Transatlantic stockholders’ best interests Has rushed headlong into the inferior and ill-advised AWAC takeover with lower market
Slide 9: Sorting Out the Winners and Losers in an AWAC Takeover
Sorting Out the Winners and Losers in an AWAC Takeover of Transatlantic 9 Transatlantic stockholders will decide the outcome, not the Transatlantic board In our view... Who Wins AWAC, although smaller, acquires a genuine franchise at a lower price Six handpicked Transatlantic board members, who woul
Slide 10: Validus, From Formation to Today: A Case Study in Value Creation
Validus, From Formation to Today A Case Study in Value Creation
Slide 11: Validus, From Formation to Today: A Case Study in Value Creation
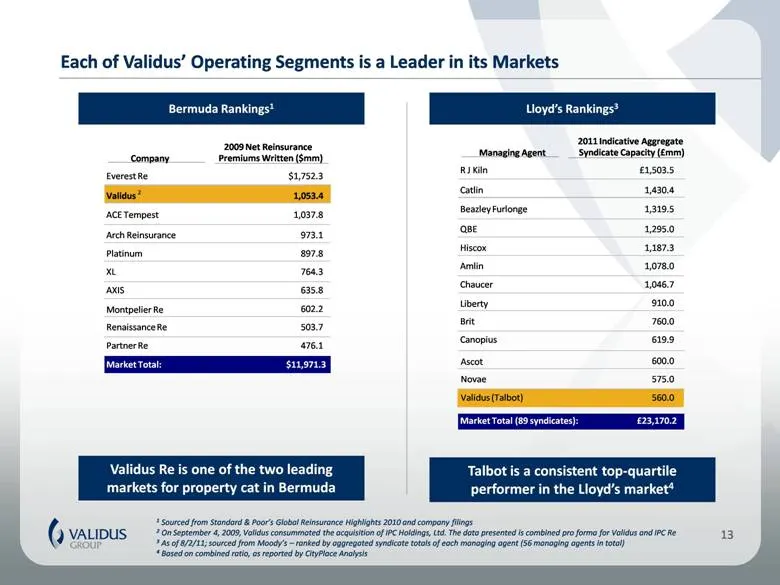
Validus, From Formation to Today: A Case Study in Value Creation Within five years of commencing operations, Validus has established leading global positions in Bermuda and at Lloyd’s Number two position in Bermuda reinsurance, the world’s most important property-catastrophe reinsurance market Top t
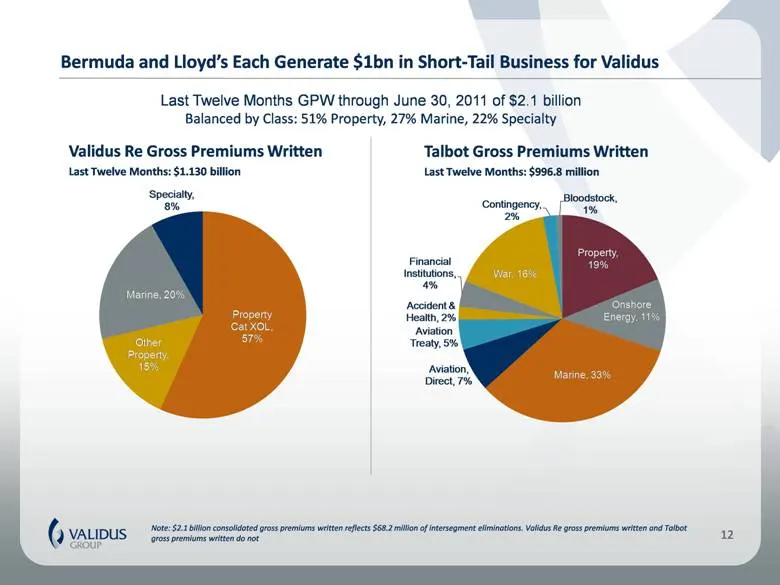
Slide 12: Bermuda and Lloyd's Each Generate $1bn in Short-Tail Business
Bermuda and Lloyd’s Each Generate $1bn in Short-Tail Business for Validus 12 Last Twelve Months GPW through June 30, 2011 of $2.1 billion Balanced by Class: 51% Property, 27% Marine, 22% Specialty Validus Re Gross Premiums Written Last Twelve Months: $1.130 billion Talbot Gross Premiums Written Last
Slide 13: Each of Validus' Operating Segments is a Leader in its Markets
Each of Validus’ Operating Segments is a Leader in its Markets 13 Bermuda Rankings1 Company 2009 Net Reinsurance Premiums Written ($mm) Everest Re $1,752.3 Validus 1,053.4 Arch Reinsurance 973.1 Platinum 897.8 XL 764.3 AXIS 635.8 Montpelier Re 2 602.2 Renaissance Re 503.7 Partner Re 476.1 Market Tot
Slide 14: Validus is Focused on Short-Tail Specialty Classes
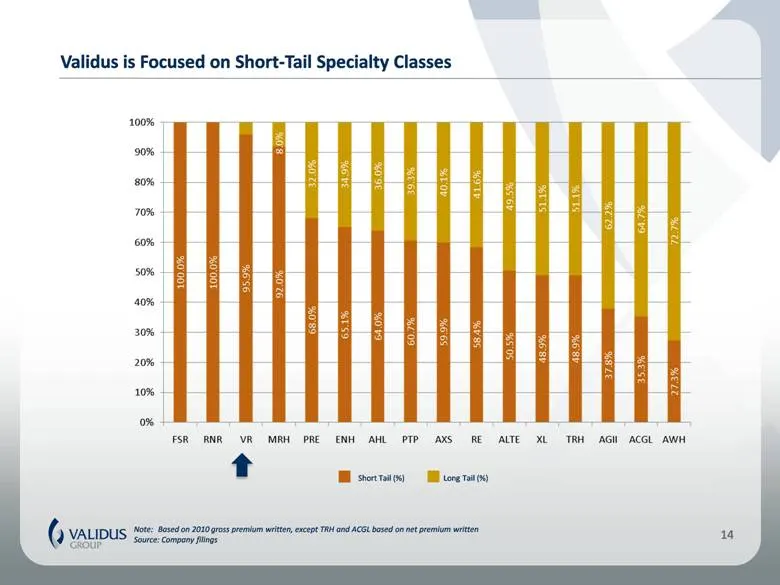
Validus is Focused on Short-Tail Specialty Classes 14 Short Tail (%) Long Tail (%) Note: Based on 2010 gross premium written, except TRH and ACGL based on net premium written Source: Company filings
Slide 15: The Property Catastrophe Rate Environment Continues to be Favorable
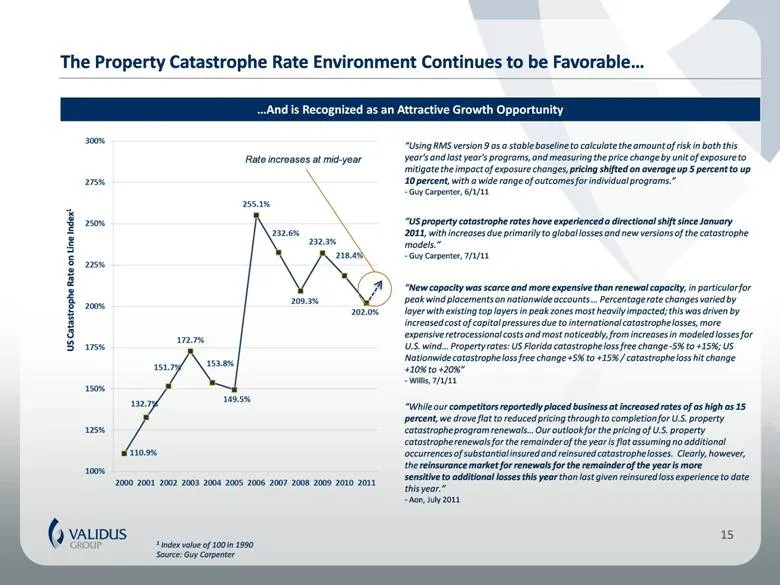
The Property Catastrophe Rate Environment Continues to be Favorable... 15 1 Index value of 100 in 1990 Source: Guy Carpenter... And is Recognized as an Attractive Growth Opportunity “Using RMS version 9 as a stable baseline to calculate the amount of risk in both this year's and last year's programs
Slide 16: Strength of Validus' Underwriting Franchise Validated by Third Parties
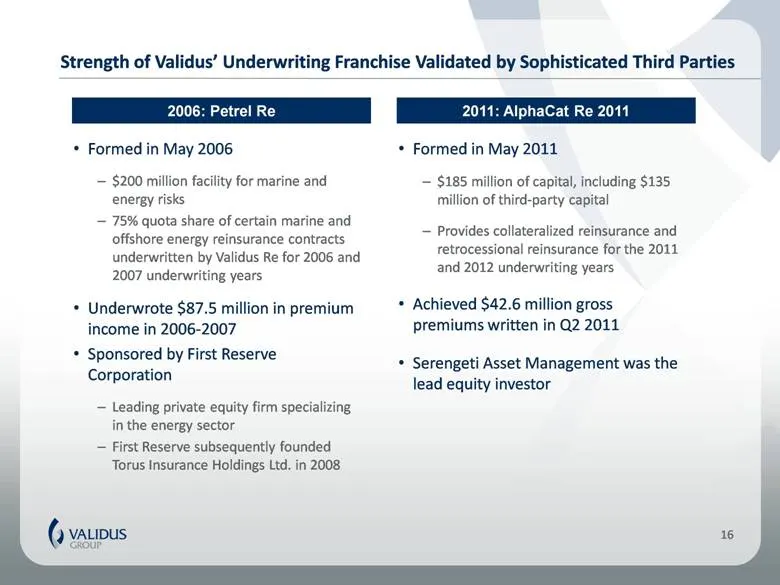
Strength of Validus’ Underwriting Franchise Validated by Sophisticated Third Parties 2006: Petrel Re Formed in May 2006 $200 million facility for marine and energy risks 75% quota share of certain marine and offshore energy reinsurance contracts underwritten by Validus Re for 2006 and 2007 underwrit
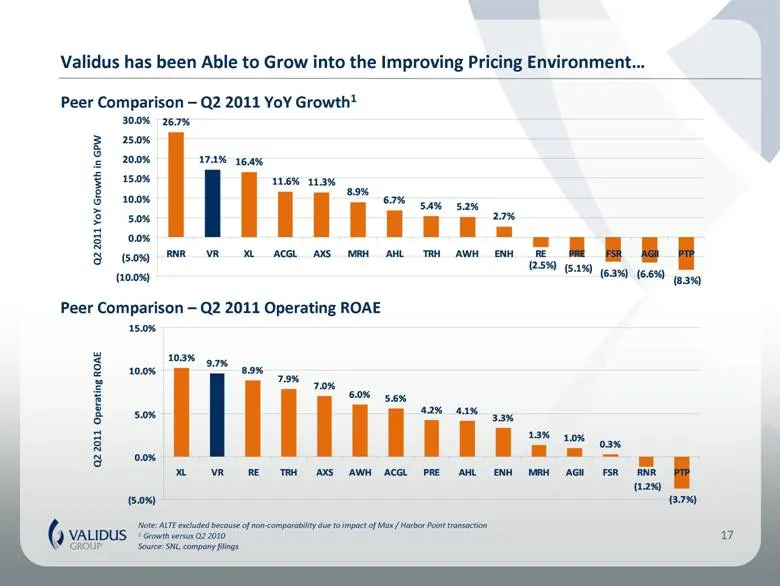
Slide 17: Validus has been Able to Grow into the Improving Pricing Environment
Validus has been Able to Grow into the Improving Pricing Environment... Peer Comparison – Q2 2011 YoY Growth1 17 Q2 2011 YoY Growth in GPW Note: ALTE excluded because of non-comparability due to impact of Max / Harbor Point transaction 1 Growth versus Q2 2010 Source: SNL, company filings Peer Compar
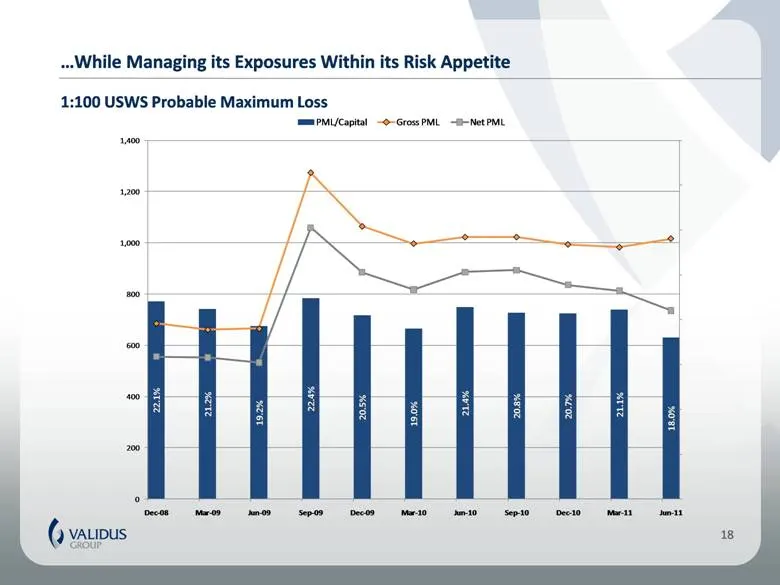
Slide 18: While Managing its Exposures Within its Risk Appetite
... While Managing its Exposures Within its Risk Appetite 18 1:100 USWS Probable Maximum Loss 22.1% 21.2% 19.2% 22.4% 20.5% 19.0% 21.4% 20.8% 20.7% 21.1% 18.0% 0 200 400 600 800 1,000 1,200 1,400 Dec-08 Mar-09 Jun-09 Sep-09 Dec-09 Mar-10 Jun-10 Sep-10 Dec-10 Mar-11 Jun-11 PML/Capital Gross PML Net P
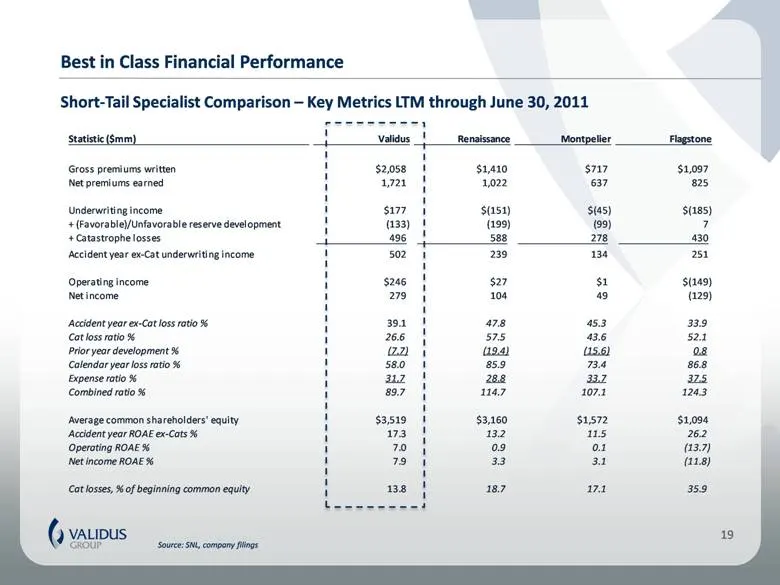
Slide 19: Best in Class Financial Performance
Best in Class Financial Performance Short-Tail Specialist Comparison – Key Metrics LTM through June 30, 2011 19 Source: SNL, company filings Statistic ($mm) Validus Renaissance Montpelier Flagstone Gross premiums written $2,058 $1,410 $717 $1,097 Net premiums earned 1,721 1,022 637 825 Underwriting
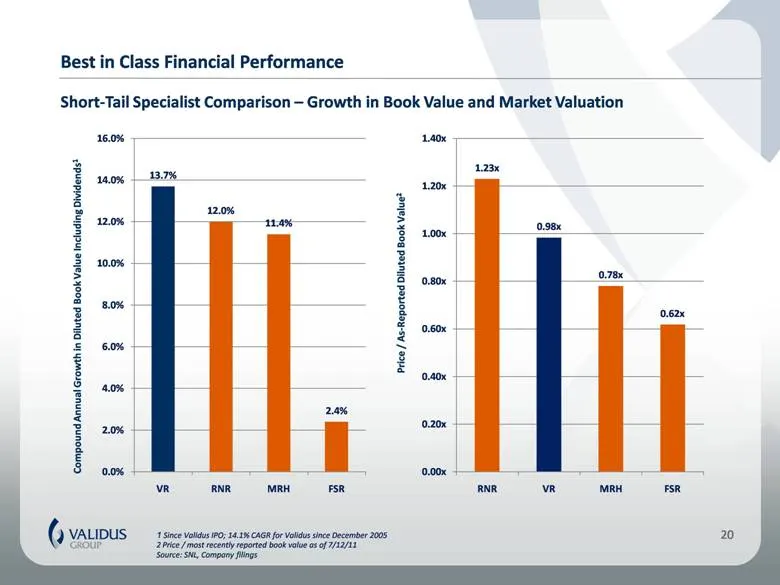
Slide 20: Growth in Book Value and Market Valuation
Short-Tail Specialist Comparison – Growth in Book Value and Market Valuation 20 1 Since Validus IPO; 14.1% CAGR for Validus since December 2005 2 Price / most recently reported book value as of 7/12/11 Source: SNL, Company filings Compound Annual Growth in Diluted Book Value Including Dividends1 Pri
Slide 21: Liquid and Short Duration Investment Portfolio
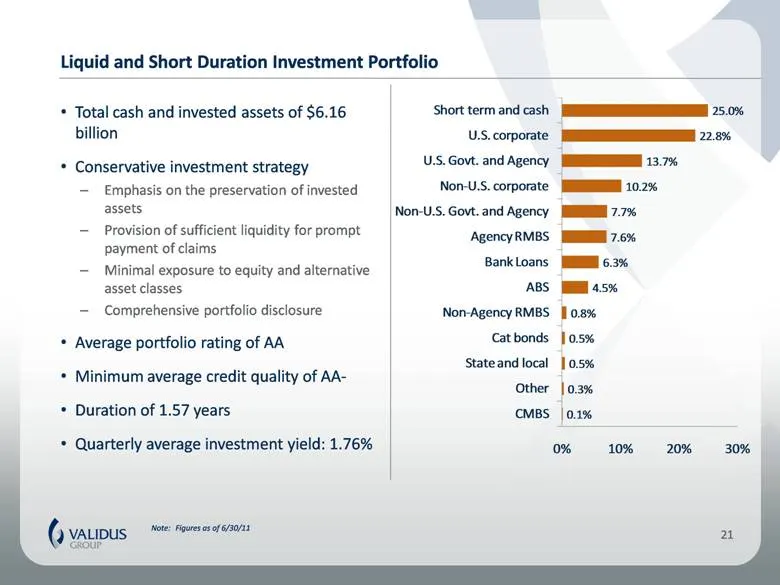
Liquid and Short Duration Investment Portfolio Total cash and invested assets of $6.16 billion Conservative investment strategy Emphasis on the preservation of invested assets Provision of sufficient liquidity for prompt payment of claims Minimal exposure to equity and alternative asset classes Comp
Slide 22: Investment Leverage vs. Peers
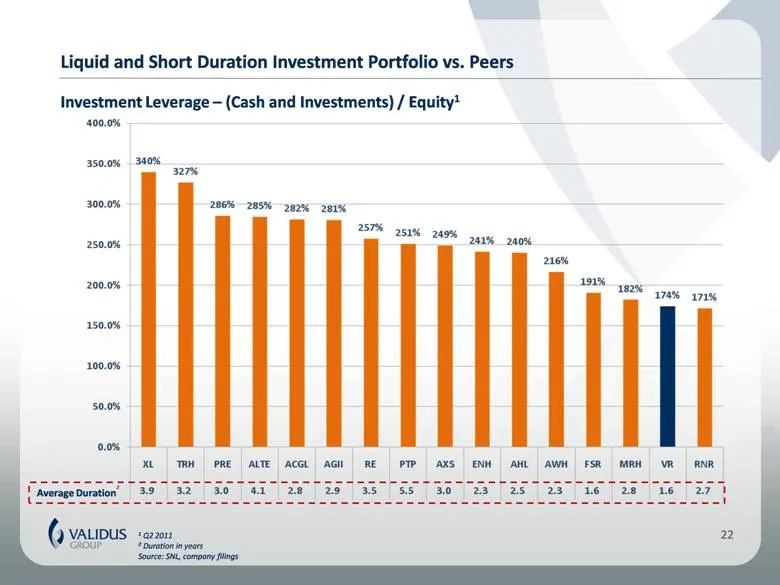
Investment Leverage – (Cash and Investments) / Equity1 22 Liquid and Short Duration Investment Portfolio vs. Peers 1 Q2 2011 2 Duration in years Source: SNL, company filings Average Duration 2
Slide 23: Loss Reserves at June 30, 2011
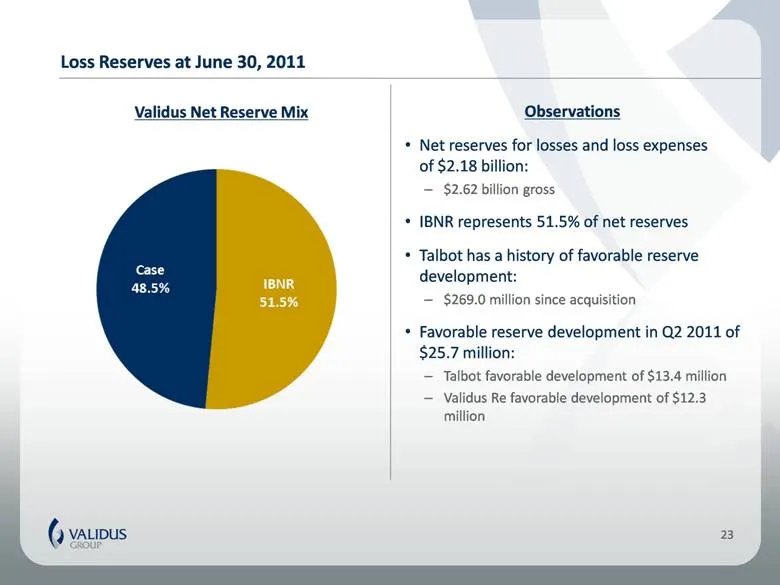
Loss Reserves at June 30, 2011 Validus Net Reserve Mix Observations Net reserves for losses and loss expenses of $2.18 billion: $2.62 billion gross IBNR represents 51.5% of net reserves Talbot has a history of favorable reserve development: $269.0 million since acquisition Favorable reserve developm
Slide 24: Active Capital Management - Rationalizing Capacity and Returning Capital
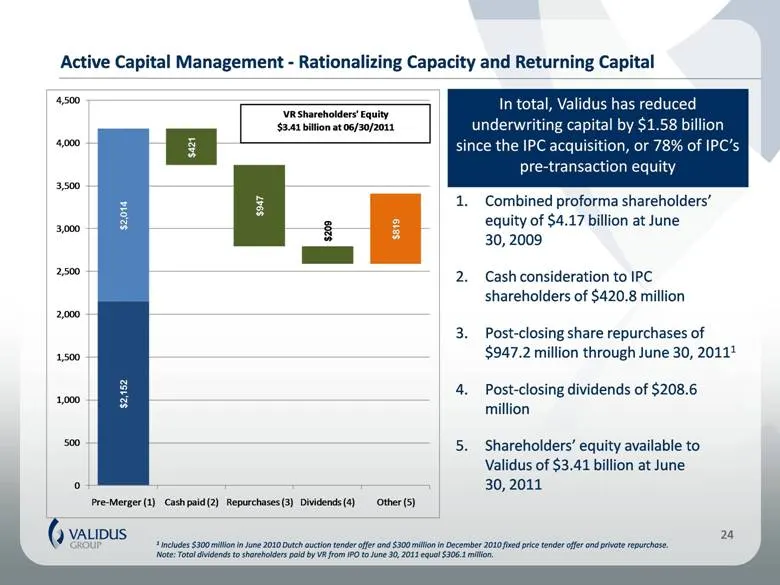
Active Capital Management - Rationalizing Capacity and Returning Capital Combined proforma shareholders’ equity of $4.17 billion at June 30, 2009 Cash consideration to IPC shareholders of $420.8 million Post-closing share repurchases of $947.2 million through June 30, 20111 Post-closing dividends of
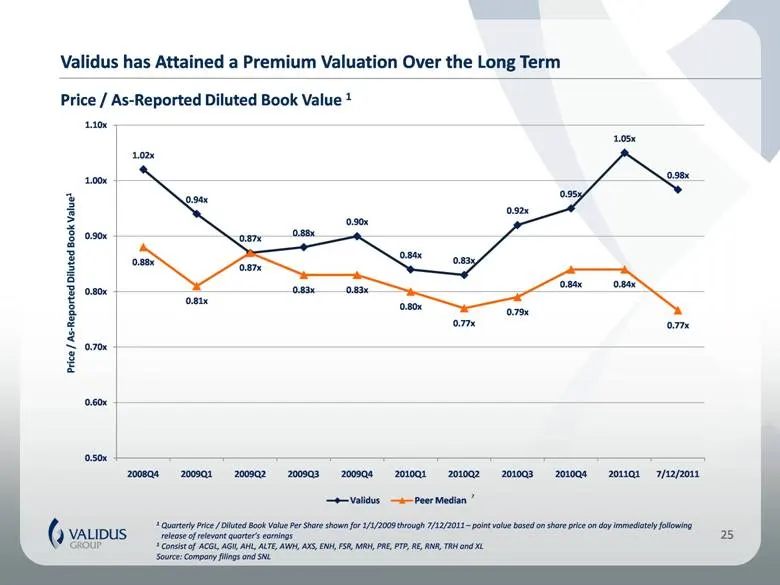
Slide 25: Validus has Attained a Premium Valuation Over the Long Term
Validus has Attained a Premium Valuation Over the Long Term 1 Quarterly Price / Diluted Book Value Per Share shown for 1/1/2009 through 7/12/2011 – point value based on share price on day immediately following release of relevant quarter’s earnings 1 Consist of ACGL, AGII, AHL, ALTE, AWH, AXS, ENH,
Slide 26: Creating a Global Reinsurance Leader with a Clear Business Plan
Creating a Global Reinsurance Leader with a Clear Business Plan Greater Current and Long-Term Value for Transatlantic Stockholders
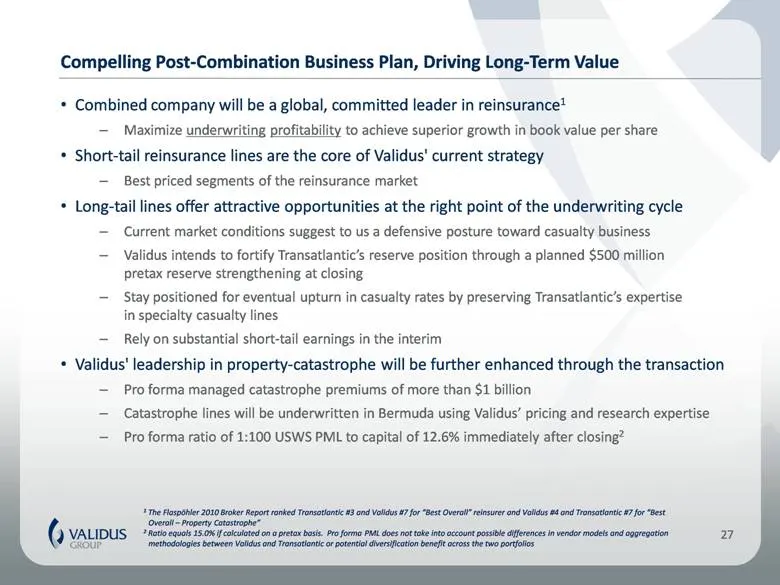
Slide 27: Compelling Post-Combination Business Plan, Driving Long-Term Value
Compelling Post-Combination Business Plan, Driving Long-Term Value Combined company will be a global, committed leader in reinsurance1 Maximize underwriting profitability to achieve superior growth in book value per share Short-tail reinsurance lines are the core of Validus' current strategy Best pr
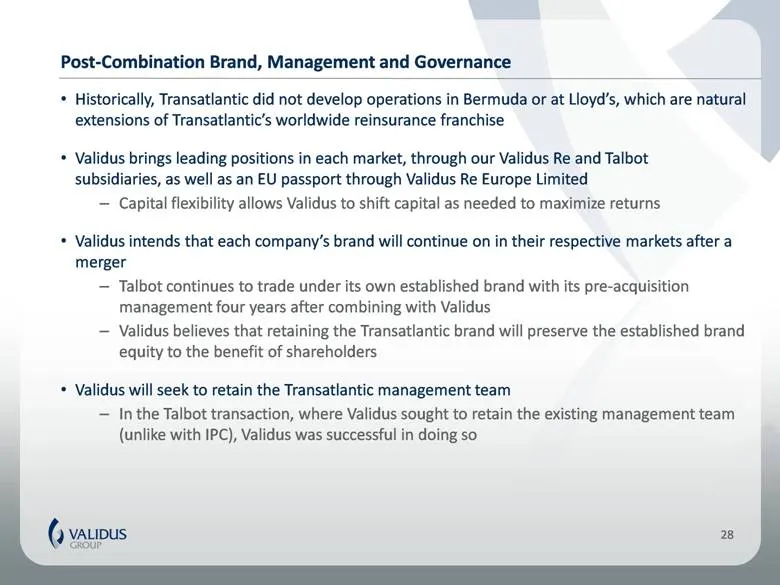
Slide 28: Post-Combination Brand, Management and Governance
Post-Combination Brand, Management and Governance Historically, Transatlantic did not develop operations in Bermuda or at Lloyd’s, which are natural extensions of Transatlantic’s worldwide reinsurance franchise Validus brings leading positions in each market, through our Validus Re and Talbot subsid
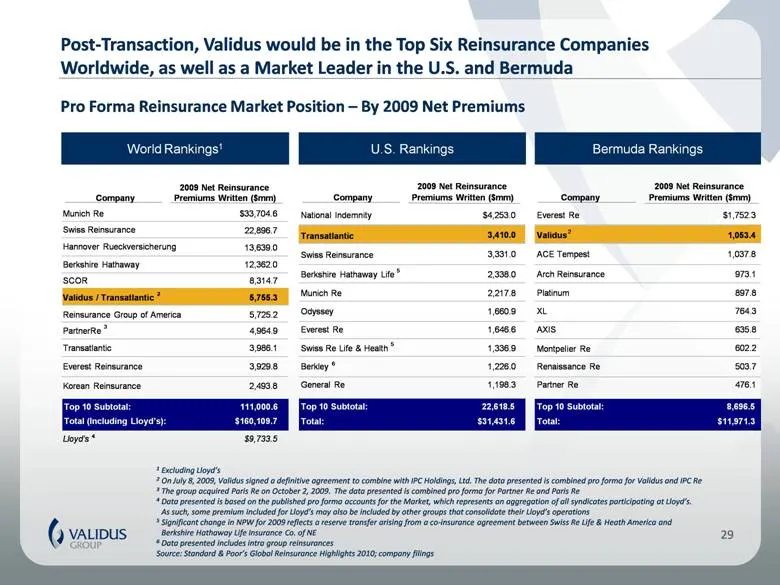
Slide 29: Post-Transaction, Validus in the Top Six Reinsurance Companies
Post-Transaction, Validus would be in the Top Six Reinsurance Companies Worldwide, as well as a Market Leader in the U.S. and Bermuda Pro Forma Reinsurance Market Position – By 2009 Net Premiums U.S. Rankings Company 2009 Net Reinsurance Premiums Written ($mm) Berkshire Hathaway Life National Indemn
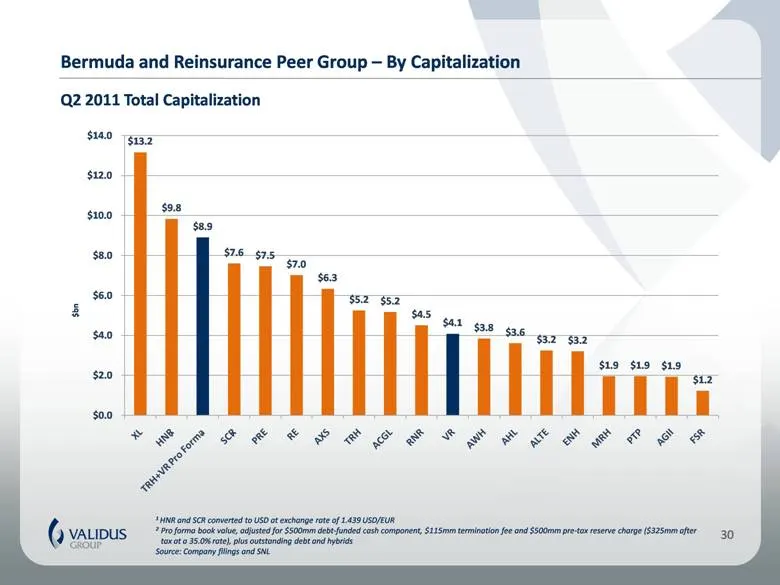
Slide 30: Bermuda and Reinsurance Peer Group – By Capitalization
Bermuda and Reinsurance Peer Group – By Capitalization 30 $bn Q2 2011 Total Capitalization 1 HNR and SCR converted to USD at exchange rate of 1.439 USD/EUR 2 Pro forma book value, adjusted for $500mm debt-funded cash component, $115mm termination fee and $500mm pre-tax reserve charge ($325mm after t
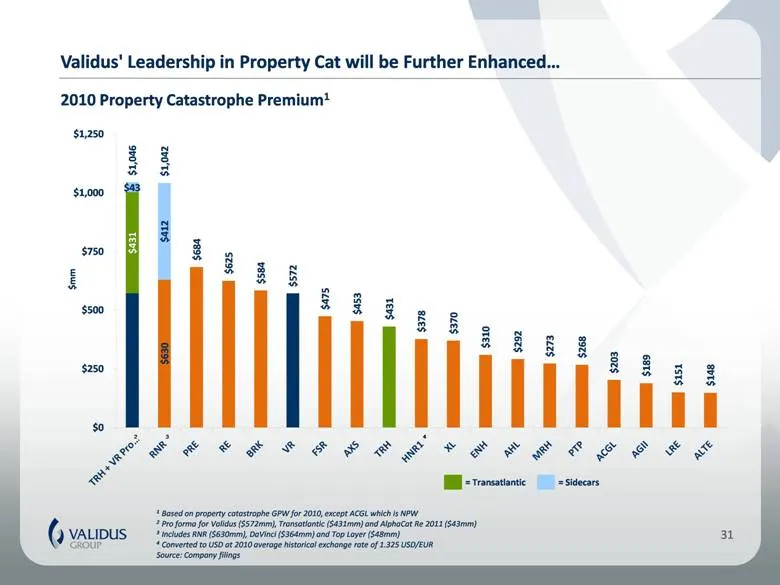
Slide 31: Validus' Leadership in Property Cat will be Further Enhanced
Validus' Leadership in Property Cat will be Further Enhanced 31 3 $mm 2 2010 Property Catastrophe Premium1 4 1 Based on property catastrophe GPW for 2010, except ACGL which is NPW 2 Pro forma for Validus ($572mm), Transatlantic ($431mm) and AlphaCat Re 2011 ($43mm) 3 Includes RNR ($630mm), DaVinci (
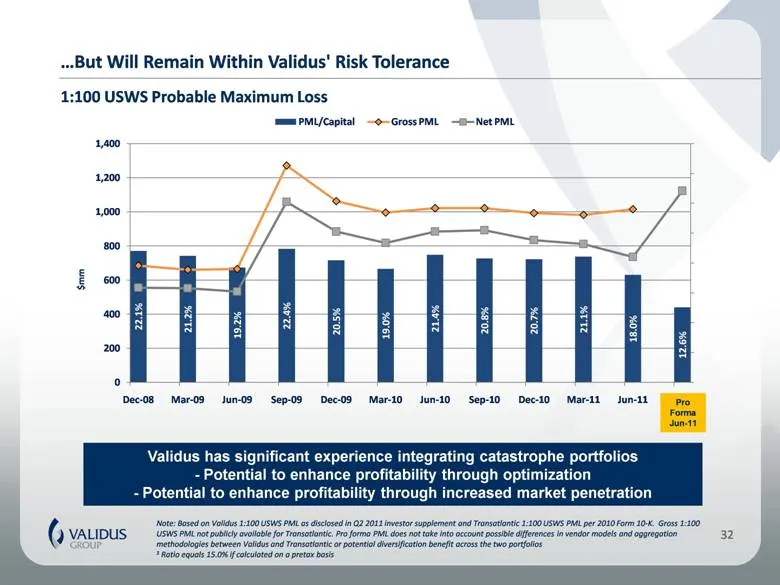
Slide 32: But Will Remain Within Validus' Risk Tolerance
32 But Will Remain Within Validus' Risk Tolerance 1:100 USWS Probable Maximum Loss Validus has significant experience integrating catastrophe portfolios - Potential to enhance profitability through optimization - Potential to enhance profitability through increased market penetration Note: Based on
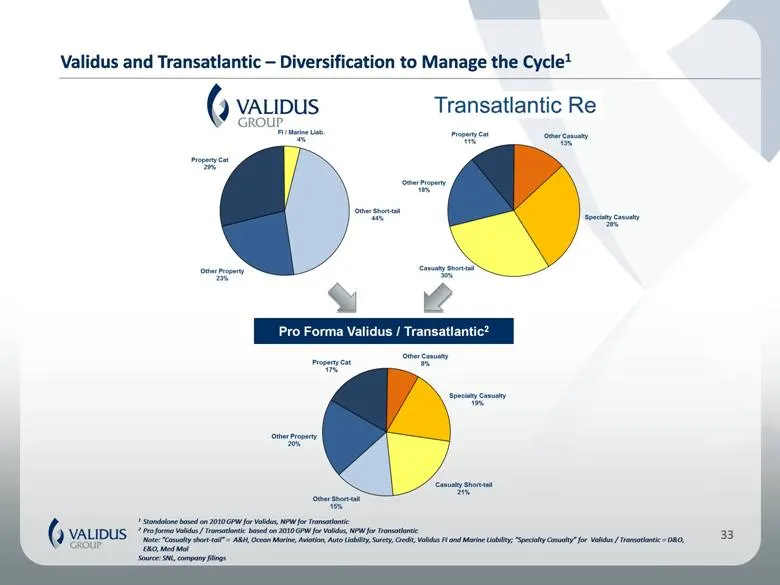
Slide 33: Diversification to Manage the Cycle
33 Validus and Transatlantic – Diversification to Manage the Cycle1 Pro Forma Validus / Transatlantic2 1 Standalone based on 2010 GPW for Validus, NPW for Transatlantic 2 Pro forma Validus / Transatlantic based on 2010 GPW for Validus, NPW for Transatlantic Note: “Casualty short-tail” = A&H, Ocean M
Slide 34: Validus Has a Track Record of Executing and Integrating Transactions
Validus Has a Track Record of Successfully Executing and Integrating Transactions Acquisition of Talbot (July 2007) In July 2007, Validus acquired Talbot, a leading Lloyd’s Syndicate for $382 million Talbot has contributed $277 million of net income since acquisition By moving first, Validus acquire
Slide 35: Potential Combination Synergies
Potential Combination Synergies In addition to the aggregate earnings power resident in a combined Validus/Transatlantic, we believe there are significant opportunities to expand earnings and ROE through combination synergies Once Validus and Transatlantic have combined, we see potential synergies i
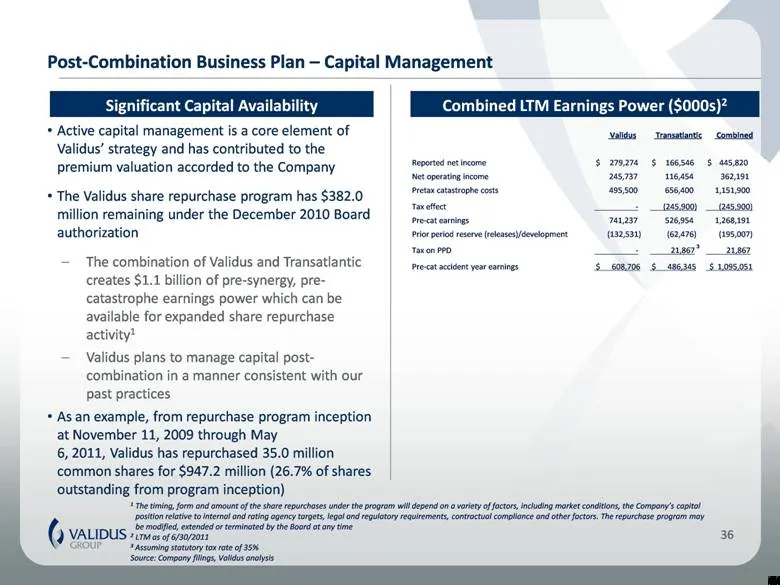
Slide 36: Combined LTM Earnings Power
Validus Transatlantic Combined Reported net income $ 279,274 $ 166,546 $ 445,820 Net operating income 245,737 116,454 362,191 Pretax catastrophe costs 495,500 656,400 1,151,900 Tax effect - (245,900) (245,900) Pre-cat earnings 741,237 526,954 1,268,191 Prior period reserve (releases)/development (13
Slide 37: Creating Long-Term Value Post-Acquisition
Creating Long-Term Value Post-Acquisition The Validus Track Record
Slide 38: Shareholder Value Creation Arising from the IPC Acquisition
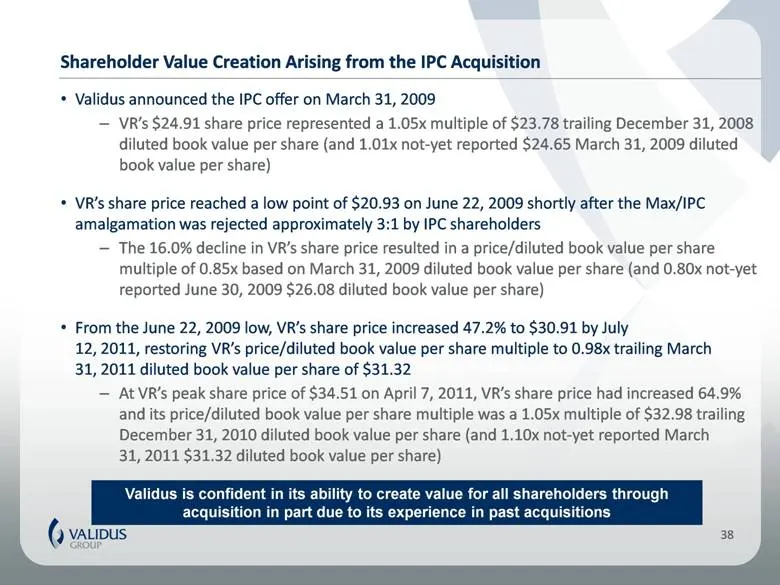
Shareholder Value Creation Arising from the IPC Acquisition Validus announced the IPC offer on March 31, 2009 VR’s $24.91 share price represented a 1.05x multiple of $23.78 trailing December 31, 2008 diluted book value per share (and 1.01x not-yet reported $24.65 March 31, 2009 diluted book value pe
Slide 39: Validus Share Price Performance and Total Return to Shareholders
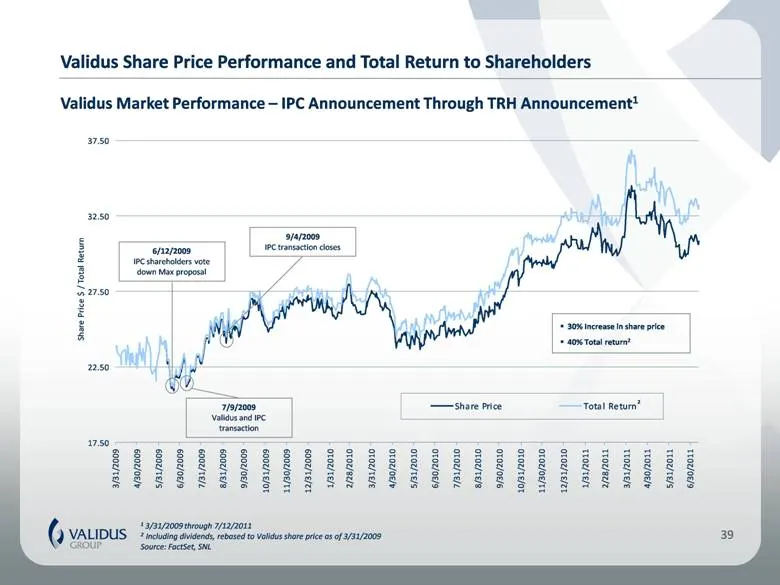
Validus Share Price Performance and Total Return to Shareholders 39 1 3/31/2009 through 7/12/2011 2 Including dividends, rebased to Validus share price as of 3/31/2009 Source: FactSet, SNL Validus Market Performance – IPC Announcement Through TRH Announcement1 6/12/2009 IPC shareholders vote down Ma
Slide 40: Validus Record of Trading at a Book Value Premium to AWAC
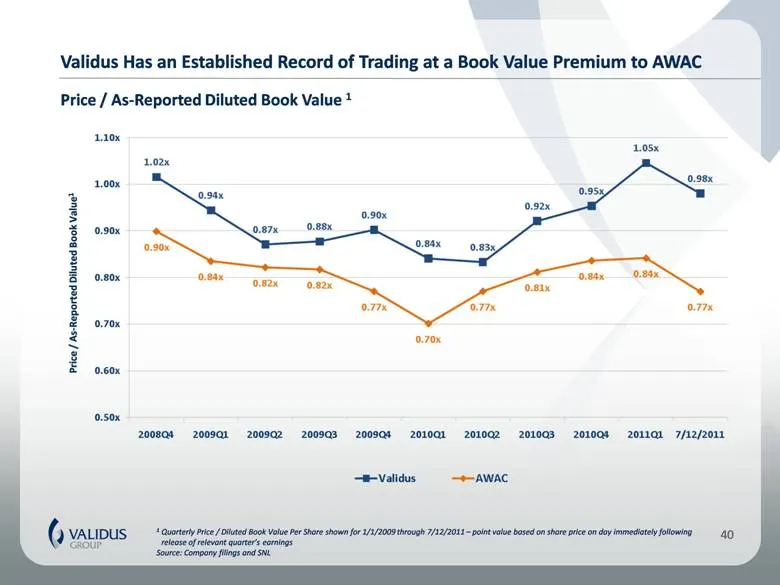
Validus Has an Established Record of Trading at a Book Value Premium to AWAC 1 Quarterly Price / Diluted Book Value Per Share shown for 1/1/2009 through 7/12/2011 – point value based on share price on day immediately following release of relevant quarter’s earnings Source: Company filings and SNL 40
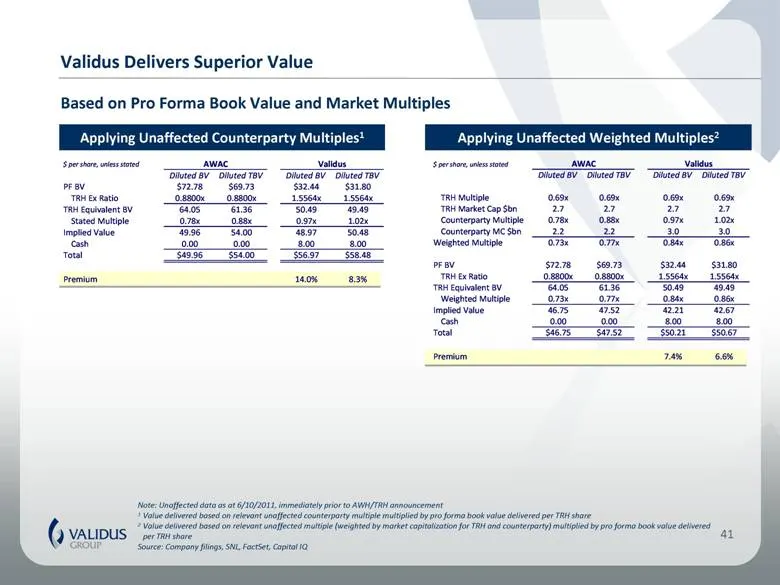
Slide 41: Superior Value Based on Pro Forma Book Value and Market Multiples
Validus Delivers Superior Value Based on Pro Forma Book Value and Market Multiples Applying Unaffected Counterparty Multiples1 Applying Unaffected Weighted Multiples2 $ per share, unless stated AWAC Validus $ per share, unless stated AWAC Validus Diluted BV Diluted TBV Diluted BV Diluted TBV Diluted
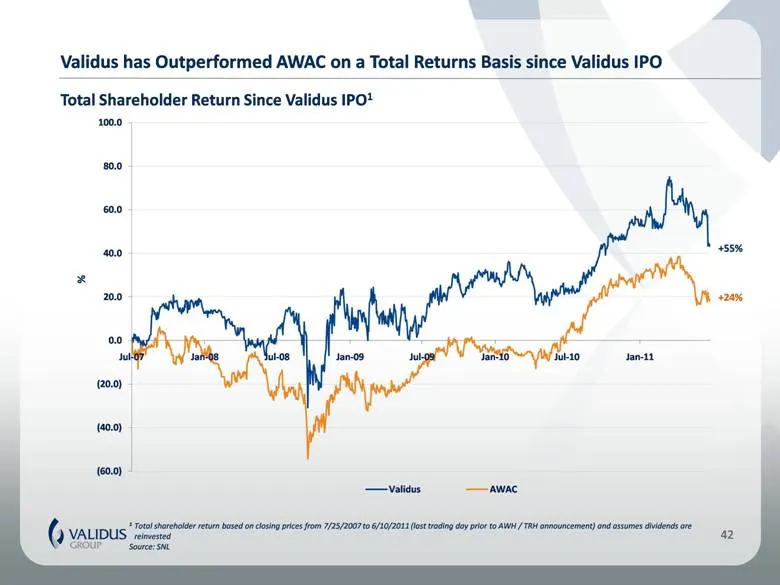
Slide 42: Validus has Outperformed AWAC on Total Returns Since IPO
Validus has Outperformed AWAC on a Total Returns Basis since Validus IPO 42 1 Total shareholder return based on closing prices from 7/25/2007 to 6/10/2011 (last trading day prior to AWH / TRH announcement) and assumes dividends are reinvested Source: SNL +55% +24% % Total Shareholder Return Since Va
Slide 43: What Transatlantic Stockholders Would be Subject to with AWAC
What Transatlantic Stockholders Would be Subject to with AWAC The Questionable Value of AWAC and its Weak Long-Term Prospects
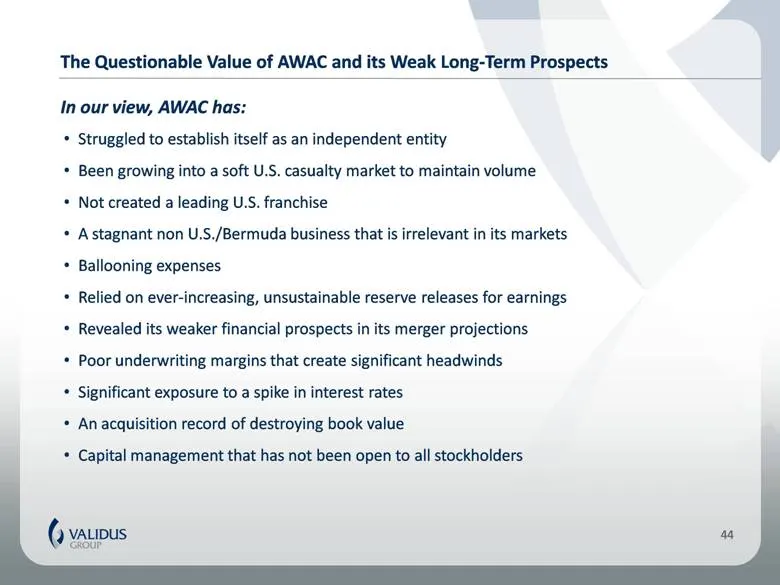
Slide 44: The Questionable Value of AWAC and its Weak Long-Term Prospects
The Questionable Value of AWAC and its Weak Long-Term Prospects 44 Struggled to establish itself as an independent entity Been growing into a soft U.S. casualty market to maintain volume Not created a leading U.S. franchise A stagnant non U.S./Bermuda business that is irrelevant in its markets Ballo
Slide 45: AWAC's Formative Years
AWAC’s Formative Years AWAC was formed in November 2001 by an AIG-led investor group, including Goldman Sachs, Chubb and Swiss Re In its initial years through 2005, AWAC’s function was to provide capacity for AIG like a “sidecar” “[AWAC distributed] products in the United States primarily through su
Slide 46: AWAC Has Struggled to Establish Itself as an Independent Entity
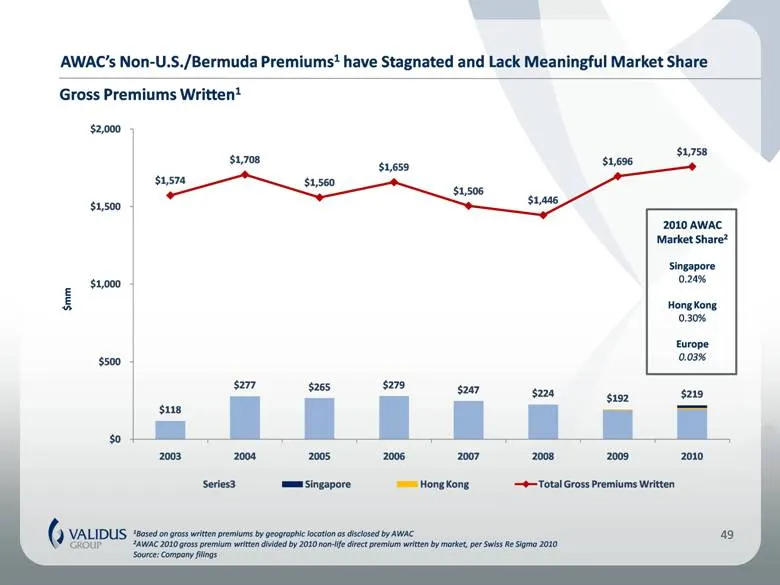
AWAC Has Struggled to Establish Itself as an Independent Entity AWAC has struggled to manage its separation from AIG 2004 consolidated GPW was $1,708 million, and it has taken AWAC six years for consolidated GPW to return to that level The original business produced by AIG was far more profitable an
Slide 47: AWAC Growing Into a Soft U.S. Casualty Market
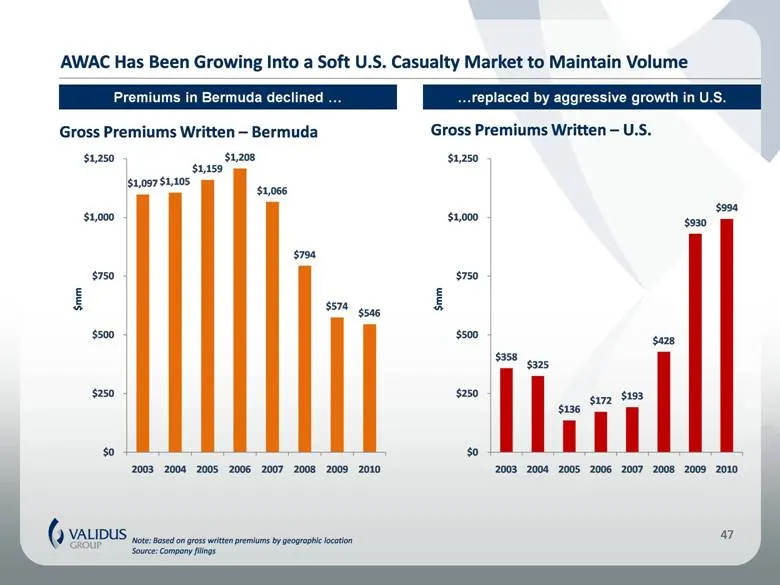
AWAC Has Been Growing Into a Soft U.S. Casualty Market to Maintain Volume 47 Premiums in Bermuda declined ....... replaced by aggressive growth in U.S. Note: Based on gross written premiums by geographic location Source: Company filings Gross Premiums Written – Bermuda Gross Premiums Written – U.S.
Slide 48: AWAC's U.S. Business is Not a Leading Franchise
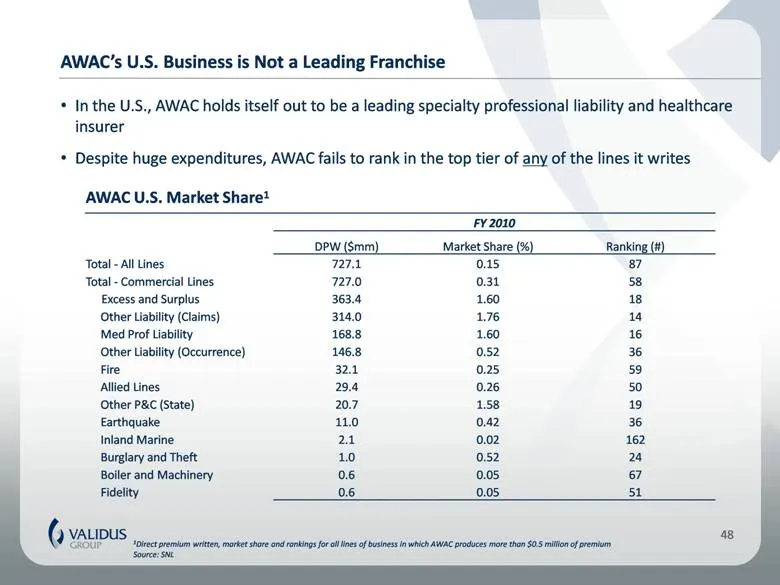
AWAC’s U.S. Business is Not a Leading Franchise In the U.S., AWAC holds itself out to be a leading specialty professional liability and healthcare insurer Despite huge expenditures, AWAC fails to rank in the top tier of any of the lines it writes 48 AWAC U.S. Market Share1 FY 2010 DPW ($mm) Market S
Slide 49: AWAC's Non-U.S./Bermuda Premiums Have Stagnated
AWAC’s Non-U.S./Bermuda Premiums1 have Stagnated and Lack Meaningful Market Share 49 Gross Premiums Written1 2010 AWAC Market Share2 Singapore 0.24% Hong Kong 0.30% Europe 0.03% 1Based on gross written premiums by geographic location as disclosed by AWAC 2AWAC 2010 gross premium written divided by 2
Slide 50: AWAC's Expense Problem
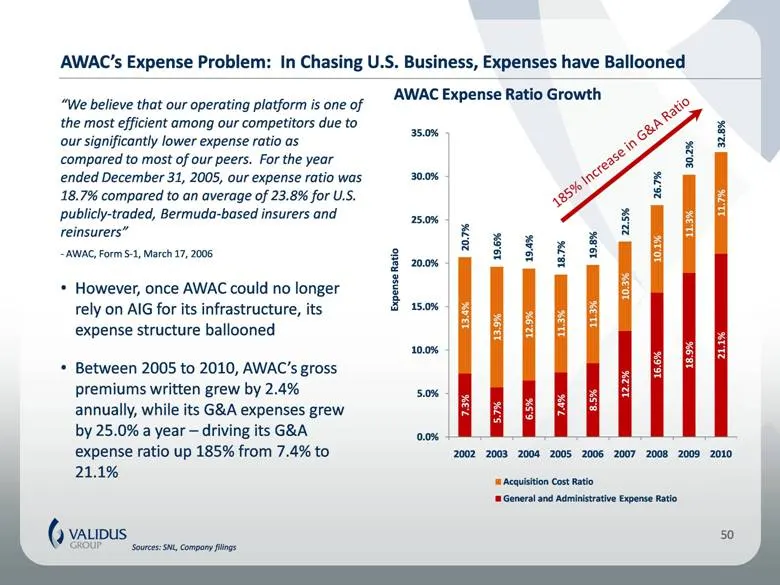
AWAC’s Expense Problem: In Chasing U.S. Business, Expenses have Ballooned Sources: SNL, Company filings 50 AWAC Expense Ratio Growth Expense Ratio “We believe that our operating platform is one of the most efficient among our competitors due to our significantly lower expense ratio as compared to mo
Slide 51: AWAC Has Relied on Ever-Increasing Reserve Releases
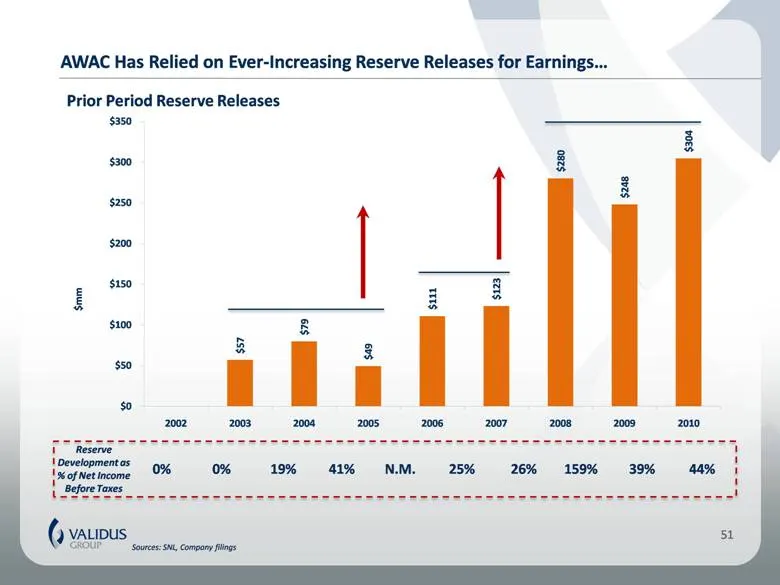
AWAC Has Relied on Ever-Increasing Reserve Releases for Earnings... Sources: SNL, Company filings 51 $mm Reserve Development as % of Net Income Before Taxes 0% 0% 19% 41% N.M. 25% 26% 159% 39% 44% Prior Period Reserve Releases
Slide 52: AWAC's Reserve Releases Come Largely From the AIG Years
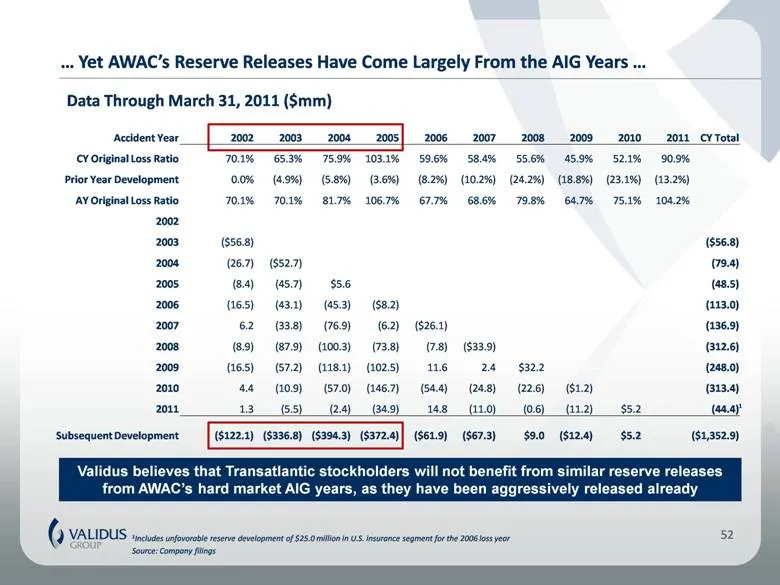
... Yet AWAC’s Reserve Releases Have Come Largely From the AIG Years... 1Includes unfavorable reserve development of $25.0 million in U.S. insurance segment for the 2006 loss year Source: Company filings 52 Accident Year 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 CY Total CY Original Loss Rat
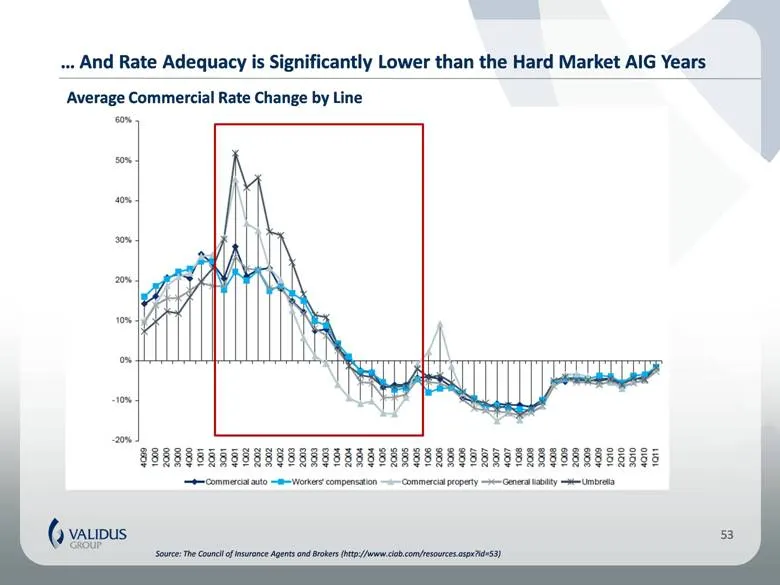
Slide 53: Rate Adequacy Significantly Lower than the Hard Market AIG Years
... And Rate Adequacy is Significantly Lower than the Hard Market AIG Years Source: The Council of Insurance Agents and Brokers (http://www.ciab.com/resources.aspx?id=53) 53 Average Commercial Rate Change by Line
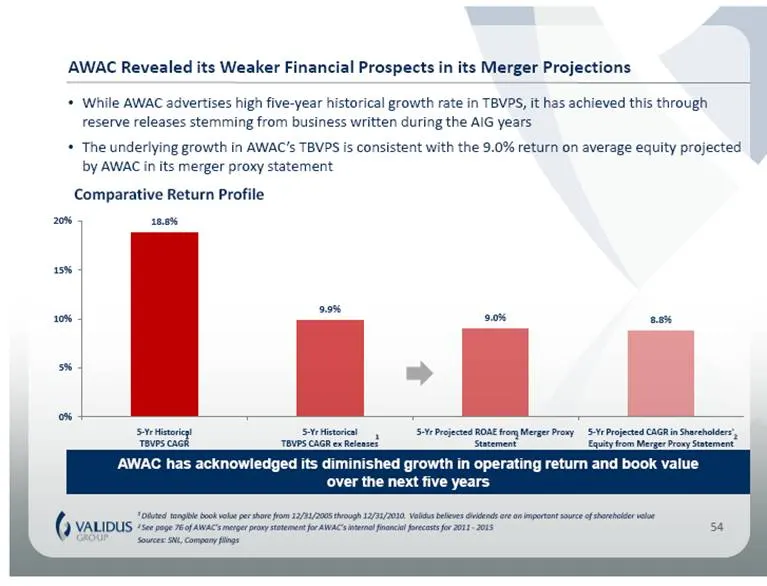
Slide 54: AWAC Revealed Weaker Financial Prospects in its Merger Projections
AWAC Revealed its Weaker Financial Prospects in its Merger Projections 1 Diluted tangible book value per share from 12/31/2005 through 12/31/2010. Validus believes dividends are an important source of shareholder value 2 See page 76 of AWAC’s merger proxy statement for AWAC’s internal financial fore
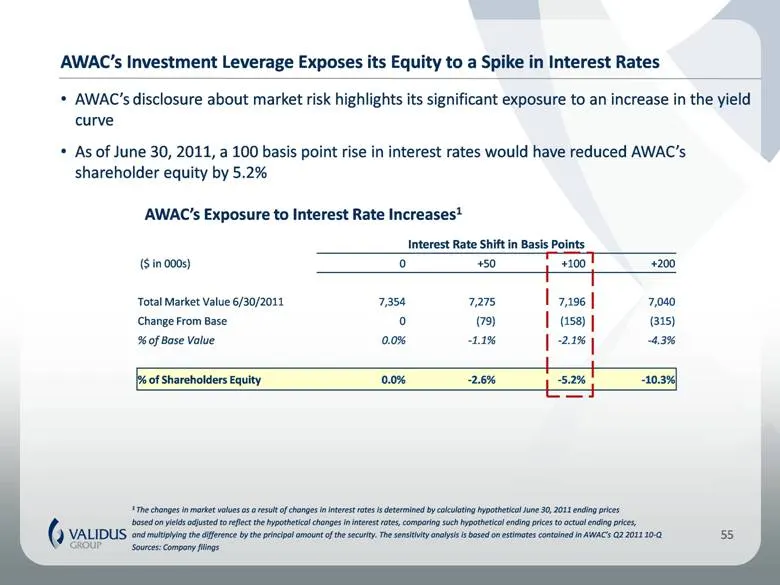
Slide 55: AWAC's Investment Leverage Exposes Equity to Interest Rates
AWAC’s Investment Leverage Exposes its Equity to a Spike in Interest Rates 1 The changes in market values as a result of changes in interest rates is determined by calculating hypothetical June 30, 2011 ending prices based on yields adjusted to reflect the hypothetical changes in interest rates, com
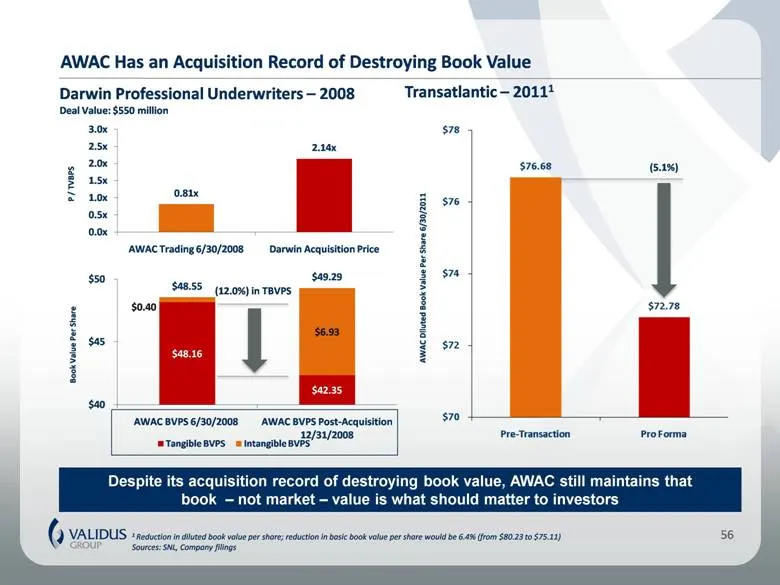
Slide 56: AWAC Has an Acquisition Record of Destroying Book Value
AWAC Has an Acquisition Record of Destroying Book Value 1 Reduction in diluted book value per share; reduction in basic book value per share would be 6.4% (from $80.23 to $75.11) Sources: SNL, Company filings 56 Despite its acquisition record of destroying book value, AWAC still maintains that book
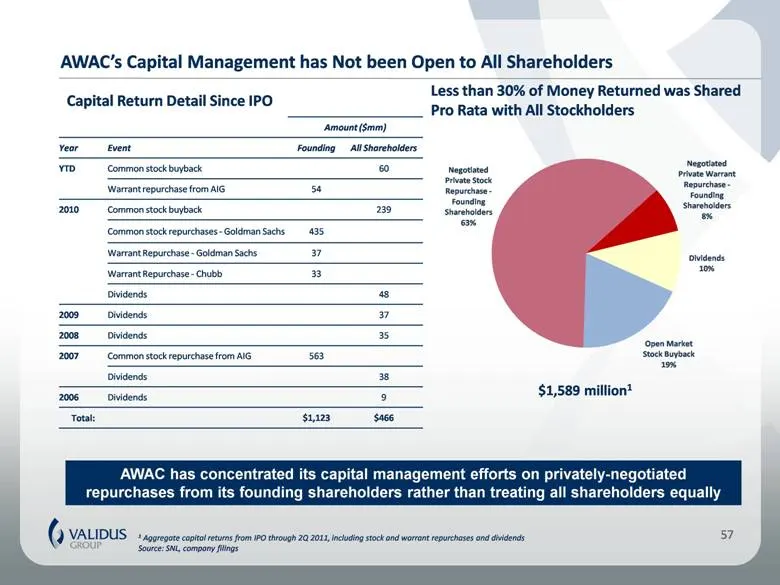
Slide 57: AWAC's Capital Management Not Open to All Shareholders
AWAC’s Capital Management has Not been Open to All Shareholders 1 Aggregate capital returns from IPO through 2Q 2011, including stock and warrant repurchases and dividends Source: SNL, company filings 57 AWAC has concentrated its capital management efforts on privately-negotiated repurchases from it
Slide 58: Setting the Record Straight on AWAC and Transatlantic's Misleading Statements
Setting the Record Straight on AWAC and Transatlantic’s Misleading Statements
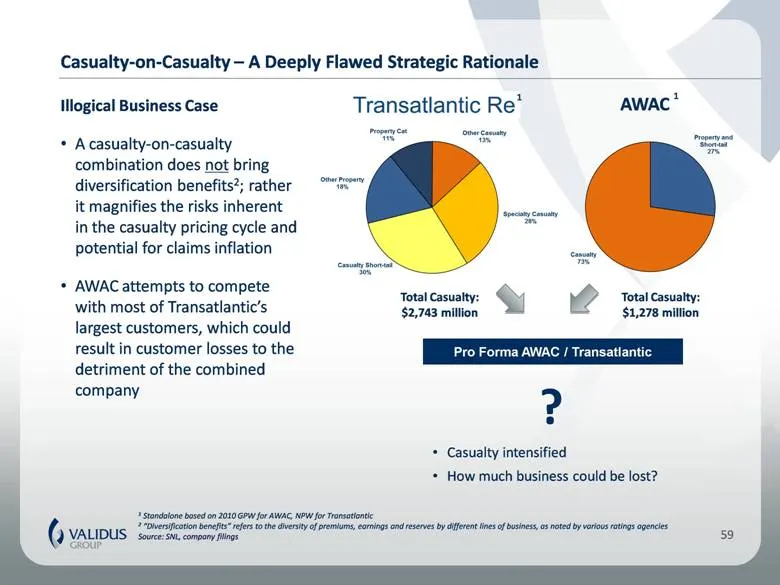
Slide 59: Casualty-on-Casualty – A Deeply Flawed Strategic Rationale
Casualty-on-Casualty – A Deeply Flawed Strategic Rationale Illogical Business Case A casualty-on-casualty combination does not bring diversification benefits2; rather it magnifies the risks inherent in the casualty pricing cycle and potential for claims inflation AWAC attempts to compete with most o
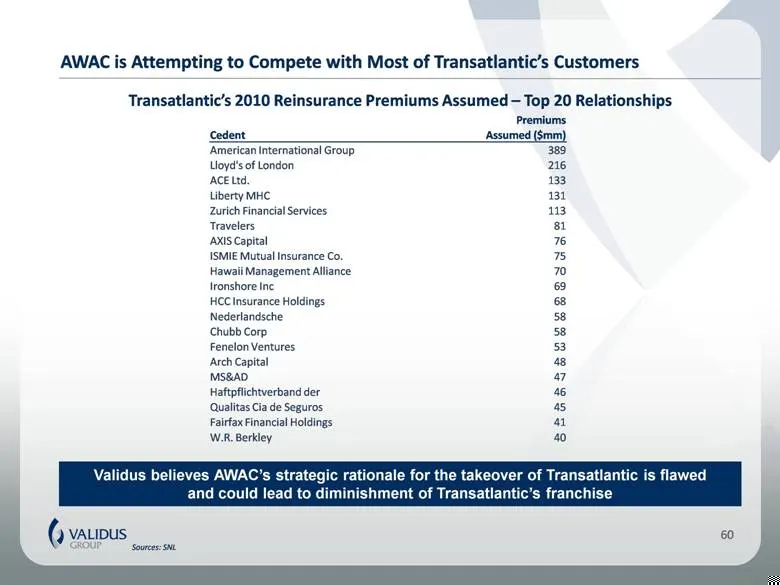
Slide 60: AWAC is Attempting to Compete with Most of Transatlantic's Customers
AWAC is Attempting to Compete with Most of Transatlantic’s Customers Sources: SNL 60 Transatlantic’s 2010 Reinsurance Premiums Assumed – Top 20 Relationships Validus believes AWAC’s strategic rationale for the takeover of Transatlantic is flawed and could lead to diminishment of Transatlantic’s fran
Slide 61: The Fallacy of AWAC and Transatlantic's Tax Inefficiency Argument
The Fallacy of AWAC and Transatlantic’s Tax Inefficiency Argument AWAC and Transatlantic claim that Validus’ Superior Proposal is tax inefficient – yet it is hard to see the logic in their argument Is the supposed “inefficiency” caused by provision of $8.00 cash to Transatlantic stockholders? Is the
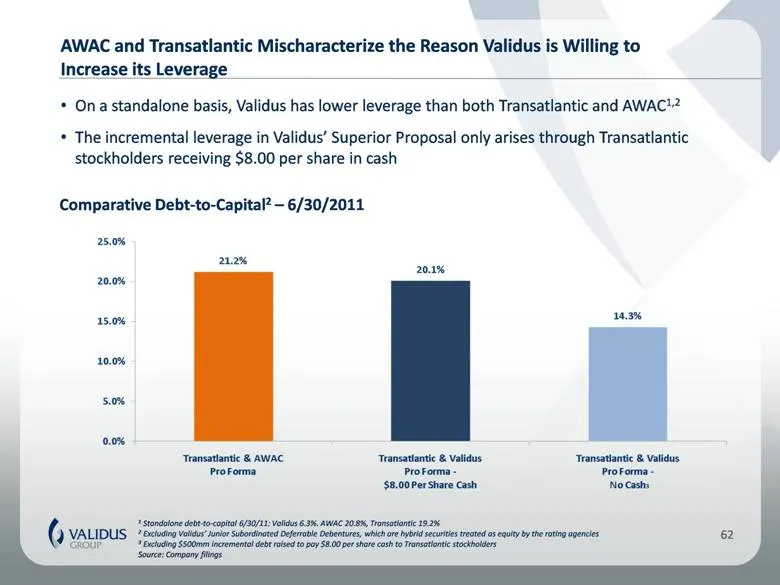
Slide 62: AWAC and Transatlantic Mischaracterize Validus' Leverage
AWAC and Transatlantic Mischaracterize the Reason Validus is Willing to Increase its Leverage On a standalone basis, Validus has lower leverage than both Transatlantic and AWAC1,2 The incremental leverage in Validus’ Superior Proposal only arises through Transatlantic stockholders receiving $8.00 pe
Slide 63: AWAC's and Transatlantic's Ownership Argument is Self-Serving
AWAC’s and Transatlantic’s Ownership Argument is Self-Serving and Hypocritical The Transatlantic board denigrates Validus’ Superior Proposal because Transatlantic stockholders would have a 48% ownership interest on a fully diluted basis Yet Transatlantic entered into an agreement with AWAC that requ
Slide 64: AWAC and Transatlantic are Misstating Ratings Agency Reactions
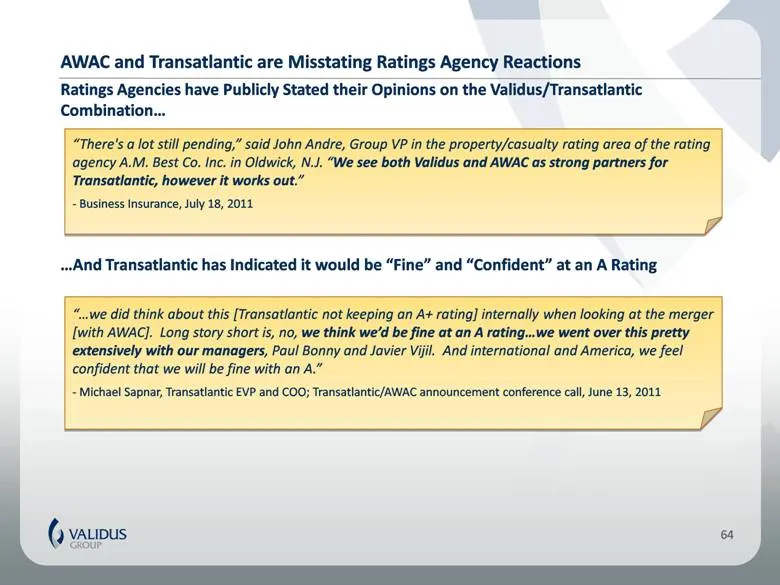
AWAC and Transatlantic are Misstating Ratings Agency Reactions “There's a lot still pending,” said John Andre, Group VP in the property/casualty rating area of the rating agency A.M. Best Co. Inc. in Oldwick, N.J. “We see both Validus and AWAC as strong partners for Transatlantic, however it works o
Slide 65: Lower Risk Appetite Doesn't Mean Lower Losses
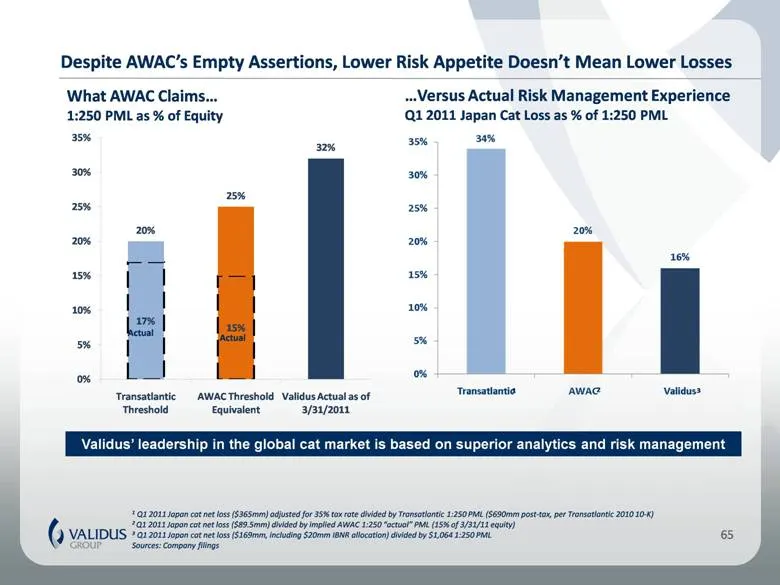
Despite AWAC’s Empty Assertions, Lower Risk Appetite Doesn’t Mean Lower Losses 65 Validus’ leadership in the global cat market is based on superior analytics and risk management What AWAC Claims... 1:250 PML as % of Equity 1 Q1 2011 Japan cat net loss ($365mm) adjusted for 35% tax rate divided by Tr
Slide 66: Validus' Proposal is No More Conditional than AWAC's Takeover
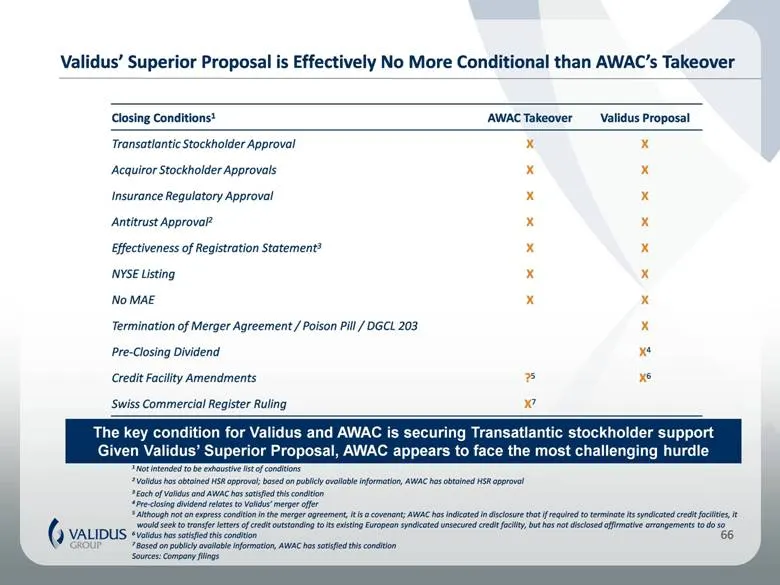
Validus’ Superior Proposal is Effectively No More Conditional than AWAC’s Takeover 66 1 Not intended to be exhaustive list of conditions 2 Validus has obtained HSR approval; based on publicly available information, AWAC has obtained HSR approval 3 Each of Validus and AWAC has satisfied this conditio
Slide 67: What AWAC and Transatlantic Have Not Told Investors
What AWAC and Transatlantic Have Not Told Investors Transatlantic’s year-end carried net loss reserves proved to be inadequate when re-estimated at December 31, 2010 for each year from 2000 through 2008, according to the loss development triangle in the most recent Transatlantic Form 10-K Other liab
Slide 68: What Investors Should Ask AWAC and Transatlantic
What Investors Should Ask AWAC and Transatlantic AWAC and Transatlantic seem fixated on book value. When was the last time AWAC shareholders have been able to sell their shares at or above book value? Given that a critical component of AWAC’s growth in book value per share has come from reserve rele
Slide 69: Conclusion: What You Get With Validus
Conclusion What You Get With Validus
Slide 70: What You Get With Validus
What You Get With Validus Greater market value than AWAC offer Better currency, with superior stock price performance Strong, long-term upside potential Board and management devoted to maximizing shareholder value, not premium volume Leading franchise positions in Bermuda and at Lloyd’s Deeply exper
Slide 71: Appendix: Reconciliation of Non-GAAP Measures
Appendix Reconciliation of Non-GAAP Measures
Slide 72: Net Operating Income Reconciliation
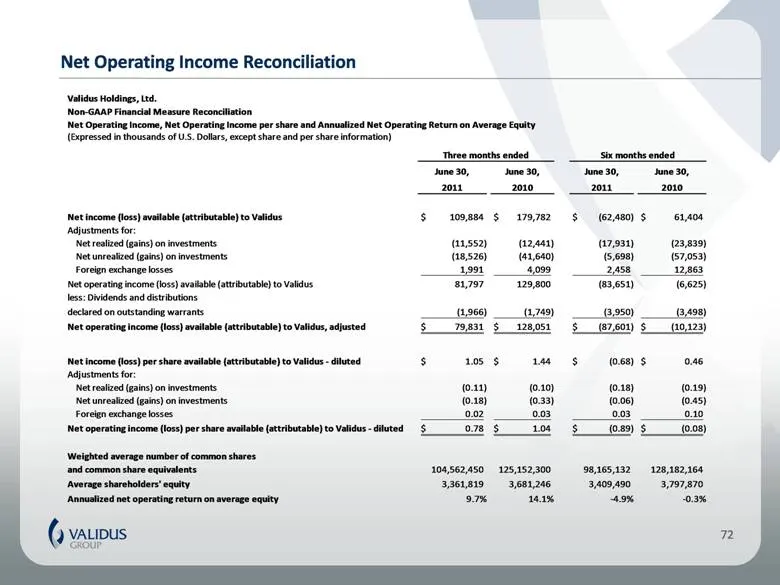
Net Operating Income Reconciliation 72 Validus Holdings, Ltd. Non-GAAP Financial Measure Reconciliation Net Operating Income, Net Operating Income per share and Annualized Net Operating Return on Average Equity (Expressed in thousands of U.S. Dollars, except share and per share information) June 30,
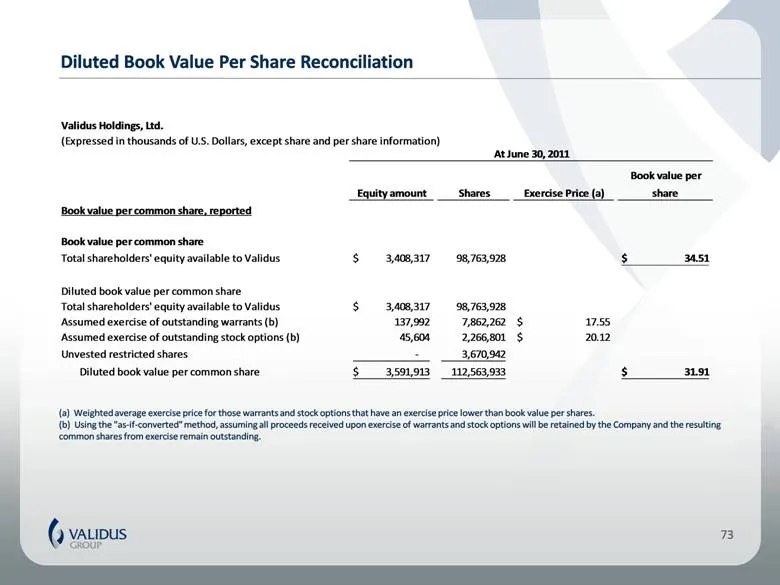
Slide 73: Diluted Book Value Per Share Reconciliation
Diluted Book Value Per Share Reconciliation 73 (a) Weighted average exercise price for those warrants and stock options that have an exercise price lower than book value per shares. (b) Using the "as-if-converted" method, assuming all proceeds received upon exercise of warrants and stock options wil
Source: SEC EDGAR · 425 filed Aug 23, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011