Strategic Hotels and Resorts Inc
Strategic Hotels and Resorts — Investor Presentation (January 2013)
35 slides from Strategic Hotels and Resorts's investor presentation, Jan 22, 2013
Slide 1: Investor Presentation
Exhibit 99.1 Investor Presentation January 2013
Slide 2: BEE's Unique Value Proposition
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview BEE’s Unique Value Proposition 1
Slide 3: BEE's Unique Value Proposition
BEE’s Unique Value Proposition o The only pure play high-end lodging REIT o High-end outperforms the industry in a recovery o Industry leading asset management expertise o Assets are in pristine condition o Embedded organic growth through revenue growth and ROI opportunities o Historically low suppl
Slide 4: High-end, Unique & Irreplaceable; Proven Track Record; Asset Management
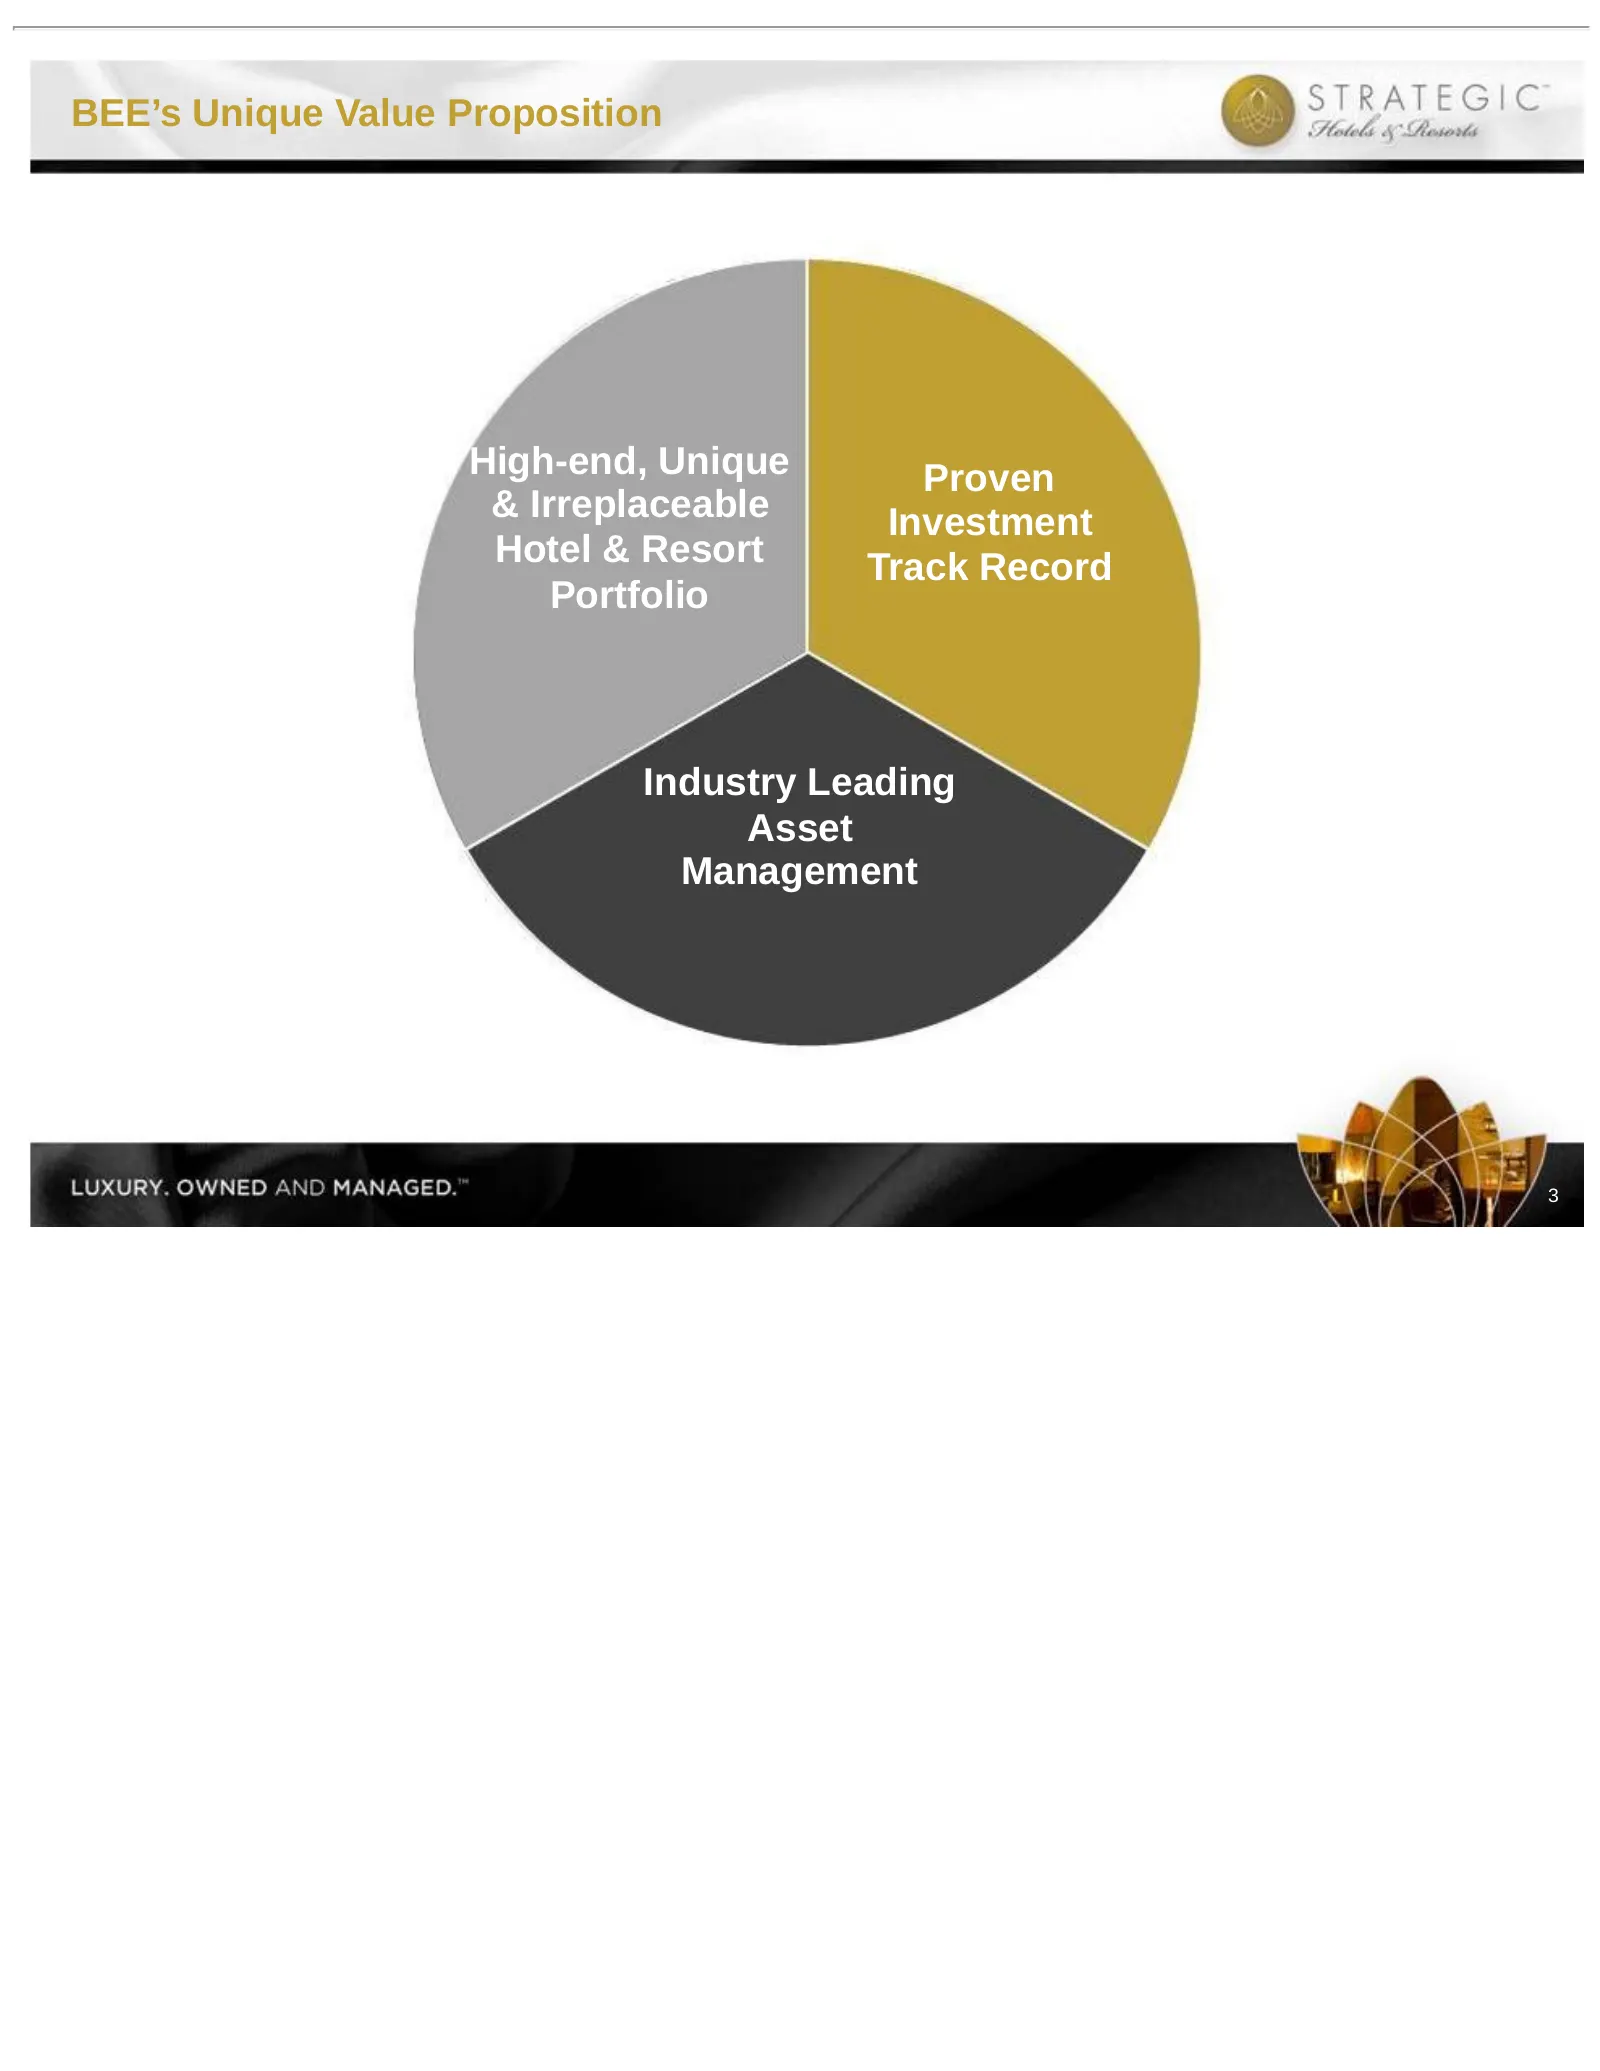
BEE’s Unique Value Proposition High-end, Unique Proven & Irreplaceable Investment Hotel & Resort Track Record Portfolio Industry Leading Asset Management 3
Slide 5: High-end, Unique & Irreplaceable Hotel & Resort Portfolio
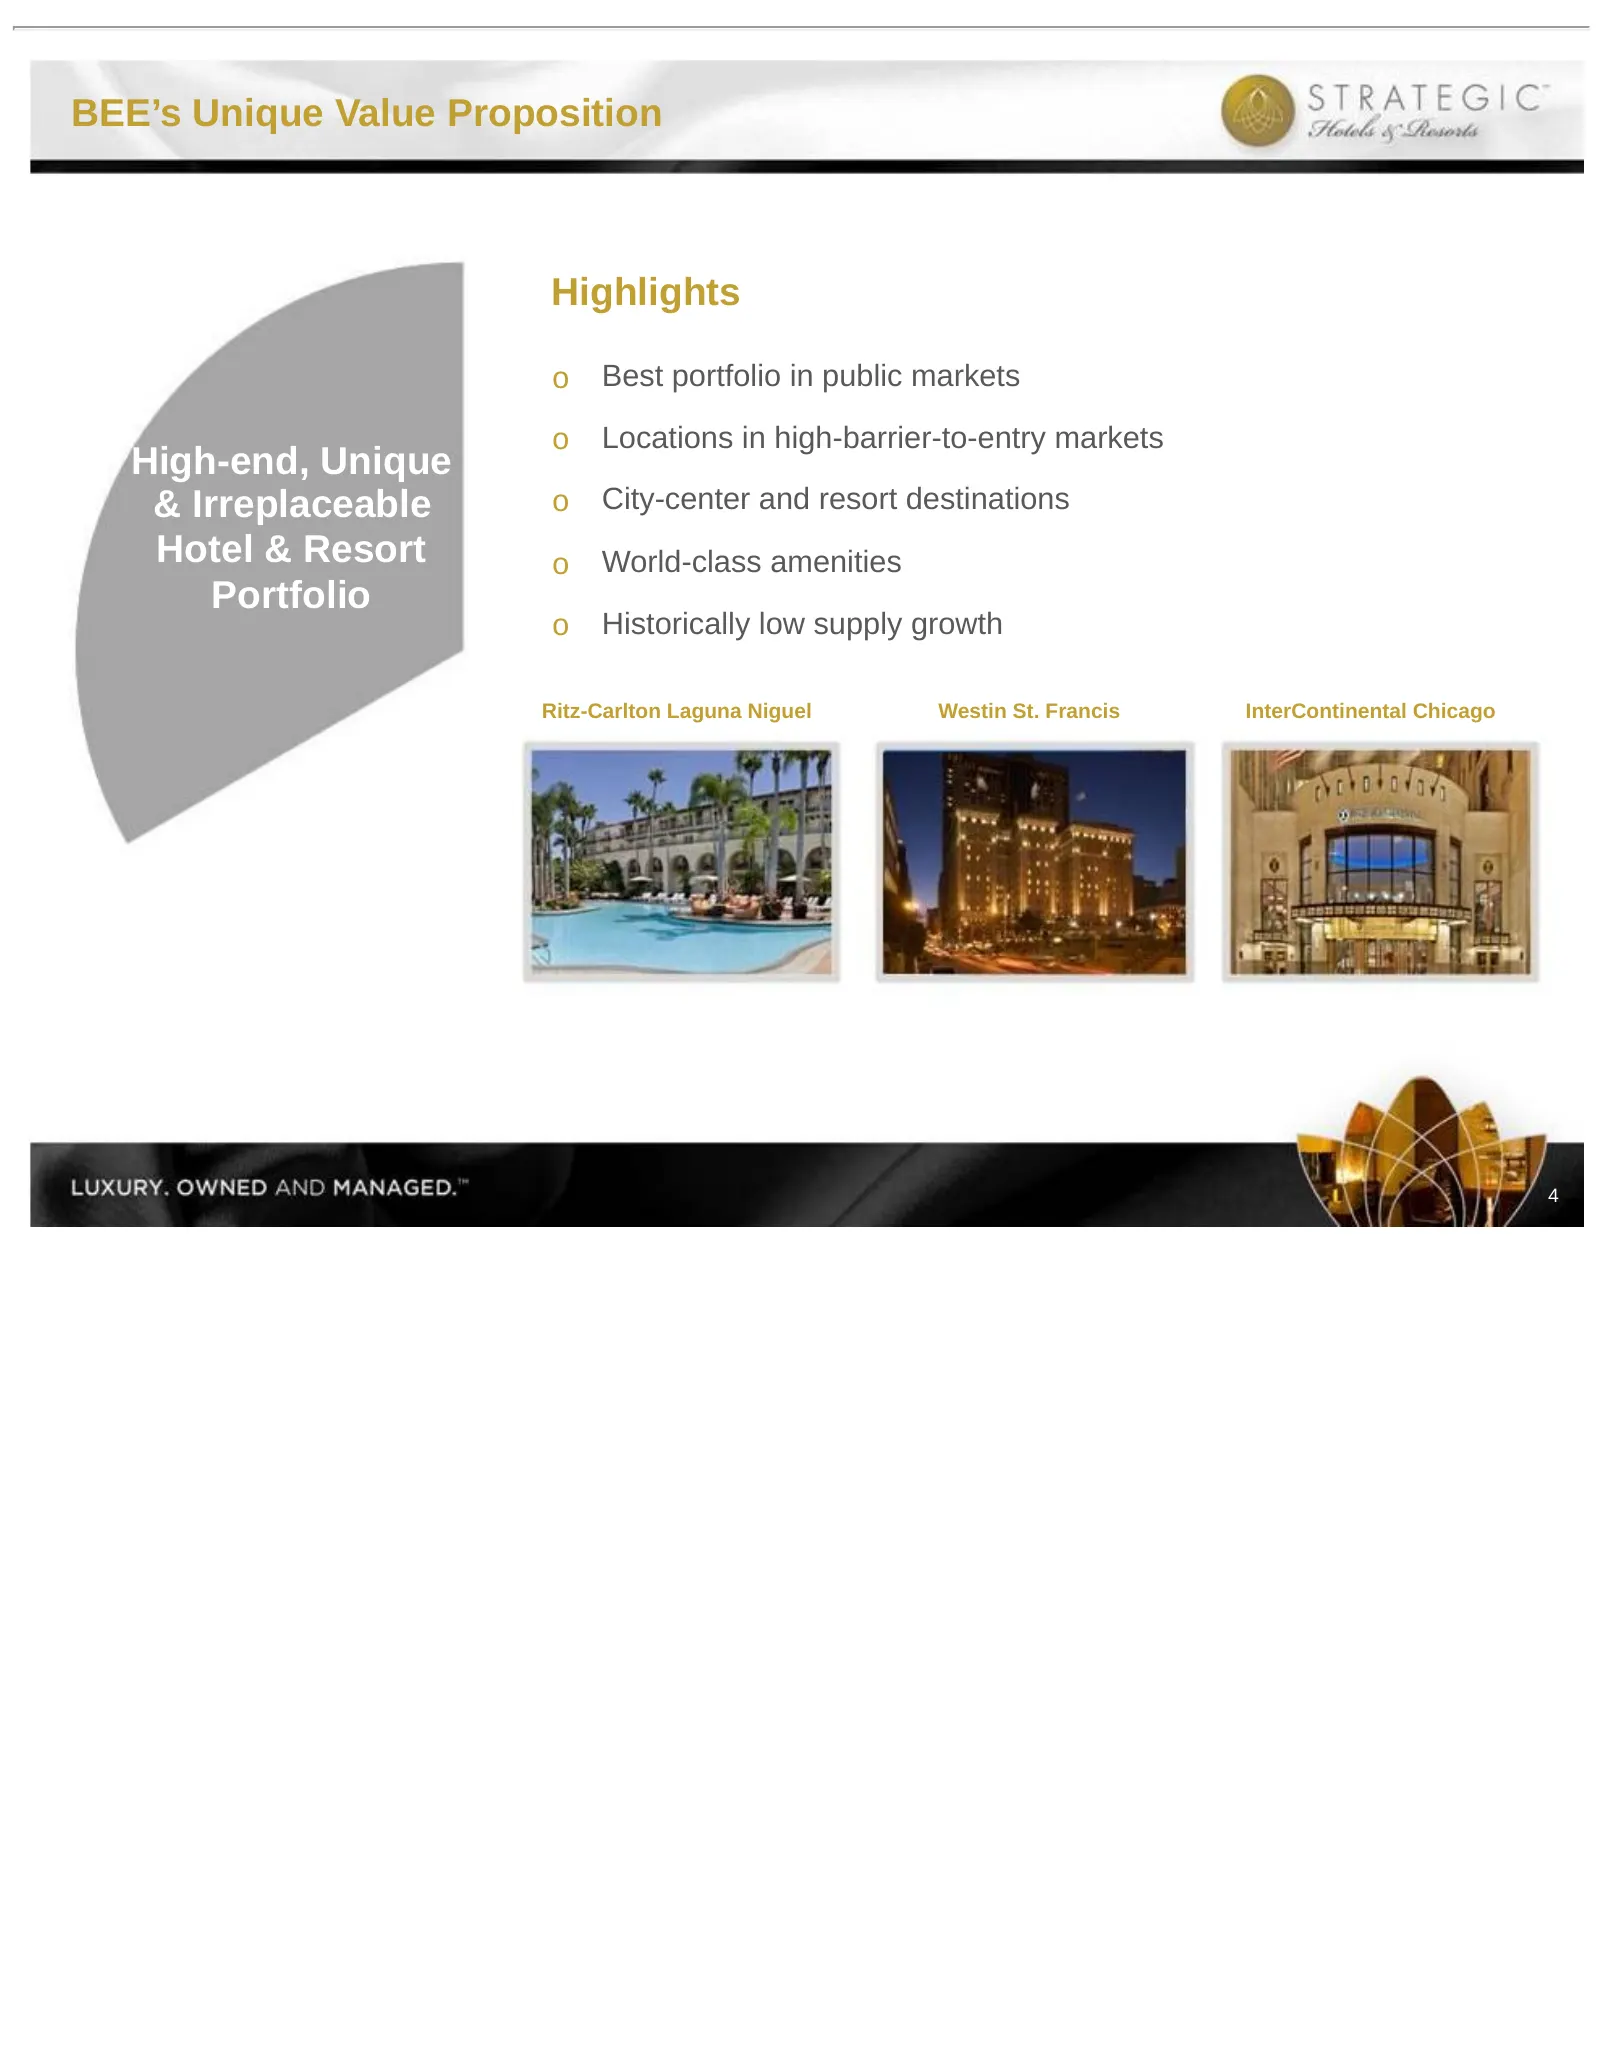
BEE’s Unique Value Proposition Highlights o Best portfolio in public markets o Locations in high-barrier-to-entry markets High-end, Unique & Irreplaceable o City-center and resort destinations Hotel & Resort o World-class amenities Portfolio o Historically low supply growth Ritz-Carlton Laguna Nigue
Slide 6: Proven Investment Track Record
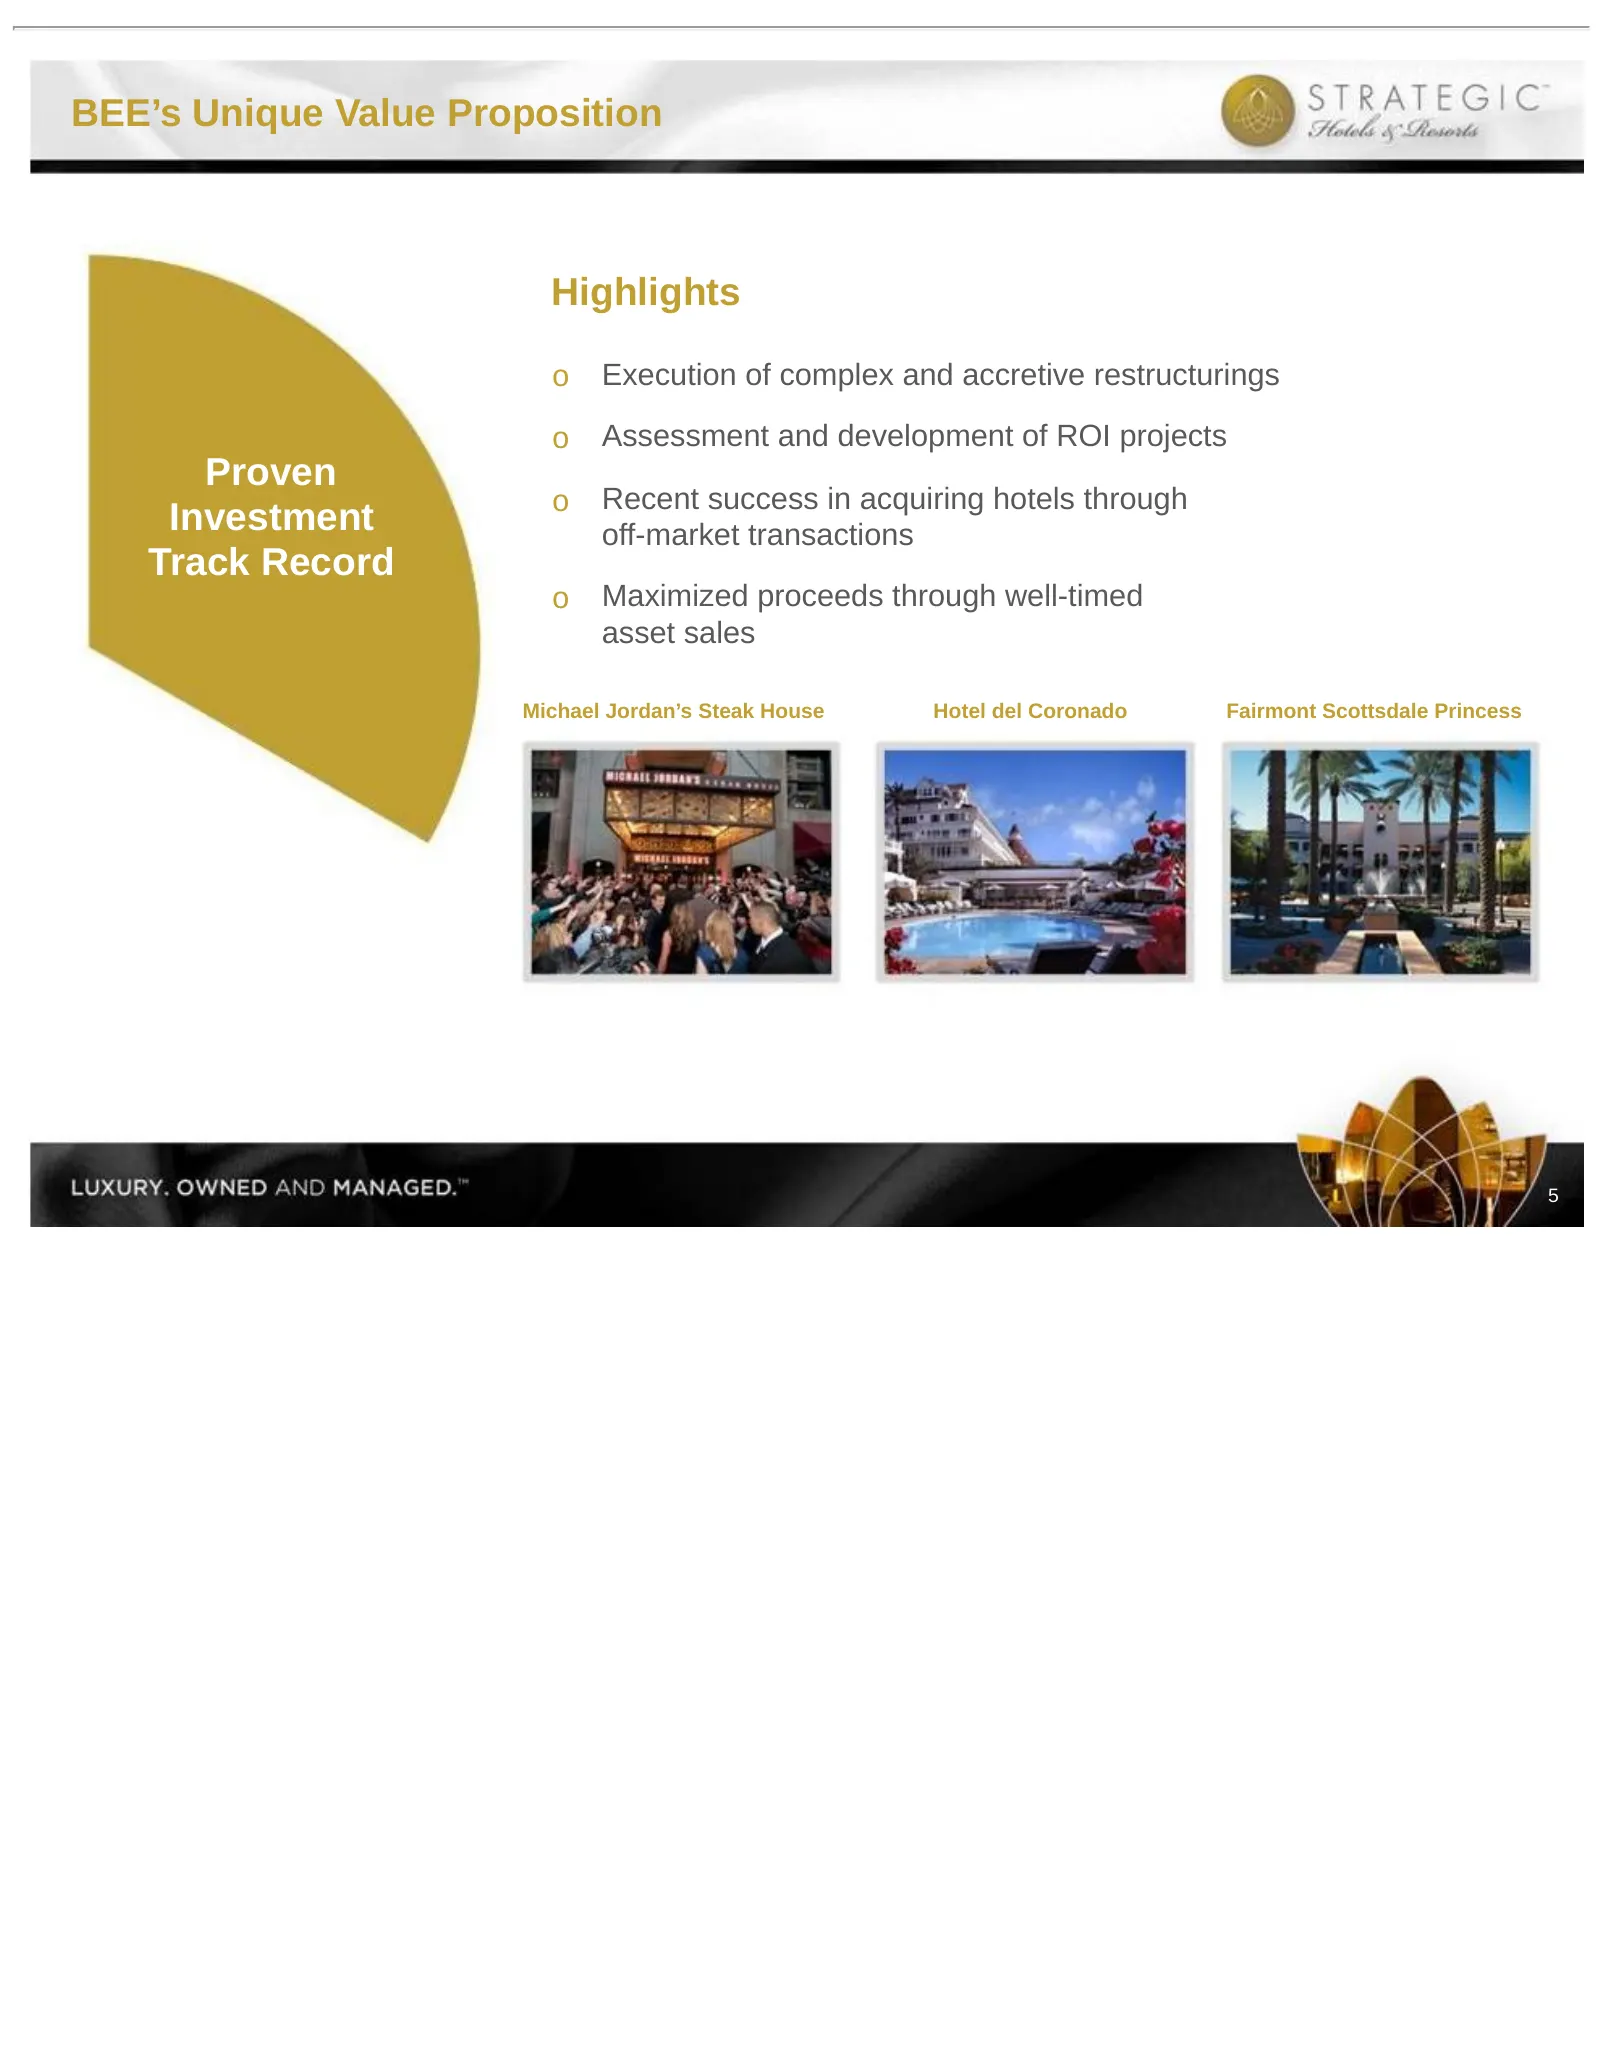
BEE’s Unique Value Proposition Highlights o Execution of complex and accretive restructurings o Assessment and development of ROI projects Proven o Recent success in acquiring hotels through Investment off-market transactions Track Record o Maximized proceeds through well-timed asset sales Michael J
Slide 7: Industry Leading Asset Management: EBITDA Per Available Room
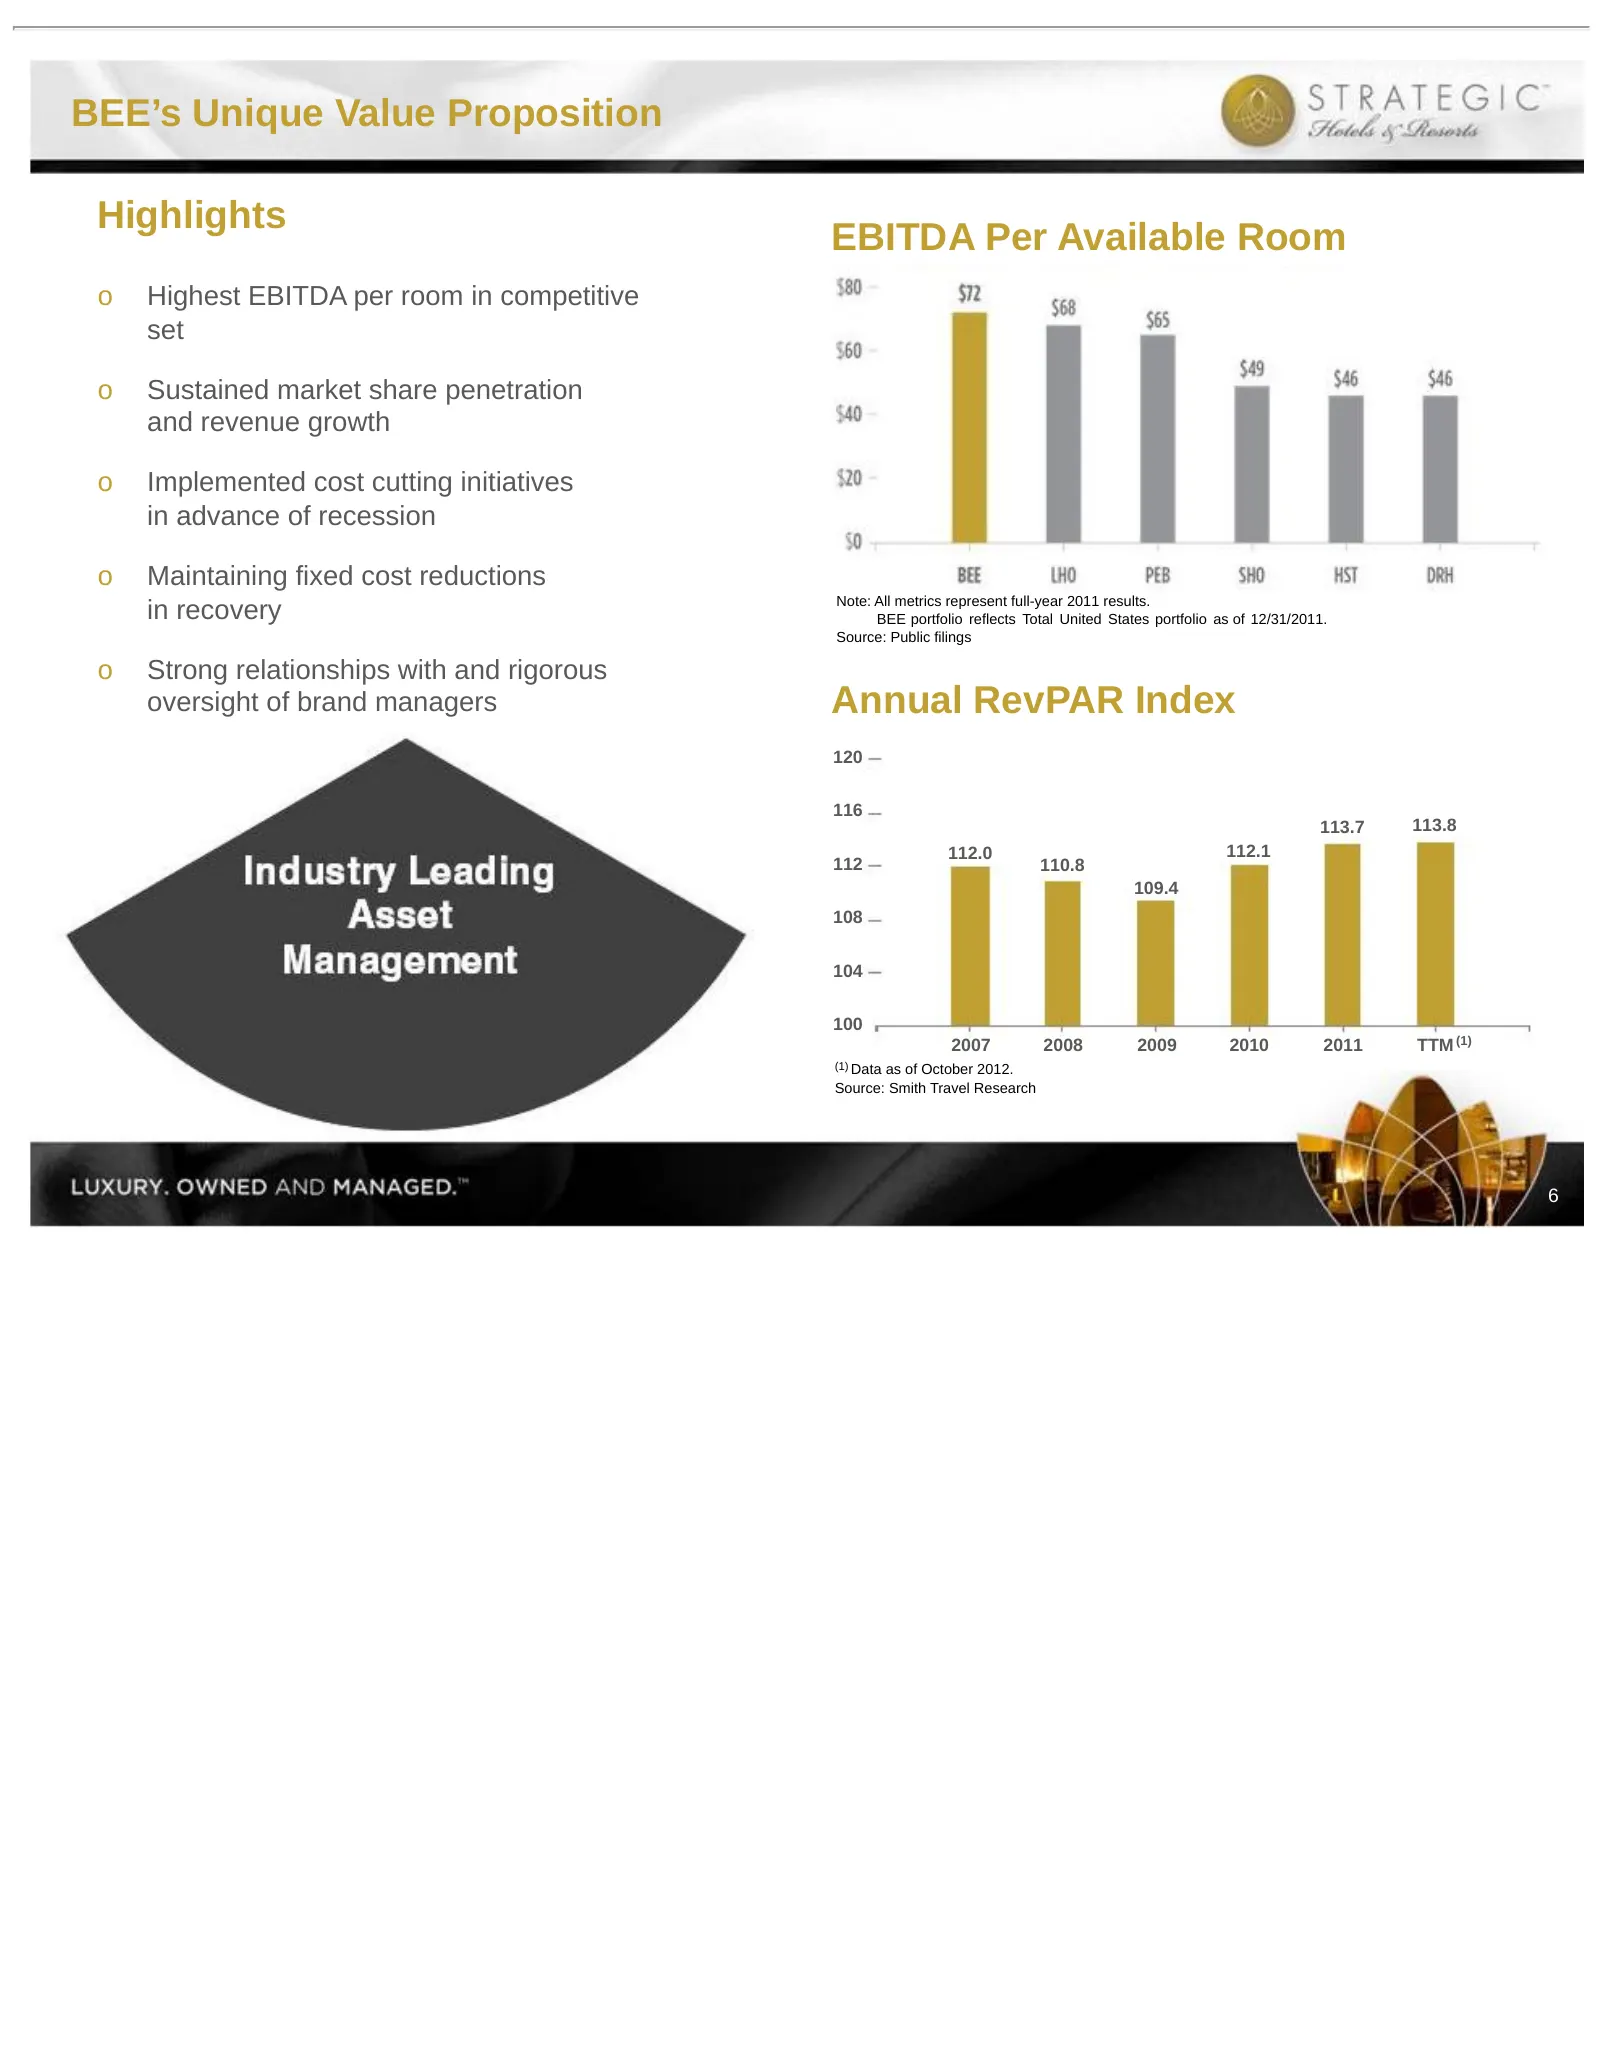
BEE’s Unique Value Proposition Highlights EBITDA Per Available Room o Highest EBITDA per room in competitive set o Sustained market share penetration and revenue growth o Implemented cost cutting initiatives in advance of recession o Maintaining fixed cost reductions Note: All metrics represent full
Slide 8: Company Overview
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Company Overview 7
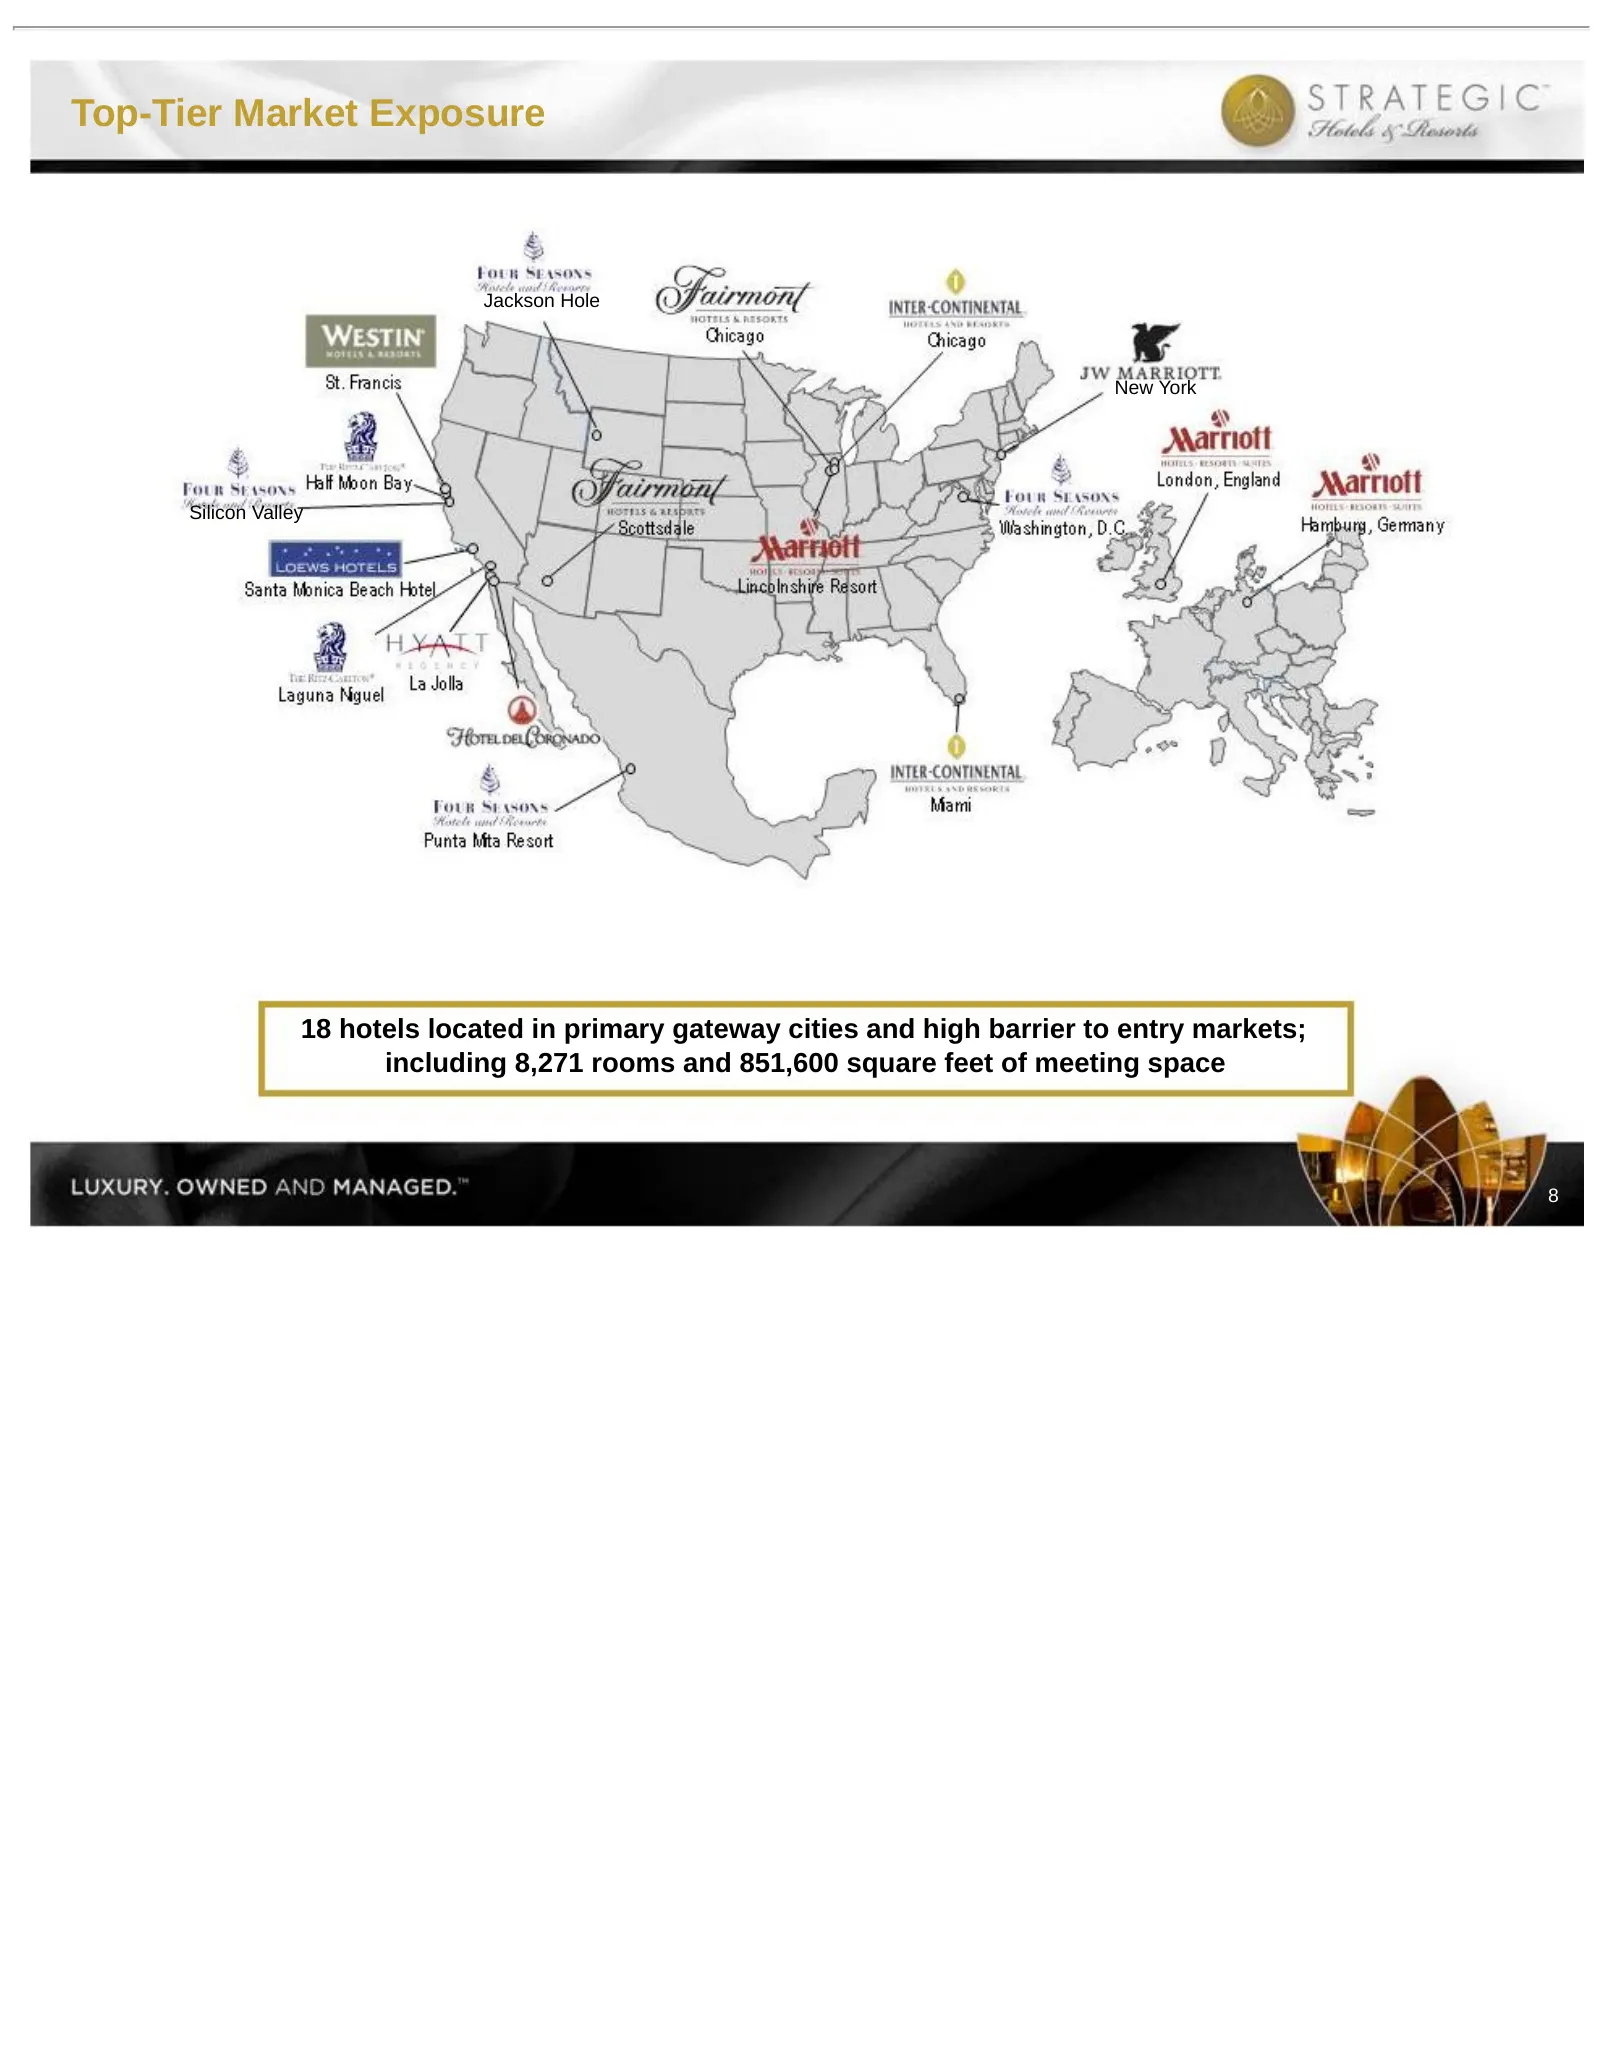
Slide 9: Top-Tier Market Exposure
Top-Tier Market Exposure Jackson Hole New York Silicon Valley 18 hotels located in primary gateway cities and high barrier to entry markets; including 8,271 rooms and 851,600 square feet of meeting space 8
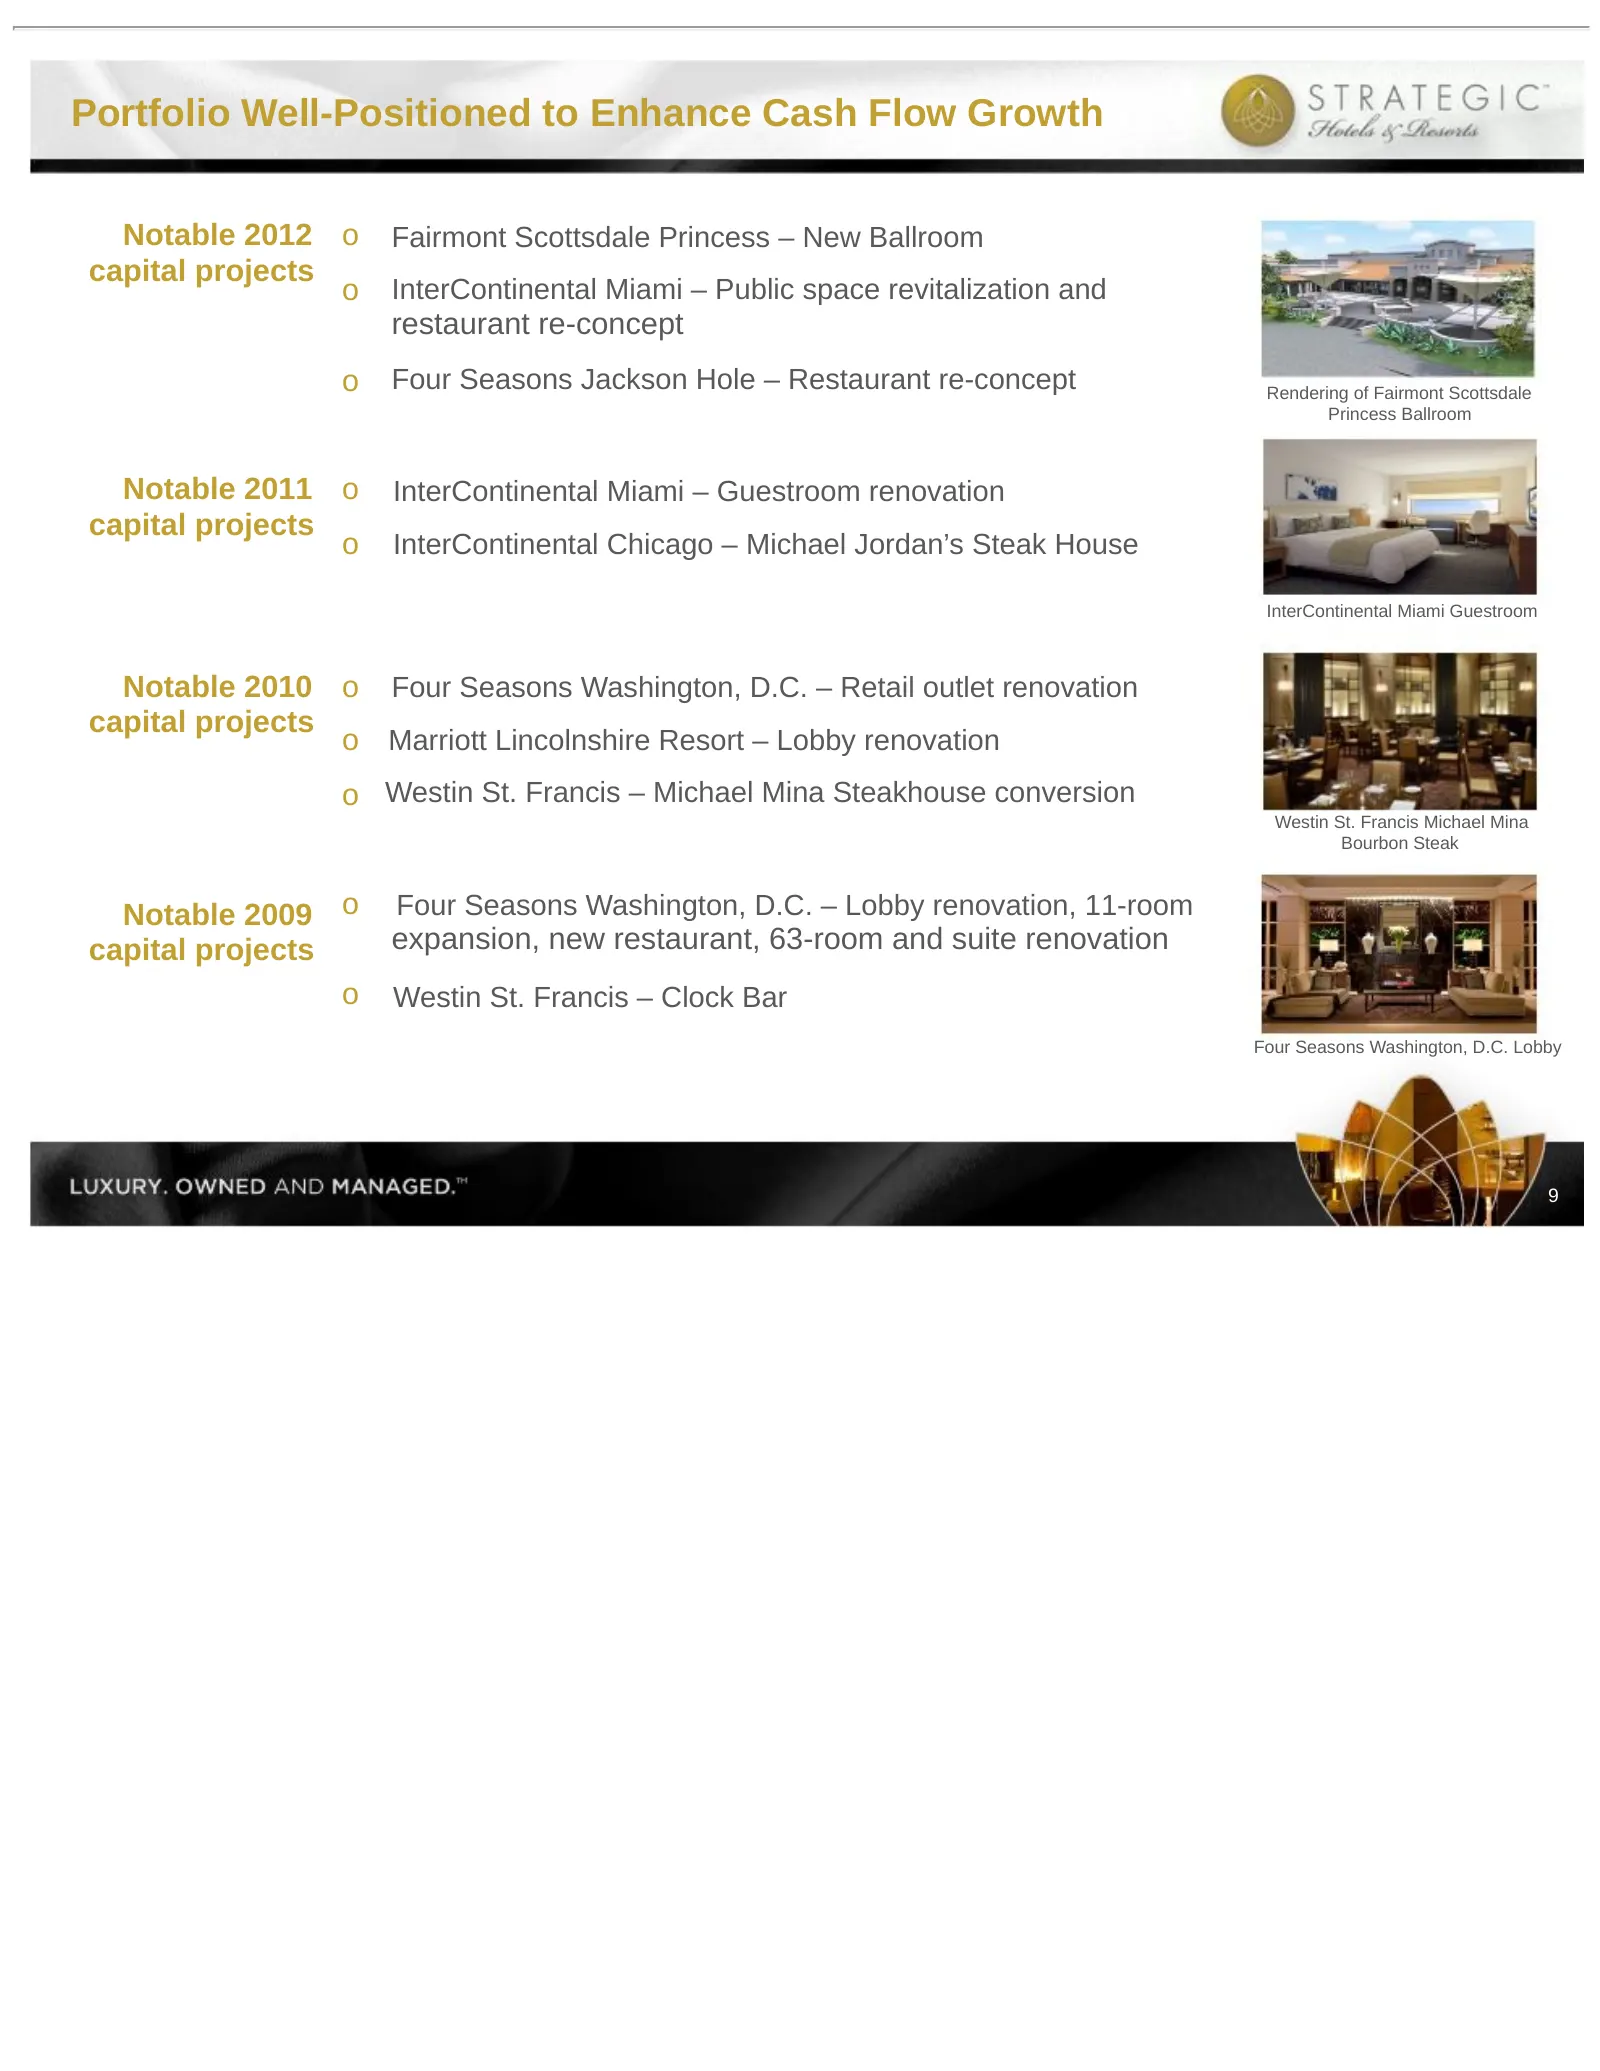
Slide 10: Portfolio Well-Positioned to Enhance Cash Flow Growth
Portfolio Well-Positioned to Enhance Cash Flow Growth Notable 2012 o Fairmont Scottsdale Princess – New Ballroom capital projects o InterContinental Miami – Public space revitalization and restaurant re-concept o Four Seasons Jackson Hole – Restaurant re-concept Rendering of Fairmont Scottsdale Prin
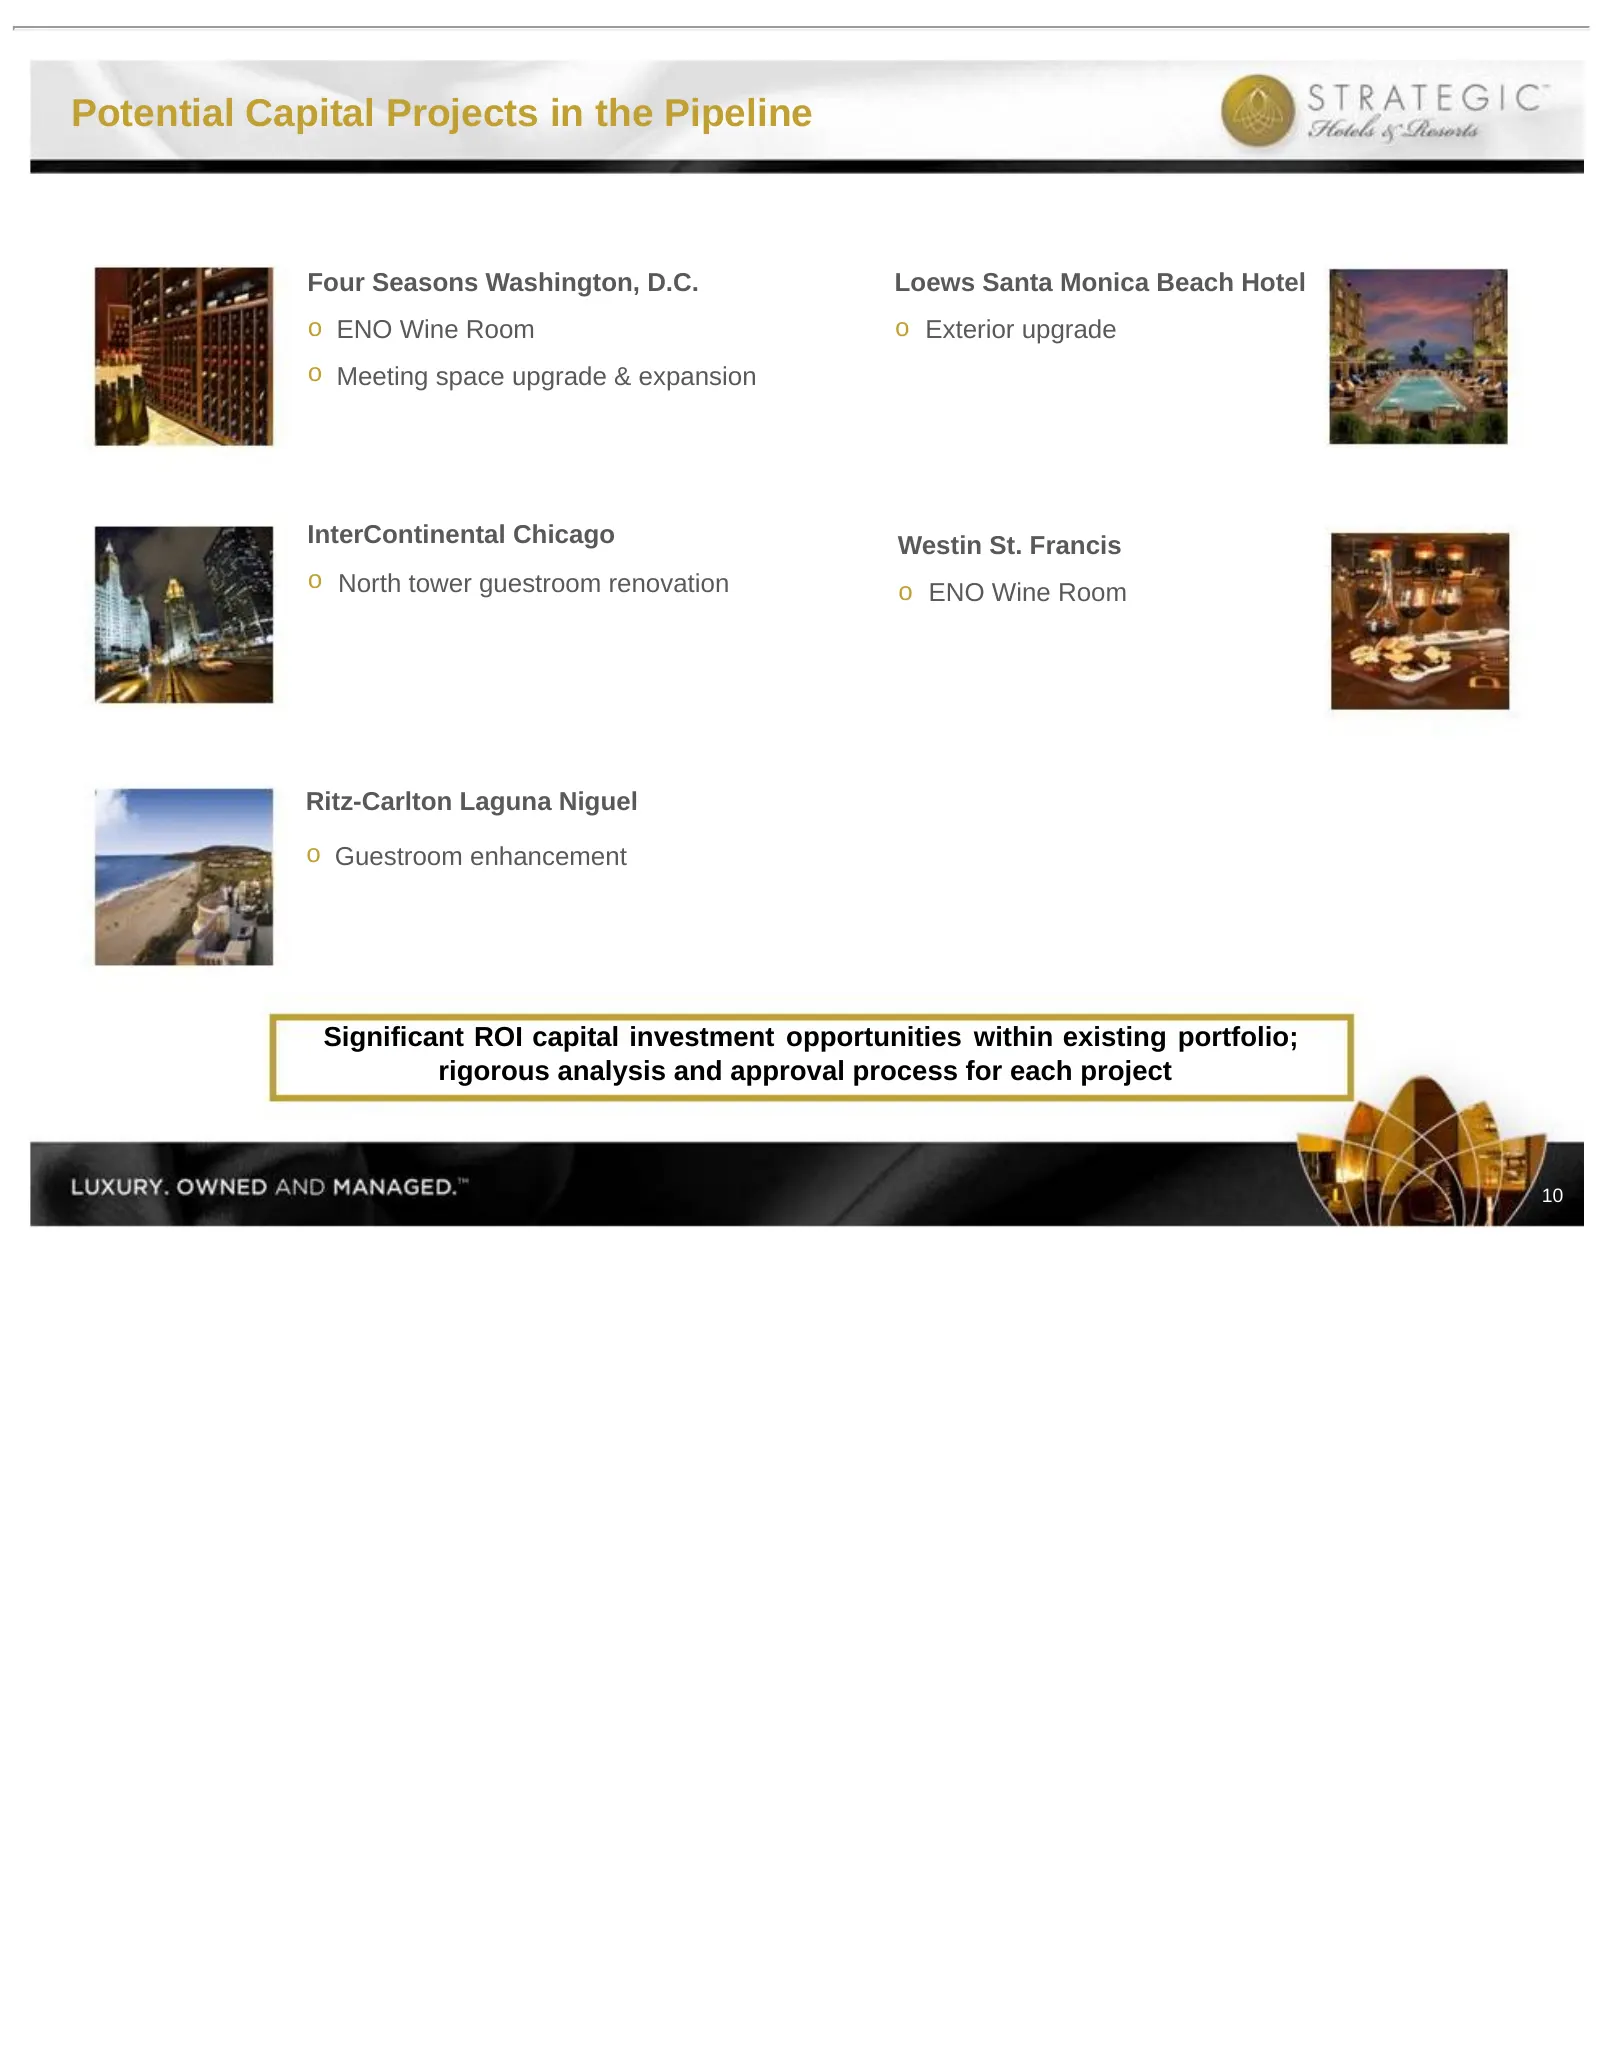
Slide 11: Potential Capital Projects in the Pipeline
Potential Capital Projects in the Pipeline Four Seasons Washington, D.C. Loews Santa Monica Beach Hotel o ENO Wine Room o Exterior upgrade o Meeting space upgrade & expansion InterContinental Chicago Westin St. Francis o North tower guestroom renovation o ENO Wine Room Ritz-Carlton Laguna Niguel o G
Slide 12: Industry Update
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Industry Update 11
Slide 13: Lodging Outlook
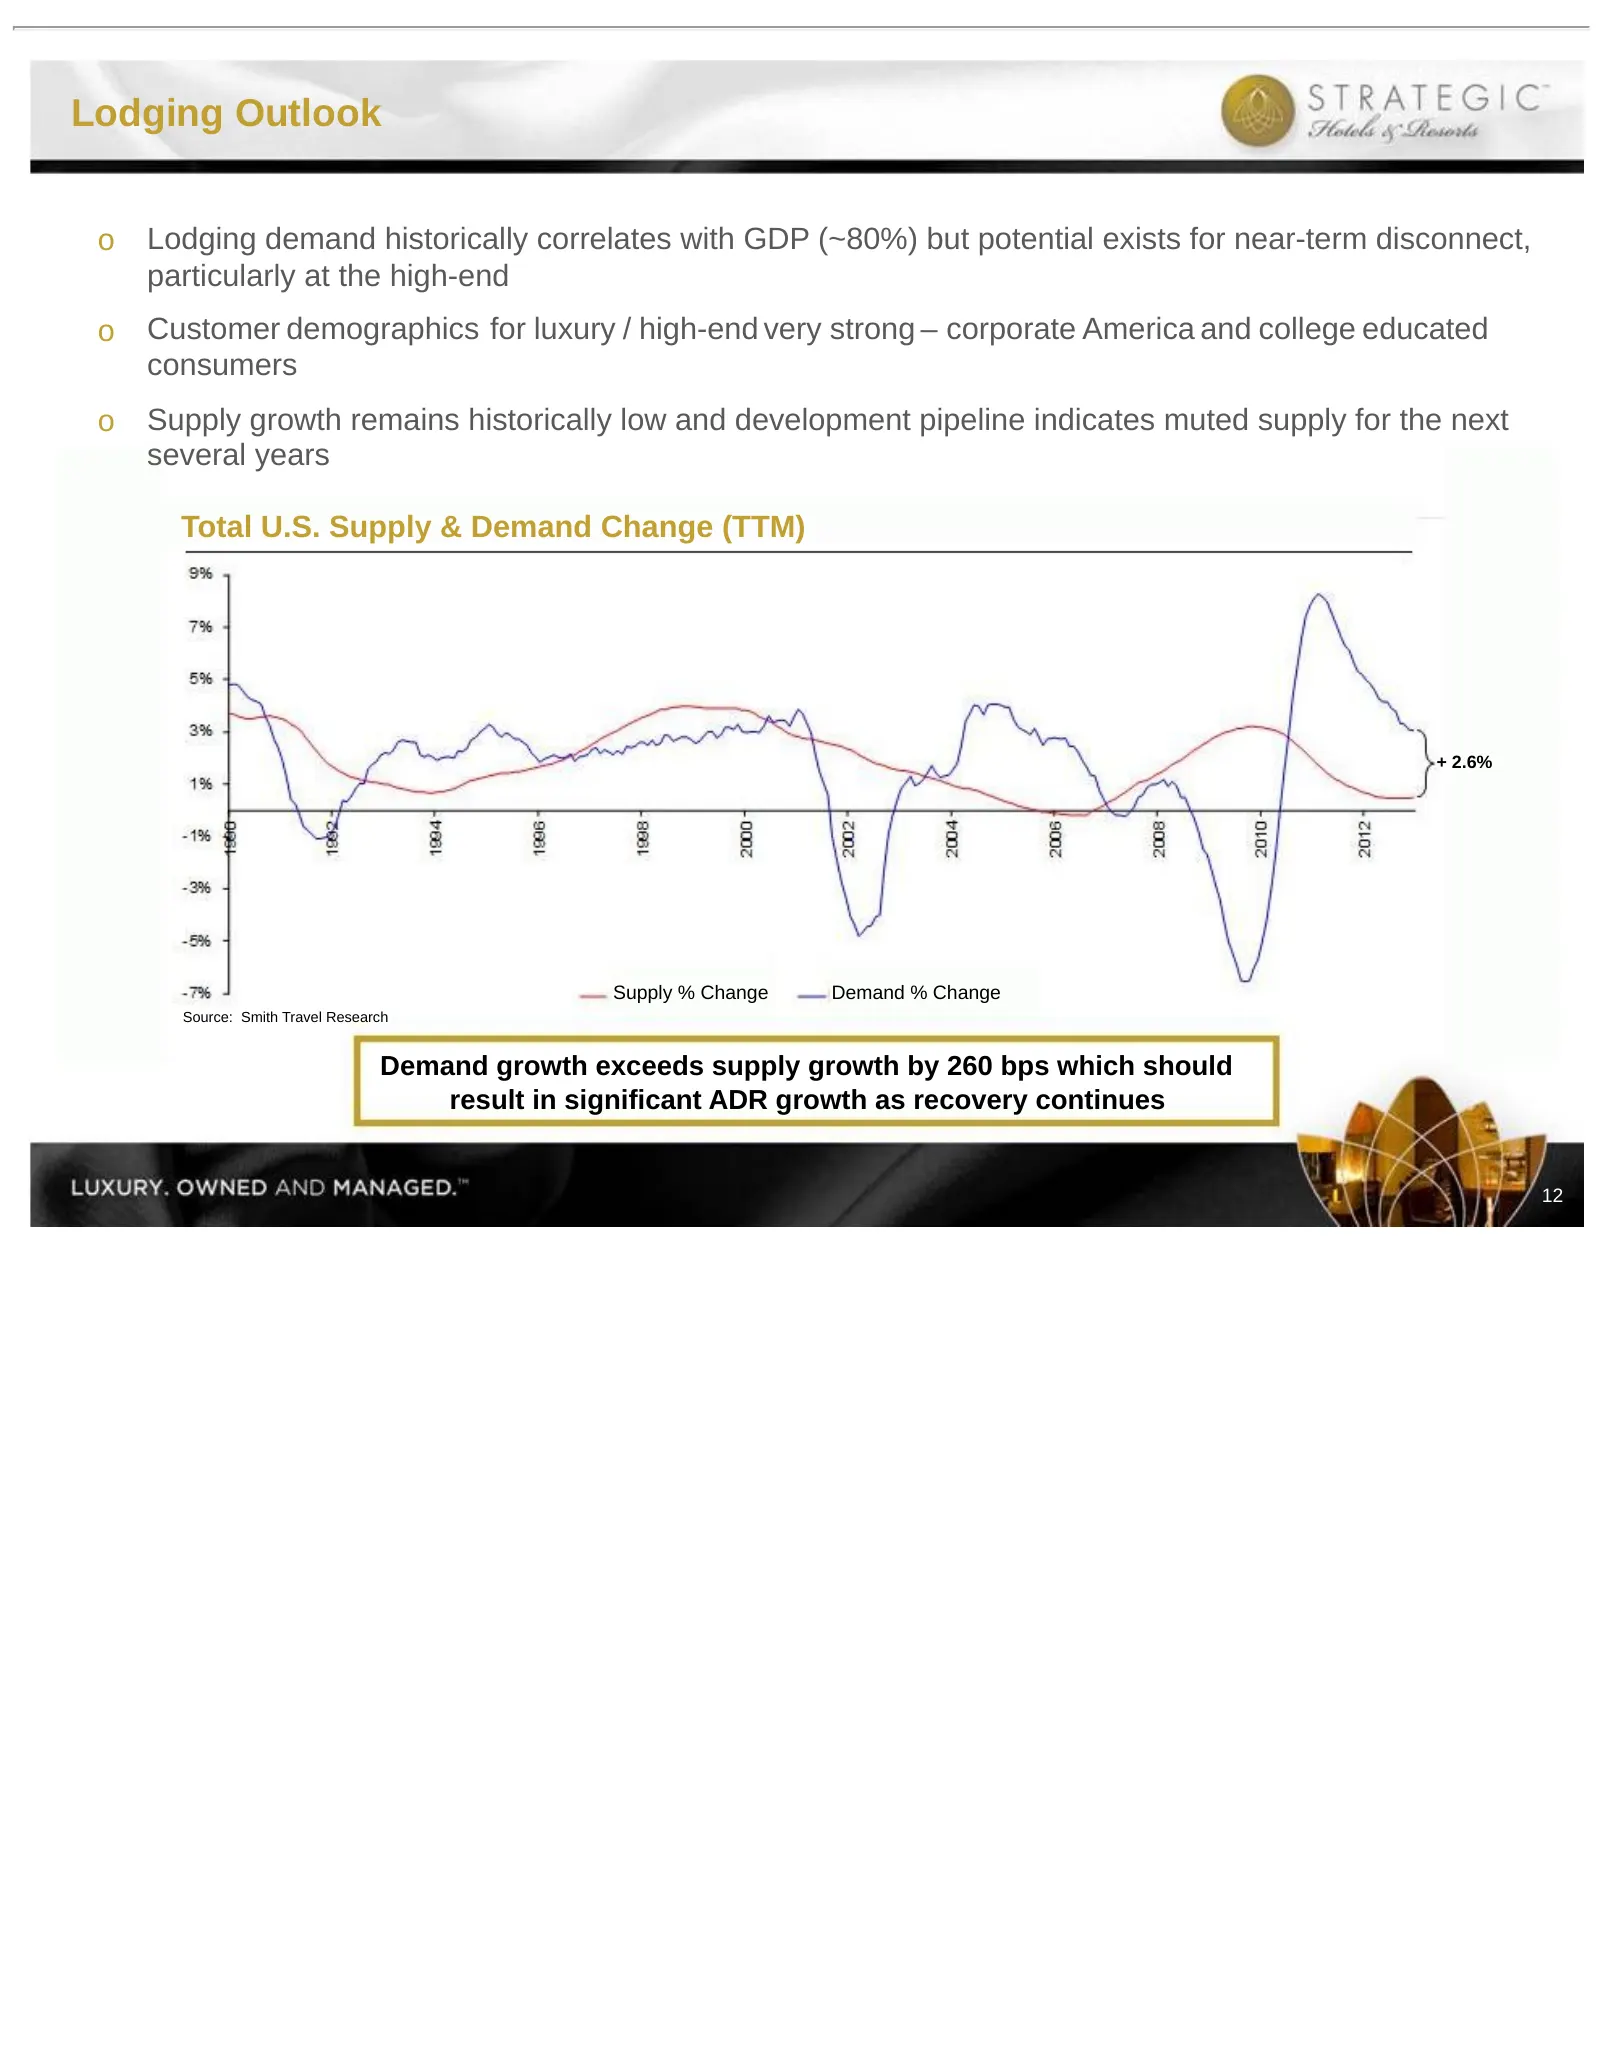
Lodging Outlook o Lodging demand historically correlates with GDP (~80%) but potential exists for near-term disconnect, particularly at the high-end o Customer demographics for luxury / high-end very strong – corporate America and college educated consumers o Supply growth remains historically low a
Slide 14: Favorable Supply Outlook
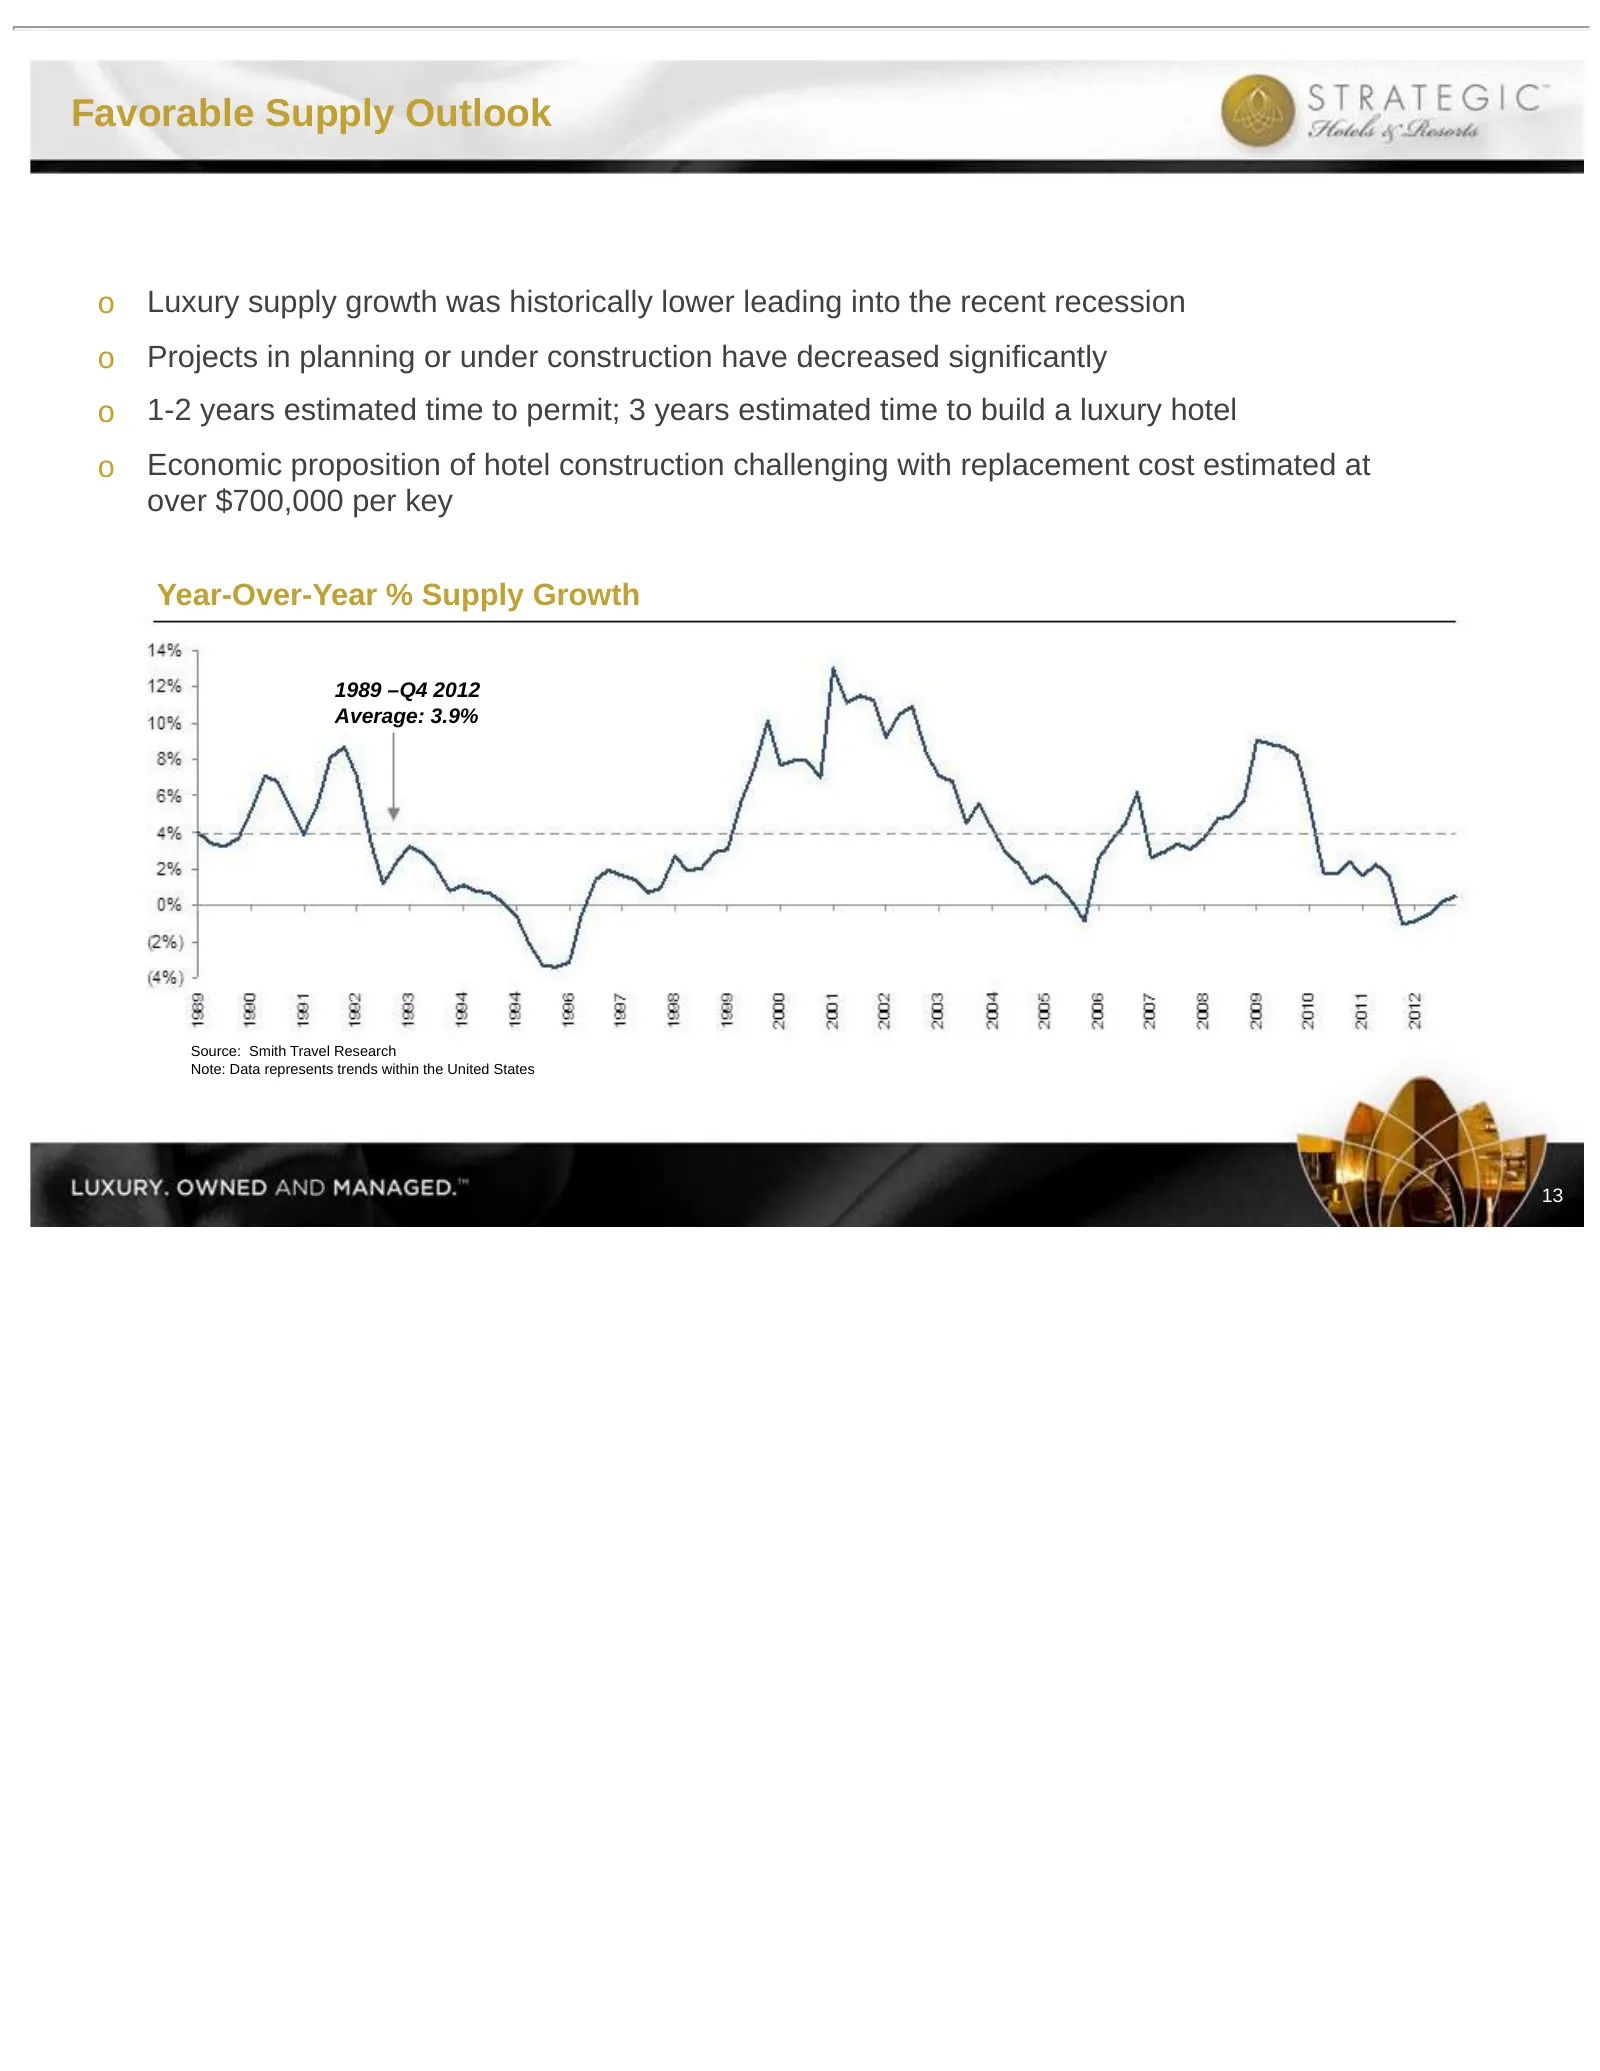
Favorable Supply Outlook o Luxury supply growth was historically lower leading into the recent recession o Projects in planning or under construction have decreased significantly o 1-2 years estimated time to permit; 3 years estimated time to build a luxury hotel o Economic proposition of hotel cons
Slide 15: Luxury Hotels Outperform in a Recovery
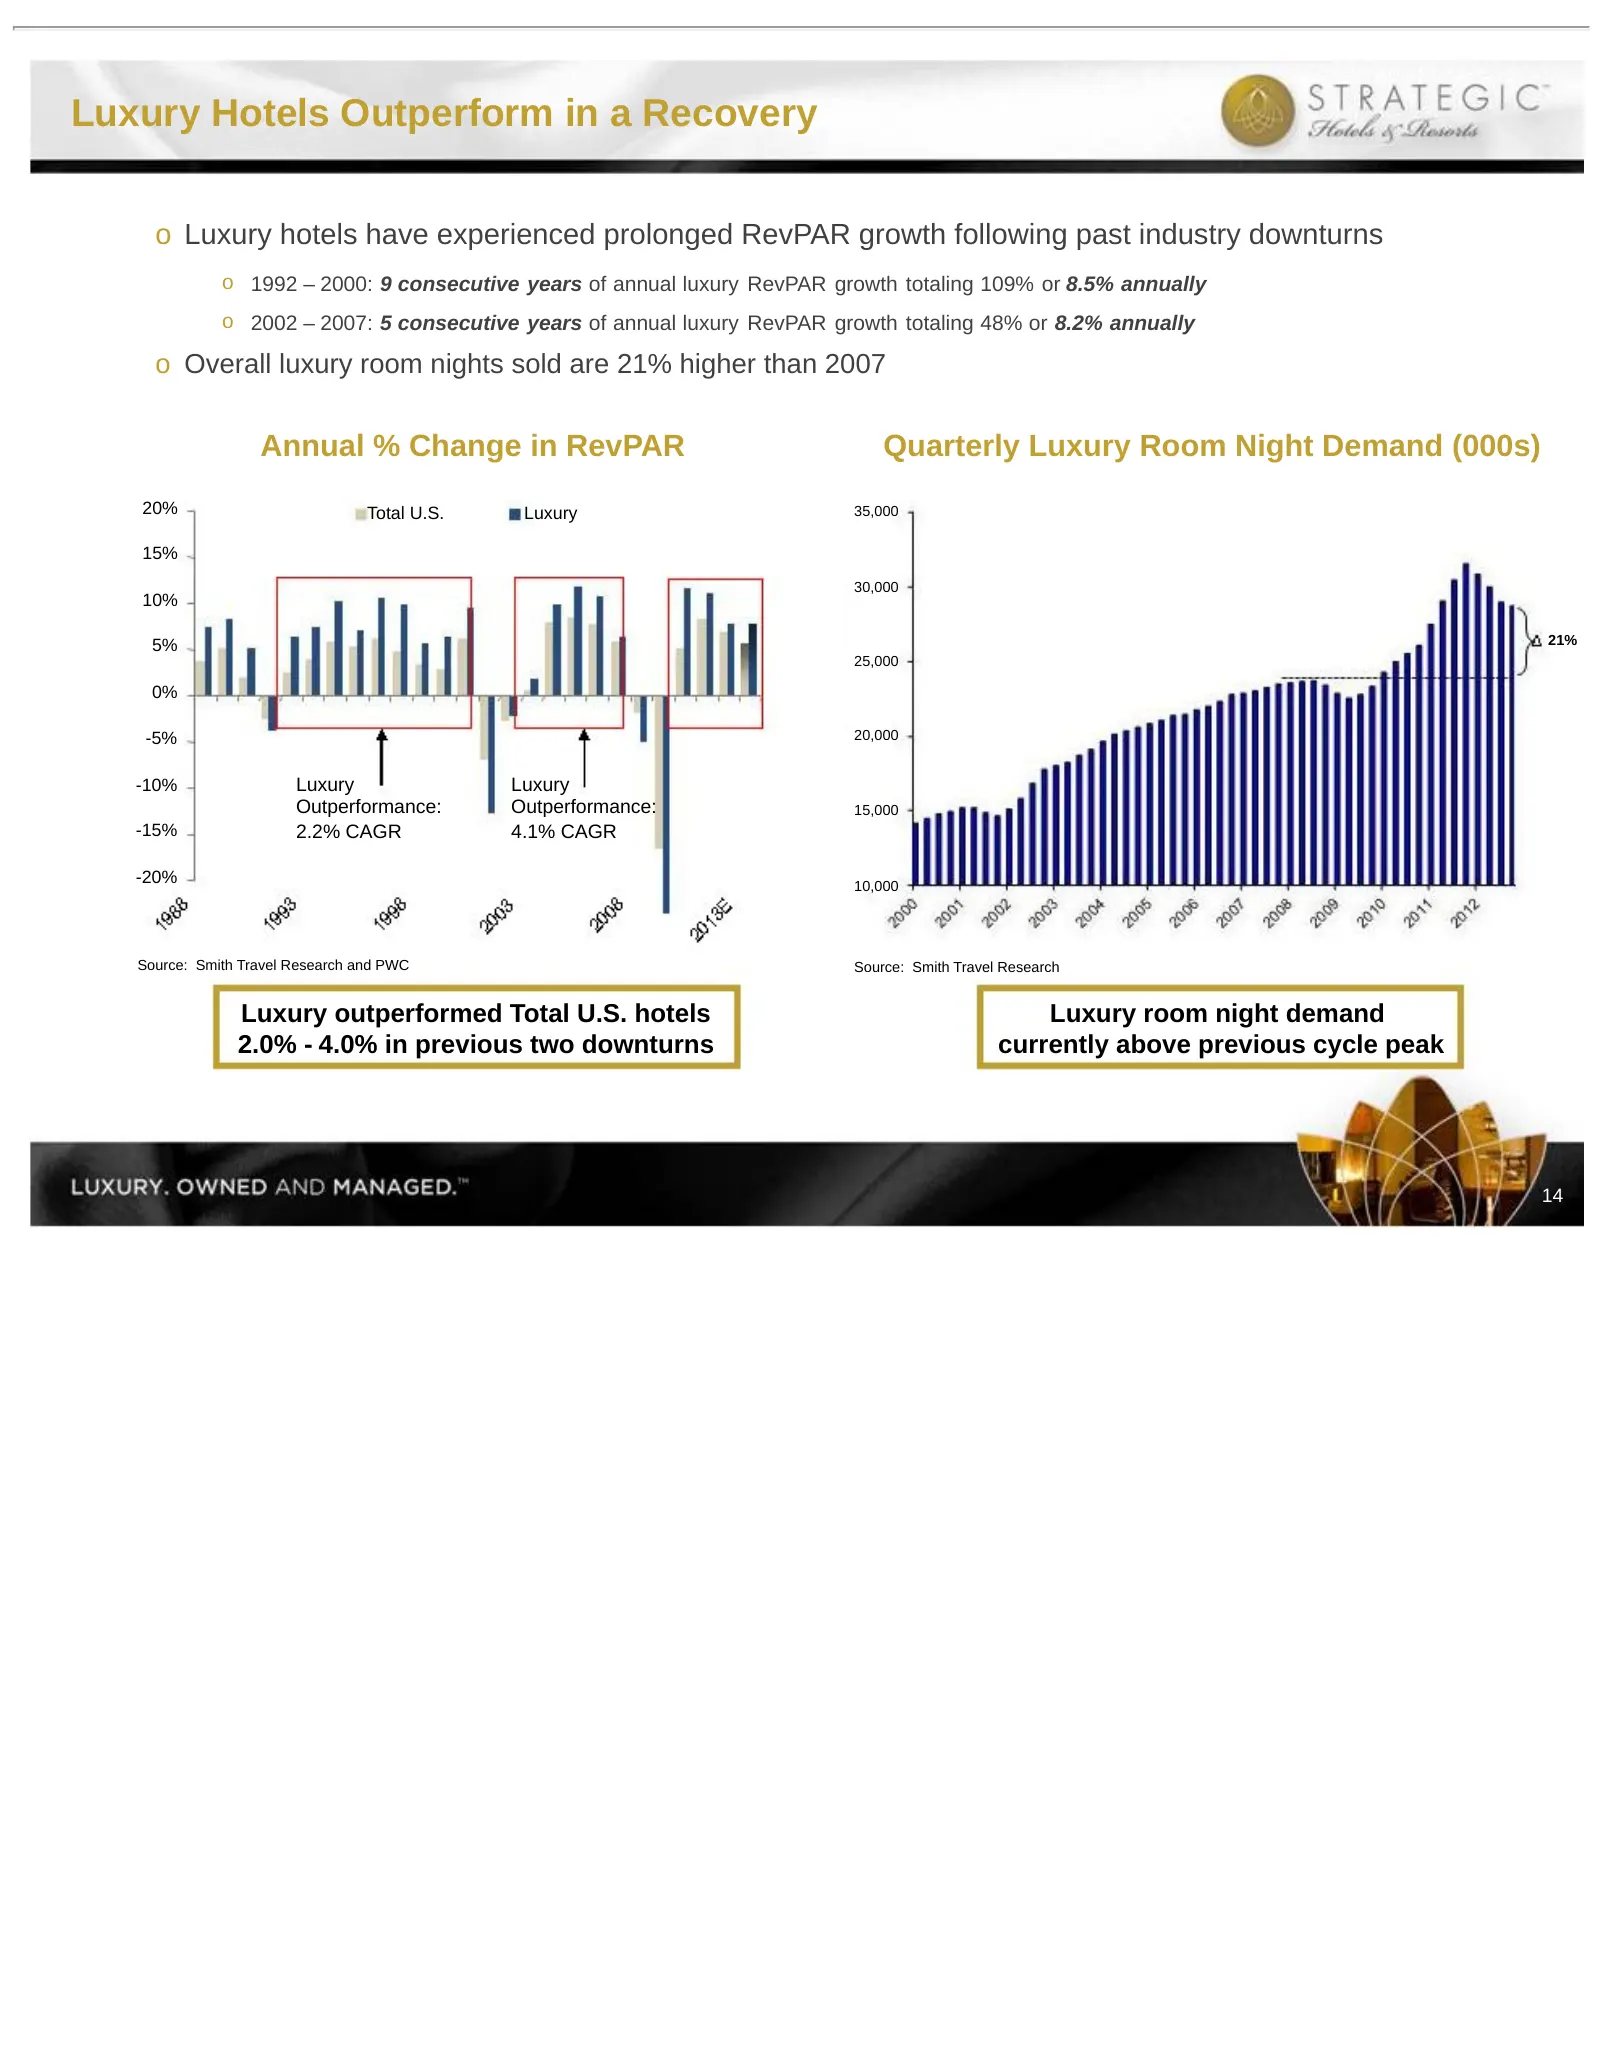
Luxury Hotels Outperform in a Recovery o Luxury hotels have experienced prolonged RevPAR growth following past industry downturns o 1992 – 2000: 9 consecutive years of annual luxury RevPAR growth totaling 109% or 8.5% annually o 2002 – 2007: 5 consecutive years of annual luxury RevPAR growth totalin
Slide 16: BEE Outperforms Competitors
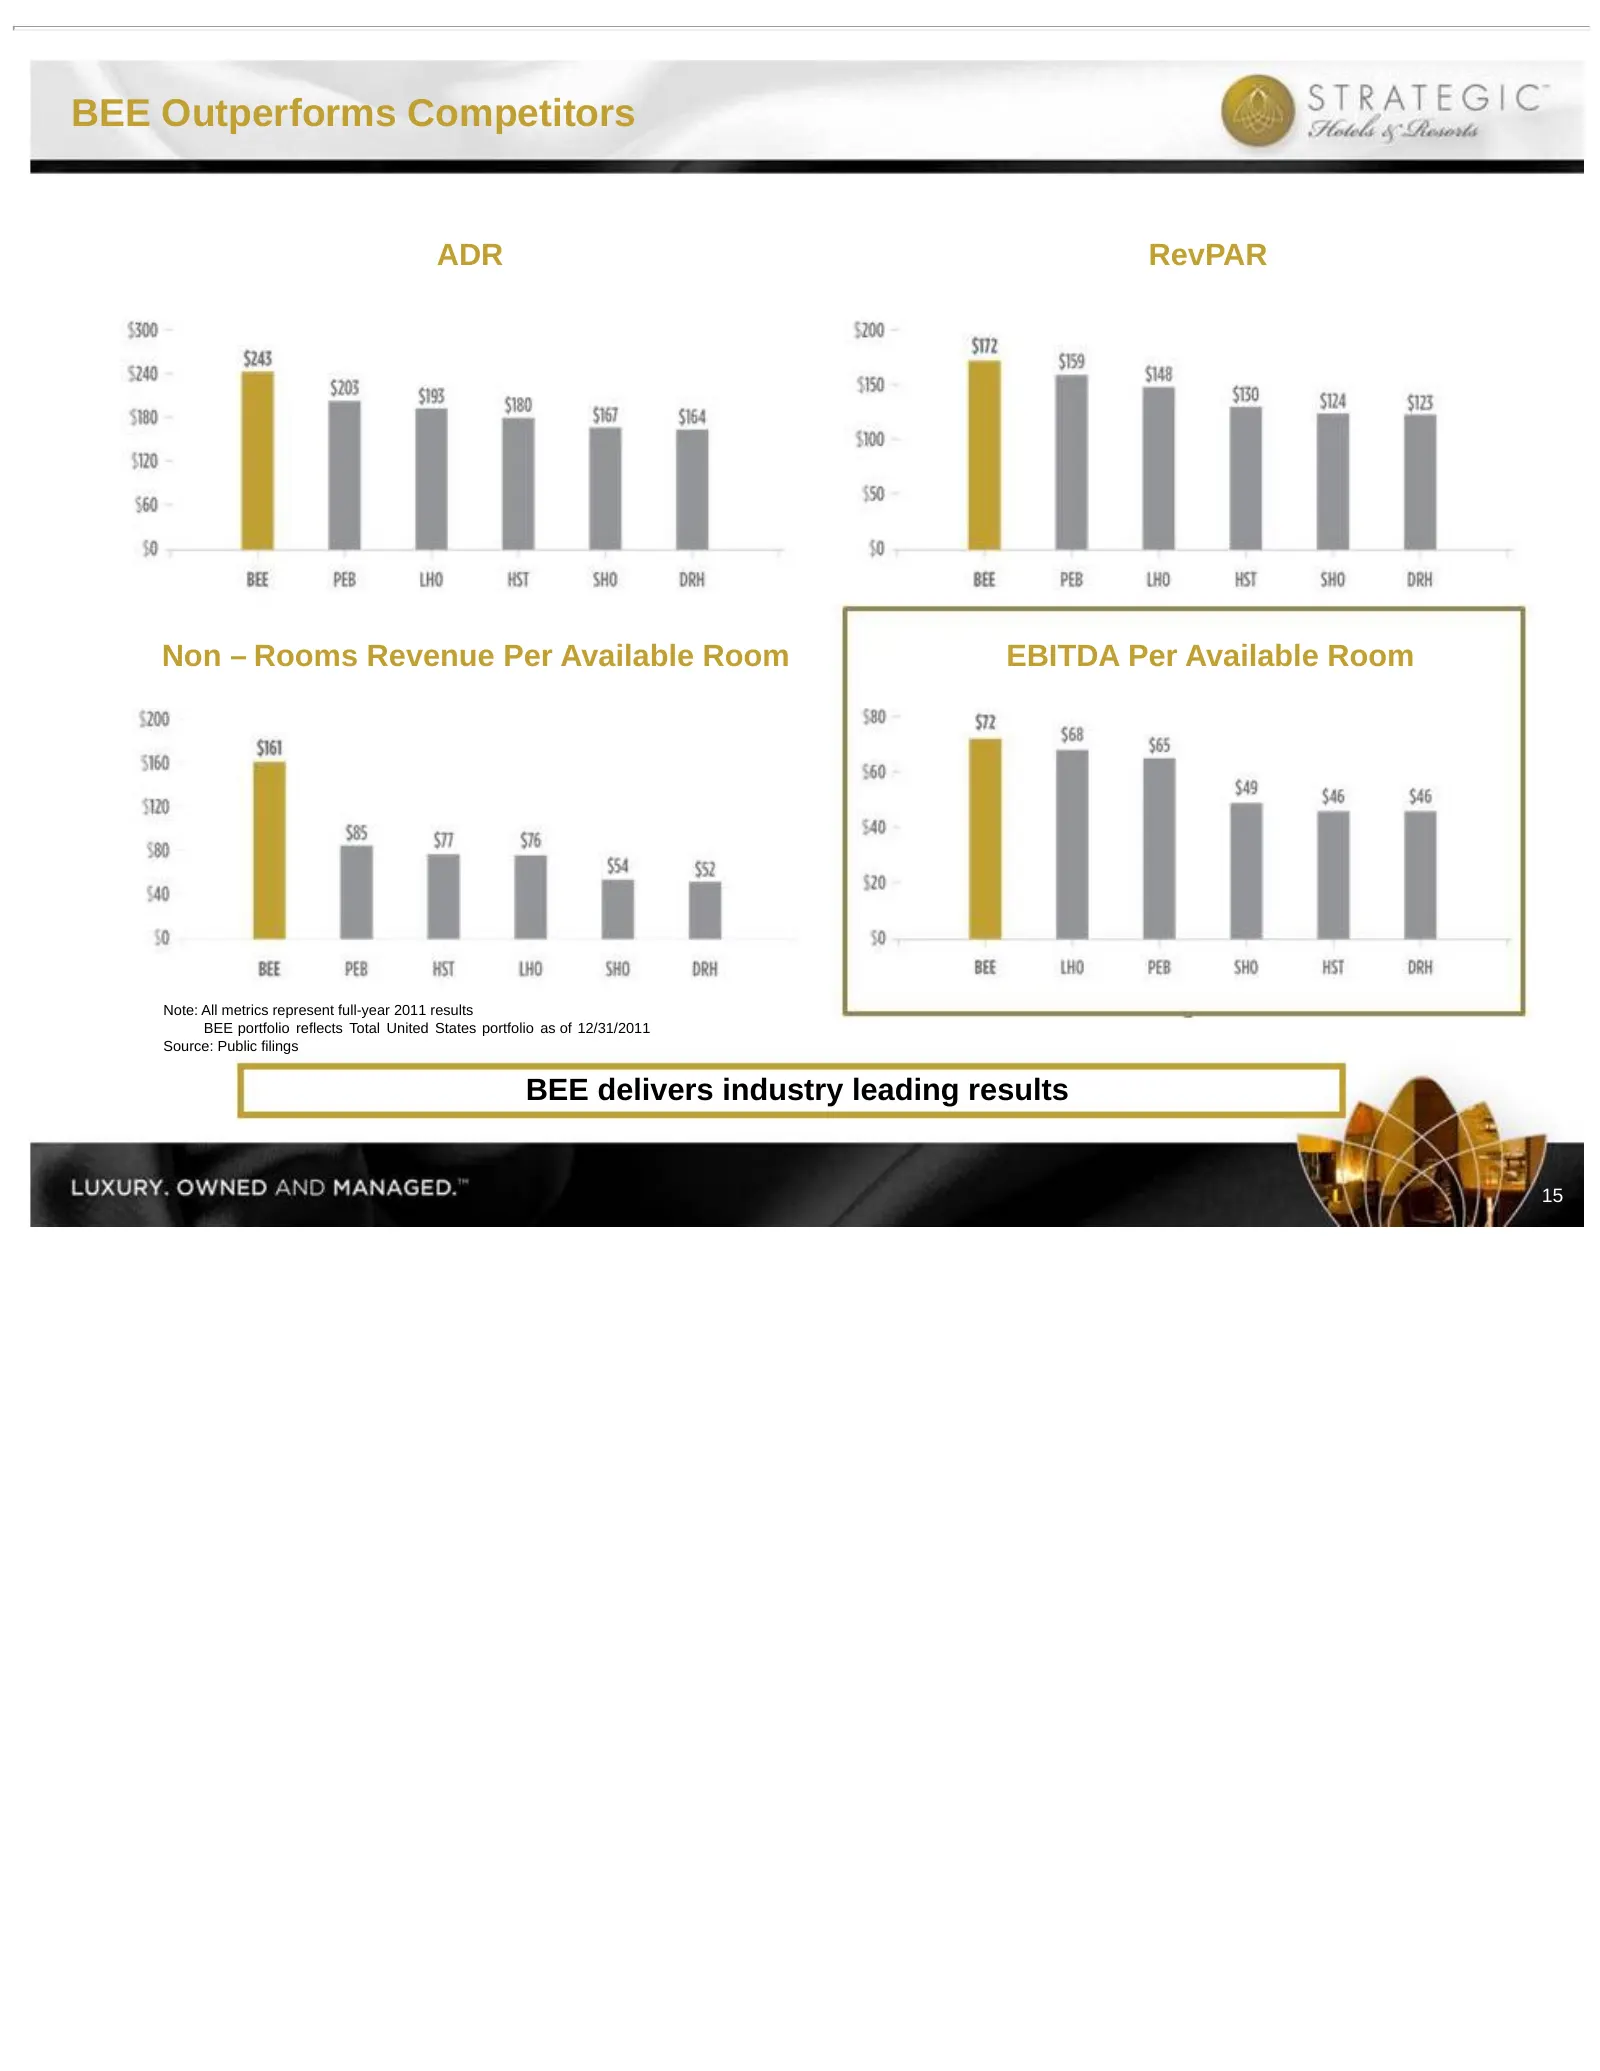
BEE Outperforms Competitors ADR RevPAR Non – Rooms Revenue Per Available Room EBITDA Per Available Room Note: All metrics represent full-year 2011 results BEE portfolio reflects Total United States portfolio as of 12/31/2011 Source: Public filings BEE delivers industry leading results 15
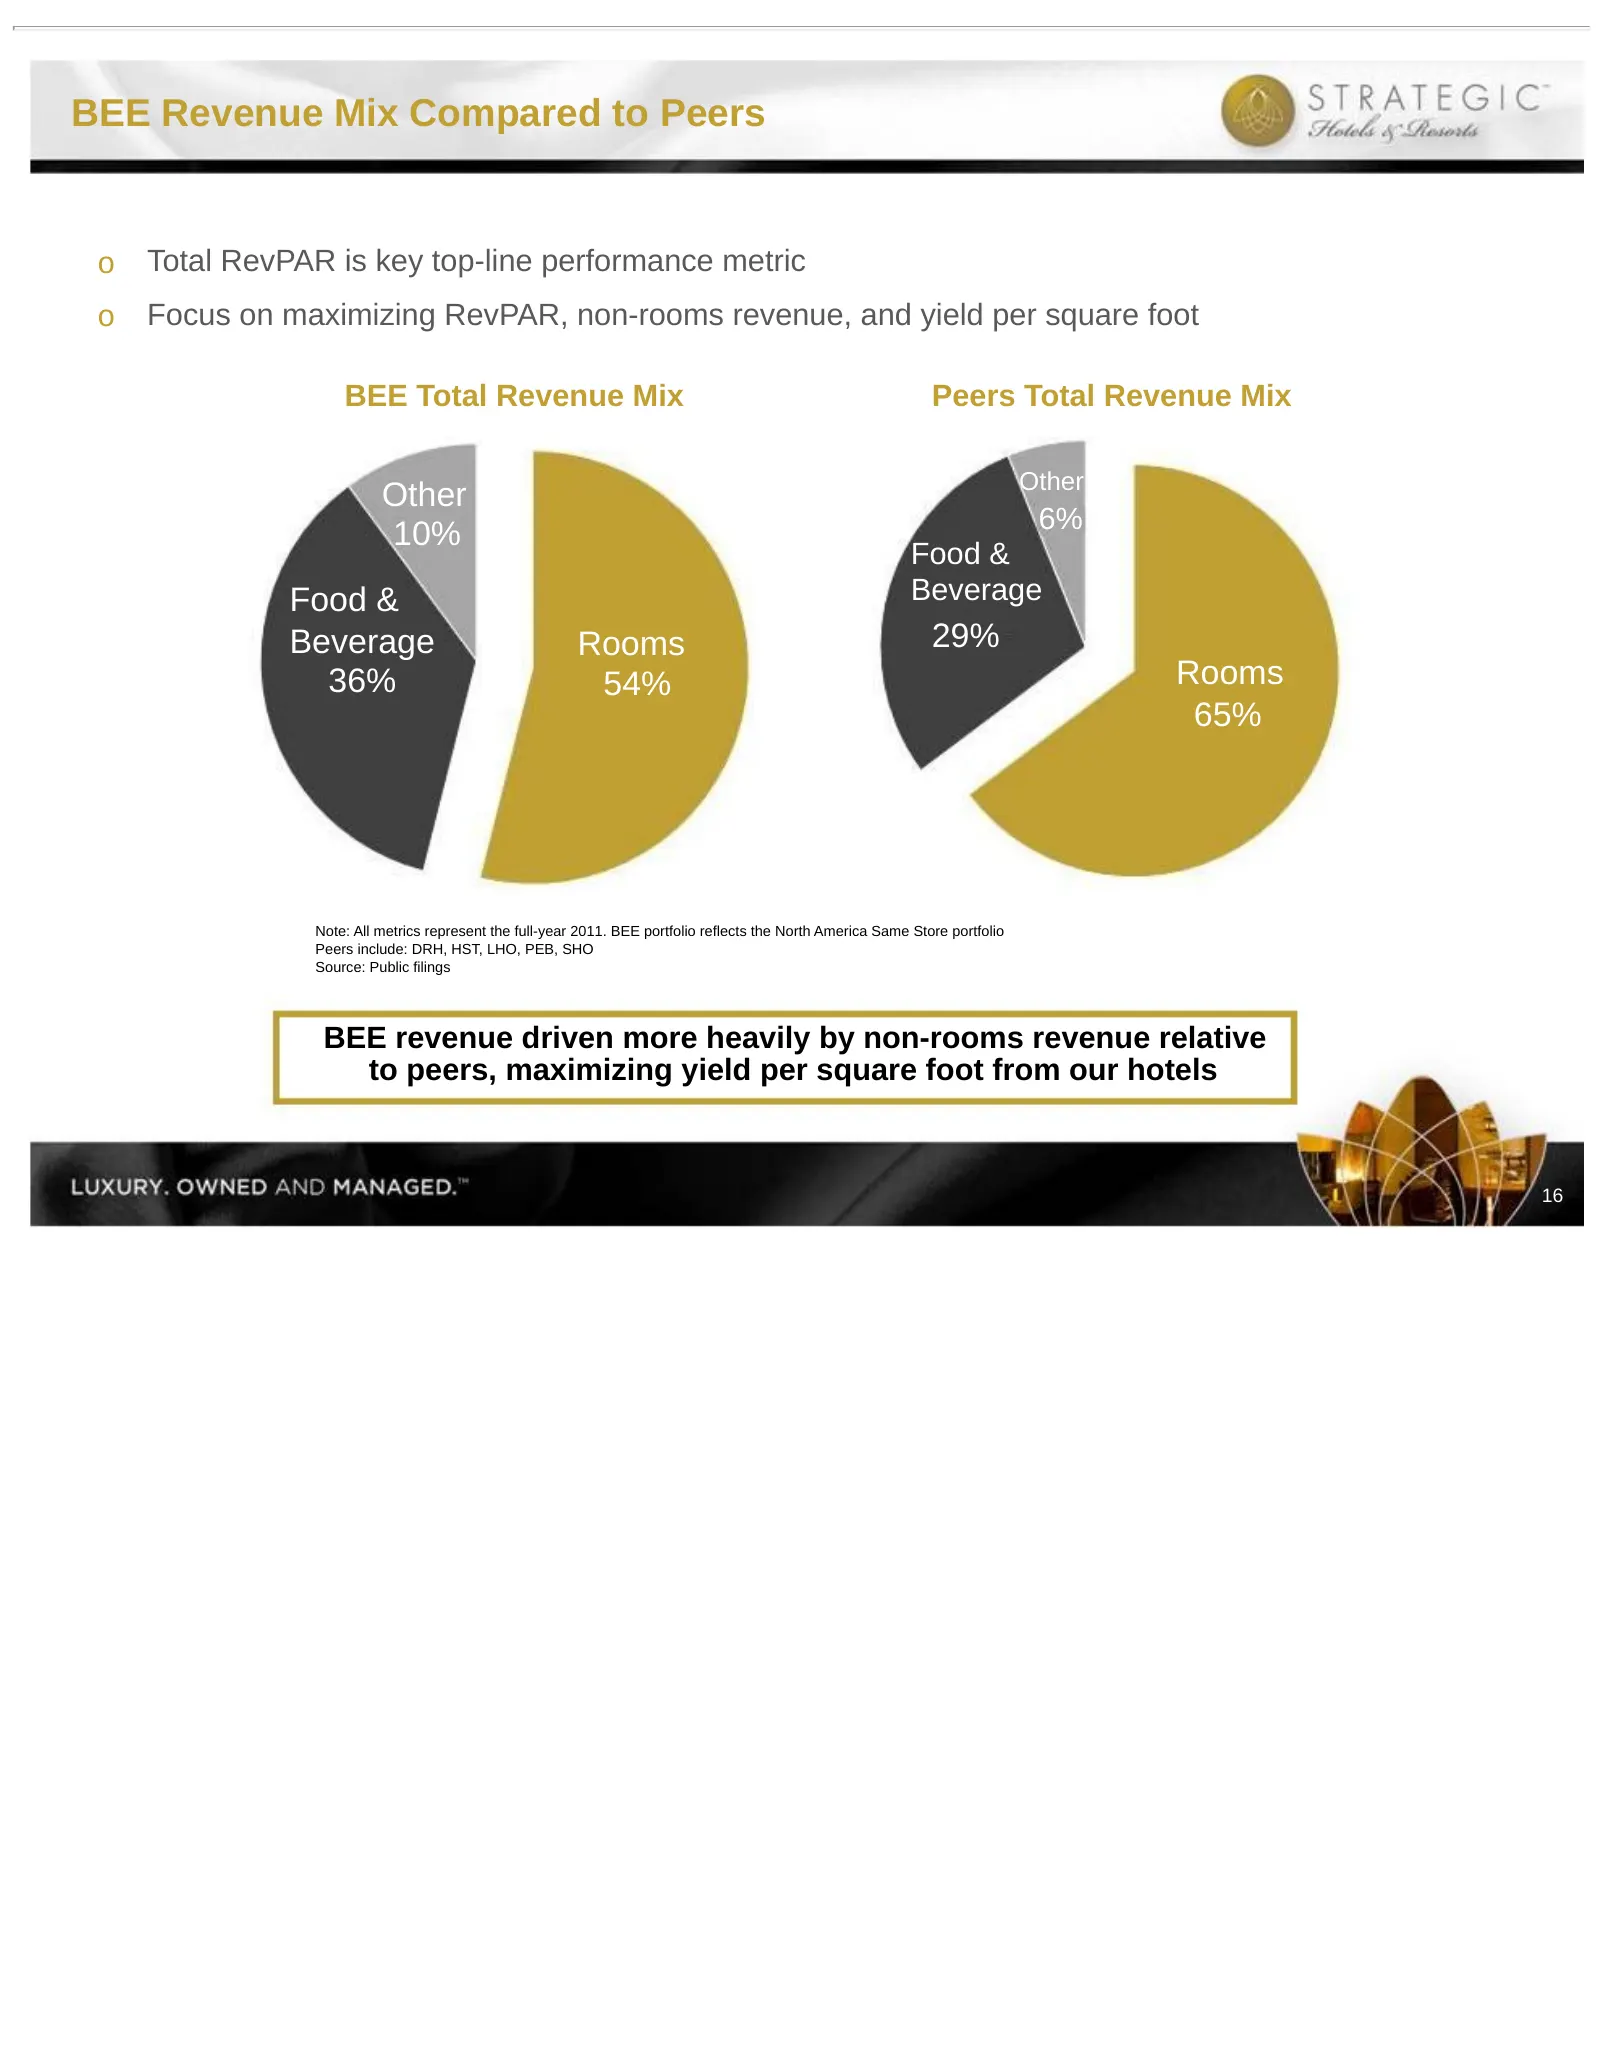
Slide 17: BEE Revenue Mix Compared to Peers
BEE Revenue Mix Compared to Peers o Total RevPAR is key top-line performance metric o Focus on maximizing RevPAR, non-rooms revenue, and yield per square foot BEE Total Revenue Mix Peers Total Revenue Mix Other Other 6% 10% Food & Food & Beverage Beverage Rooms 29% 36% 54% Rooms 65% Note: All metric
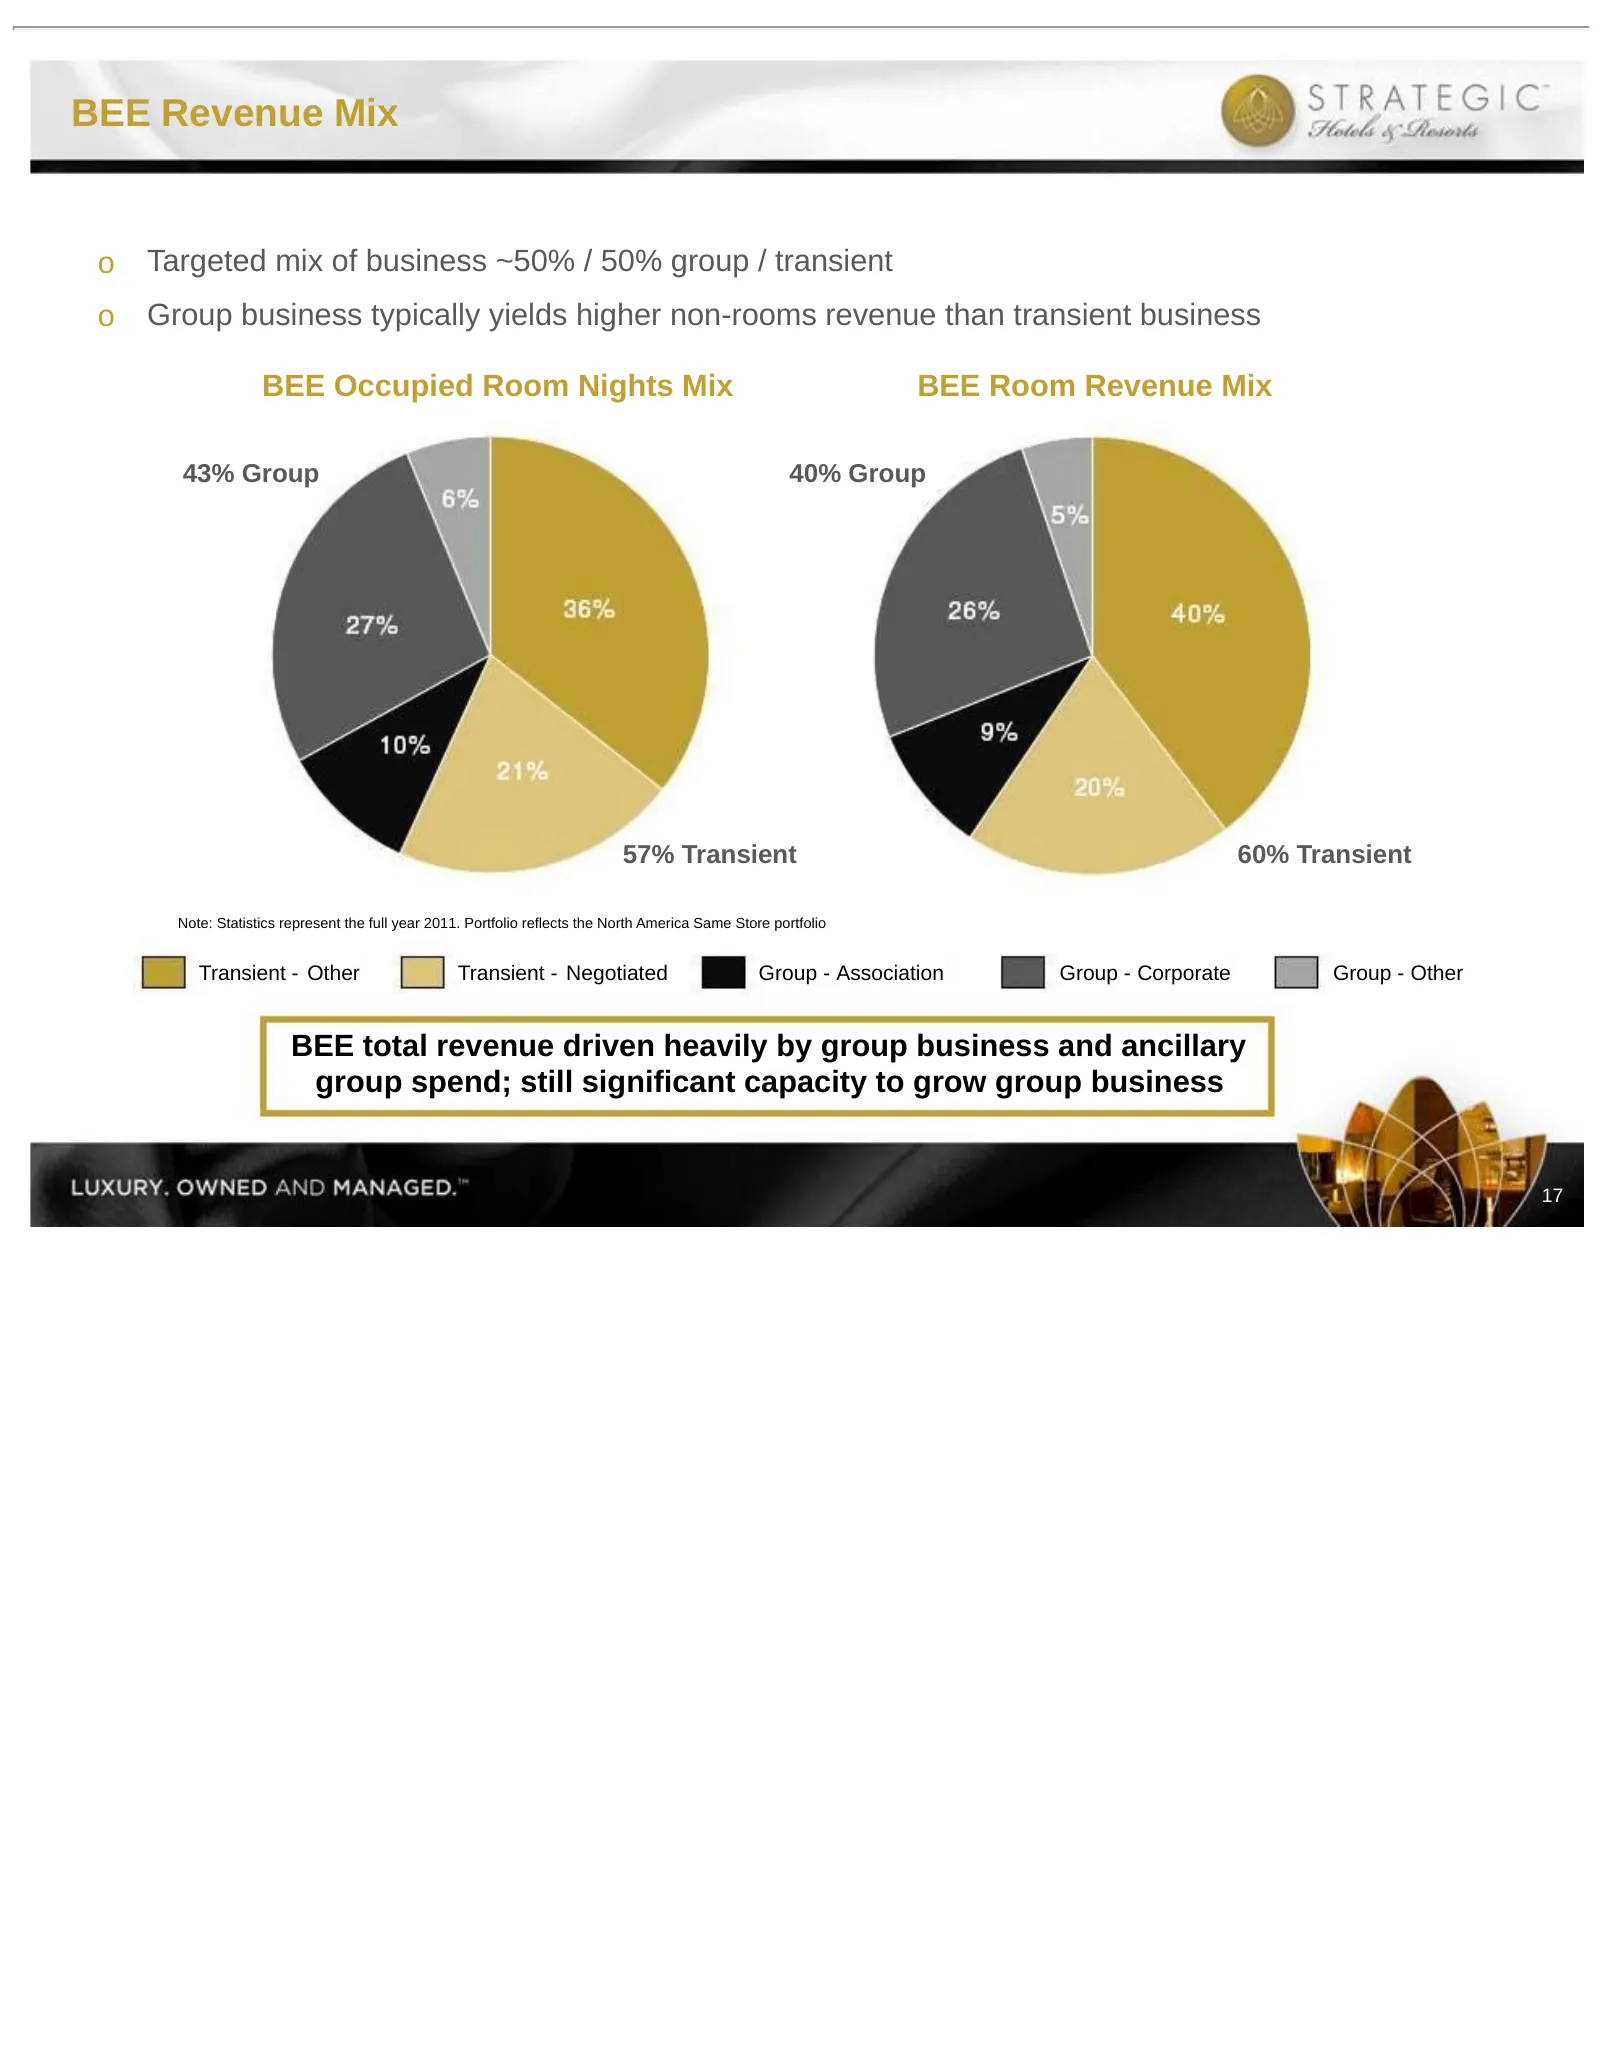
Slide 18: BEE Revenue Mix
BEE Revenue Mix o Targeted mix of business ~50% / 50% group / transient o Group business typically yields higher non-rooms revenue than transient business BEE Occupied Room Nights Mix BEE Room Revenue Mix 43% Group 40% Group 57% Transient 60% Transient Note: Statistics represent the full year 2011.
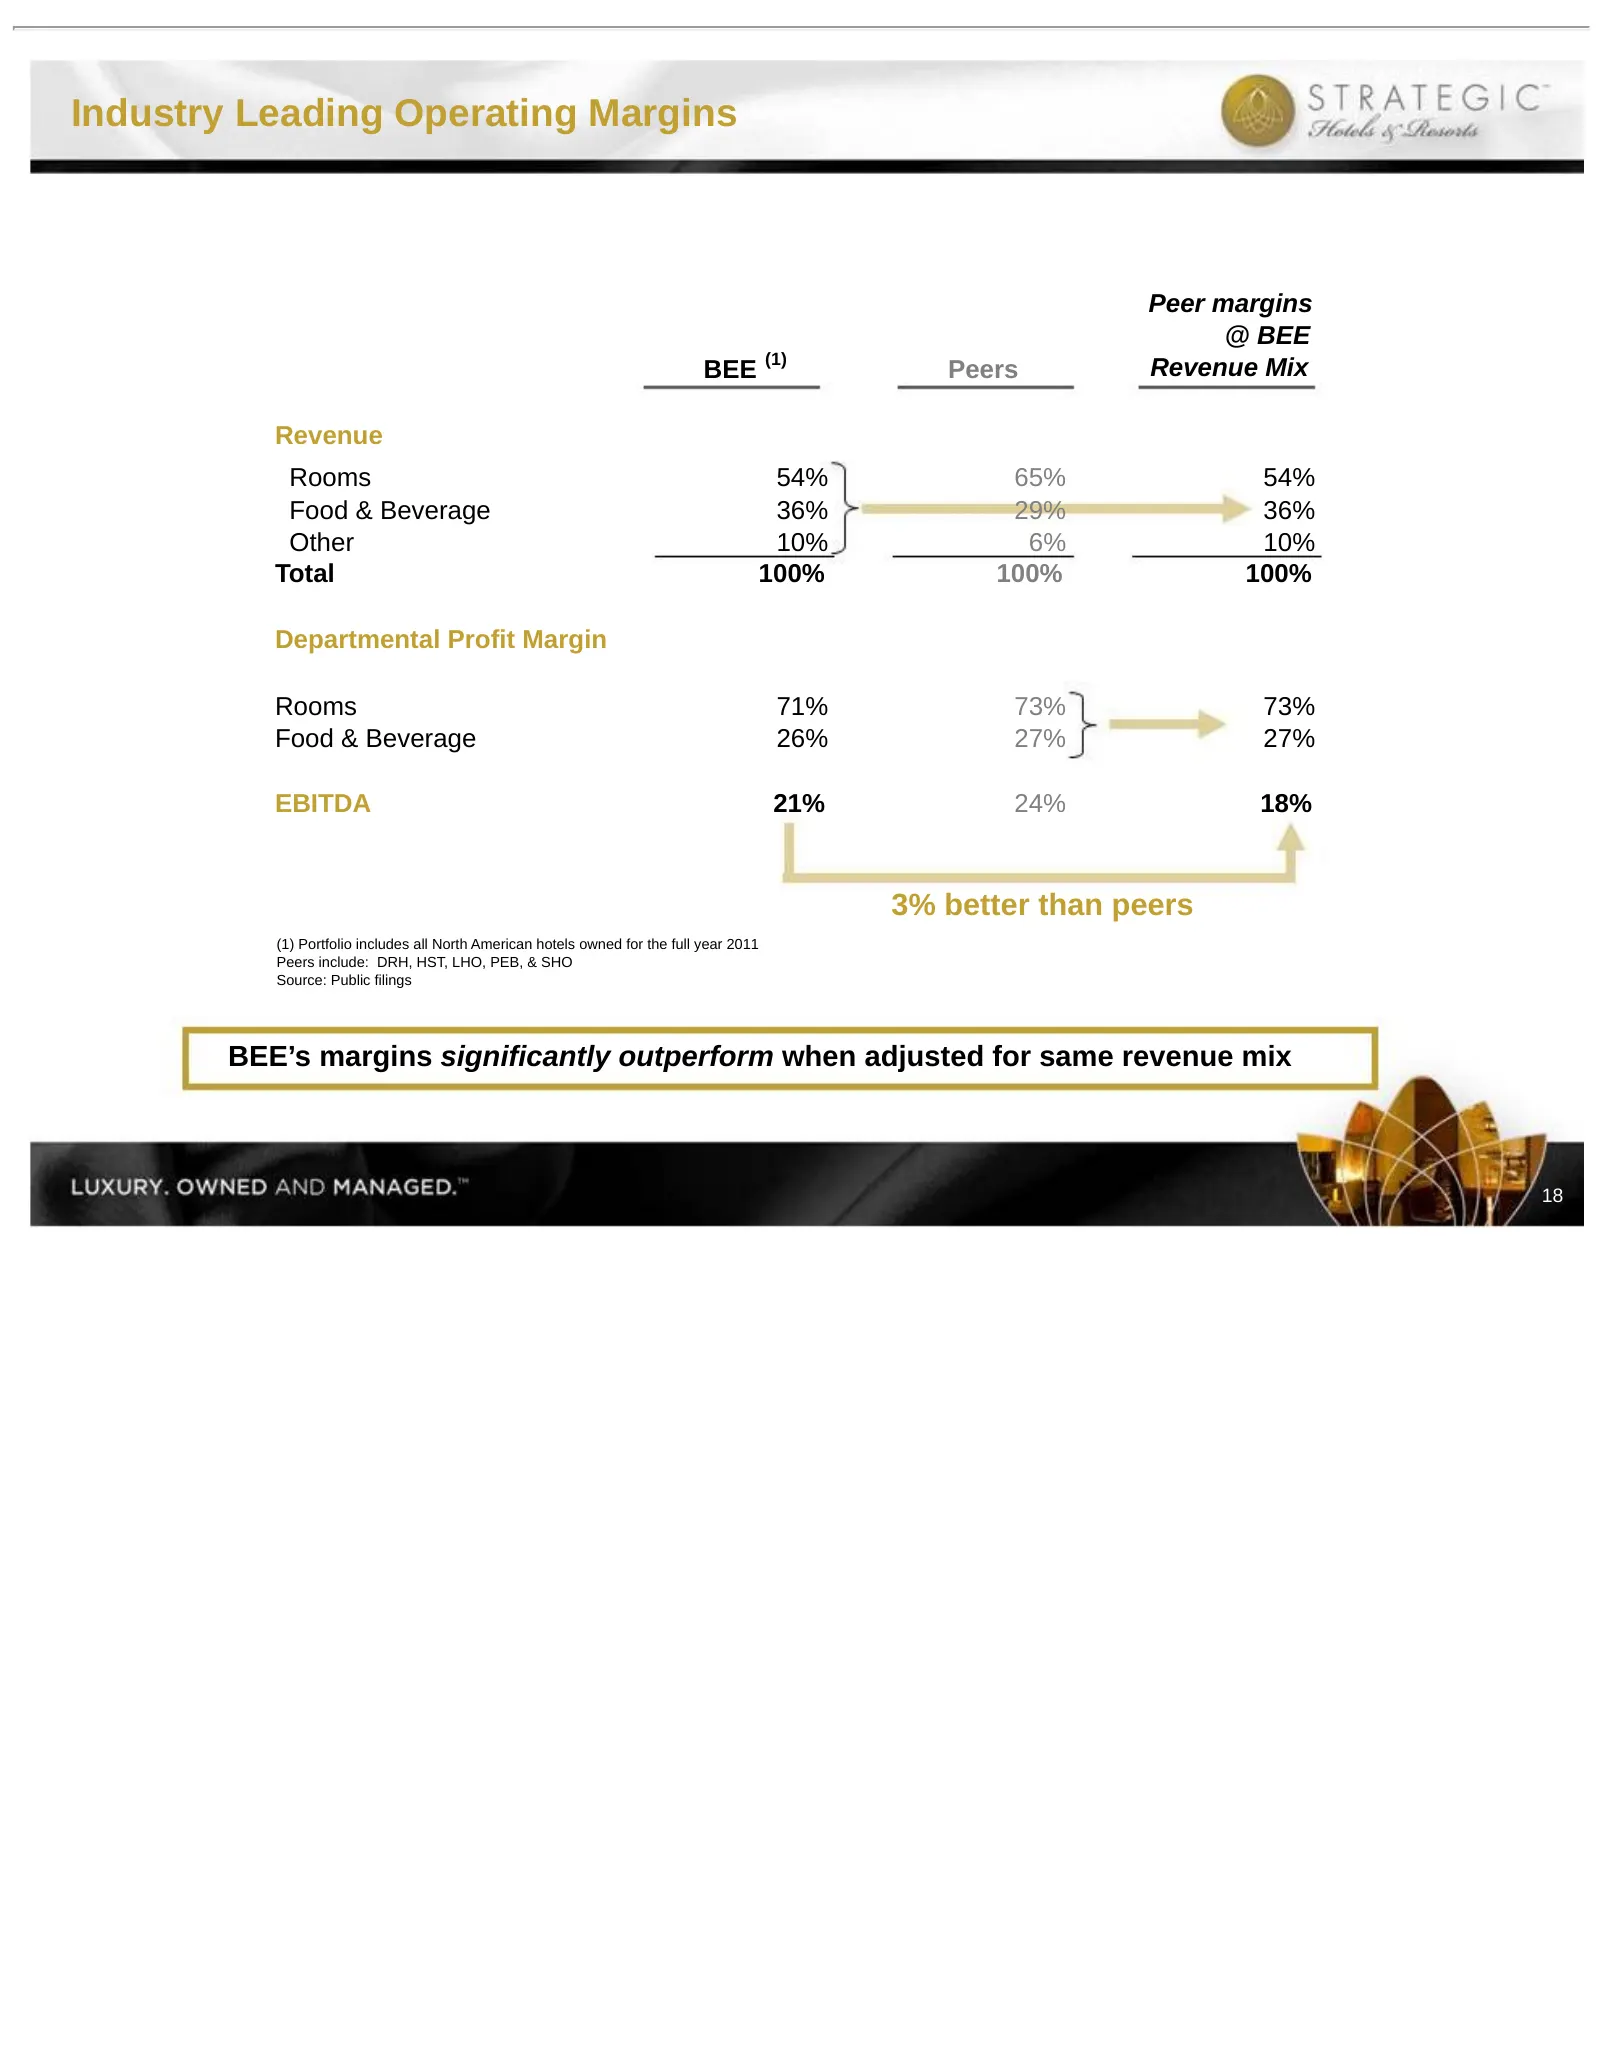
Slide 19: Industry Leading Operating Margins
Industry Leading Operating Margins Peer margins @ BEE (1) BEE Peers Revenue Mix Revenue Rooms 54% 65% 54% Food & Beverage 36% 29% 36% Other 10% 6% 10% Total 100% 100% 100% Departmental Profit Margin Rooms 71% 73% 73% Food & Beverage 26% 27% 27% EBITDA 21% 24% 18% 3% better than peers (1) Portfolio i
Slide 20: Operating Trends
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Operating Trends 19
Slide 21: Group Booking Outlook
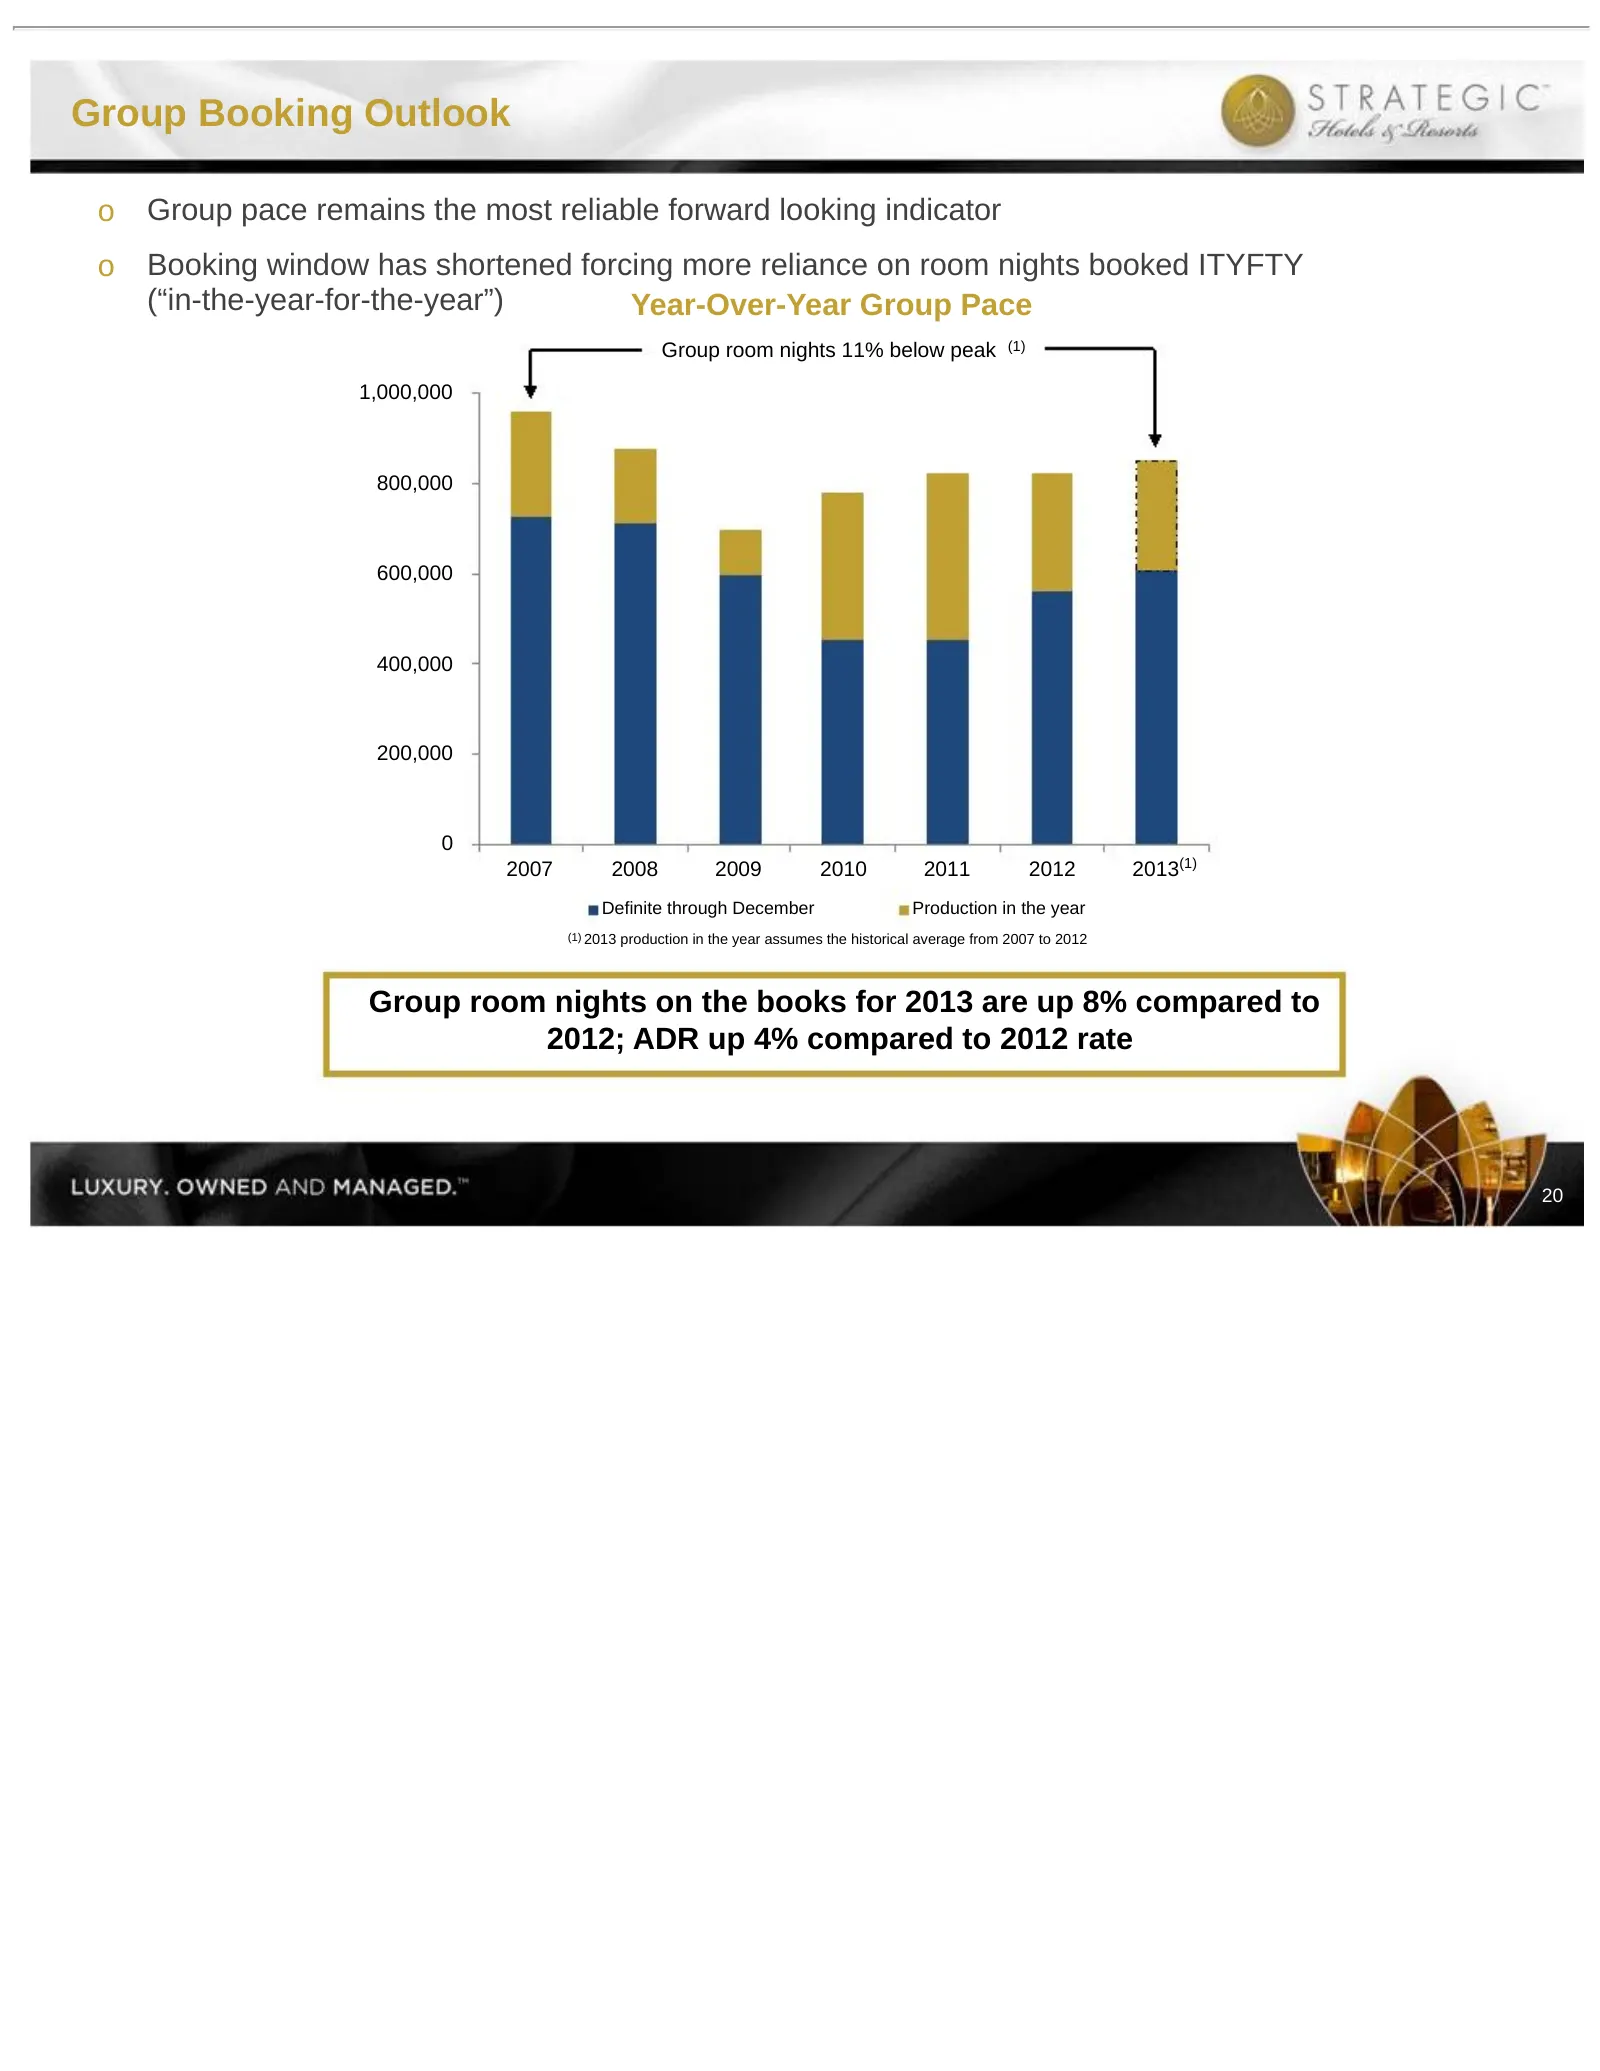
Group Booking Outlook o Group pace remains the most reliable forward looking indicator o Booking window has shortened forcing more reliance on room nights booked ITYFTY (“in-the-year-for-the-year”) Year-Over-Year Group Pace Group room nights 11% below peak (1) 1,000,000 800,000 600,000 400,000 200,0
Slide 22: Embedded Portfolio Growth
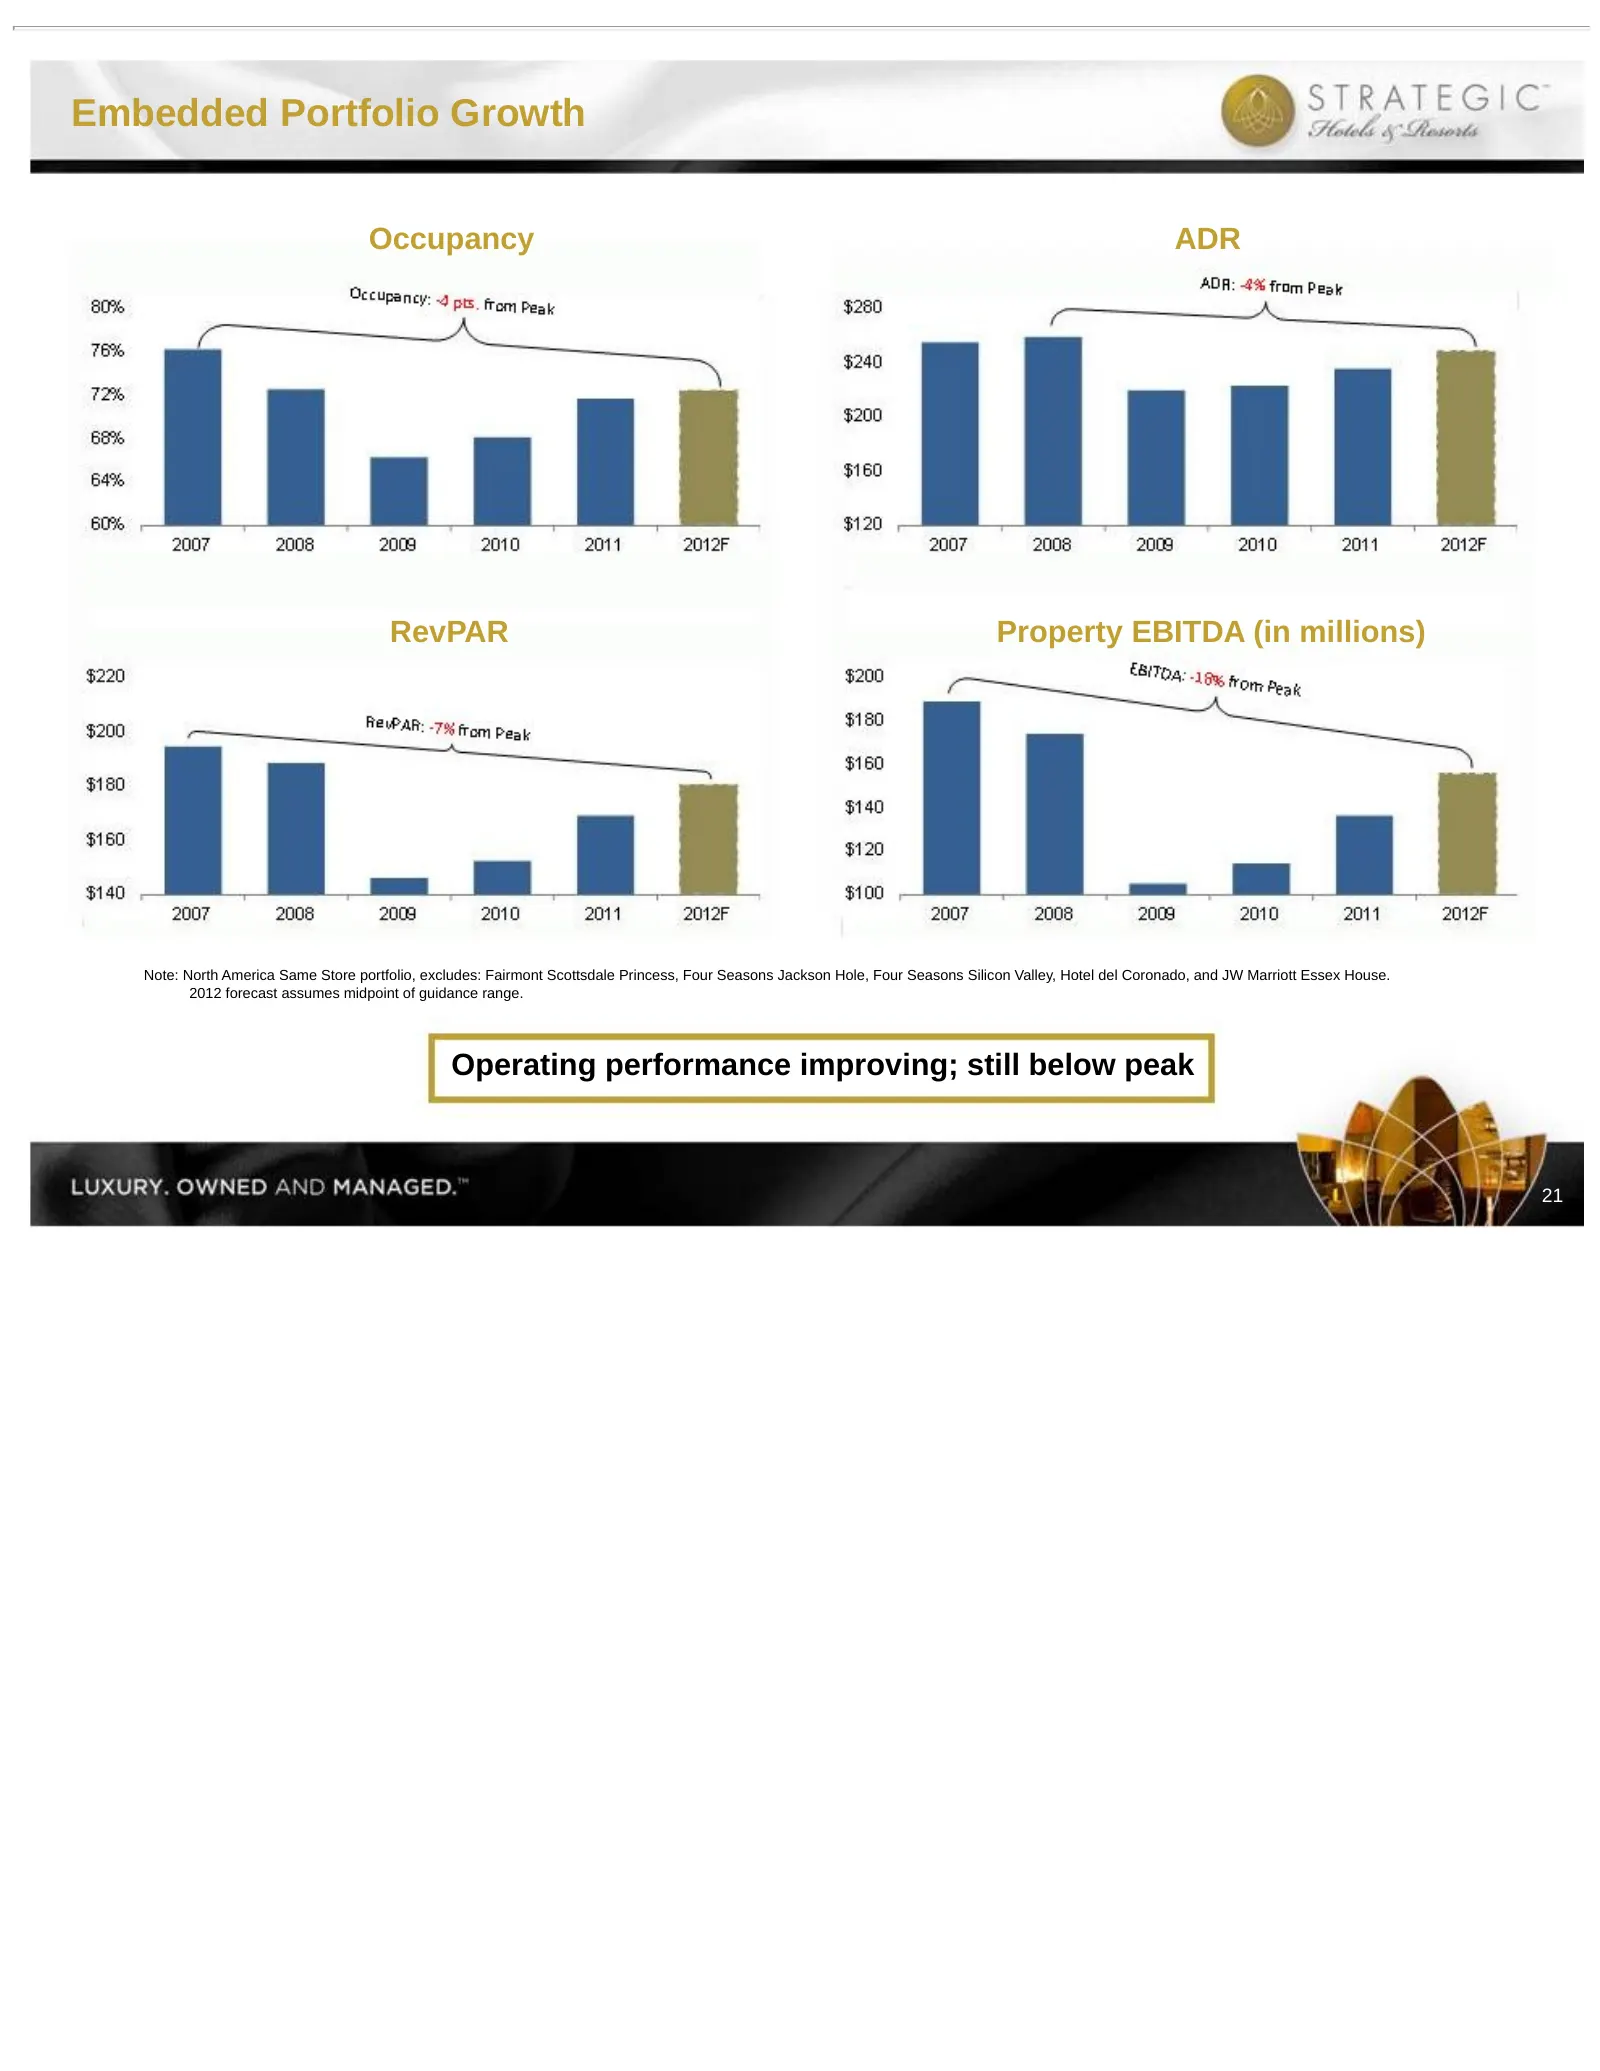
Embedded Portfolio Growth Occupancy ADR RevPAR Property EBITDA (in millions) Note: North America Same Store portfolio, excludes: Fairmont Scottsdale Princess, Four Seasons Jackson Hole, Four Seasons Silicon Valley, Hotel del Coronado, and JW Marriott Essex House. 2012 forecast assumes midpoint of gu
Slide 23: Financial Overview
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Financial Overview 22
Slide 24: Accomplishments Since January 1, 2010
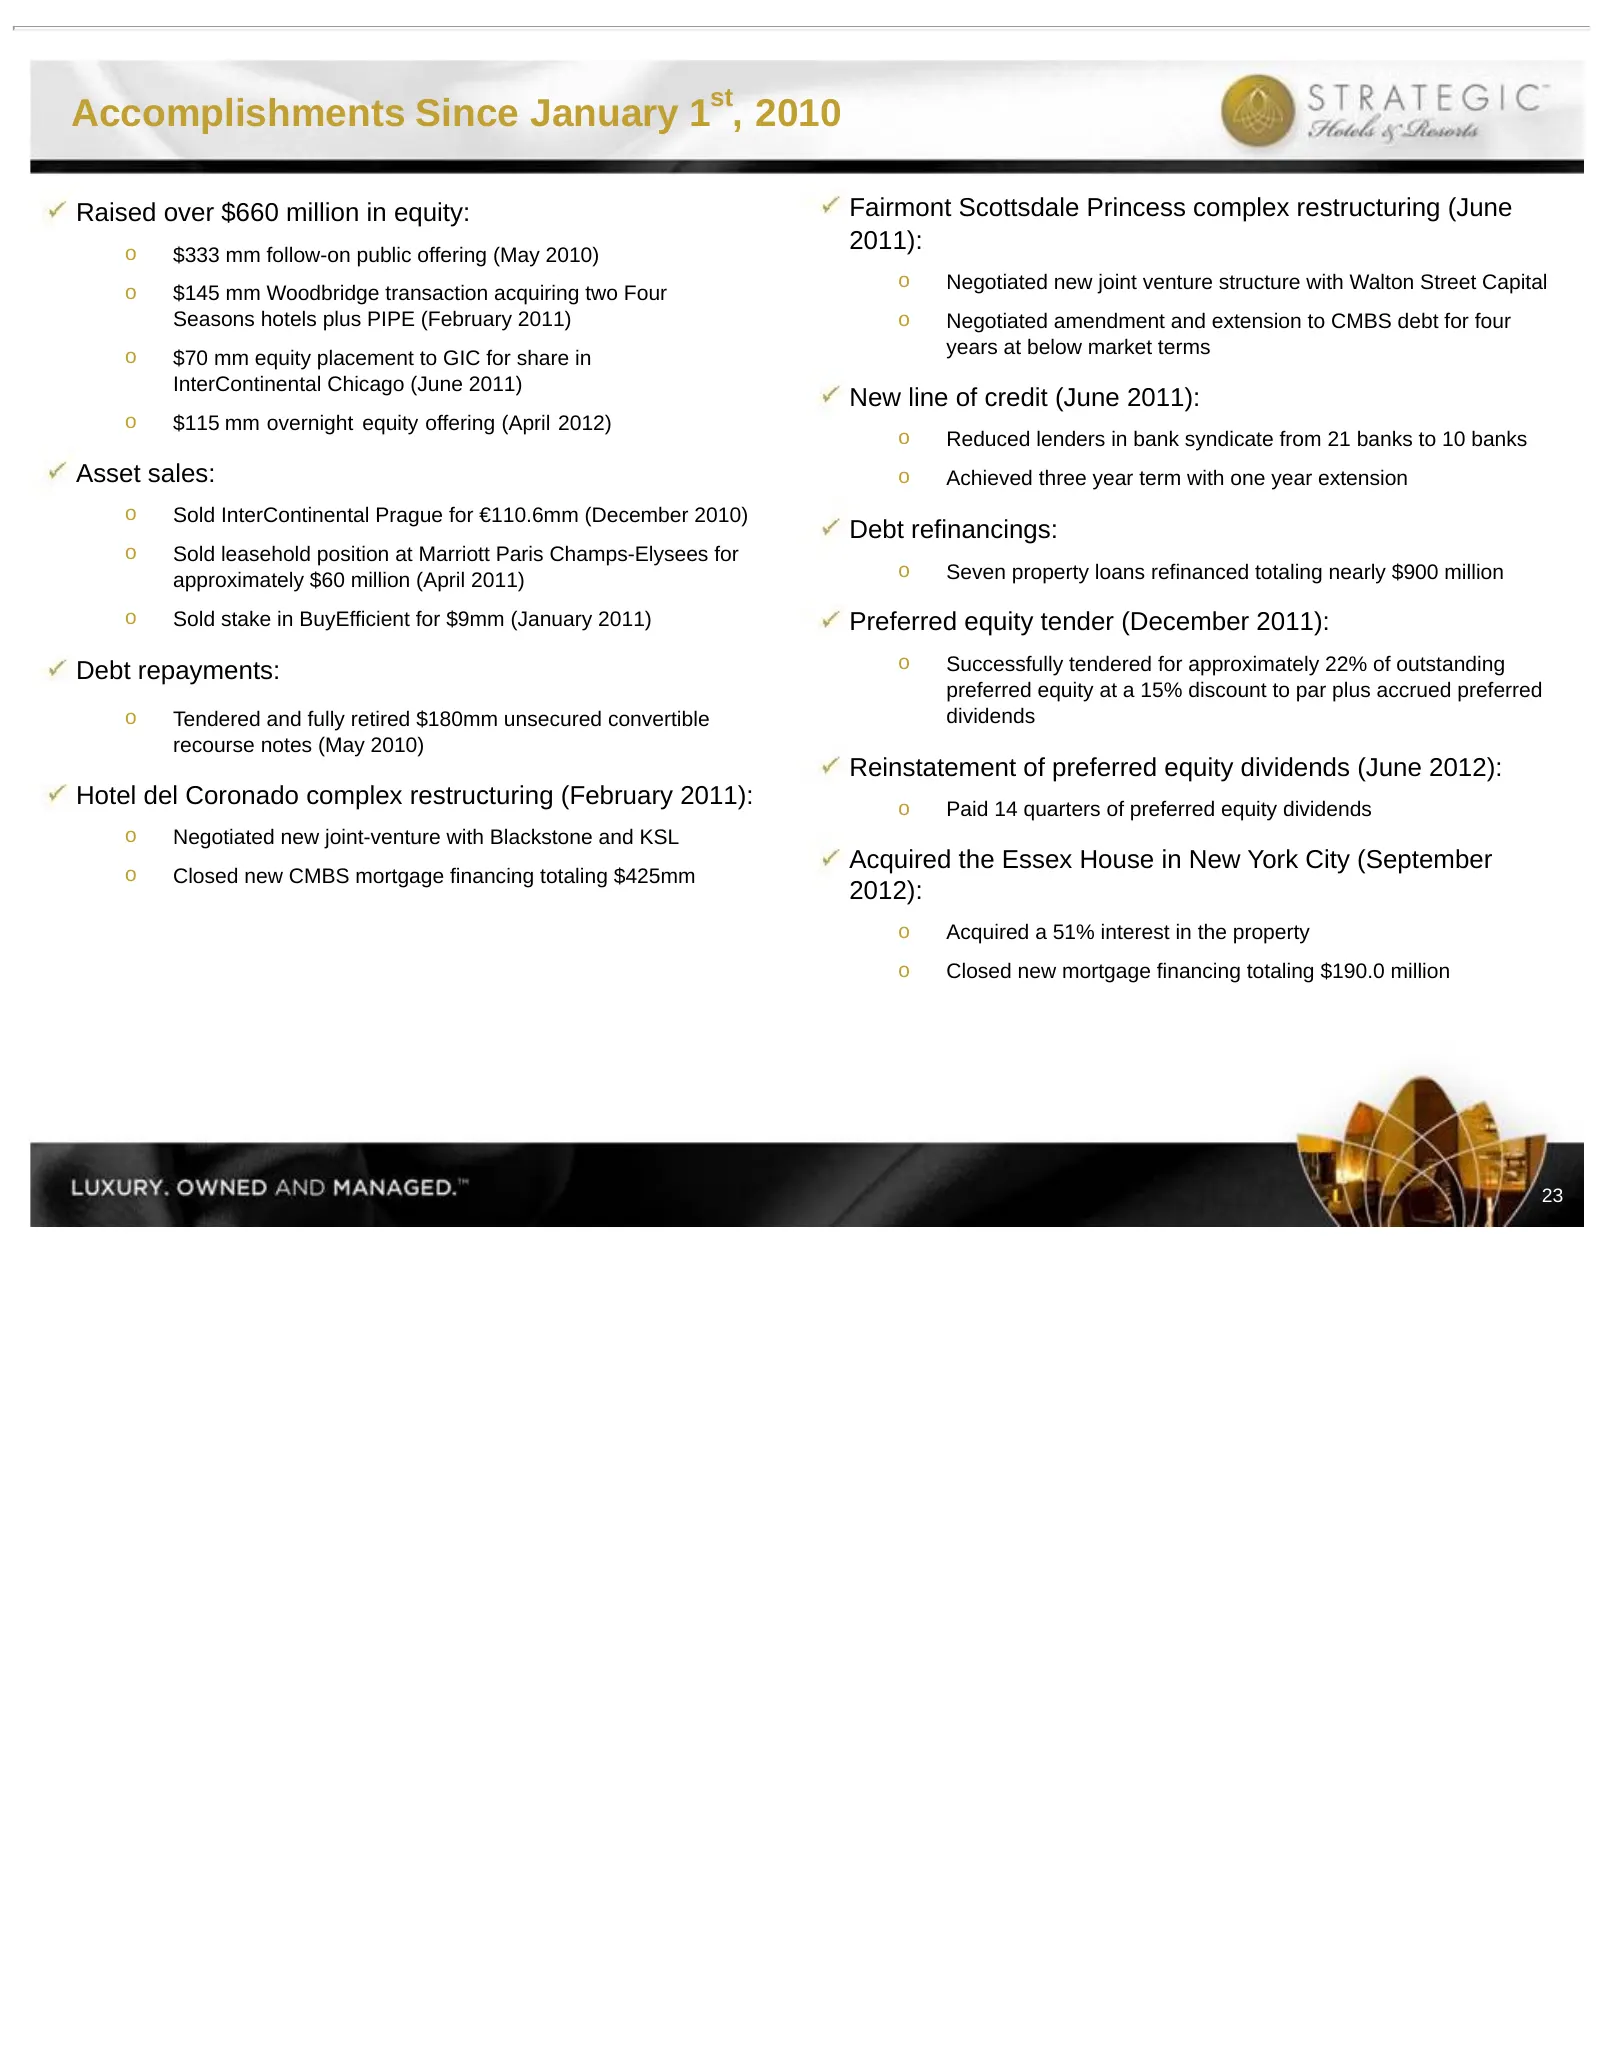
st Accomplishments Since January 1 , 2010 Raised over $660 million in equity: Fairmont Scottsdale Princess complex restructuring (June o 2011): $333 mm follow-on public offering (May 2010) o Negotiated new joint venture structure with Walton Street Capital o $145 mm Woodbridge transaction acquiring
Slide 25: Strong Recapitalized Balance Sheet
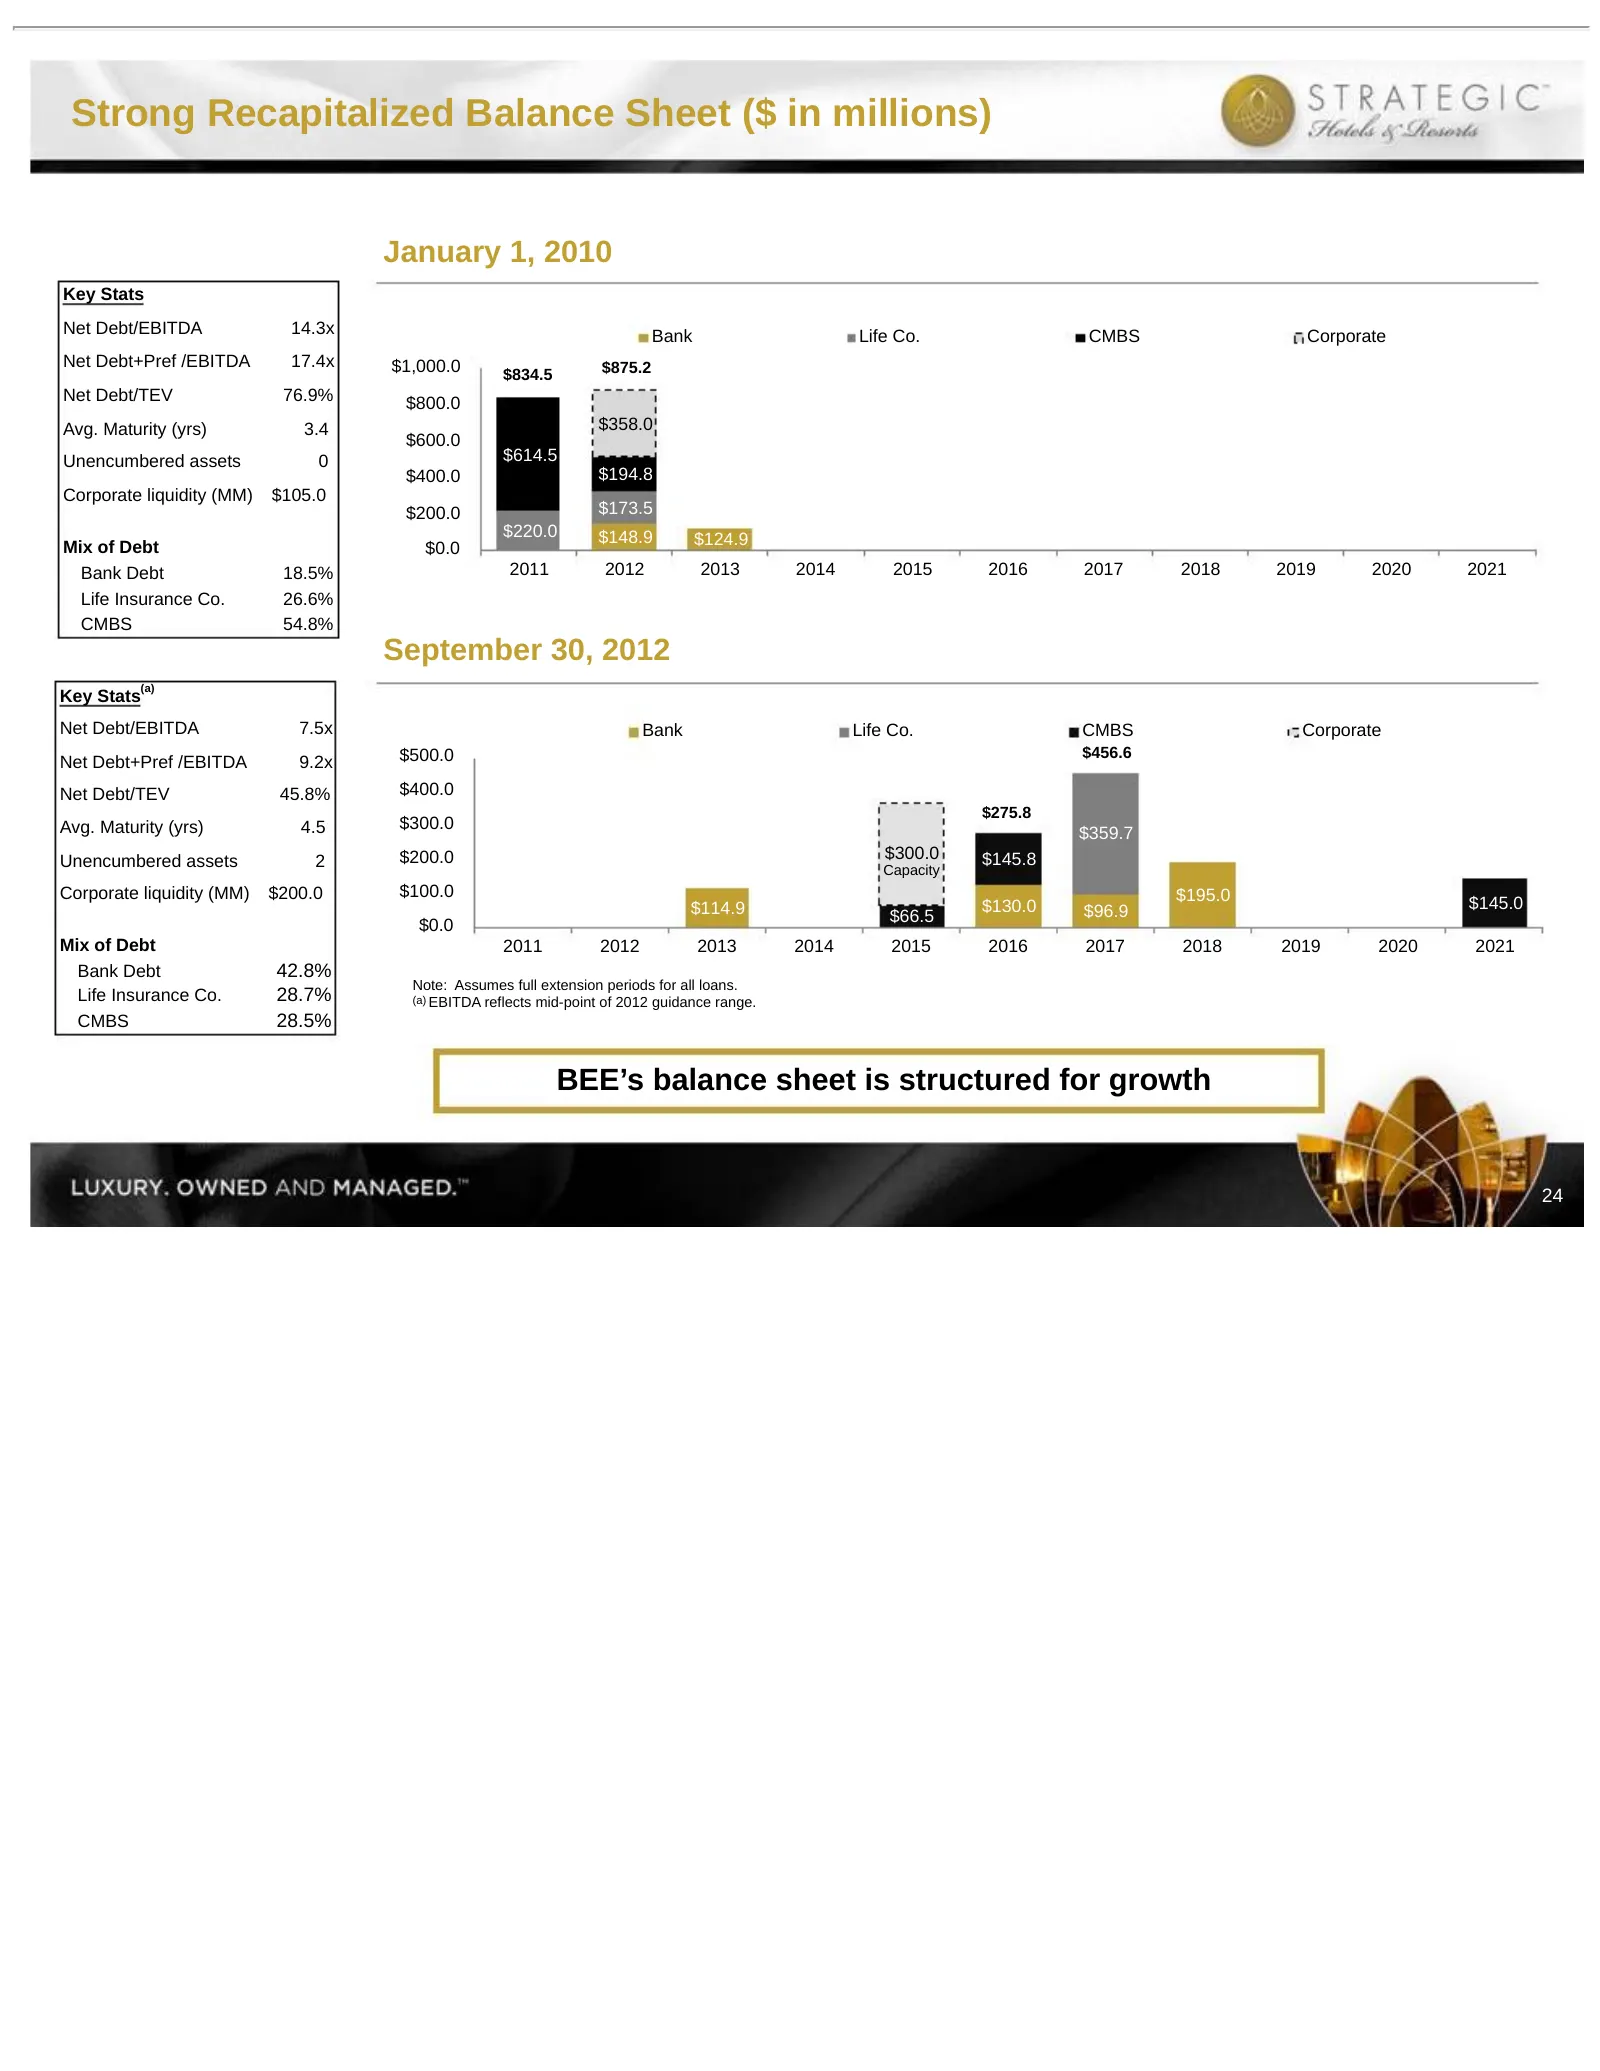
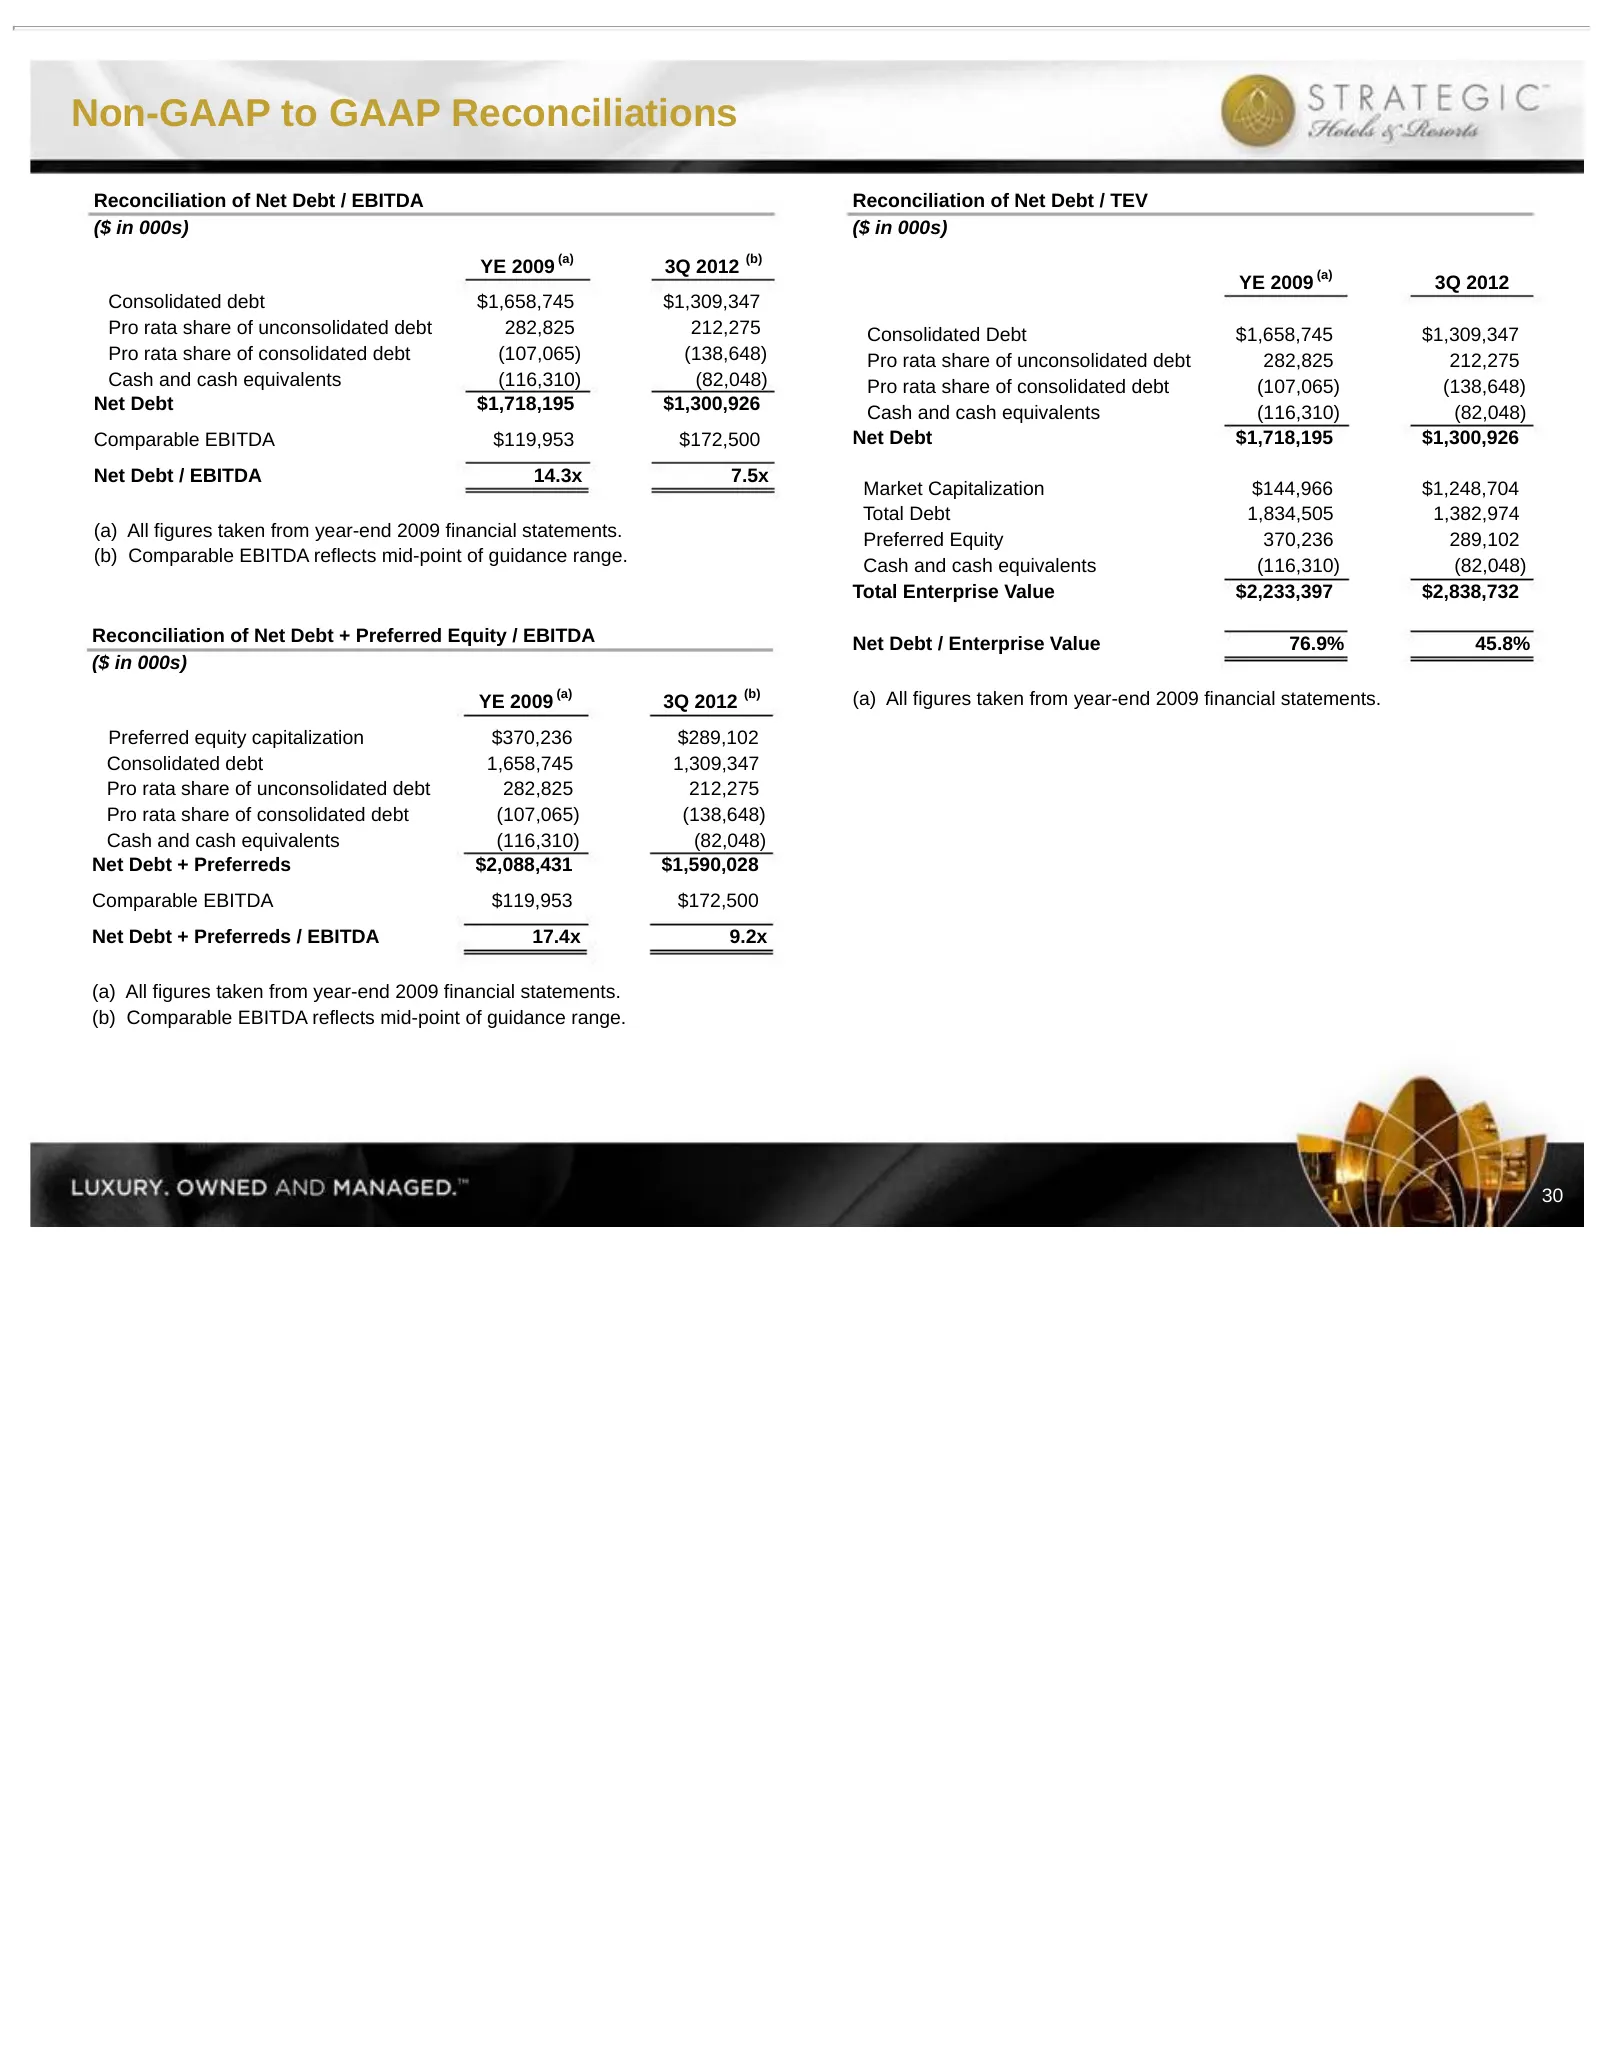
Strong Recapitalized Balance Sheet ($ in millions) January 1, 2010 Key Stats Net Debt/EBITDA 14.3x Bank Life Co. CMBS Corporate Net Debt+Pref /EBITDA 17.4x $1,000.0 $875.2 $834.5 Net Debt/TEV 76.9% $800.0 Avg. Maturity (yrs) 3.4 $358.0 $600.0 Unencumbered assets 0 $614.5 $400.0 $194.8 Corporate liqu
Slide 26: 3rd Quarter 2012 Results
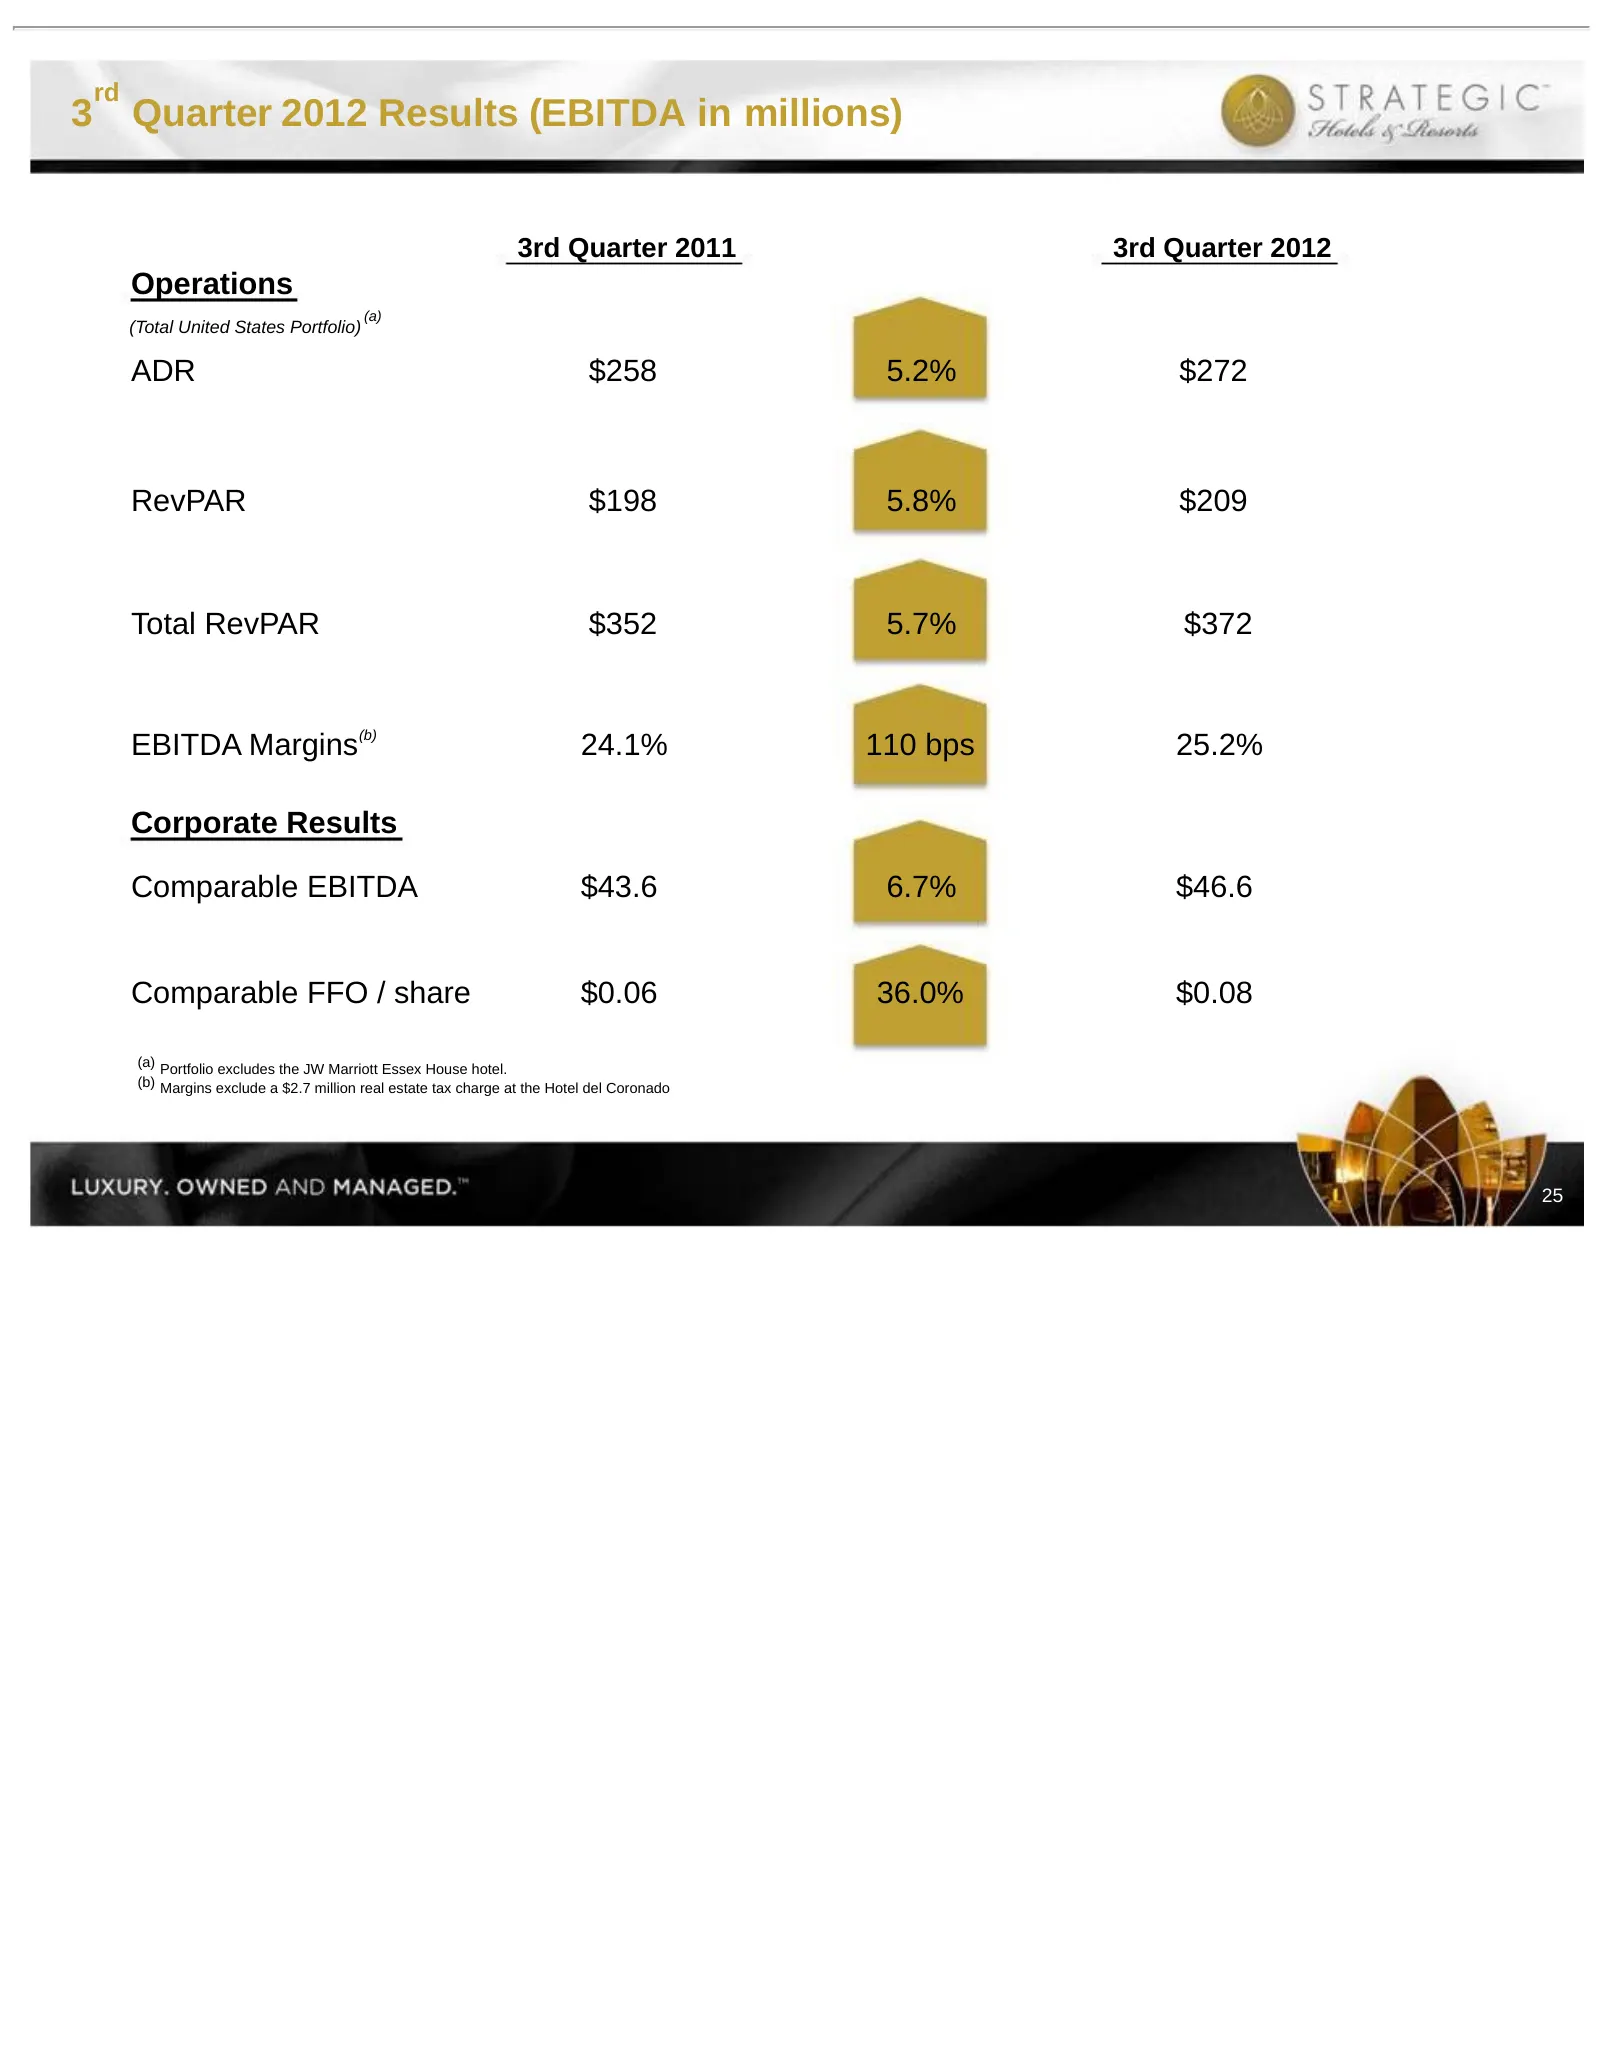
rd 3 Quarter 2012 Results (EBITDA in millions) 3rd Quarter 2011 3rd Quarter 2012 Operations (a) (Total United States Portfolio) ADR $258 5.2% $272 RevPAR $198 5.8% $209 Total RevPAR $352 5.7% $372 EBITDA Margins(b) 24.1% 110 bps 25.2% Corporate Results Comparable EBITDA $43.6 6.7% $46.6 Comparable F
Slide 27: Year to Date 2012 Results
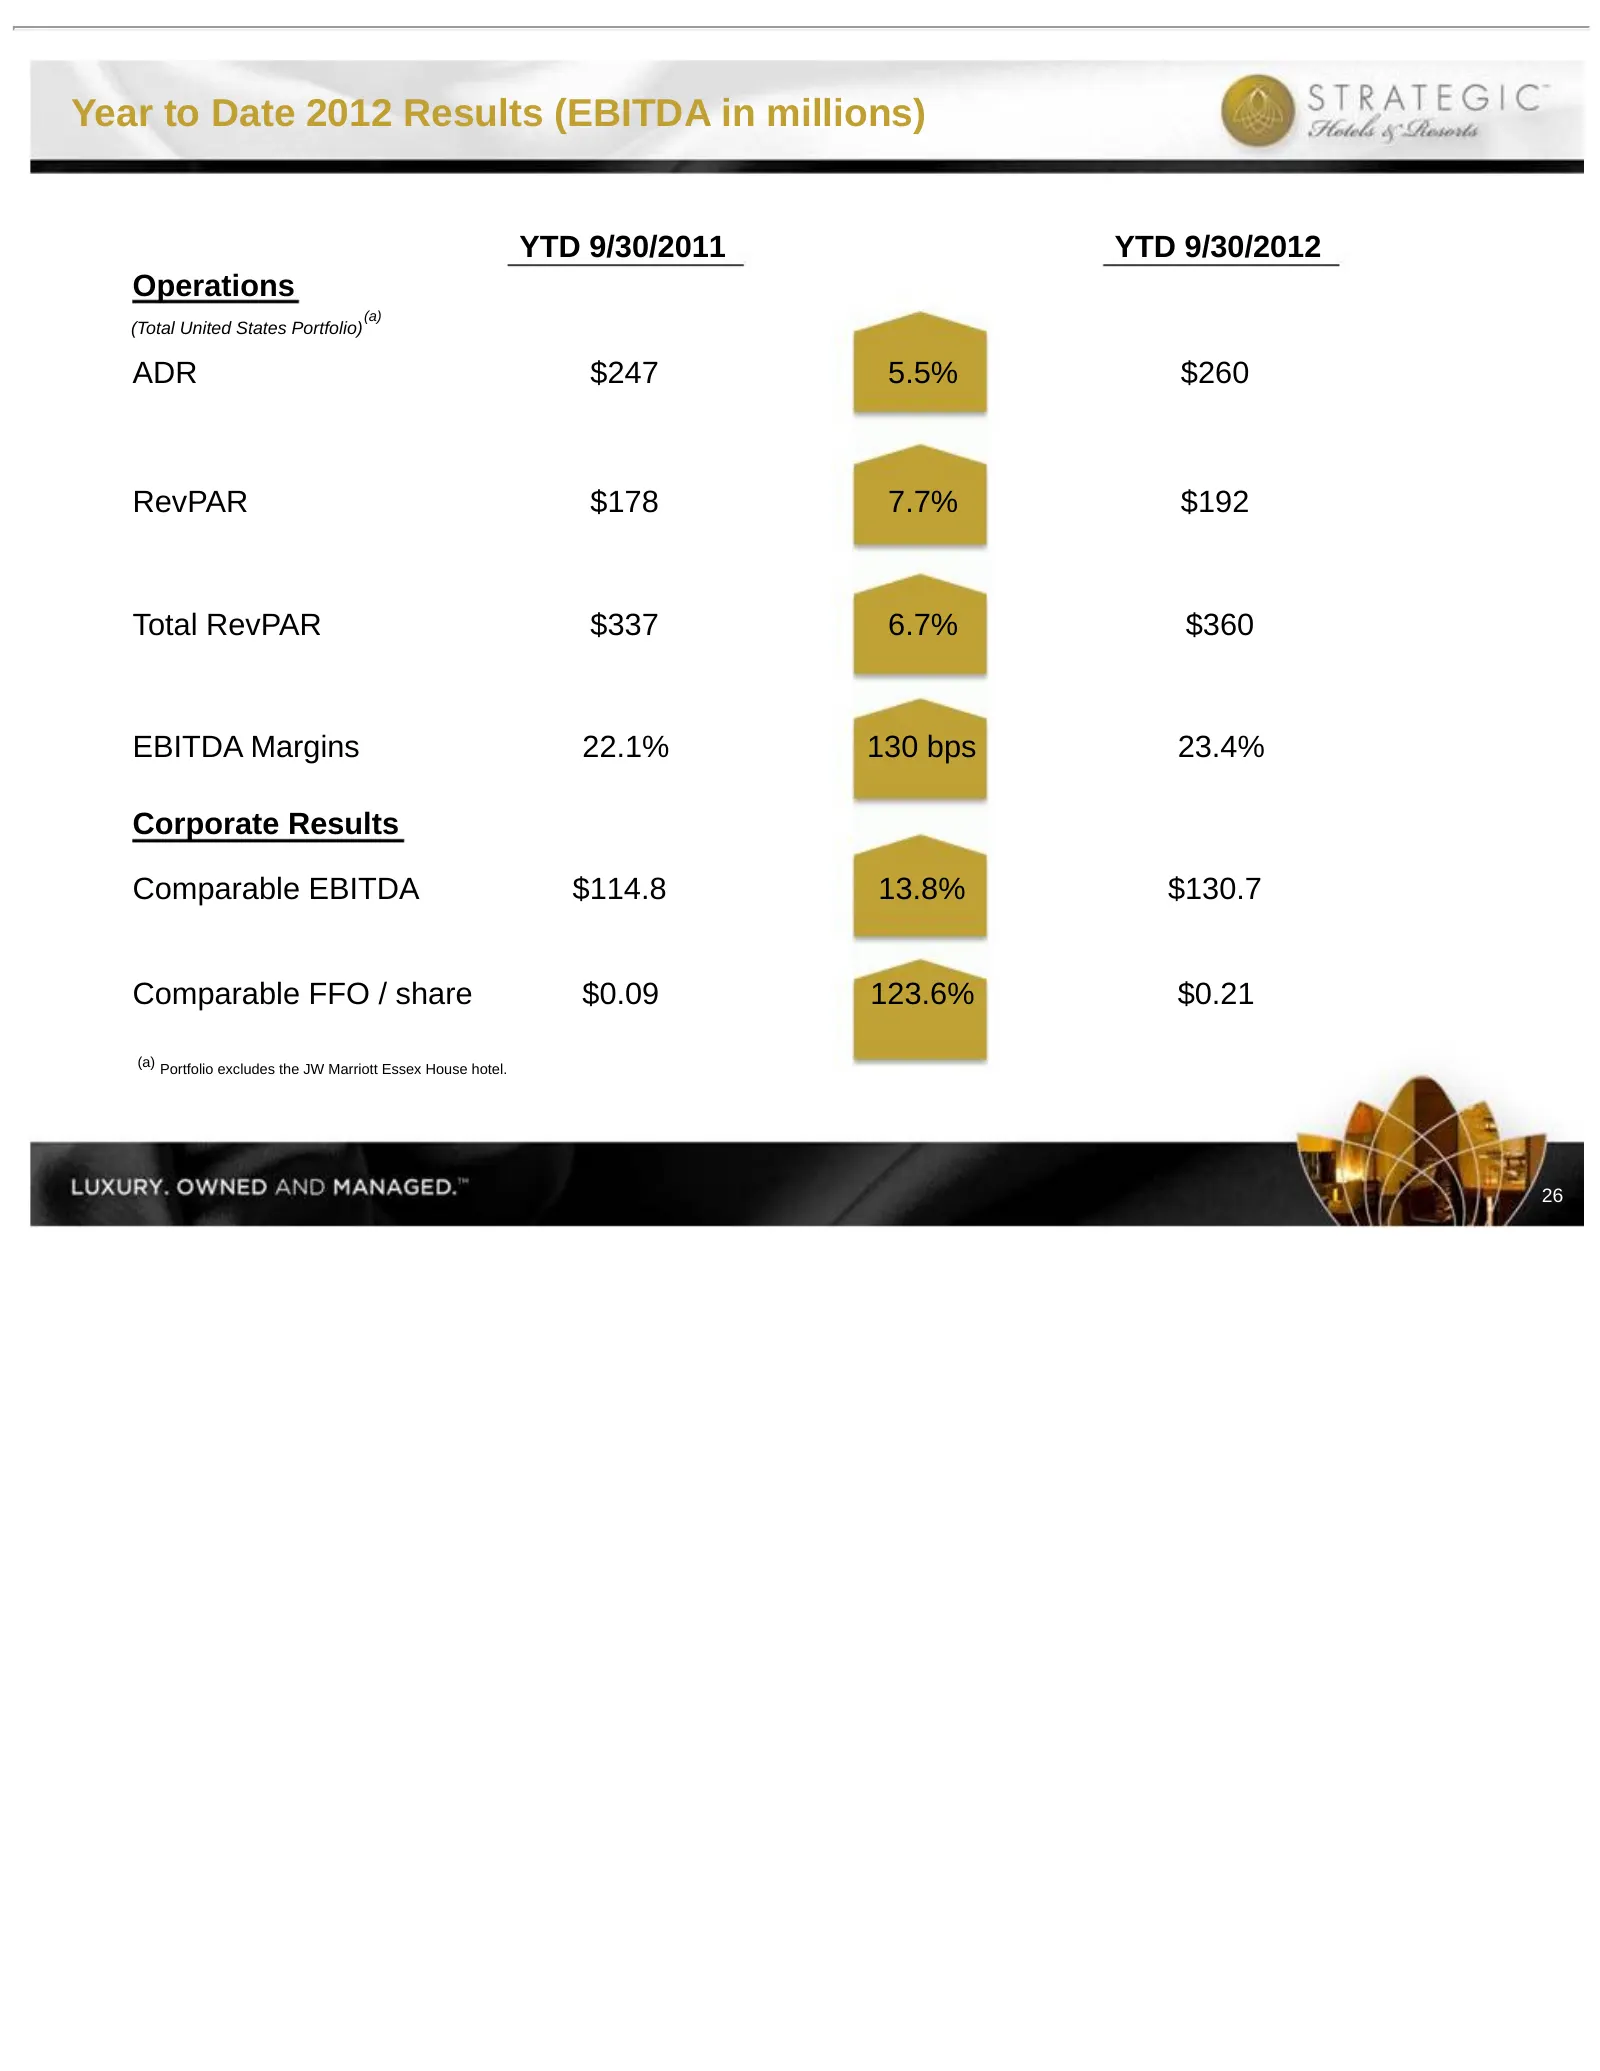
Year to Date 2012 Results (EBITDA in millions) YTD 9/30/2011 YTD 9/30/2012 Operations (a) (Total United States Portfolio) ADR $247 5.5% $260 RevPAR $178 7.7% $192 Total RevPAR $337 6.7% $360 EBITDA Margins 22.1% 130 bps 23.4% Corporate Results Comparable EBITDA $114.8 13.8% $130.7 Comparable FFO / s
Slide 28: 2012 Guidance
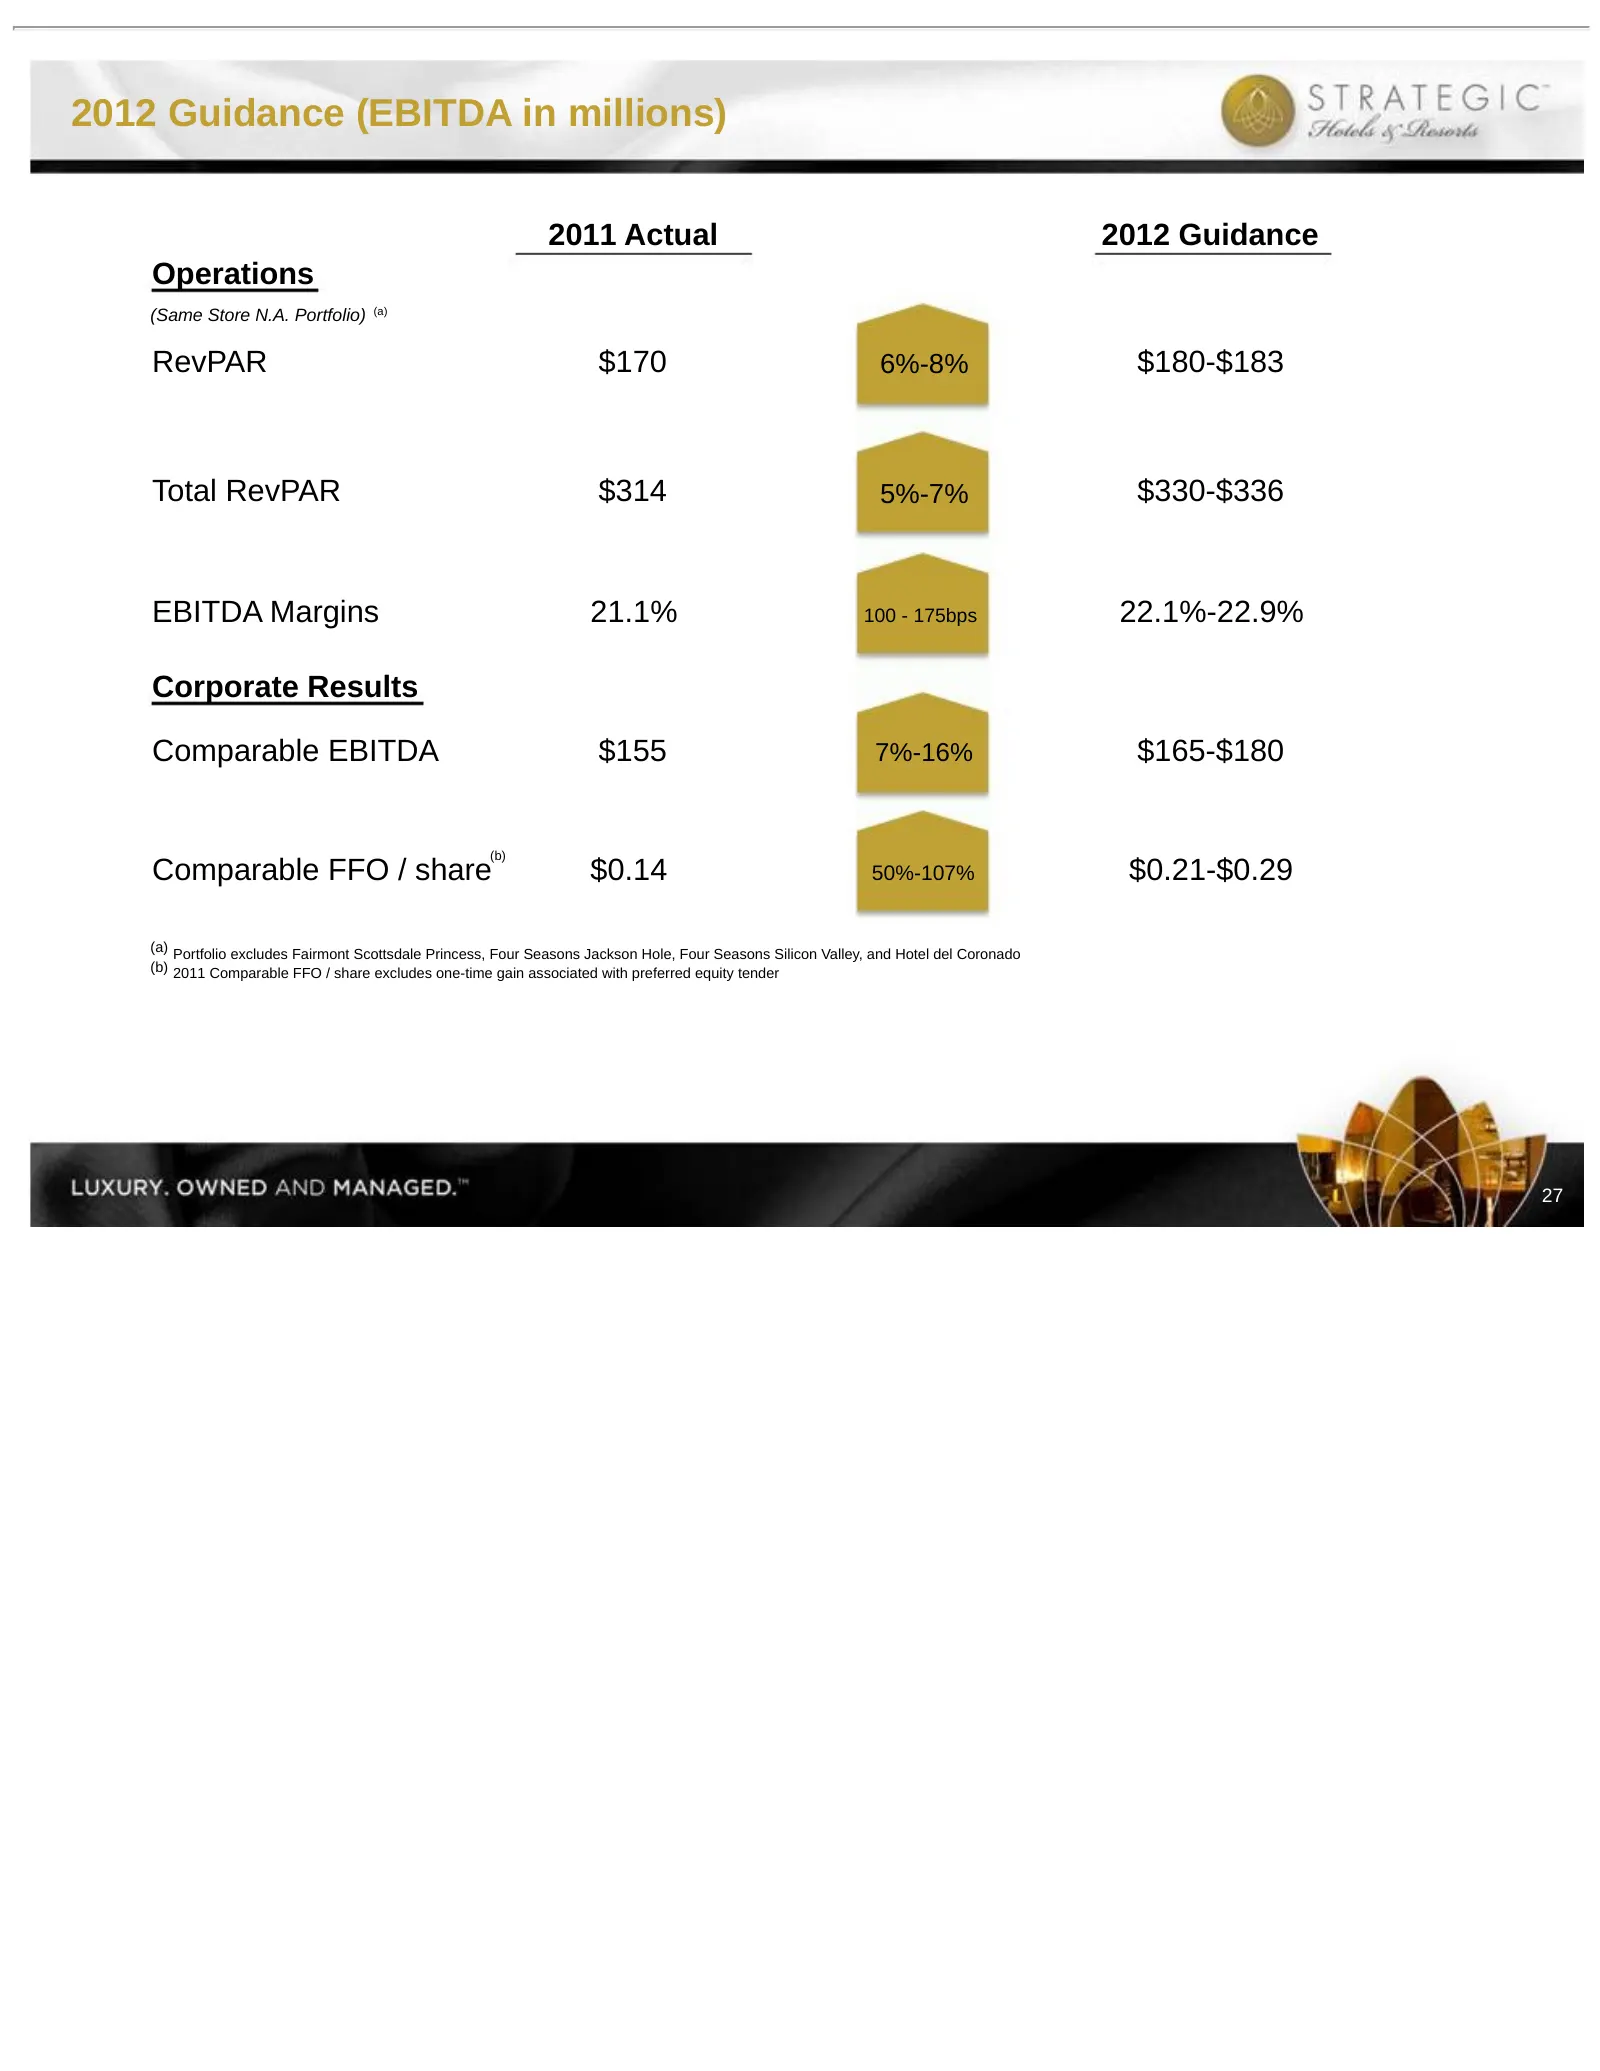
2012 Guidance (EBITDA in millions) 2011 Actual 2012 Guidance Operations (Same Store N.A. Portfolio) (a) RevPAR $170 6%-8% $180-$183 Total RevPAR $314 5%-7% $330-$336 EBITDA Margins 21.1% 100 - 175bps 22.1%-22.9% Corporate Results Comparable EBITDA $155 7%-16% $165-$180 (b) Comparable FFO / share $0.
Slide 29: BEE's Unique Value Proposition
BEE’s Unique Value Proposition o The only pure play high-end lodging REIT o High-end outperforms the industry in a recovery o Industry leading asset management expertise o Assets are in pristine condition o Embedded organic growth through revenue growth and ROI opportunities o Historically low suppl
Slide 30: Disclaimer
Disclaimer Except for historical information, the matters discussed in this presentation are forward-looking statements subject to certain risks and uncertainties. Forward-looking statements relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends, and
Slide 31: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations Reconciliation of Net Debt / EBITDA Reconciliation of Net Debt / TEV ($ in 000s) ($ in 000s) (a) (b) YE 2009 3Q 2012 (a) YE 2009 3Q 2012 Consolidated debt $1,658,745 $1,309,347 Pro rata share of unconsolidated debt 282,825 212,275 Consolidated Debt $1,658,745 $1,309,
Slide 32: Non-GAAP to GAAP Reconciliations
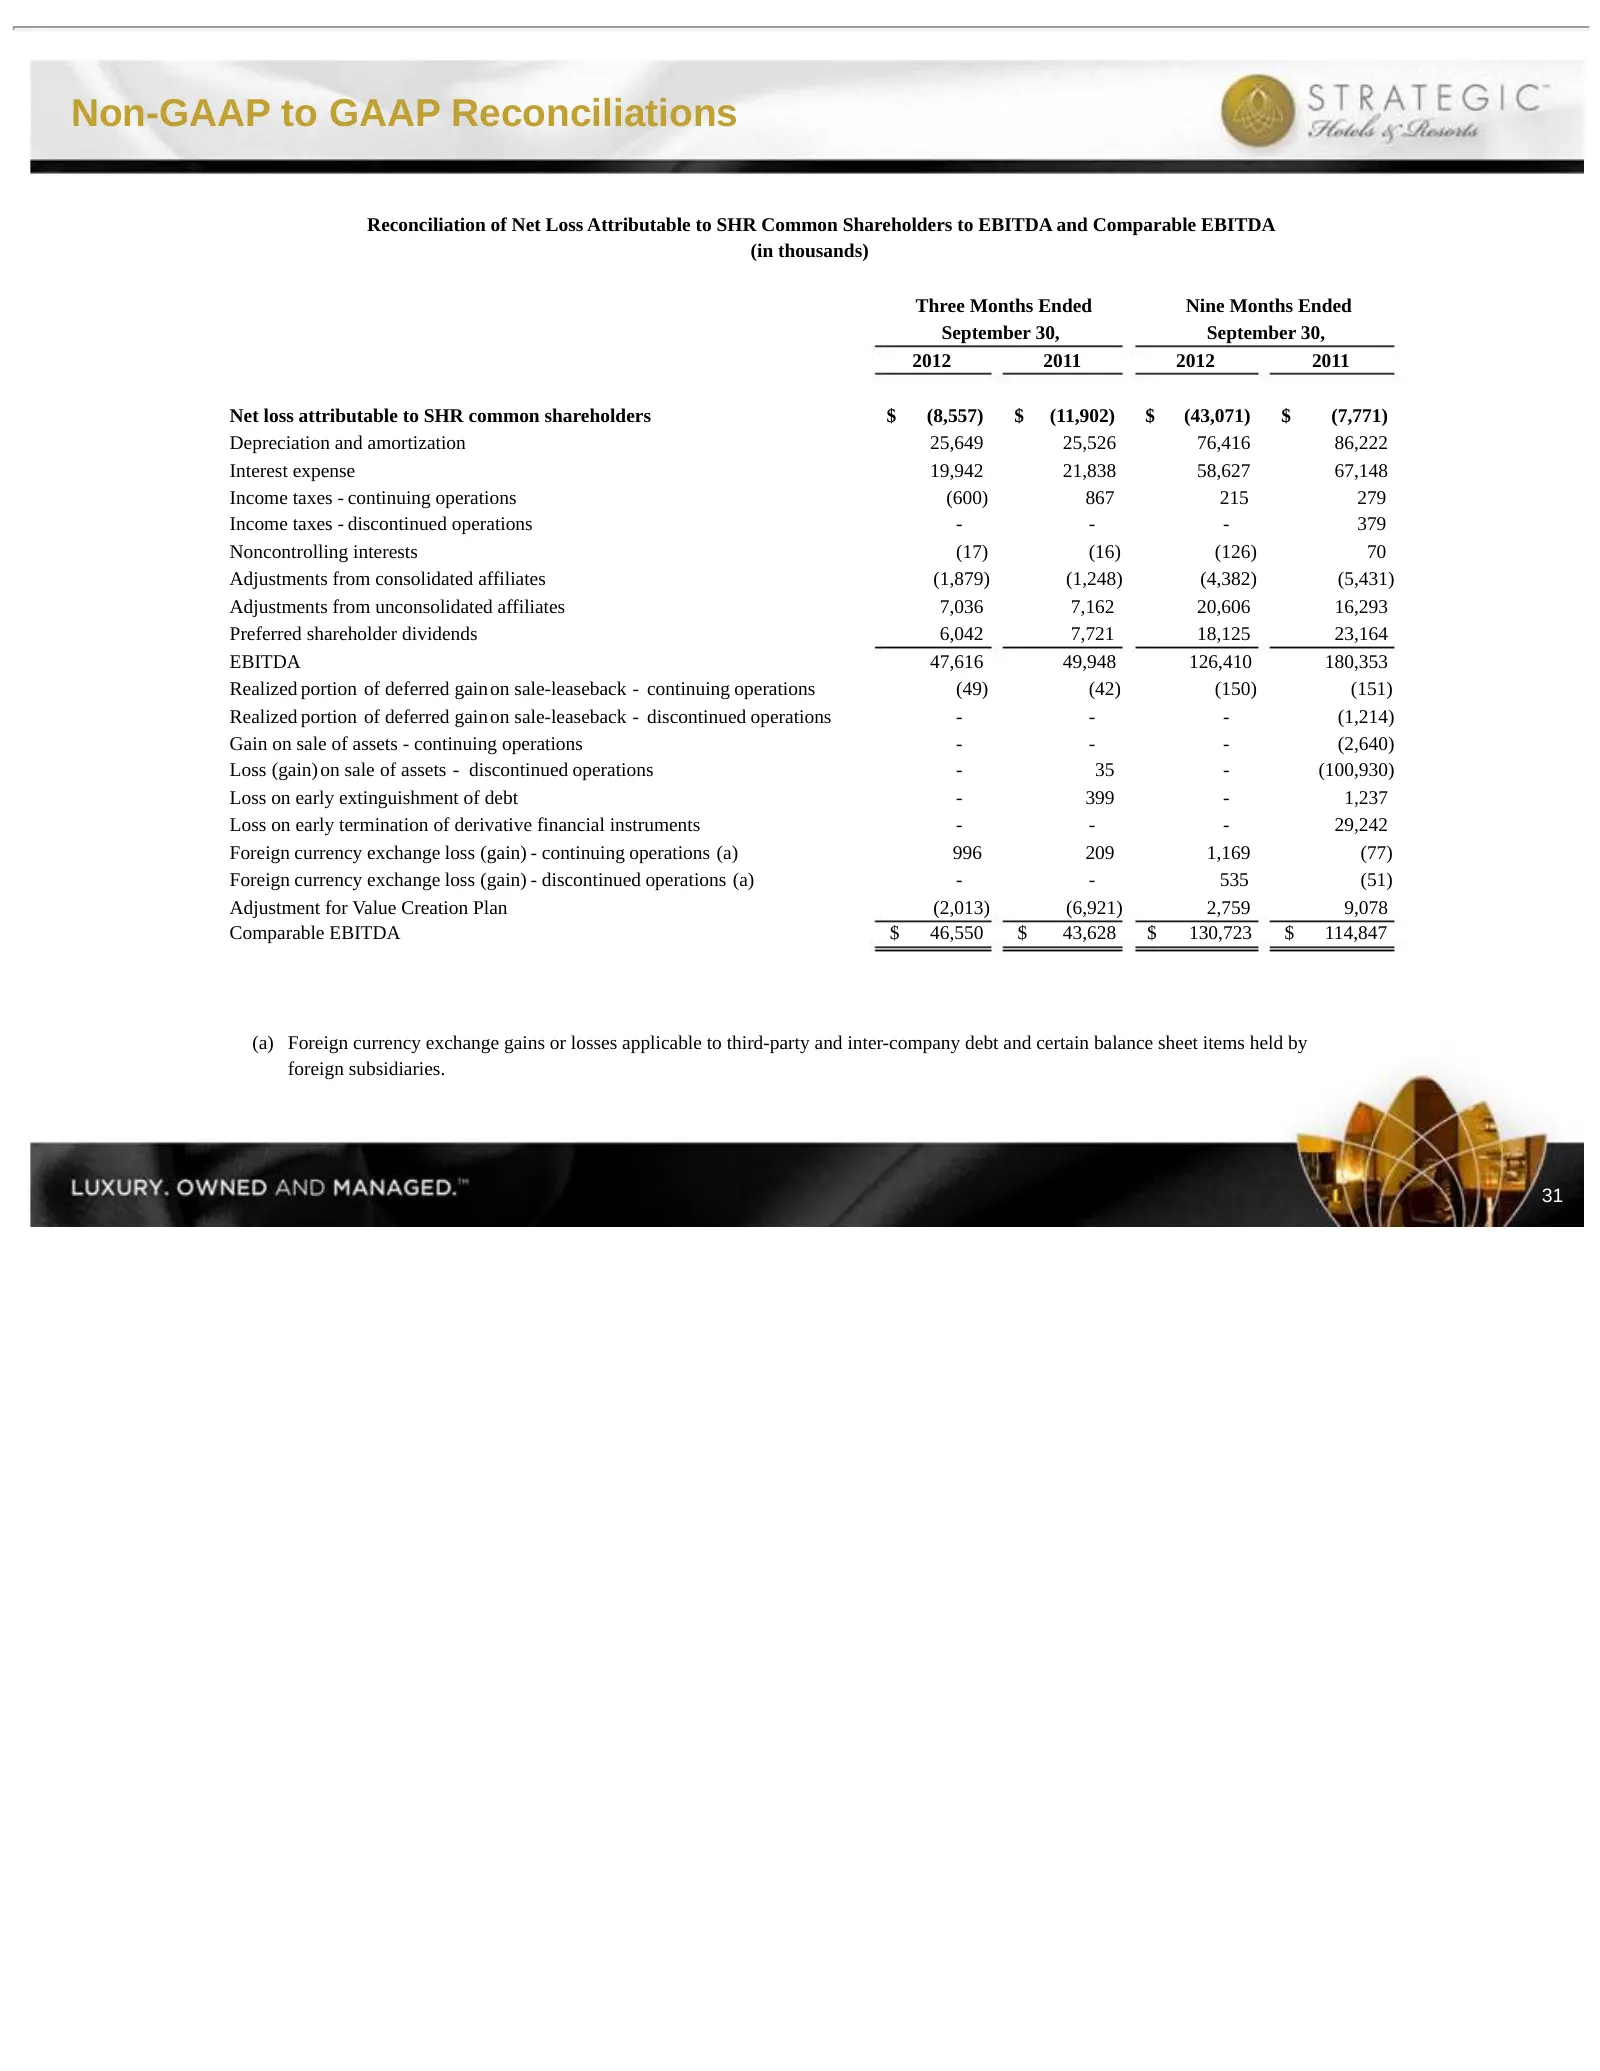
Non-GAAP to GAAP Reconciliations Reconciliation of Net Loss Attributable to SHR Common Shareholders to EBITDA and Comparable EBITDA (in thousands) Three Months Ended Nine Months Ended September 30, September 30, 2012 2011 2012 2011 Net loss attributable to SHR common shareholders $ (8,557) $ (11,902
Slide 33: Non-GAAP to GAAP Reconciliations
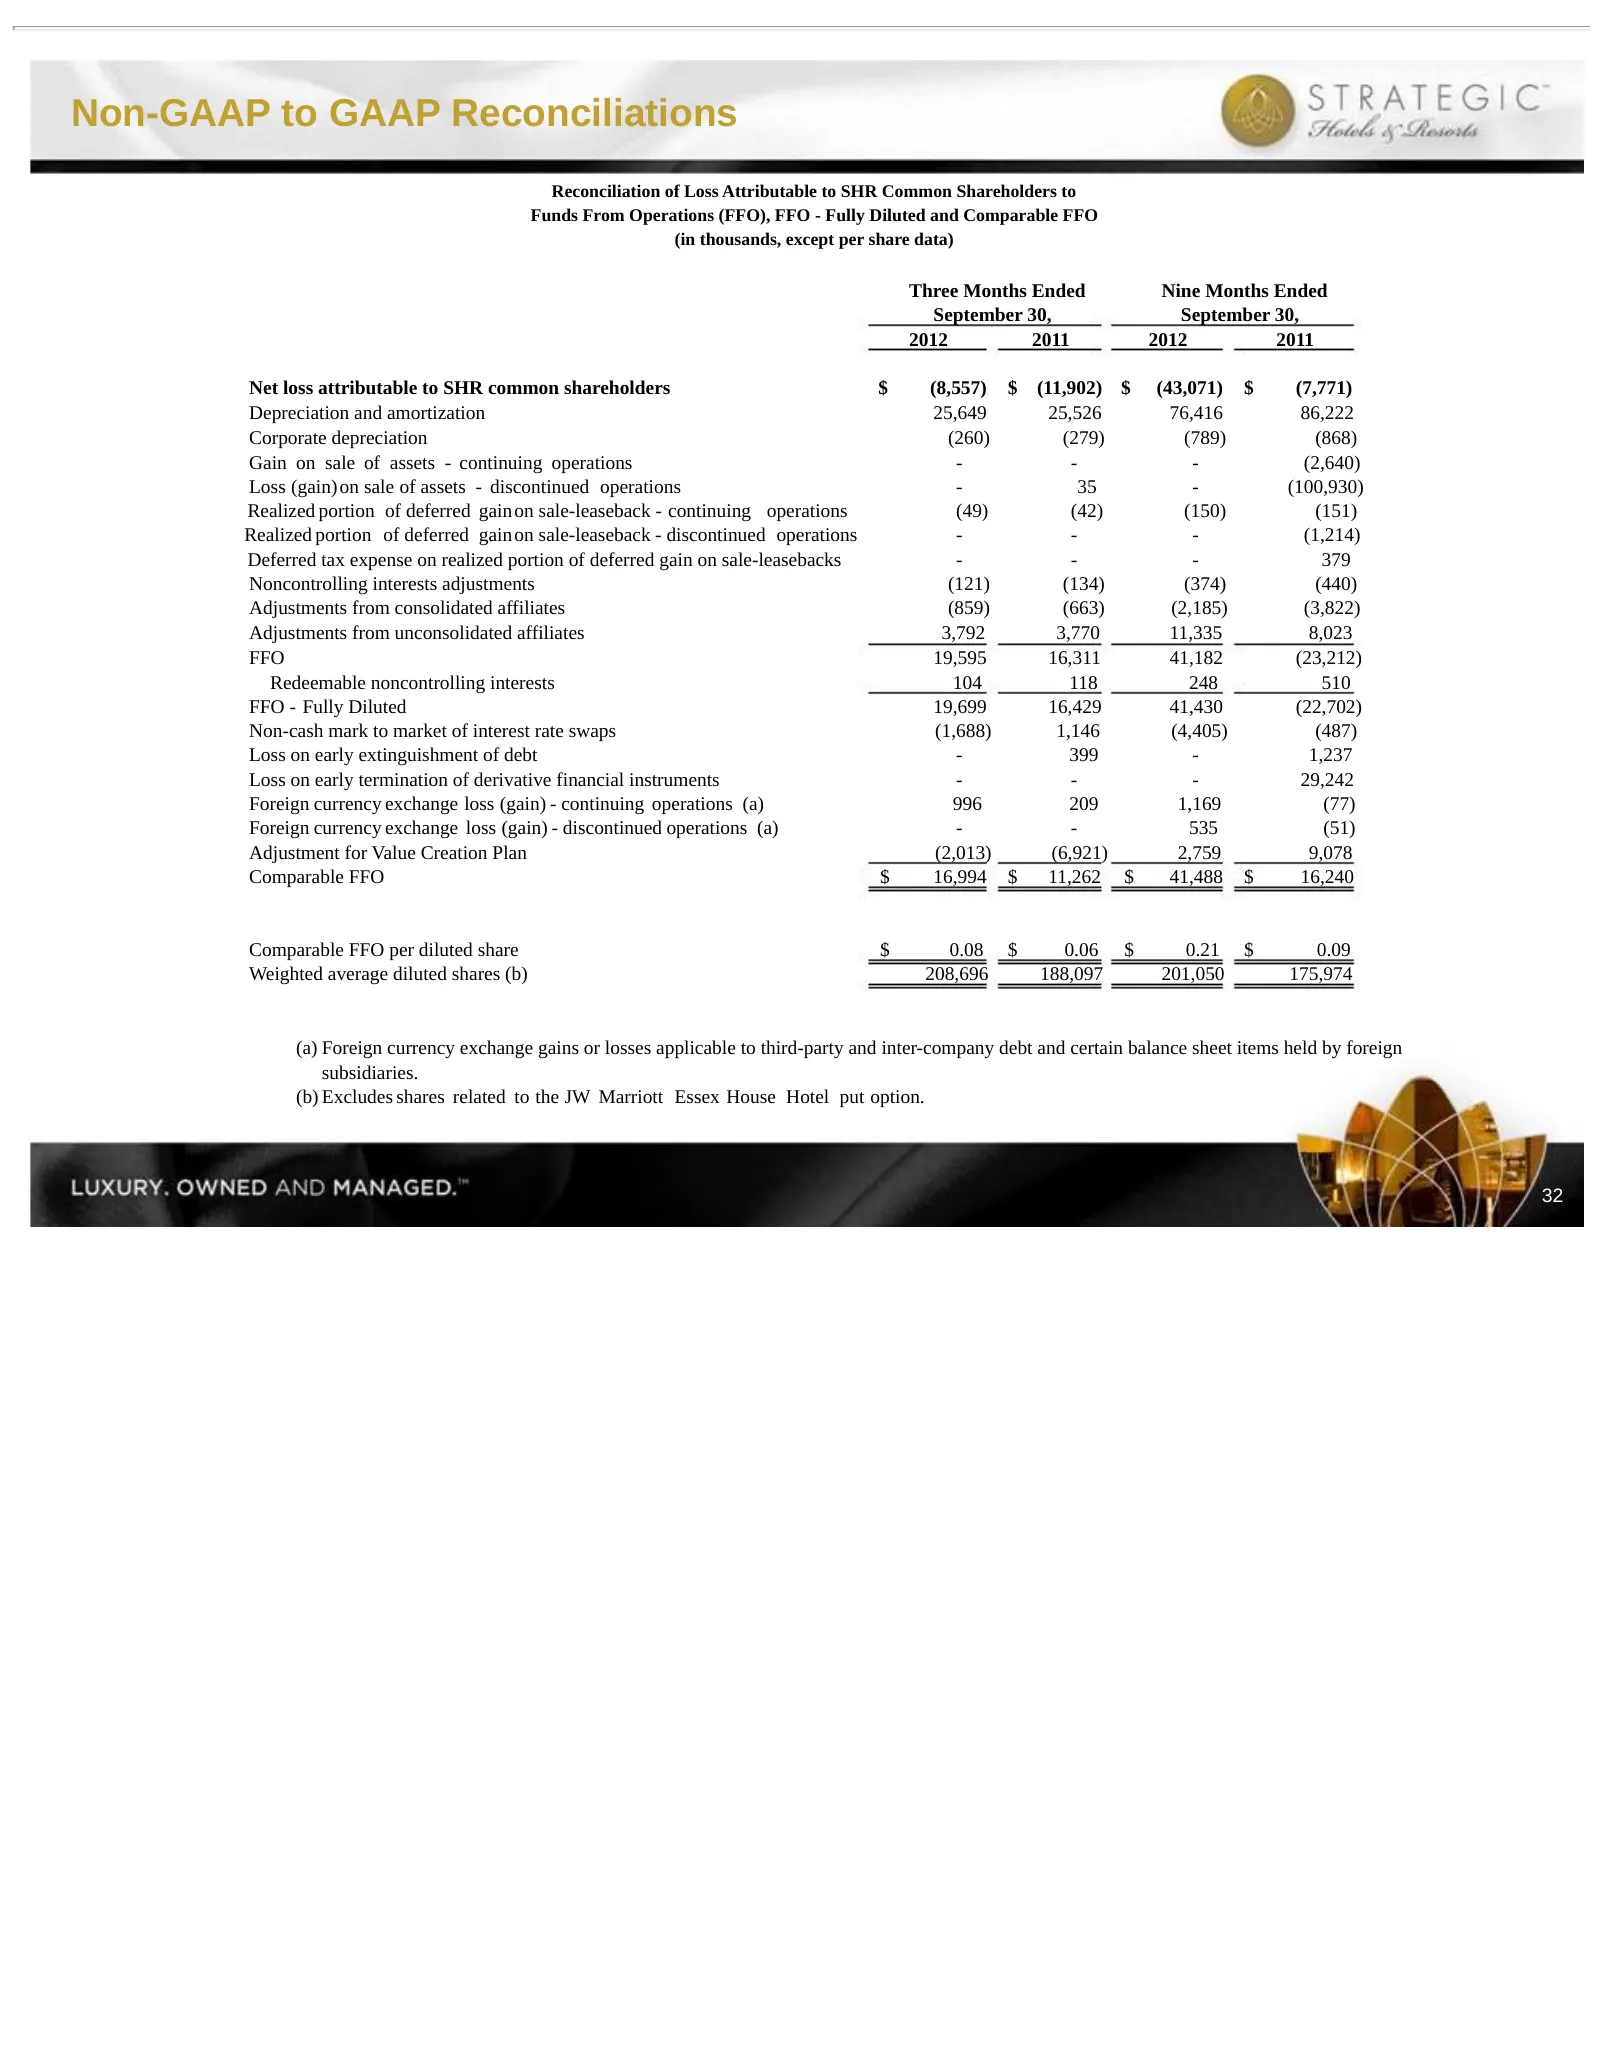
Non-GAAP to GAAP Reconciliations Reconciliation of Loss Attributable to SHR Common Shareholders to Funds From Operations (FFO), FFO - Fully Diluted and Comparable FFO (in thousands, except per share data) Three Months Ended Nine Months Ended September 30, September 30, 2012 2011 2012 2011 Net loss a
Slide 34: Non-GAAP to GAAP Reconciliations
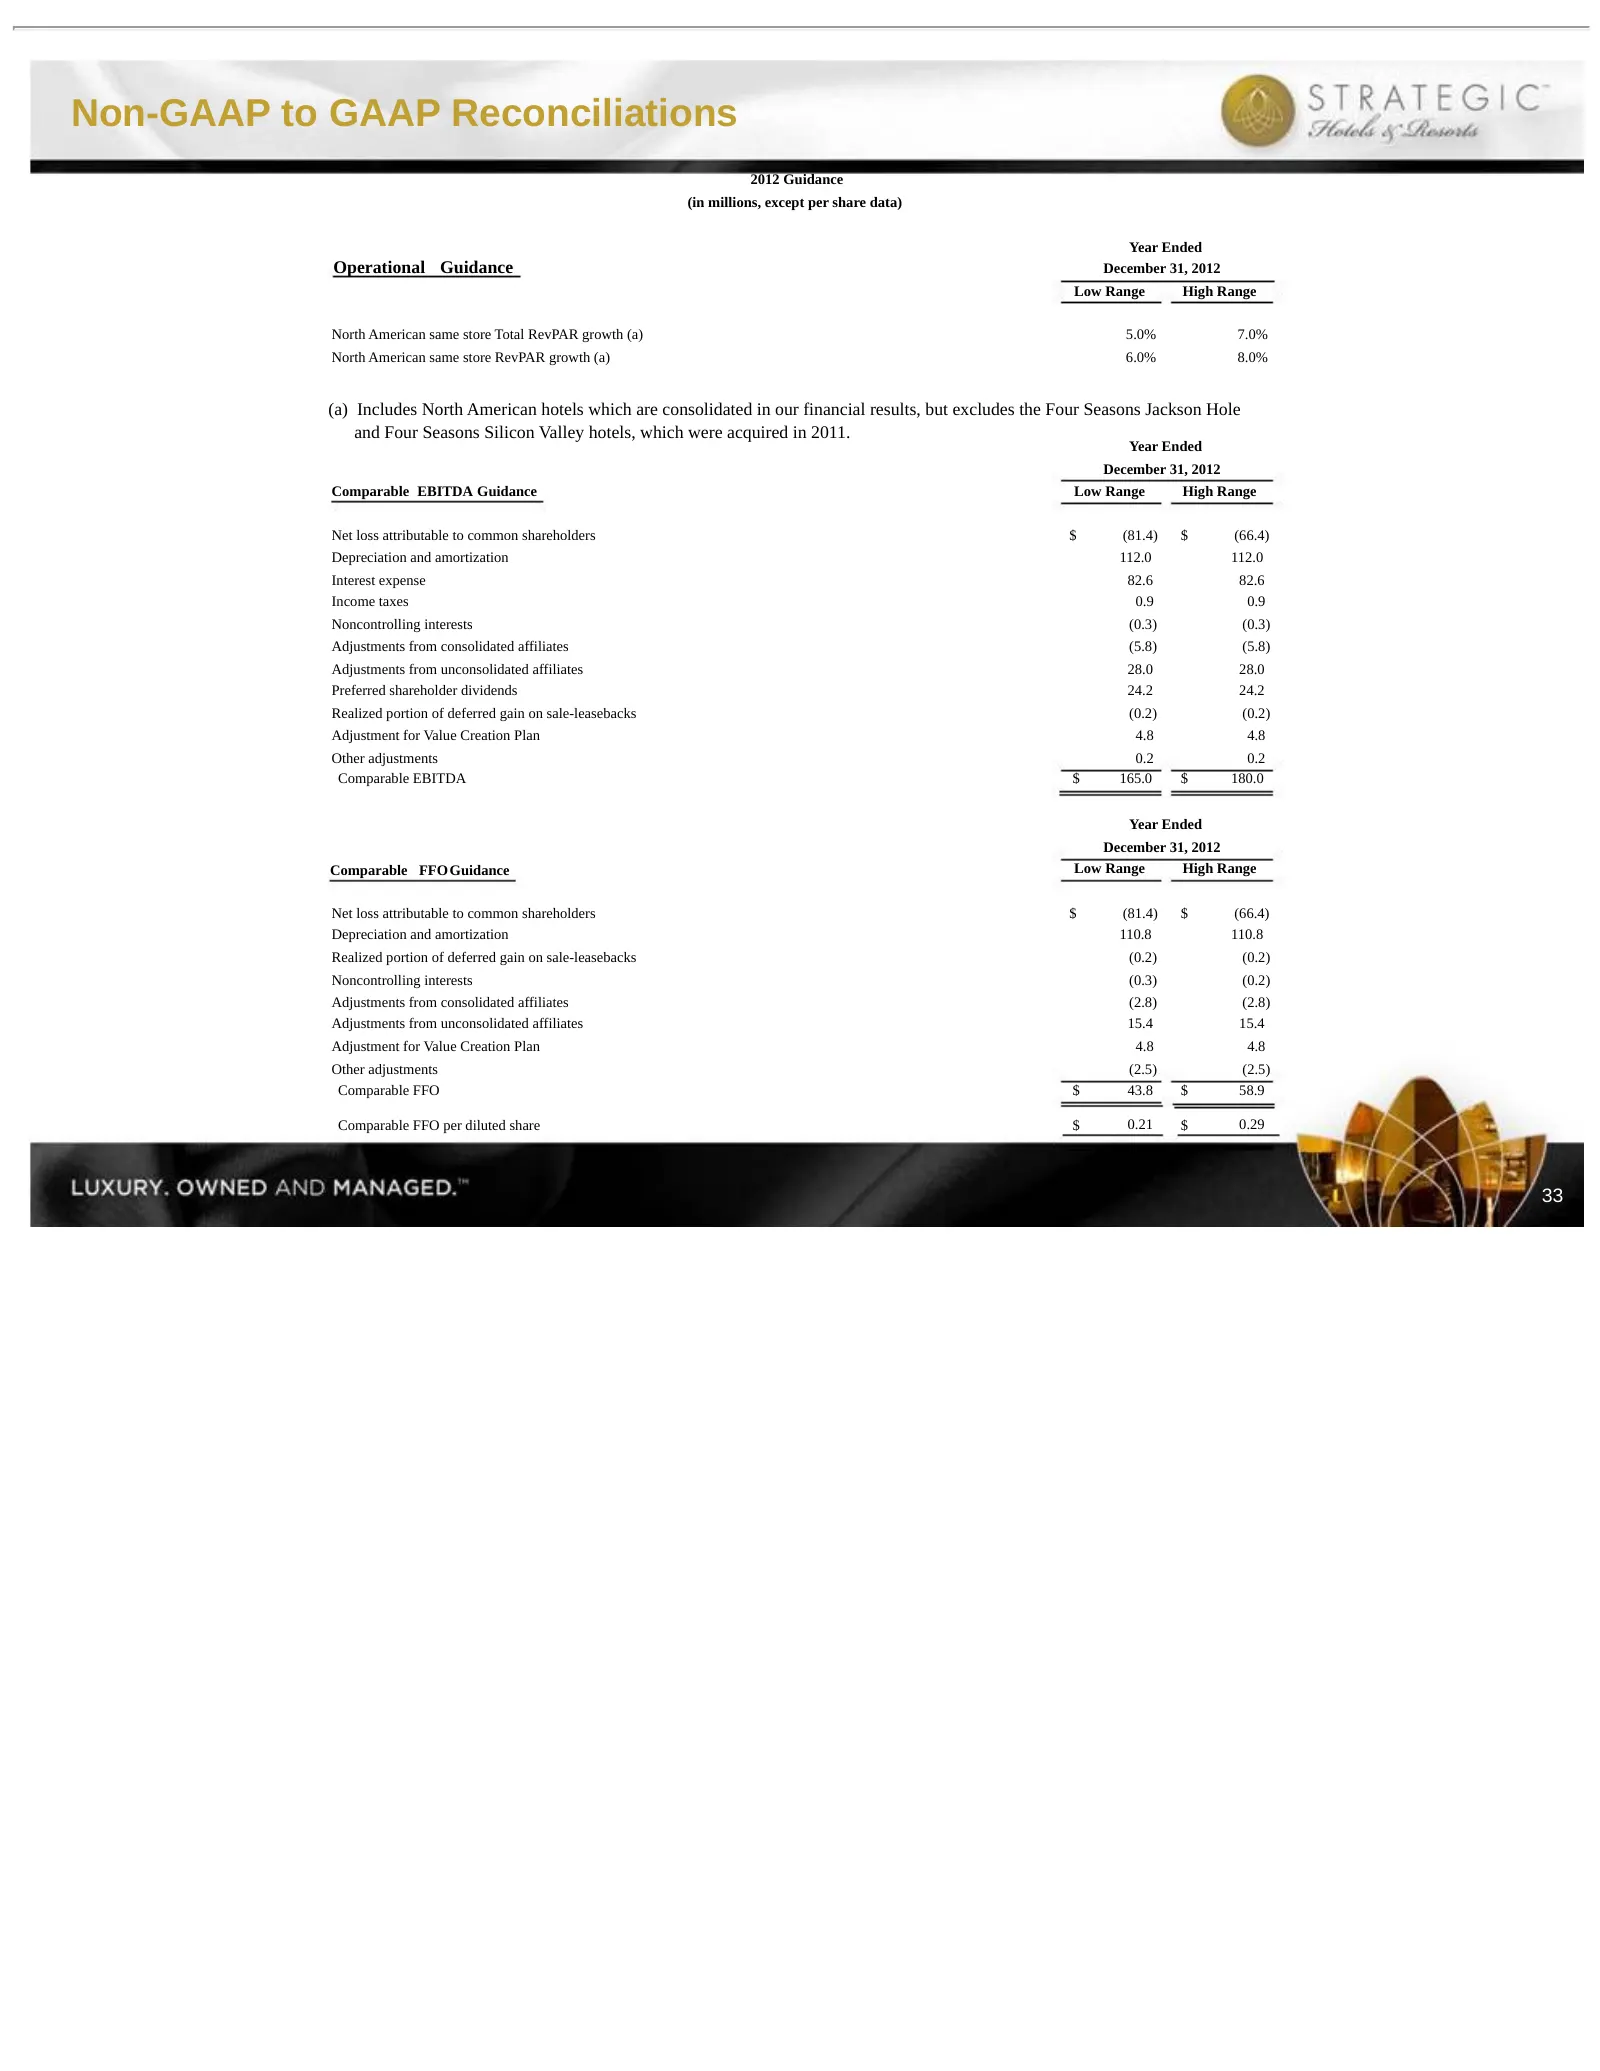
Non-GAAP to GAAP Reconciliations 2012 Guidance (in millions, except per share data) Year Ended Operational Guidance December 31, 2012 Low Range High Range North American same store Total RevPAR growth (a) 5.0% 7.0% North American same store RevPAR growth (a) 6.0% 8.0% (a) Includes North American hot
Slide 35: Thank You
STRATEGIC Slolels & Aesorts Thank You
Source: SEC EDGAR · 8-K filed Jan 22, 2013
More decks from Strategic Hotels and Resorts Inc
 Investor Presentation (June 2015)43 slides · Jun 1, 2015
 Investor Presentation (February 2015)43 slides · Feb 24, 2015
 Investor Presentation (January 2015)44 slides · Jan 26, 2015
 Investor Presentation (November 2014)50 slides · Nov 5, 2014
 Investor Presentation (October 2014)50 slides · Oct 3, 2014
 Investor Day (September 2014)67 slides · Sep 22, 2014