Transatlantic — Merger or Acquisition (July 2011)
17 slides from Transatlantic's merger presentation, Jul 25, 2011
Slide 1: Transatlantic Affirms Merger Agreement with Allied World and Responds to Validus' Unsolicited Proposal
Transatlantic Affirms Merger Agreement with Allied World and Responds to Validus' Unsolicited Proposal July 22, 2011* *Contains changes from the July 20, 2011 presentation to pages 5 and 7 to show data based on reported book values per basic share (as opposed to diluted) and minor revisions to pages
Slide 2: Cautionary Note Regarding Forward-Looking Statements
Cautionary Note Regarding Forward- Looking Statements 1 This presentation contains forward-looking statements that involve a number of risks and uncertainties. Statements that are not historical facts, including statements about our beliefs and expectations, are forward-looking statements. Any forwa
Slide 3: Transatlantic Board's Position
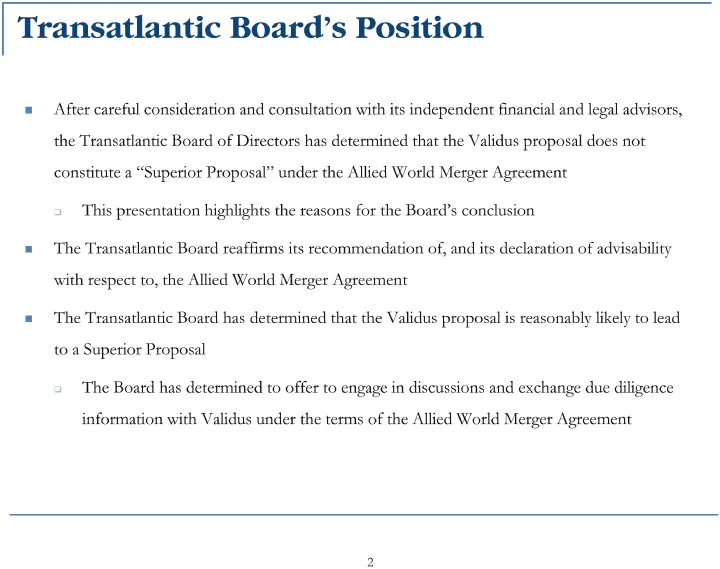
Transatlantic Board's Position After careful consideration and consultation with its independent financial and legal advisors, the Transatlantic Board of Directors has determined that the Validus proposal does not constitute a "Superior Proposal" under the Allied World Merger Agreement This presenta
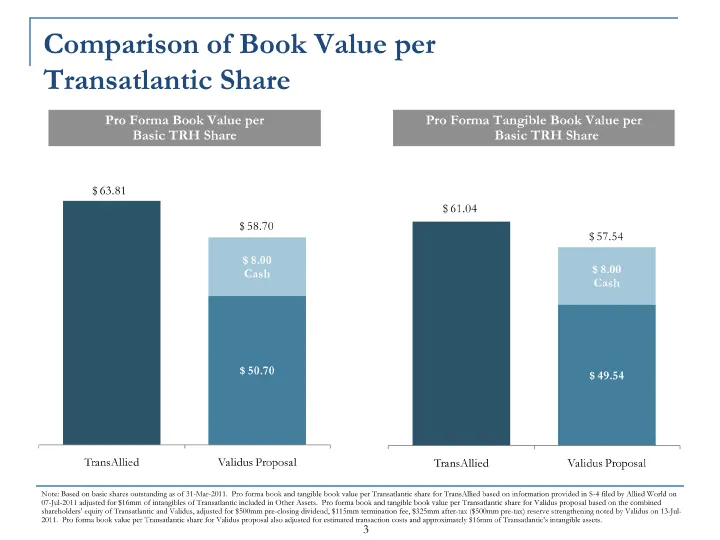
Slide 4: Comparison of Book Value per Transatlantic Share
Comparison of Book Value per Transatlantic Share 3 Note: Based on basic shares outstanding as of 31-Mar-2011. Pro forma book and tangible book value per Transatlantic share for TransAllied based on information provided in S-4 filed by Allied World on 07-Jul-2011 adjusted for $16mm of intangibles of
Slide 5: Exchange Ratio Comparison
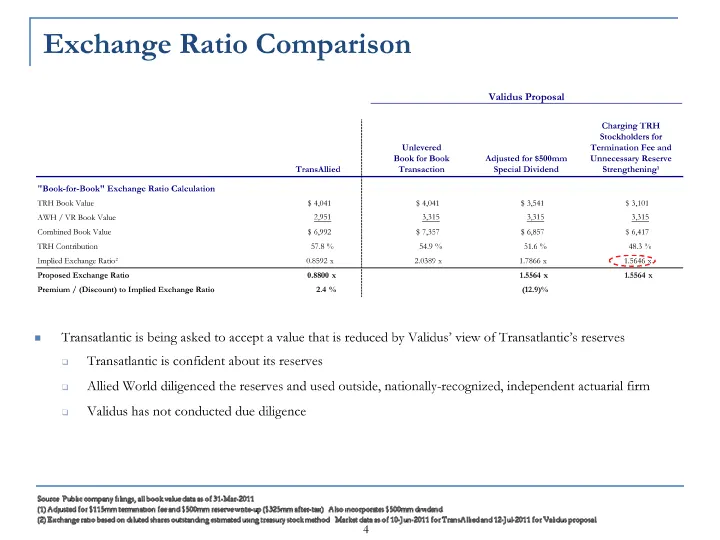
Exchange Ratio Comparison 4 Source: Public company filings; all book value data as of 31-Mar-2011 (1) Adjusted for $115mm termination fee and $500mm reserve write-up ($325mm after-tax). Also incorporates $500mm dividend. (2) Exchange ratio based on diluted shares outstanding estimated using treasury
Slide 6: Comparative Historical Trading since Validus IPO
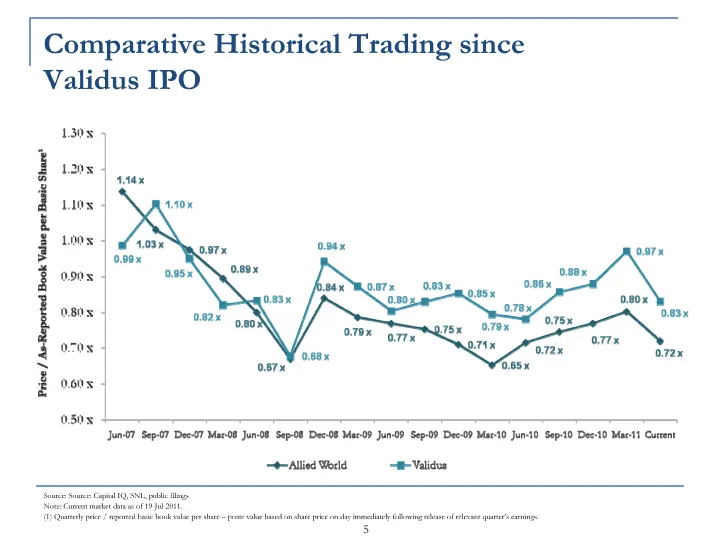
5 Source: Source: Capital IQ, SNL, public filings Note: Current market data as of 19-Jul-2011. (1) Quarterly price / reported basic book value per share - point value based on share price on day immediately following release of relevant quarter's earnings. Comparative Historical Trading since Validu
Slide 7: Book Value per Share Growth
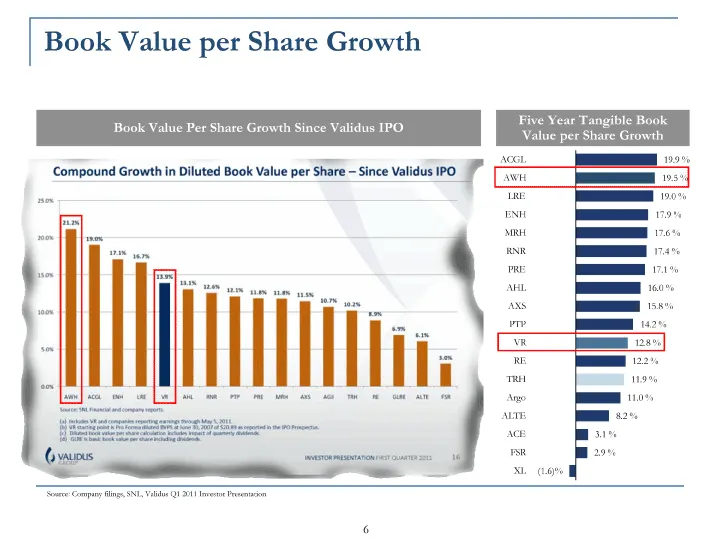
Book Value per Share Growth Source: Company filings, SNL, Validus Q1 2011 Investor Presentation 6 Five Year Tangible Book Value per Share Growth Book Value Per Share Growth Since Validus IPO
Slide 8: Relative Price to Book Valuation
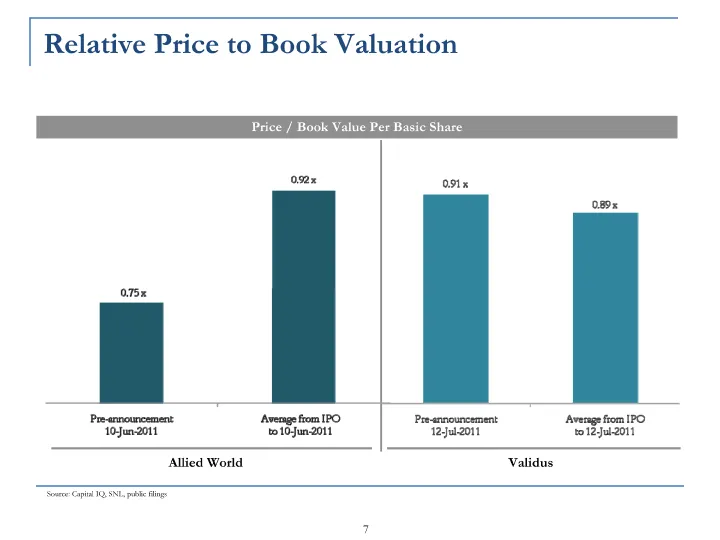
(CHART) Relative Price to Book Valuation 7 Price / Book Value Per Basic Share Allied World (CHART) Validus (CHART) Source: Capital IQ, SNL, public filings
Slide 9: Property Catastrophe Risk Tolerance
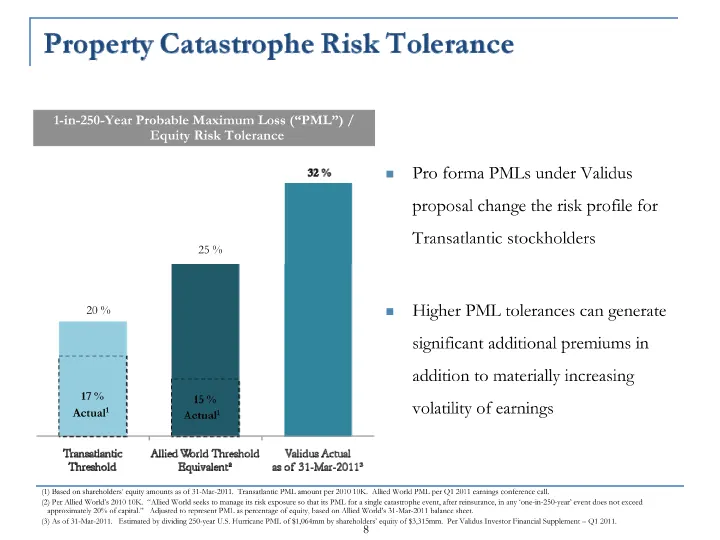
(CHART) Property Catastrophe Risk Tolerance 8 Pro forma PMLs under Validus proposal change the risk profile for Transatlantic stockholders Higher PML tolerances can generate significant additional premiums in addition to materially increasing volatility of earnings (1) Based on shareholders' equity
Slide 10: Catastrophe Losses as Percentage of NPE
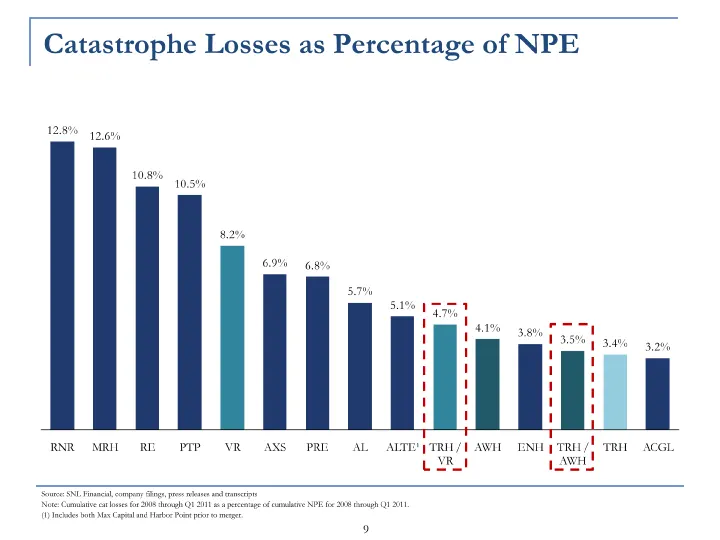
Catastrophe Losses as Percentage of NPE 9 Source: SNL Financial, company filings, press releases and transcripts Note: Cumulative cat losses for 2008 through Q1 2011 as a percentage of cumulative NPE for 2008 through Q1 2011. (1) Includes both Max Capital and Harbor Point prior to merger.
Slide 11: Ratings and Leverage Profile
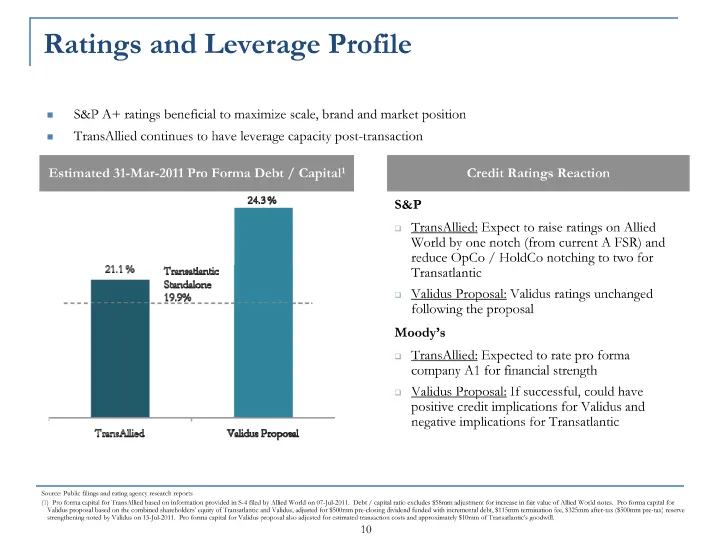
Ratings and Leverage Profile 10 S&P A+ ratings beneficial to maximize scale, brand and market position TransAllied continues to have leverage capacity post-transaction Credit Ratings Reaction Estimated 31-Mar-2011 Pro Forma Debt / Capital1 S&P TransAllied: Expect to raise ratings on Allied World by
Slide 12: Significantly Different Insurance Operations
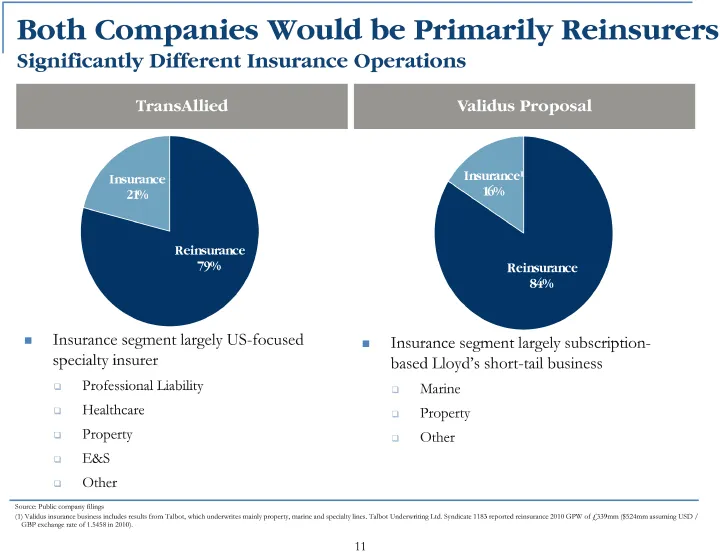
Insurance segment largely subscription- based Lloyd's short-tail business Marine Property Other Both Companies Would be Primarily Reinsurers Significantly Different Insurance Operations 11 Insurance segment largely US-focused specialty insurer Professional Liability Healthcare Property E&S Other Sou
Slide 13: Domicile Considerations
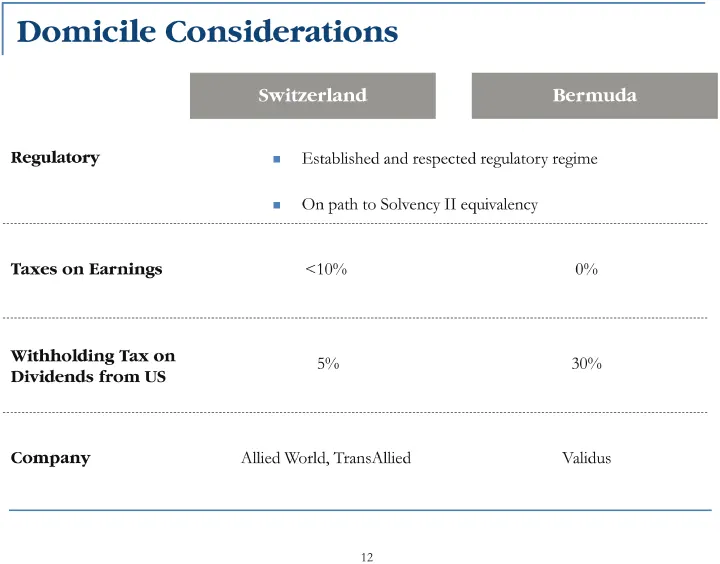
Domicile Considerations 12 Regulatory Established and respected regulatory regimeOn path to Solvency II equivalency Established and respected regulatory regimeOn path to Solvency II equivalency Taxes on Earnings <10% 0% Withholding Tax on Dividends from US 5% 30% Company Allied World, TransAllied Va
Slide 14: Stockholder Level Tax Considerations
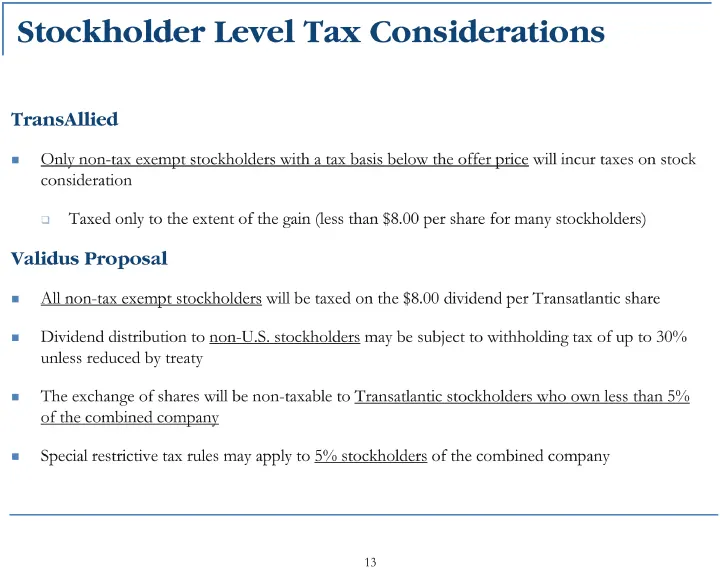
Stockholder Level Tax Considerations 13 TransAllied Only non-tax exempt stockholders with a tax basis below the offer price will incur taxes on stock consideration Taxed only to the extent of the gain (less than $8.00 per share for many stockholders) Validus Proposal All non-tax exempt stockholders
Slide 15: Quantification of Potential Synergies
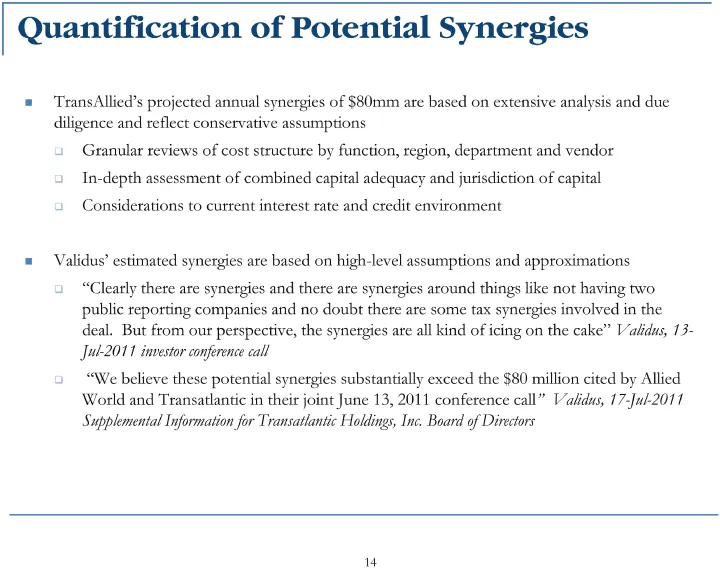
Quantification of Potential Synergies TransAllied's projected annual synergies of $80mm are based on extensive analysis and due diligence and reflect conservative assumptions Granular reviews of cost structure by function, region, department and vendor In-depth assessment of combined capital adequac
Slide 16: Key Uncertainties Remain in Validus Proposal
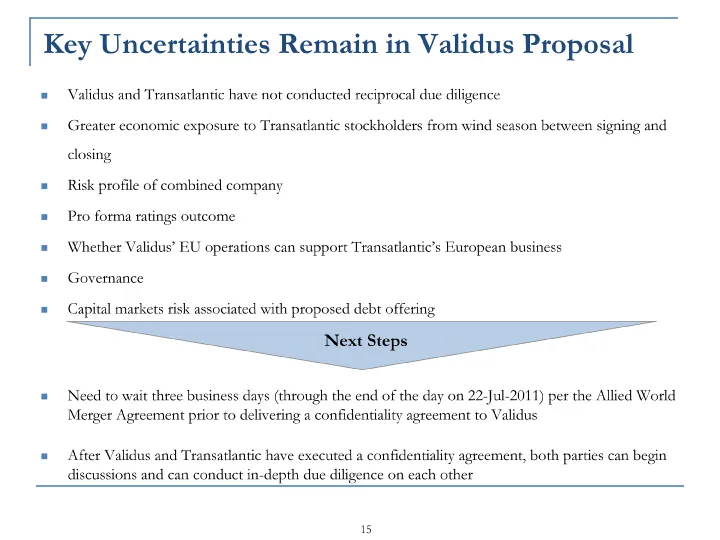
Key Uncertainties Remain in Validus Proposal 15 Validus and Transatlantic have not conducted reciprocal due diligence Greater economic exposure to Transatlantic stockholders from wind season between signing and closing Risk profile of combined company Pro forma ratings outcome Whether Validus' EU op
Slide 17: Transatlantic Board's Position
Transatlantic Board's Position After careful consideration and consultation with its independent financial and legal advisors, the Transatlantic Board of Directors has determined that the Validus proposal does not constitute a "Superior Proposal" under the Allied World Merger Agreement This presenta
Source: SEC EDGAR · 425 filed Jul 25, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011