SunCoke Energy Partners L.P — Non-Deal Roadshow (March 2015)
35 slides from SunCoke Energy Partners L.P's roadshow presentation, Mar 2, 2015
Slide 1: Investor Meetings – March 2015
Exhibit 99.1 Investor SXCP March Partners 2015 Meetings
Slide 2: Forward-Looking Statements
Forward-Looking Some projections forward-looking regulations. “anticipate,” Although plans, SXC Commission For entirety because of This are 2Investor operations, this provided more presentation and of intentions presentation by such Meetings the SXCP, information management such with Forward-looking
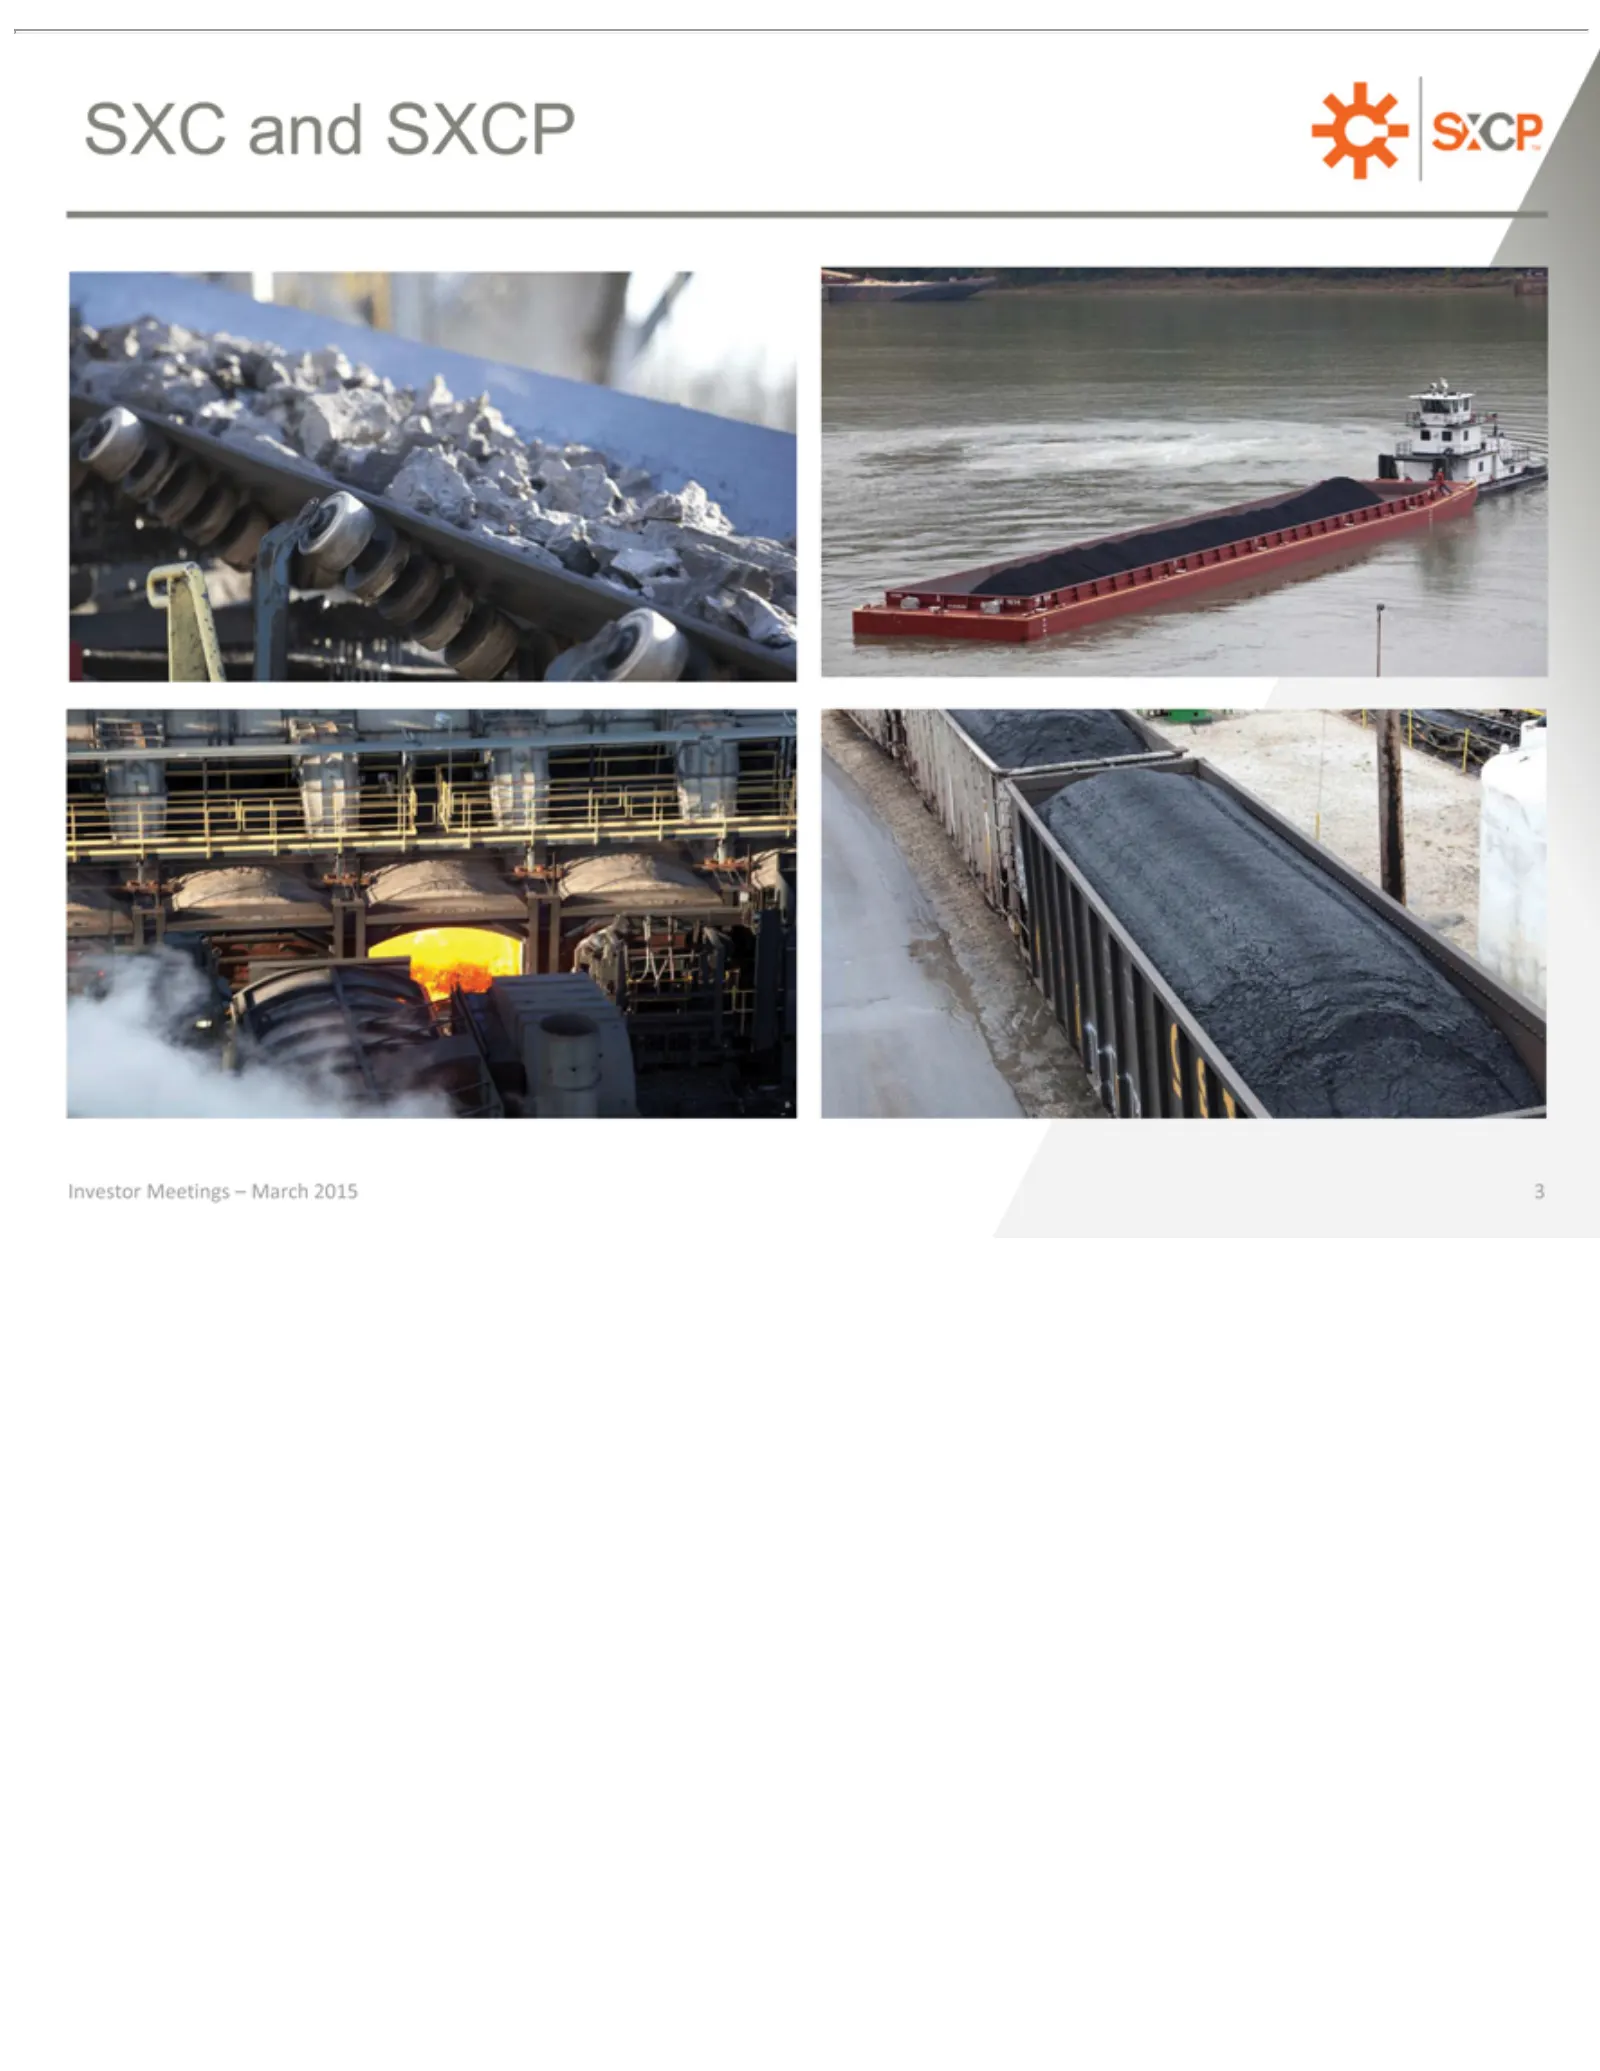
Slide 3: SXC and SXCP
SXC andMeetings 3Investor SXCP – March 2015
Slide 4: Who We Are
WHO WE 4Investor Meetings ARE – March 2015
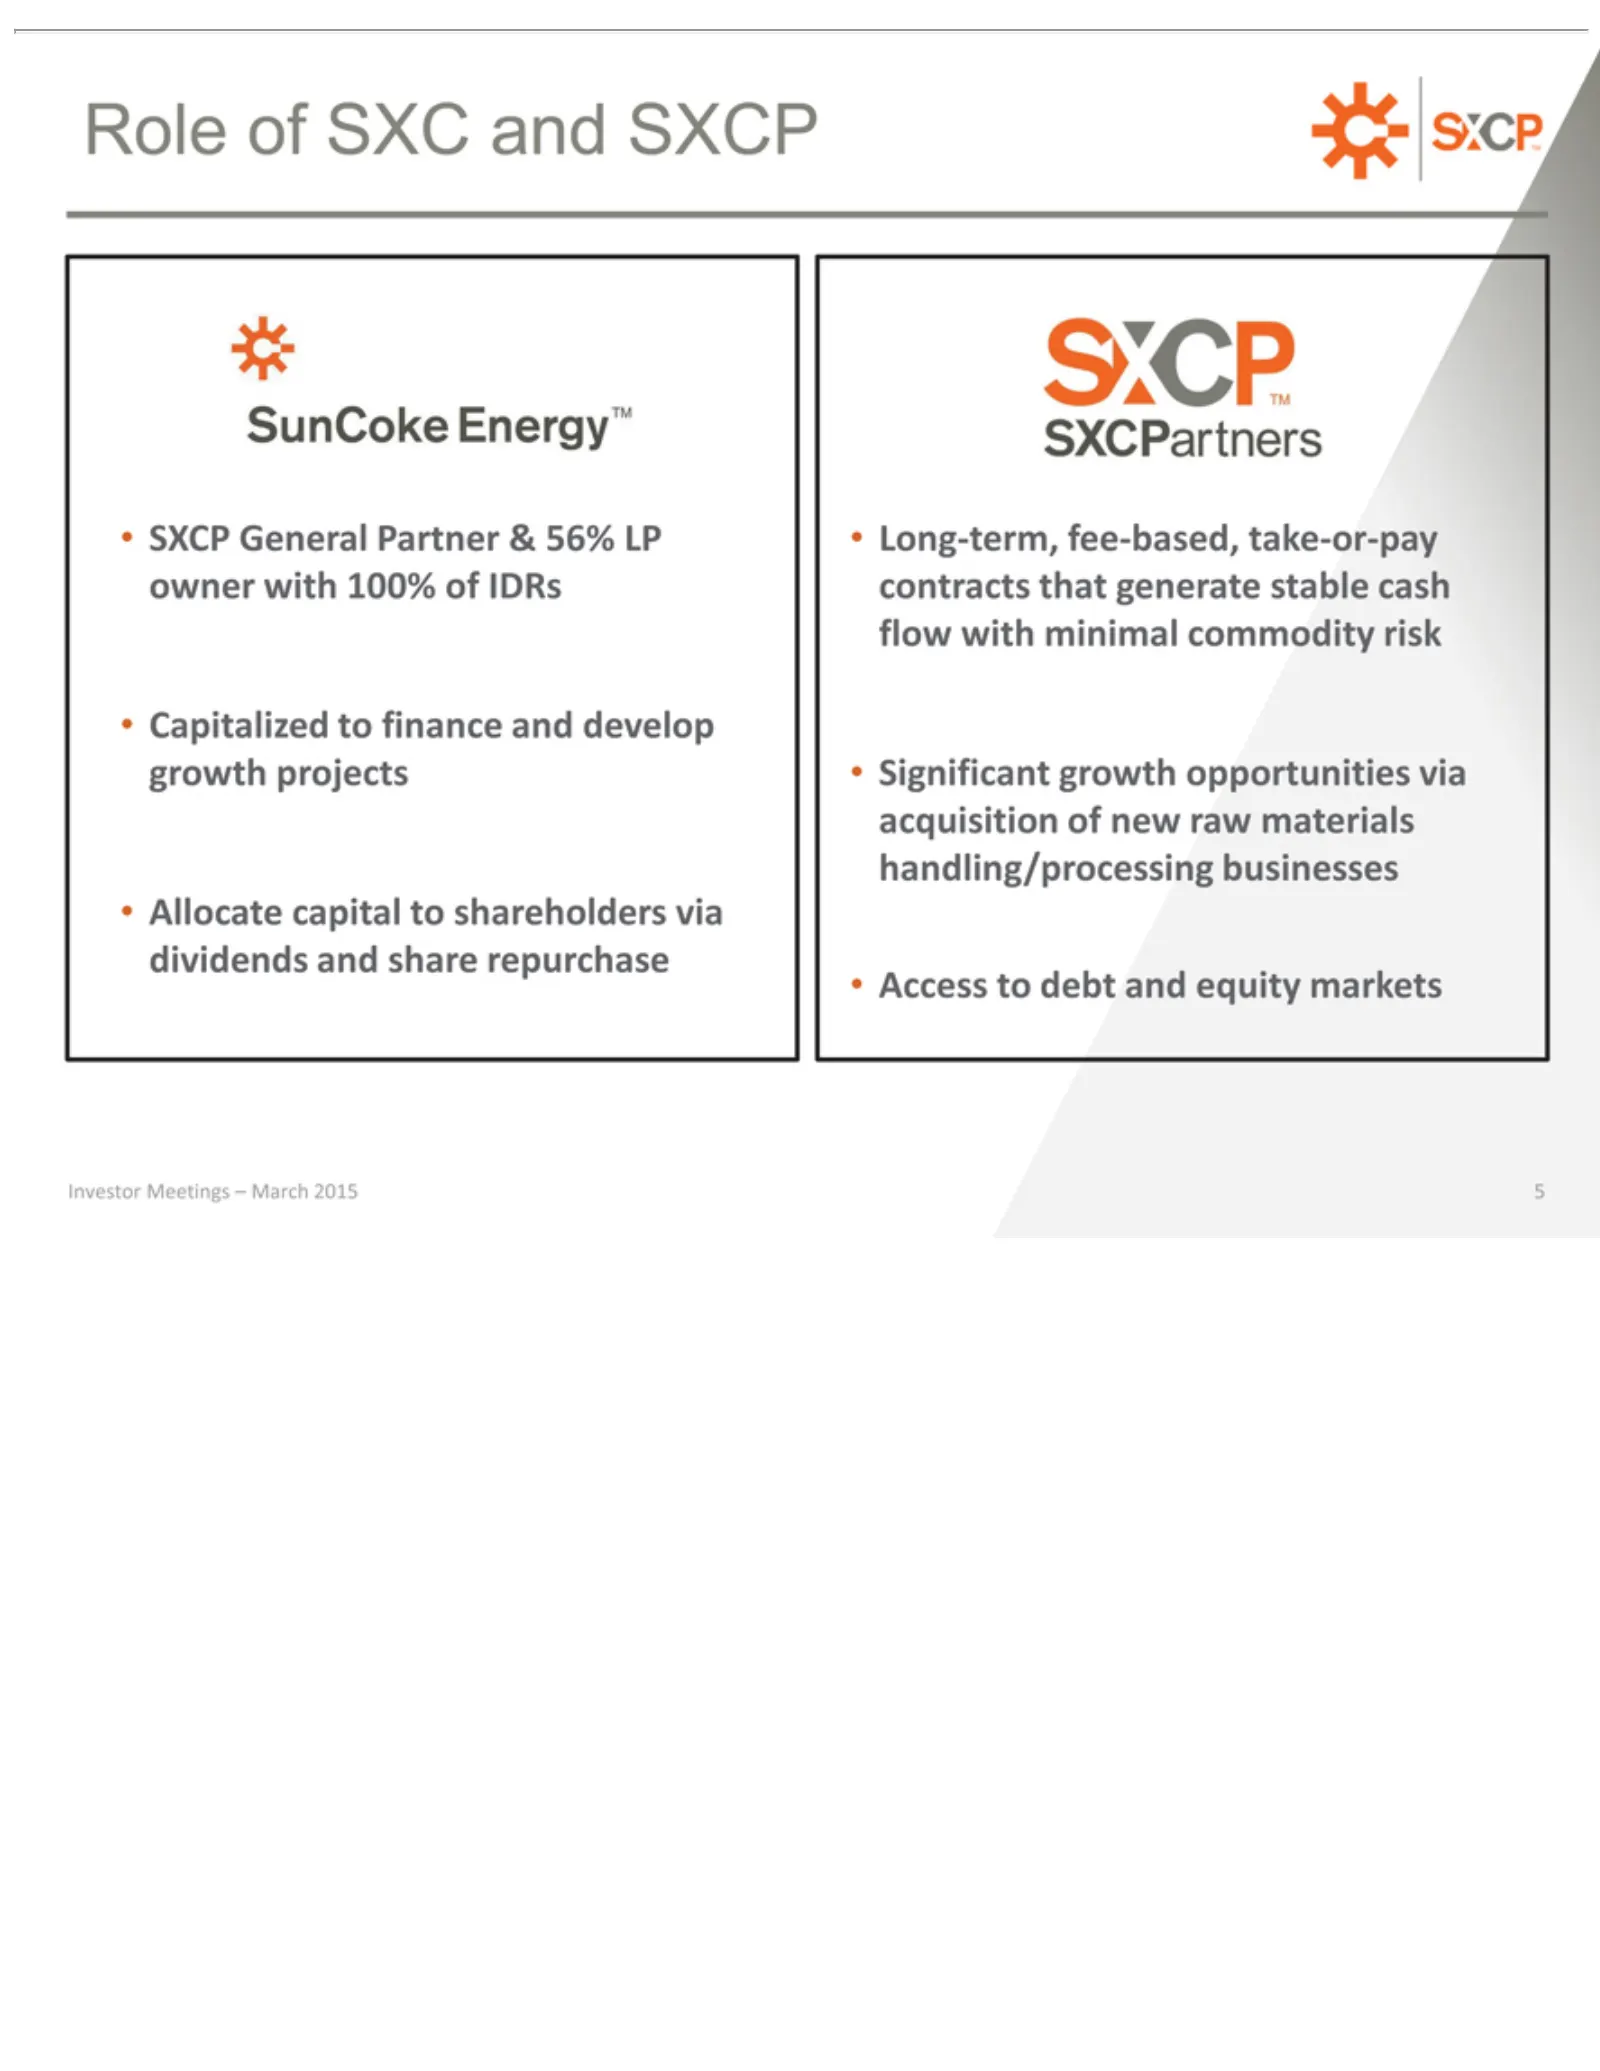
Slide 5: Role of SXCP and General Partner
Role ofGeneral SXCP Capitalized Allocate Long-term, Significant Access 5Investor to SXC Meetings capital debt growth fee-based, toand finance and Partner toSXCP –shareholders opportunities equity March and take-or-pay & 56% markets develop 2015 LP via via owner contracts growth dividends acquisition
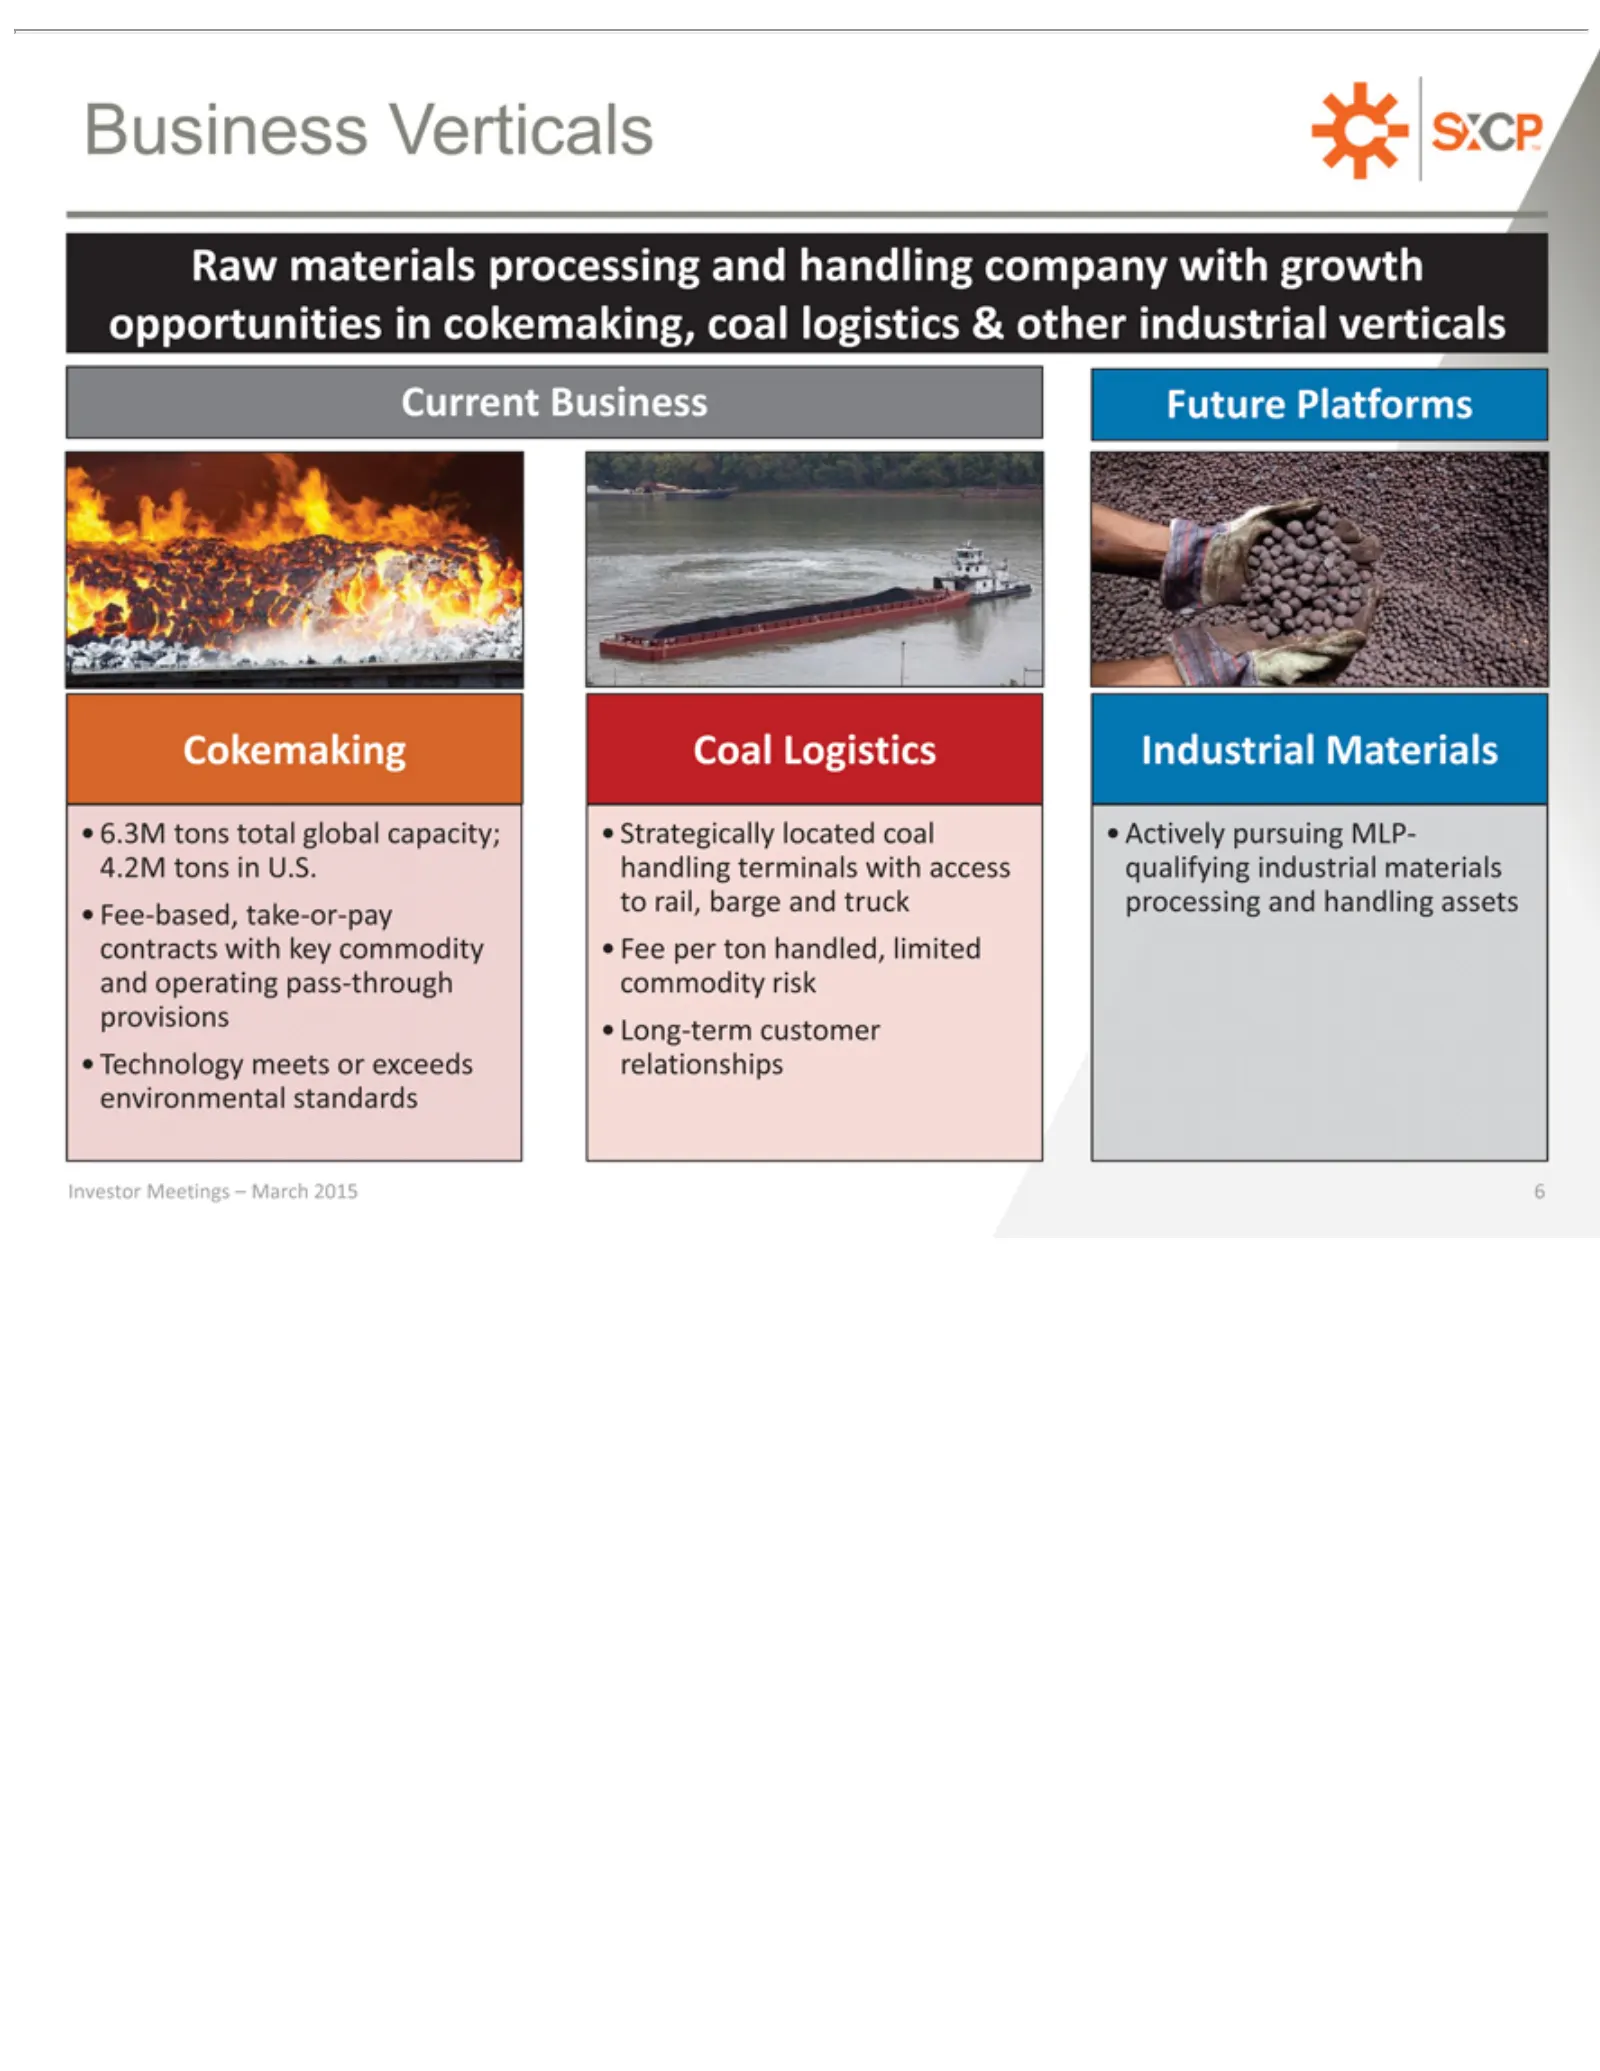
Slide 6: SXCP Business Overview
Business Raw Current Cokemaking 6.3M 4.2M Fee-based, Technology Strategically Fee Long-term Actively 6Investor per materials tons ton Business Meetings pursuing Verticals total in customer take-or-pay handled, meets located U.S. Coal processing global Future MLP-qualifying –Logistics orMarch limited
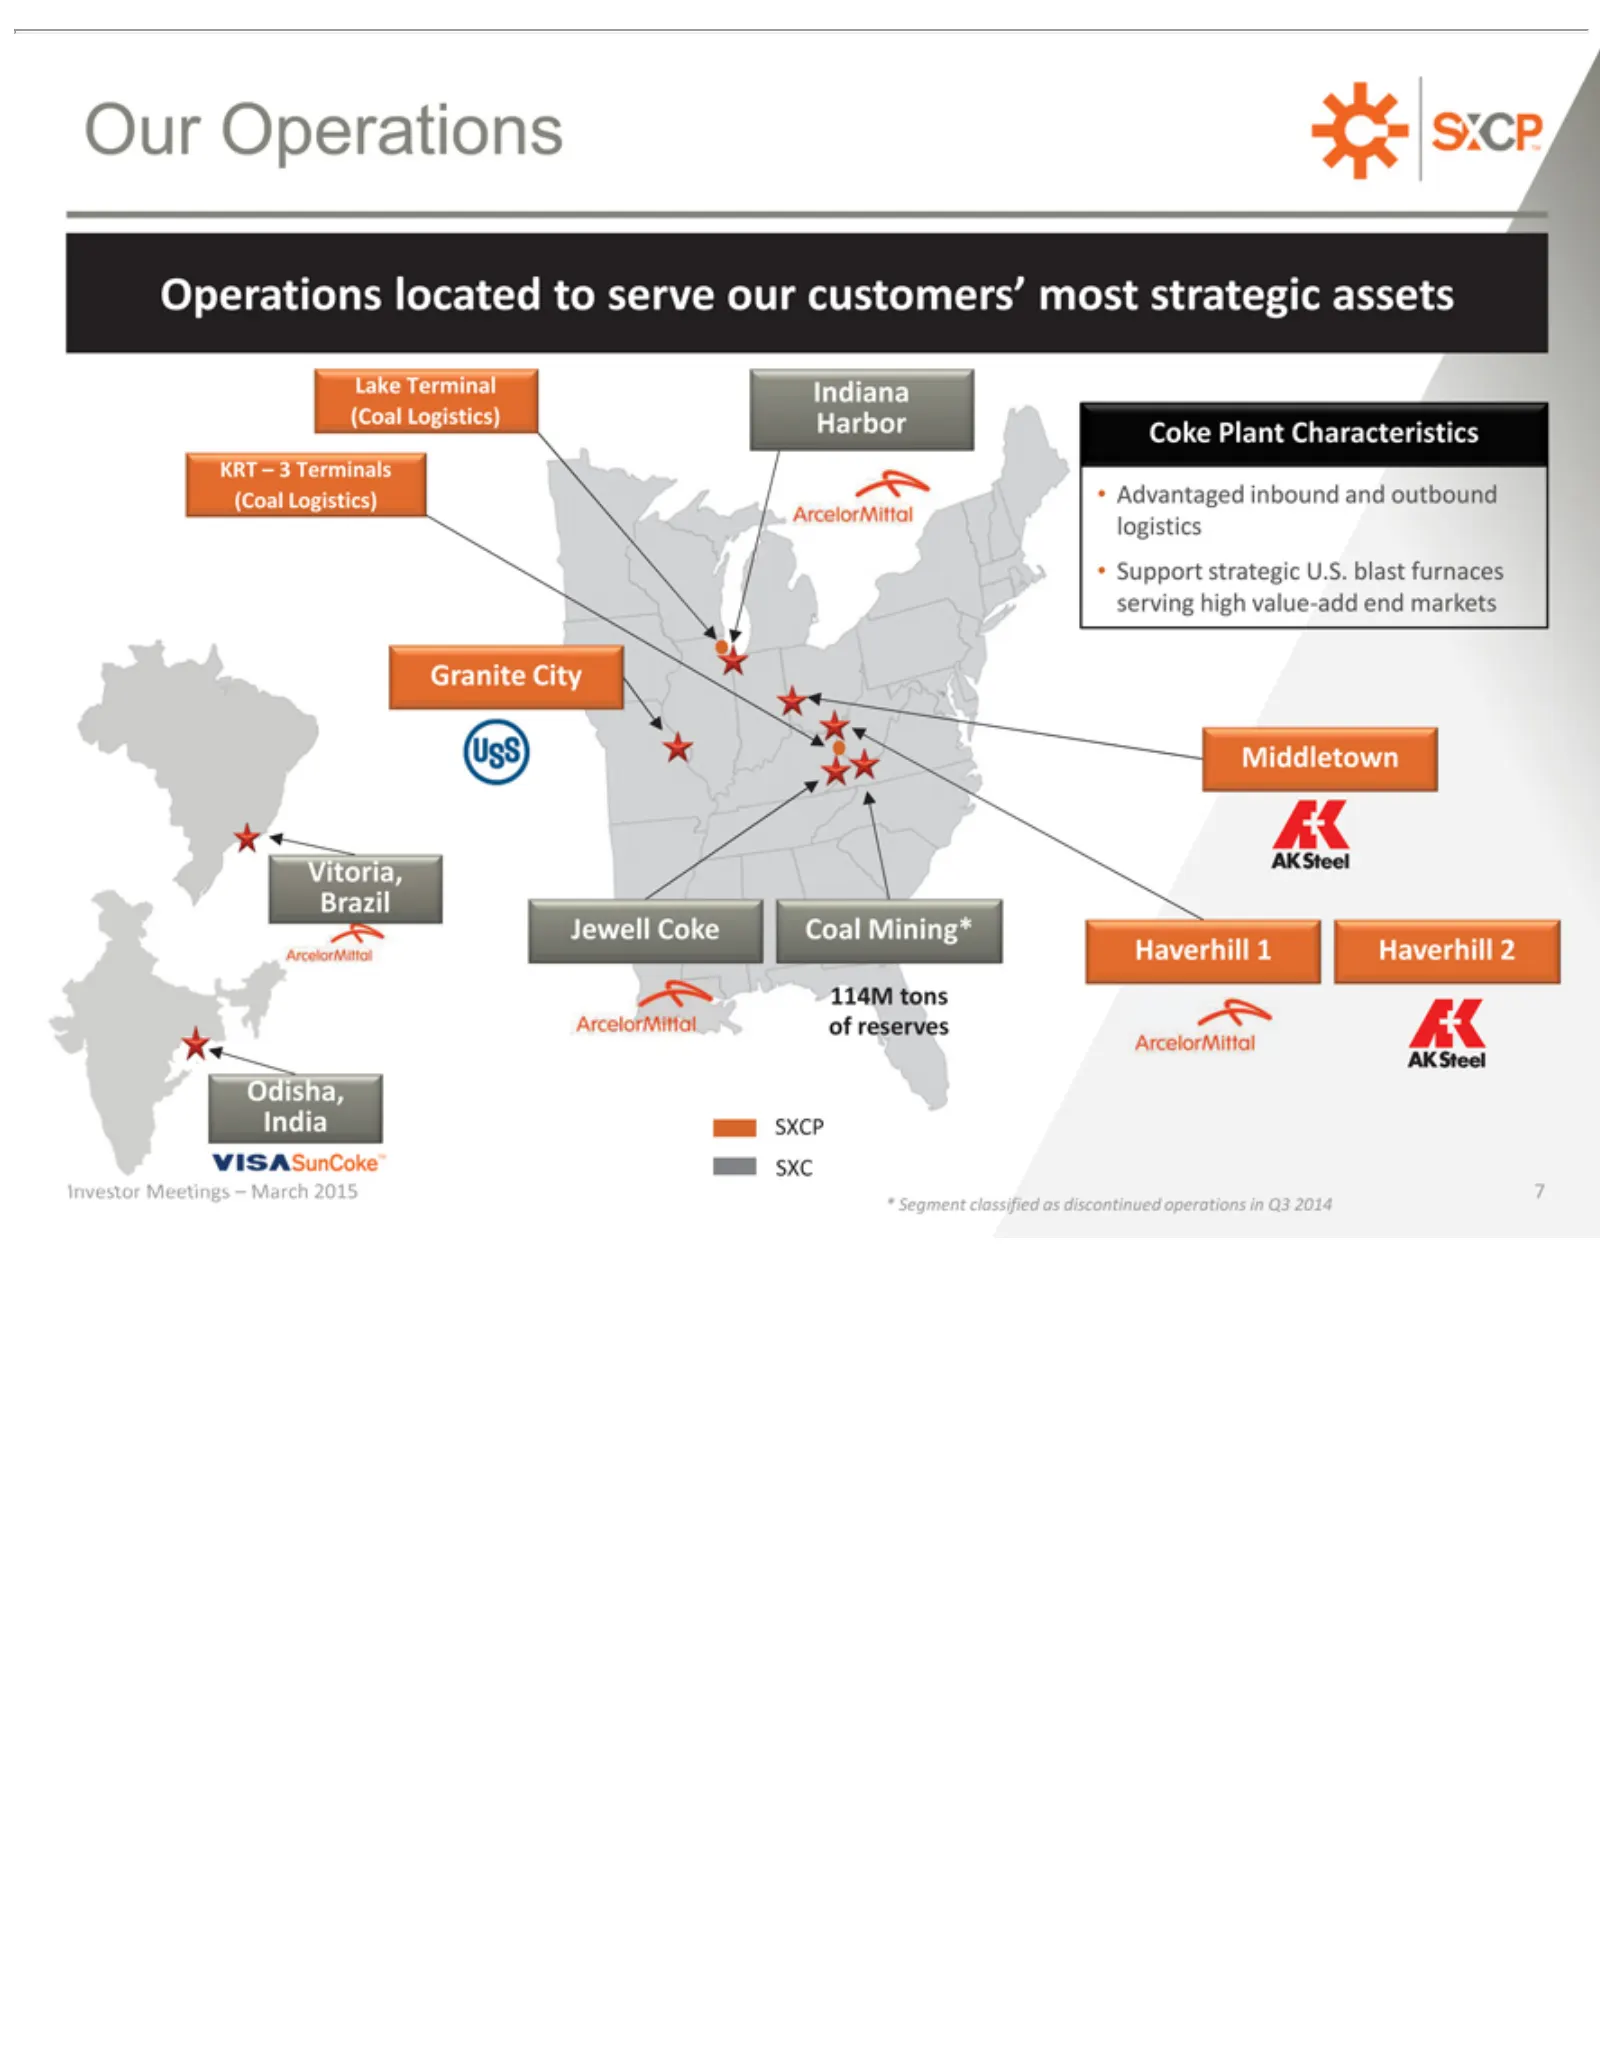
Slide 7: Our Operations
Our Operations Lake KRT Granite Vitoria, Jewell Odisha, Investor Harbor Indiana Advantaged Support Coal Middletown Haverhill 7*114M SXC SXCP Segment Operations Mining* –Terminal tons Coke 3Coke City Brazil India strategic Meetings Terminals 1classified of located Haverhill inbound Plant reserves (Co
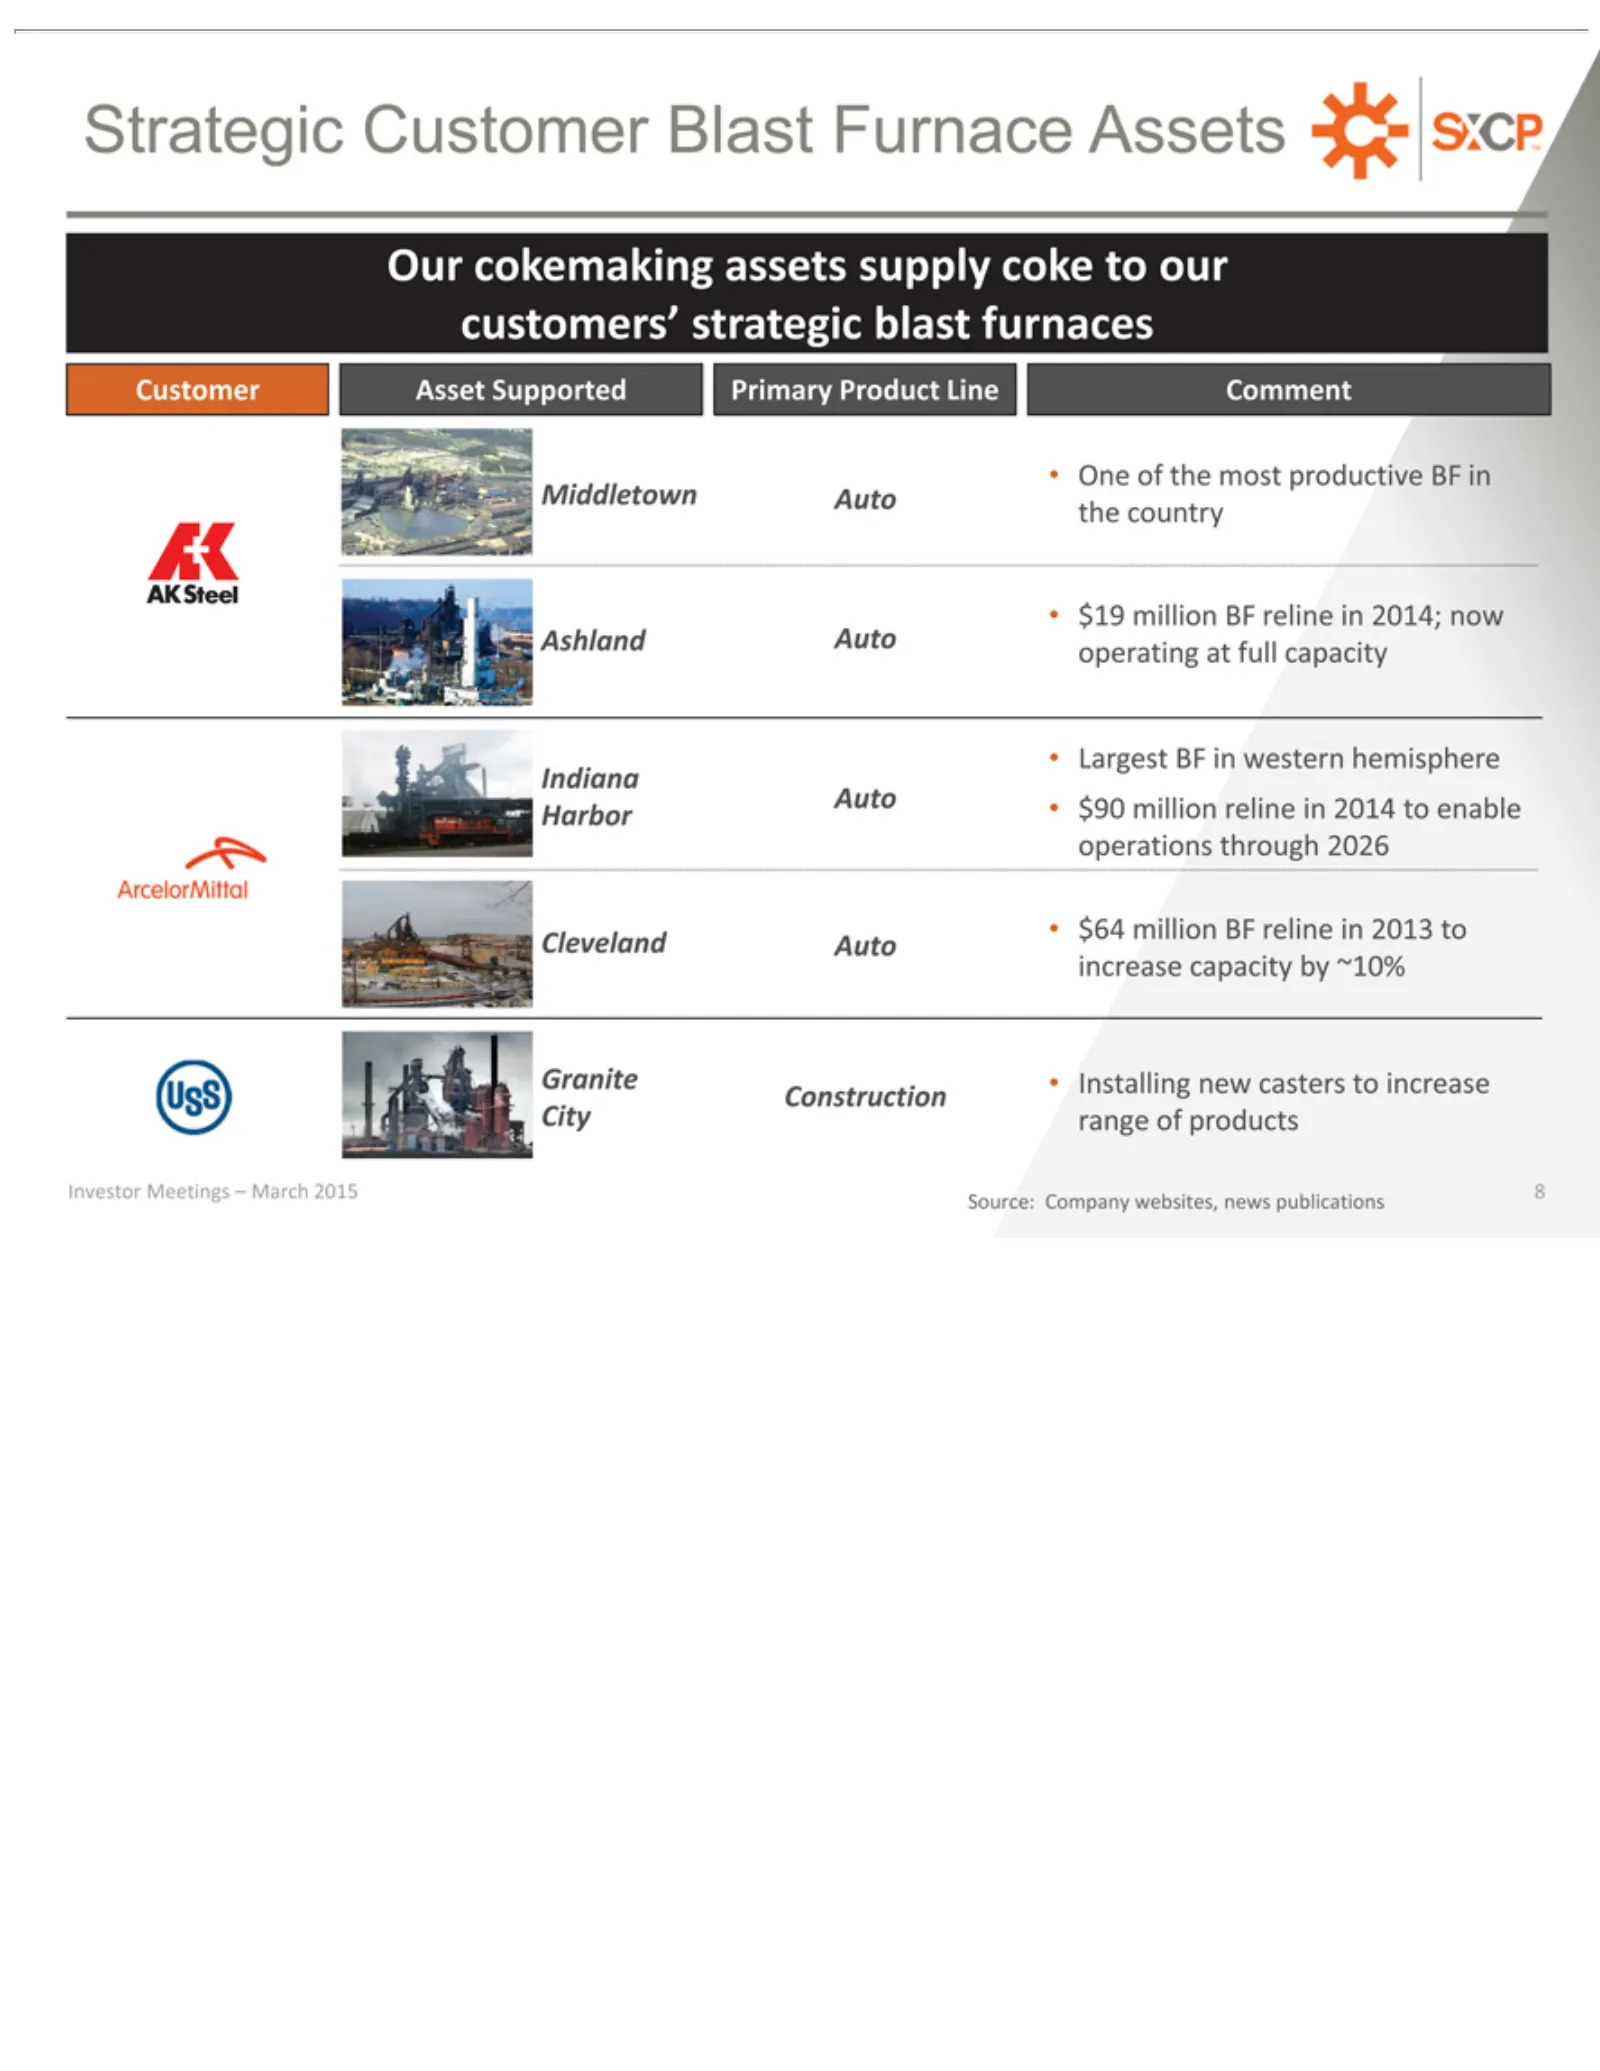
Slide 8: Strategic Customers and Assets
Strategic Our Customer One Middletown $19 Ashland Largest Auto Indiana Harbor $64 Granite City Construction Investor million cokemaking of range • $90 the operations BF •Meetings Auto Customer Installing Asset of most million in BF Auto products western operating reline Supported productive assets t
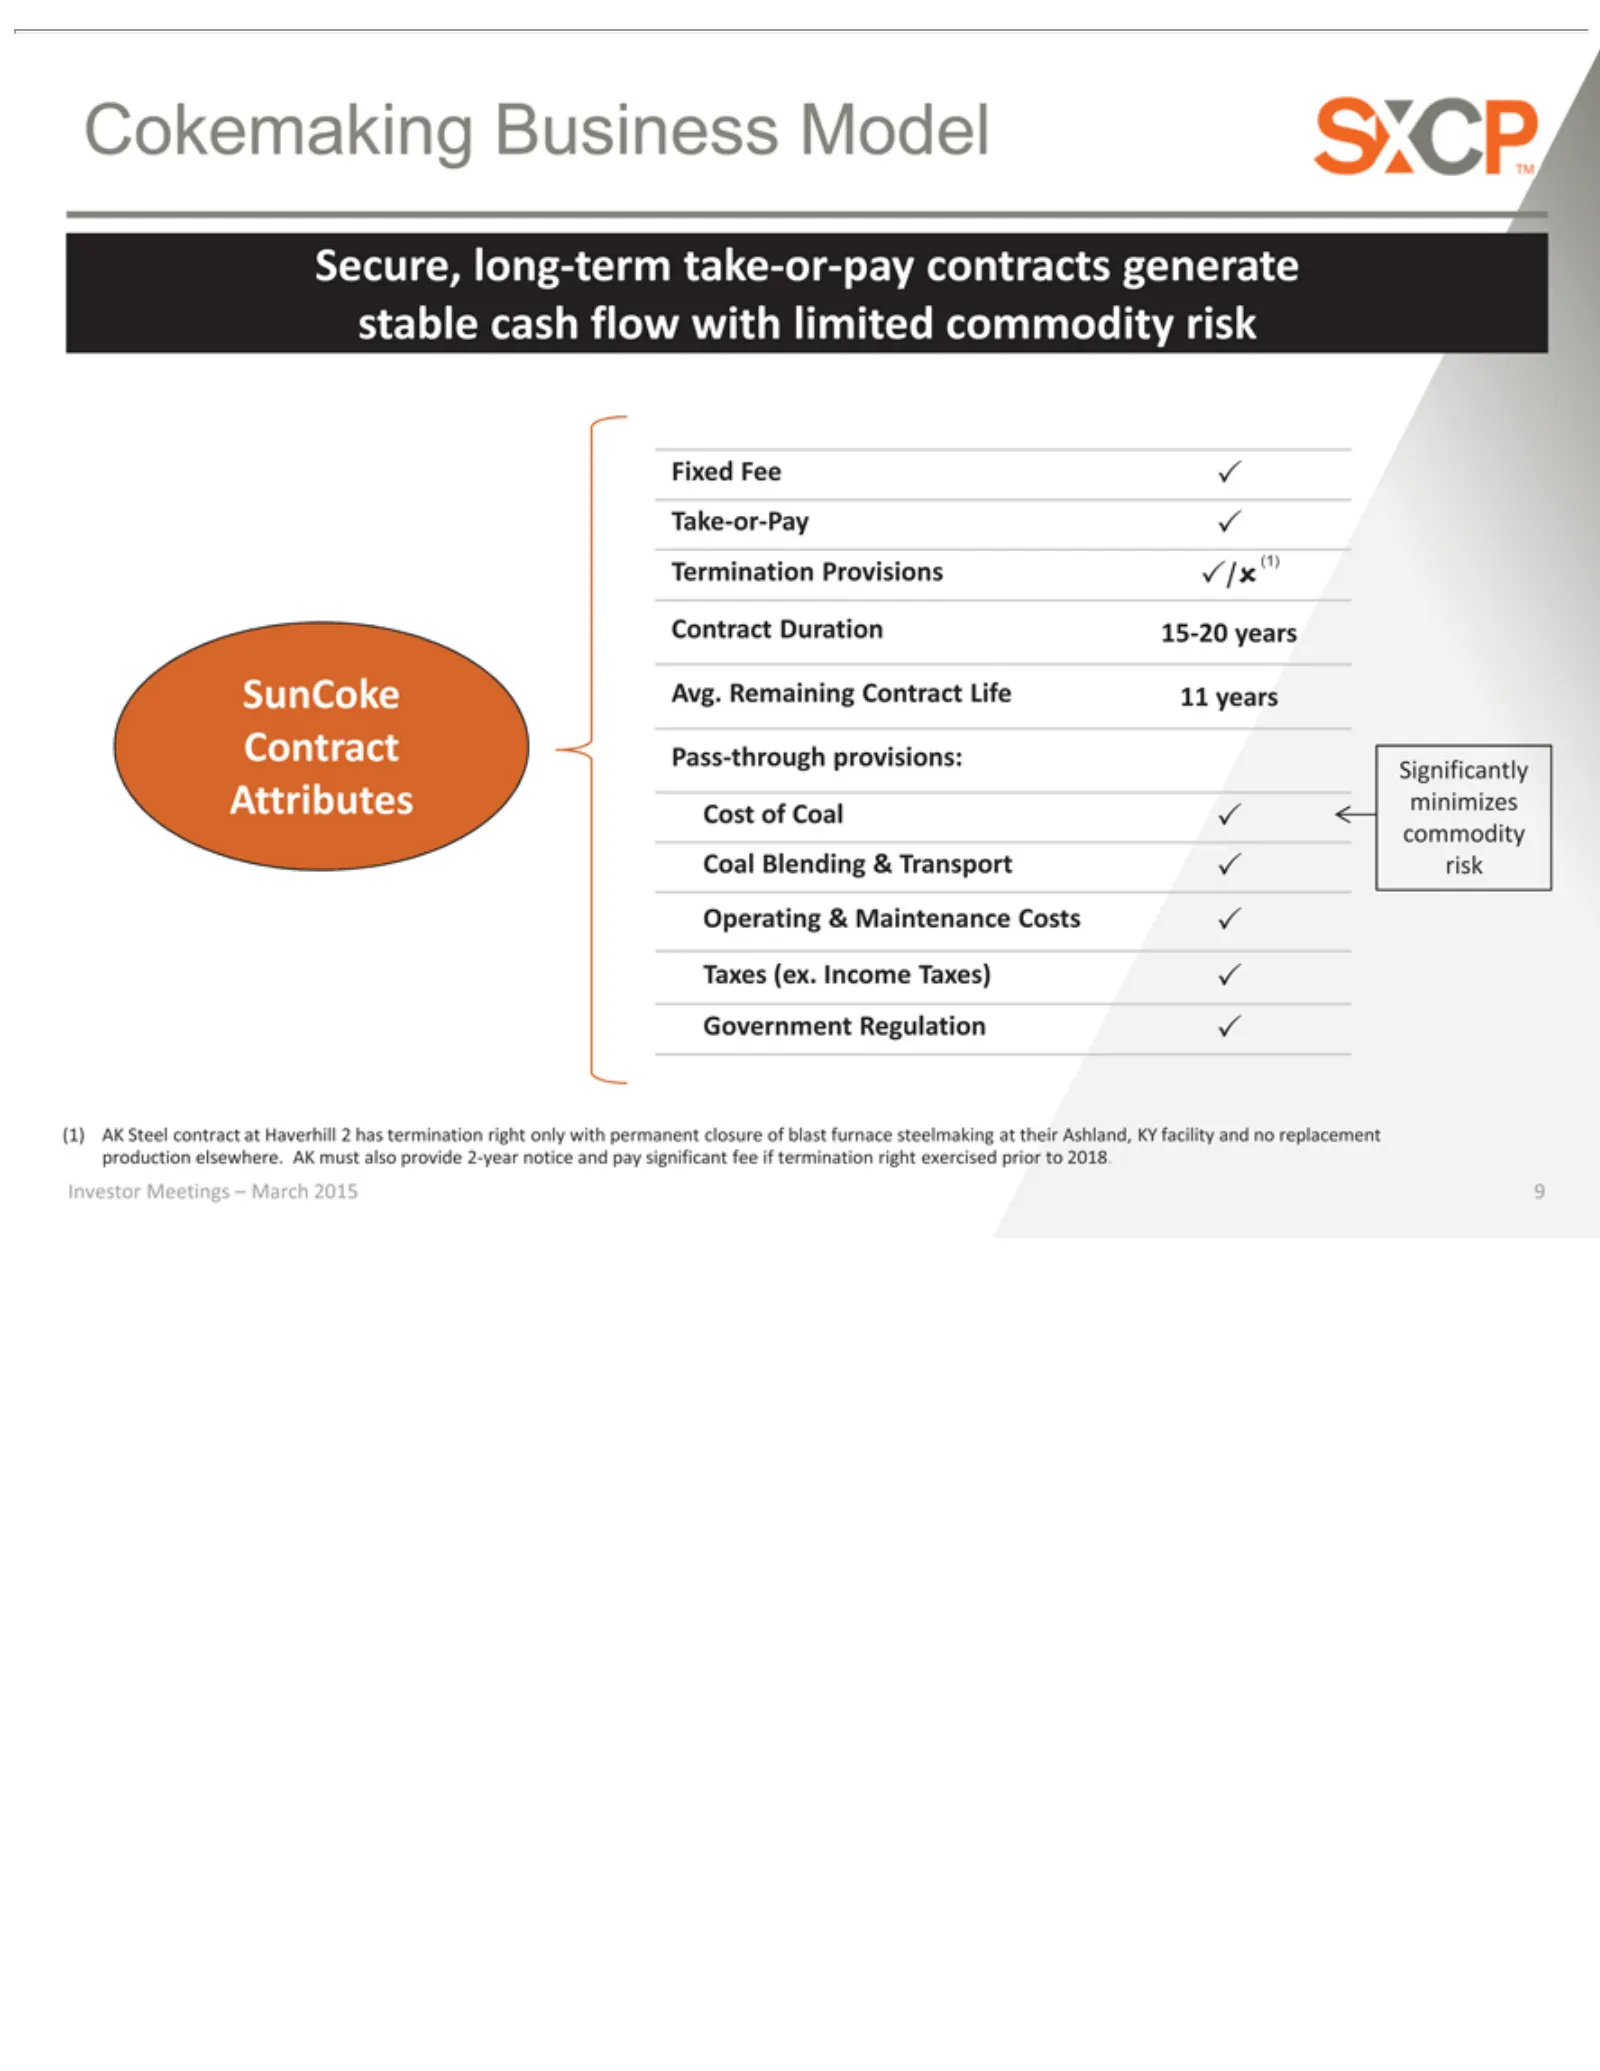
Slide 9: Cokemaking Secure, Fixed-Fee Contracts
Cokemaking Secure, Fixed Contract _/_ SunCoke Attributes Significantly Cost (1) notice 9Investor AKofFee and Steel Coal long-term Meetings Duration Avg. _minimizes pay Take-or-Pay contract _Business Remaining commodity significant take-or-pay 15-20 – March atModel Haverhill years _fee Contract Termi
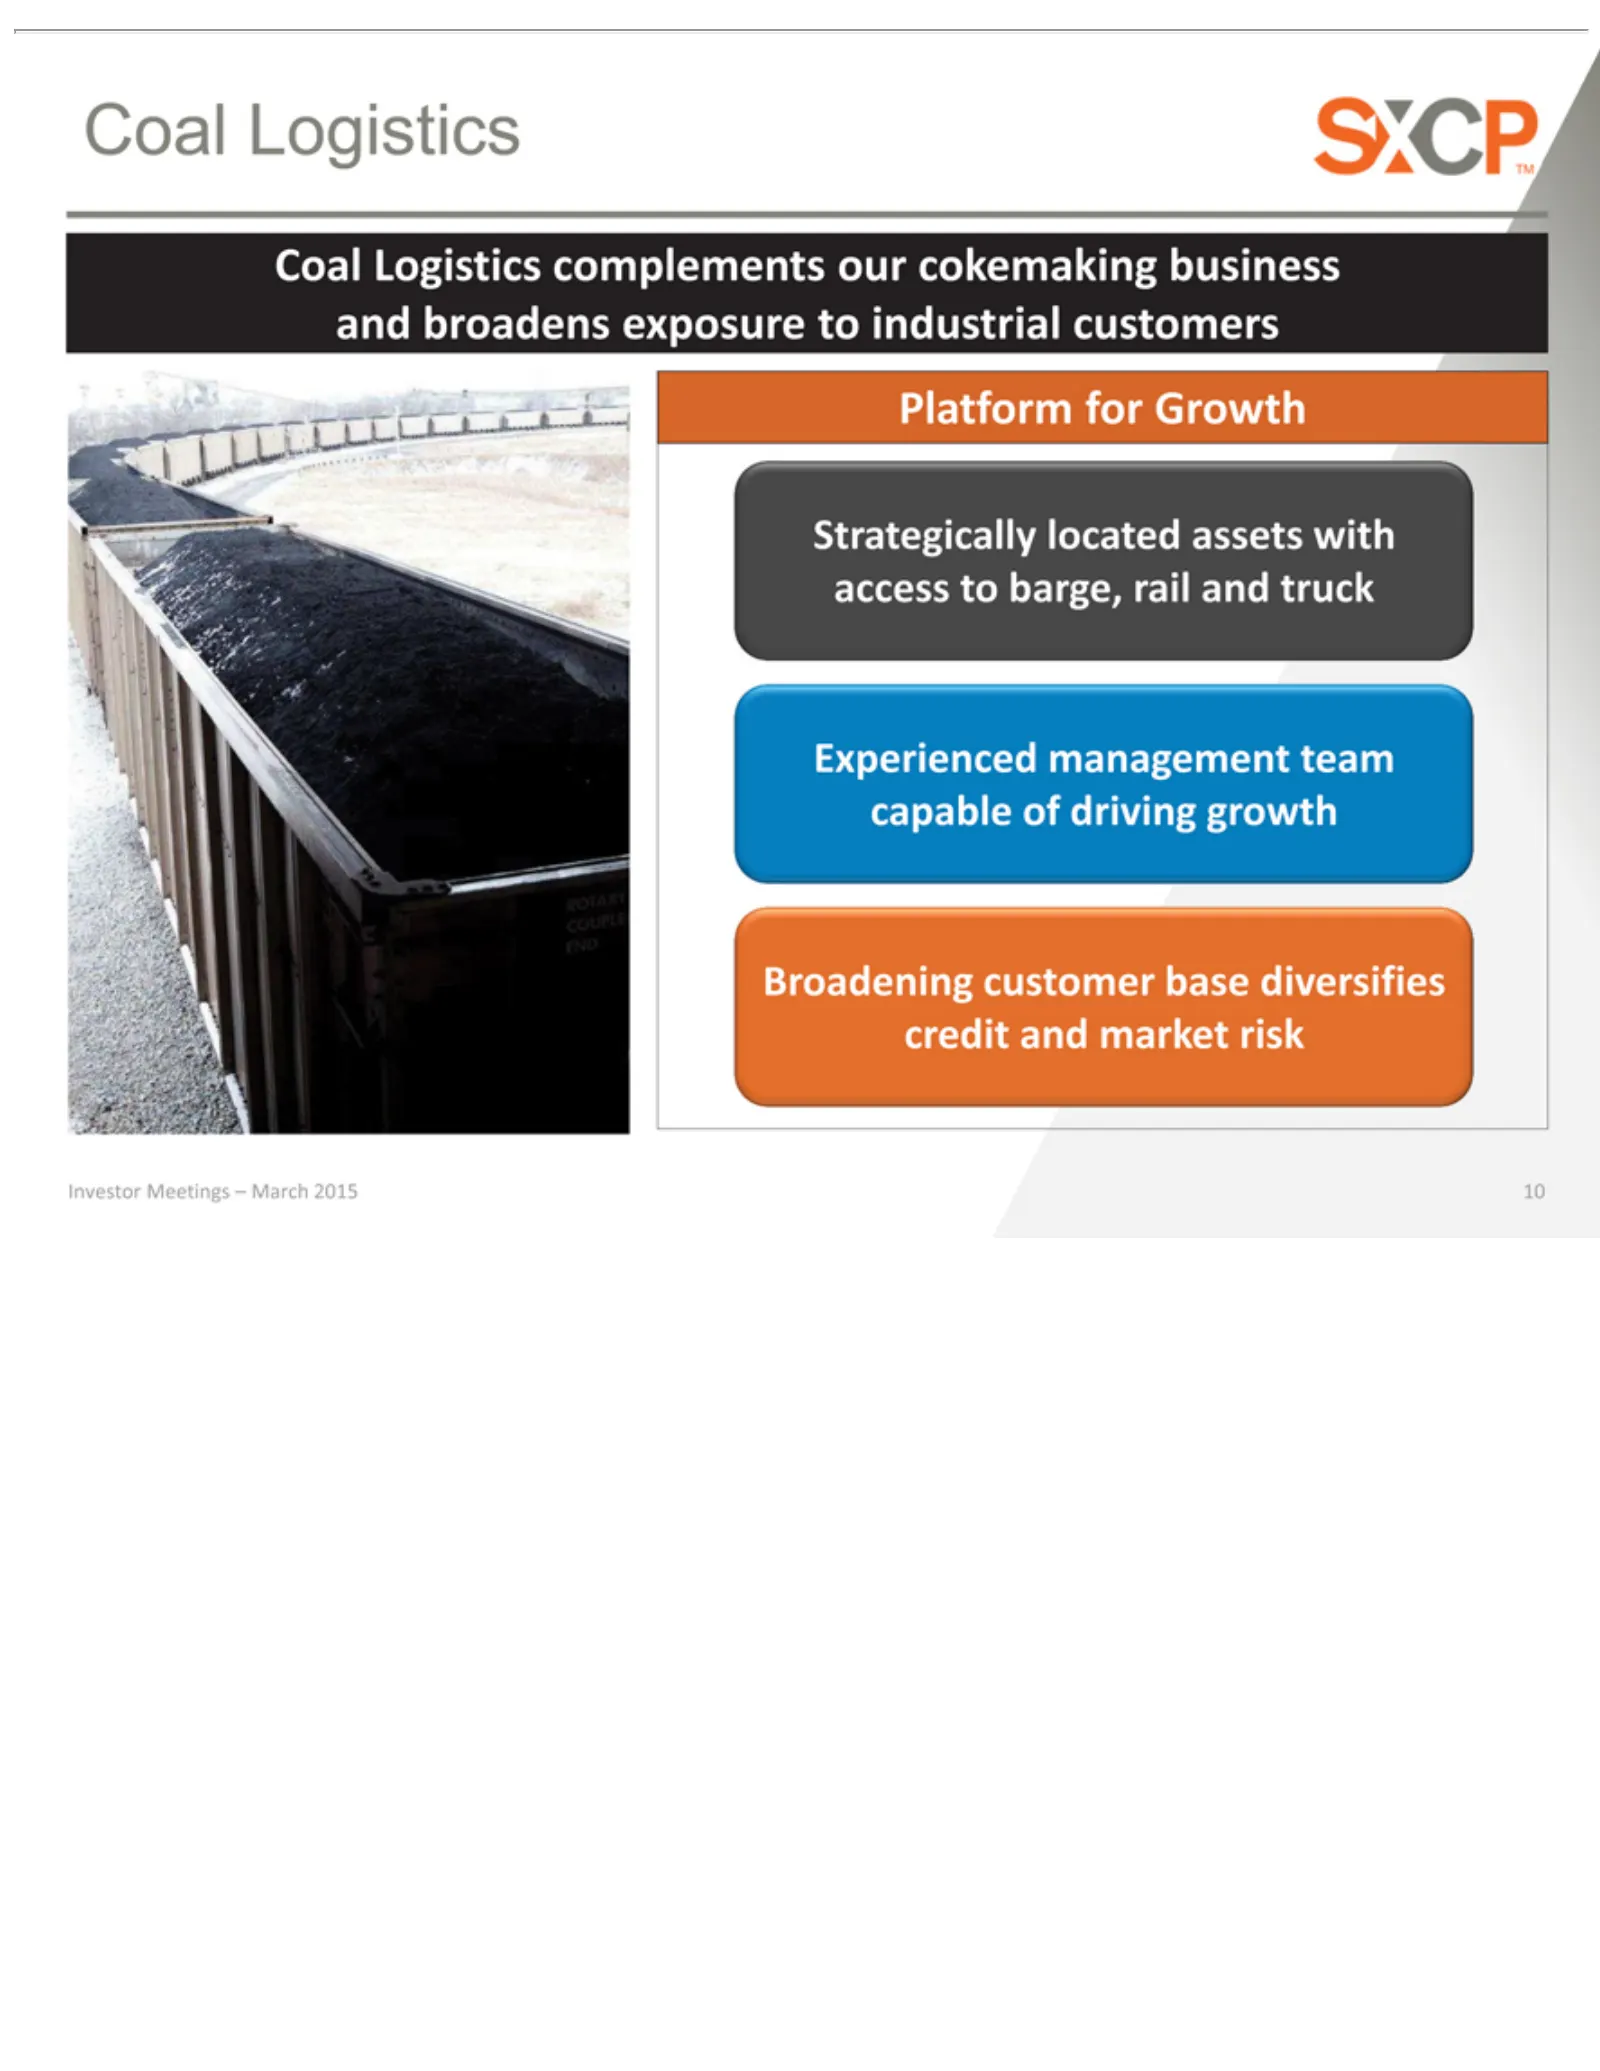
Slide 10: Coal Logistics Platform
Coal Logistics Platform Strategically Experienced Broadening Investor 10 Meetings forcustomer Growth management located complements – March assets baseteam diversifies with 2015 ourcapable access cokemaking credit to ofbarge, driving and business market rail growth and and risk truck broadens exposu
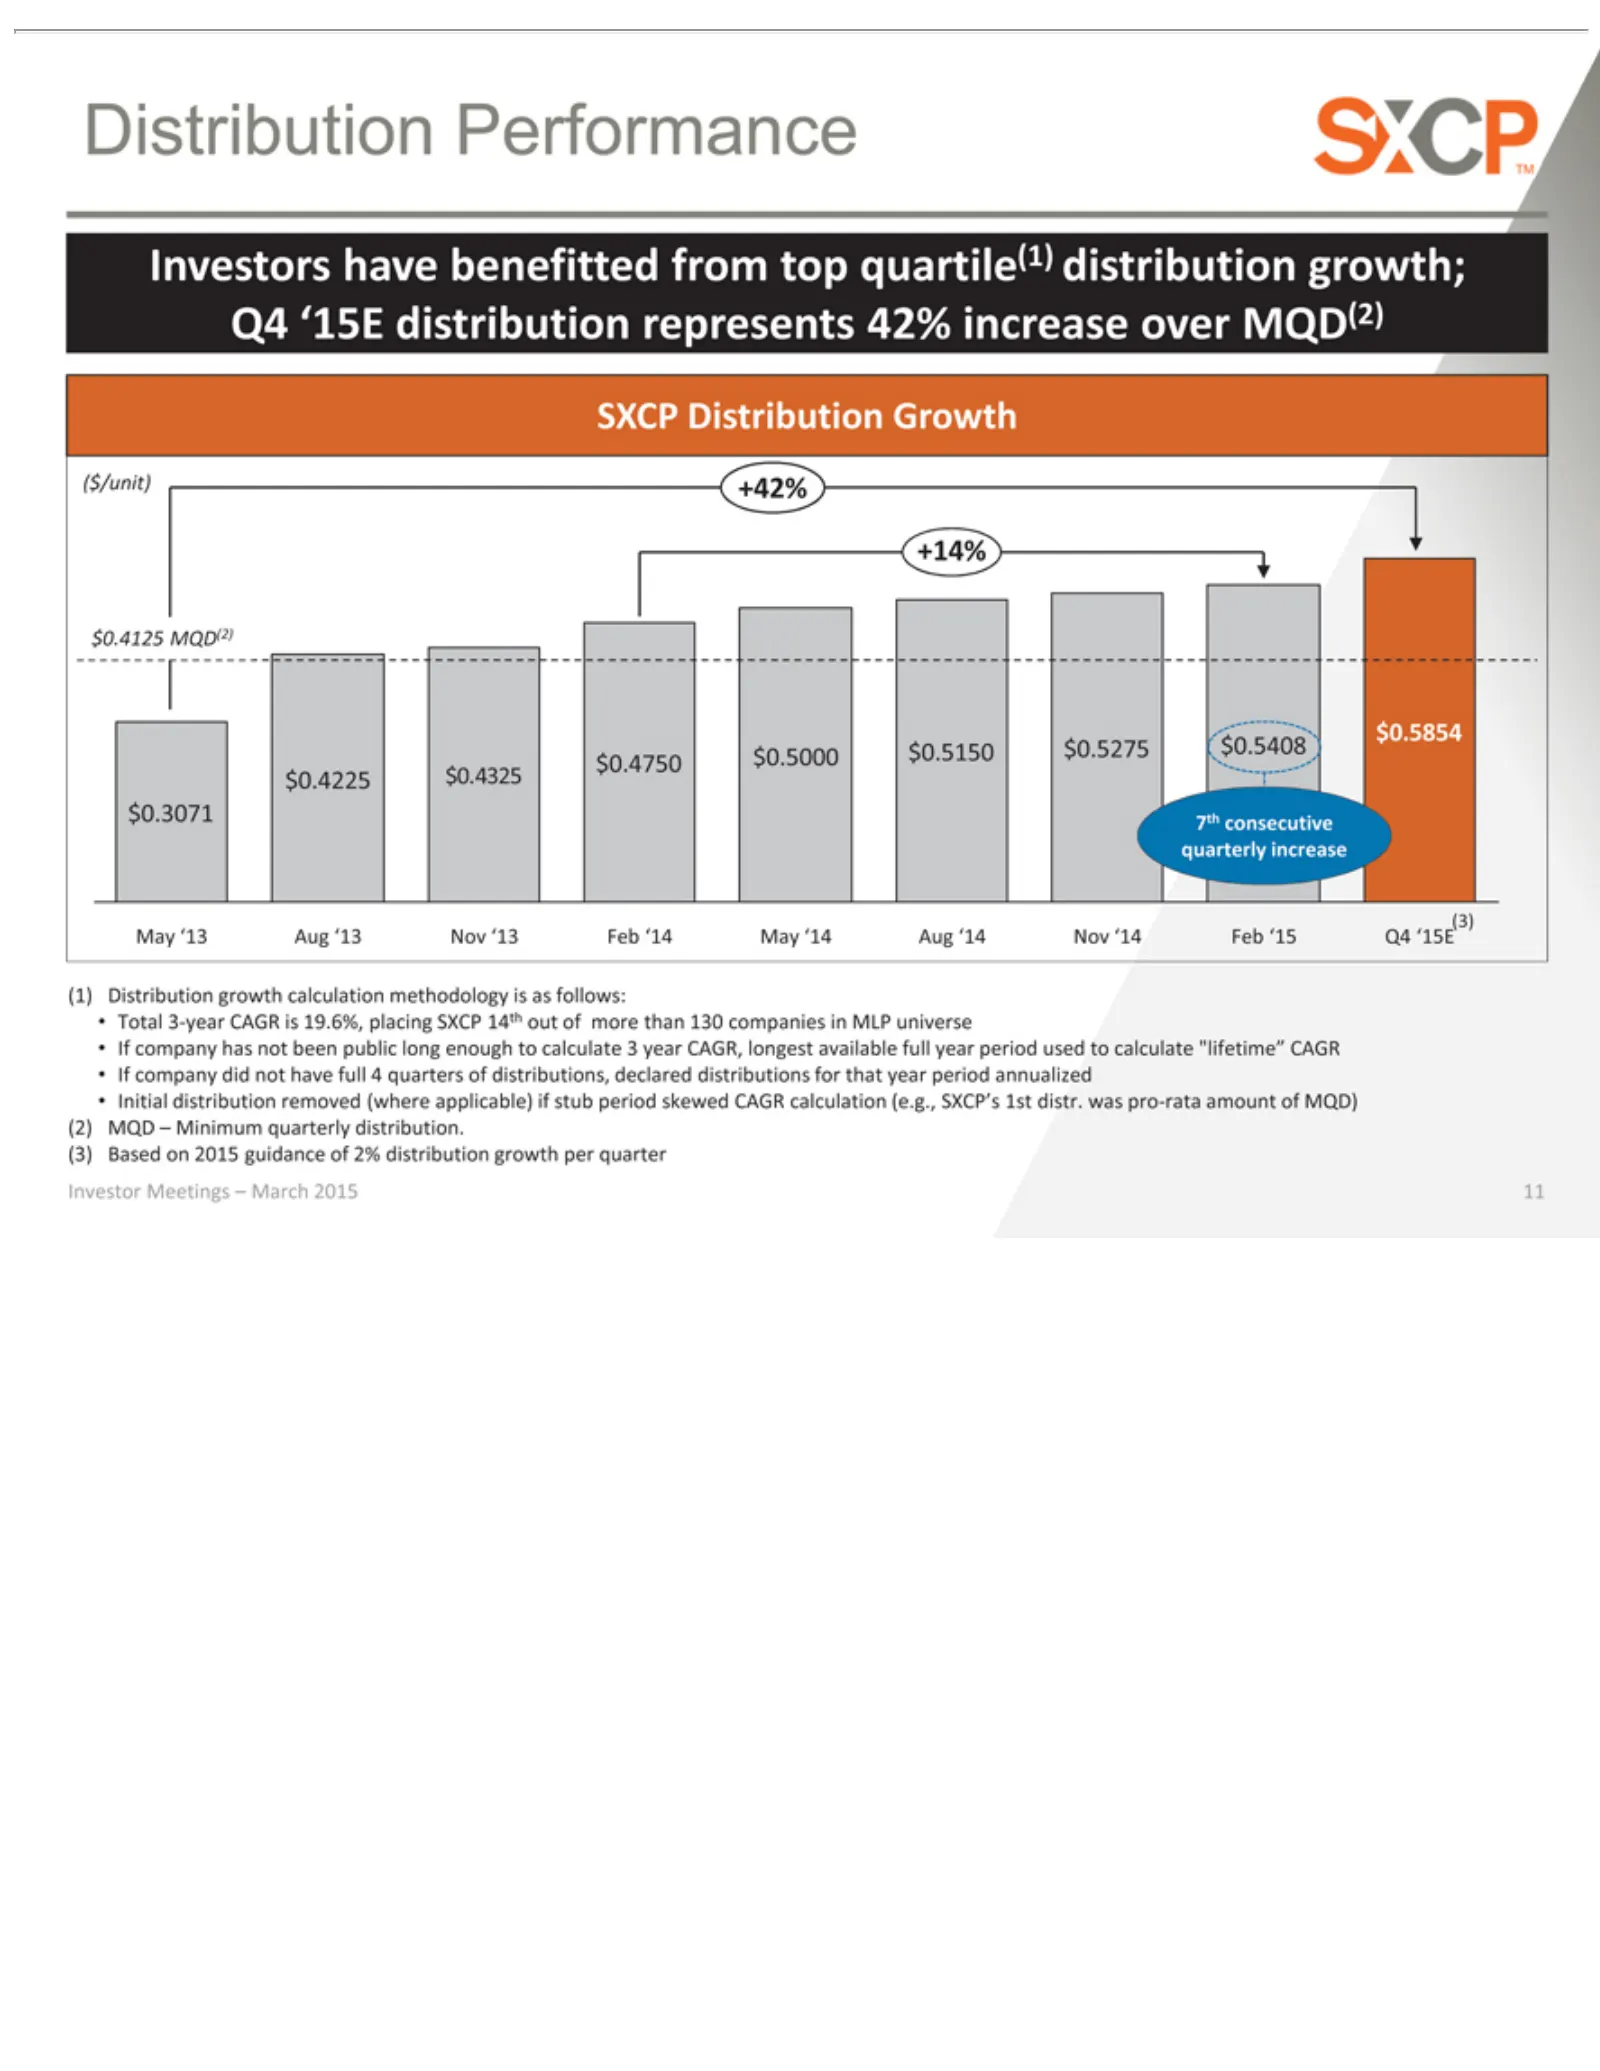
Slide 11: Distribution Growth for Investors
Distribution Investors SXCP ($/unit) $0.4125 +14% $0.5150 $0.5854 $0.3071 7$0.4225 May (1) Total If Initial (3) Investor 11 consecutive company Distribution Based ‘13 3-year distribution Distribution +42% MQD(2) $0.5275 th Meetings Aug have ondid has Performance CAGR 2015 ‘13 quarterly benefitted no
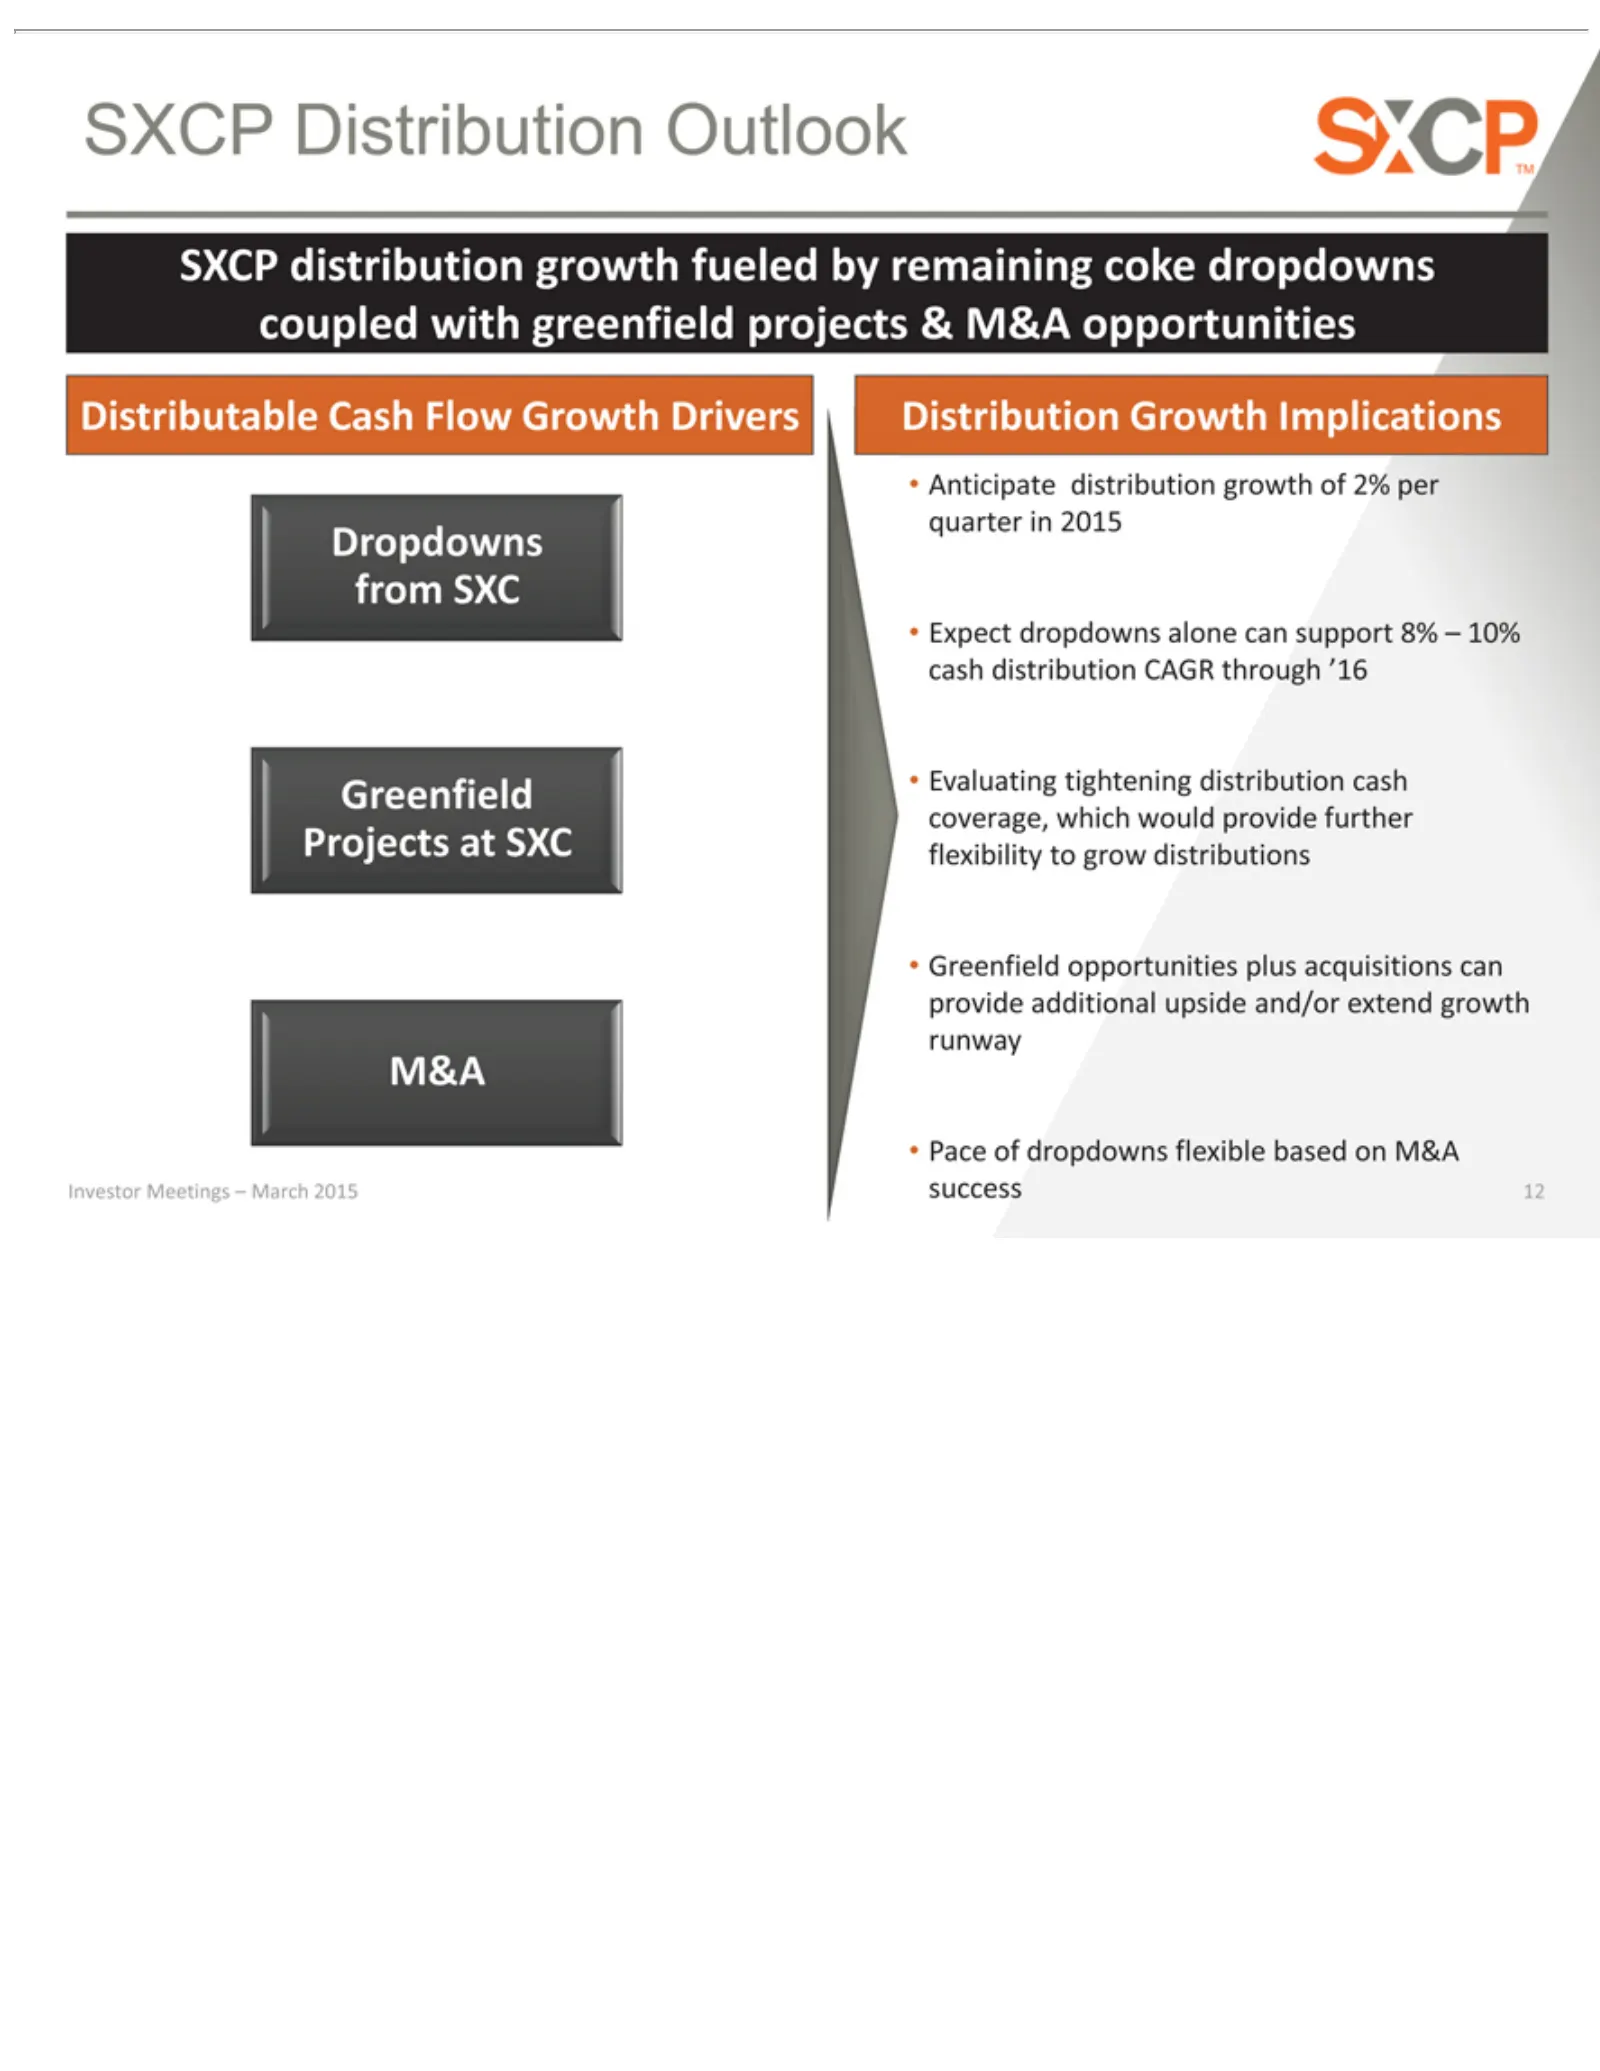
Slide 12: Distribution Growth Outlook
SXCPofdistribution Distributable Anticipate Dropdowns Expect Greenfield Pace M&A Investor 12 successDistribution dropdowns dropdowns Meetings distribution • from opportunities Evaluating CashSXC –growth alone Flow Outlook flexible March growth tightening Growth plus can fueled 2015 based support acq
Slide 13: Growth Strategy
GROWTH Investor 13 Meetings STRATEGY – March 2015
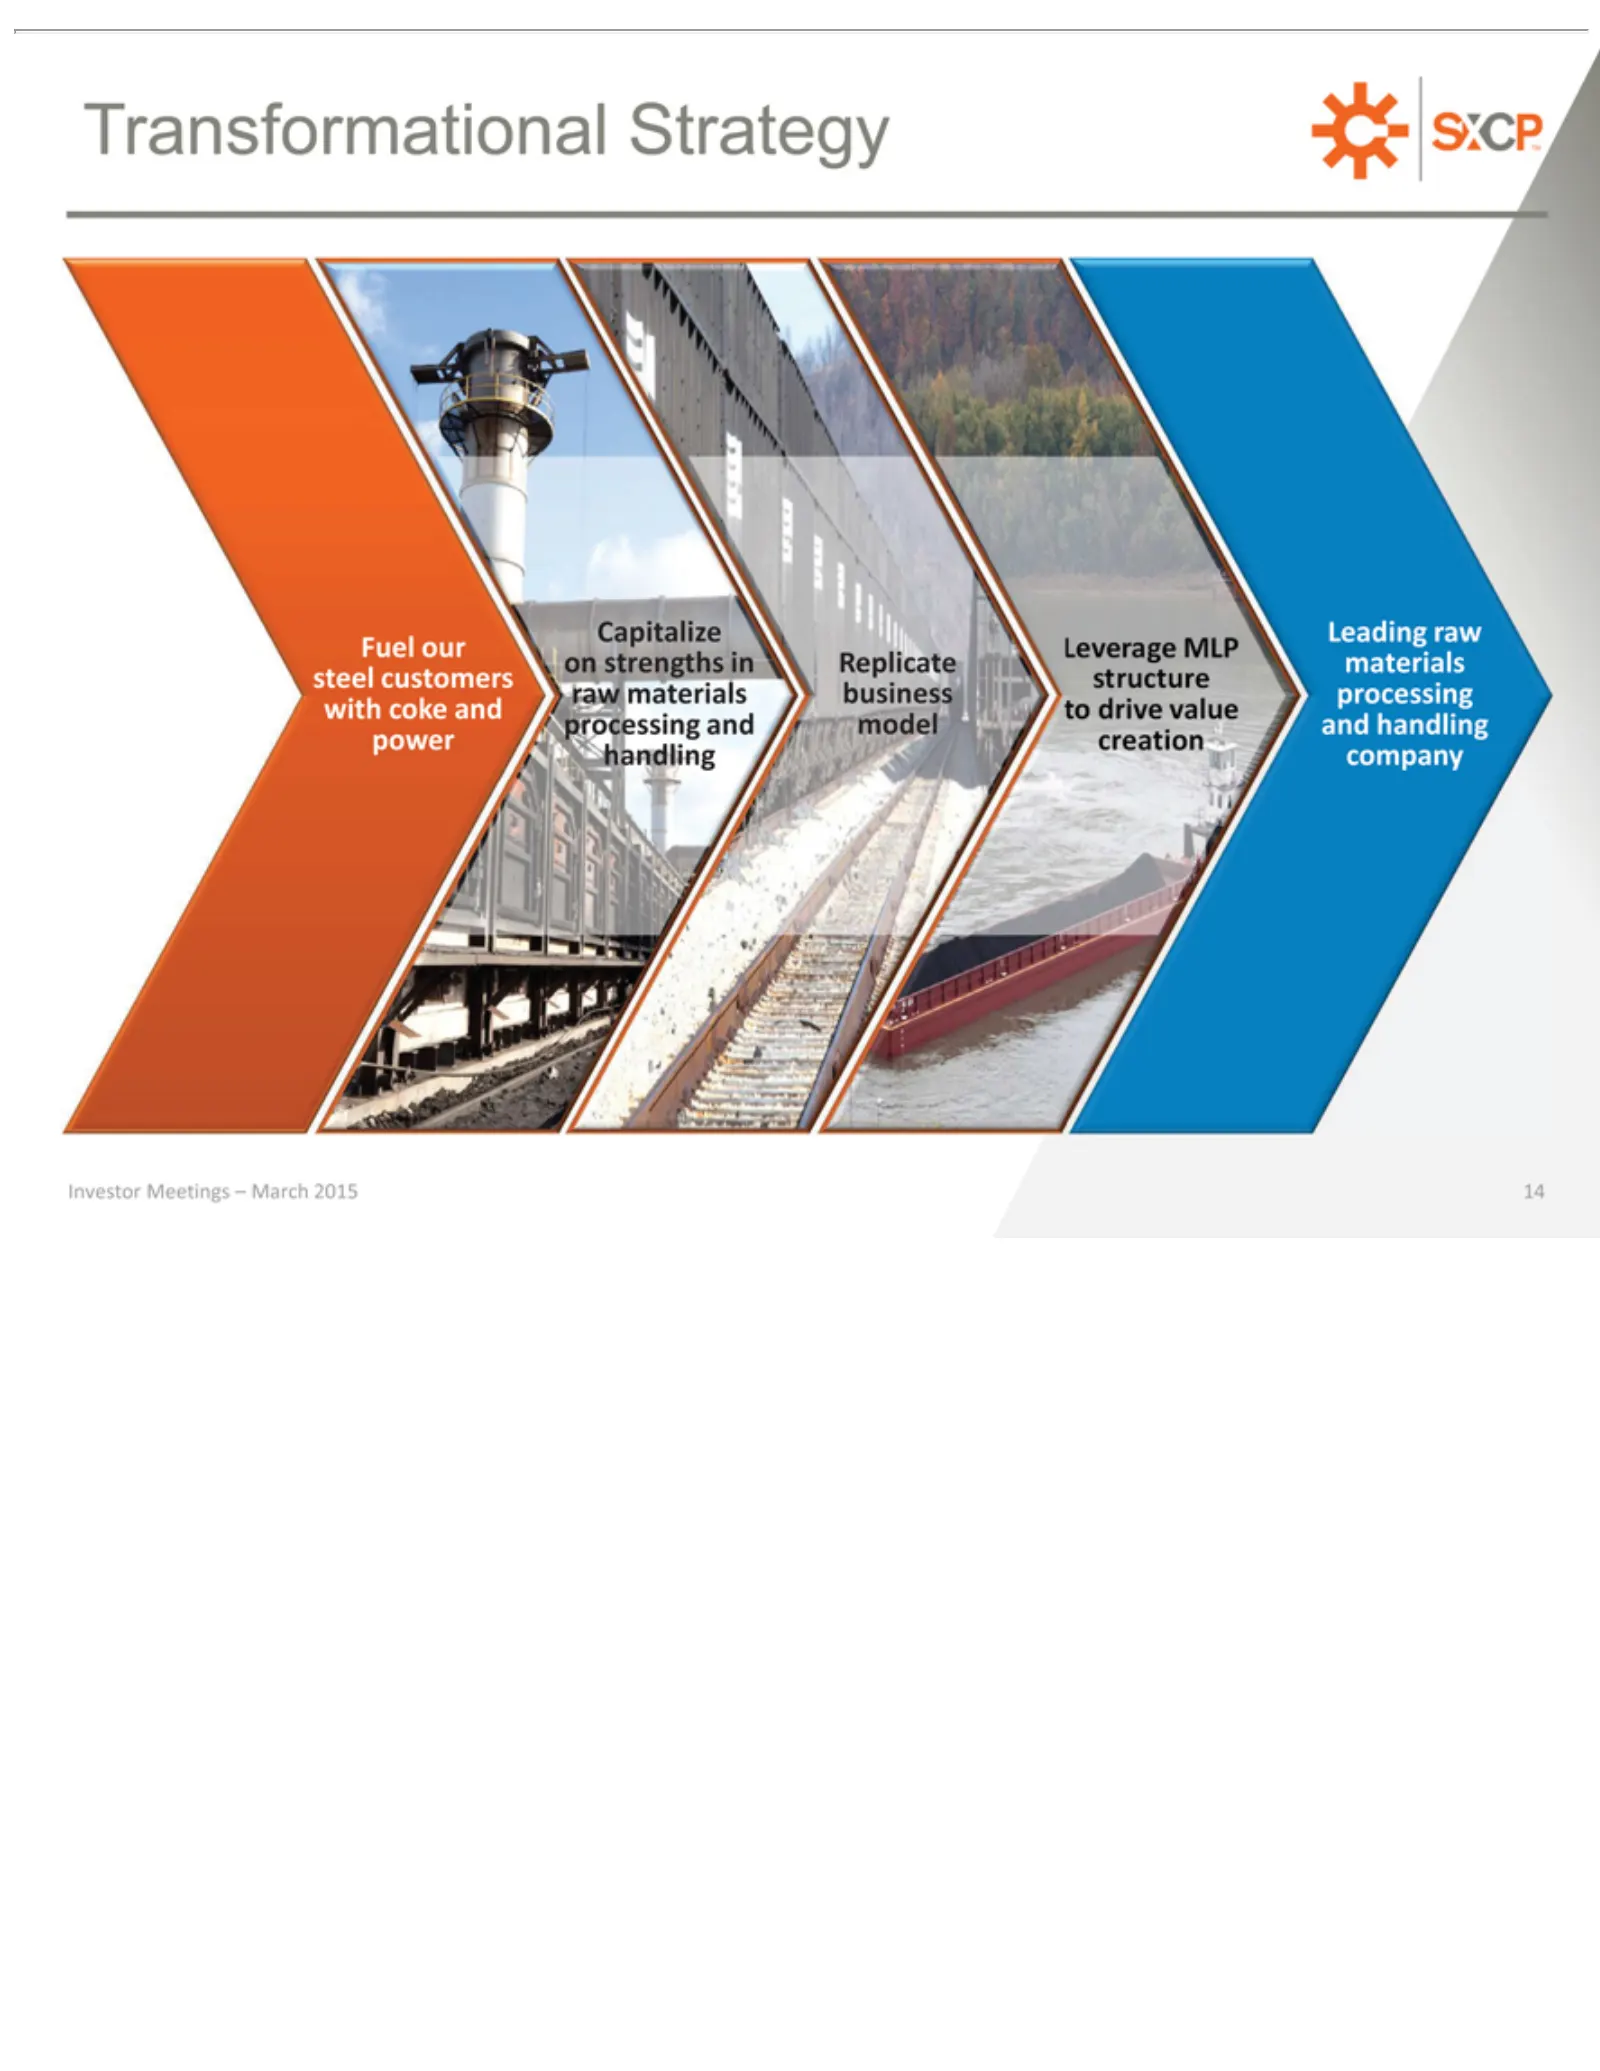
Slide 14: Transformational Growth Strategy
Transformational Capitalize Investor Meetings LeadingStrategy –raw March Fuel2015 our on 14 strengths in Replicate materials steel customers raw materials business processing with coke and processing and model and handling power handling company
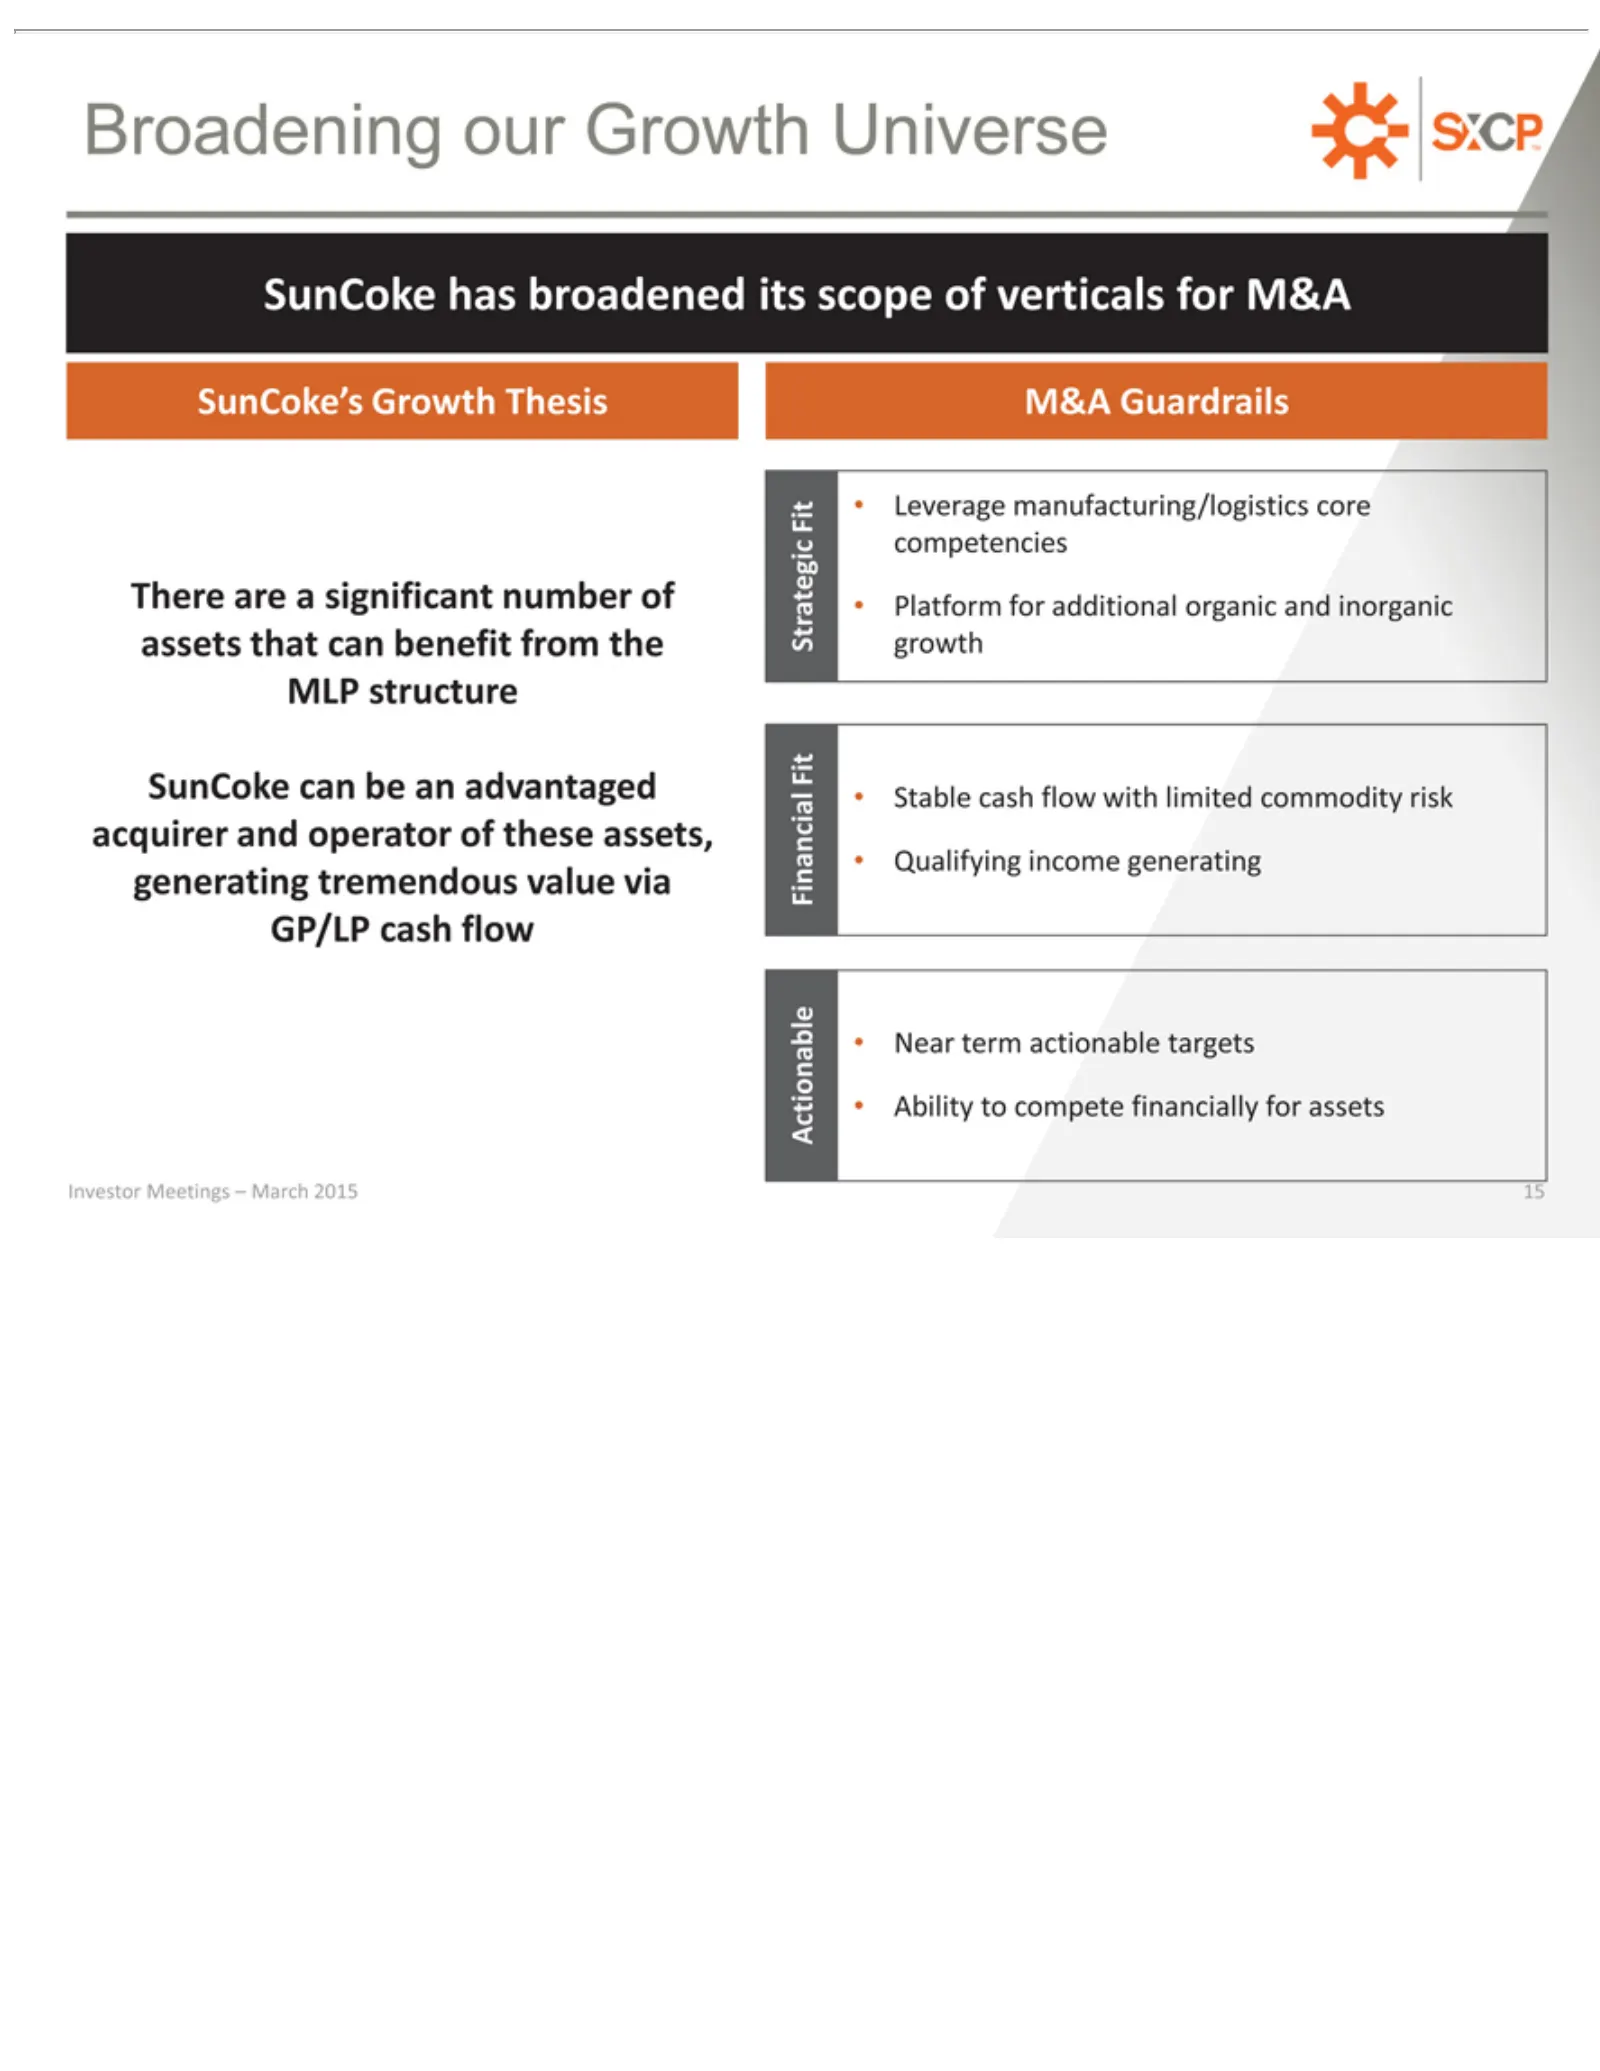
Slide 15: Broadening SunCoke's Fit for M&A
Broadening SunCoke’s Fit assets SunCoke acquirer Qualifying generating Near Actionable Investor 15 • Leverage term that and Meetings has can actionable can tremendous income Growth •our Ability operator broadened be manufacturing/logistics benefit Growth an–generating Thesis advantaged March totarge
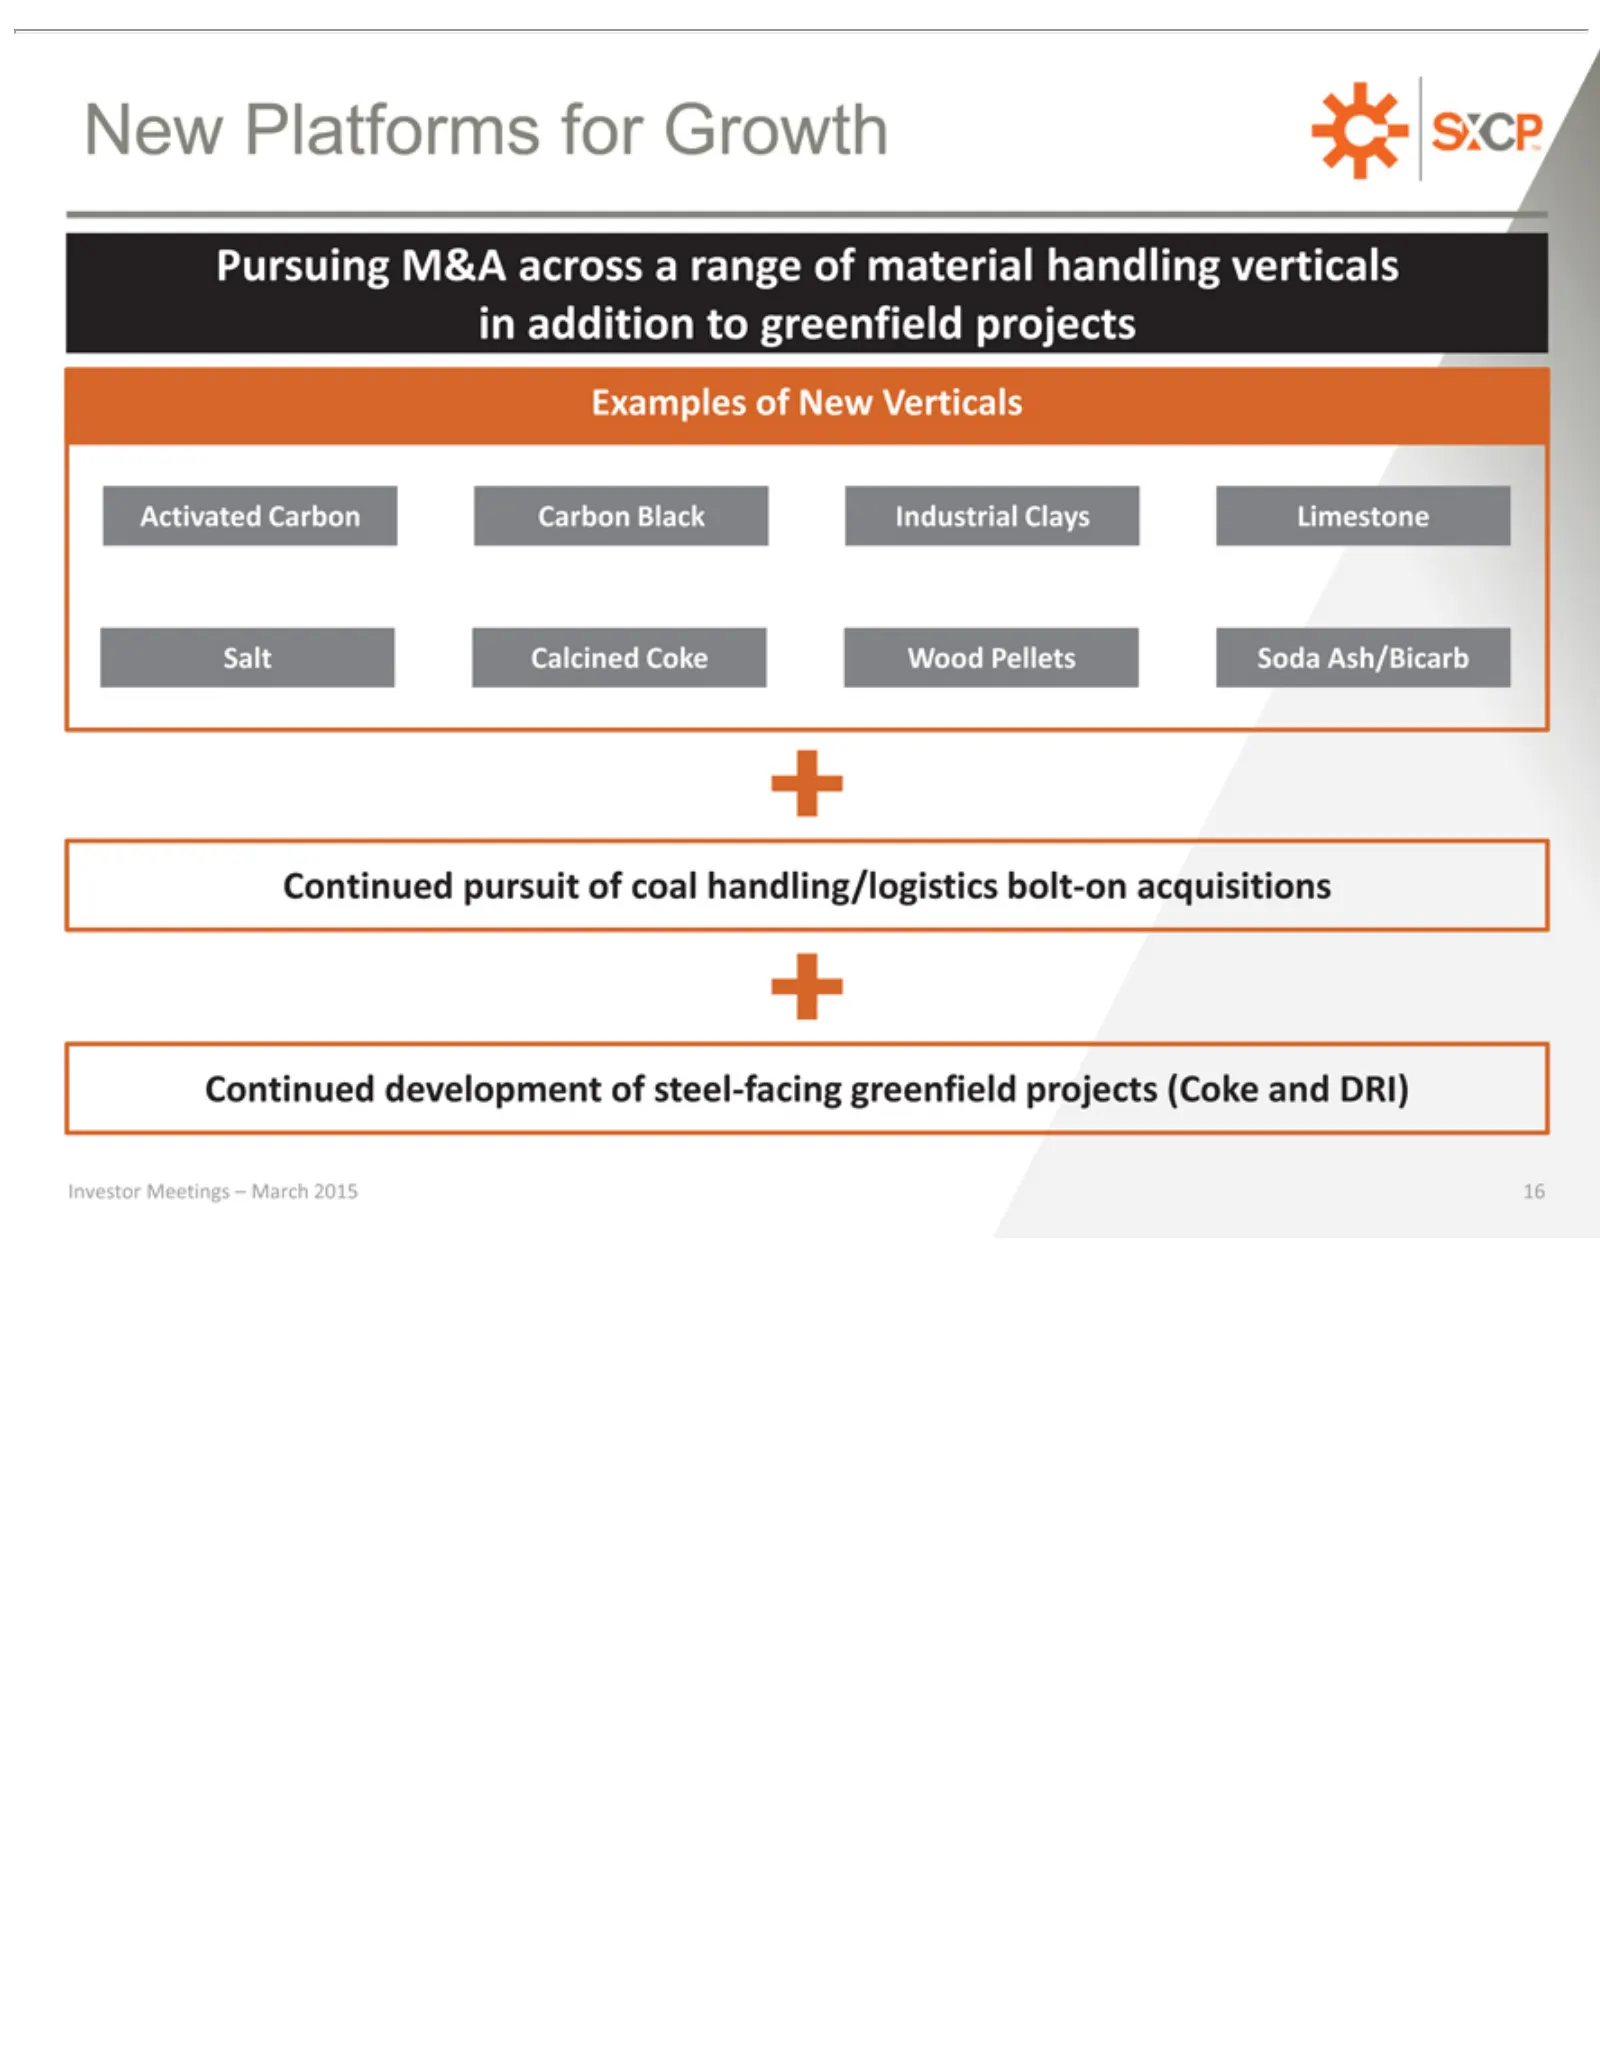
Slide 16: Pursuing New Platforms
NewCalcined Pursuing Examples Activated Salt Continued Investor Platforms Meetings M&A Carbon of pursuit development New Coke for across Carbon Verticals of –Growth Wood March coal a of range handling/logistics Black Pellets steel-facing 2015ofIndustrial 16 material Soda Ash/Bicarb greenfield handli
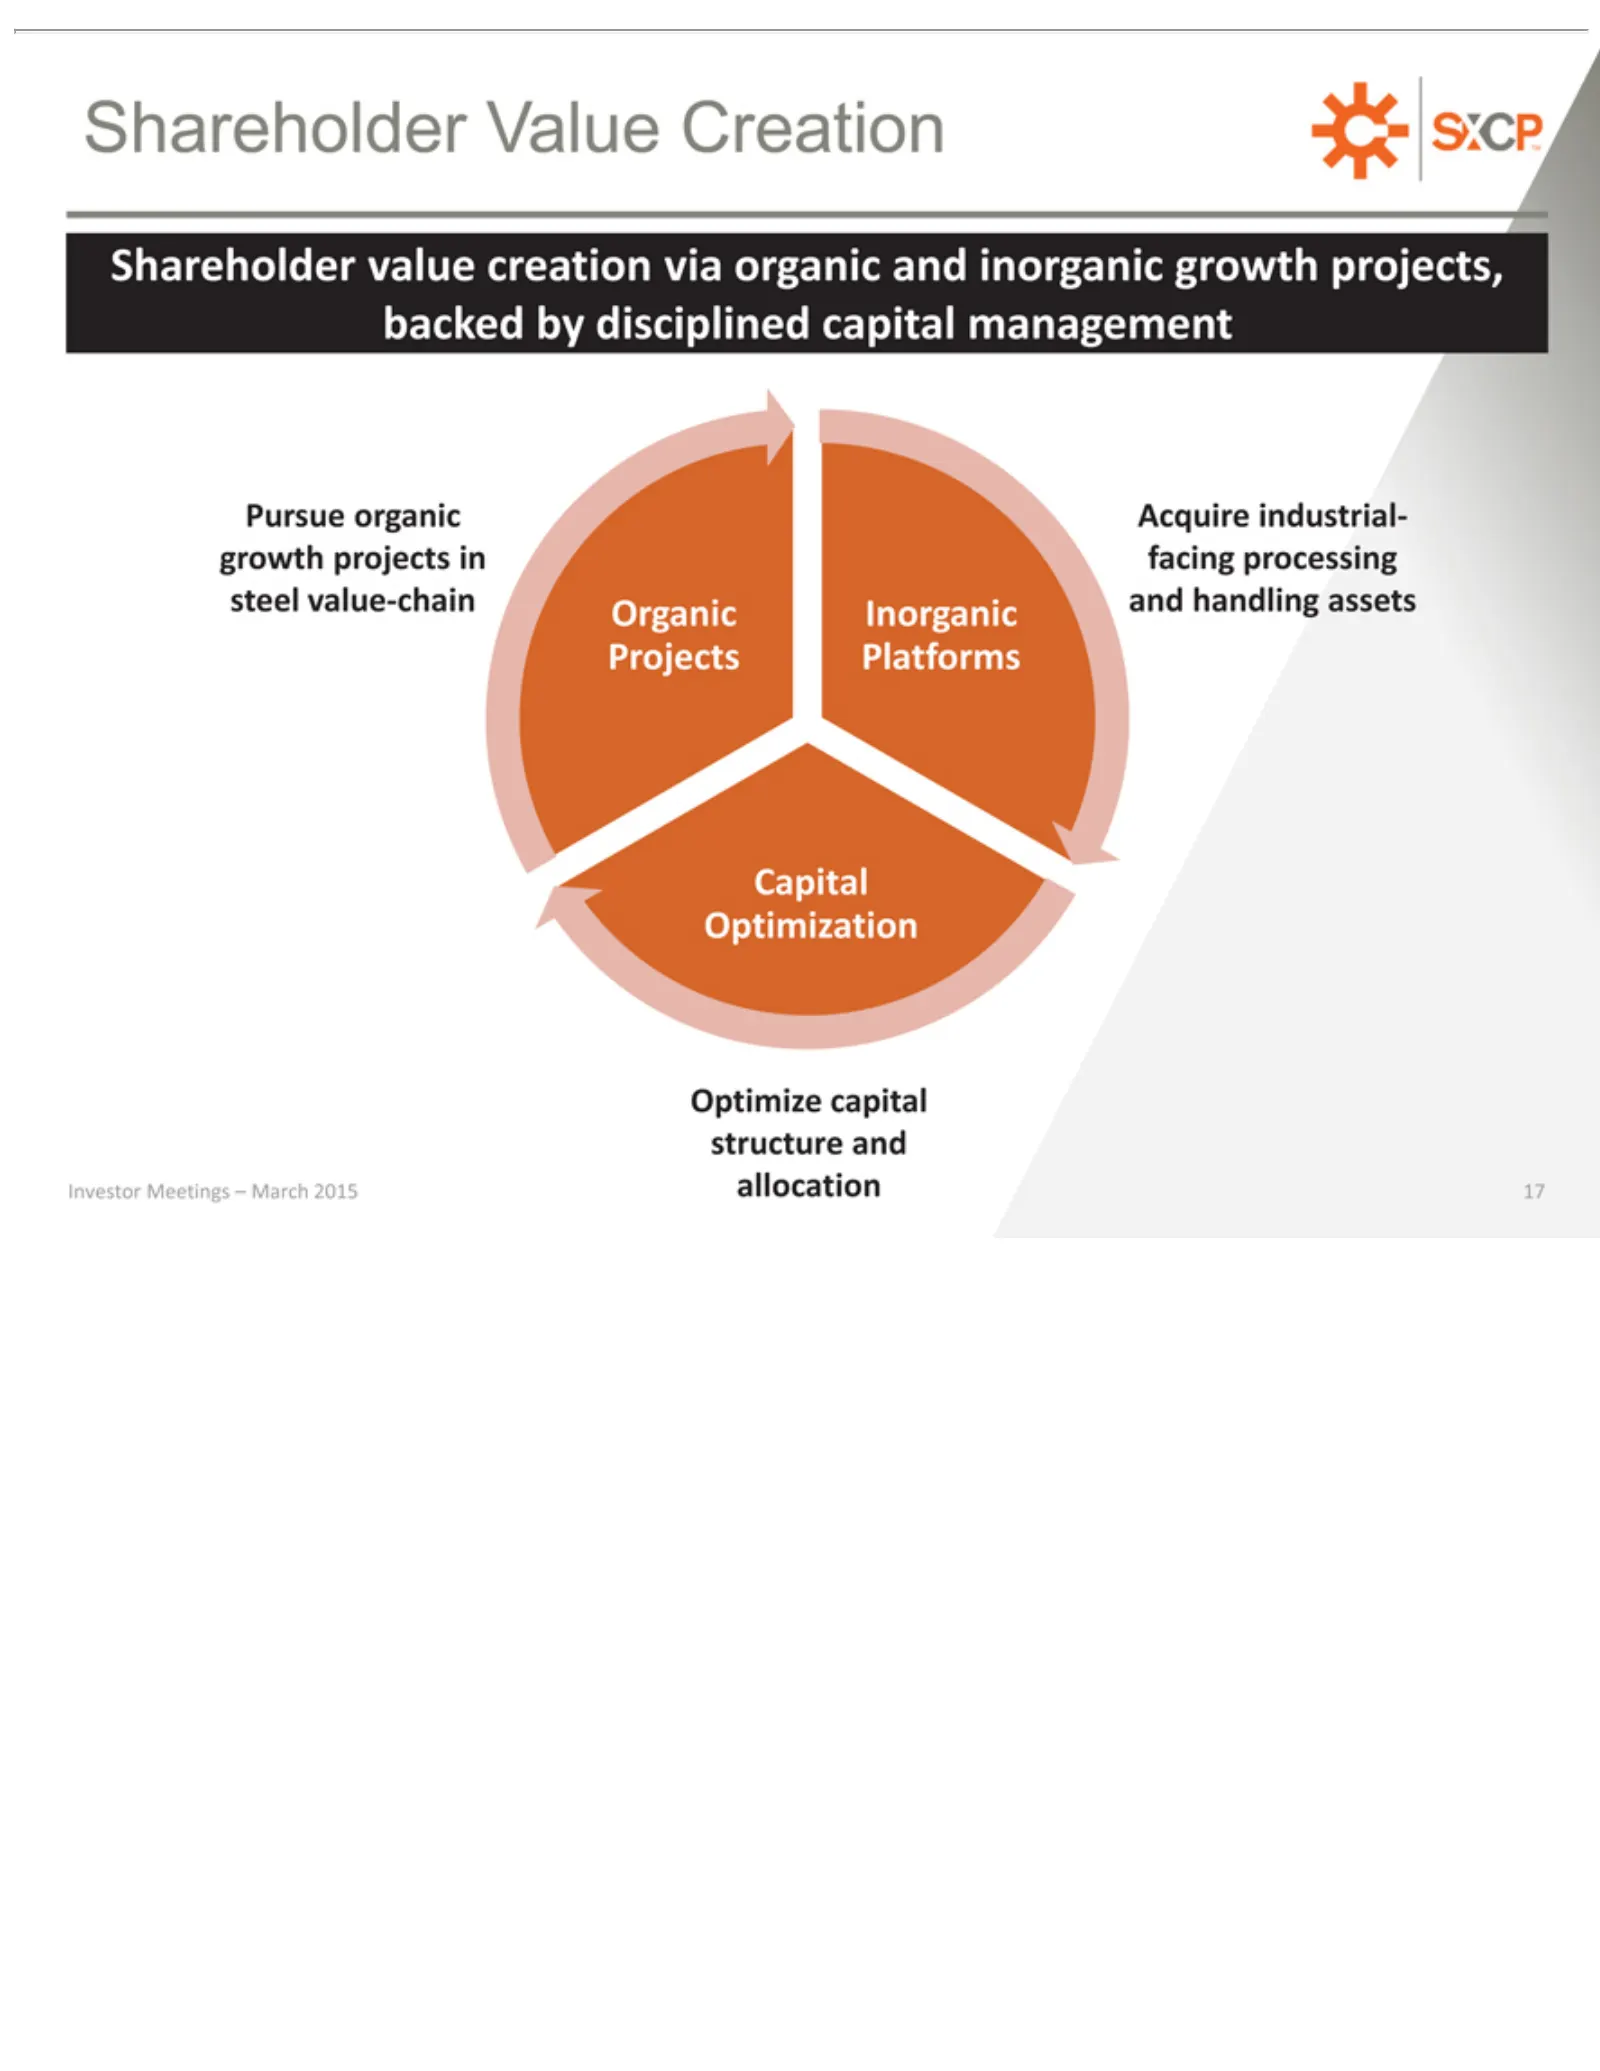
Slide 17: Shareholder Value Creation
Shareholder Pursue Projects Capital Optimize Investororganic Optimization Platforms Meetings capital Value value Acquire structure creation –Creation March industrial-growth and via 2015 organic allocation andprojects inorganic 17 in facing growthprocessing projects, backed steel value-chain by disc
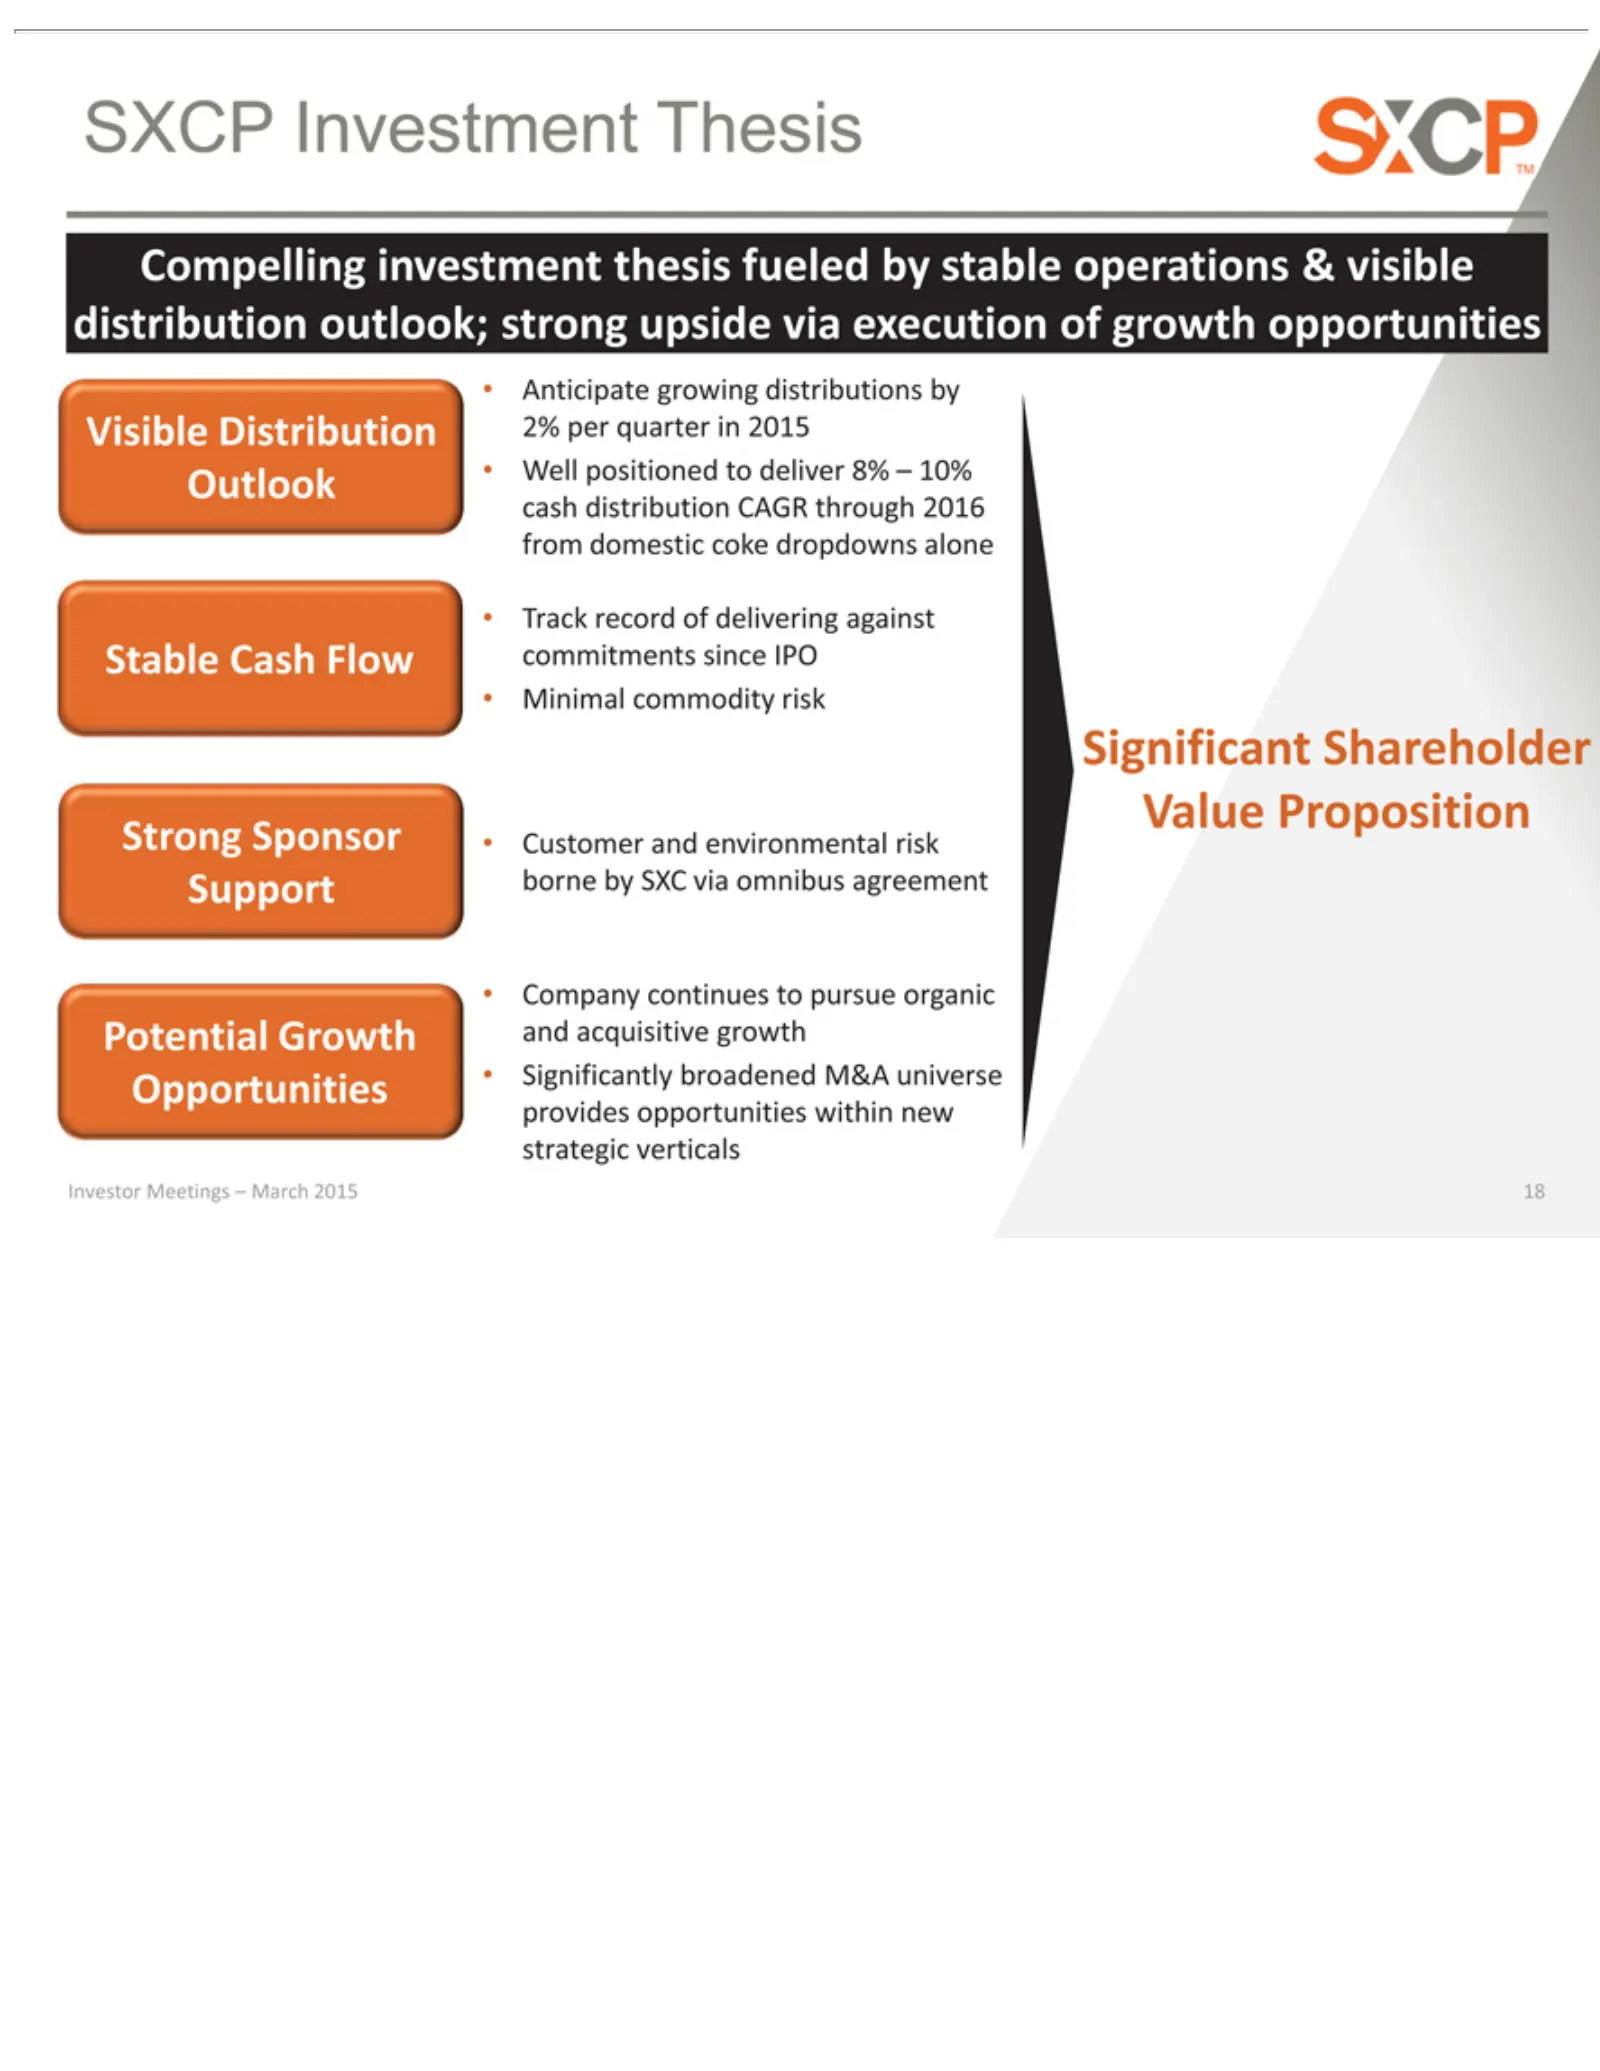
Slide 18: SXCP Investment Thesis
SXCP record Compelling Anticipate Visible Outlook Track Minimal Significant Strong Company Investor Investment Sponsor Distribution Meetings •commodity Well continues growing Shareholder investment of positioned delivering • Customer Thesis –distributions 2% to March risk pursue thesis Value perto a
Slide 19: Appendix
Investor Meetings – March 2015 APPENDIX 19
Slide 20: SXCP Reconciliations & 2015 Guidance
SXCP RECONCILIATIONS Investor 20 Meetings – March 2015 & 2015 GUIDANCE
Slide 21: Definitions
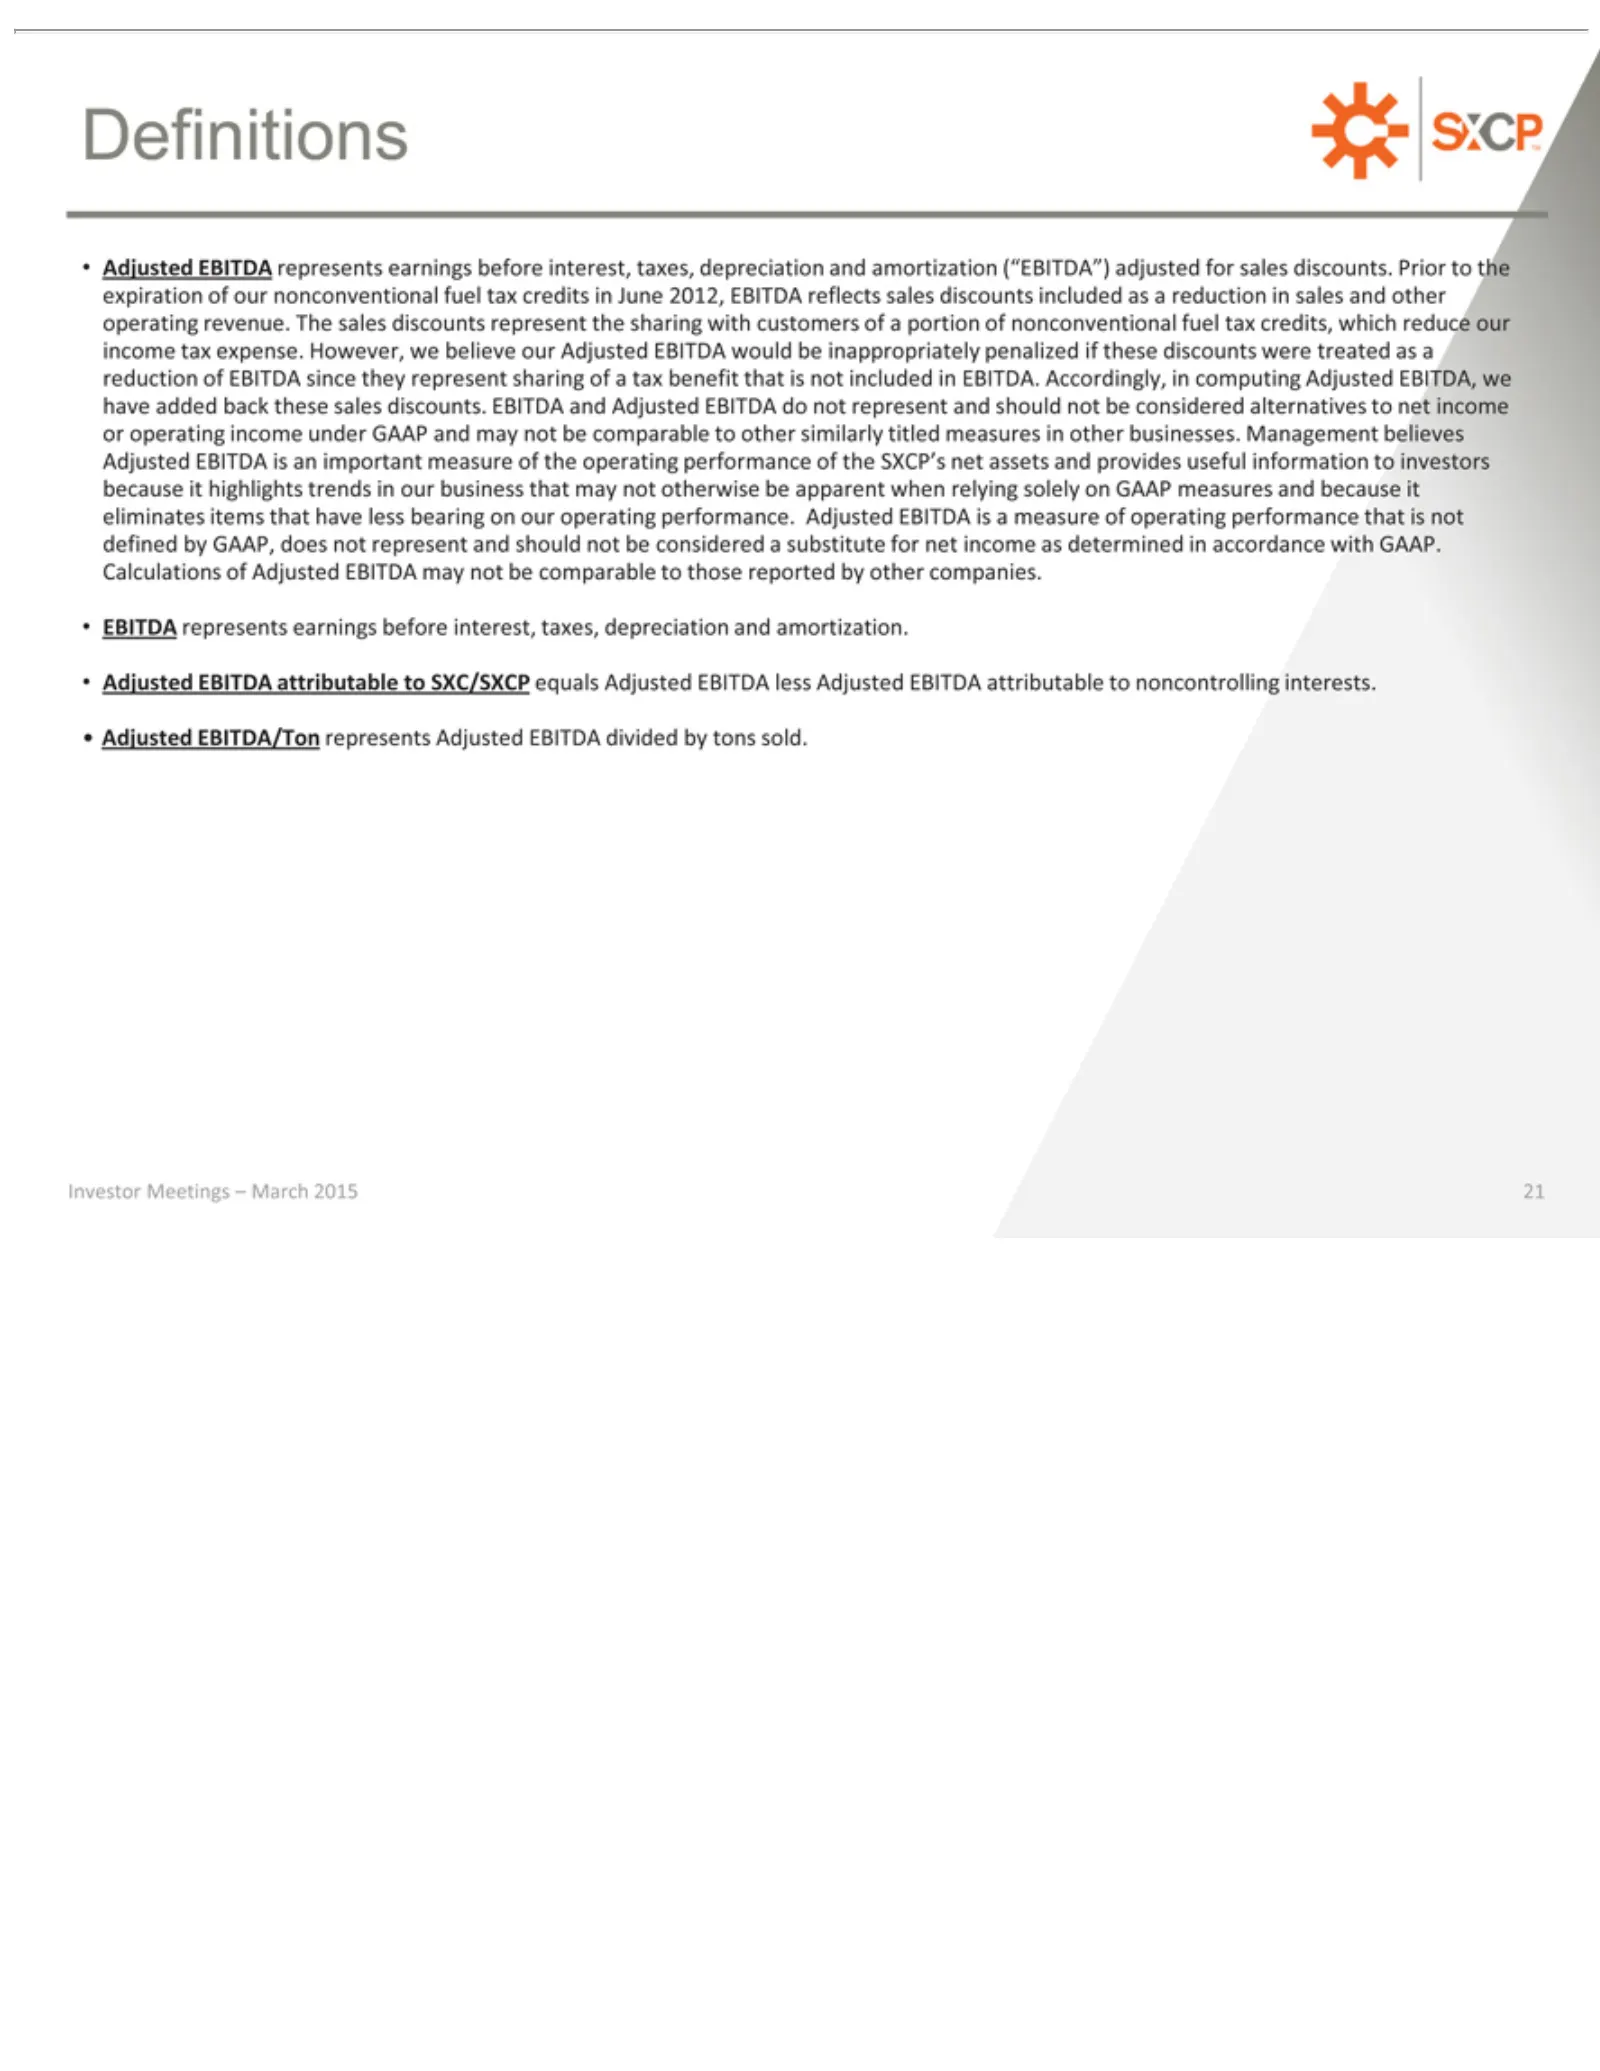
Definitions included or the items income EBITDA Adjusted Investor 21 operating SXCP’s that tax as Meetings in reflects represents EBITDA EBITDA/Ton have determined expense. EBITDA. net income less assets sales –attributable represents bearing earnings March under However, Accordingly, and in discoun
Slide 22: Definitions: Distributable Cash Flow
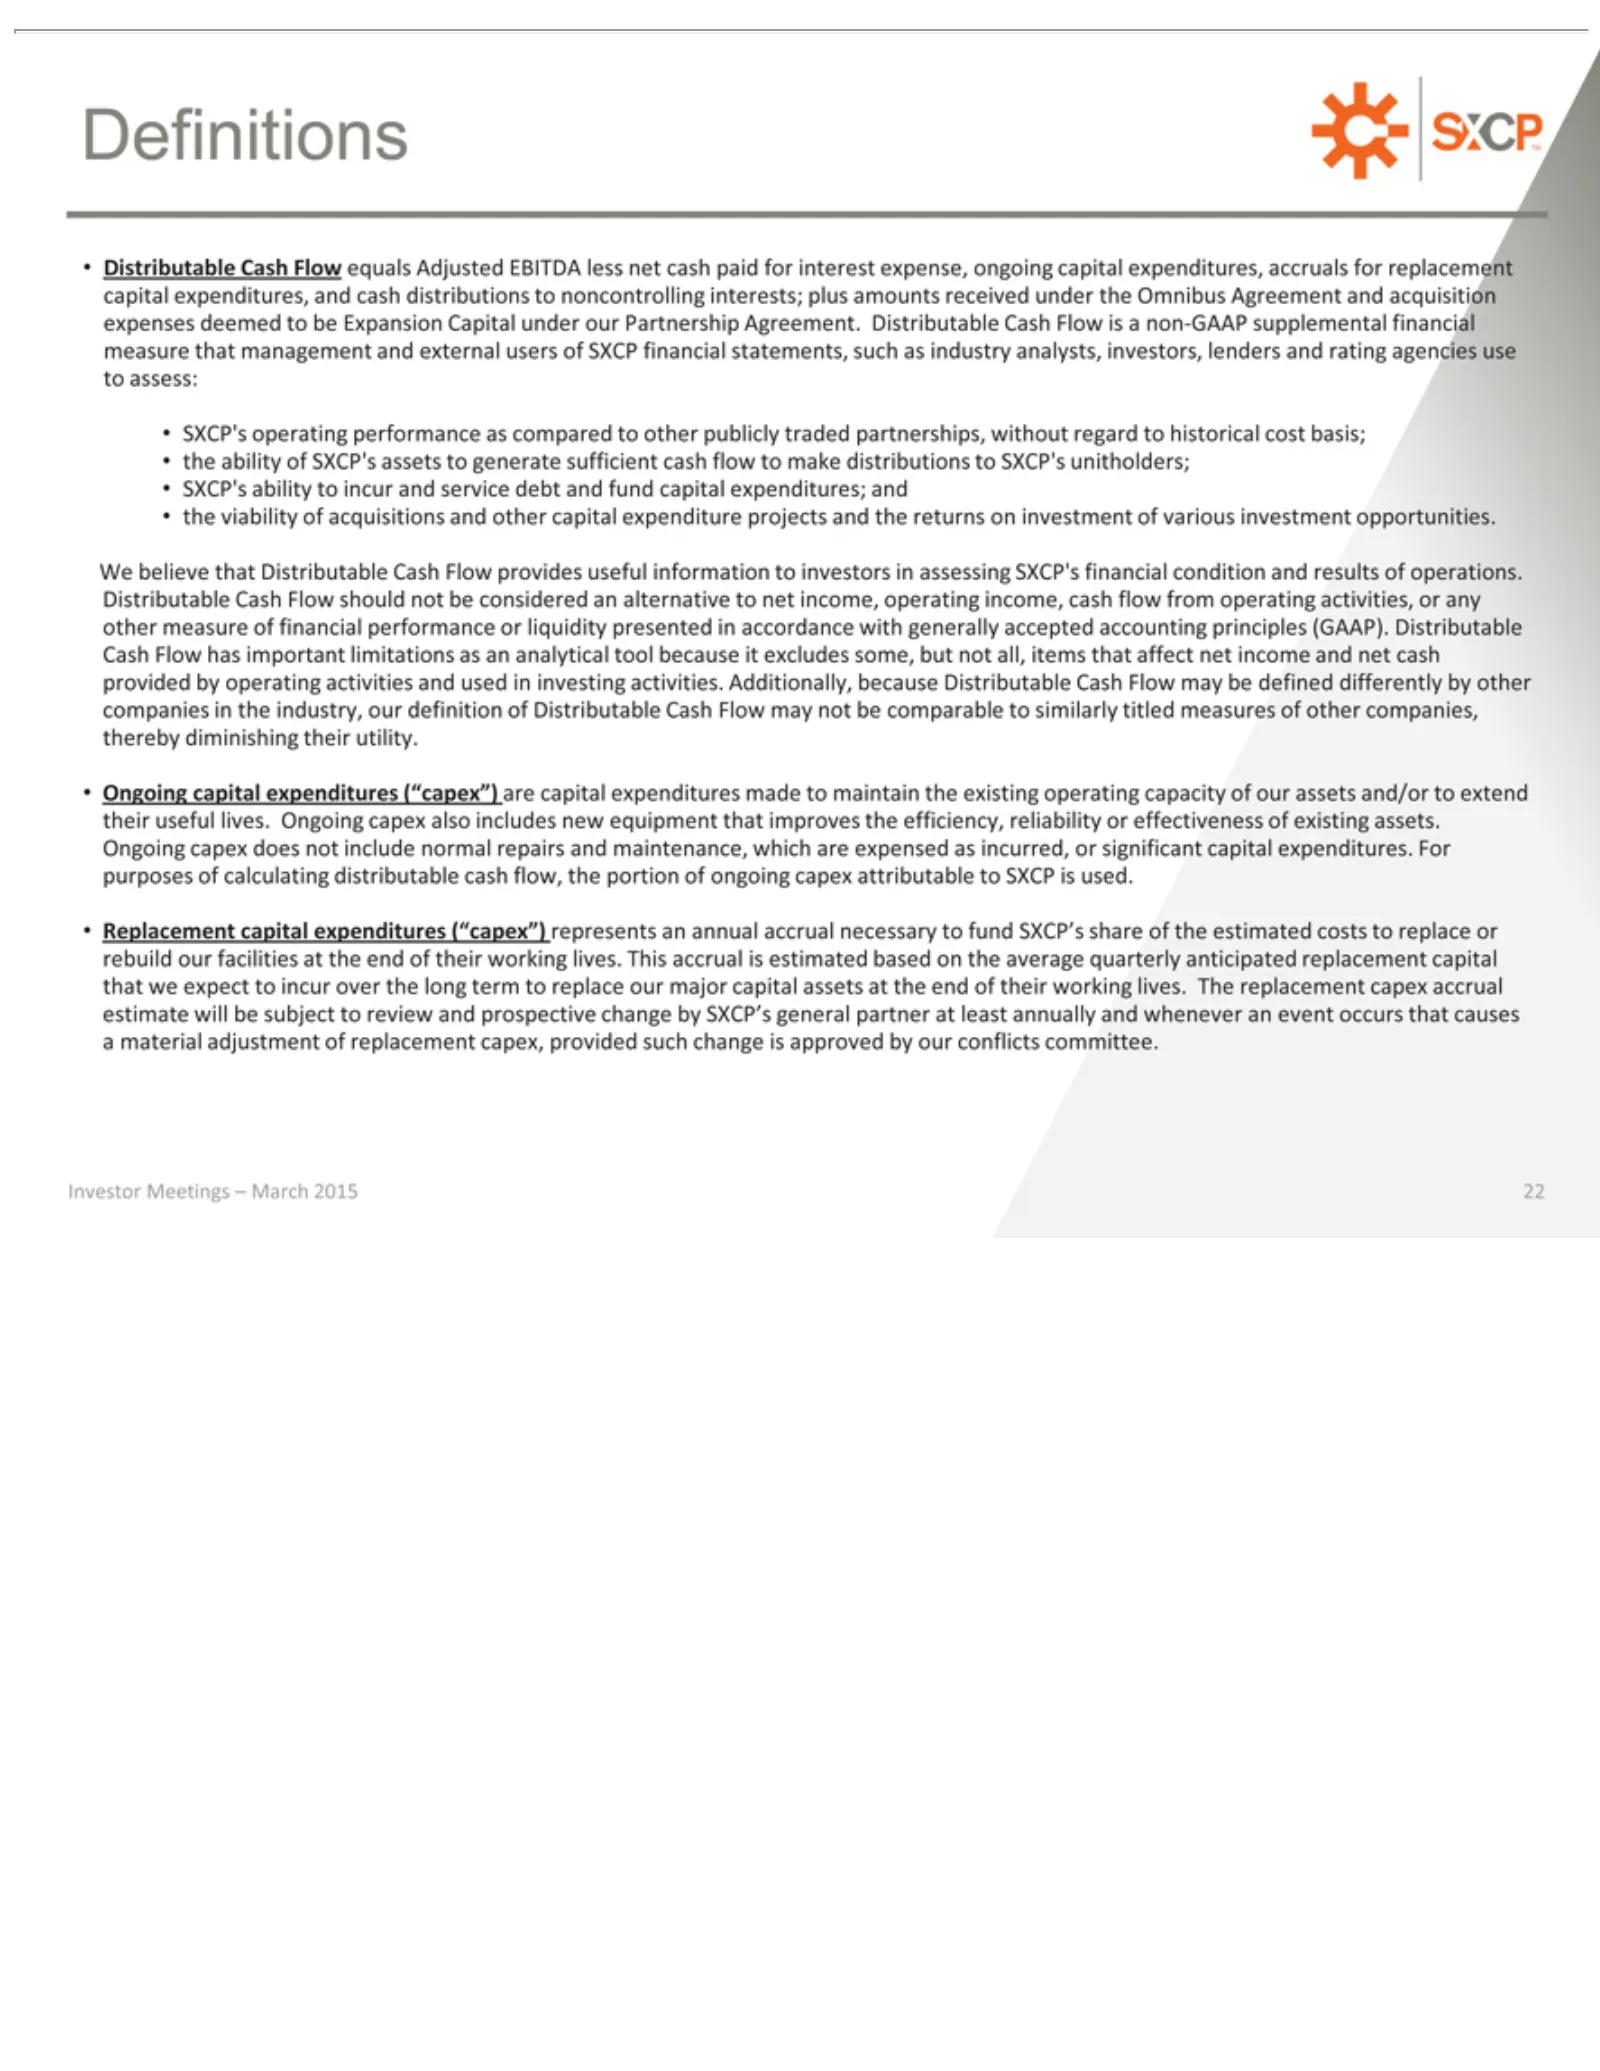
Definitions plus measure SXCP’s unitholders; the We net Distributable Additionally, companies, Ongoing improves of Replacement estimated estimate approved Investor 22 calculating viability income, believe amounts operating ability Meetings that will capital by the based that thereby operating of our
Slide 23: SXCP 2015 Outlook
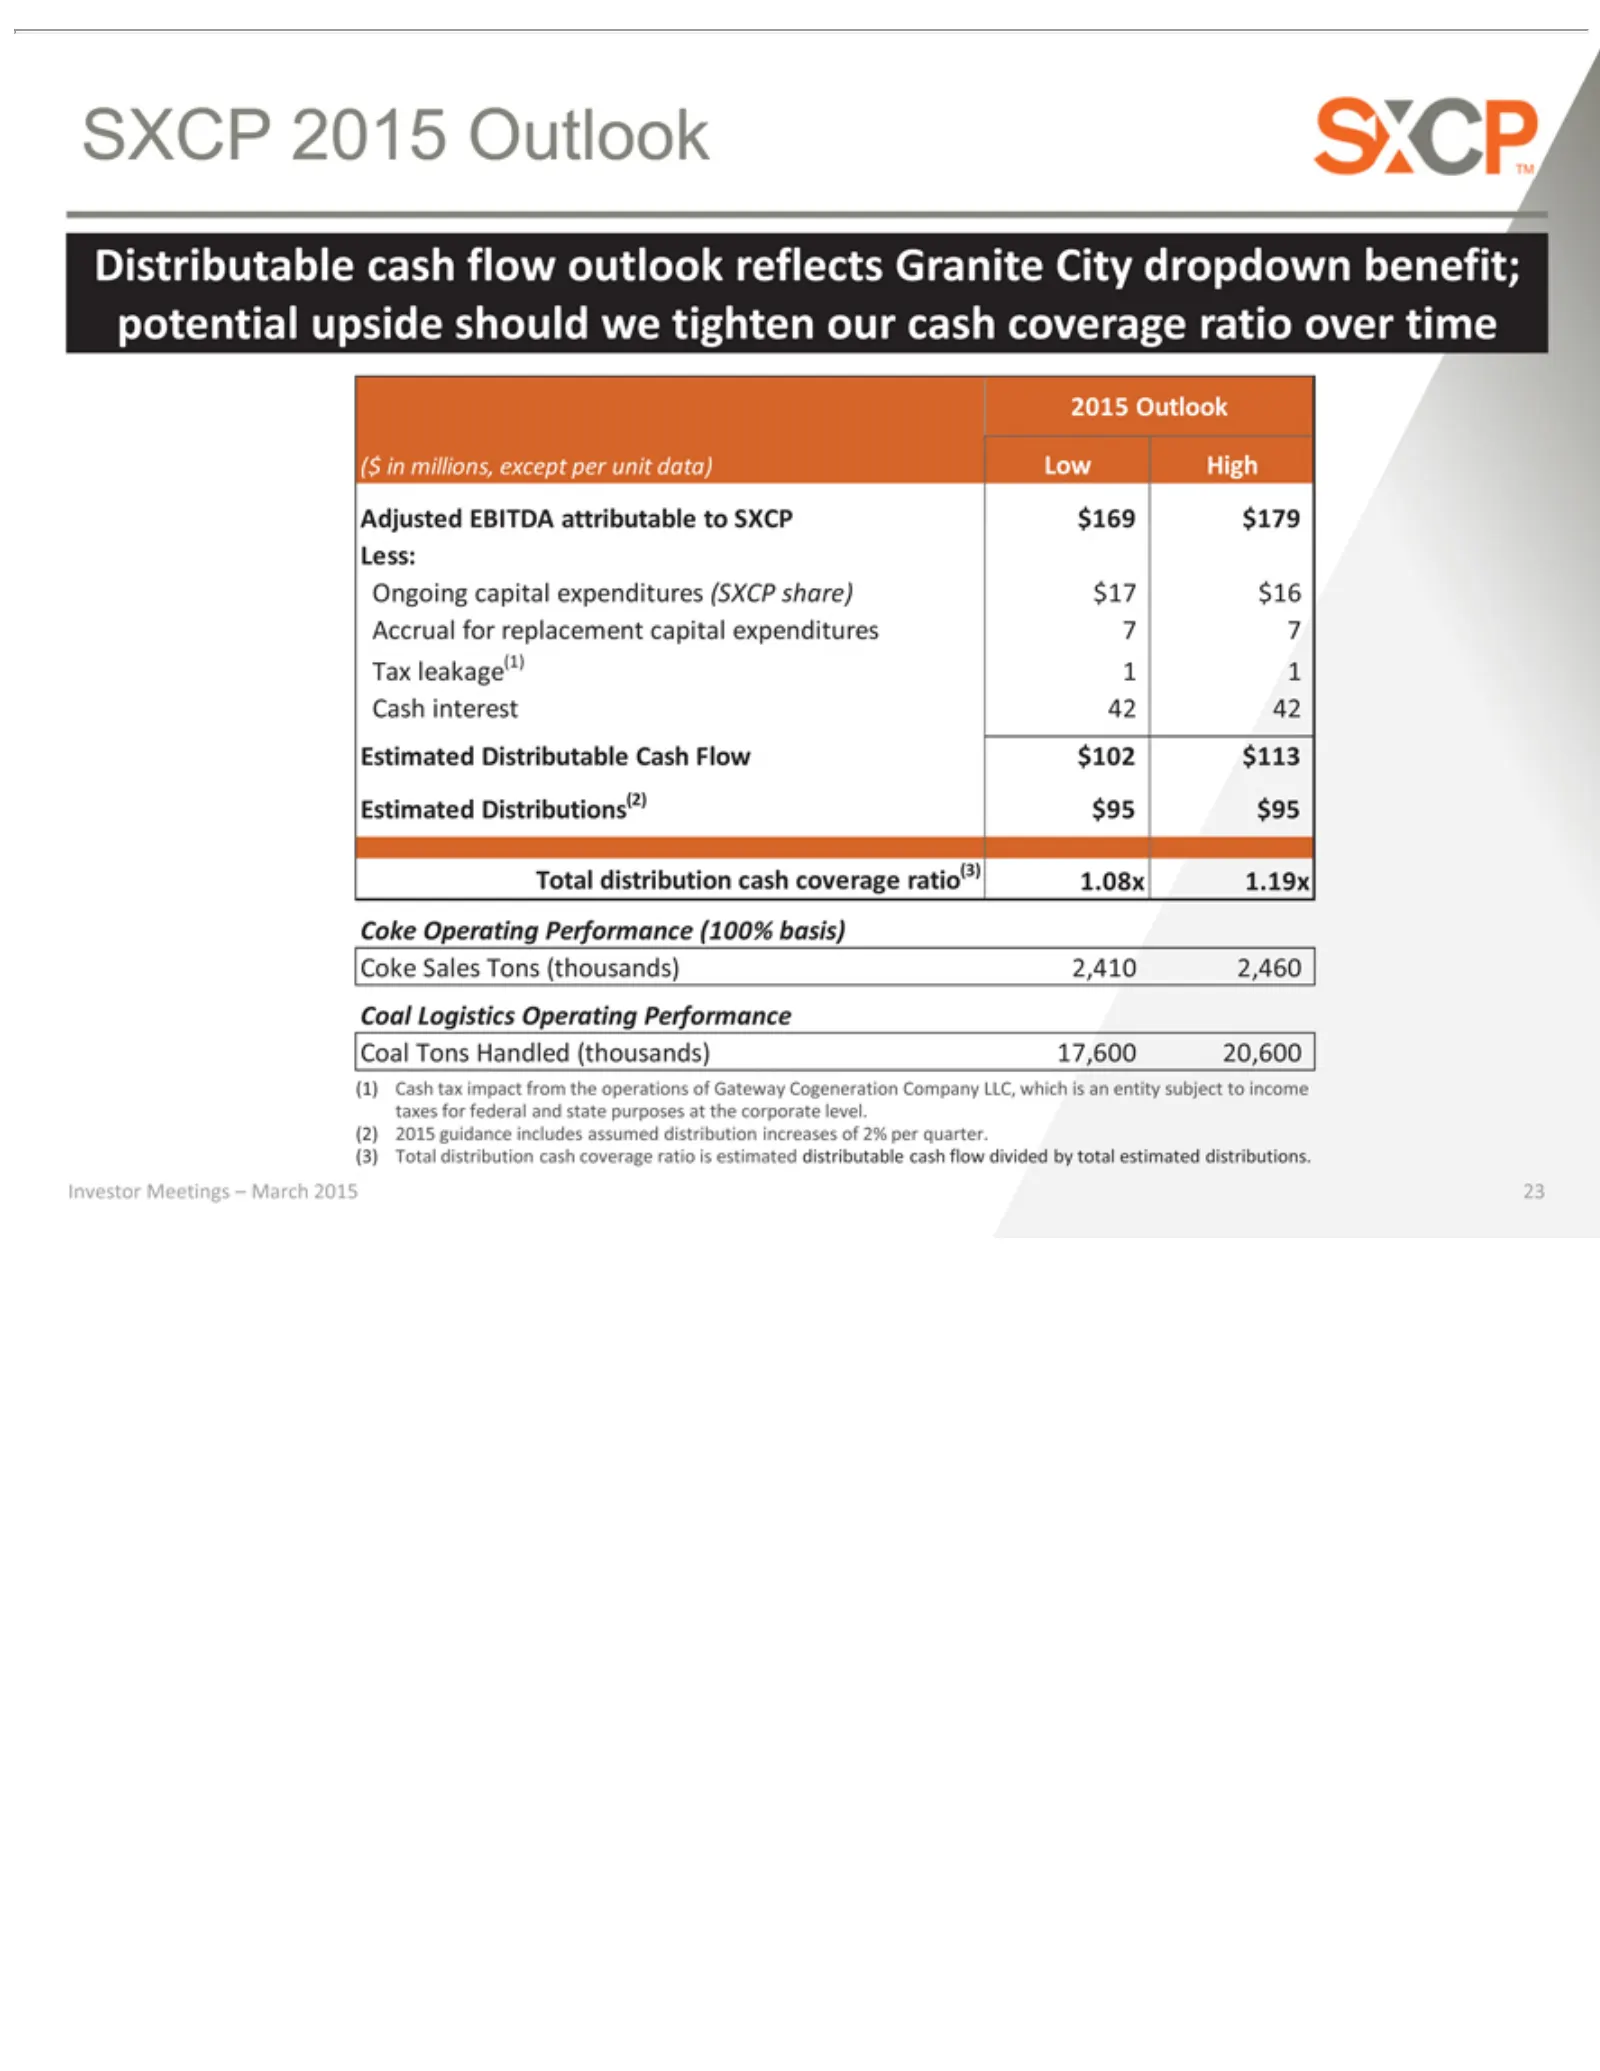
(2) SXCP Distributable 2015 ($ Adjusted Ongoing Estimated Total 1.08x Coke Coal (1) (3)inTotal Cash millions, Tons Logistics Outlook distribution Operating Sales 1.19x Investor 23 2015 2015 tax capital EBITDA Distributable Distributions(2) Handled Tons Outlook impact cash guidance except Operating M
Slide 24: 2015E Adjusted EBITDA Reconciliation
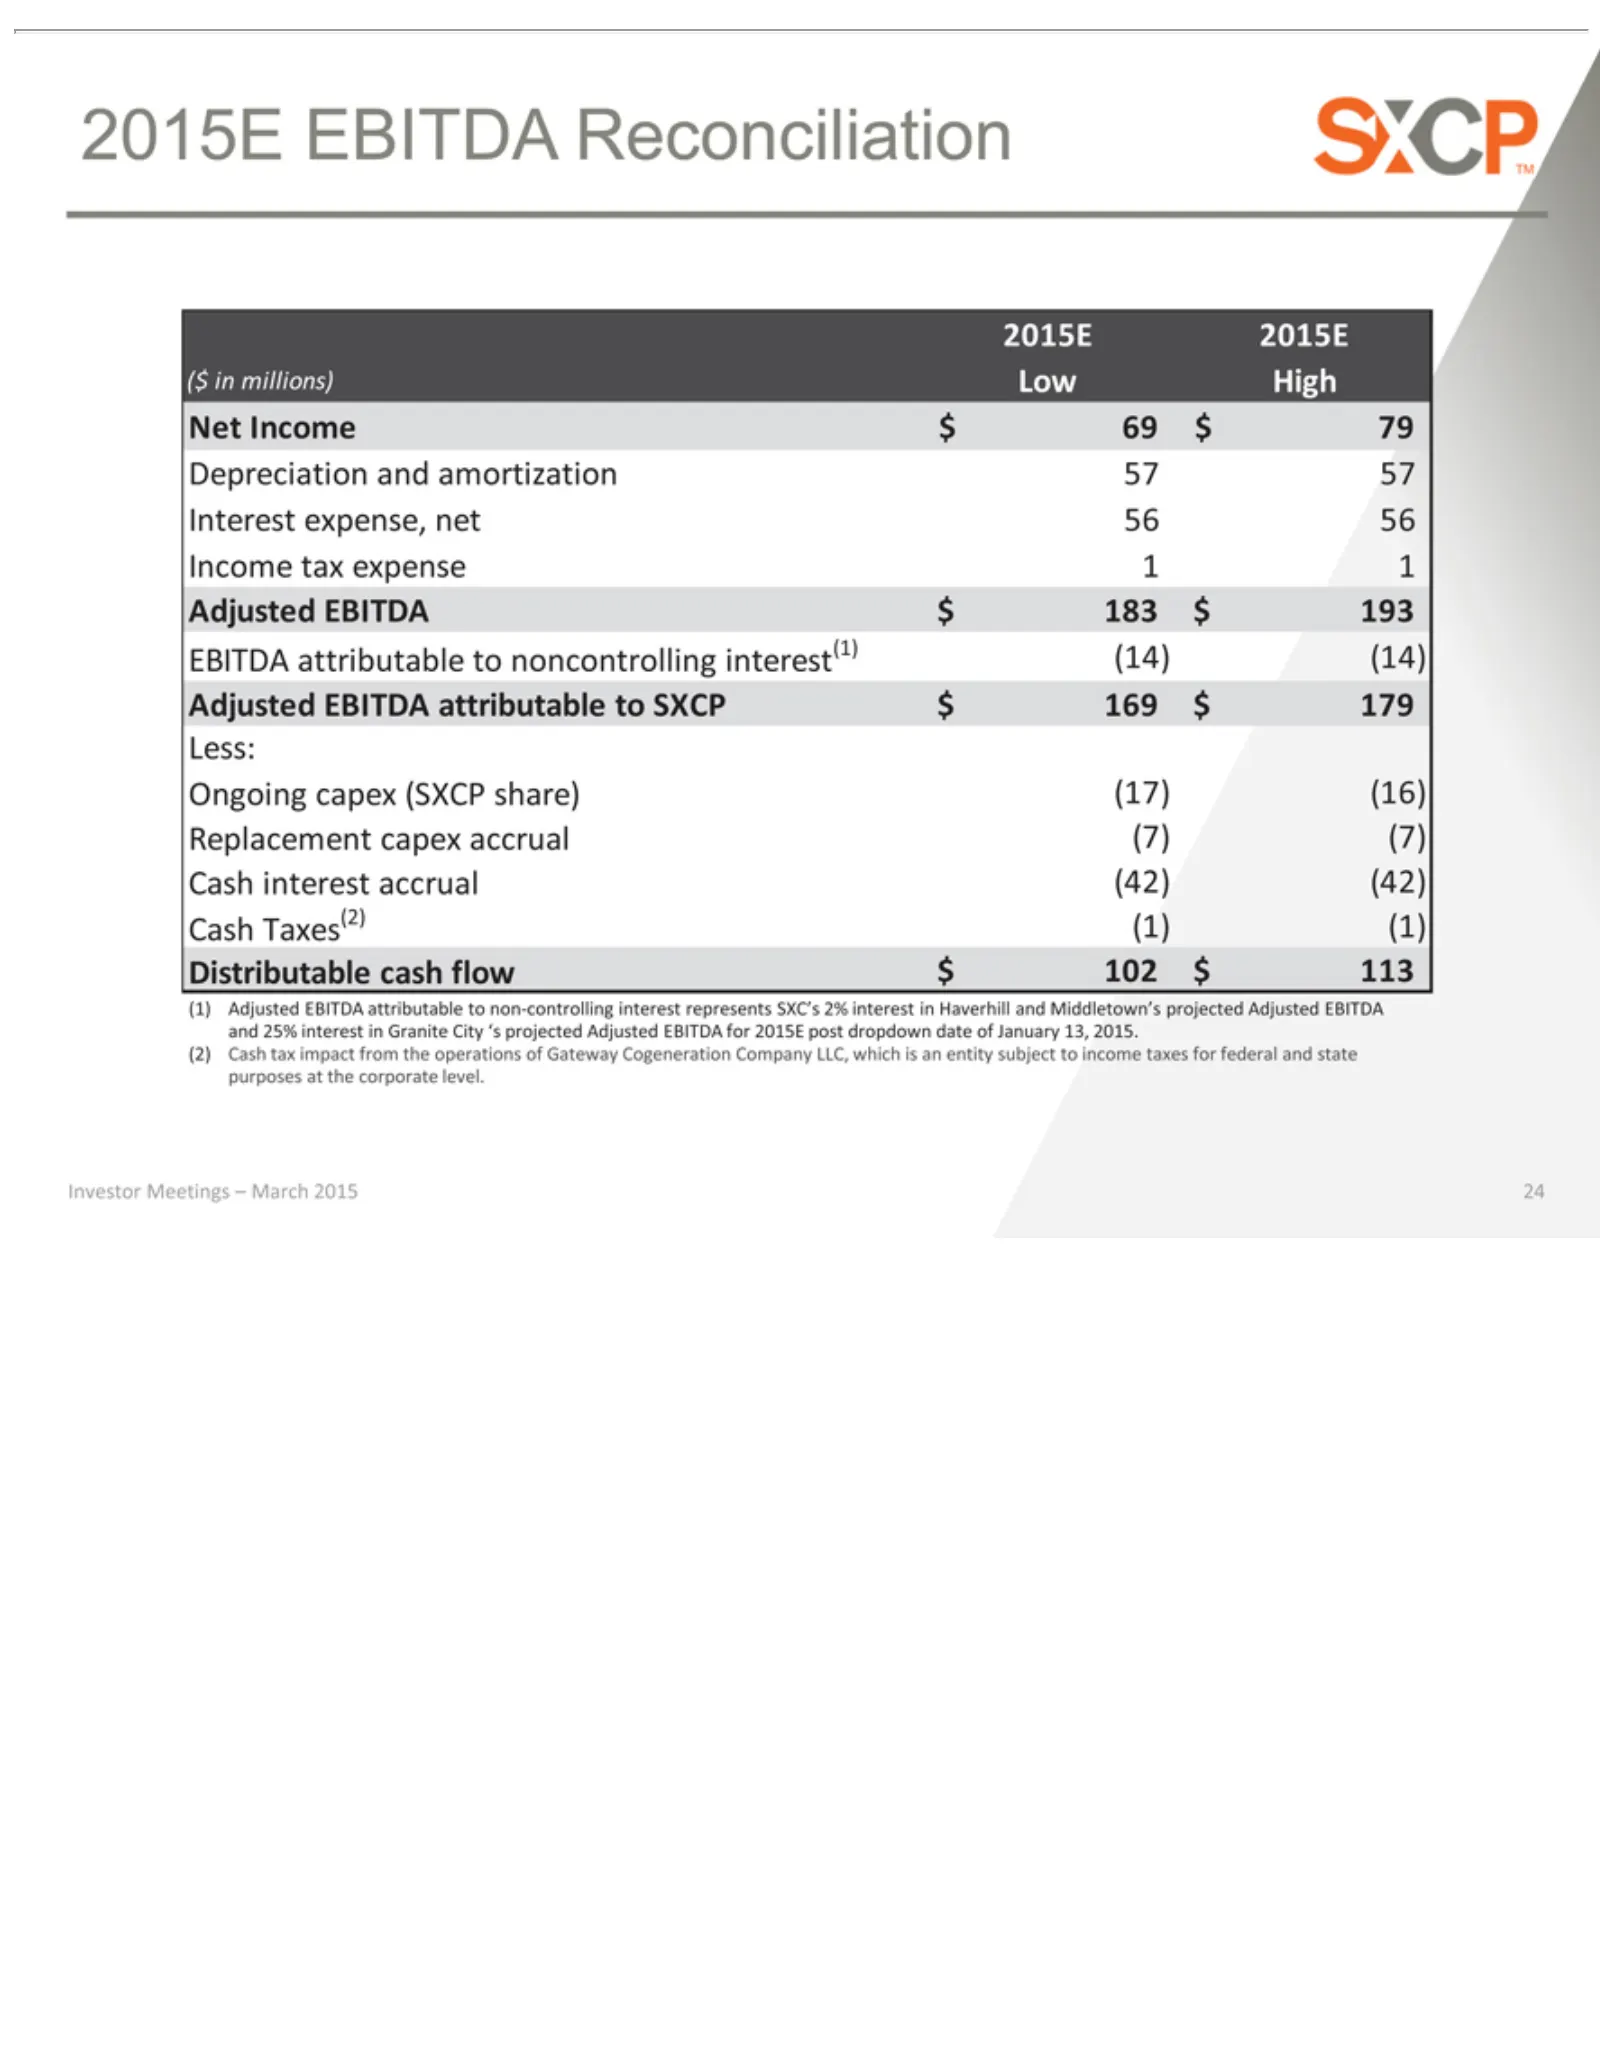
2015E ($ Net Depreciation EBITDA Adjusted Ongoing Less: Distributable (1) for (2) Investor 24 in Adjusted 2015E Cash Income millions) EBITDA 2015E Meetings tax capex attributable EBITDA post $impact EBITDA and cash 69 Low dropdown (SXCP Reconciliation $amortization flow –79 $High attributable from M
Slide 25: SXC Reconciliations & 2015 Guidance
SXC RECONCILIATIONS Investor 25 Meetings – March 2015 & 2015 GUIDANCE
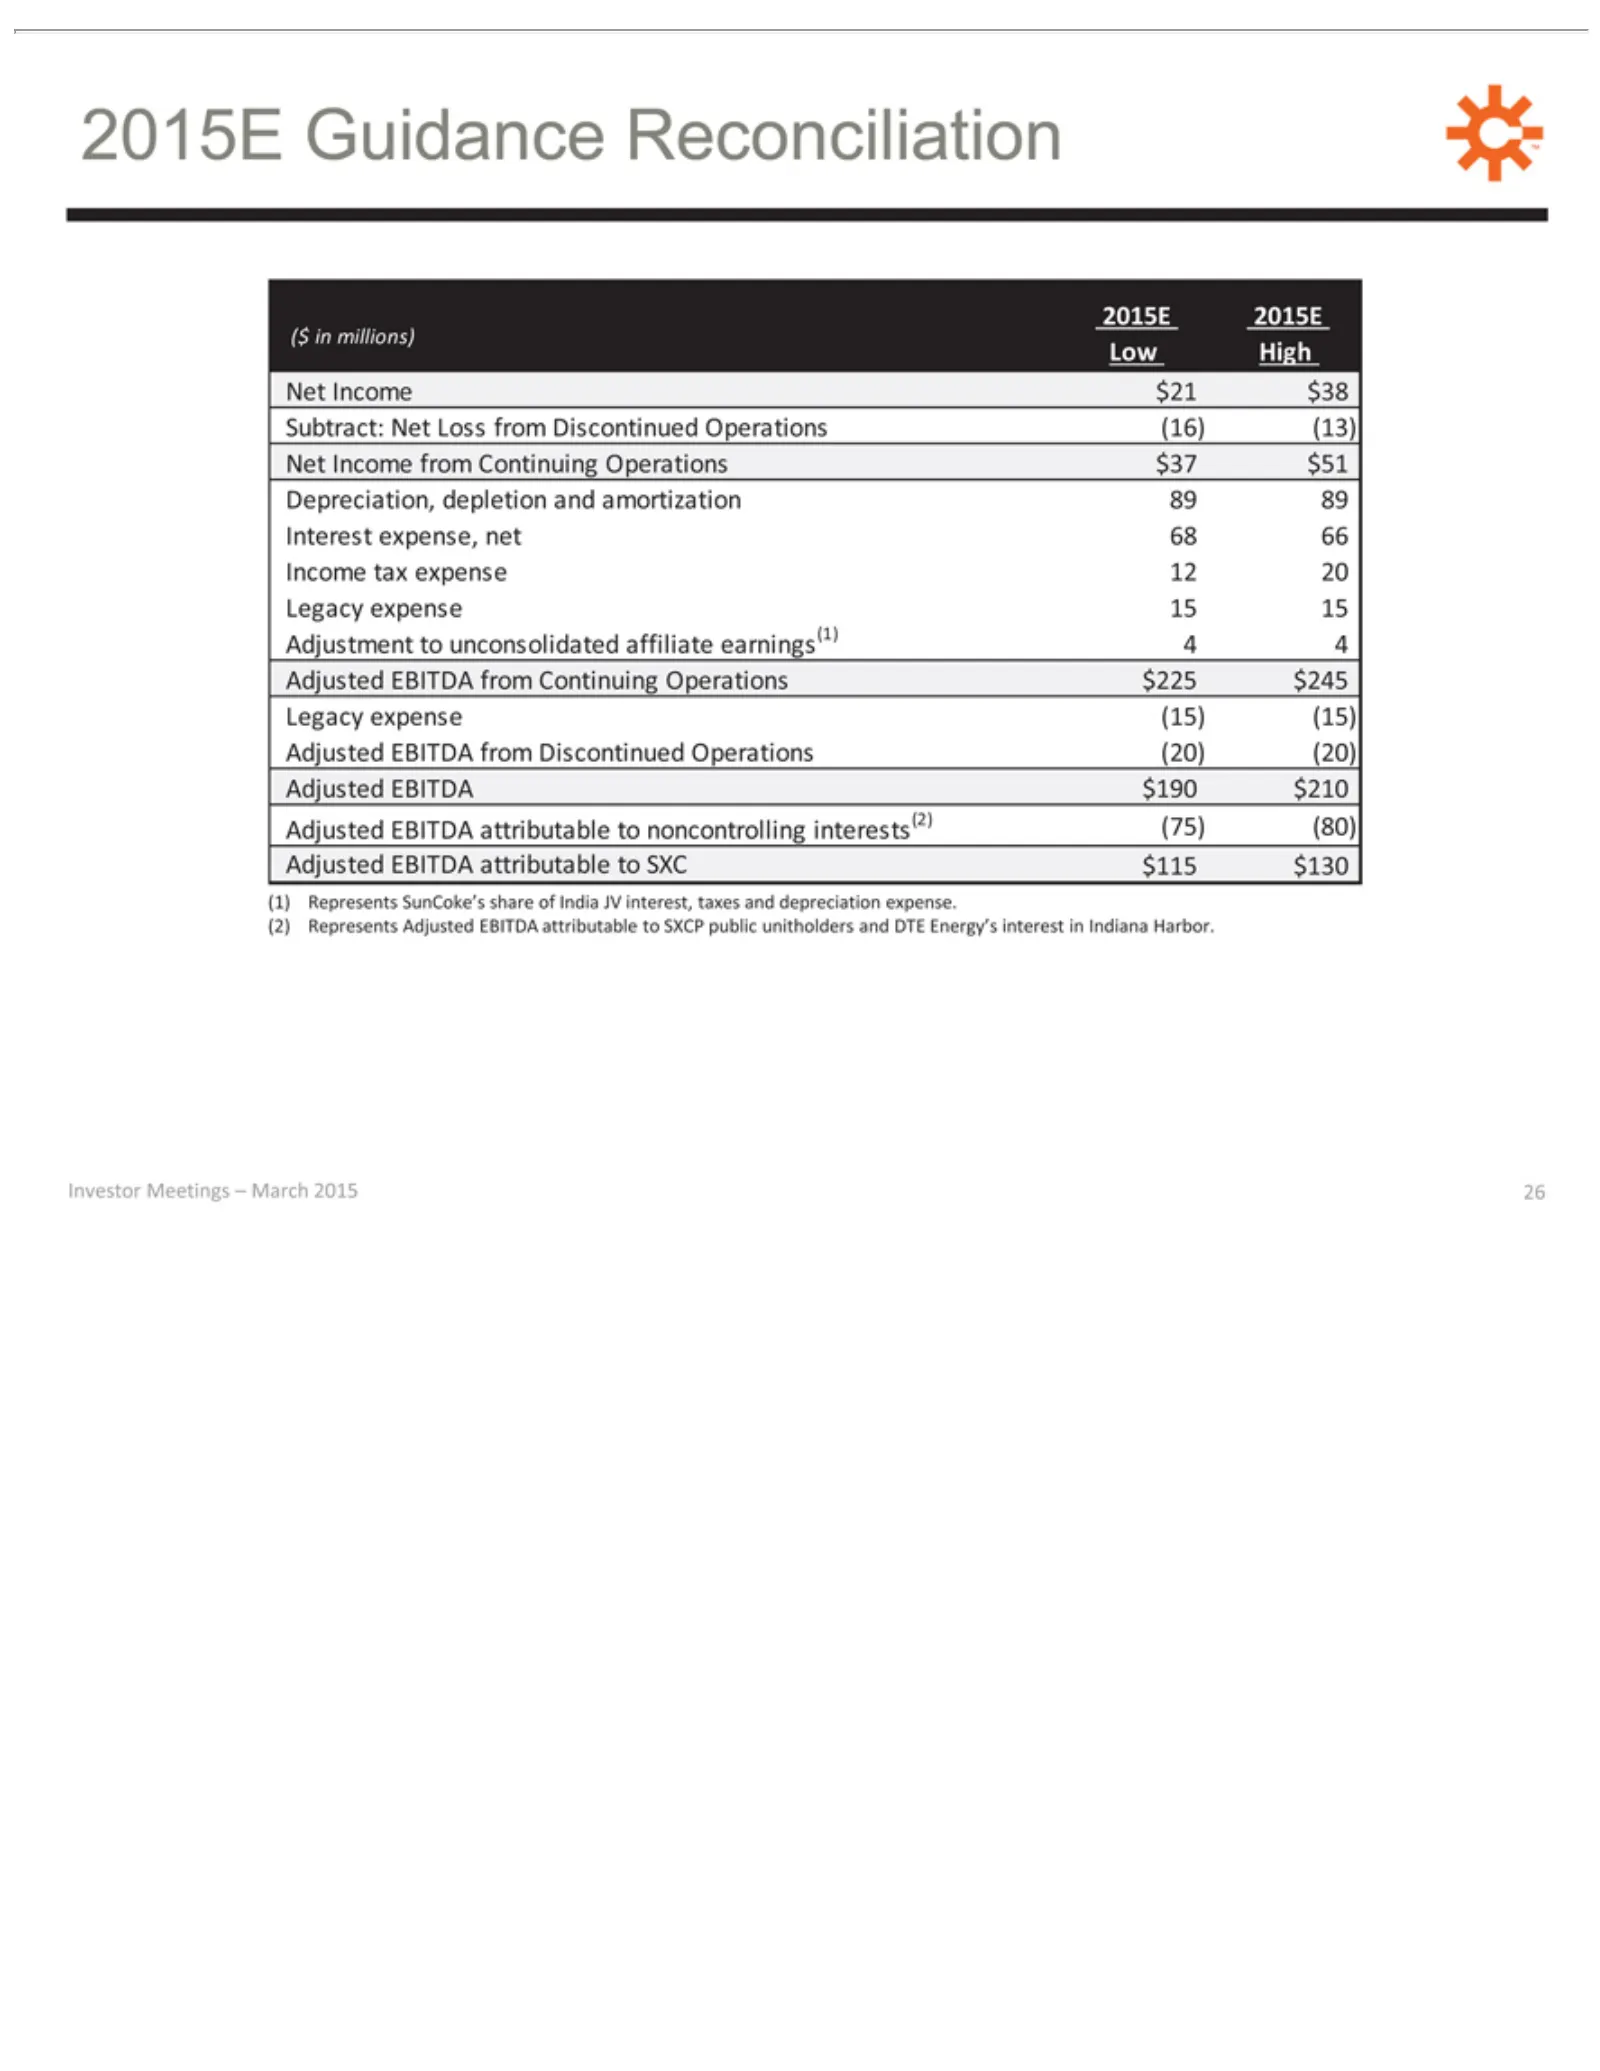
Slide 26: SXC 2015E Guidance Reconciliation
(1) 2015E ($ Low Net expense (2)in(75) Income High millions) Investor 26 Guidance 2015E Adjustment $190 12 $210 20 (80)$21 to Legacy $38 Reconciliation Adjusted Represents Meetings Subtract: expense unconsolidated SunCoke’s EBITDA – Adjusted March Net 15 15 Loss affiliate share from IndiatoDiscontin
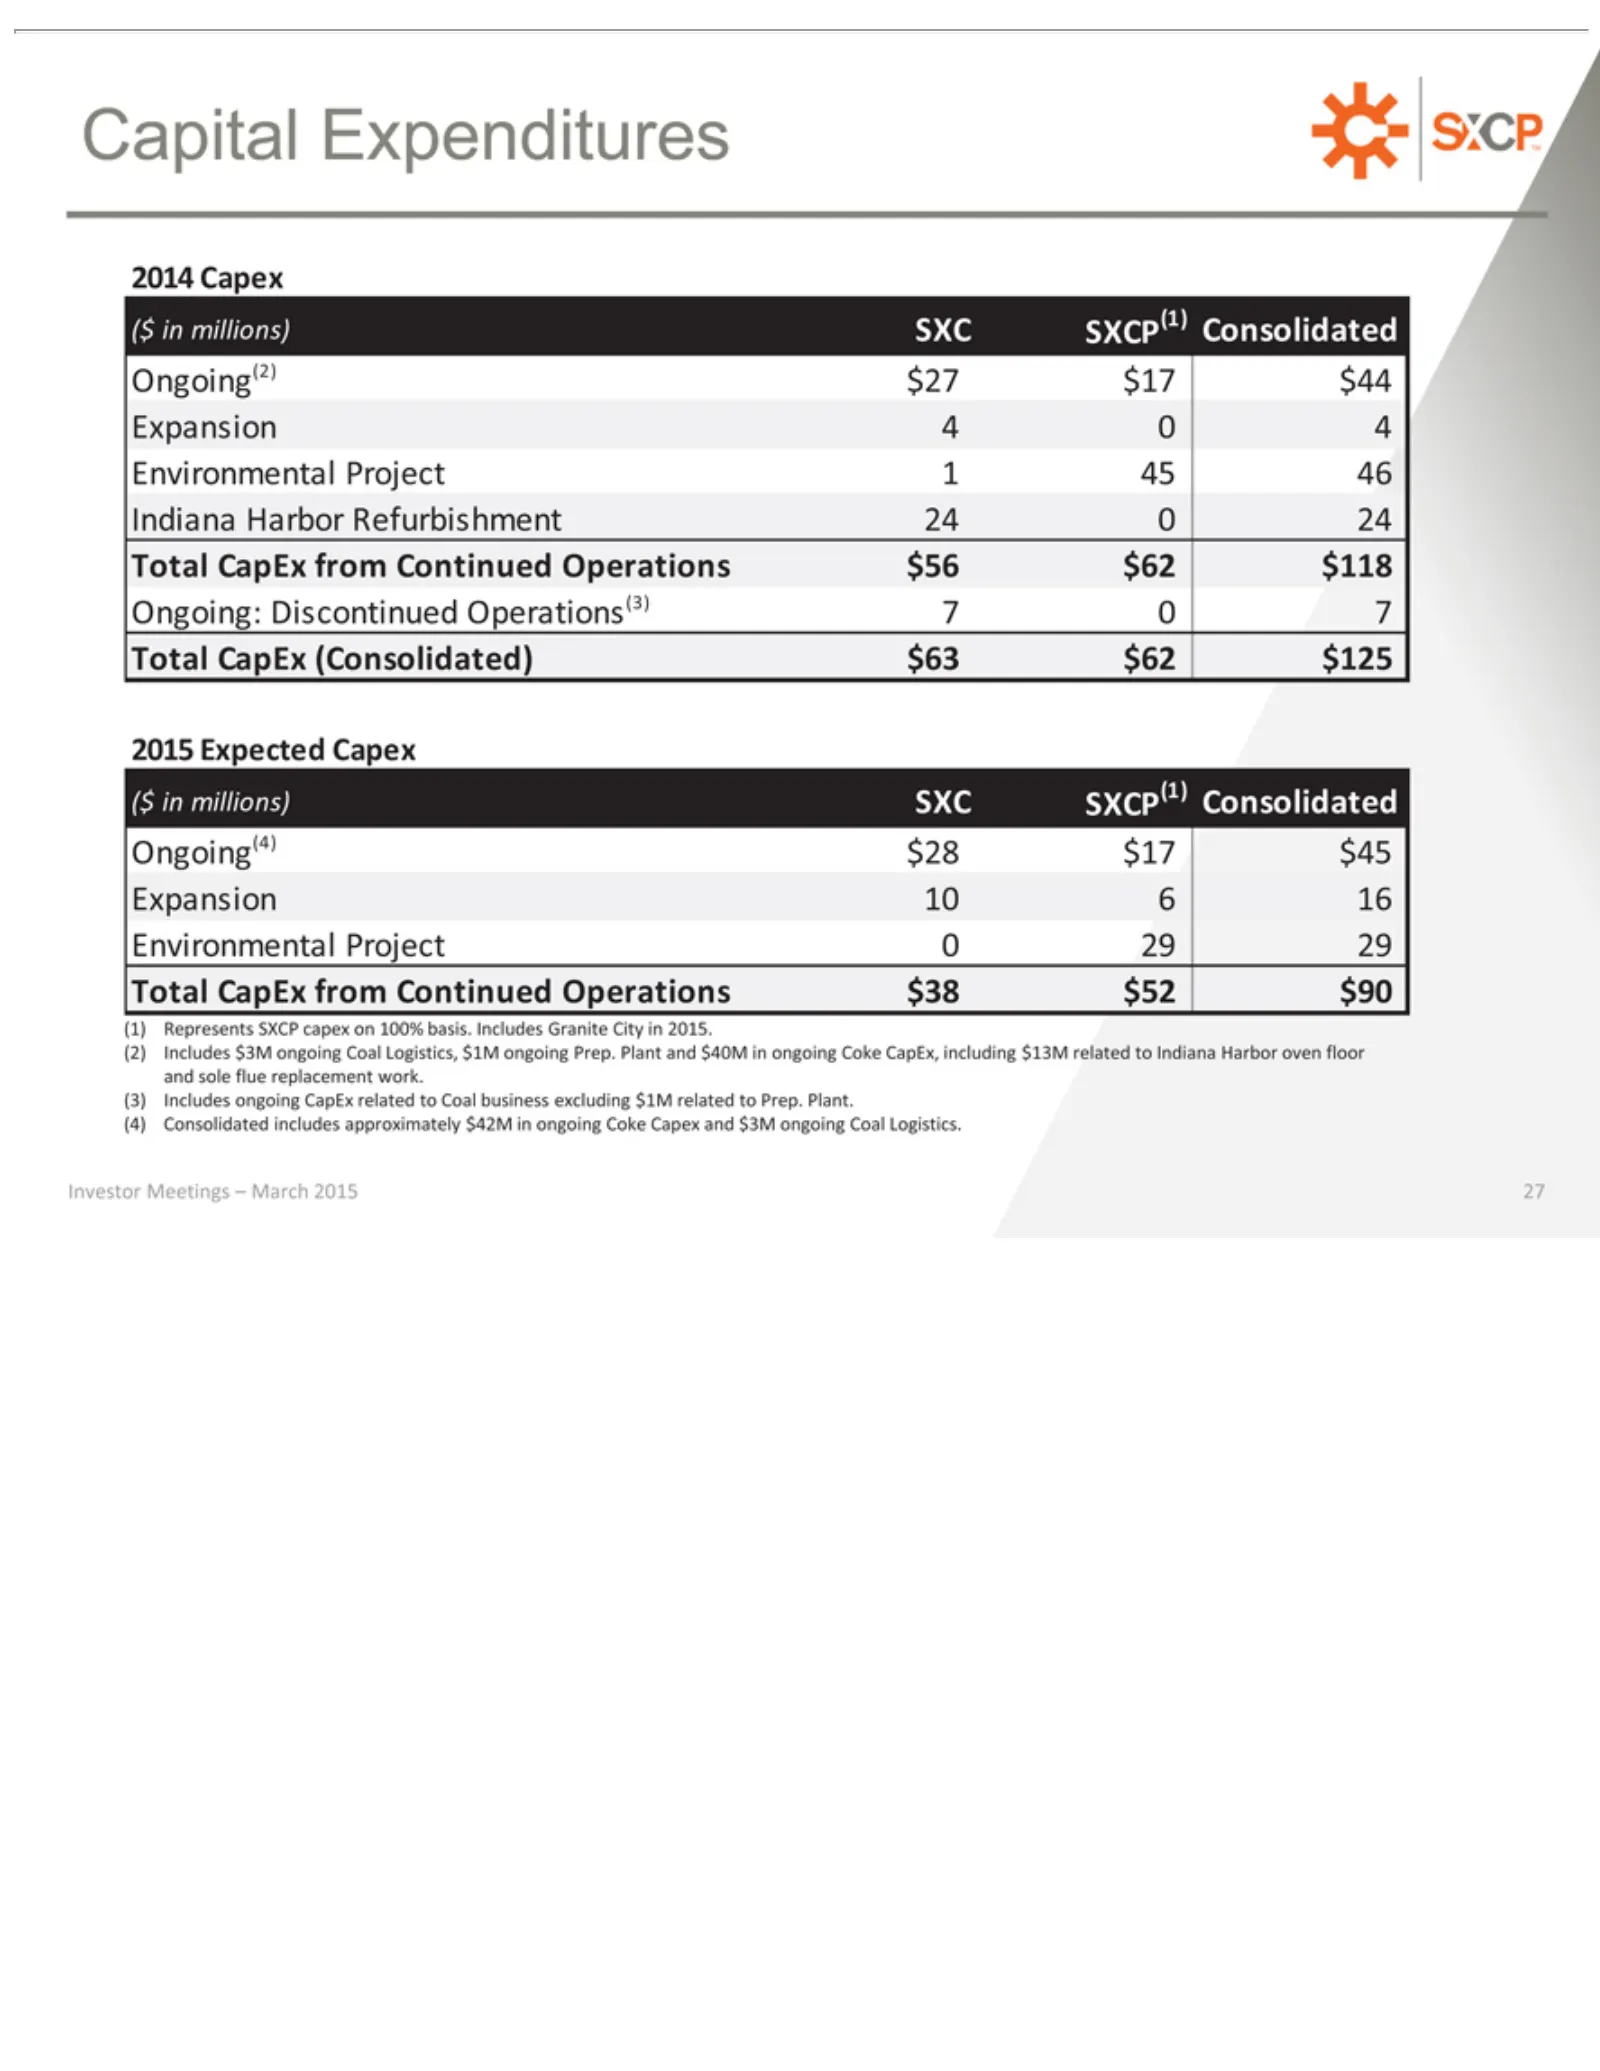
Slide 27: Capital Expenditures
(1) Capital 2014 ($ (2) (3) (4) Capex Ongoing: 2015 Investor 27 Expenditures Ongoing(2) Expected Ongoing(4) Total Discontinued inIncludes $27 (Consolidated) millions) CapEx Includes $3M Capex Represents $28 from SXC $17 $44 ongoing Consolidated Meetings Operations(3) Continued – SXCP $45 $63 CapEx C
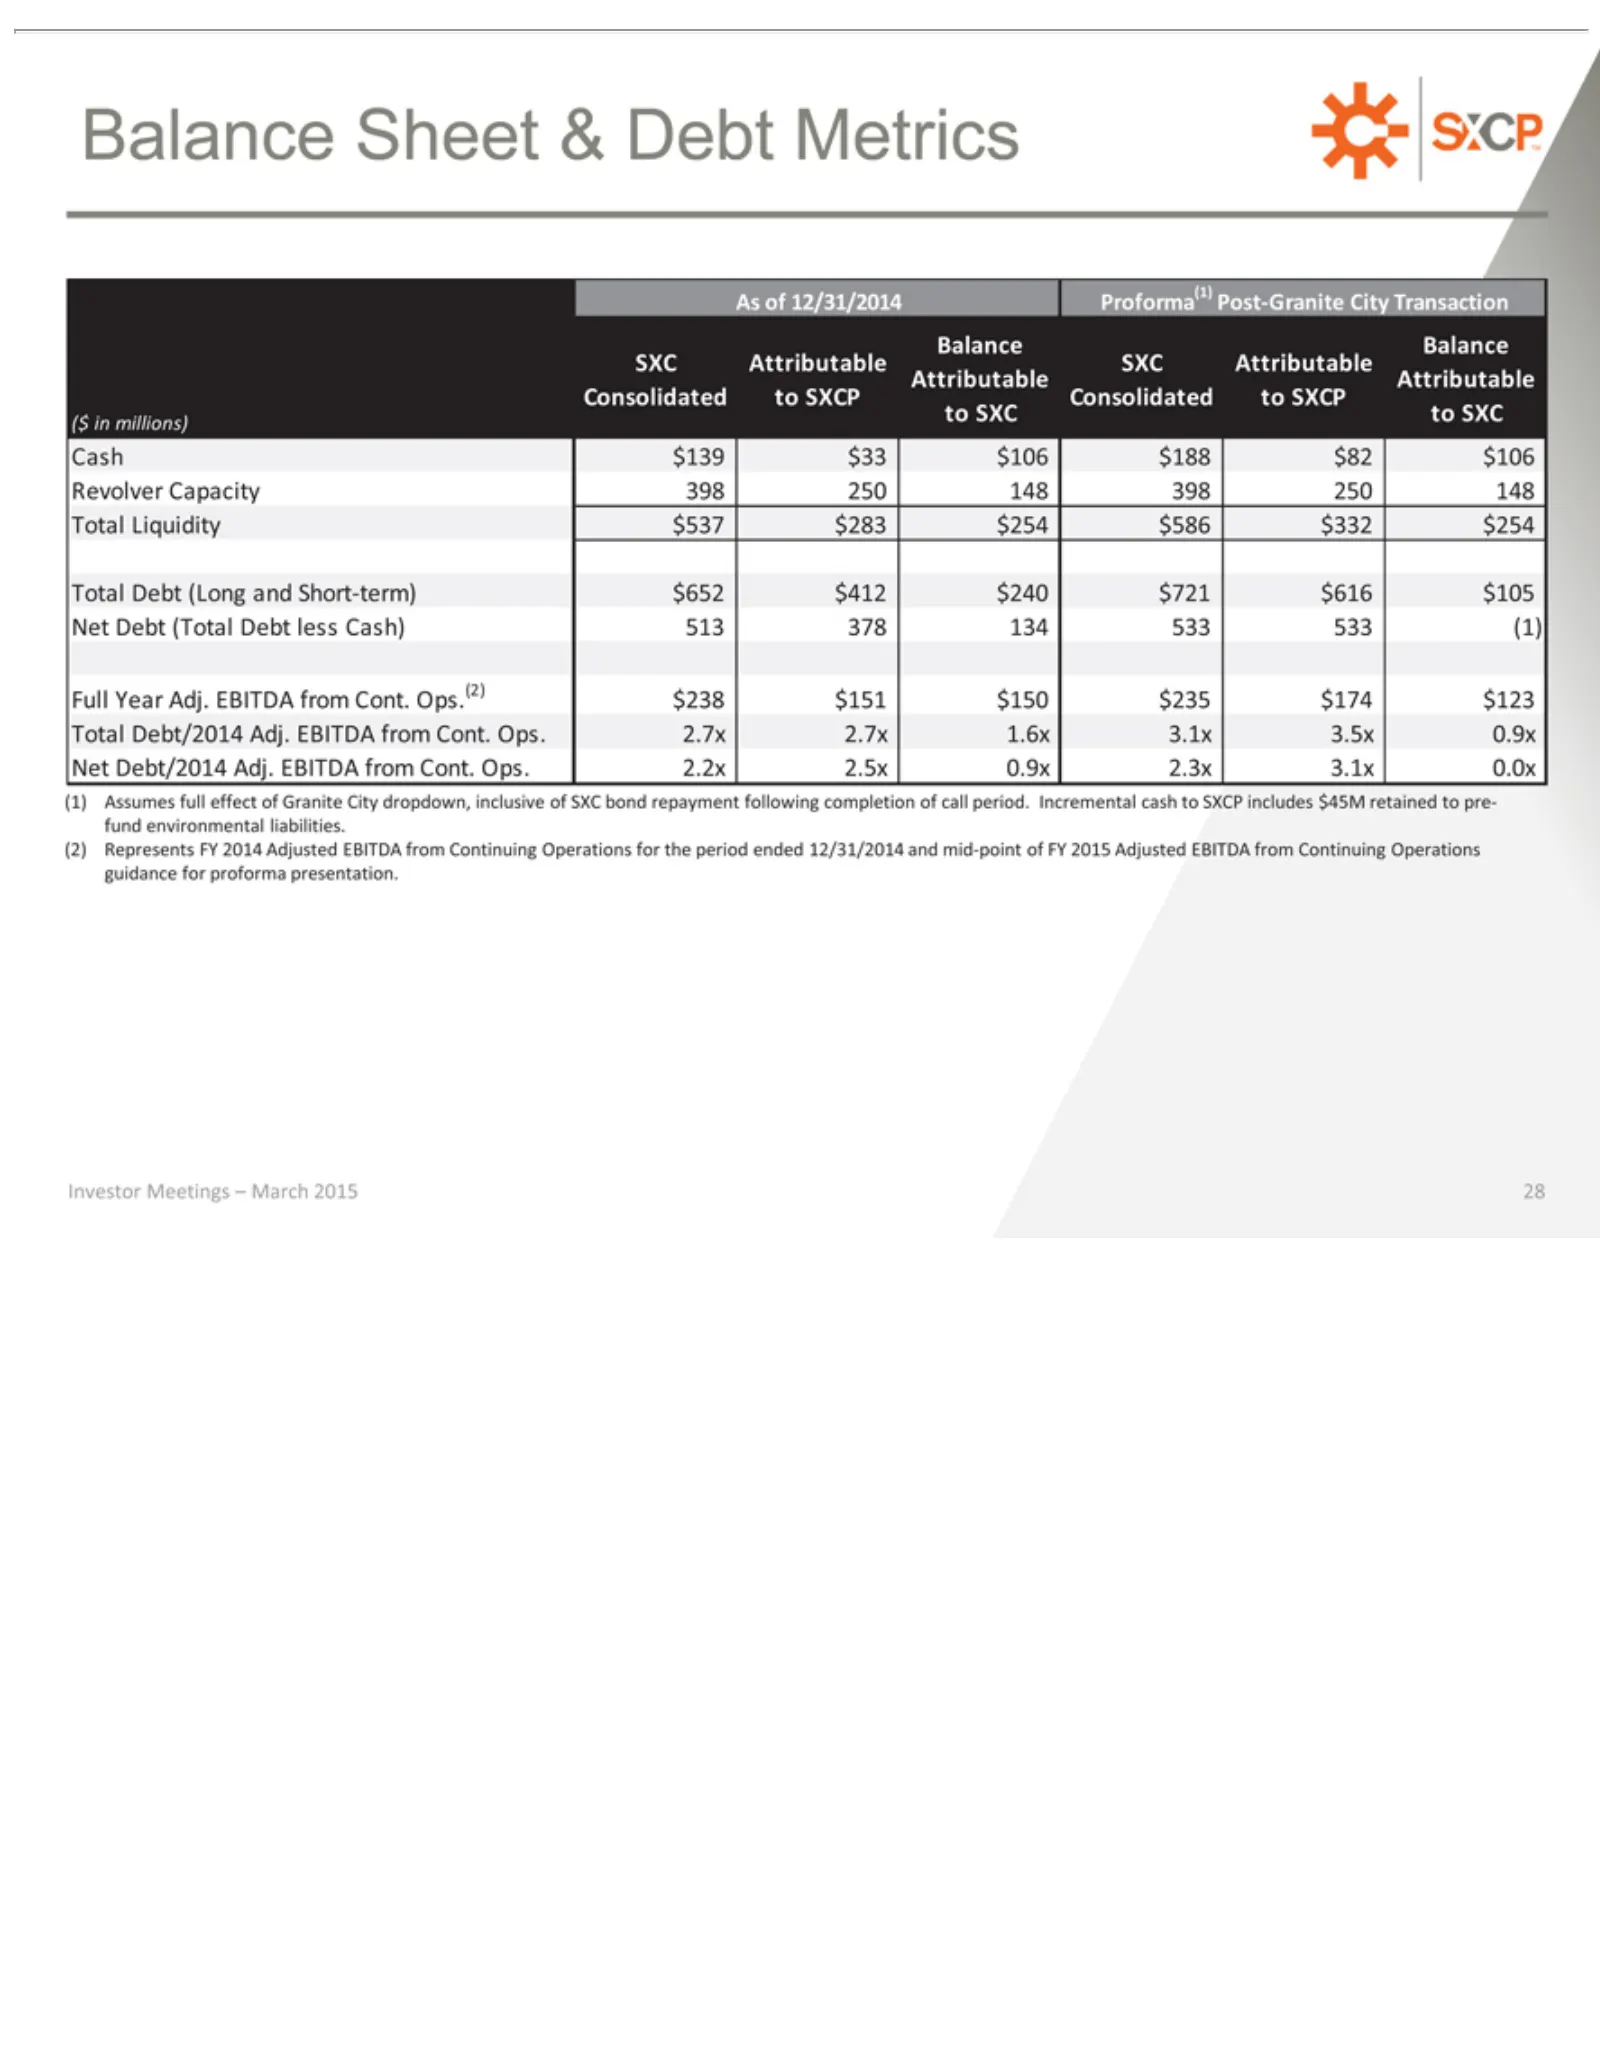
Slide 28: Balance Sheet
(1) Balance Asin SXC ($ Cash Total Full 2.3x (2) of Investor 28 Sheet millions) Assumes Represents Year 3.1x & Attributable $139 Debt 12/31/2014 (Long $33 Meetings Adj. 0.0x full Debt $106 and EBITDA FY effect –2014Metrics Balance Proforma $188 Short-term) March SXC $82 offromPost-Granite Adjusted$1
Slide 29: Additional Information About SunCoke, Our Technology and Coke Demand
ADDITIONAL AND Investor 29 COKE Meetings DEMAND INFORMATION – March 2015 ABOUT SUNCOKE, OUR TECHNOLOGY
Slide 30: SXC/SXCP Organizational Structure
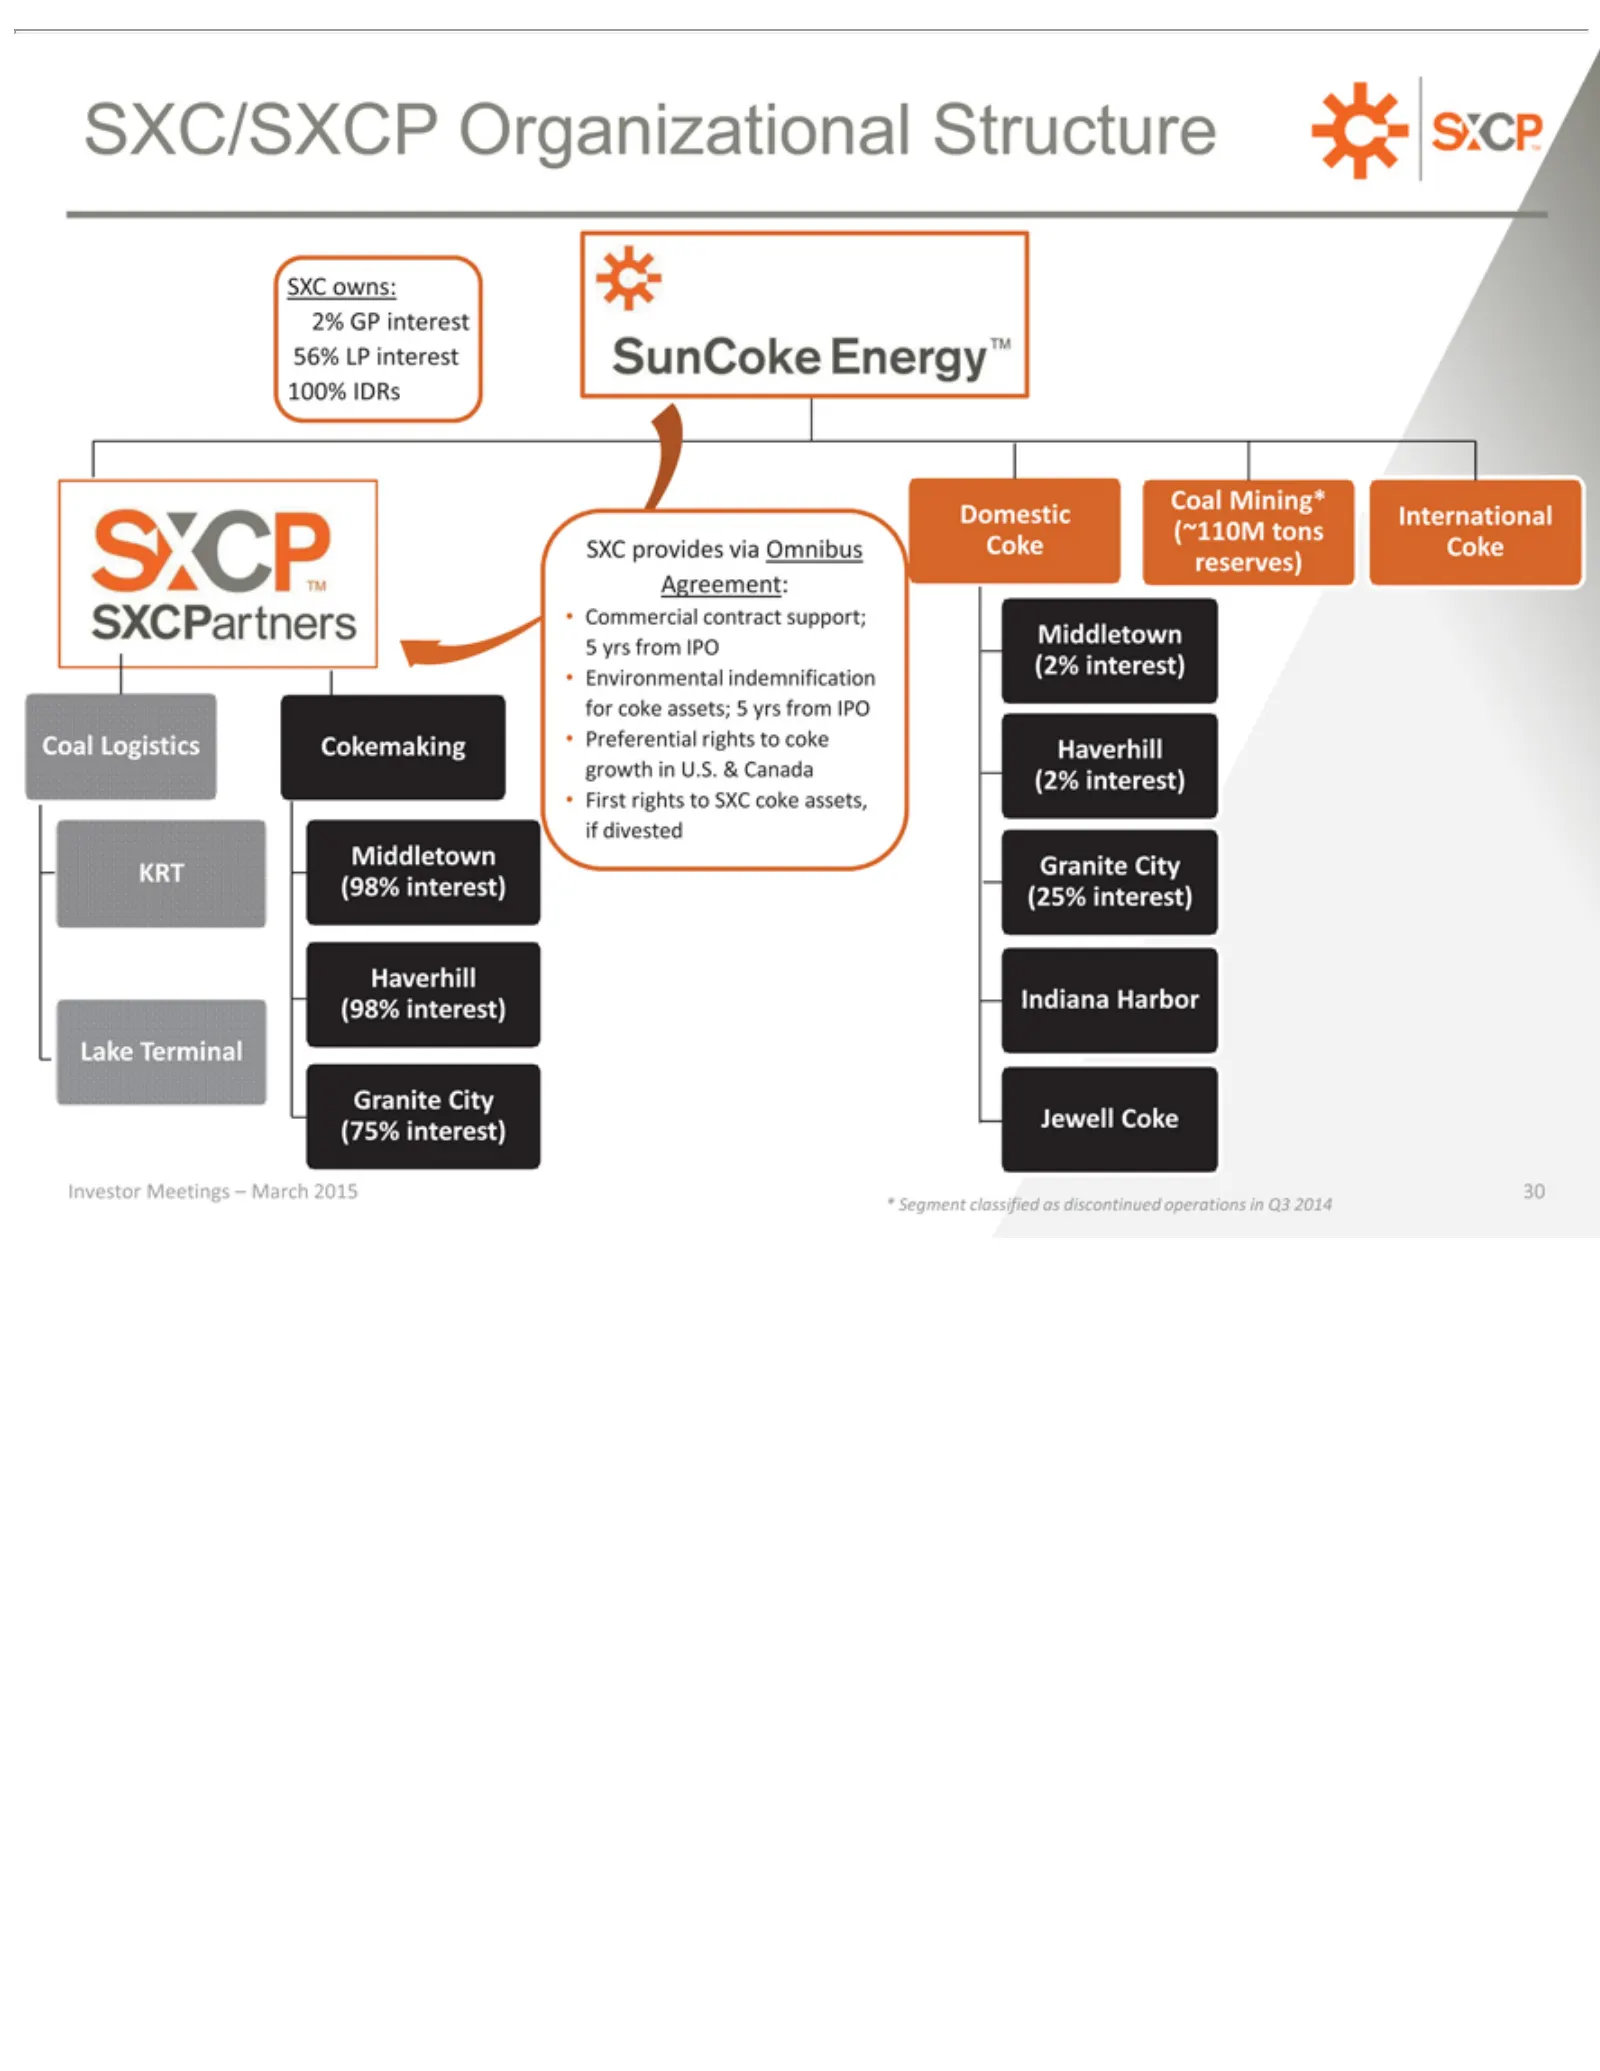
SXC/SXCP 2% 56% 100% (98% Haverhill Investor Coal Domestic SXC Commercial 5Agreement: Middletown Environmental Preferential (2% First Granite (25% Indiana *Jewell 30yrsGP Segment interest) LP rights Logistics Mining* owns: provides from interest) IDRs Coke interest City Harbor interest Meetings (98%
Slide 31: SunCoke's Industry-Leading Cokemaking Technology
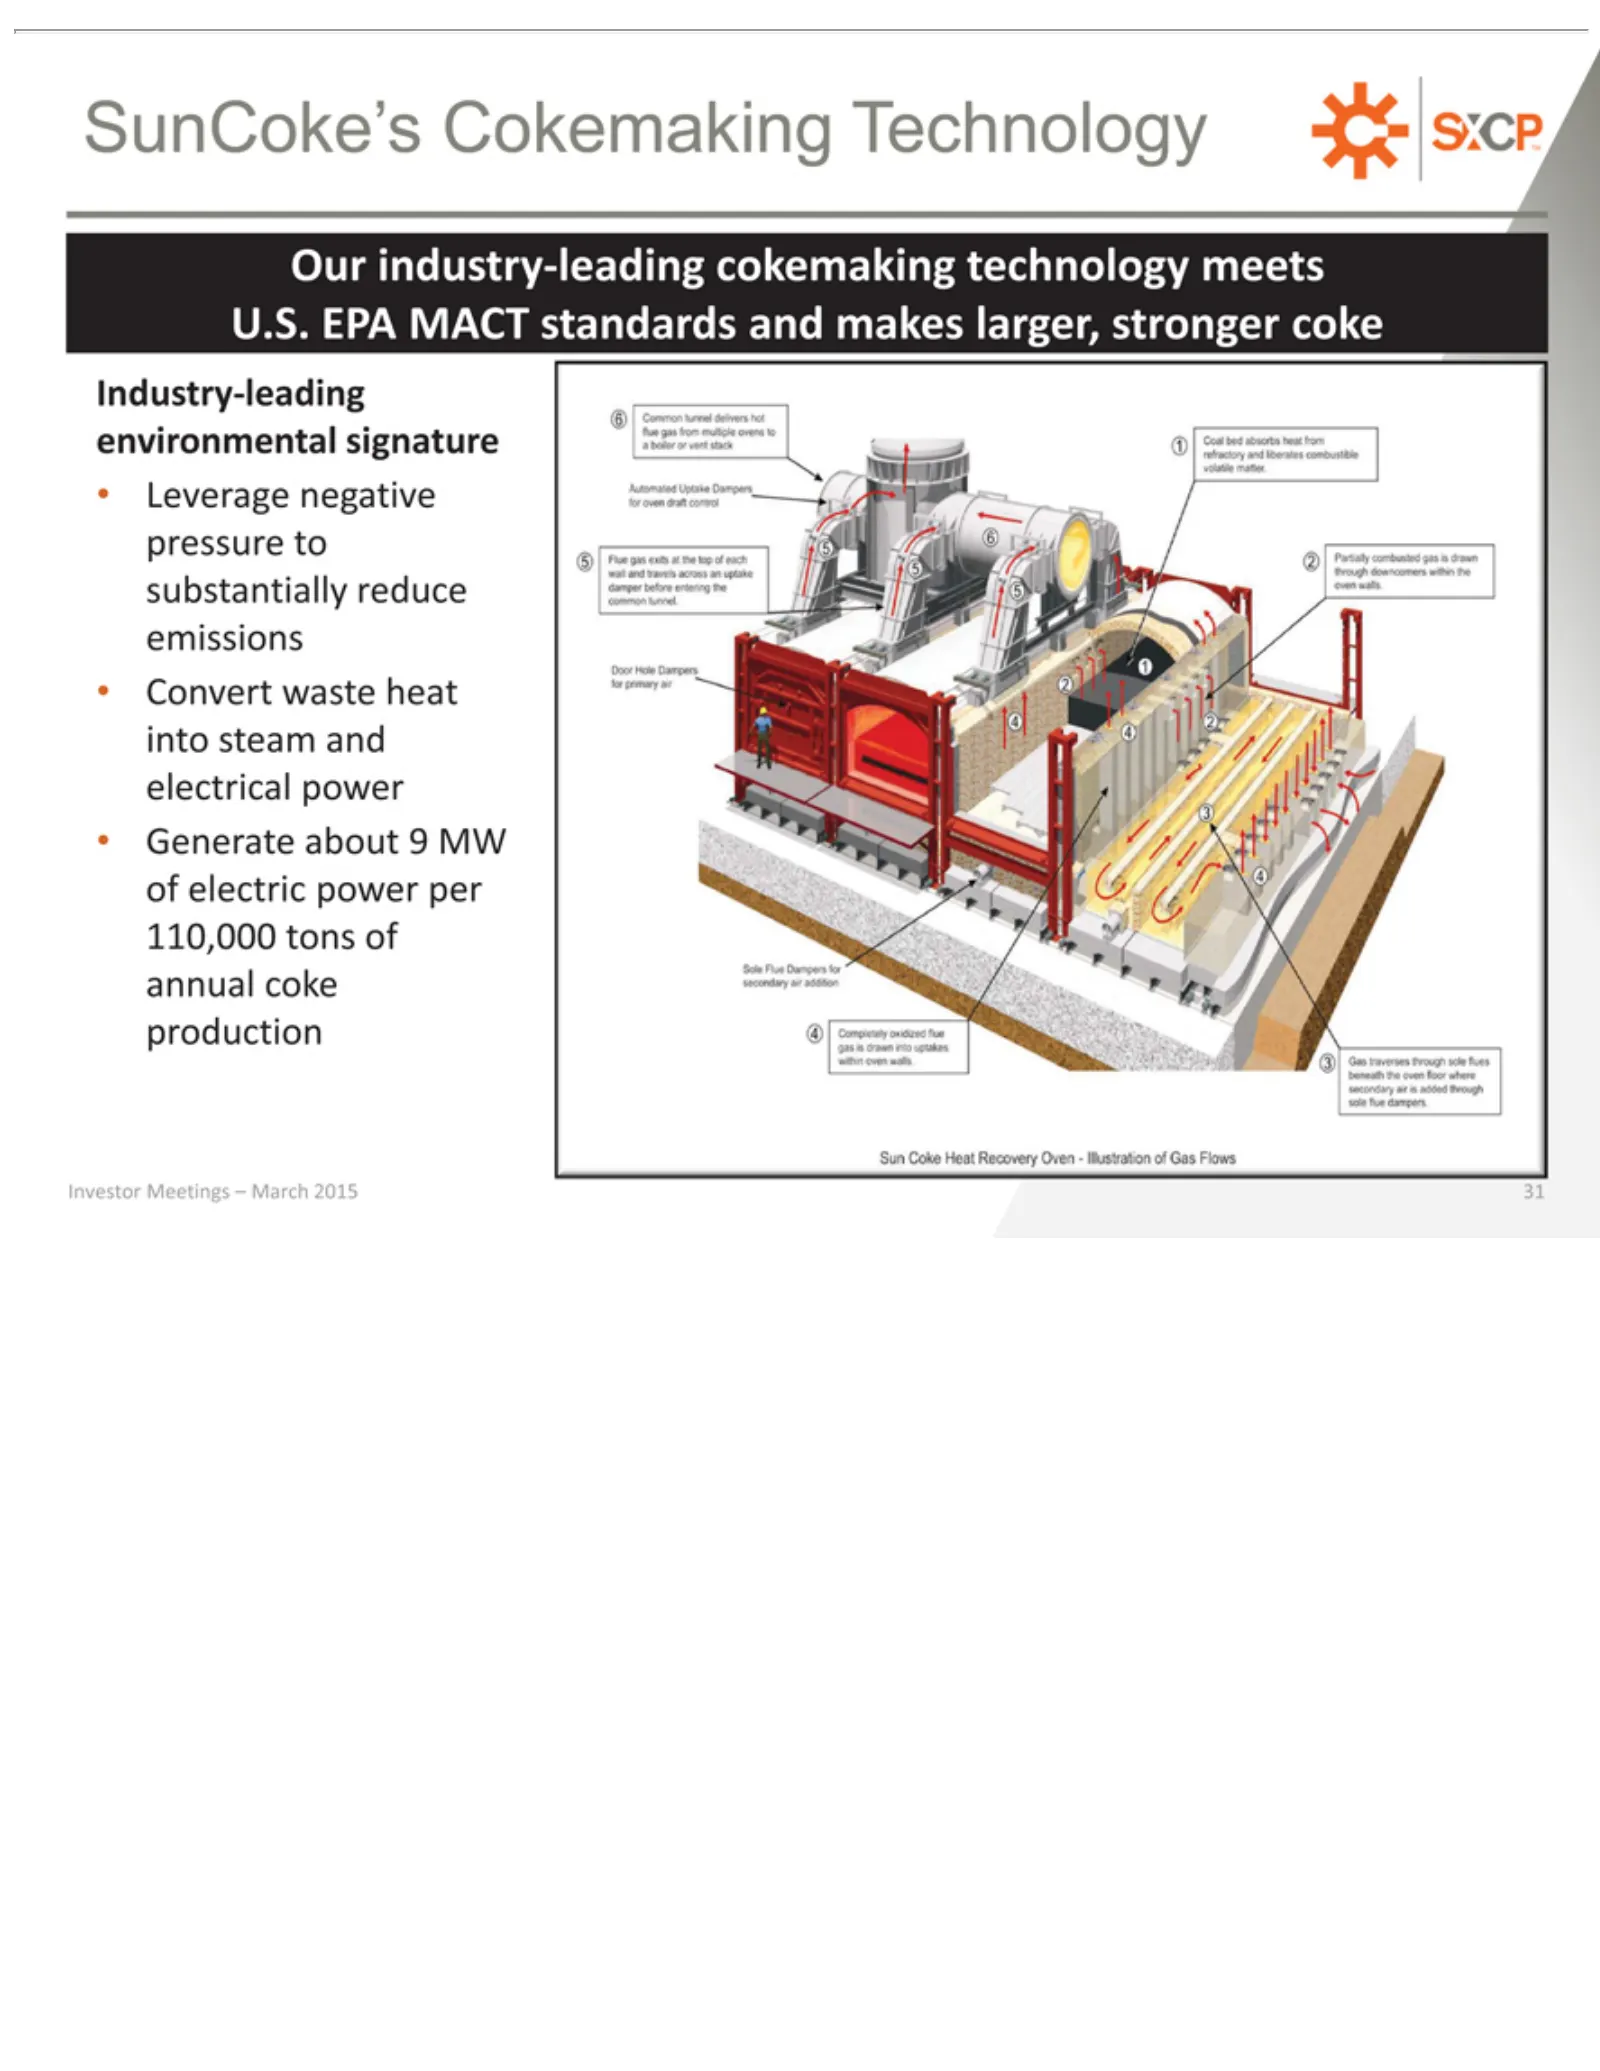
SunCoke’s Our environmental Industry-leading Leverage Convert Generate Investor 31 industry-leading waste Meetings about negative Cokemaking heat signature 9 MW –pressure into March cokemaking ofsteam Technology electric 2015 to substantially andpower technology electrical per reduce 110,000 power m
Slide 32: Expect Stable Domestic Coke Demand
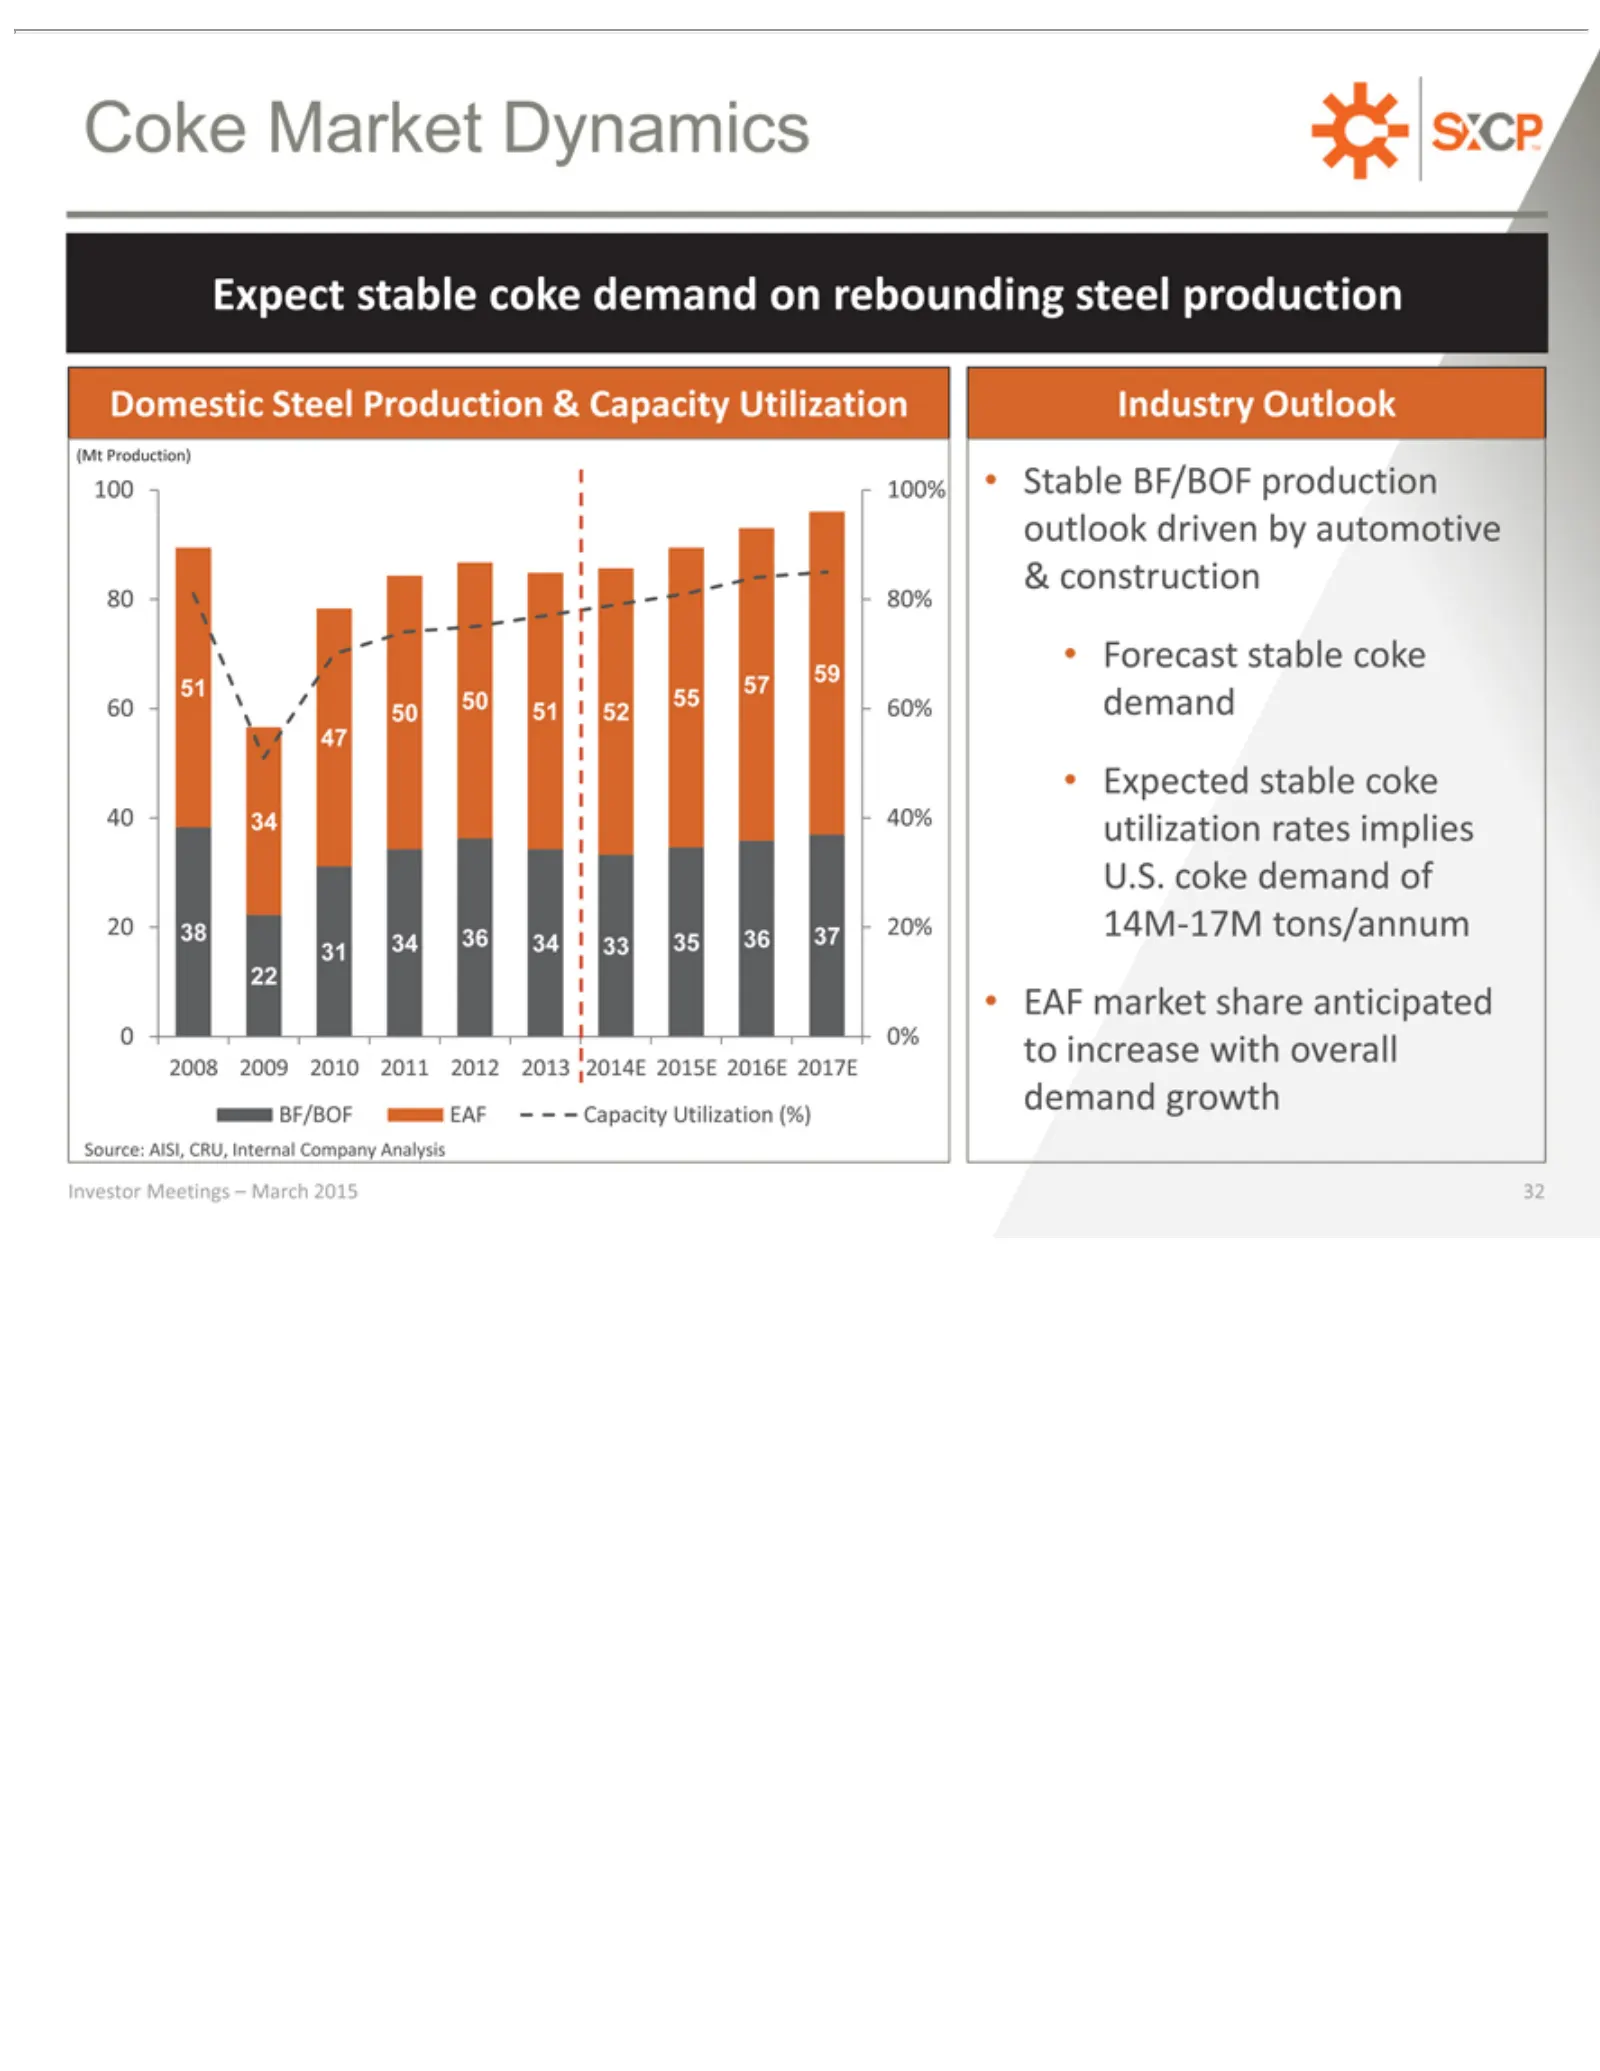
Coke Expect Domestic (Mt 100 80 51 59 60 50 40 20 34 031 2008 BF/BOF Source: Investor Industry Stable Forecast Expected EAF 320% 80% 57 50 51 34 38 36 33 Production) 100% market 2009 Market 55 52 40% 20% 34 22 BF/BOF stable AISI, Meetings Outlook stable EAF 60% 47 35 stable Steel 2010 36 share Dynam
Slide 33: Coke Market Outlook: Macro Dynamics
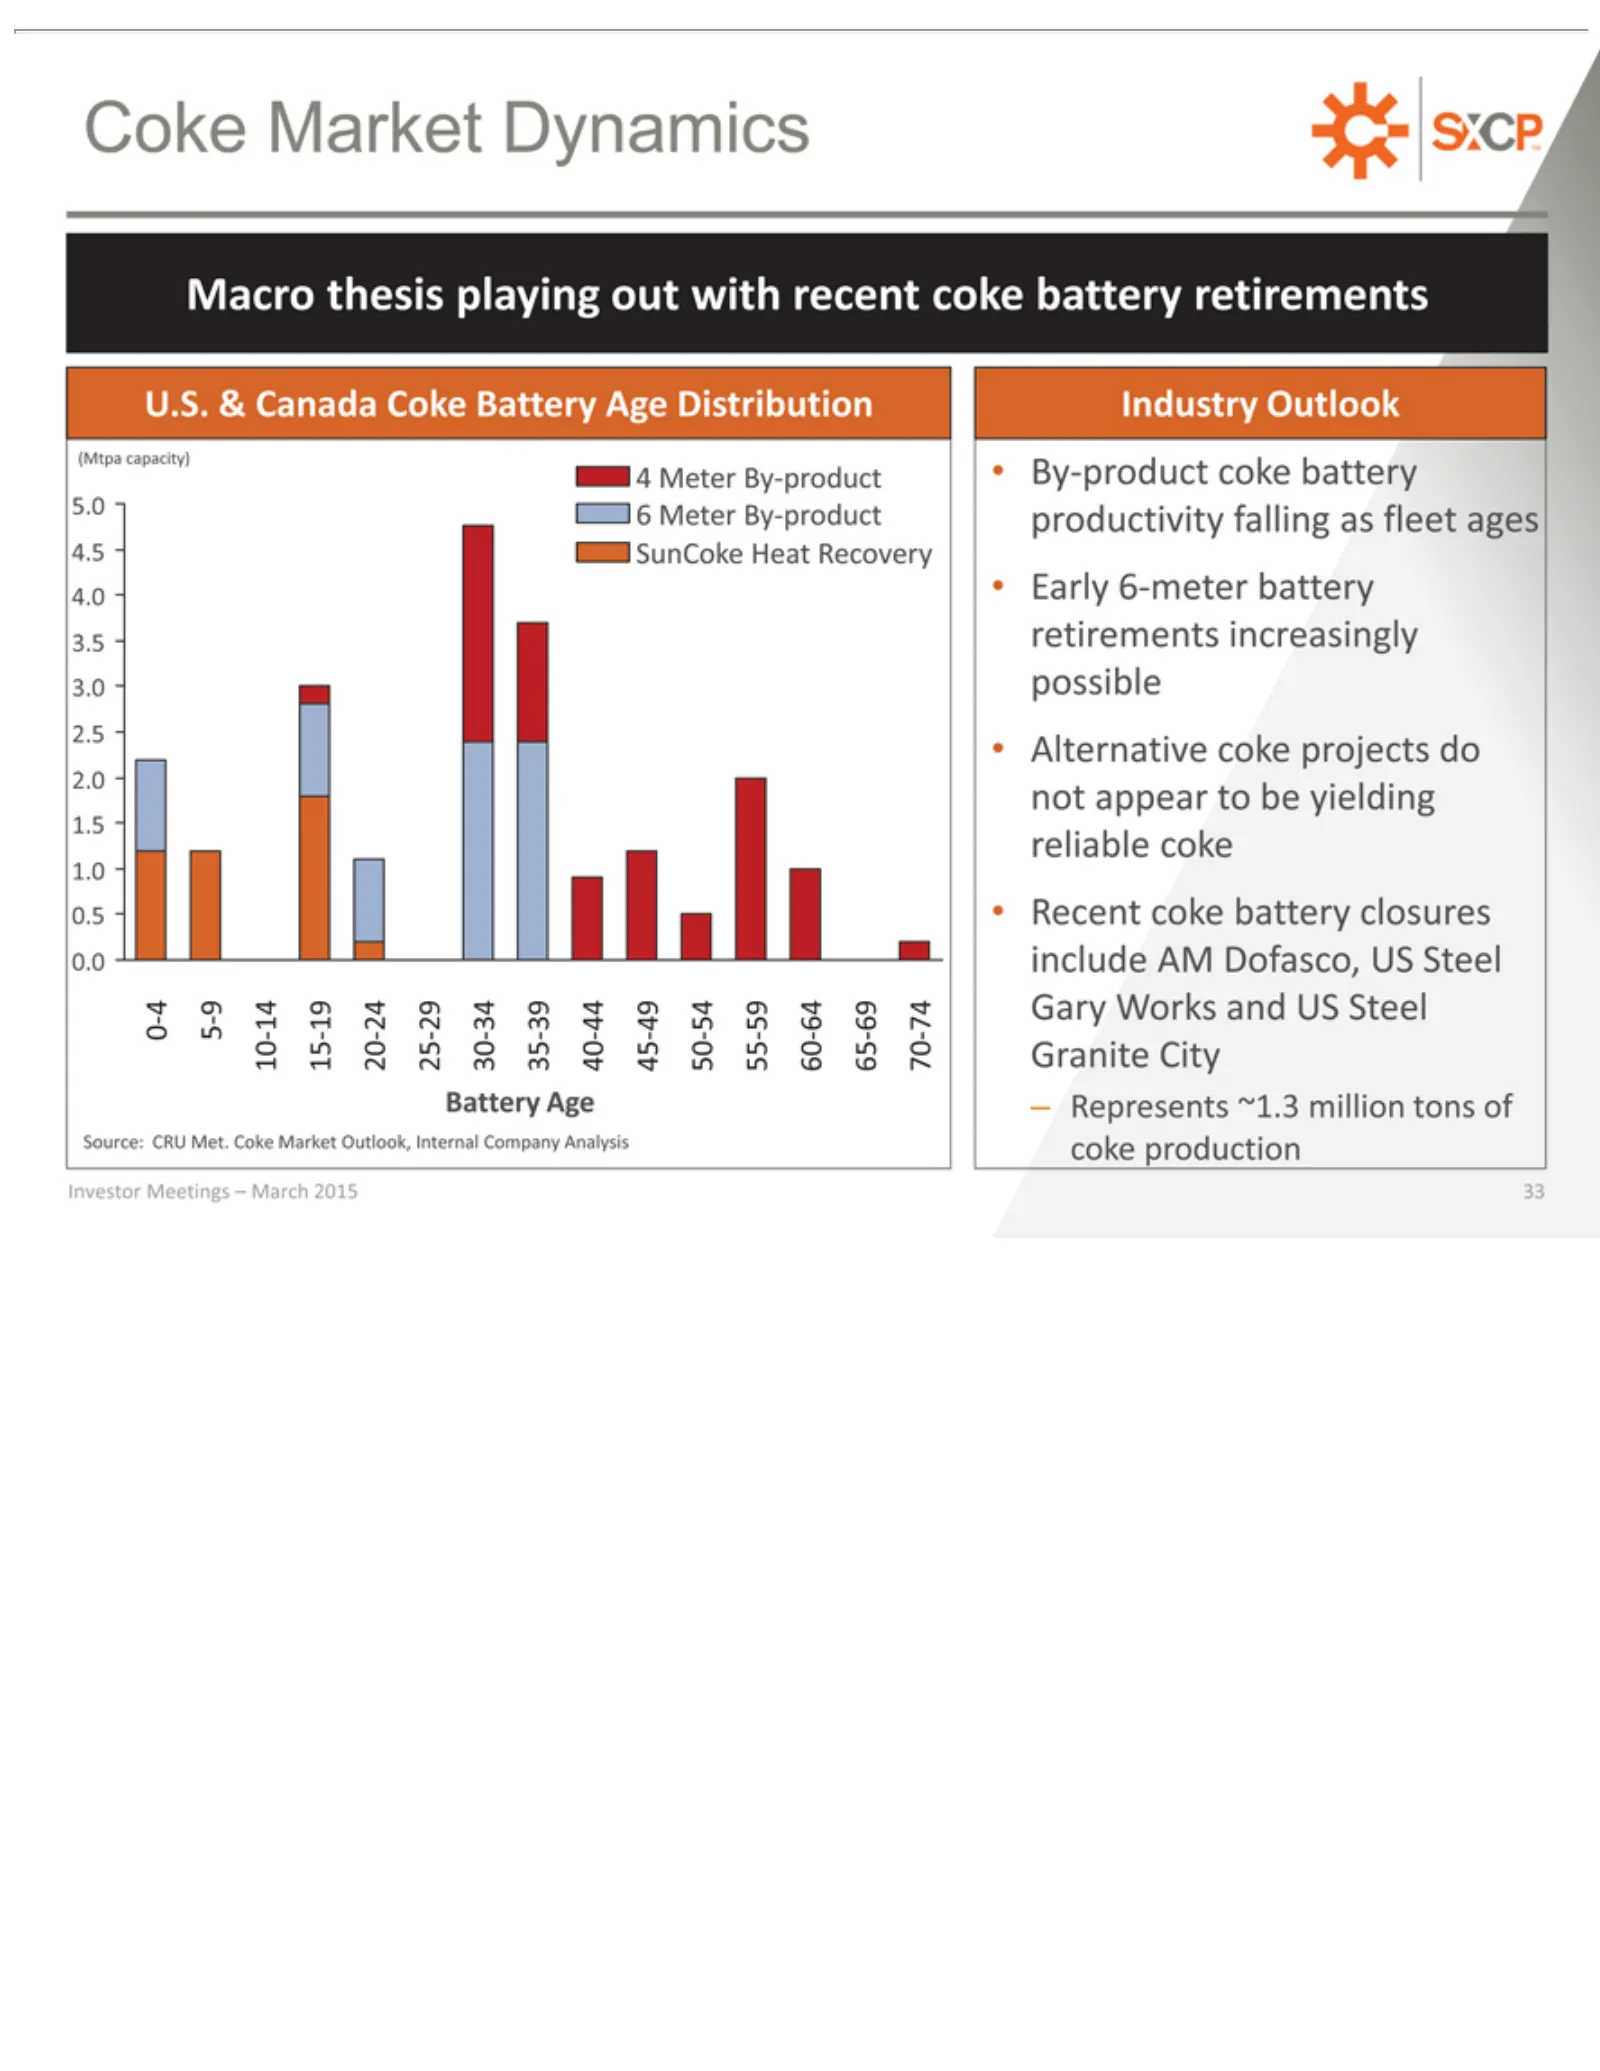
Coke Macro U.S. Industry -(Mtpa 0.0 0.5 1.0 1.5 2.0 2.5 3.0 3.5 4.0 4.5 5.0 Battery 25-29 20-24 15-19 10-14 5-9 Age Source: 40-44 64Investor By-product 70-74 65-69 60-64 55-59 50-54 45-49 Early Alternative –Recent 33 4Represents Meter 0 35-39 &Market 6-meter capacity) thesis coke Canada 30-34 CRU By
Slide 34: Coke in Blast Furnace Steelmaking
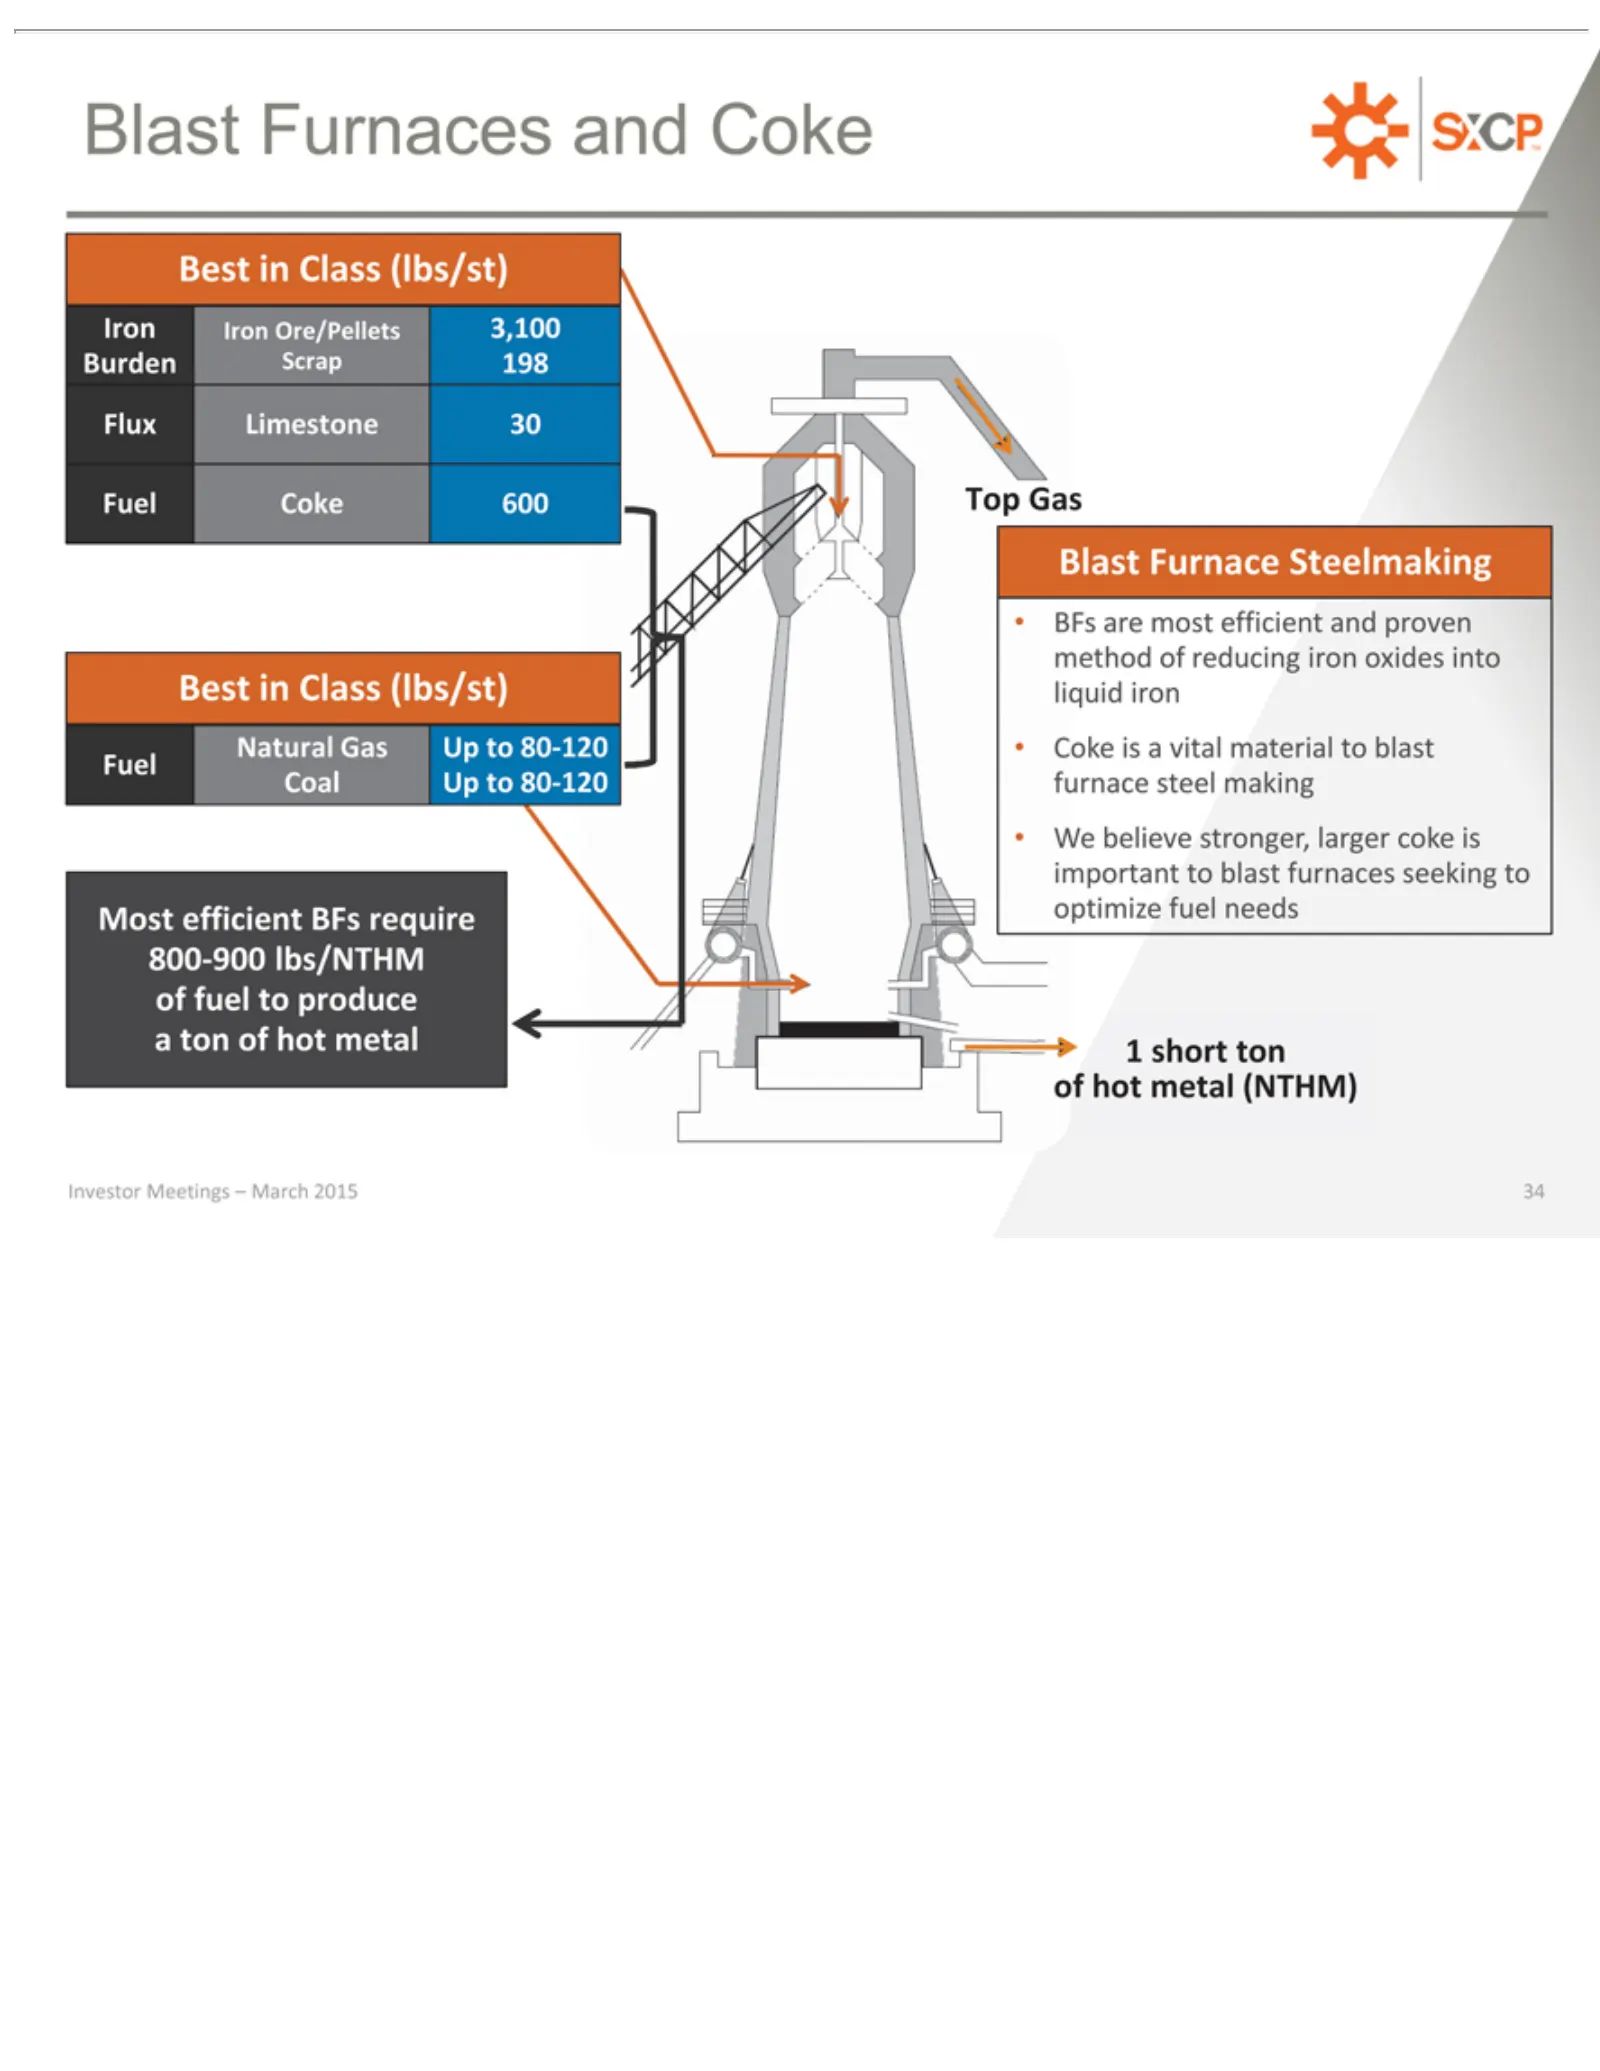
Iron Burden Flux Fuel Blast Best Natural Most BFs Coke 1We of Investor 34short hot believe are Iron Coke in Limestone Furnaces Furnace efficient ismetal ton Class Scrap Gas amost Meetings Ore/Pellets vital 600 stronger, Up (NTHM) (lbs/st) efficient 198 Steelmaking BFs material Top and to 30–80-120 r
Slide 35: Investor Relations Contact
Investor Relations: 630-824-1907 www.sxcpartners.com
Source: SEC EDGAR · 8-K filed Mar 2, 2015
More decks from SunCoke Energy Partners L.P
 Merger or Acquisition (May 2019)42 slides · May 22, 2019
 Q1 2019 Earnings Presentation26 slides · Apr 24, 2019
 Merger or Acquisition (February 2019)41 slides · Feb 26, 2019
 FY2018 Earnings Presentation37 slides · Feb 5, 2019
 FY2018 Earnings Presentation36 slides · Feb 5, 2019
 Q3 2018 Earnings Presentation25 slides · Oct 25, 2018