Pioneer Natural Resources — Pritchard Capital Partners Energize 2010 Conference
44 slides from Pioneer Natural Resources's conference presentation, Jan 6, 2010
Slide 1: Pritchard Capital Partners Energize 2010 Conference
Pritchard Capital Partners Energize 2010 Conference January 7, 2010
Slide 2: Forward-Looking Statements
2 Forward-Looking Statements Except for historical information contained herein, the statements, charts and graphs in this presentation are forward-looking statements that are made pursuant to the Safe Harbor Provisions of the Private Securities Litigation Reform Act of 1995. Forward- looking statem
Slide 3: Why Invest in PXD?
3 Large drilling inventory and resource potential with >75% liquids Accelerating oil-focused drilling activity in the Spraberry field Added 2nd rig to exploit substantial Eagle Ford Shale resource potential Attractive derivative positions for 2010 and 2011 Will continue to deliver free cash flow Str
Slide 4: Delivering Consistent Production Per Share Growth
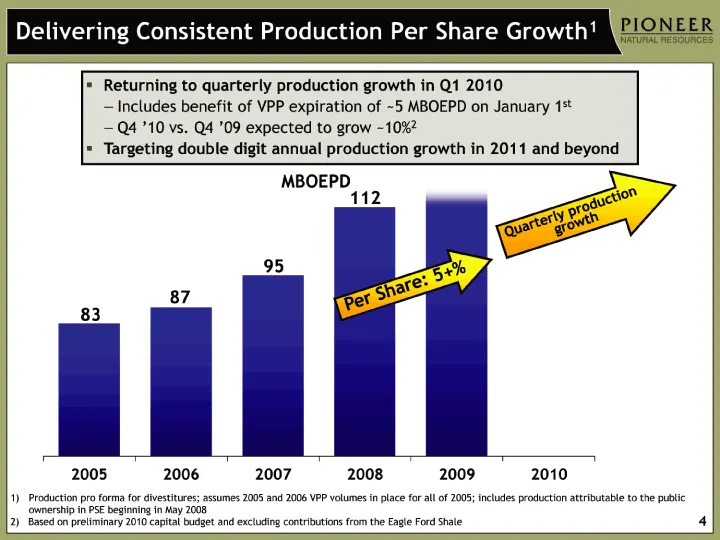
2005 2006 2007 2008 2009 2010 2011 Historical Production Production Outlook 83 87 95 112 112 0 62 5 0 7 4 Delivering Consistent Production Per Share Growth1 MBOEPD Production pro forma for divestitures; assumes 2005 and 2006 VPP volumes in place for all of 2005; includes production attributable to t
Slide 5: 2010E Cash Flow and Capital Expenditures
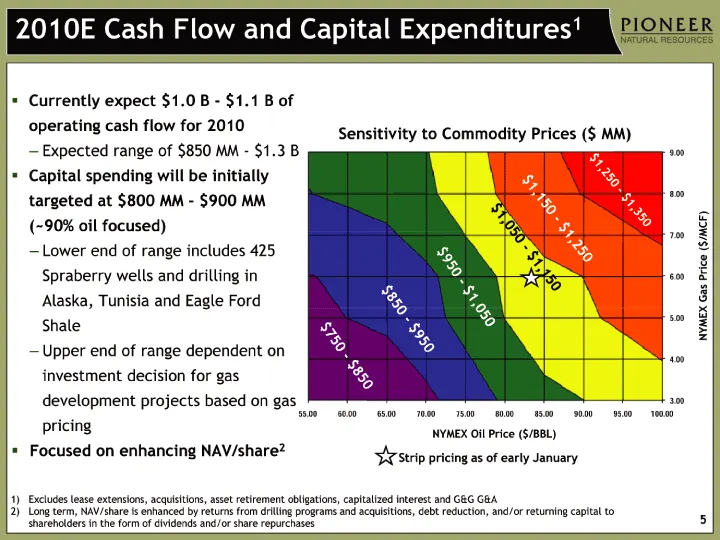
Currently expect $1.0 B - $1.1 B of operating cash flow for 2010 Expected range of $850 MM - $1.3 B Capital spending will be initially targeted at $800 MM - $900 MM (~90% oil focused) Lower end of range includes 425 Spraberry wells and drilling in Alaska, Tunisia and Eagle Ford Shale Upper end of ra
Slide 6: 2011E Cash Flow from Operations
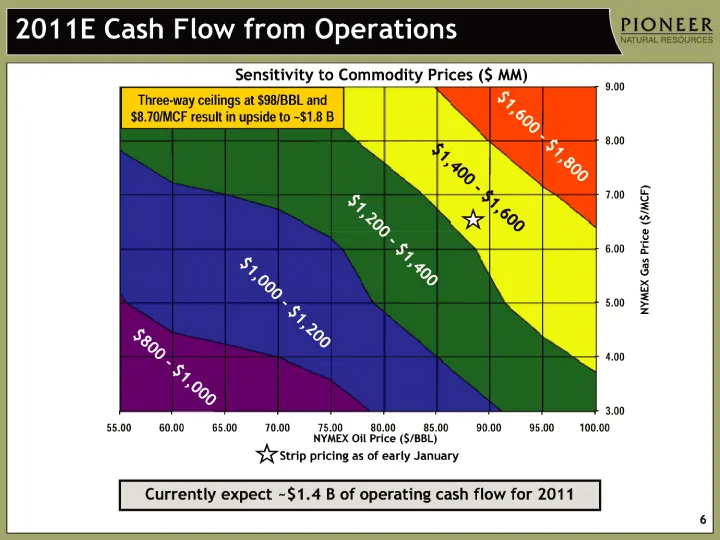
2011E Cash Flow from Operations NYMEX Oil Price ($/BBL) NYMEX Gas Price ($/MCF) $800 - $1,000 Strip pricing as of early January Sensitivity to Commodity Prices ($ MM) Three-way ceilings at $98/BBL and $8.70/MCF result in upside to ~$1.8 B 6 Currently expect ~$1.4 B of operating cash flow for 2011 $1
Slide 7: 2010 Drilling Plan Delivers Quarterly Production Growth
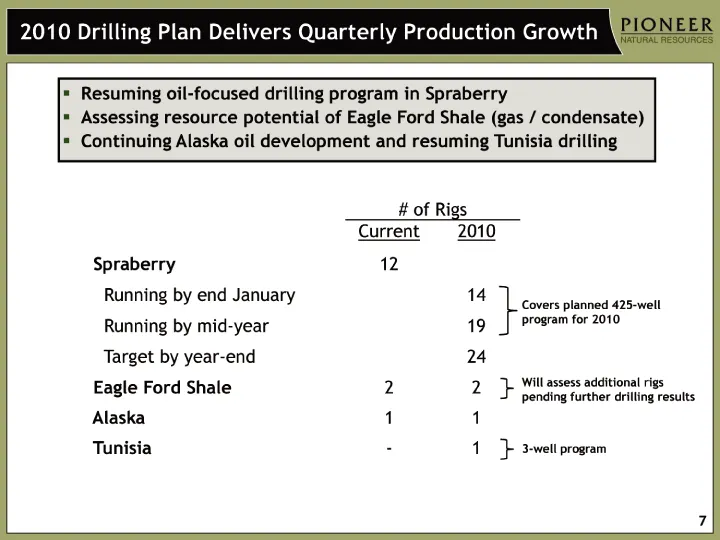
7 2010 Drilling Plan Delivers Quarterly Production Growth 2010 Drilling Plan Delivers Quarterly Production Growth Resuming oil-focused drilling program in Spraberry Assessing resource potential of Eagle Ford Shale (gas / condensate) Continuing Alaska oil development and resuming Tunisia drilling Wil
Slide 8: Spraberry is the Largest Oil Field in the Lower 48 States
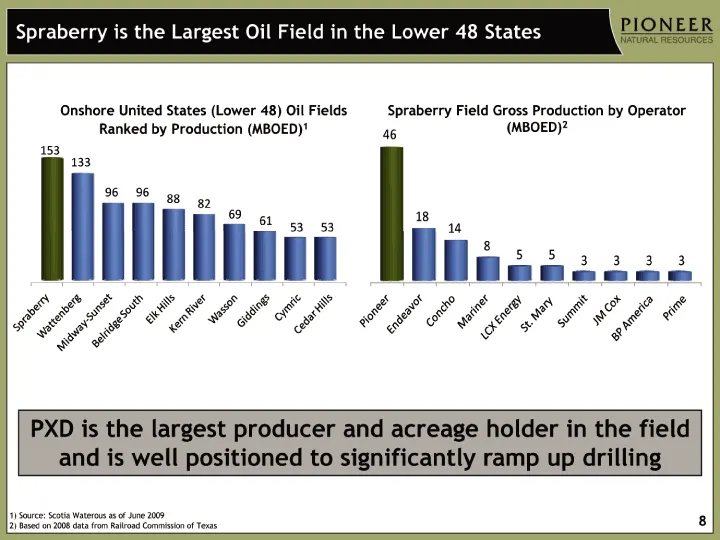
Spraberry is the Largest Oil Field in the Lower 48 States 8 PXD is the largest producer and acreage holder in the field and is well positioned to significantly ramp up drilling Onshore United States (Lower 48) Oil Fields Ranked by Production (MBOED)1 Spraberry Field Gross Production by Operator (MBO
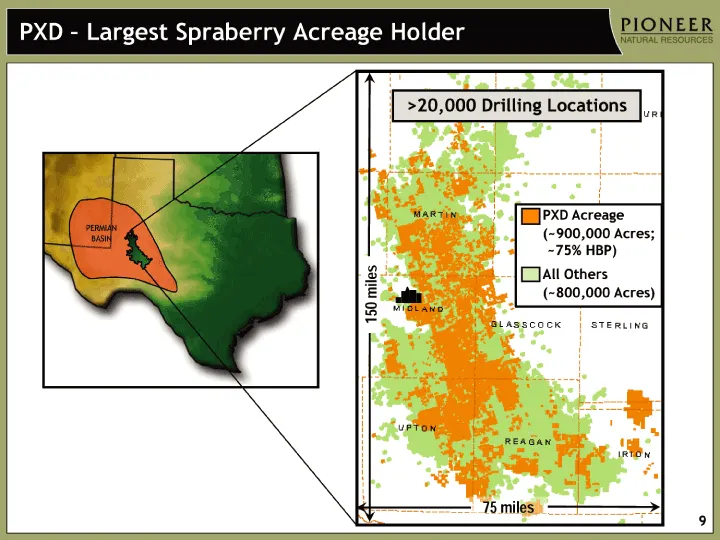
Slide 9: PXD - Largest Spraberry Acreage Holder
PXD - Largest Spraberry Acreage Holder 9 PXD Acreage (~900,000 Acres; ~75% HBP) All Others (~800,000 Acres) 150 miles 75 miles PERMIAN BASIN >20,000 Drilling Locations
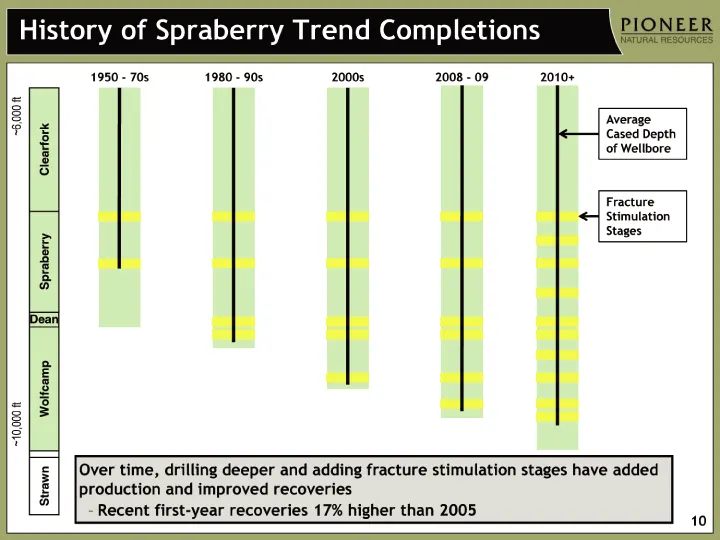
Slide 10: History of Spraberry Trend Completions
10 Dean Strawn Wolfcamp Spraberry Clearfork ~6,000 ft History of Spraberry Trend Completions 2010+ 2008 - 09 2000s 1980 - 90s ~10,000 ft 1950 - 70s Over time, drilling deeper and adding fracture stimulation stages have added production and improved recoveries Recent first-year recoveries 17% higher
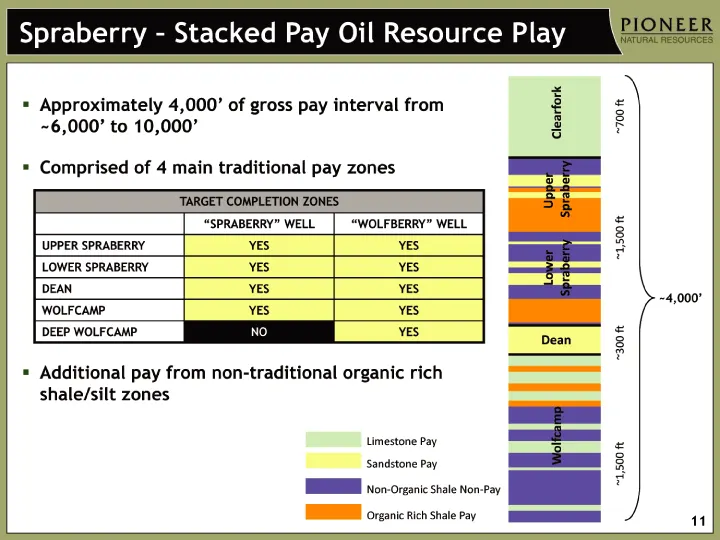
Slide 11: Spraberry - Stacked Pay Oil Resource Play
11 Approximately 4,000' of gross pay interval from ~6,000' to 10,000' Comprised of 4 main traditional pay zones Additional pay from non-traditional organic rich shale/silt zones TARGET COMPLETION ZONES TARGET COMPLETION ZONES TARGET COMPLETION ZONES "SPRABERRY" WELL "WOLFBERRY" WELL UPPER SPRABERRY
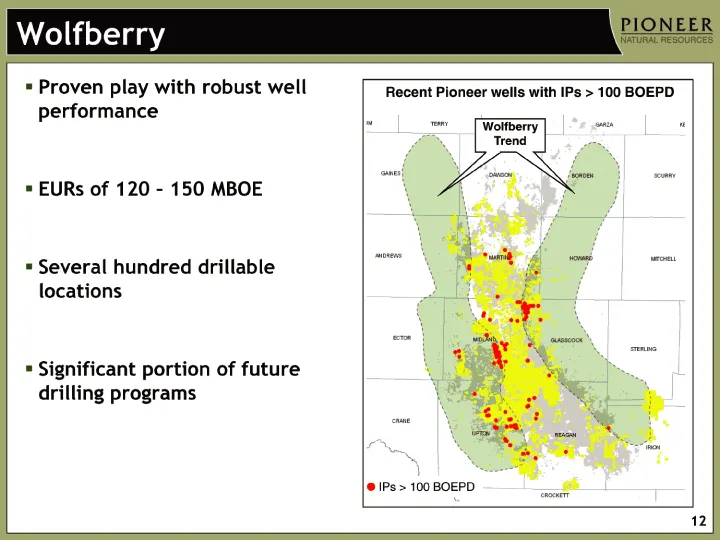
Slide 12: Wolfberry
12 Wolfberry Proven play with robust well performance EURs of 120 - 150 MBOE Several hundred drillable locations Significant portion of future drilling programs Recent Pioneer wells with IPs > 100 BOEPD IPs > 100 BOEPD Wolfberry Trend Wolfberry Trend
Slide 13: Spraberry Waterflood
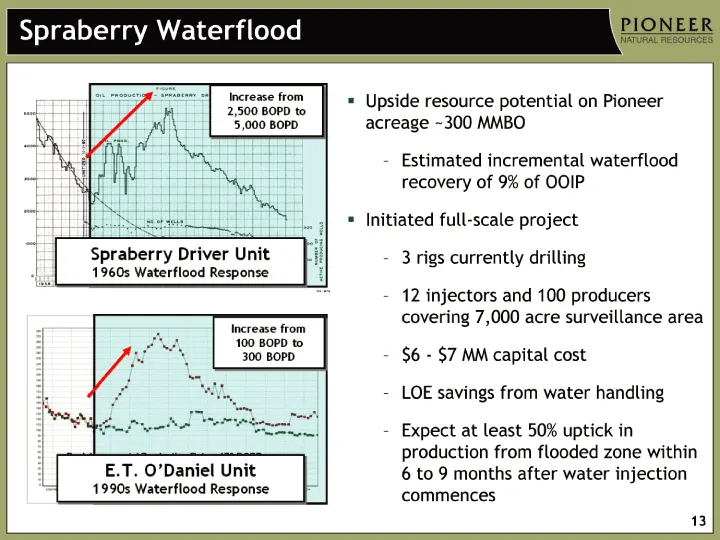
13 Spraberry Waterflood Upside resource potential on Pioneer acreage ~300 MMBO Estimated incremental waterflood recovery of 9% of OOIP Initiated full-scale project 3 rigs currently drilling 12 injectors and 100 producers covering 7,000 acre surveillance area $6 - $7 MM capital cost LOE savings from
Slide 14: Spraberry - Increasing Recovery Per Section
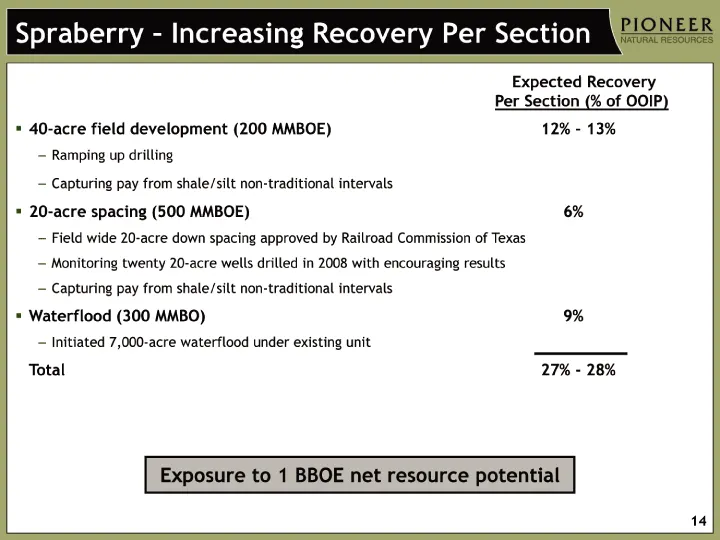
14 Spraberry - Increasing Recovery Per Section 40-acre field development (200 MMBOE) 12% - 13% Ramping up drilling Capturing pay from shale/silt non-traditional intervals 20-acre spacing (500 MMBOE) 6% Field wide 20-acre down spacing approved by Railroad Commission of Texas Monitoring twenty 20-acre
Slide 15: Spraberry - Foundation Asset
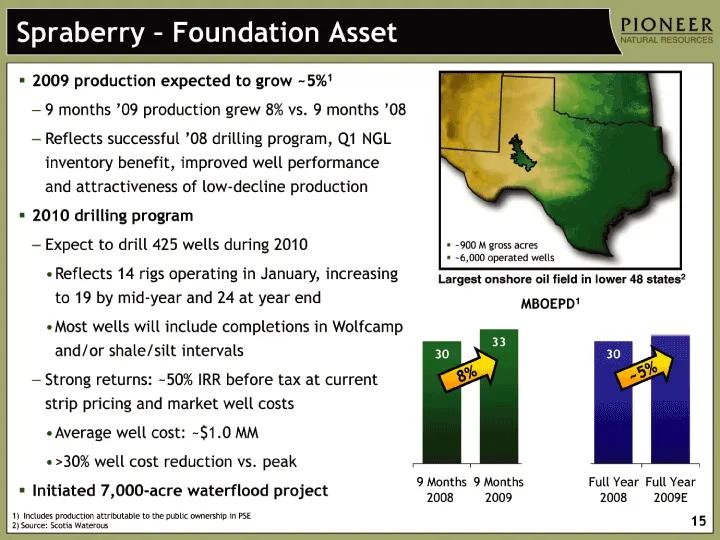
15 Spraberry - Foundation Asset 2009 production expected to grow ~5%1 9 months '09 production grew 8% vs. 9 months '08 Reflects successful '08 drilling program, Q1 NGL inventory benefit, improved well performance and attractiveness of low-decline production 2010 drilling program Expect to drill 425
Slide 16: Focused On Controlling Spraberry Well Costs
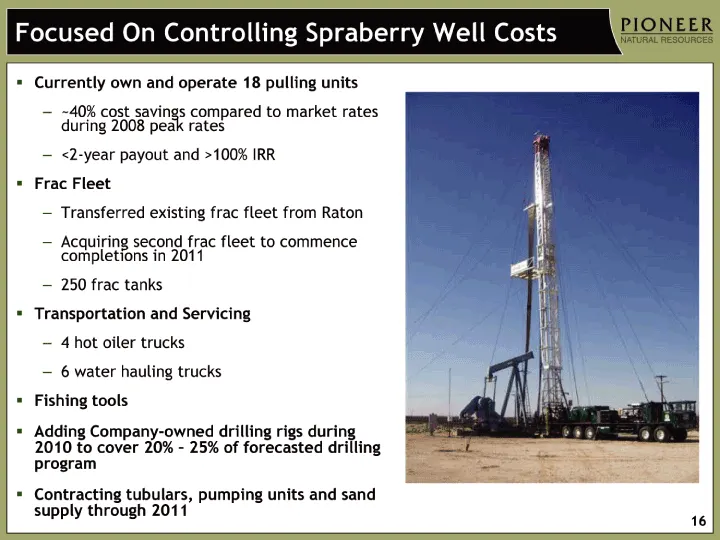
16 Focused On Controlling Spraberry Well Costs Currently own and operate 18 pulling units ~40% cost savings compared to market rates during 2008 peak rates <2-year payout and >100% IRR Frac Fleet Transferred existing frac fleet from Raton Acquiring second frac fleet to commence completions in 2011 2
Slide 17: Spraberry - PXD Production History
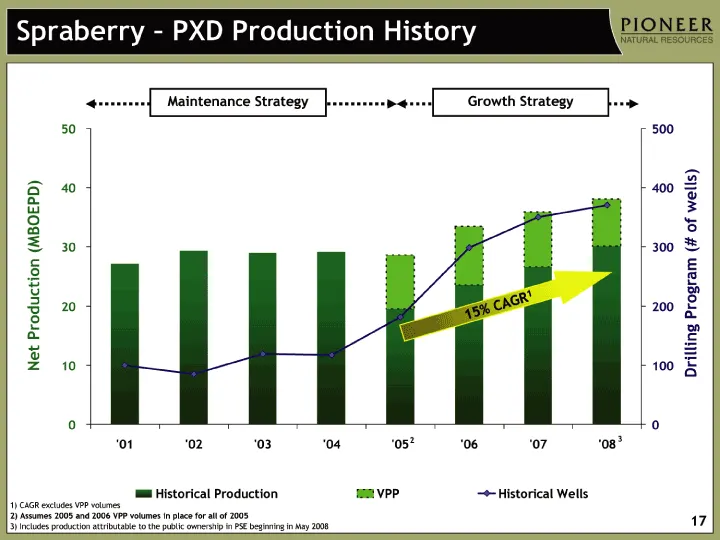
17 Spraberry - PXD Production History '00 '01 '02 '03 '04 '05 '06 '07 '08 '09E Historical Production 28.83333333 27.16666667 29.33333333 29 29.16666667 19.56 23.581 26.6 30.16 Production Outlook 36.096 VPP 9.1 9.9 9.3 7.9 7.487671233 6.832876712 3.747945205 3.509589041 Historical Wells 95 100 85 119
Slide 18: Accelerating Spraberry Development
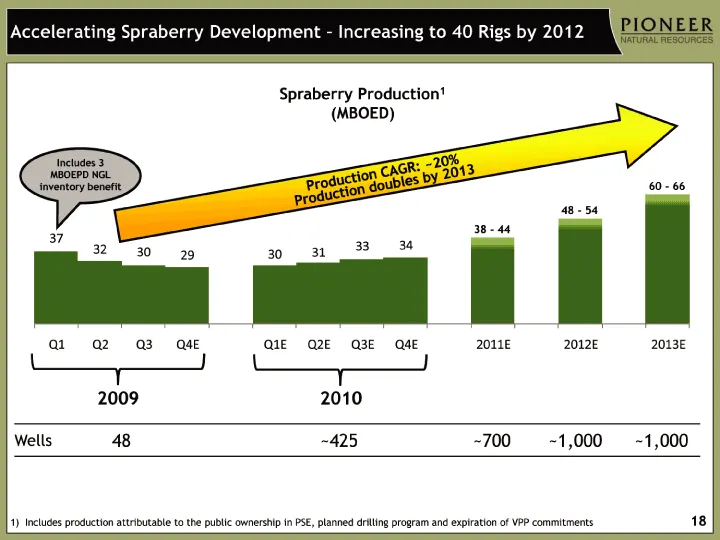
Accelerating Spraberry Development - Increasing to 40 Rigs by 2012 18 Spraberry Production1 (MBOED) Includes 3 MBOEPD NGL inventory benefit 2009 2010 Wells 48 ~425 ~700 ~1,000 ~1,000 Production CAGR: ~20% Production doubles by 2013 38 - 44 48 - 54 60 - 66 1) Includes production attributable to the p
Slide 19: Technology Leader in Eagle Ford Shale
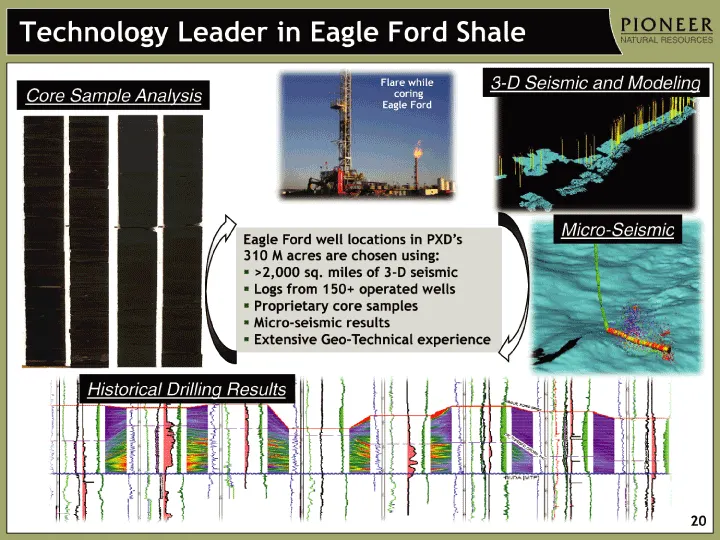
20 Technology Leader in Eagle Ford Shale Eagle Ford well locations in PXD's 310 M acres are chosen using: >2,000 sq. miles of 3-D seismic Logs from 150+ operated wells Proprietary core samples Micro-seismic results Extensive Geo-Technical experience Historical Drilling Results Flare while coring Eag
Slide 20: PXD's Eagle Ford Shale Activity Increasing
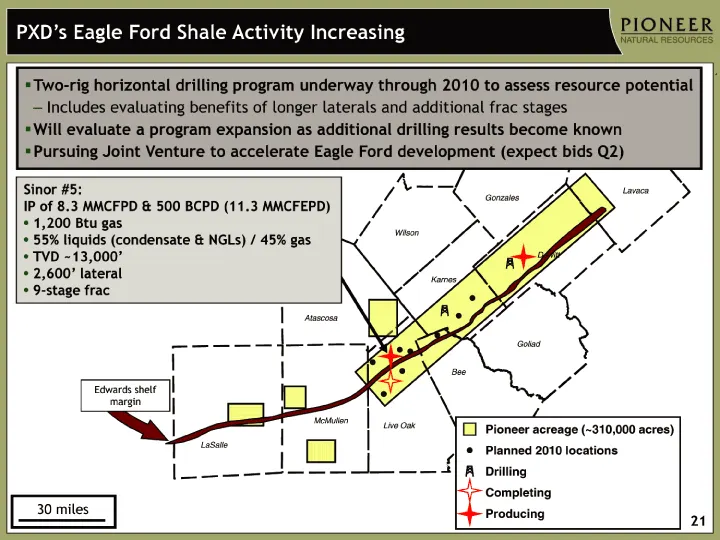
21 30 miles PXD's Eagle Ford Shale Activity Increasing Bee Goliad Live Oak Karnes McMullen LaSalle Atascosa Wilson Gonzales Lavaca Edwards shelf margin Dewitt Two-rig horizontal drilling program underway through 2010 to assess resource potential Includes evaluating benefits of longer laterals and ad
Slide 21: Eagle Ford Shale Production Stream Value Illustration
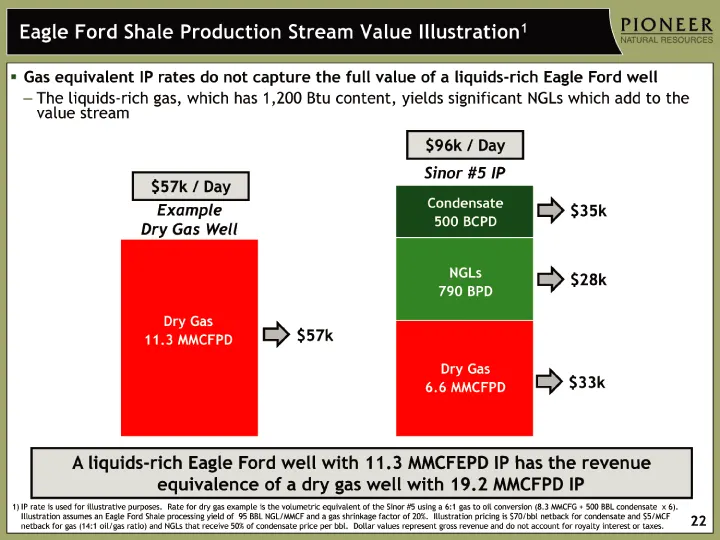
(CHART) Eagle Ford Shale Production Stream Value Illustration1 22 (CHART) A liquids-rich Eagle Ford well with 11.3 MMCFEPD IP has the revenue equivalence of a dry gas well with 19.2 MMCFPD IP Dry Gas 11.3 MMCFPD $57k $33k $28k $35k Condensate 500 BCPD NGLs 790 BPD Dry Gas 6.6 MMCFPD $57k / Day $96k
Slide 22: Higher Condensate / NGL Yields Lower Breakeven Thresholds
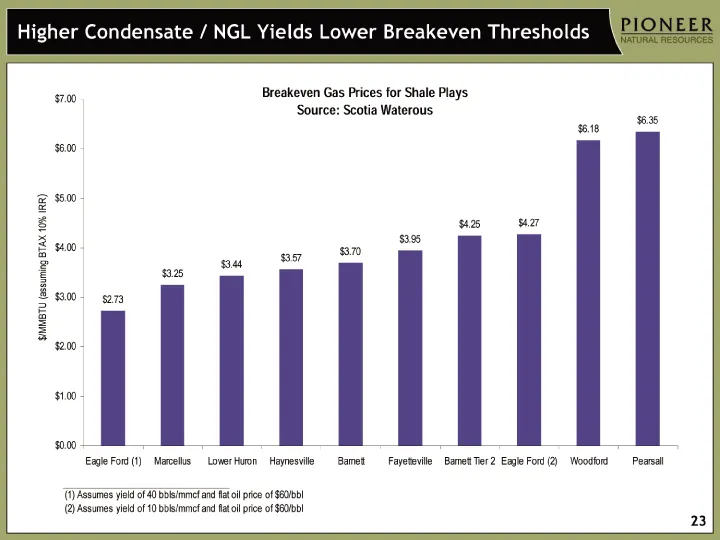
Higher Condensate / NGL Yields Lower Breakeven Thresholds 23 )
Slide 23: Why Invest In PXD?
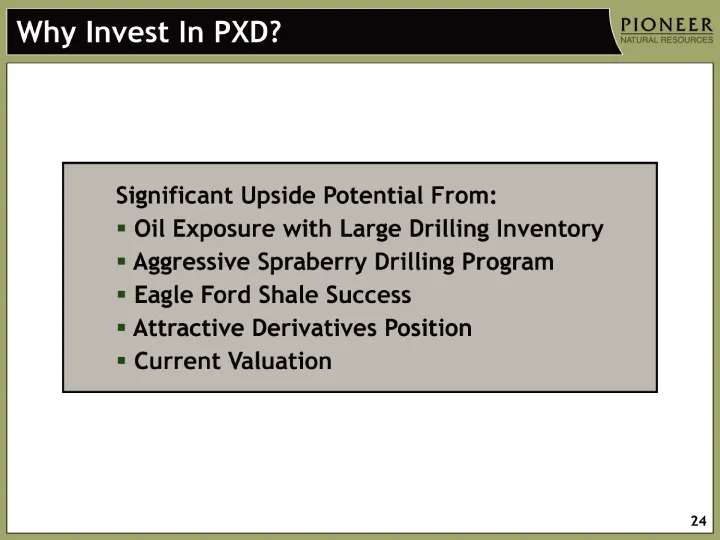
24 Why Invest In PXD? Significant Upside Potential From: Oil Exposure with Large Drilling Inventory Aggressive Spraberry Drilling Program Eagle Ford Shale Success Attractive Derivatives Position Current Valuation
Slide 24: Appendix
25 Appendix
Slide 25: Pioneer Operations
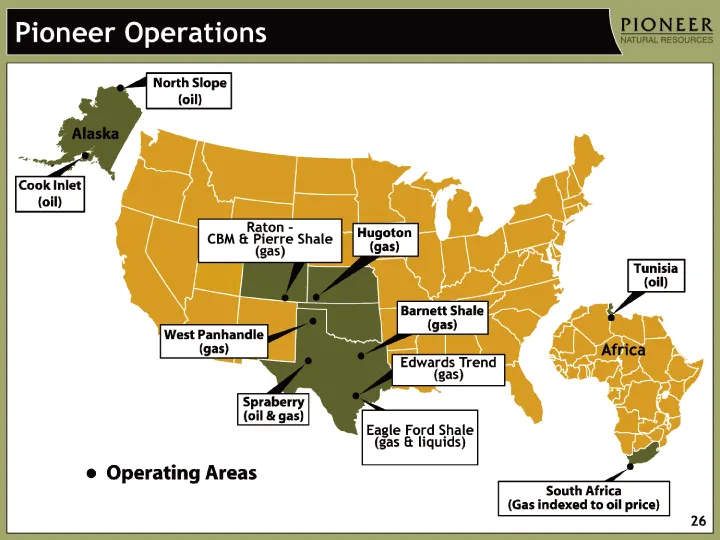
26 Pioneer Operations Raton - CBM & Pierre Shale (gas) Eagle Ford Shale (gas & liquids) Edwards Trend (gas)
Slide 26: Alaska - Oooguruk
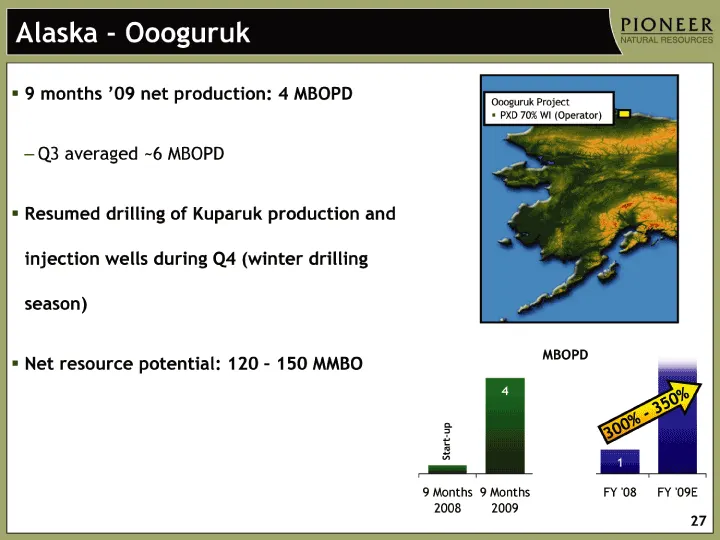
27 9 Months 2008 9 Months 2009 FY '08 FY '09E Alaska 0.345 4 1 4 1 actuals 0 3.889 1.13 5 300% - 350% Alaska - Oooguruk 9 months '09 net production: 4 MBOPD Q3 averaged ~6 MBOPD Resumed drilling of Kuparuk production and injection wells during Q4 (winter drilling season) Net resource potential: 120
Slide 27: Returning to Tunisia Oil Drilling
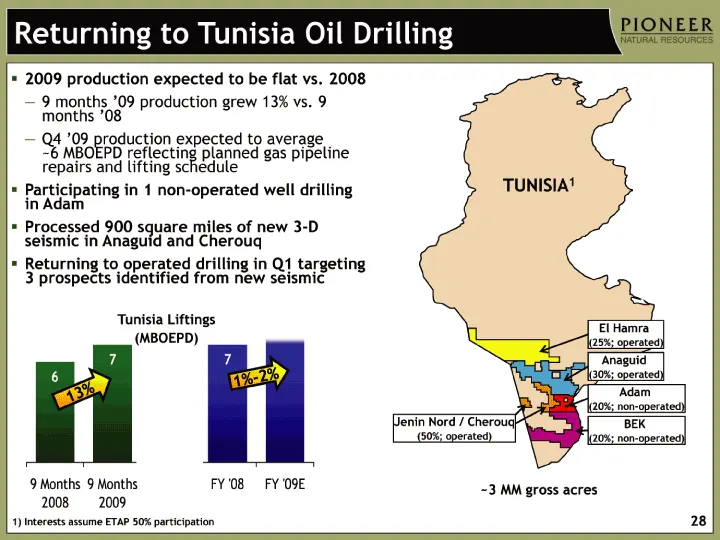
28 Returning to Tunisia Oil Drilling 1) Interests assume ETAP 50% participation 2009 production expected to be flat vs. 2008 9 months '09 production grew 13% vs. 9 months '08 Q4 '09 production expected to average ~6 MBOEPD reflecting planned gas pipeline repairs and lifting schedule Participating in
Slide 28: South Texas
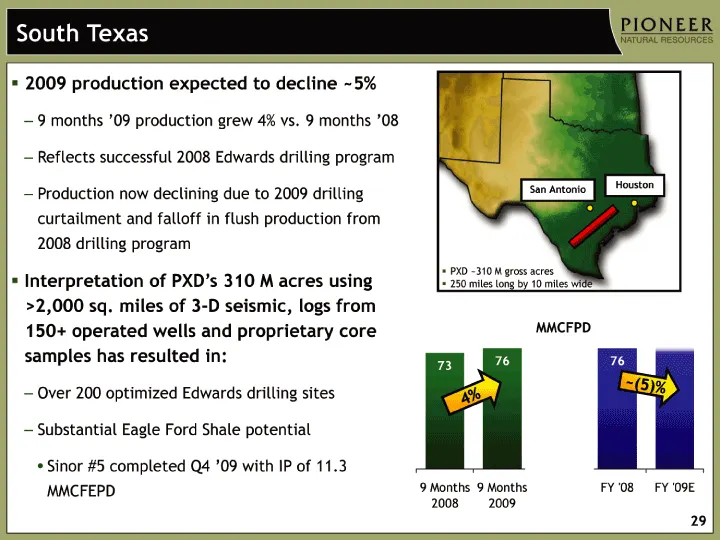
29 South Texas 2009 production expected to decline ~5% 9 months '09 production grew 4% vs. 9 months '08 Reflects successful 2008 Edwards drilling program Production now declining due to 2009 drilling curtailment and falloff in flush production from 2008 drilling program Interpretation of PXD's 310 M
Slide 29: Barnett Shale Expansion / Tier Area
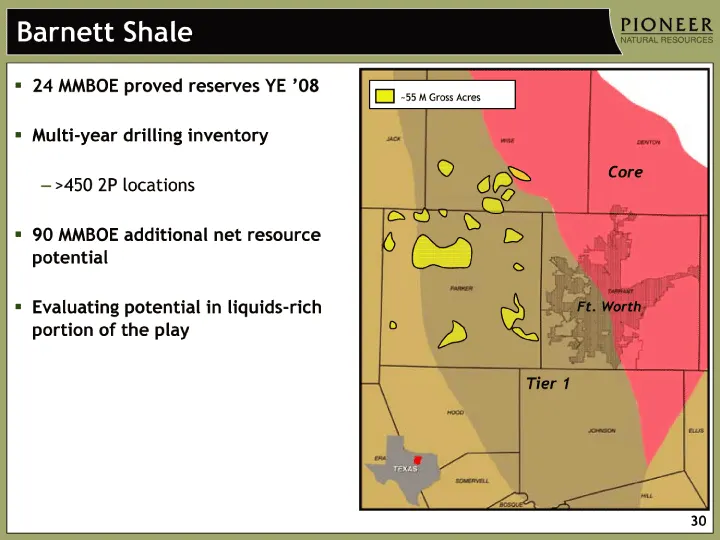
30 Barnett Shale Expansion / Tier 2 Area 24 MMBOE proved reserves YE '08 Multi-year drilling inventory >450 2P locations 90 MMBOE additional net resource potential Evaluating potential in liquids-rich portion of the play Tier 1 Core Ft. Worth ~55 M Gross Acres
Slide 30: Mid-Continent and Raton
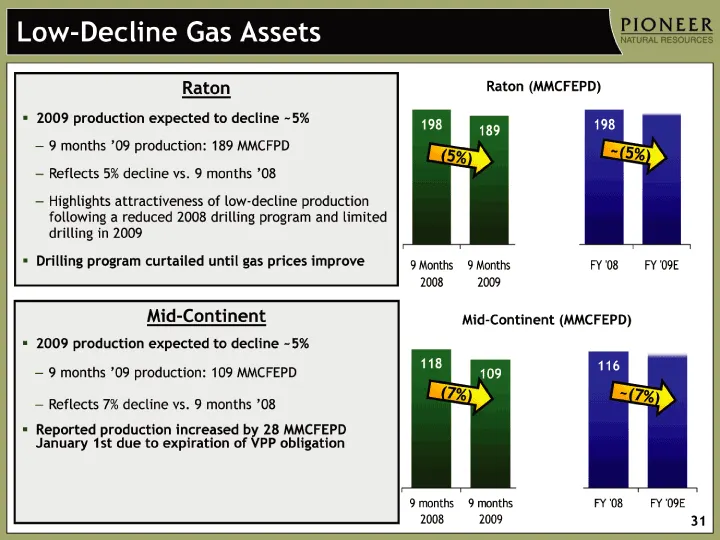
31 Mid-Continent 2009 production expected to decline ~5% 9 months '09 production: 109 MMCFEPD Reflects 7% decline vs. 9 months '08 Reported production increased by 28 MMCFEPD January 1st due to expiration of VPP obligation 9 Months 2008 9 Months 2009 FY '08 FY '09E Raton 198 189 198 188 6 actuals 4.
Slide 31: 2010 Spraberry Program Type Curve
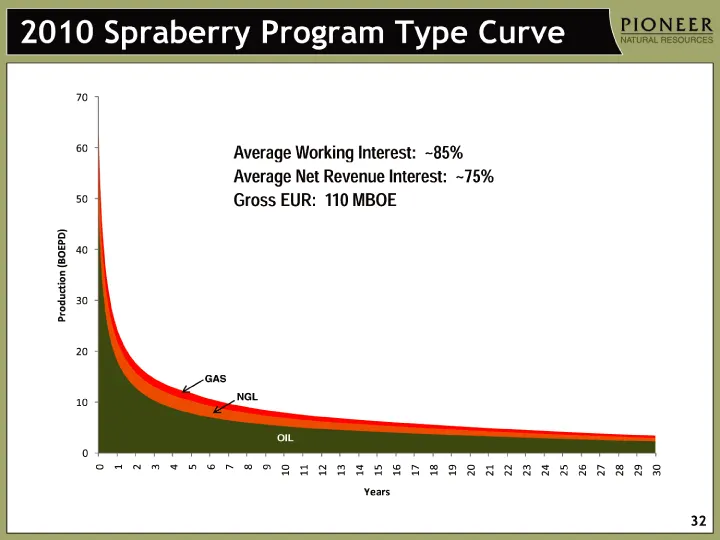
2010 Spraberry Program Type Curve 32 Average Working Interest: ~85% Average Net Revenue Interest: ~75% Gross EUR: 110 MBOE OIL NGL GAS OIL
Slide 32: Oil/Gas Ratio Trending Up Since 2006
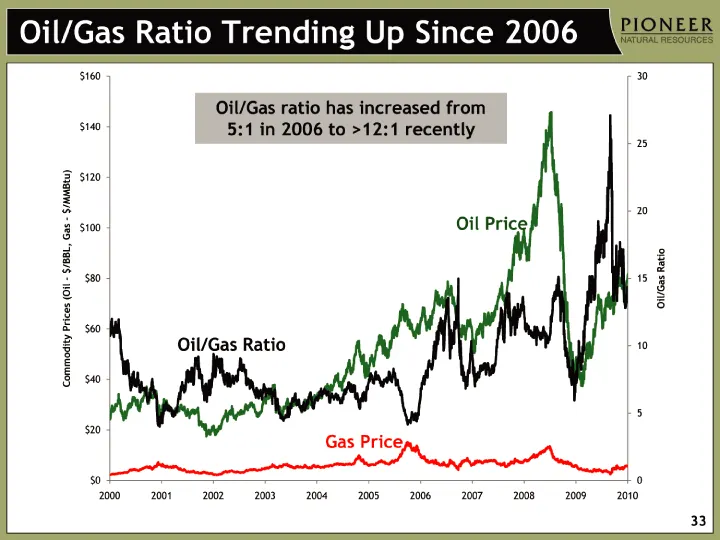
(CHART) Oil/Gas Ratio Trending Up Since 2006 33 Oil Price Gas Price Oil/Gas Ratio Oil/Gas ratio has increased from 5:1 in 2006 to >12:1 recently
Slide 33: Liquidity Position (9/30/09 Pro Forma)
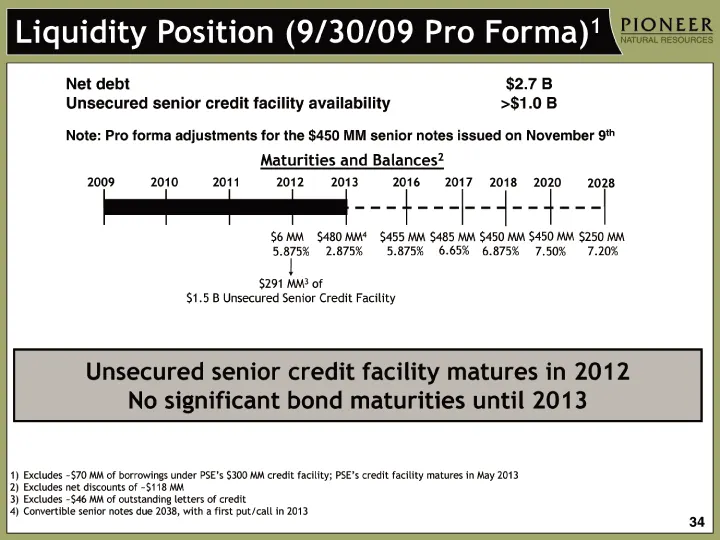
34 Liquidity Position (9/30/09 Pro Forma)1 Net debt $2.7 B Unsecured senior credit facility availability >$1.0 B Note: Pro forma adjustments for the $450 MM senior notes issued on November 9th Excludes ~$70 MM of borrowings under PSE's $300 MM credit facility; PSE's credit facility matures in May 20
Slide 34: Capital Spending by Category
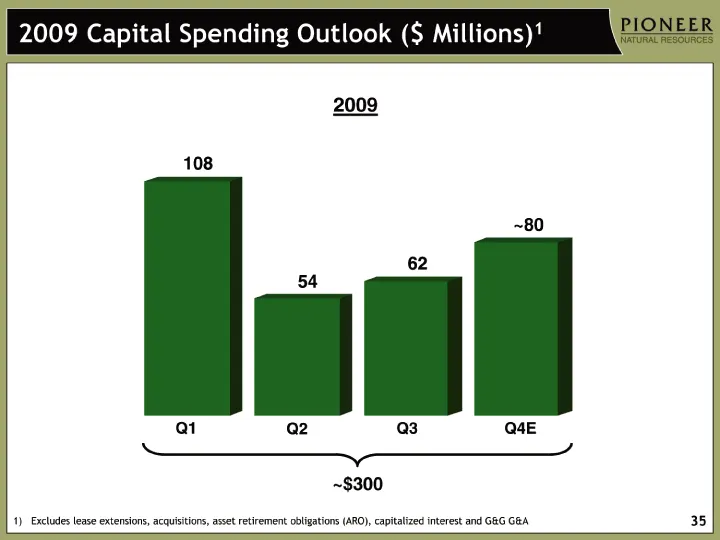
35 Volumes Q1 Q2 Q2P Q3 Q3P Q4 Q1 Q2 Q3 Q4 Q1 2001 Q2 01 Q3 01 4Q 01 Q1 02 Q2 02 Q3 02 Q4 02 Q1 03 Q2 03 Q3 03 Q4 03 Q1 04 Q2 04 Q3 04 Q4 04 Q1 05 Q2 05 Q3 05 Q4 05 Q1 2006 Q2 2006 Q3 2006 Q4 2006 Q1 2007 Q2 2007 Q3 2007 Q4 2007 Q1 2008 Q2 2008 Q3 2008 Q4 2008 Q1 2009 Q2 2009E Q3 2009E Q4 2009E Deve
Slide 35: 2009 Capital Spending Targeted to Generate Free Cash Flow
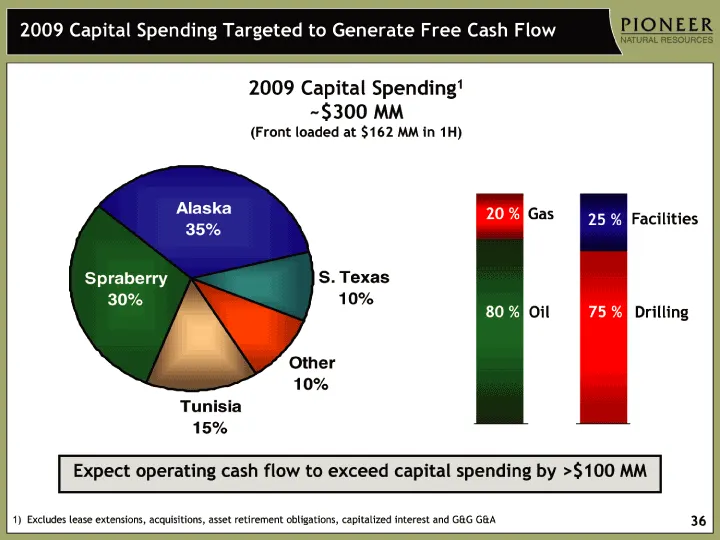
36 2009 Capital Spending Targeted to Generate Free Cash Flow Alaska S. Texas Barnett Other Raton Tunisia Spraberry Development Projects 0.35 0.1 0.05 0.1 0.1 0.15 0.3 1) Excludes lease extensions, acquisitions, asset retirement obligations, capitalized interest and G&G G&A 2009 Capital Spending1 ~$3
Slide 36: Production (MBOEPD)
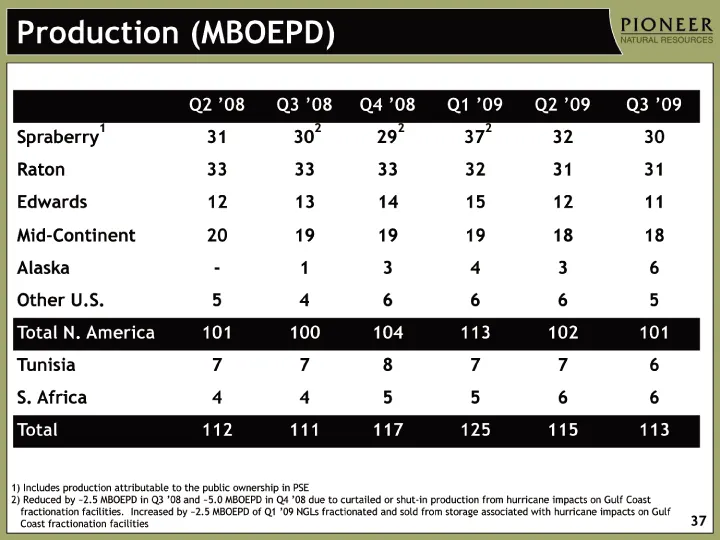
37 Production (MBOEPD) Production (MBOEPD) 1) Includes production attributable to the public ownership in PSE 2) Reduced by ~2.5 MBOEPD in Q3 '08 and ~5.0 MBOEPD in Q4 '08 due to curtailed or shut-in production from hurricane impacts on Gulf Coast fractionation facilities. Increased by ~2.5 MBOEPD o
Slide 37: PXD Open Commodity Derivative Positions - Oil and NGL
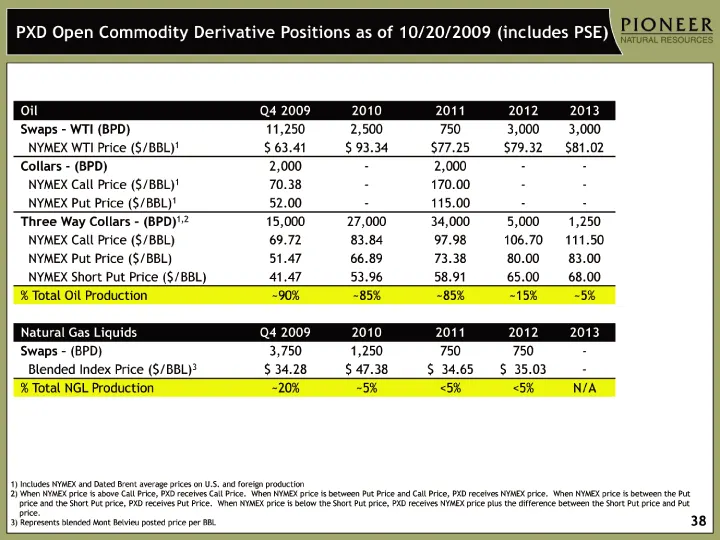
38 Oil Q4 2009 2010 2011 2012 2013 Swaps - WTI (BPD) 11,250 2,500 750 3,000 3,000 NYMEX WTI Price ($/BBL)1 $ 63.41 $ 93.34 $77.25 $79.32 $81.02 Collars - (BPD) 2,000 - 2,000 - - NYMEX Call Price ($/BBL)1 70.38 - 170.00 - - NYMEX Put Price ($/BBL)1 52.00 - 115.00 - - Three Way Collars - (BPD)1,2 15,0
Slide 38: PXD Open Commodity Derivative Positions - Gas
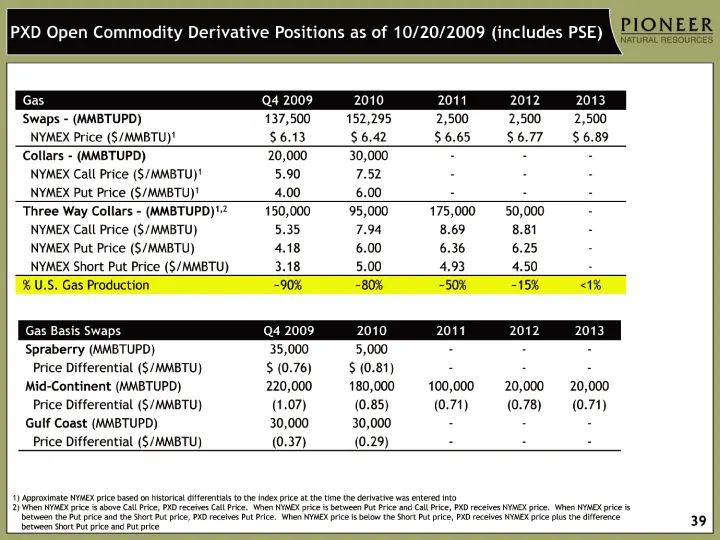
39 Gas Q4 2009 2010 2011 2012 2013 Swaps - (MMBTUPD) 137,500 152,295 2,500 2,500 2,500 NYMEX Price ($/MMBTU)1 $ 6.13 $ 6.42 $ 6.65 $ 6.77 $ 6.89 Collars - (MMBTUPD) 20,000 30,000 - - - NYMEX Call Price ($/MMBTU)1 5.90 7.52 - - - NYMEX Put Price ($/MMBTU)1 4.00 6.00 - - - Three Way Collars - (MMBTUPD
Slide 39: PSE Open Commodity Derivative Positions
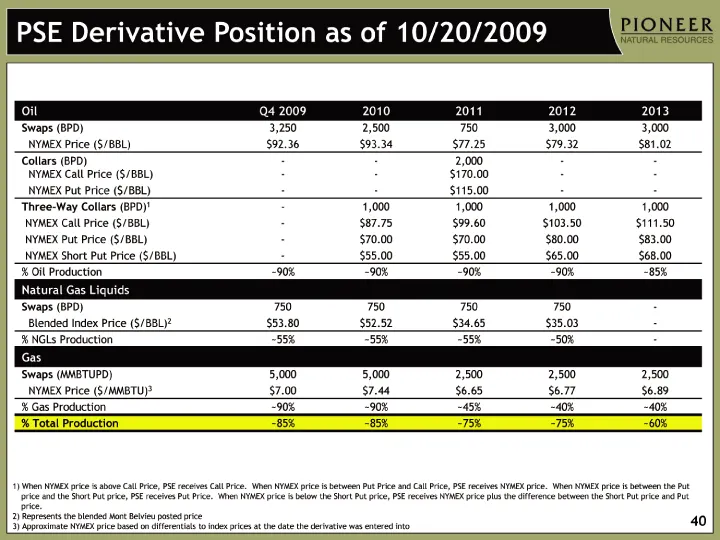
40 1) When NYMEX price is above Call Price, PSE receives Call Price. When NYMEX price is between Put Price and Call Price, PSE receives NYMEX price. When NYMEX price is between the Put price and the Short Put price, PSE receives Put Price. When NYMEX price is below the Short Put price, PSE receives
Slide 40: VPP Expirations
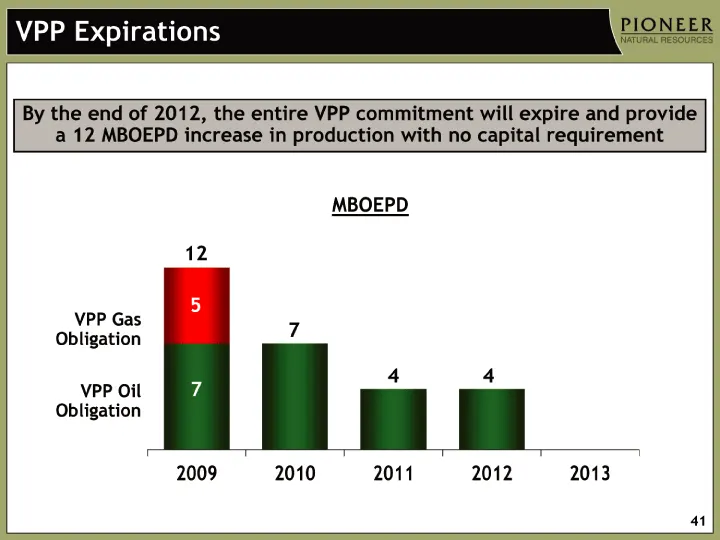
41 2008 2009 2010 2011 2012 2013 Historical Production VPP Oil 8 7 7 4 4 0 VPP Gas 5 5 Legacy Hedges VPP Expirations VPP Oil Obligation 12 7 4 MBOEPD 5 10 VPP Gas Obligation 7 4 By the end of 2012, the entire VPP commitment will expire and provide a 12 MBOEPD increase in production with no capital r
Slide 41: Competitive Cash Costs vs. Peers
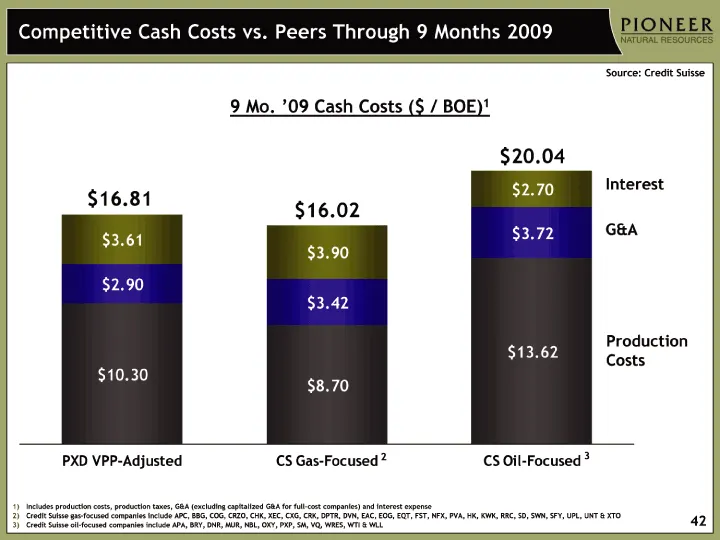
Competitive Cash Costs vs. Peers Through 9 Months 2009 Source: Credit Suisse 9 Mo. '09 Cash Costs ($ / BOE)1 Includes production costs, production taxes, G&A (excluding capitalized G&A for full-cost companies) and interest expense Credit Suisse gas-focused companies include APC, BBG, COG, CRZO, CHK,
Slide 42: Production Costs (per BOE)
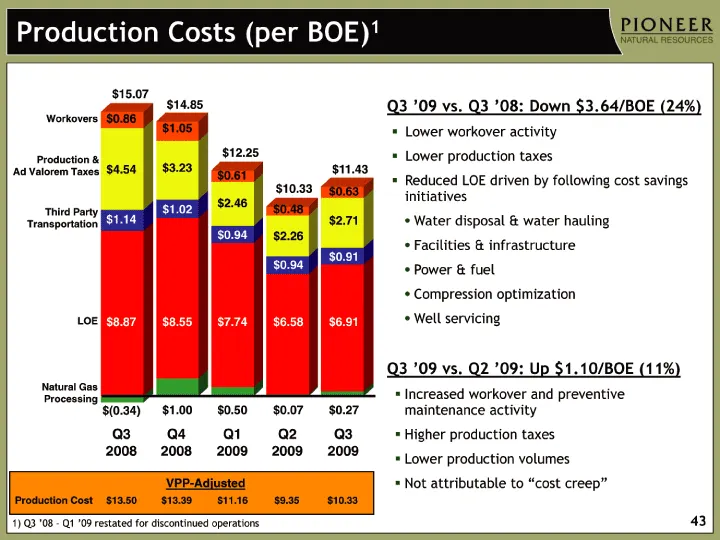
43 Q1 Q2 Q3 Q1 2000 Q2 2000 Q3 2000 Q4 2000 Q1 01 Q2 2001 Q3 01 Q4 01 Q1 02 Q2 02 Q3 02 Q4 02 Q1 03 Q2 03 Q3 03 Q4 03 Q1 04 Q2 04 Q3 04 Q4 04 Q1 05 Q2 05 Q3 05 Q4 05 Q1 06 Q2 06 Q3 06 Q4 06 Q1 2007 Q2 2007 Q3 2007 Q4 2007 Q1 2008 Q2 2008 Q3 2008 Q4 2008 Q1 2009 Q2 2009 Q3 2009 NGP 0.12 0.21 0.25 0.3
Slide 43: VPP-Adjusted Production Costs
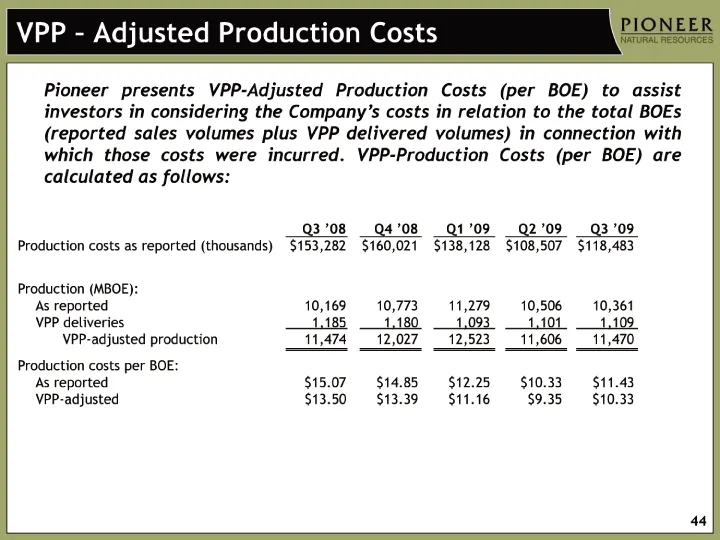
44 VPP - Adjusted Production Costs Pioneer presents VPP-Adjusted Production Costs (per BOE) to assist investors in considering the Company's costs in relation to the total BOEs (reported sales volumes plus VPP delivered volumes) in connection with which those costs were incurred. VPP-Production Cost
Slide 44: Certain Reserve Information
45 Certain Reserve Information Cautionary Note to U.S. Investors -- The U.S. Securities and Exchange Commission (the "SEC") permits oil and gas companies, in their filings with the SEC, to disclose only proved reserves that a company has demonstrated by actual production or conclusive formation test
Source: SEC EDGAR · 8-K filed Jan 6, 2010
More decks from Pioneer Natural Resources Co
 Merger or Acquisition (October 2023)15 slides · Oct 11, 2023
 Q3 2020 Earnings Presentation30 slides · Nov 4, 2020
 Merger or Acquisition (October 2020)18 slides · Oct 20, 2020
 IPAA Oil & Gas Investment Symposium 201846 slides · Apr 9, 2018
 Investor Presentation (January 2014)80 slides · Jan 6, 2014
 Q4 2012 Earnings Presentation48 slides · Feb 13, 2013