Supervalu — Bear Stearns 12th Annual Retail, Restaurants and Consumer Conference (March 2006)
29 slides from Supervalu's conference presentation, Mar 9, 2006
Slide 1: Forging the Future of Grocery Retailing
Forging the Future of Grocery Retailing Yolanda M. Scharton Vice President Corporate Communications and Investor Relations Bear Stearns 12 th Annual Retail, Restaurants and Consumer Conference March 9, 2006 Pre-proxy version Filed by SUPERVALU INC. Pursuant to Rule 425 under the Securities Act of 19
Slide 2
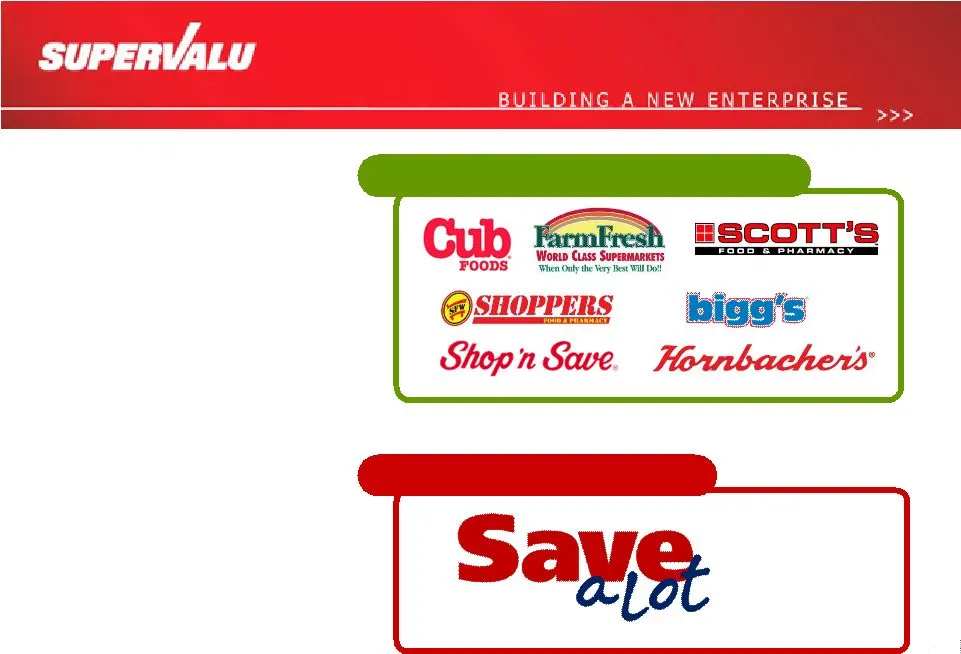
Slide 3: National Banner / Super-Regional Banners
National Banner Super-Regional Banners Extreme value • Small Box Format • Highly efficient model Super-regional • Two dominant formats: Fresh Focus and Price Impact
Slide 4
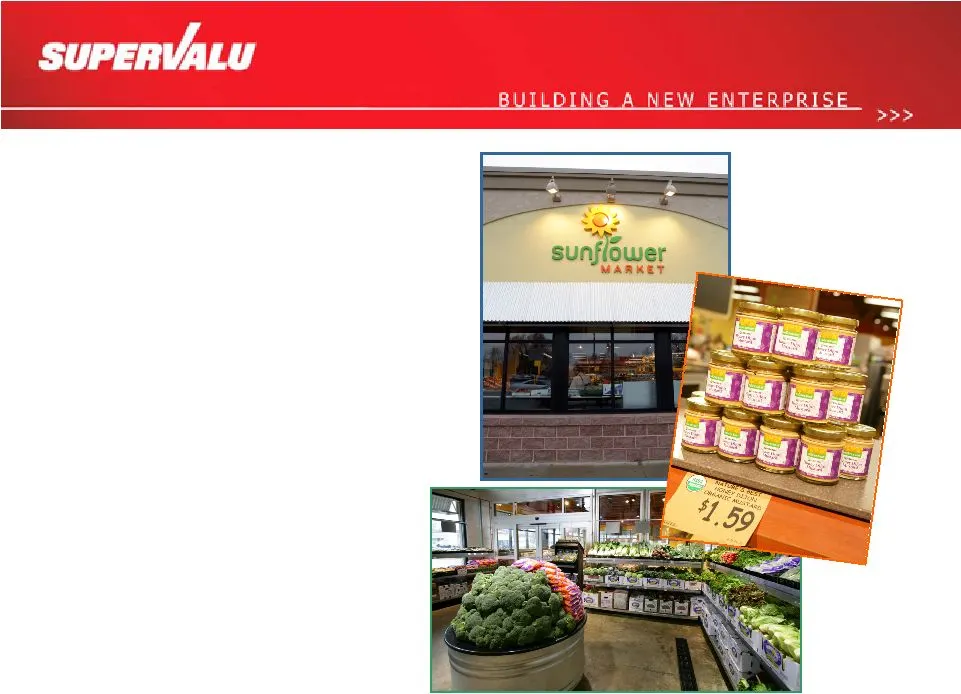
Slide 5: Our New Fresh Concept
Our New Fresh Concept • January 2006, Indianapolis • 8,000 – 12,000 SKUs • 12,000 – 15,000 sq. ft. • Limited assortment • Value-priced at 10%-15% lower than conventional and natural store competitors • Focus on perishables, especially produce • High-quality natural and organic departments
Slide 6
Slide 7: National Banner Save-A-Lot: Big Savings in a Small Box
National Banner Save-A-Lot: Big Savings in a Small Box • The fastest-growing limited assortment retailer in the U.S. – 1,154 stores in 39 states • 862 licensed • 292 corporate • Target customer – Household incomes under $35,000 – 43.3 million households • 12,000 – 15,000 sq. ft. footprint • Approxim
Slide 8: Industry leader in efficiency and service offerings to retail grocery channel
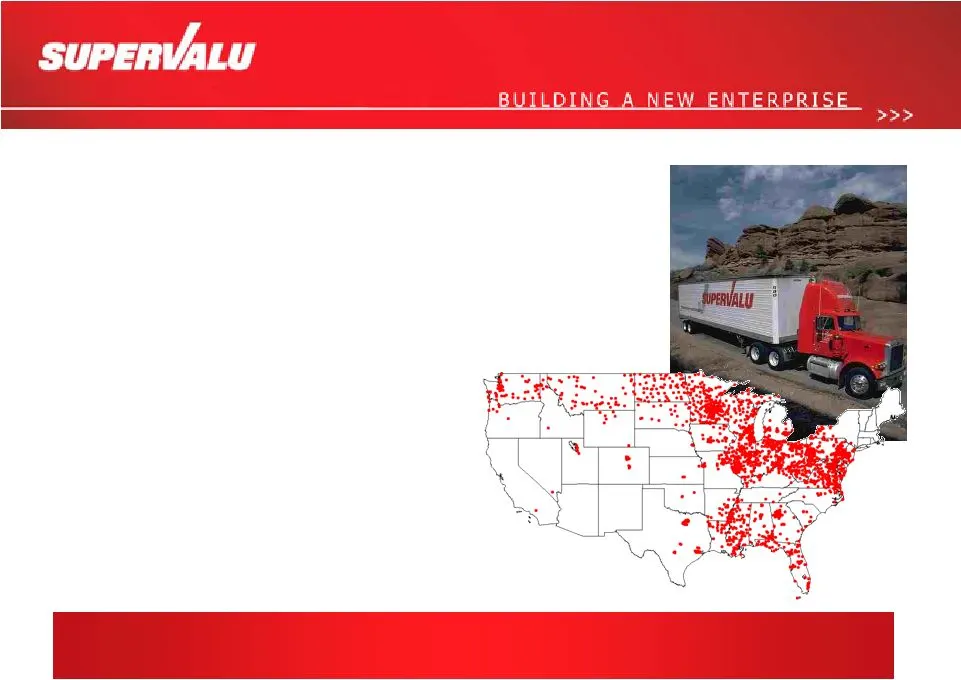
Industry leader in efficiency and service offerings to retail grocery channel Our Supply Chain Services Profile • Serving more than 2,200 primary customer sites and 227 corporate retail locations • Travel almost 100 million miles annually • Supported by 24 locations • Move more than half-billion cas
Slide 9: bigg’s
ee *. bigg’s sunfldwer
Slide 10: How We View the Market
SUPERVALU is actively shaping its future and positioning itself to succeed in the grocery retailing industry How We View the Market New Realities Creating Opportunities to Shape SUPERVALU and the Grocery Retail Sector • Channel Blur - Everybody is selling food – Non-traditional retailers using food
Slide 11: Successfully competing requires a multi-faceted approach to achieve sustainable grocery retail success
Successfully competing requires a multi-faceted approach to achieve sustainable grocery retail success Scale and Diversity of Retail Formats Strong Supply Chain Backbone Empowered People • Ideally positioned to capitalize on serving diverse customer needs and wants – Extreme Value – Price Impact – T
Slide 12
Slide 13: Our Acquisition Discipline Was Applied
Synergistic and Accretive Disciplined Selection and Rigorous Due Diligence Our Acquisition Discipline Was Applied • Strong local market leadership • Realizable synergies • Additive competencies • Don’t seek turnarounds • Fit with SVU strategy • Rigorous due diligence • Enhance shareholder value
Slide 14: The Deal
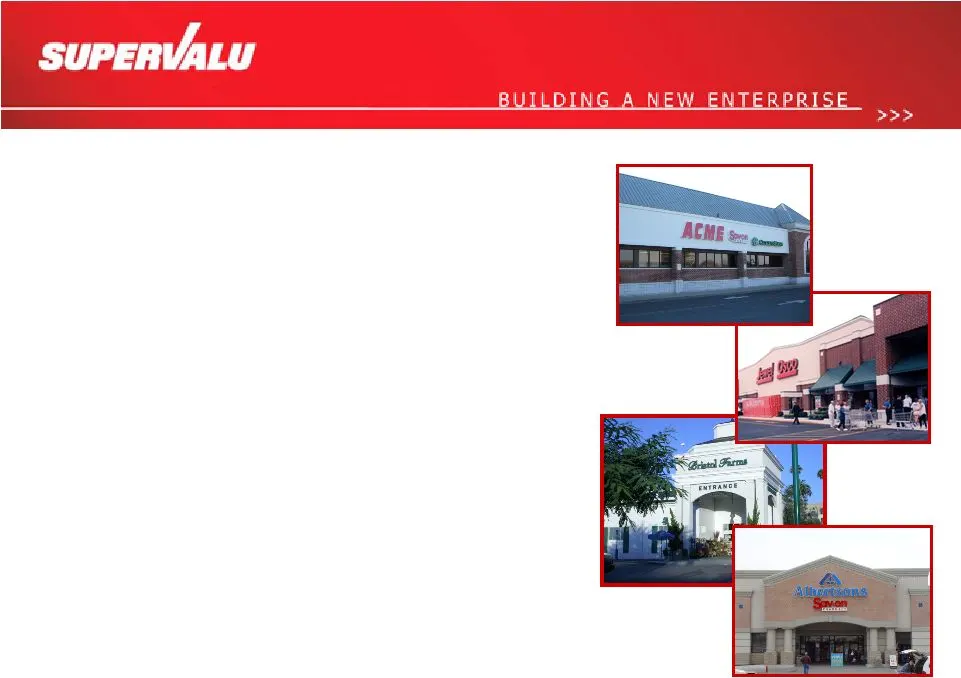
The Deal Transaction Summary • SUPERVALU, CVS and Cerberus-led investment group to acquire Albertsons for $17.4 billion in cash, stock and debt assumption (with HITS). • SUPERVALU to acquire premier retail properties - more than 1,100 stores: • Acme Markets • Bristol Farms • Jewel-Osco • Shaw’s and
Slide 15: Transformation in Scope and Scale
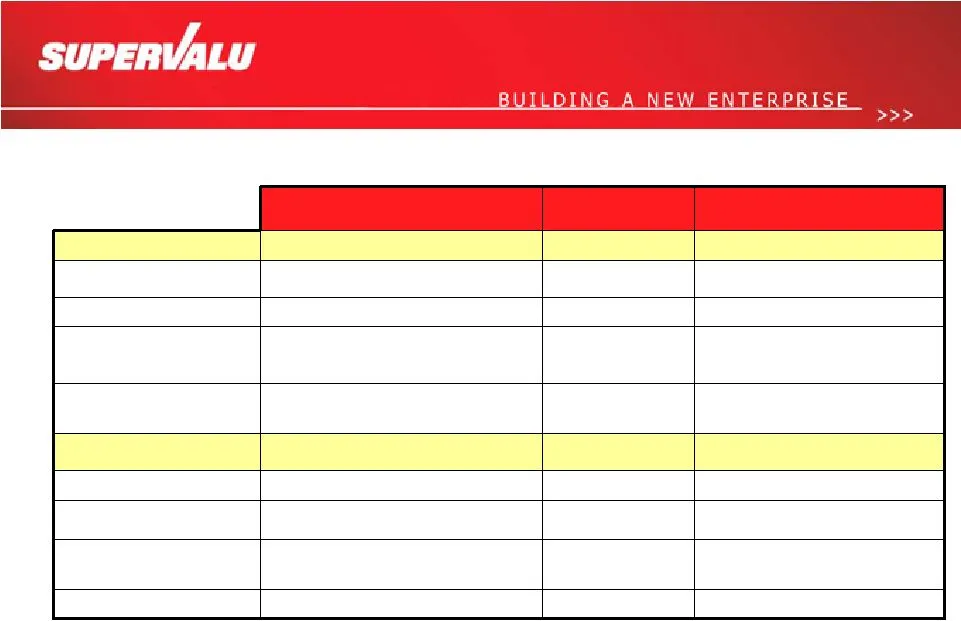
New SUPERVALU Business to be Acquired SUPERVALU In-store Pharmacies $150-$175 million pretax over 3 yrs. Synergies 89% Retail 67% Retail EBITDA Mix 80% Retail 53% Retail Revenue Mix 193,800 144,000 49,800 Employees 2,505 1,124 1,381 Store Network Financial Operational Fuel Centers $44B $25B $19B Rev
Slide 16: SUPERVALU's Current Footprint
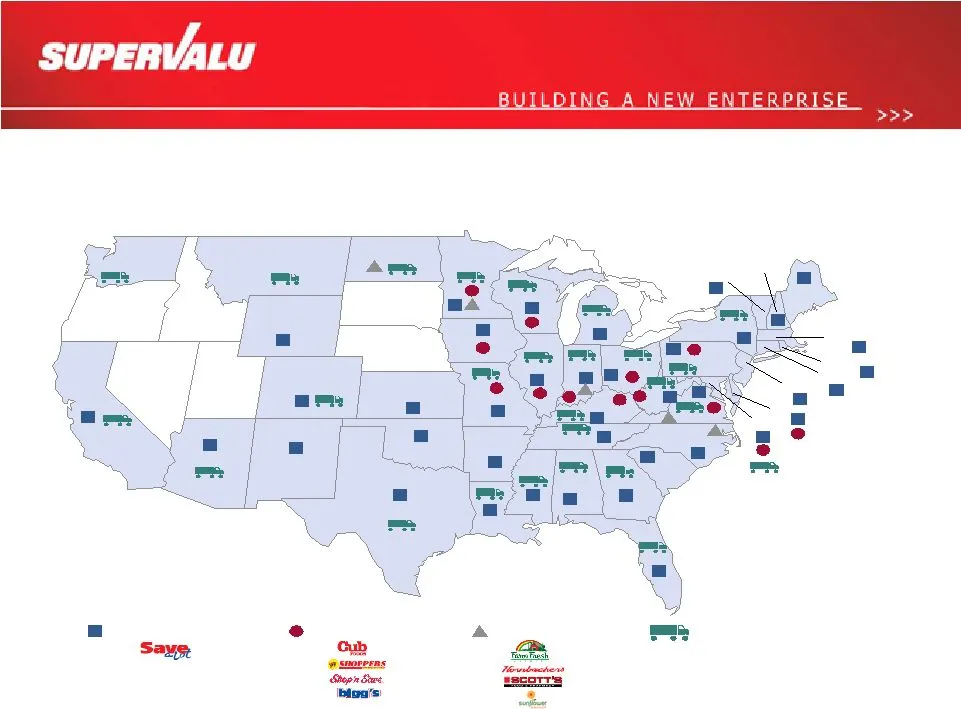
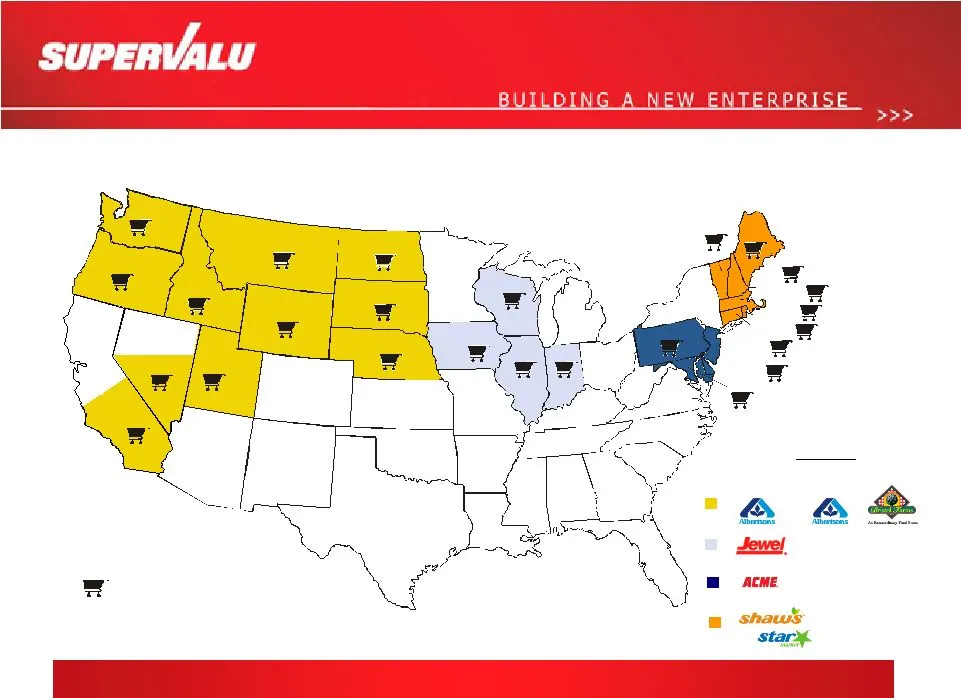
18 23 15 5 6 1 89 31 64 20 48 1 19 7 3 7 117 1 18 20 39 12 92 62 1 22 53 22 9 43 4 105 16 18 55 13 3 9 103 1 19 22 40 39 17 7 3 2 1 3 3 1 2 2 5 6 3 2 1 1 4 3 1 4 2 1 8 2 2 9 7 2 14 1 2 37 1 17 1 3 1 1 1 SUPERVALU’s Current Footprint • SUPERVALU has a retail or distribution presence in 42 states, and
Slide 17: Retail Store Footprint To Be Acquired
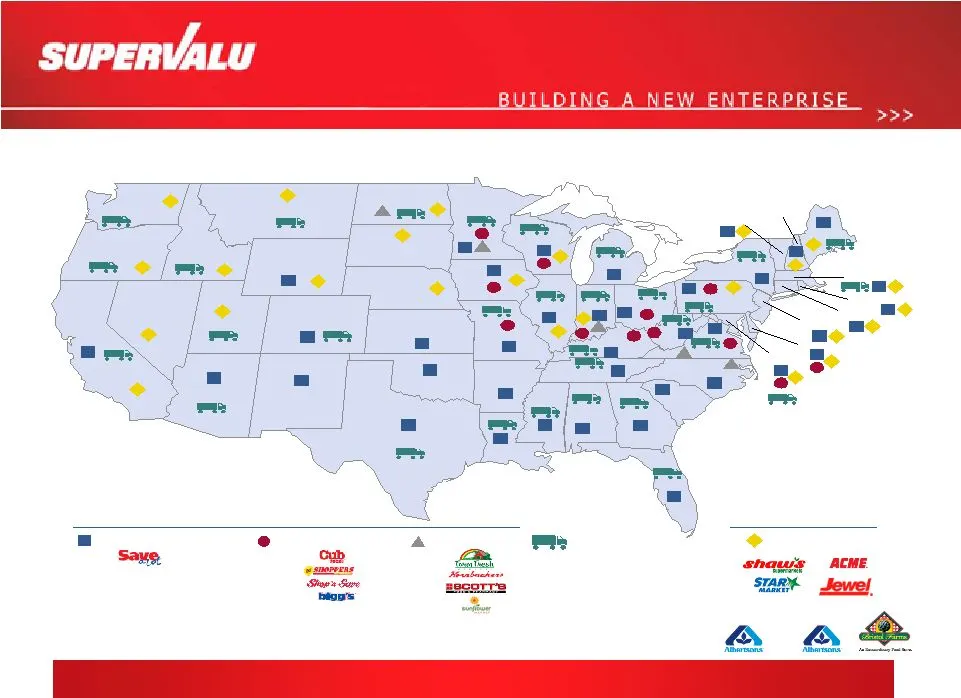
85 55 Pennsylvania 43 34 47 1 1 2 1 15 178 6 53 18 23 35 94 16 25 61 12 8 32 280 2 1,124 Locations in 24 States Retail Store Footprint To Be Acquired Banners Combination / Conventional Stores Oregon Washington Montana Idaho Utah Arizona New Mexico Colorado North Dakota South Dakota Nebraska Kansas M
Slide 18: 2,500+ Locations in 48 States…National Retail Powerhouse
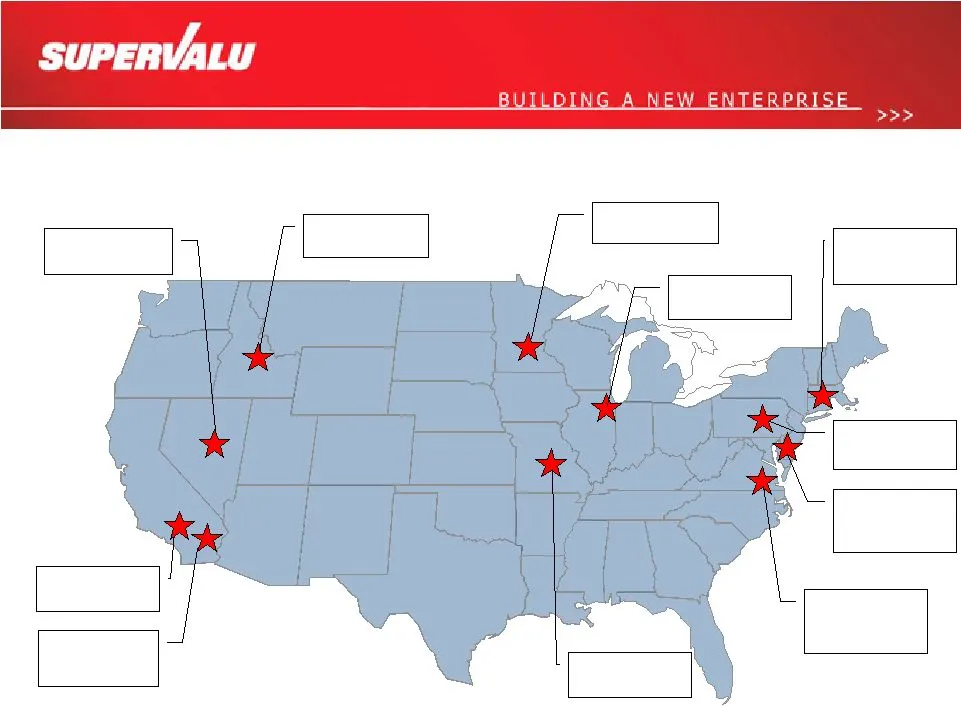
18 23 15 5 6 1 89 31 64 48 1 19 7 3 7 117 1 18 20 39 12 92 62 1 22 53 22 9 43 4 105 16 18 55 13 3 9 103 1 19 22 40 39 17 7 3 2 1 3 3 1 2 2 5 8 3 2 1 1 5 3 1 6 1 2 1 8 2 2 9 7 2 14 1 2 37 1 17 1 3 1 1 1 1 1 1 1 2,500+ Locations in 48 States…National Retail Powerhouse Proforma Operations Footprint of
Slide 19: Leading Positions in Large and Growing Markets
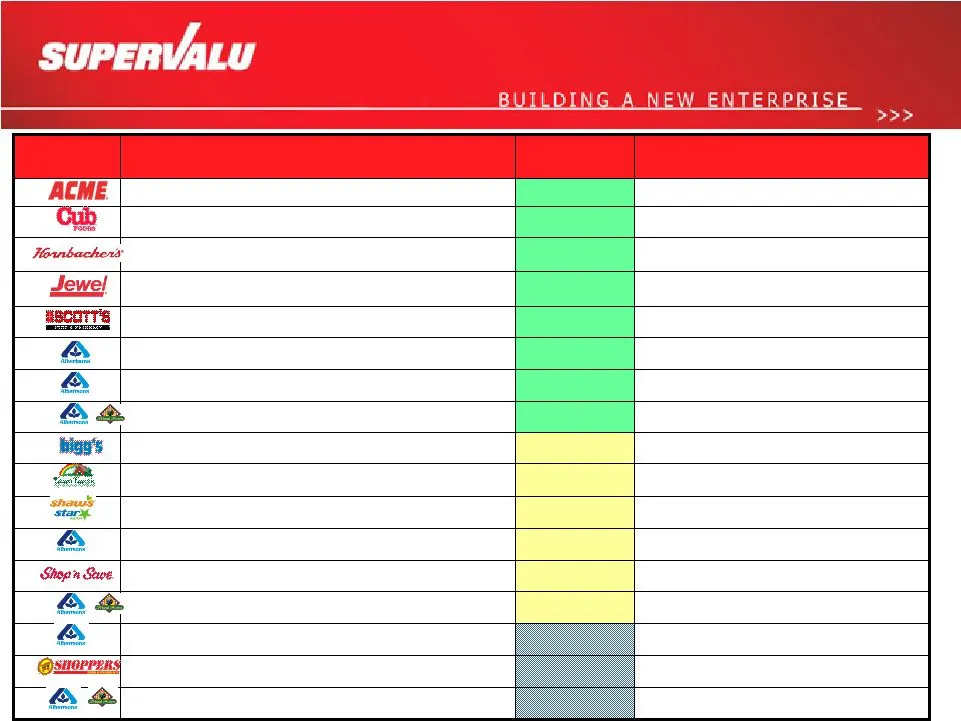
Leading Positions in Large and Growing Markets Las Vegas # 1 Market Share Southern Cal. # 1 or # 2 Market Share Mpls. / St. Paul # 1 Market Share Chicago # 1 Market Share Boston / New England # 2 Market Share Philadelphia # 1 Market Share St. Louis # 2 Market Share Washington D.C. / Baltimore # 3 Ma
Slide 20: 73% of Retail Revenues from #1 and #2 Market Positions
73% of Retail Revenues from #1 and #2 Market Positions Share Rank Banner Primary Competition MSA Markets Kroger #1 Las Vegas, NV #3 #3 #3 #2 #2 #2 #2 #2 #2 #1 #1 #1 #1 #1 #1 #1 Sun Mart Fargo, ND Giant, Safeway Washington, D.C./ Baltimore, MD Safeway, Rosauers/Kroger, Wal-Mart Spokane, WA/Salt Lake
Slide 21: Advantages of Our Expanded Retail Portfolio
Formats Strong geographic footprint, excellent market shares combined with our collective competencies offer tremendous opportunities Competencies Advantages of Our Expanded Retail Portfolio High-end Gourmet Price Impact Traditional Full-Service Fuel / Convenience Natural & Organic Extreme Value • I
Slide 22: Investing in Strong and Growing Markets
Investing in Strong and Growing Markets • Combined capital spending is $1.1B – To be allocated heavily toward remodeling and expanding store network • Remodeling – Strong commitment to well-maintained, contemporary store fleet – 85% of SUPERVALU’s current fleet is new or newly remodeled within past
Slide 23: Everyone's Favorite Question: What About Wal-Mart
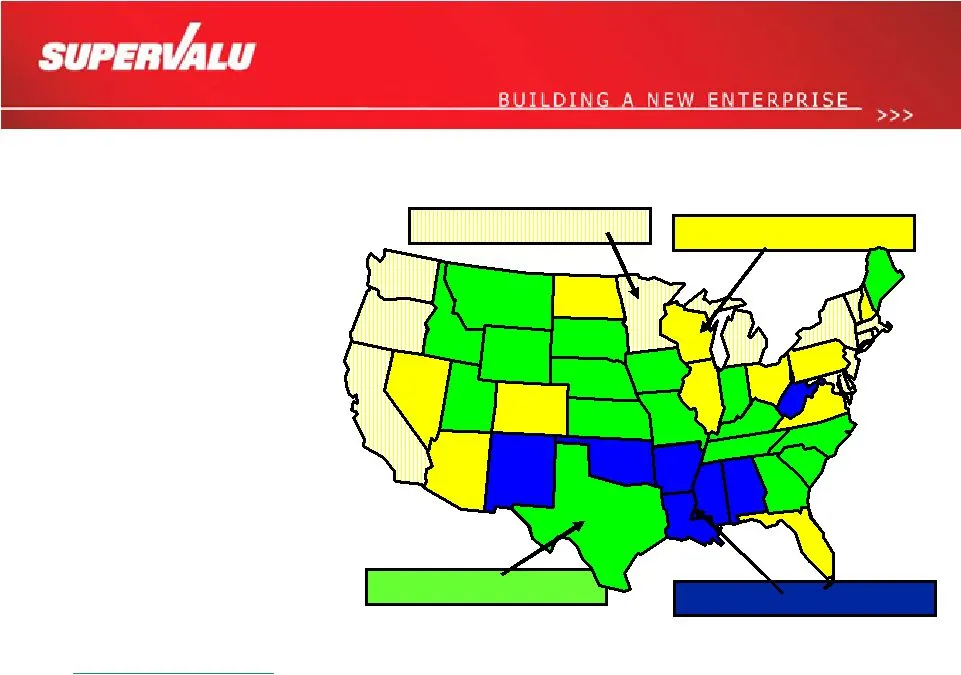
High Share States Confidential and Proprietary Copyright © 2005 ACNielsen a VNU business Everyone’s Favorite Question: What About Wal-Mart States with the most Wal-Mart stores Texas Florida California Illinois Ohio Pennsylvania Georgia Missouri North Carolina Tennessee Source: http://www.walmartfact
Slide 24: Stacking up against Wal-Mart
Chain Trend 2005 2003 Market Market Share Stacking up against Wal-Mart Not Significant Not Significant WMT 2.2% 1.8% WMT 23.3% 20.9% Acme Philadelphia 1.1% 0.7% WMT 12.2% 12.3% Albertsons Los Angeles WMT Albertsons Jewel WMT Shop’n Save WMT Farm Fresh 18.1% 25.8% 36.6% 10.8% 20.9% 22.6% 19.1% 27.6%
Slide 25: Conditions for Acquisition Approval
Status Action Date Conditions for Acquisition Approval On Track File preliminary proxy Mid-March ‘06 File Hart-Scott-Rodino (HSR) February ‘06 On Track Close By Early Summer ‘06 On Track Gain shareholder approval By Early summer ‘06 Both SUPERVALU and Albertsons boards of directors recommend shareho
Slide 26
Slide 27: Enterprise Building Framework
Collaborative, Thoughtful and Swift Process Post Close Pre-Close Enterprise Building Framework Prepare Transition Plan Implement Plan Capture Initial Synergies Execute Growth Plan Track & Validate Enterprise Executive Lead: Mike Jackson, SUPERVALU President and COO
Slide 28: Unlocking the Value in the New SUPERVALU
Unlocking the Value in the New SUPERVALU No. 2 grocery retailer in the nation, with – The industry’s best regional nameplates – A broad-based future growth potential – The right formula for sustainable grocery retail success Forging the Future of Grocery Retailing
Slide 29: The New SUPERVALU
THE NEW Northwestern / Intermountain Southern California
Source: SEC EDGAR · 425 filed Mar 9, 2006
More decks from Supervalu Inc
 Shareholder Meeting (August 2018)14 slides · Aug 16, 2018
 Proxy Contest (July 2018)175 slides · Jul 24, 2018
 Proxy Contest (July 2018)60 slides · Jul 17, 2018
 Proxy Contest (May 2018)9 slides · May 29, 2018
 Proxy Contest (March 2018)79 slides · Mar 28, 2018
 Debt Investor Presentation (January 2013)40 slides · Jan 28, 2013