Kansas City Southern — Merger or Acquisition (January 2005)
32 slides from Kansas City Southern's merger presentation, Jan 4, 2005
Slide 1: KCS and TMM amended acquisition agreement summary
KANSAS CITY SOUTHERN KCS and TMM amended acquisition agreement summary
Slide 2: Proxy statement and participant notice
KANSAS CITY SOUTHERN In connection with the proposed transaction, KCS will file relevant materials with the Securities and Exchange Commission (“SEC”), including an amended proxy statement soliciting stockholder approval of certain actions in connection with the transaction. Stockholders are urged t
Slide 3: KCSR, Tex Mex and TFM Operating Under Common Control
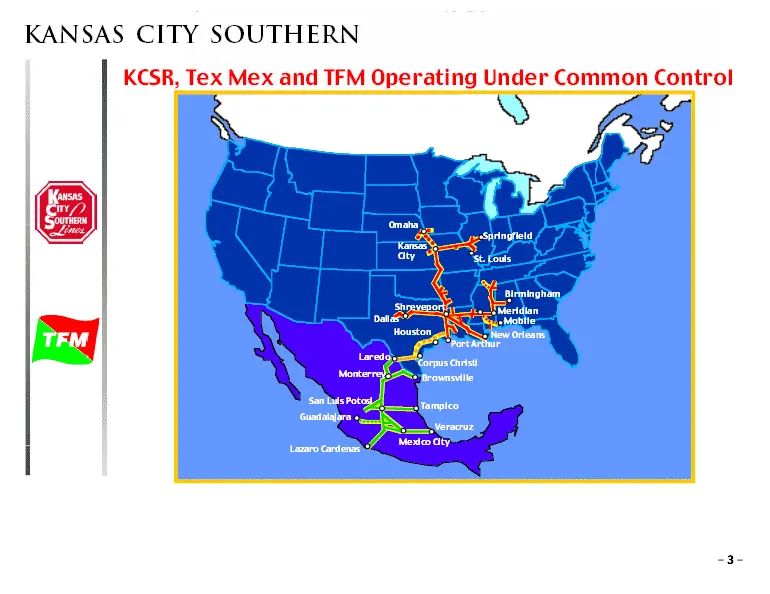
KANSAS CITY SOUTHERN KCSR, Tex Mex and TFM Operating Under Common Control Omaha Springfield Kansas City St. Louis Birmingham Shreveport Meridian Dallas Mobile Houston New Orleans Port Arthur Laredo Corpus Christi Monterrey Brownsville San Luis Potosi Tampico Guadalajara Veracruz Mexico City Lazaro C
Slide 4: Strategic Rationale for a NAFTA Rail System
KANSAS CITY SOUTHERN Strategic Rationale for a NAFTA Rail System · Enhance shareholder value by achieving consolidation of rapidly expanding TFM affiliate in Mexico, with U.S. ownership · Accretive transaction · Strengthen KCSR/Tex Mex/TFM as the “NAFTA Railroad” · Increase EPS contribution from fas
Slide 5: Common Control
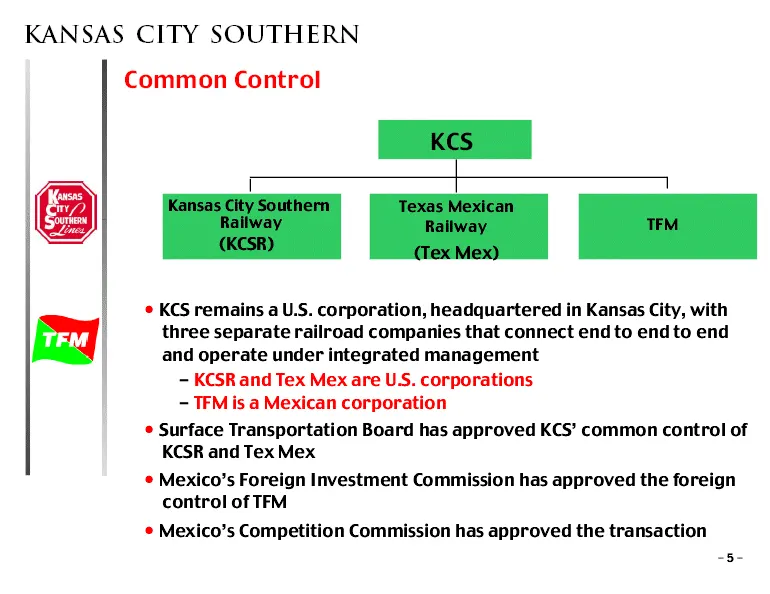
KANSAS CITY SOUTHERN Common Control KCS Kansas City Southern Railway (KCSR) Texas Mexican Railway (Tex Mex) TFM · KCS remains a U.S. corporation, headquartered in Kansas City, with three separate railroad companies that connect end to end to end and operate under integrated management — KCSR and Tex
Slide 6: Provides Enhanced Competition
KANSAS CITY SOUTHERN Provides Enhanced Competition · Three railroad companies connecting end to end to end - Maintain the unique culture of each company — Operating under integrated management - Only enhances competition-no reduction of competitors in any market · No “2 to 1 points” · No overlaps ·
Slide 7: Combined Resources lead to Enhanced Product Offerings
KANSAS CITY SOUTHERN Combined Resources lead to Enhanced Product Offerings · 1,020 locomotives • 26,044 freight cars · 119 transload/reload locations • 12 intermodal ramps • 13 ports · 180 interchange points with other railroads - 7 -
Slide 8: Amended Transaction Summary
KANSAS CITY SOUTHERN Amended Transaction Summary · KCS Acquires Grupo TMM’s 38.8% effective ownership in TFM · Consideration - $200 million cash — 18 million shares of KCS - $157 million in contingent payments over next 5 years, comprised of: • $35 million in cash or KCS stock • $35 million in KCS s
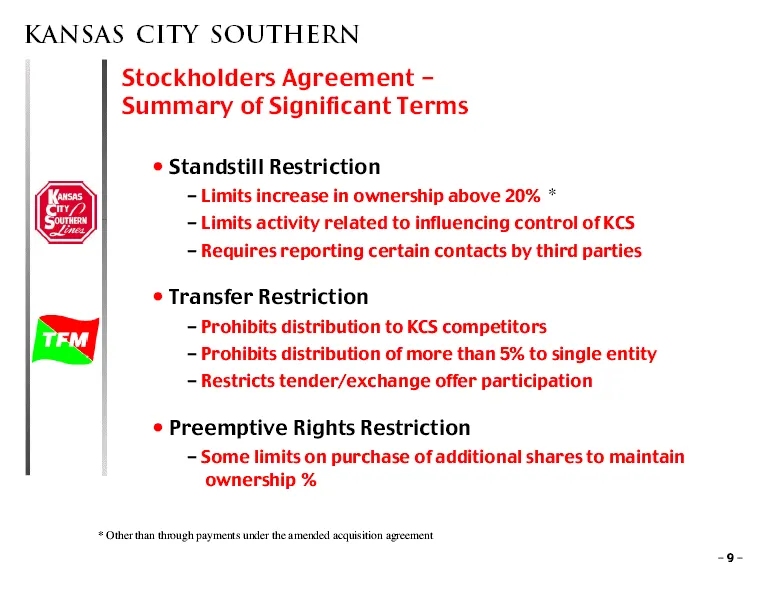
Slide 9: Stockholders Agreement - Summary of Significant Terms
KANSAS CITY SOUTHERN Stockholders Agreement -Summary of Significant Terms · Standstill Restriction - Limits increase in ownership above 20% * - Limits activity related to influencing control of KCS - Requires reporting certain contacts by third parties · Transfer Restriction - Prohibits distribution
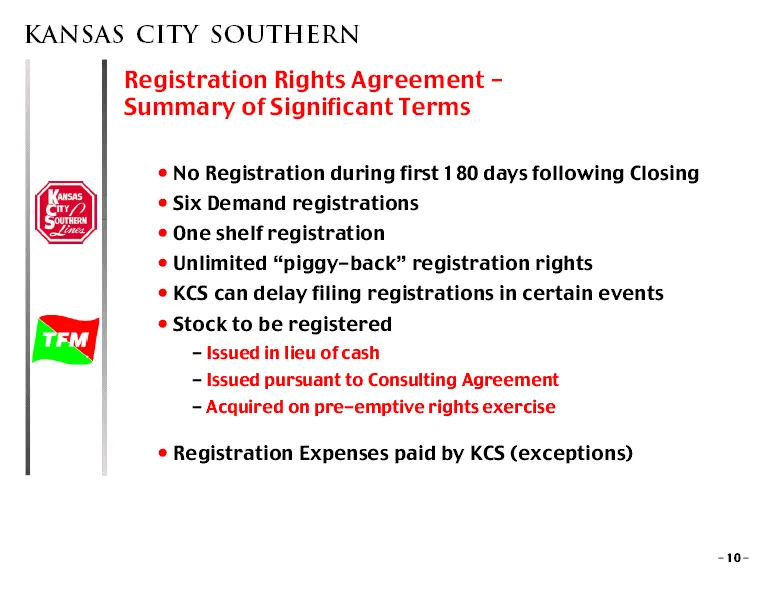
Slide 10: Registration Rights Agreement - Summary of Significant Terms
KANSAS CITY SOUTHERN Registration Rights Agreement -Summary of Significant Terms · No Registration during first 180 days following Closing • Six Demand registrations • One shelf registration • Unlimited “piggy-back” registration rights • KCS can delay filing registrations in certain events • Stock t
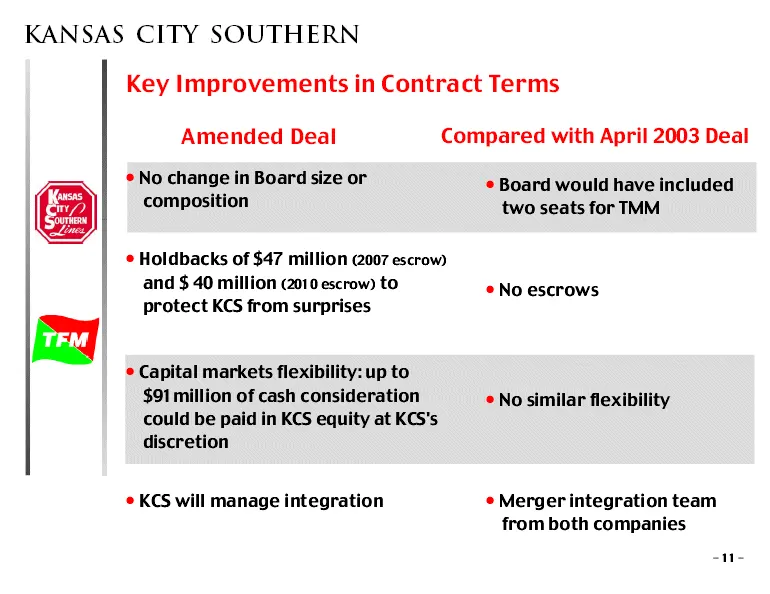
Slide 11: Key Improvements in Contract Terms
KANSAS CITY SOUTHERN Key Improvements in Contract Terms Amended Deal Compared with April 2003 Deal · No change in Board size or • Board would have included composition two seats for TMM · Holdbacks of $47 million (2007 escrow) and $ 40 million (2010 escrow) to · No escrows protect KCS from surprises
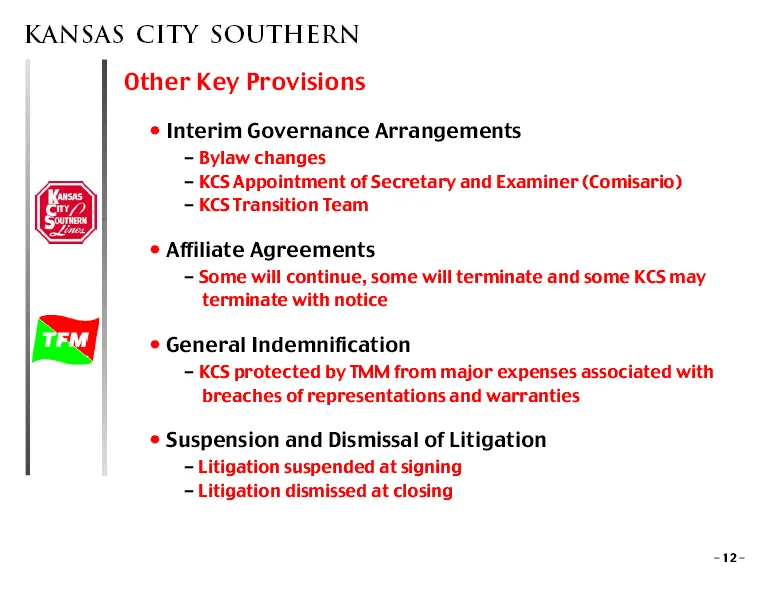
Slide 12: Other Key Provisions
KANSAS CITY SOUTHERN Other Key Provisions · Interim Governance Arrangements - Bylaw changes - KCS Appointment of Secretary and Examiner (Comisario) - KCS Transition Team · Affiliate Agreements - Some will continue, some will terminate and some KCS may terminate with notice · General Indemnification
Slide 13: Closing Protections
KANSAS CITY SOUTHERN Closing Protections · TMM shareholder approval is NOT required and is not a condition to closing, but: - The shares of TMM and its subsidiaries (TMMH and TMM Multimodal) will be placed at signing into voting trusts that provide unconditionally that the shares will be voted to ap
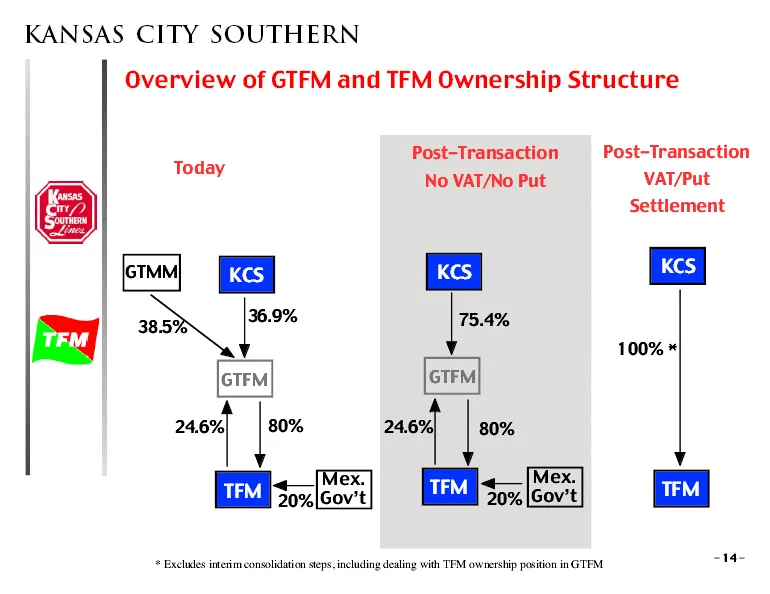
Slide 14: Overview of GTFM and TFM Ownership Structure
KANSAS CITY SOUTHERN Overview of GTFM and TFM Ownership Structure Post-Transaction Post-Transaction Today No VAT/No Put VAT/Put Settlement GTMM KCS KCS KCS 36.9% 75.4% 38.5% 100% * GTFM GTFM 24.6% 80% 24.6% 80% Mex. TFM Mex. TFM Gov’t 20% Gov’t TFM 20% * Excludes interim consolidation steps, includi
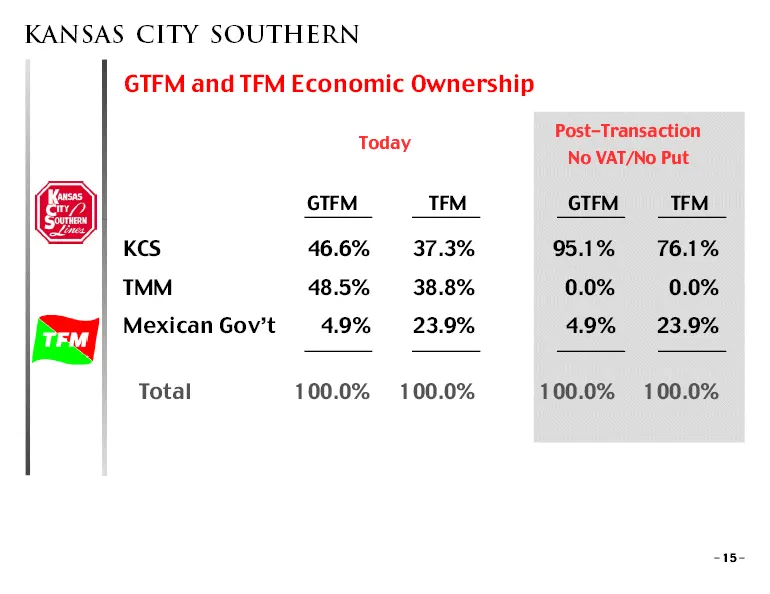
Slide 15: GTFM and TFM Economic Ownership
KANSAS CITY SOUTHERN GTFM and TFM Economic Ownership Post-Transaction Today No VAT/No Put GTFM TFM GTFM TFM KCS 46.6% 37.3% 95.1% 76.1% TMM 48.5% 38.8% 0.0% 0.0% Mexican Gov’t 4.9% 23.9% 4.9% 23.9% Total 100.0% 100.0% 100.0% 100.0% - 15 -
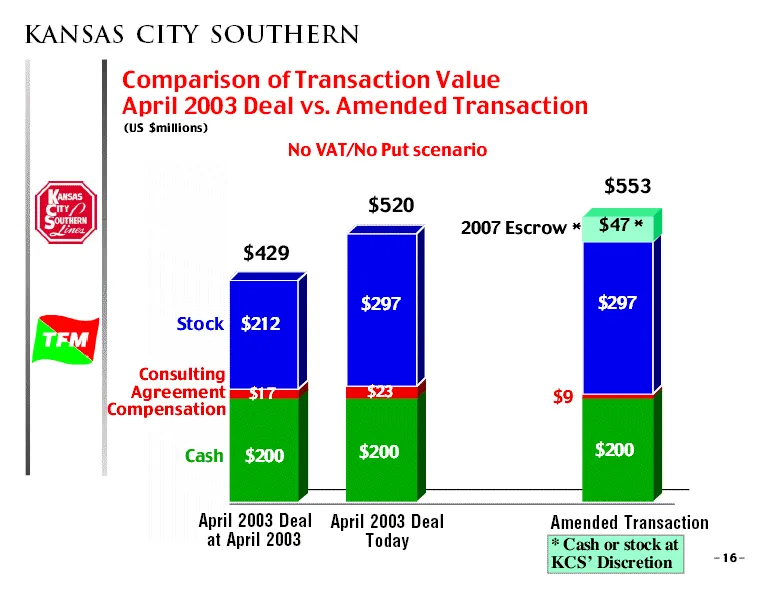
Slide 16: Comparison of Transaction Value: April 2003 Deal vs. Amended
KANSAS CITY SOUTHERN Comparison of Transaction Value April 2003 Deal vs. Amended Transaction (US $millions) No VAT/No Put scenario $553 $520 2007 Escrow *$47 * $429 $297 $297 Stock $212 Consulting Agreement $17 $23 $9 Compensation Cash$200 $200 $200 April 2003 Deal April 2003 Deal Amended Transactio
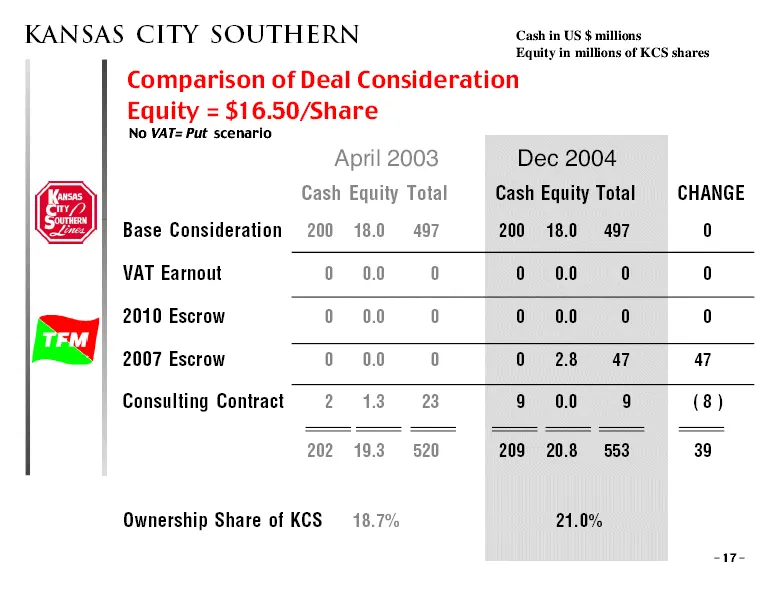
Slide 17: Comparison of Deal Consideration
KANSAS CITY SOUTHERN Cash in US $millions Equity in millions of KCS shares Comparison of Deal Consideration Equity = $16.50/Share No VAT= Put scenario April 2003 Dec 2004 Cash Equity Total Cash Equity Total CHANGE Base Consideration 200 18.0 497 200 18.0 497 0 VAT Earnout 0 0.0 0 0 0.0 0 0 2010 Escr
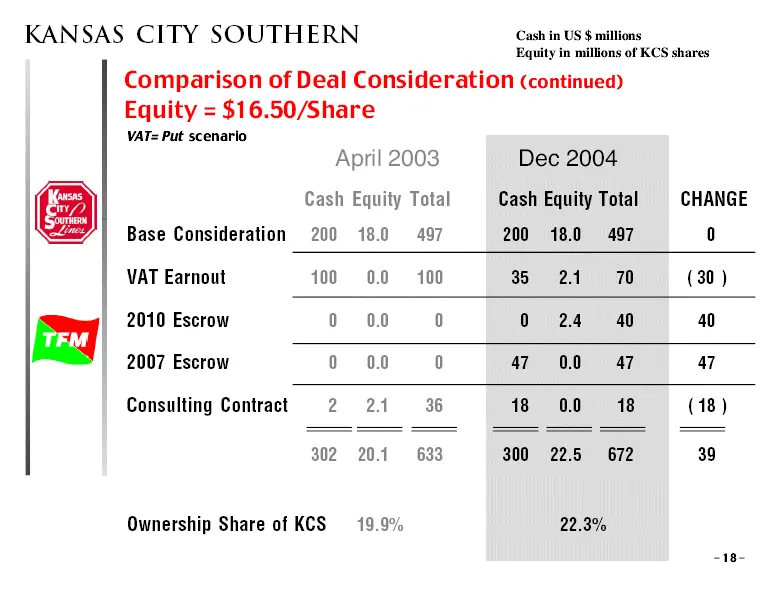
Slide 18: Comparison of Deal Consideration (continued)
KANSAS CITY SOUTHERN Cash in US $ millions Equity in millions of KCS shares Comparison of Deal Consideration (continued) Equity = $16.50/Share VAT= Put scenario April 2003 Dec 2004 Cash Equity Total Cash Equity Total CHANGE Base Consideration 200 18.0 497 200 18.0 497 0 VAT Earnout 100 0.0 100 35 2.
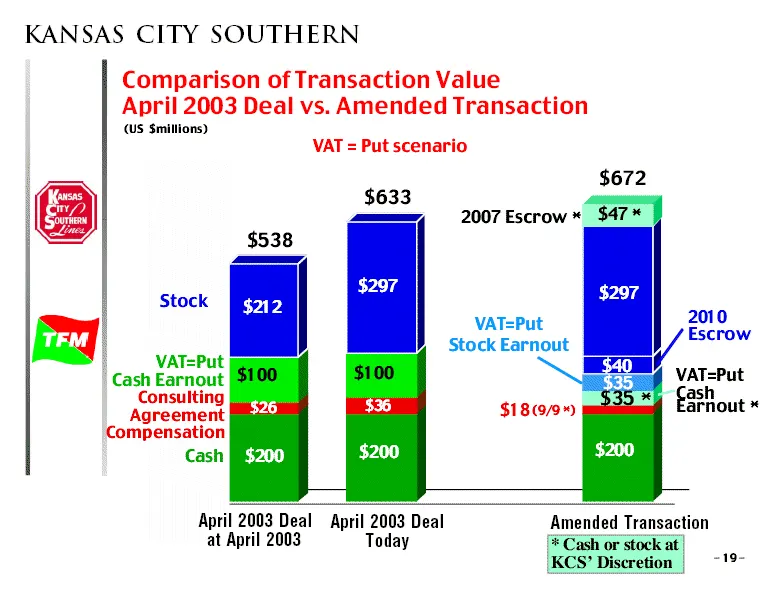
Slide 19: Comparison of Transaction Value: VAT = Put scenario
KANSAS CITY SOUTHERN Comparison of Transaction Value April 2003 Deal vs. Amended Transaction (US $millions) VAT = Put scenario $672 $633 2007 Escrow * $47 * $538 $297 $297 Stock $212 VAT=Put 2010 Escrow Stock Earnout VAT=Put $40 Cash Earnout $100$100 VAT=Put $35 Consulting $35 * Cash $26 $36 $18(9/9
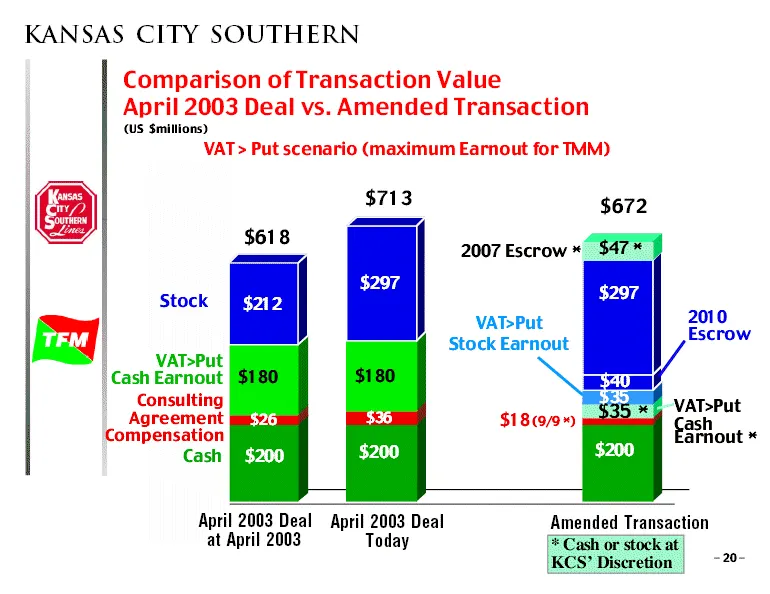
Slide 20: Comparison of Transaction Value: VAT > Put scenario
KANSAS CITY SOUTHERN Comparison of Transaction Value April 2003 Deal vs. Amended Transaction (US $millions) VAT > Put scenario (maximum Earnout for TMM) $713 $672 $618 2007 Escrow *$47 * $297 Stock$297 $212 VAT>Put2010 Escrow Stock Earnout VAT>Put Cash Earnout $180$180 Consulting $35 $40 $35 *VAT>Pu
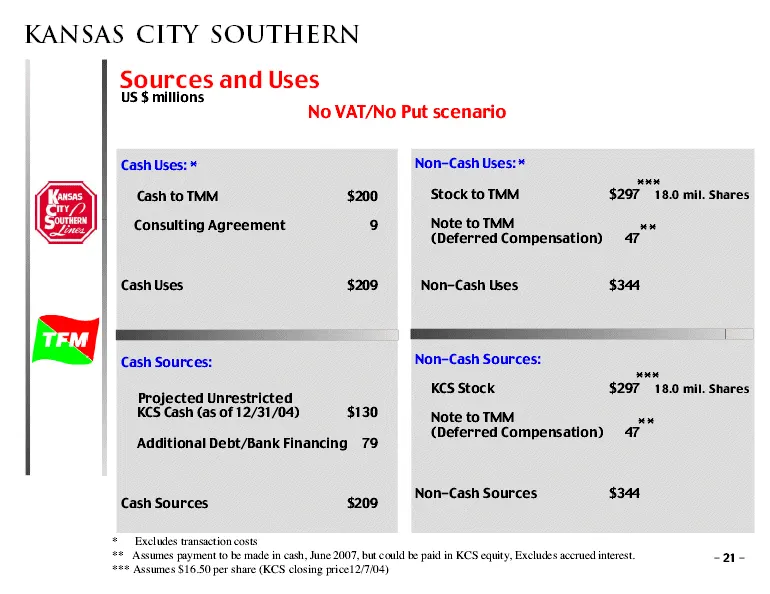
Slide 21: Sources and Uses: No VAT/No Put scenario
KANSAS CITY SOUTHERN Sources and Uses US $ millions No VAT/No Put scenario Cash Uses: * Non-Cash Uses: * *** Cash to TMM $200 Stock to TMM $297 18.0 mil. Shares Consulting Agreement 9 Note to TMM ** (Deferred Compensation) 47 Cash Uses $209 Non-Cash Uses $344 Cash Sources: Non-Cash Sources: *** KCS
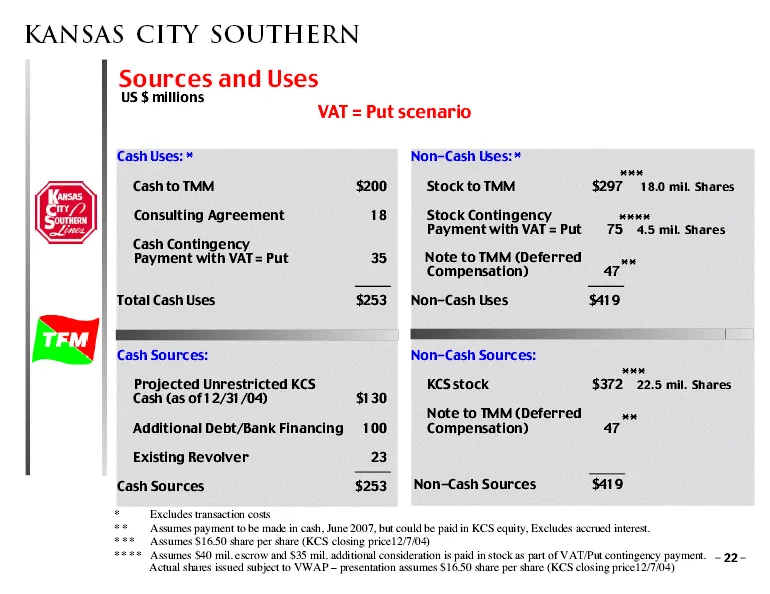
Slide 22: Sources and Uses: VAT = Put scenario
KANSAS CITY SOUTHERN Sources and Uses US $ millions VAT = Put scenario Cash Uses: * Non-Cash Uses: * *** Cash to TMM $200 Stock to TMM $297 18.0 mil. Shares Consulting Agreement 18 Stock Contingency **** Payment with VAT = Put 75 4.5 mil. Shares Cash Contingency Payment with VAT = Put 35 Note to TMM
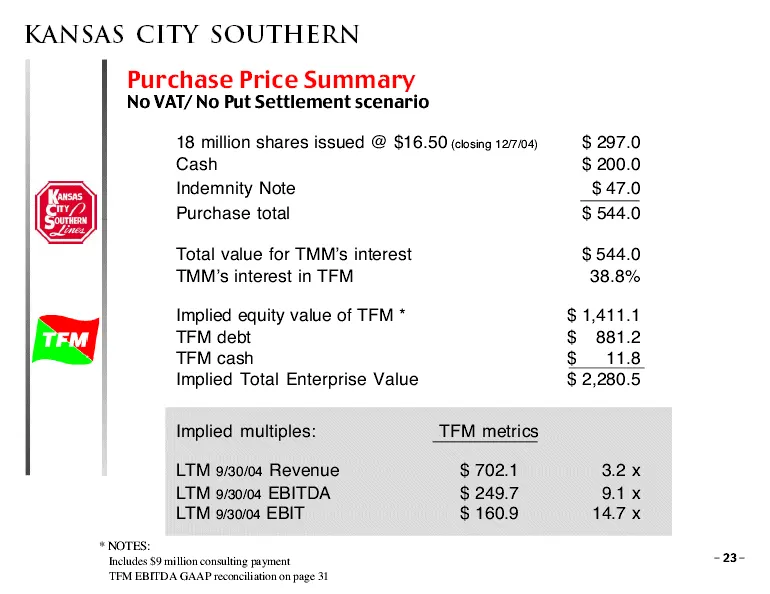
Slide 23: Purchase Price Summary
KANSAS CITY SOUTHERN Purchase Price Summary No VAT/ No Put Settlement scenario 18 million shares issued @ $16.50 (closing 12/7/04) $297.0 Cash$200.0 Indemnity Note $47.0 Purchase total$544.0 Total value for TMM’s interest $544.0 TMM’s interest in TFM38.8% Implied equity value of TFM * $1,411.1 TFM d
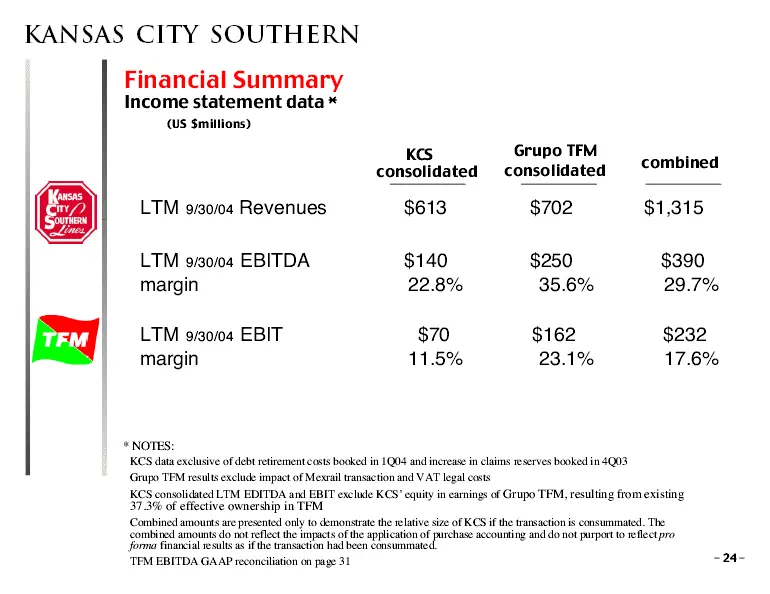
Slide 24: Financial Summary
KANSAS CITY SOUTHERN Financial Summary Income statement data * (US $millions) KCS Grupo TFM consolidated combined consolidated LTM 9/30/04 Revenues $613 $702 $1,315 LTM 9/30/04 EBITDA $140 $250 $390 margin 22.8% 35.6% 29.7% LTM 9/30/04 EBIT $70 $162 $232 margin 11.5% 23.1% 17.6% * NOTES: KCS data ex
Slide 25: Financial Summary (continued)
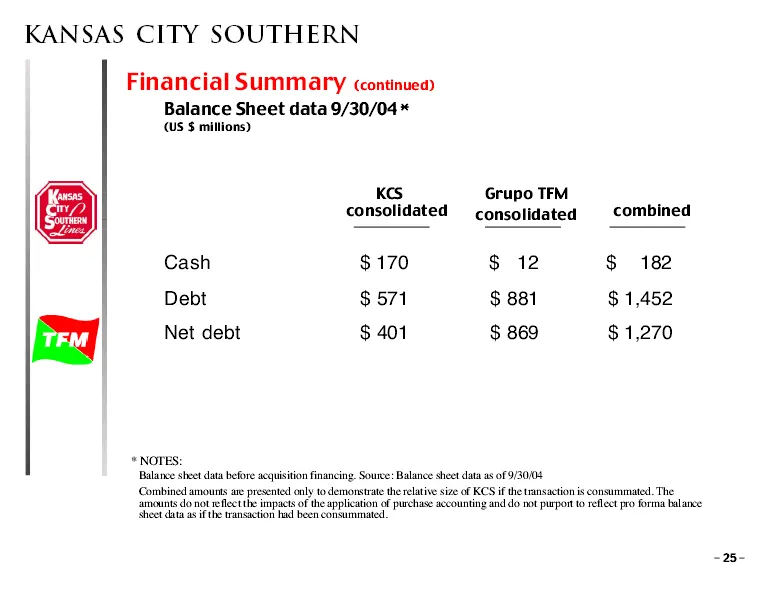
KANSAS CITY SOUTHERN Financial Summary (continued) Balance Sheet data 9/30/04 * (US $millions) KCS Grupo TFM consolidated consolidated combined Cash $170 $12 $182 Debt $571 $881 $1,452 Net debt $401 $869 $1,270 * NOTES: Balance sheet data before acquisition financing. Source: Balance sheet data as o
Slide 26: Valuation Summary: 38.8% of TFM
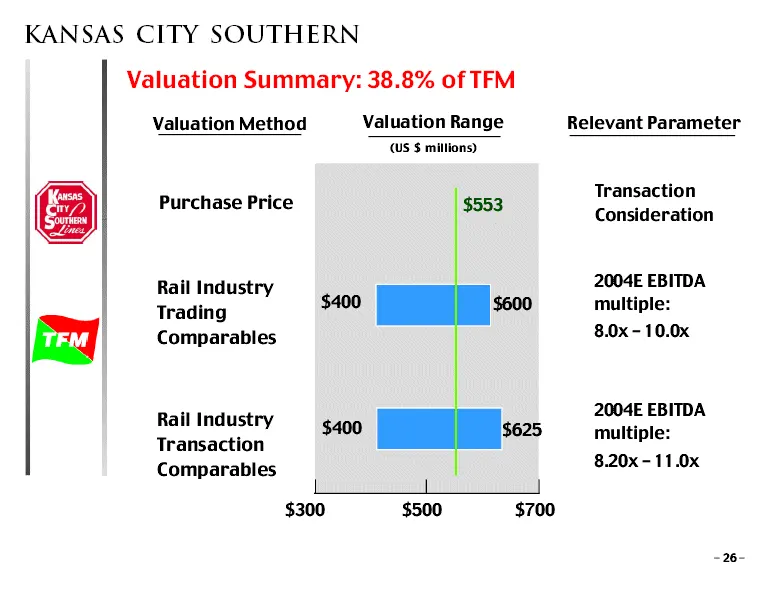
KANSAS CITY SOUTHERN Valuation Summary: 38.8% of TFM Valuation Method Valuation Range Relevant Parameter (US $ millions) Transaction Purchase Price $553 Consideration Rail Industry 2004E EBITDA $400$600multiple: Trading Comparables 8.0x — 10.0x Rail Industry 2004E EBITDA $400$625multiple: Transactio
Slide 27: Earnings Impact
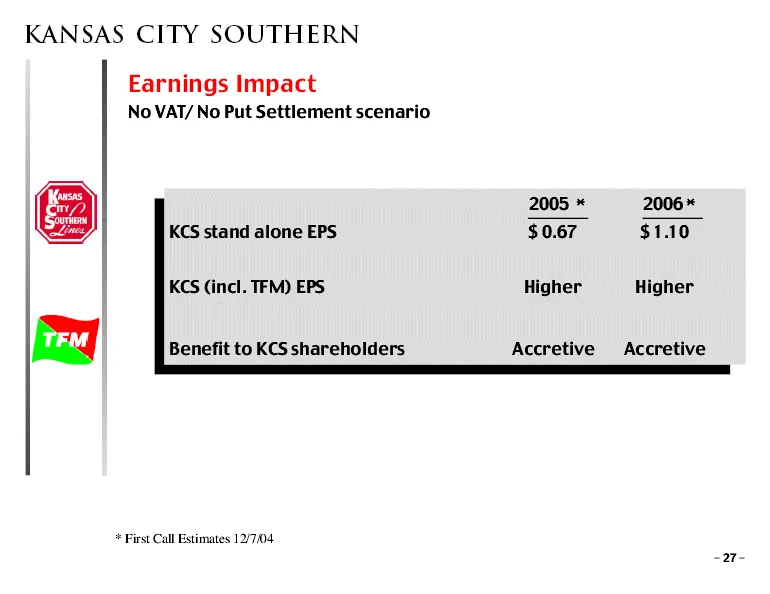
KANSAS CITY SOUTHERN Earnings Impact No VAT/ No Put Settlement scenario 2005 * 2006 * KCS stand alone EPS $0.67 $1.10 KCS (incl. TFM) EPS Higher Higher Benefit to KCS shareholders Accretive Accretive * First Call Estimates 12/7/04 - 27 -
Slide 28: Illustrating Dilutive/Accretive Impacts of Transaction
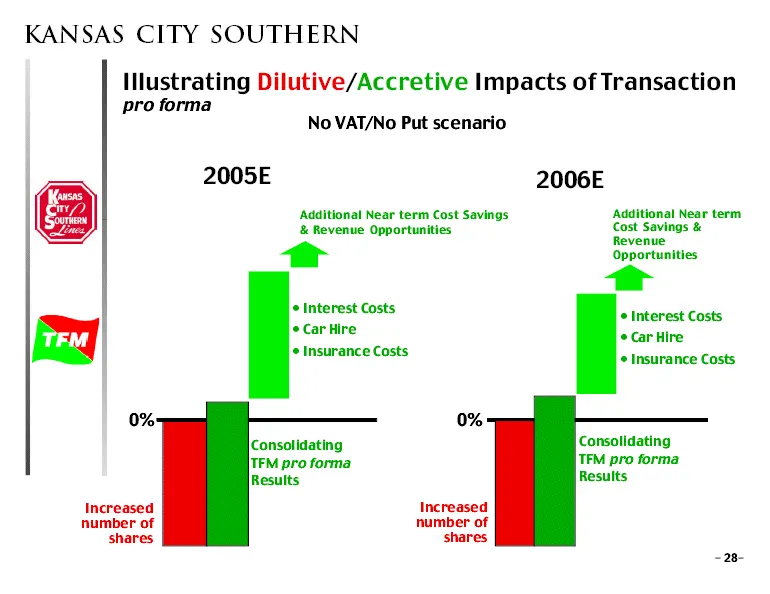
KANSAS CITY SOUTHERN Illustrating Dilutive/Accretive Impacts of Transaction pro forma No VAT/No Put scenario 2005E 2006E Additional Near term Cost Savings Additional Near term & Revenue Opportunities Cost Savings & Revenue Opportunities · Interest Costs · Interest Costs • Car Hire • Car Hire • Insur
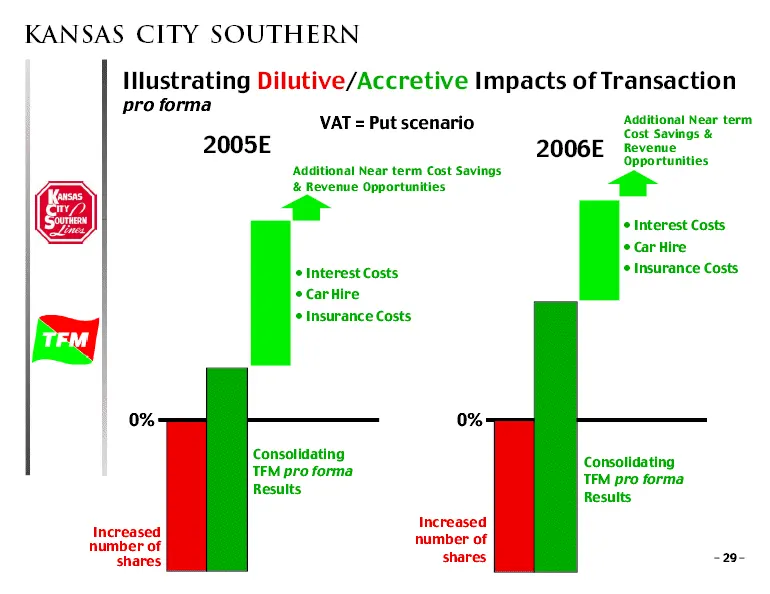
Slide 29: Illustrating Dilutive/Accretive Impacts: VAT = Put
KANSAS CITY SOUTHERN Illustrating Dilutive/Accretive Impacts of Transaction pro forma VAT = Put scenario Additional Near term Cost Savings & 2005E 2006E Revenue Opportunities Additional Near term Cost Savings & Revenue Opportunities · Interest Costs • Car Hire • Interest Costs • Insurance Costs • Ca
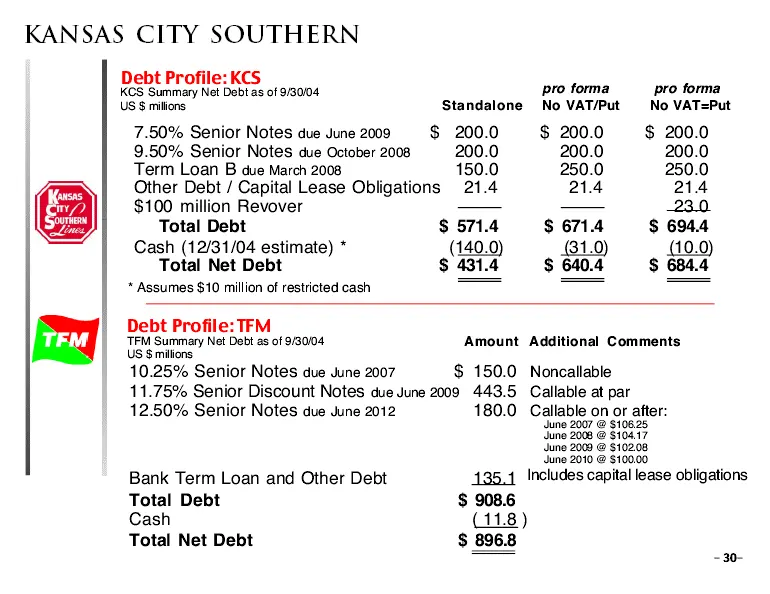
Slide 30: Debt Profile: KCS and TFM
KANSAS CITY SOUTHERN Debt Profile: KCS KCS Summary Net Debt as of 9/30/04 pro forma pro forma US $millions Standalone No VAT/Put No VAT=Put 7.50% Senior Notes due June 2009 $ 200.0 $ 200.0 $ 200.0 9.50% Senior Notes due October 2008 200.0 200.0 200.0 Term Loan B due March 2008 150.0 250.0 250.0 Othe
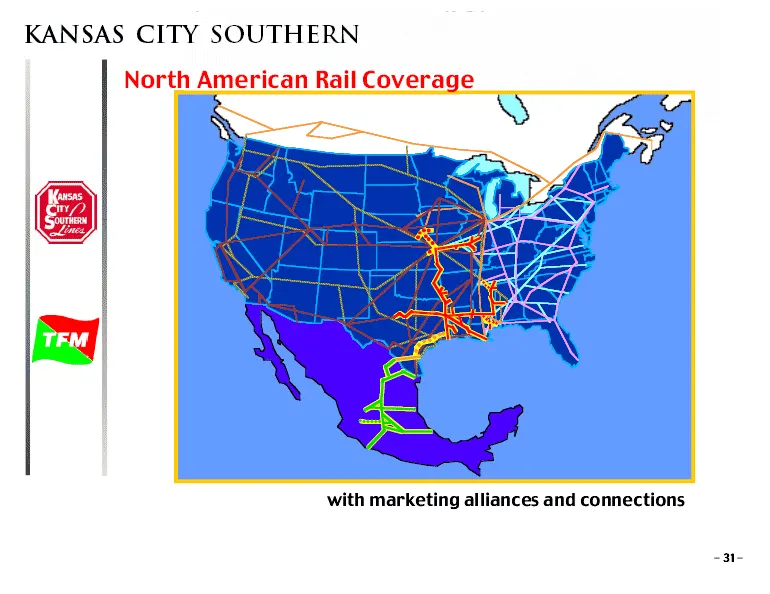
Slide 31: North American Rail Coverage with marketing alliances and connections
KANSAS CITY SOUTHERN KANSAS CITY North American Rail Coverage with marketing alliances and connections - 31-
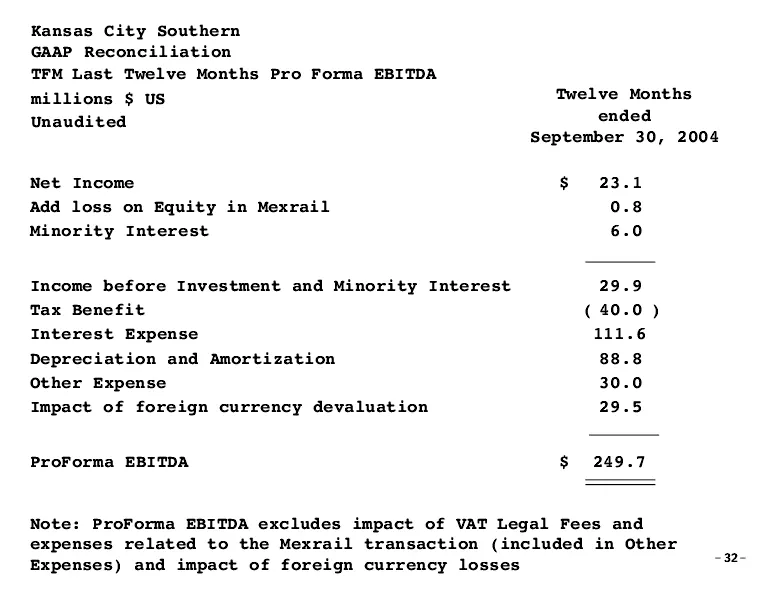
Slide 32: GAAP Reconciliation: TFM Last Twelve Months Pro Forma EBITDA
Kansas City Southern GAAP Reconciliation TFM Last Twelve Months Pro Forma EBITDA millions $US Twelve Months ended Unaudited September 30, 2004 Net Income $ 23.1 Add loss on Equity in Mexrail 0.8 Minority Interest 6.0 Income before Investment and Minority Interest 29.9 Tax Benefit ( 40.0 ) Interest E
Source: SEC EDGAR · 8-K filed Jan 4, 2005
More decks from Kansas City Southern
 Merger or Acquisition (September 2021)9 slides · Sep 16, 2021
 Merger or Acquisition (September 2021)10 slides · Sep 1, 2021
 Merger or Acquisition (August 2021)12 slides · Aug 27, 2021
 Merger or Acquisition (August 2021)11 slides · Aug 17, 2021
 Merger or Acquisition (August 2021)13 slides · Aug 10, 2021
 Merger or Acquisition (August 2021)7 slides · Aug 5, 2021