Kansas City Southern — Merger or Acquisition (August 2021)
13 slides from Kansas City Southern's merger presentation, Aug 10, 2021
Slide 1: Canadian Pacific Railway Superior Proposal to Combine with Kansas City Southern
Canadian Pacific Railway Superior Proposal to Combine with Kansas City Southern August 10th, 2021
Slide 2: Forward Looking Statements and Additional Information
Forward Looking Statements and Additional Information Forward Looking Statements and Information This presentation includes certain forward-looking statements and forward looking information (collectively, FLI). FLI is typically identified by words such as “anticipate”, “expect”, “project”, “estimat
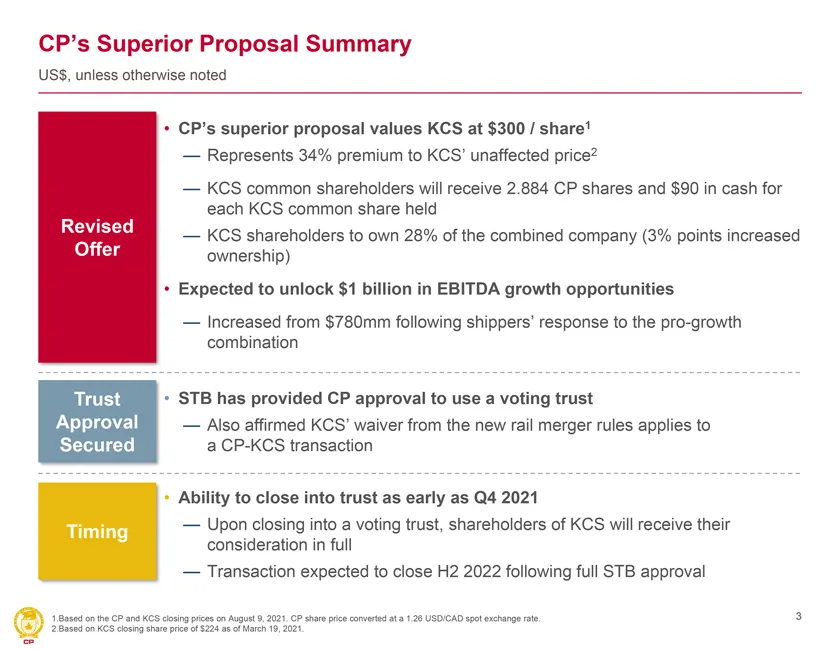
Slide 3: CP's Superior Proposal Summary
CP’s Superior Proposal Summary US$, unless otherwise noted • CP’s superior proposal values KCS at $300 / share1 — Represents 34% premium to KCS’ unaffected price2 — KCS common shareholders will receive 2.884 CP shares and $90 in cash for each KCS common share held Revised — KCS shareholders to own 2
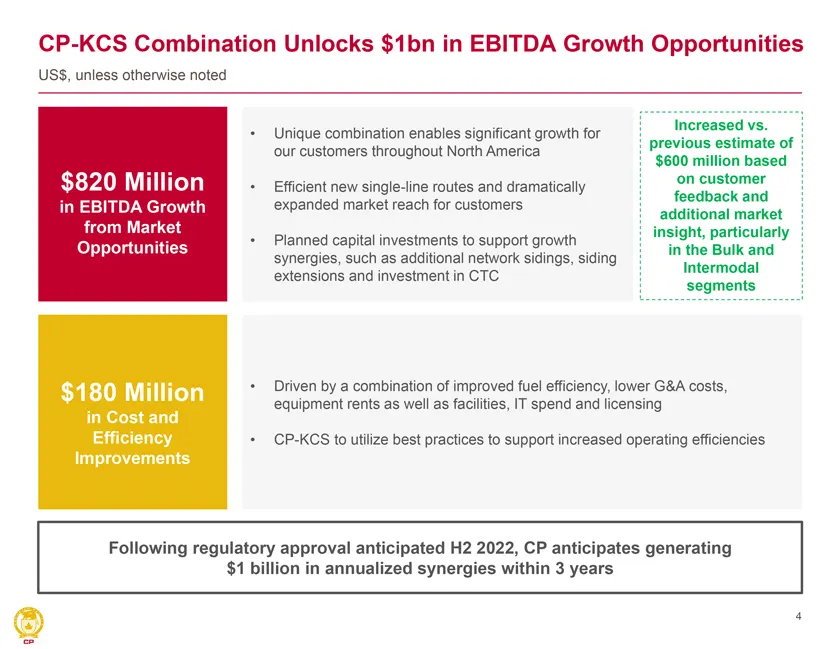
Slide 4: CP-KCS Combination Unlocks $1bn in EBITDA Growth Opportunities
CP-KCS Combination Unlocks $1bn in EBITDA Growth Opportunities US$, unless otherwise noted Increased vs. • Unique combination enables significant growth for previous estimate of our customers throughout North America $600 million based $820 Million on customer • Efficient new single-line routes and
Slide 5: Compelling Strategic Combination and the Only Viable Class 1 Combination
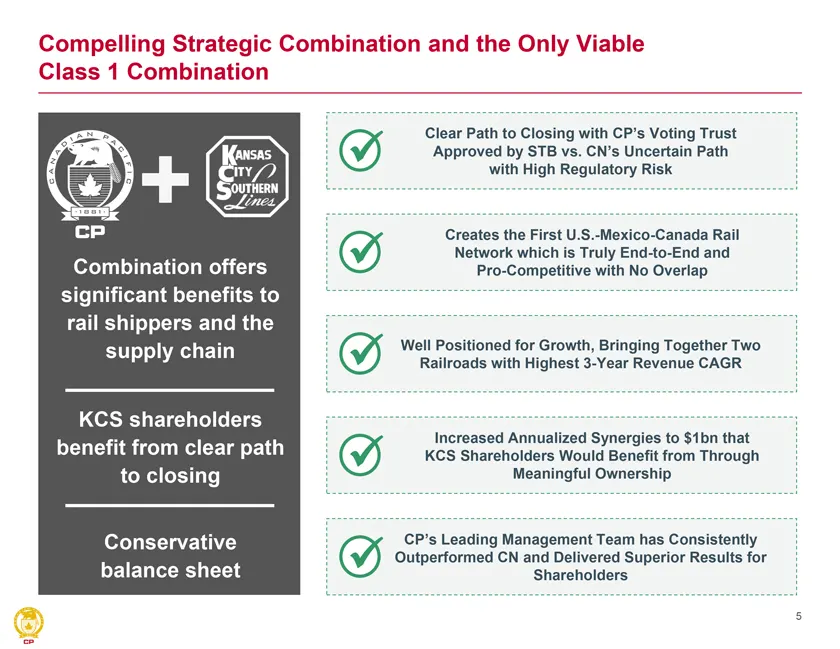
Compelling Strategic Combination and the Only Viable Class 1 Combination Clear Path to Closing with CP’s Voting Trust  Approved by STB vs. CN’s Uncertain Path with High Regulatory Risk Creates the First U.S.-Mexico-Canada Rail  Network which is Truly End-to-End and Combination offers Pro-Compe
Slide 6: CP Offers Certainty for KCS Shareholders, Especially if CN's Voting Trust is Denied
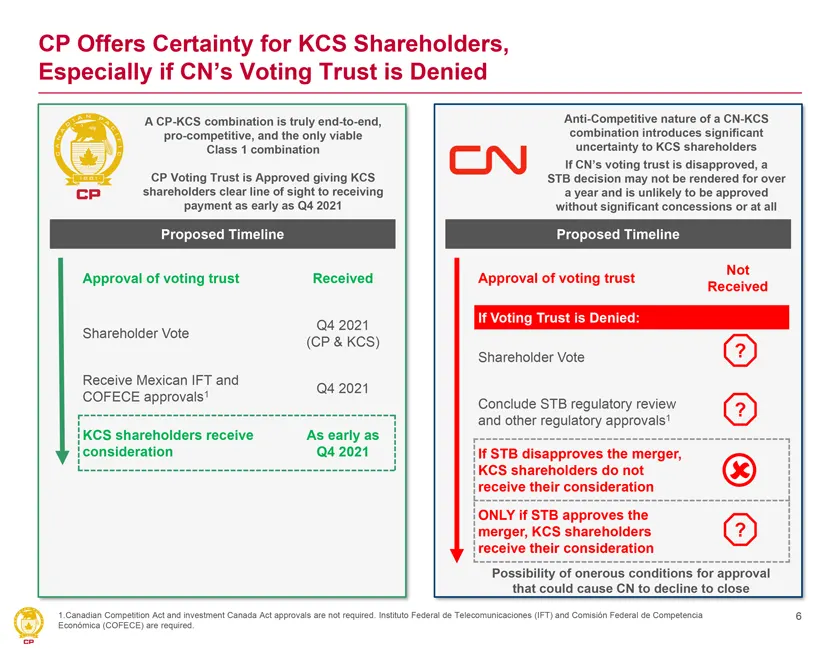
CP Offers Certainty for KCS Shareholders, Especially if CN’s Voting Trust is Denied A CP-KCS combination is truly end-to-end, Anti-Competitive nature of a CN-KCS pro-competitive, and the only viable combination introduces significant Class 1 combination uncertainty to KCS shareholders If CN’s voting
Slide 7: CP Has Continually Grown Faster than CN, While Extracting Operating Efficiencies
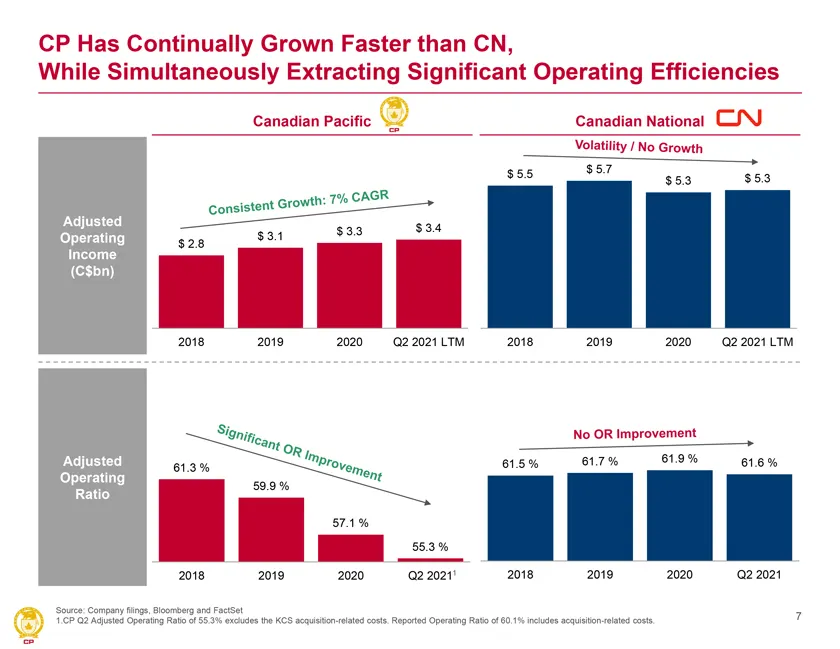
CP Has Continually Grown Faster than CN, While Simultaneously Extracting Significant Operating Efficiencies Canadian Pacific Canadian National $ 5.5 $ 5.7 $ 5.3 $ 5.3 Adjusted $ 3.3 $ 3.4 Operating $ 3.1 $ 2.8 Income (C$bn) 2018 2019 2020 Q2 2021 LTM 2018 2019 2020 Q2 2021 LTM Adjusted 61.7 % 61.9 %
Slide 8: CP Management Team Has a Consistent Track Record of Delivering on Commitments
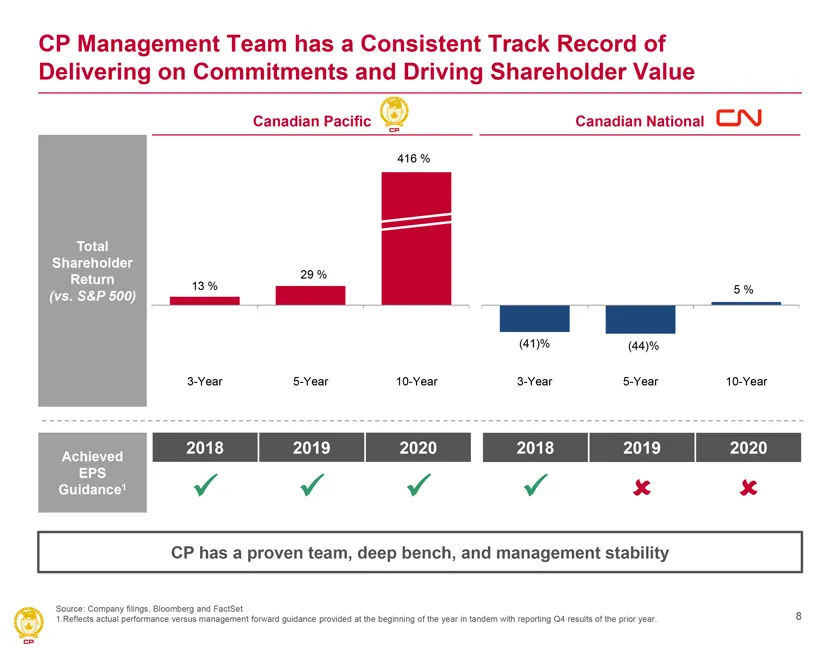
CP Management Team has a Consistent Track Record of Delivering on Commitments and Driving Shareholder Value Canadian Pacific Canadian National 416 % Total Shareholder 29 % Return 13 % 5 % (vs. S&P 500) (41)% (44)% 3-Year 5-Year 10-Year 3-Year 5-Year 10-Year 2018 2019 2020 2018 2019 2020 Achieved EPS
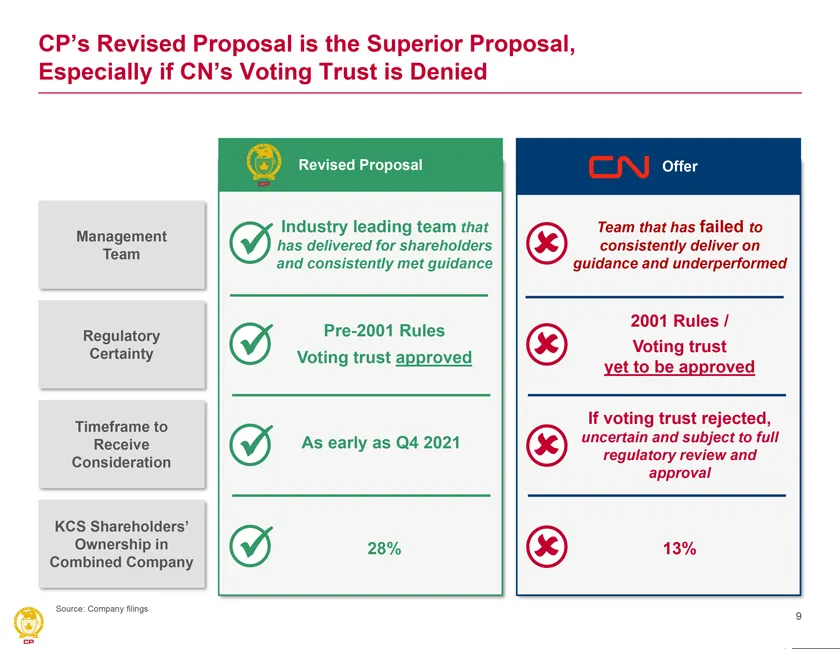
Slide 9: CP's Revised Proposal is the Superior Proposal, Especially if CN's Voting Trust is Denied
CP’s Revised Proposal is the Superior Proposal, Especially if CN’s Voting Trust is Denied Revised Proposal Offer Industry leading team that Team that has failed to Management has delivered for shareholders  consistently deliver on Team and consistently met guidance guidance and underperformed
Slide 10: Appendix
Appendix
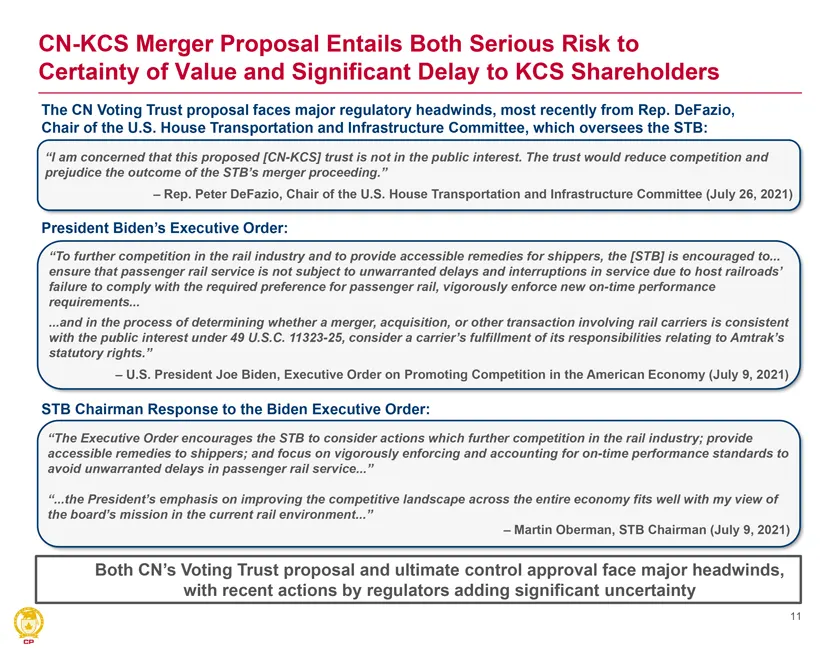
Slide 11: CN-KCS Merger Proposal Entails Serious Risk to Certainty of Value and Significant Delay
CN-KCS Merger Proposal Entails Both Serious Risk to Certainty of Value and Significant Delay to KCS Shareholders The CN Voting Trust proposal faces major regulatory headwinds, most recently from Rep. DeFazio, Chair of the U.S. House Transportation and Infrastructure Committee, which oversees the STB
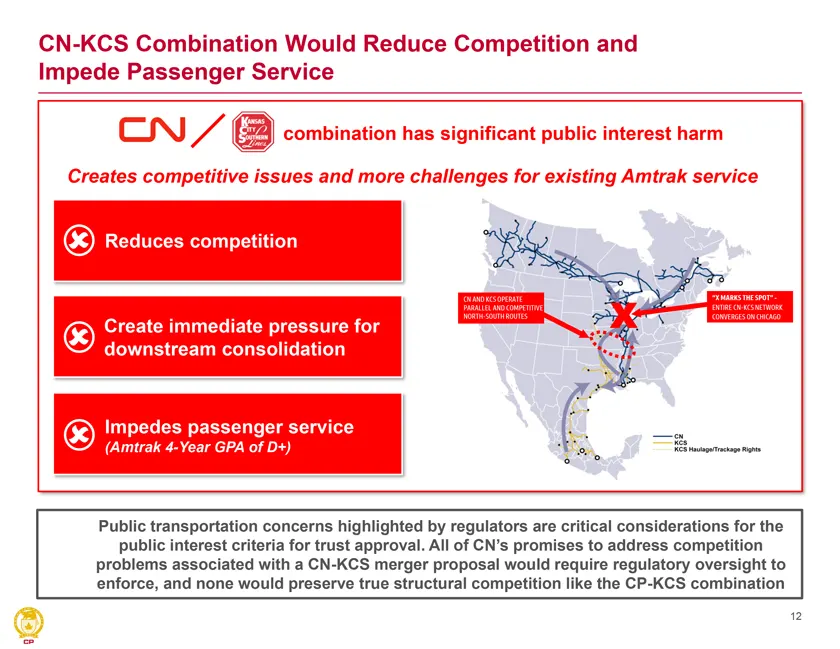
Slide 12: CN-KCS Combination Would Reduce Competition and Impede Passenger Service
CN-KCS Combination Would Reduce Competition and Impede Passenger Service combination has significant public interest harm Creates competitive issues and more challenges for existing Amtrak service  Reduces competition CN AND KCS OPERATE “X MARKS THE SPOT” -PARALLEL AND COMPETITIVE ENTIRE CN-KCS N
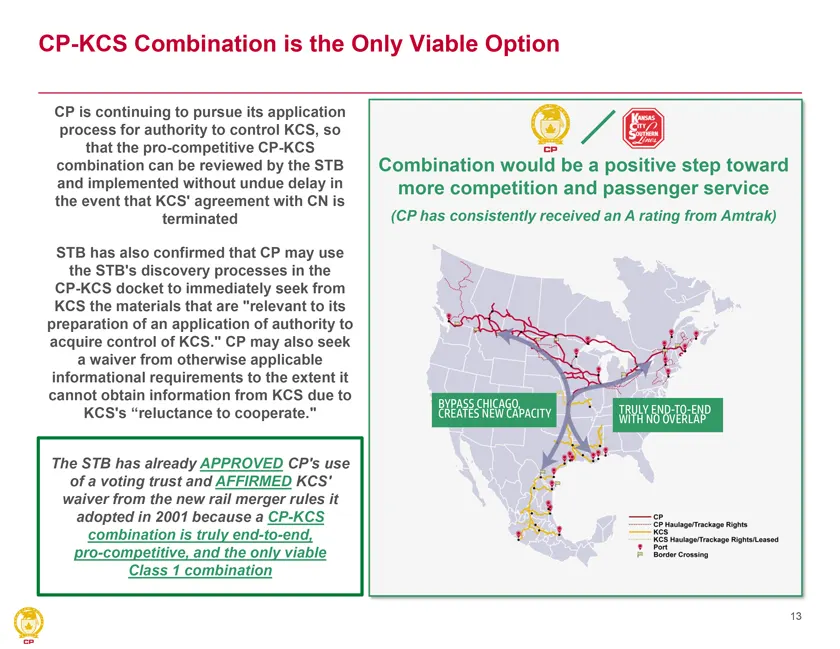
Slide 13: CP-KCS Combination is the Only Viable Option
CP-KCS Combination is the Only Viable Option CP is continuing to pursue its application process for authority to control KCS, so that the pro-competitive CP-KCS combination can be reviewed by the STB Combination would be a positive step toward and implemented without undue delay in more competition
Source: SEC EDGAR · DFAN14A filed Aug 10, 2021
More decks from Kansas City Southern
 Merger or Acquisition (September 2021)9 slides · Sep 16, 2021
 Merger or Acquisition (September 2021)10 slides · Sep 1, 2021
 Merger or Acquisition (August 2021)12 slides · Aug 27, 2021
 Merger or Acquisition (August 2021)11 slides · Aug 17, 2021
 Merger or Acquisition (August 2021)7 slides · Aug 5, 2021
 Proxy Contest (August 2021)20 slides · Aug 4, 2021