CenterState Bank — CenterState Banks — FIG Partners' 11th Annual Bank CEO Forum 2015
36 slides from CenterState Bank's conference presentation, Sep 28, 2015
Slide 1: FIG Partners' 11th Annual Bank CEO Forum
FIG Partners’ 11th Annual Bank CEO Forum Atlanta, GA September 28-29, 2015 Exhibit 99.1
Slide 2: Forward Looking Statement
This presentation contains forward-looking statements, as defined by Federal Securities Laws, relating to present or future trends or factors affecting the operations, markets and products of CenterState Banks, Inc. (CSFL). These statements are provided to assist in the understanding of future finan
Slide 3: Corporate Overview
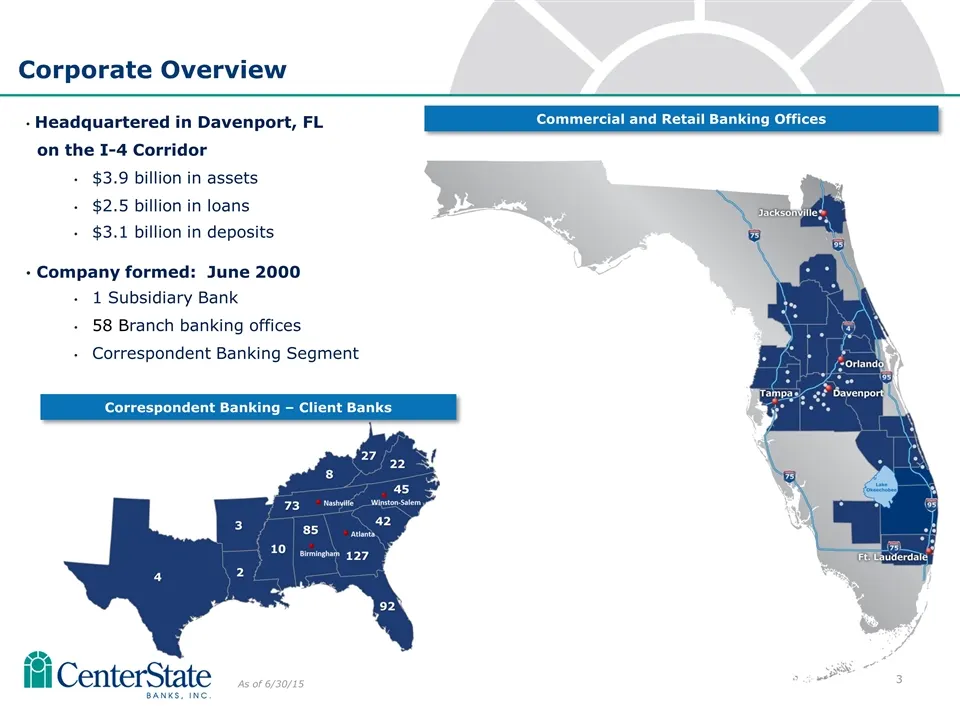
As of 6/30/15 Headquartered in Davenport, FL on the I-4 Corridor $3.9 billion in assets $2.5 billion in loans $3.1 billion in deposits Company formed: June 2000 1 Subsidiary Bank 58 Branch banking offices Correspondent Banking Segment Corporate Overview Commercial and Retail Banking Offices Correspo
Slide 4: Banking the Sunshine State
Banking the Sunshine State
Slide 5: Why invest in Florida? Economy and population
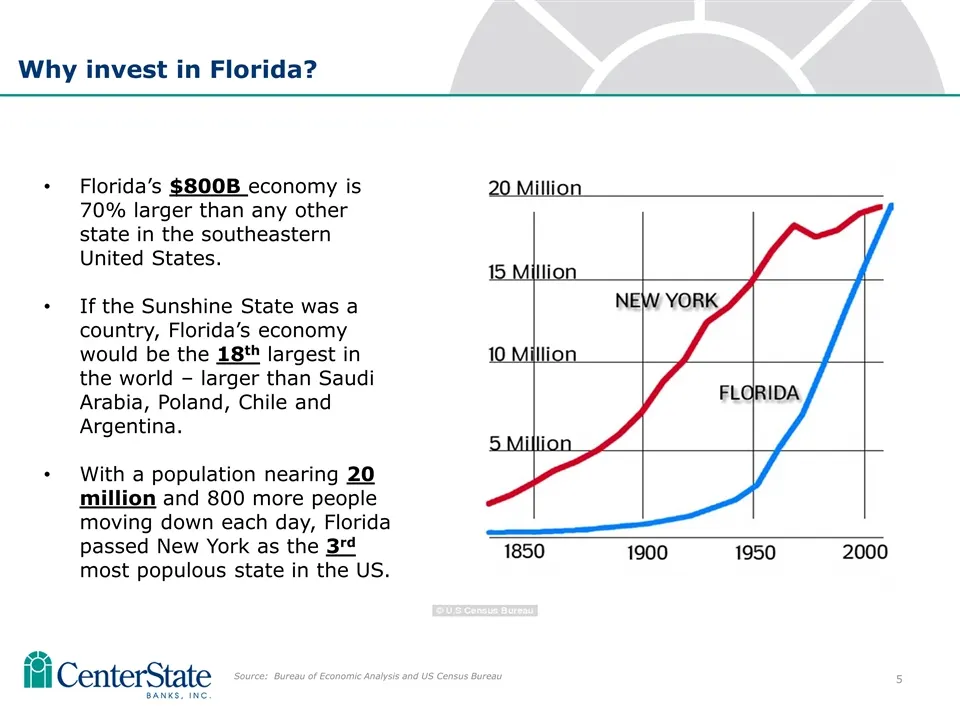
Florida’s $800B economy is 70% larger than any other state in the southeastern United States. If the Sunshine State was a country, Florida’s economy would be the 18th largest in the world – larger than Saudi Arabia, Poland, Chile and Argentina. With a population nearing 20 million and 800 more peopl
Slide 6: Why invest in Florida? Tourism
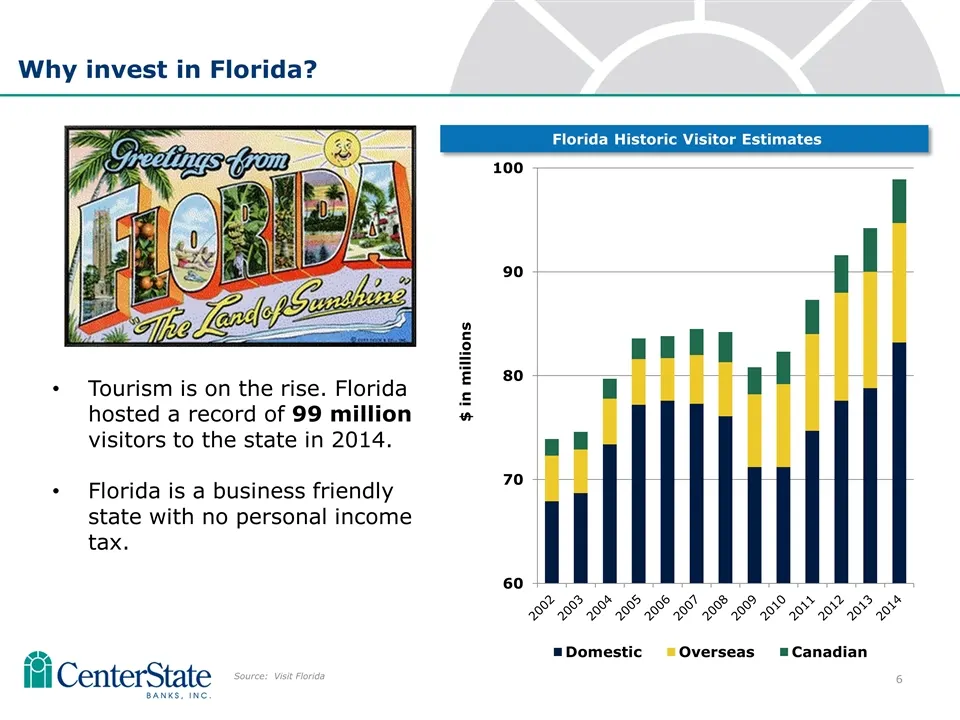
Tourism is on the rise. Florida hosted a record of 99 million visitors to the state in 2014. Florida is a business friendly state with no personal income tax. Why invest in Florida? Source: Visit Florida Florida Historic Visitor Estimates
Slide 7: Why invest in Florida? Housing and employment
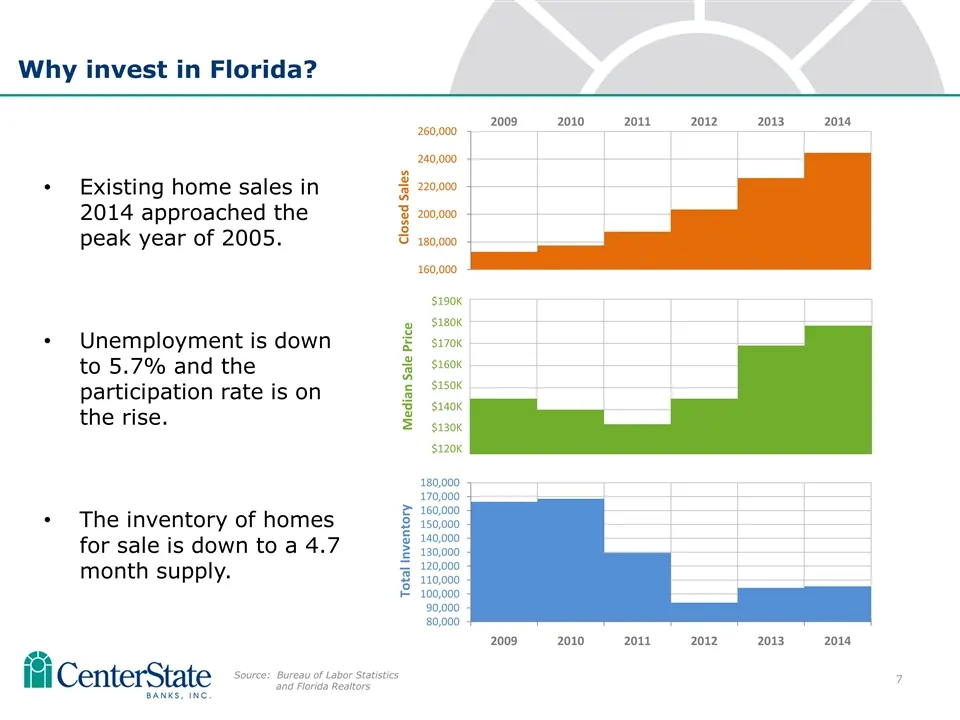
Existing home sales in 2014 approached the peak year of 2005. Unemployment is down to 5.7% and the participation rate is on the rise. The inventory of homes for sale is down to a 4.7 month supply. Why invest in Florida? Source: Bureau of Labor Statistics and Florida Realtors Median Sale Price $190K
Slide 8: Capital Management
Capital Management
Slide 9: Capital Management: excess capital
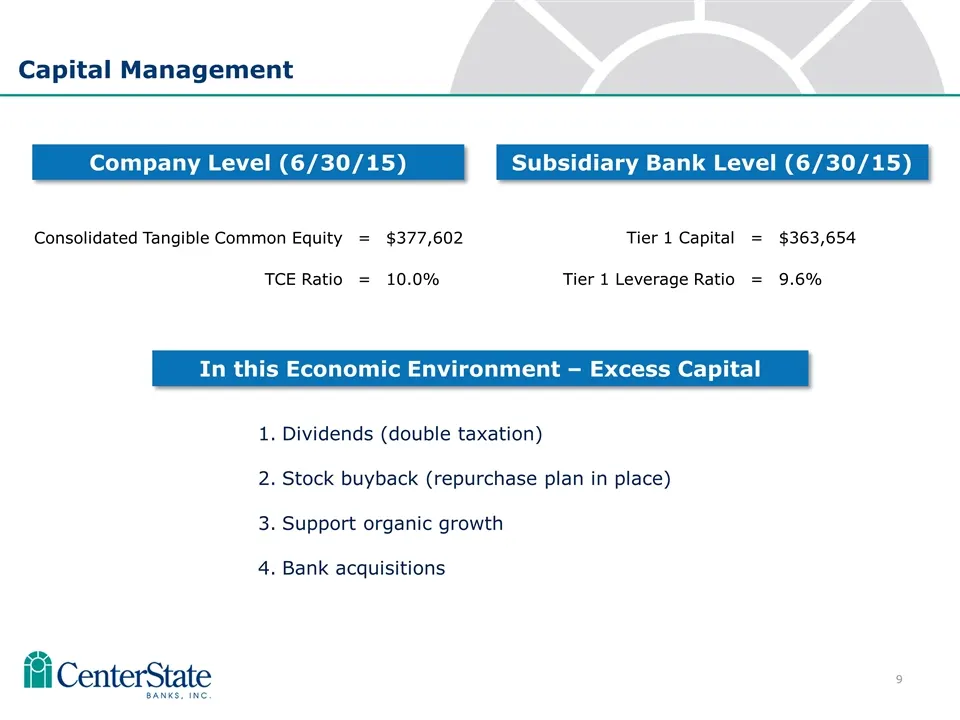
18 Capital Management Dividends (double taxation) Stock buyback (repurchase plan in place) Support organic growth Bank acquisitions Company Level (6/30/15) Subsidiary Bank Level (6/30/15) In this Economic Environment – Excess Capital Consolidated Tangible Common Equity = $377,602 TCE Ratio = 10.0% T
Slide 10: CSFL – Best Positioned Florida Consolidator
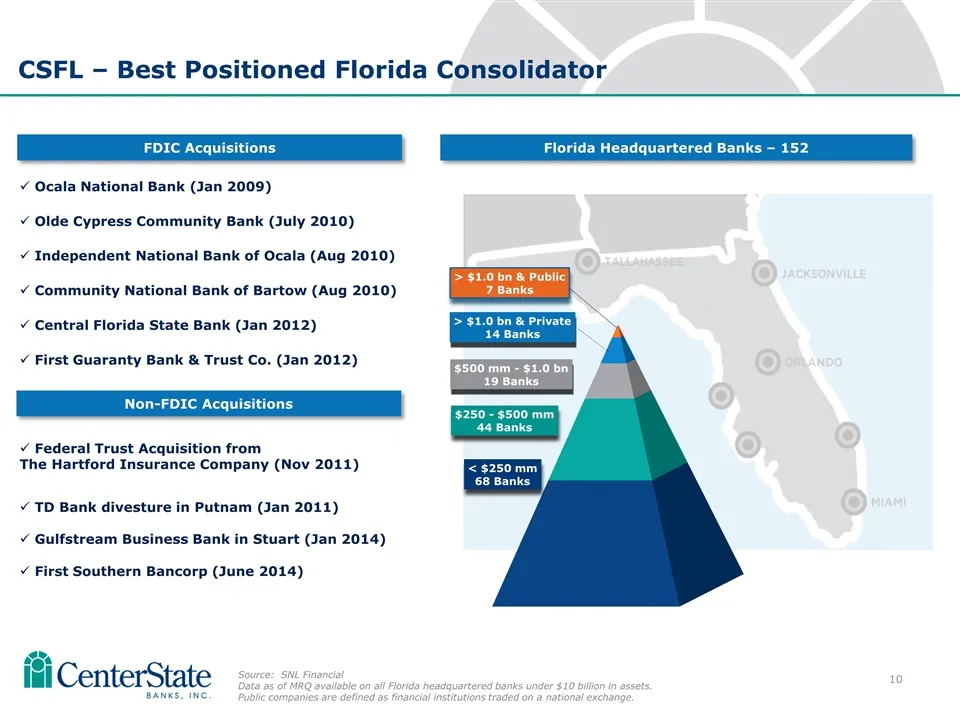
18 CSFL – Best Positioned Florida Consolidator Source: SNL Financial Data as of MRQ available on all Florida headquartered banks under $10 billion in assets. Public companies are defined as financial institutions traded on a national exchange. Ocala National Bank (Jan 2009) Olde Cypress Community Ba
Slide 11: Capital Management priorities
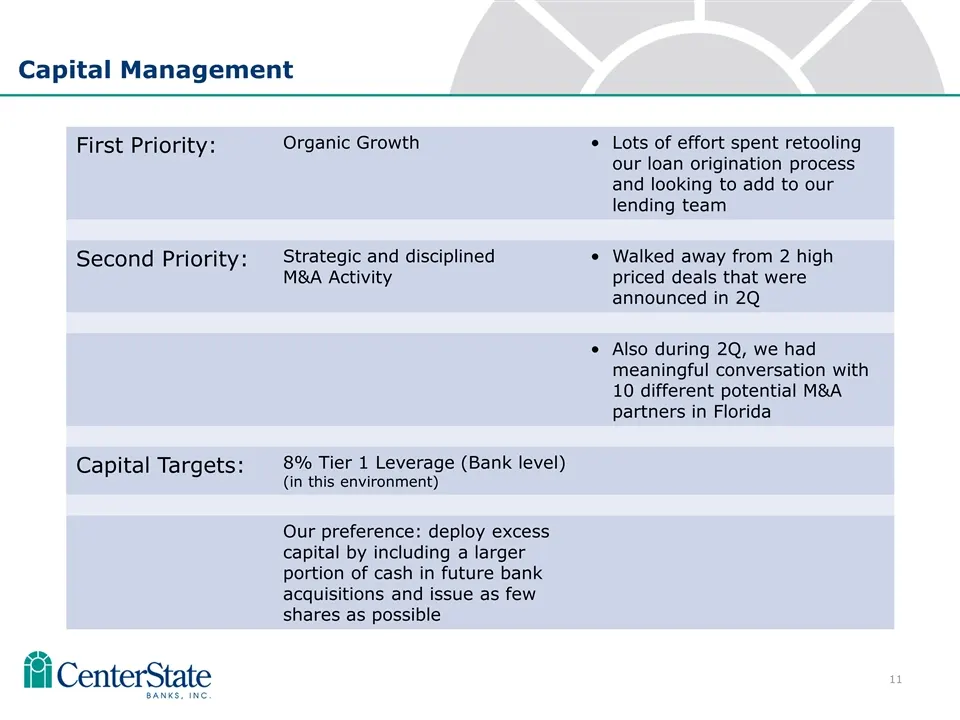
18 Capital Management First Priority: Organic Growth • Lots of effort spent retooling our loan origination process and looking to add to our lending team Second Priority: Strategic and disciplined M&A Activity • Walked away from 2 high priced deals that were announced in 2Q • Also during 2Q, we had
Slide 12: Earnings
Earnings
Slide 13: 2nd Quarter Summary of Financial Results
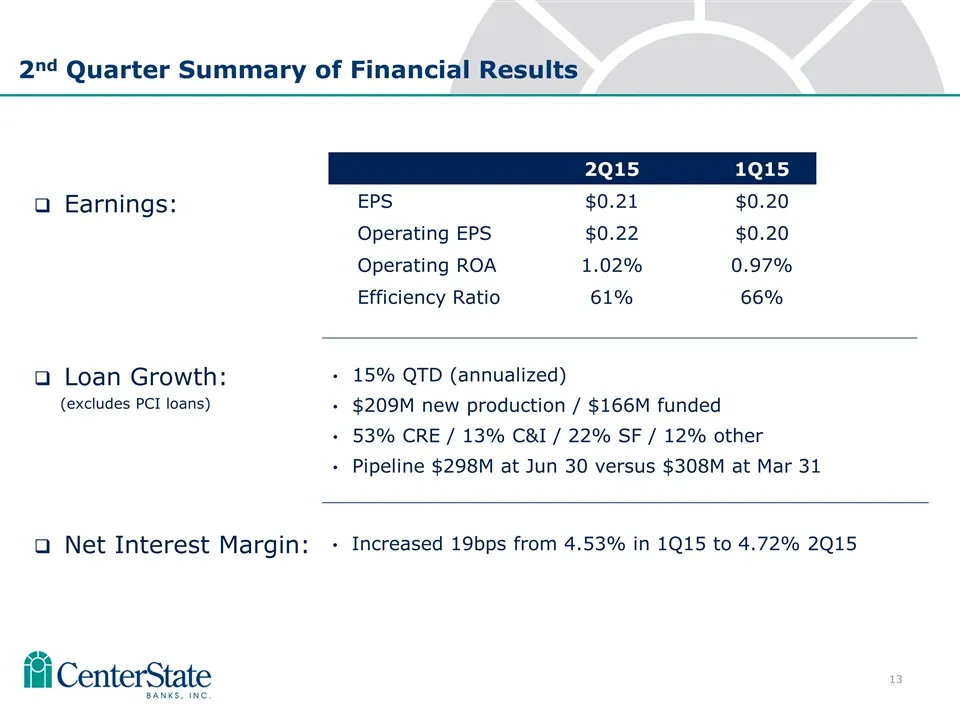
Earnings: Loan Growth: (excludes PCI loans) Net Interest Margin: 2nd Quarter Summary of Financial Results _______________________________________________________________________________________ 15% QTD (annualized) $209M new production / $166M funded 53% CRE / 13% C&I / 22% SF / 12% other Pipeline $
Slide 14: Net Interest Margin Quarter to Quarter Comparison
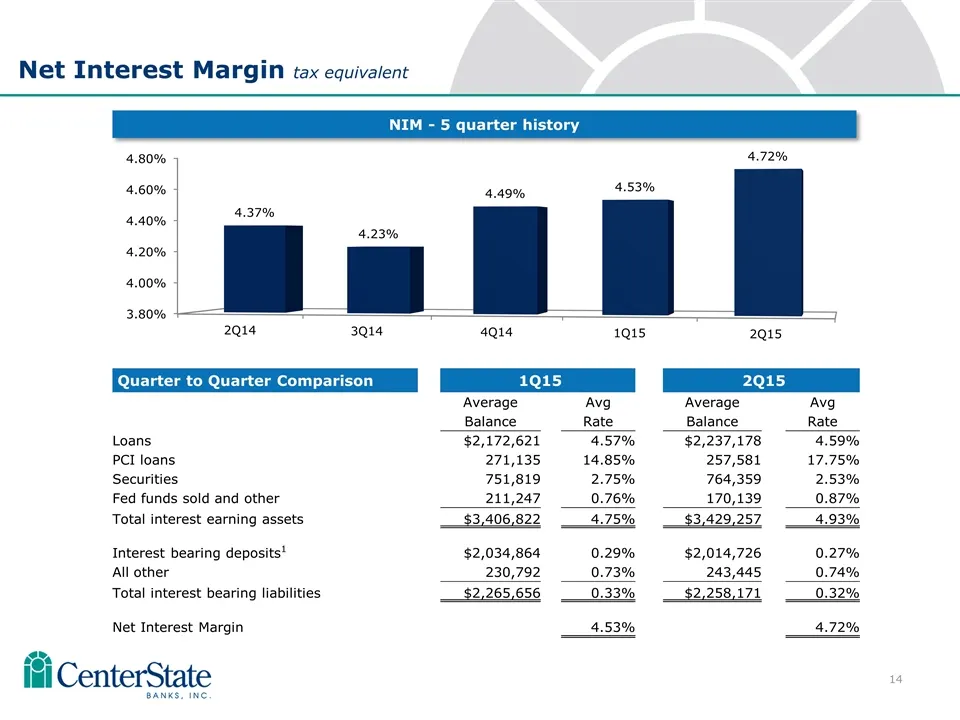
Net Interest Margin tax equivalent Quarter to Quarter Comparison 1Q15 2Q15 Average Avg Average Avg Balance Rate Balance Rate Loans $2,172,621 4.57% $2,237,178 4.59% PCI loans 271,135 14.85% 257,581 17.75% Securities 751,819 2.75% 764,359 2.53% Fed funds sold and other 211,247 0.76% 170,139 0.87% Tot
Slide 15: PCI Loans – Net Loan/IA Income Improvement
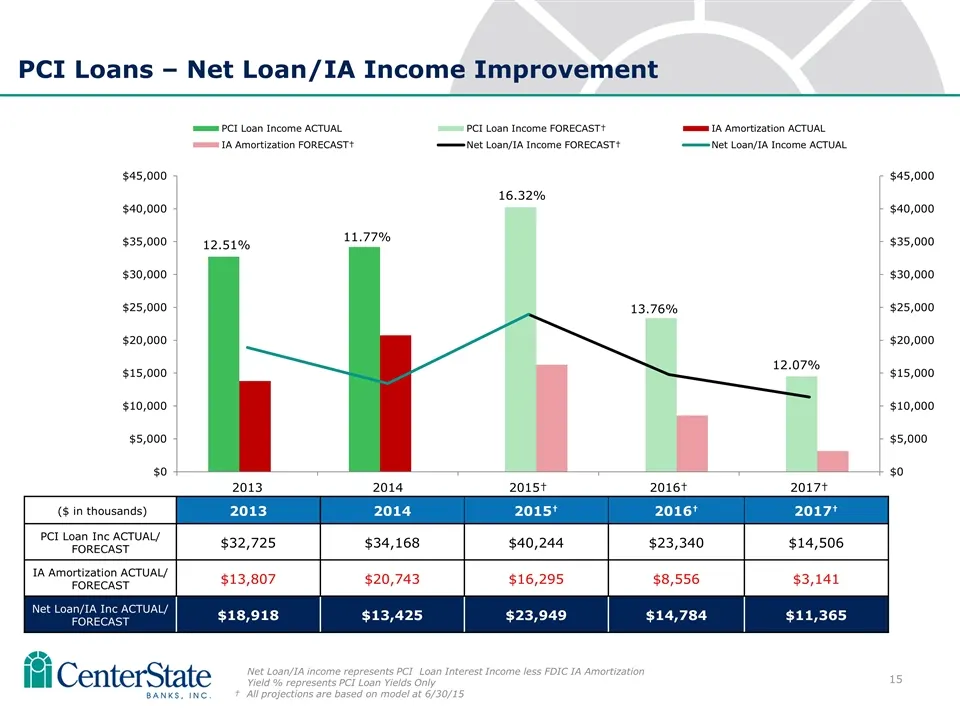
PCI Loans – Net Loan/IA Income Improvement Net Loan/IA income represents PCI Loan Interest Income less FDIC IA Amortization Yield % represents PCI Loan Yields Only † All projections are based on model at 6/30/15 ($ in thousands) 2013 2014 2015† 2016† 2017† PCI Loan Inc ACTUAL/ FORECAST $32,725 $34,1
Slide 16: Profitability Metrics
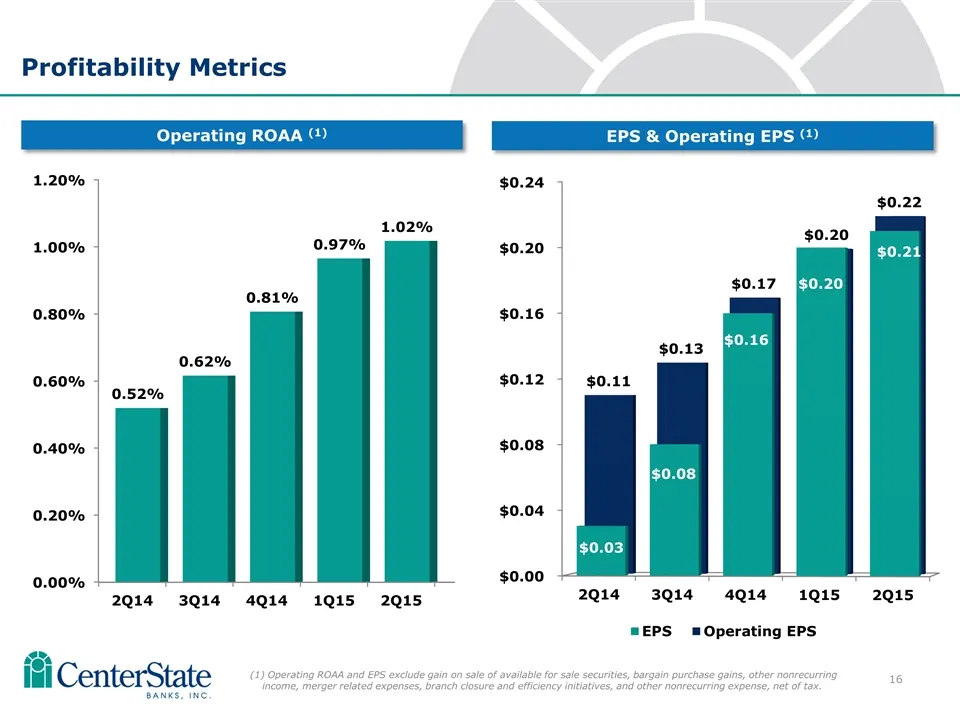
Operating ROAA (1) Profitability Metrics EPS & Operating EPS (1) (1) Operating ROAA and EPS exclude gain on sale of available for sale securities, bargain purchase gains, other nonrecurring income, merger related expenses, branch closure and efficiency initiatives, and other nonrecurring expense, ne
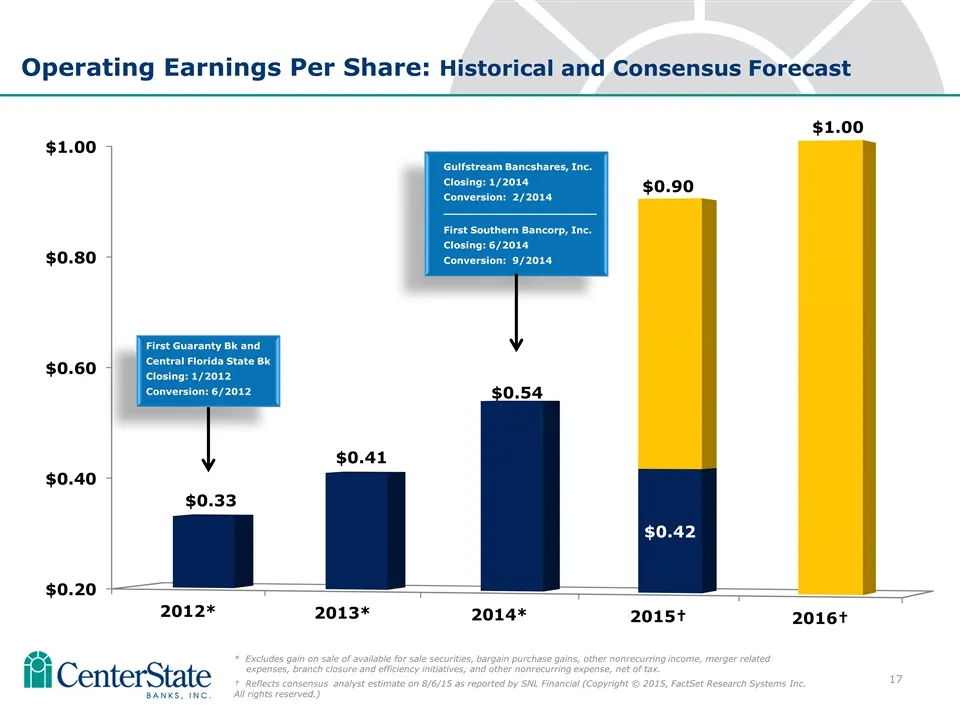
Slide 17: Operating Earnings Per Share: Historical and Consensus Forecast
$0.90 Operating Earnings Per Share: Historical and Consensus Forecast First Guaranty Bk and Central Florida State Bk Closing: 1/2012 Conversion: 6/2012 Gulfstream Bancshares, Inc. Closing: 1/2014 Conversion: 2/2014 ____________________ First Southern Bancorp, Inc. Closing: 6/2014 Conversion: 9/2014
Slide 18: Operating Performance & Efficiencies The Catalysts Ahead
Operating Performance & Efficiencies The Catalysts Ahead
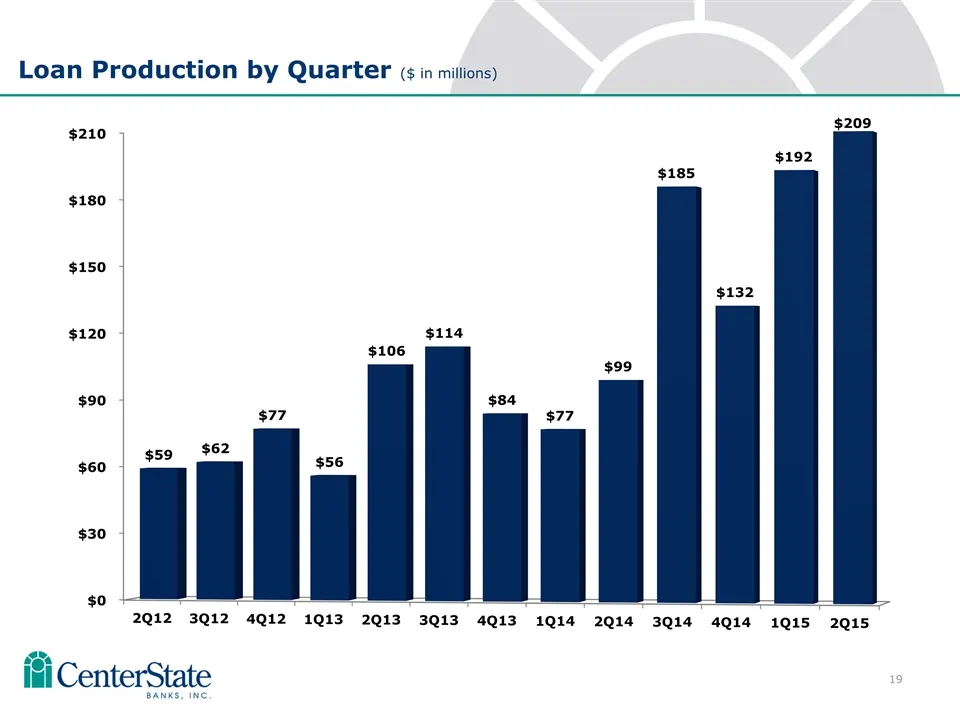
Slide 19: Loan Production by Quarter
Loan Production by Quarter ($ in millions)
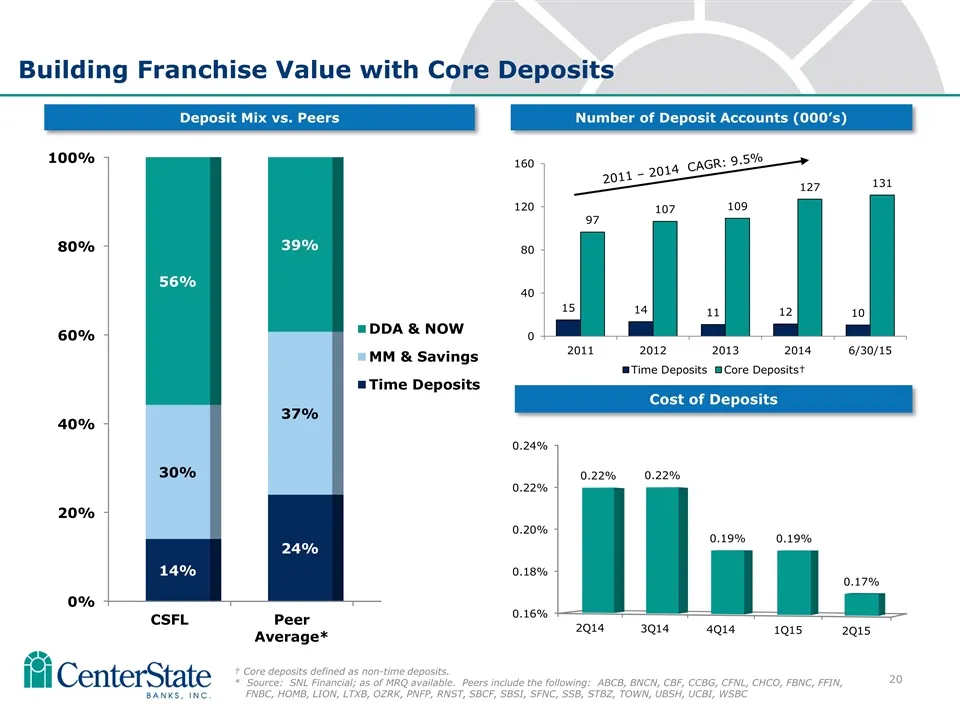
Slide 20: Building Franchise Value with Core Deposits
Number of Deposit Accounts (000’s) Building Franchise Value with Core Deposits Cost of Deposits 2011 – 2014 CAGR: 9.5% Deposit Mix vs. Peers † Core deposits defined as non-time deposits. * Source: SNL Financial; as of MRQ available. Peers include the following: ABCB, BNCN, CBF, CCBG, CFNL, CHCO, FBN
Slide 21: Operating Leverage Through Branch Consolidation
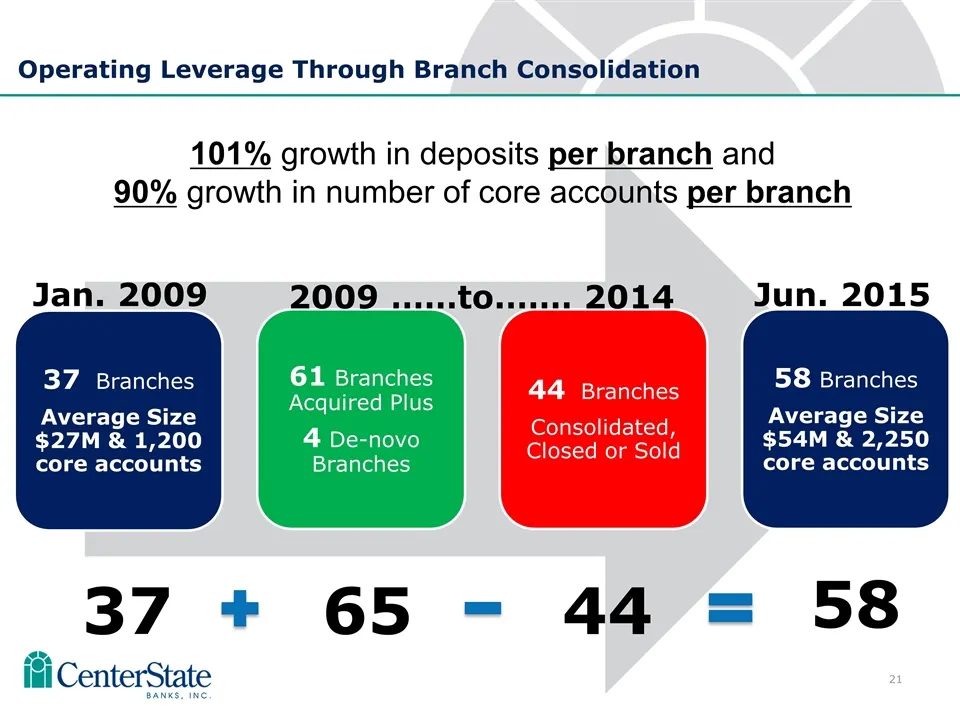
Operating Leverage Through Branch Consolidation 101% growth in deposits per branch and 90% growth in number of core accounts per branch 37 65 44 58 Jan. 2009 2009 ……to.…… 2014 Jun. 2015
Slide 22: Efficiency Ratio
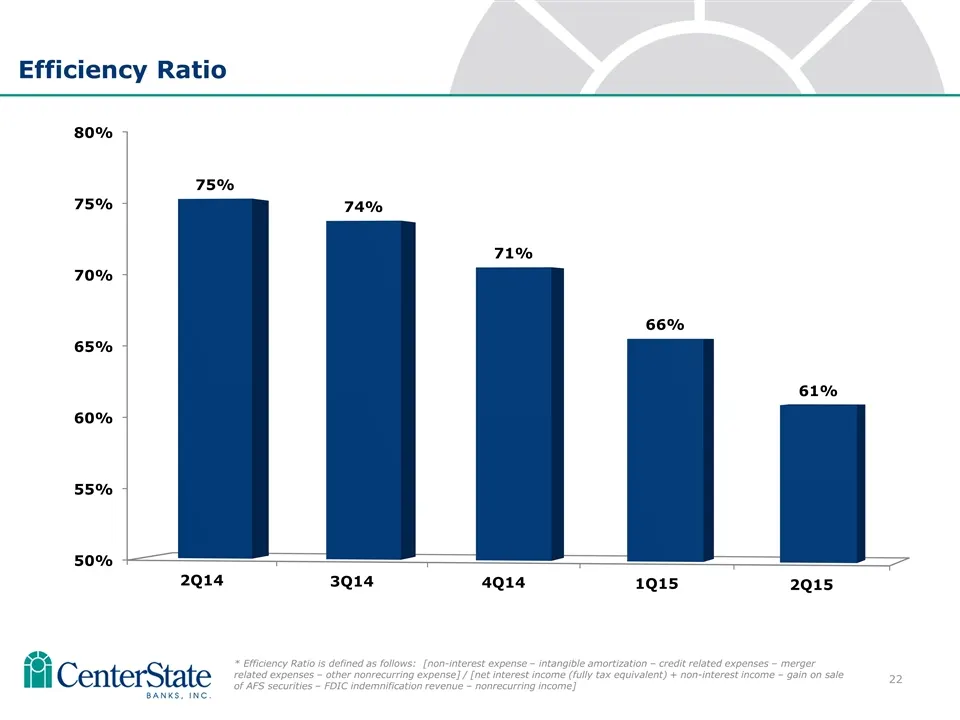
10 Efficiency Ratio * Efficiency Ratio is defined as follows: [non-interest expense – intangible amortization – credit related expenses – merger related expenses – other nonrecurring expense] / [net interest income (fully tax equivalent) + non-interest income – gain on sale of AFS securities – FDIC
Slide 23: Non-Interest Income – 2Q15 Components
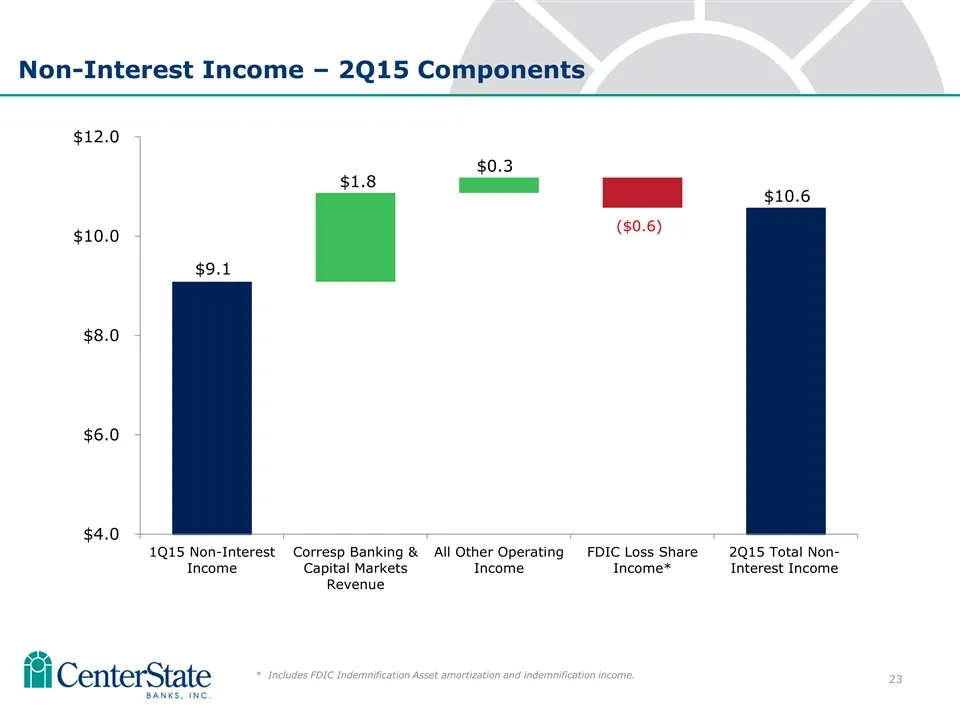
Non-Interest Income – 2Q15 Components * Includes FDIC Indemnification Asset amortization and indemnification income. ($0.6)
Slide 24: Correspondent Banking Income Analysis
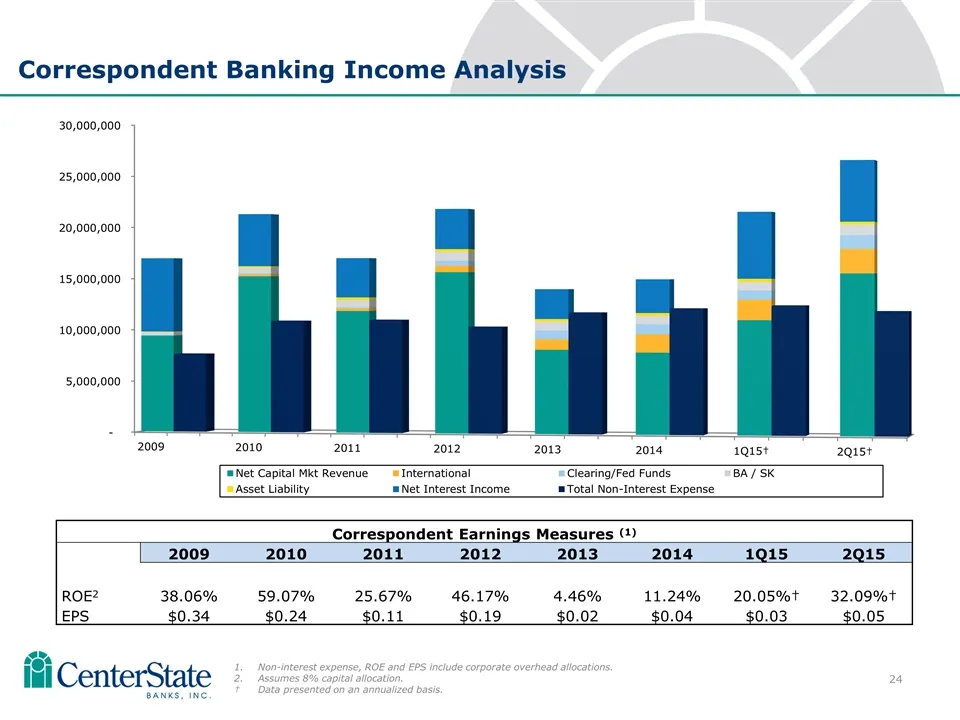
Non-interest expense, ROE and EPS include corporate overhead allocations. Assumes 8% capital allocation. †Data presented on an annualized basis. Correspondent Banking Income Analysis Correspondent Earnings Measures (1) 2009 2010 2011 2012 2013 2014 1Q15 2Q15 ROE2 38.06% 59.07% 25.67% 46.17% 4.46% 11
Slide 25: Summary and Investment Thesis
Summary and Investment Thesis Florida is an economic powerhouse and is dramatically improving CenterState is an attractive investment as one of the largest publicly traded banks headquartered in Florida Branch Efficiency / M&A Initiatives implemented in 2014 have resulted in significant improvement
Slide 26: Appendix
Appendix
Slide 27: Non-Interest Expense – 2Q15 Components
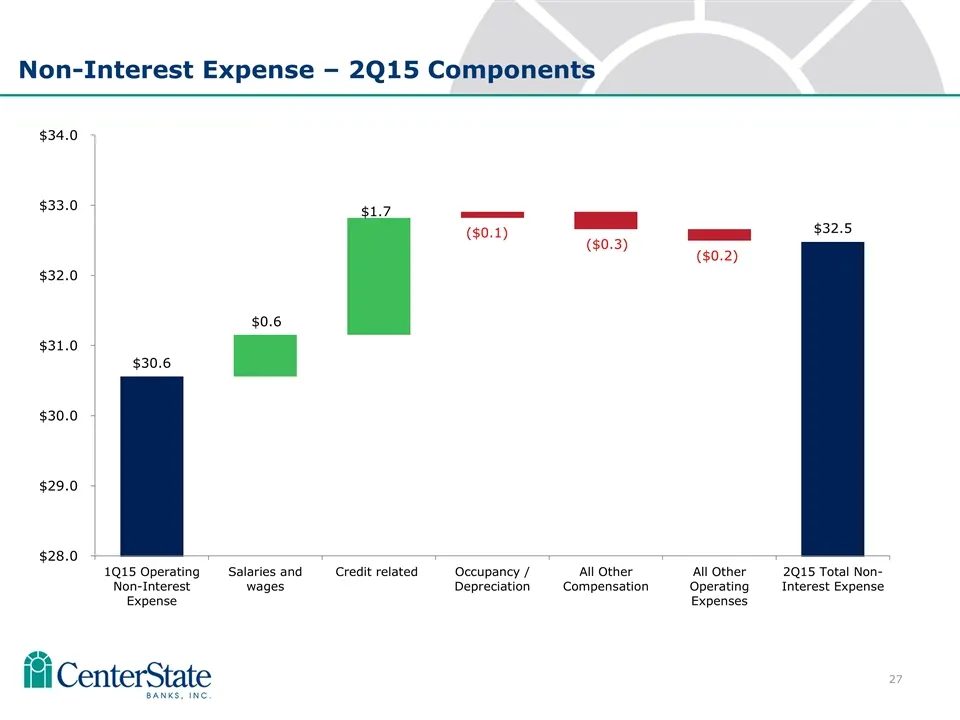
Non-Interest Expense – 2Q15 Components ($0.1) ($0.3) ($0.2)
Slide 28: Total Loans by Type
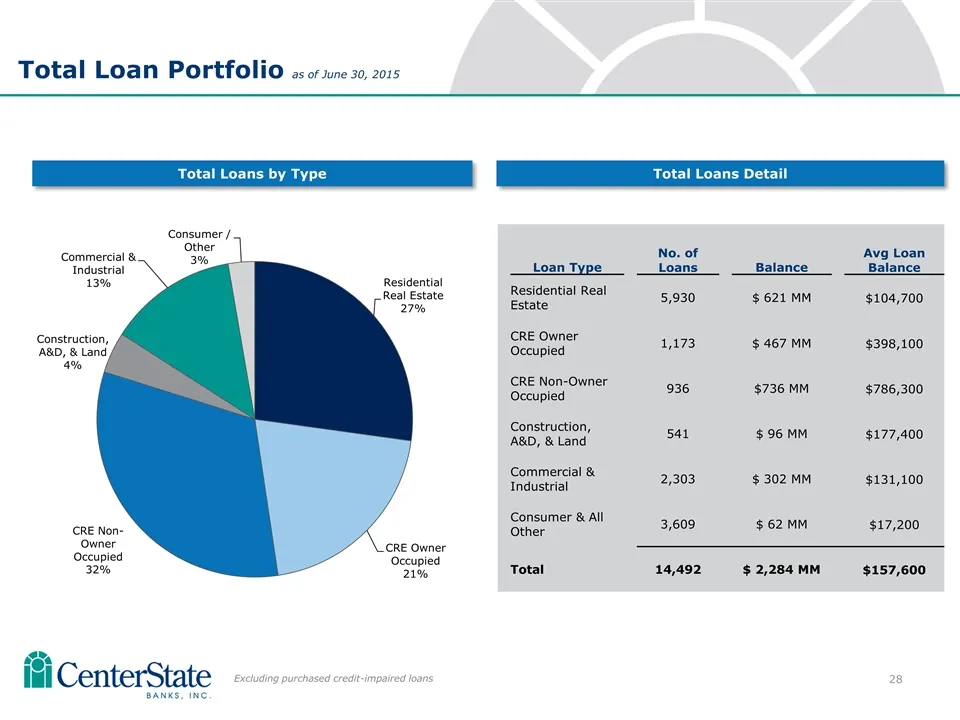
Total Loans by Type Total Loans Detail Loan Type No. of Loans Balance Avg Loan Balance Residential Real Estate 5,930 $ 621 MM $104,700 CRE Owner Occupied 1,173 $ 467 MM $398,100 CRE Non-Owner Occupied 936 $736 MM $786,300 Construction, A&D, & Land 541 $ 96 MM $177,400 Commercial & Industrial 2,303 $
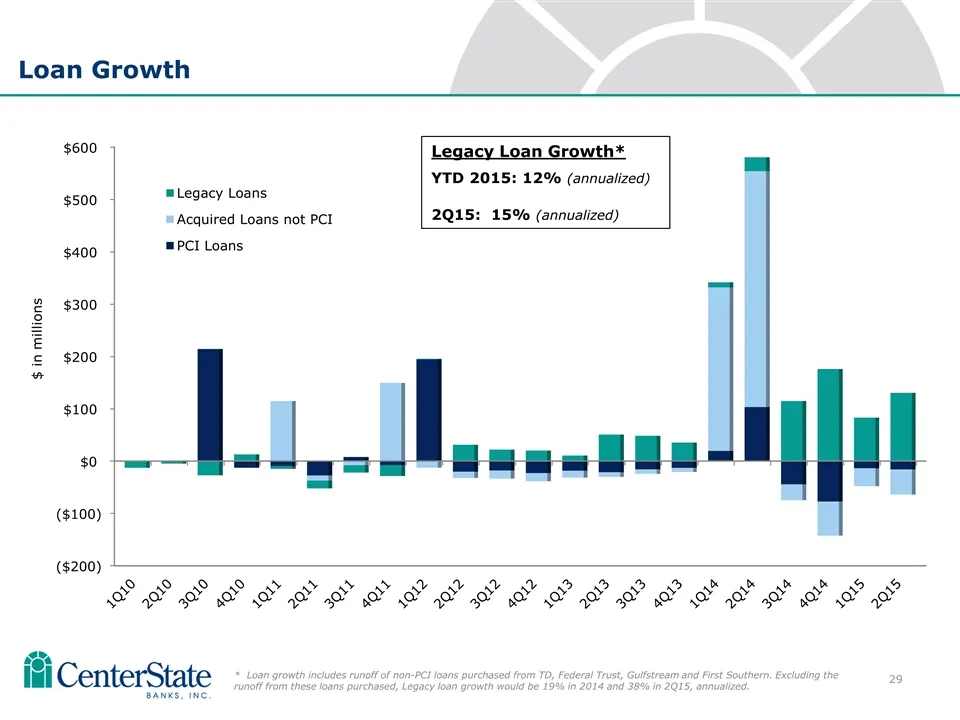
Slide 29: Loan Growth
Loan Growth Legacy Loan Growth* YTD 2015: 12% (annualized) 2Q15: 15% (annualized) * Loan growth includes runoff of non-PCI loans purchased from TD, Federal Trust, Gulfstream and First Southern. Excluding the runoff from these loans purchased, Legacy loan growth would be 19% in 2014 and 38% in 2Q15,
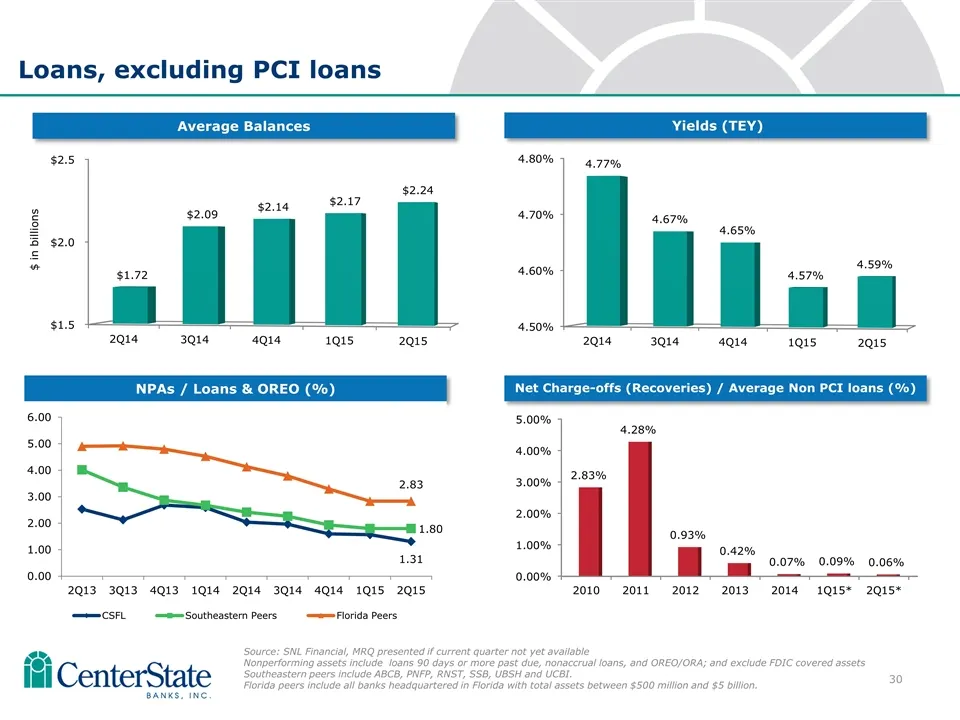
Slide 30: Loans, excluding PCI loans: yields and credit quality
Loans, excluding PCI loans Yields (TEY) Average Balances NPAs / Loans & OREO (%) Source: SNL Financial, MRQ presented if current quarter not yet available Nonperforming assets include loans 90 days or more past due, nonaccrual loans, and OREO/ORA; and exclude FDIC covered assets Southeastern peers i
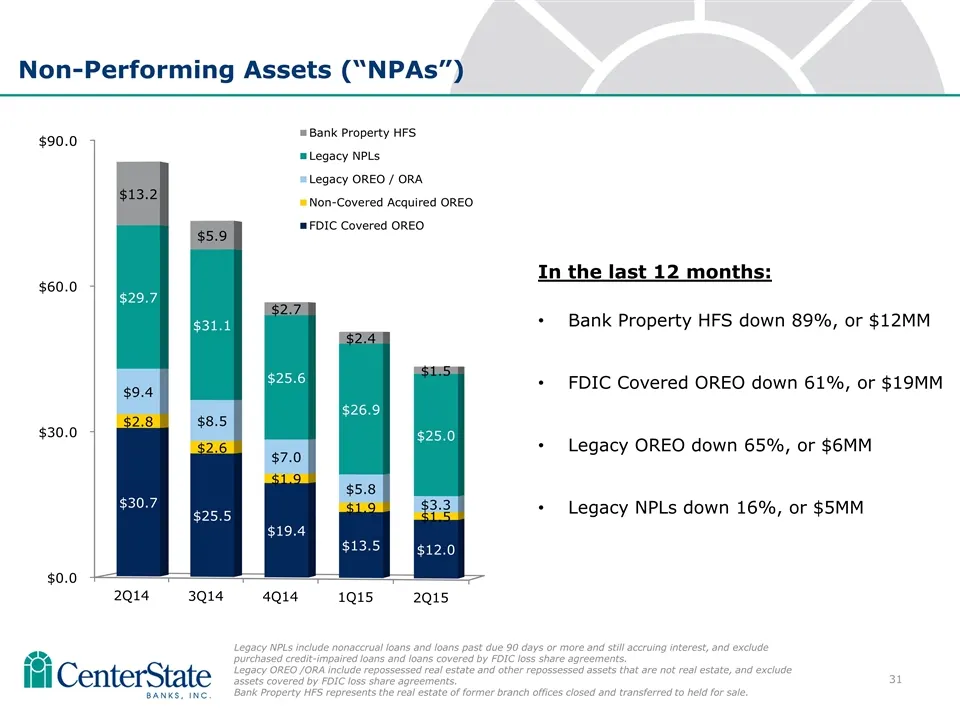
Slide 31: Non-Performing Assets
Non-Performing Assets (“NPAs”) In the last 12 months: Bank Property HFS down 89%, or $12MM FDIC Covered OREO down 61%, or $19MM Legacy OREO down 65%, or $6MM Legacy NPLs down 16%, or $5MM Legacy NPLs include nonaccrual loans and loans past due 90 days or more and still accruing interest, and exclude
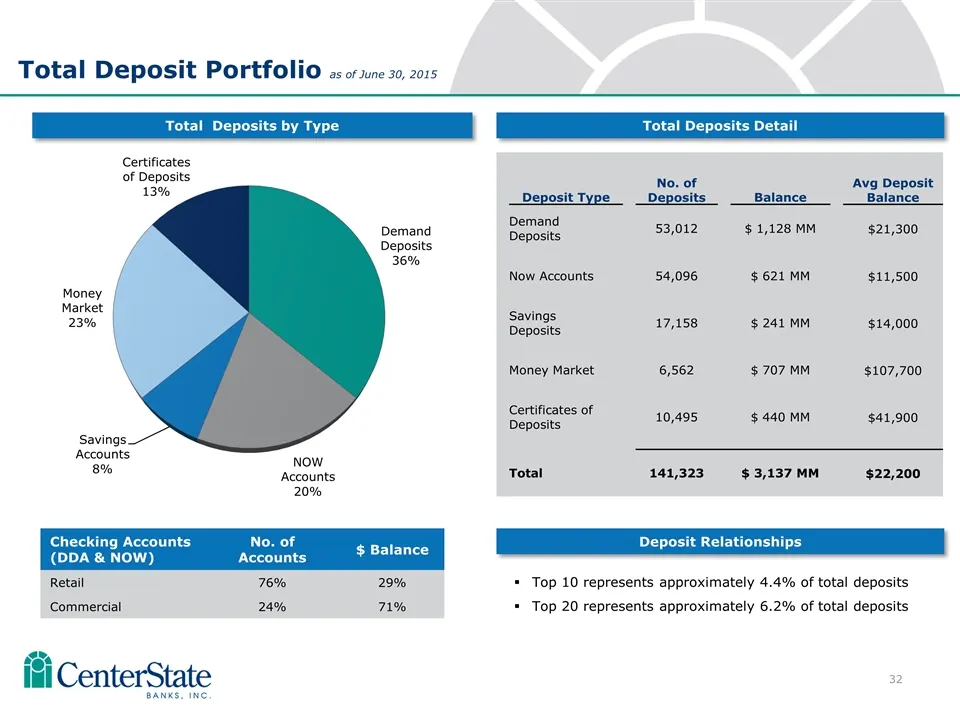
Slide 32: Total Deposits by Type
Total Deposits by Type Total Deposits Detail 23 Total Deposit Portfolio as of June 30, 2015 Deposit Type No. of Deposits Balance Avg Deposit Balance Demand Deposits 53,012 $ 1,128 MM $21,300 Now Accounts 54,096 $ 621 MM $11,500 Savings Deposits 17,158 $ 241 MM $14,000 Money Market 6,562 $ 707 MM $10
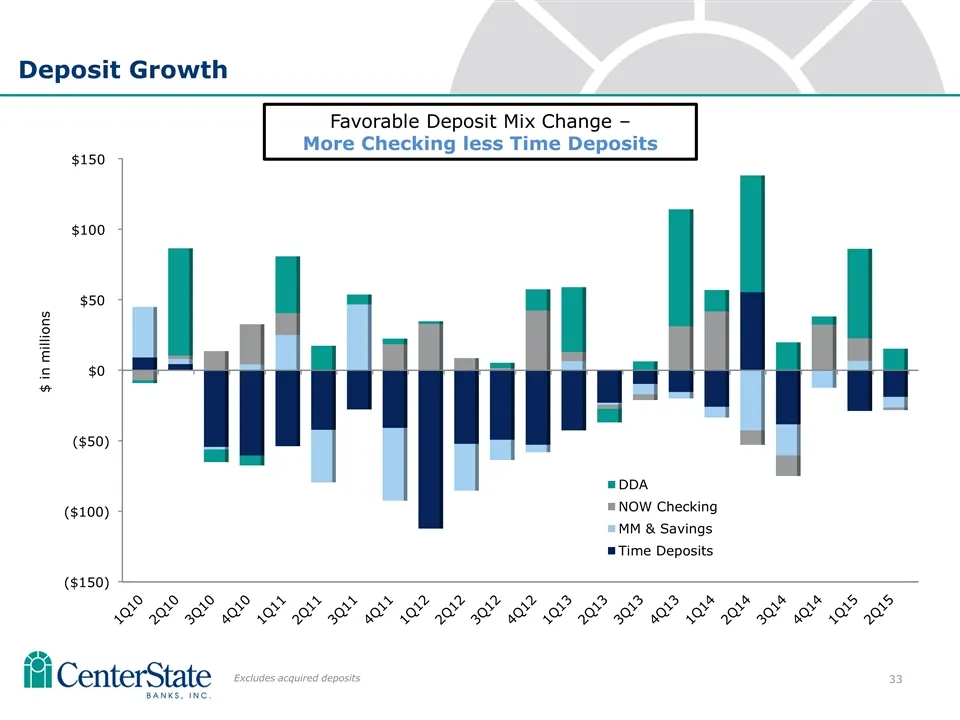
Slide 33: Deposit Growth and Favorable Deposit Mix Change
Excludes acquired deposits Deposit Growth Favorable Deposit Mix Change – More Checking less Time Deposits
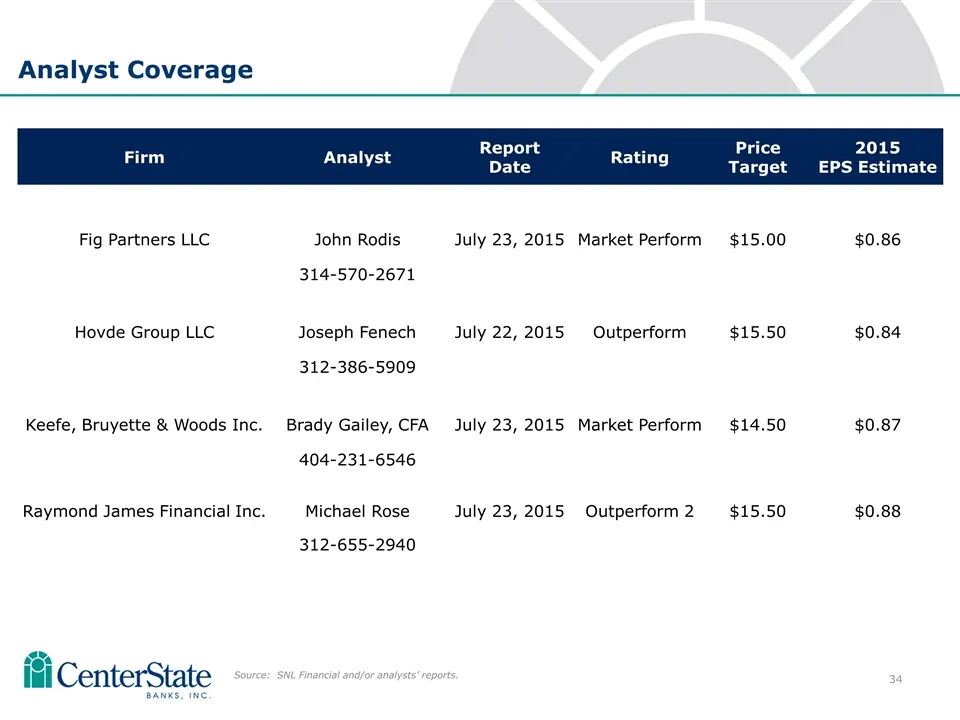
Slide 34: Analyst Coverage
Analyst Coverage Source: SNL Financial and/or analysts’ reports. Firm Analyst Report Rating Price 2015 Date Target EPS Estimate Fig Partners LLC John Rodis July 23, 2015 Market Perform $15.00 $0.86 314-570-2671 Hovde Group LLC Joseph Fenech July 22, 2015 Outperform $15.50 $0.84 312-386-5909 Keefe, B
Slide 35: Investor Contacts
Investor Contacts Ernie Pinner Executive Chairman [email protected] 863-419-7732 John Corbett President & Chief Executive Officer [email protected] 863-294-6383 Jim Antal Chief Financial Officer [email protected] 863-419-7775 Steve Young Treasurer Chief Operating Officer of
Slide 36: CenterState
iti CenterState wwww.centerstatebanks com
Source: SEC EDGAR · 8-K filed Sep 28, 2015
More decks from CenterState Bank Corporation
 IPO Roadshow (May 2020)42 slides · May 21, 2020
 D.A. Davidson 22nd Annual Financial Institution Virtual Conference (May 2020)25 slides · May 6, 2020
 Q1 2020 Earnings Presentation25 slides · Apr 23, 2020
 Merger or Acquisition (January 2020)24 slides · Jan 27, 2020
 Q3 2019 Earnings Presentation28 slides · Nov 4, 2019
 Investor Presentation (July 2019)28 slides · Jul 30, 2019