Broadmark Realty Capital — SPAC Merger (September 2019)
46 slides from Broadmark Realty Capital's SPAC merger presentation, Sep 30, 2019
Slide 1: Investor Presentation October 2019
Investor PresentationOctober 2019 Broadmark realty Capital
Slide 2: Disclaimer
Disclaimer This presentation contemplates the business combination (the “Business Combination”) pursuant to an Agreement and Plan of Merger (the “Merger Agreement”) among Trinity Merger Corporation, a Delaware corporation (“Trinity”), Trinity Sub Inc., a Maryland corporation and wholly-owned subsidi
Slide 3: Cautionary Statement Concerning Forward-Looking Statements
Disclaimer Cautionary Statement Concerning Forward-Looking Statements This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, conveying the expectations of m
Slide 4: Use of Projections
Disclaimer Use of Projections The projections included below are forward-looking statements and are subject to risks and uncertainties that could cause actual results to differ materially from those statements and should be read with caution. They are subjective in many respects and thus susceptible
Slide 5: Transaction Summary Overview
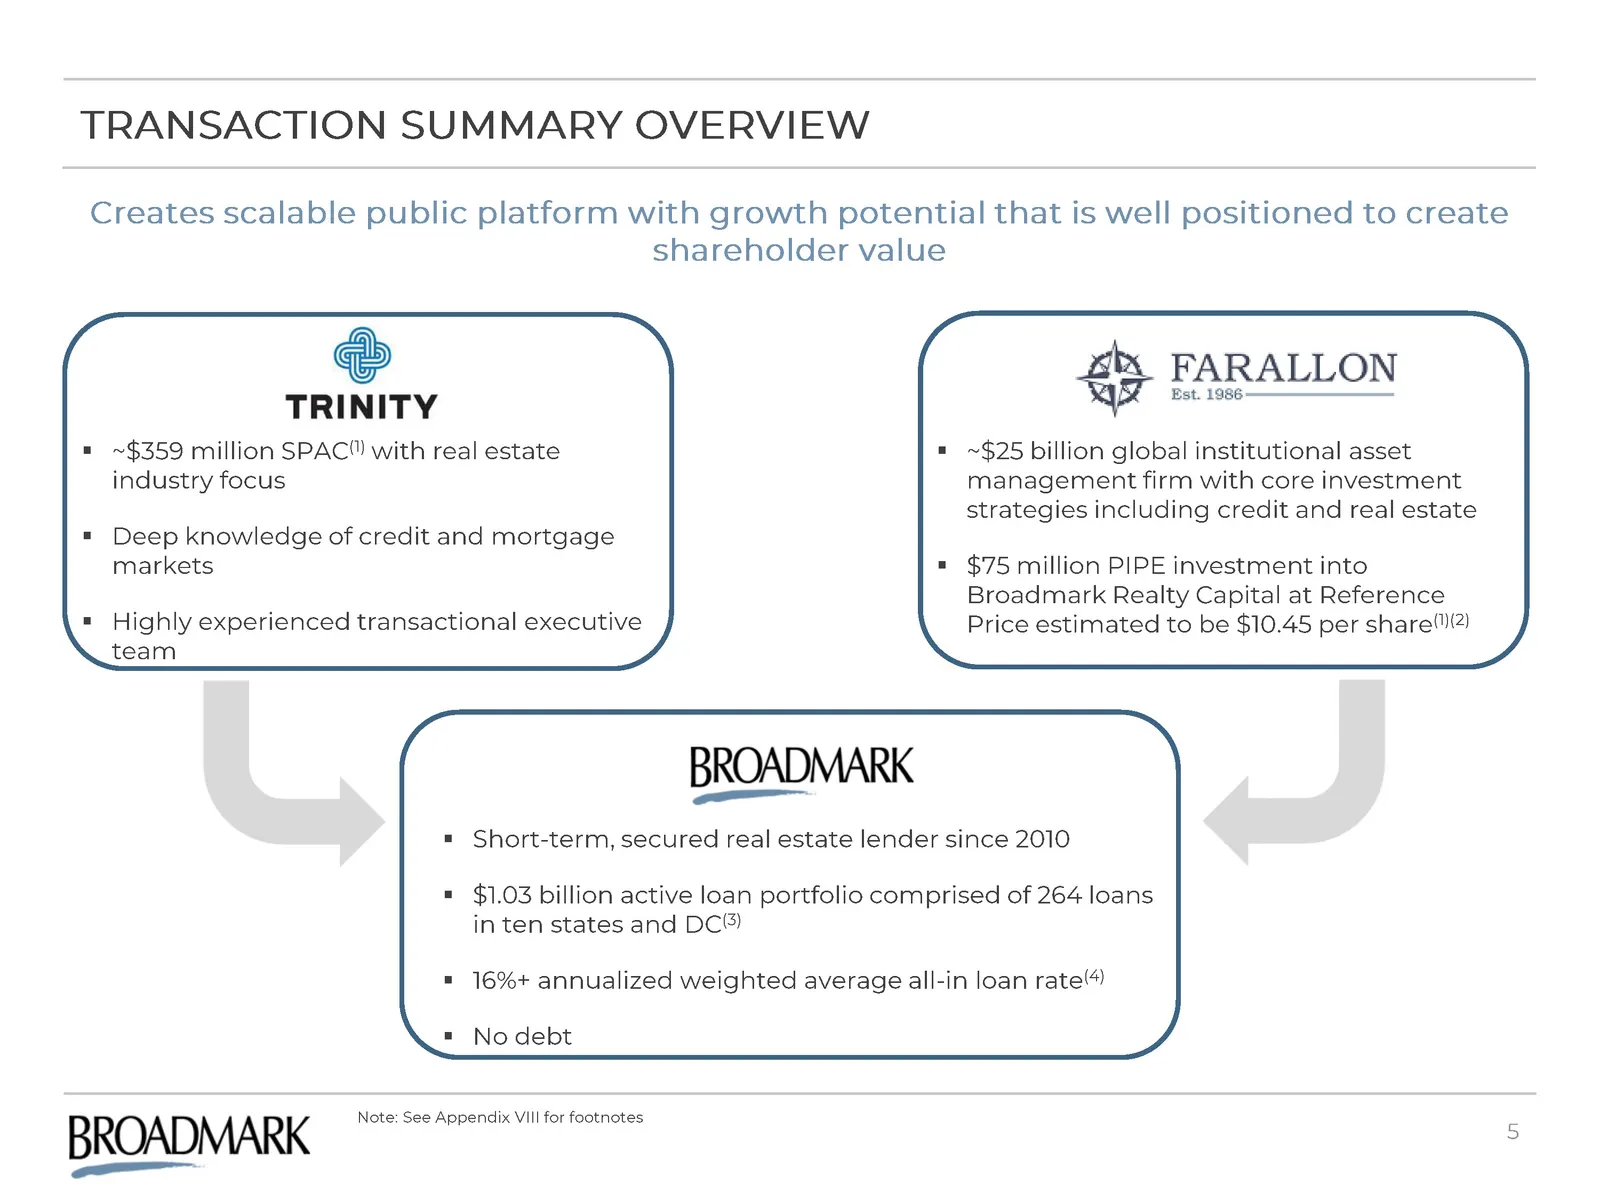
Transaction Summary Overview ~$359 million SPAC(1) with real estate industry focusDeep knowledge of credit and mortgage marketsHighly experienced transactional executive team ~$25 billion global institutional asset management firm with core investment strategies including credit and real estate$75 m
Slide 6: Transaction notes and terms
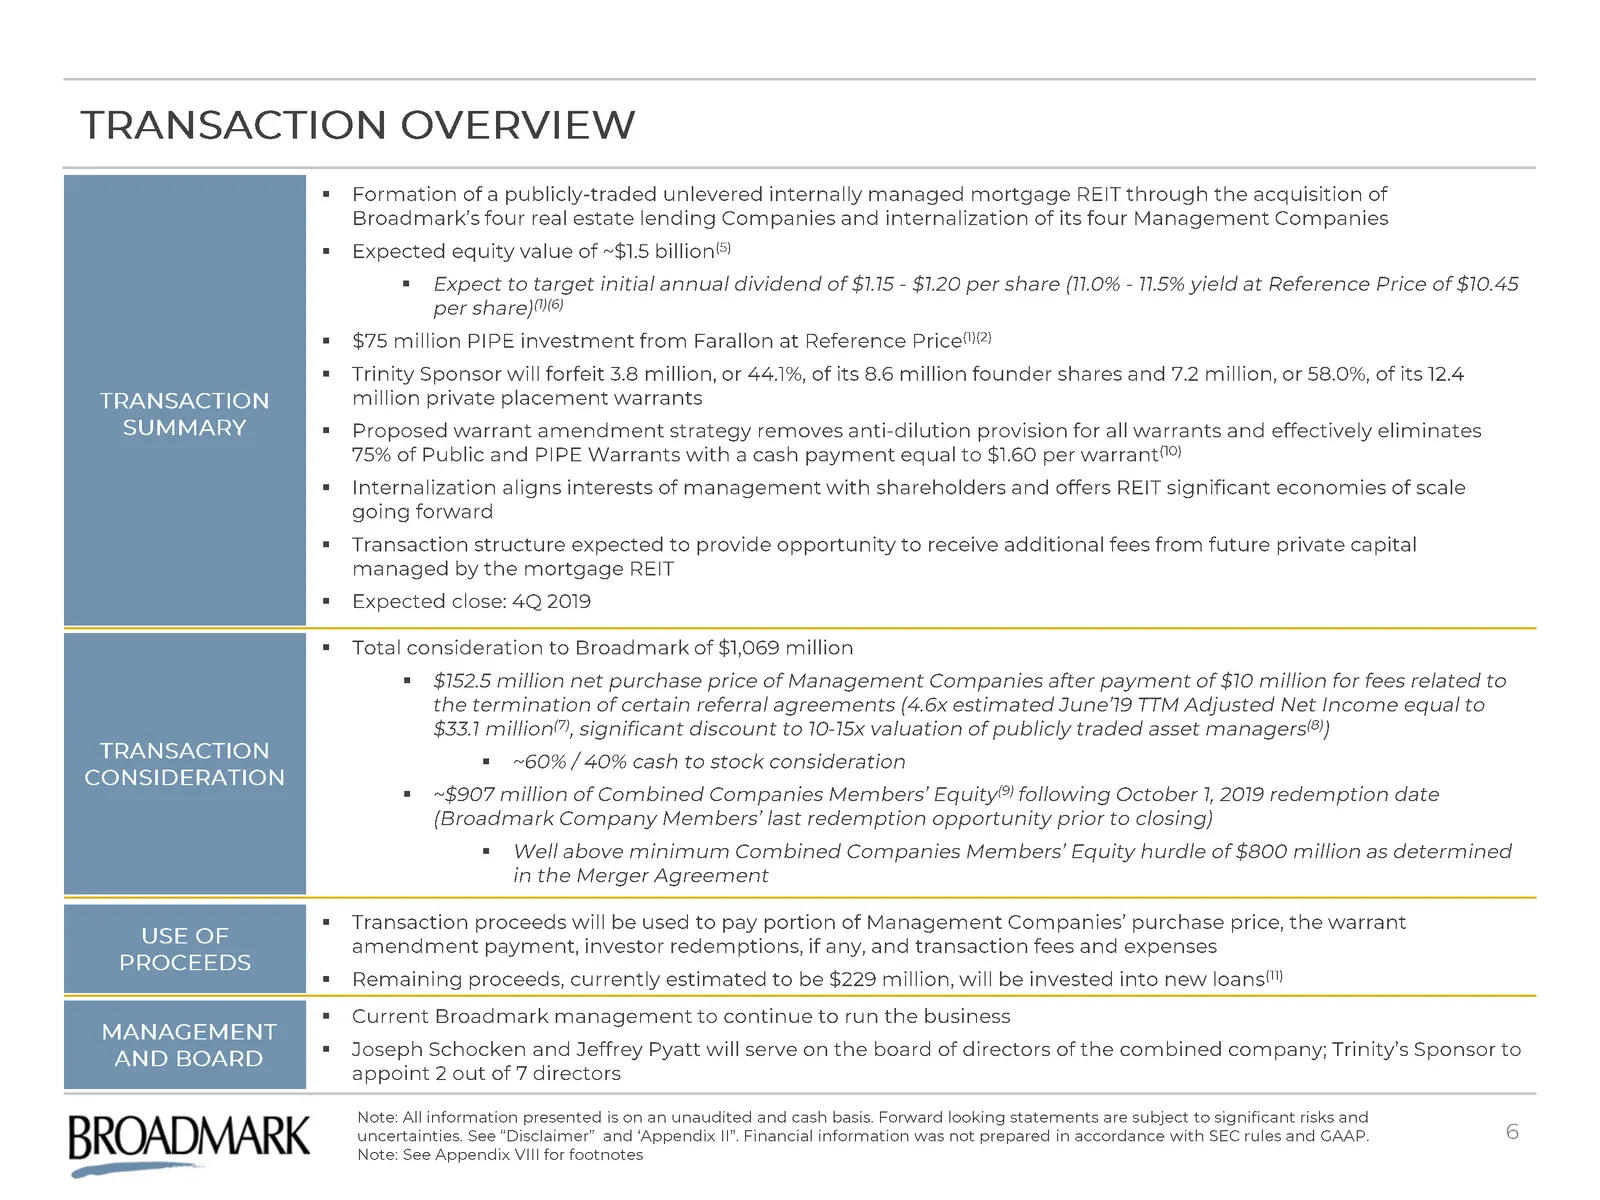
Note: All information presented is on an unaudited and cash basis. Forward looking statements are subject to significant risks and uncertainties. See “Disclaimer” and ‘Appendix II”. Financial information was not prepared in accordance with SEC rules and GAAP.Note: See Appendix VIII for footnotes For
Slide 7: Broadmark Overview
Broadmark Overview Section 1
Slide 8: Broadmark Realty Capital Overview
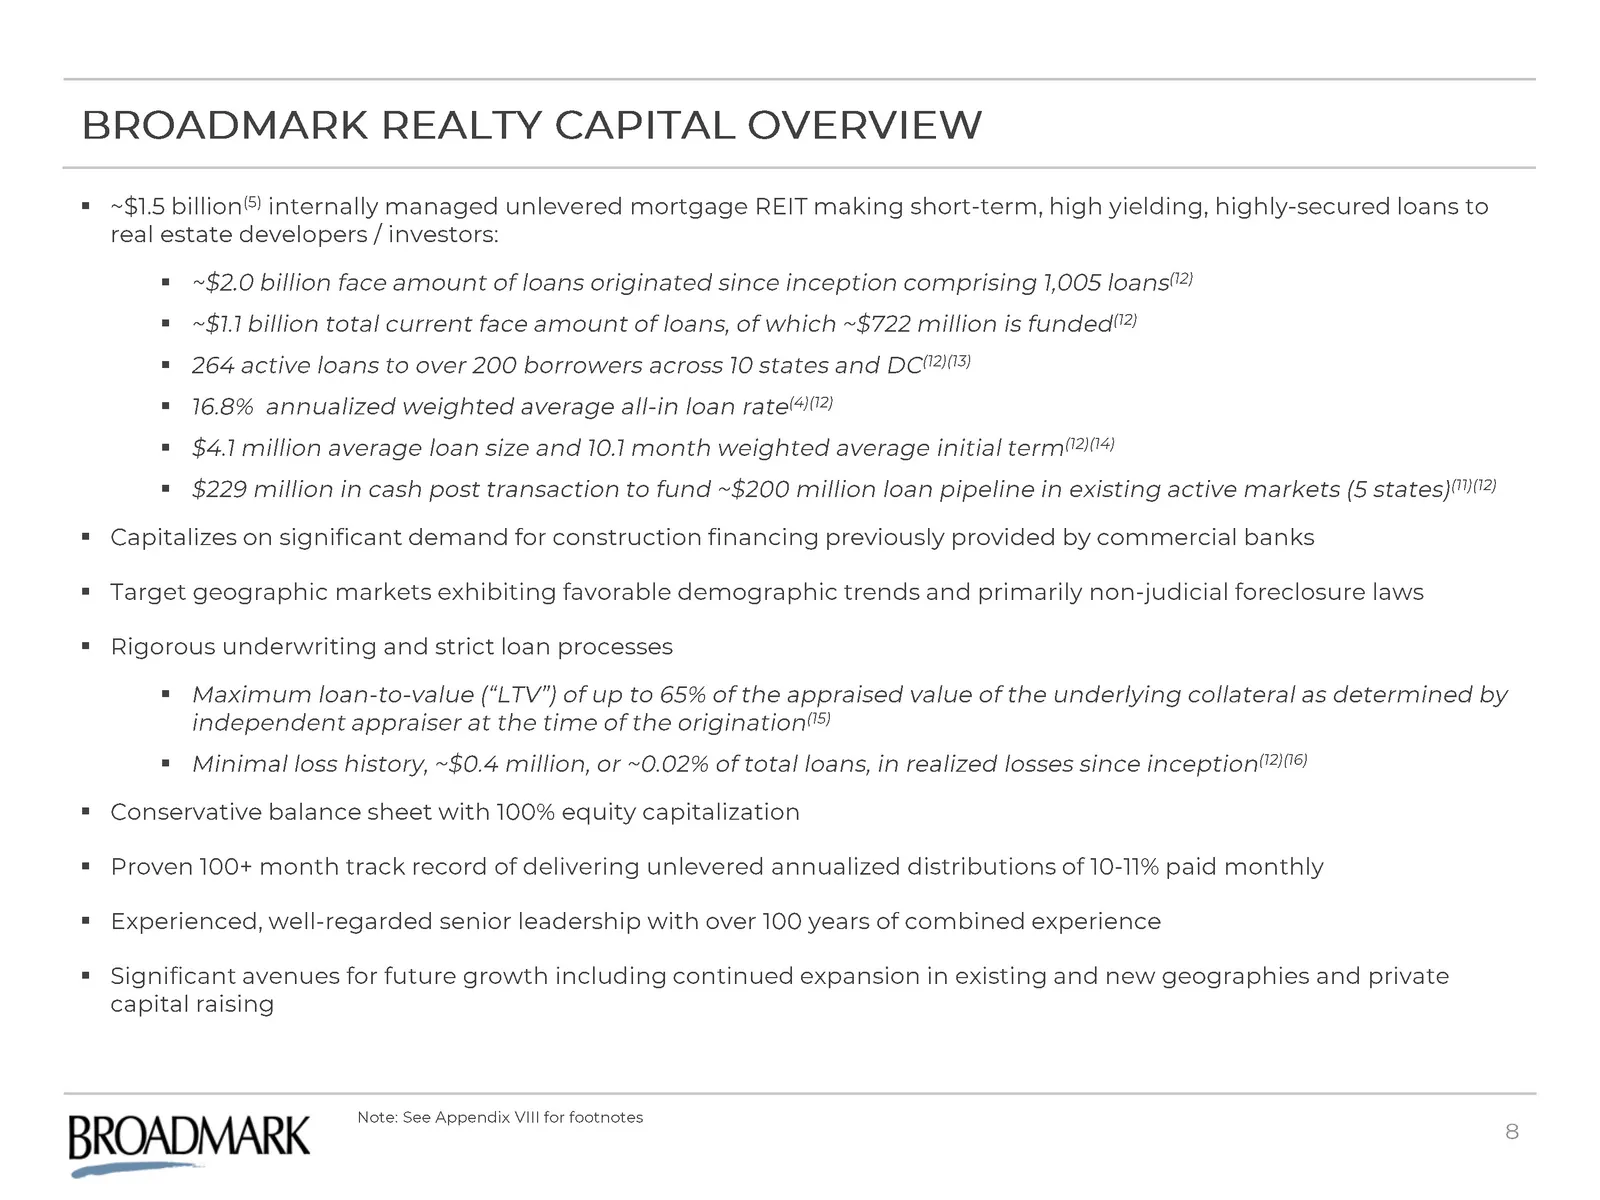
Broadmark REALTY CAPITAL Overview ~$1.5 billion(5) internally managed unlevered mortgage REIT making short-term, high yielding, highly-secured loans to real estate developers / investors:~$2.0 billion face amount of loans originated since inception comprising 1,005 loans(12)~$1.1 billion total curre
Slide 9: Investment Highlights
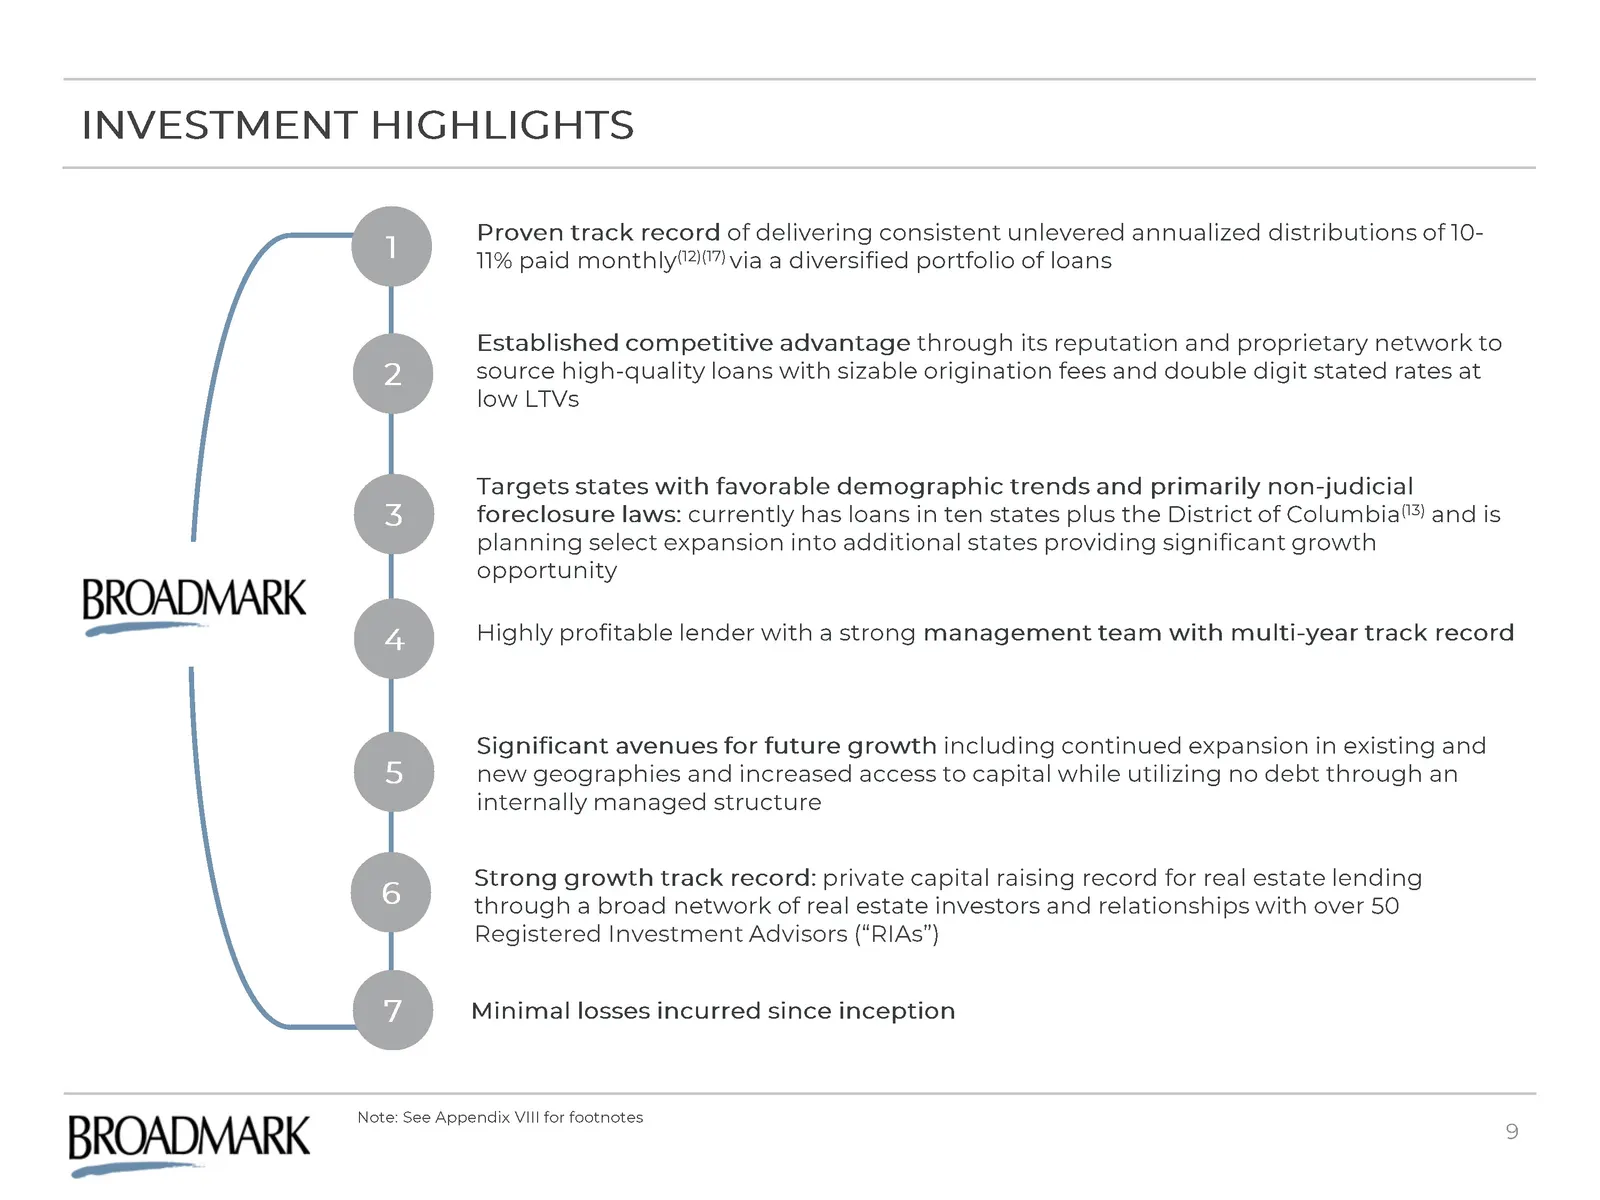
Proven track record of delivering consistent unlevered annualized distributions of 10-11% paid monthly(12)(17) via a diversified portfolio of loans Significant avenues for future growth including continued expansion in existing and new geographies and increased access to capital while utilizing no d
Slide 10: 1. Proven Track Record
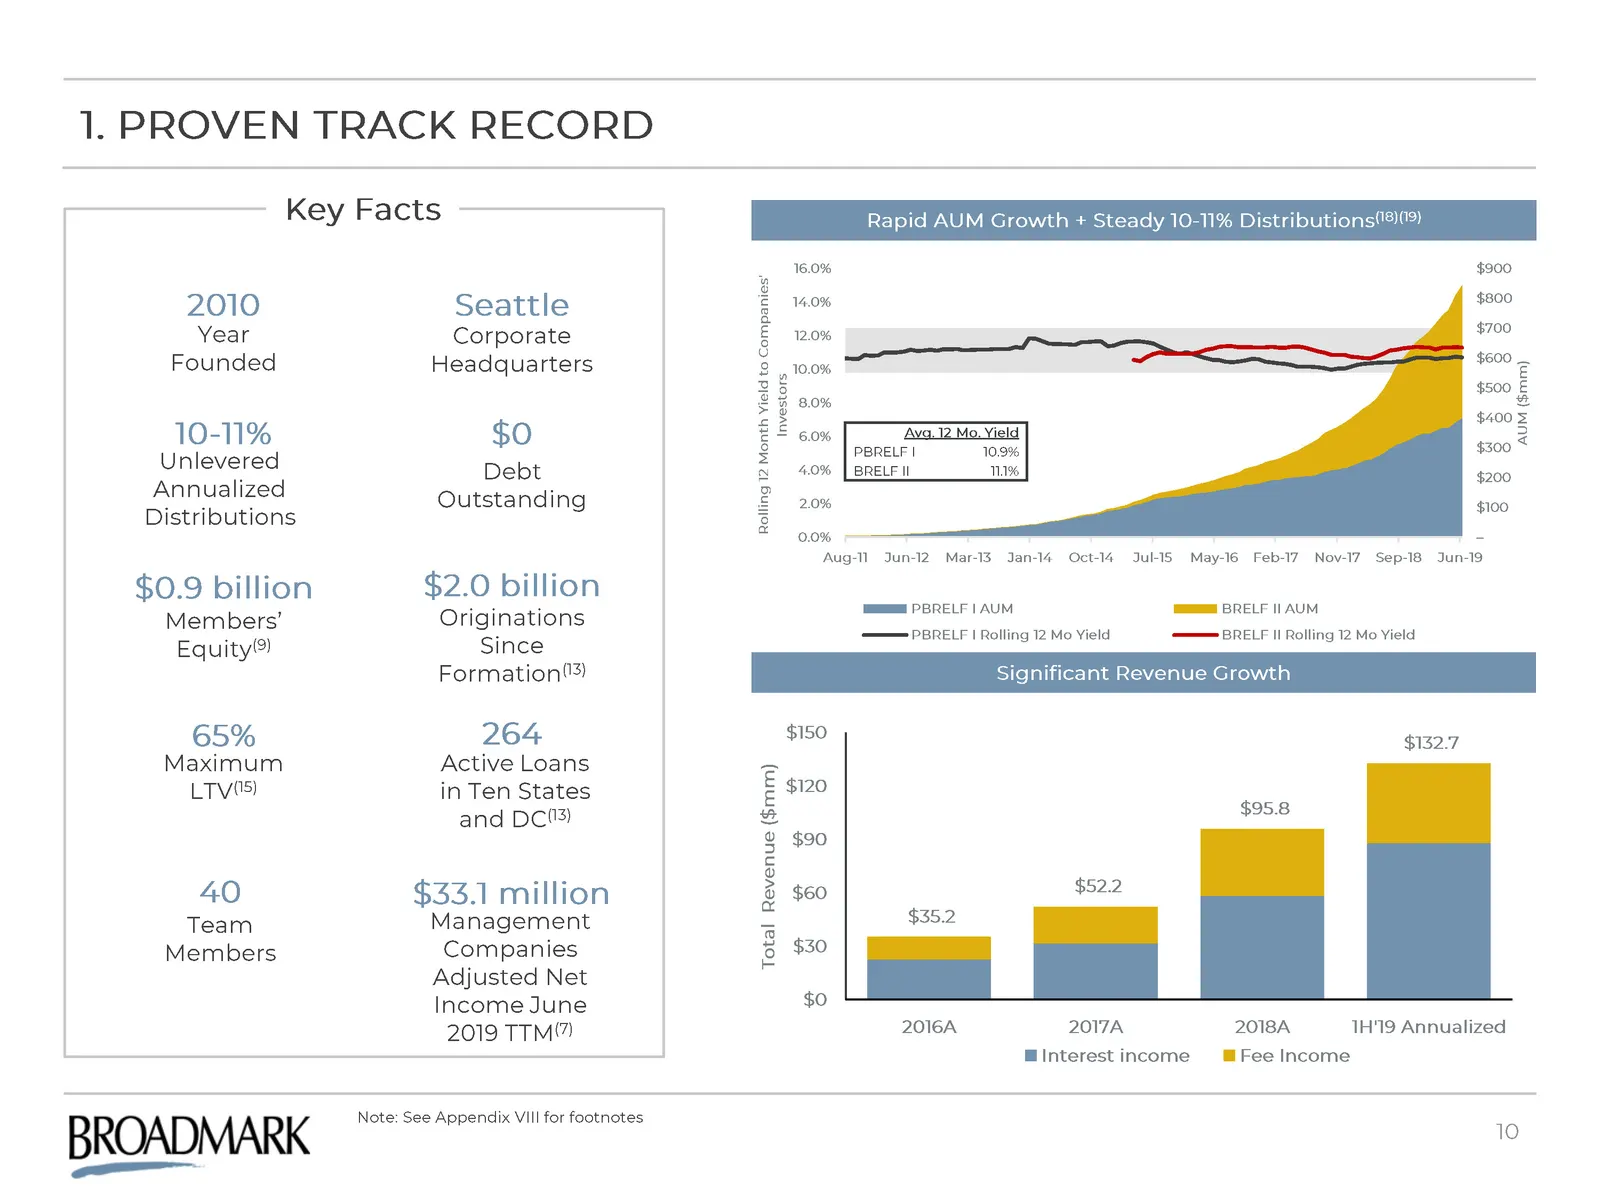
1. PROVEN Track record Rapid AUM Growth + Steady 10-11% Distributions(18)(19) 2010 Year Founded $0.9 billion Members’ Equity(9) 65% Maximum LTV(15) 10-11% Unlevered Annualized Distributions 264 Active Loans in Ten States and DC(13) Seattle Corporate Headquarters Key Facts 40 Team Members $2.0 billio
Slide 11: 1. Proven Track Record (Cont'd)
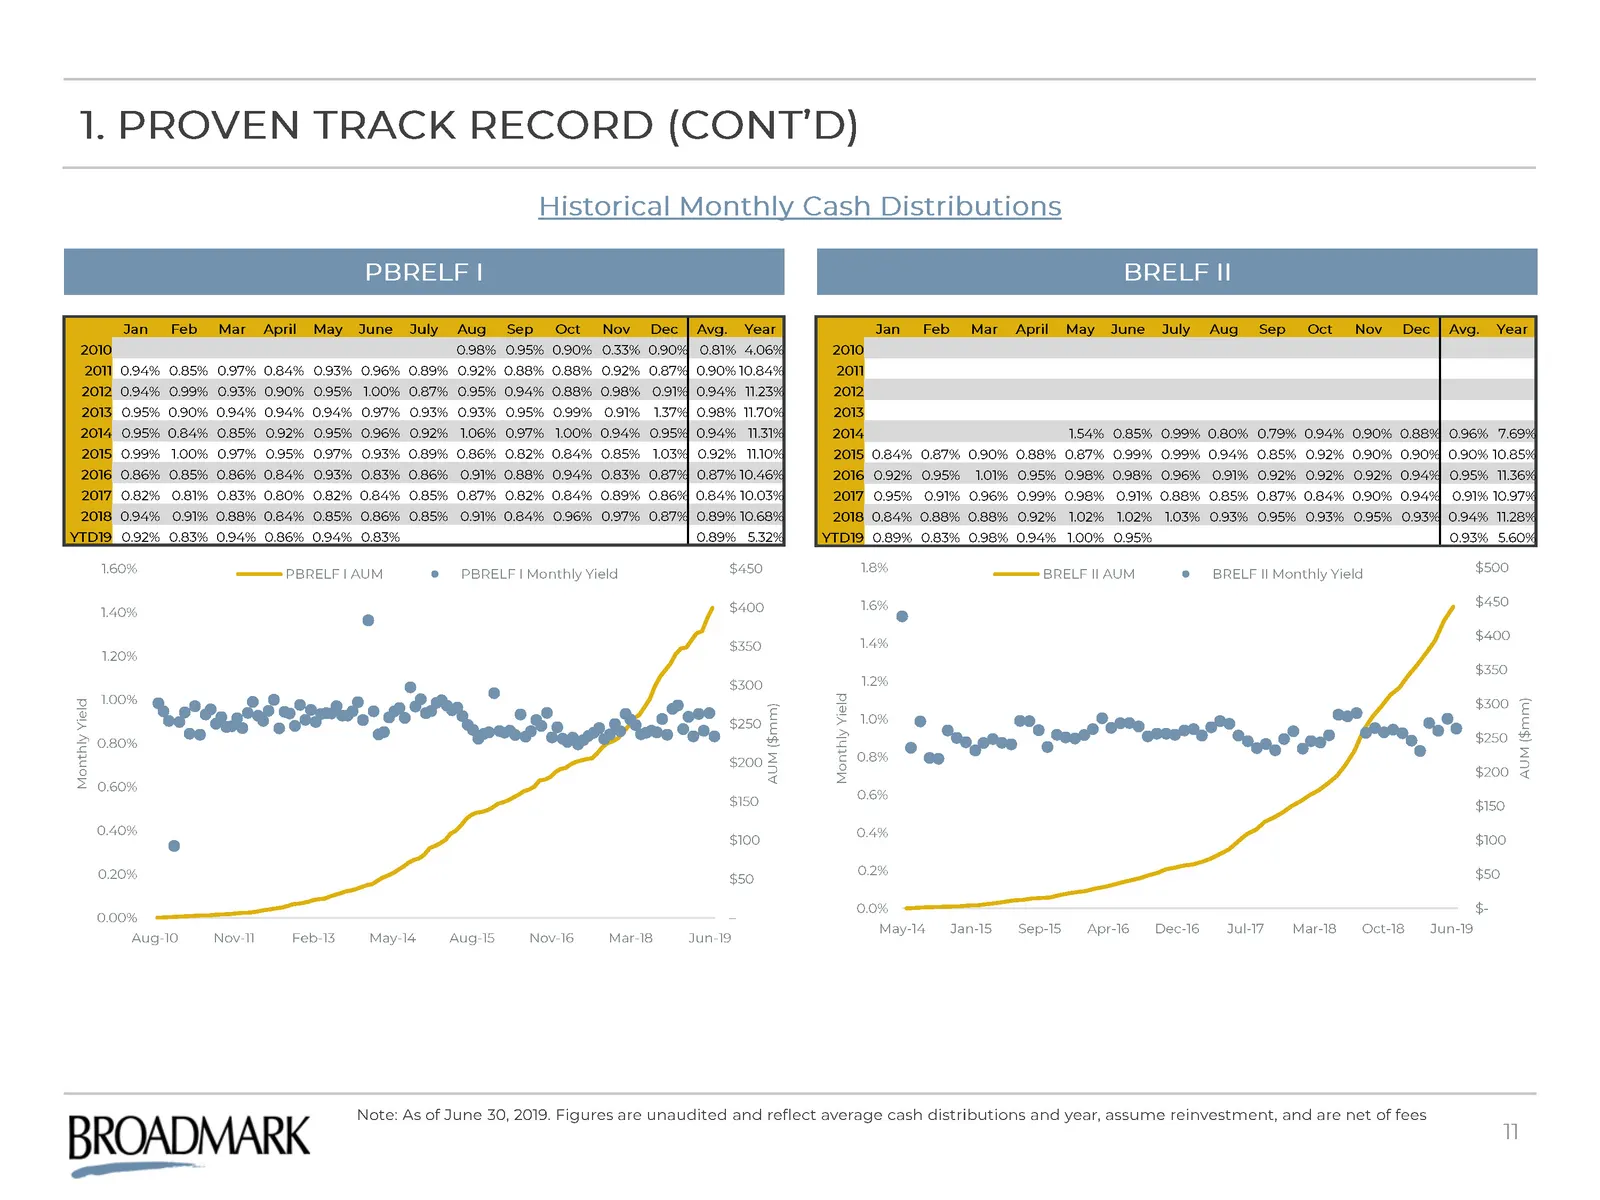
1. PROVEN Track record (Cont’d) Note: As of June 30, 2019. Figures are unaudited and reflect average cash distributions and year, assume reinvestment, and are net of fees PBRELF I BRELF II Historical Monthly Cash Distributions Jan Feb Mar April May June July Aug Sep Oct Nov Dec Avg. Year 2010 0.98%
Slide 12: 2. Established Competitive Advantage
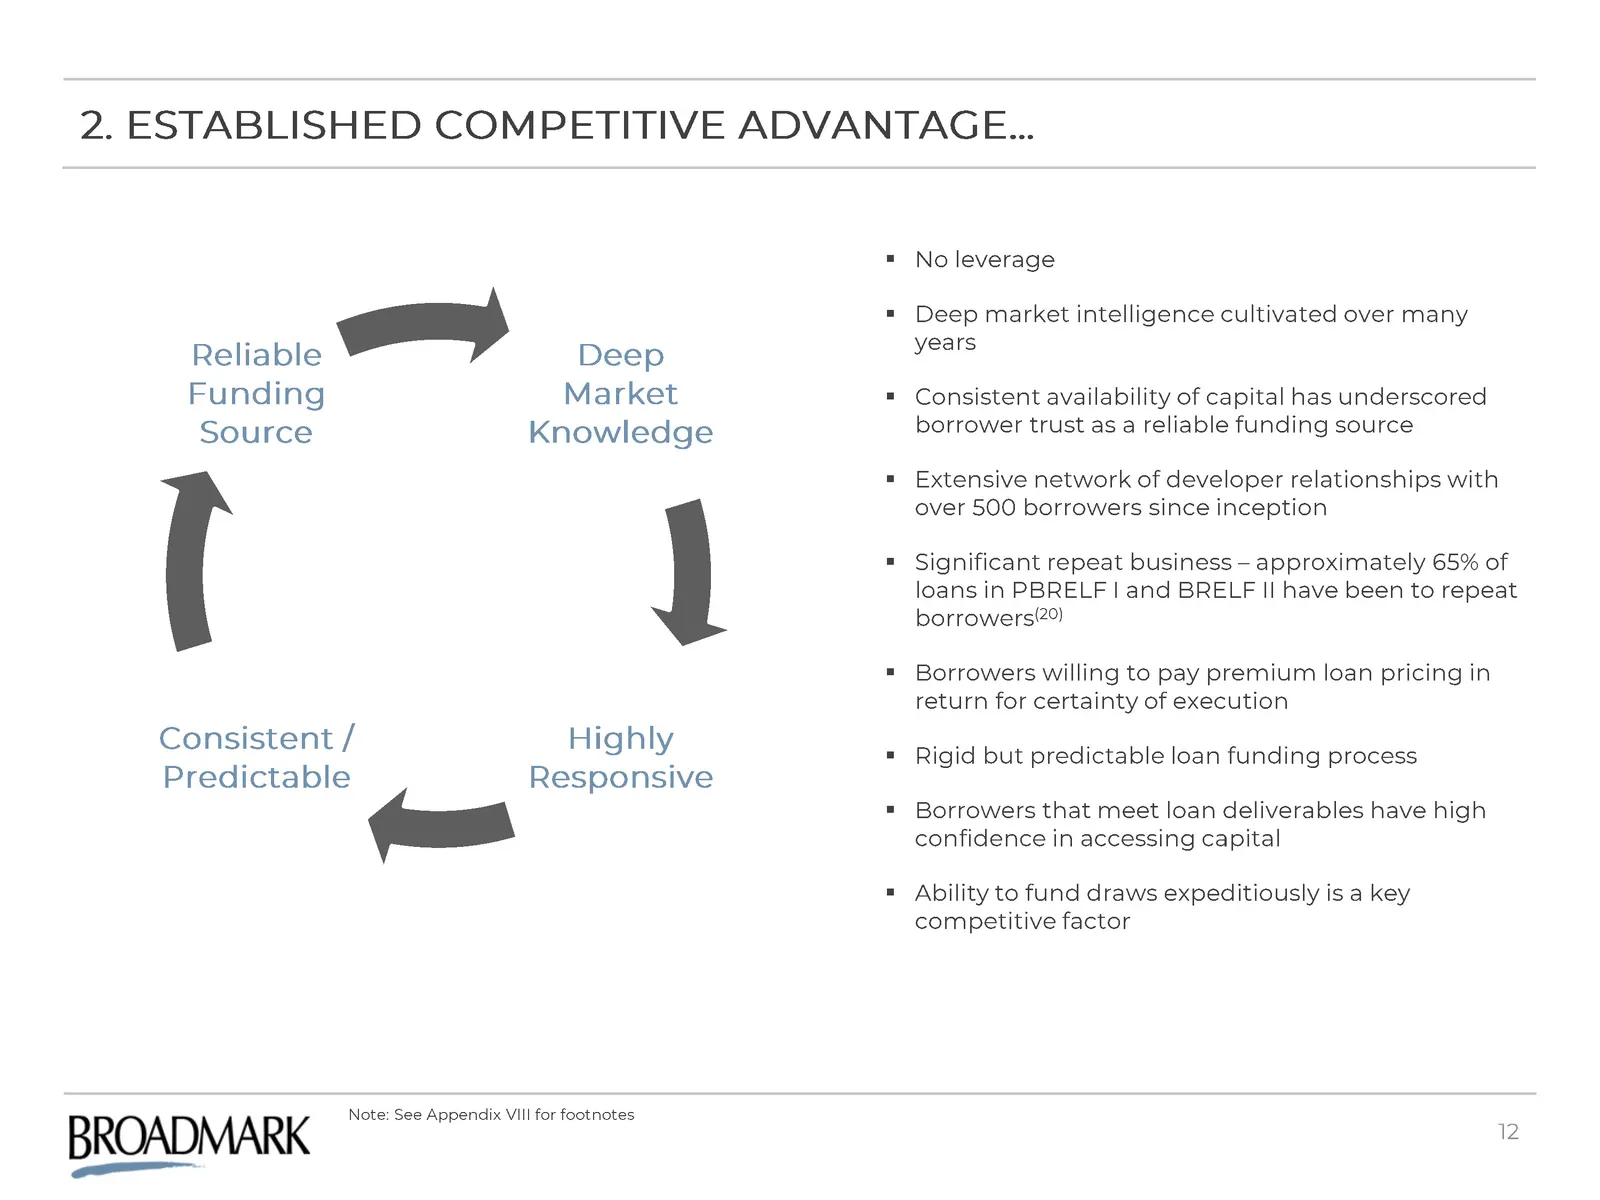
2. ESTABLISHED COMPETITIVE ADVANTAGE… No leverageDeep market intelligence cultivated over many yearsConsistent availability of capital has underscored borrower trust as a reliable funding sourceExtensive network of developer relationships with over 500 borrowers since inceptionSignificant repeat bus
Slide 13: 2. And Differentiated High-Yielding Growth Opportunity
2. …And Differentiated High-Yielding Growth Opportunity Alternative unlevered credit-focused strategy generating a double digit dividend yield with limited correlation to broader equity capital marketsProvides significant growth opportunity to generate additional fee incomeSuccessful track record of
Slide 14: 3. Target States with Favorable Demographic Trends
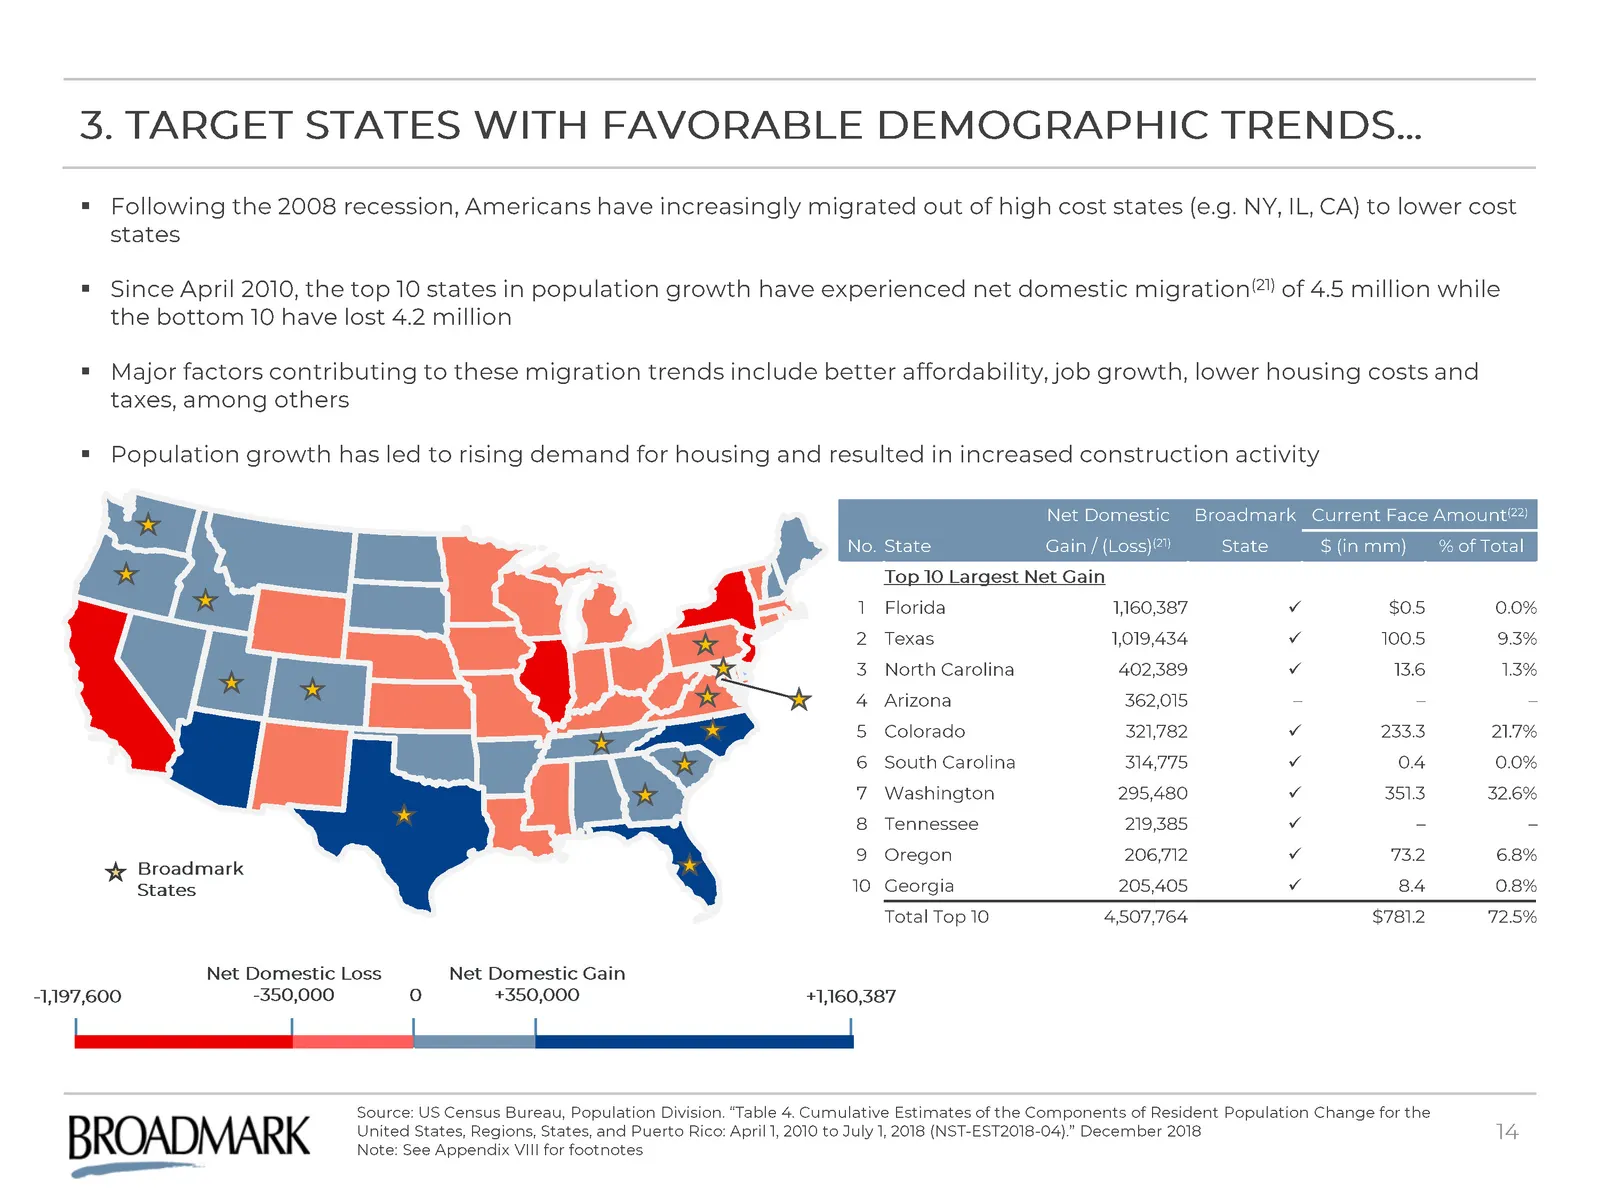
Net Domestic Broadmark Current Face Amount(22) No. State Gain / (Loss)(21) State $ (in mm) % of Total Top 10 Largest Net Gain 1 Florida 1,160,387 ü $0.5 0.0% 2 Texas 1,019,434 ü 100.5 9.3% 3 North Carolina 402,389 ü 13.6 1.3% 4 Arizona 362,015 – – – 5 Colorado 321,782 ü 233.3 21.7% 6 South Carolina
Slide 15: 3. And States with Non-Judicial Foreclosure Laws
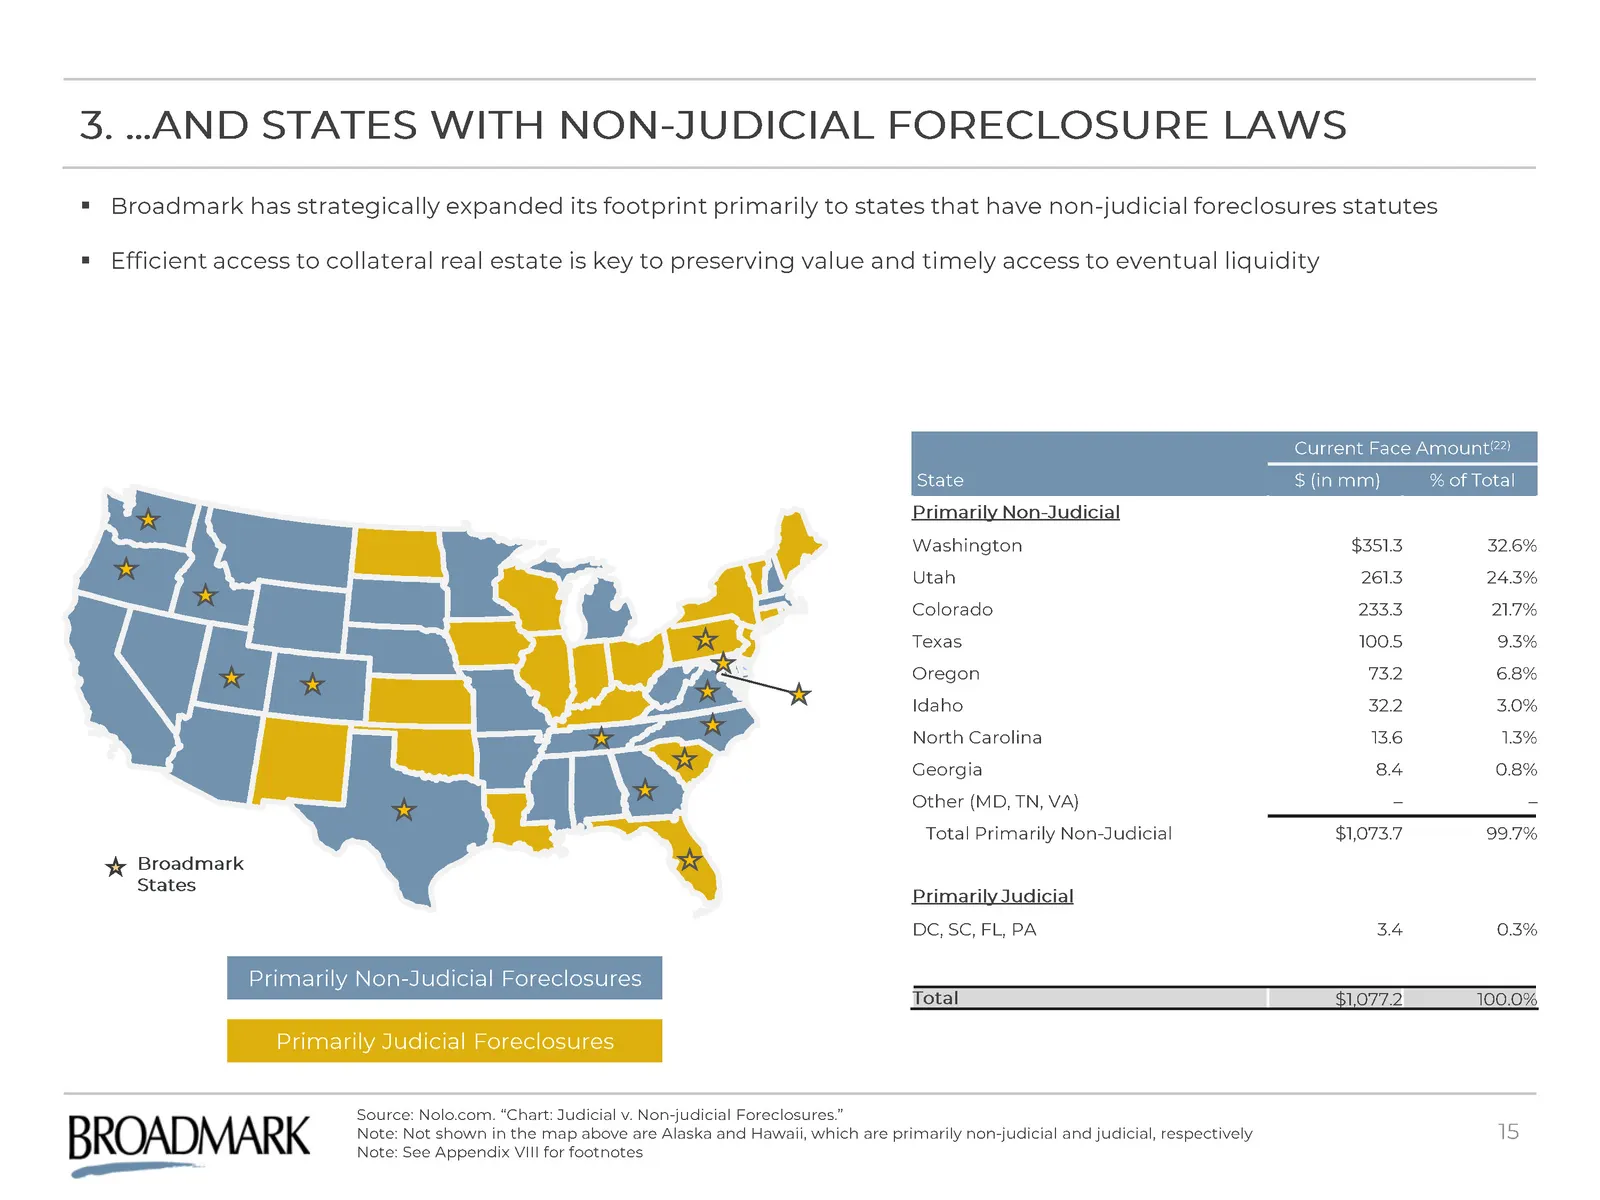
Current Face Amount(22) State $ (in mm) % of Total Primarily Non-Judicial Washington $351.3 32.6% Utah 261.3 24.3% Colorado 233.3 21.7% Texas 100.5 9.3% Oregon 73.2 6.8% Idaho 32.2 3.0% North Carolina 13.6 1.3% Georgia 8.4 0.8% Other (MD, TN, VA) – – Total Primarily Non-Judicial $1,073.7 99.7% Prima
Slide 16: 4. Management Team with Multi-Year Track Record
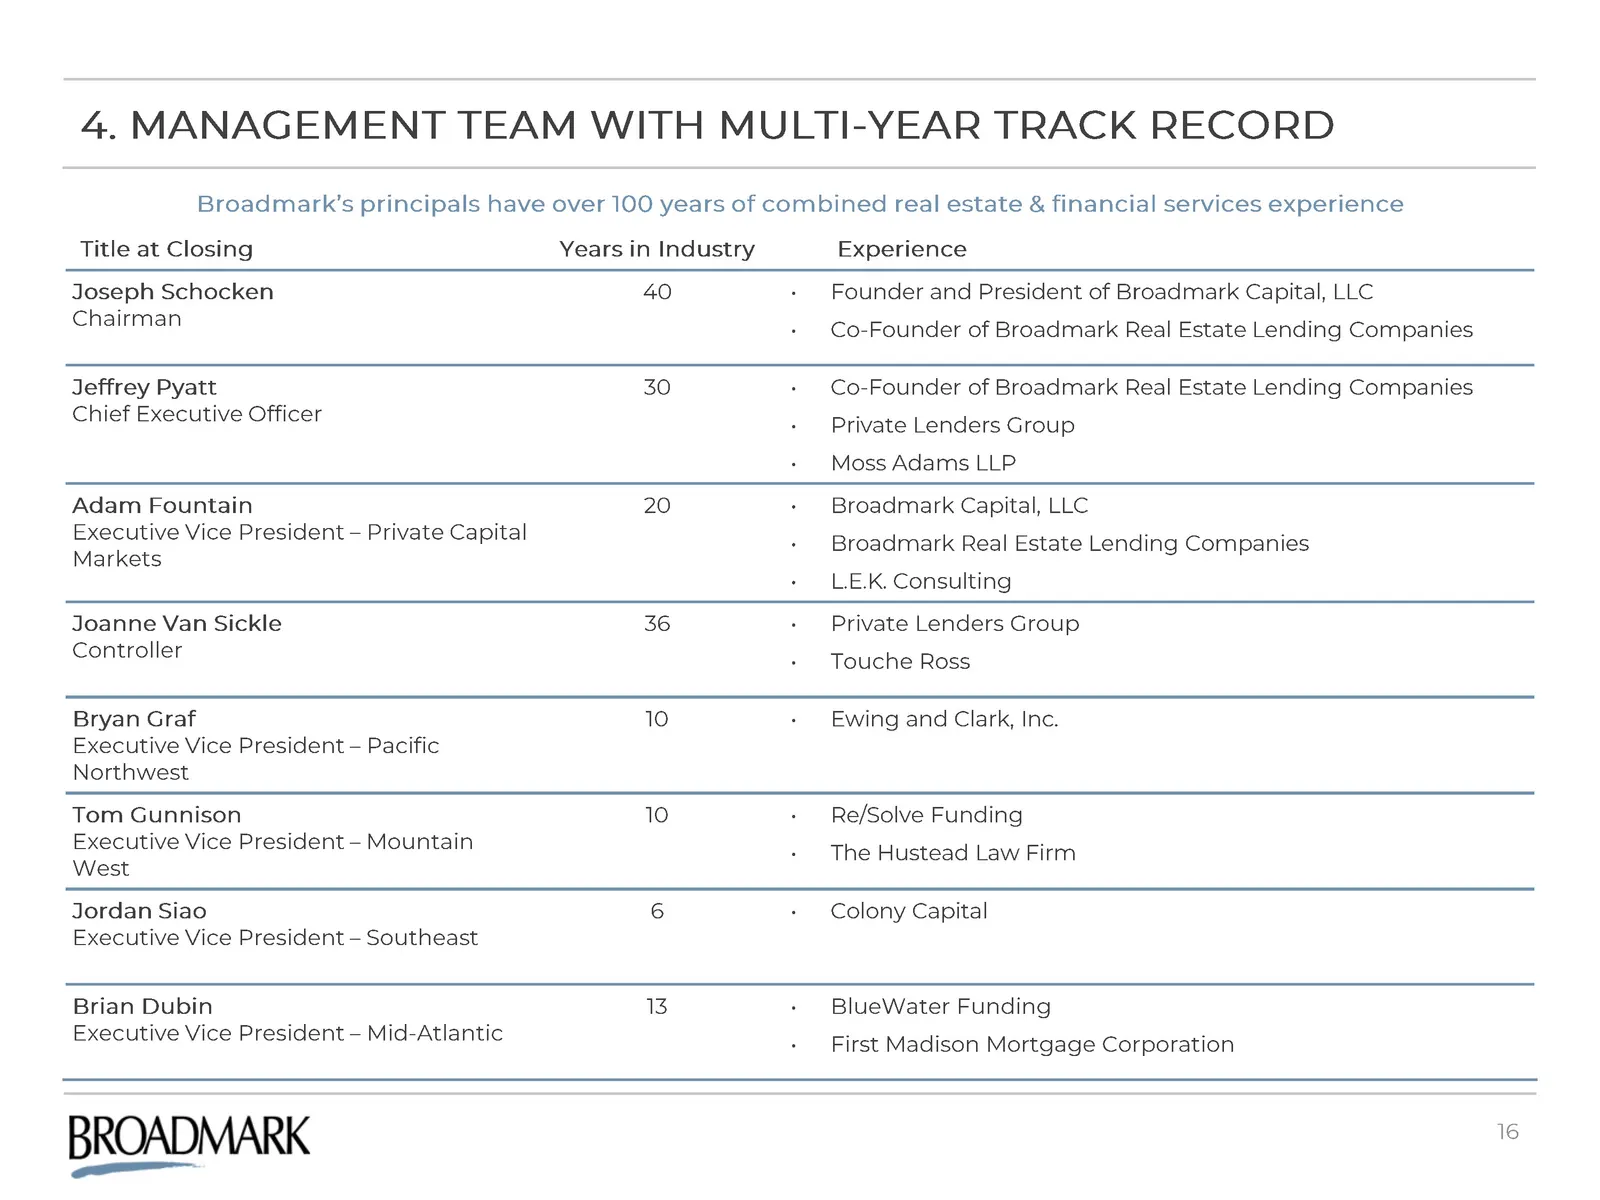
4. management team WITH MULTI-YEAR TRACK RECORD Broadmark’s principals have over 100 years of combined real estate & financial services experience Title at Closing Years in Industry Experience Joseph SchockenChairman 40 Founder and President of Broadmark Capital, LLCCo-Founder of Broadmark Real Esta
Slide 17: 5. Significant Opportunities for Future Growth
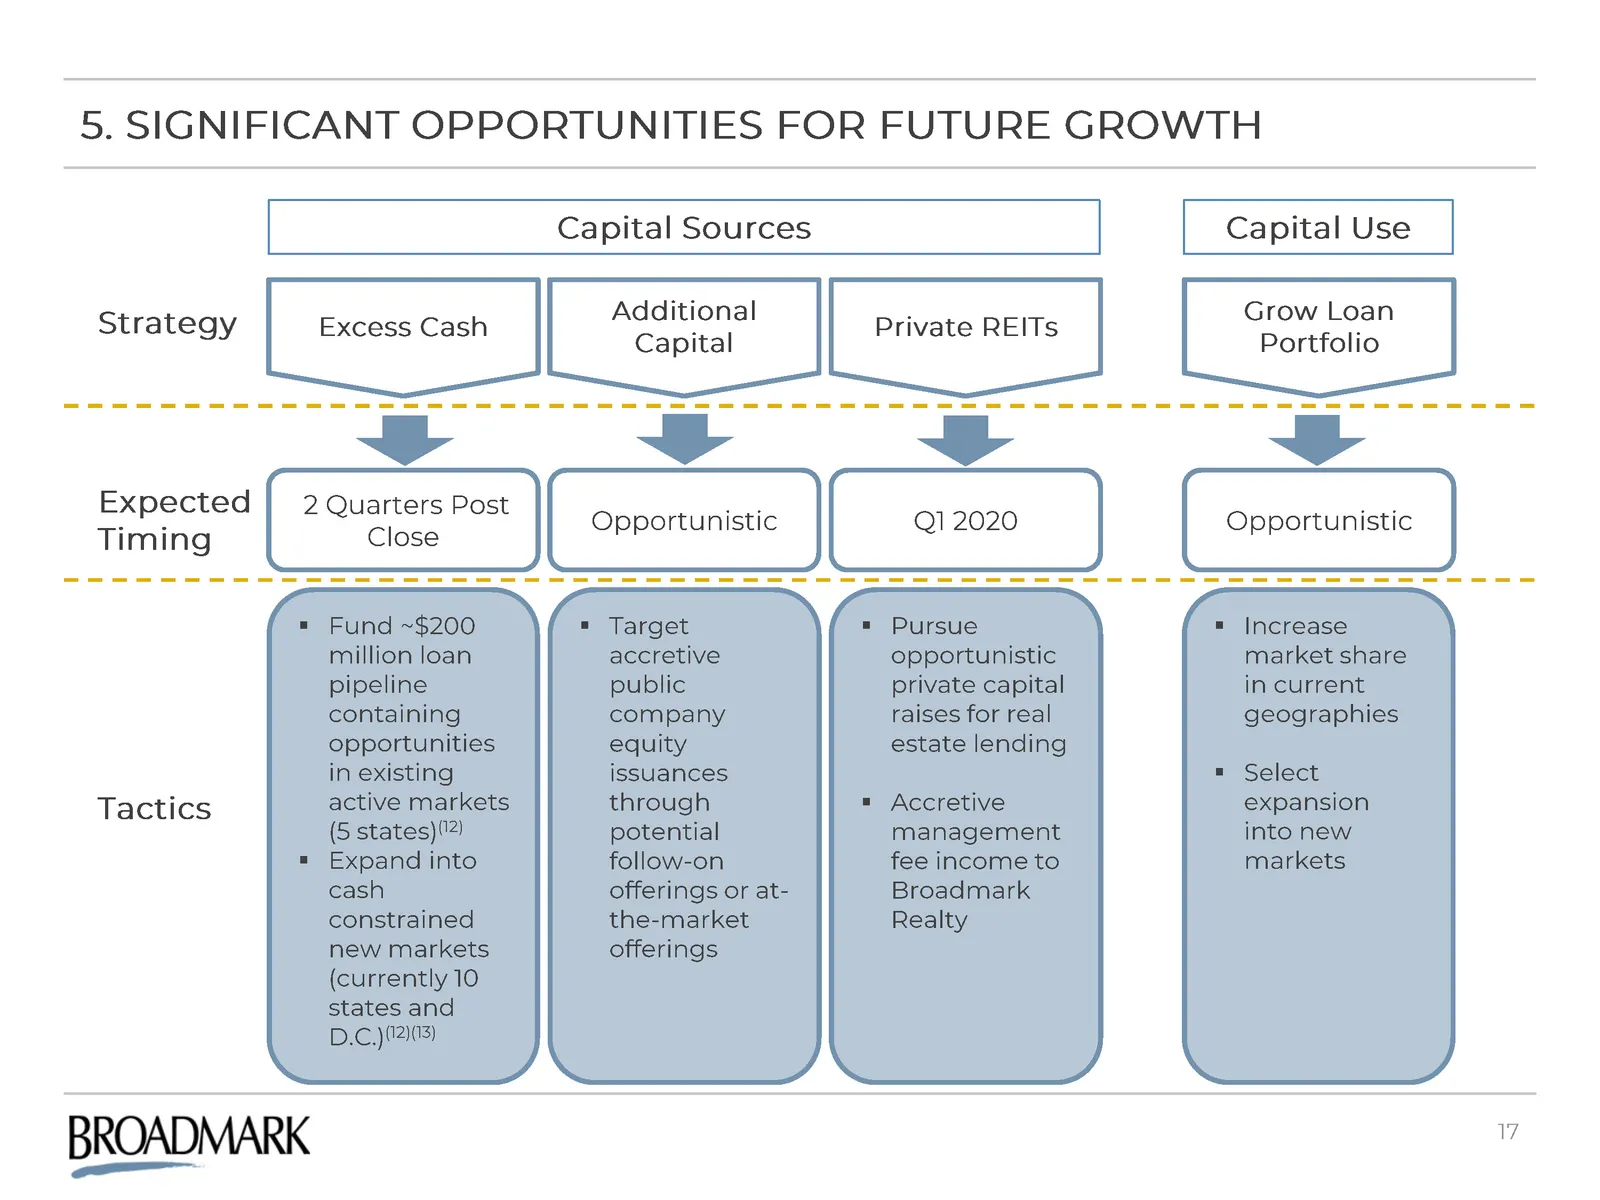
Increase market share in current geographiesSelect expansion into new markets Grow Loan Portfolio Opportunistic Tactics Fund ~$200 million loan pipeline containing opportunities in existing active markets (5 states)(12)Expand into cash constrained new markets (currently 10 states and D.C.)(12)(13) E
Slide 18: 6. Strong Growth Track Record
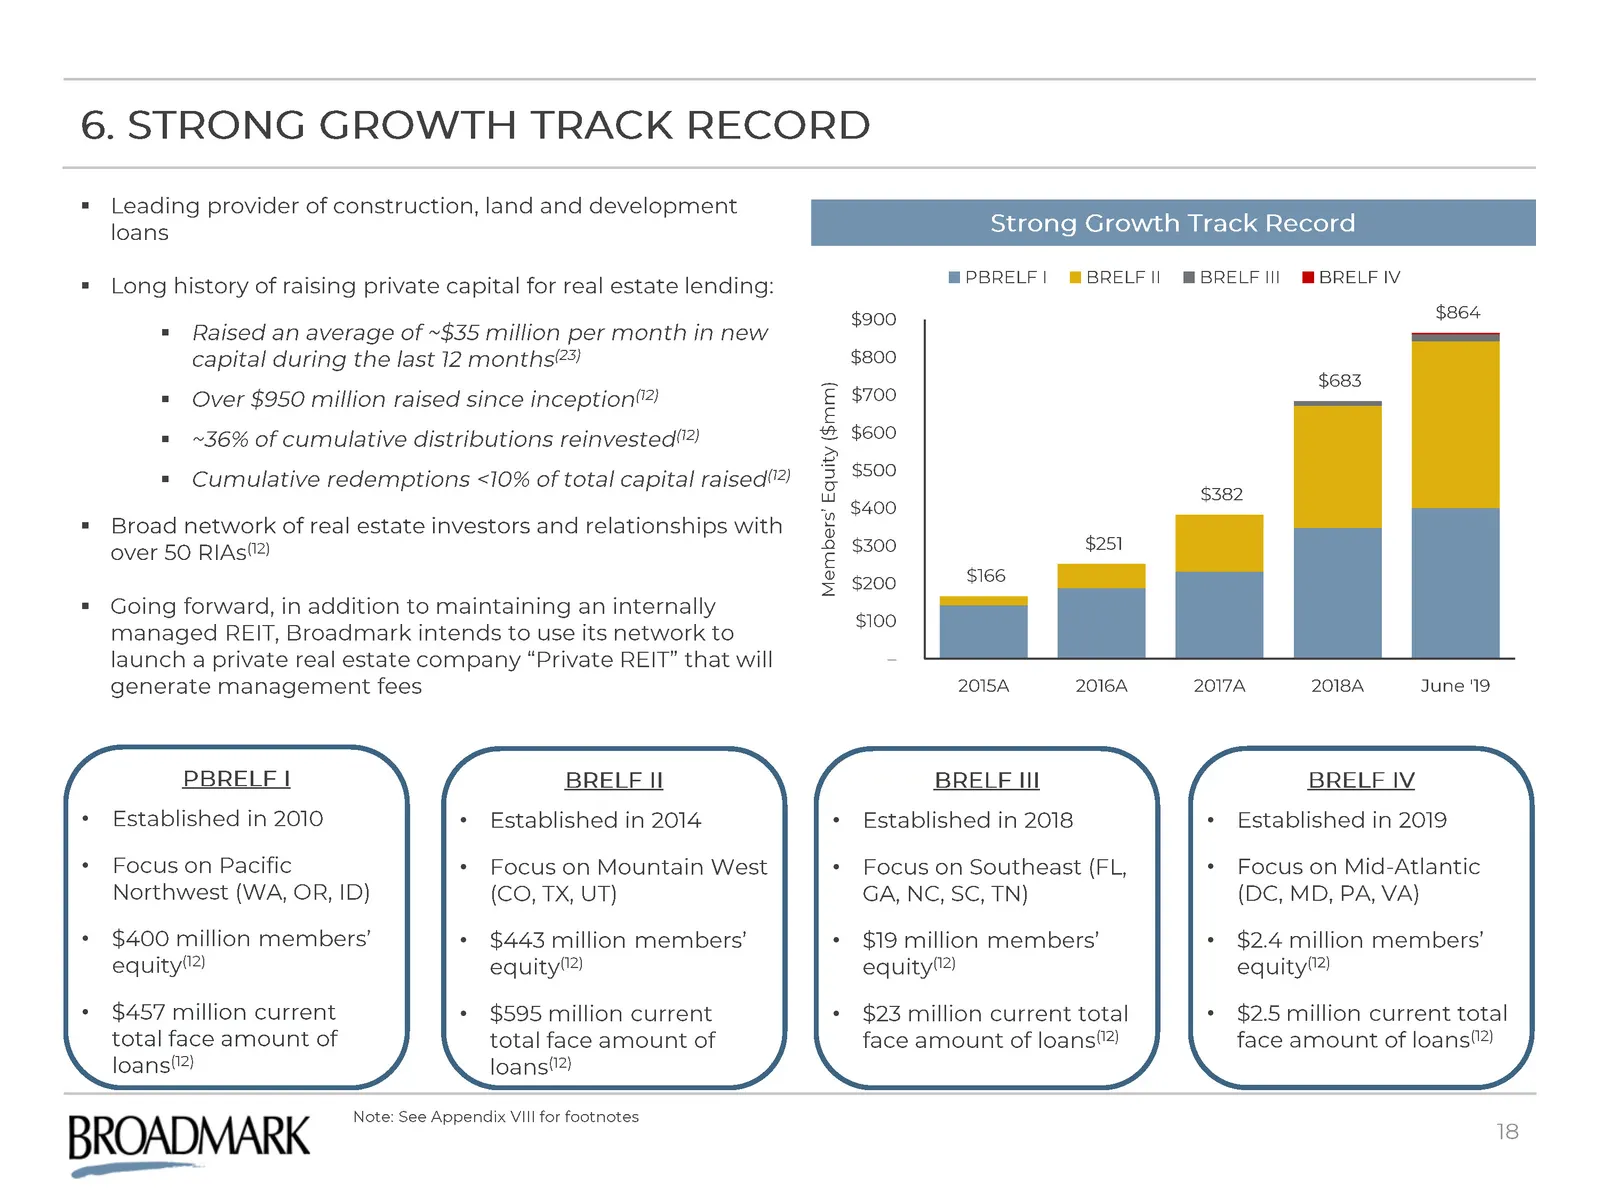
Strong Growth Track Record 6. Strong Growth Track Record PBRELF IEstablished in 2010Focus on Pacific Northwest (WA, OR, ID)$400 million members’ equity(12)$457 million current total face amount of loans(12) BRELF IIEstablished in 2014Focus on Mountain West (CO, TX, UT)$443 million members’ equity(12
Slide 19: 7. Minimal Losses Incurred Since Inception
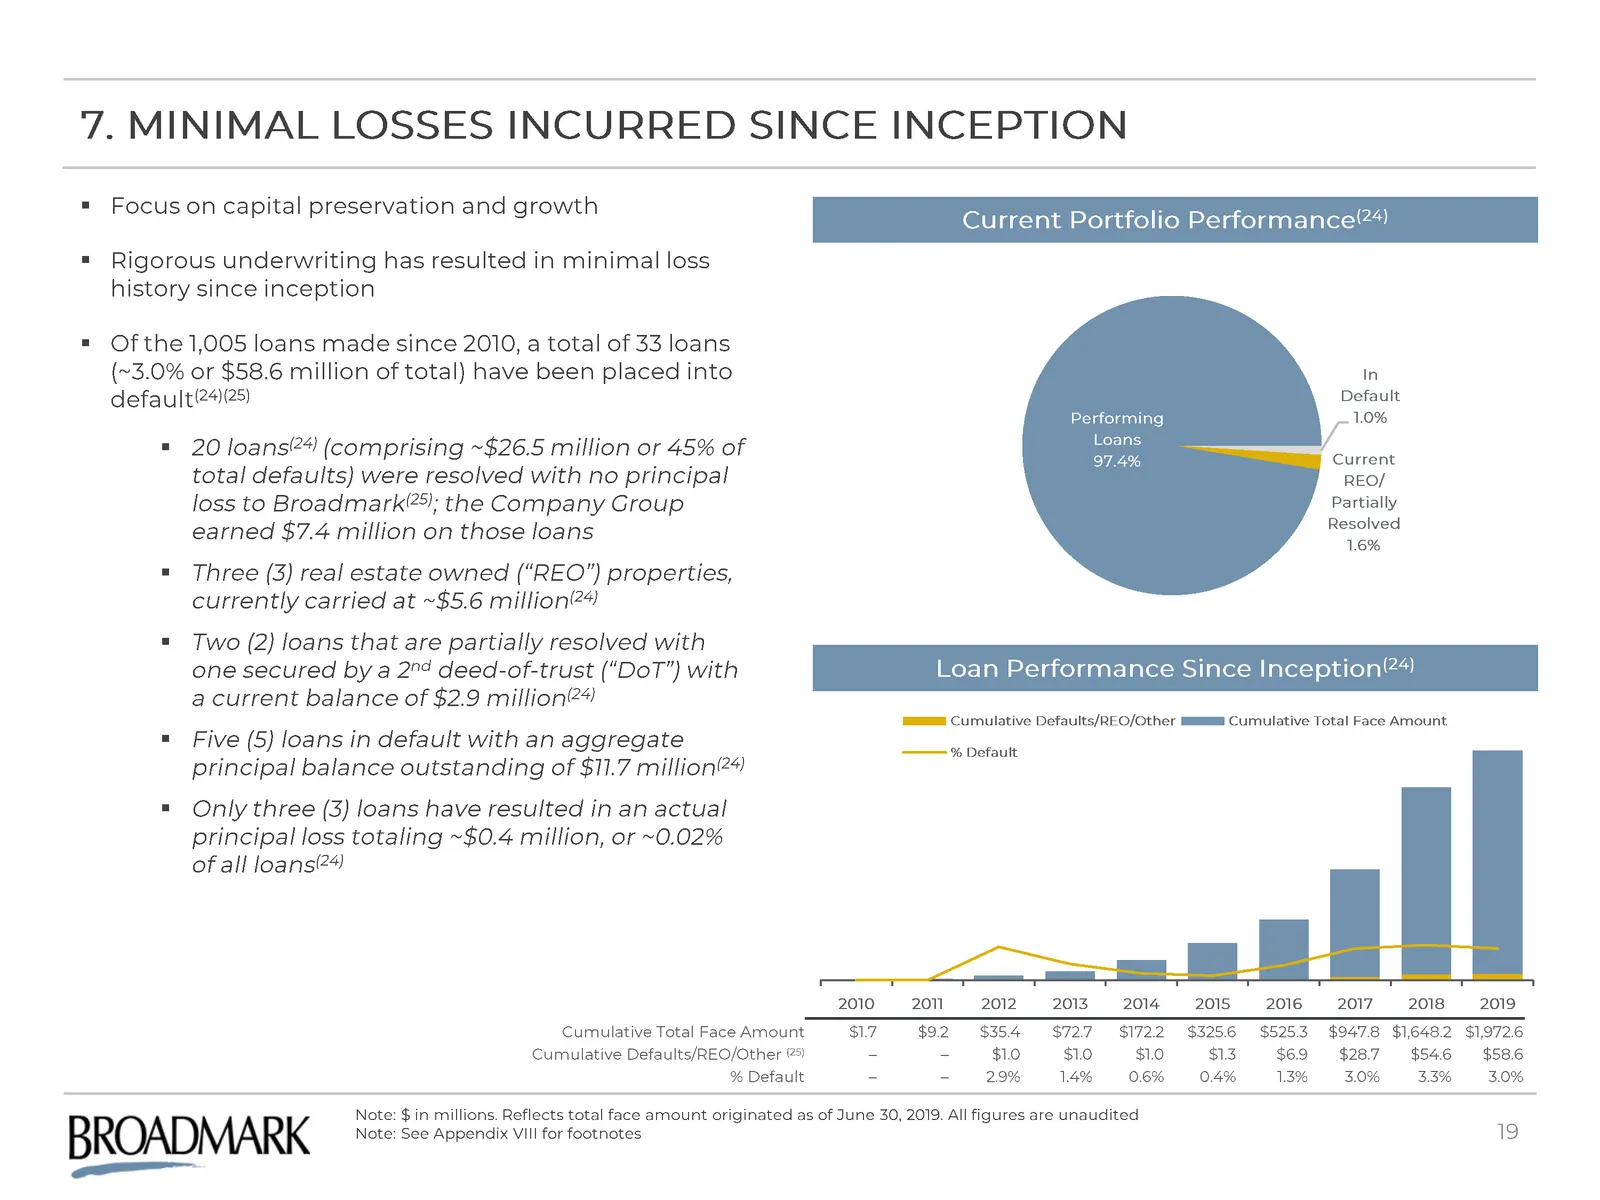
7. Minimal losses INCURRED Since Inception Note: $ in millions. Reflects total face amount originated as of June 30, 2019. All figures are unauditedNote: See Appendix VIII for footnotes Focus on capital preservation and growth Rigorous underwriting has resulted in minimal loss history since inceptio
Slide 20: Summary Loan Overview
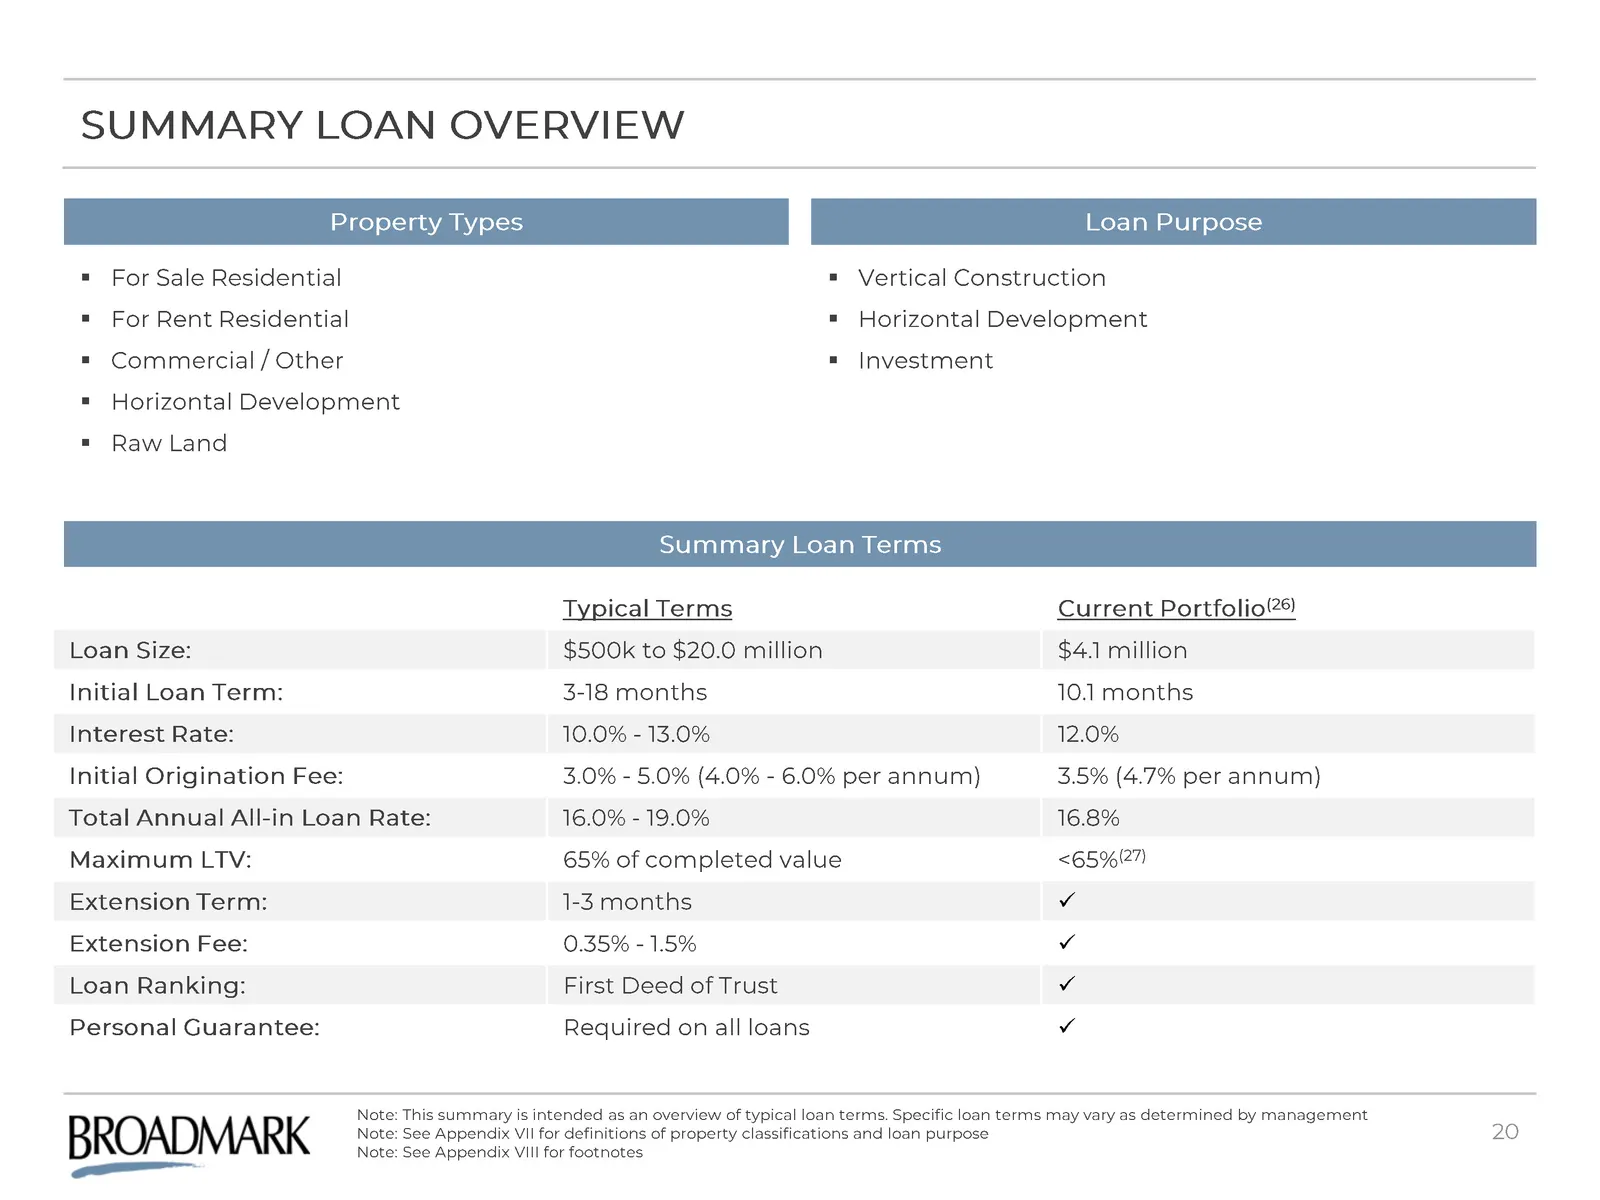
Summary loan overview Property Types Loan Purpose Summary Loan Terms For Sale ResidentialFor Rent ResidentialCommercial / OtherHorizontal DevelopmentRaw Land Vertical ConstructionHorizontal DevelopmentInvestment Note: This summary is intended as an overview of typical loan terms. Specific loan terms
Slide 21: Rigorous and Responsive Underwriting Process
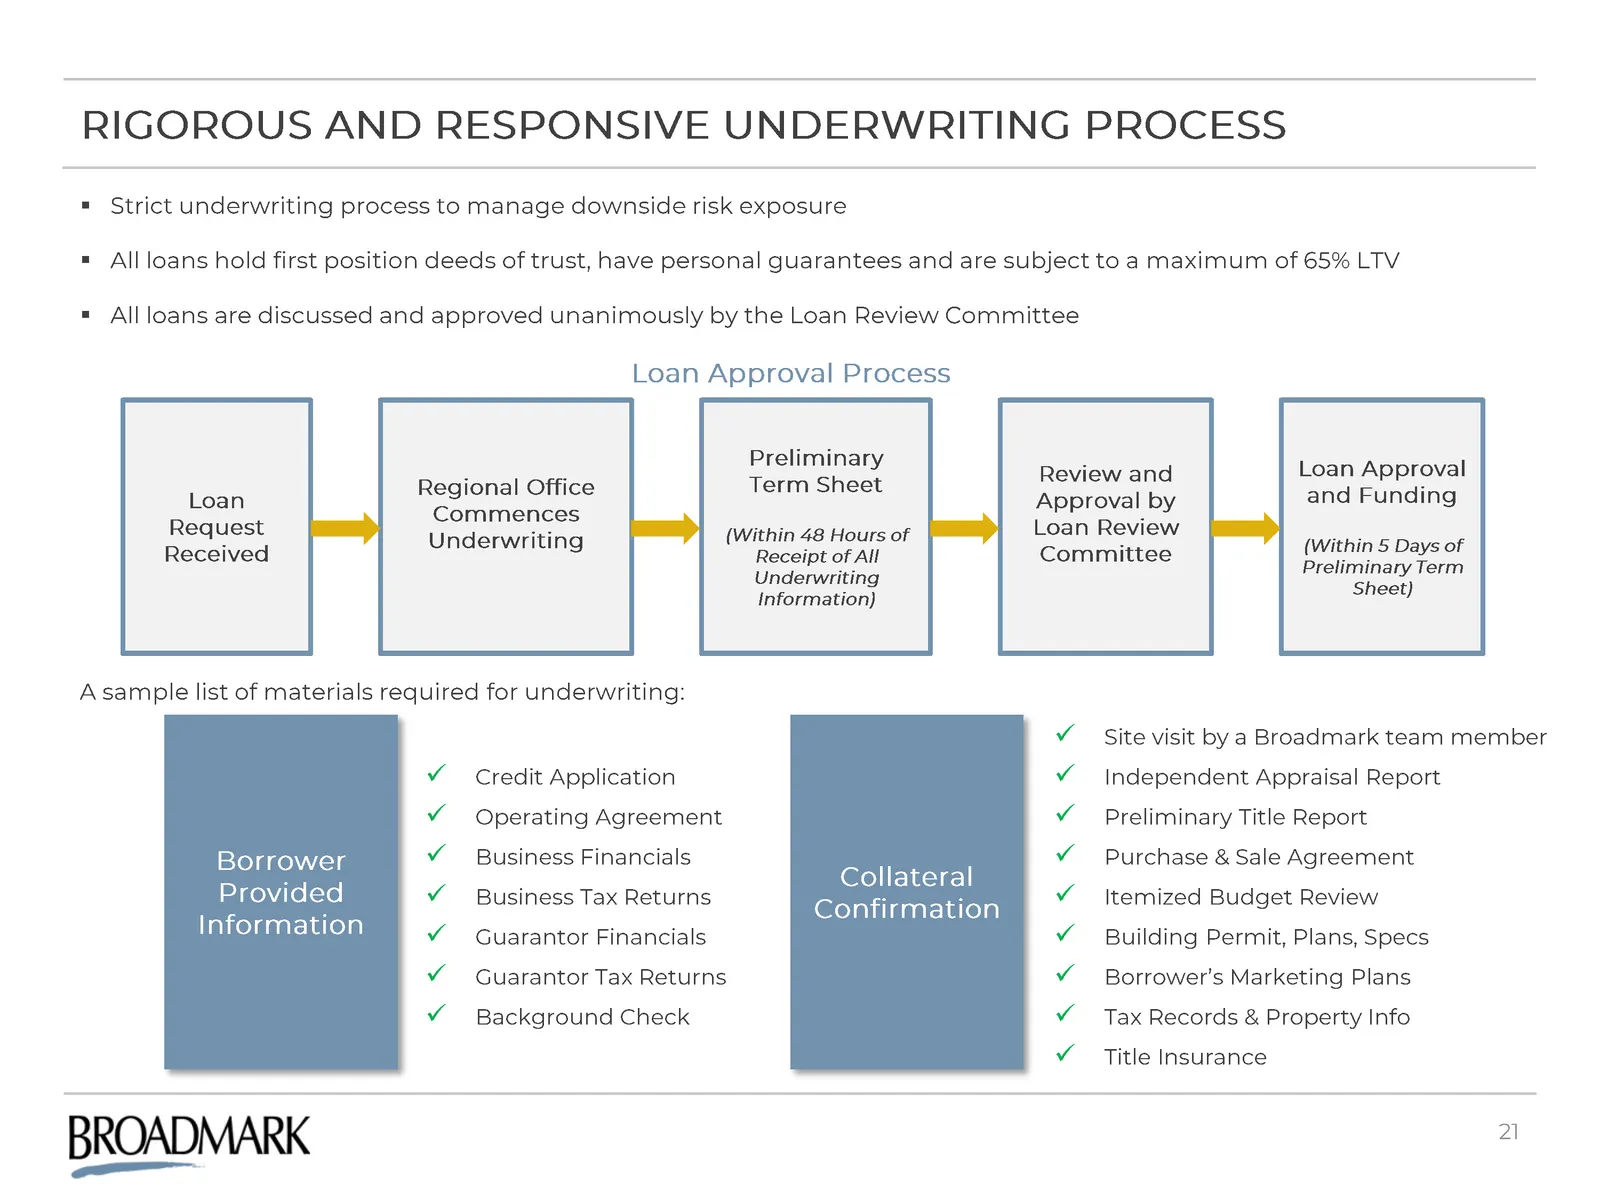
Rigorous and responsive Underwriting process Credit ApplicationOperating AgreementBusiness FinancialsBusiness Tax ReturnsGuarantor FinancialsGuarantor Tax ReturnsBackground Check Site visit by a Broadmark team memberIndependent Appraisal ReportPreliminary Title ReportPurchase & Sale AgreementItemize
Slide 22: Loan Servicing Overview
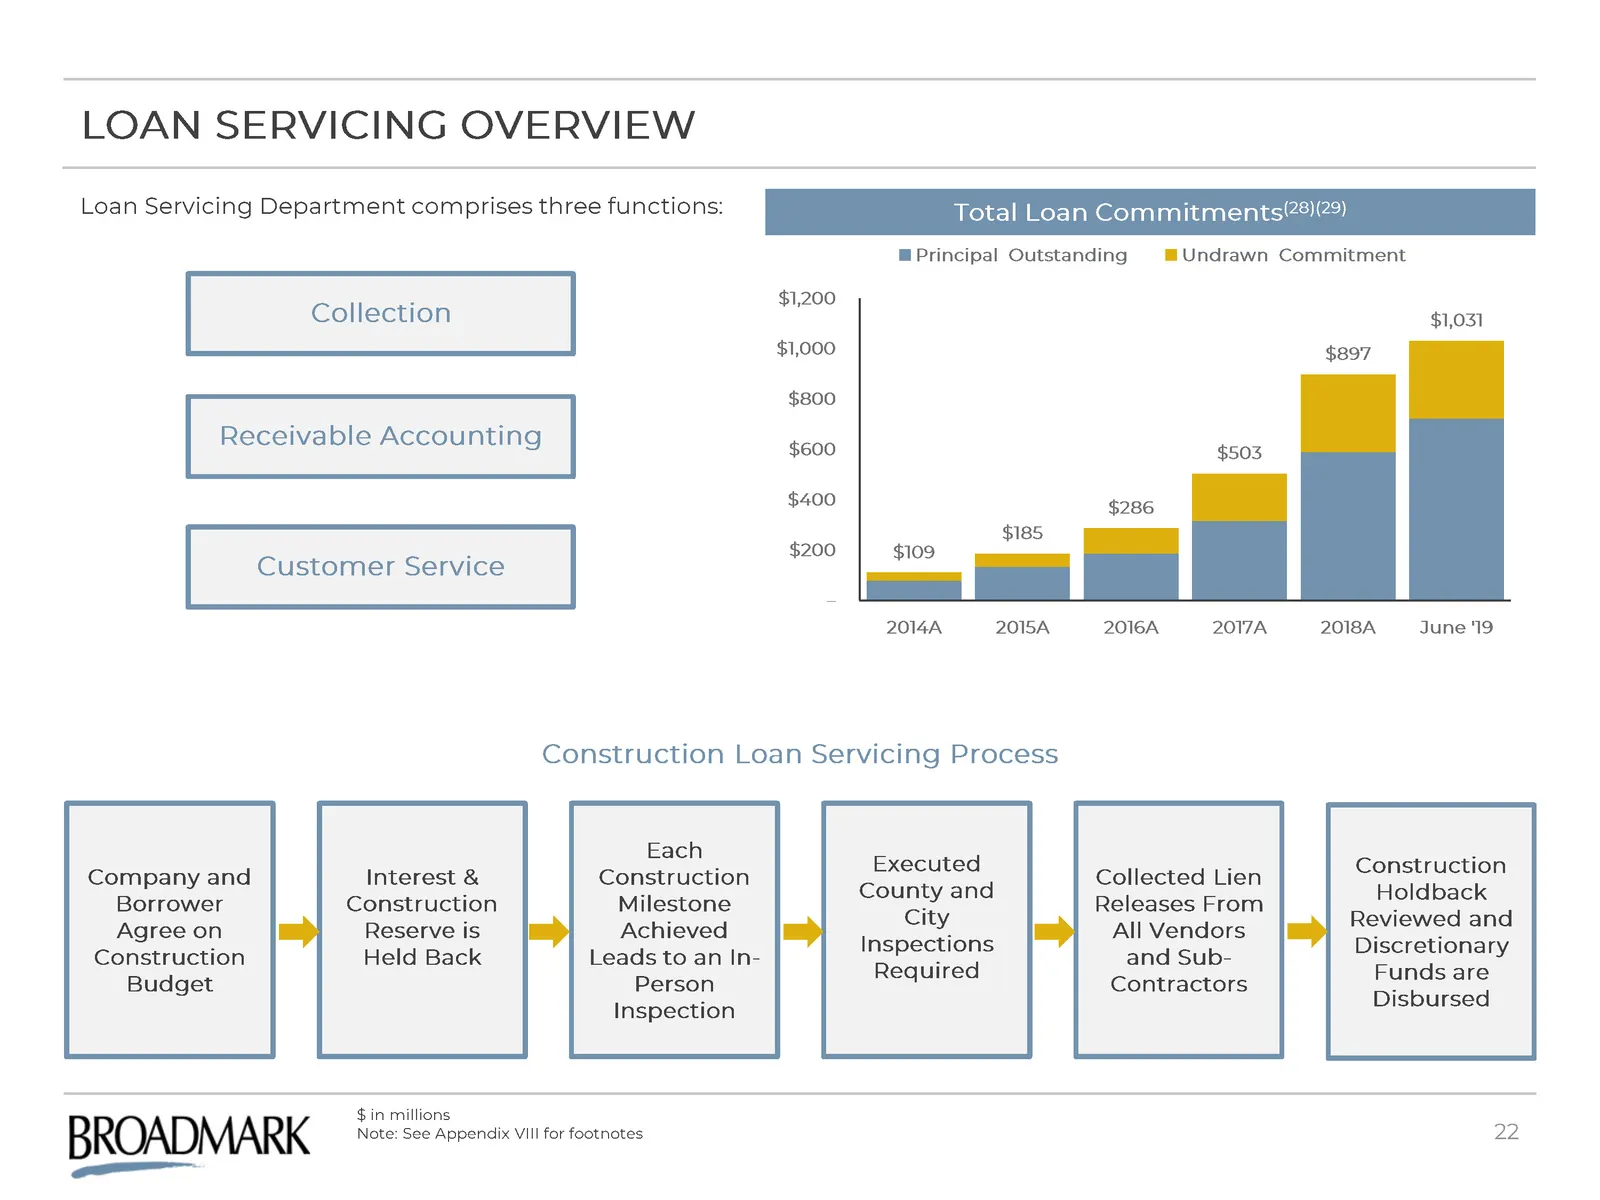
Collection Receivable Accounting Customer Service Loan servicing overview Loan Servicing Department comprises three functions: Company and Borrower Agree on Construction Budget Construction Loan Servicing Process Interest & Construction Reserve is Held Back Each Construction Milestone Achieved Leads
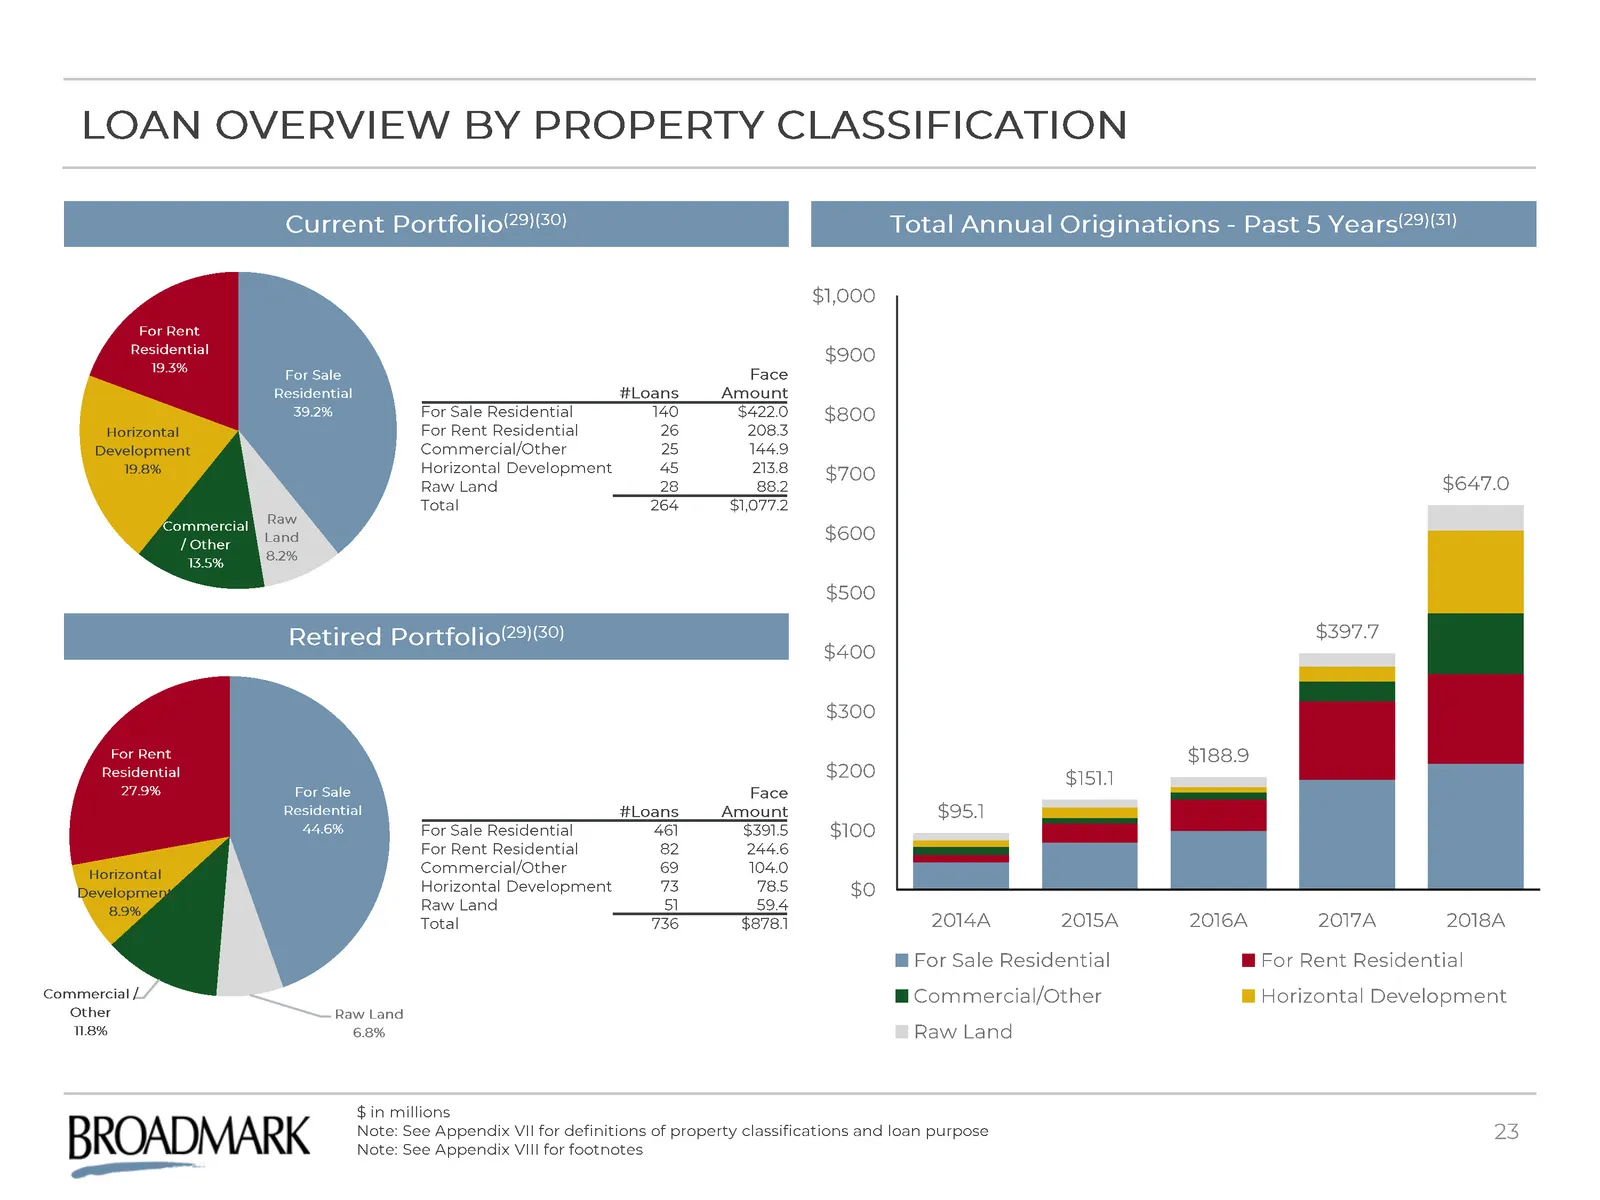
Slide 23: Loan Overview by Property Classification
Loan overview by property Classification Current Portfolio(29)(30) Total Annual Originations - Past 5 Years(29)(31) Retired Portfolio(29)(30) $ in millionsNote: See Appendix VII for definitions of property classifications and loan purposeNote: See Appendix VIII for footnotes #Loans Face Amount For S
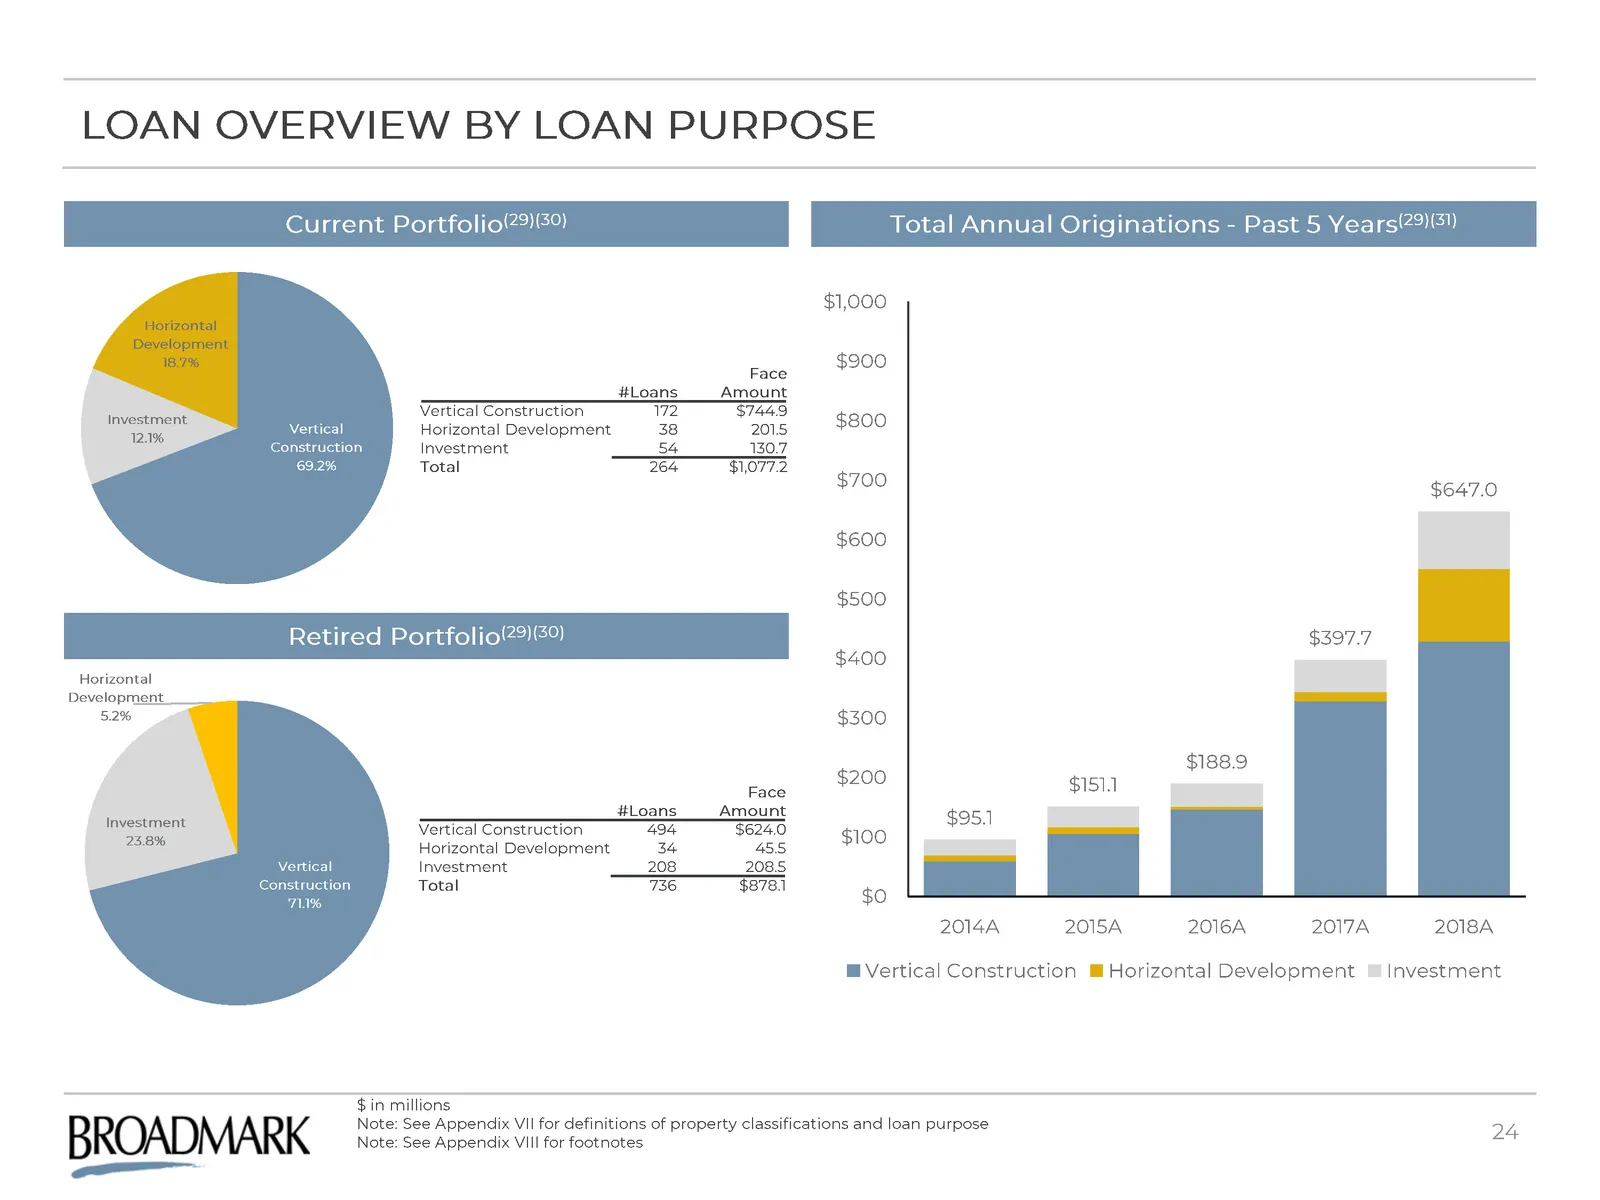
Slide 24: Loan Overview by Loan Purpose
#Loans Face Amount Vertical Construction 172 $744.9 Horizontal Development 38 201.5 Investment 54 130.7 Total 264 $1,077.2 Loan overview BY loan purpose Current Portfolio(29)(30) Total Annual Originations - Past 5 Years(29)(31) Retired Portfolio(29)(30) #Loans Face Amount Vertical Construction 494 $
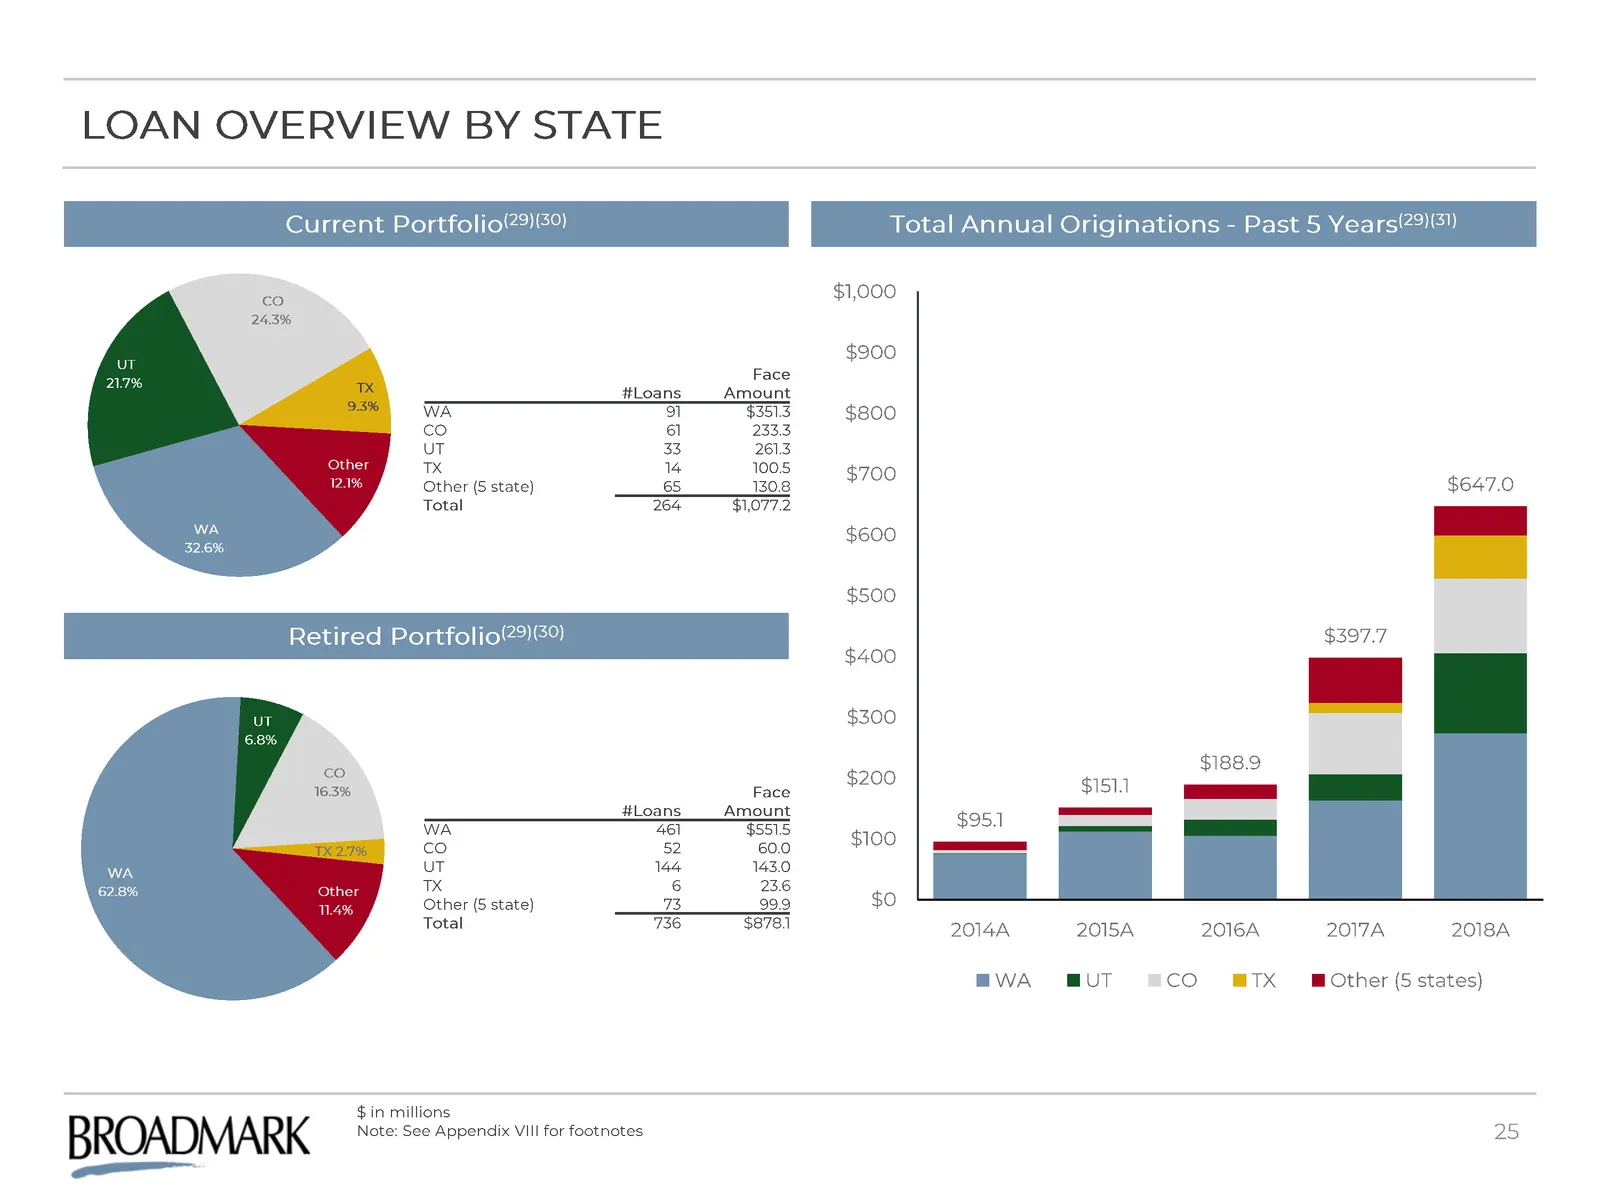
Slide 25: Loan Overview by State
#Loans Face Amount WA 461 $551.5 CO 52 60.0 UT 144 143.0 TX 6 23.6 Other (5 state) 73 99.9 Total 736 $878.1 Loan overview BY state Retired Portfolio(29)(30) Current Portfolio(29)(30) Total Annual Originations - Past 5 Years(29)(31) #Loans Face Amount WA 91 $351.3 CO 61 233.3 UT 33 261.3 TX 14 100.5
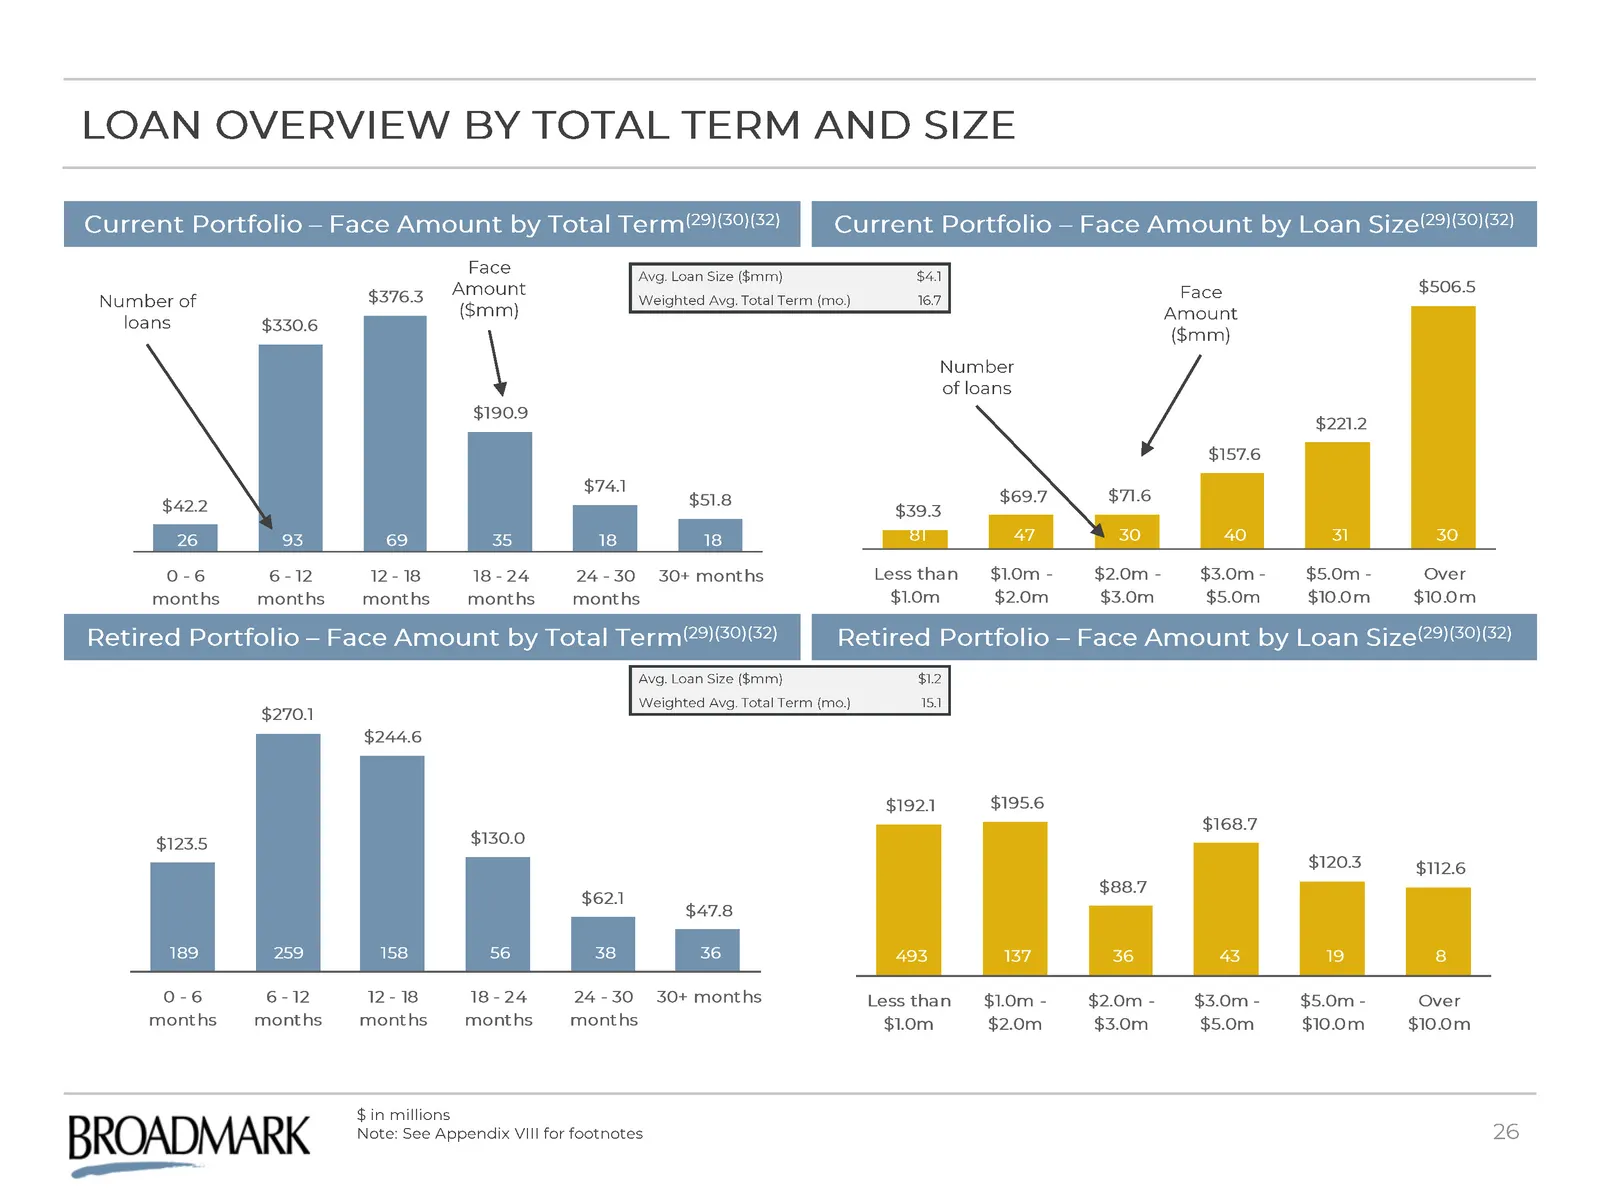
Slide 26: Loan Overview by Total Term and Size
Loan overview BY Total Term and SIZE Current Portfolio – Face Amount by Total Term(29)(30)(32) Retired Portfolio – Face Amount by Total Term(29)(30)(32) Number of loans Face Amount ($mm) Current Portfolio – Face Amount by Loan Size(29)(30)(32) Retired Portfolio – Face Amount by Loan Size(29)(30)(32)
Slide 27: Investment Highlights
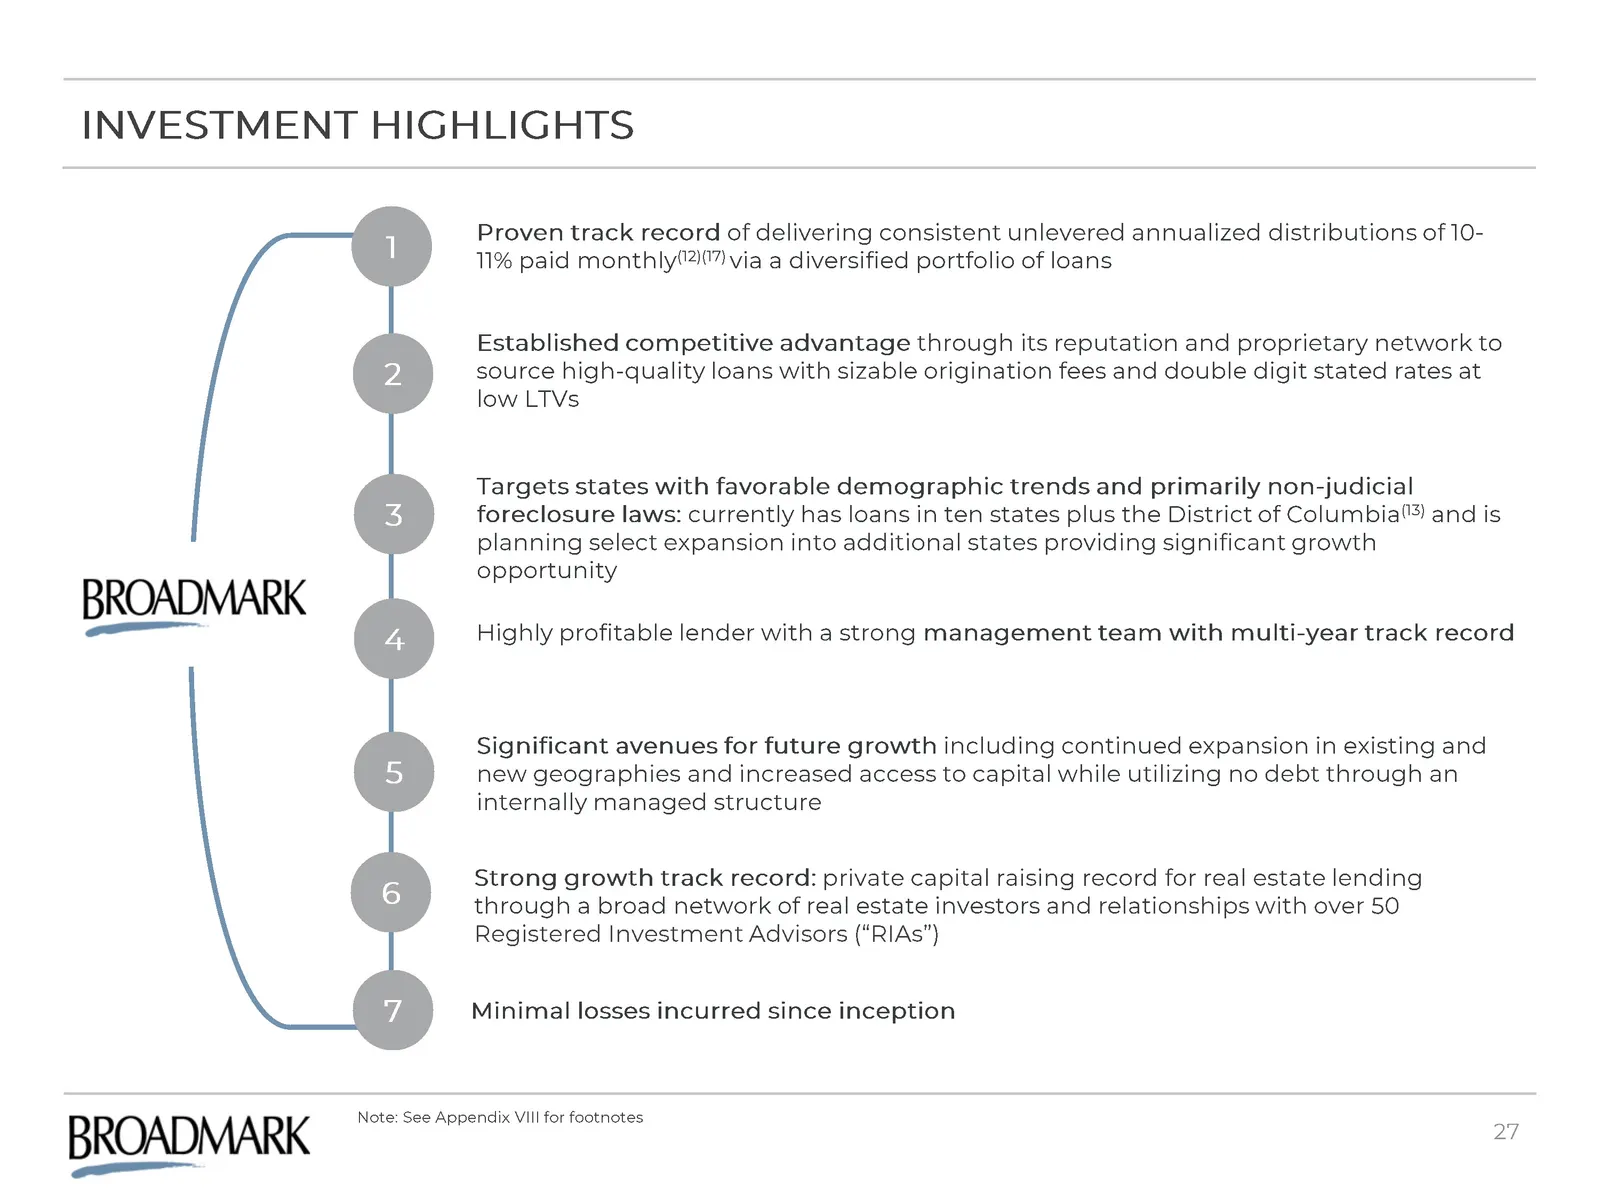
Proven track record of delivering consistent unlevered annualized distributions of 10-11% paid monthly(12)(17) via a diversified portfolio of loans Significant avenues for future growth including continued expansion in existing and new geographies and increased access to capital while utilizing no d
Slide 28: Financial Overview
Financial Overview Section 2
Slide 29: Summary Financial Overview
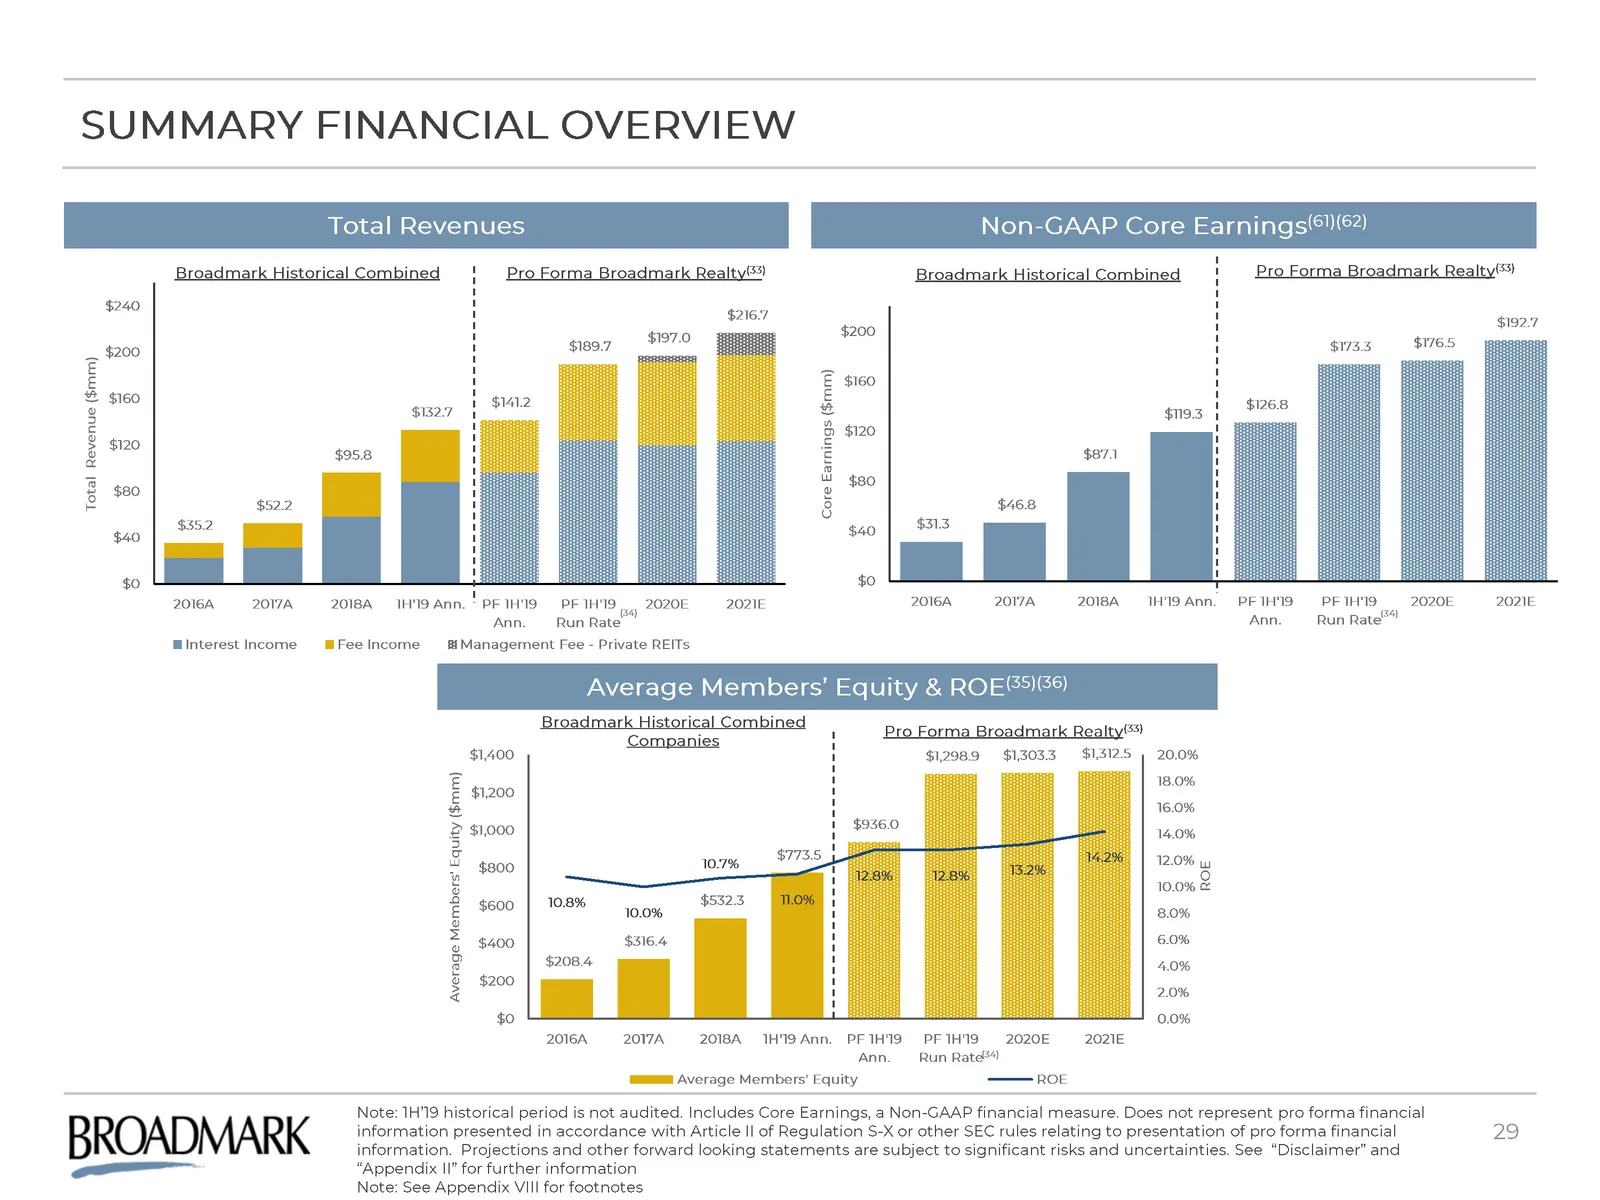
Summary Financial Overview Total Revenues Non-GAAP Core Earnings(61)(62) Broadmark Historical Combined Broadmark Historical Combined Note: 1H’19 historical period is not audited. Includes Core Earnings, a Non-GAAP financial measure. Does not represent pro forma financial information presented in acc
Slide 30: Invest Retained Cash Flow into New Loans
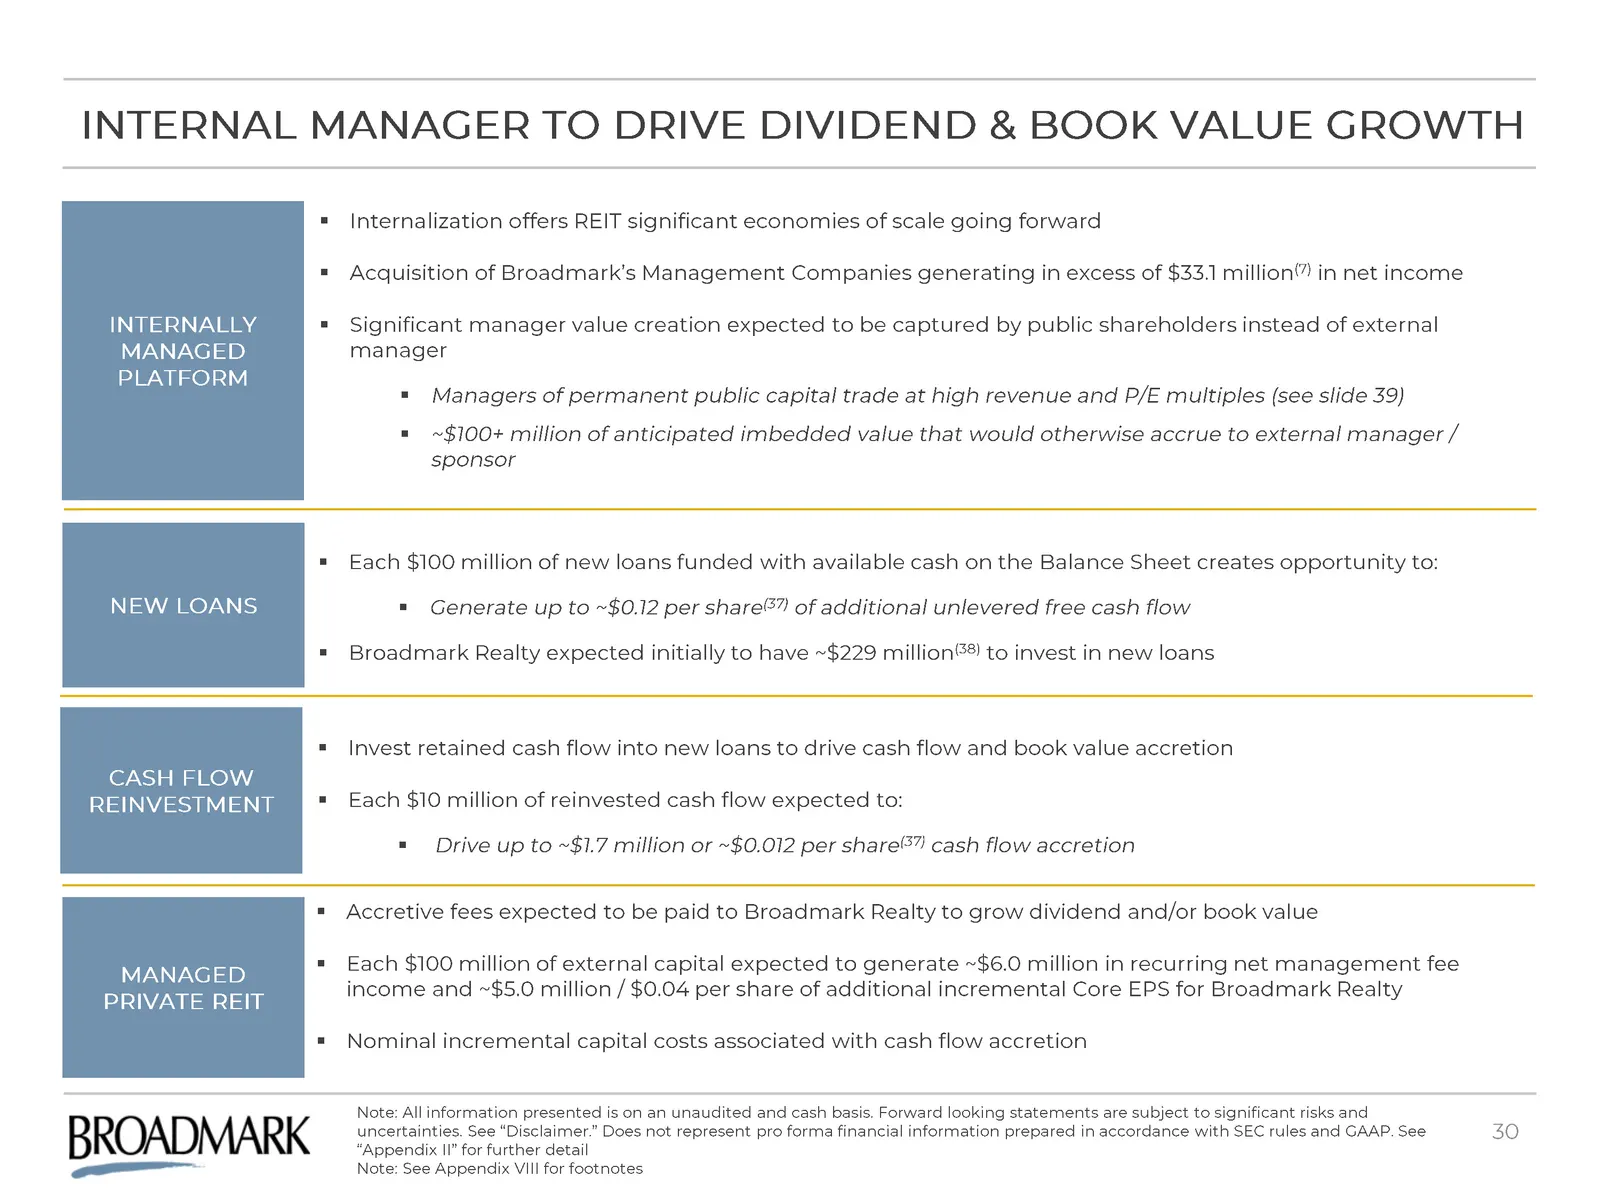
Invest retained cash flow into new loans to drive cash flow and book value accretionEach $10 million of reinvested cash flow expected to: Drive up to ~$1.7 million or ~$0.012 per share(37) cash flow accretion INTERNAL Manager to DRIVE Dividend & Book Value growth NEW LOANS Each $100 million of new l
Slide 31: Transaction Overview
Transaction Overview Section 3
Slide 32: Transaction Structure
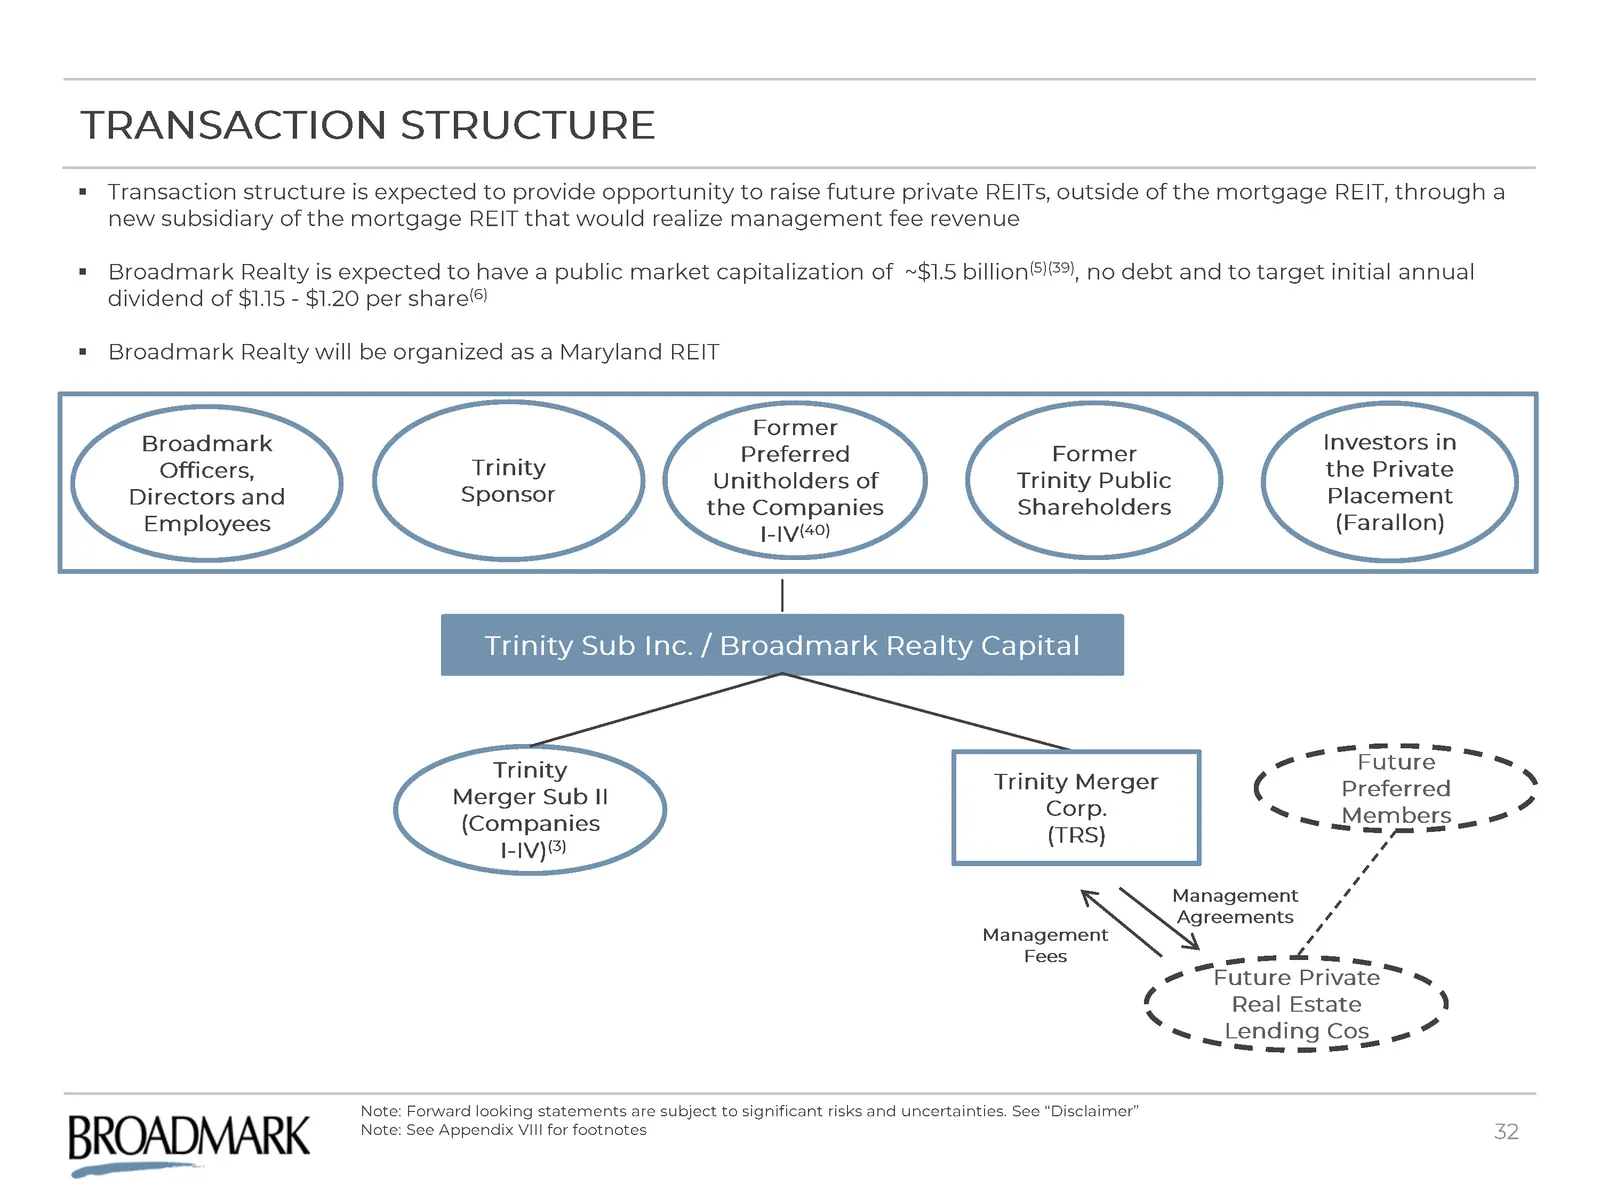
Transaction structure Transaction structure is expected to provide opportunity to raise future private REITs, outside of the mortgage REIT, through a new subsidiary of the mortgage REIT that would realize management fee revenueBroadmark Realty is expected to have a public market capitalization of ~$
Slide 33: Transaction Summary
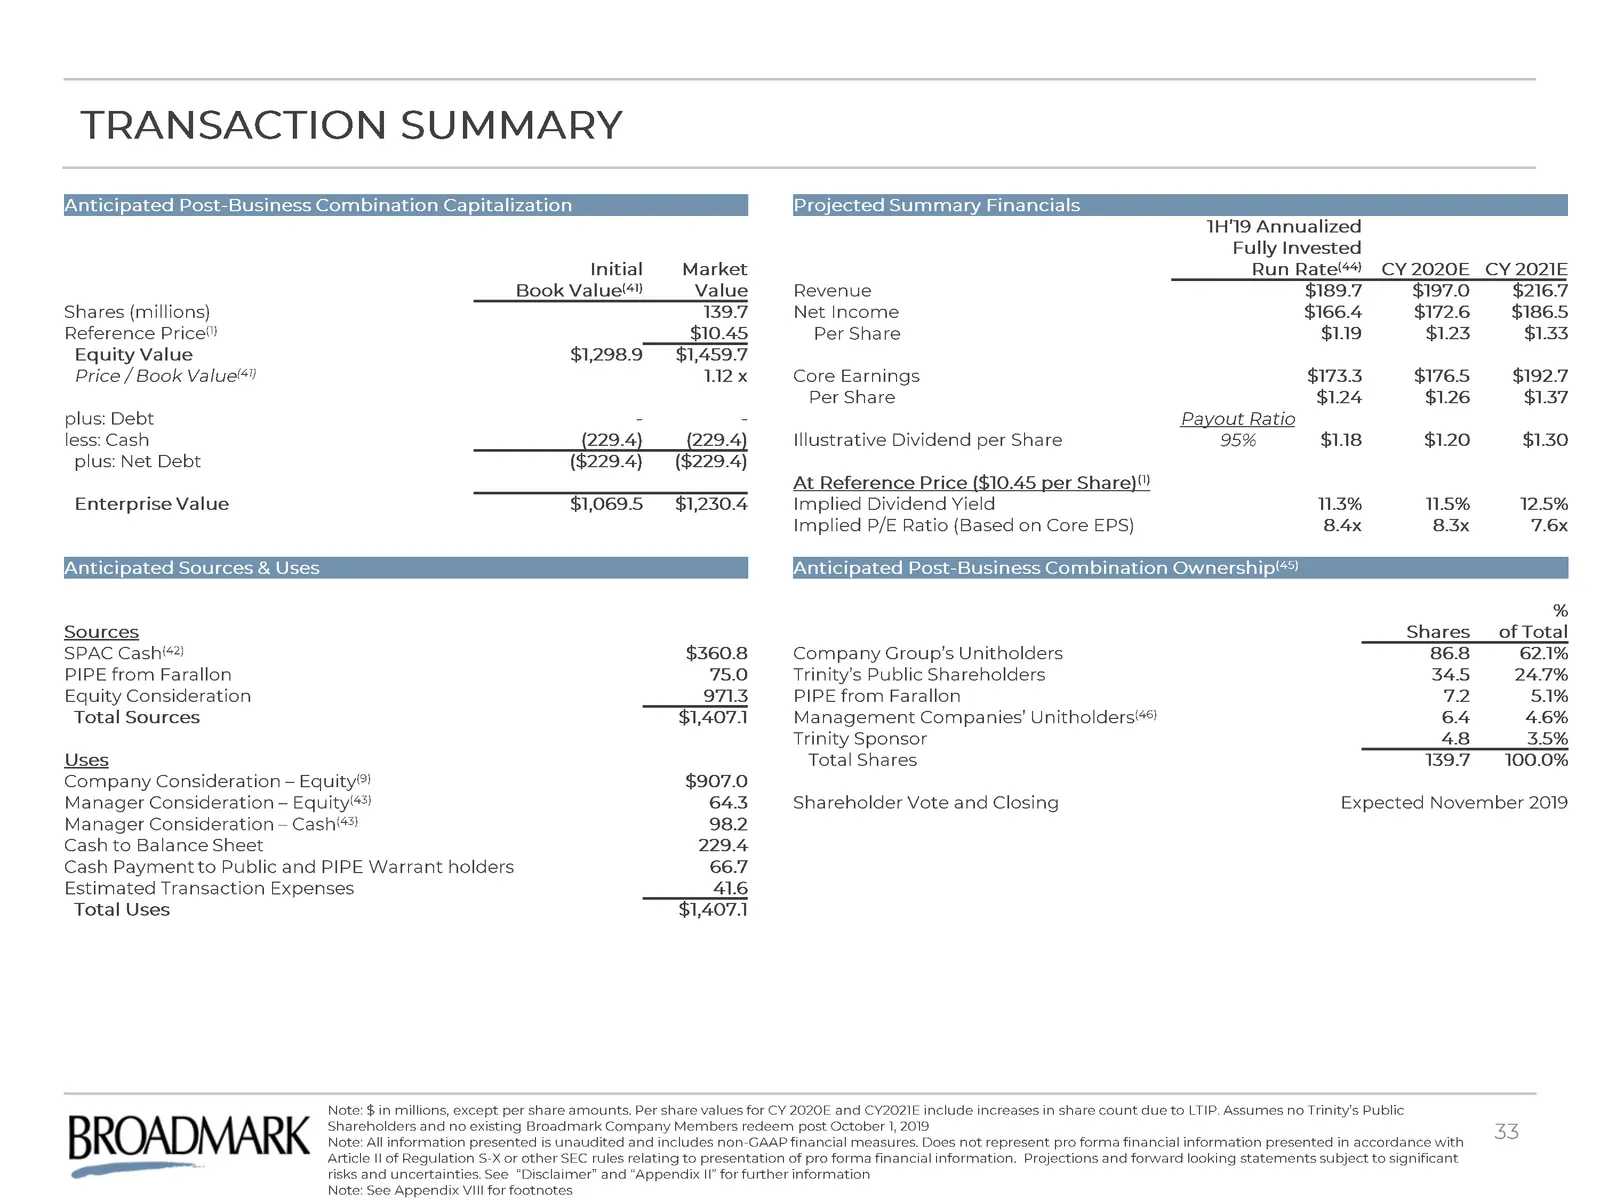
transaction summary Anticipated Post-Business Combination Capitalization Projected Summary Financials 1H’19 Annualized Fully InvestedRun Rate(44) Initial Market CY 2020E CY 2021E Book Value(41) Value Revenue $190.2 $189.7 $197.0 $216.7 Shares (millions) 139.7 Net Income 166.9 $166.4 $172.6 $186.5 Re
Slide 34: Compelling Valuation Metrics vs. Peer Group
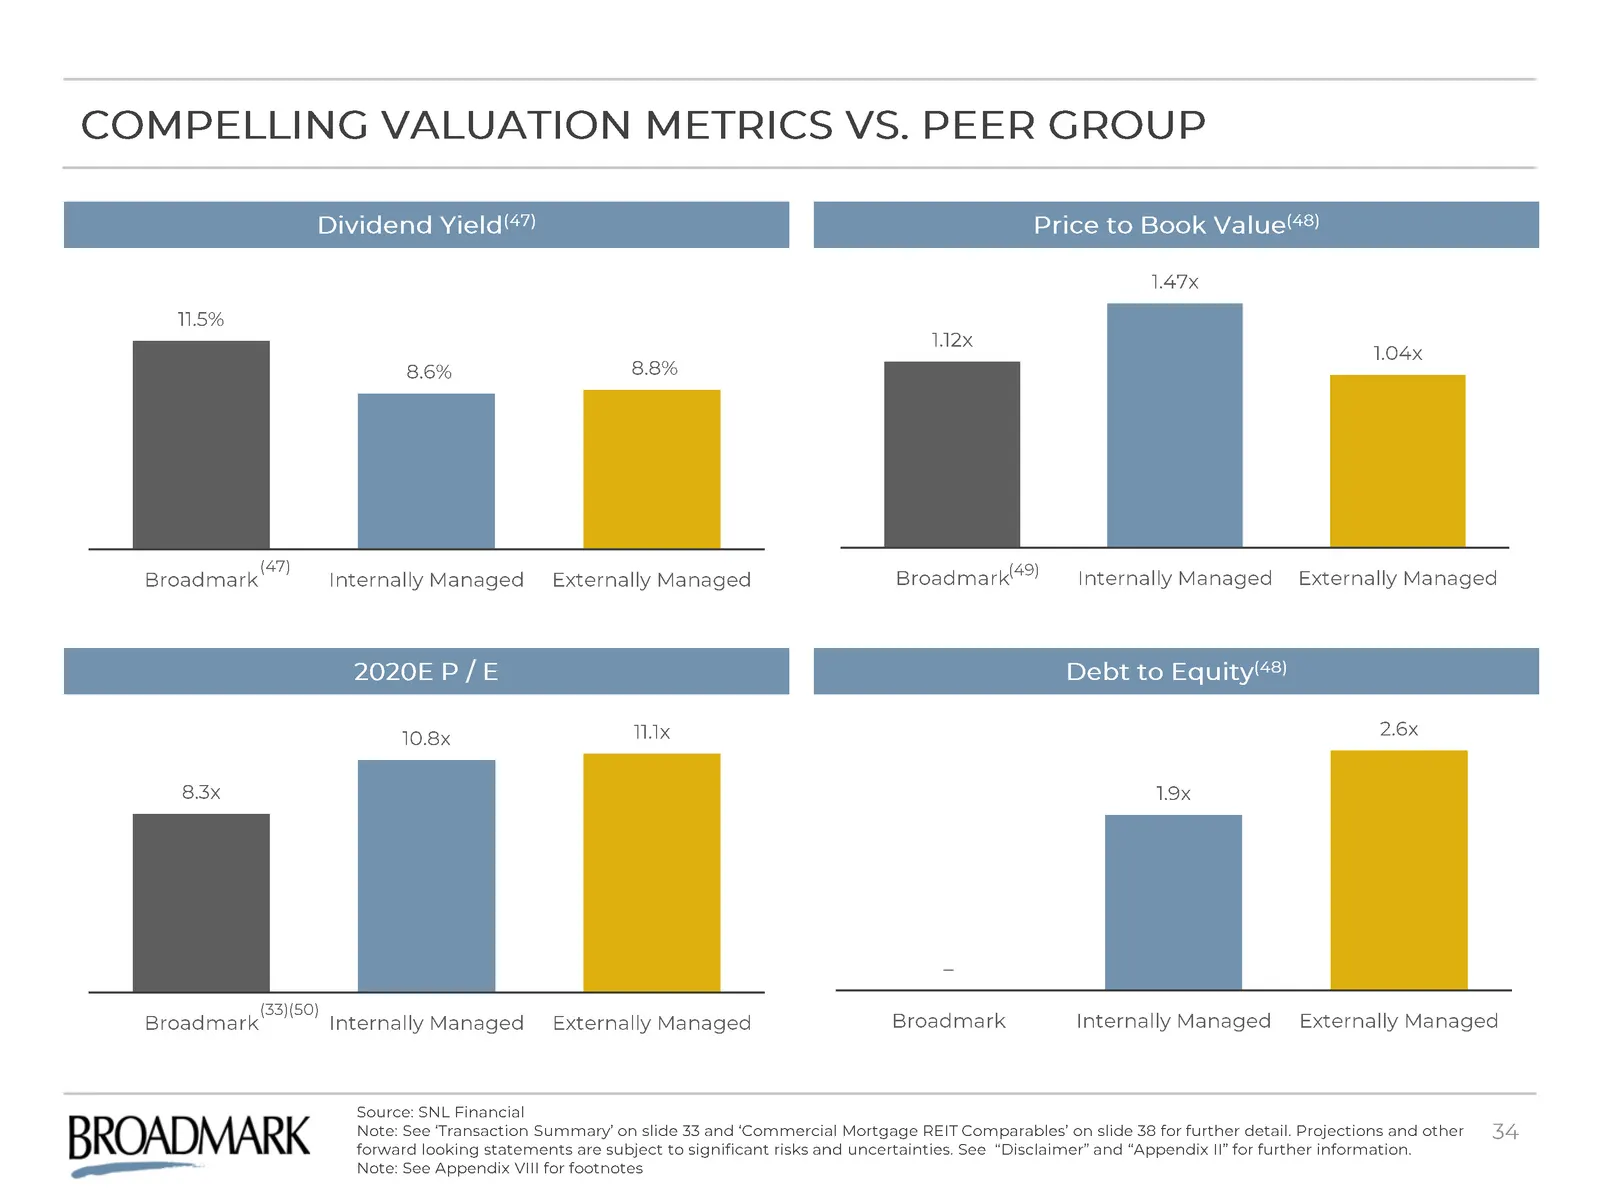
Compelling Valuation Metrics vs. PEER Group Dividend Yield(47) Source: SNL FinancialNote: See ‘Transaction Summary’ on slide 33 and ‘Commercial Mortgage REIT Comparables’ on slide 38 for further detail. Projections and other forward looking statements are subject to significant risks and uncertainti
Slide 35: Appendix
BROADMARK APPENDIX v Section 4
Slide 36: Appendix I – Illustrative Fully Invested Run Rate
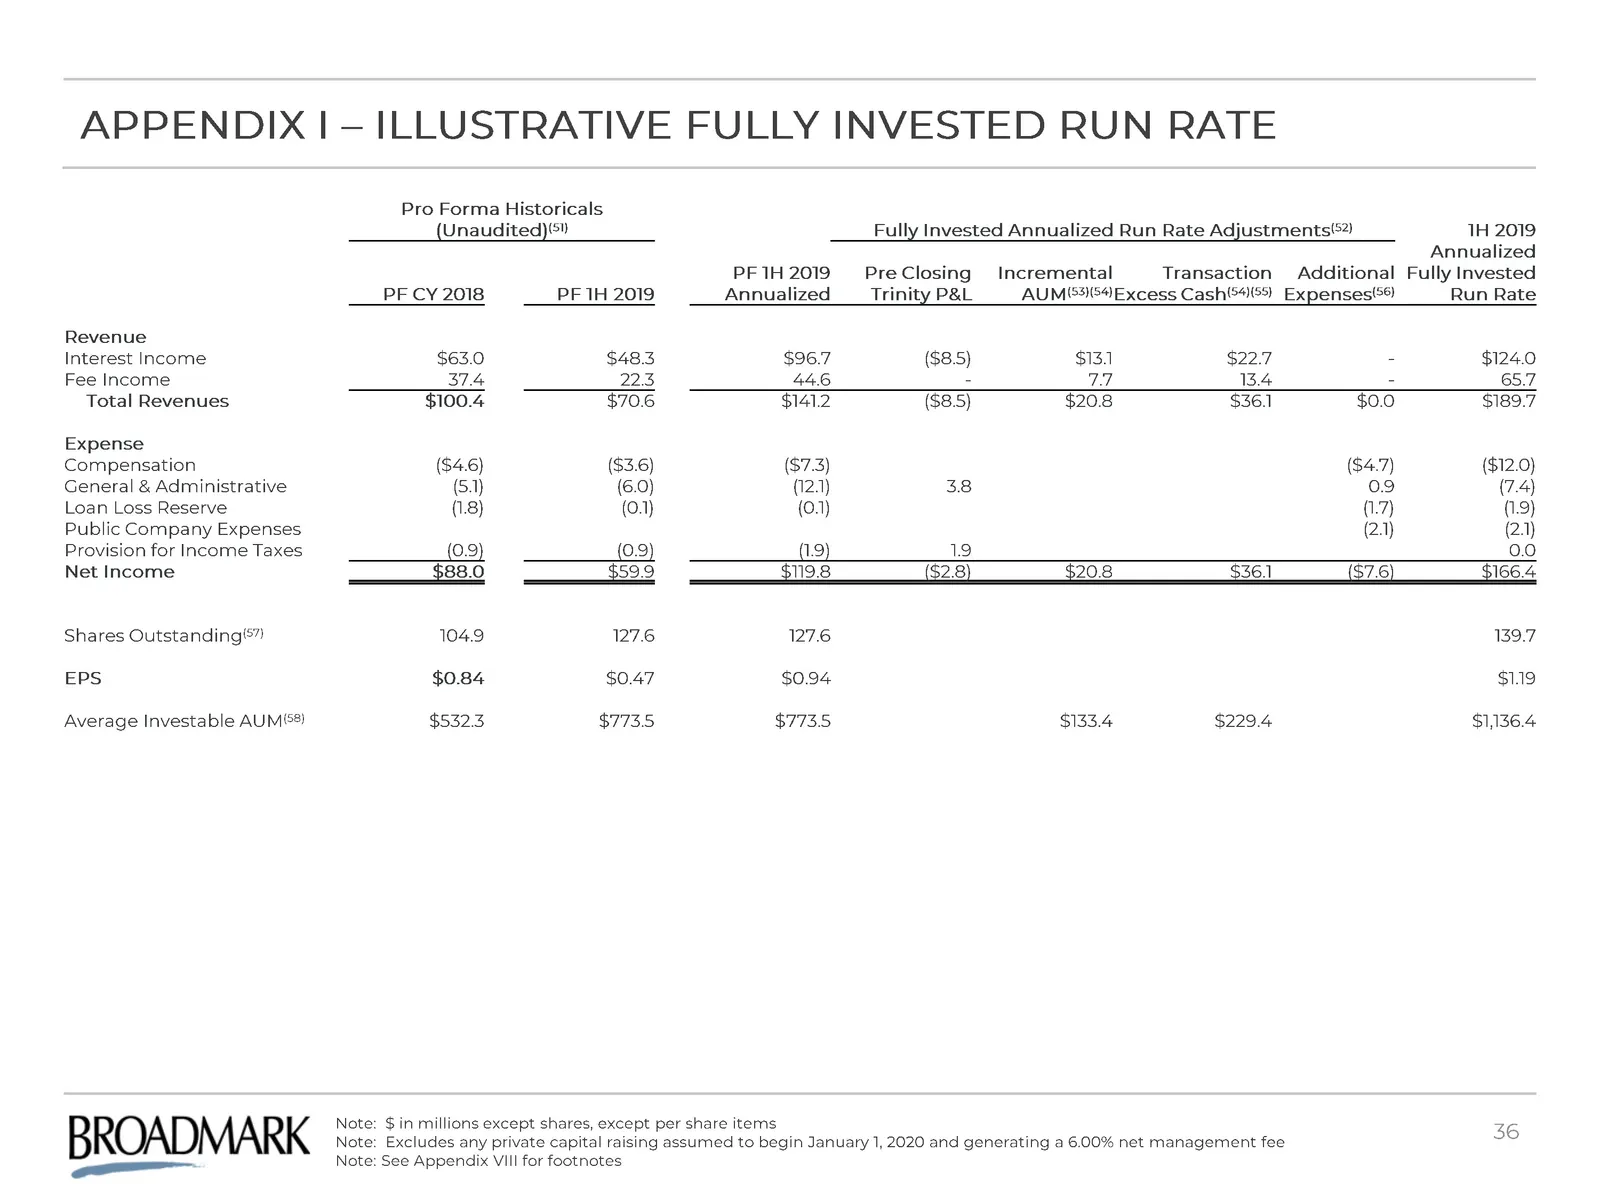
Appendix I – Illustrative Fully Invested Run Rate Note: $ in millions except shares, except per share itemsNote: Excludes any private capital raising assumed to begin January 1, 2020 and generating a 6.00% net management feeNote: See Appendix VIII for footnotes Pro Forma Historicals (Unaudited)(51)
Slide 37: Appendix II – Financial Summary
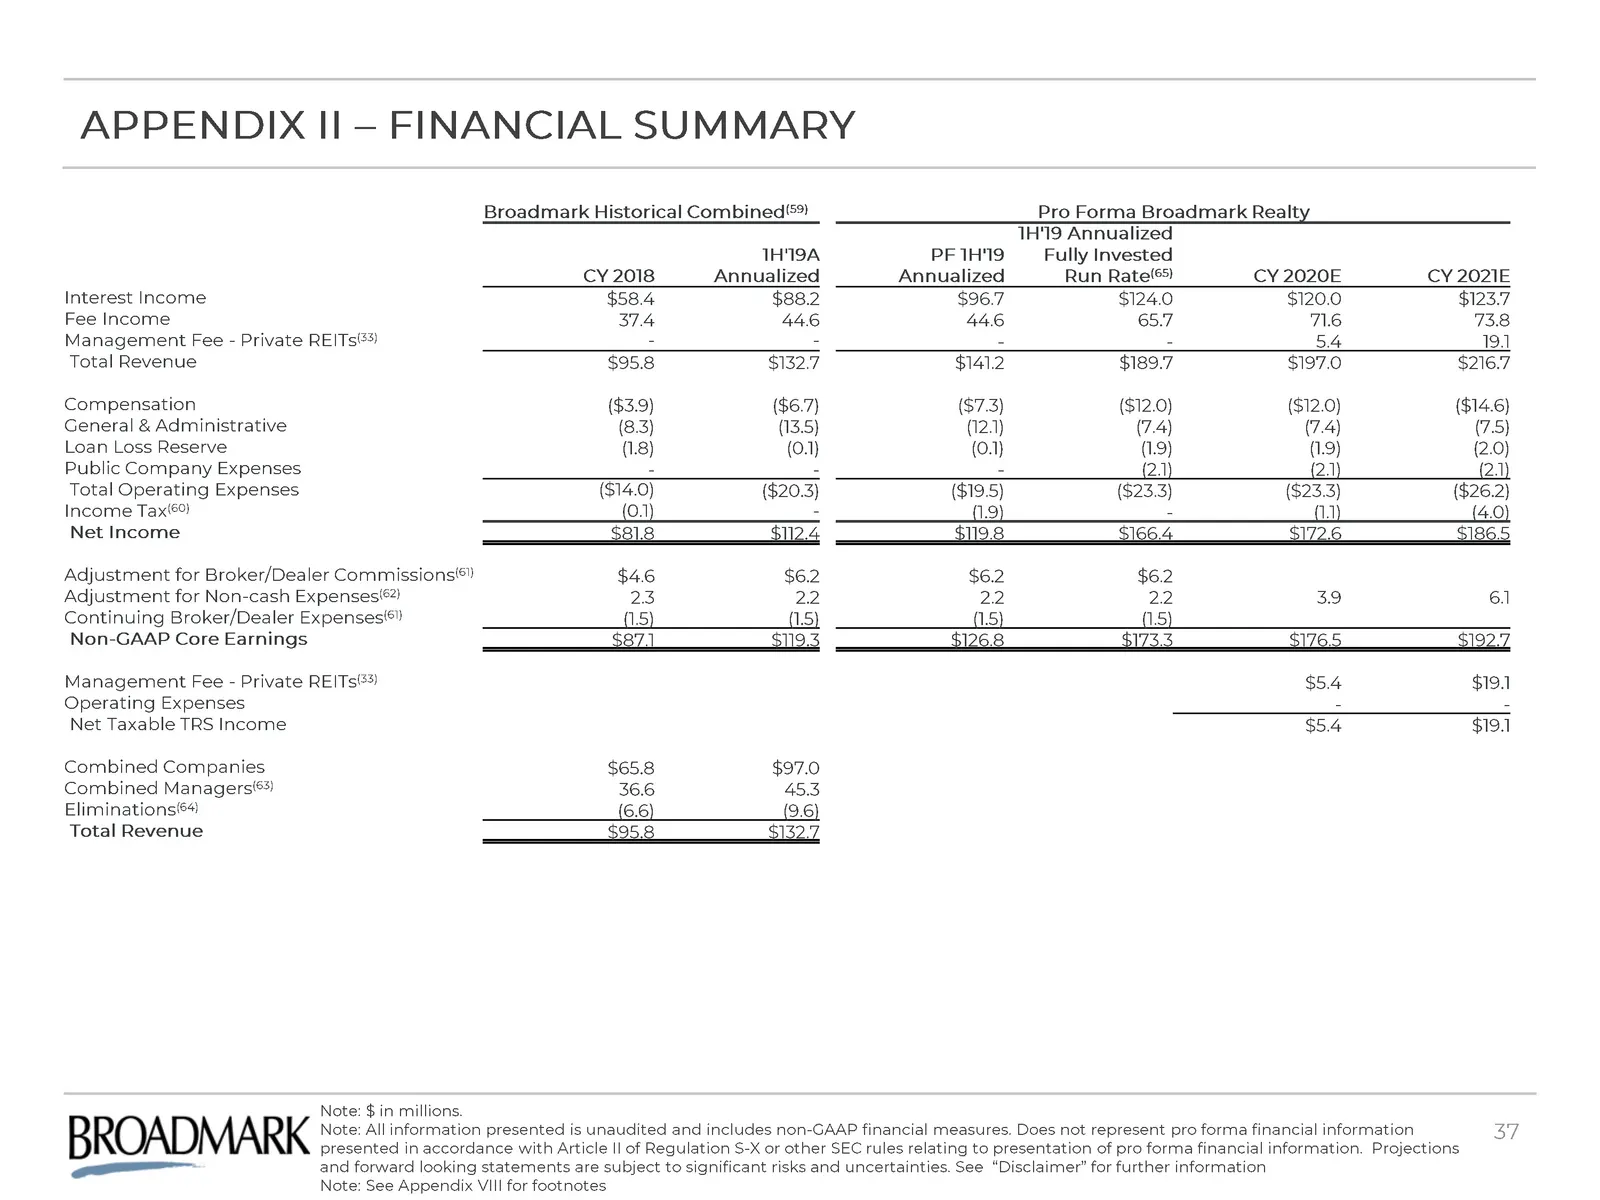
Appendix II – Financial summary Note: $ in millions. Note: All information presented is unaudited and includes non-GAAP financial measures. Does not represent pro forma financial information presented in accordance with Article II of Regulation S-X or other SEC rules relating to presentation of pro
Slide 38: Appendix III – Commercial Mortgage REIT Comparables
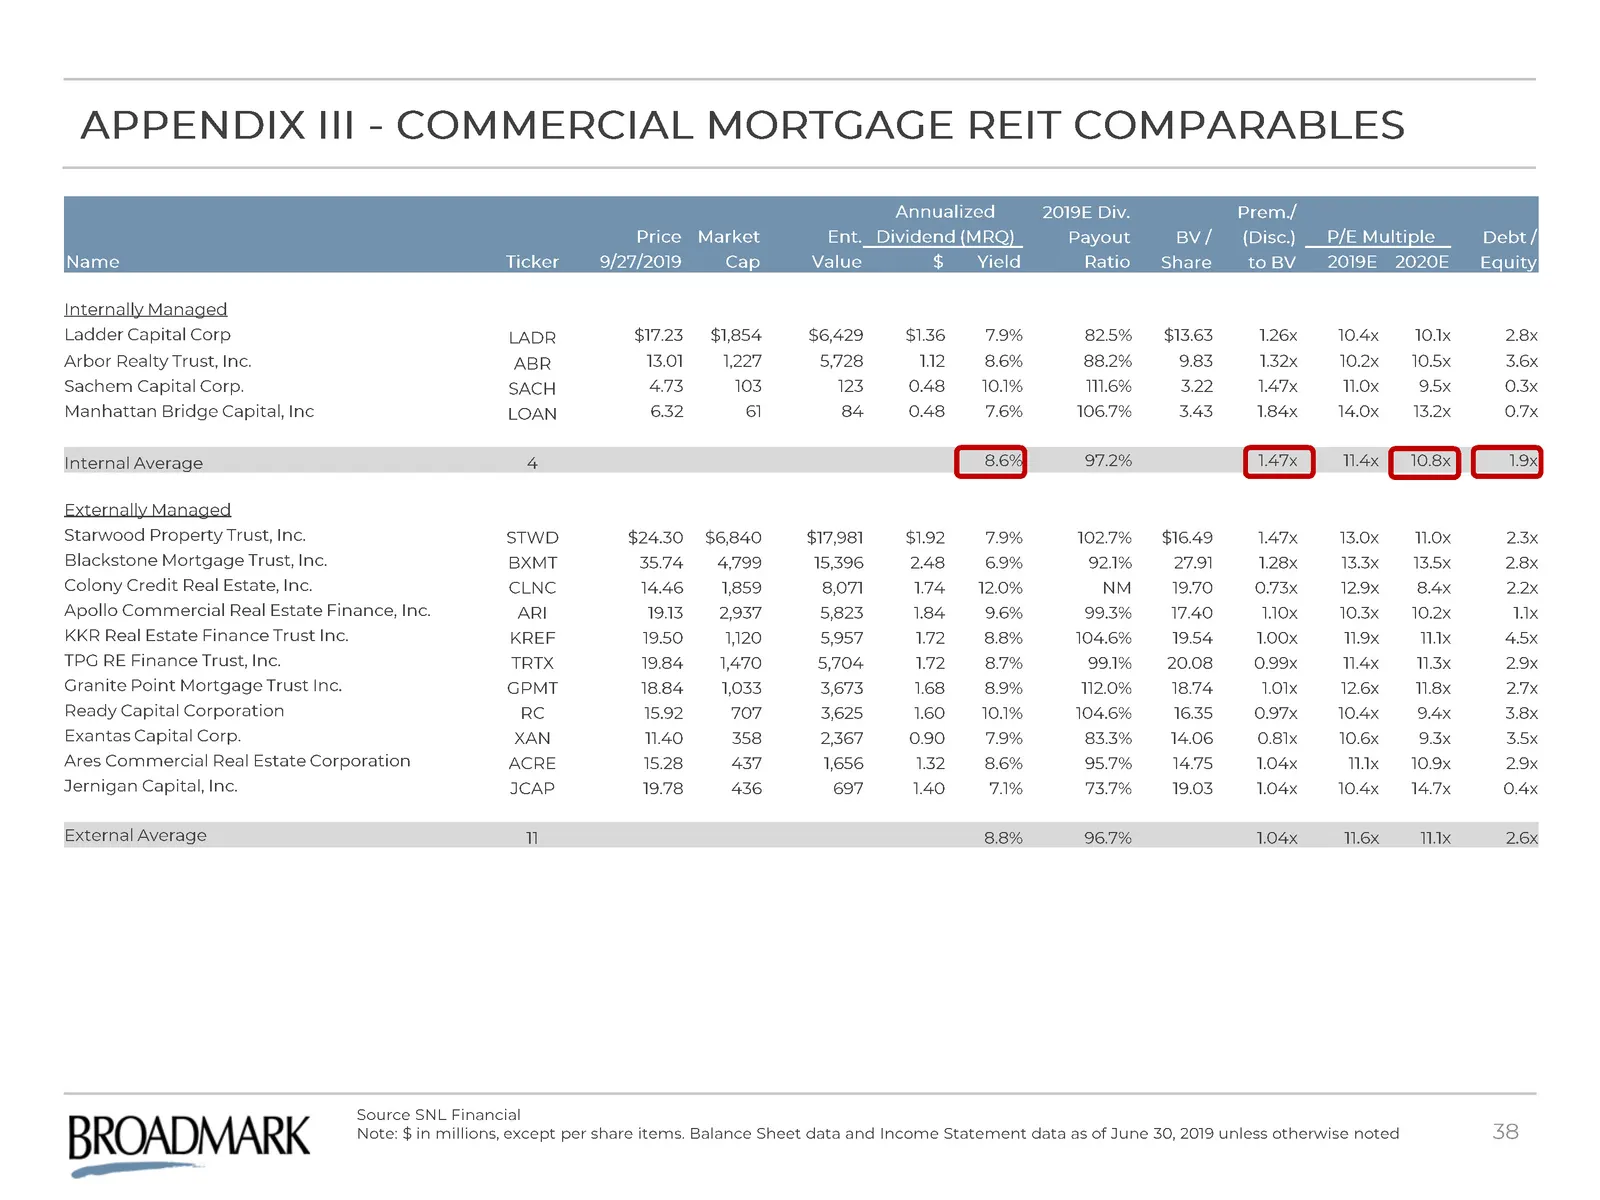
Annualized 2019E Div. Prem./ Price Market Ent. Dividend (MRQ) Payout BV / (Disc.) P/E Multiple Debt / Name Ticker 9/27/2019 Cap Value $ Yield Ratio Share to BV 2019E 2020E Equity Internally Managed Ladder Capital Corp LADR $17.23 $1,854 $6,429 $1.36 7.9% 82.5% $13.63 1.26x 10.4x 10.1x 2.8x Arbor Rea
Slide 39: Appendix IV – Asset Manager Comparables
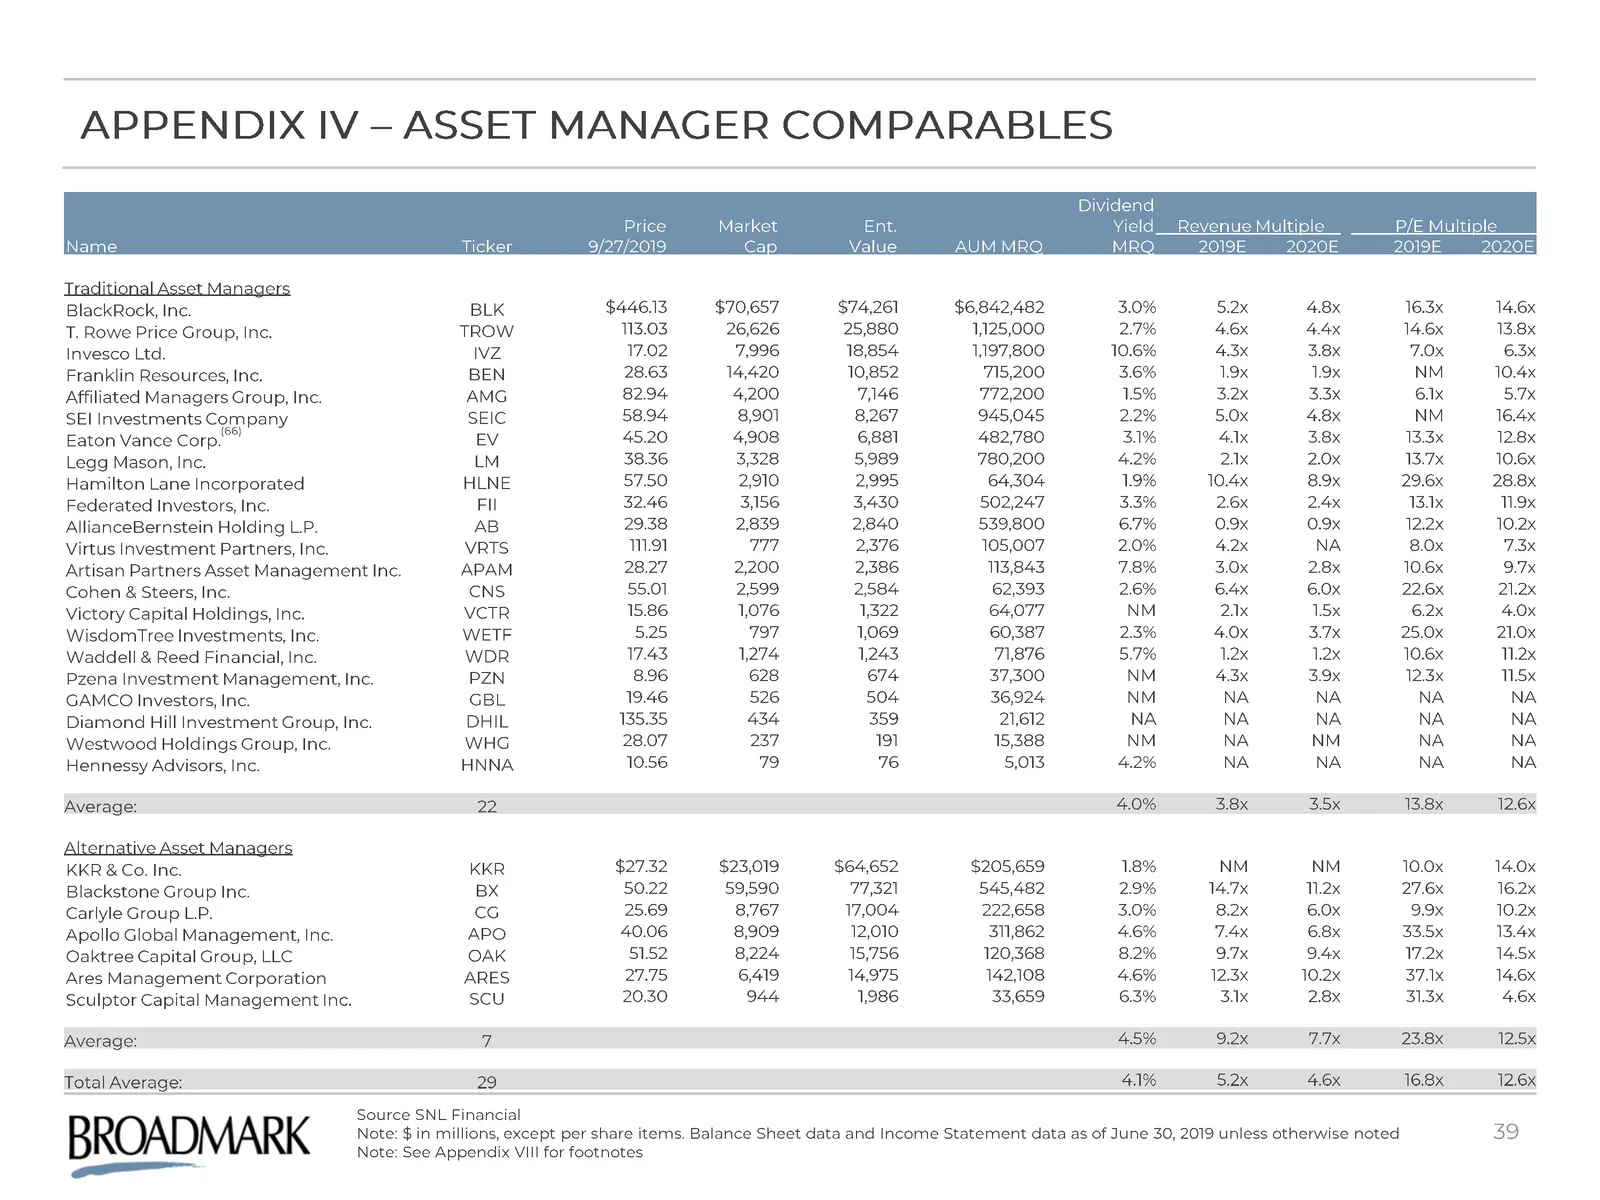
Appendix IV – Asset Manager Comparables Source SNL FinancialNote: $ in millions, except per share items. Balance Sheet data and Income Statement data as of June 30, 2019 unless otherwise notedNote: See Appendix VIII for footnotes Dividend Price Market Ent. Yield Revenue Multiple P/E Multiple Name Ti
Slide 40: Appendix V: Evolution of Construction Financing Landscape
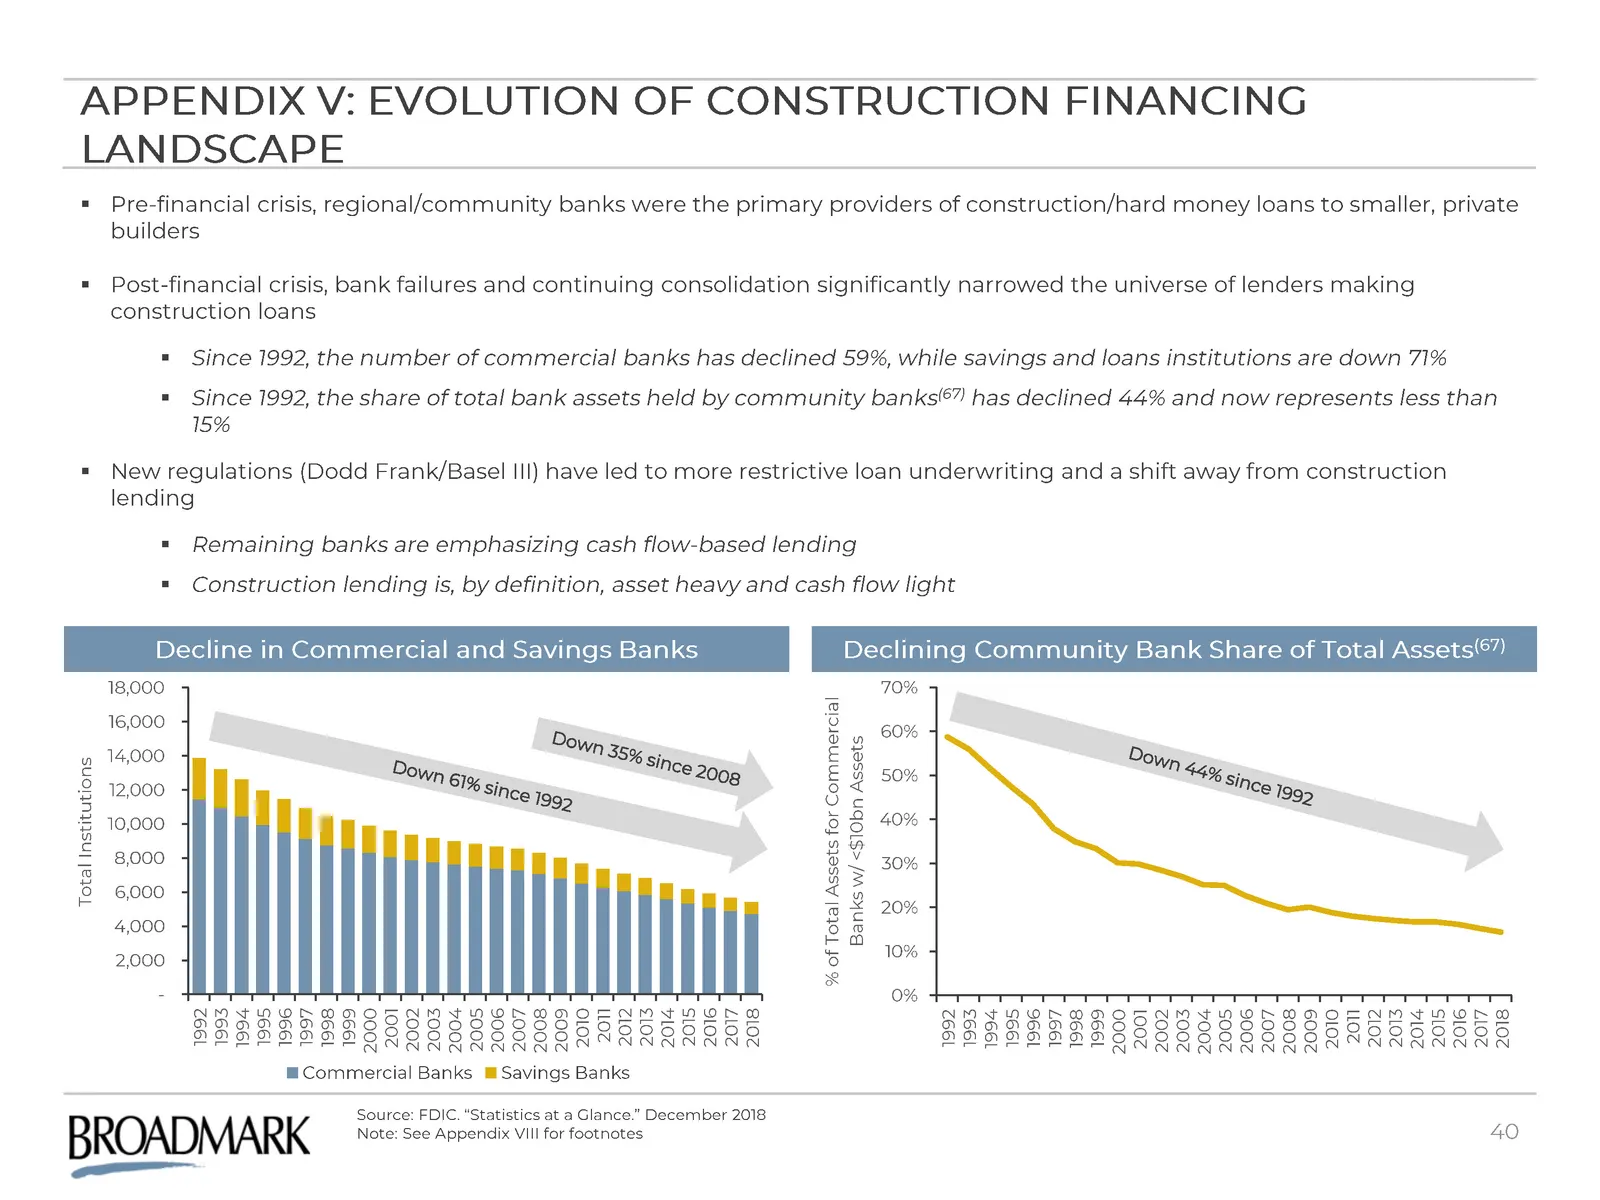
Pre-financial crisis, regional/community banks were the primary providers of construction/hard money loans to smaller, private buildersPost-financial crisis, bank failures and continuing consolidation significantly narrowed the universe of lenders making construction loansSince 1992, the number of c
Slide 41: Appendix VI: Steady Recovery in Housing Construction Trends
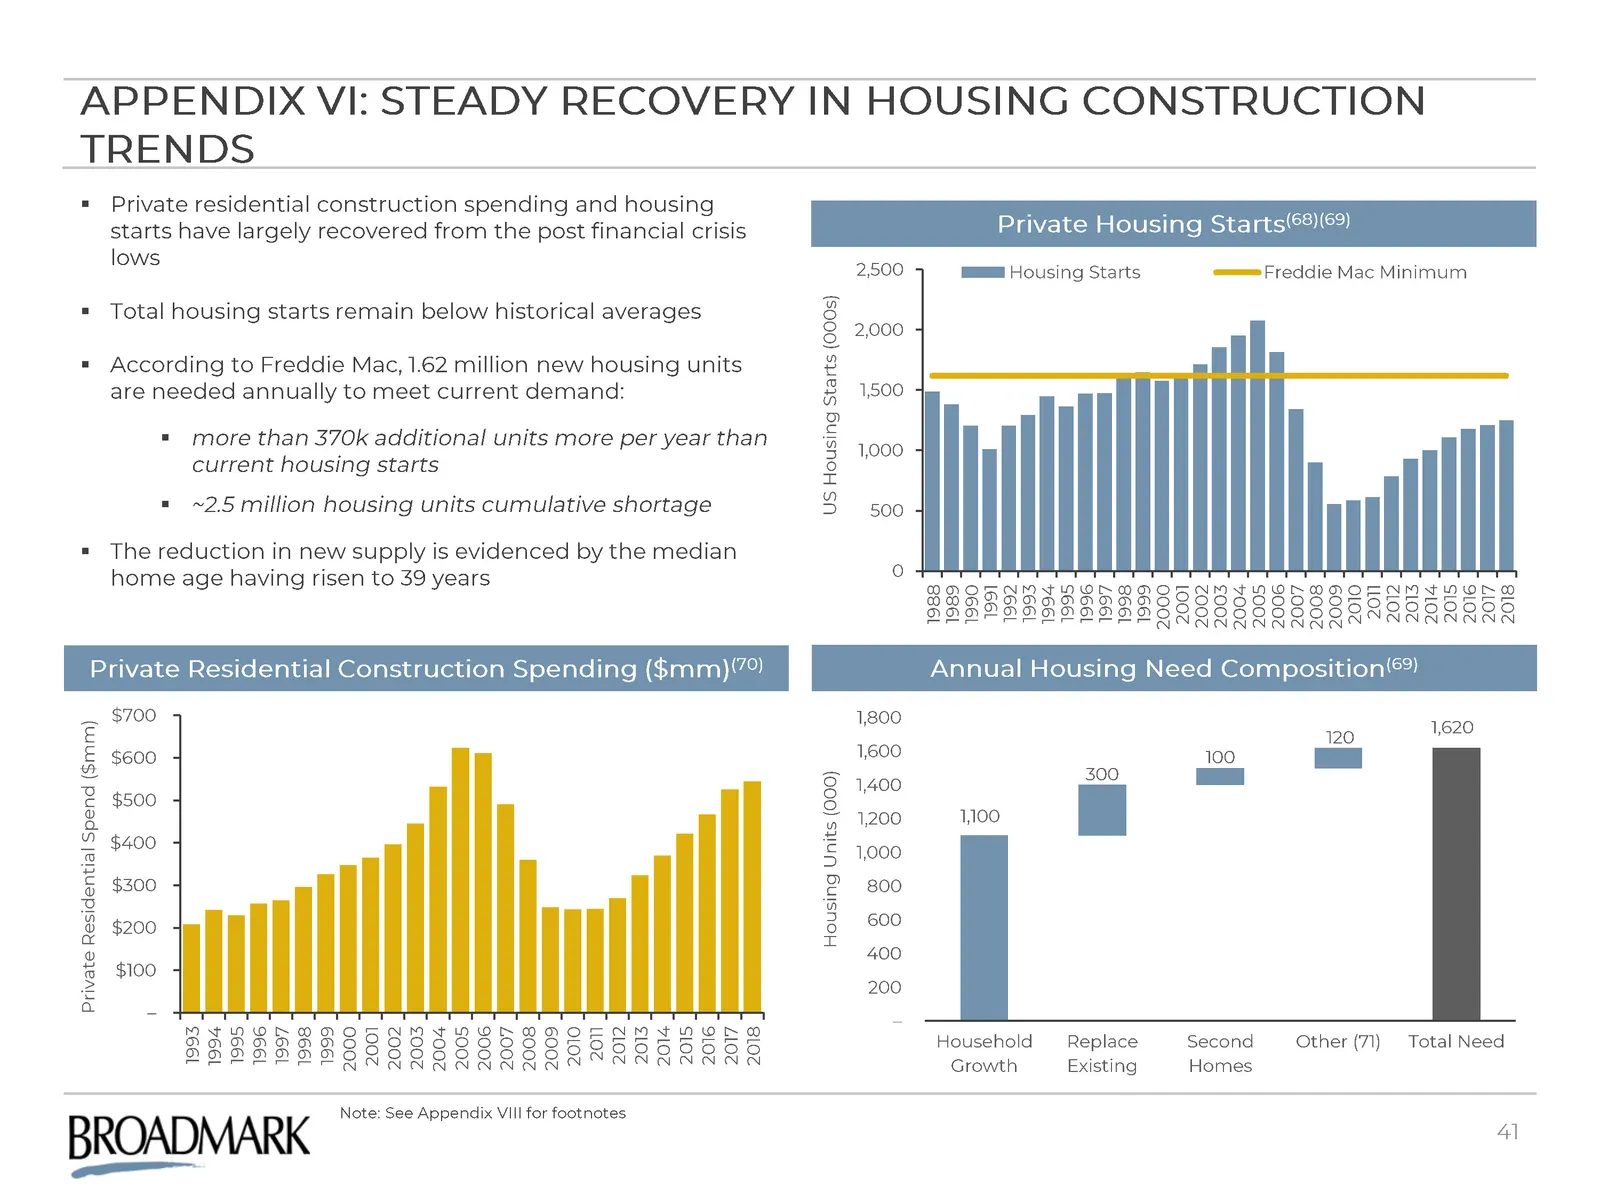
Private Residential Construction Spending ($mm)(70) Appendix VI: Steady recovery in Housing CONSTRUCTION TRENDS Private residential construction spending and housing starts have largely recovered from the post financial crisis lowsTotal housing starts remain below historical averagesAccording to Fre
Slide 42: Appendix VII: Definitions of Property Classifications and Loan Purpose
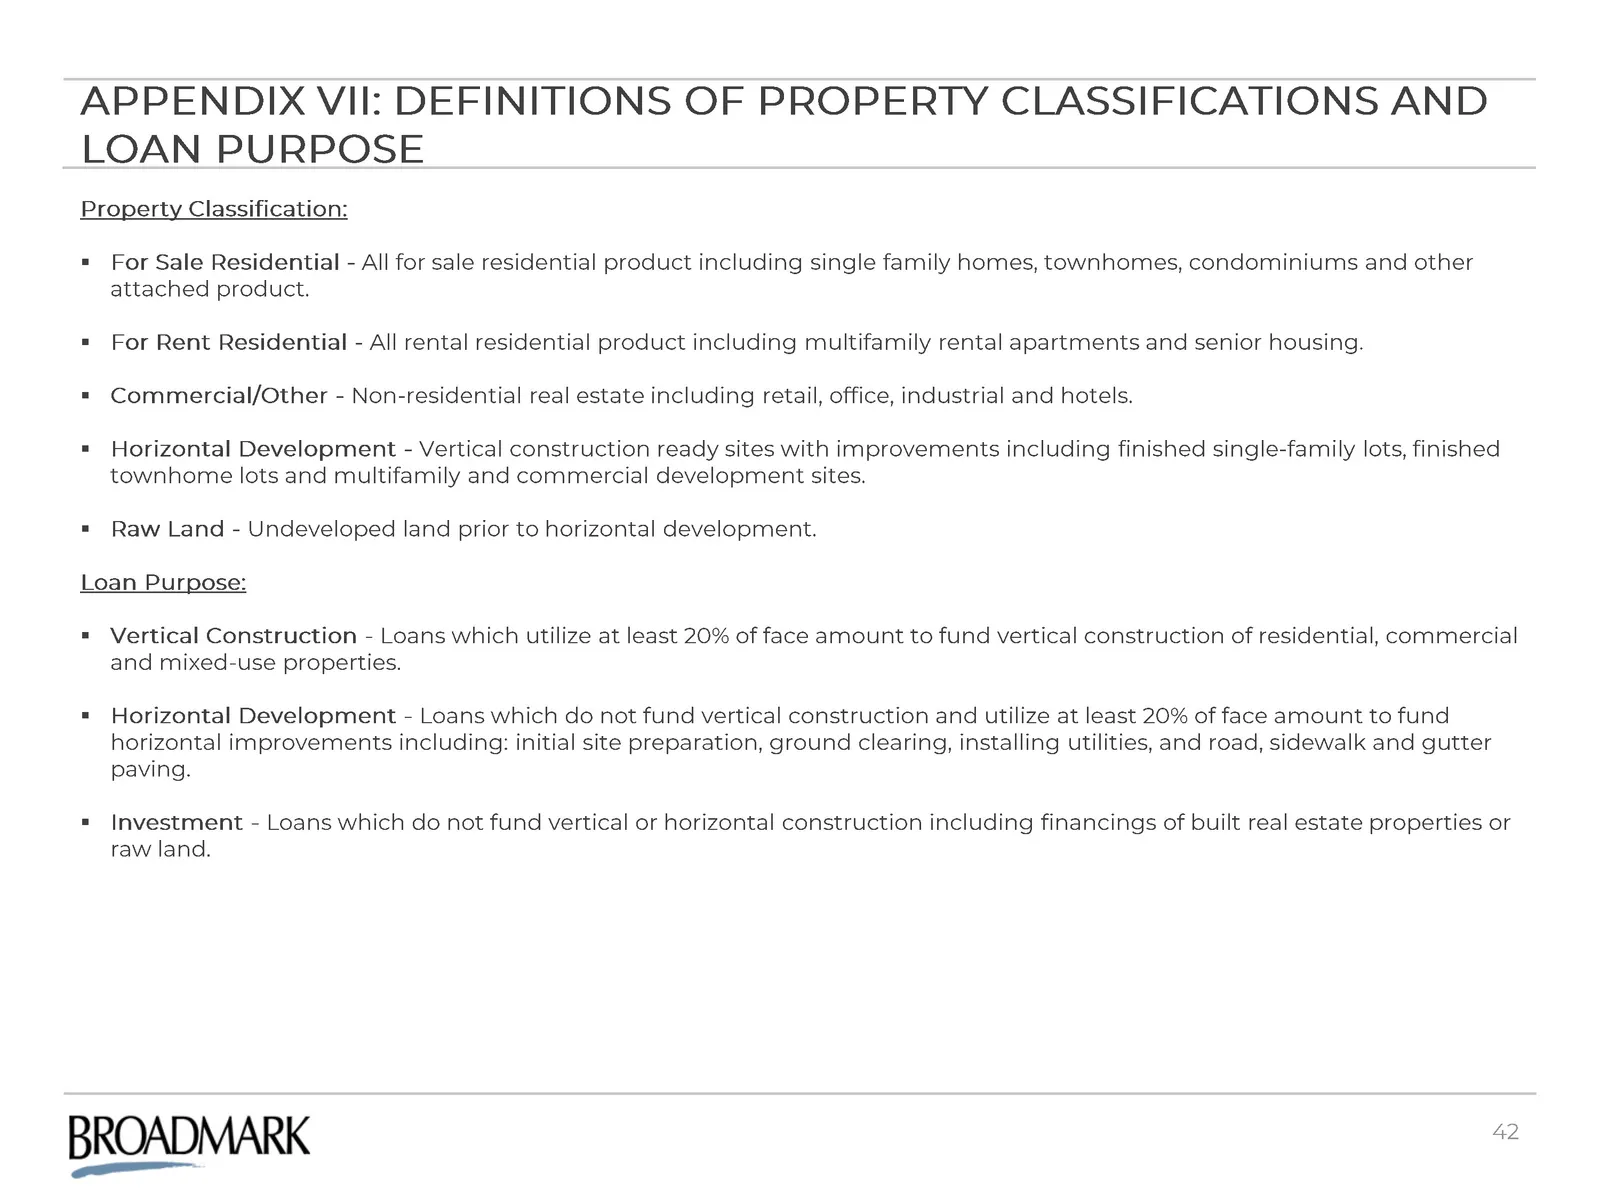
Appendix VII: definitions of property classifications and loan purpose Property Classification:For Sale Residential - All for sale residential product including single family homes, townhomes, condominiums and other attached product.For Rent Residential - All rental residential product including mul
Slide 43: Appendix VIII: Footnotes
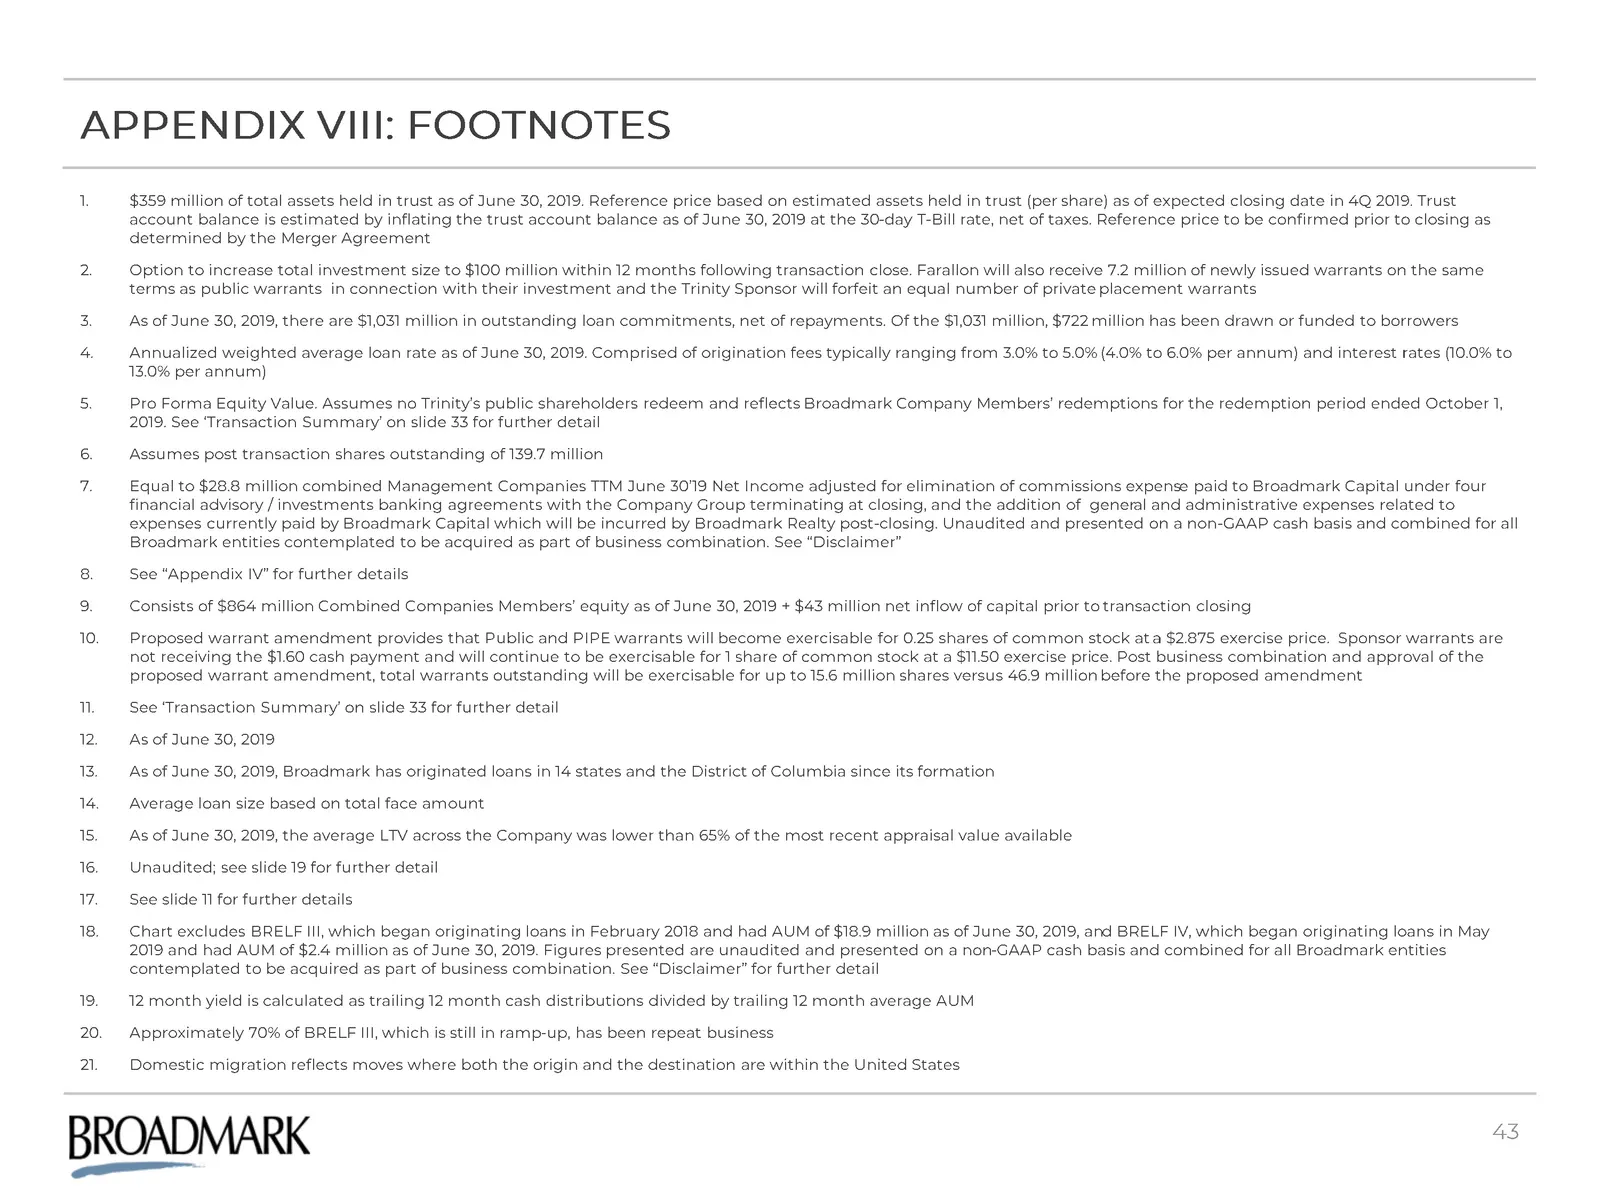
Appendix VIII: Footnotes $359 million of total assets held in trust as of June 30, 2019. Reference price based on estimated assets held in trust (per share) as of expected closing date in 4Q 2019. Trust account balance is estimated by inflating the trust account balance as of June 30, 2019 at the 30
Slide 44: Appendix VIII: Footnotes (Cont'd)
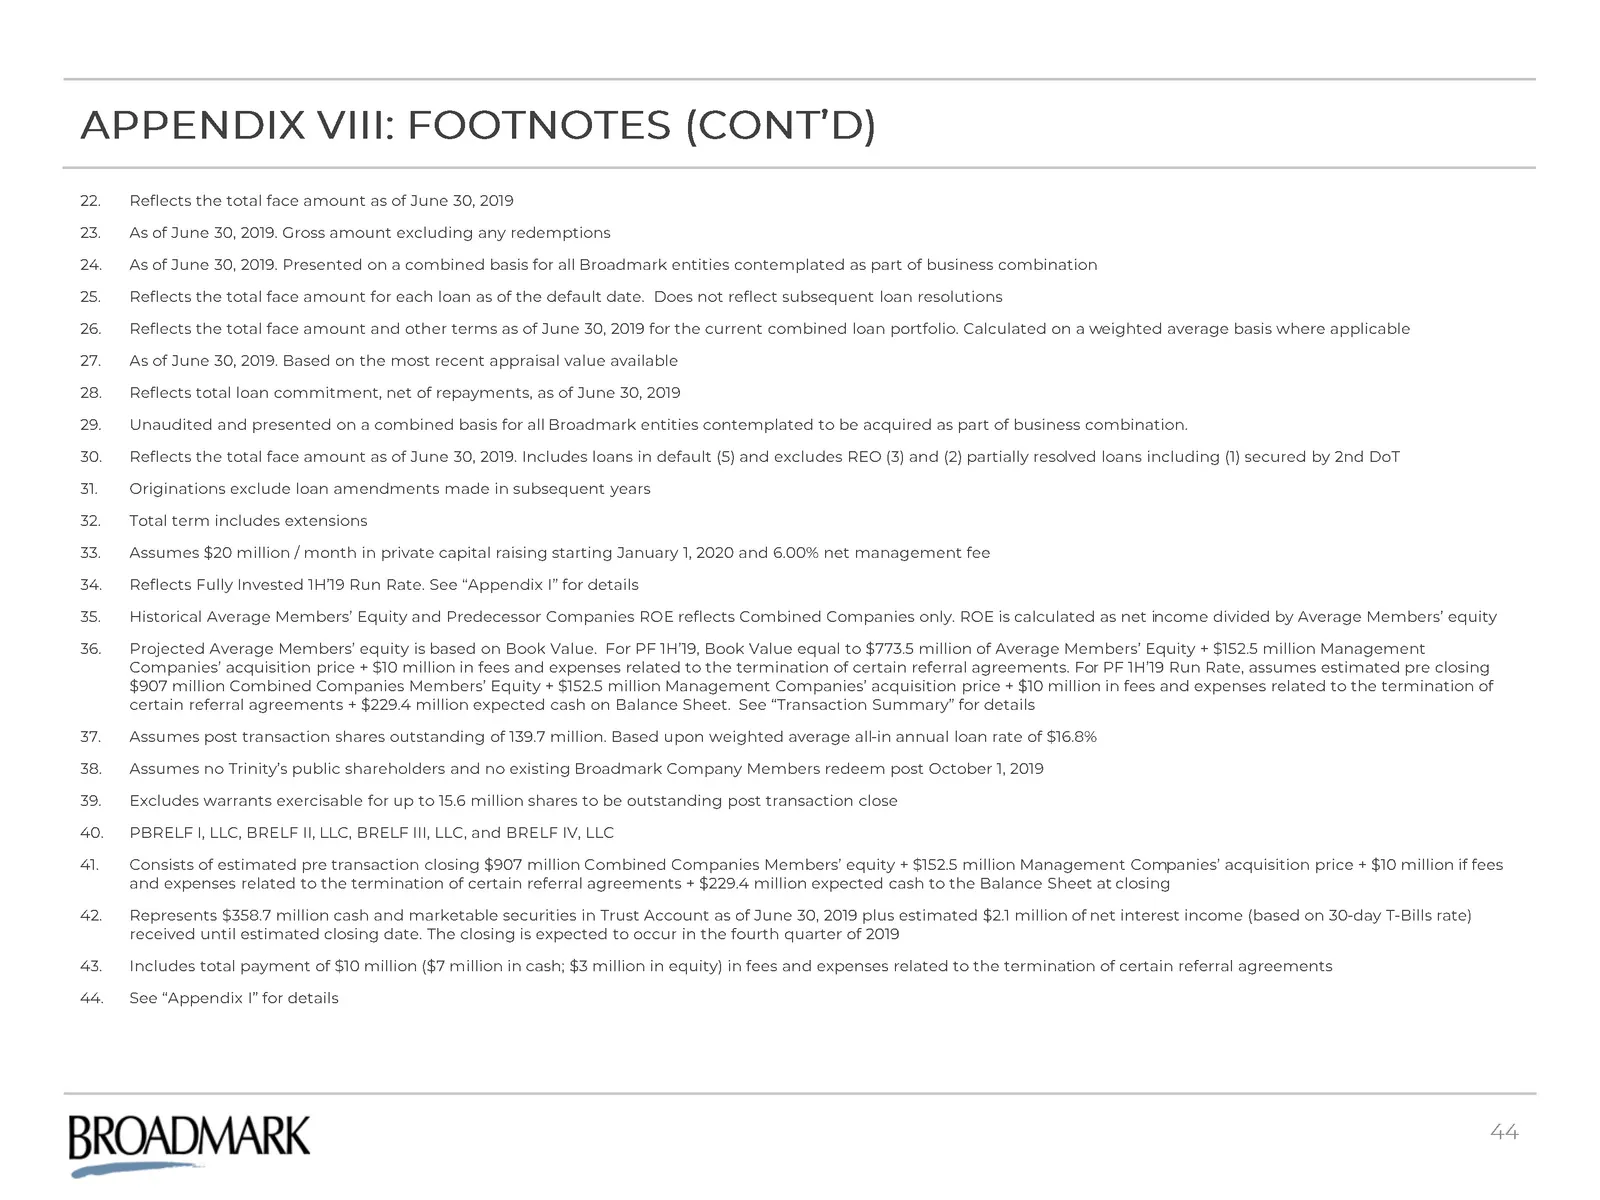
Appendix VIII: Footnotes (Cont’d) Reflects the total face amount as of June 30, 2019As of June 30, 2019. Gross amount excluding any redemptionsAs of June 30, 2019. Presented on a combined basis for all Broadmark entities contemplated as part of business combinationReflects the total face amount for
Slide 45: Appendix VIII: Footnotes (Cont'd)
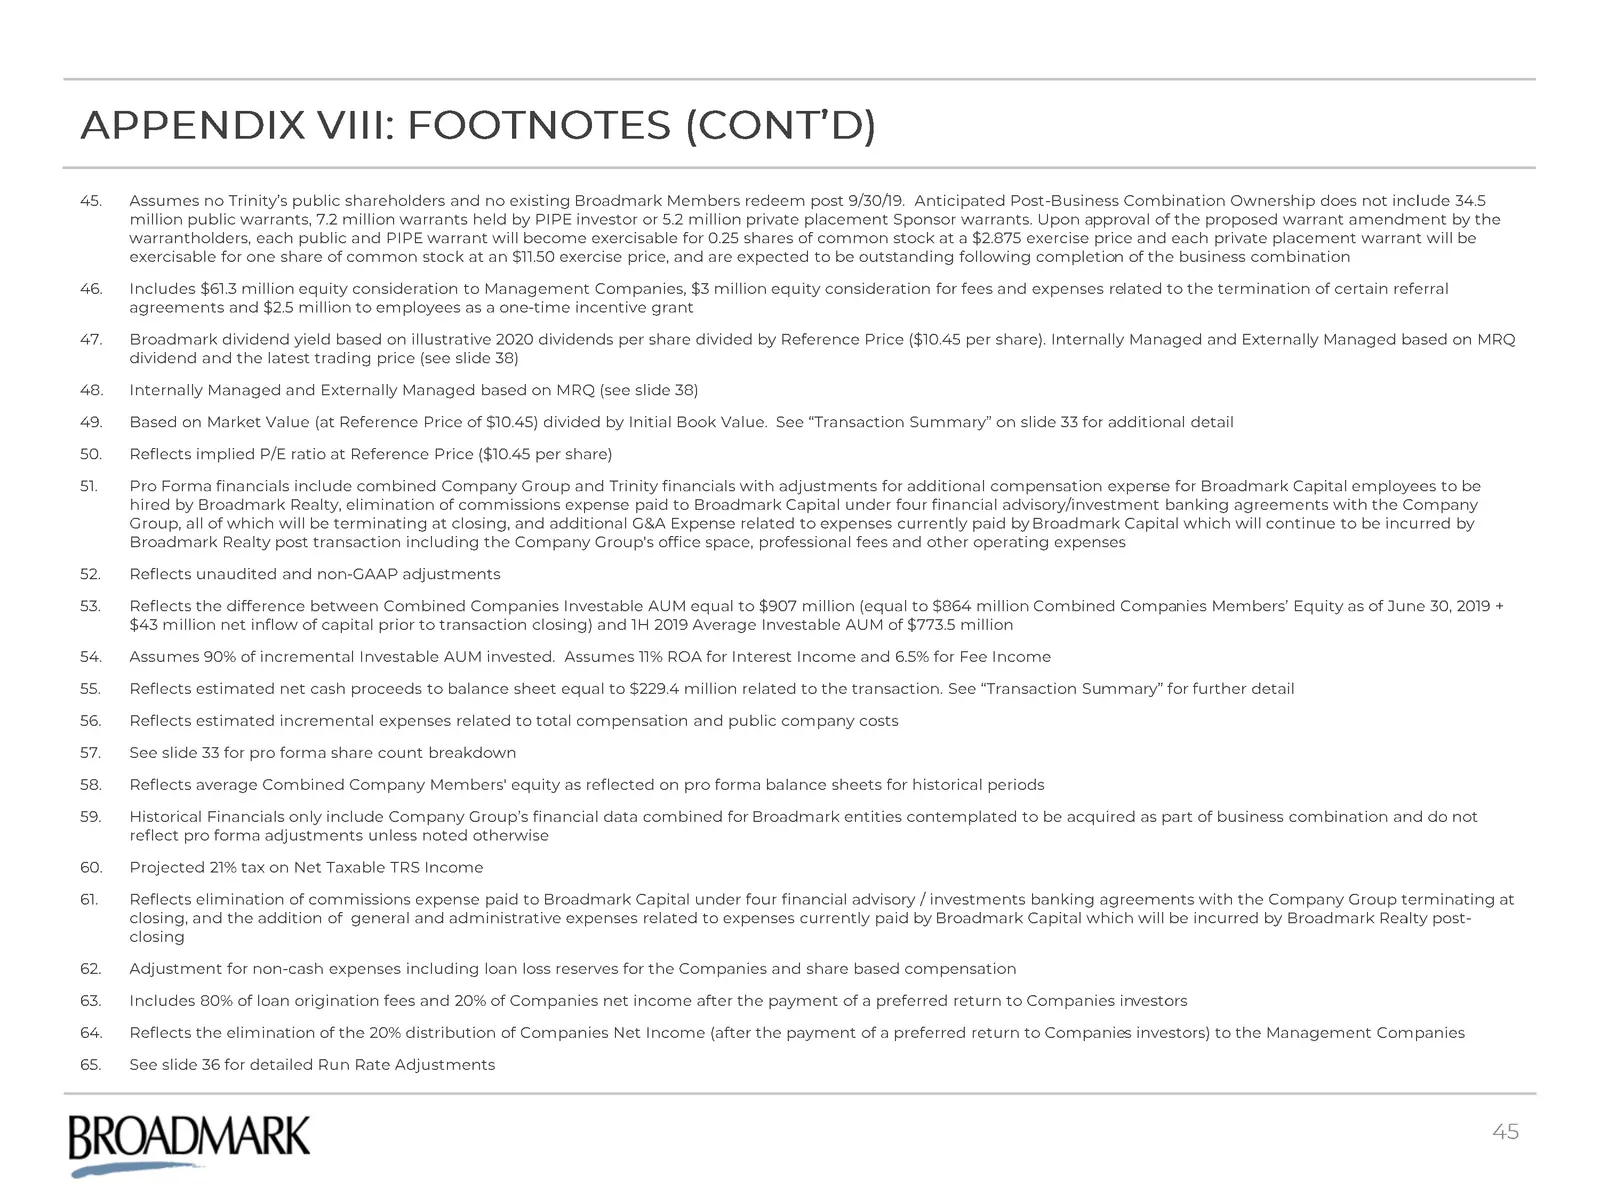
Appendix VIII: Footnotes (Cont’d) Assumes no Trinity’s public shareholders and no existing Broadmark Members redeem post 9/30/19. Anticipated Post-Business Combination Ownership does not include 34.5 million public warrants, 7.2 million warrants held by PIPE investor or 5.2 million private placement
Slide 46: Appendix VIII: Footnotes (Cont'd)
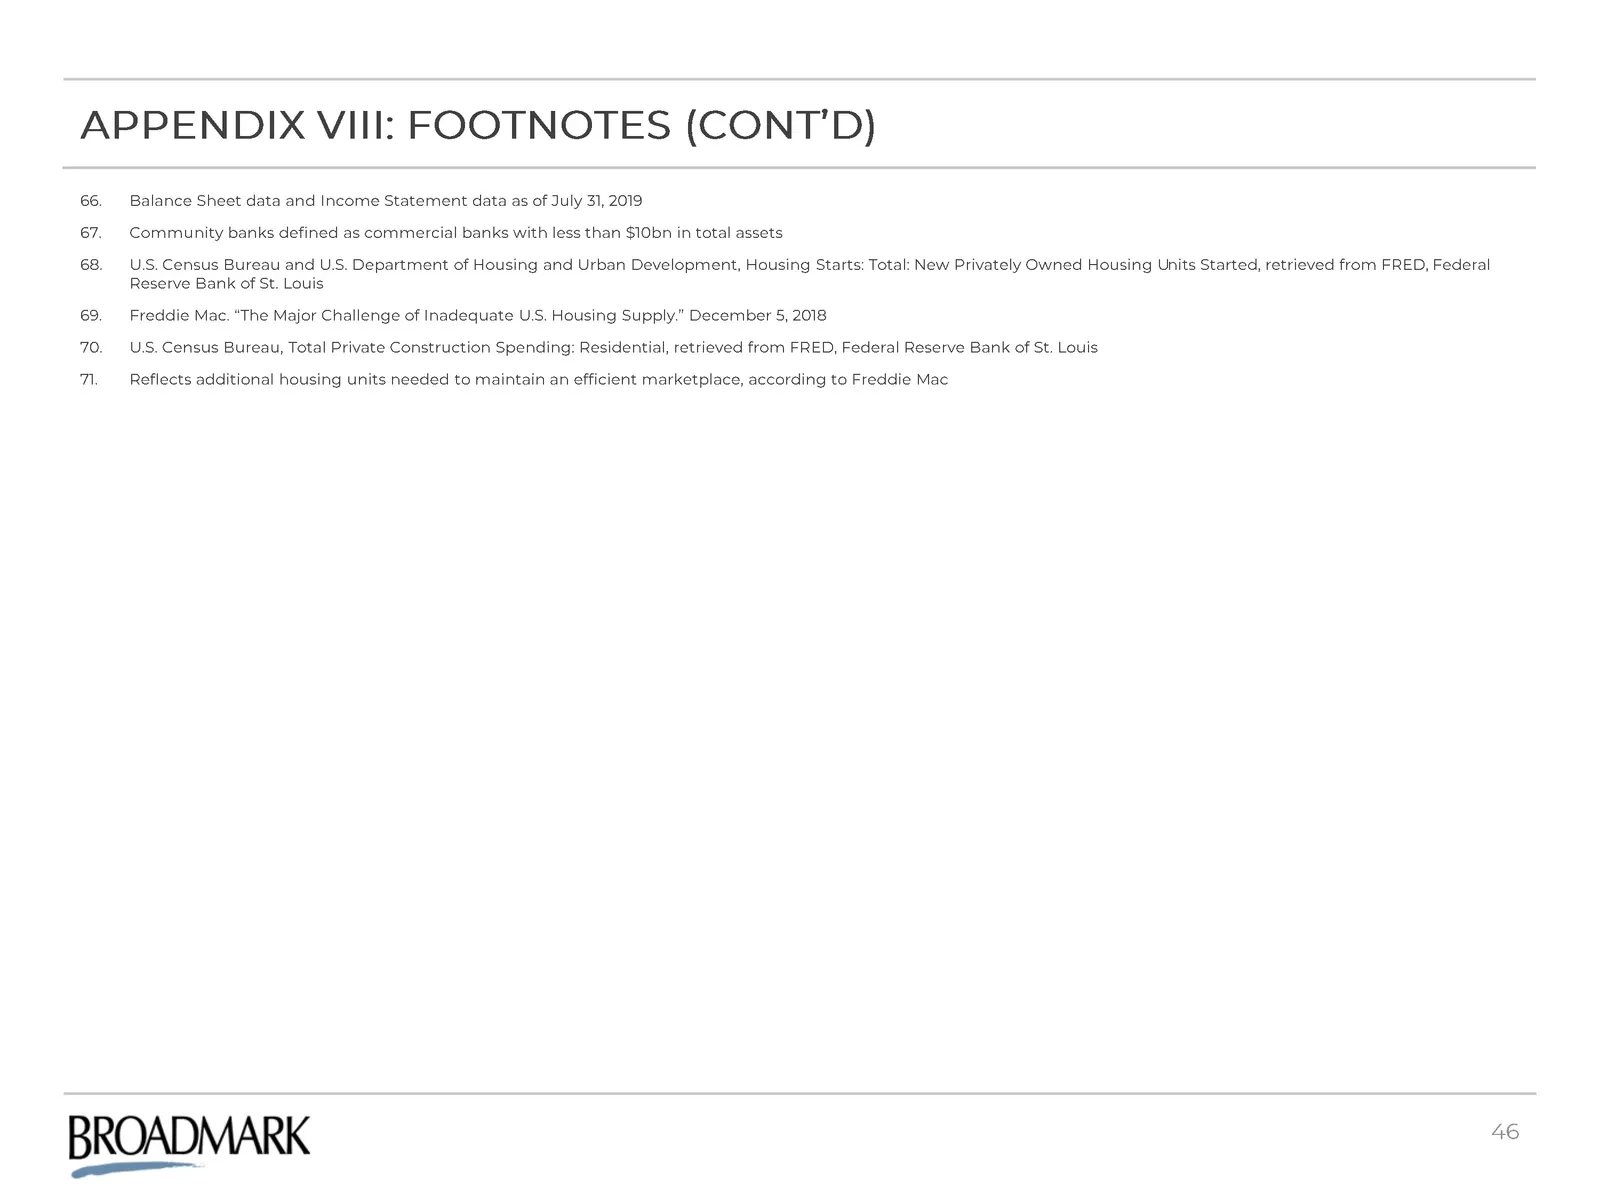
Appendix VIII: Footnotes (Cont’d) Balance Sheet data and Income Statement data as of July 31, 2019Community banks defined as commercial banks with less than $10bn in total assetsU.S. Census Bureau and U.S. Department of Housing and Urban Development, Housing Starts: Total: New Privately Owned Housin
Source: SEC EDGAR · 425 filed Sep 30, 2019