Markwest Energy Partners LP — MLP Investor Conference May 2012
33 slides from Markwest Energy Partners LP's conference presentation, May 23, 2012
Slide 1: MLP Investor Conference May 2012
MLP Investor Conference May 2012
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements and information. These forward-looking statements, which in many instances can be identified by words like “could,” “may,” “will,” “should,” “expects,” “plans,” “project,” “anticipates,” “believes,” “planned,” “proposed
Slide 3: Non-GAAP Measures
Non-GAAP Measures Distributable Cash Flow, Adjusted EBITDA , and Net Operating Margin are not measures of performance calculated in accordance with GAAP, and should not be considered separately from or as a substitute for net income, income from operations, or cash flow as reflected in our financial
Slide 4: Key Investment Considerations
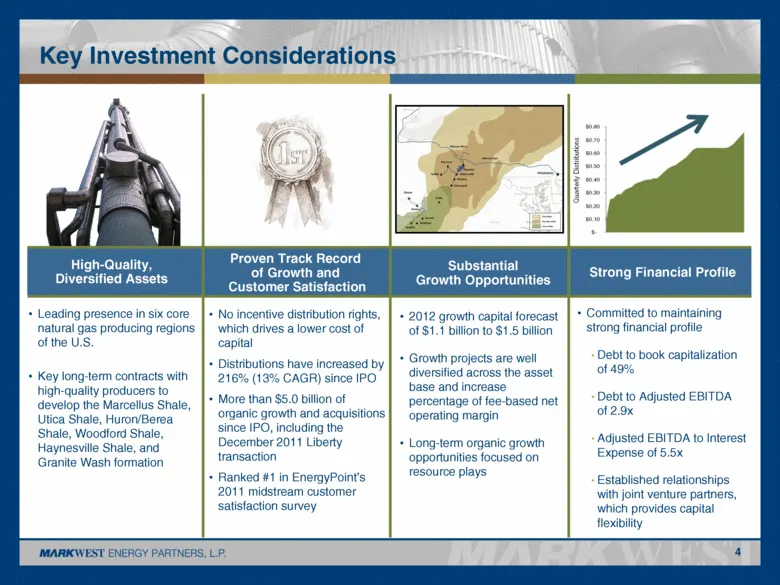
Key Investment Considerations 4 High-Quality, Diversified Assets Proven Track Record of Growth and Customer Satisfaction Substantial Growth Opportunities Strong Financial Profile Leading presence in six core natural gas producing regions of the U.S. Key long-term contracts with high-quality producer
Slide 5: Geographic Footprint
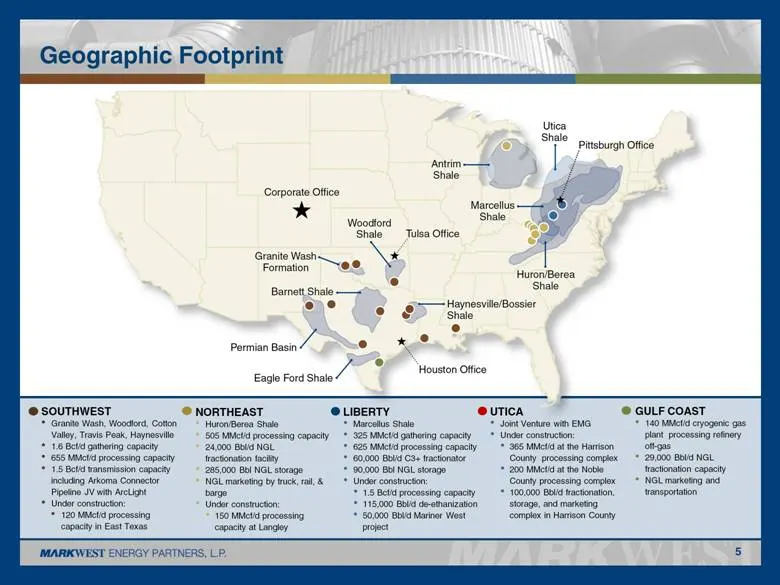
Geographic Footprint UTICA Joint Venture with EMG Under construction: 365 MMcf/d at the Harrison County processing complex 200 MMcf/d at the Noble County processing complex 100,000 Bbl/d fractionation, storage, and marketing complex in Harrison County SOUTHWEST Granite Wash, Woodford, Cotton Valley,
Slide 6: Growth Driven by Customer Satisfaction
Growth Driven by Customer Satisfaction 6 MarkWest Ranked #1 in Natural Gas Midstream Services Customer Satisfaction EnergyPoint Research, Inc. 2011 Customer Satisfaction Survey
Slide 7: Shale Plays Are Driving Natural Gas Supply
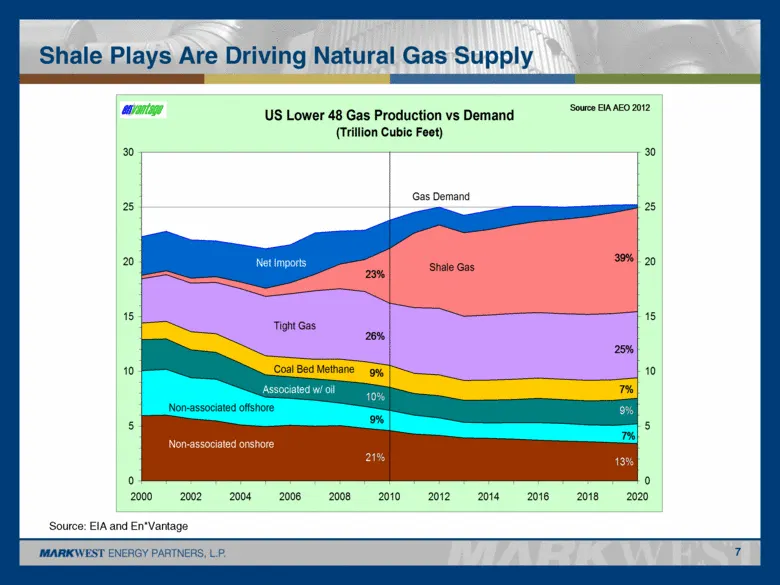
7 Shale Plays Are Driving Natural Gas Supply Source: EIA and En*Vantage US Lower 48 Gas Production vs Demand (Trillion Cubic Feet) 0 5 10 15 20 25 30 2000 2002 2004 2006 2008 2010 2012 2014 2016 2018 2020 0 5 10 15 20 25 30 Non-associated onshore Non-associated offshore Associated w/ oil Tight Gas C
Slide 8: Resource Play Economics
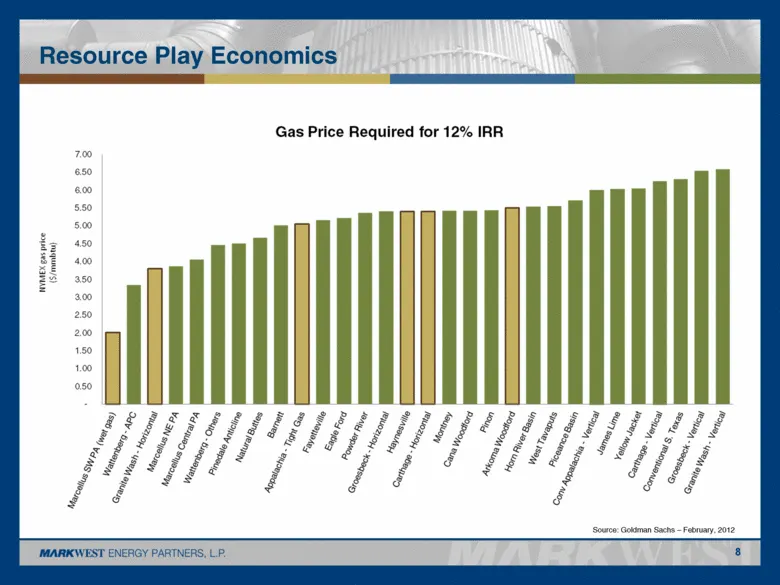
8 Resource Play Economics Source: Goldman Sachs – February, 2012 NYMEX gas price ($/mmbtu) Gas Price Required for 12% IRR
Slide 9: Commitment to Resource Plays
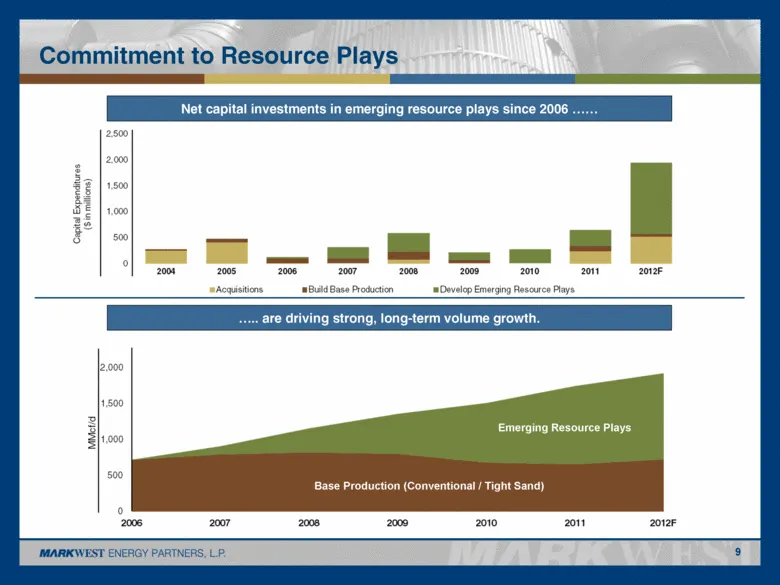
Commitment to Resource Plays 9 Net capital investments in emerging resource plays since 2006 are driving strong, long-term volume growth. Emerging Resource Plays Base Production (Conventional / Tight Sand) MMcf/d
Slide 10: Gulf Coast Segment
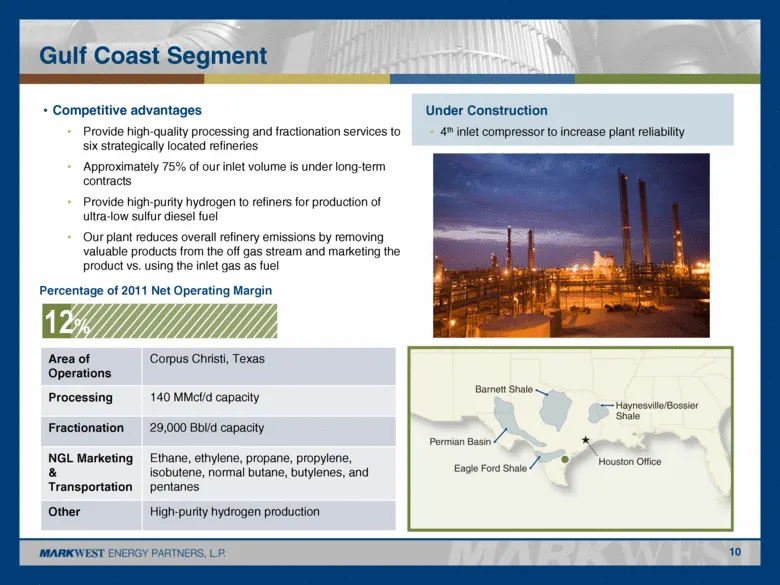
Gulf Coast Segment 10 Competitive advantages Provide high-quality processing and fractionation services to six strategically located refineries Approximately 75% of our inlet volume is under long-term contracts Provide high-purity hydrogen to refiners for production of ultra-low sulfur diesel fuel O
Slide 11: Southwest Segment
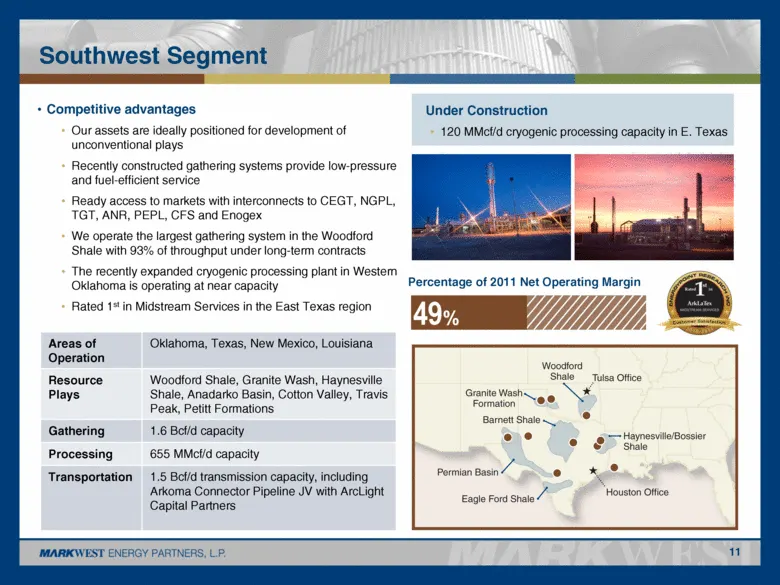
Southwest Segment 11 Competitive advantages Our assets are ideally positioned for development of unconventional plays Recently constructed gathering systems provide low-pressure and fuel-efficient service Ready access to markets with interconnects to CEGT, NGPL, TGT, ANR, PEPL, CFS and Enogex We ope
Slide 12: Northeast Segment
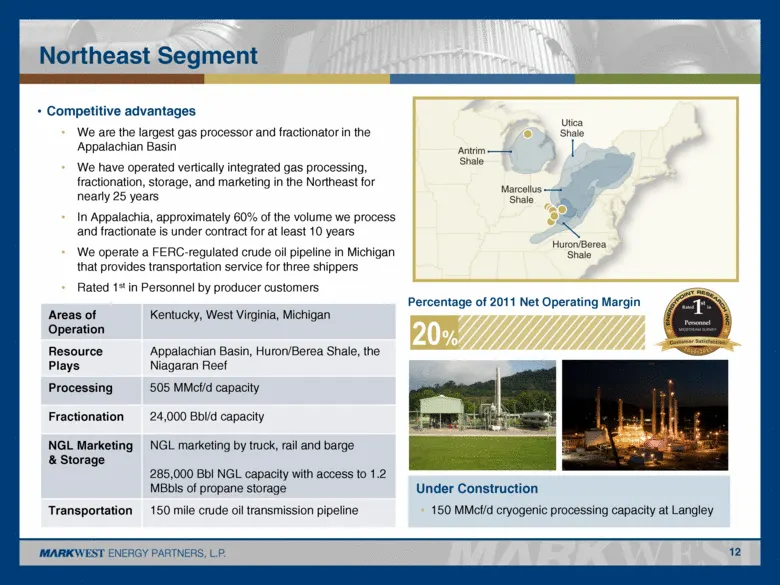
Northeast Segment 12 Competitive advantages We are the largest gas processor and fractionator in the Appalachian Basin We have operated vertically integrated gas processing, fractionation, storage, and marketing in the Northeast for nearly 25 years In Appalachia, approximately 60% of the volume we p
Slide 13: Liberty Segment
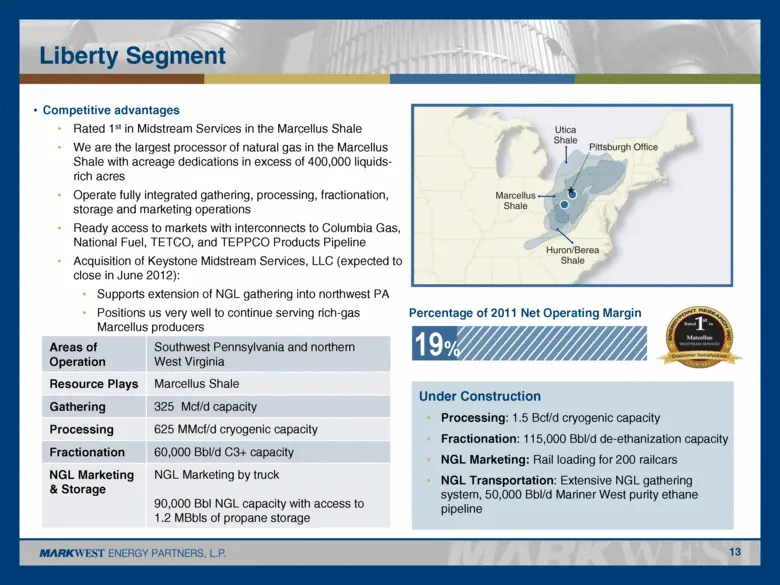
Liberty Segment Competitive advantages Rated 1st in Midstream Services in the Marcellus Shale We are the largest processor of natural gas in the Marcellus Shale with acreage dedications in excess of 400,000 liquids-rich acres Operate fully integrated gathering, processing, fractionation, storage and
Slide 14: Liberty Project Schedule
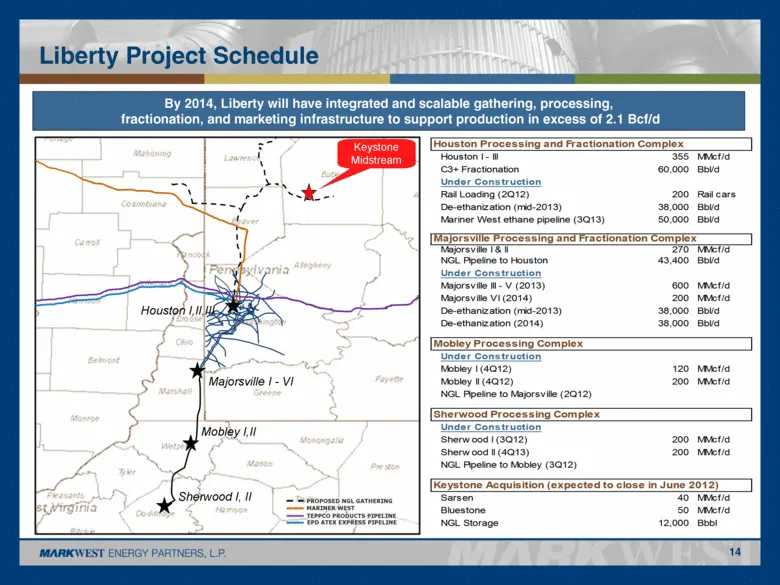
Liberty Project Schedule 14 Houston I, II, III Mobley I,II Sherwood I, II Majorsville I - VI TEPPCO PRODUCTS PIPELINE MARINER WEST EPD ATEX EXPRESS PIPELINE By 2014, Liberty will have integrated and scalable gathering, processing, fractionation, and marketing infrastructure to support production in
Slide 15: Utica Joint Venture Overview
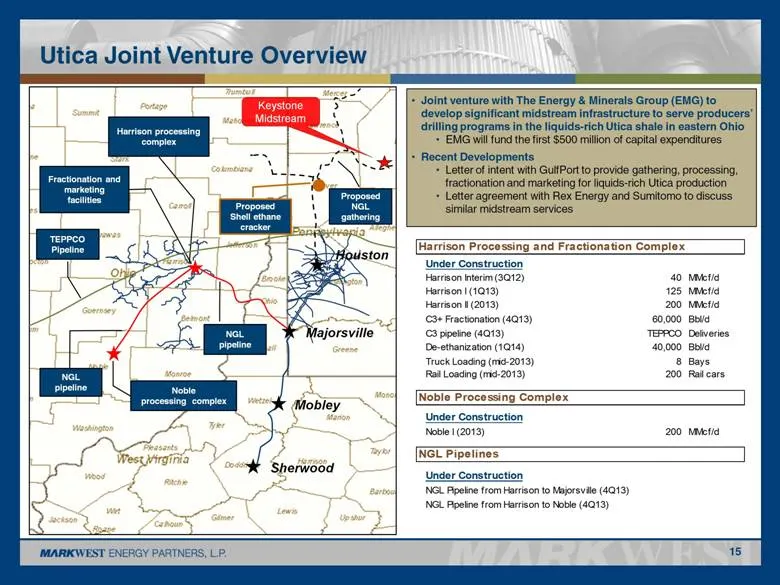
Utica Joint Venture Overview 15 Joint venture with The Energy & Minerals Group (EMG) to develop significant midstream infrastructure to serve producers’ drilling programs in the liquids-rich Utica shale in eastern Ohio EMG will fund the first $500 million of capital expenditures Recent Developments
Slide 16: The Midstream Leader in Northeast Shales
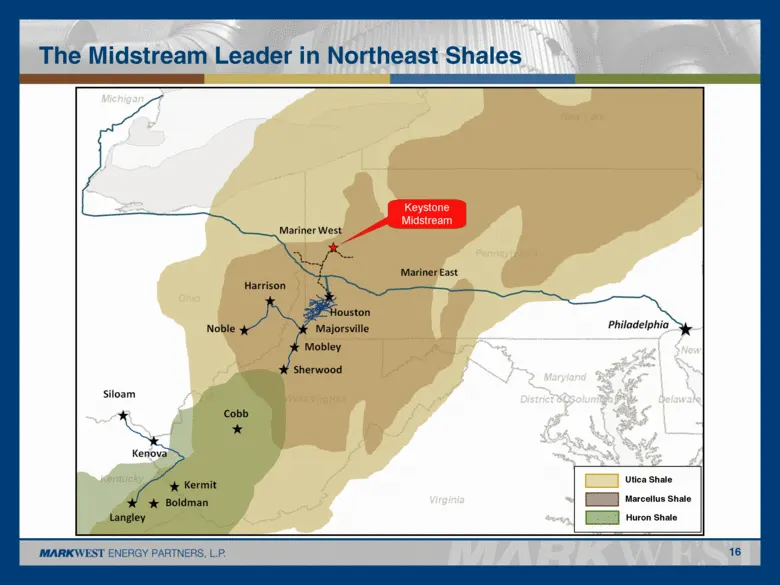
The Midstream Leader in Northeast Shales 16 Utica Shale Marcellus Shale Huron Shale Keystone Midstream
Slide 17: Keystone Midstream Services Acquisition
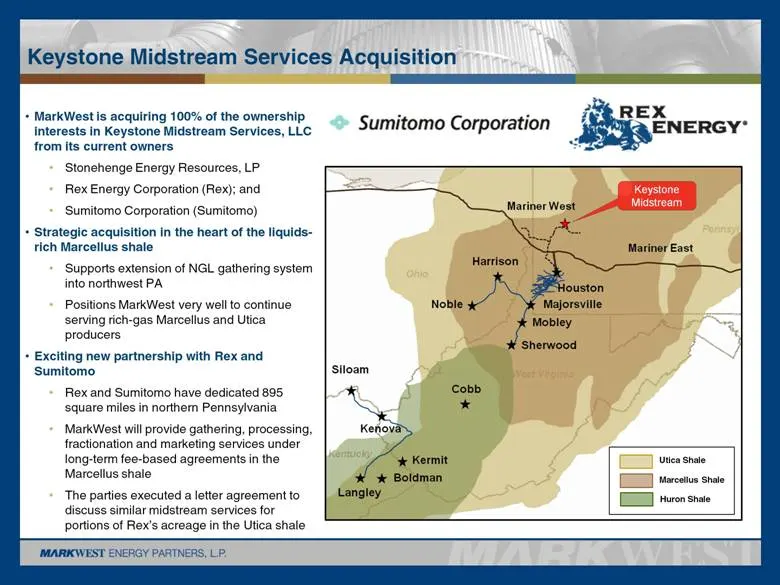
Keystone Midstream Services Acquisition MarkWest is acquiring 100% of the ownership interests in Keystone Midstream Services, LLC from its current owners Stonehenge Energy Resources, LP Rex Energy Corporation (Rex); and Sumitomo Corporation (Sumitomo) Strategic acquisition in the heart of the liquid
Slide 18: Marcellus Ethane – A Third-Party Viewpoint
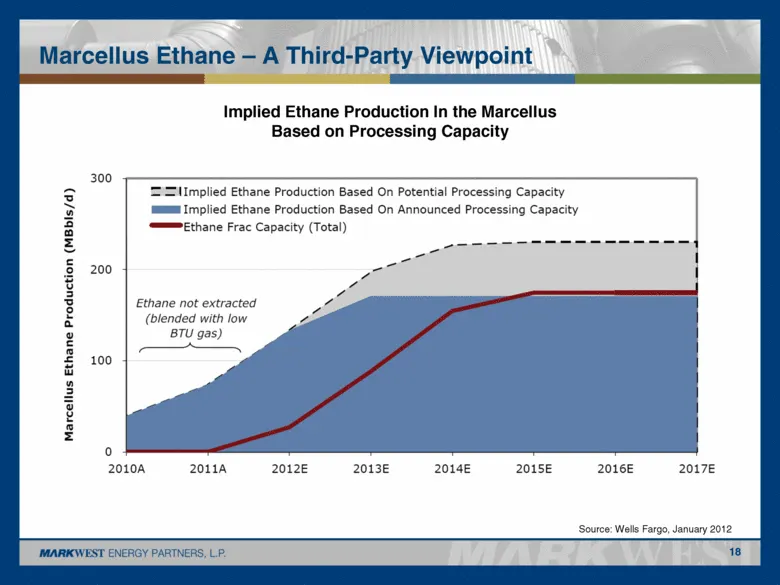
Marcellus Ethane – A Third-Party Viewpoint 18 Implied Ethane Production In the Marcellus Based on Processing Capacity Source: Wells Fargo, January 2012
Slide 19: Increasing Demand for US Ethane
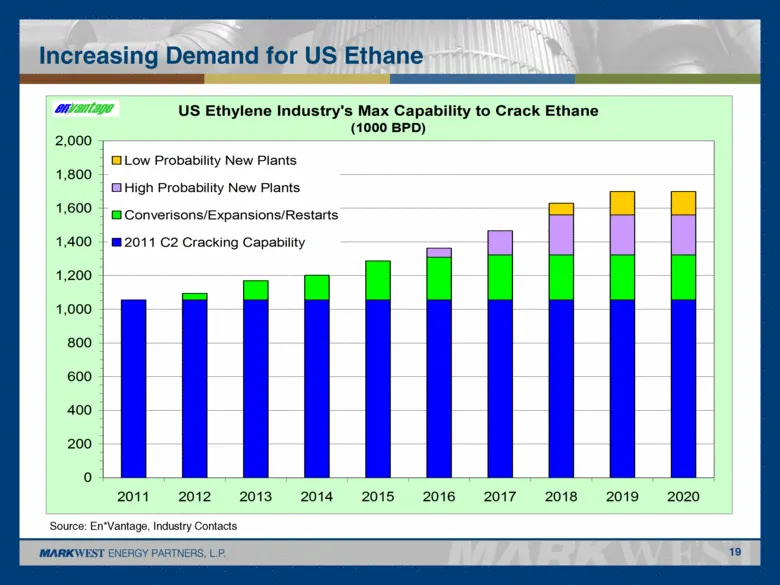
Increasing Demand for US Ethane 19 Source: En*Vantage, Industry Contacts US Ethylene Industry's Max Capability to Crack Ethane (1000 BPD) 0 200 400 600 800 1,000 1,200 1,400 1,600 1,800 2,000 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 Low Probability New Plants High Probability New Plants Con
Slide 20: Project Mariner: A Comprehensive Solution
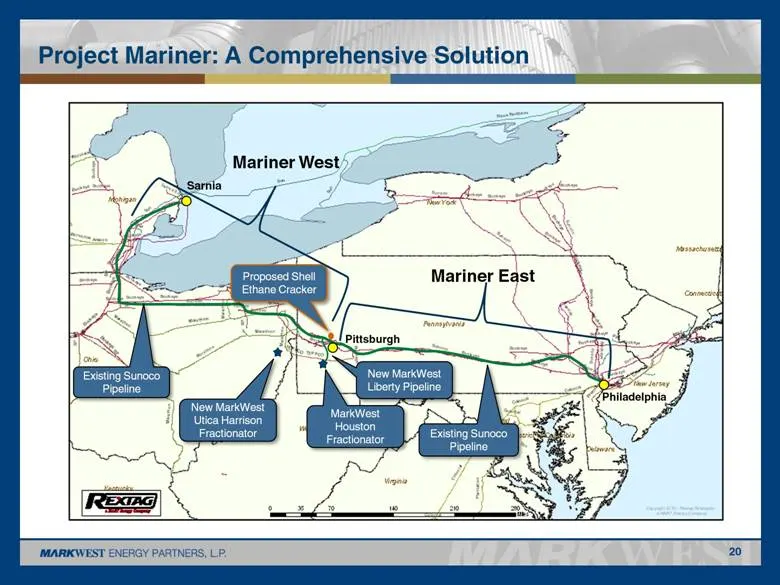
Project Mariner: A Comprehensive Solution 20 MarkWest Houston Fractionator Mariner East Mariner West New MarkWest Liberty Pipeline Existing Sunoco Pipeline Existing Sunoco Pipeline Sarnia Pittsburgh Philadelphia Proposed Shell Ethane Cracker New MarkWest Utica Harrison Fractionator
Slide 21: Financial Overview
Financial Overview
Slide 22: 2012 DCF and Capital Expenditure Forecast
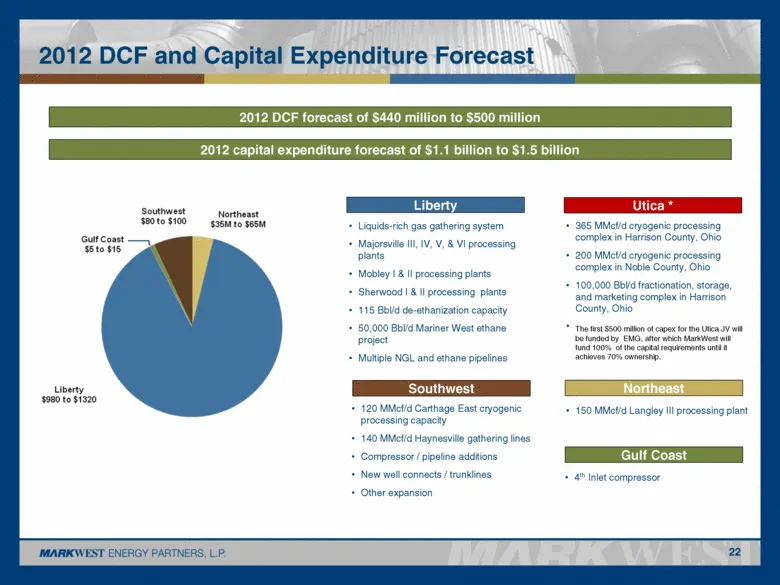
2012 DCF and Capital Expenditure Forecast Liberty Northeast Southwest 22 2012 DCF forecast of $440 million to $500 million 2012 capital expenditure forecast of $1.1 billion to $1.5 billion Utica * * The first $500 million of capex for the Utica JV will be funded by EMG, after which MarkWest will fun
Slide 23: Capital Markets and Liquidity Update
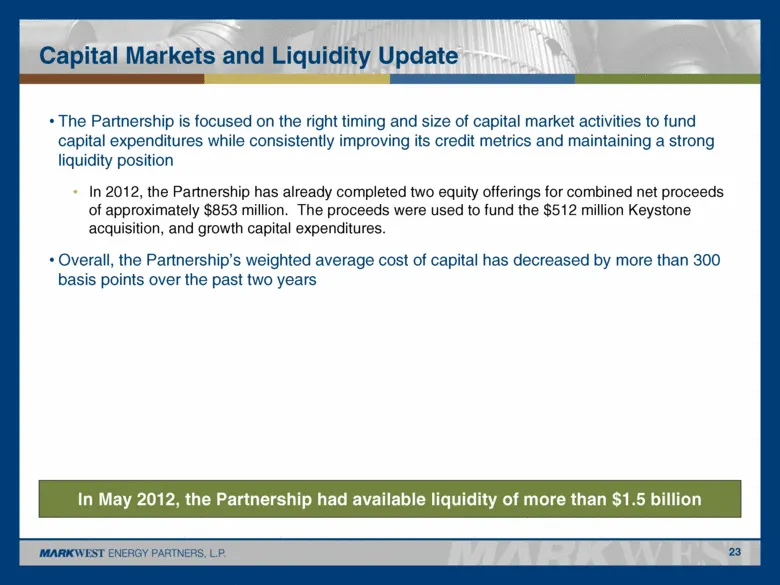
Capital Markets and Liquidity Update The Partnership is focused on the right timing and size of capital market activities to fund capital expenditures while consistently improving its credit metrics and maintaining a strong liquidity position In 2012, the Partnership has already completed two equity
Slide 24: Capital Structure
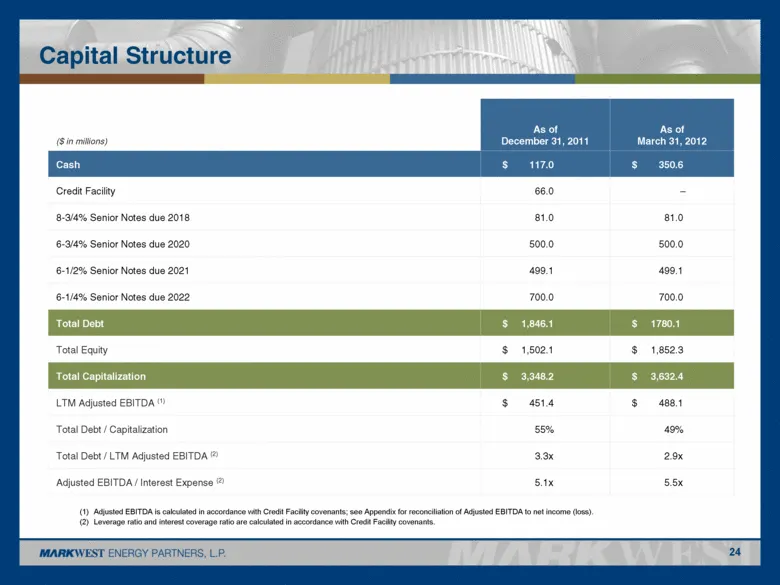
Capital Structure ($ in millions) As of December 31, 2011 As of March 31, 2012 Cash $ 117.0 $ 350.6 Credit Facility 66.0 – 8-3/4% Senior Notes due 2018 81.0 81.0 6-3/4% Senior Notes due 2020 500.0 500.0 6-1/2% Senior Notes due 2021 499.1 499.1 6-1/4% Senior Notes due 2022 700.0 700.0 Total Debt $ 1,
Slide 25: Strong Distribution Growth and Unit Performance
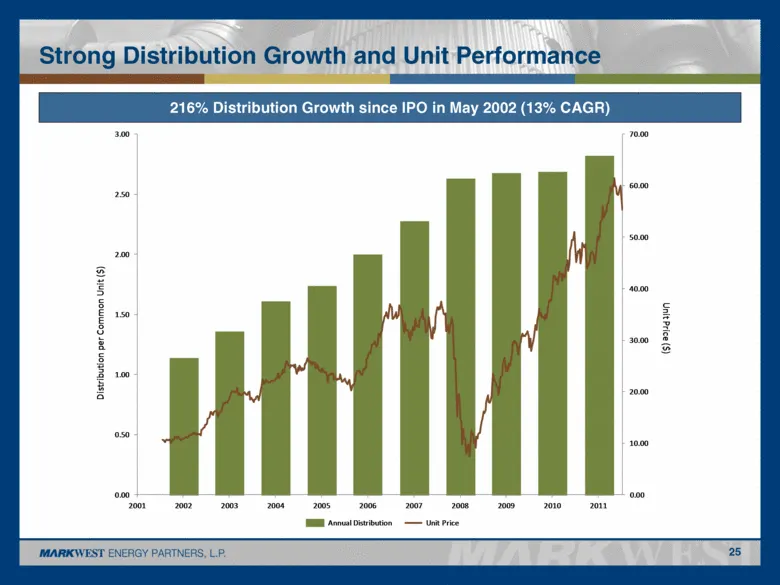
Strong Distribution Growth and Unit Performance 216% Distribution Growth since IPO in May 2002 (13% CAGR) 25 0.00 0.50 1.00 1.50 2.00 2.50 3.00 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 0.00 10.00 20.00 30.00 40.00 50.00 60.00 70.00 Distribution per Common Unit ($) Unit Price ($) Annual
Slide 26: Risk Management Program
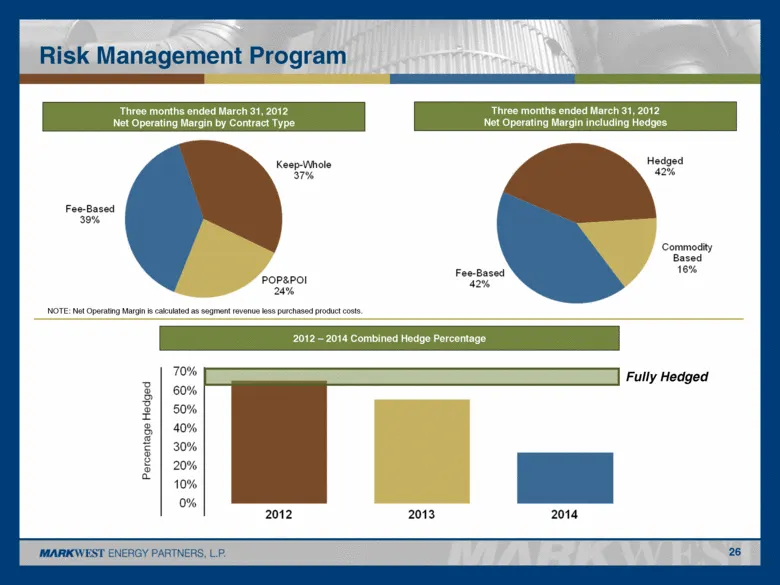
Risk Management Program 26 2012 – 2014 Combined Hedge Percentage NOTE: Net Operating Margin is calculated as segment revenue less purchased product costs. Three months ended March 31, 2012 Net Operating Margin including Hedges Three months ended March 31, 2012 Net Operating Margin by Contract Type F
Slide 27: Cost of Equity Capital
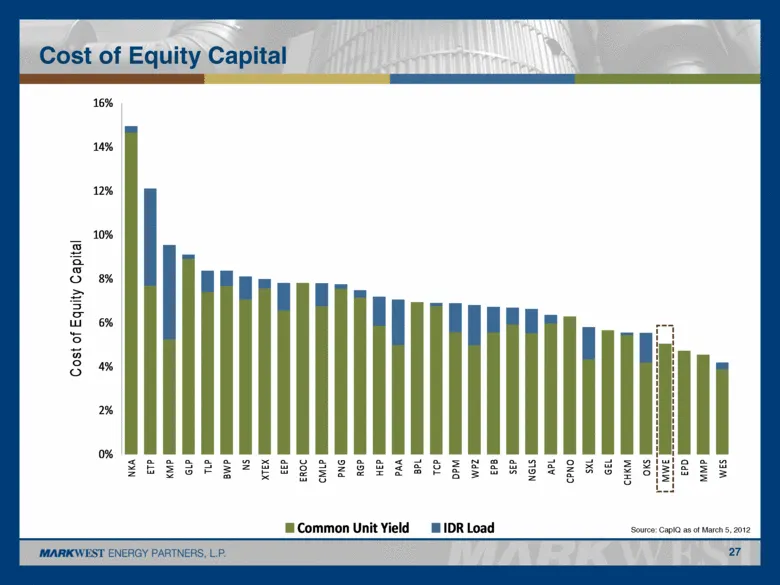
Cost of Equity Capital Source: CapIQ as of March 5, 2012 27 0% 2% 4% 6% 8% 10% 12% 14% 16% NKA ETP KMP GLP TLP BWP NS XTEX EEP EROC CMLP PNG RGP HEP PAA BPL TCP DPM WPZ EPB SEP NGLS APL CPNO SXL GEL CHKM OKS MWE EPD MMP WES Cost of Equity Capital Common Unit Yield IDR Load
Slide 28: Keys to Success
Keys to Success Maintain stronghold in key resource plays with high-quality assets Execute growth projects that are well diversified across the asset base Provide best-in-class midstream services for our producer customers Preserve strong financial profile Deliver superior and sustainable total retu
Slide 29: Appendix
Appendix MARKWEST ENERGY PARTNERS, L.P.
Slide 30: Reconciliation of DCF and Distribution Coverage
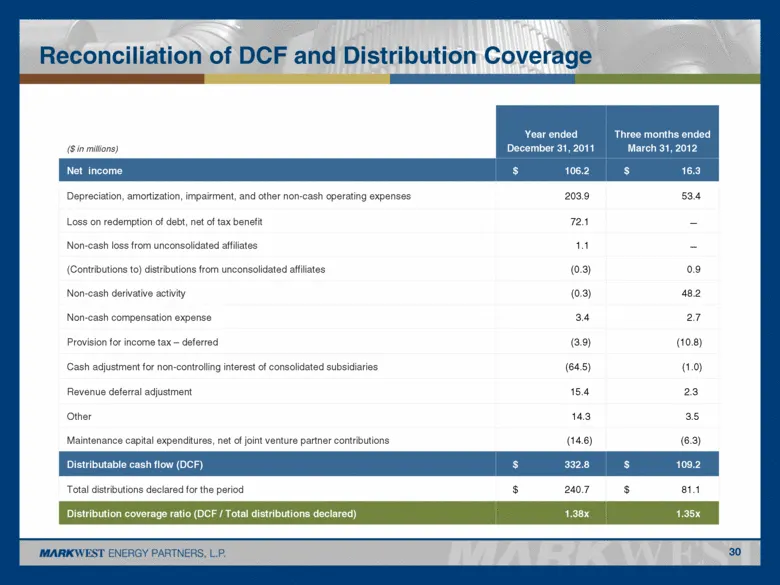
Reconciliation of DCF and Distribution Coverage ($ in millions) Year ended December 31, 2011 Three months ended March 31, 2012 Net income $ 106.2 $ 16.3 Depreciation, amortization, impairment, and other non-cash operating expenses 203.9 53.4 Loss on redemption of debt, net of tax benefit 72.1 - Non-
Slide 31: Reconciliation of Adjusted EBITDA
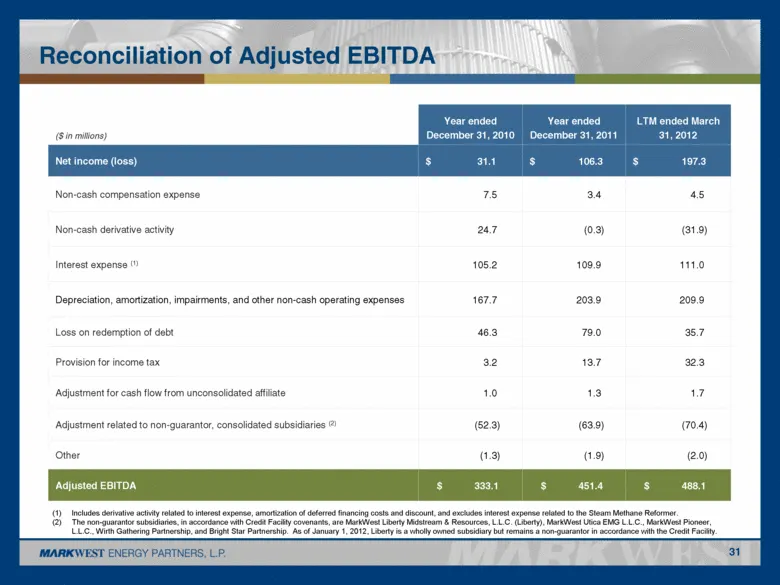
Reconciliation of Adjusted EBITDA ($ in millions) Year ended December 31, 2010 Year ended December 31, 2011 LTM ended March 31, 2012 Net income (loss) $ 31.1 $ 106.3 $ 197.3 Non-cash compensation expense 7.5 3.4 4.5 Non-cash derivative activity 24.7 (0.3) (31.9) Interest expense (1) 105.2 109.9 111.
Slide 32: Reconciliation of Net Operating Margin
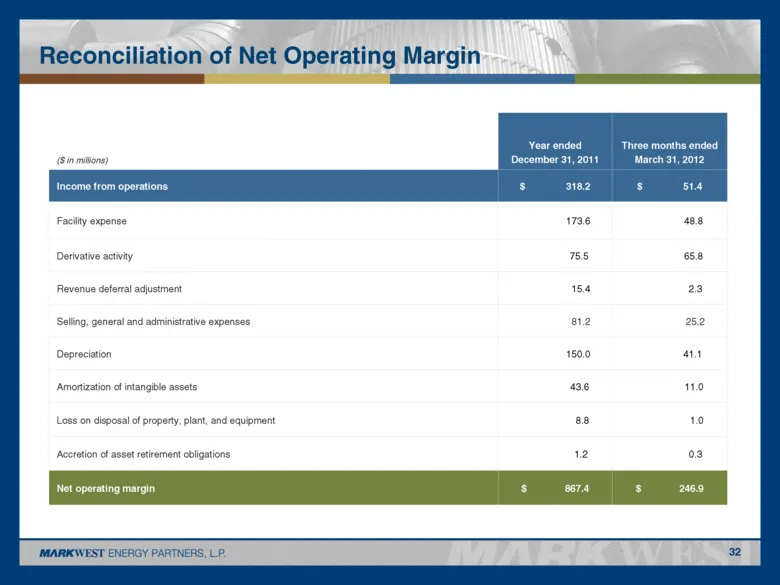
Reconciliation of Net Operating Margin ($ in millions) Year ended December 31, 2011 Three months ended March 31, 2012 Income from operations $ 318.2 $ 51.4 Facility expense 173.6 48.8 Derivative activity 75.5 65.8 Revenue deferral adjustment 15.4 2.3 Selling, general and administrative expenses 81.2
Slide 33: Contact and Investor Relations
1515 Arapahoe Street Tower 1, Suite 1600 Denver, Colorado 80202 Phone: 303-925-9200 Investor Relations: 866-858-0482 Email: [email protected] Website: www.markwest.com 33
Source: SEC EDGAR · 8-K filed May 23, 2012
More decks from Markwest Energy Partners LP
 Fact Sheet (July 2017)1 slide · July 2017
 Fact Sheet (July 2017)1 slide · July 2017
 Fact Sheet (July 2017)1 slide · July 2017
 Markwest Energy Partners L P — Investor Day (December 2015)116 slides · Dec 3, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 13, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 12, 2015