Copano Energy L.L.C — Platts Midstream Development & Management Conference 2011
18 slides from Copano Energy L.L.C's conference presentation, May 12, 2011
Slide 1: Platts Midstream Development & Management Conference
Platts Midstream Development & Management Conference May 12, 2011 NASDAQ: CPNO
Slide 2: Disclaimer
Disclaimer This presentation includes “forward-looking statements,” as defined in the federal securities laws. Statements that address activities or events that Copano believes will or may occur in the future are forward-looking statements. These statements include, but are not limited to, statement
Slide 3: Operating Segments
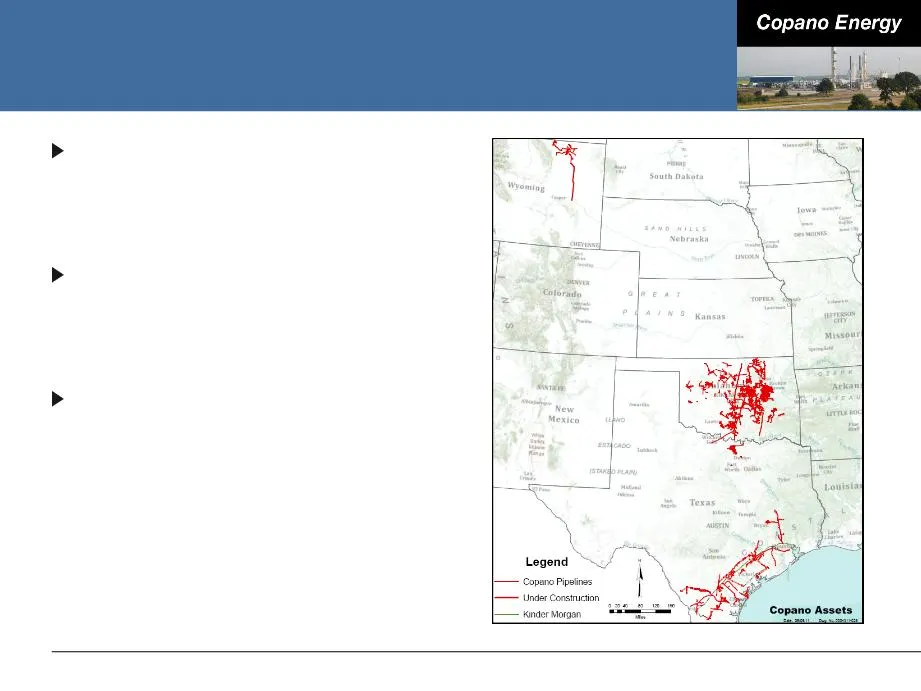
Operating Segments Texas ■ Conventional, Eagle Ford Shale and north Barnett Shale Combo play Oklahoma ■ Conventional, Hunton dewatering play and Woodford Shale Rocky Mountains ■ Powder River Basin
Slide 4: Eagle Ford Landscape
Eagle Ford Landscape Eagle Ford is currently the best-situated U.S. shale play ■ Regulatory environment familiar with industry ■ Land owners are more industry-friendly ■ Some existing infrastructure ■ Proximity to large consuming market, industrial load and petrochemical markets Significant producer
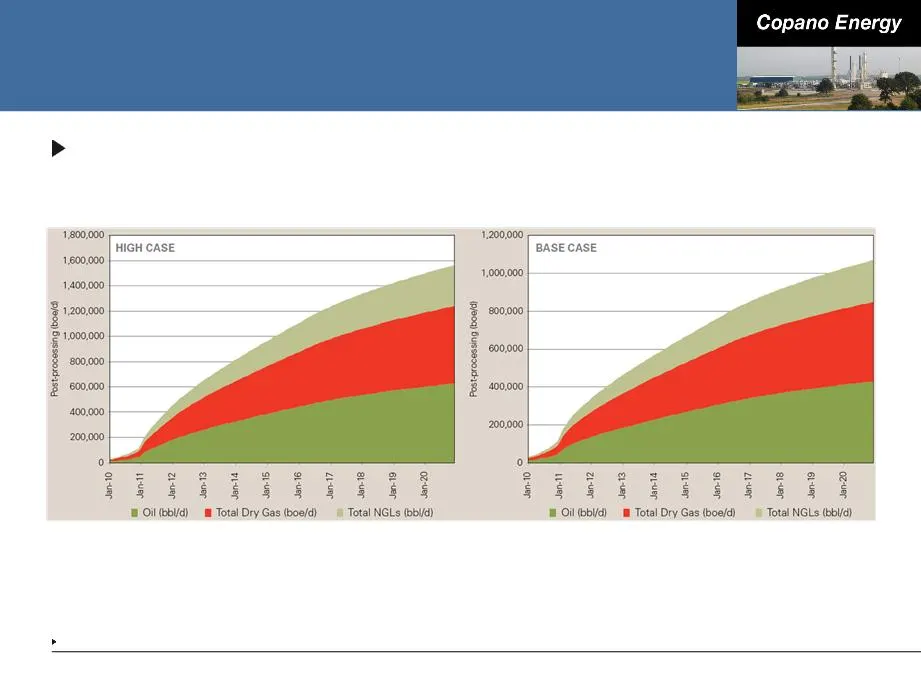
Slide 5: Eagle Ford Volume Growth Outlook
Eagle Ford Volume Growth Outlook Volume growth driven by oil, NGLs and natural gas ■ Post-processing NGLs could be over 320,000 Bbls/d by year-end 2020 (1) Source: Ross Smith Energy Group. Source: Ross Smith Energy Group
Slide 6: Copano's Strategy
Copano’s Eagle Ford Shale Strategy Utilize existing assets as a platform to provide additional midstream solutions for rich Eagle Ford Shale production in excess of 1 Bcf/d of gas and just under 100,000 Bbls/d of NGLs Leverage existing assets ■ Gathering ■ Processing ■ Fractionation ■ NGL transporta
Slide 7: Northern: DK Pipeline
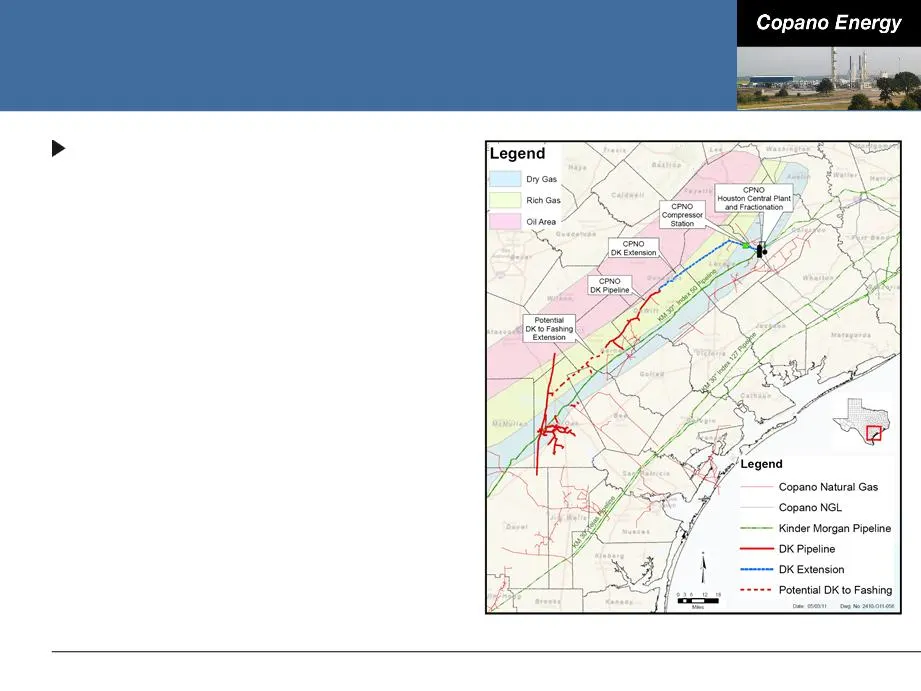
Northern Eagle Ford Shale DK Pipeline ■ Existing pipeline - 38 miles of 24” pipe placed into full service October ■ February 2011 - announced extension of existing pipeline back to Houston Central Complex ● Additional 58 miles of 24” pipe ● Expected completion in 4Q 2011 ■ Current capacity of 225,00
Slide 8: Northern: DK Pipeline
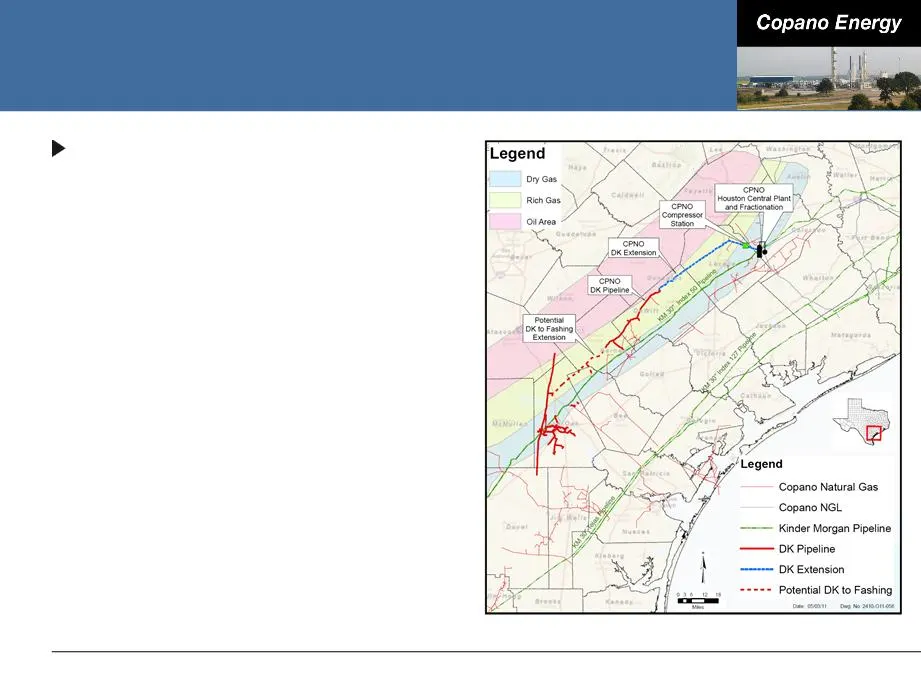
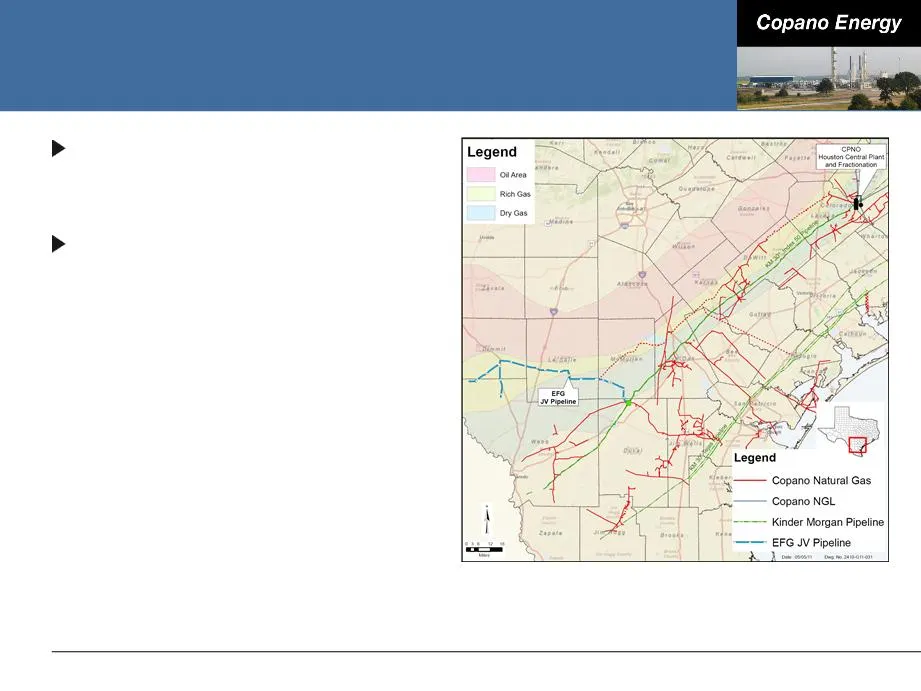
Northern Eagle Ford Shale DK Pipeline ■ Services the most prolific rich gas window in the Eagle Ford Shale ■ Loops Kinder Morgan Index 50 pipeline, effectively boosting pipeline capacity to Houston Central ■ Key producer contracts with Abraxas, GeoSouthern, Petrohawk, Pioneer, Riley and others ■ Exi
Slide 9: Southern: Eagle Ford Gathering (EFG)
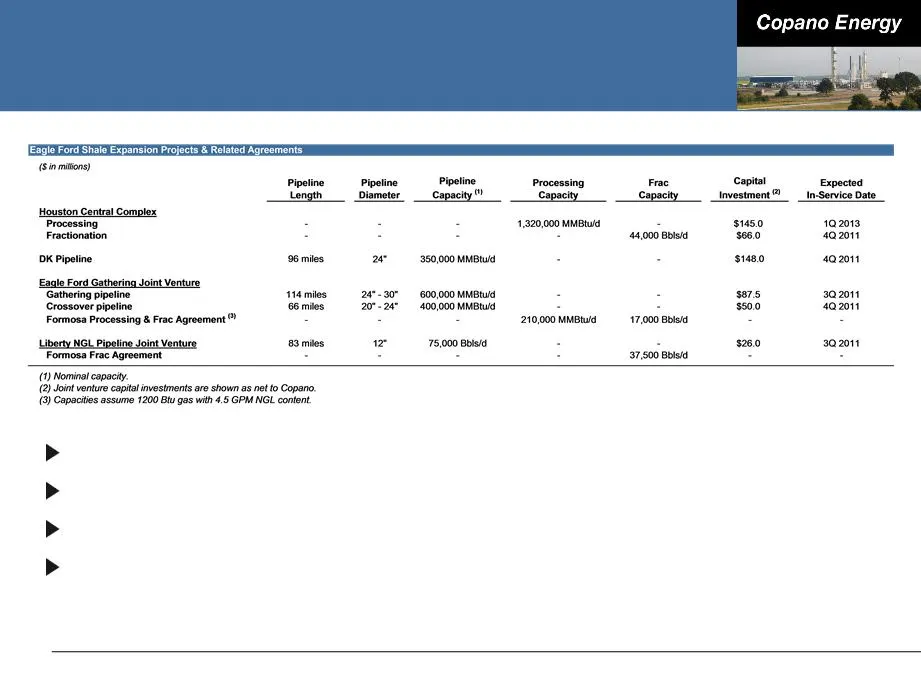
Southern Eagle Ford Shale Eagle Ford Gathering (EFG) ■ 50/50 JV with Kinder Morgan EFG pipeline ■ 114 miles of 30” and 24” pipe - currently under construction ■ Expected completion 3Q2011 ■ Nominal capacity of 600,000 MMBtu/d ■ Long-term, fee-based contracts with aggregate volume commitments approac
Slide 10: Eagle Ford Gathering Crossover Project
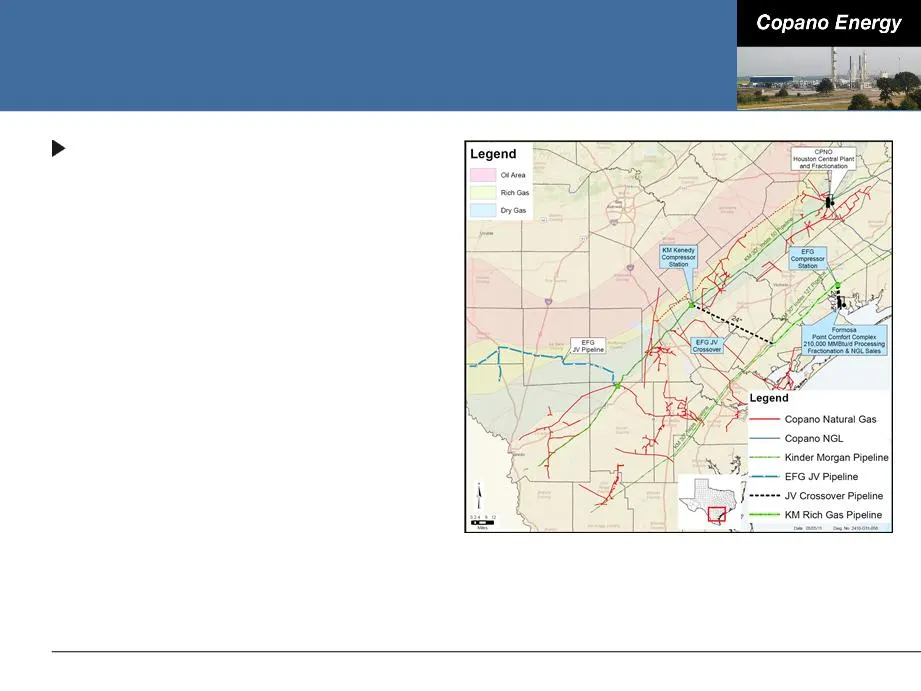
Eagle Ford Gathering Crossover Project Crossover project ■ 66 miles of 24” and 20” pipe connecting Kinder Morgan’s Index 50 and Tejas 30” pipelines to Formosa ● Nominal pipeline capacity of 400,000 MMBtu/d ● Expected completion 4Q2011 ■ Allows an incremental 210,000 MMBtu/d of gas to flow on Eagle F
Slide 11: Houston Central Complex
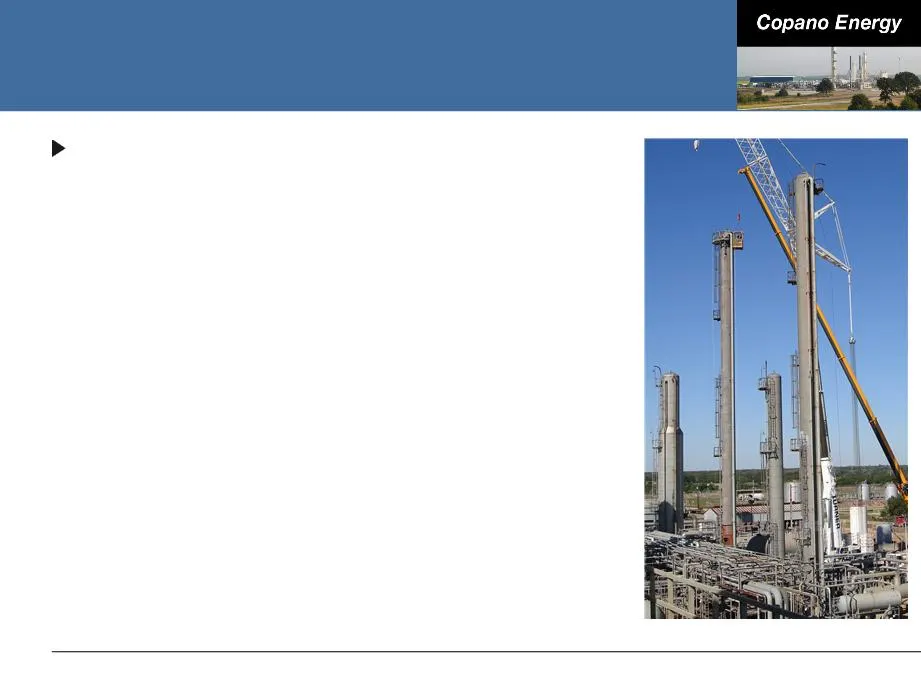
Houston Central Complex Current capacity of 700 MMcf/d ■ 500 MMcf/d of lean oil processing ■ 200 MMcf/d of cryogenic processing Multiple residue interconnects ■ Anticipated additional connection - Tres Palacios storage and header system Cryogenic processing expansion of 400 MMcf/d in progress ■ Impr
Slide 12: Houston Central Complex
Houston Central Complex Fractionation expansion ■ Responding to increased producer demand, liquids handling capacity will double at Houston Central Complex ■ Fractionation expansion from 22,000 Bbls/d to 44,000 Bbls/d ● All ethane and propane will move to Dow through Copano purity pipelines ■ Total
Slide 13: Liberty NGL Pipeline
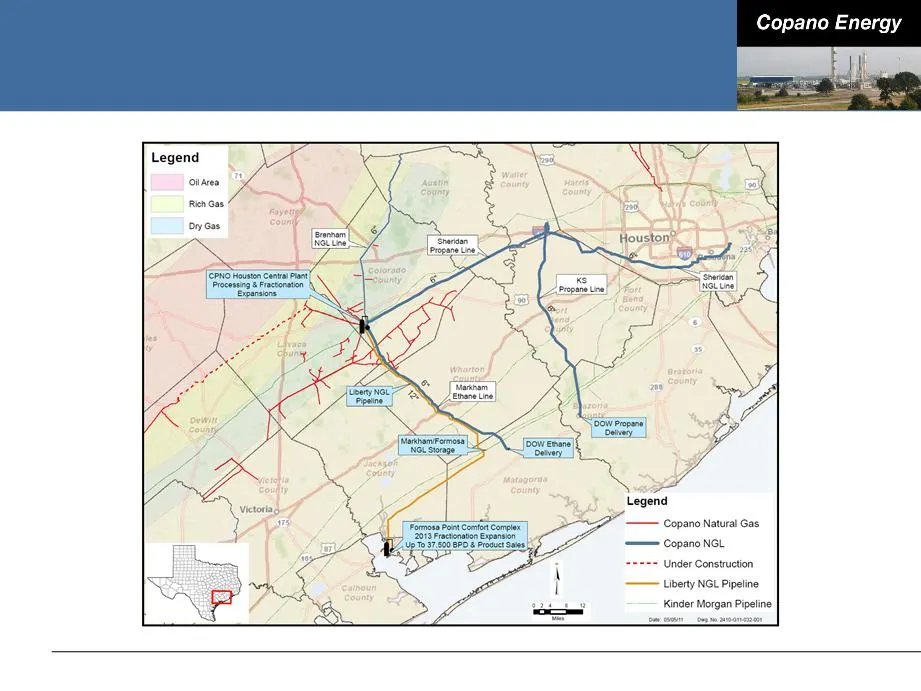
Liberty NGL Pipeline 83-mile, 12” NGL pipeline extending from the Houston Central Complex to Markham NGL storage and Formosa’s Point Comfort Complex ■ Total capacity of 75,000 Bbls/d ■ Constructed through 50/50 JV with Energy Transfer ■ Expected completion early 3Q2011 Long-term fractionation and pr
Slide 14: Houston Central NGL Infrastructure
Houston Central NGL Infrastructure
Slide 15: Gulf Coast Petrochemical Market Access
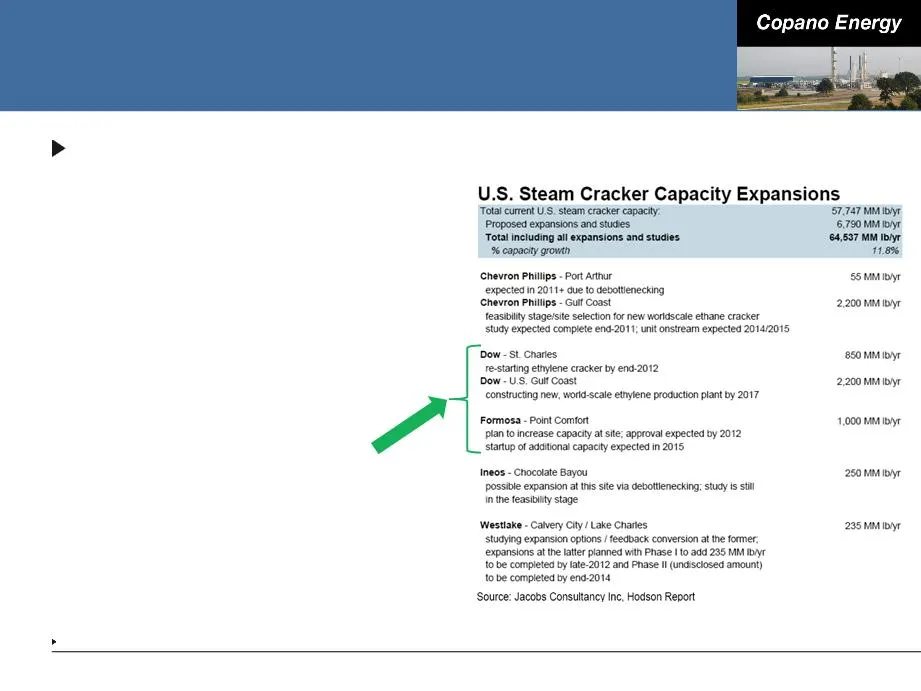
Gulf Coast Petrochemical Market Access Copano has access to Dow and, upon completion of the Liberty NGL pipeline, Formosa Source: Hodson Report. ■ Among the largest end users of NGLs in the U.S. ■ Taking into account announced expansions, Dow and Formosa’s combined steam cracker capacity is approxim
Slide 16: Summary of Infrastructure
Summary of Eagle Ford Shale Infrastructure Total capital investment of over $500 million In excess of 1 Bcf/d of pipeline and processing capacity Approaching 100,000 Bbls/d of fractionation capacity Access to multiple markets for residue gas and NGLs
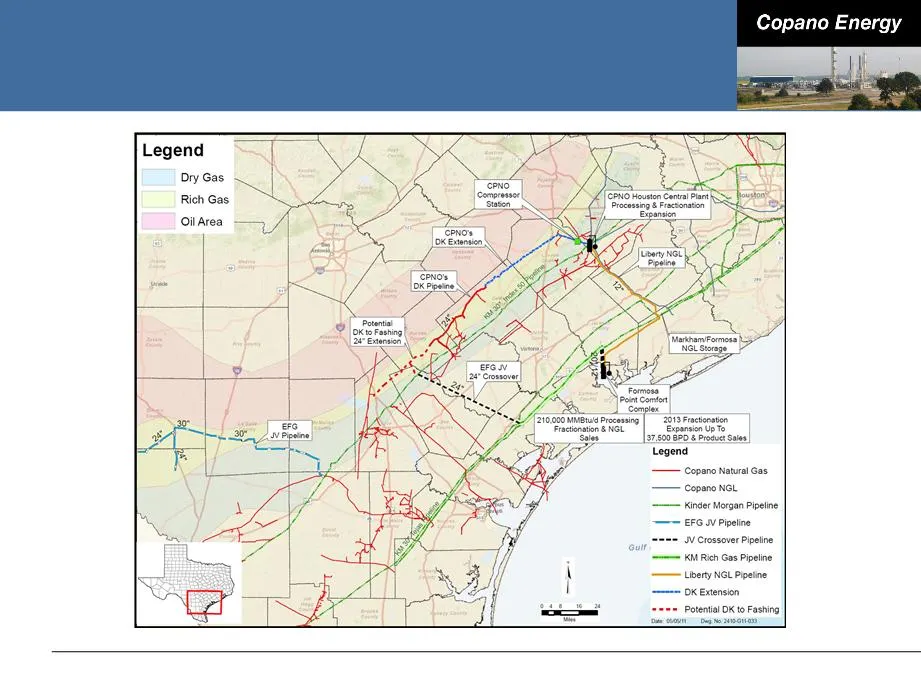
Slide 17: Combined Eagle Ford Map
Combined Eagle Ford Map
Slide 18: Conclusions
Conclusions Focused on execution in the Eagle Ford Shale Multiple projects underway with in-service dates beginning in 2011 Access to multiple residue markets and NGL markets Producer support has been strong but capacity still available Ample access to capital and liquidity for existing projects and
Source: SEC EDGAR · 8-K filed May 12, 2011
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011