Endeavour International — Pareto E&P Independents' Conference 2009
21 slides from Endeavour International's conference presentation, Jan 21, 2009
Slide 1: Pareto E&P Independents' Conference
Pareto E&P Independents’ Conference 21 January 2009 Exhibit 99.1
Slide 2: Endeavour at a Glance
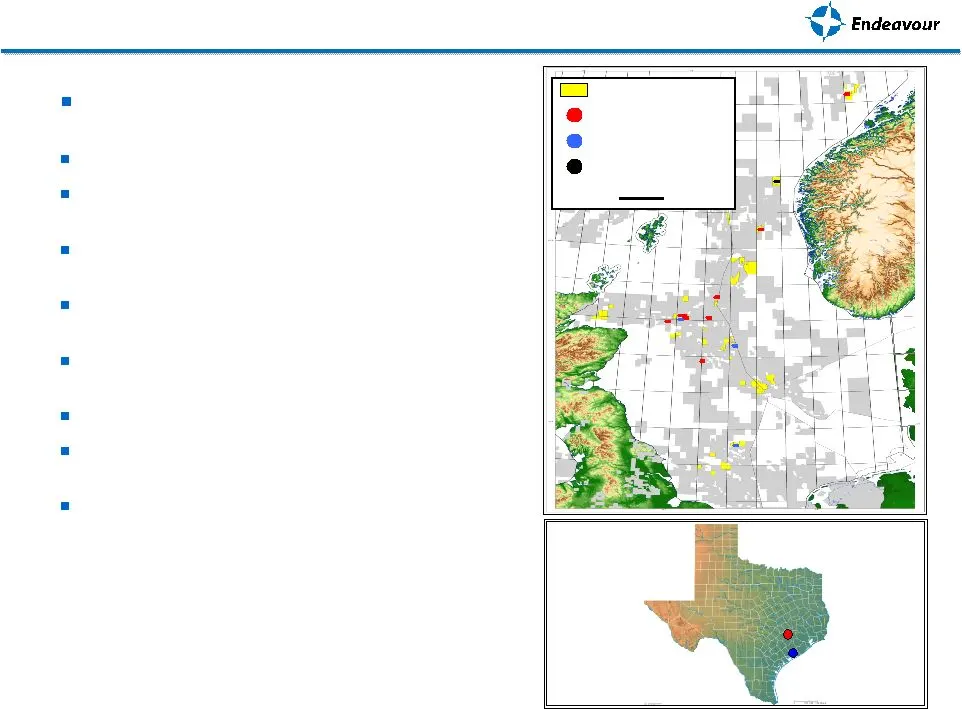
2008 discretionary cash flow $130 - $140 million 2008 ending cash balance +/-$60 million $50-$60 million value of current hedge position (4Q08 gain in excess of $100 million) 2008 production in middle of forecast range +/- 8,900 boe/d Successful E&A process – 11 consecutive successes Recent launch o
Slide 3: Potential Production Growth
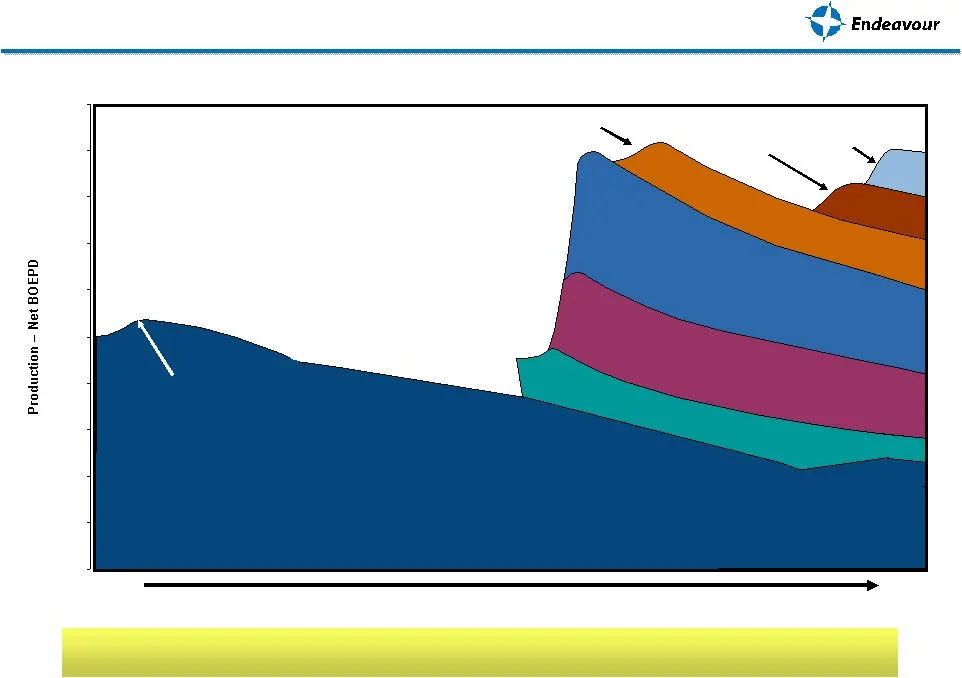
Njord Gas Blowdown Columbus US R-Blocks Base Potential Production Growth 2007 2012 Existing Opportunities Have Potential to Deliver Strong Production Cygnus Phase I 2009 Risked Exploration Cygnus Phase II 2,000 4,000 6,000 8,000 10,000 12,000 14,000 16,000 18,000 20,000
Slide 4: Endeavour's North Sea Focus Areas
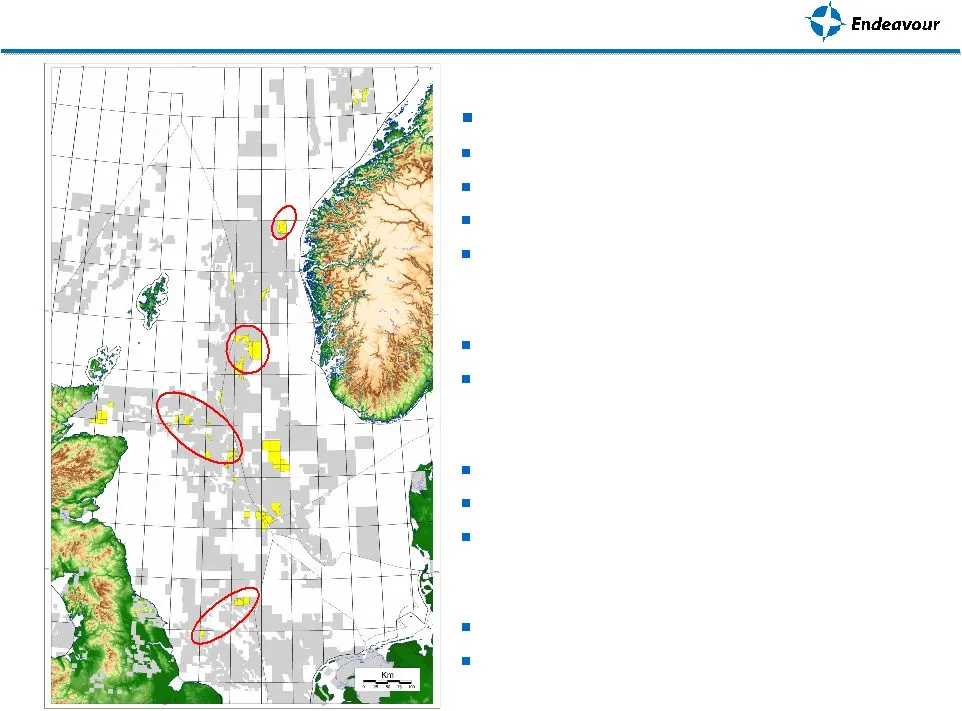
Endeavour’s North Sea Focus Areas Central North Sea Focus Area Rochelle appraisal significant success Rubie & Renee production & infrastructure 25th Round application 3 pending awards Columbus development Livingstone and 22/20b Columbus look-alikes Cygnus Focus Area Cygnus appraisal and development
Slide 5: Current North Sea Developments
Current North Sea Developments Name Current Working Interest Estimated Reserves (gross) Development Plan First Production Rochelle (operator) 55.6% 30+ mmboe (1) Recent appraisal success Q4 2008/Q1 2009, develop fast-track commercialisation scenarios. 2010 Cygnus 12.5% 570 bcf FDP filed. Phased deve
Slide 6: Rochelle Appraisal - UK Block 15/27
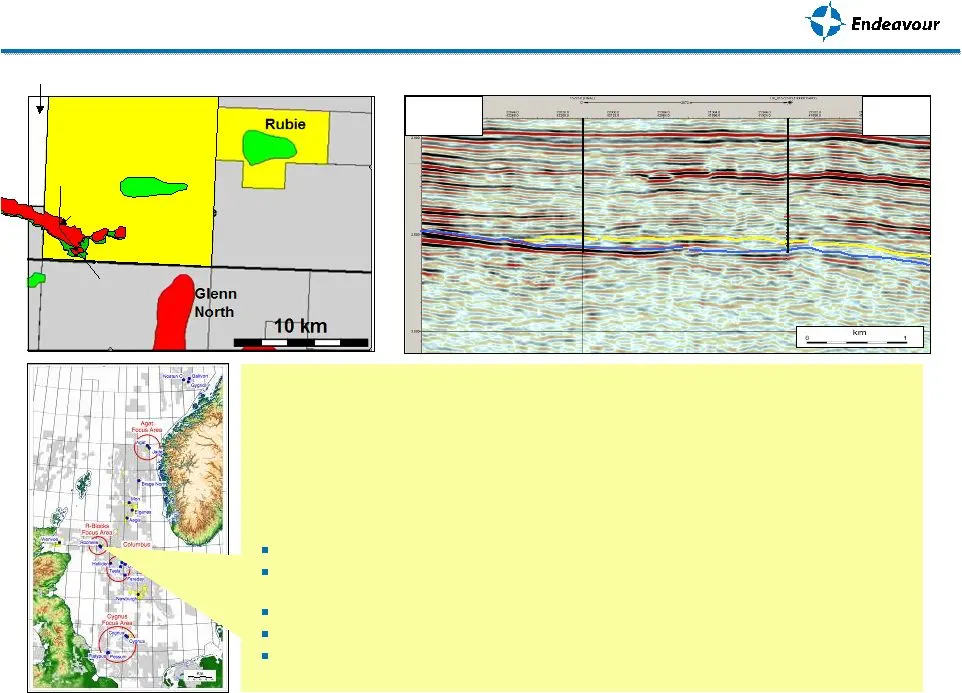
SE N Rochelle Appraisal - UK Block 15/27 Rochelle Appraisal Renee NNW SSE Appraisal Discovery ROCHELLE APPRAISAL Operator: Endeavour 55.615% Partner: Nexen 44.385% Well Timing: Well spud 30 November 2008 Rig Type: Semisubmersible Sedco Successful appraisal up-dip from the Rochelle oil and gas discov
Slide 7: Cygnus Fault Block IIb Appraisal - UK Block 44/12a
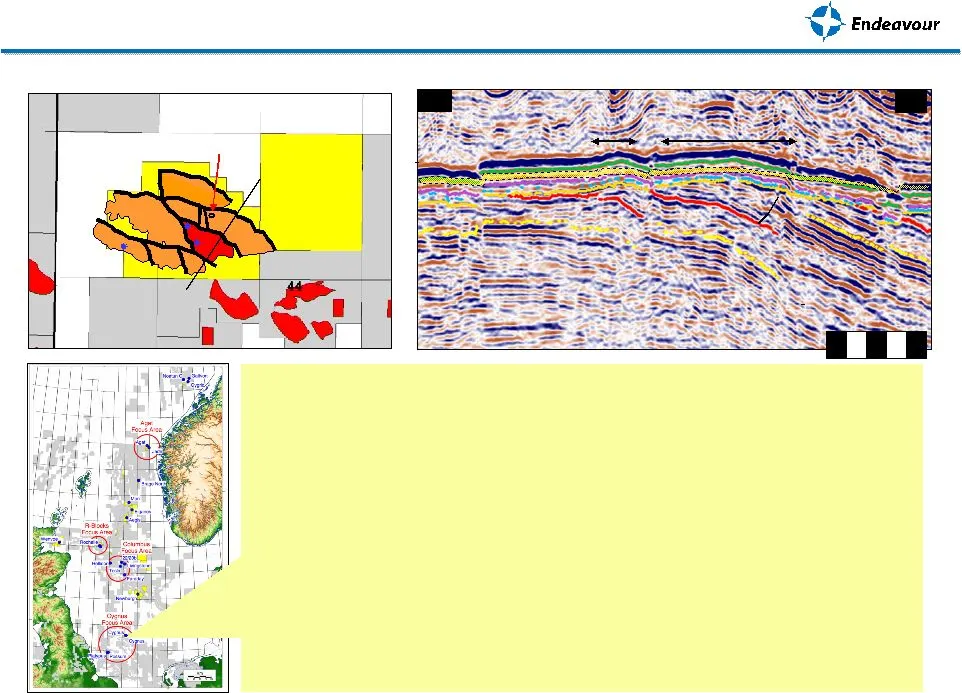
SW NE 2.2 2.5 11a 12a IIb 2 km III IV IIa IIb I Va Vb Vc I I Tyne North Hawkley Tyne South Gordon Cygnus Fault Block IIb Appraisal – UK Block 44/12a FBIIb Exploration location CYGNUS FAULT BLOCK IIB APPRAISAL Operator: Gaz de France 38.75% Partners: Endeavour 12.5% Venture 48.75% Well Timing: Q4 200
Slide 8: Columbus Development
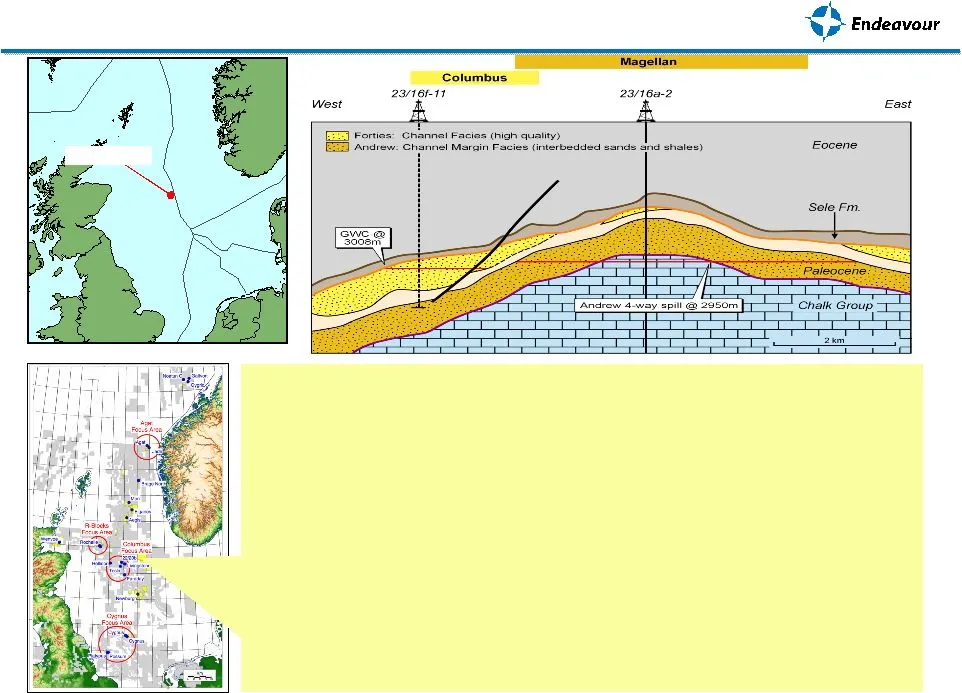
UK Norway Netherlands Columbus Development Columbus COLUMBUS DEVELOPMENT Operator: Serica 50% Partners: Endeavour 25% EOG 25% Online: 2011 FDP filed. Working to secure host platform; commercial agreements and procuring long- lead material. On block reserves of 98 bcf.
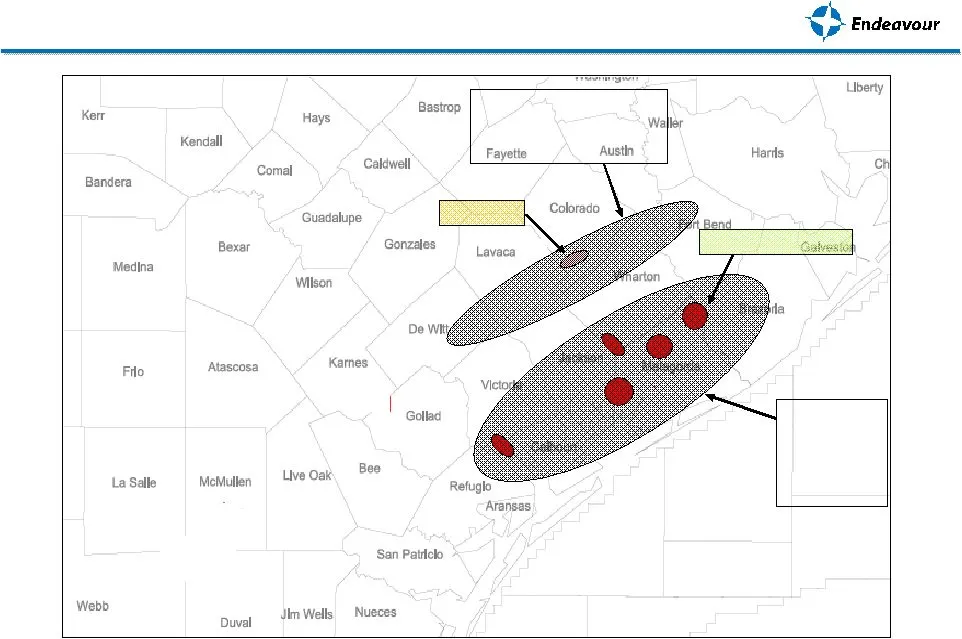
Slide 9: Kerr Hays
Kerr Hays Waller Kendall Fayette sth Hants Bandera Bexar Medina Wks McMullen Live San Patek 5 Jim Wells Duval
Slide 10
Slide 11
Slide 12: US Exploration and Development
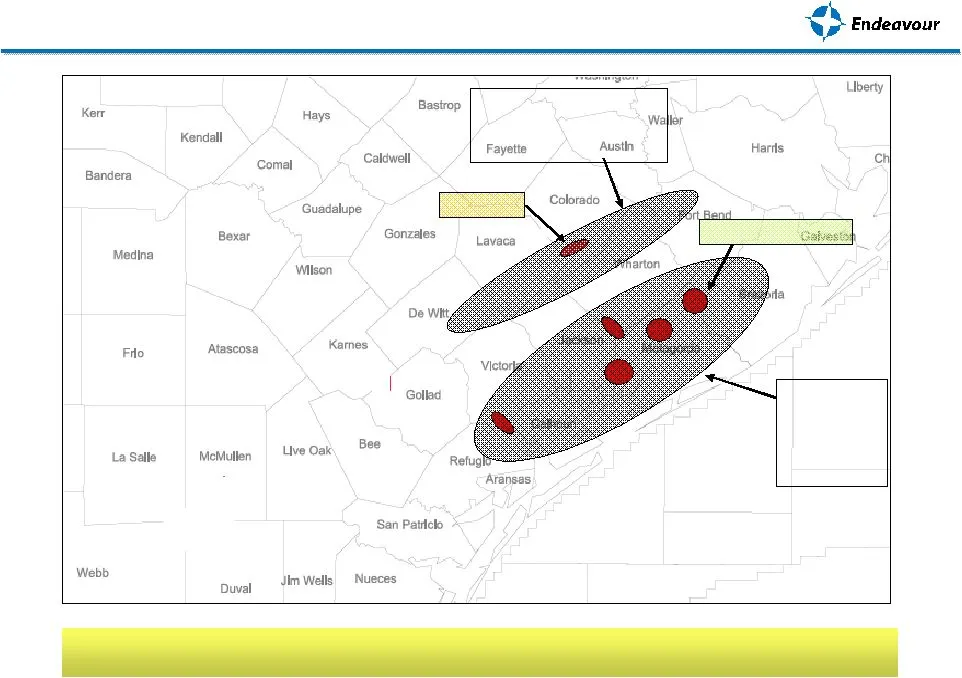
Garwood Prospect, Cochran #1 (15% Net Revenue Interest) Drilled to total depth of 16,870 feet Encountered three zones of potential natural gas pay Achieved stabilized daily flow rate of 6.2 million cubic feet gas, 96 barrels of oil On production Alligator Bayou, Armour Runnells ST#1 (7% Net Revenue
Slide 13: 2008 Exploration and Appraisal Drilling Program
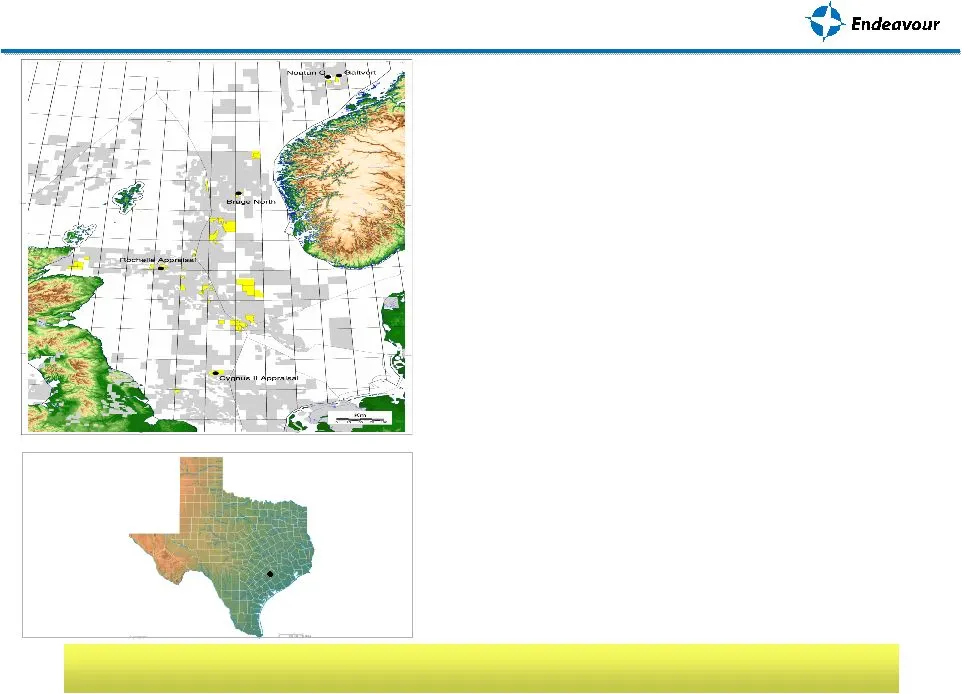
2008 Exploration and Appraisal Drilling Program 1. Galtvort (Norway) – 2.5% WI a. Gas discovery, results support decision to farmdown to 2.5% WI b. 60 to 100 BCF gross (1.5 to 2.5 BCF net or 0.25 to 0.42 MMOBE net) 2. Noatun C (Norway) – 2.5% WI a. Drilled to a total depth of 16,857 feet, target zon
Slide 14: 2009 North Sea Exploration and Drilling Program
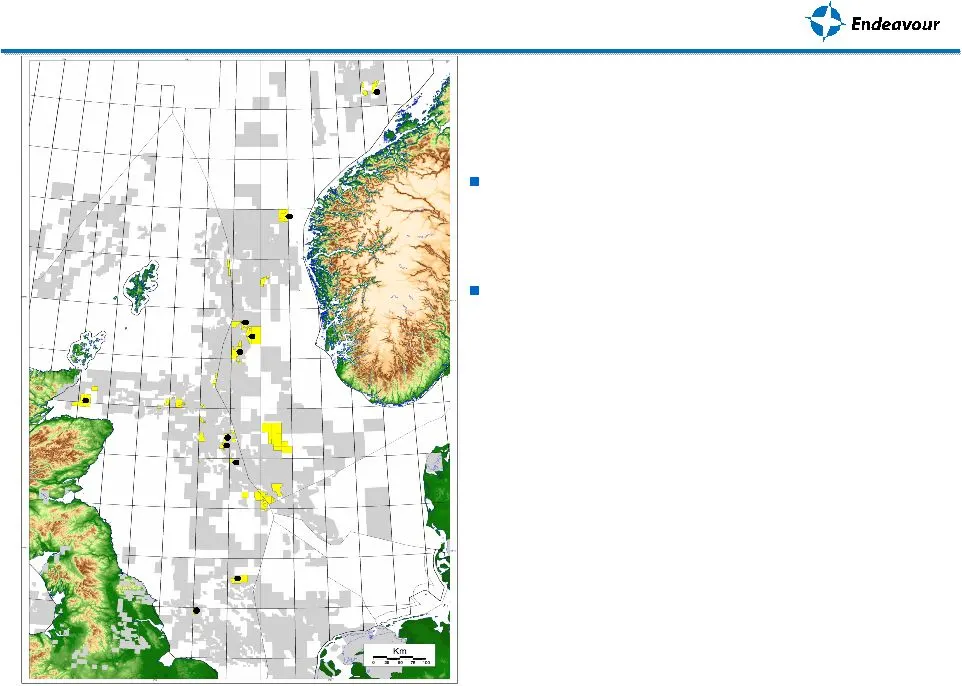
2009 North Sea Exploration and Drilling Program 11 North Sea exploration wells being planned Two appraisal wells •Cygnus Fault Block III in SNS •Cyclops in Quad 35 Norway Nine exploration wells •Three Tertiary targets in Quad 25 Norway (Mon, Aegis, Eiganes) •Two HTHP (Tesla & Faraday) & one Tertiary
Slide 15: Oo Endeavour
Mf) Oo Endeavour Kerr Bandera Medina LaSalle Webb Fayette ‘Austin Bastrop Hays Kendall Comal Caldwell Bexar Gonzales Wits Atascosa Kames MeMullen Live Oak San Patiicle Jim Wells, Nueces Duval Liberty Harts cr] Galves! - Be aS
Slide 16: Bore
ce Bore sfugh
Slide 17: Bore
ce Bore sfugh
Slide 18: Capital Structure Quiet and Improving
(millions) Capital Structure Capital Structure Quiet and Improving December 31, 2007 September 30, 2008 Cash 38.4 $ 47.7 $ Debt Characteristics Senior Bank Facility 110.0 113.0 Junior Bank Facility - - 2nd Lien (Libor plus 700 basis points) 75.0 - 6% Notes, due 2012 convertible @ $5.02 81.3 81.3 Tot
Slide 19: Hedging Statistics
Hedging Statistics OIL & NGL 2009 2010 2011 Oil Swaps (Avg 2009 $69.08/bbl) 697,020 573,084 487,356 Oil Collars (Avg 2009 $100/bbl Floor, $121.88/bbl Ceiling) 400,000 - - Bbl Hedged 1,097,020 573,084 487,356 Bbl/d Hedged 3,006 1,570 1,335 Price 80.40 $ 68.39 $ 66.01 $ GAS 2009 2010 2011 Gas Swaps (A
Slide 20: Acquisitions Show Excellent Returns
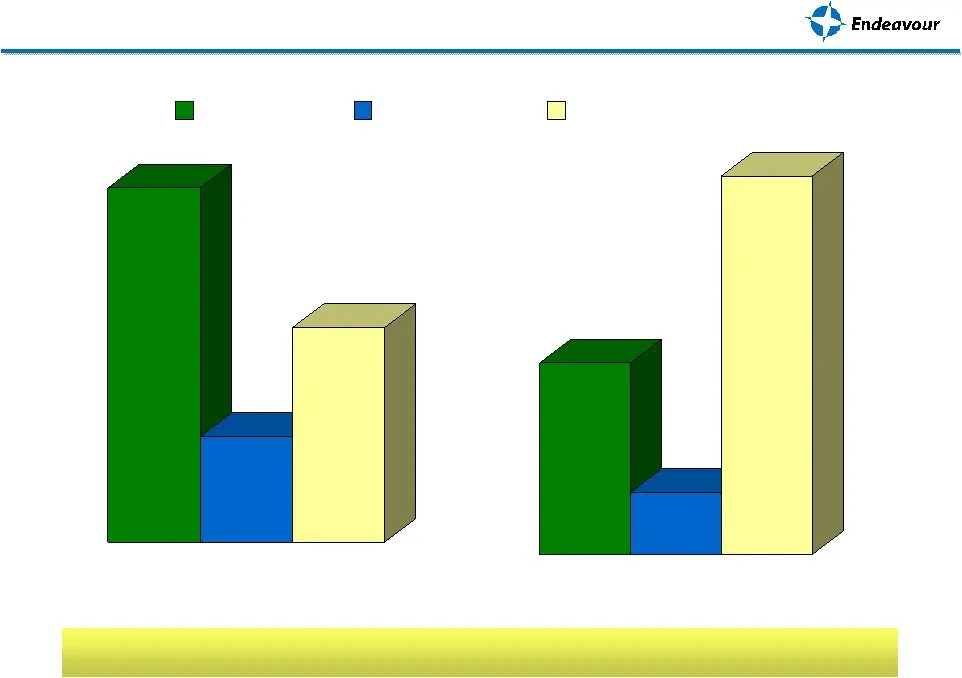
$40mm $13mm $79mm OER - Norway 163% Return Acquisitions Show Excellent Returns Acquisitions Outperforming Both Production and Price Expectations Purchase Price 2007 Net Cash Flow Inception to Date Cash Flow through September 30, 2008 $365mm $109mm $221mm Talisman - UK 51% Return
Slide 21: Conclusion
Balanced strategy with experienced global team in place — North Sea and U.S. Strong continuing cash flow from existing assets — self-funding Solid and improving capital structure Multiple growth channels to organically grow company • Development and exploitation of existing assets — North Sea and U.
Source: SEC EDGAR · 8-K filed Jan 21, 2009
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014