Tellurian — Investor Presentation (July 2022)
18 slides from Tellurian's investor presentation, Jul 13, 2022
Slide 1: Tellurian Inc. Corporate presentation
Tellurian Inc. Corporate presentation
Slide 2: Cautionary statements
Cautionary statements The information in this presentation includes “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. All statements other than statements of historical fact ar
Slide 3: The world is critically short natural gas
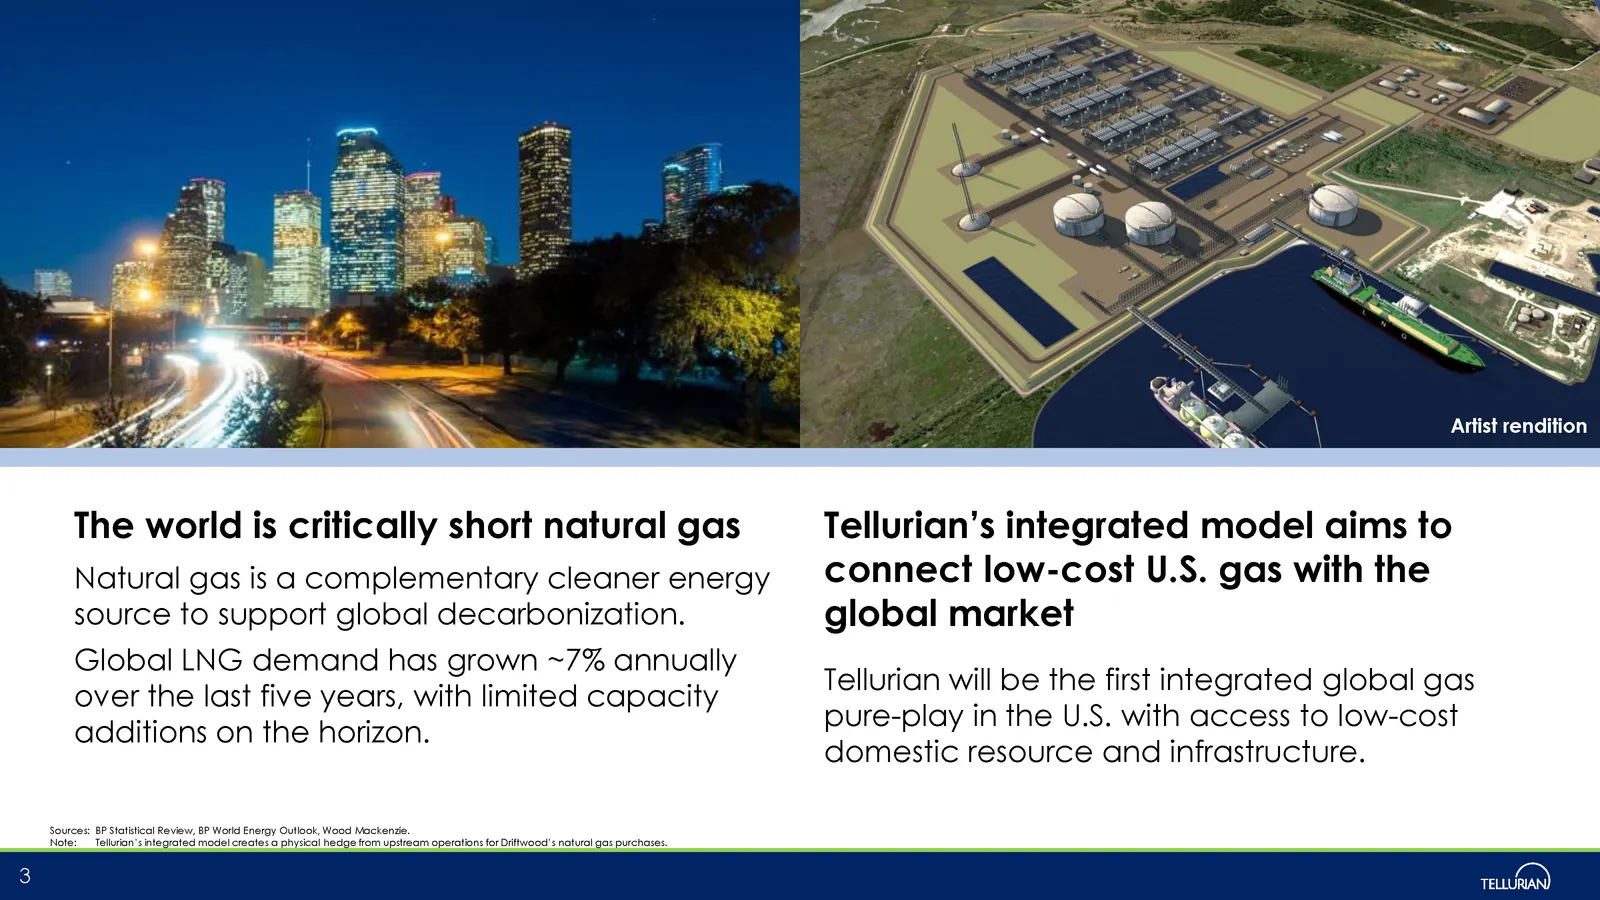
The world is critically short natural gas Natural gas is a complementary cleaner energy source to support global decarbonization. Global LNG demand has grown ~7% annually over the last five years, with limited capacity additions on the horizon. Tellurian’s integrated model aims to connect low-cost U
Slide 4: Tellurian executive summary
Tellurian executive summary 4 Bechtel commenced construction on Driftwood Phase 1 in April 2022 ▪ Completed owner’s projects on schedule in March 2022 and issued a limited notice to proceed to Bechtel in April 2022 ▪ Bechtel currently on-site performing demolition and site clearing; piling program c
Slide 5: EnSight expands Tellurian's upstream position
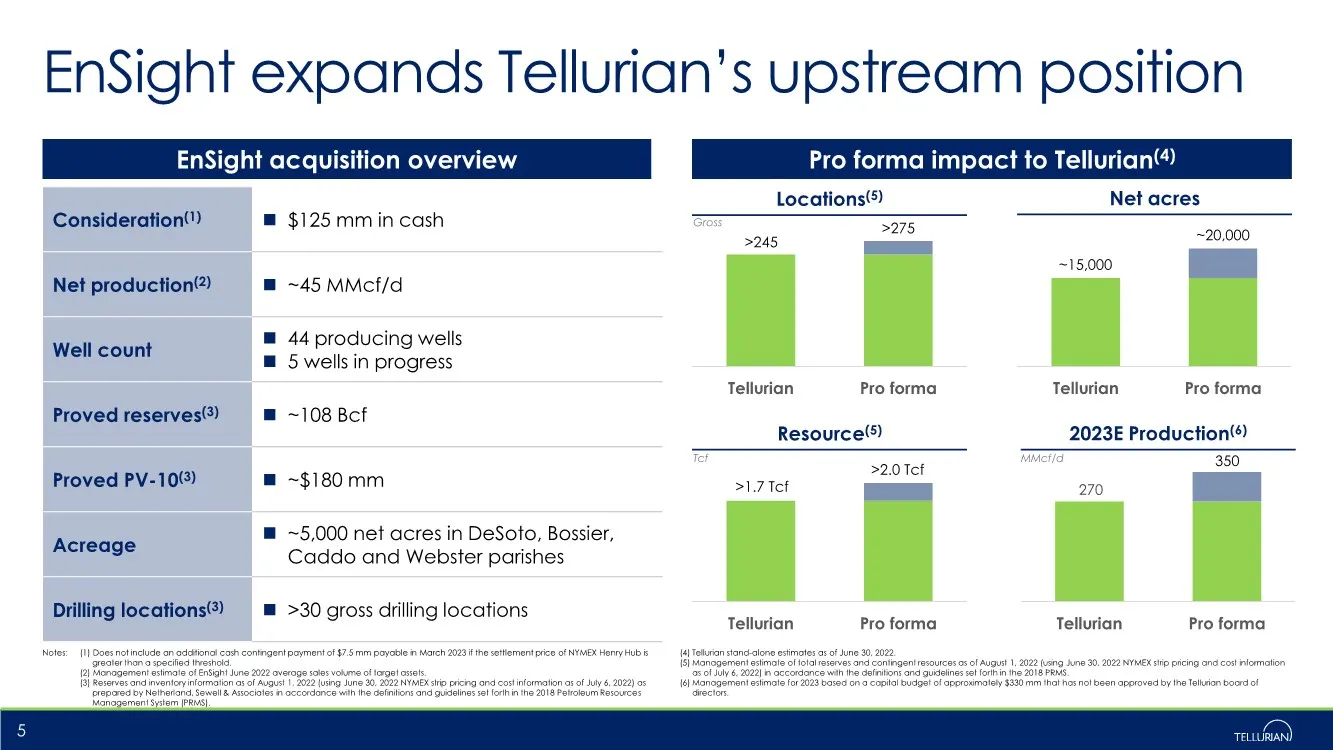
EnSight expands Tellurian’s upstream position Consideration(1) ◼ $125 mm in cash Net production(2) ◼ ~45 MMcf/d Well count ◼ 44 producing wells ◼ 5 wells in progress Proved reserves(3) ◼ ~108 Bcf Proved PV-10(3) ◼ ~$180 mm Acreage ◼ ~5,000 net acres in DeSoto, Bossier, Caddo and Webster parishes Dri
Slide 6: Tellurian: fully integrated, pure-play LNG
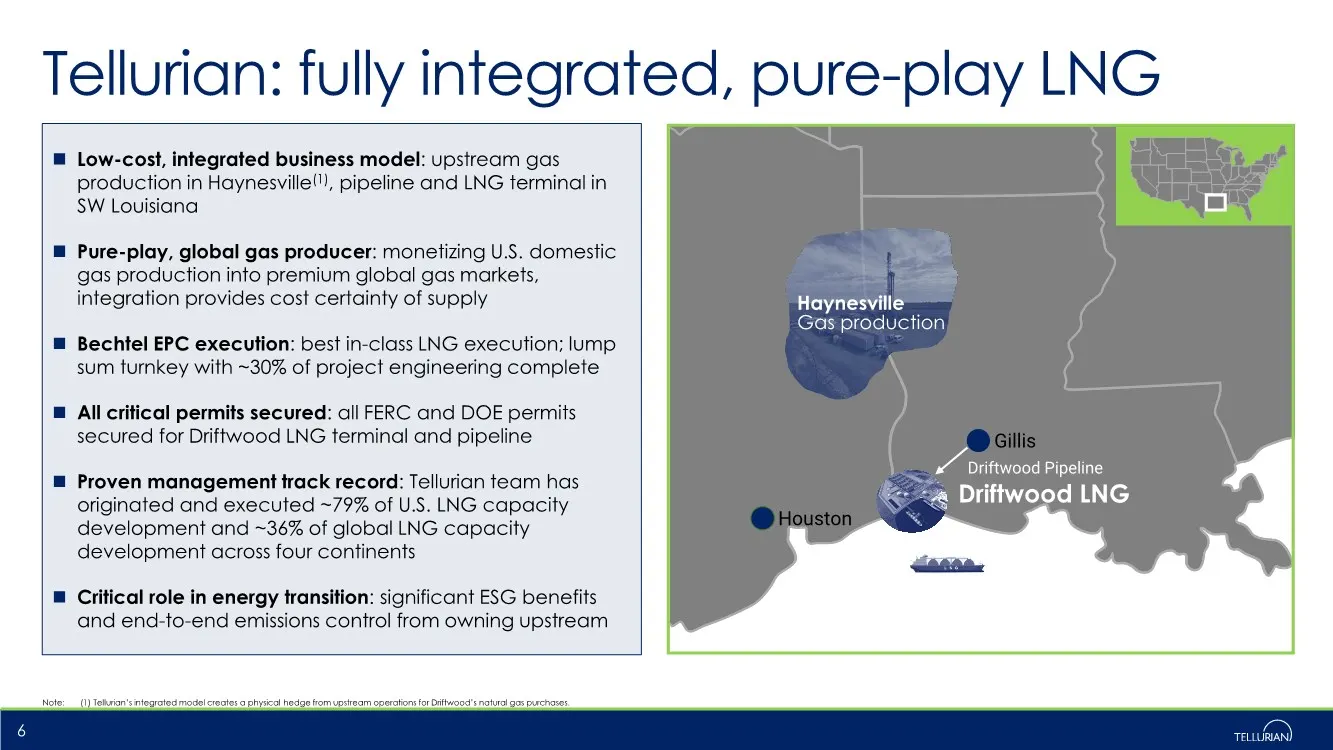
Houston Gillis Haynesville Gas production Driftwood LNG Driftwood Pipeline Tellurian: fully integrated, pure-play LNG 6 ◼ Low-cost, integrated business model: upstream gas production in Haynesville(1), pipeline and LNG terminal in SW Louisiana ◼ Pure-play, global gas producer: monetizing U.S. domest
Slide 7: Driftwood LNG Phase I (2-plant, ~11 mtpa)
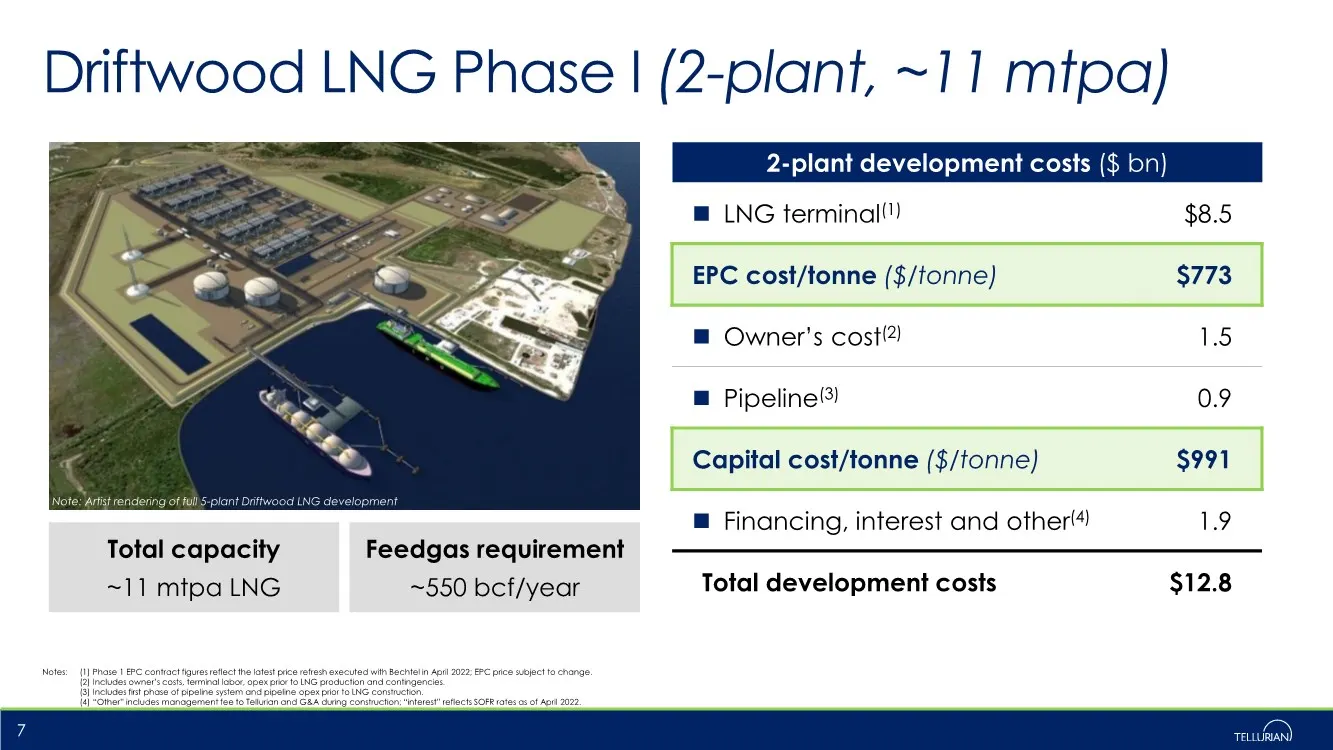
Driftwood LNG Phase I (2-plant, ~11 mtpa) Notes: (1) Phase 1 EPC contract figures reflect the latest price refresh executed with Bechtel in April 2022; EPC price subject to change. (2) Includes owner’s costs, terminal labor, opex prior to LNG production and contingencies. (3) Includes first phase of
Slide 8: Driftwood LNG: Phase I sold out
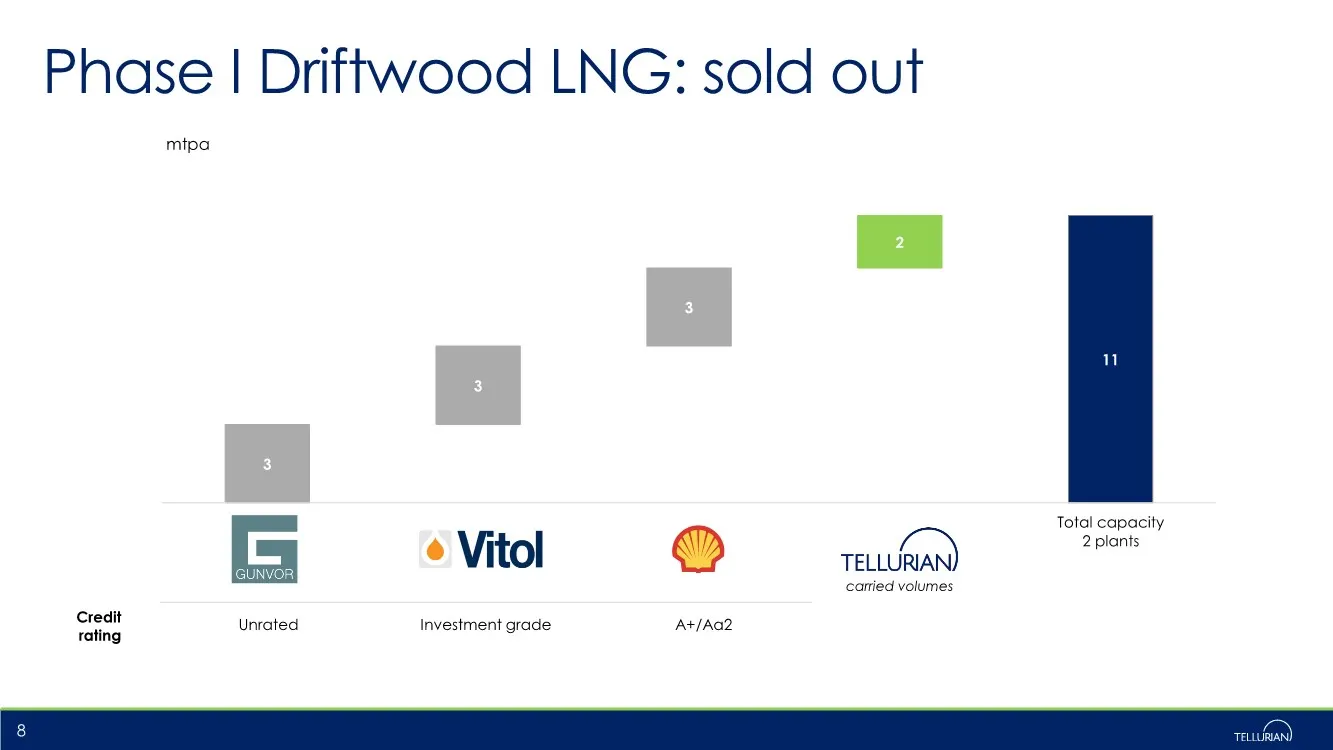
3 11 3 3 2 Total capacity 2 plants Credit rating Unrated Investment grade A+/Aa2 8 carried volumes mtpa Phase I Driftwood LNG: sold out
Slide 9: Driftwood LNG: construction in progress
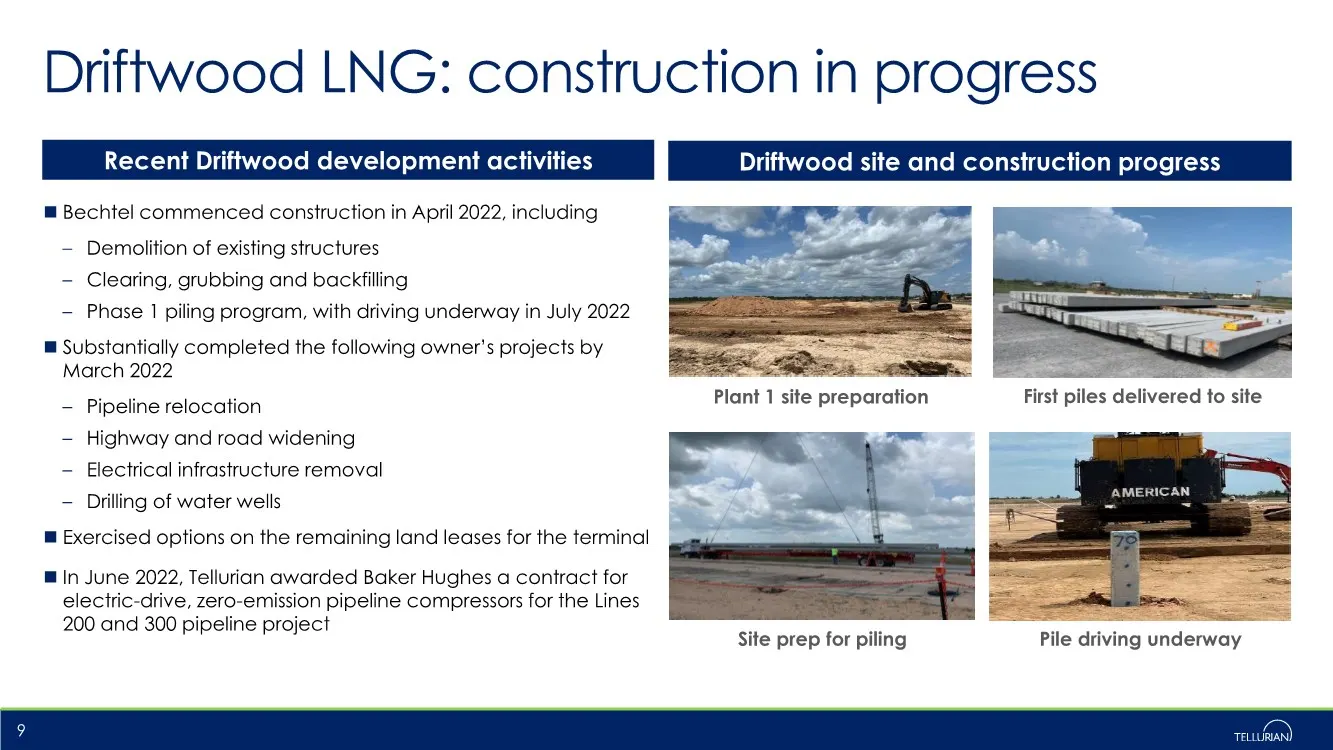
Driftwood LNG: construction in progress ◼ Bechtel commenced construction in April 2022, including – Demolition of existing structures – Clearing, grubbing and backfilling – Phase 1 piling program, with driving underway in July 2022 ◼ Substantially completed the following owner’s projects by March 20
Slide 10: Low-cost U.S. supply provides global gas arbitrage
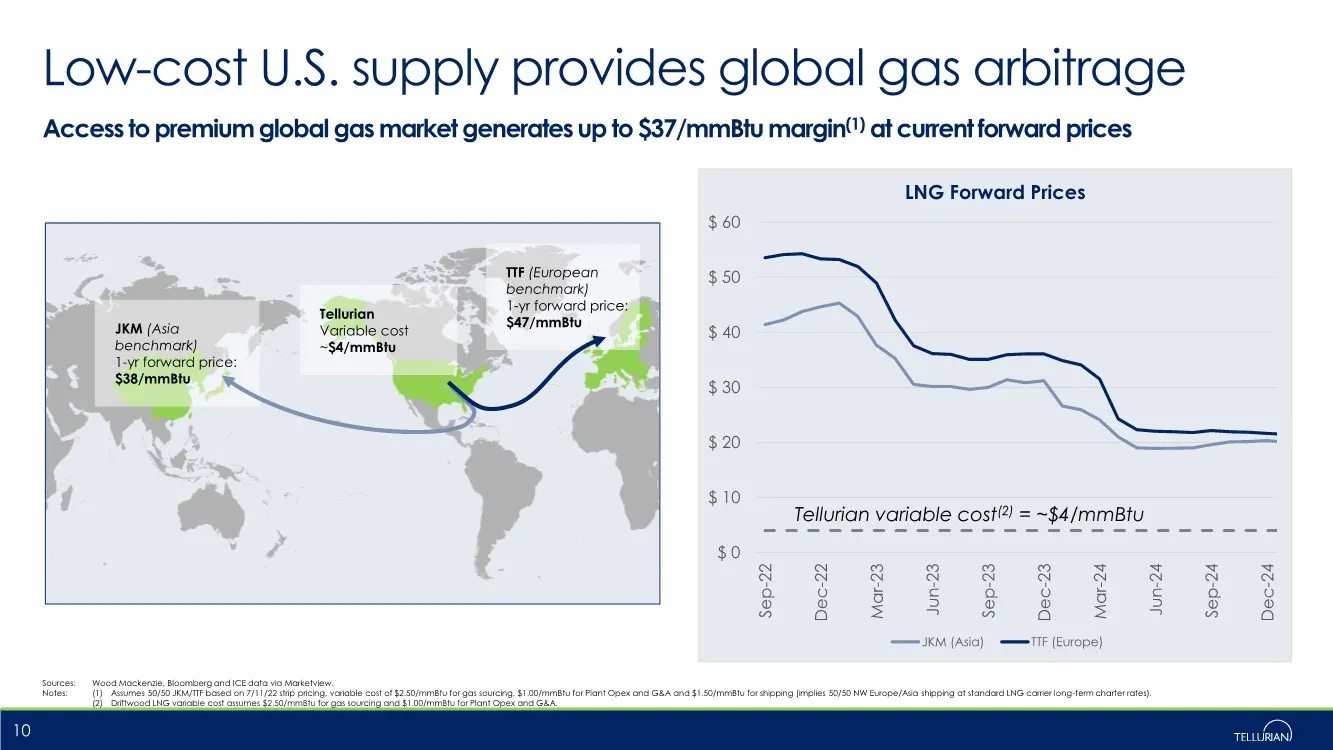
$ 0 $ 10 $ 20 $ 30 $ 40 $ 50 $ 60 Sep-22 Dec-22 Mar-23 Jun-23 Sep-23 Dec-23 Mar-24 Jun-24 Sep-24 Dec-24 LNG Forward Prices JKM (Asia) TTF (Europe) Low-cost U.S. supply provides global gas arbitrage 10 Access to premium global gas market generates up to $37/mmBtu margin(1) at current forward prices J
Slide 11: Driftwood captures upside to global prices
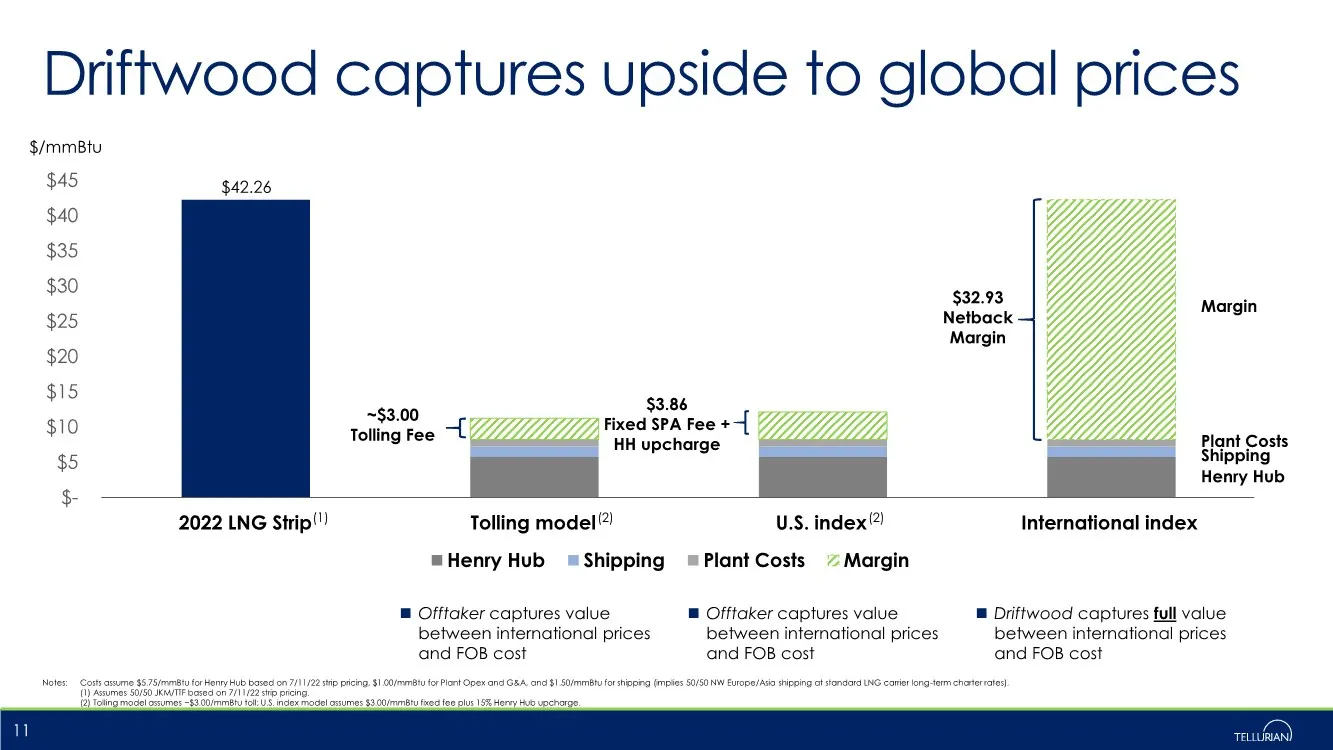
2022 LNG Strip Tolling model U.S. index International index ◼ Offtaker captures value between international prices and FOB cost ◼ Offtaker captures value between international prices and FOB cost ◼ Driftwood captures full value between international prices and FOB cost 11 Notes: Costs assume $5.75/m
Slide 12: LNG demand exceeds supply growth
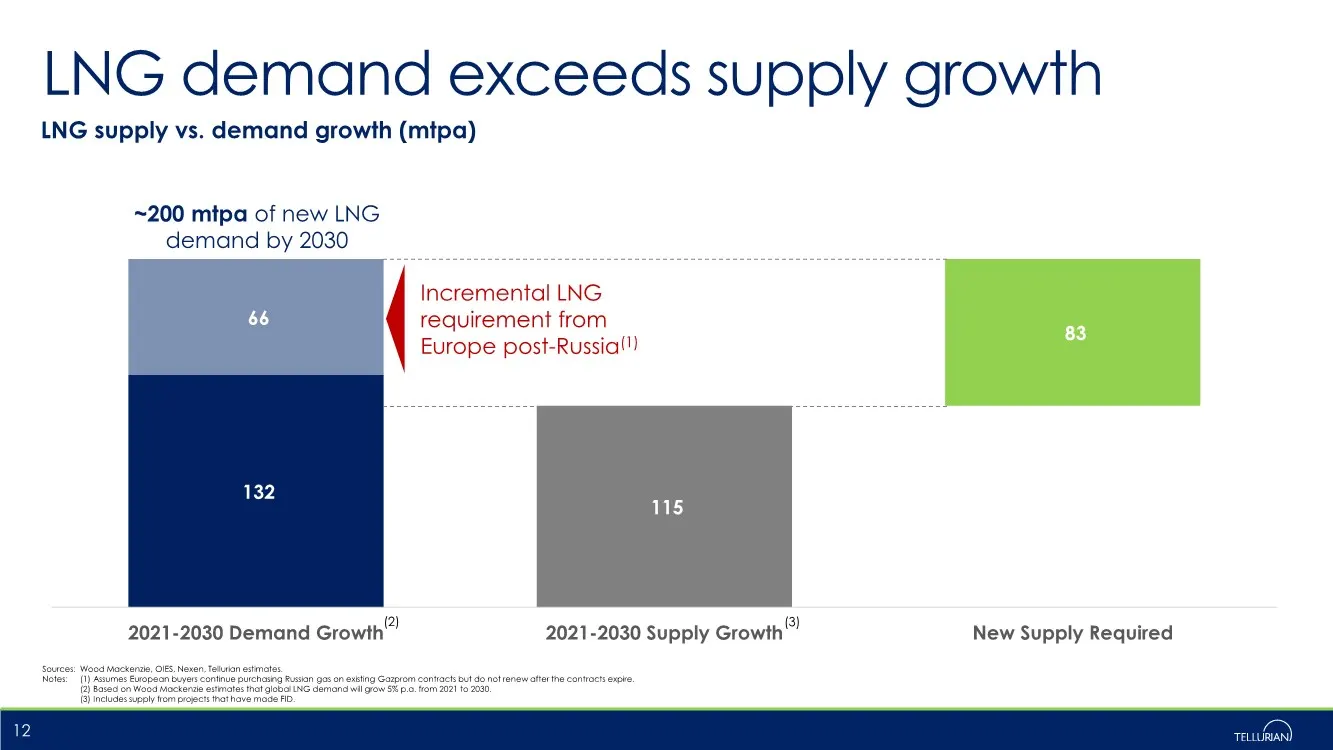
132 115 66 83 2021-2030 Demand Growth 2021-2030 Supply Growth New Supply Required LNG supply vs. demand growth (mtpa) LNG demand exceeds supply growth 12 Sources: Wood Mackenzie, OIES, Nexen, Tellurian estimates. Notes: (1) Assumes European buyers continue purchasing Russian gas on existing Gazprom
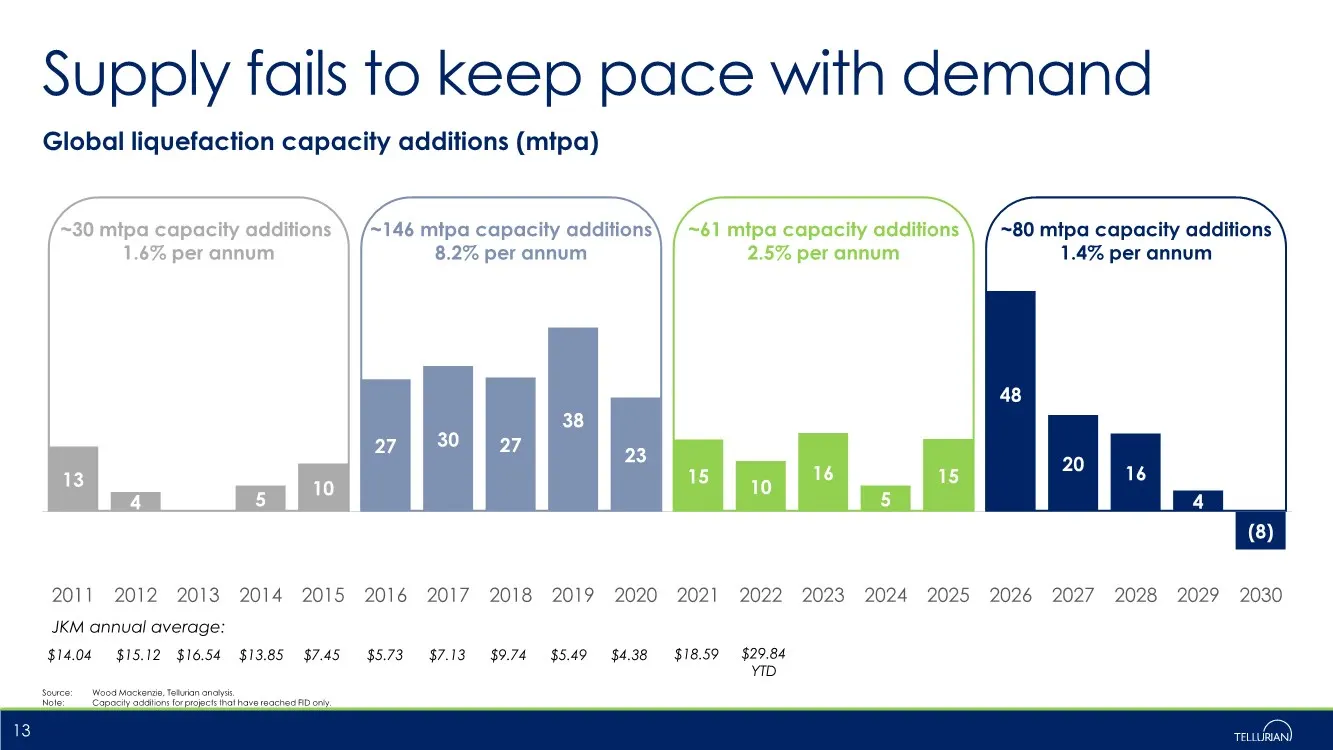
Slide 13: Supply fails to keep pace with demand
Supply fails to keep pace with demand Source: Wood Mackenzie, Tellurian analysis. Note: Capacity additions for projects that have reached FID only. 13 13 4 5 10 27 30 27 38 23 15 10 16 5 15 48 20 16 4 (8) 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 2028 2029
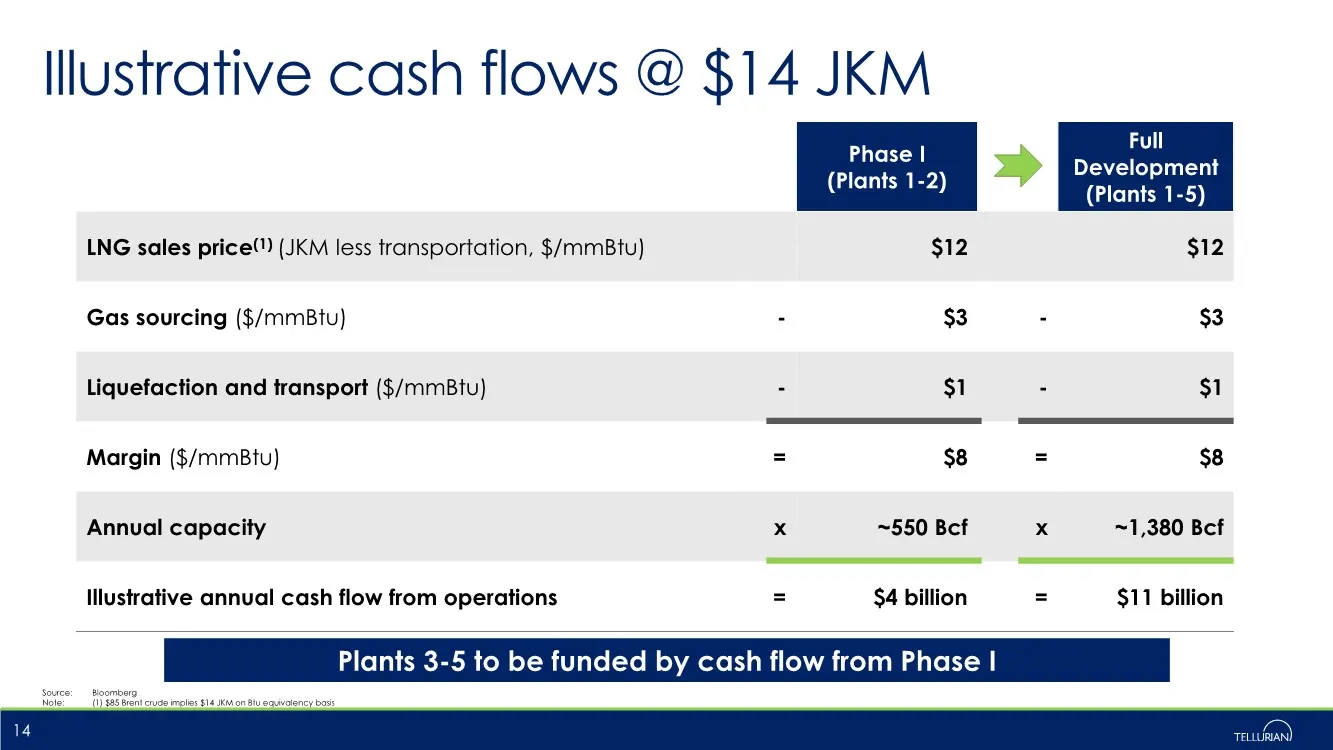
Slide 14: Illustrative cash flows @ $14 JKM
Illustrative cash flows @ $14 JKM Source: Bloomberg Note: (1) $85 Brent crude implies $14 JKM on Btu equivalency basis 14 Phase I (Plants 1-2) Full Development (Plants 1-5) LNG sales price(1) (JKM less transportation, $/mmBtu) $12 $12 Gas sourcing ($/mmBtu) - $3 - $3 Liquefaction and transport ($/mm
Slide 15: Contact us
Contact us ▪ Matt Phillips VP, Investor Relations & Finance +1 832 320 9331 [email protected] ▪ Joi Lecznar EVP, Public & Government Affairs +1 832 962 4044 [email protected] 15 ▪ Johan Yokay Director, Investor Relations & Assistant Treasurer +1 832 320 9327 johan.yokay@te
Slide 16: Appendix
Appendix
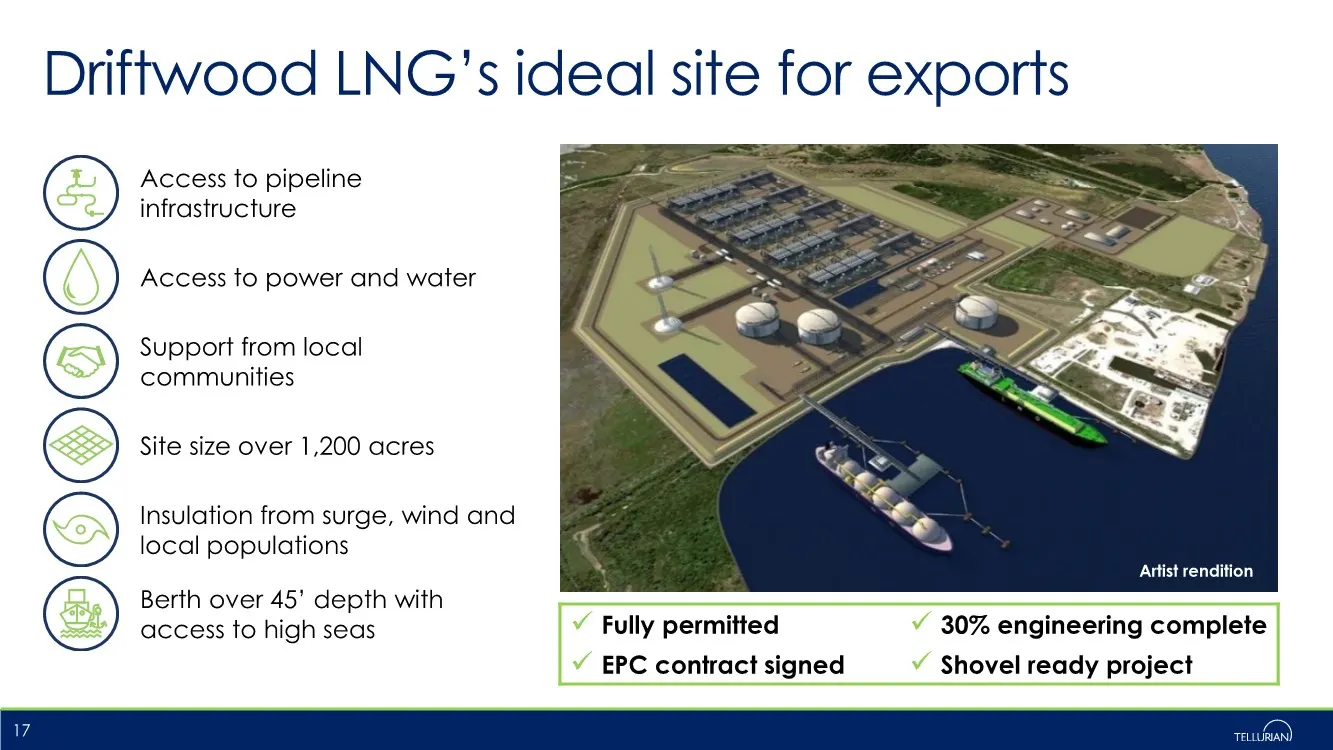
Slide 17: Driftwood LNG's ideal site for exports
Driftwood LNG’s ideal site for exports 17 Access to power and water Berth over 45’ depth with access to high seas Support from local communities Access to pipeline infrastructure Site size over 1,200 acres Insulation from surge, wind and local populations Artist rendition ✓ Fully permitted ✓ 30% eng
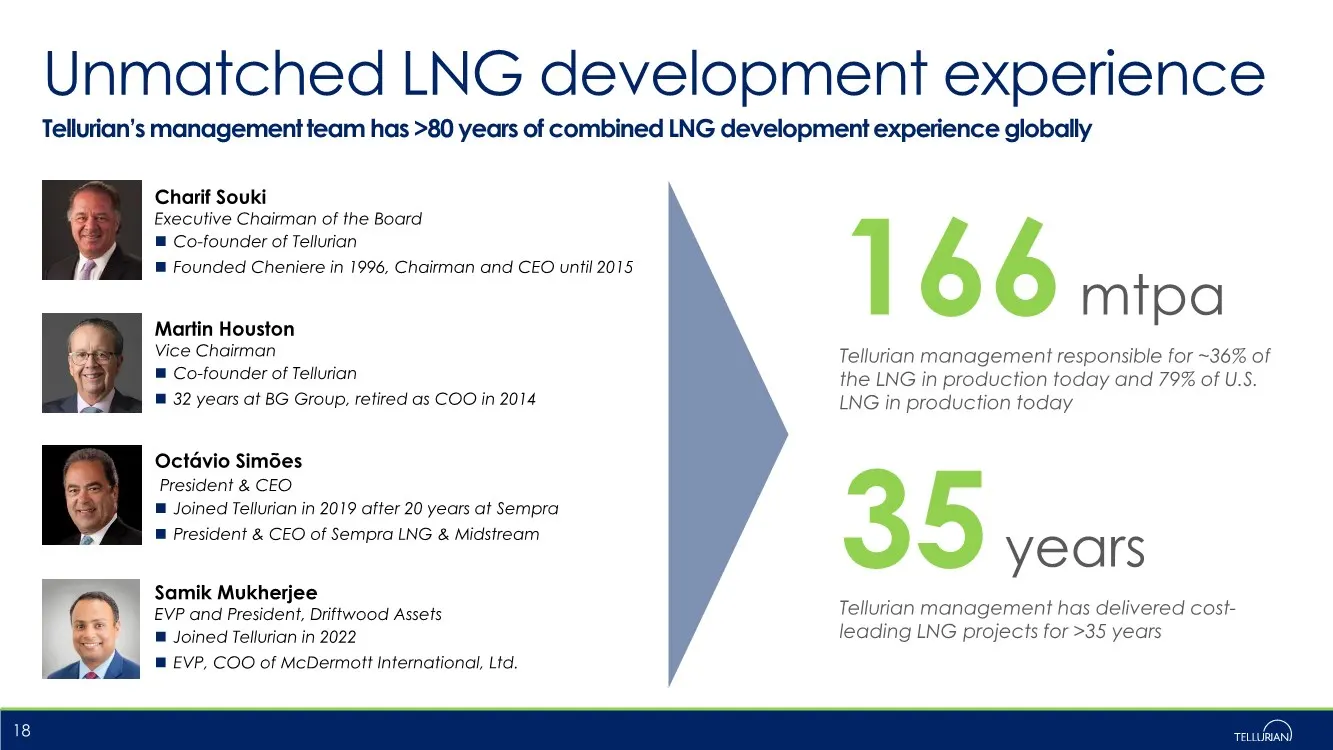
Slide 18: Unmatched LNG development experience
Unmatched LNG development experience Tellurian’s management team has >80 years of combined LNG development experience globally 18 Charif Souki Executive Chairman of the Board ◼ Co-founder of Tellurian ◼ Founded Cheniere in 1996, Chairman and CEO until 2015 Martin Houston Vice Chairman ◼ Co-founder o
Source: SEC EDGAR · 8-K filed Jul 13, 2022
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (November 2022)19 slides · Nov 2, 2022