Oiltanking Partners LP — Goldman Sachs Global Energy Conference 2015
40 slides from Oiltanking Partners LP's conference presentation, Jan 7, 2015
Slide 1: Rule 425 filing notice
Filed by Enterprise Products Partners L.P. Pursuant to Rule 425 under the Securities Act of 1933 Subject Company: Oiltanking Partners, L.P. Commission File No.: 333-200608 Enterprise Products Partners L.P. (the “Partnership”) is filing an investor presentation that discloses a variety of financial,
Slide 2: Goldman Sachs Global Energy Conference, January 7-8, 2015
ENTERPRISE GOLDMAN ENERGY January Randy EVP © ALLand Fowler RIGHTS 7–8, CFO CONFERENCE 2015 SACHS PRODUCTS RESERVED. GLOBAL PARTNERS ENTERPRISE L.P. PRODUCTS PARTNERS L.P. enterpriseproducts.com
Slide 3: Forward-Looking Statements
FORWARD–LOOKING This presentation, statements Although undue those expected, All future information, 2© ALL forward-looking presentation expected, periodic reliance RIGHTS management the regarding future words impact on reports including RESERVED. contains any events such statements of our forward-l
Slide 4: Additional Information
ADDITIONAL This subsidiary substitute SECURITY FILED Enterprise be Relations, deemed general respectively, persons statement/prospectus 3© ALL incorporated communication WITH RIGHTS partners who tofor Oiltanking and/or of beHOLDERS and may Enterprise, any “participants” THE INFORMATION by of in RESE
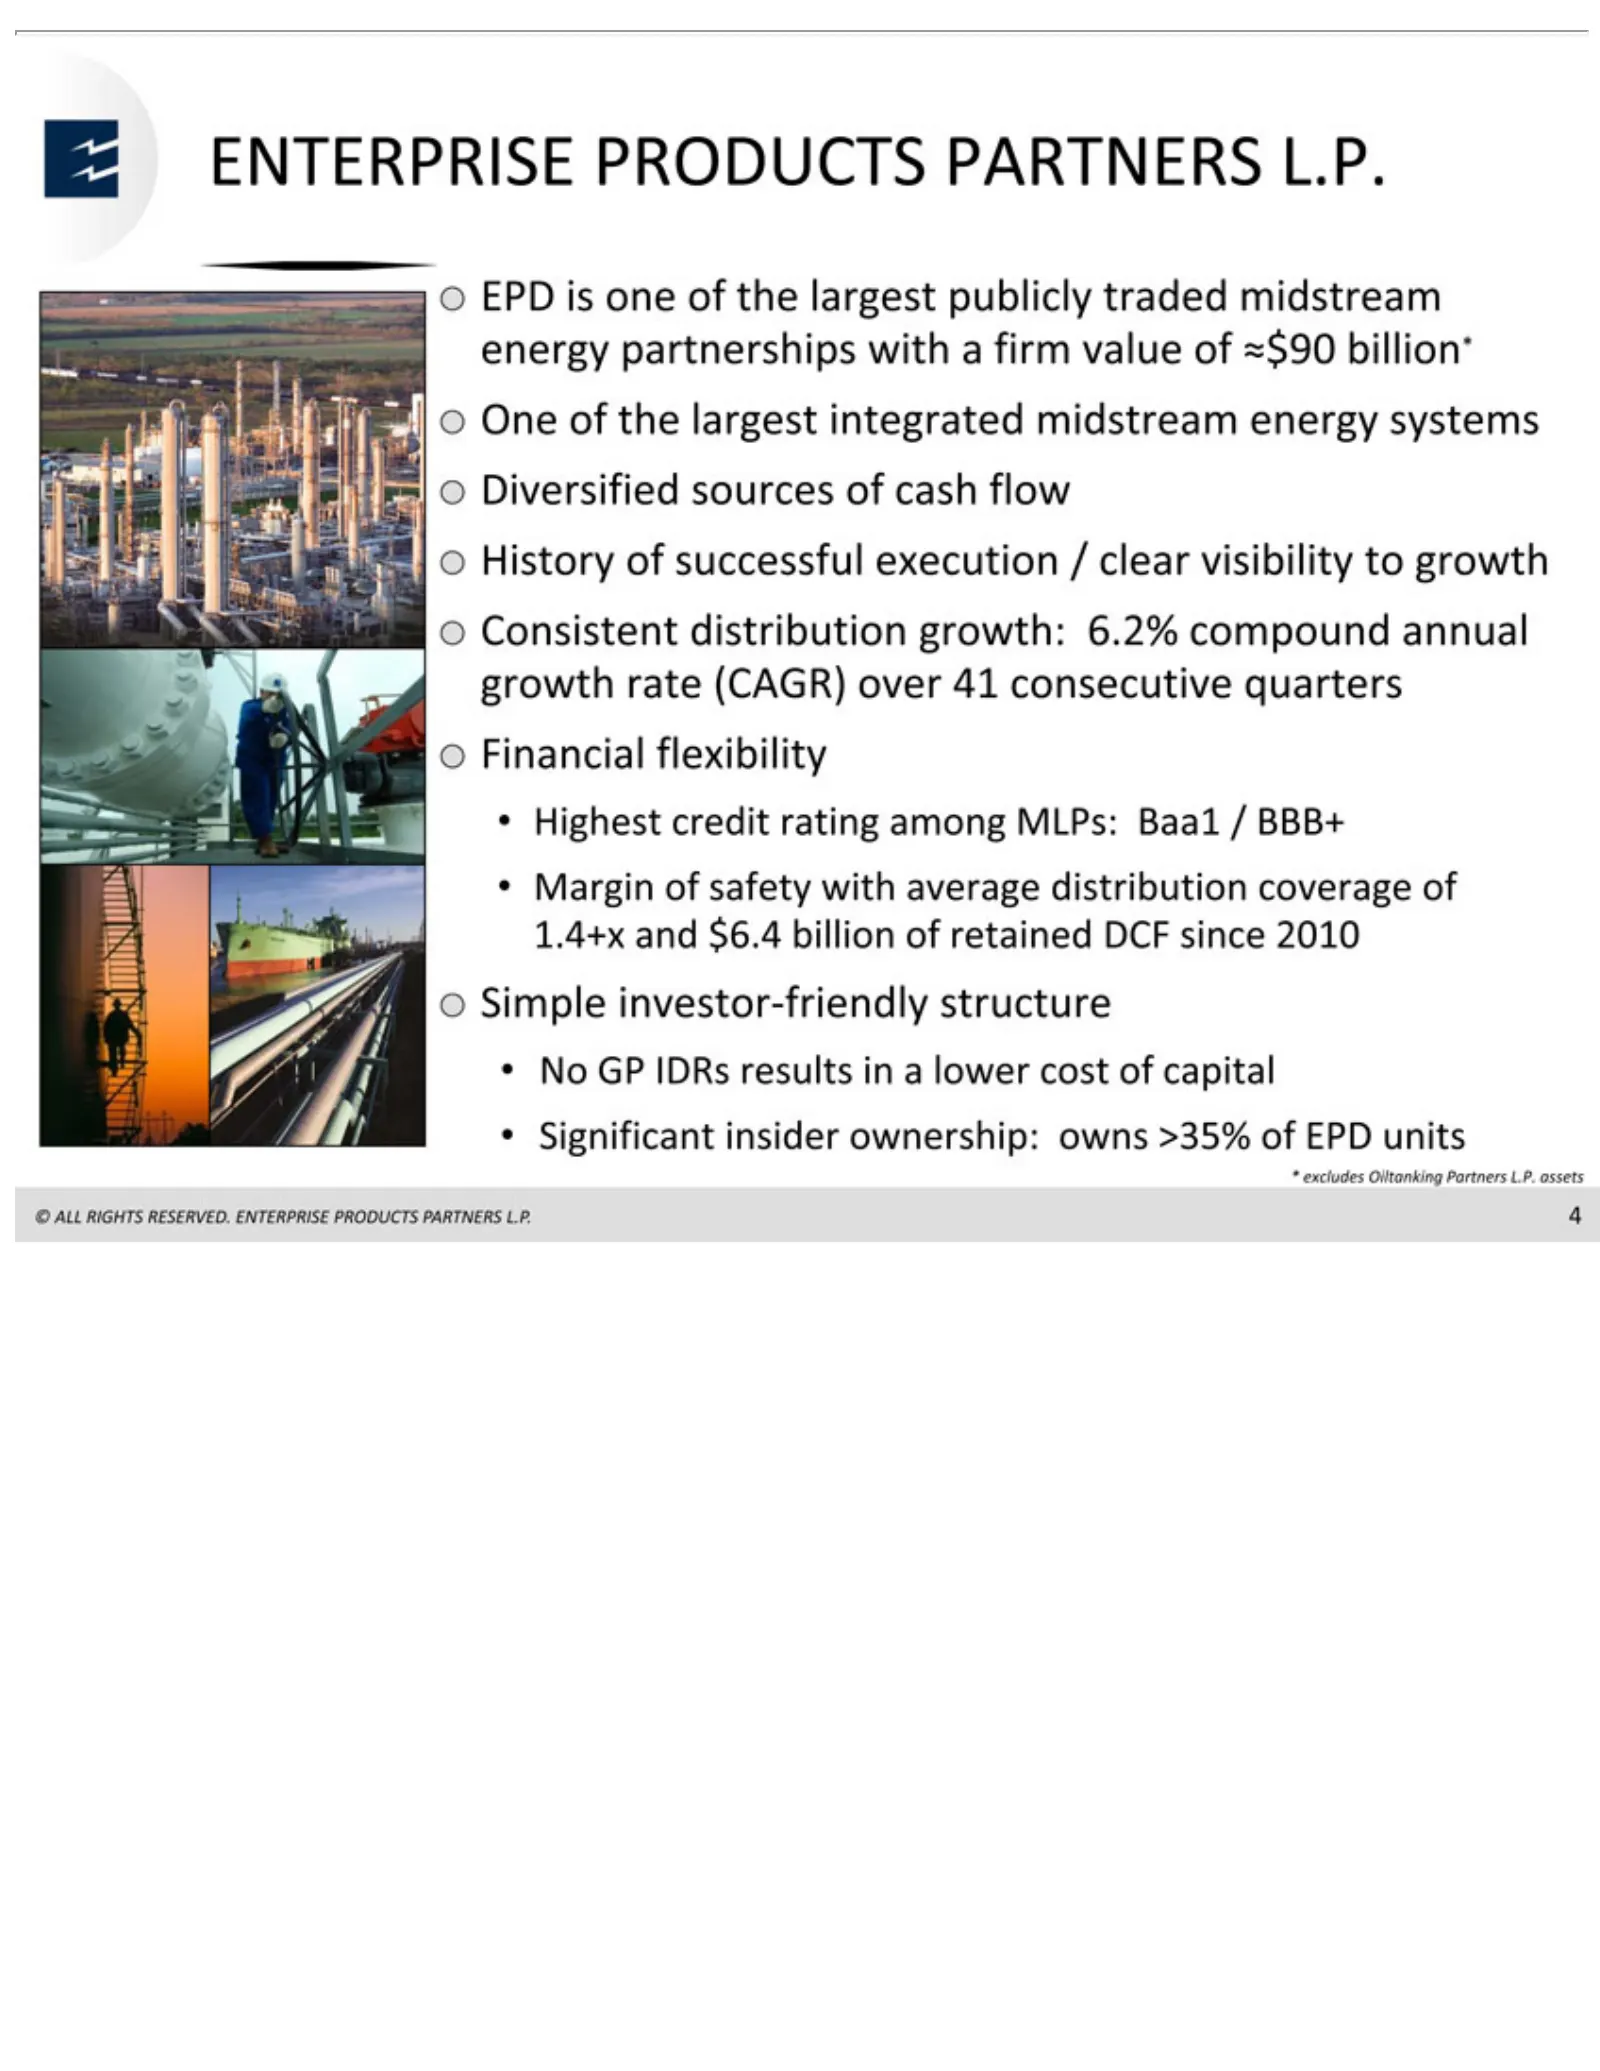
Slide 5: Enterprise: Successful Investor-Friendly Structure
ENTERPRISE EPD successful Highest Margin Simple No *Significant 4©excludes ALL GP is IDRs one investor-friendly RIGHTS of credit safety execution Oiltanking insider ofresults the rating PRODUCTS with RESERVED. largest ownership: inamong / average clear Partners a lower structure publicly visibility
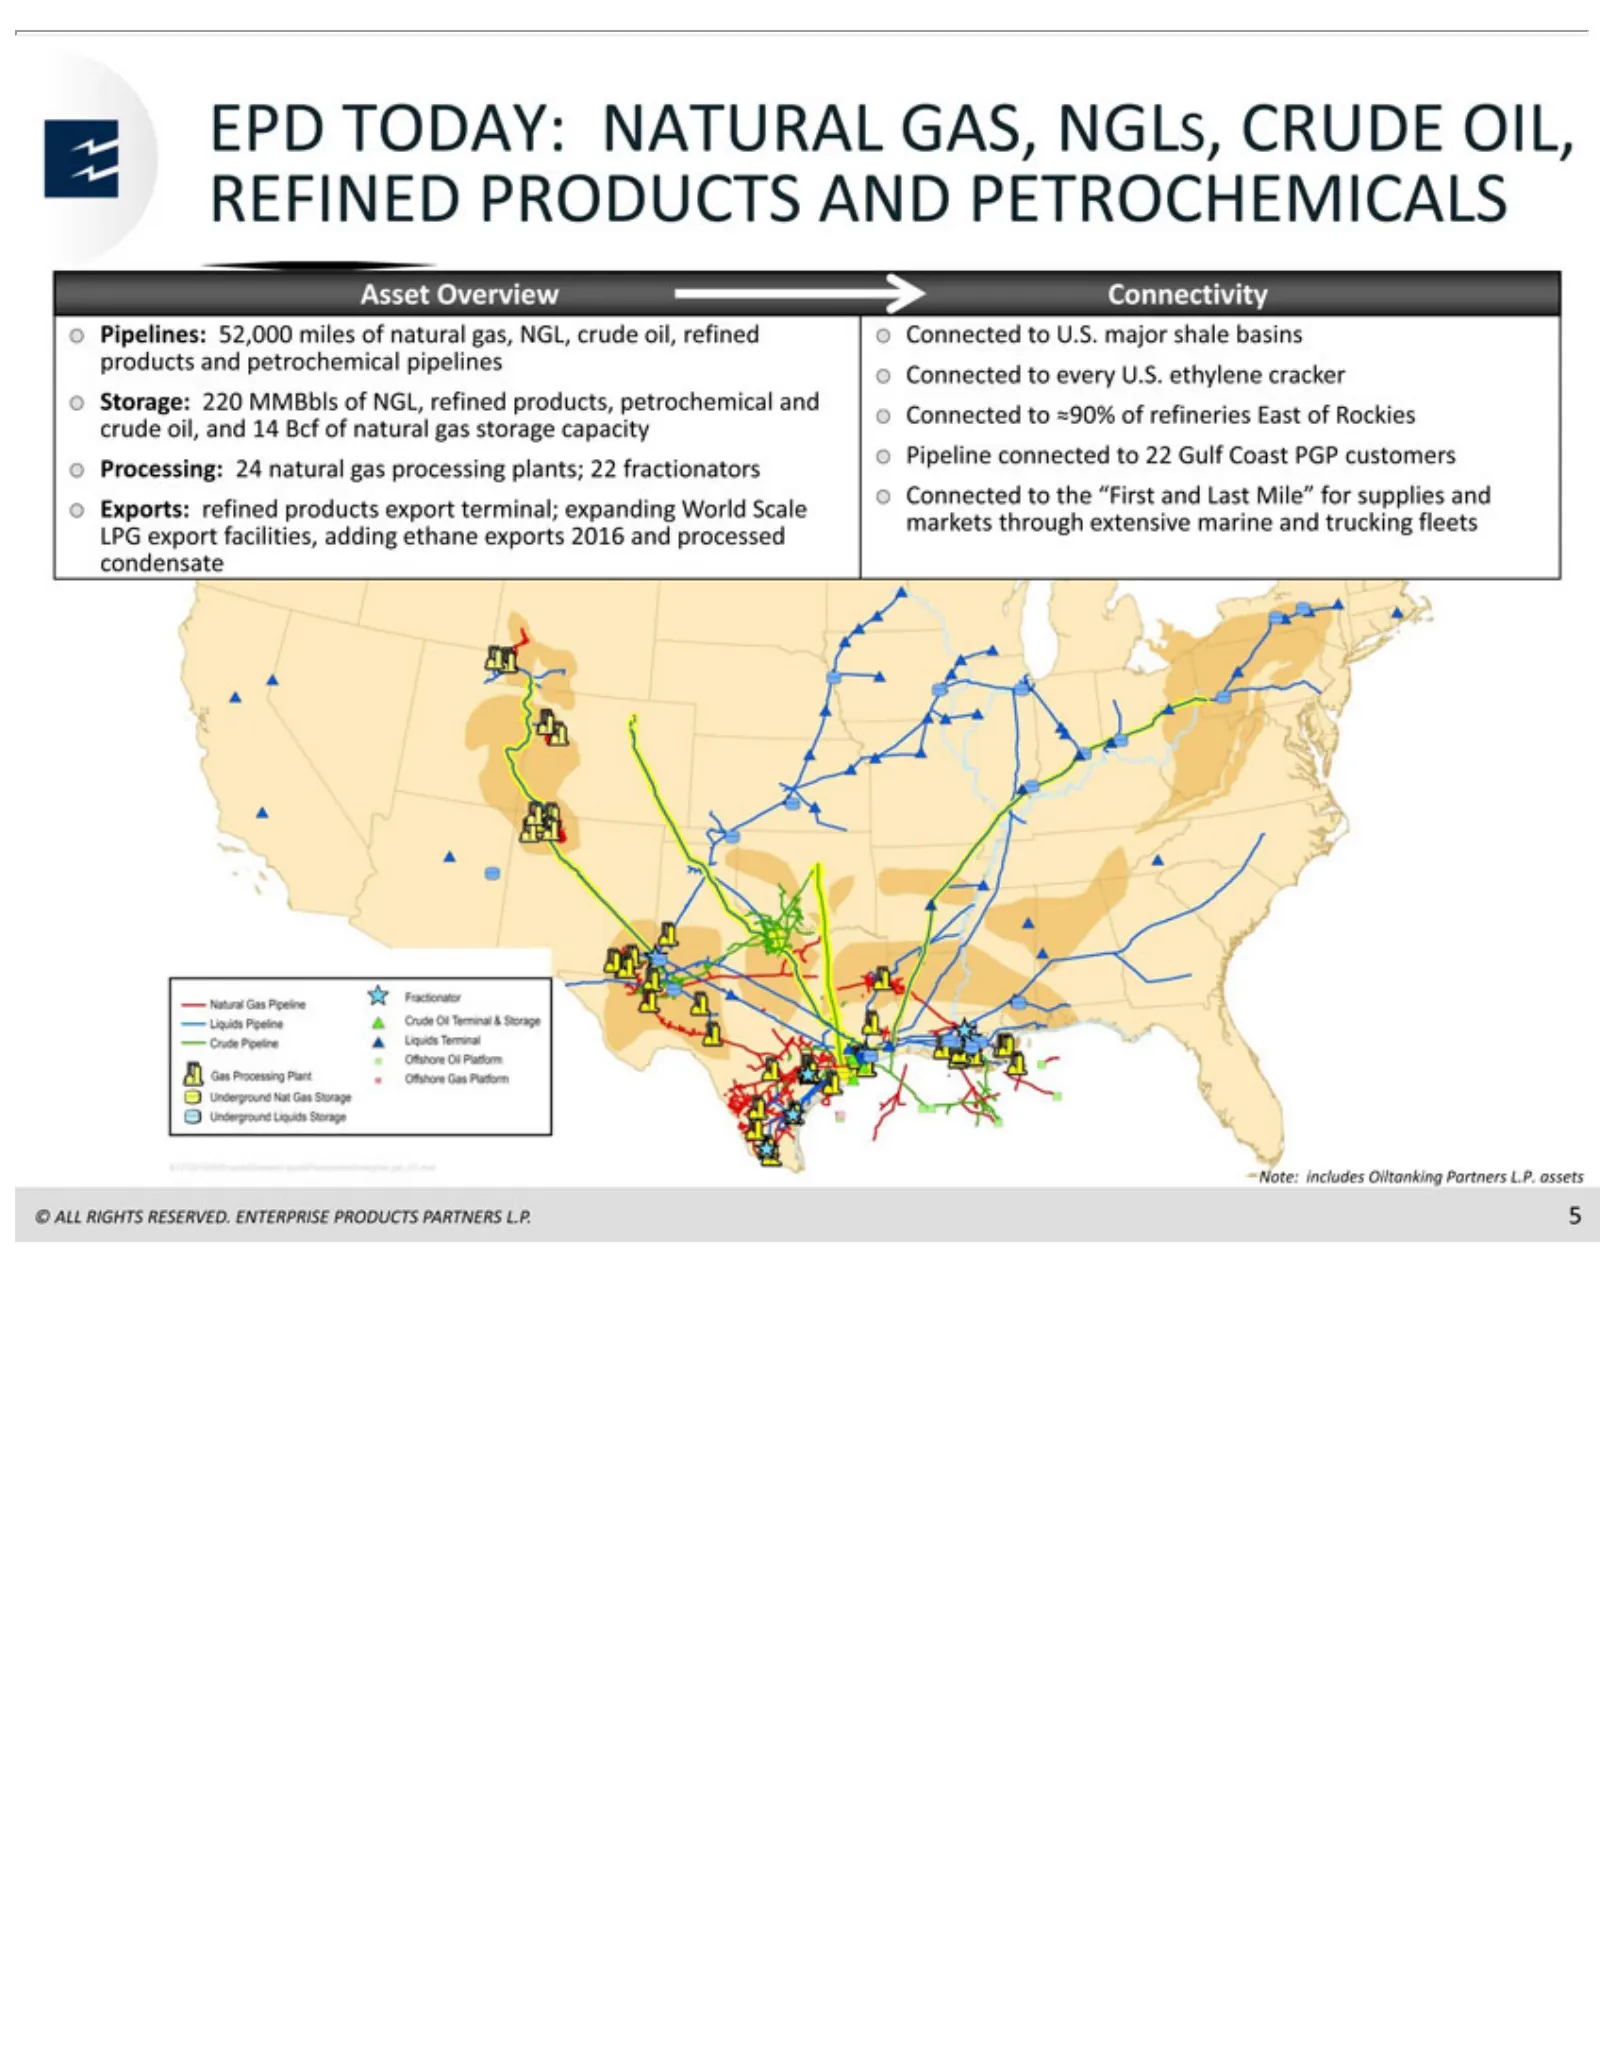
Slide 6: EPD Asset Overview
EPD sset Pipelines: products Storage: crude Processing: Exports: LPG nnectivity condensate Pipeline Connected markets Note: 5© ALL Overview TODAY: export oil, includes RIGHTS through connected 220 refined and and 52,000 to24 facilities, MMBbls petrochemical U.S. every the »90% 14 NATURAL Oiltanking
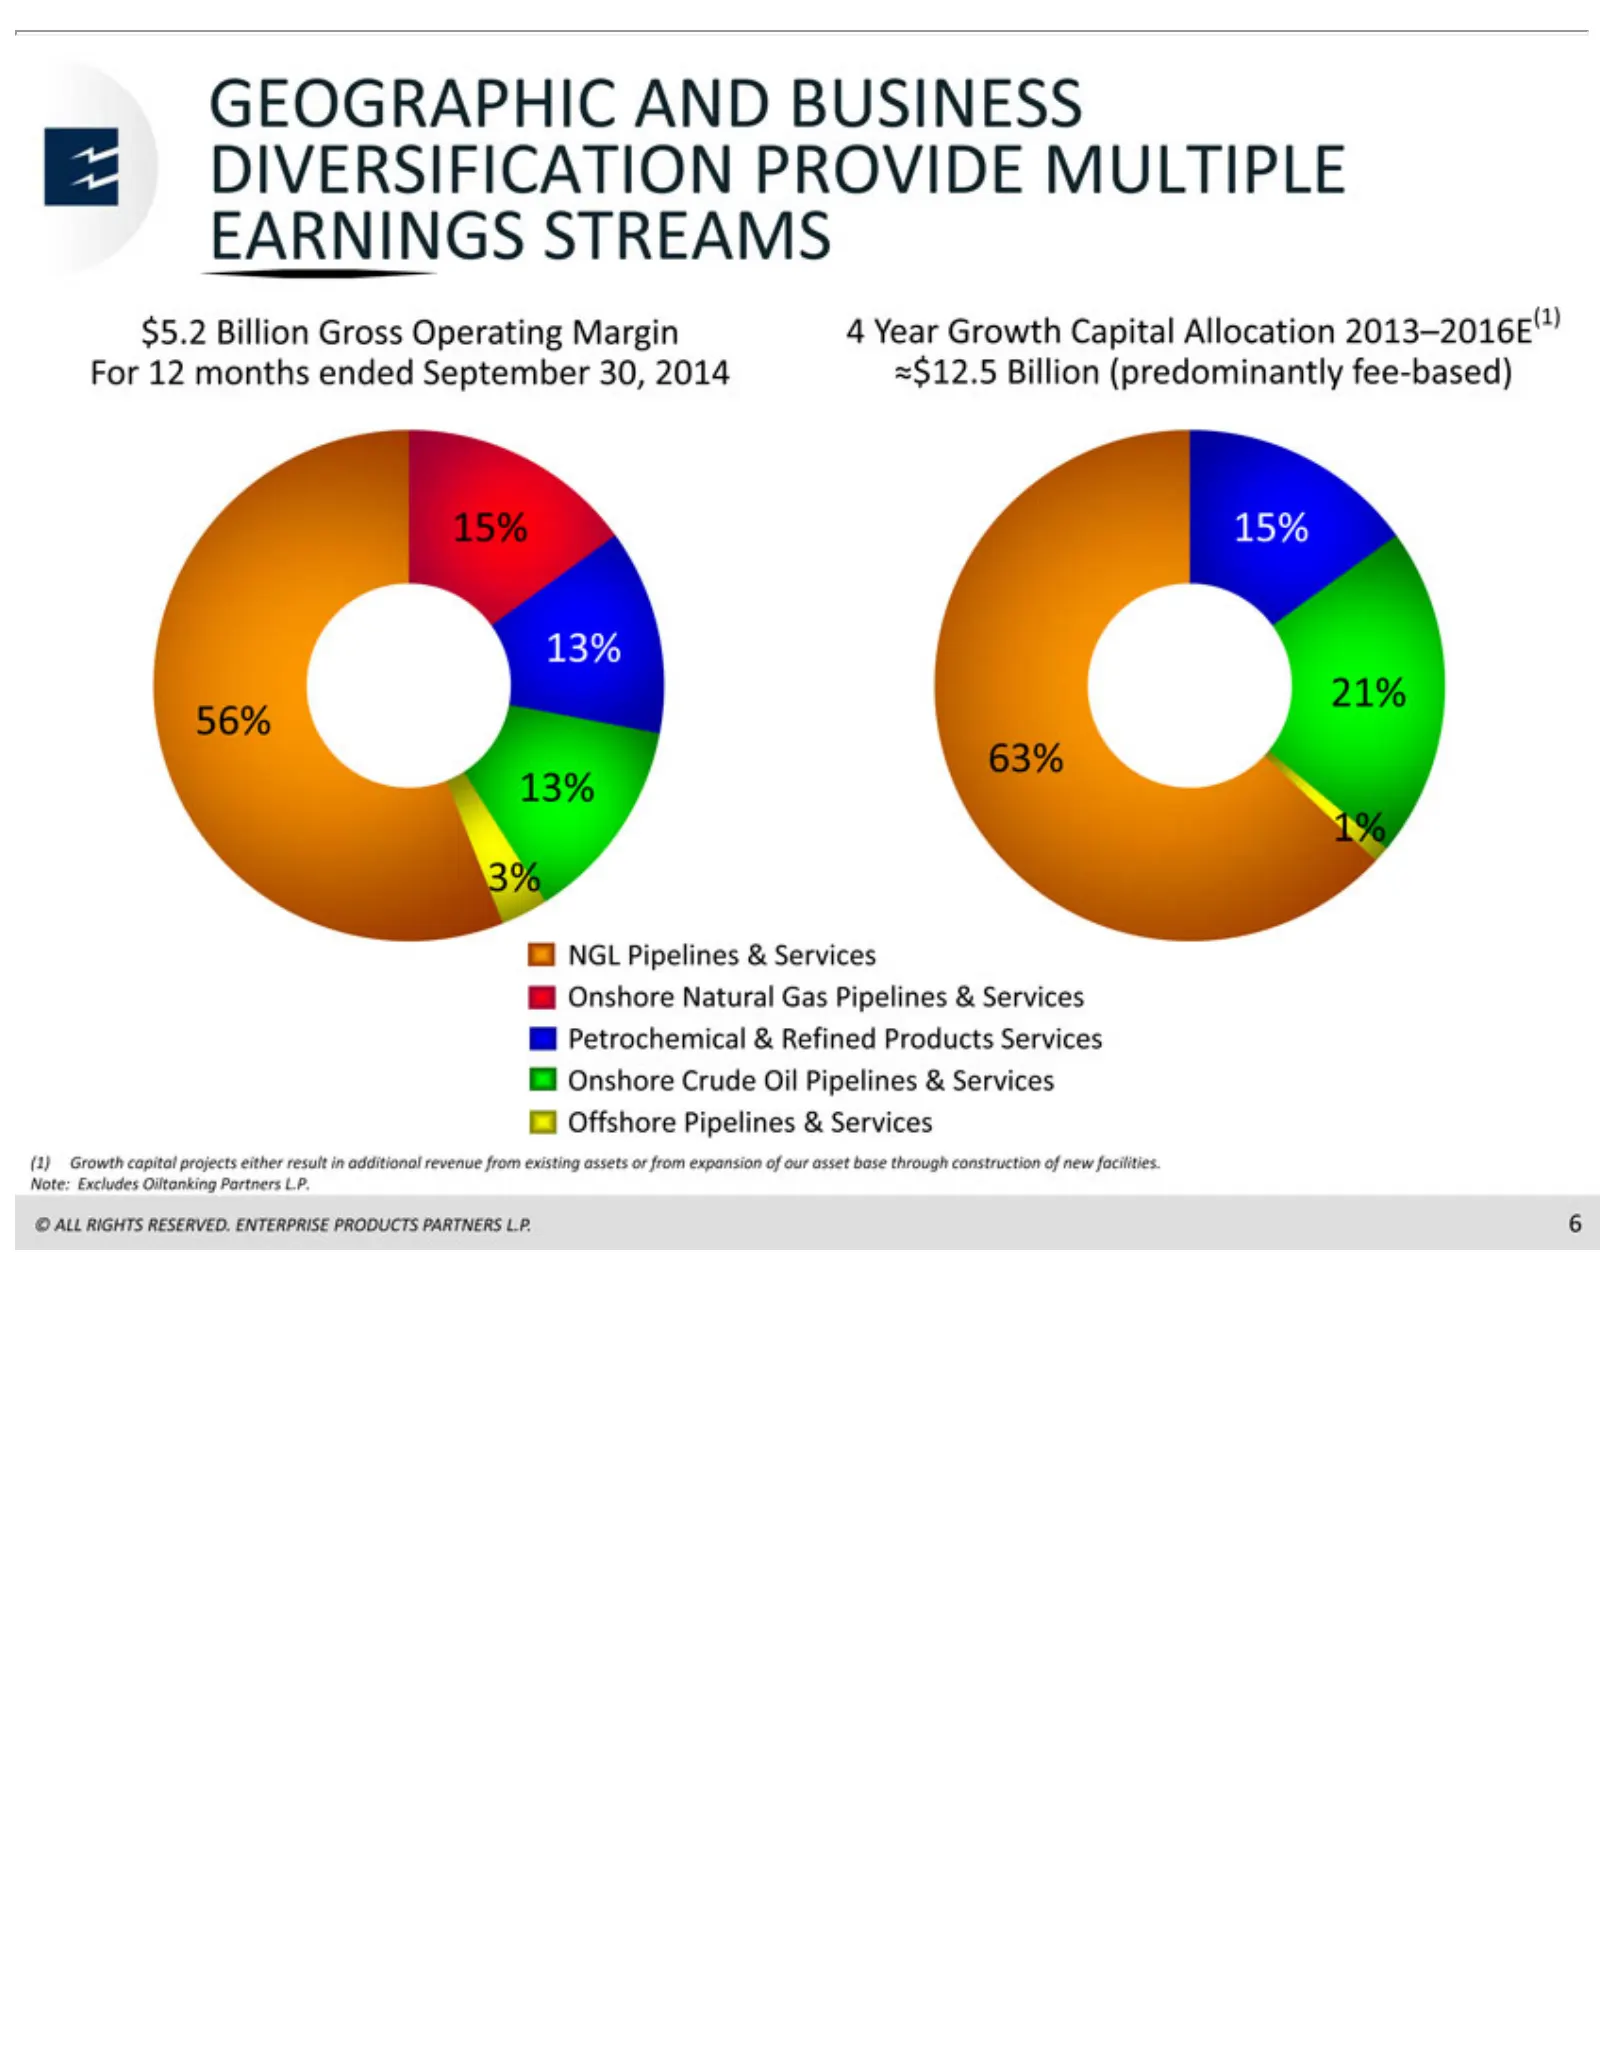
Slide 7: Geographic Diversification and Multiple Earnings Streams
GEOGRAPHIC DIVERSIFICATION 4$5.2 $12.5 NGL Onshore (1) 6©Year ALL Growth Billion Pipelines Billion Growth RIGHTS Natural capital Gross (predominantly Capital &AND Gas RESERVED. Services Operating projects Pipelines PROVIDE BUSINESS Allocation either Margin fee ENTERPRISE &MULTIPLE based) result Serv
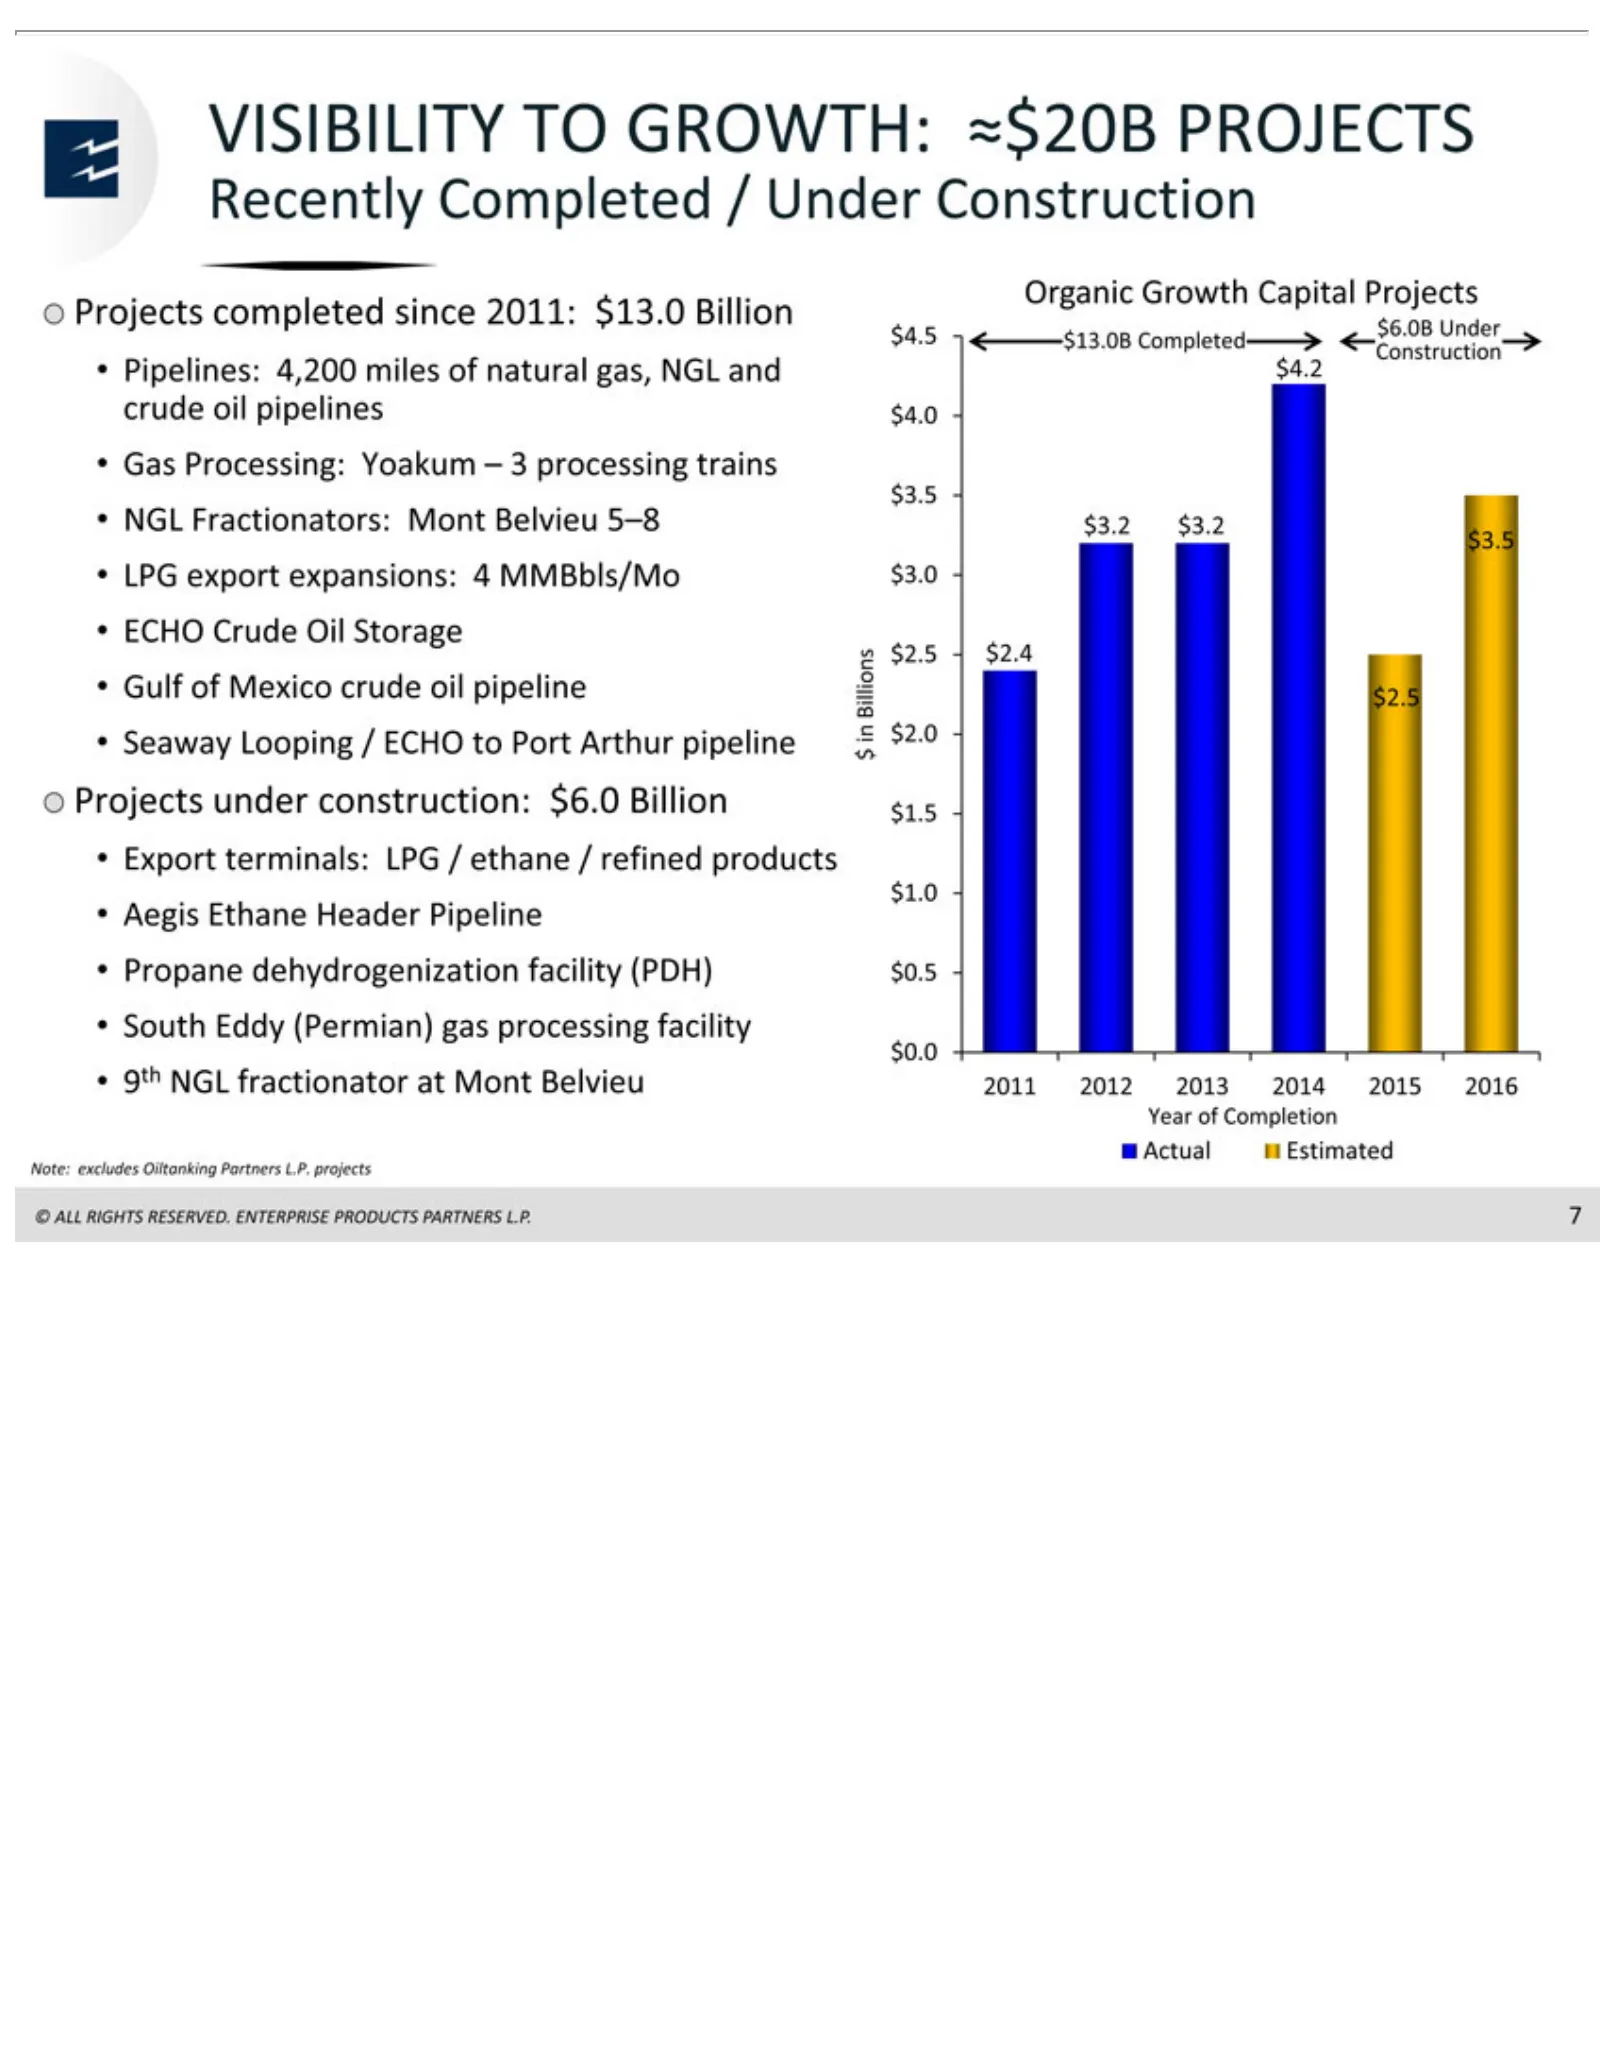
Slide 8: Visibility to Growth: Major Capital Projects
VISIBILITY Recently Pipelines: Gas NGL LPG ECHO Gulf Seaway Projects Export Aegis Propane South 9th Organic $4.5 $13.0B $4.2 Billions $1.5 2011 Year Actual Note: 7© ALL NGL Processing: $6.0B $4.0 $1.0 of export 2012 Fractionators: excludes Ethane Eddy Estimated terminals: Crude RIGHTS Mexico Complet
Slide 9: Fundamentals
© ALL RIGHTS RESERVED. ENTERPRISE PRODUCTS PARTNERS L.P. enterpriseproducts.com FUNDAMENTALS
Slide 10: Observations on Oil Prices
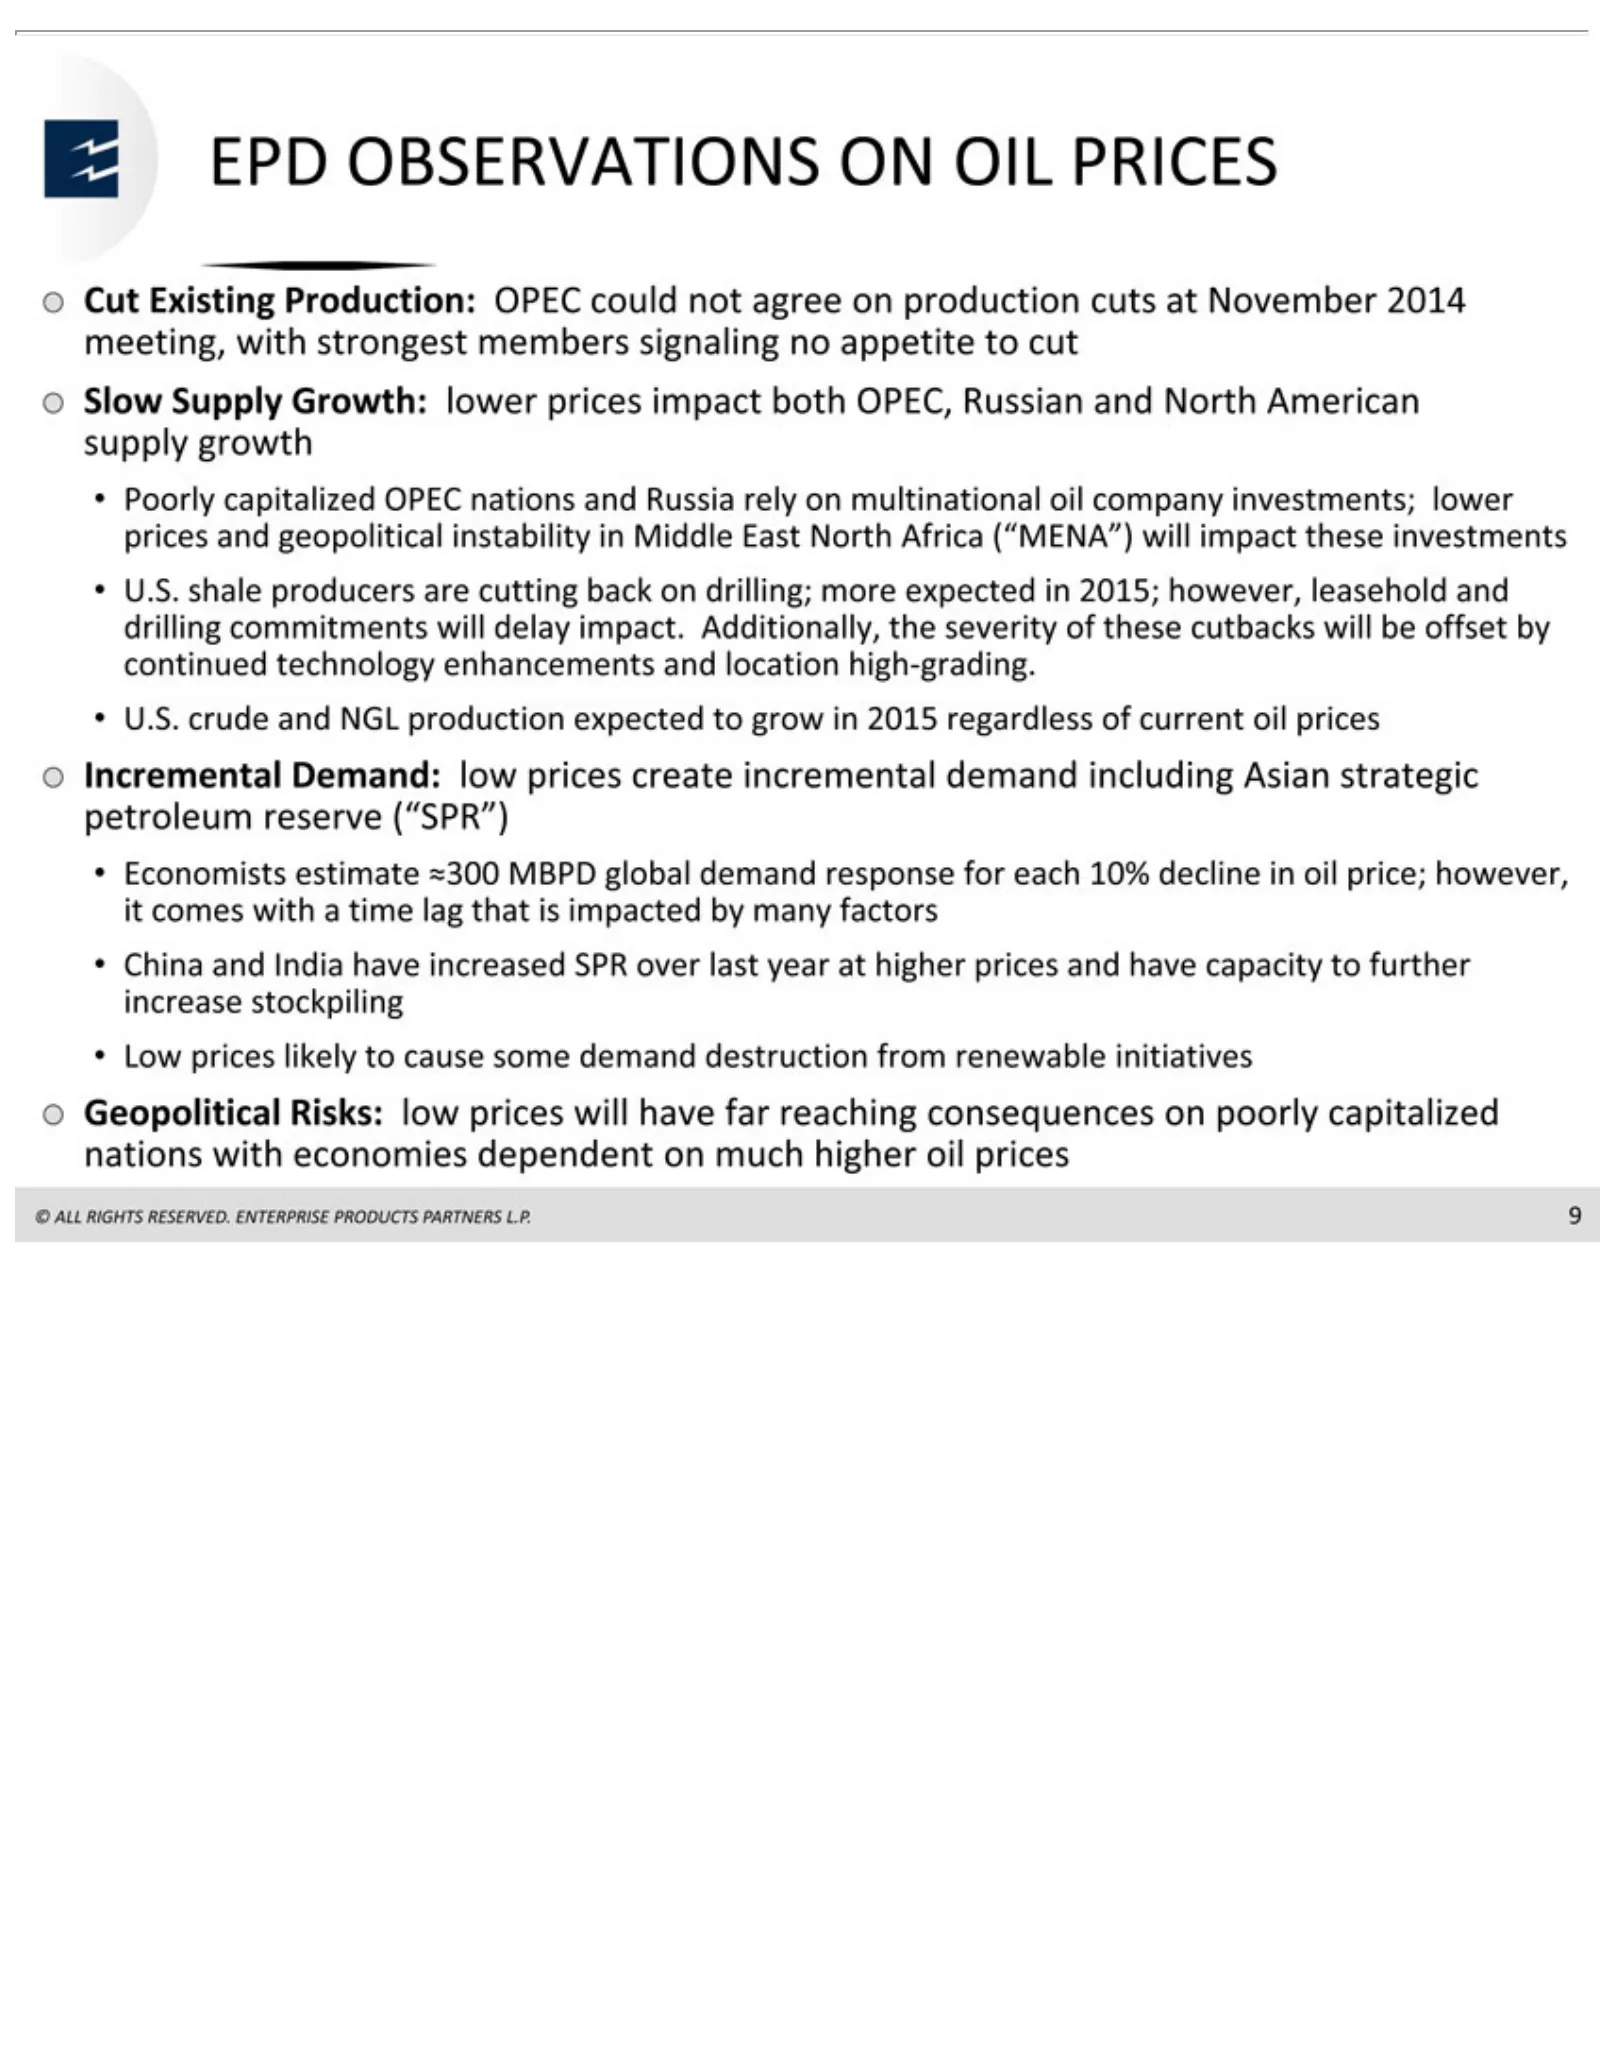
EPD Cut Russian Poorly continued U.S. Incremental Economists China Low Geopolitical 9© ALL Existing shale crude prices OBSERVATIONS and capitalized RIGHTS and technology India producers and likely estimate Demand: North Risks: Production: NGL have RESERVED. to OPEC American low cause production »300
Slide 11: Breakeven Prices for Key Oil and Condensate Plays
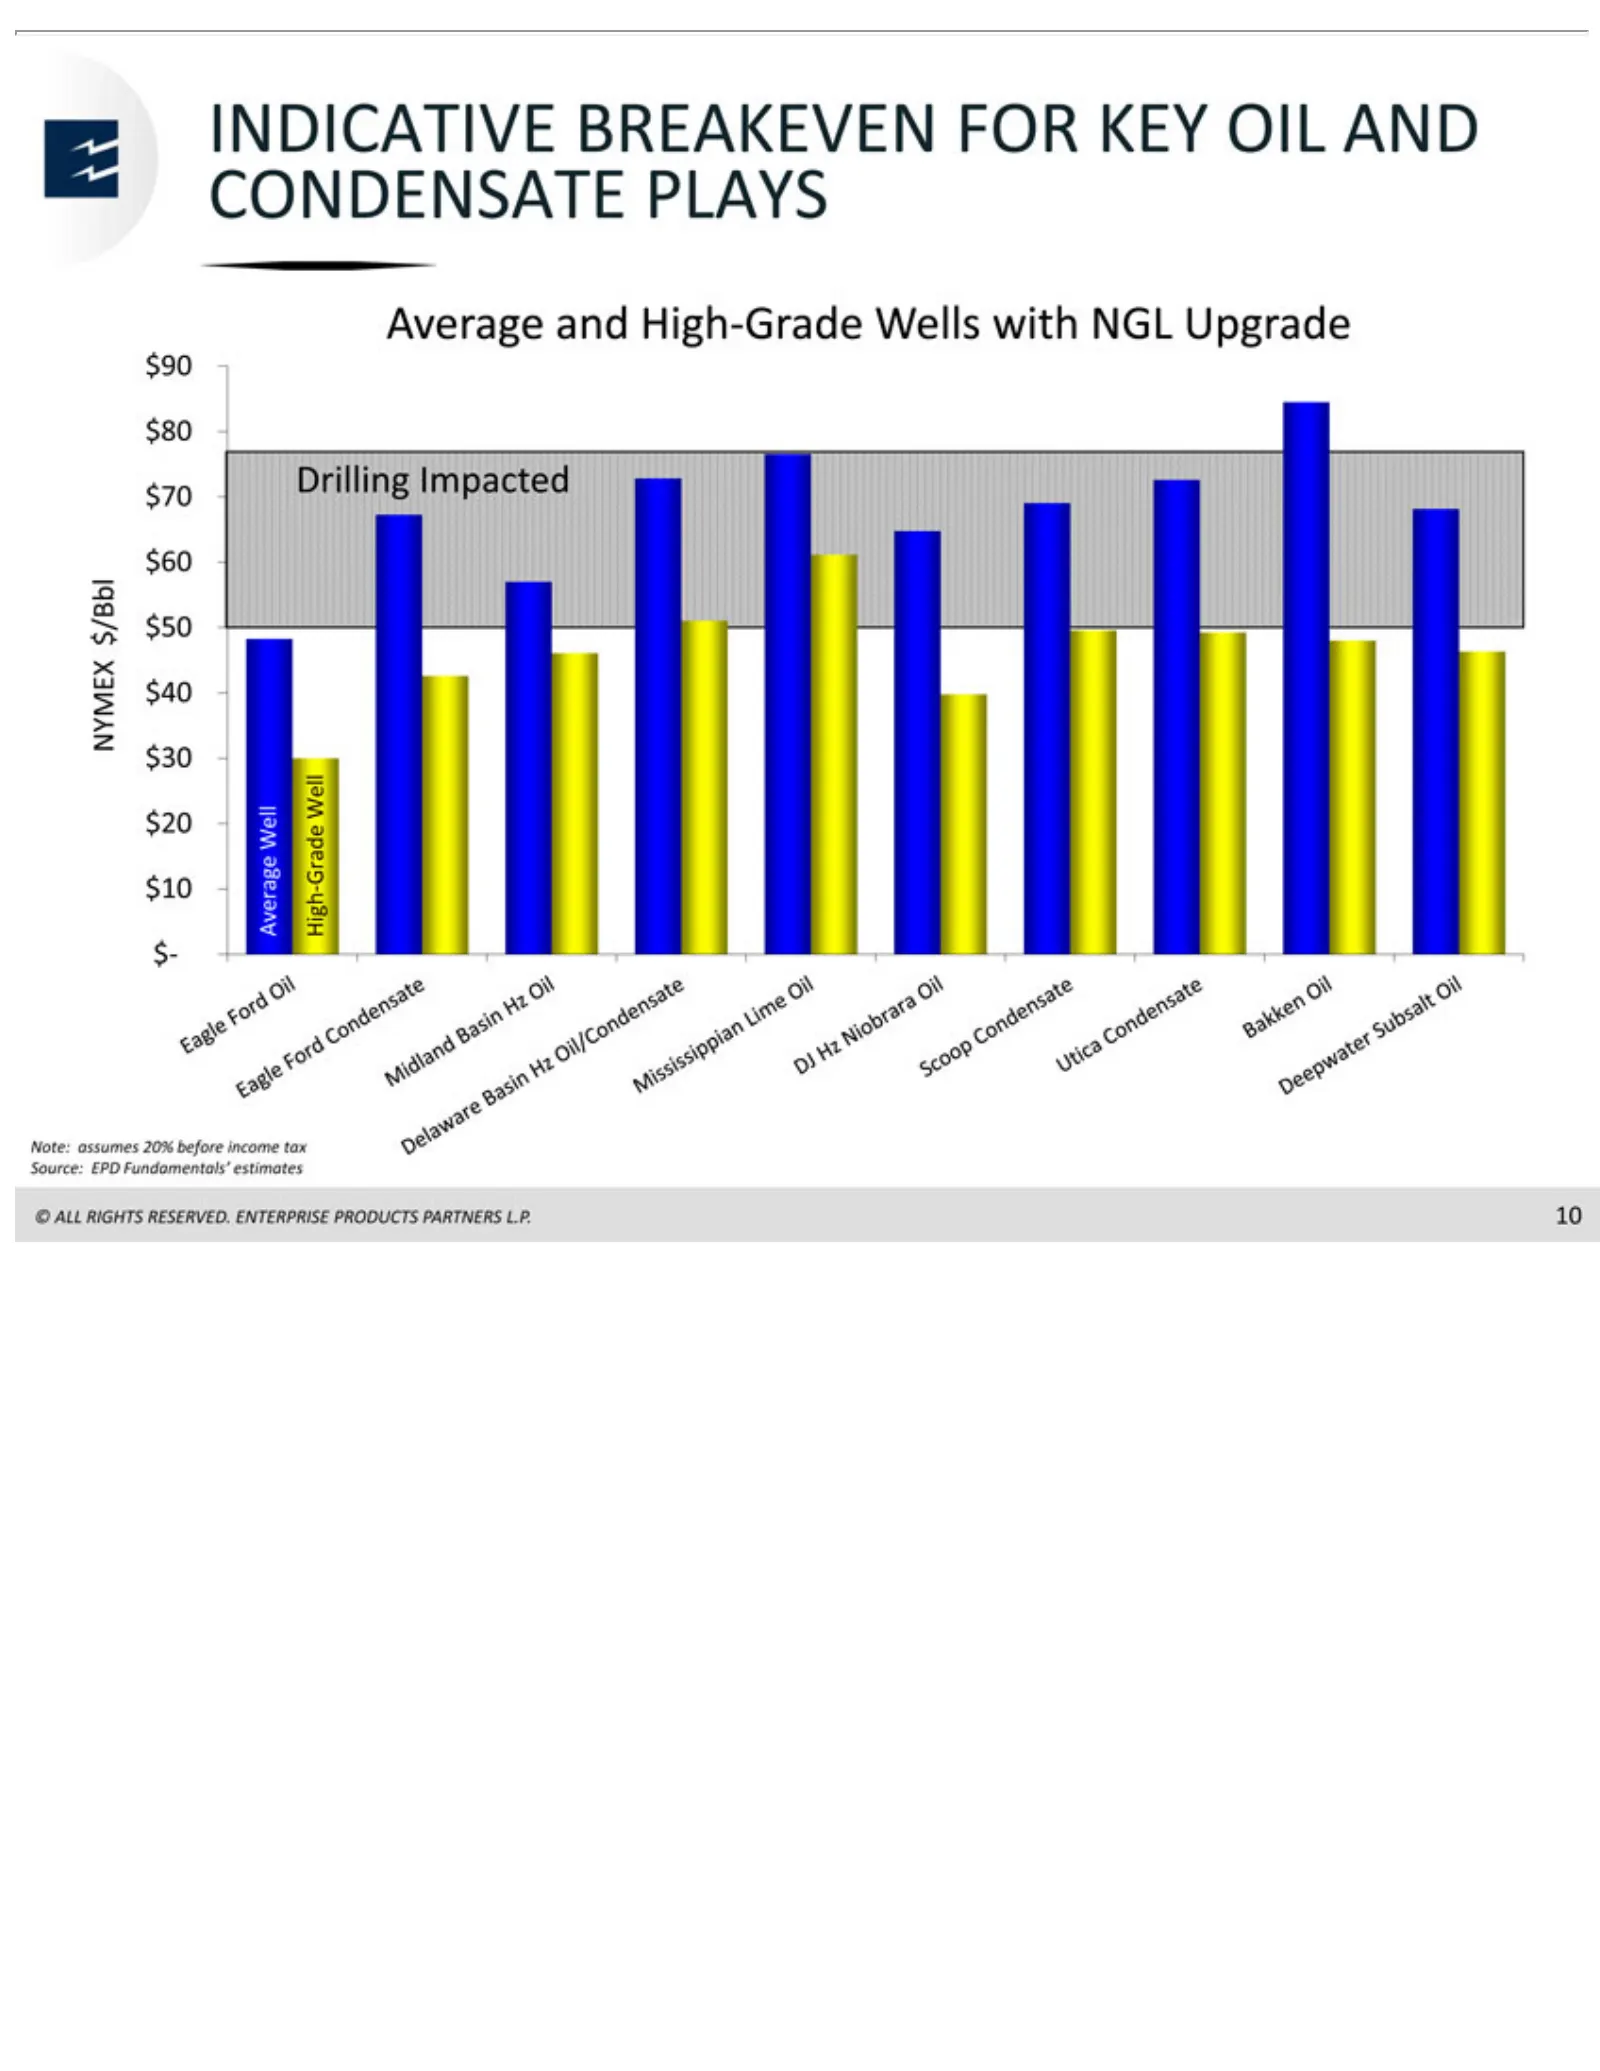
INDICATIVE Average Drilling $80 $90 $60 $70 $20 $30 $40 $10 Note: $- © 10 ALL Average Well $ assumes /Bbl RIGHTS Impacted and Well $50 High-Grade High BREAKEVEN Grade 20% NYMEX RESERVED. - beforeWells income FOR ENTERPRISE withtax KEY NGL Source: OIL Upgrade AND PRODUCTS EPD CONDENSATE Fundamentals’
Slide 12: Crude Oil Production Forecasts
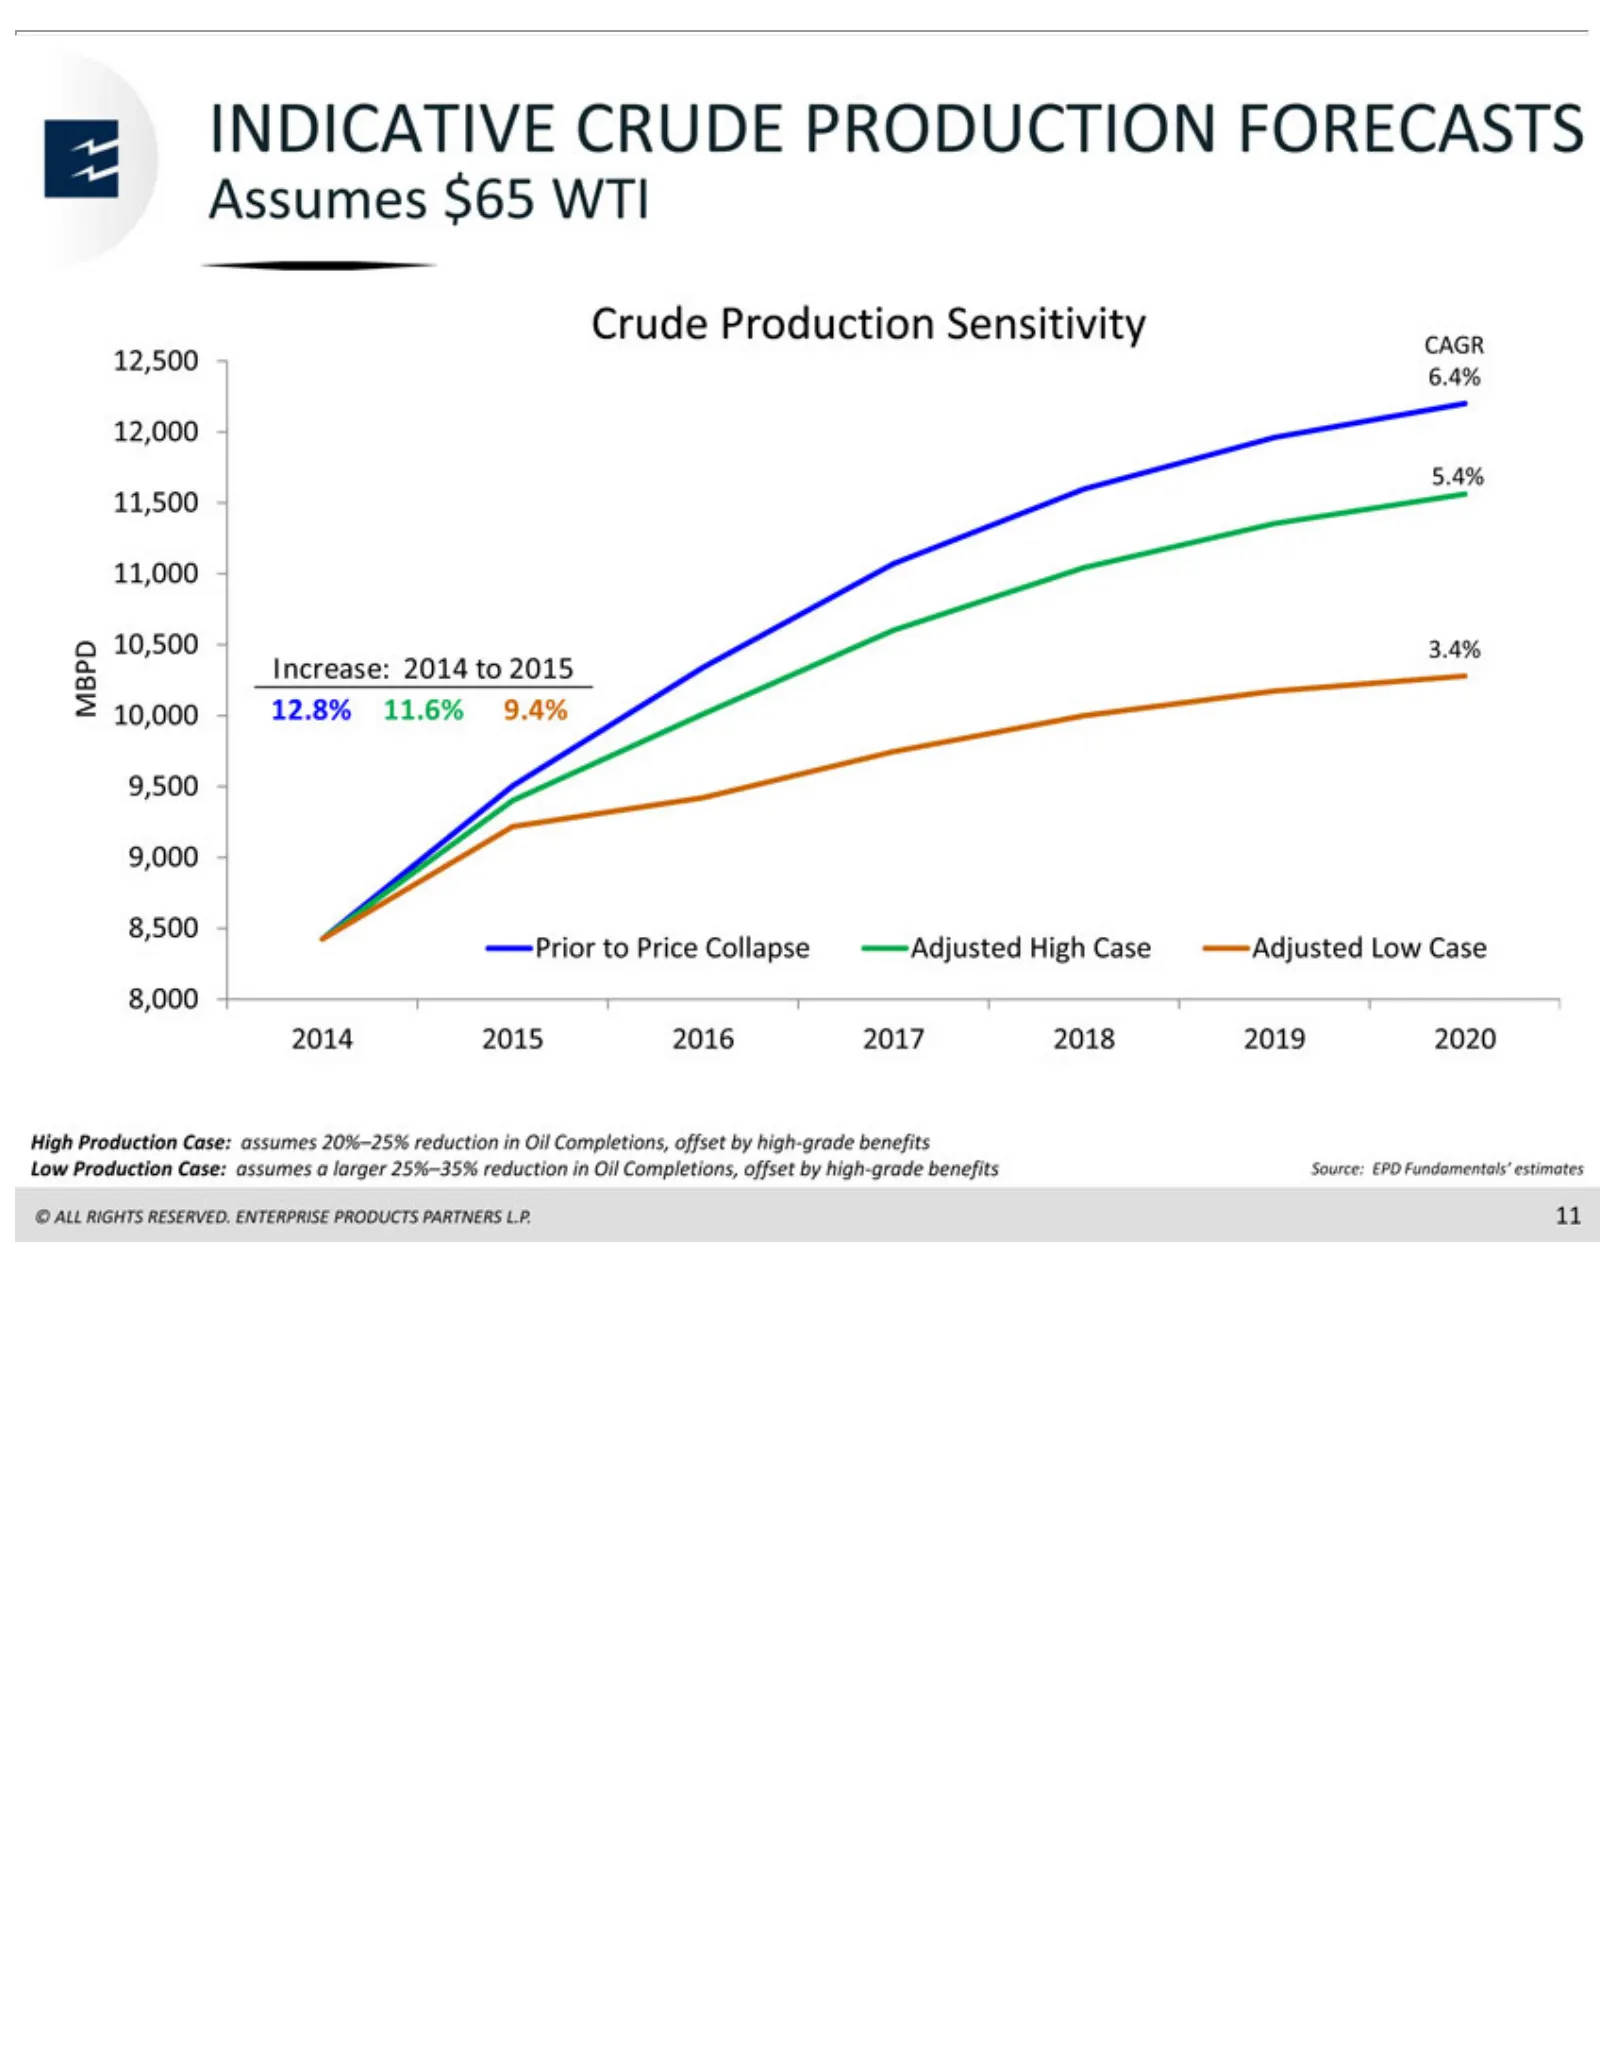
INDICATIVE Assumes Crude 10,500 11,000 11,500 5.4% 12,000 6.4% 12,500 CAGR MBPD 10,000 Prior 8,500 9,000 9,500 High Source: benefits © 11ALL to Production Production 3.4% 12.8% Increase: RIGHTS Price EPD $65 Fundamentals’ Collapse WTI 11.6% CRUDE Case: 2014 RESERVED. Sensitivity 9.4% to Adjusted ass
Slide 13: NGL Production Forecasts
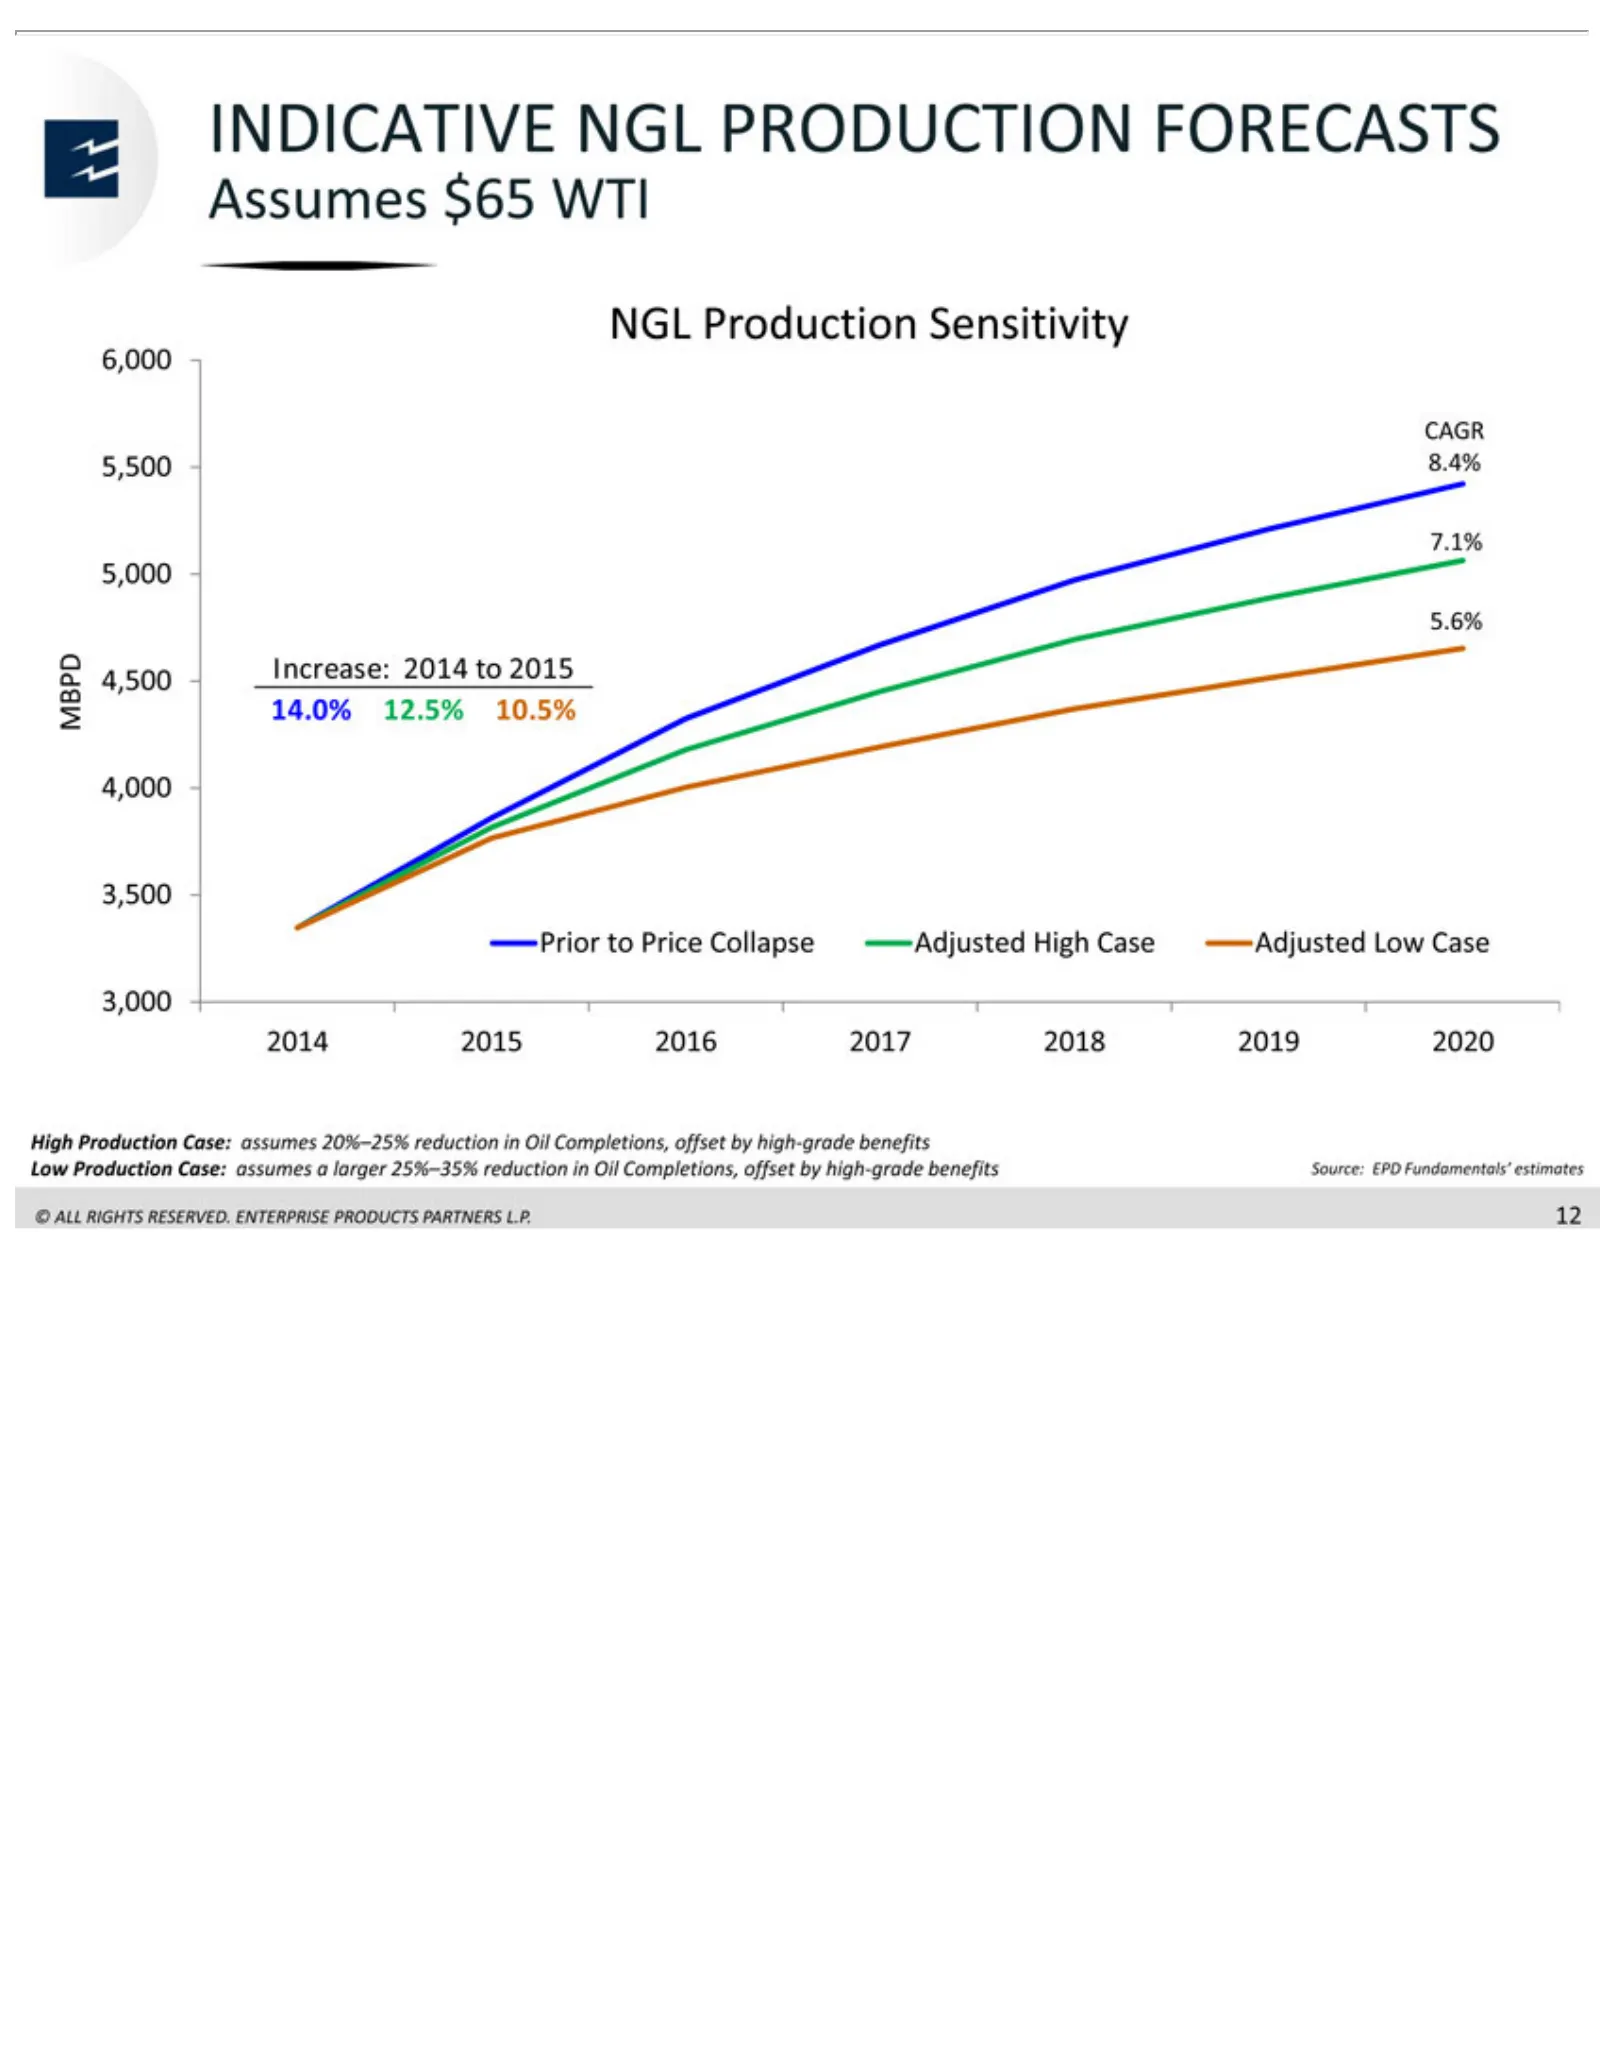
INDICATIVE Assumes NGL 5,500 CAGR 6,000 Increase: 5.6% 5,000 7.1% MBPD 4,500 Prior 3,500 4,000 2014 3,000 High Low Source: © 12ALL Production to 2015 Production 8.4% 14.0% RIGHTS Price EPD 2014 $65 2016 Fundamentals’ Collapse WTI NGL 12.5% toCase: 2017 Case: Sensitivity RESERVED. 2015 PRODUCTION 10.
Slide 14: Projects Overview
PROJECTS © ALL RIGHTS OVERVIEW RESERVED. ENTERPRISE PRODUCTS PARTNERS L.P. enterpriseproducts.com
Slide 15: Major Capital Growth Projects
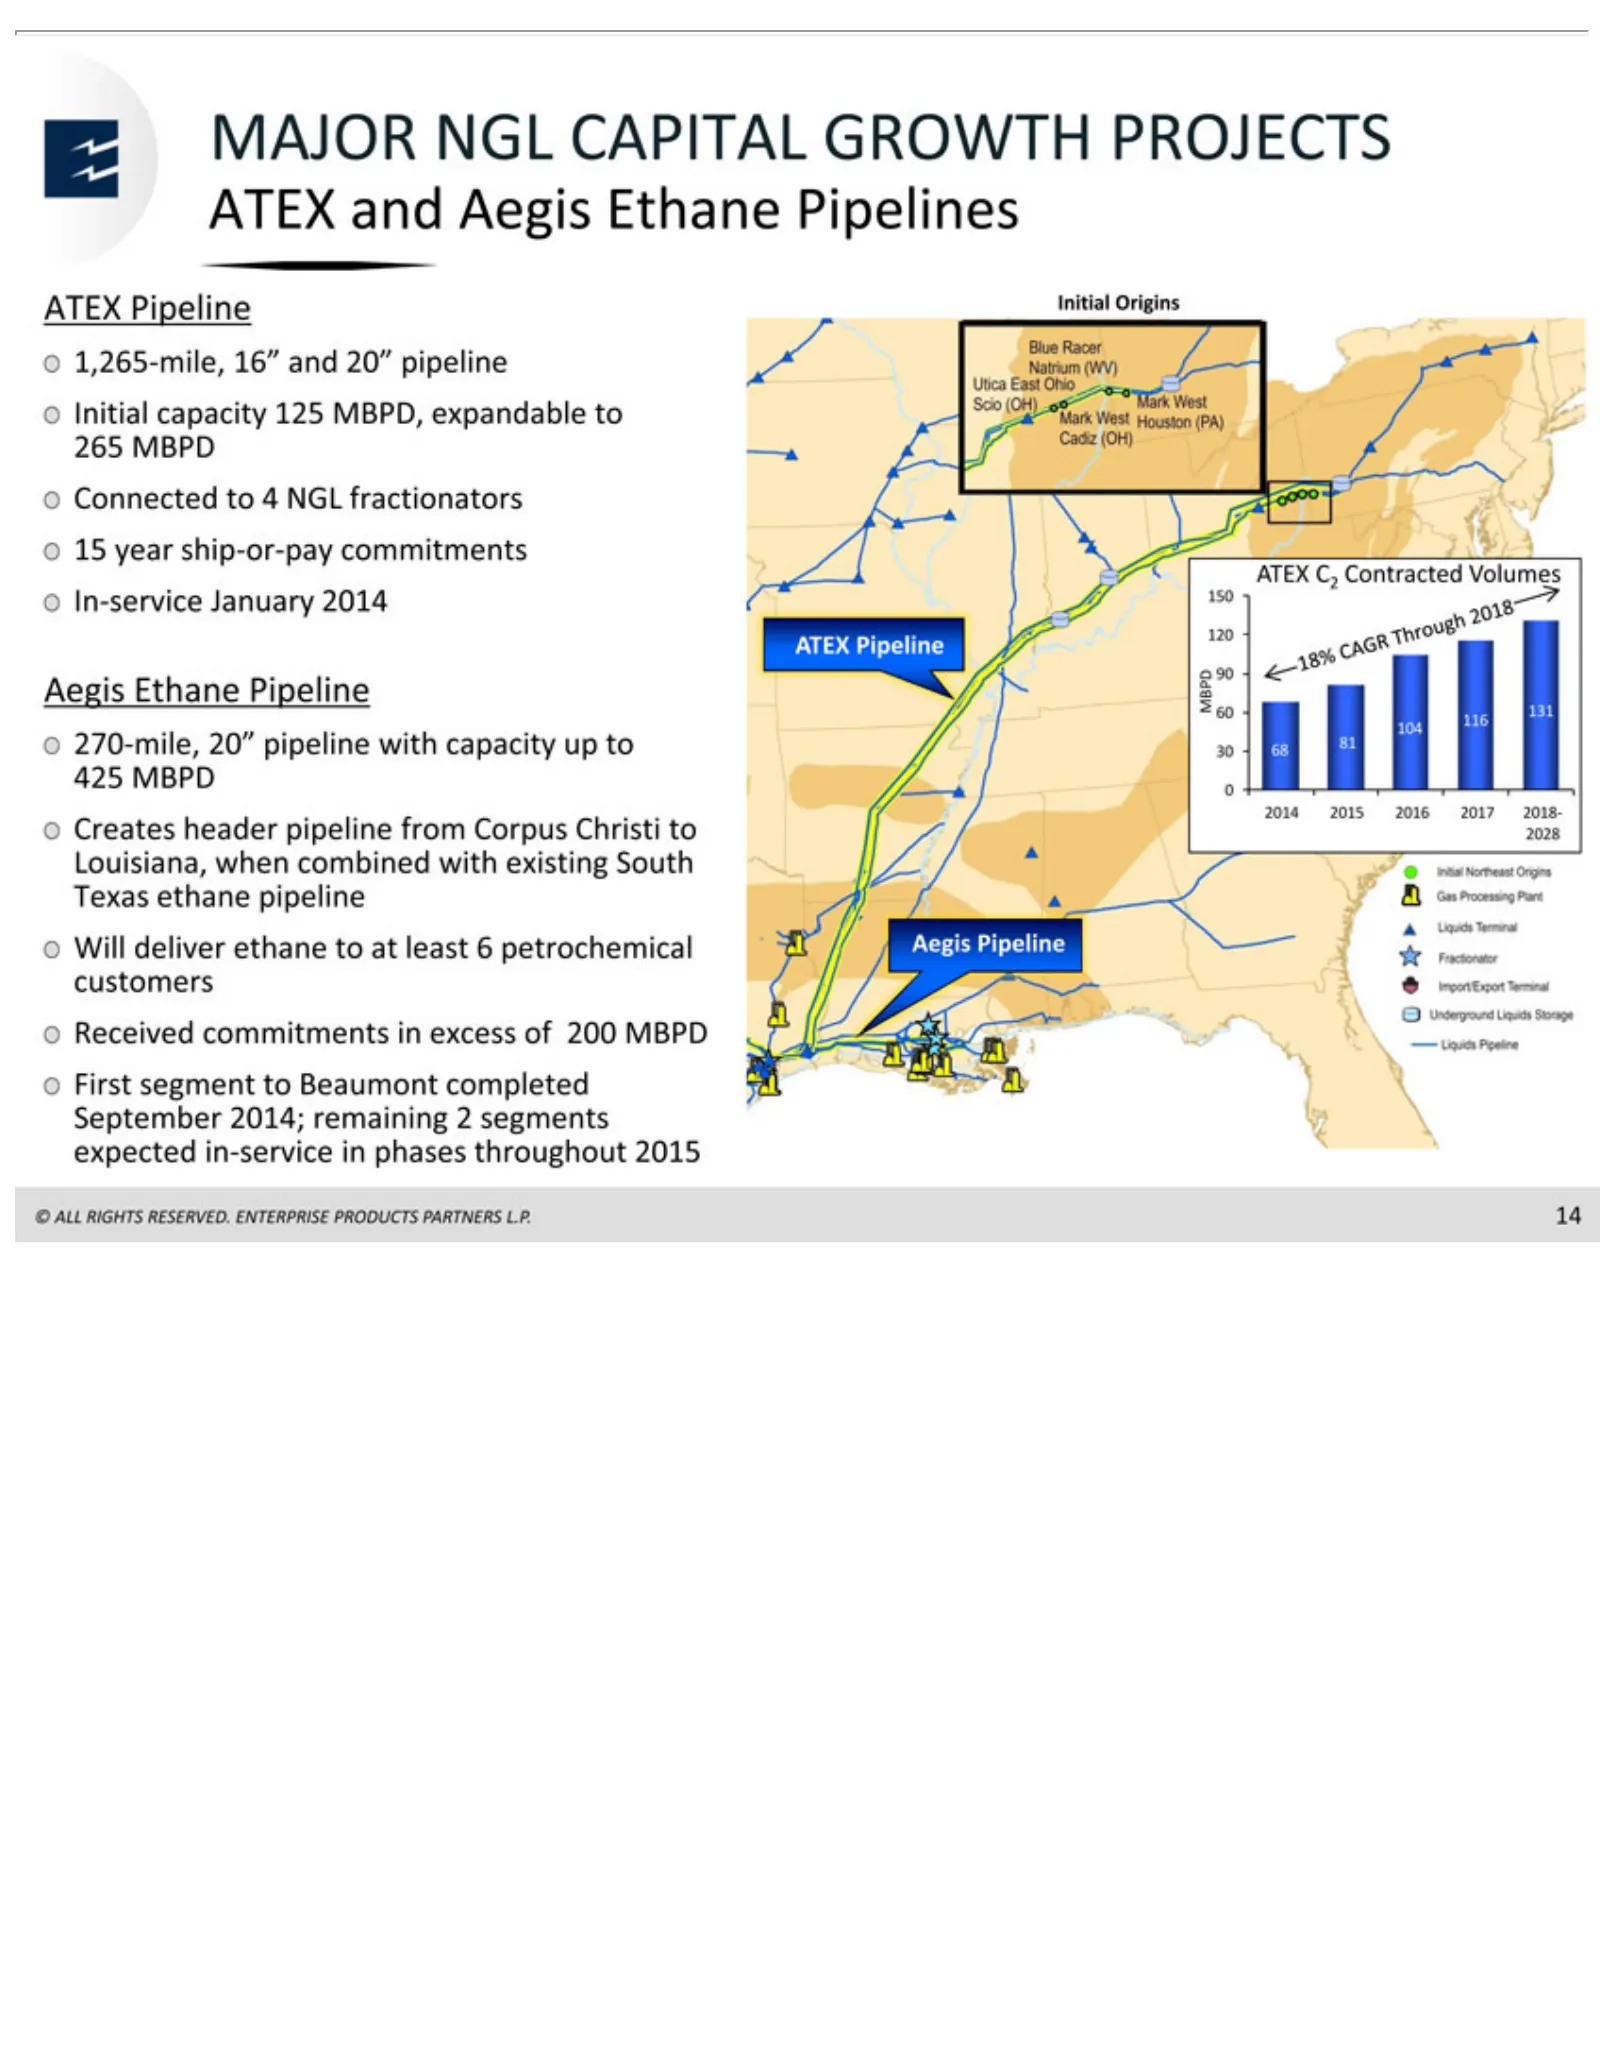
MAJOR 1,265-mile, Connected 270-mile, Creates of Initial ATEX 150 MBPD 60 0230 Aegis © 14 014 ALL 200 1312015 68 Ethane Pipeline capacity Origins and C2 Pipeline MBPD 116 90 RIGHTS header NGL 20” Contracted Aegis 2016 to 104 16” 4Pipeline pipeline CAPITAL First pipeline 125 NGL 120 81 and 2017 RESER
Slide 16: Propylene PDH Facility Update
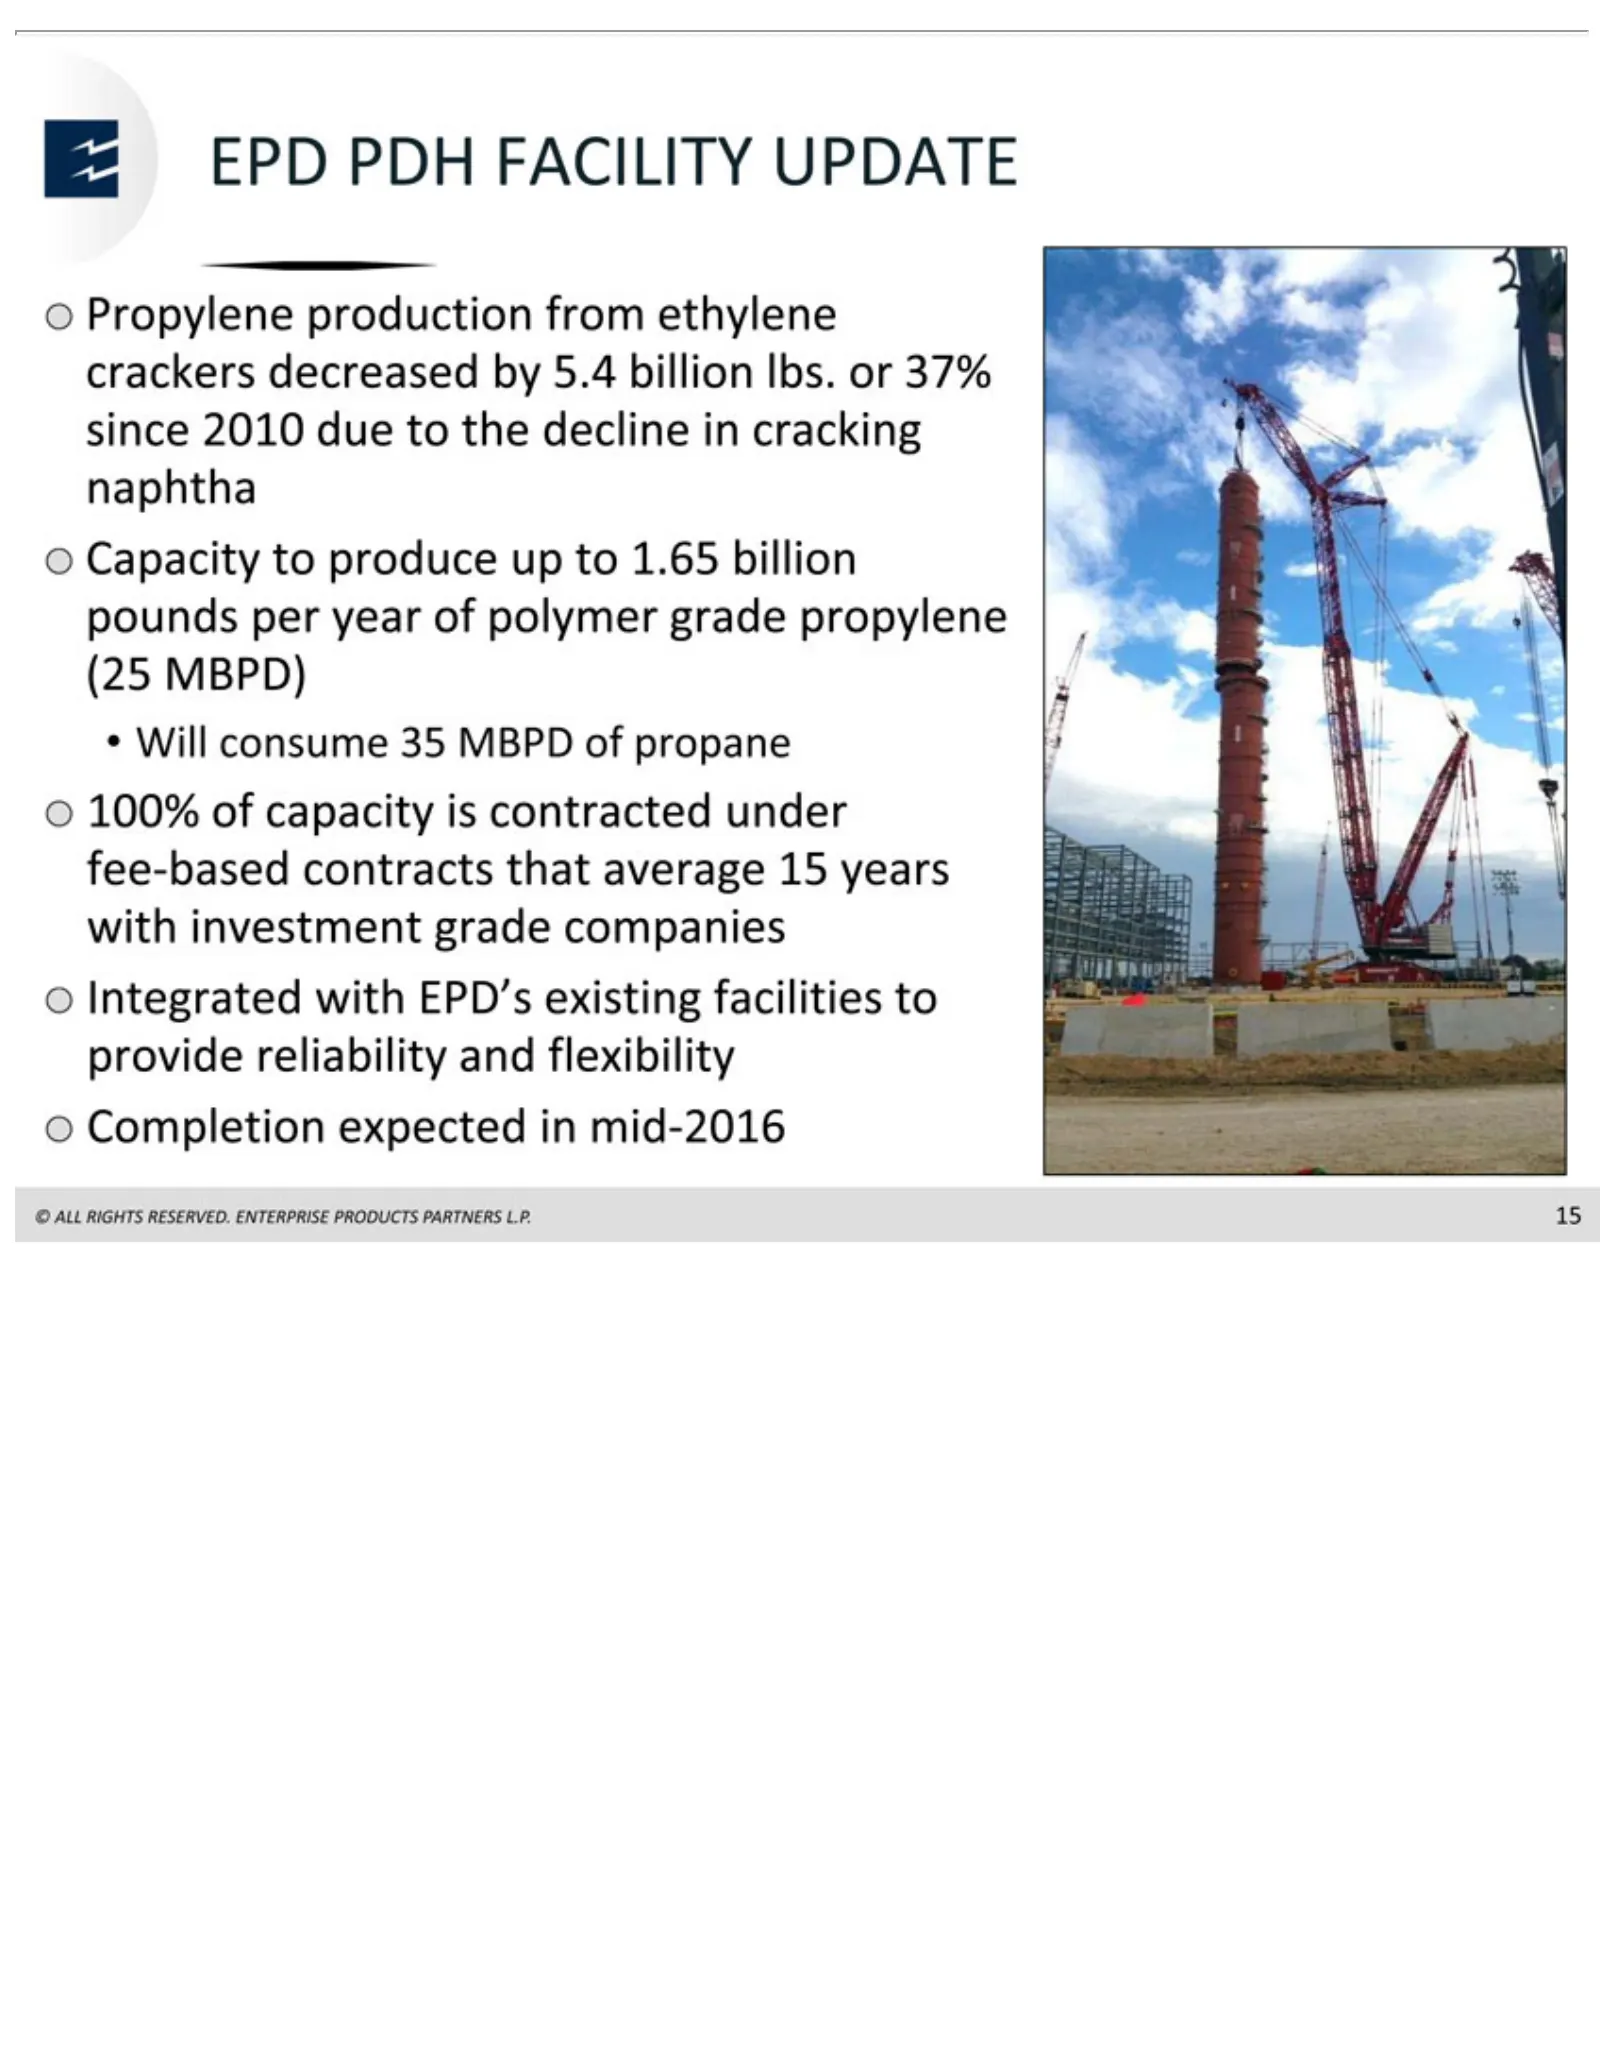
EPD Propylene propylene Will 100% expected © 15ALLconsume PDH ofRIGHTS capacity in(25 production FACILITY mid-2016 35 MBPD) RESERVED. MBPD is contracted from UPDATE of ethylene propane ENTERPRISE undercrackers fee-based decreased PRODUCTS contractsbythat 5.4 PARTNERS average billion lbs. 15 years L.
Slide 17: Export Capacity Linking U.S. Supplies to Global Demand
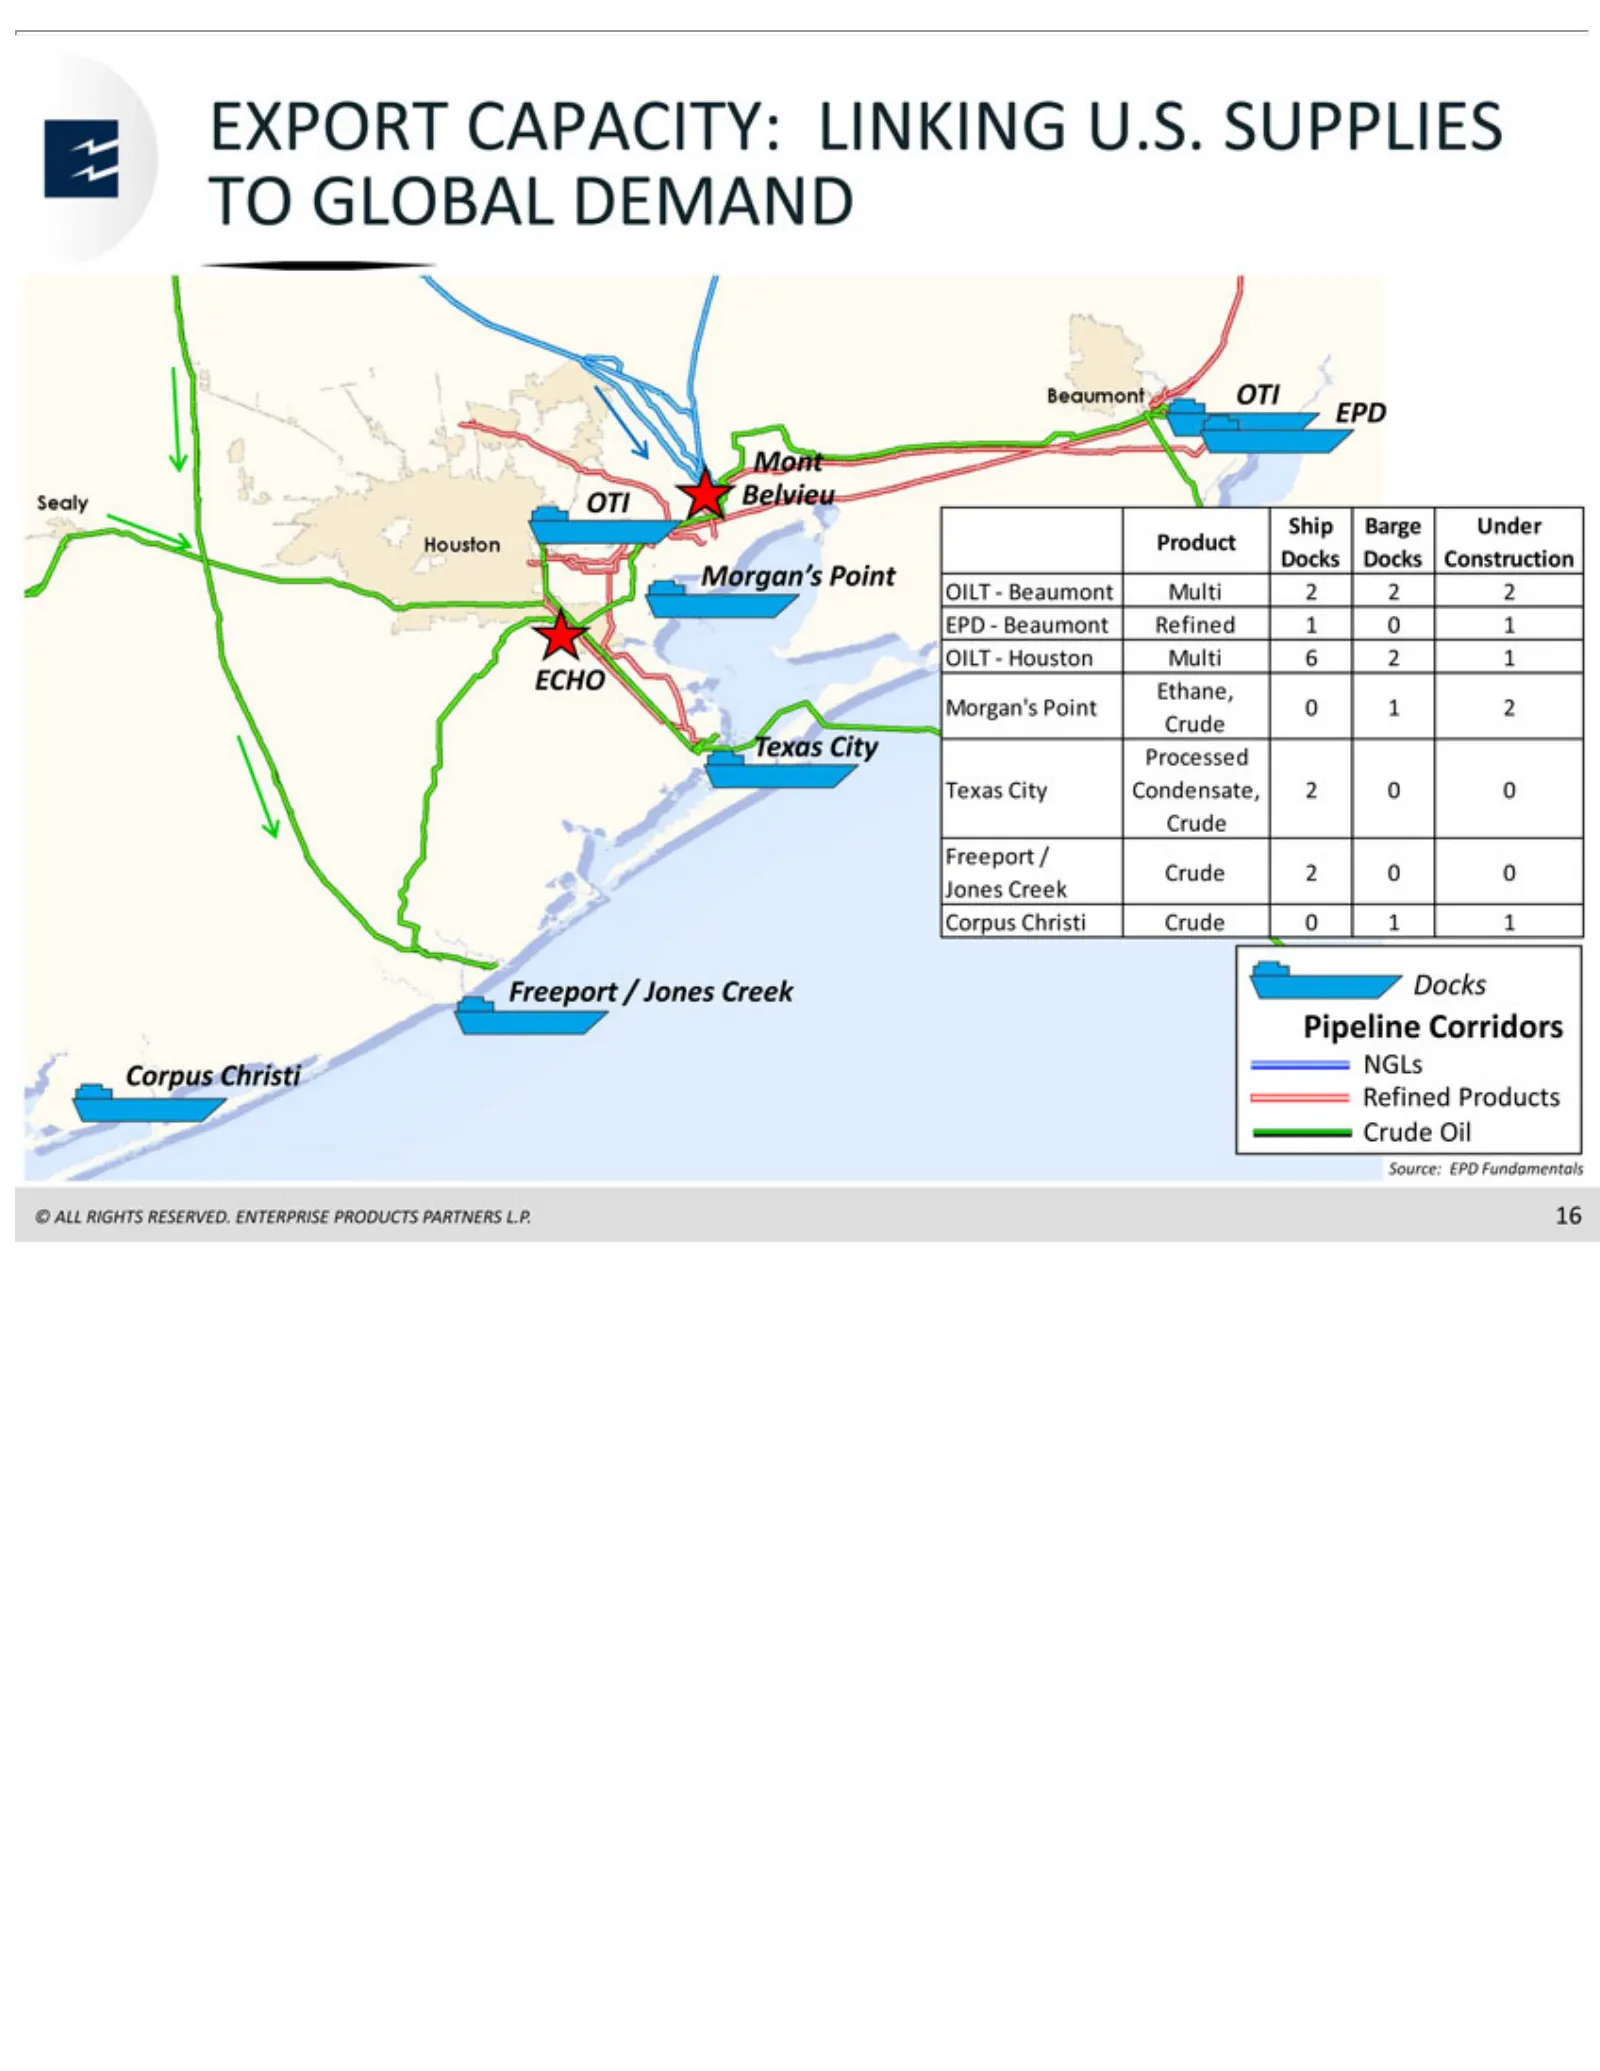
EXPORT EPD OTI Ship Morgan’s OILT Texas Crude Freeport Pipeline Corpus Refined Source: © 16ALLBarge Mont -City 2Beaumont RIGHTS Christi EPD Products 0Corridors / CAPACITY: Point Jones 0Condensate, Processed OTI Under Jones Fundamentals NGLs Belvieu Creek RESERVED. Crude Multi Creek Product Docks LIN
Slide 18: EPD Becomes Largest Propane Exporter
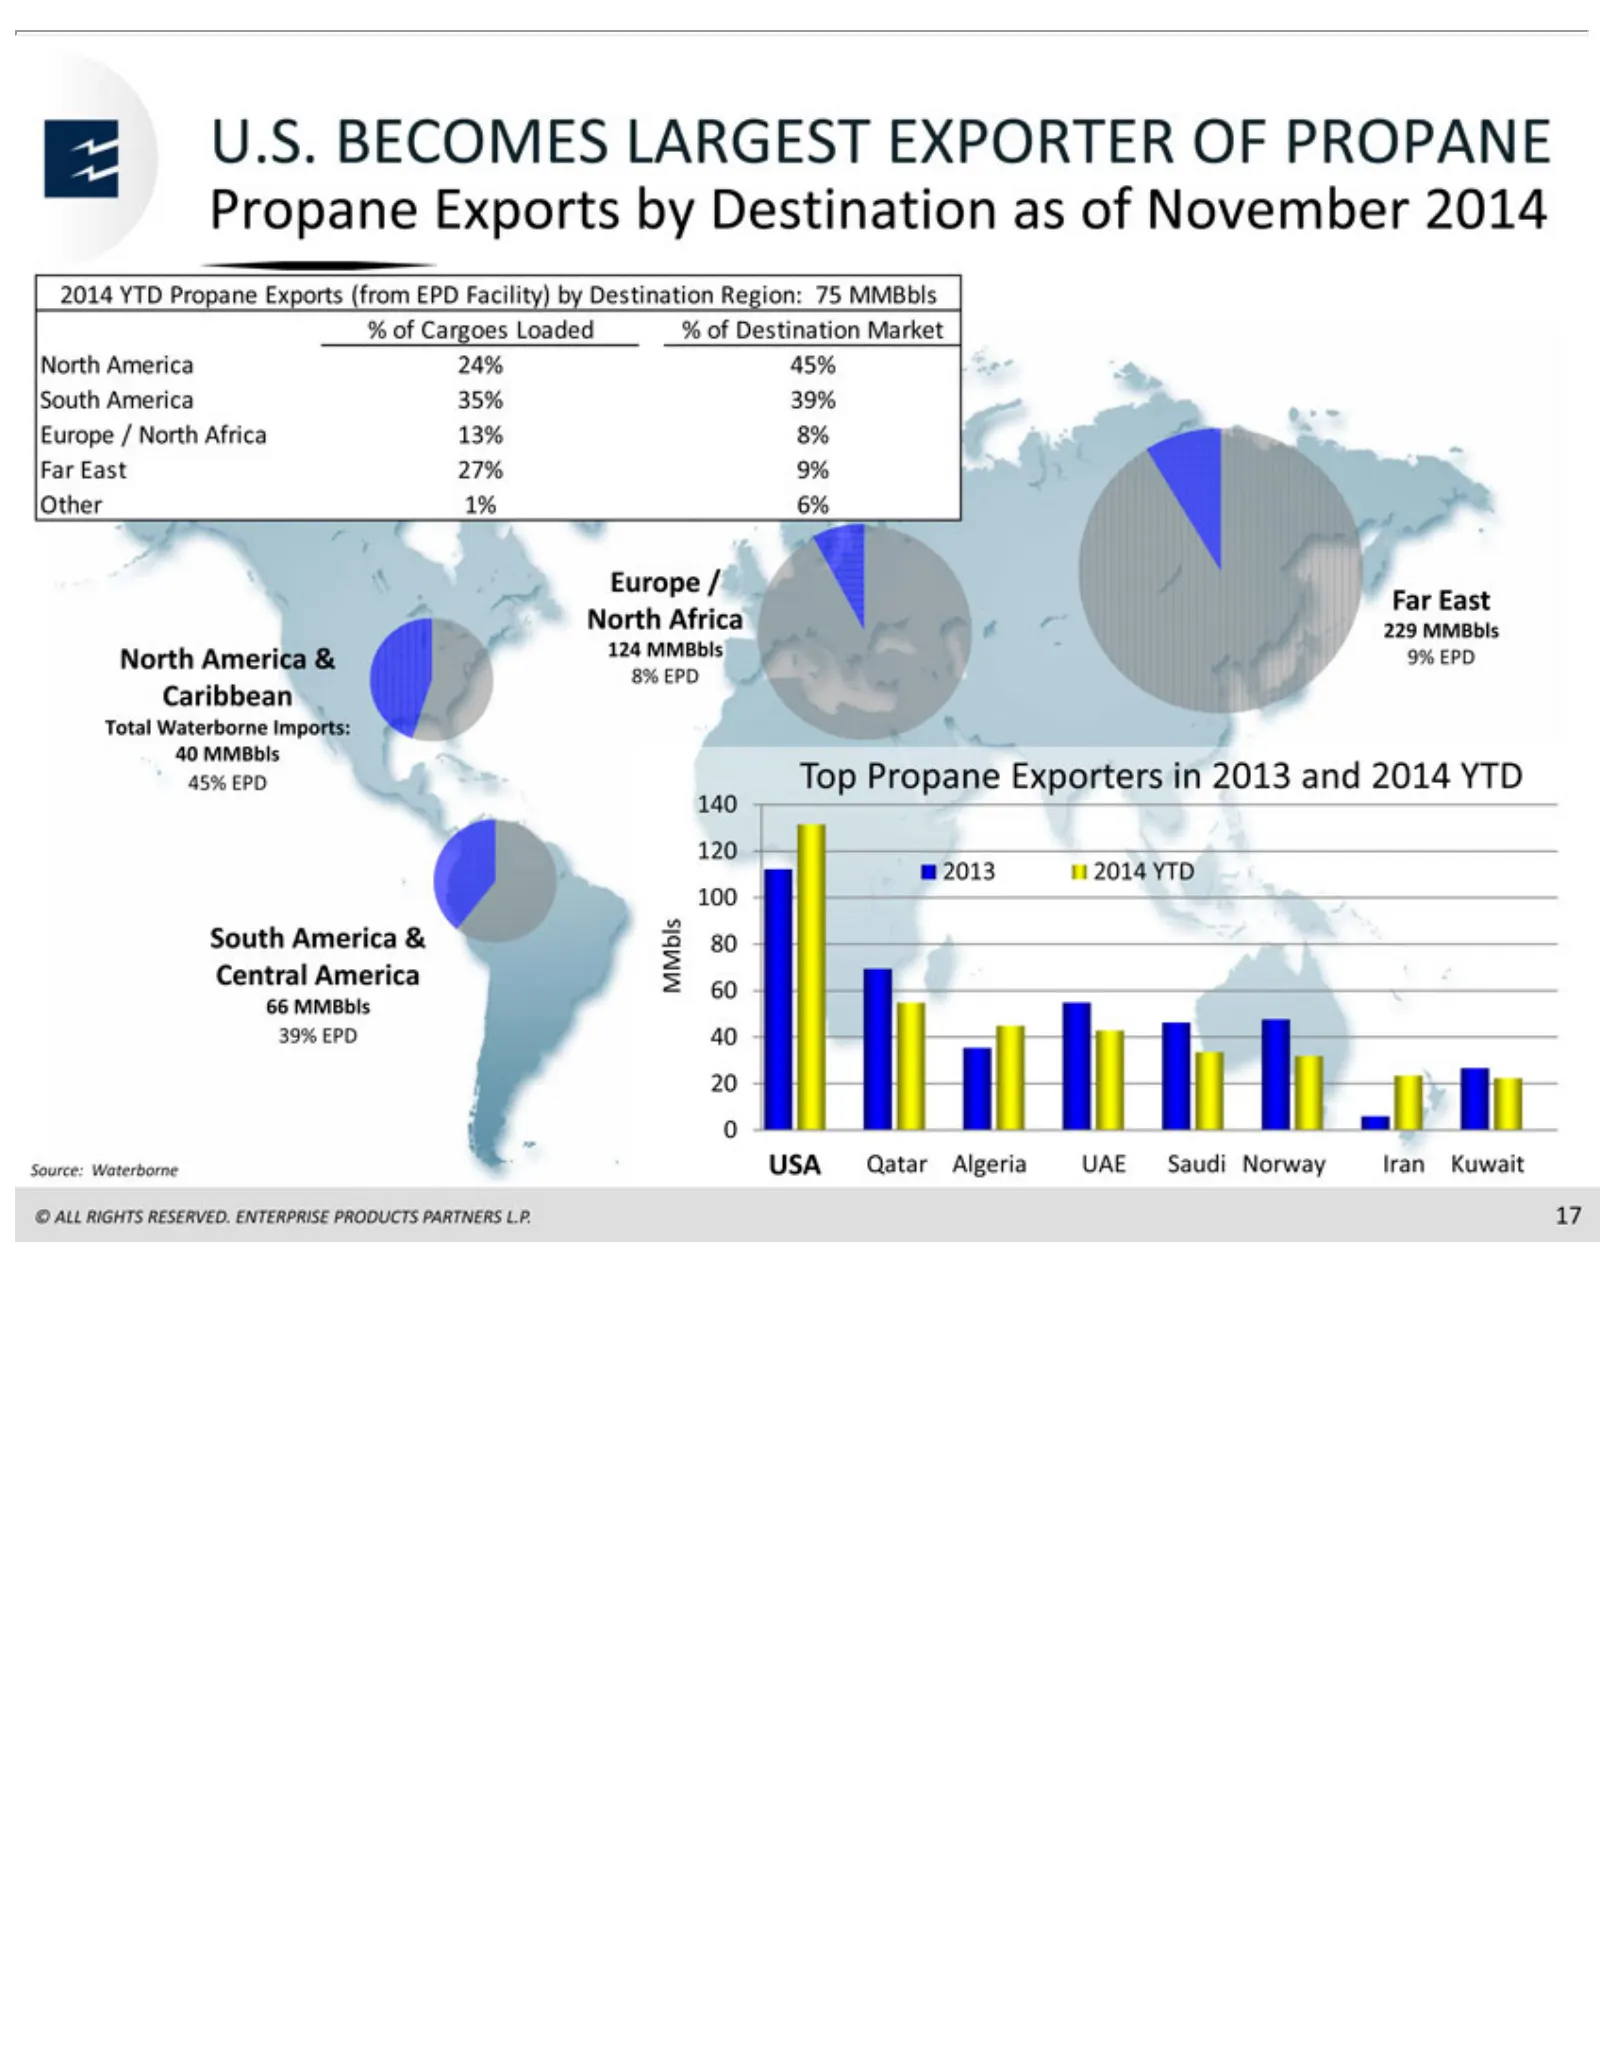
U.S. Propane 2014 13% Europe Far 229 North Total 40 45% 120 140 South 66 60 39% 0S 20 © 17ource: ALL MMBbls East MMBbls 2013 BECOMES 8% EPD YTD Waterborne America RIGHTS /Waterborne Exports North Far 2014 Top 40 Propane East Propane Africa YTD &byRESERVED. LARGEST Imports: 27% 124 80Exports Destinat
Slide 19: LPG Cargo Booking and Building Capacity
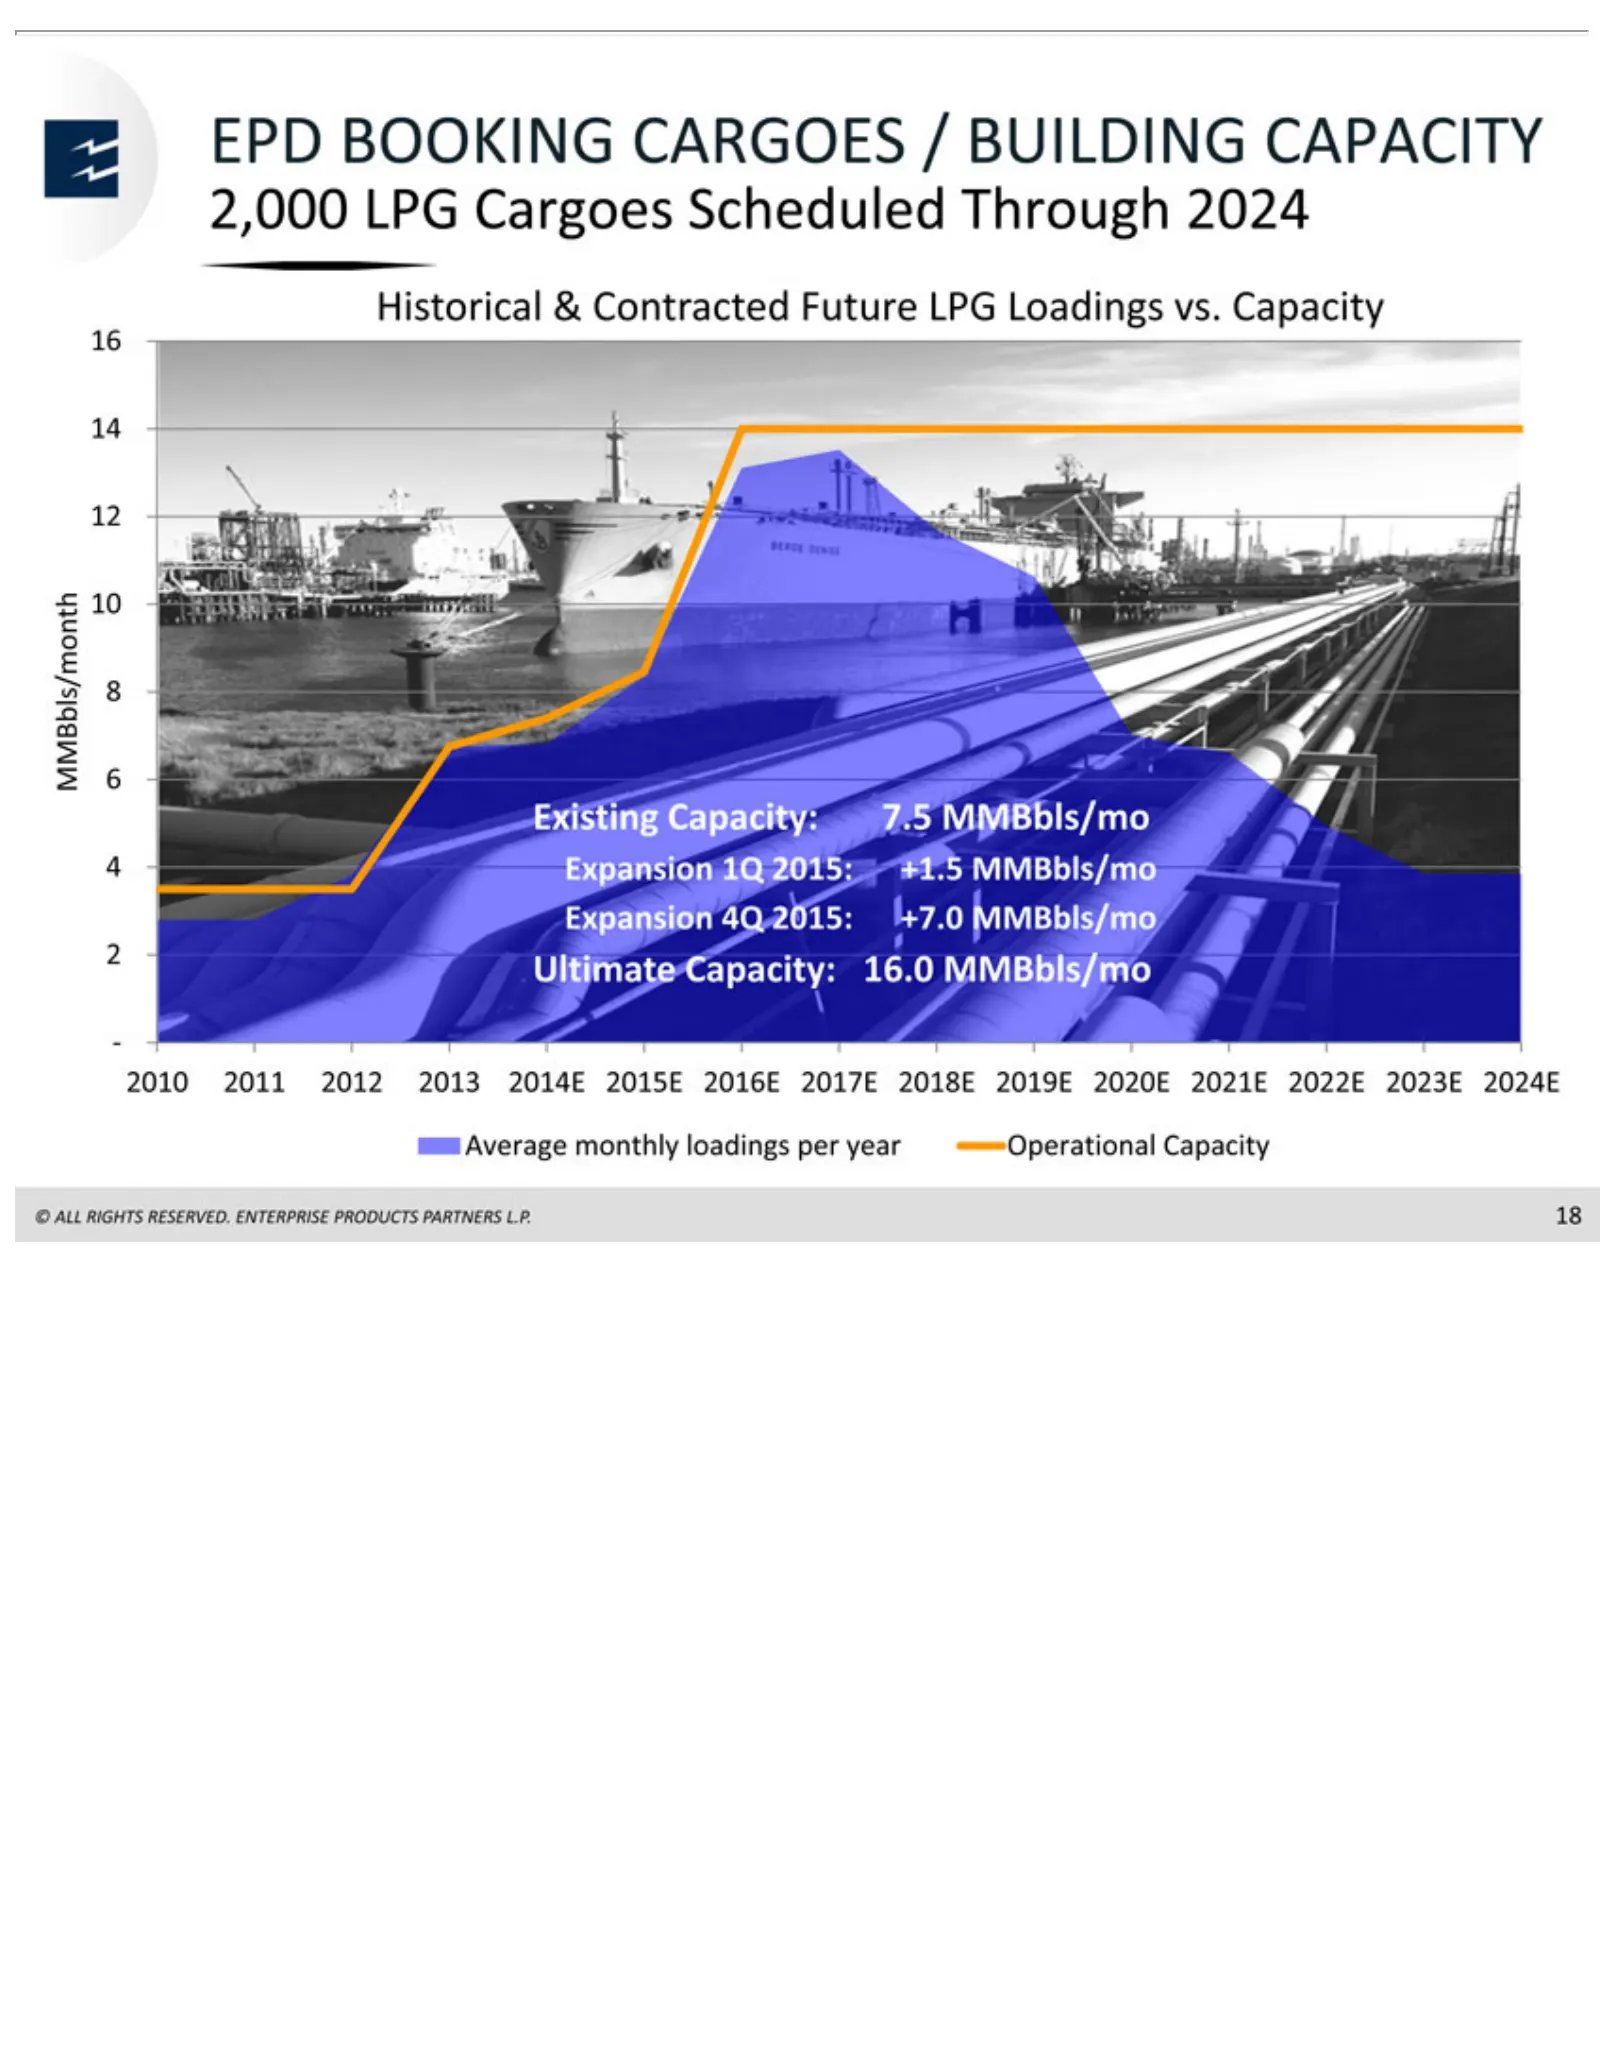
EPD 2,000 Historical 816 24Existing 2010 Average © 18MMBbls/month Expansion Ultimate ALL 14BOOKING 2011 LPG 12 RIGHTS monthly Capacity: 10 & 2012 Capacity: Cargoes Contracted 1Q 2015: 2013 RESERVED. CARGOES loadings 67.5 Scheduled 16.0 2014E MMBbls/mo +1.5 Future MMBbls/mo per MMBbls/mo 2015E / year
Slide 20: New Markets Develop for Ethane
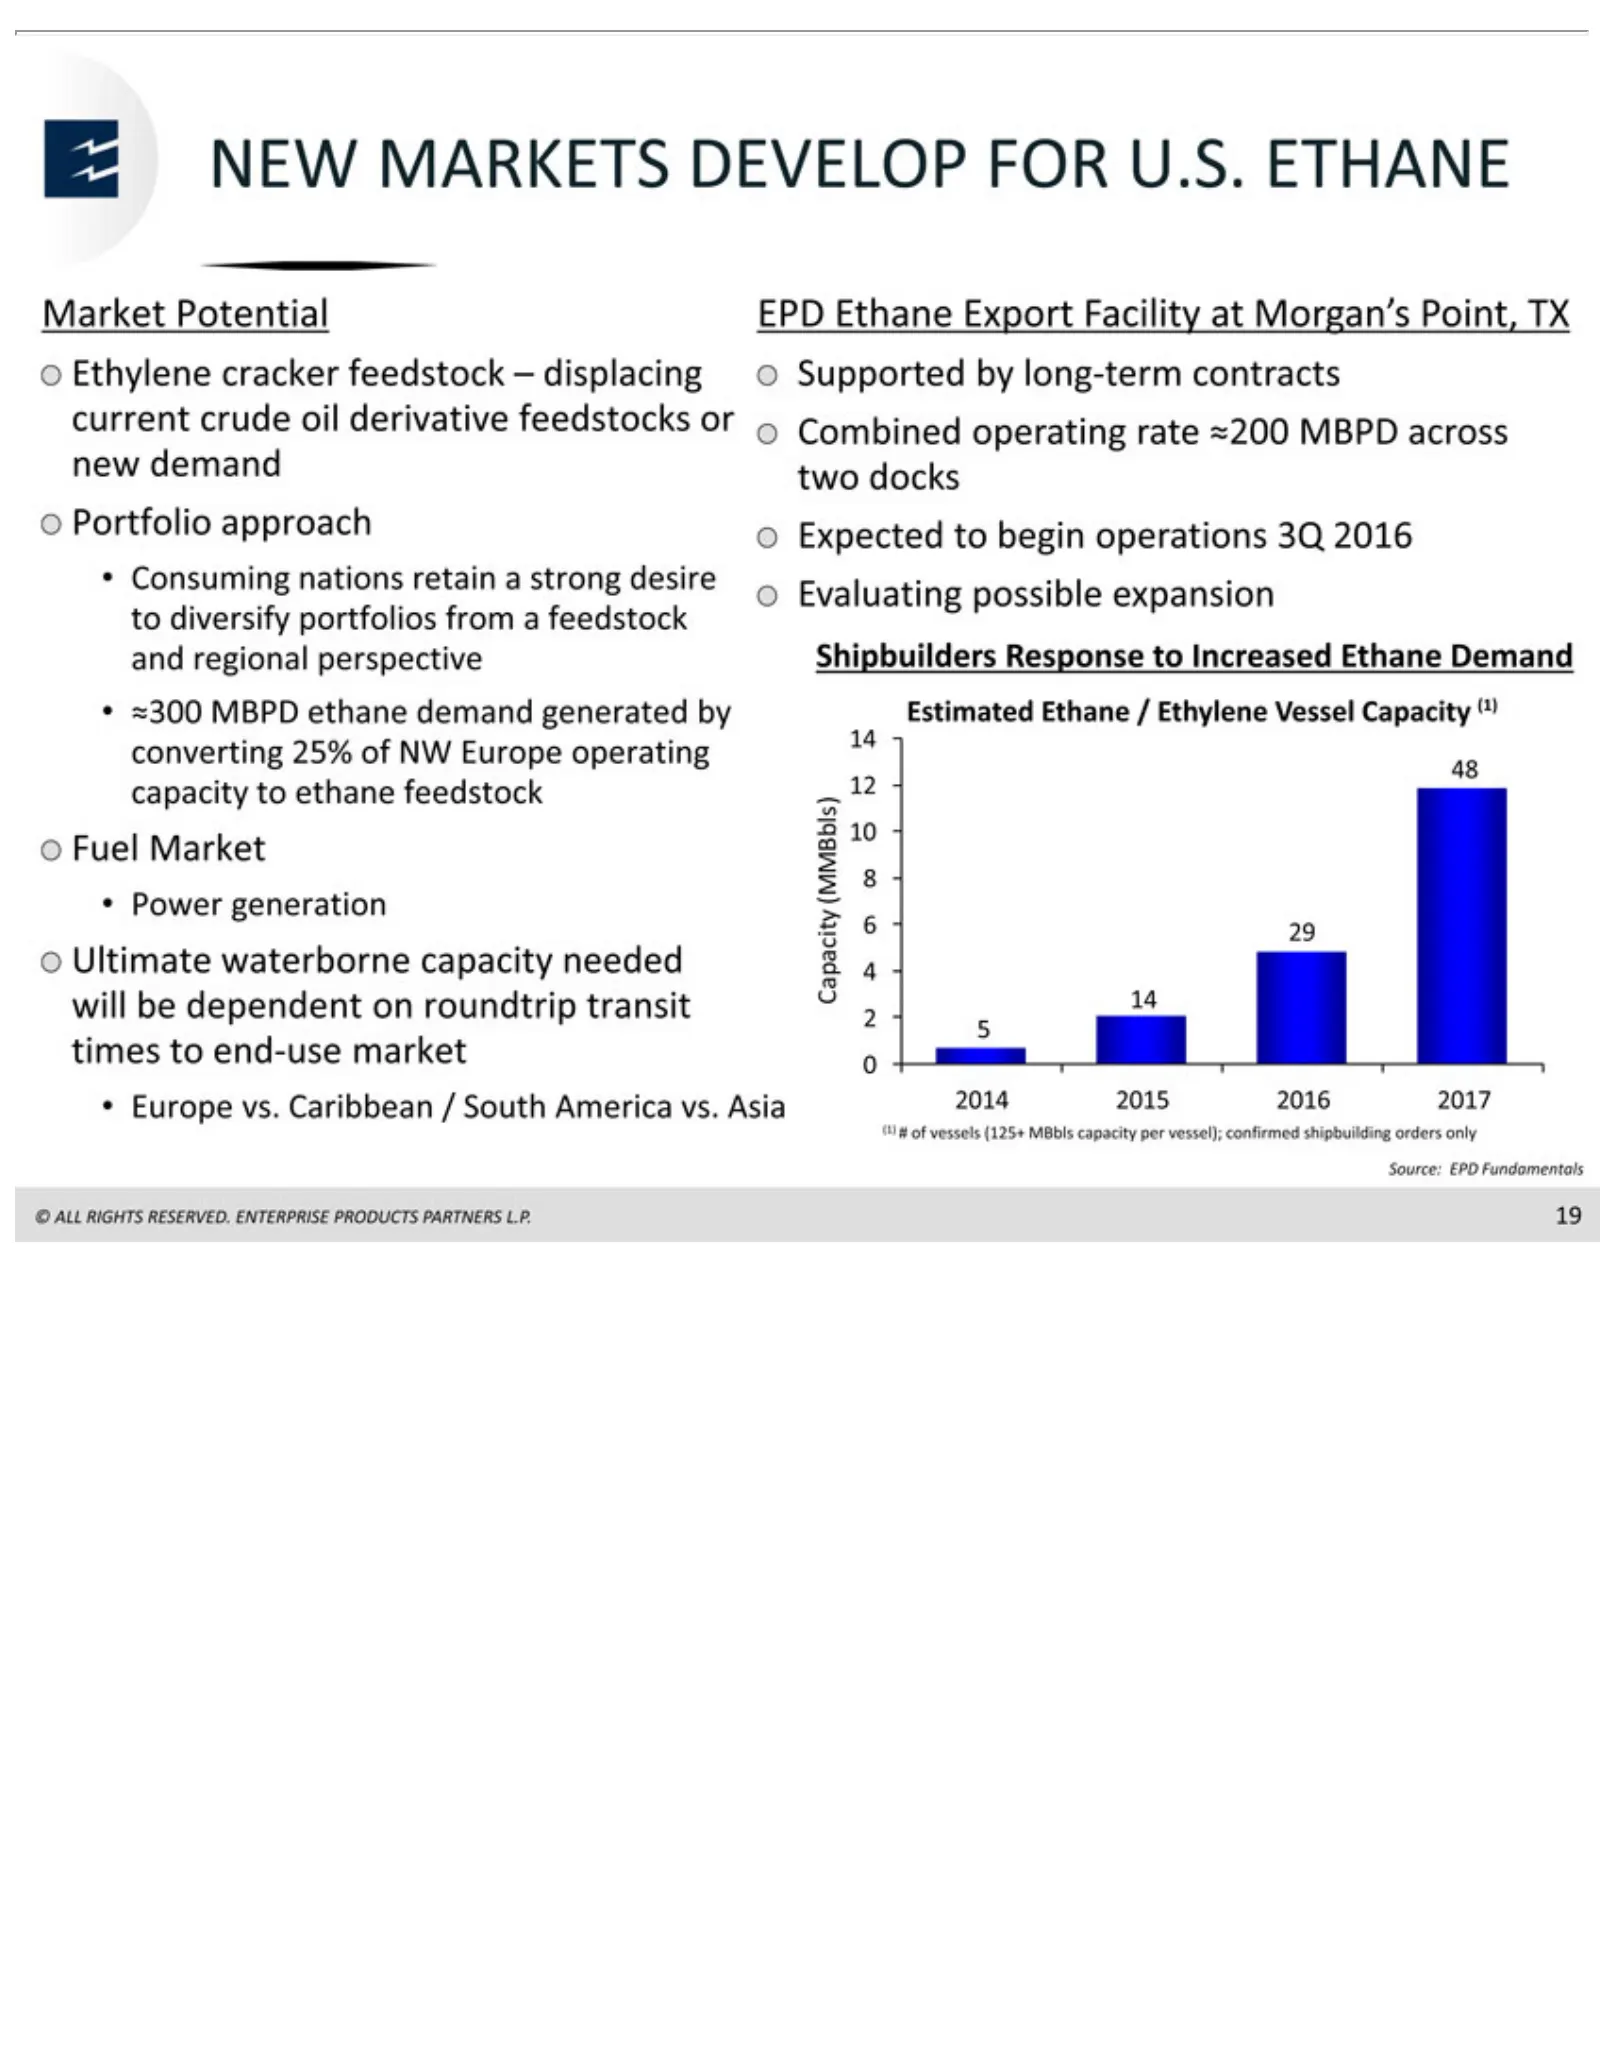
NEW Market Ethylene Consuming ethane Fuel Power Ultimate Europe EPD Supported Combined Shipbuilders Estimated 14 610 2014 (1) Source: © 1929 ALL 48 (MMBbls) # 4Market Ethane of 2015 12 MARKETS 14 generation feedstock RIGHTS vs. Potential vessels EPD waterborne cracker 2Ethane by operating 2016 Carib
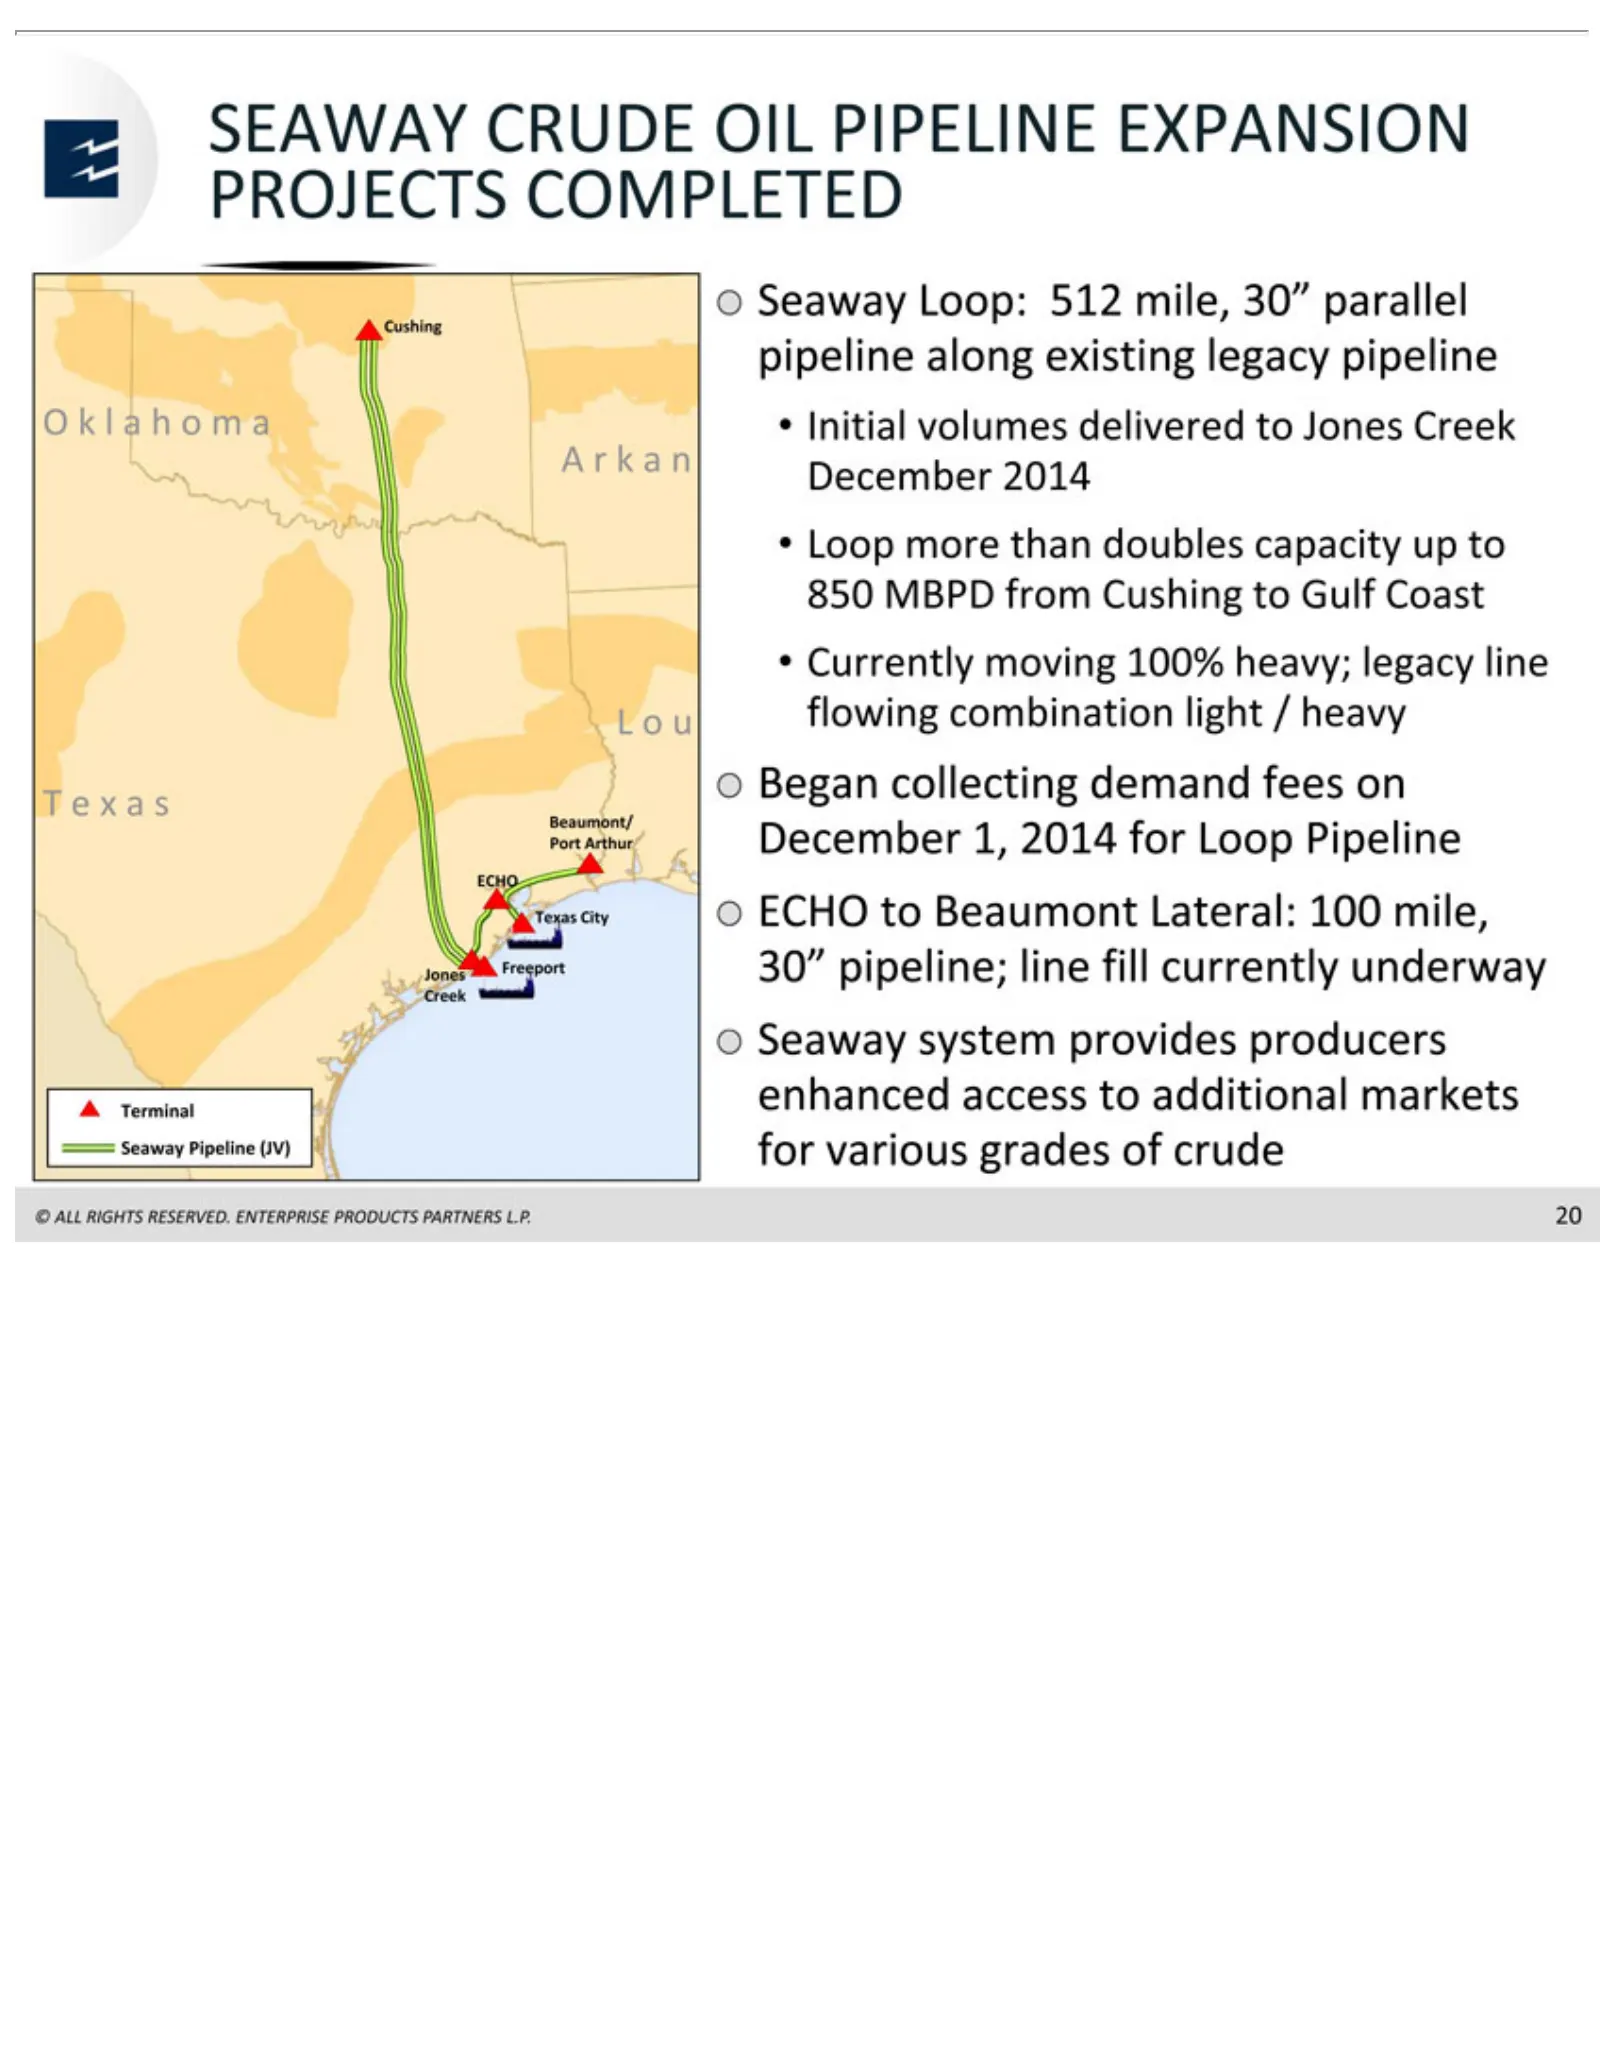
Slide 21: Seaway Crude Oil Pipeline Expansion
SEAWAY Seaway Initial Loop Currently Began additional © 20ALL more volumes collecting RIGHTS Loop: moving CRUDE markets than512 delivered doubles RESERVED. demand 100% for mile, OILvarious PIPELINE heavy; capacity 30” to fees Jones parallel on grades ENTERPRISE legacy December up Creek EXPANSION to
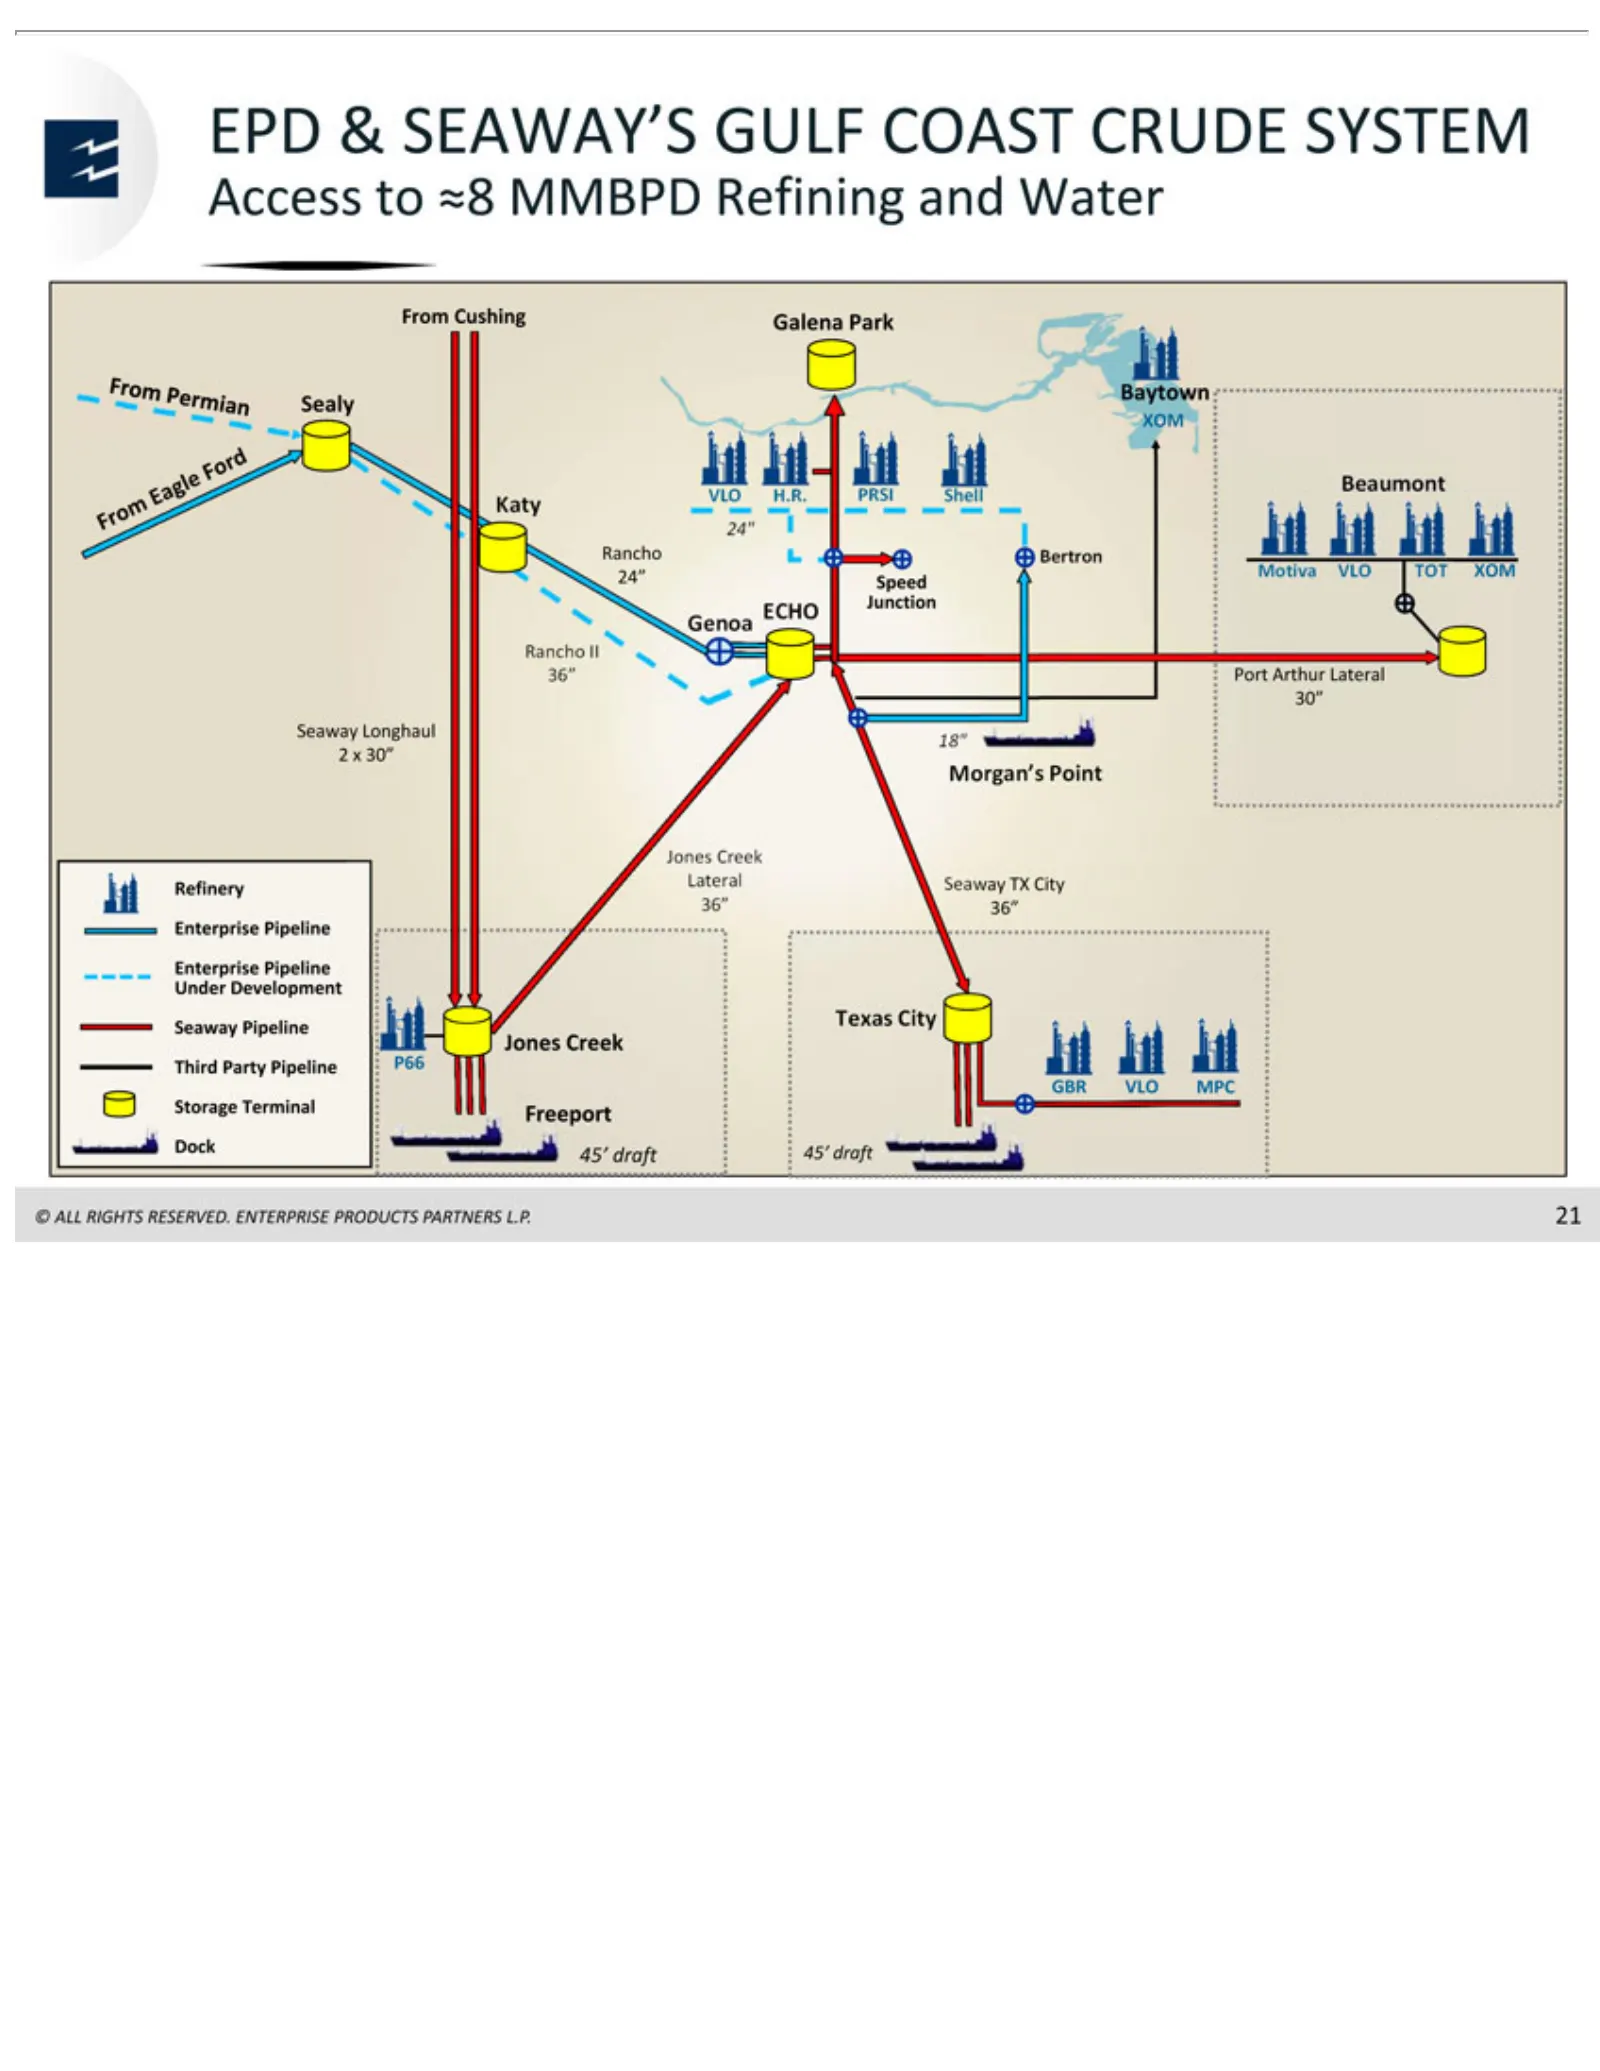
Slide 22: Seaway's Access to Gulf Coast Crude System
EPD Access From Baytown 24” Rancho Port Refinery Enterprise Seaway Jones Third GBR Dock 45’ © 21ALL draft XOM Arthur & VLO 45’ Cushing Party Creek to RIGHTS SEAWAY’S Pipeline TX Sealy draft »8 Speed Pipeline MPC Lateral Pipeline City MMBPD Galena XOM Storage Junction RESERVED. 36” 30” Under GULF P66
Slide 23: Oiltanking Partners
OILTANKING © ALL RIGHTSPARTNERS RESERVED. L.P. ENTERPRISE PRODUCTS PARTNERS L.P. enterpriseproducts.com
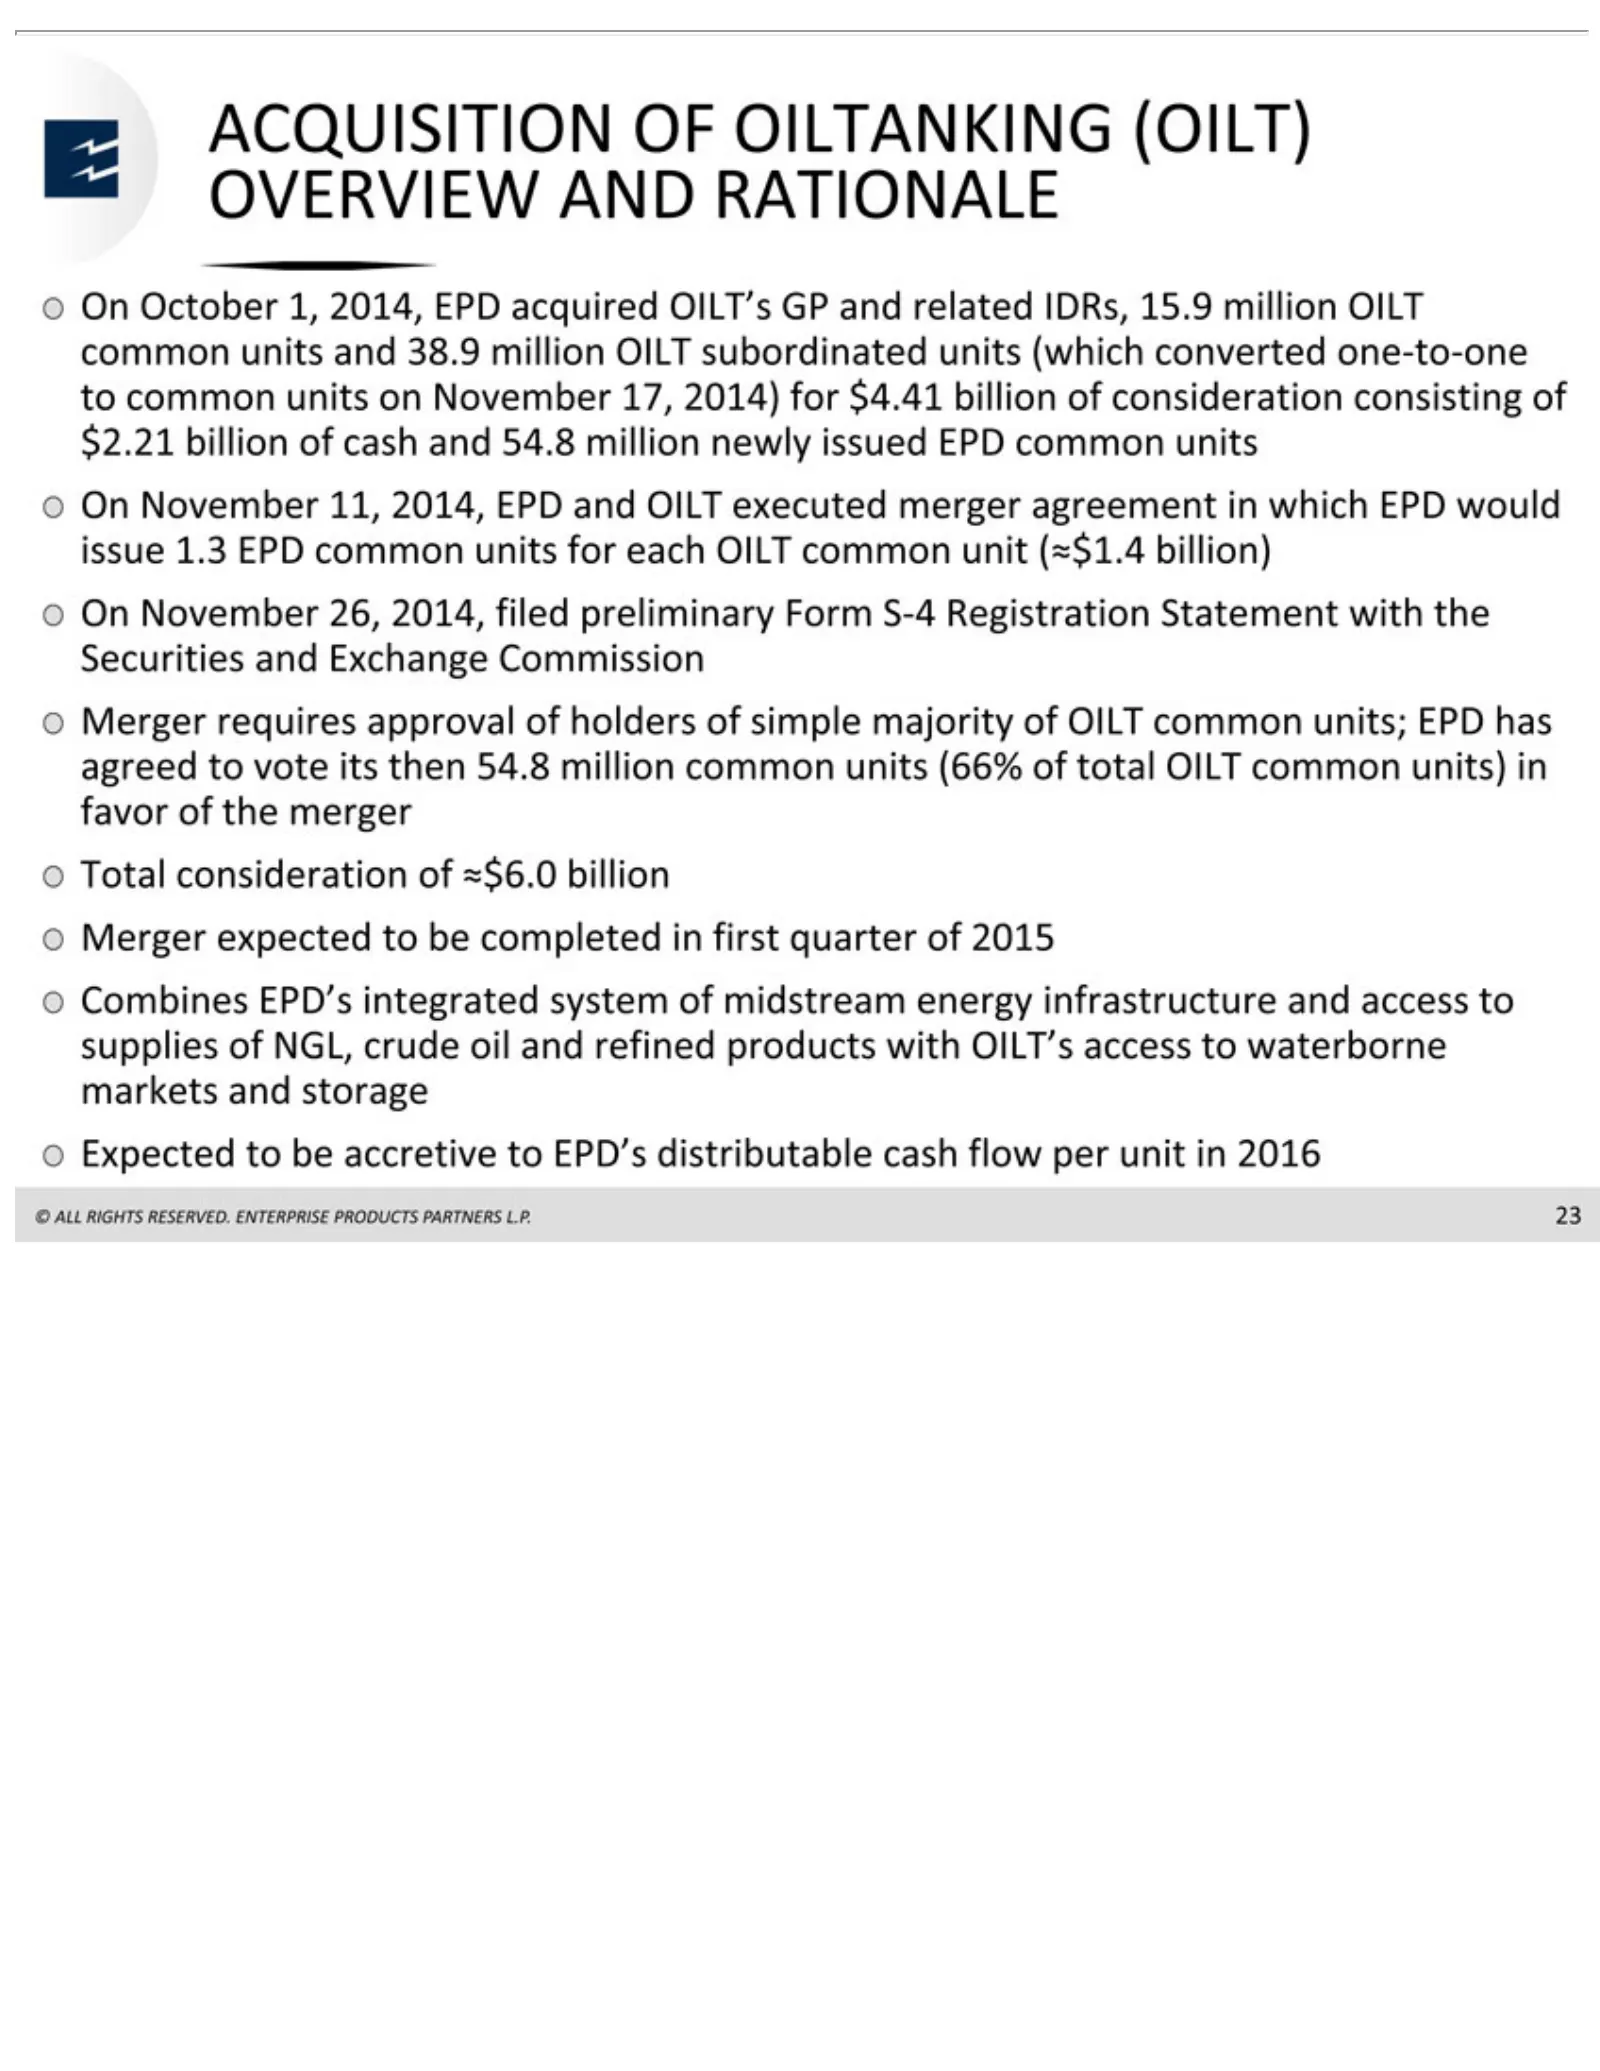
Slide 24: Acquisition of Oiltanking Overview and Rationale
ACQUISITION On 2014) EPD Merger consideration refined © 23 ALL October would for products RIGHTS requires $4.41 issue 1,of 2014, billion approval OF $6.0 with RESERVED. 1.3OILTANKING EPD EPD billion OILT’s of of consideration acquired common holders Merger access ENTERPRISE OILT’s (OILT) units of to
Slide 25: Acquisition of Oiltanking: Principal Drivers of Value Creation
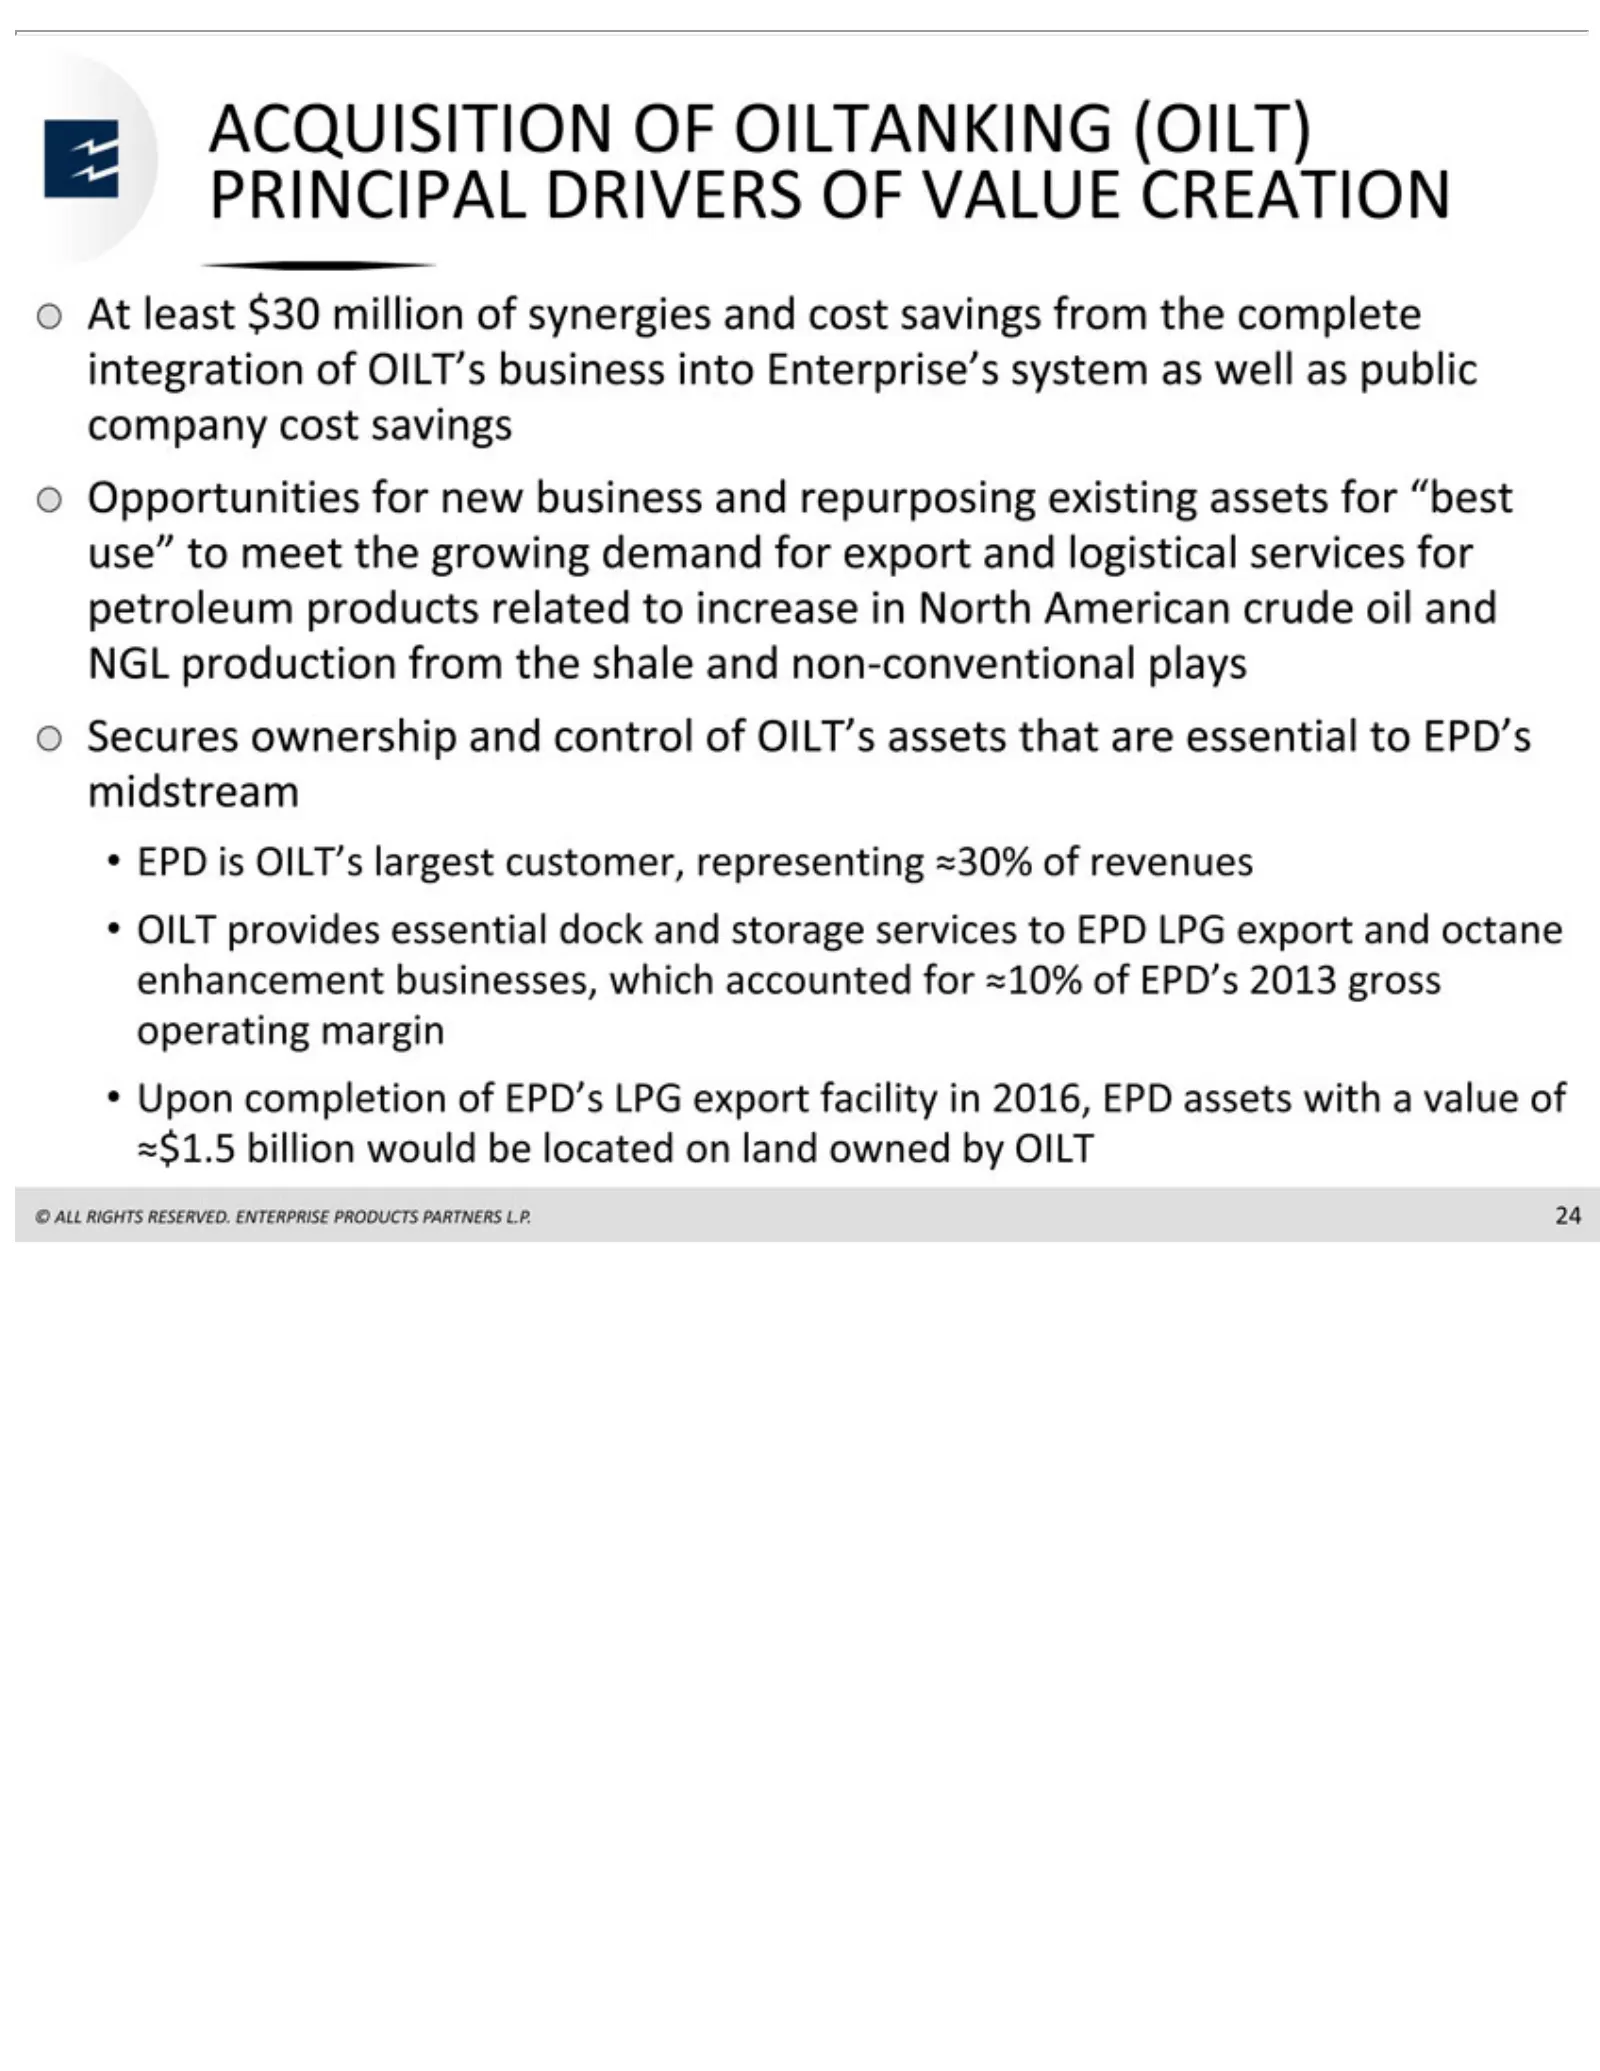
ACQUISITION At repurposing shale EPD OILT Upon »$1.5 © 24ALL least is and provides completion billion OILT’s RIGHTS $30non-conventional existing million would essential largest OF RESERVED. of be of OILTANKING EPD’s assets customer, synergies located dock for LPG plays and on “best ENTERPRISE repres
Slide 26: OILT Asset Overview: Houston
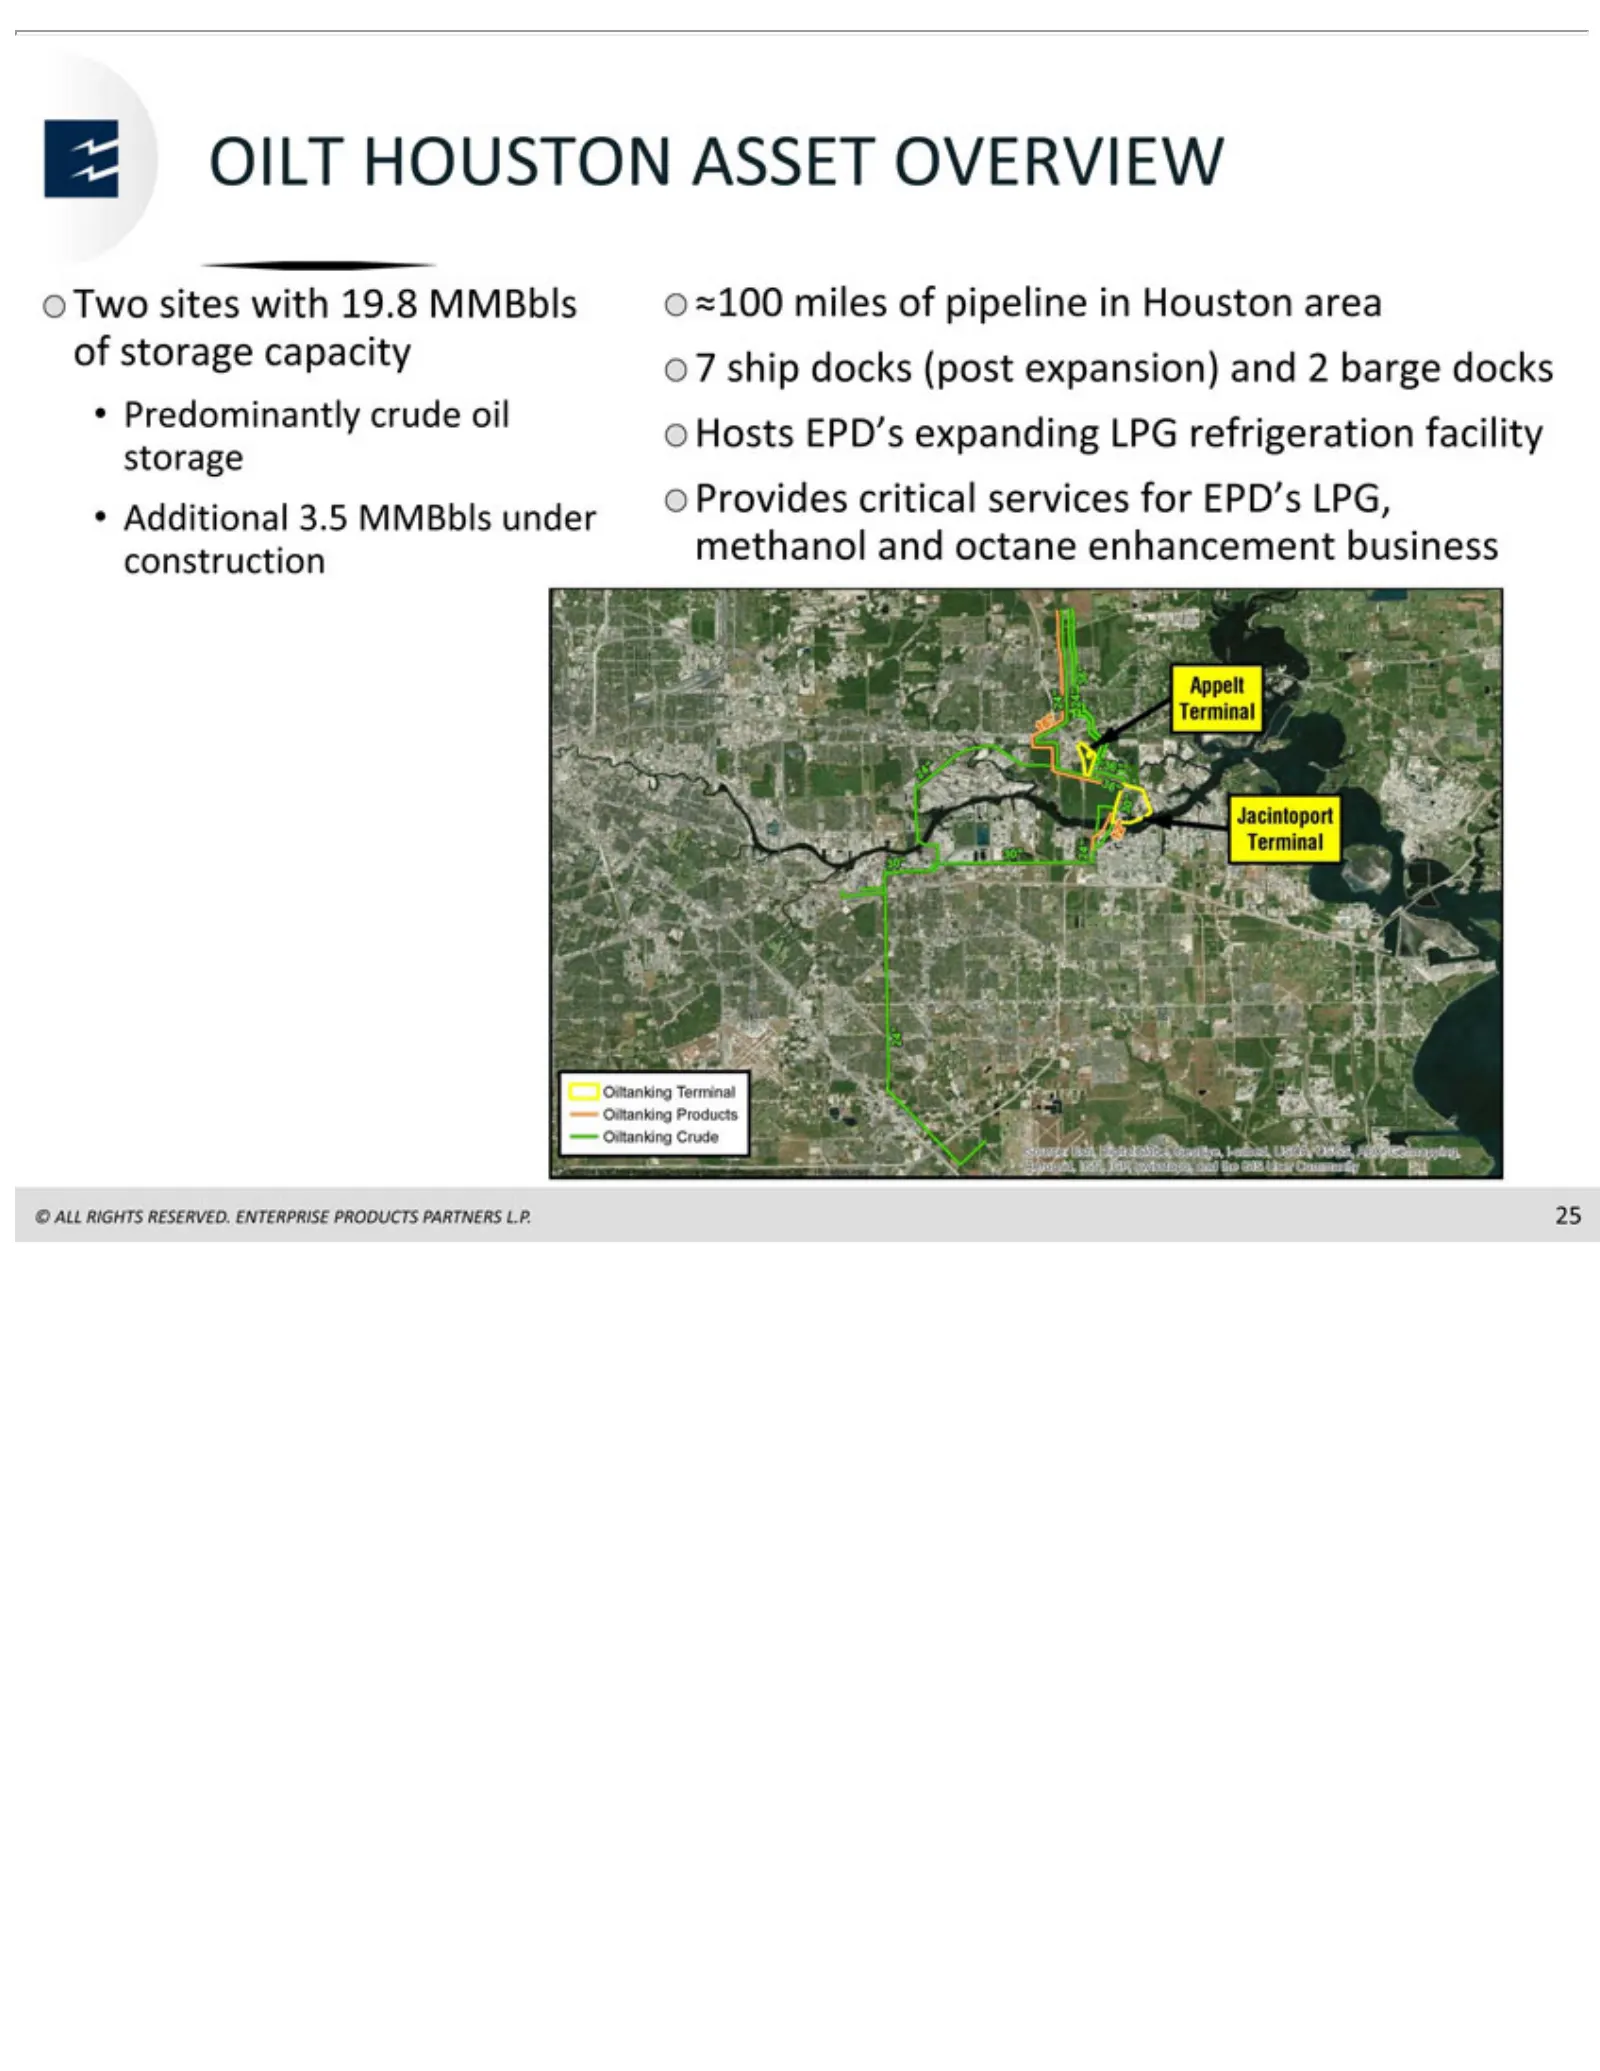
OILT Two Predominantly Additional 7»100 © 25ship ALL sites miles HOUSTON docks RIGHTS with 3.5 of(post pipeline MMBbls 19.8 crude RESERVED. ASSET expansion) MMBbls oilinunder storage Houston OVERVIEW of and construction ENTERPRISE storage 2area barge capacity docks PRODUCTS Hosts EPD’sPARTNERS expan
Slide 27: OILT Asset Overview: Beaumont
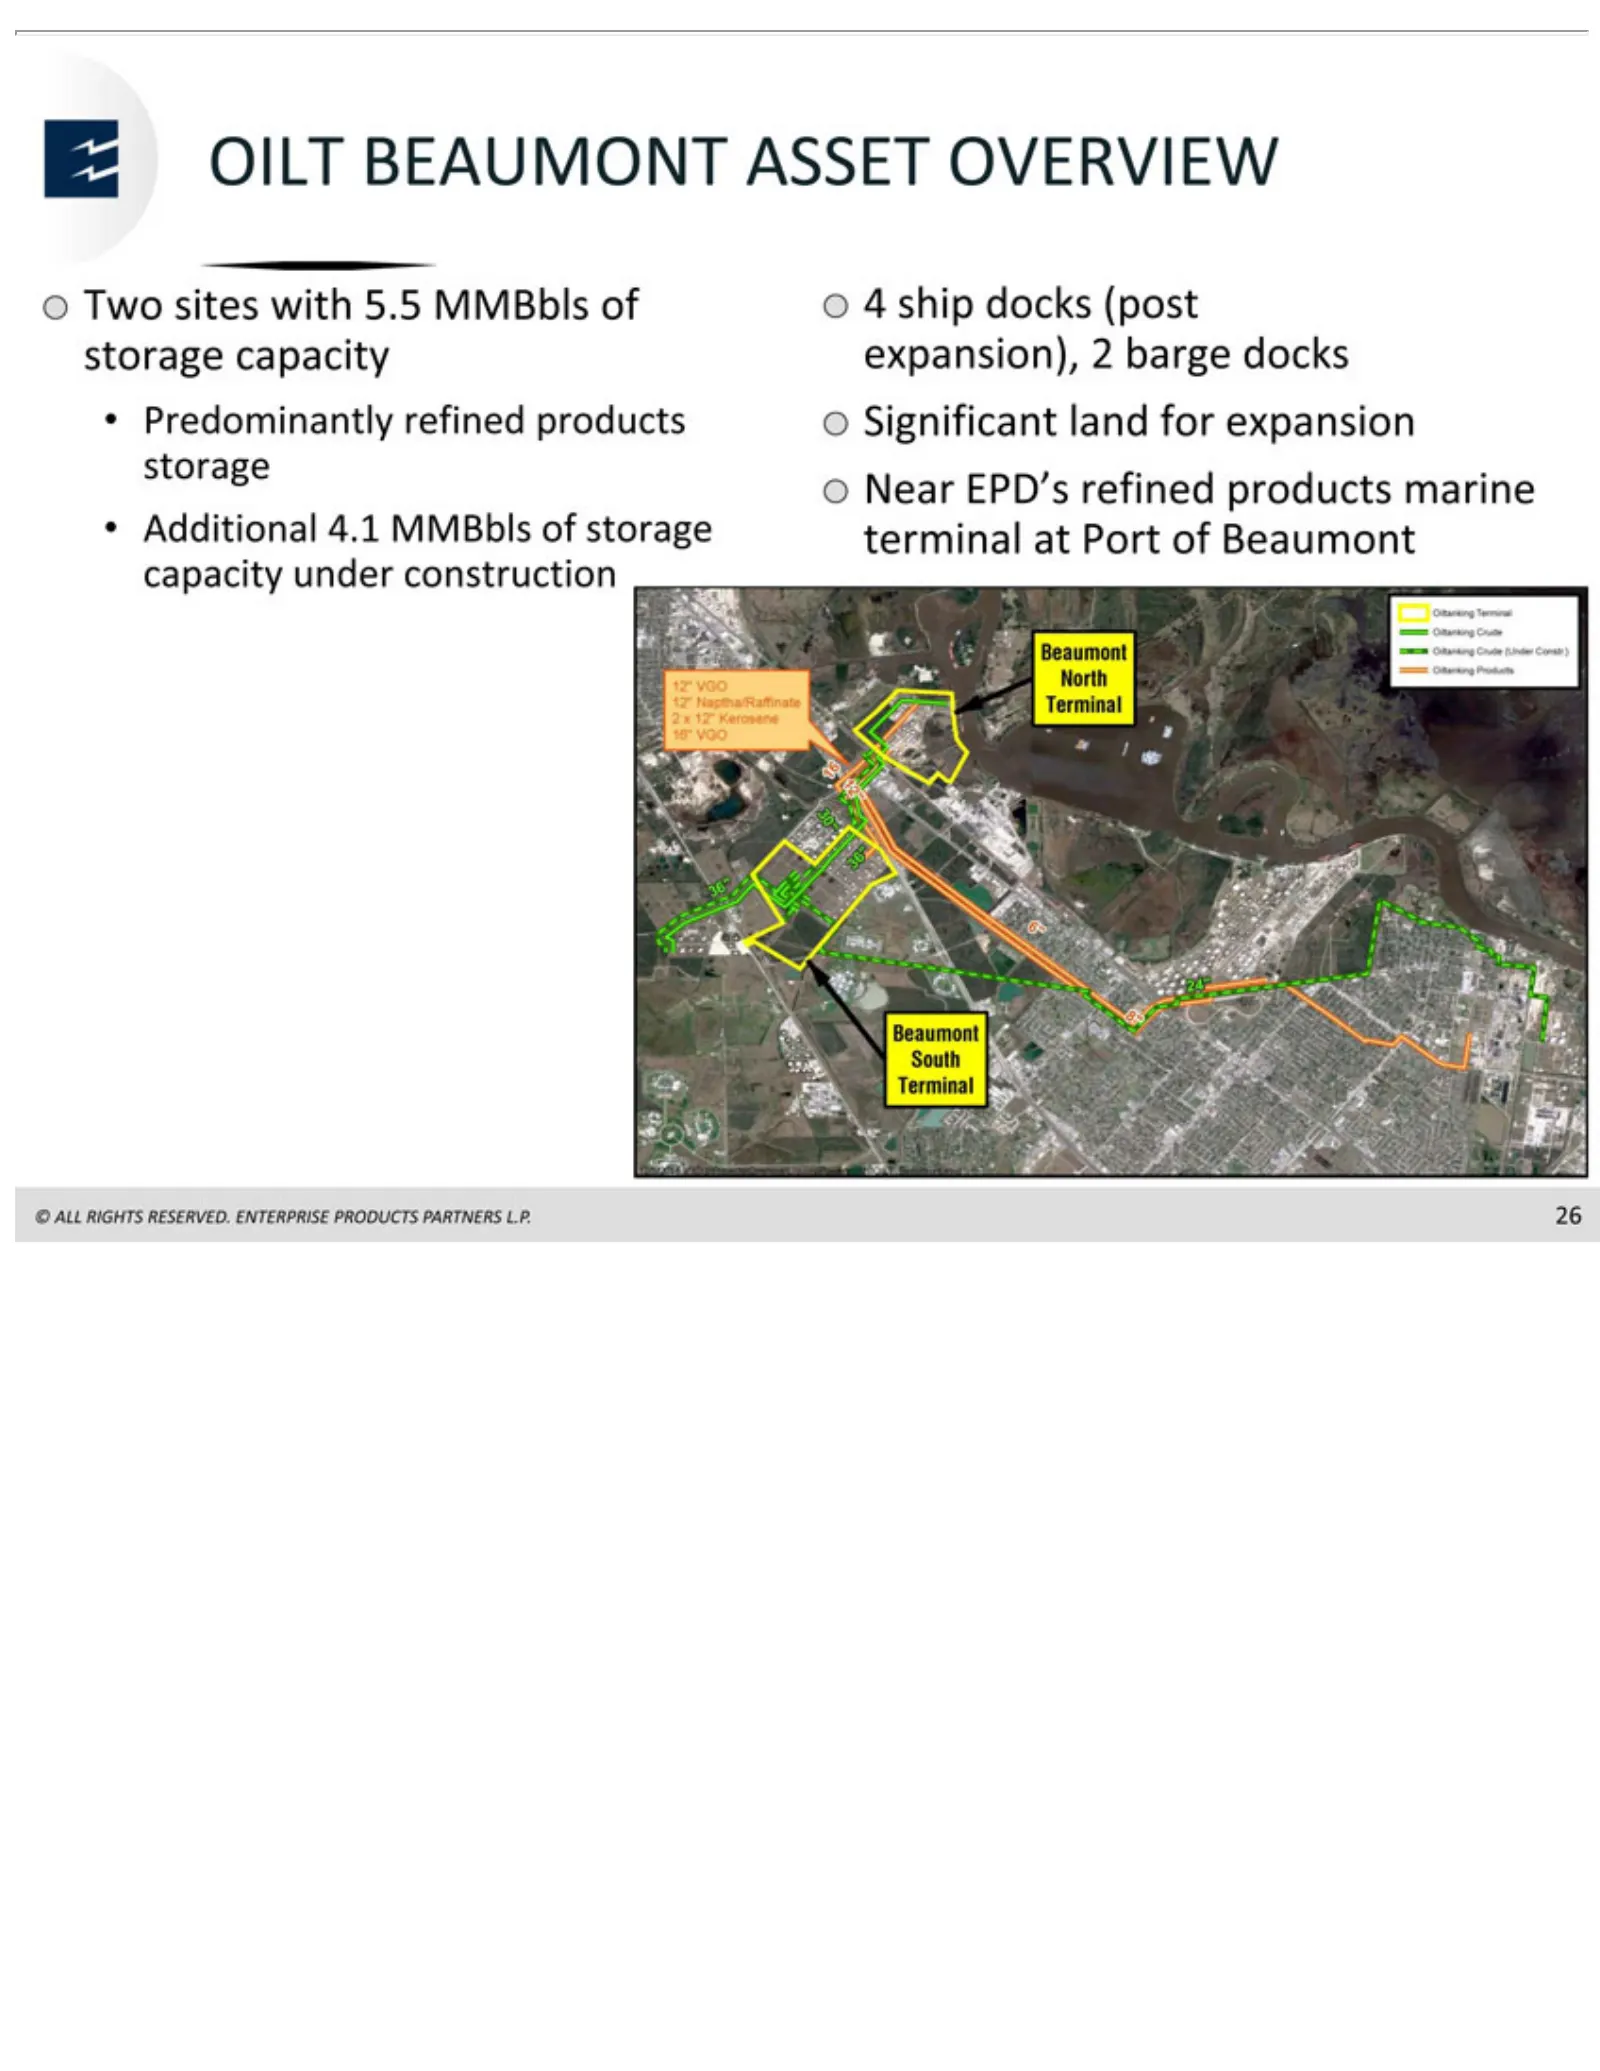
OILT Two Predominantly 4Additional © 26ship ALL sites BEAUMONT docks RIGHTS with 4.1 (post MMBbls 5.5 refined RESERVED. expansion), MMBbls ASSET products of storage of OVERVIEW 2storage ENTERPRISE storage barge capacity docks capacity under Significant PRODUCTS construction landPARTNERS for expansio
Slide 28: Financial
© ALL RIGHTS RESERVED. ENTERPRISE PRODUCTS PARTNERS L.P. enterpriseproducts.com FINANCIAL
Slide 29: Solid Operating Performance
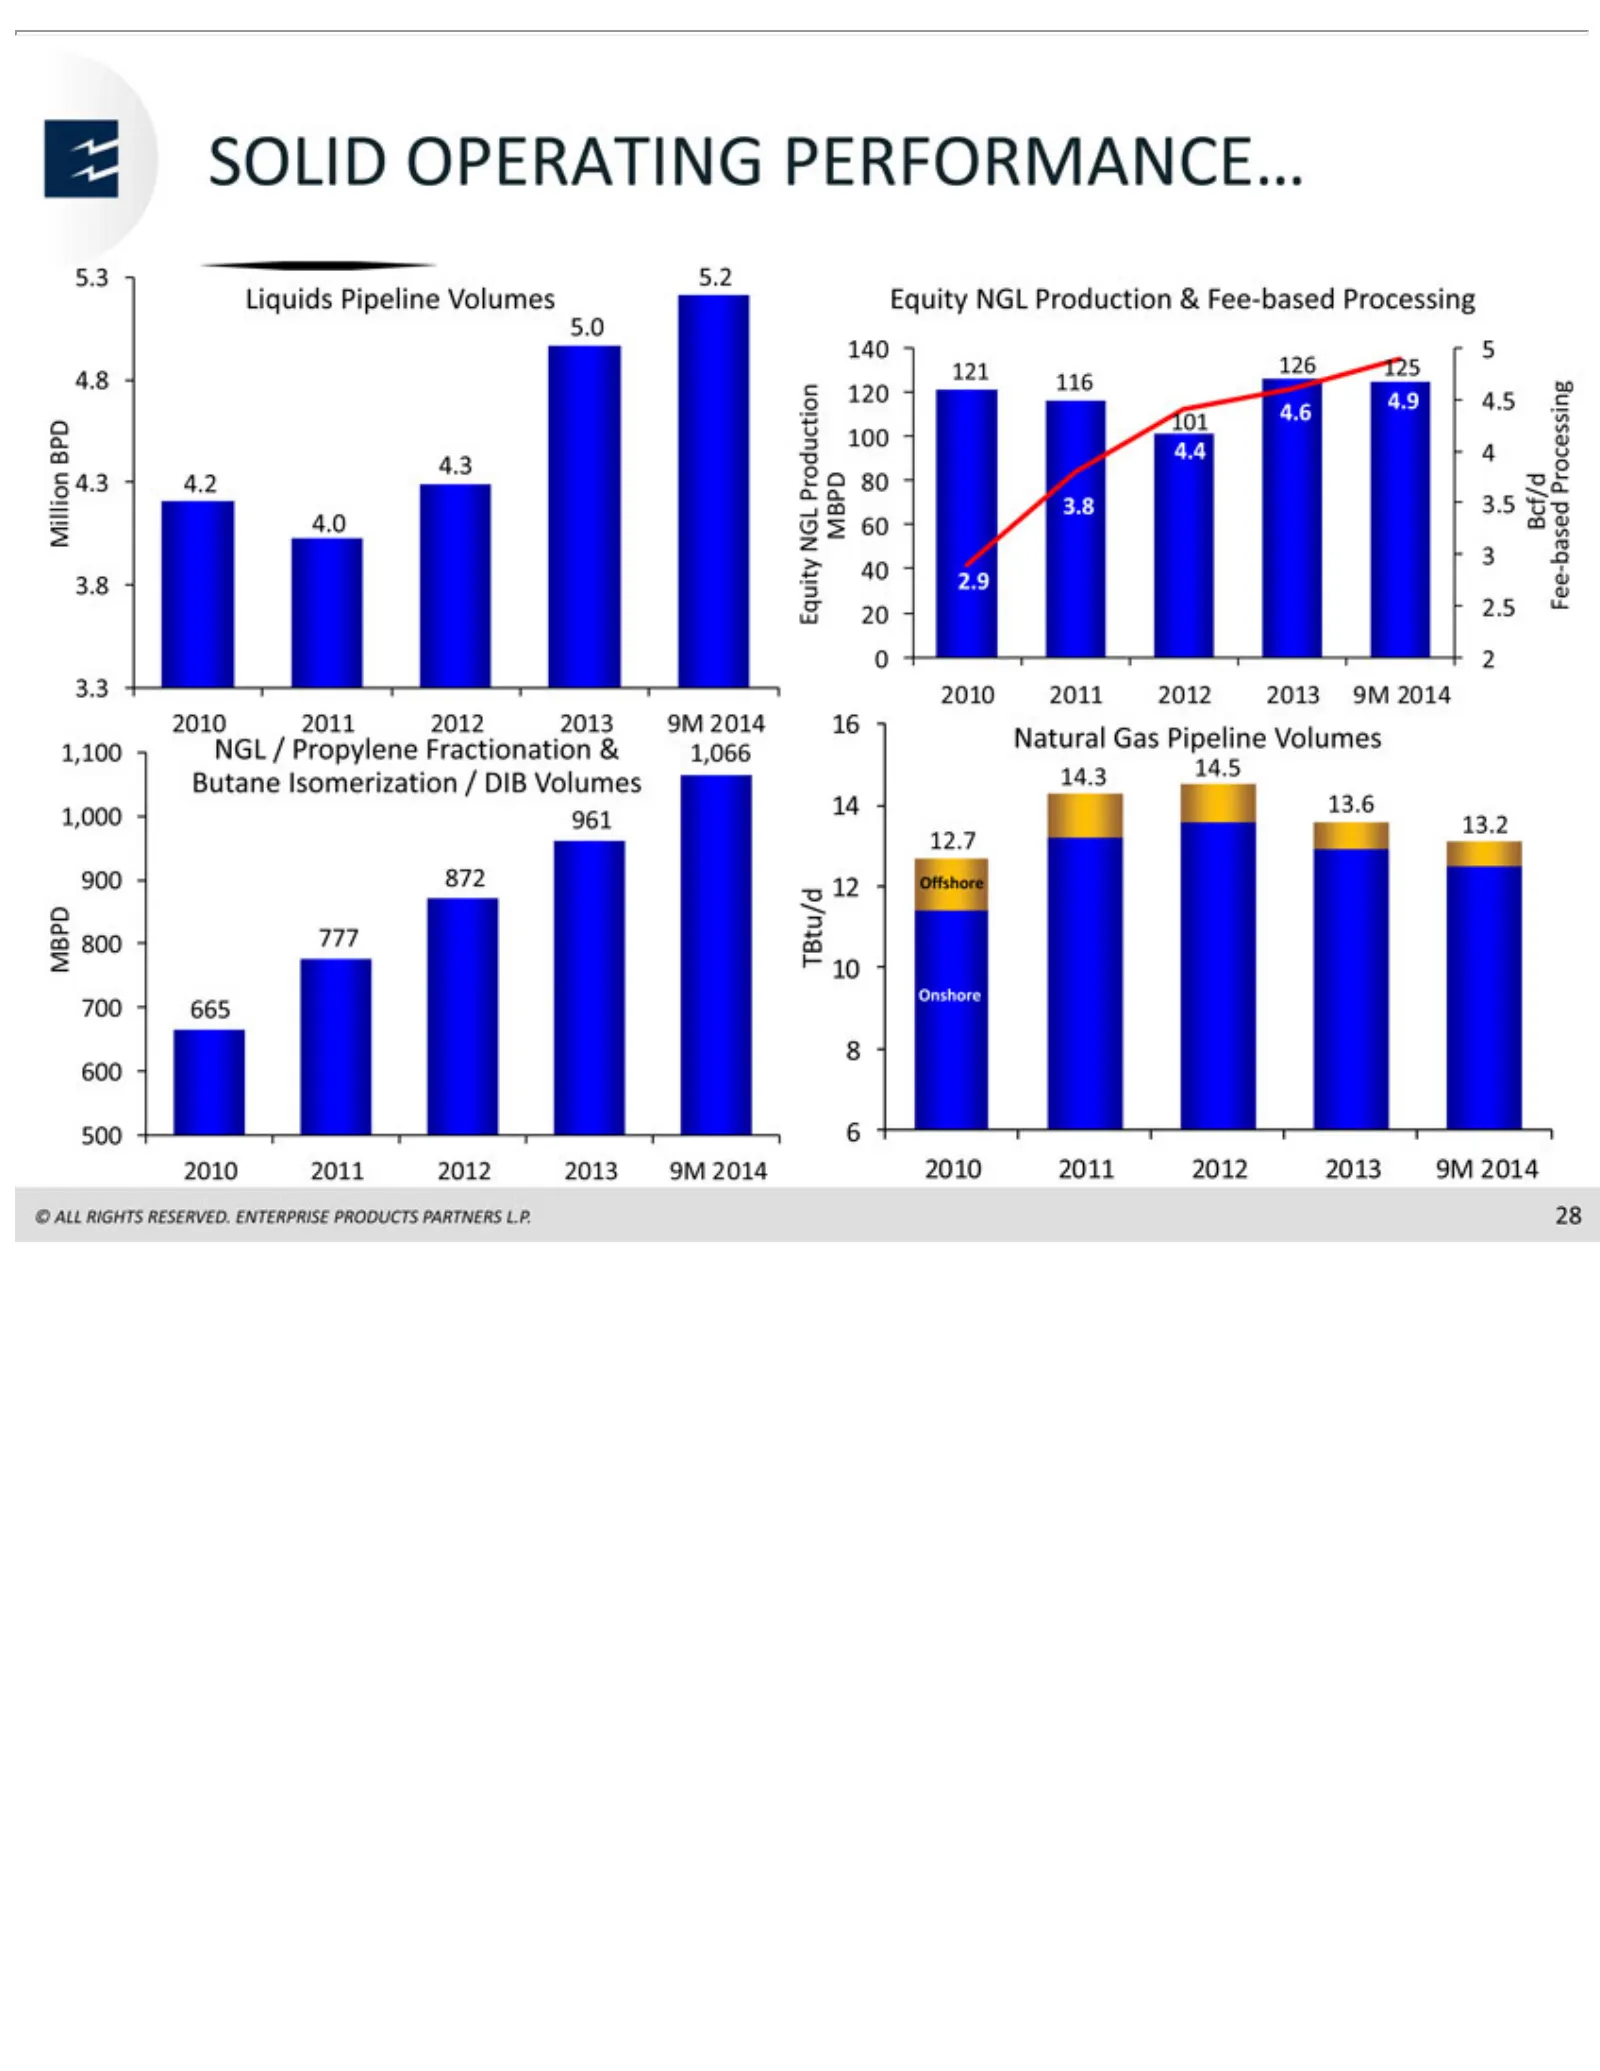
SOLID 5.3 5.0 4.8 101 BPD 4.0 Equity 40 3.8 3.3 NGL 1,100 14.3 Butane 1,000 900 MBPD 10 600 2010 © 28ALL 2.9 Onshore Liquids 140 116 MBPD 20 2010 100 8872 14.5 4.4 2011 /500 1,066 961 Fee- 2.5 Propylene 3Isomerization 800 RIGHTS OPERATING 120 512 based 42011 121 0Million 613.2 2012 60 Offshore Pipel
Slide 30: Operating Margin Drives Strong Financial Results
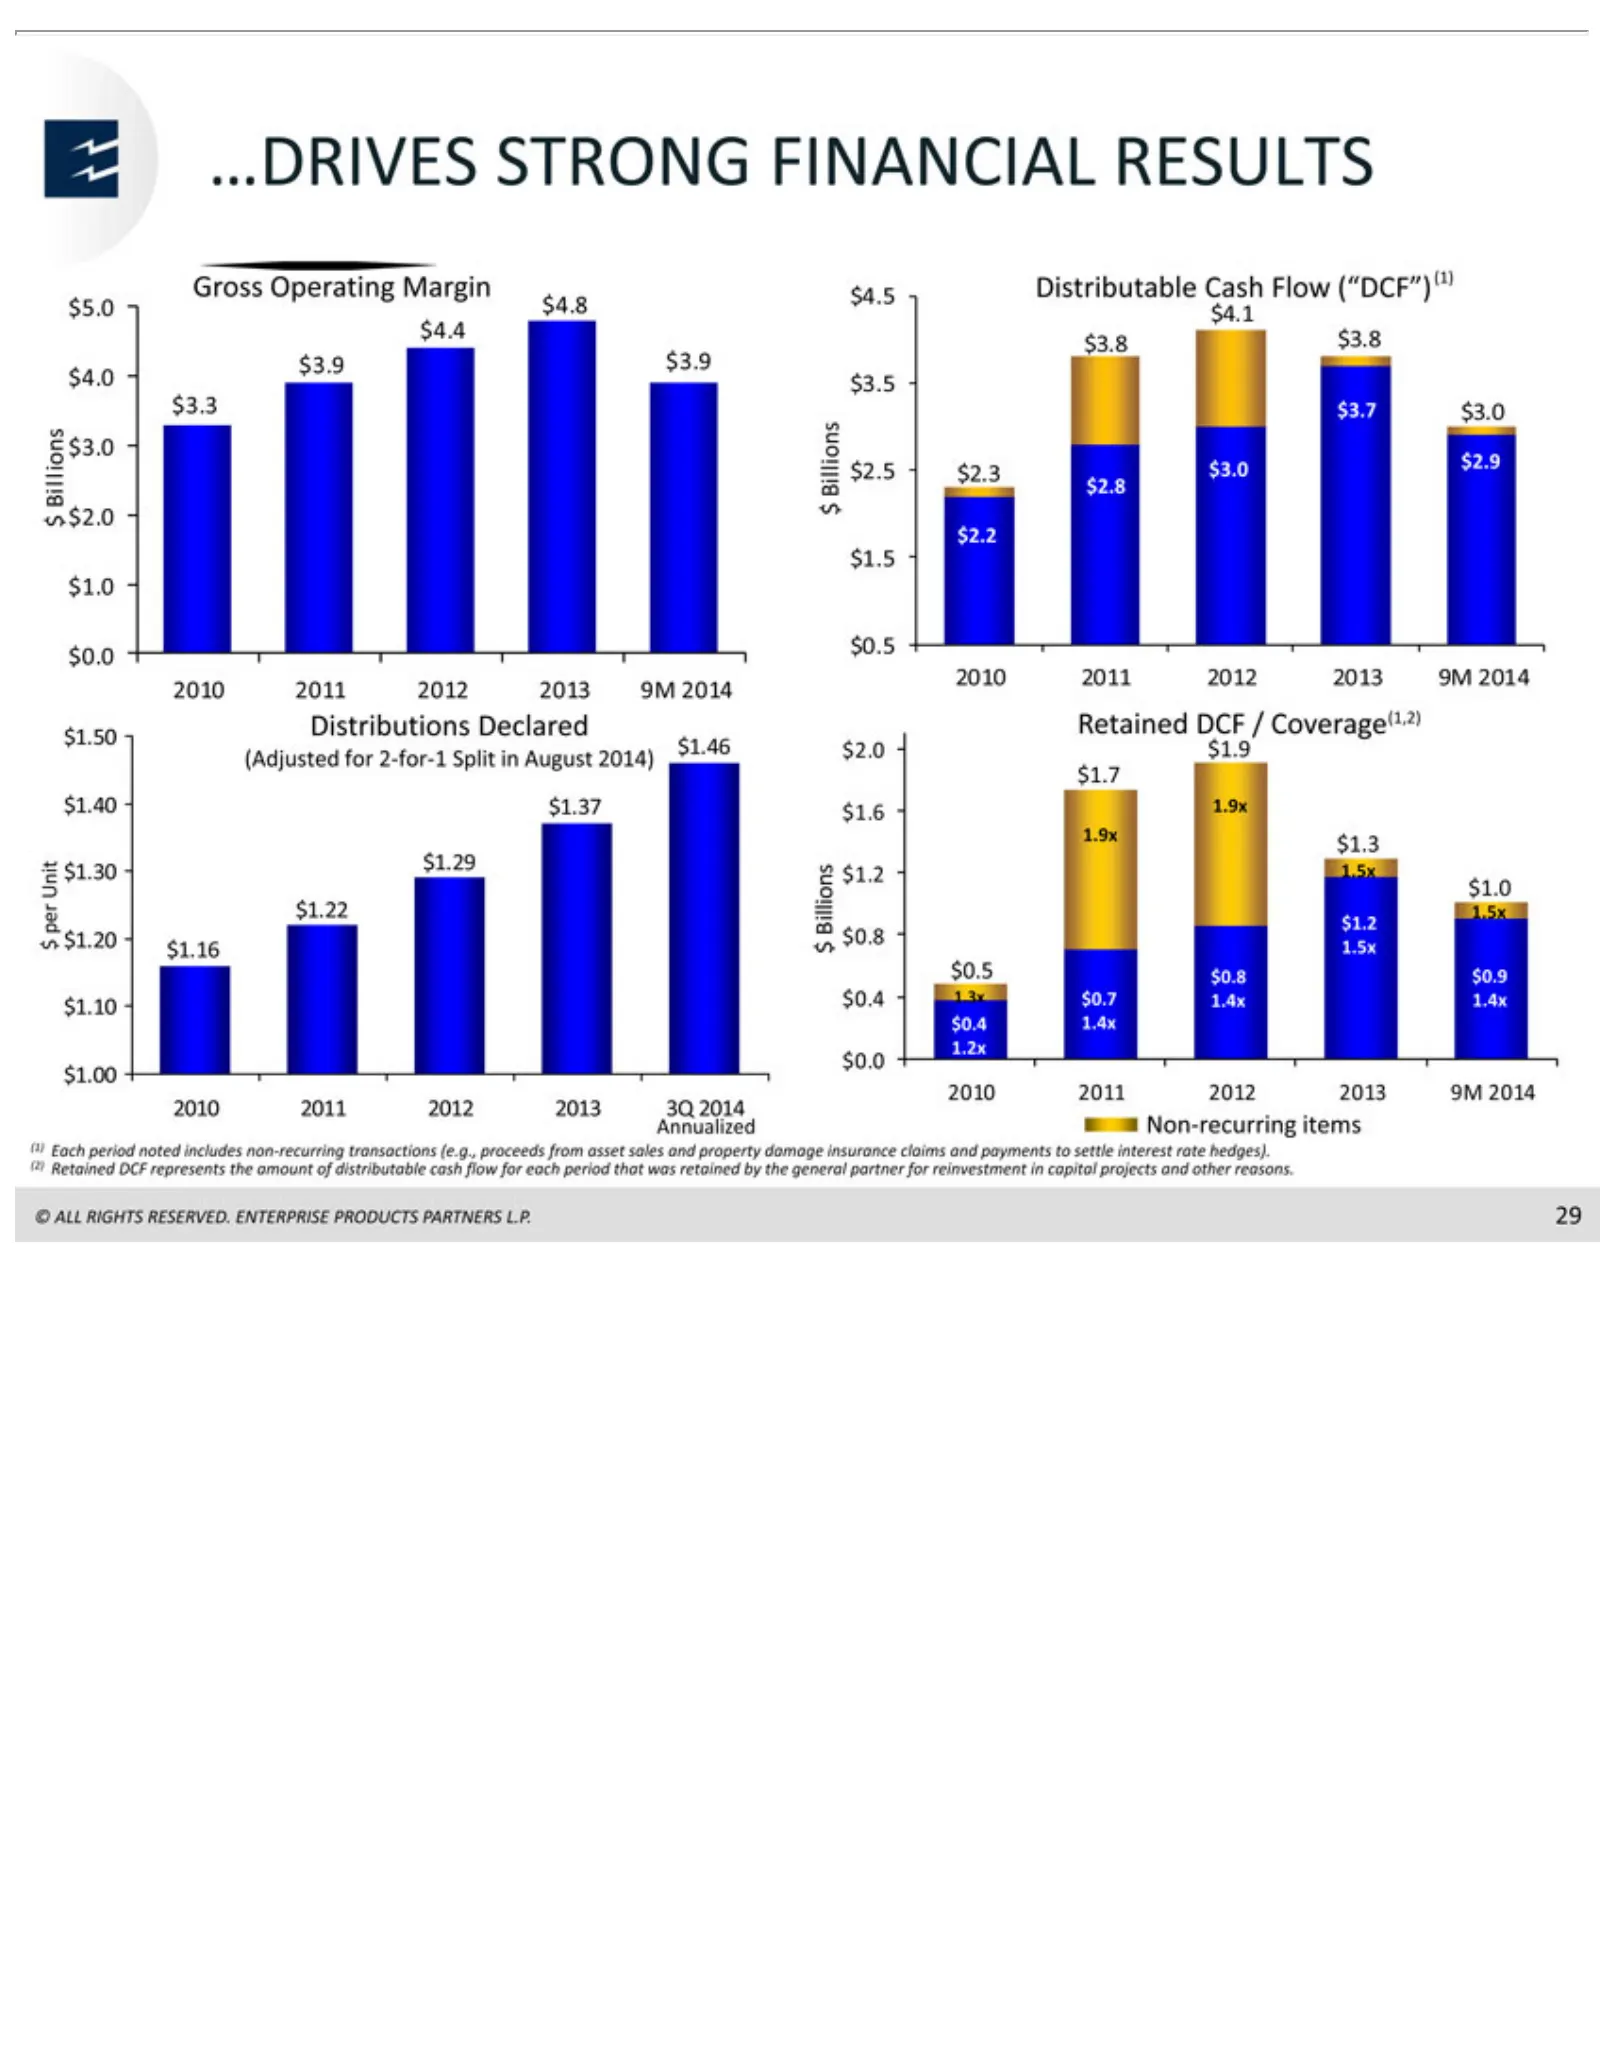
DRIVES Gross $4.8 Billions Distributions $1.50 1.9x Unit $1.29 per $1.20 $0.5 $1.10 $0.4 2010 Annualized (1) amount © 29ALL Each $1.2 $4.5 $0.0 $1.3 $0.8 1.2x $1.30 2011 $1.46 Billions 1.4x Operating RIGHTS of $$2.8 period STRONG $5.0 $0.9 $0.0 $2.0 distributable 2012 $1.2 Non-recurring $2.0 Declare
Slide 31: History of Financial Discipline While Executing Growth Strategy
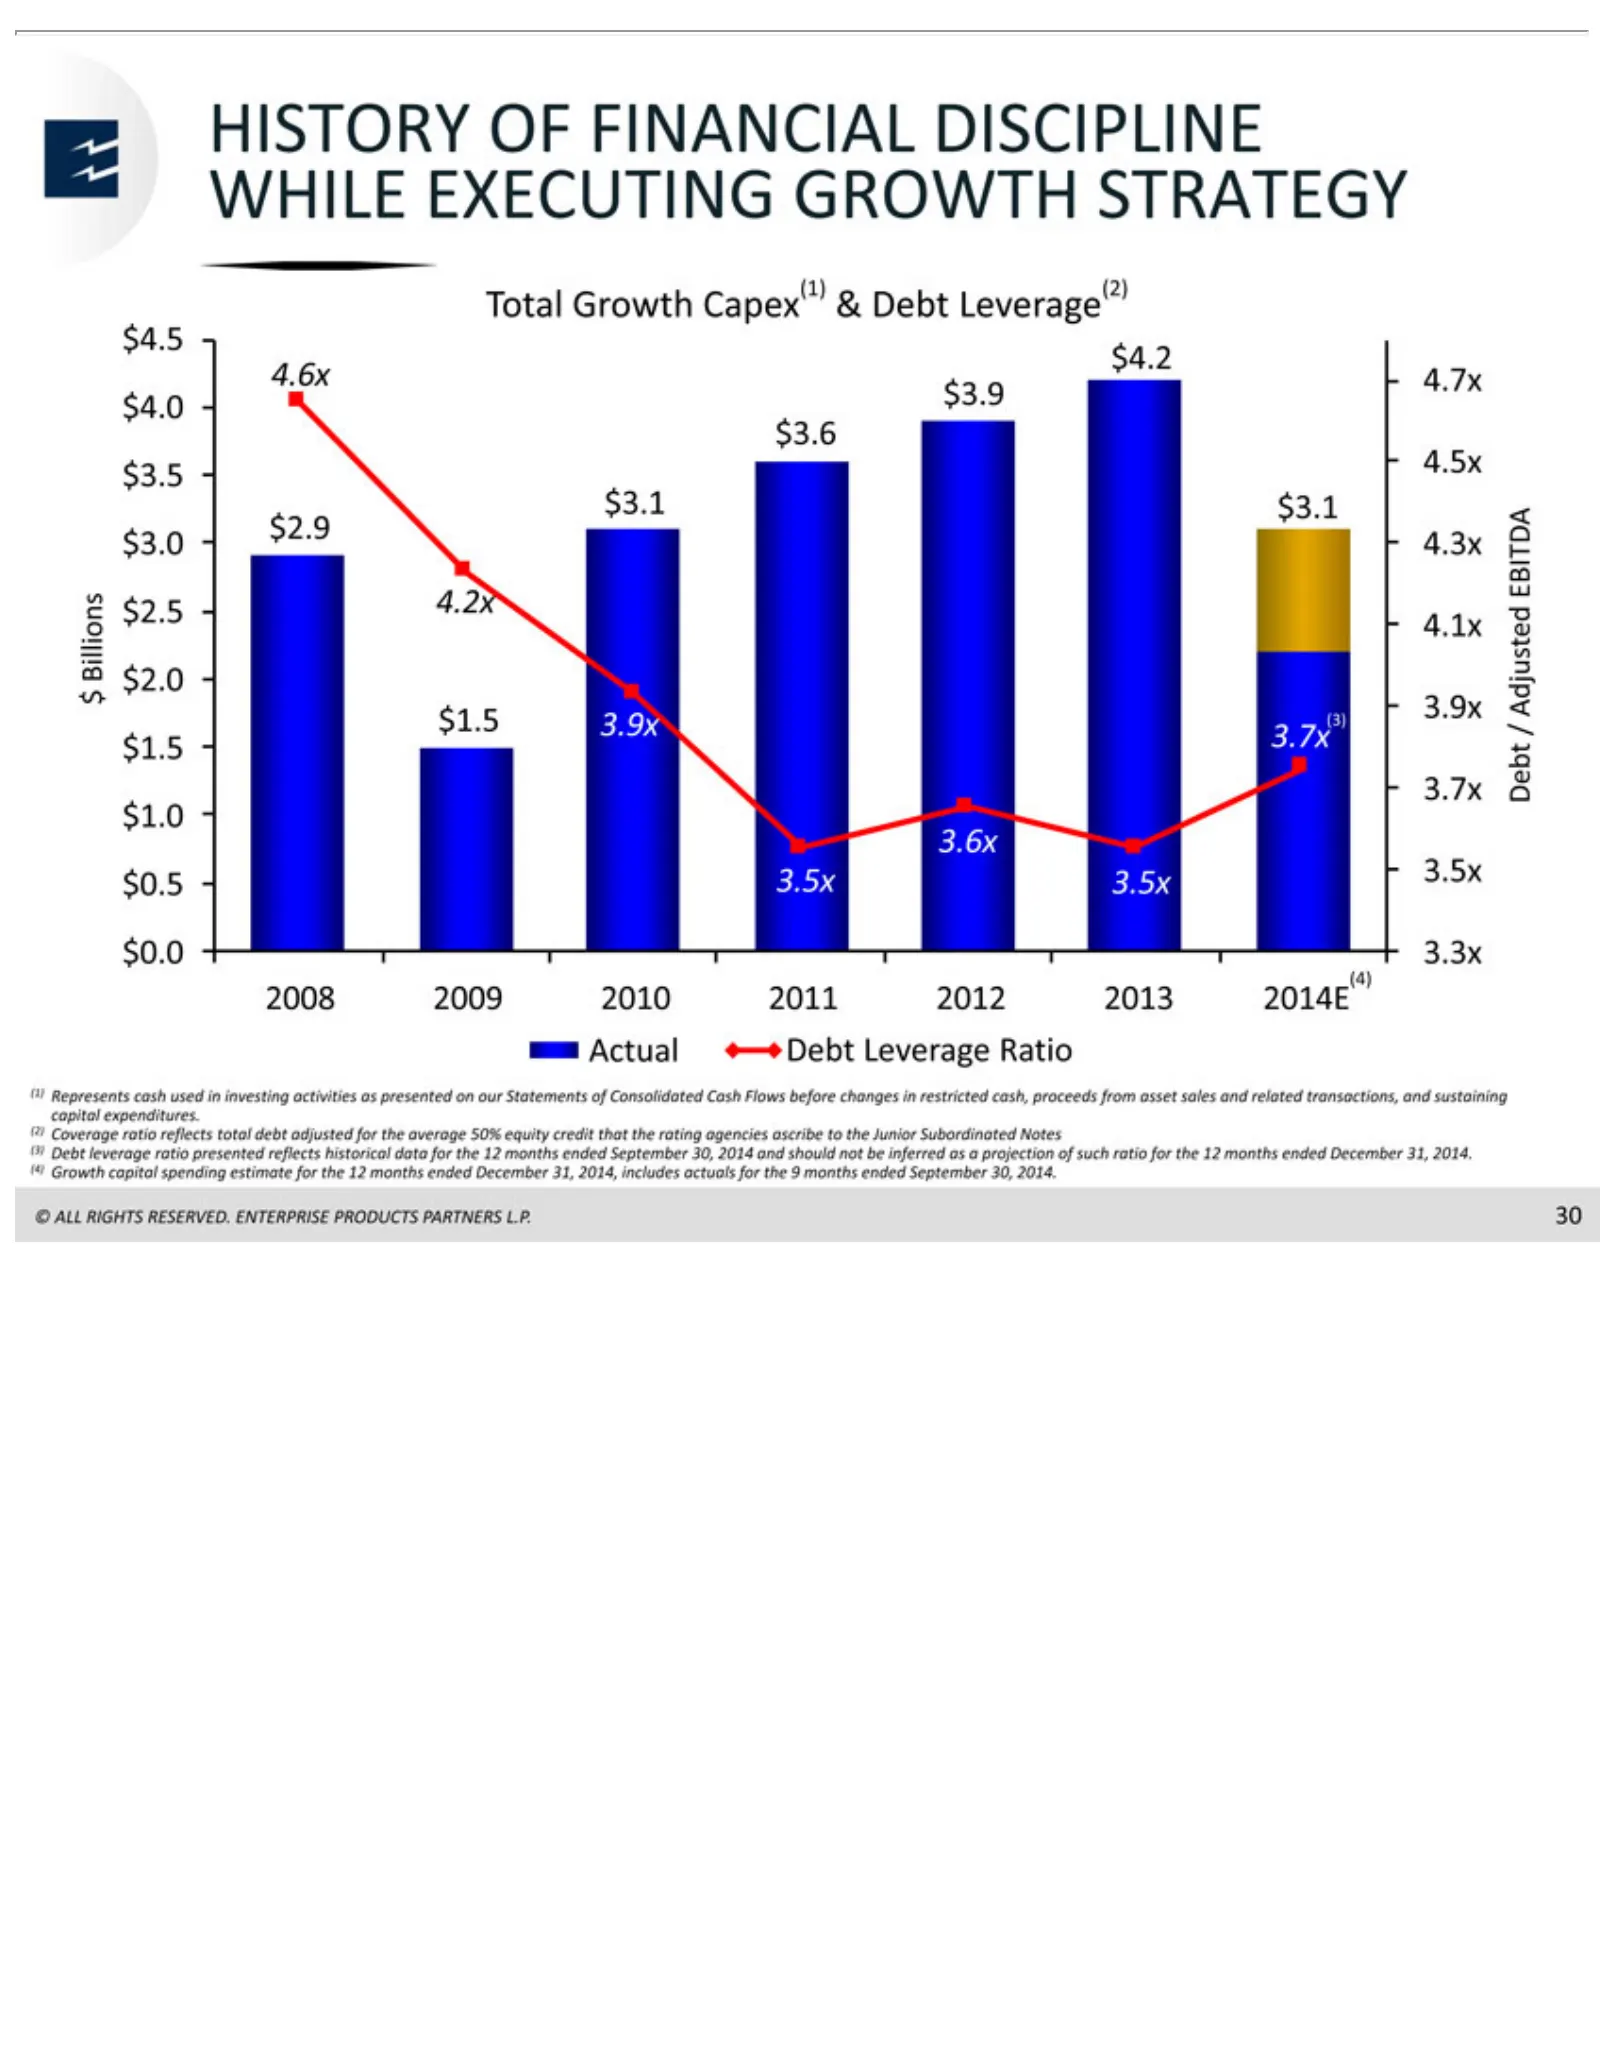
HISTORY Total $4.5 4.6x Billions$ 3.9x 3.5x 3.6x $0.0 2008 (1) capital (2) (3) (4) © 30ALL (2) Represents Coverage Debt Growth $4.2 4.7x $1.5 3.5x 3.3x 2009 Growth expenditures. RIGHTS leverage $2.0 $3.9 3.9x 3.5x OF 2010 capital ratio Capex Adjusted $4.0 (3) $0.5 FINANCIAL cash 2011 RESERVED. ratio
Slide 32: Strengthening Debt Portfolio
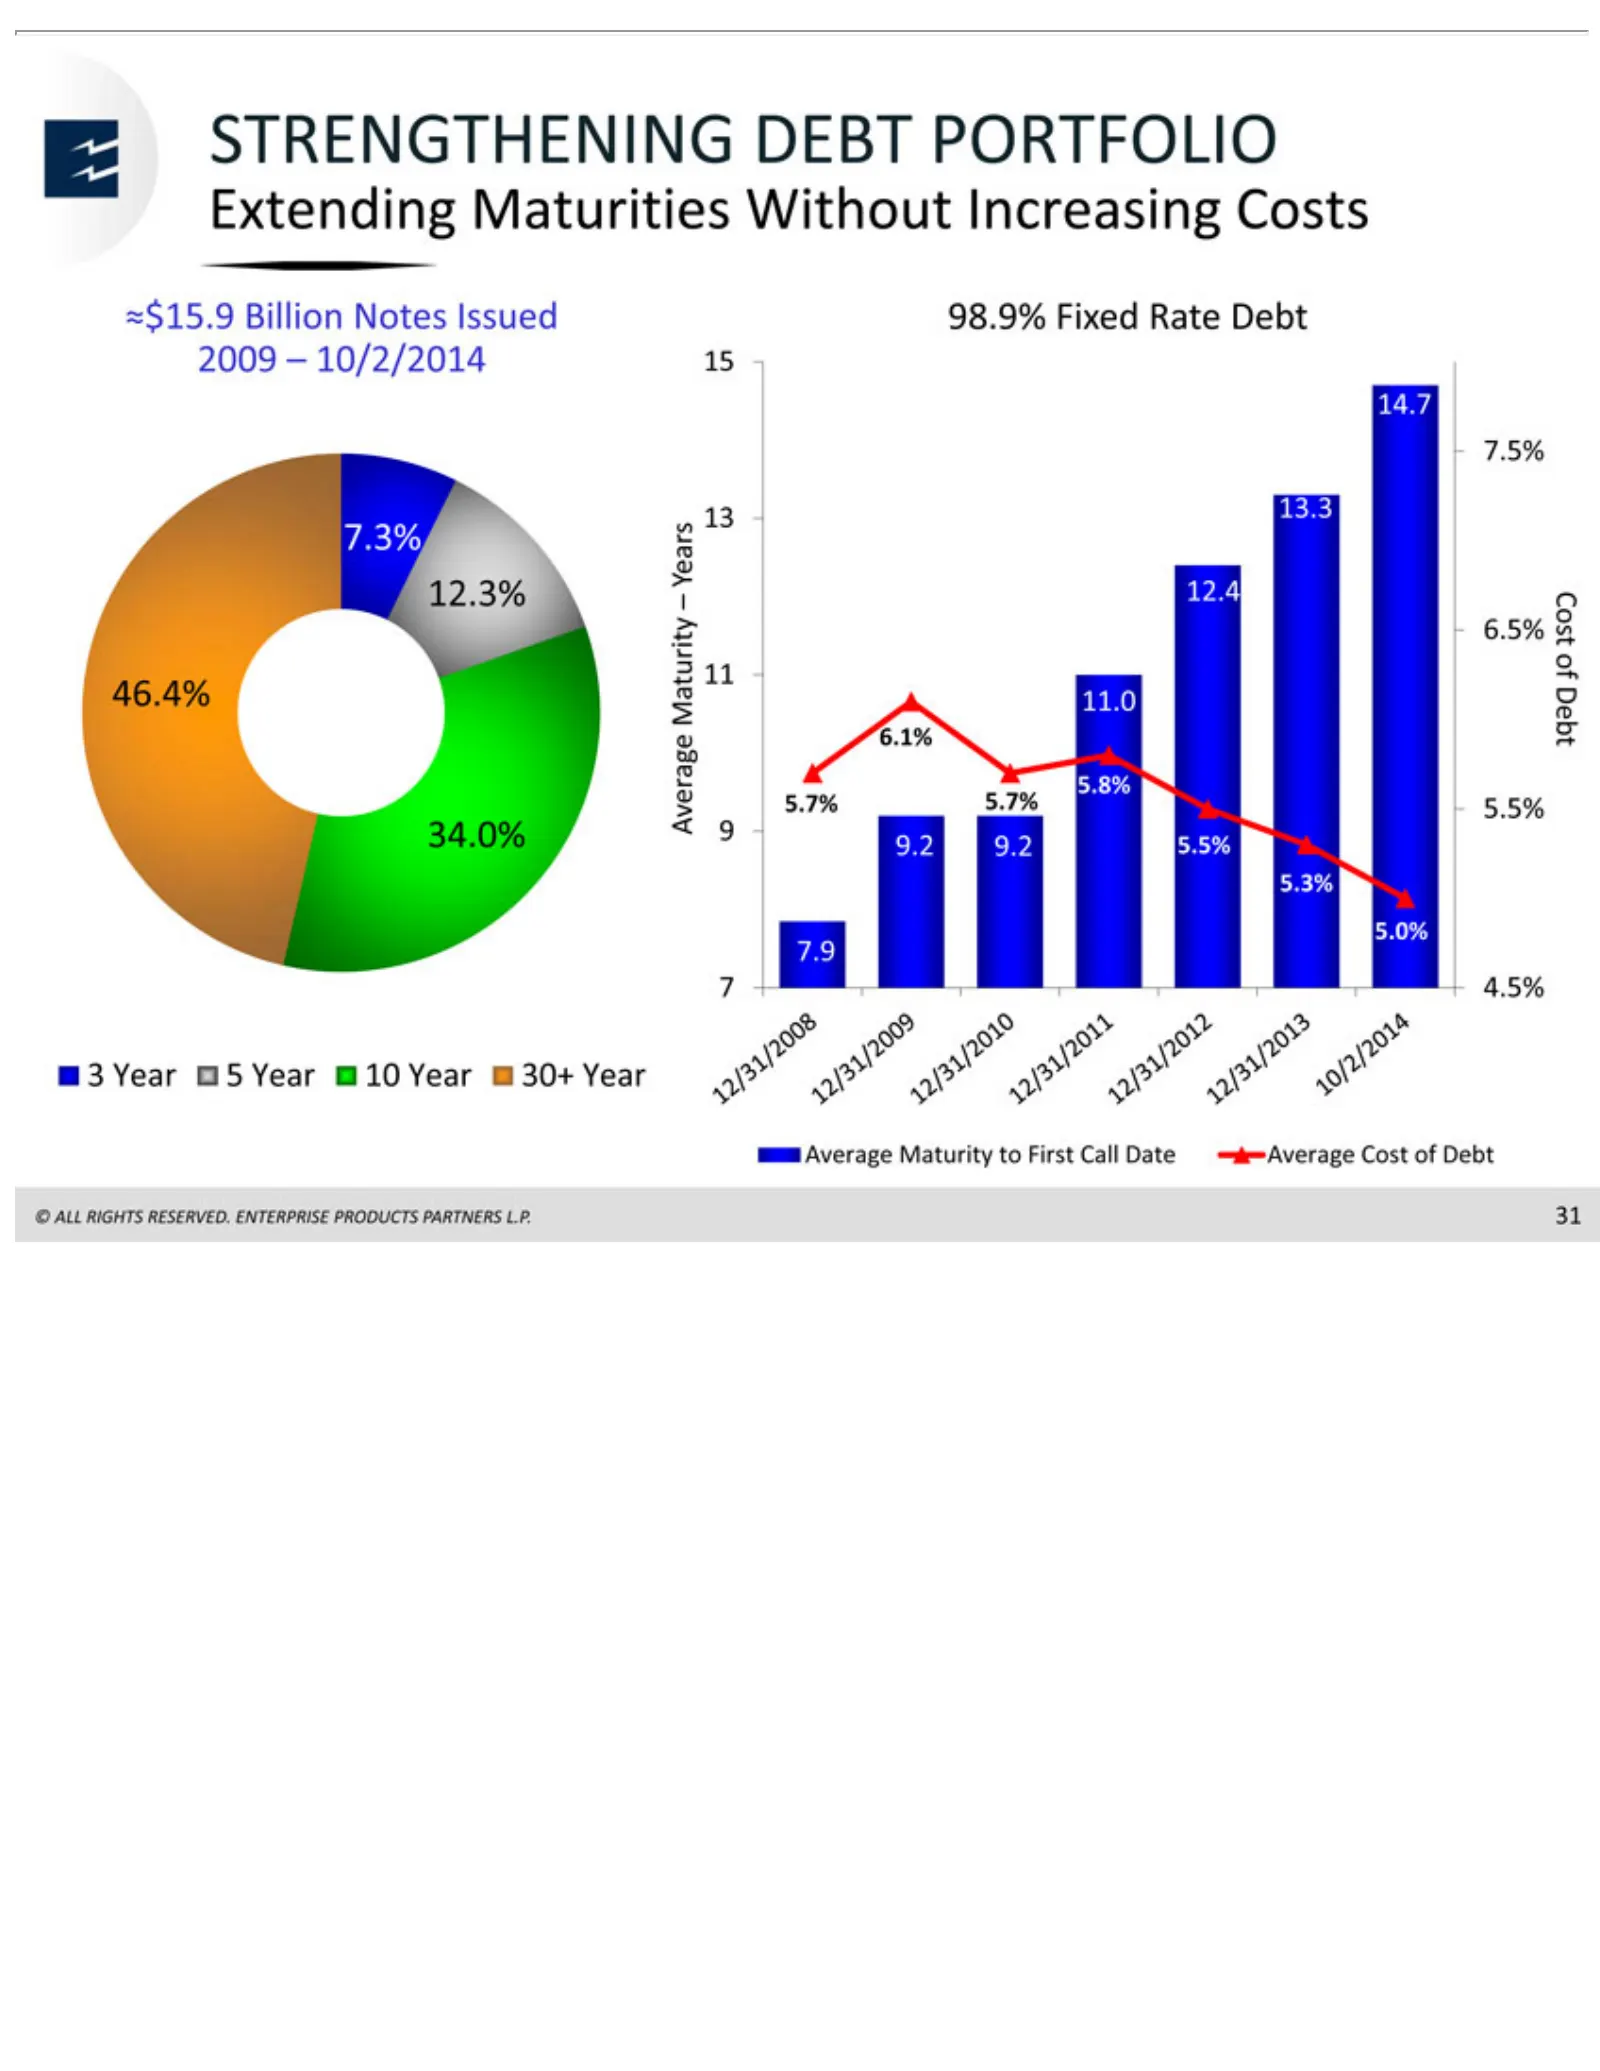
STRENGTHENING Extending »$15.9 13 7.5% 14.7 7.3% 12.3% –M 46.4% 5.7% 5.8% 34.0% 79.2 7.9 5.0% 35.3% Average © 31Year 4.5% aturity ALL 13.3 9.2Years 5.7% 5911.0 12.4 Billion 5.5% RIGHTS Year 6.1% Maturity 6.5% Maturities 5.5% 10 Cost Notes 11Year RESERVED. toofFirst DEBT Issued Without 30+ DebtCall Y
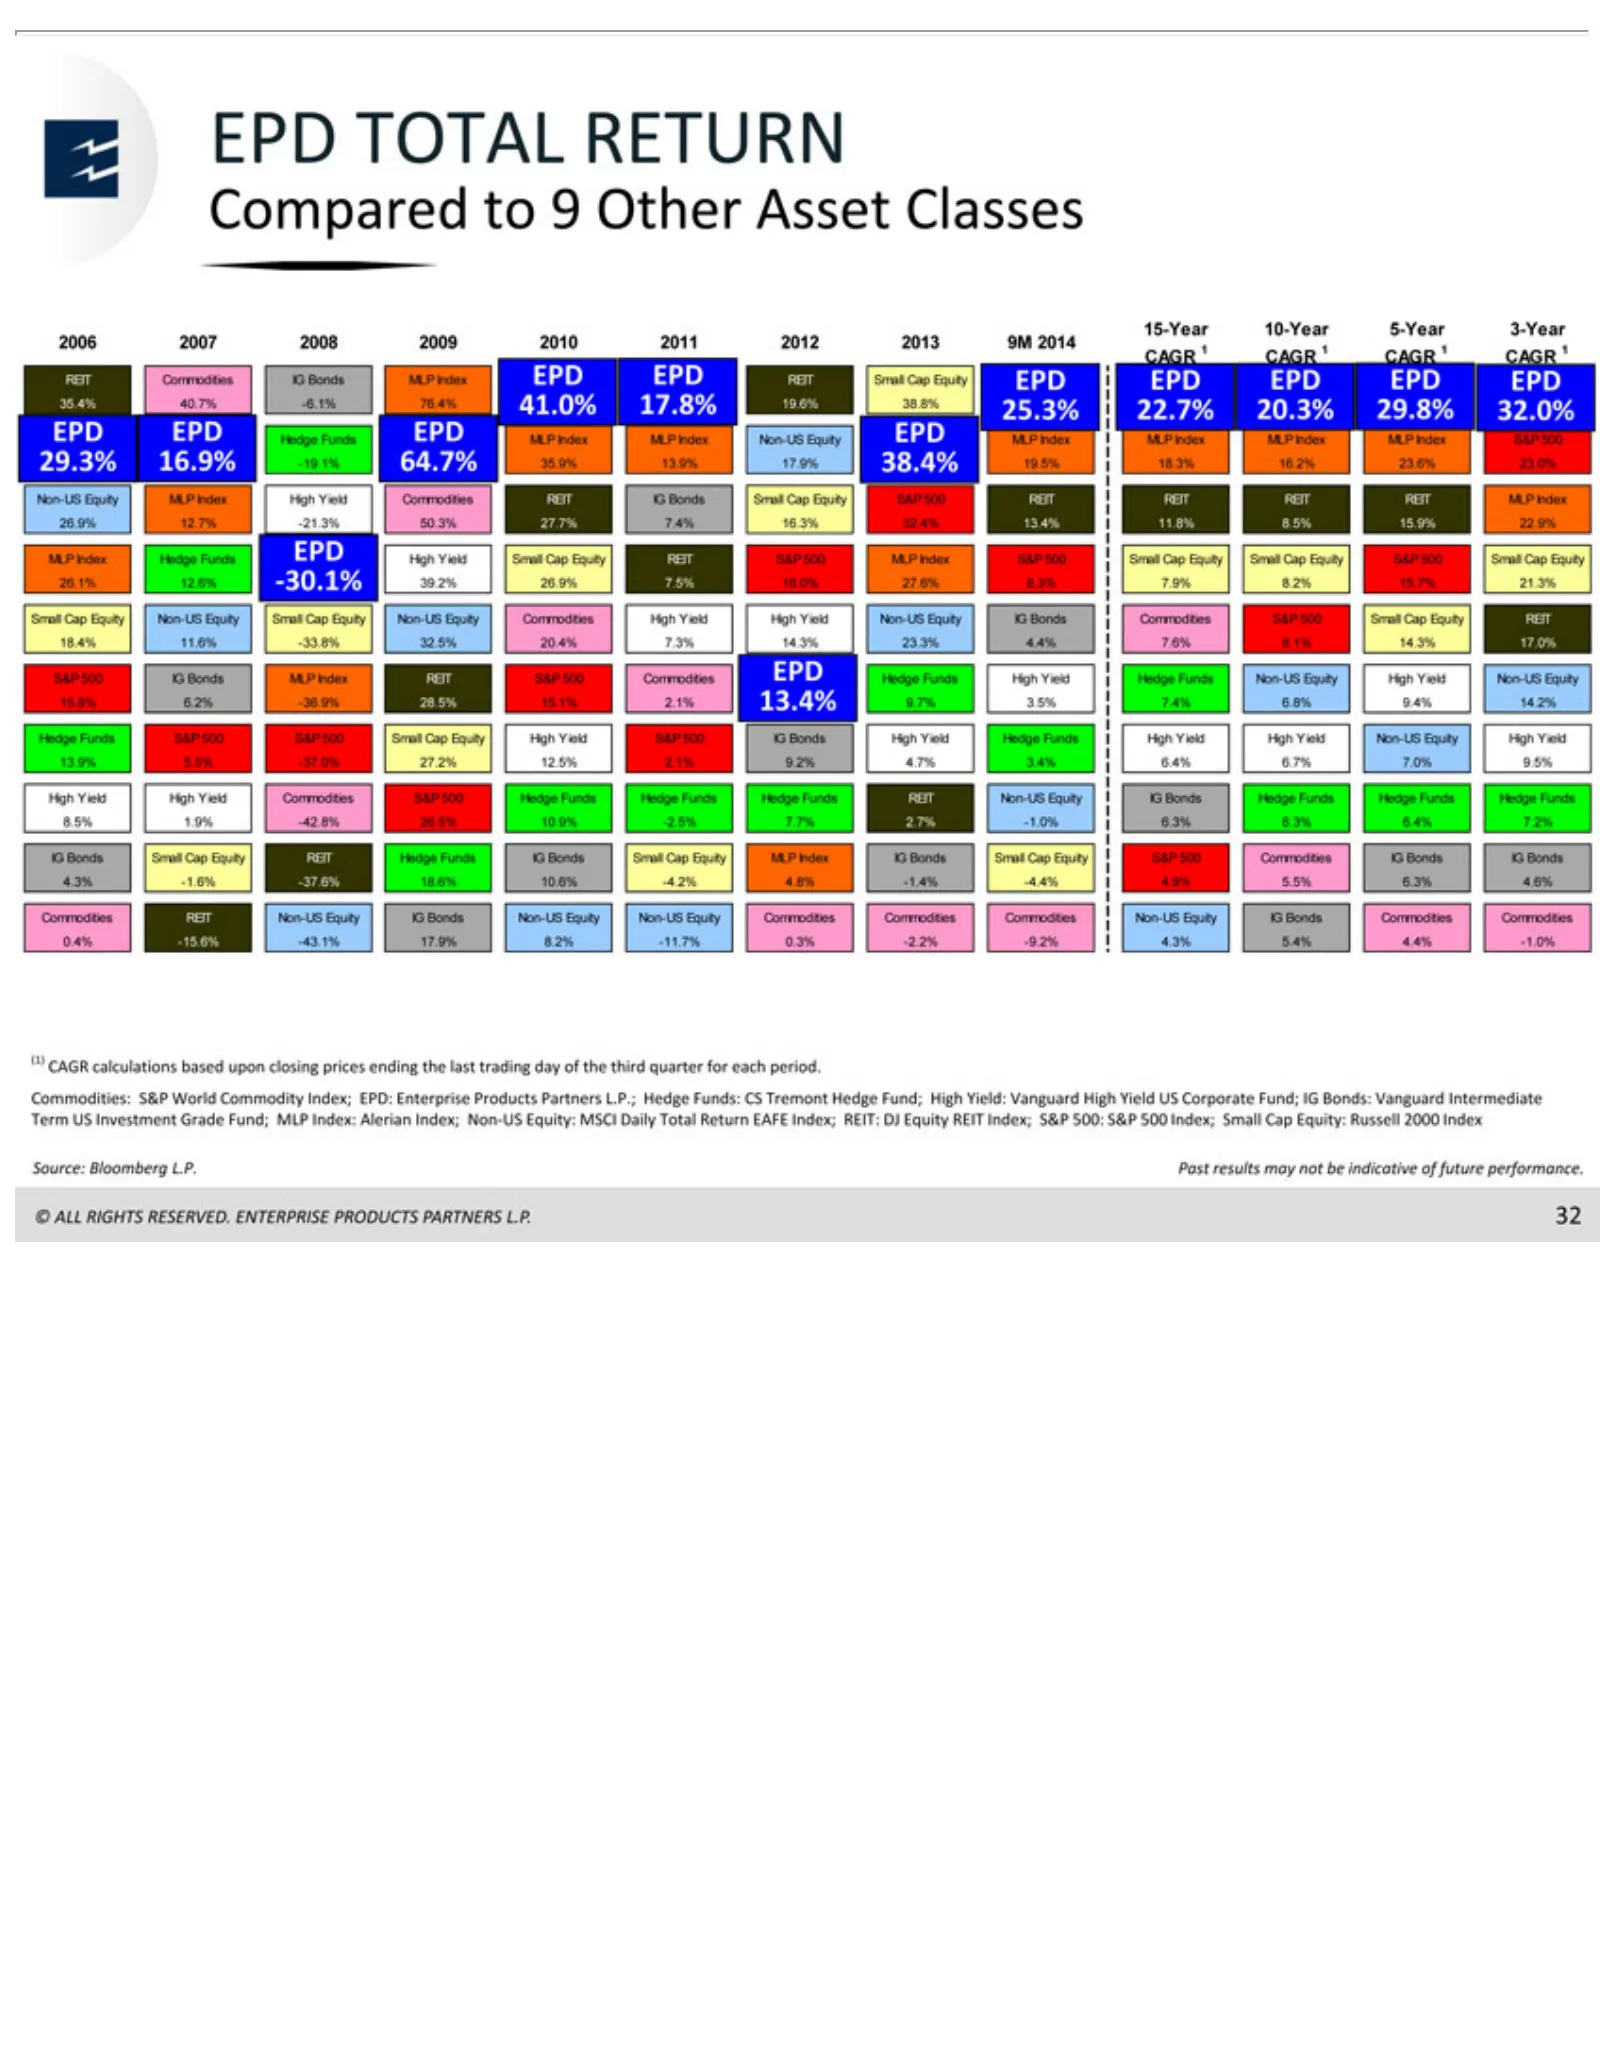
Slide 33: EPD Total Return Compared to Other Asset Classes
Compared 15-Year REIT 35.4% EPD 16.2% 32.4% 26.1% 18.4% Equity Yield High 7.7% IG 4.8% Commodities 8.2% (1) Commodities: Intermediate Equity: Source: © 32ALL Bonds CAGR TOTAL EPD Yield 2.7% -1.4% -11.7% Hedge Commodities 40.7% 23.6% 13.4% 12.6% 11.6% IG High RIGHTS Russell Bloomberg 10-Year Small Bo
Slide 34: Appendix
© ALL RIGHTS RESERVED. ENTERPRISE PRODUCTS PARTNERS L.P. enterpriseproducts.com APPENDIX
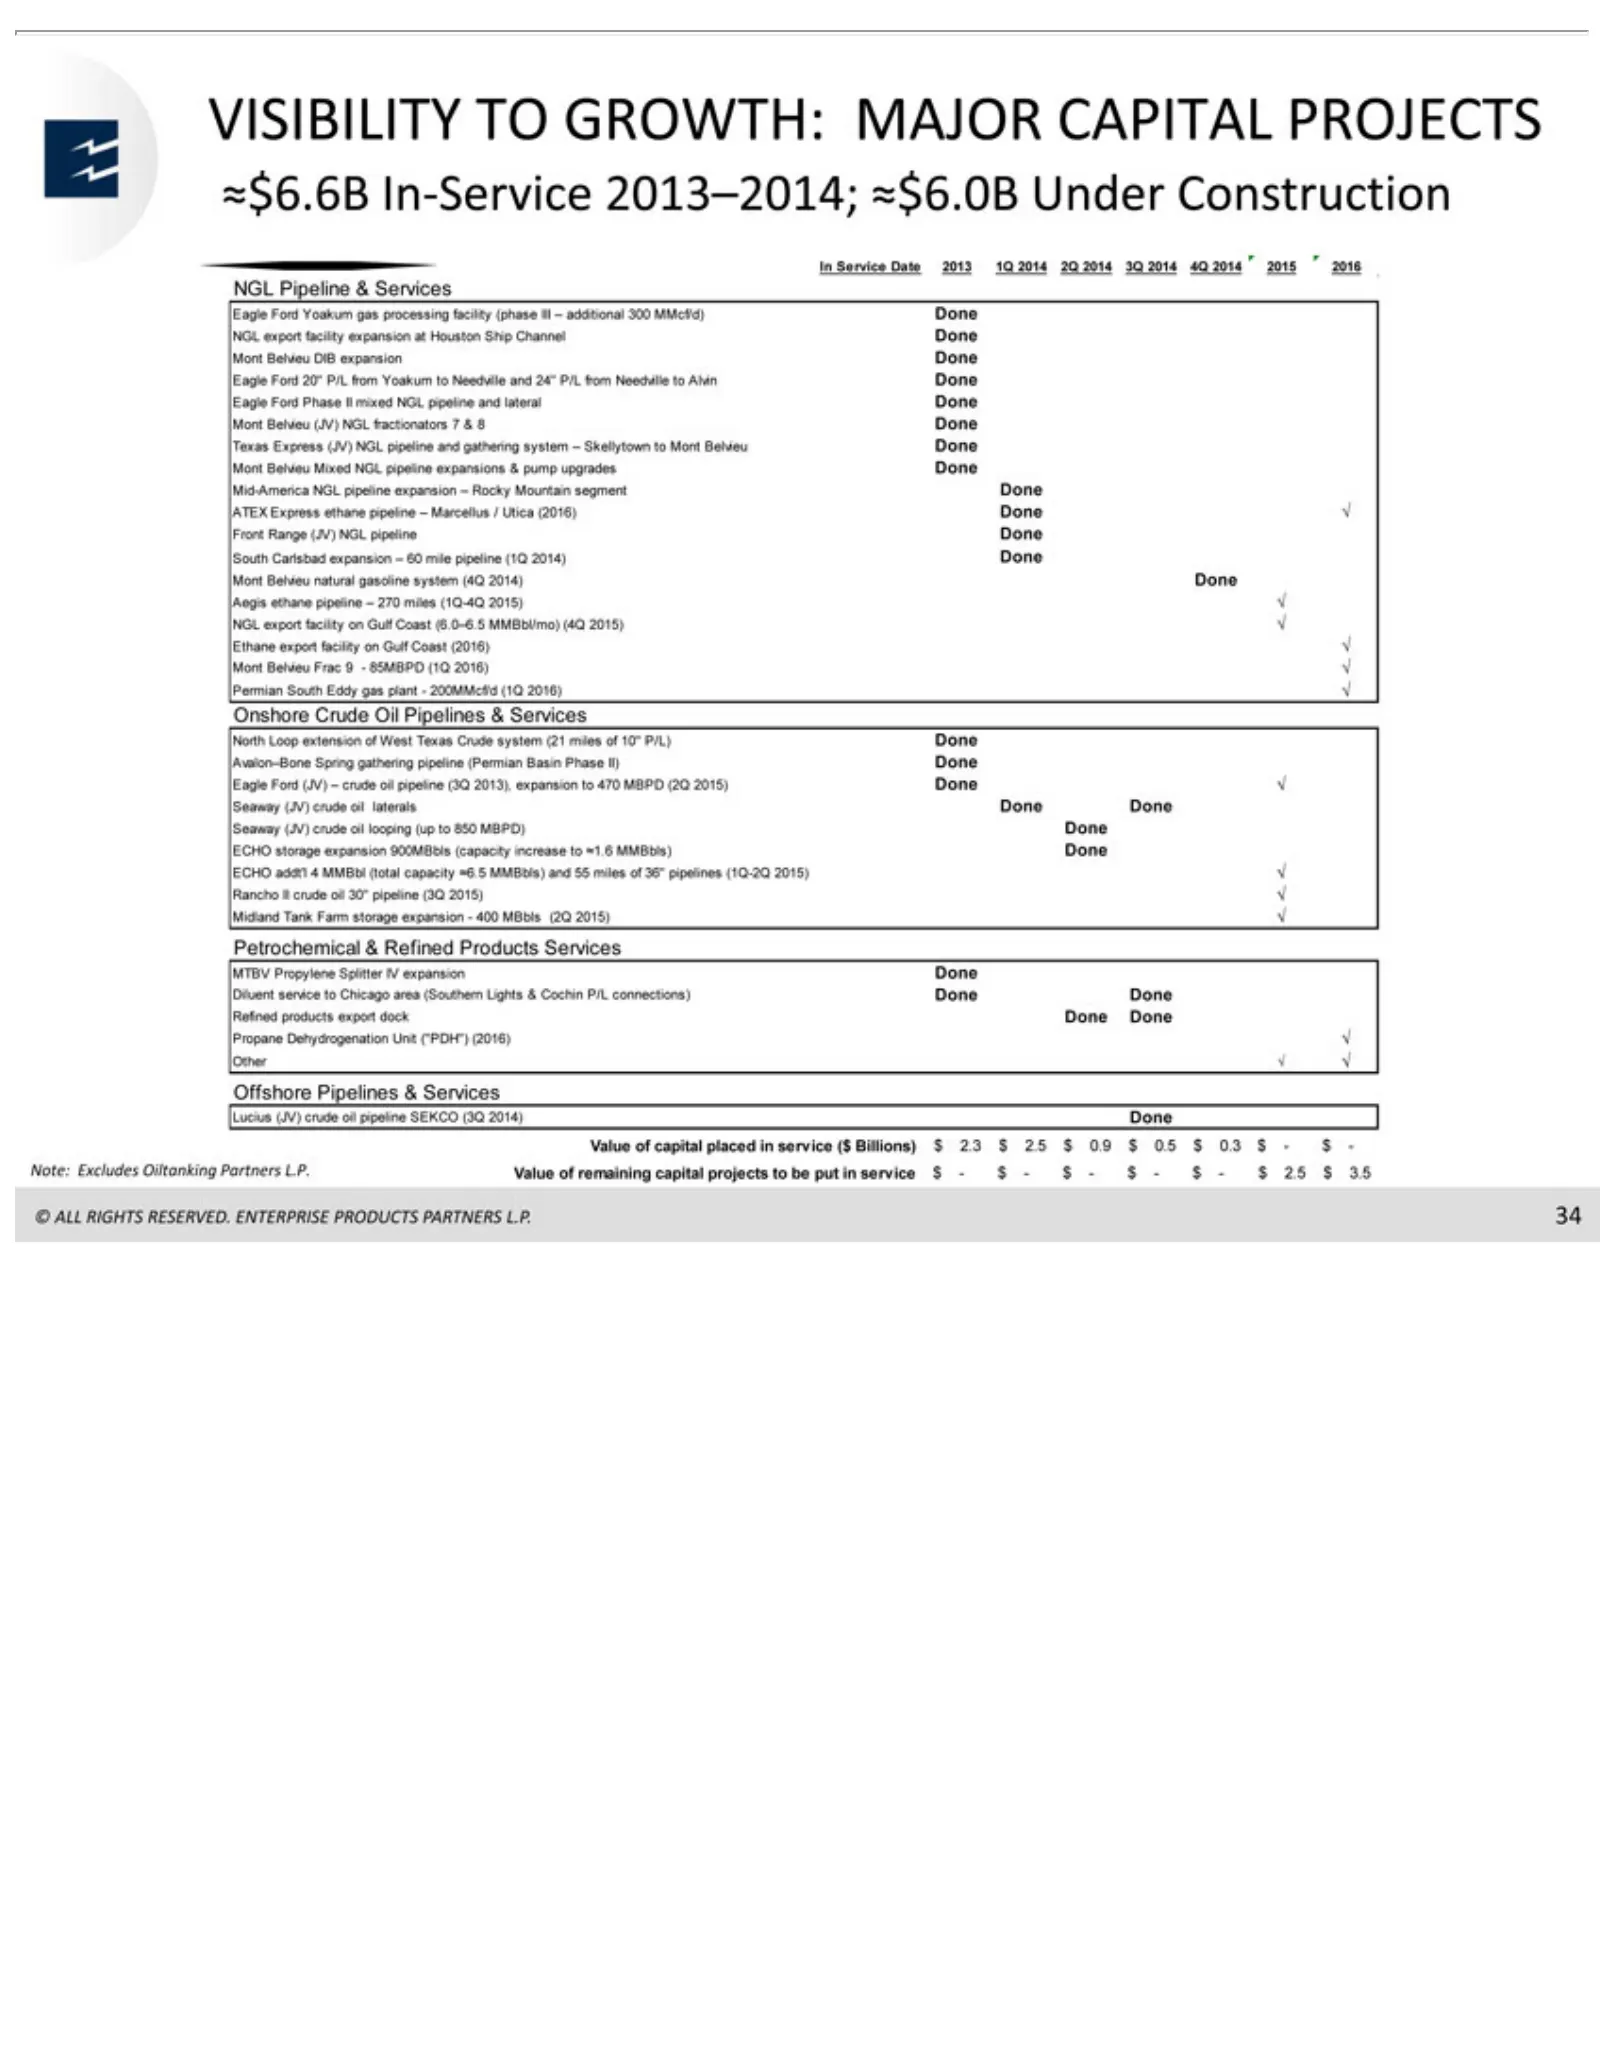
Slide 35: Visibility to Growth: Major Capital Projects
VISIBILITY »$6.6B In NGL from pipeline Mid-America ATEX (4Q —85MBPD Onshore North Eagle expansion 2015) Petrochemical MTBV Diluent Propane Offshore Lucius Value Note: © ALL Service 2014) Yoakum Pipeline Excludes Ford of Loop ÖExpress (JV) RIGHTS Propylene In-Service service and Dehydrogenation Midla
Slide 36: Non-GAAP Reconciliations
NON–GAAP © ALL RIGHTS RECONCILIATIONS RESERVED. ENTERPRISE PRODUCTS PARTNERS L.P. enterpriseproducts.com
Slide 37: Gross Operating Margin
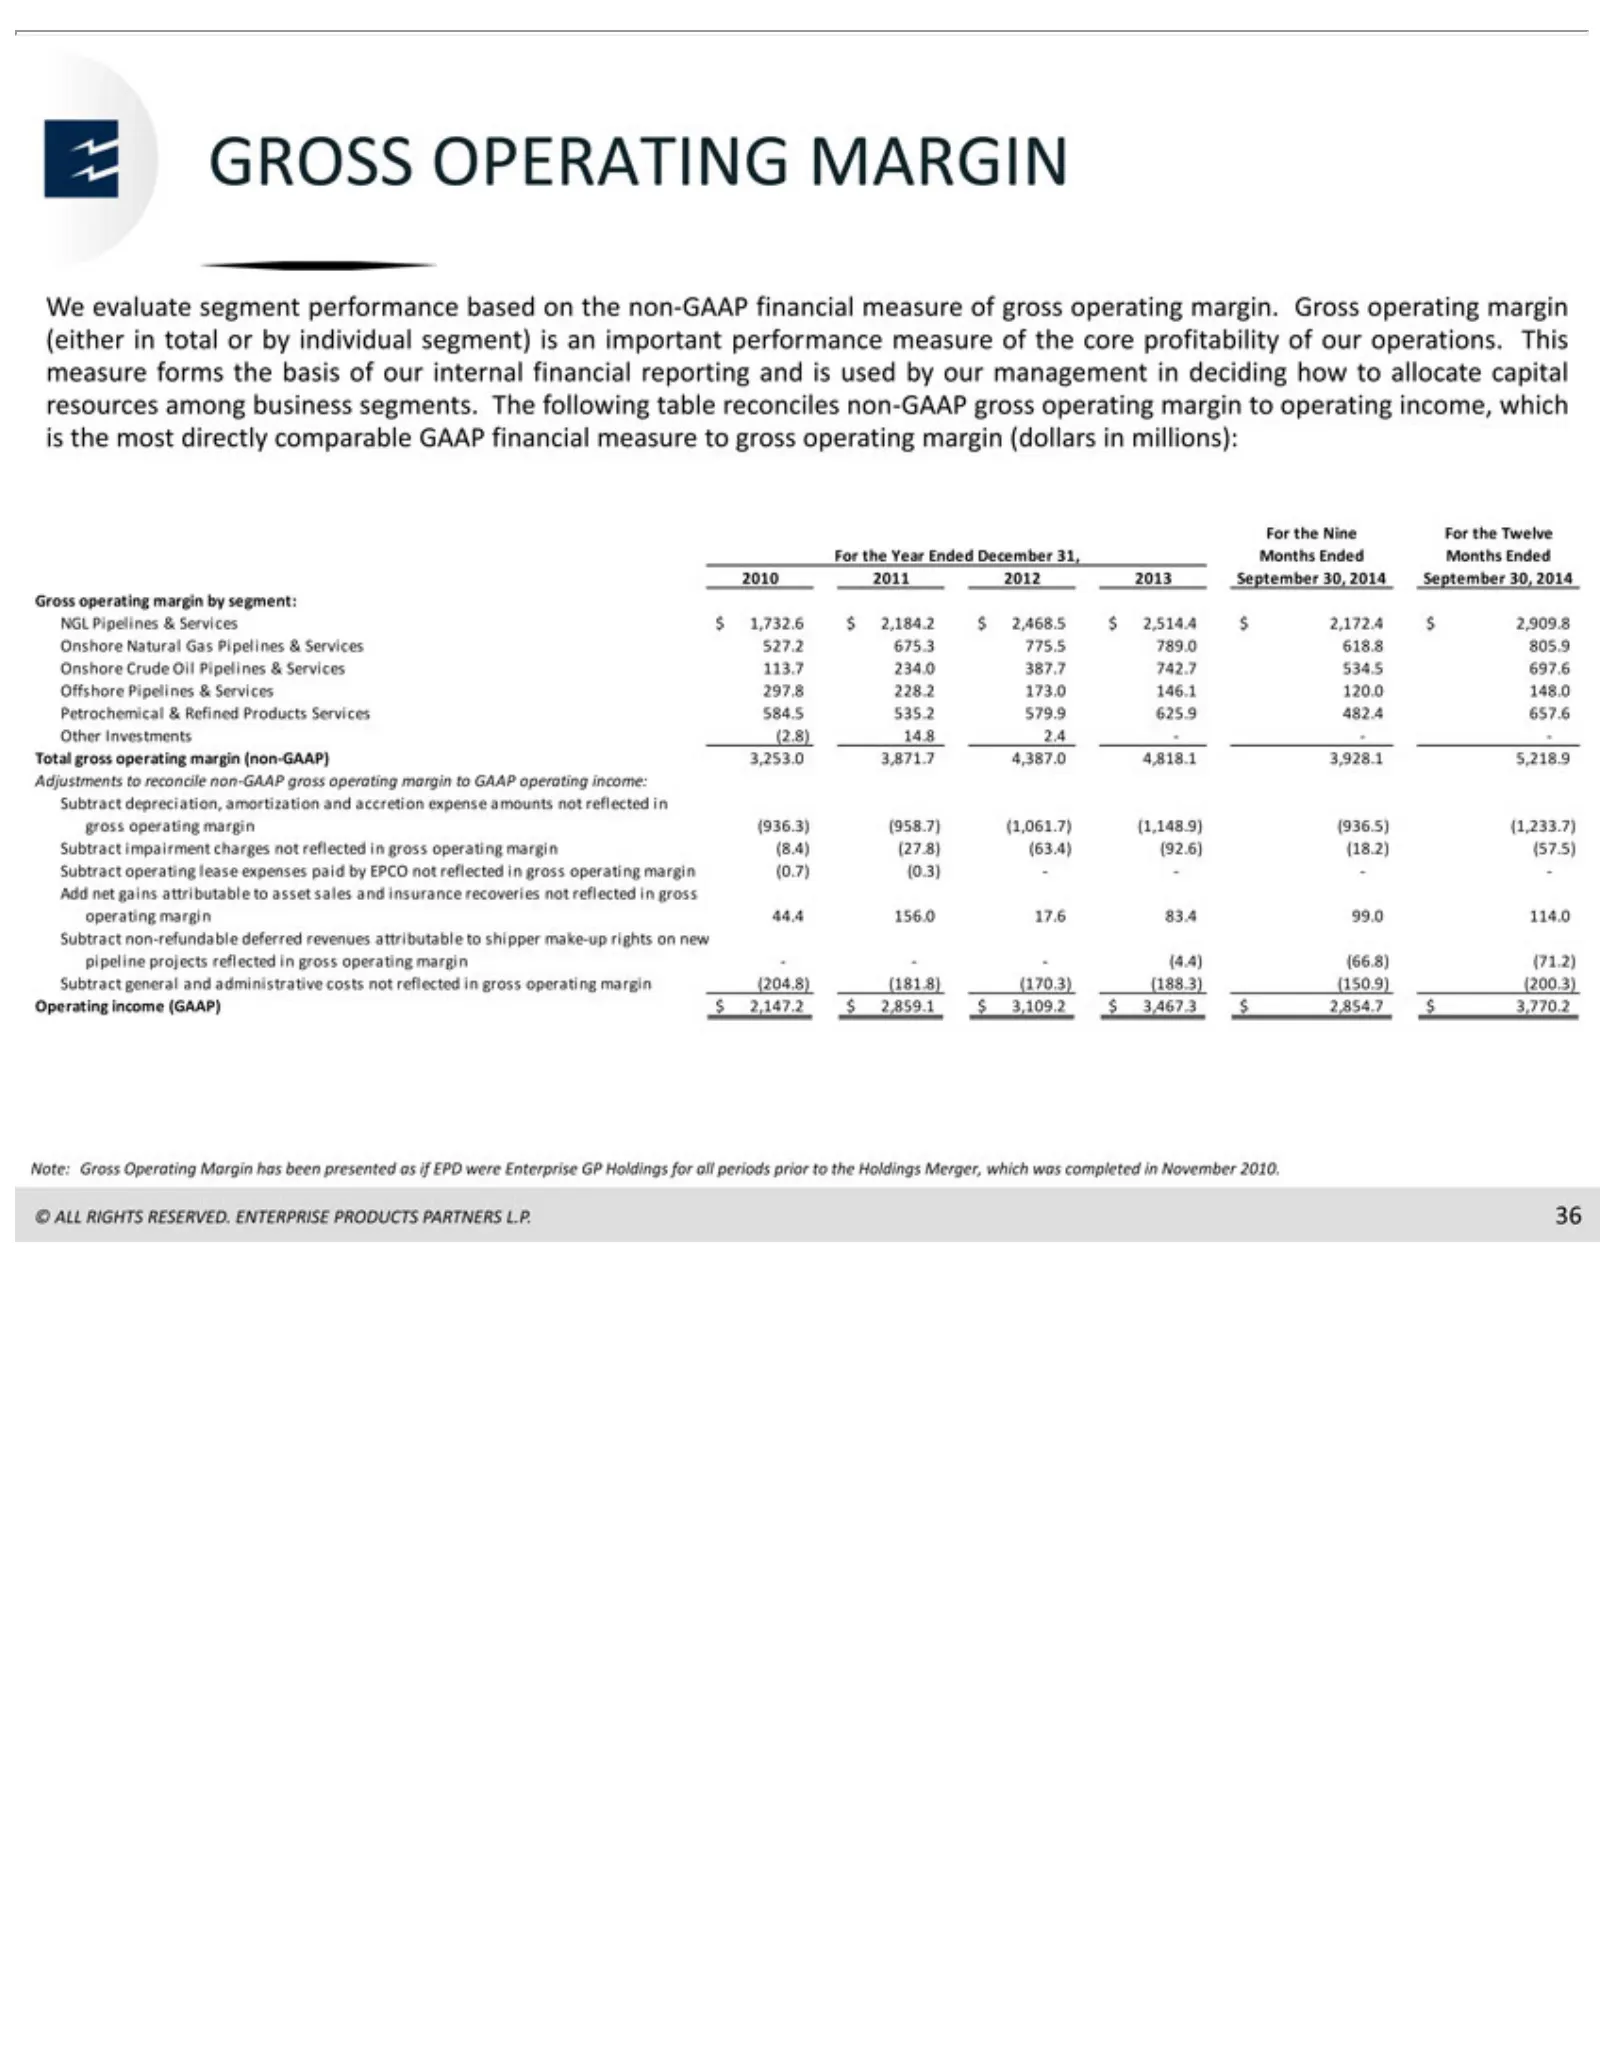
GROSS We of segments. For millions): NGL Services Investments Adjustments Subtract gross Add make-up (204.8) Operating Note: © ALL the evaluate the net Pipelines operating Gross core Nine RIGHTS (181.8) gains OPERATING depreciation, 113.7 rights The income profitability Operating (2.8)--- segment Fo
Slide 38: Adjusted EBITDA
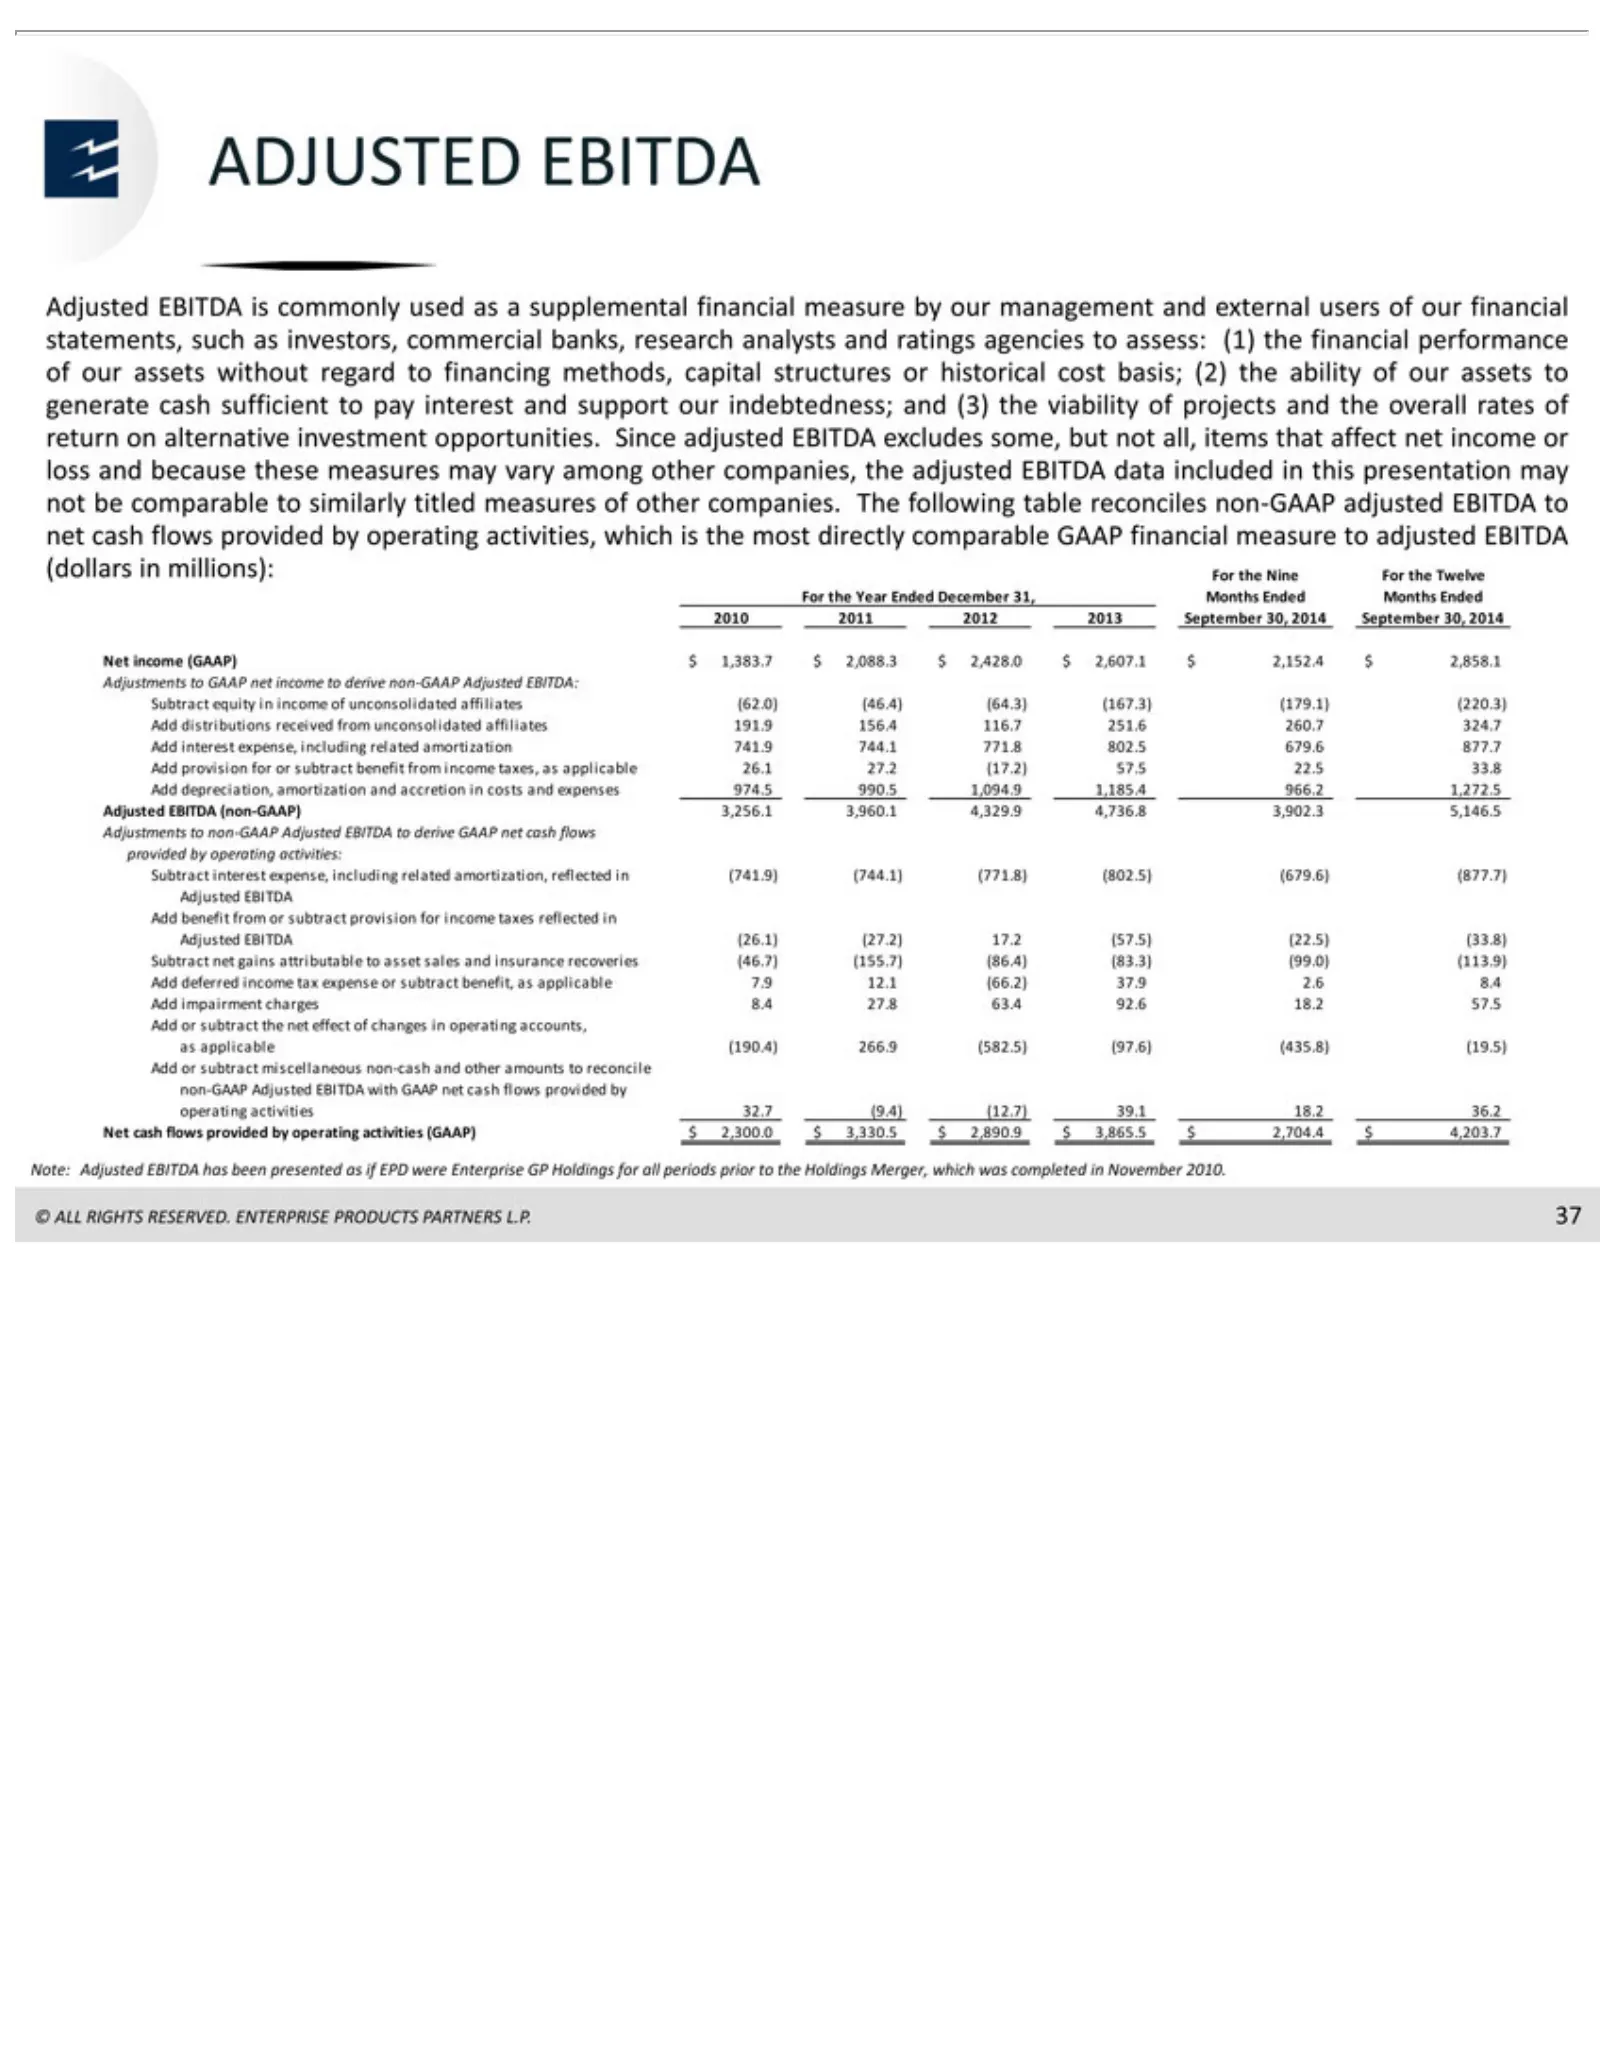
ADJUSTED ratings pay affect companies. EBITDA For Net expense, amortization Adjustments Subtract Add Adjusted subtract (582.5) (9.4) Note: © ALL the interest income benefit (12.7) Adjusted net agencies Nine RIGHTS (97.6) benefit, equity interest including (dollars EBITDA income The 39.1 and (GAAP) f
Slide 39: Distributable Cash Flow
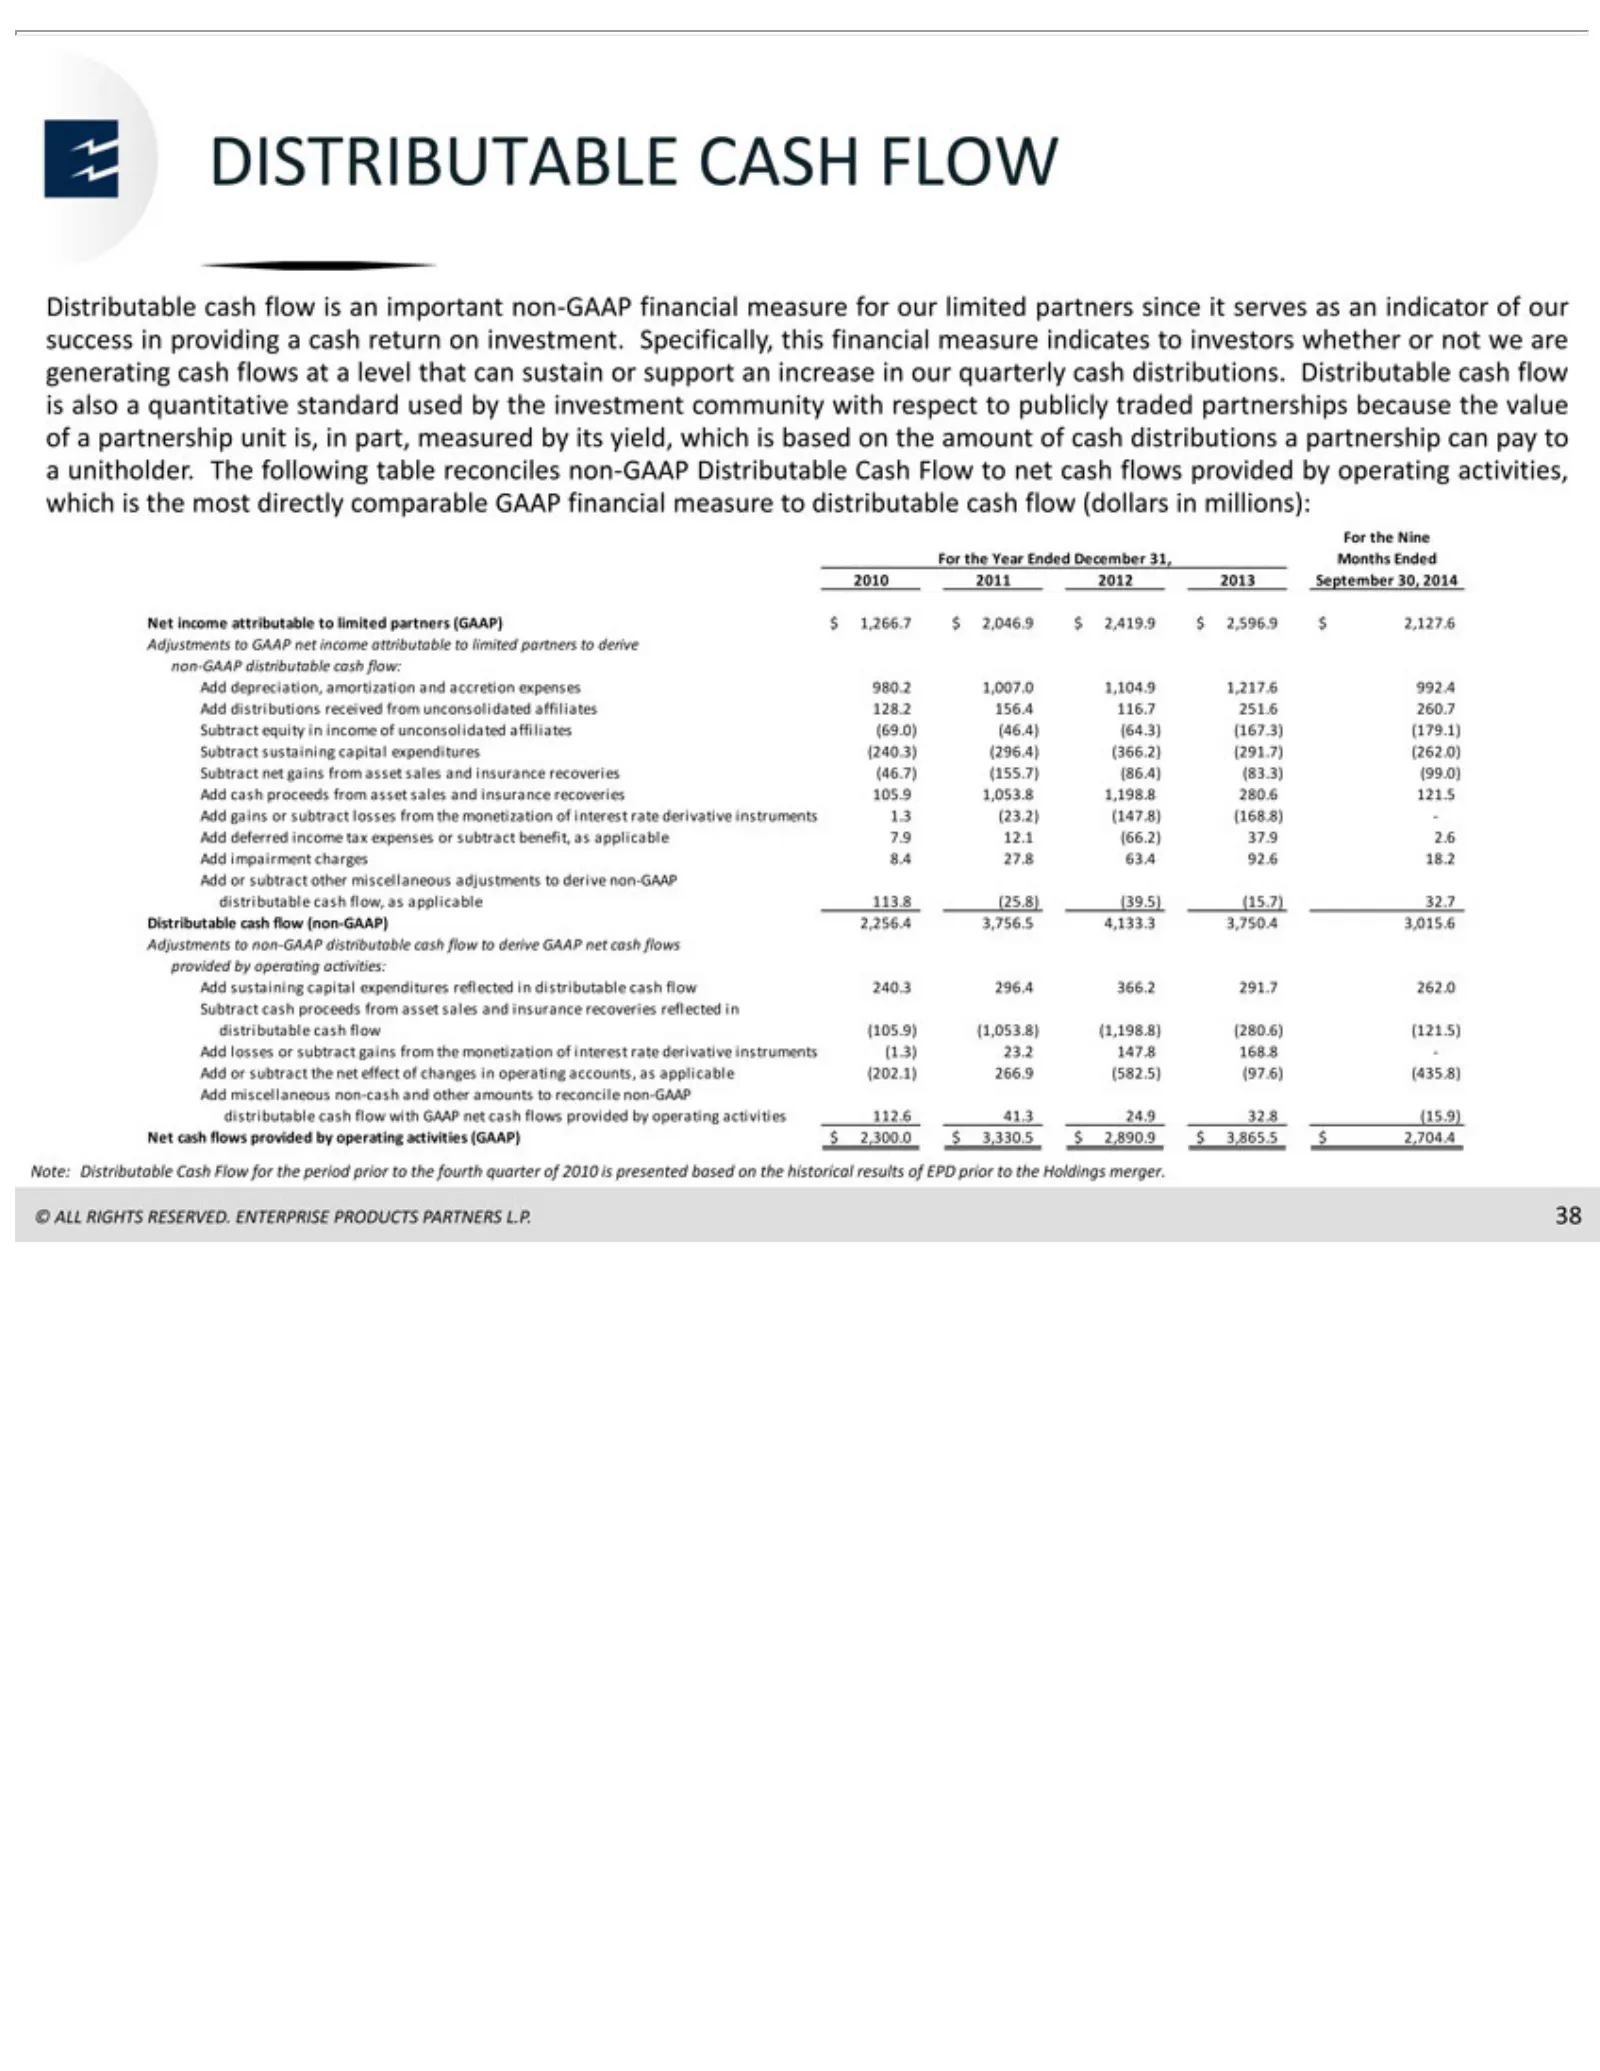
DISTRIBUTABLE Distributable measure standard distributions comparable For of (46.7) instruments GAAP Adjustments Add (105.9) operating Net Note: © ALL unconsolidated the income cash depreciation, deferred sustaining Distributable (155.7) distributable Nine RIGHTS (1,053.8) indicates used flows accou
Slide 40: Contact Information
CONTACT Randy (713) © [email protected] ALL381-6812 Burkhalter RIGHTS INFORMATION RESERVED. – Vice President, ENTERPRISE Investor Relations PRODUCTS PARTNERS L.P. 39m
Source: SEC EDGAR · 425 filed Jan 7, 2015