MidSouth Bancorp — GulfSouth Bank Conference 2008
38 slides from MidSouth Bancorp's conference presentation, May 2, 2008
Slide 1: MidSouth Bancorp, Inc.
TA MidSouth Bancorp, Inc.
Slide 2: GulfSouth Bank Conference, May 1, 2008
AMEX: MSL GulfSouth Bank Conference May 1, 2008 __________________________________________________________________________________________________________ C.R. “Rusty” Cloutier President & Chief Executive Officer J. Eustis Corrigan, Jr. Executive Vice President and Chief Financial Officer
Slide 3: Safe harbor statement
The Private Securities Litigation Act of 1995 provides a safe harbor for disclosure of information about a company’s anticipated future financial performance. This act protects a company from unwarranted litigation if actual results differ from management expectations. This discussion and analysis r
Slide 4: Corporate Profile
Corporate Profile Growth-oriented, bank holding company Headquarters: Lafayette, Louisiana Employees: 423 ● Locations: 34 ● ATMs: 120+ Market Statistics as of March 31, 2008: › Total Assets: $937 Million › Market Cap: $142.8 Million › Stock Price: $18.70 ● Book Value: $10.65 › Shares Outstanding: 6.
Slide 5: Corporate Profile: History and Business Fundamentals
Corporate Profile CORPORATE HISTORY 1985 - Chartered as a National Bank 1987 - Acquired Breaux Bridge Bank & Trust (LA) 1989 - Acquired Commerce & Energy Bank (LA) 1993 - Listed on AMEX: MSL 1995 - Acquired Sugarland State Bank (LA) 2004 - Acquired Lamar Bank (Beaumont, TX) BUSINESS FUNDAMENTALS • S
Slide 6: Strategic Focus
Strategic Focus Profitable Growth & Expansion Operational Enhancement Capital & Funds Management Maximize Shareholder Value Human Capital § Target Markets § Existing Growth Markets § Focus on TX/LA Footprint § “Buy & Build” Opportunities § Preserve Culture § CRM Implementation § Expense Governance §
Slide 7: Financial Performance: Income Statement
Financial Performance INCOME STATEMENT 1Q08 1Q07 YOY r 4Q07 LQ r Net Interest Income $9,274 $8,338 11.2% $9,613 -3.5% Loan Loss Provision $1,200 -- $525 128.6% Total Non-Interest Income $3,587 $3,263 9.9% $3,732 -3.9% Total Non-Interest Expense $10,293 $9,079 13.4% $10,569 -2.6% Income Tax Expense $
Slide 8: Financial Performance: Balance Sheet
Financial Performance BALANCE SHEET 1Q08 1Q07 YOY r 4Q07 LQ r Total Assets $937,030 $814,660 $937,030 $854,056 9.7% Total Loans $569,745 $510,561 $569,745 $569,506 0.0% Premises and Equipment $39,967 $31,488 $39,967 $39,229 1.9% Total Deposits $818,004 $728,839 $818,004 $733,517 11.5% Total Sharehol
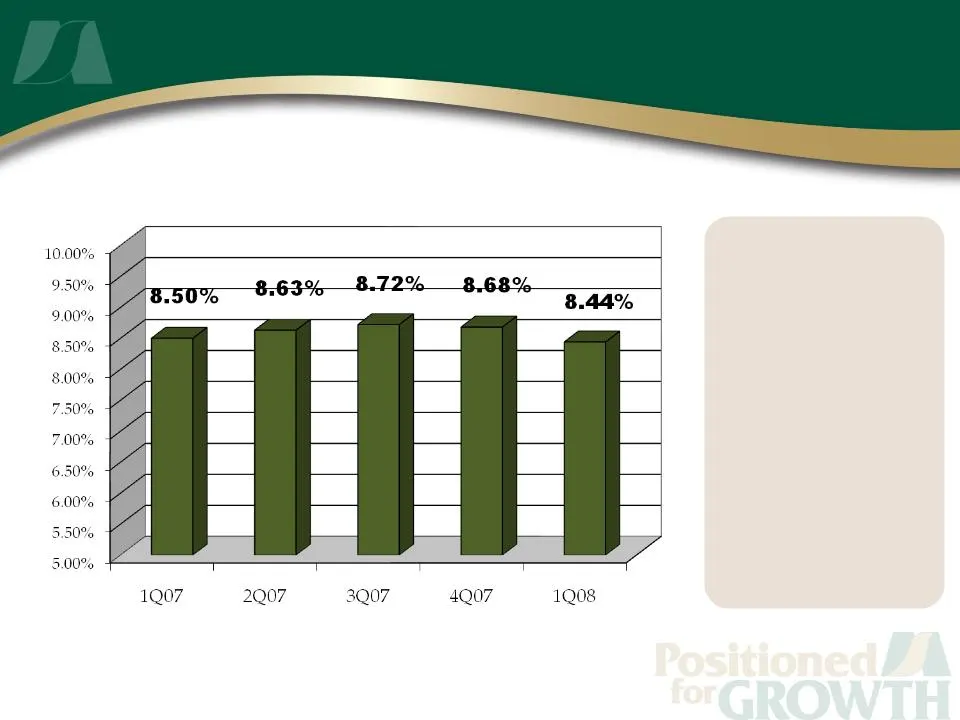
Slide 9: Financial Performance: Sound Capital Levels
Financial Performance Sound Capital Levels ▪ 5 Quarter Average Leverage Ratio: 8.59% ▪ Dividend Payout Ratio: 25% ▪ Div Yield: 1.36% Leverage Ratio
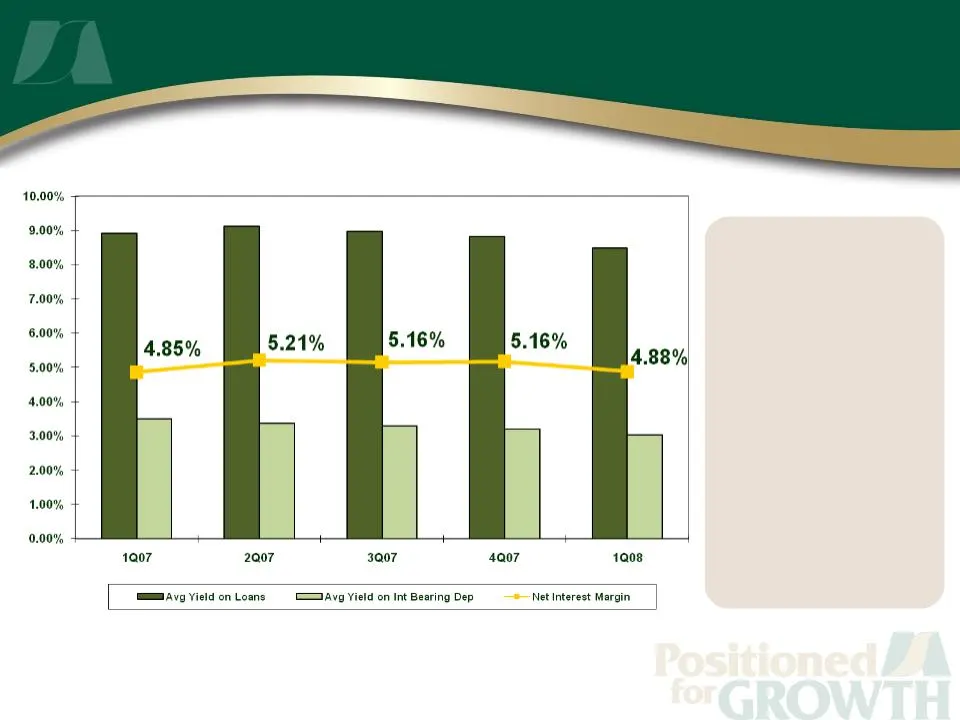
Slide 10: Financial Performance: Yields
Financial Performance Yields ▪ Consistent NIM ▪ Active management of Loan/Deposit Pricing
Slide 11: Financial Performance: Credit Quality
Financial Performance CREDIT QUALITY 1Q07 4Q07 1Q08 LQ r Allowance as a % of TTL Lns 0.96% 0.99% 1.08% bps NPA's to Total Assets 0.28% 0.35% 0.49% bps Net YTD Charge-offs to TTL Lns 0.02% 0.09% 0.12% bps
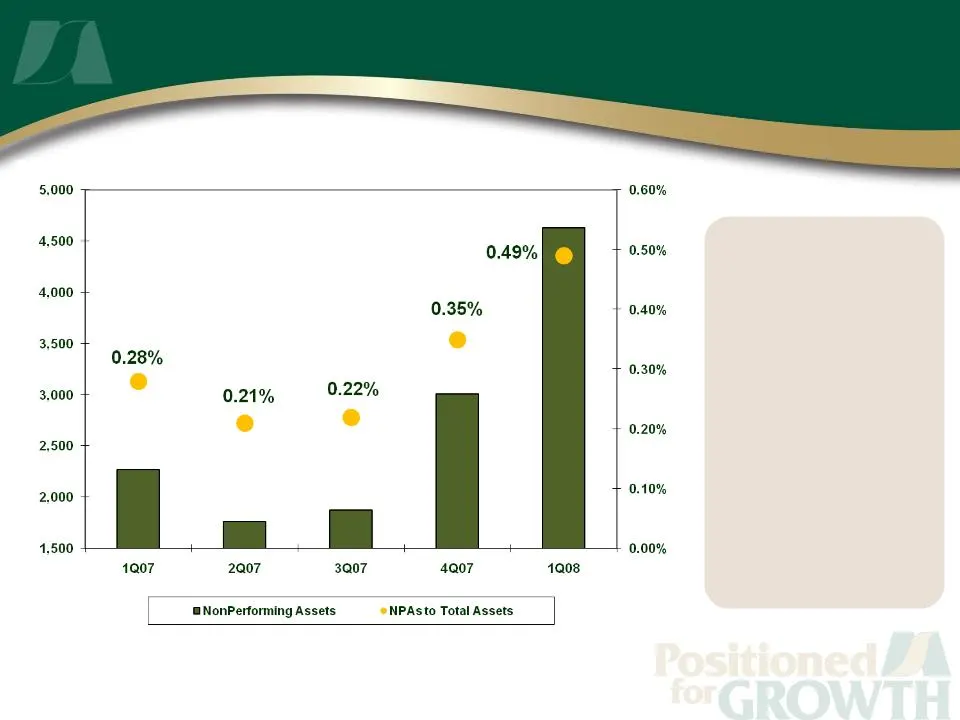
Slide 12: Financial Performance: Asset Quality
Financial Performance Asset Quality ▪ Engaged & Focused on Regional Economies ▪ Experienced and Accomplished Management & Board
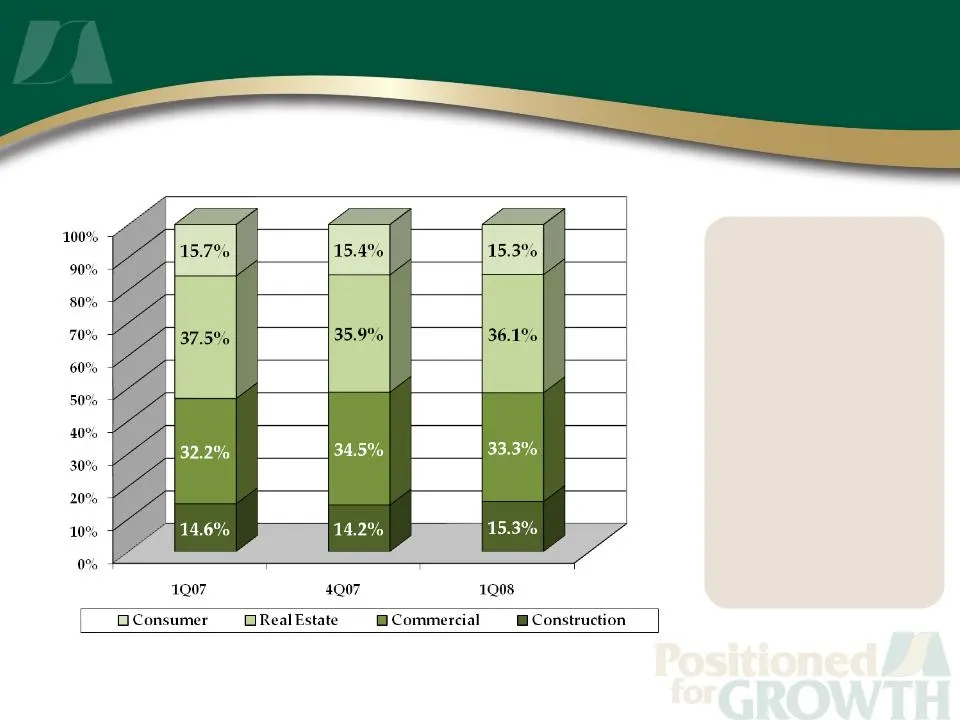
Slide 13: Financial Performance: Loan Mix
Financial Performance Loan Mix § Diversified Loan Portfolio § C&I Customers Diversified by Industry & Geography
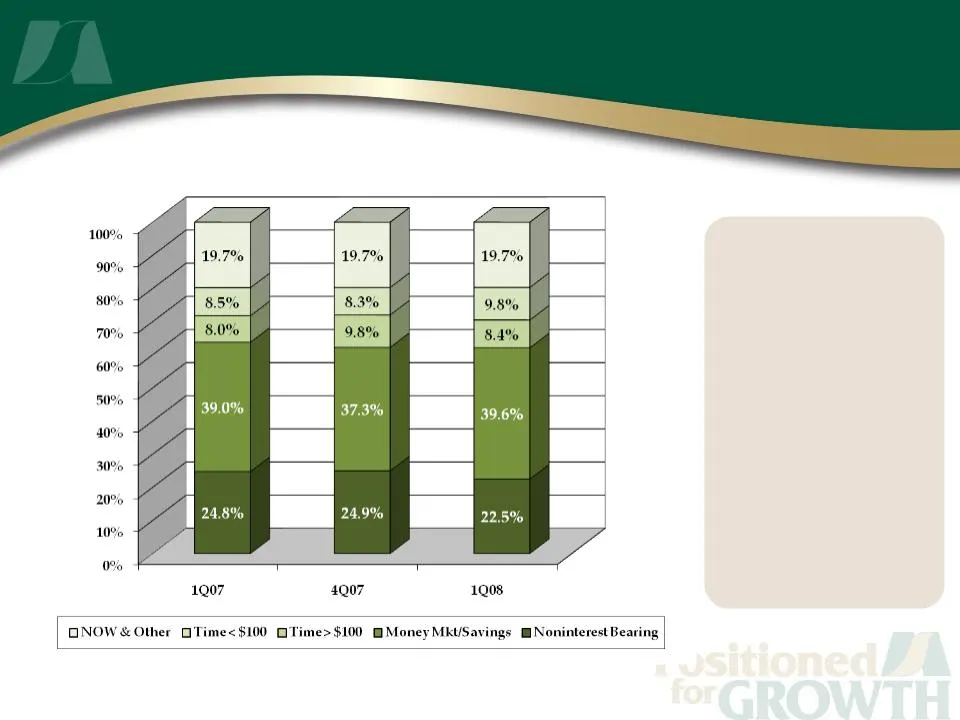
Slide 14: Financial Performance: Deposit Mix
Financial Performance Deposit Mix § Strong & Stable Core Funding Source § Maintaining Solid Non-Interest Bearing Base
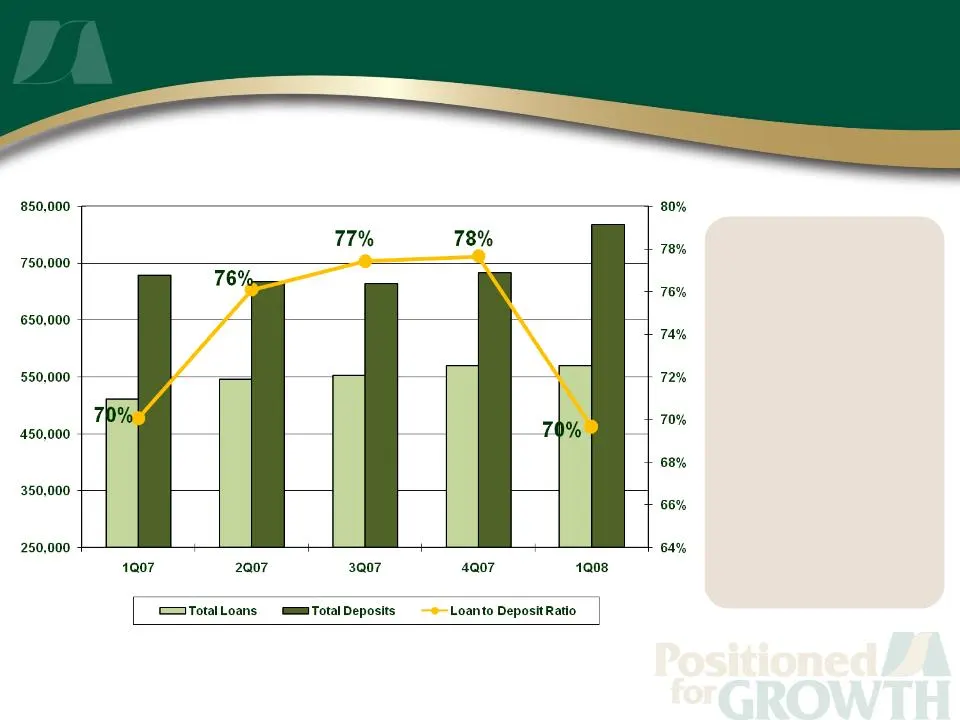
Slide 15: Financial Performance: Core Funding
Financial Performance Core Funding ▪ Funding Capacity ▪ Challenging Markets
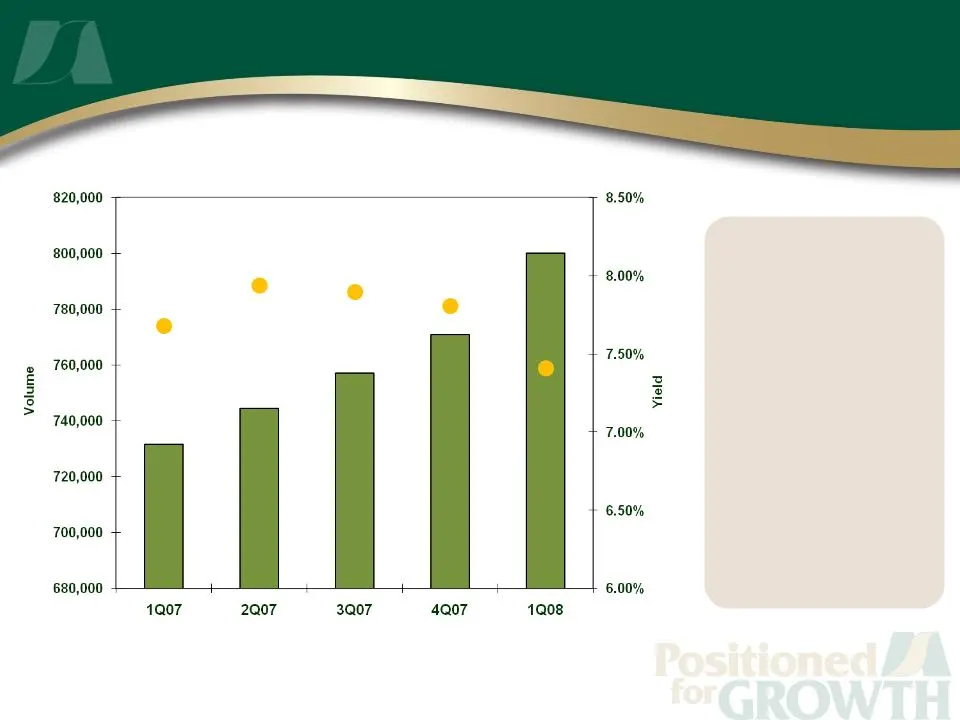
Slide 16: Financial Performance: Earning Assets
Financial Performance Earning Assets ▪ Premium Yield on Average Earning Assets ▪ Capacity to Leverage Yield 7.68% 7.94% 7.80% 7.90% 7.41%
Slide 17: Financial Performance: Earning Asset Mix
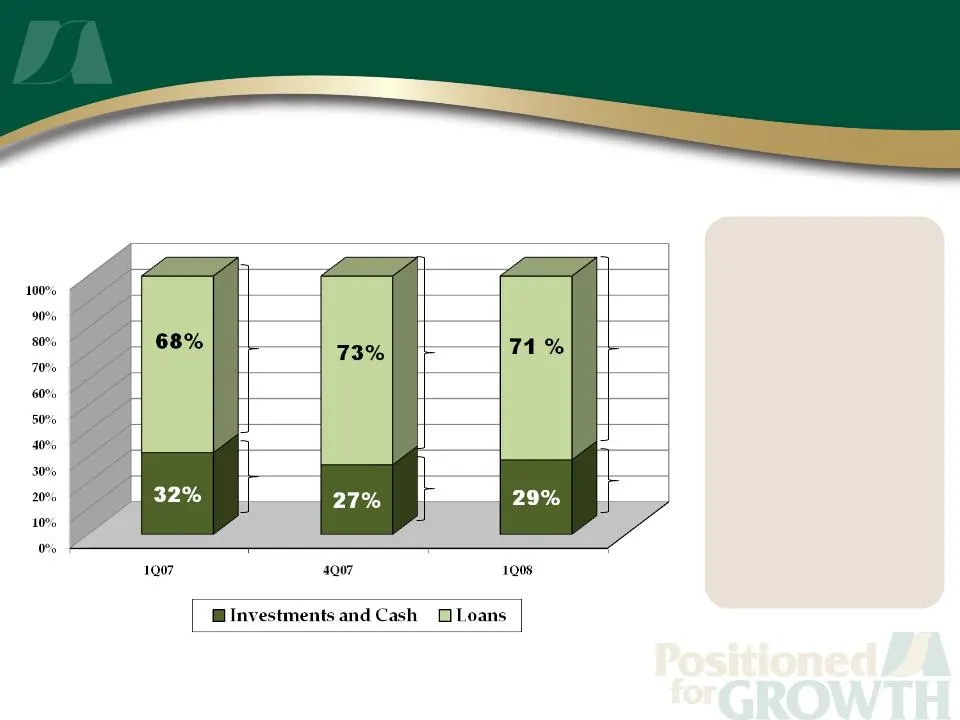
Financial Performance Earning Asset Mix ▪ Stability in Earning Assets ▪ Securities Yield: • 5.14%- 1Q08 • 4.93%- 1Q07 4.96% 5.09% 4.74% 8.91% 8.82% 8.48%
Slide 18: Franchise Footprint 2003
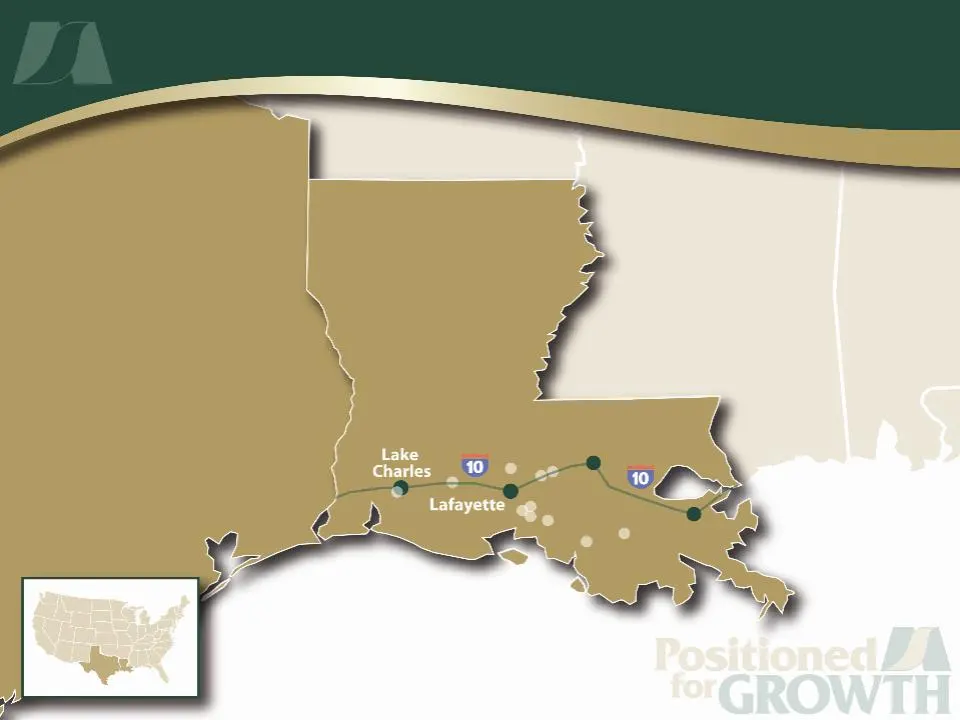
Franchise Footprint 2003
Slide 19: Franchise Expansion 2004
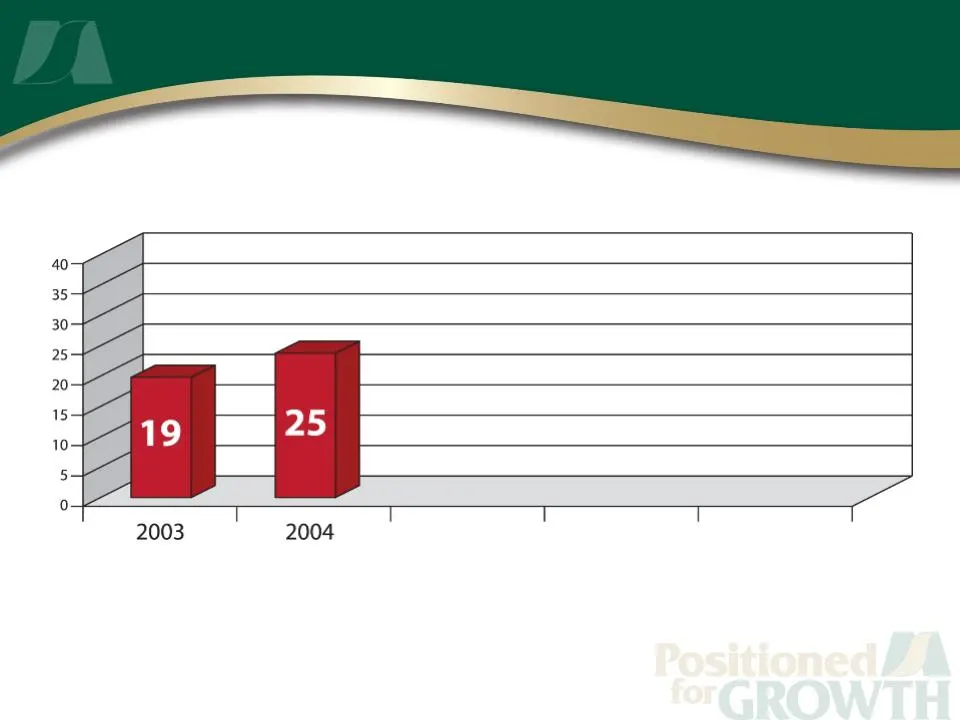
Franchise Expansion Locations 2004 • Beaumont (3), Vidor, Conroe, College Station • Expansion into Texas
Slide 20: Franchise Expansion 2005
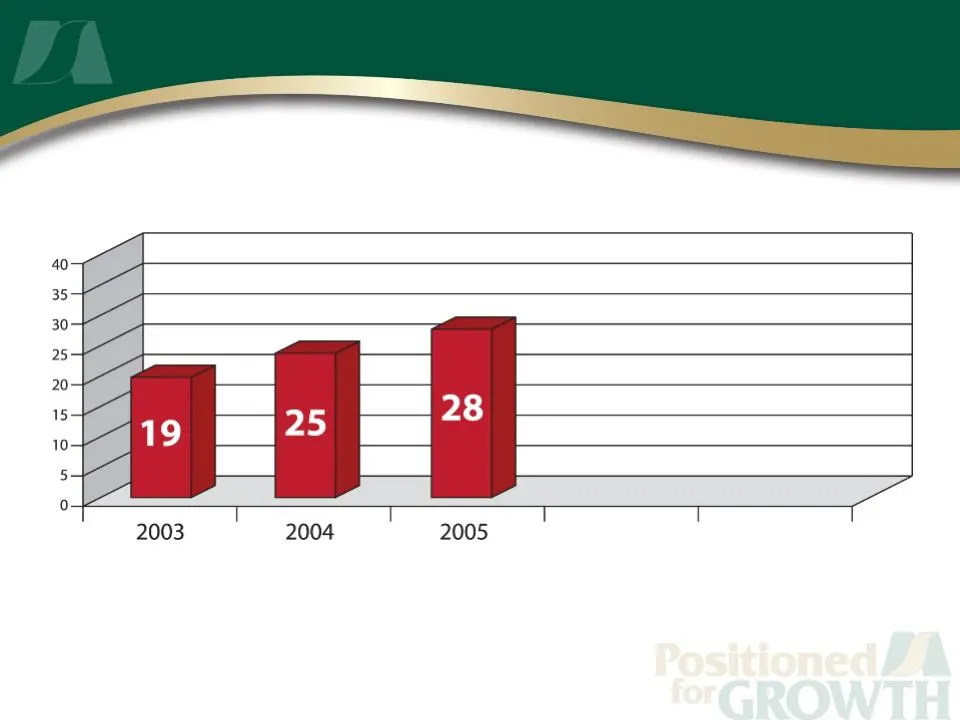
Franchise Expansion Locations 2005 Baton Rouge Houma (SE Louisiana) Lafayette (8 th location)
Slide 21: Franchise Expansion 2006
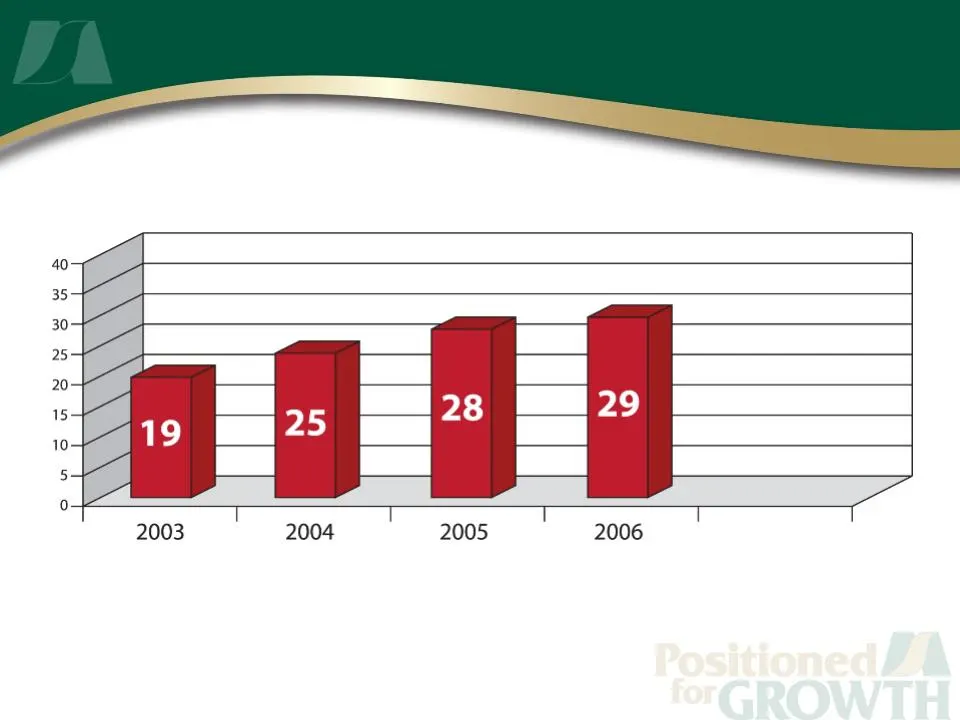
Franchise Expansion Locations 2006 Lafayette (9 th location)
Slide 22: Franchise Expansion 2007
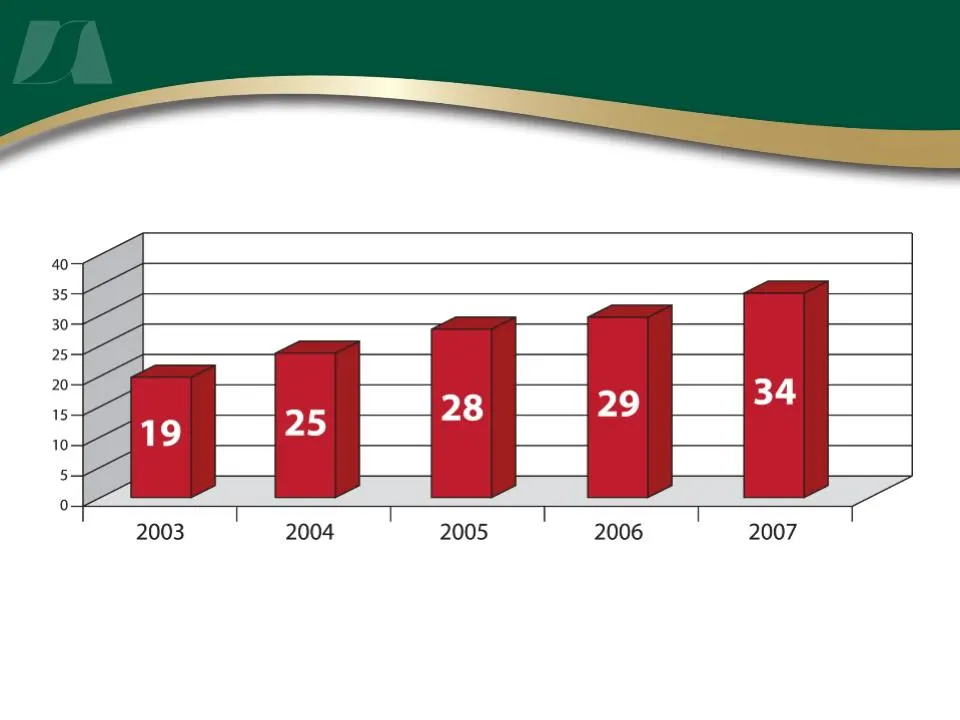
Franchise Expansion Locations 2007 TEXAS: Houston, Conroe*, College Station LOUISIANA: Baton Rouge (2 nd location), Lake Charles (2 nd location), Thibodaux*, Cut Off *Relocation
Slide 23: Franchise Footprint 2008
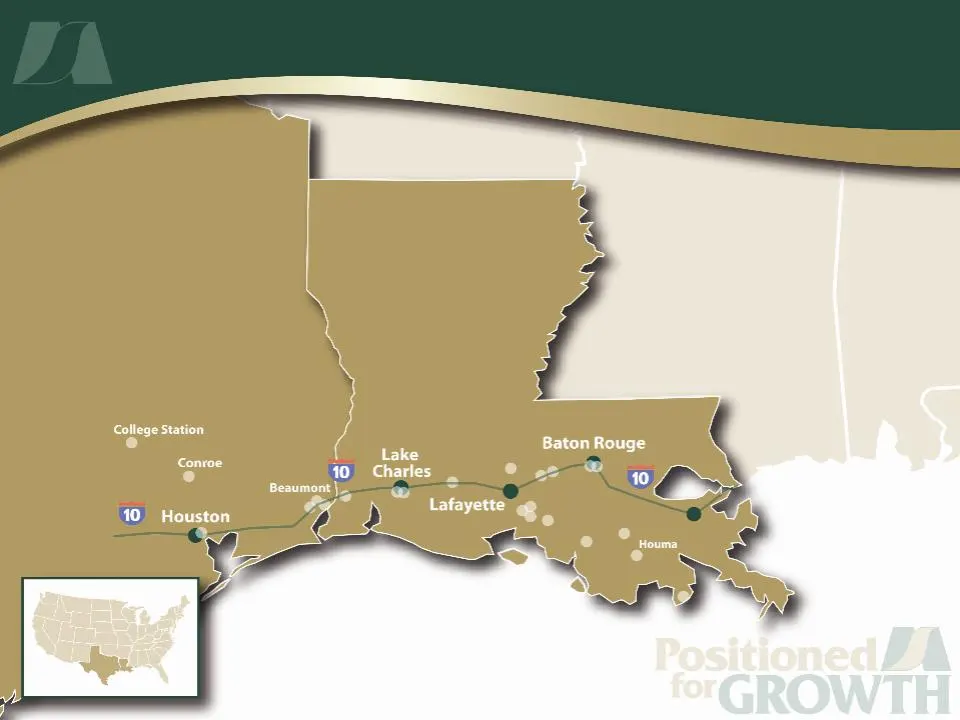
Franchise Footprint 2008
Slide 24: Personal Income Growth
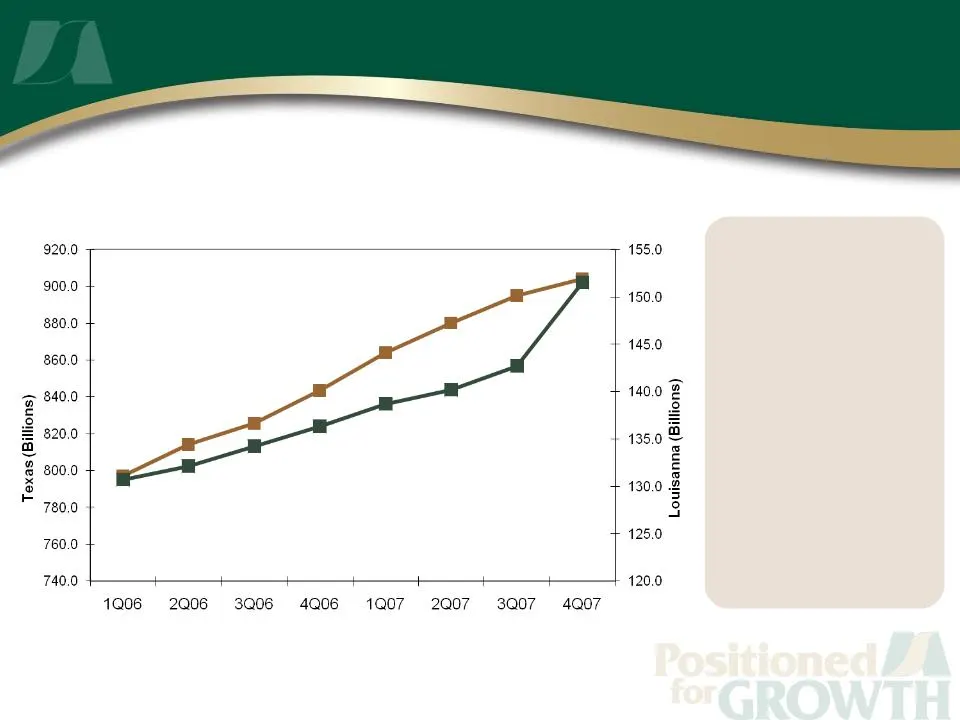
Personal Income Growth Quarterly Personal Income ▪ Sustained Income Growth Source: Federal Reserve Bank of Dallas LOUISIANA TEXAS
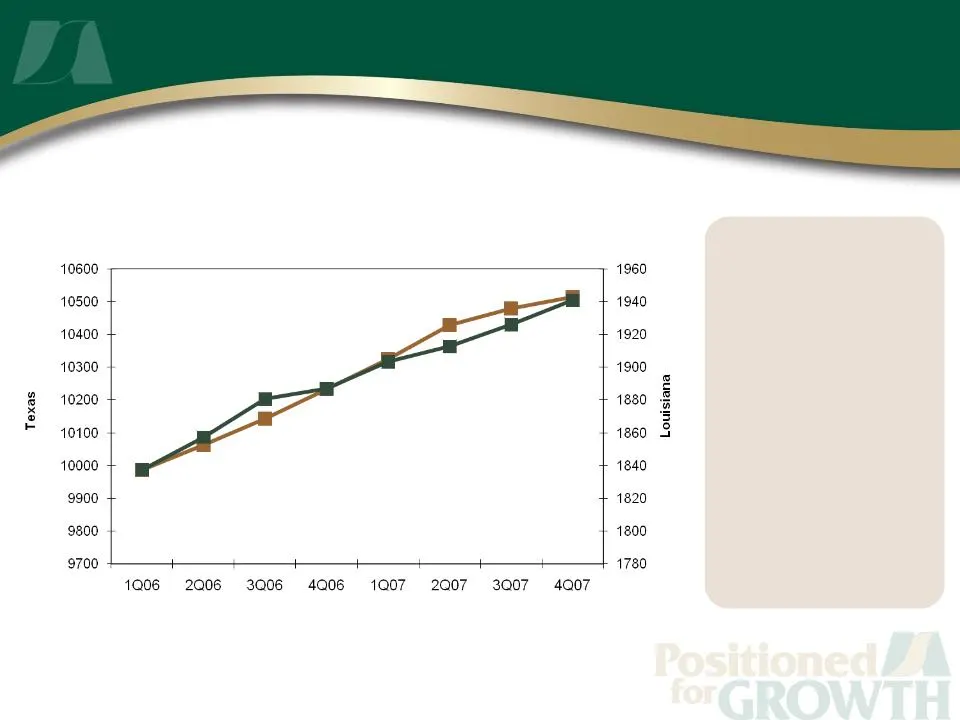
Slide 25: Employment Growth
Employment Growth Total Non-Farm Employment ▪ Sustained Employment Growth Source: Federal Reserve Bank of Dallas LOUISIANA TEXAS
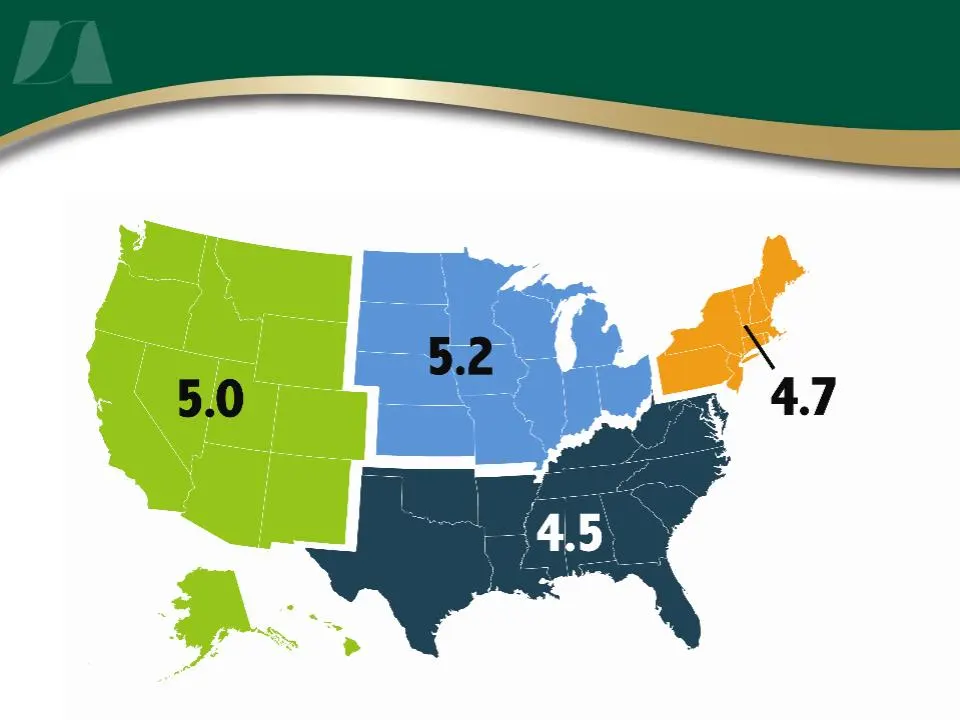
Slide 26: Unemployment Rates
Unemployment Rates Source: US Bureau of Labor Statistics (as of February 2008)
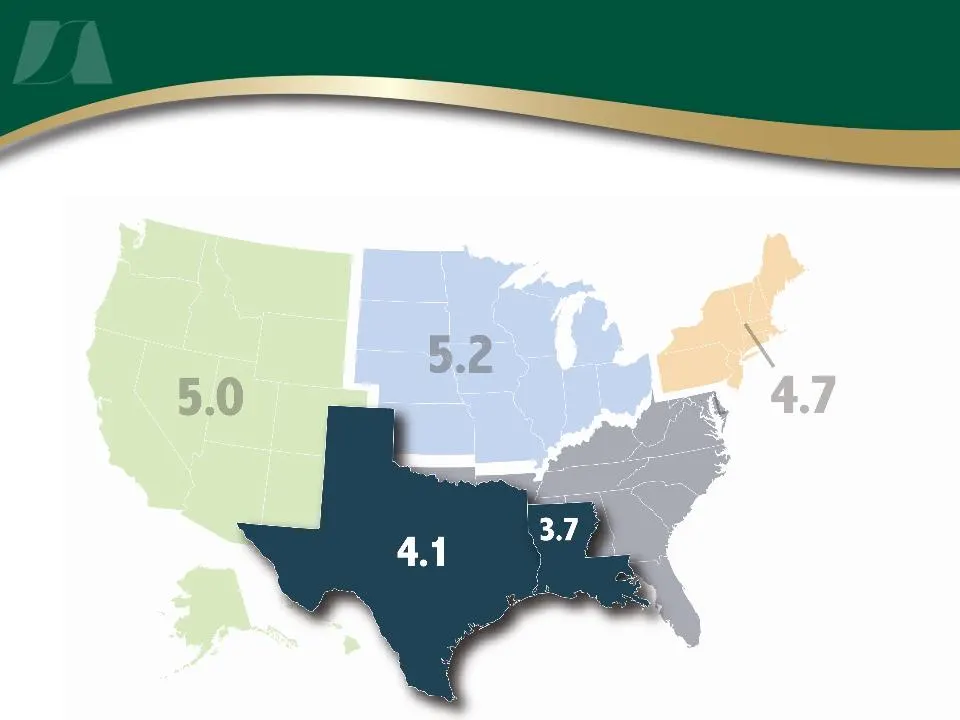
Slide 27: Unemployment Rates
Unemployment Rates Source: US Bureau of Labor Statistics (as of February 2008)
Slide 28: Unemployment Rates
Unemployment Rates Market MSAs Sep-07 Oct-07 Nov-07 Dec-07 Jan-08 Feb-08 Louisiana 3.9 3.6 3.7 4.0 4.0 3.7 Baton Rouge 4.1 2.9 2.9 3.5 4.5 3.4 Houma 2.9 2.0 2.2 2.5 3.4 2.5 Lafayette 3.1 2.1 2.3 2.6 3.4 2.6 Lake Charles 4.3 2.9 3.0 3.7 4.8 3.6 Texas 4.3 4.3 4.2 4.2 4.3 4.1 Beaumont 5.6 4.9 5.3 5.9 6
Slide 29: Wage Growth
Wage Growth Occupation % Chg in Avg Wage* Carpenters 70.9% Electricians 18.7% Engineers 14.1% Helpers 35.2% Plumbers 21.9% Technicians 41.4% Total 39.6% *2005 to 2006 Supply and Demand - Construction Labor Wage Impact Source: La. Economic Outlook: 2008 and 2009
Slide 30: Economic Drivers
Economic Drivers # 1 producer of Oil - 26.4% of U.S. production # 2 producer of Natural Gas - 18.3% of U.S. production # 2 in U.S. Refining Capacity - 16.7% of U.S. capacity Louisiana and the Nation's Energy LA / TX Energy Sector Ongoing Rebuild and Reconstruction 1 - Offshore Drilling Platforms: Be
Slide 31: Economic Drivers: Lake Charles
Economic Drivers LAKE CHARLES MSA (92,100 non-farm jobs) Projected 2,800 new jobs over 2008-09 Fully recovered from Hurricane Rita and now setting record levels of employment dominant industries: Petrochemical, Gambling, and Aircraft Repair Port of Lake Charles is expected to spend over $100 million
Slide 32: Economic Drivers: Baton Rouge
Economic Drivers Projected 14,800 new jobs over 2008-09 Home of two major universities - LSU and Southern University, the State Capitol, and the country's second largest refinery Incurred over 35,000 permanent new residents as a result of Hurricane Katrina Over $5 billion in construction projects ei
Slide 33: Economic Drivers: Lafayette
Economic Drivers Projected 6,300 new jobs over 2008-09 Third fastest growing MSA in Louisiana High concentration of firms associated with oil and gas extraction industry Home of the nation's largest jewelry settings manufacturer Planned expansion of an already robust energy sector to include: Tetra
Slide 34: Economic Drivers: Houma
Economic Drivers HOUMA MSA (94,800 non-farm jobs) Projected 5,200 new jobs over 2008-09 Fastest growing MSA in Louisiana generated by the shipbuilding, fabrication, and oil and gas extraction sectors Significant shipbuilding and fabrication sector which benefits from the rebuild effort of the offsho
Slide 35: Historical Stock Performance
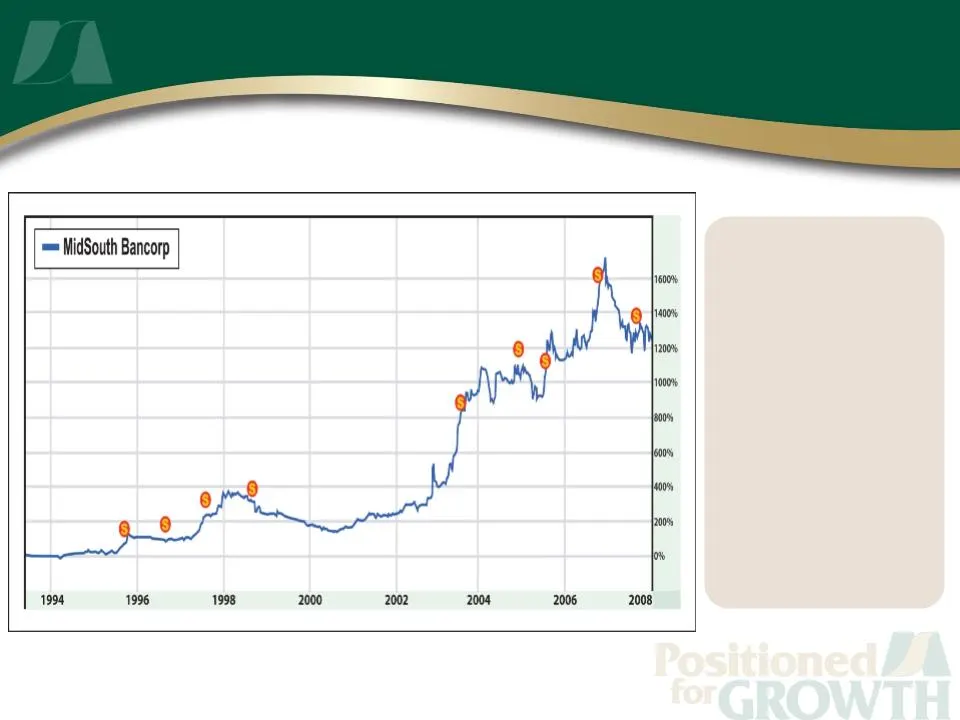
Stock Performance Historical Stock Performance ▪ Life to Date $1,000 = $12,500 ▪ Last 5 Years 89% Return Source: Finance.Yahoo.com - April 26, 1993 - April 21, 2008 April 1993 - April 2008
Slide 36: Relative Stock Performance
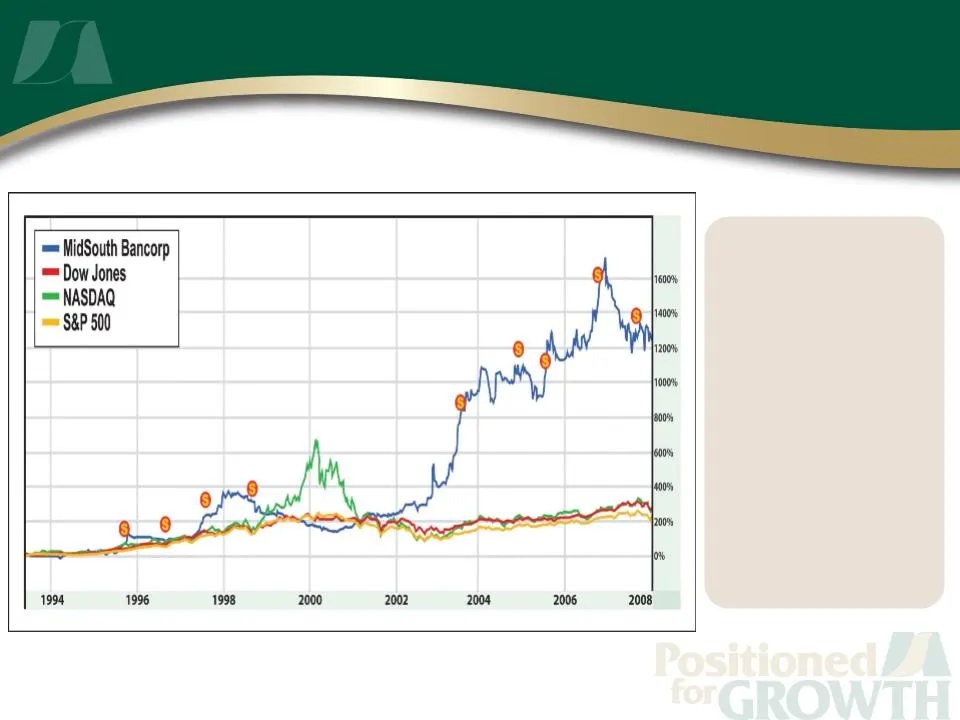
Stock Performance Relative Stock Performance ▪ MSL vs. Major Indexes ▪ Life to Date Growth Source: Finance.Yahoo.com - April 26, 1993 - April 21, 2008 April 1993 - April 2008
Slide 37: MidSouth Bancorp Summary
MidSouth Bancorp SUMMARY • Regional Strategic Growth Model • Focused & Driven Leadership • Superior Financial Performance and Focus on Credit Quality • Excellent Shareholder Returns
Slide 38: MidSouth Bancorp Contact
MidSouth Bancorp P.O. Box 3745 - Lafayette, LA 70502 ___________________________________________________________ C.R. “Rusty” Cloutier President & Chief Executive Officer [email protected] 337-237-8343 J. Eustis Corrigan, Jr. Executive Vice President and Chief Financial Officer ecorrigan@mid
Source: SEC EDGAR · 8-K filed May 2, 2008
More decks from MidSouth Bancorp Inc
 IPO Roadshow (June 2017)36 slides · Jun 7, 2017
 Shareholder Meeting (May 2017)12 slides · May 24, 2017
 Gulf South Bank Conference 201732 slides · May 8, 2017
 Gulf South Bank Conference 201319 slides · May 14, 2013
 Merger or Acquisition (September 2012)11 slides · Sep 27, 2012
 Q3 2011 Earnings Presentation6 slides · Oct 26, 2011