SunTrust Banks — BancAnalysts Association of Boston Conference 2016
18 slides from SunTrust Banks's conference presentation, Nov 4, 2016
Slide 1: BancAnalysts Association of Boston Conference
BancAnalysts Association of Boston Conference Mark Chancy, Wholesale Banking Executive, SunTrust Banks, Inc. November 4, 2016
Slide 2: Important Cautionary Statement
2 Important Cautionary Statement The following should be read in conjunction with the financial statements, notes and other information contained in the Company’s 2015 Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K. This presentation includes non-GAAP fin
Slide 3: SunTrust Overview
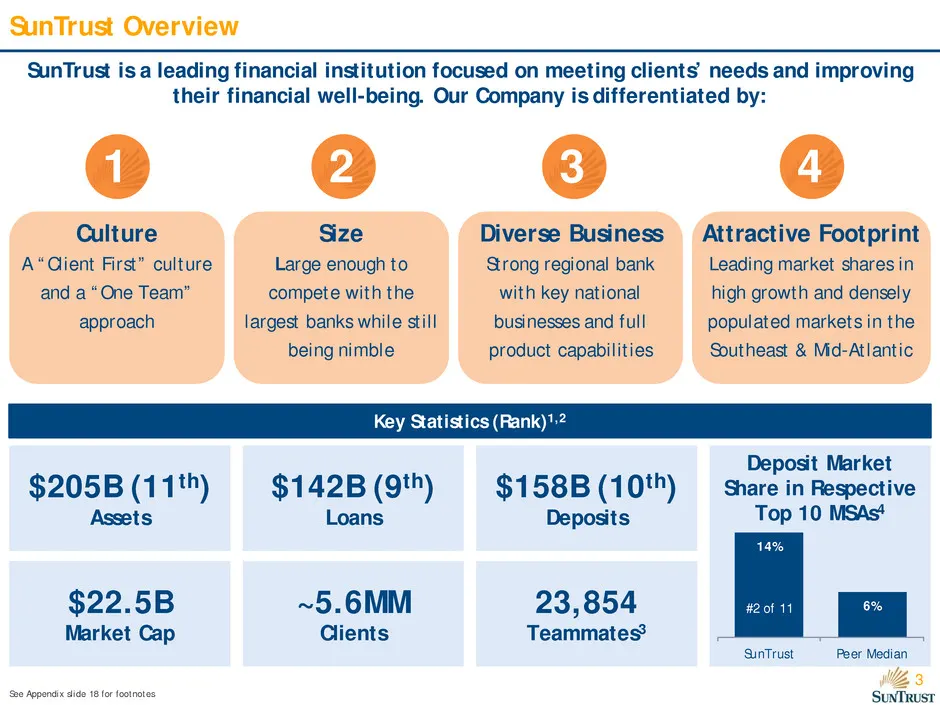
3 SunTrust Overview SunTrust is a leading financial institution focused on meeting clients’ needs and improving their financial well-being. Our Company is differentiated by: 1 Size Large enough to compete with the largest banks while still being nimble 2 Diverse Business Strong regional bank with ke
Slide 4: Section 1: Overview of Wholesale Banking
Section 1: Overview of Wholesale Banking
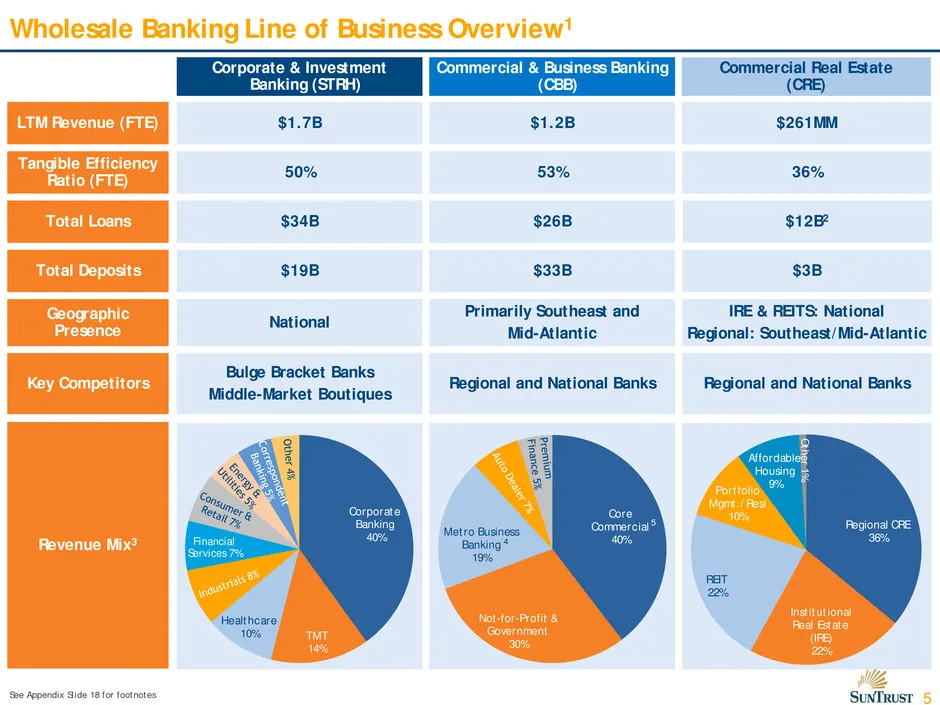
Slide 5: Wholesale Banking Line of Business Overview
5 Corporate Banking 40% TMT 14% Healthcare 10% Core Commercial 40% Not-for-Profit & Government 30% Metro Business Banking 19% Wholesale Banking Line of Business Overview1 Corporate & Investment Banking (STRH) Commercial Real Estate (CRE) Commercial & Business Banking (CBB) $1.7B $261MM $1.2B $34B $1
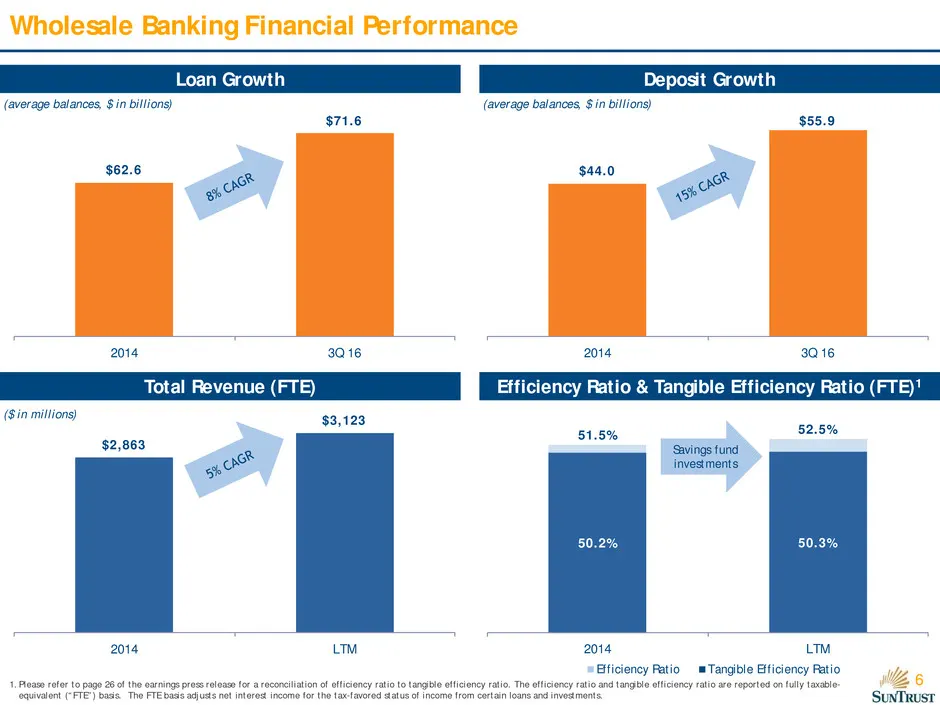
Slide 6: Wholesale Banking Financial Performance
6 50.2% 50.3% 51.5% 52.5% 2014 LTM $2,863 $3,123 2014 LTM $44.0 $55.9 2014 3Q 16 $62.6 $71.6 2014 3Q 16 Wholesale Banking Financial Performance Loan Growth Deposit Growth (average balances, $ in billions) (average balances, $ in billions) Total Revenue (FTE) Efficiency Ratio & Tangible Efficiency Ra
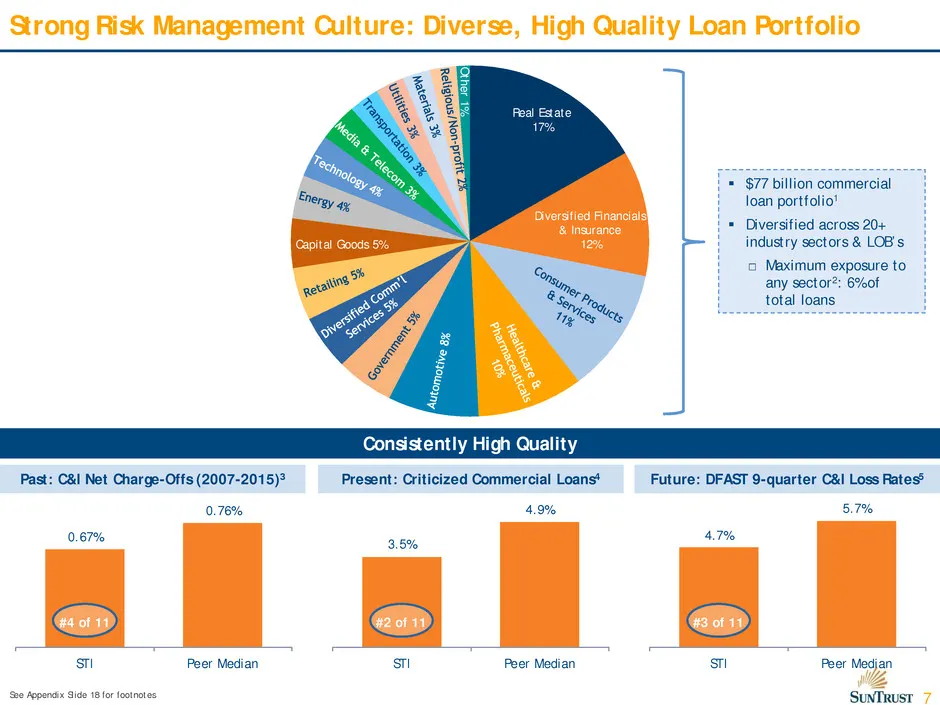
Slide 7: Strong Risk Management Culture: Diverse, High Quality Loan Portfolio
7 0.67% 0.76% STI Peer Median Strong Risk Management Culture: Diverse, High Quality Loan Portfolio Real Estate 17% Diversified Financials & Insurance 12% O ther 1% Capital Goods 5% Consistently High Quality Past: C&I Net Charge-Offs (2007-2015)3 Present: Criticized Commercial Loans4 Future: DFAST 9-
Slide 8: Section 2: Key Strategies
Section 2: Key Strategies WZ SunTrust
Slide 9: How We Differentiate
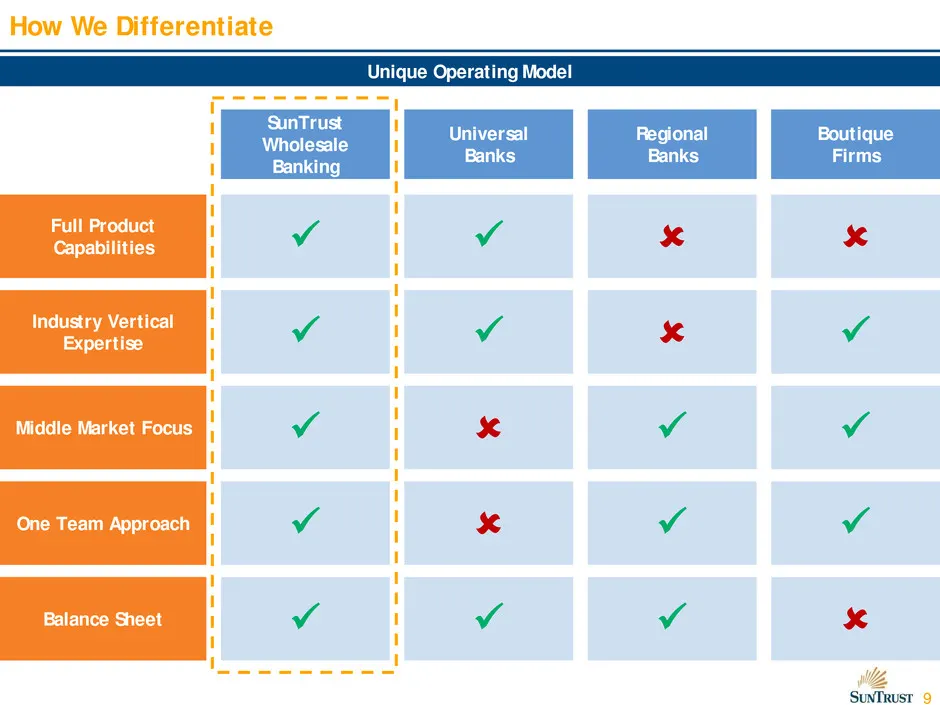
9 How We Differentiate Unique Operating Model Full Product Capabilities Industry Vertical Expertise Middle Market Focus One Team Approach Balance Sheet SunTrust Wholesale Banking Universal Banks Regional Banks Boutique Firms
Slide 10: STRH's Demonstrated Results
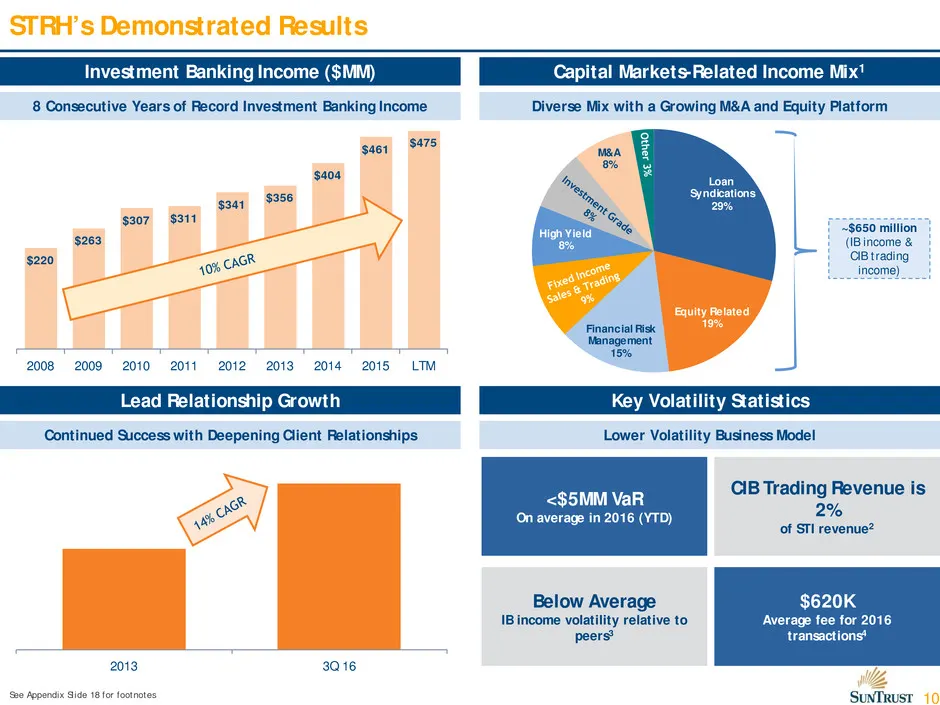
10 Loan Syndications 29% Equity Related 19%Financial Risk Management 15% High Yield 8% M&A 8% 2013 3Q 16 $220 $263 $307 $311 $341 $356 $404 $461 $475 2008 2009 2010 2011 2012 2013 2014 2015 LTM STRH’s Demonstrated Results Investment Banking Income ($MM) Capital Markets-Related Income Mix1 Lead Relat
Slide 11: Significant Progress Made….Significant Opportunity Remains
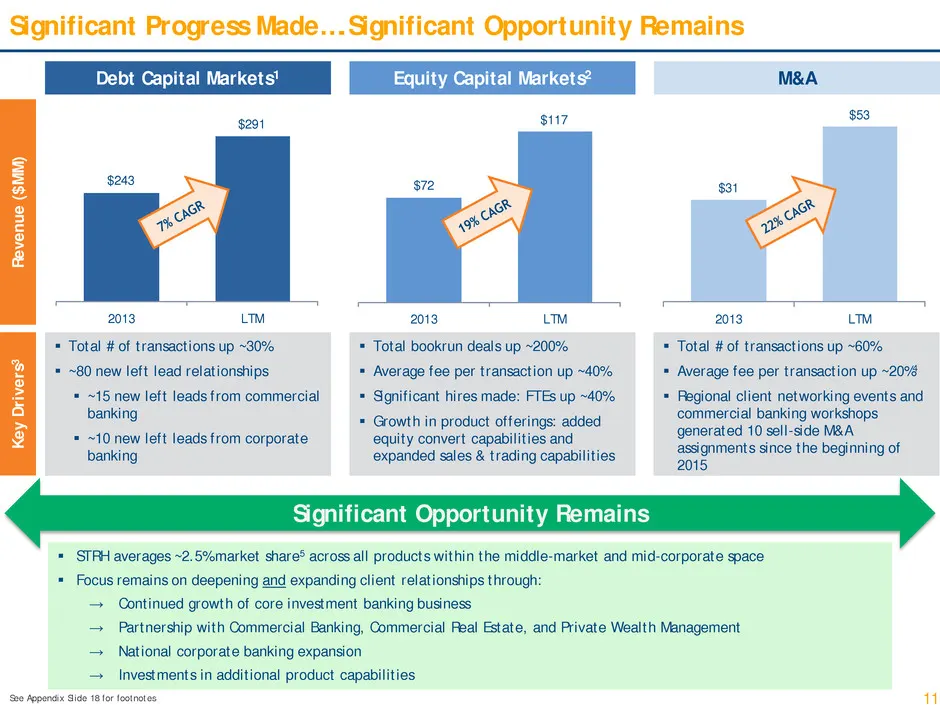
11 Debt Capital Markets1 Equity Capital Markets2 Significant Progress Made….Significant Opportunity Remains M&A Re ve nu e ($ M M ) K ey D ri ve rs 3 Total # of transactions up ~30% ~80 new left lead relationships ~15 new left leads from commercial banking ~10 new left leads from corporate b
Slide 12: CBB & CRE: Focused on Meeting the Capital Markets Needs of All Clients
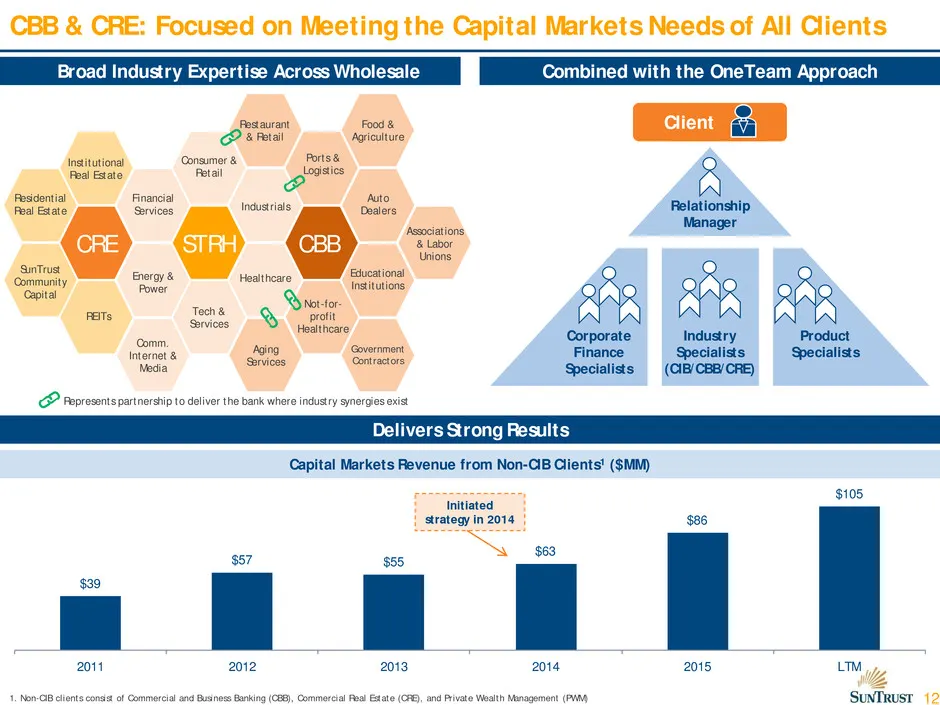
12 CBB & CRE: Focused on Meeting the Capital Markets Needs of All Clients Broad Industry Expertise Across Wholesale Combined with the OneTeam Approach Delivers Strong Results Capital Markets Revenue from Non-CIB Clients1 ($MM) CRE STRH CBB Residential Real Estate Institutional Real Estate SunTrust C
Slide 13: Recent Transaction Highlights
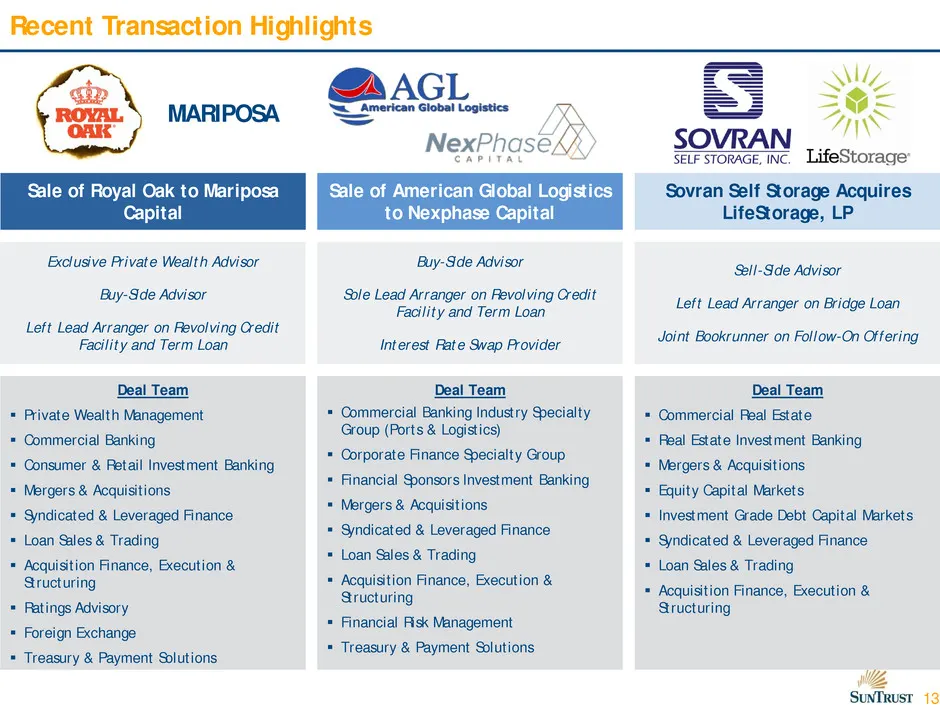
13 Recent Transaction Highlights Sale of American Global Logistics to Nexphase Capital Deal Team Commercial Banking Industry Specialty Group (Ports & Logistics) Corporate Finance Specialty Group Financial Sponsors Investment Banking Mergers & Acquisitions Syndicated & Leveraged Finance L
Slide 14: Overview of Pillar Financial Acquisition
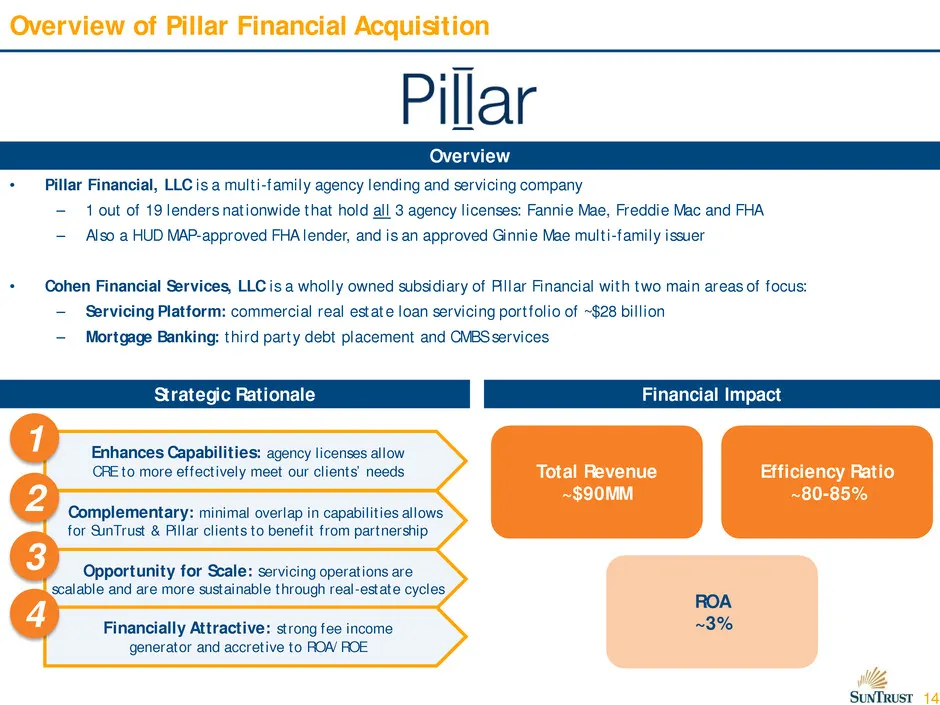
14 Overview of Pillar Financial Acquisition • Pillar Financial, LLC is a multi-family agency lending and servicing company – 1 out of 19 lenders nationwide that hold all 3 agency licenses: Fannie Mae, Freddie Mac and FHA – Also a HUD MAP-approved FHA lender, and is an approved Ginnie Mae multi-famil
Slide 15: Continuously Investing In Growth Initiatives
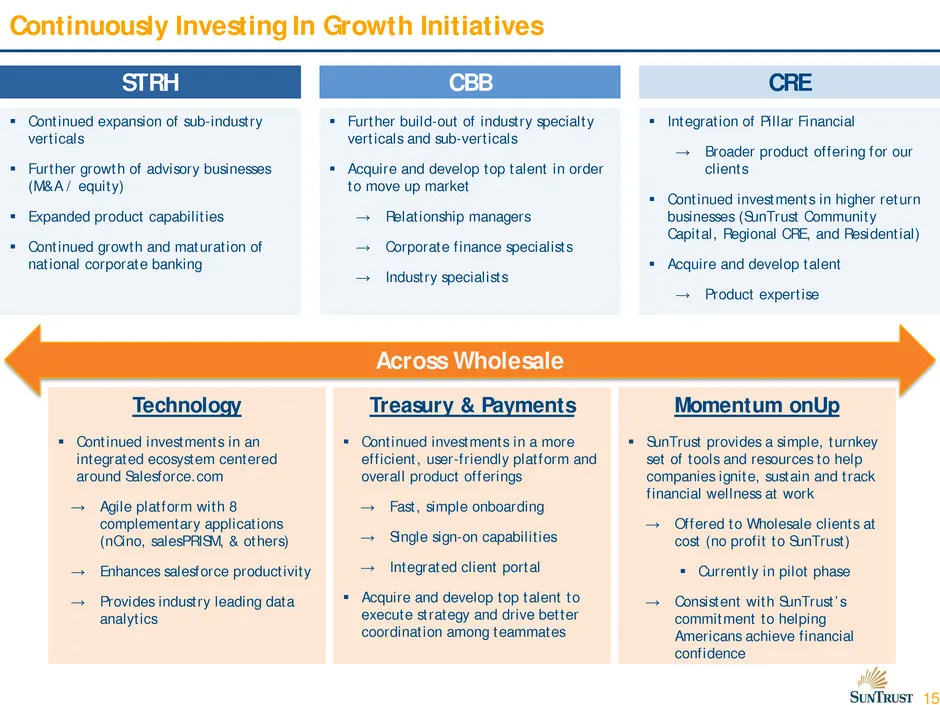
15 Continuously Investing In Growth Initiatives STRH CRE Across Wholesale Technology Continued investments in an integrated ecosystem centered around Salesforce.com → Agile platform with 8 complementary applications (nCino, salesPRISM, & others) → Enhances salesforce productivity → Provides indust
Slide 16: SunTrust Investment Thesis
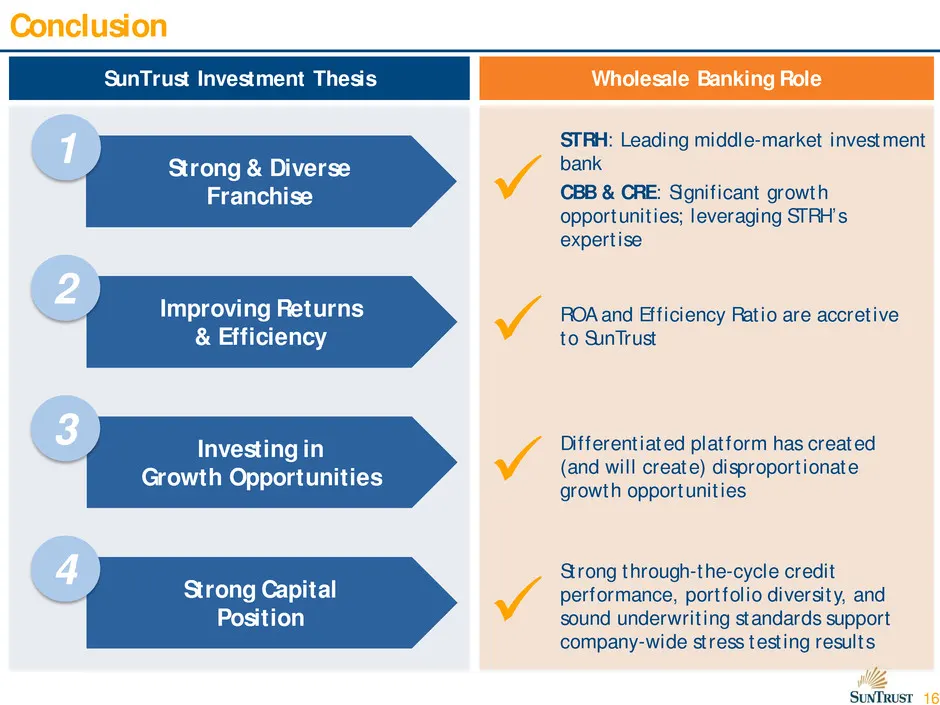
16 Strong & Diverse Franchise 1 Improving Returns & Efficiency 2 Investing in Growth Opportunities 3 Strong Capital Position 4 SunTrust Investment Thesis Wholesale Banking Role STRH: Leading middle-market investment bank CBB & CRE: Significant growth opportunities; leveraging STRH’s expertise RO
Slide 17: Appendix
Appendix WZ SunTrust
Slide 18: Footnotes
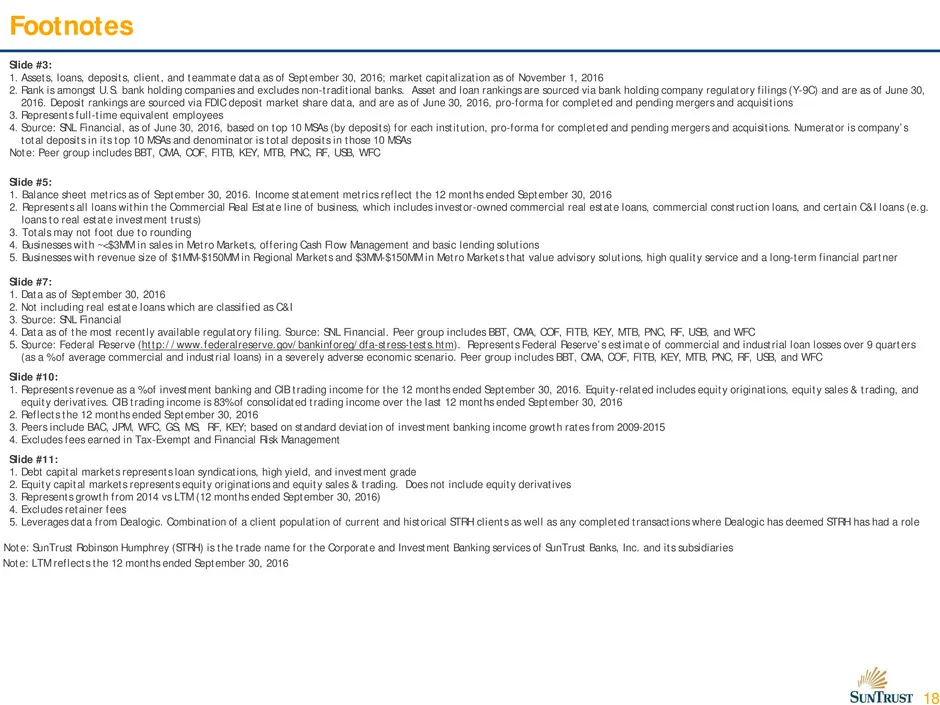
18 Footnotes Slide #3: 1. Assets, loans, deposits, client, and teammate data as of September 30, 2016; market capitalization as of November 1, 2016 2. Rank is amongst U.S. bank holding companies and excludes non-traditional banks. Asset and loan rankings are sourced via bank holding company regulato
Source: SEC EDGAR · 8-K filed Nov 4, 2016
More decks from SunTrust Banks Inc
 Q3 2019 Earnings Presentation21 slides · Oct 17, 2019
 Q2 2019 Earnings Presentation22 slides · Jul 18, 2019
 Q1 2019 Earnings Presentation22 slides · Apr 18, 2019
 Merger or Acquisition (February 2019)38 slides · Feb 7, 2019
 Q4 2018 Earnings Presentation23 slides · Jan 18, 2019
 2018 Goldman Sachs US Financial Services Conference30 slides · Dec 4, 2018