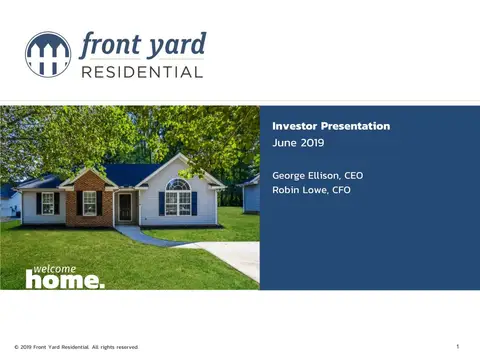
Front Yard Residential — NAREIT REITweek 2018
27 slides from Front Yard Residential's conference presentation, Jun 5, 2018
Slide 1: NAREIT Presentation June 2018
NAREIT Presentation June 2018 George Ellison, CEO Robin Lowe, CFO home.welcome © 2018 Front Yard Residential. All rights reserved. 1
Slide 2: Forward-looking Statements
Forward-looking Statements This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, regarding management’s beliefs, estimates, projections, anticipations and
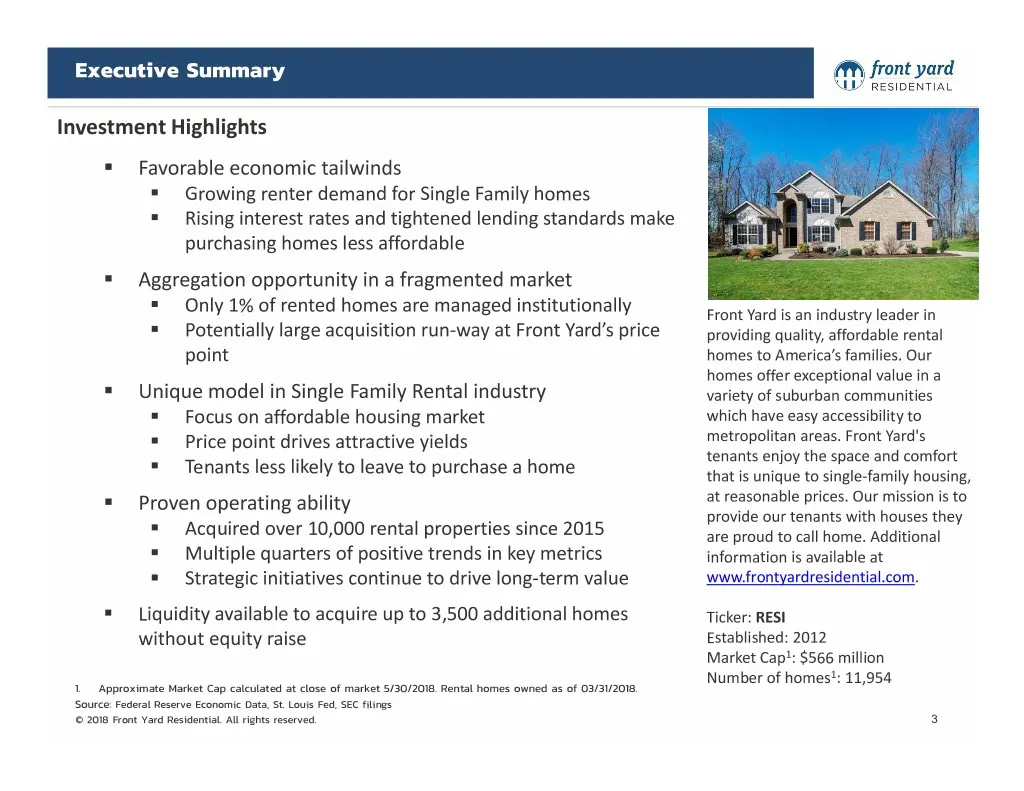
Slide 3: Executive Summary Investment Highlights
Executive Summary Investment Highlights . Favorable economic tailwinds . Growing renter demand for Single Family homes . Rising interest rates and tightened lending standards make purchasing homes less affordable . Aggregation opportunity in a fragmented market . Only 1% of rented homes are managed
Slide 4: Strong Fundamentals and Opportunity in Affordable Housing
Strong Fundamentals and Opportunity in Affordable Housing © 2018 Front Yard Residential. All rights reserved. 4
Slide 5: Housing by Population
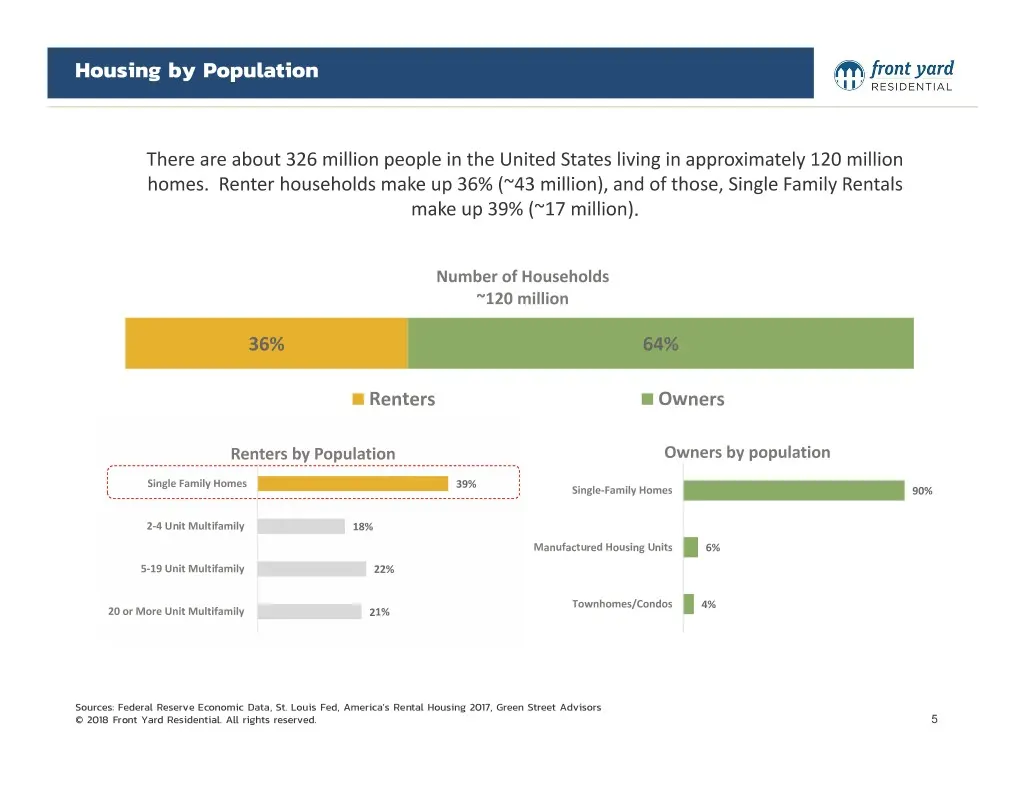
Housing by Population There are about 326 million people in the United States living in approximately 120 million homes. Renter households make up 36% (~43 million), and of those, Single Family Rentals make up 39% (~17 million). Number of Households ~120 million 36% 64% Renters Owners Renters by Pop
Slide 6: Rental Demand Increasing
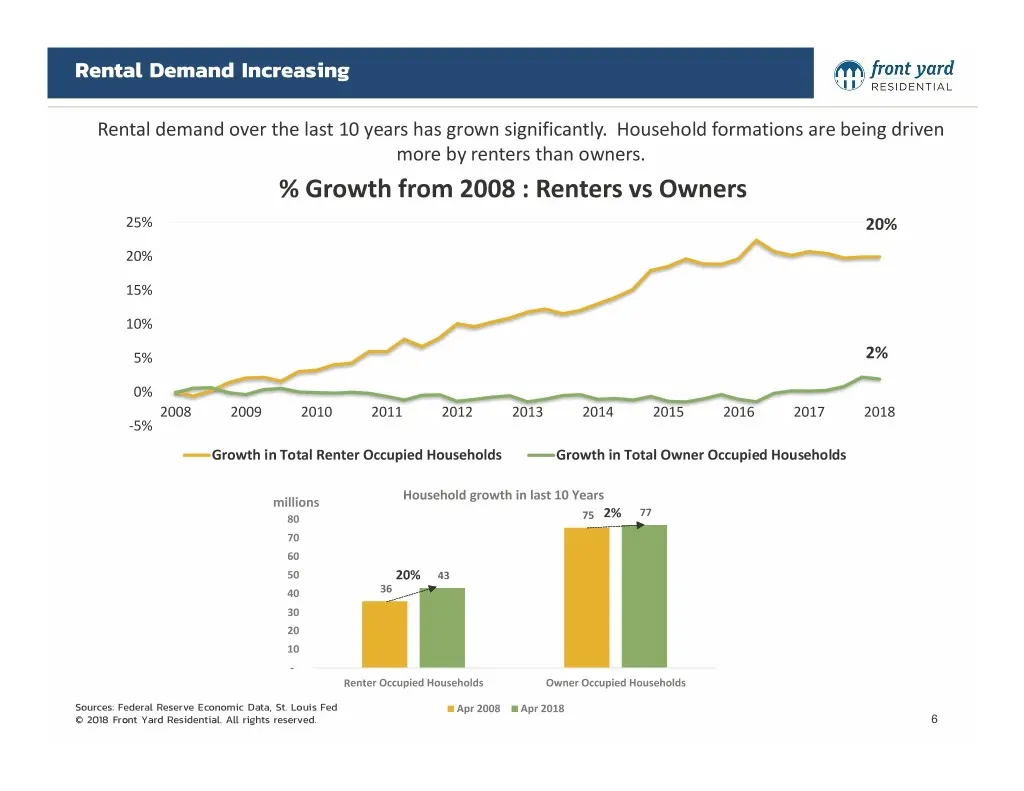
Rental Demand Increasing Rental demand over the last 10 years has grown significantly. Household formations are being driven more by renters than owners. % Growth from 2008 : Renters vs Owners 25% 20% 20% 15% 10% 5% 2% 0% 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 ‐5% Growth in Total Ren
Slide 7: Institutional Opportunity
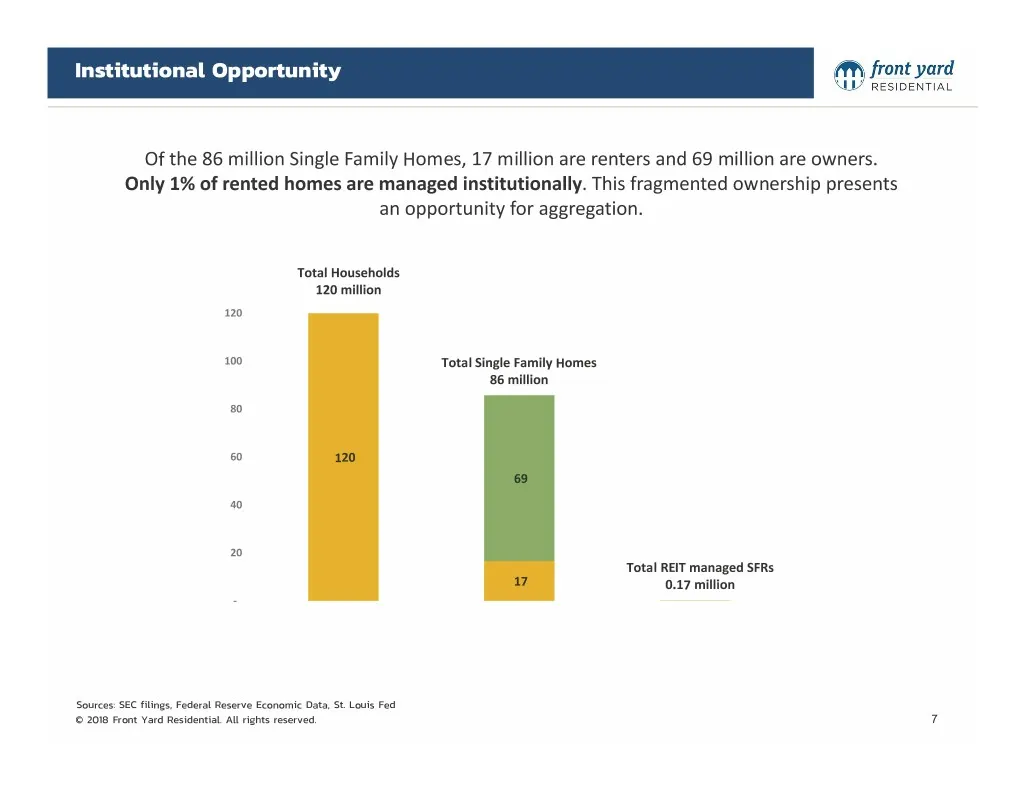
Institutional Opportunity Of the 86 million Single Family Homes, 17 million are renters and 69 million are owners. Only 1% of rented homes are managed institutionally. This fragmented ownership presents an opportunity for aggregation. Total Households 120 million 120 100 Total Single Family Homes 86
Slide 8: Positive Trends in Single Family Rental
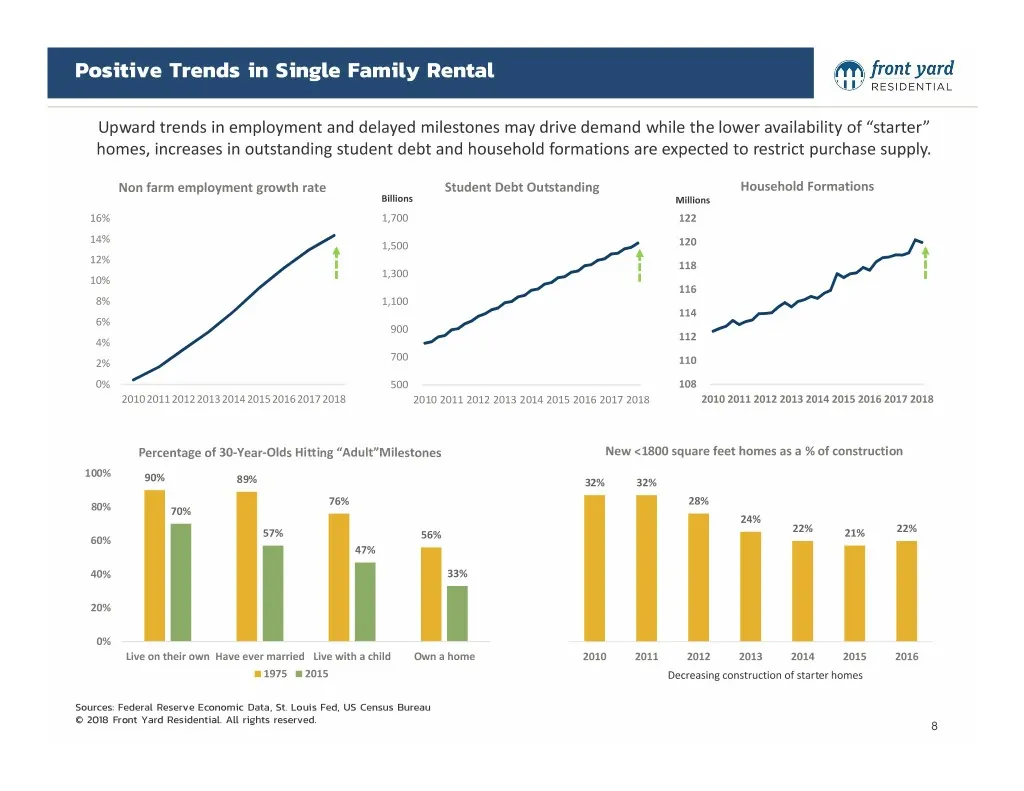
Positive Trends in Single Family Rental Upward trends in employment and delayed milestones may drive demand while the lower availability of “starter” homes, increases in outstanding student debt and household formations are expected to restrict purchase supply. Non farm employment growth rate Studen
Slide 9: Renter Household Growth; Supply Deficit of Housing Units
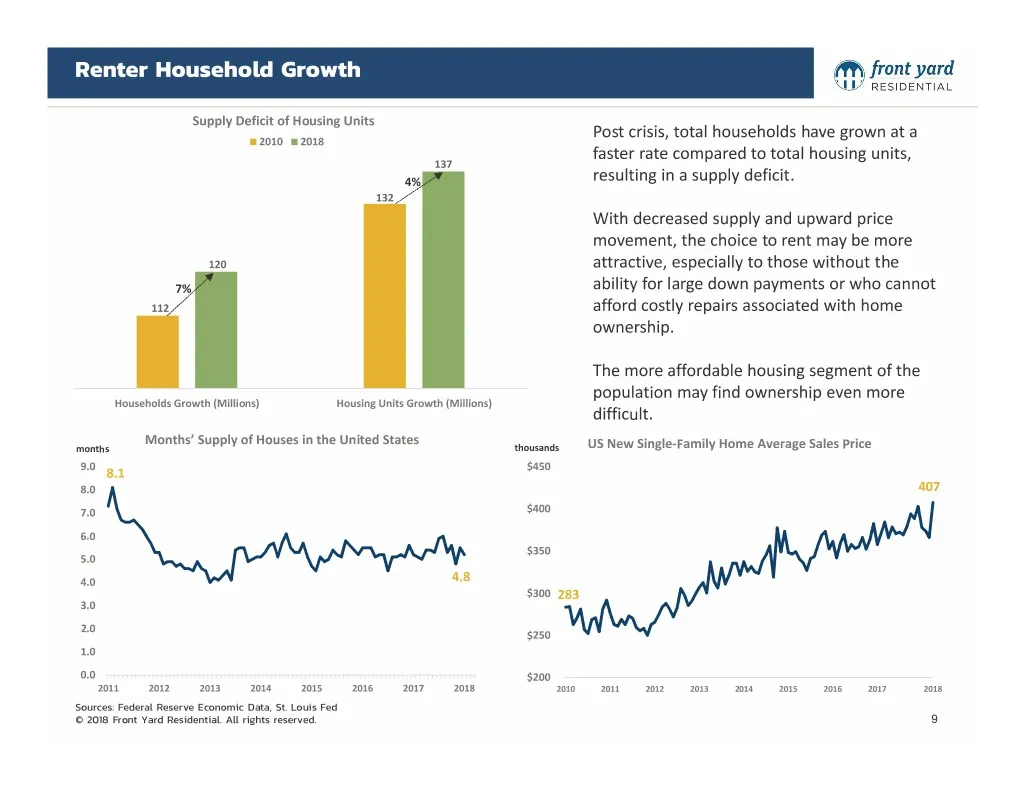
Renter Household Growth Supply Deficit of Housing Units Post crisis, total households have grown at a 2010 2018 faster rate compared to total housing units, 137 4% resulting in a supply deficit. 132 With decreased supply and upward price movement, the choice to rent may be more 120 attractive, espec
Slide 10: Challenges in Home Ownership Financing
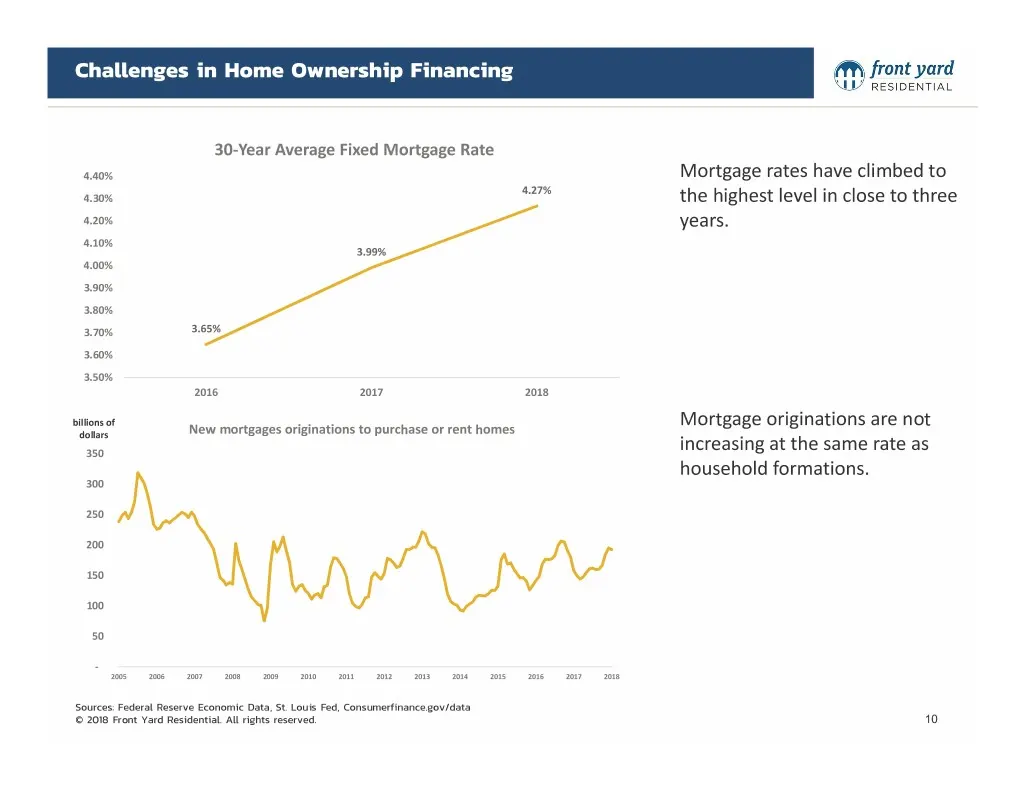
Challenges in Home Ownership Financing 30‐Year Average Fixed Mortgage Rate 4.40% Mortgage rates have climbed to 4.27% 4.30% the highest level in close to three 4.20% years. 4.10% 3.99% 4.00% 3.90% 3.80% 3.70% 3.65% 3.60% 3.50% 2016 2017 2018 billions of 2 Mortgage originations are not dollars New mo
Slide 11: FICO Distributions
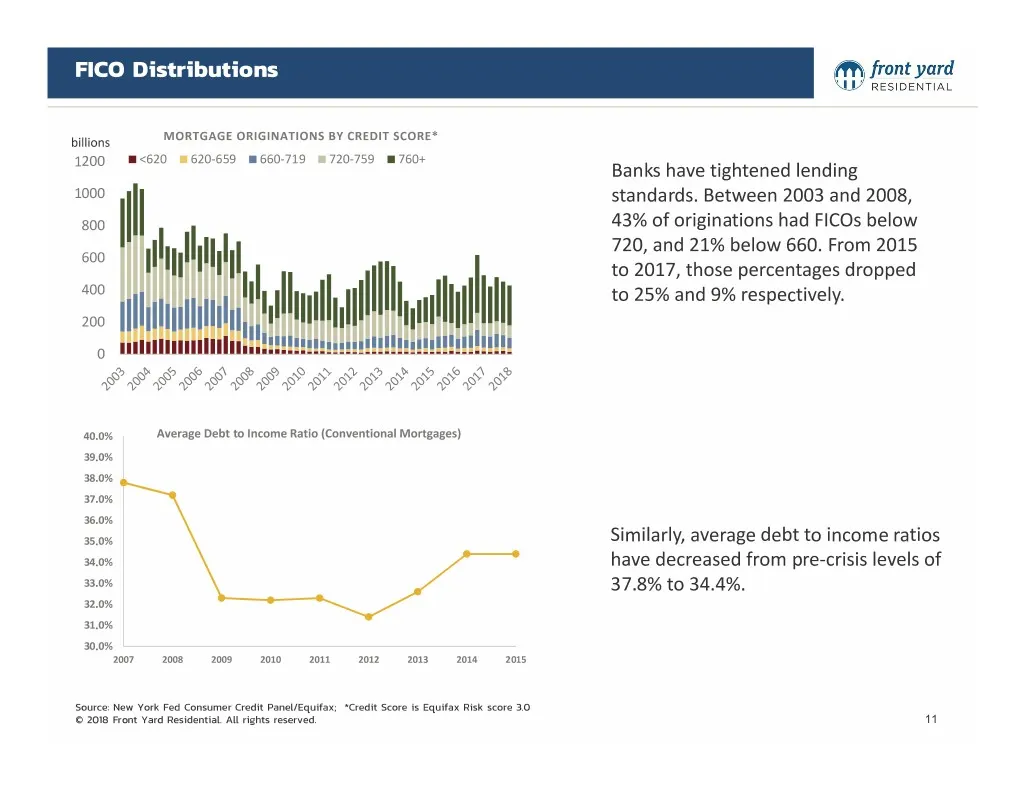
FICO Distributions billions MORTGAGE ORIGINATIONS BY CREDIT SCORE* <620 620‐659 660‐719 720‐759 760+ 1200 Banks have tightened lending 1000 standards. Between 2003 and 2008, 800 43% of originations had FICOs below 720, and 21% below 660. From 2015 600 to 2017, those percentages dropped 400 to 25% an
Slide 12: Strong Growth and Operational Performance
Strong Growth and Operational Performance © 2018 Front Yard Residential. All rights reserved. 12
Slide 13: Mission Statement
Mission Statement Front Yard Residential is an industry leader in providing quality, affordable rental homes to America’s families. Our homes offer exceptional value in a variety of suburban communities across the US with access to quality education and jobs. We renovate each property to bring it up
Slide 14: Timeline – story of growth
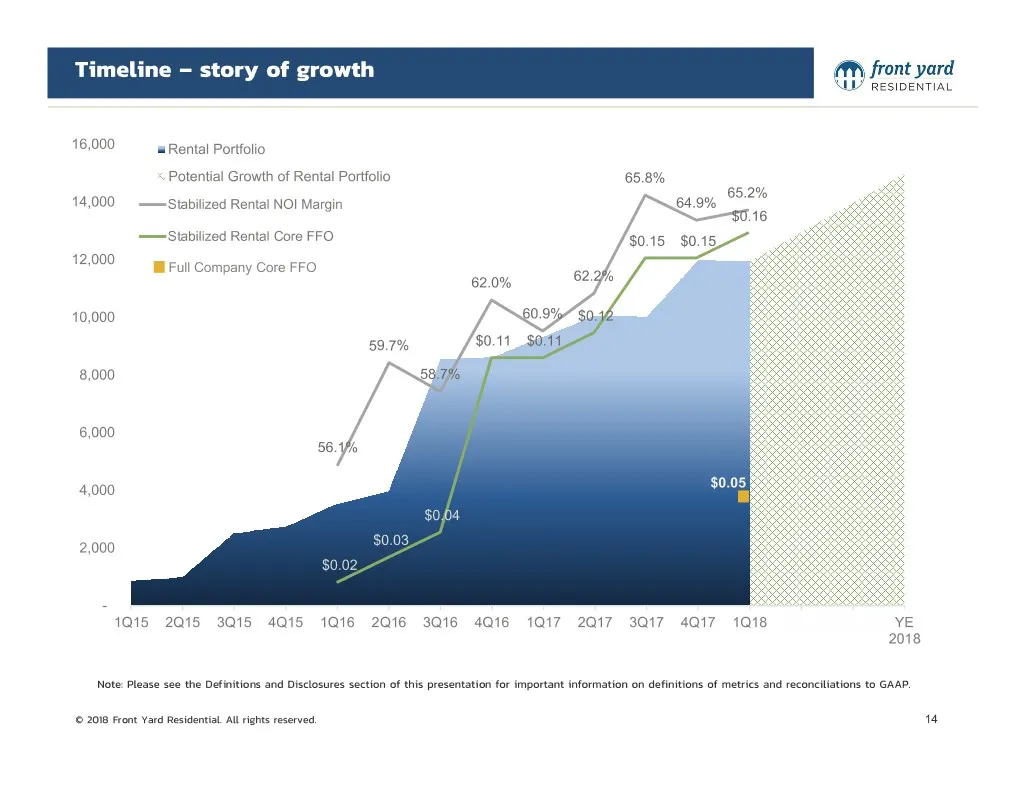
Timeline – story of growth 0.68 0.2 16,000 Rental Portfolio Potential Growth of Rental Portfolio 65.8% 0.18 0.66 65.2% 14,000 Stabilized Rental NOI Margin 64.9% $0.16 Stabilized Rental Core FFO 0.16 0.64 $0.15 $0.15 12,000 Full Company Core FFO 62.0% 62.2% 0.14 0.62 10,000 60.9% $0.12 0.12 59.7% $0.
Slide 15: Business Initiatives
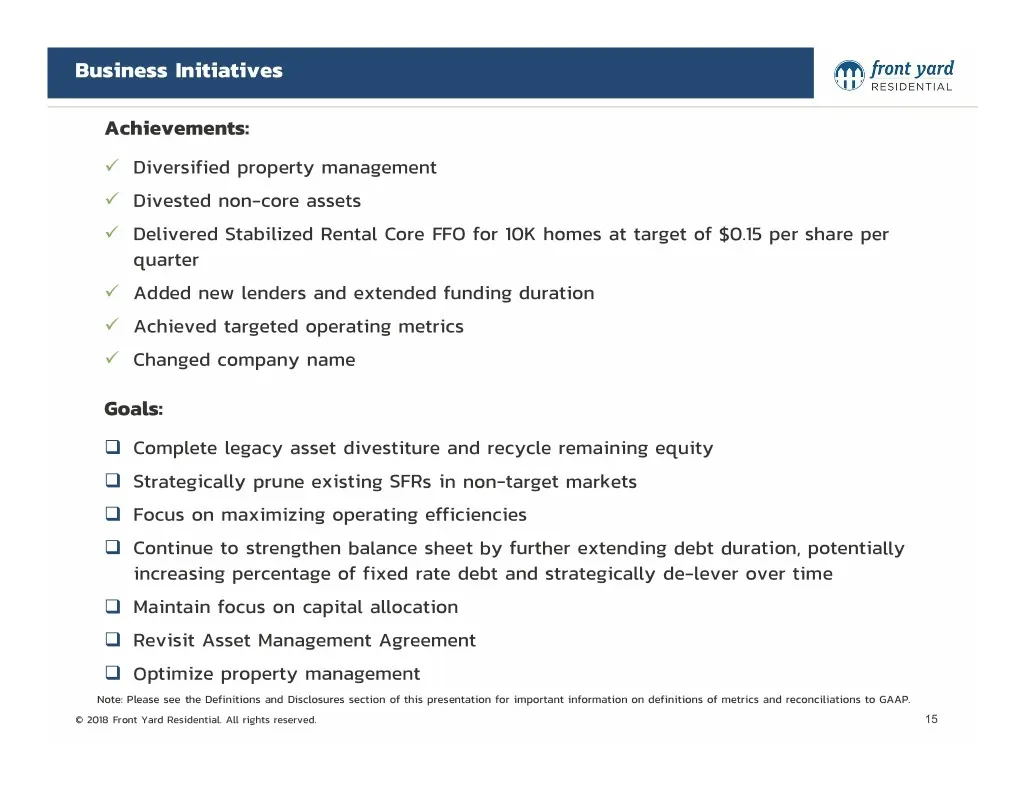
Business Initiatives Achievements: Diversified property management Divested non-core assets Delivered Stabilized Rental Core FFO for 10K homes at target of $0.15 per share per quarter Added new lenders and extended funding duration Achieved targeted operating metrics Changed company name
Slide 16: Company Snapshot
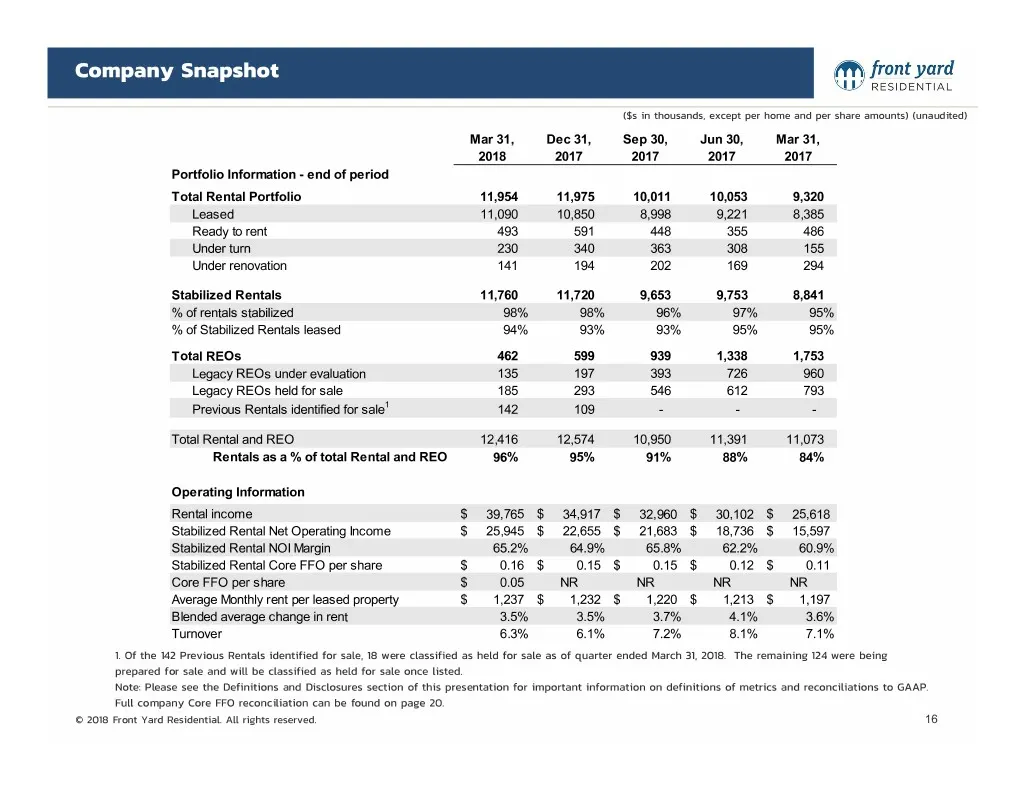
Company Snapshot ($s in thousands, except per home and per share amounts) (unaudited) Mar 31, Dec 31, Sep 30, Jun 30, Mar 31, 2018 2017 2017 2017 2017 Portfolio Information - end of period Total Rental Portfolio 11,954 11,975 10,011 10,053 9,320 Leased 11,090 10,850 8,998 9,221 8,385 Ready to rent 4
Slide 17: Map – Top Markets
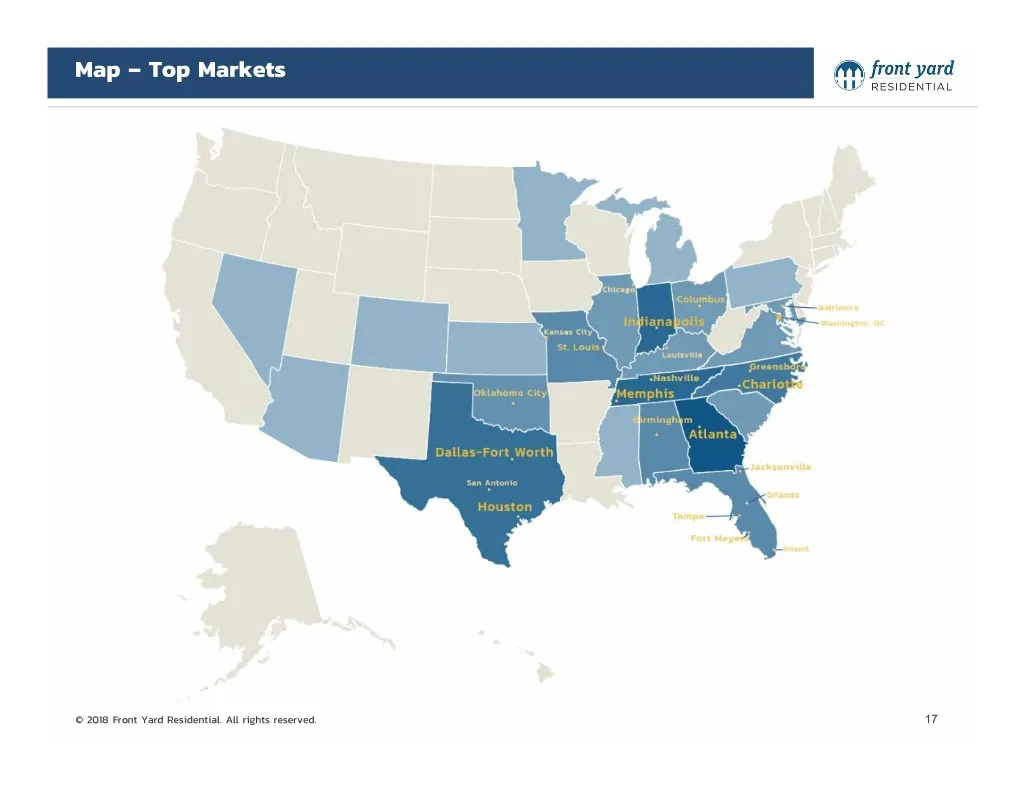
Map – Top Markets © 2018 Front Yard Residential. All rights reserved. 17
Slide 18: Rental Portfolio Detail
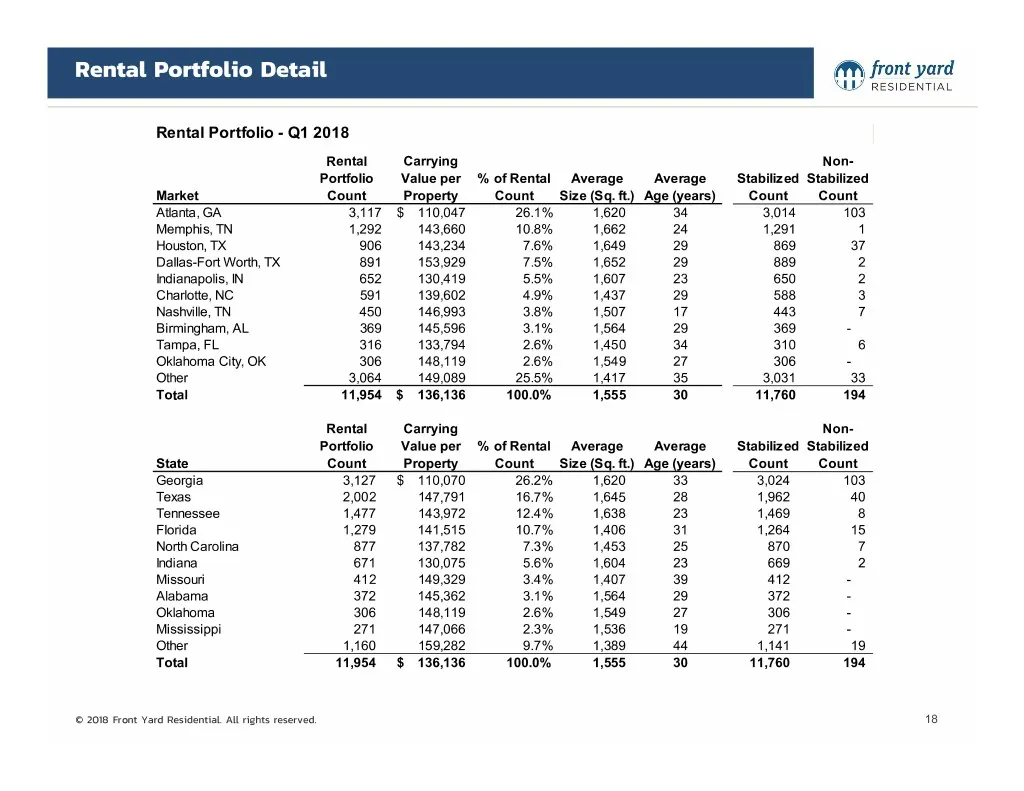
Rental Portfolio Detail Rental Portfolio - Q1 2018 Rental Carrying Non- Portfolio Value per % of Rental Average Average Stabilized Stabilized Market Count Property Count Size (Sq. ft.) Age (years) Count Count Atlanta, GA 3,117 $ 110,047 26.1% 1,620 34 3,014 103 Memphis, TN 1,292 143,660 10.8% 1,662
Slide 19: Leasing Detail
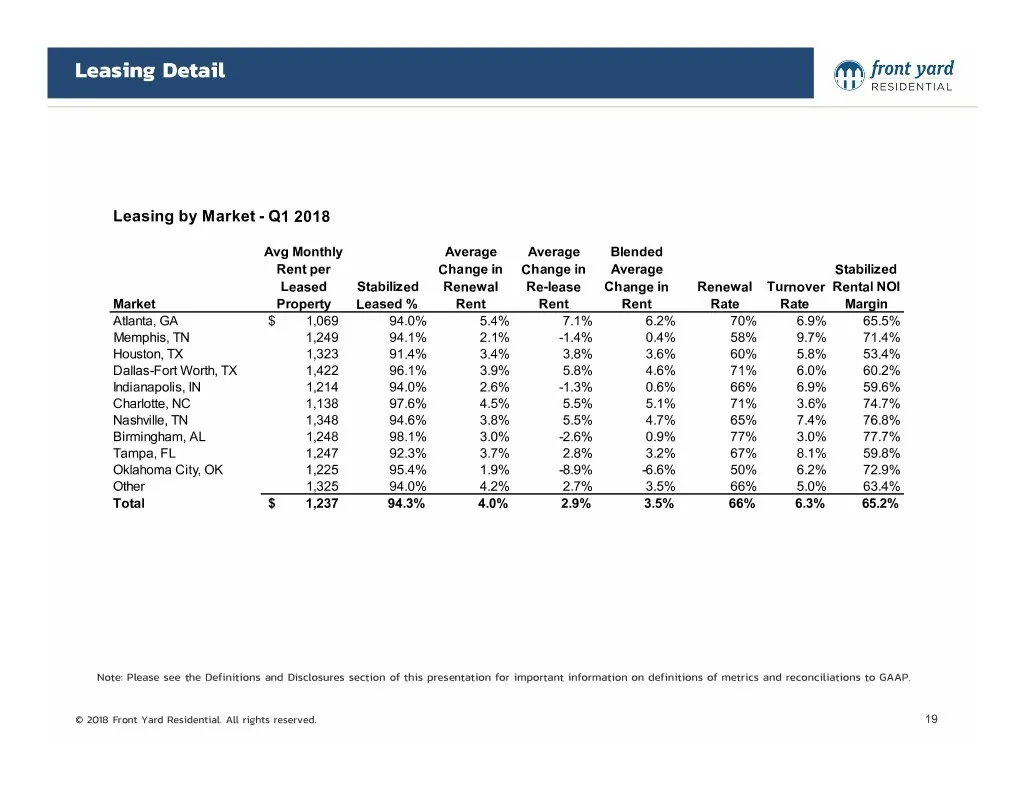
Leasing Detail Leasing by Market - Q1 2018 Avg Monthly Average Average Blended Rent per Change in Change in Average Stabilized Leased Stabilized Renewal Re-lease Change in Renewal Turnover Rental NOI Market Property Leased % Rent Rent Rent Rate Rate Margin Atlanta, GA$ 1,069 94.0% 5.4% 7.1% 6.2% 70%
Slide 20: Full Company FFO and Core FFO
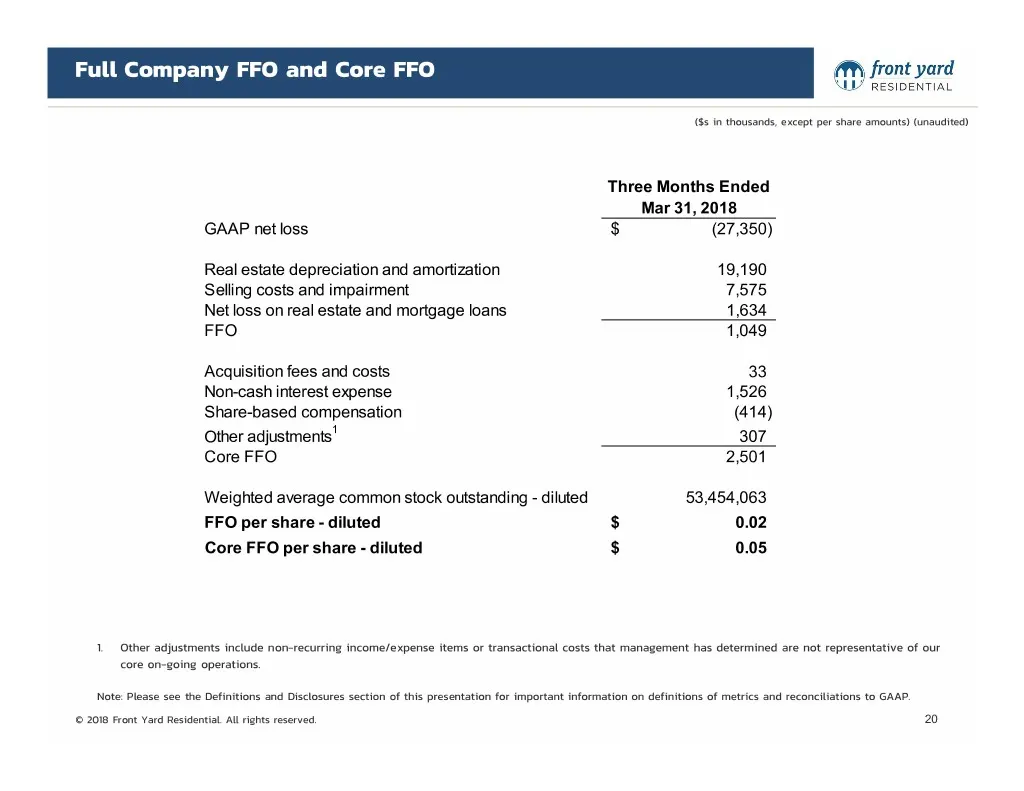
Full Company FFO and Core FFO ($s in thousands, except per share amounts) (unaudited) Three Months Ended Mar 31, 2018 GAAP net loss$ (27,350) Real estate depreciation and amortization 19,190 Selling costs and impairment 7,575 Net loss on real estate and mortgage loans 1,634 FFO 1,049 Acquisition fee
Slide 21: Definitions and Disclosures © 2018 Front Yard Residential. All rights reserved. 21
Definitions and Disclosures © 2018 Front Yard Residential. All rights reserved. 21
Slide 22: Definitions
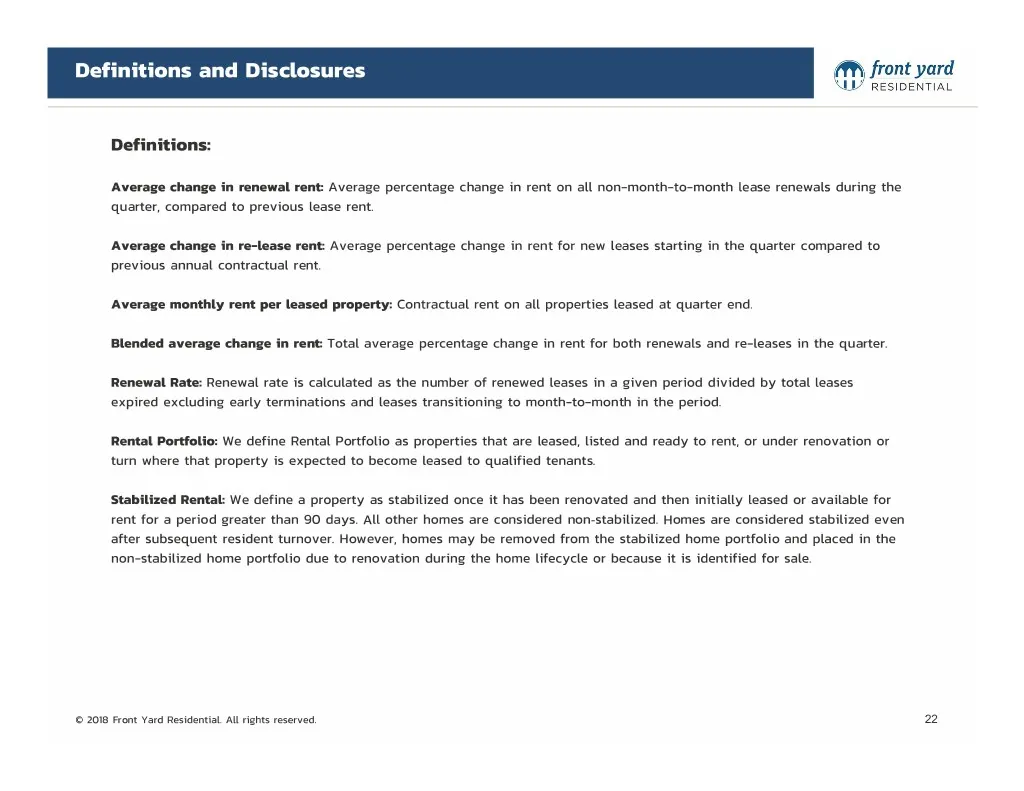
Definitions and Disclosures Definitions: Average change in renewal rent: Average percentage change in rent on all non-month-to-month lease renewals during the quarter, compared to previous lease rent. Average change in re-lease rent: Average percentage change in rent for new leases starting in the q
Slide 23: FFO, Core FFO, Stabilized Rental FFO and Stabilized Rental Core FFO
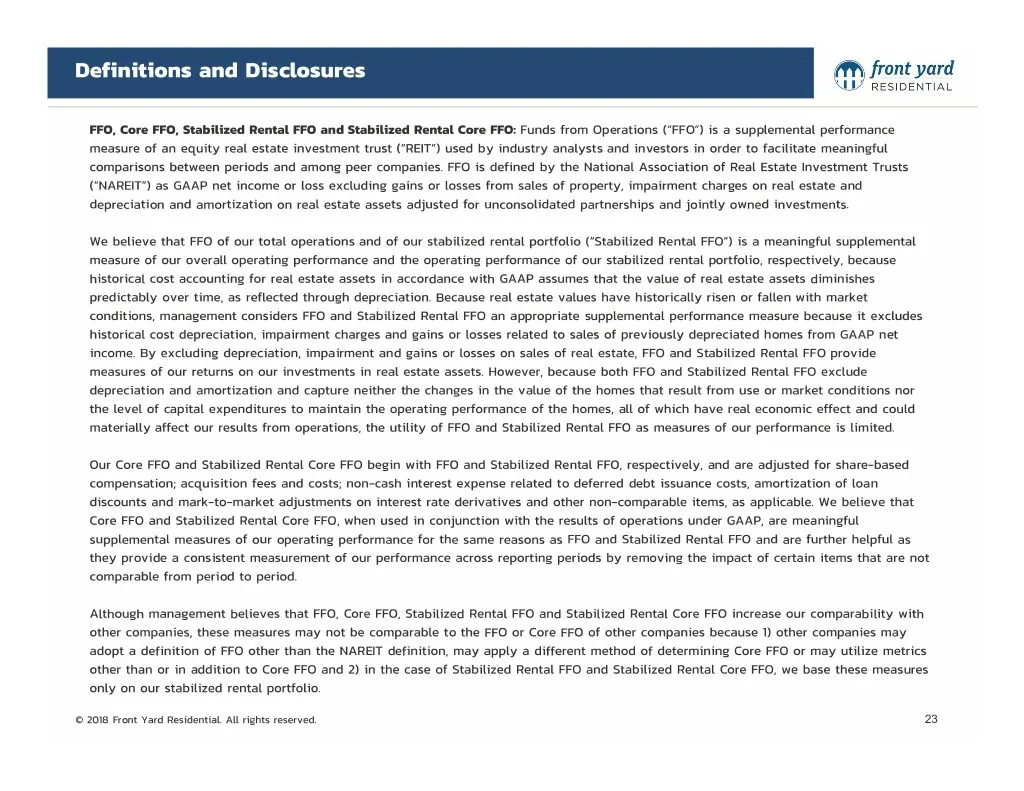
Definitions and Disclosures FFO, Core FFO, Stabilized Rental FFO and Stabilized Rental Core FFO: Funds from Operations (“FFO”) is a supplemental performance measure of an equity real estate investment trust (“REIT”) used by industry analysts and investors in order to facilitate meaningful comparison
Slide 24: Stabilized Rental NOI and NOI Margin
Definitions and Disclosures Stabilized Rental Net Operating Income (“Stabilized Rental NOI”) and Stabilized Rental NOI Margin: Stabilized Rental NOI is a non- GAAP supplemental measure that we define as rental revenues less residential property operating expenses of the stabilized rental properties
Slide 25: Reconciliation of GAAP net loss to Stabilized Rental FFO and Core FFO
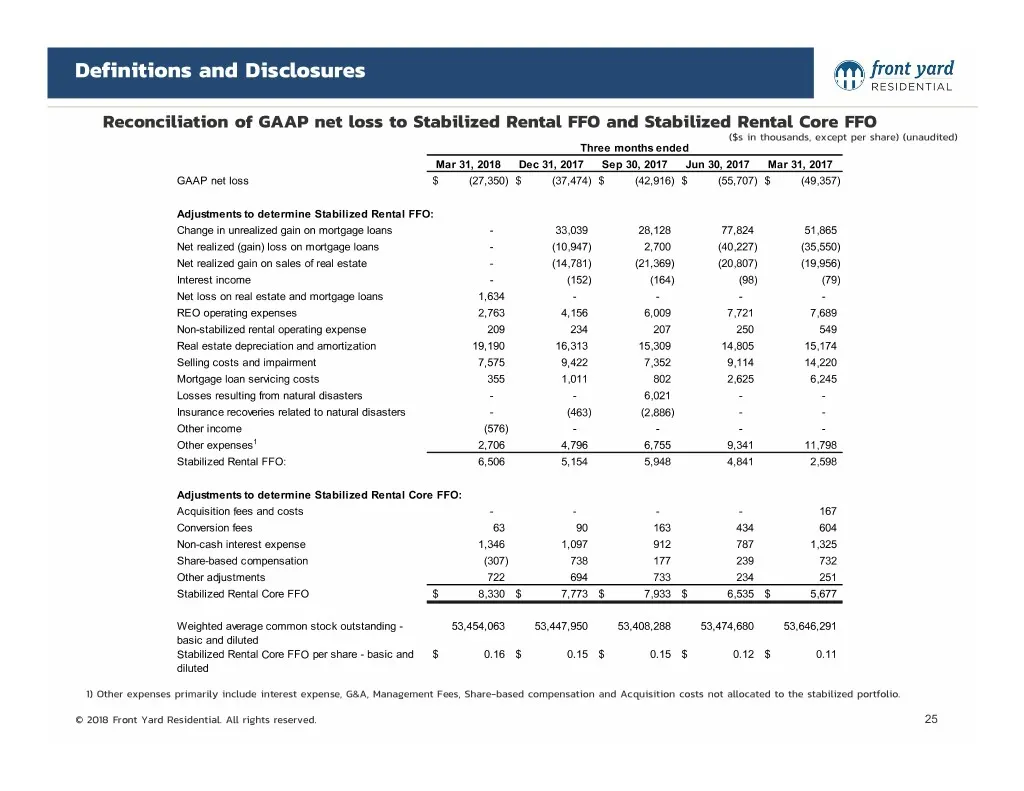
Definitions and Disclosures Reconciliation of GAAP net loss to Stabilized Rental FFO and Stabilized Rental Core FFO ($s in thousands, except per share) (unaudited) Three months ended Mar 31, 2018 Dec 31, 2017 Sep 30, 2017 Jun 30, 2017 Mar 31, 2017 GAAP net loss$ (27,350) $ (37,474) $ (42,916) $ (55,
Slide 26: Reconciliation of GAAP net loss to Stabilized Rental NOI and Margin
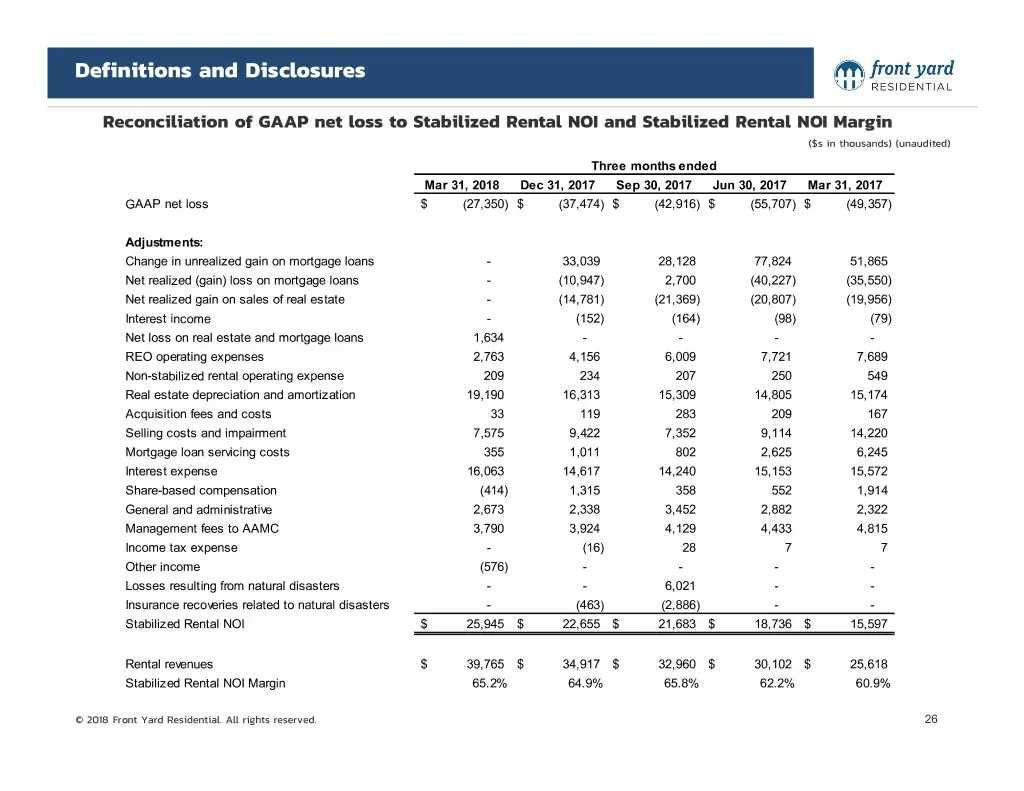
Definitions and Disclosures Reconciliation of GAAP net loss to Stabilized Rental NOI and Stabilized Rental NOI Margin ($s in thousands) (unaudited) Three months ended Mar 31, 2018 Dec 31, 2017 Sep 30, 2017 Jun 30, 2017 Mar 31, 2017 GAAP net loss$ (27,350) $ (37,474) $ (42,916) $ (55,707) $ (49,357)
Slide 27: Thank you.
Thank you. © 2018 Front Yard Residential. All rights reserved. 27
Source: SEC EDGAR · 8-K filed Jun 5, 2018