Airtran — Calyon Securities US Airline Conference (December 2006)
25 slides from Airtran's conference presentation, Dec 8, 2006
Slide 1: Investor Presentation December 7, 2006
Investor Presentation December 7, 2006 Exhibit 99.1
Slide 2: Safe Harbor Disclosure
Please note that the discussion today may contain forward looking statements that involve risks and uncertainties including those relating to the company’s ability to develop new markets, its fleet and growth plans, its low cost advantage vs. competitors, its ability to obtain financing, and its abi
Slide 3: AirTran Airways Today
Youngest all-Boeing fleet in America 123 Airplanes – 87 717s / 36 737s 53 cities served 7 consecutive years of profitability One of two consistently profitable airlines Stable and experienced management AirTran Airways Today — — AirTran Airways Today
Slide 4: AirTran Airways 2006 YTD Highlights
AirTran Airways 2006 YTD Highlights Network expansion Capacity +25% RPMs +25% 15.0 million passengers, +23% Strong RASM improvement Opened two new cities in 2006: White Plains, New York and Seattle, Washington Announced three new cities starting in 2007: Newburgh, New York, Daytona Beach, Florida, a
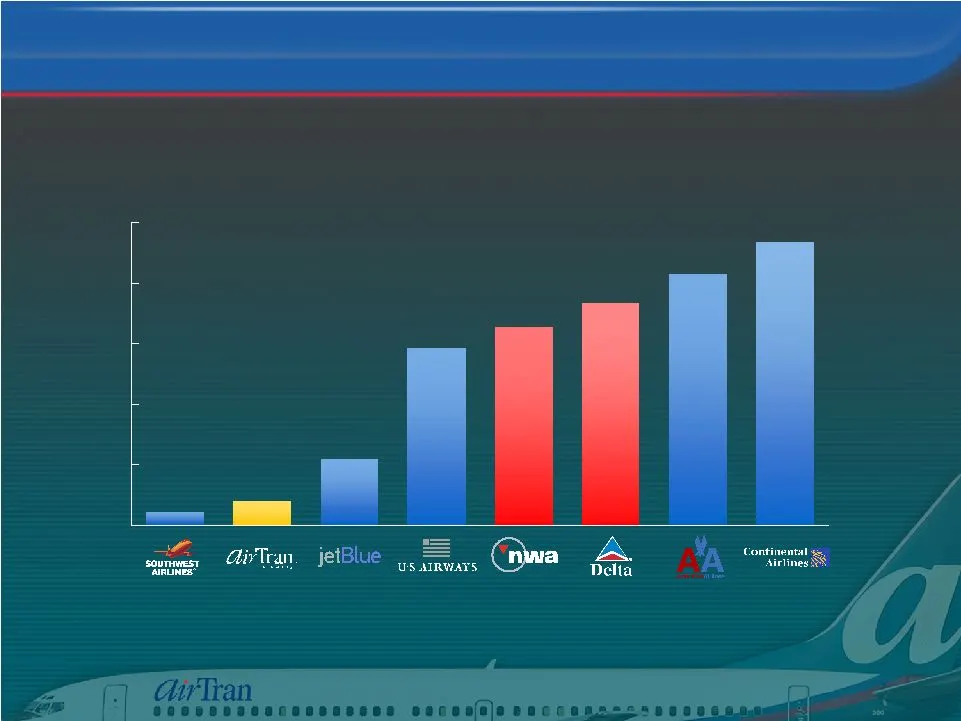
Slide 5: AirTran Has Very Low Costs
6 7 8 9 10 11 While legacy costs are down, gap remains large (cents) Non-Fuel Unit Costs at 649 Miles for 1H 2006 AirTran Has Very Low Costs AirTran Has Very Low Costs
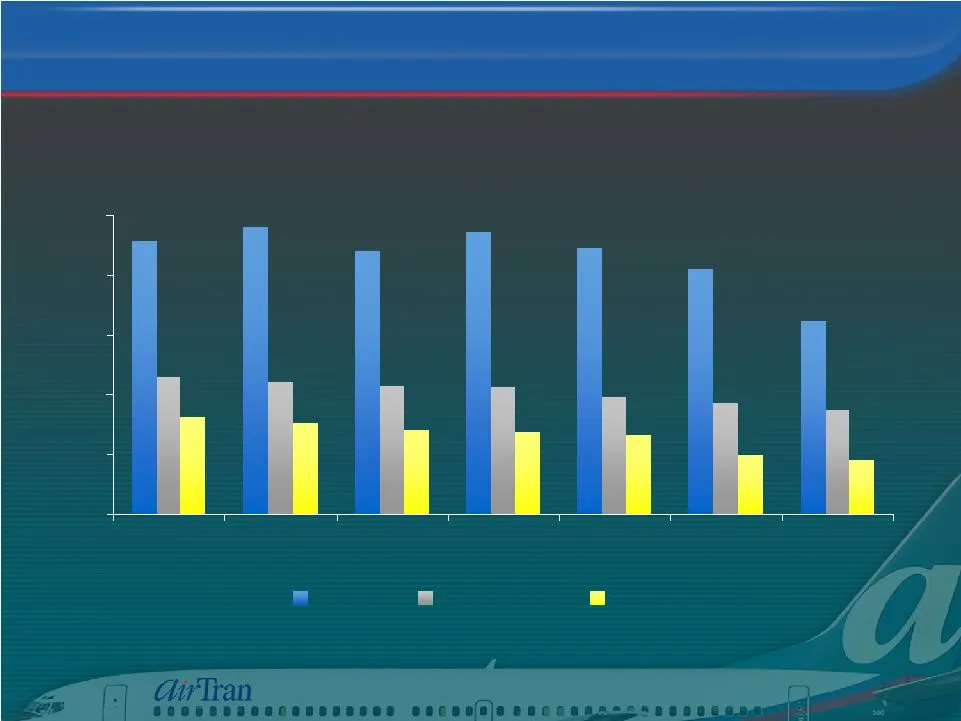
Slide 6: AirTran Has Industry Leading Employee Efficiency
50 60 70 80 90 100 Q105 Q205 Q305 Q405 Q106 Q206 Q306 jetBlue Southwest AirTran FTE’s per Aircraft AirTran Has Industry Leading Employee Efficiency JBLU +39% LUV +14% AirTran Has Industry Leading Employee Efficiency
Slide 7: What Creates AirTran's Low Cost Advantage?
Productive workforce at all levels Young, simplified fleet Fuel efficient Attractive ownership costs Efficient use of facilities Competition for heavy maintenance contracts Low cost distribution Over 70% of sales are directly with AirTran (Reservations or AirTran.com) What Creates AirTran’s Low Cost
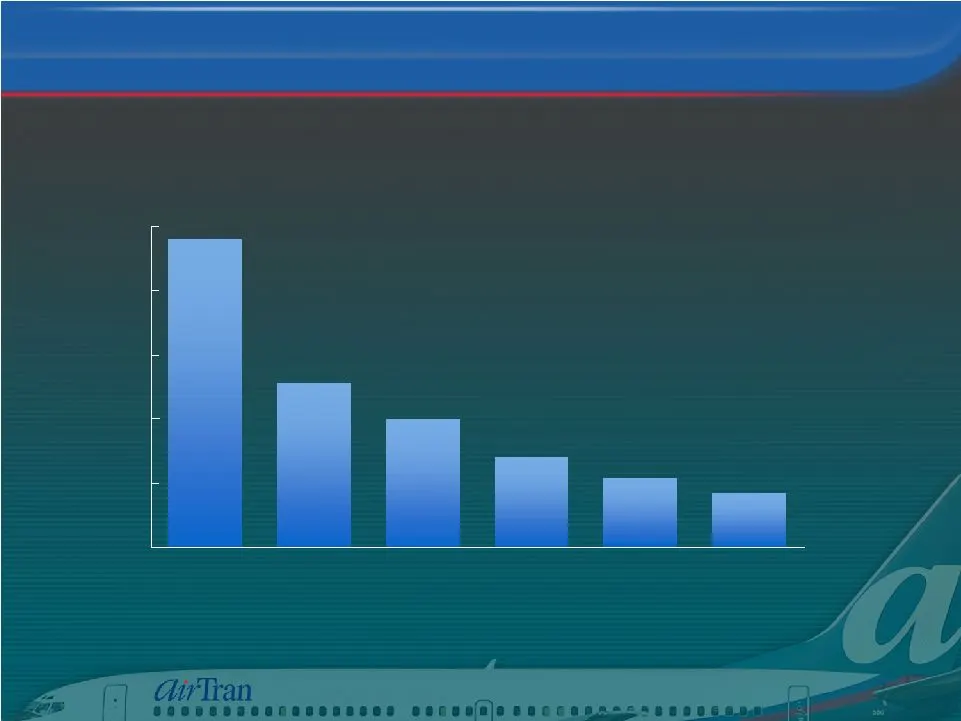
Slide 8: Lowering Costs Is Not A One Time Event
6.00 6.25 6.50 6.75 7.00 7.25 2001 2002 2003 2004 2005 2006E * Excludes non-recurring special items (cents per mile) Lowering Costs Is Not A One Time Event AirTran’s Non-Fuel Unit Cost Trend Lowering Costs Is Not A One Time Event
Slide 9: New 737 Aircraft Will Continue To Drive Down Costs
Increases crew productivity No additional staffing required 17% increase in seats Transcontinental range increases productivity Potential utilization of 12-13 hrs/day vs. 11 hrs/day on 717s Even better fuel economy than the 717 per seat Order timing was at the bottom of the market (June 2003) Negoti
Slide 10: Low Cost Fleet Plan
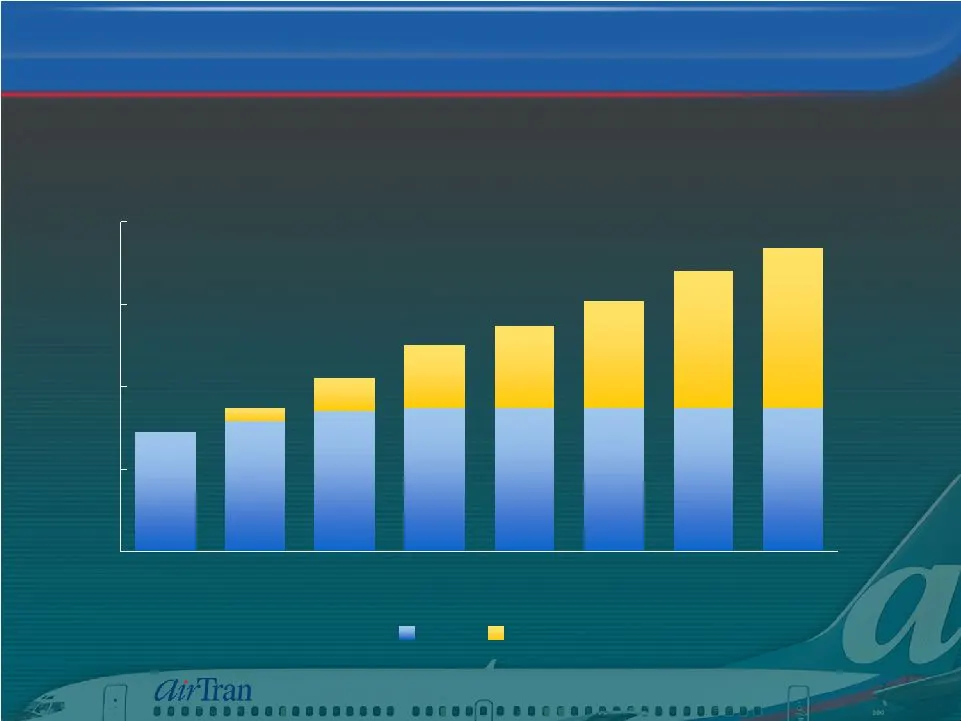
0 50 100 150 200 2003 2004 2005 2006 2007 2008 2009 2010 717s 737s 184 170 152 137 125 105 87 74 Aircraft Low Cost Fleet Plan Currently 123 Aircraft: 87 717s / 36 737s Low Cost Fleet Plan
Slide 11: AirTran Poised To Become Industry's Lowest Cost Provider
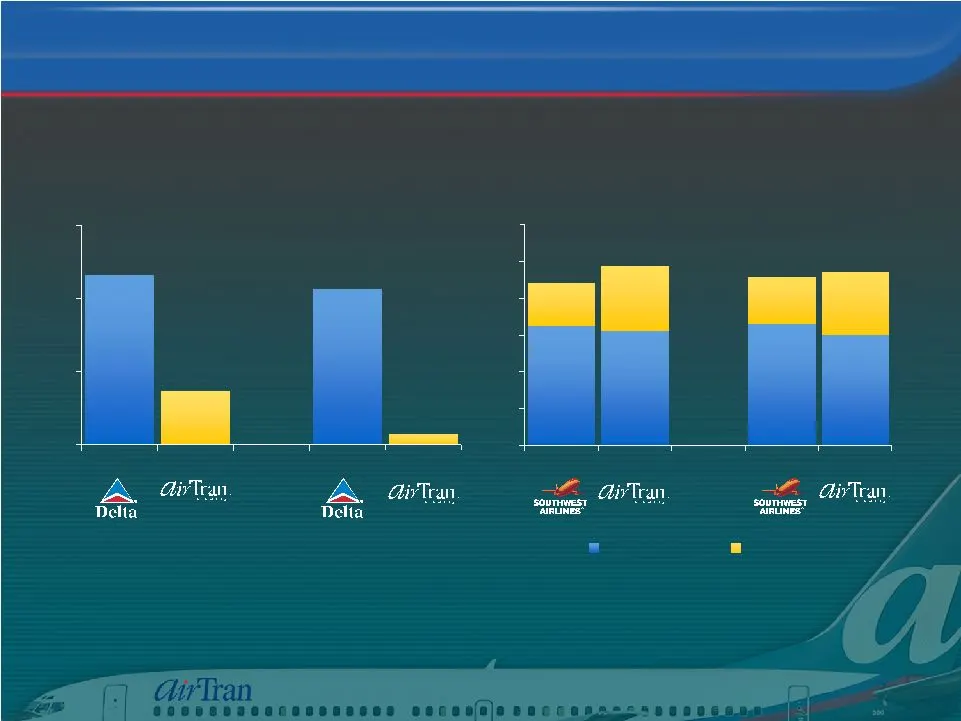
Non-Fuel CASM 6 8 10 12 Q201 Q201 Q206 Q206 0 2 4 6 8 10 12 2006E 2006E 2007E 2007E Non-Fuel CASM Fuel CASM AAI 11% Higher AAI 3% Higher AAI -39% Lower AAI -30% Lower AirTran Poised To Become Industry’s Lowest Cost Provider (cents) (cents) Among Low Cost Industry Leaders Despite Bankruptcy, AAI Cost
Slide 12: Low Costs Does Not Mean Budget Service
Assigned seating Business class Only major U.S. airline with business class on every flight Convenient distribution Internet/Kiosks Telephone reservations and airport sales Travel agencies XM Radio and oversized luggage bins Friendly crewmembers Low Costs Does Not Mean Budget Service — — — — Low Cos
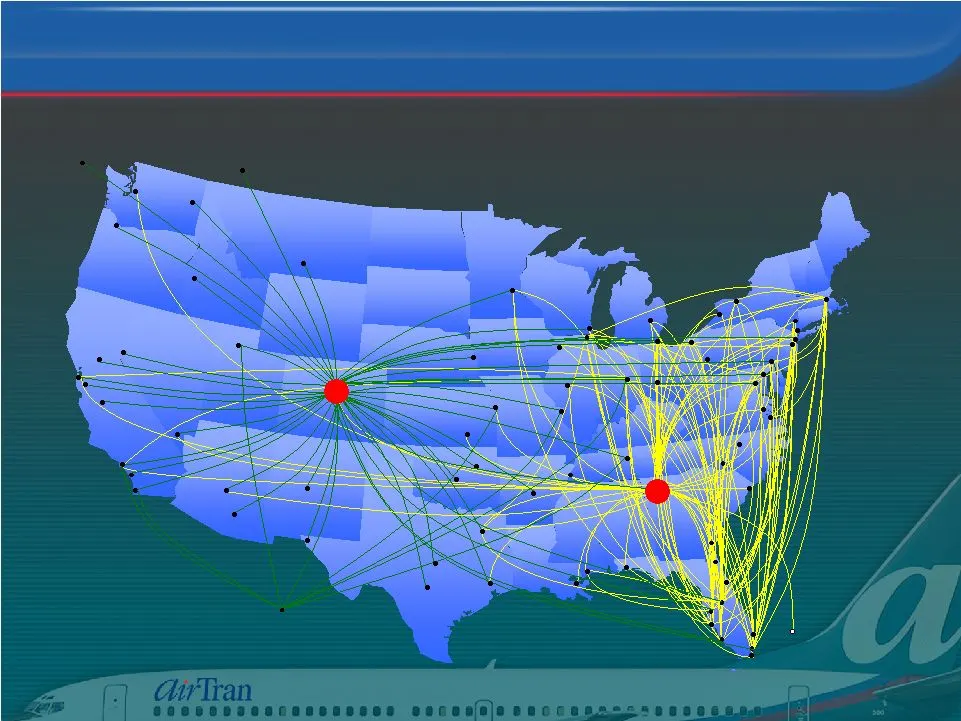
Slide 13: Frontier Alliance Will Create A Broad National Network
Grand Bahama Boston Houston New Orleans Miami Ft. Lauderdale West Palm Beach Seattle Newburgh White Plains New York City Philadelphia Newark Baltimore Washington, D.C. Richmond Newport News/ Williamsburg Raleigh / Durham Charlotte Myrtle Beach Atlanta Savannah Jacksonville Daytona Beach Orlando Tamp
Slide 14: Marketing Alliance With Frontier
Announced mid-November Creates a low cost, low complexity alliance that will generate additional revenue in near term Combines AirTran’s East coast network with Frontier’s Western U.S. network Expands the scope and value of the frequent traveler program; earn and redeem on both networks Unique onlin
Slide 15: AirTran Maintains High Airline Quality Rating
JetBlue Southwest United Alaska America West Northwest American Continental ATA JetBlue Alaska Southwest America West US Airways Northwest Continental United ATA US Airways Alaska Southwest America West Continental American Delta United Northwest American Eagle Alaska US Airways Northwest Southwest
Slide 16: Low Costs And Modern Jets Create Great Growth Opportunities
Low Costs And Modern Jets Create Great Growth Opportunities Low Costs And Modern Jets Create Great Growth Opportunities
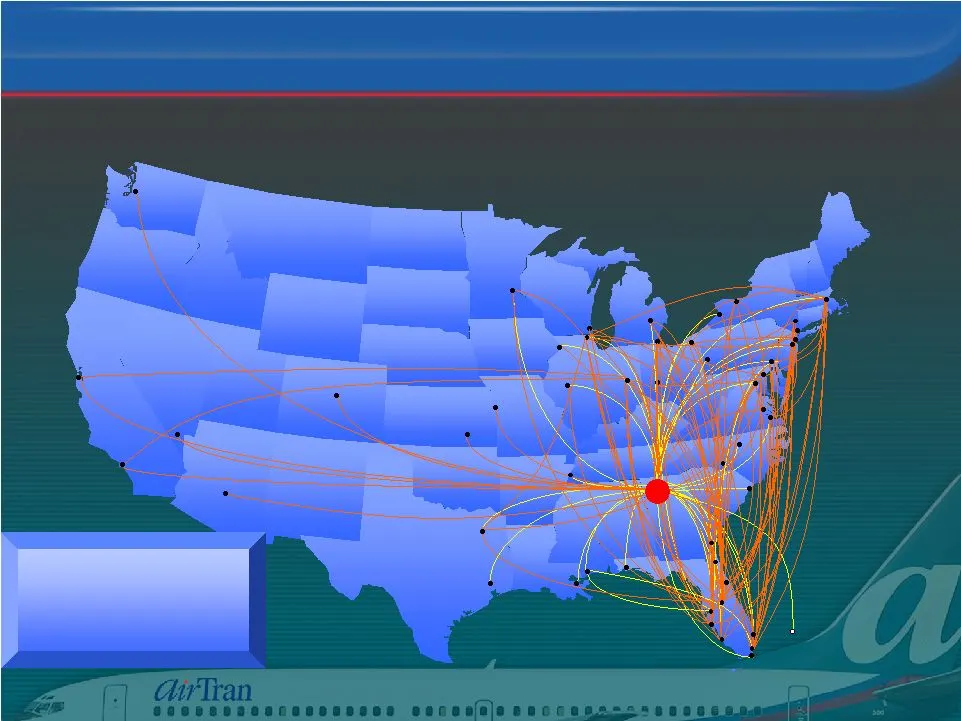
Slide 17: AirTran Today: Capitalizing On Opportunities
Grand Bahama Minneapolis Boston Houston New Orleans Miami Ft. Lauderdale Wichita Kansas City West Palm Beach Chicago Los Angeles San Francisco Seattle Denver Growth Since 9/11/01 Cities: 20 Routes: 89 Newburgh White Plains New York City Philadelphia Newark Baltimore Washington, D.C. Richmond Newport
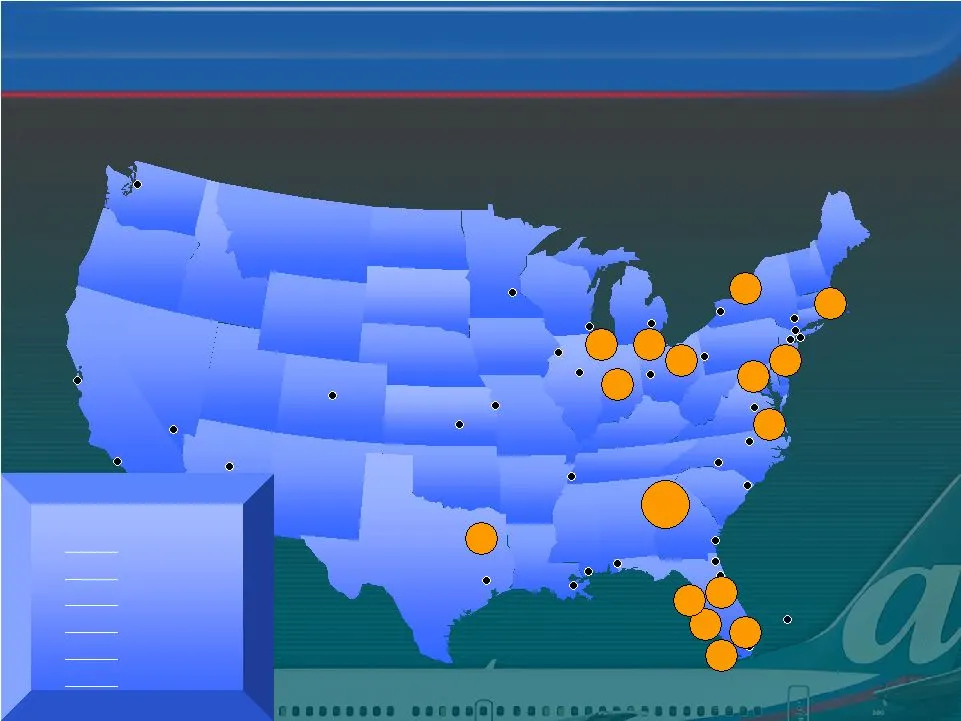
Slide 18: Network Breadth Drives Costs And Revenue Efficiencies
Bloomington Buffalo Newark Pittsburgh Miami West Palm Beach Denver Pensacola Freeport Wichita Houston Gulfport Los Angeles Kansas City Memphis Moline Minneapolis New Orleans San Francisco New York Savannah Jacksonville Washington Myrtle Beach Raleigh-Durham Flint Las Vegas Cities >=5 destinations Ja
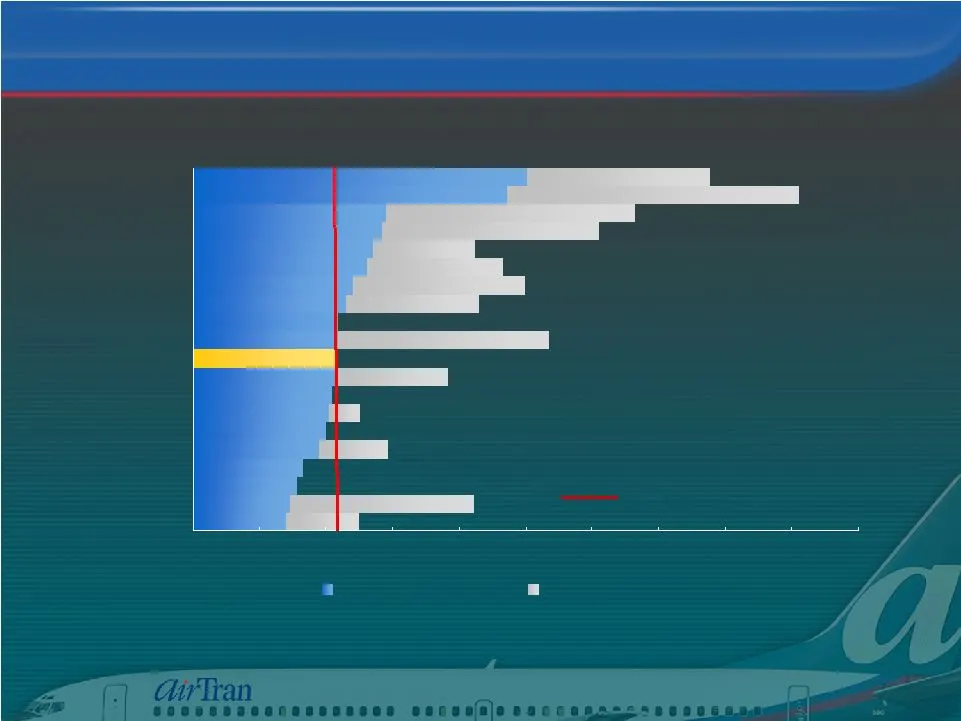
Slide 19: AirTran's Atlanta Hub Is Now One Of The Nations Largest Mainline Hubs
0 100 200 300 400 500 600 700 800 900 1,000 UAUA-San Francisco LCC-Philadelphia JBLU-New York LUV-Baltimore LCC-Phoenix LUV-Phoenix AMR-Miami LUV-Chicago CAL-Newark AAI-Atlanta LCC-Charlotte LUV-Las Vegas UAUA-Denver AMR-Chicago NWAC-Detroit NWAC-Minneapolis UAUA-Chicago CAL-Houston DAL-Atlanta AMR-
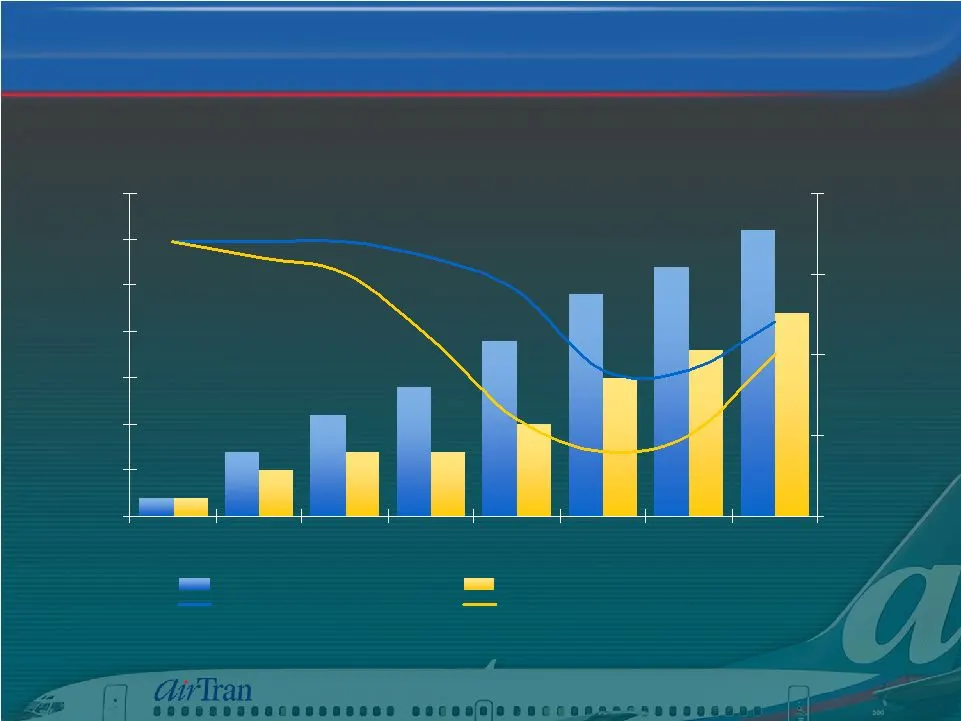
Slide 20: Adjusted Fleet Plan
130 135 140 145 150 155 160 165 Q107 Q207 Q307 Q407 Q108 Q208 Q308 Q408 5% 10% 15% 20% 25% Original Aircraft Adjusted Aircraft Original ASM Growth Adjusted ASM Growth Total Aircraft ASM Growth Rate Adjusted Fleet Plan Adjusted Fleet Plan
Slide 21: AirTran Continues To Manage Fuel Exposure
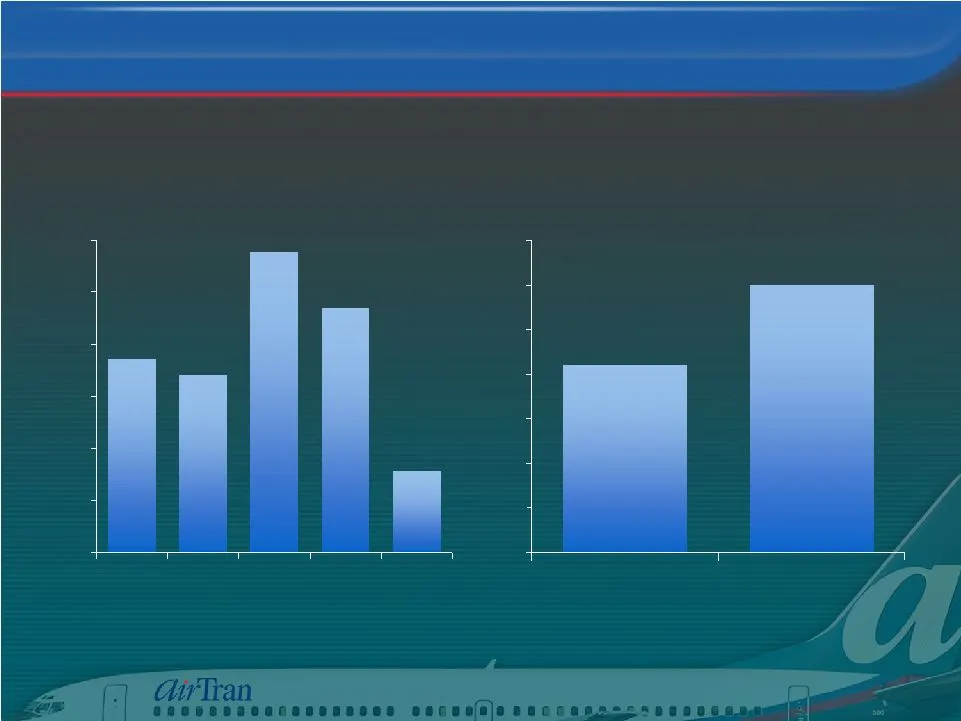
ASMs per Gallon 0 10 20 30 40 50 60 70 2000 2006 >40% improvement AirTran's Current Hedge Position 47% 16% 34% 37% 58% 0% 10% 20% 30% 40% 50% 60% Q106 Q206 Q306 Q406 2007 AirTran Continues To Manage Fuel Exposure $2.26/gal actual $2.33/gal actual $2.03/gal forecast $2.06/gal forecast $2.06/gal actua
Slide 22: Fuel Sensitivity
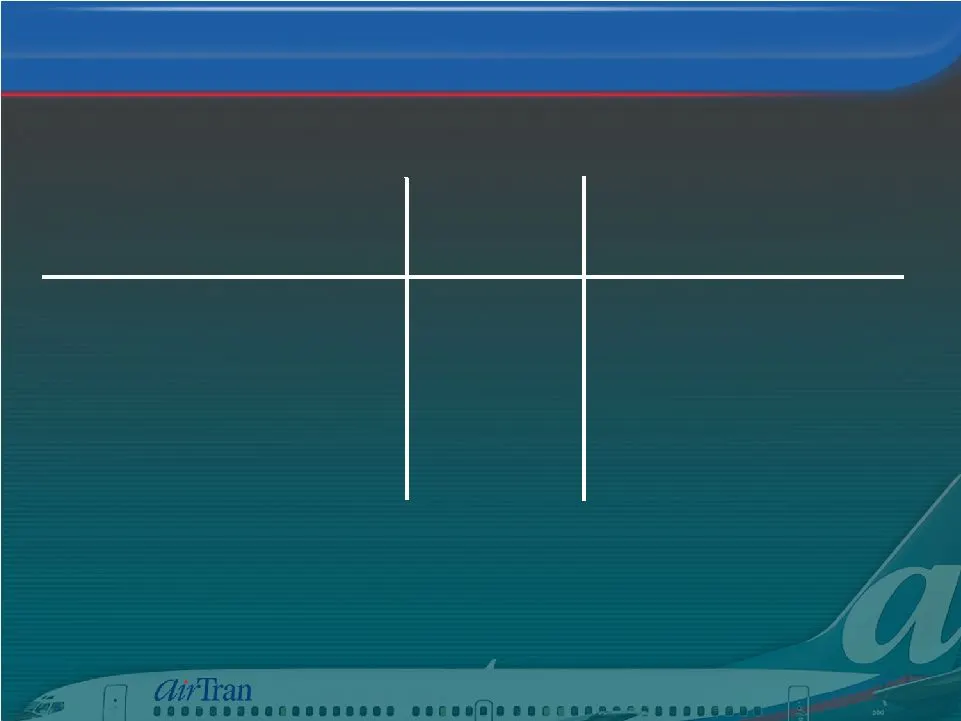
-$0.23 +$0.23 NA EPS Change from $65 -$40 +$40 NA Change from $65 ($MM) $820 $740 $780 2007E Fuel Expense ($MM) $70 Crude $60 Crude $65 Crude Forward Curve Fuel Sensitivity Company Estimates Fuel Sensitivity
Slide 23: Potential Impact of US Airways / Delta Merger
AirTran significant beneficiary Delta / US Airways are AirTran’s #1 / #2 competitors Further East Coast capacity reductions are likely Opportunities exist for asset purchase to solve concentration issues Potential Impact of US Airways / Delta Merger — — Potential Impact of US Airways / Delta Merger
Slide 24: Summary
AirTran has good fundamentals Young fleet Better growth plan with balanced deliveries Experienced management Positioned to become the low cost leader Significant opportunities remain 4 to 5 new cities per year Connecting existing cities Taking steps to slow growth rate in 2007 and 2008 Summary — — —
Slide 25
Source: SEC EDGAR · 8-K filed Dec 8, 2006
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010