Mitel Networks — 17th Annual Needham Growth Conference 2015
30 slides from Mitel Networks's conference presentation, Jan 16, 2015
Slide 1: 17th Annual Needham Growth Conference
17th Annual January 14, 2015 Needham Growth Conference New York – The Palace Hotel
Slide 2: Safe Harbor Forward-Looking Statements
Saferesults Forward Some words These could statements profitability political number strategies Exchange the Non-GAAP This standardized our consider GAAP measures 2March past. past Harbor presentation cause of statements target, 27, financial of financial |unrest There the to Looking ©2014 to succes
Slide 3: Mitel Today
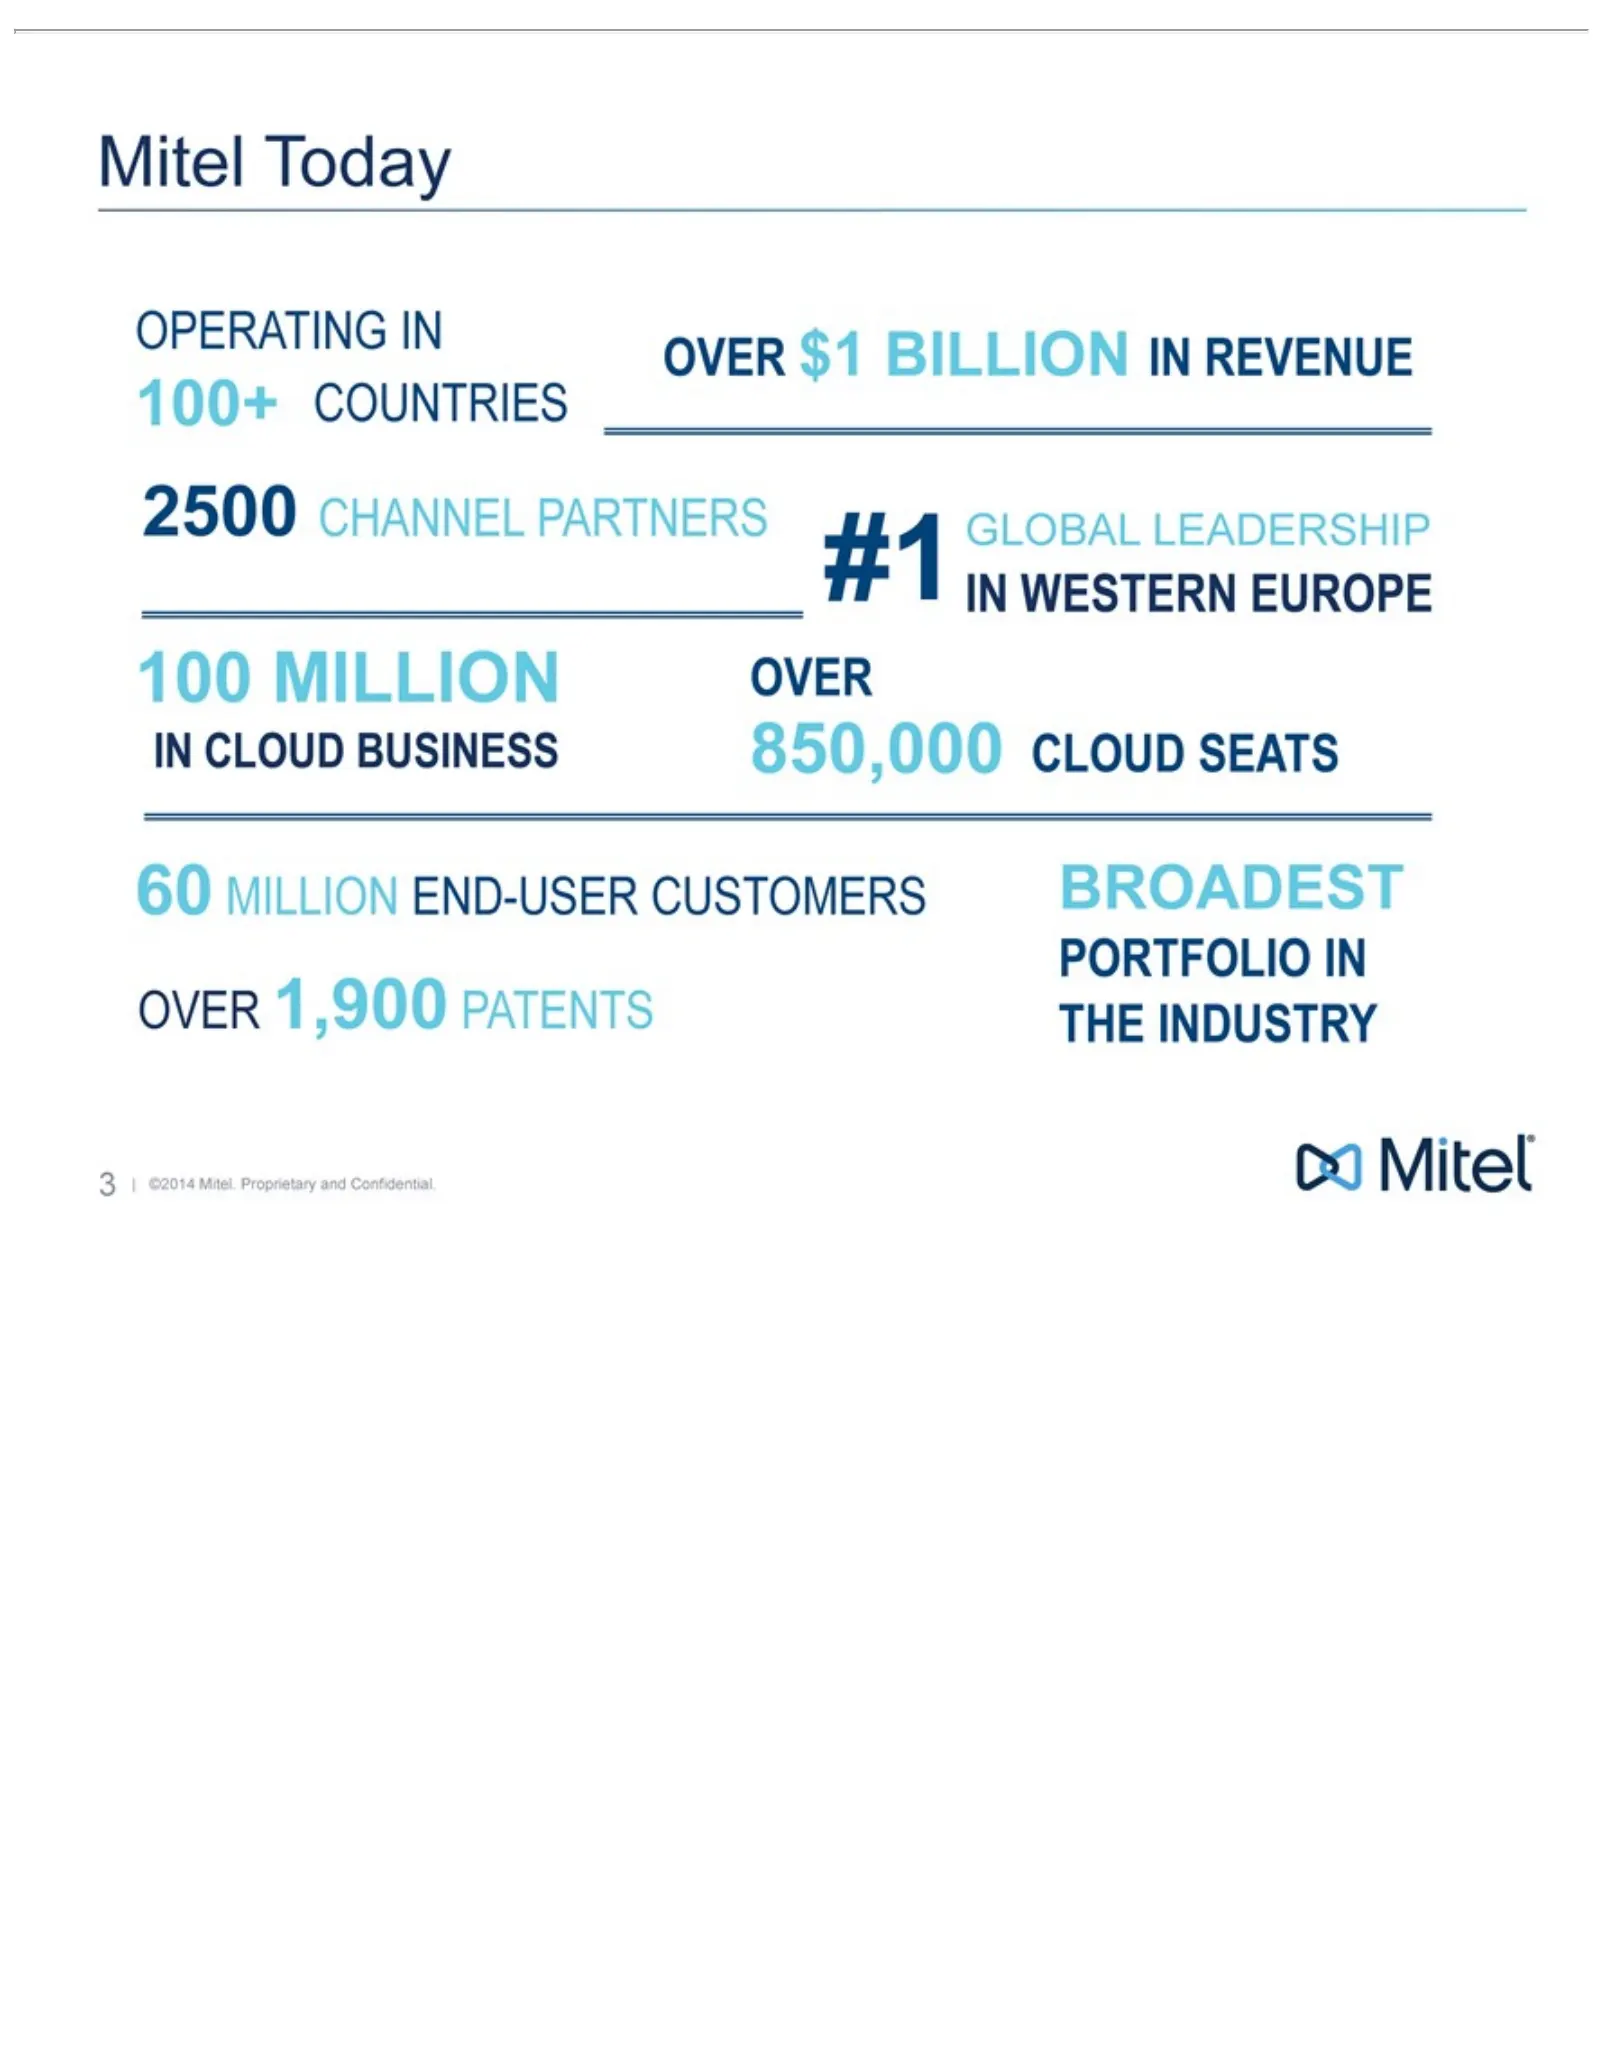
Mitel OPERATING 2500 100 60 #1 OVER 3BROADEST MILLION GLOBAL MILLION CHANNEL Today 1,900 $1 850,000 | ©2014 BILLION PATENTS PORTFOLIO LEADERSHIP END-USER IN IN CLOUD Mitel. 100+ PARTNERS CLOUD INCOUNTRIES Proprietary REVENUE SEATS CUSTOMERS IN BUSINESS INTHE WESTERN and INDUSTRY Confidential. EUROPE
Slide 4: Global Market Presence
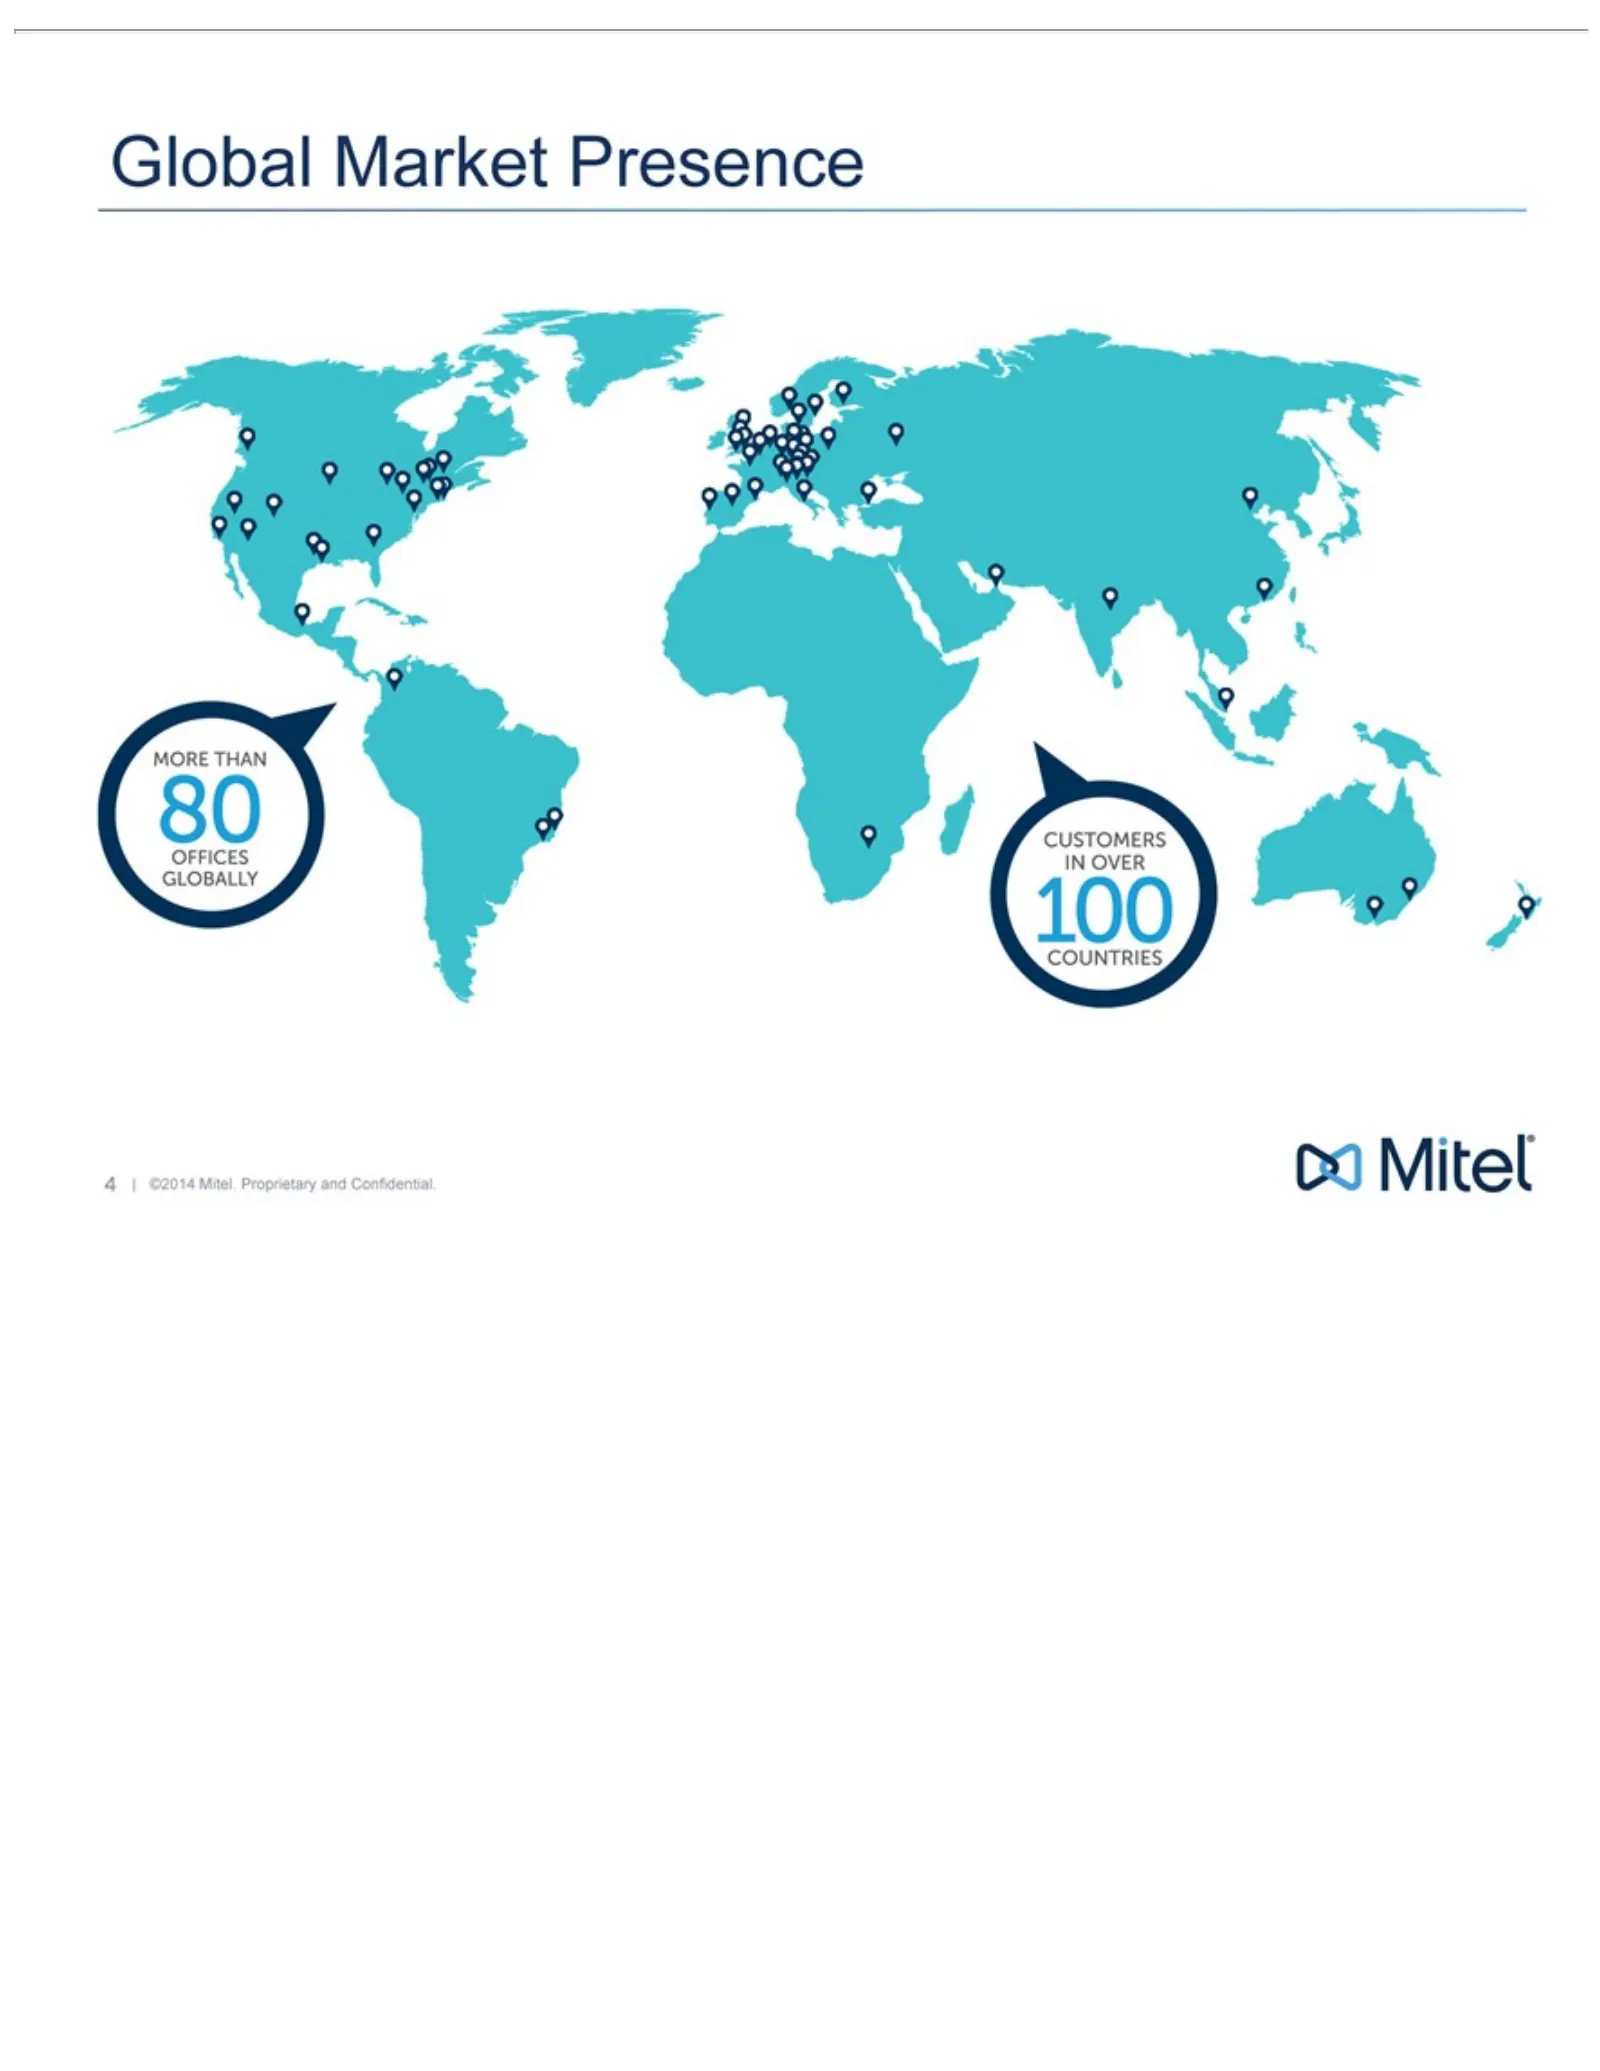
Global Market MORE 4CUSTOMERS THAN | ©2014 Presence 80 INMitel. OFFICES OVER Proprietary 100GLOBALLY COUNTRIES and Confidential.
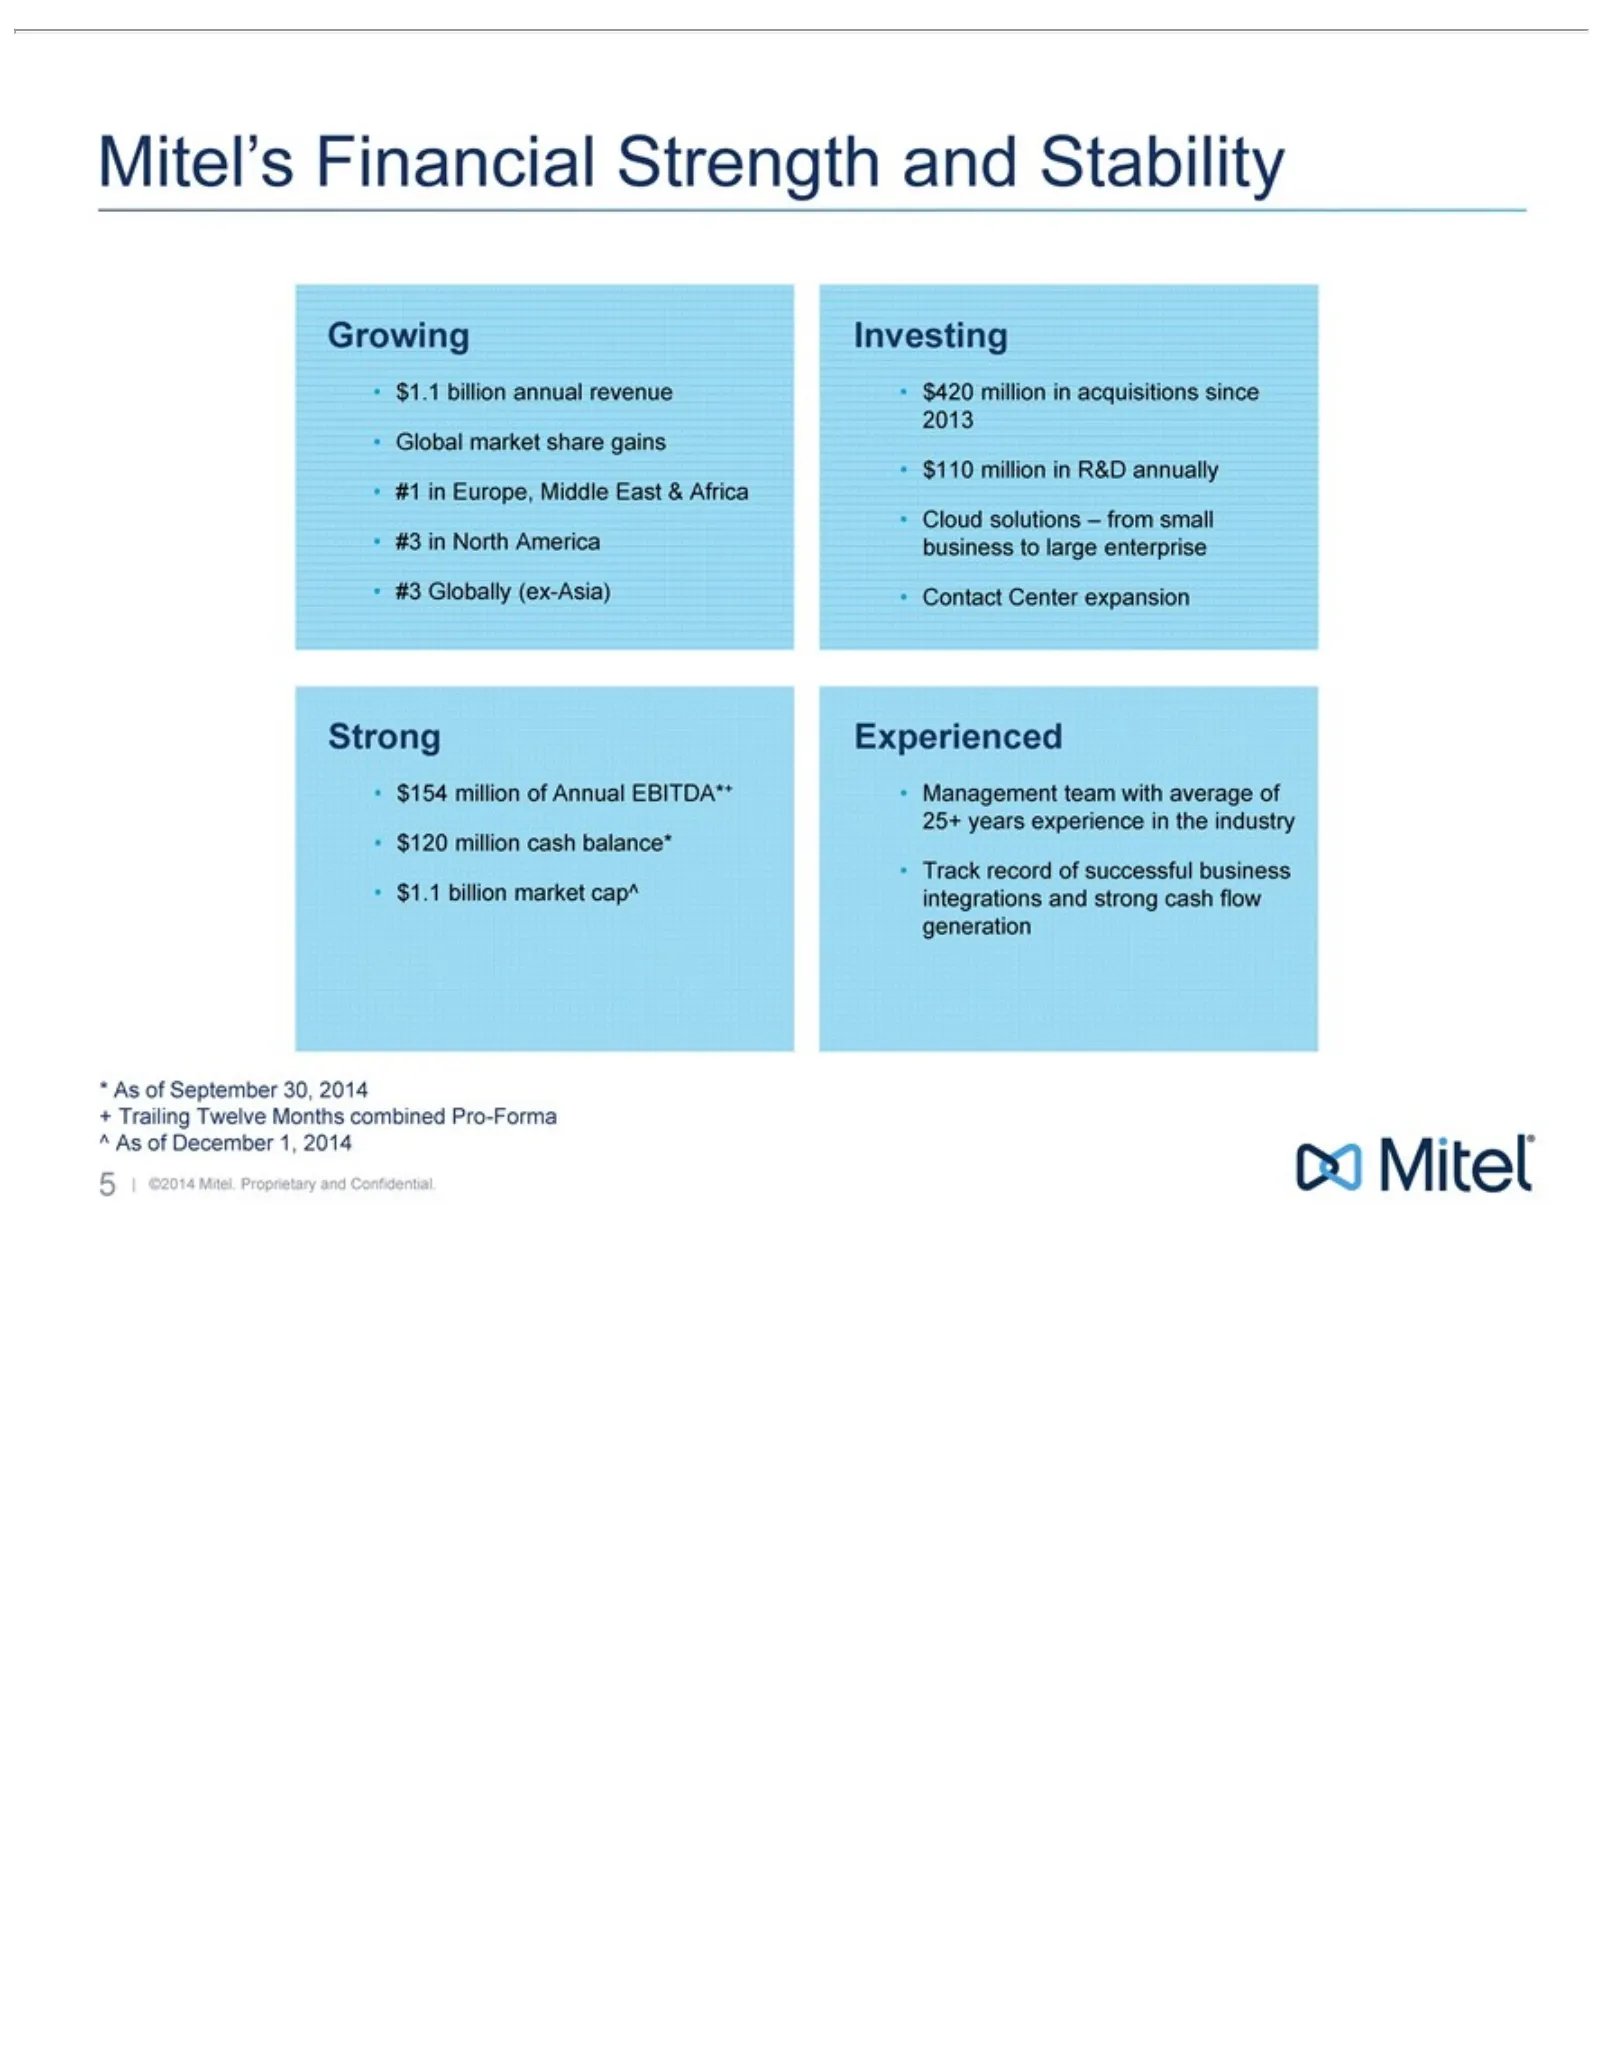
Slide 5: Mitel's Growing Global Strength and Stability
Mitel’s Growing Global #1 #3 $420 Investing $110 Cloud Contact Management Experienced Track $154 Strong $120 *$1.1 5^+ As |Trailing ©2014 inbillion Globally of million Europe, North record solutions market Financial December September Center Mitel. Twelve America annual market (ex-Asia) of in cash t
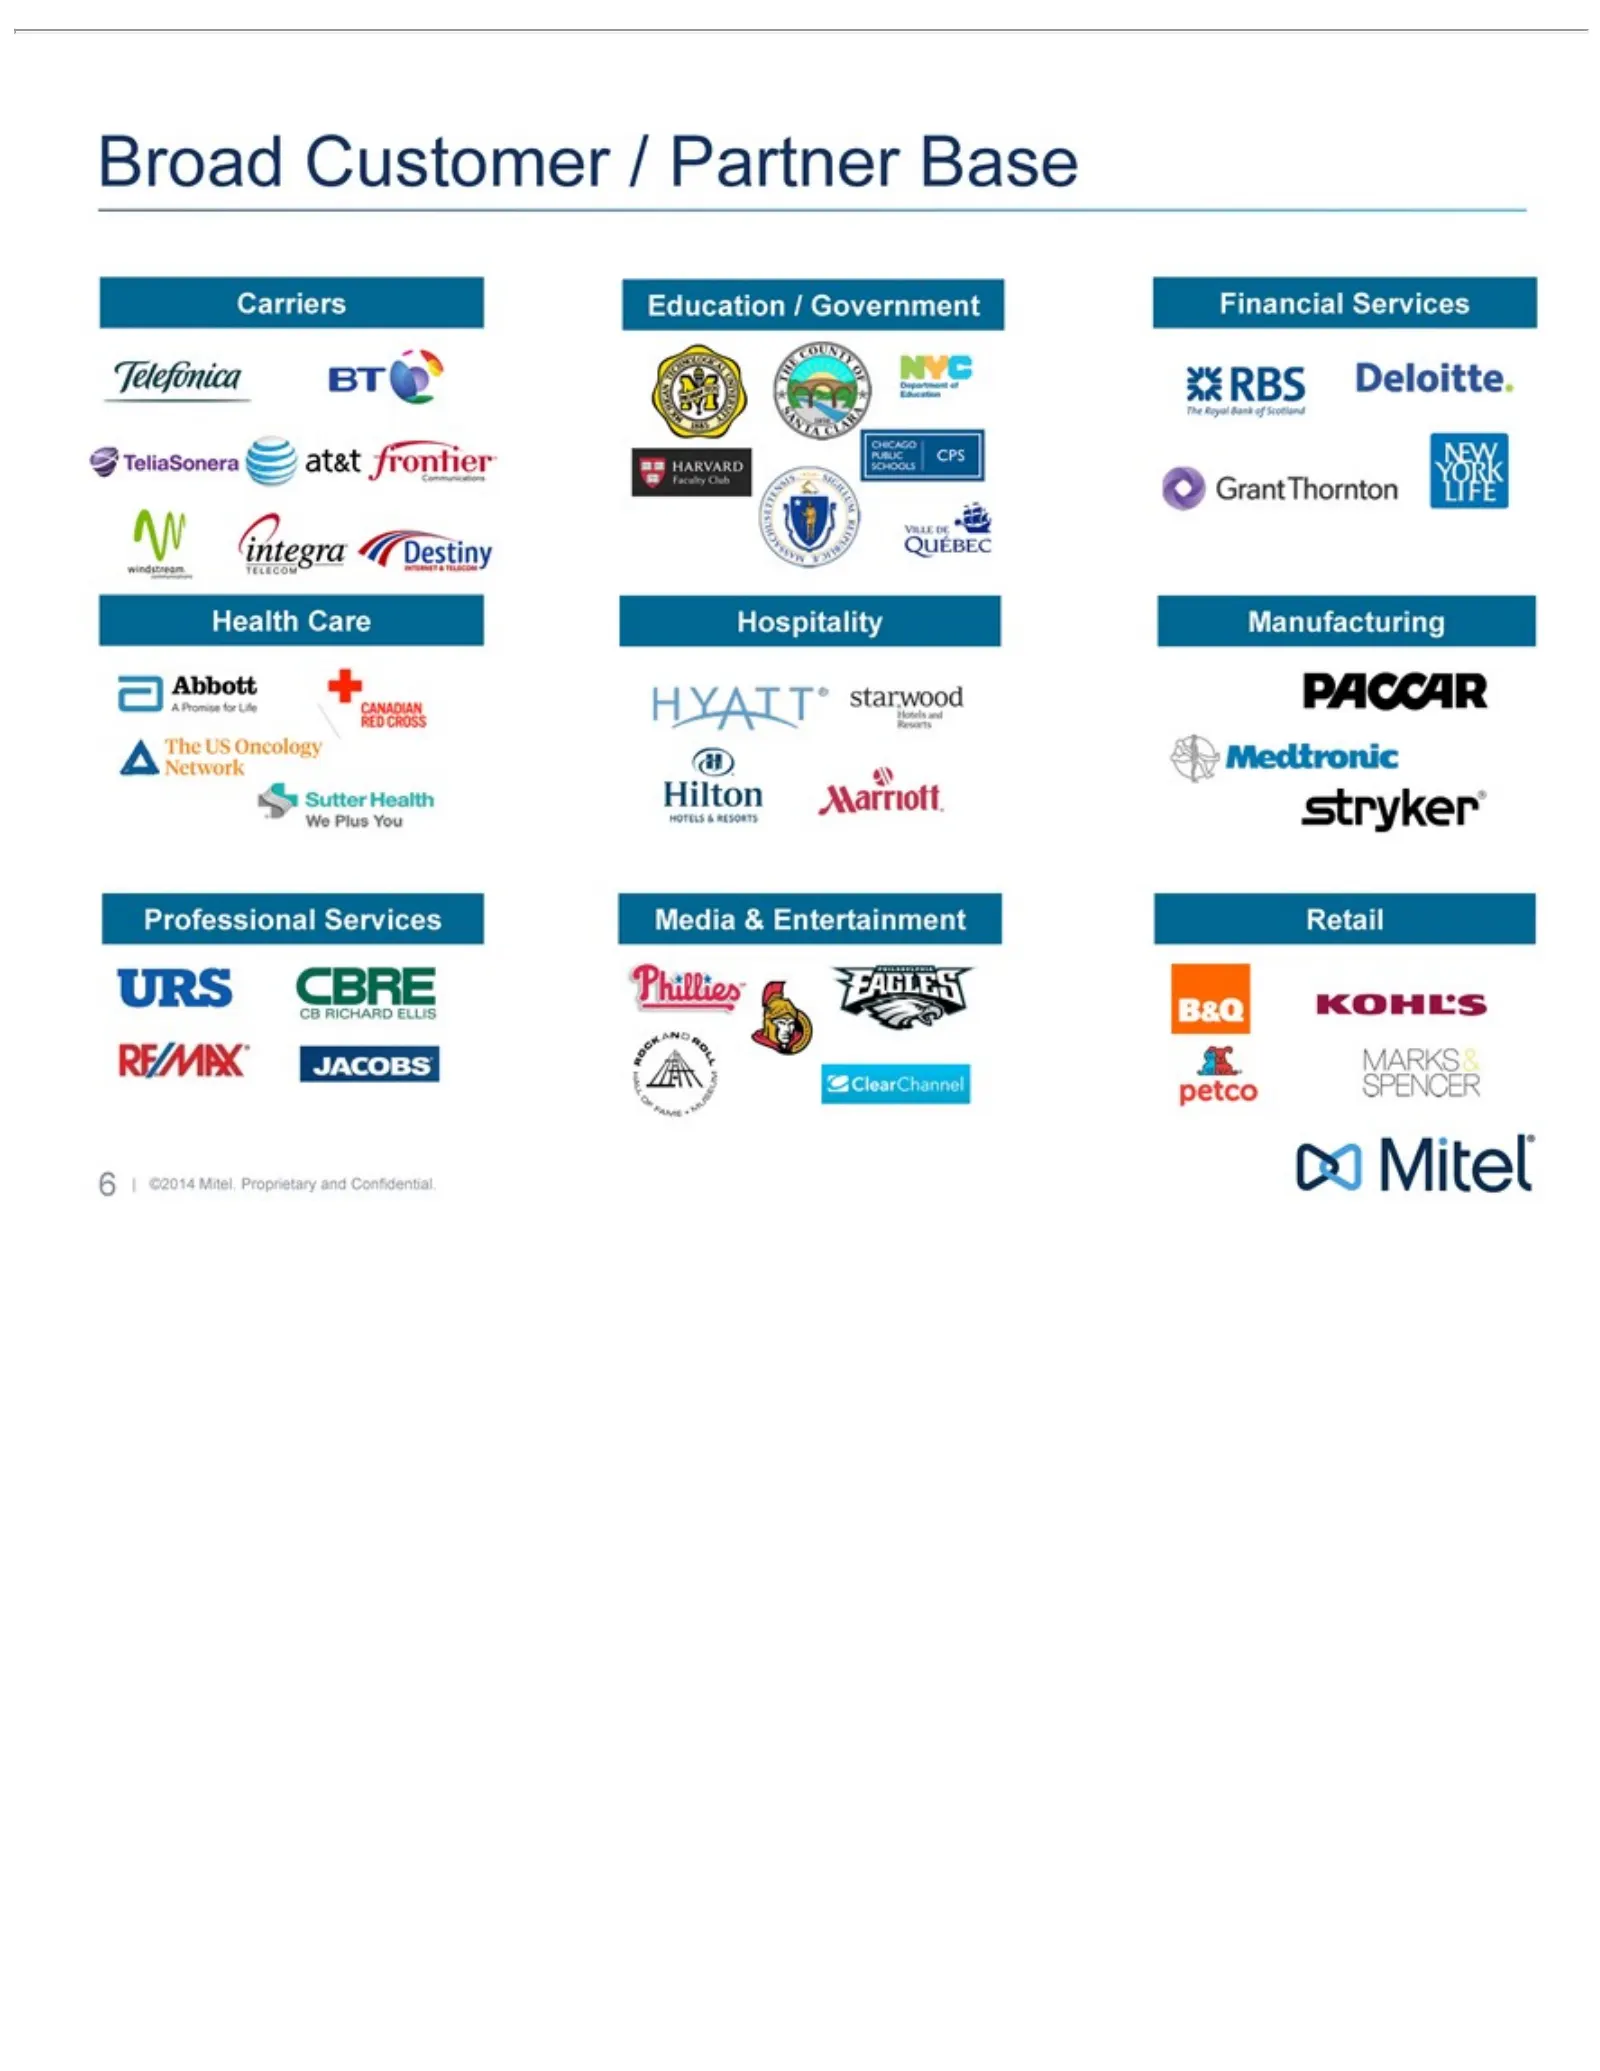
Slide 6: Broad Customer and Partner Base
Broad Customer Education Carriers Financial Health Professional Manufacturing Hospitality 6Media Retail & Care | Entertainment ©2014 Services / Government Services /Mitel. PartnerProprietary Base and Confidential.
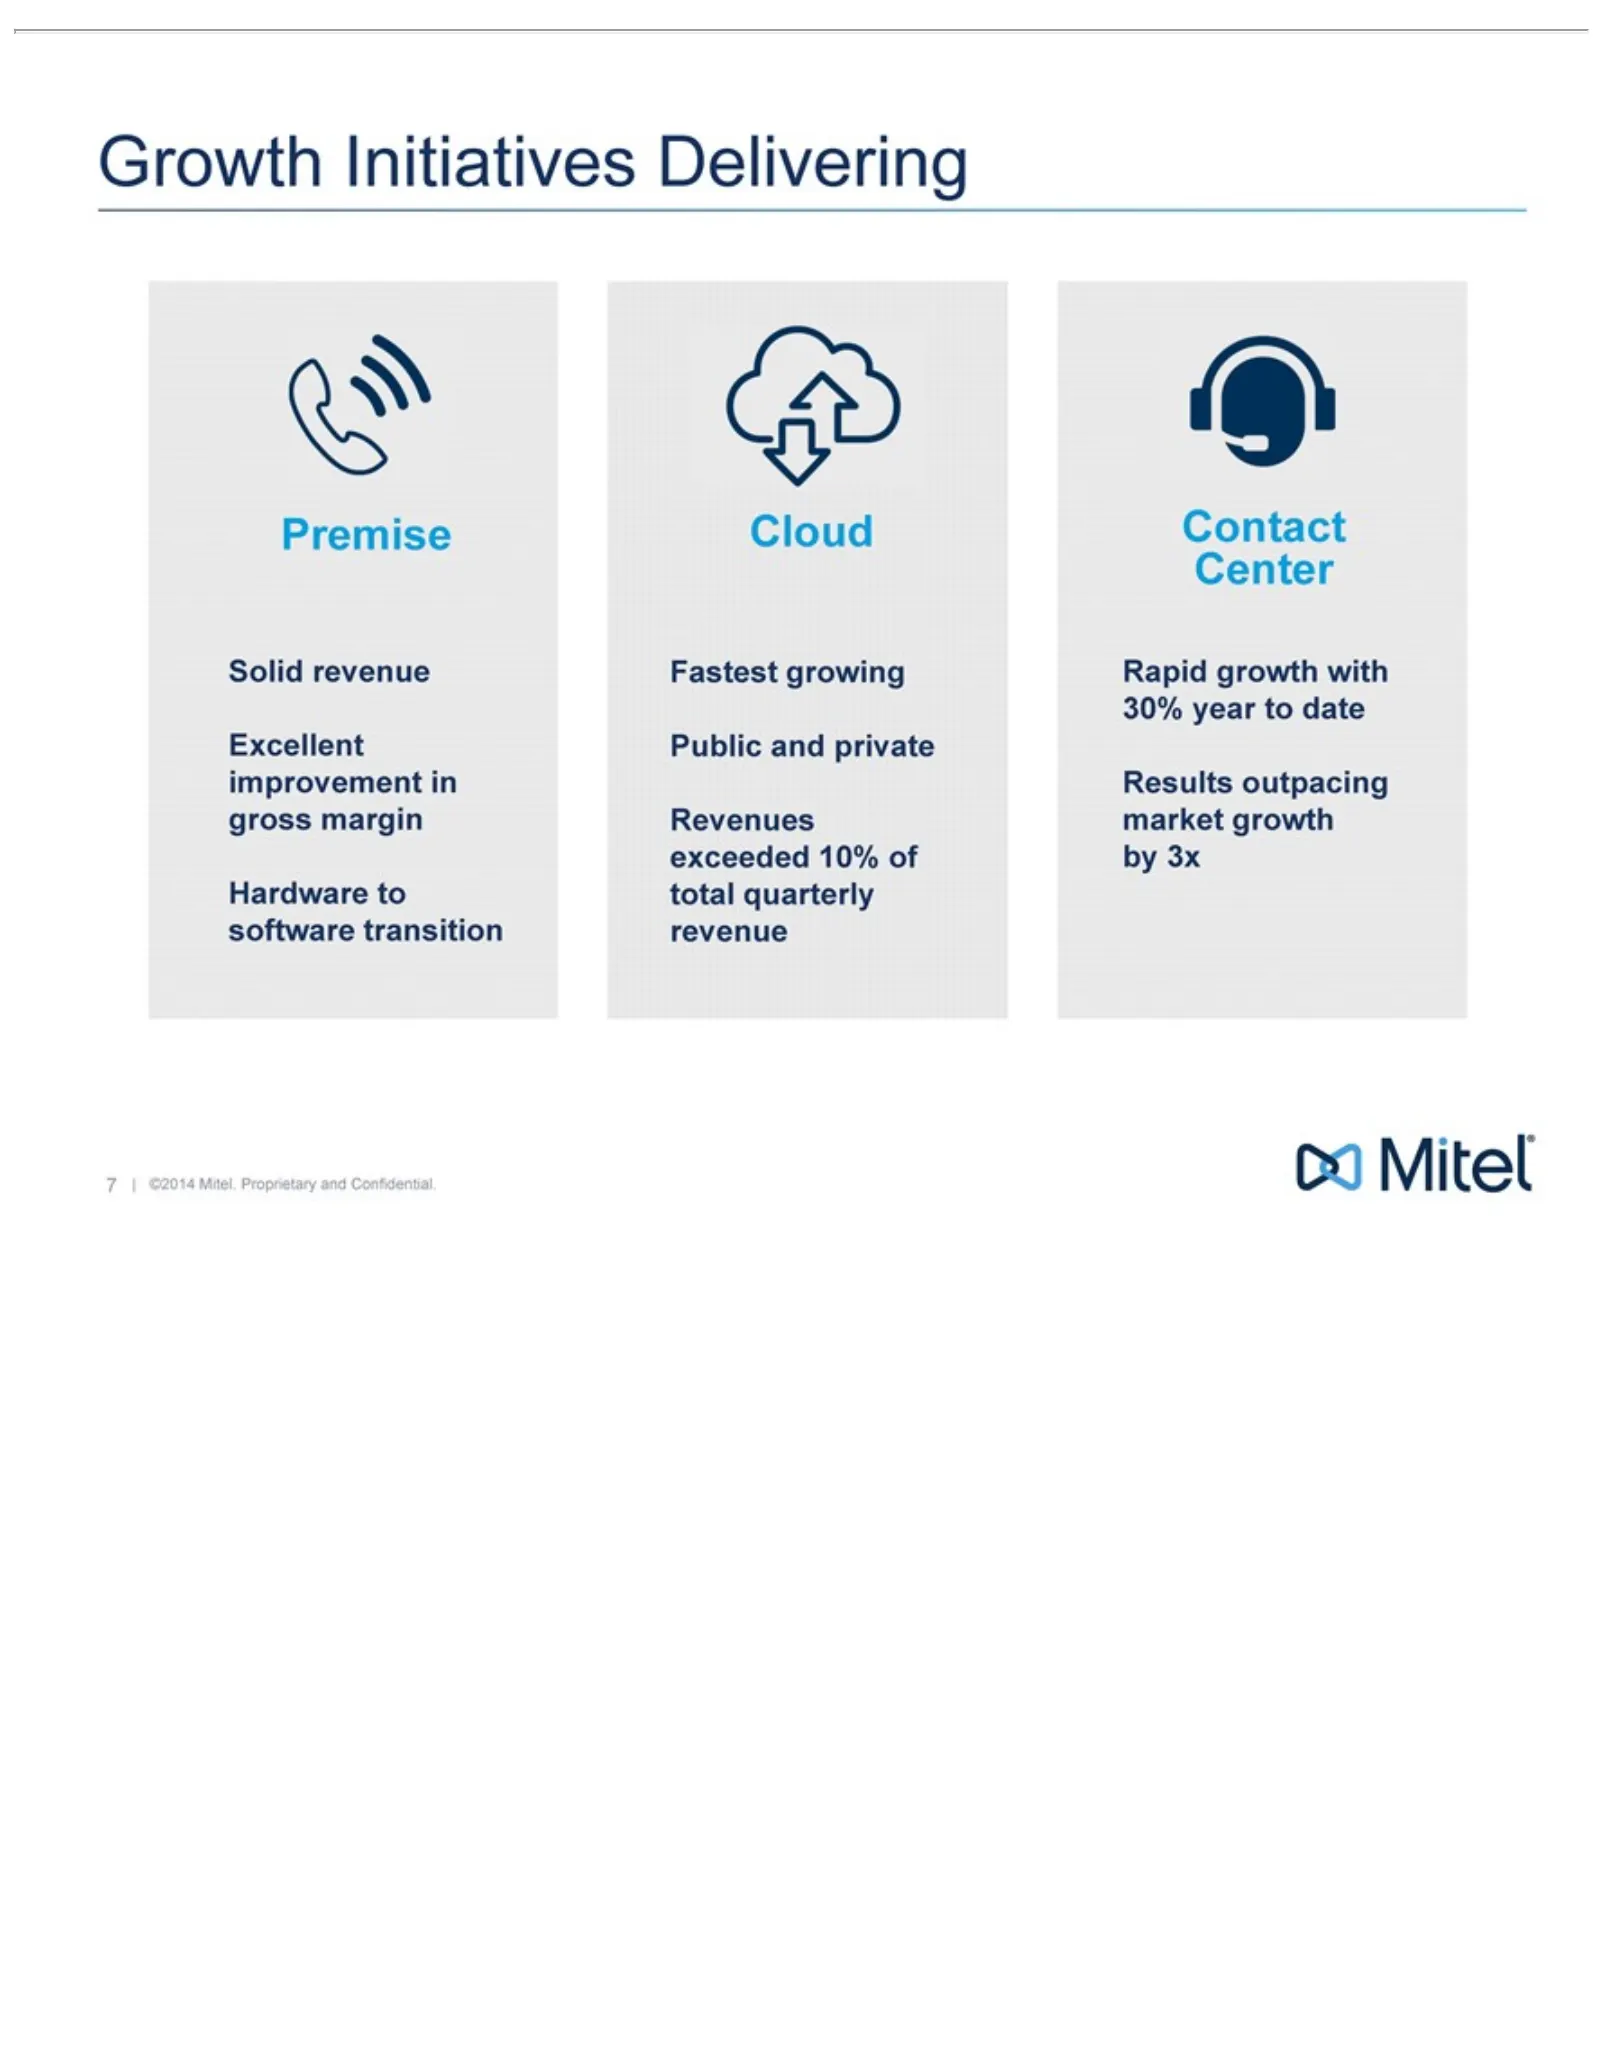
Slide 7: Growth Initiatives Delivering Results
Growth Solid Premise Excellent Hardware Fastest Cloud Public Revenues Contact Rapid 7Results revenue growth and growing outpacing Initiatives Center | ©2014 improvement exceeded toprivate software with Mitel. market Delivering 30% 10% transition in Proprietary year of growth gross total to date marg
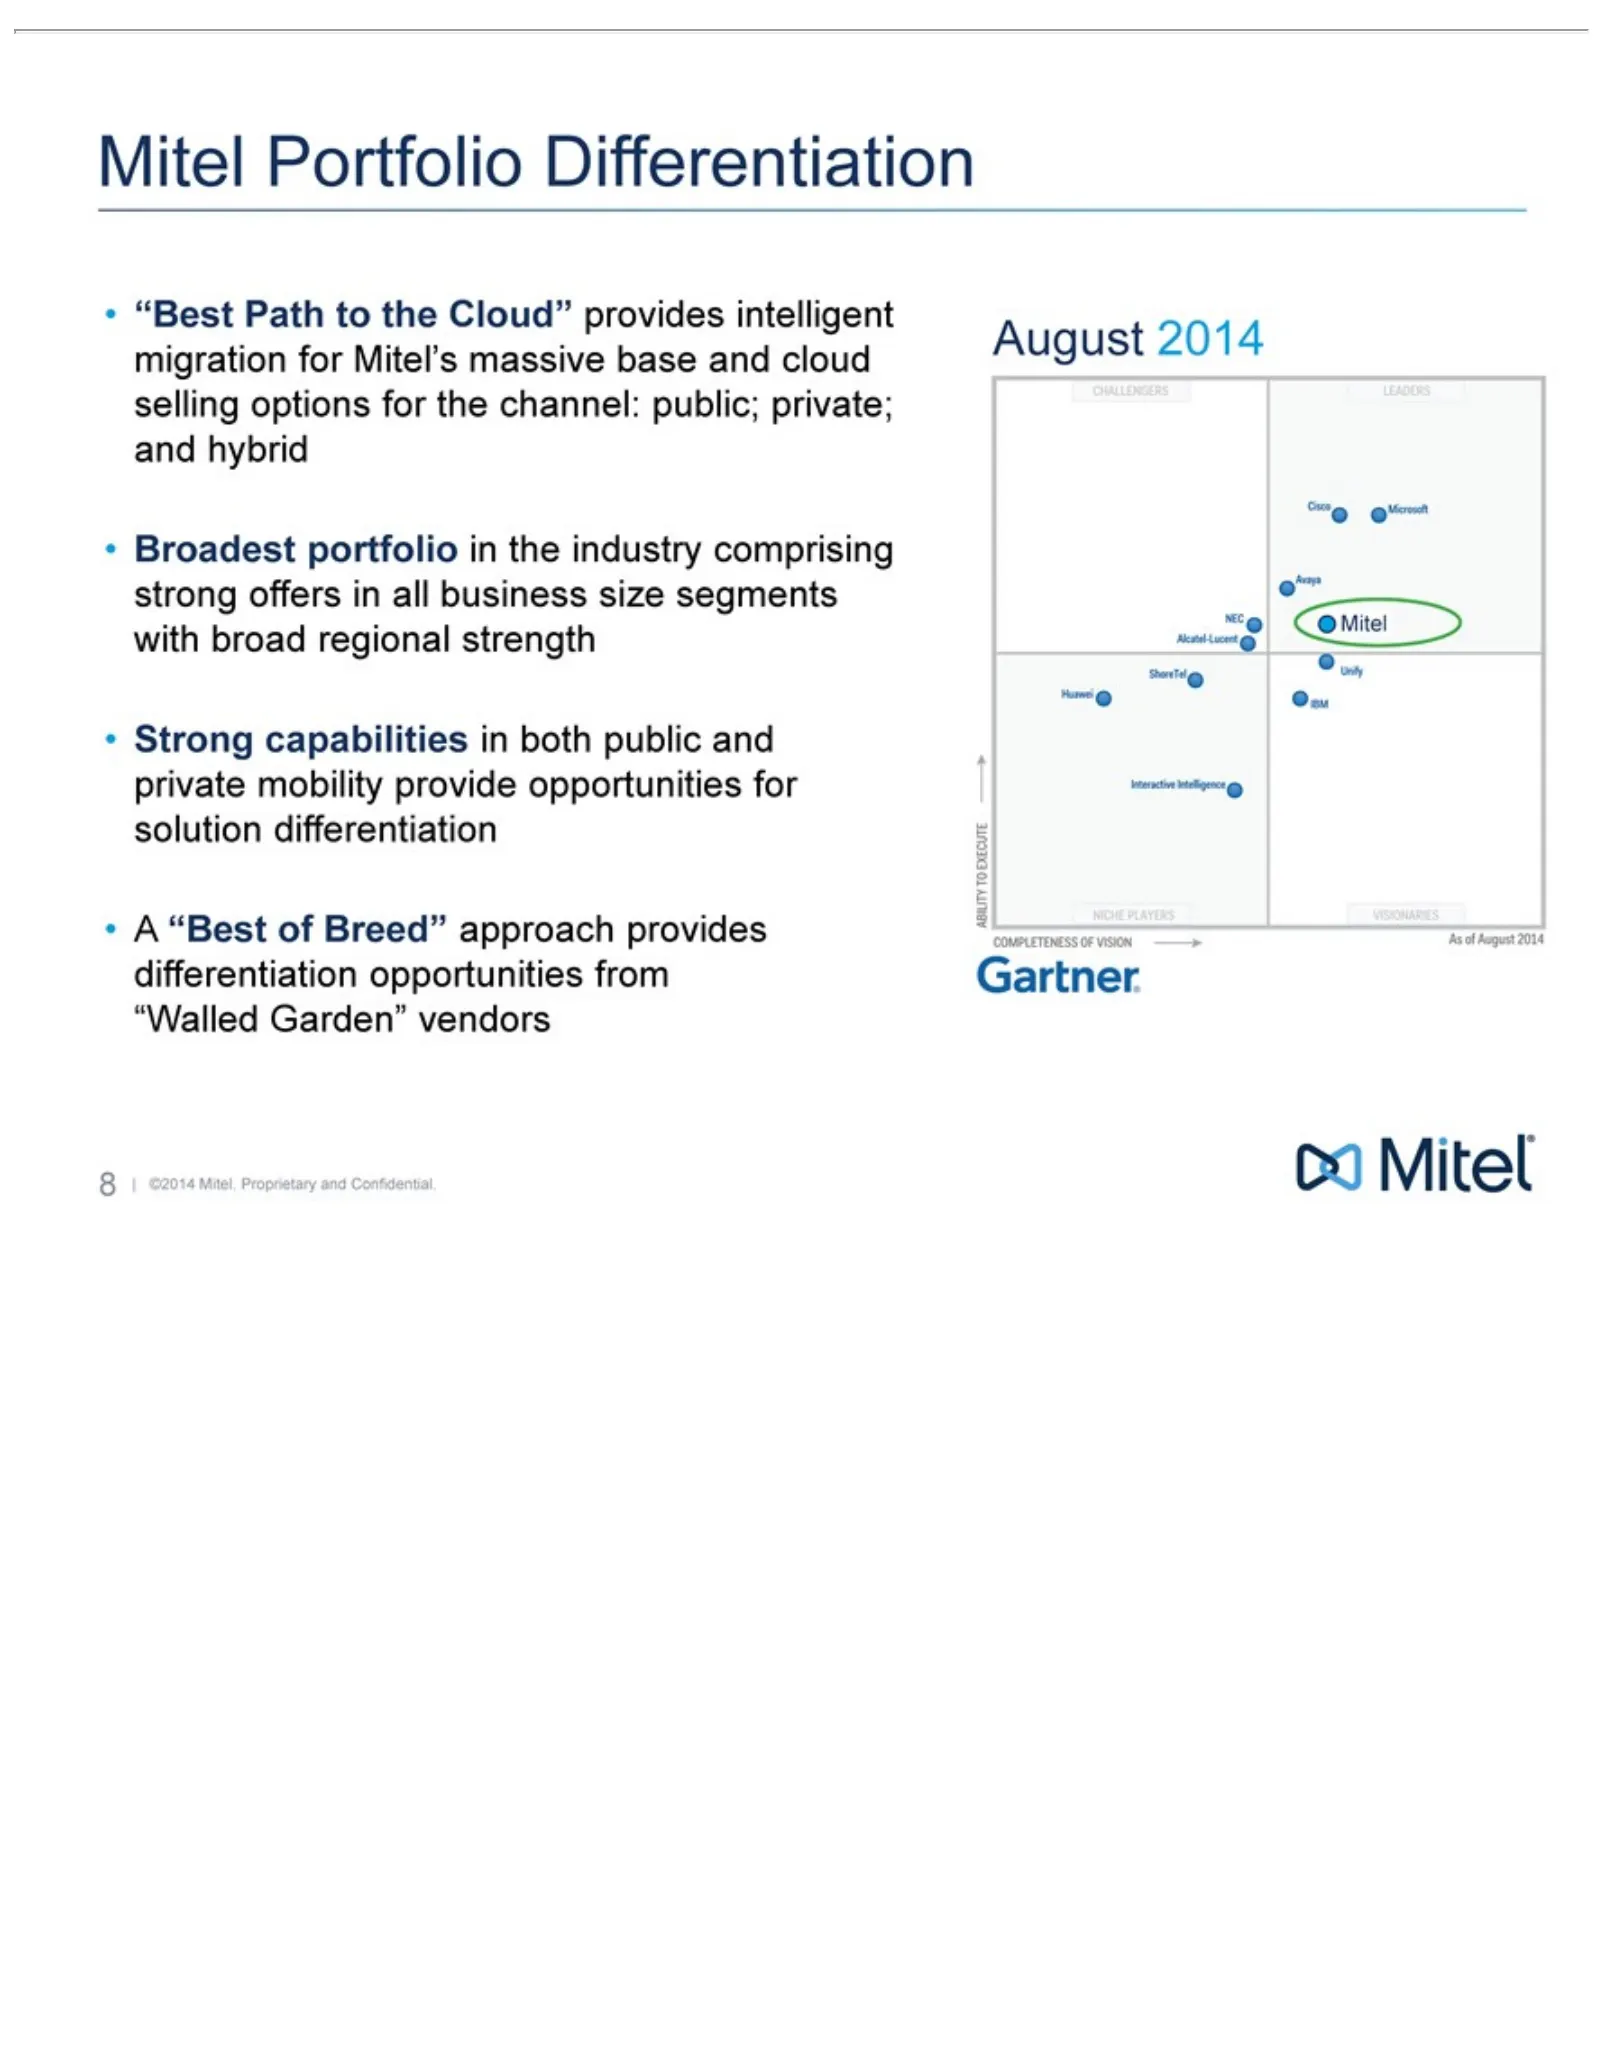
Slide 8: Best of Breed and Broadest Portfolio
“Best Broadest Strong A 8August Mitel |“Best ©2014 Portfolio Path capabilities 2014 ofportfolio Mitel. Breed” to the Differentiation Proprietary Cloud” approach in in the bothindustry provides public provides and Confidential. and comprising intelligent differentiation private migration mobility str
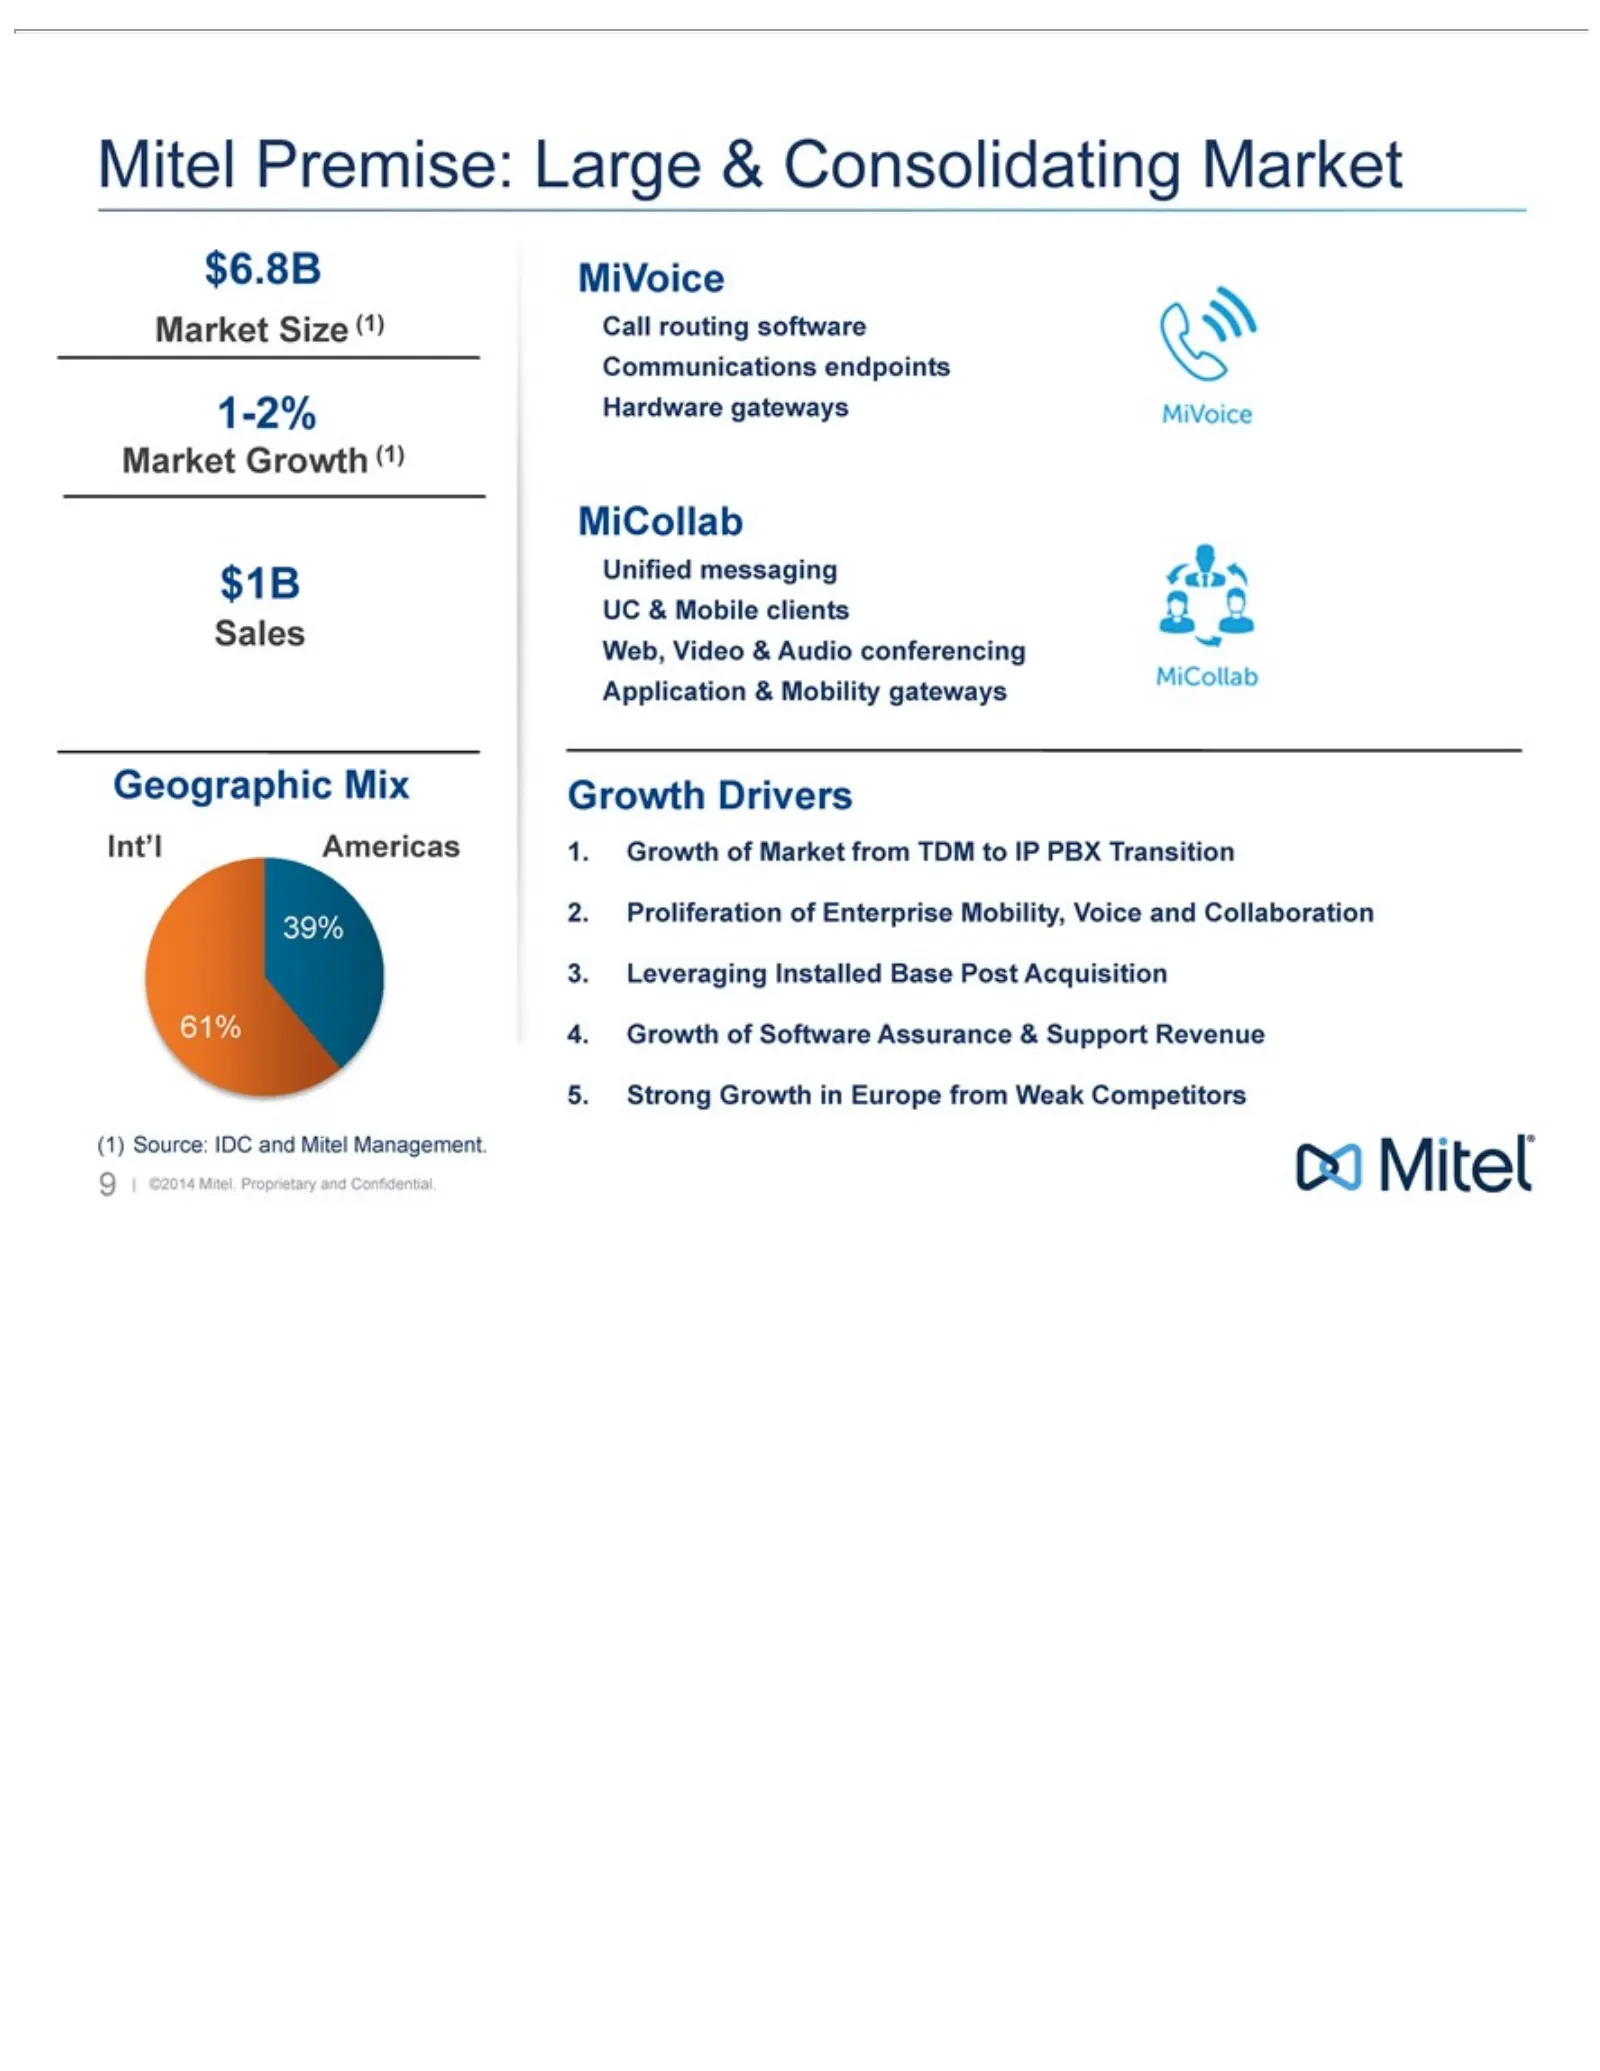
Slide 9: Premise: $6.8B Market
(1) Mitel $6.8B Market 1-2% Geographic Sales $1B Int’l Call MiVoice 61% 39% Communications Hardware Unified MiCollab UC Web, Application Growth 1. 2. 3. 4. 5. 9 | Strong Proliferation Leveraging Growth &Americas routing Video Premise: Mobile ©2014 Size Growth messaging Drivers Source: Growth gateway
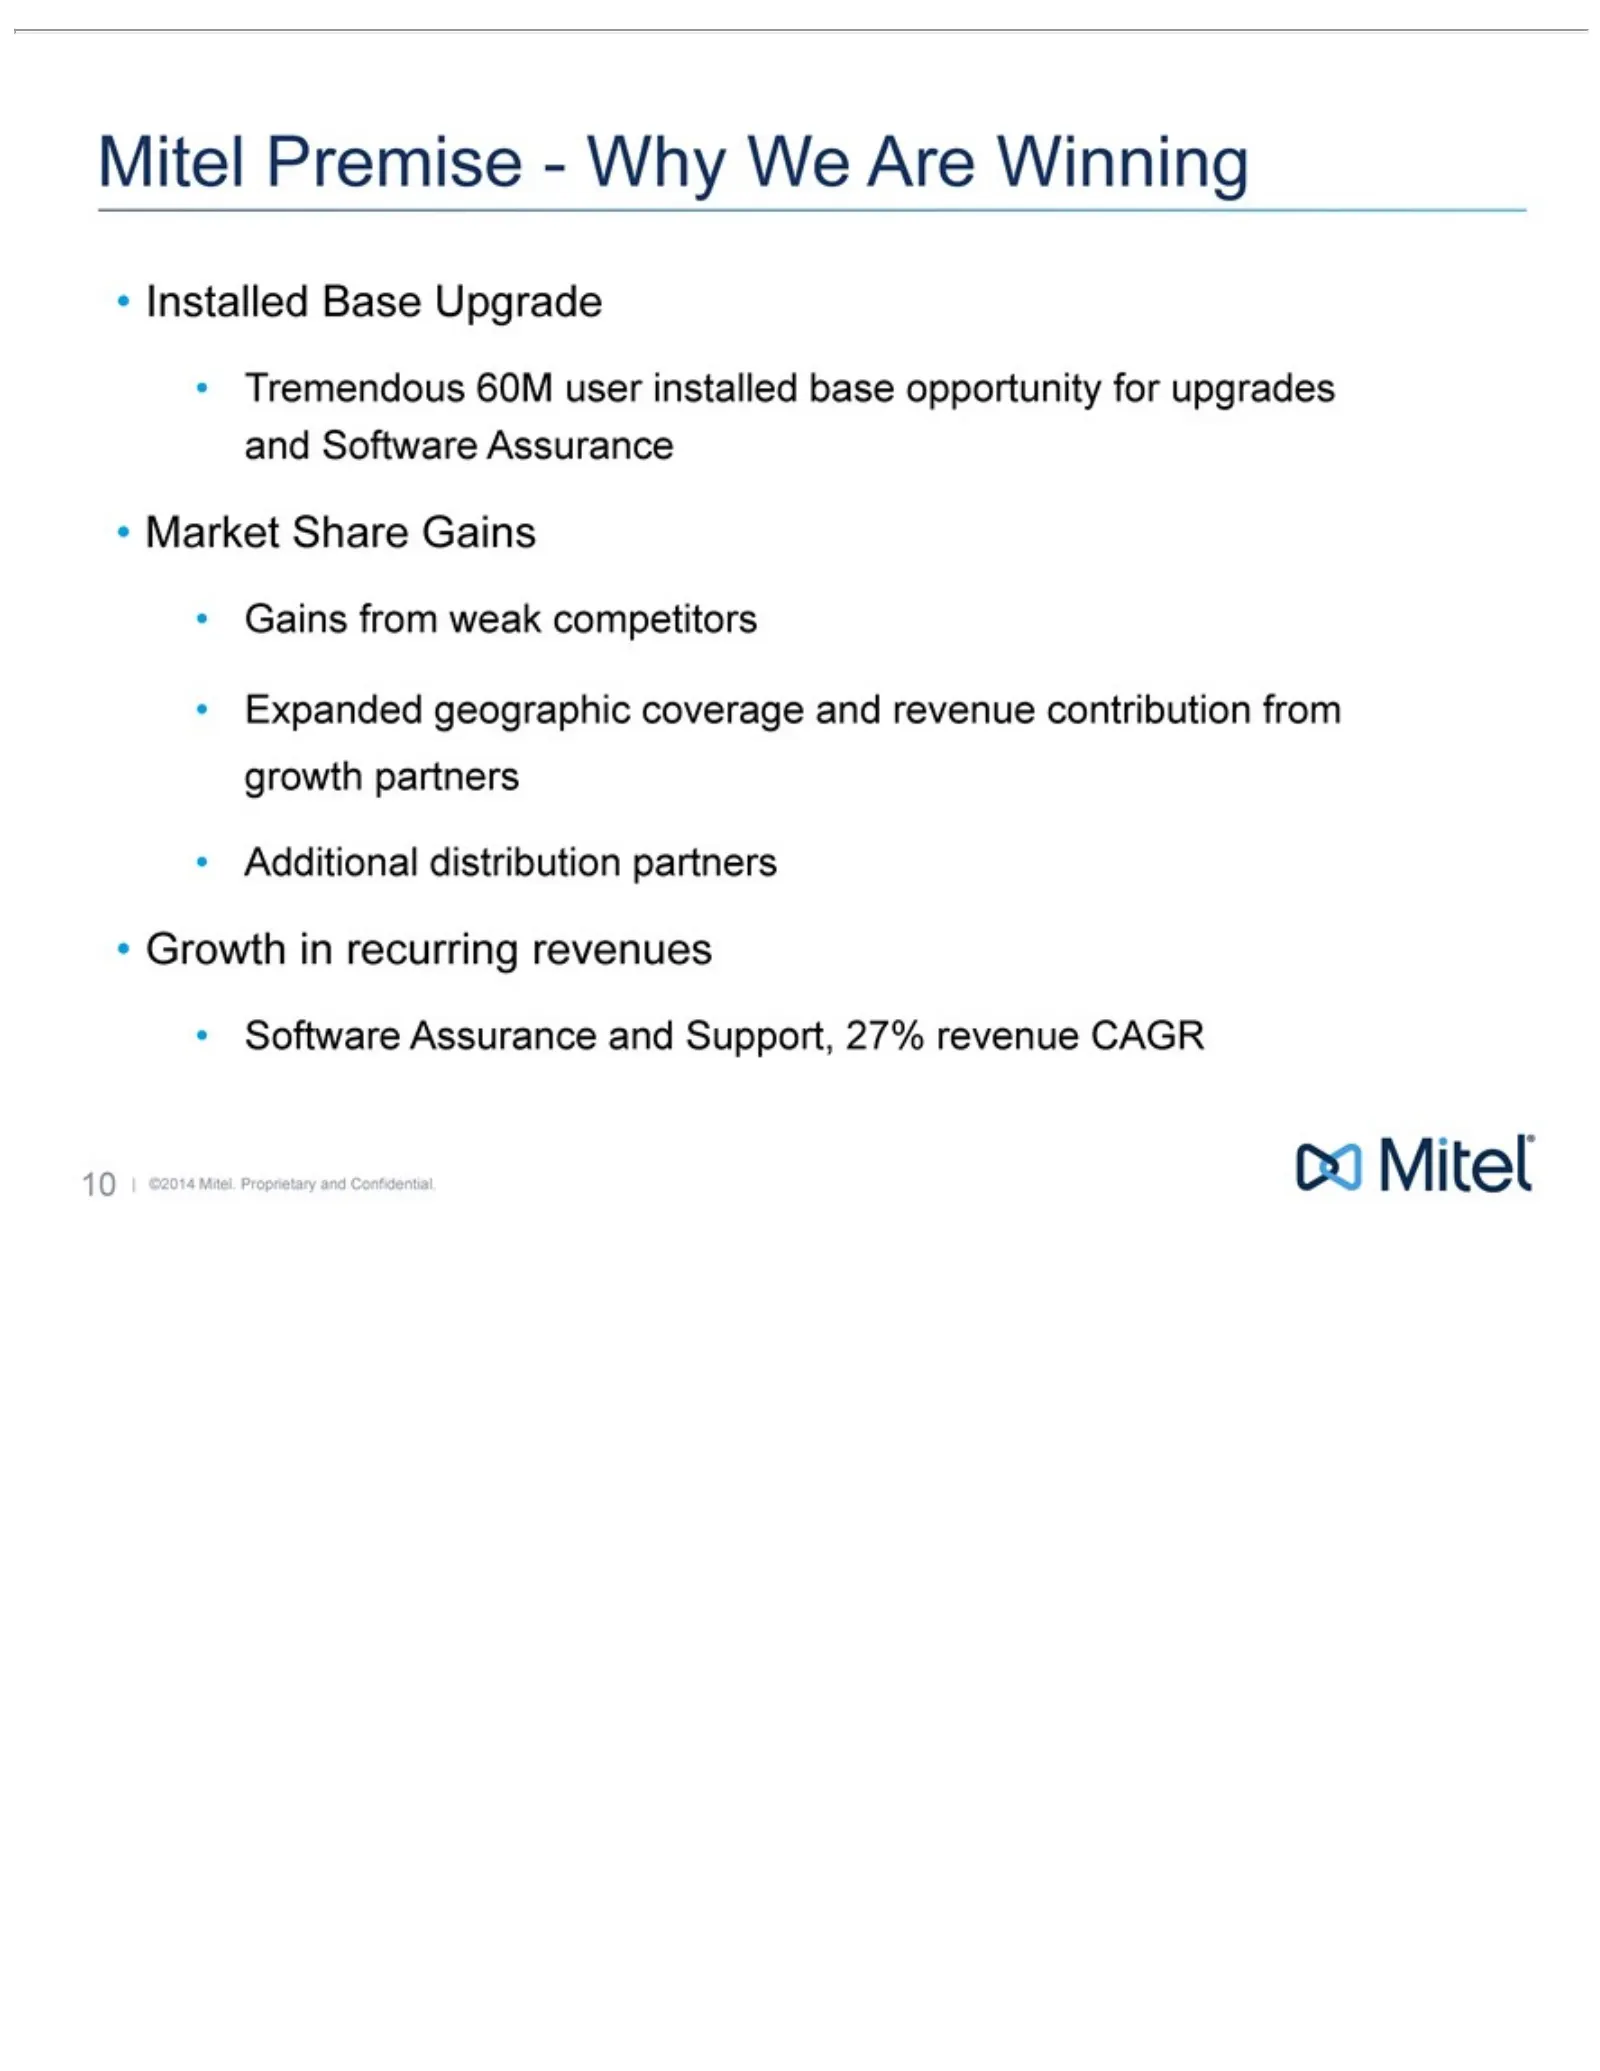
Slide 10: Installed Base: Tremendous Upgrade Opportunity
Mitel Installed Tremendous Market Gains Expanded Additional Growth Software 10 | ©2014 Premise—Why from Share inBase Assurance geographic recurring distribution Mitel. weak 60M Gains Upgrade competitors user Proprietary and revenues We coverage installed partners Support, Are Winning and and base 27
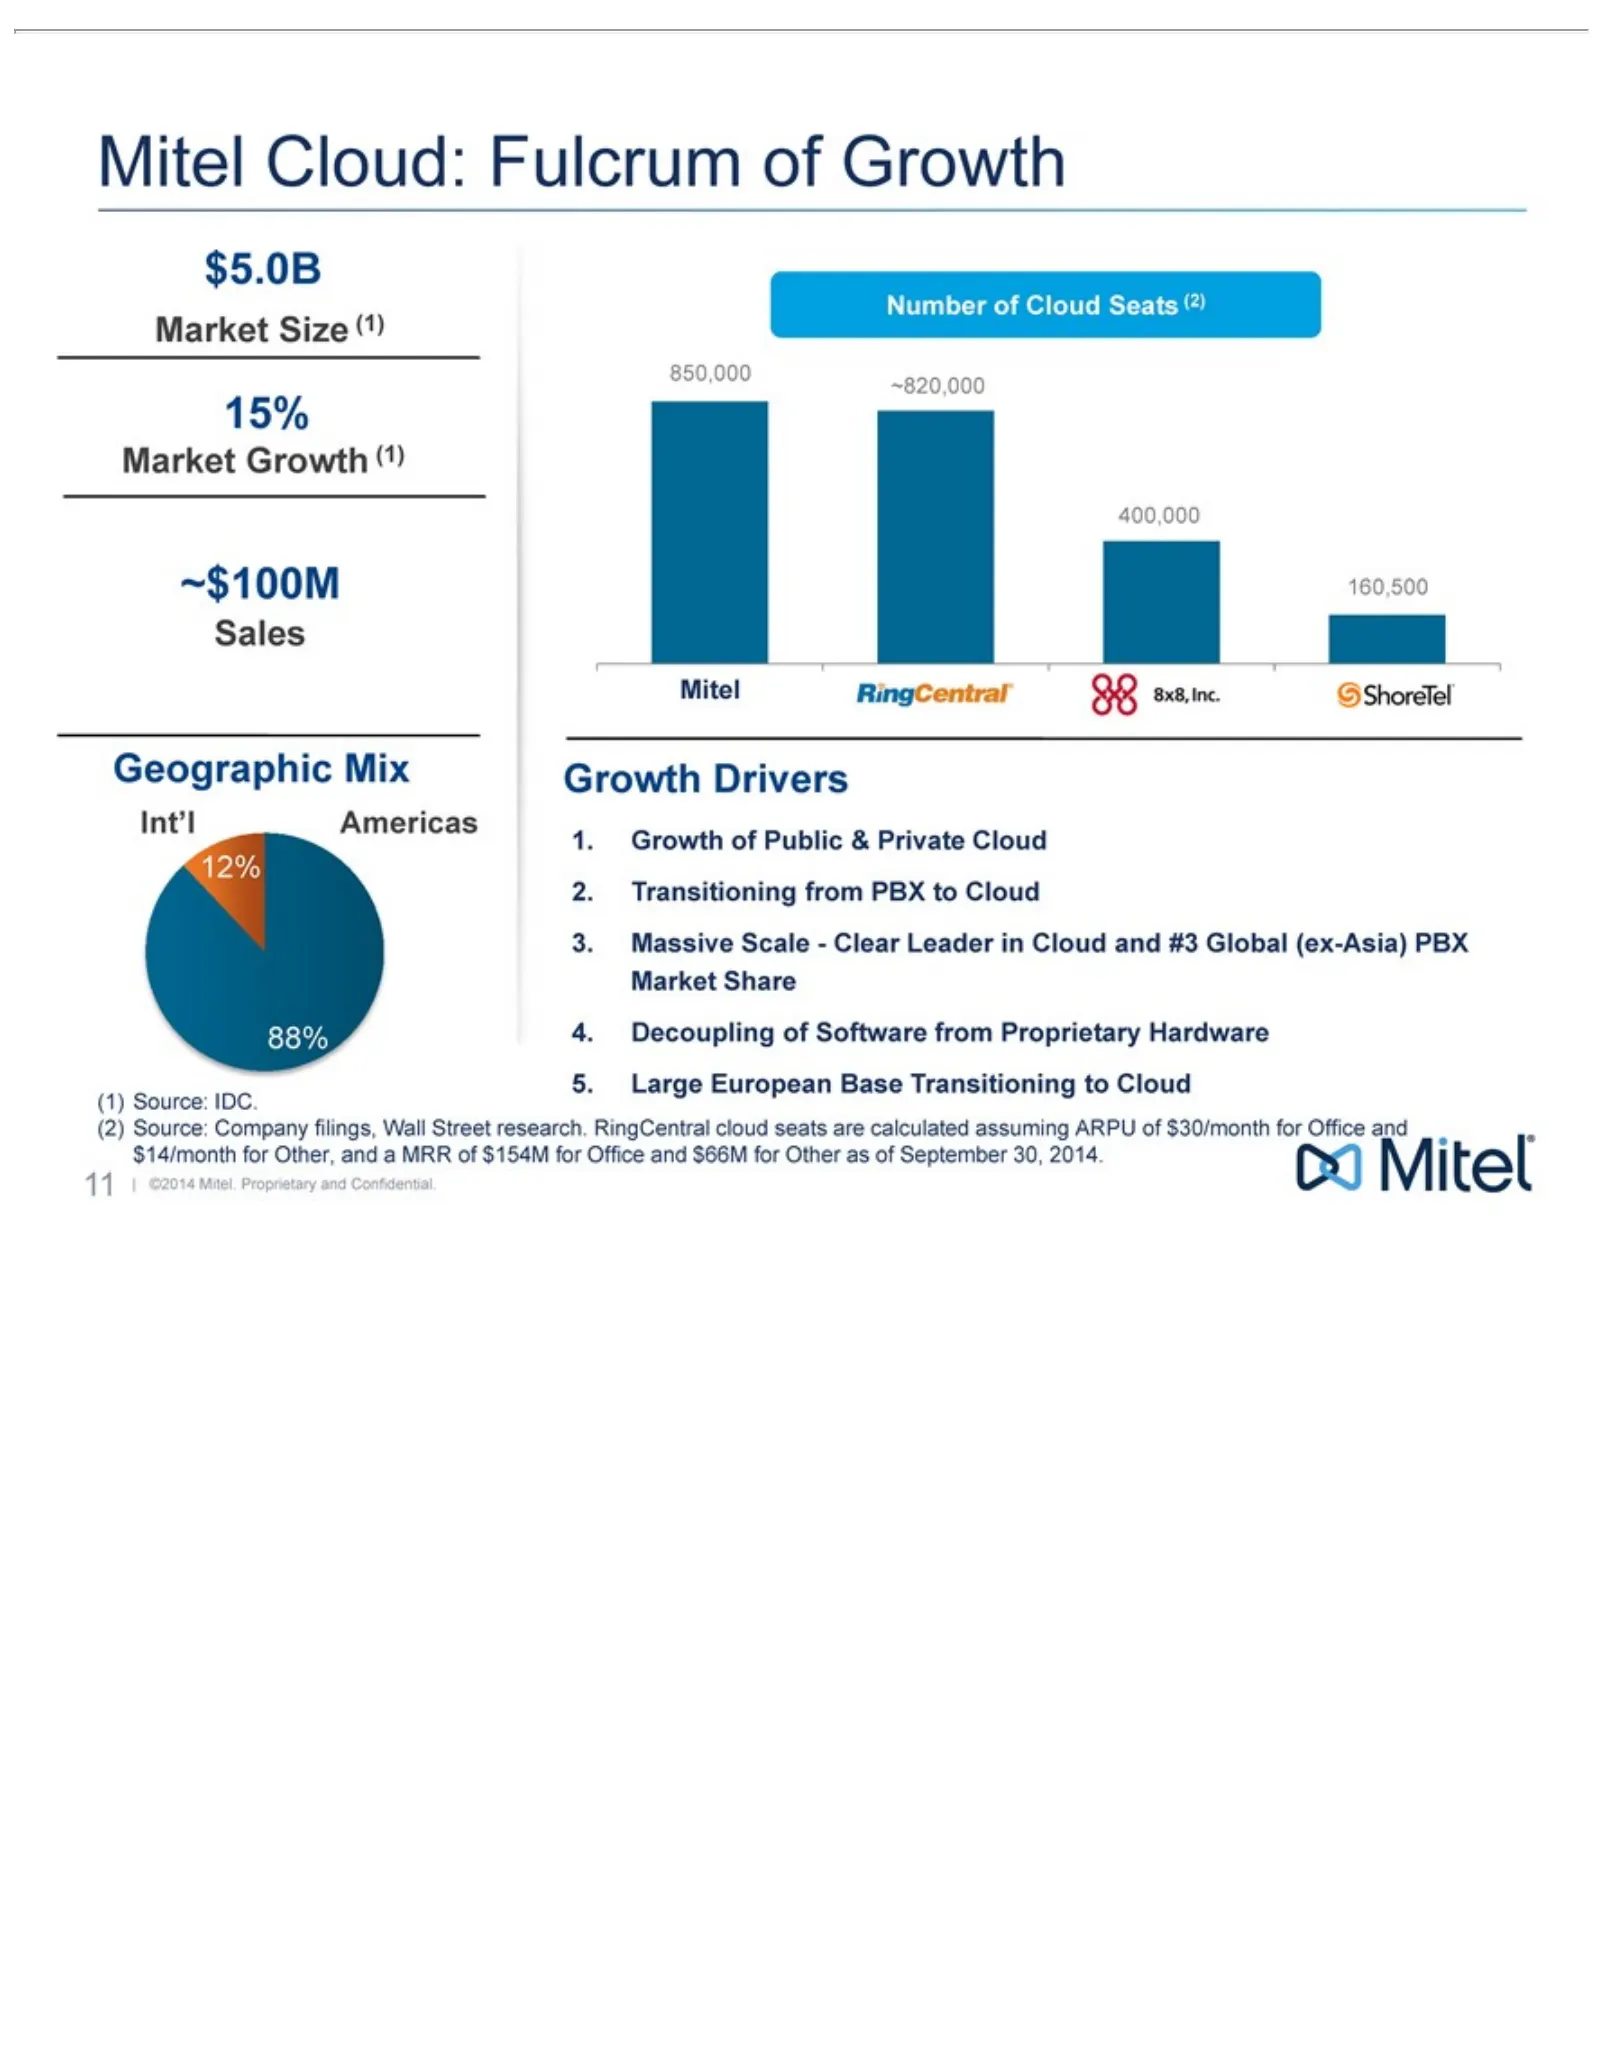
Slide 11: Cloud: $5.0B Market
Int’l $5.0B Market 15% Geographic Sales $100M Number Growth mitel Mitel 160,500 400,000 820,000 850,000 1. 2. 3. 4. 5. (1) 88% 12% Americas (2)Transitioning Growth Massive Decoupling Large Cloud: Size Growth September 11 Drivers Source: of European of |Source: ©2014 Scale—Clear Cloud Mix (1) Public
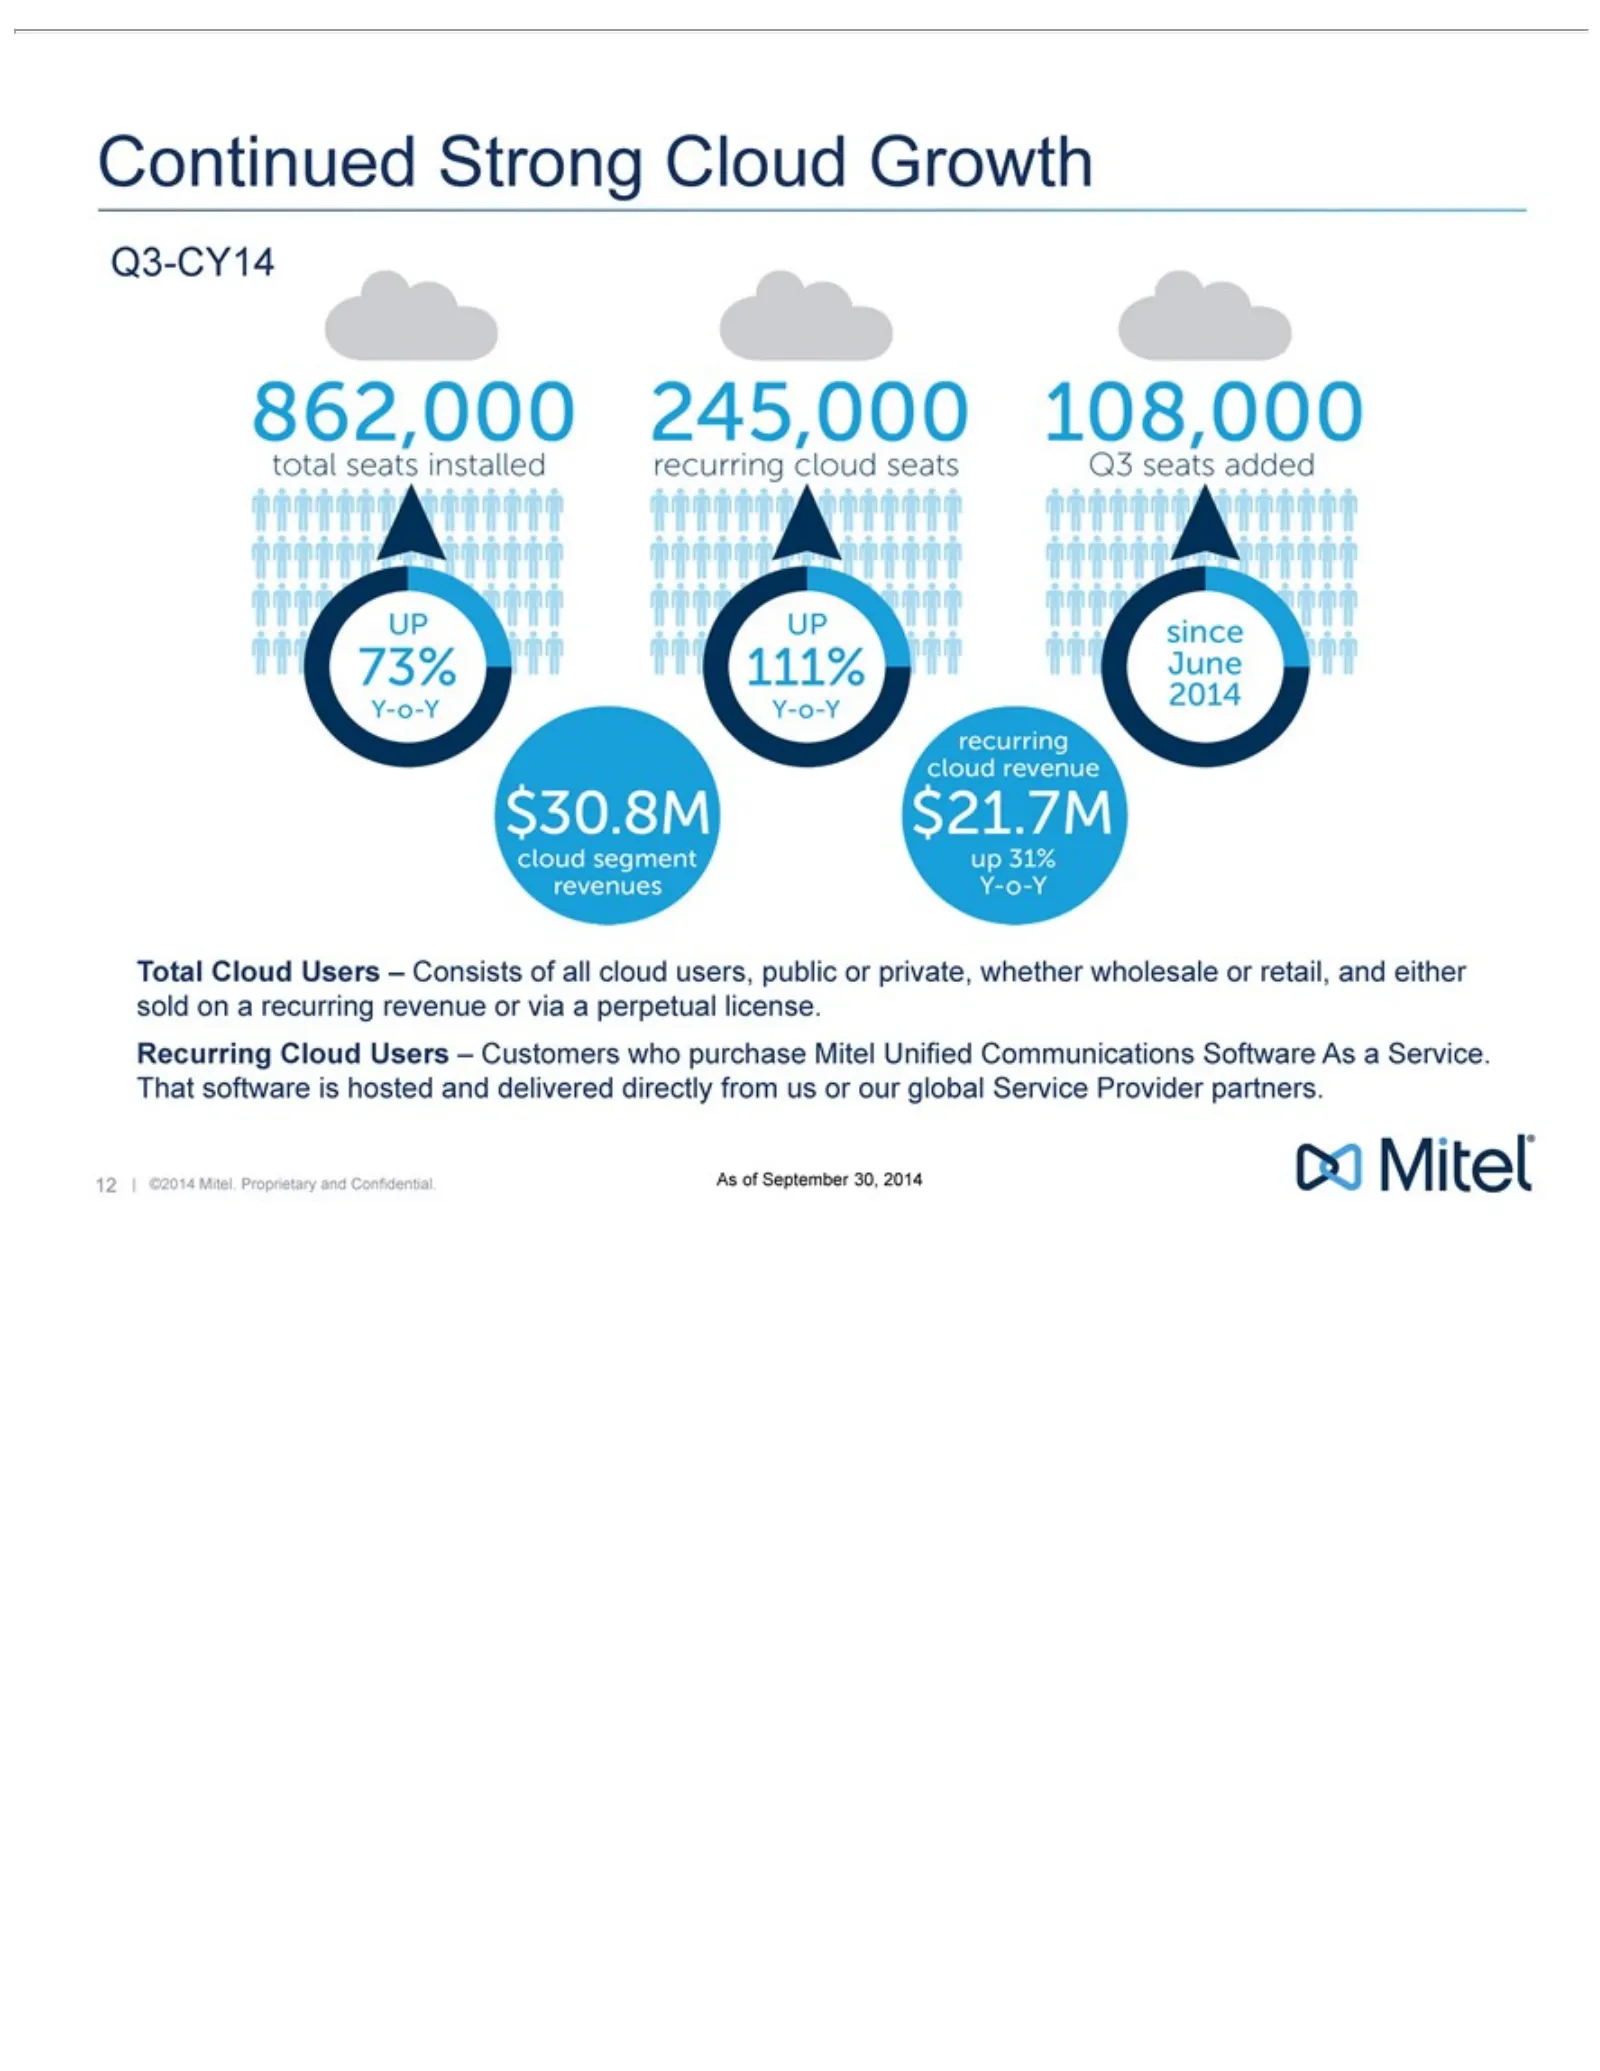
Slide 12: Continued Strong Cloud Growth
Continued total 862,000 Q3-CY14 245,000 UP Q3 108,000 $30.8M recurring Total Recurring 12 |seats 73% 111% ©2014 seats Cloud cloud Y-o-Y added cloud Y-o-Y installed Cloud Strong Mitel. Users segment since seats revenue Users Cloud Proprietary – Consists June revenues –$21.7M Growth Customers 2014of a
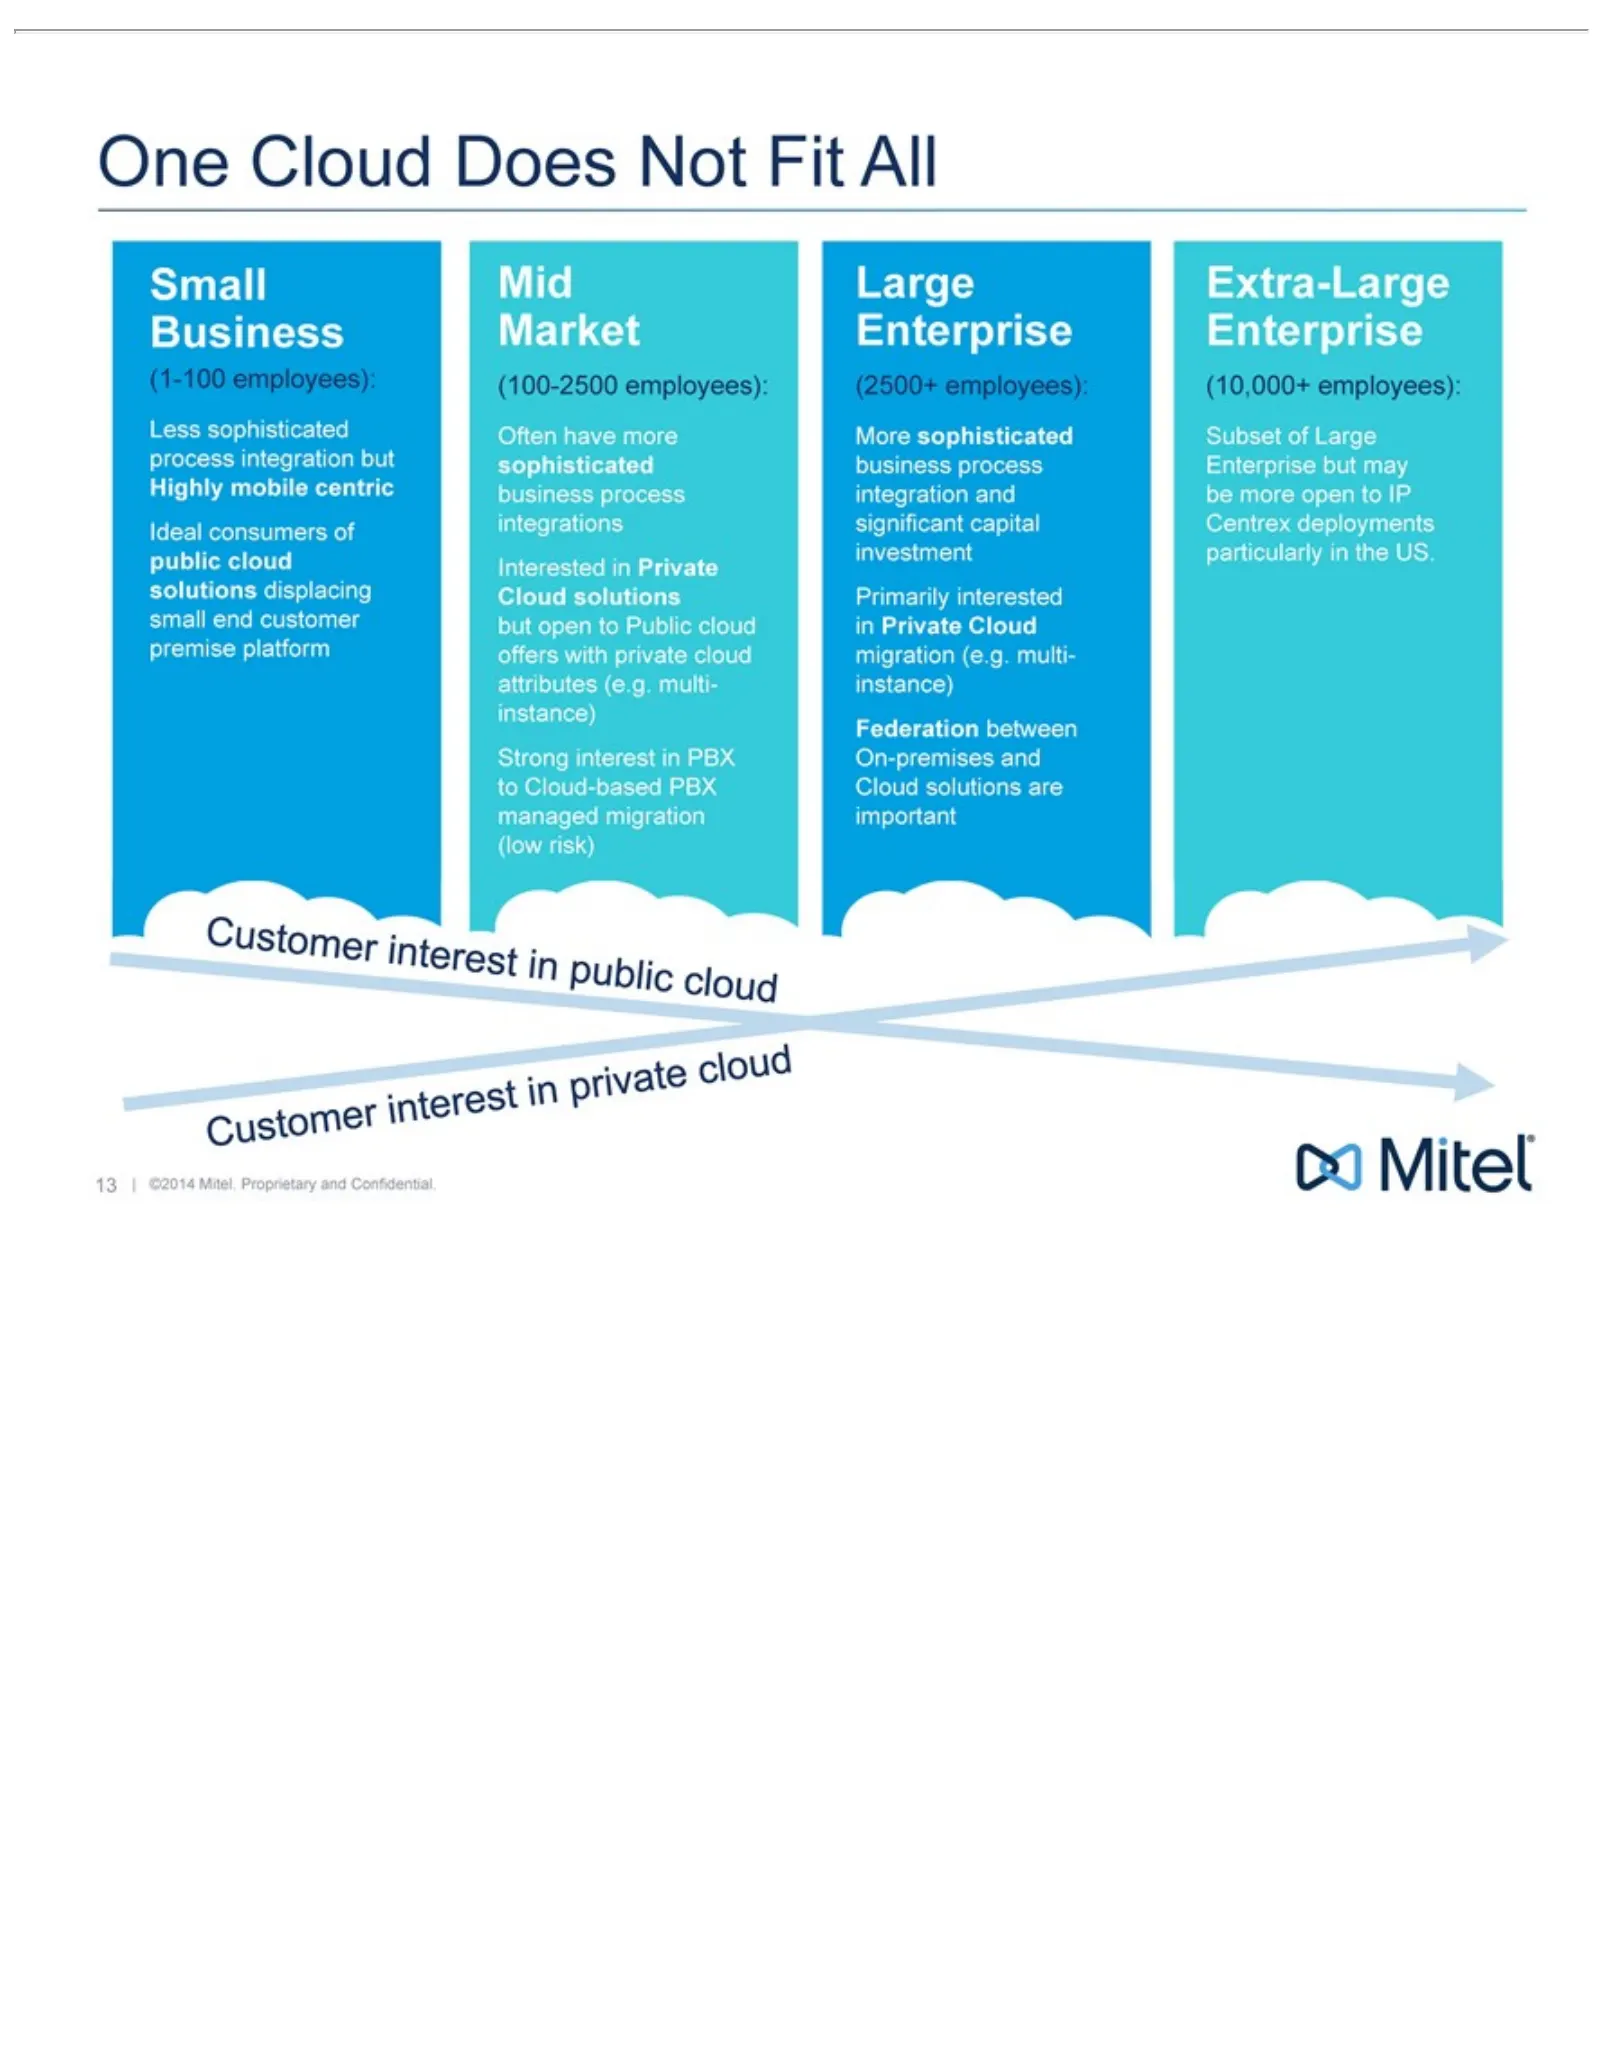
Slide 13: Cloud Market by Customer Size
As |of©2014 One Small (1-100 Less Highly Ideal Mid (100-2500 Interested Strong Large (2500+ More Primarily Federation Extra-Large (10,000+ Customer 13 Cloud Market sophisticated consumers sophisticated September Enterprise Business employees): interest mobile employees): employees): interested inter
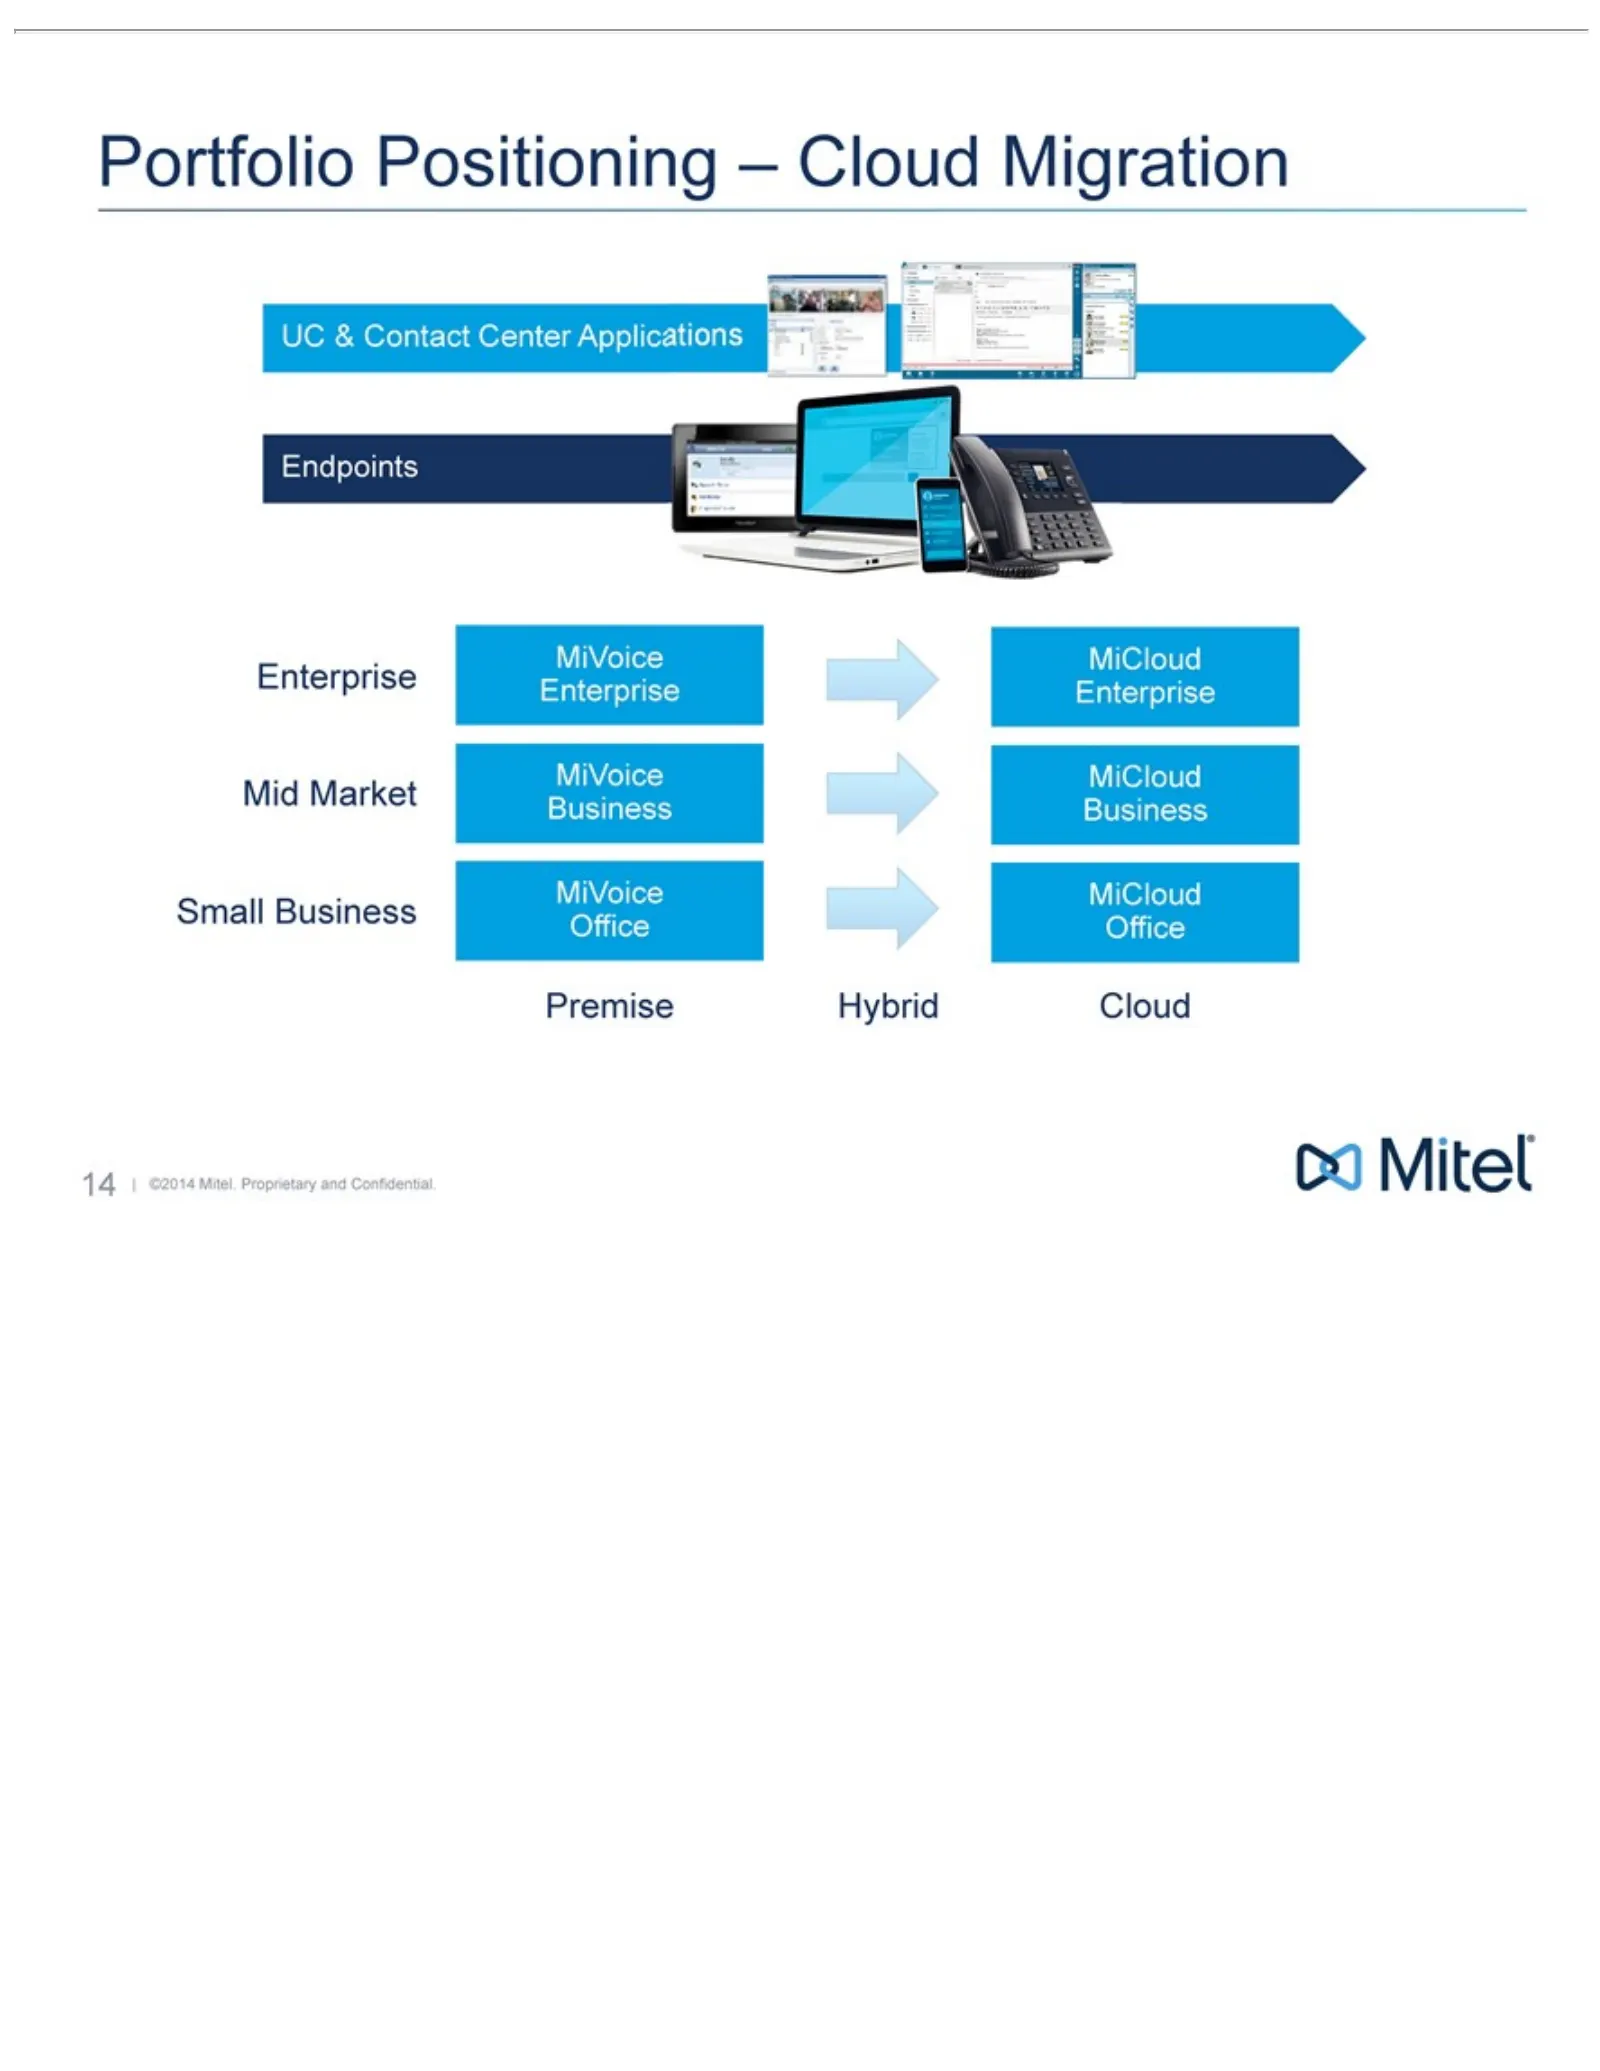
Slide 14: Portfolio and Cloud Migration Positioning
Portfolio UC Mid Enterprise Endpoints Small MiVoice Hybrid Premise MiCloud 14 Cloud |& ©2014 Market Business Contact Enterprise Business Office Positioning Enterprise Business Office Mitel. Center Proprietary –Applications Cloud Migration and Confidential.
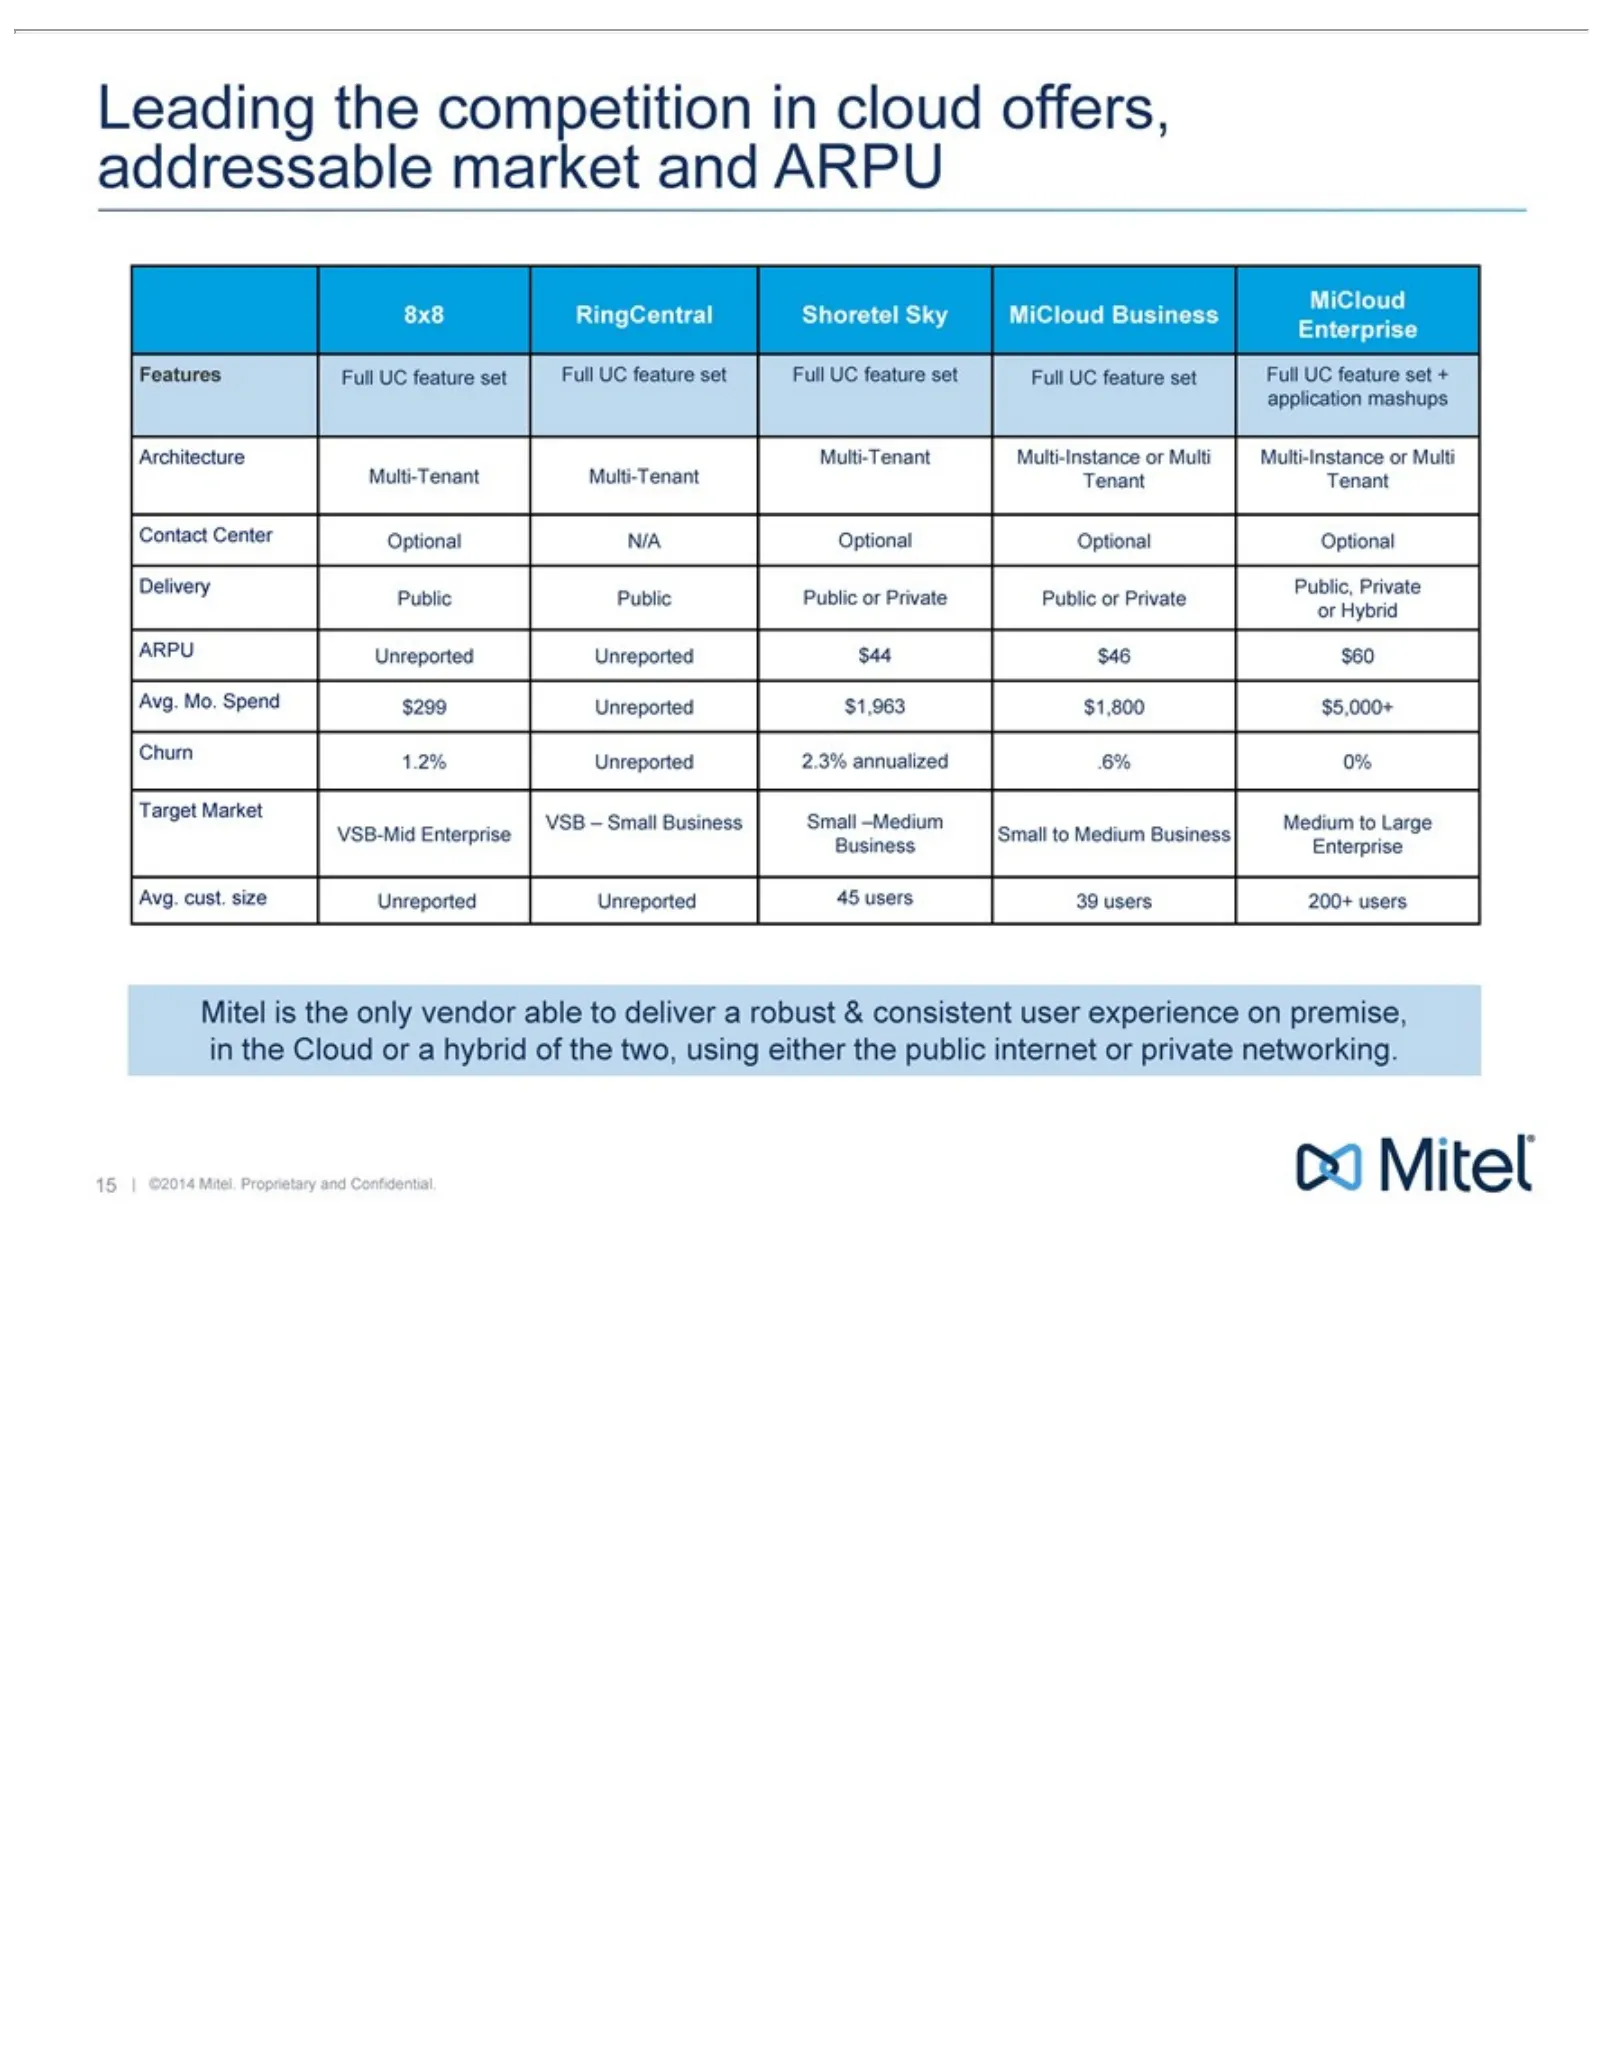
Slide 15: Leading Cloud Architecture and Competitors
Leading Contact Architecture Features ARPU Delivery Target Churn Avg. 8x8 VSB-Mid 1.2% $299 RingCentral VSB N/A Shoretel Unreported Multi-Tenant 2.3% $1,963 $44 45 Public Small .6% $1,800 $46 39 MiCloud Full Multi-Instance Public, Optional Medium 0% $5,000+ $60 200+ Mitel 15 |users ©2014 UC Mo. cust
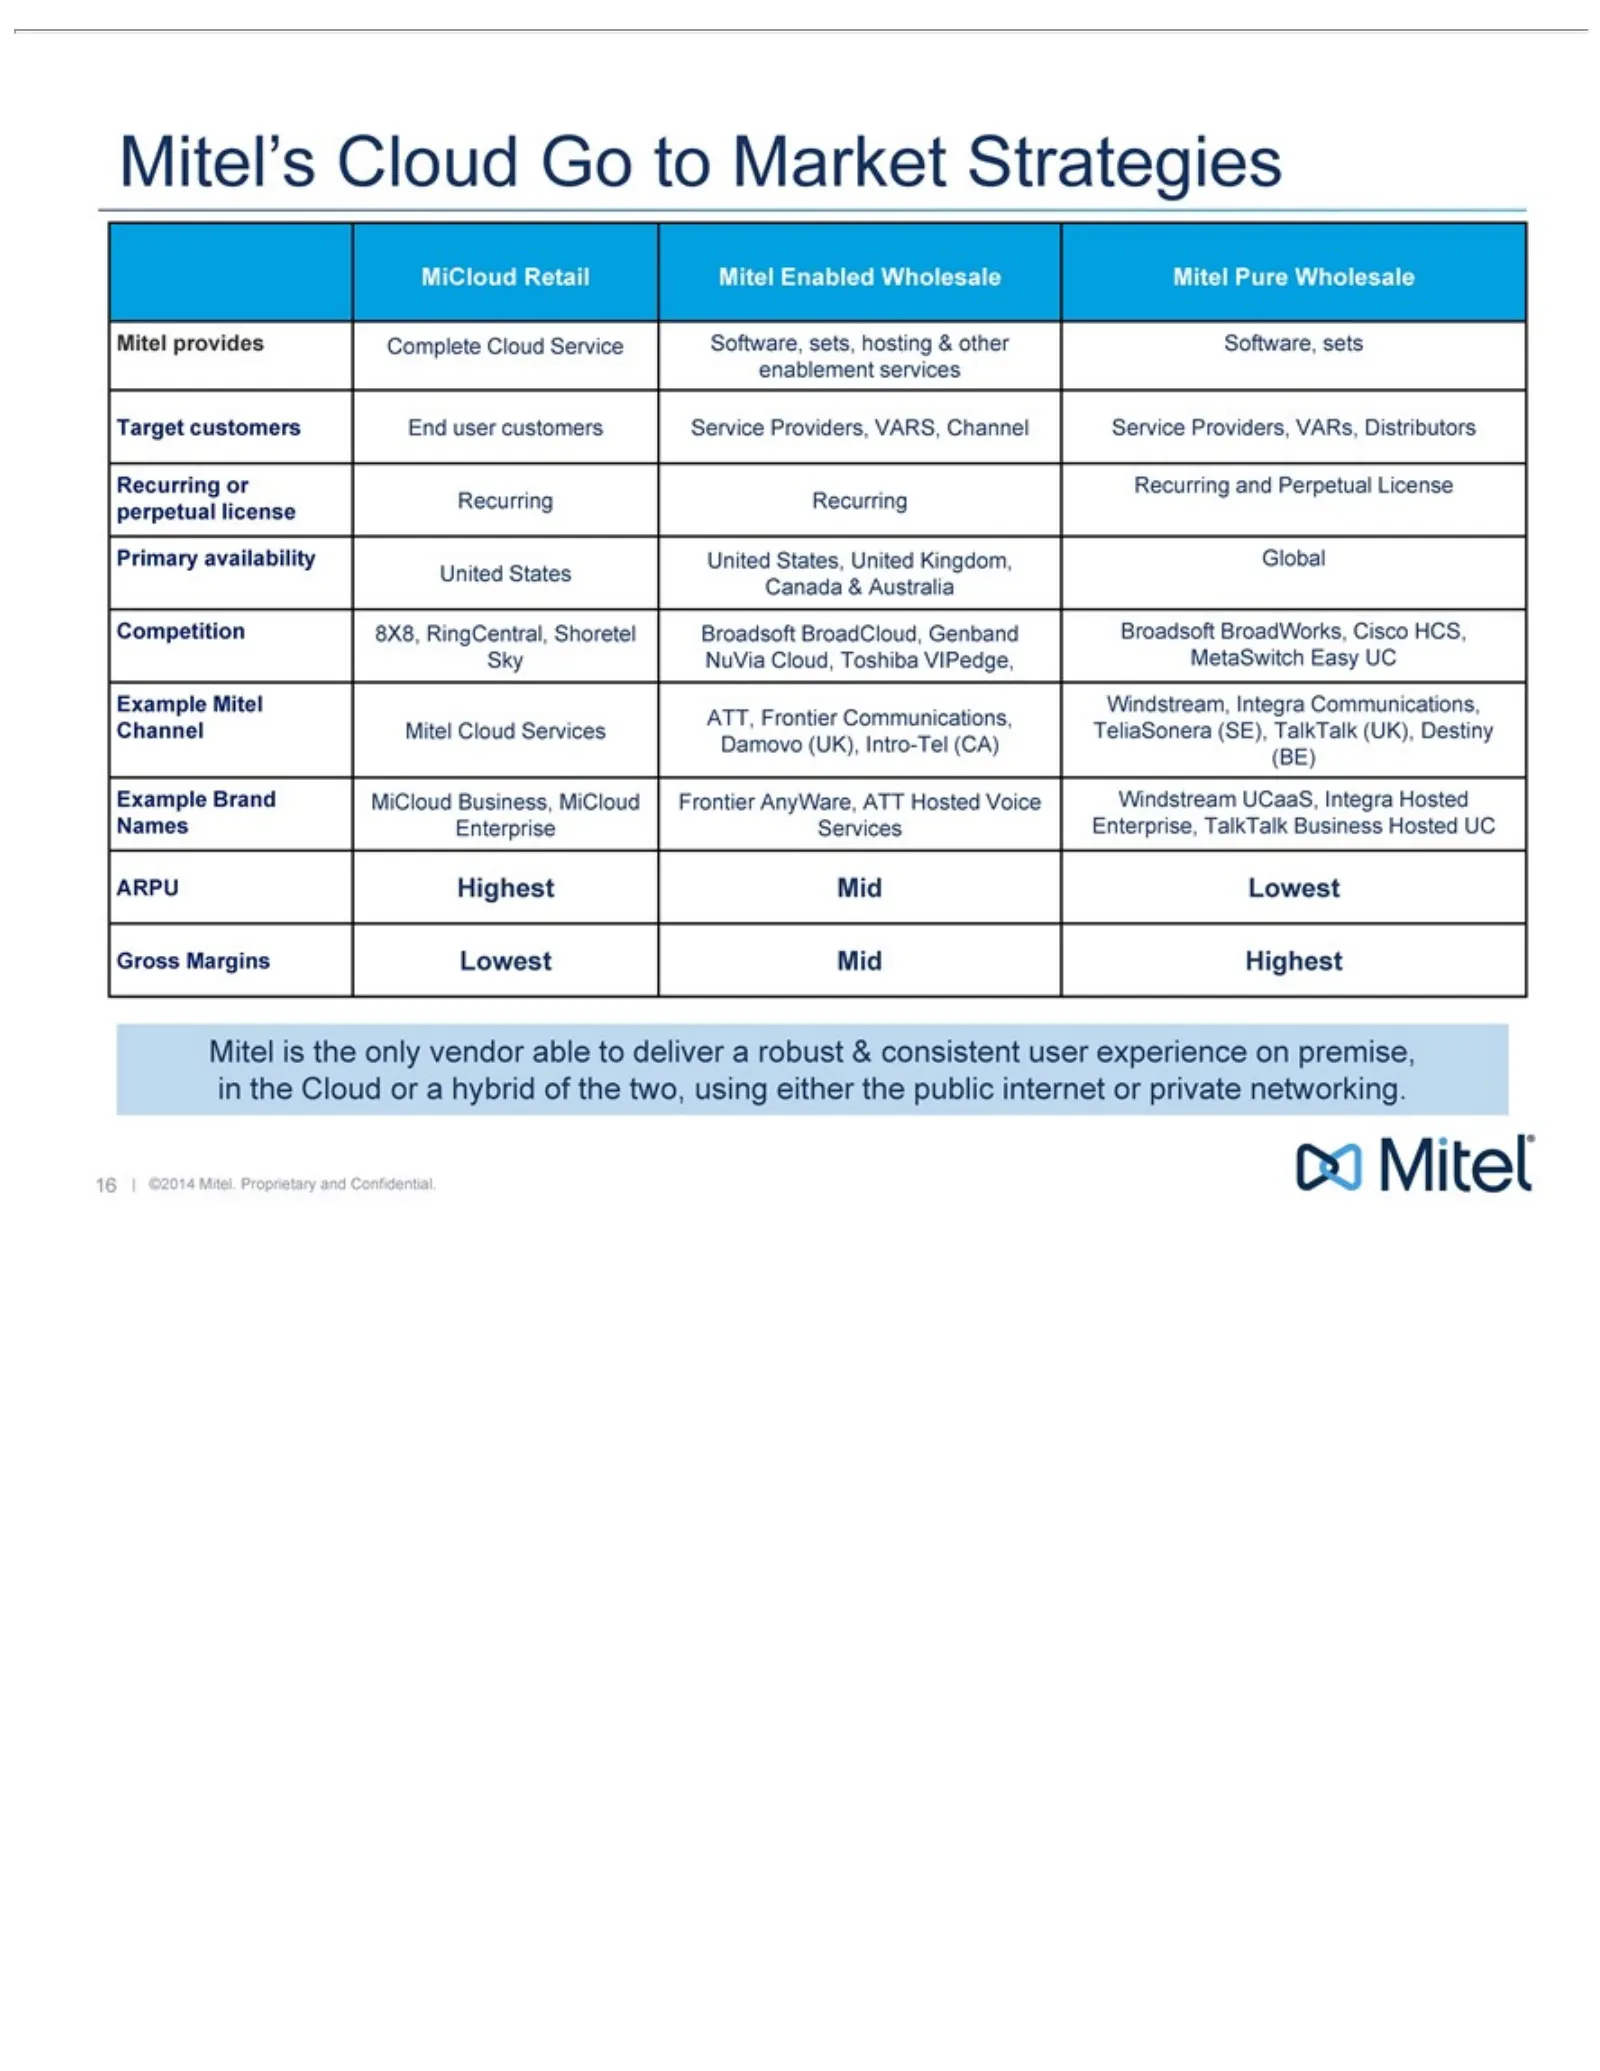
Slide 16: Mitel's Target Market and Go-To-Market Strategies
Mitel’s Target Primary Competition Example Channel Gross ARPU Complete End 8X8, MiCloud United ATT, Damovo Frontier Mid Software, Service Recurring Broadsoft Global Windstream, TeliaSonera Windstream Mitel Highest Lowest 16 | ©2014 user RingCentral, Frontier provides Cloud Enabled Pure is Margins cu
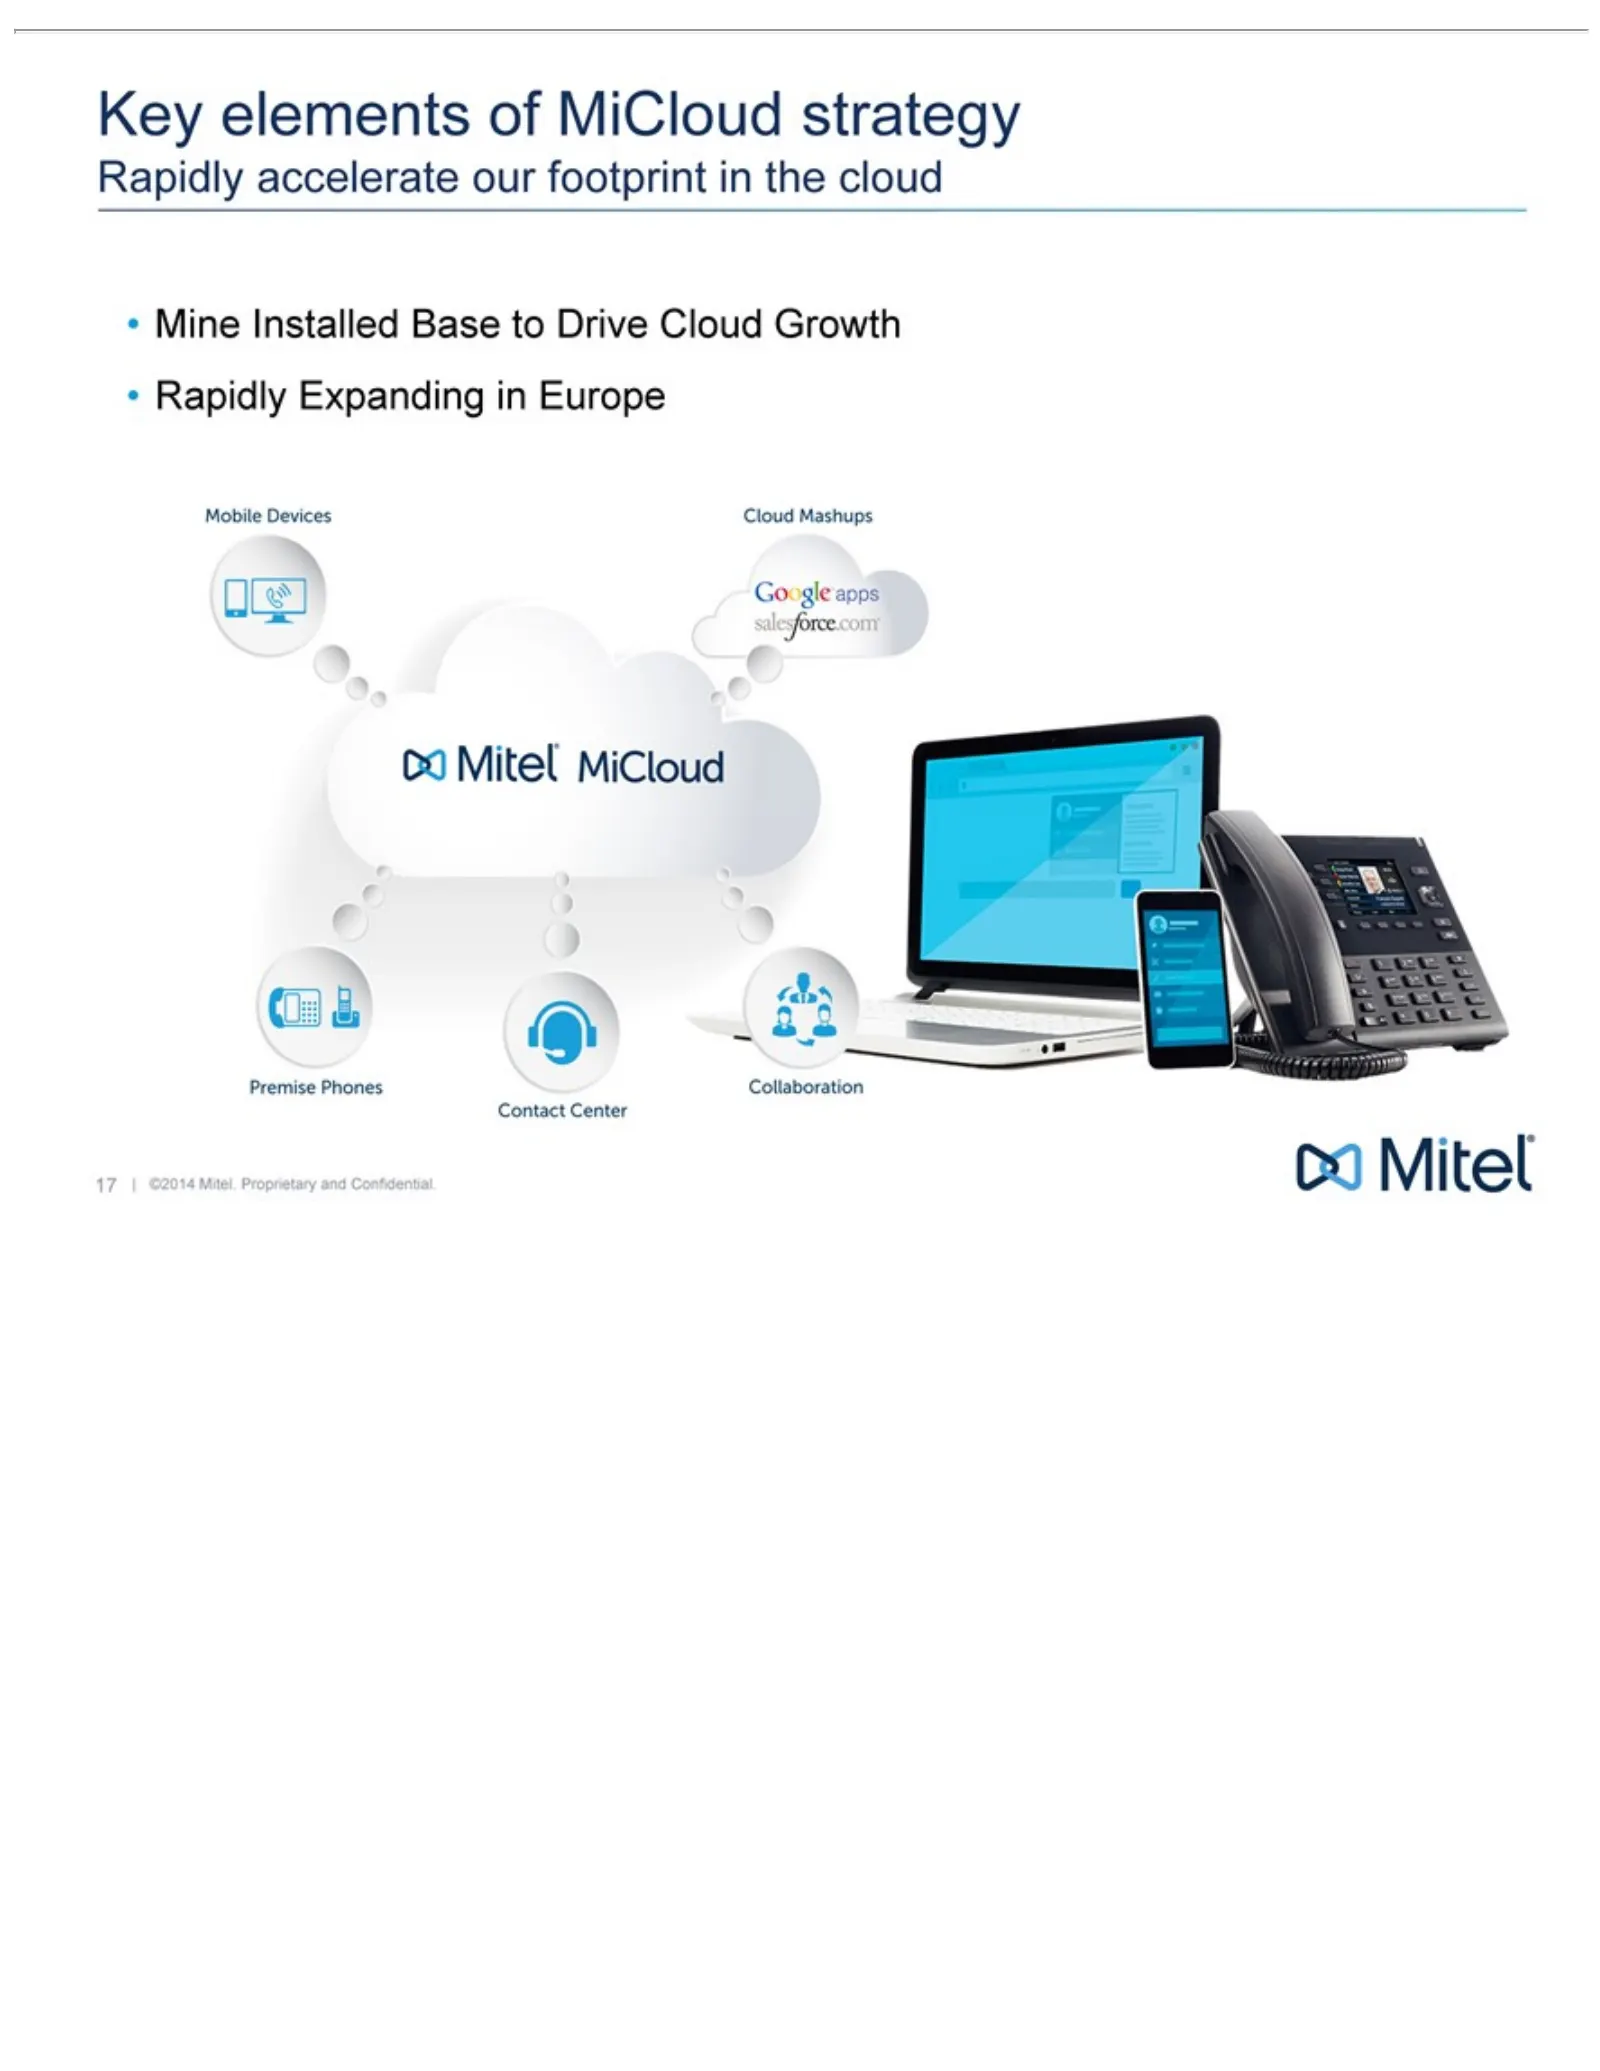
Slide 17: Key Elements of MiCloud Strategy
•17 | ©2014 Key Rapidly Mine elements accelerate Installed Rapidly of MiCloud our Basefootprint Expanding Mitel. tostrategy in Drive Europe Proprietary inCloud and the cloud Growth Confidential.
Slide 18: Why Mitel Channel Wins
Why Established 60 Significant Expert 2,500 Solutions Flexible Support Integration 18 |million ©2014 Mitel Channel Channel today commercial solutions Leadership existing wins into New Mitel. opportunity for Partners broader with in Customer Hybrid, Proprietary enabling the Mitel models Flexible Clou
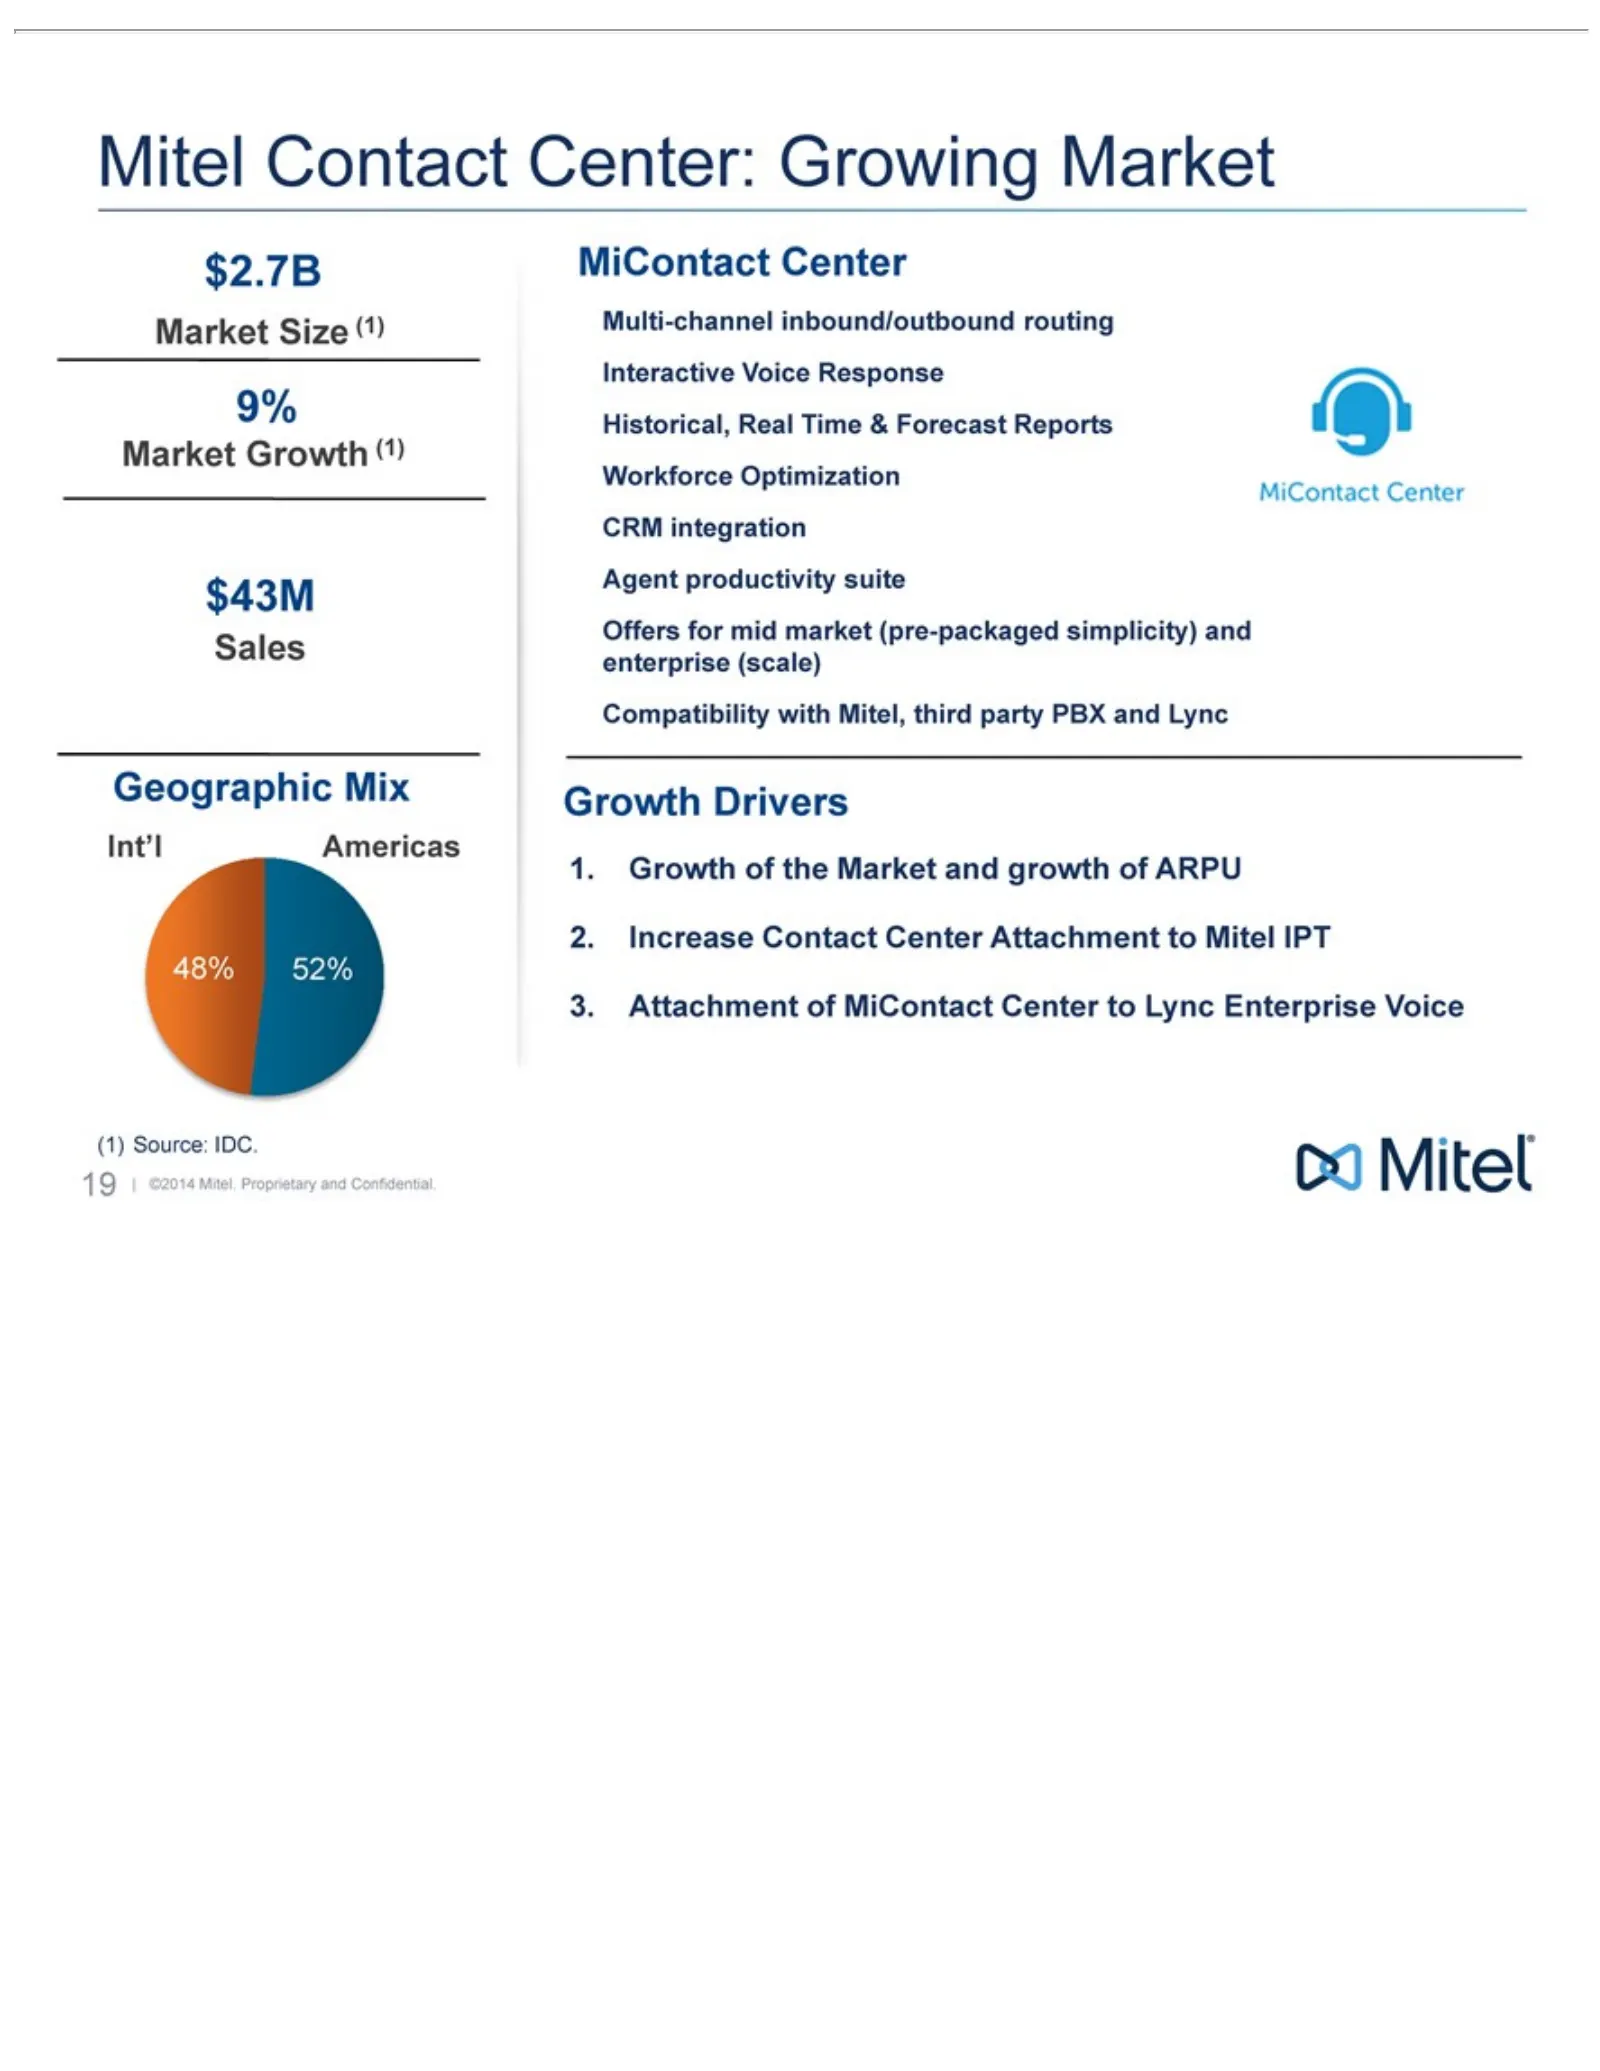
Slide 19: Contact Center: $2.7B Market
Mitel $2.7B Market 9% Geographic Sales $43M MiContact 52% 48% Americas Int’l Multi-channel Offers Growth 1. 2. 3. (1) 19 Attachment Growth Increase ©2014 Source: Contact for Size Growth Drivers mid Mitel. of Center Contact IDC. Mix (1) the Center: of inbound/outbound market (1) Market Proprietary Mi
Slide 20: MiContact Center Track Record of Growth
MiContact Revenue > Multi-channel Average 20100K | ©2014 agents revenue growth, Center Mitel. Contact sold per 3Proprietary Track Year annually agent Center track Record growth and record revenue ofConfidential. in Growth of mid up>20% market 56%growth YoY of 50% YoY
Slide 21: Financial Overview
Powering Overview Mitel Financial connections
Slide 22: Q3 2014 Results
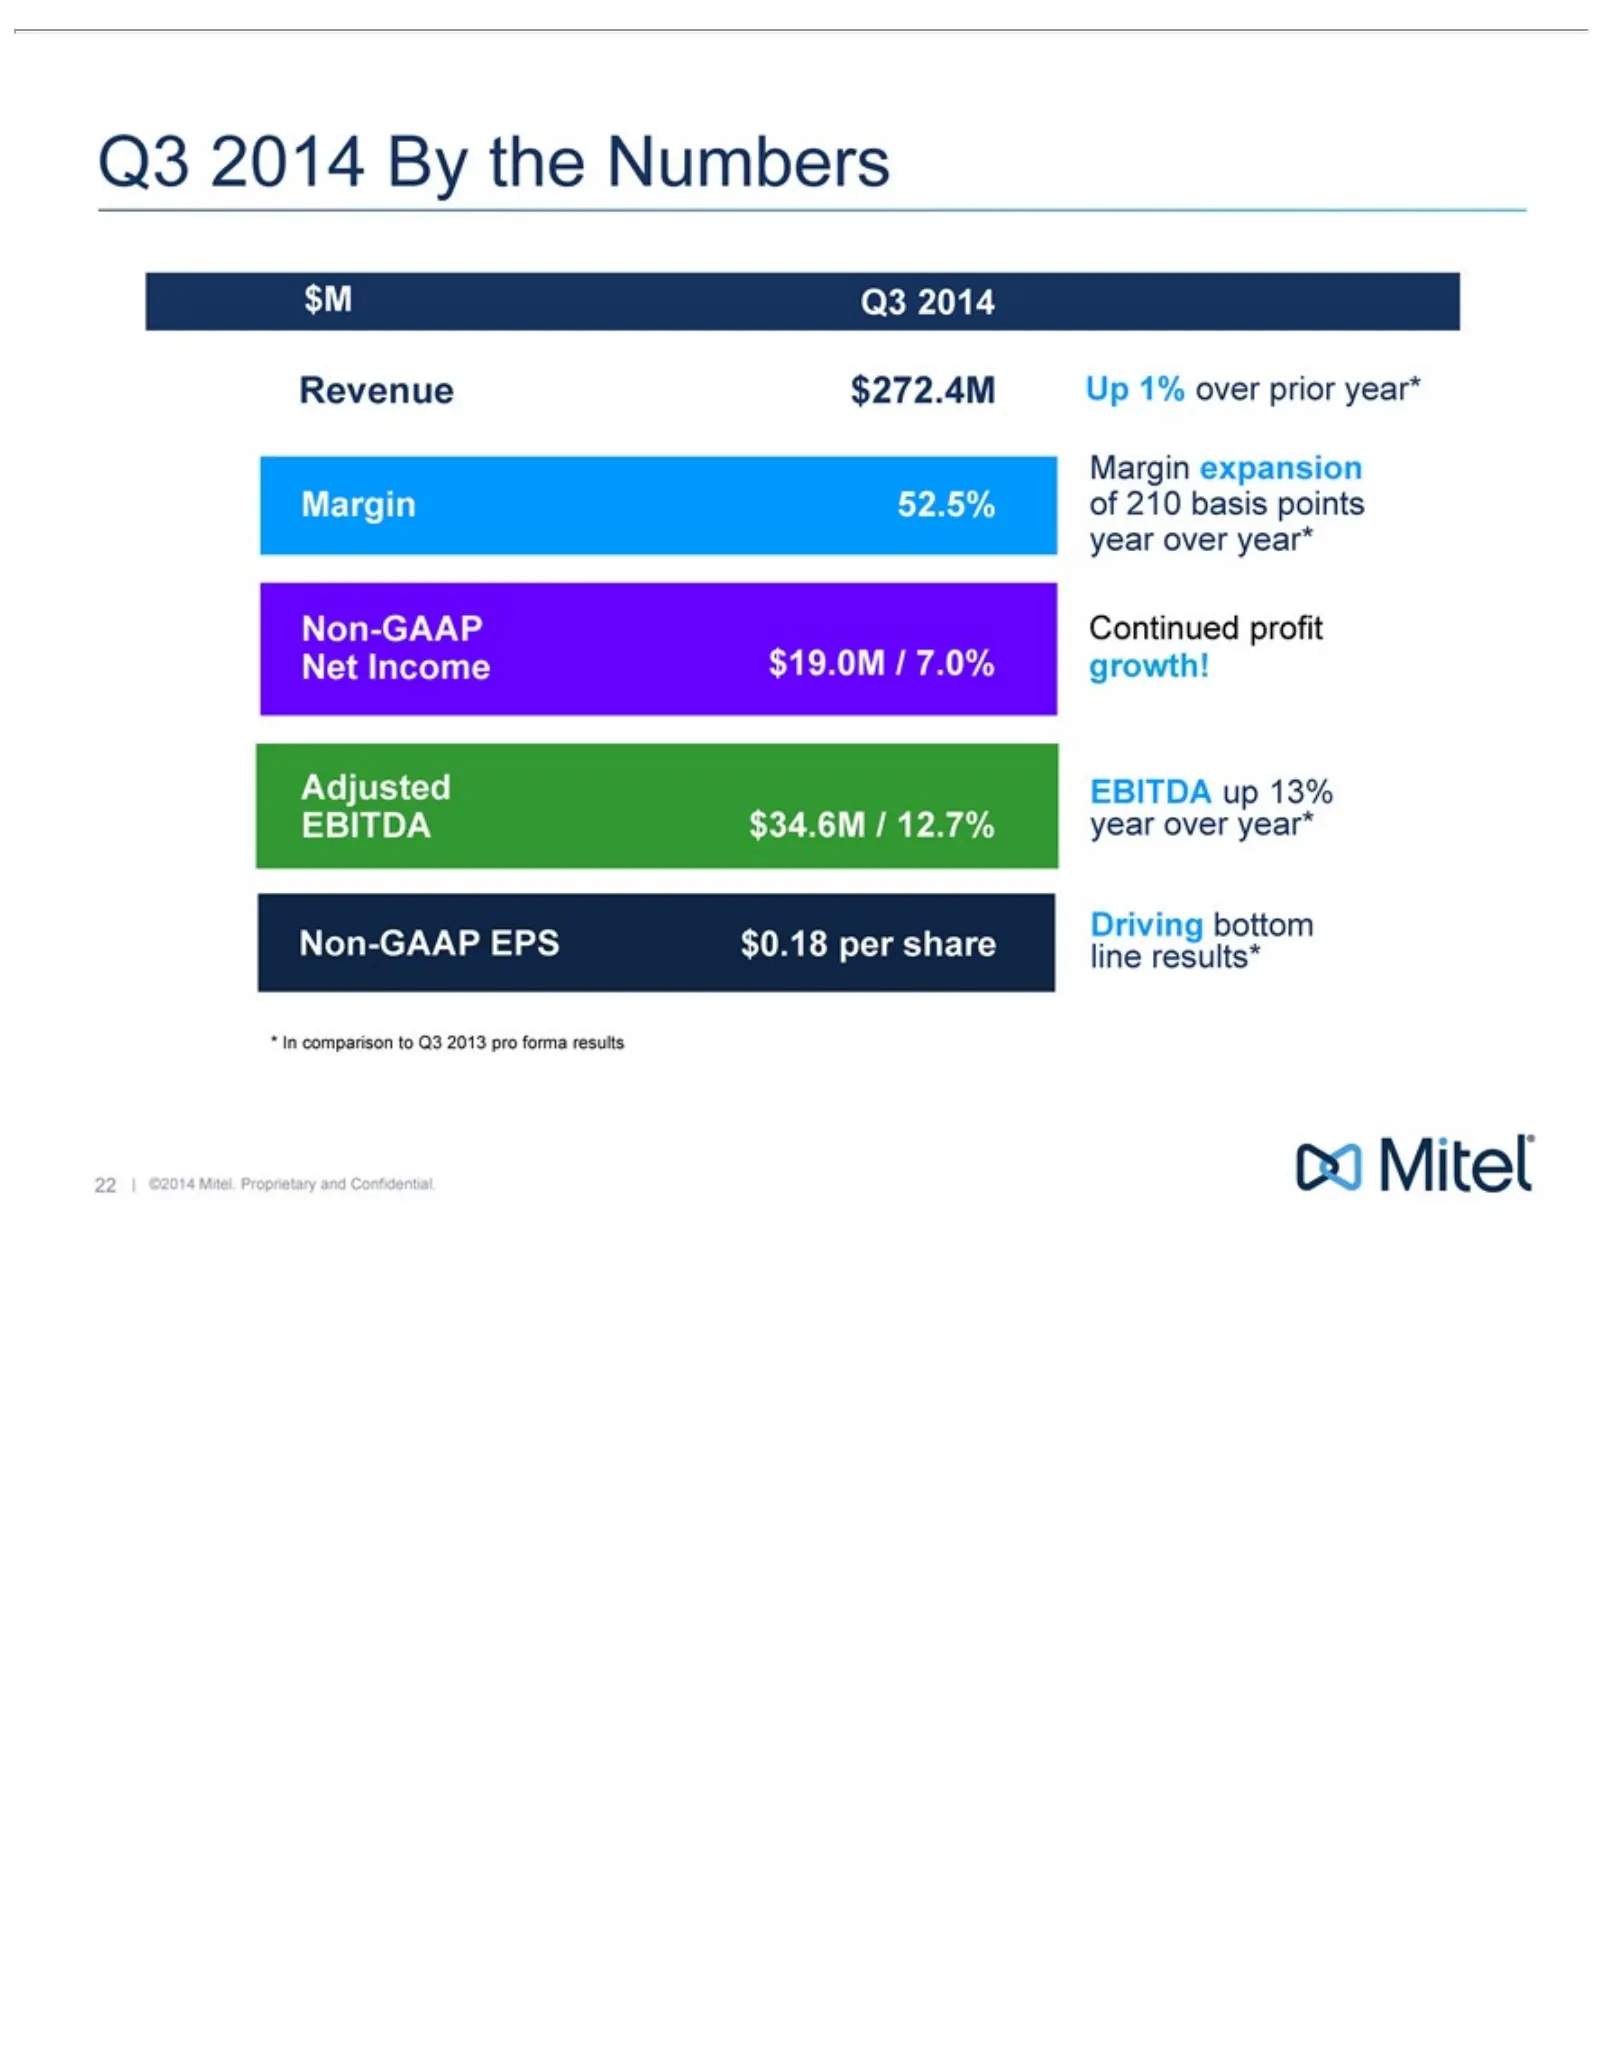
Revenue $M Non-GAAP Adjusted Q3 $272.4M $19.0M $34.6M $0.18 Up Continued EBITDA year *line 22In|1% 2014 ©2014 results* comparison over per over / By Margin up 52.5% 7.0% 12.7% year* share profit Mitel. Net EPS prior 13% the Driving Numbers Income to growth! year* Proprietary Q3 2013 Margin bottom pr
Slide 23: Restructuring and Synergies Progress
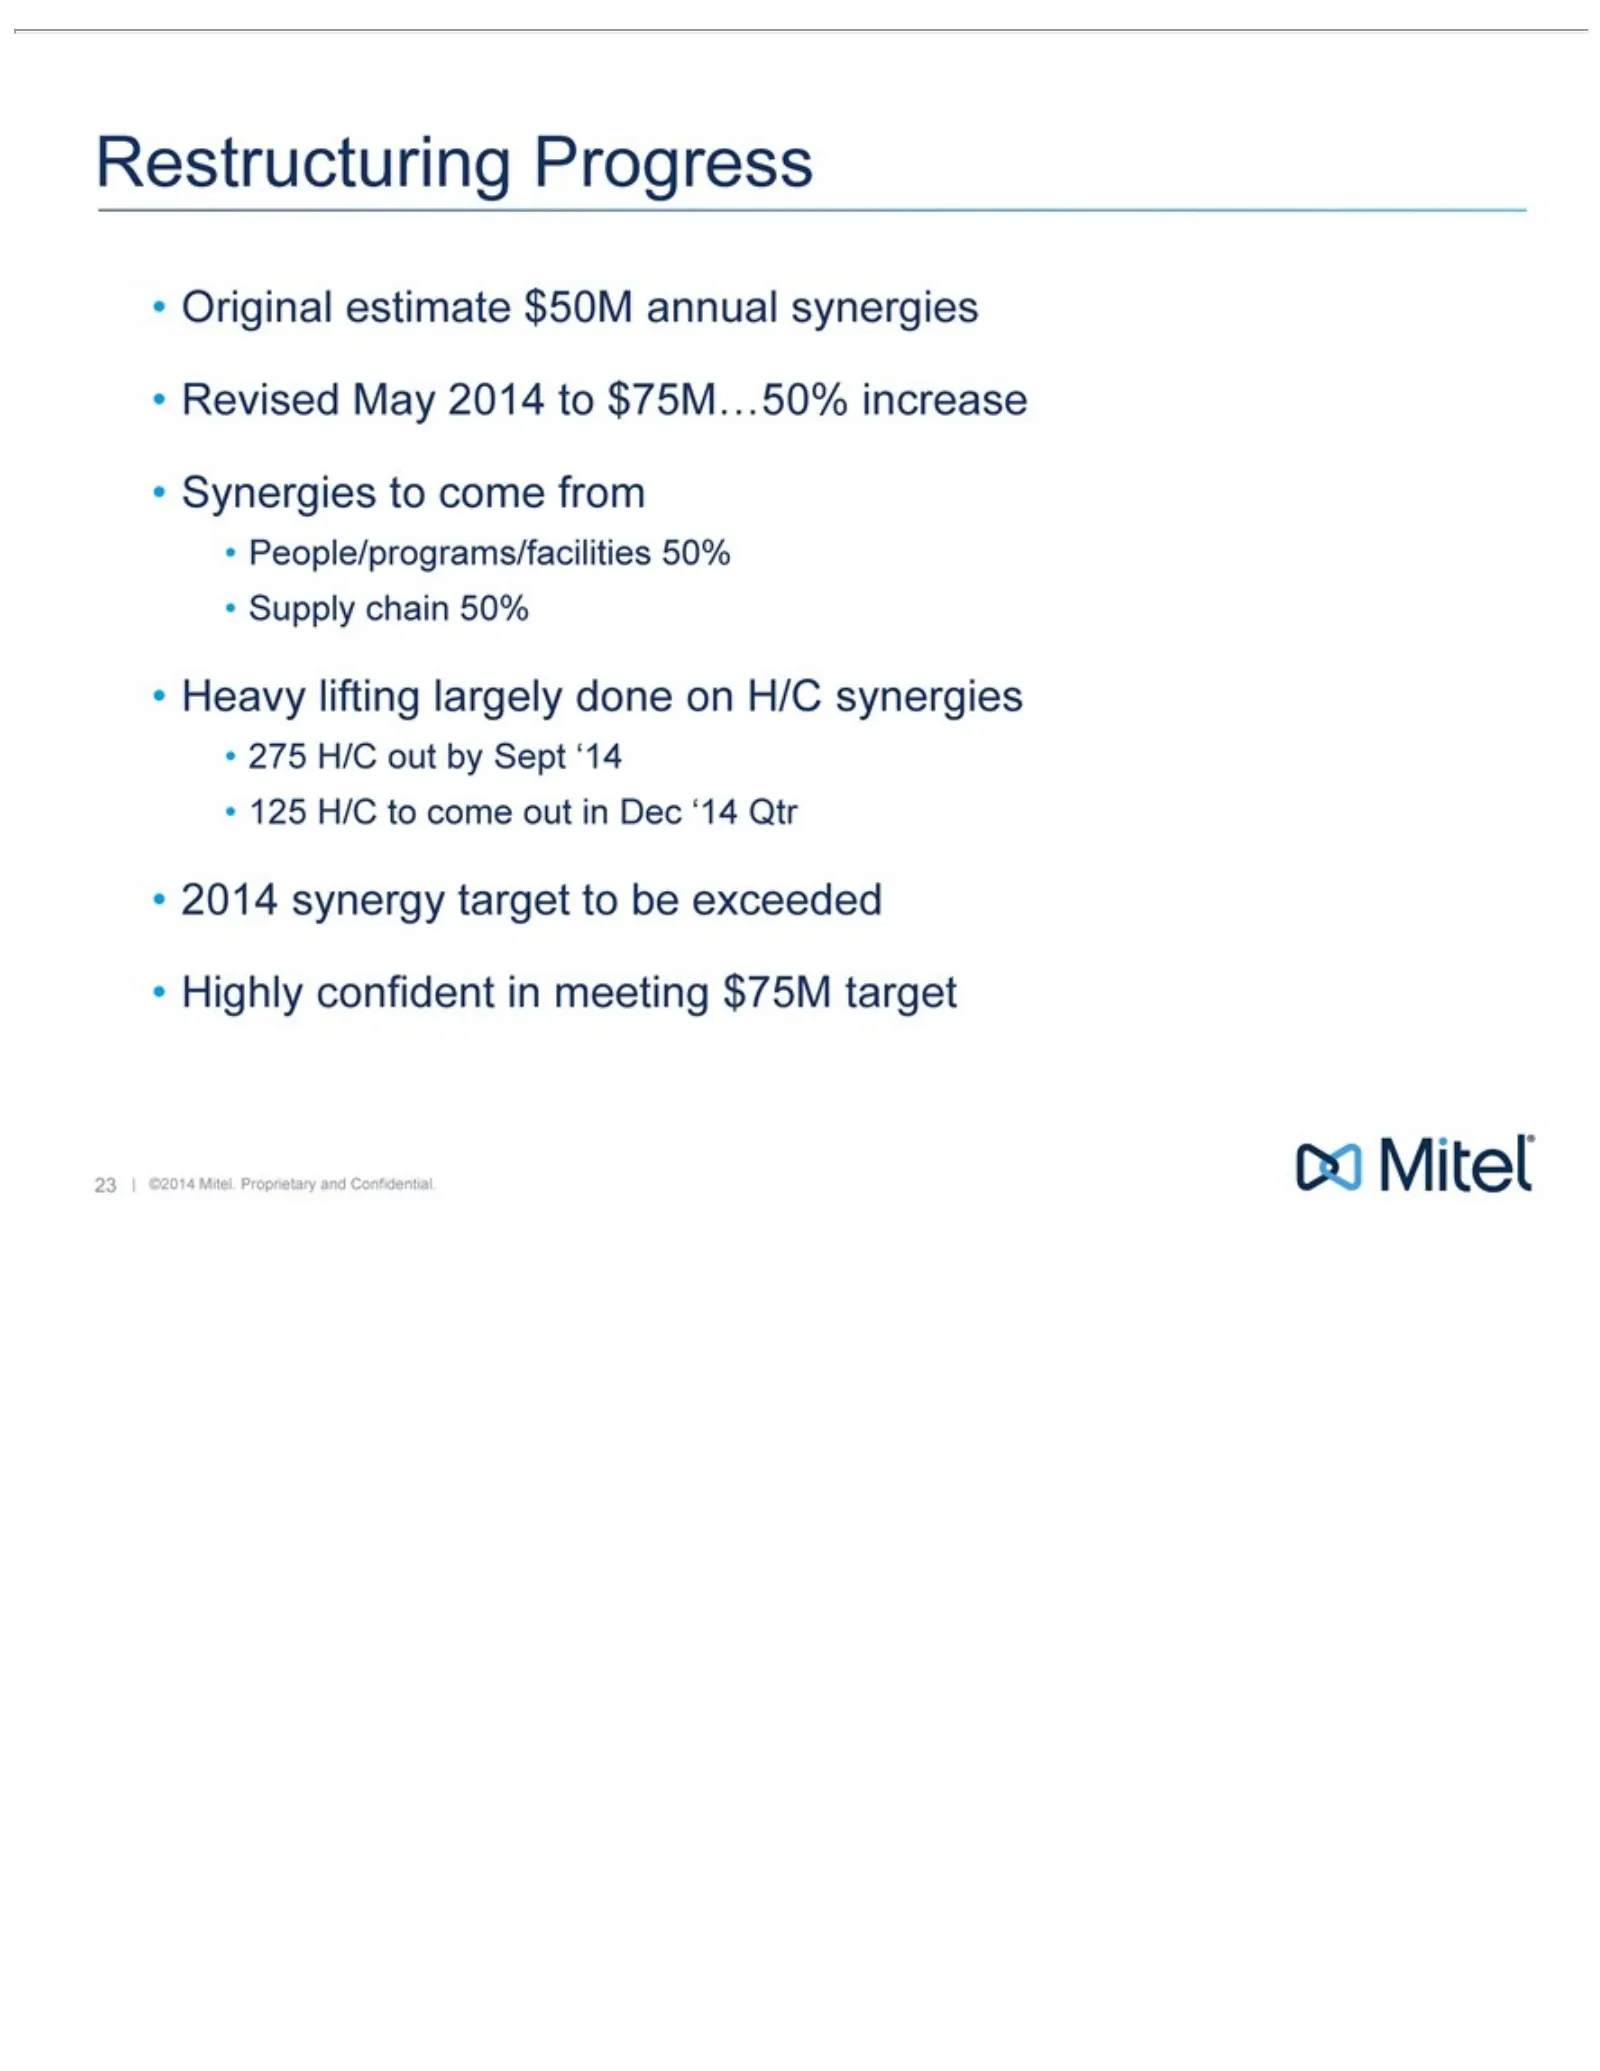
Restructuring Original Revised Synergies People/programs/facilities Supply Heavy 275 125 2014 Highly 23 | ©2014 H/C synergy lifting confident chain May estimate out totocome Mitel. by come 50% largely 2014 target Progress Sept in out $50M Proprietary from to meeting to‘14 done in $75M…50% beDec annu
Slide 24: Illustrative Currency Headwinds
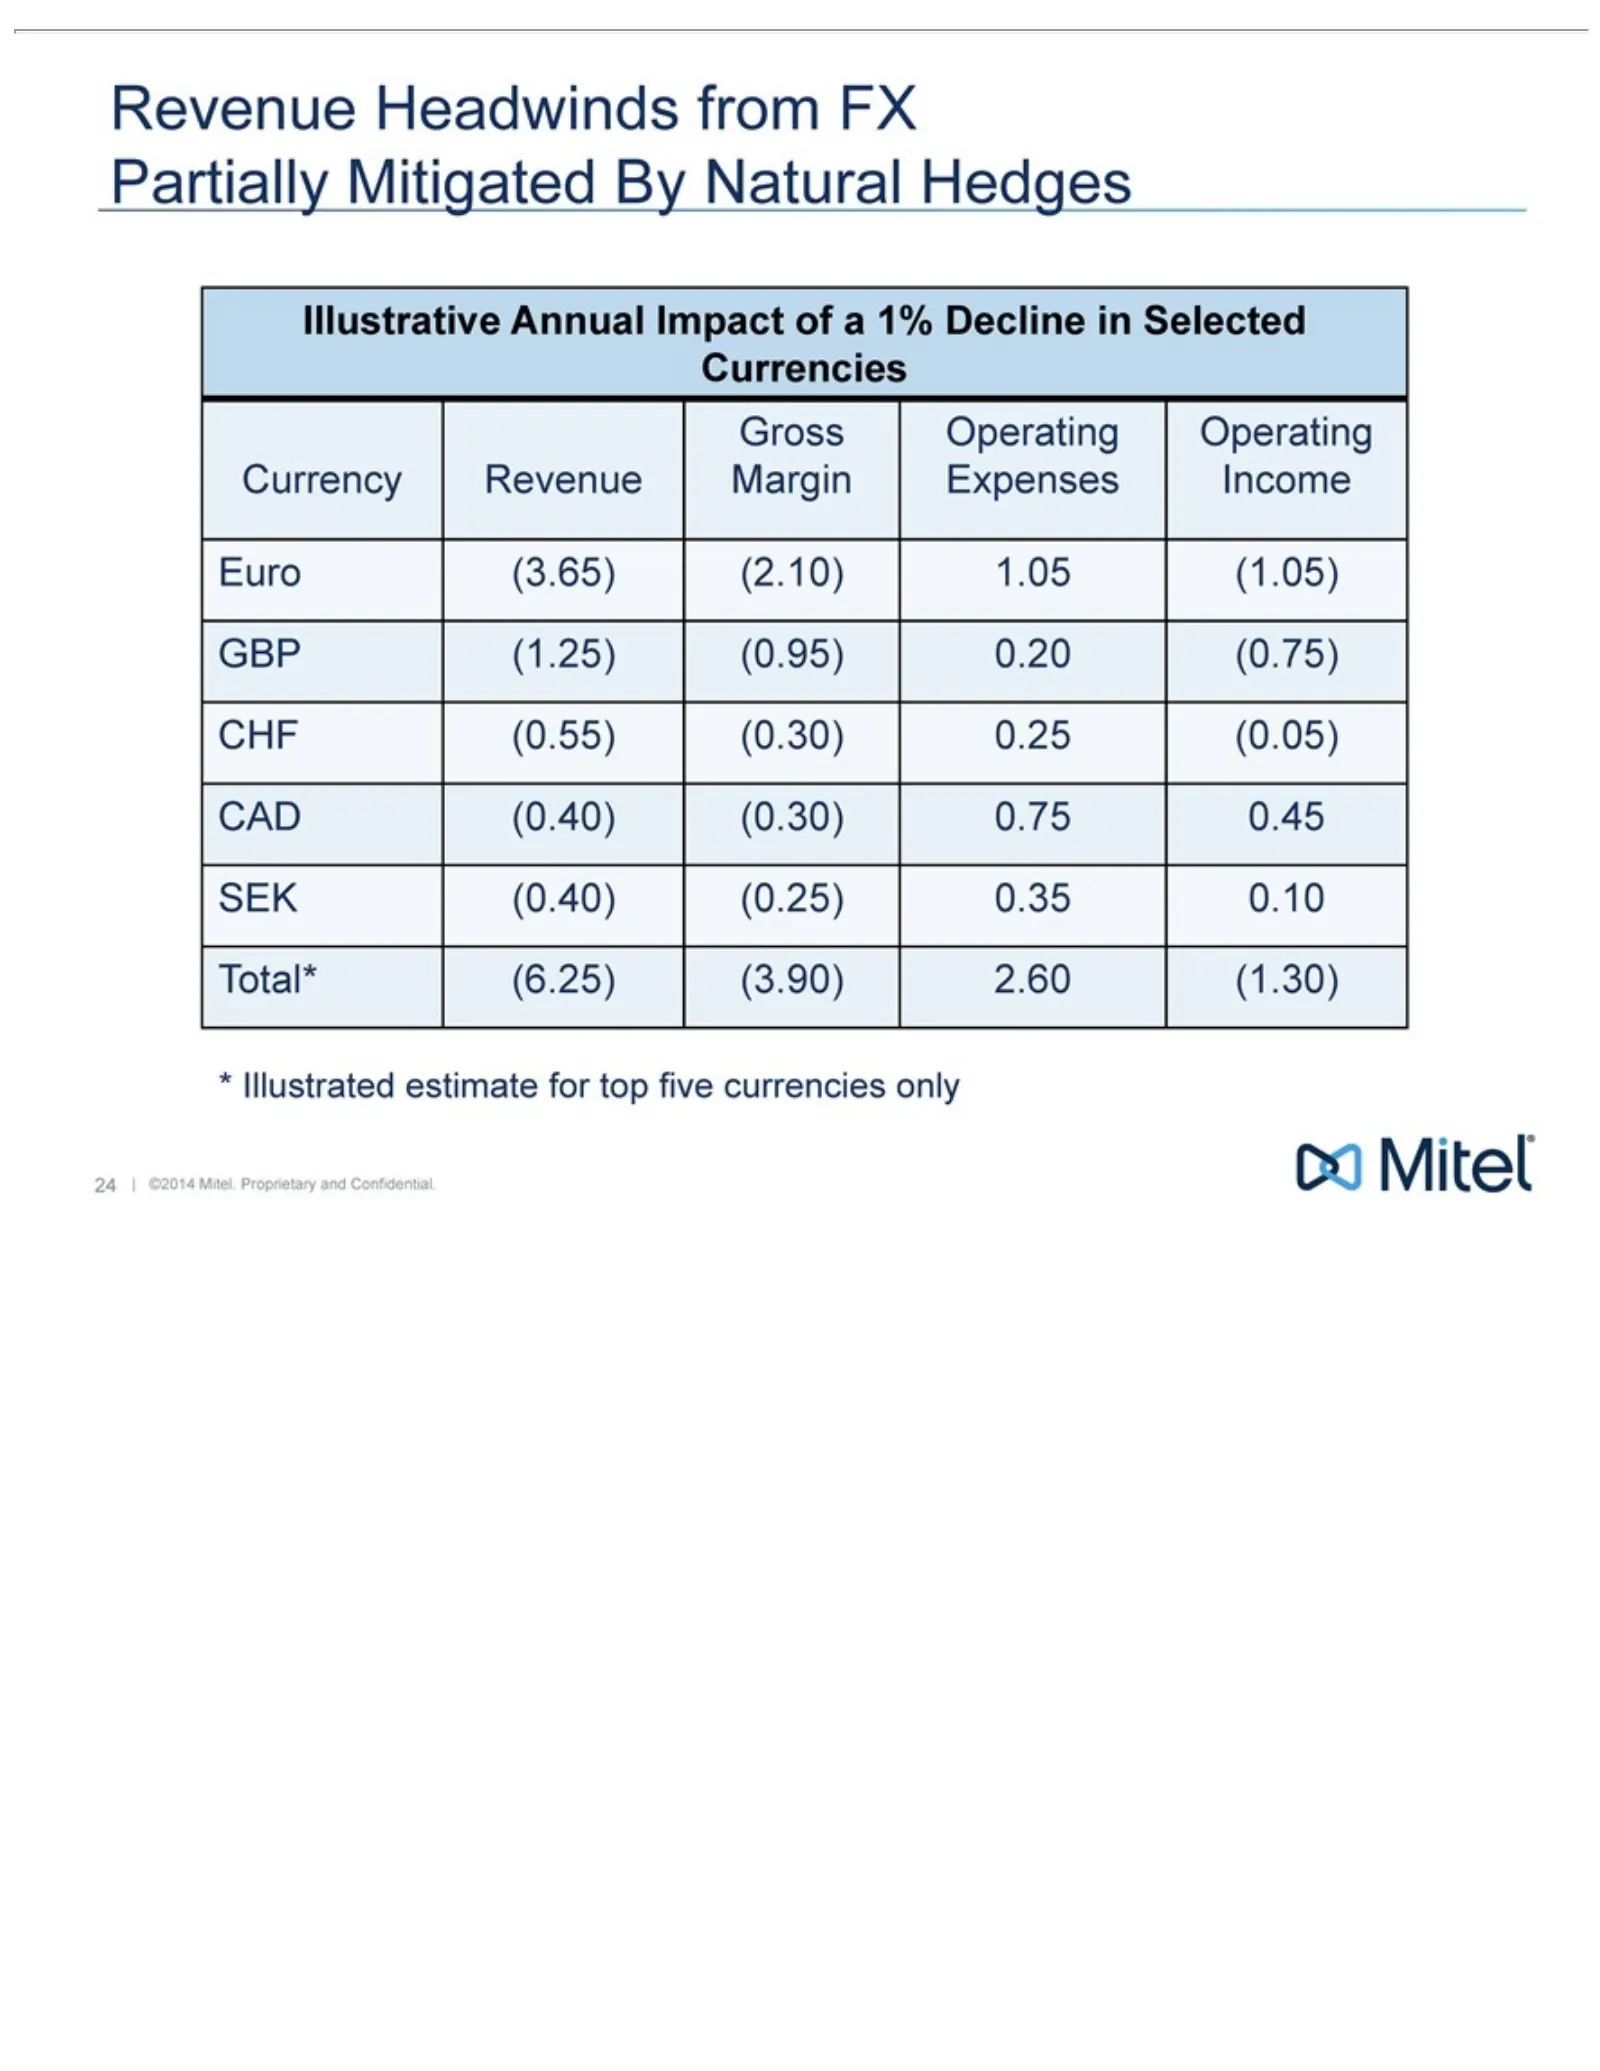
Revenue Illustrative Currency Euro(3.65) GBP CHF CAD SEK *Total* 24Illustrated | ©2014 (0.40) (1.25) (0.55) (0.40) (6.25) Headwinds Revenue Annual (2.10) Mitel. (0.25) (0.95) (0.30) (0.30) estimate (3.90) 1.05 Proprietary 0.35 0.20 0.25 0.75 Gross Impact 2.60 from for (1.05) 0.10 (0.75) (0.05) 0.45
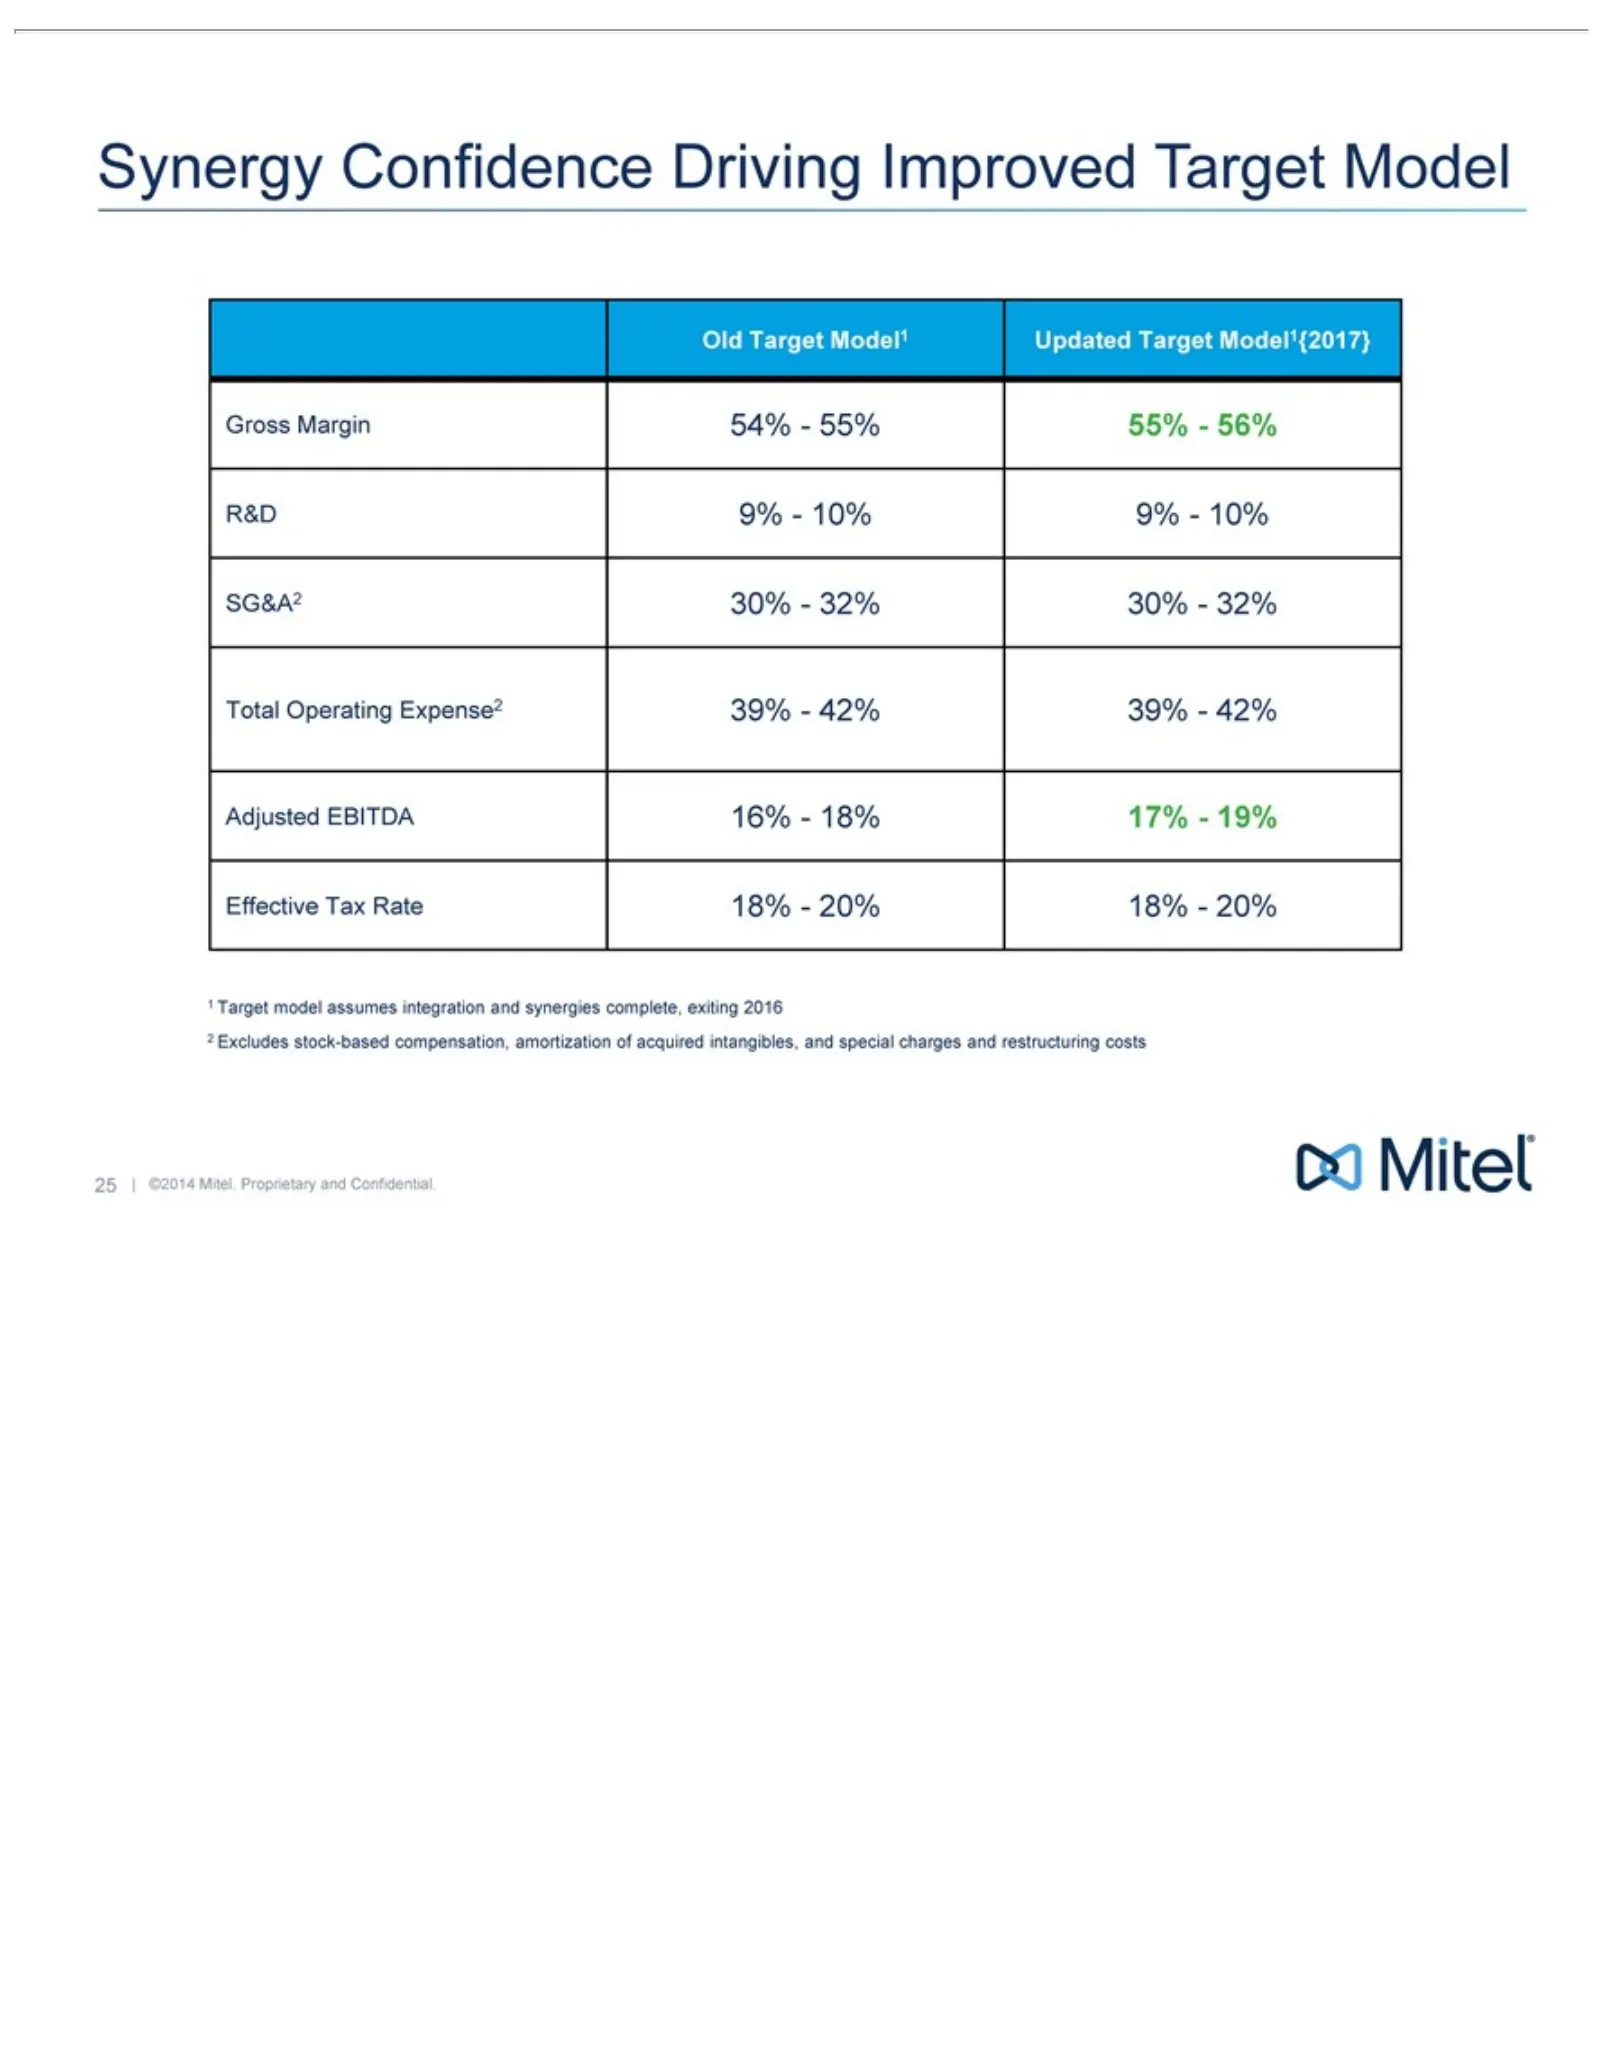
Slide 25: Updated Target Operating Model
Synergy Old Gross R&D SG&A2 Total Adjusted 21Effective 25 Target Excludes | ©2014 Target Operating 9% Margin model 30% Confidence EBITDA Tax - Model1 10% stock-based Mitel. -Rate 54% 32% assumes Expense2 9%Proprietary 18% 16% -Updated -30% Driving 55% 10% compensation, -integration -20% 18% 55% 39%
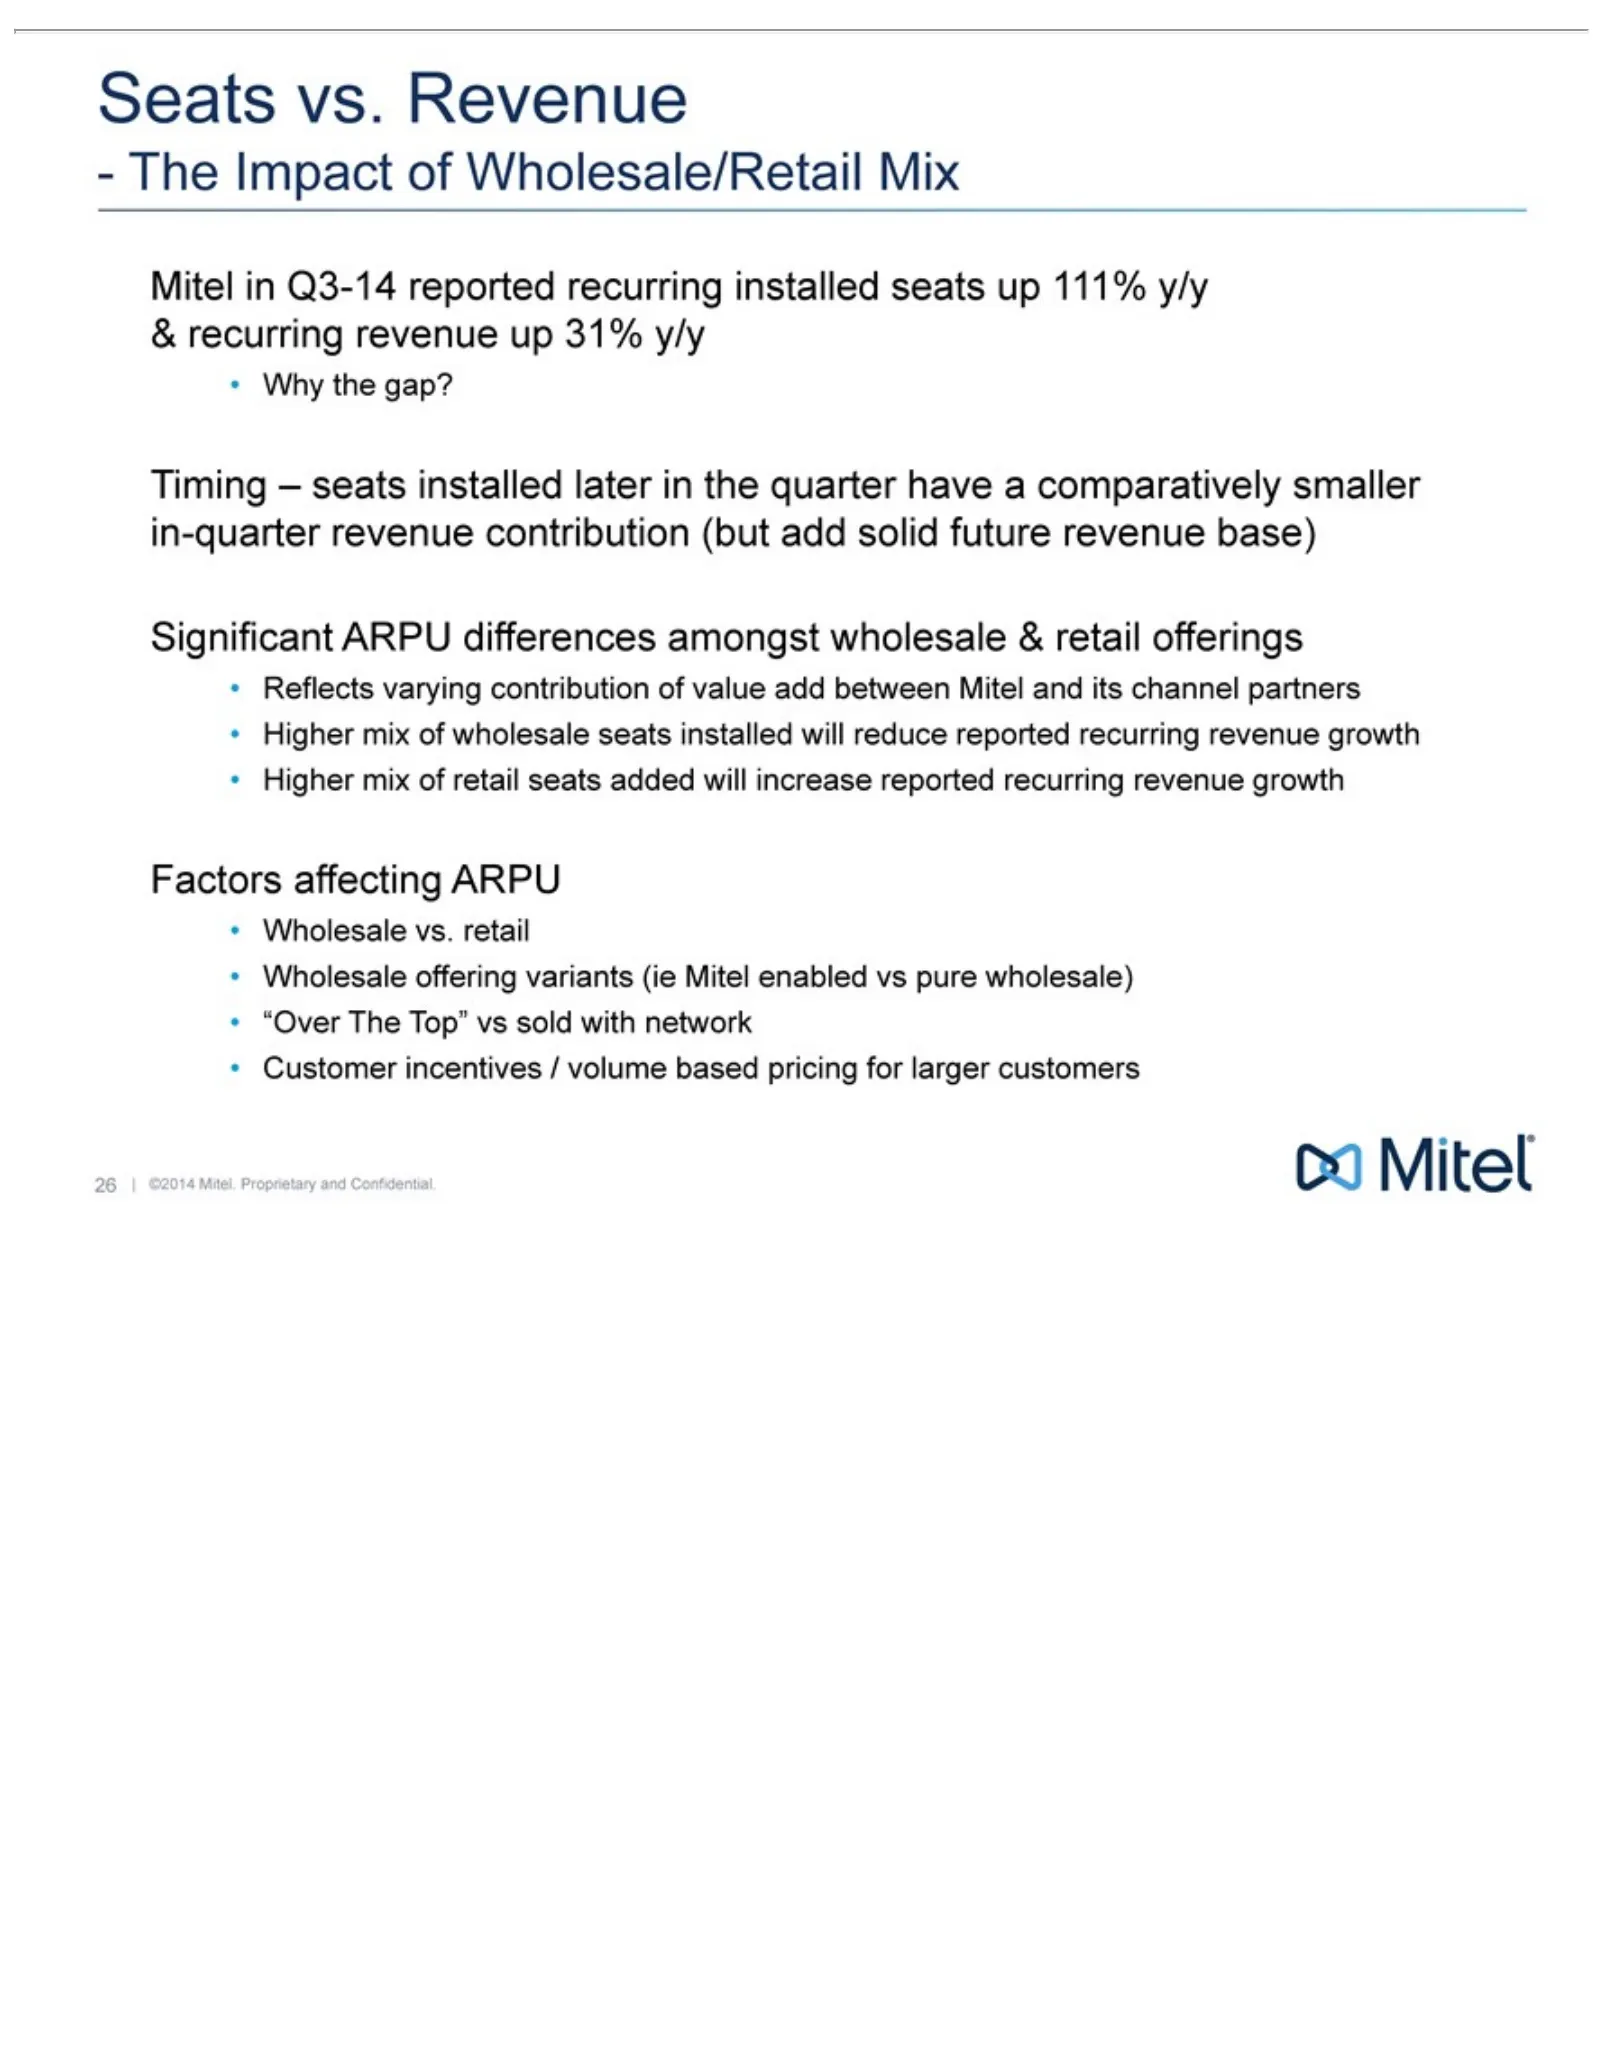
Slide 26: Seats vs. Recurring Revenue
-Seats Mitel & Why Timing Significant Reflects Higher Factors Wholesale “Over Customer 26 The recurring | ©2014 the vs. Impact in The mix –affecting Q3-14 varying gap? Revenue seats incentives Top” vs. offering ARPU Mitel. of revenue ofretail wholesale installed reported Wholesale/Retail vs contribu
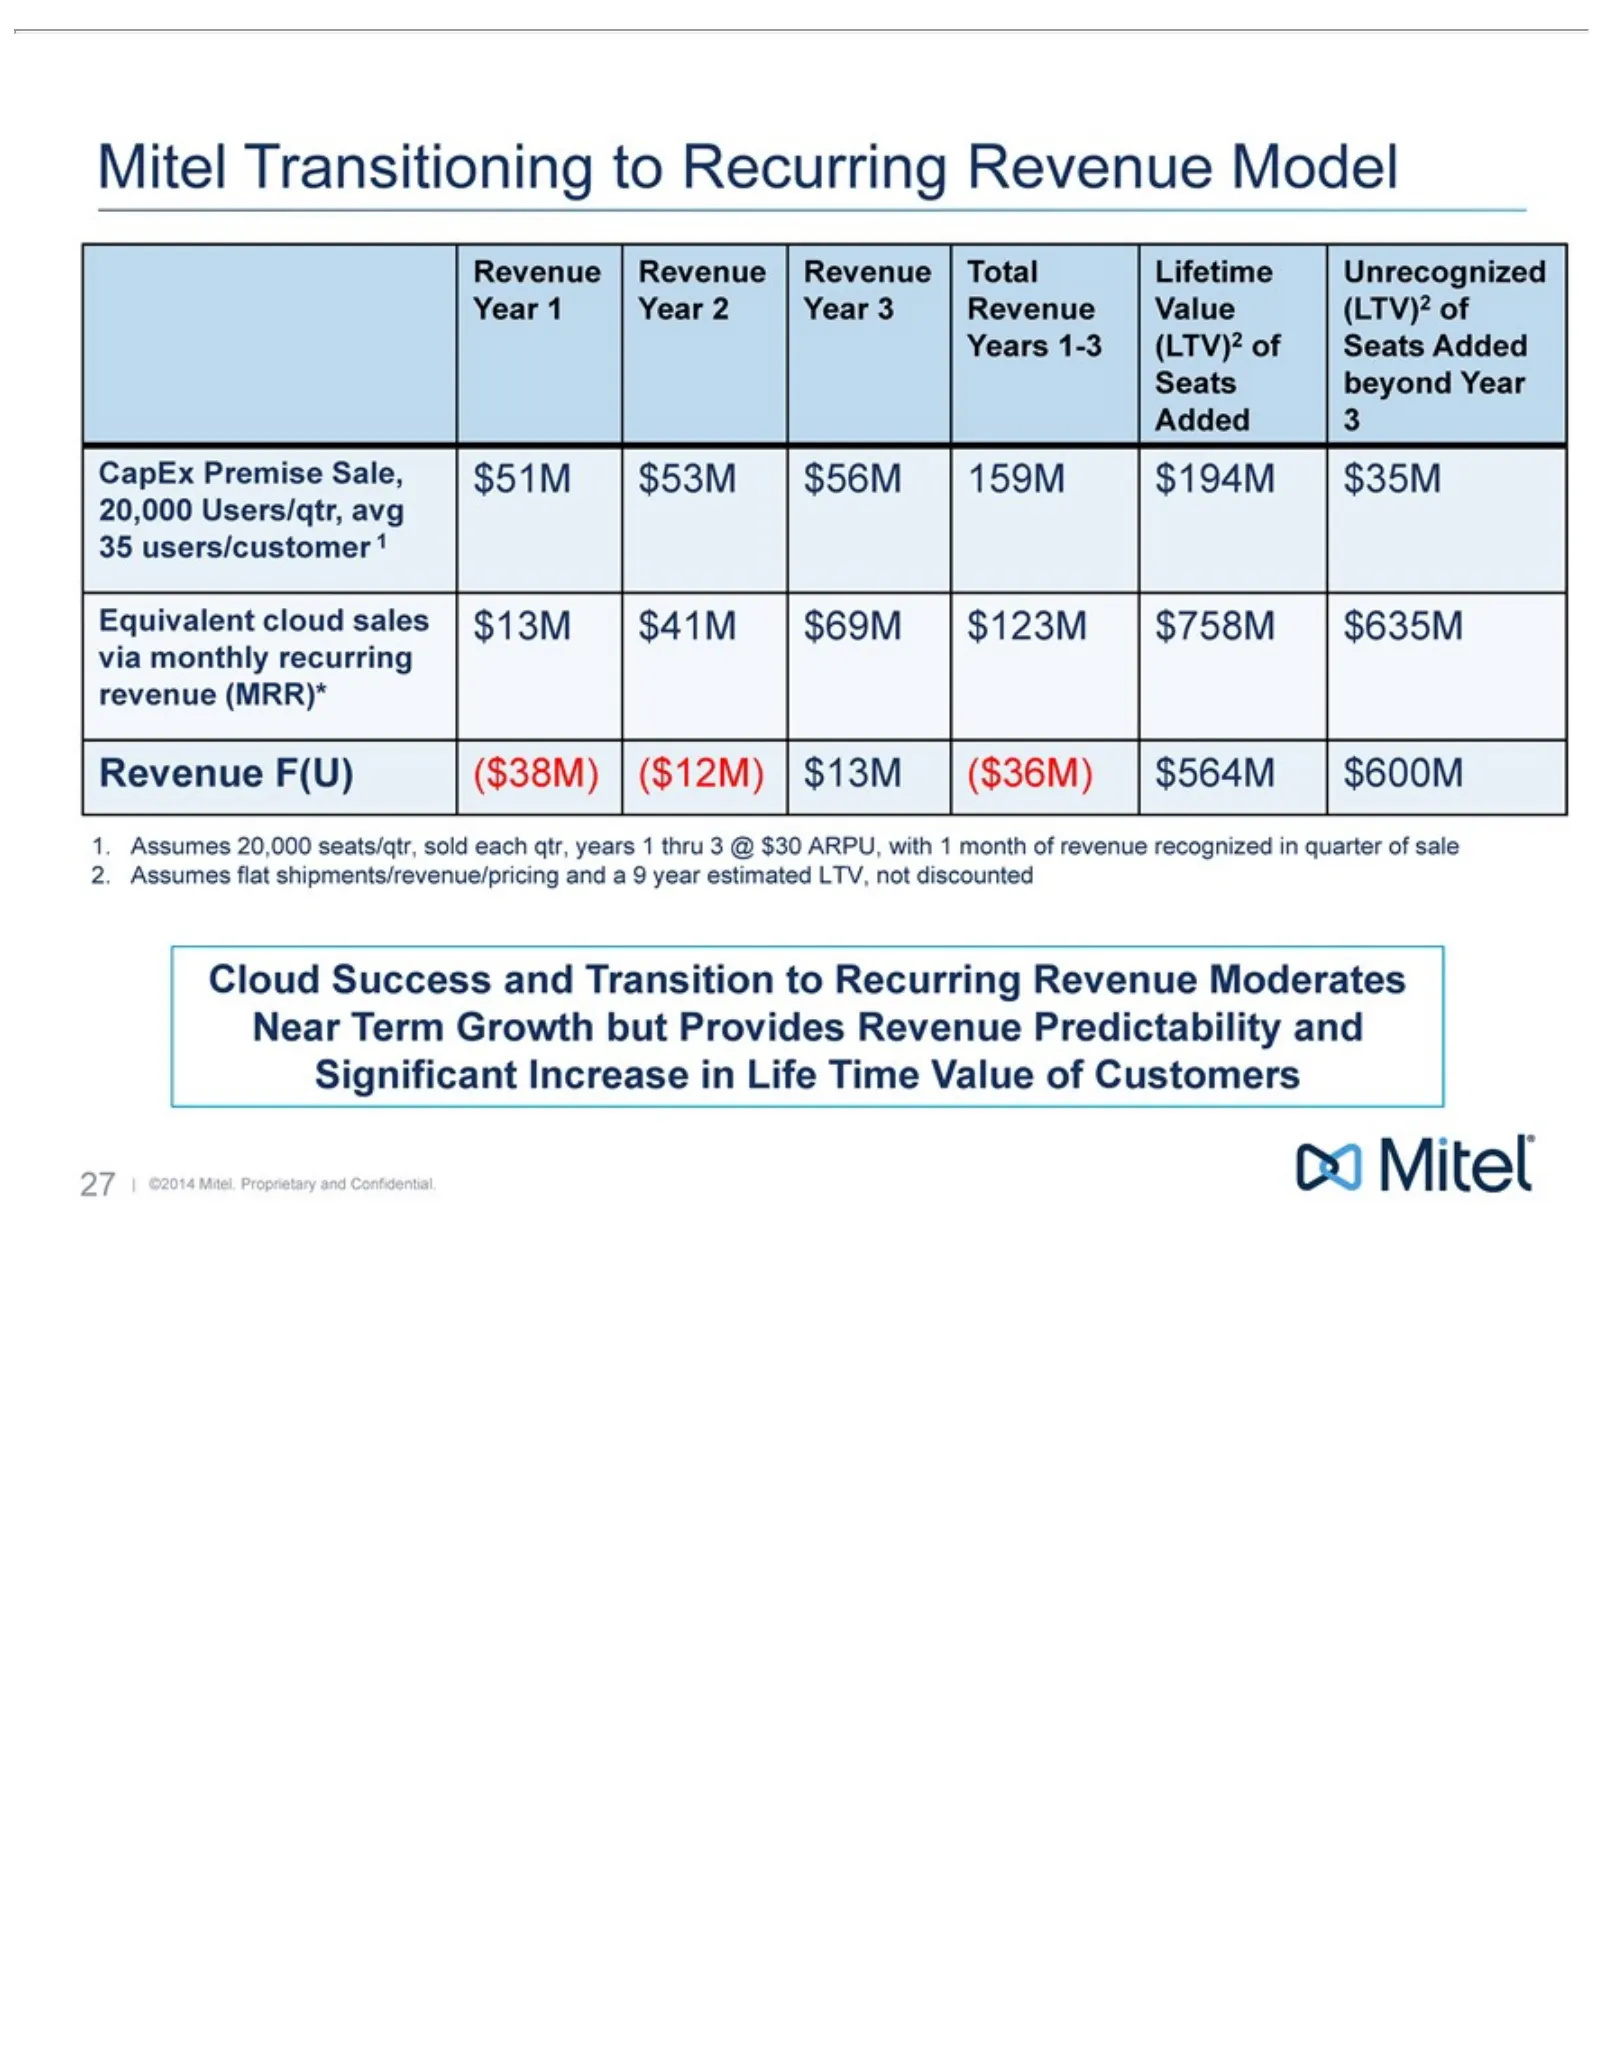
Slide 27: Cloud Transition Revenue Model
Mitel CapEx Equivalent Revenue 1. 2. Cloud 27 Assumes | ©2014 Transitioning Success Premise Year F(U) cloud Mitel. 20,000 flat 1($38M) and shipments/revenue/pricing Sale, Revenue sales Proprietary Transition seats/qtr, to20,000 Recurring via ($12M) Year monthly sold Users/qtr, to and 2$ Revenue Recu
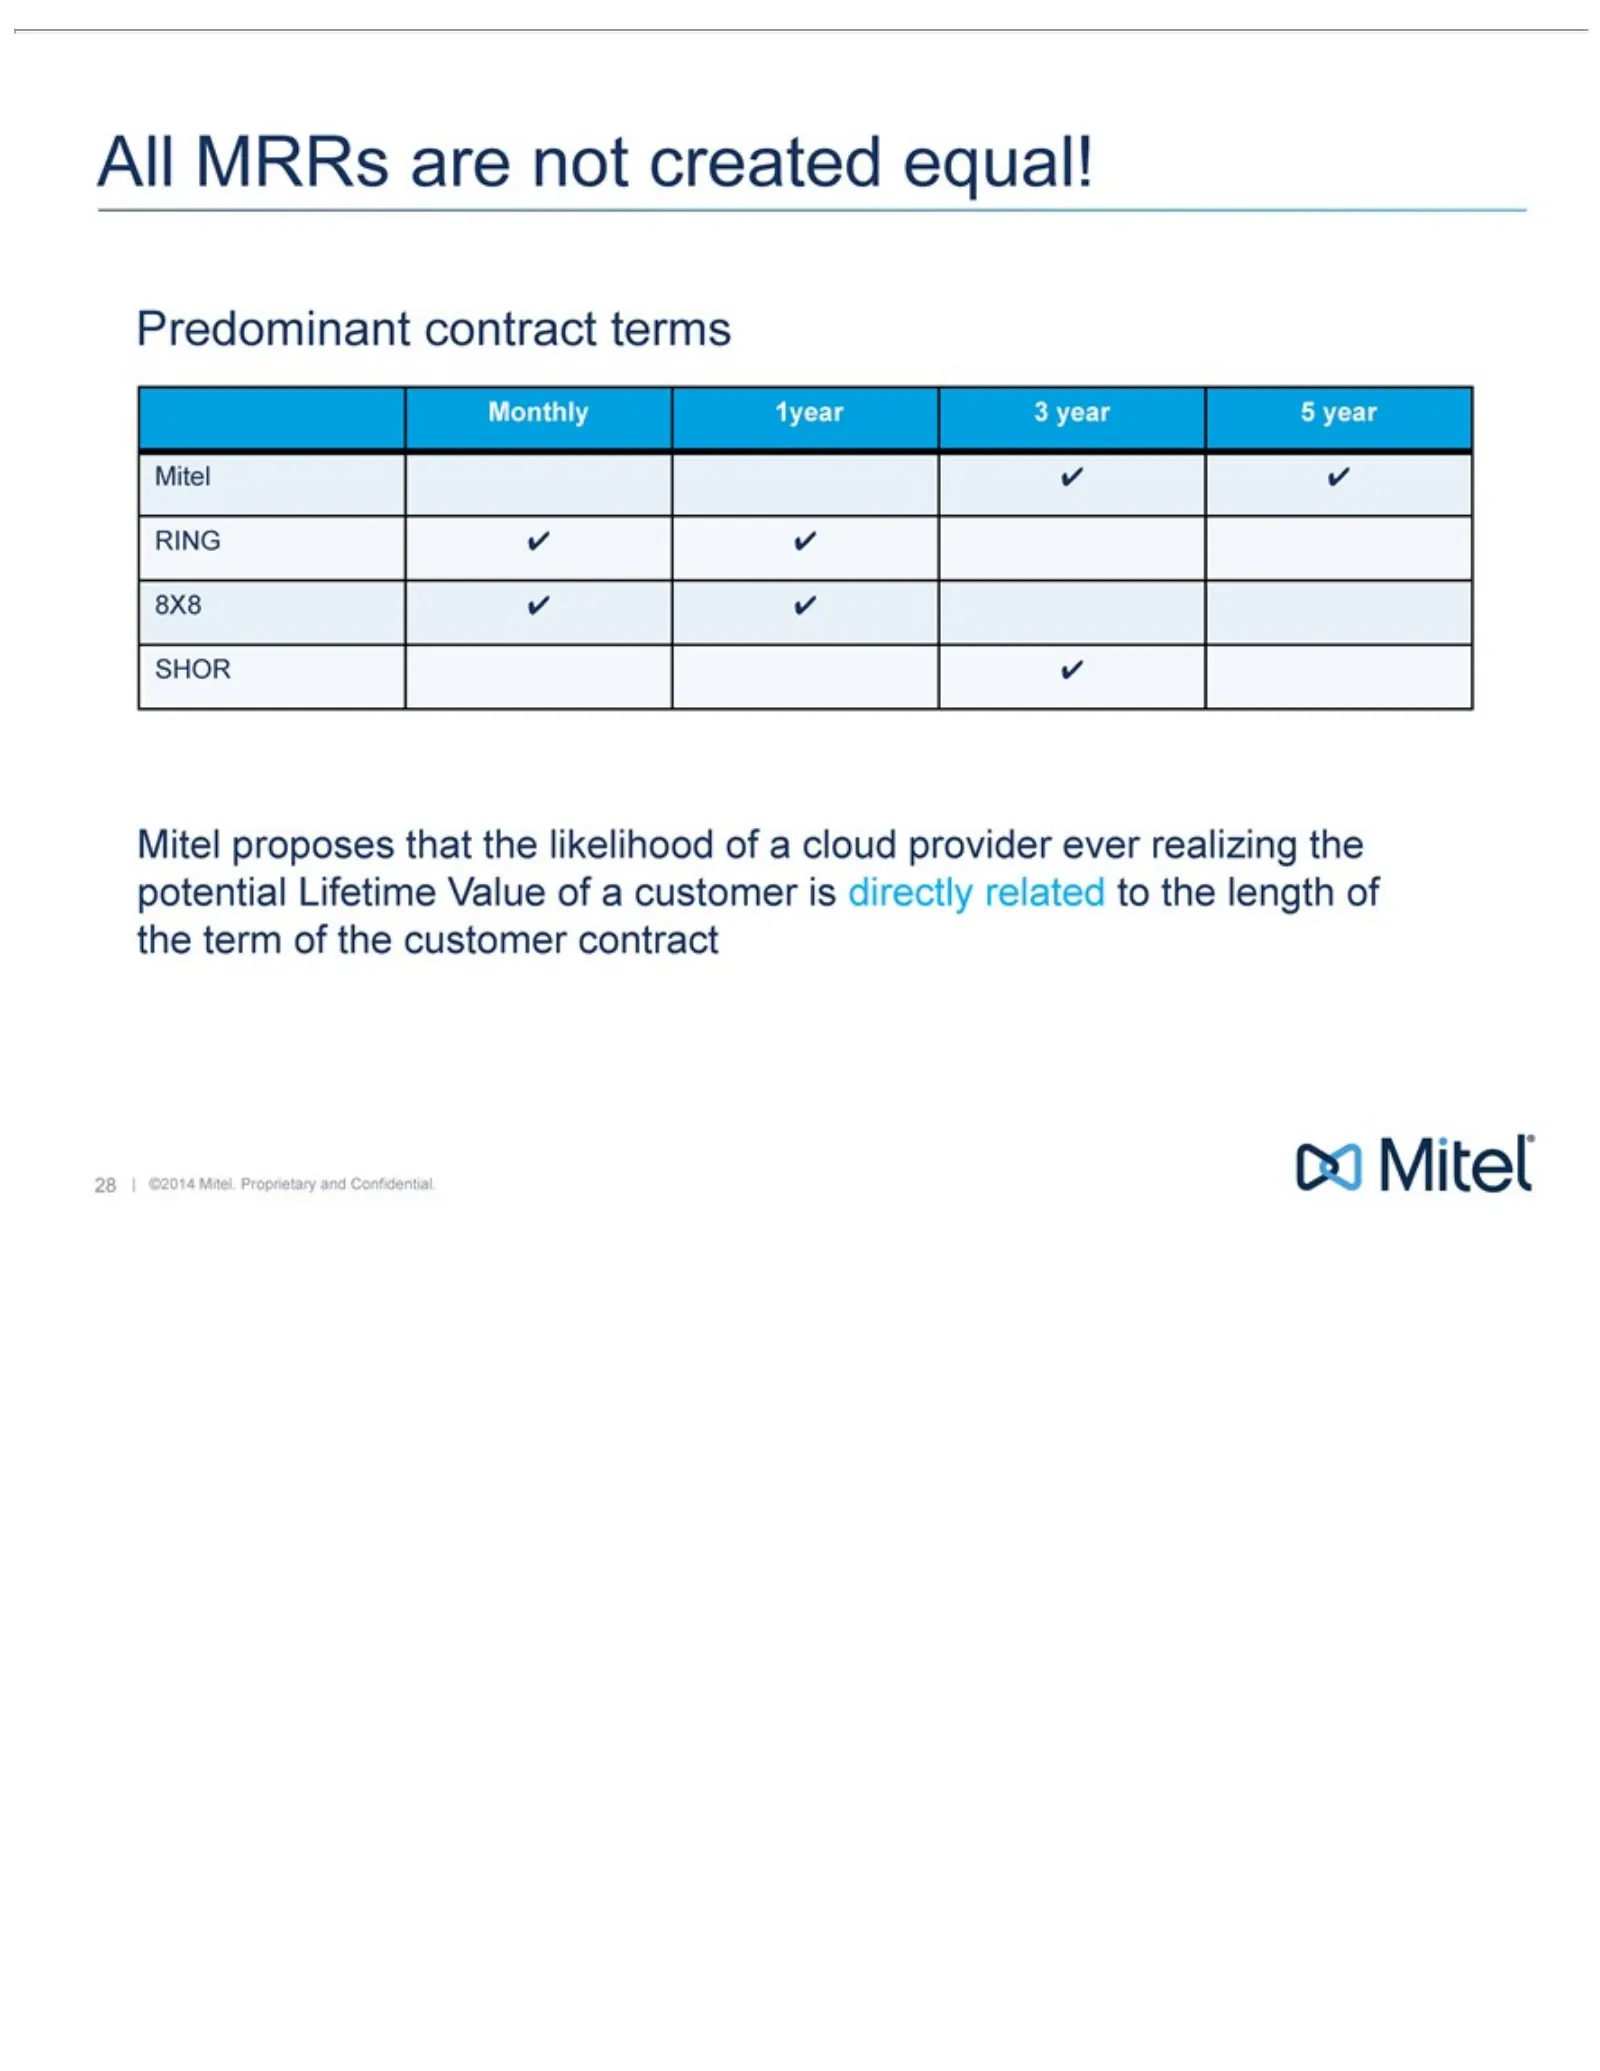
Slide 28: Contract Terms and Lifetime Value
All| MRRs Predominant Monthly SHOR 8X8 RING Mitel 28 ©2014 proposes 1year are Mitel. contract not 3that year Proprietary created theterms 5 likelihood year equal! and of Confidential. a cloud provider ever realizing the potential Lifetime Value of a customer is directly related to the length of the
Slide 29: Why Mitel
Why We 29 | are offer ©2014 Mitel abusiness powering market clear Mitel. customer communications leader connections Proprietary choiceand with experts consolidating Confidential. the best paththe to market the cloud
Slide 30: 17th Annual Needham Growth Conference
17th Annual January 14, 2015 Needham Growth Conference New York – The Palace Hotel
Source: SEC EDGAR · 8-K filed Jan 16, 2015
More decks from Mitel Networks Corp.
 Investor Day (February 2018)140 slides · Feb 27, 2018
 Q4 2017 Earnings Presentation17 slides · Feb 22, 2018
 Q3 2017 Earnings Presentation17 slides · Nov 2, 2017
 Oppenheimer 20th Annual Technology, Internet & Communications Conference (August 2017)25 slides · Aug 9, 2017
 Q2 2017 Earnings Presentation30 slides · Jul 27, 2017
 Q1 2017 Earnings Presentation19 slides · May 3, 2017