CH Energy — Merger or Acquisition (May 2012)
20 slides from CH Energy's merger presentation, May 31, 2012
Slide 1: Schedule 14A Definitive Additional Materials
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A PROXY STATEMENT PURSUANT TO SECTION 14(a) OF THE SECURITIES EXCHANGE ACT OF 1934 Filed by the Registrant þ Filed by a Party other than the Registrant ¨ Check the appropriate box: ¨ Preliminary Proxy Statement ¨ Conf
Slide 2: Shareholder Presentation: Overview of Fortis Transaction
Shareholder Presentation Overview of Fortis Transaction Thursday, May 31, 2012
Slide 3: Forward-Looking Statements
Forward-Looking Statements Statements included in this presentation which are not historical in nature are intended to be, and are hereby identified as, “forward-looking statements” for purposes of the safe harbor provided by Section 21E of the Exchange Act. Forward-looking statements may be identif
Slide 4: Fortis Transaction: Compelling value for shareholders
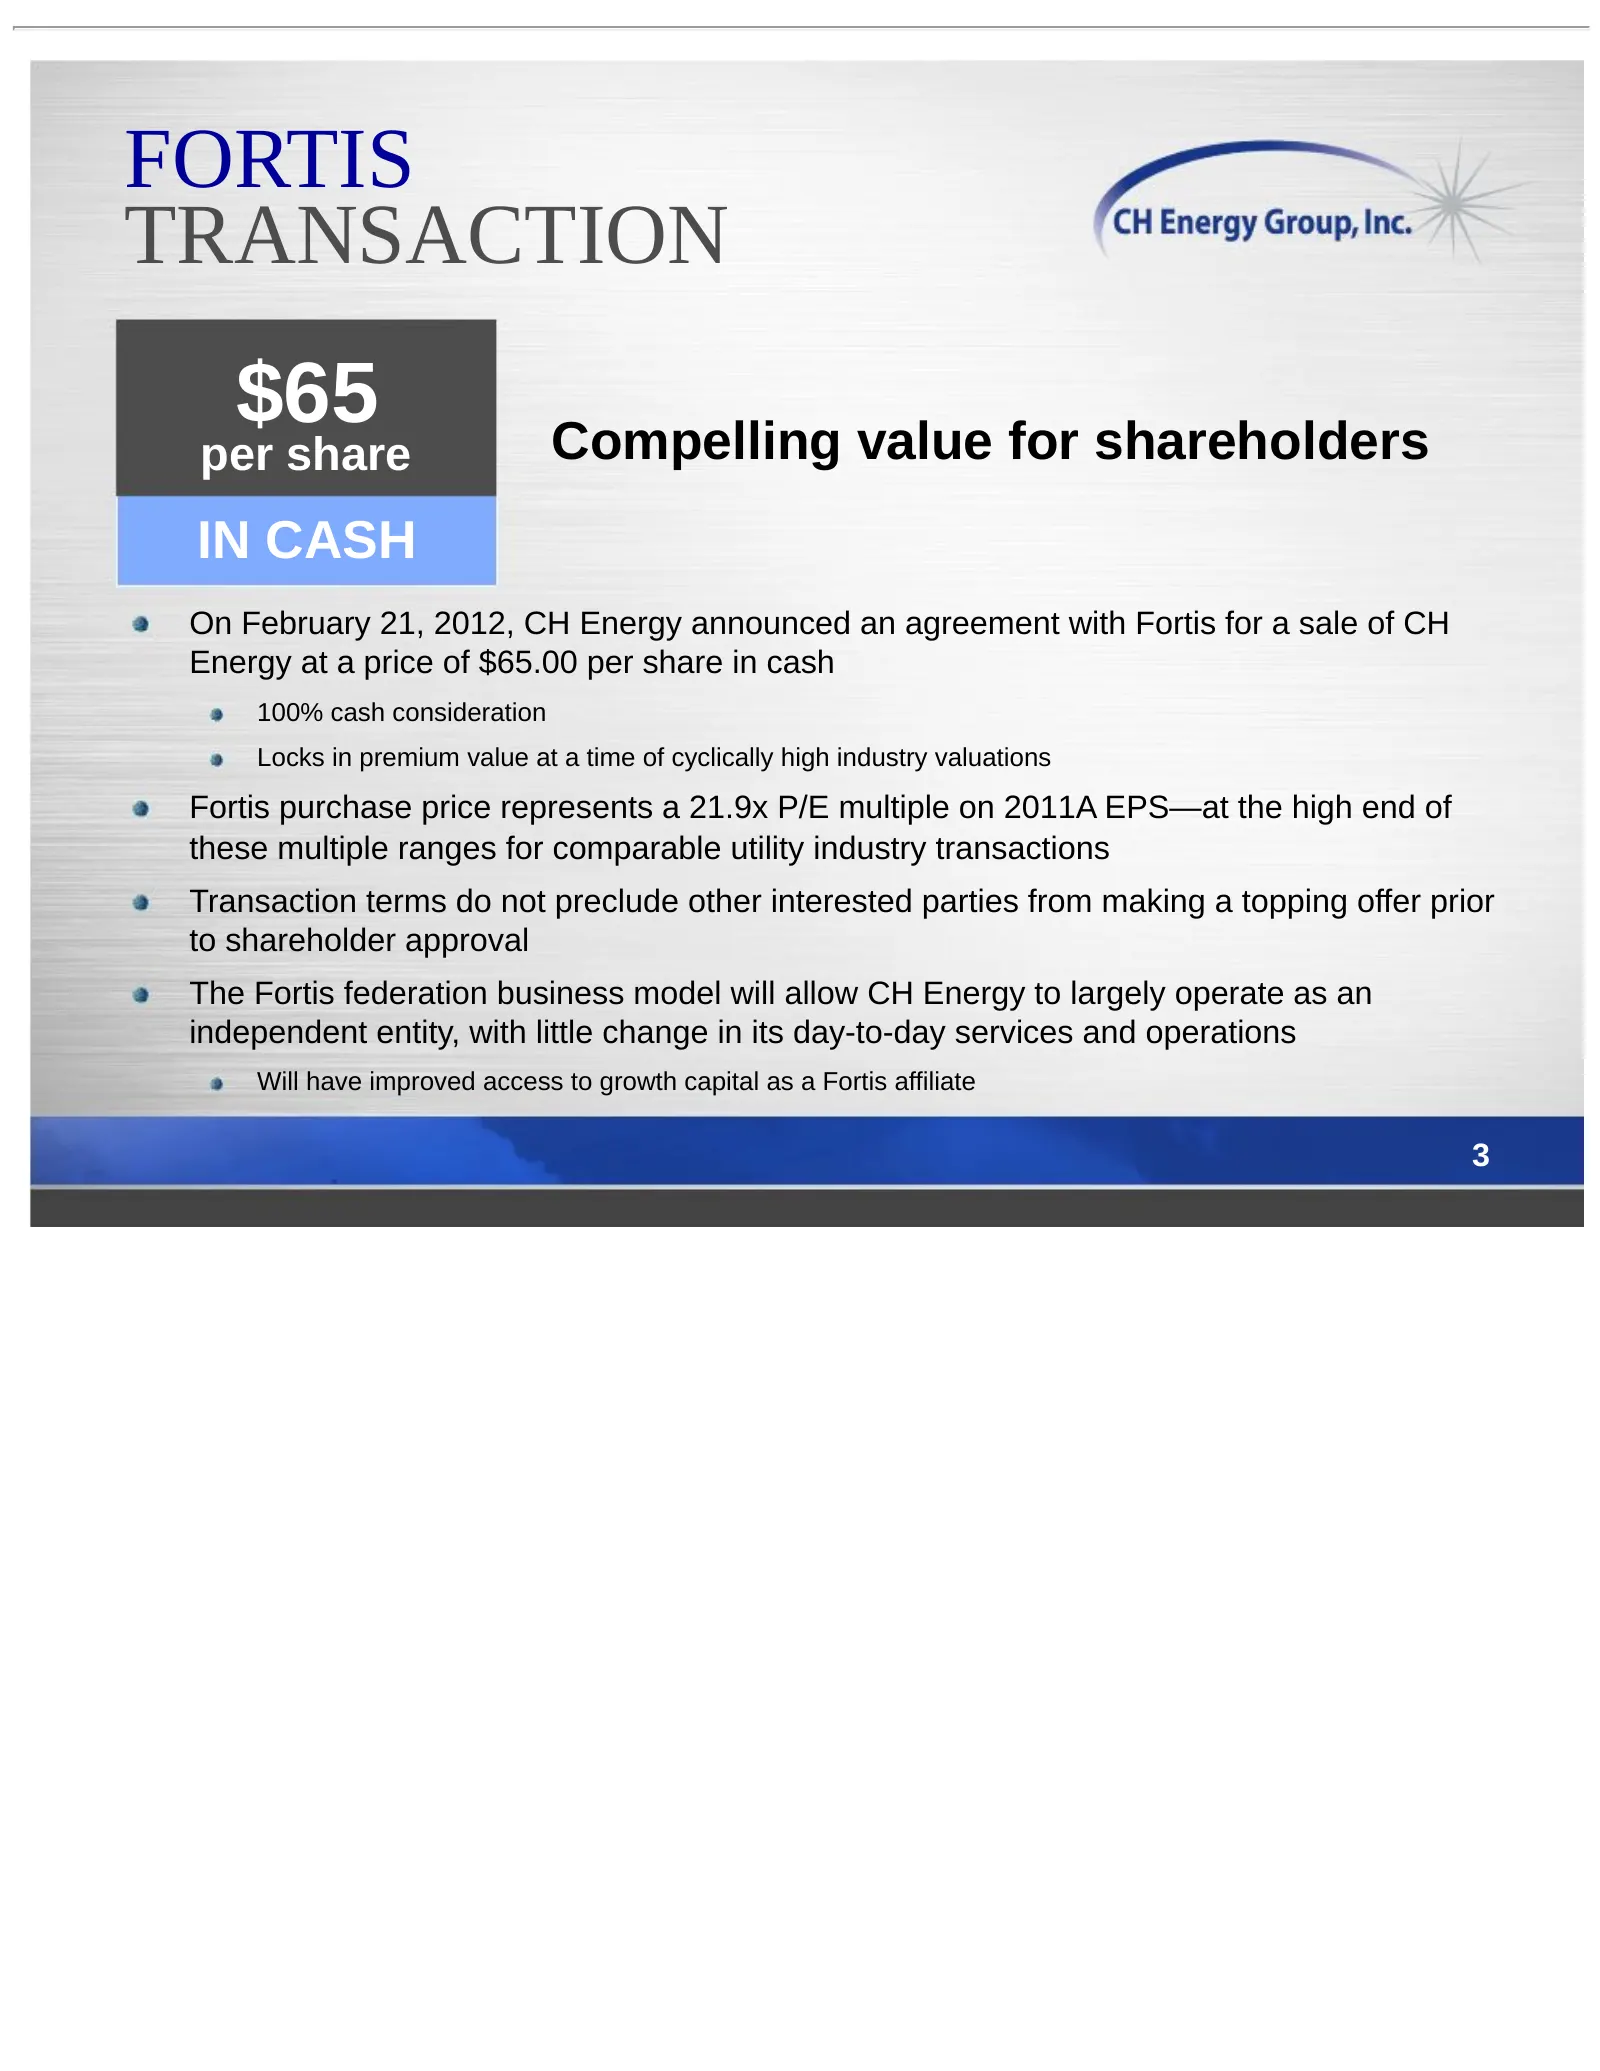
FORTIS TRANSACTION $65 Compelling value for shareholders per share IN CASH On February 21, 2012, CH Energy announced an agreement with Fortis for a sale of CH Energy at a price of $65.00 per share in cash 100% cash consideration Locks in premium value at a time of cyclically high industry valuations
Slide 5: Key transaction terms
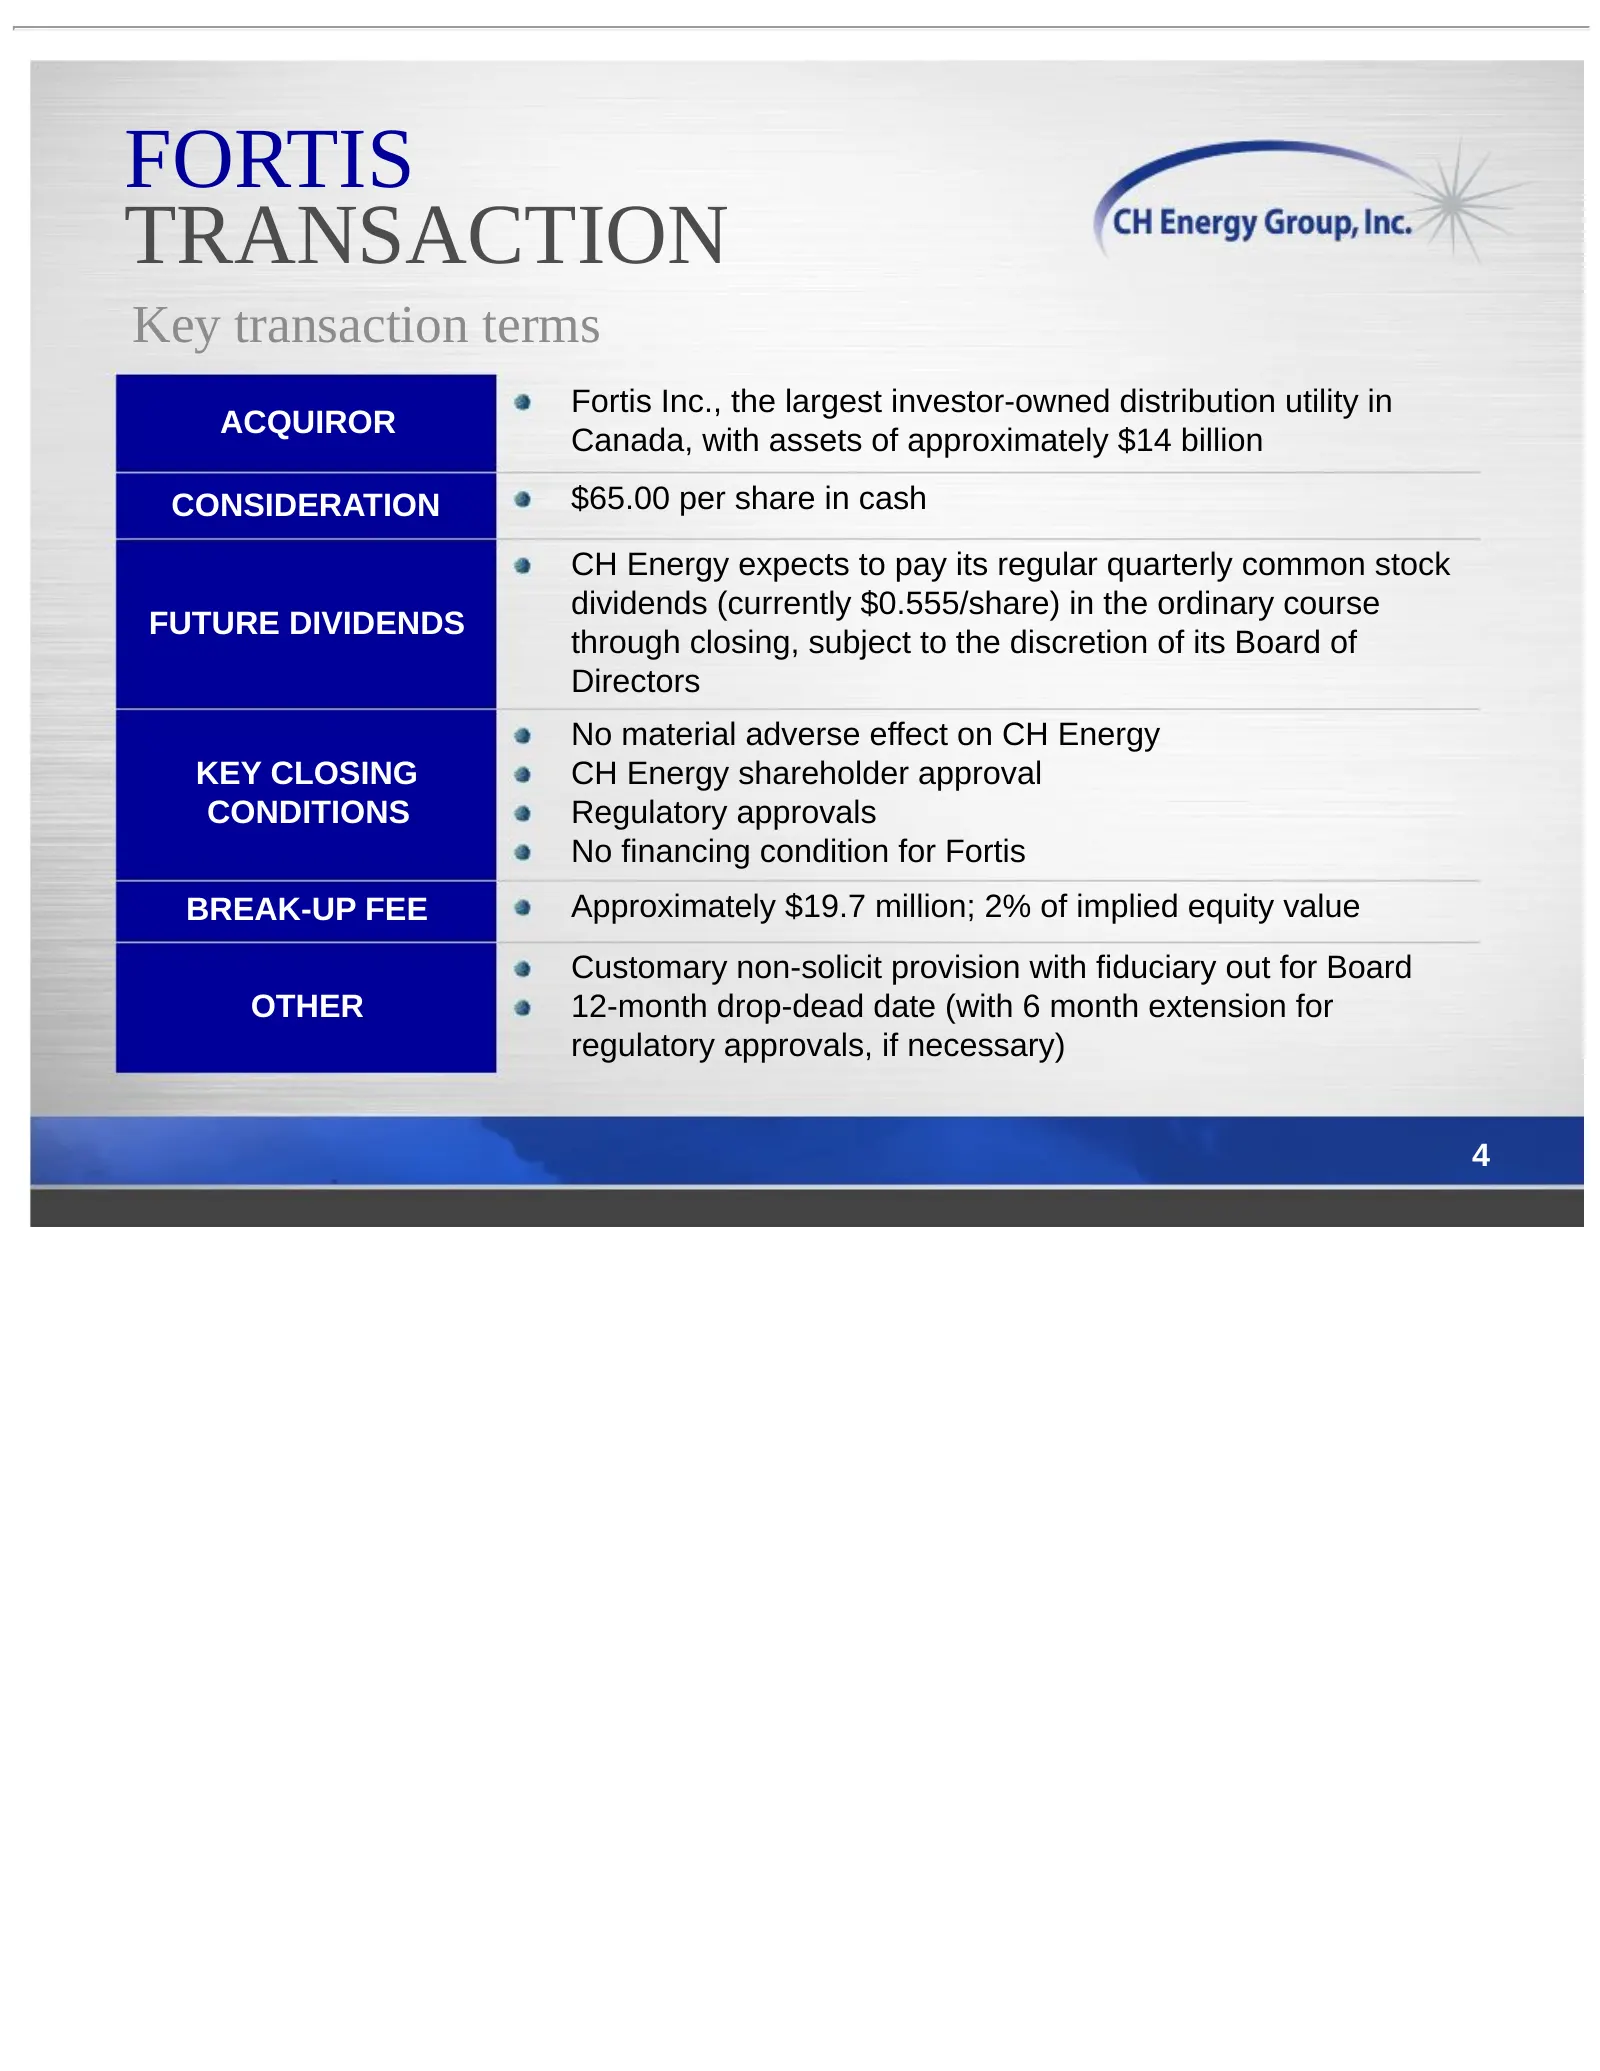
FORTIS TRANSACTION Key transaction terms Fortis Inc., the largest investor-owned distribution utility in ACQUIROR Canada, with assets of approximately $14 billion CONSIDERATION $65.00 per share in cash CH Energy expects to pay its regular quarterly common stock dividends (currently $0.555/share) in
Slide 6: How did our Board maximize shareholder value?
FORTIS TRANSACTION How did our Board maximize shareholder value? In May 2011, CH Energy was approached by a representative of Fortis to ascertain CH Energy’s interest in pursuing a potential transaction with Fortis Fortis had very recently agreed to pay an attractive multiple of earnings for Central
Slide 7: How did our Board maximize shareholder value? (continued)
FORTIS TRANSACTION How did our Board maximize shareholder value? CH Energy’s Board determined CH Energy should seek a higher price from Fortis and provide further access to confidential information to encourage Fortis to find additional value, but not to approach other potential transaction partners
Slide 8: Benefits of the transaction
FORTIS TRANSACTION Benefits of the transaction Secures premium for CH Energy shareholders, on top of CH Energy’s already above-peer and historically high trading value and trading multiples Cash consideration Locks in value at a time of cyclically high valuations for the industry Eliminates downside
Slide 9: Benefits of the transaction: full and fair value
FORTIS TRANSACTION Benefits of the transaction Full and fair value Offer evaluated by experienced financial advisor (Lazard) to be fair, from a financial point of view, to CH Energy shareholders Fortis price is at the top end of financial advisor’s private market valuation range Process involved sig
Slide 10: Completion of Strategic Shift
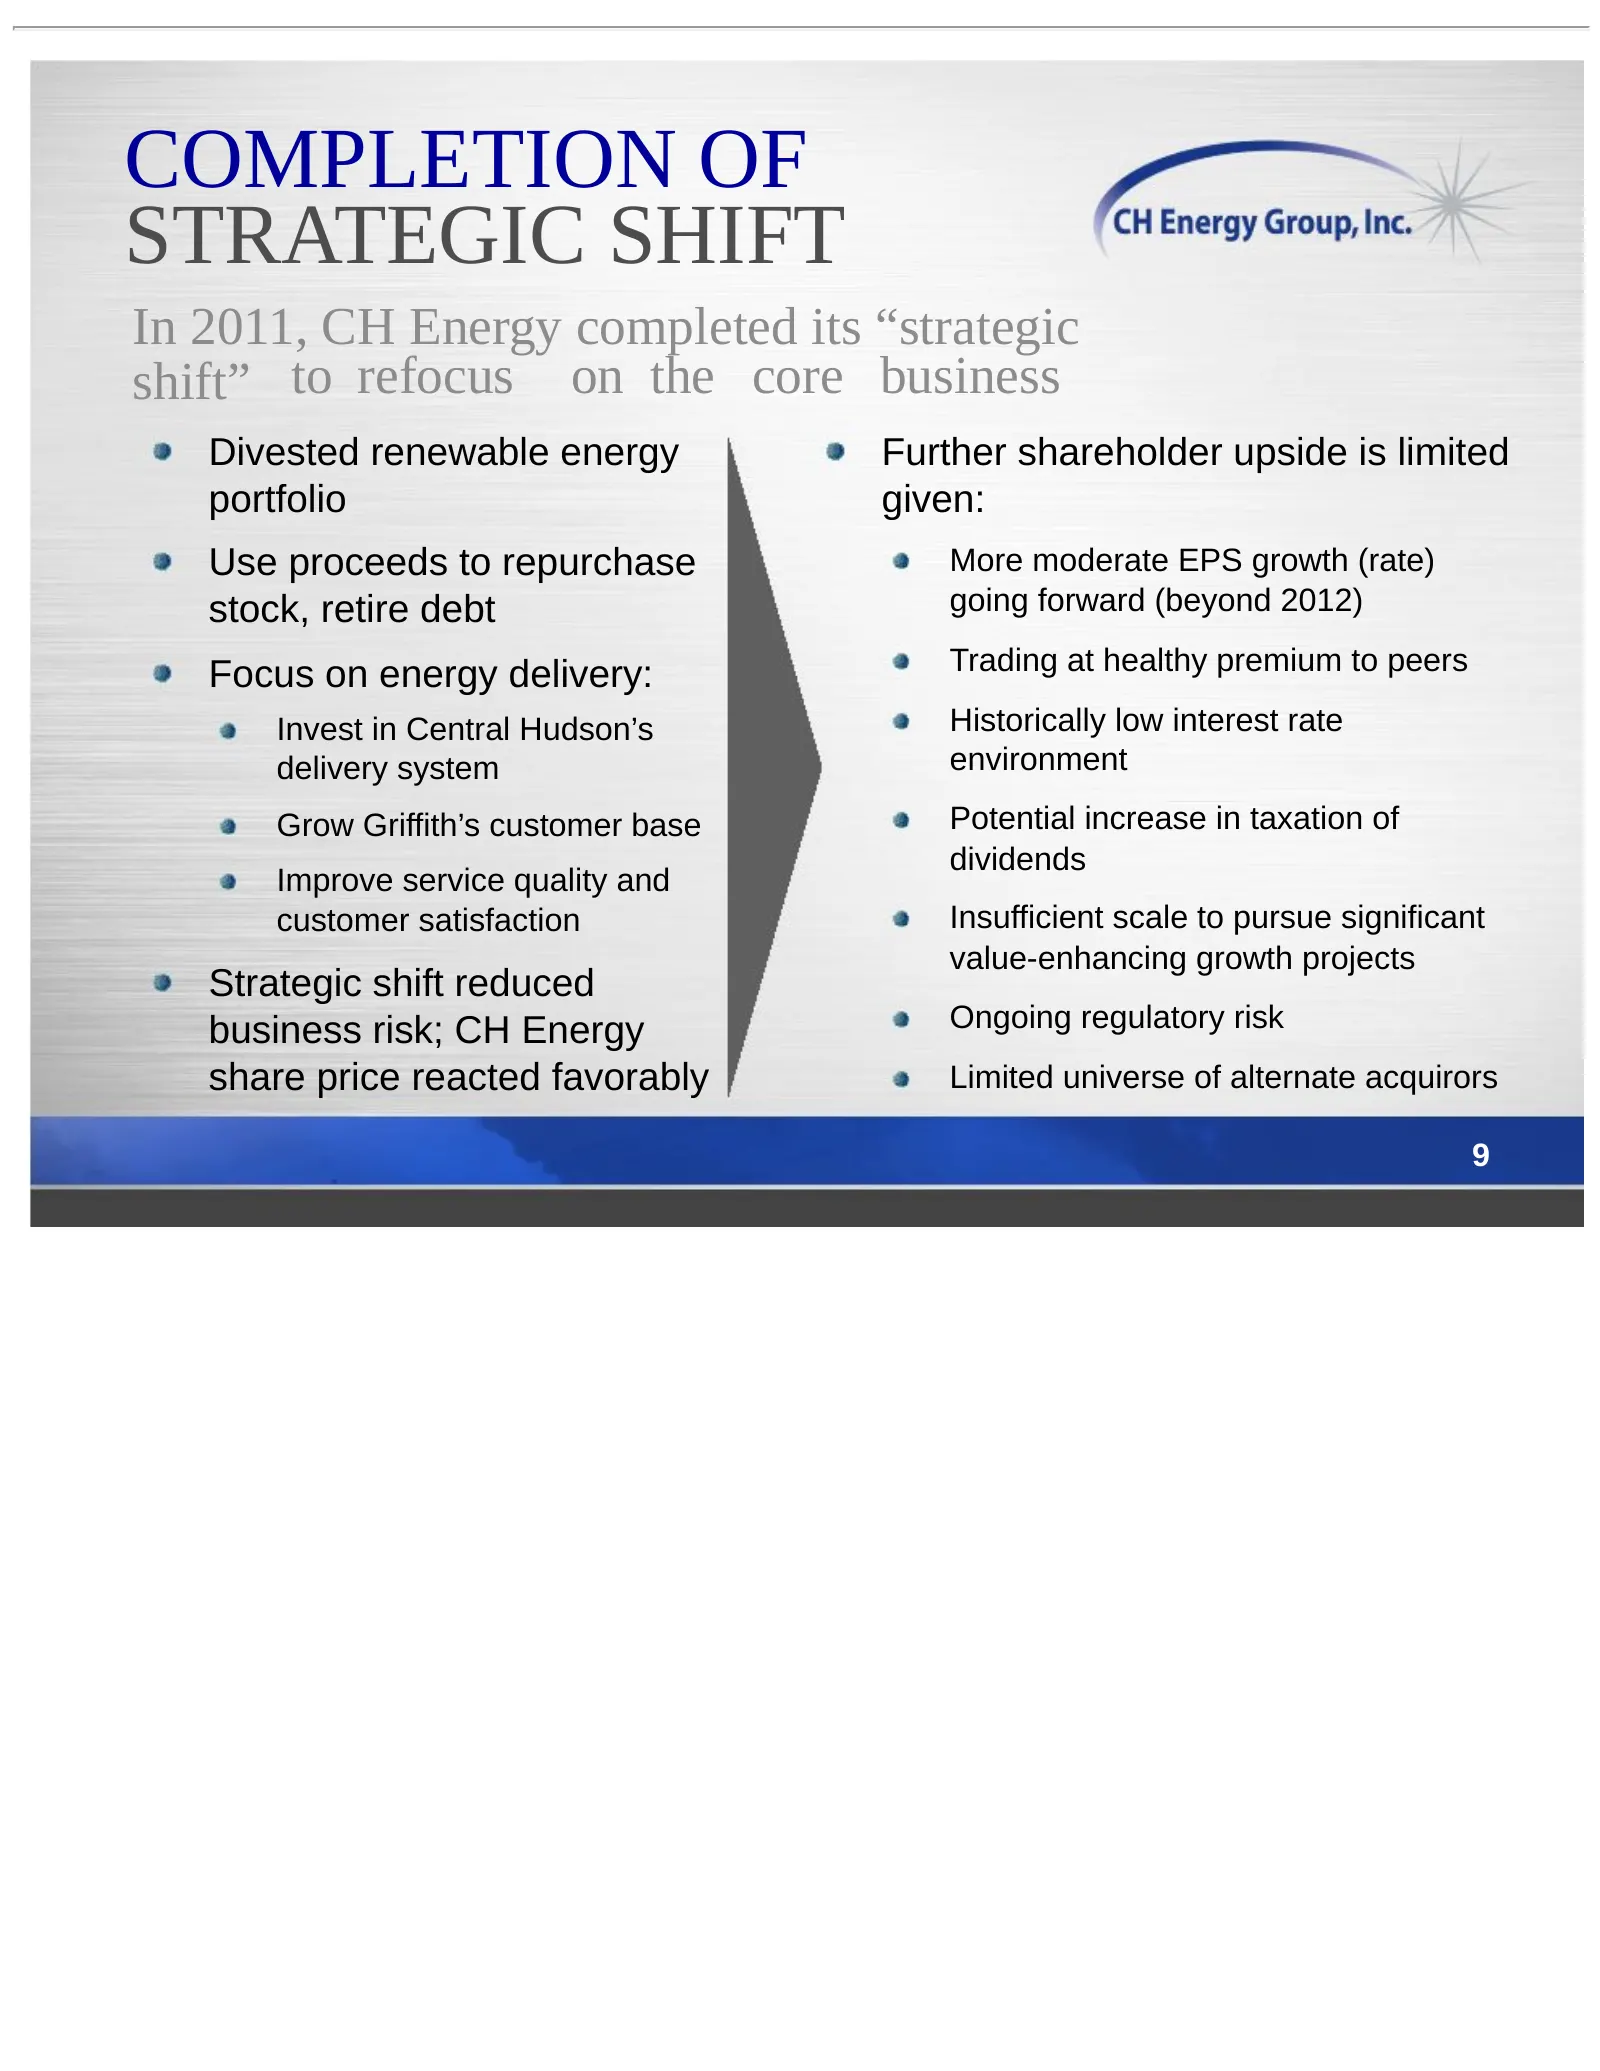
COMPLETION OF STRATEGIC SHIFT In 2011, CH Energy completed its “strategic shift” to refocus on the core business Divested renewable energy Further shareholder upside is limited portfolio given: Use proceeds to repurchase More moderate EPS growth (rate) stock, retire debt going forward (beyond 2012)
Slide 11: Management has created significant shareholder value
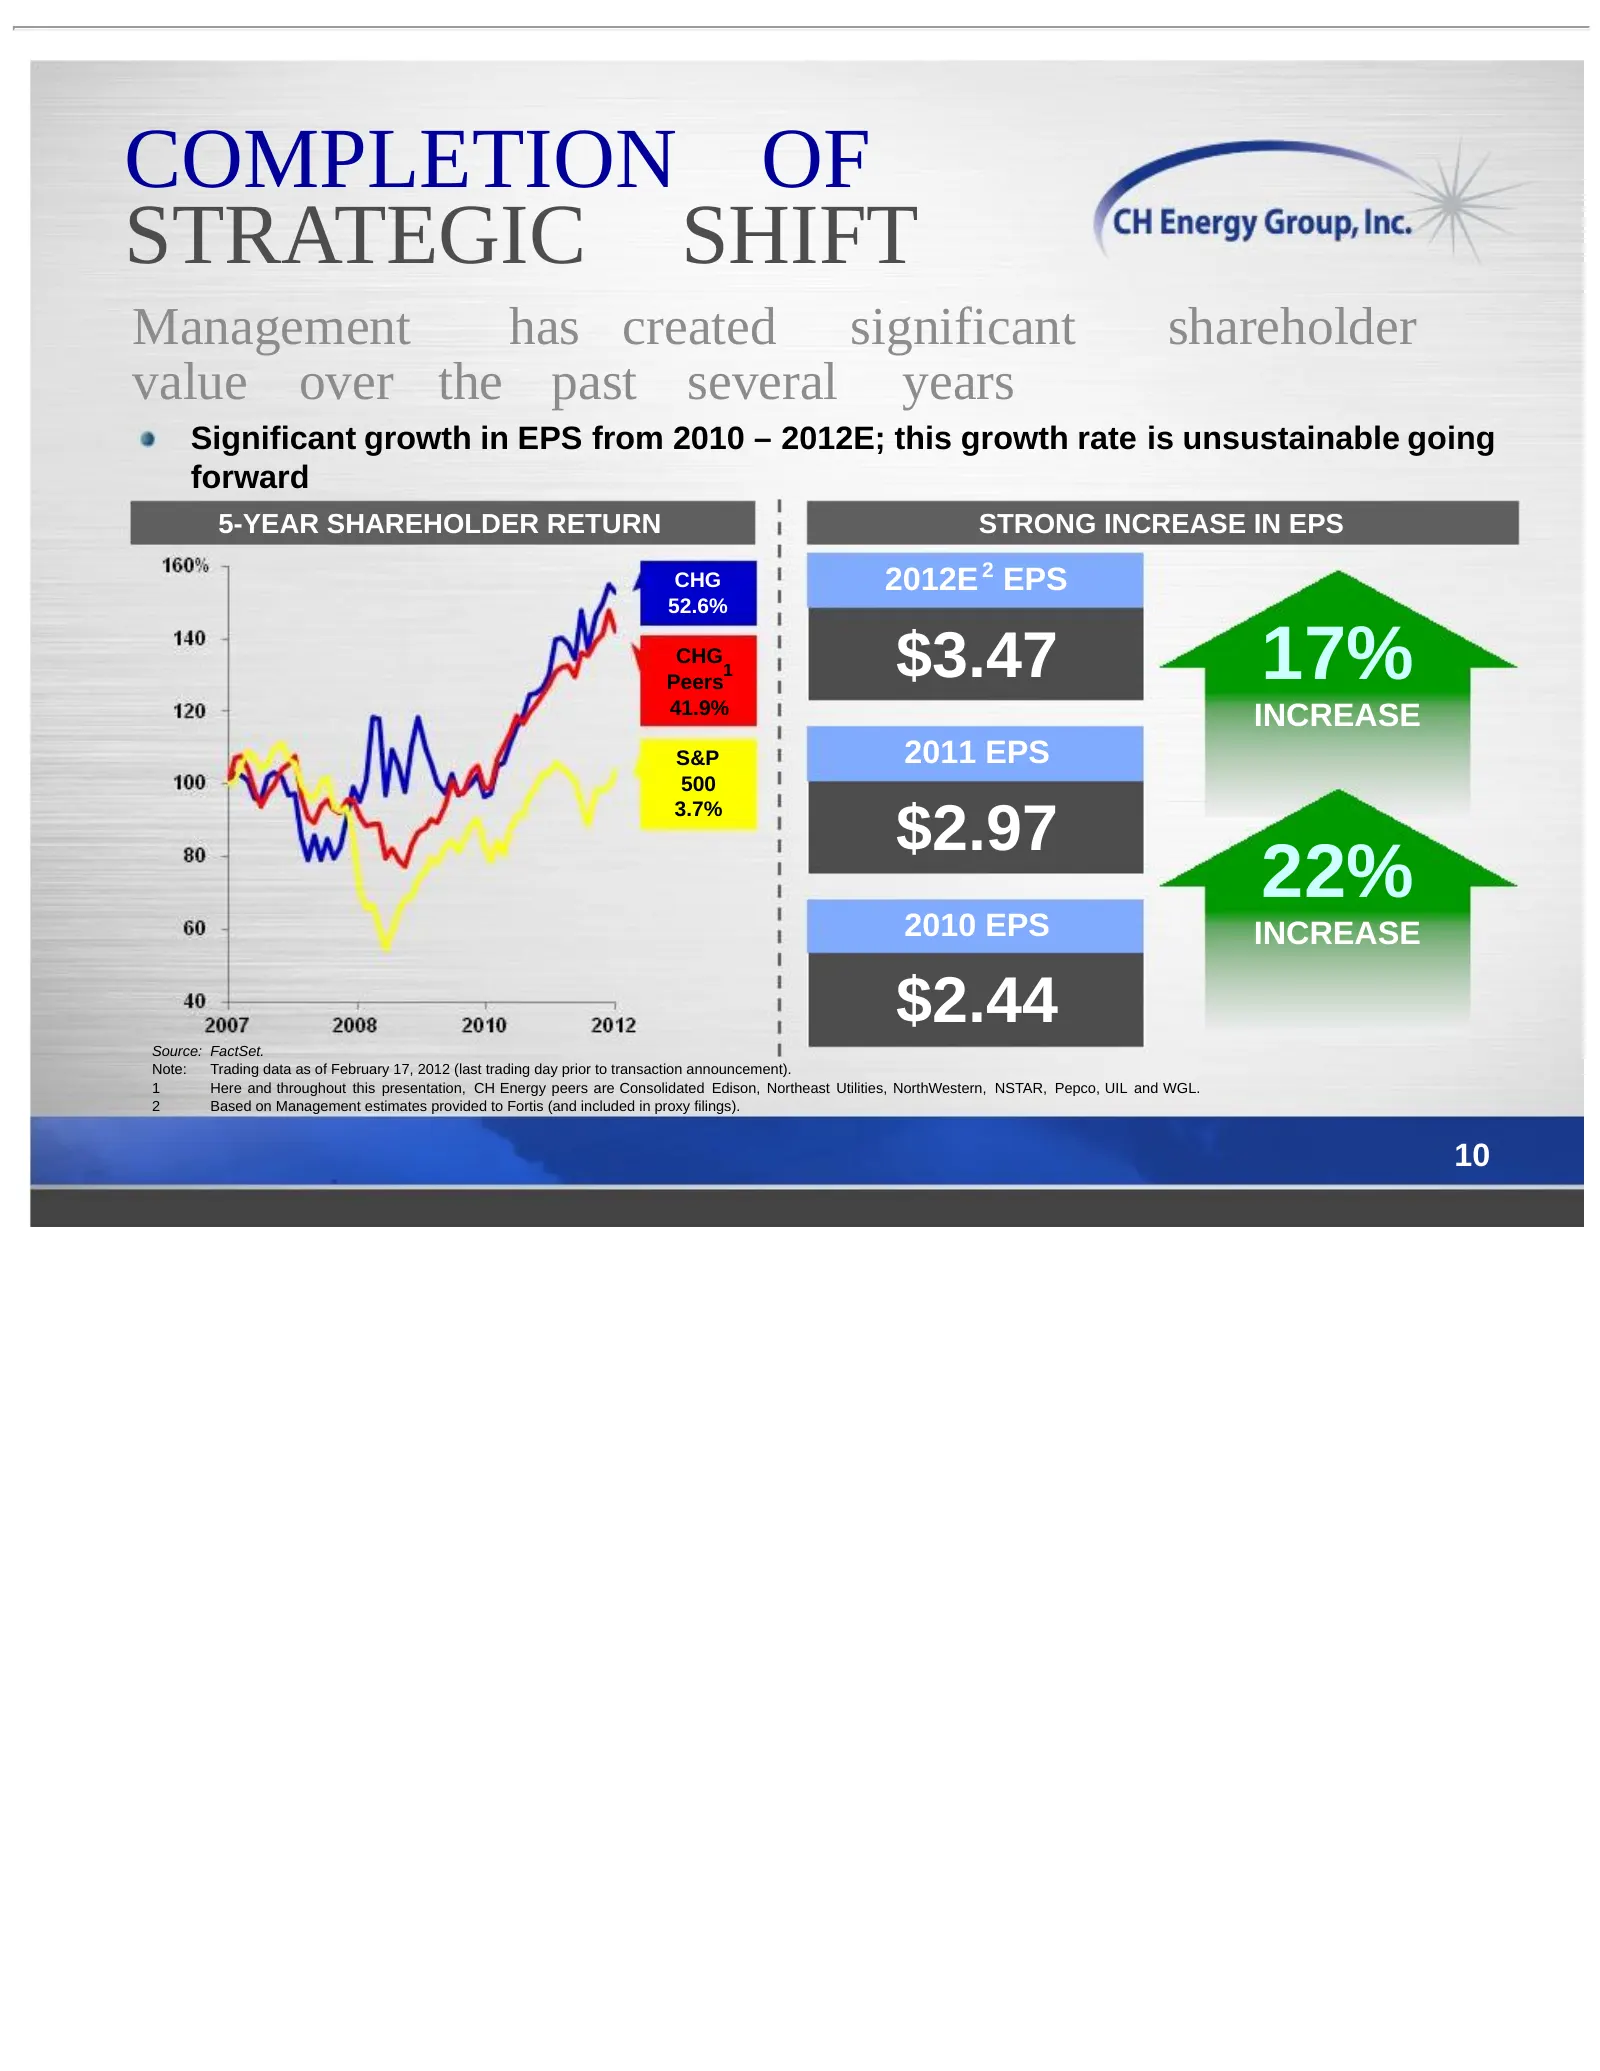
COMPLETION OF STRATEGIC SHIFT Management has created significant shareholder value over the past several years Significant growth in EPS from 2010 – 2012E; this growth rate is unsustainable going forward 5-YEAR SHAREHOLDER RETURN STRONG INCREASE IN EPS CHG 2012E 2 EPS 52.6% CHG Peers 41.9% 1 $3.47 1
Slide 12: Trading Performance: near all-time high
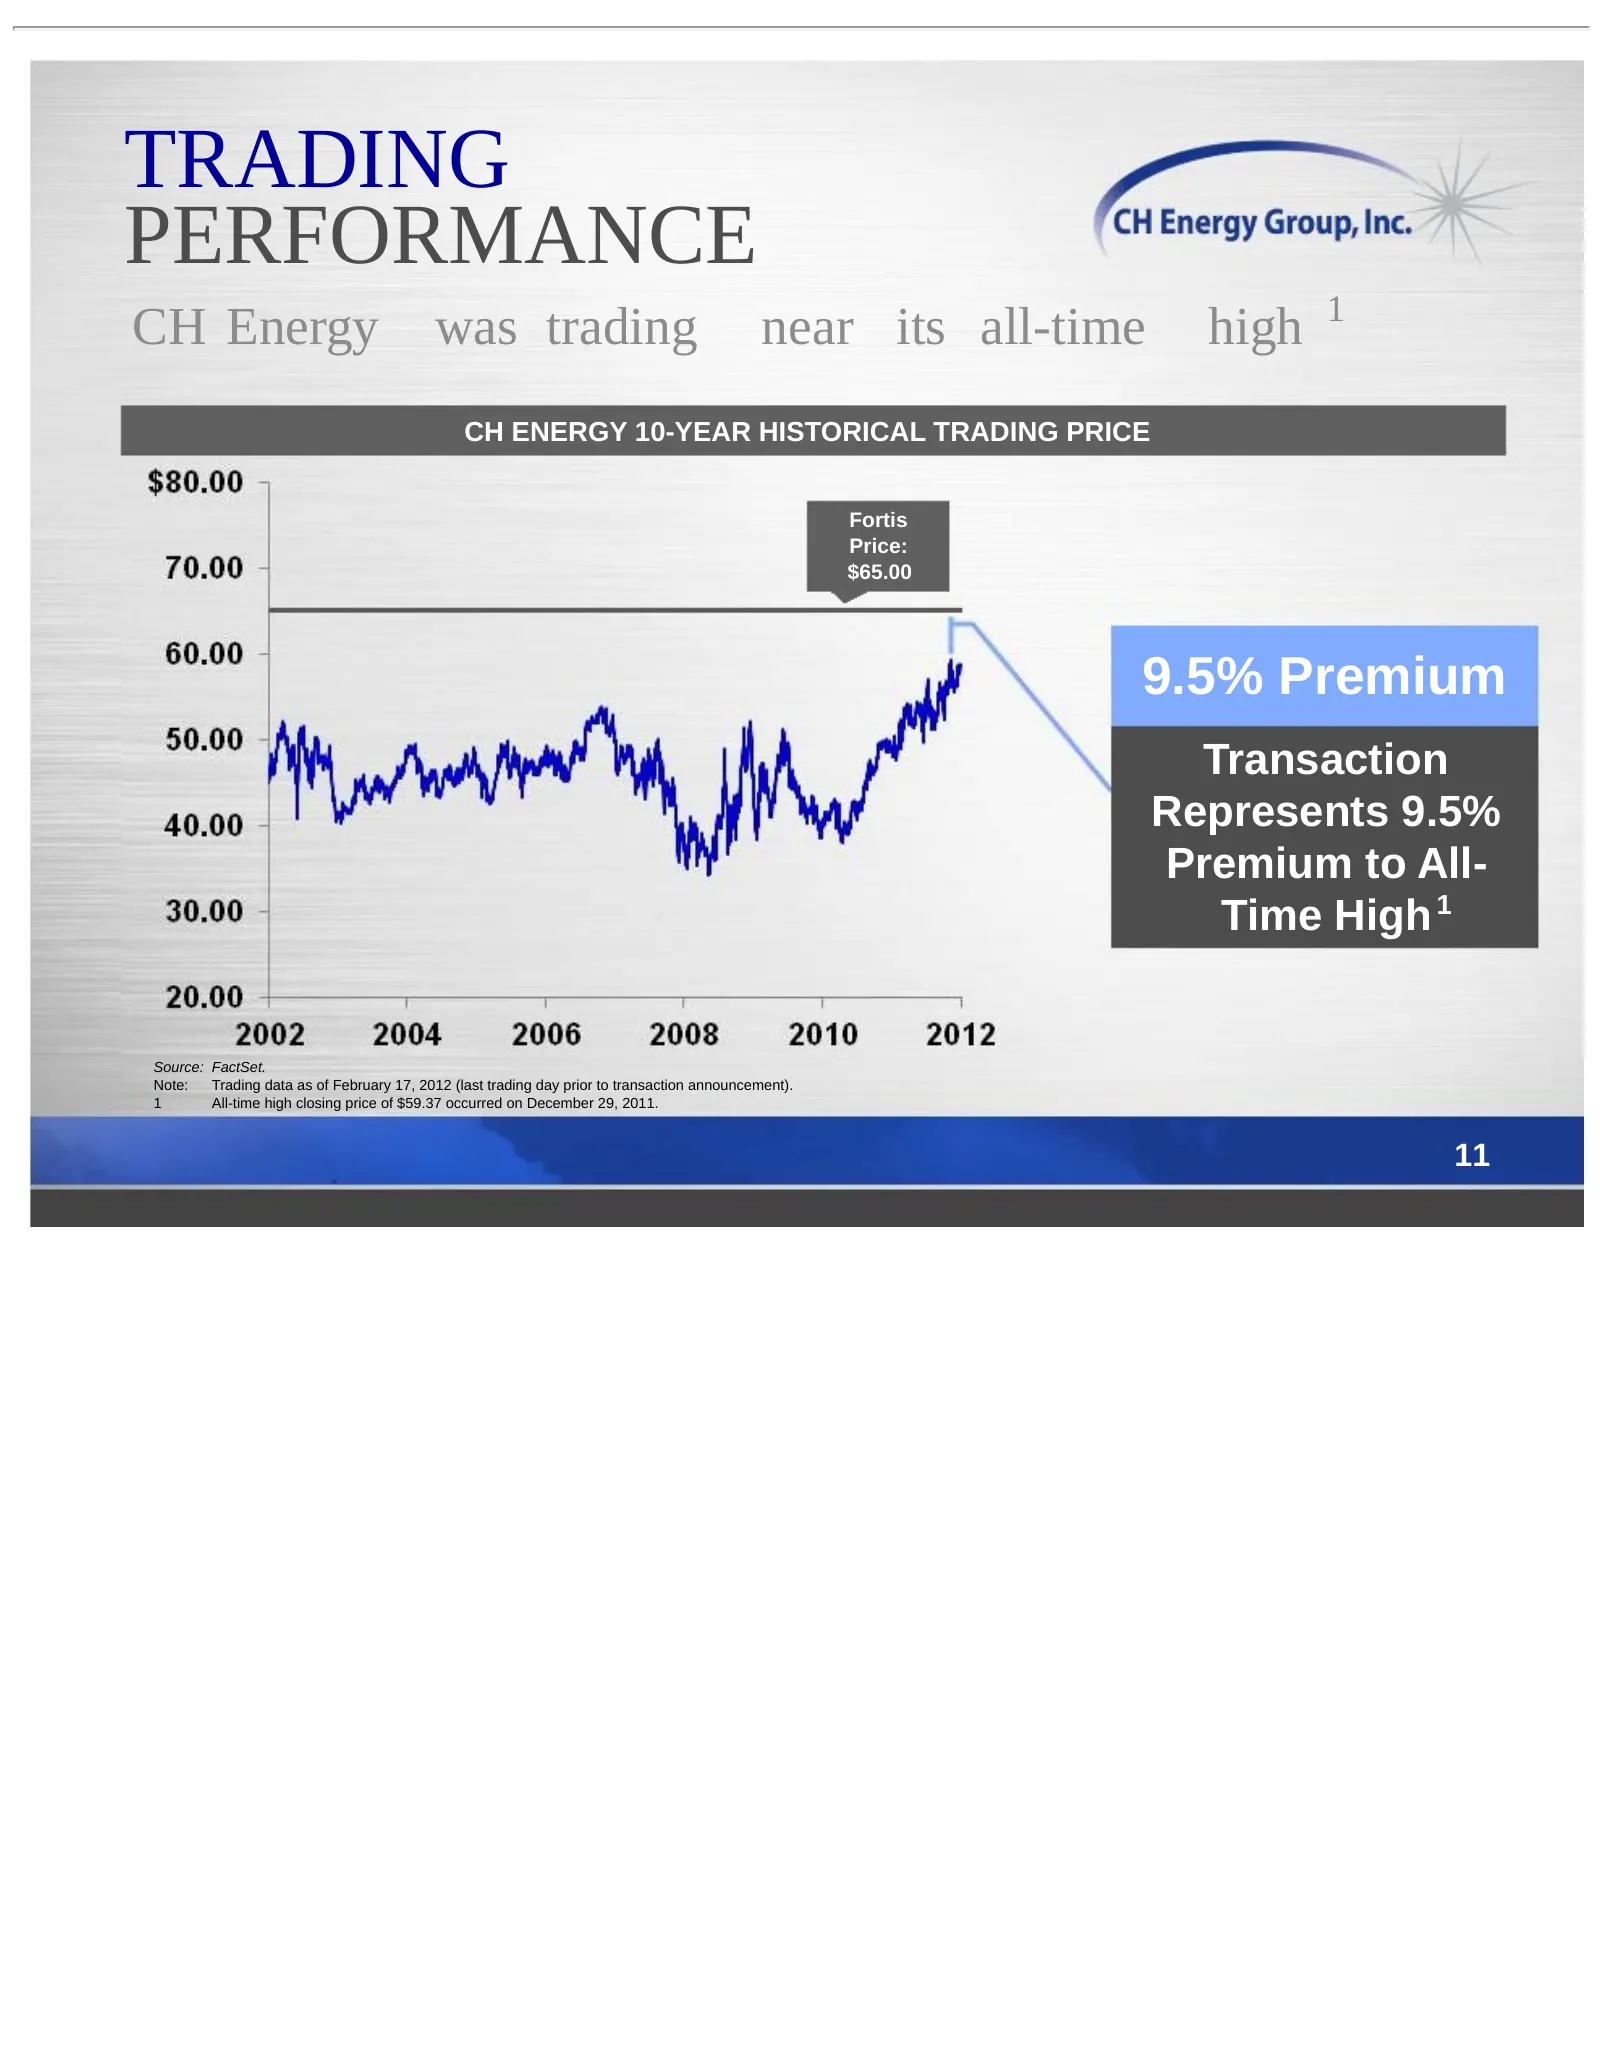
TRADING PERFORMANCE CH Energy was trading near its all-time high 1 CH ENERGY 10-YEAR HISTORICAL TRADING PRICE Fortis Price: $65.00 9.5% Premium Transaction Represents 9.5% Premium to All- Time High 1 Source: FactSet. Note: Trading data as of February 17, 2012 (last trading day prior to transaction a
Slide 13: CH Energy trading at a forward P/E premium
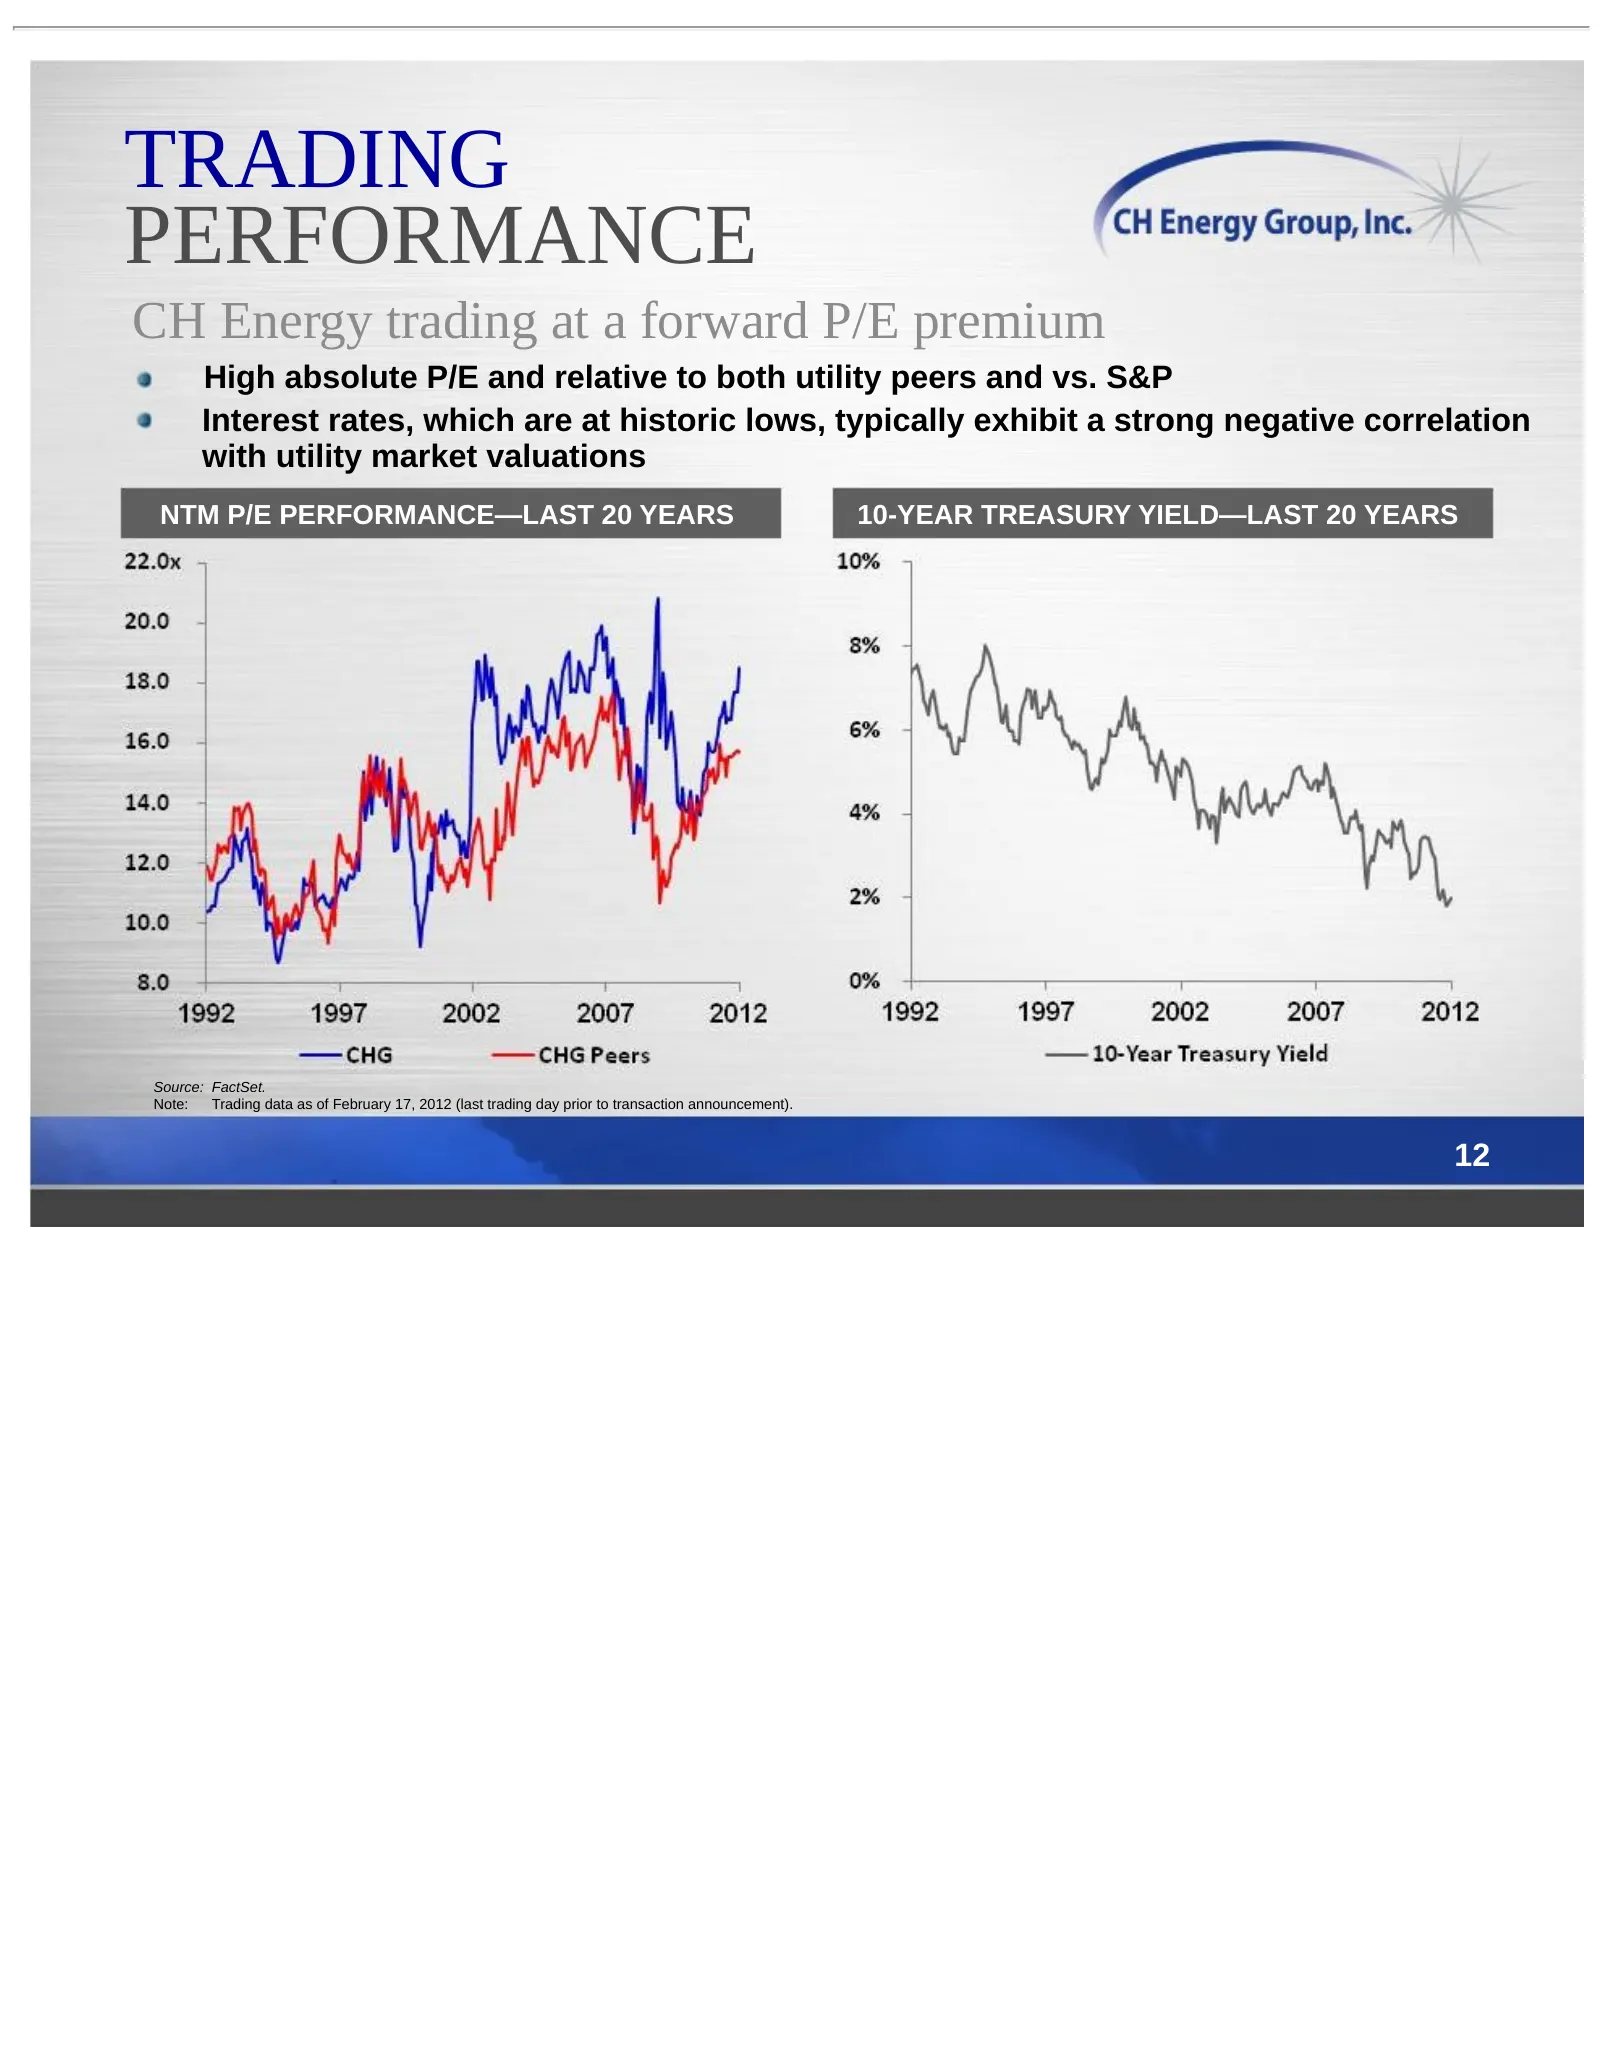
TRADING PERFORMANCE CH Energy trading at a forward P/E premium High absolute P/E and relative to both utility peers and vs. S&P Interest rates, which are at historic lows, typically exhibit a strong negative correlation with utility market valuations NTM P/E PERFORMANCE—LAST 20 YEARS 10-YEAR TREASUR
Slide 14: Attractive Value Proposition: precedent transactions
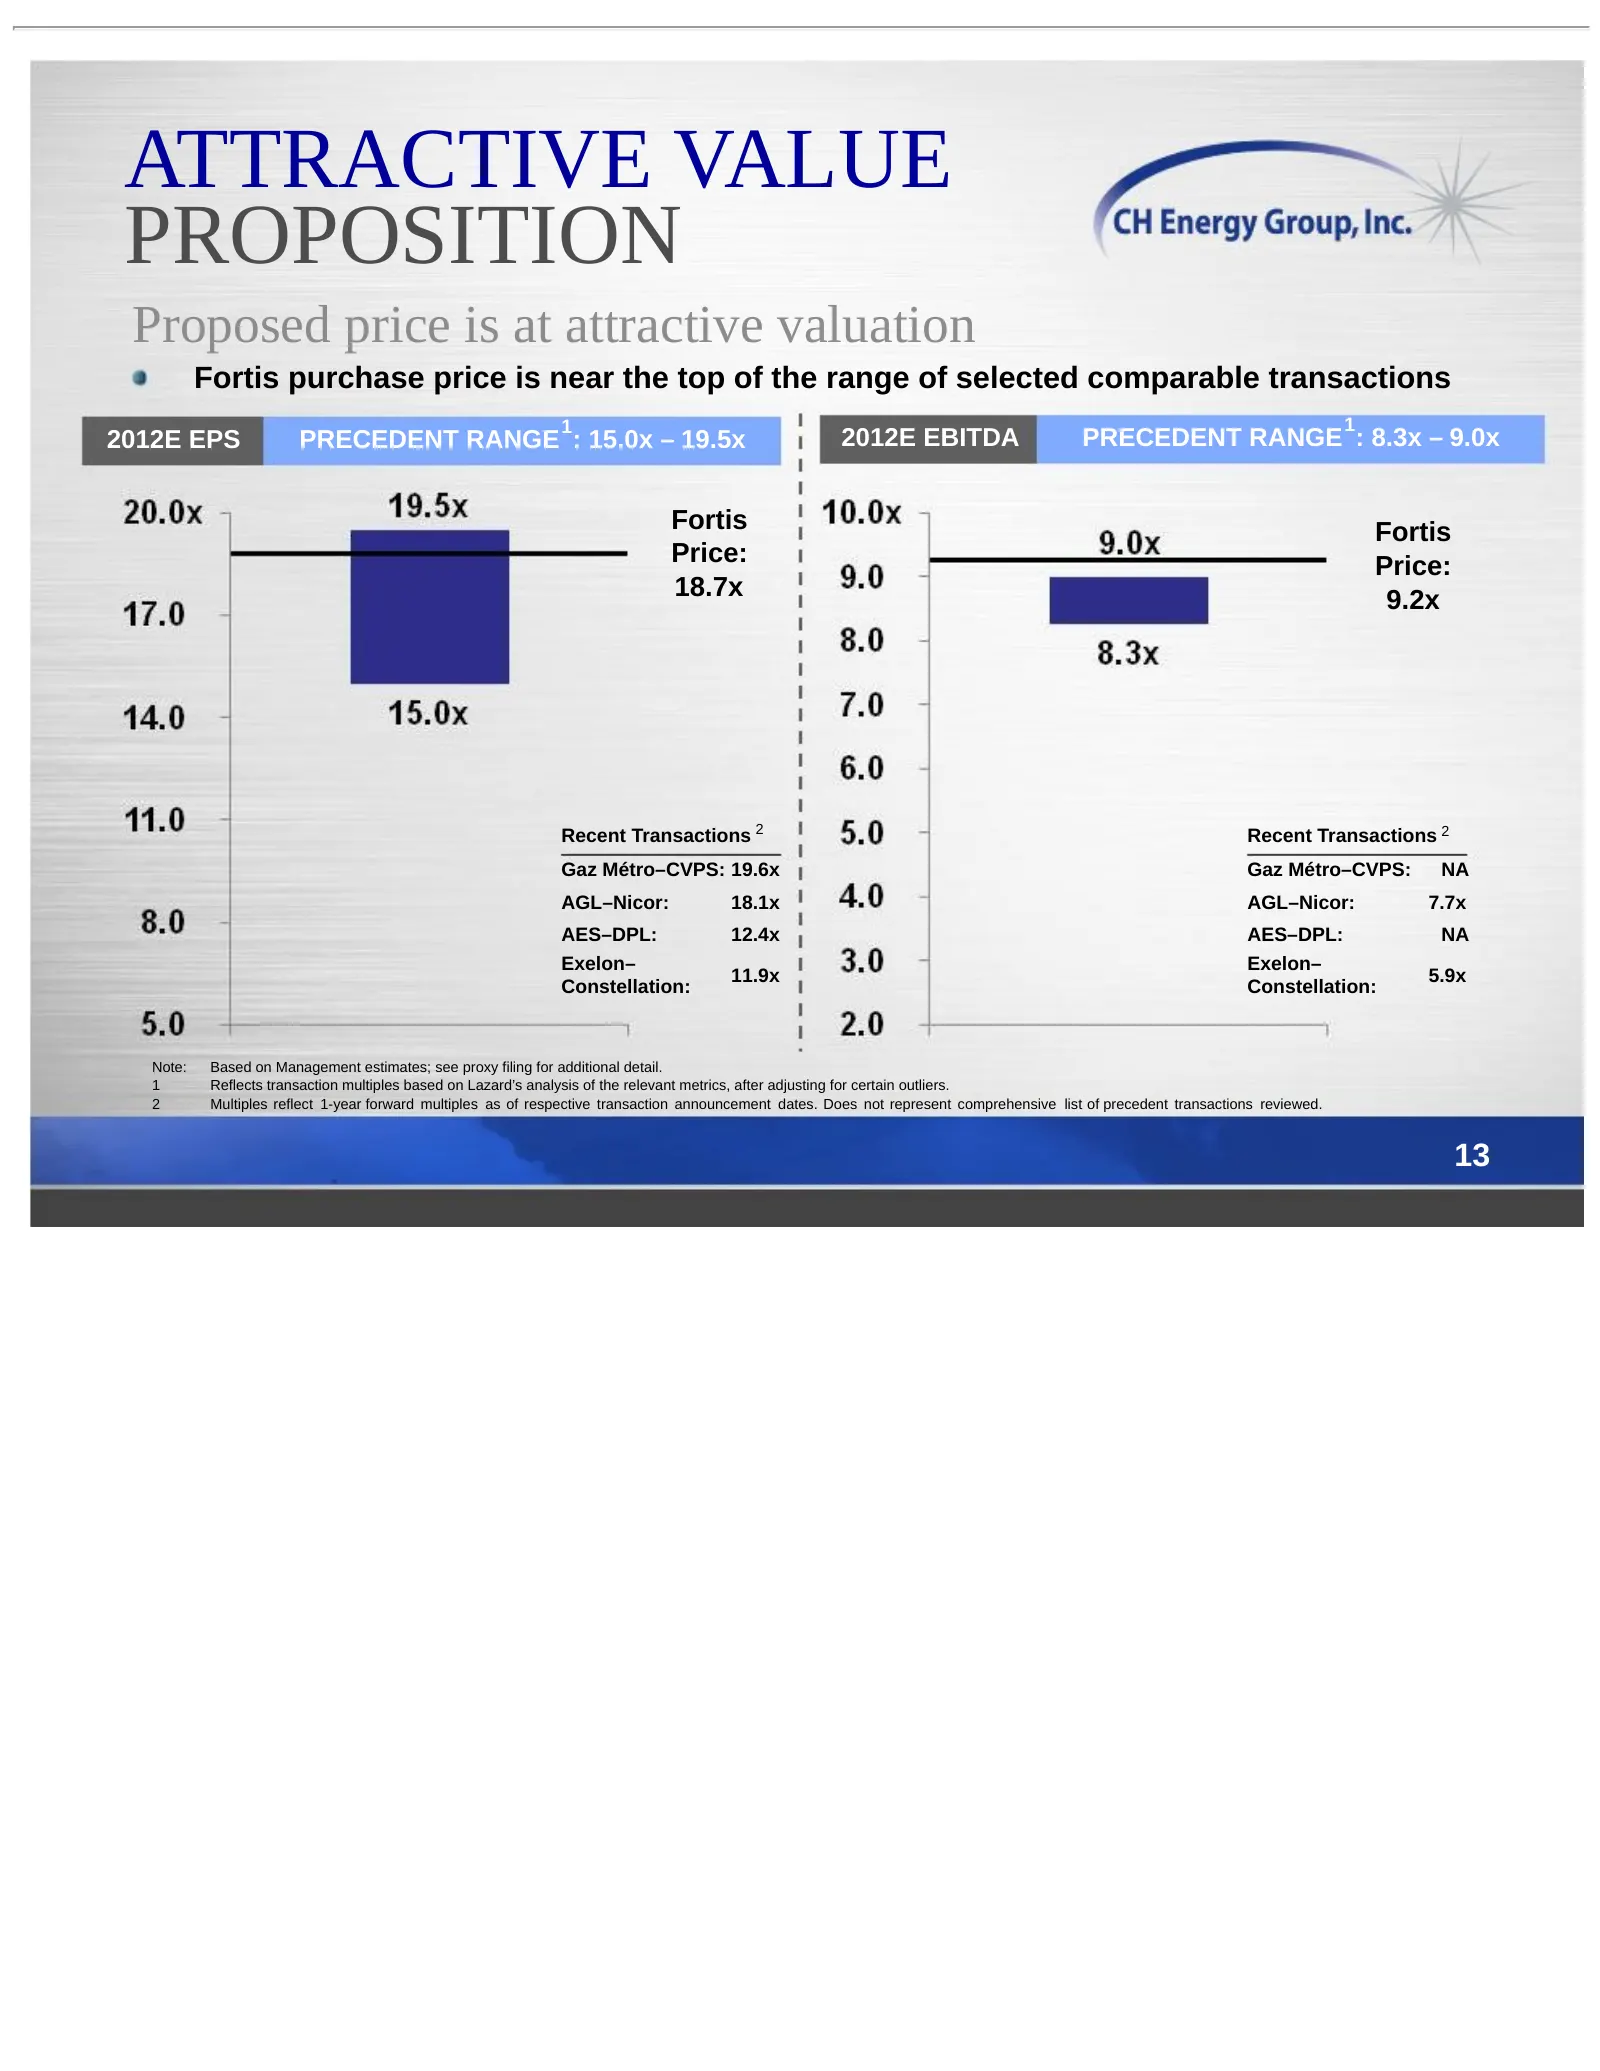
ATTRACTIVE VALUE PROPOSITION Proposed price is at attractive valuation Fortis purchase price is near the top of the range of selected comparable transactions 1 1 2012E EPS PRECEDENT RANGE : 15.0x – 19.5x 2012E EBITDA PRECEDENT RANGE : 8.3x – 9.0x Fortis Fortis Price: Price: 18.7x 9.2x Recent Transac
Slide 15: Fortis price well above peer P/E trading multiples
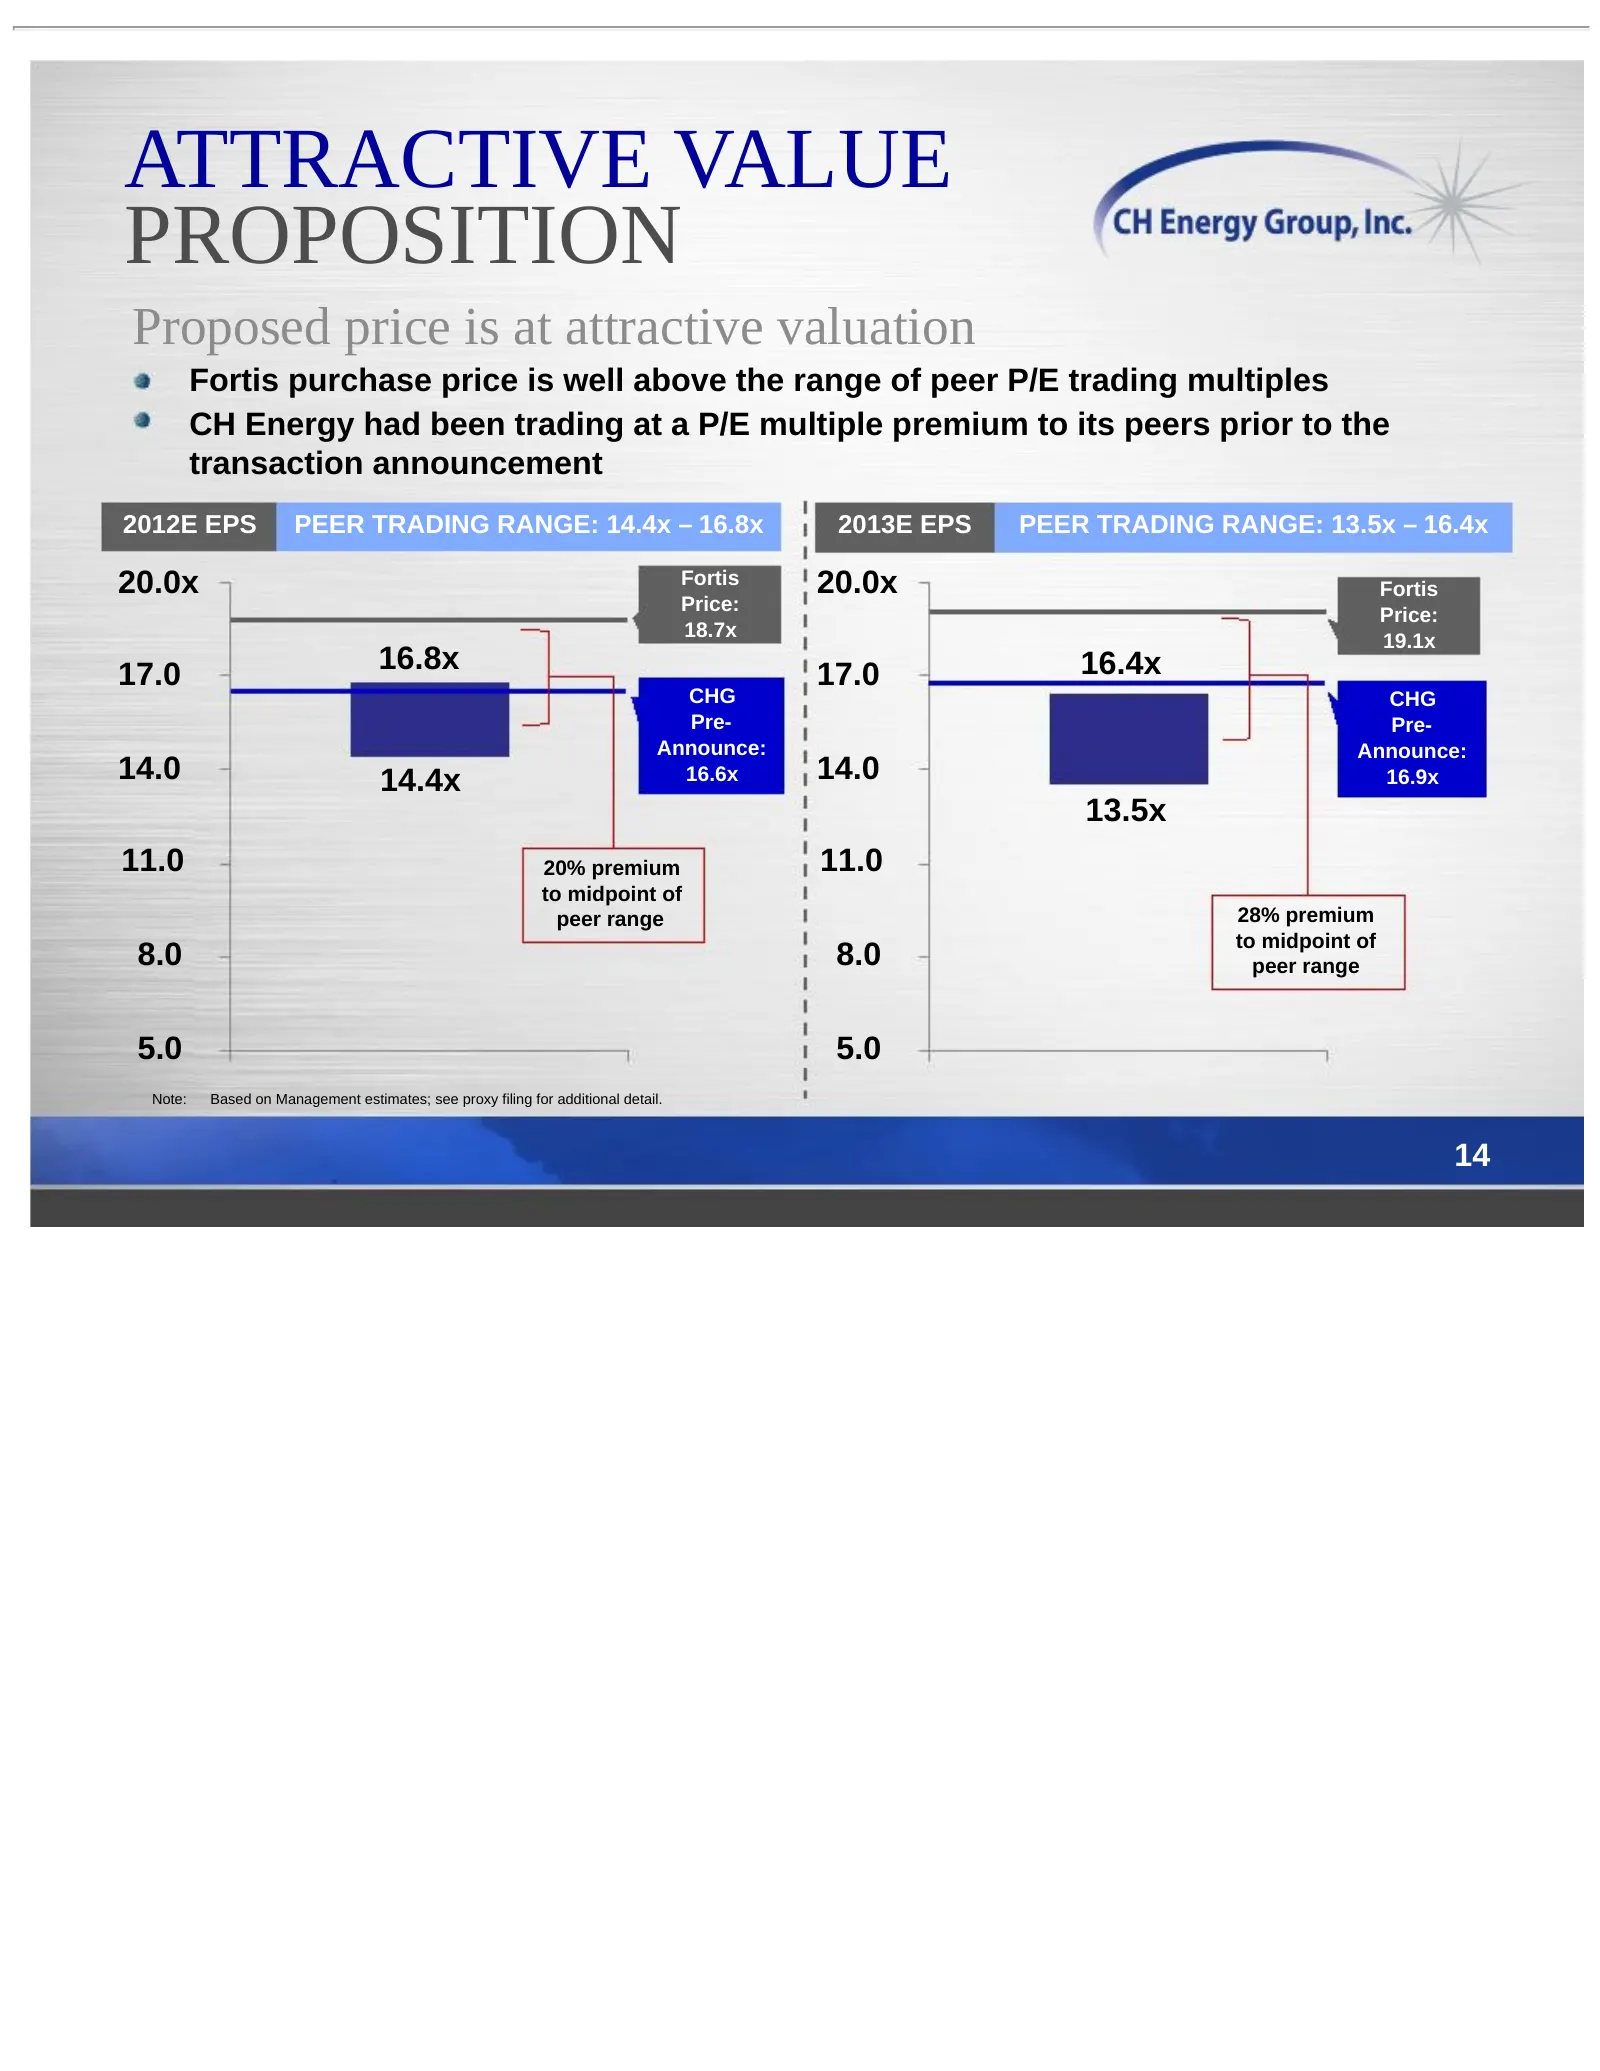
ATTRACTIVE VALUE PROPOSITION Proposed price is at attractive valuation Fortis purchase price is well above the range of peer P/E trading multiples CH Energy had been trading at a P/E multiple premium to its peers prior to the transaction announcement 2012E EPS PEER TRADING RANGE: 14.4x – 16.8x 2013E
Slide 16: Fortis price well above peer EV/EBITDA trading multiples
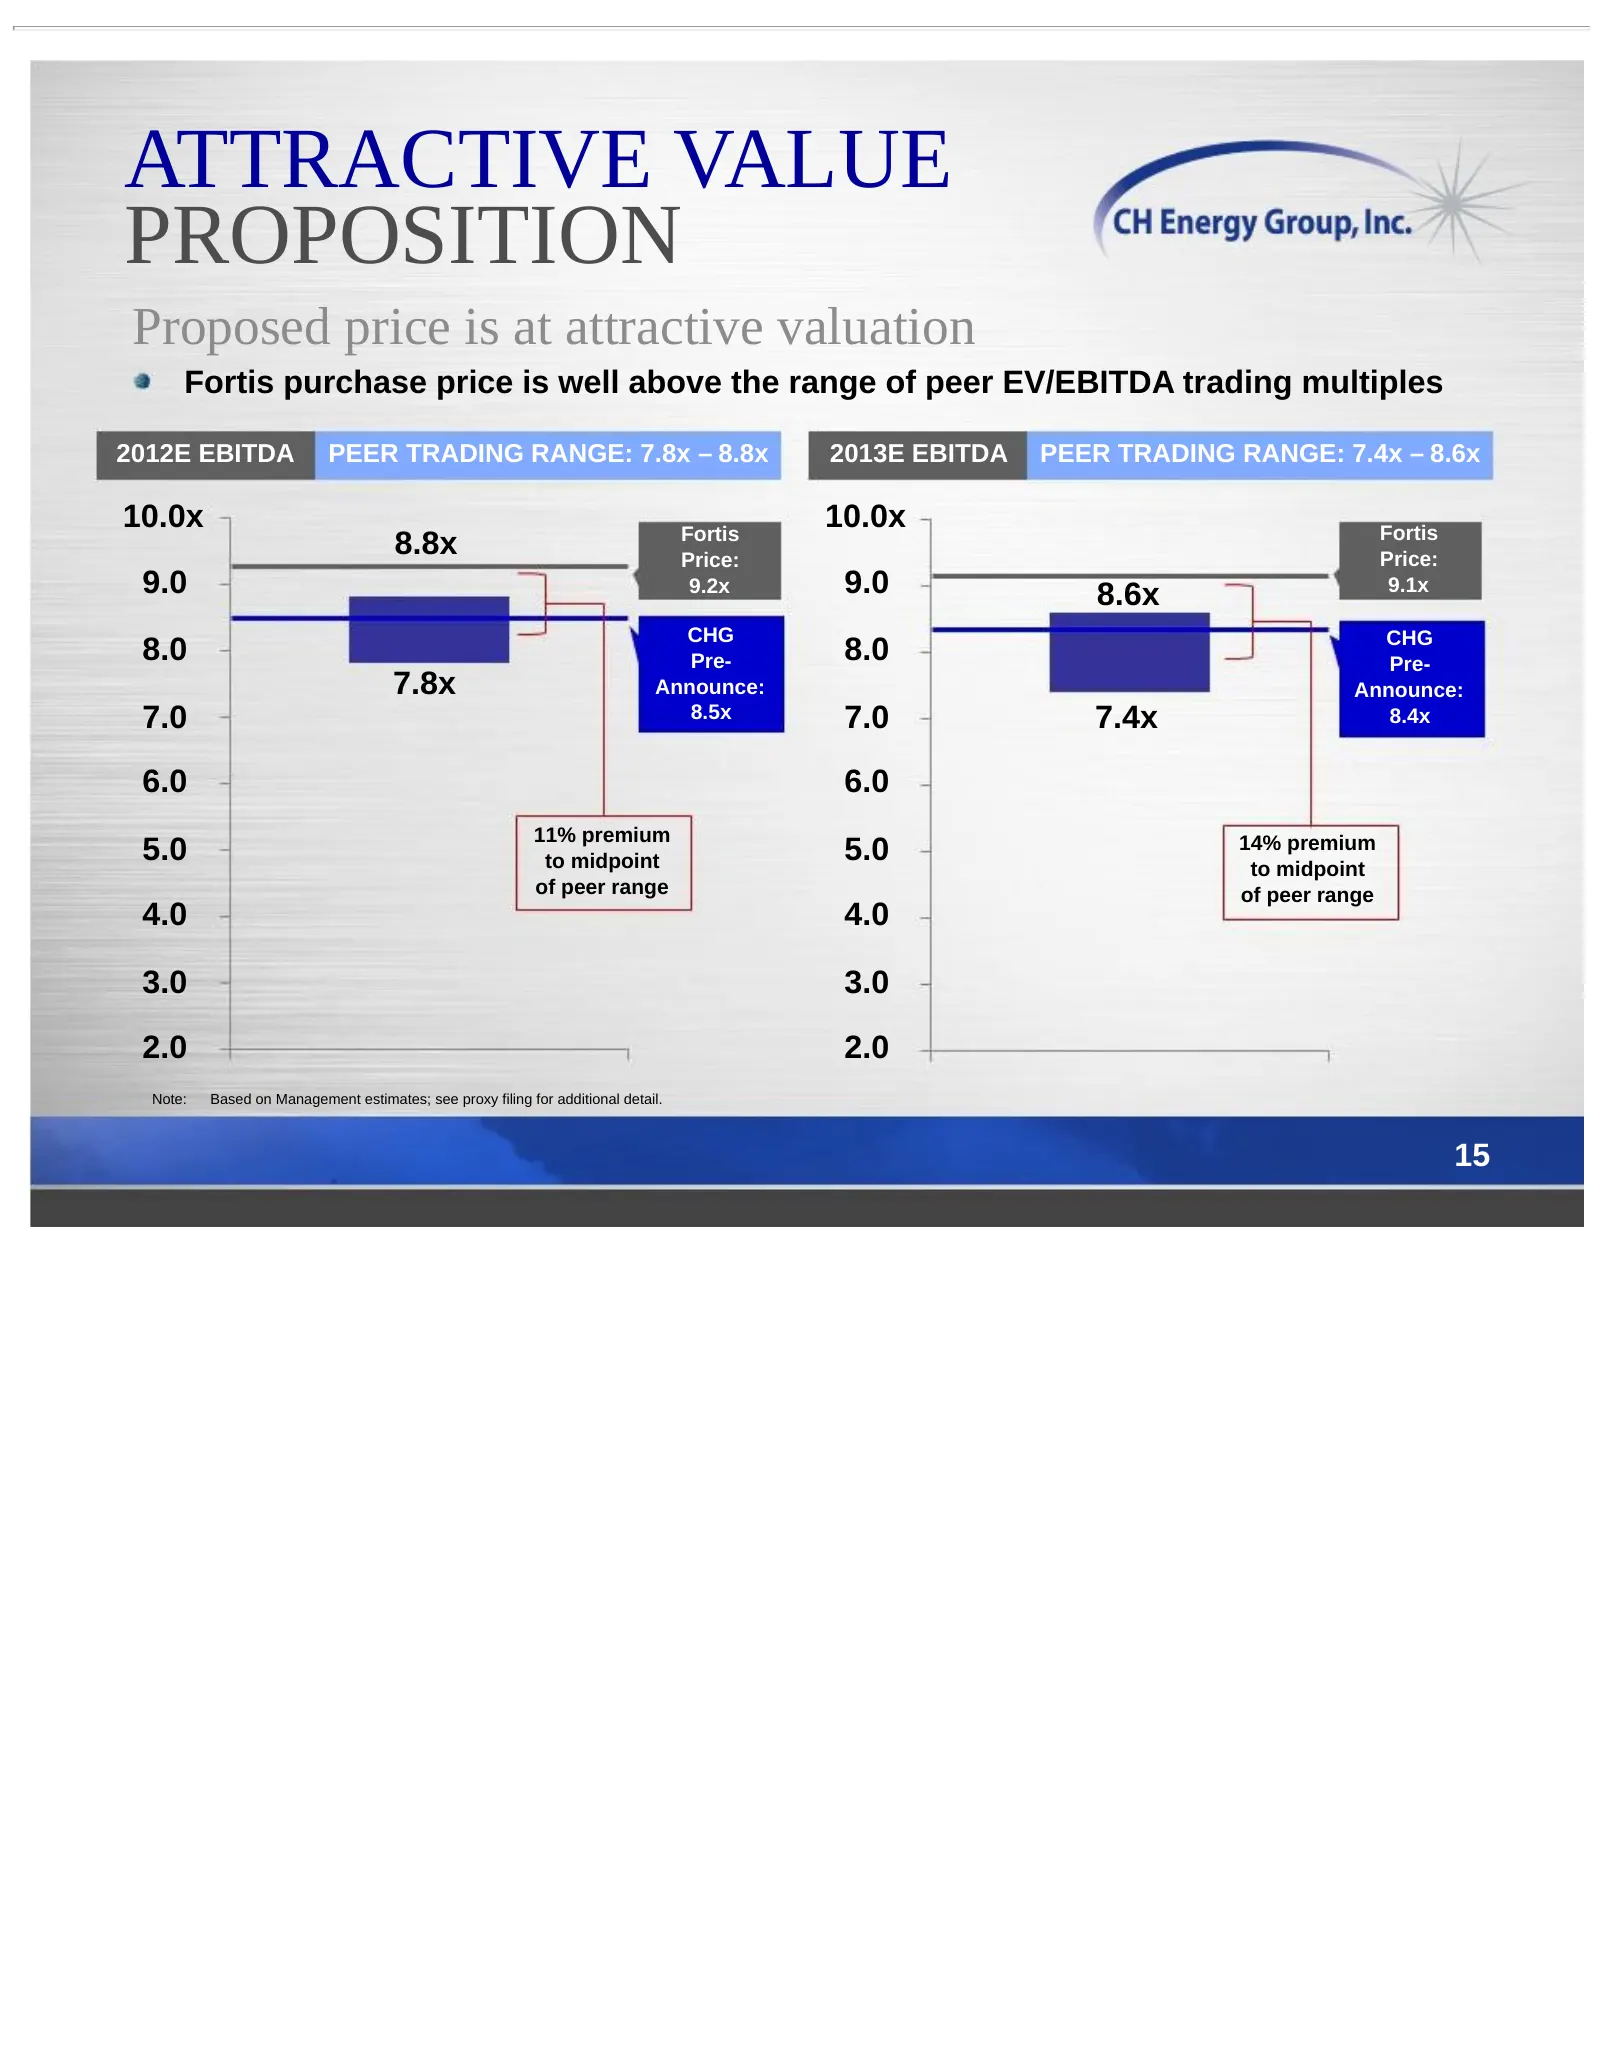
ATTRACTIVE VALUE PROPOSITION Proposed price is at attractive valuation Fortis purchase price is well above the range of peer EV/EBITDA trading multiples 2012E EBITDA PEER TRADING RANGE: 7.8x – 8.8x 2013E EBITDA PEER TRADING RANGE: 7.4x – 8.6x 10.0x Fortis 10.0x Fortis 8.8x Price: Price: 9.0 9.2x 9.0
Slide 17: Methodologies used by Lazard to evaluate the transaction
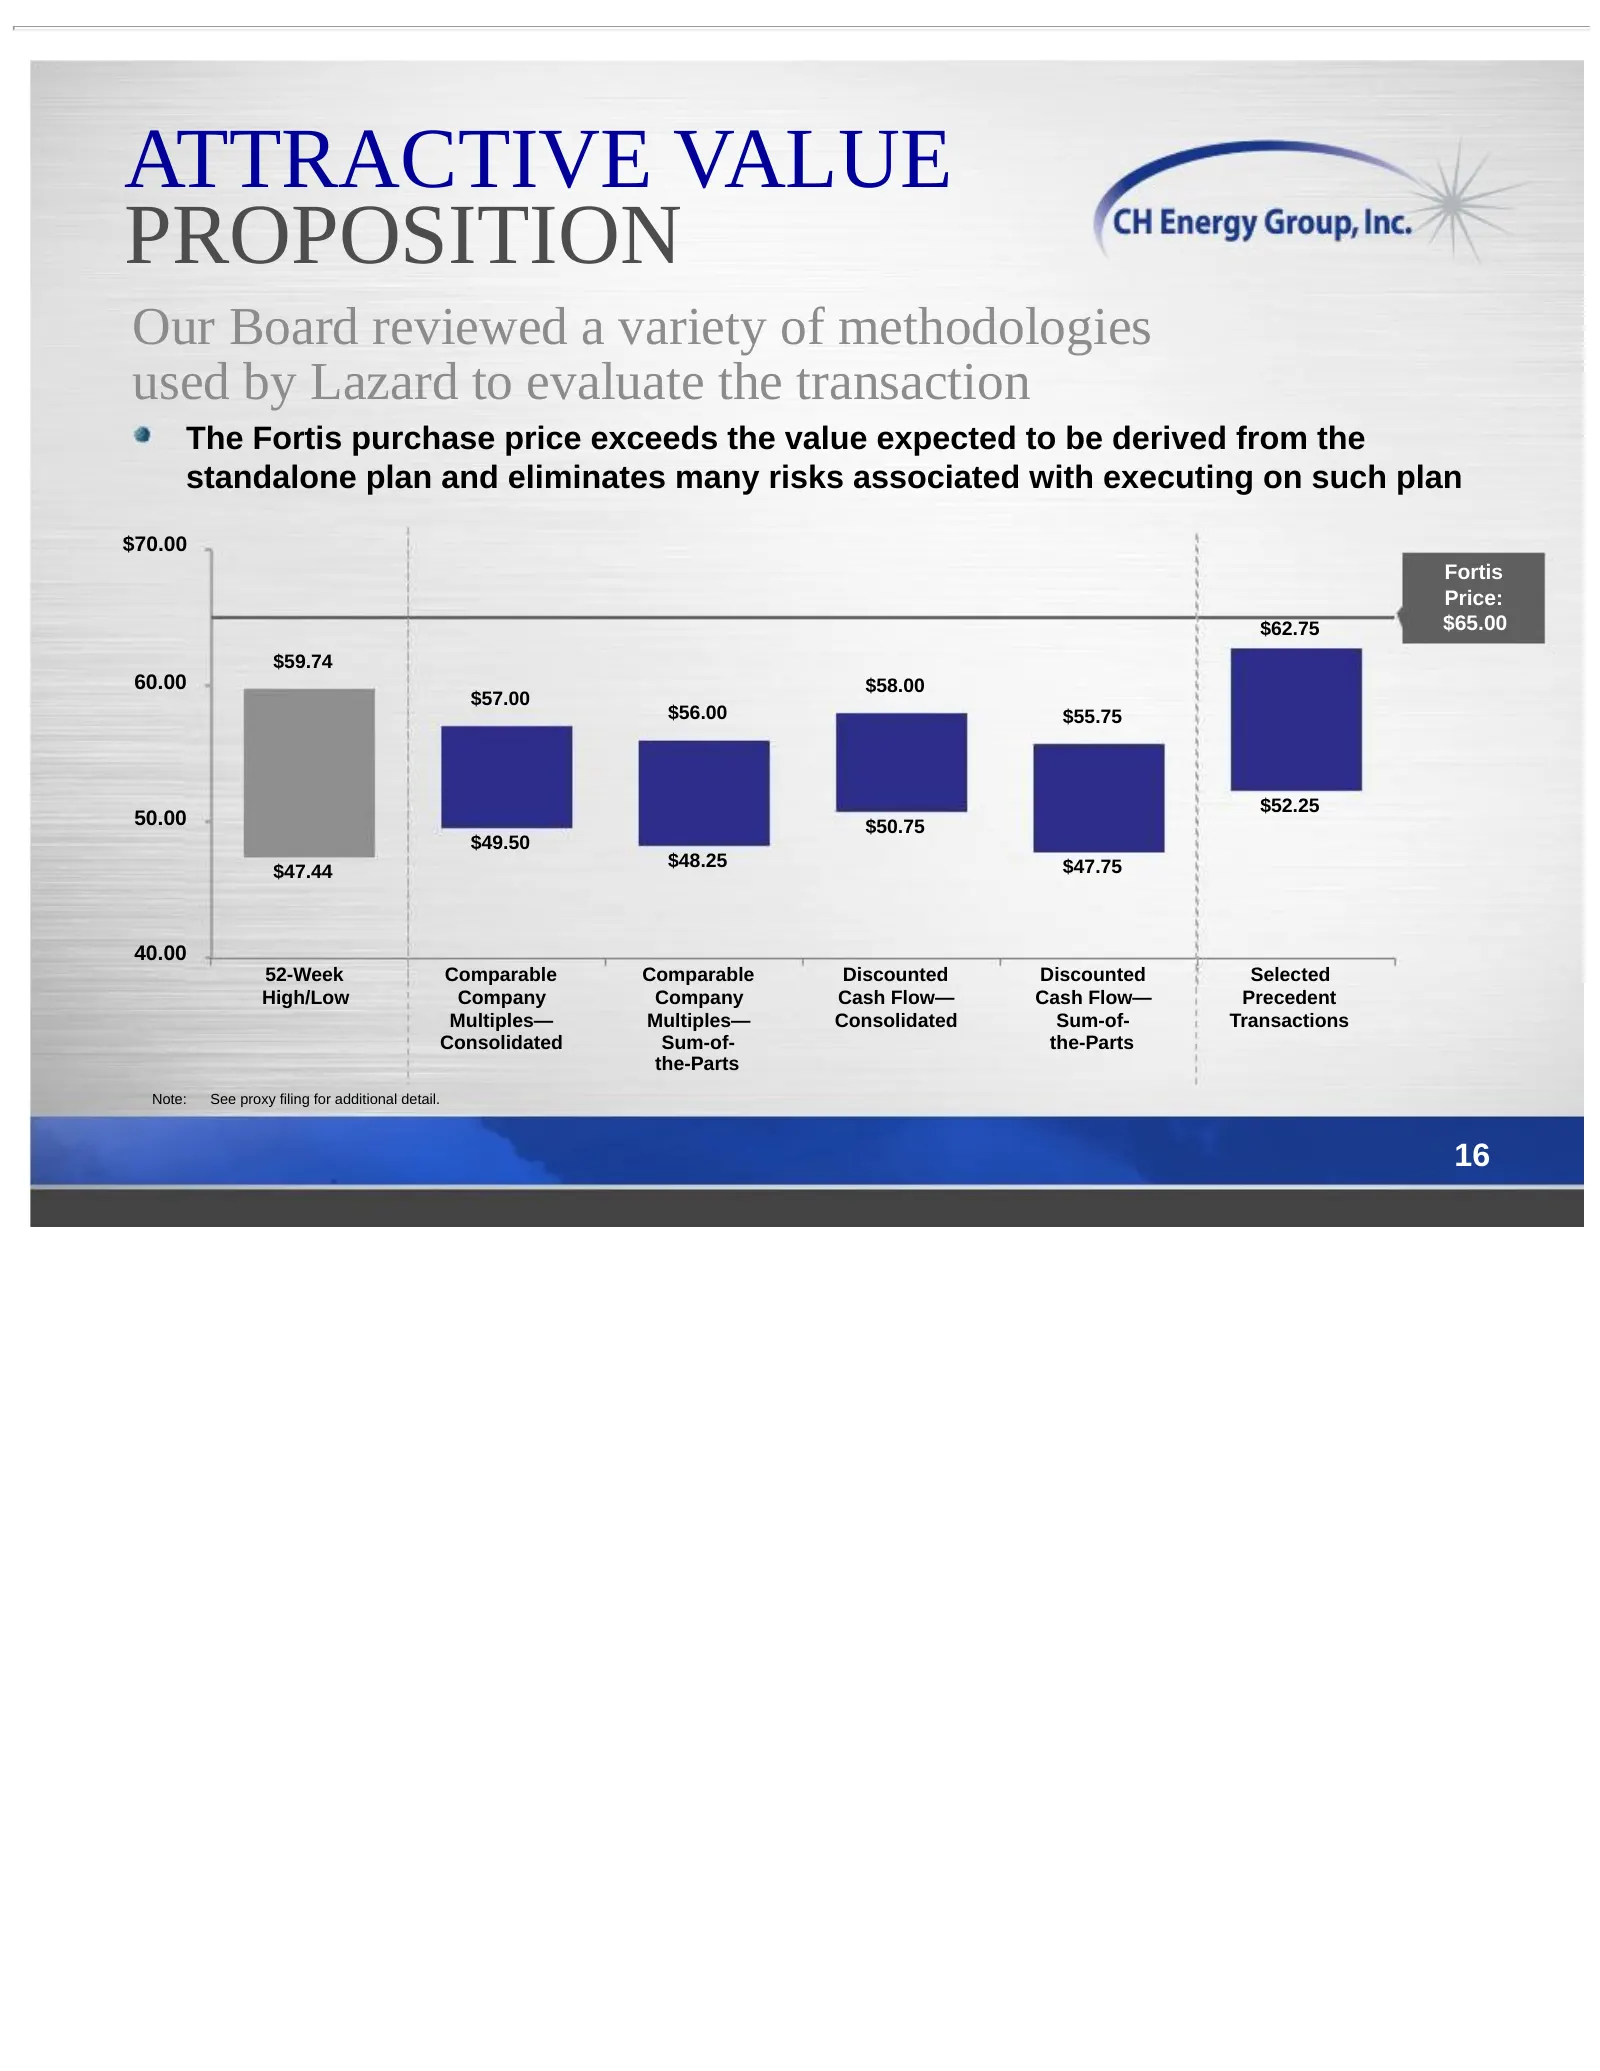
ATTRACTIVE VALUE PROPOSITION Our Board reviewed a variety of methodologies used by Lazard to evaluate the transaction The Fortis purchase price exceeds the value expected to be derived from the standalone plan and eliminates many risks associated with executing on such plan $70.00 Fortis Price: $62.
Slide 18: Merger terms minimize risk to shareholders
FORTIS TRANSACTION Merger terms minimize risk to shareholders Transfers regulatory, operational, interest rate, and general market/utility valuation risk away from shareholders Fixed price, cash transaction avoids “equity valuation risk” (both market and company specific) present in stock-for-stock
Slide 19: Summary Recommendation
SUMMARY RECOMMENDATION The Board concluded that the Fortis offer represents a significant premium over CH Energy’s standalone value and other strategic alternatives Low break-up fee does not preclude other interested parties from making a topping offer prior to shareholder approval The Board recomme
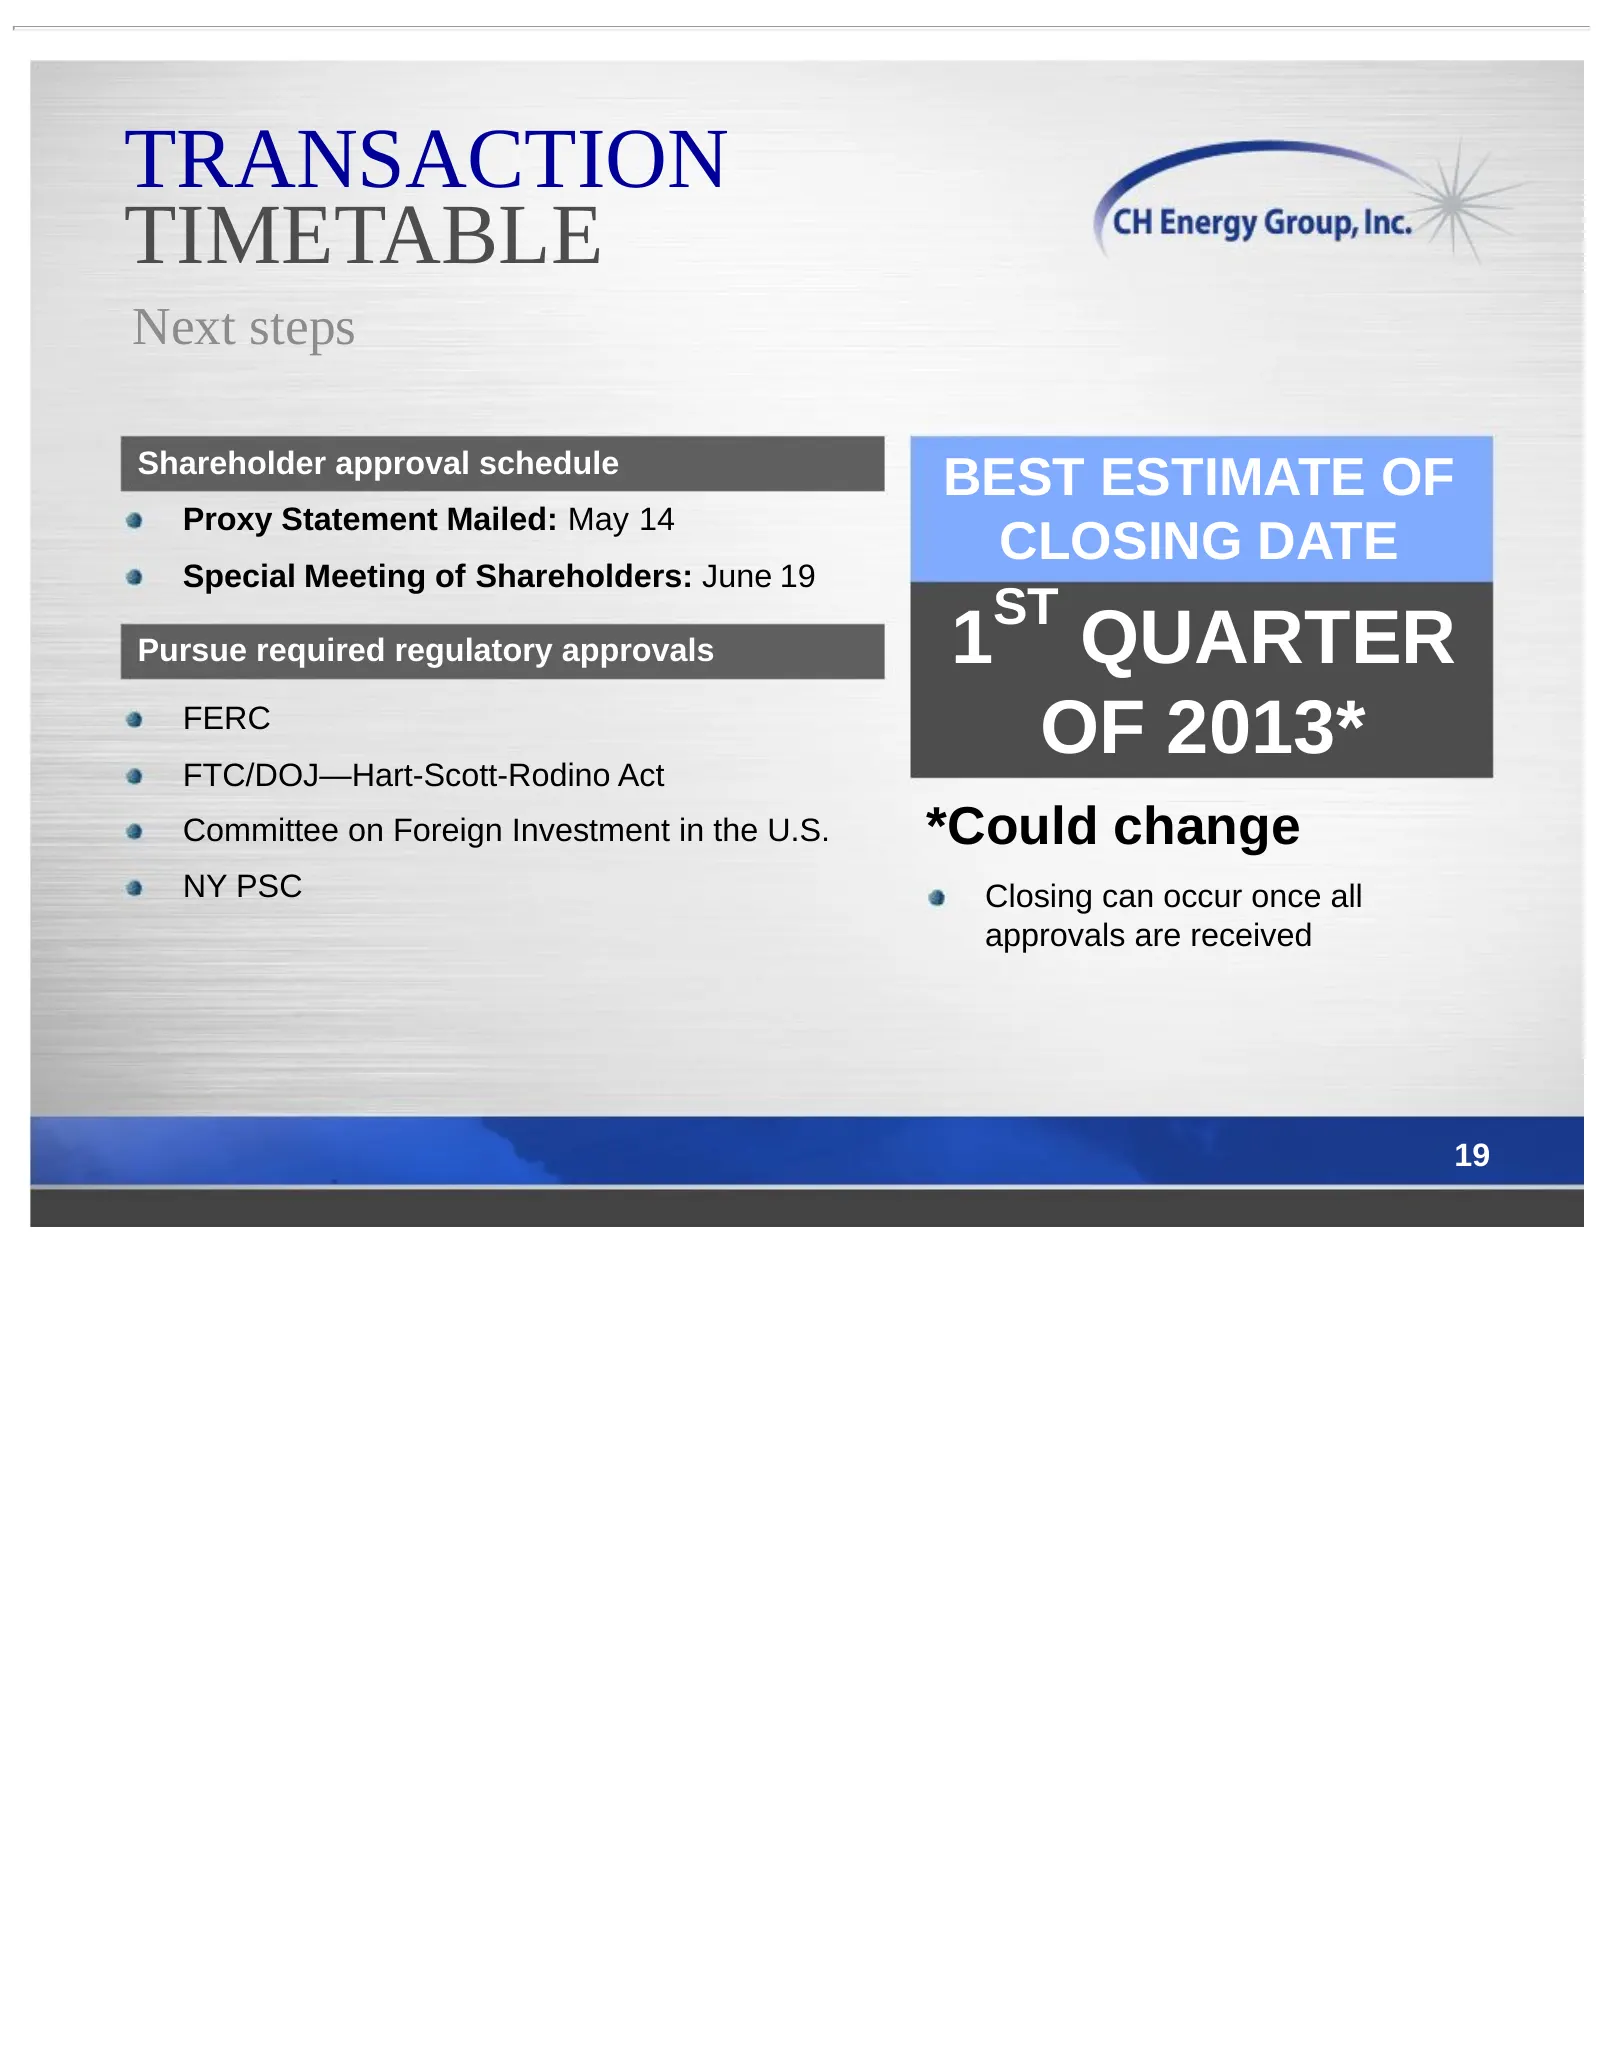
Slide 20: Transaction Timetable
TRANSACTION TIMETABLE Next steps Shareholder approval schedule BEST ESTIMATE OF Proxy Statement Mailed: May 14 CLOSING DATE Special Meeting of Shareholders: June 19 ST Pursue required regulatory approvals 1 QUARTER FERC FTC/DOJ—Hart-Scott-Rodino Act OF 2013* Committee on Foreign Investment in the U.
Source: SEC EDGAR · DEFA14A filed May 31, 2012